Unfair-ish

Well, Jay and the doves got their wish
As CPI data went squish
In fact, it’s not clear
Why cuts aren’t here
Already, it’s just unfair-ish
 
But something surprising occurred
‘Cause rallies in stocks weren’t spurred
But yields and the buck
Got hit by a truck
While gold was both shaken and stirred
 
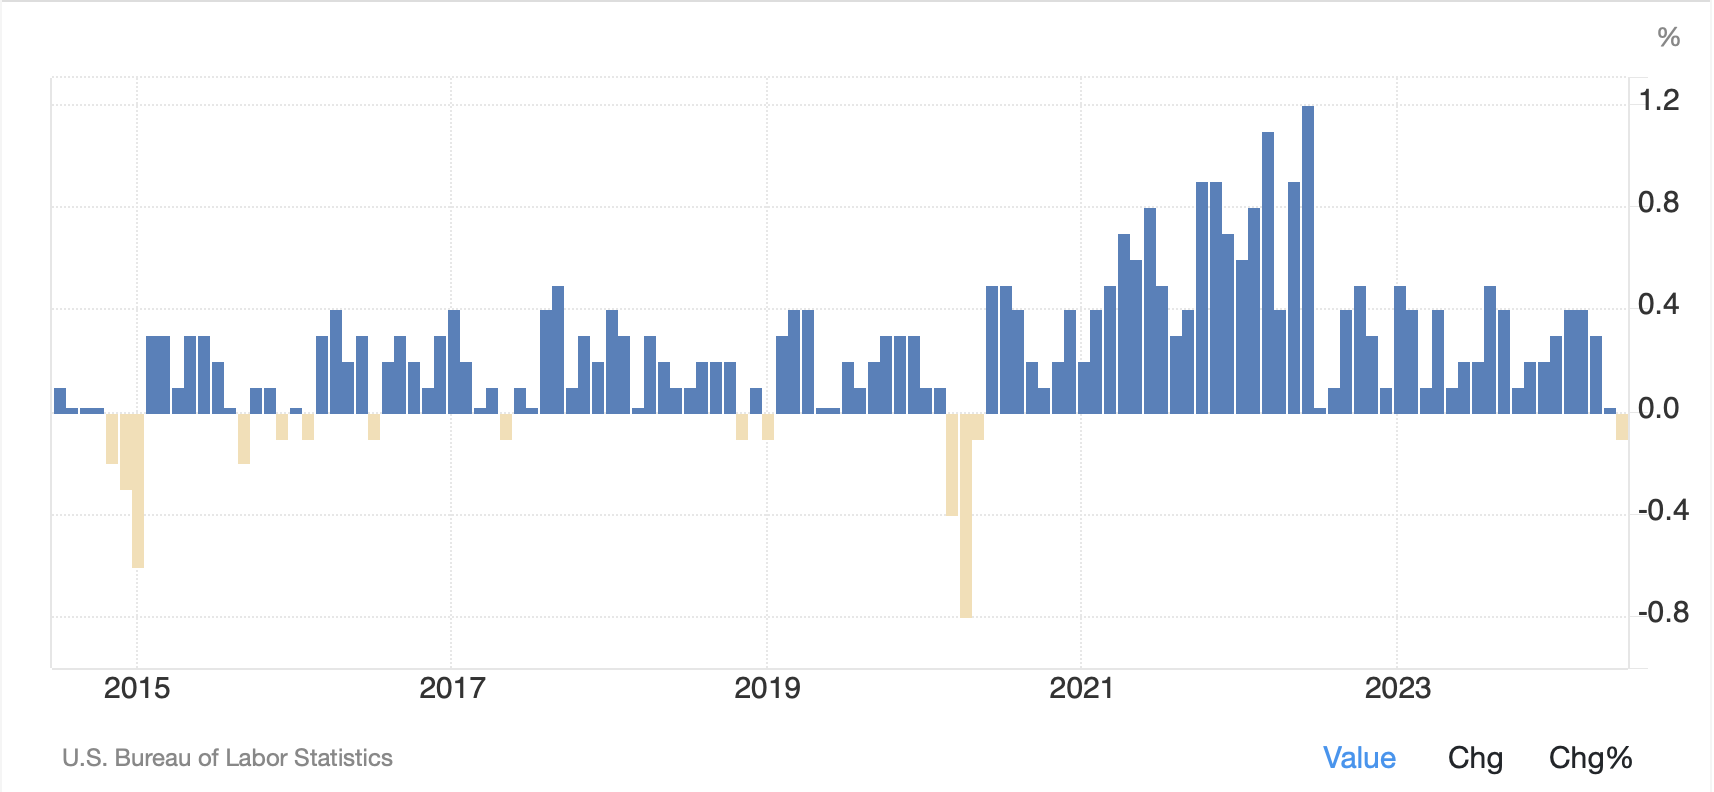
Chairman Powell must be doing his happy dance this morning as the CPI data was the softest seen since May 2020 during the height of the Covid shutdowns.  Now, after four years of steadily rising prices, the Fed is undoubtedly feeling better.  One look at the chart below, though, shows that the inflation rate since the end of Covid was clearly much higher than that to which the population became accustomed prior to Covid.
 

Source: tradingeconomics.com

While the annualized data for both core and headline readings remains above 3.0%, there was certainly good news in that shelter and rental costs rose more slowly than they have in nearly three years.  However, for market participants, they are far less concerned over the whys of the soft reading than in the fact that the reading was soft and so they can now anticipate a rate cut even sooner than before.  As of this morning, the Fed funds futures market is now pricing a 92.5% probability that the Fed cuts in September and a total of 61bpsof cuts by the end of the year.  

In truth, I was only partially joking at my surprise they didn’t call an emergency meeting and cut yesterday. While the market is only pricing a 6% chance of a cut at the end of this month, I think that is a pretty good bet. Speaking of bets, the trader(s) who established that big SOFR options position earlier in the week is set to have a really good weekend!

To recap, we’ve had the softest inflation reading in 4 years and the market is anticipating the end of higher for longer.  As I have written consistently, my take is when the Fed starts cutting, the dollar will fall, commodity prices will rise, yields will start to decline, but if (when?) inflation reasserts itself, those yields will head higher.  And finally, stocks are likely to see support, but a very good point was made today that if prices stop rising, then so to do profit margins at companies and profits in concert.  Perhaps, slowing inflation is not so good for the stock market, even if it means that rates can be lowered.  Ultimately, there is still a lot to learn, and this was just one number, but boy, is everyone excited!

Did the BOJ
Take advantage of the news
And sell more dollars?

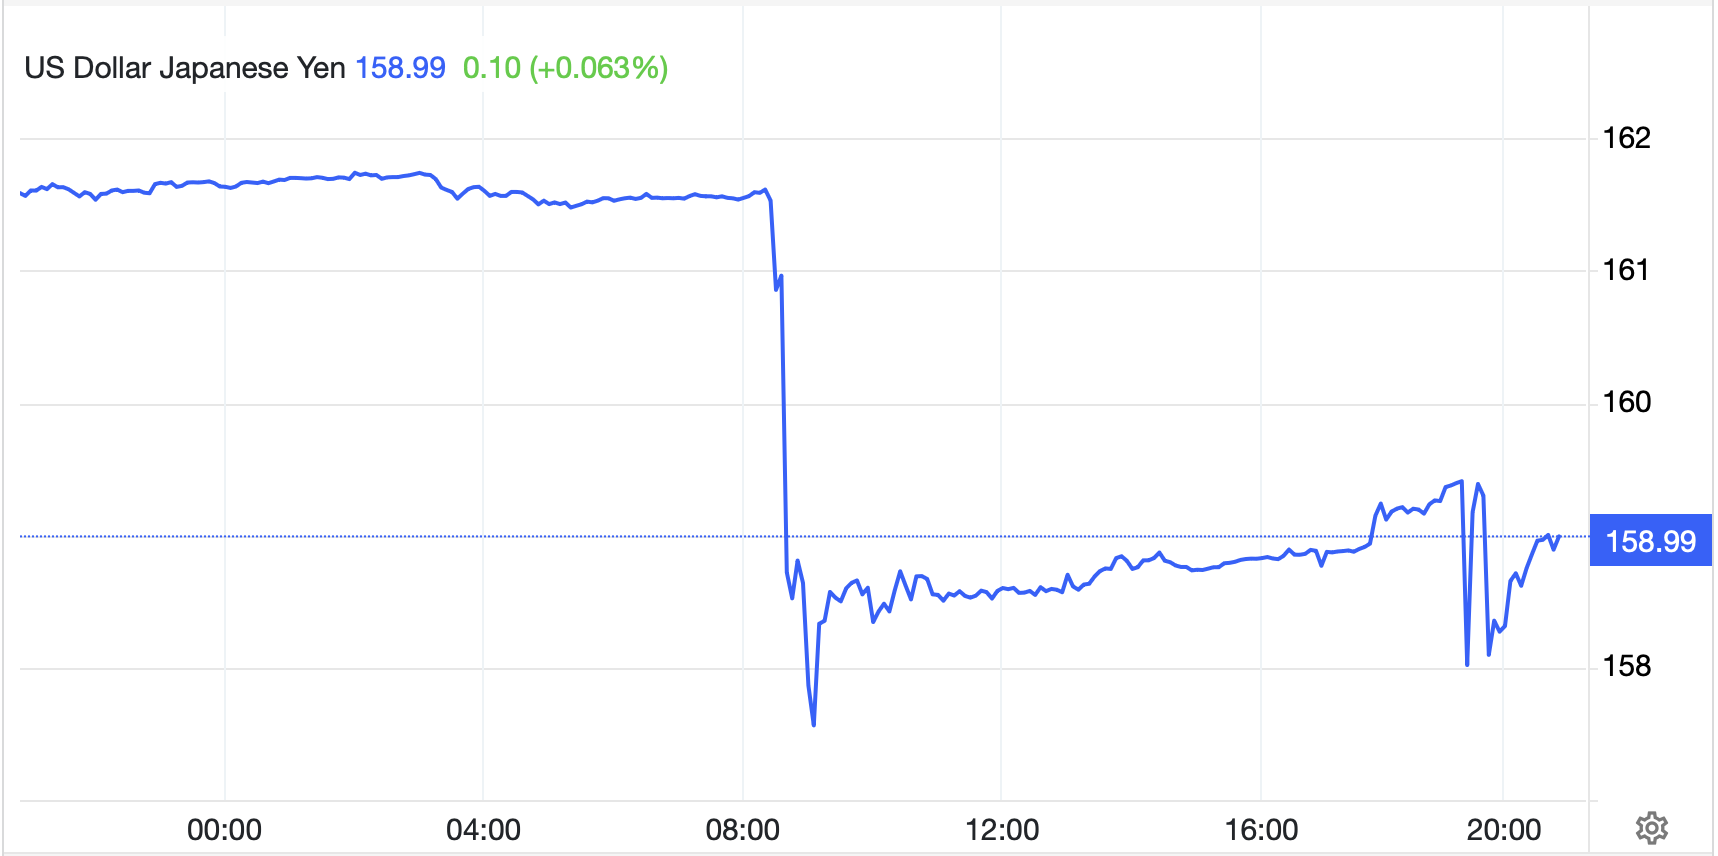
In the FX markets, the biggest mover, by far, was the yen, which at its high point of the session (dollar’s lows) had risen 4 full yen, or 2.5%.  The move was virtually instantaneous as can be seen in the chart below, and it is for that reason that I do not believe the BOJ/MOF was involved in the market.
Source: tradingeconomics.com

While I understand that the BOJ is pretty good at their jobs, it seems highly unlikely that the MOF made a decision in seconds and was able to convey that decision to Ueda-san’s team to sell dollars.  Rather, my sense is that since the short yen trade is so incredibly widespread as the yen has served as a funding currency for virtually every asset on the planet, the fact that the story about higher for longer may be ending led to instant algorithmic selling by hedge funds everywhere and a massive rally in the yen.  When the MOF was asked about intervention, Kanda-san, the current Mr Yen, gave no hint they were in and said only that people will find out when they release their accounts at the end of the month, by which time this episode will have been forgotten.  Remember, too, the yen has fallen, even after today’s rally, nearly 13% thus far in 2024.  It needs to rally a great deal further before it has any macroeconomic impact on Japan’s economy.  For my money, this was just a market that was caught long dollars and weak hands got stopped out, although Bloomberg is out with an article this morning claiming data showing it was intervention.  One thing in favor of the intervention story, though, is that this morning, USDJPY is higher by 0.6% and pushing 160.00 again.

And lastly, the story in China
Continues to give Xi angina
Domestic demand
Is stuck in quicksand
So, trade is his only lifeline-a
 
The other story that is on market minds this morning is about the Chinese data that was released last night.  The Trade Balance there expanded to $99B, much larger than last month and forecast.  A deeper look also shows that not only did exports grow more than expected but imports actually declined.  Declining imports are a sign of weak domestic demand, a harbinger of weak economic growth.  Later, they released their monetary data showing that loan growth, along with M2 growth, continue to slide as Chinese companies are reluctant to take on debt to expand.  While Xi’s government is pushing some money into the system, it is apparent that the collapsing property market remains a major obstacle to any sense of balanced economic activity in China.
 
Of course, this is a problem because of the international relation problems it continues to raise, notably with respect to charges of Chinese dumping of manufactured goods, and the proposed responses from both the US and EU on the subject.  While my crystal ball is somewhat cloudy, when viewing potential future outcomes of this situation it seems increasingly likely that both the US, regardless of the election outcomes in November, and the EU are going to impose tariffs and other restrictions on Chinese goods, if not outright bans.  Neither of these two can afford the social disruption that comes with domestic companies being forced out of business by subsidized Chinese competition.  While inflation looks better this morning than it did last month, its future is far less certain given this growing political attitude.
 
Ok, let’s see how markets have behaved in the wake of all the new information.  Arguably, the biggest surprise is that the US equity markets did not really have a good day with the NASDAQ tumbling -2.0% although the DJIA eked out a 0.1% gain.  Given the yen’s strength, it is no surprise that the Nikkei (-2.5%) fell sharply, and given the Chinese trade data, it is no surprise that the Hang Seng (+2.6%) rallied sharply.  But mainland shares were lackluster, and the rest of APAC was mixed with some gainers (Australia, India, New Zealand) and some laggards (South Korea, Taiwan, Malaysia).  European bourses, though, are all in the green as traders and investors there look to the increased odds of the US finally cutting rates, therefore allowing the ECB and other central banks to do the same, as distinct positives.  As to US futures, at this hour (7:00), they are unchanged to slightly higher.
 
In the bond market, after US yields fell sharply yesterday, with 10yr yields closing lower by 8bps, although they traded as low as 4.17%, a 12bp decline from the pre-data level, this morning, we are seeing a modest rebound with yields 1bp higher.  European sovereign yields are all firmer this morning as well as markets there closed before the US yields started to creep back up.  So, this morning’s 4bp-5bp moves are simply catching up to the US activity.  Lastly, JGB yields dipped 2bps last night as traders sought comfort in the decline in US yields.
 
In the commodity markets, yesterday saw a sharp rally immediately after the CPI print with gold jumping nearly $40/oz and back above $2400/oz, while oil had a more gradual rise, although is higher by nearly $1/bbl since the release.  This is all perfectly in line with the idea that the Fed is going to start to cut rates soon.  However, gold (-0.4%) is giving back some of those gains today.
 
Finally, the dollar, which fell sharply against all currencies after the CPI print, notably against the yen, but also against the rest of the G10 and most EMG currencies, is slightly softer overall this morning with both the euro (+0.15%) and pound (+0.3%) doing well and offsetting the yen’s weakness this morning.  Elsewhere throughout the G10 and EMG blocs the picture is far less consistent with CE4 currencies all following the euro higher although ZAR is unchanged as it suffers on gold’s weakness this morning. 
 
On the data front, this morning brings PPI (exp 0.1% M/M, 2.3% Y/Y) and its core (0.2% M/M, 2.5% Y/Y) although given yesterday’s surprisingly low CPI data and the ensuing market movements, it doesn’t feel like this number has the potential for much surprise.  After all, a soft reading would already be accounted for by the CPI and a strong one would be ignored.  We also see Michigan Sentiment (exp 68.5) at 10:00, but that, too, seems unlikely to shake things up.  There are no Fed speakers scheduled and really, the big thing today is likely to be the Q2 earnings releases from the big banks.
 
It has been an eventful week with Powell’s testimony being overshadowed by yesterday’s CPI data.  While the market is almost fully priced for a September cut, I think the best risk reward is to expect the Fed to act at the end of July.  Next week we hear from 10 Fed speakers, including Chairman Powell on Monday afternoon.  I would not be surprised to hear them start to guide markets to a July cut which would bring dollar weakness alongside commodity price strength.  As to bonds and equities, the former should do well to start, but as yesterday showed, and history has shown, equities tend to underperform when the Fed starts cutting rates.
 
Good luck and good weekend
Adf
 

Towards the Stars

As the yen declines
Pressure on the BOJ
Climbs up towards the stars


Intervention in the currency markets has a long and undistinguished history.  At least that is true for nations that have open capital accounts.  In fact, a key reason that countries impose and maintain capital account restrictions is to avoid the situation of having their currency collapse when the locals fear future loss of purchasing power, i.e. inflation is rising. While there have been situations where a central bank has been able to prevent a significant movement in the past, it has almost always been in an effort to prevent too much currency strength, never weakness.  

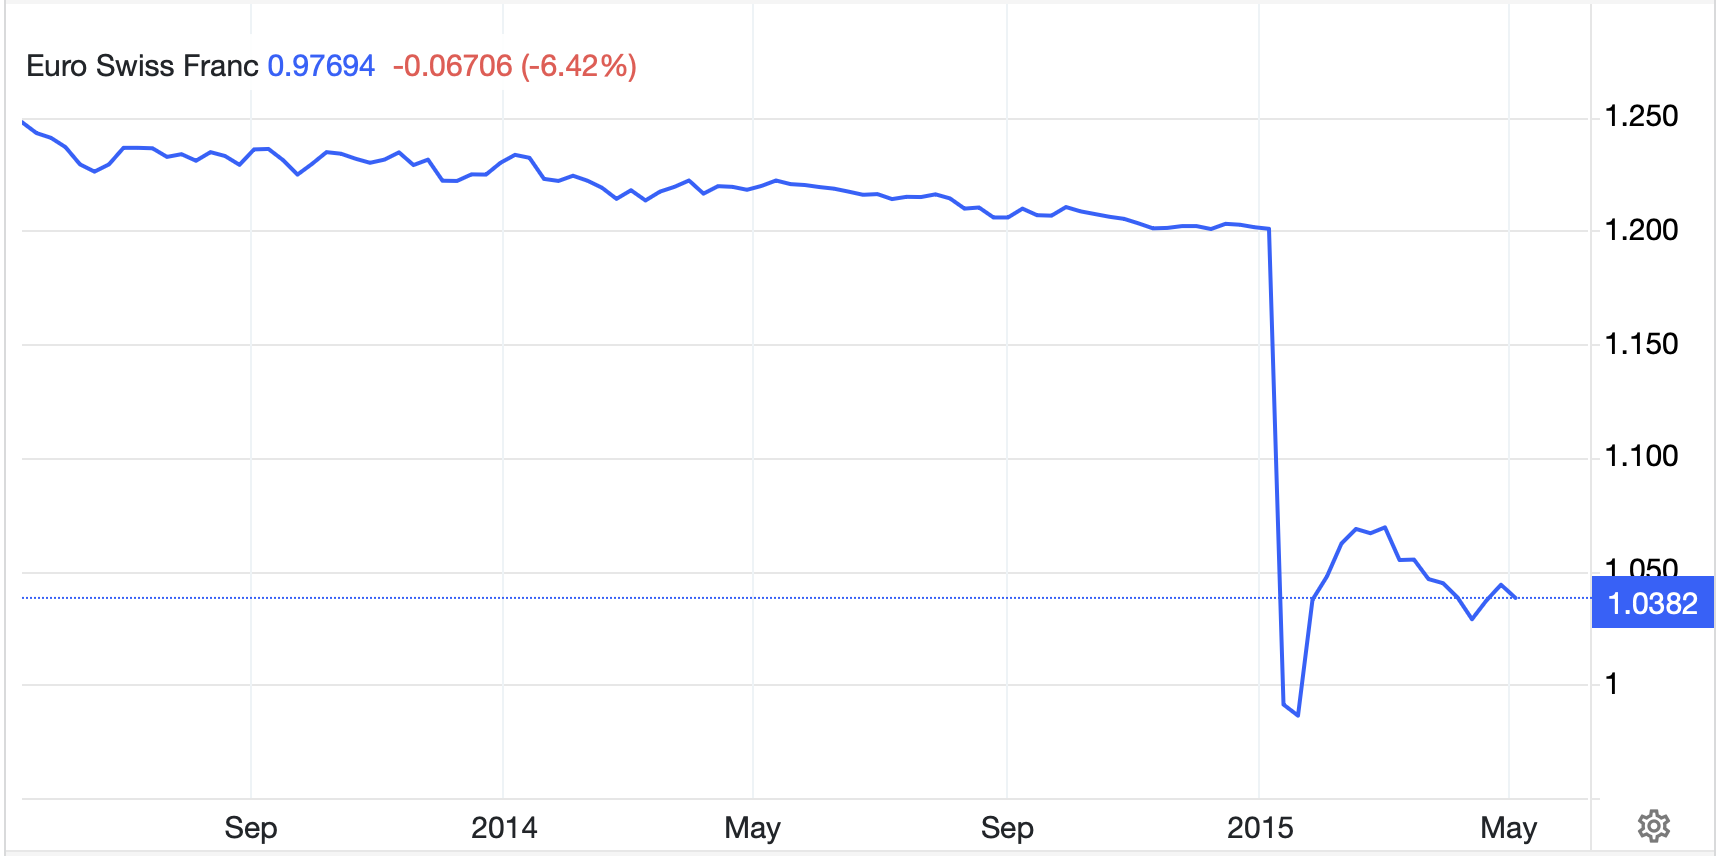
A great example is Switzerland in January 2015.  As you can see from the chart below of the EURCHF cross, Switzerland was explicitly targeting a level, 1.20, in the cross as the strongest the Swiss franc could trade (lower numbers indicate a stronger CHF).  This was in an effort to support the export sectors of the economy during a period shortly after the Eurozone crisis when Europeans were quite keen to convert their funds to Swiss francs as a more effective store of value.  

Source: tradingeconommics.com

The upshot was that the Swiss National Bank wound up effectively printing and selling hundreds of billions of francs, receiving dollars and euros and then investing those proceeds into the US stock market.  At one point, they were the largest shareholder in Apple!  But even in this case, where you would expect a nation could prevent their currency from rising too far or too fast, the process overwhelmed the SNB and one day in January 2015 they simply said, enough.  That 25% appreciation in the franc took about 15 minutes to accomplish and as evidenced by today’s exchange rate of 0.9768, it has never been unwound.

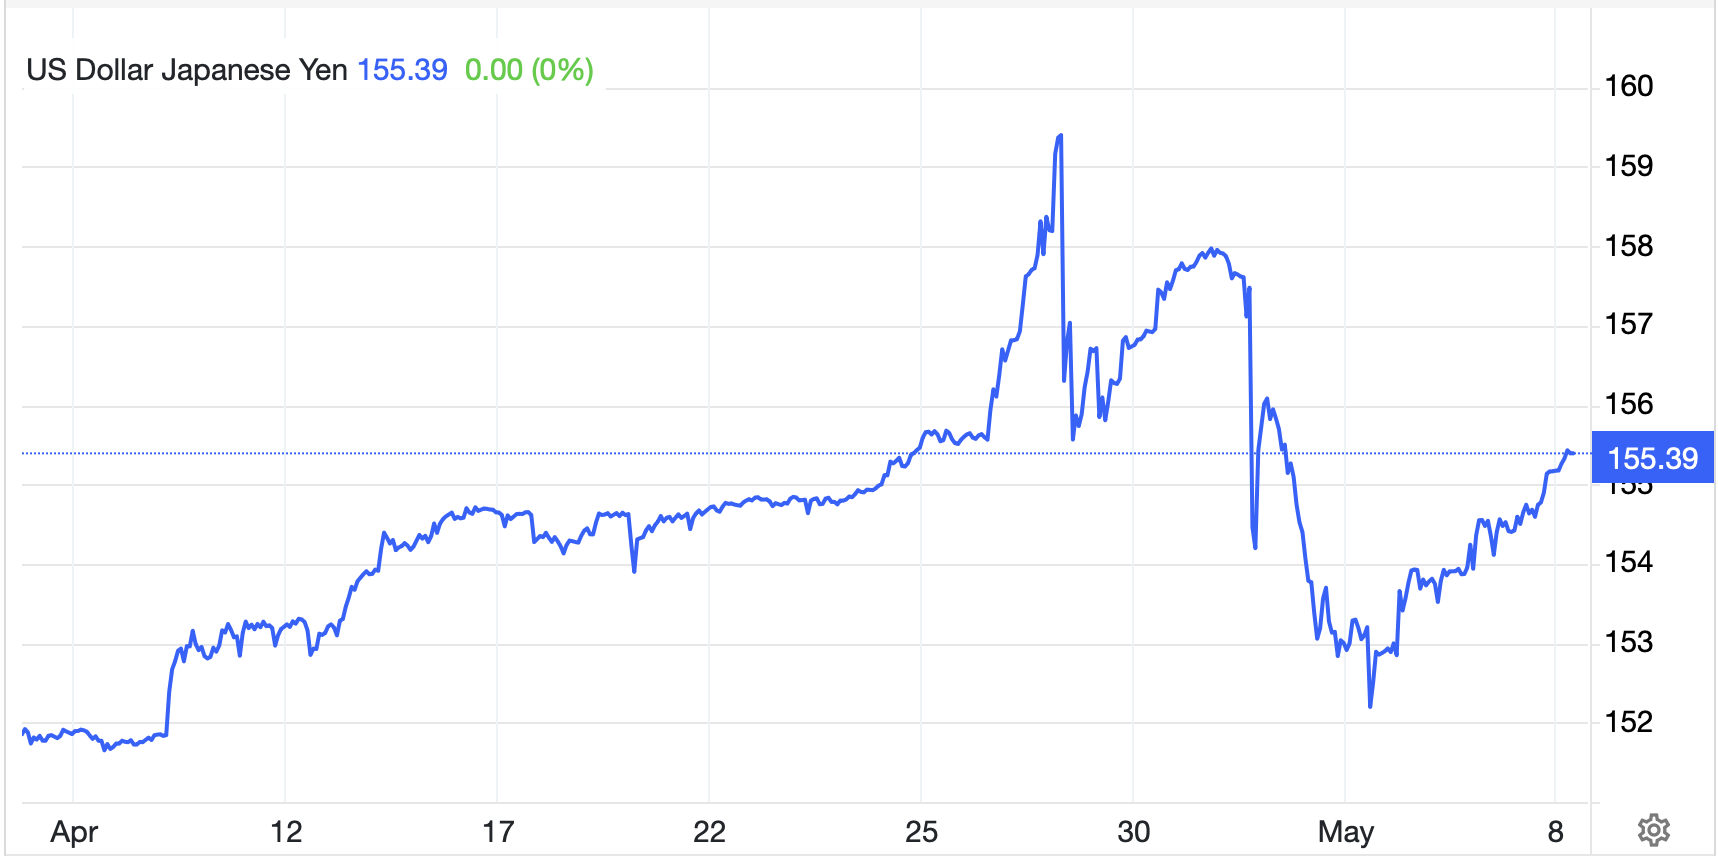
And that’s what happened to a central bank that is trying to prevent its own currency from strengthening.  For central banks to prevent weakness is an entirely different story and a MUCH harder task.  As I have repeatedly explained, the only way to change the trajectory of a currency is to alter monetary policy.  At this time, given the Fed’s commitment to higher for even longer, the only way Japan can prevent more substantial yen weakness is for the BOJ to tighten policy even further.  This is made evident in the below chart of the price action in USDJPY for the past month.  In it, you can see when it spiked above 160 on April 28th, and the subsequent intervention that day and then two days later.  

Source: tradingeconomics.com

However, in both cases, despite spending upwards of $60 billion intervening, the yen immediately resumed its downtrend (dollar uptrend) and this morning it is back above 155.  It is this price action that appears to have finally awoken Ueda-san as last night, in an appearance at the Japanese parliament, he explained the following, “Foreign exchange rates make a significant impact on the economy and inflation.  Depending on those moves, a monetary policy response might be needed.”  Ya think!  Ueda-san was followed in parliament by FinMin Suzuki who repeated something he said last week, “Since Japan relies on overseas markets for food and energy, and a large portion of its transactions are denominated in dollars, a weaker yen could raise prices of imported goods.”  While those comments are self-evident, the fact that he needed to repeat them is indicative of the idea that Japan is getting increasingly uncomfortable with the current yen exchange rate.

So, will Ueda-san raise rates at the next meeting in June?  Will he alter their QQE policy and explicitly explain they will no longer be buying JGBs?  Certainly, the market is on edge right now given the two bouts of intervention from last week, but not so on edge that it isn’t continuing to sell the currency and capture the carry.  At this point, you cannot rule out a third wave of intervention, and certainly we should expect more jawboning.  But in the end, if they are serious about the yen being too weak, Ueda-san will have to move.  At this point, I am not convinced, but the meeting is on June 14th, so there is plenty of time for things to become clearer.

And other than that, quite frankly, not much is going on.  So, let’s take a tour of markets to see how things stand this morning.

Yesterday’s equity markets in the US were tantamount to being unchanged across the board, at least that is true of the major indices.  There were certainly individual equities that moved.  In Asia, it was a mixed picture with both Japanese (Nikkei -1.6%) and Chinese (CSI 300 -0.8%) shares in the red, which dragged down HK shares.  But elsewhere in the region, we saw more gains than losses, albeit none of the movement was that large overall.  Meanwhile, in Europe, all the markets are looking robust this morning with gains ranging from 0.5% (DAX, FTSE 100) to 1.0% (CAC) and everywhere in between.  The Swedish Riksbank cut rates by 25bps, as anticipated this morning, and perhaps that has encouraged investors to believe the ECB is going to embark on a more significant easing campaign starting next month.  Certainly, the limited data we saw this morning, (German IP -0.4%, Spanish IP -1.2%, Italian Retail Sales 0.0%) are not indicative of an economy that is growing strongly.  Finally, US futures are just a touch lower, -0.2%, at this hour (7:15).

Despite the weakness in Eurozone data, and the absence of US data, yields are rebounding a bit this morning with Treasuries higher by 3bps and the entire European sovereign spectrum seeing yields rise by 3bps to 4bps.  It seems unlikely that the weak Eurozone data is the driver and I suspect that this movement is more a trading reaction based on the recent decline in yields.  After all, just one week ago, yields were more than 20 basis points higher, so a little rebound can be no surprise.

In the commodity markets, oil (-1.1%) is under pressure as rising inventories outweigh ongoing concerns over Israel’s Rafah initiative.  While the EIA data is generally considered the most important, yesterday’s API data showed a build of more than 500K barrels vs. expectations of a 1.4M barrel draw.  At the end of the day, this is still a supply/demand driven price, and if supply is more ample, prices will fall.  In the metals markets, precious metals continue to trade choppily around recent levels, but we are starting to see some weakness in the industrial space with both copper (-1.25%) and aluminum (-1.6%) under pressure this morning.  Certainly, if economic activity is starting to wane, these metals are likely to suffer.

Finally, in the FX markets, the dollar is continuing to rebound from its recent selloff, gaining against virtually all its counterparts, both EMG and G10.  SEK (-0.5%) is the biggest mover in the G10 after the rate cut, but JPY (-0.45%) is not far behind.  We are also seeing weakness in AUD (-0.4%) on the back of those metal declines.  As to the EMG bloc, ZAR (-0.7%) is the laggard there, also on the metals weakness, but we saw KRW (-0.5%) suffer overnight as well amidst the general dollar strength.

Once again, there is no US data on the calendar although we hear from three more Fed speakers, Boston’s Collins as well as governor’s Cook and Jefferson.  Yesterday, Mr Kashkari did not give us any new information, indicating that higher for longer still makes the most sense and even questioning the level of the neutral rate, implying it may be higher than previously thought.  But there have been no cracks in the current story that the Fed is not going to alter policy soon.

While day-to-day movements remain subject to many vagaries, the reality is that the trend in the dollar has been higher all year and as long as monetary policies around the world remain as currently priced, with the Fed the most hawkish of all, the dollar should grind higher over time.

Good luck

Adf

Tortured

Intervention is
The last bastion of tortured
Finance ministers


Apparently, Japanese FinMin Suzuki did not want the spotlight to remain on Chairman Powell and the Fed so last night, in what was surprising timing given the absence of additional jawboning ahead of the move, it appears there was a second round of intervention orchestrated by the MOF and executed by the BOJ.  Looking at the chart below, courtesy of tradingeconomics.com, it is pretty clear as to the activity and timing, although as is often the case, 50% of the move has already been retraced.

According to Bloomberg’s calculations, they spent an additional ¥3.5 (~$22B) in the effort, so smaller than last time, but still a pretty decent amount of cash.  As of yet, there has been no affirmation by the MOF that they did intervene, although the price chart alone is strong evidence of the action.  Will it matter?  In the long run, not at all.  The only thing that will change the ultimate trajectory of the yen’s exchange rate is a policy change and based on last week’s BOJ meeting, there is no evidence a monetary policy change is in the offing.  Therefore, we need to see a US policy change and based on yesterday’s FOMC meeting and the following press conference, that doesn’t seem to be coming anytime soon either.  To my eye, the yen will continue to weaken until something changes.  This could take a few more years and USDJPY could wind up a lot higher than 160.

Said Jay, it is, frankly, absurd
A rate hike will soon be preferred
But neither will we
Soon cut, we agree
While ‘flation’s decline is deferred

To me, the encapsulation of the entire FOMC statement and Powell press conference can be summed up in the following two quotes from the Chairman while answering questions.  “I think it’s unlikely that the next policy rate move will be a hike,” and “inflation has shown a lack of further progress… and gaining confidence to cut will take longer than thought.”  In other words, we are not likely to change policy anytime soon absent a complete black swan event.

Since the press conference ended, there has been an enormous amount of speculation regarding what message Powell was trying to send.  I would argue the consensus is that he wants to cut but the data is just not in a place that would allow the Fed to go down that path without destroying what’s left of their credibility.  To me, the question is, why is he so anxious to cut rates?  Arguably, an unbiased Fed chair would simply ‘want’ to follow whatever is the appropriate course to achieve the mandate.  

One of the popular views is that there is substantial pressure from the White House to cut as the Biden administration believes lower rates will help Biden’s reelection bid, however Powell, when asked about the political issue, was explicit in rejecting that hypothesis and claiming that politics is never even part of the conversation, let alone the decision.  I accept that at face value, although certainly all 17 members of the FOMC have political biases that drive their actions.  But here is a take I have not heard elsewhere.  Perhaps Powell is keen to cut because it will help the private equity sphere, the place where he not only made his fortune, but where he also maintains a large social circle and he simply wants to help his friends.  There is no doubt that lower rates help the PE space!  Regardless of why, I have to agree that it appears he is leaning in that direction.

There was one other thing that was a minor surprise and that had to do with the balance sheet program.  As expected, the Fed explained they would be reducing the pace of QT starting in June, but they would be doing so by more than anticipated, slowing the runoff to $25 billion/month of Treasuries before reinvesting, down from the current level of $60 billion/month.  For MBS, the runoff remains at $35 billion/month, although if that number is exceeded, they would replace the MBS with Treasuries so allow the MBS portion of the portfolio (currently $2.38 trillion) to slowly disappear.  The operative word here, though, is slowly, as they have not come close to seeing that $35 billion since the program started.  After all, nobody is refinancing their mortgage with current rates thus reducing the churn in that part of the portfolio.  At any rate, that was very mildly dovish, I believe.

The market response to the entire show was quite positive with equity investors taking the dovish message to heart and equities and bonds both rallied in the immediate wake of the meeting, although the equity markets sold off on the close and wound up slightly lower for the session.  Not so bonds, where yields fell and continue at those levels, down about 5bps on the day.

So how have things fared overnight since the Fed?  Well, the Hang Seng (+2.5%) was the big winner as investors there took Powell’s dovishness to heart and that combined with confirmation that the Chinese Plenary meeting would be occurring in July, thus a chance for more stimulus to come, got investors excited.  However, the mainland was closed.  Japanese shares were basically unchanged after the intervention and the story throughout the rest of the region was mixed with some gainers (Australia, India) and some laggards (South Korea, Indonesia).  

In Europe, it is also a mixed picture as investors respond to the PMI data releases, which were also a mixed bag.  For instance, Spain saw a jump in PMI and the IBEX is firmer by 0.3% while France saw a 1-point decline in the index and the CAC is down by -0.7%.  Looking at the overall mix of data, it appears that European economic activity is bumping along the bottom, although not yet clearly turning higher.  Arguably that is a big reason the ECB has penciled in that June rate cut.  Finally, US futures are pointing higher at this hour (7:00) between 0.5% and 1.0%, so quite solidly so.

In the bond market, the doves are still in charge as Treasury yields have drifted lower by another 2bps and are back to 4.60%.  but in Europe, the story is even better with yields down between 4bps and 7bps as the modest growth outturn added to oil’s recent price declines has investors gaining confidence that inflation there, at least, is truly on its way back to target.  As to JGB’s, a 1bp rise overnight has yields back to 0.90%, obviously much closer to the previous limit at 1.0%, but still not moving there rapidly.

Going back to oil prices, while they have bounced 0.5% this morning, they are down more than 5.2% in the past week as rising inventories and growing hopes of a ceasefire in Gaza have been enough to get the CTAs and hedge funds to close their positions.  In something of a surprise to me based on the ostensible dovish tone of the Fed, metals markets are back under pressure after yesterday’s bounce so all of them, both precious and industrial, are lower by about -1.0% this morning.

Finally, the dollar, aside from the yen, is edging higher this morning, although edging is the key term here.  Against most majors it is firmer by just a bit, 0.15% or so, although in the G10 there are two outliers, CHF (+0.45%) which rallied after their CPI release this morning was much hotter than expected at 0.3% M/M indicating the SNB may be holding off on its next rate cut, and NOK (-0.6%) which is continuing to suffer from the oil decline in the past week.  It should also be no surprise that ZAR (-0.5%) is under pressure given the metals movement.  But elsewhere, things are far less interesting with modest dollar gains the rule today.  This seems at odds with the ostensible dovish Fed tone, but there you have it.

On the data front, we see Initial (exp 212K) and Continuing (1800K) Claims as always on a Thursday, as well as the Trade Balance (-$69.1B) and then Nonfarm Productivity (0.8%) and Unit Labor Costs (3.3%) all at 8:30 with Factory Orders (1.6%) coming at 10:00.  As of now, there are no Fed speakers on the docket, but I would not be surprised to see an interview pop up.  The Fed will be closely watching the productivity data as that is an important part of the macro equation regarding sustainable growth and inflation.  Certainly, the expectations do not bode well for a dovish stance.

Explain to me that policy has changed, and I will accept that it is time to change my view.  However, at this point, the dollar still gets the benefit of the doubt.

Good luck

Adf

Top of Mind

Will they or won’t they?
The intervention question
Is now top of mind


As we approach Japanese Fiscal Year end, and while we all await Friday’s PCE data, the FX markets have taken on more importance, at least for now.  The big question is, will there be intervention by the Japanese?  Late last night, USDJPY traded to a new thirty-four year high of 151.96, one pip higher than the level touched in September 2022 which catalyzed the last intervention by the BOJ/MOF.  Recall, last week the BOJ “tightened” monetary policy by exiting their 8-year experiment with negative interest rates and ‘promised’ that they were just getting started.  Granted, they didn’t indicate things would move quickly in this direction and they also explained they would remain accommodative, but they did seem confident that this would change a lot of opinions.  Remember, too, that the market response to that policy shift was to weaken the currency further while JGB yields actually drifted lower.

So, here we are a bit more than a week later and the yen has fallen to new lows.  What’s a country to do?  In the timeless fashion of governments everywhere with respect to currency moves, they immediately started jawboning.  Last night we heard from BOJ Board member Naoki Tamura as follows, “The handling of monetary policy is extremely important from here on for slow but steady progress in normalization to fold back the extraordinarily large-scale monetary easing.  The continuation of an easy financial environment doesn’t mean there won’t be any more rate hikes at all.”  Traders did not exactly quake in fear that the BOJ was suddenly going to tighten aggressively, let’s put it that way, and so nothing has really changed.  One other thing to note is that Tamura-san is seen as the most hawkish member of the current BOJ, at least per Bloomberg Intelligence’s analysts.  Take a look at their views below.

But wait, there’s more!  We also heard from Japanese FinMin, Shunichi Suzuki, that the government would take “decisive steps” if they deemed it necessary to respond to recent currency movement.  And the, the coup de grace, an emergency meeting between the MOF, the BOJ and the Financial Services Agency (FSA) is ongoing as I type (6:30) to help come up with a plan.  

Does this mean intervention is coming soon to a screen near you?  While it is certainly possible, the ultimate issue remains that the relative monetary policy settings between the US (higher for longer) and Japan (still at ZIRP with a hike expected in…October) remain such that the yen is very likely to remain under pressure.  Remember, too, that Japan is in the midst of a technical recession, so tightening monetary policy is not likely to be appreciated by Mr and Mrs Watanabe.  At the end of the day, the politics of inflation are very different in the US and Japan, and I would contend that in Japan, it is still not the type of existential problem for the government that it appears to be in the US.

FWIW, which is probably not much, I expect the MOF to follow their playbook, talk tougher, check rates and ultimately intervene over the next several days.  They will take advantage of the upcoming Easter holiday weekend and the reduced liquidity in markets to seek an outsized impact for the least amount of money possible.  But I do not see them changing their monetary policy before the autumn and so I look for continued yen weakness over time.  Be careful in the short run, but the direction of travel is still the same, USDJPY will rise.

For China, the fact the yen’s weak
Has Xi and his staff set to freak
They’re all quite dismayed
‘Cause Japanese trade
Has lately been on a hot streak
 

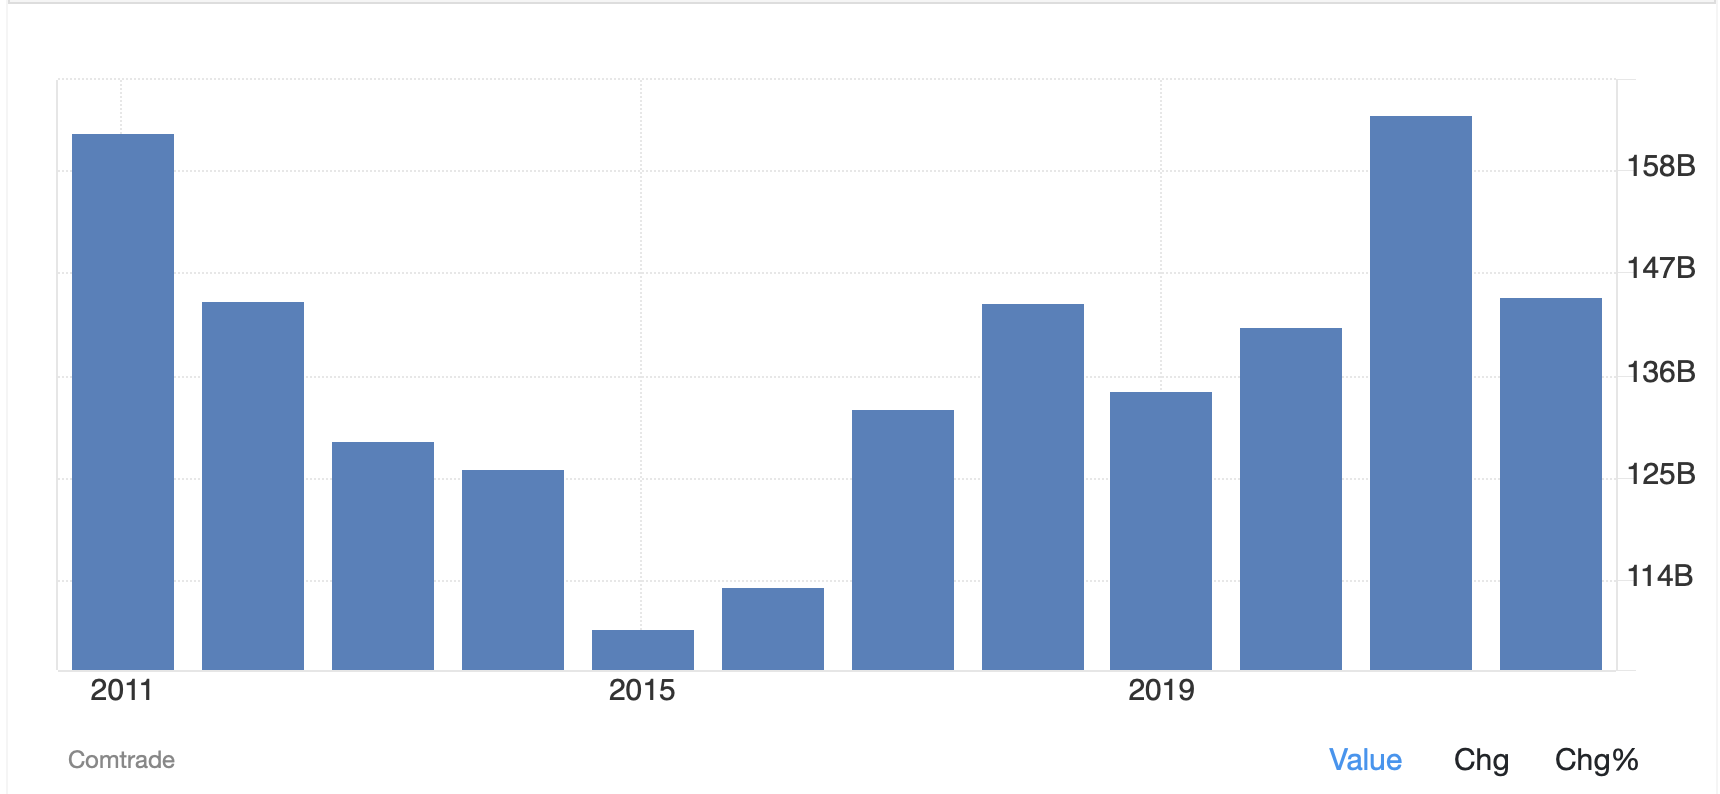
The other story in markets has been the ongoing ructions in the Chinese renminbi market.  It is key to understand that this is directly related to the yen story above as China and Japan are fierce competitors in many of their export activities.  But of even more concern to Xi and his gang is that Japanese exports to China are growing so rapidly and Japan ran a trade surplus with China in December (the last month with data released).  When you are a mercantilist nation like China, having a key competitor, like Japan, allow its currency to weaken dramatically against your own is a major problem.  Last week I highlighted the dramatic decline of the yen vs. the renminbi, and that has not changed.  Below is a chart from tradingeconomics.com showing Japanese exports to China ($billions) showing just how much this trend has changed and continues to do so.

Ultimately, both of these countries rely on exports as a critical part of their economic growth and activity, and in both cases, exports to the US and Europe are crucial markets.  If the Japanese continue to allow the yen to weaken, China has a problem.  Remember, Japan does not have capital controls, so while they don’t want the yen to collapse, they are perfectly comfortable with capital outflows in general.  China, on the other hand, is terrified of massive outflows if they were to even consider relaxing capital controls.  The fact is both companies and individuals work very hard to get their money out of the country.  This is one reason that gold is favored there by the population, and the reason that the government banned bitcoin as it was an open channel for funds to leave the country. 

This battle has just begun and seems likely to last for quite a while going forward.  The Chinese are caught between wanting to devalue the renminbi to compete more effectively and maintaining a stable exchange rate to demonstrate there are no fiscal or economic problems in the country.  Alas for Xi and the PBOC, never the twain shall meet.  I would look for a continuation of the recent market volatility here as they will use that uncertainty to discourage large position taking by speculators.  But, as I have maintained for a long time, I expect that USDCNY will trade to 7.50 and beyond as time progresses.

And that’s really it for today.  Ultimately, very little happened in markets overnight, certainly there were no changes in the recent data trajectory nor in any commentary from speakers (other than that mentioned above).  It is a holiday week and a key piece of data, PCE, is set to be released on a broad market holiday this Friday.  Do not look for large moves before then.

There is no US data due today but we do hear from Fed Governor Christopher Waller this afternoon so there is an opportunity for some market movement then.  But for now, consolidation seems the most likely outcome.

Good luck

Adf

Towel Throwing

Did they sell?  Or not?
The new Mr Yen, Kanda
Explained, “No comment”

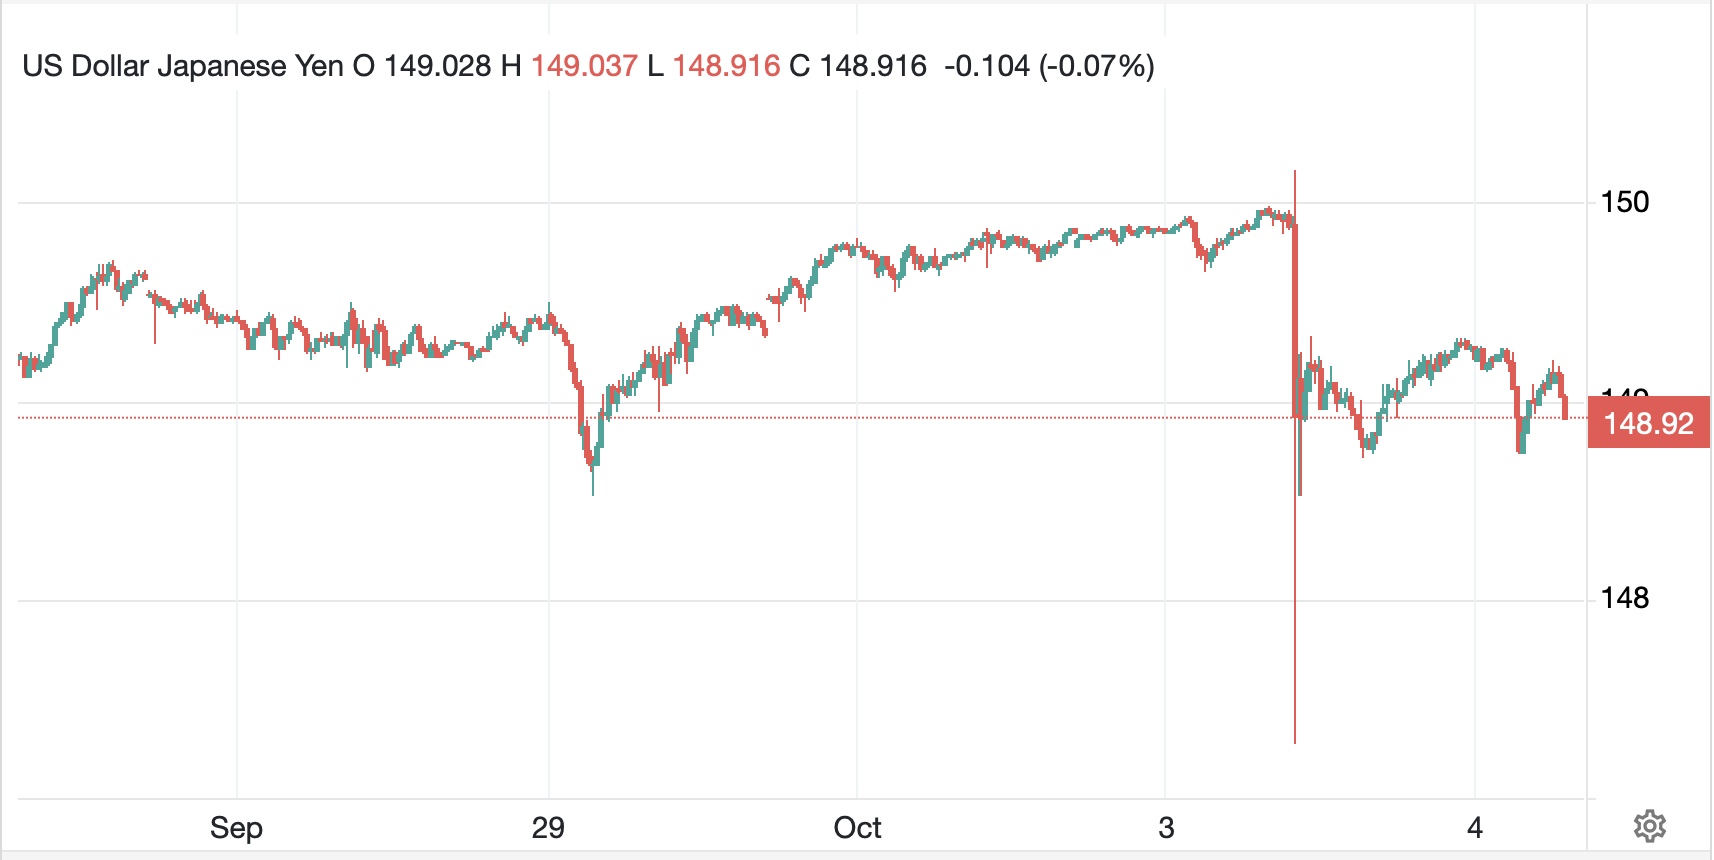
As is clear from the chart below (source tradingeconomics.com), there was a bit of movement in the USDJPY market yesterday morning.  The price action certainly had the feel of intervention, with a nearly 2% decline that occurred in seconds, but there has been neither confirmation nor denial of any BOJ trading activity.  Kanda-san, who is vice minister of international affairs which is the MOF role that deals with the currency, is the current Mr Yen.  His comments were certainly cryptic and as such, not very informative.  “We will continue with the existing stance on our response to excessive currency moves,” said Kanda. “While we are basically like a Gulliver in the market, we’re also coming and going as a market player, so usually we won’t say whether or not we’ve intervened each time,” Kanda said.  

The story that makes the most sense is that the BOJ reached out to the major Japanese banks in NY and London and checked rates.  The fact that the move happened minutes after the spot rate finally breeched the 150 level certainly was suspicious and indicated that contrary to yesterday’s comments by Watanabe-san, a former Mr Yen, the level really does matter, not just the speed of the move.  Others have tried to explain that breeching 150 triggered selling levels, but if there were exotic option barriers at 150, and I’m sure there were, the more typical move would be an acceleration higher as stop-loss orders by dealers were triggered.  The spike down, at least in my experience, is a sign of exogenous activity, not market internals.

Looking ahead, are we likely to see more of this type of activity?  You can never rule out currency support from any nation whose currency is weakening sharply, but there are G7 and G20 constructs that are supposed to limit these, and are designed to focus on volatility of movement, not levels.  This appeared contrary to those concepts, so we have much yet to learn.  At the end of the month, the BOJ will publish any intervention activity as part of their transparency initiative, but that might as well be next year for all the information it will provide.  Be wary of further movements like this, but the fundamentals continue to point to a higher USDJPY, especially given the accelerating rise in US Treasury yields.

The bond market rout keeps on going
As we see more folks towel throwing
The question at hand
Is can Powell stand
The pressure that’s certainly growing

Thus far, there’s no sign that the Fed
Is worried when looking ahead
More speakers were heard
To follow the word
That higher for longer’s not dead

Of course, away from the FX market, where the dollar has continued to show remarkable strength overall, the big story is the Treasury market.  After yesterday’s sharp move, the 10-year yield is higher by 23bps so far in October and it is only the morning of the third session of the month!  The yield curve inversion is down to -32bps and 30-year Treasury yields are pressing 5% now, a level not seen since summer 2007.  This sharp move has been the true driver of almost all markets and as long as it continues, there is going to be more pain for risk assets.  There has been no change in the fundamentals and yesterday’s move was ascribed to a much higher than expected JOLTS Job Openings number, which printed at 9.61M, far above the forecast 8.8M and a huge jump from last month’s outcome.  This seemed to encourage the Fed speakers to maintain their higher for longer attitude with a number still looking for one more rate hike this year.  Once again, I will point to Friday’s NFP number and its importance as a key driver of Fed policy.  If that number remains strong, and Unemployment remains low, the Fed can maintain this policy stance with limited fallout politically.

The rise in Treasury yields is being copied elsewhere around the world with yields following the US higher.  While today is seeing a bit of consolidation, with European sovereign and Treasury yields currently softer by 1bp-2bps, this is a trading effect, not a change of heart.  Interestingly, even JGB yields are getting dragged along higher as they closed last night at 0.80%, their highest level since 2012, the beginning of Abenomics.  But in the end, this is all about US yields with the rest of the world continuing to follow their lead.  I heard some analysts claiming this was a blow-off top in yields and we have seen the end.  Alas, I don’t believe that as history shows the yield curve will move back to a normal stance and with the Fed firmly in the higher for longer camp, 10-year yields have further to rise.  Yes, something is likely to break at some point, but so far, the few hiccups have been contained.

Not surprisingly, risk assets had a tough time in yesterday’s session with US indices all falling sharply, by -1.3% or more.  Yesterday’s European bourses were also under significant pressure and the Asian markets open overnight got hit hard as well with the Nikkei (-2.3%) and Hang Seng (-0.8%) the biggest movers.  However, this morning, Europe has a touch of green on the screen, with small gains on the order of 0.3% and US futures are also edging higher, +0.15% at this hour (7:45).  I wouldn’t read too much into this modest bounce and fear that there is further, and potentially much further, to go.  One of the remarkable things about the equity market is that earnings estimates for 2024 are for a rise of 12% on 2023 earnings.  Given the ongoing rise in energy costs and the increasing probability of a recession, those seem quite optimistic.  As they are revised lower, that, too, will weigh on equities, and by extension all risk assets.

Lastly, in the energy space, oil (-1.7%) is under further pressure this morning, although the fundamentals wouldn’t indicate that is the right move.  Not only did we see a further draw in inventories in the US, notably at the key Cushing, OK storage depot, but we heard from Russia that they are going to continue to restrict production by 300K bbl/day through the end of the year.  Meanwhile, the law in the US is set that the government cannot sell oil from the SPR when the inventory level falls below 330 million barrels.  Currently, it sits at 327 million, so that supply has ended.  Nothing has changed my view that oil has much higher to go, albeit not in a straight line.

Metals prices remain generally under pressure although gold (+0.2%) seems to be bouncing with other risk assets this morning on a technical trading basis.  However, both copper and aluminum are still sliding, typically a harbinger of weaker economic activity to come.

As to the dollar broadly, it, too, is a touch softer this morning, pulling back from highs seen yesterday in sync with all the markets.  But the same fundamentals driving the bond and stock markets are in play here, higher yields leading to more demand and a higher dollar.  Yes, this will end at some point, but we need to see a change in policy for that to happen.  The next real chance we have for something like that is on Friday with the payroll report.  A weak report, which seems unlikely at this time given the other employment indicators, would almost certainly change the market’s tone.  However, until then, look for positioning to continue to favor a stronger dollar, and for more and more dollar short sellers to get stopped out.

On the data front, this morning brings ADP Employment (exp 153K) as well as Factory Orders (-2.1%) and ISM Services (54.5).  the PMI Services data from Europe indicated that the worst may be over, but that there is, as yet, no real rebound.  We hear from a few more Fed speakers, but thus far they remain consistent, higher for longer is appropriate.

Today could see more consolidation of the recent moves across the board, but I do not believe that we have come to the end.  Calling a top or bottom is always impossible but remembering that the trend is your friend is likely to keep your activities in good shape.

Good luck

Adf

Beggar Thy Neighbor

A story that’s making the rounds
Although, it, so far, lacks real grounds
Is that the US
Might try to depress
The dollar ‘gainst euros and pounds

If so, that’s incredible news
And dollar bulls need change their views
But beggar thy neighbor
Does naught but belabor
The trade war, instead, it, defuse

The most interesting story that has started to gain traction is the idea that the Trump administration is considering direct intervention in the FX markets. While most pundits and investors focus on the Fed and how its monetary policy impacts the value of the dollar (which is completely appropriate), the legal framework in the US is that the Treasury is the department that has oversight of the currency. This means that dollar policy, such as it is beyond benign neglect, is formulated by the Secretary of the Treasury, not the FOMC. This is why the Treasury produces the report about other countries and currency manipulation every six months. Also, this is not a new situation, it has been the case since the abandonment of the Bretton Woods Agreement in 1971.

Since the Clinton Administration, the US policy has been a ‘strong dollar is in the US best interest’. This was made clear by then Treasury Secretary Robert Rubin and has been an accepted part of the monetary framework ever since. The issue with a strong dollar, of course, is that it can be an impediment for US exporters as their goods and services may become uncompetitively priced. Now, during the time when the US’s large trade deficits were not seen as problematic, the strong dollar was not seen as an issue. Clearly, earnings results from multinational corporations were impacted, but the government was not running policy with that as a priority. However, the current administration is far more mercantilist than the previous three or four, and as we have seen from the President’s Twitter feed, dollar strength has moved up the list of priorities.

It is this set of circumstances that has analysts and economists pondering the idea that the Treasury may direct the Fed to intervene directly in the FX market, selling dollars. History has shown that when a country intervenes by itself in the FX market, whether to prevent strength or weakness, it has generally been a failure. The only times when intervention has worked has been when there has been a general agreement amongst a large group of nations that a currency is either too strong or too weak and that intervention is appropriate. The best known examples are the Plaza Accord and the Louvre Accord from the mid-1980’s, where the G7 first agreed that the dollar was overvalued, then that it had reached an appropriate level. The initial announcement alone was able to drive the dollar lower by upwards of 10%, and the active intervention was worth another 5%. The result was a longer term weakening of nearly 40% before it was halted by the Louvre Accord. But other than those situations, for the large freely floating currencies, intervention has been effective at slowing a trend, but not reversing one. And the current dollar trend remains higher.

If the US does decide to intervene directly, this will have an enormous short-term impact on the FX market (and probably all markets) as it represents a significant policy reversal. However, in the end, macroeconomic fundamentals and relative monetary policy stances are still going to drive the value of every currency. With that in mind, it could be a long time before those influences become dominant again. Of course, the other thing is that the history of beggar-thy-neighbor FX policy is one of abject failure, with all nations seeking the same advantage, and none receiving any. Certainly, this is something to keep on your radar.

Away from that story, the dollar is actually stronger this morning, with the euro having breached 1.12, the pound tumbling toward 1.24 and most currencies, both G10 and EMG on the back foot. In fact, this is the problem for the Trump administration on this front, the growth situation elsewhere in the world continues to deteriorate more rapidly than in the US. Not only did Friday’s employment data help support the dollar, but this morning we saw very weak UK and Italian Retail Sales data to add to the economic malaise in those areas. In fact, economists are now forecasting negative GDP growth in the UK for Q2, and markets are pricing in a 25bp rate cut by the BOE before the end of the year. Meanwhile, in the Eurozone, all the talk is about how quickly the ECB is going to restart QE, with new estimates it could happen as soon as September with amounts up to €40 billion per month. While that seems to be a remarkably quick reversal (remember, they just ended QE six months ago), with the prospect of an ECB President Lagarde, who has lauded QE as an excellent policy tool, it cannot be ruled out.

Pivoting to the trade story, the latest news is that senior officials will be speaking by phone this week and the chances of a meeting, probably in Beijing in the next few weeks are rising. The problem is that there are still fundamental differences in world views and unless one side caves, which seems unlikely right now, I don’t see a short-term resolution. What is more remarkable is the fact that the lack of any discernible progress on trade is no longer seen as an issue by any markets. Or at least not a major one. While equity markets have softened over the past two sessions, the declines have been muted and, at least in the US, indices remain near record highs. Bond yields have risen a bit, implying the worst of the fear has passed, although in fairness, they remain incredibly low. But most importantly, the dialog has moved on, with trade no longer seen as the key fundamental factor it appeared to be just two months ago.

Turning to this morning’s news, there is only one data point, JOLT’s Job Openings (exp 7.47M) but of much more importance we hear from Chairman Powell at 8:45 this morning, followed by Bullard, Bostic and Quarles later in the day. Powell begins his testimony to Congress tomorrow morning, but everyone will be listening carefully to see if he is going to try to walk back expectations for the July rate cut that is fully priced into the market. My money is on confirming the cut on the basis of continued low inflation readings. However, given that is the market expectation, there is no reason to believe the dollar will suffer on the news, unless he is hyper dovish. So, the current strong stance of the buck seems likely to continue for the rest of the day.

Good luck
Adf