A juxtaposition of note
Is France and the Albertan vote
The French are imploding
Midst radical goading
While seperatists’ visions were smote

I fear, though, that o’er the next weeks
Most risk market valleys and peaks
Will highlight reactions
To campaign distractions
As we watch the havoc that wreaks
While equity markets in the US were mixed yesterday beneath the shadow of the anniversary of Black Monday 1987, the rest of the world is having a tougher go of it this morning. Last night, as you can see from the below Bloomberg screenshot, the major Asian markets all fell, and we are seeing similar price action in Europe this morning.
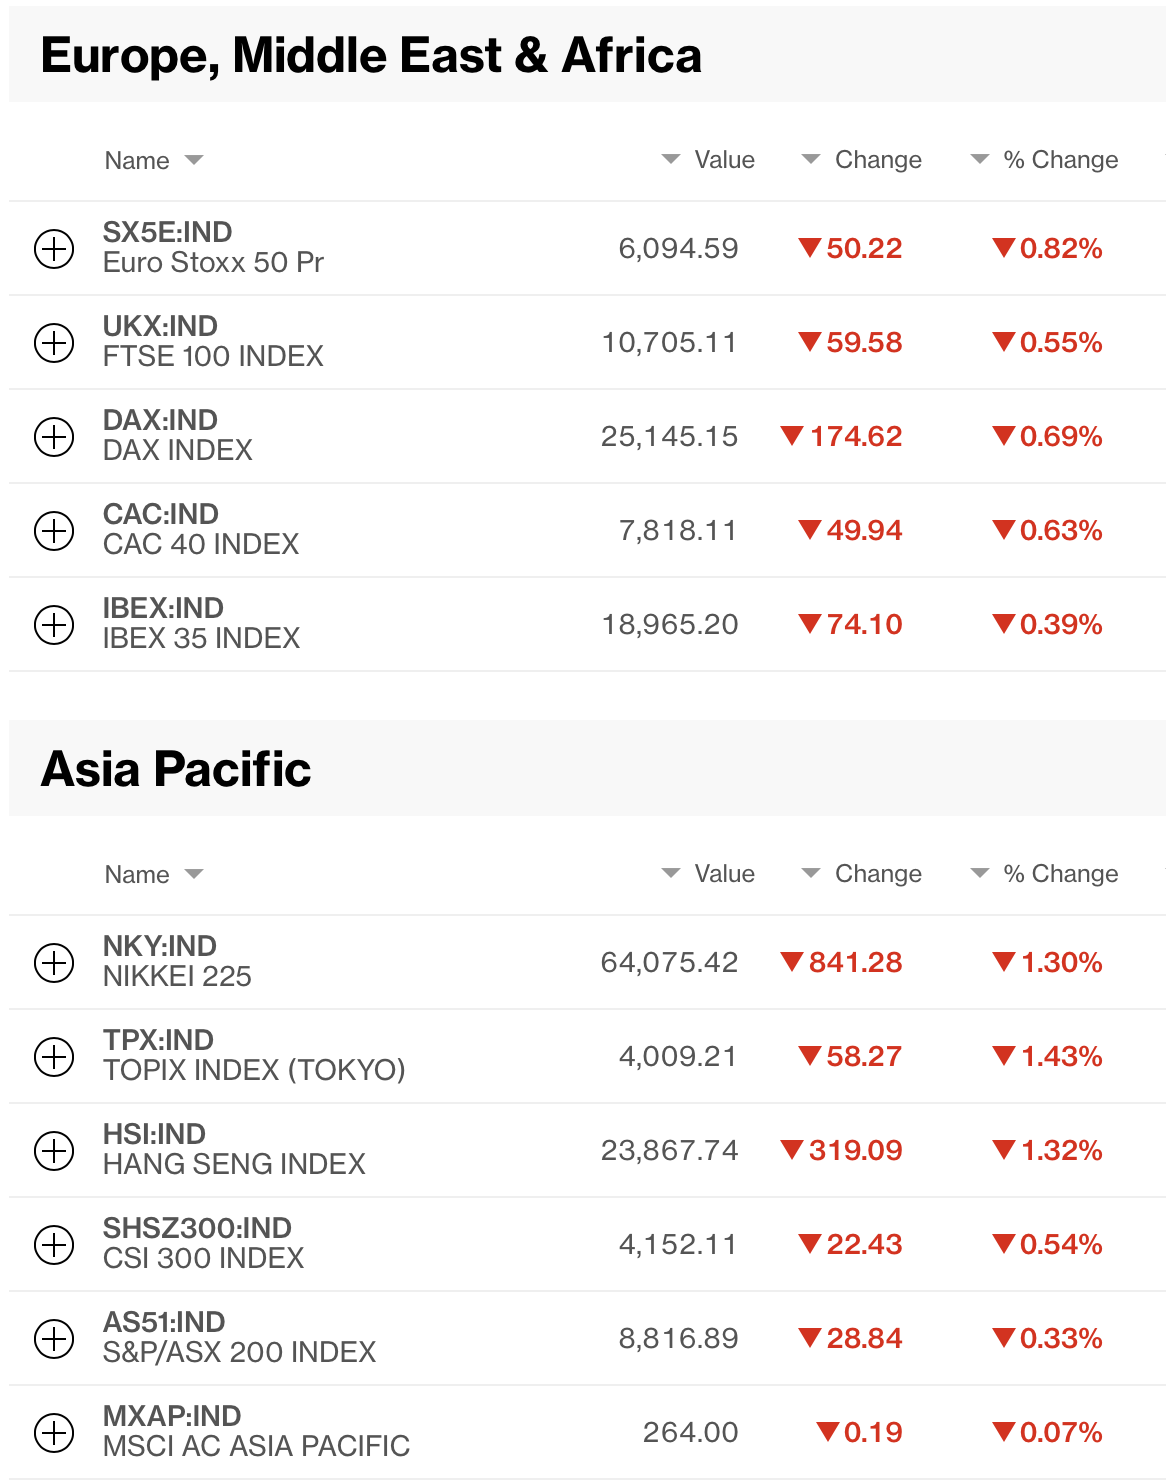
In fact, if you look across the regional Asian bourses, they all fell as well with one outlier, Indonesia, which after its 15% decline in the previous three sessions amid fears it would be removed from the MSCI indices, rose 5% upon hearing from the securities regulator that changes were afoot to placate MSCI, thus opening the way for some opportunistic buying of the dip. But otherwise, it’s been a very red day.
Arguably there are two drivers of this market angst, continued high oil prices and the uptick in violence across Europe as those ‘student’ protests have evolved into a much wider spread action being egged on by numerous explicitly left-wing groups. In fact, Jean-Luc Melanchon, the far-left Parliament member running for president there is their biggest cheerleader, although it currently appears that in the two round election process there, the result will be Marine LePen, the National Rally candidate from the right who will be the next French president. But that election is still six months away, so much can happen between now and then.
However, that is all of a piece with the runup to the US midterm elections to be held two weeks from today as the President barnstorms the nation supporting mostly Senate candidates around the country. While the current polling shows the Democrats have a lead and are likely to win the House with a decent chance of taking the Senate, the history of polling since Donald Trump put his name on the ballot is that the Republican vote is consistently undercounted. I see no reason that situation has changed this year, so my take is the race is much closer than the punditry currently explains. In fact, my call several months ago was that the Republicans will hold the House and actually pick up a seat in the Senate based on the candidates on the ballots around the country. Obviously, that is far out of consensus, but that is my sense. I’ve been wrong before and will be again, but at least I’m not wishy-washy!
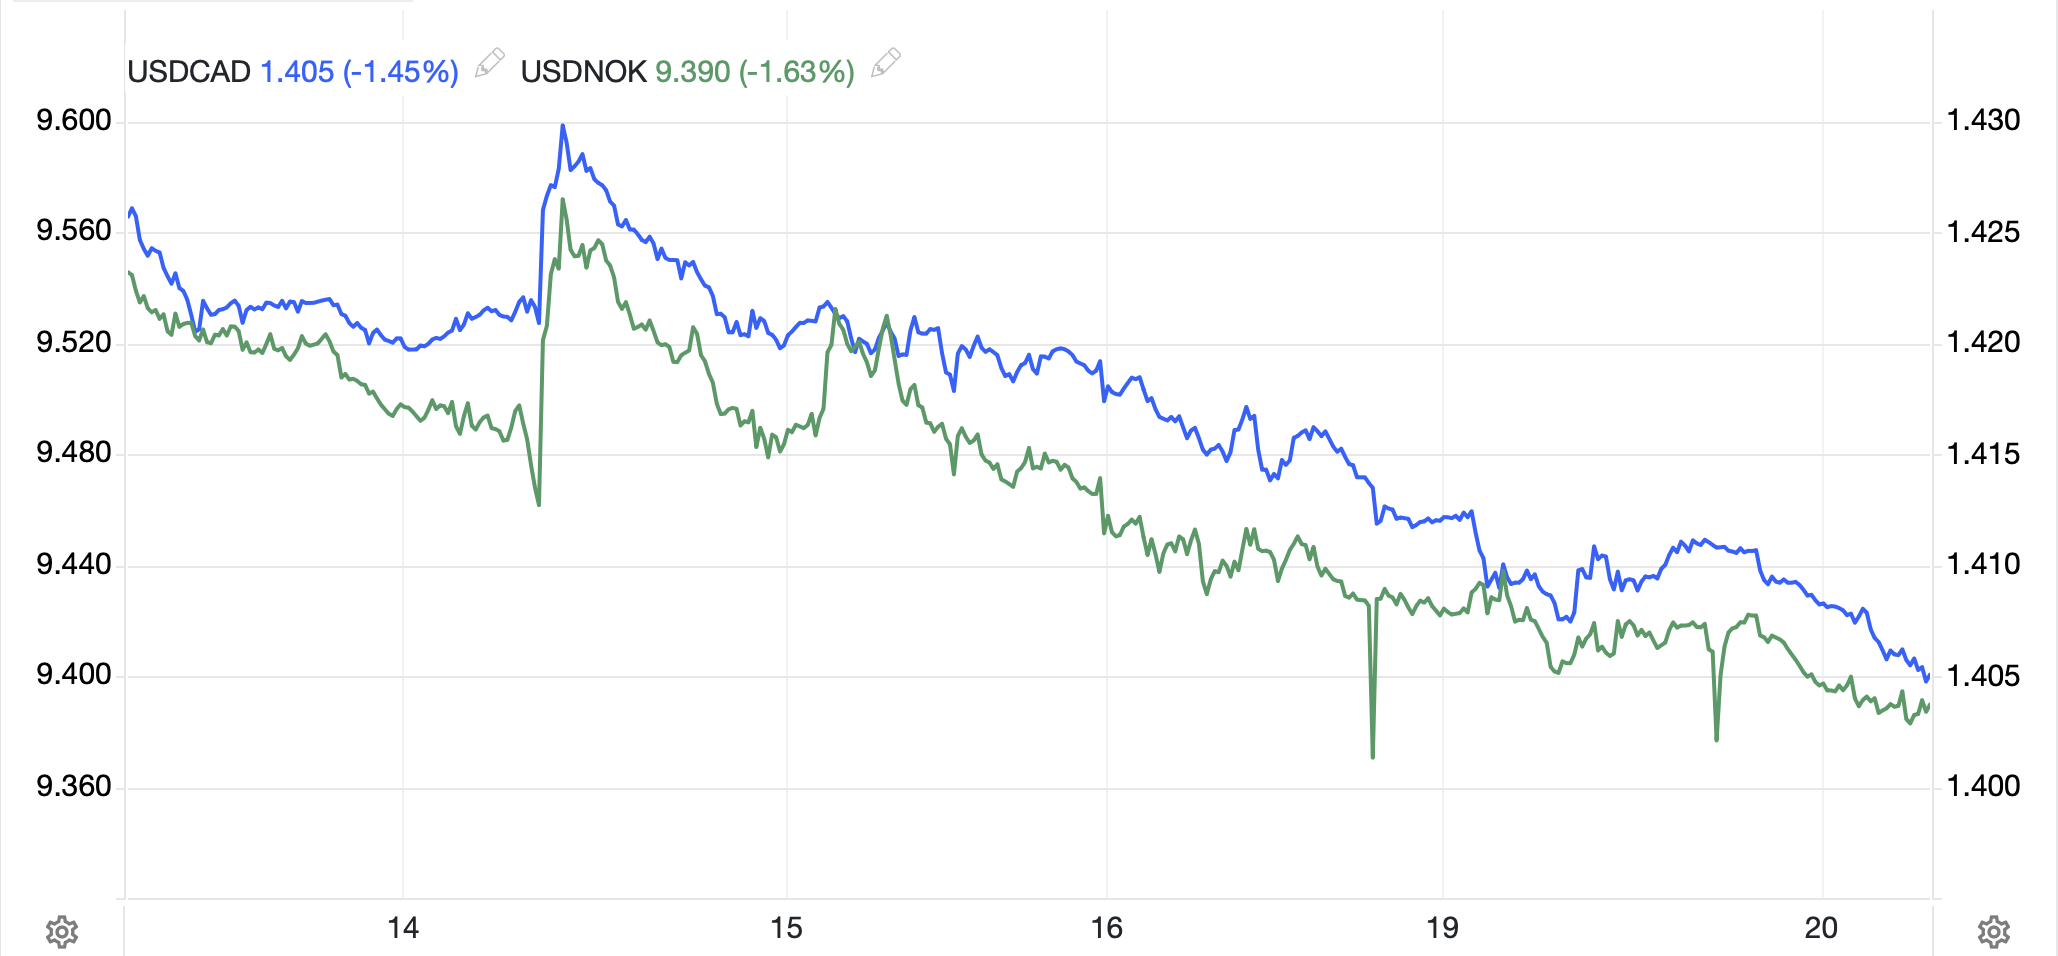
Perhaps the most interesting electoral outcome was yesterday’s referendum in Alberta, Canada regarding the desire of the population there to put an actual separation referendum to a vote. It appears, though, that the remainers won resoundingly, with more than 75% of the vote, so for now, Canada remains in one piece. Perhaps that helps explain the Loonie’s recent performance as it has, along with NOK, been the best performing currency for the past week, gaining 1.5%. Of course, oil’s rally helped both those currencies as well.
Source: tradingeconomics.com
Don’t misunderstand me, there is still plenty of discussion regarding AI and whether that trade is over with violent disagreement between the bulls and the bears. Meanwhile, the most disturbing, thing is that so much activity is taking place in the options markets, with Friday seeing a record volume in S&P 500 puts as per the below chart (taken from Market Vibes)
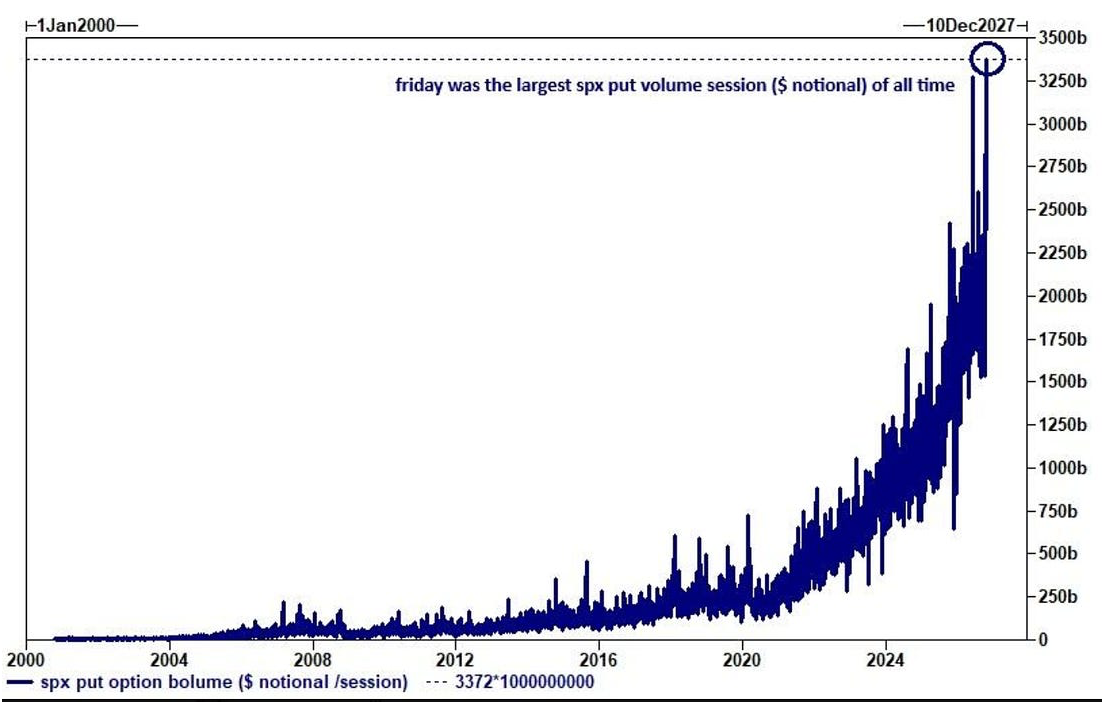
Having been an option trader for a very long time, my concern is that most people do not understand the nature of these contracts and the possible ramifications of the growth in activity. It wasn’t that long ago that the GameStop call buying wound up impacting the entire market, significantly impacting the understanding of fair value. The fact that this was put buying tells me many folks jumped on the Black Monday theme, so perhaps it will all fade away soon, but given the absolute increase in leverage we have seen (as an example, Goldman Sachs made more money in securities lending than trading last quarter) I fear there are large potential pitfalls ahead. Perhaps because I was an options trader, I rarely use leverage in my PA, only if I am buying some protection, but I believe I am the exception these days.
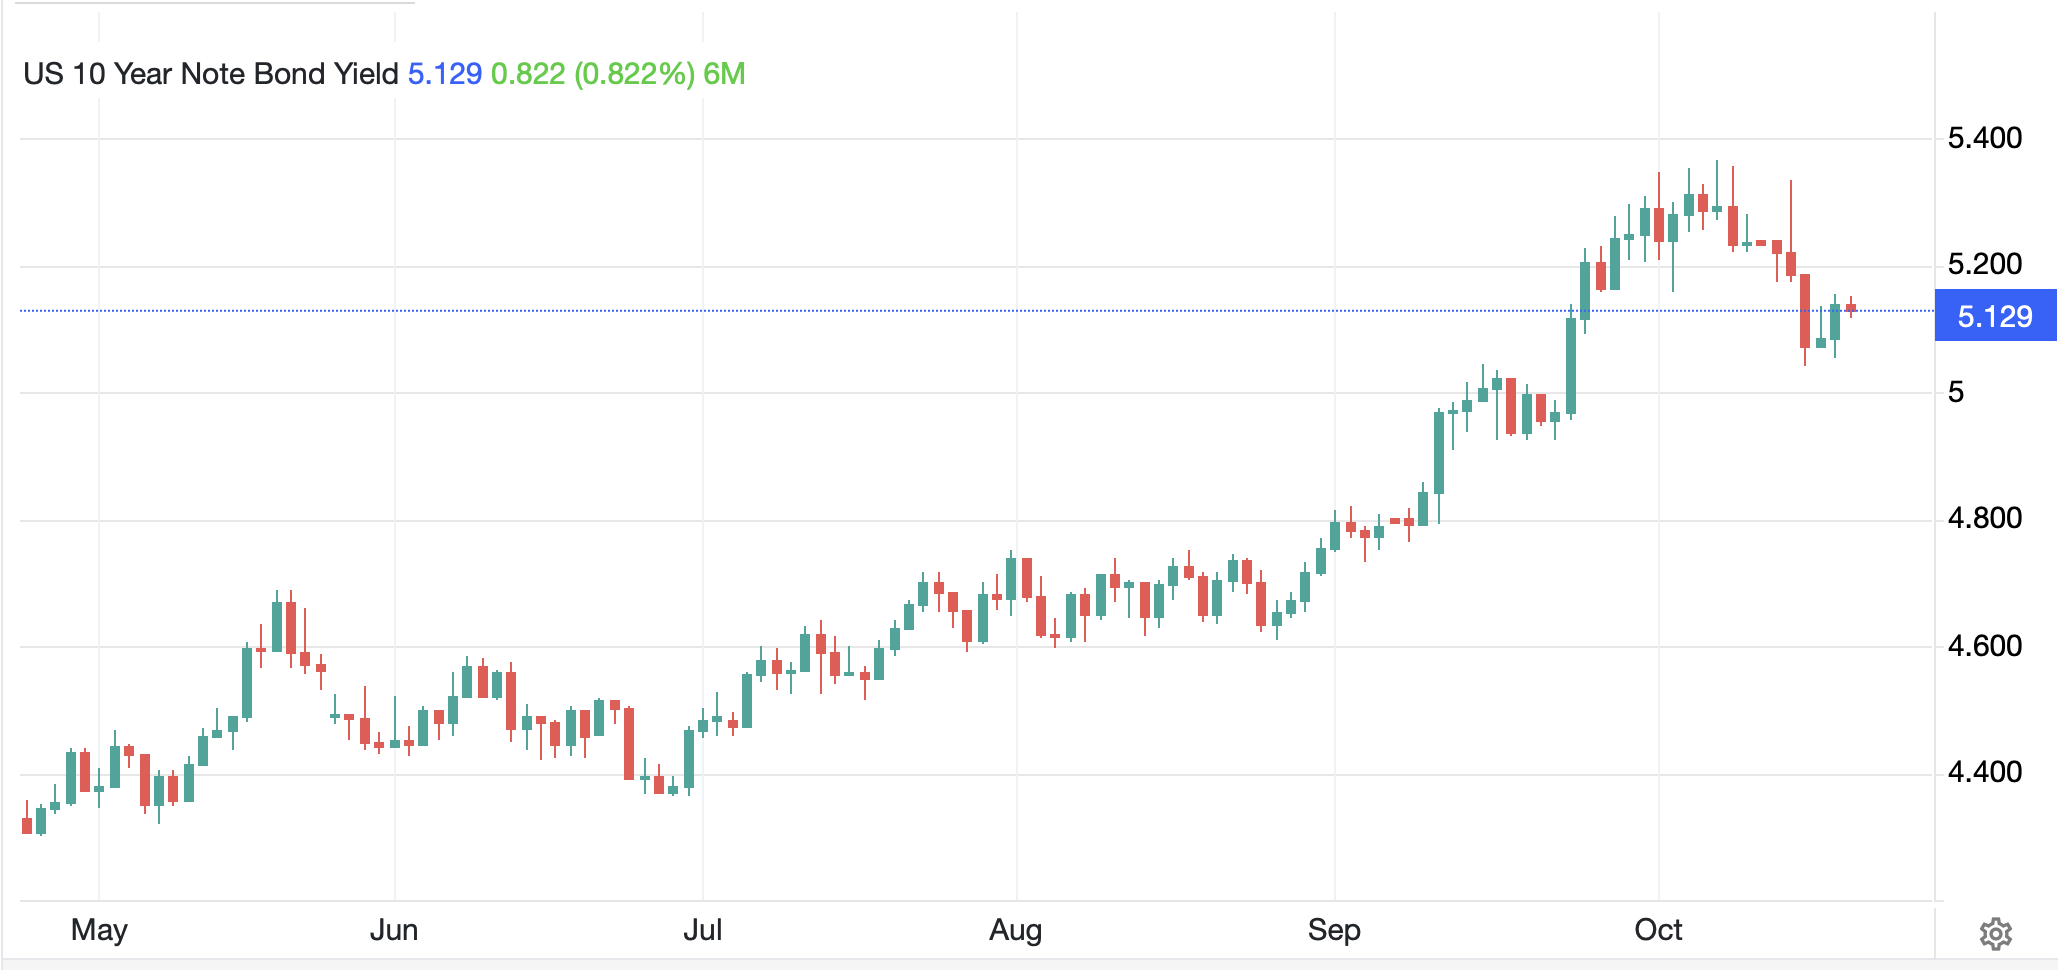
On to other markets. Bonds, for instance, are still there and have not imploded yet. Treasury yields (-1bp) did climb a bit yesterday, but as you can see from the below chart, remain well off the recent highs. Given there is virtually no data of importance, and the Fed is in their quiet period, it seems unlikely that we see much movement here this week.
Source: tradingeconomics.com
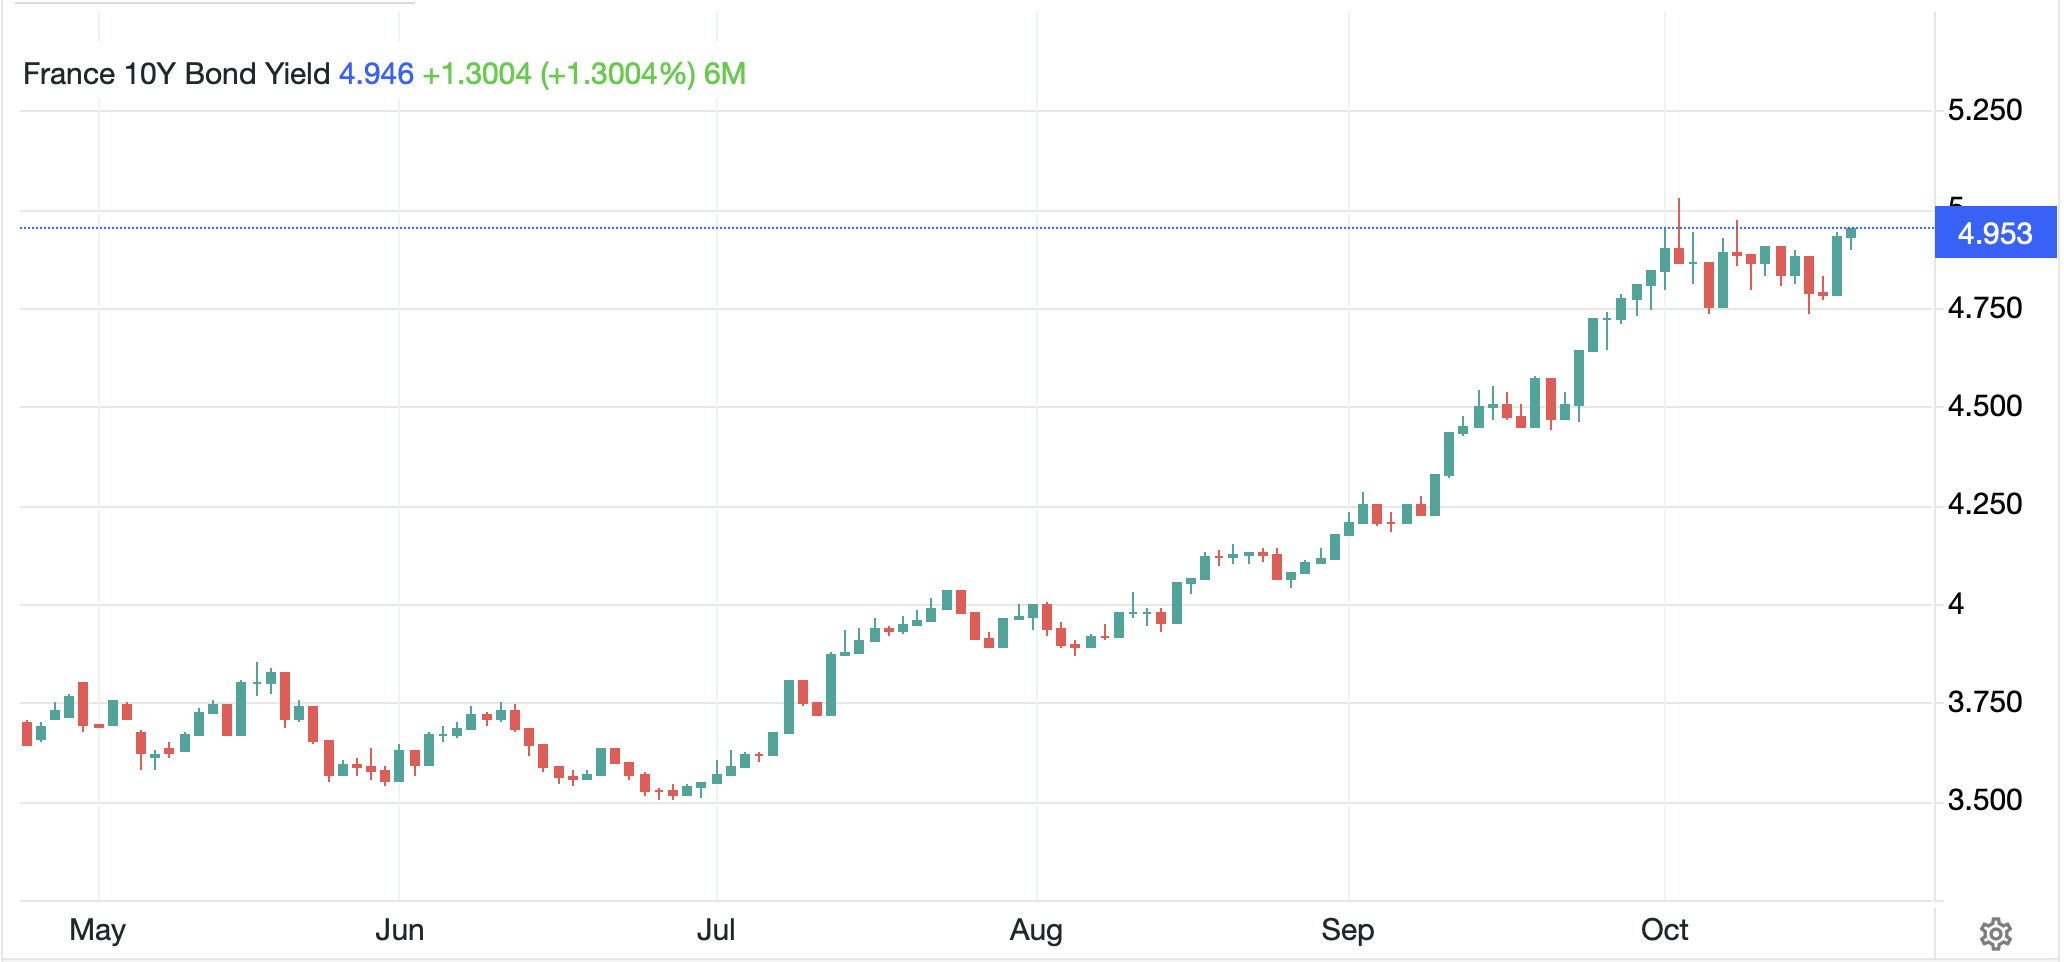
However, the same is not necessarily true for some other bond markets, notably France (+3bps) which is pushing its recent spike high and showing no signs of reversing course. Given the ongoing violence and the fact that the government is not merely ineffective, but essentially broke, this should be no surprise. The spread with German yields is above 150bps and I see no reason for that to compress anytime soon. Rather, widening further makes more sense.
Source: tradingeconomics.com
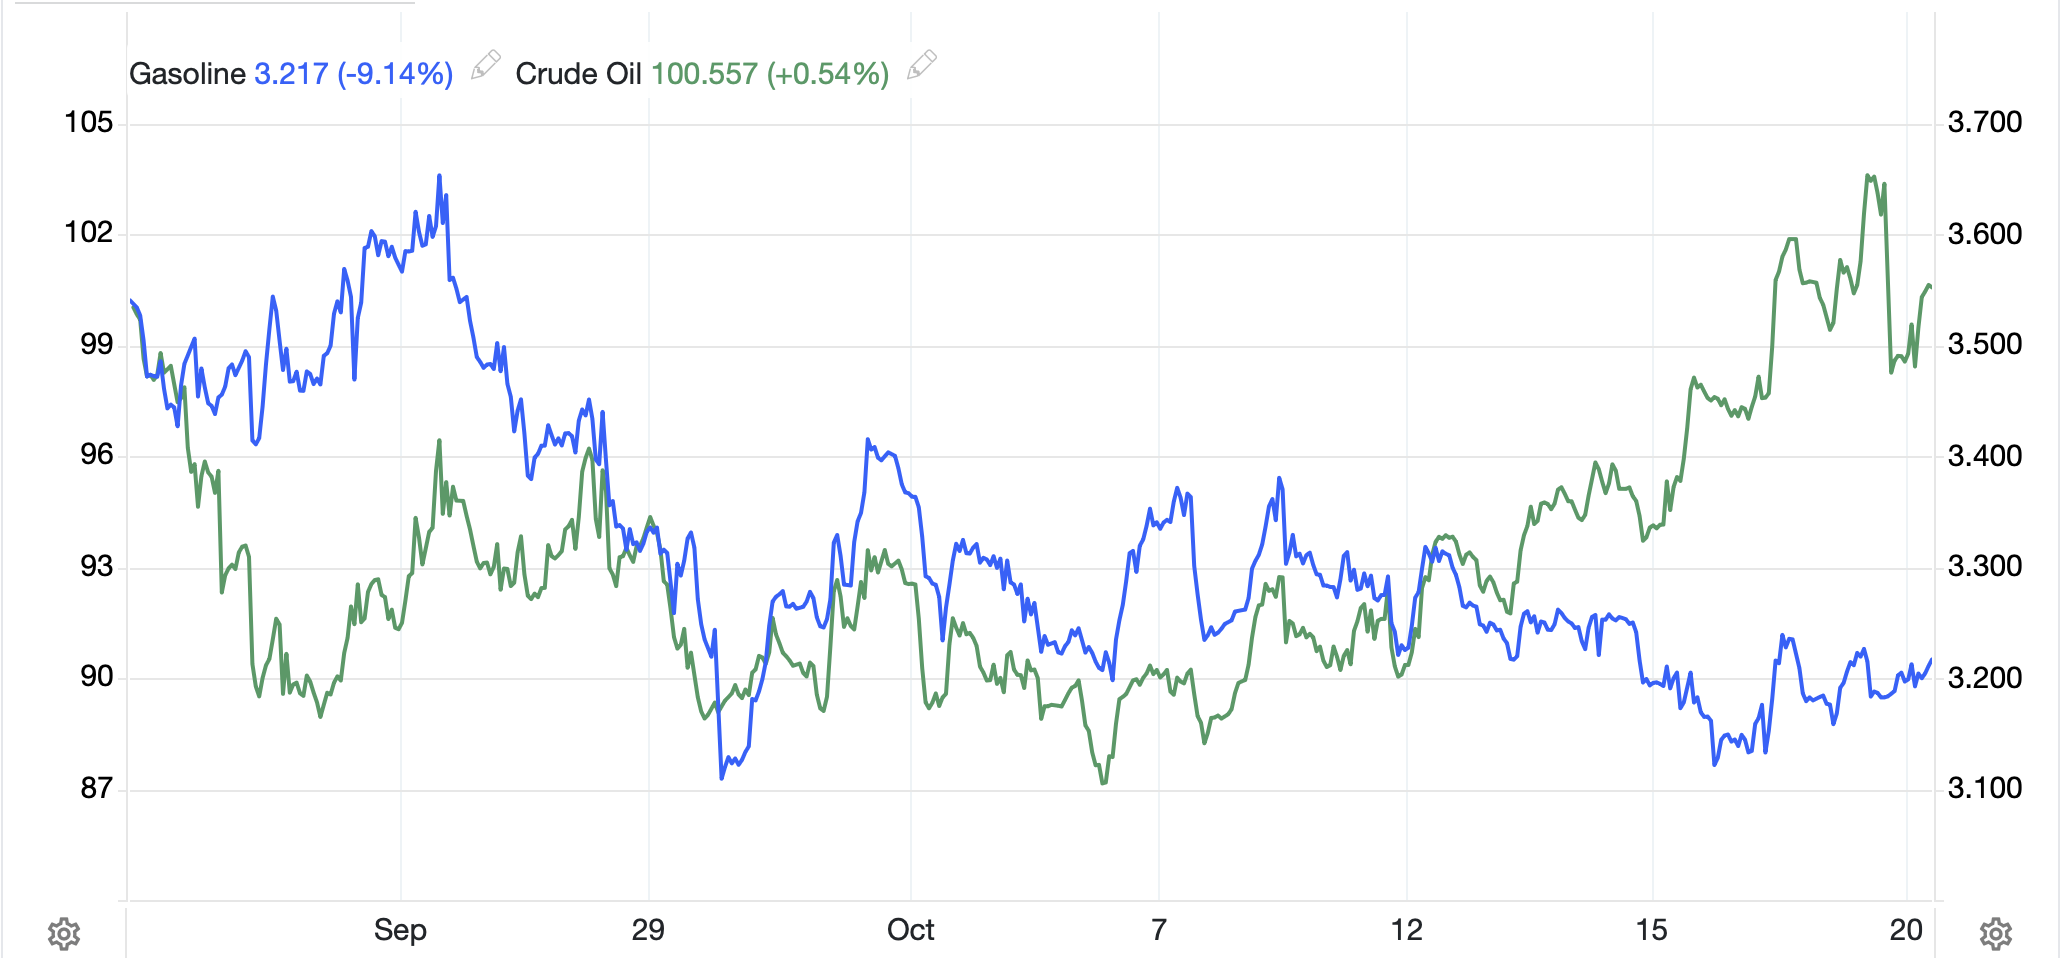
In the commodity space, oil (+2.0%) is higher again this morning with yesterday’s decline seemingly the aberration. Nothing has really changed in the Iran situation, nor in the Ukraine/Russia situation with Ukraine continuing to attack Russian refinery capacity. Perhaps the most interesting thing in the energy markets is that gasoline has broken away from crude in its price action as per the below chart. Perhaps that is the end of summer driving season impacting things, or maybe there isn’t the shortage that people believe.
Source: tradingeconomics.com
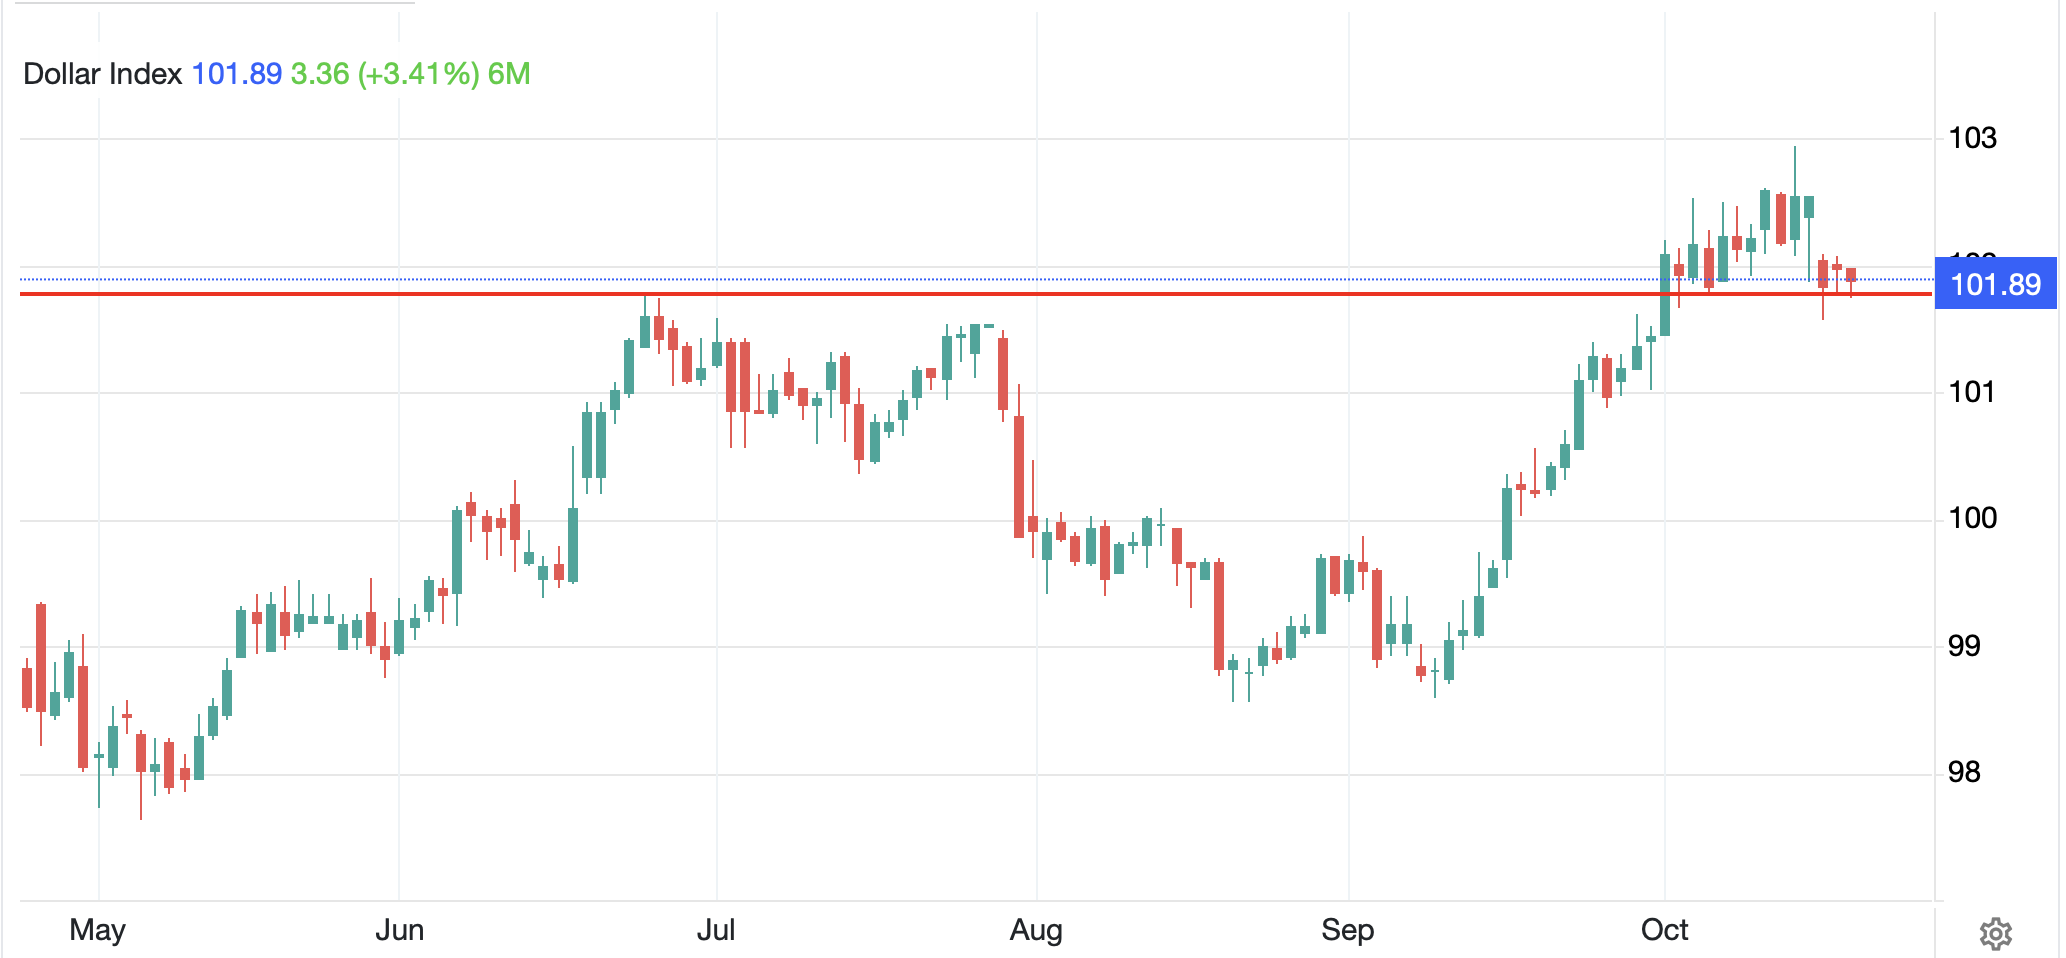
As to other markets, nobody cares about the metals markets anymore except the dyed in the wool long-term bulls (like me) but price action has been desultory at best. Their time will come again. And FX? It’s pretty dull here as well. There was excitement 3 weeks ago when the DXY broke above its range top near 102.00 and the technicians all thought that it was going to head a lot higher. But it was not to be and here we are, back below that key range top and it is a tertiary conversation at best.
Source: tradingeconomics.com
While the long-term picture hasn’t changed in my view, as economic activity continues apace in the US relative to the rest of the world, it’s just not that interesting right now.
On the data front, Housing Starts (exp 1.30M) and Building Permits (1.39M) are today’s numbers but tend not to be market movers. And that’s really all there is for today. To the extent the FX market is going to do anything, it will be a response to something in equities, but as of this time (7:30) US futures are mixed to slightly softer, hardly a harbinger of anything substantive. I think it’s setting up to be a dull day.
Good luck
Adf

