Seems markets are not paying heed
To France where the riots proceed
Instead, it’s AI
And bonds gone awry
Where fears are replacing past greed

So, is this the end of the run
Which two decades past had begun?
Or is this a blip
Which soon will round-trip
As recent downdrafts are undone?
While there are always a group of voices singing a song of doom right around the corner, Keynes’ saying that markets can remain ‘wrong’ longer than you can remain solvent continues to be the reality. One need only look at the barchart.com 20-year chart of the NASDAQ below to realize that since the GFC, while there have been two pretty sharp blips along the way, Covid and the Liberation Day, with the latter really short-lived, this is a chart that has been largely unidirectional. Everyone who has explained that valuations are too high, and that earnings are shaky and that rising interest rates will undermine the structure of the market has basically been wrong for nearly 20 years. I understand that there were calls for another Black Monday today, as this is the 39th anniversary of that remarkable day, but is this time different?
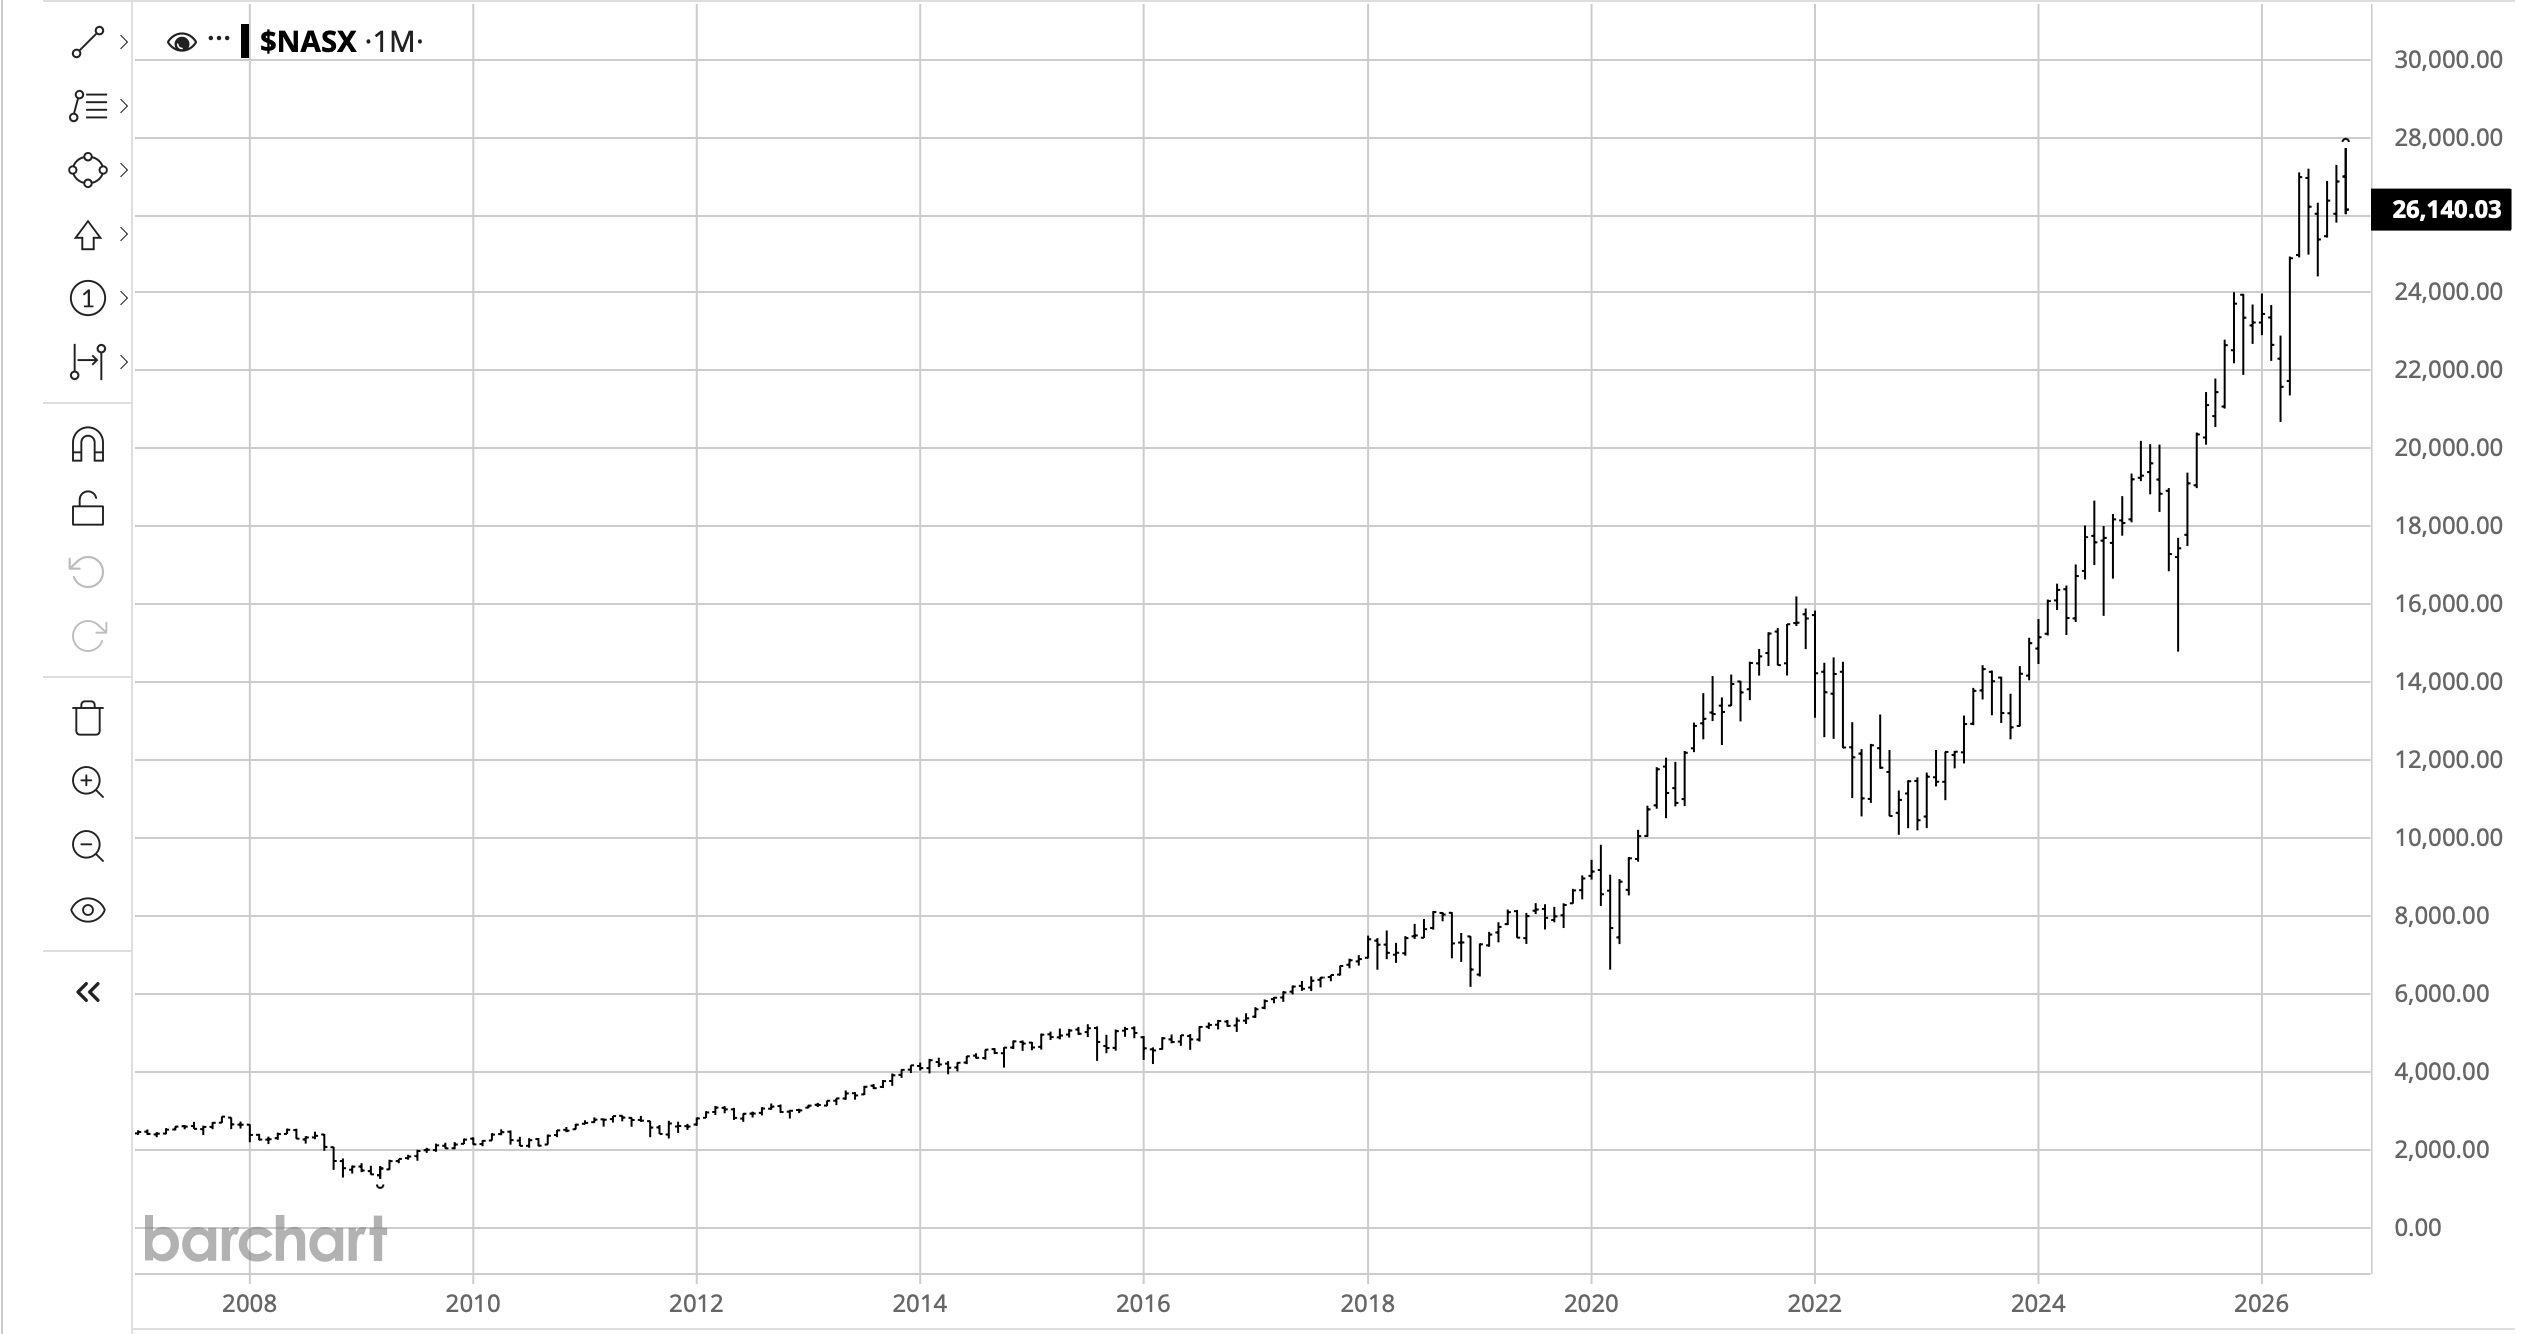
Those four words are the most dangerous in markets, there is no question about that. You can make the case that AI has changed everything about the economy and that the old rules are no longer valid, but whatever AI’s capabilities may turn out to be over time, it’s still people who control the money, and the one thing of which I am certain is that people haven’t changed in the past 20 years.
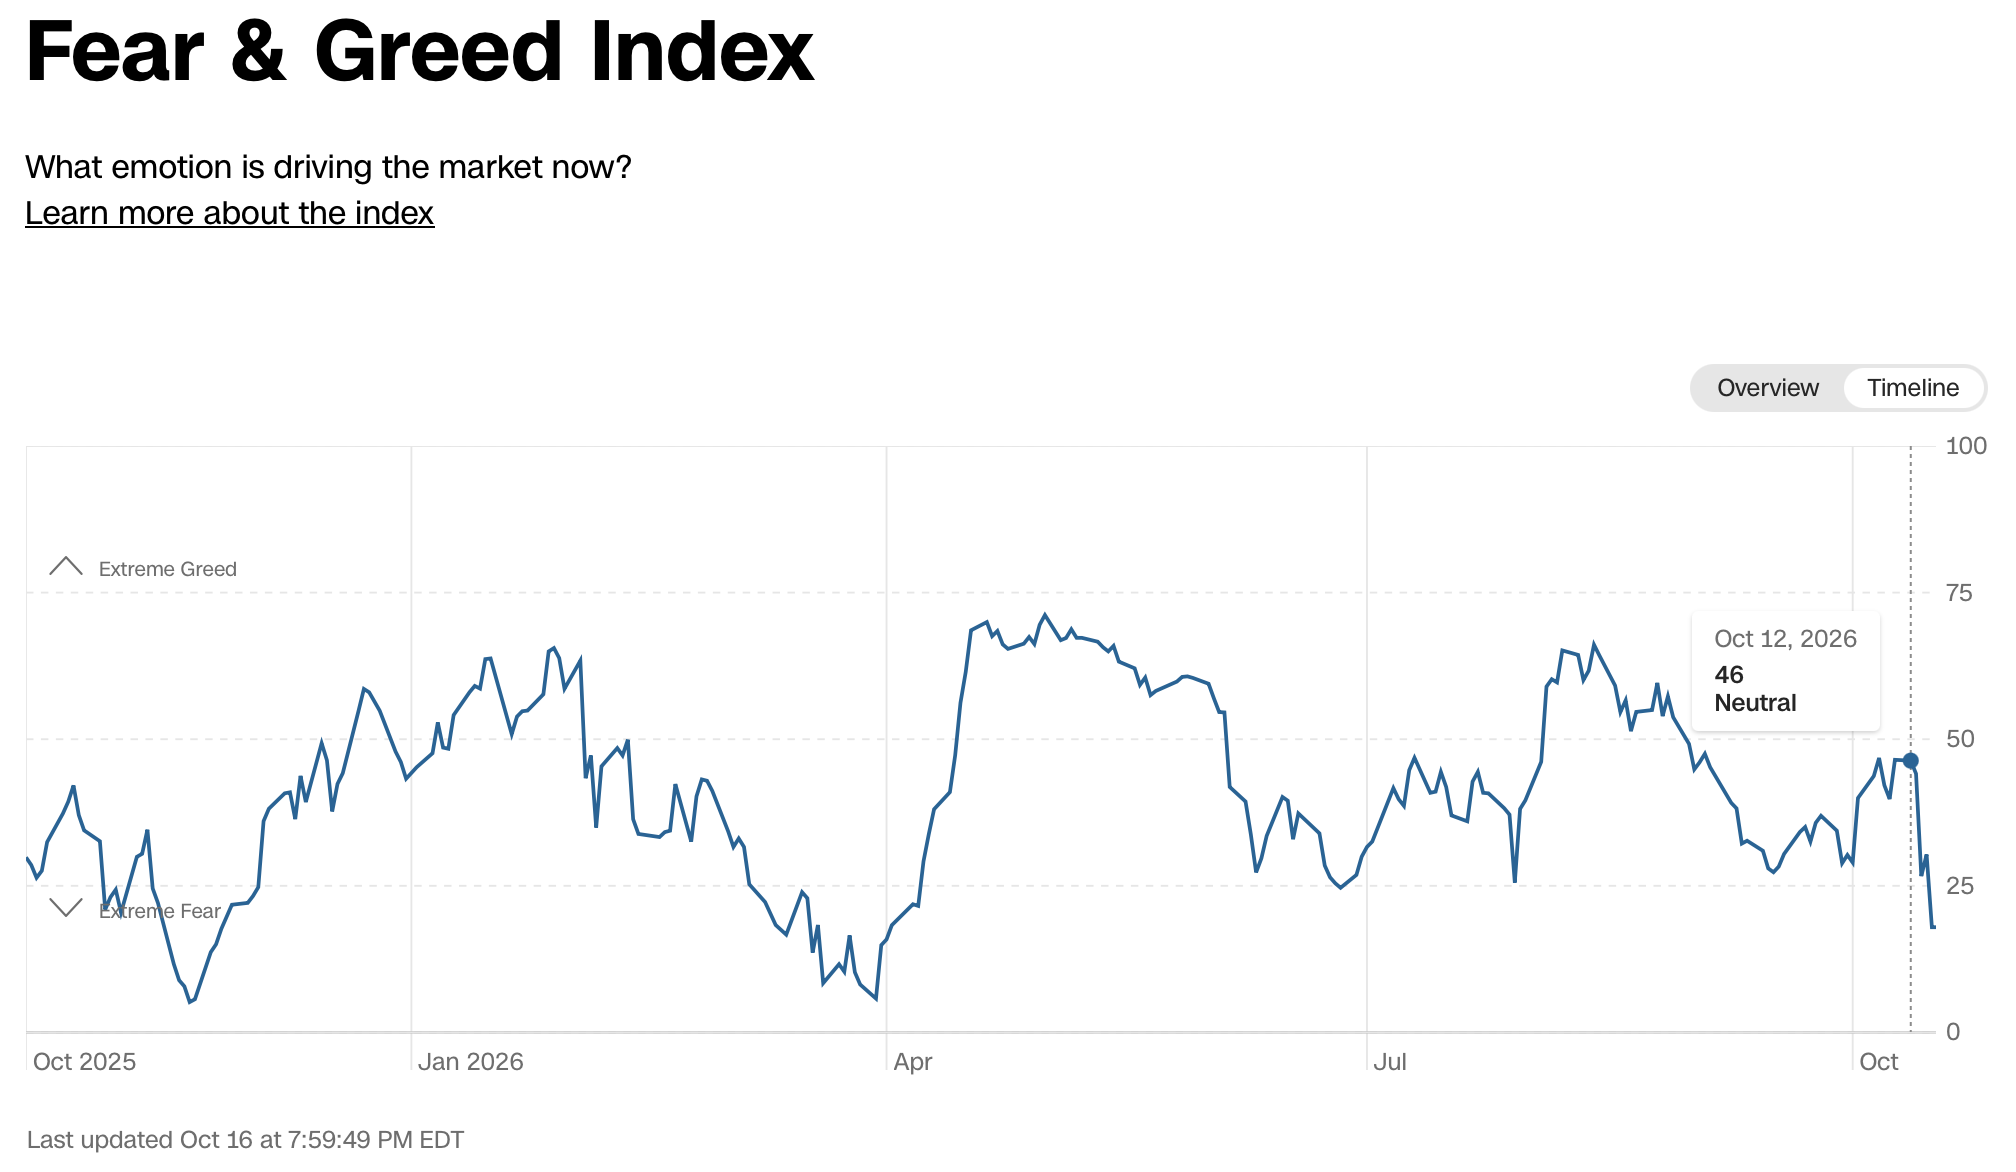
Now, last week was a tough one for the Pollyannas who have been cheerleading the rally, and you can see that in the history of the CNN Fear & Greed Index below. It has fallen quite sharply, from 46 to 18 in just a week.
Arguably, part of that has been the movement in the price of oil (-0.6%), which while modestly lower this morning, has rallied >14% during the past two weeks as Iran has increased its attacks on ships in the Strait of Hormuz while the Houthis have increased their attacks on Saudi Arabia. It appears they are trying to goad President Trump to respond in an effort to help the Democrats take control of the House and the Senate, but so far, Trump has let things play out. I suspect that no matter who wins the election, come November 4th, things in the Persian Gulf are going to intensify. In fact, it would not surprise me if the Democrats win that the military campaign will be that much more intense.
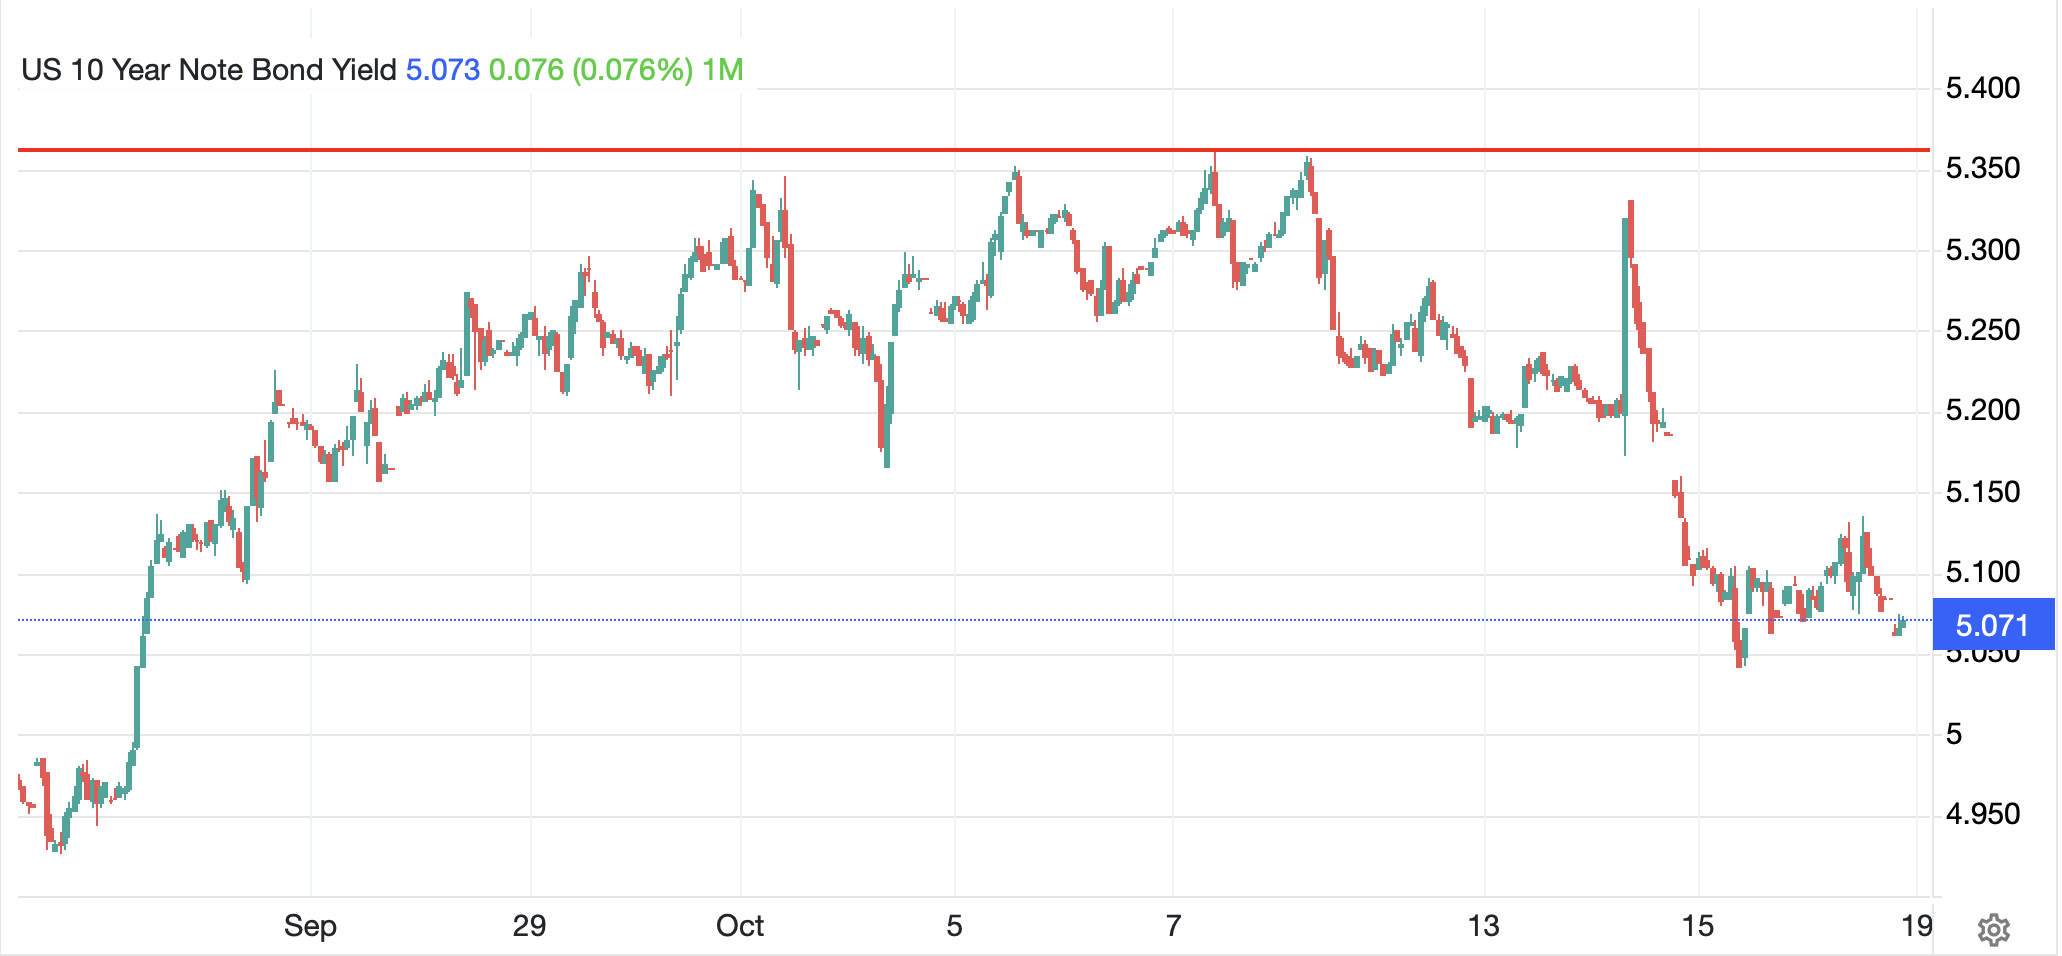
Adding to the pressure of higher oil prices were hotter than expected inflation data last week with both CPI and PPI printing at higher-than-expected numbers. But a funny thing happened, bond yields stopped climbing, at least for the moment, as it seems investors are both far more comfortable with the current yield structure as real yields reach multi-year highs, and the riots in France, that seem to be spreading elsewhere in Europe, have investors turning away from European sovereigns as an alternative. After all, 10-year Treasury yields are down by 30bps from the highs reached just two weeks ago.
Source: tradingeconomics.com
This is not to imply that things are great, clearly multiple problems and concerns remain, but I still cannot see the end of days. So, let’s turn to the market behavior from last night and this morning as we open.
Friday’s weakness in the US raised concerns that we were on the cusp of the end of the bull market run. But as we have consistently seen over the past many years, those fears have abated just as quickly as they arrived. Overnight, equity markets were mixed in Asia as while the Nikkei (-0.6%) slid a bit and that weighed on India (-1.2%), Taiwan (-0.6%) and several other smaller regional markets, China (+0.5%), Korea (+1.7%) and Australia (+0.4%) all managed gains. As an aside, recall I mentioned the Jakarta Index last week? Well, as you can see below, investors are still fleeing the country with the index now down -15% in the past three sessions.
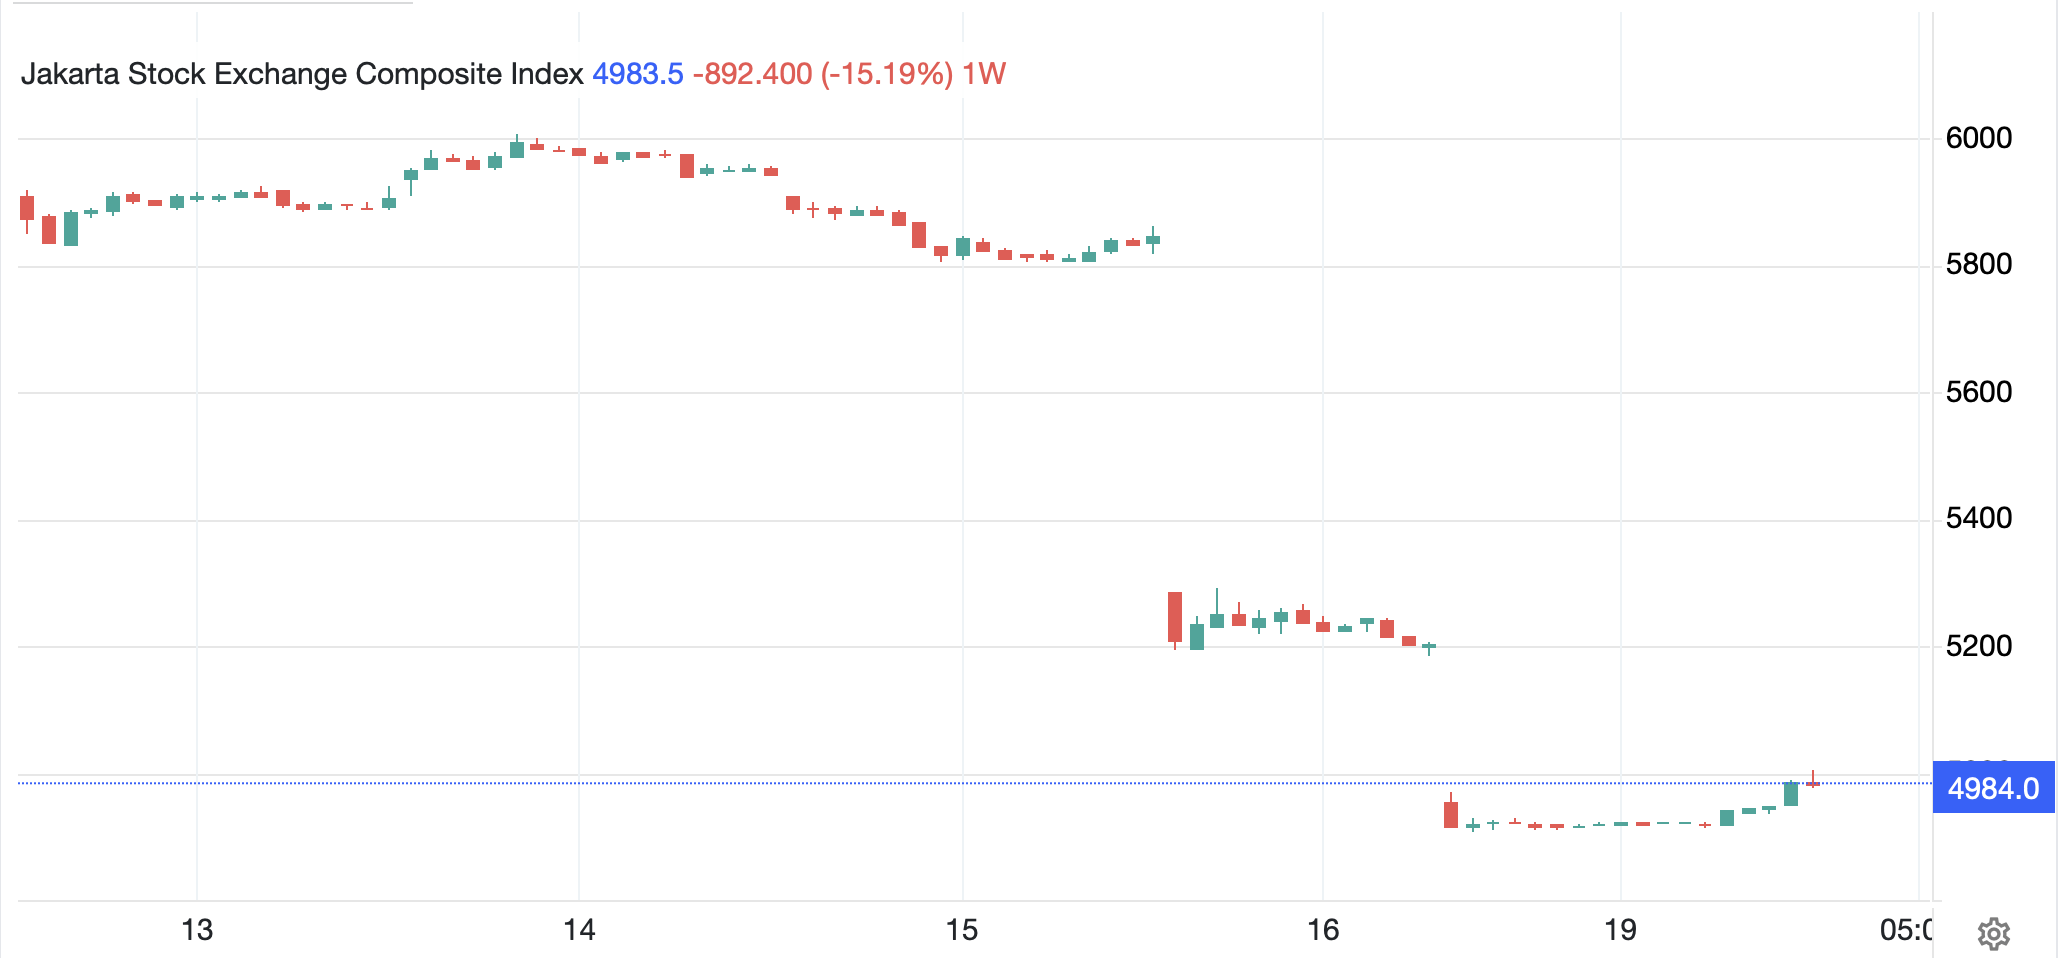
Source: tradingeconomics.com
However, there is a region that is feeling the heat from the rioting in France, and that is Europe. The below screenshot is eloquent in its depiction of today’s trading on the continent.
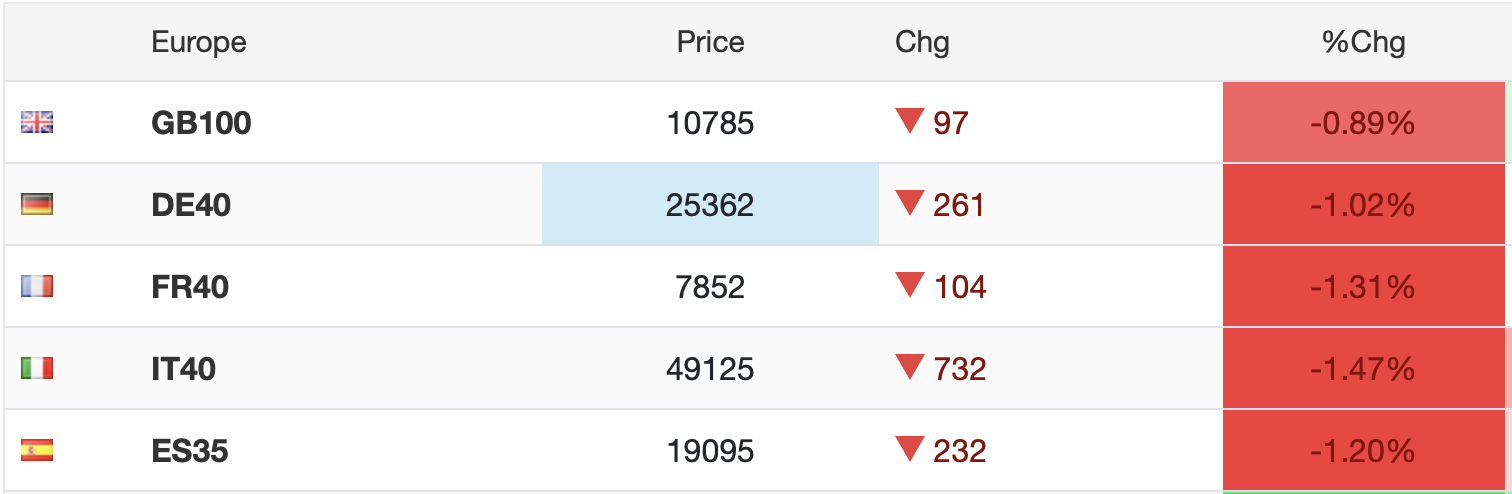
Apparently, there are several concerns, notably the fact that growth continues to be anemic while fiscal spending grows uncontrollably, but then the rioting in France, which seems to be spreading is adding pressure to governments across the continent. As to the US, both SPX (+0.6%) and NASDAQ (+1.1%) futures are higher as I type (6:45am), hardly the stuff of Black Monday.
Perhaps the bond market is making a better case for apocalypse today. Alas for those seeking such an outcome, other than French OATs (+8bps and now the widest spread vs. Germany since the Eurozone crisis in 2012, see below) which have dragged Italian BTPs (+4bps) higher as well, the rest of the continent has seen only a marginal movement today, +1bp or 2bps.
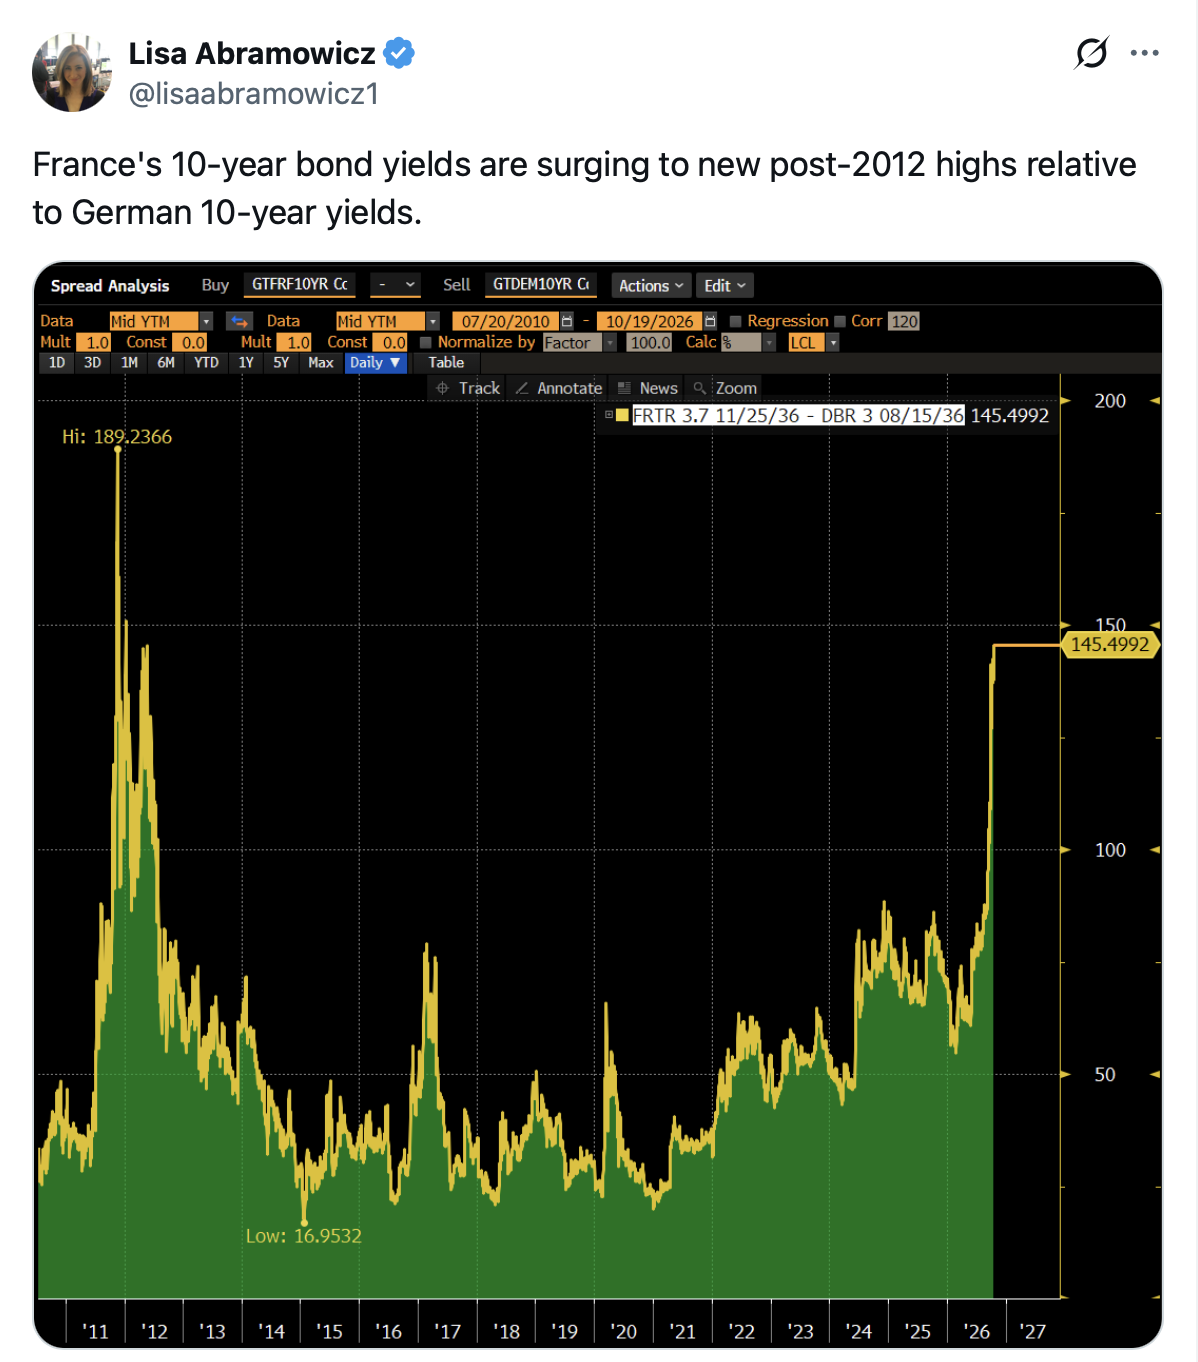
Turning to the commodity sector, while oil, as mentioned above, is pretty benign this morning, a note about Natural Gas, (+1.0%) which is seeing increased demand as the weather cools off. Now, even though we have seen prices here increase nearly 20% since early August, that is a seasonal outcome entirely expected. And let’s face it, $3.15/MMBtu is still an order of magnitude lower than European prices of nearly $30/MMBtu. If you wonder why European growth is stagnating, look no further than this. As to the metals sector, modest gains this morning are the order of the day, (Au +0.1%, Ag +1.2%, Cu +0.3%). Nothing has changed my longer-term view that the supply-demand imbalance in metals markets remains firmly in the lack of supply situation. Ironically, in oil, it is just the opposite, with ample oil around, it is simply the politics of war that is creating this price event.
Finally, the dollar is mixed this morning, with commodity currencies like AUD (+0.6%), CAD (+0.4%), NOK (+0.25%) and ZAR (+0.25%) all gaining while the euro (-0.15%) and yen (-0.1%) slip a bit. It doesn’t feel to me like FX is the focus right now. Rather bond markets and the question of the next Black Monday have a lot more press. I imagine the euro will be an interesting case study going forward depending on how the ECB responds to the ongoing unrest in Europe. Can more fiscal spending supported by more ECB bond buying be far away? I have a feeling the euro may be setting up for another leg lower.
On the data front, it is an extremely quiet week:
| Tuesday | Housing Starts | 1.31M |
| Building Permits | 1.40M | |
| Thursday | Initial Claims | 200K |
| Continuing Claims | 1712K | |
| Leading Indicators | -0.2% | |
| Friday | Flash Manufacturing PMI | 55.5 |
| Flash Services PMI | 57.9 | |
| Michigan Confidence | 46.3 |
Source: tradingeconomics.com
With the FOMC meeting a week from Wednesday, there are no Fed speakers this week. Interestingly, despite the higher-than-expected inflation readings last week, the market is pricing only a 15% probability of a hike although there is virtual certainty that there will be a hike in December. One other data issue to note was last night’s Chinese data as follows:

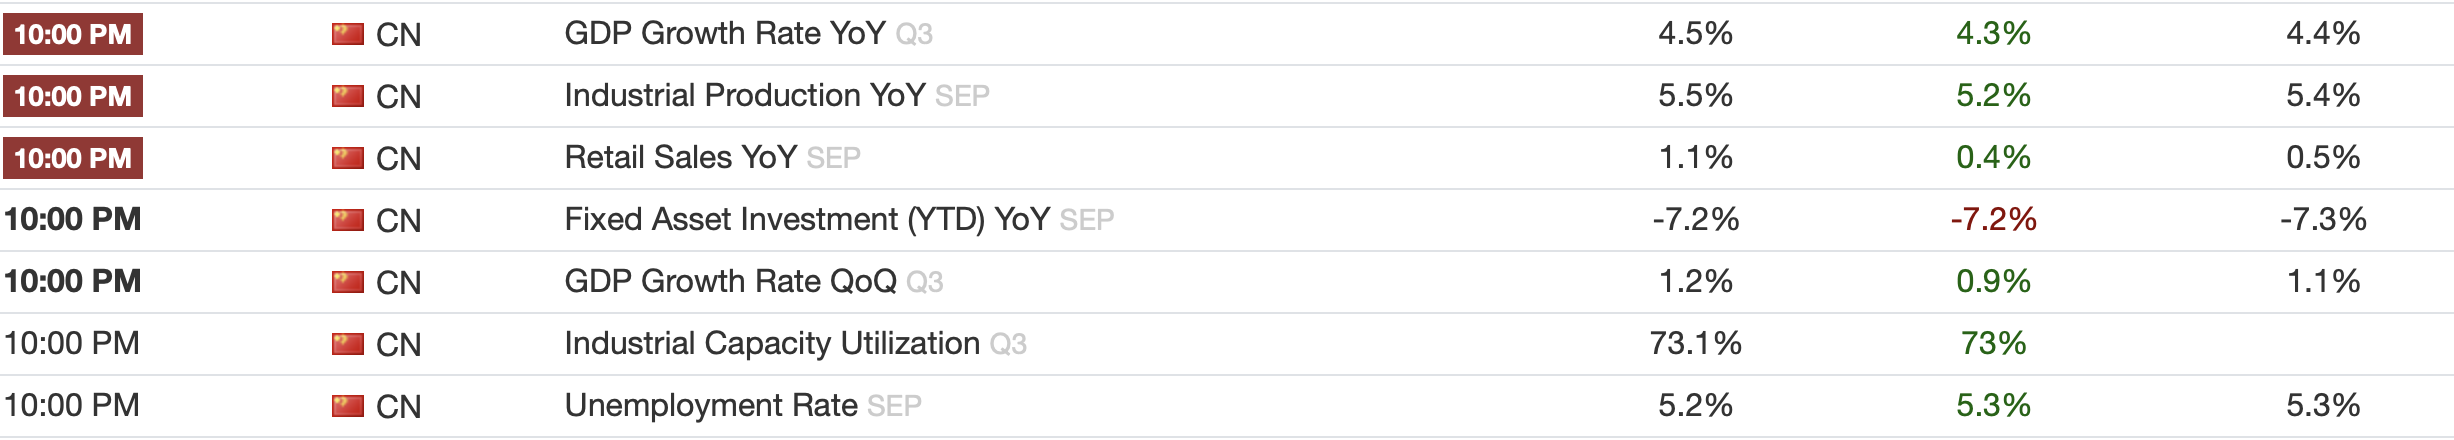
The situation there remains one of weak domestic activity alongside excess manufacturing capacity with China’s growing Trade Surplus becoming an issue in more and more nations around the world. Alas for President Xi, the two choices to achieve his GDP goals are the current mercantilist process or a true effort to focus resources on the Chinese people. I don’t see any changes coming despite some lip service to the contrary. Even the WSJ wrote about it this morning.
My view remains that while there are many problems extant around the world, both economically and politically, we will get through this period just like we have made it through tough times in the past. And undoubtedly, the US remains extremely well positioned to continue its economic strength given the willingness to utilize its natural resources. While there are political divisions here, they don’t rise to the level of what we are currently witnessing in Europe. Overall, it is hard not to like the dollar as the cleanest dirty shirt in the laundry for a while yet.
Good luck
Adf

