In China, three Presidents met
And though there is no deal quite yet
The talk is of nukes
With several rebukes
On wars, but no word on bad debt

The question is, can these three men
Succeed without bombs, but with pen
Reducing the tension
In every dimension
Or will this fall flat once again

And lastly, the story ‘bout tech
Has grown from a glitch in a spec
To actions against
The US, dispensed
By enemies seeking our wreck
Several pieces of history were made yesterday starting with the unprecedented meeting between Presidents Trump, Xi and Putin on the sidelines of the APEC meetings currently ongoing in Shenzhen, China. Apparently, the discussions ranged from nuclear weapons to increased energy supply and, possibly of more importance, the necessity to maintain open dialog amongst the three nations. While there are many who rail against President Trump for speaking warmly about both men, I would ask those folks why they think these adversaries would be willing to speak with the US if the president continuously called them the worst people on earth. If someone curses you out and calls you names and epithets, how willing are you to sit down and have a discussion with them? Here’s hoping that they can make progress on reducing nuclear weapons around the world.
The other piece of history was the Anthropic IPO, which sold more shares at a higher price than had been expected as the company raised some $81 billion, the largest amount of an IPO in history. While yesterday’s equity market performance was mixed in the US, futures this morning are following that IPO higher with the NASDAQ (+2.0%) leading the way although the other two are solidly higher as well. I know that will be welcome to investors everywhere!
Of course, we cannot forget about the tech problems we have seen recently and that remains a significant issue overhanging not just markets, but our lives and activities. Given the number of incidents in such a short period of time, the cyberattack thesis is gaining credence amongst many, and it may well be the reality. Certainly, I would not expect the government to offer that explanation unless they were going to use it as a pretext for a retaliatory response, i.e. a military strike.
But a very interesting thesis that seems to fit the pattern of incidents as well as the evolving technology landscape and AI is that AI agents are discovering an increasing number of bugs in widely used software and companies are racing to fix these bugs before they can be exploited to nefarious ends. As any of you who have worked in large organizations are well aware, every time there is a system upgrade, at least in my experience, the systems don’t work effectively for several days, at least. If I keep this in mind when observing the serial technology glitches, it is a very realistic scenario that as companies discover potential flaws in their systems, they race to fix them, and some of those fixes don’t work well. Sir William of Ockham would approve.
This is not to say that the cyberattack thesis is dead, just that there is an alternative hypothesis that can be equally likely and have similar outcomes. Plus, if a rogue actor was going to attack the US, would they really attack Zelle? It seems to me they would go for a bit more critical infrastructure.
It’s time now to turn to the Fed
Who, to a man, looking ahead
Said rates need to rise
As they now surmise
Inflation they’ve caused, they now dread
So far this week, we’ve had six Fed speakers explain that further tightening will be needed going forward as “almost all” participants at the last FOMC meeting judged more rate hikes would be appropriate. Several of these folks, notably Waller, Williams and Musalem, would clearly vote for 50bps next month although the market is only currently pricing a 10% probability of that move. But here’s the thing. Governor Waller is suddenly concerned that core services inflation is running above 3%. However, if you look at the chart below, I got from James Thorne (@DrJStrategy on X) and read his little blurb, it helps explain why this is likely to be a distinct negative for the economy.
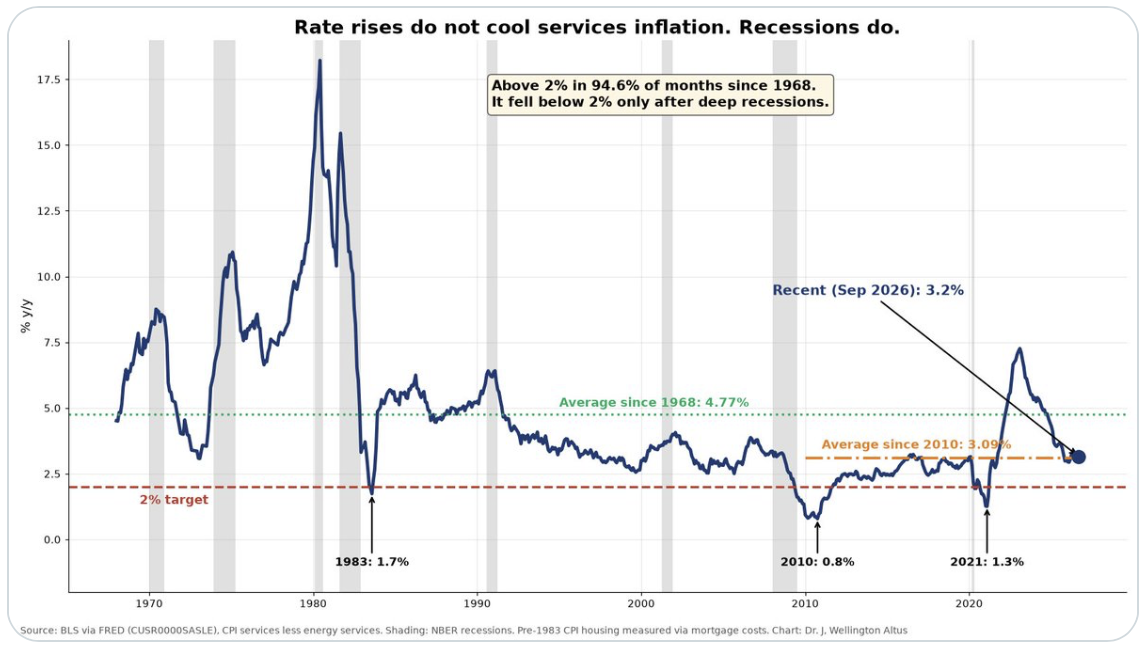
Arguably, the only reason that broad inflation hung around the 2% level for so long was because goods inflation had turned negative on the back of globalization and cheap imports mostly from China, but other nations as well. Those cheap goods offset steadily rising services prices. But the ongoing reshoring of US manufacturing has altered the price impact of goods, raising it substantially.
So, let’s play this scenario out a bit. The Fed hikes aggressively over the next several quarters, a total of 100bps by June, let’s say. Economic activity starts to falter, and the economy rolls over into recession, finally. How frequently do you think FOMC members will be on the tape bragging about their performance at that time? Historically, nobody knew the names of any FOMC members except, perhaps, the Chairman. But everybody knows these folks’ names now. I imagine they will need to go into hiding!
Ok, let’s move on to markets. Mixed is the word to describe what we saw overnight (Tokyo +0.7%, China 0.0%, HK -2.0%, Korea +1.4%, India +1.2%, Taiwan -4.4%) as there was no strong unifying theme to be had. Europe, though, has been generally firmer (Germany +0.3%, France +0.2%, Spain +0.1%) although the UK (-0.4%) is flailing a bit despite a complete lack of news or data.
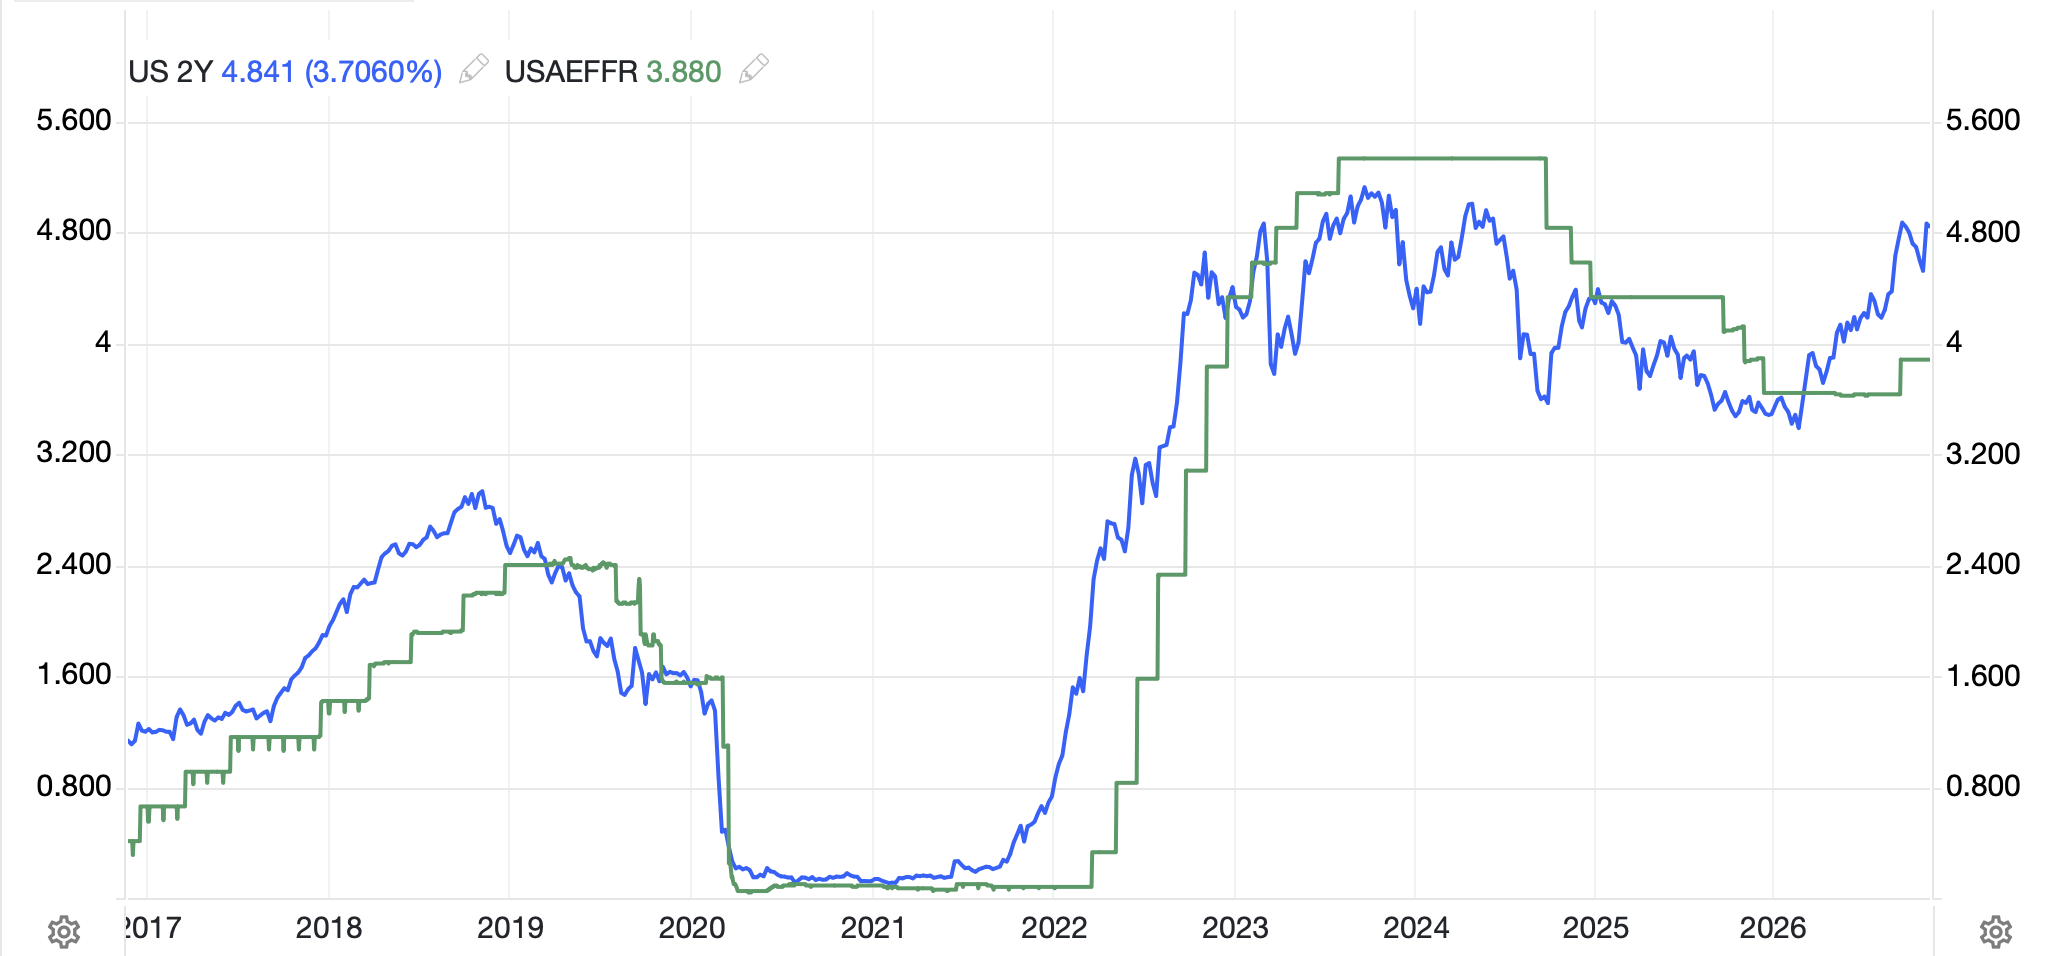
In the bond market, yesterday’s risk-off saw 10-year yields slip -4bps but this morning, they have rebounded 3bps and sit right at 5.10%. All the hawkish talk from Fed speakers has the 2yr creeping higher as well with the current yield nearly 100bps above the Fed funds rate. As you can see from the below chart, that’s a pretty big gap and history has shown that the Fed funds rate tends toward that 2-year yield over time.
Source: tradingeconomics.com
So, whether or not I think it is the correct move, it is abundantly clear that the Fed is going to hike rates further going forward.
As to global bond markets, once again the US is leading the way as Asian markets overnight saw yields follow Treasury yields lower, but the reversal is playing out in Europe where all sovereign yields are higher by 2bps this morning.
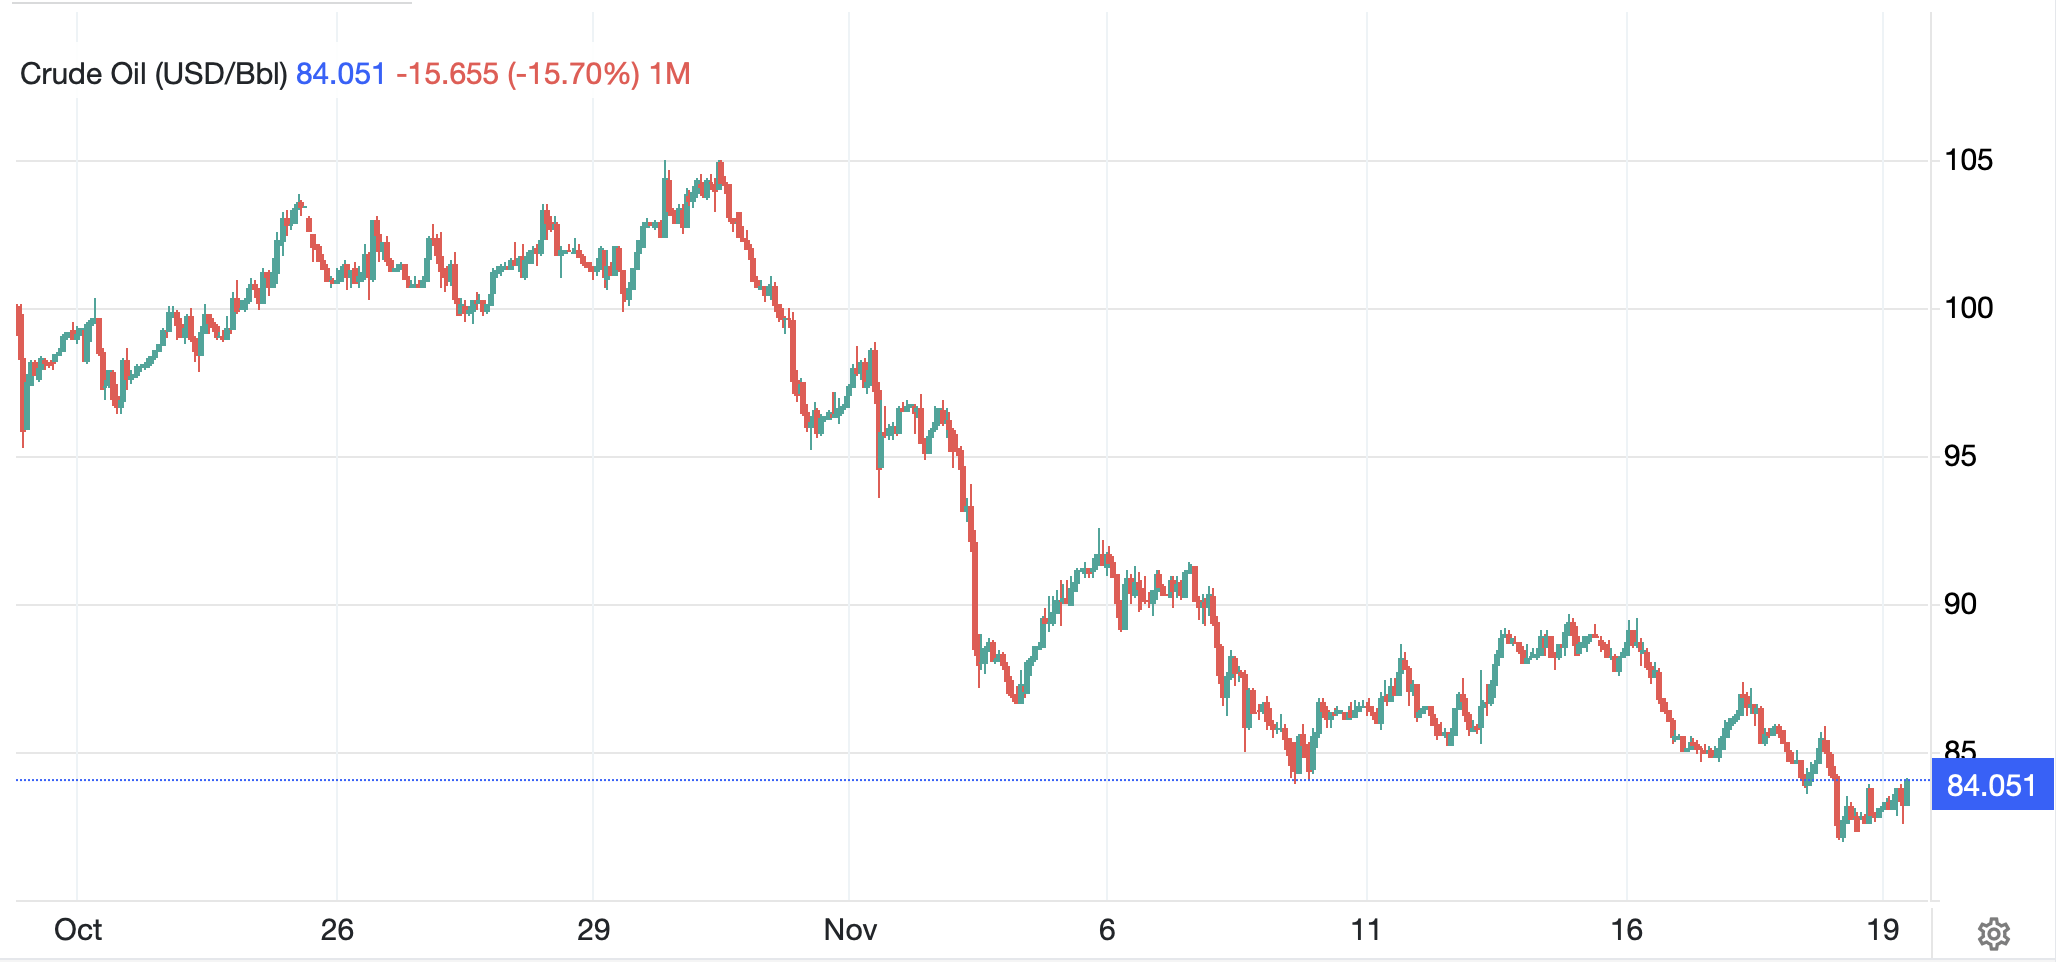
In the commodity space, oil (+1.0%) is higher this morning but it has been generally falling as you can see in the below chart and is still lower by more than -5.0% in the past week and -14% in the past month.
Source: tradingeconomics.com
Too, gasoline prices (+0.7%) while slightly higher this morning remain below $2.50/gallon, but when was the last time you saw that news broadcast? Whatever is currently ongoing in the Gulf and Iran, there is clearly plenty of oil and gasoline around. In fact, both crude oil and gasoline inventories rose sharply last week in the US. As to the metals markets, they remain under severe pressure as yields climb and expectations of Fed rate hikes are growing by the day. Price action (Au -0.3%, Ag 0.0%, Cu -0.3%) does feel like serious short selling is the driver, but that is where we are.
Finally, the dollar is a touch softer this morning although remains within spitting distance of its recent trading highs. Again, while expectations are for virtually every central bank to raise rates going forward, in fact we had two ECB members explaining just that again this morning, the dollar seems to be the net beneficiary for now. Just remember, if my mooted scenario above regarding a recession plays out, you can look for the dollar to decline quite sharply at that time, even though that recession is very likely to be global.
Data this morning brings Initial (exp 197K) and Continuing (1710K) claims as well as Philly Fed (20.0) and Leading Indicators (0.0%). The Housing data from yesterday was mixed with Starts stronger than expected but Permits much weaker than expected. We also saw the latest GDPNow figure from the Atlanta Fed and that fell to 3.2% for Q4, still strong, but fading a bit.
The Anthropic story has everyone in a good mood this morning, but we shall see how long that lasts. As to the dollar, as long as the indications are the Fed is going to be hawkish, and we hear from 5 more speakers today, it will remain bid.
Good luck
Adf

