The markets have made their decision
For Lula, they have great derision
It seems the divide
Twixt left and right sides
Is wider than most can envision
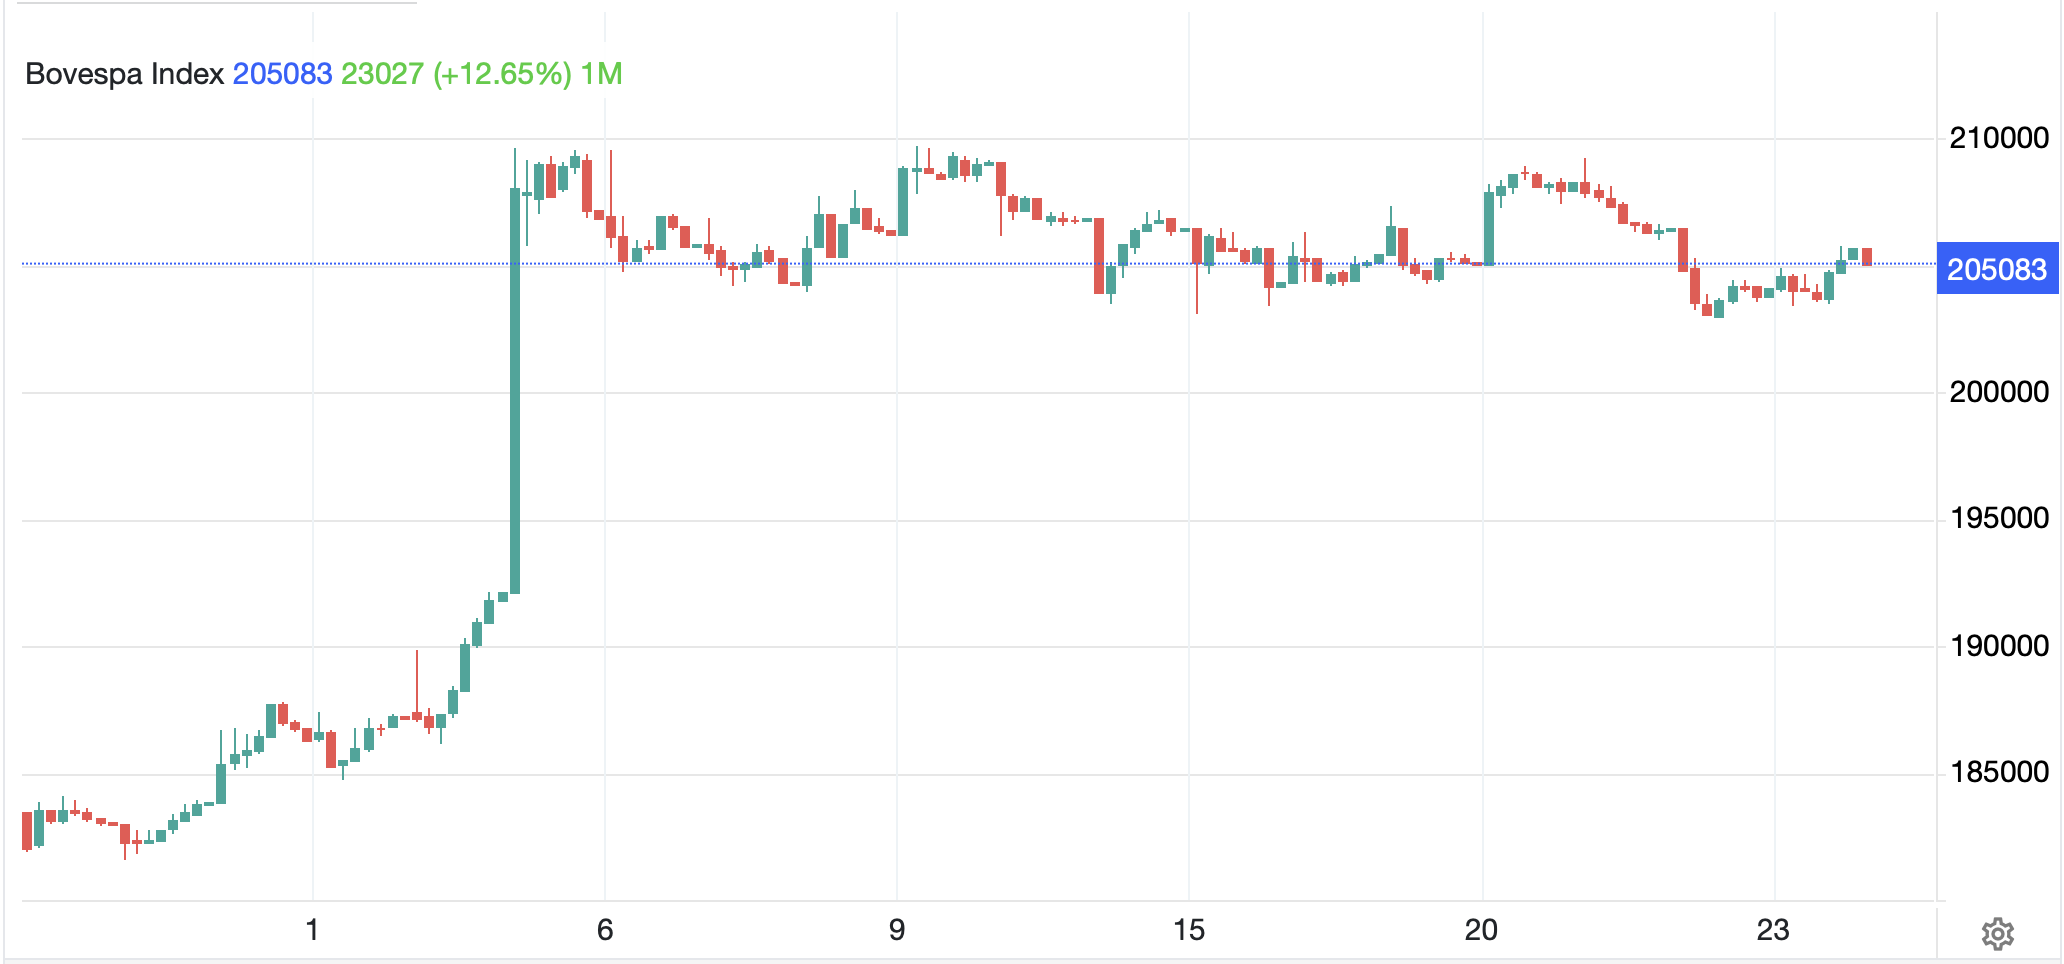
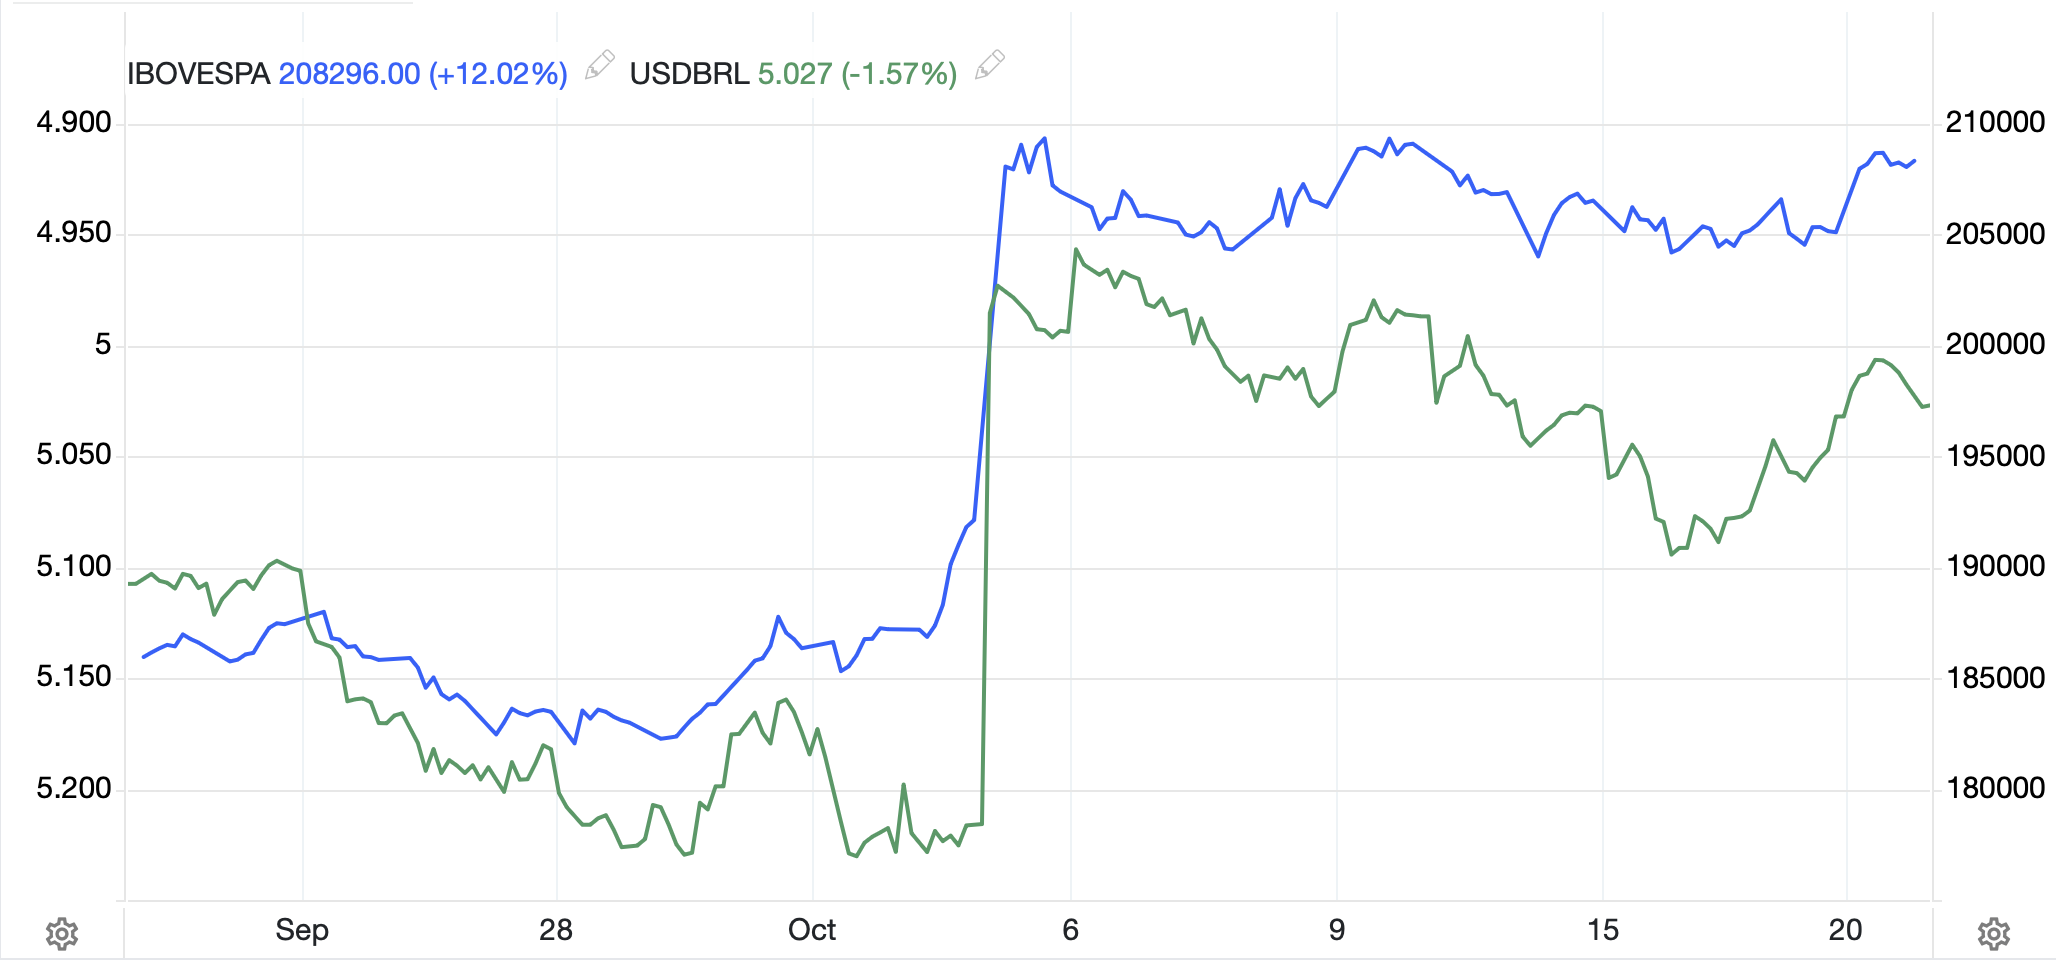
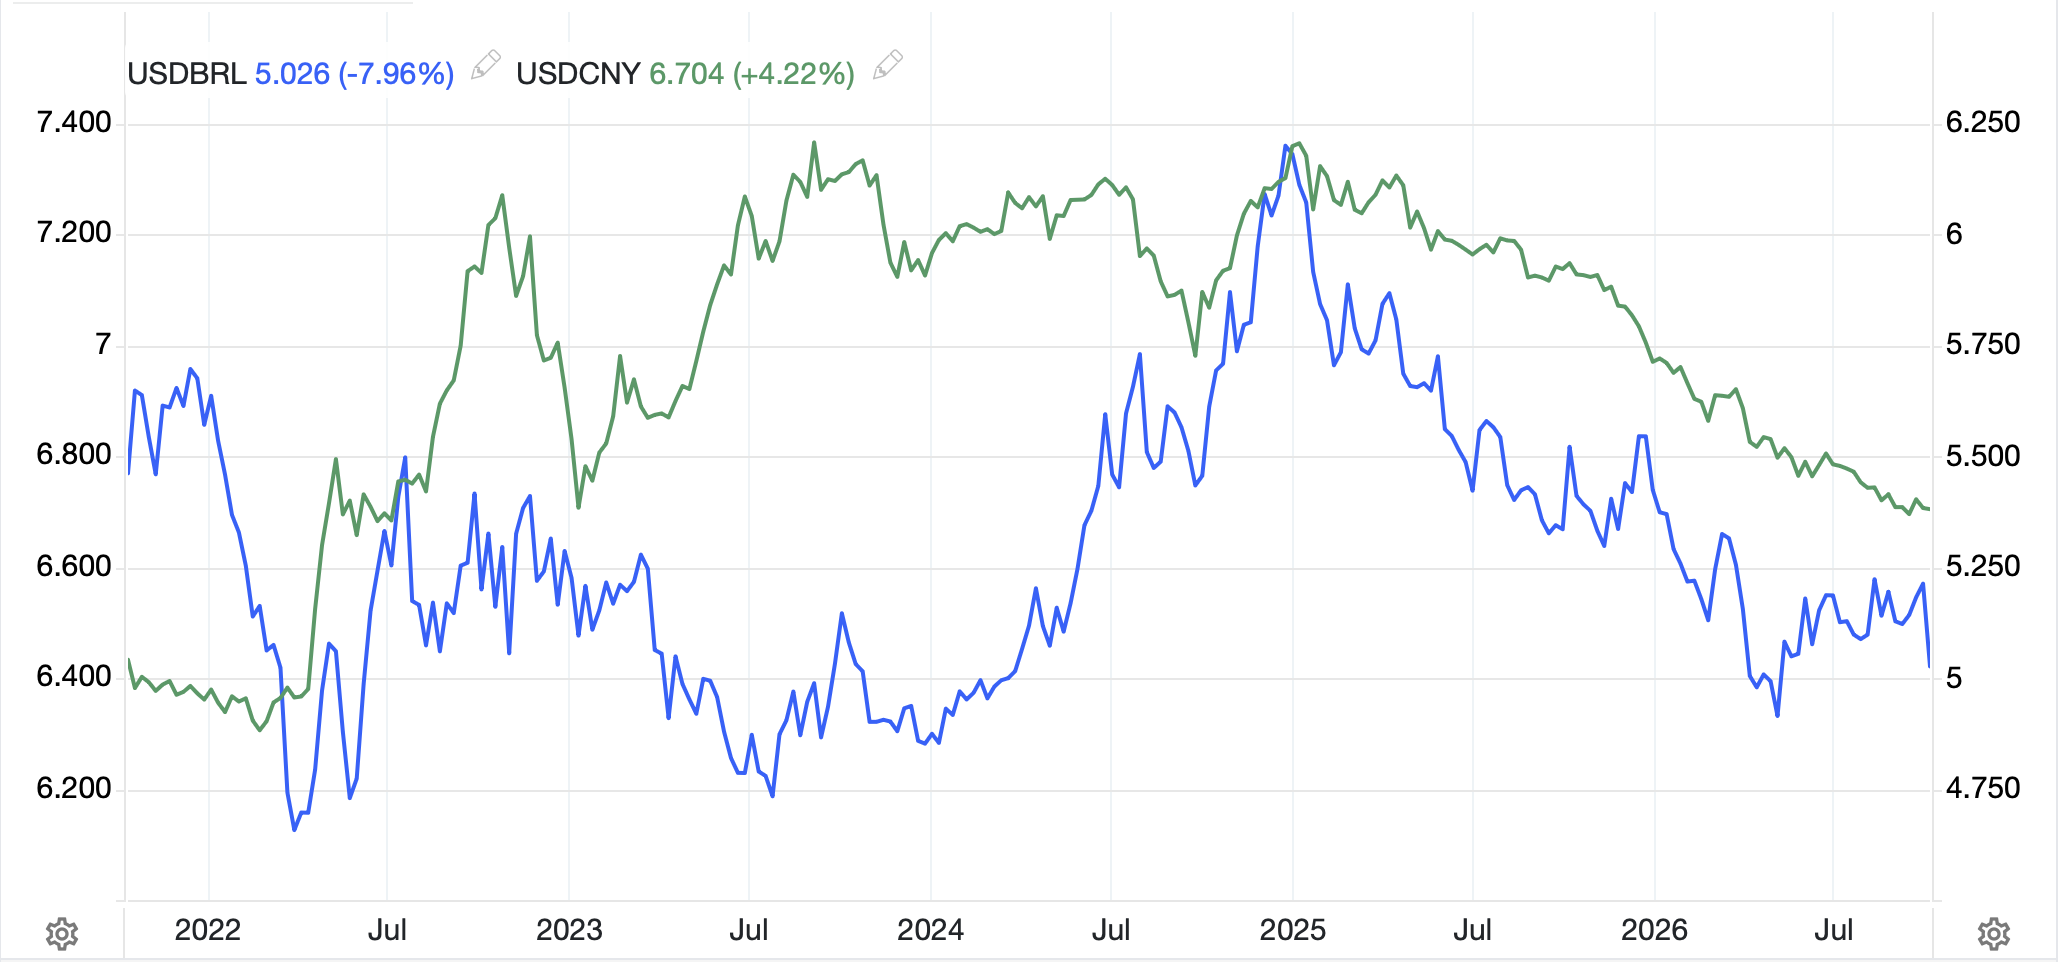
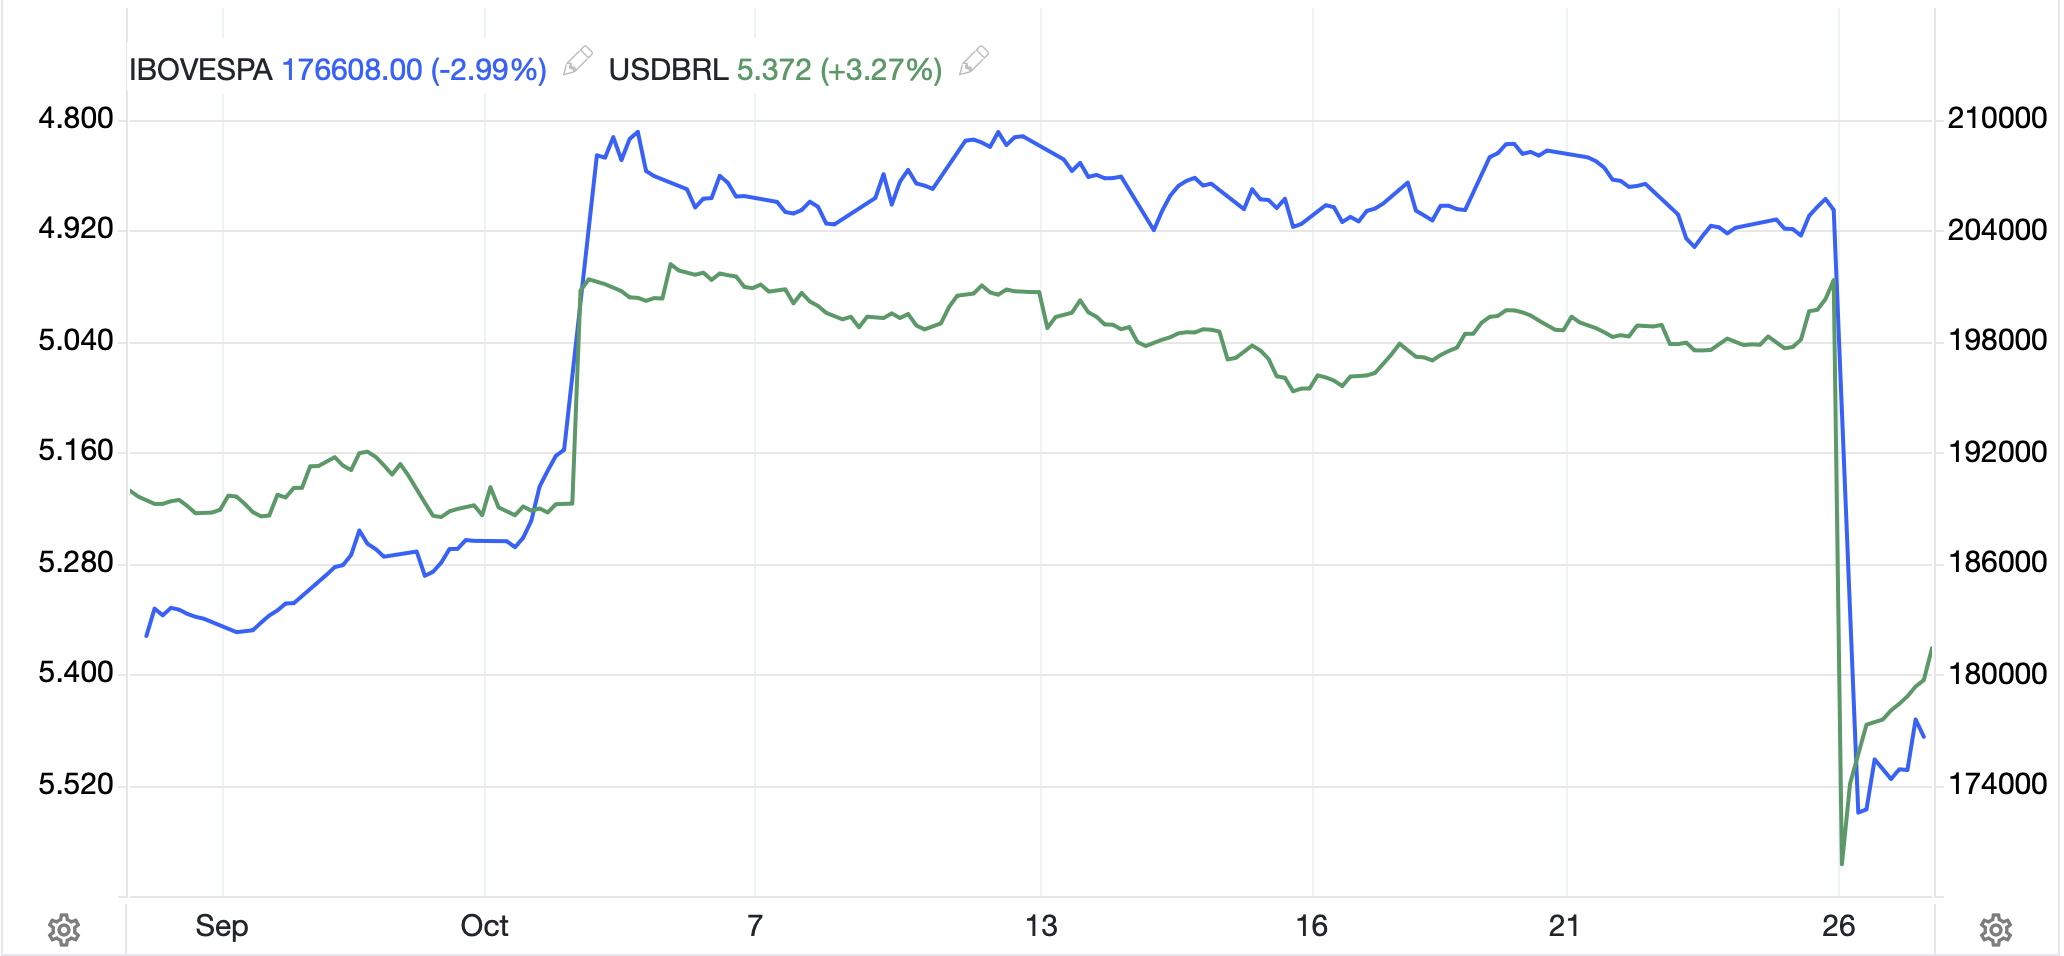
If you wondered why I bought put protection for my portfolio as I mentioned last week to cover the mid-term elections next week, look no further than Brazil’s market this morning after Lula surprised almost everyone by winning. It seems that investors look at his policy objectives and don’t really like what they see. Not surprisingly, as you can see in the chart below, the BRL also suffered dramatically with both stocks and the currency now weaker than prior to Bolsonaro’s surprise first round lead.
Source: tradingeconomics.com
For good order’s sake, the BOVESPA Stock Index fell -13.85% while the BRL fell -8.65%. Now, if you don’t think that can happen in the US should the Democrats win both the House and the Senate next week, you are mistaken. I am old enough to have seen several moves of that magnitude during my career. And given the extraordinary amount of leverage that exists within the system, when margin calls start to come, there is no stopping things. Again, I continue to believe that the Republicans hold the Senate for sure and the House as well, but I put on protection!
Despite the results from Brazil
The rest of the markets were chill
The stock market rallied
While bonds dilly-dallied
And FX remains a buzzkill
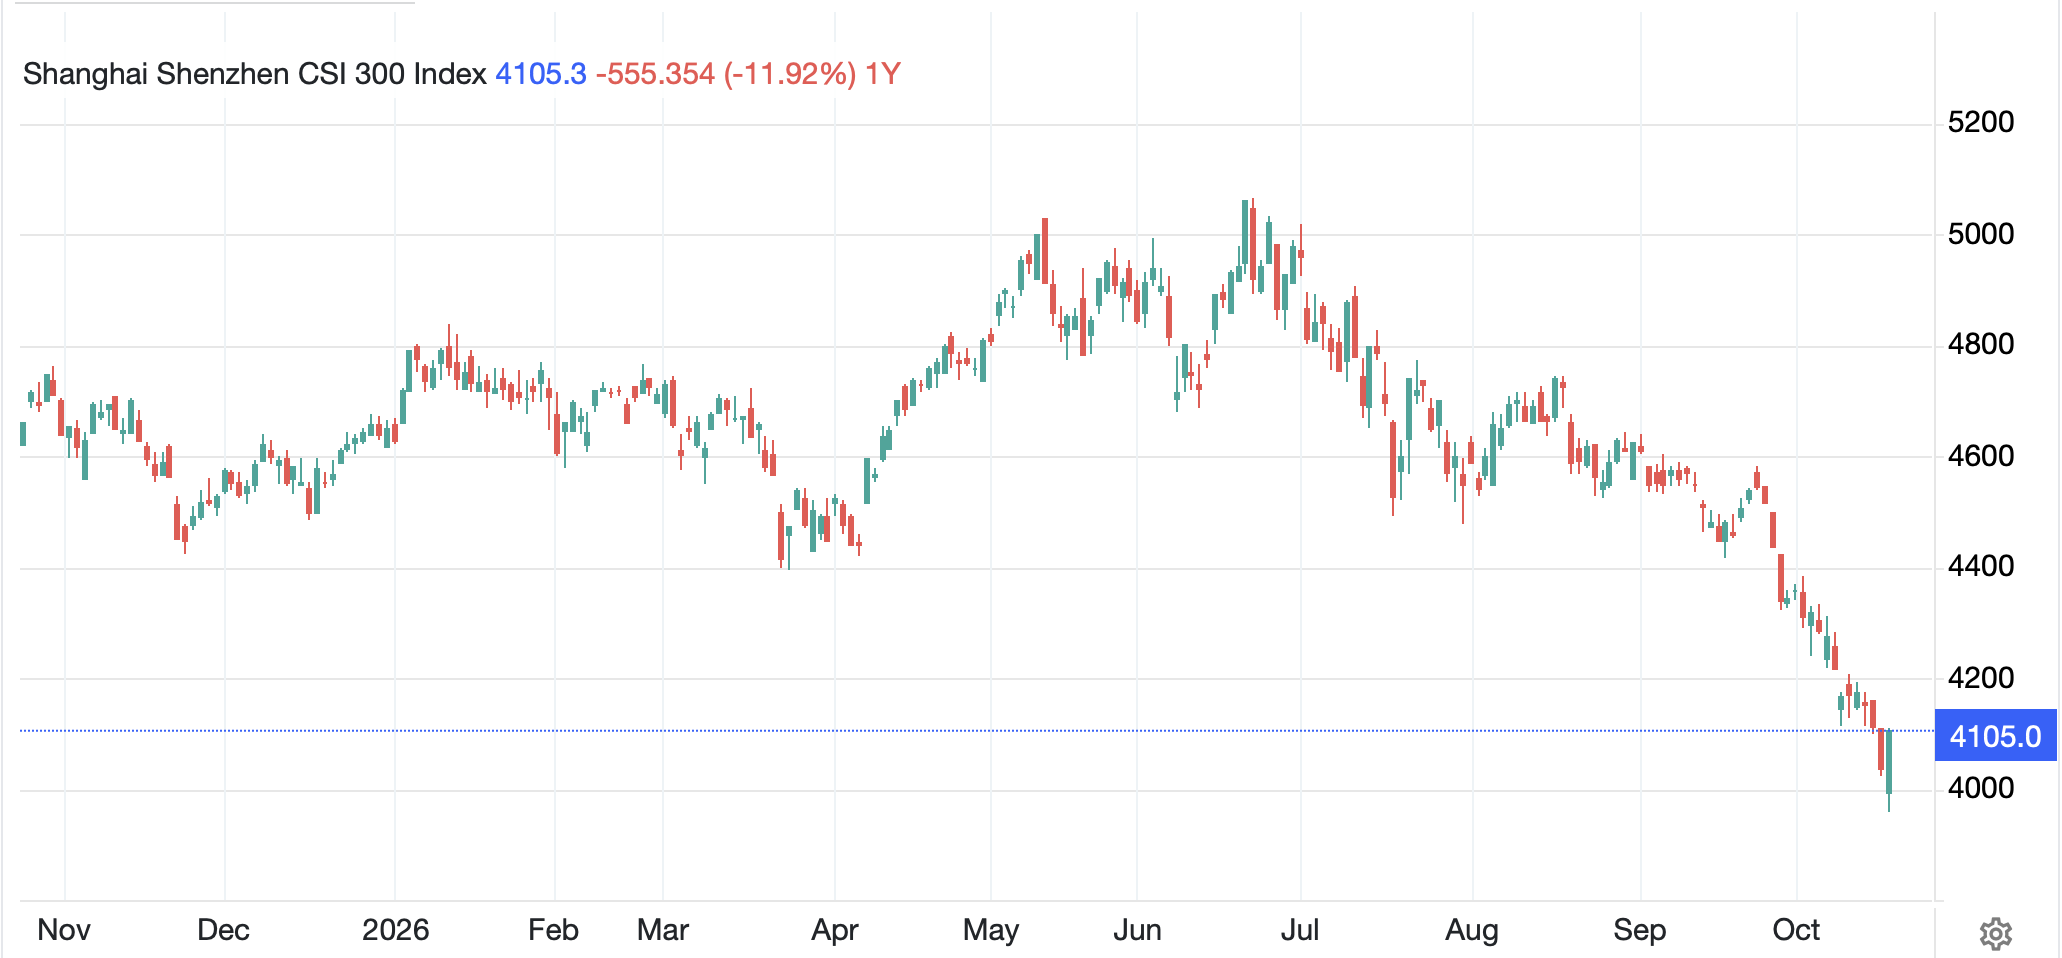
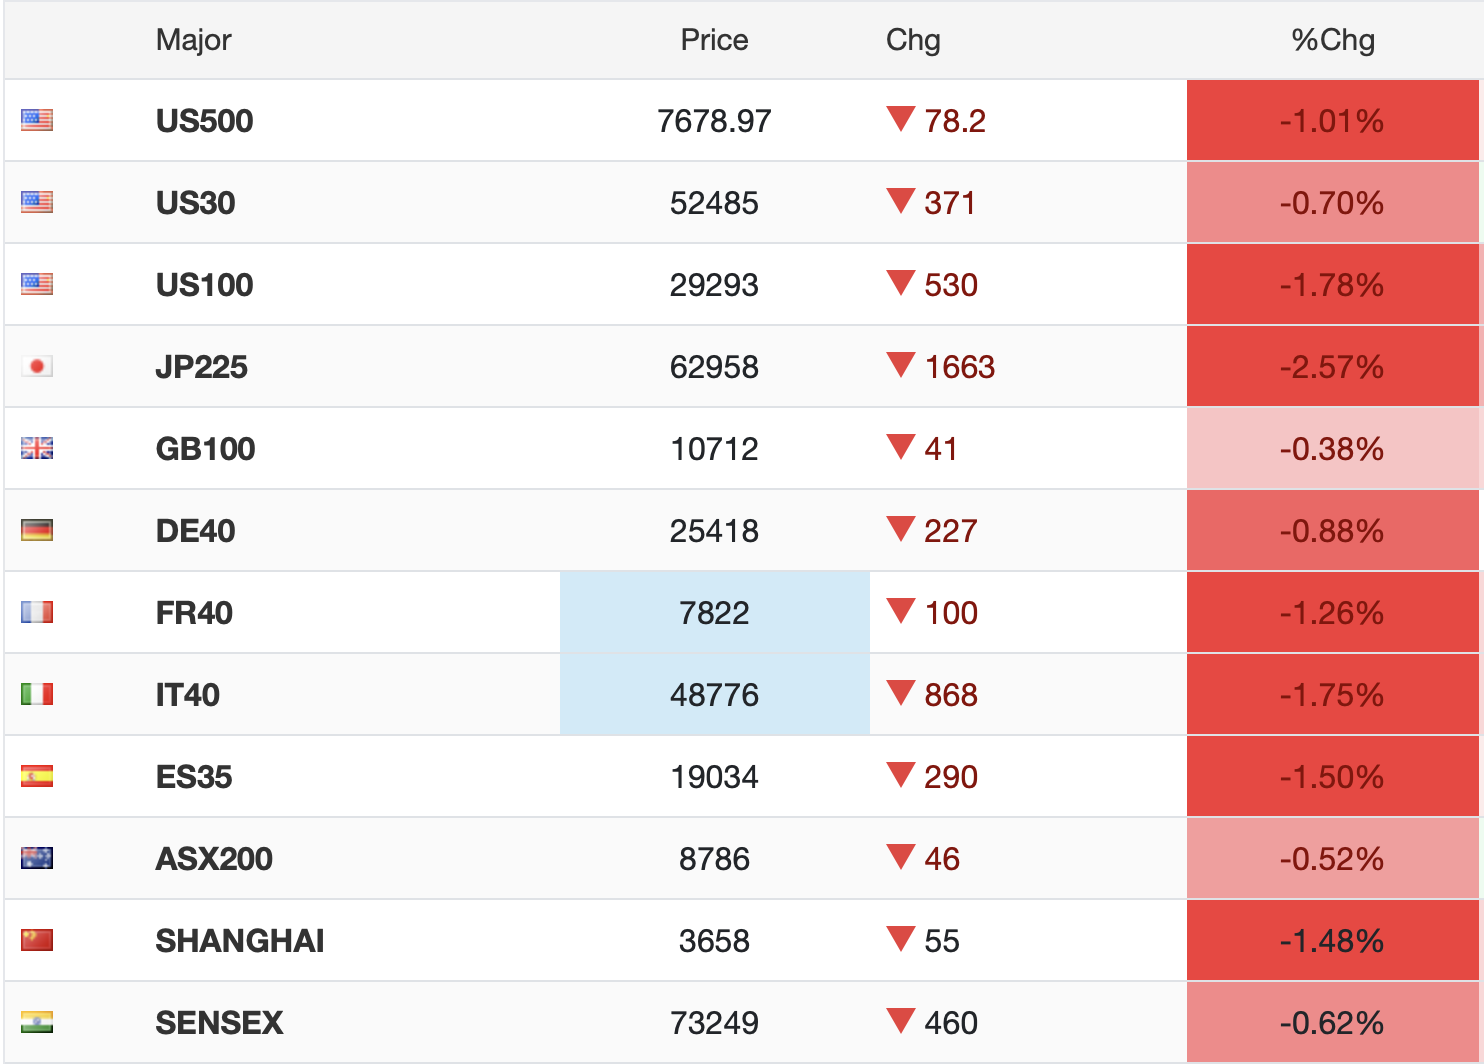
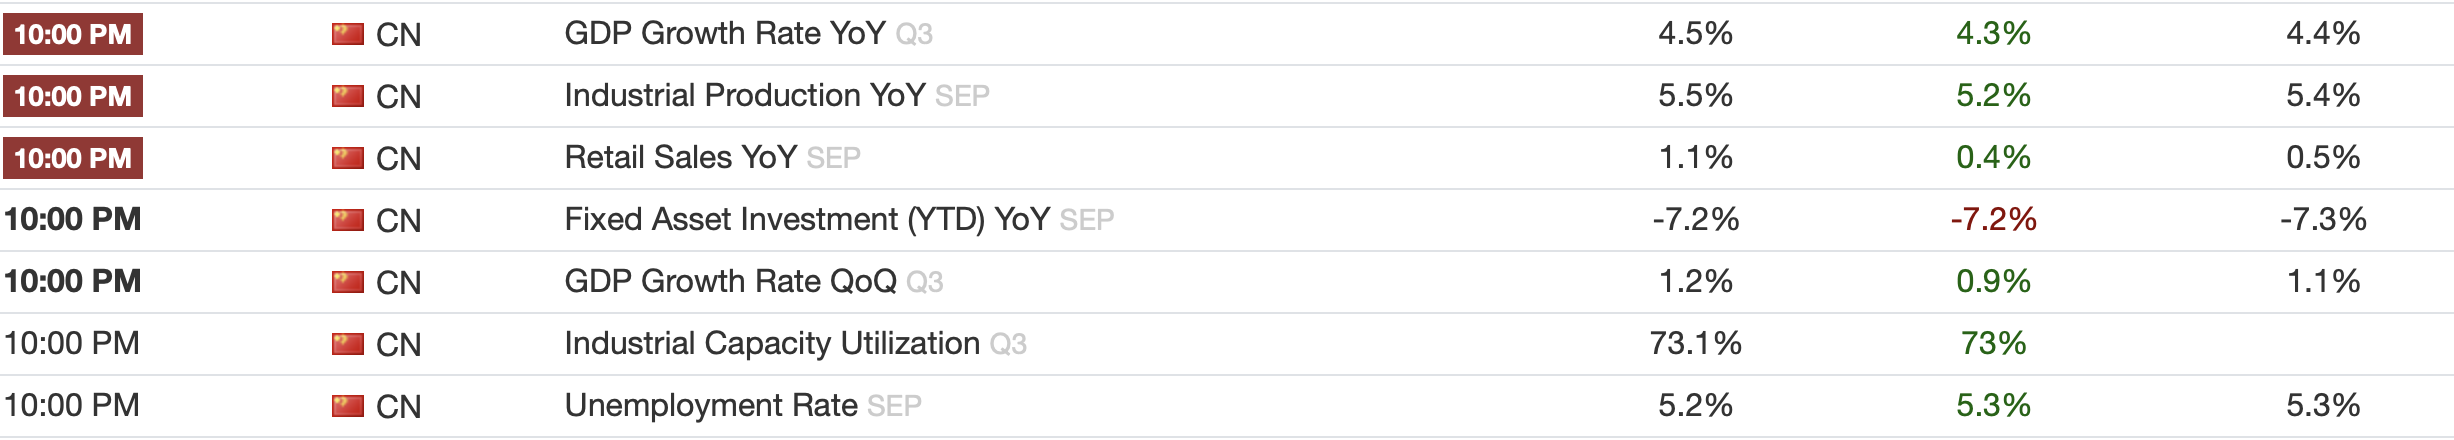
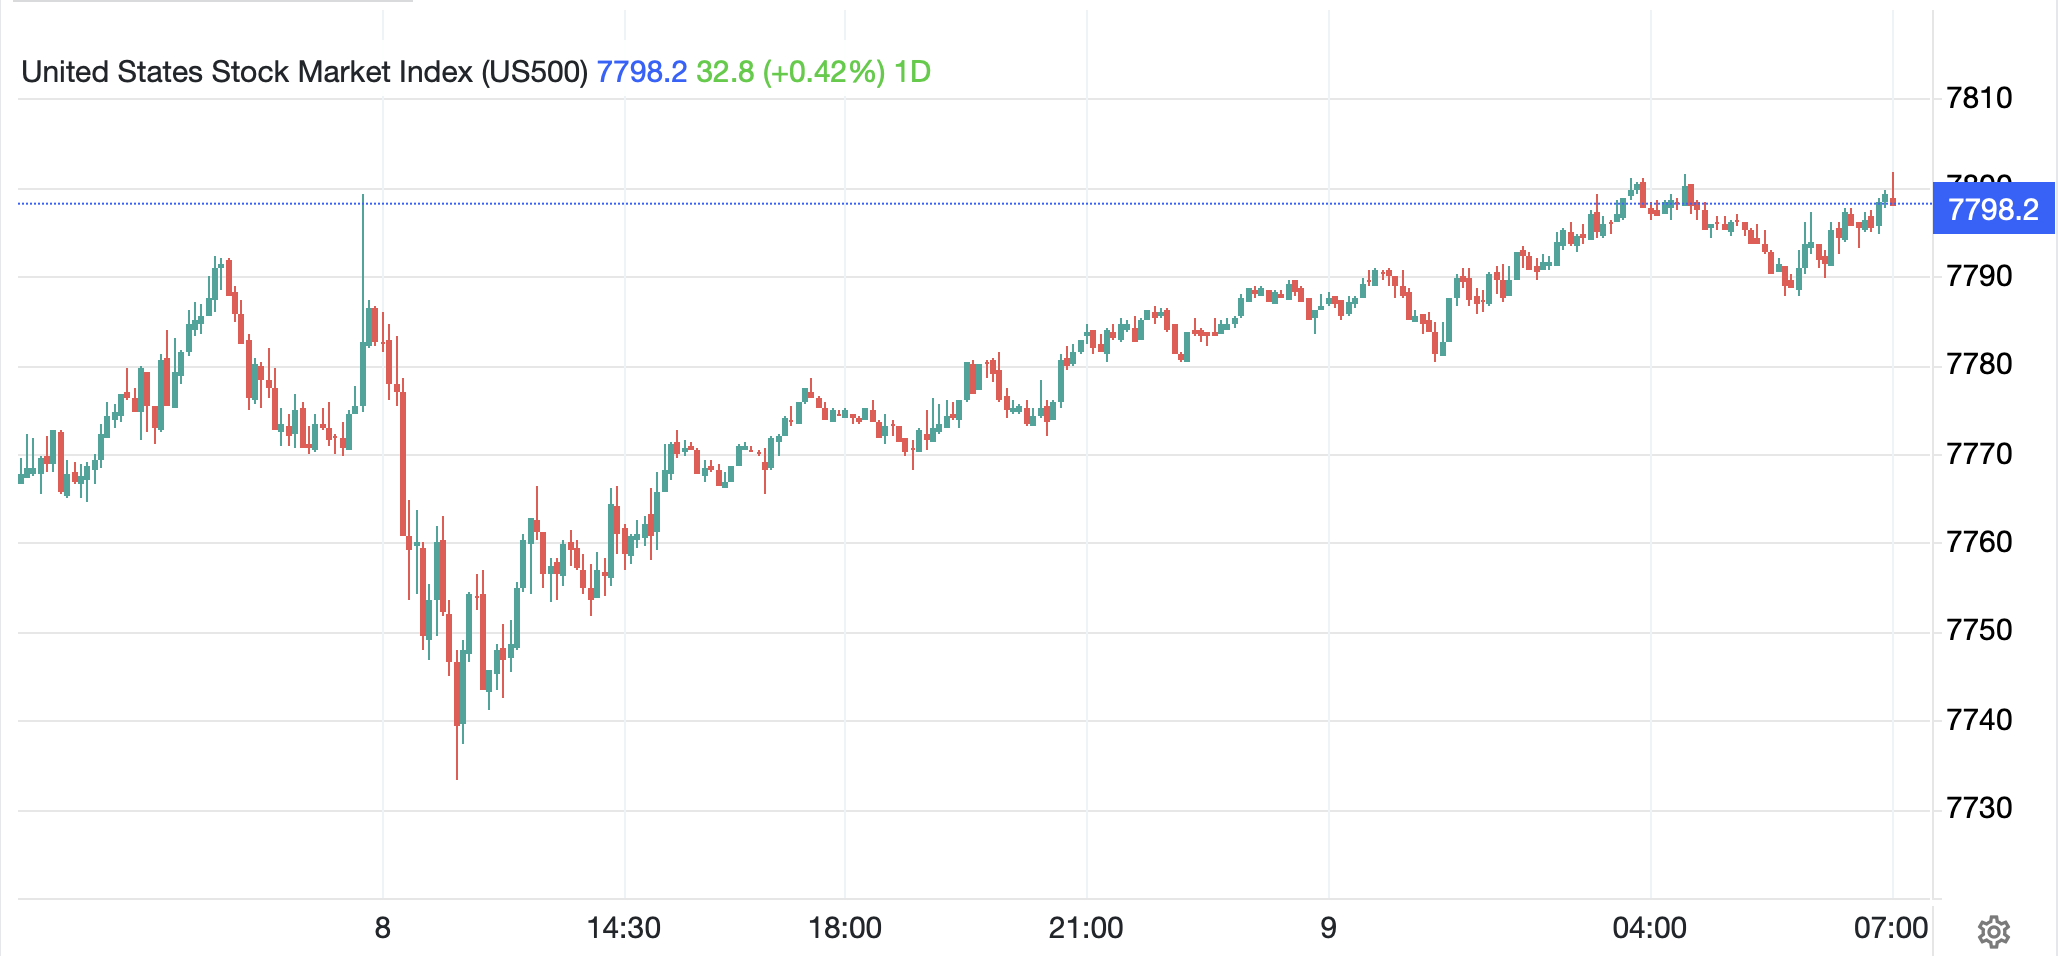
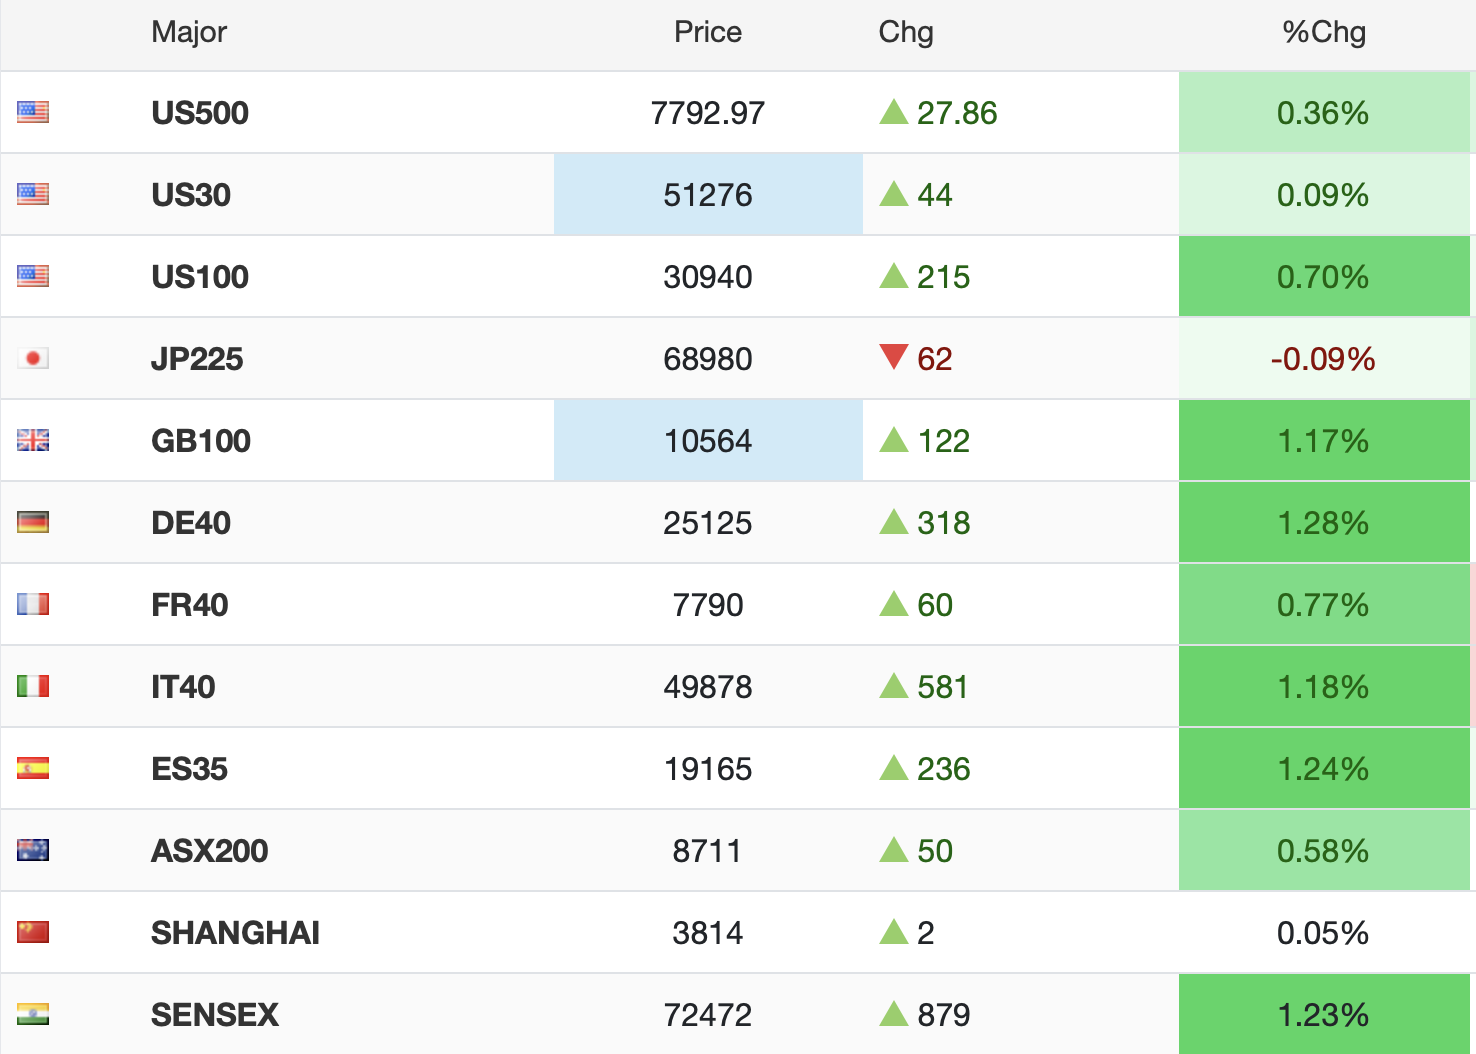
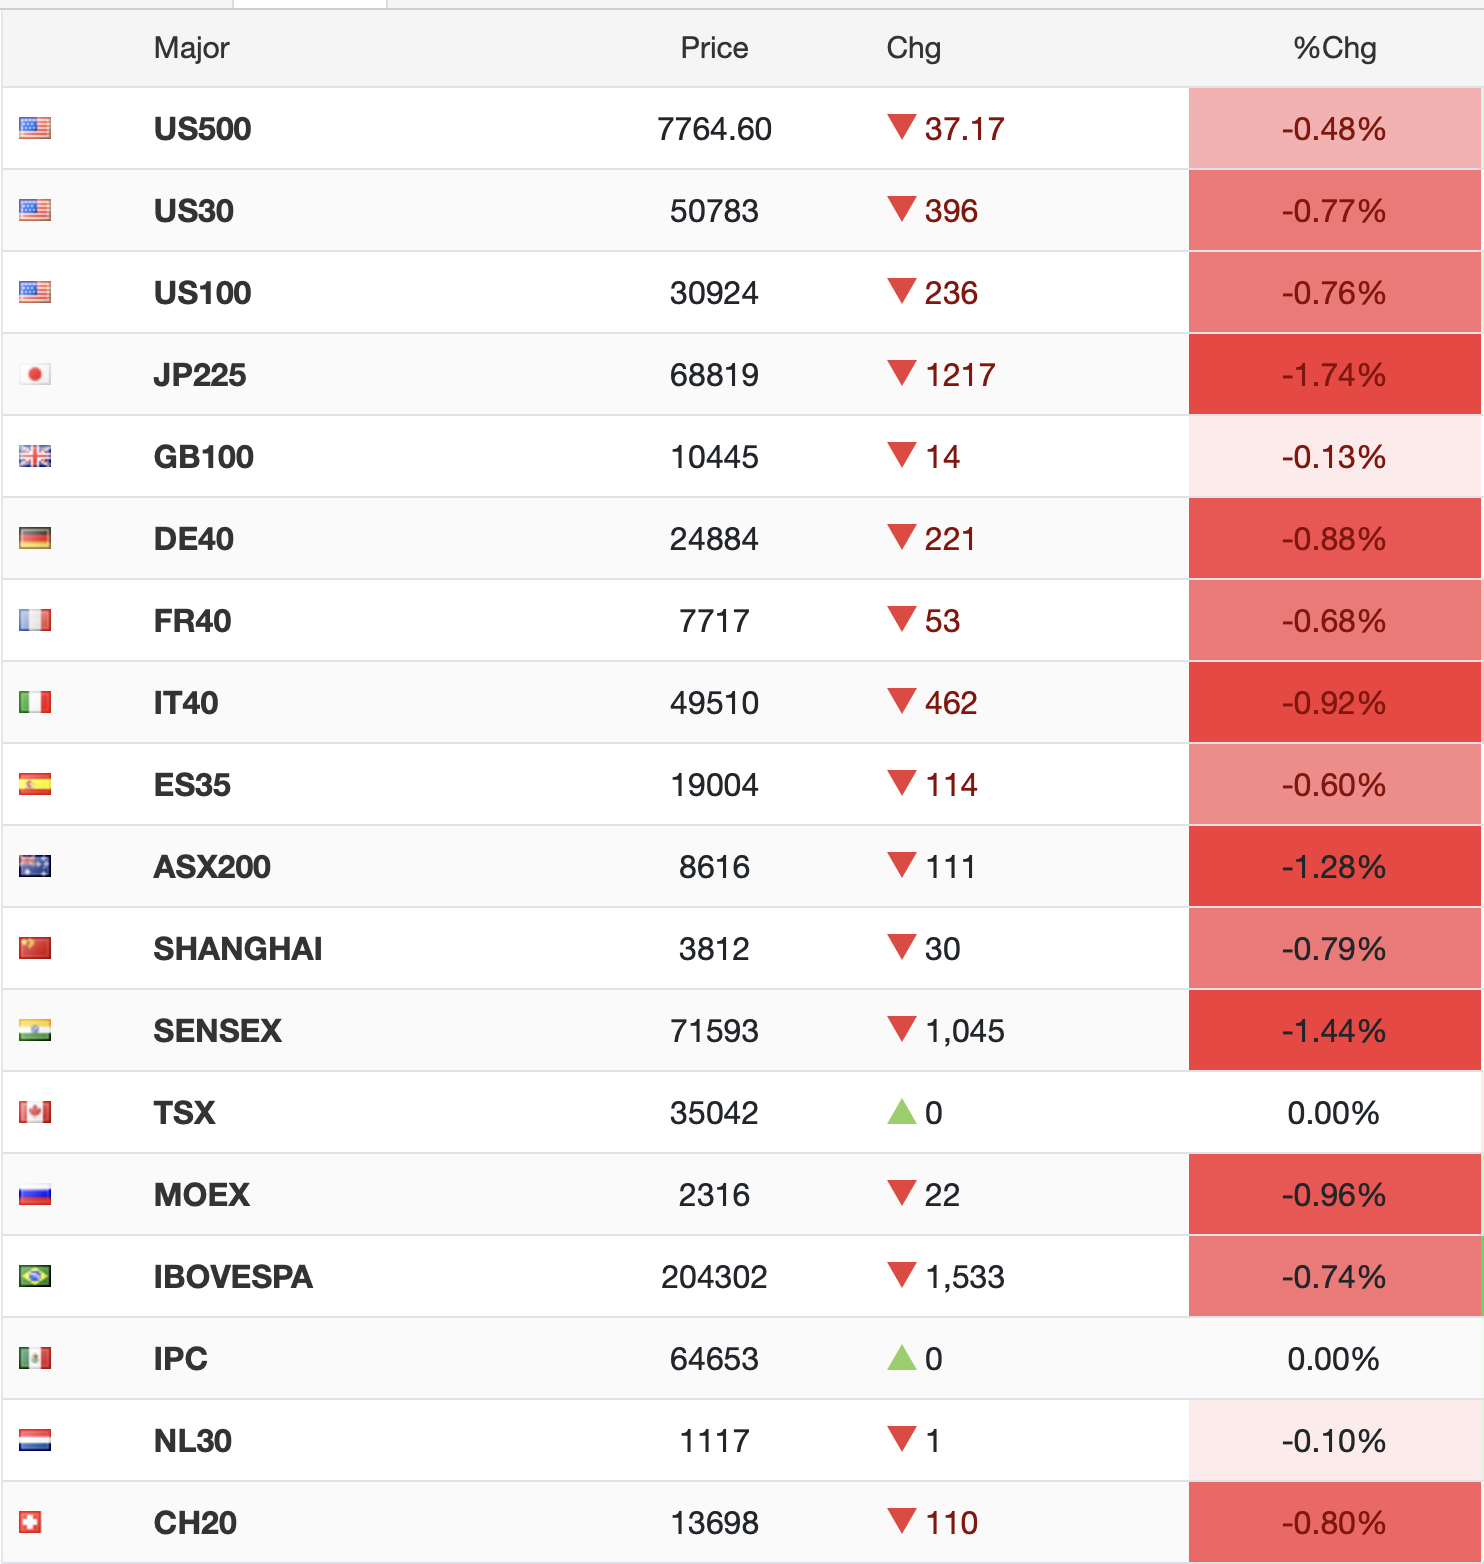
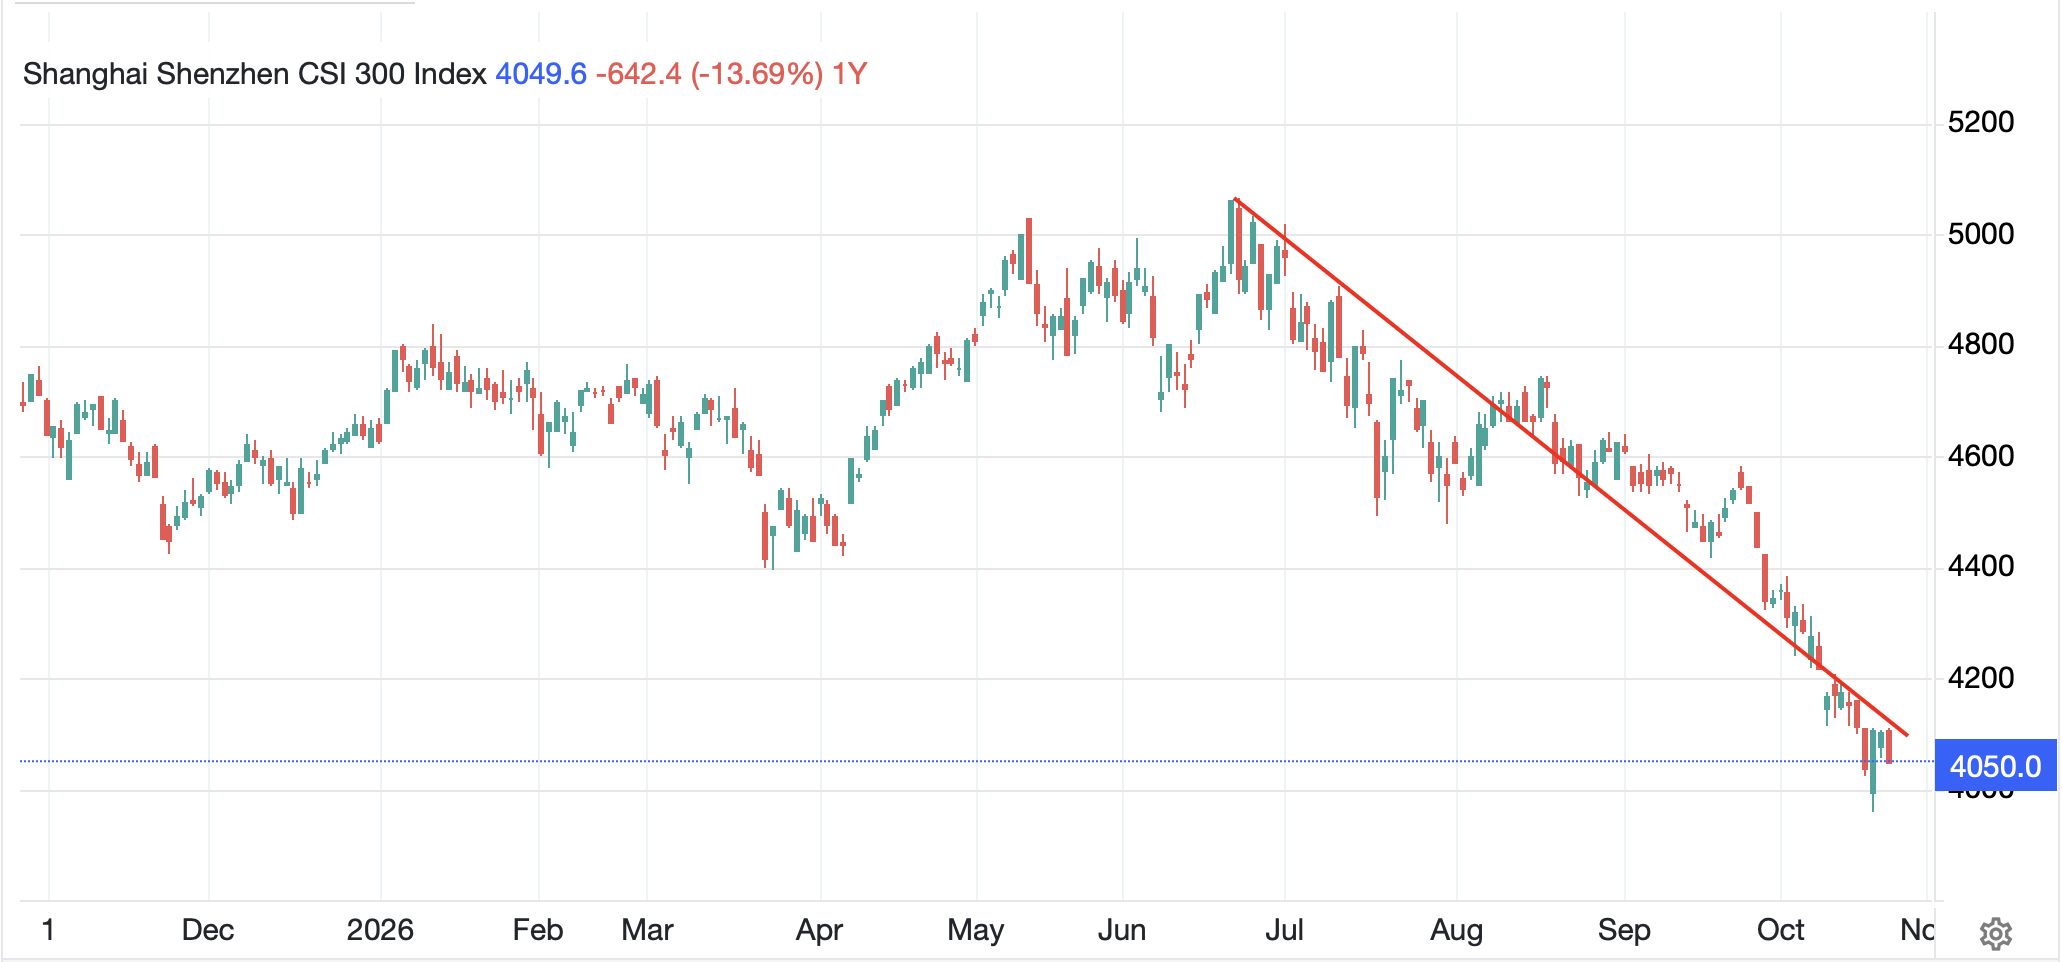
The Brazilian market movements were the very definition of isolated events. While those in the trade were scrambling to adjust their positions and, mostly, licking their wounds, the spillover to other markets was essentially nil. US markets continue to perform generally well, with all three major indices higher yesterday and that followed through into Asia with Tokyo (+1.7%) and Korea (+3.2%) both benefitting from renewed positivity regarding the AI trade after Anthropic filed to go public. But elsewhere in Asia things were less sanguine as China (-1.3%) and HK (-0.7%) found limited support as official buying was absent last night. It tells us a great deal, I believe, that without the Plunge Protection Team, Chinese stocks remain in a sharp downtrend. In fact, from its recent high in late June, that market, as defined by the CSI 300, has fallen -20%.
Source: tradingeconomics.com
It’s a very interesting conundrum, I think, the fact that the Chinese equity markets are declining so sharply and steadily. After all, equity markets are deemed to be forward looking indicators, anticipating economic activity 6-9 months in the future. At least that’s what I was taught all those years ago and have heard repeated consistently since then. If that is the case, what does it say about the future of the Chinese economy? It doesn’t seem to me that it portends great strength, but then, I’m just an FX poet. Is it possible, and I’m just spit balling here, that socialism and communism are not coincident with economic growth? Inquiring minds want to know!
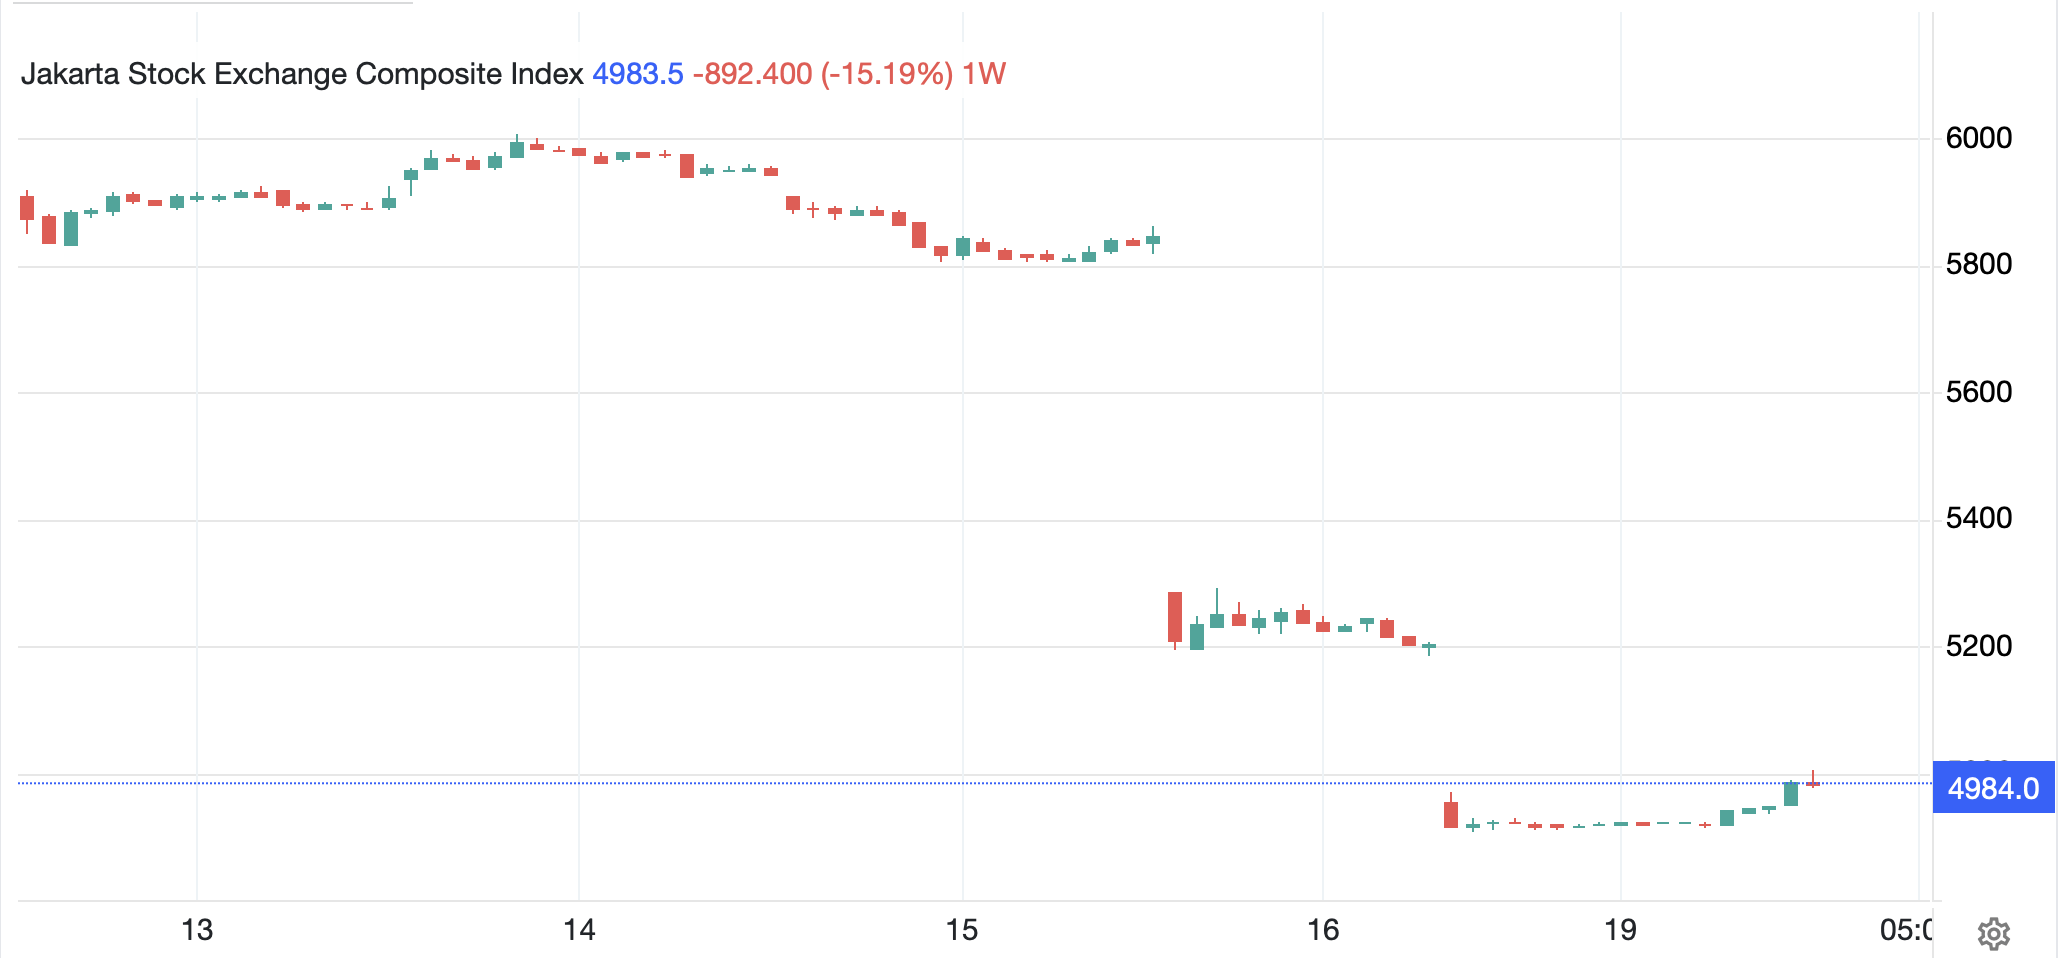
As to the rest of Asia, the other big loser was Indonesia, which continues to suffer based on the fears that MSCI is going to remove their Frontier Market designation and institutional investors will be forced to exit. Whatever signs they have shown regarding making changes have not been deemed sufficient, at least by the market. As you can see below, that massive gap remains wide open, and the initial bounce seems to be reversing. Absent concrete moves by the securities regulators there, I believe we could see another sharp leg lower.
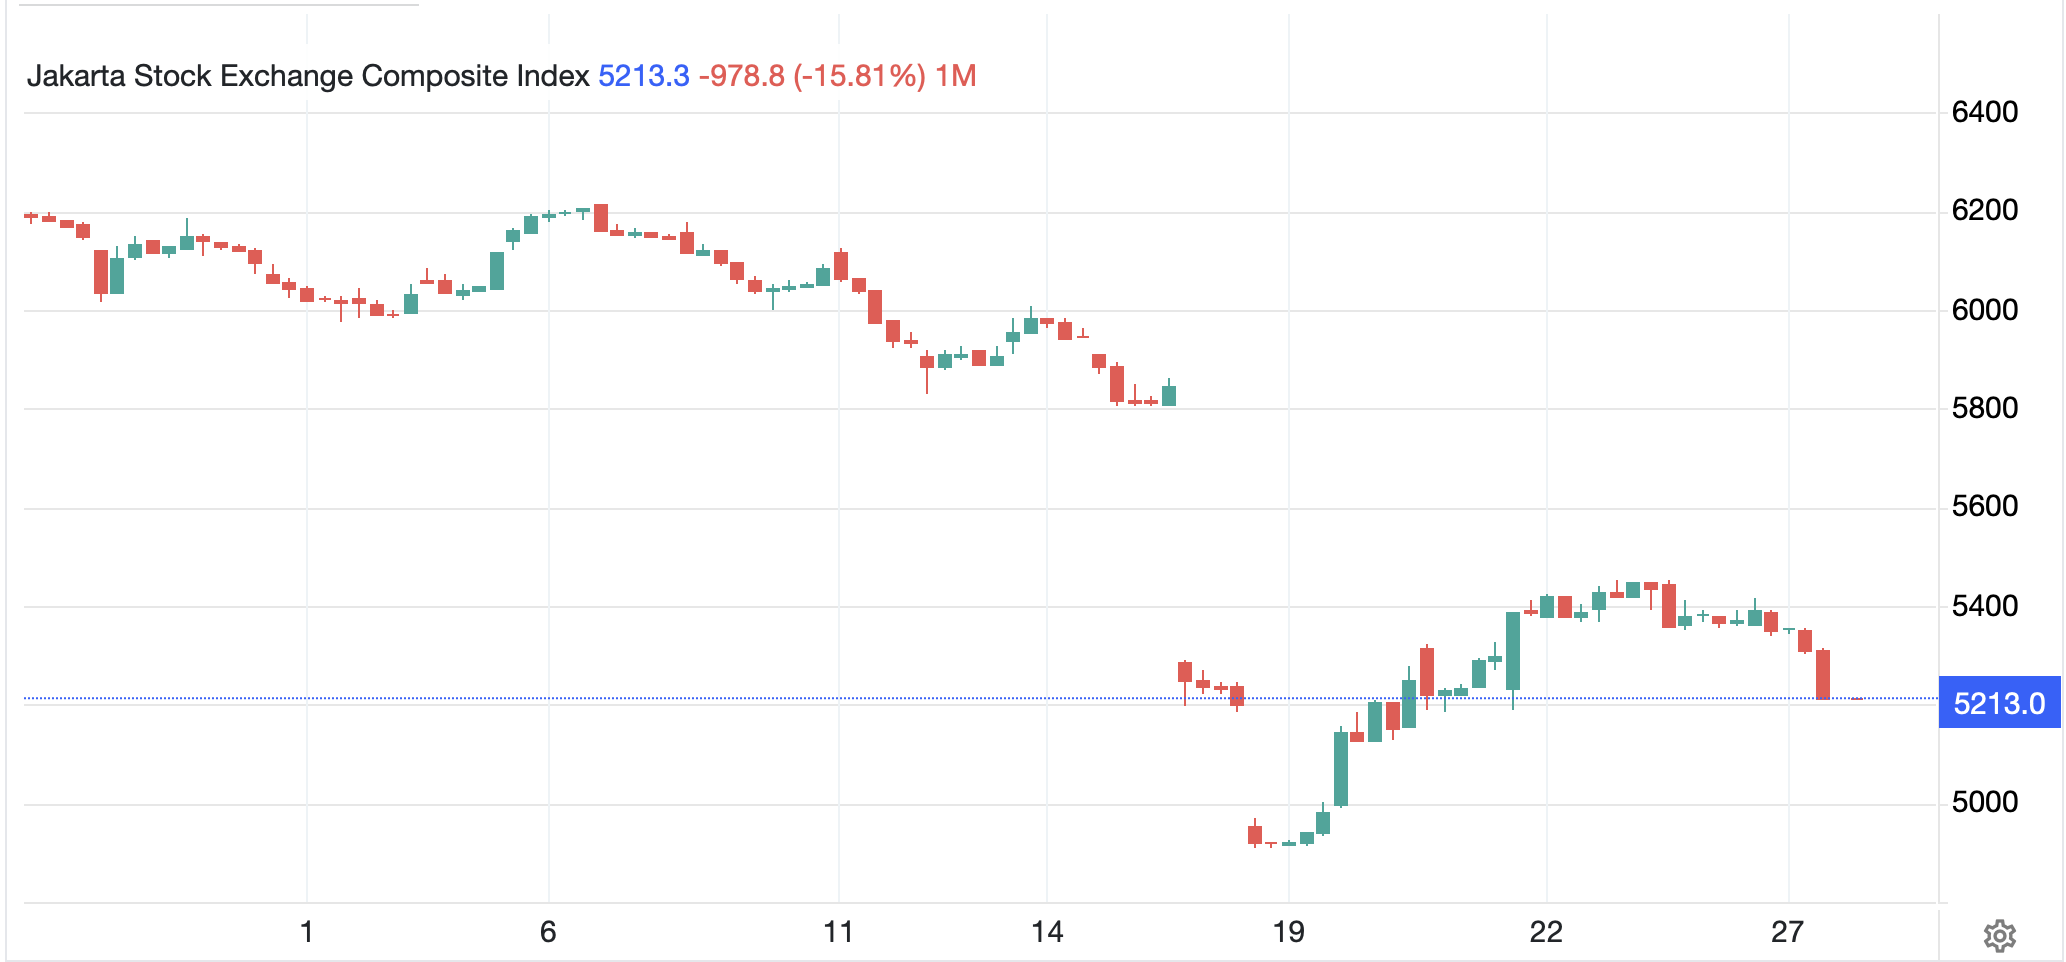
Source: tradingeconomics.com
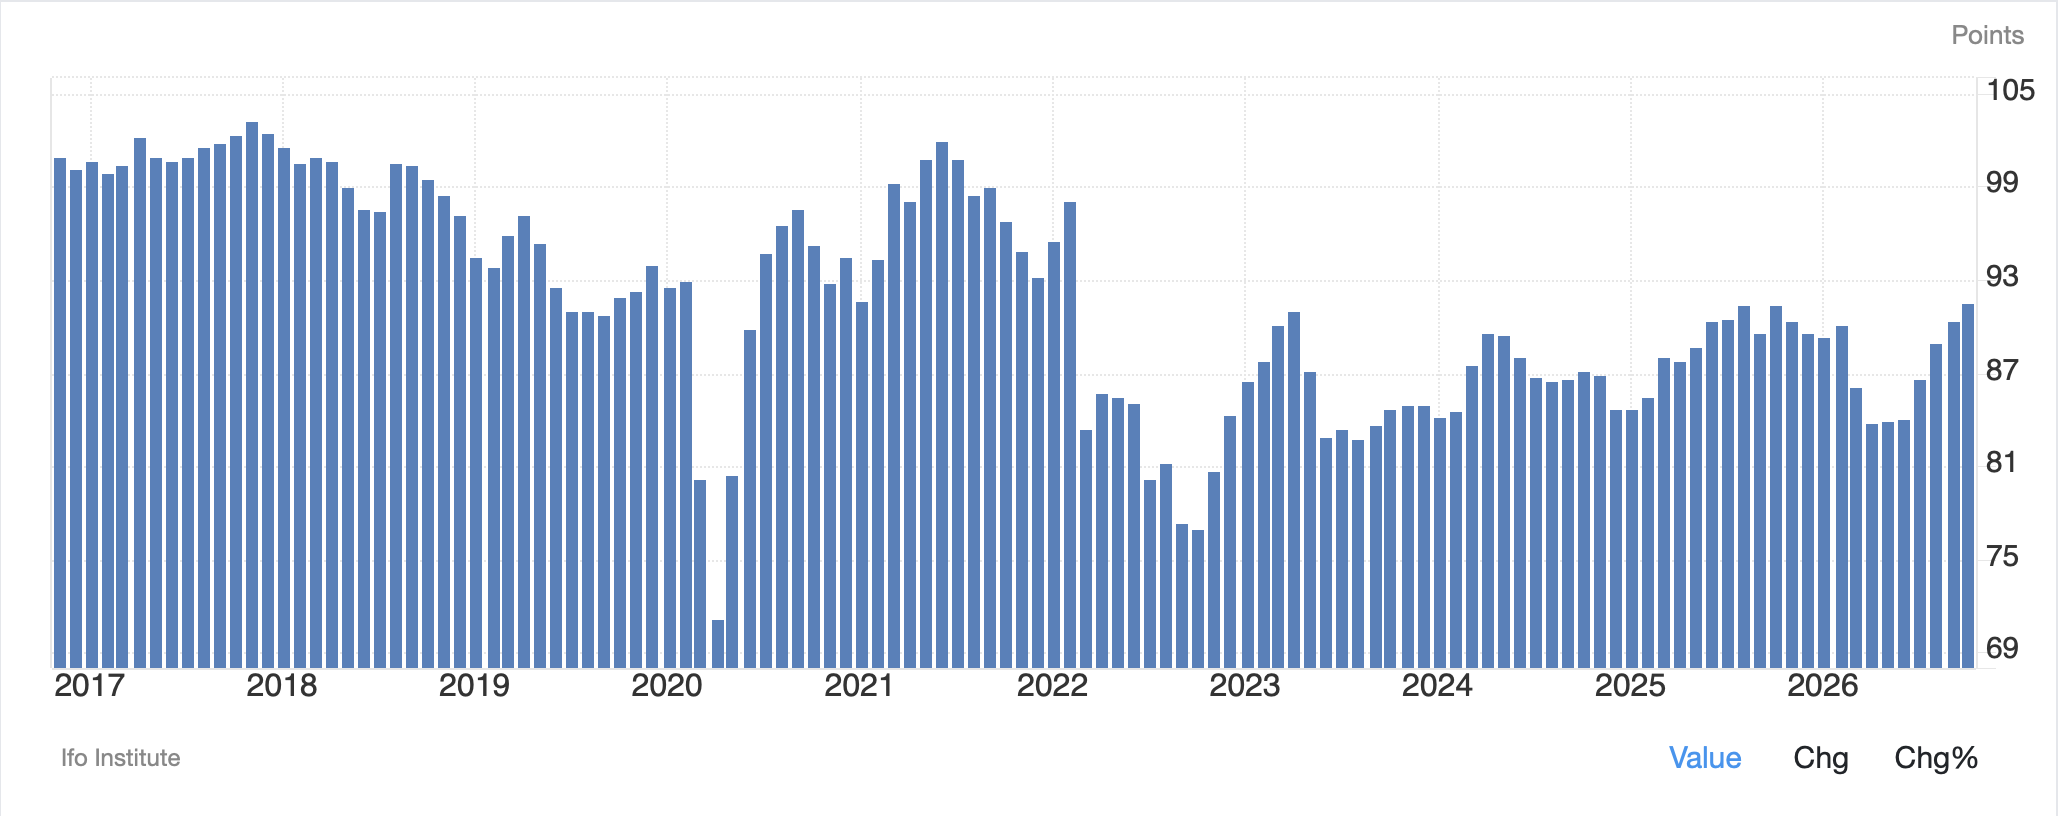
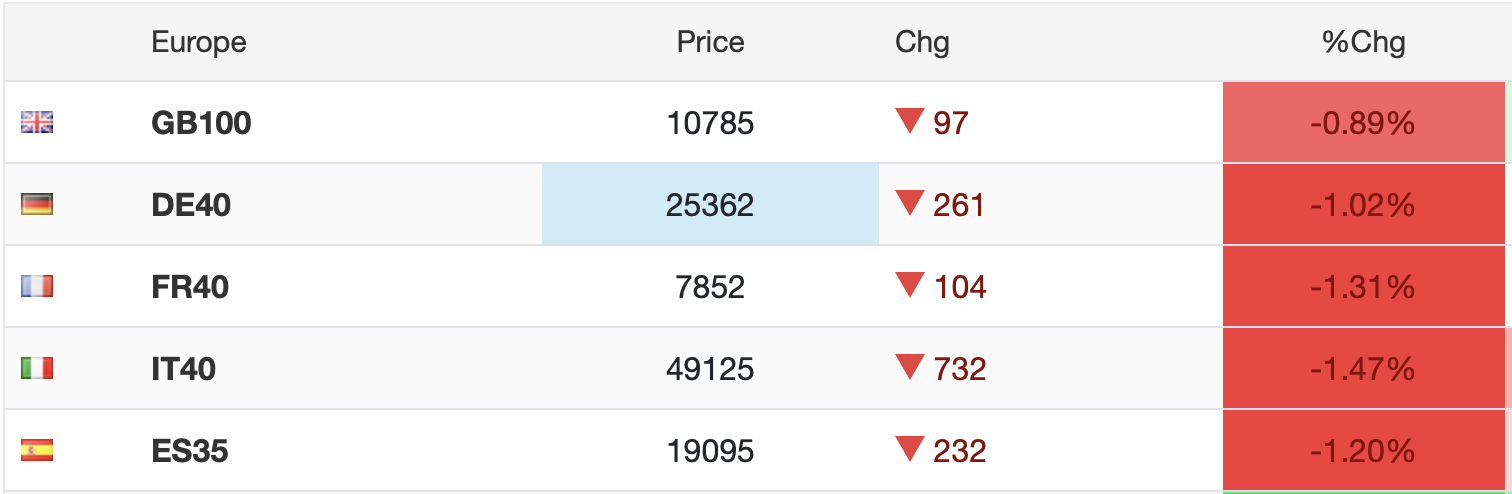
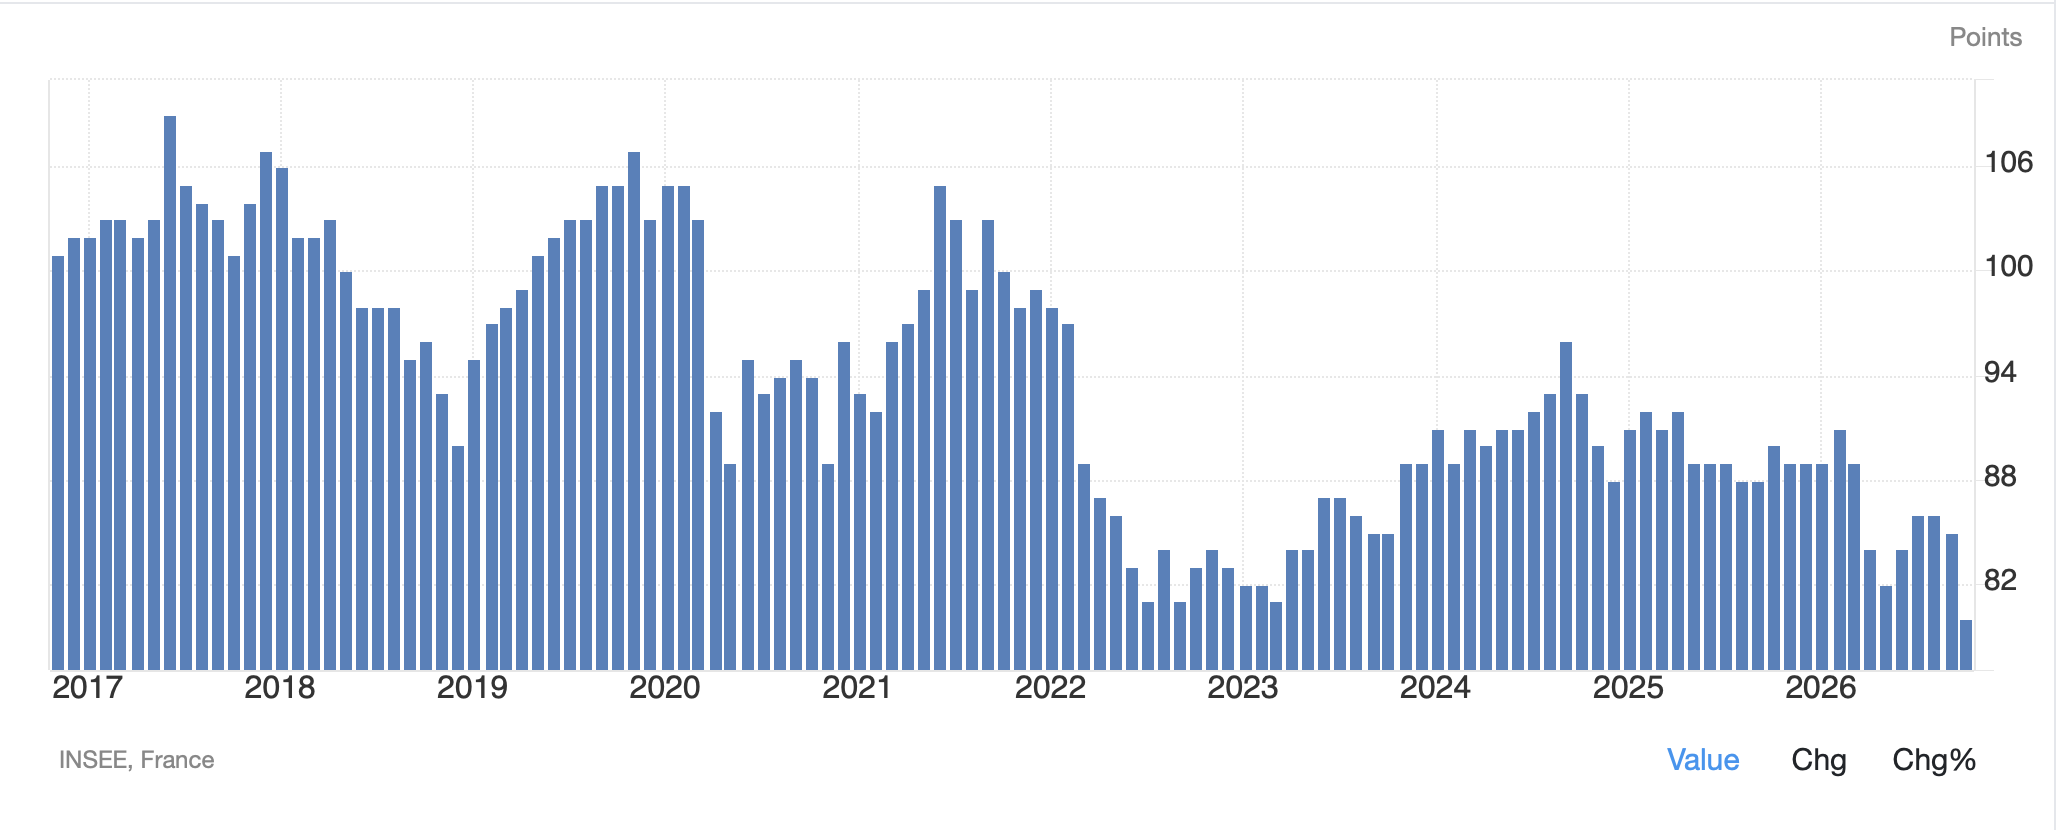
In Europe, UK stocks (-0.9%) are under pressure this morning after weak earnings from HSBC dragged the FTSE 100 down, but the rest of Europe is doing little. Surprisingly, Paris (0.0%) is unchanged despite the lowest Consumer Confidence reading (80) since June 2013.
Source: tradingeconomics.com
As to US futures, at this hour (7:00), they are pointing slightly higher, 0.3% or so.
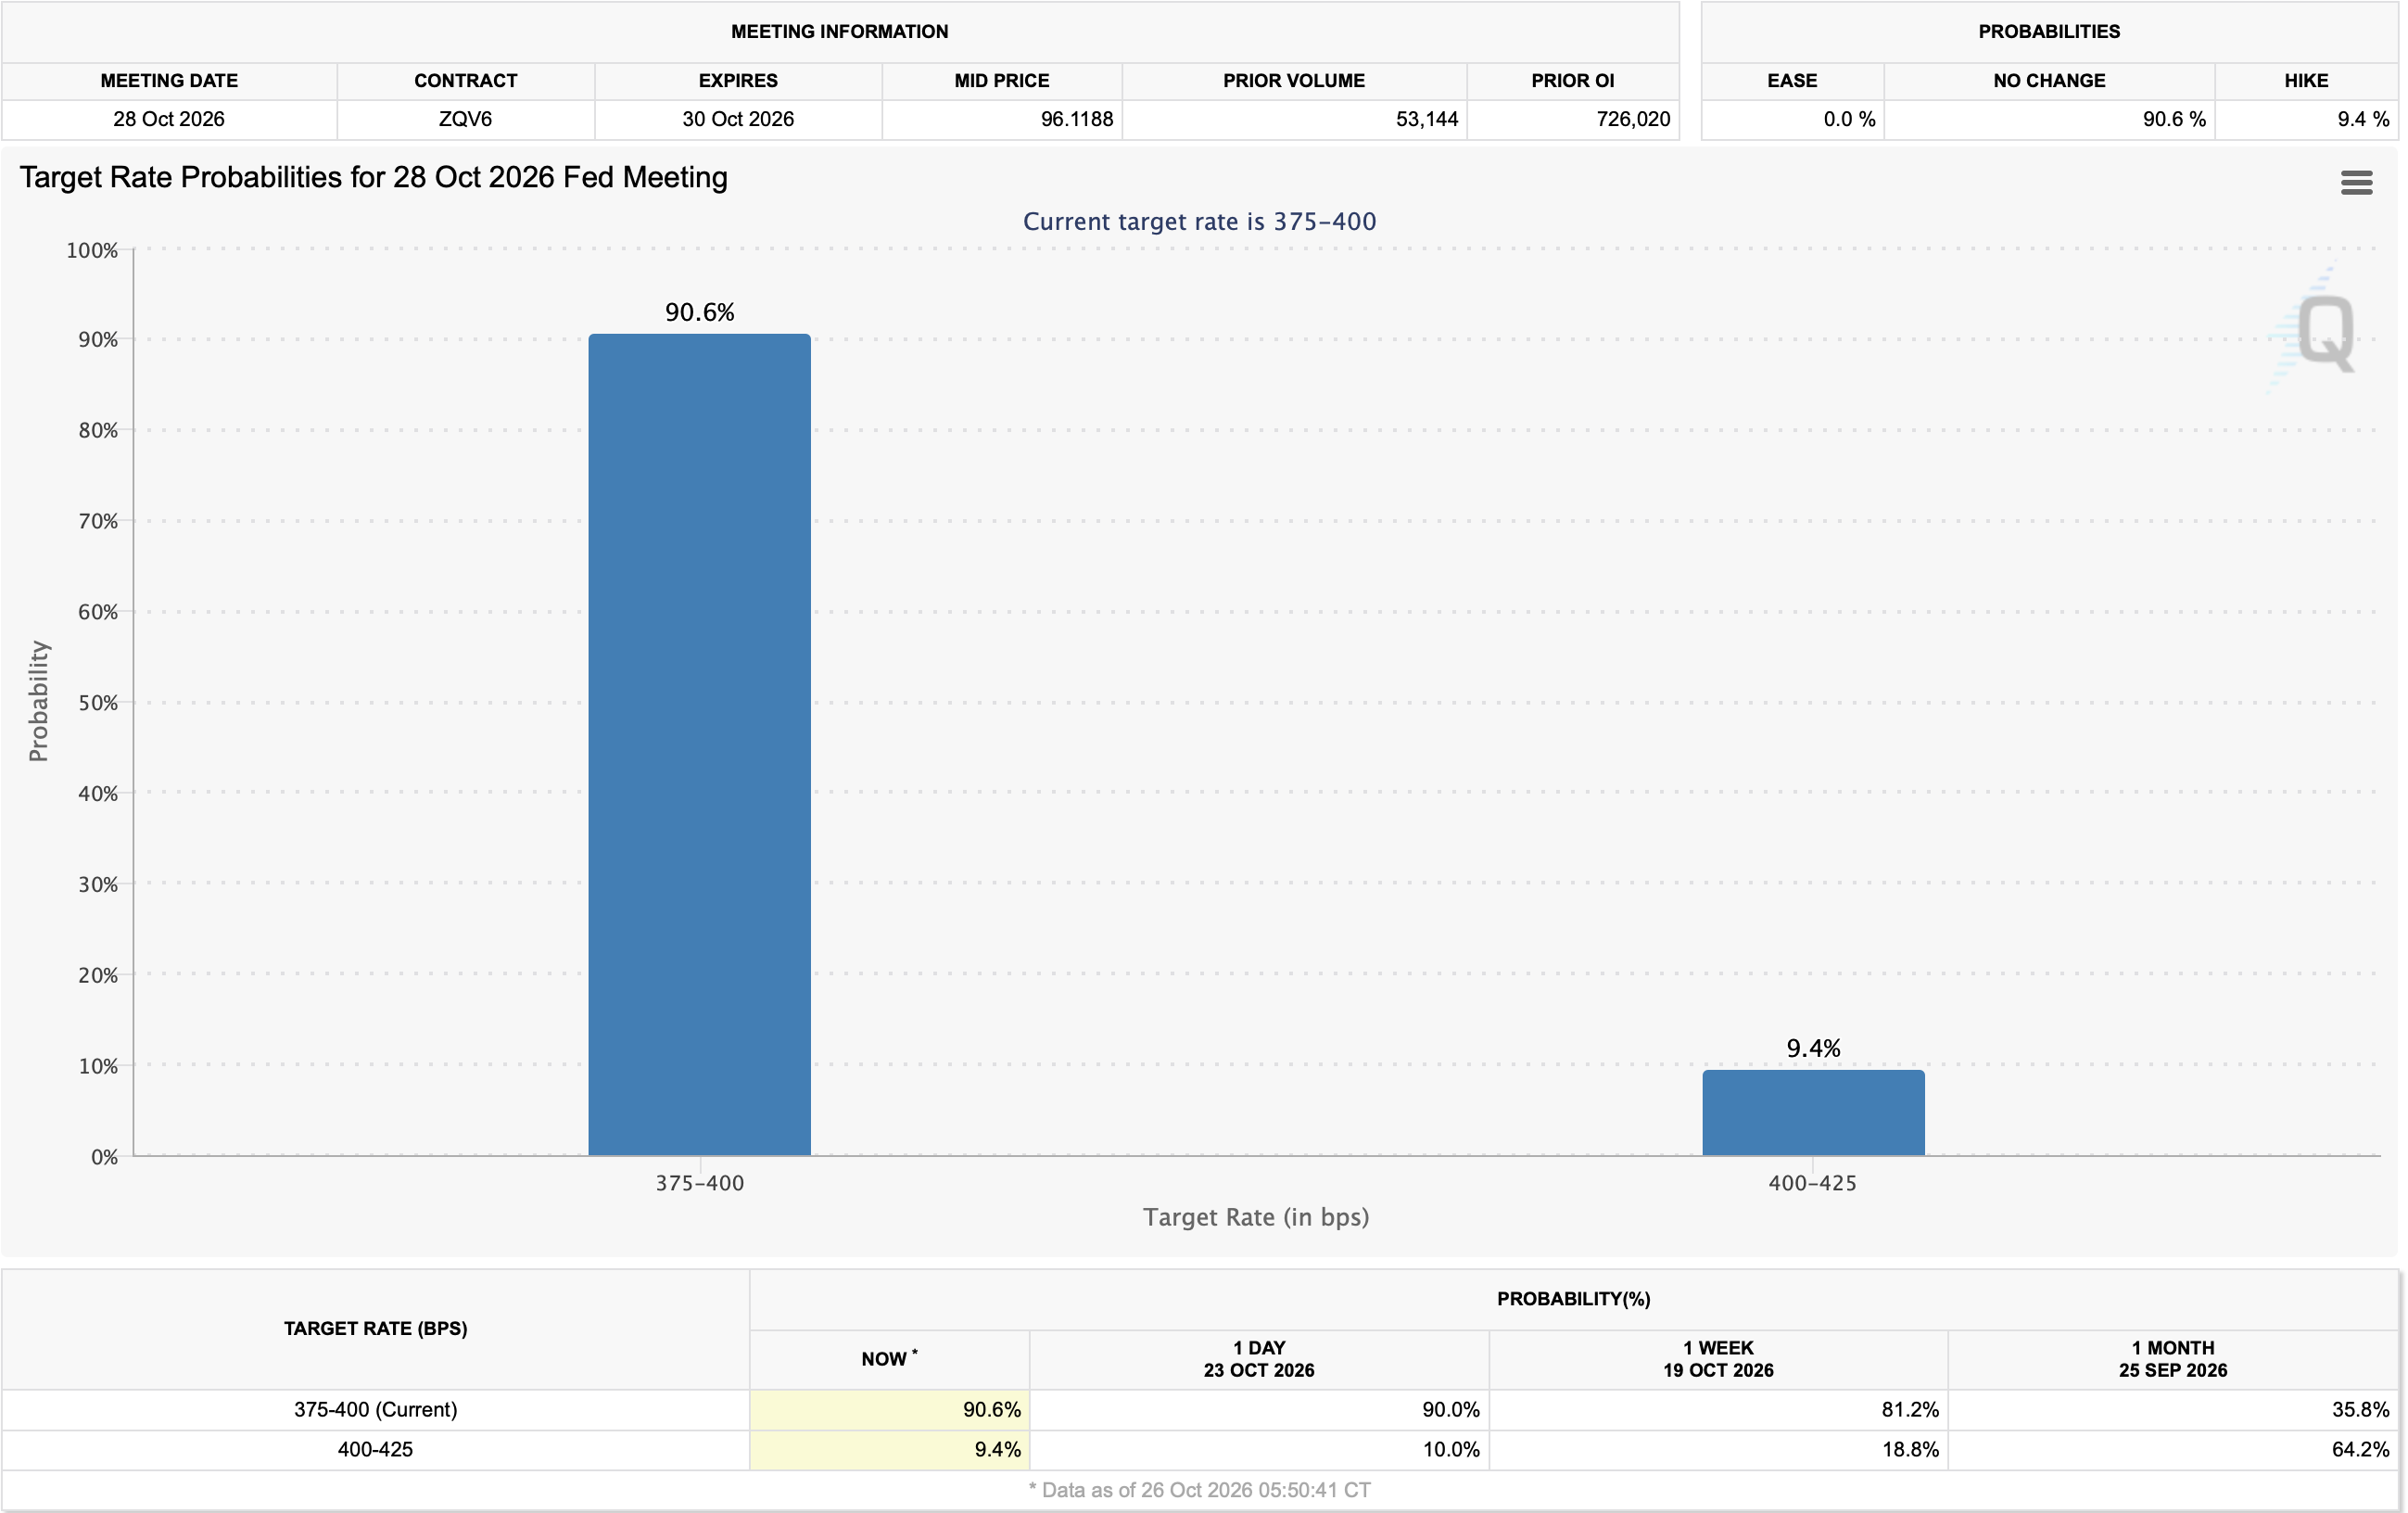
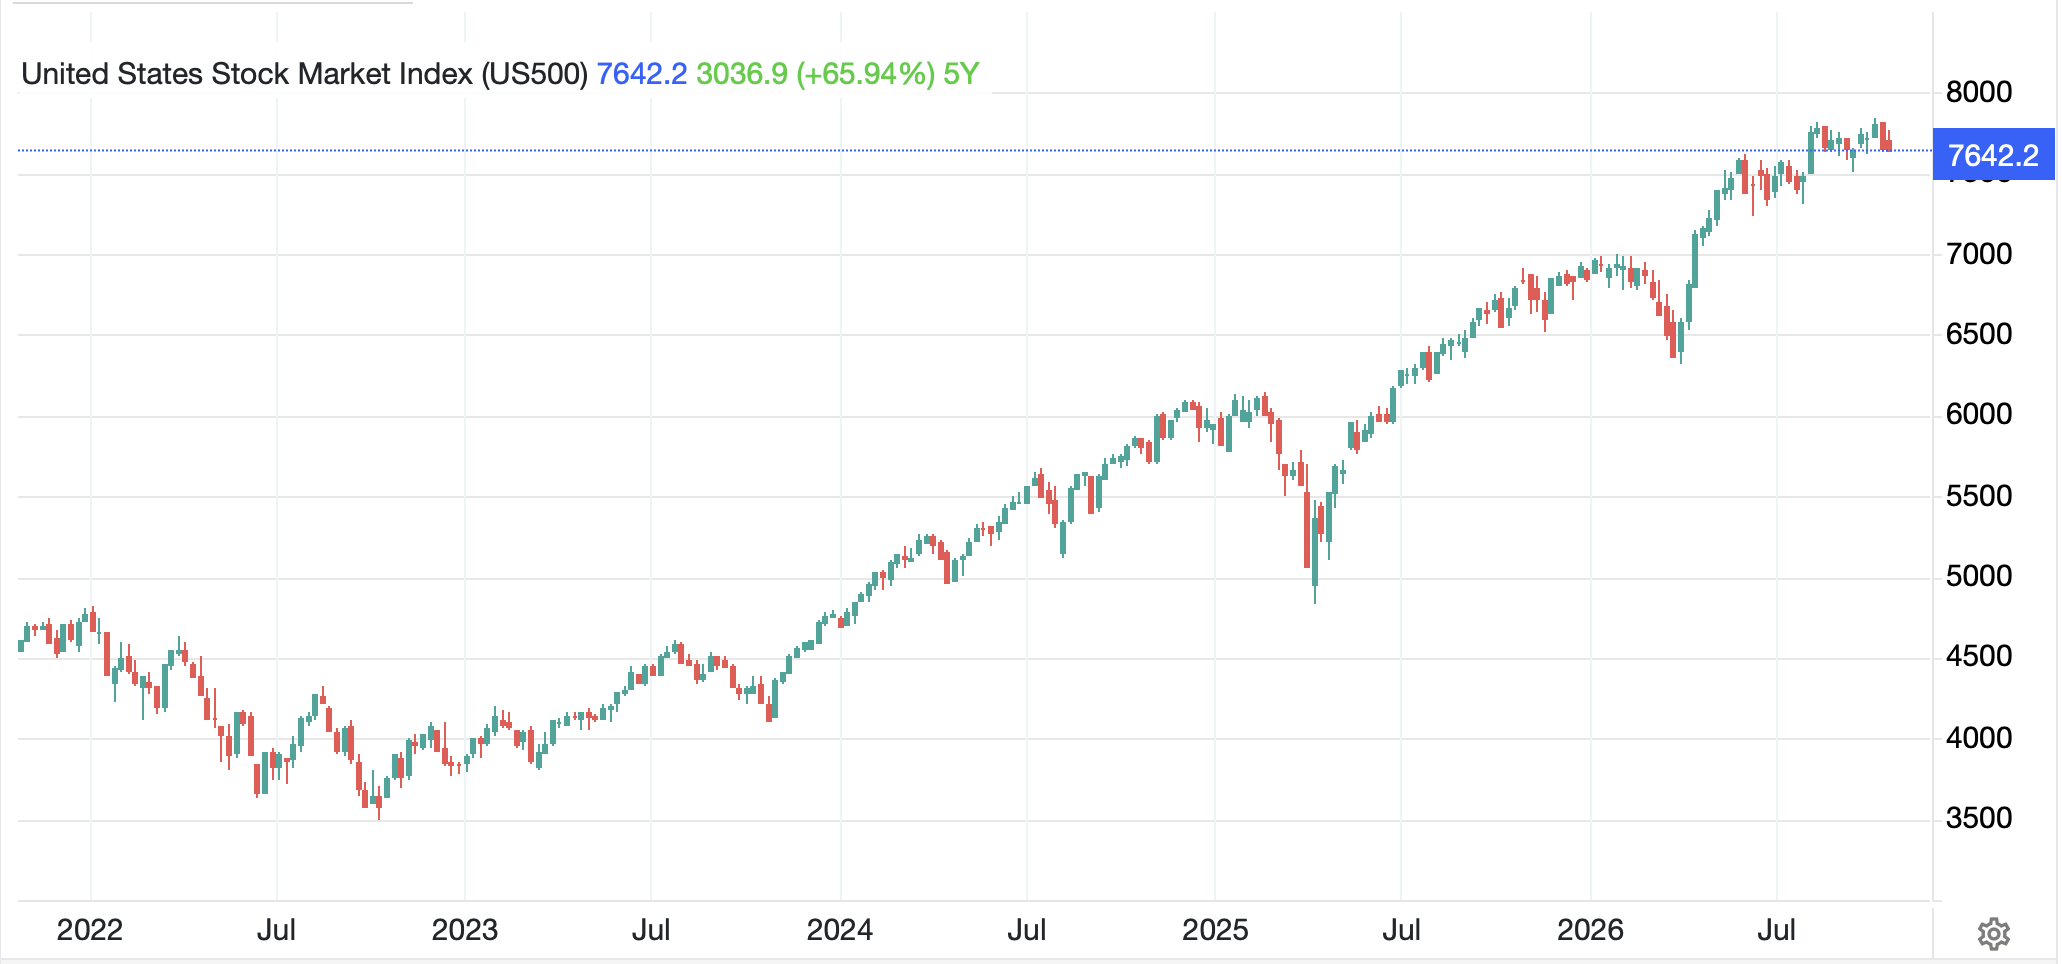
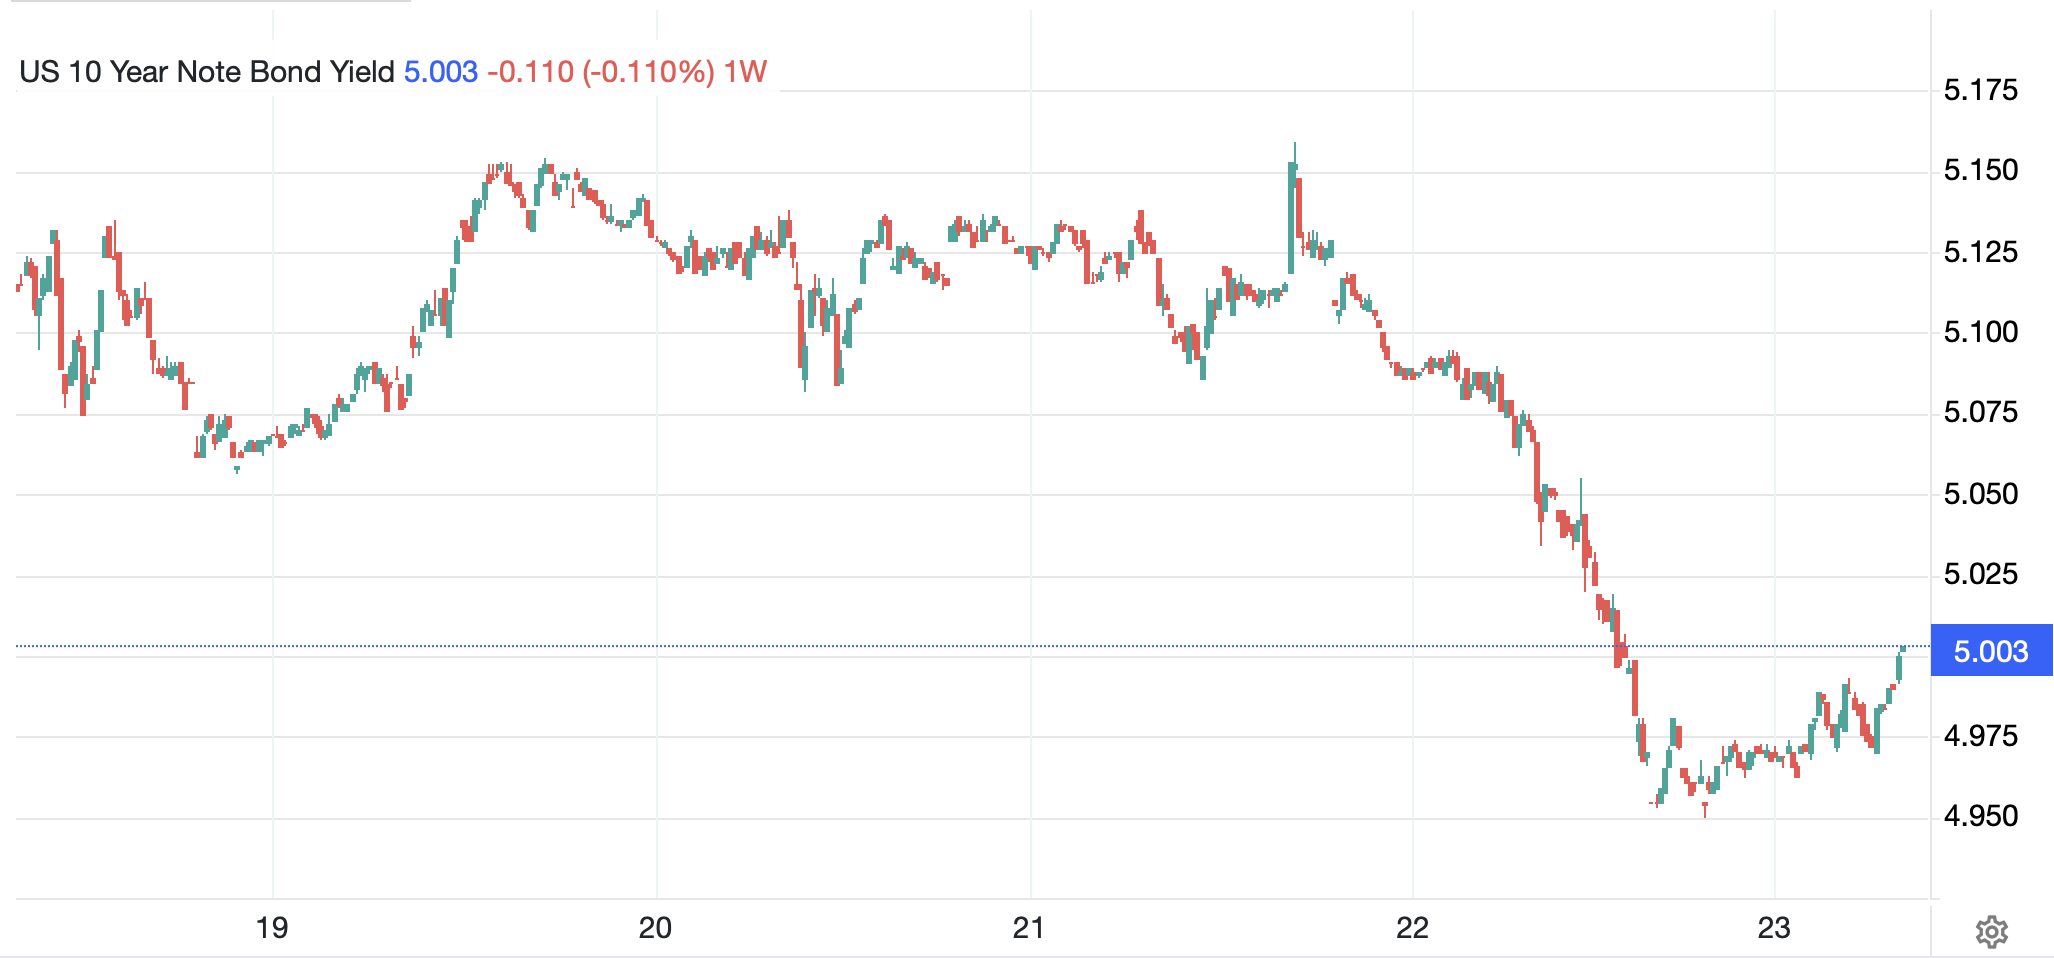
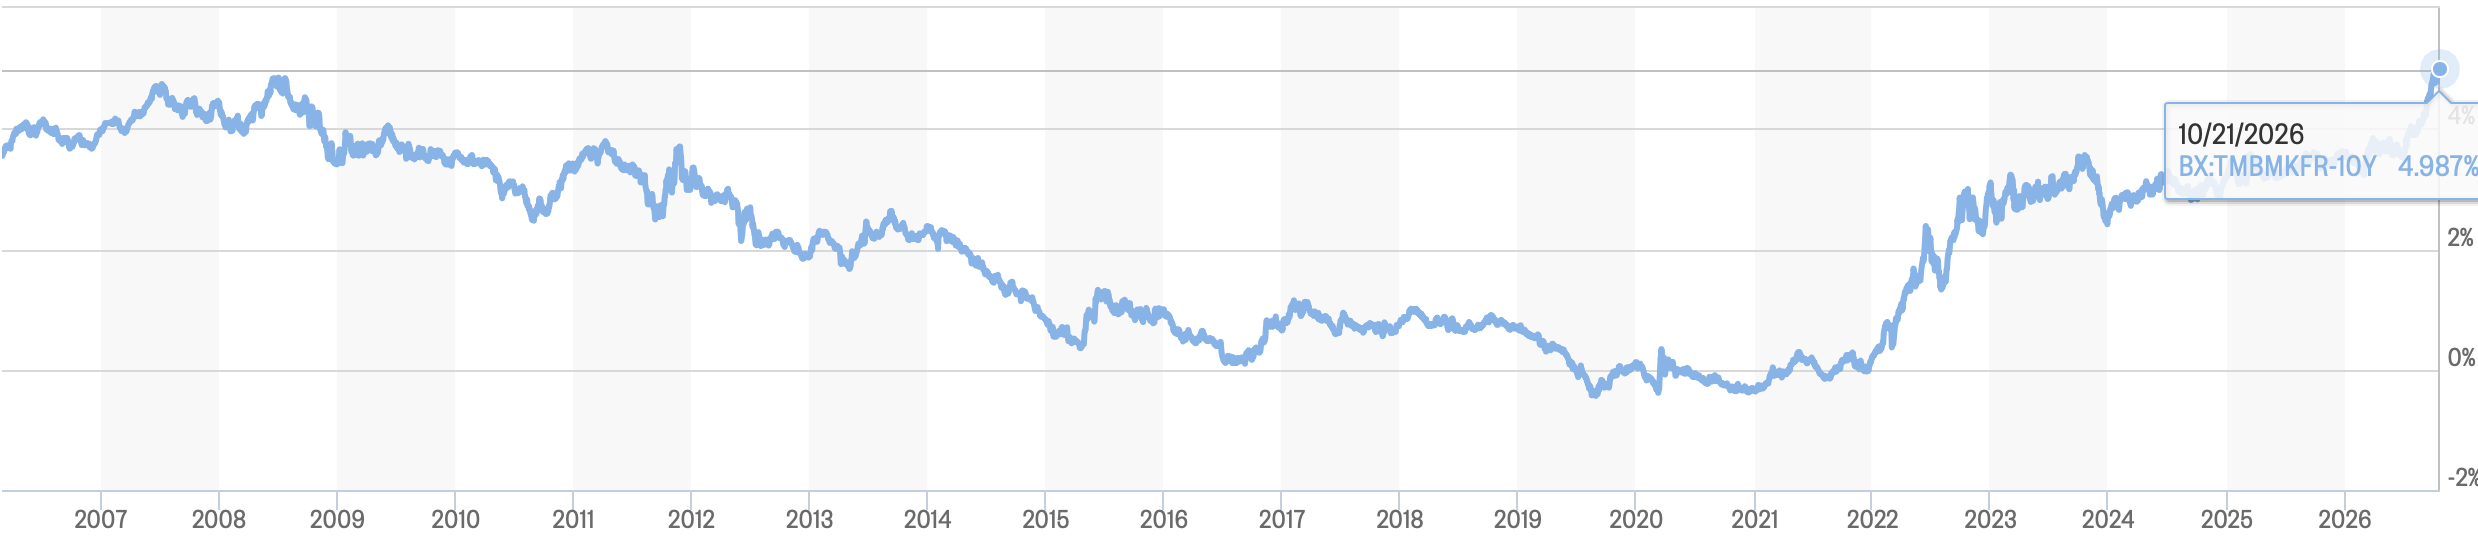
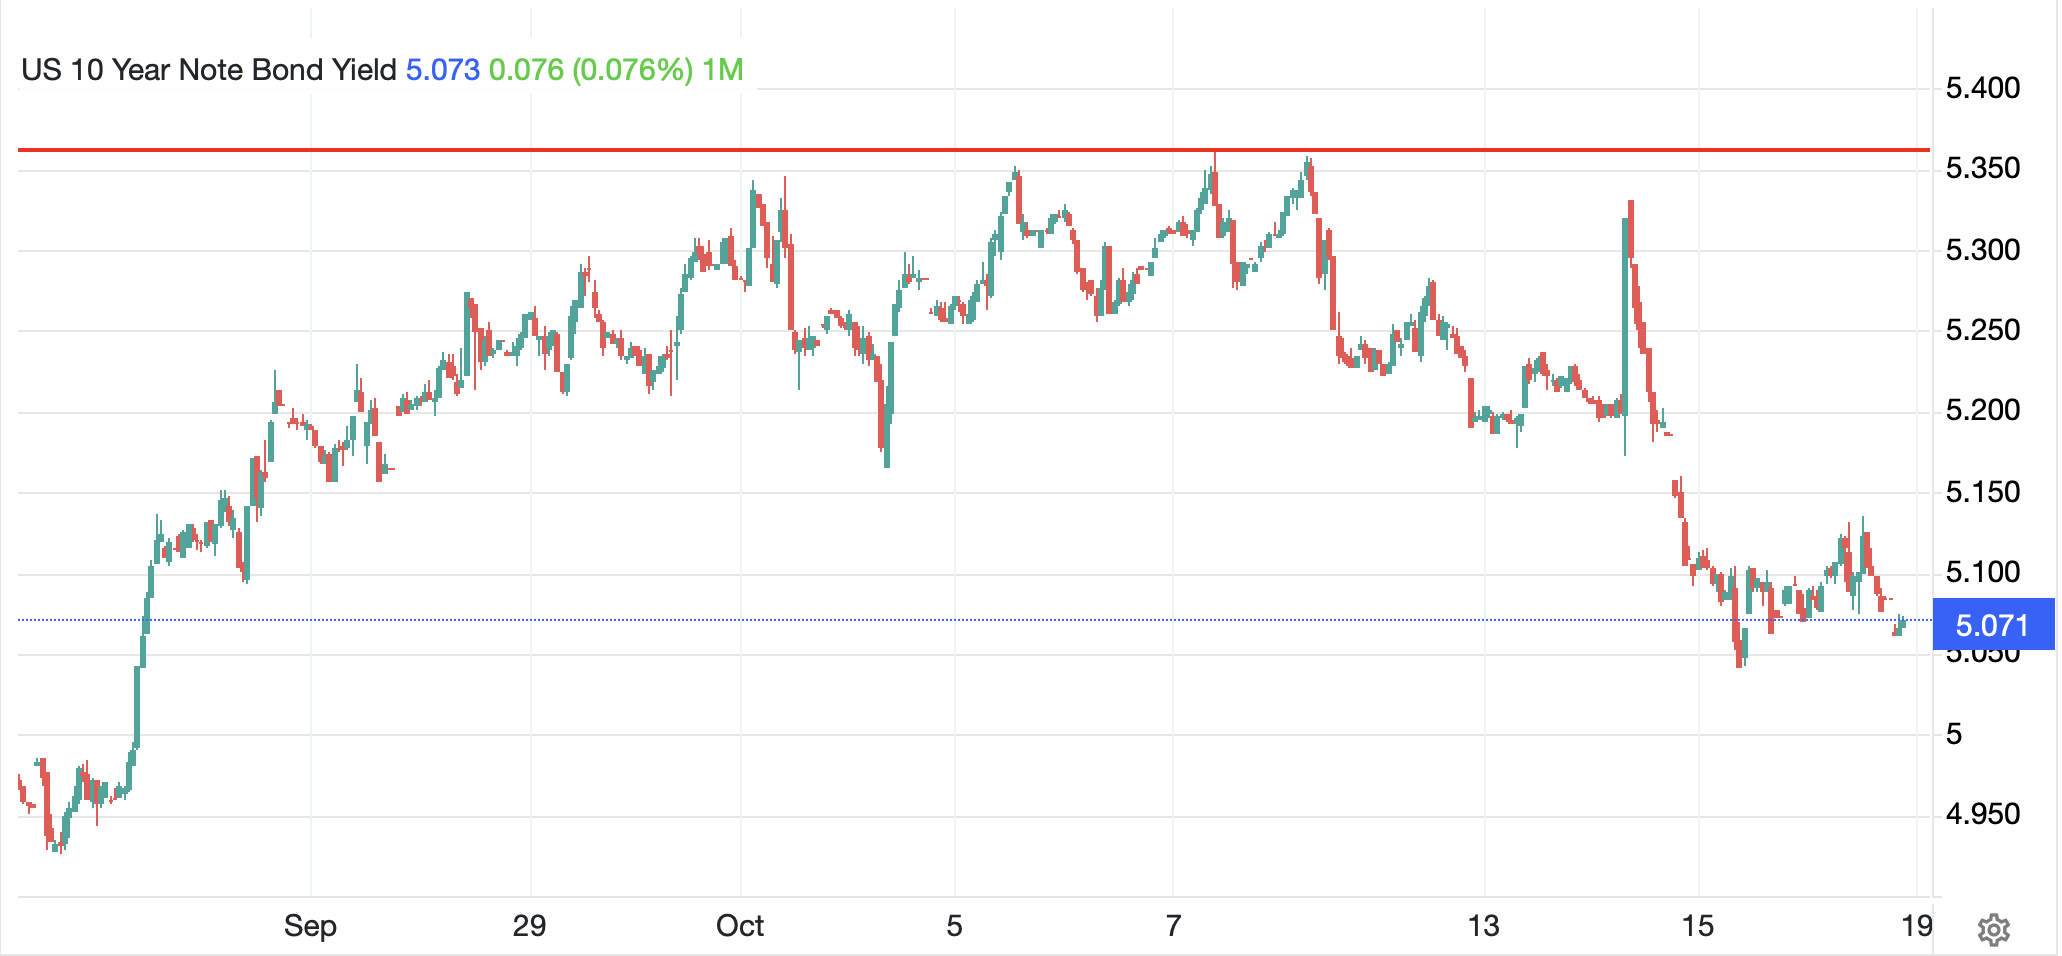
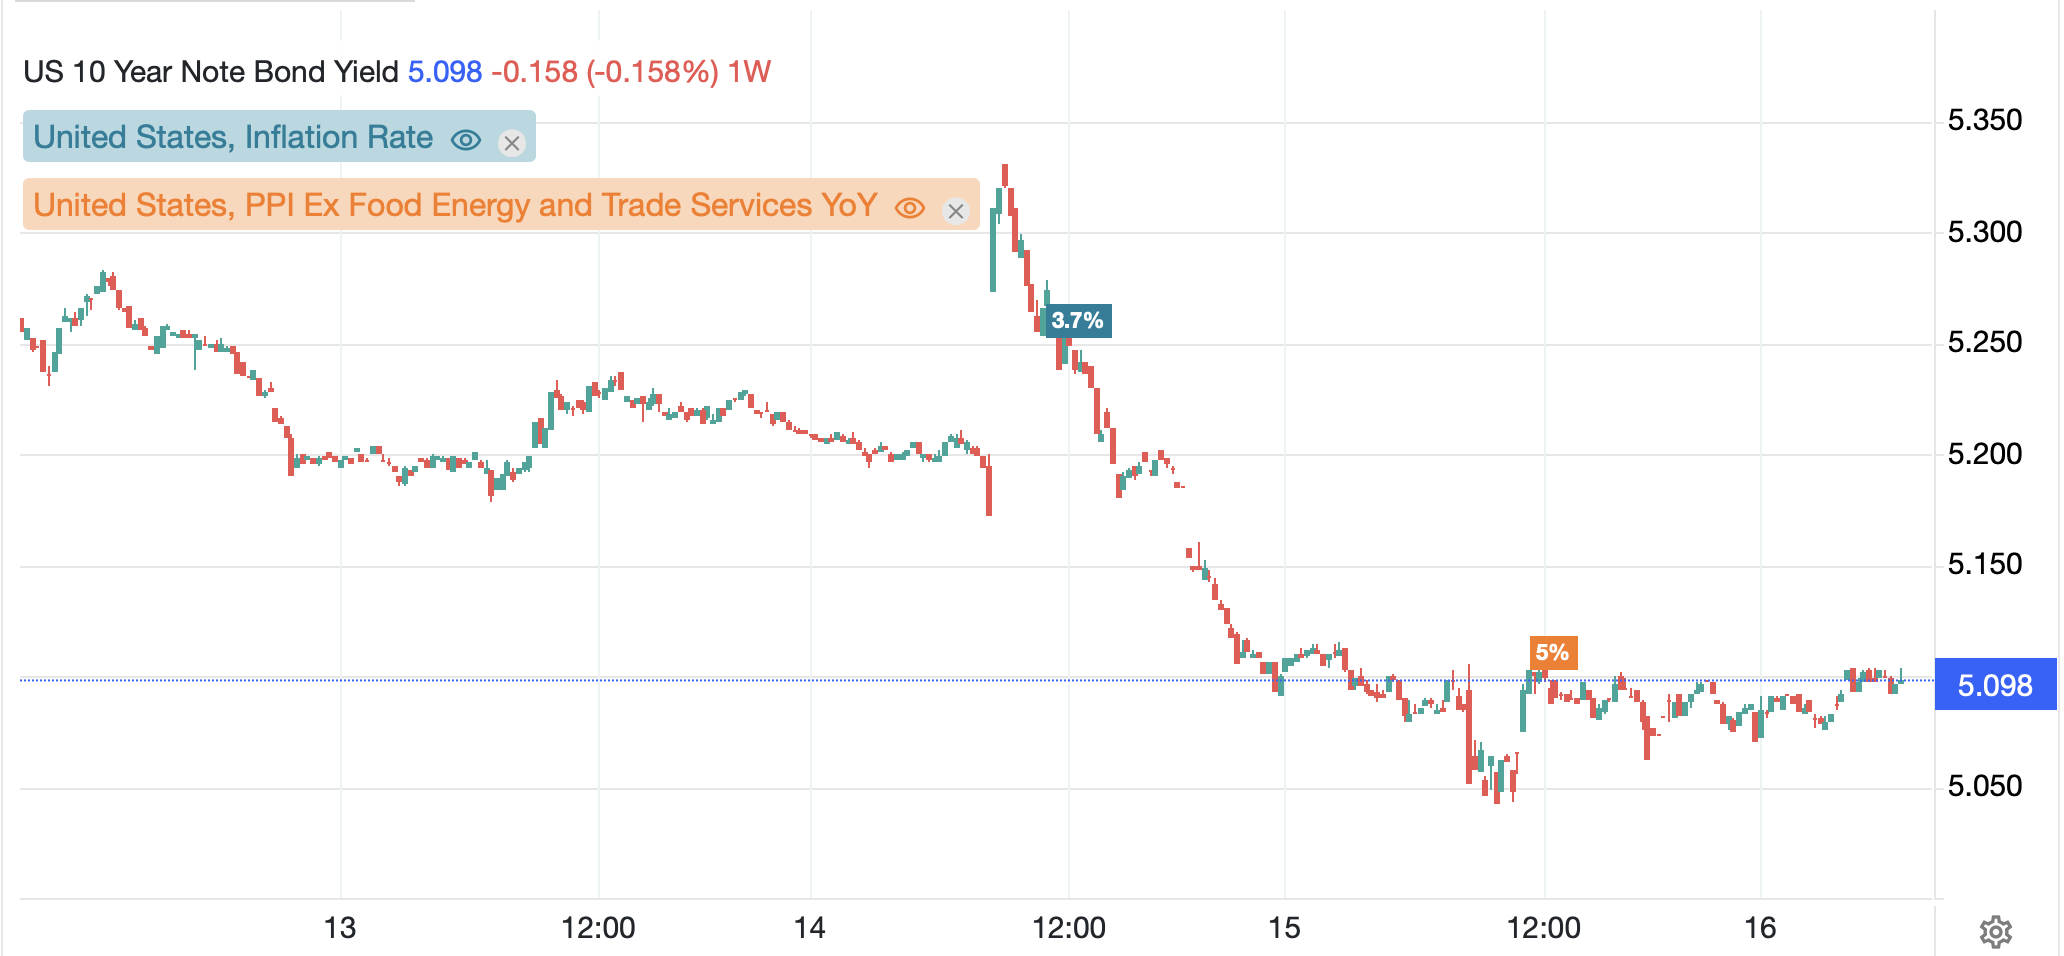
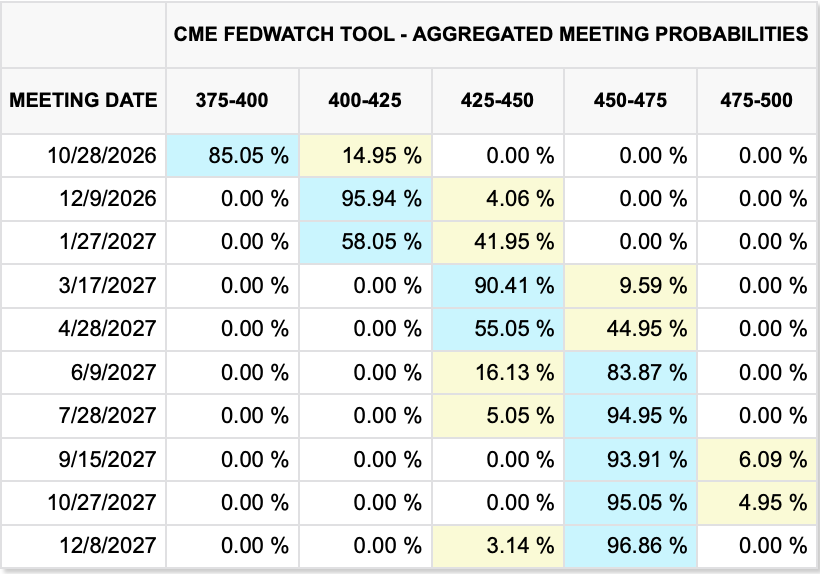
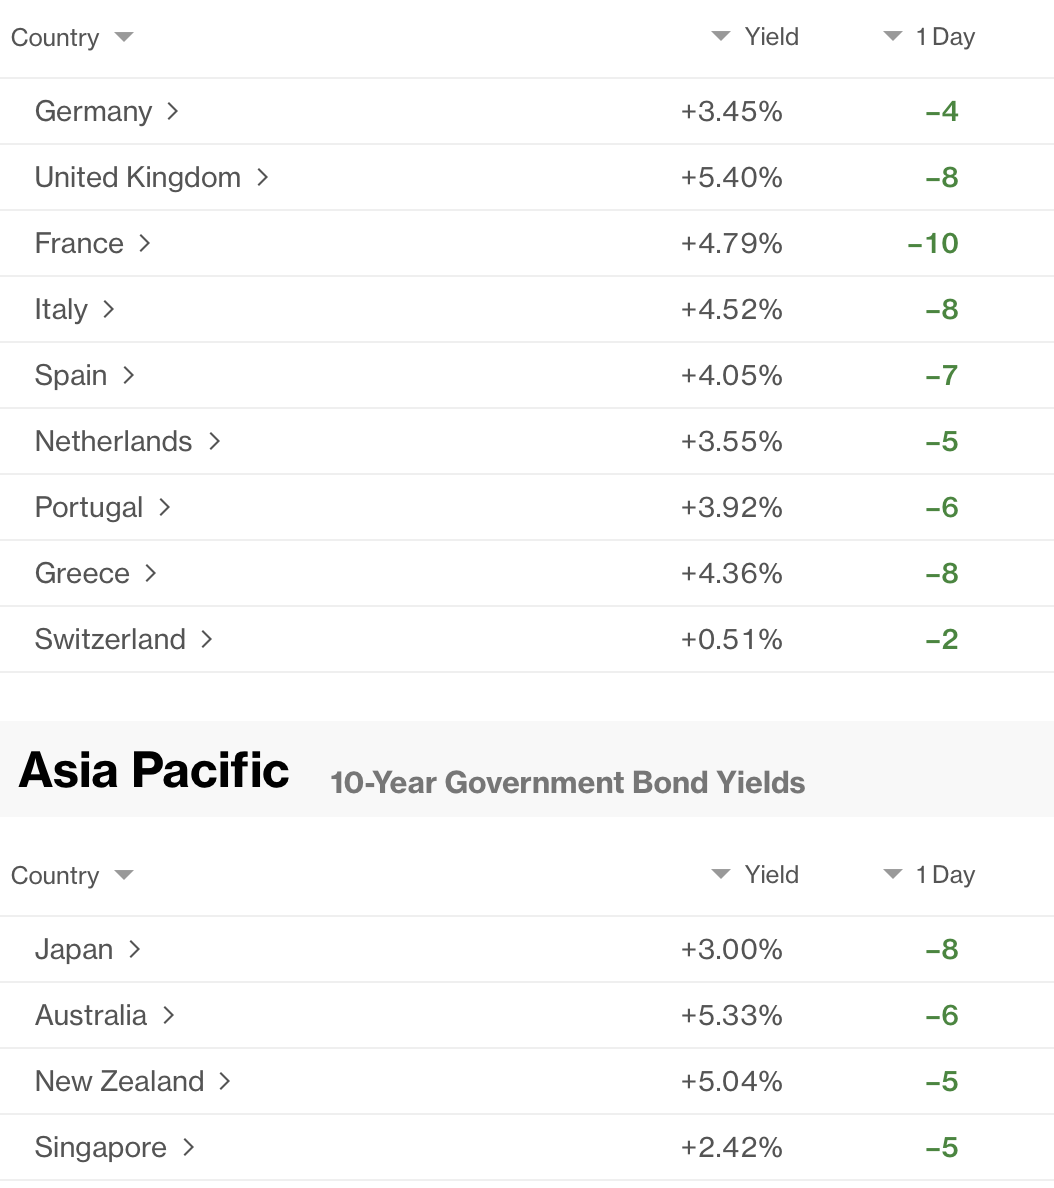
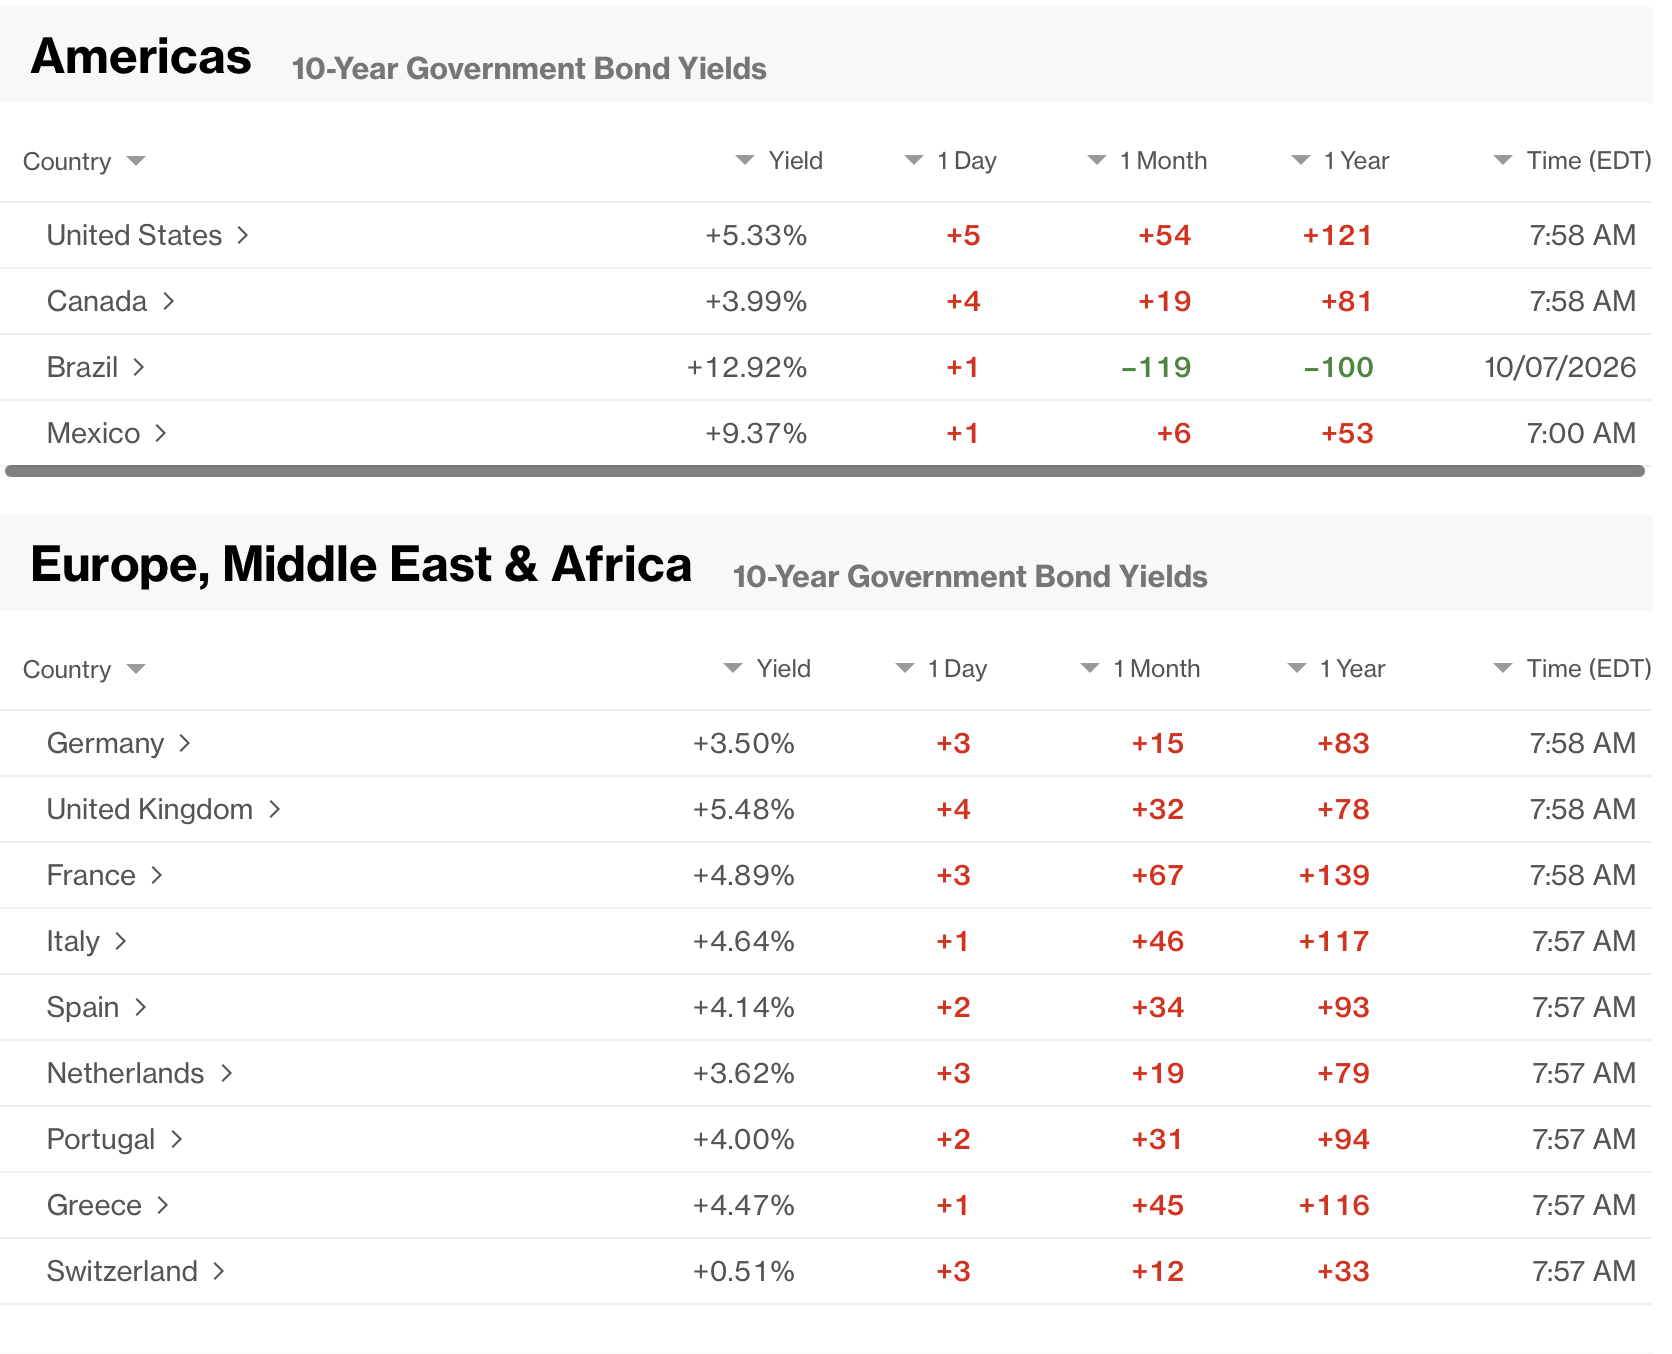
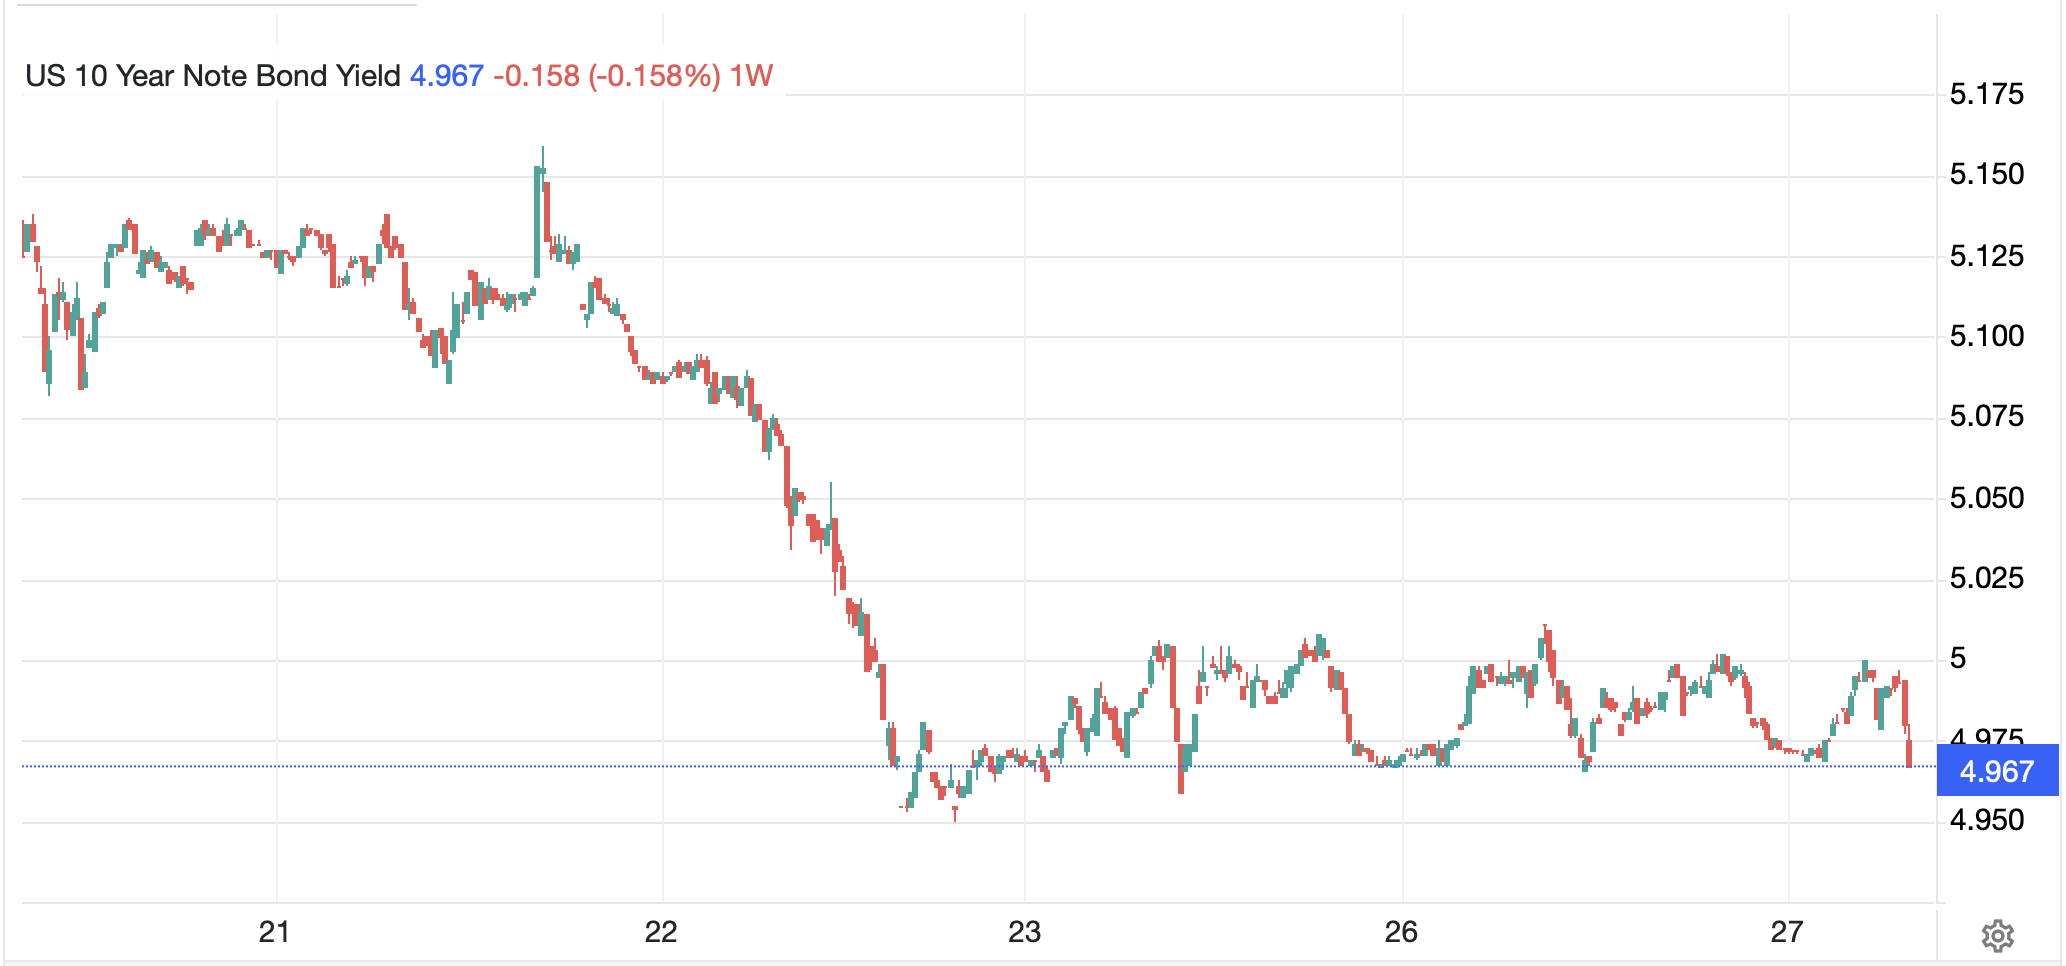
Treasury yields (-1bp) have been rangebound for the past several sessions as traders and investors await tomorrow’s FOMC statement, and perhaps more importantly, to hear what Chairman Warsh has to say.
Source: tradingeconomics.com
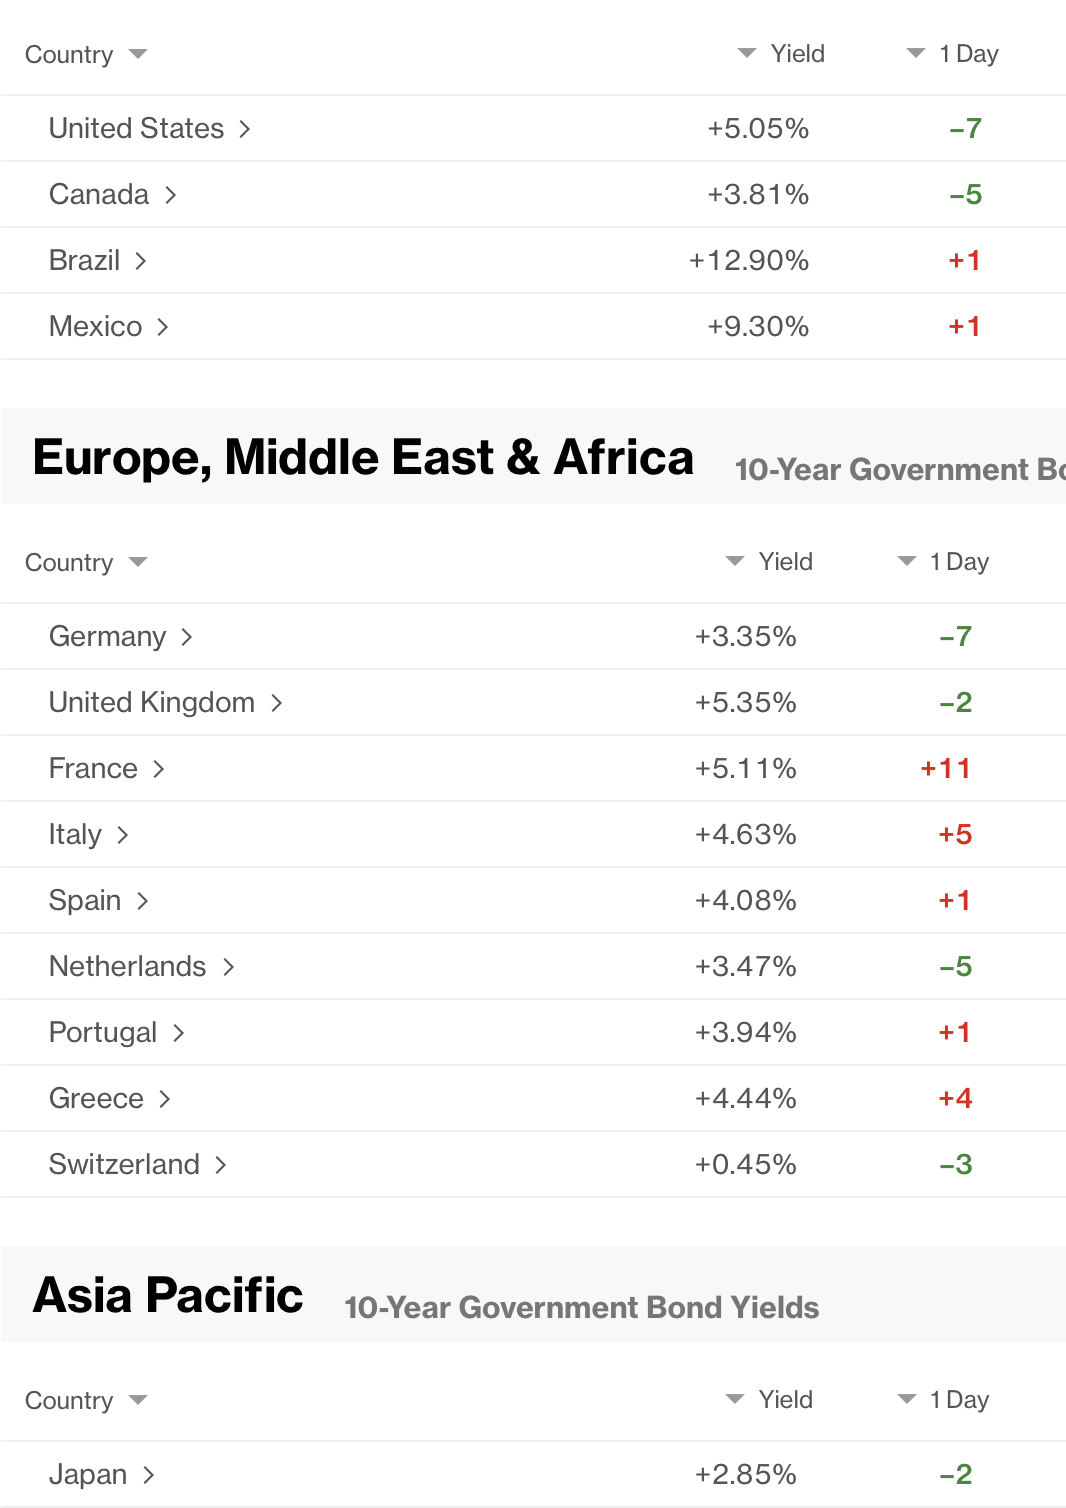
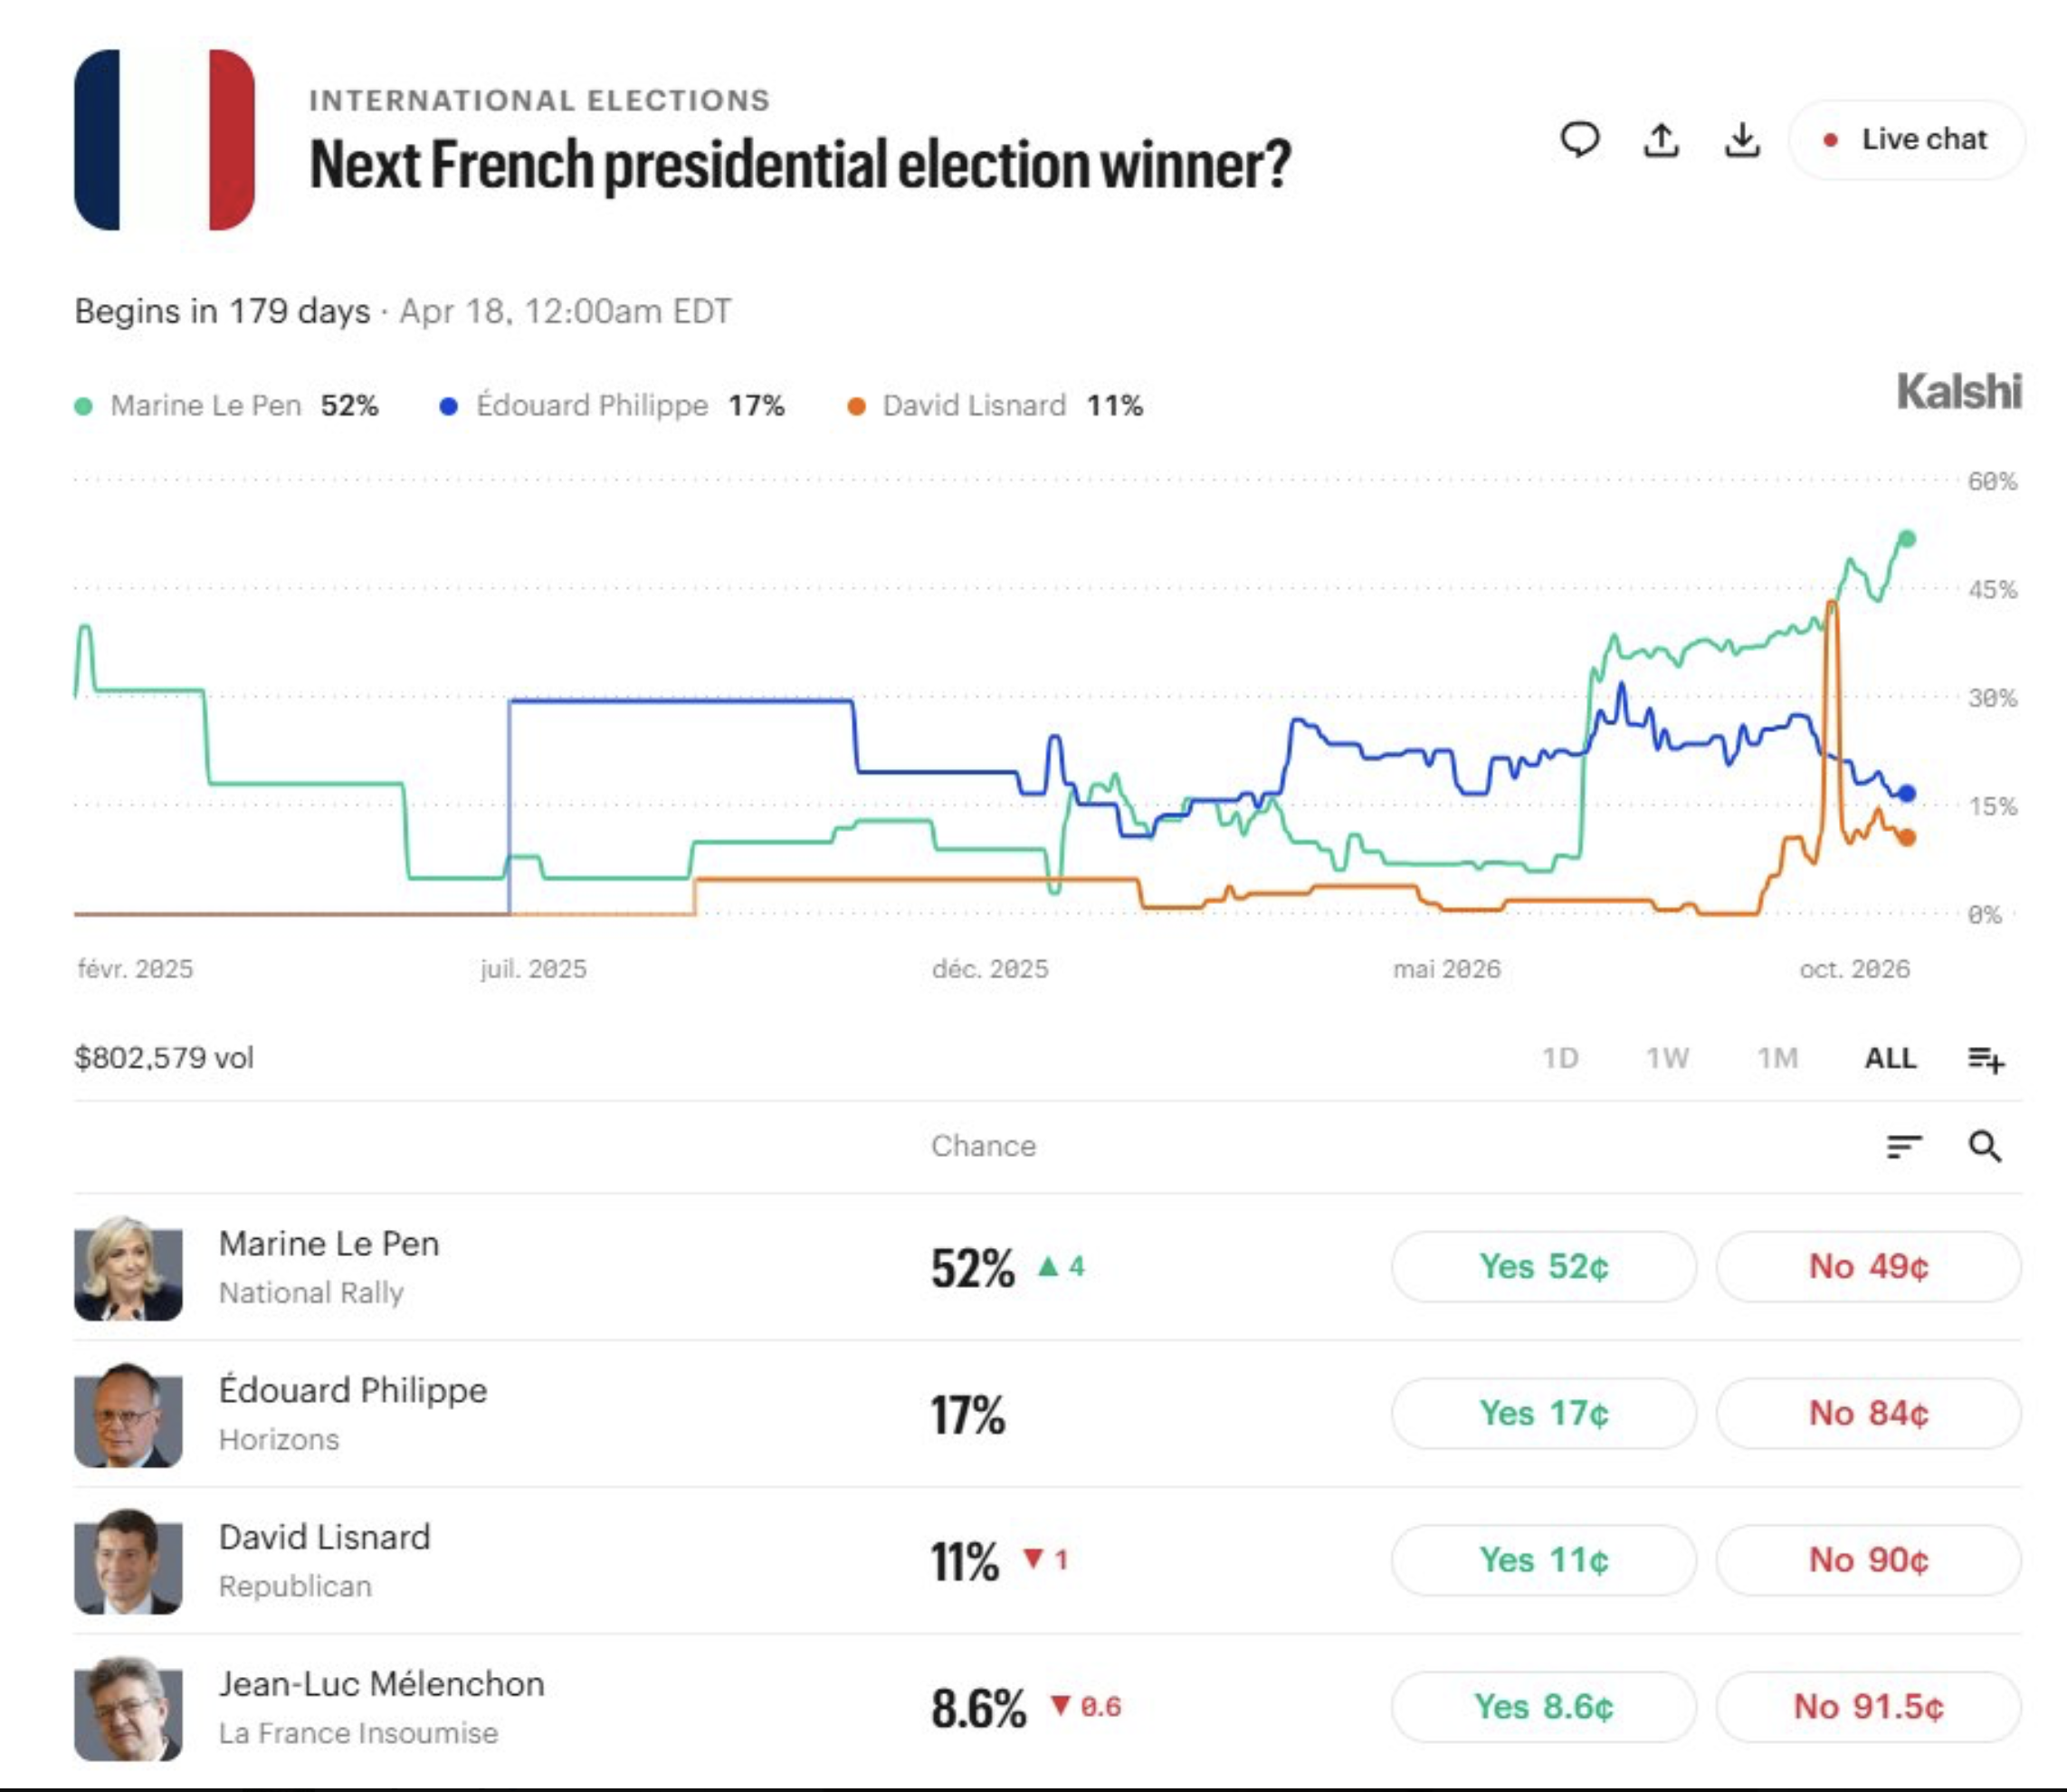
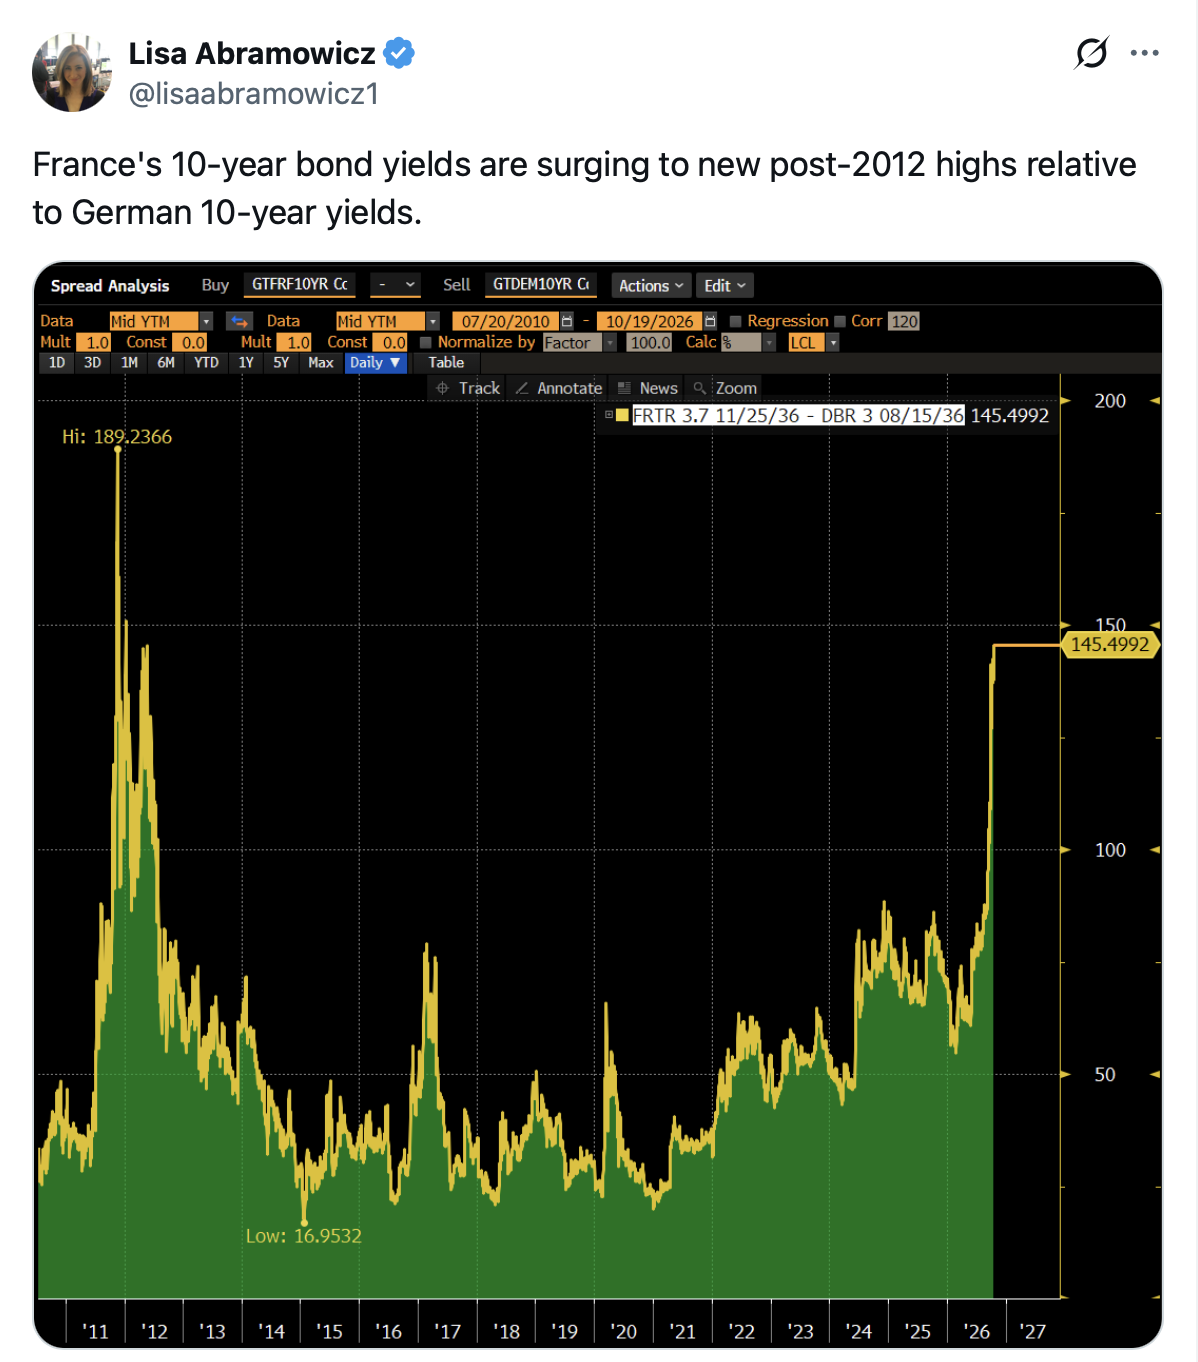
It should be no surprise that other bond markets are also doing little right now as the Treasury market remains the driver of global investment. The one exception to that rule is France, where OATs (+5bps) are back under pressure as market participants try to determine what comes next there. Calls for increased protests have been coming from various groups involved while Marine LePen offers herself as a voice of calm in the chaos as she campaigns for the presidency. However, both sides of the campaign are claiming they will lower the retirement age from the current 62 down to 60, a move the nation simply cannot afford. Perhaps they will and simultaneously pull themselves from the euro so they can print worthless French francs to pay those increased pensions.
As an aside, I neglected to mention two other central bank meetings this week with the BOC expected to announce a 25bp hike Wednesday morning before the Fed stands pat, and then the ECB expected to sit on its hands on Thursday, although recent commentary has them considering another hike before the end of the year as they are trying to entrench a recessionprevent inflation from becoming entrenched.
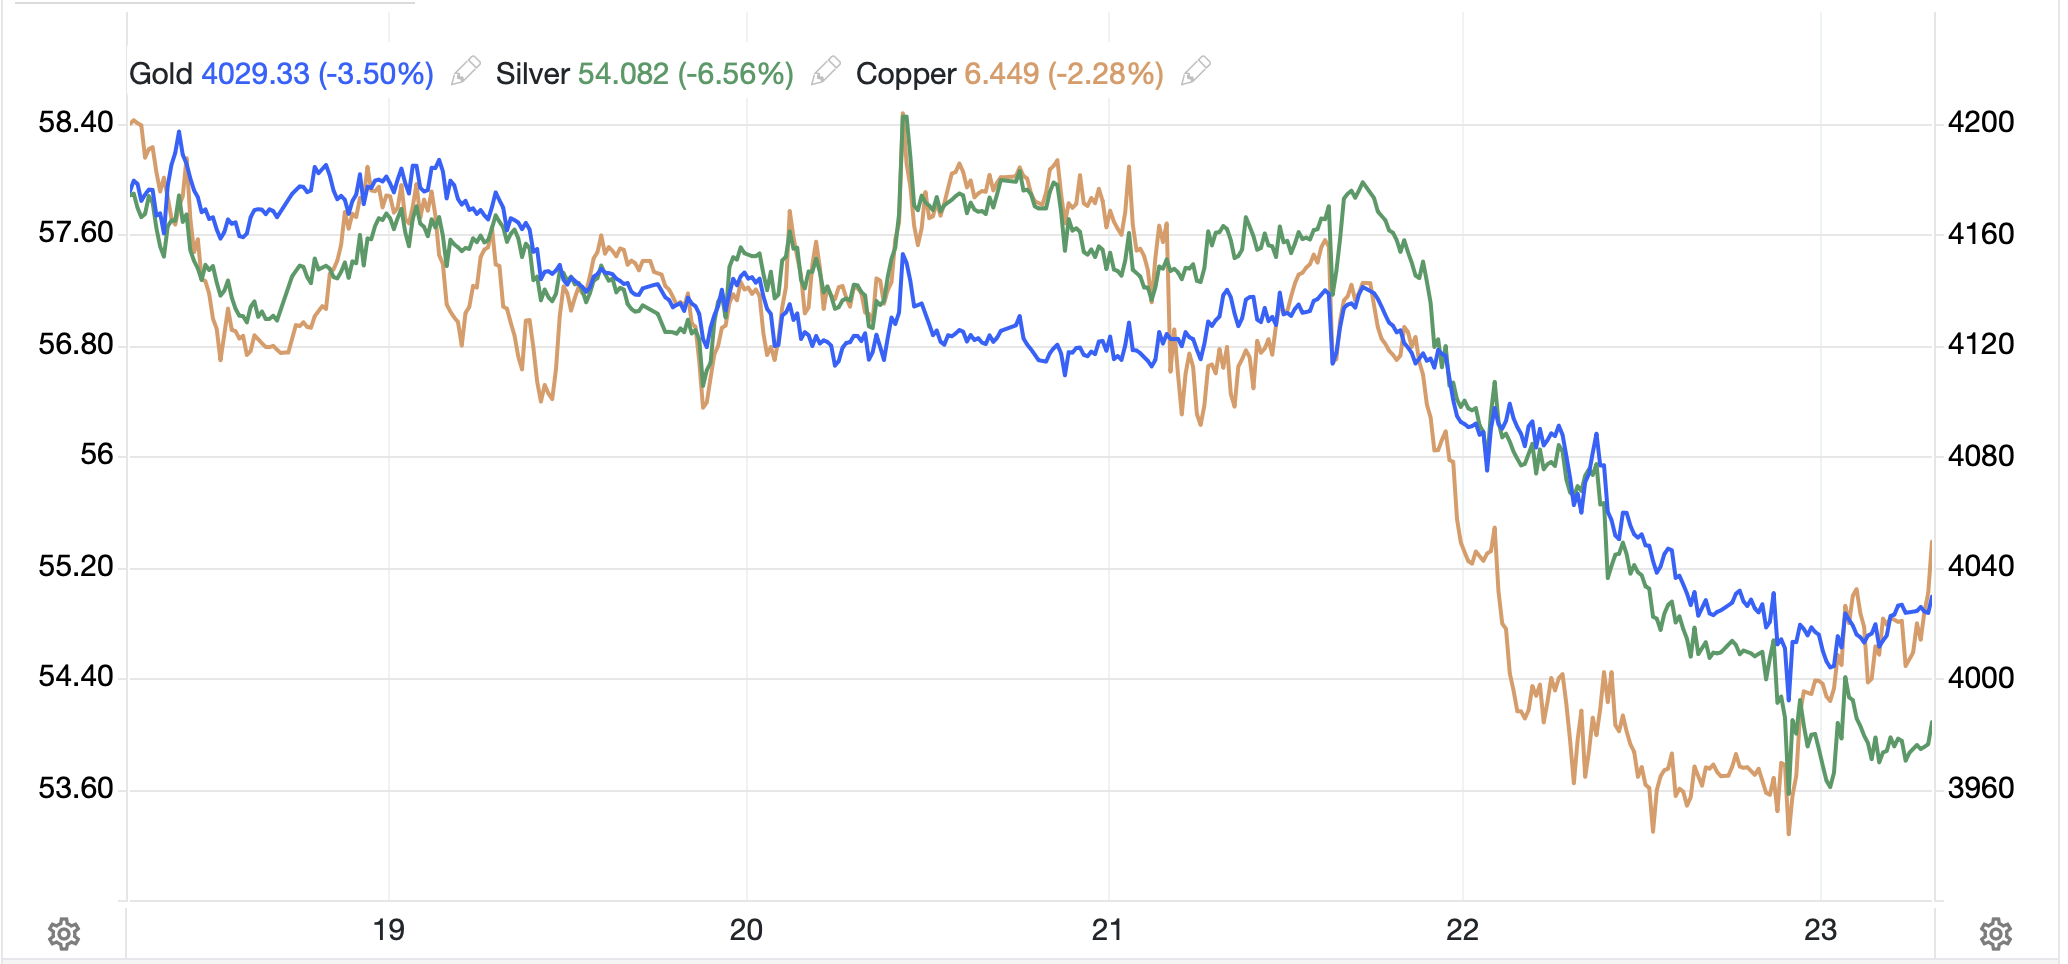
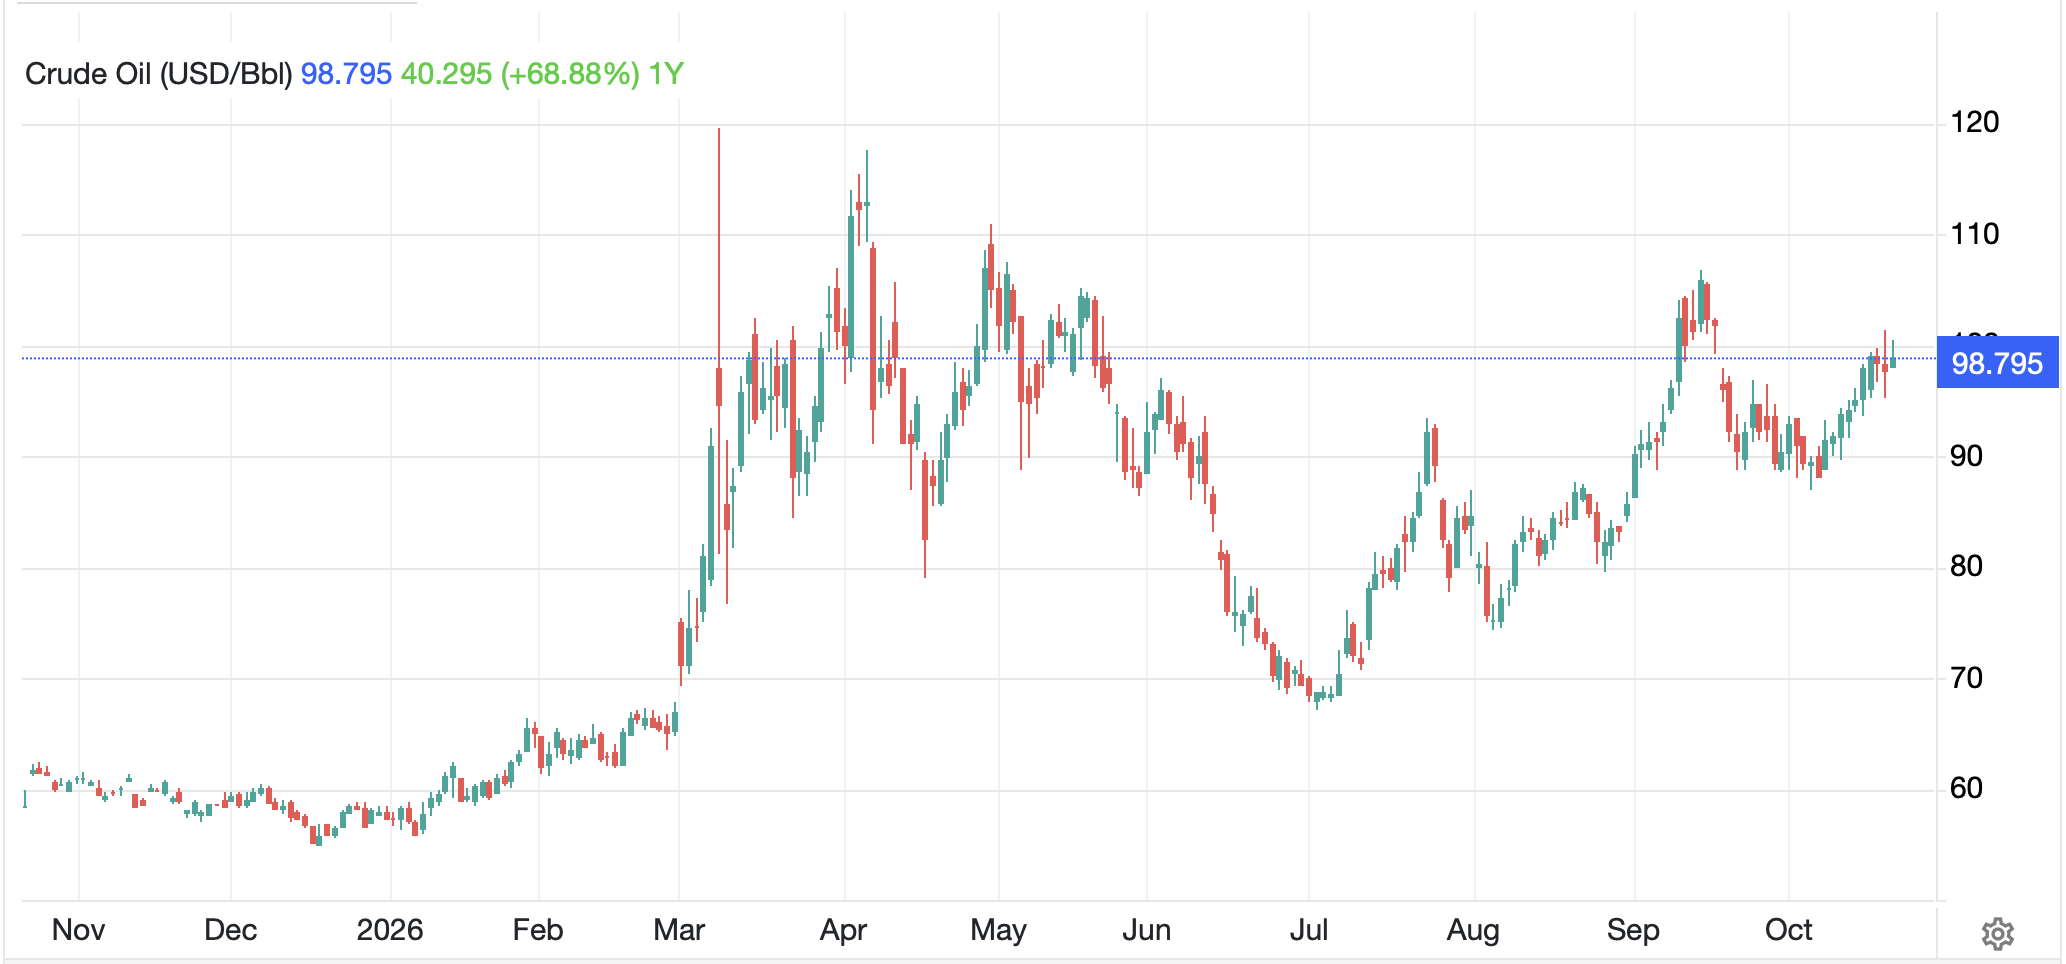
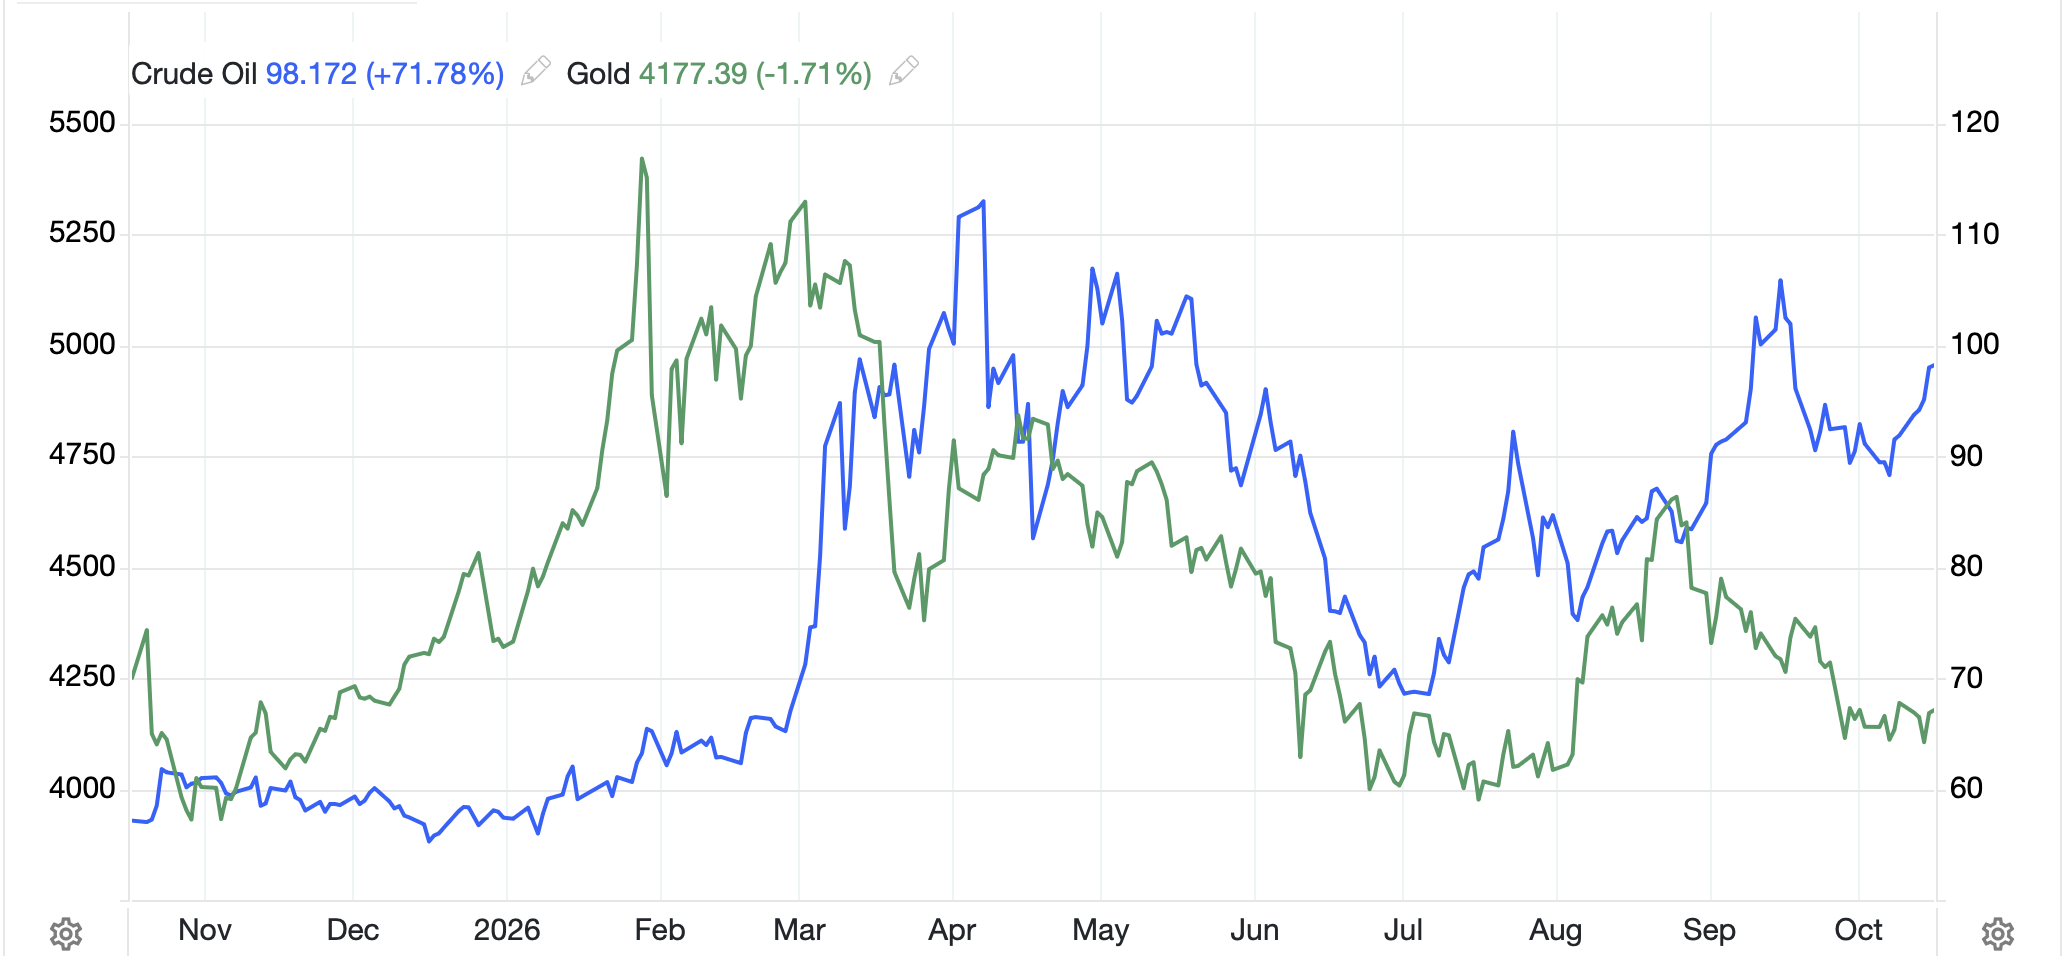
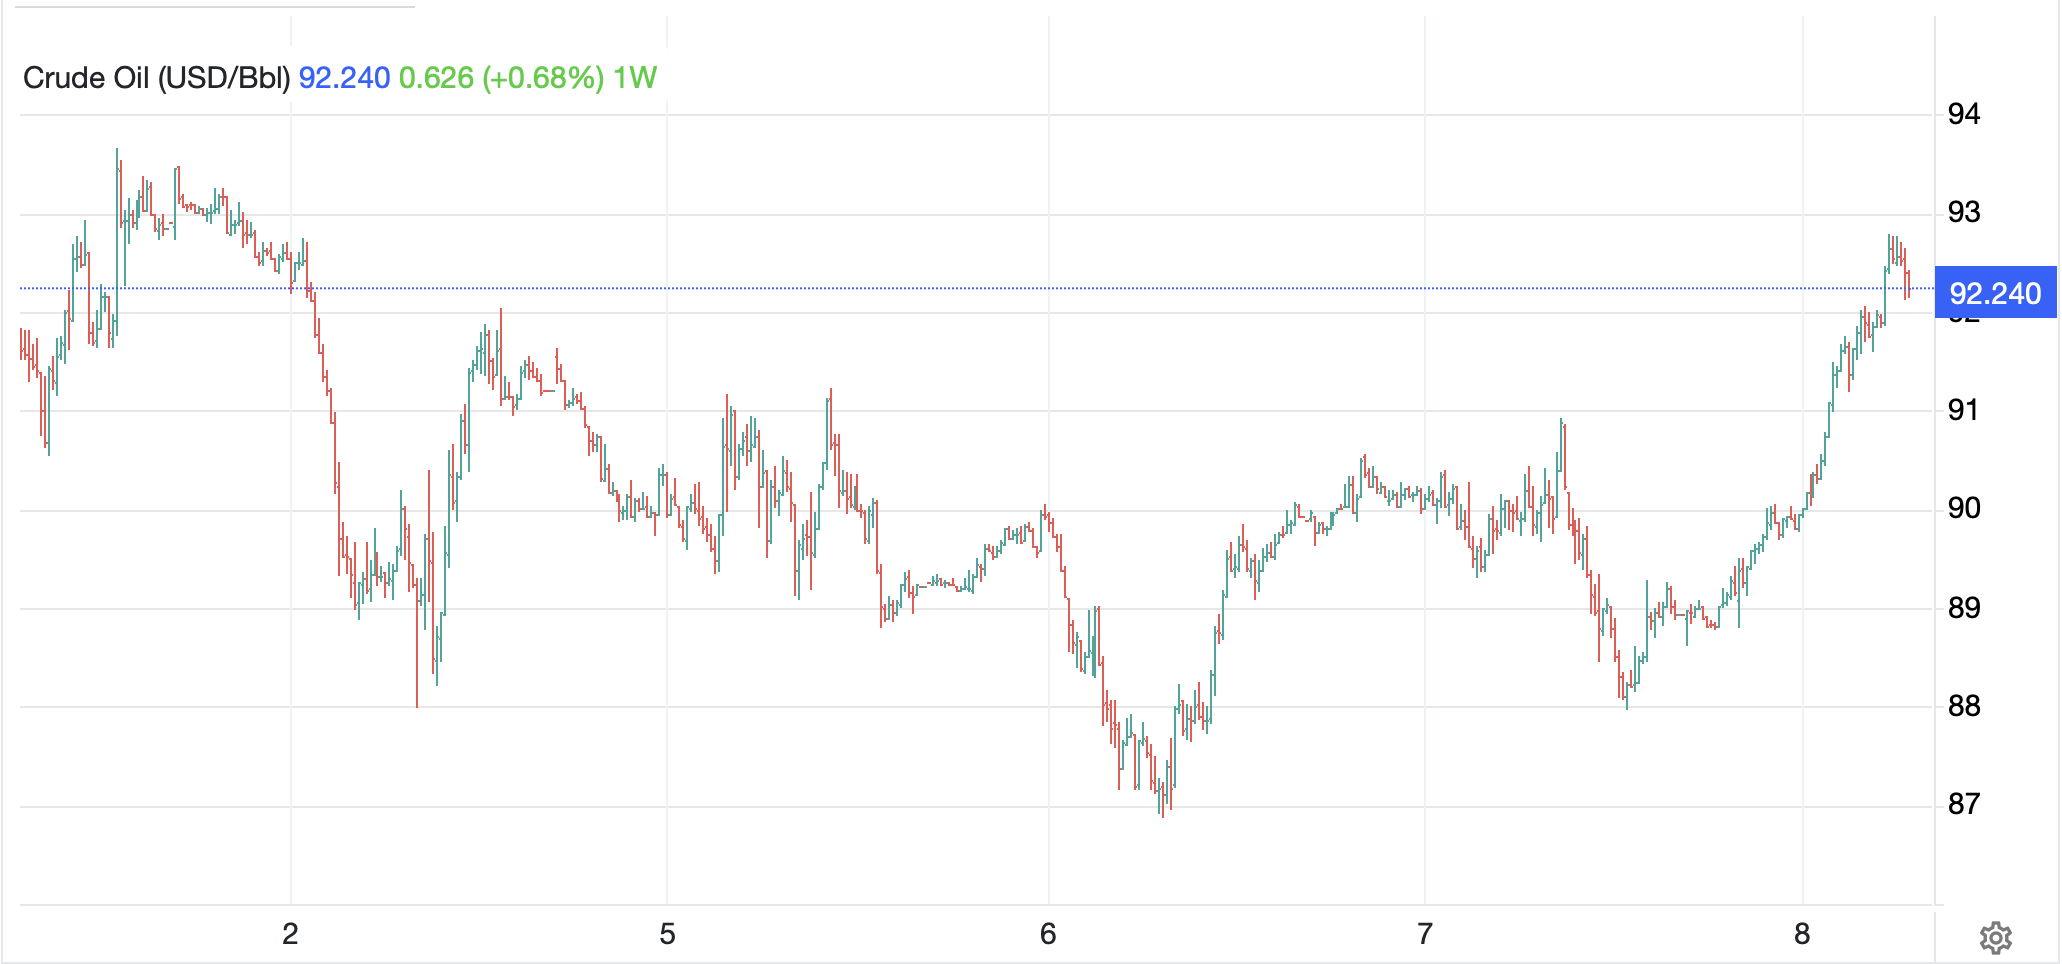
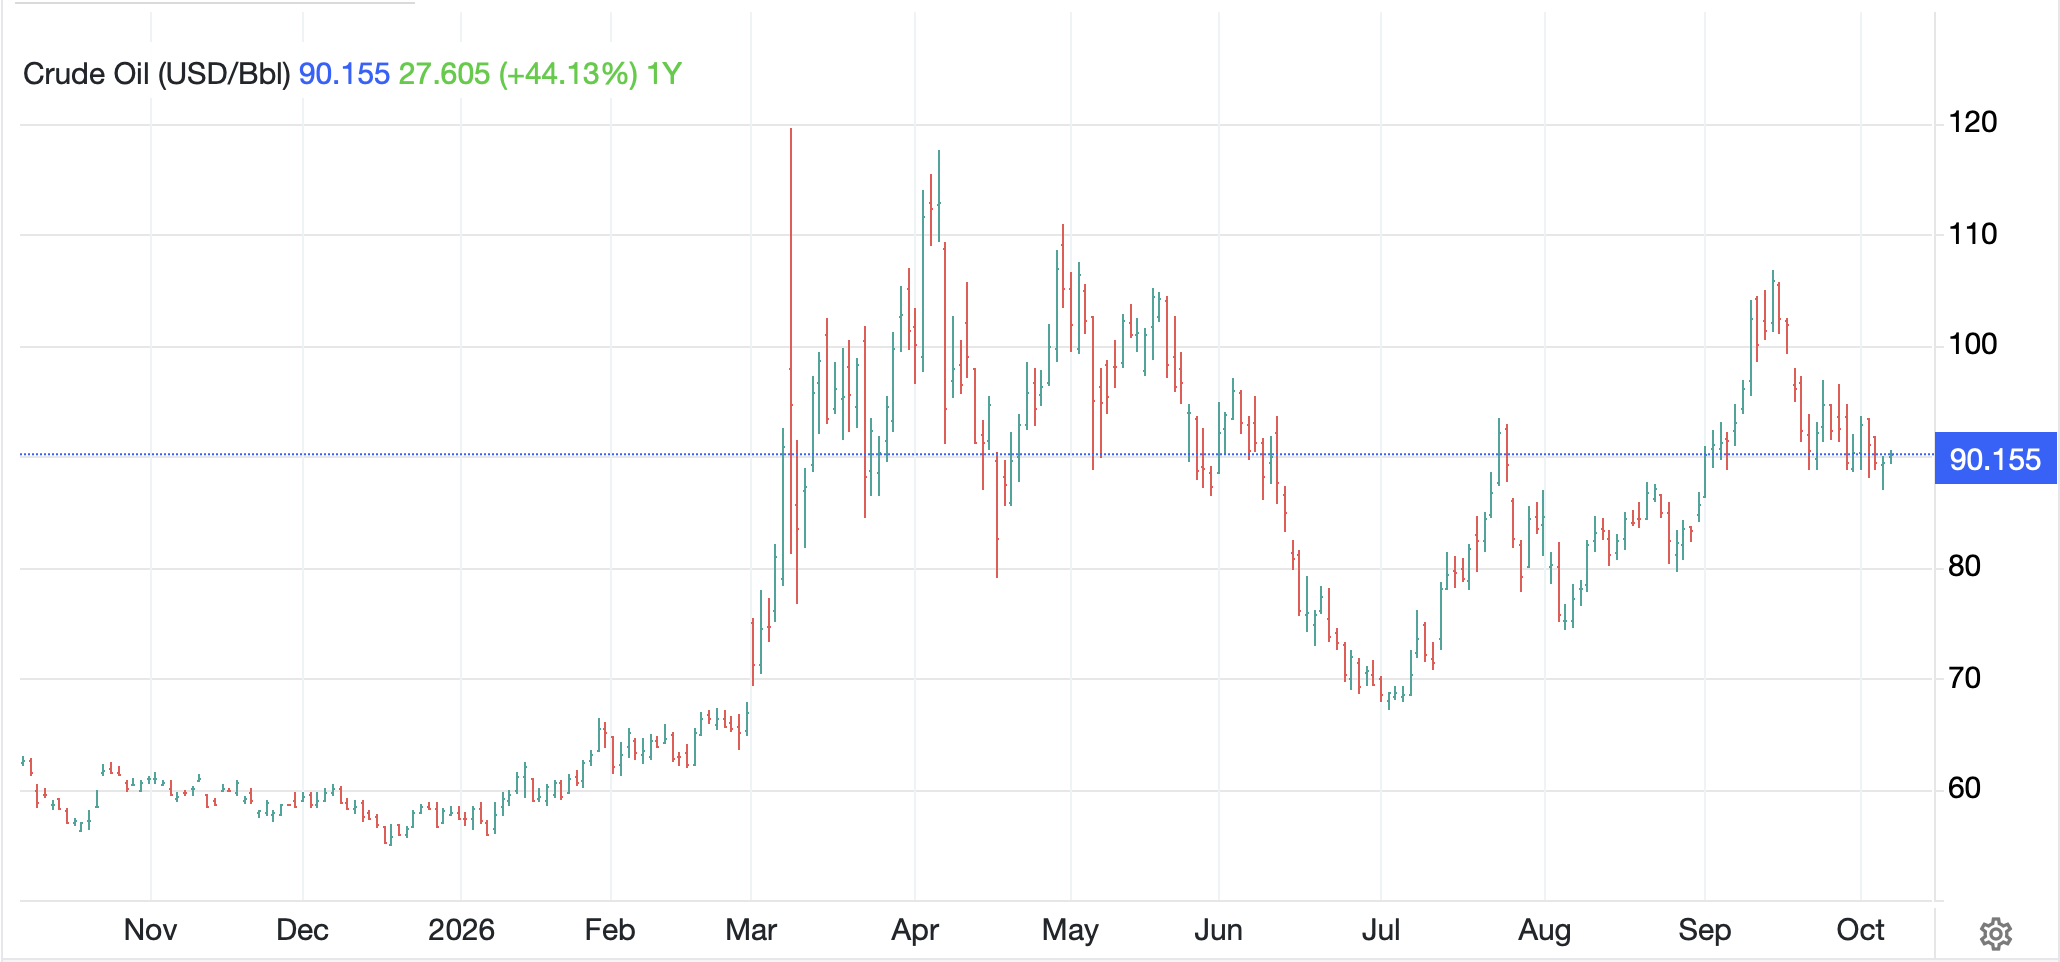
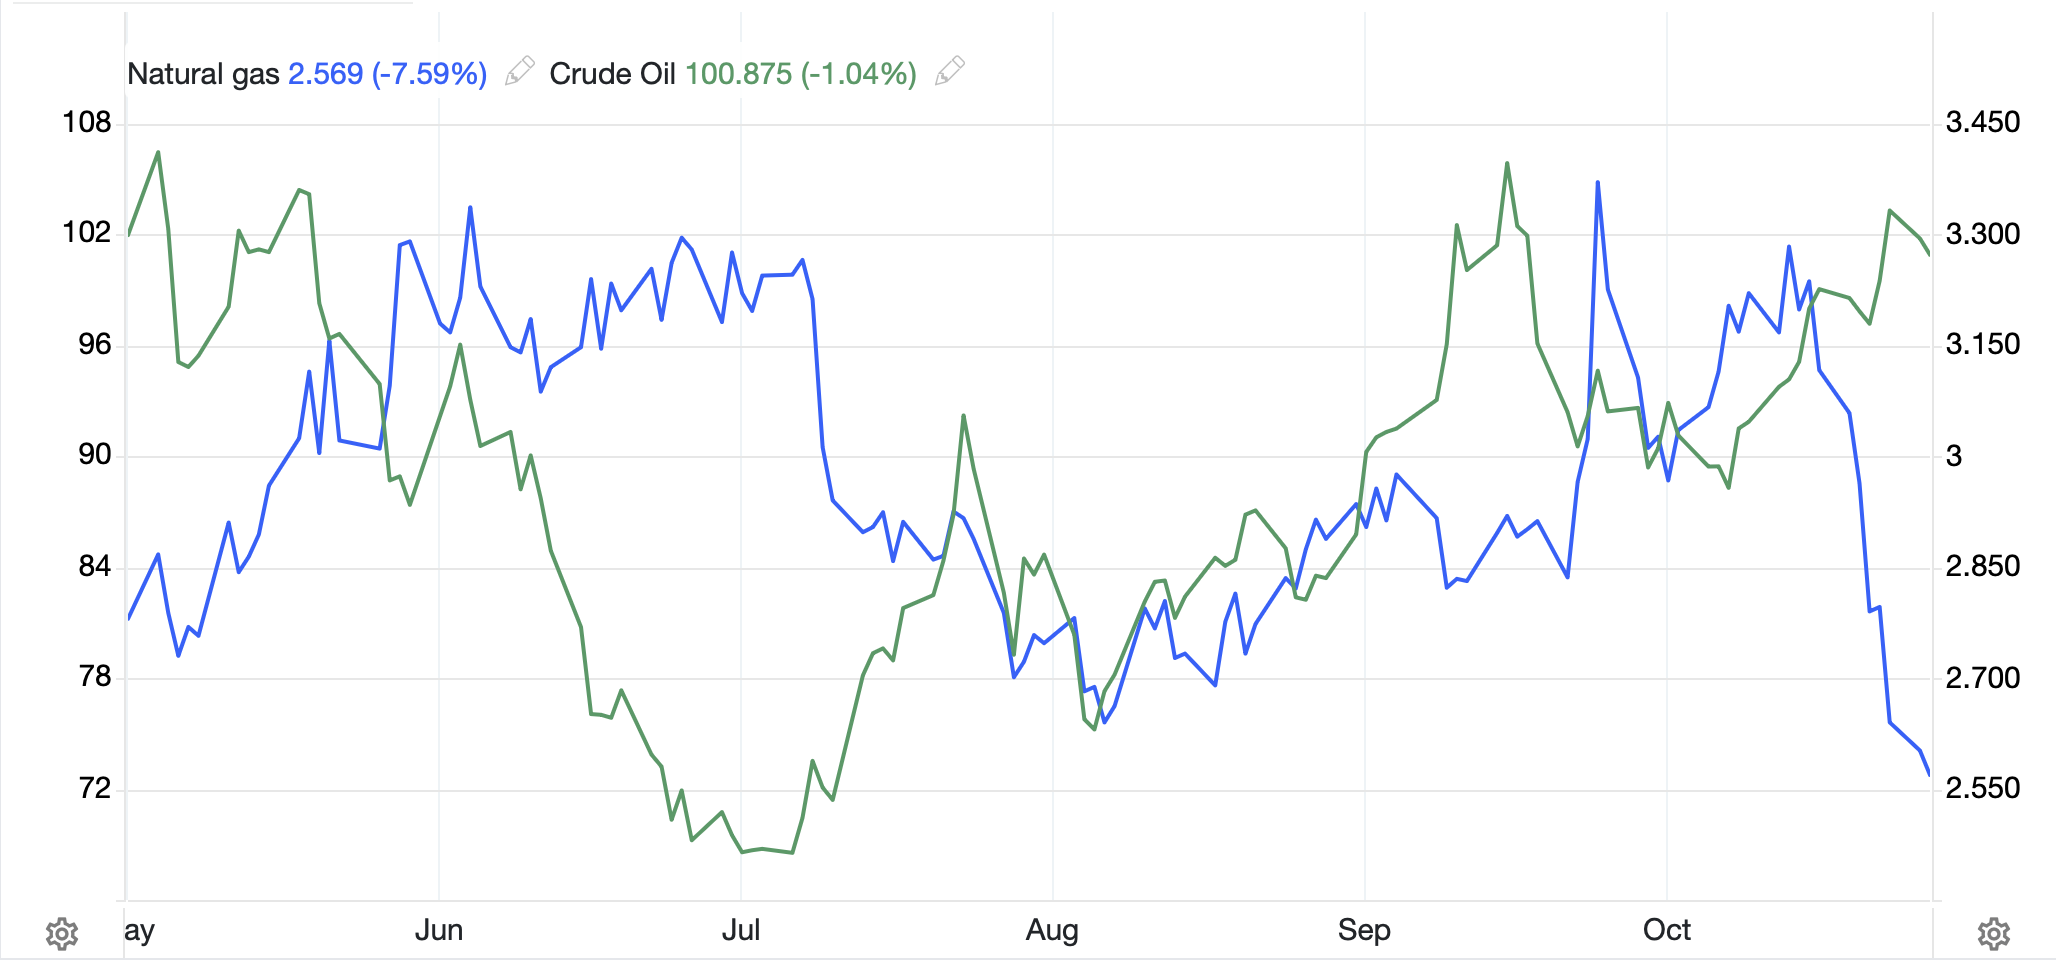
In the commodity space, oil (-1.0%) continues to bide its time ahead of the US election as there is a great deal of uncertainty regarding President Trump’s decision about renewed attacks going forward after the election. Certainly, there have been threats going back and forth but it is very difficult to try to ascertain what will happen as I don’t believe even he knows what he will do yet.
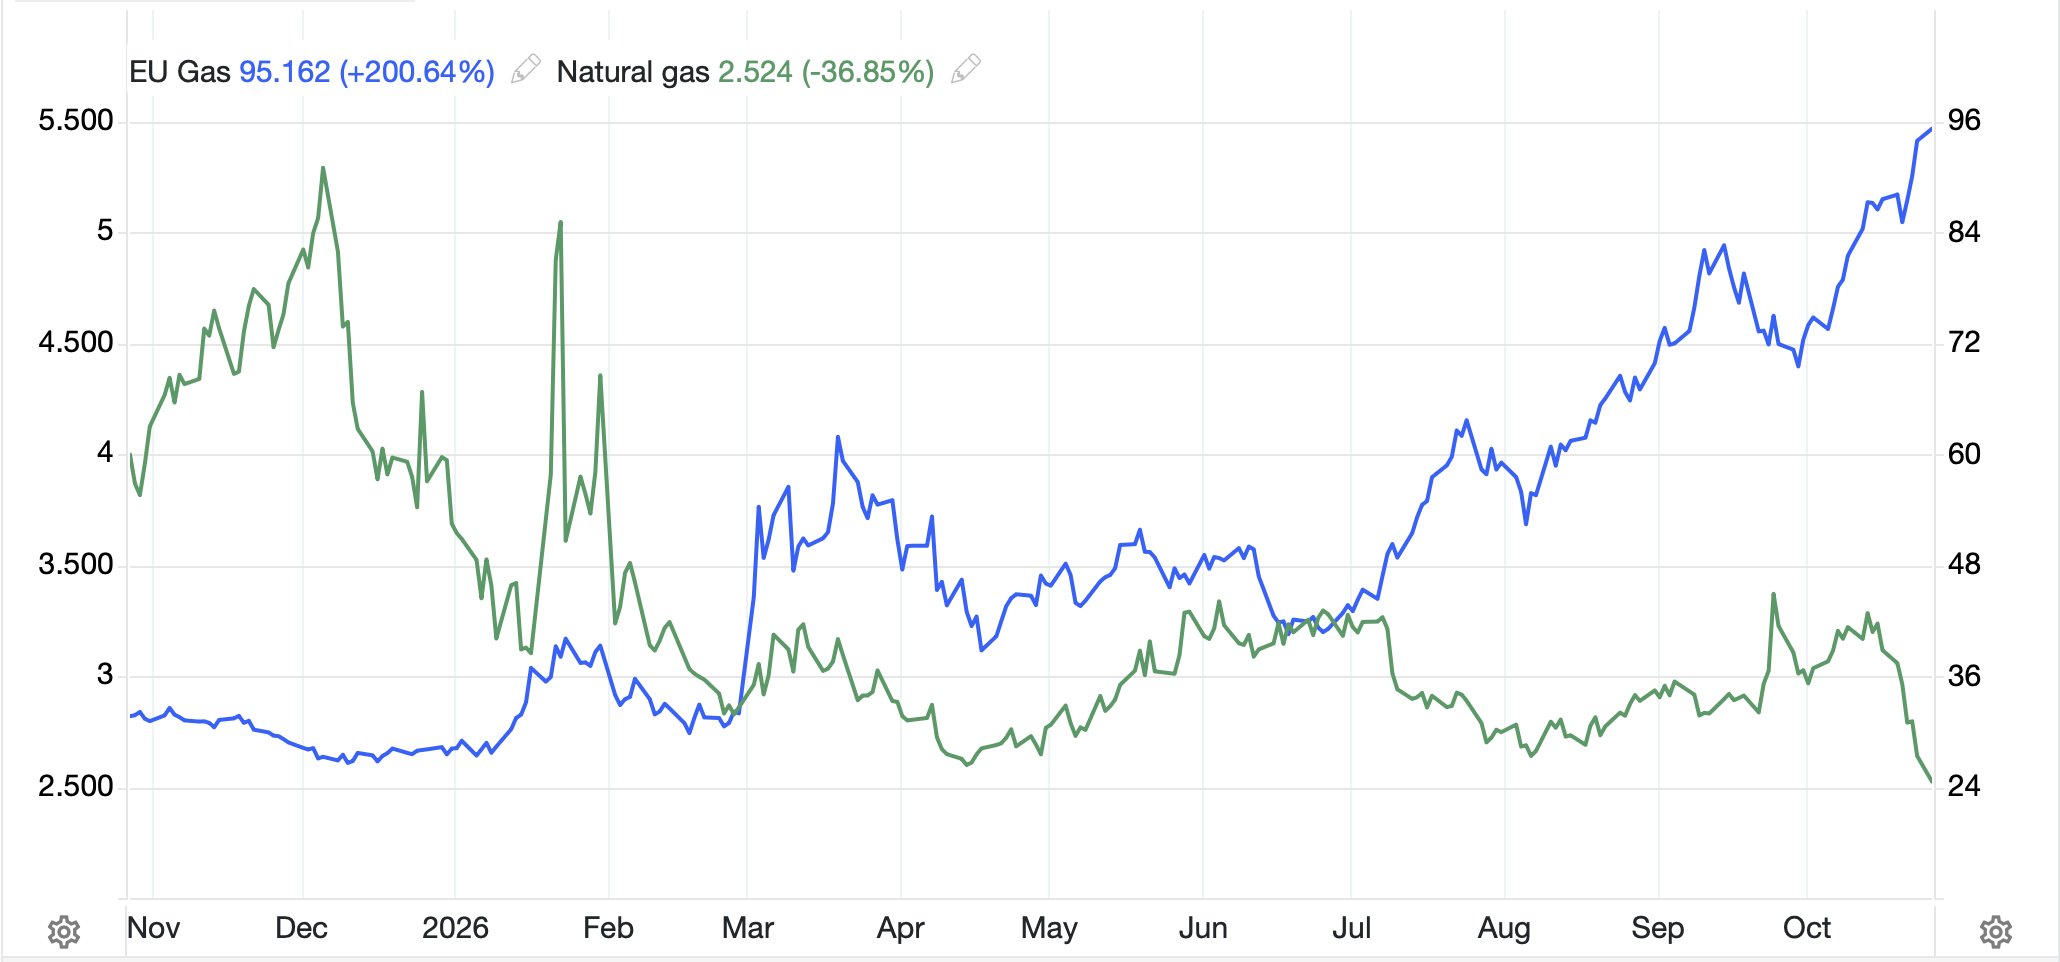
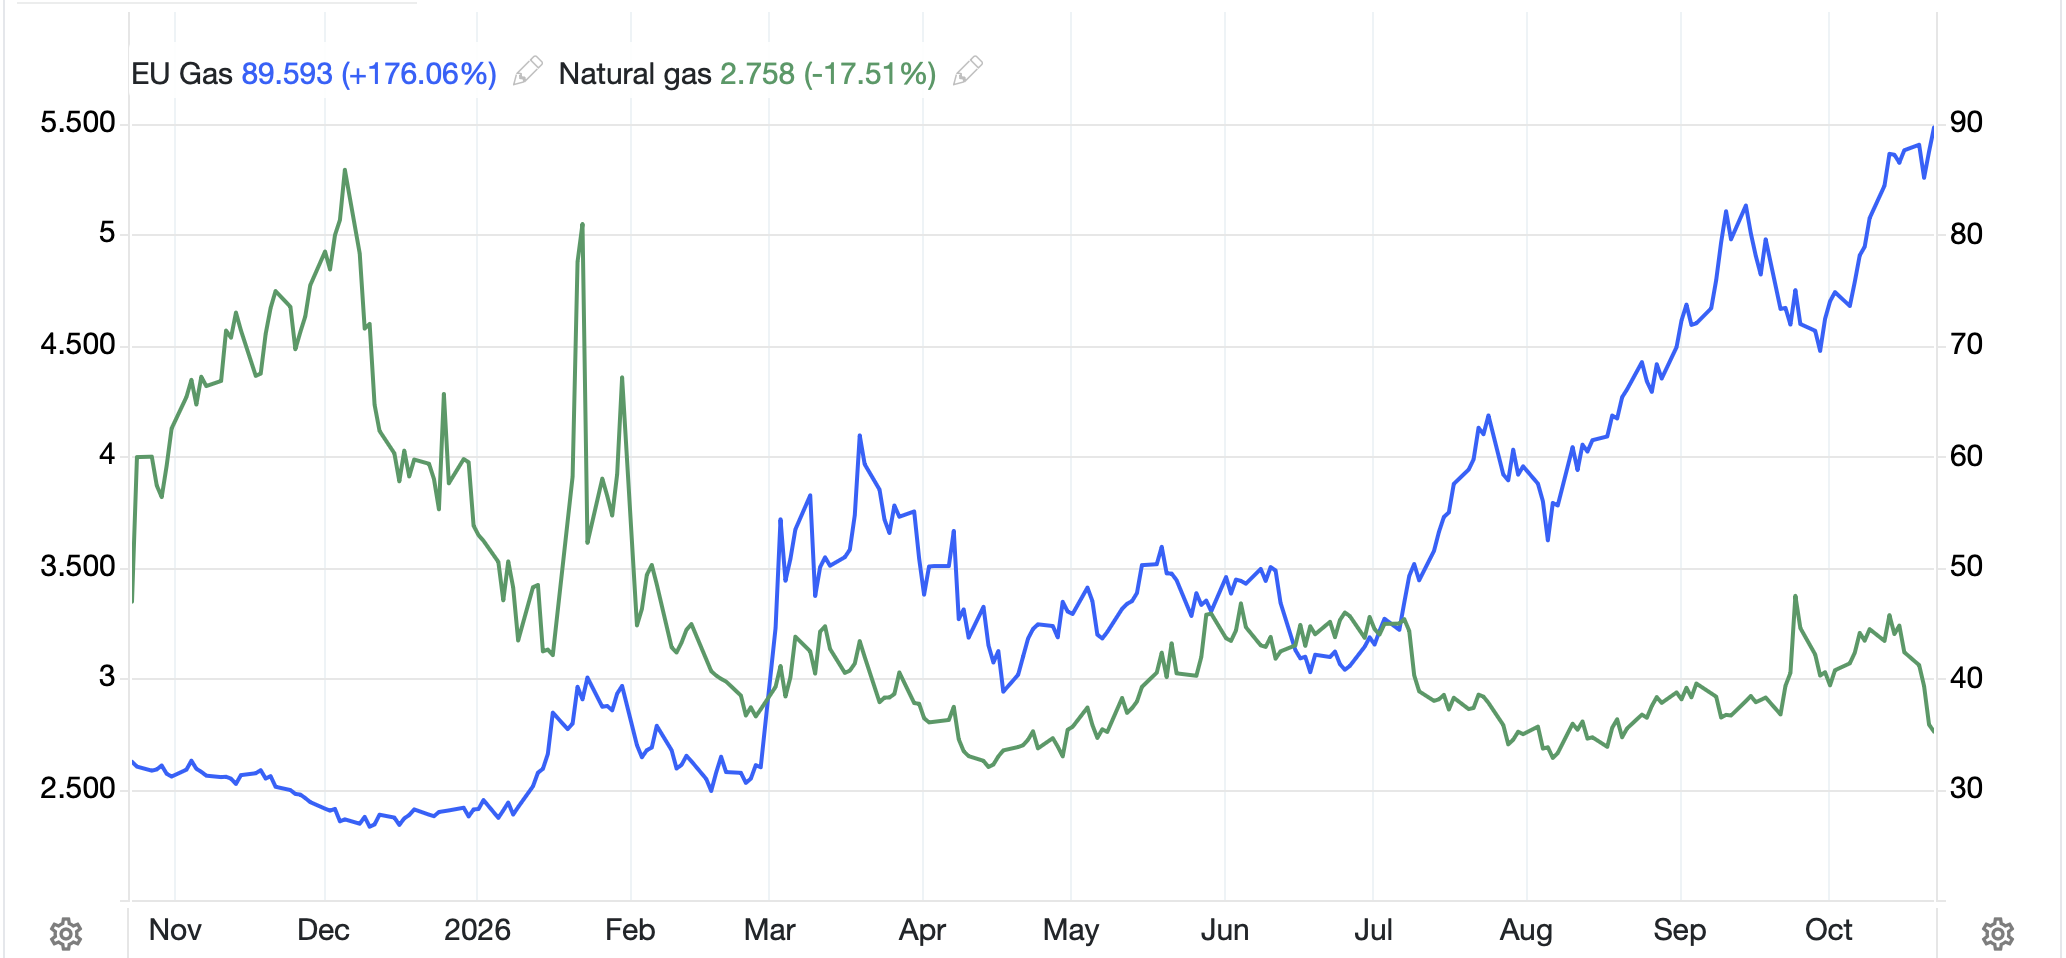
While timing is everything in life, I think it remains abundantly clear that the long-term prospects are for more oil coming from more places outside the Middle East and a diminution of the importance of the Gulf and OPEC. But until then, things can remain spicy. Also, you cannot help but look at the price of NatGas (-1.5% today, -17.9% in the past month) and recognize just how much of the stuff is being produced as associated gas given the uptick in oil production. One other thing to note is that the energy value of oil vs. natural gas and the arbitrage that exists right now. At current prices, the same amount of energy from one barrel of oil at $100 can be had for <$15.50 in natural gas, at least in the US. I suspect that conversions of oil to gas are going to continue apace for a long time until that gap is closed, but so far, demand for gas continues to lag.
Source: tradingeconomics.com
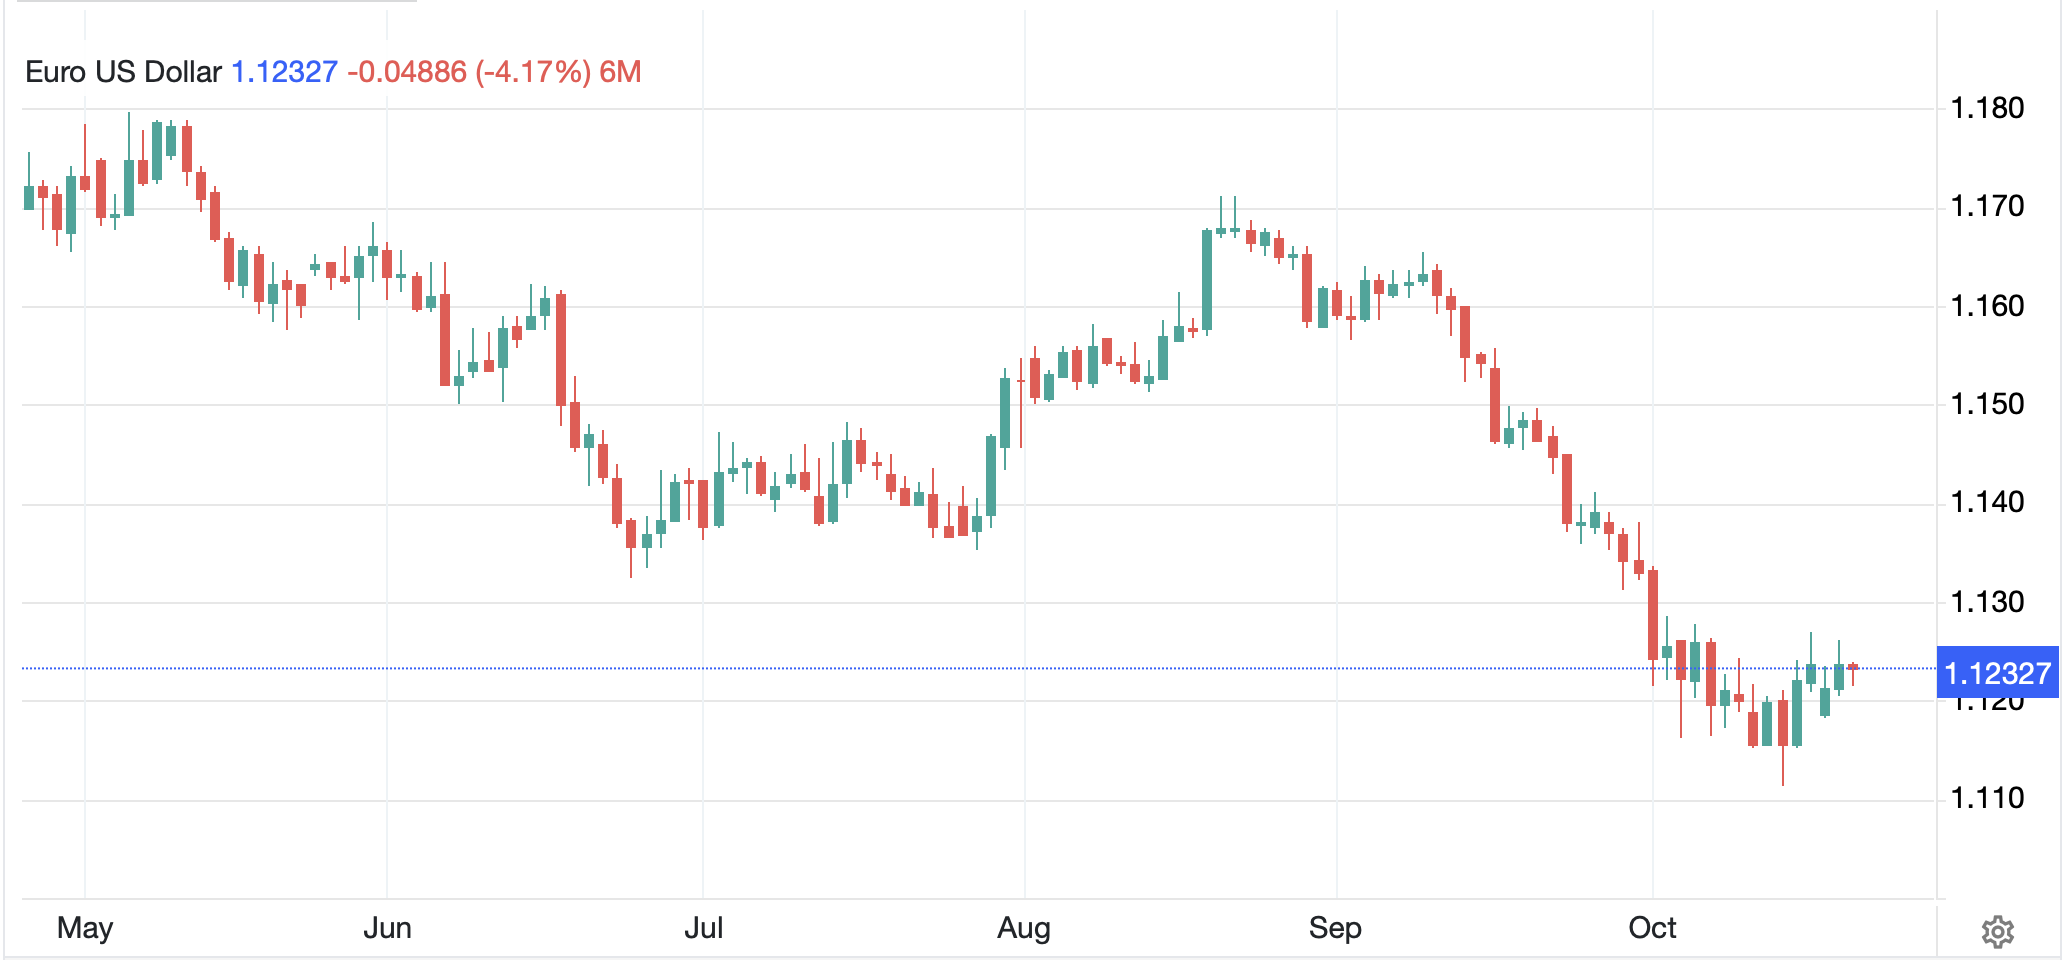
Finally, the FX markets are generally dull outside the Brazilian real. Net, this morning is showing modest USD strength, with the euro (-0.2%) under some pressure but both AUD (+0.2%) and NZD (+0.4%) are firmer, and that is the extent of the movement away from Brazil. It remains difficult to get excited about FX for now and I continue to believe it is segregating itself from other markets.
On the data front, we see Durable Goods (exp 1.5%, 0.6% ex-Transport) along with Case-Shiller Home Prices (2.5%), Consumer Confidence (81.0) and New Home Sales (650K). Speaking of Consumer Confidence, and comparing to the French data this morning, things here are also back at their lowest level since 2013 as per the below chart from conference-board.org. And that was rebounding from the GFC.
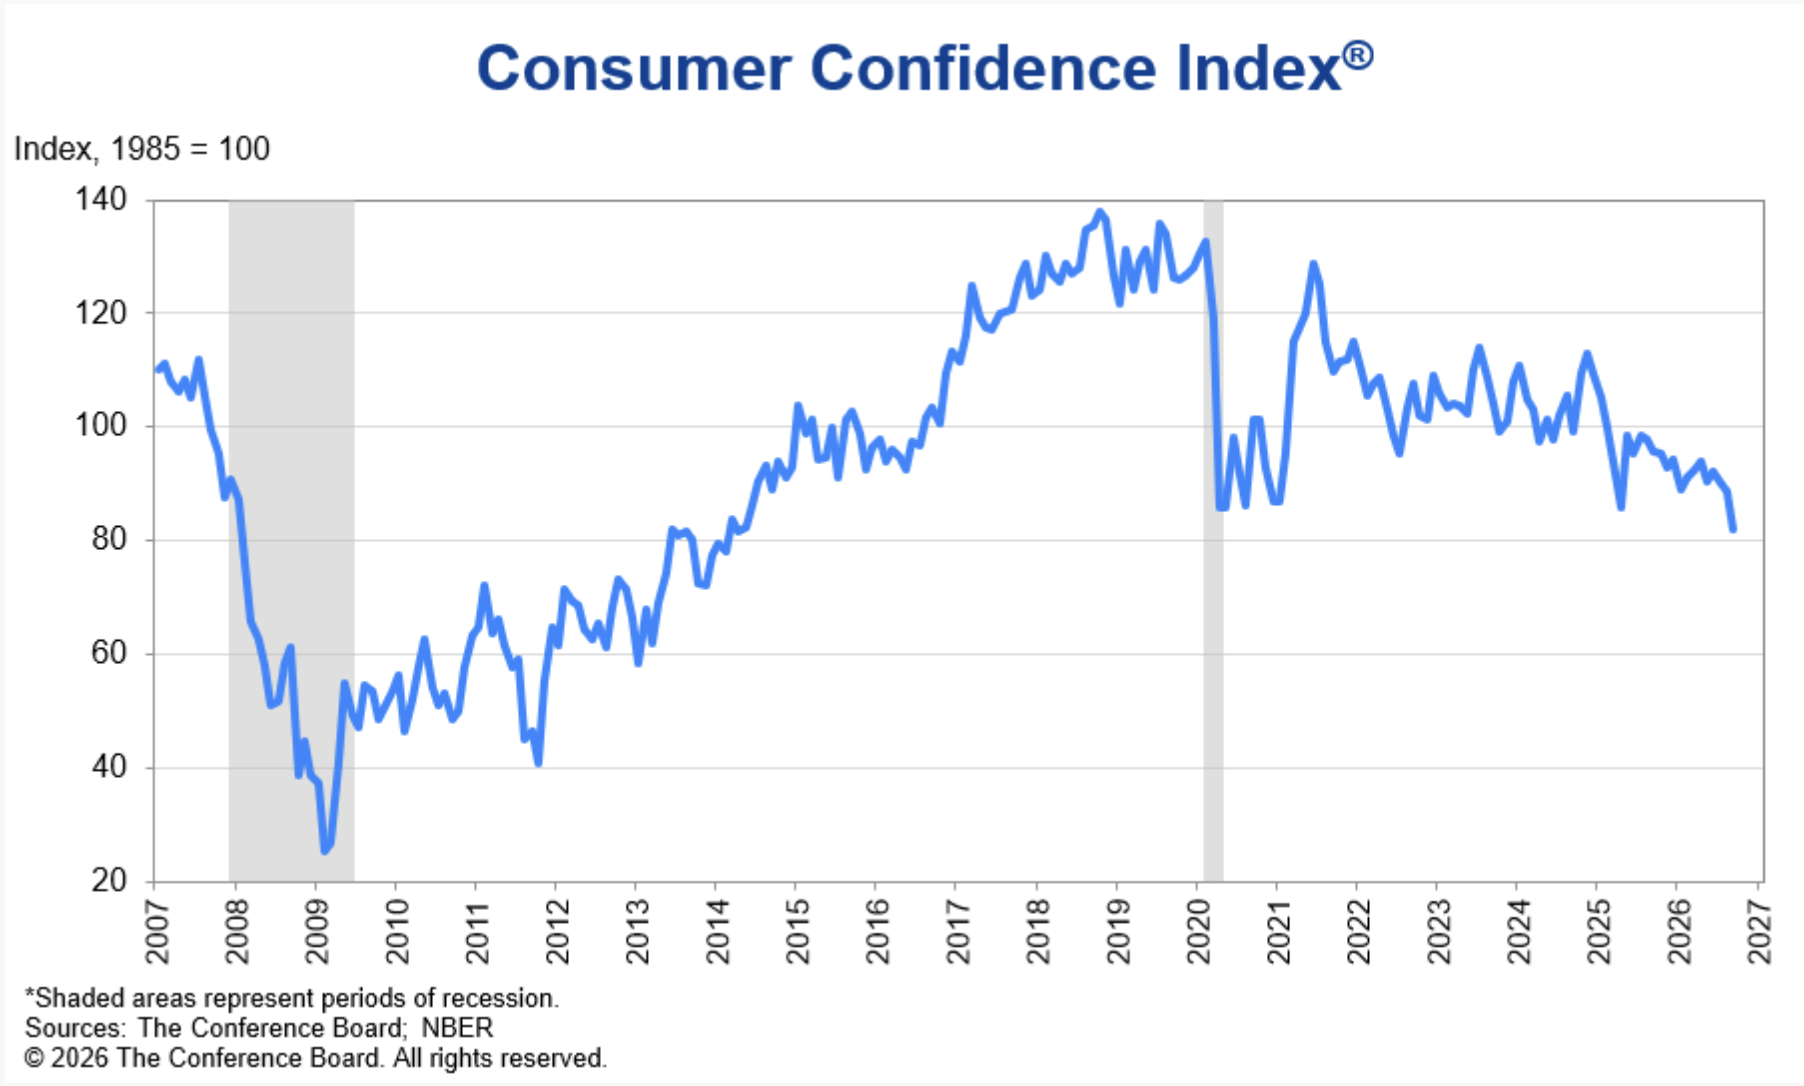
Certainly, if the old adage is correct that people vote their pocketbooks, things are not looking good for the Republicans based on this.
And that’s all there is, I think. I continue to believe that markets remain constrained ahead of the elections and I continue to look at the dollar and find vanishingly few alternatives in the current world.
Good luck
Adf