The question on everyone’s lips
Is whether they should buy the dips
Can things get much worse?
Or will they reverse?
Doom scrollers chant apocalypse!

The upshot is havens are hot
Well bonds are, though gold clearly not
The dollar is strong
But it would be wrong
To think things can’t get more distraught
As we head into the weekend, investors are an unhappy bunch right now as evidenced by the Fear & Greed Index sitting at the Extreme Fear side of the scale.
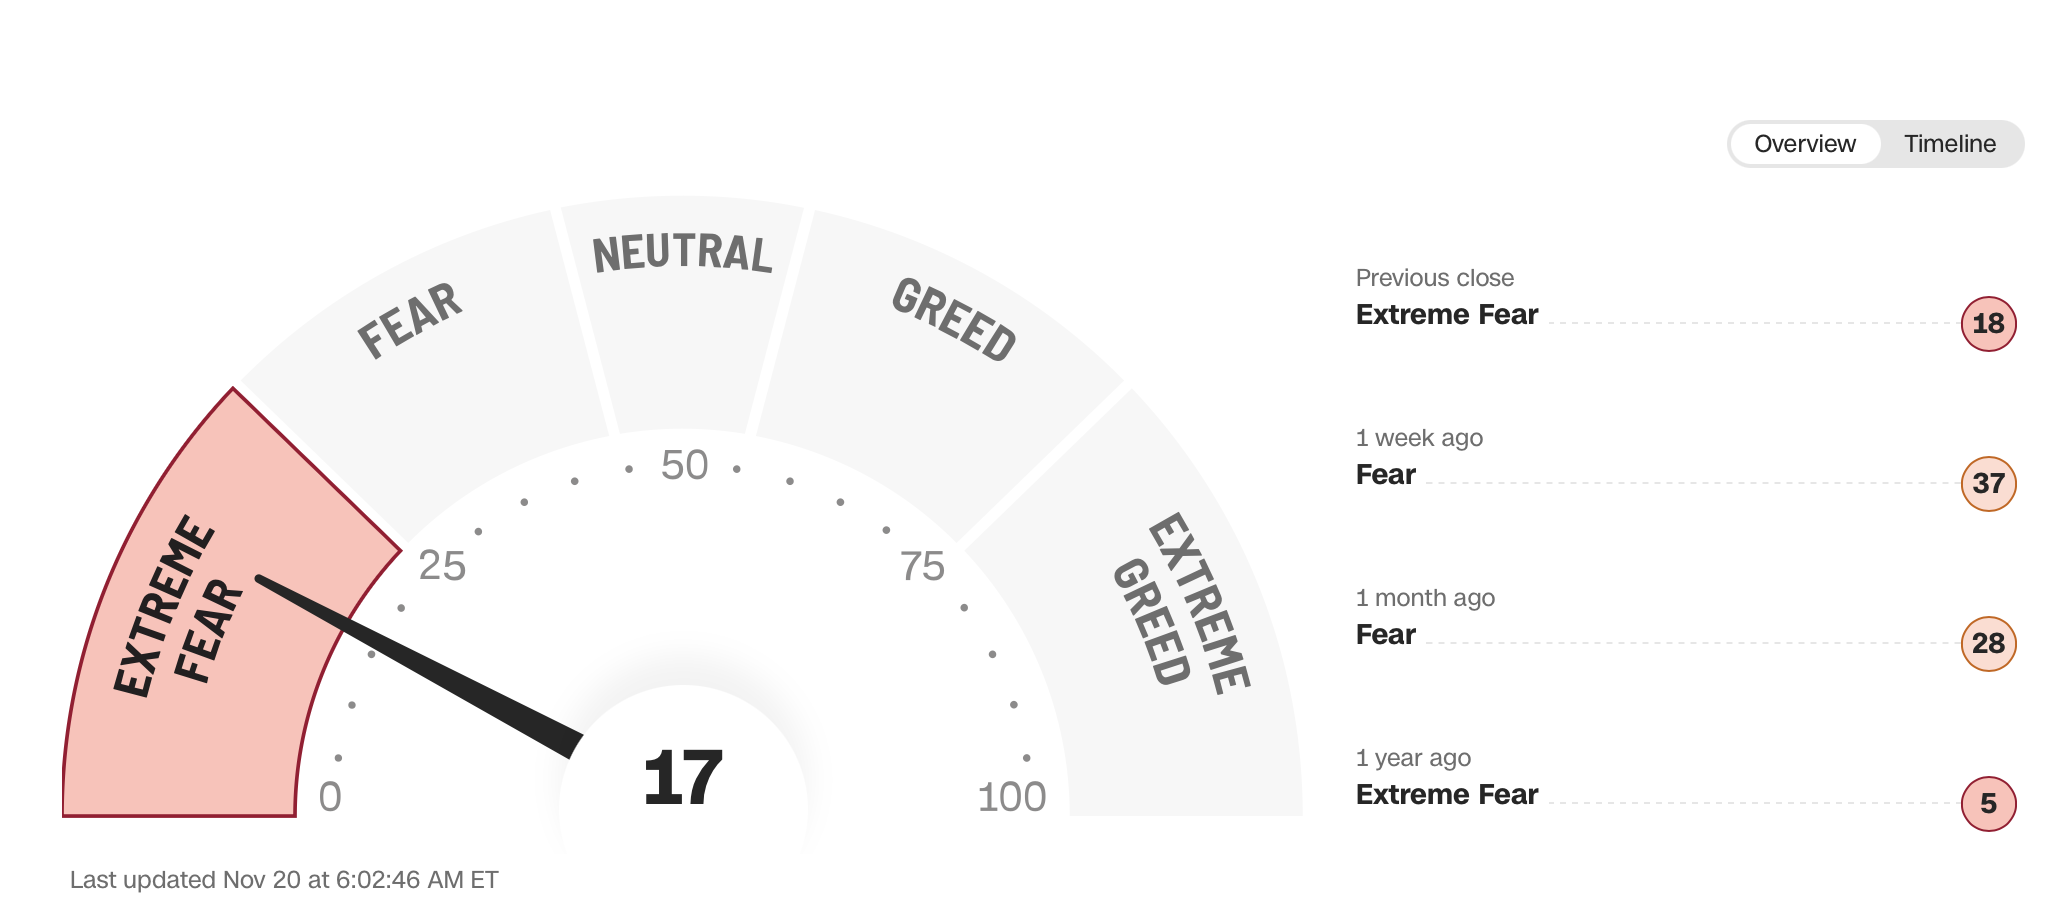
As you can see from the right-hand side of the illustration above, things have gotten progressively worse over the past month but are not as bad as they were a year ago. Last year at this time we were going through the massively long government shutdown and markets were just coming to grips with the idea the Fed may not be cutting rates going forward. As well, there were indications that the AI trade was overdone (LOL). Here’s the thing about this indicator, as we know, it can go lower but also, historically, when it falls into the extreme fear reading, there is a subsequent rebound in risk appetite as the index seems to describe an excess, perhaps unwarranted, amount of fear.
But right now, the below screenshot from Bloomberg.com shows that this fear is very widespread, global in fact.
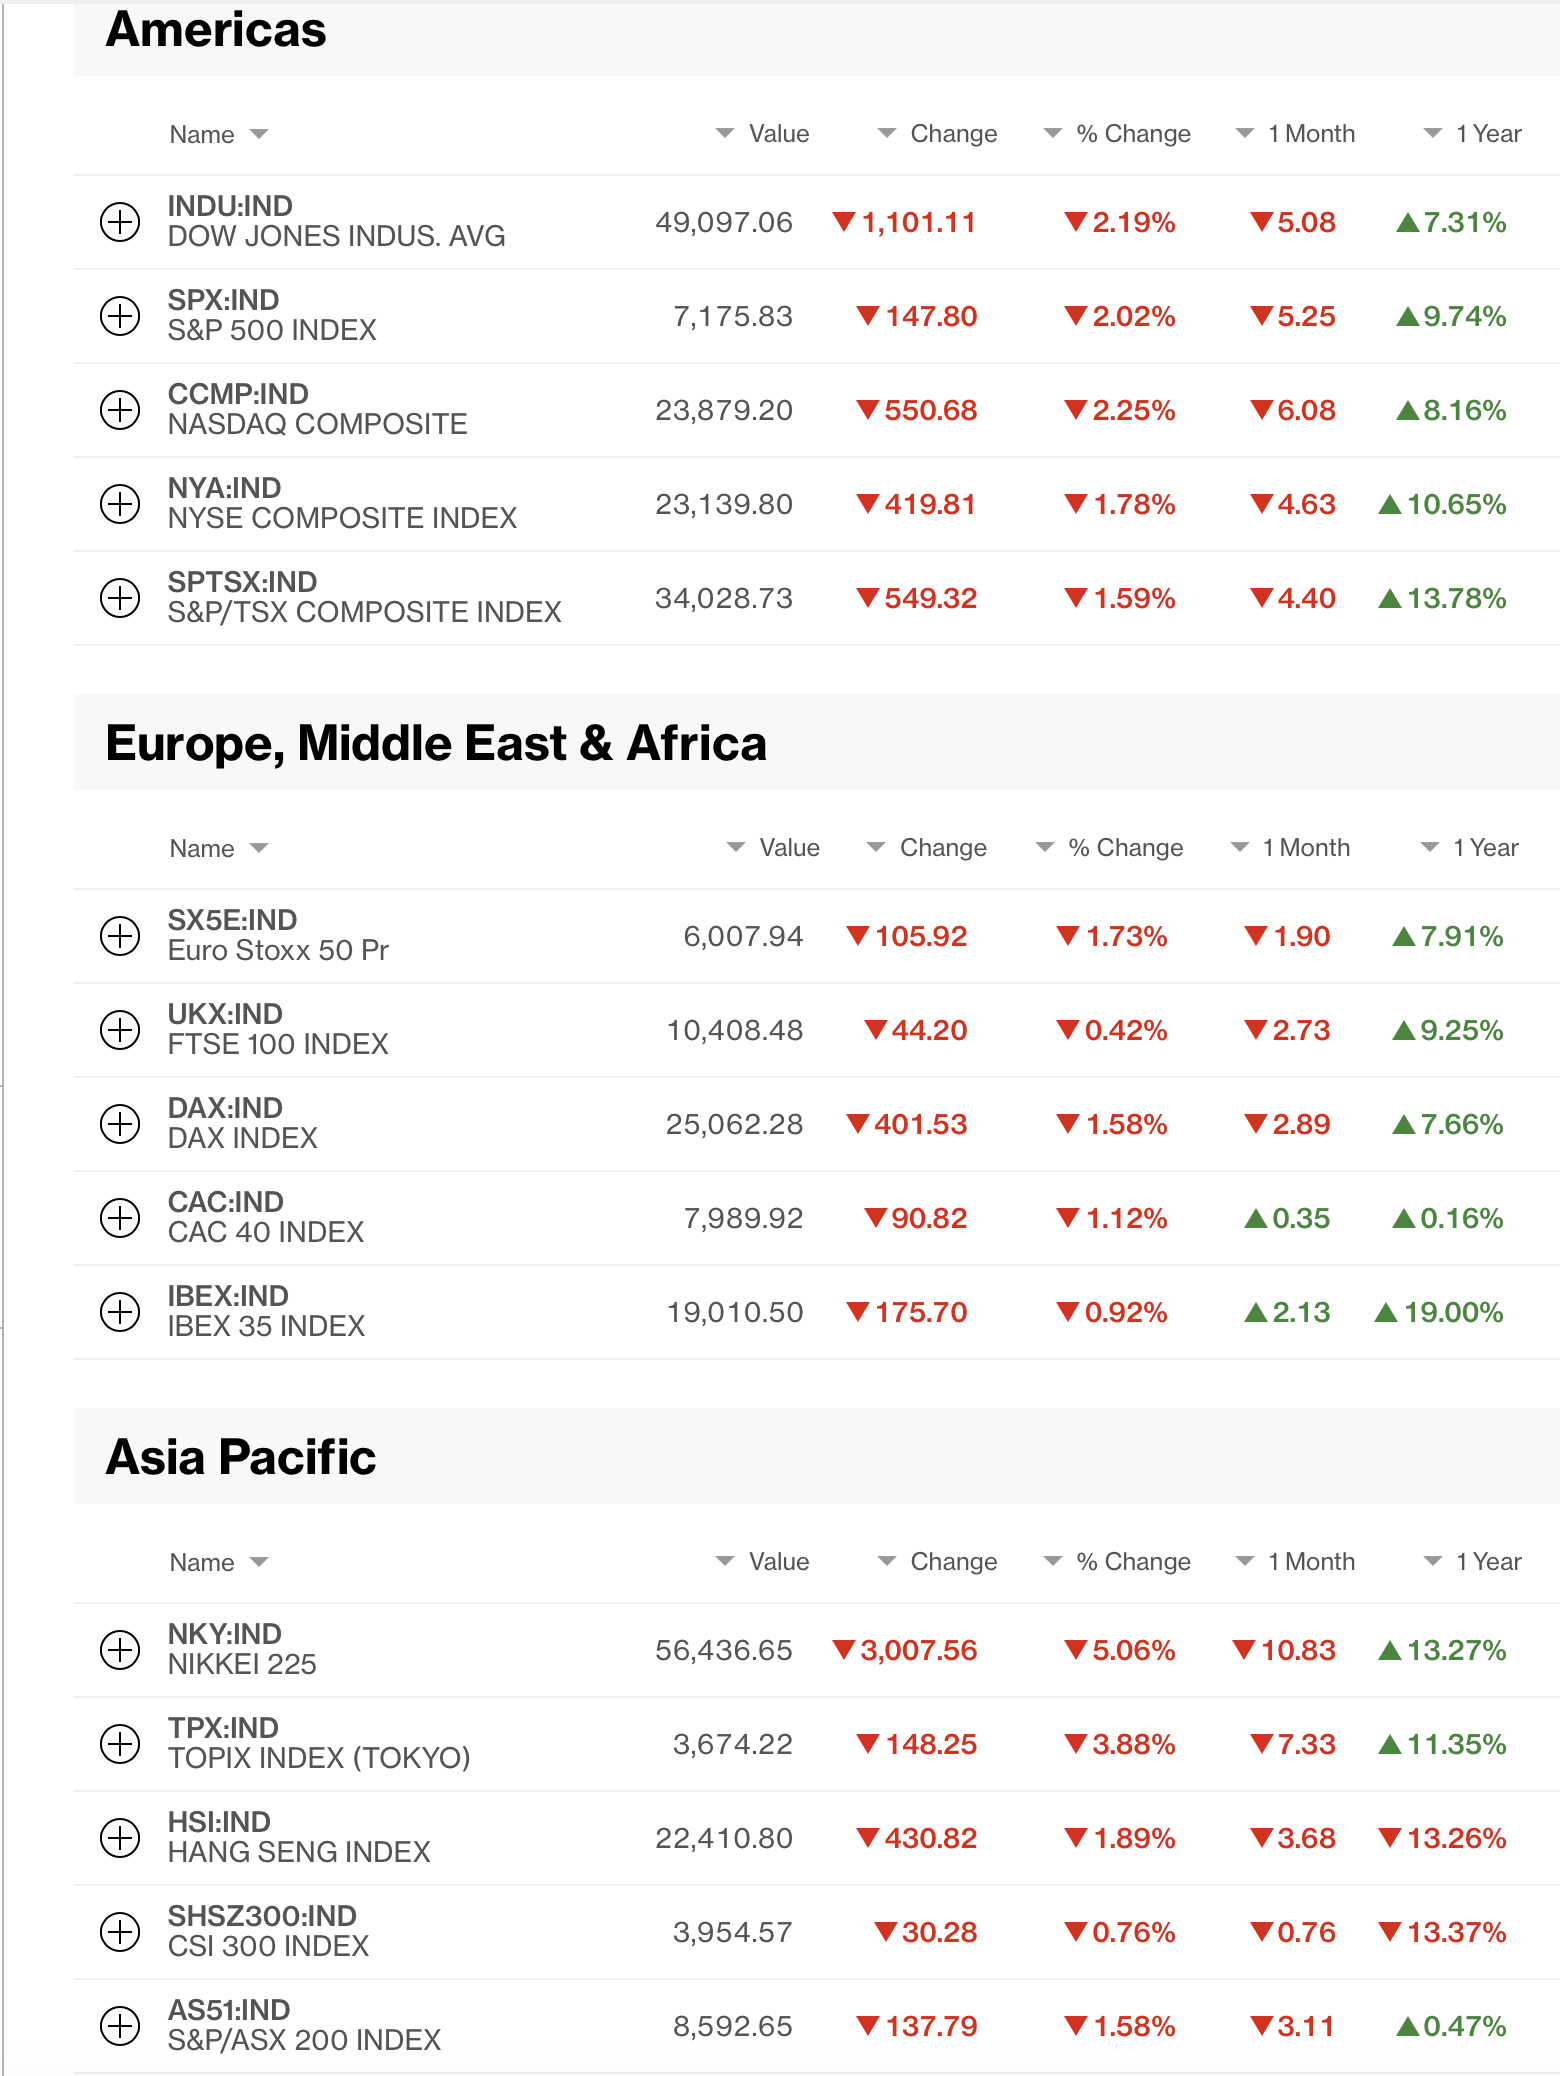
It has been a rough month for equity markets, that’s for sure, but most are still higher than they were a year ago. Of course, the $64 trillion question is what is in store for the future? Alas, nobody really knows. But consider the idea that one of the key drivers of recent price action is the increased hawkishness seen by central banks around the world. As you can see in the below chart from rateprobability.com, other than the RBA, where the economy appears to have already rolled over, expectations are for at least two, and mostly three, rate hikes by next summer.
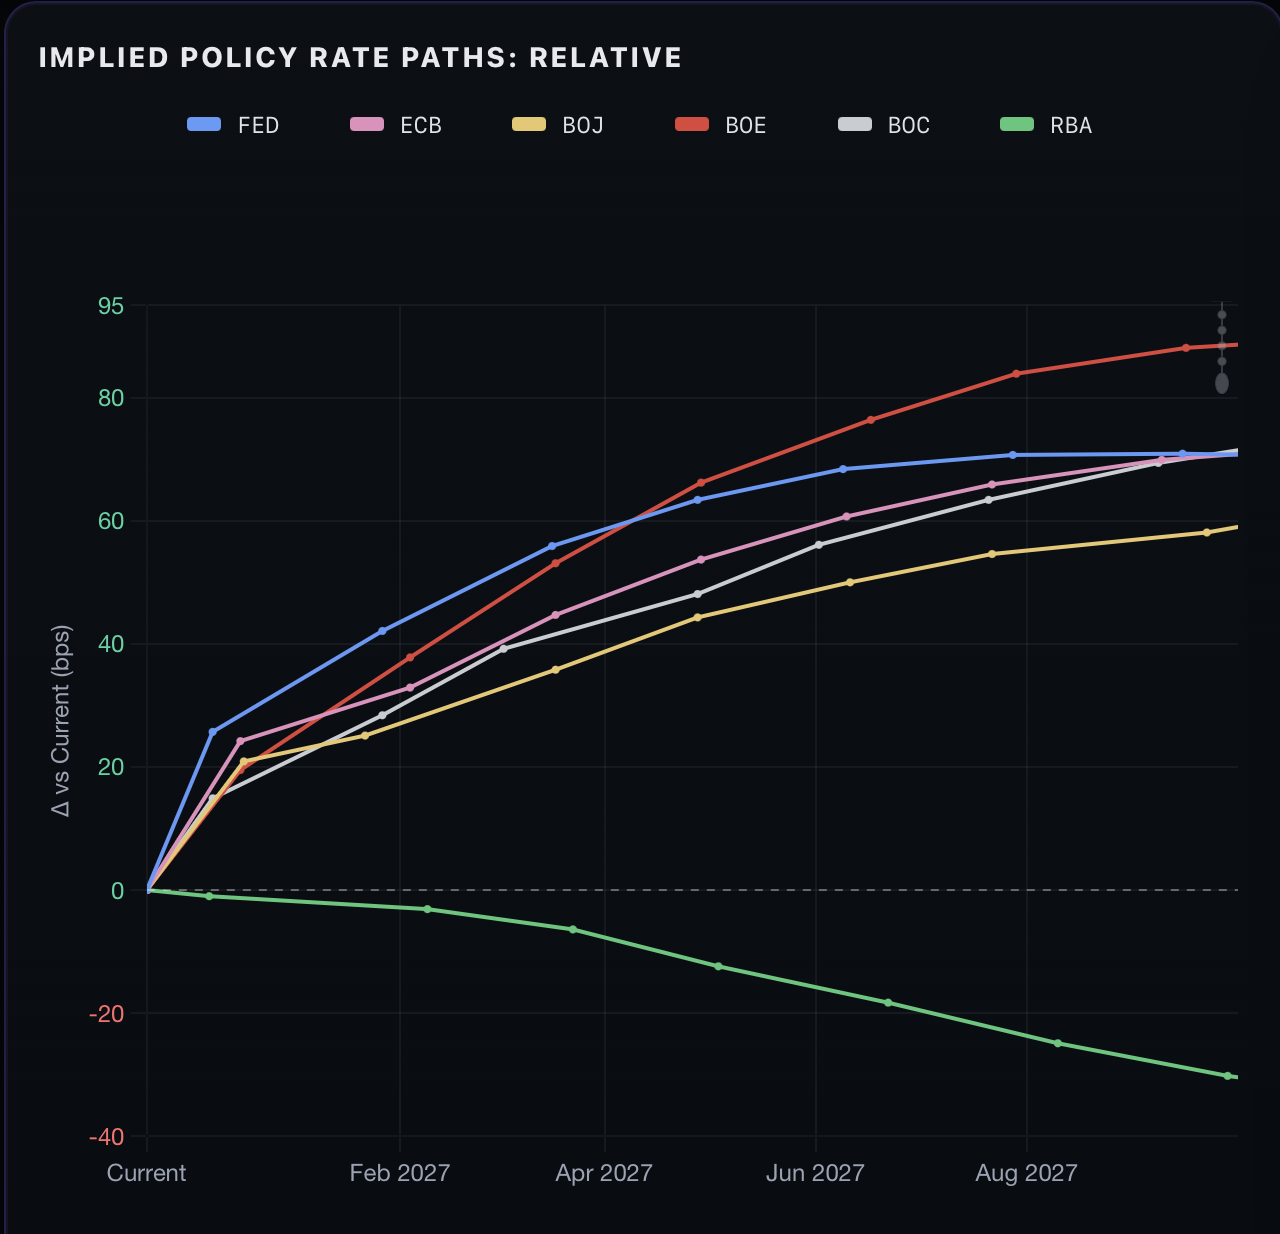
Will they all materialize? Certainly, the first 25bps is baked in the cake everywhere. But there is a lot of time between now and next summer and these markets are subject to change and change quickly.
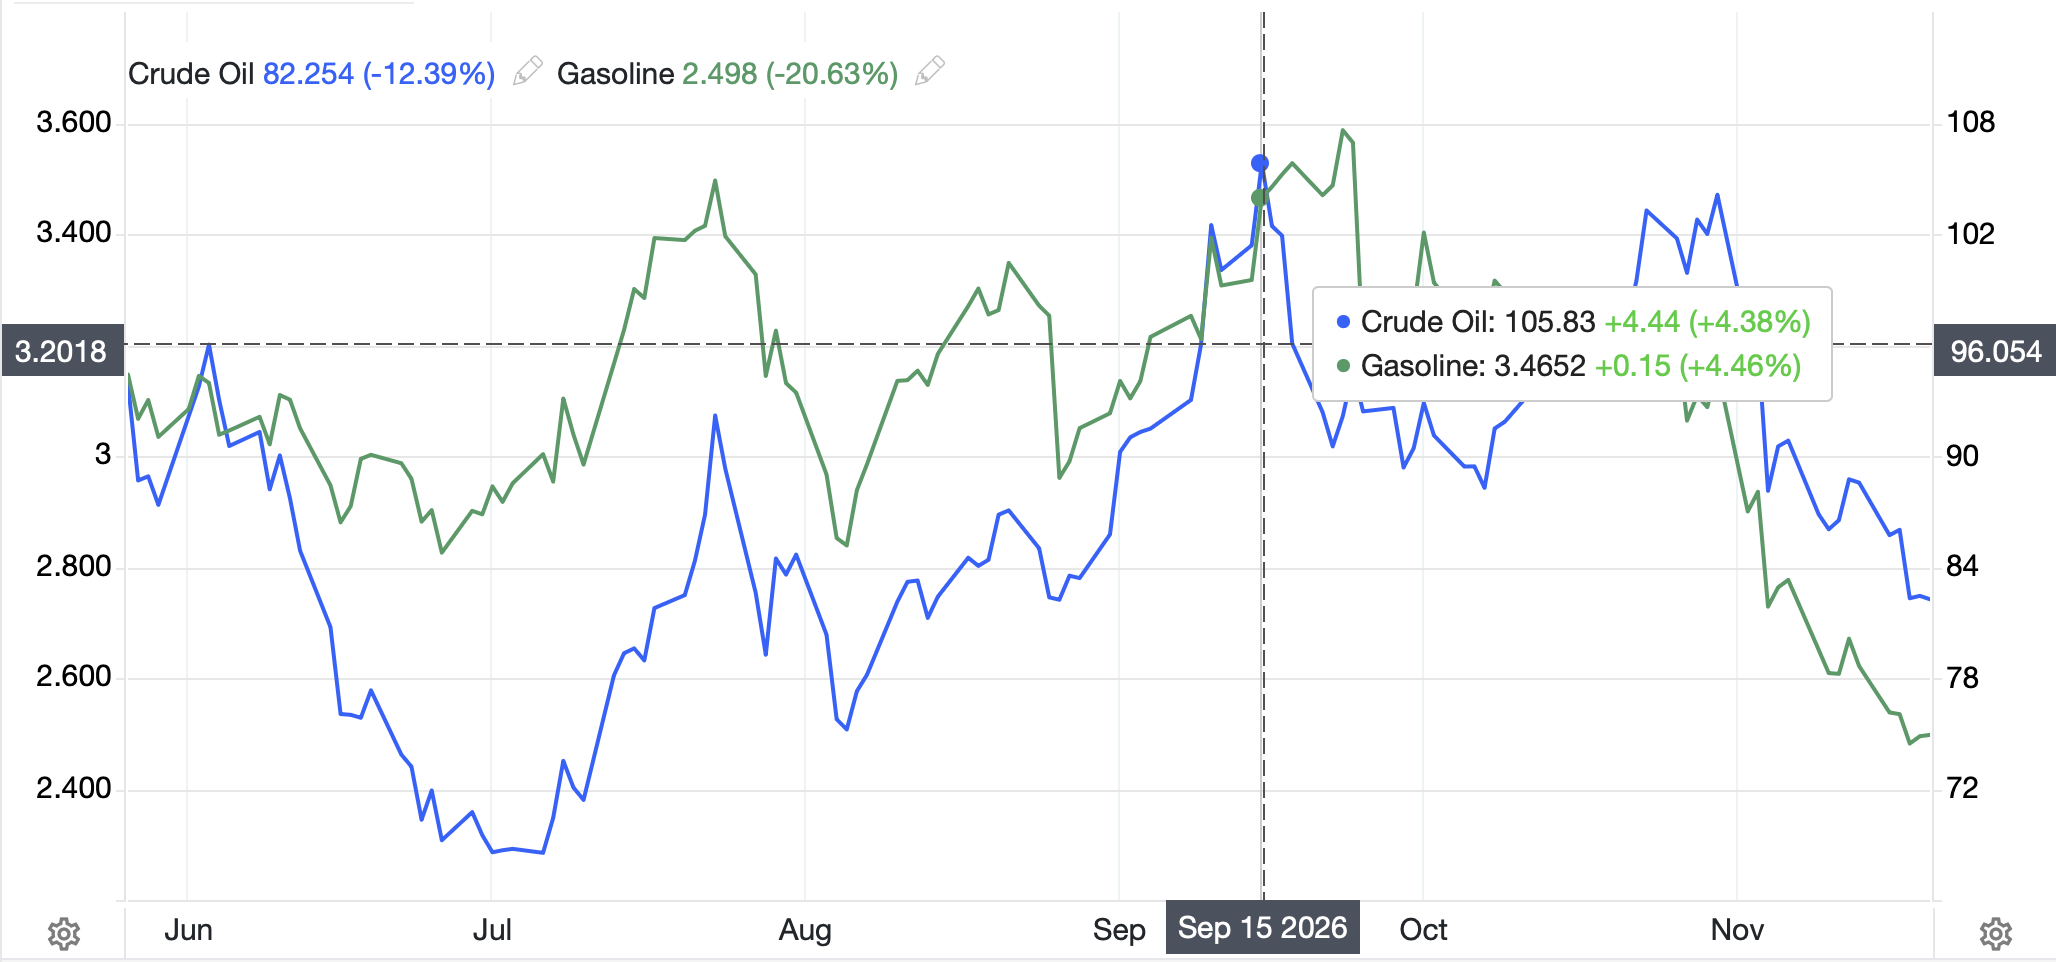
Consider what the primary driver of all this inflation has been, oil prices in the wake of the Iran conflict with the added impetus of Ukrainian attacks on Russian refineries. So, perhaps it is time to give the energy piece of the inflation narrative some second thoughts. After all, as you can see in the below chart from tradingeconomics.com, both crude and gasoline (the direct CPI/PCE impact) have fallen sharply in the past two months, more than 20% in WTI and more than 30% in gasoline.
In fact, this is the reason that central banks hiking rates into energy price shocks has been such a catastrophic error since the beginning of central banking. Every shortage of a commodity is followed by a glut of that same commodity. It always has been that way and there is no indication that is going to change. But there is no doubt that central banks around the world are keen to hike rates. Realistically the US has not had a recession since the GFC (the Covid impact on GDP was incredibly short-lived although we continue to pay the price of all the money that was printed) so it can be no surprise that a recession is going to arrive at some point.
As has been said many times, although I don’t know who coined the phrase, ‘economic expansions don’t die of old age, they are murdered, and frequently it is the Fed that is holding the smoking gun.’ If the Fed does indeed get aggressive going forward, and so do the ECB, BOE, BOC, BOJ, etc., economic activity is almost certainly going to slow down, potentially quite sharply. Remember, equity markets are seen as forward-looking economic indicators, somewhere in the 6mo to 9mo area. If we are seeing serious weakness now, next summer we could well be in that recession, with the Fed suddenly reversing course and a short-term decline in inflation. Alas, the employment situation may not be as favorable. Something to keep in mind going forward.
But for now, red is the color of the day. Virtually every equity market in Asia and in Europe has fallen, some quite substantially with Korea (-5.2%) and Taiwan (-6.2%) getting decimated although India (+1.1%) is the lone exception. As this appears to be a tech/AI led decline, India is not nearly so impacted as we discussed earlier this week. As to Europe, literally every equity index is lower this morning, although lacking any tech companies of note, the declines are more muted than what we saw in Asia. And US futures are also pointing lower, with the NASDAQ (-1.8%) still leading the way and dragging everything along for the ride.
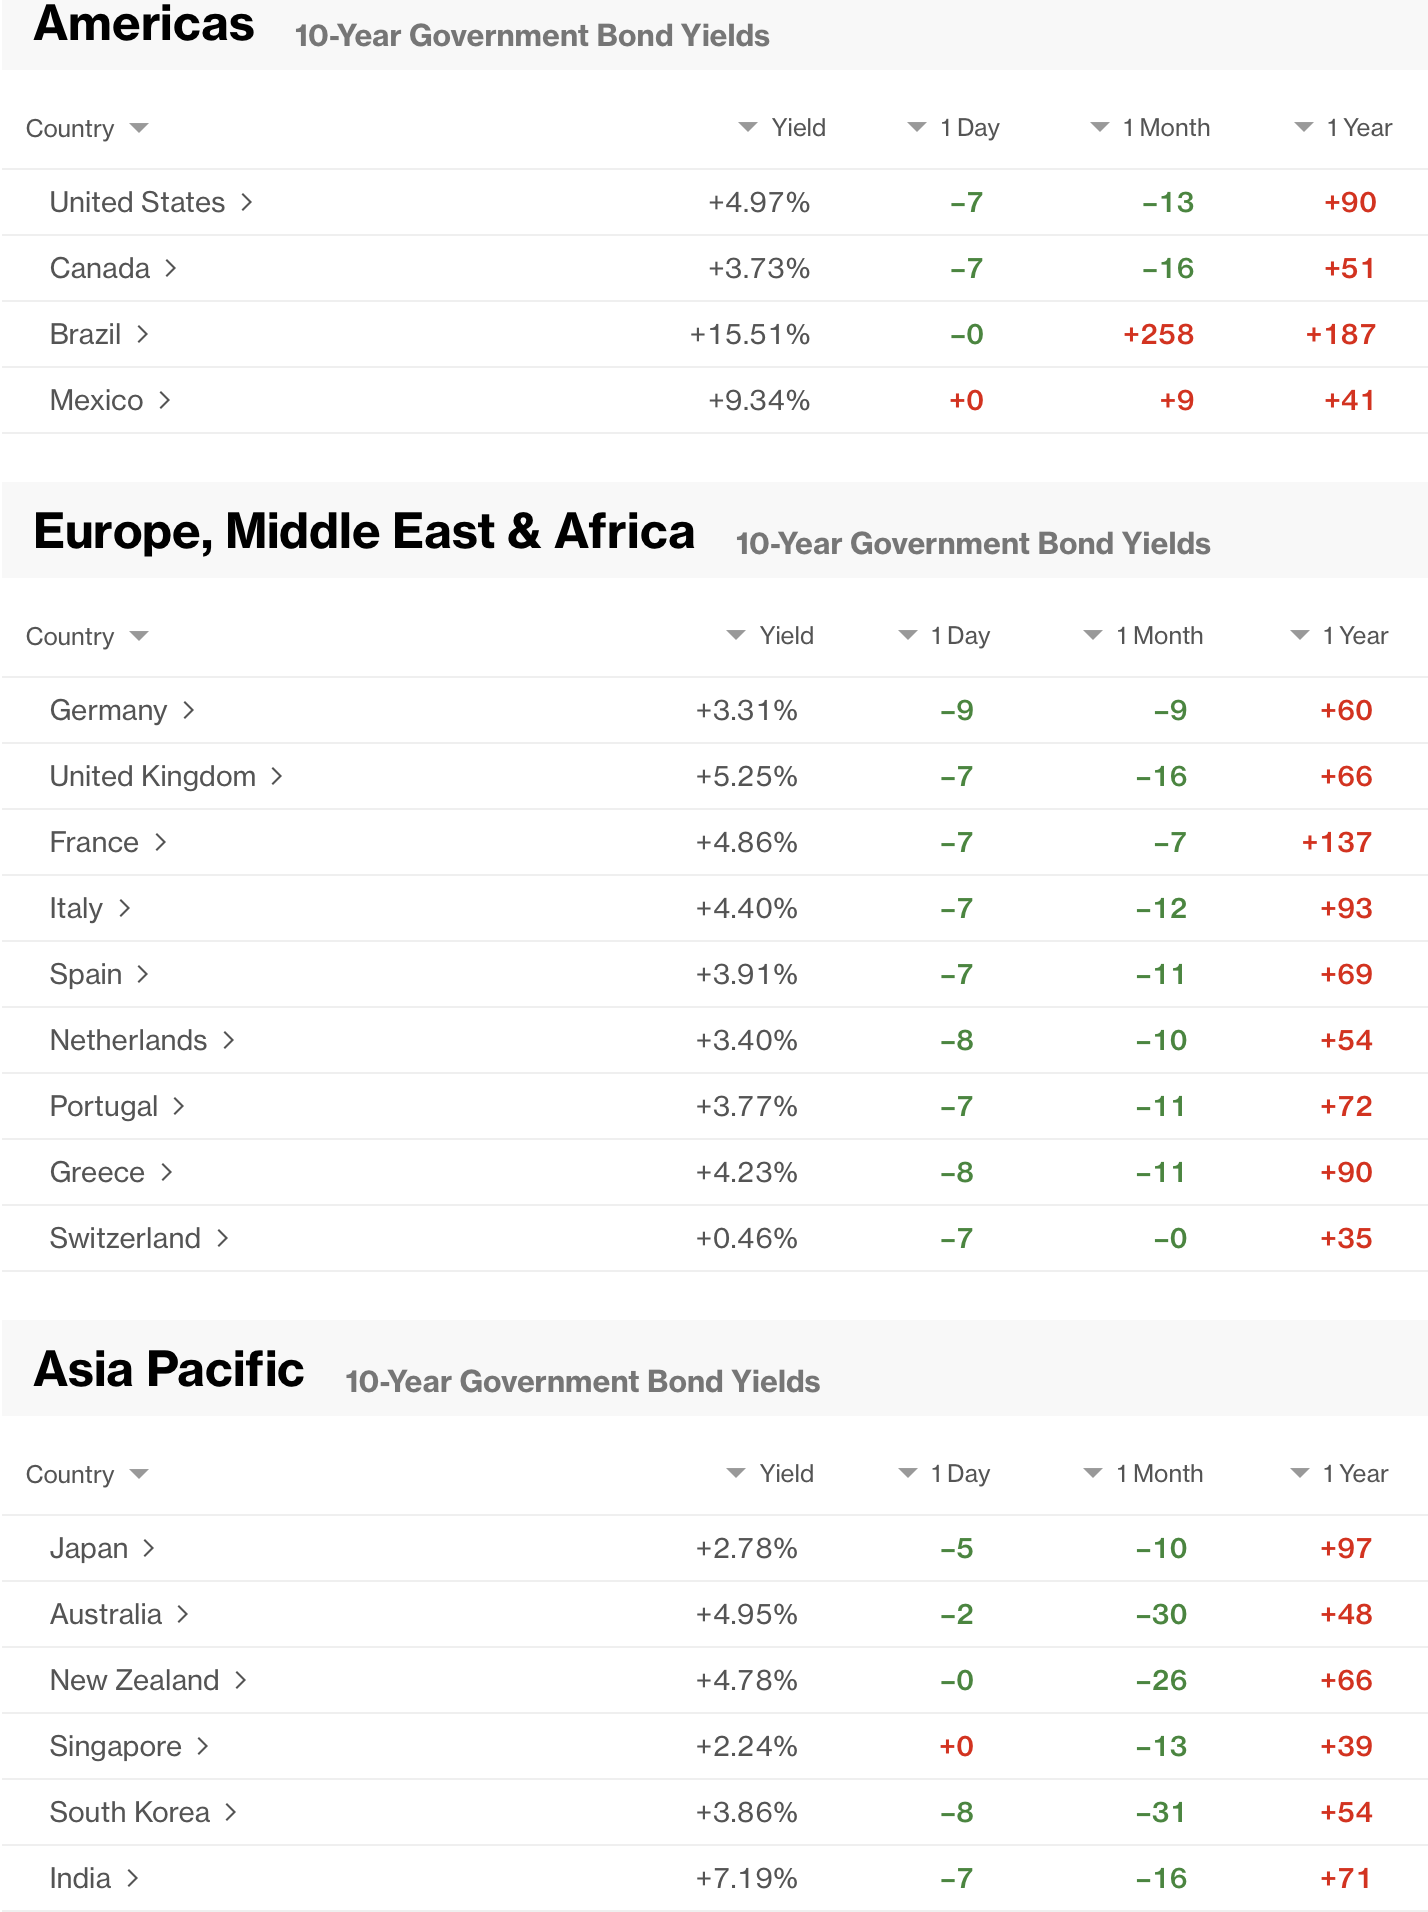
But there is a market that is having a renaissance, the Treasury market. Well, global government bonds are in demand this morning as you can see in the below Bloomberg.com screenshot with 10-year Treasury yields falling back below 5.0%.
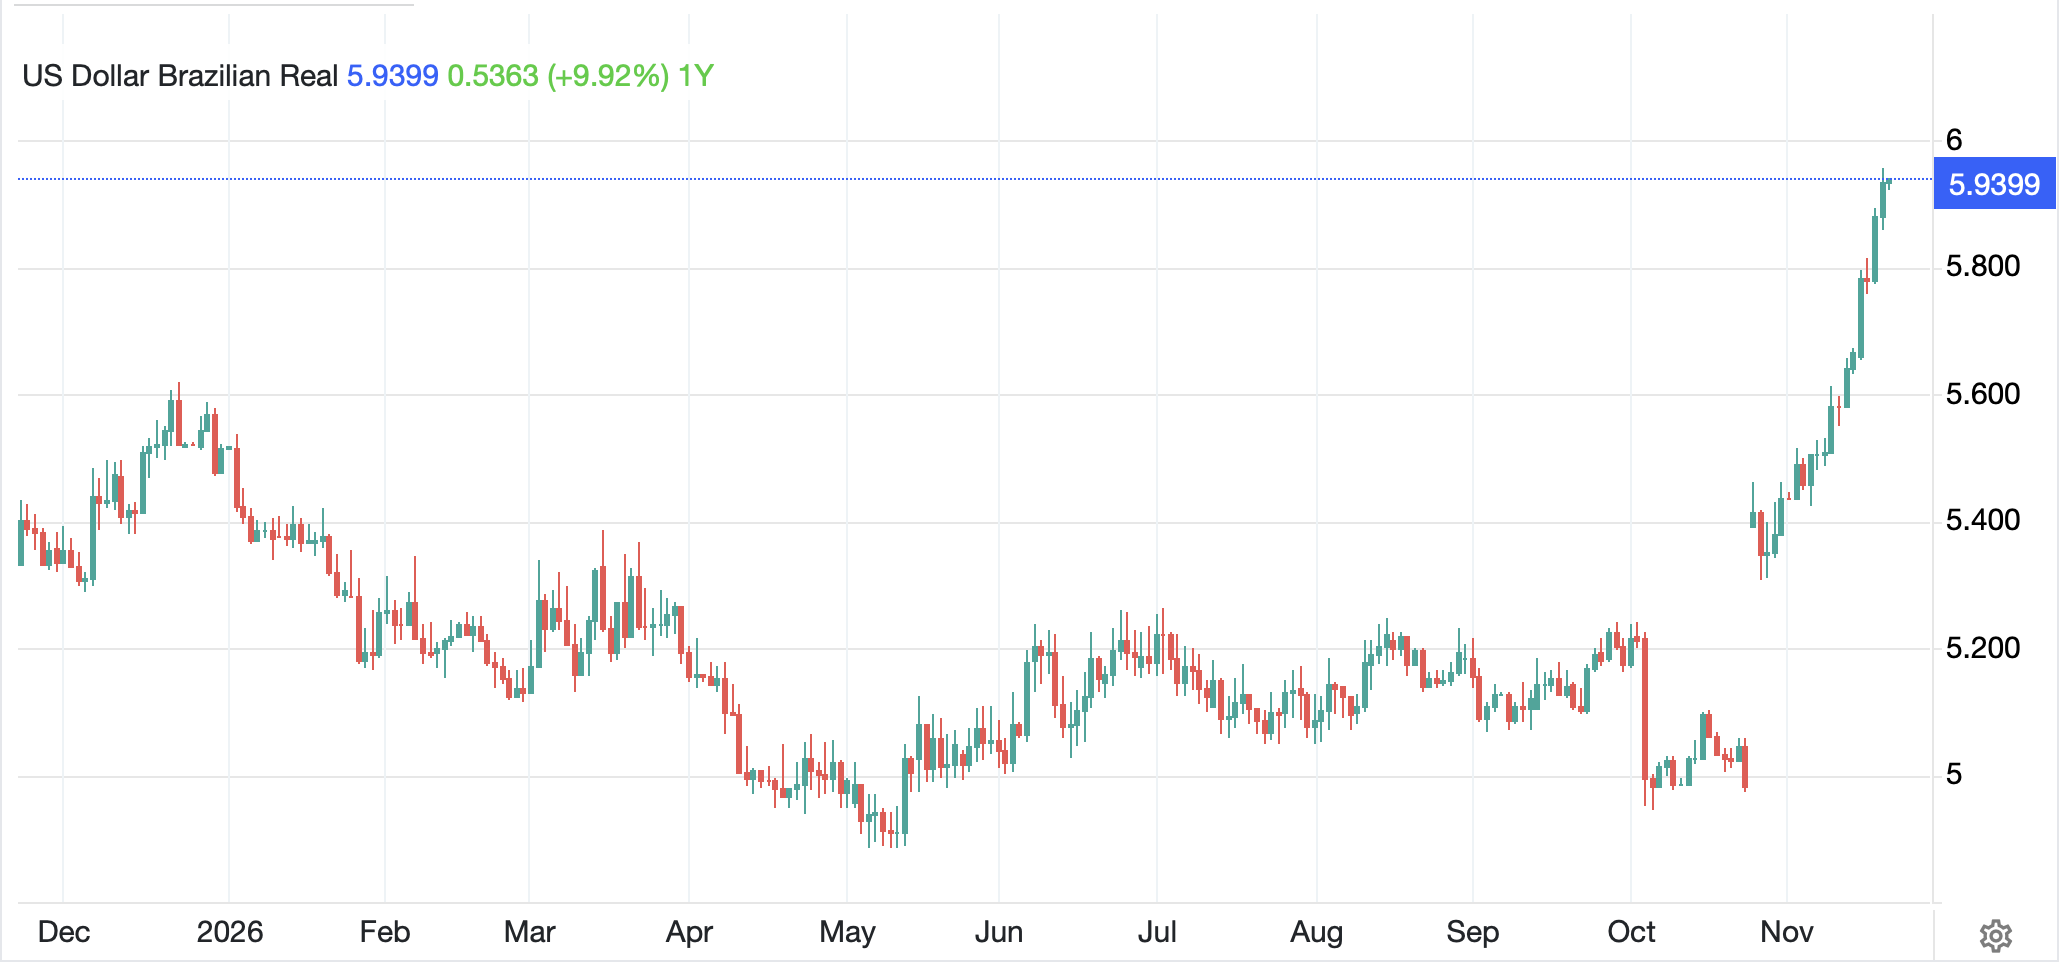
One thing to note is that Brazilian markets haven’t opened yet, but it is also worth noting that investors are shunning Brazilian assets, whether stocks, bonds or the currency, as concerns over Lula’s unfunded spending plans continue to grow. We are very fortunate in the US to have the government be able to overspend and still have access, nay demand, for our bonds. In Brazil, that is not the case. In fact, I have highlighted the real’s recent weakness but yesterday, again, it fell sharply and is pushing back to 6.00 for the first time in two years. The key problem is that historically, legislative branches of government don’t really pay attention to markets so this could go a lot further before the pain gets too great to ignore.
Source: tradingeconmics.com
As to the rest of the currency market, the dollar is maintaining the bulk of its recent gains although we have seen the yen (+0.5%), CHF (+0.3%) and INR (+0.8%) all rally today. The first two are classic haven plays and amid a global risk sell-off, it is not surprising to see them perform well. As to the rupee, I would contend its movement is directly related to the fact that global investors are buying more Indian equities (buying rupees to do so) as a hedge against their other positions.
Finally, commodities markets show that there is no love for anything right now as investors look at the prospect of higher yields on fixed income and dump anything that is not paying interest. So, oil (-0.25%) is slipping again today with whatever news that comes from the Gulf completely ignored. As to the metals, it has been extraordinary, with gold (-1.3%), silver (-1.2%) and copper (-1.8%) all under continued pressure. While copper is suffering on the back of the new concerns regarding AI, gold is the big surprise. After all, governments haven’t stopped deficit spending and central banks haven’t stopped printing money, the two underlying drivers of the debasement trade that was so popular earlier this year. Fashion is fickle, and metals are out of fashion now, that is for sure.
On the data front, yesterday’s Claims data was worse than expected with Initial slightly higher but Continuing much higher. Maybe the job market is not so robust. Philly Fed was also weaker than expected. Today brings only the University of Michigan Expectations (exp 51.5) a slight tick up from the preliminary number, and a few more Fed speakers with the newly crowned uberHawk, Waller as well as the barely functioning idiot, Cook.
The momentum is for risk off, and I see no reason for that to change going into the weekend. Will this continue much longer? While it certainly can, my sniff is we are running out of steam to the downside. Dip buying is still a default and there is still a massive passive bid from 401K accounts. While the bottom may not yet be in, I think we are pretty close, at least I hope so!
Good luck and good weekend
Adf

