THE earnings report was released
But none of the chatter has ceased
Is Huang really gone?
Or does he live on
For traders who’ve lately been fleeced

Meanwhile, Trump’s in China to meet
With Xi, who came out, him, to greet
Today we are lacking
In cyberattacking
Thus, risk has now shown a heartbeat
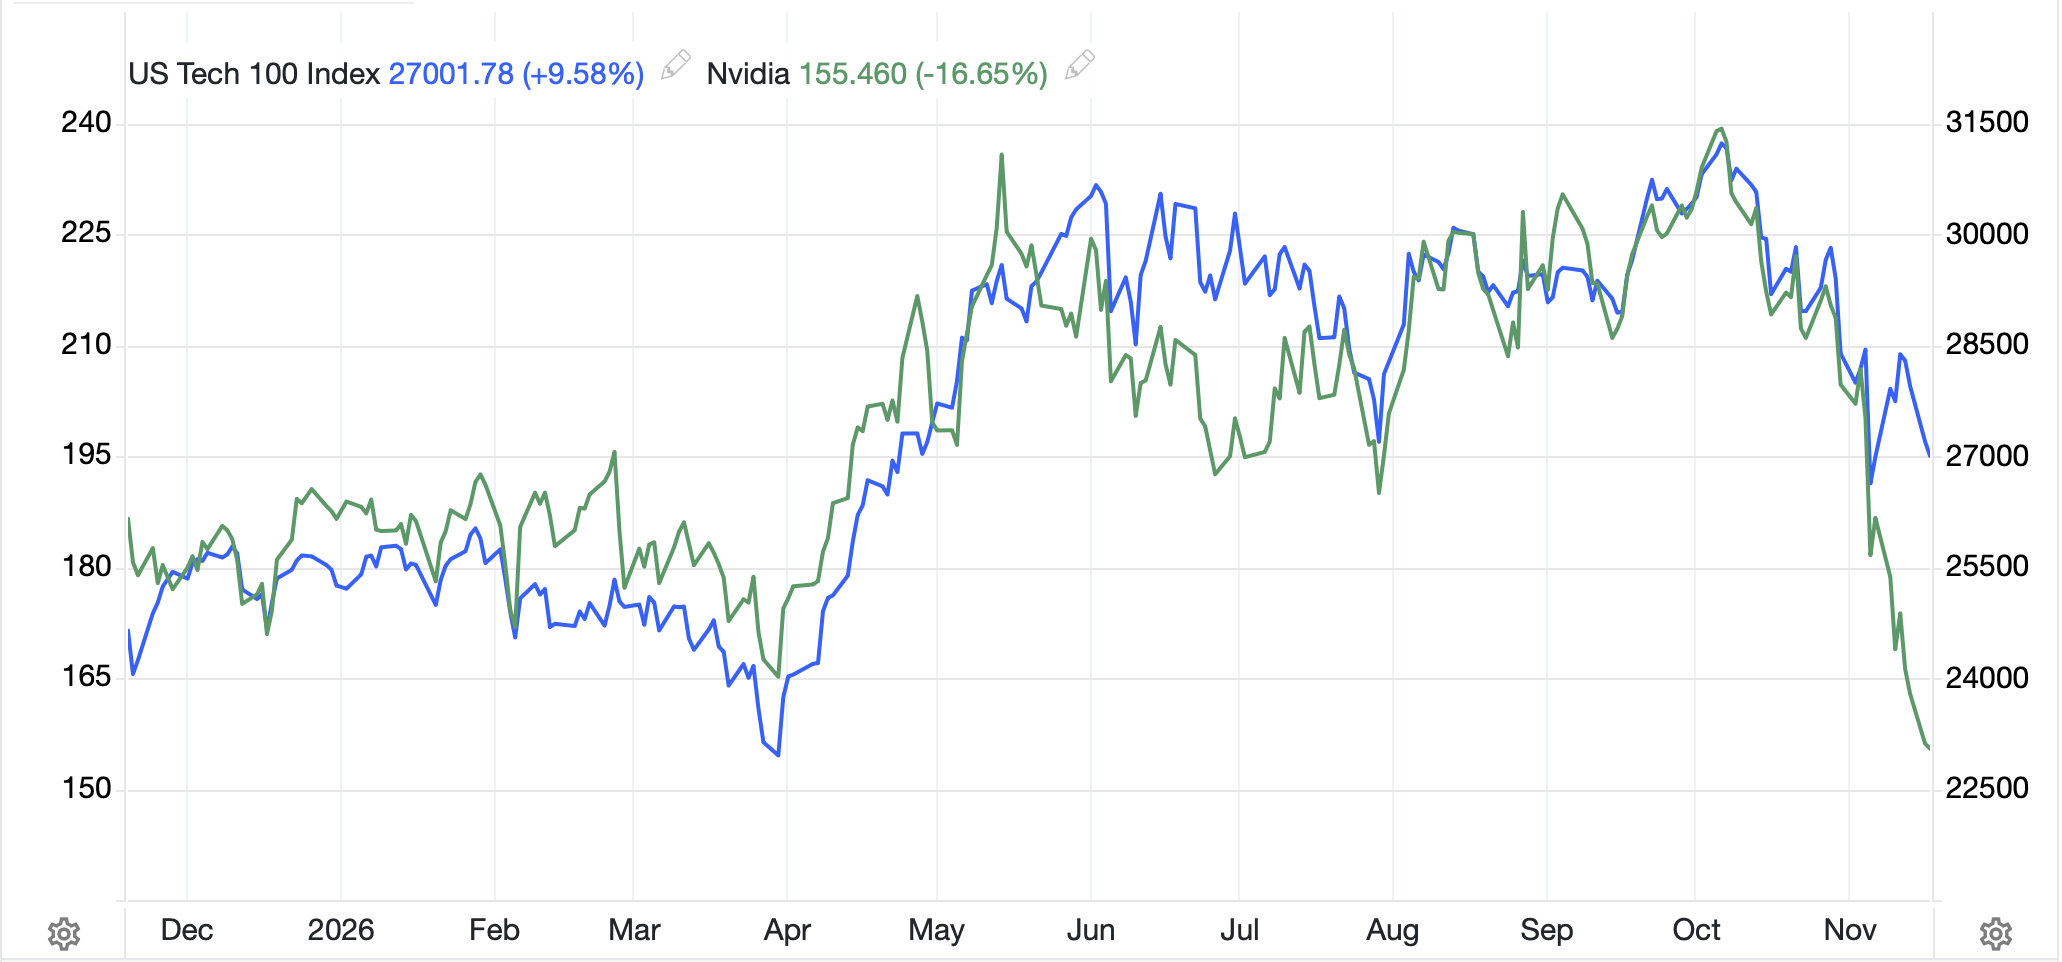
I’m not an equity guy, certainly not regarding the details of any company’s reports, but the biggest equity news was Nvidia’s earnings yesterday which were humongous by any accounting. However, this is backward looking, not forward looking, and with Jensen now gone, and despite talk he might return, seemingly gone for good, what does this mean for the markets in general. I thought the following chart was worthwhile, showing just how much further Nvidia has fallen than even the NASDAQ, of which it was a huge part. This is not to say things are great, just that the market appears to be figuring out there are other companies worthy of investment.
Source: tradingeconomics.com
However, risk appetite has certainly been reduced over the past month, and many are calling that the top is in, at least for the time being. There are battles on XFin regarding whether this is a good time to buy AI stocks or not with passionate cases made on both sides. Remember, too, that Anthropic’s IPO is slated for tomorrow, targeting a $1.4 trillion market cap in what would be the largest IPO of all time. (I won’t be involved!)
The next big story is that President Trump landed in Shenzhen, China for the APEC meetings and was personally greeted on the tarmac by President Xi. Much has been made of this as Xi has never greeted any US president before in this manner. President Putin is also arriving there and the three are set to meet tomorrow, although the agenda has not been released leading to much speculation. The most positive spin I’ve seen is that they are working toward a framework to reduce their nuclear arsenals. Certainly, the US and China would probably agree that makes sense, but will Russia given they have threatened their use in their current Ukraine encounter? Others have mooted the idea that they are going to split the world into spheres of influence with China getting Asia, the US the entire Western Hemisphere and Russia getting Europe (boy they come out the worst but have the least leverage.). It seems hard to believe there is an economic motive that is valuable to all three, but you never know. However, at this stage, I would contend the market is not paying much attention.
Lastly, the good news is there have been no new technology glitches reported today, although the cyberattack thesis remains the most popular discussion, at least on X. Two of my readers (H/T Martin and Consumer Girl) laid out the issues and made the following point:
“We had a saying…. alpha testing done by in-house personnel, beta testing done by a few paying customers, full release was testing by all customers! Subsequent releases to fix all the bugs! Murphy’s Law lives everywhere all the time.”
If you’ve ever worked in a large organization, you know just how correct that sounds.
Ok, let’s see how markets are responding to the latest. Starting in equities, yesterday’s US performance was lousy, but markets closed well off their intraday lows and futures this morning are higher across the board as I type (7:00). Is a bottom in or is this a dead-cat bounce? While it has been a rough past week, remember, the market indices are all higher this year. The end is probably not nigh.
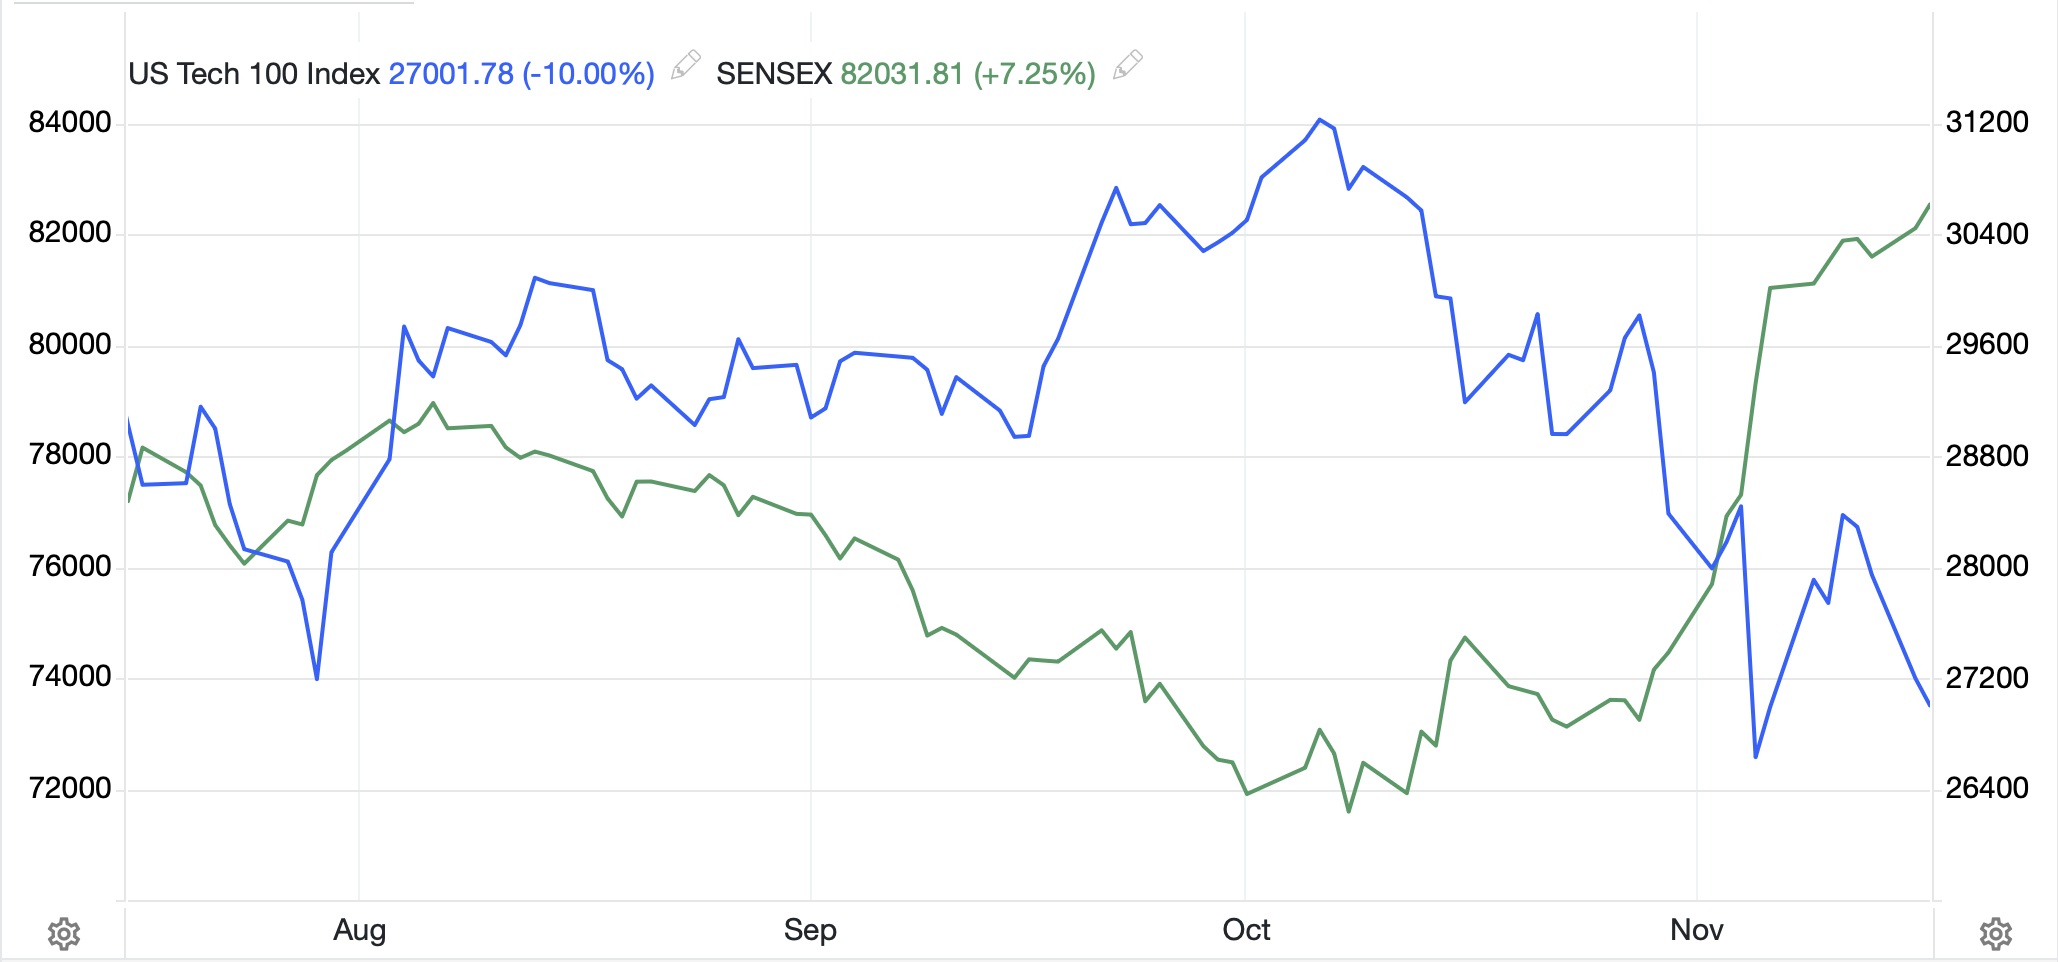
In Asia, equities were mixed with some modest gainers (Japan +0.3%, China +0.2%, Korea +2.0%, Taiwan +0.3%) with a few more laggards (HK-0.9%, India -0.6%, Australia -0.7%, Singapore -1.1%) and the smaller exchanges generally softer. I guess the APEC meeting has not instilled enough excitement regarding future economic activity in the region. Someone pointed out that India has been outperforming lately arguably because they are not really part of the AI discussion lacking semiconductor manufacturing or any frontier models as well as being home to companies that are likely to be devastated by AI (all those call centers). Yet, if we look at their market over the past month and compare it to the NASDAQ, it is almost perfectly negatively correlated as per the below chart. Similarly to my claims about Europe lacking tech, India seems to be benefitting right now for the lack of AI exposure.
Source: tradingeconomics.com
As to European bourses, they continue to be nondescript, with some modest declines (Uk -0.4%, Spain -0.4%) while the other major exchanges are essentially flat.
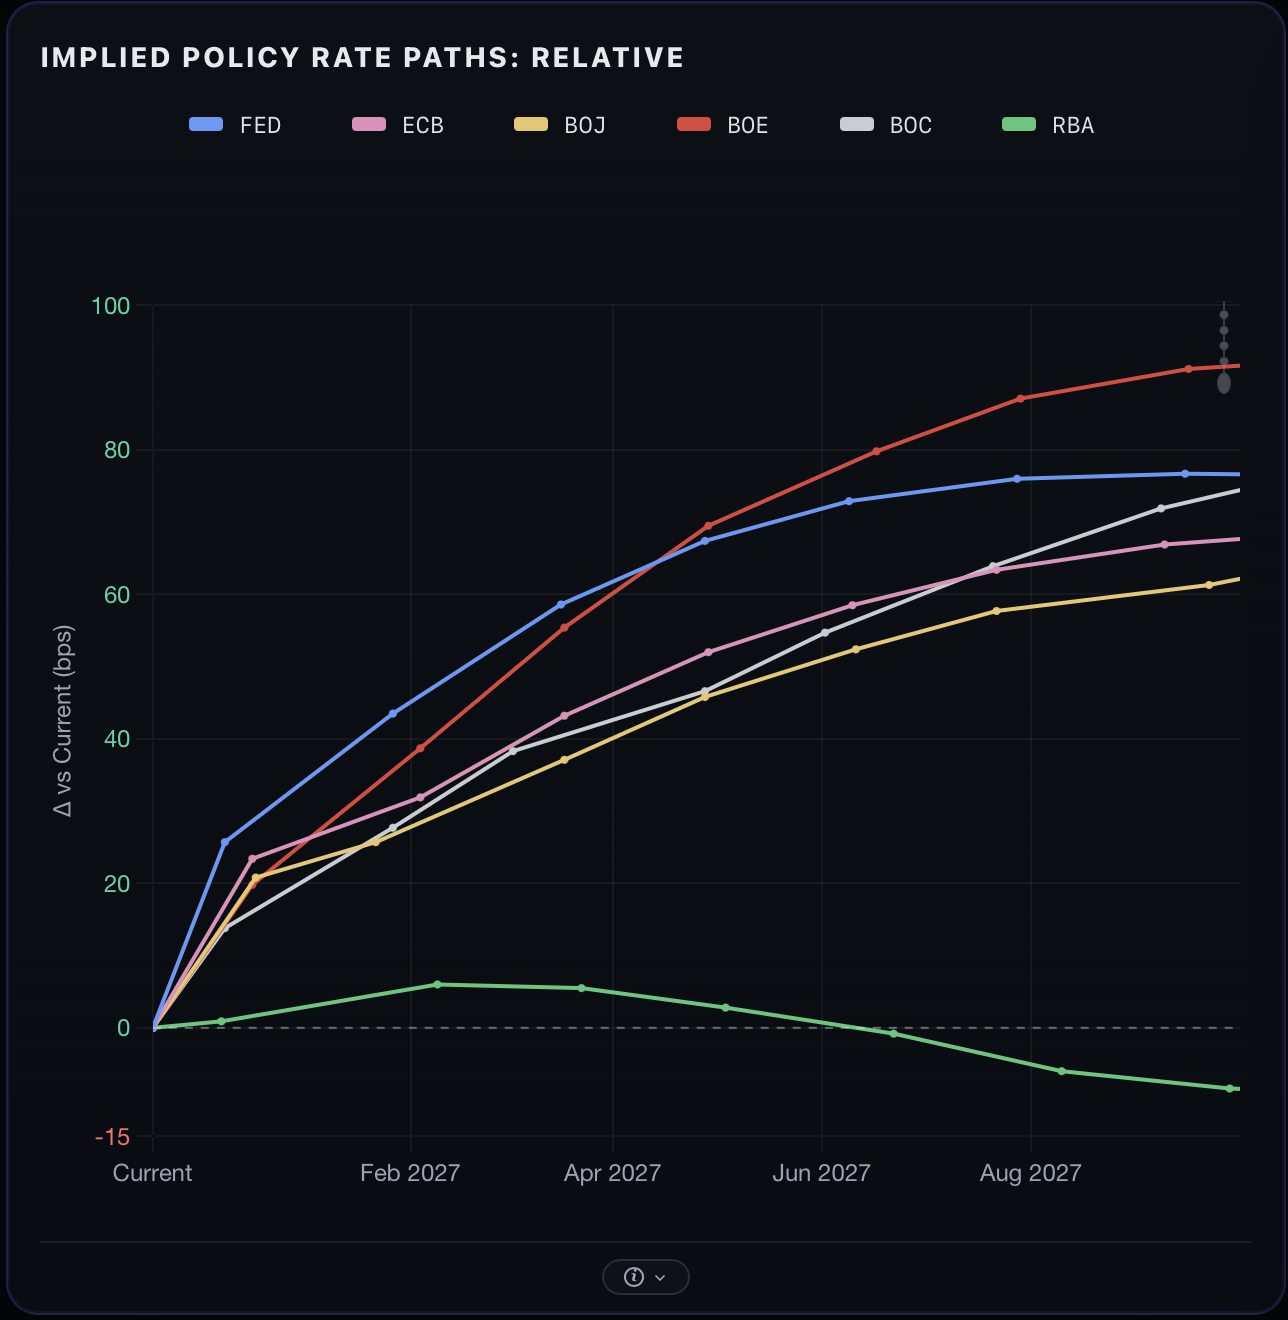
Bonds continue to be attractive with 10-year Treasury yields slipping -1bp this morning after sliding -2bps yesterday. European sovereign yields are also somewhat lower with UK gilts (-5bps) the outlier despite (because of?) higher than forecast inflation readings. In fact, inflation was higher across Europe and, of course, has been firmer in the US. More Fedspeak is focused on raising rates with St Louis Fed president Musalem the latest hawk explaining rates need to be higher and soon. Consider, though, this is a global trend as if you look at the chart from rateprobability.com below, only Australia is priced to leave rates on hold while every other major central bank is priced to hike rates at least 60bps by next summer.
And central bank speakers are out in force still with virtually every one of them calling for higher rates. (As an aside, Chairman Warsh did speak on Monday, but his comments were entirely regarding AI and how the task force was studying potential impacts. He didn’t say anything about monetary policy.)
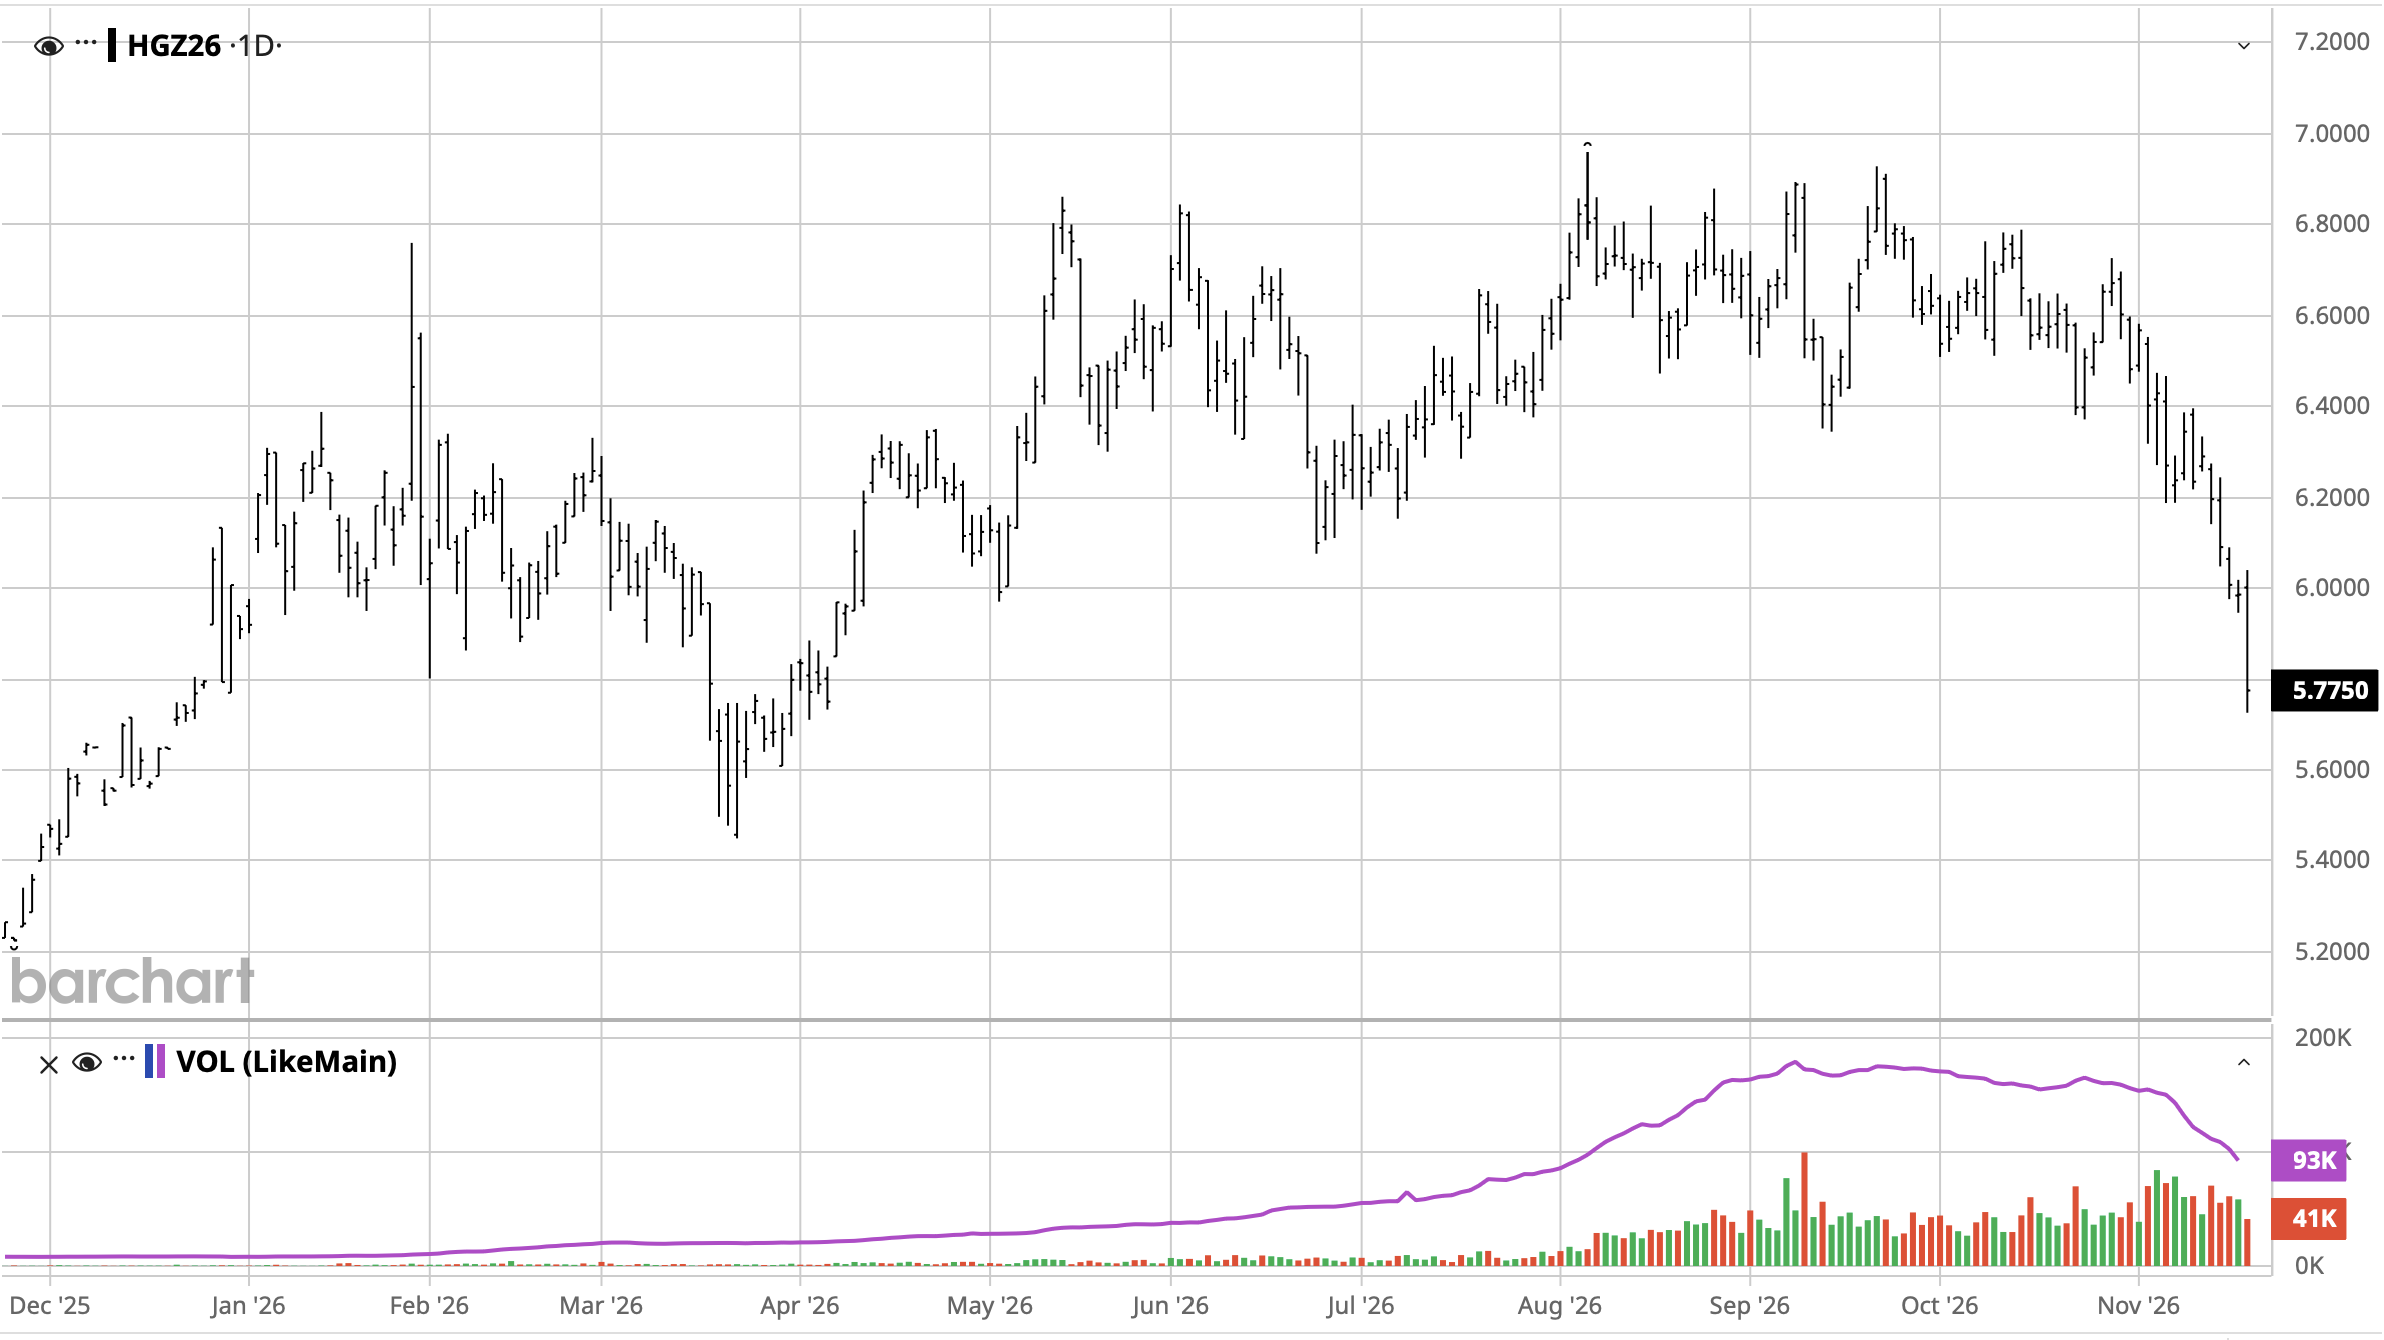
In the commodity markets, oil (-0.7%) continues to slip as do the ancillary products, but lower gasoline prices, a good news story, are not likely to make the news. Metals, though, have been under extreme pressure (Au -2.1%, Ag -3.2%, Cu -3.6%) with both gold and silver down on the year while copper is back to unchanged. If Dr Copper is going to live up to that moniker, anticipating economic activity, then growth seems set to slow going forward. Perhaps it is anticipating the damage that central banks are getting set to inflict on the global economy.
Source: barchart.com
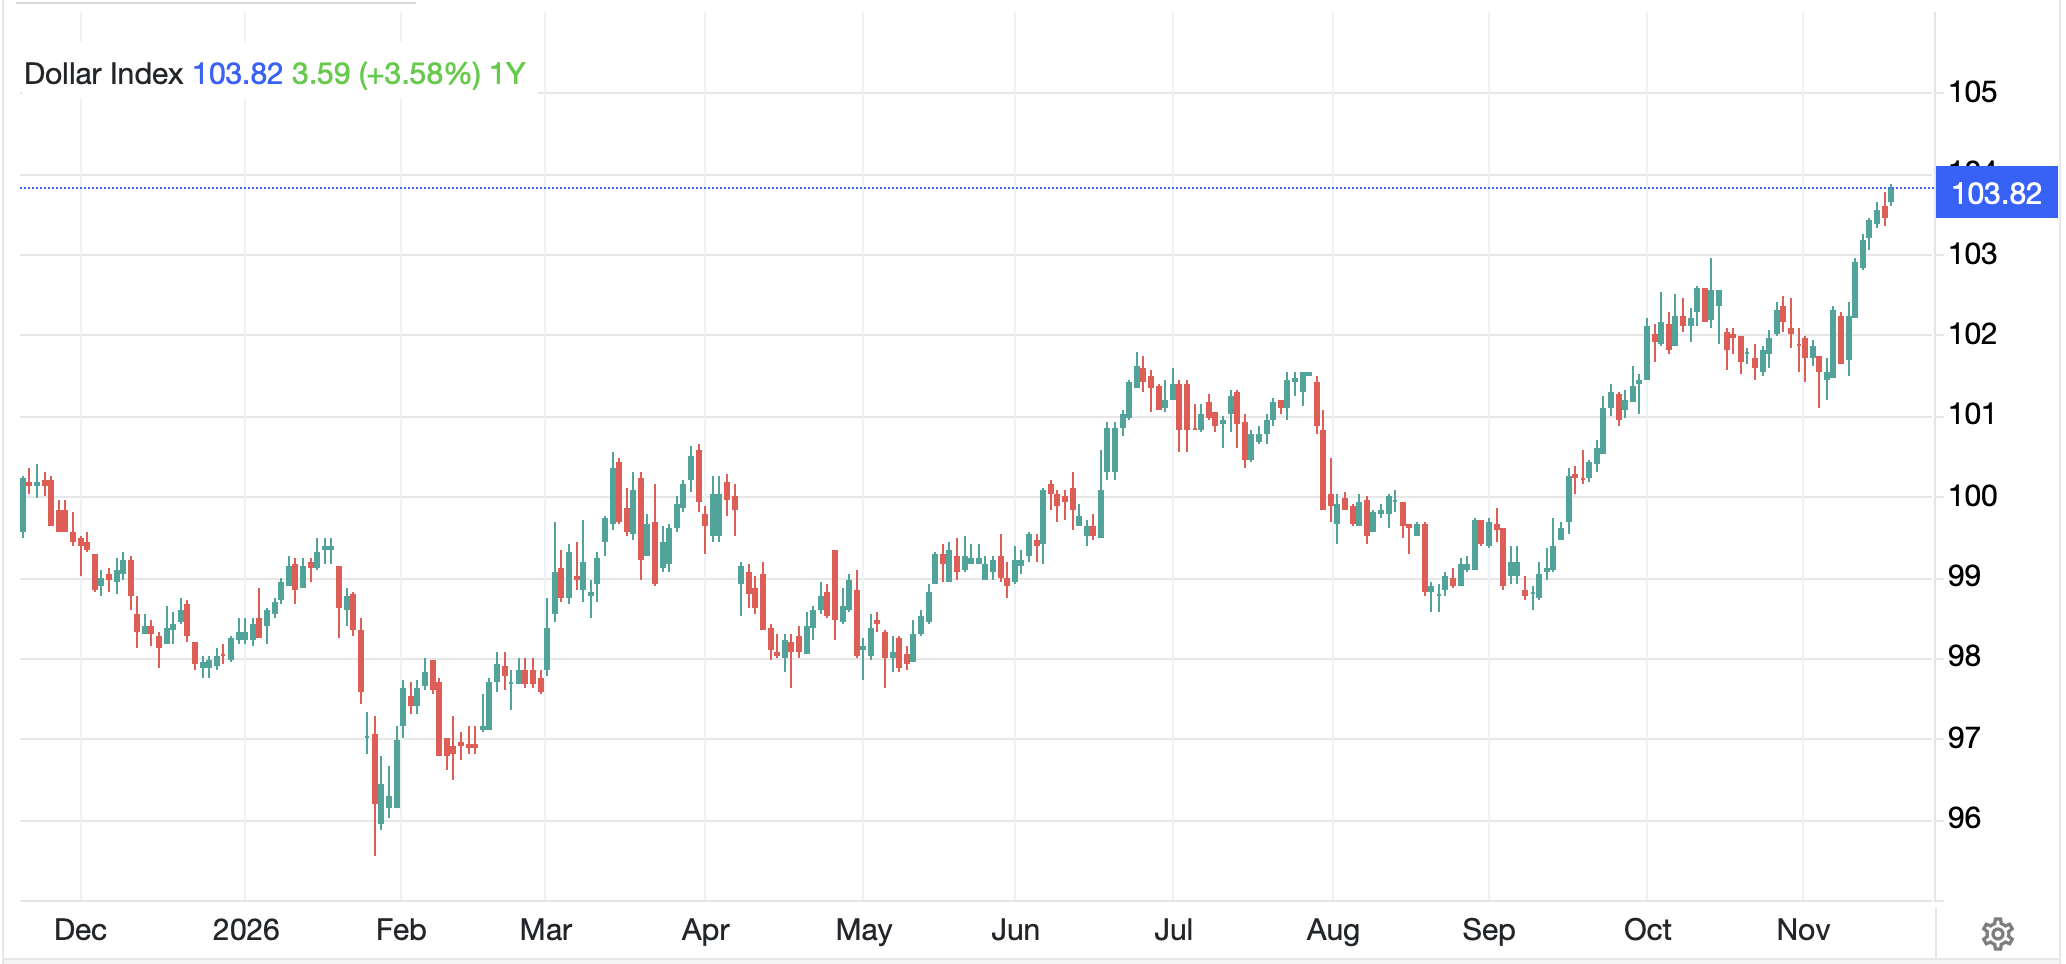
Finally, the dollar remains firm with DXY (+0.3%) climbing to new highs for the move as per the below chart.
Source: tradingeconomics.com
The funny thing here is that the relative interest rate story doesn’t seem to be driving things. After all, as per that rate probability chart above, other than AUD, all the major central banks are expected to hike rates by virtually the same amount, thus leaving the differentials essentially unchanged. So please explain why the dollar is the beneficiary if that is the case. For everyone who believes the dollar is going to crumble, this price action is a problem. The dollar’s haven status remains unparalleled compared to other currencies, even the Swiss franc and Japanese yen. As I wrote last week, my biggest concern is that the luddite view of data centers holds sway and that will dramatically, and negatively, impact the economy, and by extension the dollar.
On the data front, today brings Housing Starts (exp 1.27M), Building Permits (1.38M) and then the EIA oil data with a small build expected. Then, at 2:00 we get the FOMC Minutes, but given how much commentary we have heard since the meeting, are they really important? And we hear more today with Governor Barr and NY Fed President Williams on the calendar.
Risk is clearly under pressure, although today there is a respite. If we see another tech glitch in the next several days I would suggest that we will see a significant selloff as the cyberattack theory will take on a life of its own. But absent that, most market eyes will be on tomorrow’s IPO of Anthropic. There is nothing stopping the dollar for now, although bonds, too, remain in favor. I guess investors are buying dollars to buy bonds.
Good luck
Adf

