Said Lula, it might be confusing
But there is no way that I’m losing
So, I’ll lie and cheat
In order to beat
The other guy you could be choosing

Meanwhile it’s a central bank week
With Warsh, come this Wednesday, to speak
So, what will he say?
Are hikes still in play?
Or have Fed funds climbed to their peak?
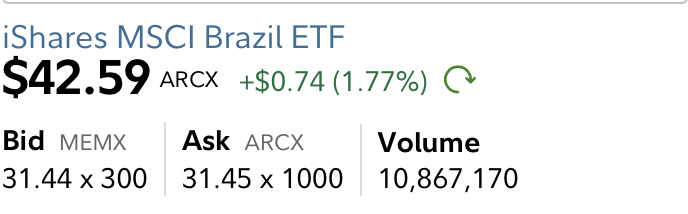
In the biggest surprise of the weekend, Lula da Silva won the Brazilian presidential election. It seems that right as the polls were due to close, a single member of the Brazilian Supreme Court, Christiano Zanin (who happened to be Lula’s personal attorney before being put on the Court) extended voting by 2 hours despite the rest of the court voting against that action. I do not know if that changed the outcome, nor do I imagine we will ever really get the story, but the result stands for now. I suspect the Senor Bolsonaro will sue for a recount or something, but the market has spoken, at least the equity market has as you can see from the following quote for the Brazil stock ETF, EWZ, before the market opens this morning. That’s a 26% decline!
You may remember after the first round of the election three weeks ago, the market rallied sharply on the idea that Bolsonaro would be unwinding many of Lula’s policies as per the below chart.
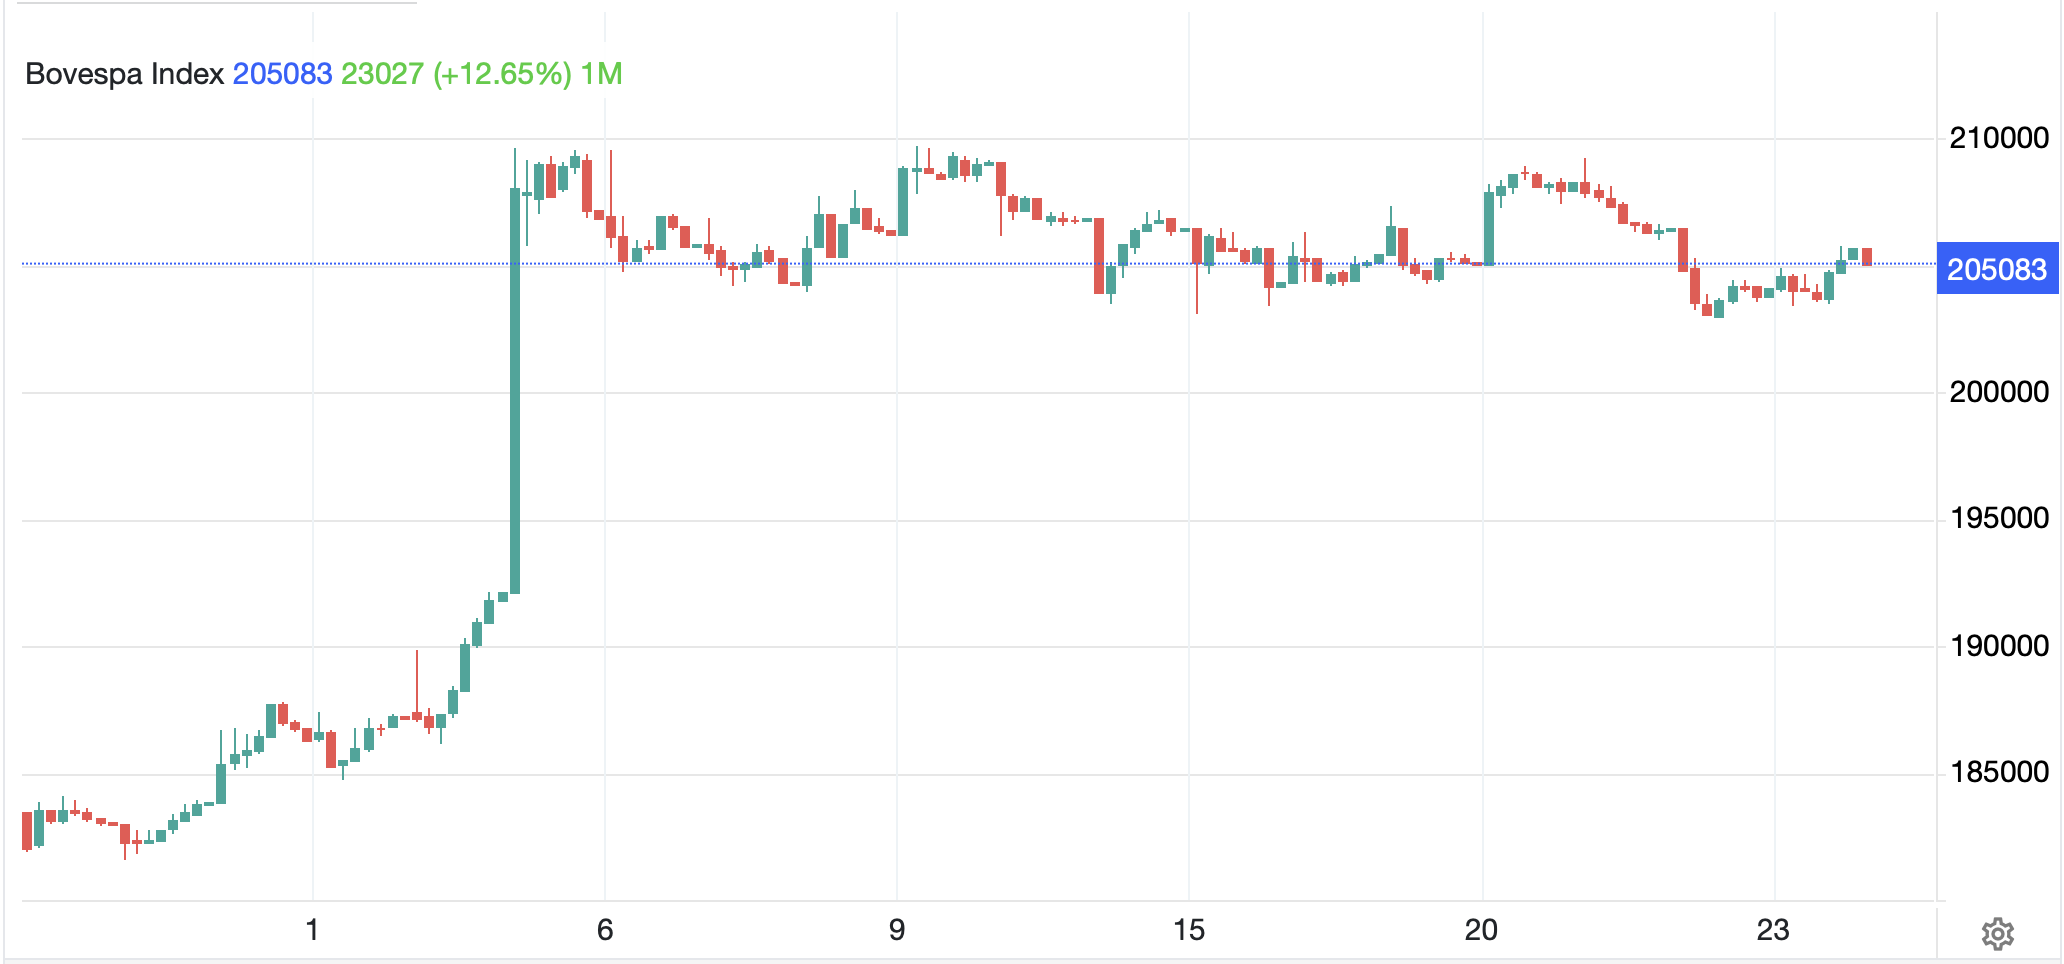
Source: tradingeconomics.com
But perhaps the most interesting thing is the fact that the prediction markets, the new “fount of truth” was also completely wrong on this outcome. Going into the weekend, there was a more than 80% probability of a Bolsonaro victory. It just goes to show that there are no guarantees when it comes to events.
It is still too early to tell what will happen in the FX markets as BRL is a restricted currency and won’t start trading until Brazilian markets open in a few hours, but I suspect that the real will fall pretty sharply as well. After all, it mirrored the stock market rally on the first-round news.
Away from that story, and the ongoing riots in France, which seem to have been absorbed by markets now as there has not been much movement overall, at least not in government bond markets, focus is turning to the FOMC meeting that begins tomorrow with the statement and press conference on Wednesday afternoon. As of this morning, futures markets are pricing less than a 10% probability of a hike, which as you can see is a substantial change from a month ago when there was nearly a 2/3 probability priced in.
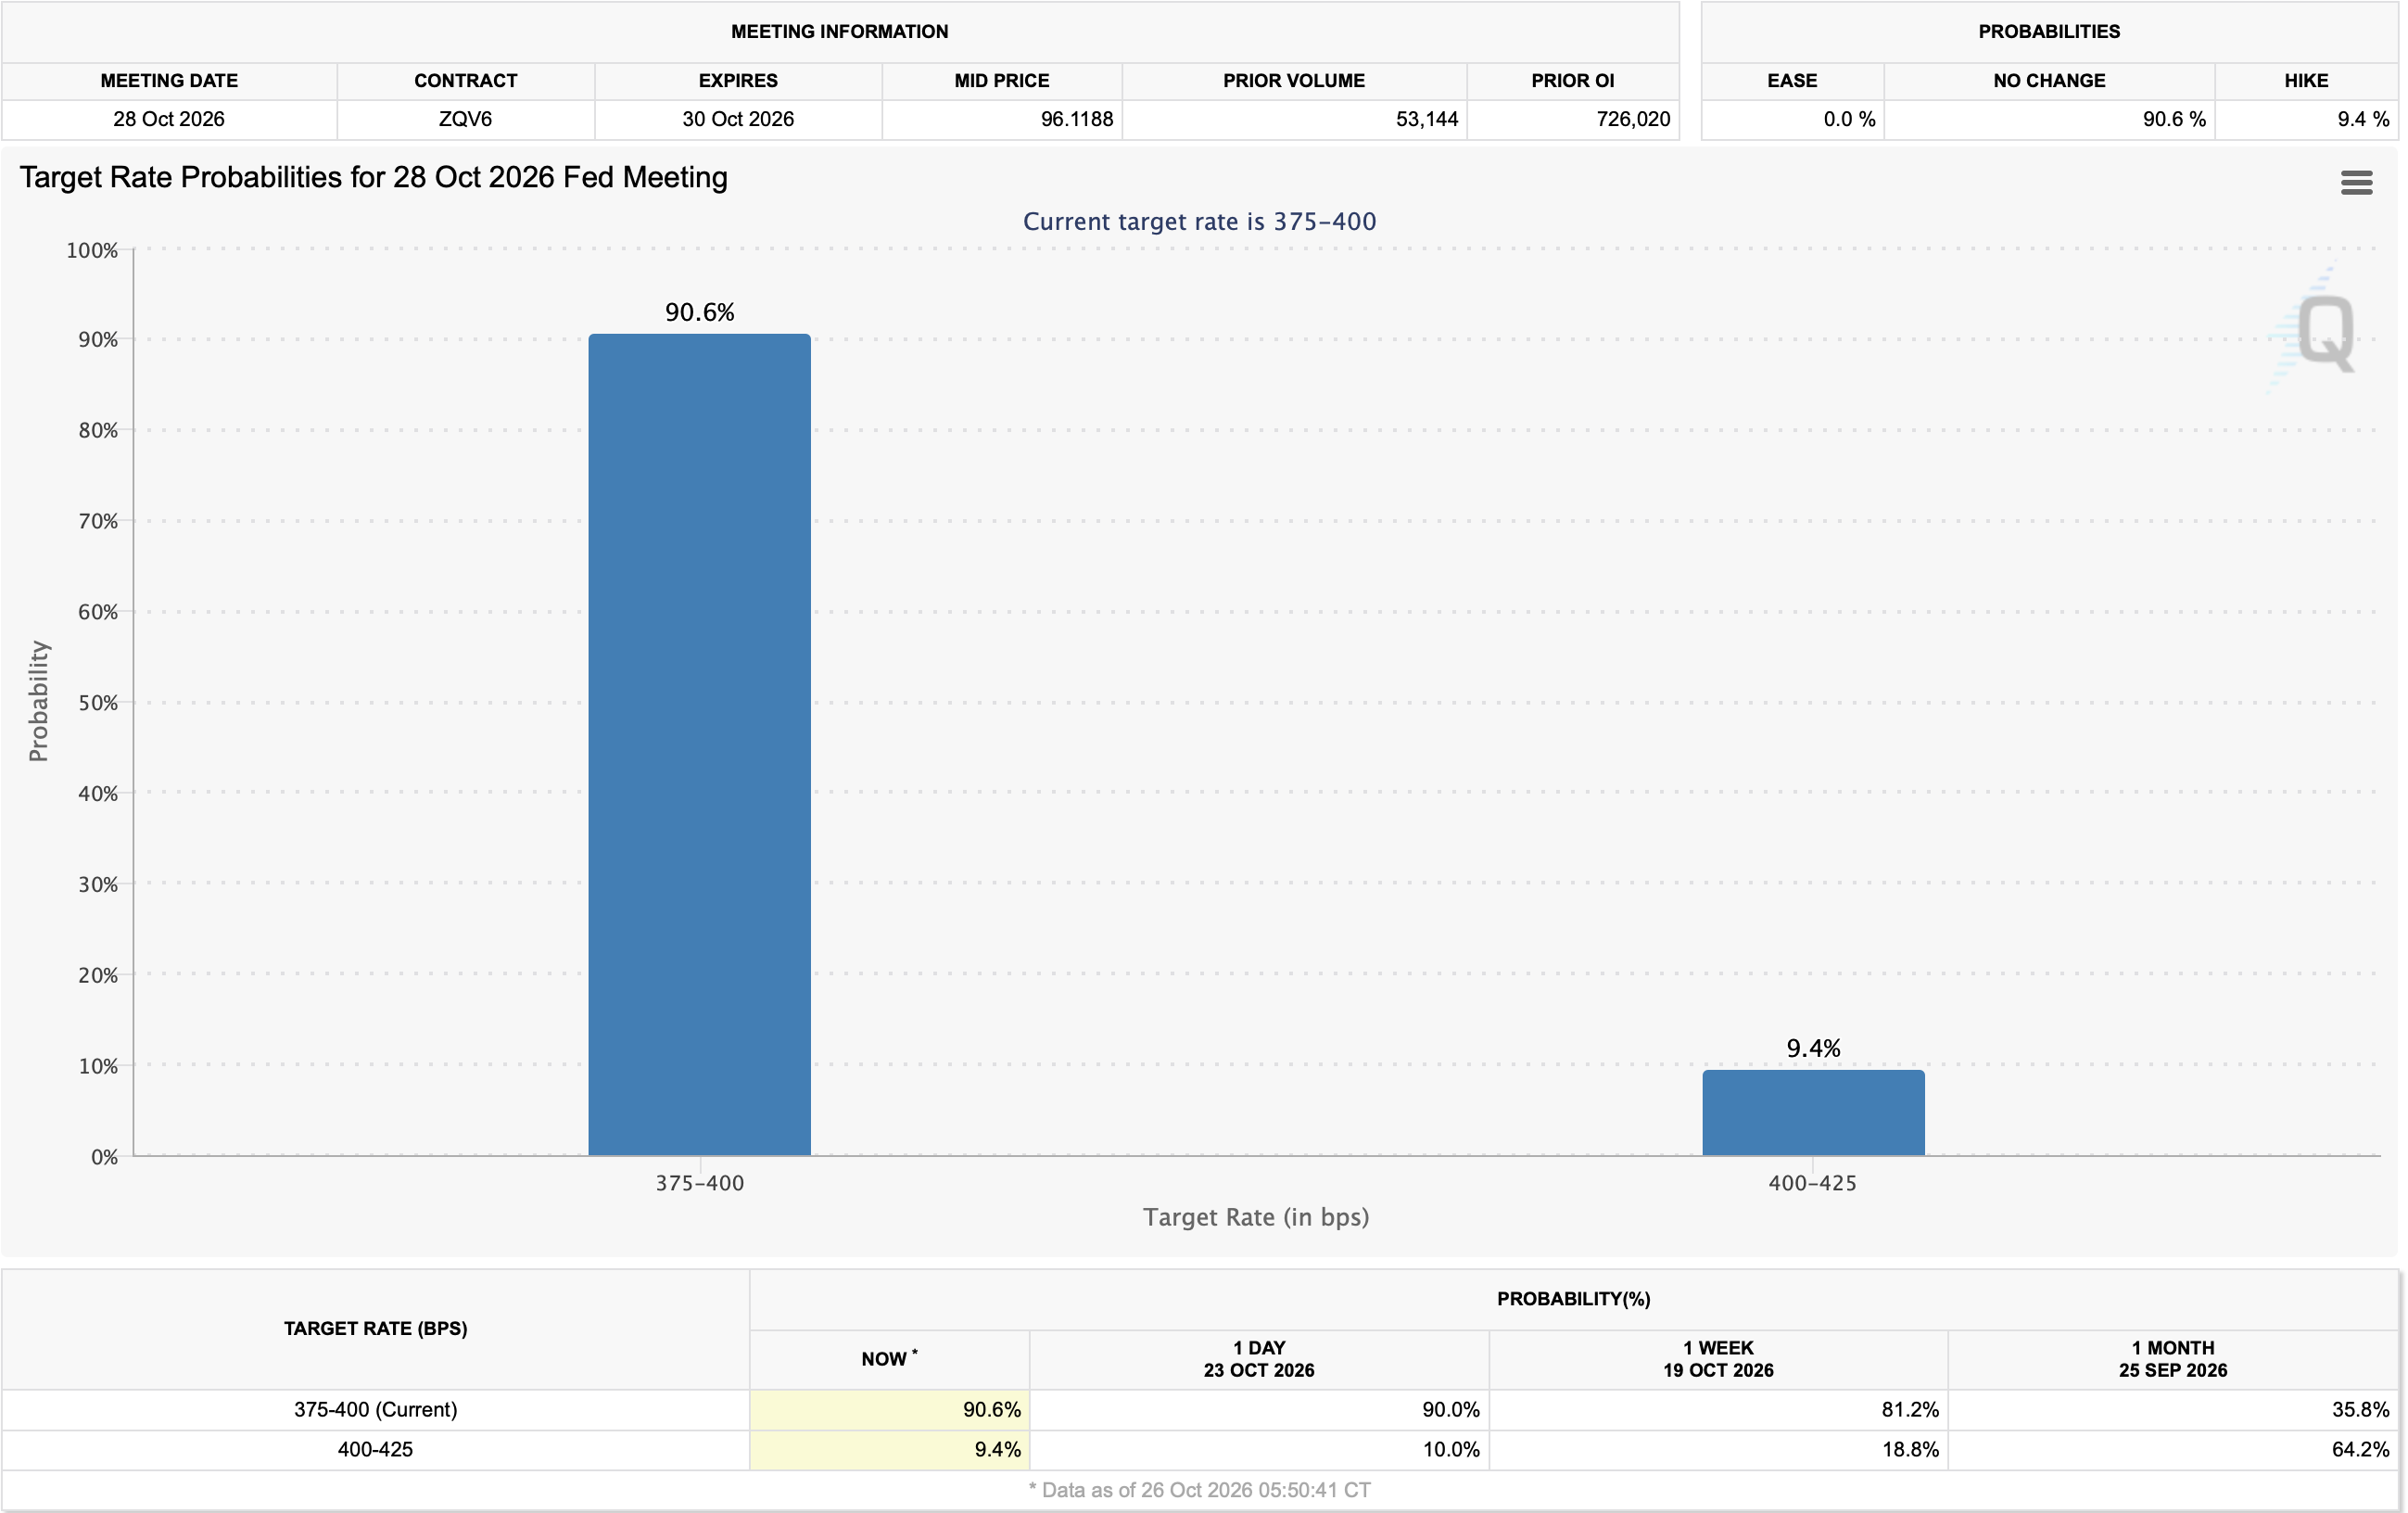
Source: cmegroup.com
This is an important lesson, I believe, regarding markets. I always refer to market pricing as the best descriptor of current information. However, information changes, situations change and so prices do change. Just because a future event seems to be priced in at some point in time doesn’t offer certainty, it is simply a reflection of the sum of knowledge at that time. In this case, in the weeks since that pricing existed, a number of Fed speakers explained they were in no hurry to raise rates again and given the timing of the Fed meeting relative to the mid-term elections, the market has discounted the idea of a Fed move as it could be seen as political. (LOL, as though all their moves aren’t political!). Nonetheless, at the moment, all the fears of Treasury yields exploding higher to 6% and beyond and the Fed turning more hawkish have faded away. In fact, I suspect that this meeting will pass uneventfully. The one thing of which I am confident is that at the press conference, Chairman Warsh will not offer any guidance but will instead reiterate that they will achieve their inflation goals, dammit!
And that’s how things are shaping up this morning, so let’s see how other markets look. Friday’s weakness in US equity markets has not been the norm either overnight or in Europe this morning. While Tokyo (-0.8%), Korea (-1.5%) and Taiwan (-1.8%) all fell on the same tech sell-off story, India (+0.7%), HK (+0.5%) and Thailand (+1.1%) all rallied while China’s Plunge Protection team was able to stabilize markets there with a basically unchanged session. There is much discussion about how neocloud firms are going to run out of funding and how this is the beginning of the end of the AI trade which is clearly weighing on certain companies and markets, but as we saw this weekend, surprises are quite possible.
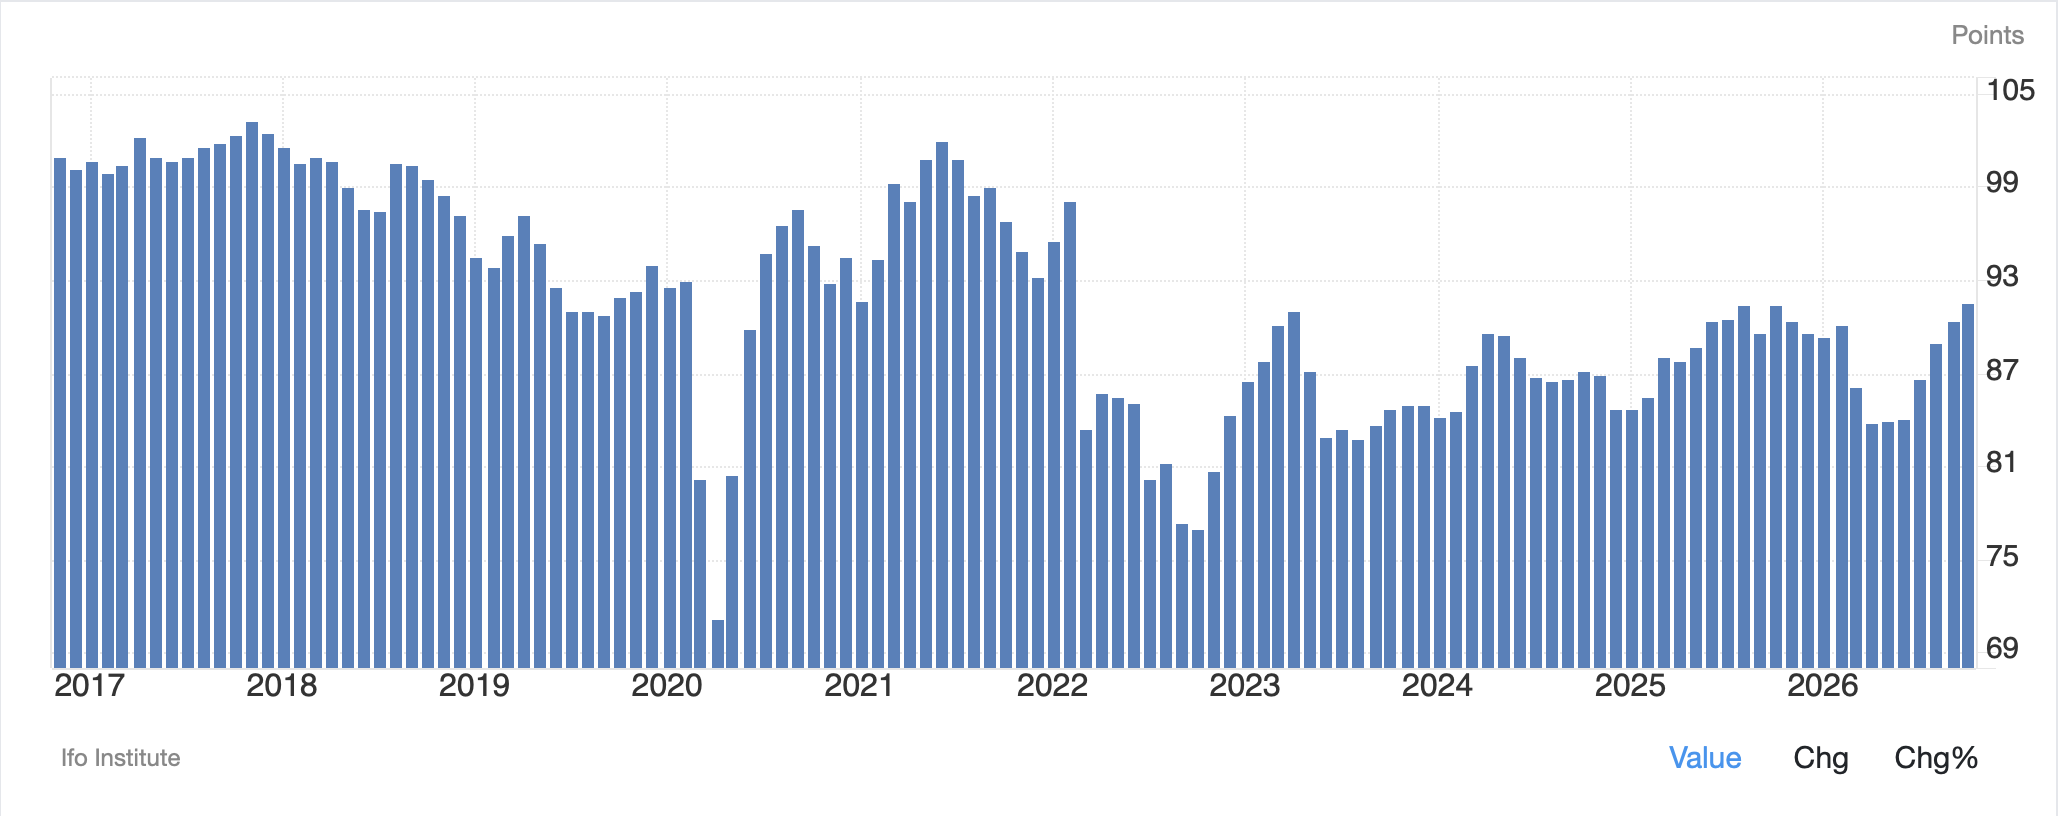
In Europe, only Spain (-0.2%) is lagging, and it is only slightly lower. Otherwise, the major nations are all seeing gains (UK +0.5%, Germany +0.9%, France +0.75%, Italy +0.6%) with the only news of note the German Ifo reports which showed current conditions sagging but hope for the future as the Expectations reading was 91.6, higher than expected, but as you can see from the chart below, still well below the pre-Covid readings and the long-term average of 95.1.
Source: tradingeconomics.com
But it’s better than nothing! As to US futures, they are little changed to slightly higher this morning.
In the bond market, Treasury yields are little changed from Friday’s close at 4.99%. The real movement today has been in the Bund-OAT spread, which you may recall blew out above 175bps last week, but has now fallen back to 160bps with German yields edging higher by 3bps while French yields have slipped -4bps. The thing about this movement is there is nothing I can see to drive a change in the concern over France’s fiscal future. Riots continue there and are spreading to Barcelona and Italy in Milan I understand, and the Macron government can do nothing to change the fiscal accounting as it does not have the strength to pass legislation to address the issues. This seems much more like a trading move with some profit taking than anything fundamental.
In the commodity markets, oil (-2.1%) is slipping as reports are coming through that more oil is transiting the Strait of Hormuz than before the Iran war began! I cannot confirm that, but it is a widely read story this morning. Remaining in the energy sphere, the dichotomy between US NatGas and TTF is extraordinary with the divergence accelerating as per the below chart from tradingeconomics.com.
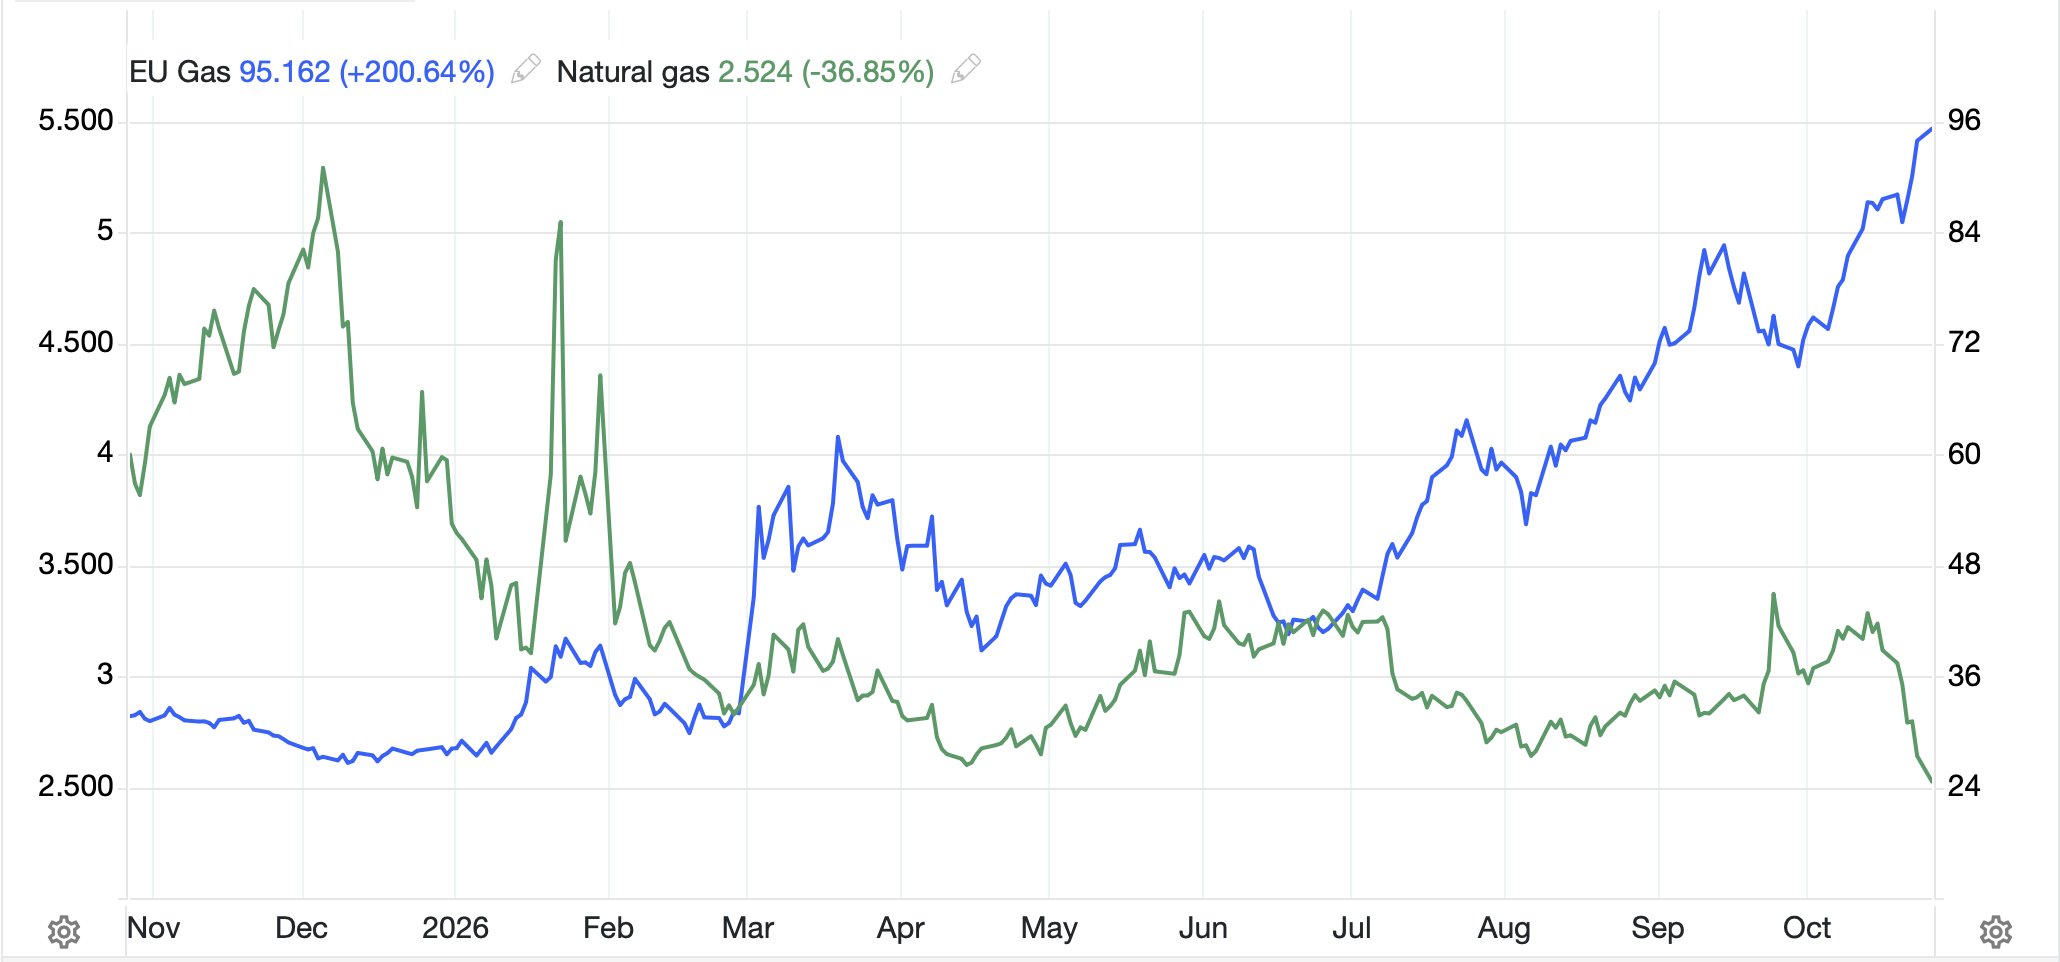
At its current level, TTF is priced at ~$31/MMBtu, more than 12X US Henry Hub gas, and apparently, Asia is outbidding Europe for US LNG cargoes even though European storage is far below targeted levels. If it is a cold winter in Europe, it could be quite problematic as their energy policy insufficiencies will make themselves very clear. As to the metals markets, gold (+0.5%) is bouncing a bit as it trades either side of $4000/oz and silver and copper are little changed this morning. There has been a story going round that gold has been successfully synthesized which is a reason that it cannot go higher, however, asking Grok, it is estimated to cost $1,000,000,000,000,000/oz to make it this way, so perhaps it is not an immediate threat.
Finally, the dollar is modestly higher this morning with the most exciting prospects remaining in Brazil when that opens in a bit. The BOVESPA stock market doesn’t open until 9:00 EDT but I think the FX markets there will open an hour earlier than that, so pretty soon. I suspect the BRL will weaken on the opening.
On the data front, there is plenty to digest this week as follows:
| Today | Chicago Fed National Activity | -0.1 |
| Tuesday | Durable Goods | 1.5% |
| -ex Transport | 0.6% | |
| Case Shiller Home Prices | 2.5% | |
| Consumer Confidence | 81.0 | |
| New Home Sales | 650K | |
| Wednesday | Goods Trade Balance | -$130B |
| FOMC Rate Decision | 4.0% (unchanged) | |
| Thursday | Q3 GDP | 3.2% |
| Personal Income | 0.3% | |
| Personal Spending | 0.5% | |
| Initial Claims | 200K | |
| Continuing Claims | 1730K | |
| PCE | 0.5% (3.6% Y/Y) | |
| Core PCE | 0.3% (3.1% Y/Y) | |
| Friday | BOJ Rate Decision | 1.25% (Unchanged) |
| Employment Cost Index | 0.8% | |
| Chicago PMI | 55.5 |
Source: tradingeconomics.com
So, while two major central banks meet, no action is anticipated. I have maintained that things would remain range bound ahead of the elections here next week and nothing has changed that view. I also believe that if the Democrats sweep both House and Senate, equities will suffer greatly, although I don’t believe that is going to be the outcome. However, as we just learned yesterday, we won’t know until the votes are counted. In the end, nothing has changed to make the dollar the least worst alternative, that’s for sure.
Good luck
Adf


ecb meeting?
just goes to show you how little I think it matters. but seriously, I thought they met this week buy in my look over my indicators, I missed it. thanks for following up