Seems I just can’t leave you alone
Lest havoc and fear you’ll have sown
So, now that I’m back
Let’s try to change tack
And work on a positive tone

But seriously, what I read
Is doomsters in screed after screed
All preening and bragging
That all their chin-wagging
Was right while the markets recede
All I can say is, it’s so good to be home. While the past three weeks have been enjoyable and traveling across half the country by car offers a great perspective on just how amazing this nation really is, I’m sure all of you will agree that there is nothing more comfortable than sleeping in your own bed. And this is just as true for Marvel, as it is for the rest of us.
But seriously, I appreciate your patience as it is tough to keep up while driving 10 hours a day. But now that I’m back, I think it is worthwhile to take a look at how things have moved since I first left back in late September. Between closing on Friday, September 25 and last night at 9:00pm, these are the moves across major markets that I discuss.
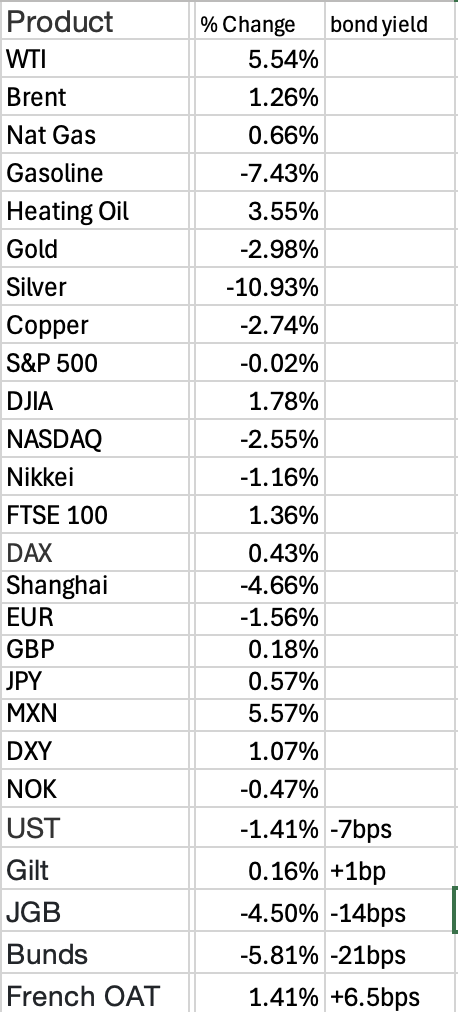
Frankly, it is hard to look at this and conclude that the world is ending. In fact, despite constant discussion about how the AI (or is it SI?) trade is imploding, the NASDAQ has fallen just -2.5% over the past three weeks and is less than 5% from its all-time highs. I don’t see the reason for all the excitement. In fact, the biggest mover, by far, has been silver, which is the least liquid and least important of all these markets. Despite the end of days discussion about Treasuries, yields have slipped, as have JGB and Bund yields. One other thing to note is the decline in gasoline prices given the political implications. I’m confident the White House would like to see them fall further, but there is no indication there is a supply issue there.
I’m just trying to level set here. I’m sorry if I’m not breathlessly describing the apocalypse, but I just don’t see it. Perhaps I’m simply blind. But the data continues to lean toward economic growth, not weakness, at least based on the Retail Sales and Initial Claims data we saw yesterday, as well as the ISM and other numbers. And inflation, to the extent that growth is a driver of that, remains well above the Fed’s 2% target, although based on its causes (read the Inflation Guy’s blog to really understand it), hiking rates is not going to be the solution to inflation, although it certainly has the opportunity to impede growth.
Anyway…
The rules of the road used to be
That nothing defied gravity
But Elon replied
We oughtn’t be tied
To earth, and his car, he set free!
I am sure there is a parable in the contrast between the doom and gloom that consistently dominates the discussion, the vibe as it were, and the fact that the richest man in the world continues to build extraordinary things. I’m sure you have all seen the video clip of the new Tesla roadster that actually flies, but if not, it’s right there. No matter your view of the man, you cannot dismiss his extraordinary genius when it comes to building things. I guess the question is, will the flying car be a metaphor for the economy? The markets? Or will it crash a burn?
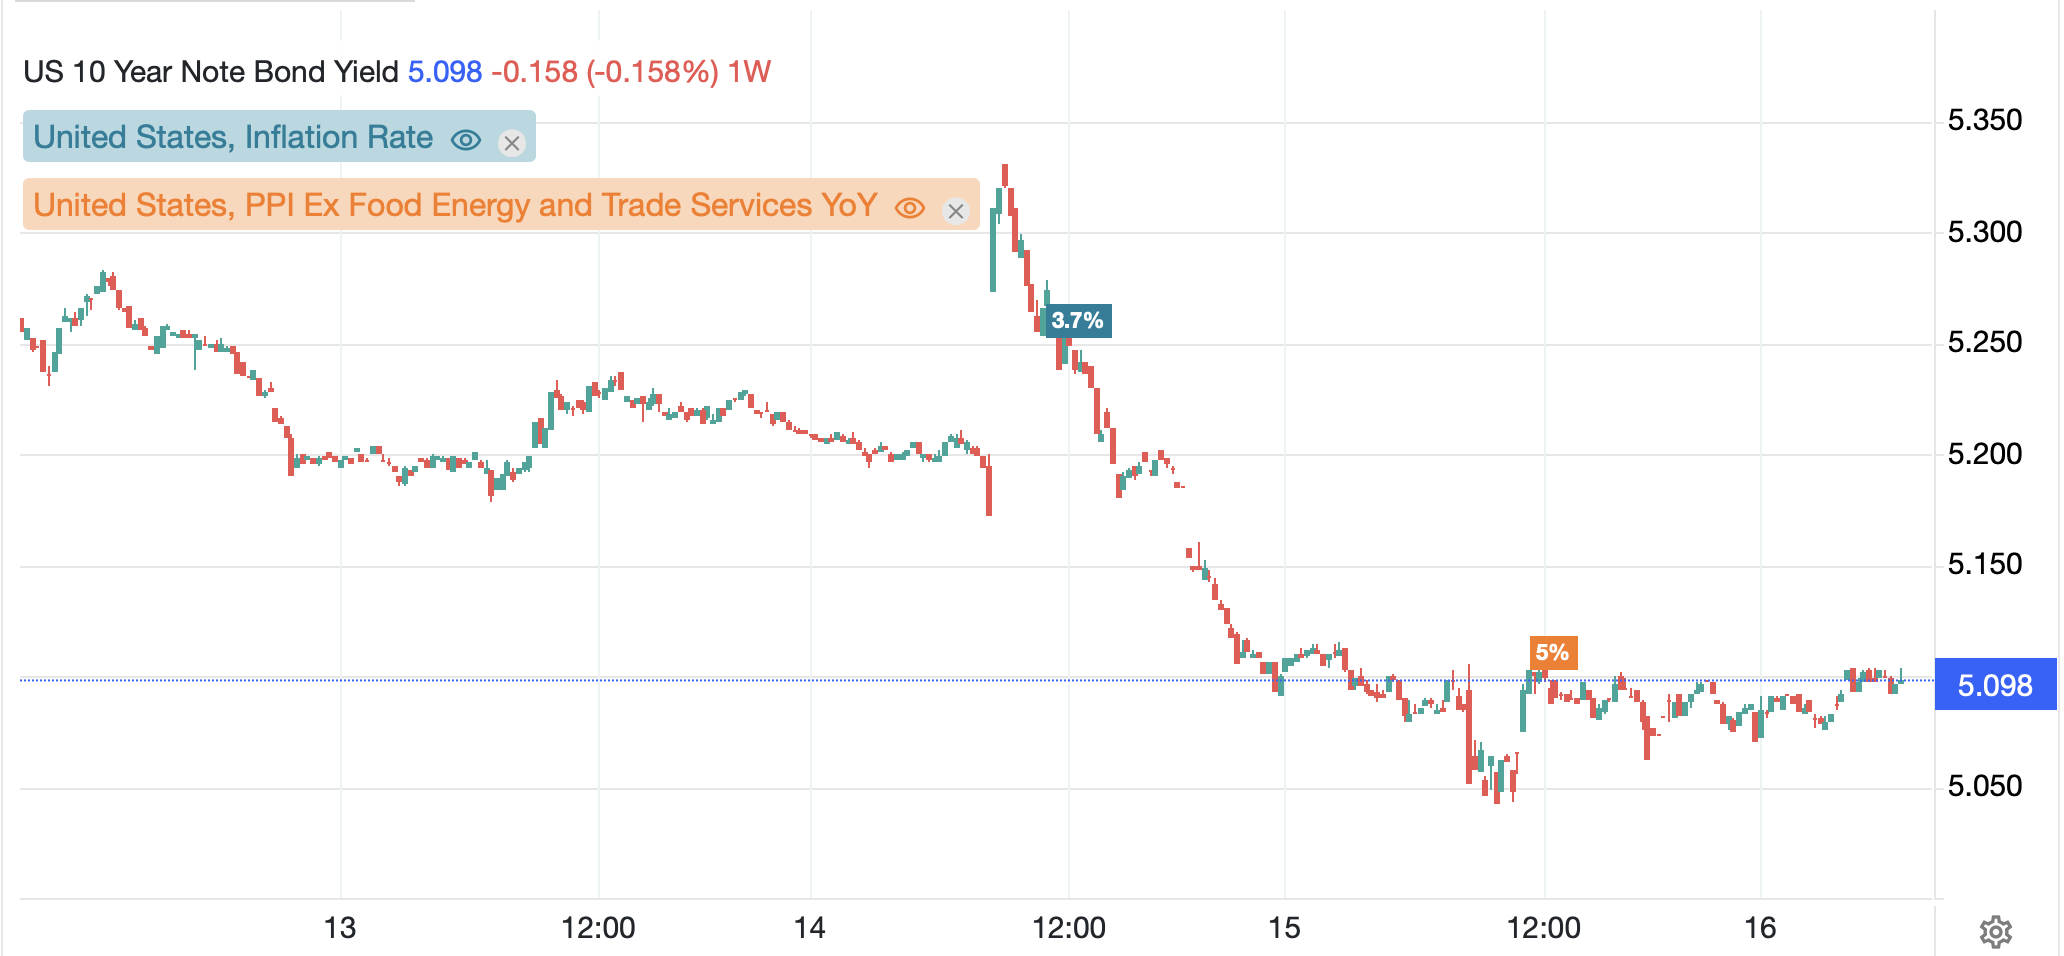
So, now let’s turn to the markets, and I feel like bonds are the right place to start. The below chart of the 10-year over the past week is remarkable given the CPI, PPI and Retail Sales data released.
Source: tradingeconomics.com
The huge gap was the immediate response to Wednesday’s CPI release which came in a tick hotter than forecast. Yet much higher-than-expected PPI and Retail Sales data saw yields decline sharply. Ostensibly, I continue to read about a flight to safety trade, but that seems at odds with the idea that Treasury debt is going to implode because there is so much of it. I wish the punditry would get their stories straight. No matter the cause, yesterday saw a complete reversal of the yield rally from Wednesday. Maybe, and I’m just spit balling here, the punditry doesn’t have any idea about the way things work but simply try to drive a preferred narrative. And given the underlying visceral hatred of the US administration, specifically President Trump, are very keen to do all in their power to make things worse for him.
Regardless, it appears that despite the higher-than-expected inflation data, yields at current levels represent an attractive opportunity to some investors. While this morning, 10-year yields have bounced 4bps from yesterday’s closing levels, as I showed above, they are still lower on the month. And it is no surprise that European sovereign yields have also rebounded this morning, although more on the order of 2bps across the board. Frankly, it seems to me there is far more risk in owning Bunds or OATs or BTPs than in owning Treasuries. At least the US is growing pretty well compared to the utter lack of growth in Europe. Exactly how are the French going to repay their debt, or maybe more importantly service their debt, if growth remains <1%?
As to equities, they, too, have stopped tumbling for now with markets higher yesterday in the US and almost the entirety of Asia and Europe this morning with the one glaring exception of Indonesia (-10.8%) which suffered from MSCI explaining they could downgrade the country to standalone market status (a decisive negative outcome regarding the lack of transparency and liquidity) offering the potential for significant capital outflows. I understand that there are AI names that have had problems and the banking sector, despite mostly strong earnings, has underperformed, but the end has not shown itself yet.
Gold (+0.2%) is another market that seems confused, or at least the trading of it seems so, as its relationship with oil (+0.1%), which had a very clear negative correlation for quite a while, arguably since the beginning of the Iran war, (although according to Grok, the numbers show that correlation to be -0.1% to -0.15% over the past year, hardly a strong relationship), are both higher this morning. But looking at the chart below, the direction of travail since the summer has been largely opposite directions.
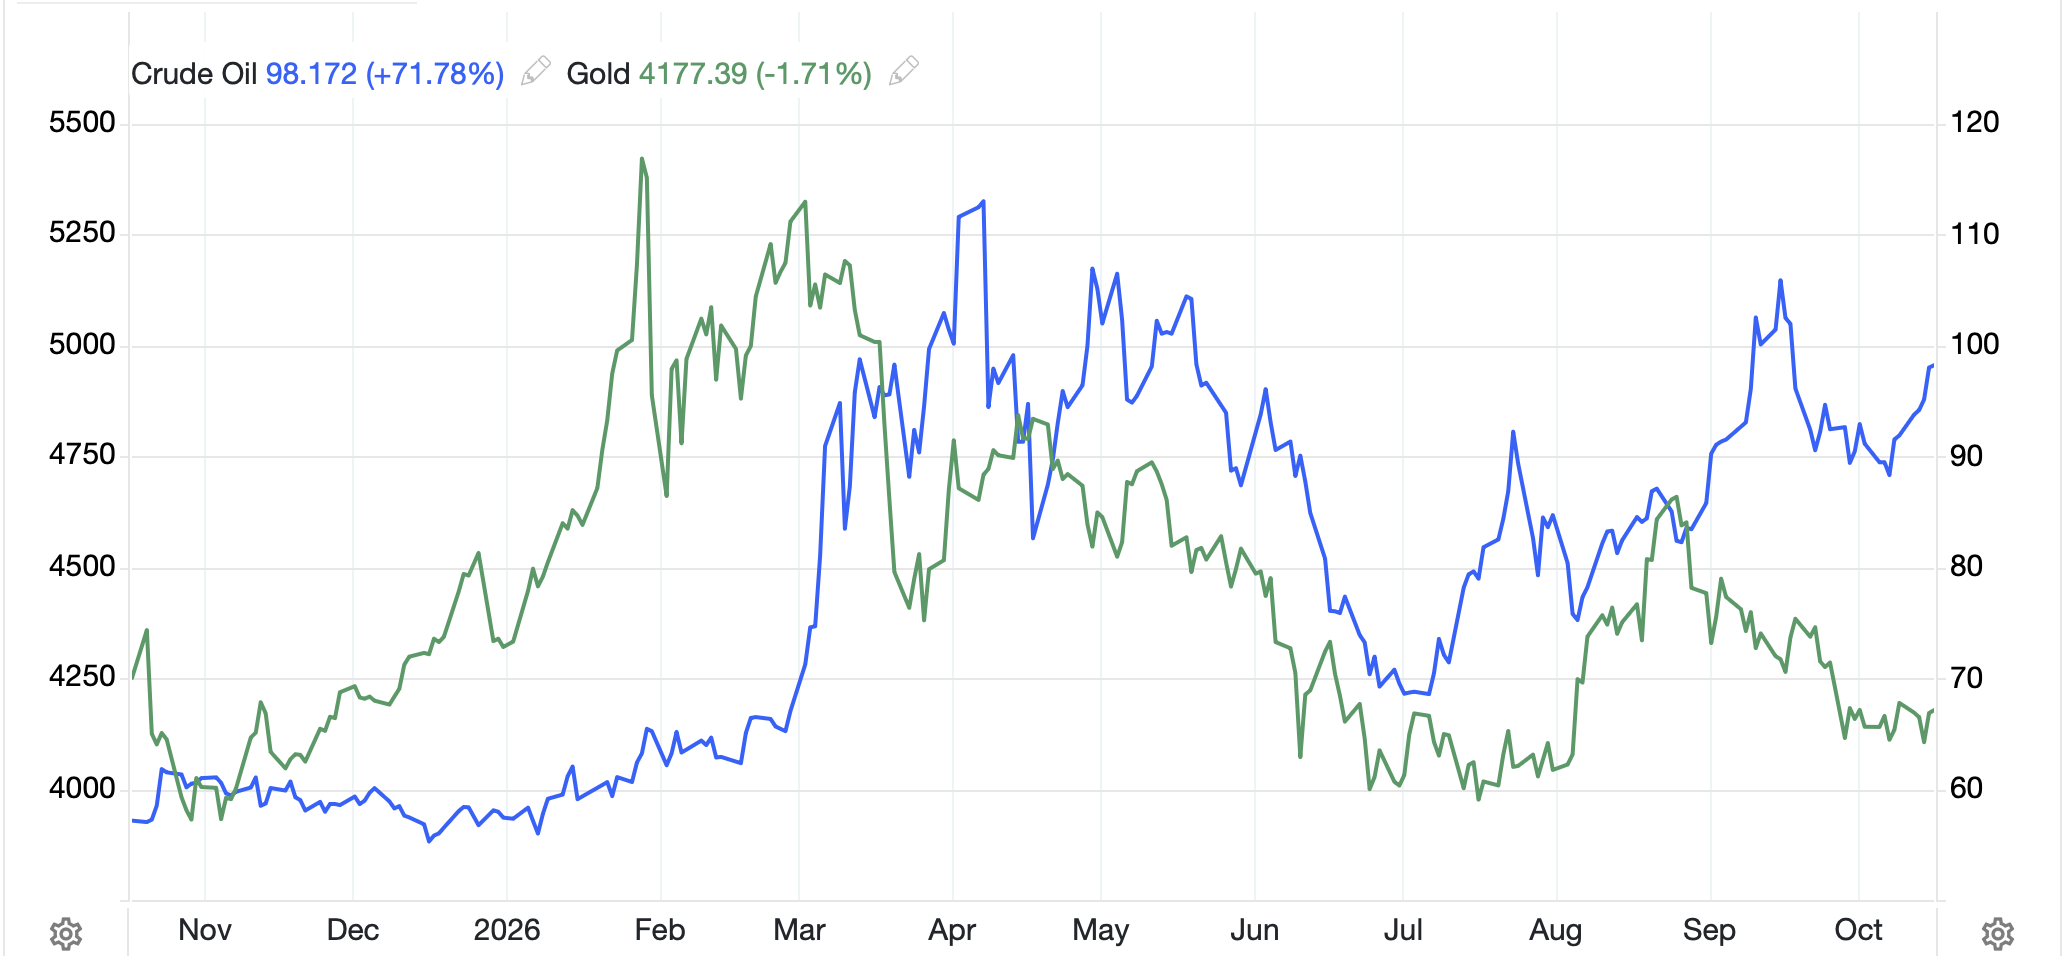
Source: tradingeconomics.com
Obviously, oil is a far more important commodity than gold, which can be seen as a sentiment indicator more than anything else. But despite the recent rebound in oil prices, economies around the world seem to be figuring out how to cope. Now, the recent uptick in Iranian and Houthi attacks on ships in Hormuz and Saudi infrastructure are having a clear impact and given the fact that the IRGC literally wrote an open letter to the US to elect Democrats to try to impede President Trump’s ongoing campaign, I have to believe things are getting a lot tougher over there. It is not impossible to believe that after the election, especially if the Republicans hold both Houses of Congress, that the Iran conflict may end soon. It does seem that the blockade has starved Iran of the one thing they need, capital, and that is running out quickly.
As to the FX market, I find it interesting that even though yields are rising around the world, the dollar has been the main beneficiary here. In the wake of the CPI and PPI data, the probability of a rate hike at the end of the month has jumped to 85%, as per the below cmegroup.com table.
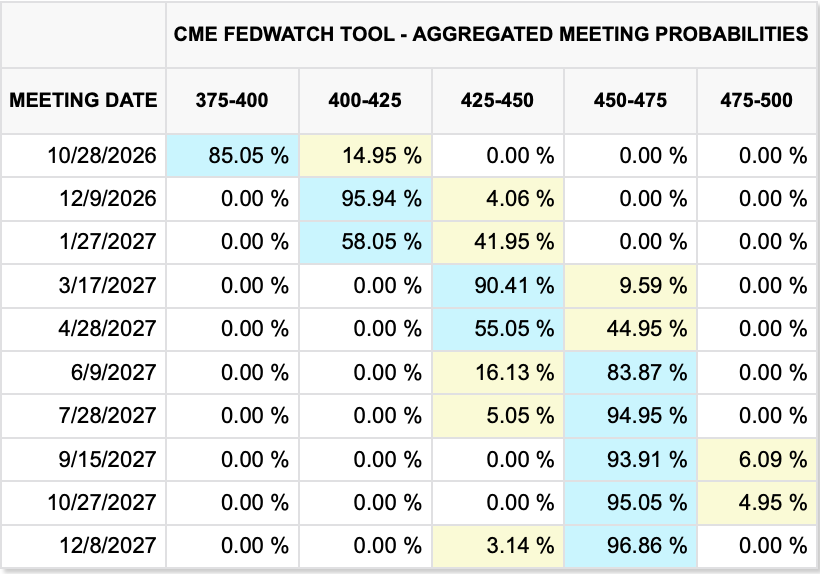
At the same time, Chairman Warsh spoke last night at the IMF meeting in Bangkok but once again, refused to discuss potential Fed moves going forward. “I don’t prejudge meetings. I don’t believe in saying now what I might do at the meetings we have in the balance of this year. It’s a new chapter at the Fed, and we’re not in that business anymore.” While virtually every other member of the FOMC likes the fame/notoriety they get by speaking, Warsh has remained true to his initial comments. I guess the question is, has the data been sufficient to drive another hike? It all depends on the membership’s view of economic activity. If they see strength, I imagine that is what we will get despite the fact it is unlikely to do anything positive for the economy.
Back to the dollar, while it has backed off a bit this morning, with the DXY (-0.85%) the leading decliner despite the fact its components haven’t moved nearly that much (EUR -0.35, JPY unchanged), I guess broadly it is following the 10-year yield. It is worth noting that while most currencies have not done very much in my absence, (MXN +0.1% today, -5.6% since Sept 25) has suffered on expectations that Banxico is going to cut rates further, thus reducing one of its key supports, the carry trade.
On the data front, this morning we see IP (exp 0.4%) and Capacity Utilization (76.5%). Those tend not to be market movers so as is frequently the case, the FX market will take its cues from equities and bonds. Right now, equity futures are essentially unchanged, so if the positivity we saw yesterday fades, perhaps the dollar will rally back some on that flight to safety trade.
Good luck and good weekend
Adf

