Smote

A juxtaposition of note
Is France and the Albertan vote
The French are imploding
Midst radical goading
While seperatists’ visions were smote

I fear, though, that o’er the next weeks
Most risk market valleys and peaks
Will highlight reactions
To campaign distractions
As we watch the havoc that wreaks

While equity markets in the US were mixed yesterday beneath the shadow of the anniversary of Black Monday 1987, the rest of the world is having a tougher go of it this morning.  Last night, as you can see from the below Bloomberg screenshot, the major Asian markets all fell, and we are seeing similar price action in Europe this morning.
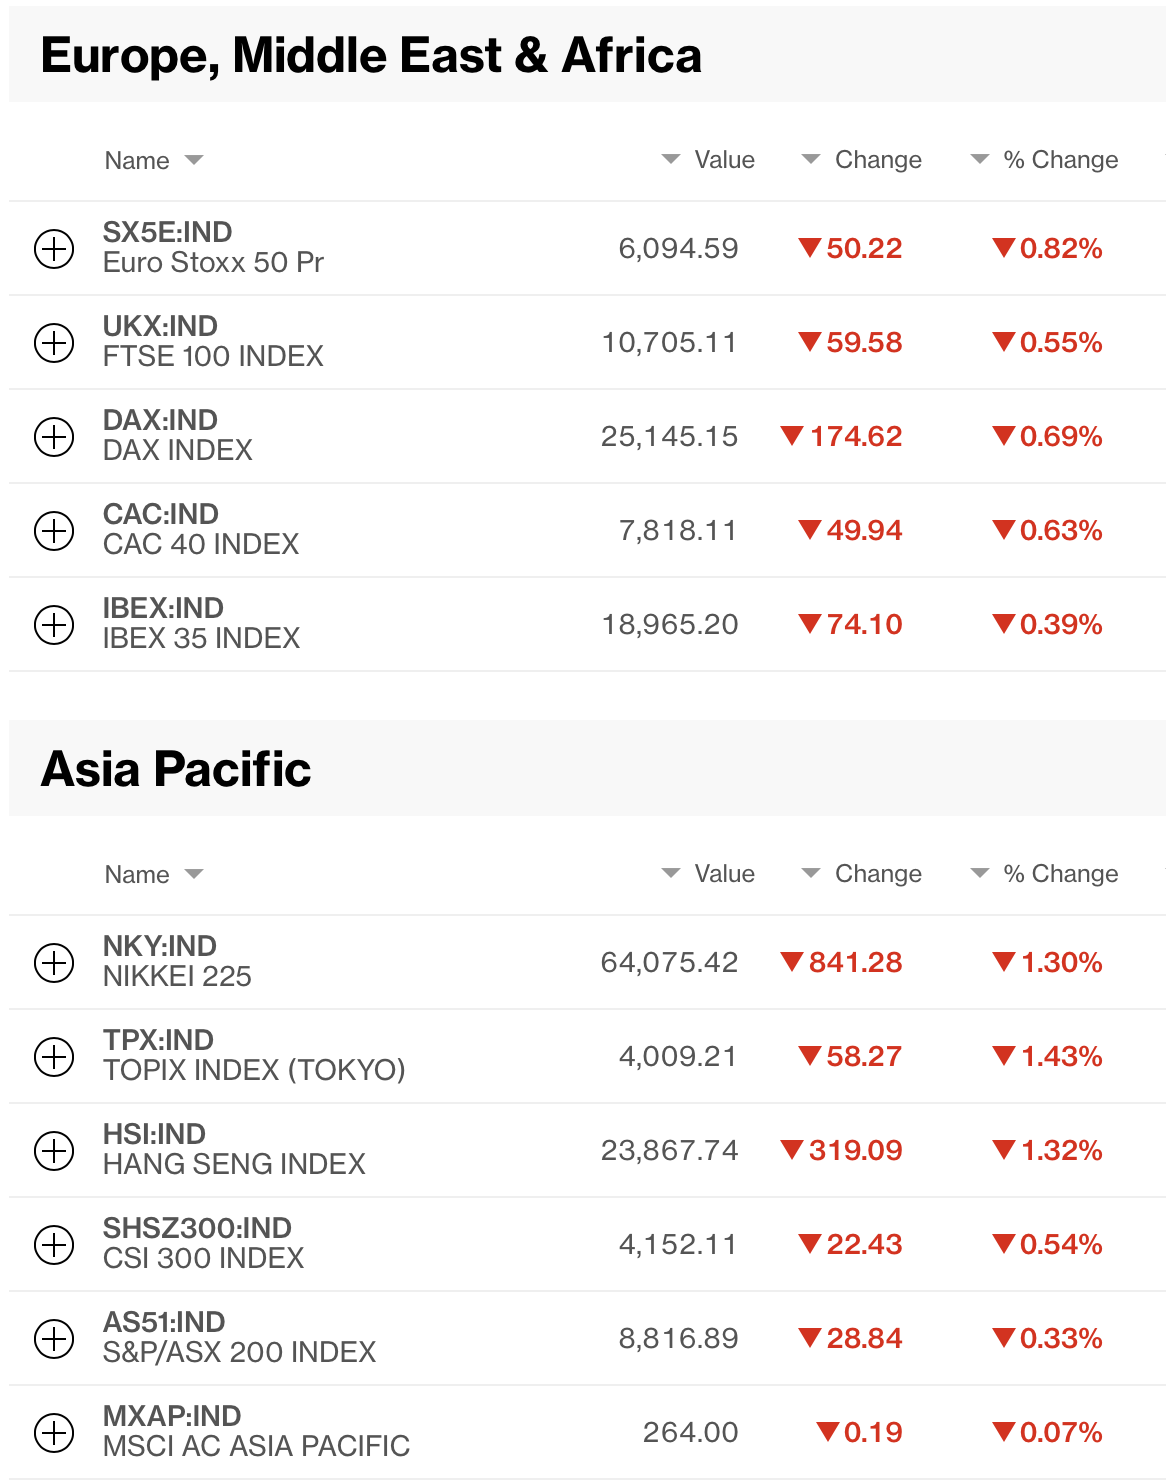
In fact, if you look across the regional Asian bourses, they all fell as well with one outlier, Indonesia, which after its 15% decline in the previous three sessions amid fears it would be removed from the MSCI indices, rose 5% upon hearing from the securities regulator that changes were afoot to placate MSCI, thus opening the way for some opportunistic buying of the dip.  But otherwise, it’s been a very red day.

Arguably there are two drivers of this market angst, continued high oil prices and the uptick in violence across Europe as those ‘student’ protests have evolved into a much wider spread action being egged on by numerous explicitly left-wing groups.  In fact, Jean-Luc Melanchon, the far-left Parliament member running for president there is their biggest cheerleader, although it currently appears that in the two round election process there, the result will be Marine LePen, the National Rally candidate from the right who will be the next French president.  But that election is still six months away, so much can happen between now and then.

However, that is all of a piece with the runup to the US midterm elections to be held two weeks from today as the President barnstorms the nation supporting mostly Senate candidates around the country.  While the current polling shows the Democrats have a lead and are likely to win the House with a decent chance of taking the Senate, the history of polling since Donald Trump put his name on the ballot is that the Republican vote is consistently undercounted.  I see no reason that situation has changed this year, so my take is the race is much closer than the punditry currently explains.  In fact, my call several months ago was that the Republicans will hold the House and actually pick up a seat in the Senate based on the candidates on the ballots around the country.  Obviously, that is far out of consensus, but that is my sense.  I’ve been wrong before and will be again, but at least I’m not wishy-washy!

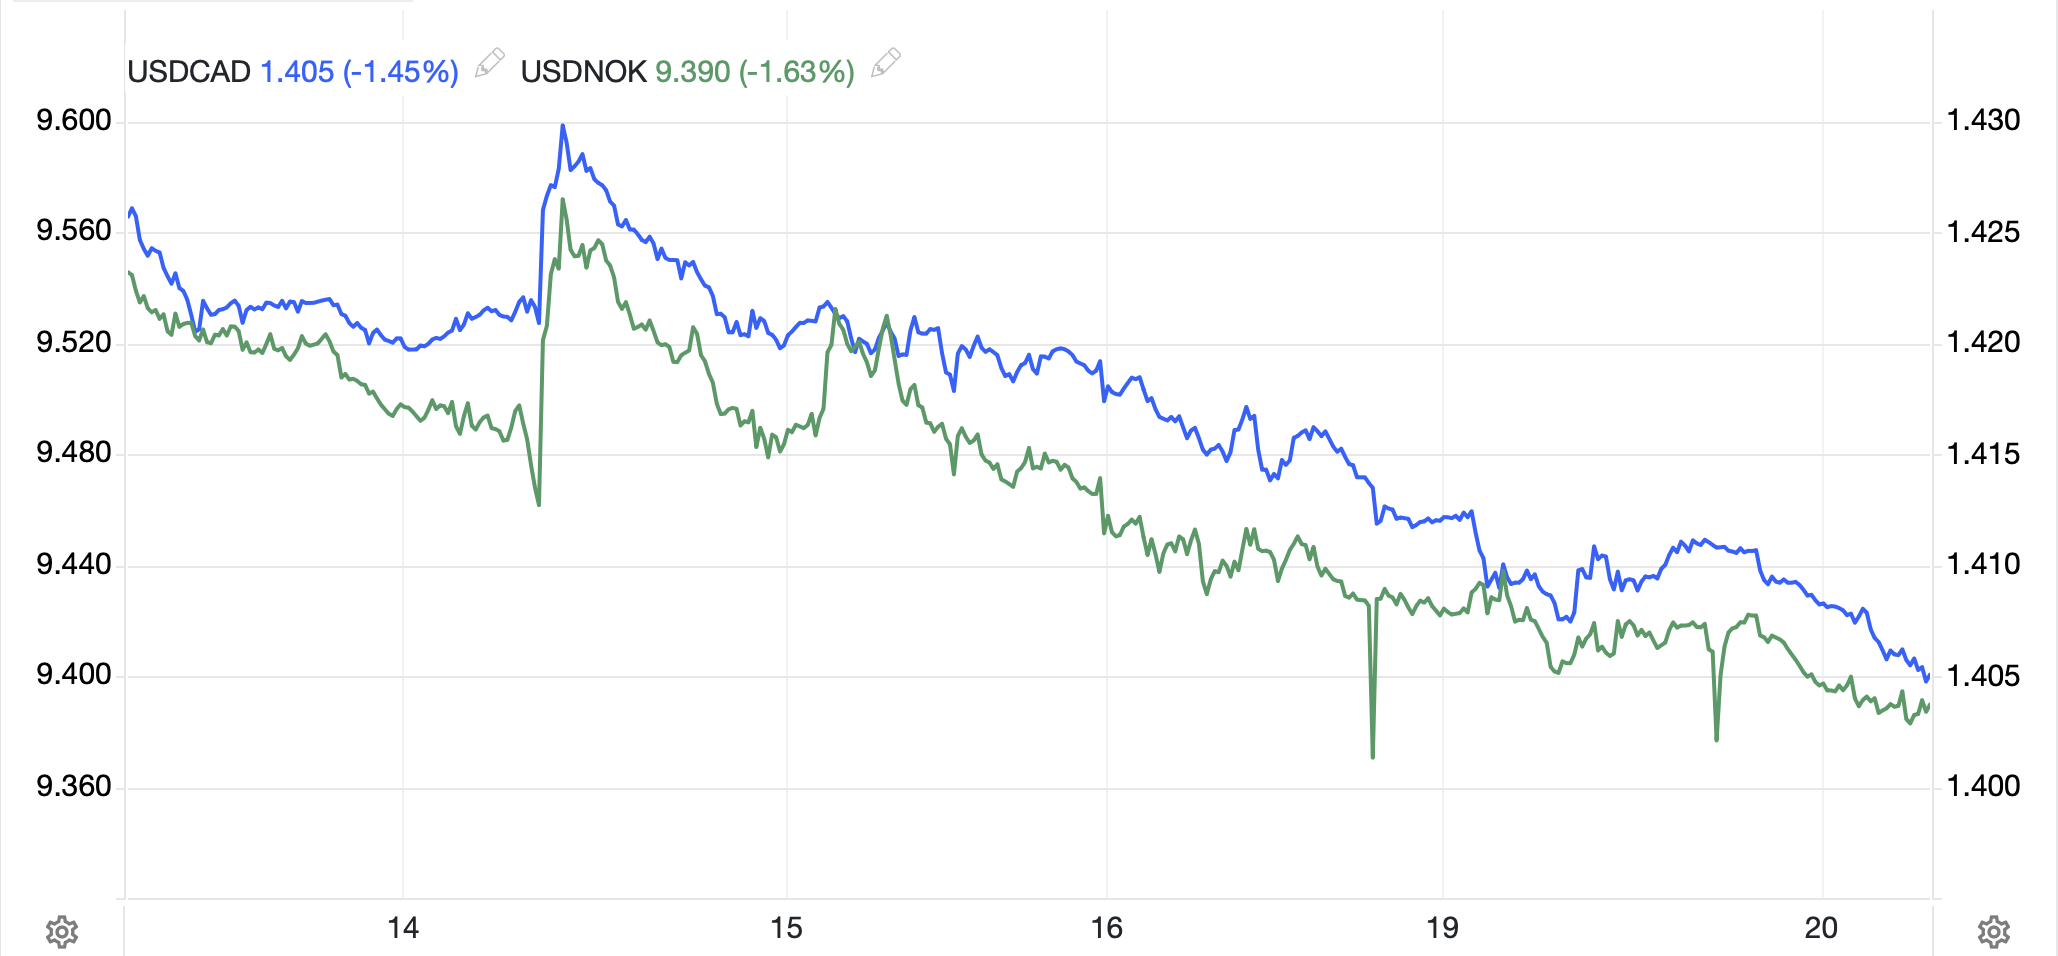
Perhaps the most interesting electoral outcome was yesterday’s referendum in Alberta, Canada regarding the desire of the population there to put an actual separation referendum to a vote.  It appears, though, that the remainers won resoundingly, with more than 75% of the vote, so for now, Canada remains in one piece.  Perhaps that helps explain the Loonie’s recent performance as it has, along with NOK, been the best performing currency for the past week, gaining 1.5%.  Of course, oil’s rally helped both those currencies as well.
Source: tradingeconomics.com

Don’t misunderstand me, there is still plenty of discussion regarding AI and whether that trade is over with violent disagreement between the bulls and the bears.  Meanwhile, the most disturbing, thing is that so much activity is taking place in the options markets, with Friday seeing a record volume in S&P 500 puts as per the below chart (taken from Market Vibes)
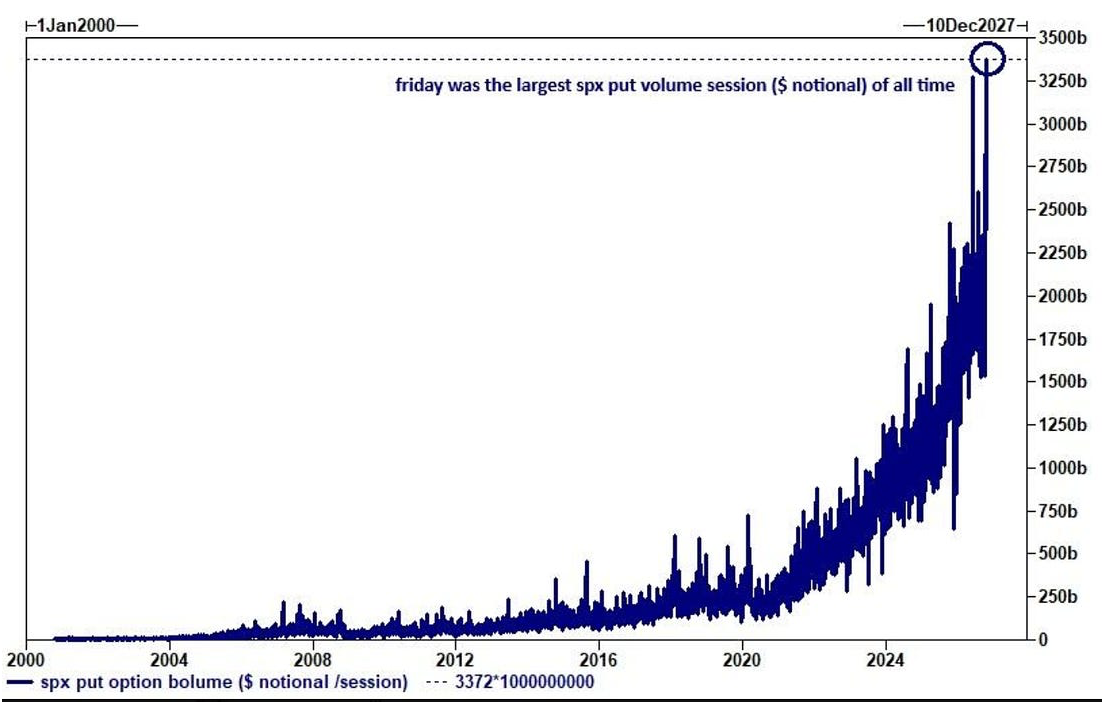
Having been an option trader for a very long time, my concern is that most people do not understand the nature of these contracts and the possible ramifications of the growth in activity.  It wasn’t that long ago that the GameStop call buying wound up impacting the entire market, significantly impacting the understanding of fair value.  The fact that this was put buying tells me many folks jumped on the Black Monday theme, so perhaps it will all fade away soon, but given the absolute increase in leverage we have seen (as an example, Goldman Sachs made more money in securities lending than trading last quarter) I fear there are large potential pitfalls ahead.  Perhaps because I was an options trader, I rarely use leverage in my PA, only if I am buying some protection, but I believe I am the exception these days.

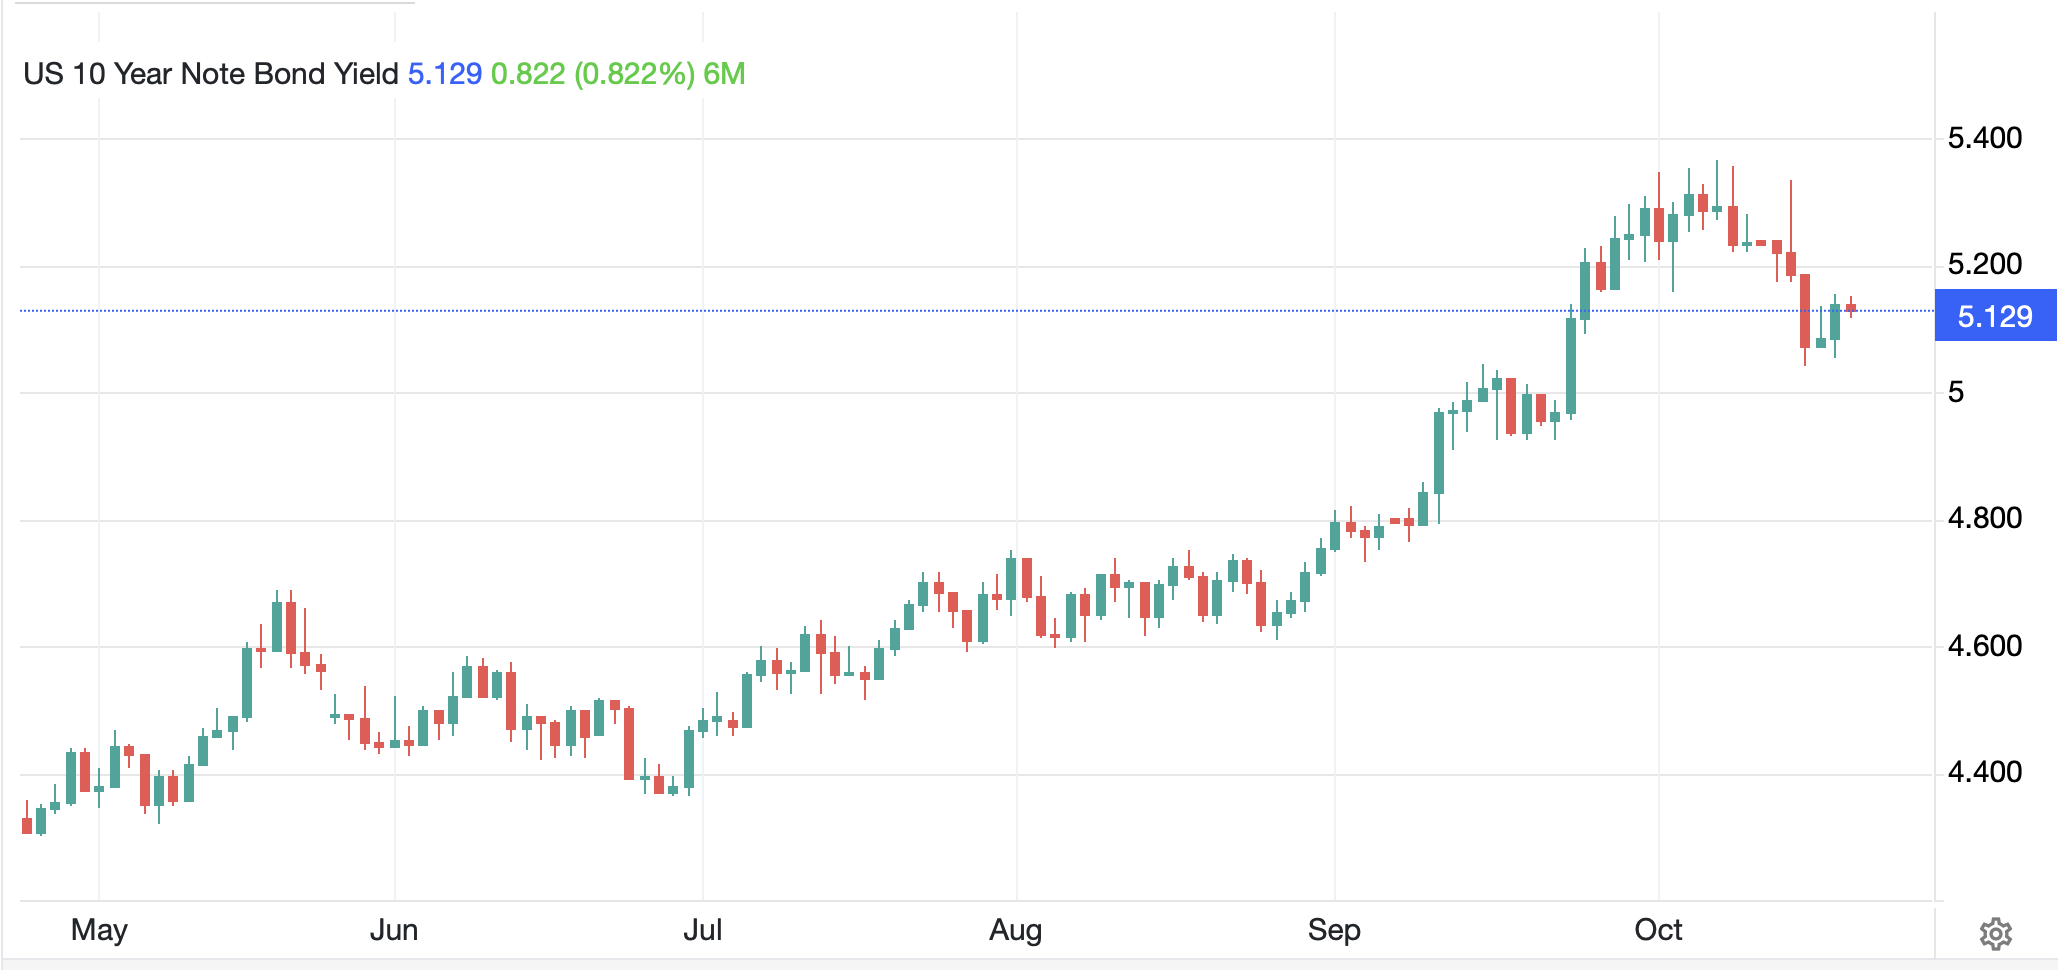
On to other markets.  Bonds, for instance, are still there and have not imploded yet.  Treasury yields (-1bp) did climb a bit yesterday, but as you can see from the below chart, remain well off the recent highs.  Given there is virtually no data of importance, and the Fed is in their quiet period, it seems unlikely that we see much movement here this week.
Source: tradingeconomics.com

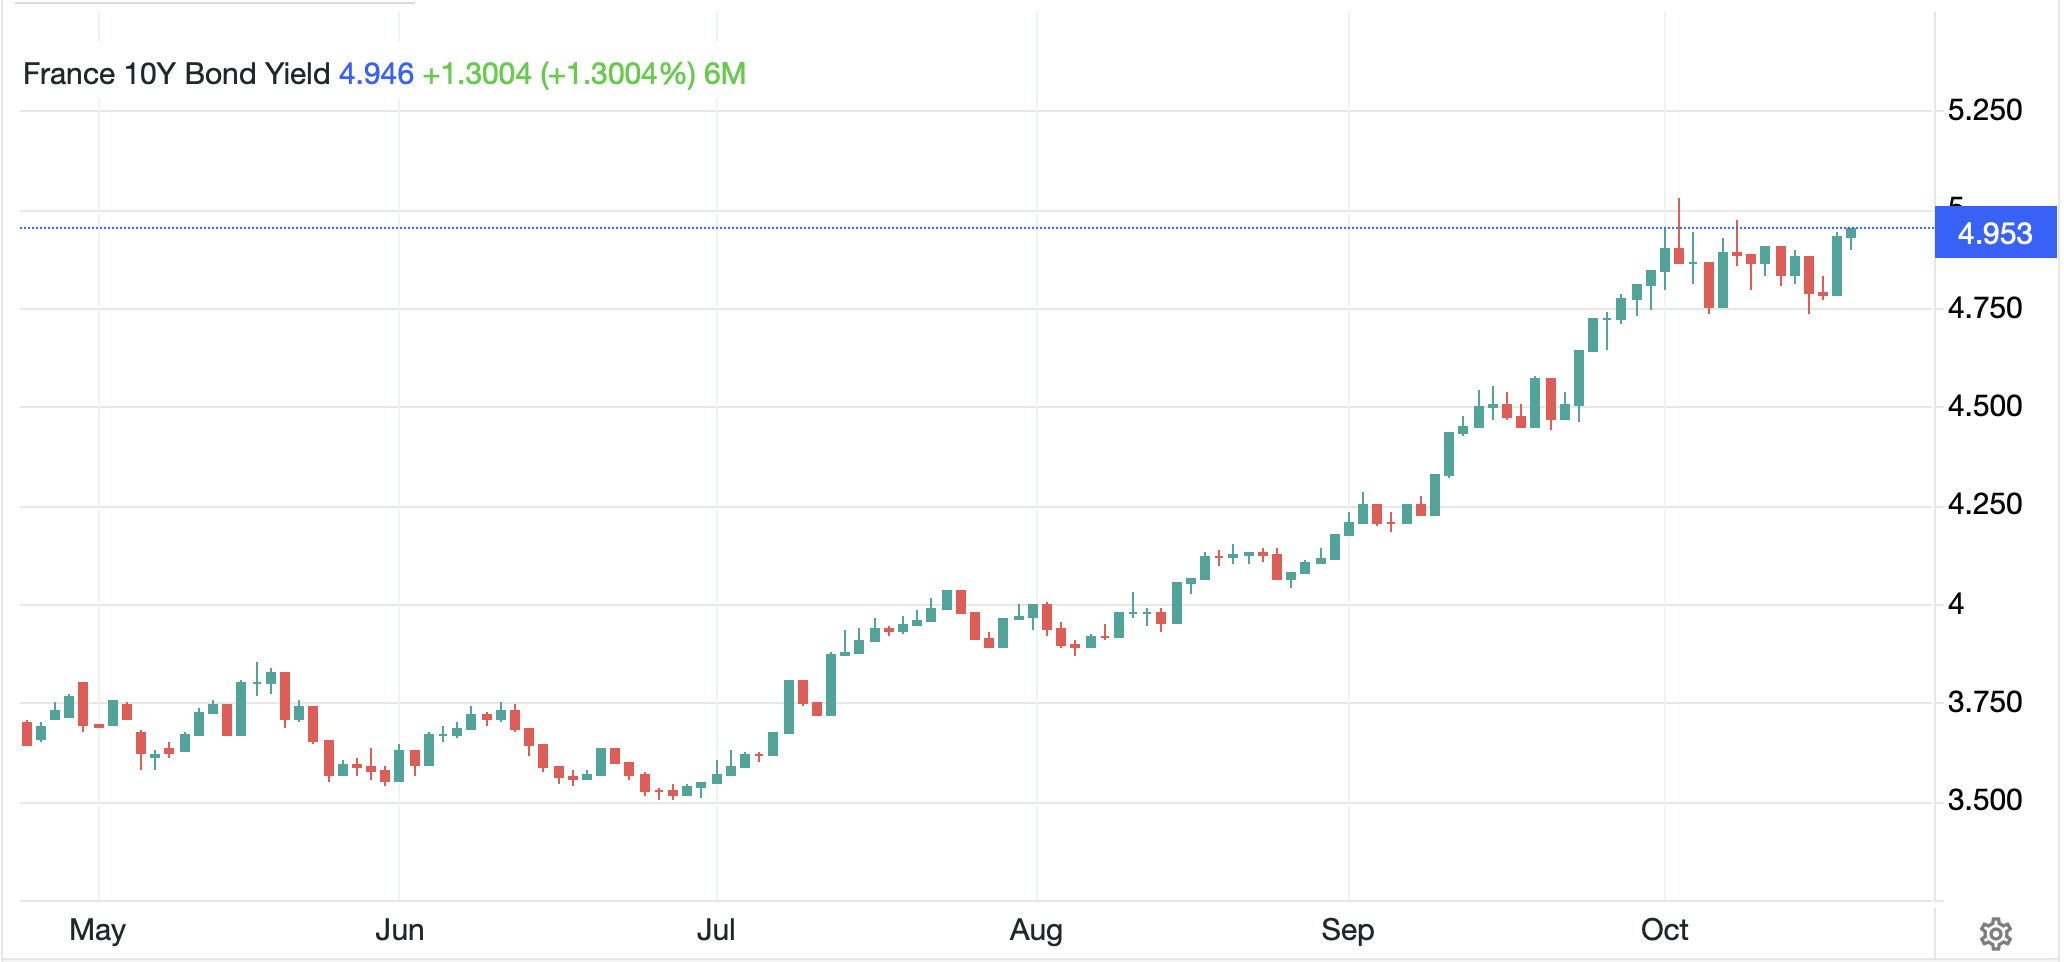
However, the same is not necessarily true for some other bond markets, notably France (+3bps) which is pushing its recent spike high and showing no signs of reversing course.  Given the ongoing violence and the fact that the government is not merely ineffective, but essentially broke, this should be no surprise.  The spread with German yields is above 150bps and I see no reason for that to compress anytime soon.  Rather, widening further makes more sense.
Source: tradingeconomics.com

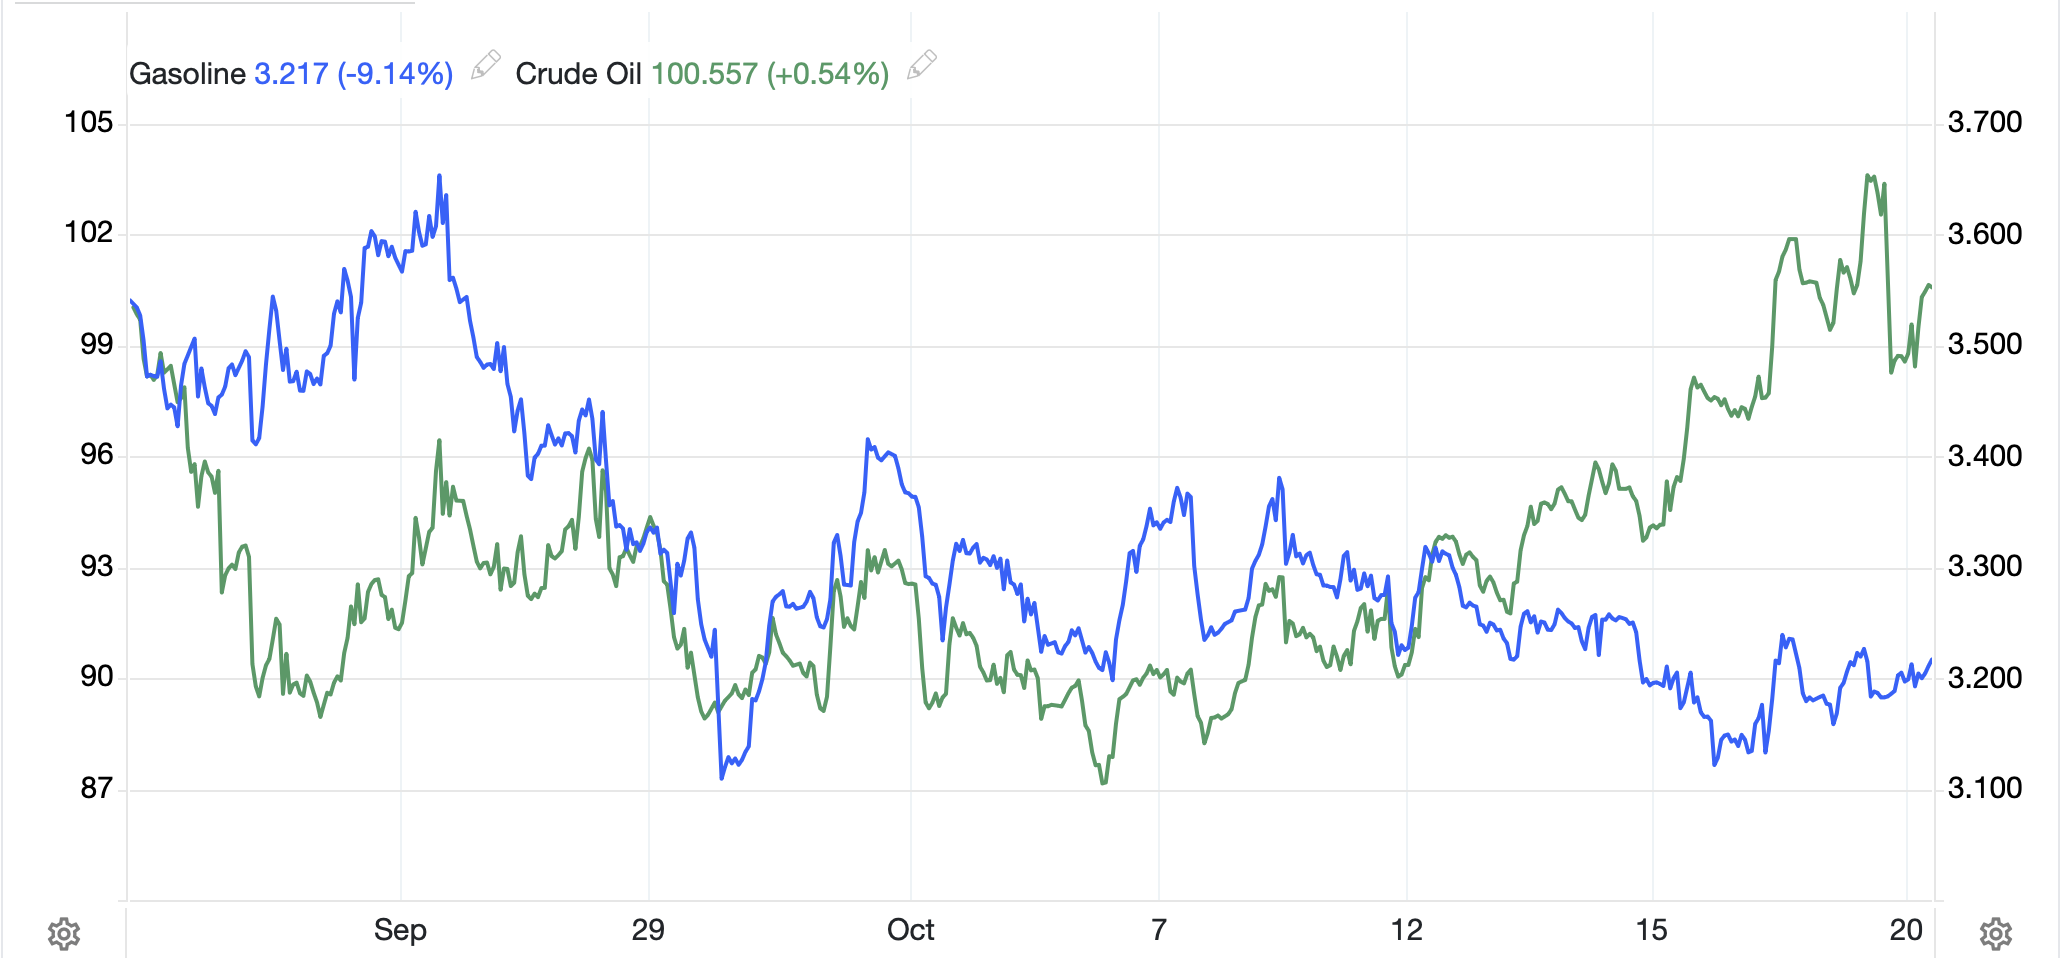
In the commodity space, oil (+2.0%) is higher again this morning with yesterday’s decline seemingly the aberration.  Nothing has really changed in the Iran situation, nor in the Ukraine/Russia situation with Ukraine continuing to attack Russian refinery capacity.  Perhaps the most interesting thing in the energy markets is that gasoline has broken away from crude in its price action as per the below chart.  Perhaps that is the end of summer driving season impacting things, or maybe there isn’t the shortage that people believe.
Source: tradingeconomics.com

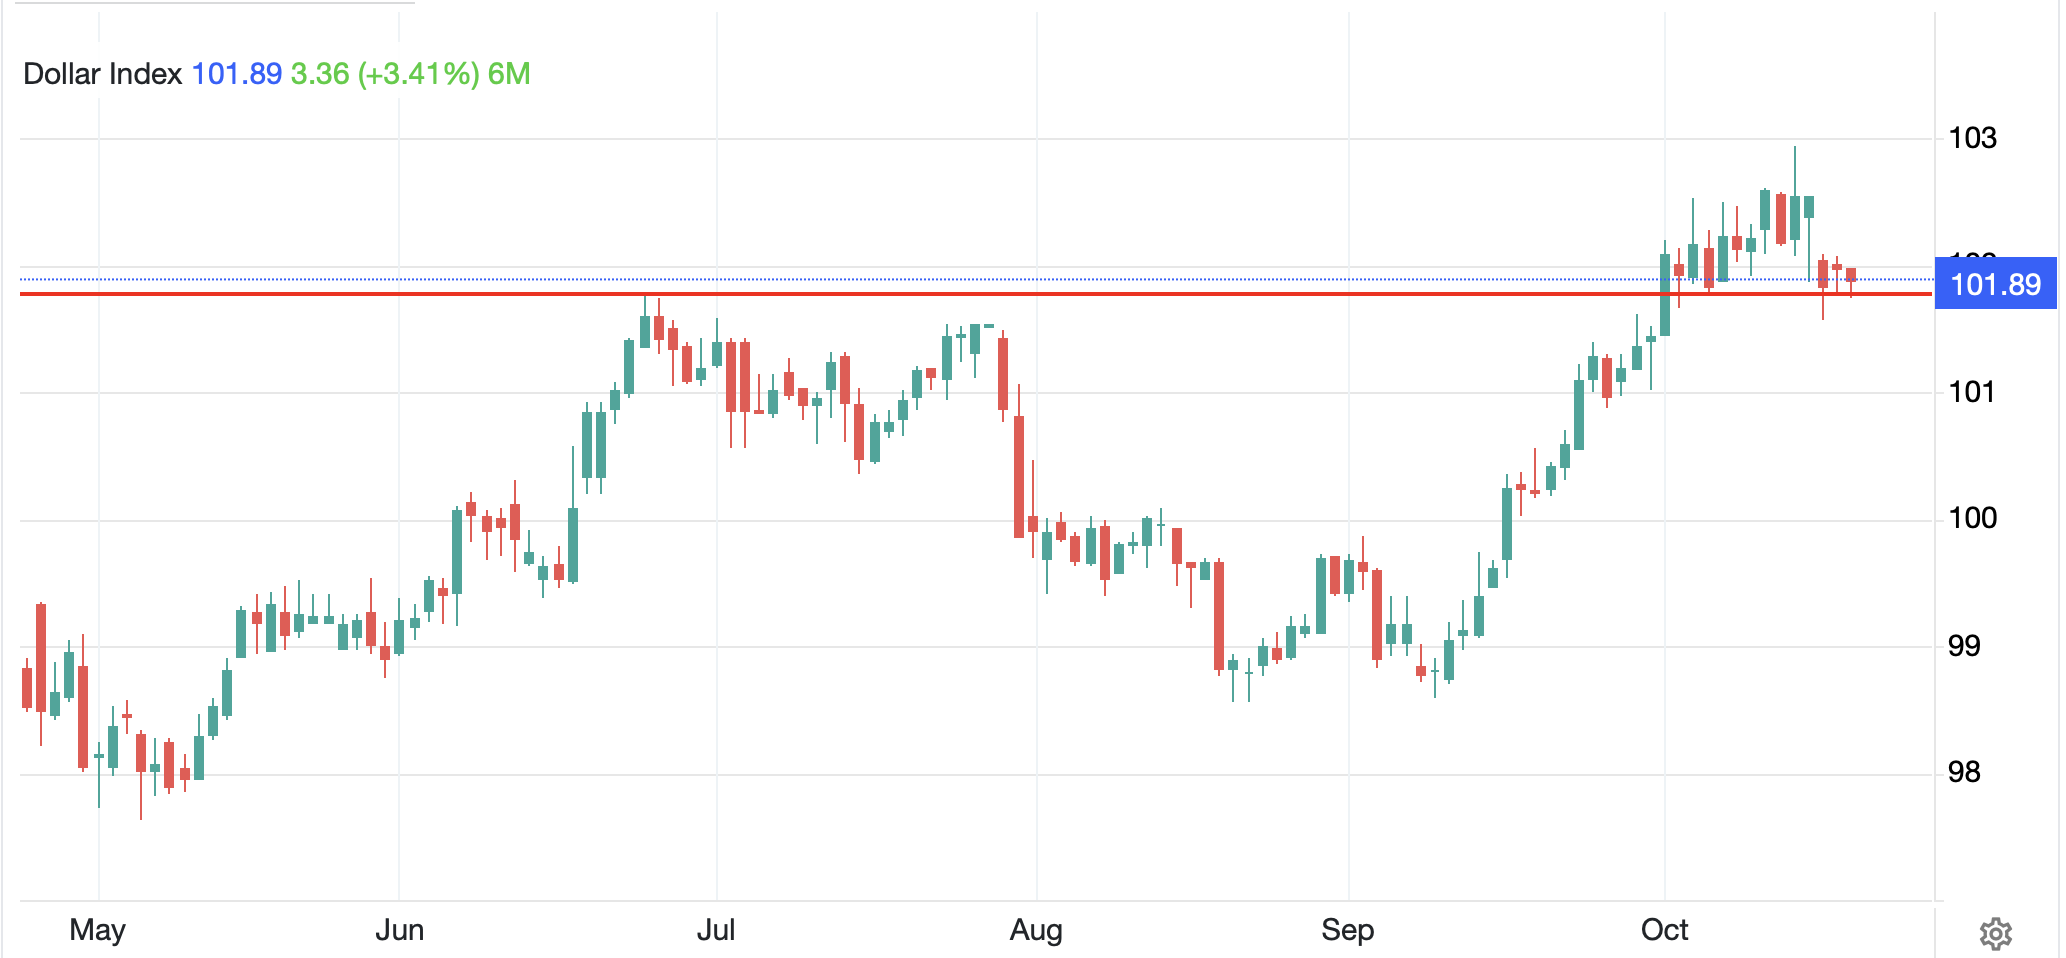
As to other markets, nobody cares about the metals markets anymore except the dyed in the wool long-term bulls (like me) but price action has been desultory at best.  Their time will come again.  And FX?  It’s pretty dull here as well.  There was excitement 3 weeks ago when the DXY broke above its range top near 102.00 and the technicians all thought that it was going to head a lot higher.  But it was not to be and here we are, back below that key range top and it is a tertiary conversation at best.
Source: tradingeconomics.com

While the long-term picture hasn’t changed in my view, as economic activity continues apace in the US relative to the rest of the world, it’s just not that interesting right now.

On the data front, Housing Starts (exp 1.30M) and Building Permits (1.39M) are today’s numbers but tend not to be market movers.  And that’s really all there is for today.  To the extent the FX market is going to do anything, it will be a response to something in equities, but as of this time (7:30) US futures are mixed to slightly softer, hardly a harbinger of anything substantive.  I think it’s setting up to be a dull day.

Good luck

Adf
No-Holds Barred

The rumor is Madame Lagarde
Who, through her incompetence, scarred
The ECB, now
Is set to, out, bow
To run for French Prez, no-holds barred
 
The fear that this move does display
Is Madame LePen’s making hay
So, globalists now
Will hardly allow
Their efforts to just go away

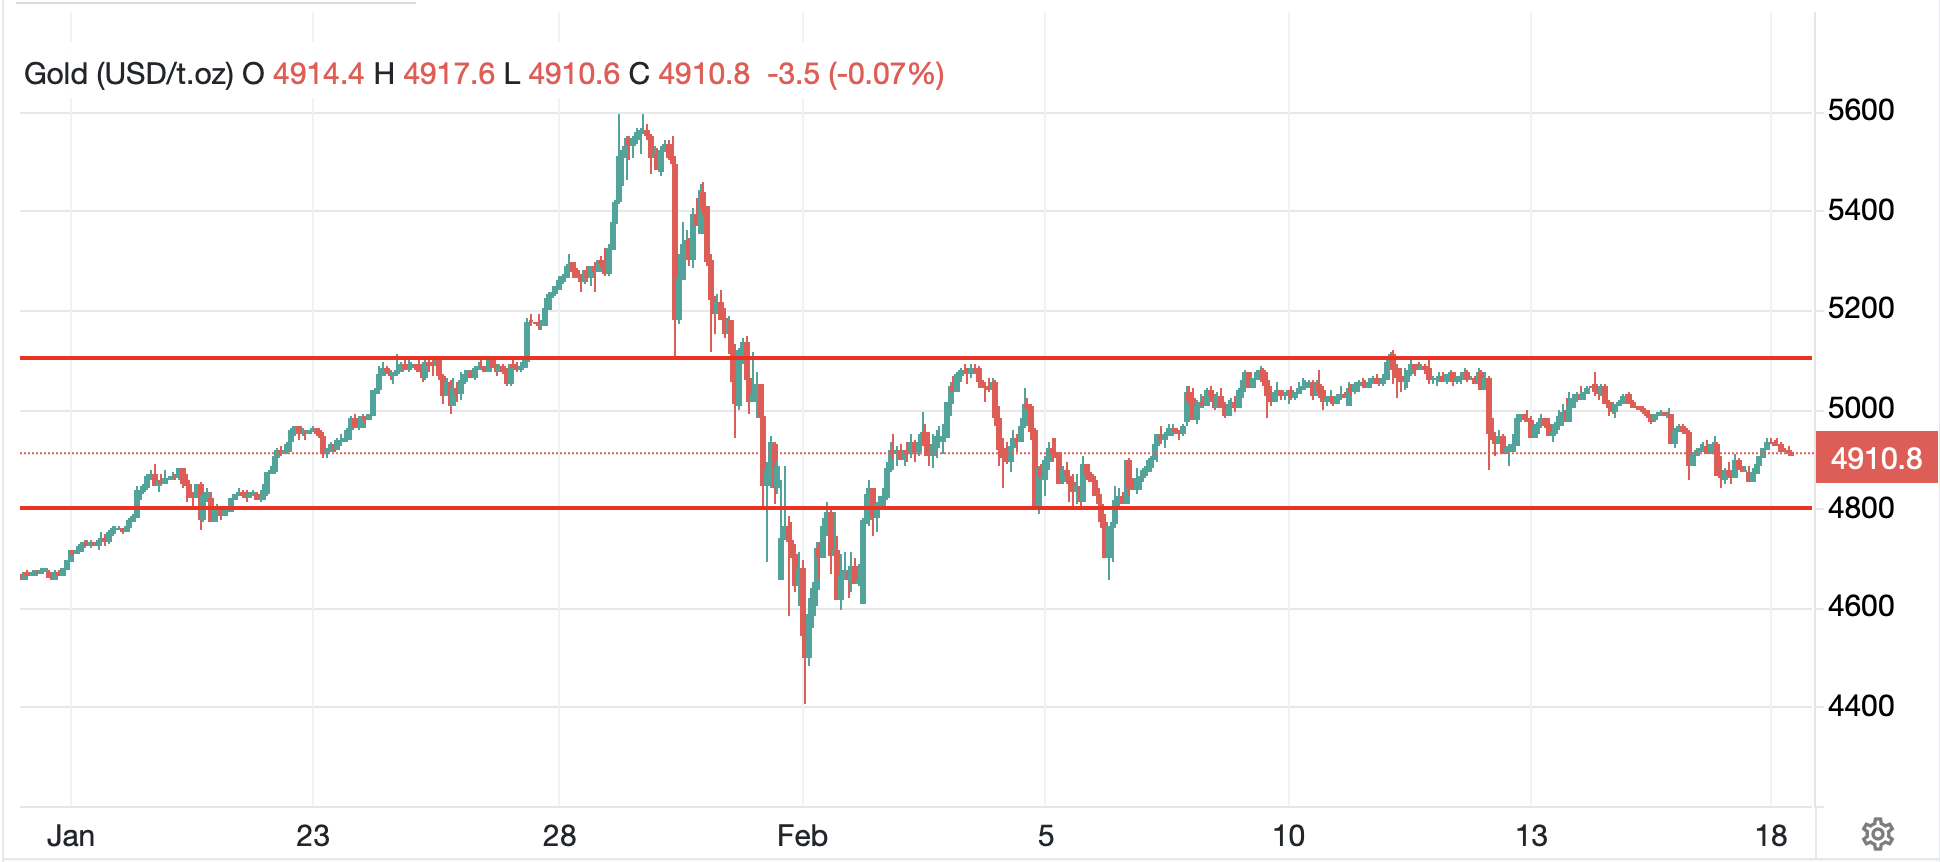
We continue to trade in recent ranges across most products in financial markets as investors and traders seek the next catalyst for secular movement.  Even precious metals, which have shown the most volatility of any sector, are now developing a new range as per the chart below.

Source: tradingeconomics.com

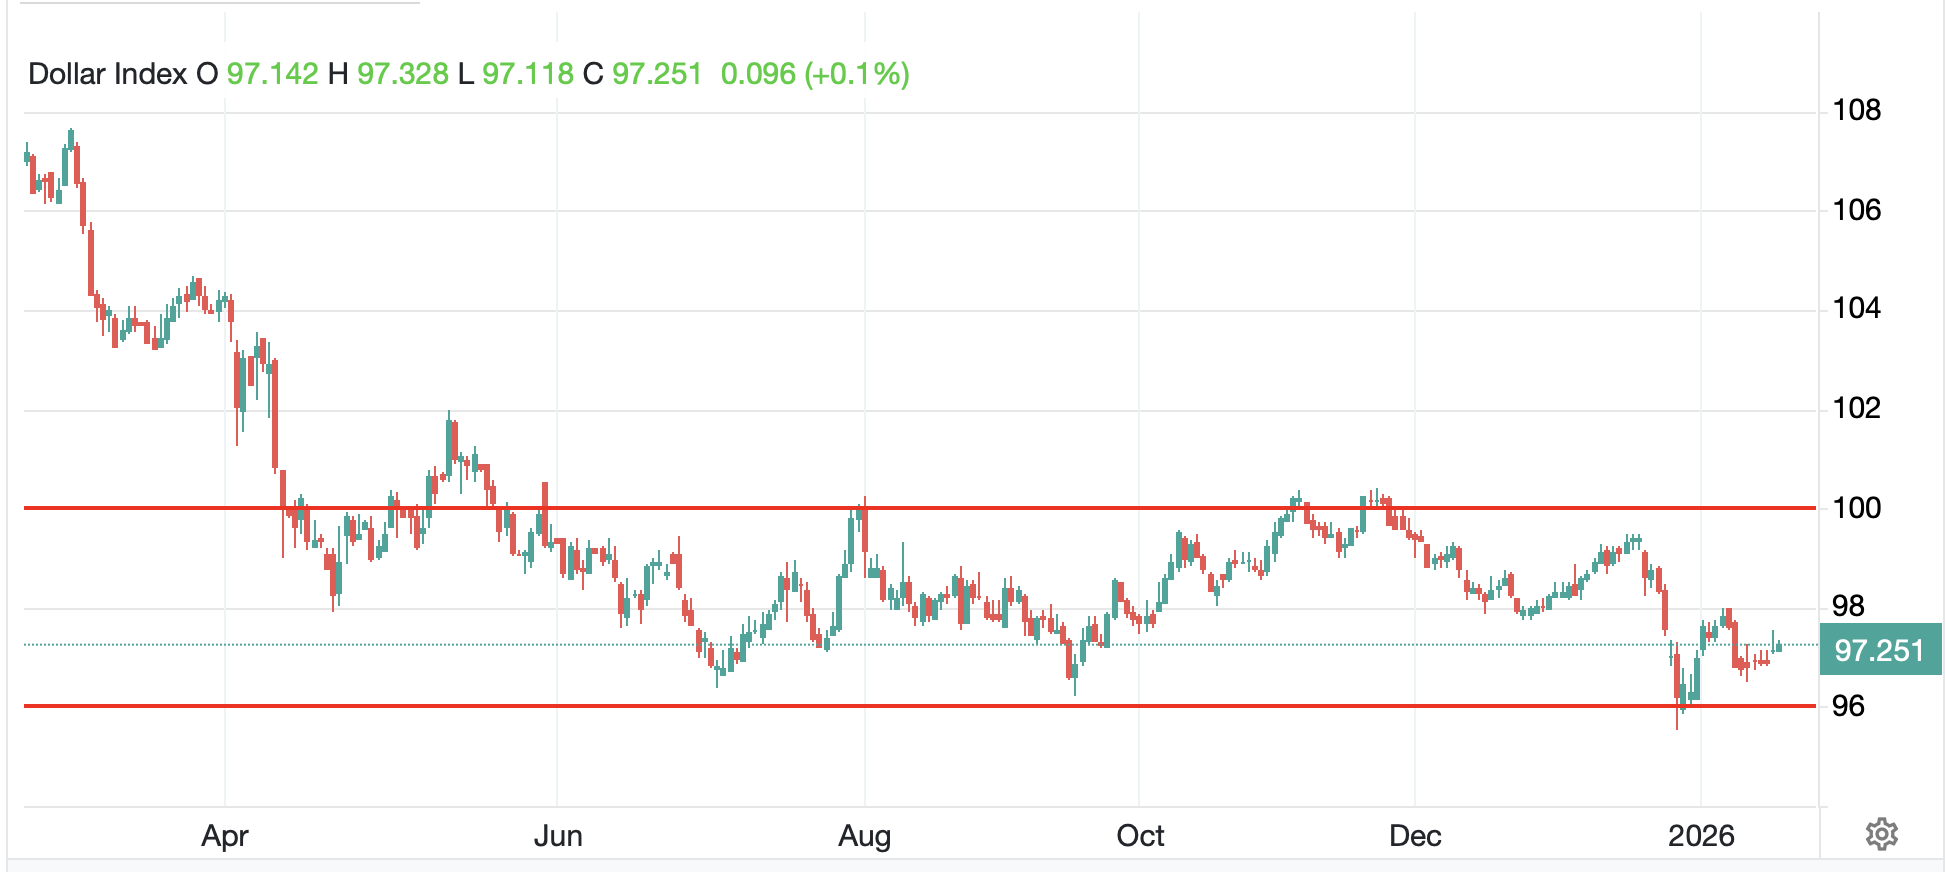
Now, I will grant the range in gold (+0.7%) is wider than many other products, but the chart clearly looks, at least to me, like an ongoing consolidation awaiting the next big thing.  As to other products, I have shown bonds, the dollar and even stocks doing the same thing lately, consolidating, and as of this morning, none of them are breaking out in either direction.  (As an aside, there is still a very loud group claiming the dollar is about to collapse, but thus far, their views have been unrequited). In fact, if we use the DXY as today’s dollar proxy, we appear to be heading back to the middle of the range rather than breaking lower.

Source: tradingeconomics.com

Net, there is not much to discuss in the markets which leads me to the most interesting topic, what will be the catalyst to break these ranges?  Historically, there are two types of things that act as a market catalyst, a change in the data trajectory or a geopolitical shift.  Right now, the former does not appear to be in the cards.  We know this because there are vocal proponents of both substantial economic strength and economic weakness in the future.  The lesson from this is that the data remains quite mixed, with some areas of the economy performing well, while others are struggling, but not enough on either side to expect a major trend.  

For instance, in the US, recent data showed relative employment market strength while inflation data continues to compress.  Now, you can quibble with the construction of both data sets, and there are many valid concerns, but for policymakers, especially those steeped in the view that strong growth necessarily drives inflation higher and vice versa, the current data set does not argue for any policy shift.  

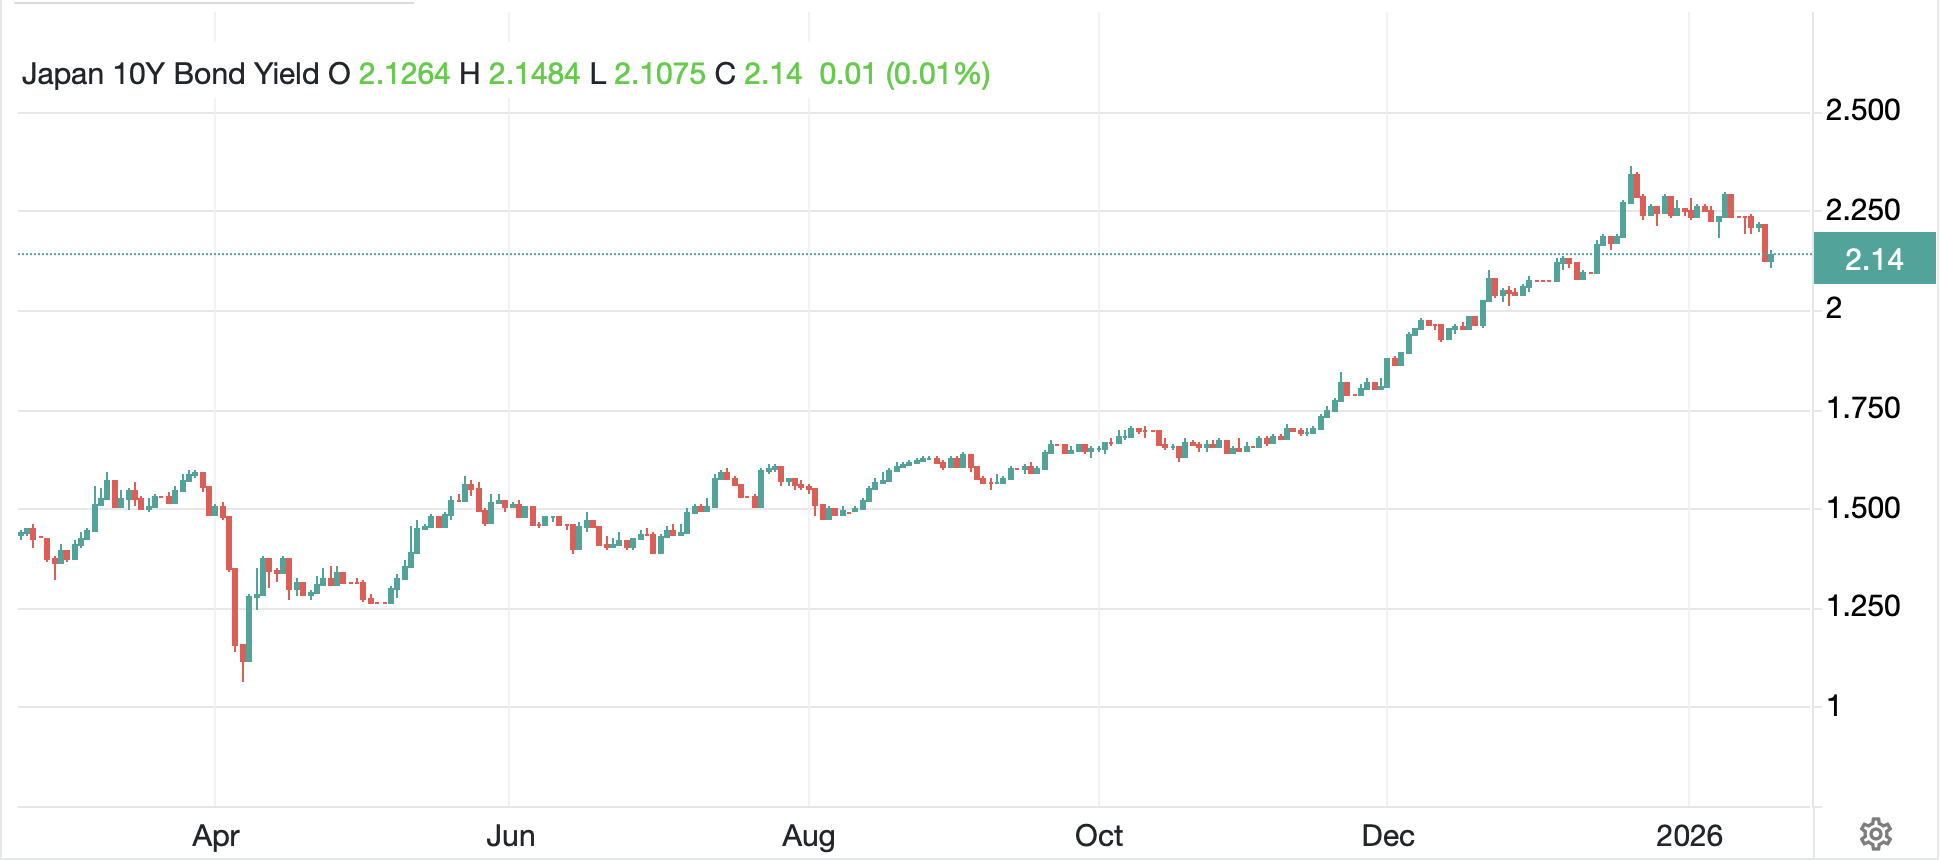
Arguably the biggest geopolitical change of late was the dramatic Takaichi-san victory in Japan, which has enabled her to impose her will on the economy.  As such, we can expect more ‘run it hot’ actions there.  However, thus far, the JGB market has not rebelled against further unfunded government spending.  We are one month, and 20bps, removed from the recent peak in yields.  We shall see how long that lasts and if, a change in that view impacts bond markets elsewhere in the world, but as you can see below, it does not look that scary right now.

Source: tradingeconomics.com

But otherwise, Russia/Ukraine continues apace with negotiations going nowhere and the US/Iran talks, with articles this morning claim progress is being made there.  Arguably, some type of deal with Iran ought to be bearish oil as it would seemingly involve the lifting of sanctions on their oil sales, but who knows.

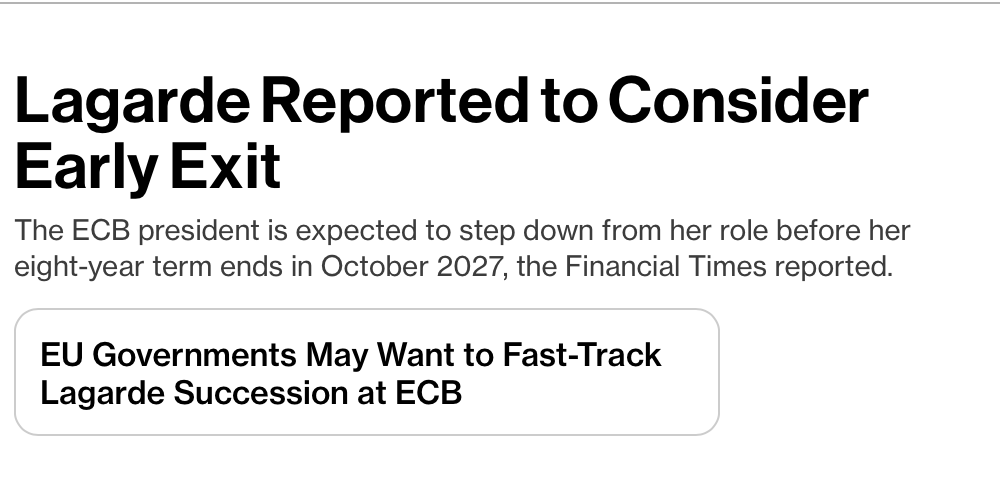
Which takes us to the most interesting headline this morning (see Bloomberg’s headline below), the story that Madame Lagarde is rumored to be stepping down as ECB president before her term expires next year.  While, naturally, she has denied the story, there is certainly enough palace intrigue to dig a little deeper.

Ask yourself why, a woman who has spent her career striving to reach the pinnacle of geopolitics, would willingly give up a role at the top.  While the initial punditry stories indicate she wants to allow President Macron to be involved in the discussions as to her replacement (if she serves out her term, he will be gone and they fear Marine LePen on the right will be able to influence the next decision), Occam’s Razor tells me it is far more likely she is going to prepare to run for president of France herself.  After all, did she not just see her erstwhile colleague, Mark Carney, be elected PM of Canada?  And as powerful as major central bank president is, it pales in comparison to national president.  Added to her impetus was the resounding Takaichi victory, demonstrating that a woman can be elected in the CEO role, and I must believe, this is her motivation.

If you are of a globalist mindset, Christine Lagarde is the perfect French president, completely beholden to your ideals, and yet, as a woman, believed to be able to work effectively with others (notably President Trump) in order to prevent further damage to your goals.  Mark my words, she will step down and announce her candidacy before the summer. Funnily enough, I expect if she leaves, it will be a benefit for the euro!

Ok, the briefest of turns around markets shows that Asian equities followed yesterday’s US market rally higher, at least those that were open, with New Zealand (+1.5%) leading the way after the RBNZ left rates on hold, as expected, but came across as more dovish than expected.  Otherwise, Tokyo (+1.0%) and Australia (+0.5%) were the next best gainers with the former responding to the news that the first major Japanese investment into the US was announced, a $36 billion set of deals including a massive NatGas power project in Ohio.

European bourses (DAX +0.85%, CAC +0.55%, IBEX +1.25%) are also higher, rising on hopes that the announced increases in defense spending will be spent at home and boost European companies across the continent.  As to the UK (+1.0%), softer inflation readings this morning have raised hopes that the BOE will be more aggressive easing policy soon.  US futures are higher by about 0.5% this morning as it seems many of the fears about overinvestment in AI have suddenly waned.

Bond yields, which have fallen steadily over the past several weeks have all backed up 1bp, in the US, Europe and Japan.  Overall, nothing really to mention here.

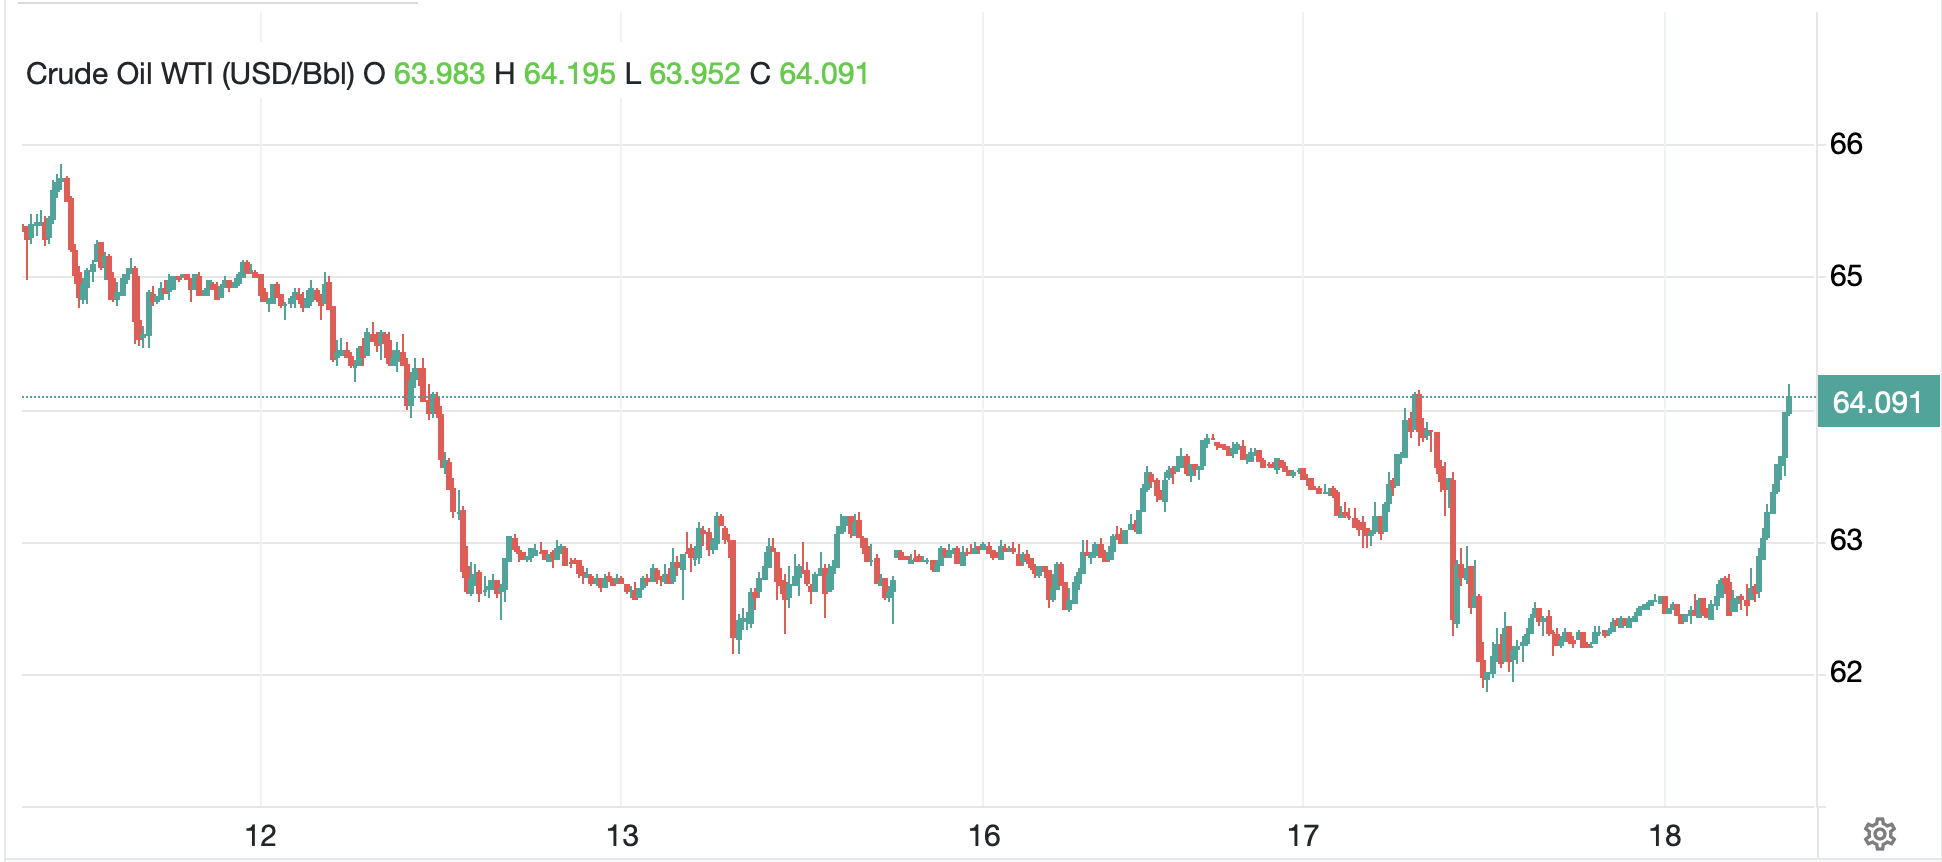
In the commodity markets, oil (+2.9%) just jumped after the Russia/Ukraine peace talks broke up abruptly after just 2 hours.  Fears of more strikes on Russian infrastructure have risen.

Source: tradingeconomics.com

As to the metals, after yesterday’s declines, this morning they are all bouncing (Au +0.9%, Ag +2.8%, Cu +1.2%, Pt +1.6%) as they continue to consolidate.

Finally, the FX markets are showing very modest net USD strength with NZD (-0.7%) the laggard after the RBNZ while NOK (+0.7%) is the leader, jumping right after the oil news.  Otherwise, +/- 0.15% is the order of the day.

On the data front, we get some second-tier information as follows: Durable Goods (exp -2.0%, +0.3% ex transport), Housing Starts (1.33M), Building Permits (1.40M), IP (0.4%) and Capacity Utilization (76.5%).  (An interesting tidbit regarding Capacity is that I read China’s Capacity Utilization is just 74.3%.  Based on their trade balance, I would have expected a much higher number.  It tells me that over (mal?) investment there is even greater than I thought.). 

Too, we hear from Fed Governor Michelle Bowman and get the FOMC Minutes at 2:00.  Yesterday, Governor Barr said there was no reason to adjust policy for the reasons I stated above, nothing is clear, and I suspect Ms Bowman will be similarly inclined.

It is hard to get excited in today’s market, that’s for sure.  In fact, I expect we will need to see something pretty dramatic to drive a break of these ranges, and I have no idea what that will be.  Play it close to the vest for now.

Good luck

Adf