
The poet is back to his pen
And thinking ‘bout euros and yen
And oil and gold
As bonds all get sold
While indices rise yet again

Remarkably, o’er the past week
Though headlines, to havoc, did speak
The movement of note
Showed oil got smote
While dollars have reached a new peak
I have not been keeping close tabs on markets overall during my road trip, although am back to focusing again. But first, the news from Topeka was that, while Marvel showed beautifully, we did not get placed amid very stiff competition.
Plus, as in every judged event, there is a measure of politics involved, and I am just not politically correct!
One other issue is that today is the first day I’ve had viable Wi-Fi to work with as the previous places I stayed just didn’t have it.
So, with all that in mind, I will be brief this morning. Prior to leaving, I left myself records of where markets closed on September 25th so I could see how much things changed. And the truth is, not all that much, at least on net since I last wrote.
In the equity markets, while the NASDAQ made new all-time highs, it is just 2% higher than when I left. The S&P managed a much smaller gain, 0.7% and the DJIA actually slipped a bit during the period. Elsewhere in the equity space, Japan (+7%) was the big winner while France (-2.5%) cannot keep up as the student riots and the fiscal problems, which are bad enough to garner a top WSJ story this morning, are obviously weighing on things there.
Of course, all the equity moves are happening within the context of the bond market, which continues to see yields climb around the world. US yields (+11bps) are the talk of the market, but Japanese yields (+3bps and up to yet more 30+nyear highs) are also still climbing. But arguably, the biggest news is Brazil, which in the wake of the surprising first round lead in the presidential election by Flavio Bolsonaro (son of previous president Jair Bolsonaro) where we have seen Brazilian yields collapse (-115bps) while the Brazilian stock market rocketed 7.7% in the wake of the election results
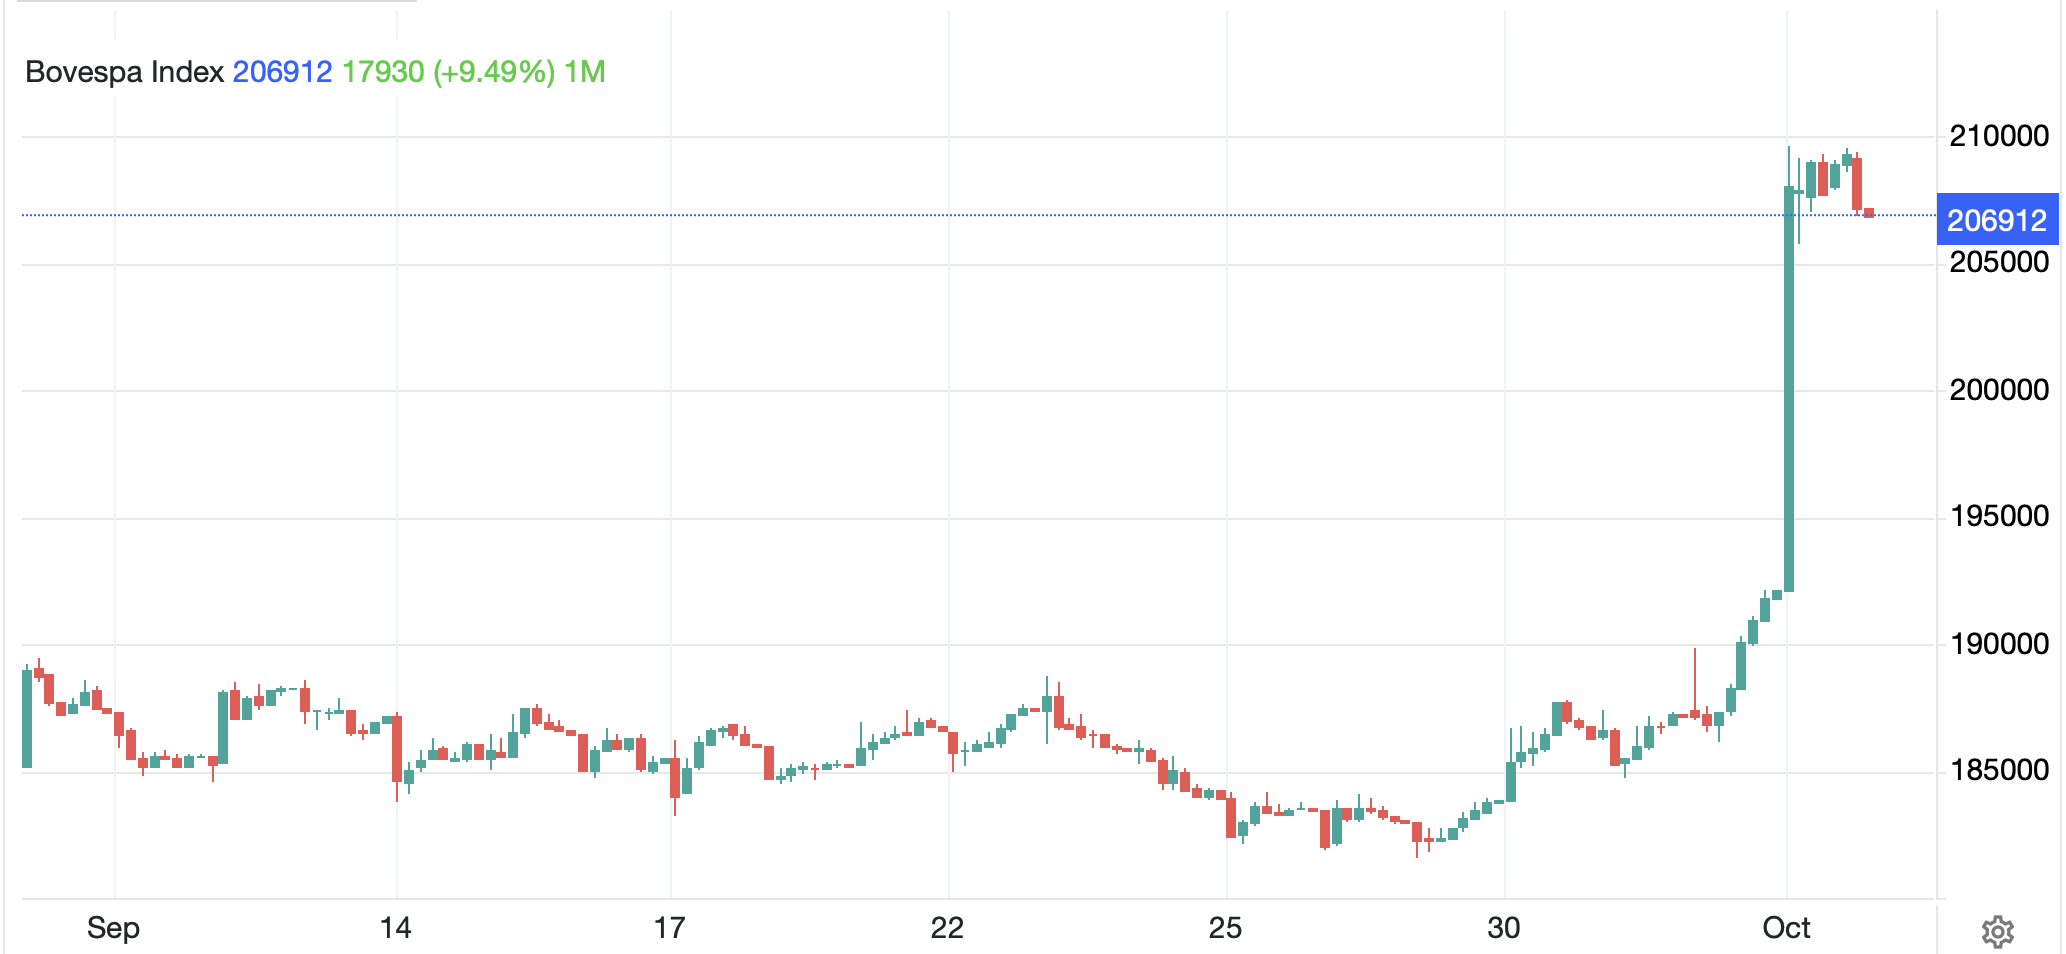
Source: tradingeconomics.com
Elsewhere, both oil (-5.1%) and gold (-2.9%) have slipped as the former continues to seesaw based on comments about the amount of oil coming out of the Strait of Hormuz, although it is clear product prices are not falling, while the latter has just lost its appeal. Gold is a funny thing, it is a wonderful long-term store of value and has been so for millennia, but it cares not a whit about day-to-day movements in prices. Arguably, gold has done its job as that store of value as many holders have utilized their reserves to shore up their own financial situation, thus selling the barbarous relic. However, it remains difficult for me to look at the fiscal policies extant around the world and think that fiat currencies are going to be embraced.
Speaking of fiat currencies, while the dollar is just that, fiat, it is also the currency of the strongest current economy around, so despite all its flaws, and all the questions about the Fed and whether they will be hiking again and what that means, and despite all the angst over the selloff in Treasuries, the dollar continues to be the safest play around. For instance, the euro, saddled with French misery and Germany fiscal and energy incompetence (as well As Spanish insanity regarding housing policy) has slipped -1.3% over the past week while the DXY has rallied a similar amount. Despite the Nikkei’s rally, the yen (-0.6%) has slipped as well. In fact, the only currency of note that has performed well is, not surprisingly, BRL (+3.5%) as money is flowing to the country in anticipation of a Bolsonaro win in the runoff election at the end of the month. That, my friends, is a serious gap opening!
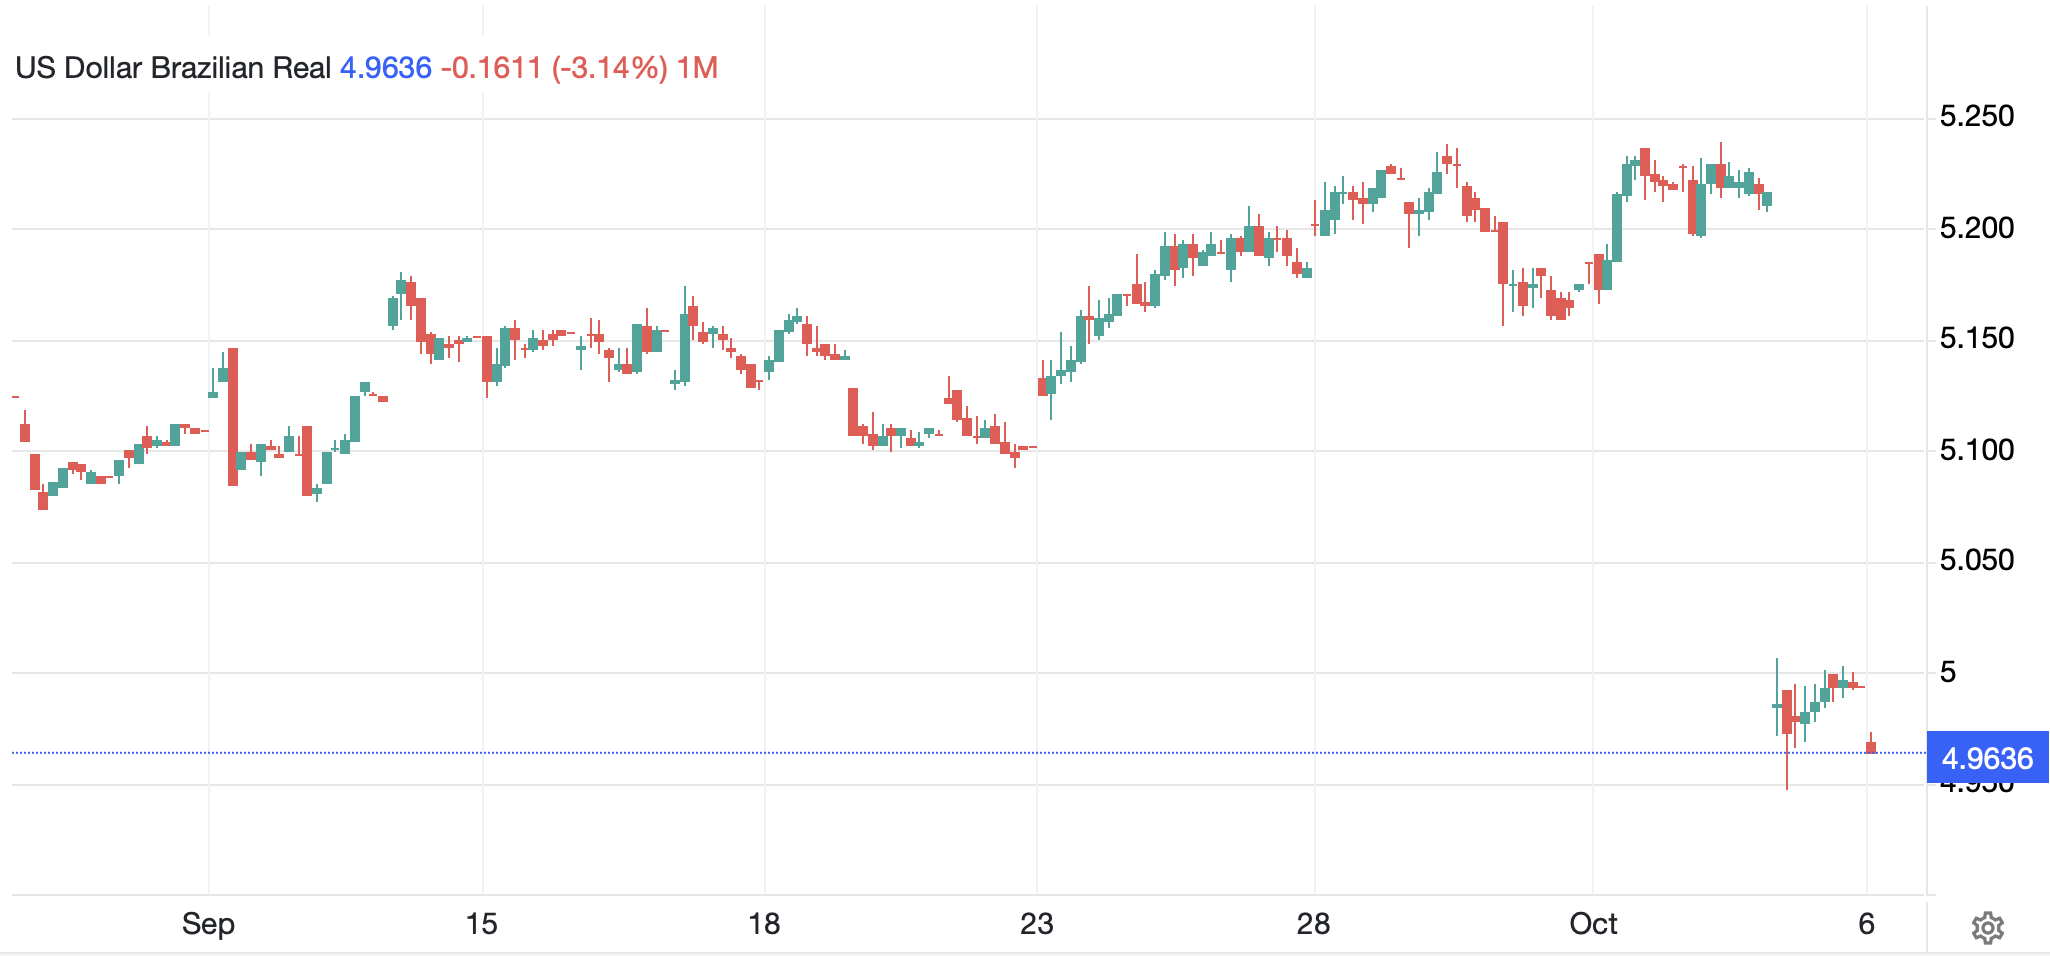
Source: tradingeconomics.com
And that’s really all I have this morning, but I will be back going forward, most days, I believe.
On the calendar, there is not a ton this week after last week’s disappointing payroll report.
| Today | Trade Balance | -$102B |
| Thursday | Initial Claims | 200K |
| Continuing Claims | 1710K | |
| Friday | Michigan Sentiment | 47.6 |
Source: tradingeconomics.com
The payroll report served to reduce the probability of a Fed hike this month dramatically and it is now down to 21% from above 60% when I left. I still don’t think they need to hike more, although the market remains convinced they will do so in December. But December is a long time from now and much can happen in the interim. As to the dollar, it remains the cleanest dirty shirt around.
Good luck
Adf

