Apparently inside Tehran
The pressure that Trump has brought on
By blockading ships
Is set to eclipse
Their goal to be Agamemnon

At least with respect to his win
In Troy, though much to their chagrin
They may meet his fate
Because of a Strait
And views they should be its kingpin
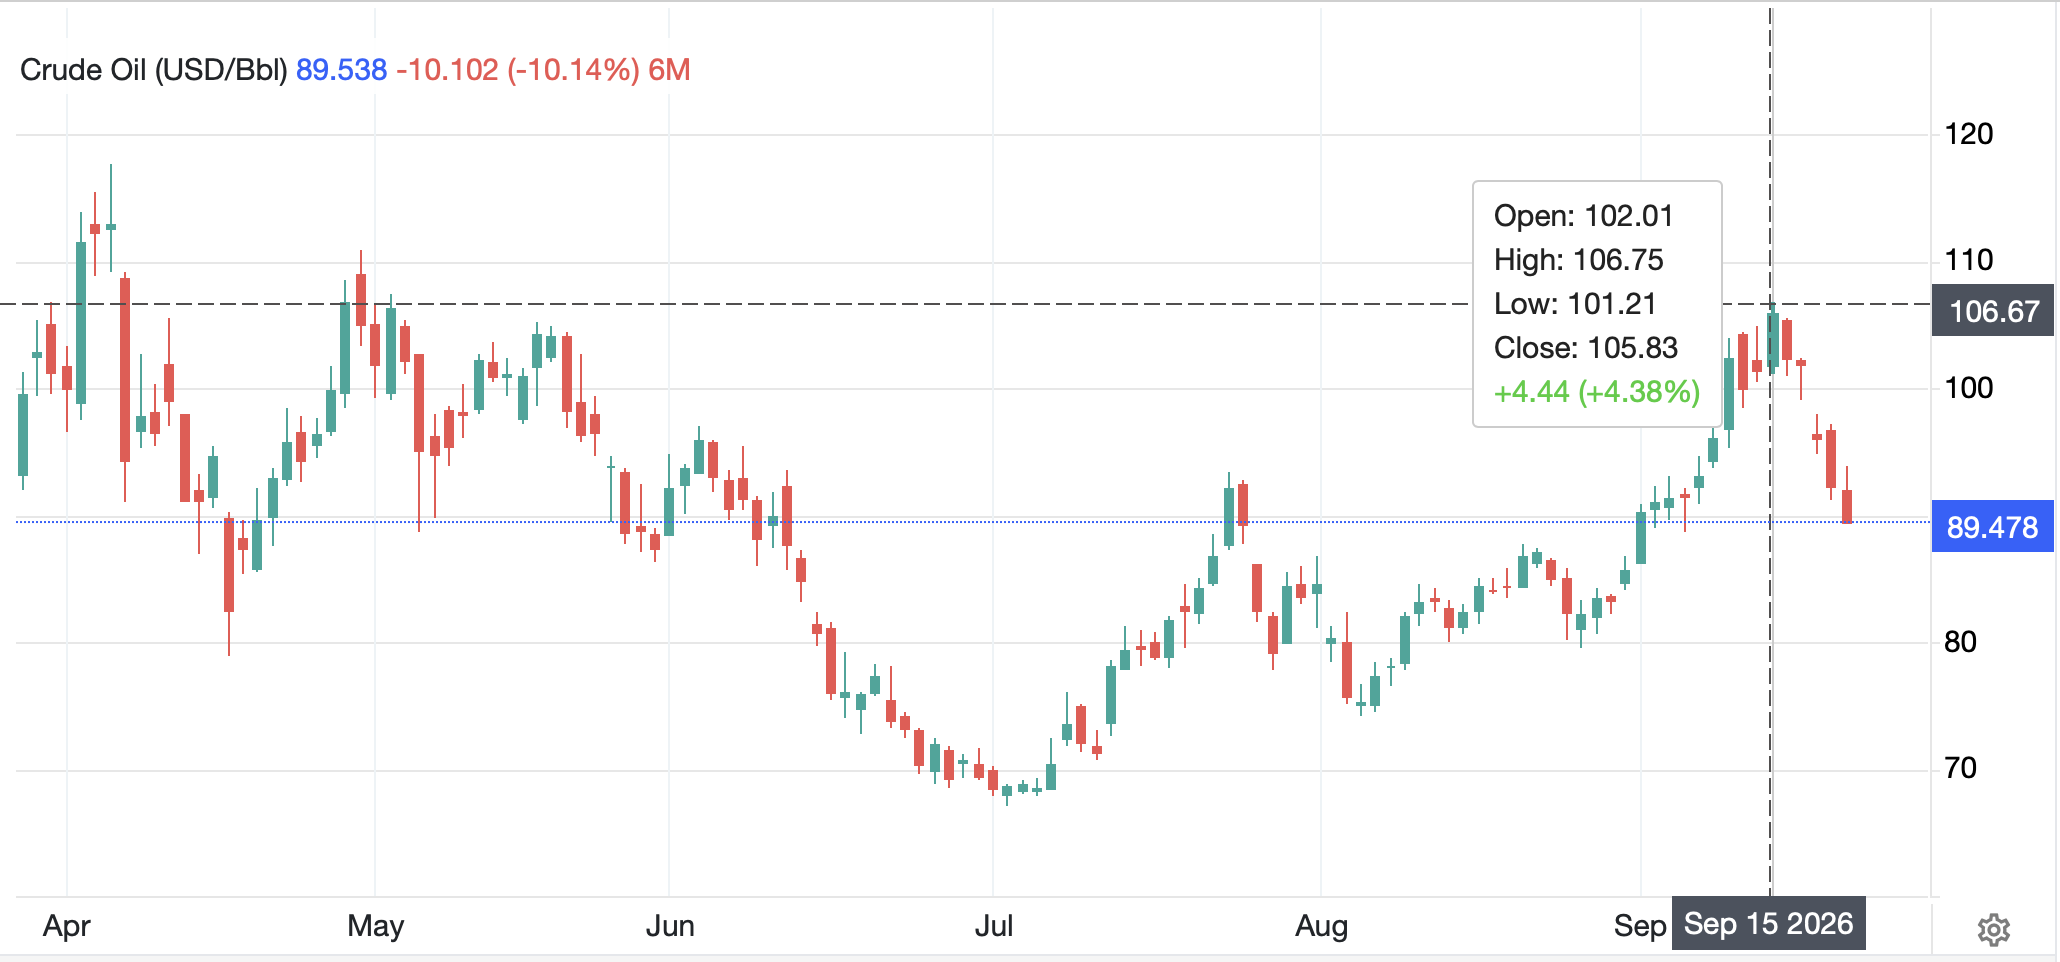
One week ago today, oil traded above $106/bbl as concerns about Iran’s ability to inflict further damage on Gulf capacity along with their Houthi allies reached a peak. The punditry was going all-in on the idea that as oil prices rose, and especially as product prices rose, that President Trump would have to back off his pressure campaign because rising diesel prices would collapse the Republican hopes for retaining the Senate, let alone the House, in the upcoming midterm elections.
What a difference a week makes, 168 little hours (my apologies to Dinah Shore) as the news this morning is that Iran has just pledged to reopen the Strait of Hormuz if the US ends the blockade. Oil prices (-2.6% today, -15.5% in the past week) are responding as one would expect.
Source: tradingeconomics.com
According to Kyodo news, Iran is really feeling the pain now and discussing reopening negotiations as per the below report.
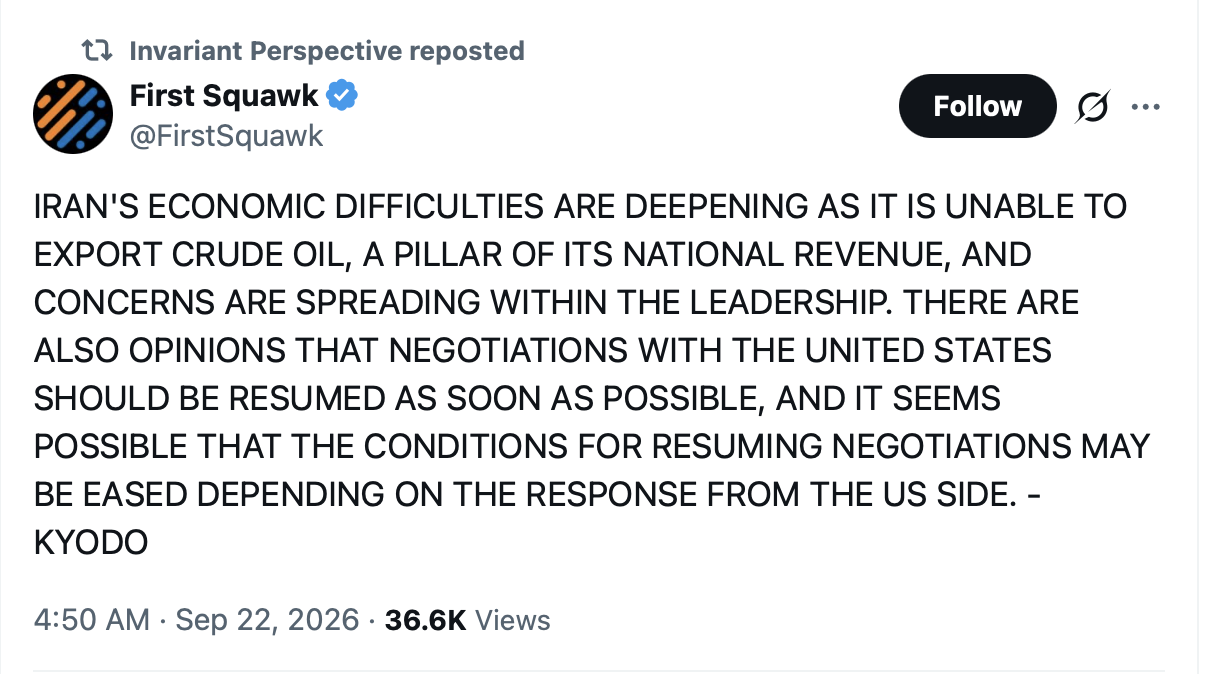
Now, as I have maintained all along, there is no way for any of us to really know what is going on in Iran as the propaganda from all sides runs fast and heavy. And it is entirely possible that this is another head fake that will precede another series of attacks on vessels in the Strait, or on the Saudi East-West pipeline. But markets are certainly buying it right now, hence the oil price decline as well as the continuation lower in bond yields with Treasuries and European sovereigns all lower by -2bps, except for French OATs (+1bp) as investors continue to look at French finances and worry further.
Seemingly, adding to the good vibe is the word that Iranian President Pezeshkian may meet with President Trump this week in a side meeting during the UN General Assembly thus priming views that something real may come of this. I certainly hope that is the case, but I would not bet the farm on that outcome. Until IRGC leadership feels significant pressure, it is hard to believe much will change. But that, too, could be in our future. If all 8+ million people in Tehran march in defiance of their rules, will the IRGC shoot them all? Seems hard to believe, but the stories that have gotten out of Tehran paint a terrible picture there and a larger popular uprising cannot be ruled out in my view.
In the meantime, this is the best news we have seen in a while, and at least it has diverted attention from the AI death throes that are promised soon.
So, was this the driver behind yesterday’s equity rally? It doesn’t seem so as that was very tech focused with the Mag7 all having strong sessions although I continue to read the dire stories of terrible market breadth. That is a measure of the relative performance of different parts of the market and the concern is that somewhere around 50% of companies are below their 200-day moving average, a bearish signal, while the market indices are making new highs. Some say this is a sign of a weak rally while others explain the index can work to drag all stocks higher. But, as with everything else, both sides are certain they are correct!
Let’s look at how things have behaved overnight away from oil and bonds. After the strong US equity performance, Asia was generally more subdued as Japan remained on holiday (they are back tonight) while China (+0.1%), HK (+0.2%) and even Korea (+0.15%) all saw minor gains only. Korea is the most surprising given the tech led nature of the US markets. Elsewhere in the region I see many markets having risen something like 0.3% with one major outlier on the downside, Indonesia (-1.7%) as concerns over a pending rate hike and higher fiscal deficits has international investors fleeing.
In Europe, though, things are a bit greener with gains nearly across the board (Spain +0.7%, France +0.5%, Germany +0.45, UK +0.15%) although Italy (-0.15%) is bucking that trend. The confusing thing to me is France, where concerns reign regarding their fiscal picture in the bond market, but the equity markets are non-plussed on the subject. And at this hour (7:00), US futures are pointing slightly higher, +0.1% or so.
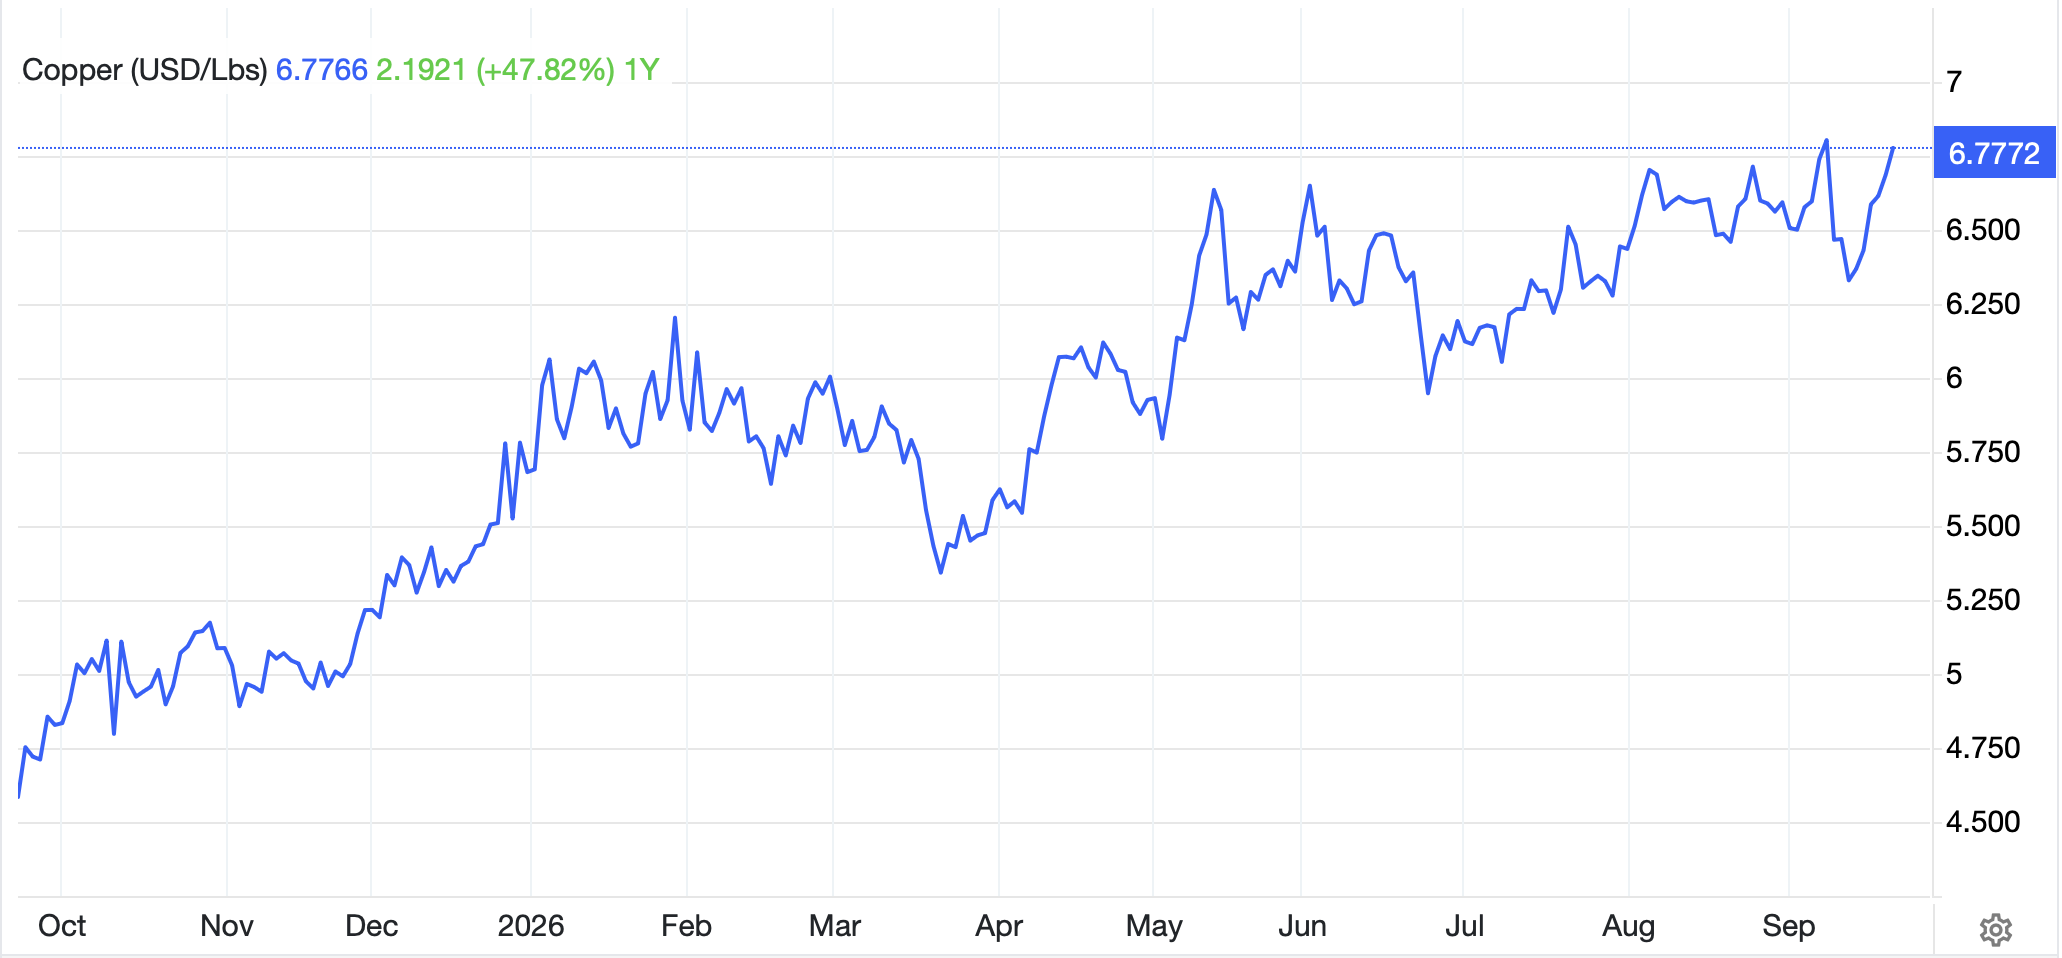
Quickly in the metals markets, while gold (-0.5%) and silver (-0.7%) continue to struggle despite the decline in oil prices, copper (+1.3%) is back to within pennies of its all-time high set two weeks ago. Certainly, the trend here is higher and, once again, I will remind you that current production is insufficient to meet demand and the timeline to bring new production online is measured in decades. In my view, this metal could go much higher over time.
Source: tradingeconmics.com
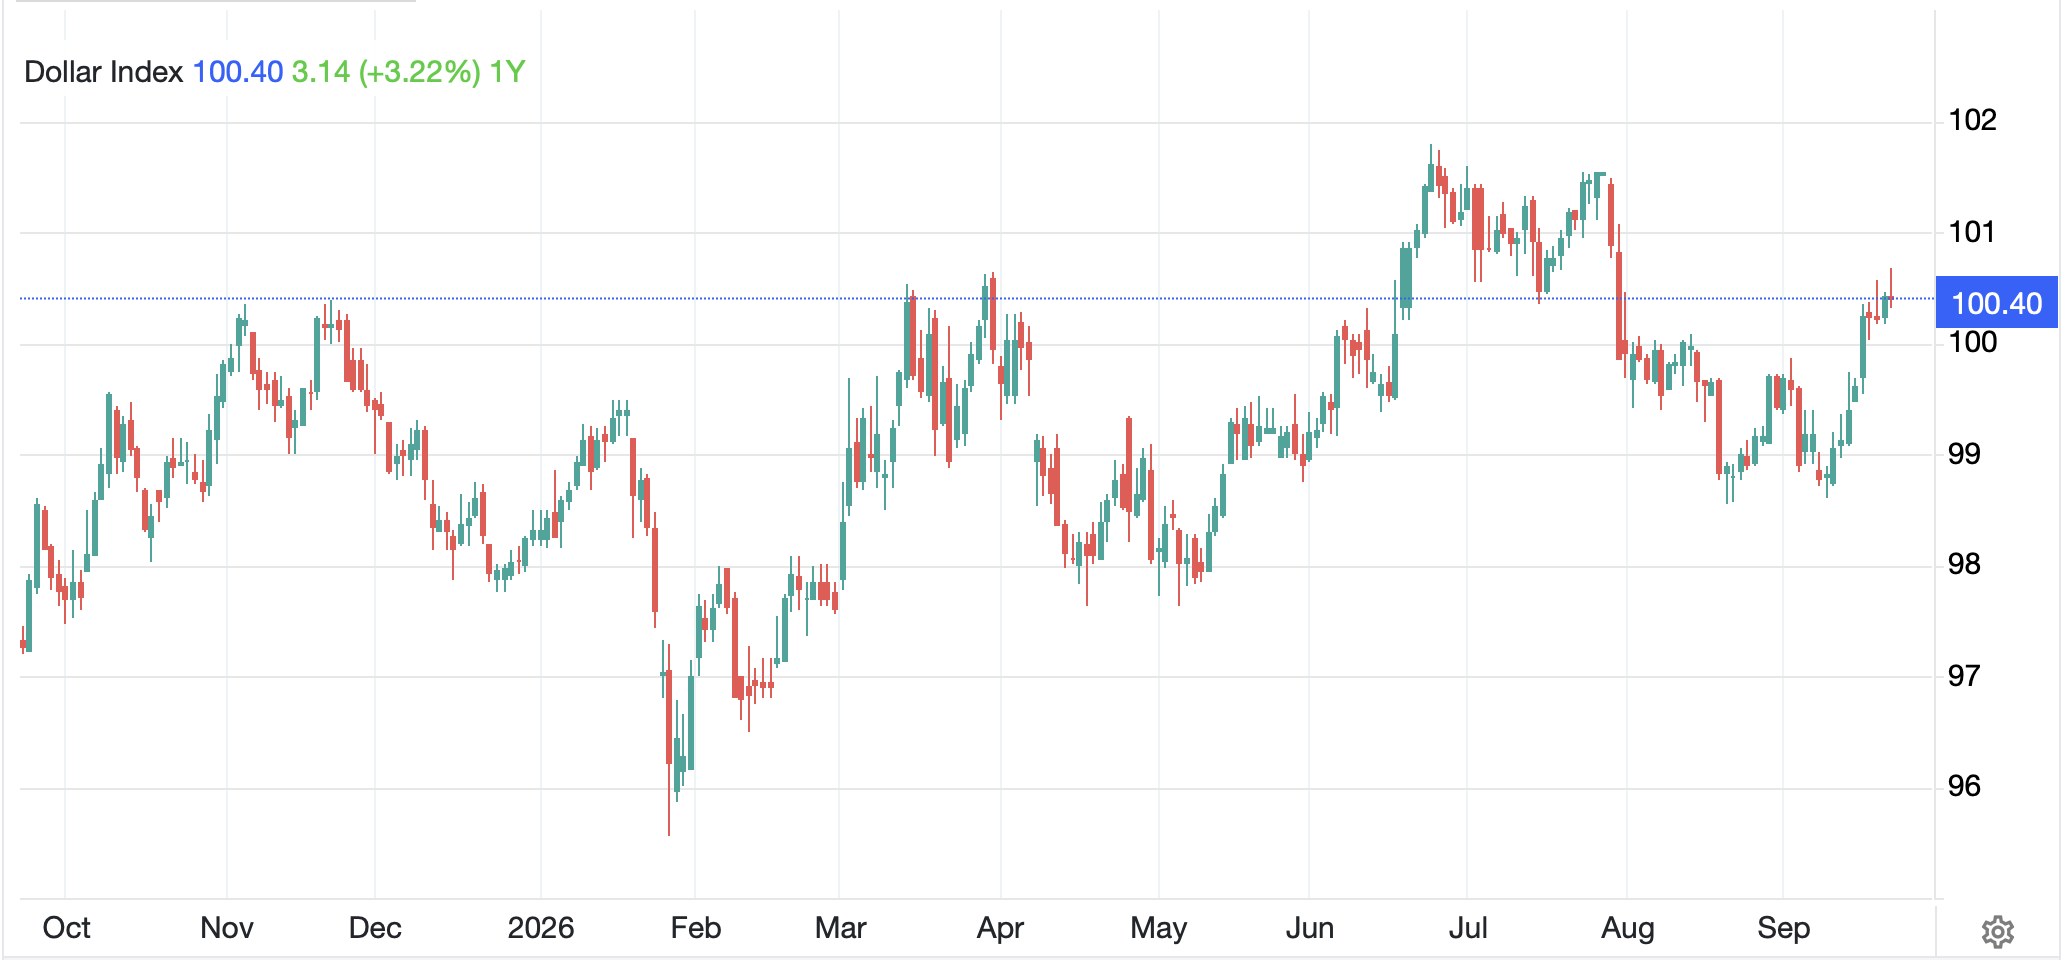
Finally, the dollar refuses to collapse despite so much wishin’ and hopin’ by a large part of the punditry. While it has not risen substantially of late, it has not fallen either. In fact, the DXY (0.0%) sits above 100 currently which is clearly near the top of its trading range for the past year as per the below.
Source: tradingeconomics.com
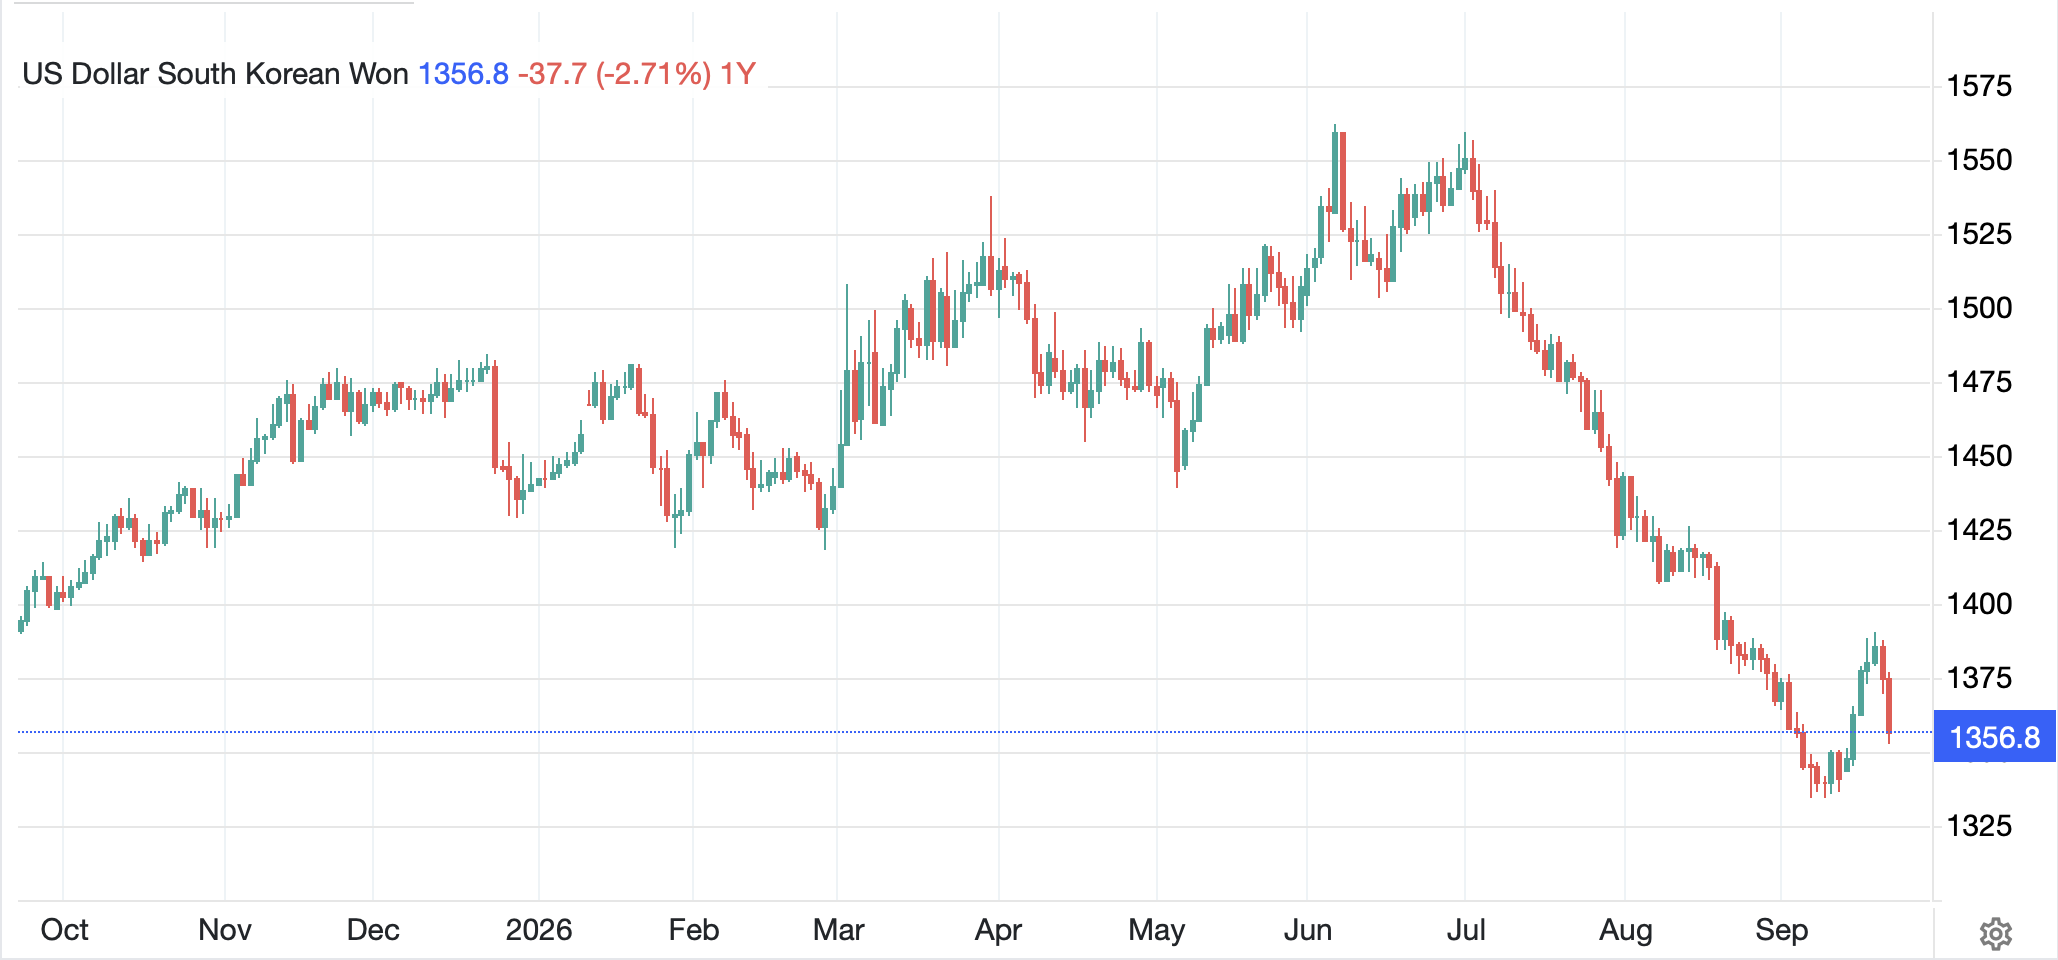
Perhaps the biggest news here today is that the ECB has begun its experimentation with a CBDC, a terrible sign for the people of Europe, I believe, but a typical European response to US activity. While private sector stablecoins are seen as a key part of the future for the US, Europe went the government route. Now, they make the laws and can certainly force some uptake, but my money is on USD stablecoins dominating electronic payments going forward. As to major movers here, there is only one, KRW (+1.35%) which has seen increasing volatility, but is really just back on the track it has been since early July as per the below. I guess the rebound was just corrective in nature.
Source: tradingeconomics.com
On the data front, there is nothing of note on the calendar although we get plenty more Fedspeak with Williams, Jefferson and Barkin all on the calendar. Yesterday, not only did Goolsbee say rates would need to rise further, but so did St Louis Fed President Musalem. The interesting thing to me is they all talk about the oil price shock and then still say we must hike rates. This is quite odd to me given the inherent dovishness of almost every central banker. I cannot tell whether this is a result of their virtually religious belief in Keynesianism or if it is all TDS. It is, however, a mistake for them to raise rates further.
And that’s all there is today. Potential Iranian-US talks seem like the biggest opportunity for a change in the narrative, but I don’t give them that high a probability of being successful. In the meantime, ain’t nobody selling the dollar!
Good luck
Adf
 fxpoetry
