Risk appetite’s back on the menu
Across almost every stock venue
Bond yields are declining
As traders are pining
For times when our lives were less tenu (ous)

The proximate cause driving prices
Is hope the Iranian crisis
Is nearing its end
Thus, bulls all contend
‘You must buy’ when they give advices
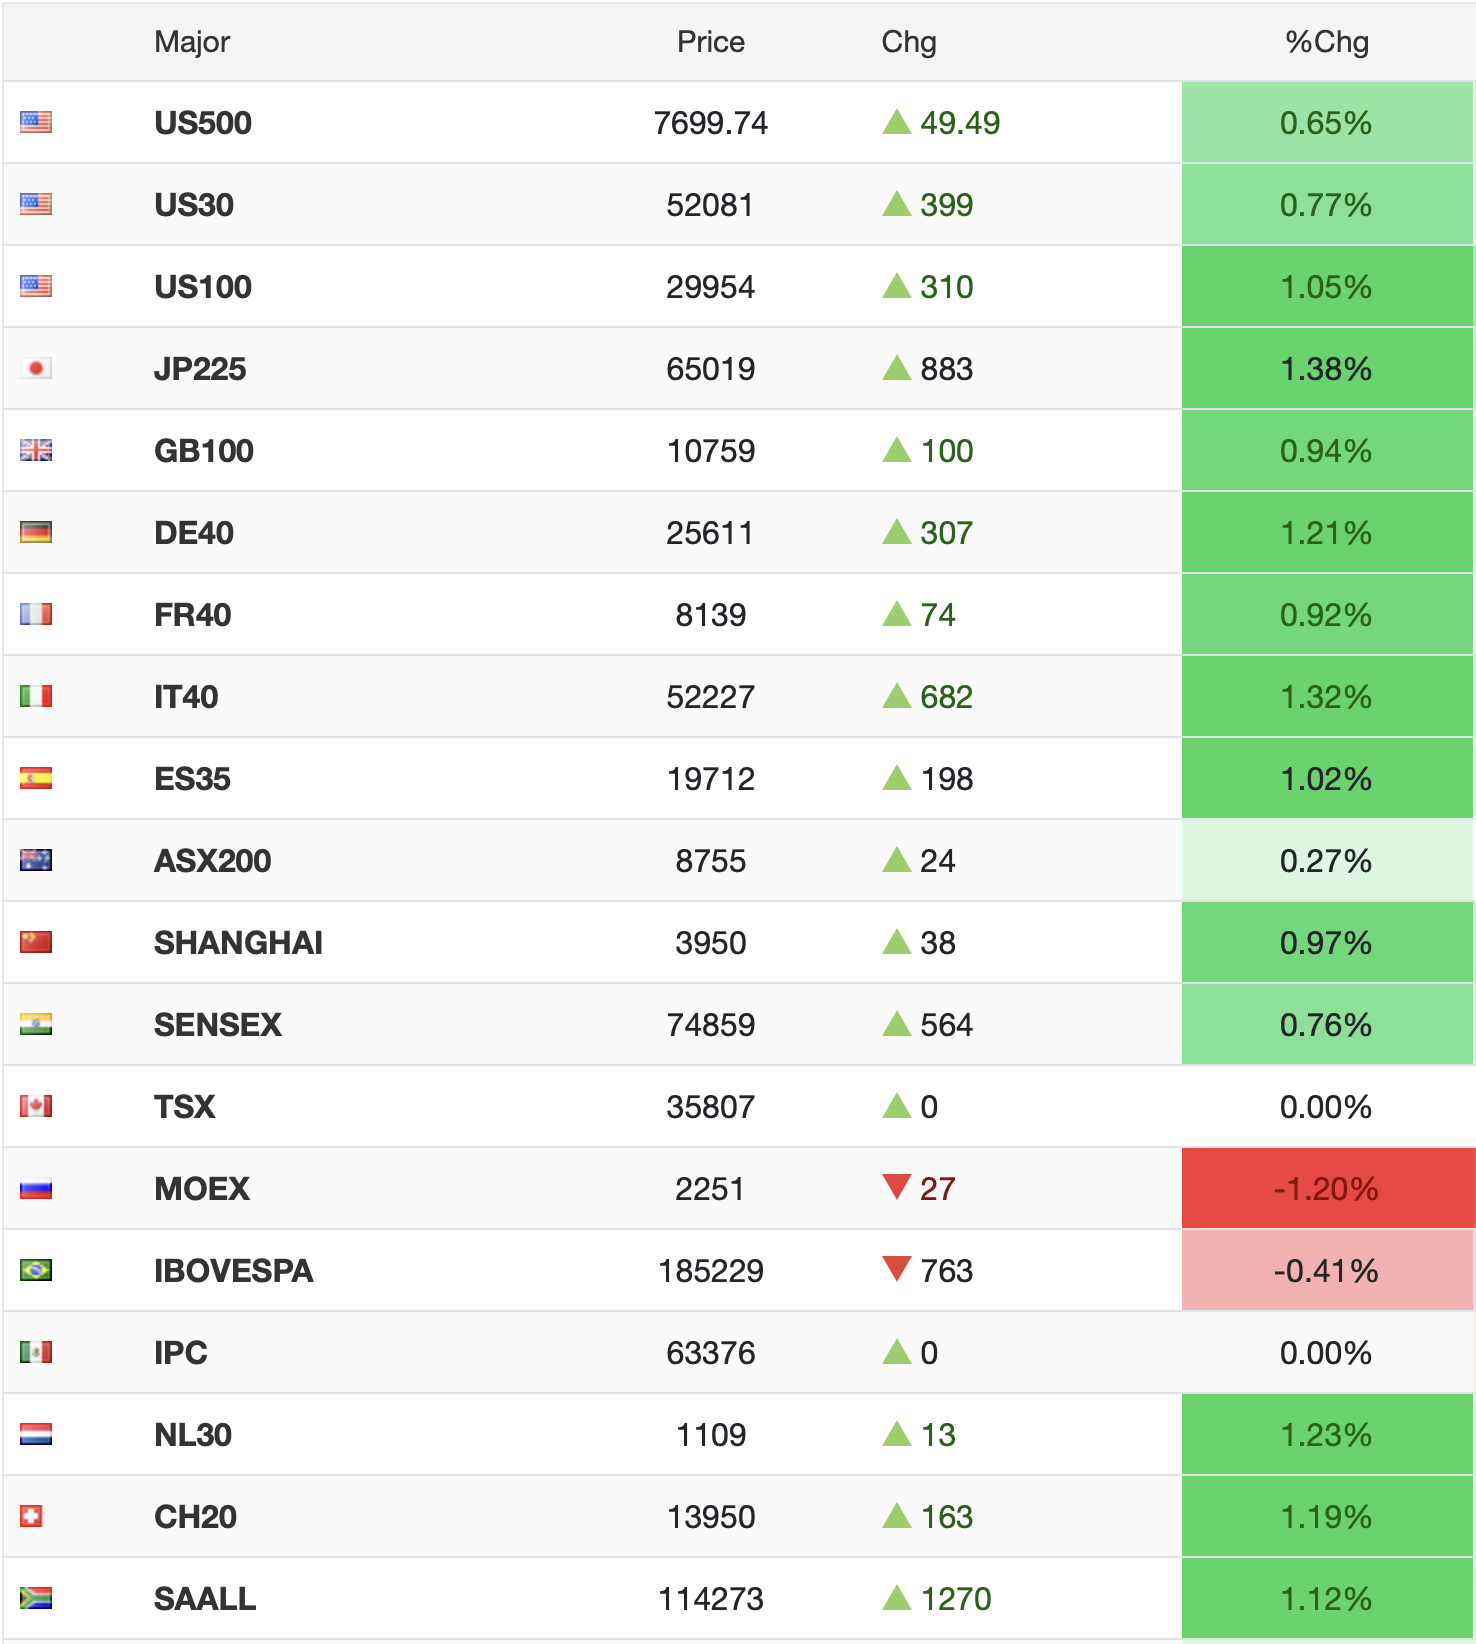
While it may be the first day of Autumn, the markets have a distinctly summer doldrums feel to them this morning. Crude prices (-3.1%) are sliding and that has encouraged buying of stocks and bonds across the board. For instance, looking at the below screenshot from tradingeconomics.com, you can see that only Russia, of markets currently open (Tokyo was closed for Autumnal Equinox Day, and Canada, Mexico and Brazil are not open yet) has suffered today, and given oil’s decline, that makes sense,
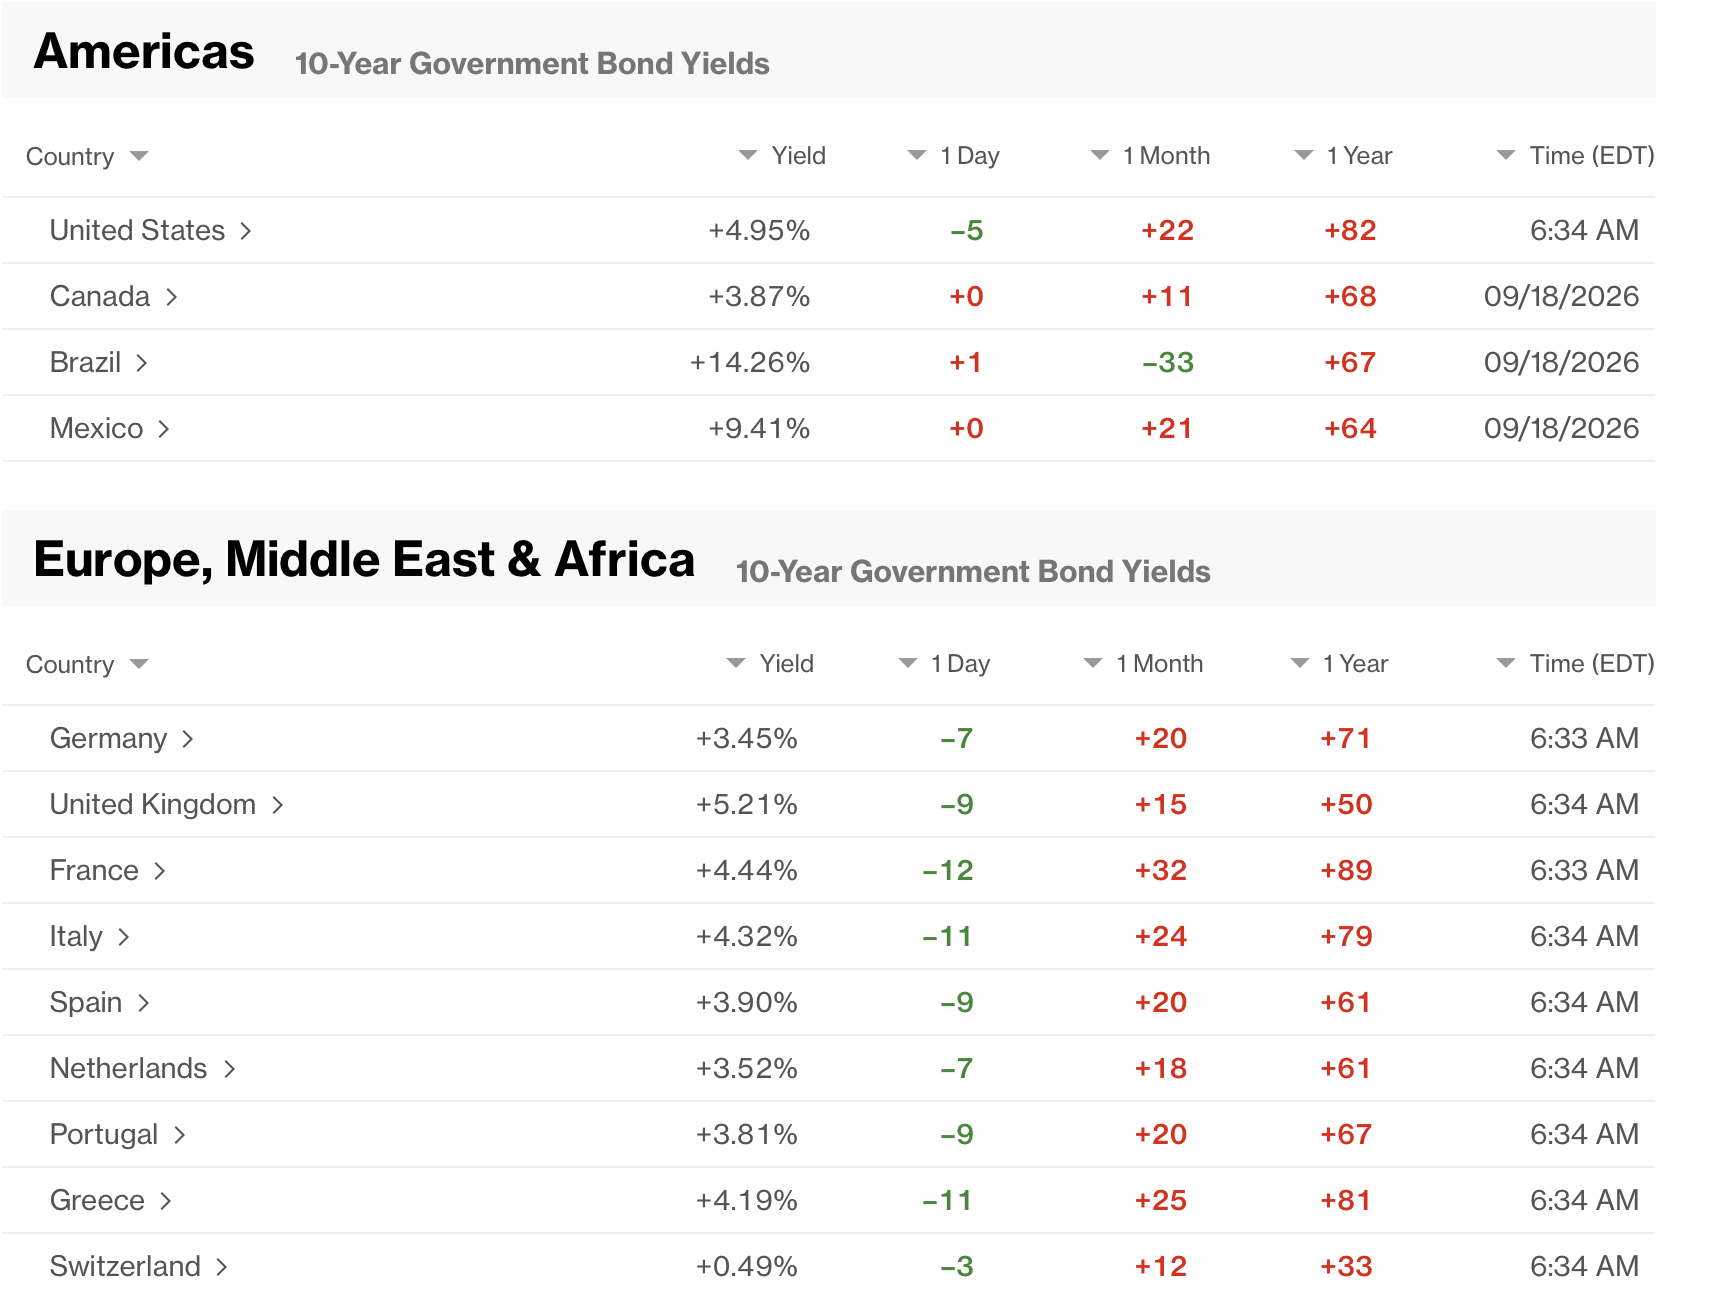
If we look at the bond market, we also see bonds in demand (yields falling sharply) as Treasuries and all of Europe are having great days per the Bloomberg screenshot below.
So, is this all about oil prices? In truth, I believe that is the largest part by far. If we look at a chart of WTI prices vs. the S&P 500 over the past month, you can see that the tendency is toward a negative correlation, especially over the last week.
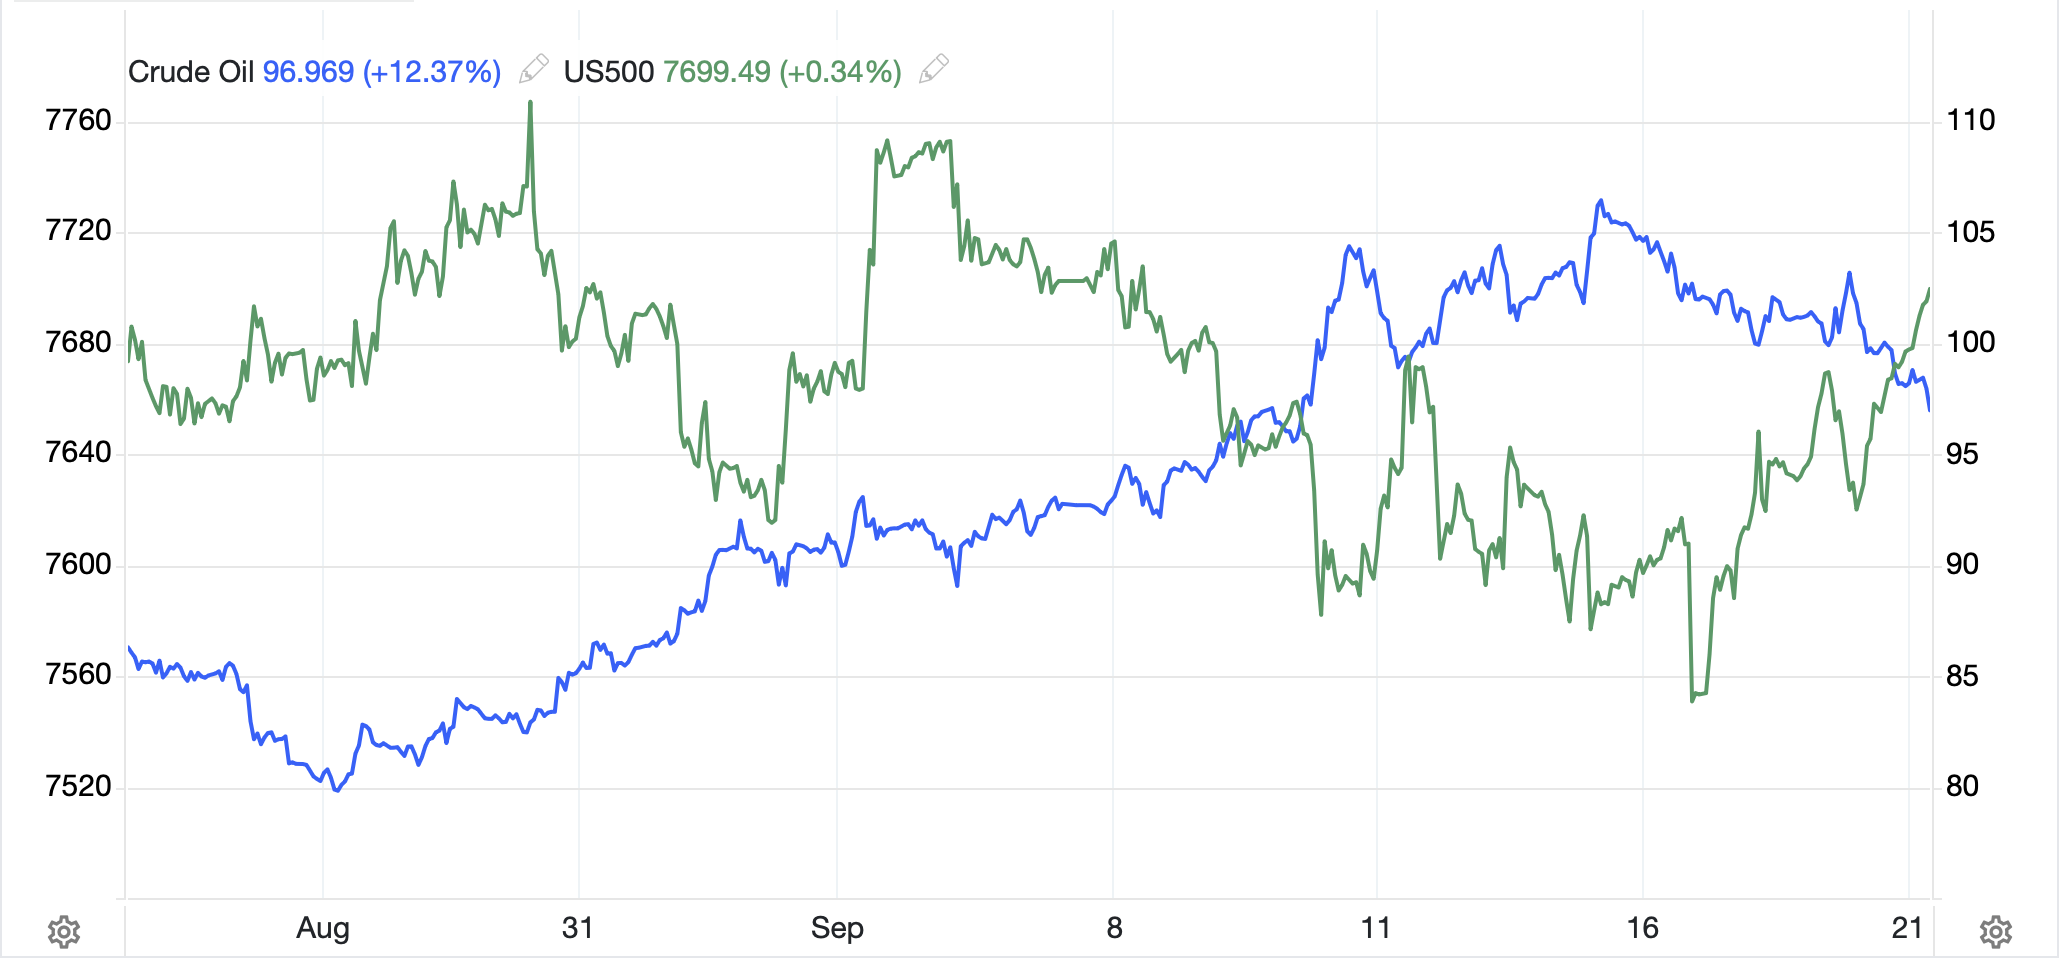
Source: tradingeconomics.com
And sometimes, things are just that simple. While this is UN week and much has been made of the fact that President Trump is going to be meeting with President Xi later this week, as well as Japanese PM Takaichi, discussions of that nature, while potentially important on a geopolitical scale, typically don’t involve or impact financial markets directly. In the meantime, we have just gone through every major central bank meeting in the past two weeks, so nothing is on the immediate horizon and there is no economic data of note scheduled to be released this week. Which brings me back to oil as the driving force in markets right now.
As I scan headlines across the WSJ and Bloomberg and look at my X feed for the key information, things are turning toward the upcoming midterm elections as the next source of interest. And of course, now that the NFL is back at it, along with college football, MLB and the approaching NBA and NHL seasons, there is plenty of nonmarket stuff to keep people busy. And after all, there are many who believe it is their birthright to earn 15%+ each year on their equity investments, so aren’t worried about little things like earnings or business conditions.
Speaking of elections, one cannot ignore the two state elections in Germany this past weekend where in the state of Mecklenburg-Western Pomerania (they need better state names), not only did AfD win the largest share, 38.2%, but Chancellor Friedrich Merz’s CDU failed to win the requisite 5.0% of votes to remain in the state parliament chamber, a historical first. I raise the point because it is simply another demonstration of the idea that people around the world are unhappy with the current situation in their countries and are seeking change.
The nature of that change remains uncertain, as both populist left and populist right have been gaining votes, while the center is getting decimated. And there are many other elections in large countries coming up, notably Brazil, where the polls are basically tied between incumbent Lula da Silva and the challenger, Flavio Bolsonaro, son of former president Jair Bolsonaro and where there is additional political intrigue regarding how the courts there have been behaving.
In fact, as I survey the world, it appears that the 4th Turning is clearly on track, and whether it peaks in 2027 or 28 or 30, it is coming soon to a screen near you. I know that I have been looking at my personal investments through the lens of what can happen in a situation where institutions change and I believe that would be something important to consider as we all look ahead.
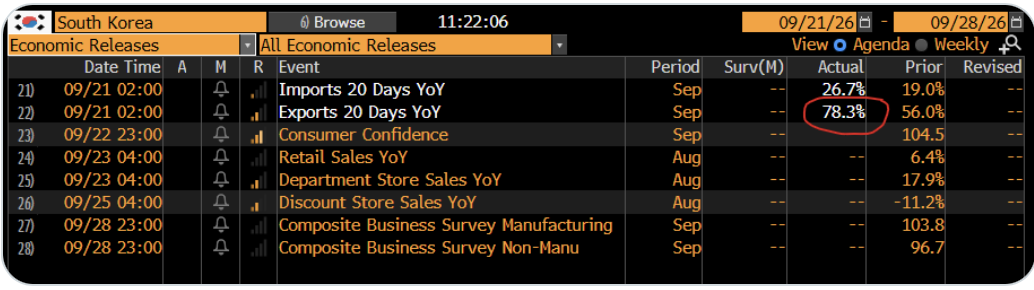
Ok, as to the markets not covered, FX is the main one but other than KRW (+1.0%) which saw the 20-day Export data jump 78.3%, nothing else happened.
Otherwise, the dollar is +/-0.15% or less vs. every major currency although the trend is very mildly positive for the dollar.
And in the metals markets, that modestly stronger dollar is seeing weakness in gold (-0.7%) and silver (-0.2%) although copper (+1.5%) is having a good day as there are more and more discussions regarding long-term shortages and absence of new supplies.
On the data front, the noteworthy thing is we get too much Fedspeak this week, but here are the few data points coming.
| Today | Chicago Fed National Activity | 0.2 |
| Wednesday | Flash Manufacturing PMI | 53.5 |
| Flash Serv ices PMI | 56..0 | |
| Thursday | Initial Claims | 203K |
| Continuing Claims | 1735K | |
| New Home Sales | 620K | |
| Friday | Durable Goods | -0.3% |
| -ex Transport | 0.6% | |
| Michigan Sentiment | 47.5 |
Source: tradingeconomics.com
As to Fed speakers, we hear from eight speakers across eleven different venues this week and we have already seen the Chicago Fed’s Austan Goolsbee tell us the road to 2% inflation may not be painless in Bloomberg this morning and he is not one of the eight. The point is, these folks love to hear themselves speak about things and love their 15 minutes of fame, that’s for sure.
To me the question is, has any part of the long-term story changed? I don’t really think so. In fact, while I usually believe politics doesn’t really impact markets, at least not directly, I have a feeling that we could see some major policy changes upcoming if elections bring in new views as to how things should be done. That is the biggest wild card I see in the future but have no idea which way that card will fall. In the meantime, I believe that we are going to see increased volatility overall, despite today’s lack of movement, so keep positions close to the vest.
Good luck
Adf
 fxpoetry
