Like Love Unrequited

Said Trump, we can all use $5K
To help with our life’s day-to-day
So, vote for the R’s
And your cookie jars
Will fill up with this bonus pay

The pundits are clearly united
That this idea’s crazy and blighted
But of more concern
Is buyers will spurn
The 10-year like love unrequited

I guess we cannot be but so surprised that populist President Donald Trump has said he will hand out $5000 to every adult US citizen if the Republicans retain both the House and the Senate during the mid-term elections.  He is, after all, a populist.  And that is what populists do; they promise things to the people to get elected.  While this may be abhorrent to the alleged ‘hard’ money analysts on Wall Street, it strikes me that this is a brilliant way to get those leaning Socialist to vote for the Republicans.  After all, their entire MO is to get money for no work, and that’s exactly what this is.  It is laughable to me that there is now concern that if this were to go forward, it would cost ~$1 trillion and ‘where would the money come from?’ is now the big question.  The money would come from where all the money for government spending comes from, more Treasury issuance.  

Which brings us to a more important question regarding markets, if there is a new line item in the 2027 budget, $5000 bonuses, how will the bond market respond?  Here the situation is very clear, yields continue to rise.  If you look at the chart below comparing 10-year yields with their counterpart TIPS yields, you can see that inflation is edging higher as a concern (nominal yields are rising more quickly than real yields).
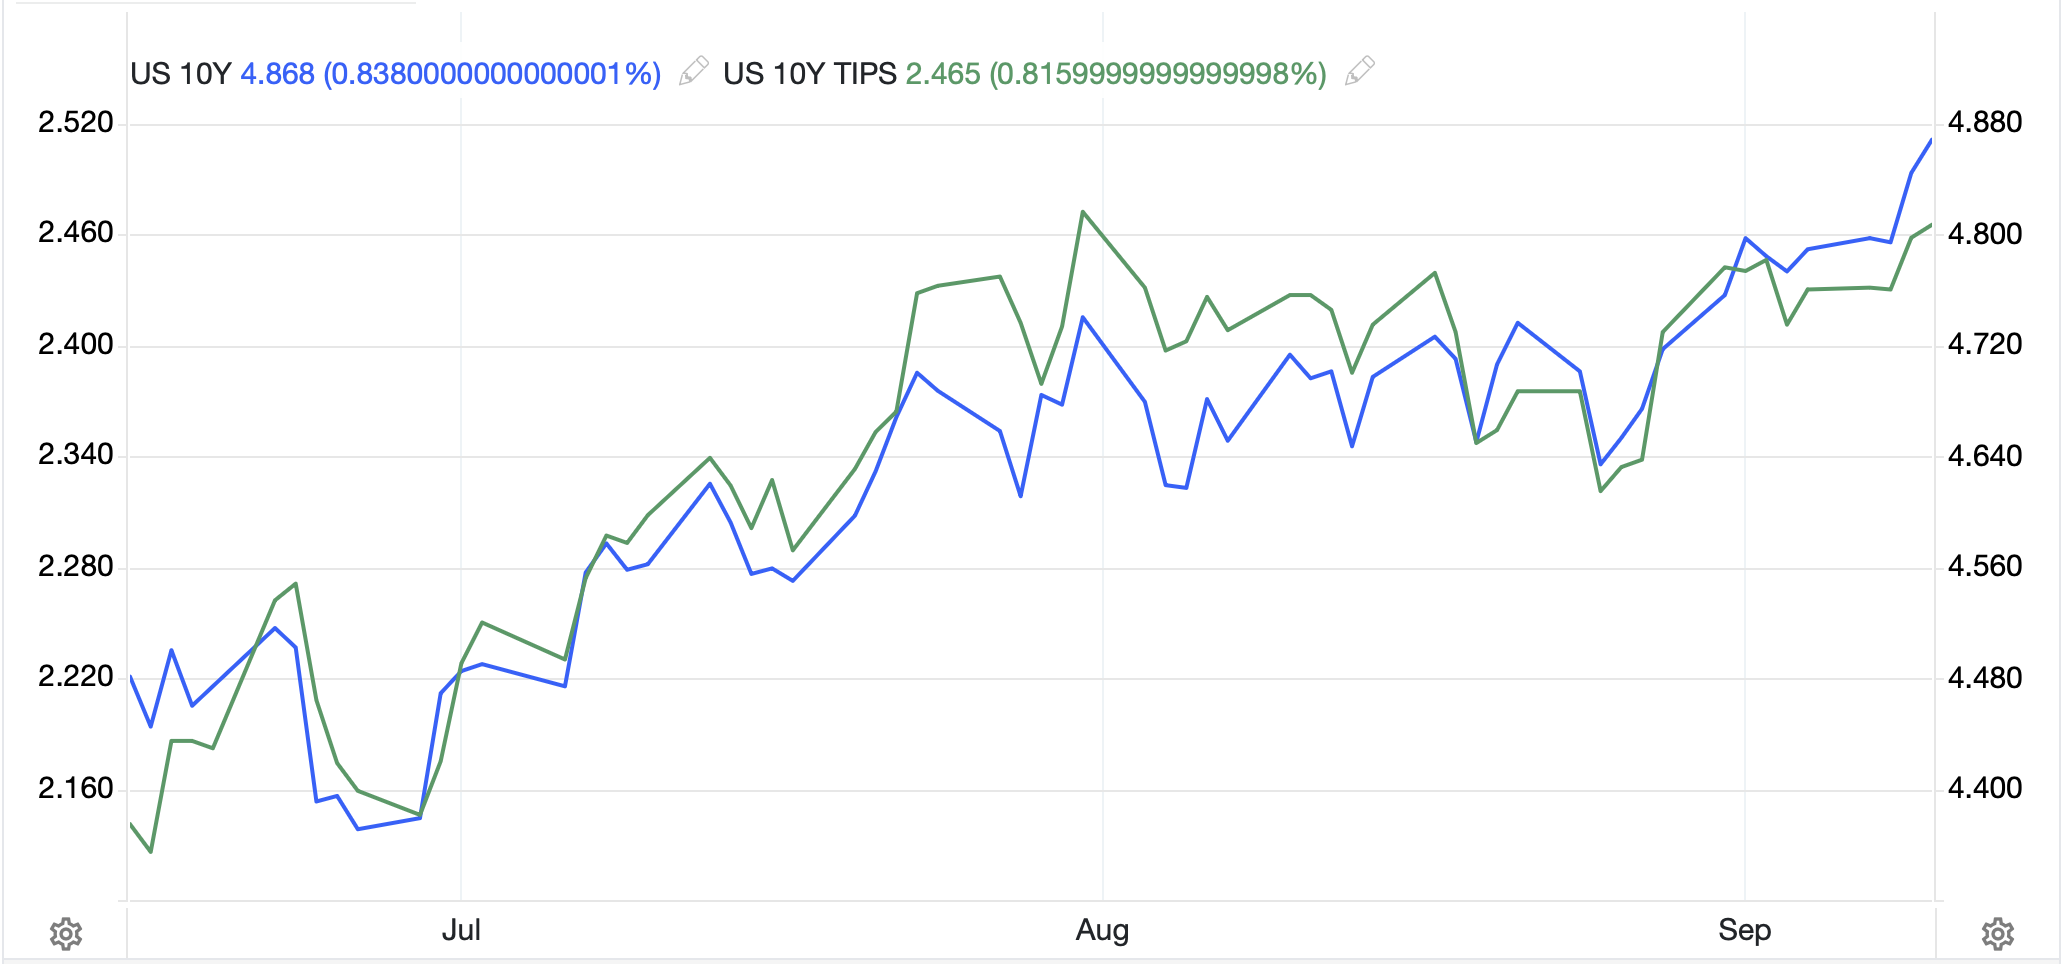
Source: tradingeconomics.com

While I don’t believe this is a direct response to the Trump bonus plan, rather to the ongoing climb in oil and related energy prices, I’m confident the bonus plan is not helping the situation.  

This dovetails nicely with the other key topic of discussion in the market; how the Fed will respond to this information as well as the PPI/CPI data to be released later today and tomorrow.  I chuckled at the WSJ headline, A Tiny Shift in the Inflation Rate Could Decide the Fed’s Next Move as the implication is that if the M/M reading for core CPI is 0.2%, the Fed will stand pat but if it is 0.3% it will hike.  And maybe that is the way things will work out.  But if that is the case, it sure seems to me like they would be missing the forest for the trees.  This is especially so since Chairman Warsh was explicit in that he wanted to see the underlying trend, and as we all know, a single data point does not a trend make.

Currently, the Fed funds futures market is back to pricing a 64% probability of a rate hike next week, although as per the below chart from rateprobability.com, you can see that the Fed appears to be one of the most dovish central banks around.
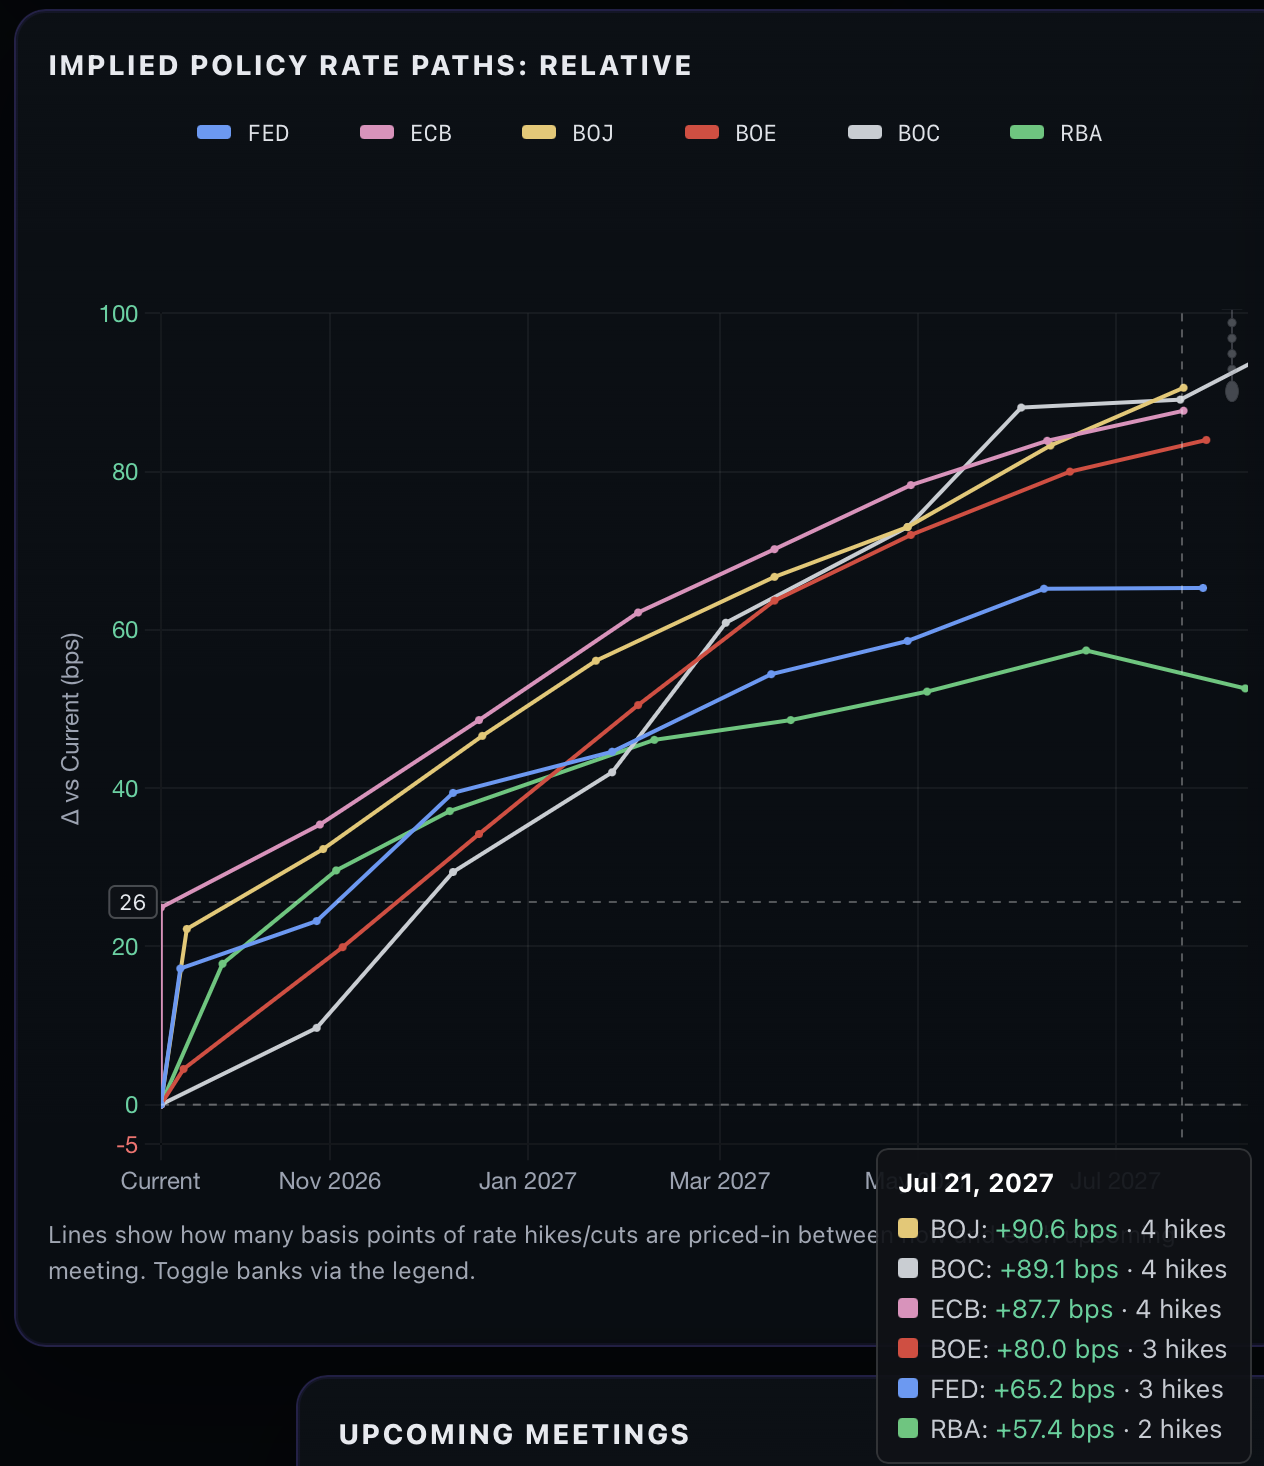
The ECB is virtually guaranteed to hike 25bps this morning and are priced to hike 3 more times during the next 10 months.  I keep wondering how they reconcile a Eurozone economy that is barely growing with hiking rates to reduce demand, and by extension, inflation.  This is where Keynesianism has a really hard time.  In fact, one of the big benefits of Kevin Warsh not having a PhD in economics is that he has never been indoctrinated into that school of thought.

In fact, if you recall Warsh’s first press conference, he lauded the bond market for doing the Fed’s job, raising the cost of funding so the Fed didn’t need to move.  Well, after a lull, the bond market is doing the hard work again.

As an aside, Secretary Bessent’s bond buybacks will take place today and, certainly in no surprise to me, the amount has been increased to $6 billion.  (Remember the ‘at least double’?). In truth, I expect that this program will increase in size each week going forward and ultimately become meaningful with respect to the size of the bond market.  Of course, looking at the bond market’s pricing today, with yields rising another 2bps, the punditry is once again calling out Bessent for not being able to do what he explained.  Funnily, though, they have stopped talking about the yen continuing to decline even though they were quick to dismiss Bessent’s activities there as well.  Personally, I’m going to wait a little longer before I declare the program a success or failure!

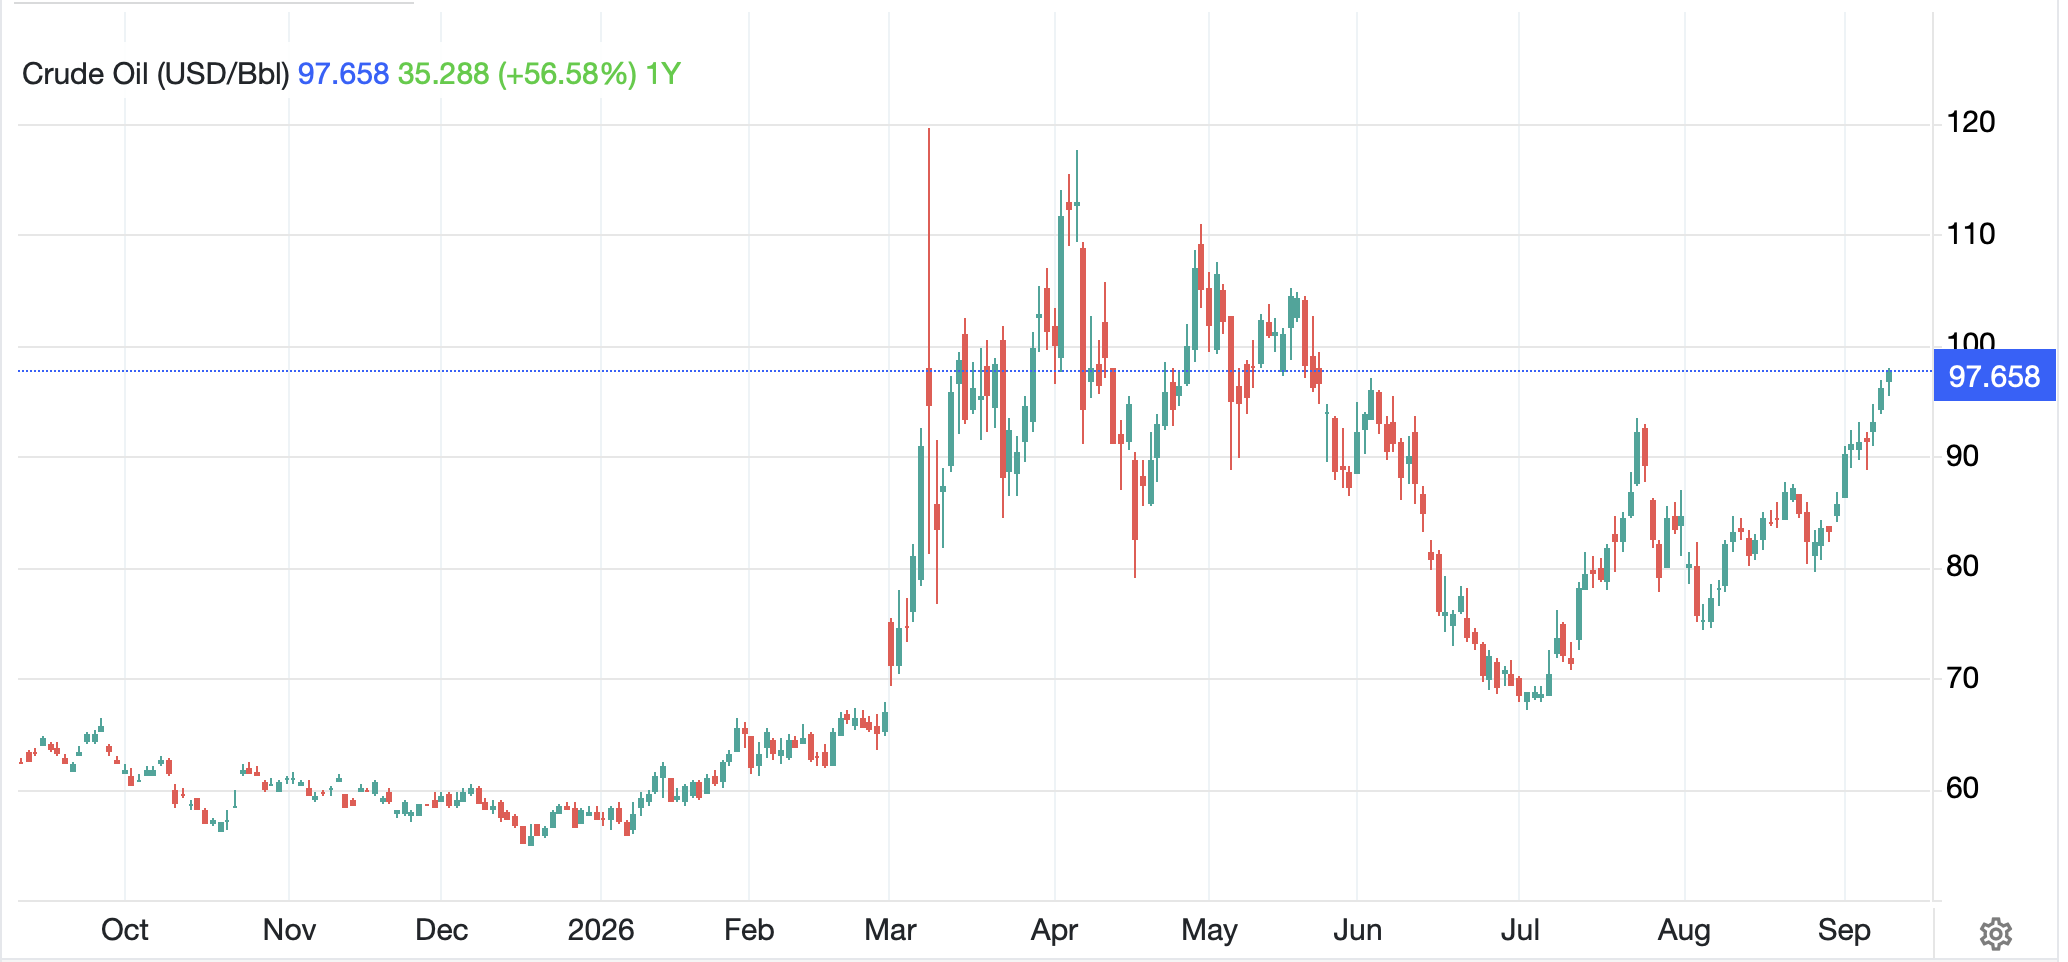
Ok, let’s turn to markets this morning.  Oil (+1.7%) continues to climb as the Iran conflict is showing no signs of cooling off.  It is not hard to see the trend in the chart below, and it is not clear what will alter this trend absent a major change in Iran.
Source: tradingeconomics.com

At the same time, the metals markets are under pressure this morning, with copper (-4.75%) leading the way lower and taking gold (-0.3%) and silver (-2.2%) down as well.  I don’t believe anything has changed with respect to the long-term prospects of metals, but they are quite volatile and always have been.  Copper has been subject to tariffs and the LME – COMEX spread and arbitrage is a key part of the price action there, dwarfing fundamentals right now.

But higher energy prices have weighed on risk appetite everywhere with equity markets struggling in most places around the world.  Yesterday’s US weakness was followed by a general decline throughout Asia (China -0.5%, HK -1.3%, Australia -1.0%, Taiwan -0.5%, Indonesia -1.3%) with only Tokyo (+0.2%) bucking the trend.  The only real news came from Down Under where two RBA members were explicitly hawkish, essentially promising a rate hike at the end of this month and the market has priced in two more going forward, a tightening of expectations.

In Europe, though, despite (because of?) the imminent rate action by the ECB today, equity markets are mixed with some gainers (Italy +0.4%, Spain +0.3%) and some laggards, (UK -0.4%) with Germany essentially unchanged.  There has been no data to alter any views, but I guess we will need to hear what Madame Lagarde has to say later this morning.

Quickly, European sovereign yields are little changed this morning but broadly continue to follow Treasury yields higher and JGB yields (+3bps) bounced after their recent dip.  Recall, I mentioned this pattern yesterday.

Finally, the dollar remains generally quiet, although in the last few hours, we have started to see a bit of dollar strength.  JPY (-0.4%) is edging lower as are NOK (-0.7%) despite rising oil prices and ZAR (-0.45%) because of declining metals prices.  However, most other currencies remain +/-0.1% from yesterday’s closing levels.

On the data front, we get a bunch today.

Initial Claims205K
Continuing Claims1780K
PPI0.4% (5.3% Y/Y)
Core PPI0.3% (4.6% Y/Y)
Existing Home Sales3.98M

Source: tradingeconomics.com

We also see the EIA oil inventory data with a slight draw expected.  I suspect that the ECB is likely to be a nonevent and that PPI, unless it is dramatically different than forecasts, will also have a limited impact.  Oil prices are back in the driver’s seat so we will have to see if this rally continues, or it is, like we have seen in both bonds and yen, speculative driven.

Good luck

Adf
All-Knowing

The war in Iran’s getting hotter
With tankers now under the water
So, oil is climbing
Which right now is priming
A stock market starting to totter

Meanwhile, Scotty Bessent is crowing
Take care ‘bout the shade that you’re throwing
Now, I am the house
And while you may grouse
In markets, I now am all-knowing

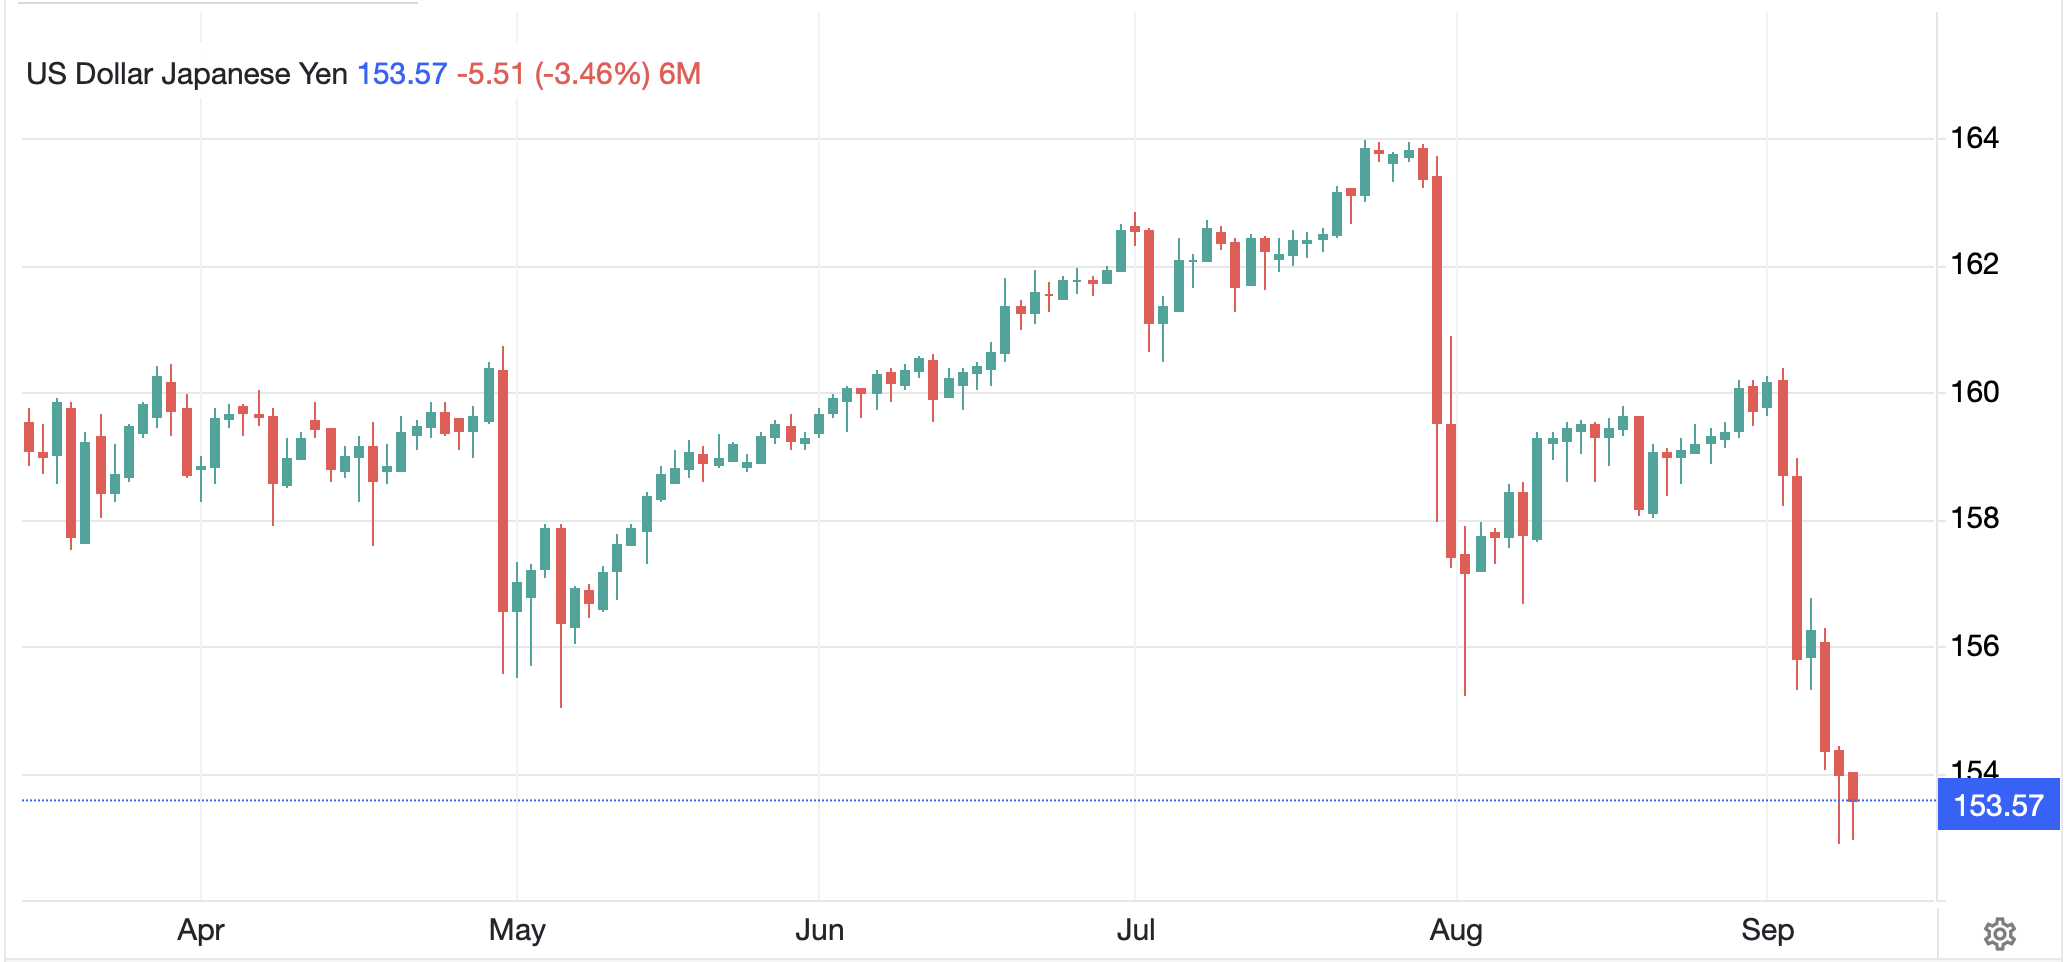
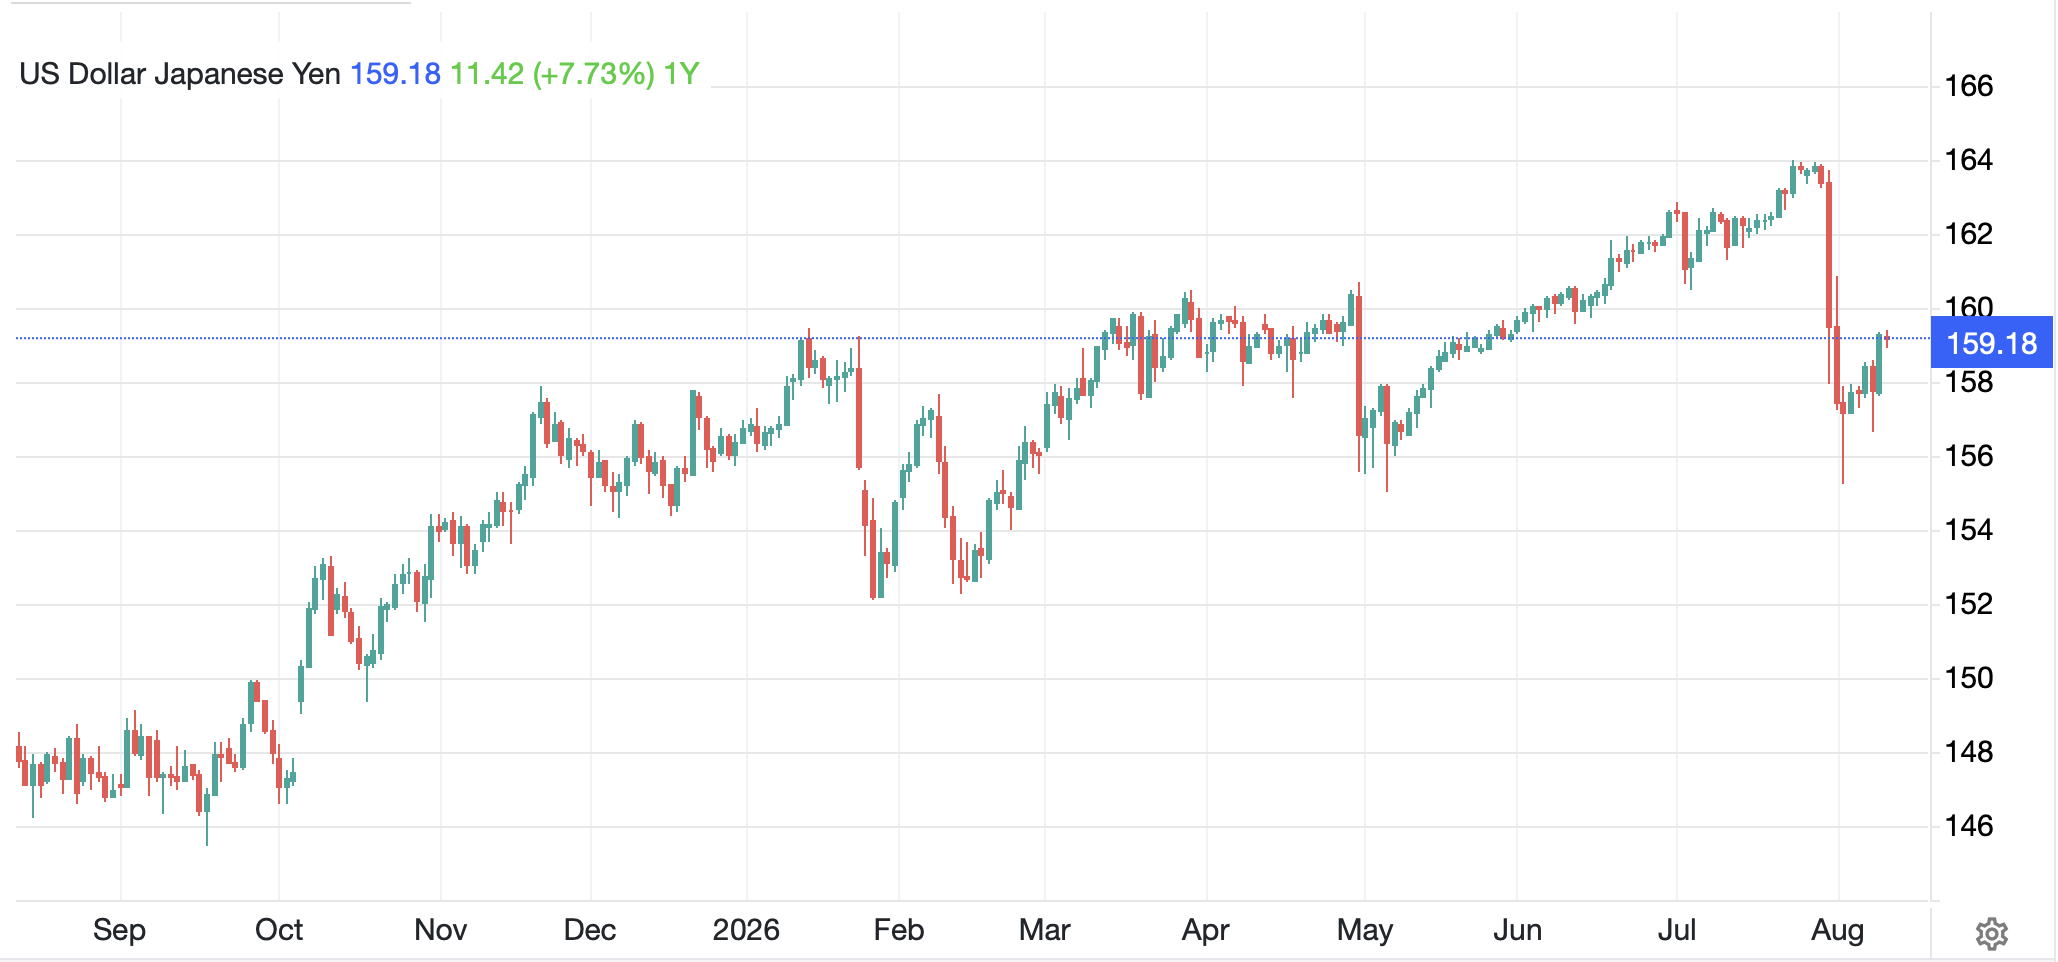
Remember back at the end of July when the MOF/BOJ intervened in the FX markets and the US Treasury was ostensibly right alongside them, selling €13 billion vs. yen, give or take a nickel.  And then, for the next month, the yen behaved as it ordinarily does after an intervention, it slowly crawled lower (dollar higher) as per the chart below.

Source: tradingeconomics.com

So far, so normal.  But something changed a week ago as there has been another significant leg lower in the dollar with no sign of official activity.  The story at the time, which has been neither confirmed nor denied, was that the GPIF was moving funds back into Japan to the tune of several billion dollars’ worth, and that certainly fit the price action.  But that was a one-day event.  And yet, here we are this morning with USDJPY plumbing new lows for the move, more than 2% below levels reached last week.  Something else is happening.

Which brings us to Secretary Bessent.  Yesterday, speaking at an event at SMU in Dallas, he made the following comments, “I am the house now, so when we intervene with the Japanese yen, I have pretty good insight into what the Japanese, what the Bank of Japan is going to do, what Japanese policymakers are going to do.  And you can bet against me if you want.”   On the one hand, those are pretty arrogant comments to come from any politician, especially one who knows exactly the limits of power governments have when it comes to markets.  (Remember, he was instrumental in the trade that broke the pound back in 1992 and forced it out of the Exchange Rate Mechanism).  On the other hand, not only does he understand markets extremely well, he also has a setup where one of the key drivers of the market he is pushing against has been increasing leverage, and leverage is very fragile.  

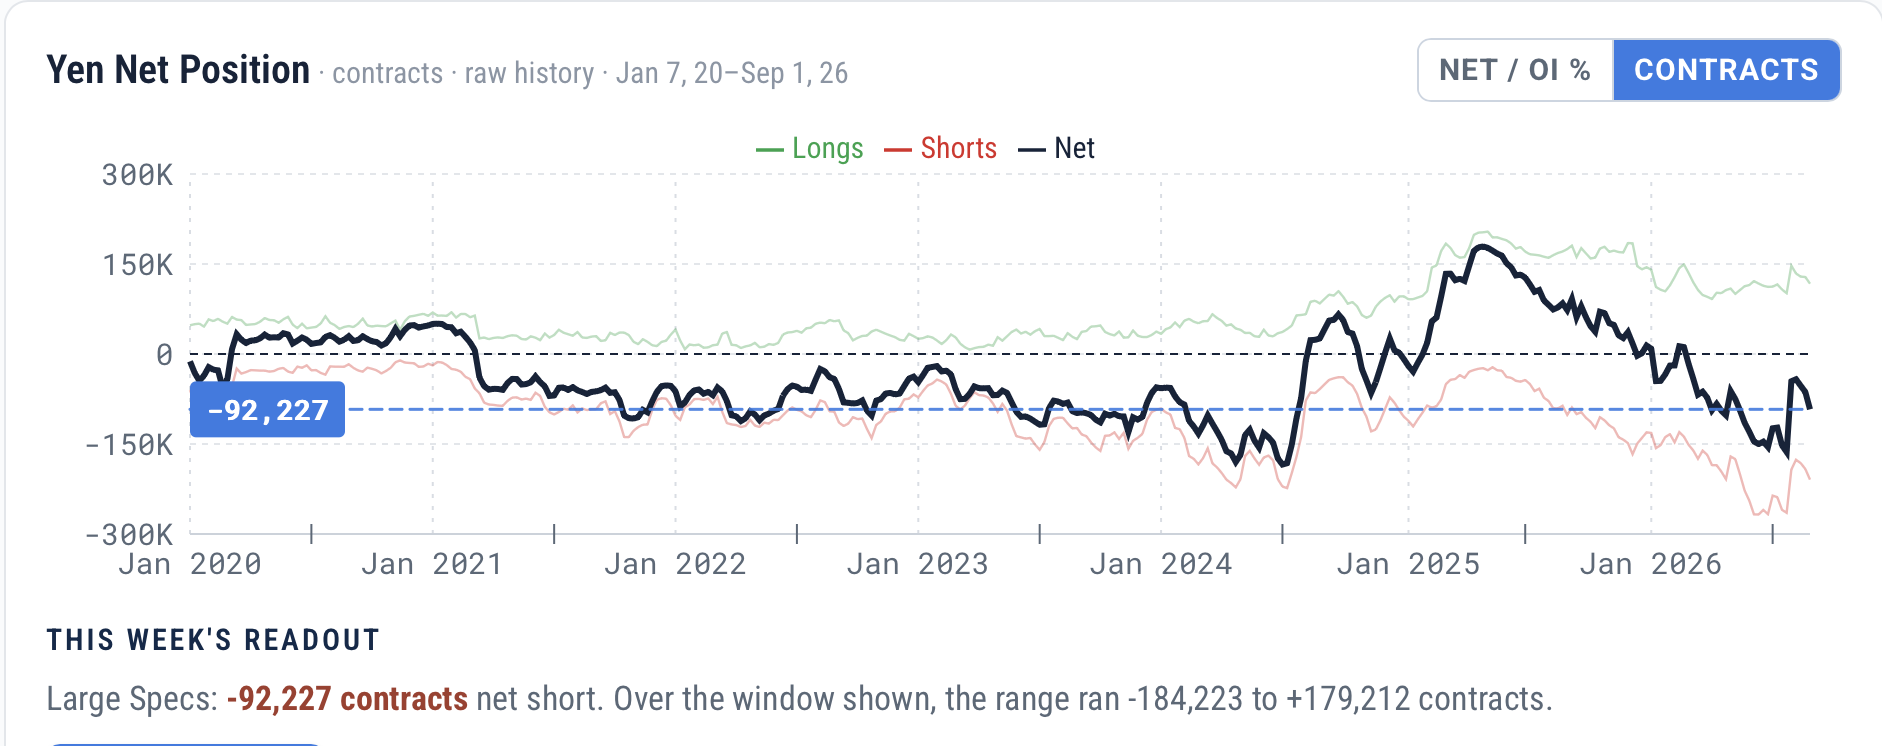
If we look at futures positioning as our proxy, you can see in the below chart from cotsignal.com that there are still quite a few net short JPY futures positions, although those positions have been reduced over the past month.

Remember, too, when looking at currency futures positions, they represent a tiny fraction of the market, <1%, but they do offer directional views.  The point is that the net short JPY trade remains quite large, and if Japanese investors are truly starting to bring their money home, the yen can strengthen quite a bit further.  As an aside, while this may correlate with a sell-off in risk assets, it is important to understand that the causality in this case would be reversed, so yen strength would be the driver, not the risk-off response.  As I wrote yesterday, my take is 140-145 is a viable target, a level that would offer a solid adjustment without necessarily resulting in a major negative response in other risk assets.  We shall see.

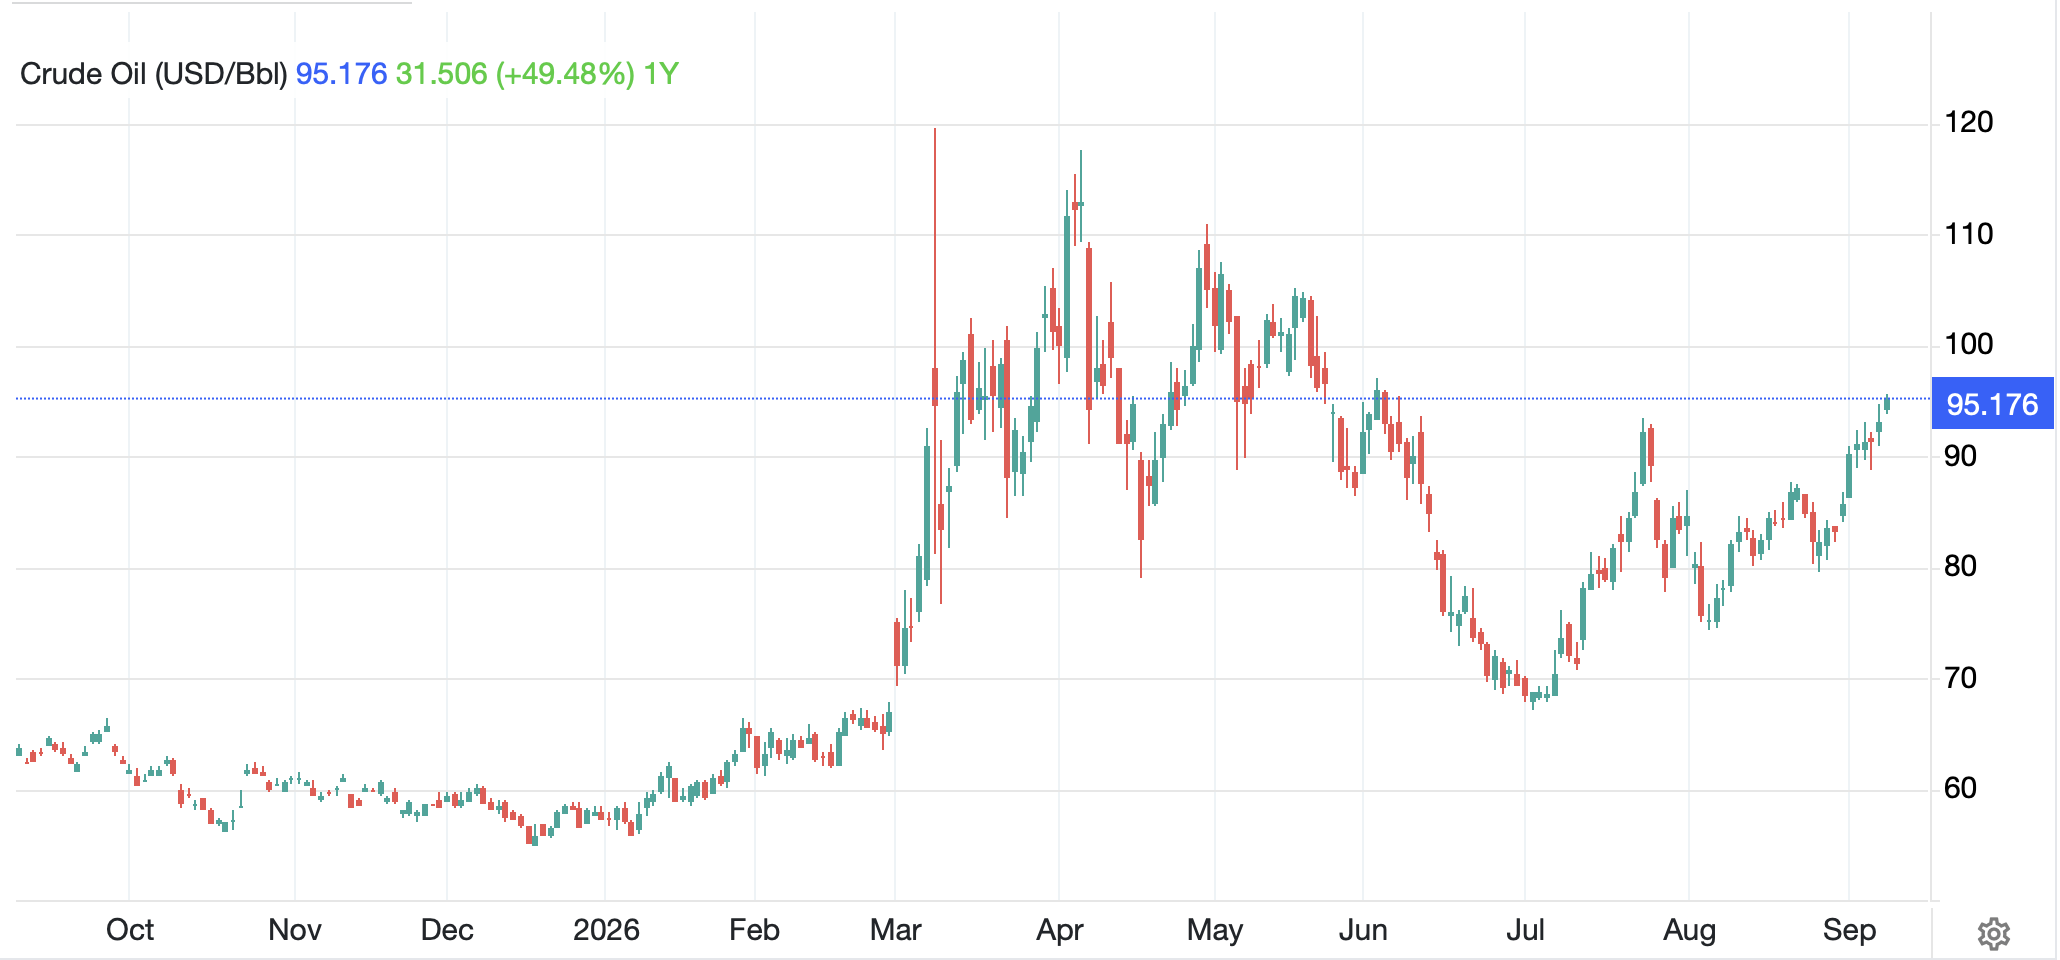
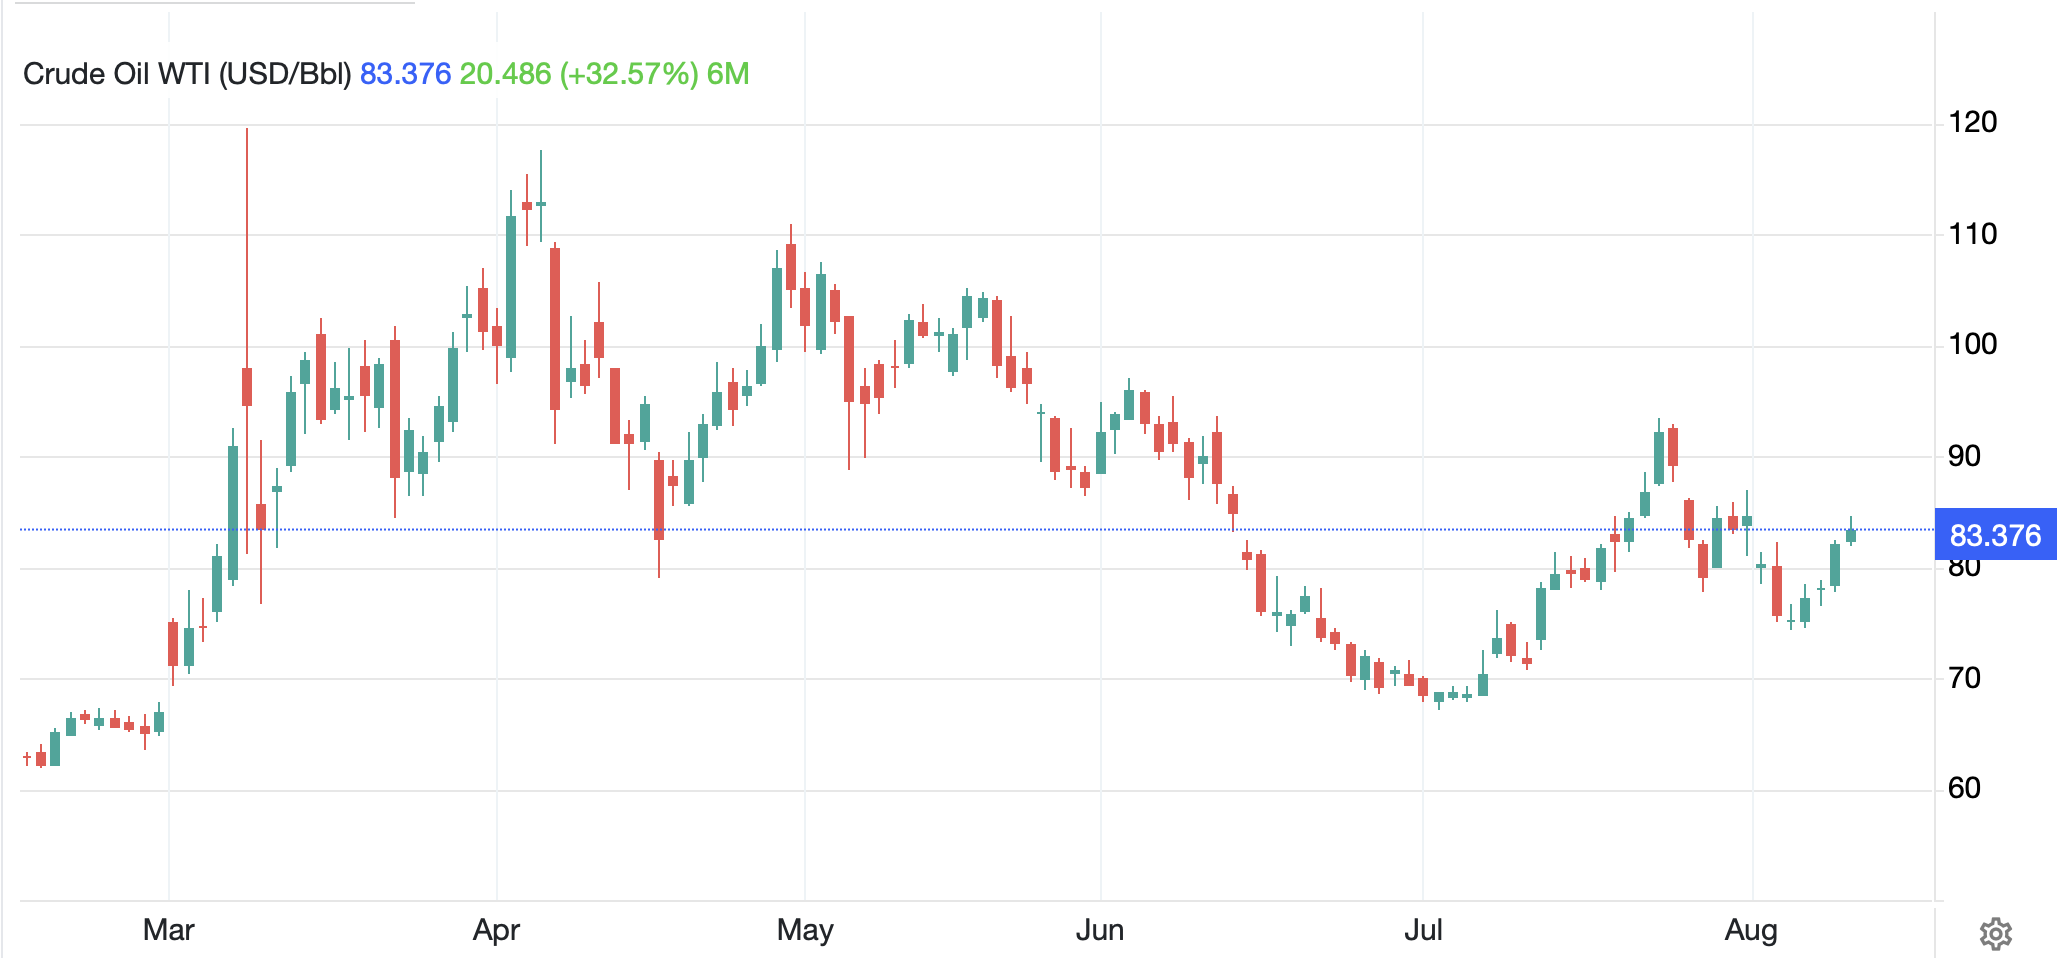
Turning to oil (+2.3%), over the past two months, we have seen WTI rally from a low of $67.0/bbl to today’s price of $95.17/bbl, a 42% climb as per the below chart.

Source: tradingeconomics.com

Clearly things are not getting better in Iran, or Russia/Ukraine, but the former appears to be the proximate cause for this move.  Ostensibly, the US sank three Iranian oil tankers near Kharg Island after the Iranians fired ballistic missiles at two US warships.  The Iranians claimed they hit the ships, the US claimed they didn’t and that is what you would expect to hear.  I have no idea what is true, although it appears to be true that those tankers are sunk.

My two cents, if they are worth even that, is that Iran has decided that if it can force gasoline and diesel prices high enough ahead of the midterm elections, that can serve to weaken President Trump and his resolve in this war if the Republicans lose power.  Maybe yes, maybe no.  Today is the beginning of the Republican mid-term convention in Dallas, a new idea designed to excite the Republican base to get out and vote.  From what I have read, polls remain close in several key states where senatorial elections are going to take place, and both the House and Senate are up for grabs.  This will certainly be the main story for the next two months.

Which takes us to action in other markets.  Equities remain under pressure almost universally.  After yesterday’s weak US performance, Asia had a more subtle performance with only a few markets showing substantial strength (Korea +1.4%) or weakness (India -1.1%, Singapore -0.7%) while the rest of the region saw movement of just +/-0.2% or so.  However, the same cannot be said for Europe, where substantial declines are the order of the day (Spain -2.3%, France -1.7%, Germany -1.5%, UK -0.8%) as rising oil prices, Brent is over $100/bbl, have weighed heavily on profit prospects there.  Too, US futures at this hour (7:10) are pointing lower with declines on the order of -0.5% or so.

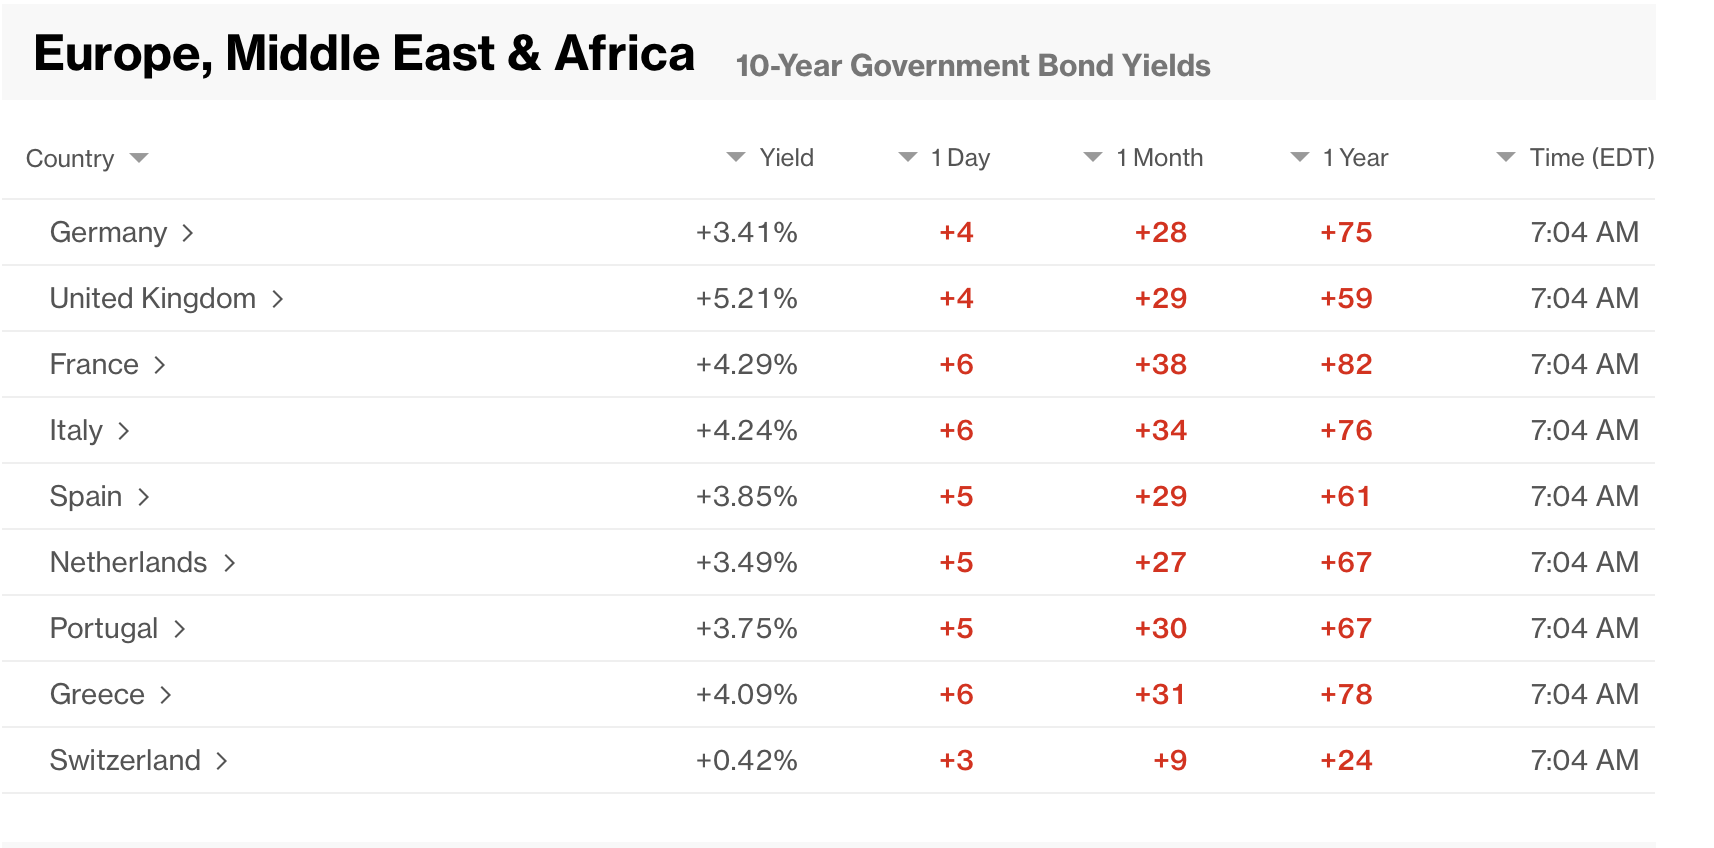
In fact, Europe is having a rough day overall as bond markets there are all under pressure as you can see in the below Bloomberg screenshot.

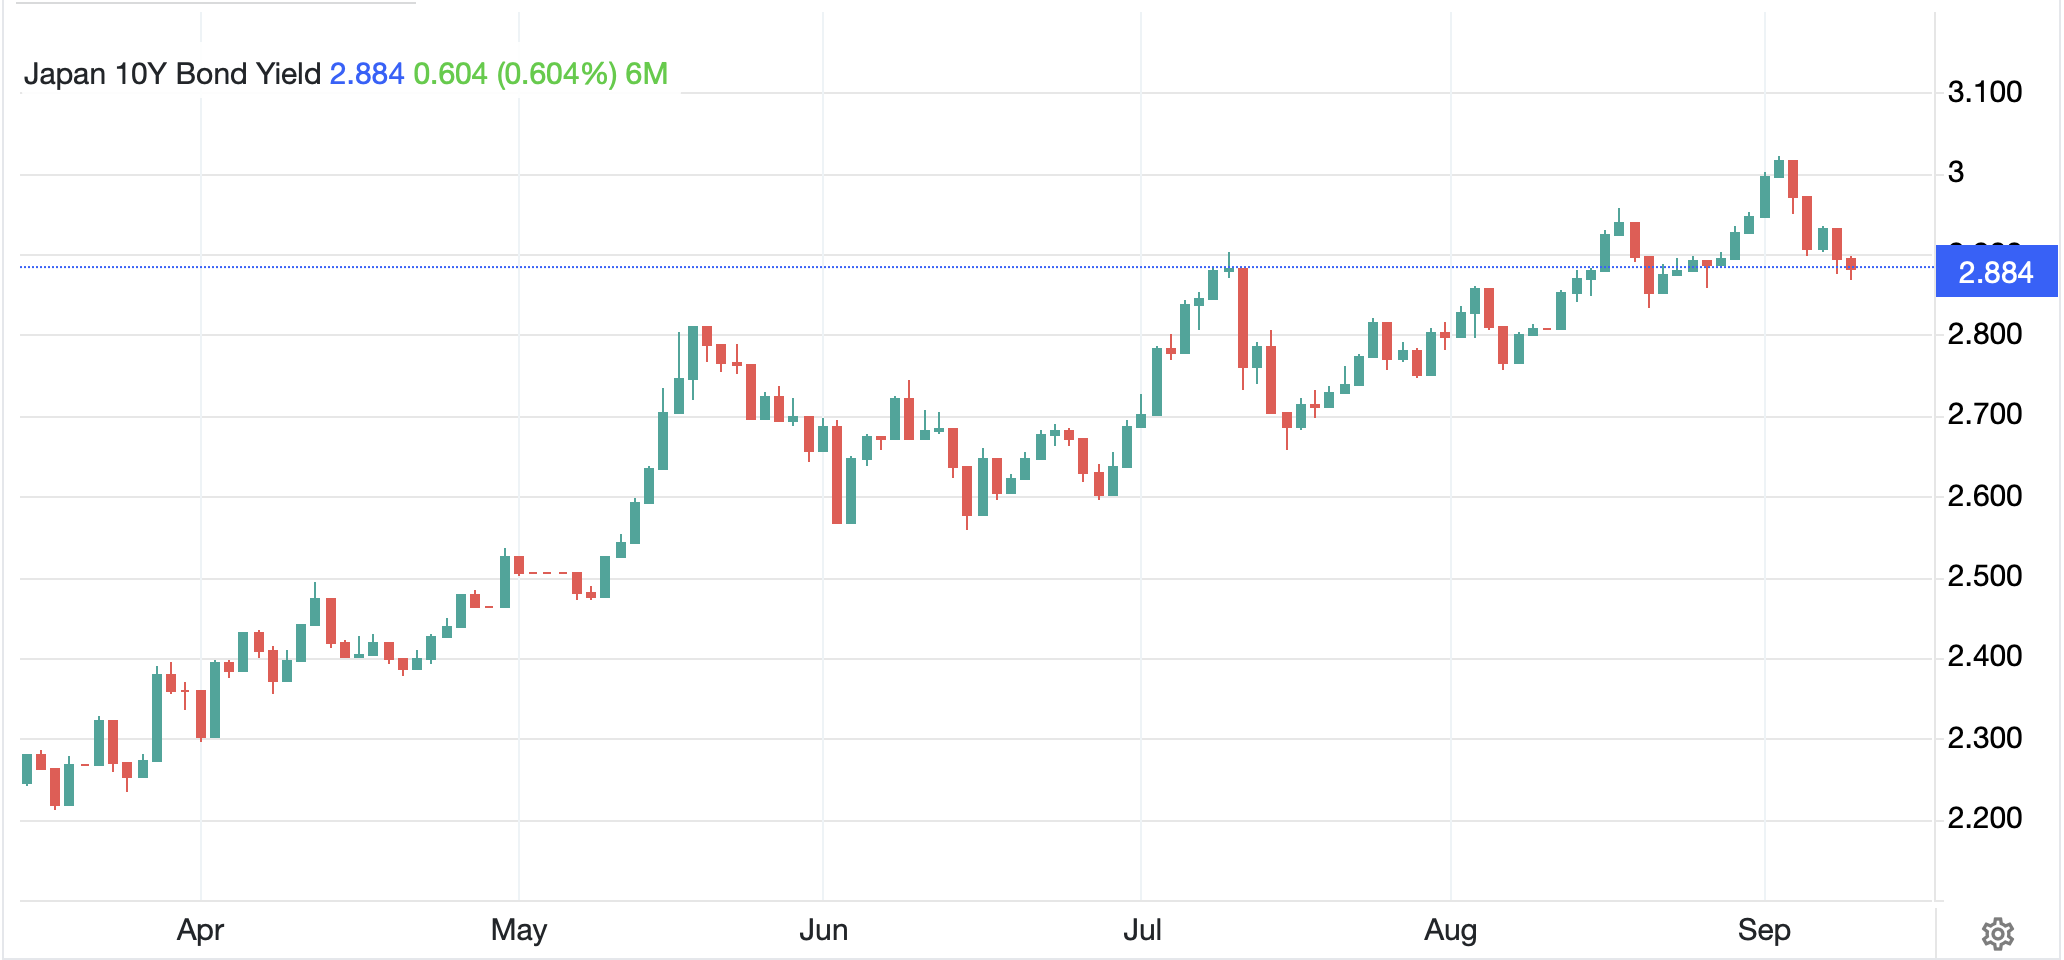
While the ECB is almost certain to hike rates tomorrow by 25bps, it appears bond investors in Europe are seeking a greater commitment to fight inflation.  Alas for Madame Lagarde, the fact that Eurozone growth is hovering just below 1% per annum makes it hard for the Keynesian view of how to fight inflation (raise rates) to help the economies there.  As to Treasury yields, they continue to creep higher, up 2bp this morning at 4.81% and the recent winner continues to be JGB markets, with the 10yr yield there slipping -1bp.  However, before we get too enamored of the JGB price action, a quick look at the chart for the past 6 months shows that we have seen this type of movement, a move higher with a several session retracement, at least eight times during this period.  It could be nothing more than ordinary trading here.

Source: tradingeconomics.com

Looking briefly at the metals markets, gold (+1.1%) is rallying this morning despite the rise in oil, a break from that recent negative correlation, and it is dragging silver (+0.9%) along for the ride.  Copper (-0.8%) however, is not playing the same game.

Finally, the dollar…well away from the yen, the dollar is doing nothing.  The DXY is still hovering either side of 99.0 and other than the yen’s move today, +0.3%, there are really no currencies that have moved more than 10 basis points in either direction.  Right now, FX is secondary except USDJPY.

On the data front, there are no releases and as we are in the Fed’s quiet period, there are no Fed comments on the calendar.  For now, markets are going to maintain their focus on Iran and oil prices and on the yen story.  Absent more headlines in either of those, I see no reason for major excitement today.  But remember, we do get CPI on Friday, so there is still something critical on the near horizon.

Good luck

Adf
Center of Blame

It's not just the 'economy's heat
Why we're at the edge of our seat
But also, Iran
Where this all began
That's left traders feeling downbeat

Thus, crude oil's back in the game
As being the center of blame
How high can crude rise
Til bonds paralyze
Activity, snuffing that flame

Bond yields remain topic A this morning as they continue to climb around the world.  There are many opinions as to why that is happening but I think it boils down to either 1) increasing deficit spending by governments around the world resulting in significant increases in supply thus driving yields higher, or 2) rising oil prices after the US-Iran conflict has seen an increase in military action on both sides thus driving the inflation narrative further.  Arguably, it is a combination of both these things.

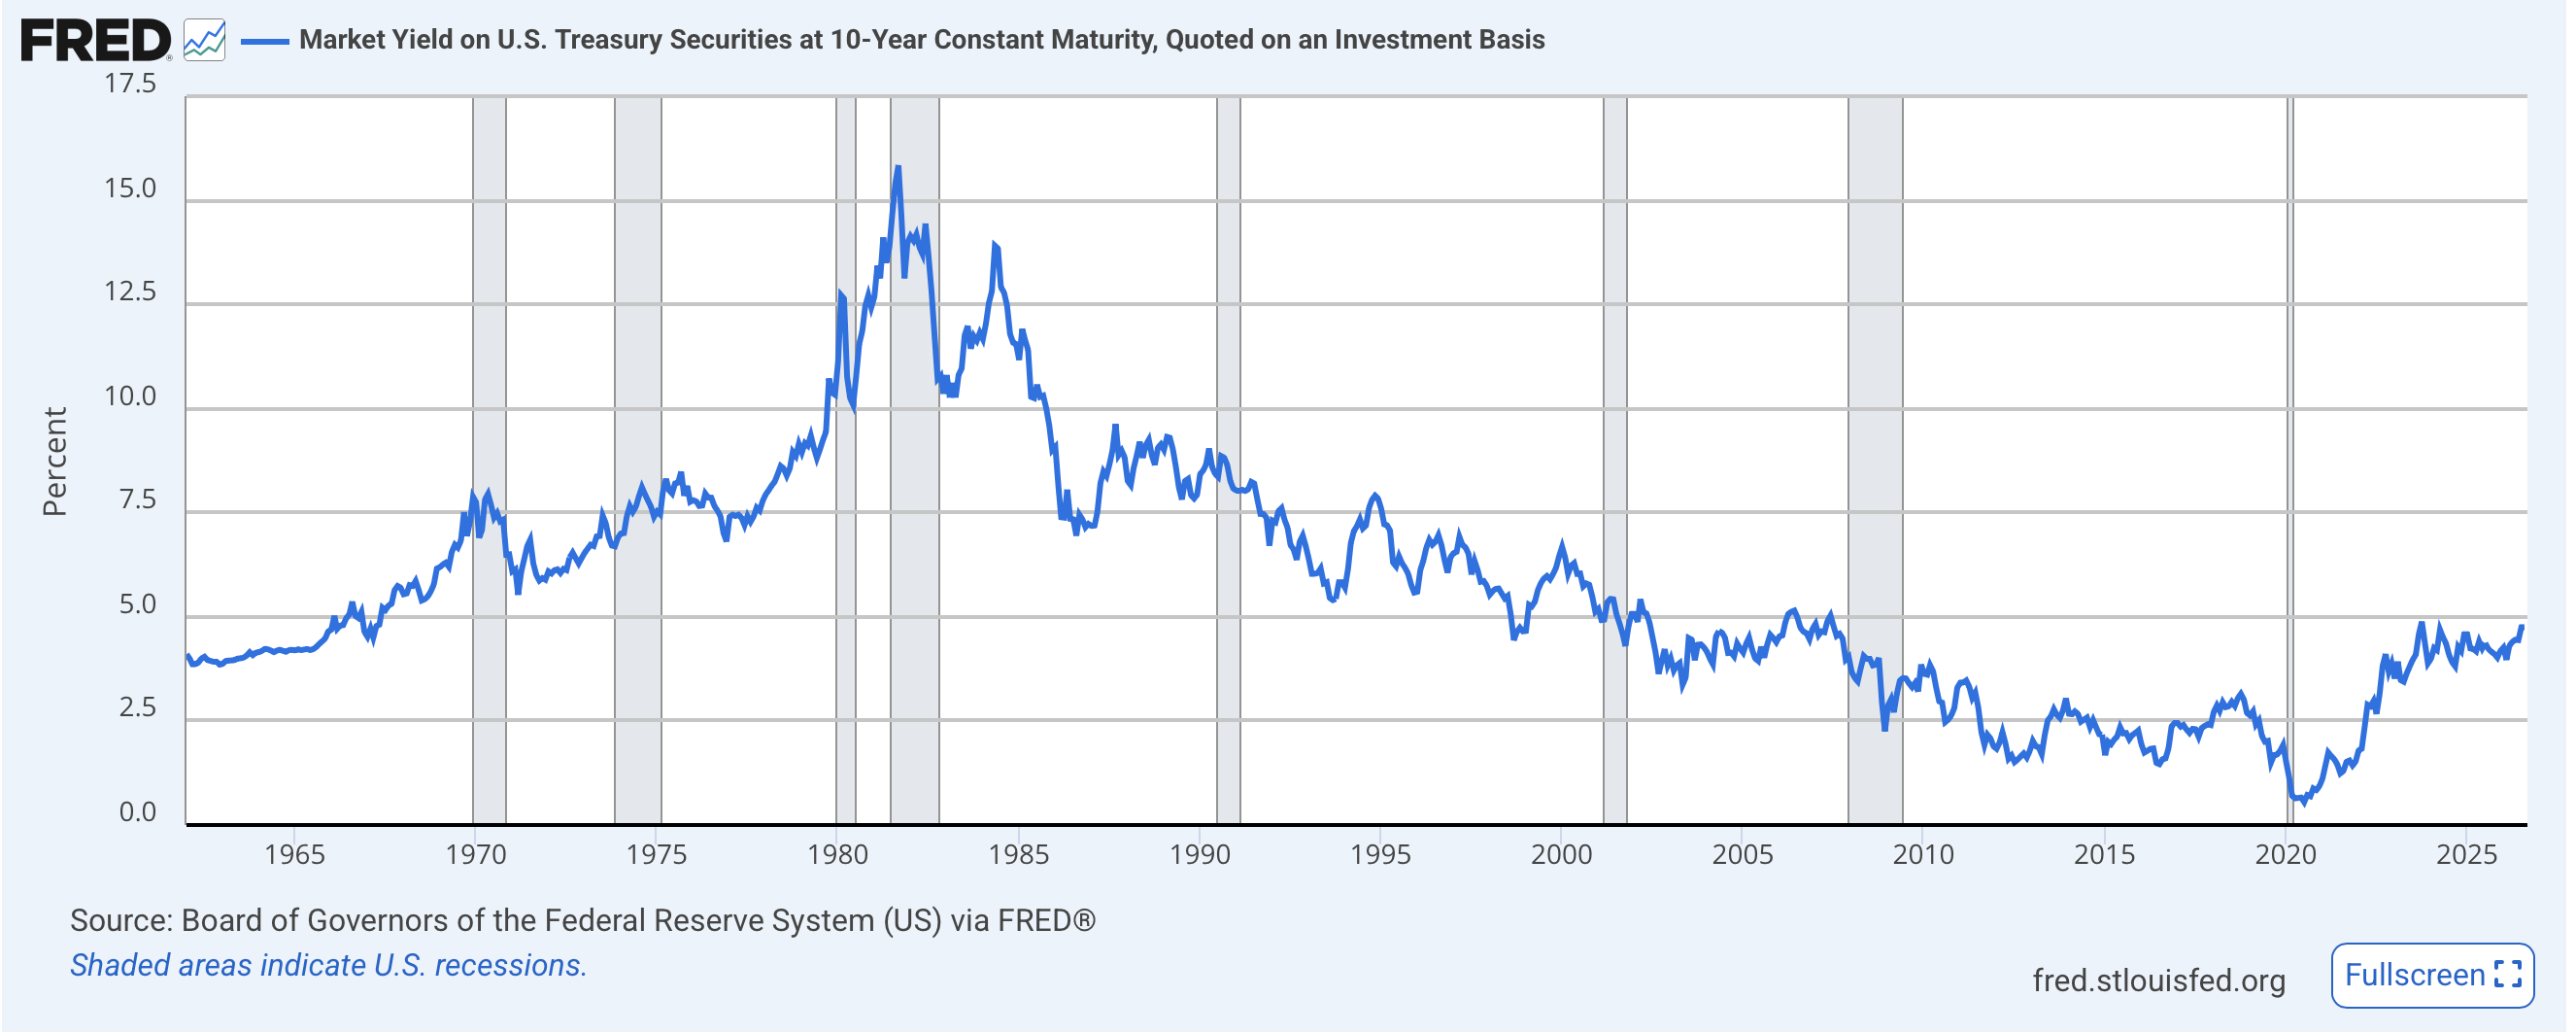
Much has been written that these are the highest yields since 2011 or 2008 (or 1996 in Japan’s case) and how that makes them, somehow, more dangerous.  Or at least that is the implication.  When it comes to bond yields though, I always like to maintain perspective by looking at the long-term history of 10-year yields.  If you look at the chart below from FRED, I think it fair to ask the question, what is the aberration, current yields at 4.8% or yields at 2.5% or lower seen post the GFC?

As I have written before, the average 10-year yield over the past 60 years is 5.81%, still 100bps higher than current levels.  I understand that debt outstanding has grown dramatically over the years, but it’s not like it wasn’t growing during Covid.  In fact, it was exploding higher then too.  Ultimately, the original sin is excess government spending relative to the economy’s overall size and, unfortunately, the underlying thesis of RIH is that is not going to change.  To me the question becomes, how does one prepare for the impacts of this policy.  And remember, this is not a US only policy, it is now the default policy of every government in the world, save perhaps Switzerland.

How can it get fixed?  That is the $64 trillion question and there is no easy answer.  If governments around the world reduced their spending, especially on things that add no true economic value (subsidies for green energy are huge and immediately come to mind), it would help but not solve the problem.  Entitlement spending is the major expense everywhere in the G10 and as those nations age demographically, that will only get worse. 

I haven’t discussed the 4th Turning in a while, but this is all of a piece with that scenario, massive institutional changes as old institutions, be they corporations, central banks, government structures or educational organizations, will be redesigned for the new age.  Perhaps that is the promise of AI, a “voice” that can analyze history and help guide future decisions.  Alas, mankind is mankind, and I don’t foresee that changing so whatever comes out on the other side, it, too, will only have four generations of life!

Was it hint or threat?
Could Ueda hike fifty?
No breath holding, please

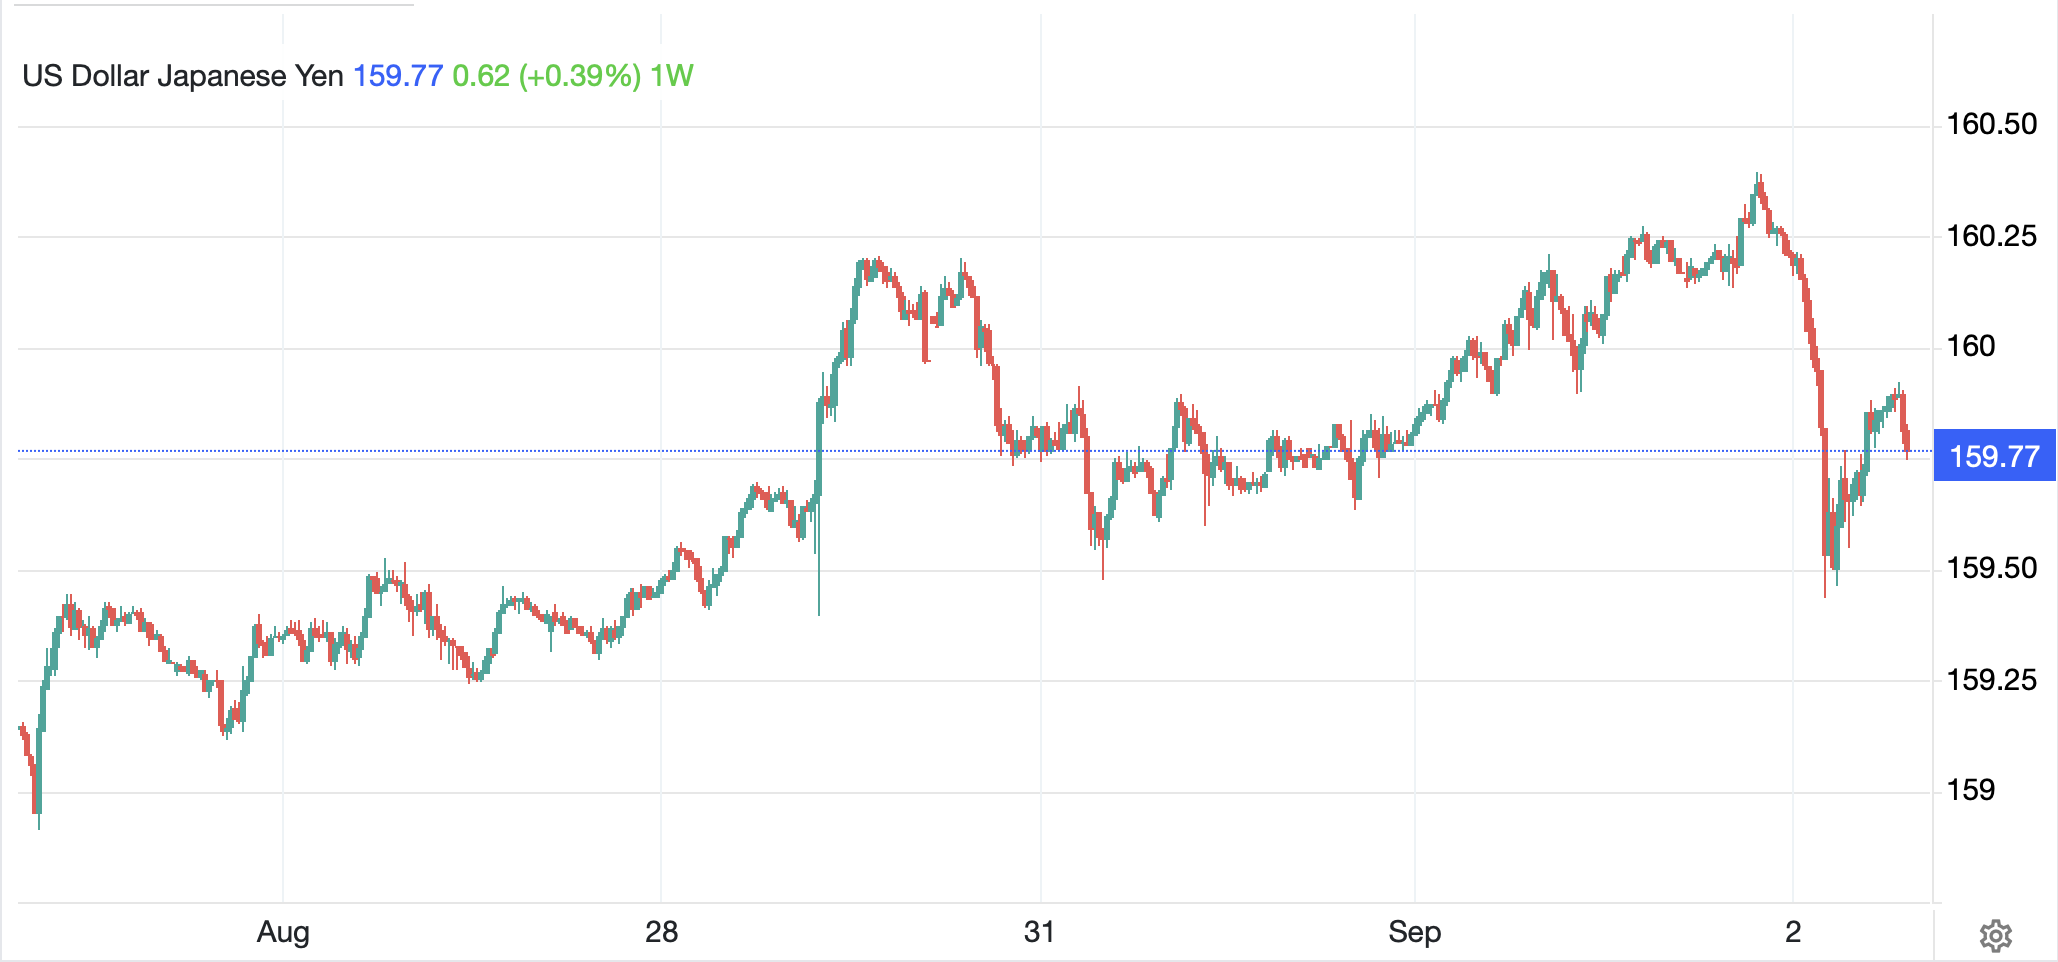
The other story of note this morning was that BOJ Board Member Takata, a known hawk, gave a speech and indicated that the BOJ could surprise with a 50bp hike this month, or perhaps hike two months in a row rather than their current once every six months cadence.  Bloomberg’s article was succinct.  This story did have a modest impact on the yen (+0.25%) as you can see in the chart below.

Source: tradingeconomics.com

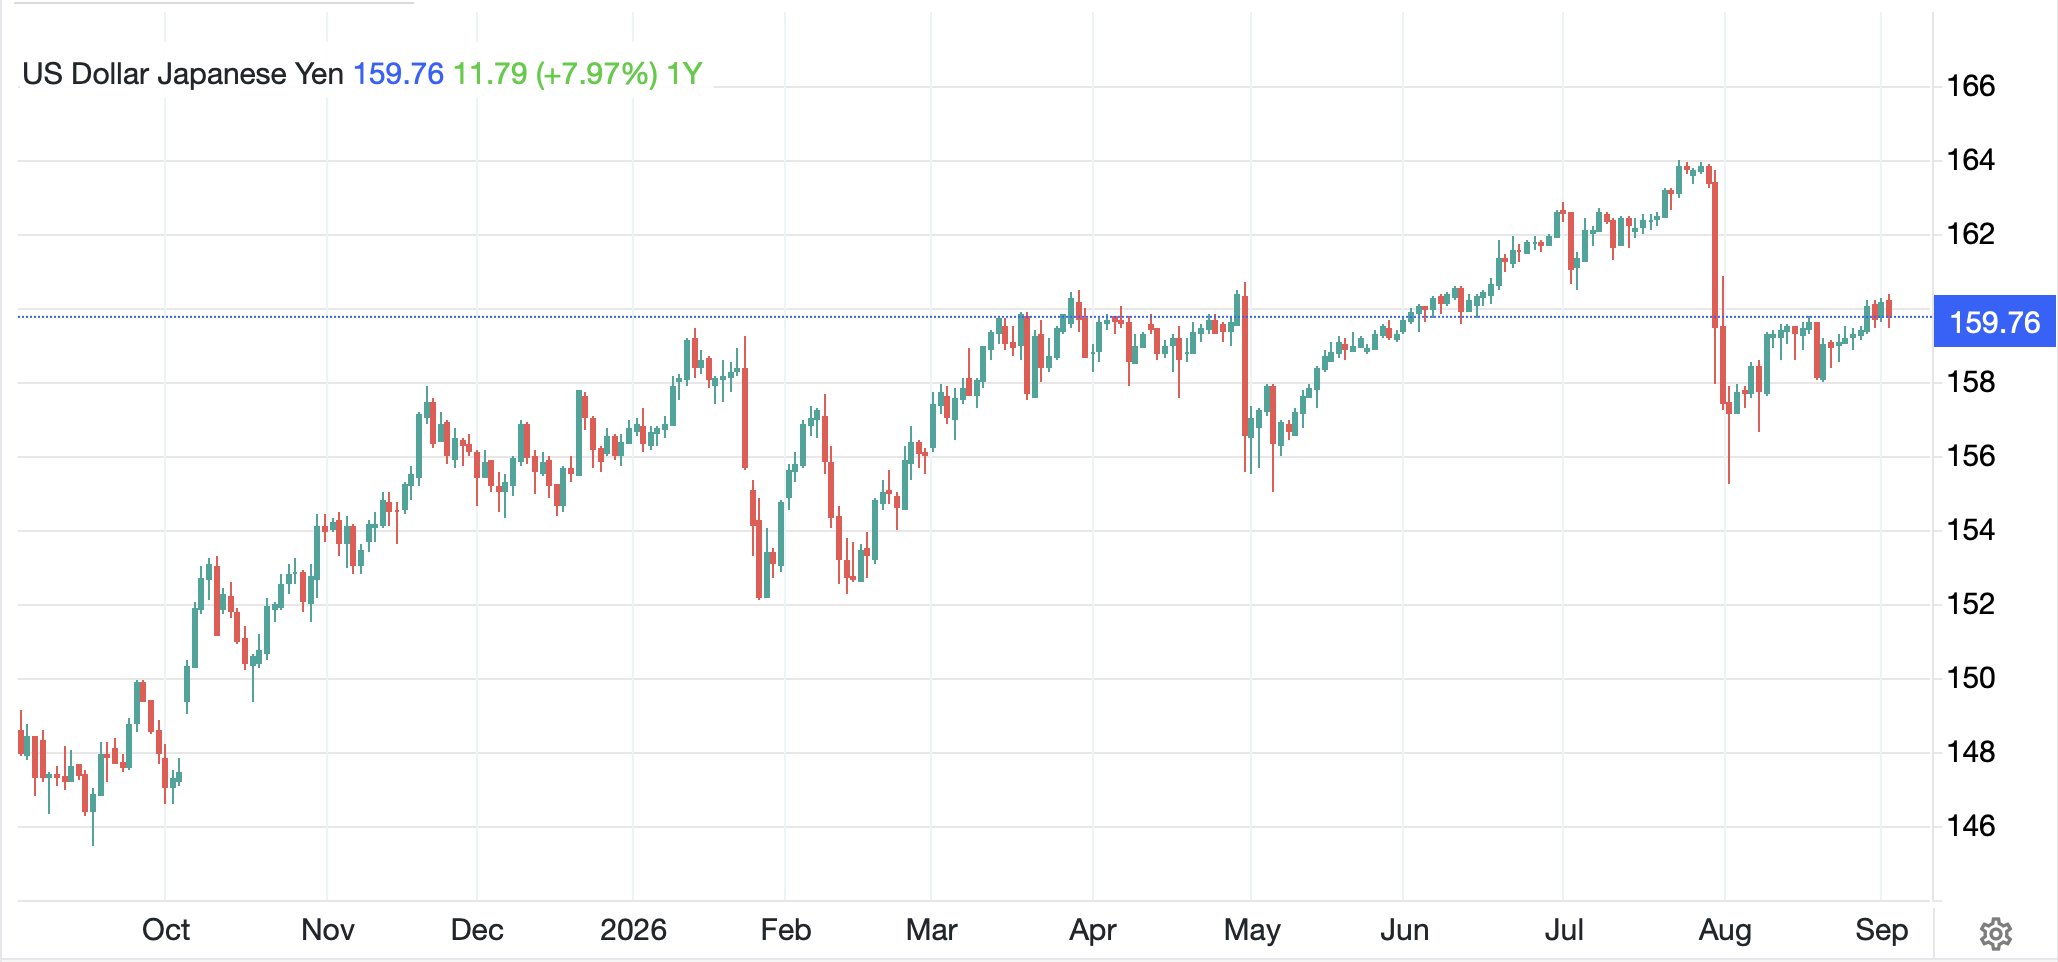
But if we step back from the 1-week view above to the movement over the past year, as per the below chart, it doesn’t appear to have had a significant impact.

Source: tradingeconomics.com

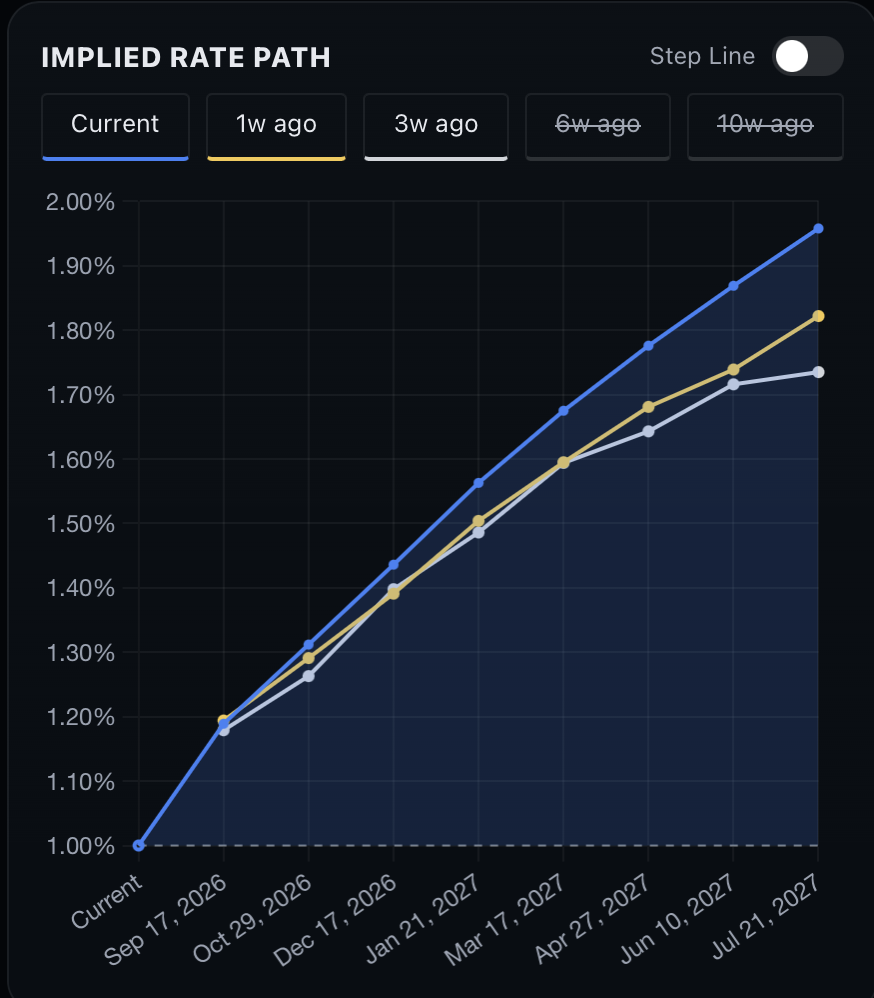
The post-intervention pattern remains perfectly intact.  However, it did help increase the probability of further rate hikes by the BOJ as you can see in the rateprobability.com chart below.  The blue line is the current market compared to previous readings, with the market now expecting a total of 100bps of hikes during the next year. 

Alas, that did not help the JGB market, where yields remain at the 3.0% level, although they did not rise further last night.  Speaking of bonds, Treasury yields, which climbed 3bps yesterday, are unchanged this morning but European sovereign yields are all higher by between 3bps and 5bps, with France the worst case.

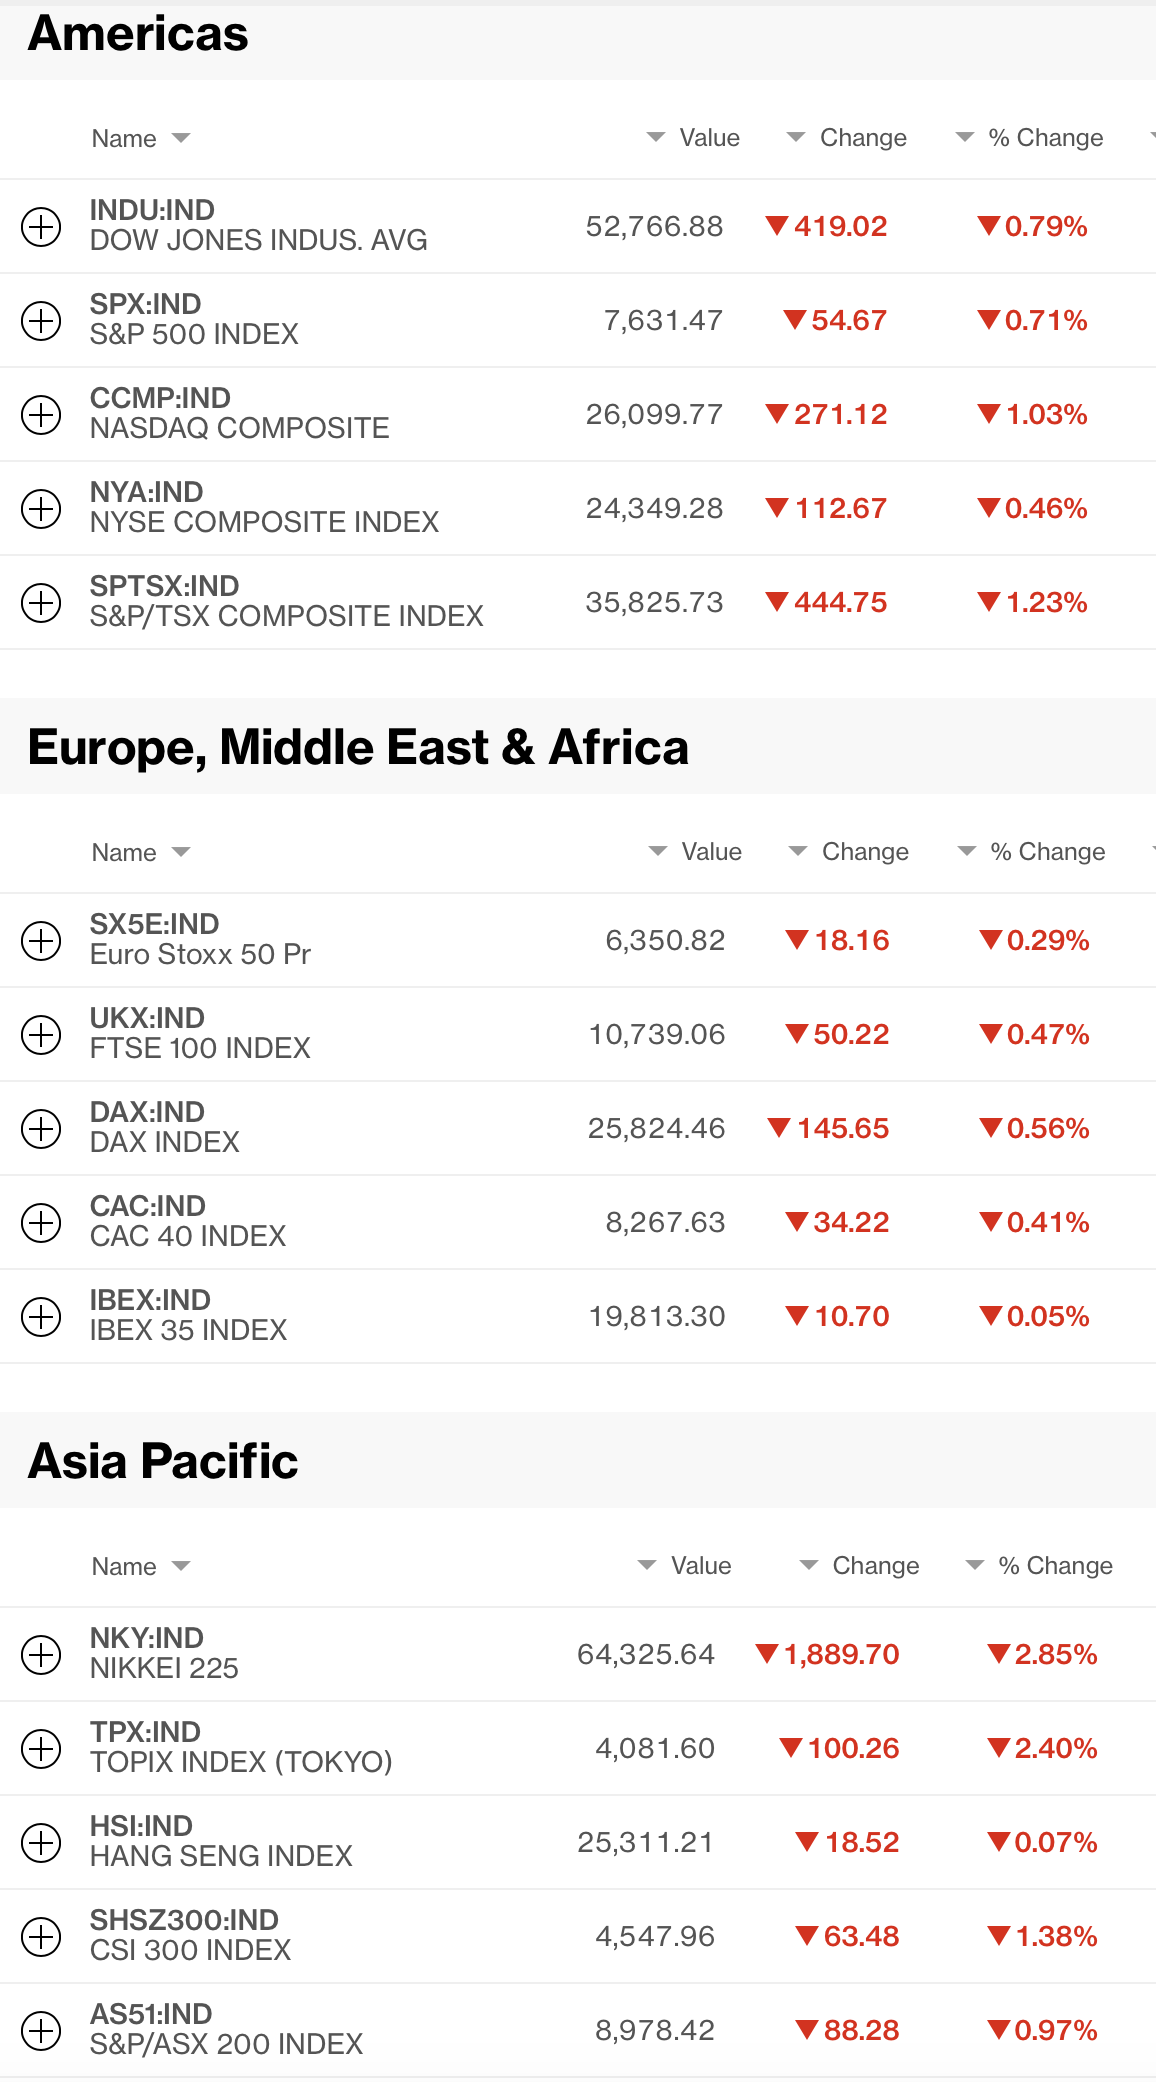
Looking at equity markets, red is the color of the day as every major market either declined last night or is in the process of doing so as I type as per the below Bloomberg screenshot.

Certainly, there is a great deal of angst in equity markets right now, but when I looked at the S&P 500, it is still just 2.5% off its all-time highs from the middle of August.  And this morning, while the NASDAQ futures are lower by -0.7%, the other two indices are unchanged as we await this morning’s ADP data (exp 47K) and this afternoon’s Beige Book.  Higher yields are always a struggle for equity markets, but there is no collapse yet, that’s for sure.

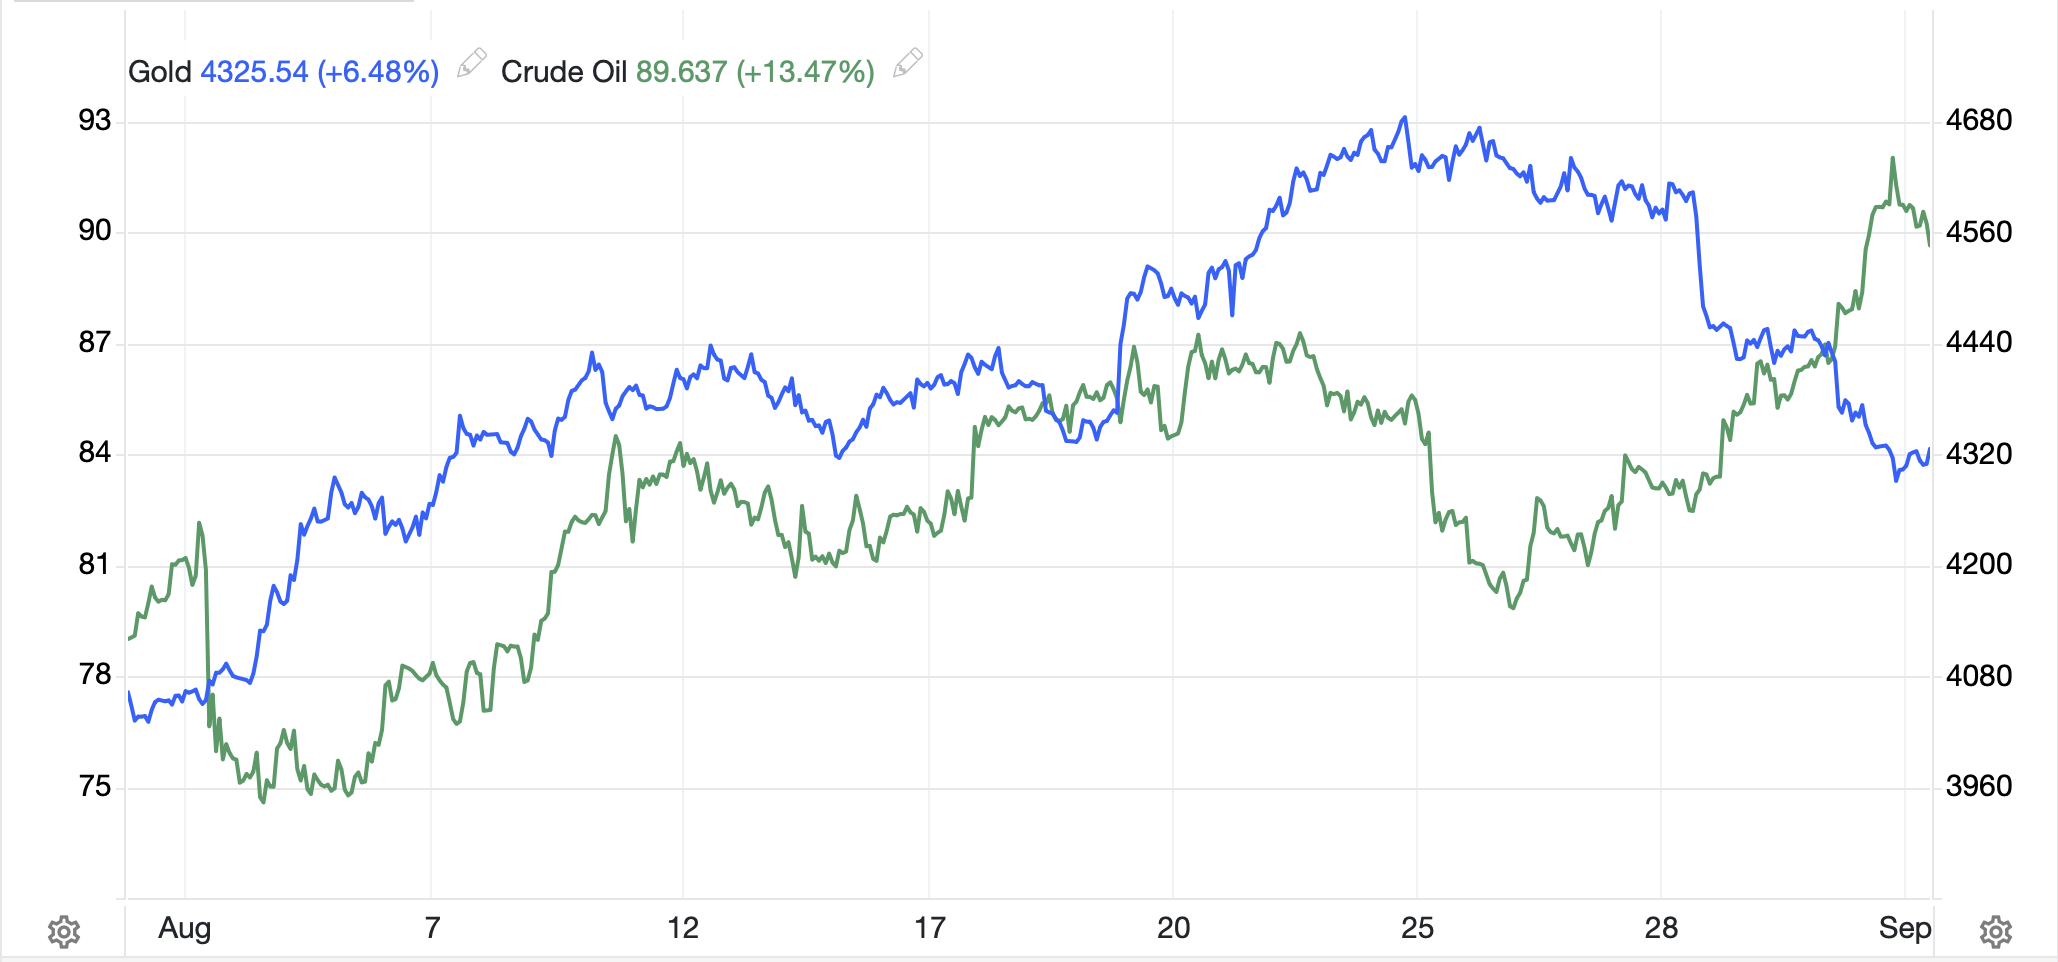
In the commodity markets, oil (-0.7%) has backed off the highs from yesterday and has traded back below $90/bbl, although that remains far higher than just a few weeks ago.  The escalation of fighting has certainly got traders nervous.  As to the metals markets, while they have been getting crushed the last few days, this morning they are essentially unchanged, perhaps consolidating after that rough ride.  You may remember there had been a strong negative correlation between oil and gold for a while which seemed to dissipate during the summer when things in the Gulf settled down.  Well, as you can see in the chart below, that negative correlation is back in spades for the past two weeks.  We will have to see how long that lasts, as historically, the two traded together more often than not.

Source: tradingeconomics.com

Finally, the dollar is creeping higher again this morning with the DXY (+0.1%) a pretty good proxy of the entire market with just a few exceptions.  We already noted the yen but NZD (-1.2%) fell sharply after the RBNZ raised rates by 25bps, as expected, but sounded more dovish in their comments afterwards.  As it happens, that helped the NZ stock market buck the negative trend as well.  The other outlier was KRW (+0.8%) which continues to rally strongly on positive inflows and positive economic news.  Last night, inflation data was better than expected, which helped the currency, rather than set it up for a rate hike.

And that’s really it today.  We also get Factory Orders (0.6%, 0.2% ex Transport) and the EIA oil inventories.  ADP could be interesting, but all eyes remain on Friday’s NFP on the data front.  And of course, who knows what will happen in the Gulf.

There will be no poetry tomorrow as we show GCH Nubia’s Take Your Breath Away on the road to the Nationals next month.

Good luck

Adf
Hike!

Said Kevin, well, not really much
And pundits, their pearls, they did clutch
The haters all said
He's over his head
While others admired his touch

The hawks, meanwhile, think he said "Hike!"
And two-year yields promptly did spike
The dollar exploded
And gold just eroded
Though stocks drifted somewhat dreamlike

I must have listened to a different Kevin Warsh speech than most in the market on Friday morning, as the extreme hawkishness that seems to be the consensus outcome was completely lost on me.  Perhaps this is simply another Warshach Test.  He certainly repeated that the Fed is going to be successful at achieving their 2% target, although I clearly missed the part where he said they would be hiking in September.  But I must be the only one.  Futures traders clearly heard a hike was coming as the probability for a hike has risen to 62%, from about 32% prior to Warsh’s comments as you can see below.

In addition, a second hike in January seems highly probable and the chance of another one next summer has risen to 25%.  

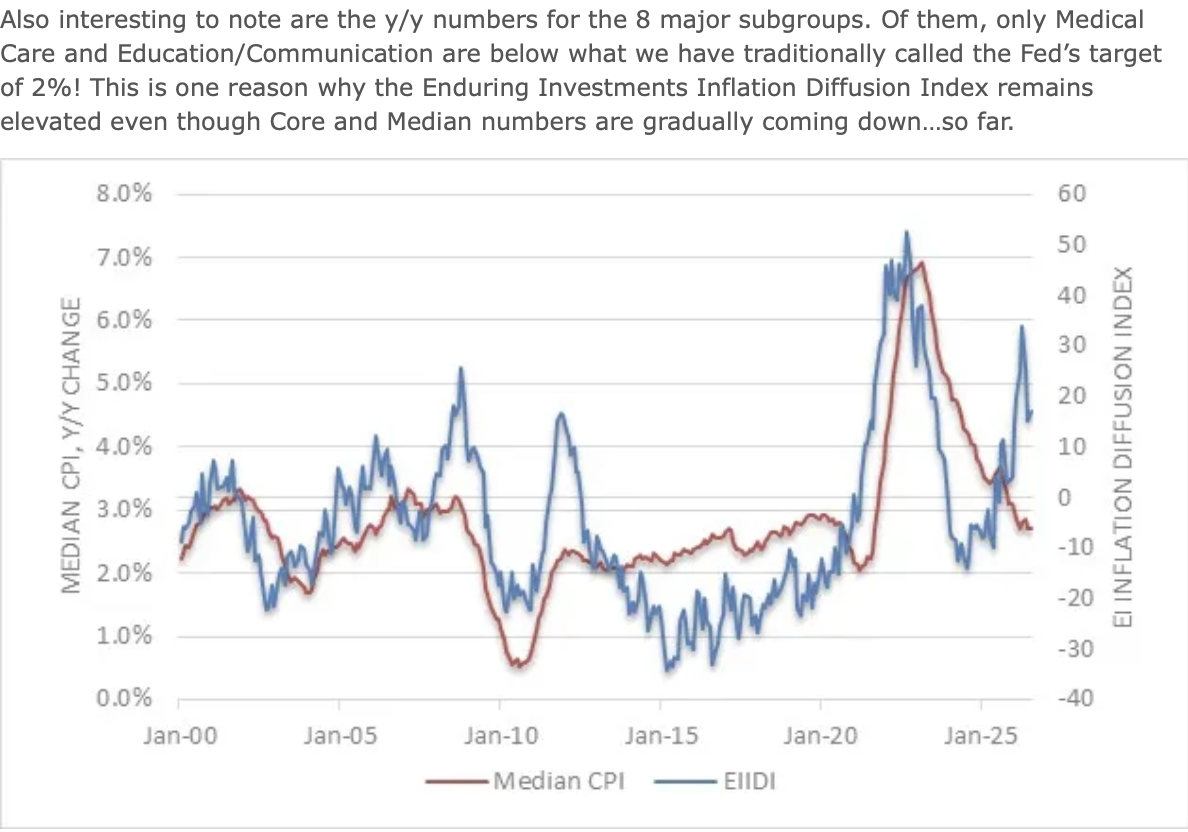
Personally, I thought the most interesting, and encouraging, feature of the speech was his willingness to discuss the details of how PCE is created, a combination of 199 subcategories.  This is akin to the way my favorite inflation analyst, @inflation_guy, Mike Ashton, views the CPI data, and he has created a diffusion index to follow just how many categories are rising rapidly and how many are either falling or rising less rapidly than the overall rate.  Here is his discussion of the July data, released in August.  And here is a chart from that note (which you all should read and subscribe to as it’s free) showing his diffusion index and why inflation is not likely to subside quickly.

But clearly, the market is not interested in my spin, nor in the spin of anyone who disagrees that a hike is on the way.  The behavior of the Treasury market was quite interesting with 2yr yields jumping 12bps while 10yr yields rose 4bps and 30yr yields rose only 1bp.  This was a classic bear flattening of the curve, and it was the driver behind the dollar’s strength (+0.55%) and more impressively, the 3+% decline in the price of gold and silver.  If yields are going up, there is no reason to own gold, apparently.  That seems at odds with all last week’s talk about the resurrection of the debasement trade, but then, I’m just a poet.

One last thing.  After rereading the speech several times (talk about a boring life) my interpretation of the following comment within his Key Principles seems to be very different than the rest of the Street.  

Fifth, short-term interest rates are the predominant tool to achieve the dual mandate. Unconventional policies to spur economic activity may suit genuine crises but should otherwise be used sparingly, if at all.”

I read this as he wants to reduce the balance sheet to reduce the Fed’s market impact and use interest rates as their policy tool and that currently, reducing the balance sheet will result in tighter policy with the same Fed funds rate.  But it appears the first part of my view, which is something Warsh has explained numerous times, is being ignored by the trading community.  Of course, it will take a change of the ‘ample reserves’ framework to get the Fed to reduce its balance sheet, and that will need the imprimatur of the balance sheet task force as well as time for the rest of the committee to get on board.

Regardless of my views, though, the market is now increasingly convinced the Fed is going to hike next month absent much weaker than expected NFP and CPI releases.

It wasn't all that long ago
When war in the Gulf ran the show
When fighting expanded
The market demanded
More havens as risk was the foe

But now, when the fighting gets hot
Most traders don't give it a thought
We're back to the Fed
And all that they've said
As key to what's sold or what's bought

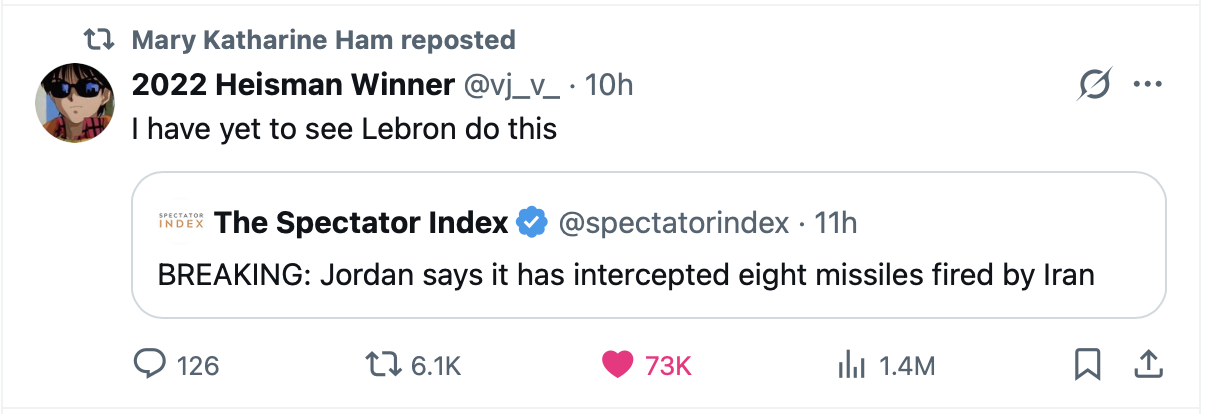
Apparently, there was further military action in the Persian Gulf and the Strait of Hormuz yesterday as the US struck missile launchers on a small island there, claiming the IRGC was planning to launch more naval mines.  Iran said there will be great consequences, but the missile volleys they sent at US bases in Jordan were intercepted which prompted one of the funniest responses on X that I have seen.

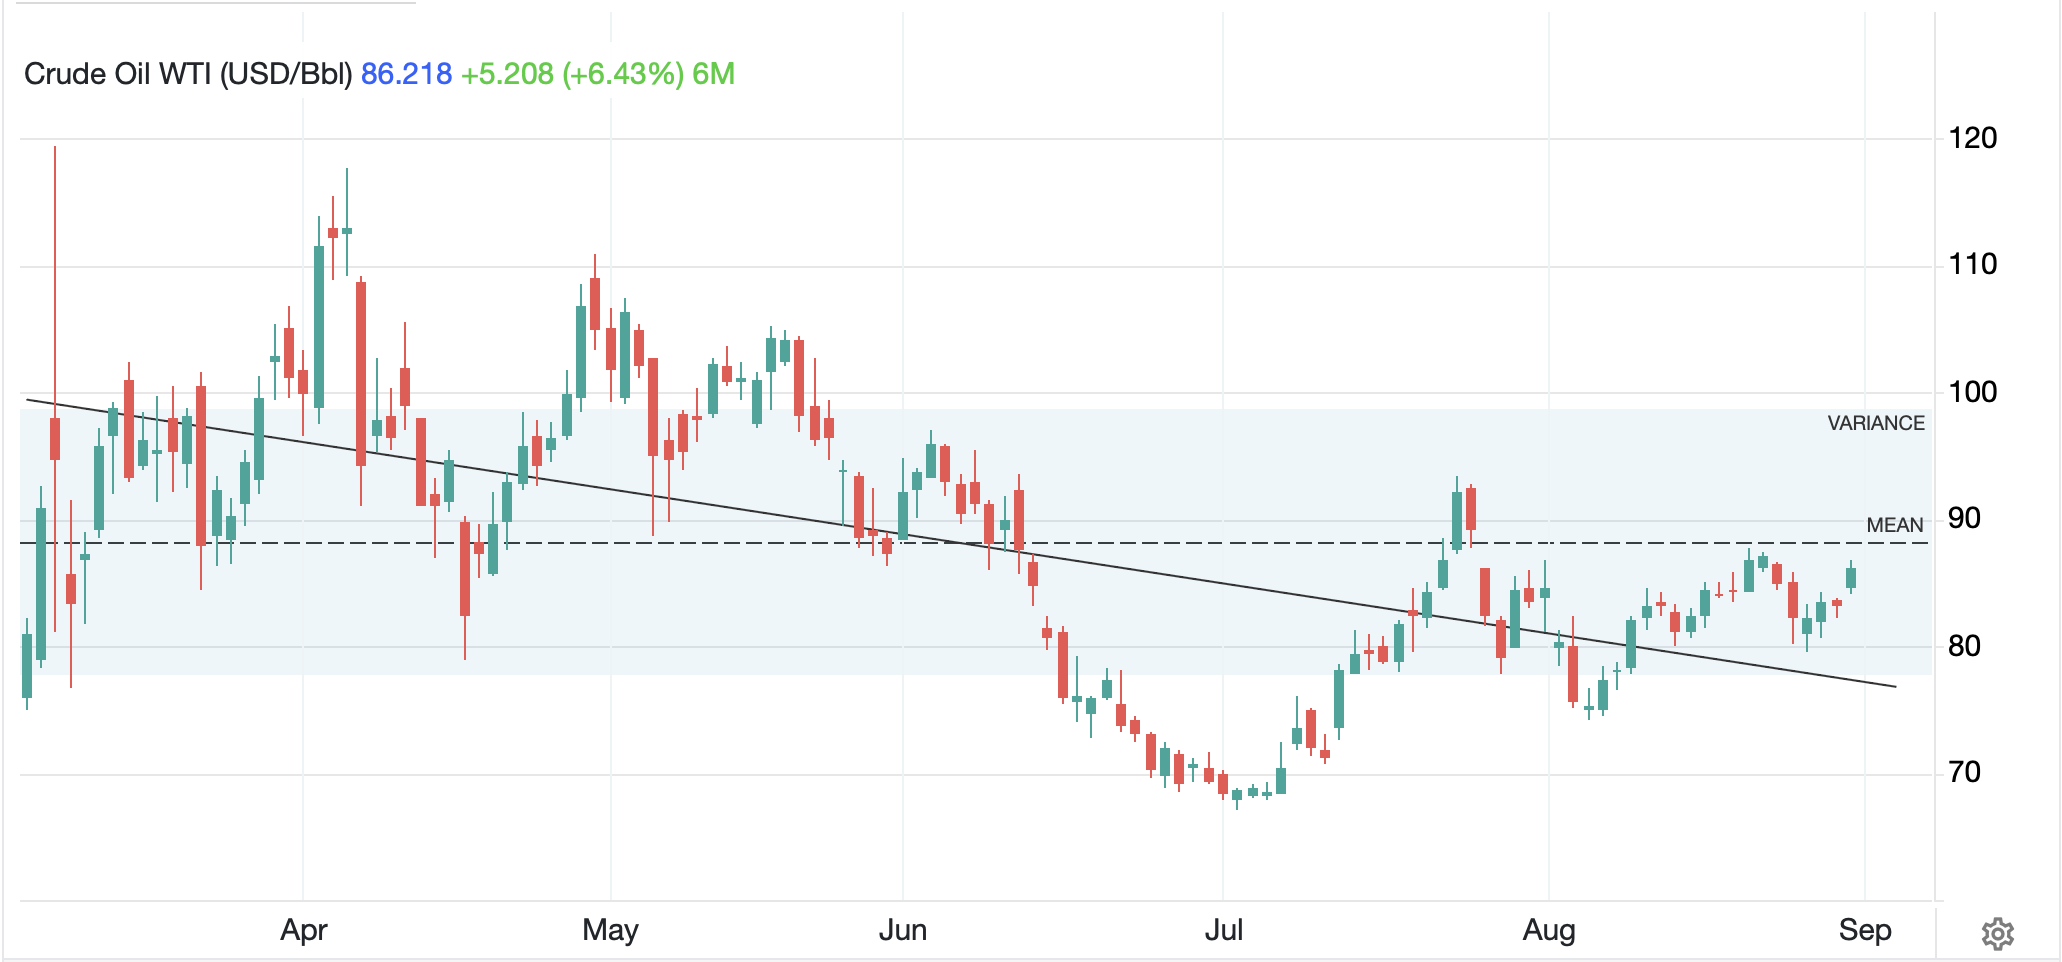
Meanwhile, oil (+3.3%) prices have risen in response, but it has not generated nearly the excitement that we have seen in the past.  And I cannot help but look at the price action in oil over the past six months, since the war began, and remain unconcerned about the future.  Certainly, there has been volatility, but as I have highlighted in other markets, volatile markets are anti-fragile, and that is worth a lot.

Source: tradingeconomics.com

As to the metals markets, after Friday’s washout across the board, this morning gold is unchanged, silver (+1.7%) has rebounded more than $1/oz and copper (+0.4%) has basically recouped its much smaller decline from Friday.  Nothing has changed my view that all metals remain in uptrends.

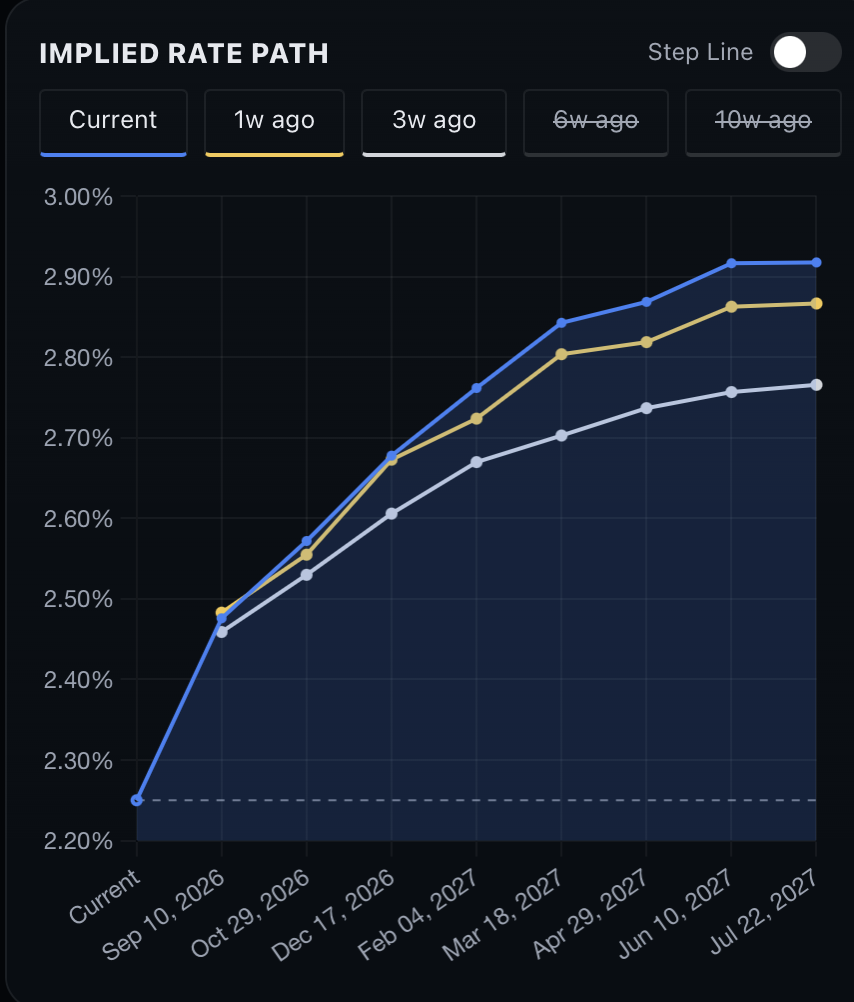
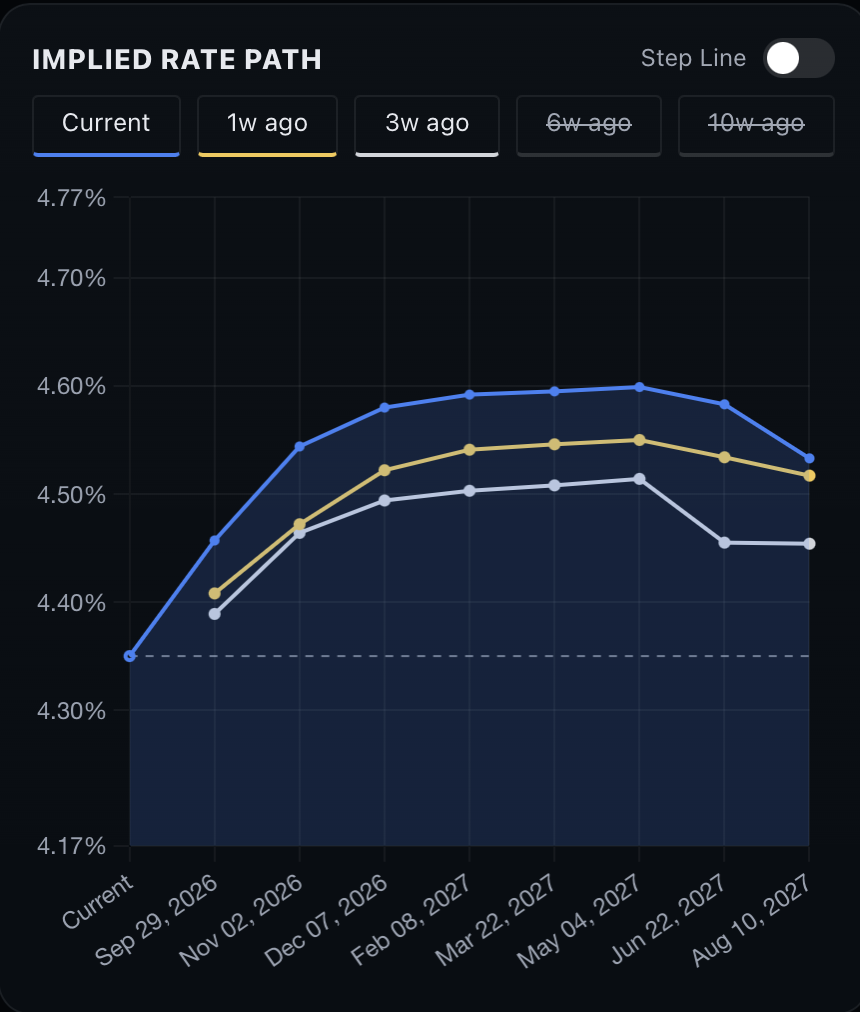
Perhaps the most interesting reaction to the Warsh speech was the equity market on Friday, where the main indices only fell by very modest amounts.  There was no indication from that price action that there is concern about a major tightening cycle.  Turning overseas, the picture was mixed last night in Asia (Tokyo -0.15%, China +0.35%, HK -0.1%, Korea +0.5%, India -0.4%) and is mixed this morning in Europe (Germany -0.8%, France 0.0%, Spain +0.1%) with Germany the obvious outlier.  I might argue that is a response to higher-than-expected inflation readings there and concerns that it might drive the ECB tighter.  I guess if you look at the curve below from rateprobability.com it does imply slightly tighter policy over time, but that’s really at the margin.

As to US futures, at this hour (7:10) they are pointing slightly softer, -0.2% or so.

Of course, Friday was much more exciting for the bond market but this morning Treasury yields are unchanged from the Friday close.  Europe, however, has seen yields climb higher with continental sovereigns all higher by 3bps.

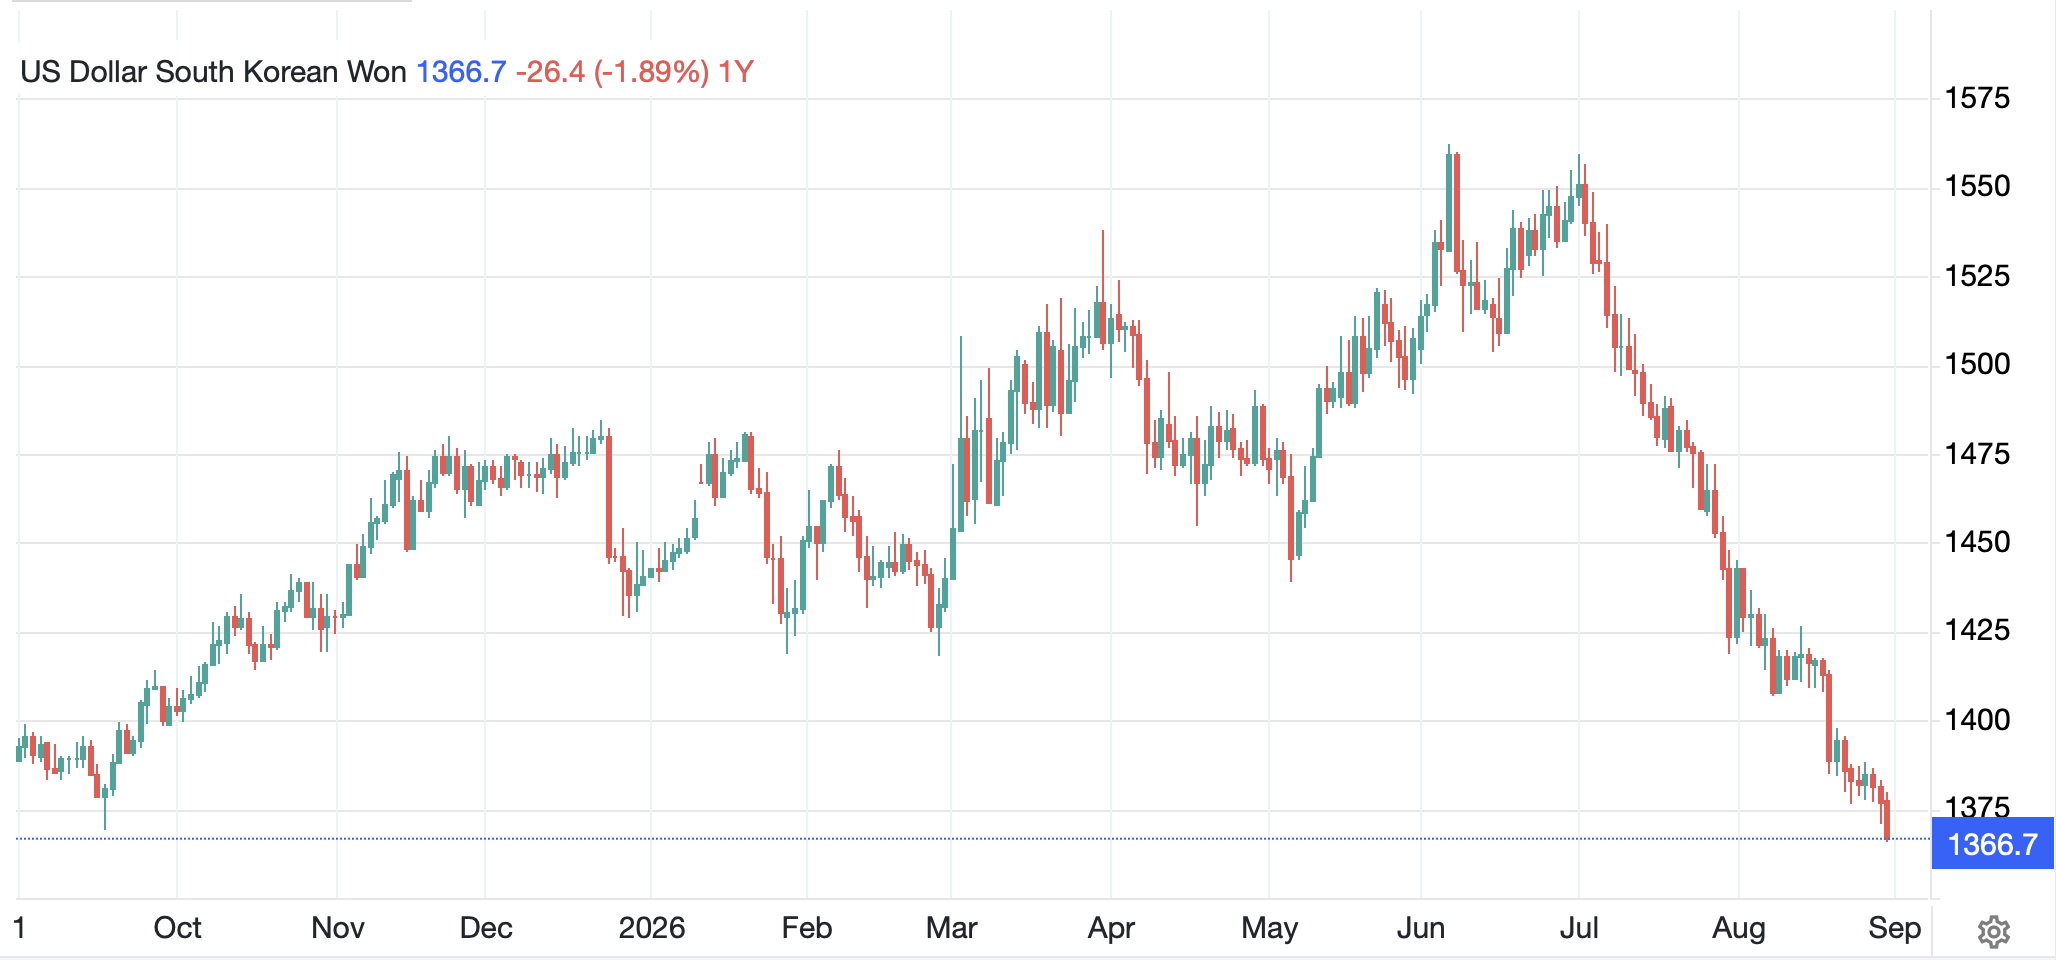
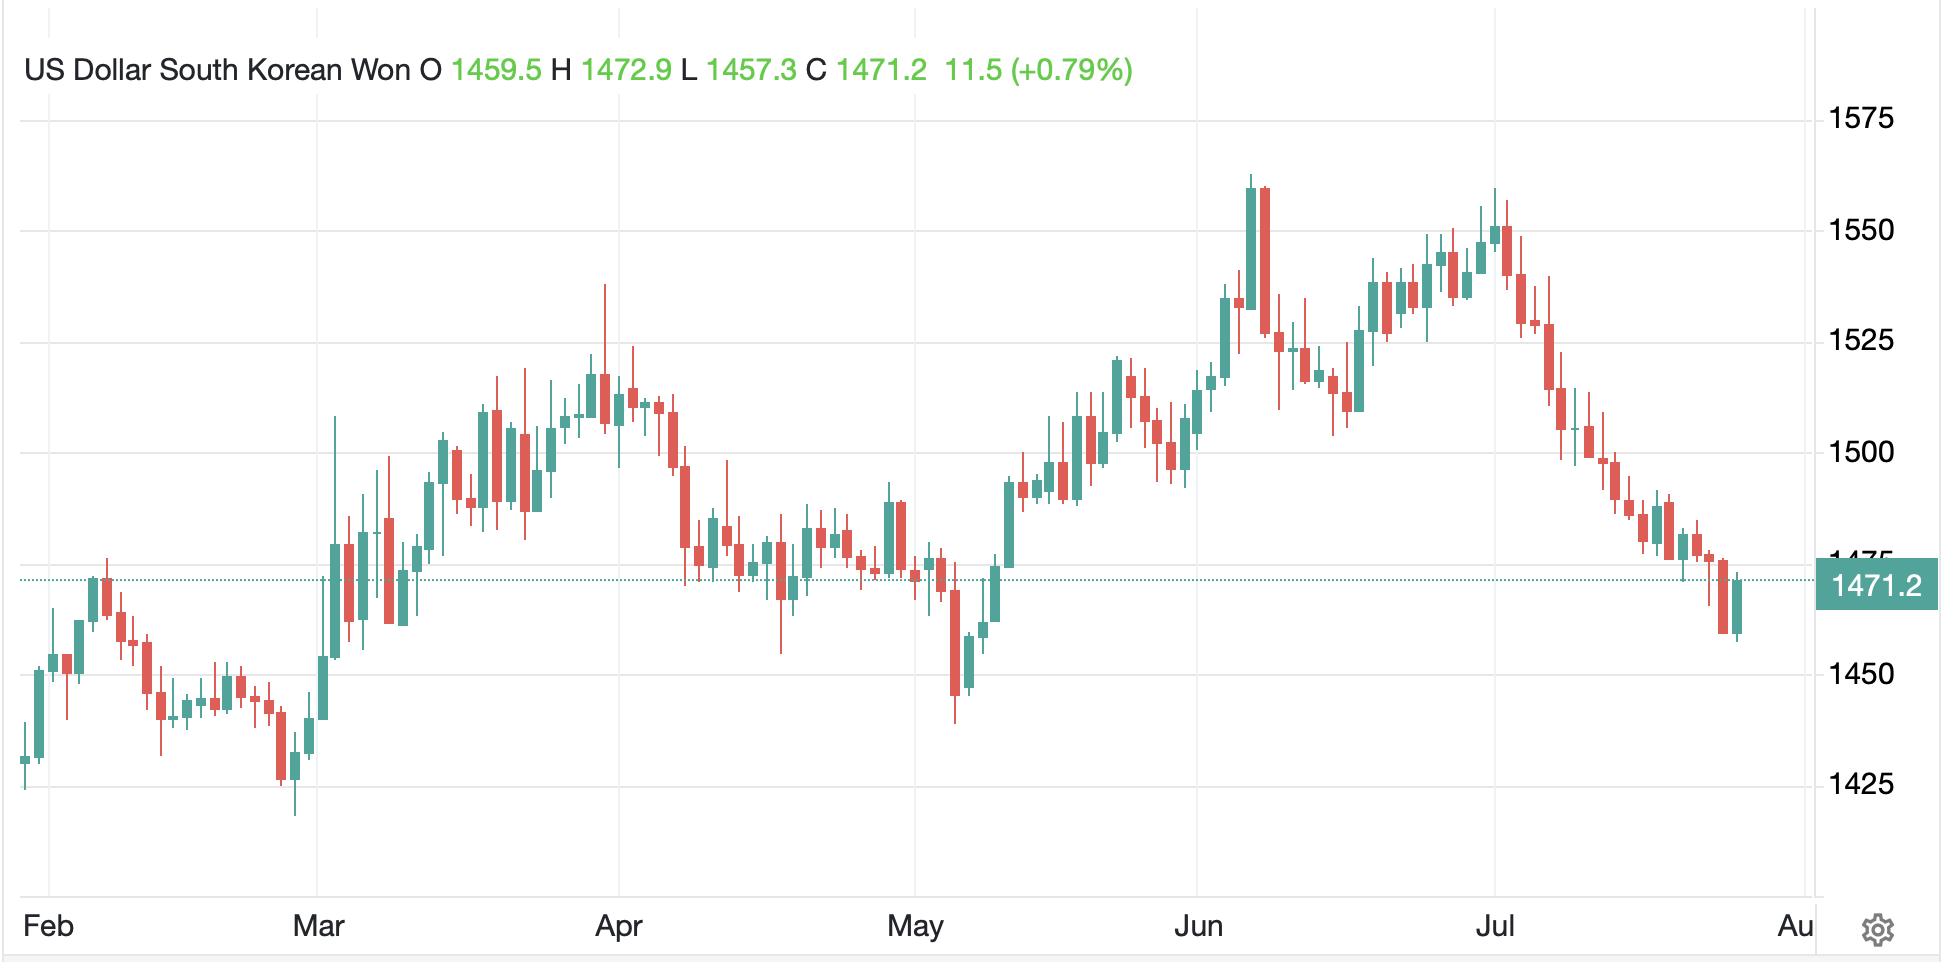
Finally, the dollar, which rallied sharply on Friday is giving back some of those gains with USDJPY back below 160, having closed above that level on Friday, while the bulk of the G10 currencies have gained between 0.1% and 0.2%.  The one exception here has been KRW (+0.7%) which has been on a remarkable roll over the past two months.  Between efforts to internationalize the currency and repatriation by the big semiconductor producers, the won has risen ~12% in the past two months, largely in a straight line.

Source: tradingeconomics.com

On the data front, there is nothing today but there is a big week coming culminating in NFP on Friday.

TuesdayISM Manufacturing55.2
 ISM Prices Paid72.0
 JOLTs Job Openings7.3M
WednesdayADP Employment47K
 Factory Orders0.6%
 -ex Transport0.2%
 Fed’s Beige Book 
ThursdayTrade Balance-$90.0B
 Initial Claims205K
 Continuing Claims1816K
 Nonfarm Productivity1.4%
 Unit Labor Costs1.3%
 ISM Services54.3
FridayNonfarm Payrolls58K
 Private Payrolls58K
 Manufacturing Payrolls5K
 Unemployment Rate4.1%
 Average Hourly Earnings0.3% (3.0% Y/Y)
 Average Weekly Hours34.4
 Participation Rate61.4%

Source: tradingeconomics.com

In addition to this, we hear from three Fed speakers.  The data we have seen of late indicates that the economy remains quite resilient in the face of higher energy prices.  Corporate earnings remain on fire and that continues to underpin risk assets overall.  However, all eyes will be on Friday’s NFP as that will serve to reconfirm prior opinions or perhaps change them.  The hawks will have a hard time making their case if the number is weak, and similarly, the doves if it is strong.  One little noticed thing from Friday was the NFP revisions for the 12 months from April 2025 through March 2026, which were revised lower by ‘just’ 79K.  Last year, the revision was -911K, so if nothing else, the BLS counted better!  But this begs the question, if the population is not growing, or even shrinking after all the deportations, and Baby boomers are retiring, thus reducing headcount, how many jobs are needed to maintain strong economic output?  

It makes a great deal of sense that Chairman Warsh wants to rethink the data because it does feel like the current data is outdated when it arrives, and that does not help forward looking policy decisions.  As to today’s session, it is hard to get too excited about anything right now, certainly in the FX markets.

Good luck

Adf
Run-Of-The-Mill

The funniest thing that I read
Was Bloomberg, in which someone said
That Bessent's bond buys
Have seen prices rise
So maybe, he's not a blockhead

Meanwhile, today brings PCE
Which pundits are anxious to see
If it comes out hot
They'll claim Warsh has wrought
Disaster and sip their Chablis

But if PCE remains chill
The pundits, when ink meets their quill,
Will pivot to stories
In new categories
And claim it was run-of-the-mill

As we await this morning’s PCE data (exp 0.1%, 3.6% Headline; 0.2%, 3.3% Core), as well as a bunch of other stuff like Personal Income (0.2%), Personal Spending (0.1%) and GDP (1.5%), many in the market continue to discuss the pros and cons of Treasury Secretary Bessent’s efforts to push down longer dated Treasury yields.  Before this morning, it was widely reported, or perhaps loudly reported is more accurate, that this was a desperate act and demonstrated that he didn’t know what he was doing and was simply a Trump puppet.  But the top story in Bloomberg this morning is titled “Bessent Bounce Starts to Emerge in Long Bond Market Metrics”.  In the story, they describe that despite all the controversy and certainty it would fail, it seems to be working for now.

Certainly, based on yesterday’s bond market price action, where 10-year yields slid -6bps, that may be the case.  And remember, the increased buybacks aren’t going to take place for another two weeks, so we still don’t know how much the Treasury is going to buy.  Personally, I like the idea of Treasury buying bond futures, where there is a massive speculative short position, and squeezing them all badly.  Remember, he was a hedge fund manager and knows exactly how that process works.  (As an aside, I have a feeling that Druckenmiller’s op/ed was him talking his book because he is short futures as well.)

At any rate, now that complaining about Bessent is not in tune with today’s market, the punditocracy has pivoted back to Chairman Warsh trying to anticipate what he is going to say Friday morning.  As Warsh remains tight-lipped about everything, it is much easier for the pundits to make claims without being proven instantly wrong.  And whatever Warsh says, you can be sure the pundits will claim they knew it all along!

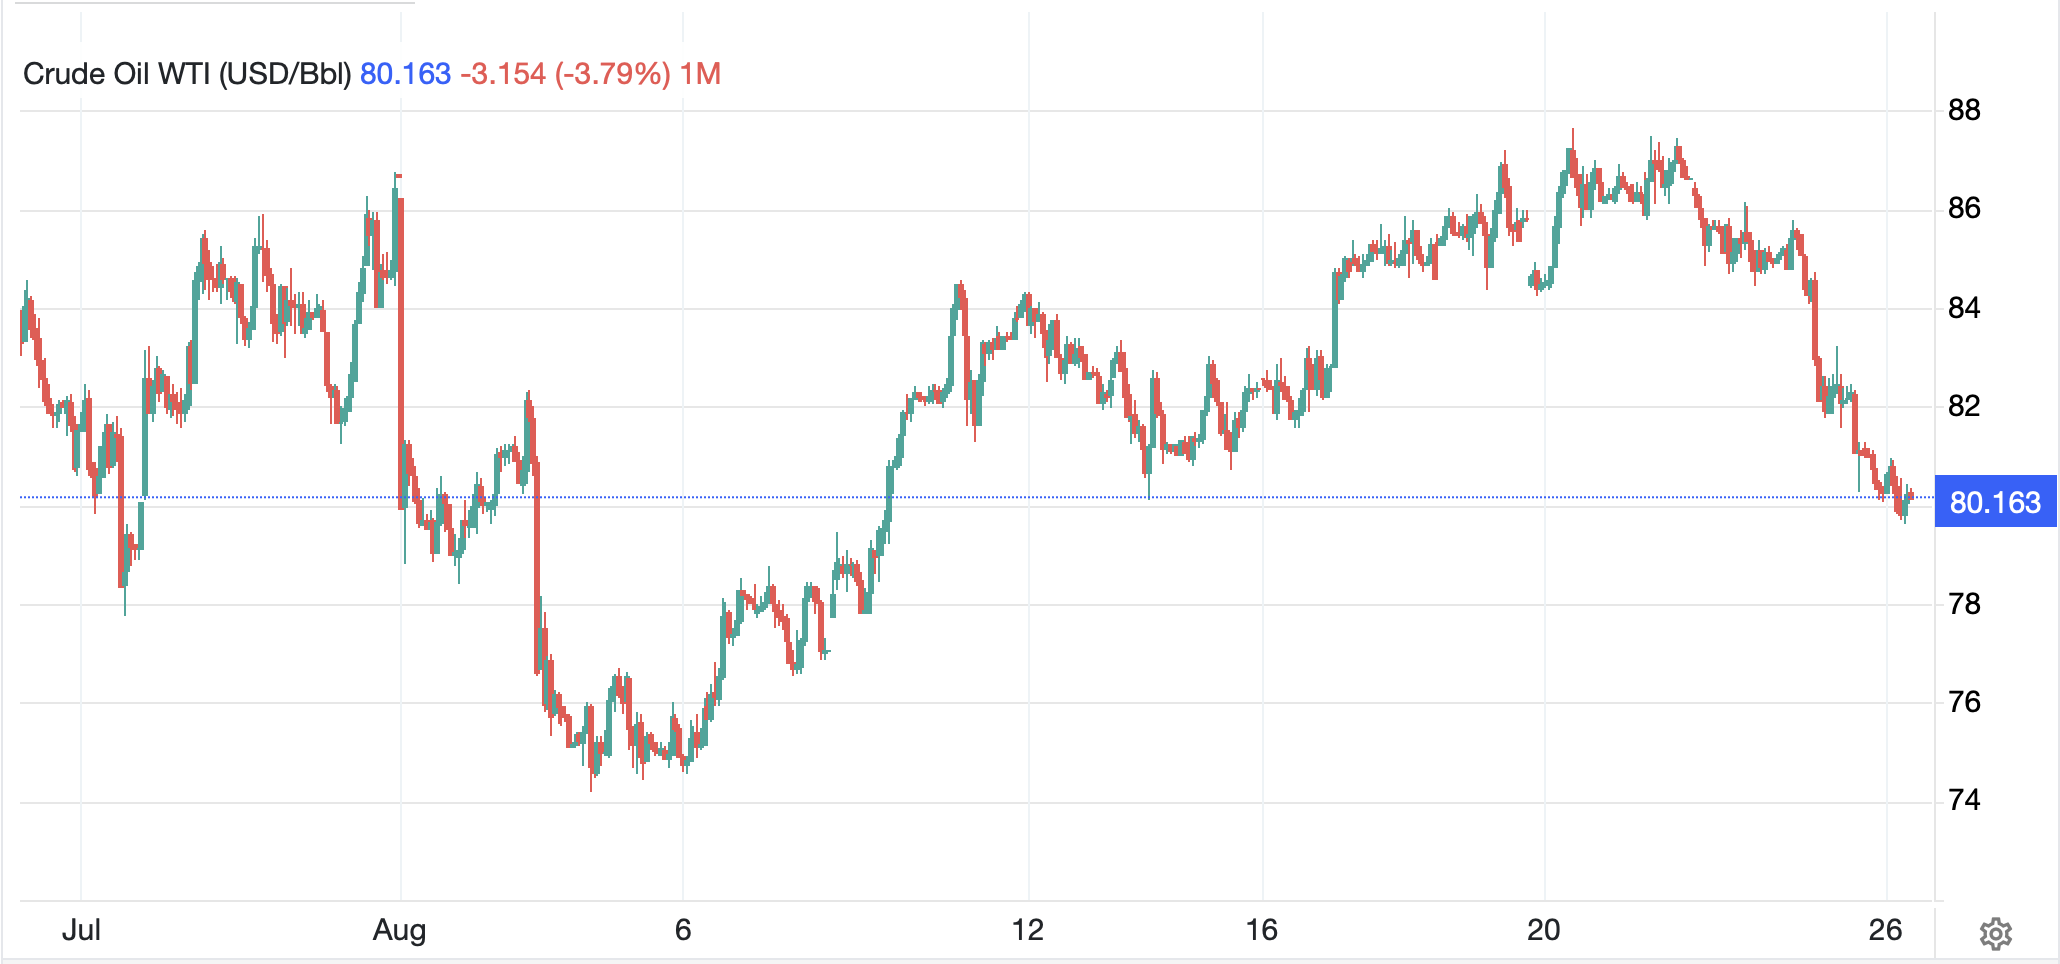
Meanwhile, in the markets, I believe oil (-2.6% today, -5.0% in the past week) continues to slide and is back at levels seen earlier this month around $80/bbl as per the below chart. 

Source: tradingeconomics.com

I am continually amazed at the commentary regarding oil and Iran and potential peace talks as the response to virtually every statement by the Trump administration about the situation, whether about the ability to traverse the Strait, or the status of talks with Iran, is to dismiss it out of hand by many commenters on X, but when Iranian propaganda media makes claims, it is taken as gospel.  Yesterday I recall Iran claiming economic sanctions won’t matter, they are prepared, and yet today there are stories of how Iran and Oman are furiously trying to come to some type of agreement.  I do not know the situation on the ground there but after 6 months of bombardment and embargos on their oil exports, my sense is the IRGC is feeling a lot of pressure.  I guess we shall see, but in the meantime, oil inventories remain robust with no shortages seen.

As to other markets, let’s tour around to see what’s happening.  Completing the commodity group, metals are consolidating weekly gains with gold (-0.8%) and silver (-0.2%) slipping a bit although both remain higher by more than 2% this week and about 15% in the past month.  Copper is little changed.

In the bond market, after yesterday’s sharp decline in yields, where European sovereigns followed Treasuries, albeit not quite as far, this morning has seen yields back up 1bp across both the treasury and European markets.  As I have been saying, I believe this market is waiting for Chairman Warsh to speak before deciding its next move.

In the equity markets, US markets all rallied yesterday afternoon and closed near their highs with that price action following across most of Asia.  Tokyo (+0.6%), HK (+0.6%) and China (+0.85%) all had good sessions as did Korea (+1.0%) and Taiwan (+1.5%) as all those tech related markets await Nvidia’s earnings to be reported after today’s US close.  The exception here was Australia (-0.4%) which slipped after higher than forecast inflation readings were released and markets have increased the probability of a rate hike by the RBA at their September meeting to 45% from about 25% prior to the release as you can see in the chart below from rateprobability.com.

In Europe, equity markets are fairly quiet overall with modest gains of 0.2% to 0.4% everywhere except the UK which has seen a decline of -0.2%.  Ironically, despite the problems the UK is having with energy prices, two key members of the FTSE 100, Shell and BP are lower on the lower oil price and that is dragging down the index.  As to US futures, at this hour (7:40), NASDAQ (-0.5%) futures are softer, but the other major indices are little changed.

Finally, the dollar is slightly firmer this morning but continues to be an afterthought in markets.  The DXY is exactly where it was yesterday when I wrote and the only true outlier today is AUD (+0.25%) which is benefitting from higher interest rate expectations.  Otherwise, the dollar is modestly firmer against most every counterparty of note.  At some point, the dollar will get interesting again, I just don’t know when that will be.

And that is really it today.  Perhaps there will be a deal from Iran although I doubt it.  

Instead, a tribute to one of the true superstars of our time, and by all accounts one of the finest human beings ever, Ms Dolly Parton.

Good luck

Adf
A Desperate Act

A key market story yesterday was that the Treasury buyback operations, you know the ones that would be “at least” doubled to $4 billion per event, could grow much larger as secretary Bessent would tap the Treasury General Account (TGA) for this purpose.  Now the TGA is the federal government’s checking account.  It is where your taxes get paid into, along with the receipts from bond sales and tariffs.  It is also the account that pays all the federal government’s obligations like salaries and purchases of defense and other equipment.  The current balance (a/o Aug 21st) is about $936 billion according to the Treasury website.  Obviously, that is a huge amount of money, but then the federal government has a huge amount of payment obligations.  I bet it is a hard checking account to balance!

Now, technically, I presume that all their operations are paid by the TGA.  The mechanics would work that Treasury would issue T-bills, receive the cash in the TGA and use that cash to buy back bonds.  But the implication was that he would just spend the money that was already there.  Personally, I doubt that will be the outcome, and frankly, it almost sounded more like a threat than a future course of action.  But it did get tongues wagging.  

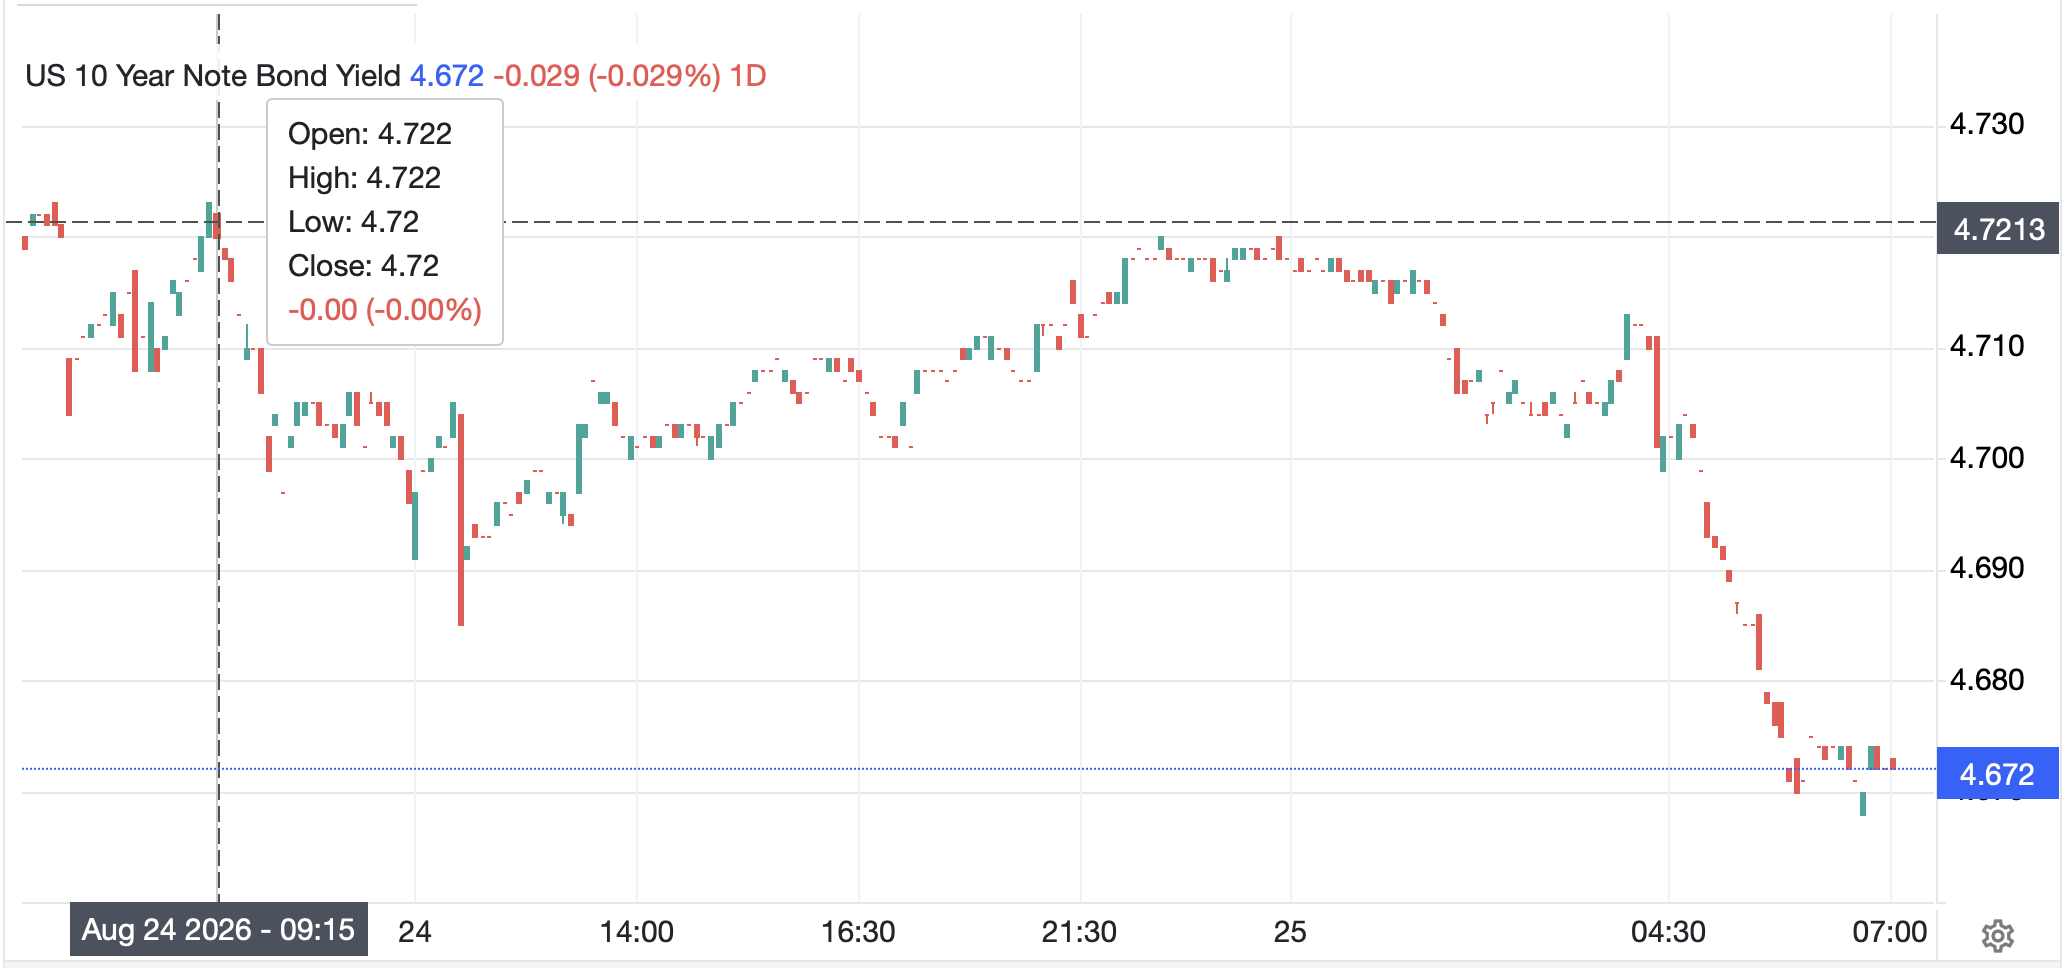
According to Grok, these comments came in an interview on CNBC at a bit after 9:00 yesterday morning.  The chart below shows the bond market price action from that point onward, which tells me that while there was a modest initial response, it completely disappeared until another catalyst (lower oil prices I believe) helped push yields down early this morning.

Source: tradingeconomics.com

But this clearly struck a nerve as in this morning’s WSJ, Stan Druckenmiller, Bessent’s mentor at the old Soros hedge fund, wrote an op/ed decrying the move.  As I survey all that I have learned thus far, it seems clear that Bessent is looking to remove duration from the market in an effort to drive longer dated yields lower.  But his tools are limited compared to the Fed’s abilities and, at least right now, it does not appear the Fed is going to cooperate.  The first operations aren’t scheduled until September 7th, so until then, it is all just speculation, and I’m not even going to try.

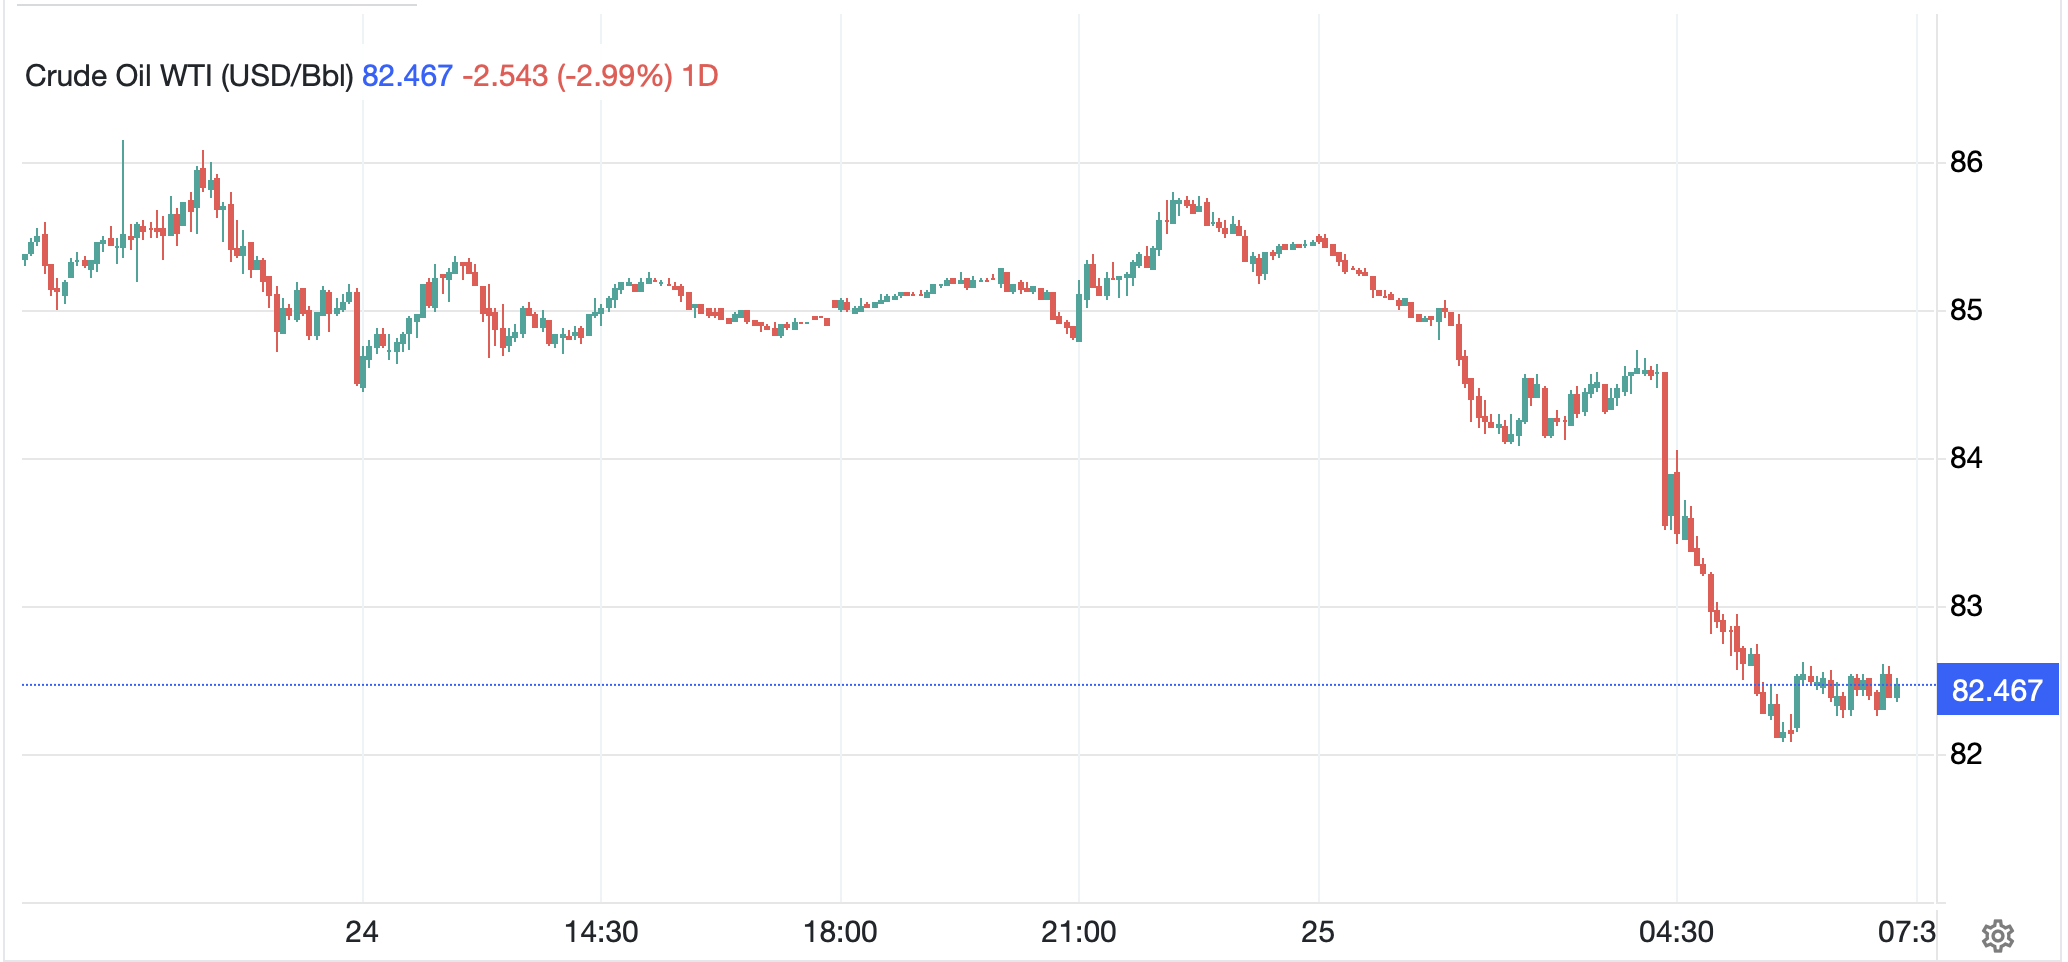
The other thing that Secretary Bessent did yesterday, that may have a larger impact on things, was announce sweeping new sanctions on Iran and countries that do any residual business with Iran in an effort to add further pressure on the regime.  It is possible, but not clear to me, that this is part of the rationale for this morning’s decline in the price of oil (-3.0%).  However, if you look at the chart of oil for the past 24 hours, it is remarkably similar to that of the 10-year Treasury above.

Source: tradingeconomics.com

Ostensibly, the news here, which of course would impact bond yields, is that the Pakistani army chief was intermediating between the US and Iran in an effort to find a solution and reduce tensions in the Gulf.  That would certainly be a welcome outcome for all, but I’m not holding my breath.  However, this price action has set the tone for risk markets this morning, so let’s take a look.

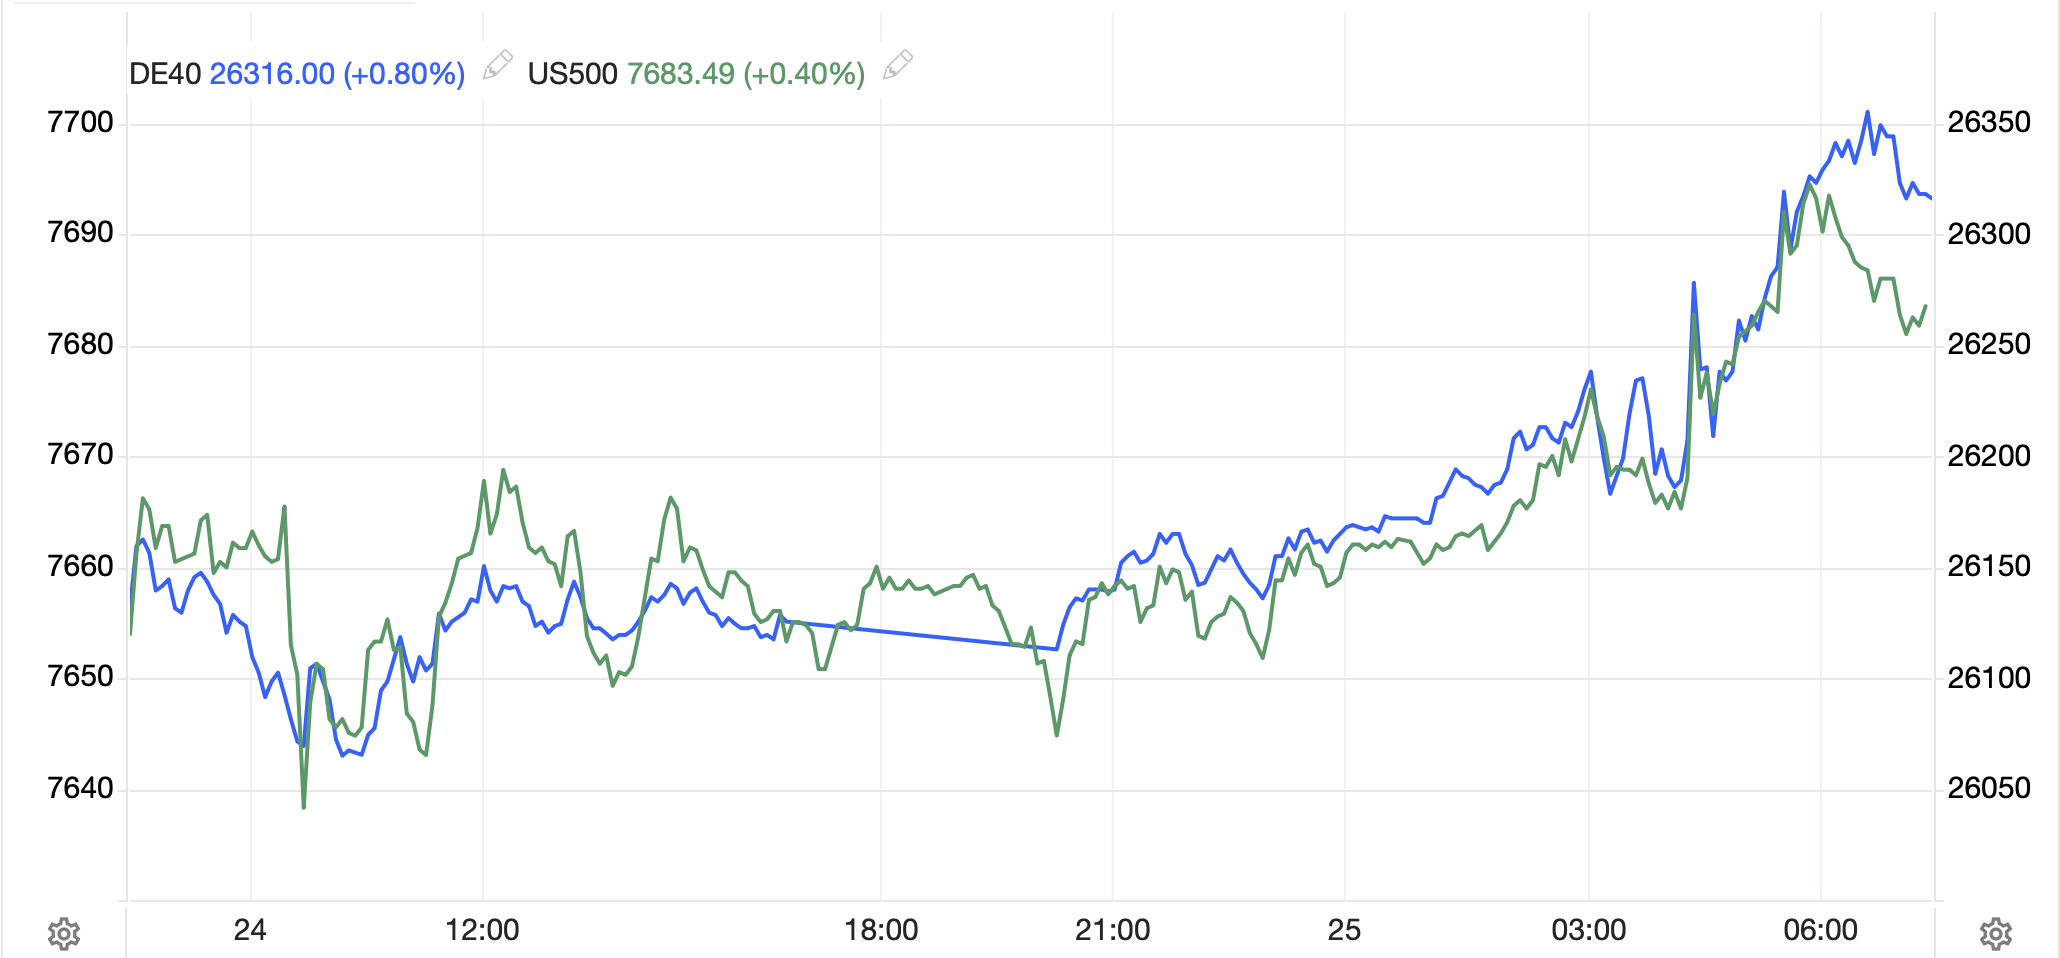
While Asia was mixed overnight (Tokyo +0.5%, China -0.3%, HK 0.0%) following the mixed US session, with pressure still evident on the tech sector, Europe is firmer this morning across the board (Germany +0.8%, Spain +0.4%, France +0.4%, UK +0.25%) with all those rallies timed almost exactly alongside the oil and bond moves.  As you can see in the chart below, the same is true in the US where futures at this hour (7:25) are also higher and moved right alongside other equity markets.  As to specific stories here, I think there is a great deal of breath holding for the Nvidia earnings report tomorrow after the close.

Source: tradingeconomics.com

In the bond market, as mentioned above, yields are lower across both Treasuries (-3bps) and all European sovereigns with the entire bloc seeing yields decline by between -3bps and -4bps.  It appears this all revolves on the same story driving oil and equities.

In the metals markets, gold (-0.2%) is edging lower but basically consolidating another strong day yesterday.  It is reasonable to conclude that market participants are growing cautious regarding US debt given there is no indication of spending restraint.  But the reality is that markets are growing cautious of all G10 debt given that statement regarding spending restraint is universally true in that bloc.  I continue to believe we are going to see governments around the world try to ‘run it hot’ with nominal GDP growth rising faster than government spending, thus reducing the real burden.  However, running it hot generally means higher inflation, and that is something that is a political problem.  As to the other metals, silver (-1.2%) is under pressure, although still far higher over the past week and month, while copper (+0.5%) is a bit firmer this morning.

Finally, the dollar is still sleeping this morning, virtually unchanged on the DXY at 99.00 and virtually unchanged vs. almost every major counterpart.  The biggest mover is INR (+0.35%) a major beneficiary of lower oil prices and not surprisingly, NOK (-0.2%) is suffering on the same catalyst.  But otherwise, everything is +/- 0.1% from yesterday’s close.

On the data front, there is not a ton this week, although PCE comes tomorrow, but really all eyes remain on Chairman Warsh’s speech Friday morning.

TodayCase-Shiller Home Prices1.7%
 New Home Sales620K
 Consumer Confidence90.2
WednesdayPCE0.1% (3.7% Y/Y)
 Core PCE0.2% )3.3% Y/Y)
 Q2 GDP1.5%
 Durable Goods0.7%
 -ex Transport0.5%
 Personal Income0.3%
 Personal Spending0.2%
ThursdayGoods Trade Balance-$99.0B
 Initial Claims208K
 Continuing Claims1811K
FridayChicago PMI57.0
 Warsh Speech 
 Michigan Sentiment51.0

Source: tradingeconomics.com

In addition, the EIA oil inventories are expected to see another build as there remains ample supply, at least so it seems.  While PCE is important, I think it will be less so given the pending Warsh comments.  To me, tomorrow’s Nvidia earnings and then Warsh are the keys for the rest of the week, absent a major change in Iran, and alas, I don’t see that.

The bond brouhaha is much ado about nothing I believe as it will not change the trajectory of Federal spending, and that is what is necessary to have a long-term impact.  Unfortunately, that usually takes a crisis, and those are unpleasant.  They also take a VERY long time to develop, after all Argentina imploded for nearly 100 years before electing Javier Milei who promised to do something about it.  It has only been 25 years here since we last ran a budget surplus.  I fear it could be much longer before things really change.

Good luck

Adf
They Mostly Confuse

We’re back to the Strait of Hormuz
As driver to all traders’ views
Both Trump and Iran
Have proffered a plan
But really, they mostly confuse

The, otherwise, story of note
Is coming as CPI’s quote
If hot, Chairman Warsh
Will field comments, harsh
If cool, he’ll be able to gloat

Oil prices (+1.5%) are higher again this morning and have now been up five consecutive sessions, rising 10% in that run as you can see in the chart below.

Source: tradingeconomics.com

There is a theory that the rhetoric in Iran increases when they have oil to sell so need higher prices, but once those cargoes have been sold, they talk peace again.  I don’t think you can rule out that hypothesis although I certainly have no corroborating evidence it’s true.  The one thing I did note yesterday is an Iranian comment that as long as sanctions remain, diplomacy cannot happen which tells me that economic sanctions are biting harder.  Whatever, the situation on the ground (or water) is over there, I have no insight per se. 

Much has been made over the fact that the SPR is at its lowest level since 1983 and has fallen below 300 million barrels with all the attendant pearl clutching while simply ignoring the fact that the SPR releases have been oil swaps with the back ends starting to come back in the next several months in greater amounts than have been released.  Maybe the end is nigh regarding oil, and the doomsters will get their $200/bbl outcome, but I would still take the under there.

In sync with the oil price rise we have seen yields rise, as well (see chart below), around the world.  But here, it appears that Chairman Warsh is the favored scapegoat for all the world’s inflation problems.  To hear his critics explain, if only he would give us forward guidance, everything would be fantastic.  Hedge funds could load up on leverage and increase their profits, real money investors would be comfortable that future real returns would be acceptable and, most importantly, the punditry would be able to explain all this to us plebes and burnish their beliefs in their own brilliance.

Source: tradingeconomics.com

But I wonder if there is not another explanation for rising yields that has nothing to do with the Fed, the idea that debt issuance, from both government and private sources, is growing dramatically and all that supply is weighing on prices, hence driving up yields.  We already know that governments around the world continue to issue debt willy-nilly, so there is nothing to discuss there.  But now the AI hyper scalers are issuing massive amounts of debt to pay for all the GPUs and data centers and power as the race to “win” in AI continues at an increasing pace.  

It is, of course, this last issue which has many pundits explaining that QE will soon reemerge as the only viable way for all that debt to get bought.  If central banks buy government debt that will leave funds for private investors to buy AI related debt.  And maybe that is the way it will work out although Chairman Warsh has thus far only discussed shrinking the balance sheet, not expanding it.

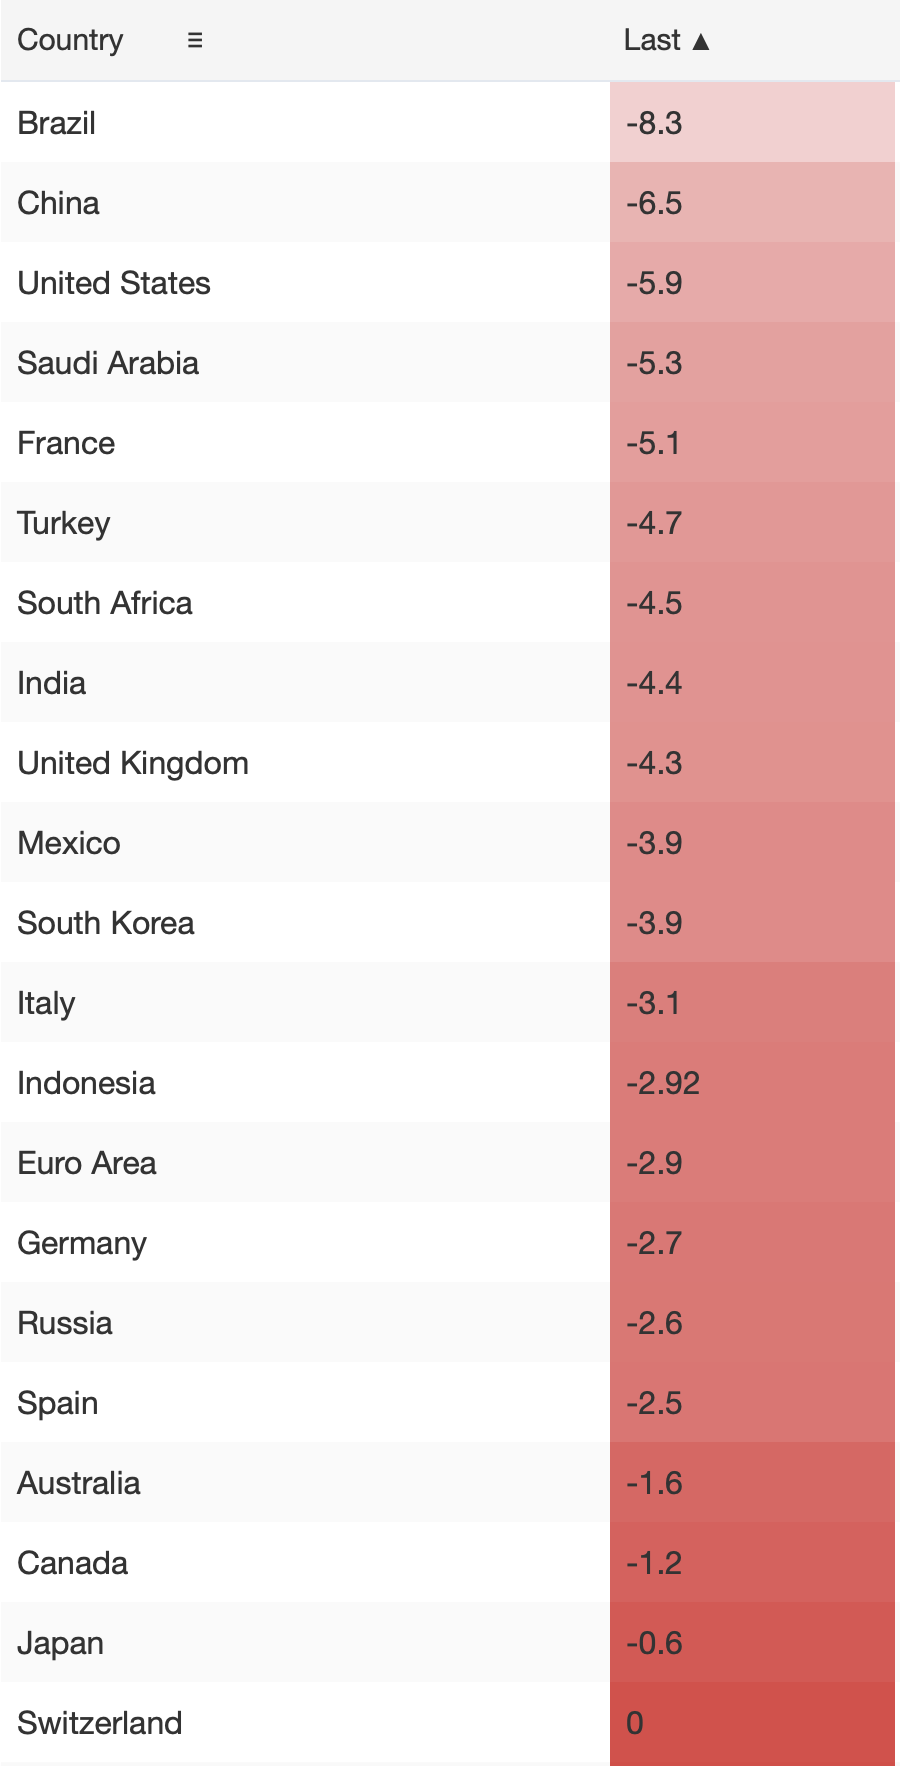
Please understand I am not ignoring the many serious problems that exist within the current fiscal and monetary frameworks around the world.  Government spending remains excessive as evidenced by the fact that virtually every nation in the world is running significant budget deficits as per the below table from tradingeconmics.com (notice China, a country that seems to get a pass on this score from the punditry).

All I am saying is that the idea that all of this is going to fall apart quickly is highly improbable.  As much as purists would like for there to be consequences for bad policy decisions, governments everywhere have an enormous number of tools to delay the pain, and they use them all the time.  Whether that is subsidies or tax cuts or regulations prohibiting competition, all these things substitute short-term gains for long-term problems.  But they will still be used regularly.

So, to recap, increasingly hawkish rhetoric on the Iran situation has driven oil prices higher which is increasing inflation concerns.  Adding to that is the ongoing fiscal profligacy of virtually every major government which is also weighing on bond prices and driving yields higher in sync.  And basically, the punditry has decided it’s all Kevin Warsh’s fault.  Too much will be made of tomorrow’s CPI report, whether it is hot or cool, that is the one things of which I am certain.

Ok, yesterday’s lackluster US session with all three major indices slipping a bit was followed by weakness in China (-0.8%) and HK (-1.1%) but elsewhere in Asia, things were mixed with Korea (+0.7%) gaining and the other regional bourses generally +/-0.5% or so.  Tokyo was closed for Mountain Day and the only other news of note from the region was the RBA left rates on hold at 4.35%, as expected, but expressed concerns about both slowing growth and future inflation.  Interestingly, Australian stocks were slightly higher despite that news, +0.2%.

In Europe, Spanish stocks (+0.5%) are the leader on the strength of Banco Santander’s share repurchase announcement while the rest of the continent and the UK are little changed.  As to US futures, at this hour (7:35) they are little changed.

While we have broadly discussed bond yields rising, and yesterday they were higher by 4bps-5bps in the US and Europe, this morning they are unchanged across the board.  Now, they were higher again this morning when I started to write, but it seems there was just a comment from Pakistan that the US and Iran are close to an agreement which has turned things around.  Oil prices, too have slipped back to unchanged on the day from an hour ago.

In the metals markets, gold (-0.2%) and silver (-0.9%) are backing off solid sessions yesterday and copper (+0.8%) continues to march higher.

Finally, the dollar is, net, little changed this morning, although we cannot ignore the fact that the yen fell -1.0% during yesterday’s session.  In fact, a look at the yen chart continues to show the market response to intervention, an immediate rally and a gradual decline resuming.

Source: tradingeconomics.com

As to the rest of the space, KRW (+0.3%) is the actual largest mover today, and that is not enough of a move to spin any story.  The DXY remains just below 100 and firmly within its yearlong trading range and some pundits are saying the fact that it is not rallying during the current conditions, with yields rising and fear all about, is an indication that the dollar is losing its status.  However, I am confident if you offered those same pundits payment in dollars, they would grab them as greedily as possible!

On the data front, this is inflation week plus a few more things as follows:

TodayExisting Home Sales4.05M
WednesdayCPI0.1% (3.4% Y/Y)
 Ex food & energy0.2% (2.5% y/Y)
ThursdayInitial Claims202K
 Continuing Claims1800K
 PPI0.2% (4.9% Y/Y)
 Ex food & energy0.3% (4.2% Y/Y)
FridayRetail Sales0.1%
 -ex autos0.2%
 Michigan Sentiment54.5

Source: tradingeconomics.com

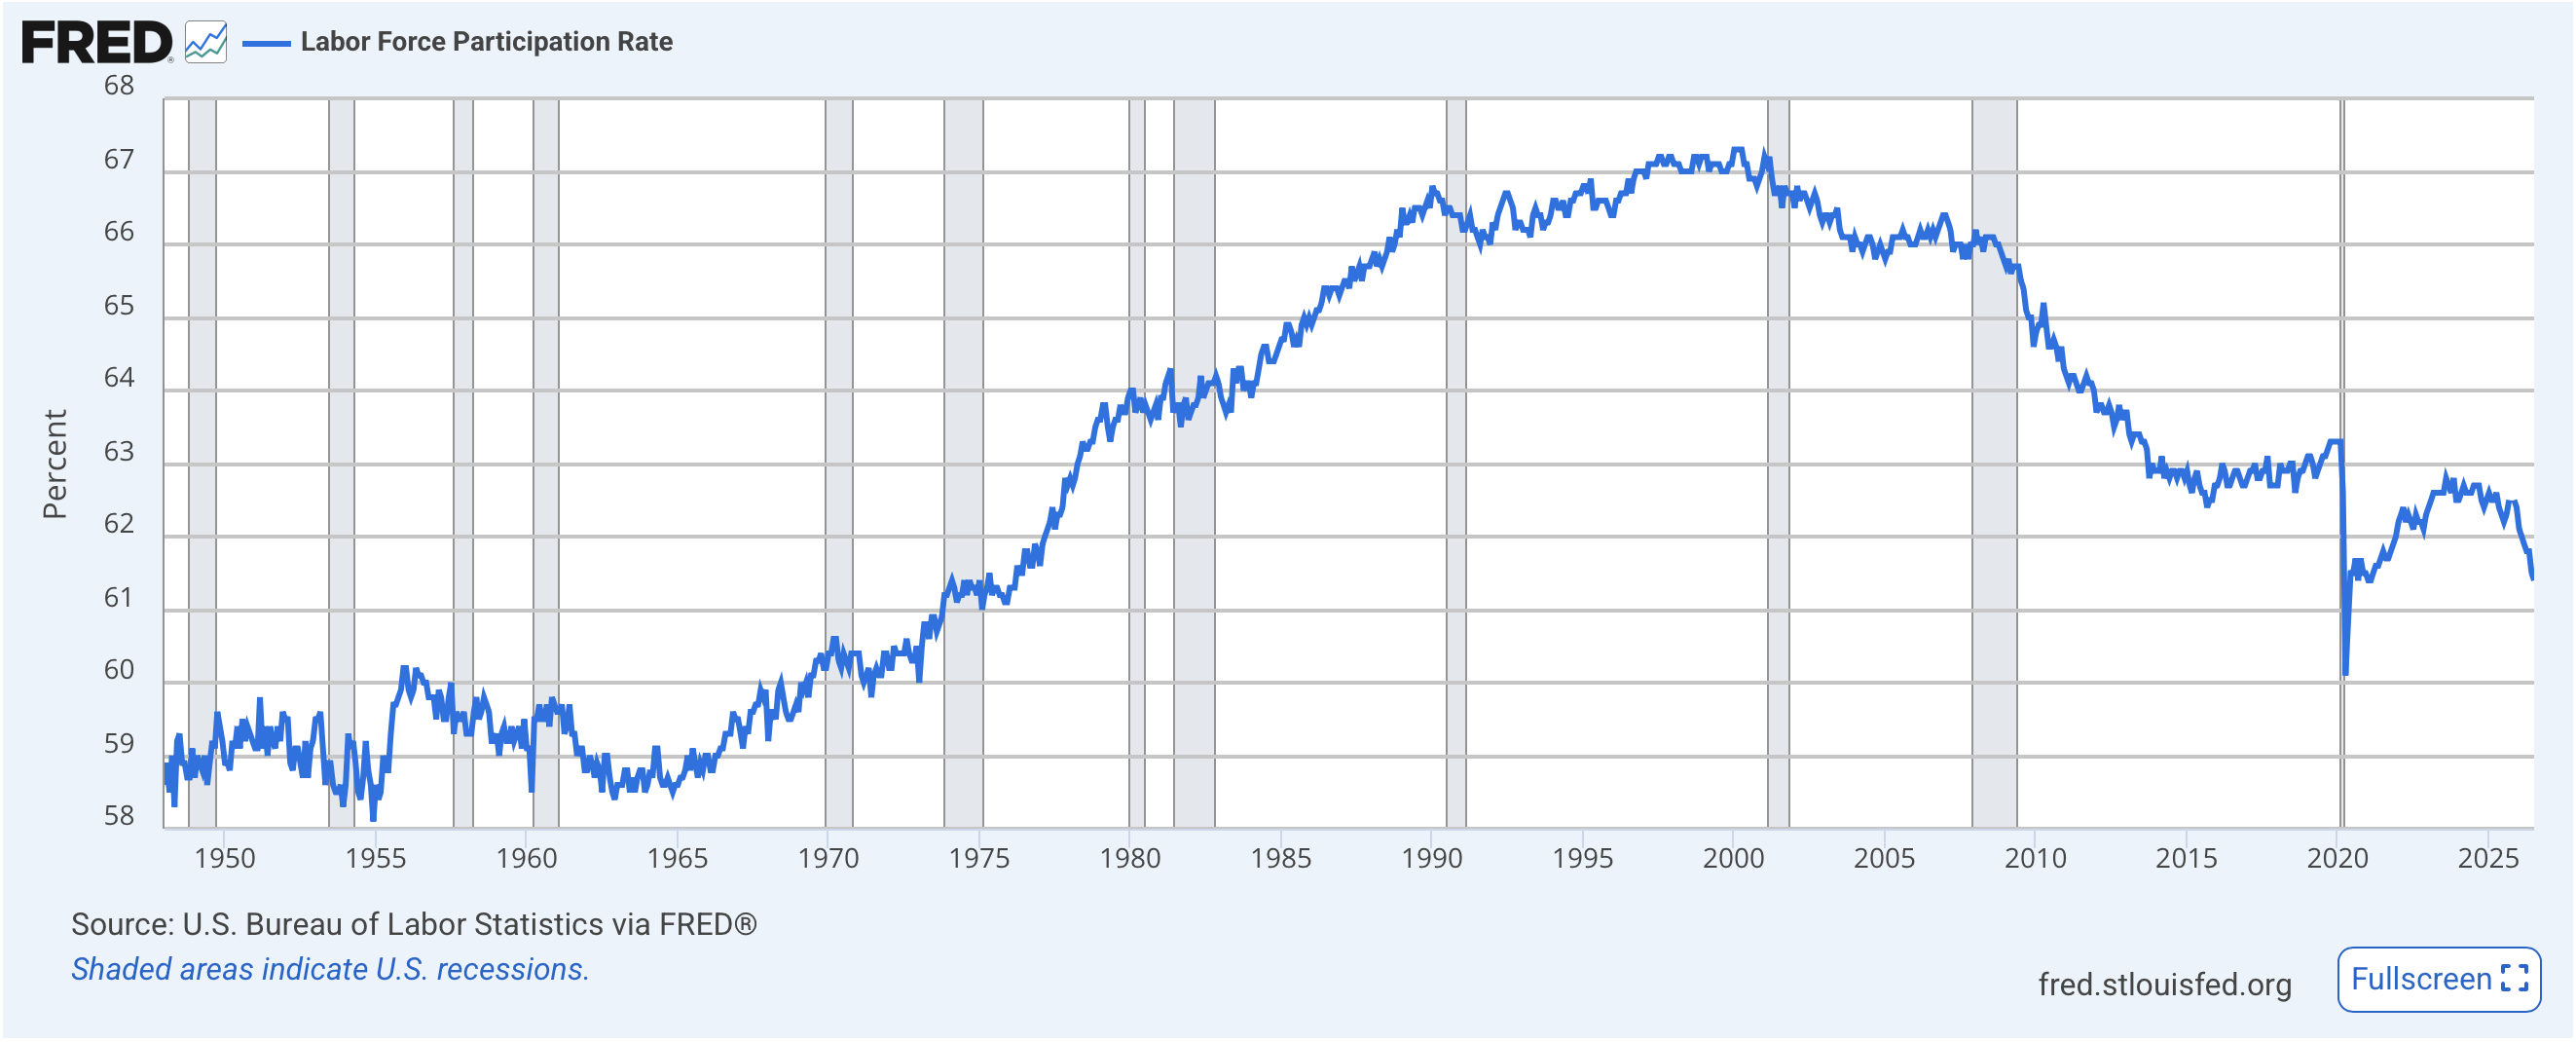
Obviously, all eyes will be on CPI tomorrow as investors and analysts look for clues as to how the Fed may behave going forward.  Speaking of the Fed, Cleveland Fed president Hammack said in an interview yesterday that she thought the Fed needed to raise rates more than 25bps to get inflation under control.  But as I think about the Fed and its dual mandate, of maximum employment and stable prices, I cannot help but wonder what they consider maximum employment.  While they have defined stable prices (incorrectly in my view) as Core PCE rising 2.0% per annum, they have never tied themselves to a number on employment.  So, here’s a thought.  Look at the Labor Force participation rate, which as per the data last Friday fell to 61.4%, that is the lowest level since 1975 (excepting Covid) as per the below chart from FRED.

That hardly seems maximal, but then, I’m just an FX guy, not a Fed PhD.  After all, if we take the plain meaning of the word maximum, as per the American Heritage Dictionary, I cannot look at the chart above and conclude they have achieved that part of their mandate either.

But that’s just me.  Anyway, if there is going to be movement on the Iran story, that will drive the immediate market movements, but you can be sure that in the current environment, it will all come back to the Fed and whatever they may do going forward.

Good luck

Adf
Quite Spicey

Though Friday things looked pretty dicey
With tech stocks then seen as quite pricey
New word that the bombing
Has ended was calming
And stock markets opened quite spicey

Of course, it can be no surprise
That oil’s now well off its highs
The dollar is slipping
Though yields are just dripping
As bond traders still agonize

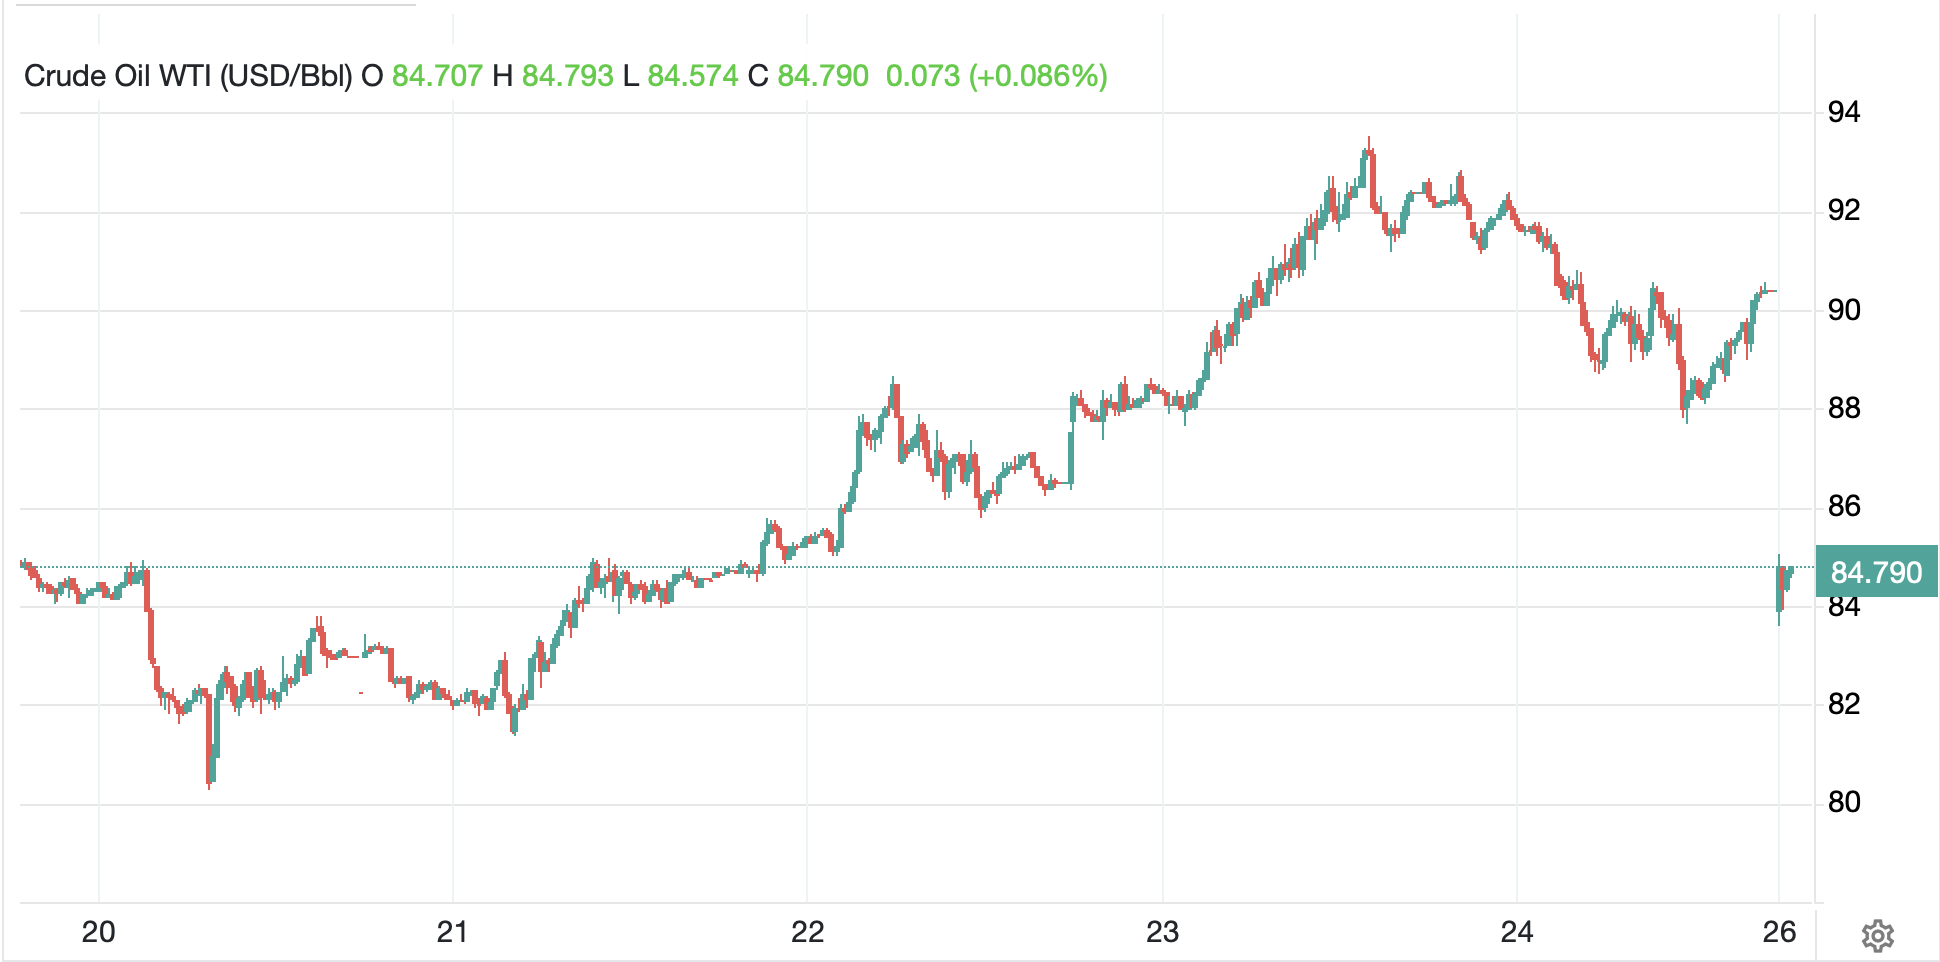
President Trump changed his mind about continuing the recent bombing campaign against Iran over the weekend amid questions about alleged US munitions supplies.  But whatever the reason, this was music to the risk markets with oil (opening -6.4%) falling sharply while equity futures (NASDAQ opening +1.25%) rebound from last week’s declines.  Once again, headline risk remains the biggest risk there is in markets.  Note the huge gap lower in the oil market early Sunday evening in the chart below from tradingeconomics.com

At this point, it is a fool’s errand to try to estimate where oil prices are heading going forward as the next headline is likely to be the key driver, and that is a complete unknown.

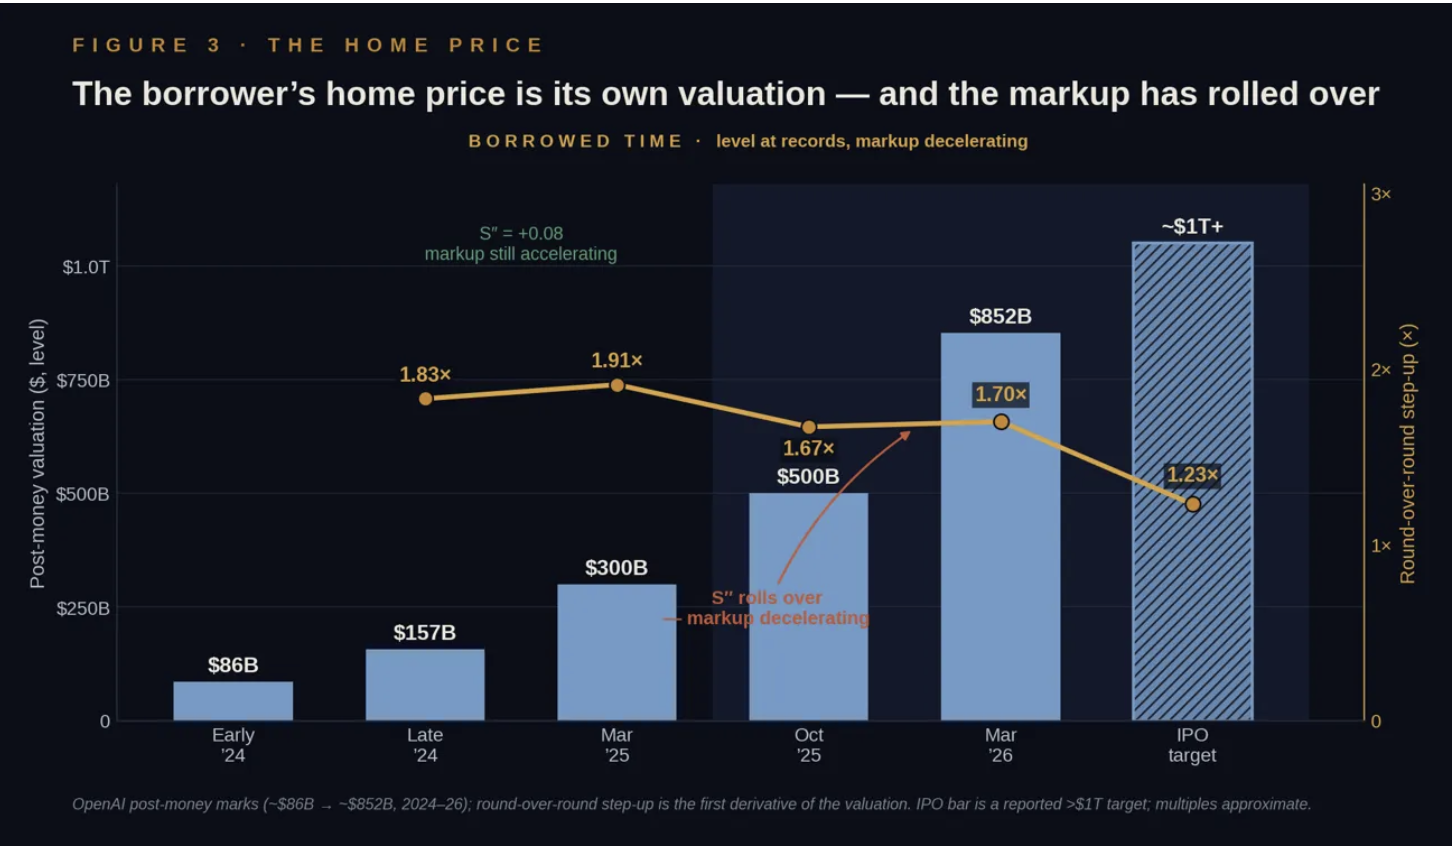
So, let’s turn our attention to some more fundamental questions that have been brewing in the background and are pretty complex.  I want to start with a remarkable Substack piece I read this weekend which had a completely different perspective on the AI investment thesis than anything that I have seen anywhere else.  And it is quite a persuasive piece.  While I have linked it above, it is quite a long read, so the highlights are as follows:

  • The AI boom is not a tech boom; it is a credit driven real estate cycle
  • This is virtually identical to the run-up to the subprime housing crisis and GFC
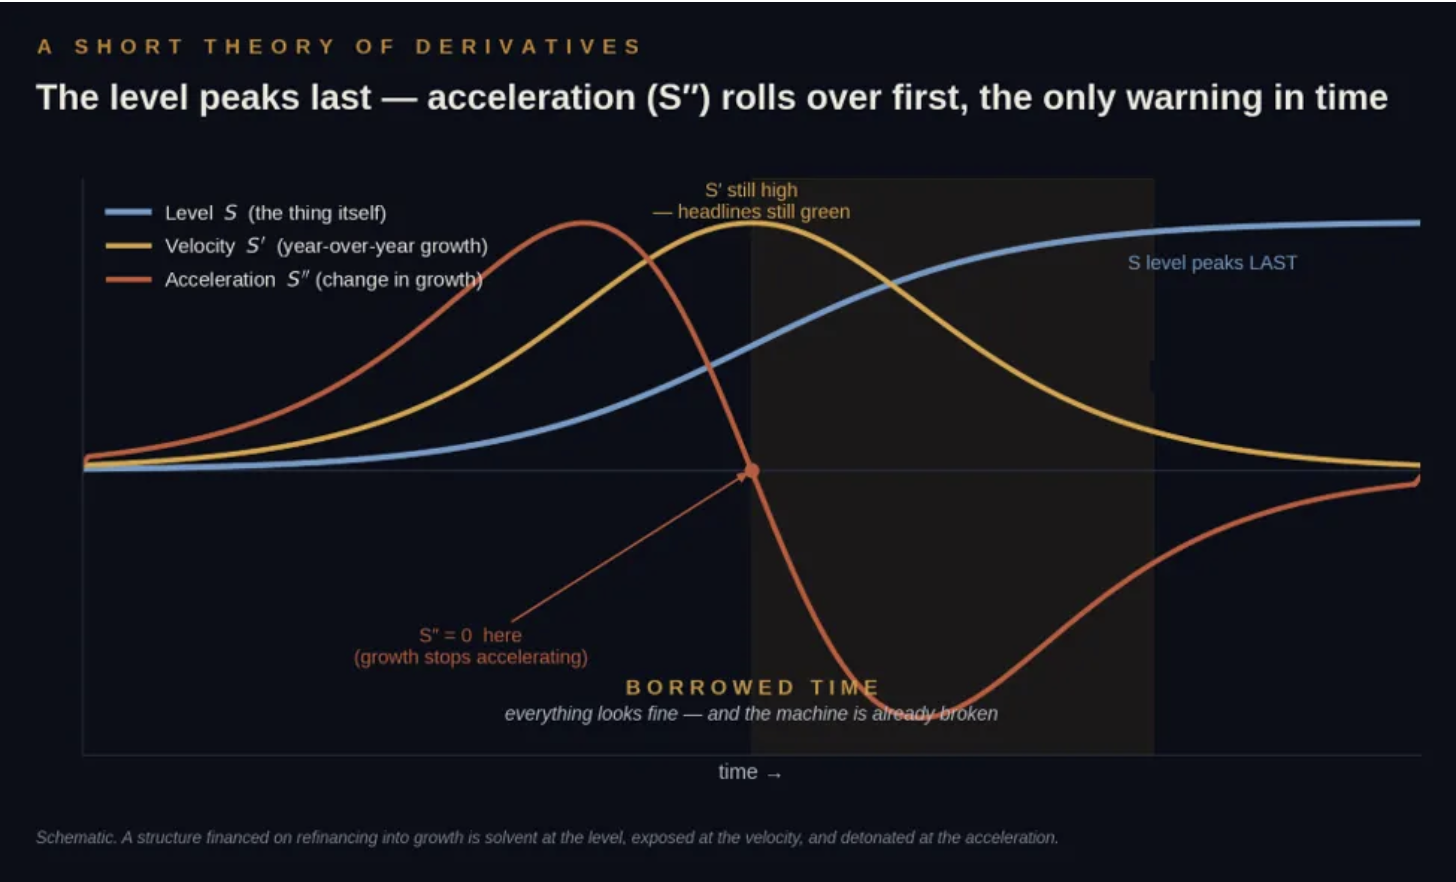
  • The key to understand is the second derivative of growth, acceleration.
  • GroundBreaker’s (the author) thesis is that the second derivative on AI valuation has already rolled over and the future for AI stocks is pretty bleak, at least in the medium term.

Below are two charts from his Substack to help describe the issue:

This is a basic description of the movements of the underlying (blue line), its velocity (growth rate, yellow line) and its acceleration (the change in its growth rate, red line).  As you can seem growth can still be increasing, but at a slower rate, and that’s the problem he highlights.  

Below is a chart of OpenAI’s valuation metrics (remember it’s private so the values are episodic, not continuous, but the point is if the change in the rate of growth of the valuation metric starts declining, that is the break where things become a problem, i.e. they may not be able to finance their projected growth going forward.  

And as you can see, it is already heading lower.  This does not speak well to the future for OpenAI, and I would argue, the entire space, as many have made the case this is all Ponzi finance, meaning the funding cannot be repaid on cashflows, only on increasing valuations.  

Now consider the subprime crisis where the problems started when the rate of housing price increases rolled over and all those 2-year teaser rates could no longer be financed at higher valuations.  That’s when they all went bust!  Here’s the thing; the 2nd derivative rolled over in late 2006, the first hiccups didn’t happen until mid-2007 with SocGen closing some funds, Lehman didn’t go bust until September 2008 and the equity market didn’t bottom until March 2009.  It can take a long time for this to play out, but beware the cycle, it could well repeat in AI linked investments.

So, there’s that to consider.

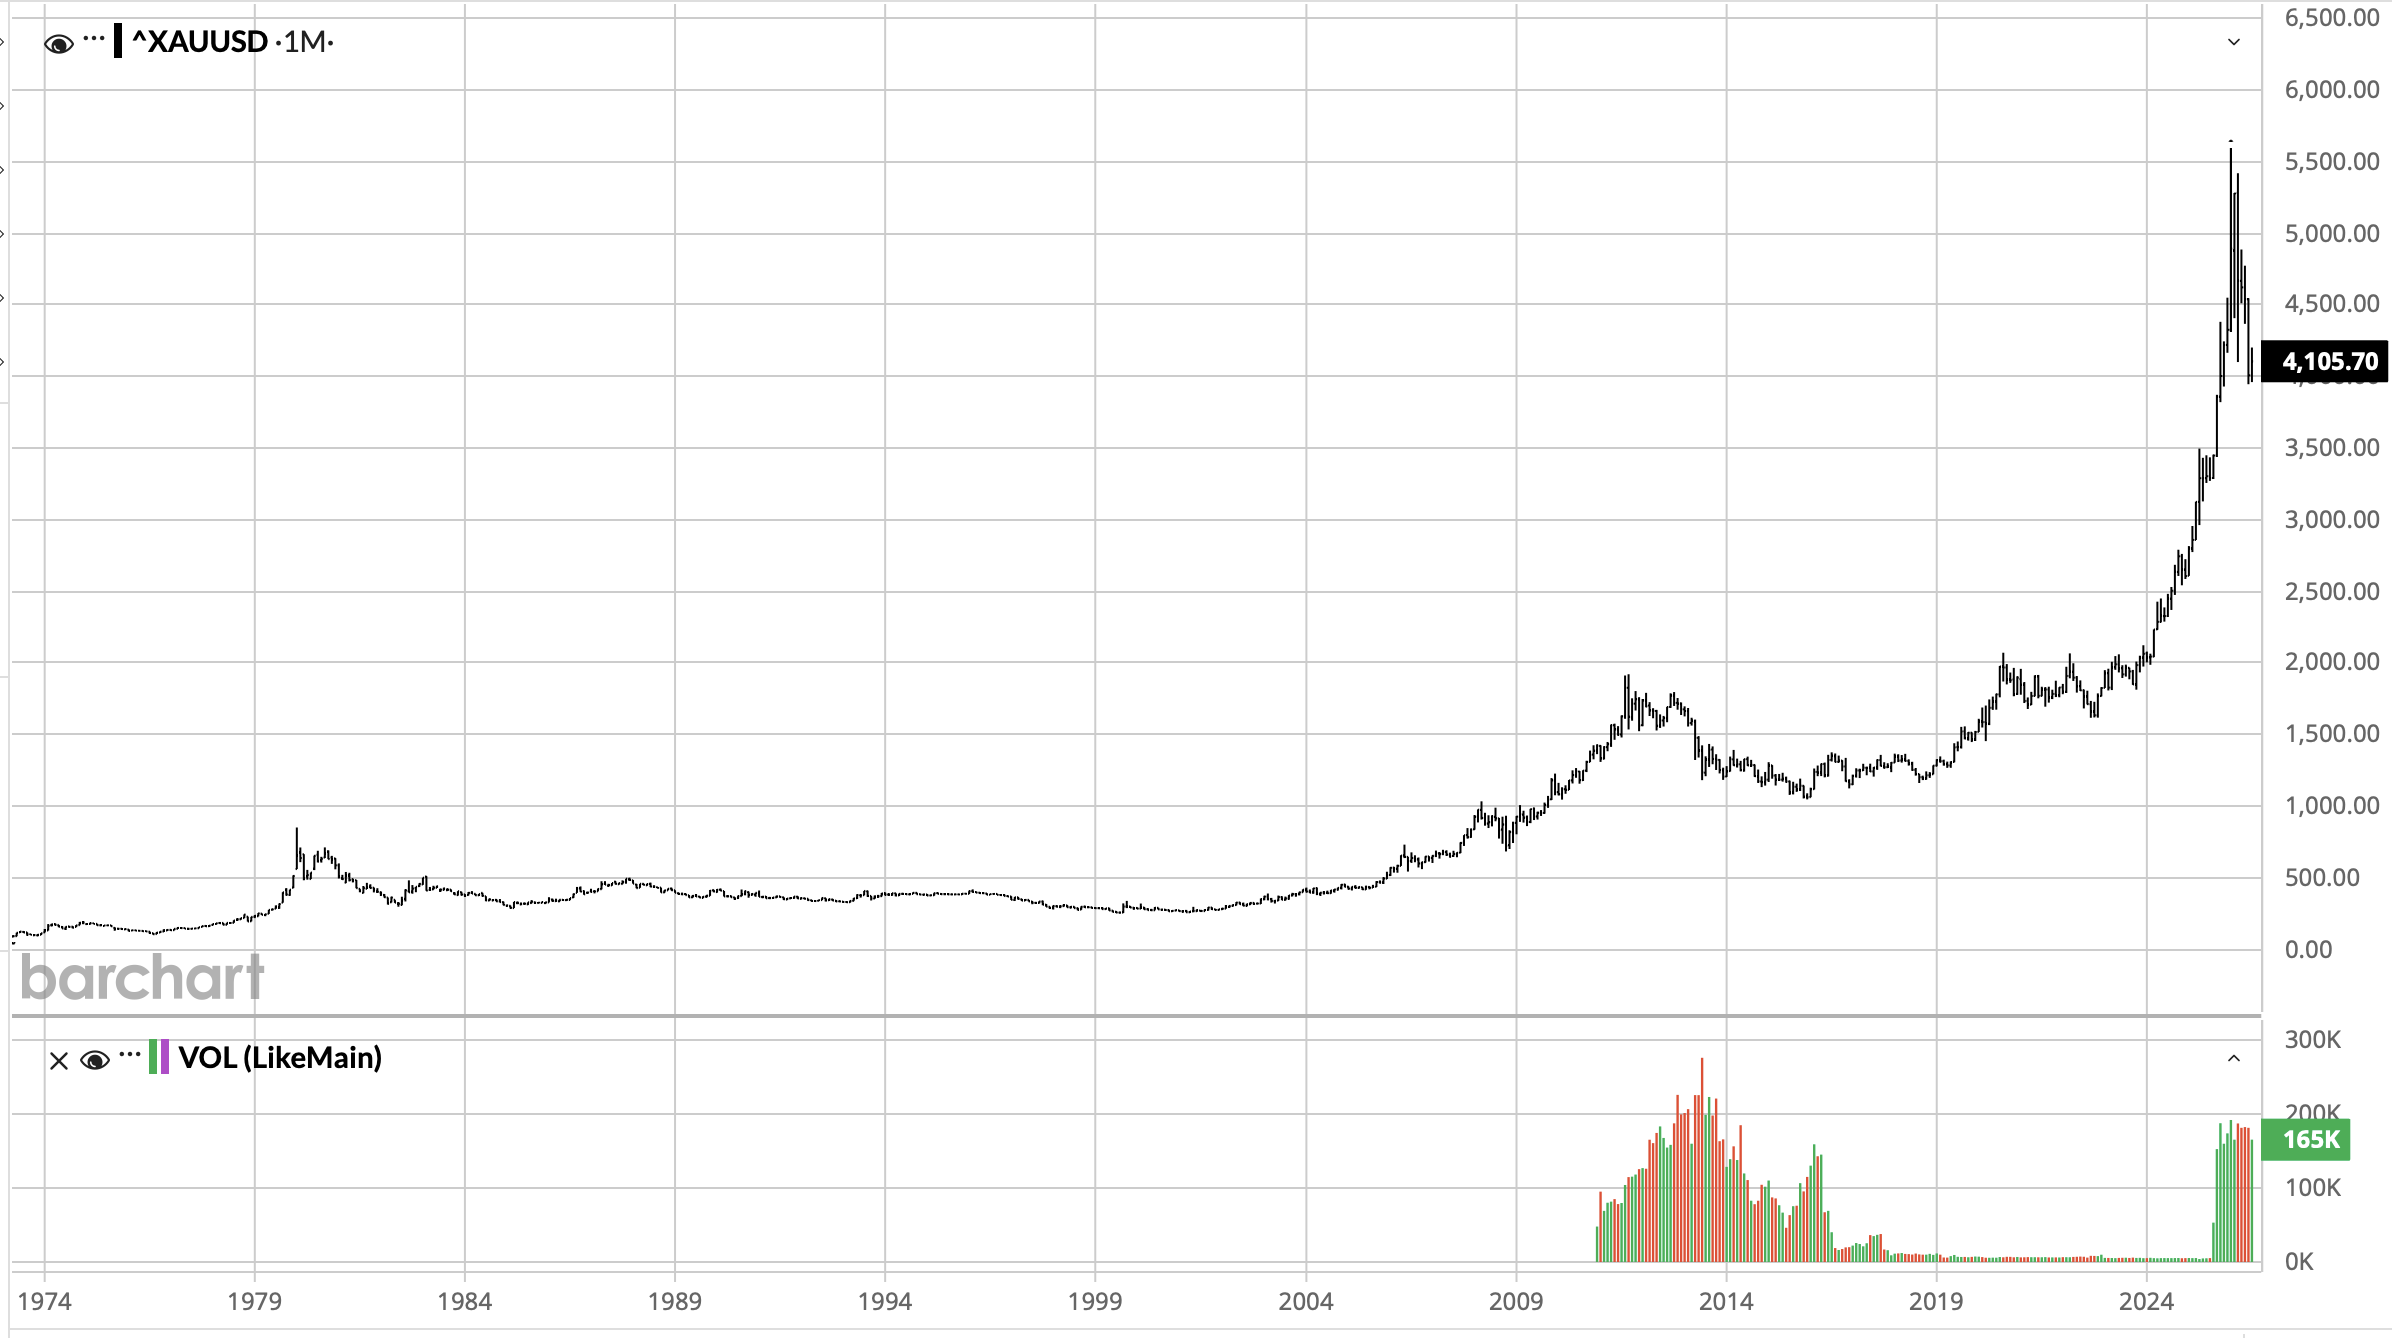
The other thing that I’ve been pondering is gold and its meaning within the financial markets.  Unlike the AI discussion above, I want to discuss two very real sides to this story.  On the one hand, the ongoing destruction of the value of fiat currencies by all major central banks’ policies is real.  Money continues to get printed and inflation continues to rise debasing those fiat currencies.  Adding to the problem is the massive government debt issuance which, if history holds, will be sopped up by those very same central banks, adding to the debasement.  The search for a neutral reserve asset to replace US treasuries is real, but the transition will take a very long time, in my view.  However, all this speaks to increased demand for the barbarous relic, and when that is priced in declining fiat currencies, a higher price.  I think it’s a very strong argument and has been made by many, including this poet.  After all, gold is often thought of as the ultimate inflation hedge.

So, what is the flipside?  As I have written frequently regarding oil prices, we cannot ignore the market pricing and what it is telling us.  Understand that I have been a gold bull for a long time and strongly believe in the long-term debasement concern.  But as a long-time trader and market participant, it is very difficult for me to look at the below, long-term chart of gold and not think that there is a much further decline on the cards.  Parabolic moves, historically, do not resolve by trading sideways for extended periods of time, they fall back… a lot!

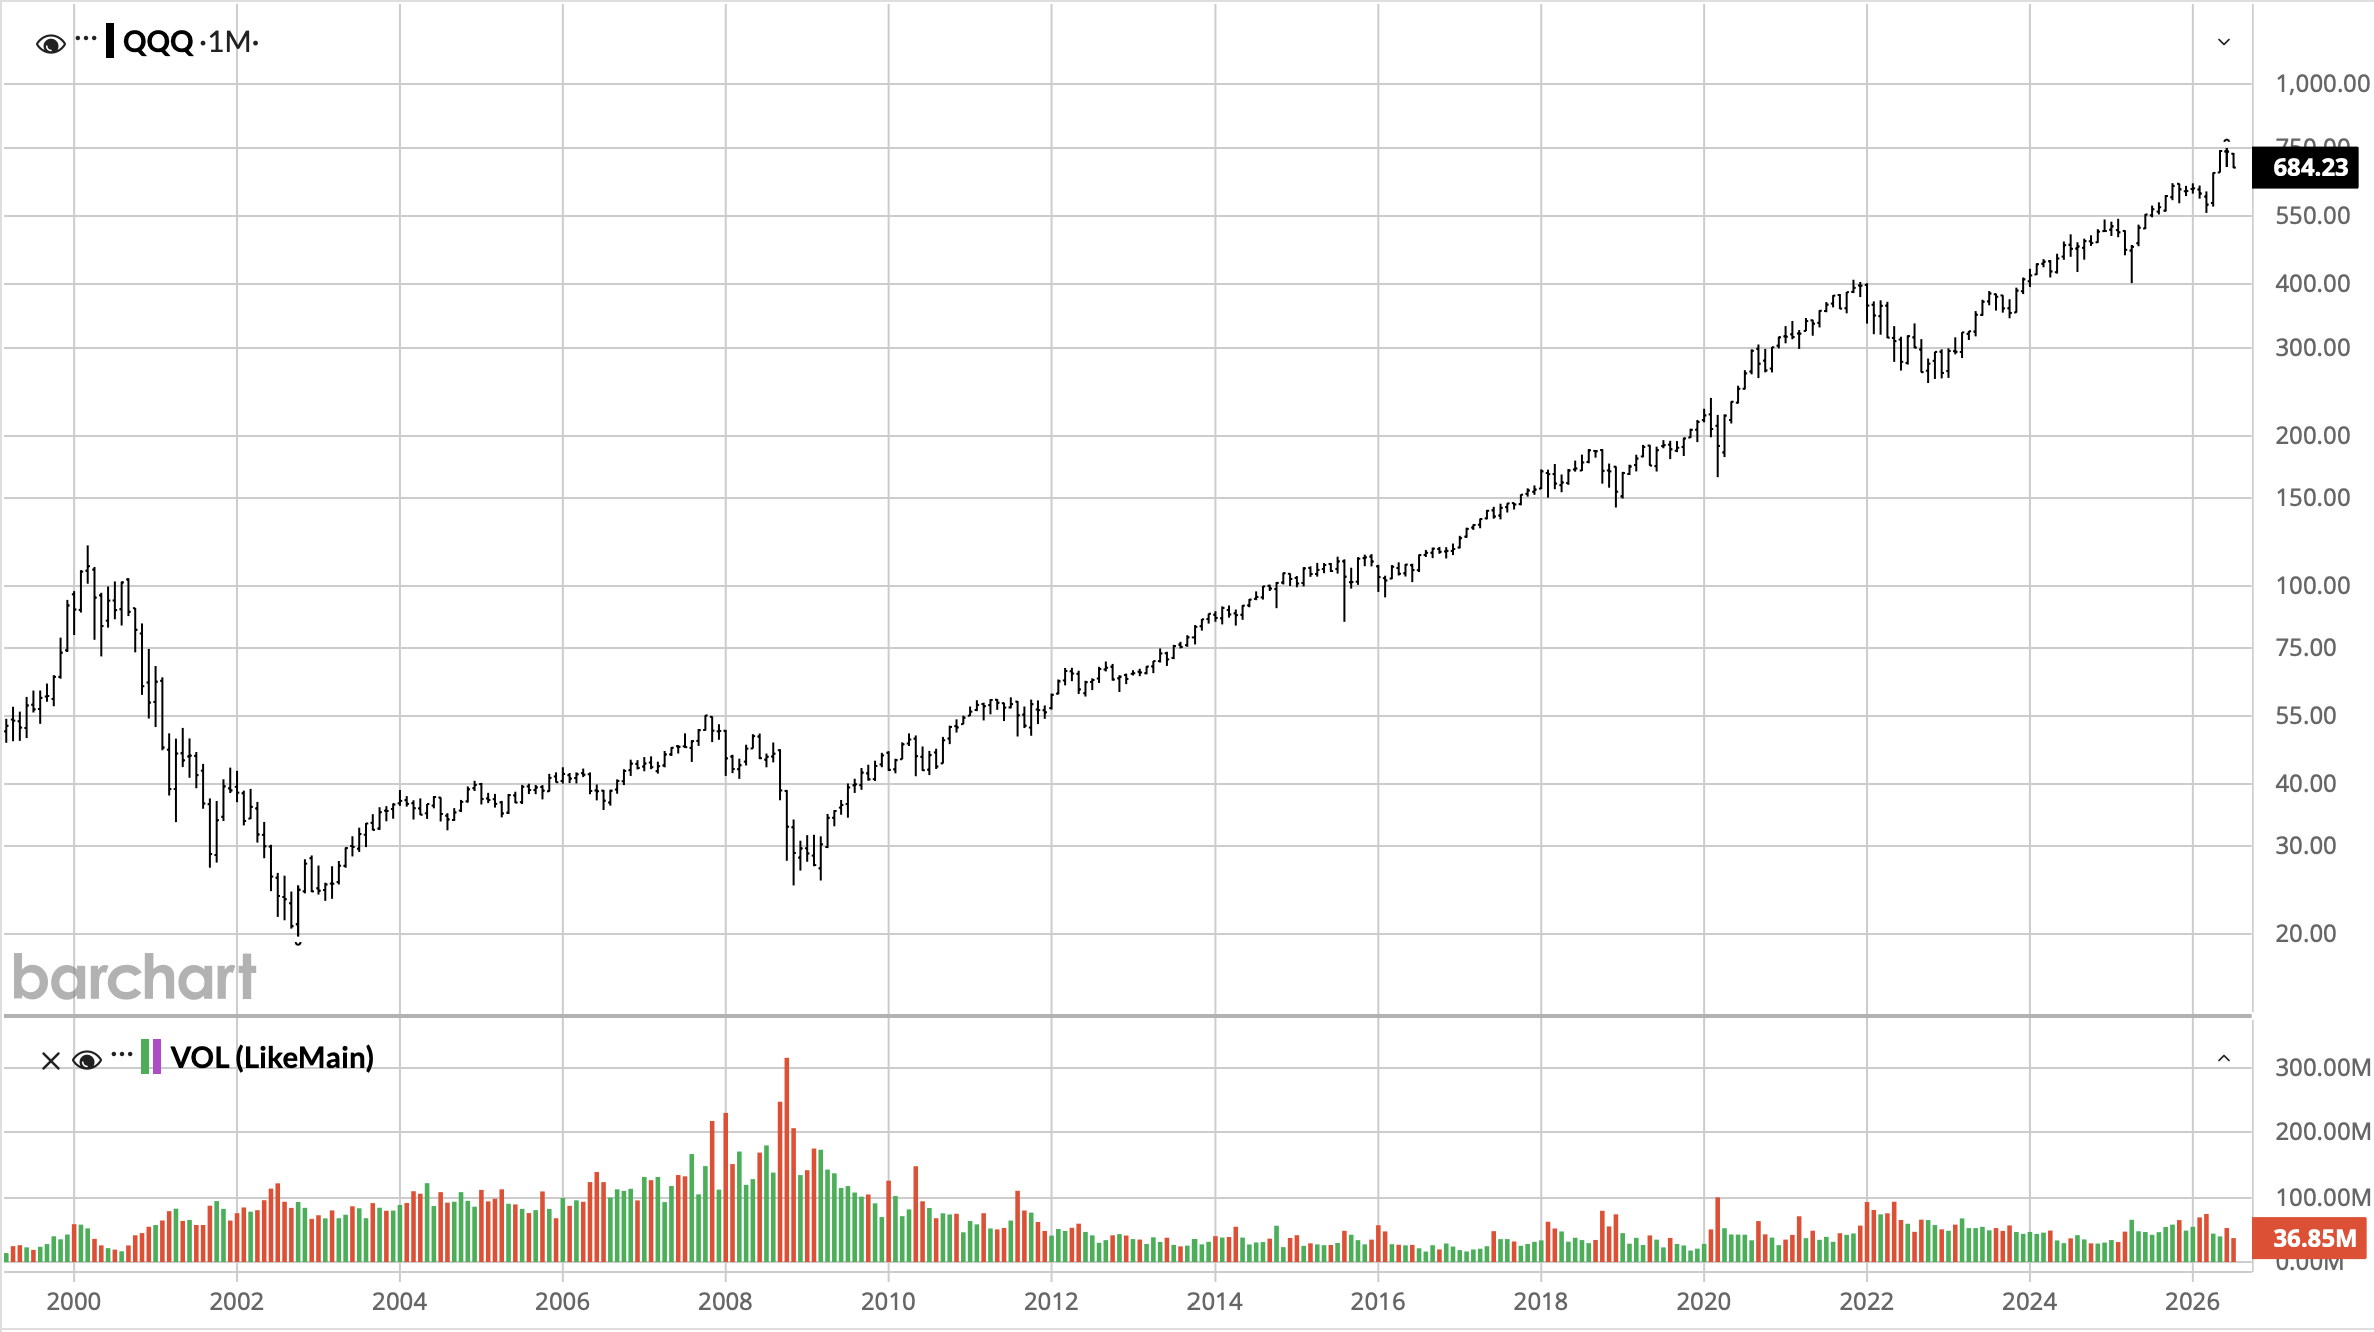
While we have recently seen several parabolic moves in market prices, notably the NASDAQ and KOSPI, I want to highlight the last time the NASDAQ had a parabolic move, during the tech bubble in 1999-2000.  The chart below is a logarithmic chart of the QQQ ETF.  As you can see back in 2000 – 2002, it fell a very long way after the bubble burst, some 88%, a much larger move than during the GFC!  

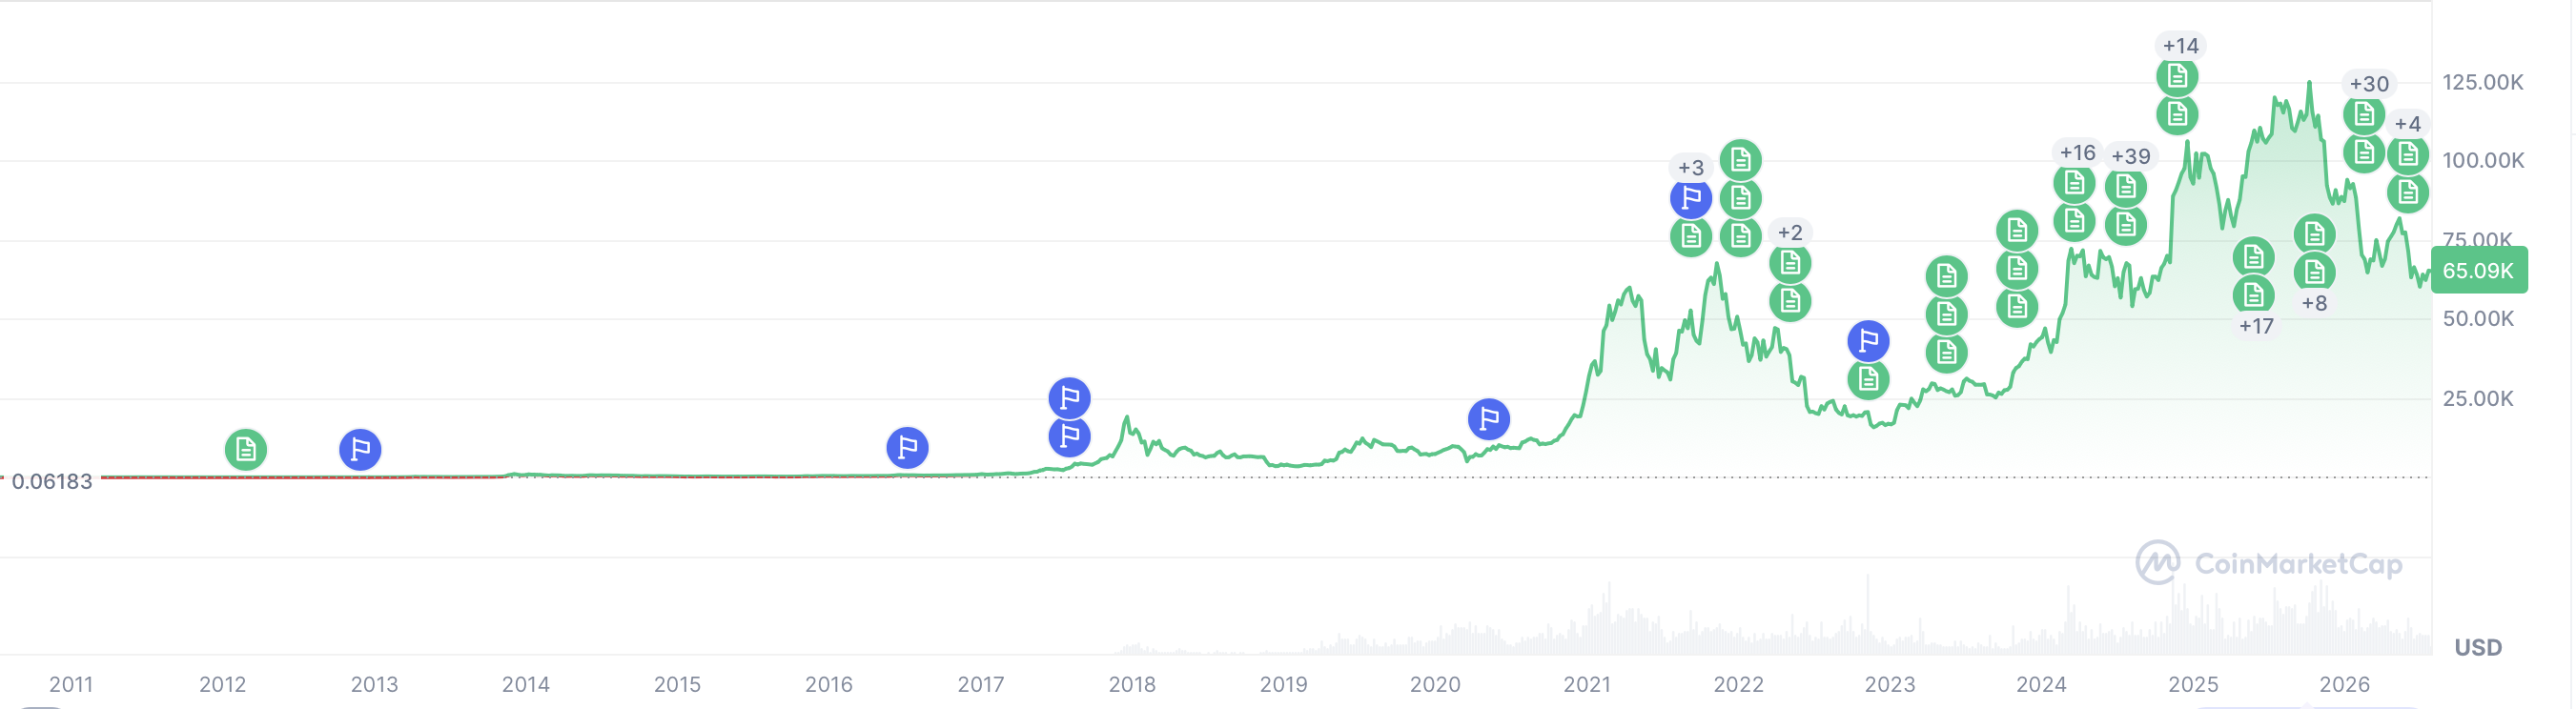
There is one other trading market, that while many may dismiss its meaning, I would contend is very representative of the way markets behave across all asset classes, Bitcoin.  The below chart shows it from its beginning, and you can see a number of essentially parabolic moves higher, each resolving with a decline of at least 50% and at times more than 70%.

Source: coinmarketcap.com

My point is that gold shows all the signs of having peaked for a while, and it has ‘only’ fallen some 25% from its highs.  From a trading history perspective, there is nothing that would seem to prevent a move down to $2800/oz or so, a 50% retracement from the high.  

So, which is it?  As I remain long gold in the personal portfolio, I have been a beneficiary of the long climb higher and would love to see it continue.  And there is much to be said for the debasement theory.  But both sides of this argument can be correct with the time frame the key differentiator. We could see a further short-term decline before a renewed upward move of significant magnitude.  Much will depend on how global macroeconomics and economic statecraft plays out over the coming months/years.  And this is why trading is hard!  One last thing describing just how much things have changed regarding gold and sentiment around it, this headline in Bloomberg this morning is remarkable, Gold Climbs as Pause in Mideast Fighting Curbs Inflation Risk.  

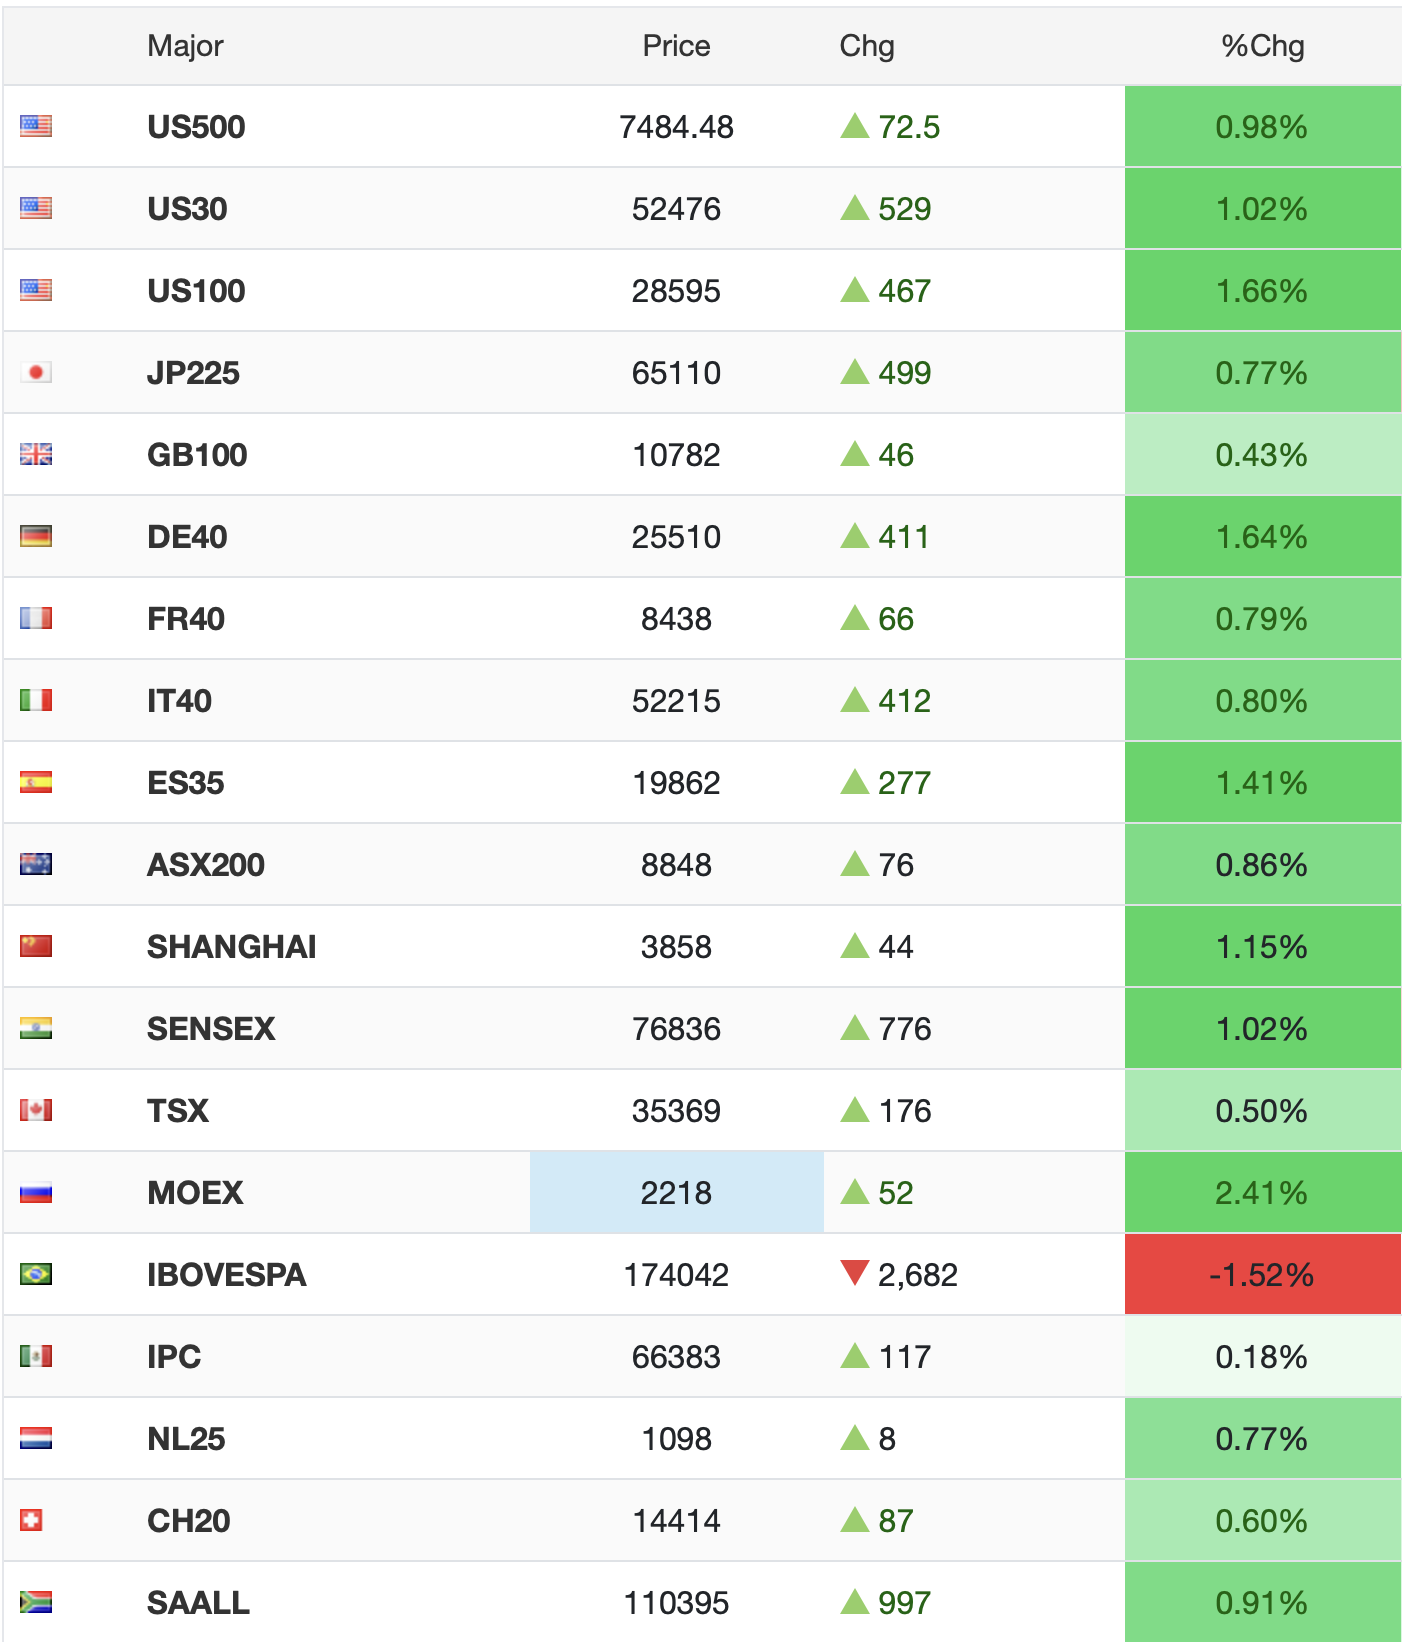
Ok, sorry for my rants, but a brief tour of markets show things are exactly as you would expect based on the reduction of tensions in Iran. Equity markets are higher around the world as per the below tradingeconomics.com screen shot, and don’t be fooled by Brazil, it hasn’t opened yet and there are no futures, so that was Friday’s performance.

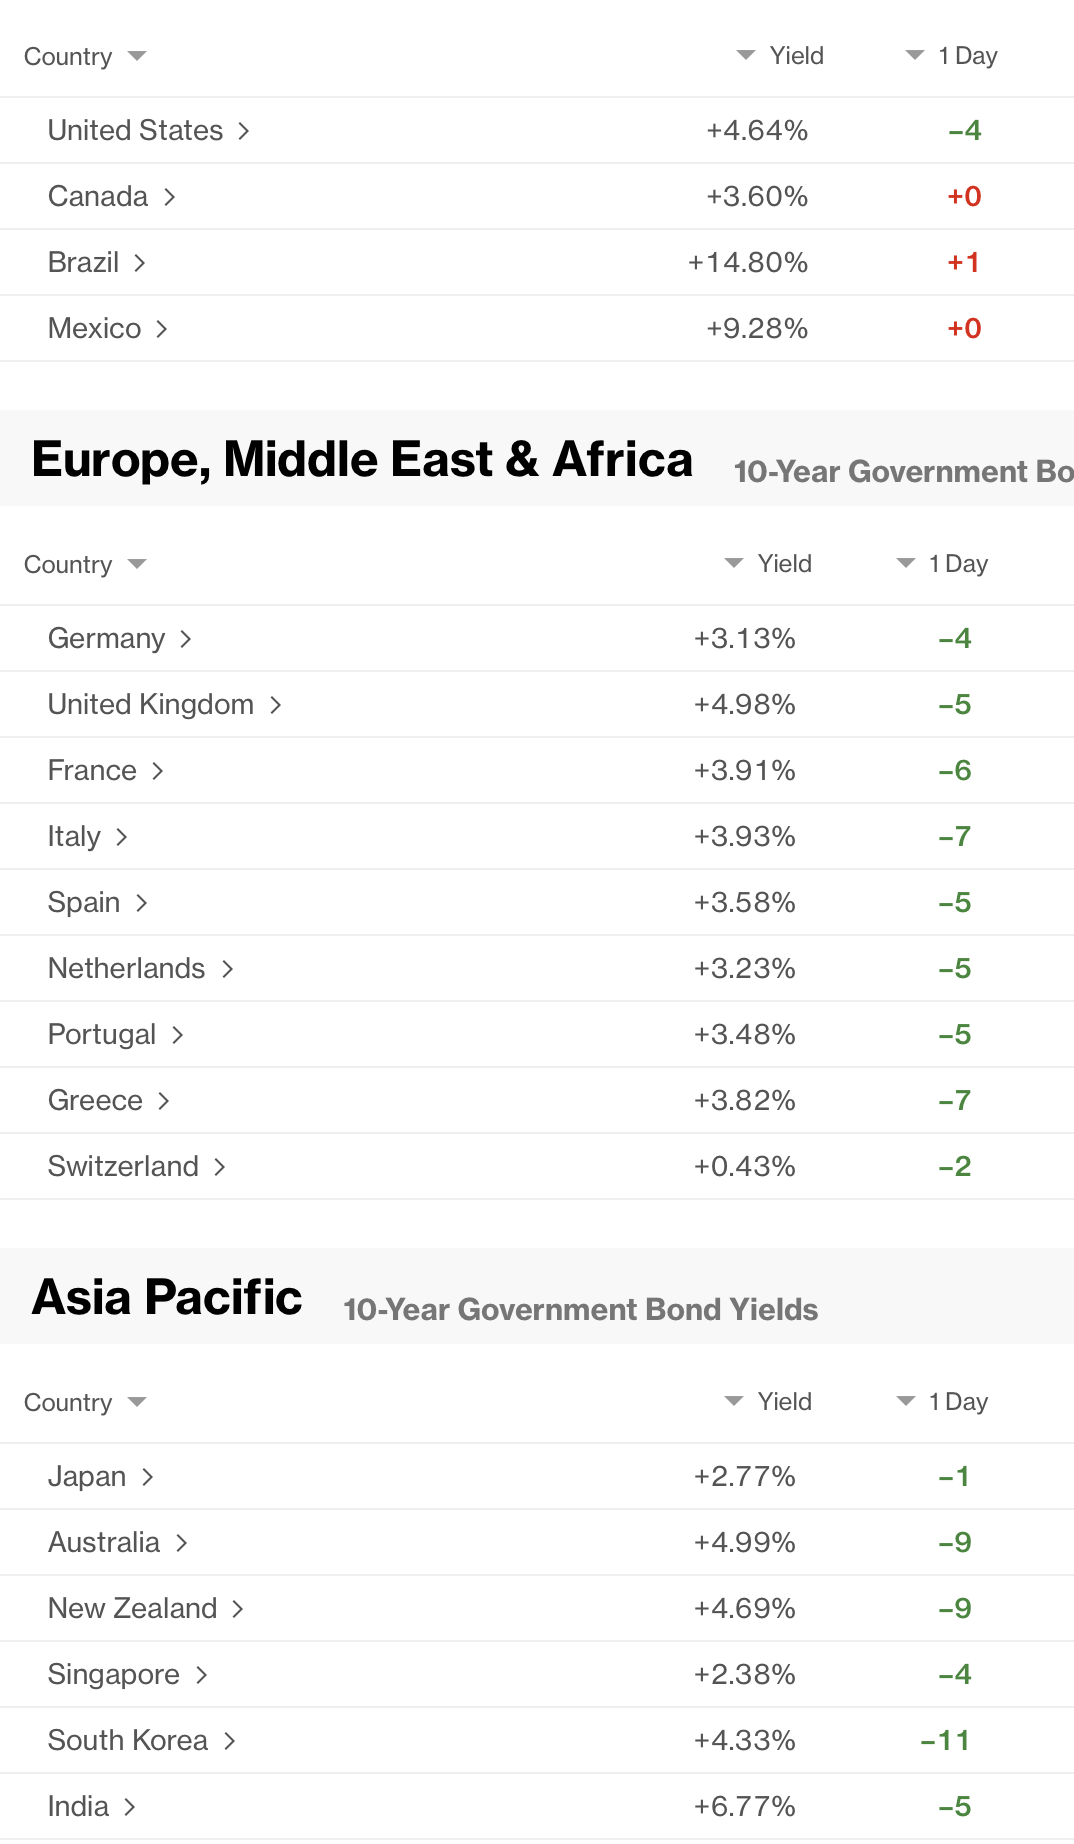
As to bond yields, they too, are lower across the board as per the below Bloomberg.com screenshot.  Canada, Mexico and Brazil markets are not yet opened, hence the lack of movement.

Oil has fallen further than when I started writing last evening with WTI (-8.2%) and Brent (-9.7%) both sharply lower.  Regarding Brent, apparently there has been a resumption of flows through Kazakhstan which is helping even more there.  Metals are higher (Au +1.1%, Ag +2.2%, Cu +0.9%), which is keeping with the latest theme.  And finally, the dollar is broadly softer, as also would be expected given the movement in other markets.  The two key exceptions here are NOK (-0.7%) which is clearly a reaction to the movement in oil prices and KRW (-0.8%) which actually started the session much stronger but has reversed.  While I read a rationale about concerns over a Fed rate hike, given the movement in oil and yields, that doesn’t seem right.  Rather, after a more than 6% appreciation over the course of the past 3 weeks, it seems more like a reflexive bounce in the dollar.

Source: tradingeconmomics.com

On the data front today, this morning brings Durable Goods (exp 2.5%, 0.8% ex-Transport) but that is all.  I will go deeper tomorrow, and remember, the FOMC meets this week with the current pricing 33% for a hike, even after the decline in oil prices today.  I remain in the no move camp but will discuss tomorrow.

And that’s more than enough.

Good luck

Adf
Commit Seppuku

Alas, nothing’s changed in Iran
And feces is hitting the fan
So, pundits feel strongly,
Although I think wrongly
A rate hike is part of the plan

In fairness, the bond market, too
Is on board, that ere July’s through
The Fed will have raised
Won’t they be amazed
If Warsh won’t commit seppuku?

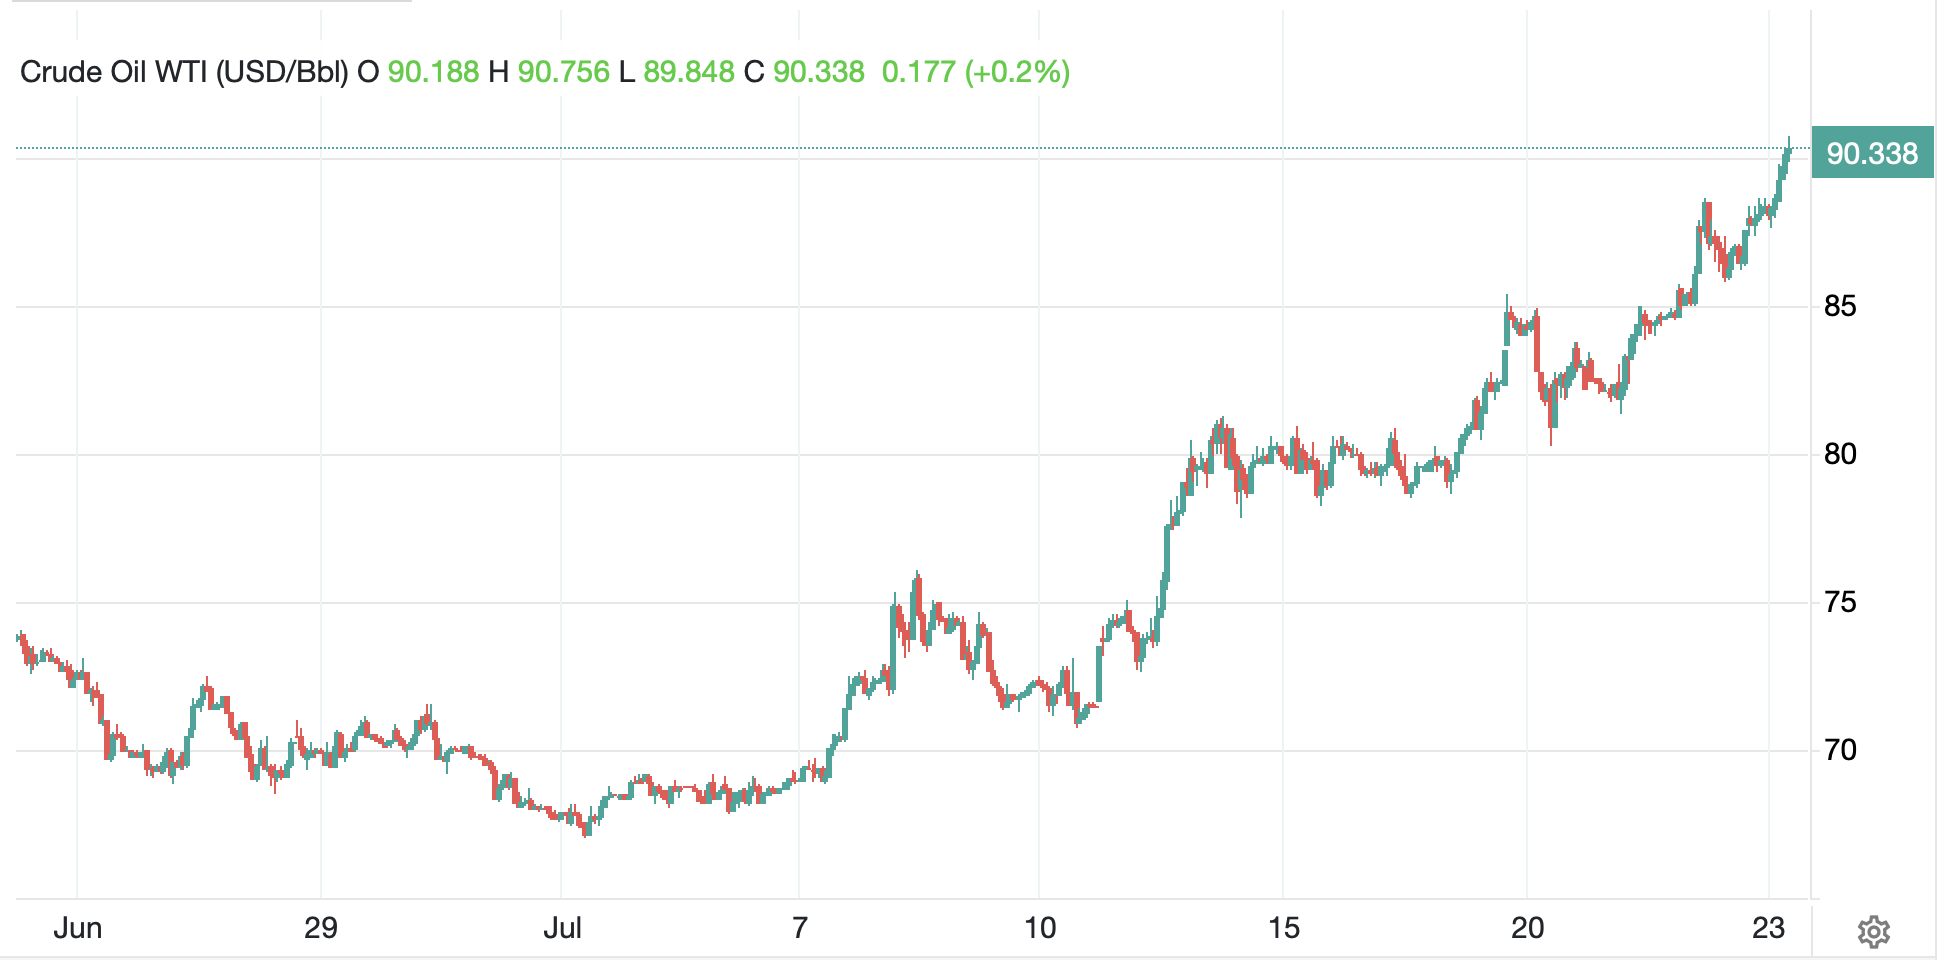
Yesterday’s dominant theme was the fact that oil prices had risen so aggressively with WTI above $90/bbl and Brent touching $100/bbl.  Interestingly, both are lower this morning, WTI (-2.5%) and Brent (-2.7%) and both are back below those big psychological levels despite no seeming changes on the ground in Iran.  The Houthis are still causing trouble in the Bab al Mandeb, the US is still attacking sites along the Persian Gulf and there are no peace discussions ongoing.  A headline in the WSJ this morning explained, Trump Is Losing Patience Over an Iran War With No Clear End in Sight.

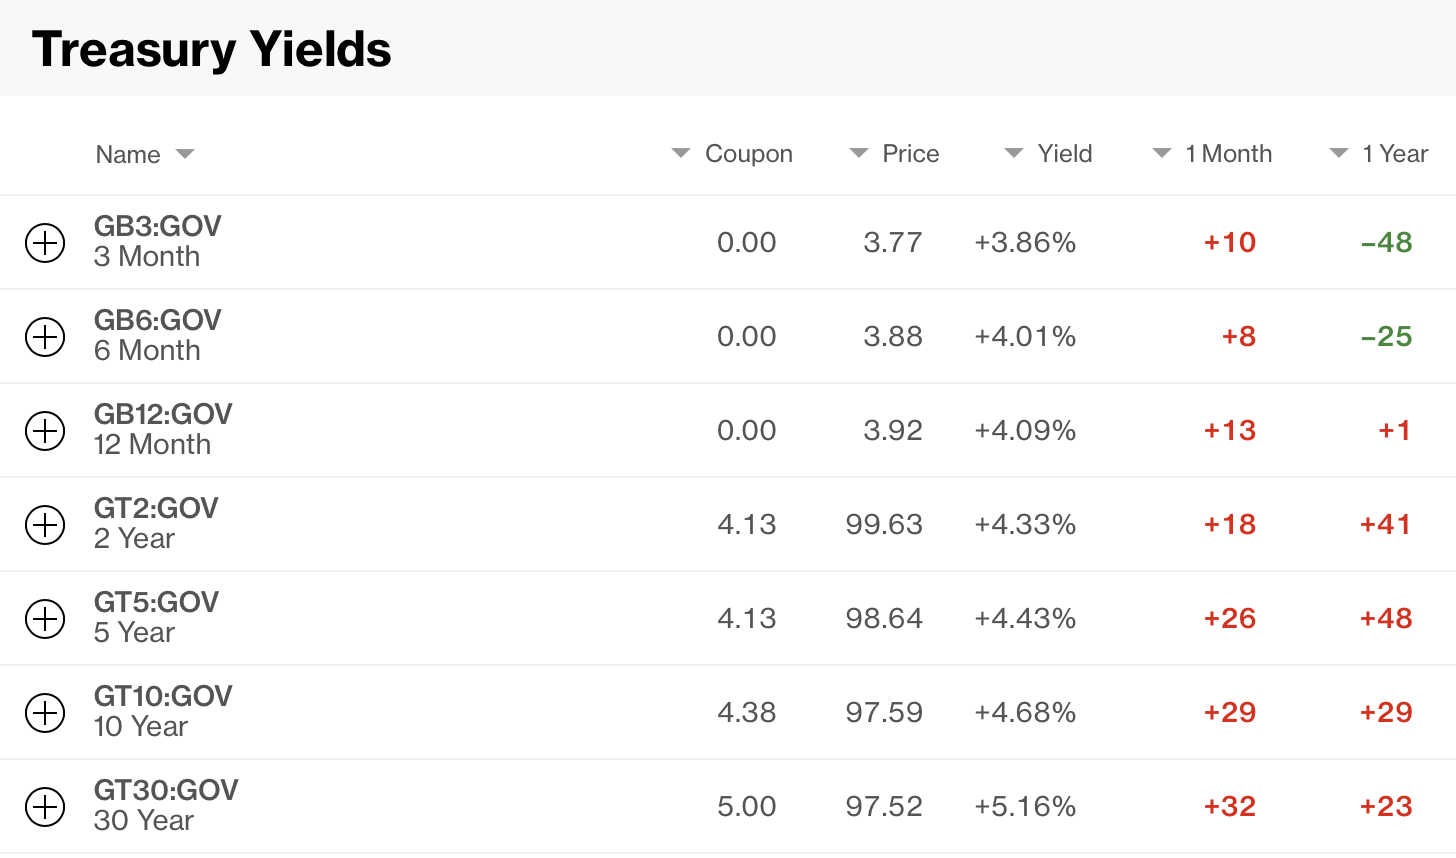
But really, the bigger discussion has been about US yields (and correspondingly global yields) as they continue to head higher.  Below is a screenshot from Bloomberg showing the yield curve and how yields have changed in the past month and year.

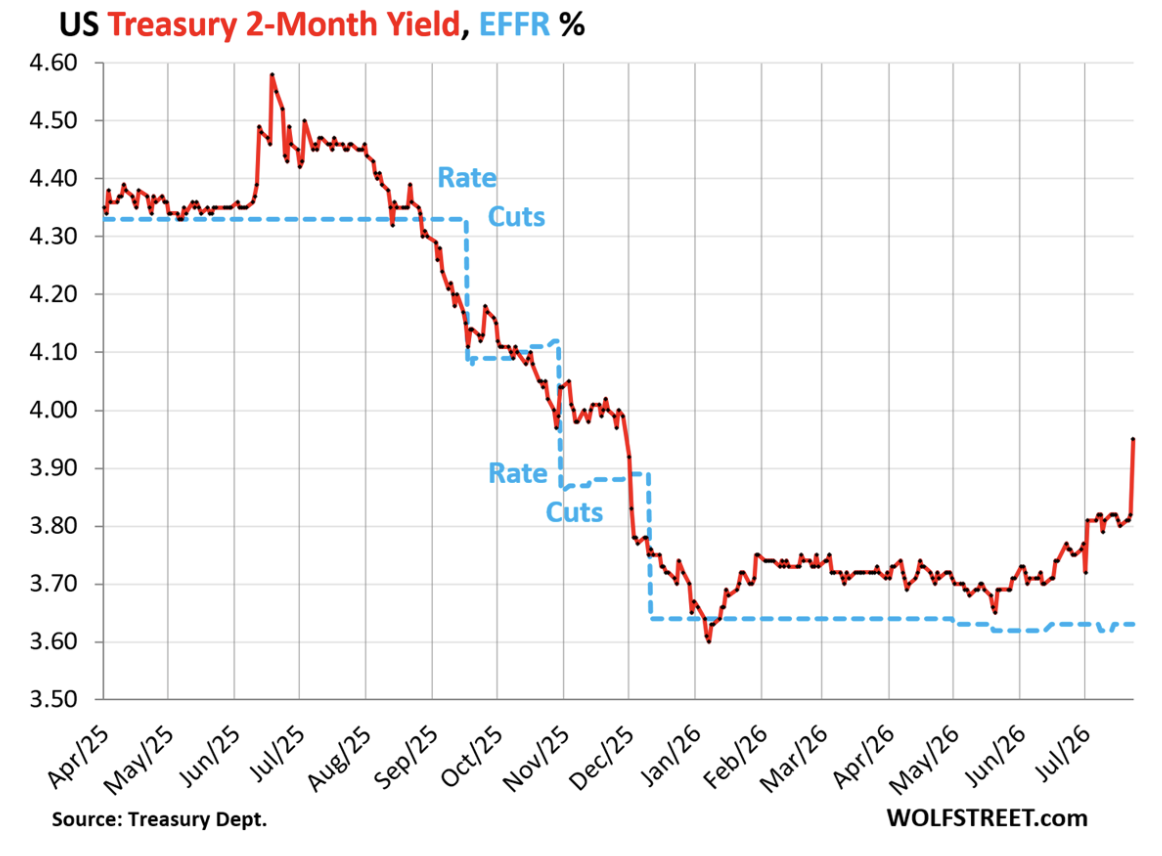
There has been quite a bit of digital ink spilled over the concept that short-dated T-bills have now priced in a rate hike next week, as per Wolfstreet.com,

The 2-month Treasury yield spiked by 13 basis points today and by 15 basis points during the week to close at 3.95%, according to Treasury Department’s yield calculation. This is at the upper end of the Fed’s target range after it hikes by 25 basis points, which would bring its target range to 3.75%-4.0%. And it is 32 basis points above the Effective Federal Funds Rate (EFFR, blue), which the Fed targets with its policy rates. This is a stunning move, pricing in a “surprise” rate hike at the FOMC meeting next week.

And here is his accompanying chart.

Of course, what makes all this so juicy is that Chairman Warsh has gone out of his way to end forward guidance so market participants are now left to their own devices to determine what the Fed may do, something most of them have either forgotten, or never knew, how to do.  

Let’s consider, for a moment, some potential outcomes and the rationales behind them.  First, it is critical to remember that Warsh needs a majority of the voters, so at least 7, to get to a result.

  • No change (poet’s estimated probability 90%) – the most recent inflation data, both CPI and PPI were much cooler than expected thus offering significant cover to leave policy on hold.  Add to that the fact that the task forces will not have completed their work and report on anything.  This means Warsh can reasonably say, before we do anything, let’s make sure we are looking at things that are fit for purpose.  One last thing to recall is that if energy prices are the driver, raising interest rates will not produce more energy, so it is the wrong action to solve the problem.
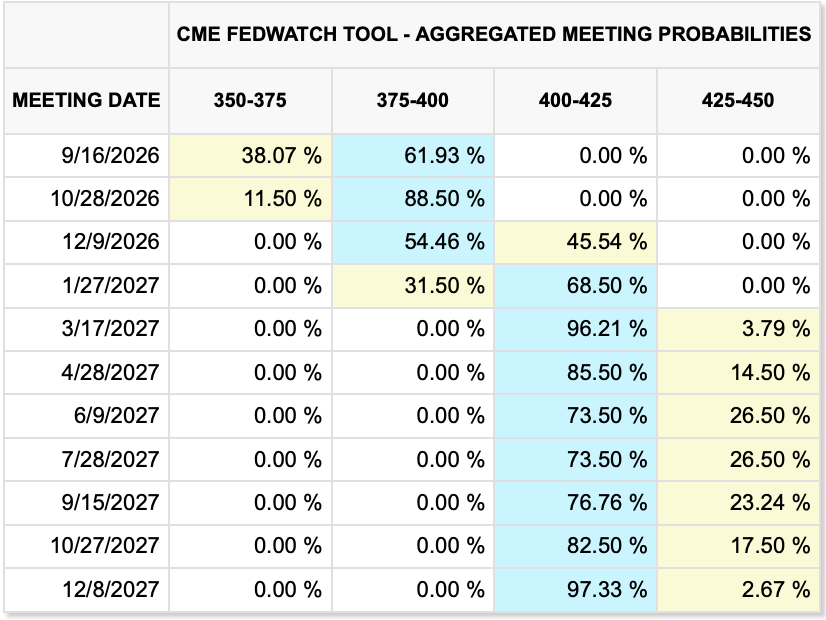
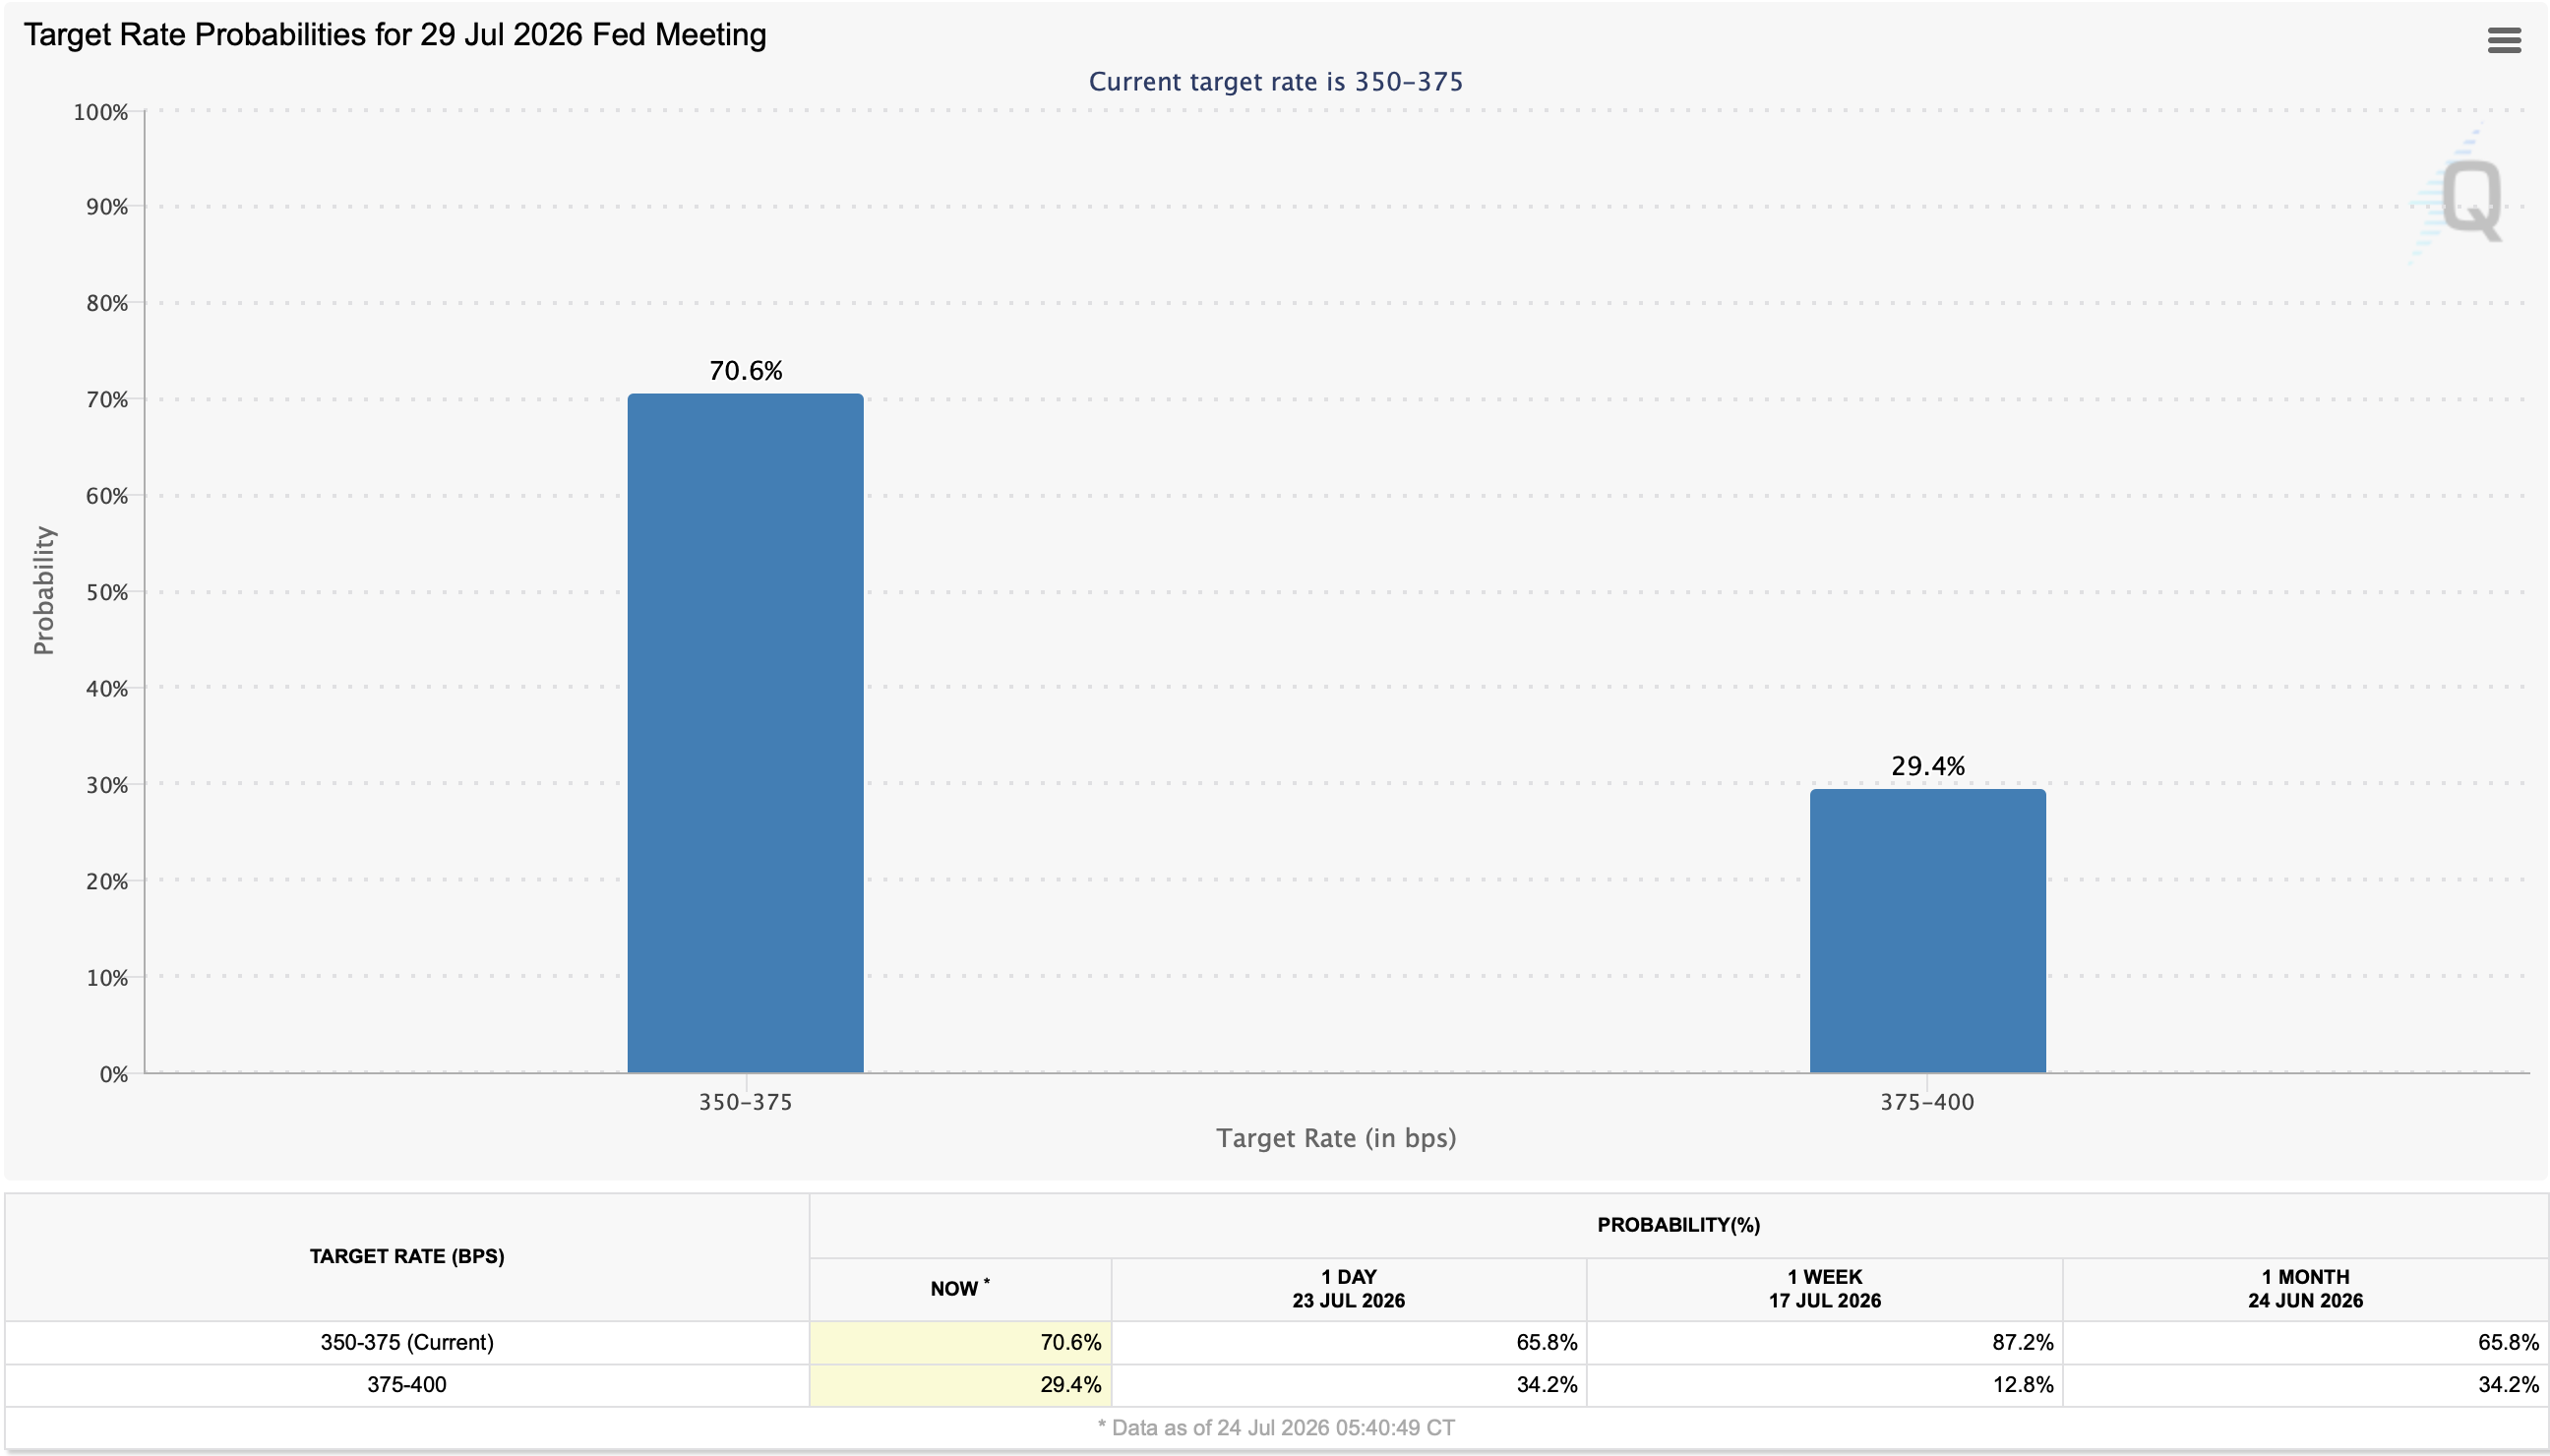
  • 25bp hike (10% probability) – while there have been several FOMC members who discussed the needs for hiking rates as inflation was becoming uncomfortably high, I don’t believe that contingent is large enough to make up a majority, especially of voters.  In addition, the history of central bank rate hikes into energy price spikes is replete with disasters across the board.  After all, the same pundits who are calling for a hike explain that rising energy prices are like a tax and weaken economic activity.  Certainly, the Treasury market price action indicates there are many who believe a hike is coming and if we look at Fed funds futures markets, the probability is higher than mine at about 30% as per the below chart from cmegroup.com, but look at how much that has changed over the past month.  My point is that there is no consistency of view.
  • 50bp hike (NO CHANCE) – there is a group in the analyst community who are calling for a shock maneuver of a 50bp hike.  The rationale seems to be that this would burnish Warsh’s hawkish credentials, and the bond market would rally on the news.  But even if he wanted to do this, and I don’t think that is the case at all, it would require him to get six others to go along.  There is no way that type of viewpoint exists on the committee, I am convinced.  This is clickbait in my view, analysts making outlandish calls so people will read their stuff.

In the meantime, though, yields do continue to rise around the world.  While this morning, they have backed off from yesterday’s recent highs (UST -1bp, bunds -2bps, gilts -4bps, OATs -3bps, BTPs -3bps), they remain just below levels not seen in several years.  One interesting thing about the European sovereign market is the fact that yields in Greece (3.90%) are lower than in either France (3.99%) or Italy (4.01%).  It wasn’t that long ago that Greece was the poster child for fiscal profligacy and lived through a depression.  But give them credit, they learned and now run a primary surplus in their fiscal account, something not seen in many other nations these days, certainly not the US, France or Germany.

But rising rates are wreaking havoc with equity markets, and that has become another fiscal problem since tax receipts from capital gains is such a significant part of the tax base these days, at least in the US.  So, yesterday’s desultory performance in the US, led lower by the NASDAQ’s -2.15% decline, was followed with a similarly negative feeling in Asia (Tokyo -2.7%, China -1.7%, HK -1.0%, Korea -5.7%, Taiwan -2.7%) with the similarity that they are all tech focused.  But weakness in the region was virtually universal, albeit not as dramatic.

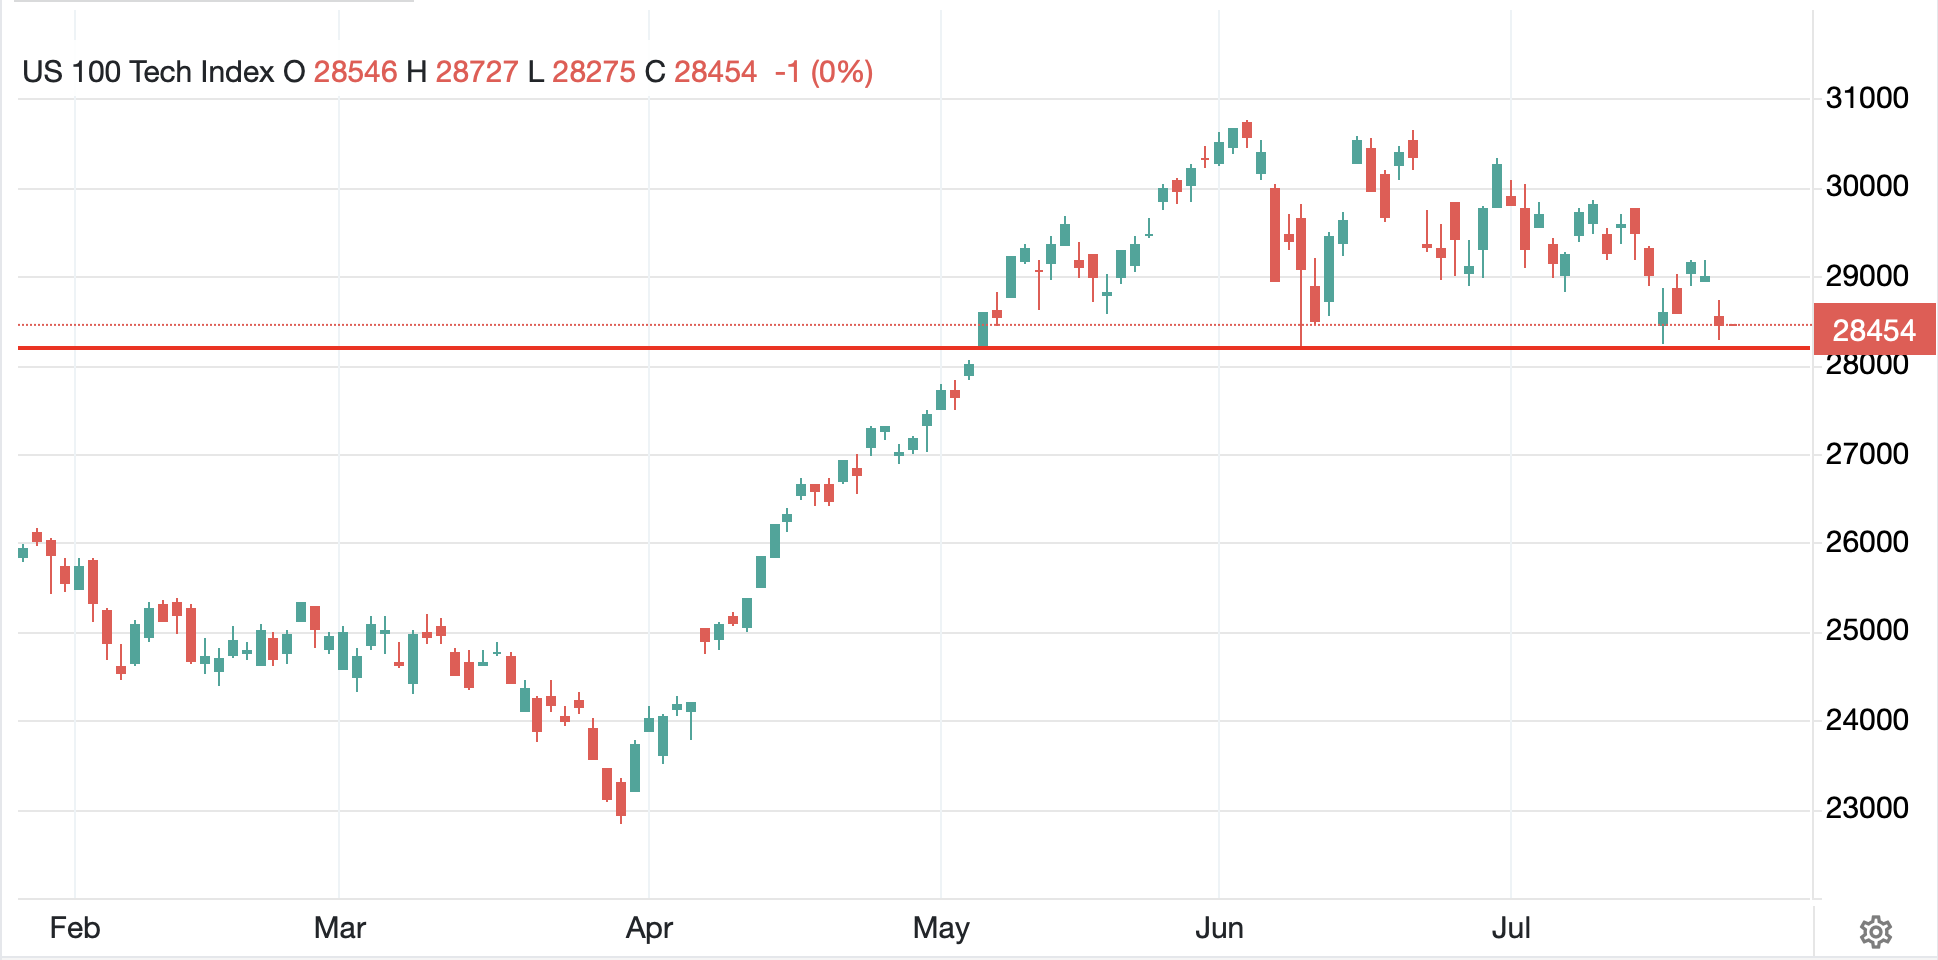
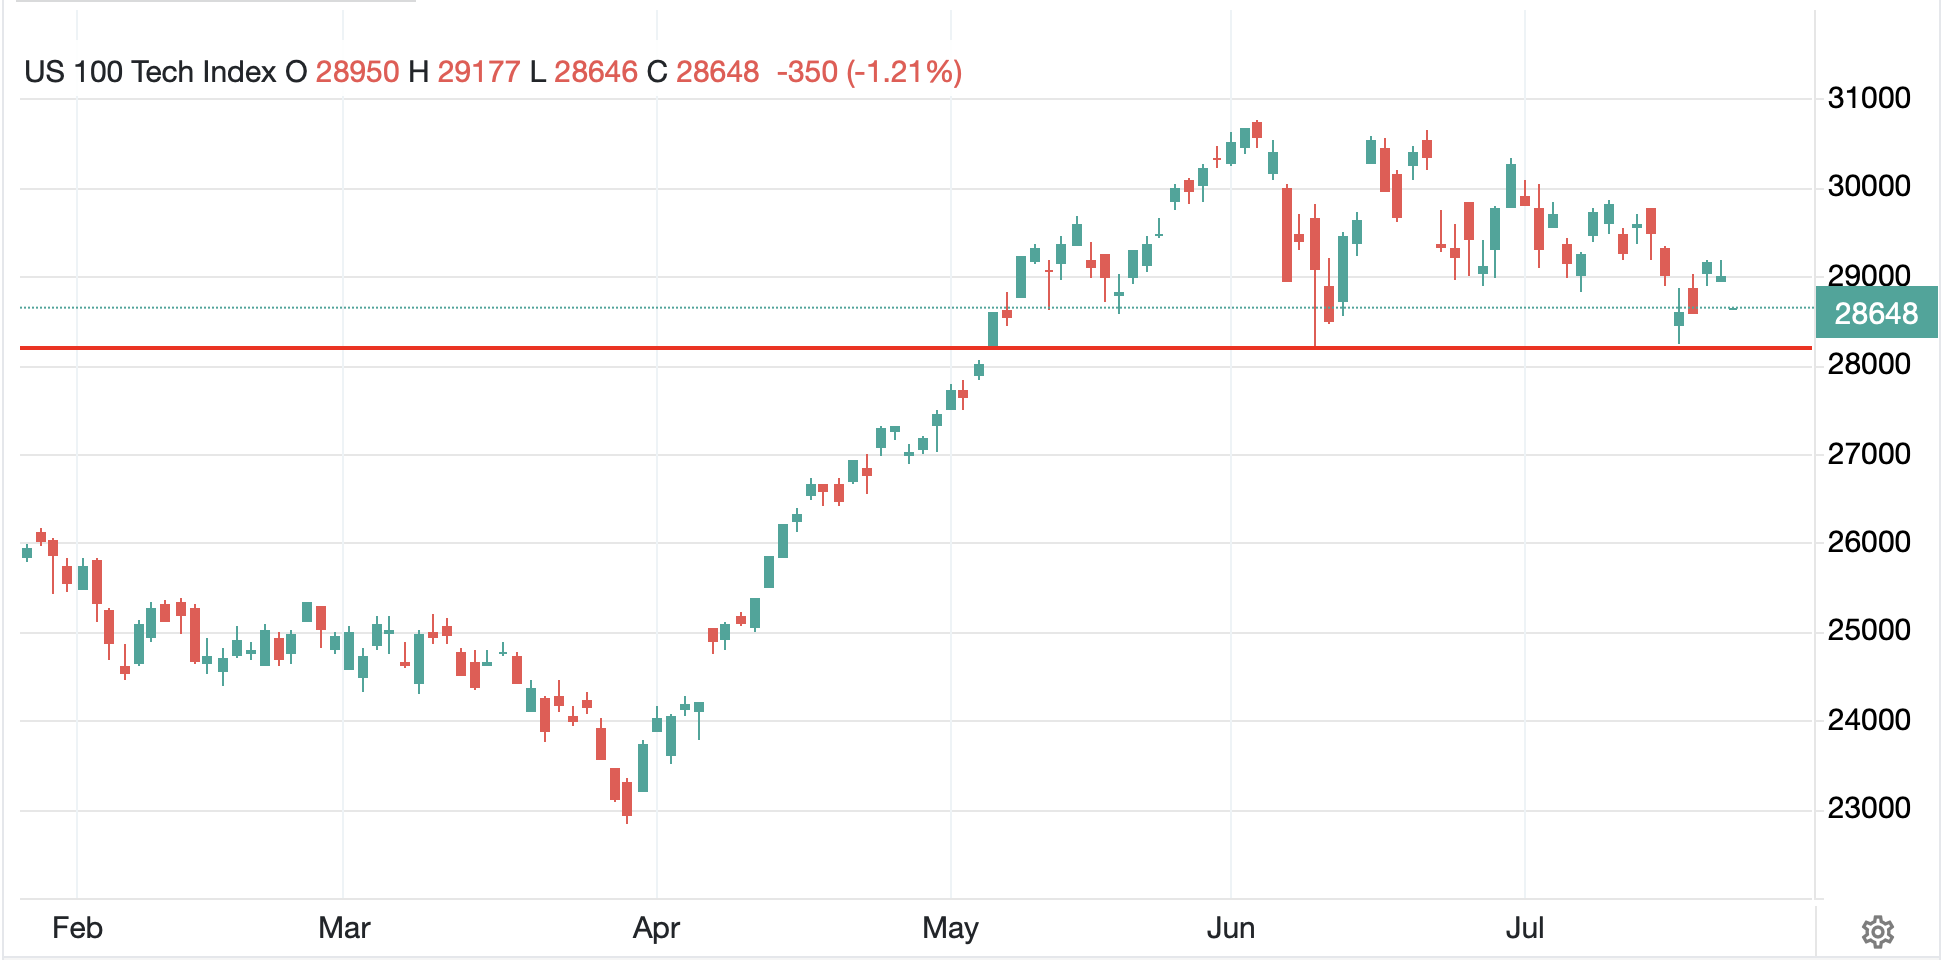
In Europe, though, things are looking better after very solid Flash PMI data across the board.  So, Germany (+0.7%) is leading the way higher along with Spain (+0.8%) although France (+0.3%) and the UK (+0.1%) are also in the green, with the latter despite the fact that new PM Burnham is already discussing raising property taxes.  As to US futures, at this hour (7:30) they are marginally higher.  Despite yesterday’s angst, the NASDAQ has not been able to breach the key support level I am watching, as per the below chart.  (If it does, I will be looking to buy QQQ puts, but we shall see if that happens.)

Source: tradingeconomics.com

Briefly regarding metals markets, with oil under pressure today, we cannot be surprised that the metals markets are climbing with gold (+0.2%), silver (+1.2%) and copper (+0.1%) all in the green.  Earlier this week it appeared that relationship may have broken, but it has reasserted itself for now.

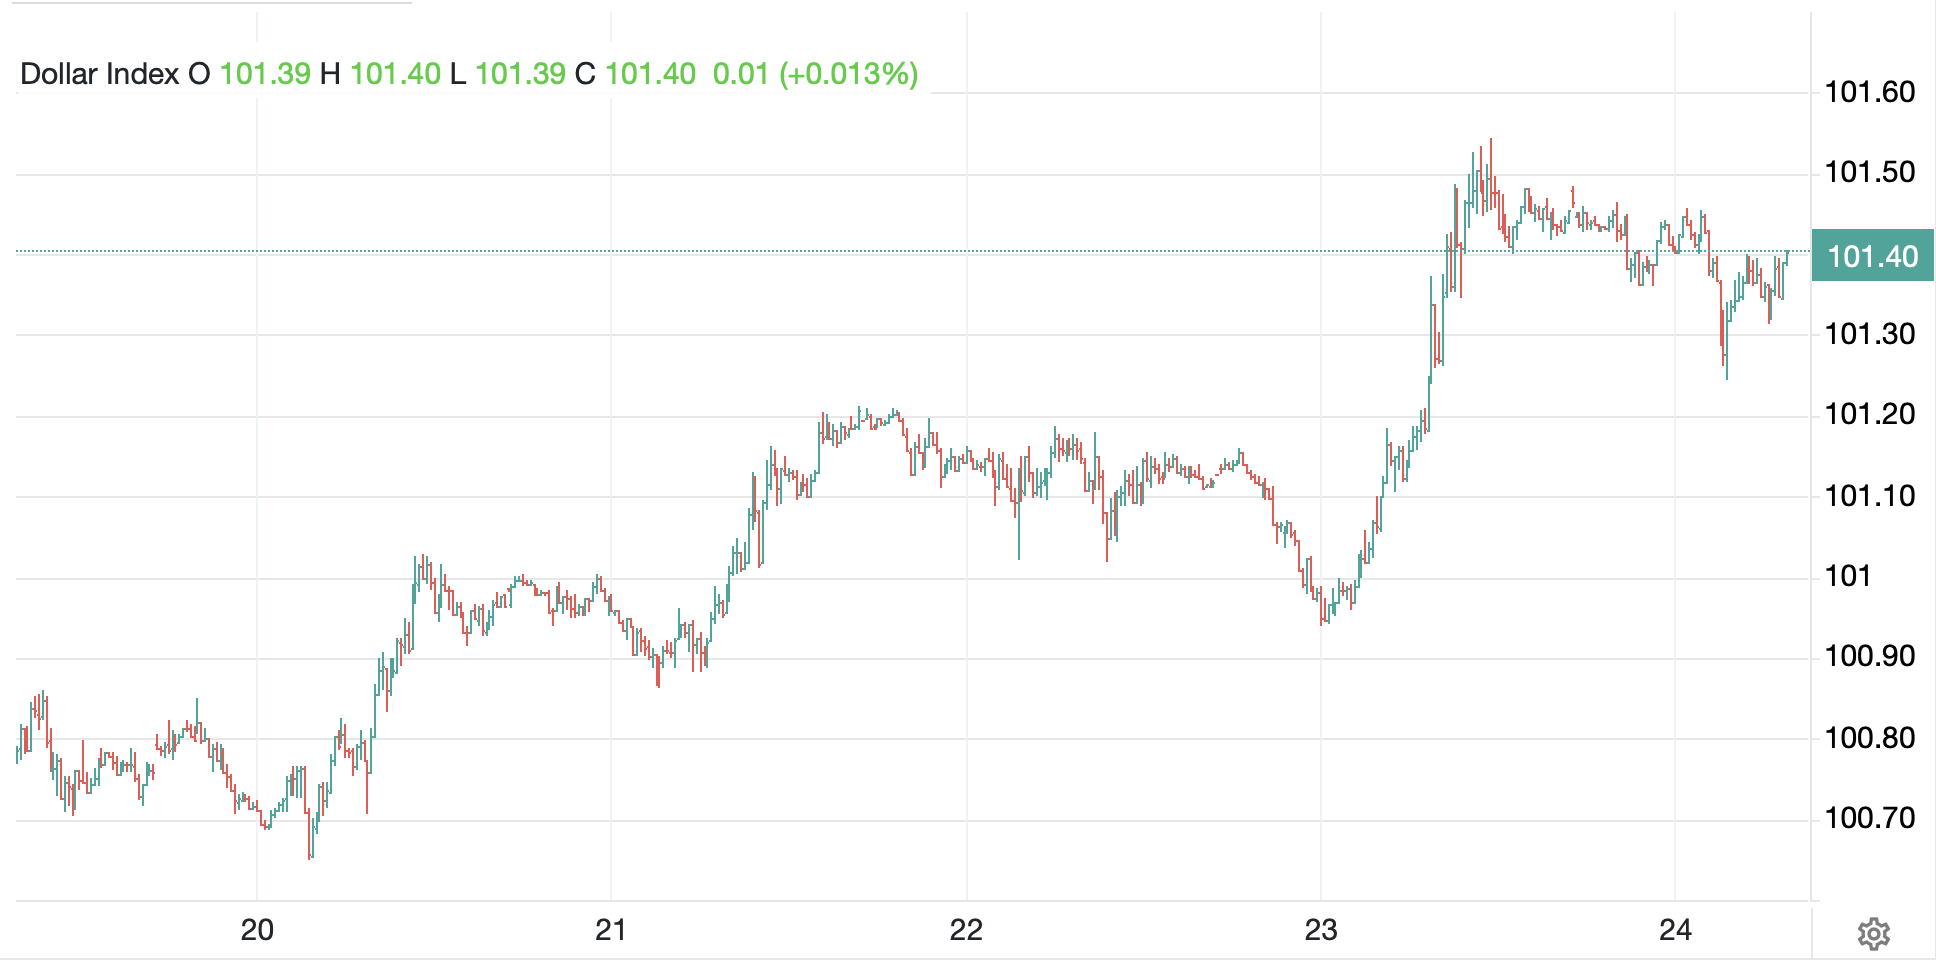
Finally, the dollar is little changed this morning, perhaps slightly softer.  But it has rallied over the past week alongside yields as per the below chart of the DXY.

Source: tradingeconomics.com

The major outlier today is KRW (+0.9%) although that is simply an ongoing extension of the central bank’s efforts to add liquidity and internationalize the currency.  Thus far, it has been pretty successful, at least their discussions of the process.  Since things don’t really change until January 2027, I guess we will need to wait until later to find out if it holds up.

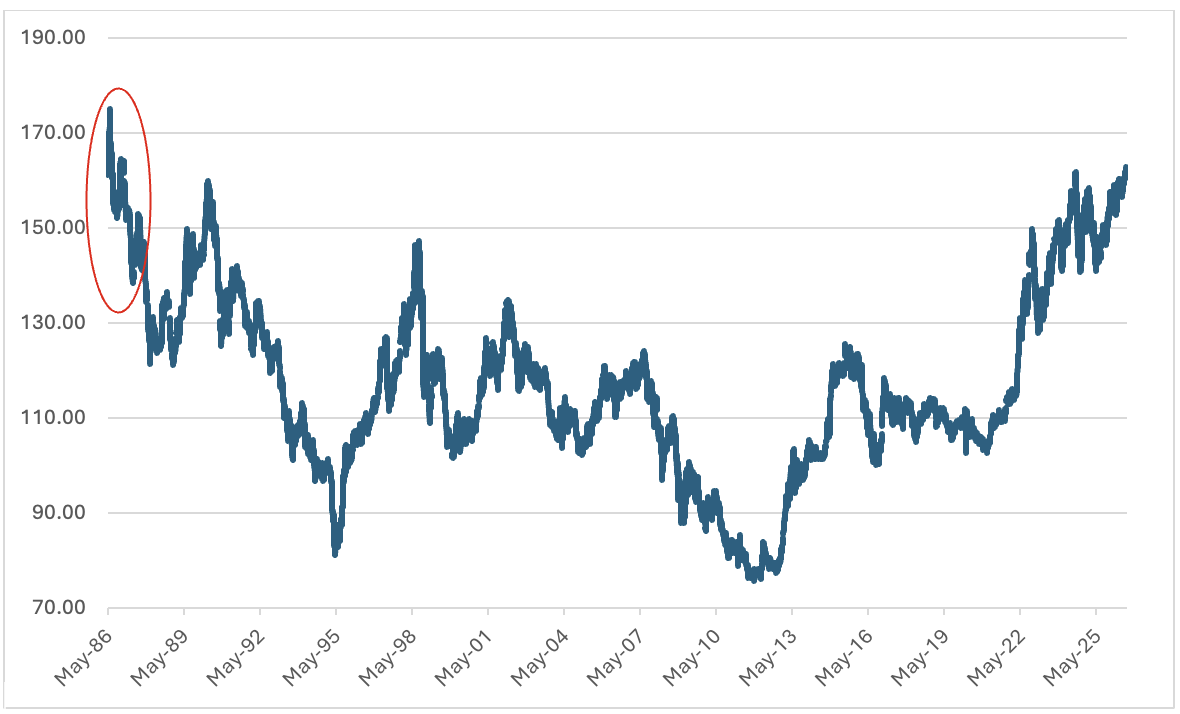
But I also wanted to mention the yen (0.0%) which yesterday touched yet another new 40-year low (dollar high).  I have created a chart of USDJPY from FRED data so you can get a sense of how quickly the yen appreciated back then in the wake of the Plaza Accord.  The red circled area down leg took place almost entirely in June 1986.

And that’s pretty much it.  On the data front we get Flash PMIs (exp Manfacutring 54.3, Services 51.5) and New Home Sales (610K).  Once again, we are at a summer weekend so I expect that by noon, things will really slow down.  I don’t believe today’s data will have an impact, and I expect a pretty dull day overall.  Arguably, until the FOMC, absent a major turn in the Gulf, things should remain fairly stagnant as there is no data of note to change opinions. 

Good luck and good weekend

Adf
A Bad Taste

For weeks, things appeared to get better
As yields slipped and helped every debtor
But we’ve seen some changes
With yields breaking ranges
And oil back to the pacesetter

So, stocks are not really embraced
While bonds have left all a bad taste
The dollar’s moved higher
While gold’s back to dire
With analysts worldwide disgraced

Investors are not as happy this morning as they had been for the past several weeks as the situation in Iran and the Middle East appears to be deteriorating again.  The US continues to attack Iranian missile launchers and fortifications on a daily basis while Iran continues to fire missiles at targets throughout the Gulf region.  As well, the Houthis are back at it in the Red Sea restricting oil flows through there as well.  Arguably the chart below of oil (+4.0%) is the most descriptive view of what is driving everything.
Source: tradingeconomics.com

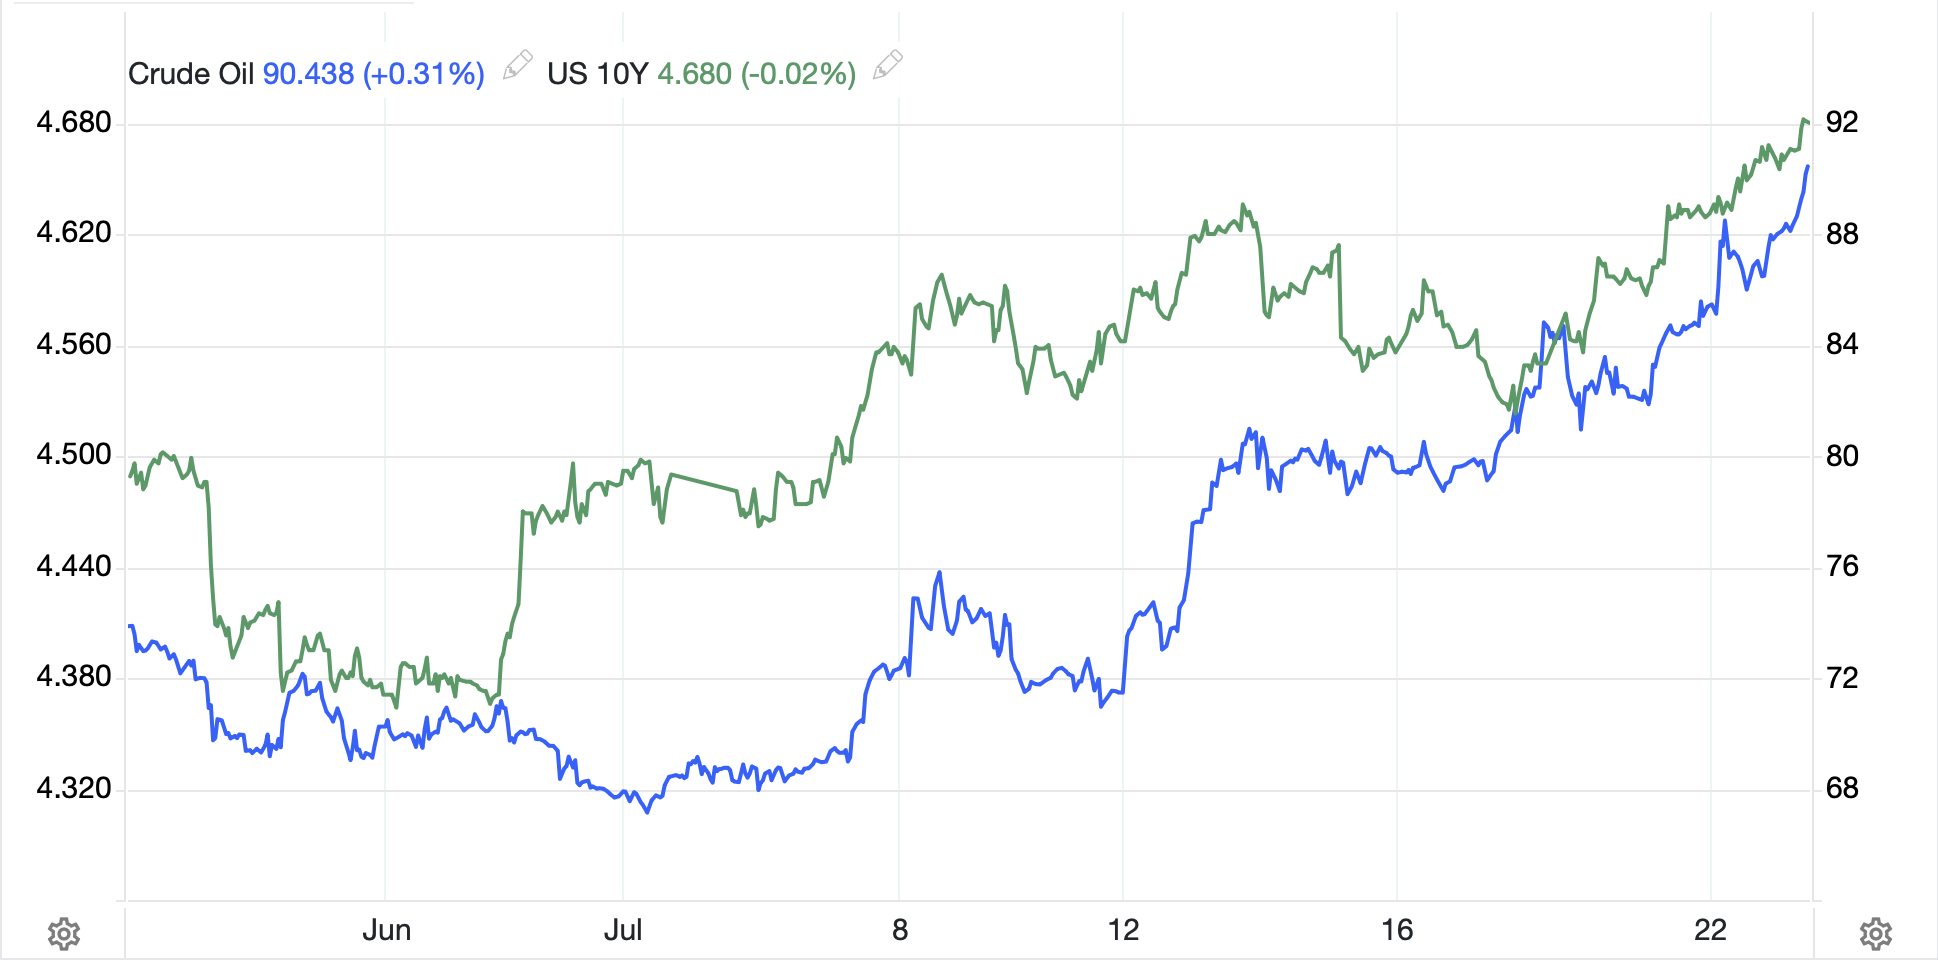
Crude is higher by 29% in the past month and back above $90/bbl.  This makes things tough on everybody but the oil companies.  Does this mean we are running out of oil?  I don’t think that is the case.  Rather, the short-term impediments to shipping it are driving the price.  But the price is rising nonetheless and that is impacting everything else.  If you recall when things kicked off in this war back in March, the oil price was the primary catalyst for movement in every market. As things seemed to settle down and it appeared there was an opportunity for a resolution, focus turned back to things like earnings for equities and interest rate differentials for currencies with oil in the background.  But it appears we are back to, as oil goes, so goes every other market.

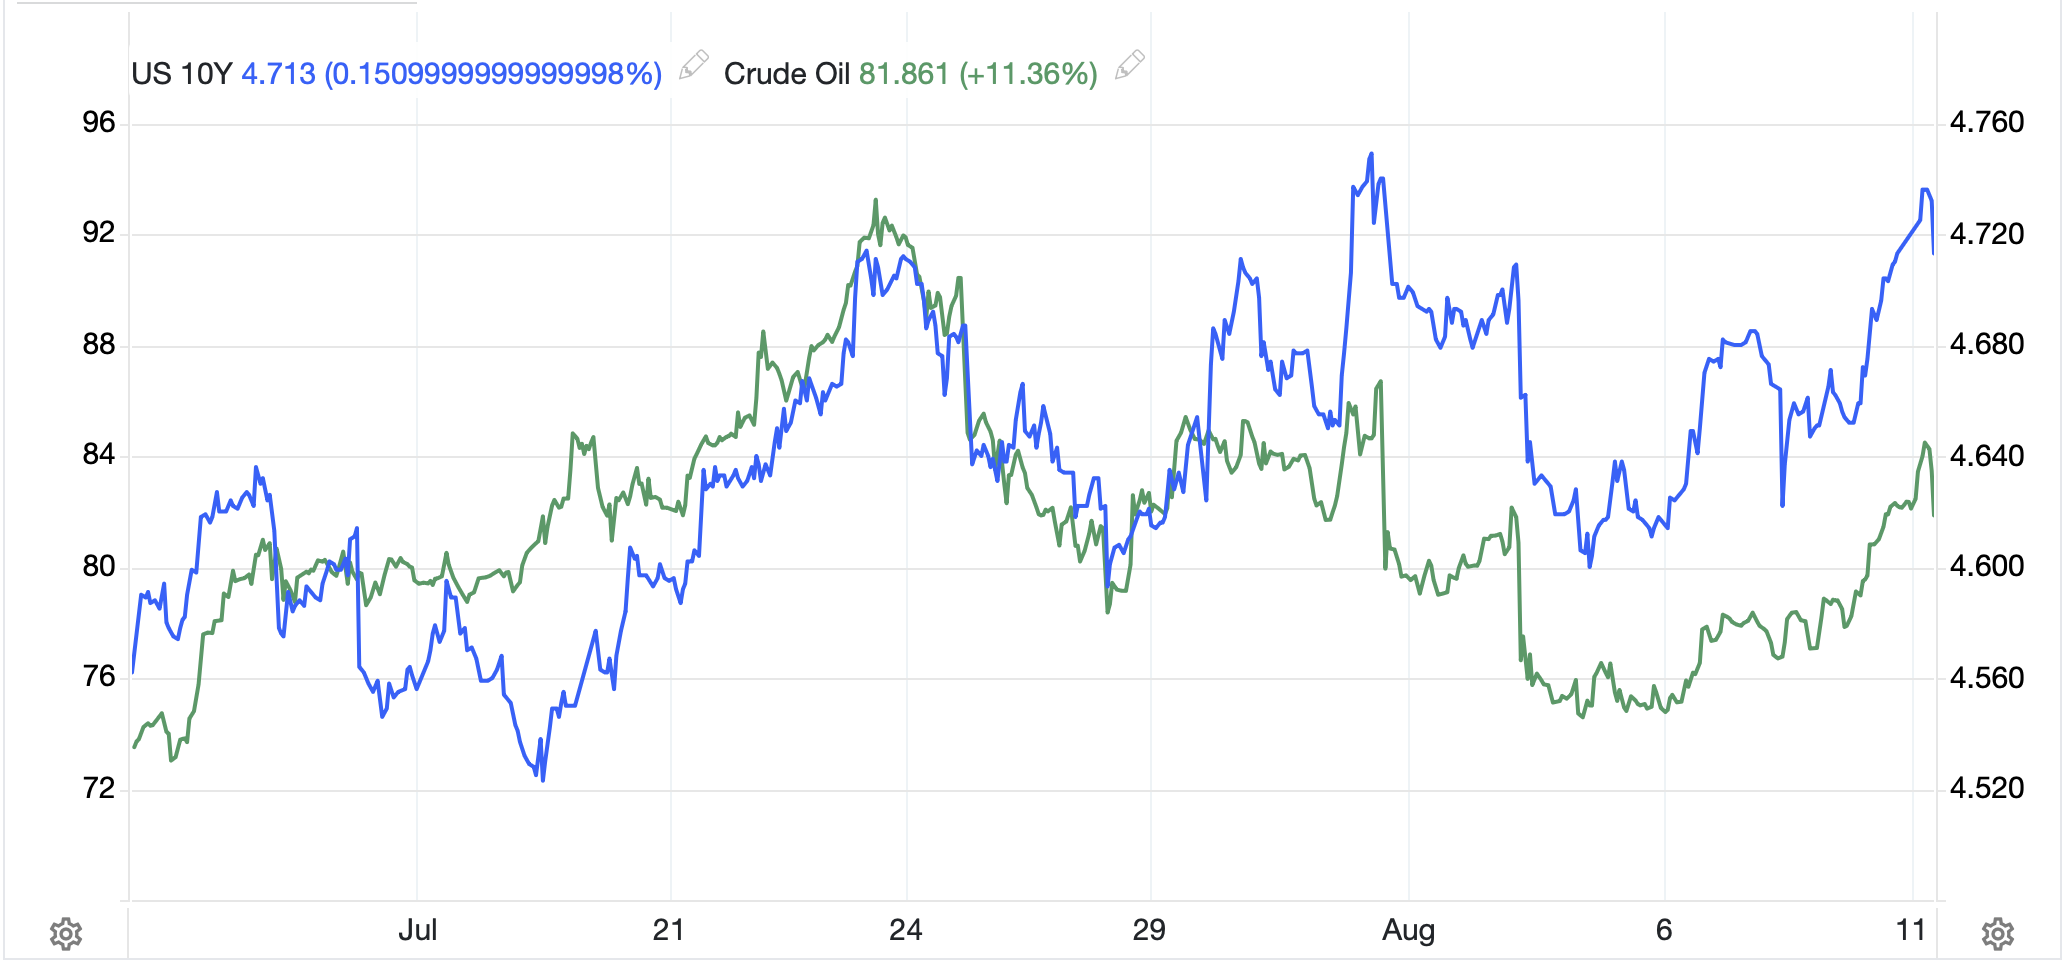
For instance, here is a chart of oil and 10-year Treasury yields over the past month.  As you can see, the trajectory, especially over the past several sessions, is quite similar.

Source: tradingeconomics.com

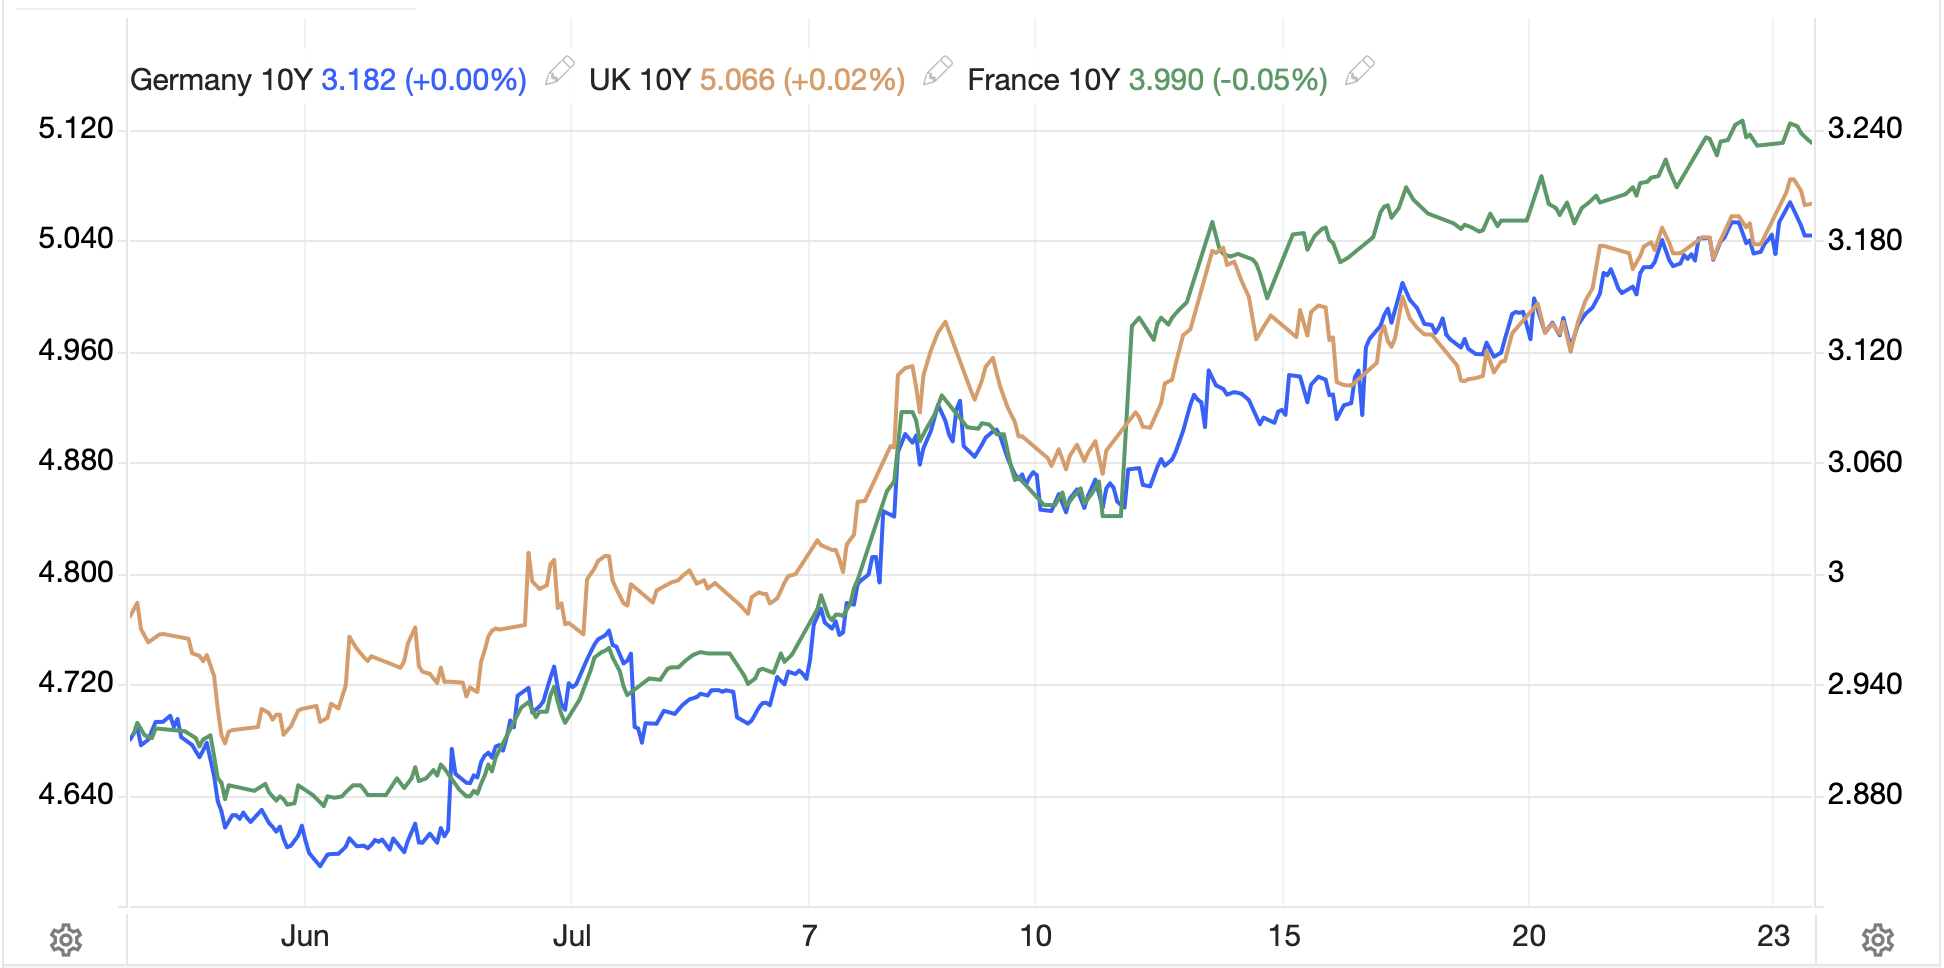
But if we look at 10-year yields across Europe, we can see that they are all climbing in sync as well.

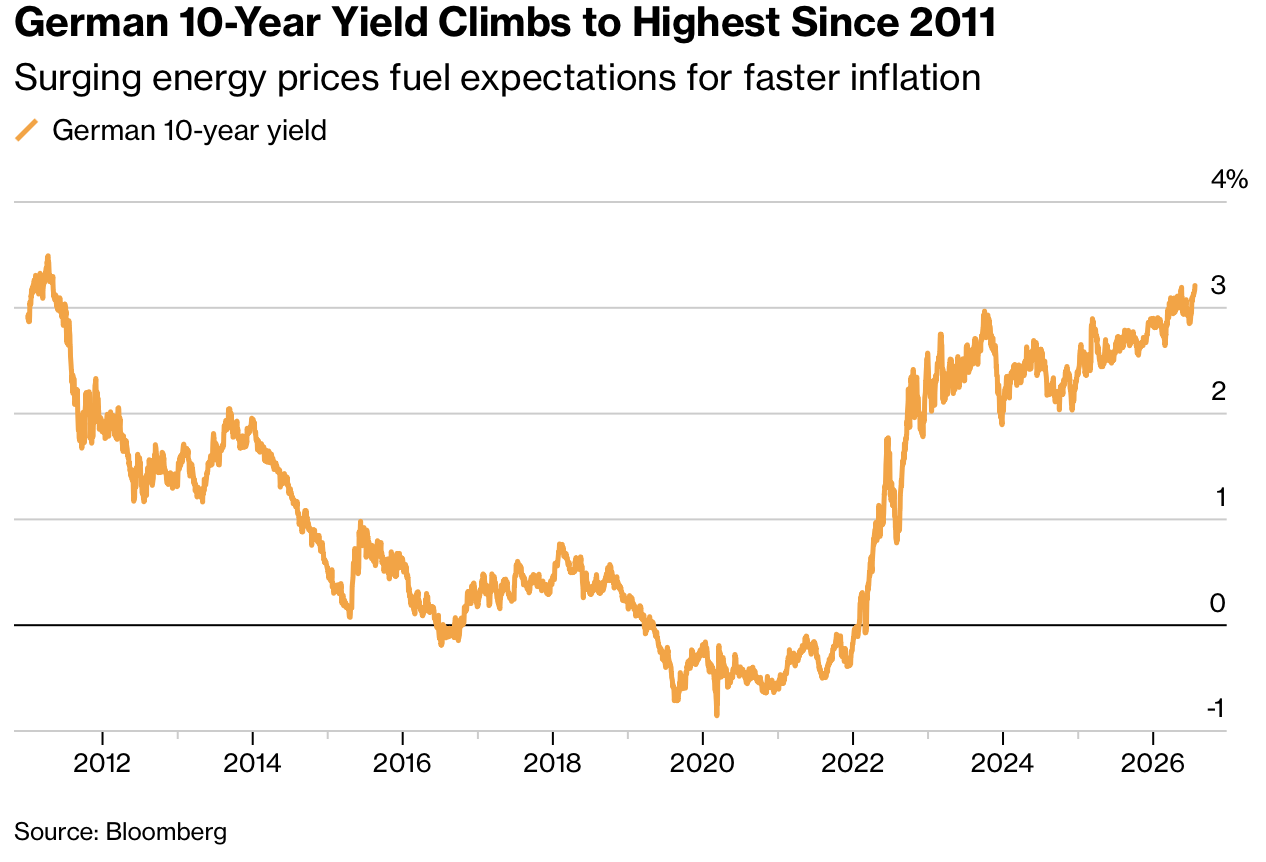
German yields have reached their highest level in 15 years according to Bloomberg.

The entire moderation story is falling apart.  So, now instead of conversations discussing the relative merits of AI and whether it will be a boon for mankind or end it, we are discussing the probability that the world will end soon.  I guess it’s no surprise that risk is under pressure.  Of course, the latter conversation doesn’t seem that coherent to me as if there is concern over the end of the world, I would have thought gold would have a better bid!

At any rate, oil is the main story and the driver of every market.  It underpins the question of whether the ECB will hike rates today (they won’t) or whether the FOMC will do so next week (also, they won’t) but the probabilities for those moves have risen.  It has also detracted from the earnings stories, or perhaps exacerbated the negatives, or perceived negatives.

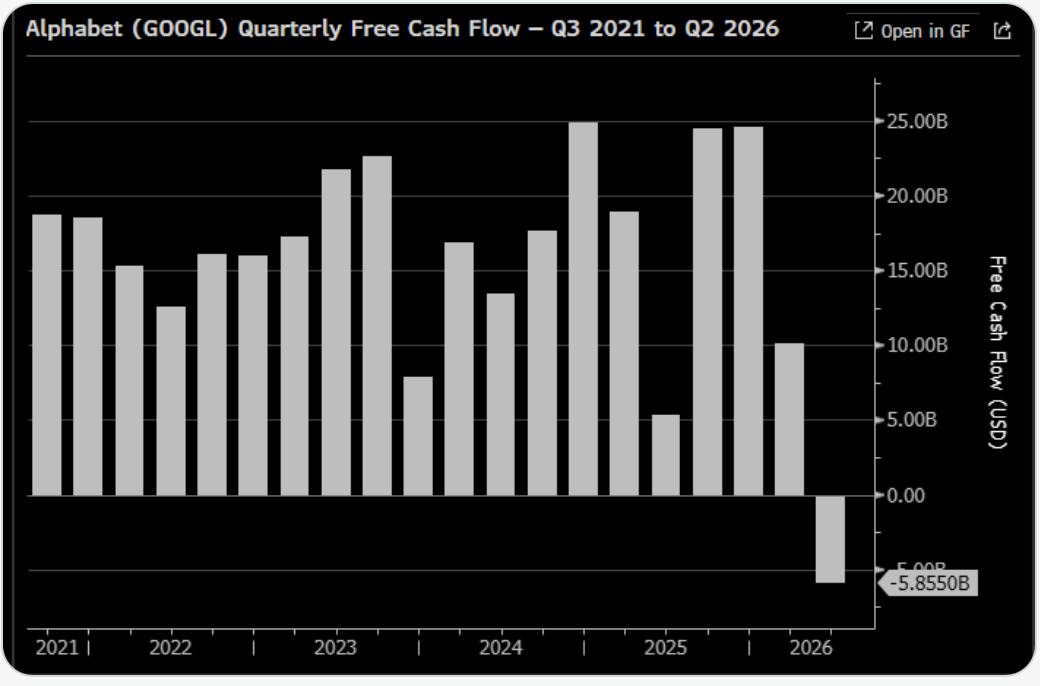
For instance, Alphabet reported last night and Q2 revenues beat estimates coming in at $119.8 billion.  But all the talk is of free cash flow, which in this Bloomberg chart shows how much they are spending on the AI buildout.

Here’s my question, is it bad that Alphabet is spending its money to improve its future?  If it recognizes the criticality of AI to the future of its own existence, it seems like a reasonable move.  Of course, the naysayers claim that spending all that cash is a waste.  I don’t know the answer, and I suspect nobody does yet, but companies spending their cash flow on improving their business seems to be the whole idea behind having companies in the first place.  

It begs the question, on what did investors base the value of Alphabet before AI?  If it was seen as only a cash cow, it certainly traded at a very high multiple for a boring business.  But today, it will be tarred with the oil brush along with all stocks.

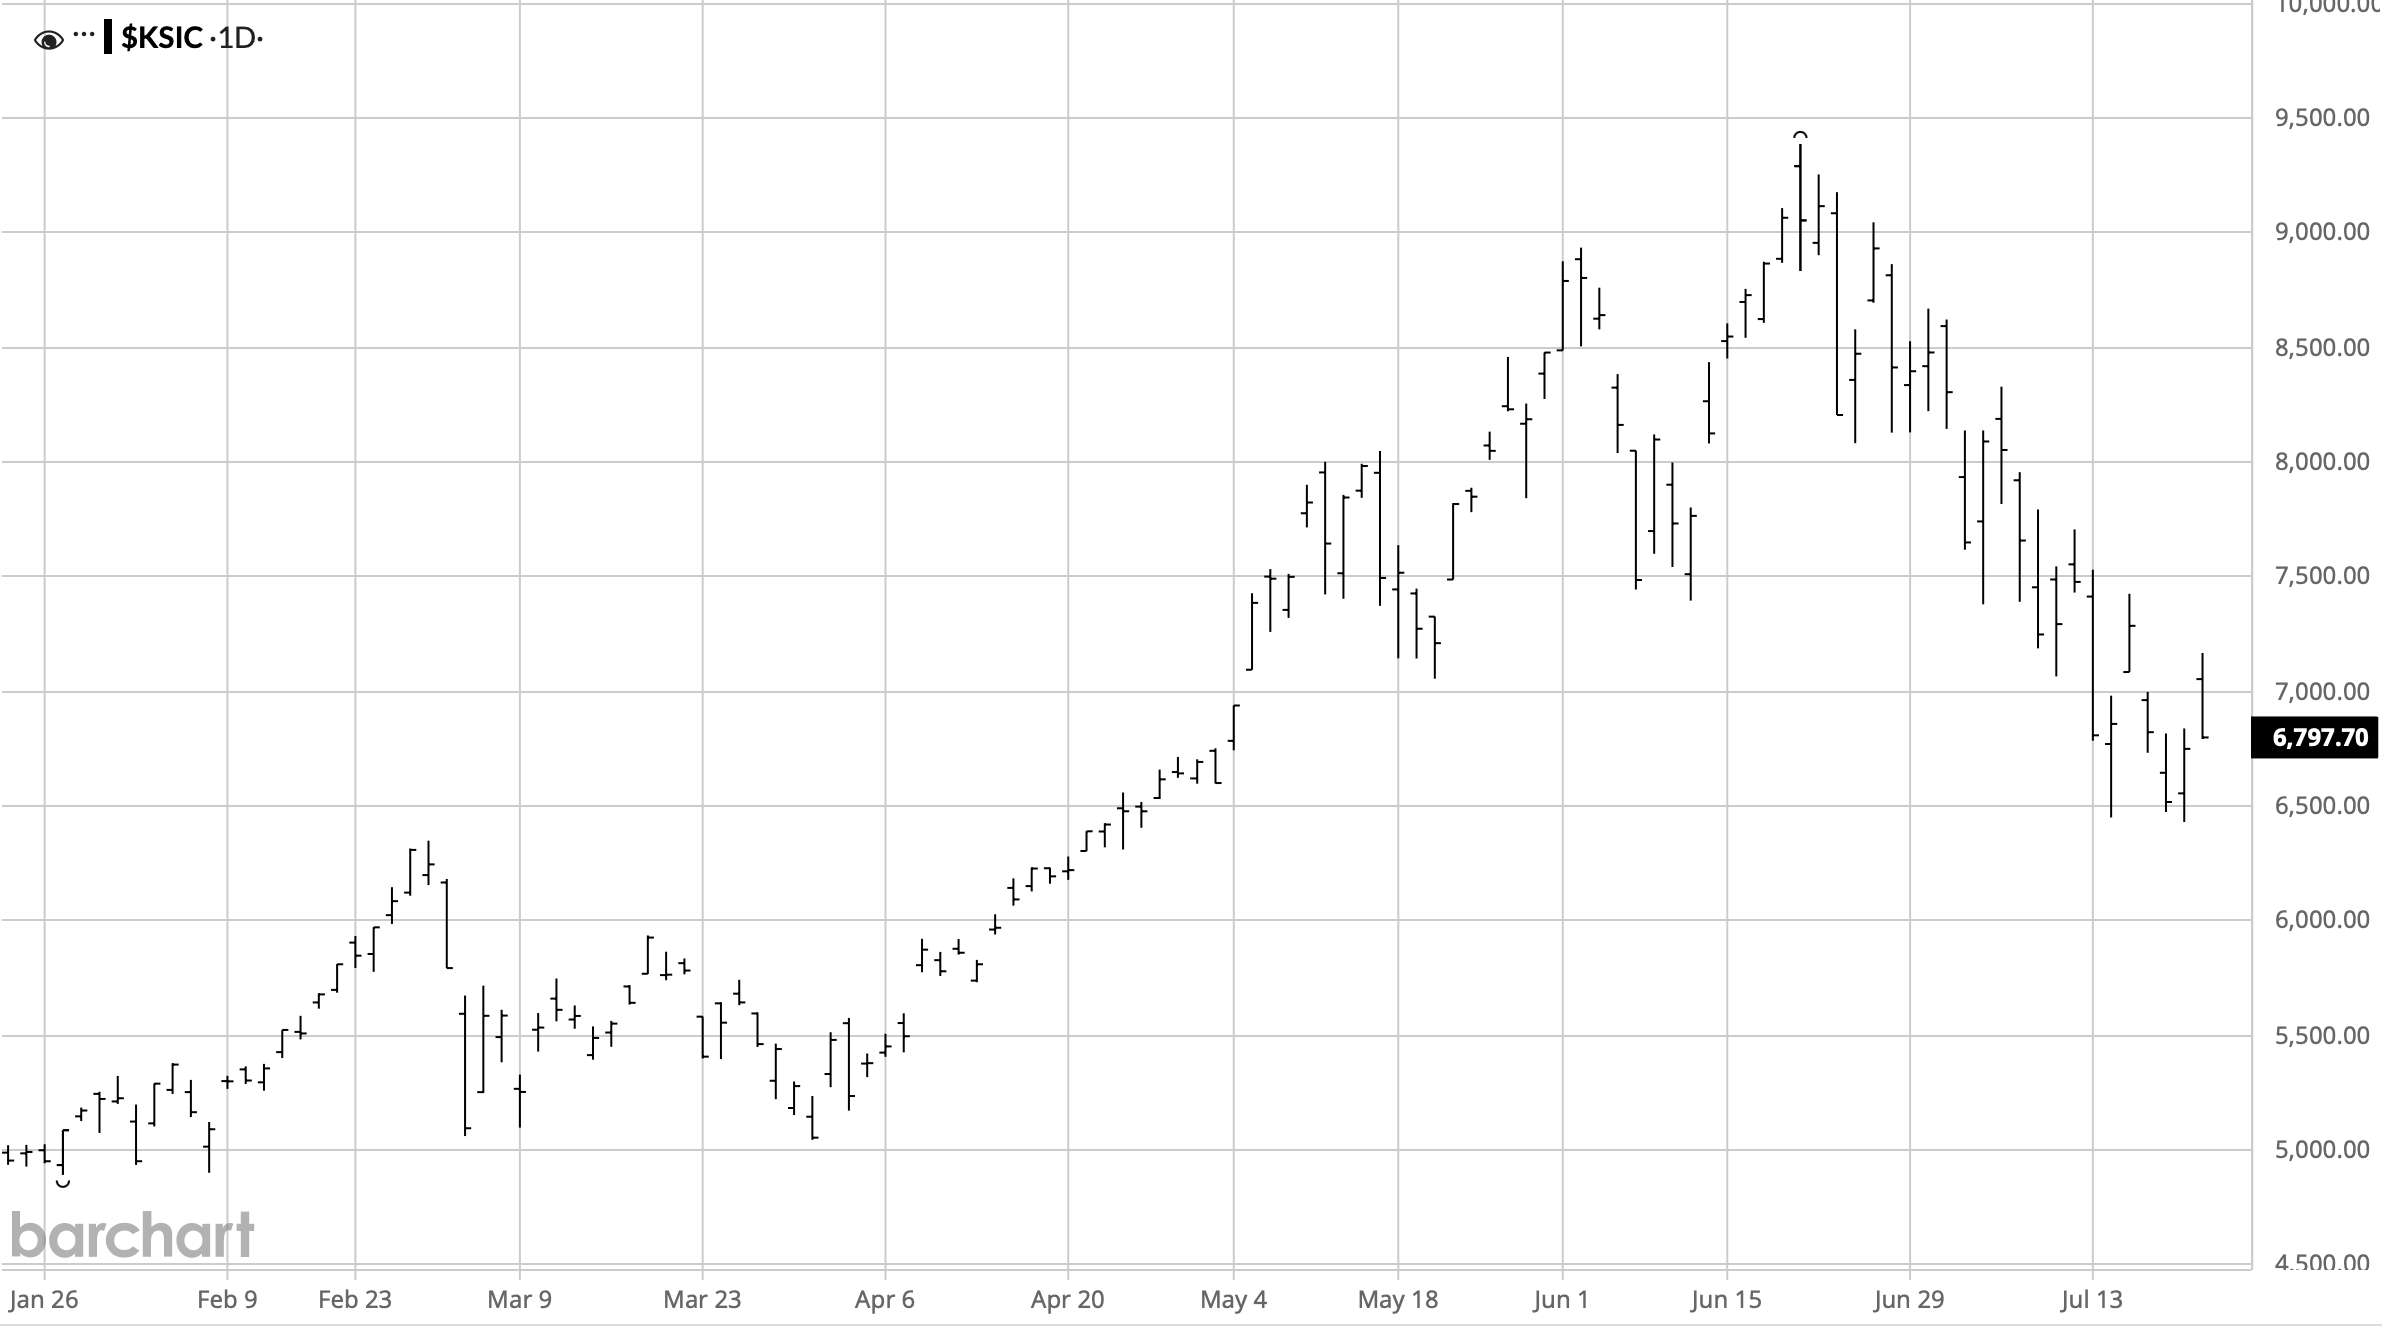
Ok, I have gone far afield here, let’s get back to markets overnight.  Yesterday’s lackluster US session was followed by strength throughout most of Asia.  Tokyo (+0.5%), China (+0.25%), HK (+1.3%) and Korea (+4.4%) all had solid sessions with Korea continuing to define what volatility means in equity markets.  Look at the expansion in the daily ranges in this barchart.com chart of the KOSPI over the past month.  It’s remarkable!

European bourses, though, are having a much rougher go of things this morning as Brent crude approaches $100/bbl.  France (-1.1%), Italy (-1.9%), Spain (-0.6%) and Germany (-0.6%) are under real pressure this morning as earnings numbers there have been lackluster and the broader macro picture deteriorates all the while.  As to US futures, right now (7:40), they are pointing lower led by the NASDAQ (-1.2%) although it has not yet breached that critical support level as per the below chart.

Source: tradingeconomics.com

We’ve already discussed bond markets, with yields higher this morning by between 2bps and 3bps across Treasuries and all European sovereign markets.  Turning to the metals, while we had a couple of days where they rallied alongside oil, this morning they have reversed course with gold (-1.3%), silver (-2.6%) and copper (-0.7%) all under pressure.  It seems the interest rate story is today’s discussion as higher yields are the topic du jour.

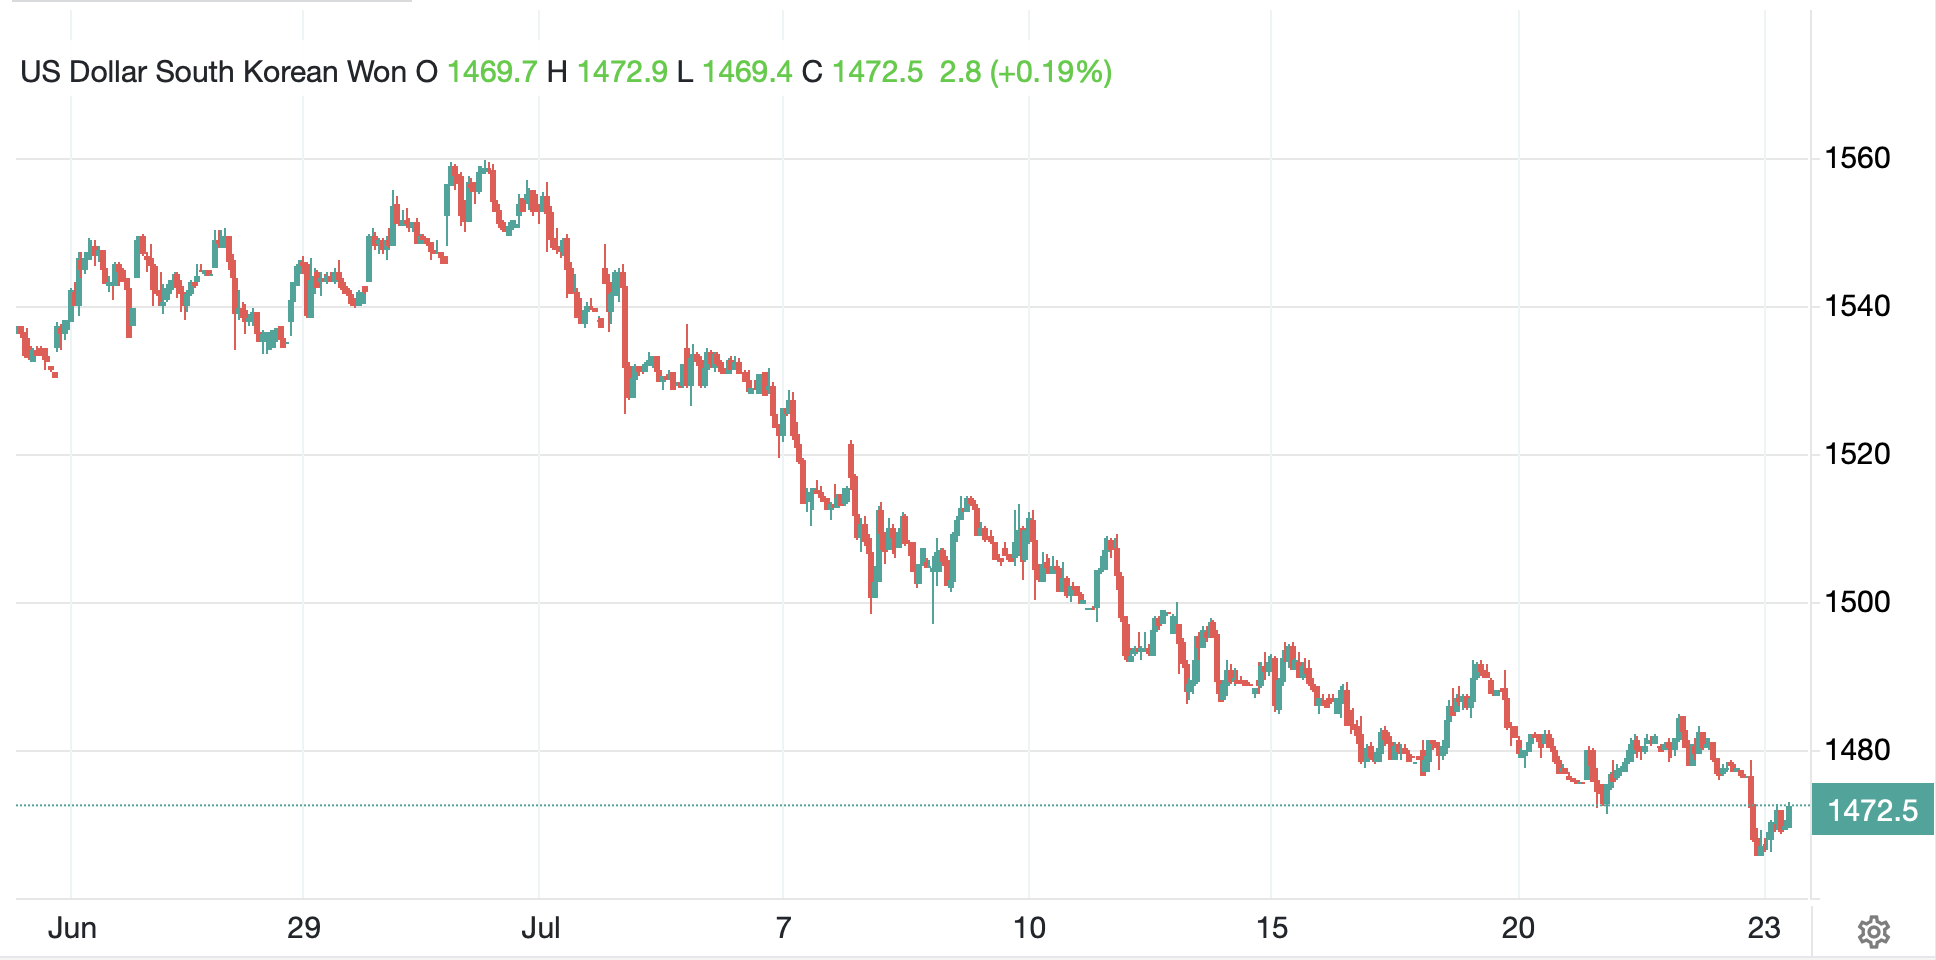
Finally, the dollar is stronger across the board this morning, although most of this strength just materialized over the past few hours with the Asia session broadly unchanged.  But no matter how you slice it, the dollar is firmer vs. all its G10 counterparts by about 0.25% and almost all of its EMG counterparts by a similar amount.  The exceptions this morning are BRL (+0.25%) and KRW (+0.3%).  Regarding Brazil, you must remember they are an oil exporter, so benefit from high oil prices and have amongst the highest real interest rates around, so draw capital for that as well in the carry trade.  The real has appreciated about 8.5% during the past year, so this is nothing new.  As to KRW, the government’s efforts at internationalization continue to be paying off and a look at the chart below shows that this trend is quite strong right now.

Source: tradingeconomics.com

There was an interesting article in Bloomberg this morning explaining how the dollar’s weakness vs. LATAM currencies has begun to bite for local companies but I find it quite interesting when it comes to discussions about the dollar; some find it too strong and are looking for it to tumble while others complain it is too weak!  Seems nobody is ever happy here!

On the data front we see Chicago Fed National Activity (exp 0.14) as well as Initial (212K) and Continuing (1809K) Claims.  Of course, we have the ECB announcement shortly, although no change is expected.  Something getting very little press is the fact that Crude Oil stocks rose in the US last week, but I guess that doesn’t suit the narrative!

This market is entirely focused on oil, and as it moves, so will everything else.  If oil keeps climbing, look for stocks and gold to fall while yields and the dollar rise.  If oil reverses, so with those moves.

Good luck

Adf