Doomed

Is civilization now doomed
As bond yields, o’er 5%, bloomed?
Or are those who say
The end’s any day
Just hoping their clicks will have boomed?

I ask because it’s hard to square
The stock market with yields up there
The pundits explain
High yields are a bane
Investors, though, don’t seem to care

A PSA to start.  For the next several weeks FX Poetry is going to be sporadic, if it shows up at all as I will be embarking on a road trip to the Doberman Pinscher Club of America National dog show in Topeka, Kansas and following that visiting family in Texas.  We have been told that Marvel has a good chance to do well there, although the competition will be stiff.  Nonetheless, here he is.
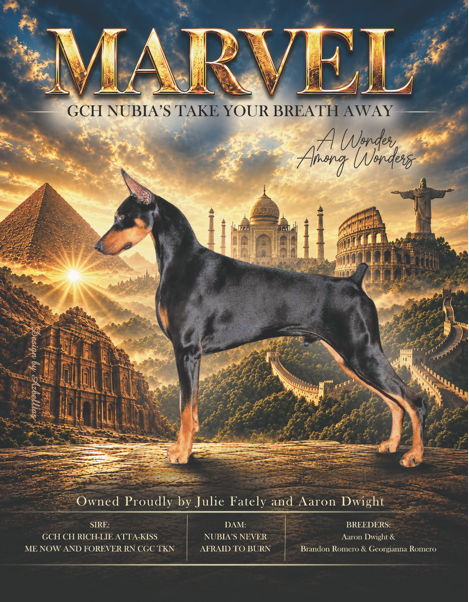
When I have time, I will try to write, but I am confident that the markets will continue to function while I am gone.  And more importantly, I am confident that the world will not end, even if bond yields head a little higher from here.

Let’s start with bonds since that is the topic du jour.  Below is the history of 10-year Treasury prices since 1953 from the FRED database.  I have taken the month-end data and drawn both the average and median lines in as well.
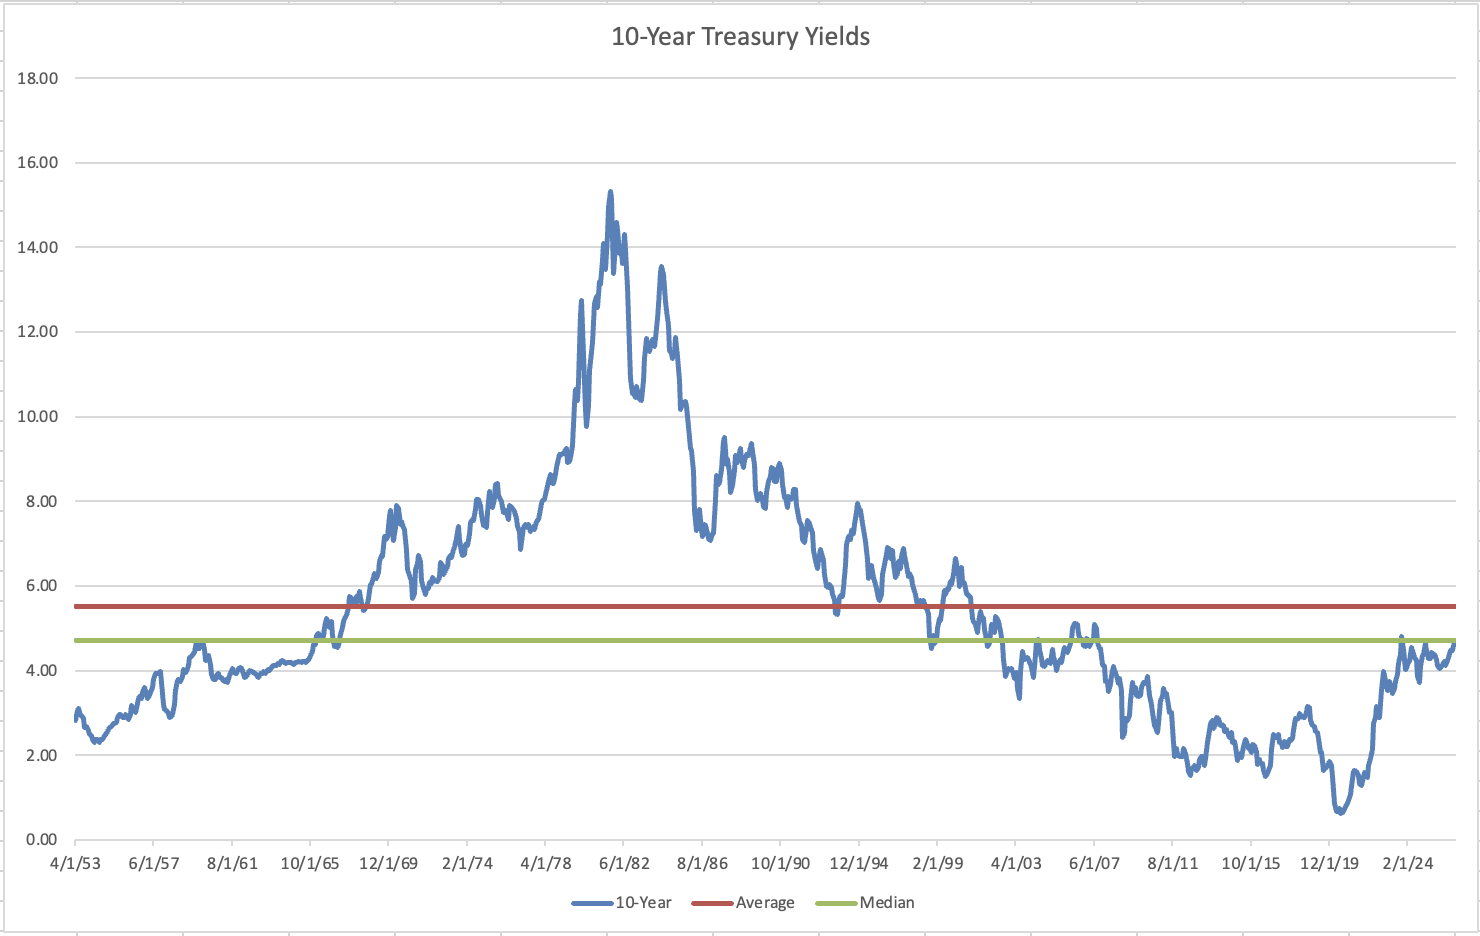
Once again, I ask you is 5% on the 10-year the anomaly?  Or was 1% on the 10-year the anomaly?  Throughout this entire time, the US economy managed to get by.  Certainly, there were difficult times as rampant inflation in the 1970’s led to Paul Volcker’s dramatic efforts to withdraw liquidity from the system, thus driving rates higher which resulted in the twin recessions of the early 1980’s.  Now, to my eye, the current level of 5.18% (-2bps on the day) does not look like it is unusual.  In fact, it is firmly between the median (4.79%) and average (5.52%) levels on the chart.

And as I wrote yesterday, economic activity continues apace, in fact I would argue faster than apace.  The Trump administration is all-in on the run it hot thesis and with inflation at 3.4% and real GDP at 5.1%, that implies nominal GDP is rising at 8.5% annualized.  Even with the excessive government spending, and it is excessive, nominal GDP growth at that pace will result in a reduction in the debt/GDP ratio over time.  Remember, the budget deficit is running at 6% or so, far lower than that GDP figure.

This is by no means an ideal situation, however, it is a sustainable one.  And consider this as well, all that interest getting paid is part of the income streams for all the holders, many of whom are domestic.  Recall, a major angst among the doomporn writers is that foreigners stopped buying Treasuries.  That means domestic accounts own more and get paid more interest to recycle into the economy.  Again, not ideal but certainly sustainable.  The end is not nigh.

What about the rest of the world?  Well, while their yields are rising as well as you can see in the below chart from tradingeconomics.com, their growth rates are not keeping pace with the US.
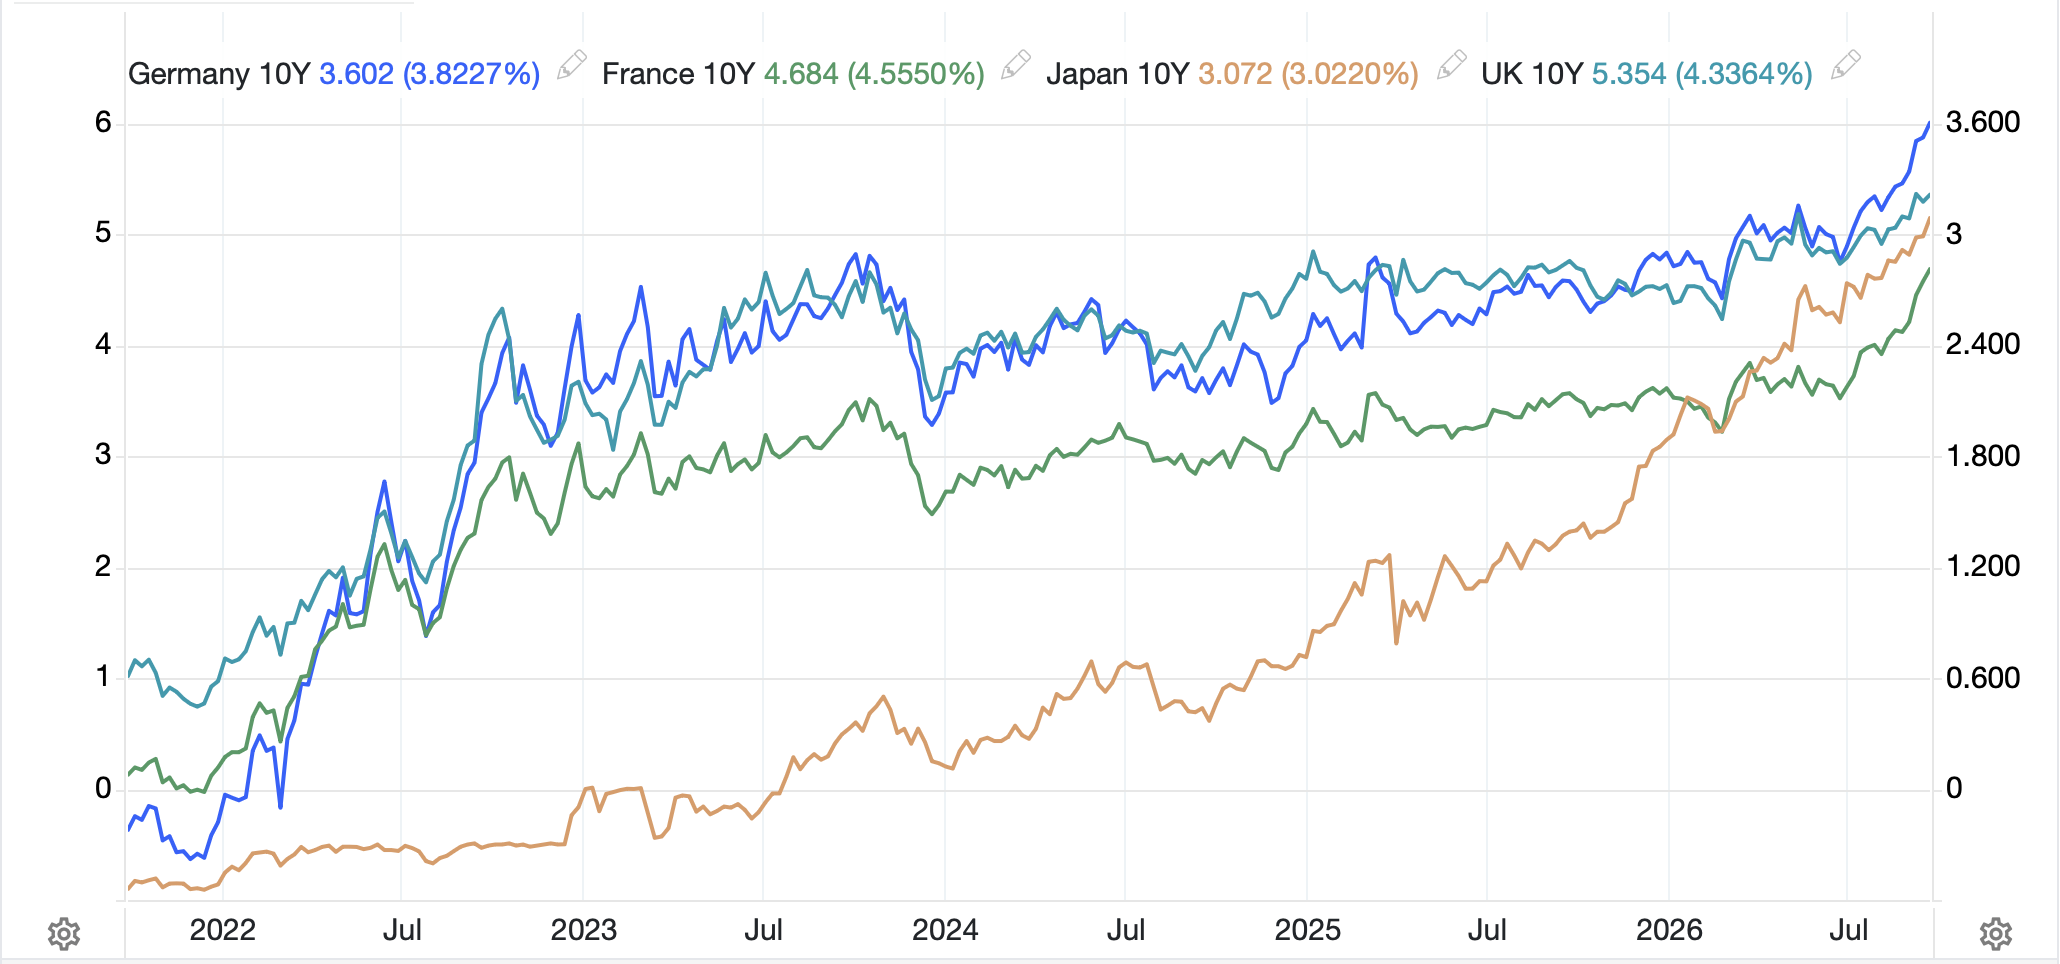
As you can see in the below table from tradingeconomics.com, the rest of the world has a much bigger problem with rising yields than does the US.  
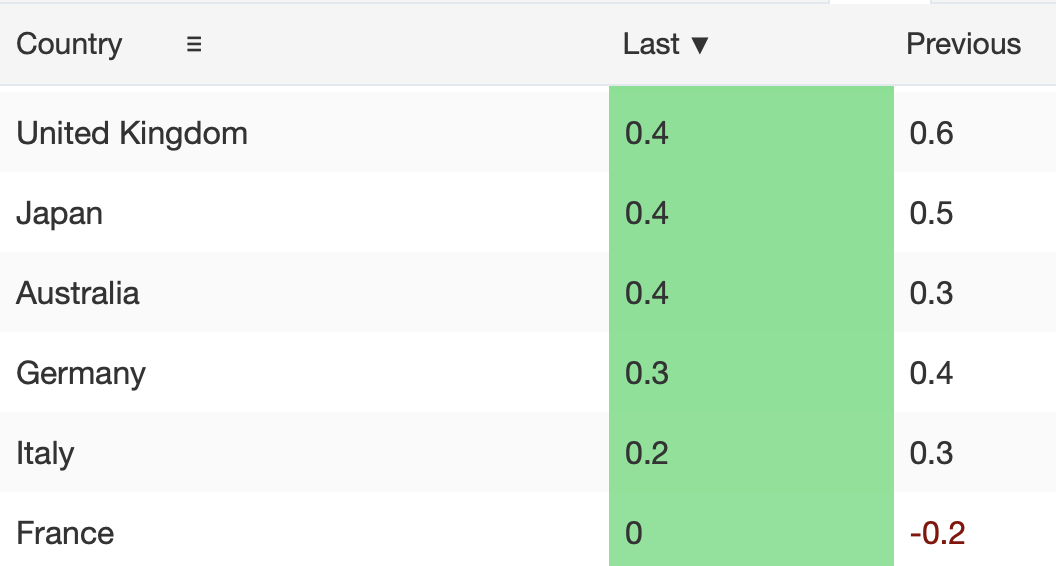
Our economy can clearly sustain them far better than any other economy which is one of the reasons that the equity markets in the US continue to perform so well and the primary reason that the dollar continues to perform so well.  After all, the consistent drumbeat of announcements of new factories to be built in the US from Honda and Hyundai to TSMC and Samsung and every defense and pharma company in between, not to mention Nippon Steel’s expansion of the old US Steel facilities, is driving demand for dollars.

Again, doom may get clicks, but reality is far better than they make it out to be.  And we know this because equity investors continue to be willing to hold US equities in record numbers.  Earnings in the US continue to grow, in fact fast enough to reduce some of the overvalued multiples that we have seen over the past several years.  So, while yesterday was a nonevent in US equity markets, the fact that was the outcome despite another sharp rise in yields tells you all you need to know.  Overnight, China and Taiwan were closed, but we saw gains in Tokyo (+1.3%), Korea (+0.9%), India (+0.4%) and most of the region although HK (-1.0%) and Australia (-0.4%) lagged.  

In Europe, though, the week is ending on a positive note with gains across the board (Spain +1.0%, Germany +0.7%, UK +0.3%, France +0.1%) and US futures are also higher at this hour, +0.4% or so.  And Germany managed this despite a terrible reading from the GfK Consumer Confidence survey of -30.6, far worse than last month or forecasts.

In the commodity markets, oil (-2.4%) is sliding this morning as there appear to be ongoing talks to both reopen the Strait of Hormuz and end the US naval blockade, an outcome that would likely see oil prices, and the products as well, fall sharply.  Meanwhile, gold (+0.7%) and silver (+1.6%) are bouncing a bit this morning as the chain of thought appears to be lower oil prices => lower interest rates => more attractive gold, or something like that.  Nothing has changed my long-term view on the precious metals nor on copper, which if the US economy continues to grow like it has been will see significant demand going forward.

Finally, the dollar, after a two-week run is backing off this morning on two things.  First, apparently when PM Takaichi and President Trump met, the yen was part of the discussion and last night we heard verbal intervention from FinMin Katayama taking the yen higher by 0.75%.  As to the rest of the G10, smaller gains, on the order of 0.1% to 0.2% are the order of the day.  In the EMG bloc, we are also seeing strength with KRW (+0.95%) the leader although ZAR (+0.8%) is also having a fine day as gold rebounds while the rest of the bloc, whether LATAM, CEE or APAC has seen much smaller gains, 0.3% or less.  Again, the dollar is not going to disappear or be replaced.  And frankly, I think we remain in the range of the past year for a while still.

On the data front, this morning brings Durable Goods (exp -0.4%, +0.6% -ex Transport) and then Michigan Sentiment (47.6).  We also hear from a few more Fed speakers which will almost certainly serve to reinforce the idea that they are going to tighten policy further.  Currently, the futures market is pricing a 2/3 probability of an October hike.  Personally, I wish they would stop expanding the balance sheet before hiking again, but Keynesianism won’t allow them to think that way it seems.

Wrapping up, I see more good than bad on the horizon which should be positive for risk assets.  At the same time, at 5.2%, 10-year yields are very attractive for a lot of people as an alternative to equities.  After all, the hype about the highest yields in more than 20 years means that those on a fixed income have not been able to get these yields in more than 20 years.  Historically, 5% was seen as a pretty fair return for bonds.  Maybe this is the new equilibrium.

Good luck and good weekend

Adf
To Be Agamemnon

Apparently inside Tehran
The pressure that Trump has brought on
By blockading ships
Is set to eclipse
Their goal to be Agamemnon

At least with respect to his win
In Troy, though much to their chagrin
They may meet his fate
Because of a Strait
And views they should be its kingpin

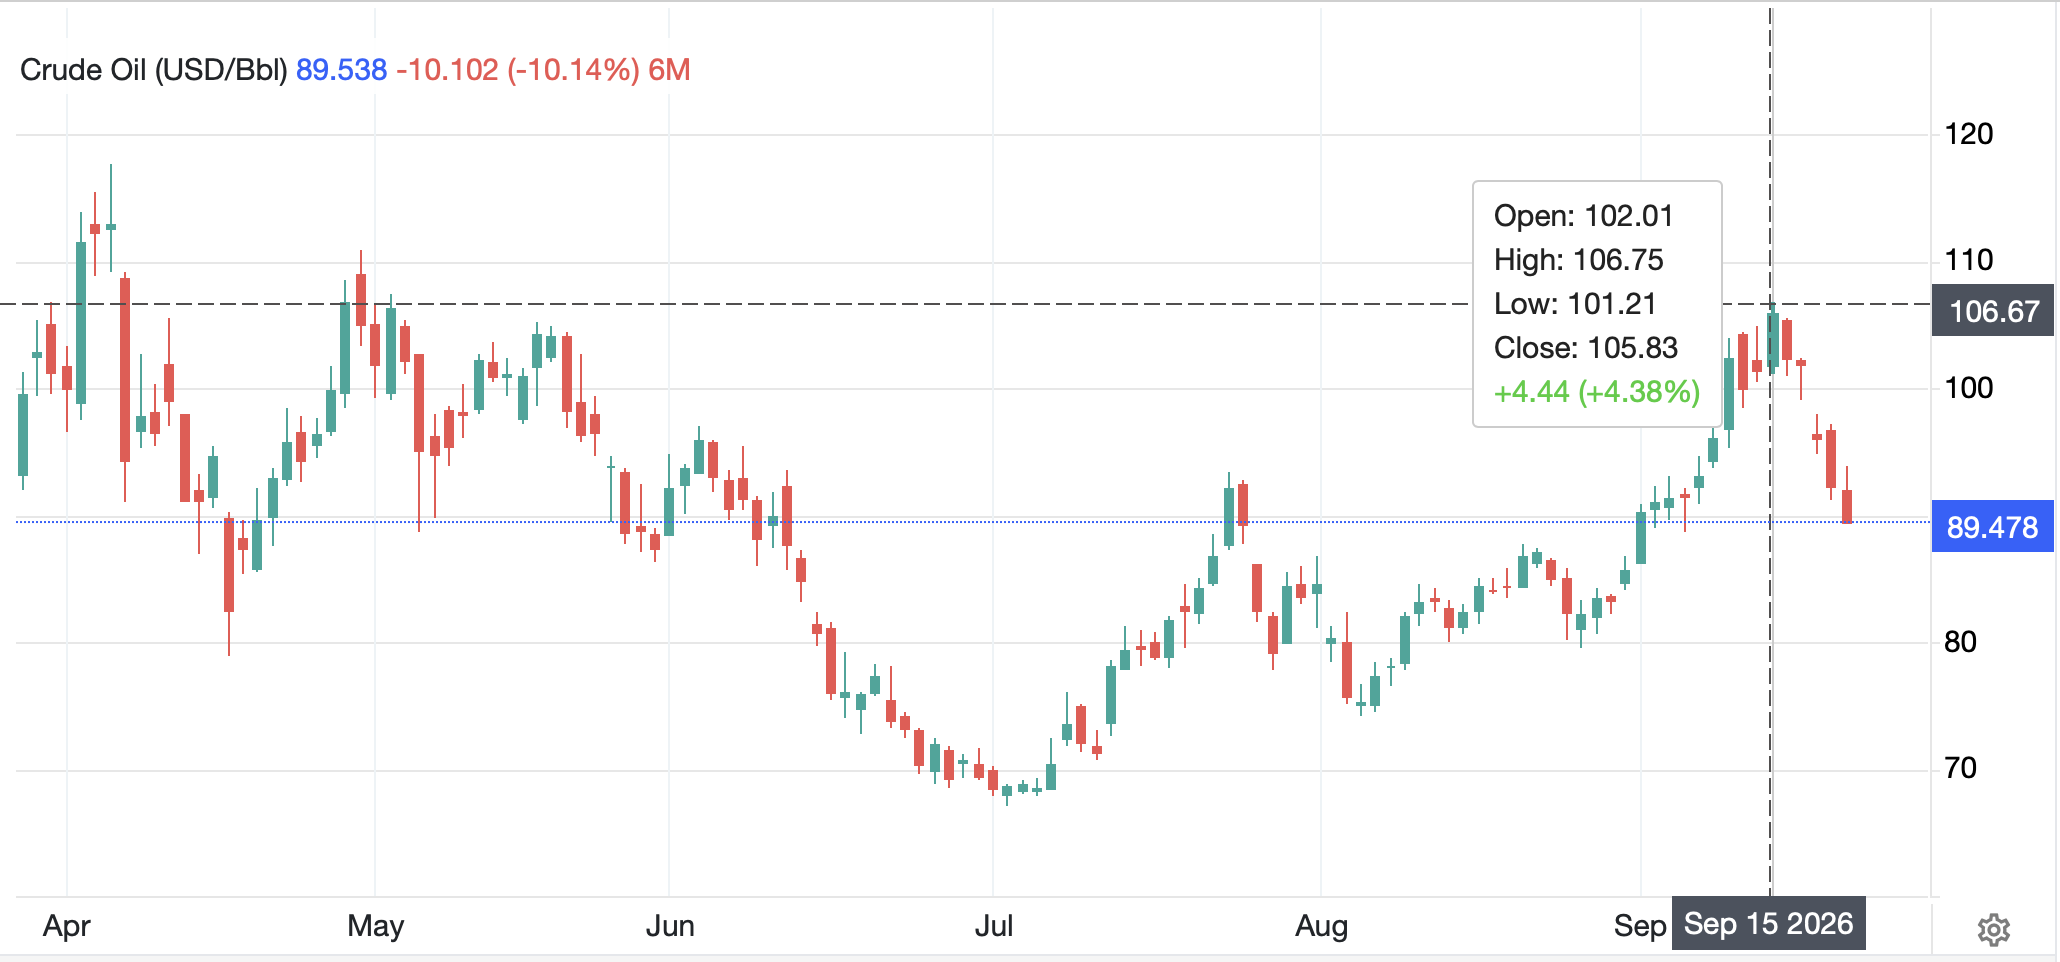
One week ago today, oil traded above $106/bbl as concerns about Iran’s ability to inflict further damage on Gulf capacity along with their Houthi allies reached a peak.  The punditry was going all-in on the idea that as oil prices rose, and especially as product prices rose, that President Trump would have to back off his pressure campaign because rising diesel prices would collapse the Republican hopes for retaining the Senate, let alone the House, in the upcoming midterm elections.

What a difference a week makes, 168 little hours (my apologies to Dinah Shore) as the news this morning is that Iran has just pledged to reopen the Strait of Hormuz if the US ends the blockade.  Oil prices (-2.6% today, -15.5% in the past week) are responding as one would expect.

Source: tradingeconomics.com

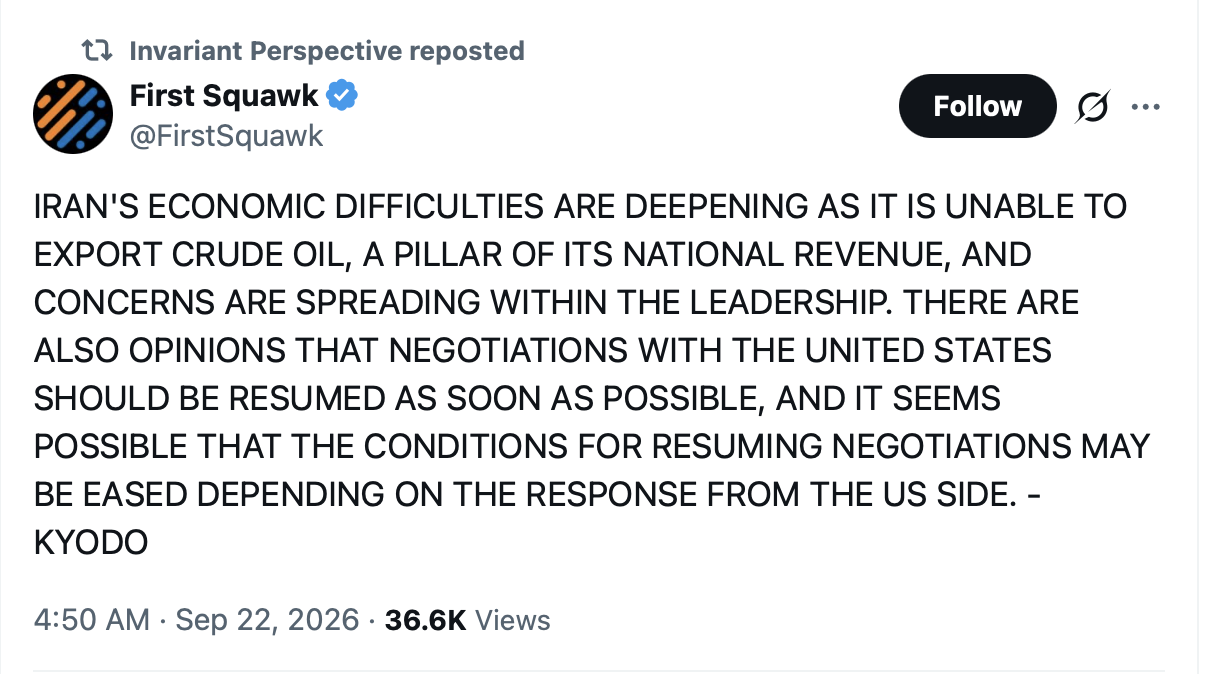
According to Kyodo news, Iran is really feeling the pain now and discussing reopening negotiations as per the below report.

Now, as I have maintained all along, there is no way for any of us to really know what is going on in Iran as the propaganda from all sides runs fast and heavy.  And it is entirely possible that this is another head fake that will precede another series of attacks on vessels in the Strait, or on the Saudi East-West pipeline.  But markets are certainly buying it right now, hence the oil price decline as well as the continuation lower in bond yields with Treasuries and European sovereigns all lower by -2bps, except for French OATs (+1bp) as investors continue to look at French finances and worry further.

Seemingly, adding to the good vibe is the word that Iranian President Pezeshkian may meet with President Trump this week in a side meeting during the UN General Assembly thus priming views that something real may come of this.  I certainly hope that is the case, but I would not bet the farm on that outcome.  Until IRGC leadership feels significant pressure, it is hard to believe much will change.  But that, too, could be in our future.  If all 8+ million people in Tehran march in defiance of their rules, will the IRGC shoot them all?  Seems hard to believe, but the stories that have gotten out of Tehran paint a terrible picture there and a larger popular uprising cannot be ruled out in my view.

In the meantime, this is the best news we have seen in a while, and at least it has diverted attention from the AI death throes that are promised soon.

So, was this the driver behind yesterday’s equity rally?  It doesn’t seem so as that was very tech focused with the Mag7 all having strong sessions although I continue to read the dire stories of terrible market breadth.  That is a measure of the relative performance of different parts of the market and the concern is that somewhere around 50% of companies are below their 200-day moving average, a bearish signal, while the market indices are making new highs.  Some say this is a sign of a weak rally while others explain the index can work to drag all stocks higher.  But, as with everything else, both sides are certain they are correct!

Let’s look at how things have behaved overnight away from oil and bonds.  After the strong US equity performance, Asia was generally more subdued as Japan remained on holiday (they are back tonight) while China (+0.1%), HK (+0.2%) and even Korea (+0.15%) all saw minor gains only.  Korea is the most surprising given the tech led nature of the US markets.  Elsewhere in the region I see many markets having risen something like 0.3% with one major outlier on the downside, Indonesia (-1.7%) as concerns over a pending rate hike and higher fiscal deficits has international investors fleeing.

In Europe, though, things are a bit greener with gains nearly across the board (Spain +0.7%, France +0.5%, Germany +0.45, UK +0.15%) although Italy (-0.15%) is bucking that trend.  The confusing thing to me is France, where concerns reign regarding their fiscal picture in the bond market, but the equity markets are non-plussed on the subject.  And at this hour (7:00), US futures are pointing slightly higher, +0.1% or so.

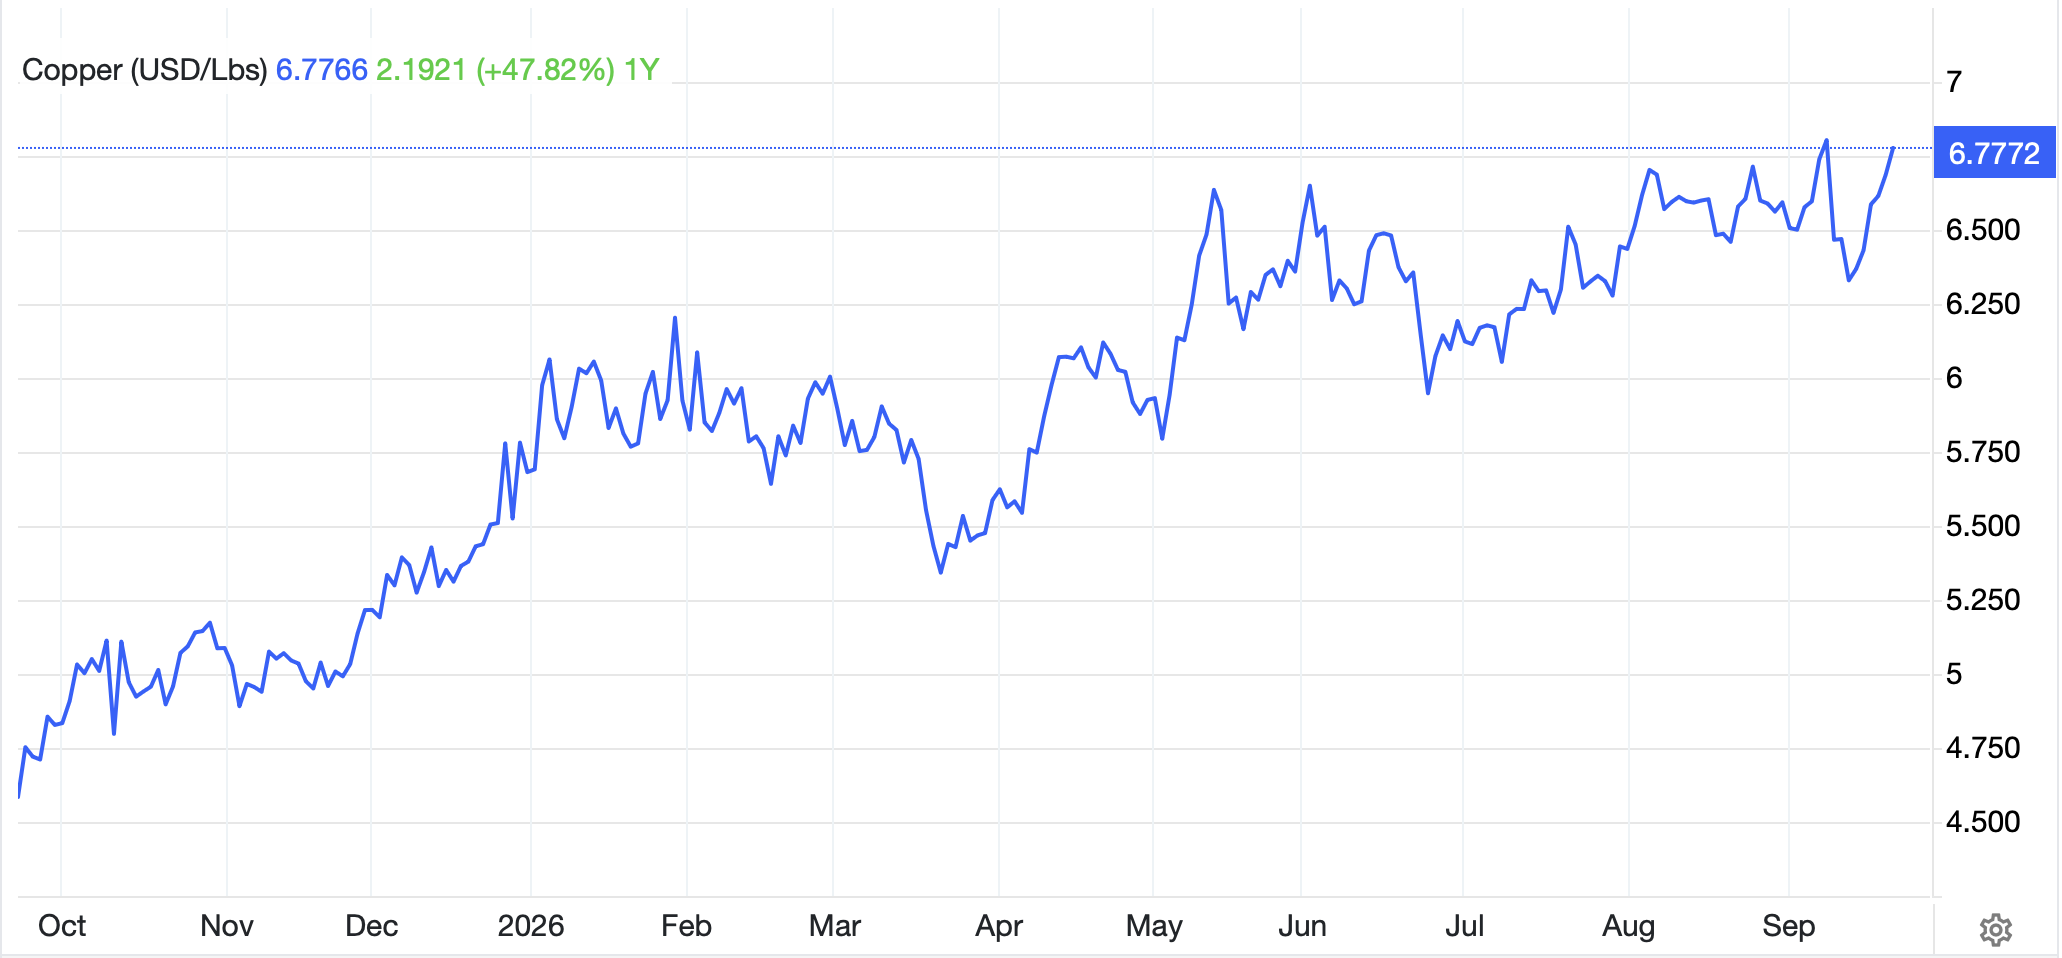
Quickly in the metals markets, while gold (-0.5%) and silver (-0.7%) continue to struggle despite the decline in oil prices, copper (+1.3%) is back to within pennies of its all-time high set two weeks ago.  Certainly, the trend here is higher and, once again, I will remind you that current production is insufficient to meet demand and the timeline to bring new production online is measured in decades.  In my view, this metal could go much higher over time.

Source: tradingeconmics.com

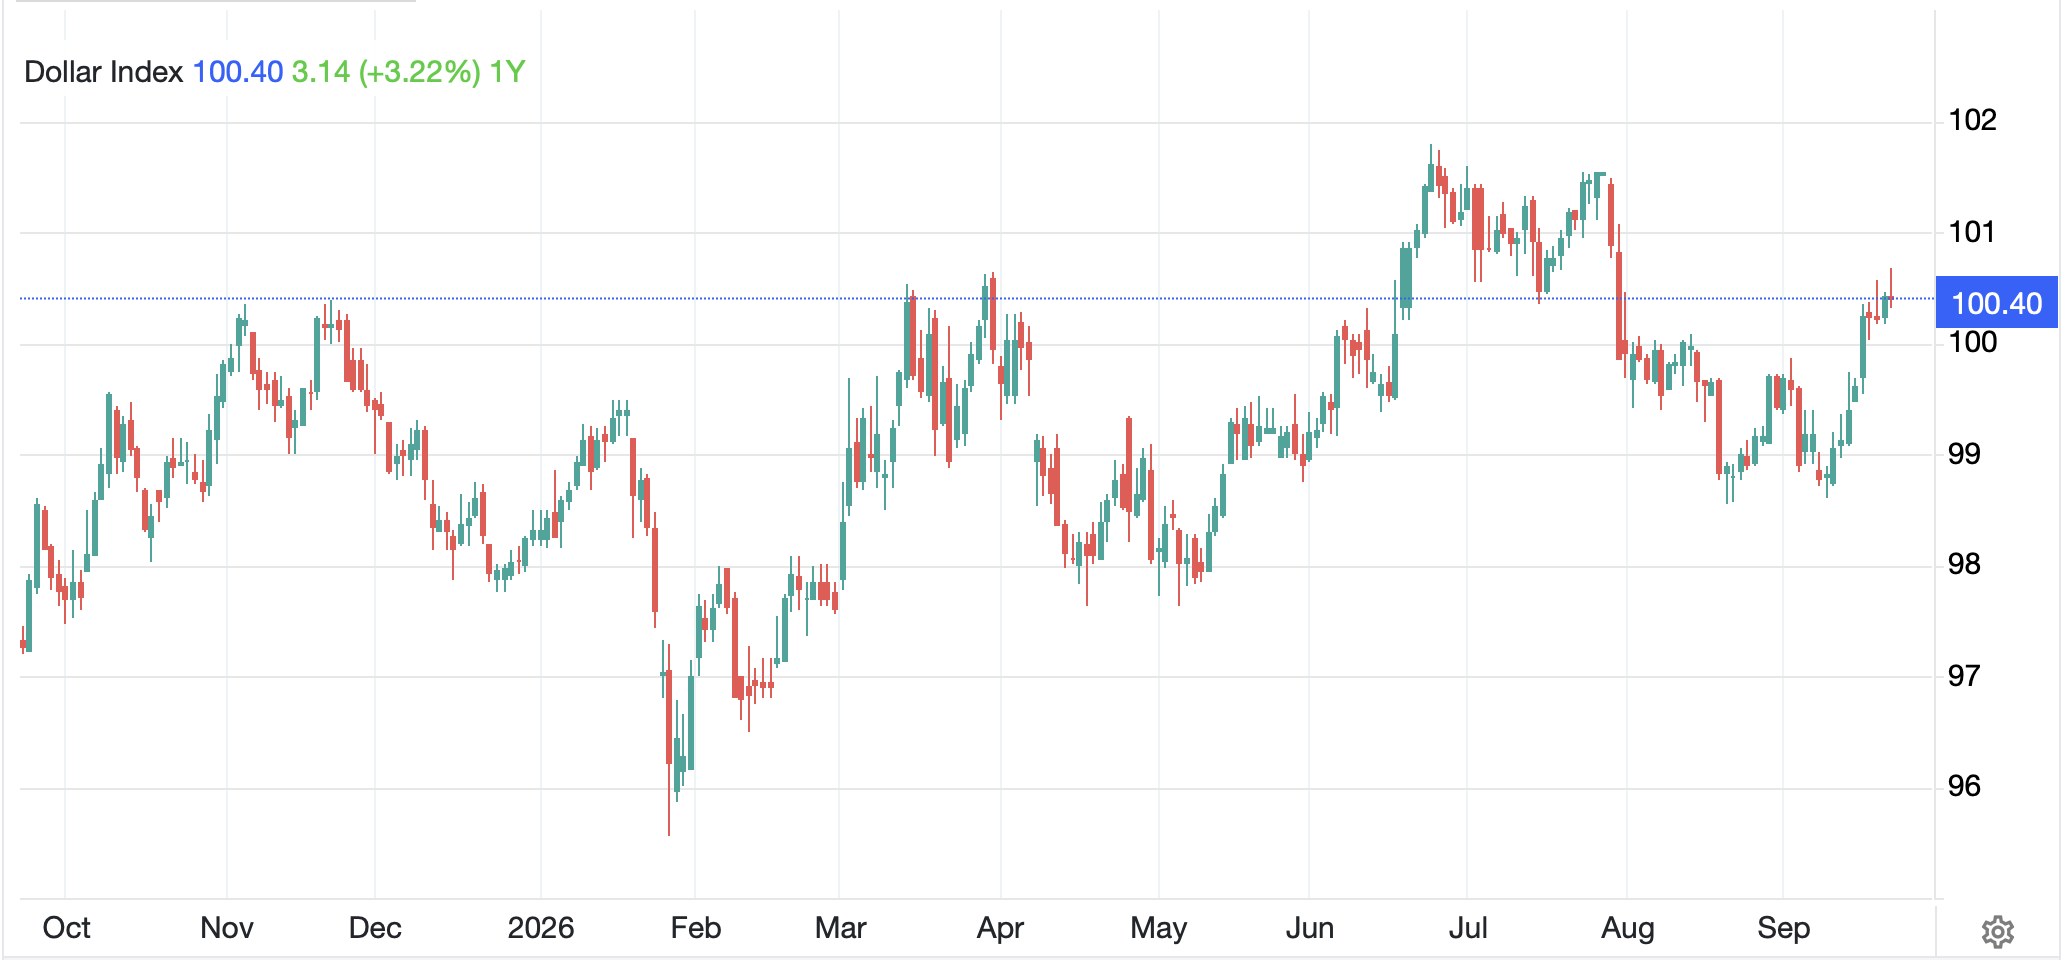
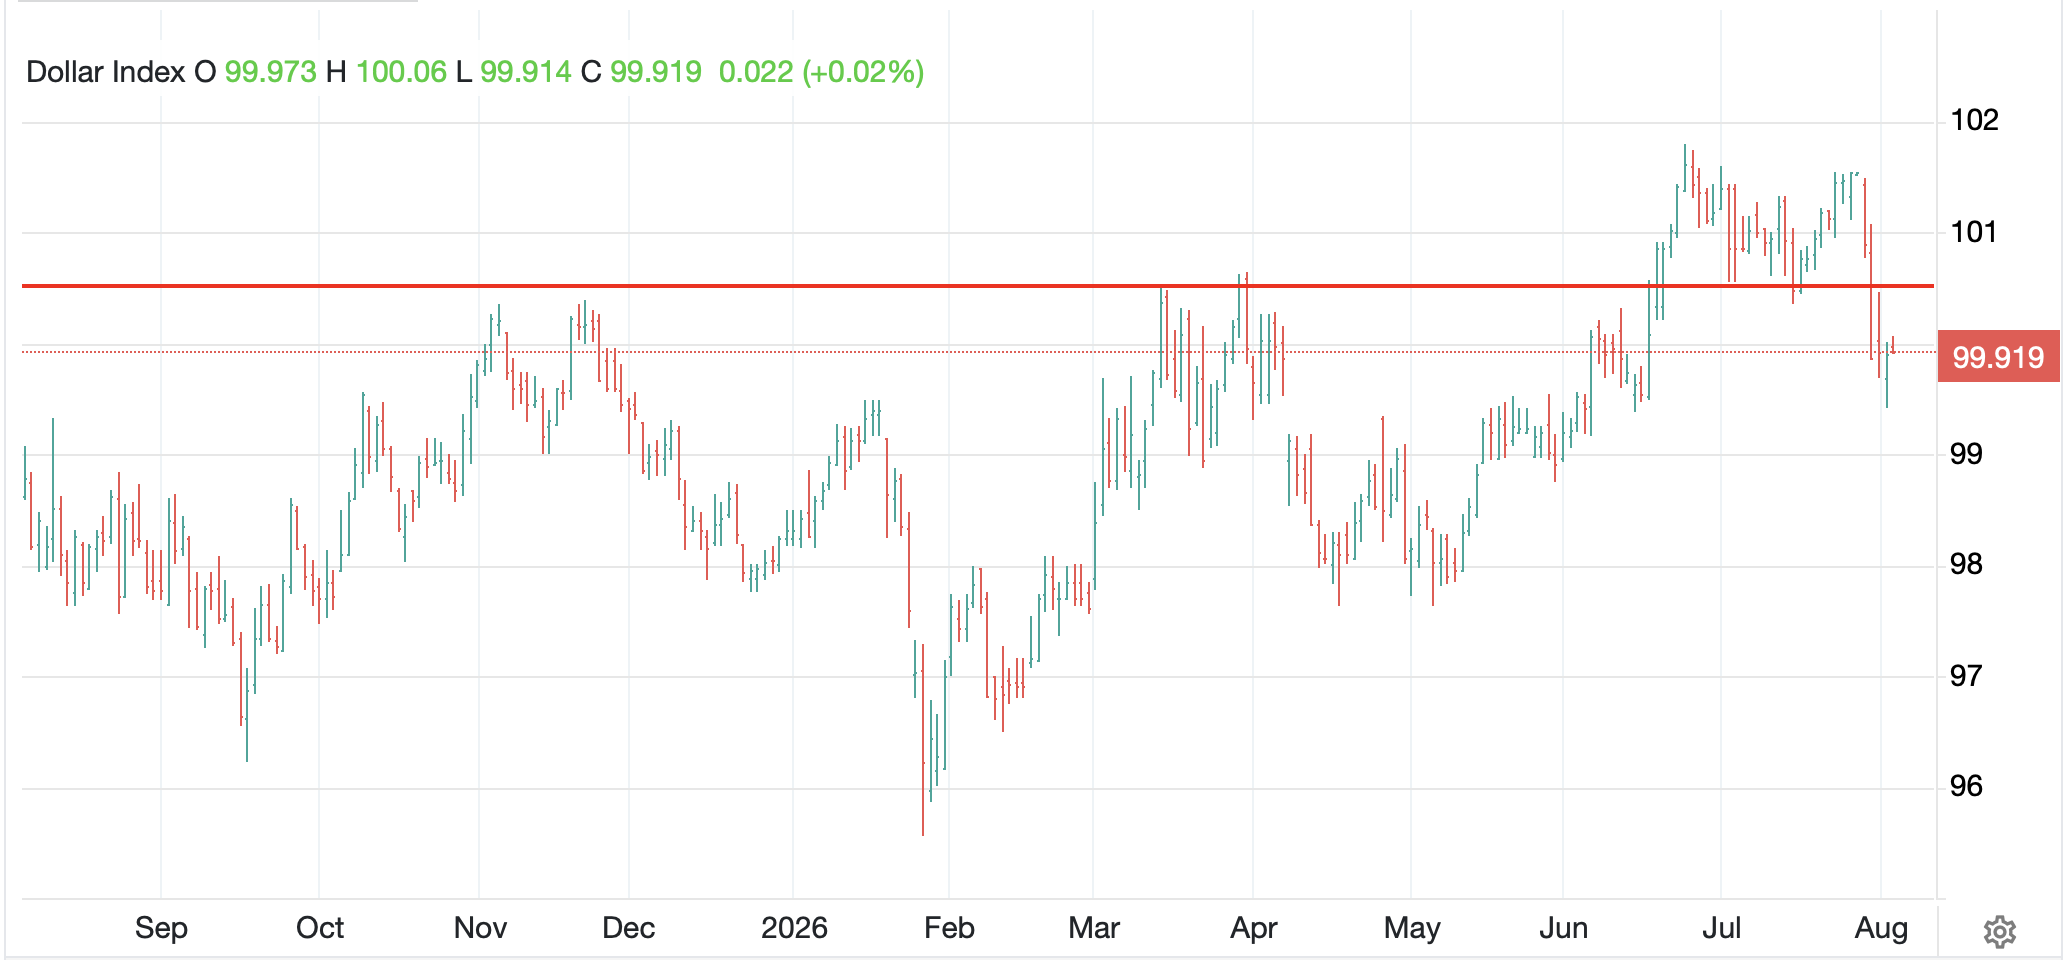
Finally, the dollar refuses to collapse despite so much wishin’ and hopin’ by a large part of the punditry.  While it has not risen substantially of late, it has not fallen either.  In fact, the DXY (0.0%) sits above 100 currently which is clearly near the top of its trading range for the past year as per the below.

Source: tradingeconomics.com

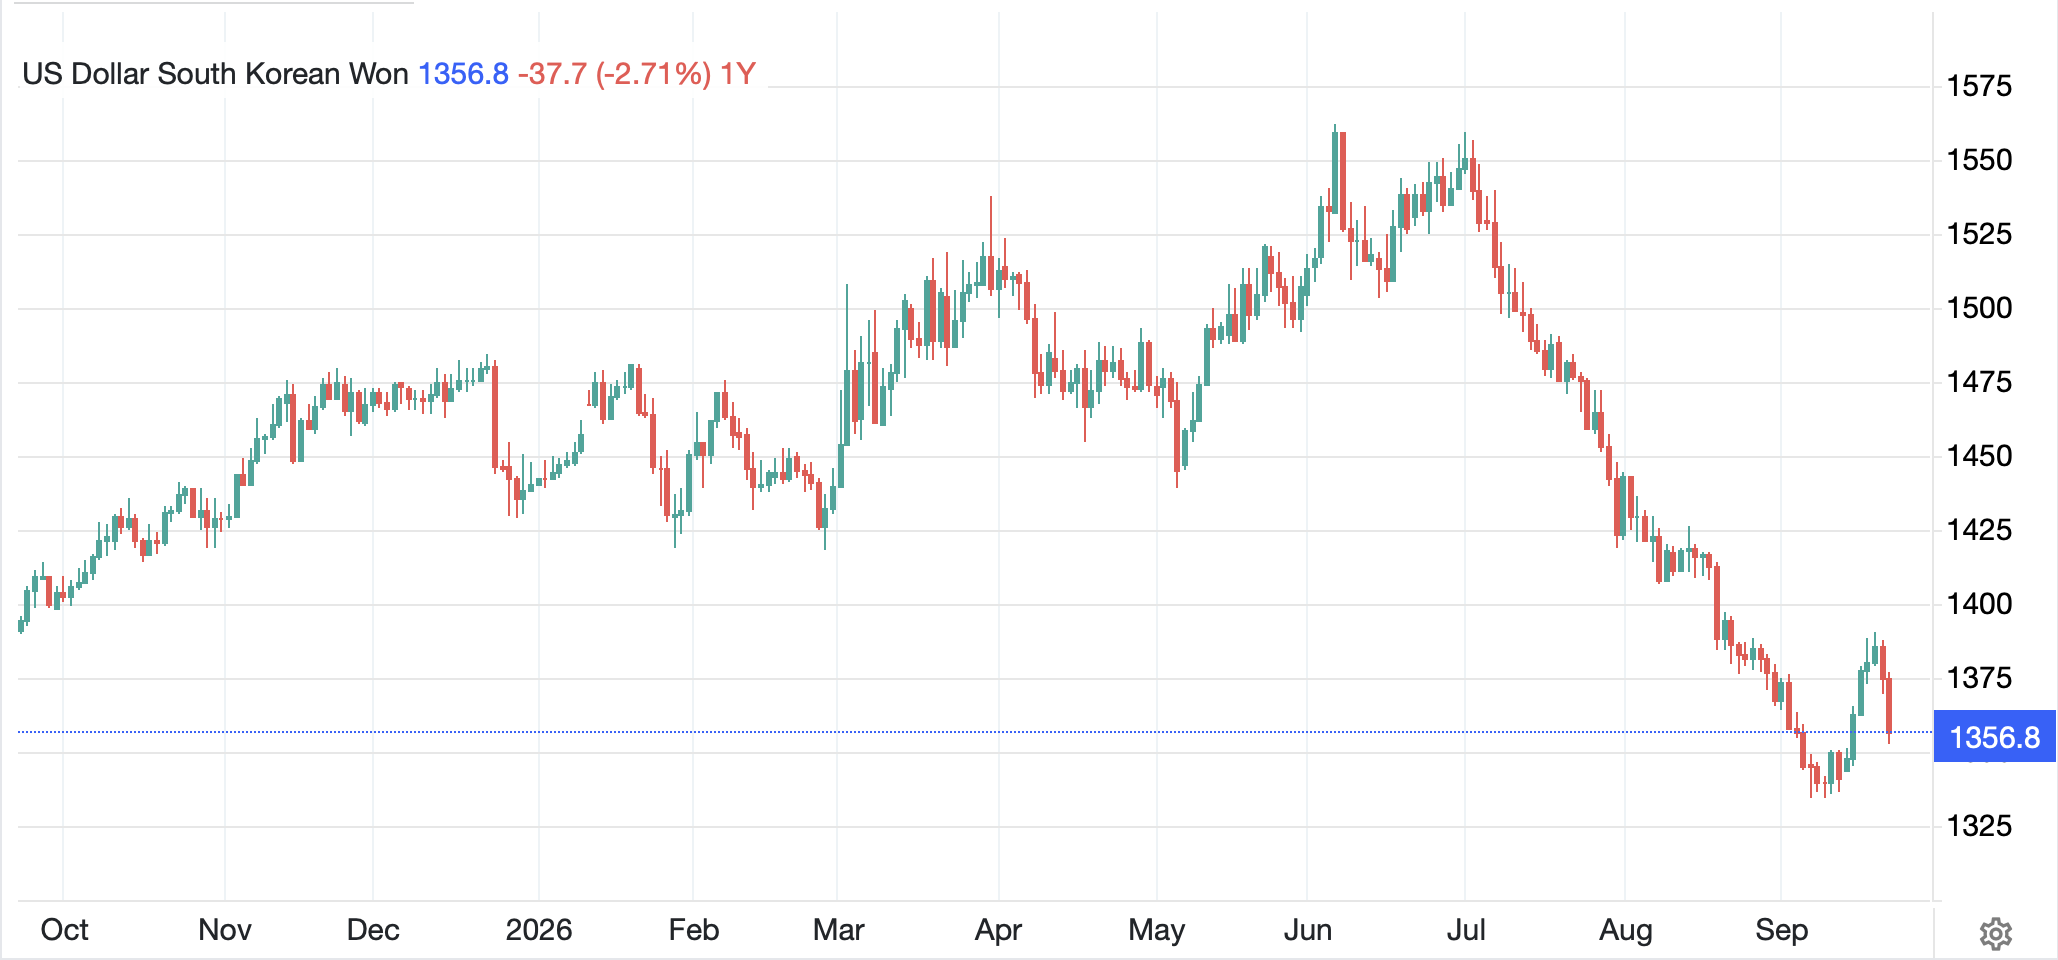
Perhaps the biggest news here today is that the ECB has begun its experimentation with a CBDC, a terrible sign for the people of Europe, I believe, but a typical European response to US activity.  While private sector stablecoins are seen as a key part of the future for the US, Europe went the government route.  Now, they make the laws and can certainly force some uptake, but my money is on USD stablecoins dominating electronic payments going forward.  As to major movers here, there is only one, KRW (+1.35%) which has seen increasing volatility, but is really just back on the track it has been since early July as per the below.  I guess the rebound was just corrective in nature.

Source: tradingeconomics.com

On the data front, there is nothing of note on the calendar although we get plenty more Fedspeak with Williams, Jefferson and Barkin all on the calendar.  Yesterday, not only did Goolsbee say rates would need to rise further, but so did St Louis Fed President Musalem.  The interesting thing to me is they all talk about the oil price shock and then still say we must hike rates.  This is quite odd to me given the inherent dovishness of almost every central banker.  I cannot tell whether this is a result of their virtually religious belief in Keynesianism or if it is all TDS.  It is, however, a mistake for them to raise rates further.

And that’s all there is today.  Potential Iranian-US talks seem like the biggest opportunity for a change in the narrative, but I don’t give them that high a probability of being successful.  In the meantime, ain’t nobody selling the dollar!

Good luck

Adf

Before We All Die

Like a fledgling bird
Rates in Japan edged higher
Will they really fly?

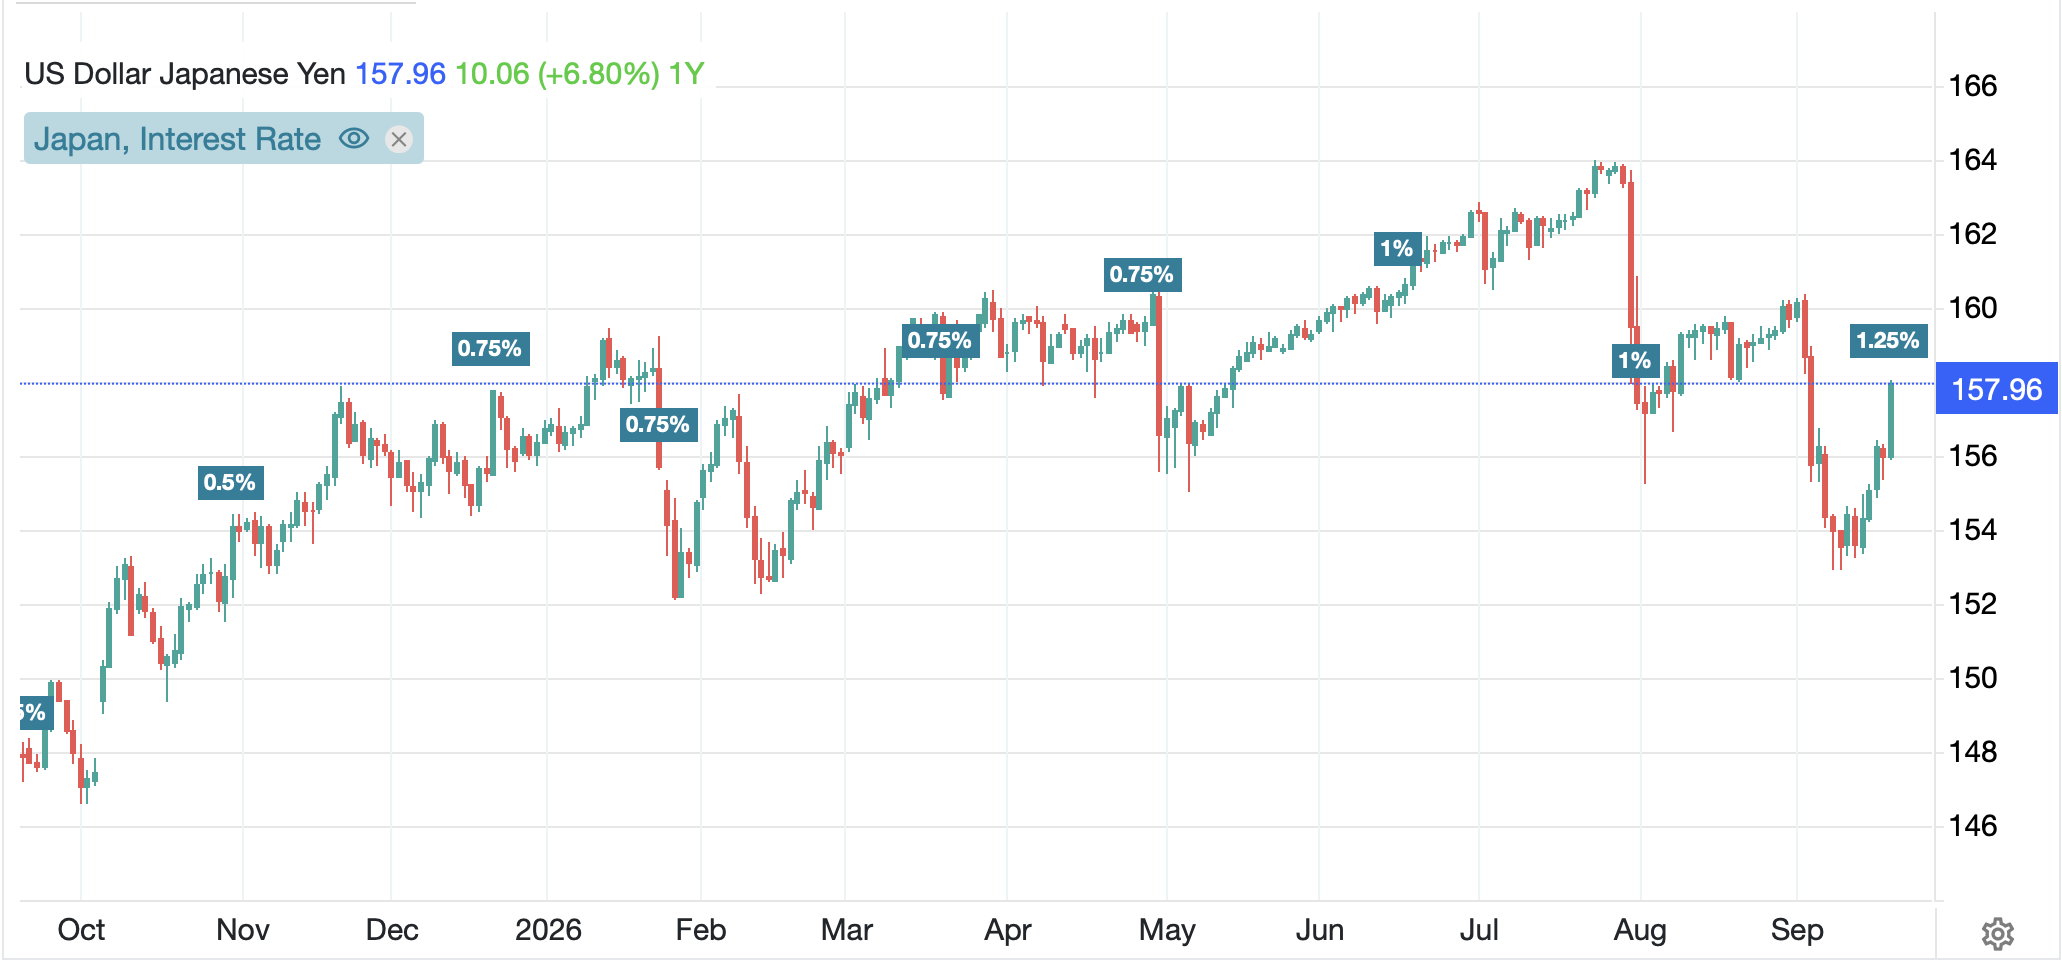
As universally expected, the BOJ raise their base rate last night by 25 basis points to 1.25%.  Much has been written about how this is the highest rate since 1995 which only tells me that Japan has had major problems for more than 30 years.  If you simply consider the idea that the interest rate represents the demand for money, either Japanese companies and people didn’t need any, or had a surplus of the stuff.  My money is on the latter.  At any rate, as you can see from the below chart, the rate hike did nothing to help support the still-beleaguered yen.

Source: tradingeconomics.com

On the chart, it shows all the interest rate moves of the last year and while the last two hikes coincided with MOF intervention and saw yen strength, I think the combination of the lack of intervention, the ostensible hawkishness from Fed Chair Warsh (I still don’t see that but I am in a minority) and the fact that the vote was 7-2 with two BOJ doves, Sato and Asada, voting to leave rates on hold seem to have undermined any chance for the hike to support the currency.  So, JPY (-1.1%) is the worst performer on the board today.  Now, we are still basically at the levels seen in the wake of the joint intervention at the end of July, but the recent trend cannot be comforting for Ueda-san, Takaichi-san or Secretary Bessent.

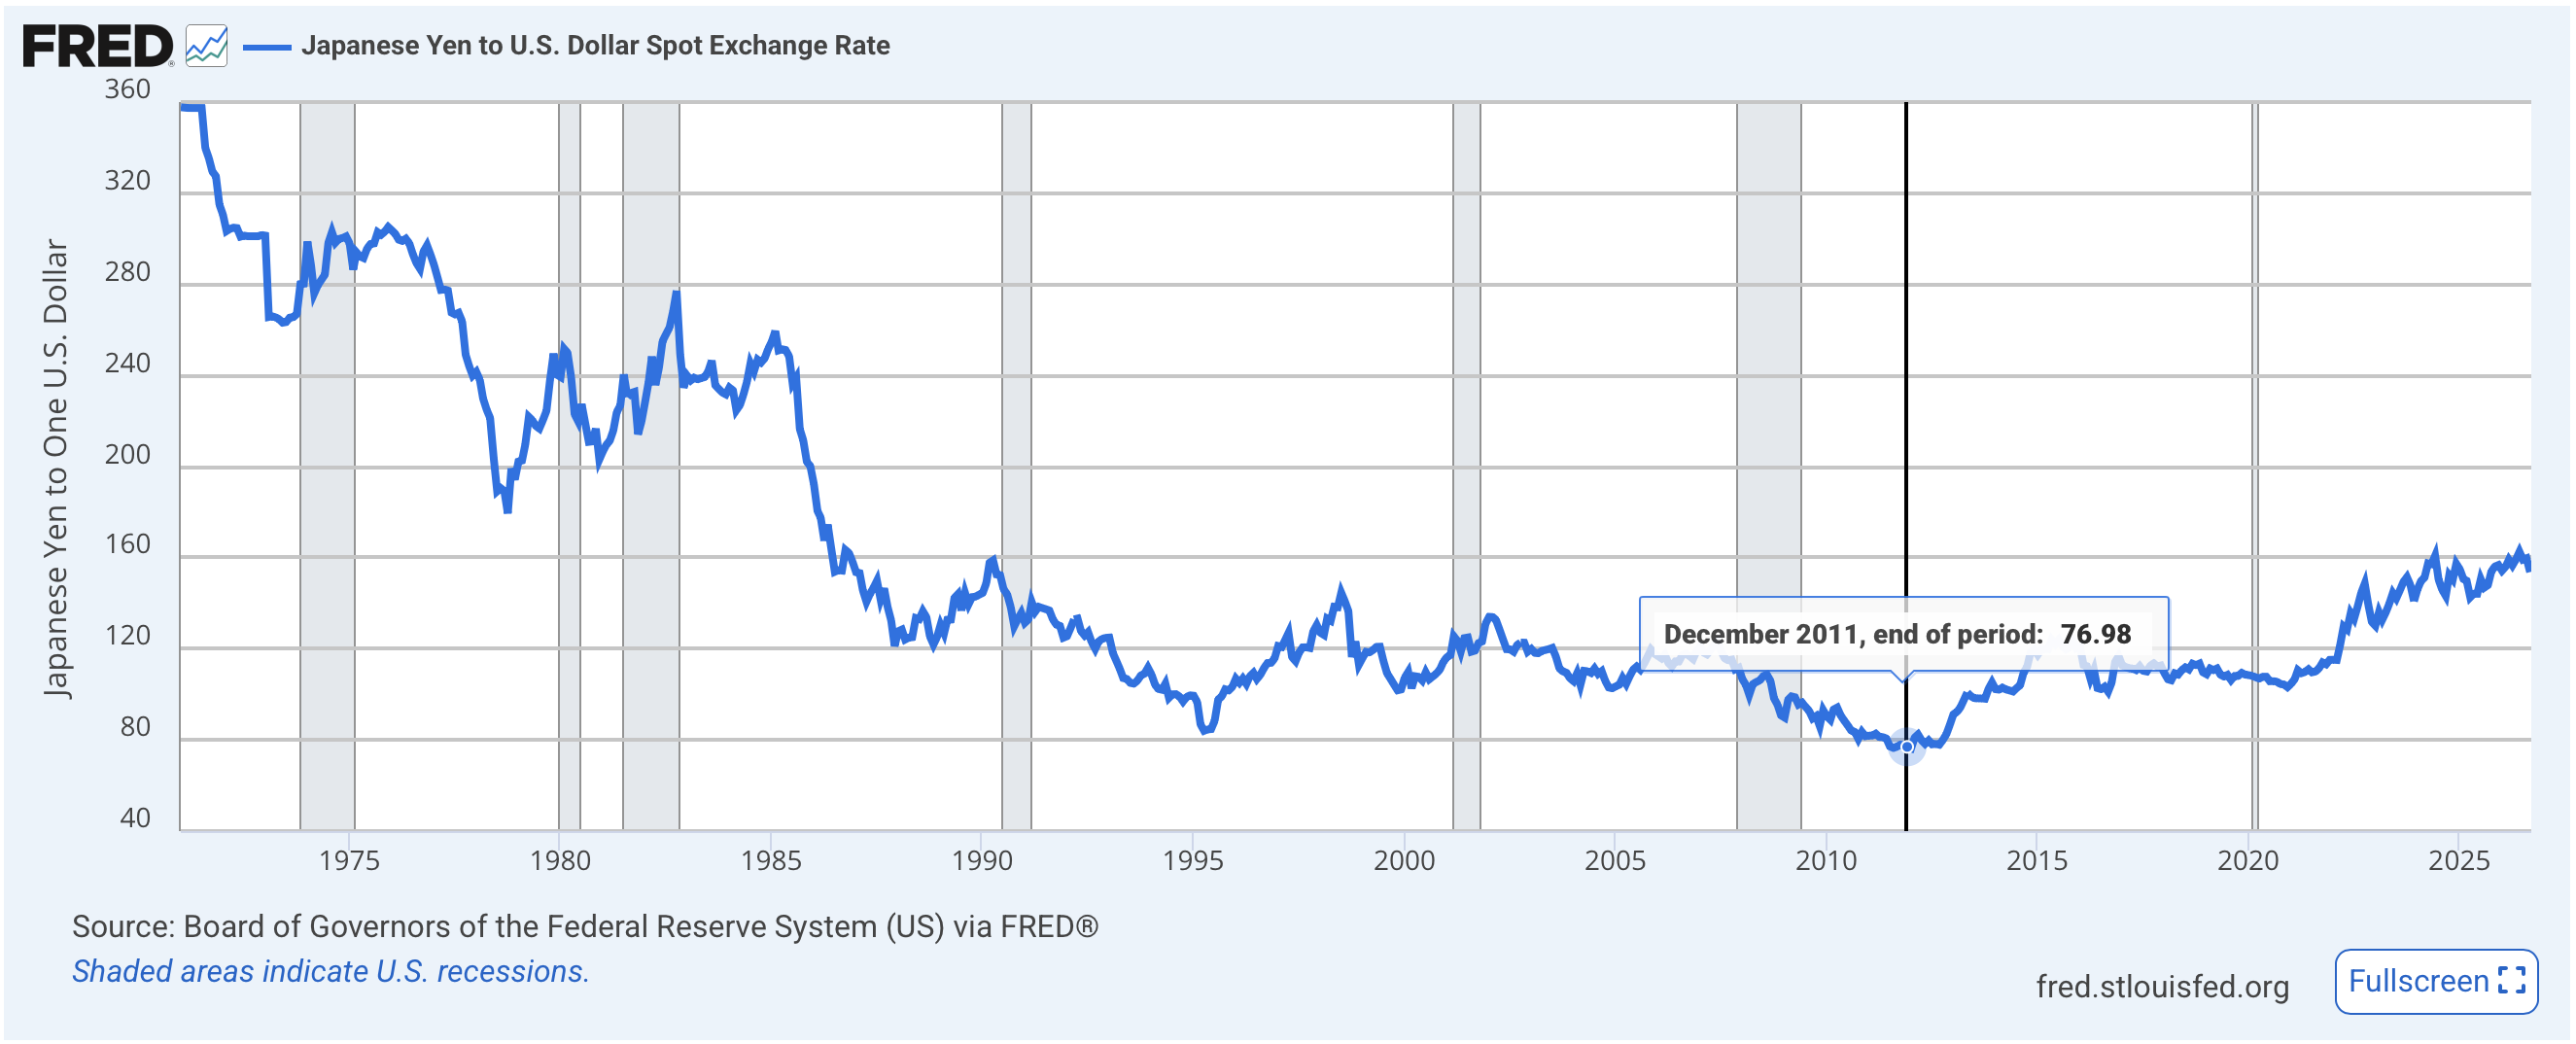
For now, the carry traders are back in fine fettle, especially those who added to their positions (and I’m sure many did) after the GPIF JPY purchases.  Here’s the thing about currencies: they tend to trend for long periods of time.  While many markets e.g., (interest rates, volatility) show reversion to the mean as an underlying property, that is not the case in FX (or equities!)  So, if we step out to a longer view of USDJPY, as you can see from the FRED chart below, after a 40-year trend of a stronger yen which peaked (dollar bottomed) in 2011, for the past 15 years, the yen has largely weakened.  Back in the beginning of the year, I forecast 180 as a year-end level, and while that may be aggressive, absent massive fiscal policy changes in Japan (i.e. austerity) or in the US, I fear we will be closer than further three months hence.

But meantime, while stocks here are rising
The narrative still is advising
To shackle AI
Before we all die
When there is a robot uprising

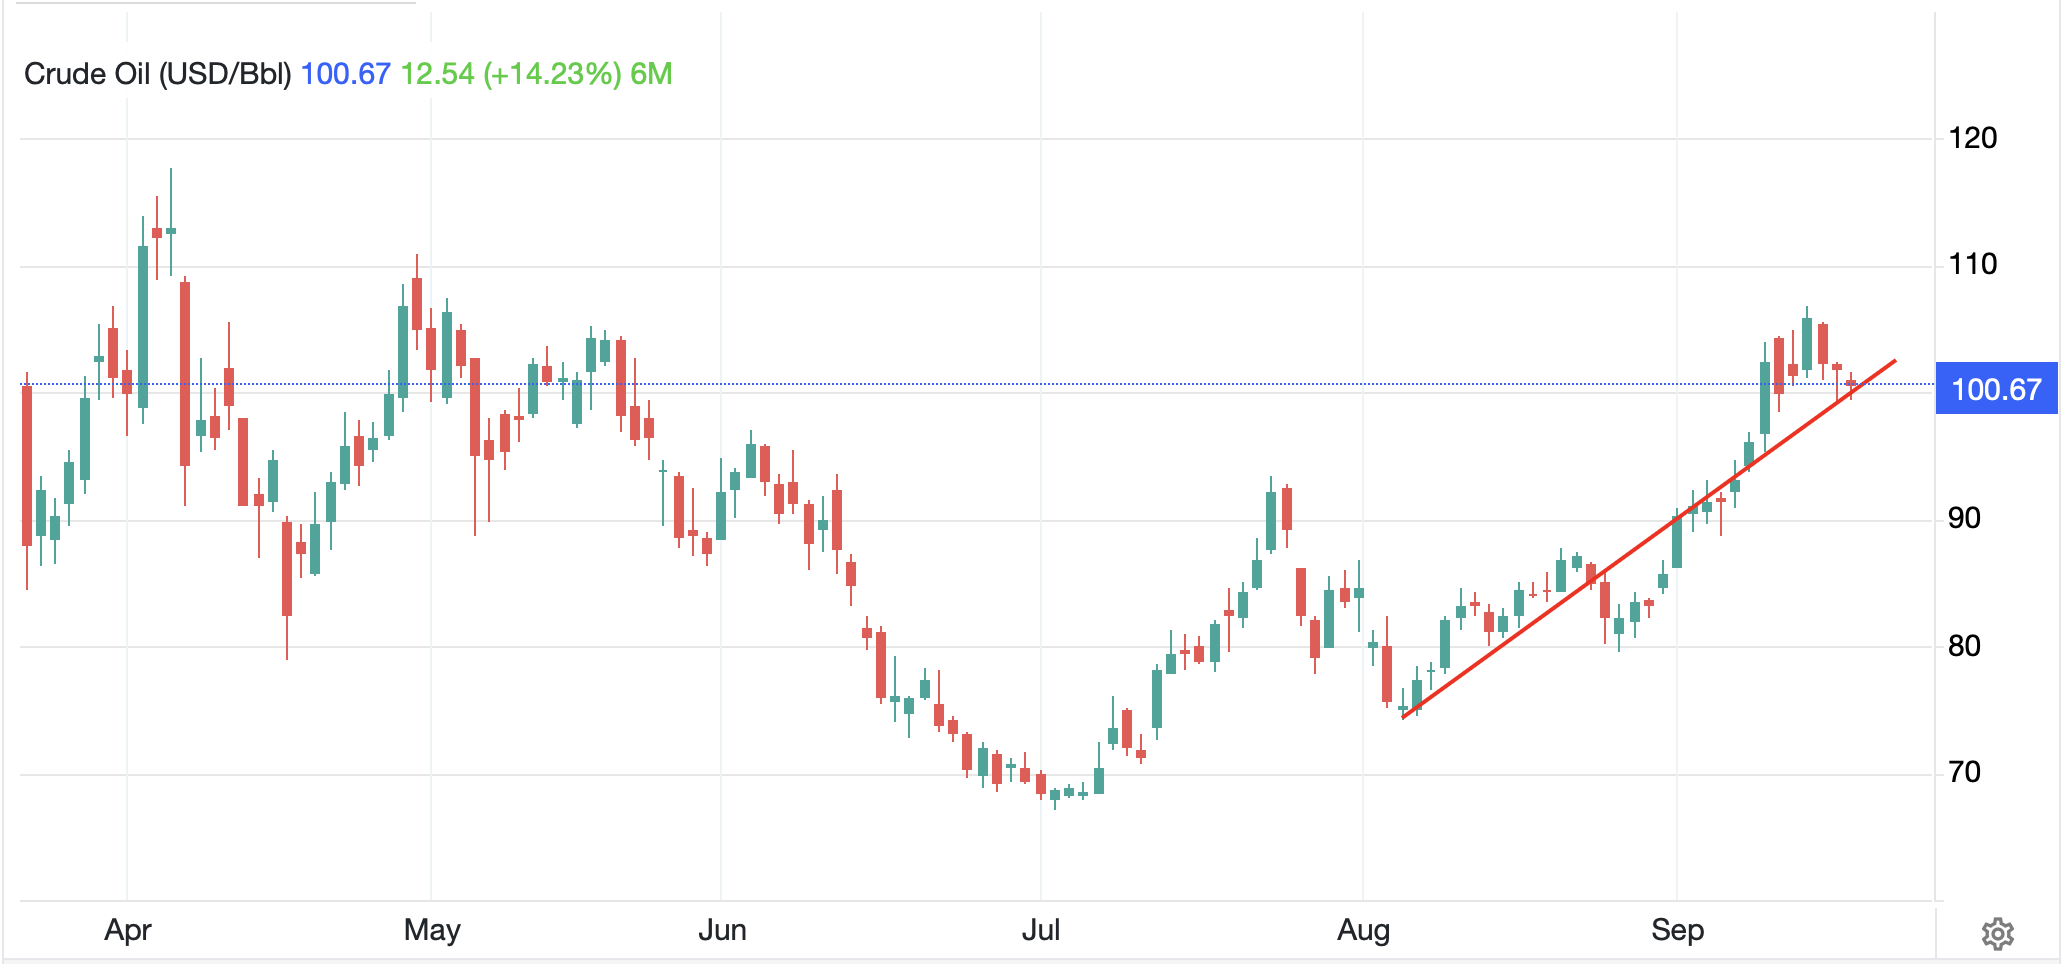
So, here’s the thing.  It’s not that I want to ignore what is happening in the Middle East, obviously, it is very important with respect to energy prices and supplies and by extension the evolution of economic activity around the world.  But it is hard to make much sense out of the recent price action in oil, which, while lower today by -1.2%, and by -4.8% in the past three sessions is still very clearly trending higher and has been since early August as per the below chart from tradingeconomics.com.

I read the same news you do, about the Houthis taking over much of the Red Sea, although the Yemenis apparently did them some material damage this morning, and who really knows what is going on in Iran since everything about it is propaganda from both sides.  One truth is Ukraine continues to destroy Russian refineries and that is having the biggest impact, I think, as products are not being produced and while I doubt we will see shortages in the US, prices here for gasoline and diesel can certainly head higher.  But I wonder, if global diesel prices rise, is the US really at a relative disadvantage economically?  After all, we are amongst the most energy efficient economies in the world.  Nonetheless, it will be painful on the pocketbook.

Which takes me back to the ongoing AI discussion/argument and what is happening there.  Let me start by saying, there are exactly zero companies that are altruistic.  With that as background, the idea that Anthropic and OpenAI are begging for regulation because they are afraid what they are doing will end mankind is, truthfully, pathetic.  AI is a remarkable tool, and one that is clearly improving at lightning speeds, but unfortunately for those who are trying to make the case that it is the most dangerous thing ever built, the story of the boy who cried wolf has too many similarities.  This can be seen from the politicians who are now pushing this story with the demise of their climate change narrative, and their covid narrative and every other narrative they have foisted on us over the past 50 years.  But it is regularly the same people.  And we all know that doom sells hence the amount of doomporn that sells itself as financial analysis or geopolitical analysis.  This is the best clip I have seen from a serious individual describing the situation at these companies.  I think it is worth the one minute plus to listen to Steve Eisman here.

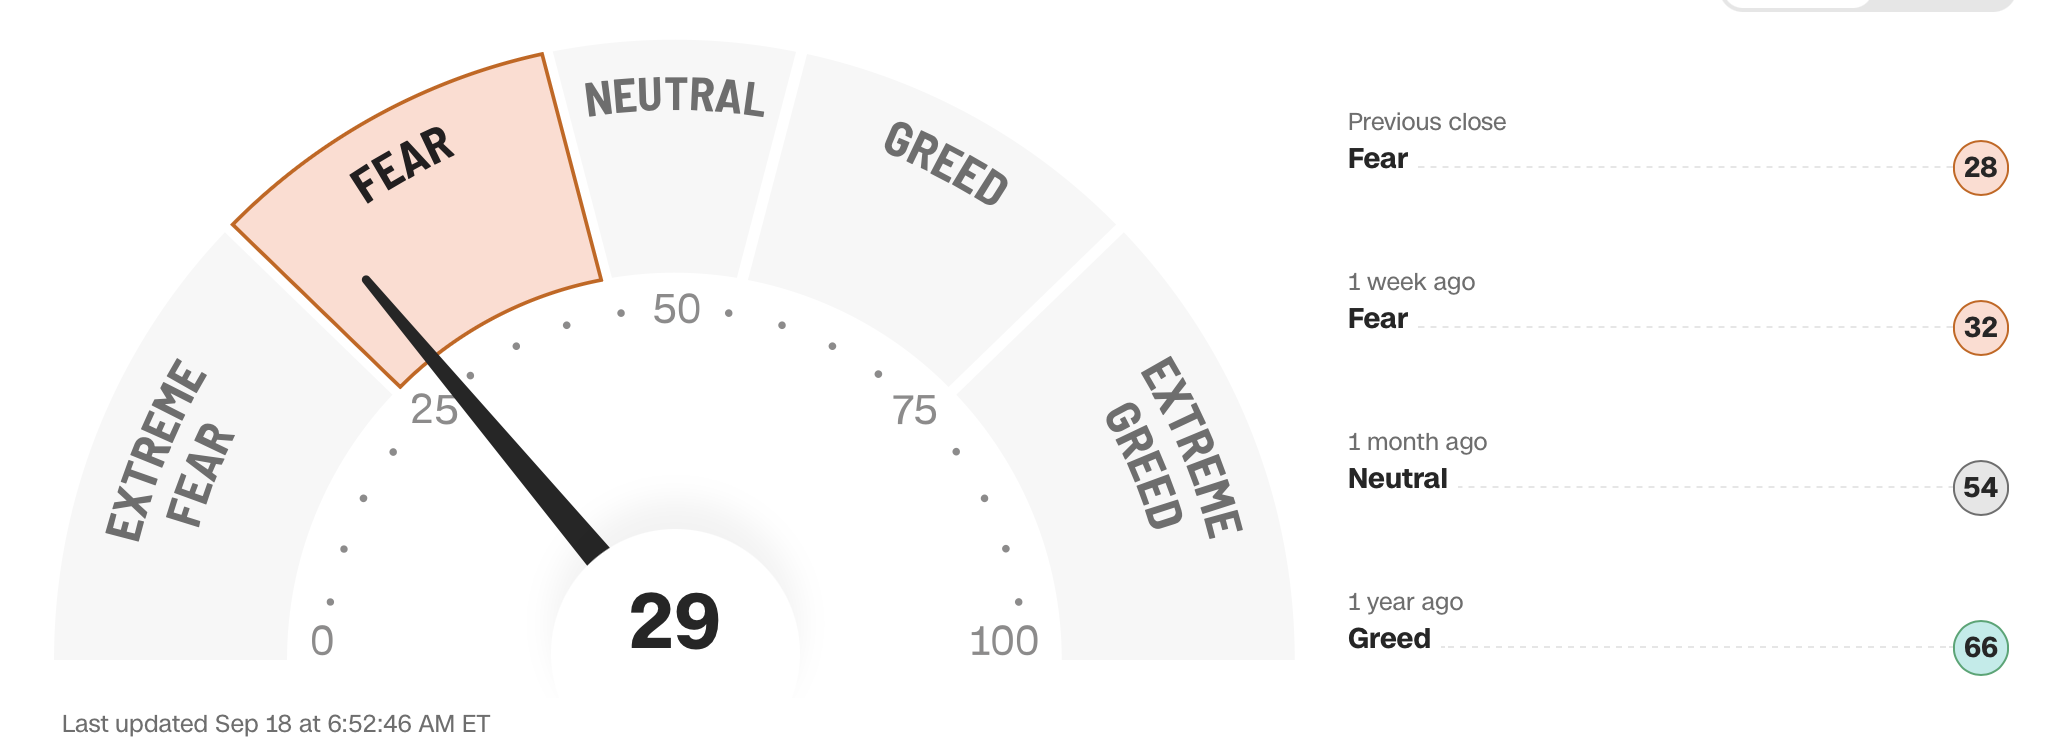
 As to the rest of the markets, equities had a nice day yesterday with oil’s decline, as US markets, and basically every major Asian market overnight all showed material strength.  Alas for Europe, this morning has seen declines of -0.7% to -0.9% across the board.  There don’t appear to be any specific catalysts to drive this movement with most attributing it to some profit taking after several positive sessions in a row.  If we look at the Fear and Greed Index, it is heading lower as per the below chart, so perhaps that is some of the driver, although that wouldn’t explain Asia or the fact that US futures are all pointing higher this morning by +0.2% or so.

Turning to the bond market, yields, which had slipped a bit yesterday are higher by 2bps in Treasuries and European sovereign yields are all higher by between 2bps (Germany) and 6bps (France).  It seems the fact that Europe appears to be preparing to enter the Russia/Ukraine war and need to borrow yet more money to arm themselves, is not helping things.  As to JGB yields, after the BOJ move last night, they slid -1bp.

With oil prices slipping this morning, we are seeing metals behave quite well (Au +1.0%, Ag +2.9%) although copper is unchanged on the day.  That negative correlation remains firmly intact.

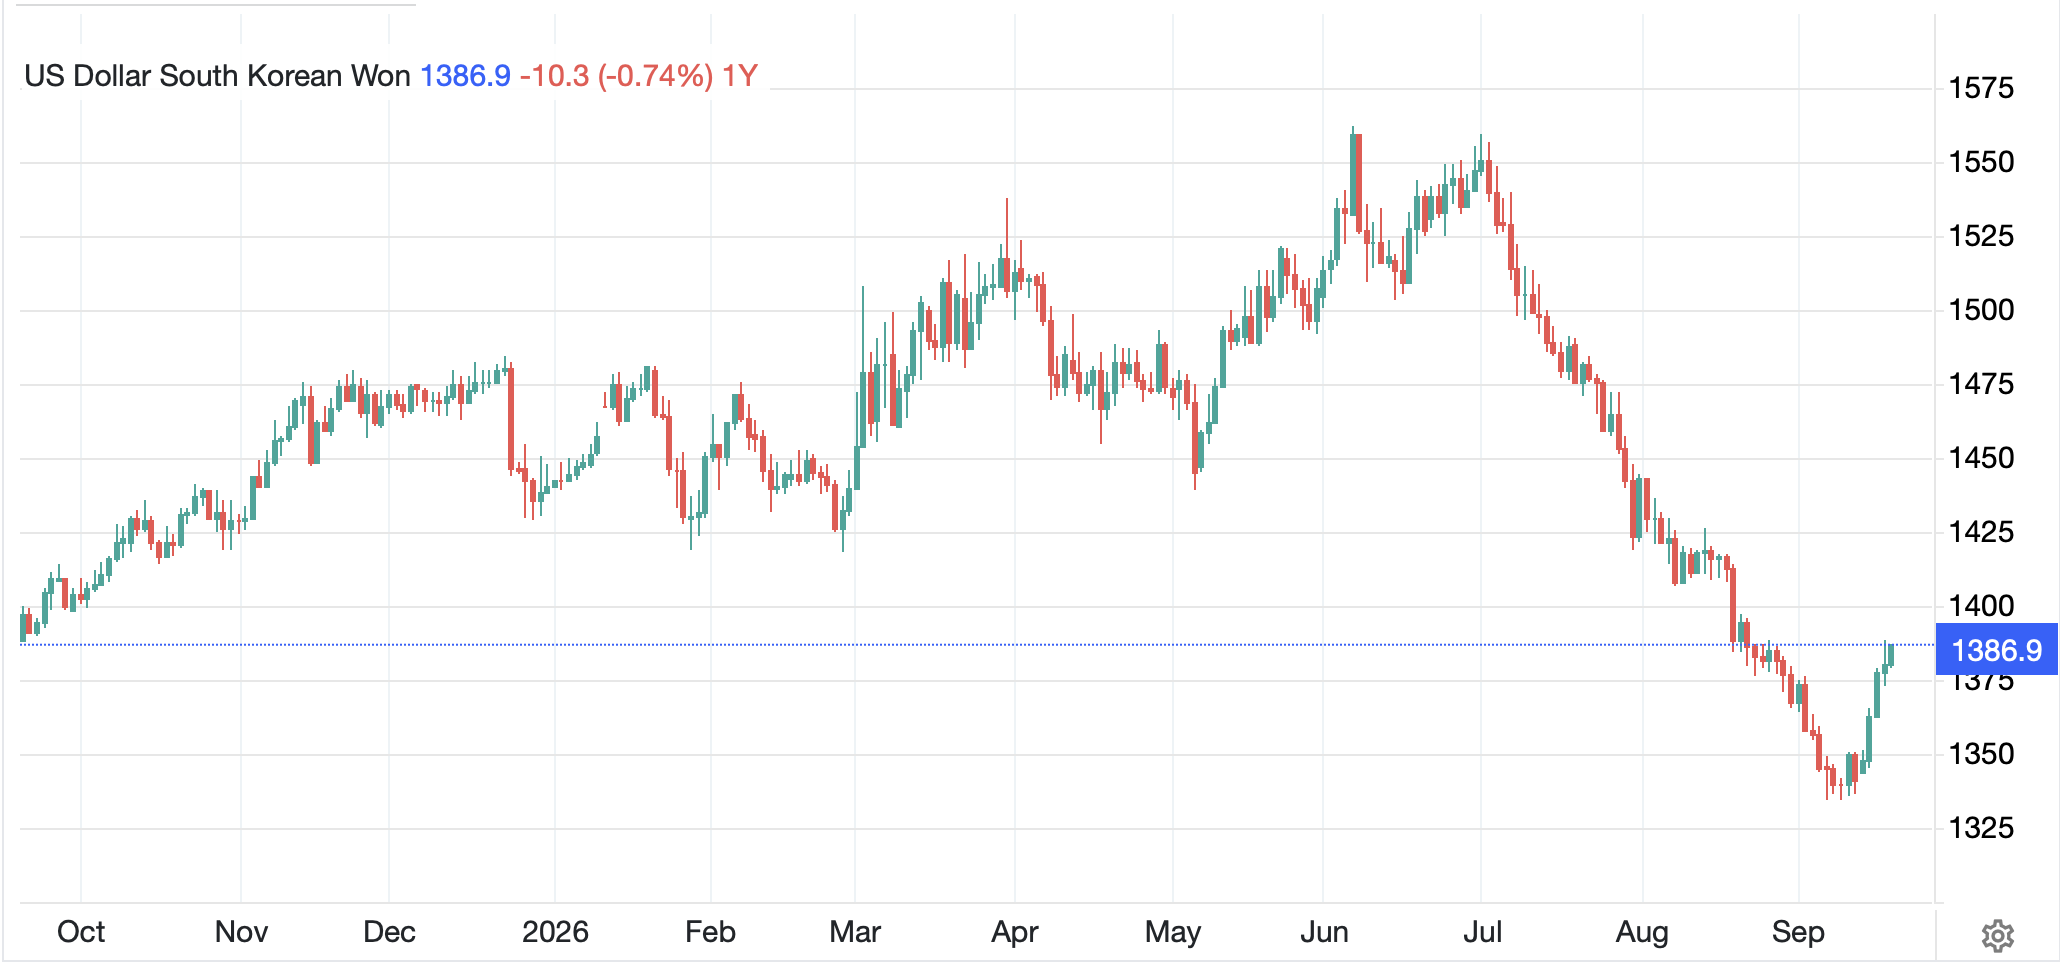
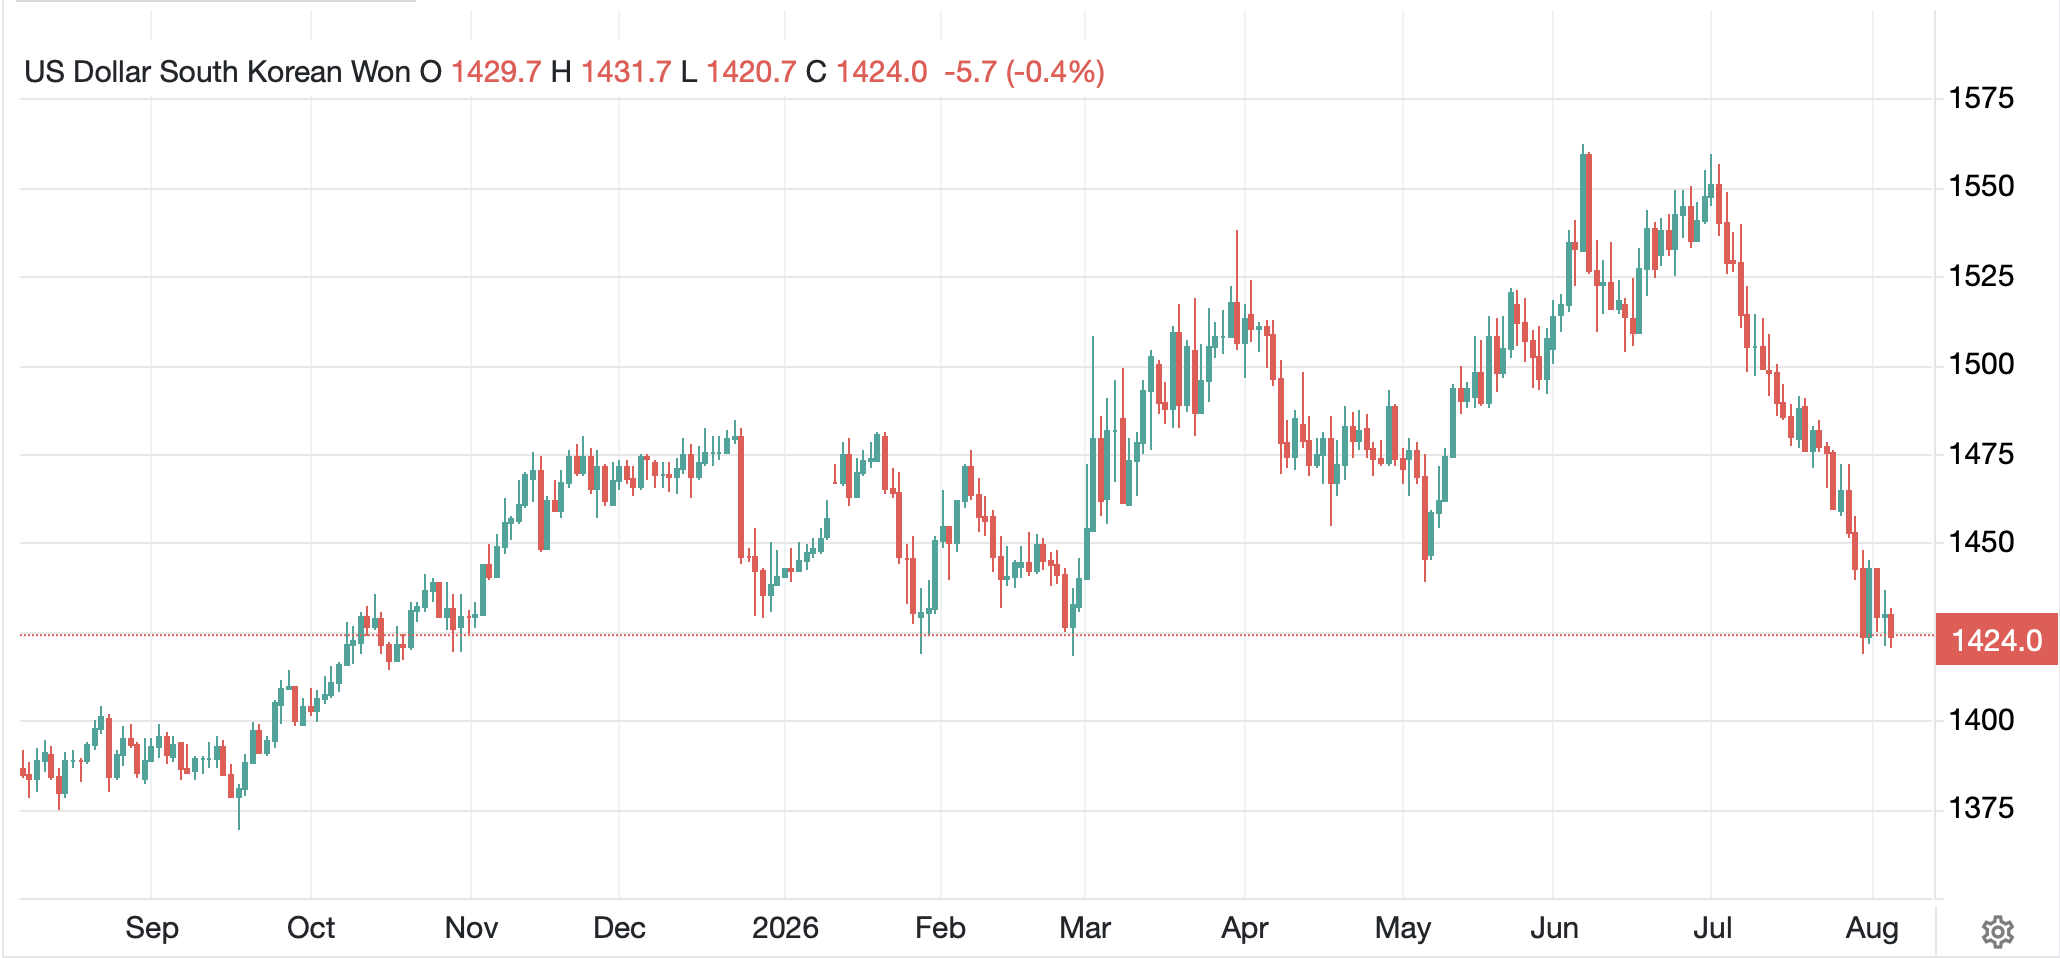
Finally, the dollar continues to hold its recent gains.  Away from the yen, most currencies are softer by between -0.1% and -0.3% in both G10 and EMG spaces, but I must admit, most of the discussion remains dollar focused rather than currency specific focused.  One thing worth mentioning is KRW (-0.45%) which after a remarkable rally since early July increased the value of the won by nearly 17%, it has reversed course over the past two weeks and given back nearly 5% of that move.  In truth, it wouldn’t be surprising if this was just a trading reaction, but the consistency of movement in both directions has me wondering if there is something else going on, although at this point, I am not sure what it is.

Source: tradingeconomics.com

On the data front, this morning brings IP (exp 0.3%) and Capacity Utilization (76.4%) at 8:30 and then Leading Indicators (0.1%) at 10:00, with Governor Bowman speaking at 9:30.  It will be interesting to hear if she is hawkish or not, but I wonder, will the narrative call her that regardless?  Certainly, it appears that there are a lot of folks who really want the Fed to continue to hike rates.  Personally, I am not in that group.

As to today, absent some new news from the Middle East, I suspect that we are going to finish the week the way it has been going, firmer stocks, lower oil and a dollar stuck in the middle.

Good luck and good weekend

Adf
Investors Are Troth

The doom mongers are up in arms
As though they raise many alarms
Investors don’t care
And add risk with flair
Ignoring the much-mooted harms

So, war is no longer concerning
And though hyperscalers are burning
Through all of their cash
Amid much backlash
Investors, their shares, are still yearning

And what about data and growth?
Investors care naught about both
Concerns about yen?
Not that trope again!
To stocks most investors are troth

As I read through my X feeds in the morning, as well as the WSJ and Bloomberg, the overriding theme appears to be the end is nigh.  Whether discussing Iran and the oil price and the future of the Strait of Hormuz, AI and the bubble or the potential for massive job losses and the creation of Skynet, the economic data and the incipient recession coming because people cannot afford to continue their consumption habits, or the idea that we are on the precipice of a Treasury bond market collapse because the Japanese yen is weak, the dominant theme is disaster is around the corner.  It is really tiresome, I have to say.

Now, you might say that I simply follow the wrong people, and that may be true, but my feed hasn’t changed, and I never look at the algorithm’s selections for me, I only look at my followings.  So, I cannot tell if people have become that much more bearish on the overall situation, or if they simply write these things because they believe they will get more engagement.  I fear it is the latter, but that simply devalues anything useful they may have to say.  Mostly, it’s frustrating to try to get an unbiased sense of what is happening in the world these days.  After all, while I understand that governments put out propaganda constantly, I thought the idea behind X and Substack was you could avoid that.  I think I am going to go back to reading books!

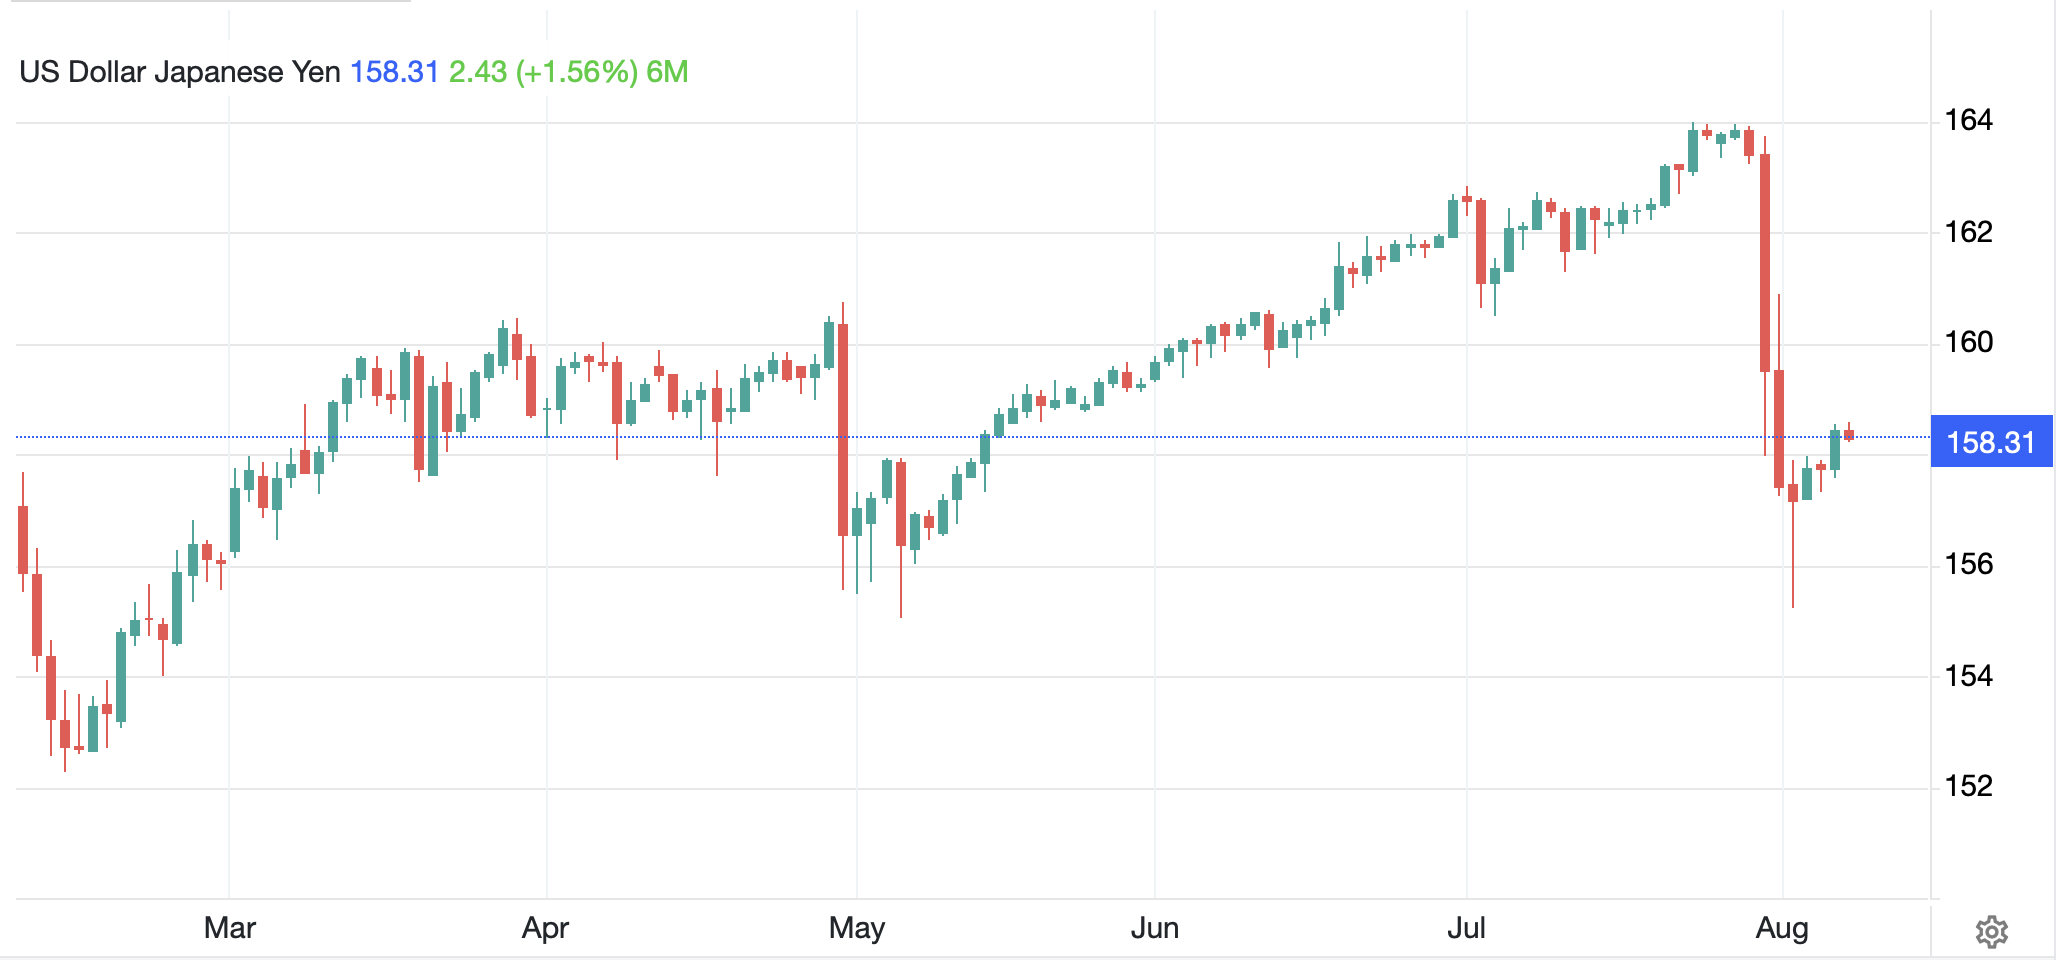
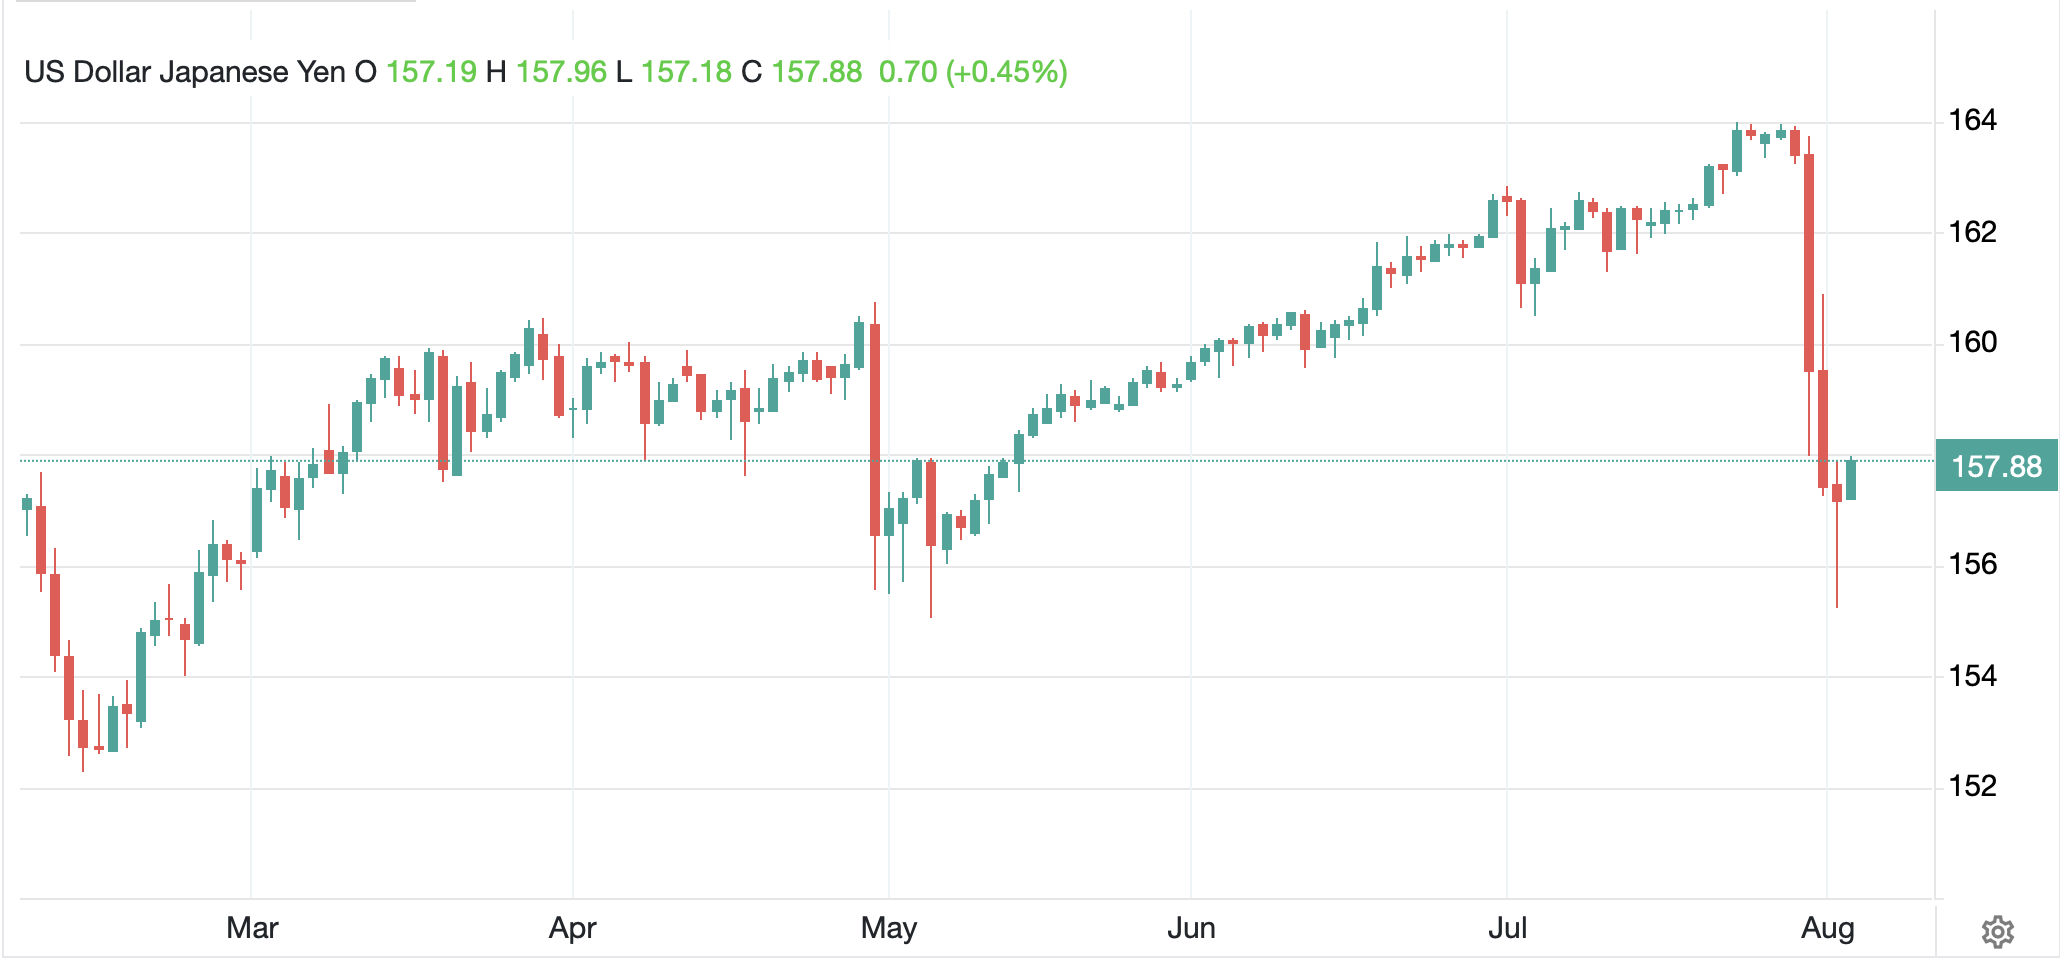
So, as we await this morning’s payroll report, I’ll try to touch on the key issues I believe matter.  Starting with the yen, which continues to garner attention, or more accurately, the joint intervention garners attention, I first have to laugh at the following Bloomberg headline, “Yen Surrenders Nearly Half Its Gains From US-Japan Intervention”.  This was written by Mia Glass, and I don’t know anything about her except her grasp of arithmetic is tenuous.  Here is the chart of USDJPY and while the yen has been weakening steadily since the intervention last week, half?  Even taking the spike low into account, we are nowhere near a 50% retracement and on a closing basis, it is a ridiculous claim.

Source: tradingeconomics.com

There continues to be much fodder made about Secretary Bessent trying to prevent a meltdown in the Treasury market but Occam’s Razor tells me that it is far more likely that a too-weak yen is bad for Japan because of its inflationary impact and the US because it impedes US exports so joint intervention made sense.  And as I have maintained all along, unless underlying fiscal and monetary policies change, the yen is going to continue to weaken.

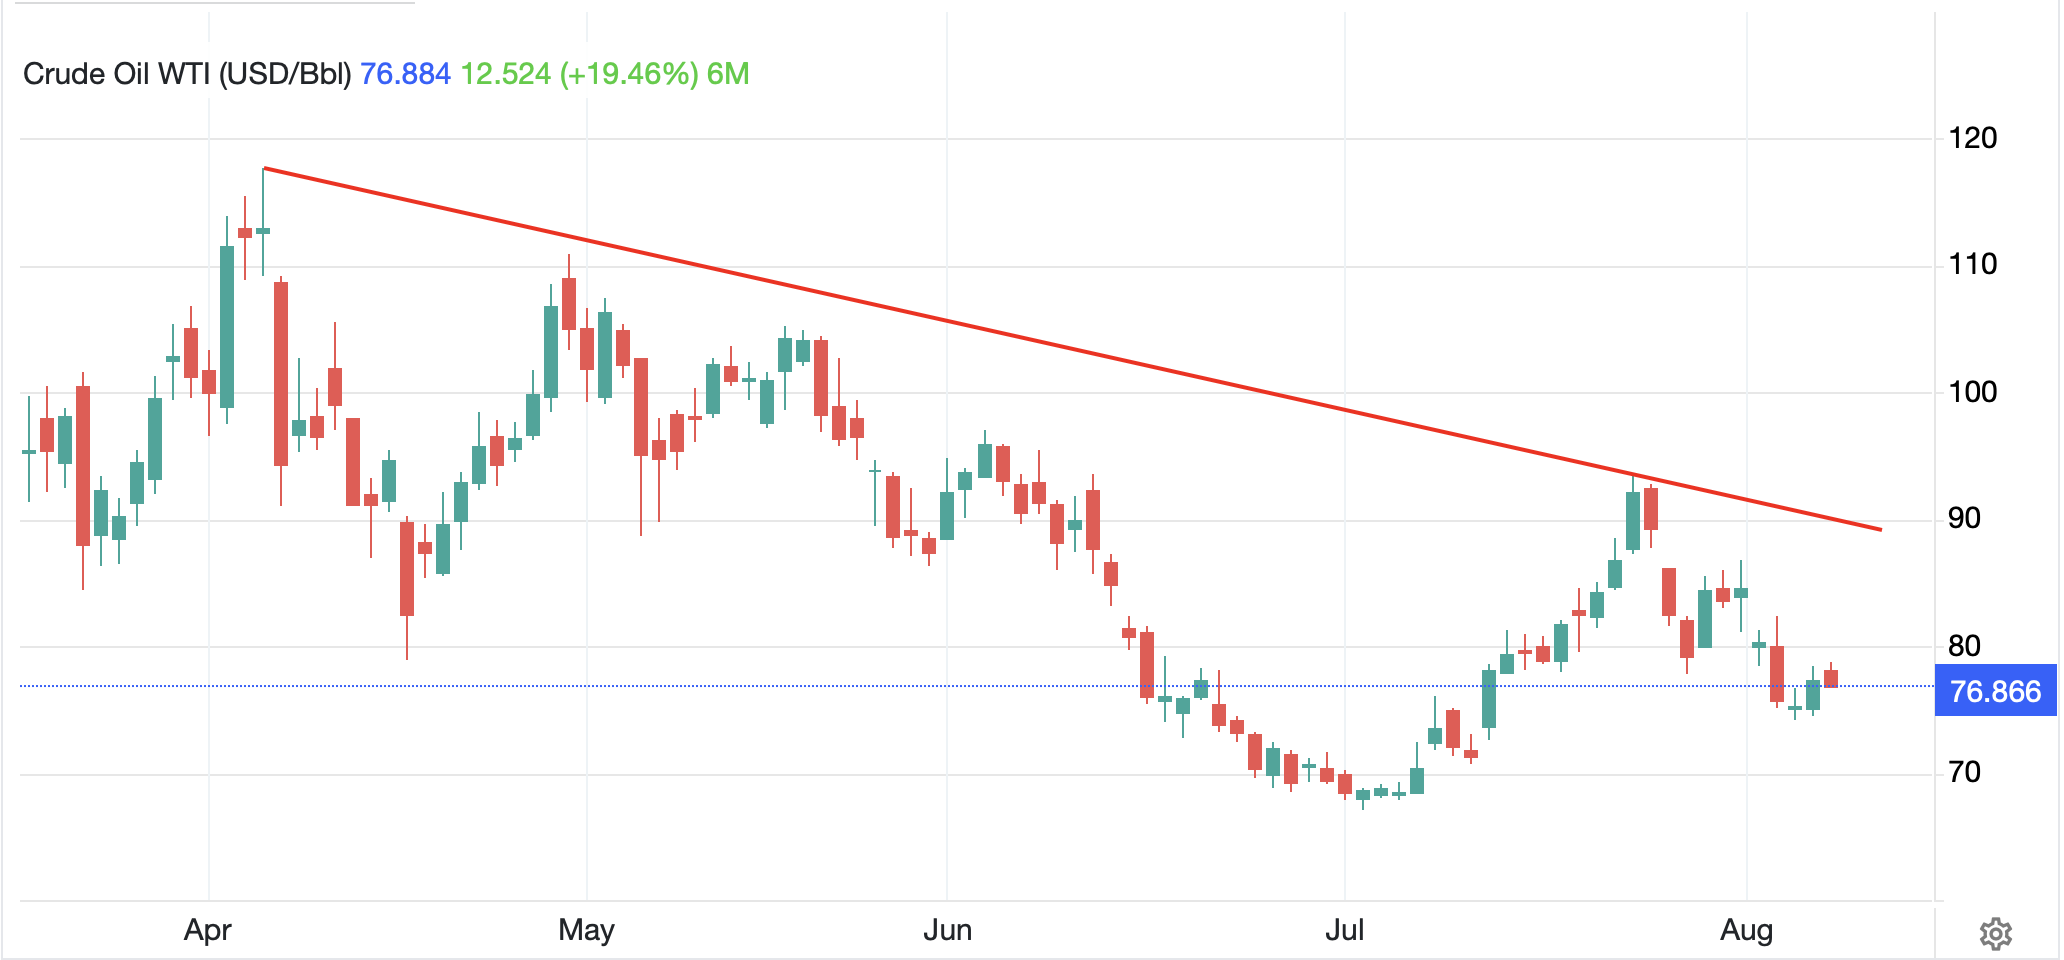
Turning to Hormuz, the press continues to write with glee about President Trump’s miscalculation and the US losing the war and whether Iran and Oman are going to come to some agreement on the Strait, but oil prices, while they rallied a bit yesterday, are lower this morning by -0.6% and -9.25% in the past week.  Looking at the chart below, despite all the discussion of inventory depletion, which are real, but obviously not as important to the price as many previously believed, the trend remains downward and we are well below the trend.  Frankly, at $75/bbl, it appears the world works fairly well.

Source: tradingeconomics.com

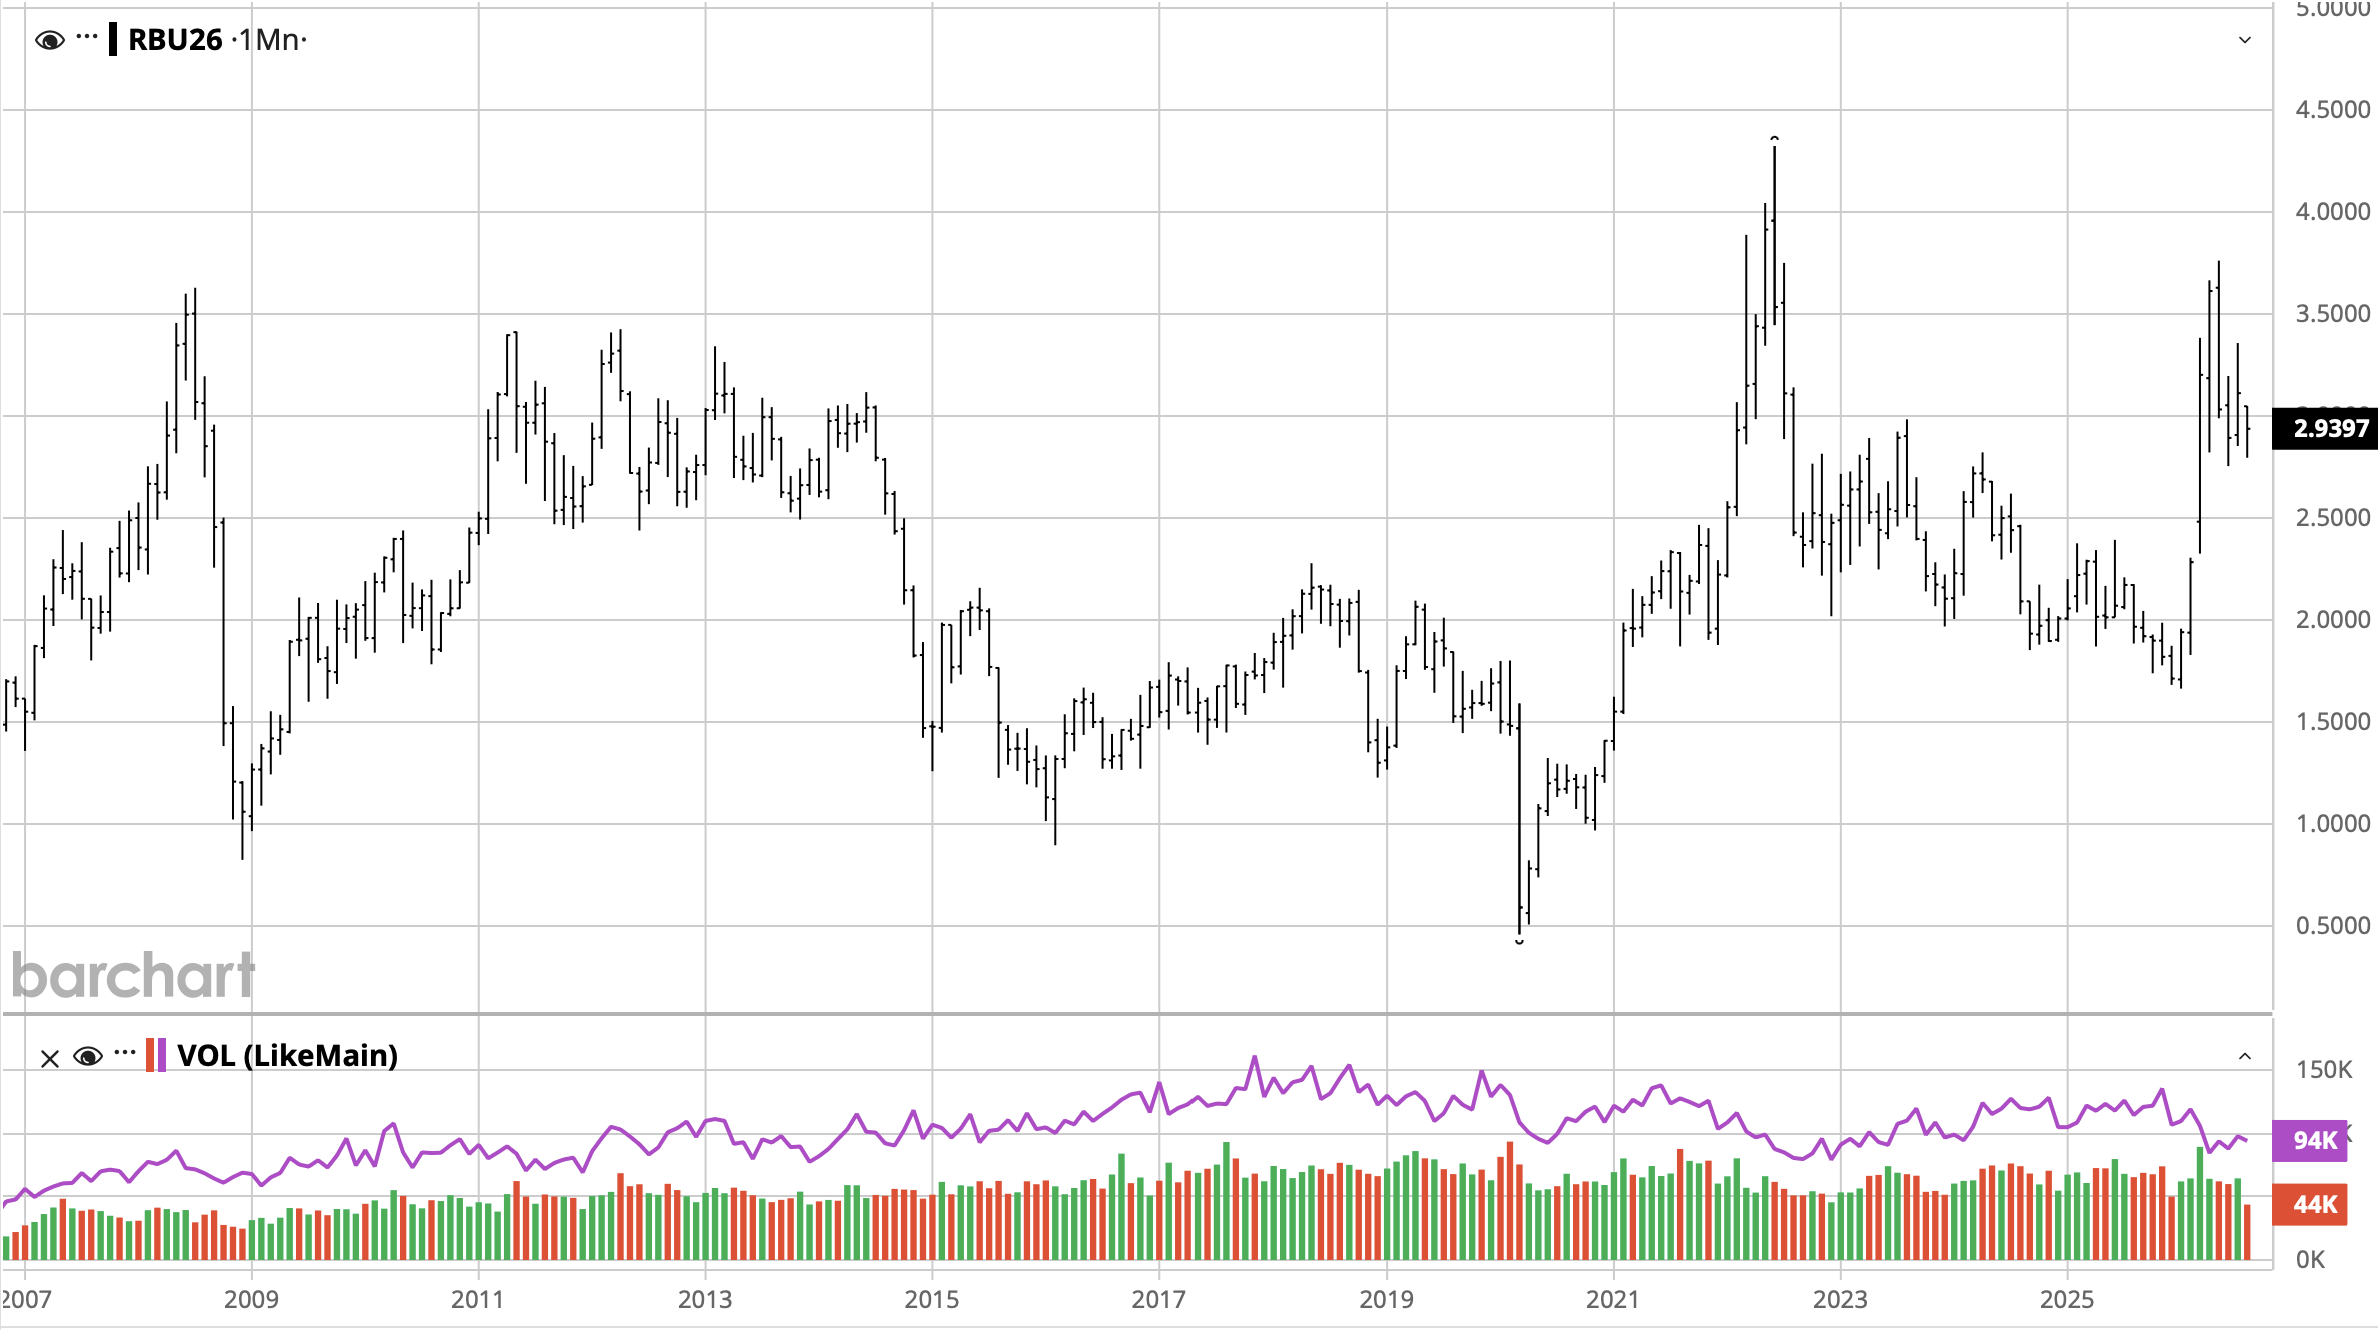
Look, I would rather pay less for my diesel, and I know you would all like to pay less for your gasoline, but here’s a 20-year history of the RBOB (NYMEX gasoline) contract.  We are hardly in unprecedented territory having spent a lot of time around here from 2011 through 2015 as well as the beginning of the Russia/Ukraine war.

I have no idea how things will end up in Iran, nor does any other commentator.  I know I am happier if Iran does not have a nuclear weapon and ballistic missiles that can reach Europe, let alone the US.  But I would say the market has almost lost interest in the war.

As to the hyperscalers and the AI bubble, in truth, it seems much of the animosity has been turned toward SpaceX as everyone loves to hate Elon almost as much as they love to hate Trump.  But it appears by many metrics that equity markets continue to benefit across the board from strong earnings results, with ~85% of companies (depending on your source) beating estimates which is well above the average of 77%.  So, the economy continues to grow pretty strongly, and companies continue to make money, and investors continue to want to buy shares.  The hyperscalers aren’t leading the pack anymore, but they have not collapsed either.  There are many who continue to explain this cannot go on forever and there will be a reckoning, and they may well be correct, but in this case, being early and being wrong are the same thing.

Ok, enough of that.  Let’s see if anything noteworthy has happened overnight.  The truth is, not especially.  Asian shares were mixed with Chinese shares doing well after solid trade data, but the rest of the region drifted lower.  European shares are firmer across the board after broadly positive data (German IP and Trade, French Trade) although the French Unemployment Rate ticked higher to 8.3%.  And US futures are higher this morning as well ahead of the NFP report.  Despite the doom and gloom, equity markets are doing fine.

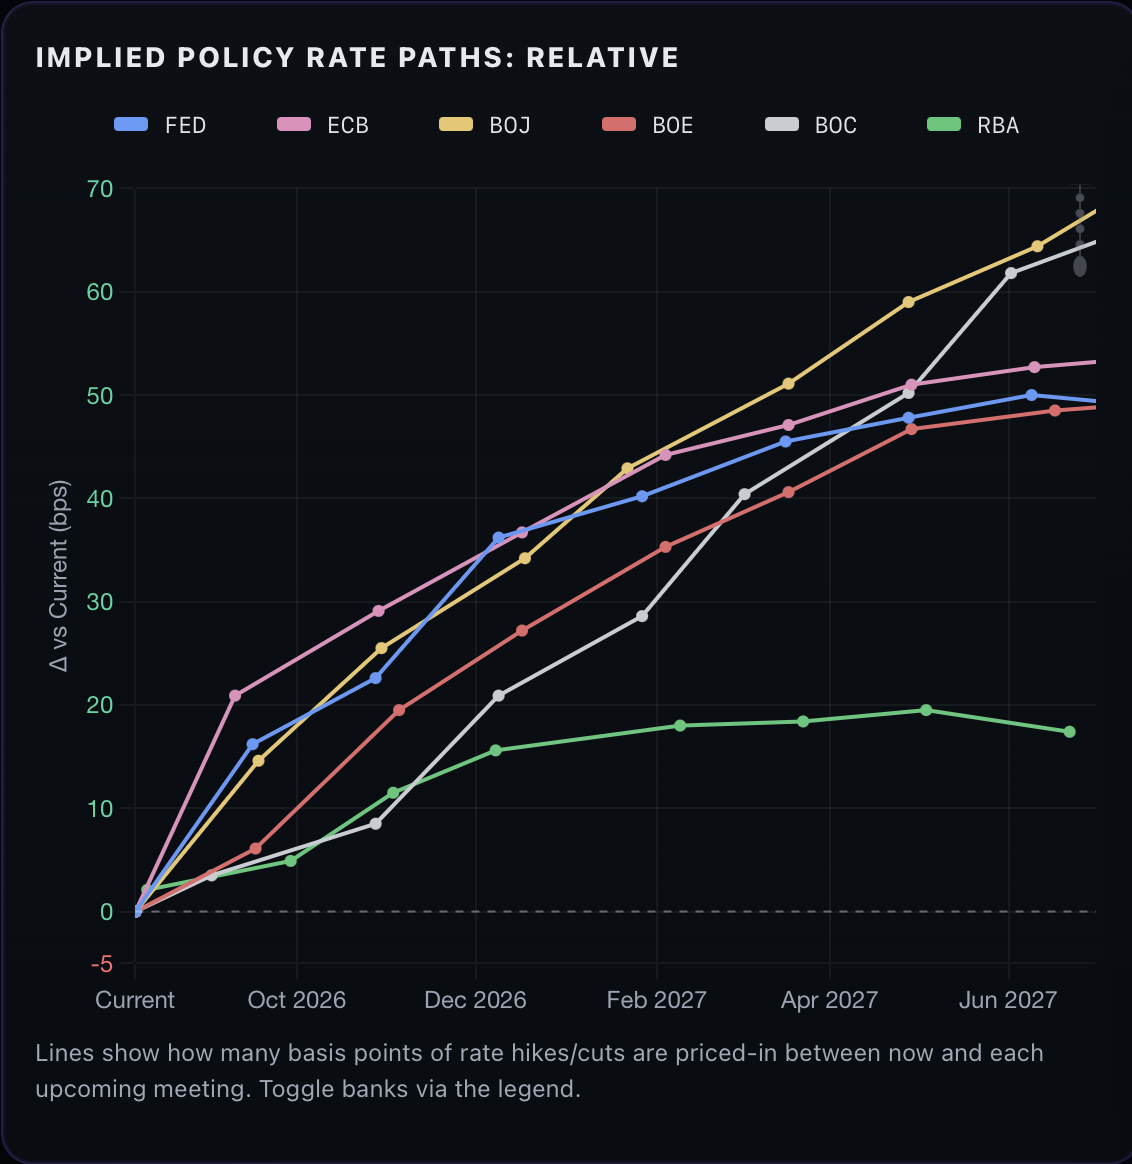
Bond markets have barely moved overnight, although we did see Treasury yields back up 5bps yesterday.  That appears to have been on the back of the oil price rise, although as I look at probabilities of central bank rate hikes, there is a growing belief that the Fed, ECB and BOJ are all going to raise rates next month as hiking rates into an energy shock seems to be their MO.

Source: rateprobability.com

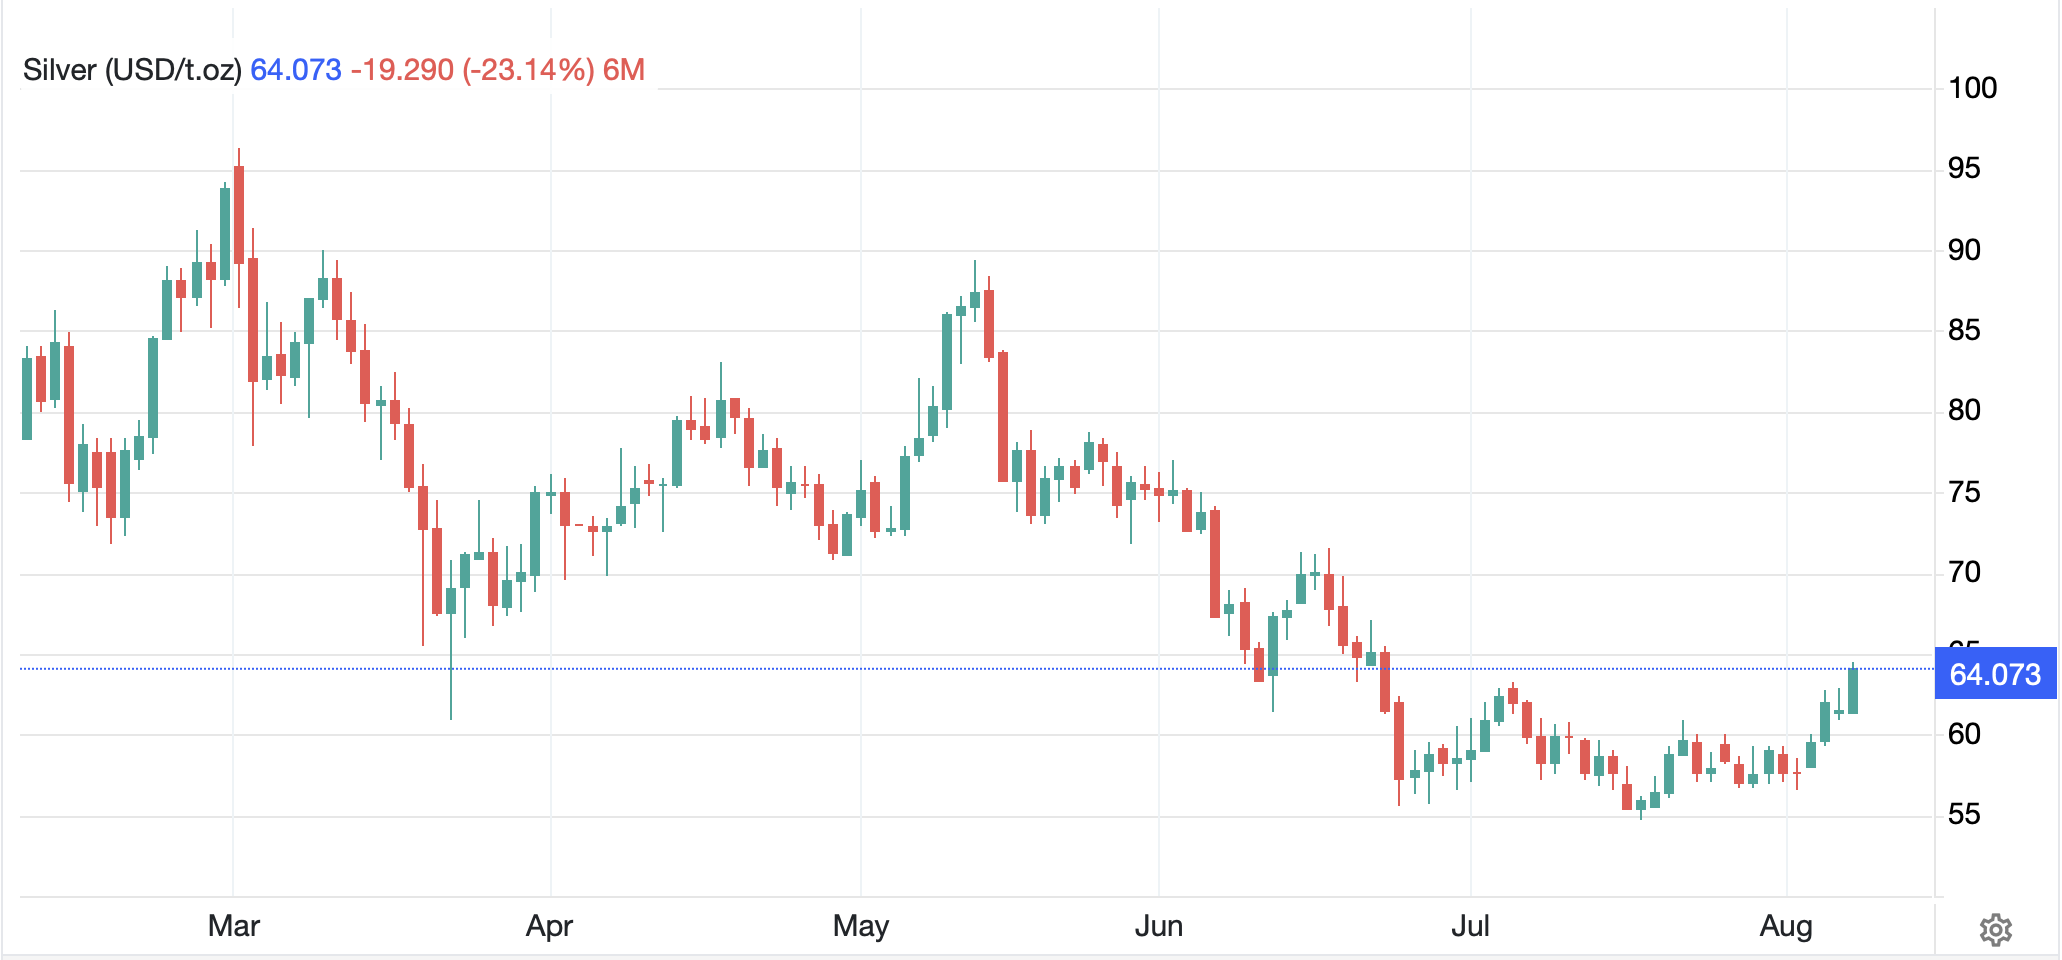
We discussed oil but gold (+2.0%) and silver (+4.1%) are the real story in commodities as both are extending their recent rallies from the consolidation lows.  For instance, silver is higher by 11% this week and $9/oz since July 17th.

Source: tradingeconomics.com

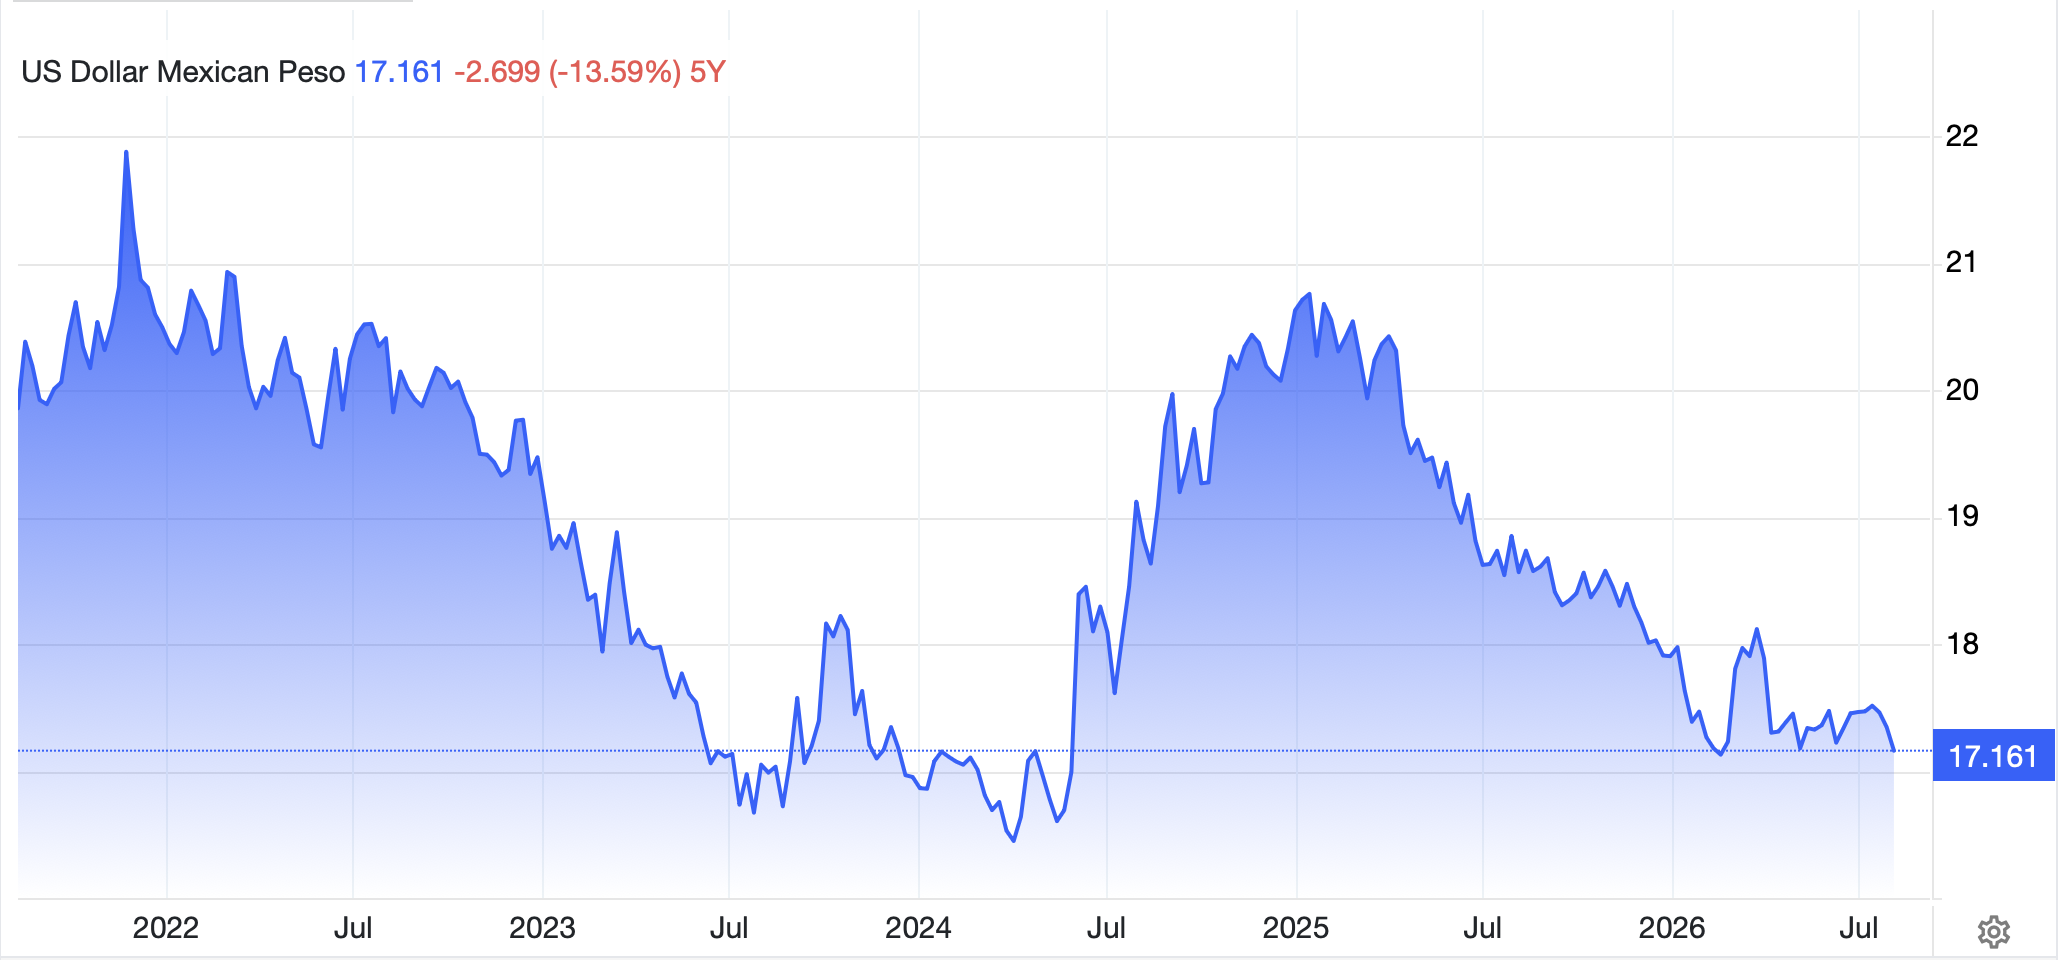
Finally, the dollar, despite all the anxiety about the yen, remains quiet overall.  The DXY is below 100, back in its range and showing no inclination to move in either direction.  This morning ZAR (+0.7%) is the king of the hill on the rally in gold while MXN (+0.3%) is a touch higher after Banxico left rates on hold.  But remember, peso rates are still high and economic growth continues apace so investment opportunities abound.  The peso has strengthened more than 17% since the beginning of 2025, shaking off any tariff concerns easily.

Source: tradingeconomics.com

As to the data, here are consensus forecasts:

Nonfarm Payrolls80K
Private Payrolls78K
Manufacturing Payrolls4K
Unemployment Rate4.2%
Average Hourly Earnings 0.3% (3.5% Y/Y)
Average Weekly Hours34.3
Participation Rate61.6%

Source: tradingeconomics.com

We also see Canadian employment data (exp 6.5% Unemployment Rate) and hear from Thomas Barkin, the Richmond Fed president.  But it is a summer Friday and typically, about an hour after the NFP release, traders are gone for the weekend so don’t expect too much today.

The world is not ending, the dollar is not collapsing, the Treasury market is not collapsing, and equity markets are not about to implode.  My take is the big stories from the past months have lost their luster and I suspect after a lull, we are going to start to focus on the politics of the midterm elections in November.  But until then, have a cold one and relax.

Good luck and good weekend

Adf
Why People Screech

Investors enamored with risk
Are active, some might e’en say brisk
In buying up stocks
In very large blocks
And feeling, right now, very frisk-y

But this simply highlights the breach
Twixt markets and why people screech
The ‘conomy’s ailing
And policy’s failing
To help, so for more, they beseech

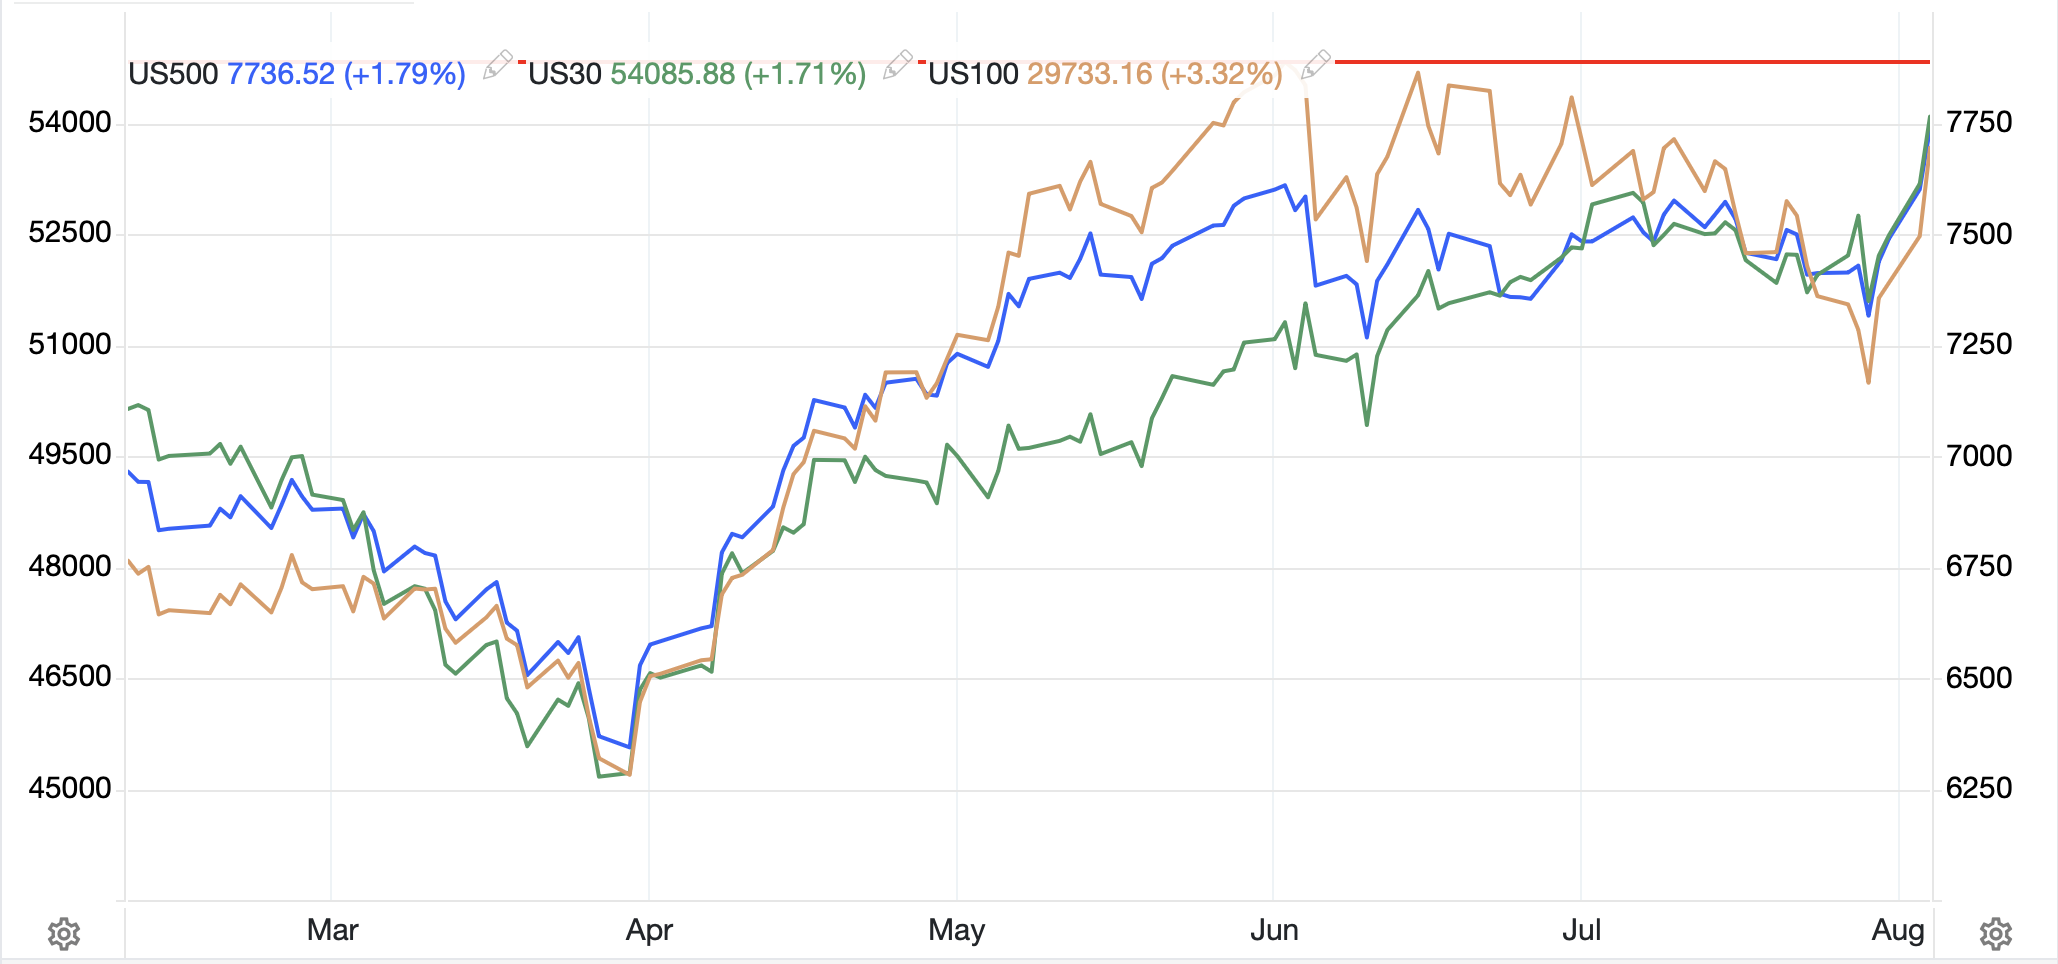
If you ever wanted to see the definition of the K-shaped economy, there is no more accurate representation than the fact that equity markets are making all-time highs at the same time Socialists are winning elections.  Now, I don’t know many voters in Michigan, but I’m pretty sure the ones who have an equity portfolio are not voting for the candidate who wants to abolish the Senate, the Supreme court and the Presidency as well as the police and the Department of War.  But here we are, with both the DJIA and the S&P 500 trading to another new all-time high yesterday, although as you can see in the chart below, the NASDAQ is still a few percentage points away from its recent highs and the DSA candidate poised to win the Democratic primary election for US Senator in Michigan.  Strange times indeed.

Source: tradingeconomics.com

While there is no doubt that earnings continue to be quite strong, and that is the proximate cause for the equity market rally, earnings are a function of economic activity, so it is highly unlikely they would be so strong without underlying economic strength.  The upshot is that we continue to ‘reap’ the benefits of the original Portfolio Balance channel defined by then Fed Chair Ben Bernanke as he began the process of inflating the Fed’s balance sheet and all that liquidity spilled into financial markets rather than the real economy.  At this point, we have seen money moving back toward production (I saw that a new steel mill was being built in California, the first new mill there in over 50 years) but it remains the case that more money flows to markets than to production. And that, I would argue, is the crux of the dichotomy that we are currently observing, fabulous wealth being created but an extremely uneven distribution.

Can it, or will it change?  It took a long time to create the problem, and I fear it will take a long time to unwind it, although I believe that politicians on both sides of the aisle recognize the problem.  And this is the classic case where they have very different solutions.  Arguably, the fate of the nation rests on which solutions are implemented, reshoring American industrial capacity, or a state takeover of the means of production and redistribution.  You know which side I’m hoping wins out.

But in the meantime, equity markets here are strong as is economic activity, at least as measured by the government, and that has been sufficient to drive market behavior.  And that, my friends, is why Wall Street is happy.  Well, that and the following headline:

Wall Street bankers’ bonuses set for significant rise

With that in mind, let’s see how markets are behaving.  That US strength was followed almost universally in Asia with every major market rallying except Singapore (-0.55%) and Thailand (-0.5%).  Otherwise, the gains ranged from +3.7% (Tokyo and Korea) down to +0.25% (HK) with more strong gains above 1.0% than below that level.  Tech stocks remain the story and that has been helped along by the latest Hormuz story that indicates a deal is coming soon.  Frankly, writing about Hormuz at this point seems absurd given the numerous claims and counterclaims with very little ability for most of us to discern truth from propaganda.

The interesting thing about a tech-led rally is how completely it ignores European bourses with France, Germany and the UK all unchanged on the day, although Spain has managed a modest gain of 0.4%.  But I think that gain is a function of the better-than-expected PMI Services number from Spain, 58.3, which is its highest reading in more than 3 years while the rest of Europe managed to basically meet expectations at lower levels.  As to US futures, as we await the ISM Services data today (exp 54.5) you will not be surprised that they are higher at this hour (7:45).

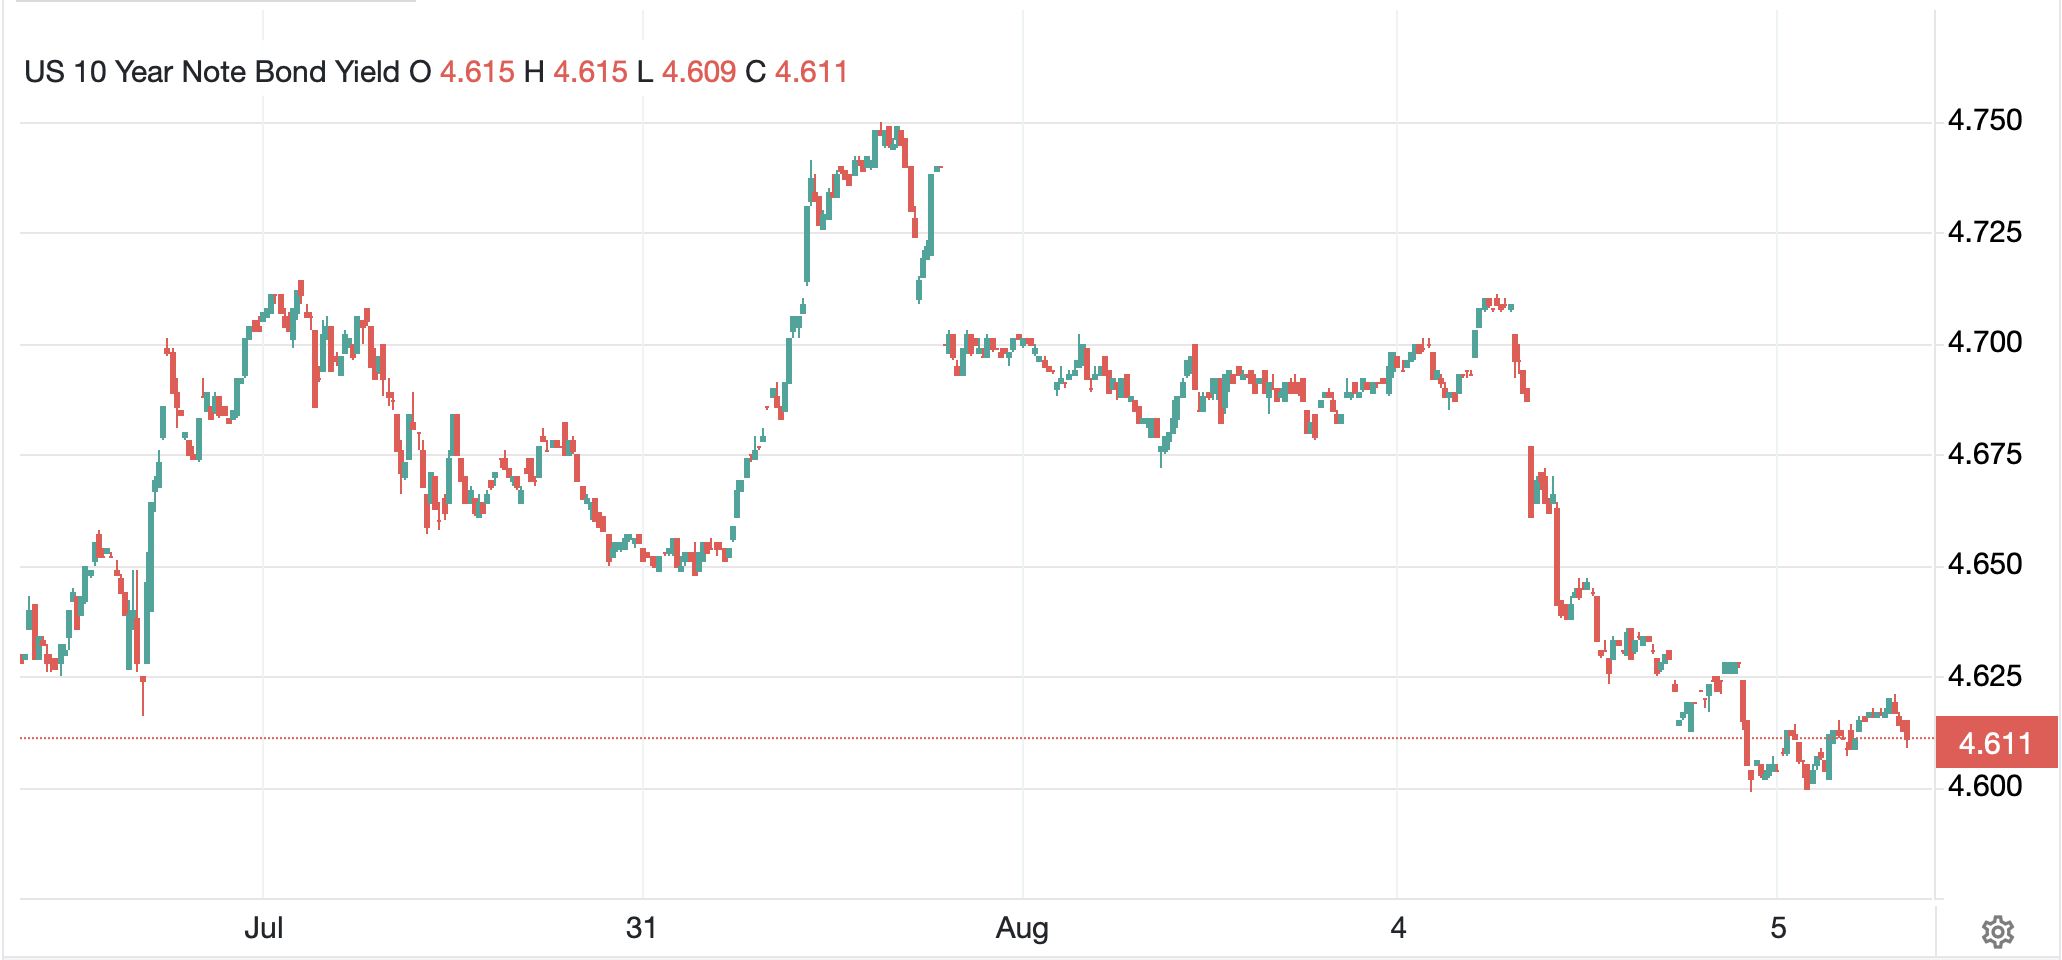
Perhaps the bigger story has been bond yields as they have slipped -13bps in the past two sessions and are down -1bp this morning as per the chart below.  European sovereign yields have also backed off a bit although this morning they are basically unchanged while JGB yields (-3bps) continue to trade near their recent multi-decade highs.  So far, the US-Japanese joint yen intervention has not been enough to change that story.

Source: tradingeconomics.com

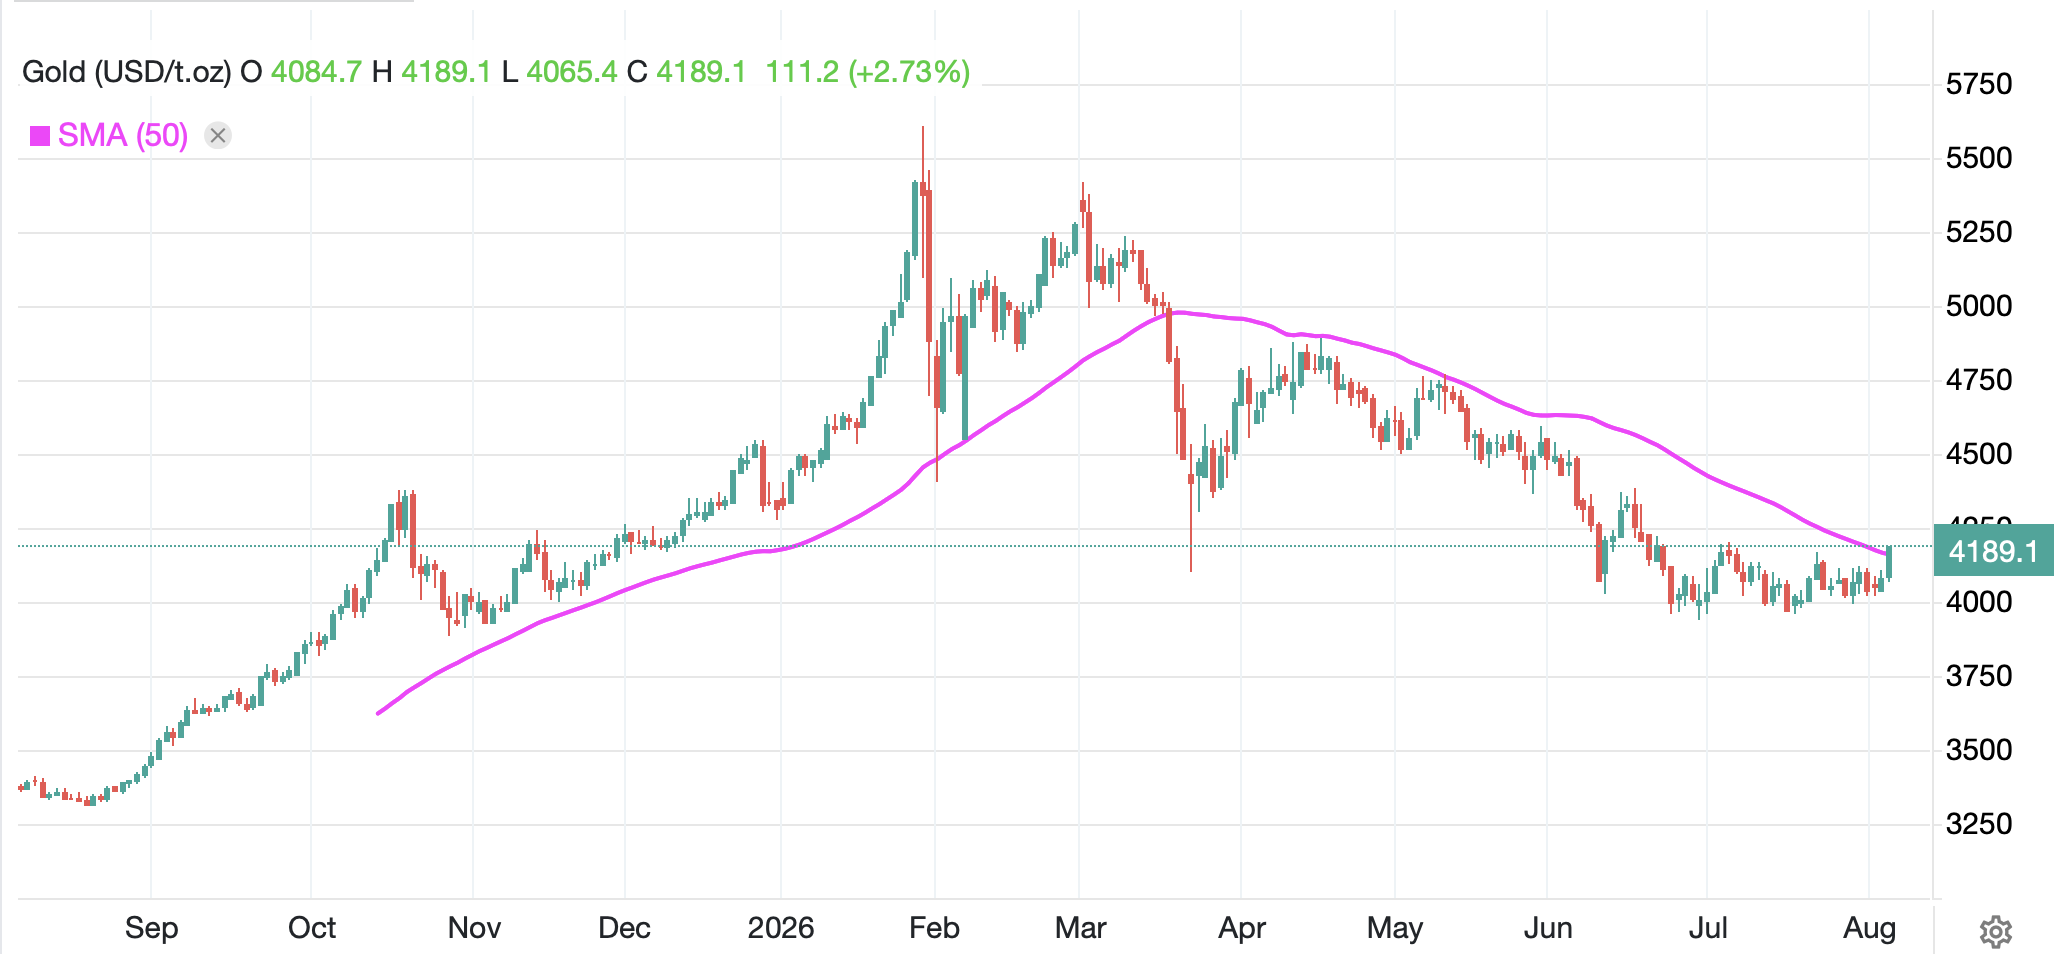
In the commodity space, it is the metals markets that are the most interesting this morning with gold (+2.7%) and silver (+4.1%) leading the way as hopes for the Hormuz reopening and the end of the Iran conflict percolate.  Either that or people have begun to realize that the demand for metals remains impervious to other stories.  Now, I am not a market technician, but frankly, the fact that the gold price is breaking above its 50-day moving average as per the below chart, and the general price action is telling me that we have put in a bottom and seem poised to break higher.

Source: tradingeconomics.com

Copper (+0.4%) continues to trade near its all-time highs and I suspect a move higher in gold and silver will take it along for the ride.  As to oil (+0.4%), the fact remains it is lower by -10.0% this week, which has been a key driver of sentiment in markets overall.

Finally, the dollar is a bit softer this morning, but not too much.  The euro and pound are both firmer by 0.2% while the yen is little changed along with CHF, CAD and AUD.  NZD (-0.4%) is an outlier after weaker than expected jobs data undermined the idea of another rate hike by the RBNZ.  In the EMG bloc, most currencies are a bit stronger as well, 0.1% to 0.3% or so with KRW (+0.4%) and CLP (+0.8%) the outliers, with the former continuing its recent trend as you can see from the chart below, while the latter is benefitting from the overall strength of copper.

Source: tradingeconomics.com

And that’s really it for the day.  In addition to the ISM data, we do see EIA oil inventories later this morning and we get the Treasury Refunding Announcement at 8:30, although there is no expectation for a massive change in the current issuance schedule.  Late this afternoon, the central bank of Brazil is expected to cut the SELIC rate by 25bps to 14.0%, which is arguably why BRL has been such a strong performer all year, very high real interest rates.

As to the dollar writ large, it is on its heels right now and I don’t think Secretary Bessent minds that very much.  Using the DXY as the proxy, do not be surprised to see it trade to 97 by the end of summer.

Good luck

Adf
Smart or Insane

While pundits all like to complain
About everything, smart or insane
When stock markets rise
It’s no real surprise
That few people care what they’re sayin’

As penance for yesterday’s overly long diatribe, I will keep this morning’s much shorter, especially since there is not nearly so much interesting to discuss.  There are still many discussions on the whys and wherefores of the US joining with Japan in intervening in the FX markets, with a pretty even mix of those saying it won’t matter and those saying it is a game changer.  As you can see from the chart below, this morning the beleaguered JPY (-0.45%) is slipping a little, but hardly enough to matter in the context of last week’s gains.

Source: tradingeconomics.com

Of course, we won’t really know how effective this bout of intervention has been for at least a few weeks/months, as the history, clearly shown on the chart is a big move higher followed by a gradual depreciation in the yen.  Will that play out again?  My suspicion is that absent a policy change by the BOJ (i.e. a more aggressive rate hike schedule) or the Japanese government (i.e. less fiscal stimulus) the answer is no.  This is especially true if the Fed raises rates, although I still do not believe that is coming soon.  

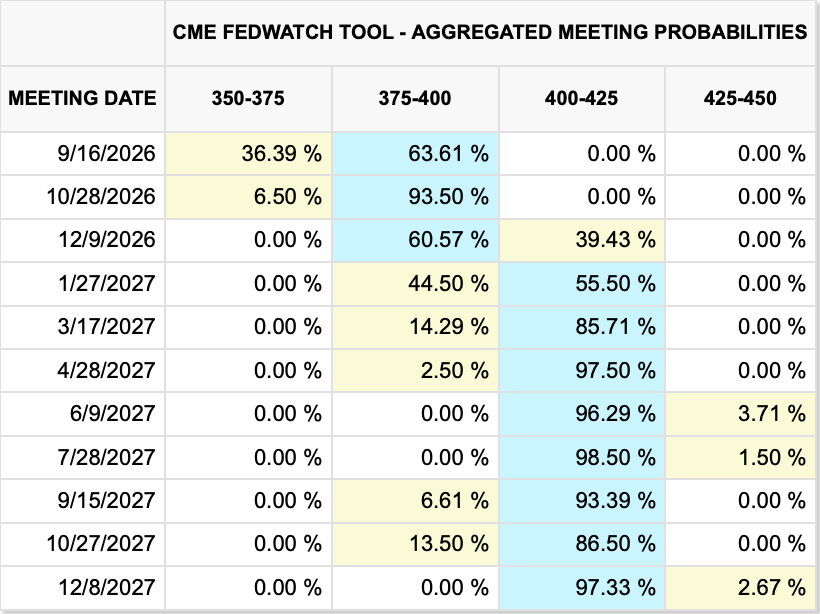
However, it is important to remember that the Fed funds futures market is confident of a hike by October, with a two-thirds probability of one next month as per the below cmegroup.com table.

Turning to the other major discussion from yesterday, the ongoing feedback/blowback from the Fed’s no movement, and more importantly from Warsh’s behavior during the press conference, that too remains a topic of discussion with pundits on both sides adamant that he was either right or wrong on both measures.  The only thing I am sure about is that he doesn’t care much about what the pundits are saying.  Rather, he is very likely focusing on getting his points across to the rest of the committee, and that will be a tough job.

In 2025, FOMC members gave, on average, one speech a day which added to the forward guidance which was a key tool in their toolbox.  You know I often railed against the ongoing verbal diarrhea from these folks as from the best I could tell, nothing said was ever designed to sway opinion, merely to burnish each speaker’s credentials.  And they clearly loved the quasi fame that came with it.  In fact, I suspect it is that very quasi fame the committee is most reluctant to cede.  Chairman Warsh has his work cut out for him.

As to today’s new stories, there are none, at least none of note.  There are more conflicting comments from President Trump and the Iranians about negotiations or not.  Yesterday’s ISM data was quite positive, coming in at 55.6 vs 54.0 expected, just another indication that the US economy continues to tick along quite nicely.  After that, the news heads towards the political with several key primary elections to be held today with DSA candidates picked to win and run in the general elections in November.

But what has everybody happy is the fact that equity markets are showing strength once again.  I read that of the S&P companies that have already reported, 85% have beaten estimates, a much higher than normal percentage (76% is the norm), and another positive for market bulls.  

So, let’s take a look at how markets behaved overnight with that theme.  The strong US performance was followed by a more mixed session in Asia, although there were more gainers (Tokyo, China, Korea, Australia, Indonesia, New Zealand) than laggards (HK, India, Philippines).  The tech story remains the major story since the oil story has become so confusing on a daily basis, I feel like most investors have moved on.  Meanwhile, in Europe, it is a broadly positive session as well led by Germany (+0.6%) and the UK (+0.35%) while France (+0.1%) and Spain (0.0%) are not quite as happy.  Arguably, the biggest news in Europe continues to be the unprecedented flood of illegal immigrants into Ceuta, Spain and the punditocracy is actively expressing their opinions on the issue, although whether there is a direct impact on the equity market in Madrid is unclear.  Lastly, US futures at this hour (7:20), are all pointing higher again as the market awaits earnings from SpaceX this afternoon after the close.

In the bond market, there continues to be a great deal of garment rending and teeth gnashing amongst the financial illuminati as yields hold the bulk of their recent gains.  This morning Treasury yields have backed up 1bp after yesterday’s -5bp decline, although European sovereign yields are generally lower by -1bp this morning.  As of now, there is no answer to the question of is the bond market focused on inflation or excess issuance although it could well be a little of both.

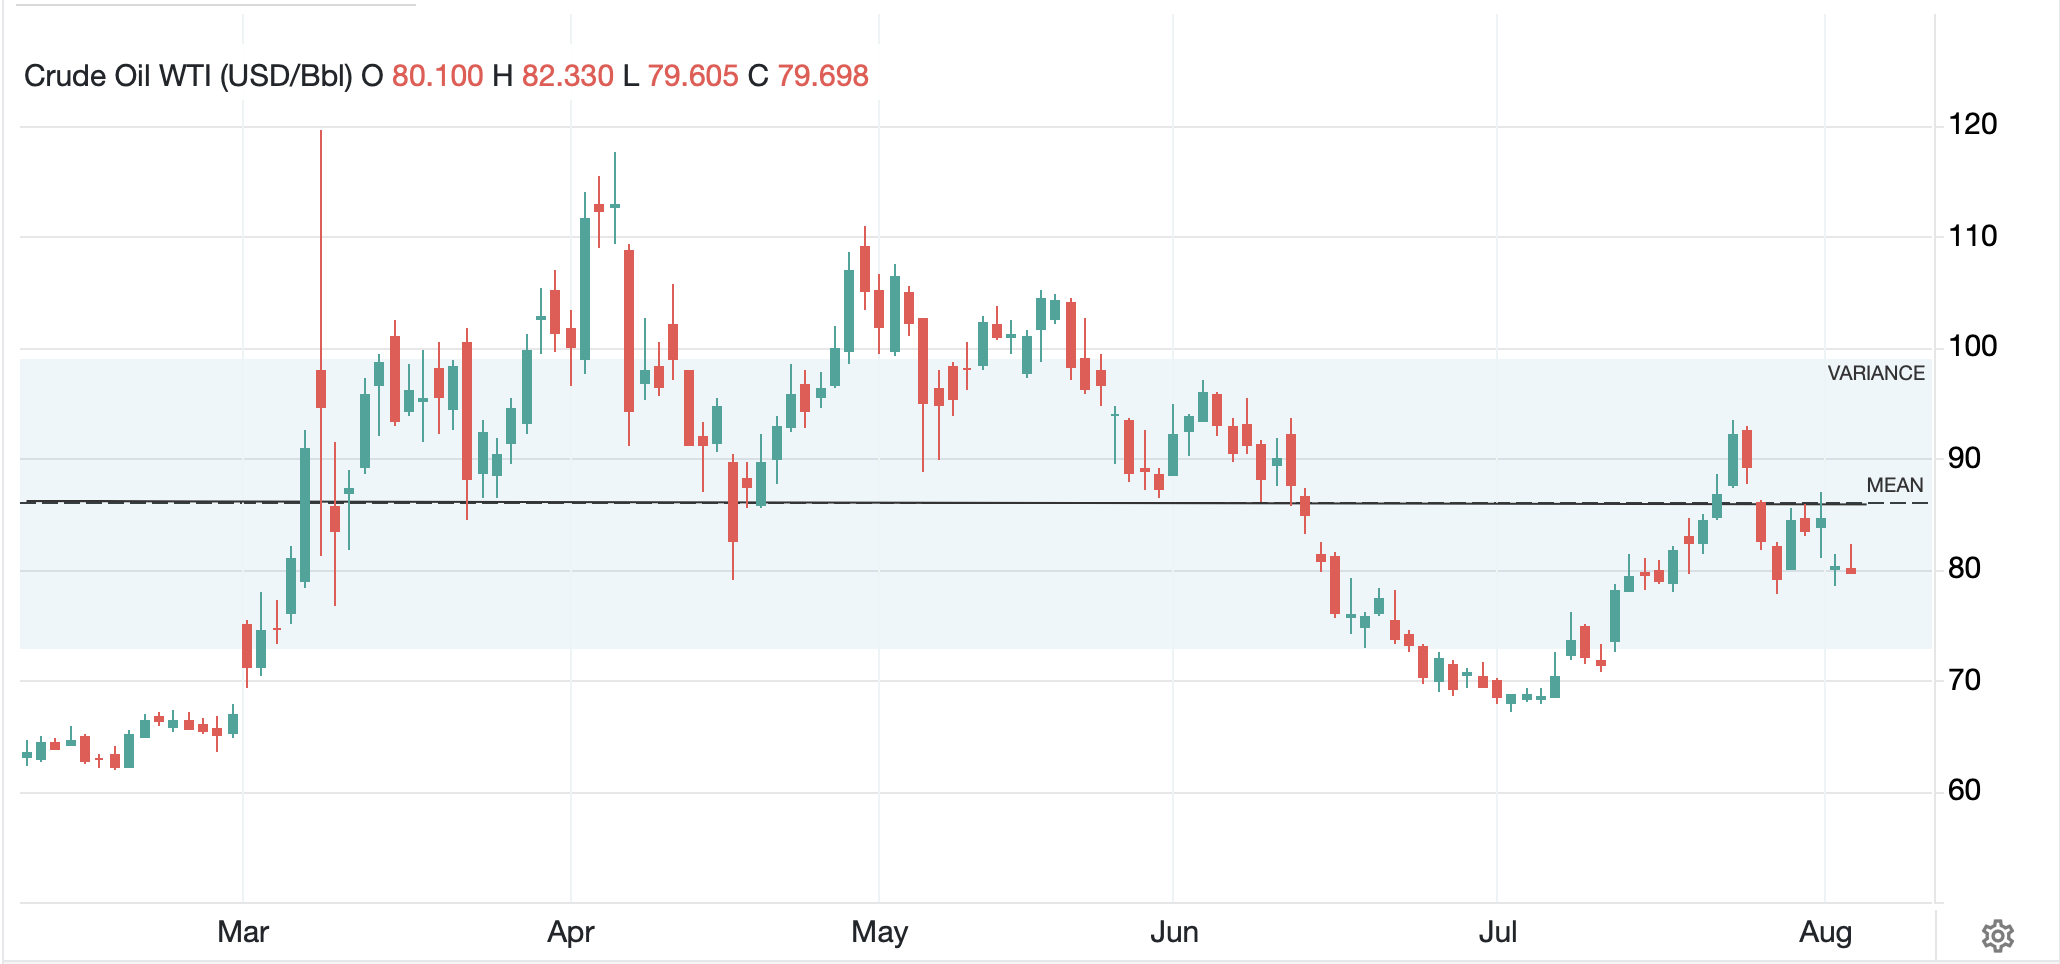
Remember when oil (-0.8%) was the only market that mattered, and all other trading looked there first.  We heard stories about $200/bbl coming soon and tank bottoms as reserves emptied and a growing concern about future economic activity.  Well, that never really happened.  As I type, WTI is back below $80/bbl and I particularly like this chart that calculates the mean price over the past 6 months ($86/bbl) and shows no trend whatsoever.  

Source: tradingeconomics.com

To me, this implies there is a new equilibrium although I suspect that when the hostilities cease, and I believe they will at some point this year, we will see sharply lower prices for crude and products.  As to metals markets, they remain relatively uninteresting with modest gains today (Au +0.2%, Ag +2.4%, Cu +1.7%).

Finally, in the FX markets, away from the yen the dollar is under a bit of pressure this morning.  First, for all of you who follow the DXY and were excited by the ostensible breakout above 100.50, as you can see in the below chart, that story appears to have ended for now.

Source: tradingeconomics.com

But away from the yen this morning, the rest of the G10 have all shown modest gains led by AUD (+0.5%) after some positive household spending data.  Otherwise, 0.1% to 0.2% is the state of the day.  In the EMG bloc, ZAR (+0.4%) is the leader of the pack on the combination of softer oil prices and stronger metals prices.  Too, BRL (+0.25%) and MXN (+0.25%) seem to be benefitting on the same basis.  Otherwise, it’s hard to get excited here.  Perhaps another bout of intervention will perk things up, but I doubt that will happen soon.

On the data front, there’s quite a bit to be released this week culminating in the Friday NFP report.

TodayTrade Balance-$73.0B
 JOLTs Job Openings7.4M
 Factory Orders0.2%
 -ex Transport0.5%
WednesdayASP Employment70K
 ISM Services54.5
ThursdayInitial Claims202K
 Continuing Claims1790K
 Nonfarm Productivity0.6%
 Unit Labor Costs2.1%
FridayNonfarm Payrolls80K
 Private Payrolls79K
 Manufacturing Payrolls4K
 Unemployment Rate4.2%
 Average Hourly Earnings0.3% (3.5% Y/Y)
 Average Weekly Hours34.3
 Participation Rate61.6%
 Consumer Credit$10.85B

Source: tradingeconomics.com

In addition, there are three Fed speakers, and I wonder (and am hopeful) that we hear less and less from them going forward.  Obviously, all eyes will be on the payrolls on Friday, and we can dive into that later in the week.  But today, it is hard to get excited about anything.

Good luck

Adf
Quite Spicey

Though Friday things looked pretty dicey
With tech stocks then seen as quite pricey
New word that the bombing
Has ended was calming
And stock markets opened quite spicey

Of course, it can be no surprise
That oil’s now well off its highs
The dollar is slipping
Though yields are just dripping
As bond traders still agonize

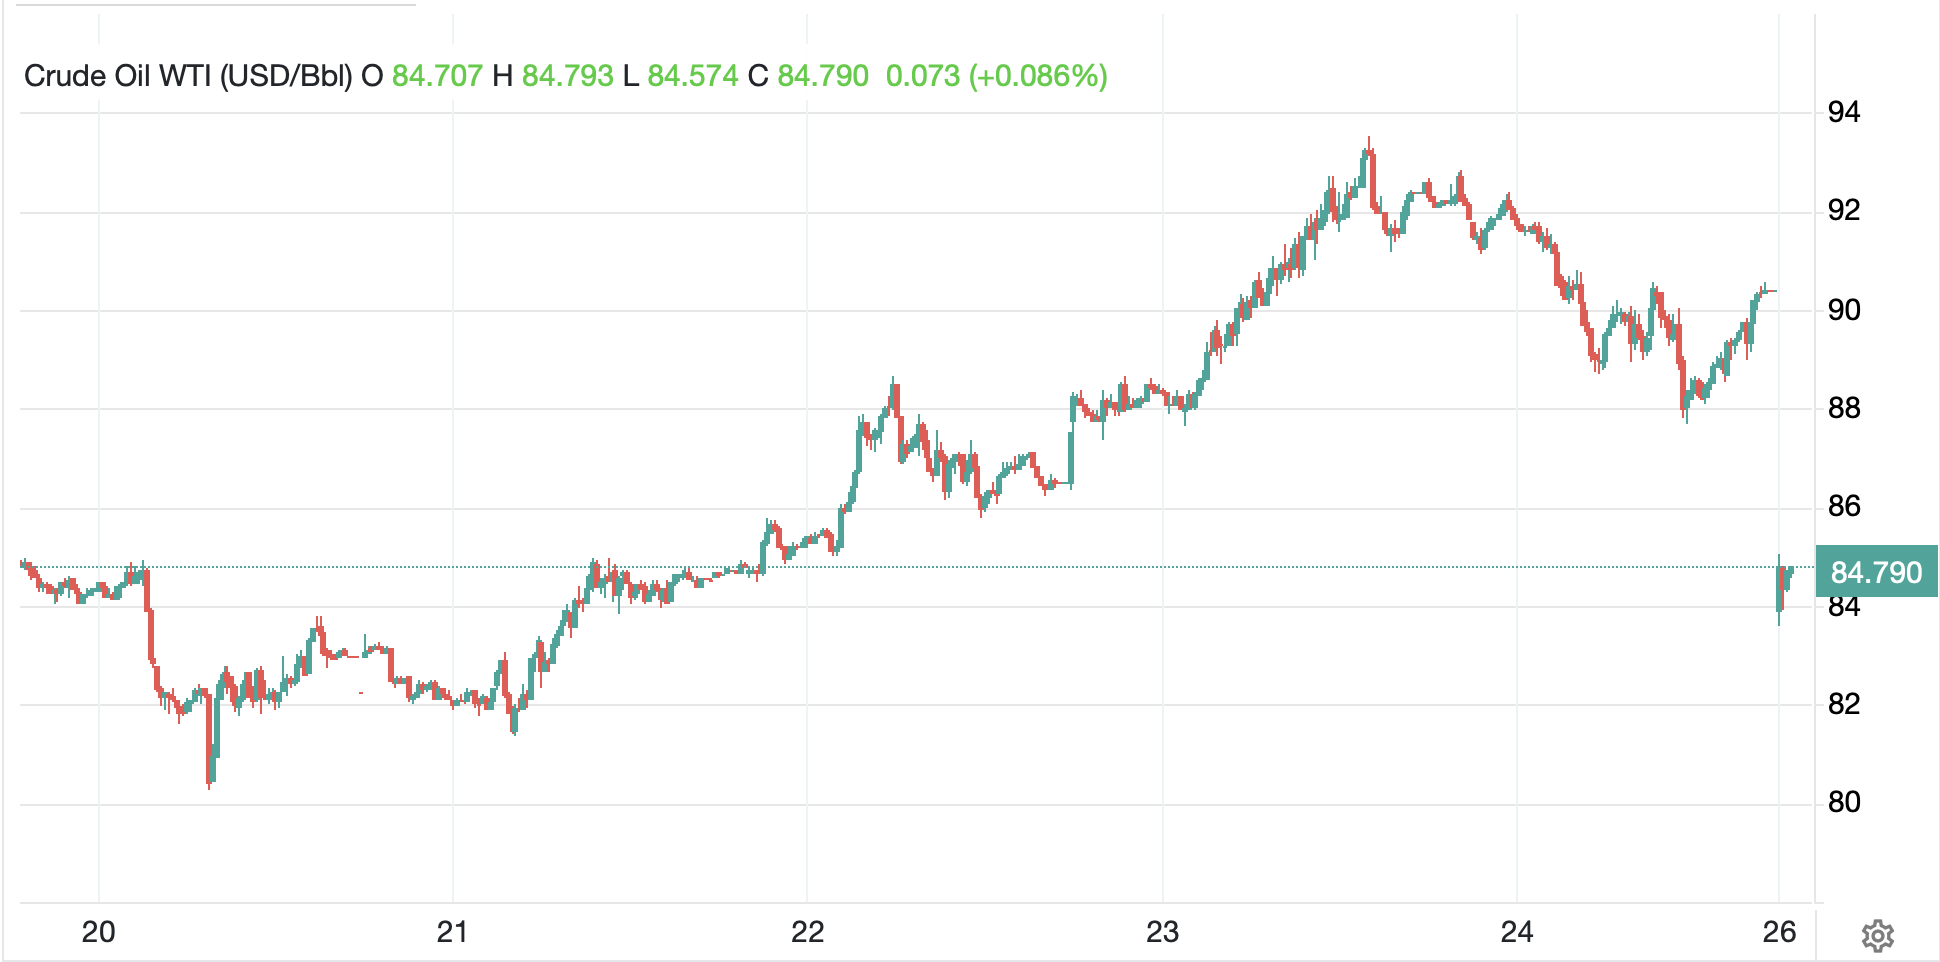
President Trump changed his mind about continuing the recent bombing campaign against Iran over the weekend amid questions about alleged US munitions supplies.  But whatever the reason, this was music to the risk markets with oil (opening -6.4%) falling sharply while equity futures (NASDAQ opening +1.25%) rebound from last week’s declines.  Once again, headline risk remains the biggest risk there is in markets.  Note the huge gap lower in the oil market early Sunday evening in the chart below from tradingeconomics.com

At this point, it is a fool’s errand to try to estimate where oil prices are heading going forward as the next headline is likely to be the key driver, and that is a complete unknown.

So, let’s turn our attention to some more fundamental questions that have been brewing in the background and are pretty complex.  I want to start with a remarkable Substack piece I read this weekend which had a completely different perspective on the AI investment thesis than anything that I have seen anywhere else.  And it is quite a persuasive piece.  While I have linked it above, it is quite a long read, so the highlights are as follows:

  • The AI boom is not a tech boom; it is a credit driven real estate cycle
  • This is virtually identical to the run-up to the subprime housing crisis and GFC
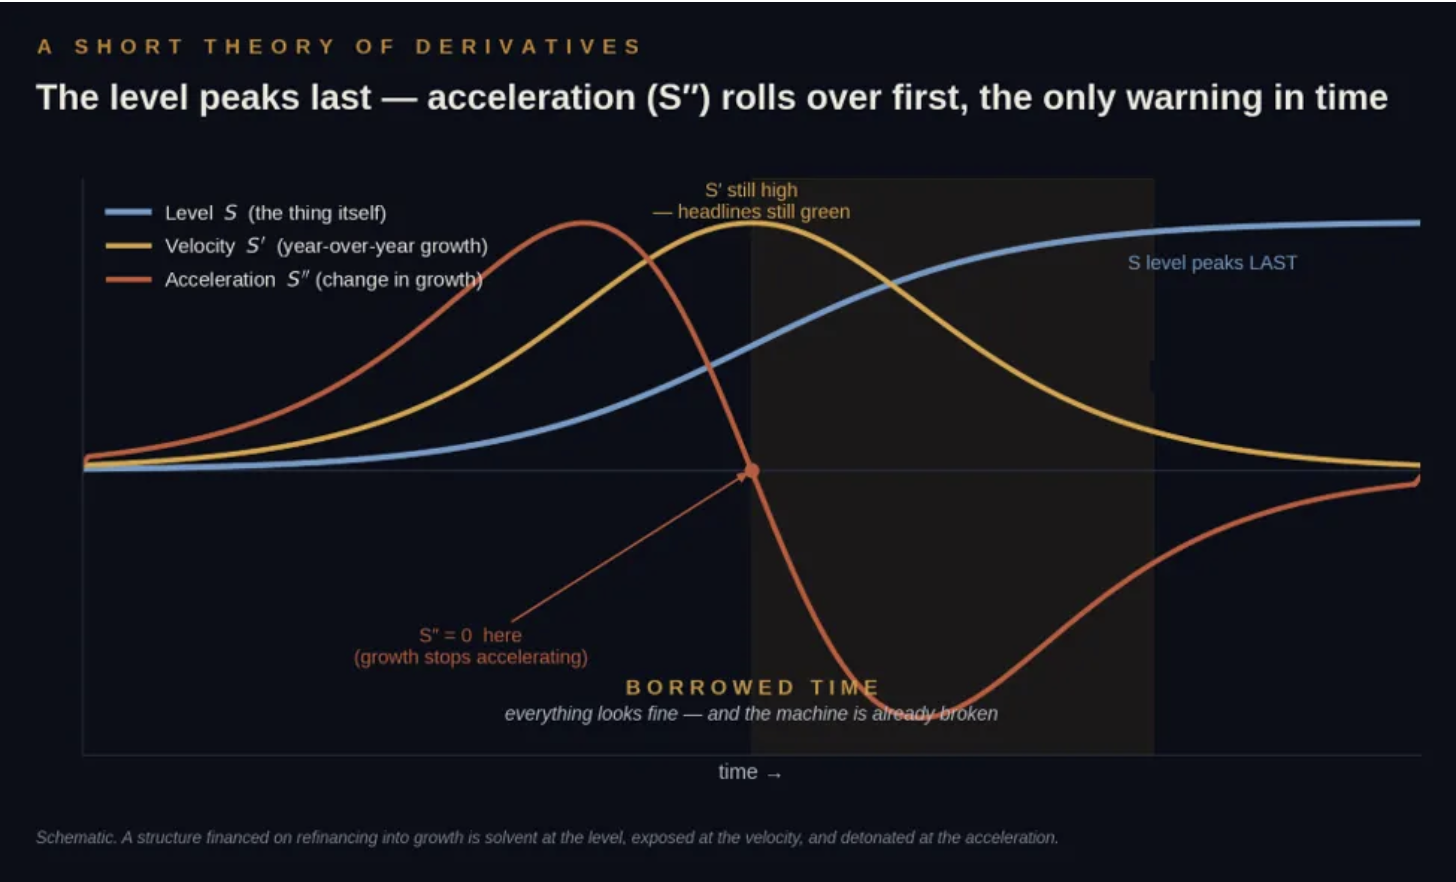
  • The key to understand is the second derivative of growth, acceleration.
  • GroundBreaker’s (the author) thesis is that the second derivative on AI valuation has already rolled over and the future for AI stocks is pretty bleak, at least in the medium term.

Below are two charts from his Substack to help describe the issue:

This is a basic description of the movements of the underlying (blue line), its velocity (growth rate, yellow line) and its acceleration (the change in its growth rate, red line).  As you can seem growth can still be increasing, but at a slower rate, and that’s the problem he highlights.  

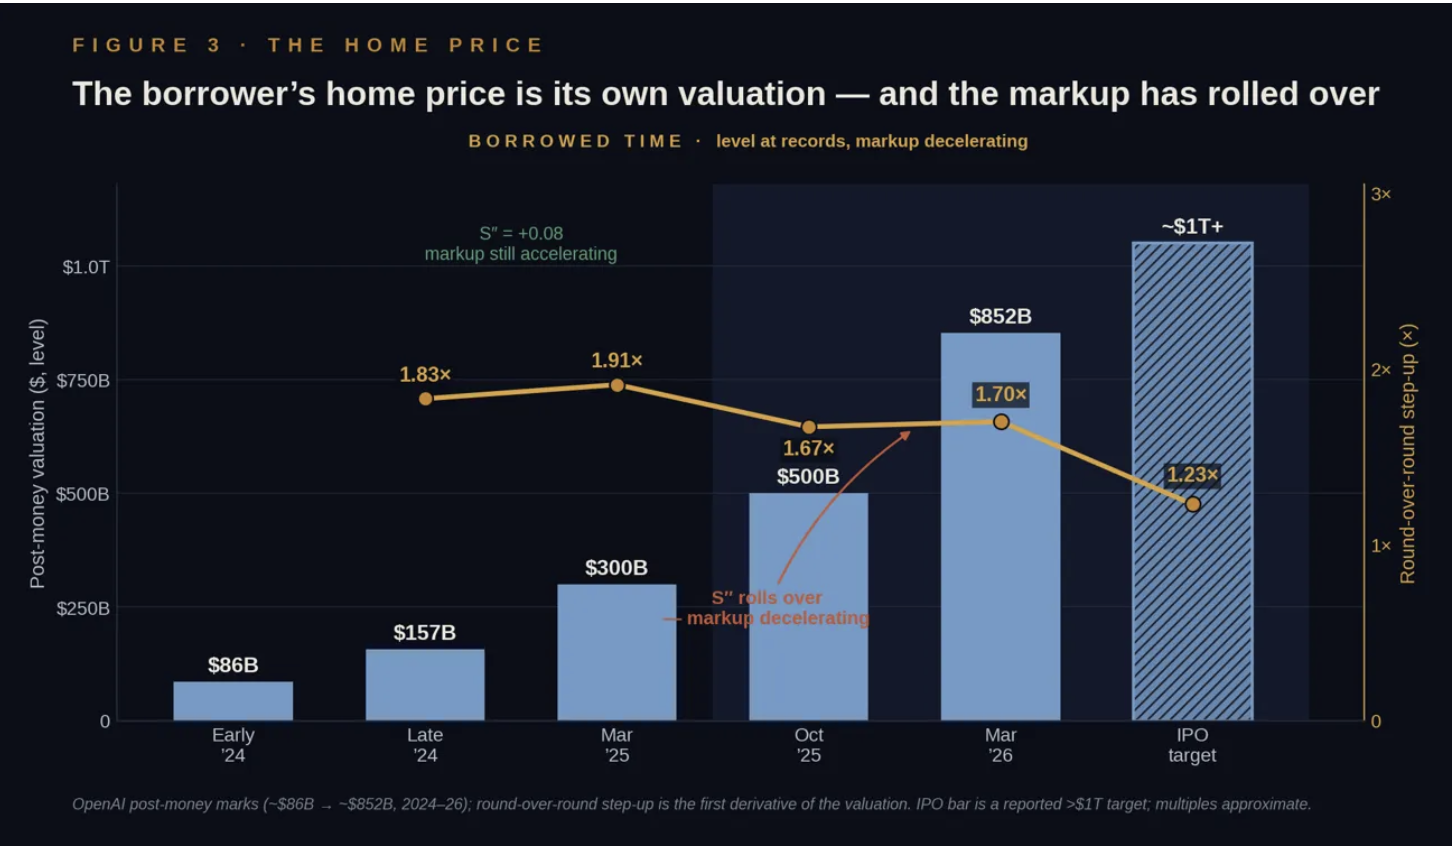
Below is a chart of OpenAI’s valuation metrics (remember it’s private so the values are episodic, not continuous, but the point is if the change in the rate of growth of the valuation metric starts declining, that is the break where things become a problem, i.e. they may not be able to finance their projected growth going forward.  

And as you can see, it is already heading lower.  This does not speak well to the future for OpenAI, and I would argue, the entire space, as many have made the case this is all Ponzi finance, meaning the funding cannot be repaid on cashflows, only on increasing valuations.  

Now consider the subprime crisis where the problems started when the rate of housing price increases rolled over and all those 2-year teaser rates could no longer be financed at higher valuations.  That’s when they all went bust!  Here’s the thing; the 2nd derivative rolled over in late 2006, the first hiccups didn’t happen until mid-2007 with SocGen closing some funds, Lehman didn’t go bust until September 2008 and the equity market didn’t bottom until March 2009.  It can take a long time for this to play out, but beware the cycle, it could well repeat in AI linked investments.

So, there’s that to consider.

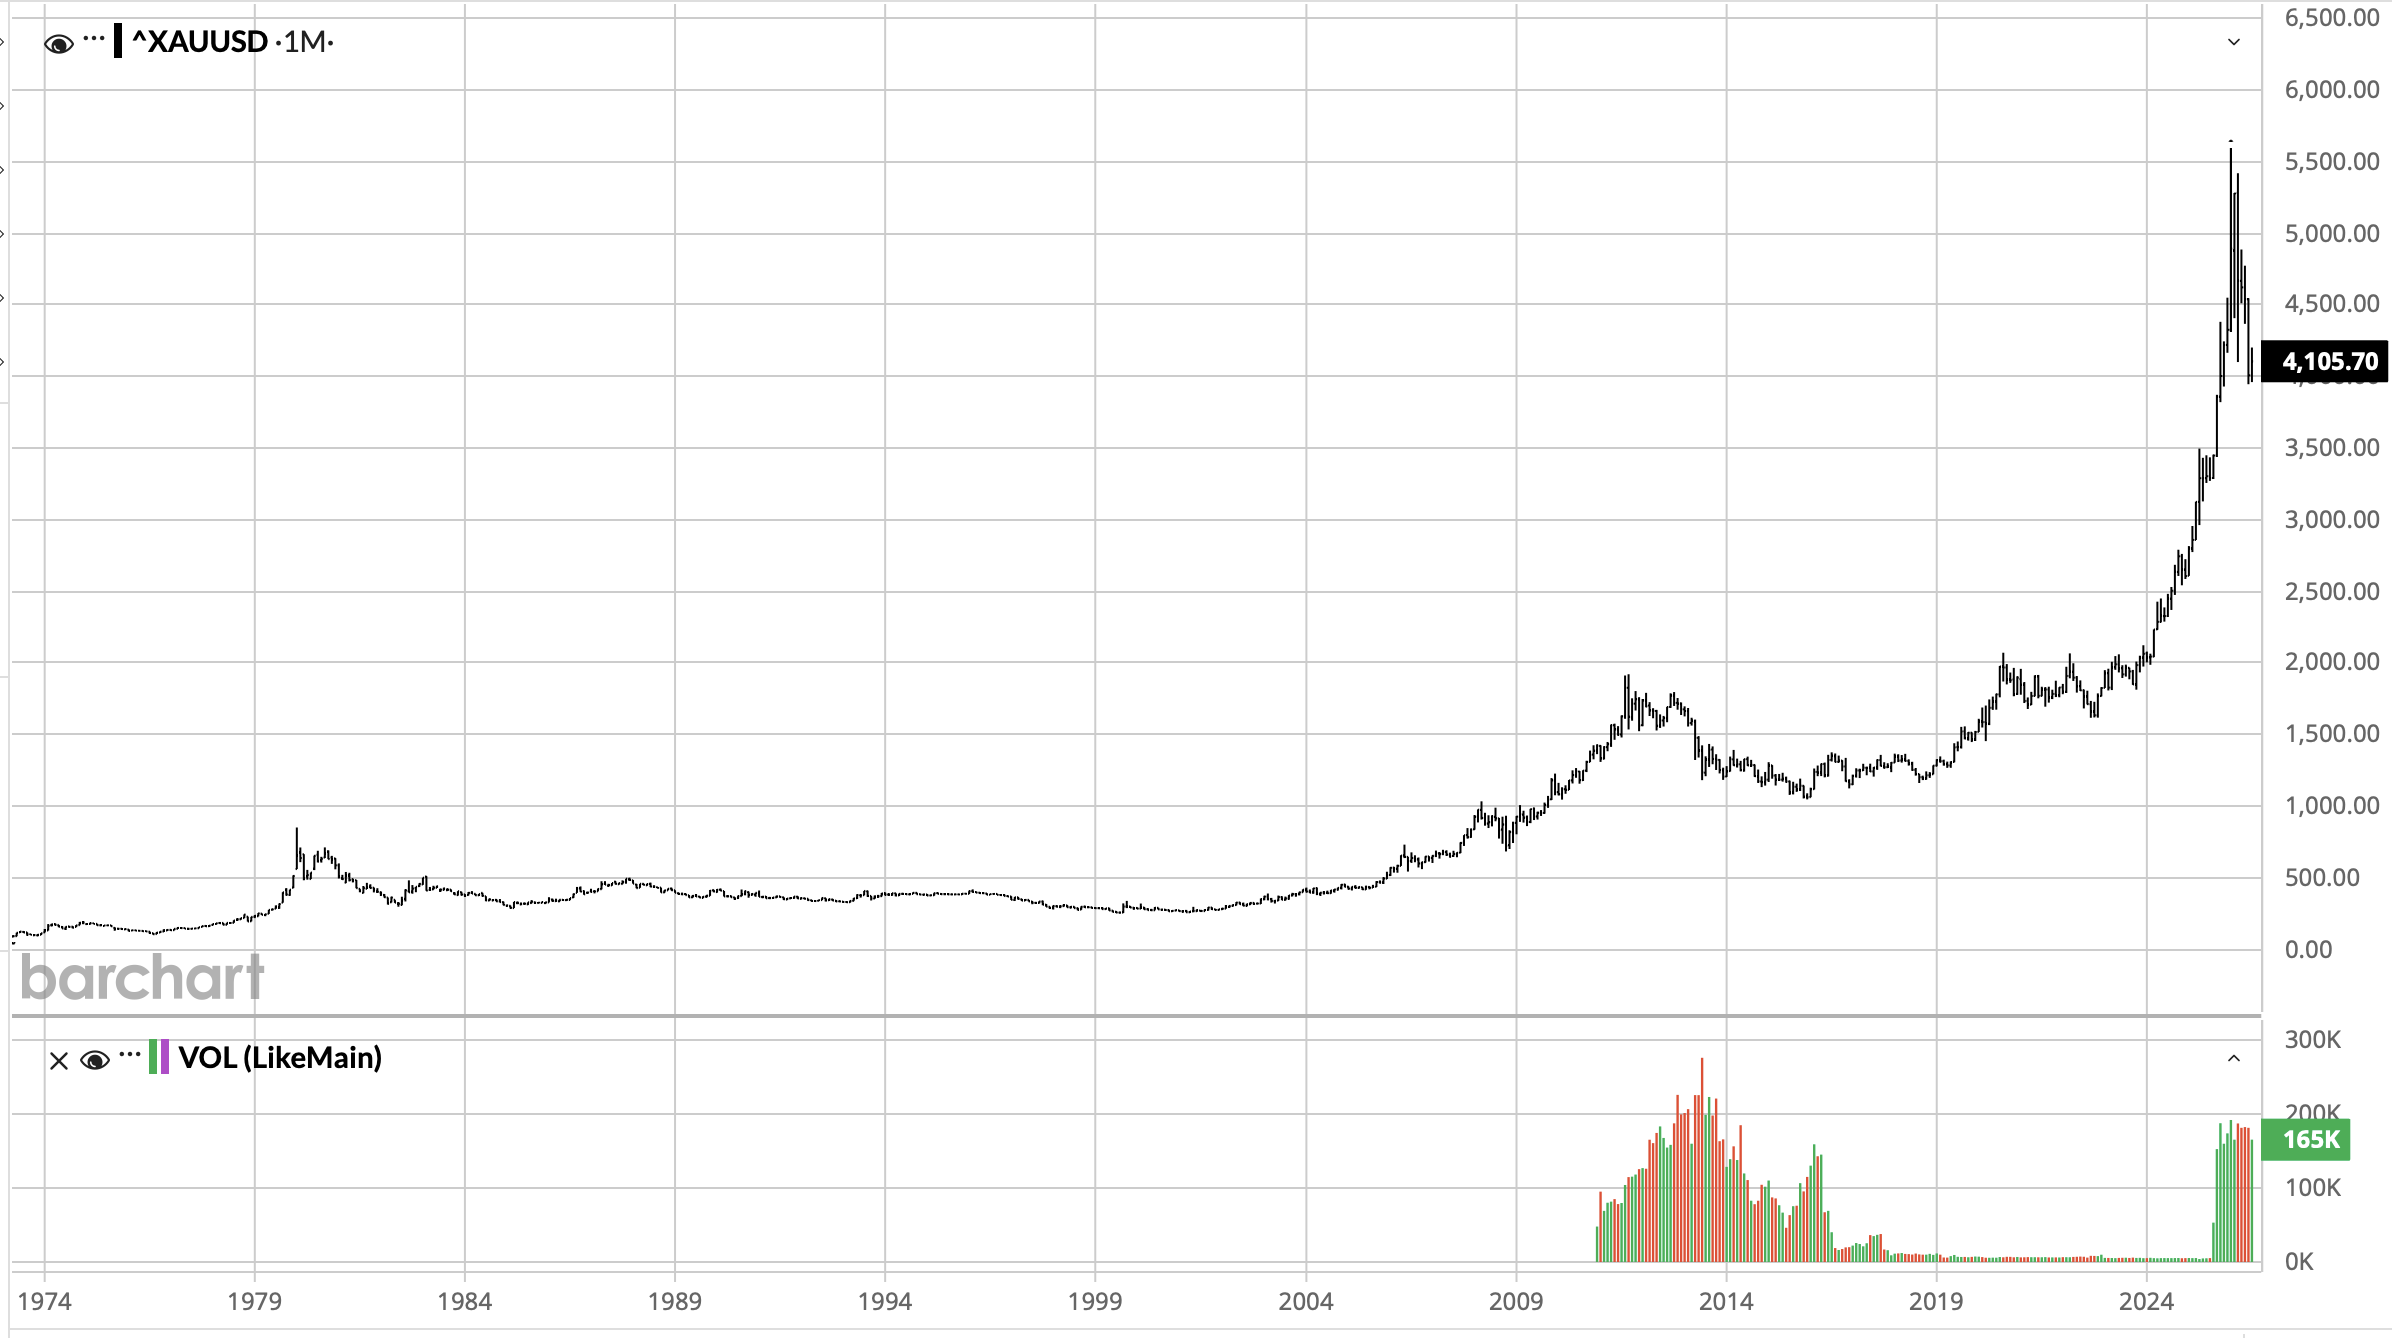
The other thing that I’ve been pondering is gold and its meaning within the financial markets.  Unlike the AI discussion above, I want to discuss two very real sides to this story.  On the one hand, the ongoing destruction of the value of fiat currencies by all major central banks’ policies is real.  Money continues to get printed and inflation continues to rise debasing those fiat currencies.  Adding to the problem is the massive government debt issuance which, if history holds, will be sopped up by those very same central banks, adding to the debasement.  The search for a neutral reserve asset to replace US treasuries is real, but the transition will take a very long time, in my view.  However, all this speaks to increased demand for the barbarous relic, and when that is priced in declining fiat currencies, a higher price.  I think it’s a very strong argument and has been made by many, including this poet.  After all, gold is often thought of as the ultimate inflation hedge.

So, what is the flipside?  As I have written frequently regarding oil prices, we cannot ignore the market pricing and what it is telling us.  Understand that I have been a gold bull for a long time and strongly believe in the long-term debasement concern.  But as a long-time trader and market participant, it is very difficult for me to look at the below, long-term chart of gold and not think that there is a much further decline on the cards.  Parabolic moves, historically, do not resolve by trading sideways for extended periods of time, they fall back… a lot!

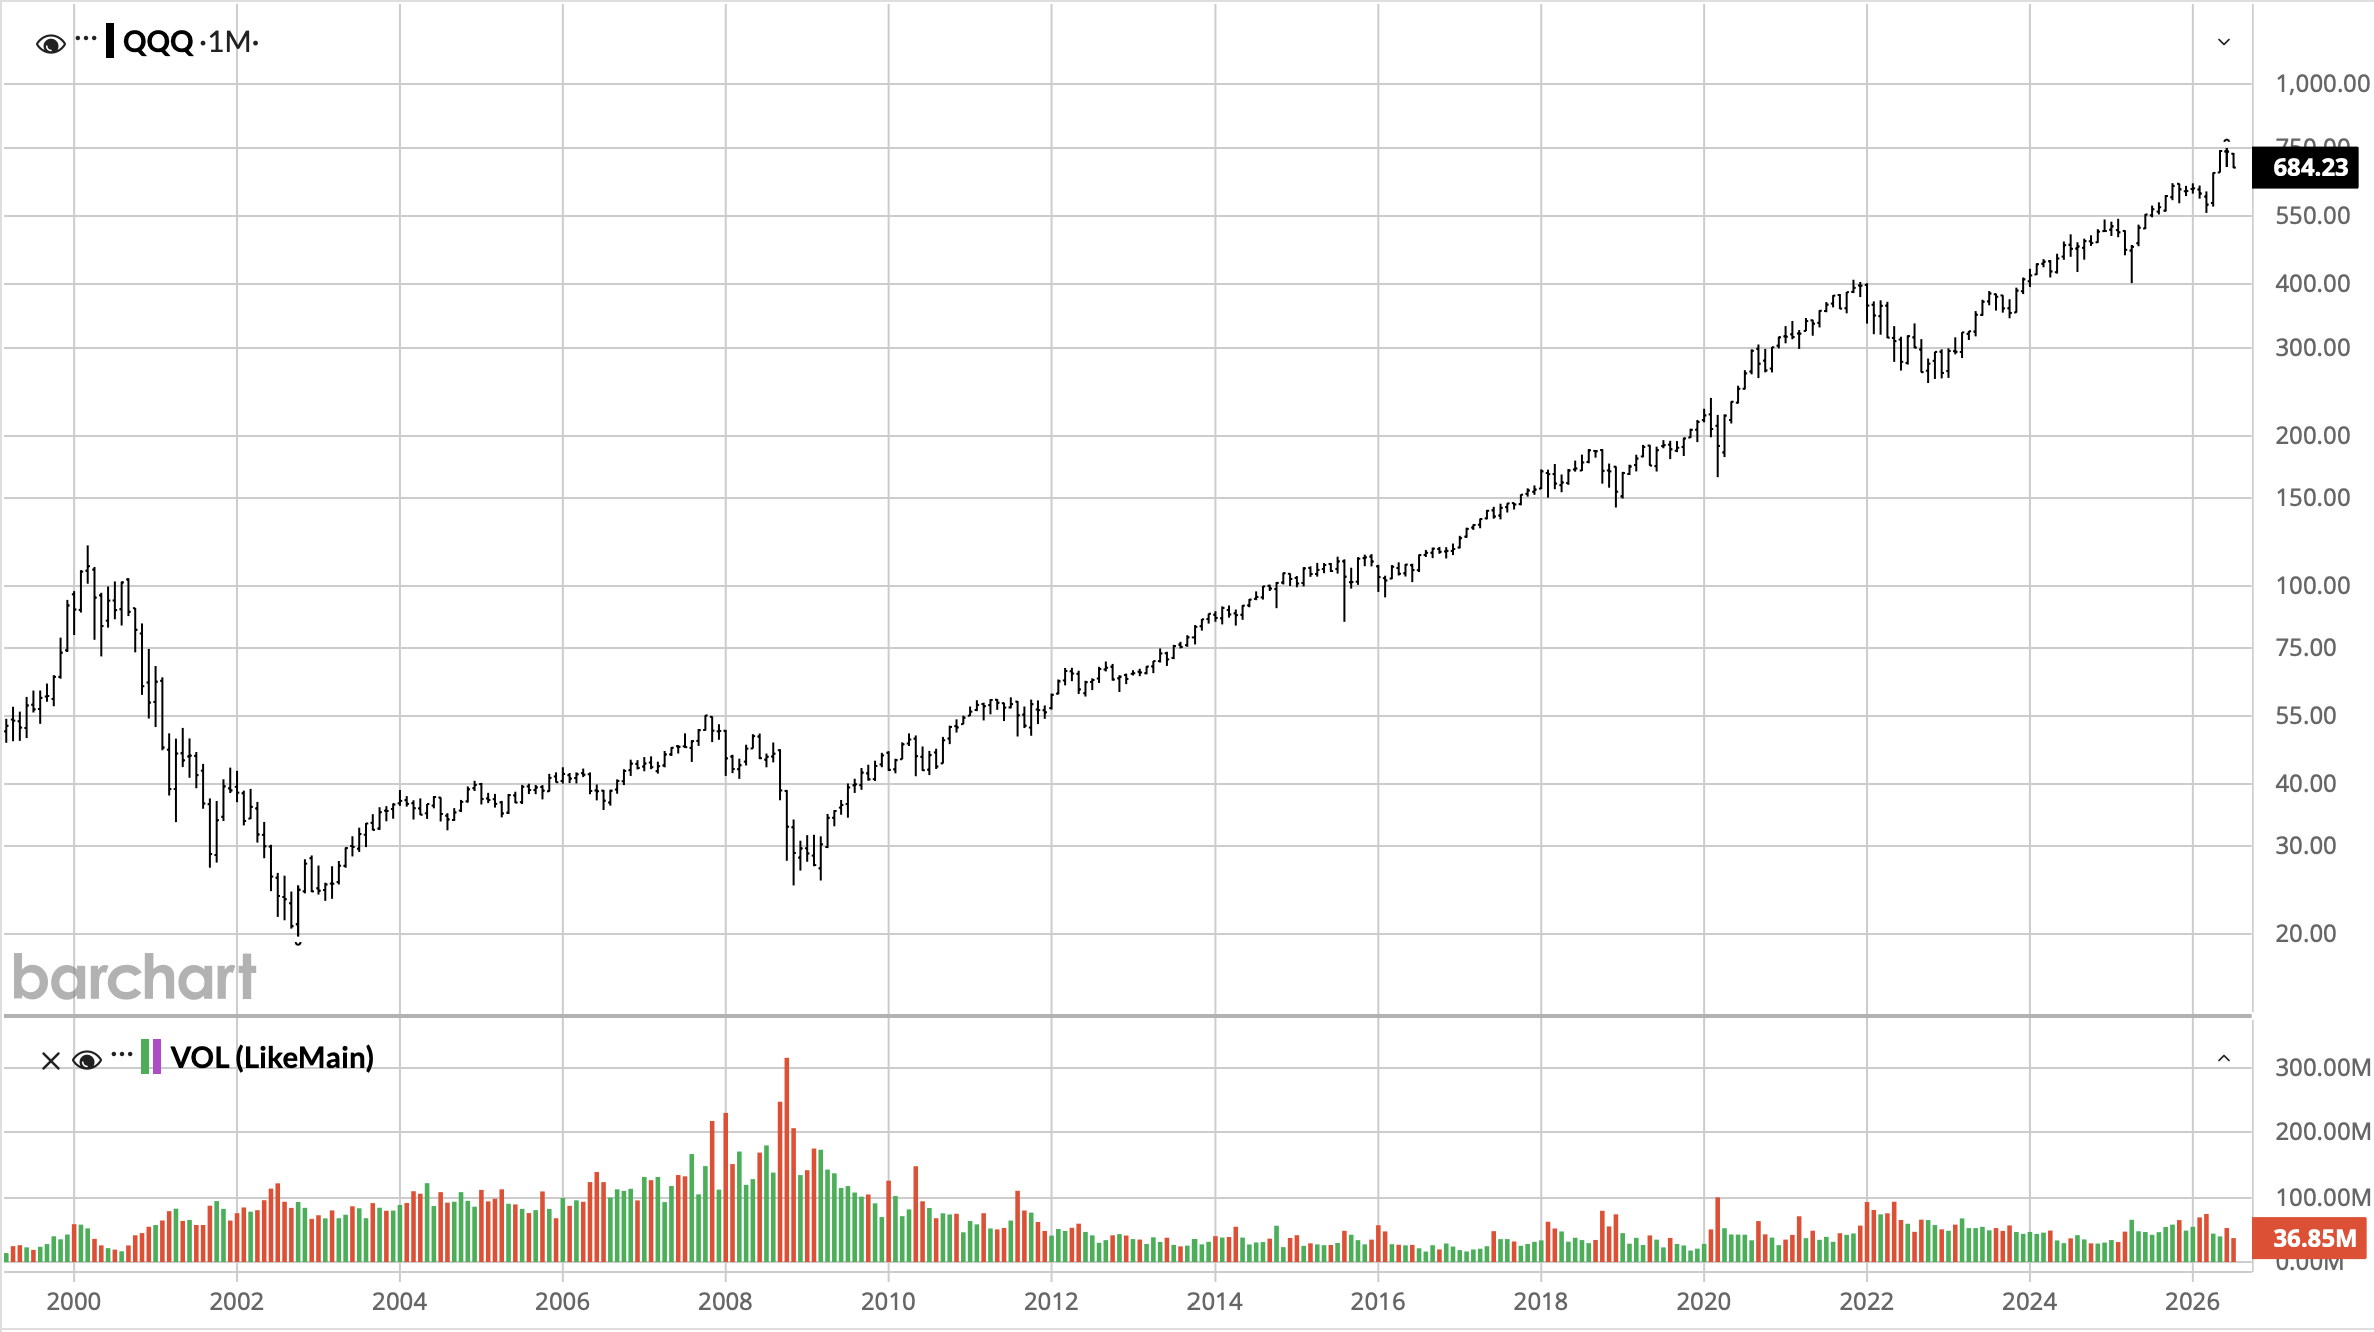
While we have recently seen several parabolic moves in market prices, notably the NASDAQ and KOSPI, I want to highlight the last time the NASDAQ had a parabolic move, during the tech bubble in 1999-2000.  The chart below is a logarithmic chart of the QQQ ETF.  As you can see back in 2000 – 2002, it fell a very long way after the bubble burst, some 88%, a much larger move than during the GFC!  

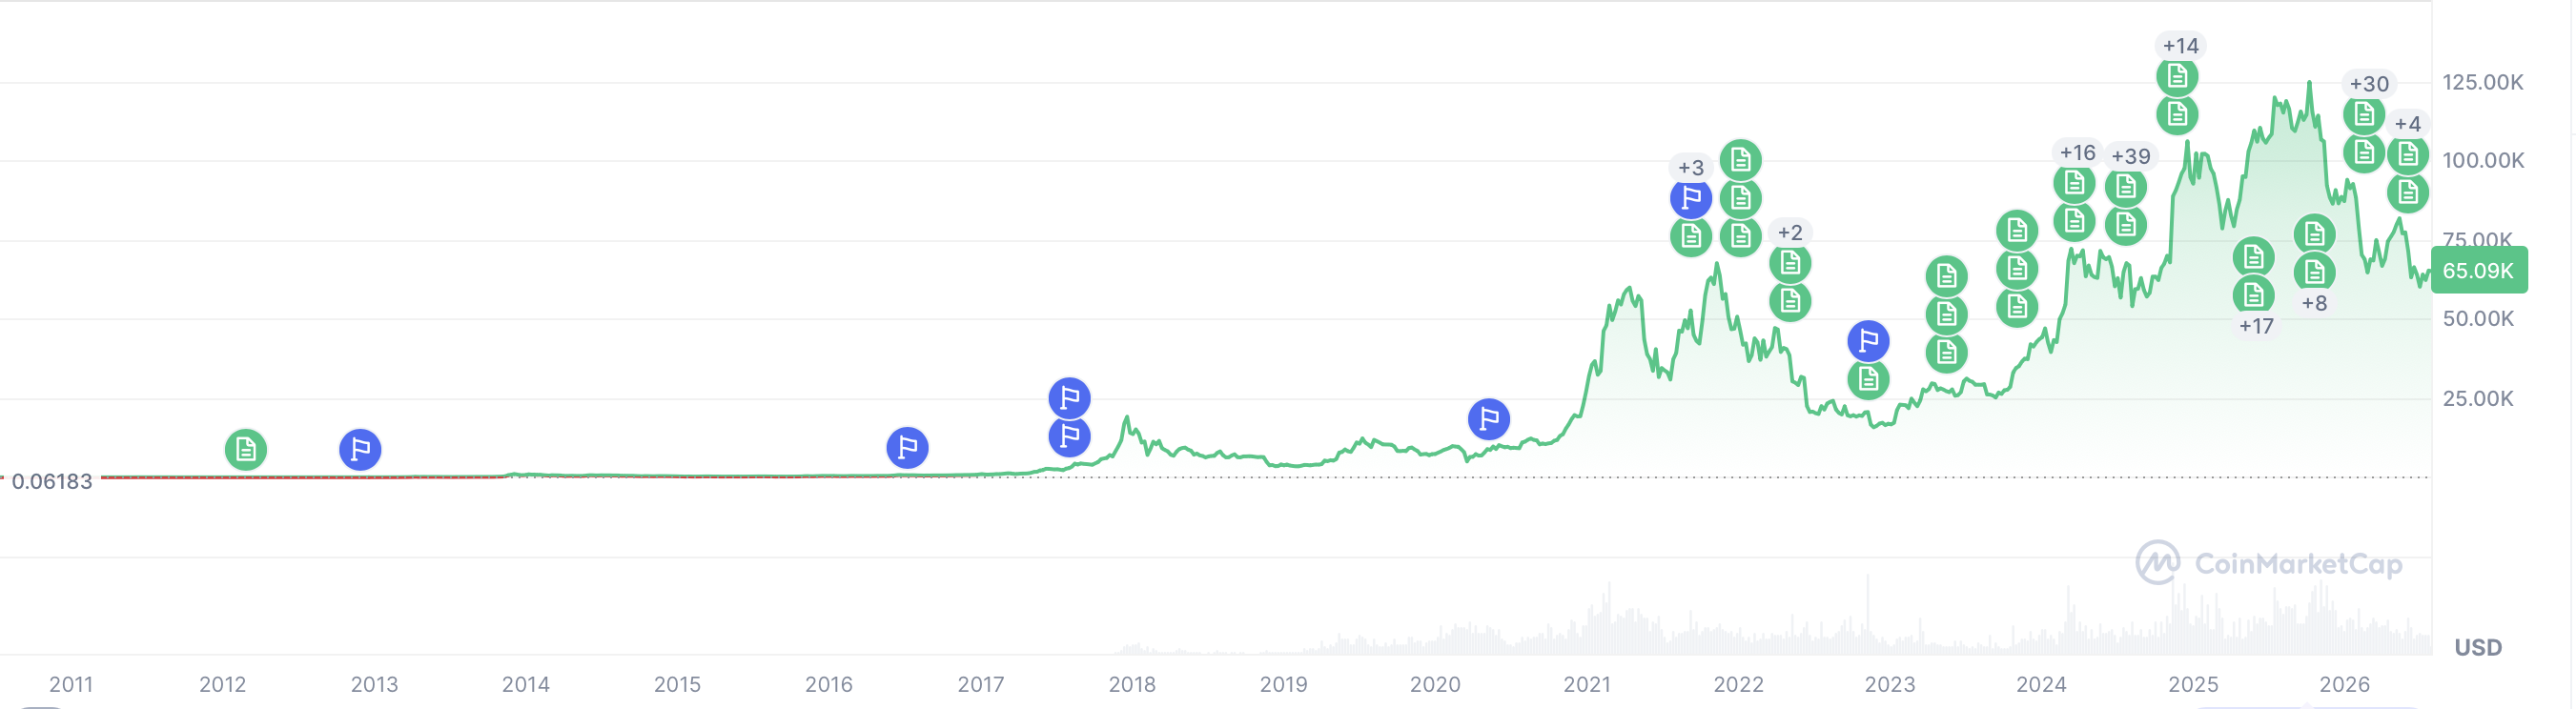
There is one other trading market, that while many may dismiss its meaning, I would contend is very representative of the way markets behave across all asset classes, Bitcoin.  The below chart shows it from its beginning, and you can see a number of essentially parabolic moves higher, each resolving with a decline of at least 50% and at times more than 70%.

Source: coinmarketcap.com

My point is that gold shows all the signs of having peaked for a while, and it has ‘only’ fallen some 25% from its highs.  From a trading history perspective, there is nothing that would seem to prevent a move down to $2800/oz or so, a 50% retracement from the high.  

So, which is it?  As I remain long gold in the personal portfolio, I have been a beneficiary of the long climb higher and would love to see it continue.  And there is much to be said for the debasement theory.  But both sides of this argument can be correct with the time frame the key differentiator. We could see a further short-term decline before a renewed upward move of significant magnitude.  Much will depend on how global macroeconomics and economic statecraft plays out over the coming months/years.  And this is why trading is hard!  One last thing describing just how much things have changed regarding gold and sentiment around it, this headline in Bloomberg this morning is remarkable, Gold Climbs as Pause in Mideast Fighting Curbs Inflation Risk.  

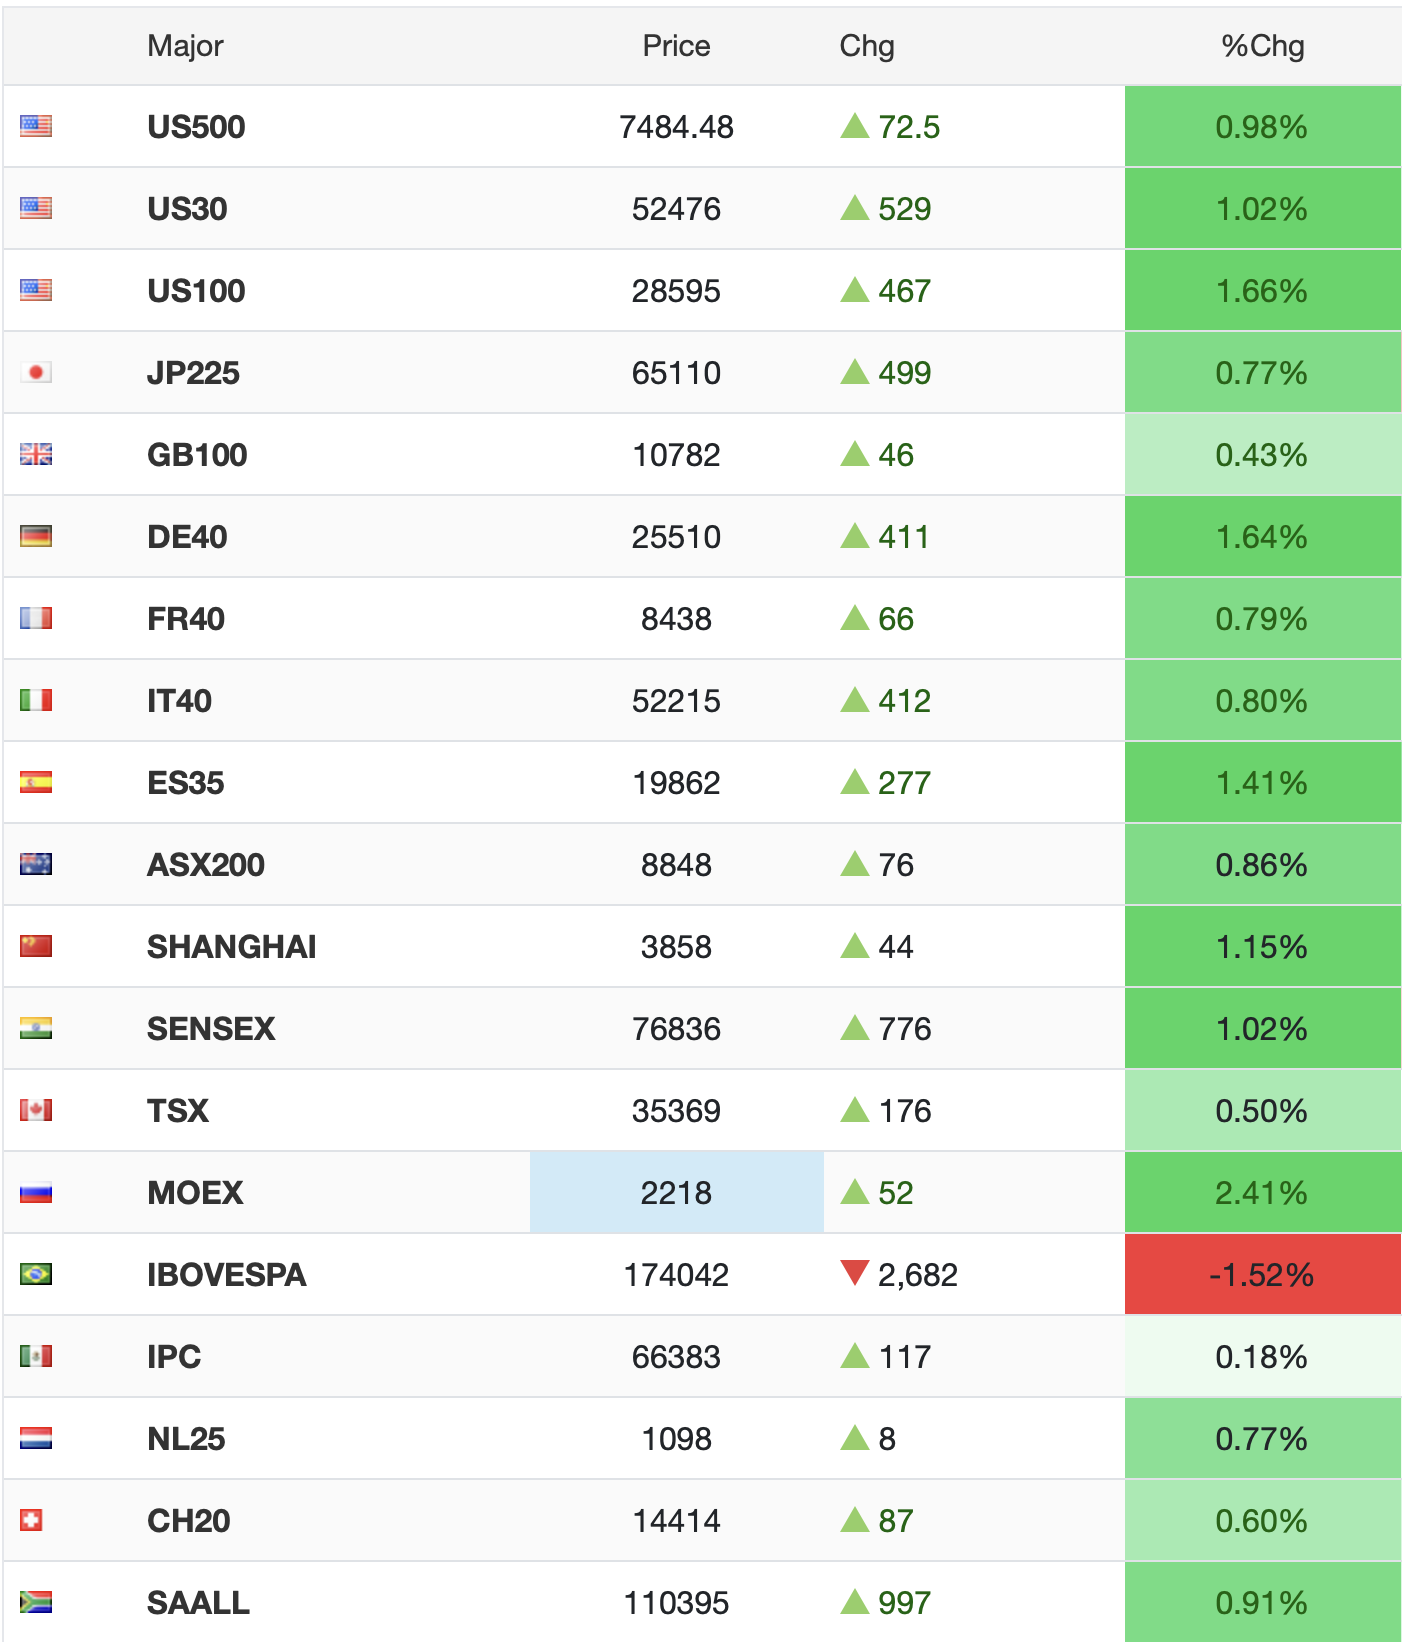
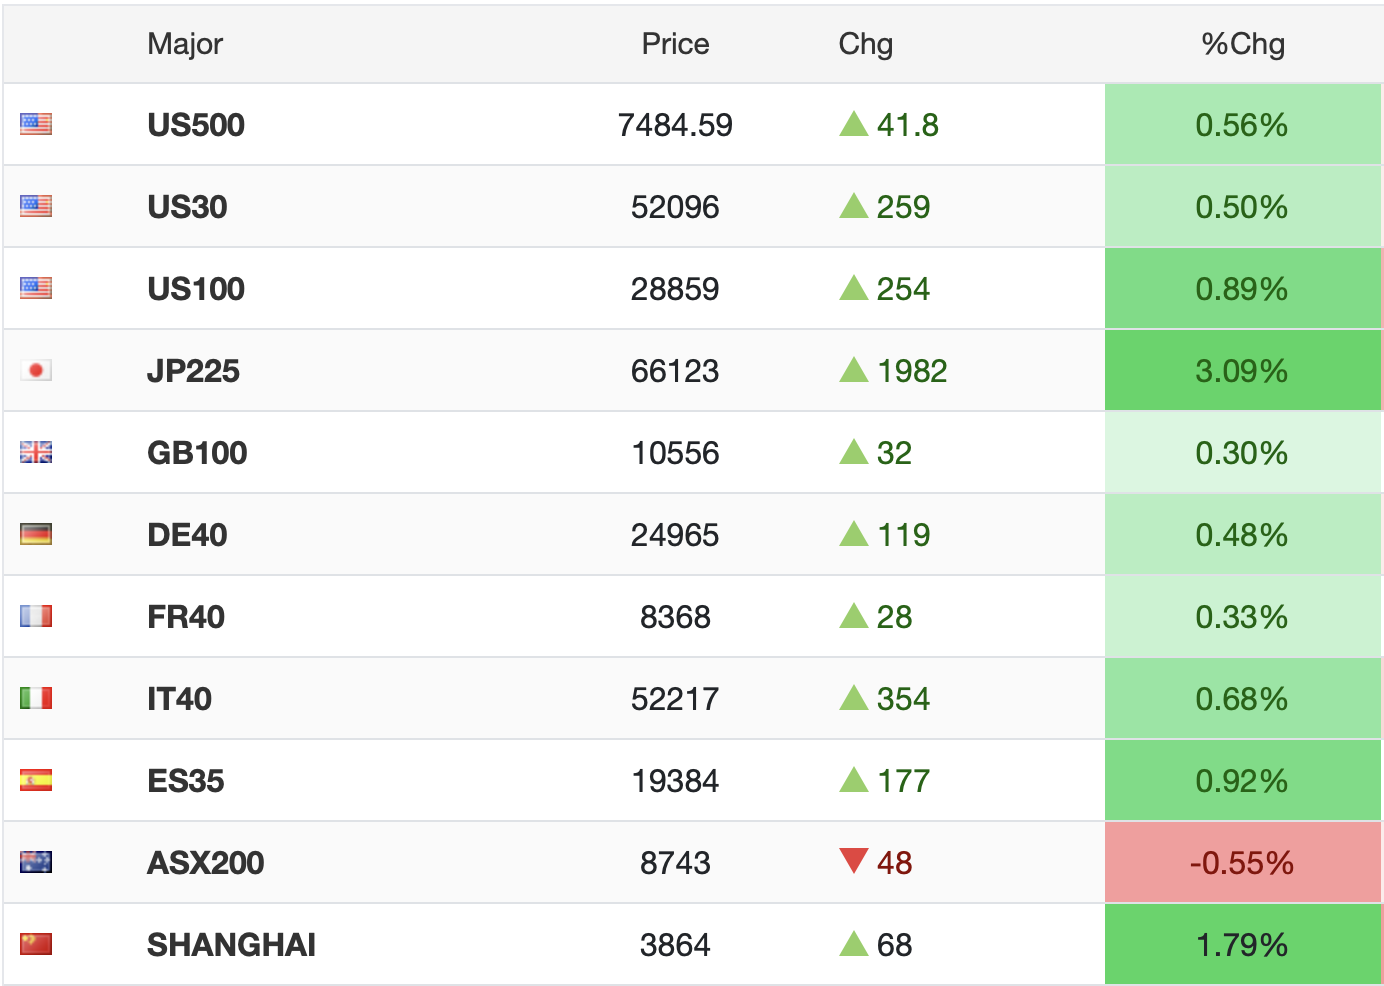
Ok, sorry for my rants, but a brief tour of markets show things are exactly as you would expect based on the reduction of tensions in Iran. Equity markets are higher around the world as per the below tradingeconomics.com screen shot, and don’t be fooled by Brazil, it hasn’t opened yet and there are no futures, so that was Friday’s performance.

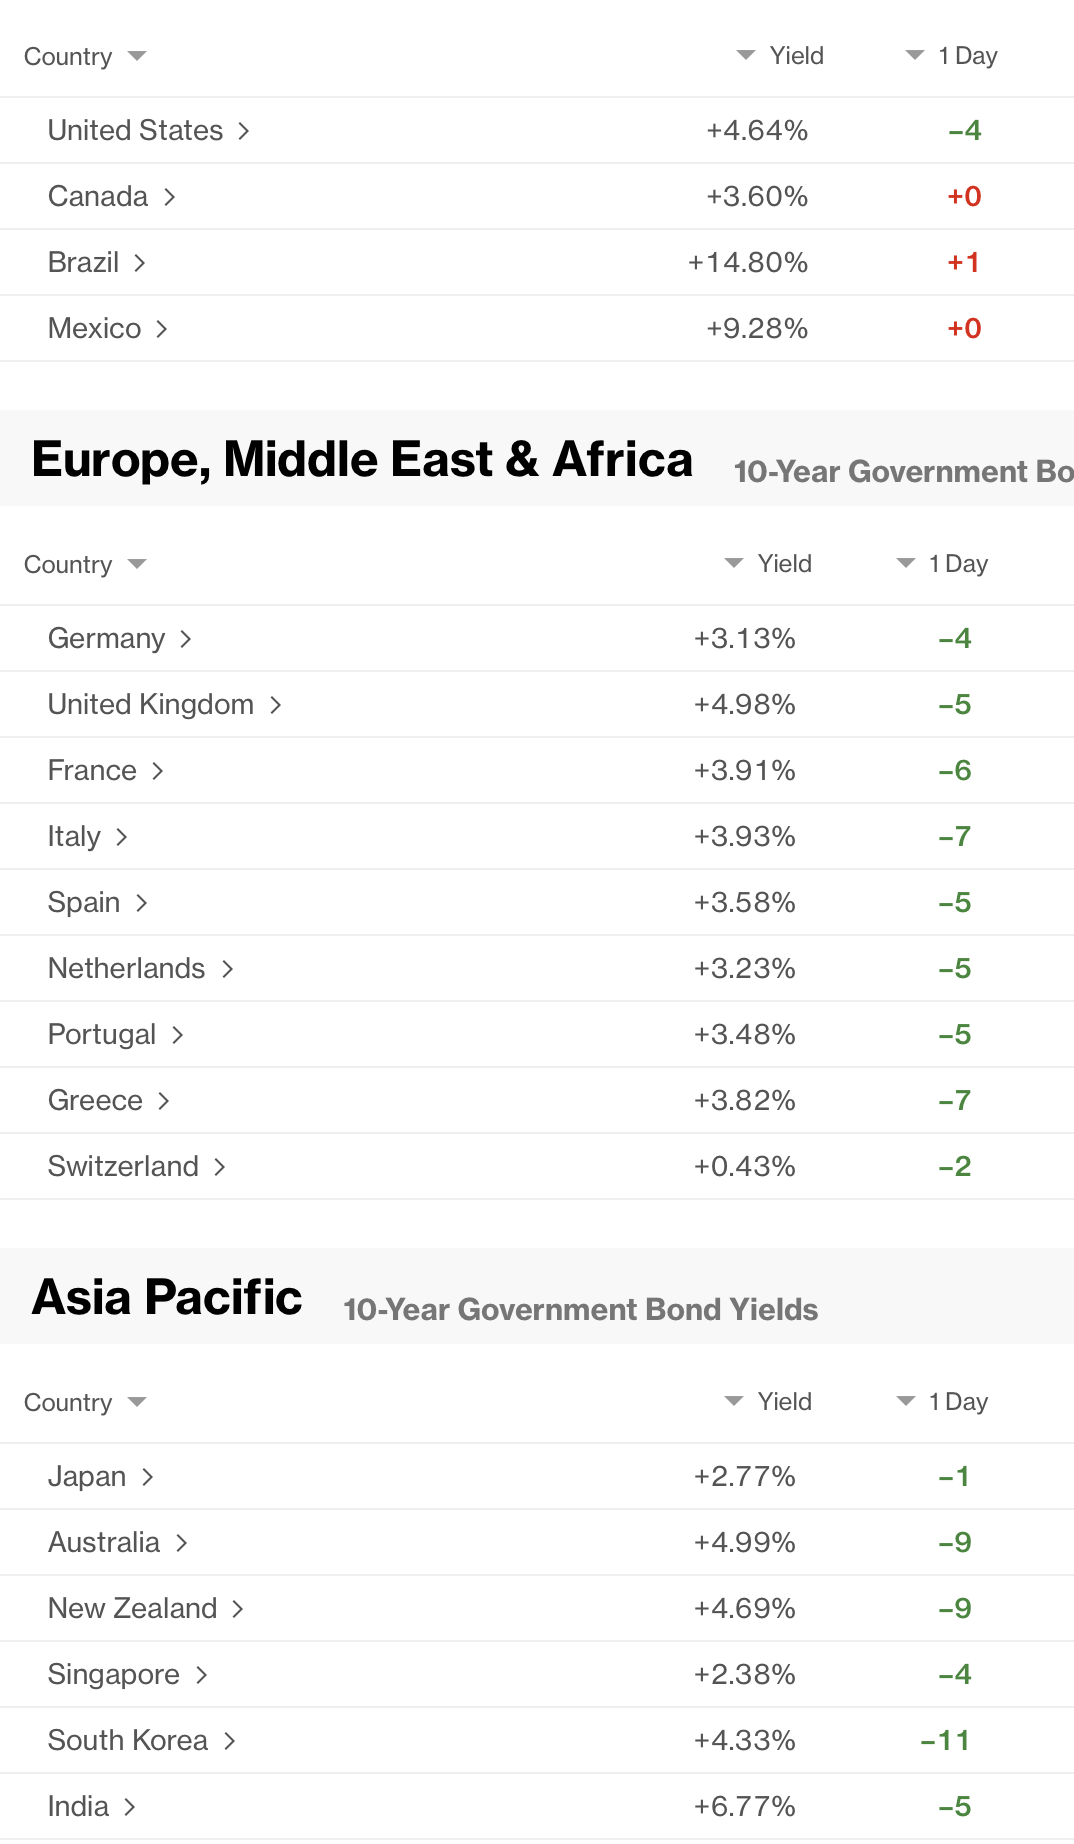
As to bond yields, they too, are lower across the board as per the below Bloomberg.com screenshot.  Canada, Mexico and Brazil markets are not yet opened, hence the lack of movement.

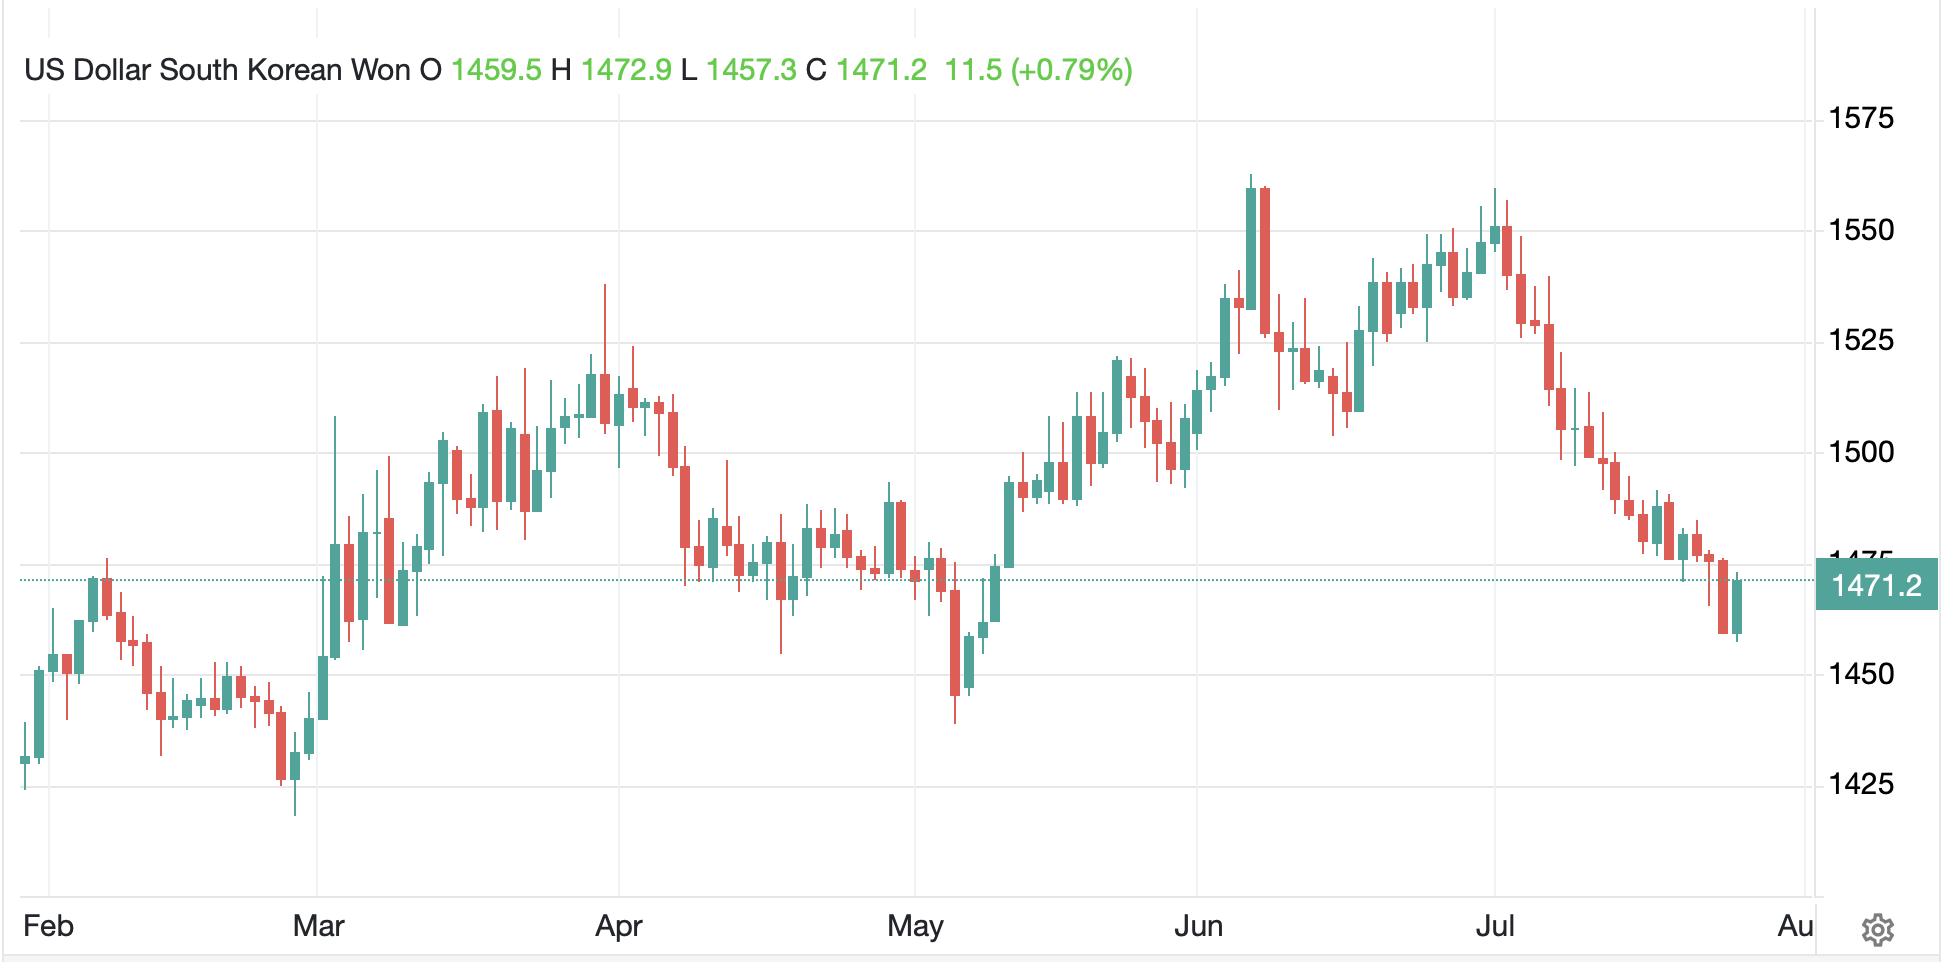
Oil has fallen further than when I started writing last evening with WTI (-8.2%) and Brent (-9.7%) both sharply lower.  Regarding Brent, apparently there has been a resumption of flows through Kazakhstan which is helping even more there.  Metals are higher (Au +1.1%, Ag +2.2%, Cu +0.9%), which is keeping with the latest theme.  And finally, the dollar is broadly softer, as also would be expected given the movement in other markets.  The two key exceptions here are NOK (-0.7%) which is clearly a reaction to the movement in oil prices and KRW (-0.8%) which actually started the session much stronger but has reversed.  While I read a rationale about concerns over a Fed rate hike, given the movement in oil and yields, that doesn’t seem right.  Rather, after a more than 6% appreciation over the course of the past 3 weeks, it seems more like a reflexive bounce in the dollar.

Source: tradingeconmomics.com

On the data front today, this morning brings Durable Goods (exp 2.5%, 0.8% ex-Transport) but that is all.  I will go deeper tomorrow, and remember, the FOMC meets this week with the current pricing 33% for a hike, even after the decline in oil prices today.  I remain in the no move camp but will discuss tomorrow.

And that’s more than enough.

Good luck

Adf
Decidedly Iffy

Though war in Iran keeps on going
The impact is not really showing
Risk assets seem fine
And oil’s benign
So, bubbles still need some more blowing

As I often say, markets are perverse and recent price action is a perfect example of this reality. As the US struck Iranian targets for the 10th consecutive day, and risk appetite during yesterday’s US session clearly waned such that all three major indices closed slightly in the red after solid openings, it was easy to expect a continuation of a risk-off attitude this morning.  But as you can see from the tradingeconomics.com screenshot below at 6:45 this morning, only Australia last night did not get the memo.
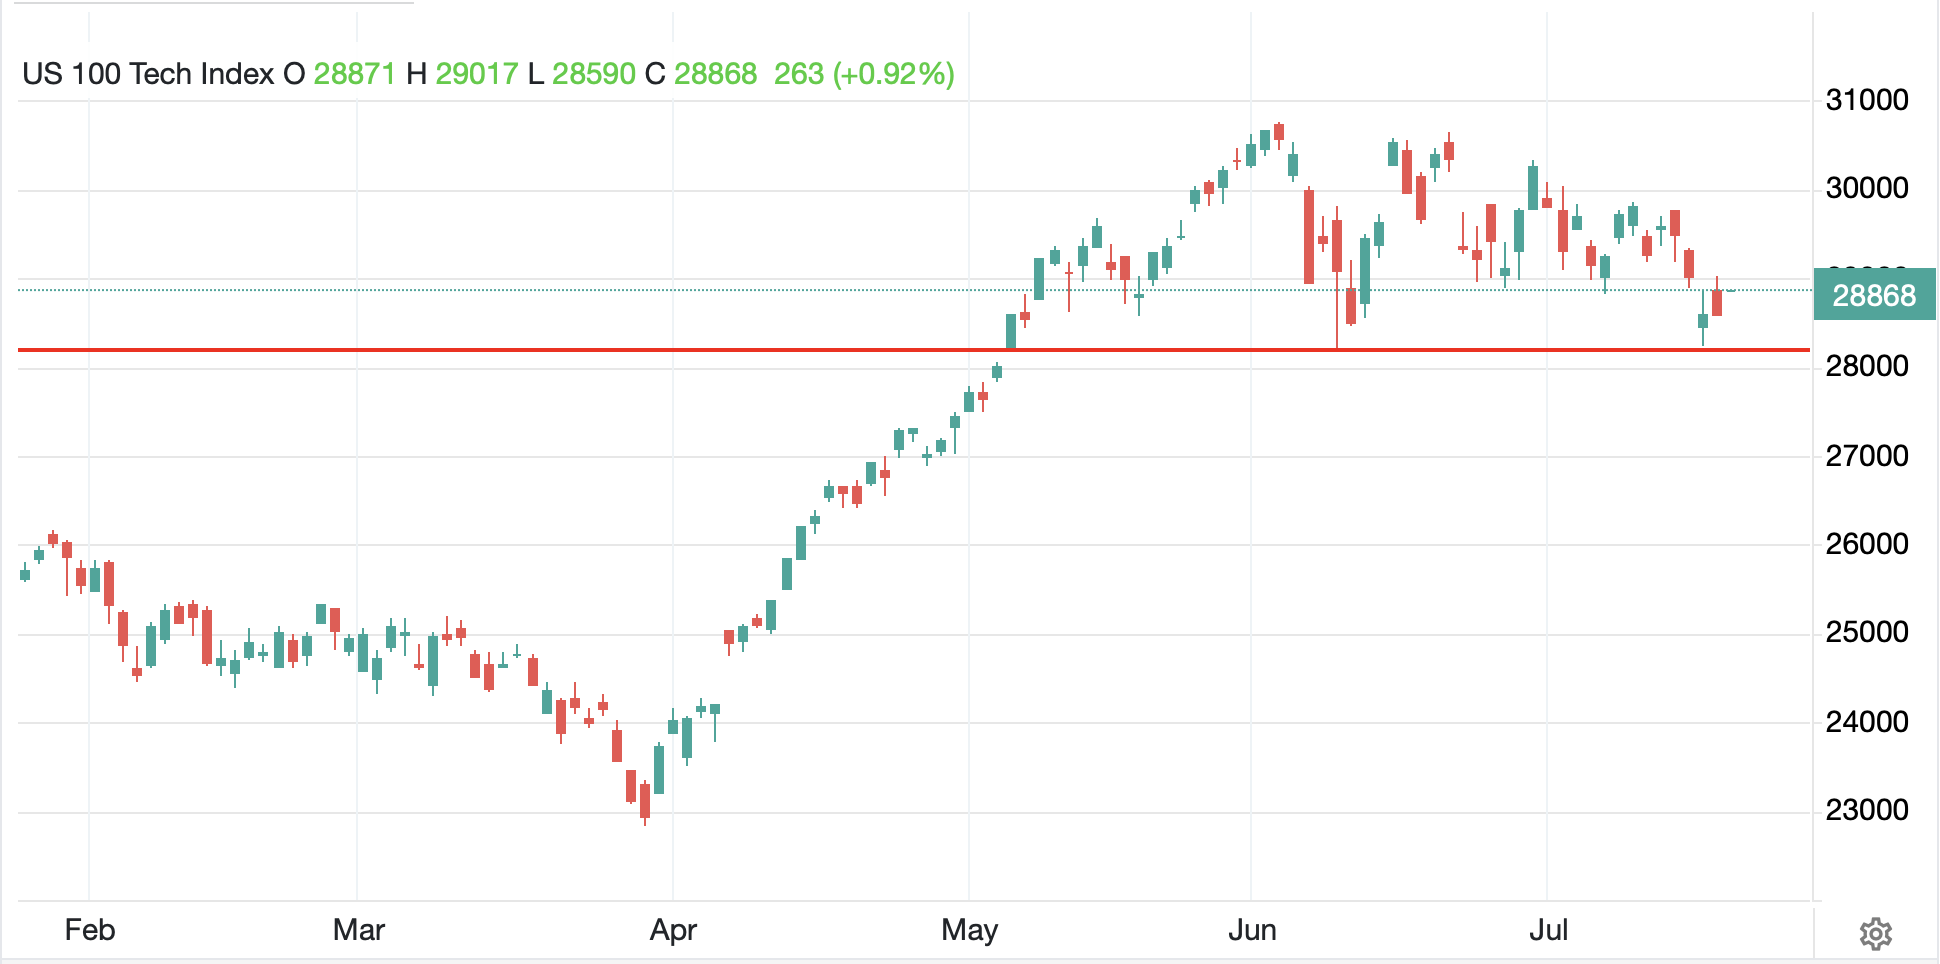
So, for now, it appears that everything is just fine.  The big banks all reported blow-out earnings last week and next week we are looking forward to the big tech names’ earnings reports.  Now, recent price action has shown that companies that miss their estimates are punished severely, so there is ample opportunity for more fireworks this week.  But so far, a look at the chart of the NASDAQ below shows the line in the sand that must hold in many market technicians’ eyes to keep the party going, and it continues to hold.

Source: tradingeconomics.com

It’s funny, yesterday afternoon I was considering buying some QQQ puts as my concern was that we were about to break down and a 5%-8% correction would be quite reasonable.  My read on the sentiment was turning decidedly negative, although I didn’t pull the trigger, deciding to wait for the actual break before acting.  And last night I wrote the following limericks, expressing my sense of things.

The mood is decidedly iffy
With stock market bulls getting miffy
And now we’ve heard calls
For much further falls
With bears’ attitudes, oh so sniffy

So, two things have risk-takers tense
The first is the increasing sense
That war in Iran
Has no master plan
And may cause, more problems, immense

The second is whether AI
Has peaked, or has further to fly
If we’ve seen the top
The ensuing drop
Will bring a Wall Street hue and cry

In fact, I think it is instructive to help understand just how quickly sentiment can change without any obvious catalyst.  For the life of me, reading through the headlines this morning, there is nothing I have seen that would cause me to believe things are so much better today than at the close yesterday.  But perhaps this is a case of less market activity allowing a bit more volatility in markets.  After all, it is summer and there are many market participants on vacation on any given day.  According to Grok, in the past 5 trading sessions, average volume for NASDAQ shares was about 7.6 billion, but as large as that is, it is well below the YTD average of around 9.0 billion.  In reduced volume markets (no matter how large they are) there can be large, unexplained moves based on individual flows.  I’m grasping at straws here!

Regardless, this is where we stand this morning.  There are headlines dueling between further military action and further efforts at peace talks, with markets clearly preferring the latter rather than the former.  Oil prices (+0.9%) remain within their recent range although are creeping higher this morning.  Is this a prelude to a move back to $100/bbl?  

Source: tradingeconomics.com

The problem with that story is that there continues to be a massive supply of crude oil around.  And Ukraine’s success in attacking Russian refineries has actually brought more crude to market as the Russians can no longer refine their own in the same volumes thus are shipping it to anyone who will buy it. 

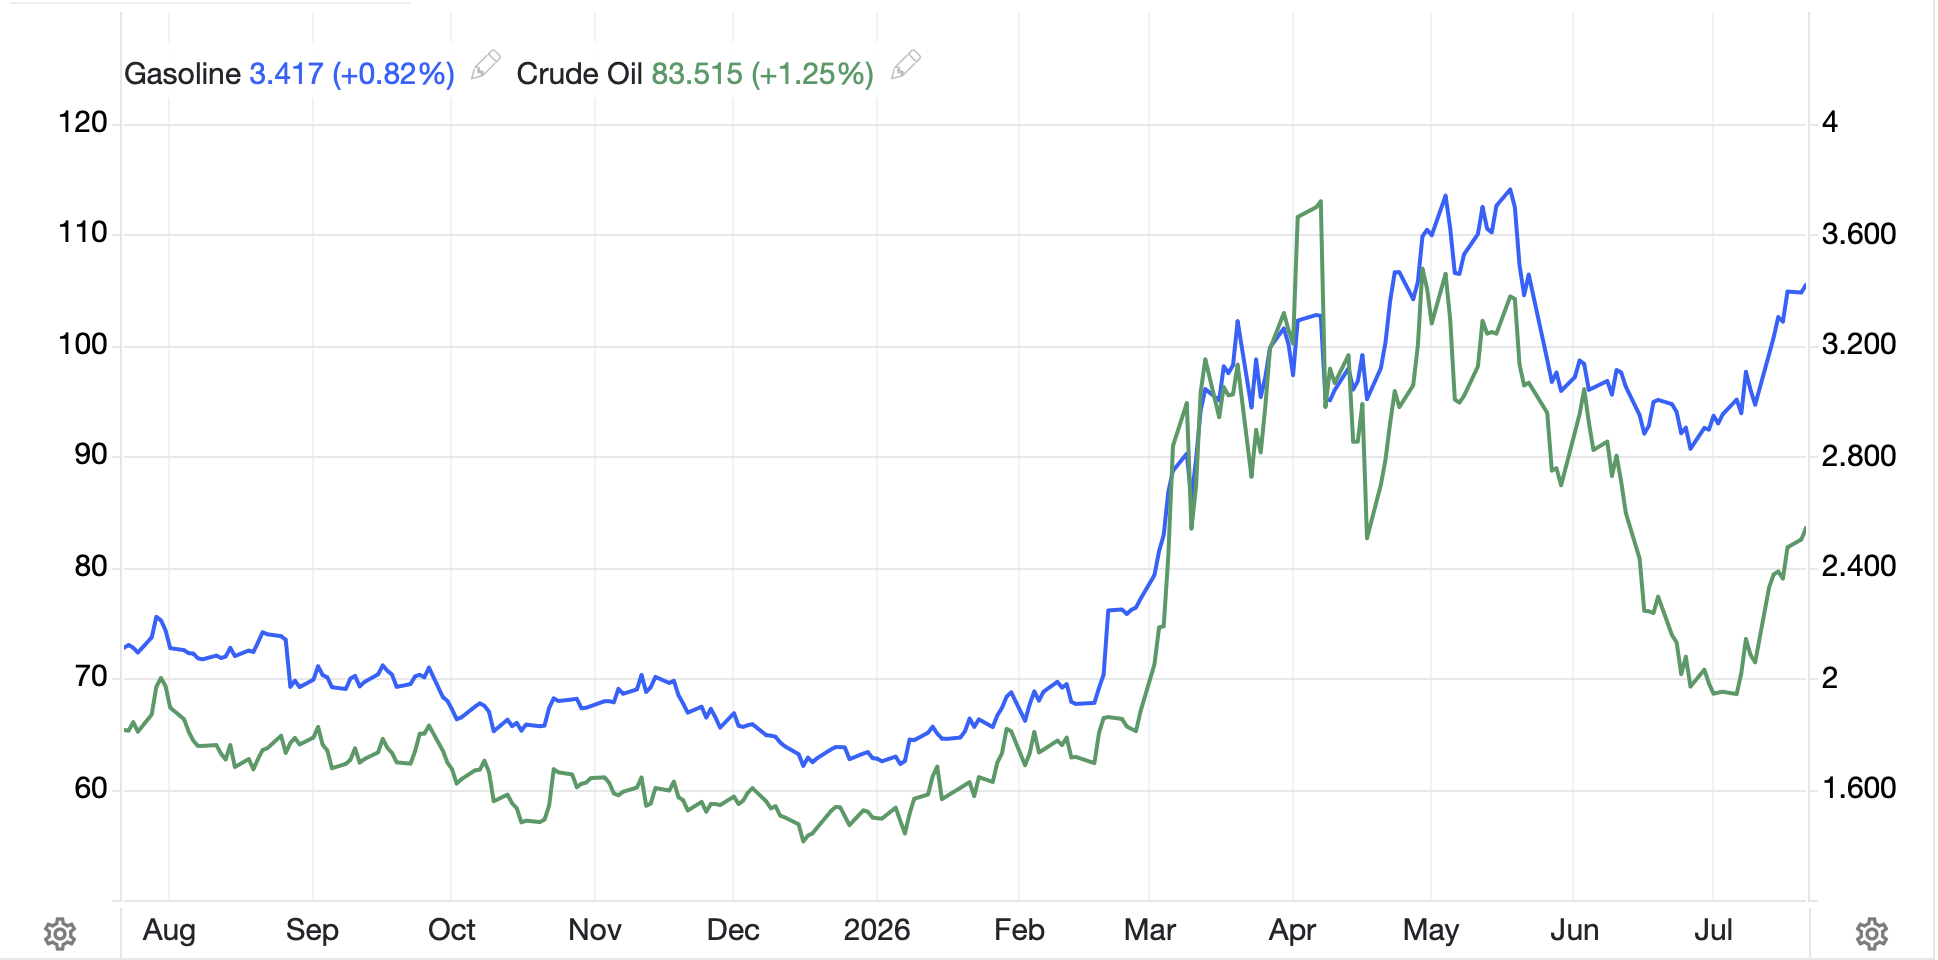
Products, though, are a different story as the lack of refining capacity (US refiners are running at about 98% capacity) has led to record high crack spreads.  (The crack spread is the value of the products created from crude; gasoline, jet fuel and diesel largely, compared to the price of a barrel of crude.  The higher that spread the more profitable the business is for refiners, and the more we pay at the pump). Referring back to the chart above, the blue line is gasoline futures in NY, which as you can see are much closer to their early war highs despite the more dramatic decline in oil (green line).

In fact, this chart may be the best metaphor for the current sentiment in the US with the population suffering from rising gasoline prices while the government touts the decline in crude prices.

Net, I am having trouble finding a single coherent narrative that is widely believed.  So, let’s look at how other markets behaved overnight, having already seen equities and oil.  Bond yields rose yesterday with Treasury yields higher by 5bps and a further tick up this morning.  Similar price action was seen in Europe although more of these markets are +2bps this morning, rather than the +1bp in Treasuries.  And JGB yields rose 3bps overnight.  

Speaking of Japan, you may recall the story from about two weeks ago where Japanese FinMin Katayama expressed the idea that Japanese pension funds should consider investing more domestically, bringing home some of their massive $3+ trillion in assets.  The market got quite excited about that and as you can see in the below chart, the yen immediately rallied.  

Source: tradingeconomics.com

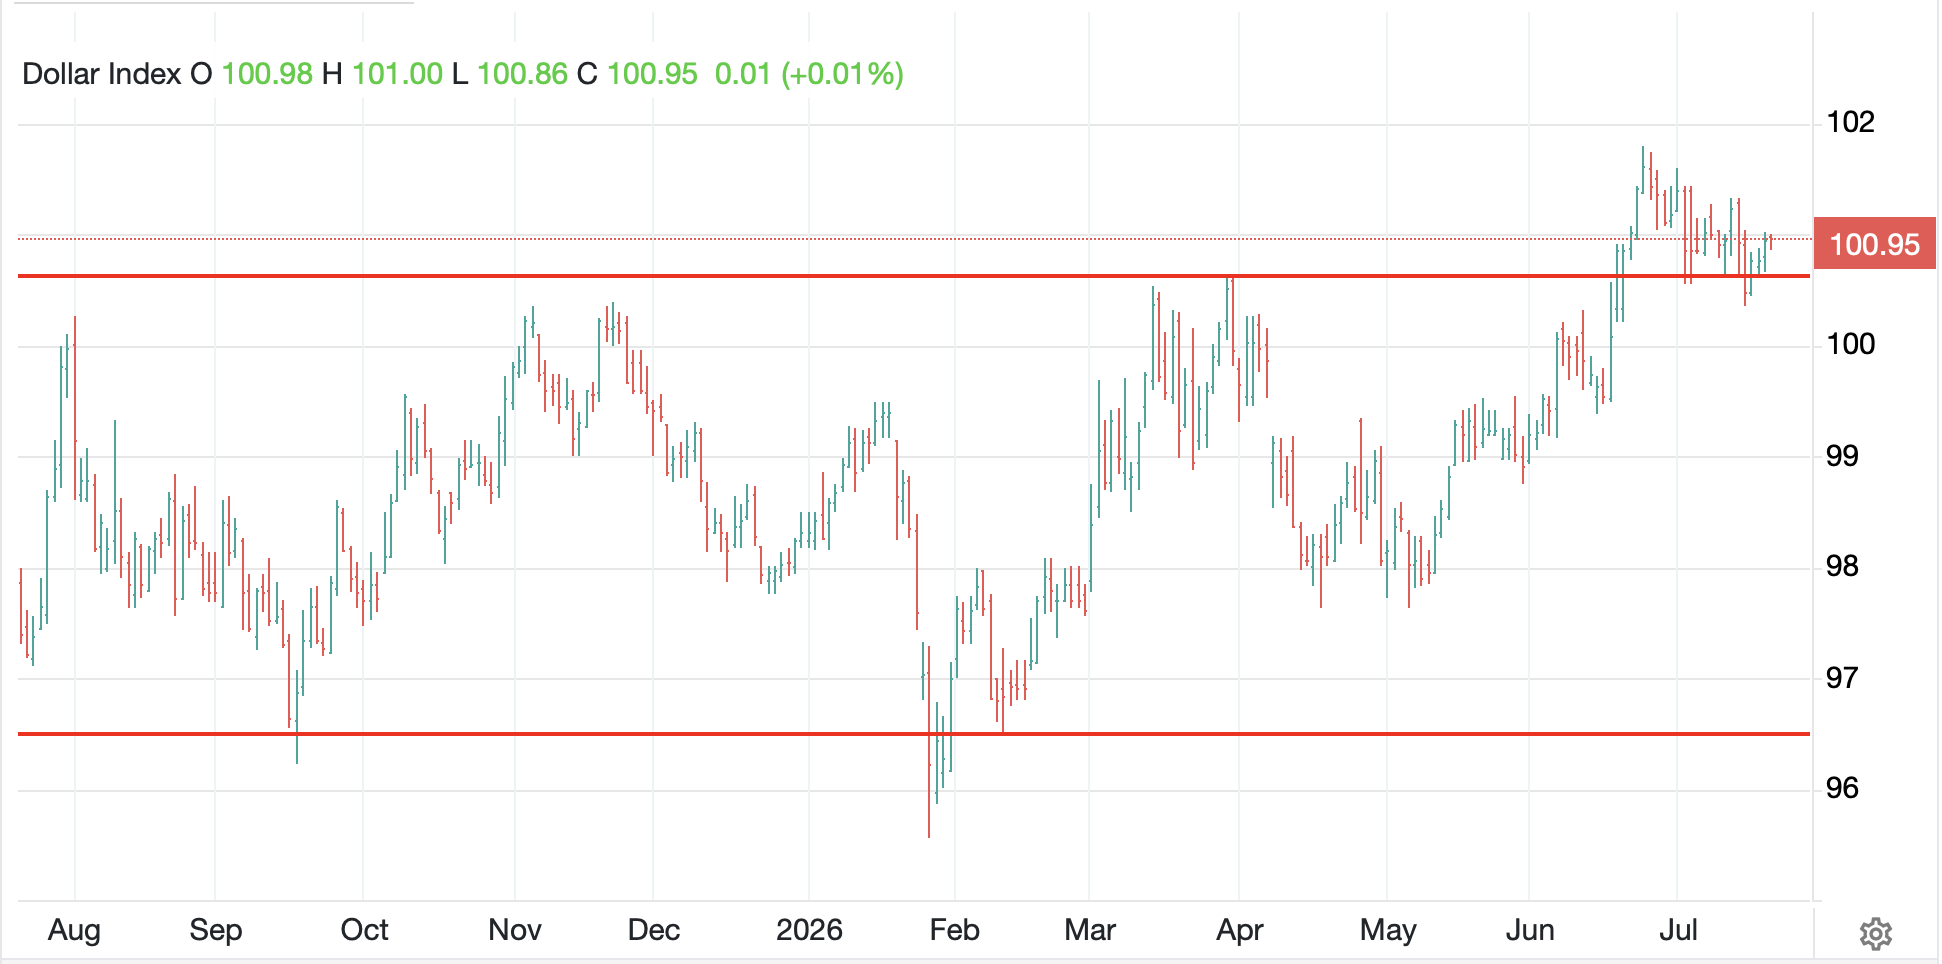
Well, that was sooooo two weeks ago!  This morning, the yen is just 5 pips, as I write, from breeching the peak seen before the last intervention scare.  As you can see in the chart, the move is extremely gradual, but in this case, the tortoise is being played by the yen.  I saw more discussion on this pension story this morning but while I think it is highly probable to play out over time, I think the timeline is better measured in years, not weeks, or even months.  As such, the gradual depreciation of the yen seems likely to continue.  Elsewhere, it remains very hard to get excited about the dollar vs. any currency right now.  Sure, NOK (+0.6%) is rallying on the oil rally, and perhaps the real surprise today is ZAR (+0.5%) which despite higher oil has seen higher gold prices help sustain it.  But if we look at the dollar writ large, the ‘breakout’ from its year-long range seen back in mid-June has been a damp squib as per the below chart of the DXY.

Source: tradingeconomics.com

Perhaps the big surprise this morning is the metals (Au +1.2%, Ag +4.2%, Cu +3.1%) are all higher despite the rise in oil prices and yields.  While I remain long term constructive on the metals sector, it is very difficult to understand what is driving today’s price action at this point.

And that’s really it today.  There are no frontline data points to be released so I expect that oil sentiment will continue to lead markets although there will certainly be excitement about equities if they can maintain the rally today.  As to the dollar, nobody seems to care.

Good luck

Adf

Rise Like the Sea

So, let’s take a sec to discuss
Inflation, and why it’s a plus
At least for some folks.
In gentle broad strokes,
Though most of us see it and cuss

For those who hate Trump it’s a key
To help destroy his legacy
For Congress, they need
Inflation to plead
That taxes must rise like the sea

And what of the Fed and their role
To keep it in check, on the whole
Now, if they’re successful
T’would truly be stressful
For everyone on their payroll

If you were a government and wanted to design the perfect process by which to extract more money from your citizens allowing you to spend more money on the things you wanted, whatever their views, all while explaining that their lying eyes were deceiving them when they complained, it would be hard to come up with a better process than the official inflation figures.  Of course, today we get more of those figures with PCE and its variants set to be released at 8:30.  While I am here, these are the current market median estimates: PCE (0.5%, 4.1% Y/Y), Core PCE (0.3%, 3.4% Y/Y) although I see no forecast for the Dallas Fed Trimmed Mean reading, the one that Chair Warsh says he wants to focus on.  Too, it is key to remember that they are May numbers.  How many of you can remember what happened in May?

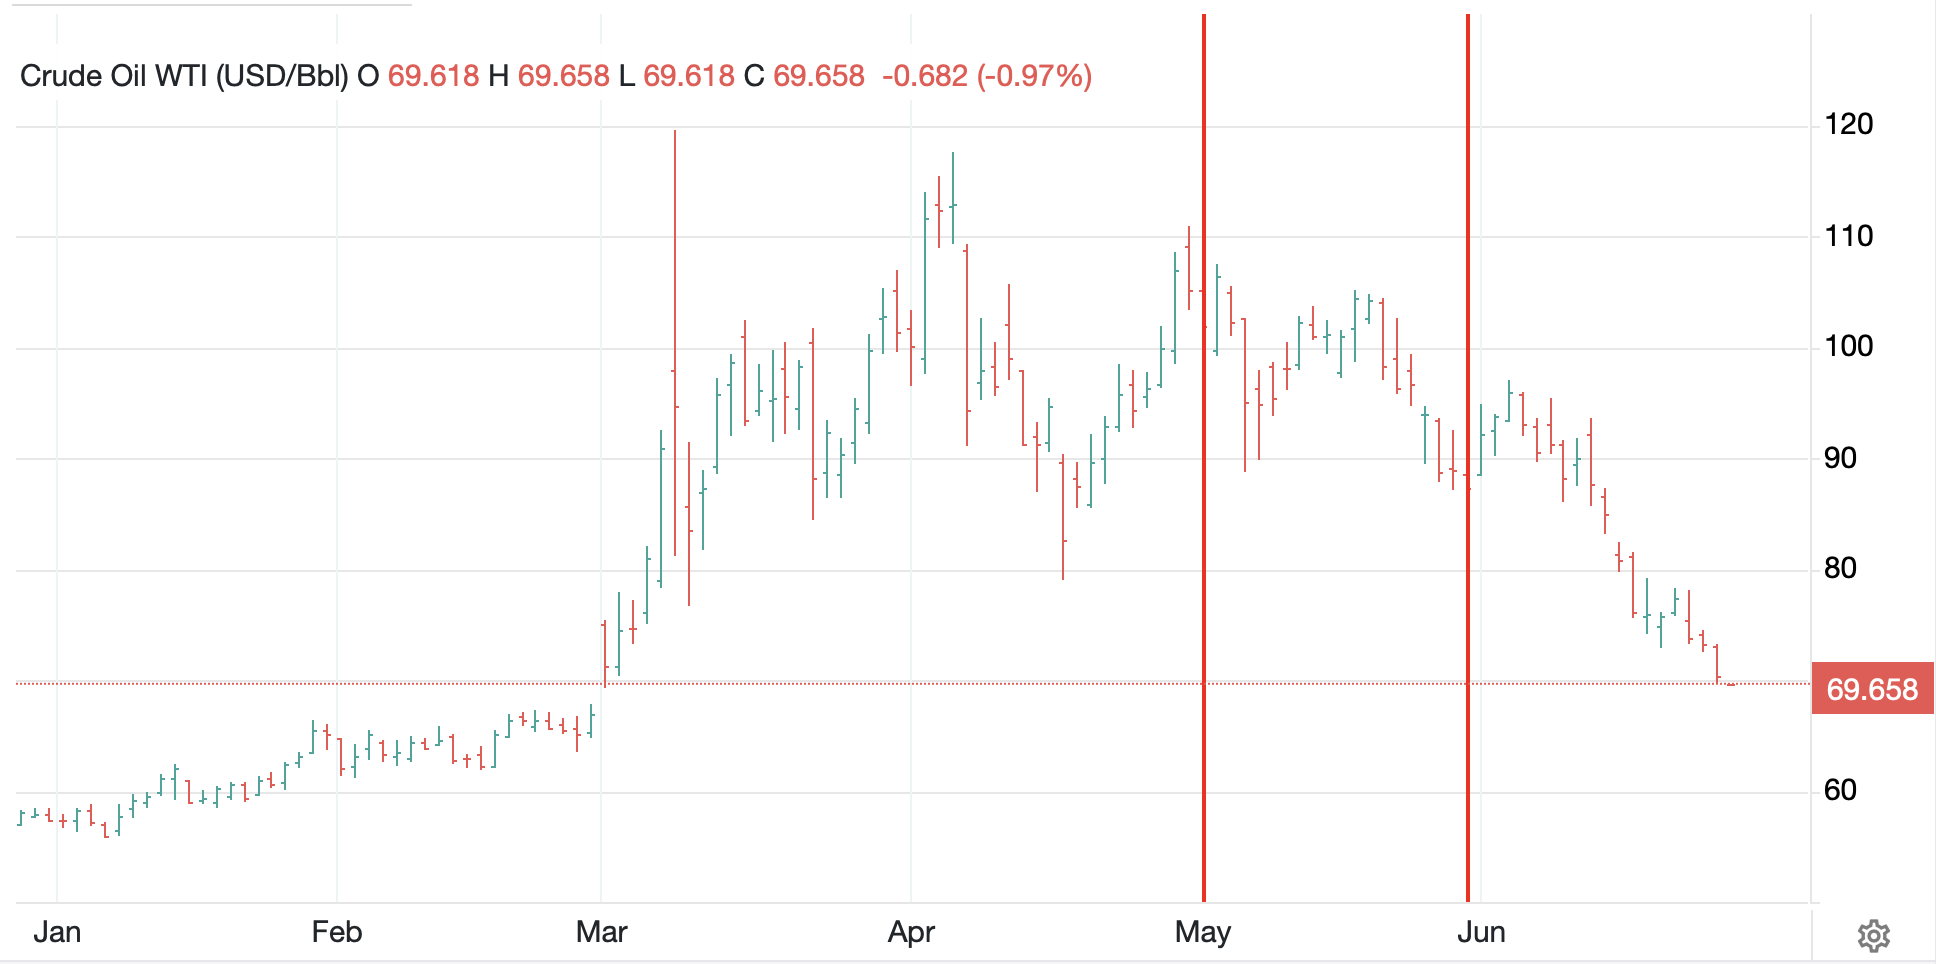
For instance, looking at the easiest one, oil (-1.0% today), as per the below chart, you can see that WTI ranged between 86.50 and 106.50 during May, mostly sliding, bur arguably averaging in the low 90’s.

Source: tradingeconomics.com

This morning, it is trading below $70/bbl, back to the price on March 2nd, the first market day of the Iran conflict.  The BLS indicated that upwards of 60% of the rise in CPI was driven by the rise in energy prices, which tells me that whatever today’s numbers are, they are ancient history and next month’s are going to be lower.  I don’t know about you, but I am quite happy that energy prices are falling back to pre-war levels as, a) it makes life more affordable, and b) cheap and abundant energy leads to significant economic output, something good for us all.

But here’s the thing, with energy prices declining, those who benefit from high inflation need a new story, and there is none better than semiconductors.  The top headline in the WSJ this morning is The Data-Center Boom Is Sparking a Third Wave of Inflation, right on time for the next big inflation scare.  The big winner, at least today, Micron Technology, which had blowout earnings last night and jump-started a serious Techquity™ rally overnight with Tokyo (+4.6%), China (+1.6%) and Korea (+5.4%) leading the way.  HK (-1.4%) lagged and the rest of Asia was mixed, but that gives you an idea.

But the point of the article was that we all need to be prepared and accept that higher inflation is coming because the massive resource demands to build AI are coming along before the productivity gains can moderate the price impact.  And I have no doubt that the resource demands are going to support prices.  I remain uncertain over how quickly AI’s impact will be deflationary, even disinflationary.

And here’s the thing, my lived experience, plus my frequent conversations with The Inflation Guy, Mike Ashton, have me in the camp that CPI is going to live in the mid to high threes for a while to come, regardless of the metrics the Fed uses to measure things.

But I have begun to discern that there is a large community that benefits from rising inflation because it helps them achieve their goals.  After all, we know that governments love inflation as it devalues the real value of their outstanding debt, so a steady depreciation is their best friend.  As well, Congress’s baseline budgeting ruse, which starts each year from the previous year’s expenditures, not from zero, is a huge beneficiary of inflation.  I understand that since about 1980, the BLS has adjusted the CPI calculation somewhere between 30 and 40 times and you can guess the direction of most of those adjustments.  Of course, companies that sell products are a big fan as well, as they tend to adjust prices to both include new costs, and increase margins.  And they have a natural scapegoat; CPI is out of their hands.

All I’m saying is that while there appears to be a strong effort to fight inflation, I’m not a believer.  (And here I should highlight that I use the term ‘inflation’ in the manner it has become understood, rising prices, and not in its classical form of an increase in the money supply, which is 100% the Fed’s doing.)

One other thing.  My friend JJ who writes Market Vibes, posted a chart of 1yr breakevens as of yesterday and I reproduce it below.

This is not a signal that the market expects prices to rise, but rather is following the decline in oil prices pretty well.  Once again, I will ask, please explain given market signals, why everyone is so sure the Fed is going to hike.  I maintain my one cut by year end view which is at least 50bps below the current Fed funds futures market pricing.  Ask yourself how the FOMC ‘hawks’, and I use that term loosely, will be able to argue for higher rates if oil continues its trajectory and inflation readings decline.  Precautionary?  How about they will simply say, we want to screw Trump, at least they would be honest then.

Ok, on to other markets overnight.  European bourses are all higher this morning, but since none of them have any real tech exposure, they are not running away.  Rather, 0.3% to 0.7% encompasses the magnitude of movement we have seen.  As to US futures, at this hour (7:25), NASDAQ (+2.0%) is leading the way, but the whole group is higher.

In the bond market, yesterday saw yields decline about -8bps in the 10-year Treasury and -6bps in the 2-year.  this morning they are little changed, consolidating those price gains.  As to European sovereigns, yields there also slipped yesterday, but not as dramatically, about -4bps, and this morning they are largely unchanged.  Overnight, JGB yields fell -3bps as declining oil prices are feeding through to inflation expectations.

The precious metals complex continues to get hurt, with gold (-0.6%) and silver (-0.5%) still under pressure and at new lows for the year, but copper (+1.25%) seems to have found a short-term floor at $6.00/lb.

And finally, the dollar, which has been en fuego lately, rising for the past six consecutive sessions, as per the below chart, is consolidating for now.

Source: tradingeconomics.com

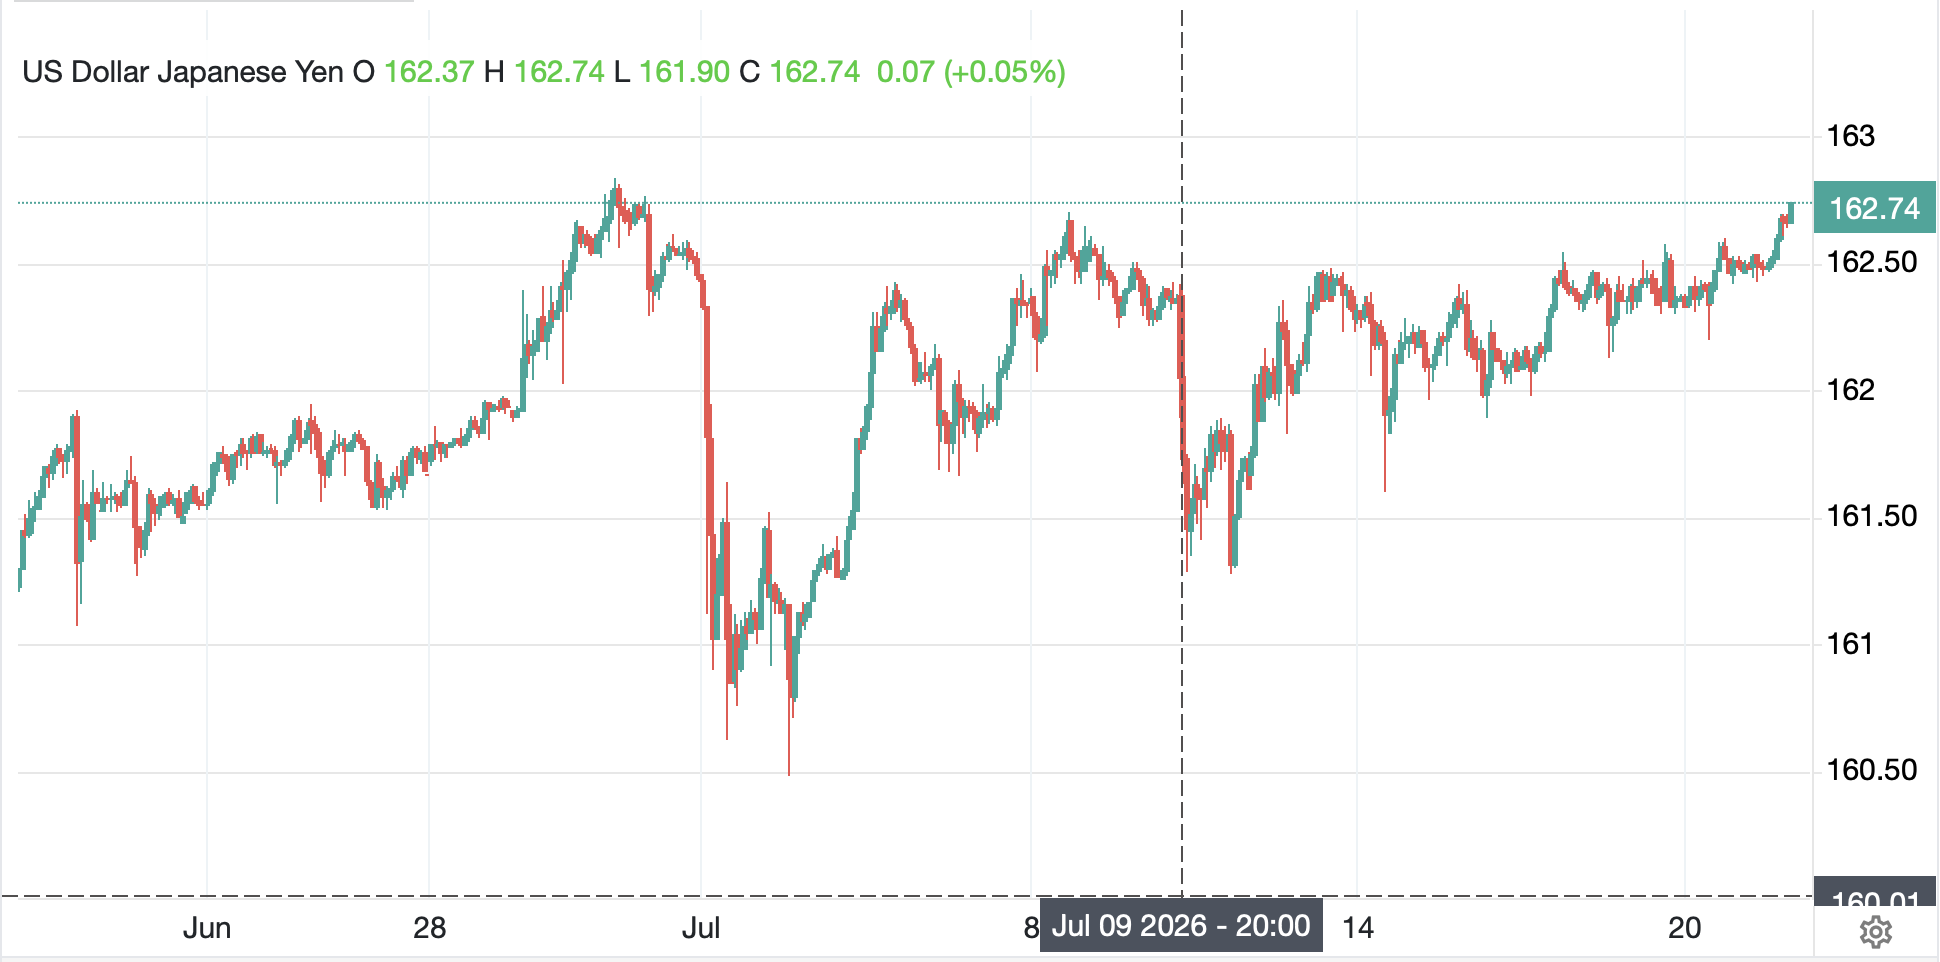
Nothing has changed the yen story, where the dollar creeps ever so slightly higher each day, now just below 162.00 but overall, today’s movement has been quite muted, about +0.15% in the dollar against most currencies, as the focus turns to inflation, at least for today.

On the data front, in addition to the PCE data we get a bunch more as follows:

Initial Claims225K
Continuing Claims1800K
GDP Q1 Final1.6%
Personal Income0.4%
Personal Spending0.6%
Durable Goods-4.5%
-ex Transport0.6%
Chicago Fed National Activity0.12

Source: tradingeconomics.com

Will anyone care about this data?  I doubt it, Core PCE is THE thing today, so we will watch and see how that comes out. But mark my words, if it is soft, the hawkish Fed narrative is going to come under real pressure as stocks rally and yields and the dollar slip.

Good luck

Adf

Leverage Doomsday

Though oil continues to be
The lens through which most of us see
The current events
In dollars and cents
There’s more going on causing glee

For instance, as stock markets rise
It cannot be such a surprise
The narrative writers
Are pulling all-nighters
Adjusting their views to seem wise

But naysayers need to say nay
And here’s what they’re pushing today
The Bank of Japan
And their current plan
Will lead to a leverage doomsday

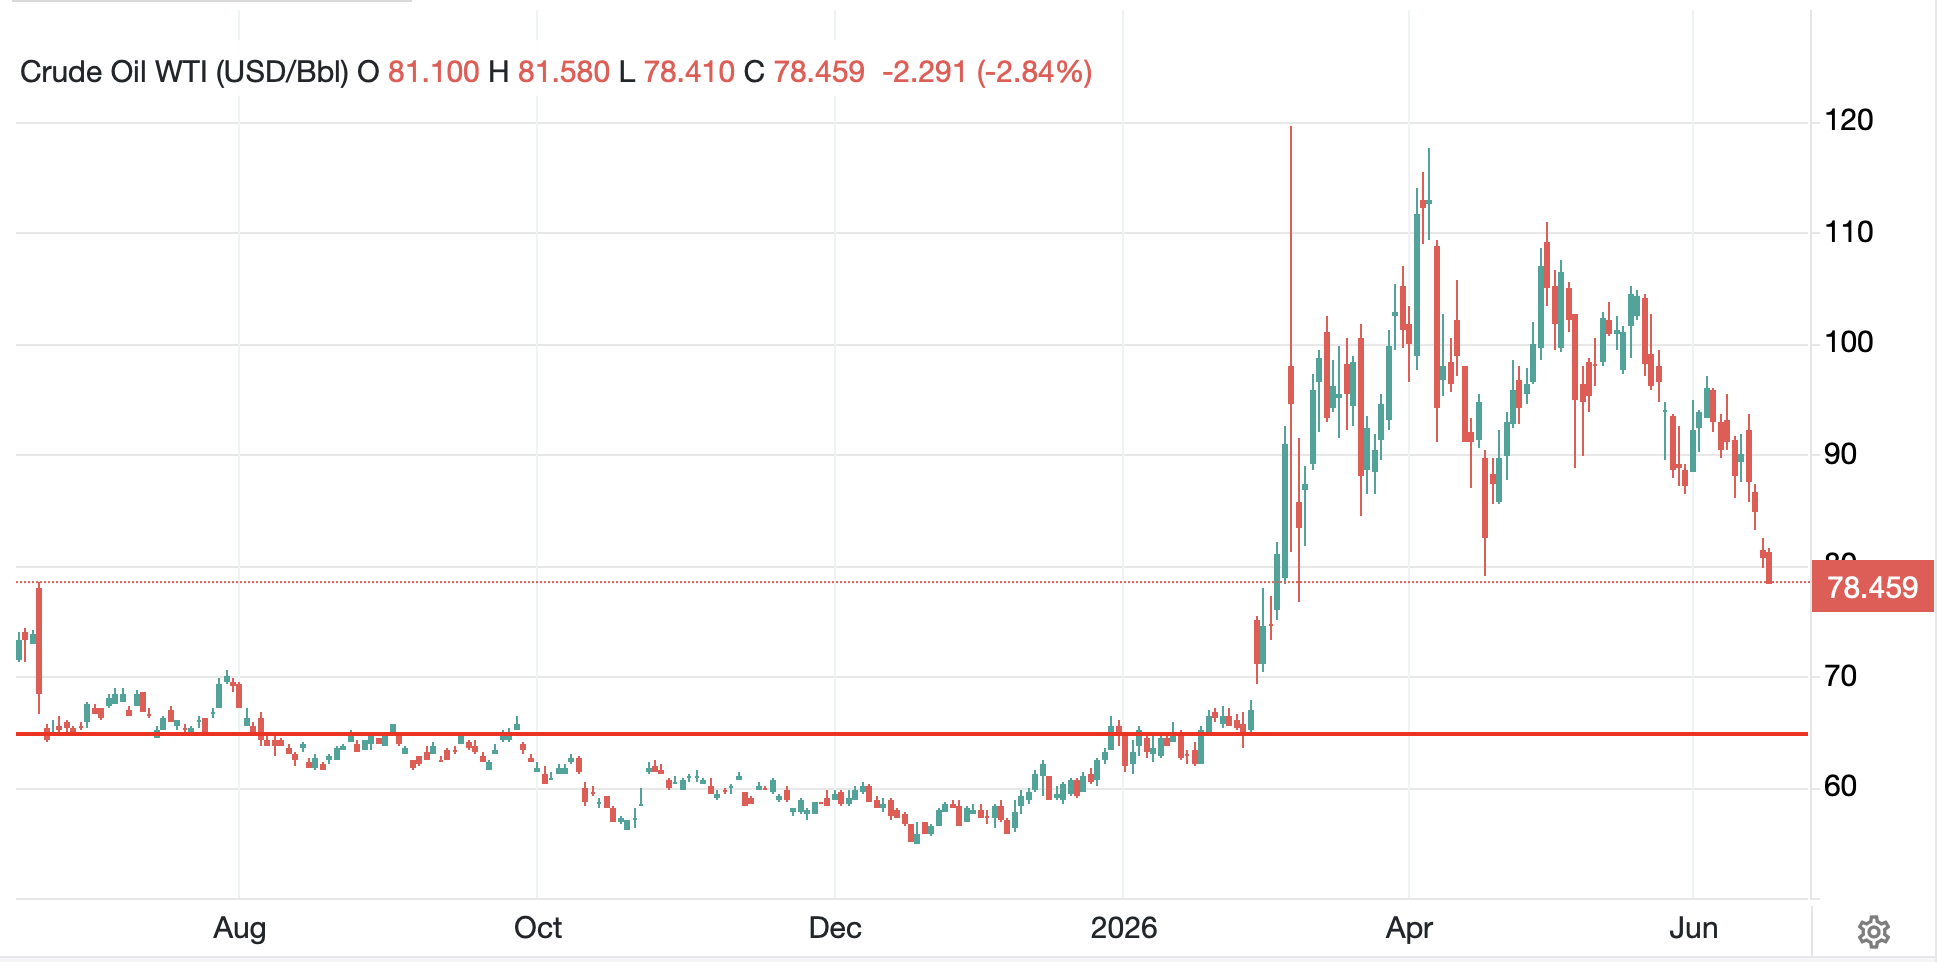
We might as well start off with oil this morning since it is still the top story in markets, and still the major catalyst.  It is lower again this morning, down a further -2.8%, and despite many questions as to whether the deal will hold, both sides appear to be moving toward a signing on Friday.  The below chart from tradingeconomics.com shows WTI prices for the last year.  As you can see, the current price is the lowest since March 10th, which was a reaction low after the spike high on March 9th when it touched its highs for the entire situation.

I eyeballed a line at about $65.00/bbl as an estimate of what prices were like prior to the Iran conflict.  Based on that, the current front month futures price remains about 20% above the pre-war price, certainly high, but it doesn’t seem crippling.  I believe it is very clear that the analysts who were calling for $150/bbl or $200/bbl are now working hard to determine what they got wrong.  Doomberg wrote an interesting piece this morning (it is paywalled, but their stuff is fantastic) describing two likely reasons for the fact that oil prices never rose that high.  First, the original estimates of how much oil was stuck behind the Strait were overstated as all the players there found ways to export some, whether through tankers going dark or via rail or truck or pipeline.  But the more interesting observation was that China was able to reduce its imports by between 3mm and 4mm bpd and things were just fine.  China has altered their energy mix such that oil, while still important, can be substituted out as necessary.  That is a very interesting outcome with respect to one of China’s greatest perceived weaknesses, its lack of natural energy capacity.  If they don’t need as much oil to run their economy (which by the way based on overnight data is struggling) then they have less geopolitical weakness.  

Enough on oil, but while I’m here, it is not surprising that as oil slides, metals prices rise so gold (+0.9%) and silver (+0.8%) are continuing to benefit as is copper (+0.1%) although the latter not so much today.

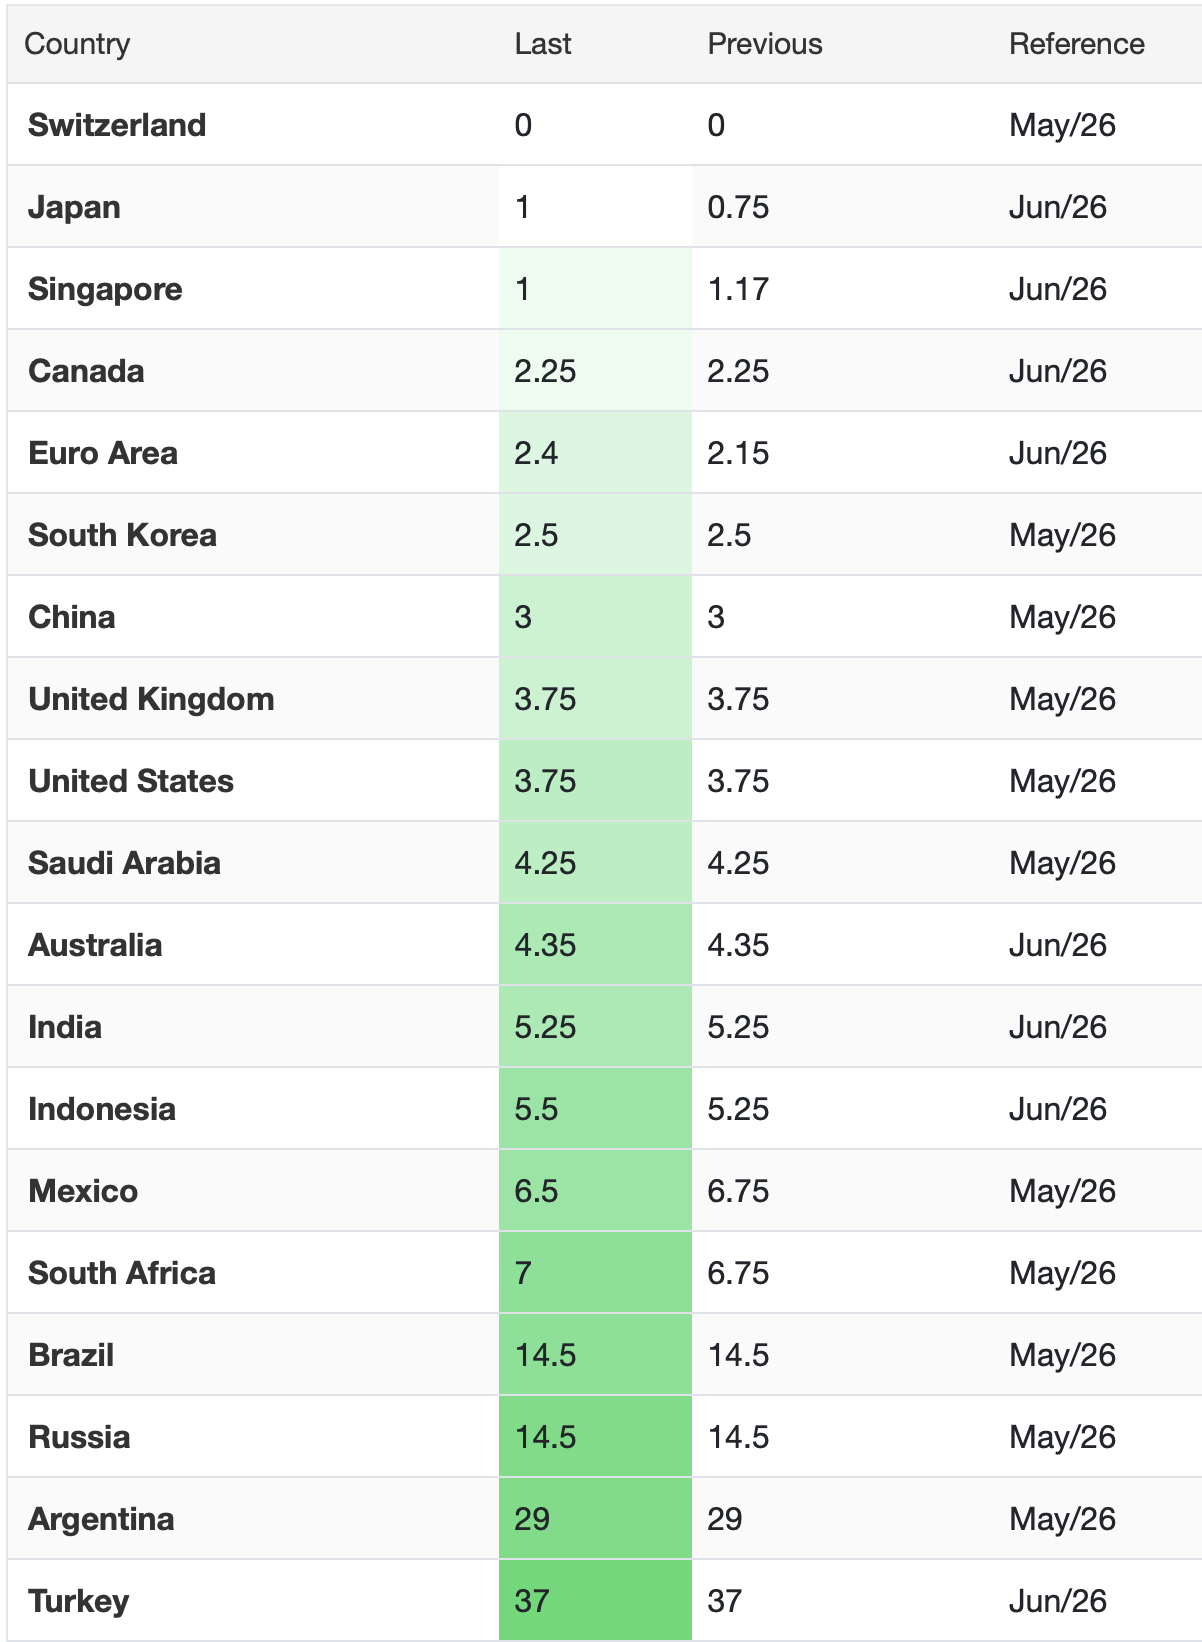
Turning to the other story that has tongues wagging, the BOJ raised their base rate to 1.00% last night as had been universally expected by markets.  Now, the interesting thing here is that there is a group of analysts who believe that this will lead to net position liquidation by leveraged fund managers (i.e. hedge funds) as their funding costs will have risen.  I disagree, and so far, markets are on my side.  This is evident by the fact that equity markets continue to perform well, and USDJPY has shown no inkling of reversing its multi-year trend of rising.  Below is a table of the base interest rates of the G20 nations.  While Switzerland does have a lower rate, and Singapore is the same, if you are thinking about borrowing in a currency to lever up positions, Japan, given the yen’s depth and liquidity, remains the currency of choice by a long shot.

Source: tradingeconomics.com

Ask yourself if your borrowing costs rose 0.25% but you were still earning a net 13.5% return on your BRL deposits, would you flee the trade?  And if you have been buying equities, you are even less likely to get out.  Japan’s problem is not specifically that their base rate is low, it is that they currently are fighting a terrible demographic position of a shrinking population and they have a massive debt/GDP ratio.  They cannot afford to raise rates enough to have a meaningful impact on the yen without bankrupting the country and decimating the yen.  It is not clear to me how they get out of their current situation, but despite concerns elsewhere in the world about the yen’s weakness being a competitive advantage, I think it has further to go.  Basically, there needs to be another Plaza Accord type agreement to change things, and that doesn’t seem likely right now.  After all, in Evian, it doesn’t sound like things are going smoothly.

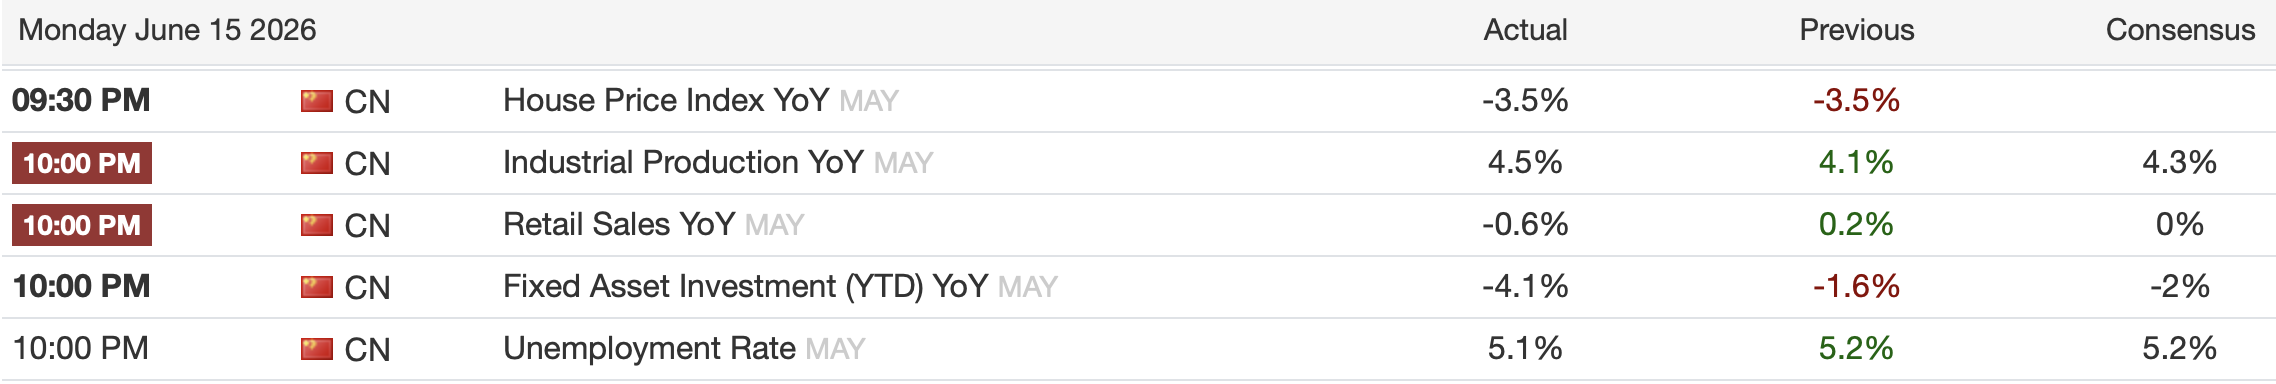
So, how have markets behaved overnight?  Well, risk is still in vogue.  Following yesterday’s strong US performance, where the DJIA made another all-time high, there were far more gainers (Korea, India, Taiwan, Malaysia, New Zealand, Indonesia) than laggards (HK -1.4%, China -0.2%) while Tokyo was little changed.  As I mentioned above, the Chinese data was pretty lousy as per the below table:

So, the housing market continues to suffer, and the domestic economy along with it, although the export economy continues to grow.

In Europe, the decline in oil prices is clearly helping as all major indices are higher between 0.4% and 0.75%.  As to US futures, at this hour (7:20), they are pointing slightly higher, about 0.15% across the board.

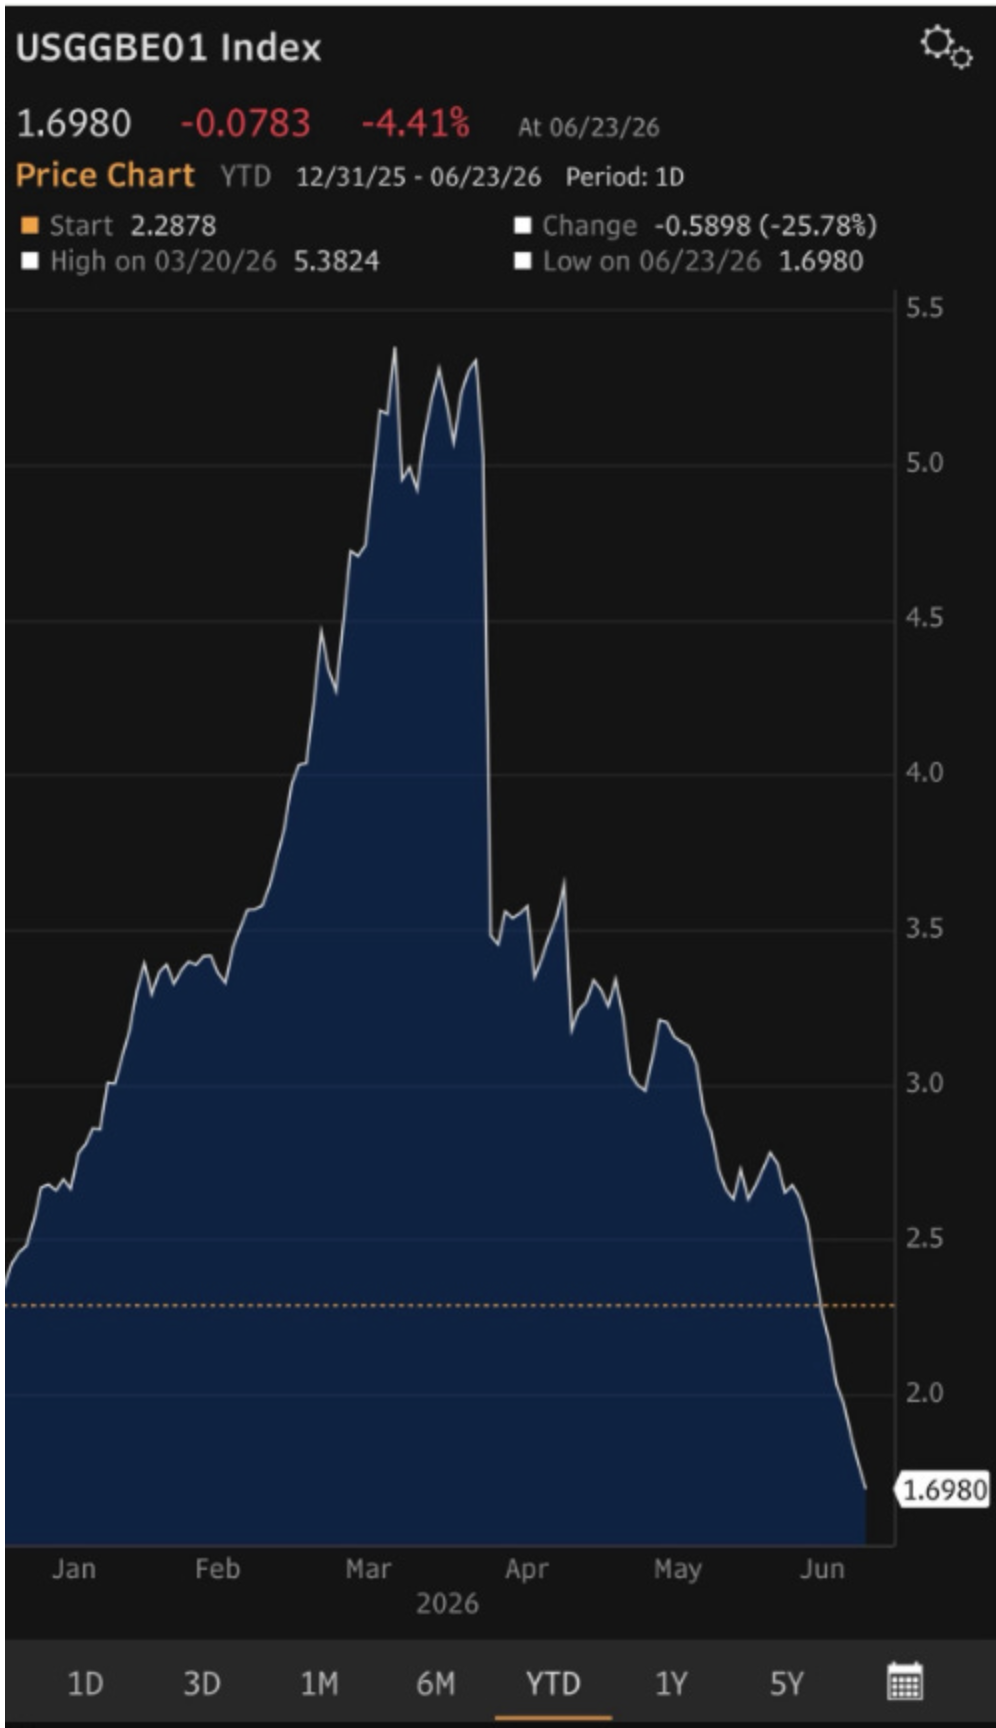
In the bond market, yields continue to decline with Treasuries (-3bps) back below 4.5% which had been seen as a real problem just a few weeks ago.  European sovereigns are also lower by between -3bps and -4bps, duly following both Treasury yields and oil prices.  The outlier here is JGB yields (+6bps) which responded to the rate hike by rising, perhaps an indication that investors don’t believe the BOJ is doing enough.  However, my wager would be the BOJ is done.

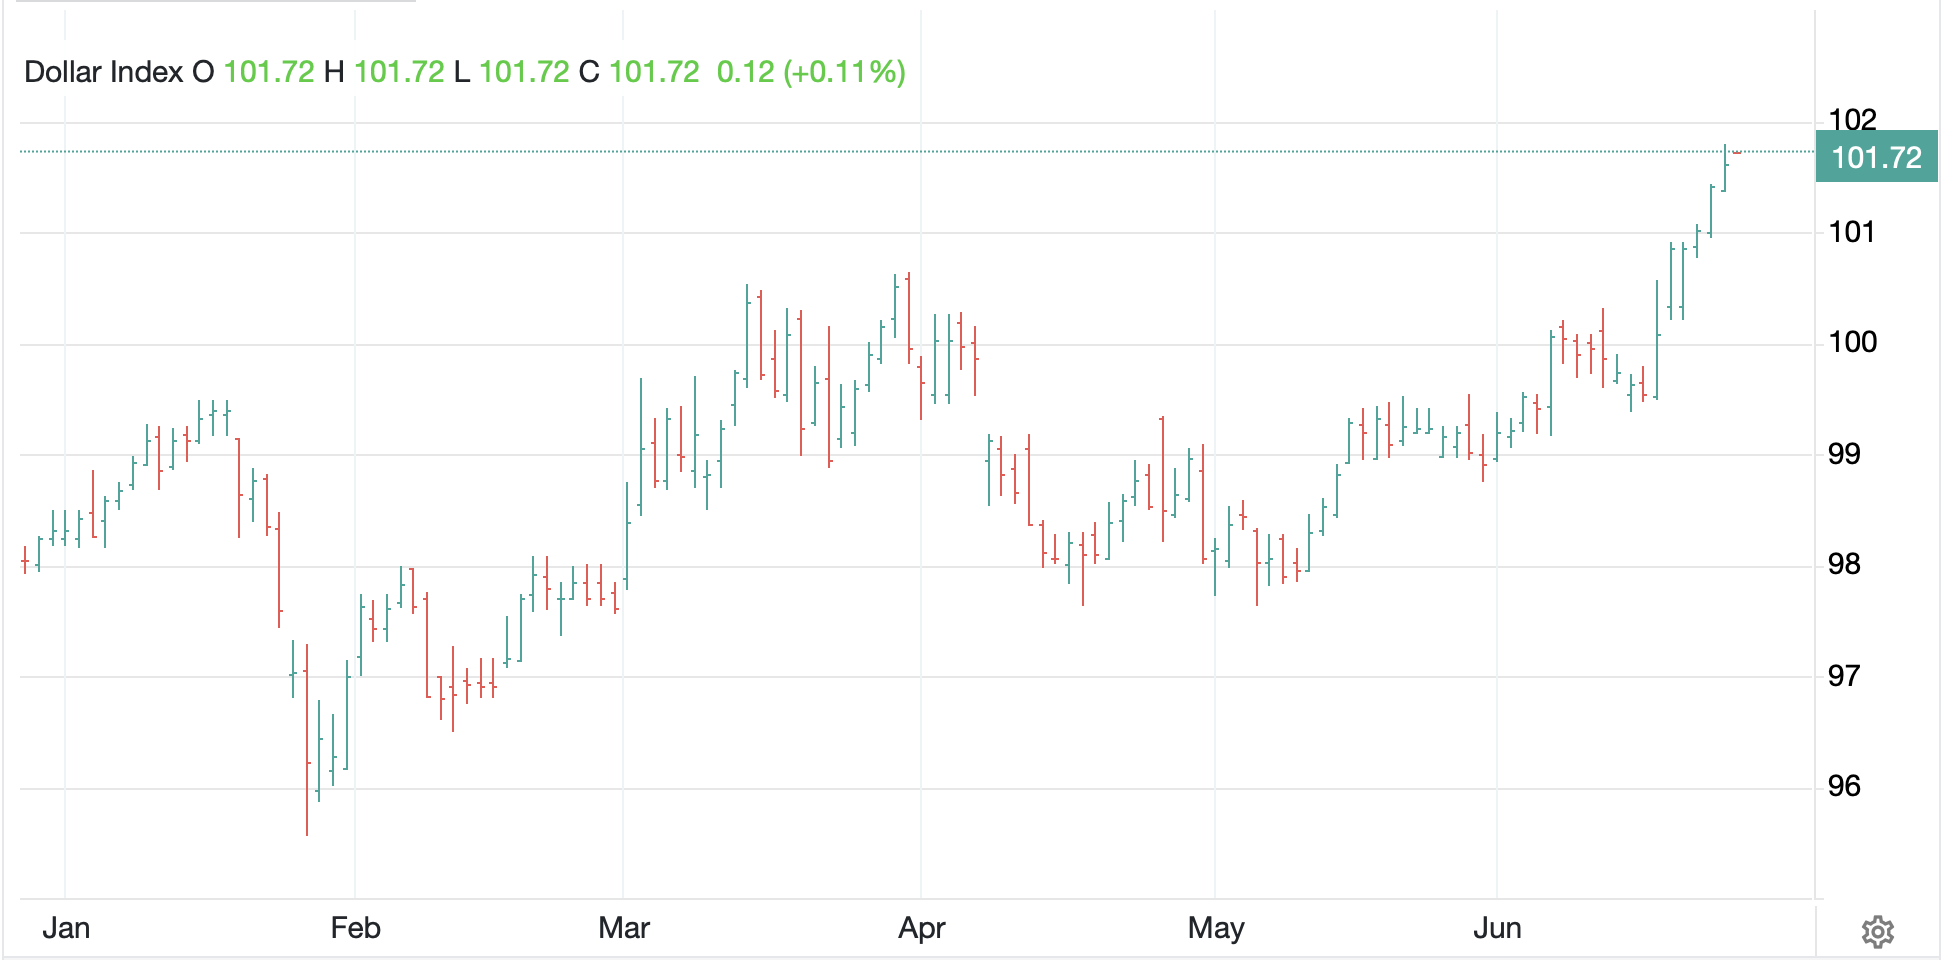
Finally, the dollar is a touch softer, as one would expect given the movements in other markets, but there is very little excitement in the FX markets.  Using the DXY (-0.05%) as proxy, you can see things are little changed.  The biggest movers are BRL (+0.4%) and KRW (+0.4%) both of which are seeing capital inflows supporting the currency.  But otherwise, +/-0.2% defines the session in both G10 and EMG currencies.  Note that despite the BOJ rate hike, USDJPY sits at 160.32 showing no sign of heading lower, even in an environment where the dollar is modestly softer.

On the data front, this morning brings Housing Starts (exp 1.43M) and Building Permits (1.42M) and that’s really it.  With the FOMC tomorrow, and Iran ostensibly solved, Mr Warsh and his press conference will get a great deal of focus.  Until then, I don’t see any reason for recent trends to change absent a complete collapse of the Iran deal, which seems unlikely at this point.

Good luck

Adf