Like Love Unrequited

Said Trump, we can all use $5K
To help with our life’s day-to-day
So, vote for the R’s
And your cookie jars
Will fill up with this bonus pay

The pundits are clearly united
That this idea’s crazy and blighted
But of more concern
Is buyers will spurn
The 10-year like love unrequited

I guess we cannot be but so surprised that populist President Donald Trump has said he will hand out $5000 to every adult US citizen if the Republicans retain both the House and the Senate during the mid-term elections.  He is, after all, a populist.  And that is what populists do; they promise things to the people to get elected.  While this may be abhorrent to the alleged ‘hard’ money analysts on Wall Street, it strikes me that this is a brilliant way to get those leaning Socialist to vote for the Republicans.  After all, their entire MO is to get money for no work, and that’s exactly what this is.  It is laughable to me that there is now concern that if this were to go forward, it would cost ~$1 trillion and ‘where would the money come from?’ is now the big question.  The money would come from where all the money for government spending comes from, more Treasury issuance.  

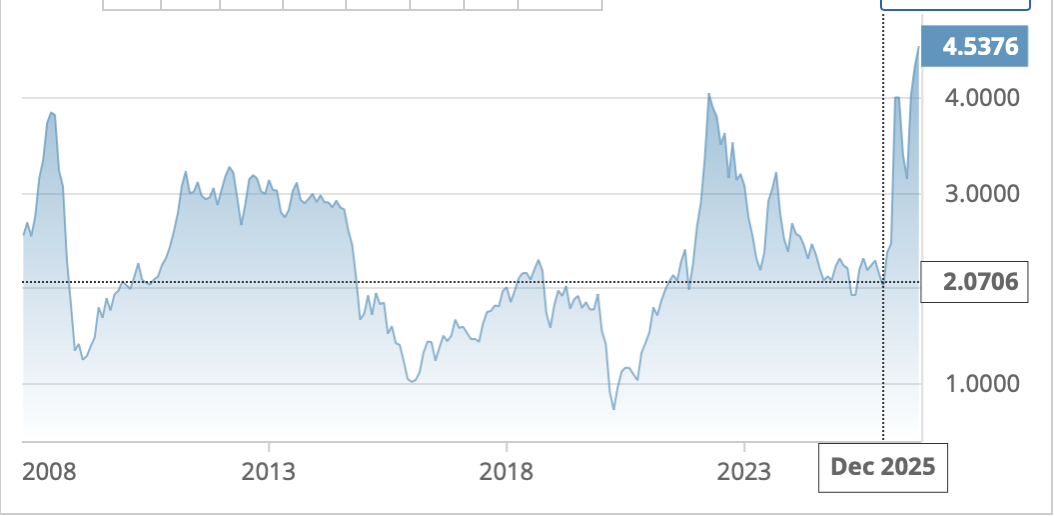
Which brings us to a more important question regarding markets, if there is a new line item in the 2027 budget, $5000 bonuses, how will the bond market respond?  Here the situation is very clear, yields continue to rise.  If you look at the chart below comparing 10-year yields with their counterpart TIPS yields, you can see that inflation is edging higher as a concern (nominal yields are rising more quickly than real yields).
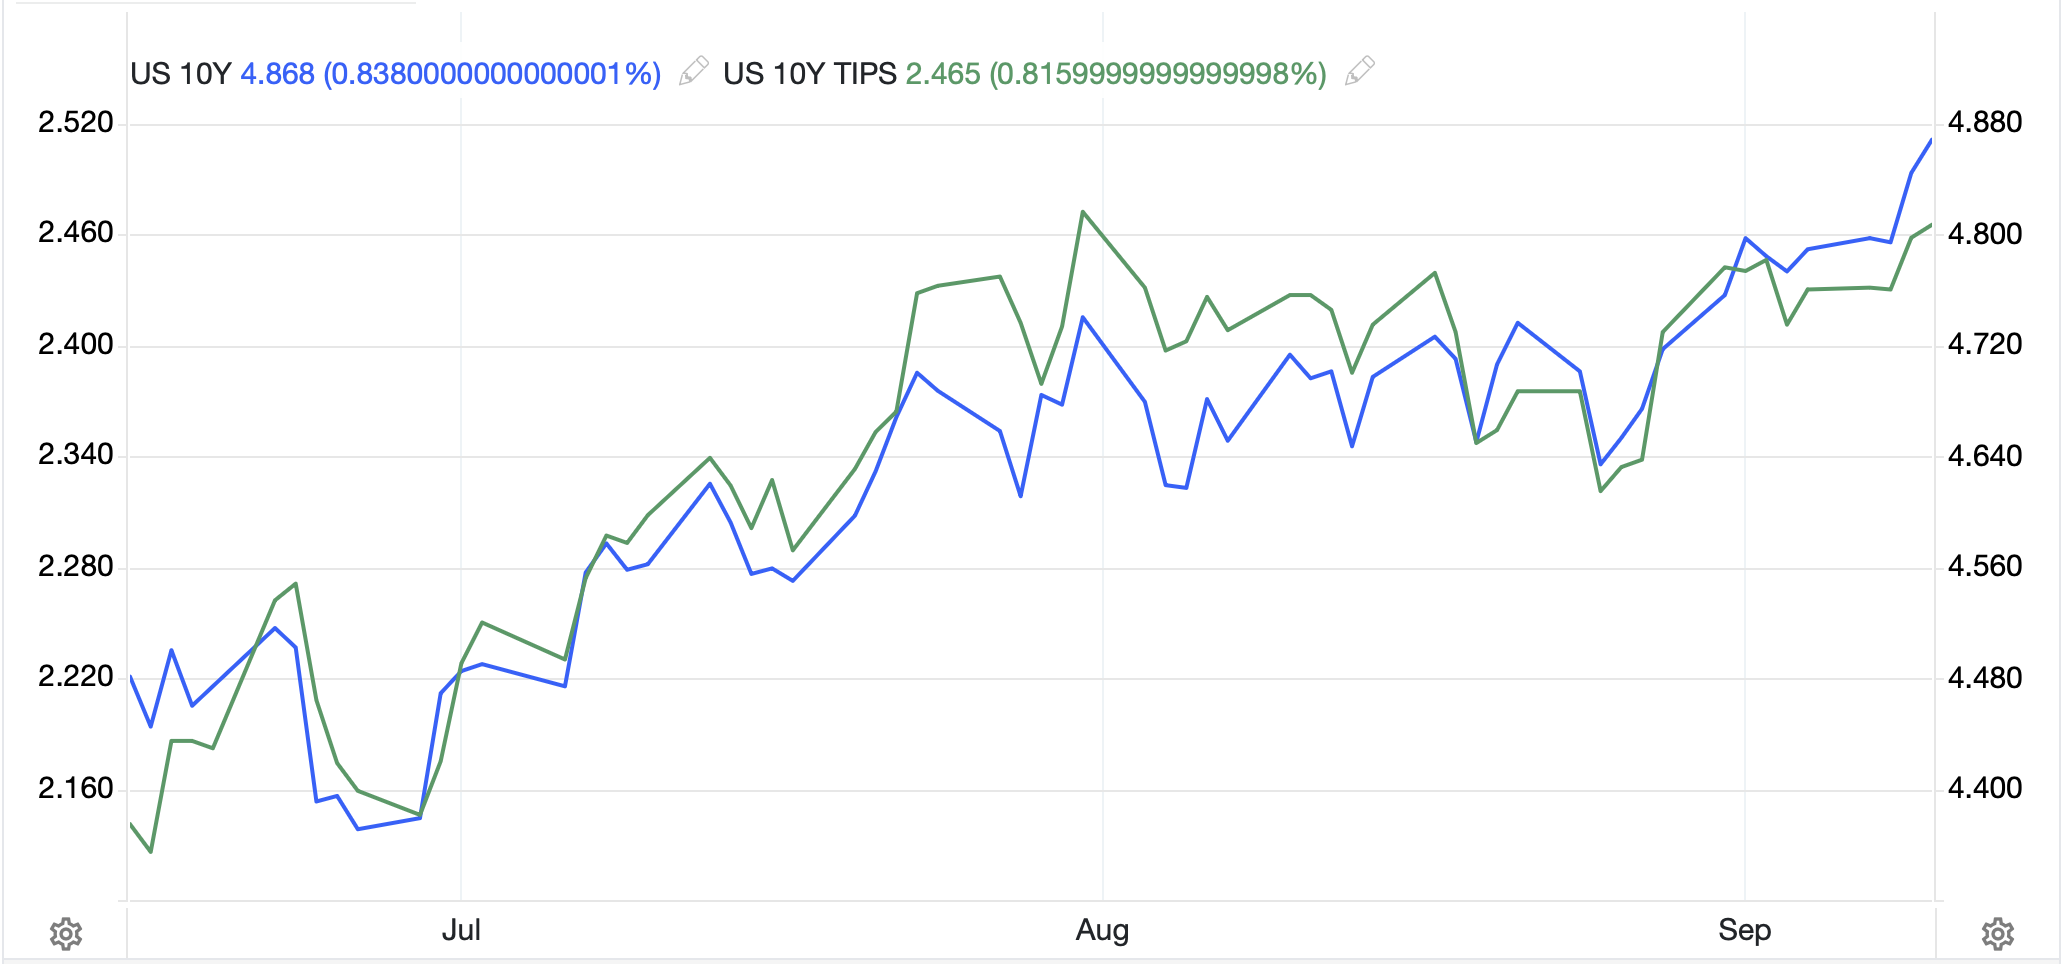
Source: tradingeconomics.com

While I don’t believe this is a direct response to the Trump bonus plan, rather to the ongoing climb in oil and related energy prices, I’m confident the bonus plan is not helping the situation.  

This dovetails nicely with the other key topic of discussion in the market; how the Fed will respond to this information as well as the PPI/CPI data to be released later today and tomorrow.  I chuckled at the WSJ headline, A Tiny Shift in the Inflation Rate Could Decide the Fed’s Next Move as the implication is that if the M/M reading for core CPI is 0.2%, the Fed will stand pat but if it is 0.3% it will hike.  And maybe that is the way things will work out.  But if that is the case, it sure seems to me like they would be missing the forest for the trees.  This is especially so since Chairman Warsh was explicit in that he wanted to see the underlying trend, and as we all know, a single data point does not a trend make.

Currently, the Fed funds futures market is back to pricing a 64% probability of a rate hike next week, although as per the below chart from rateprobability.com, you can see that the Fed appears to be one of the most dovish central banks around.
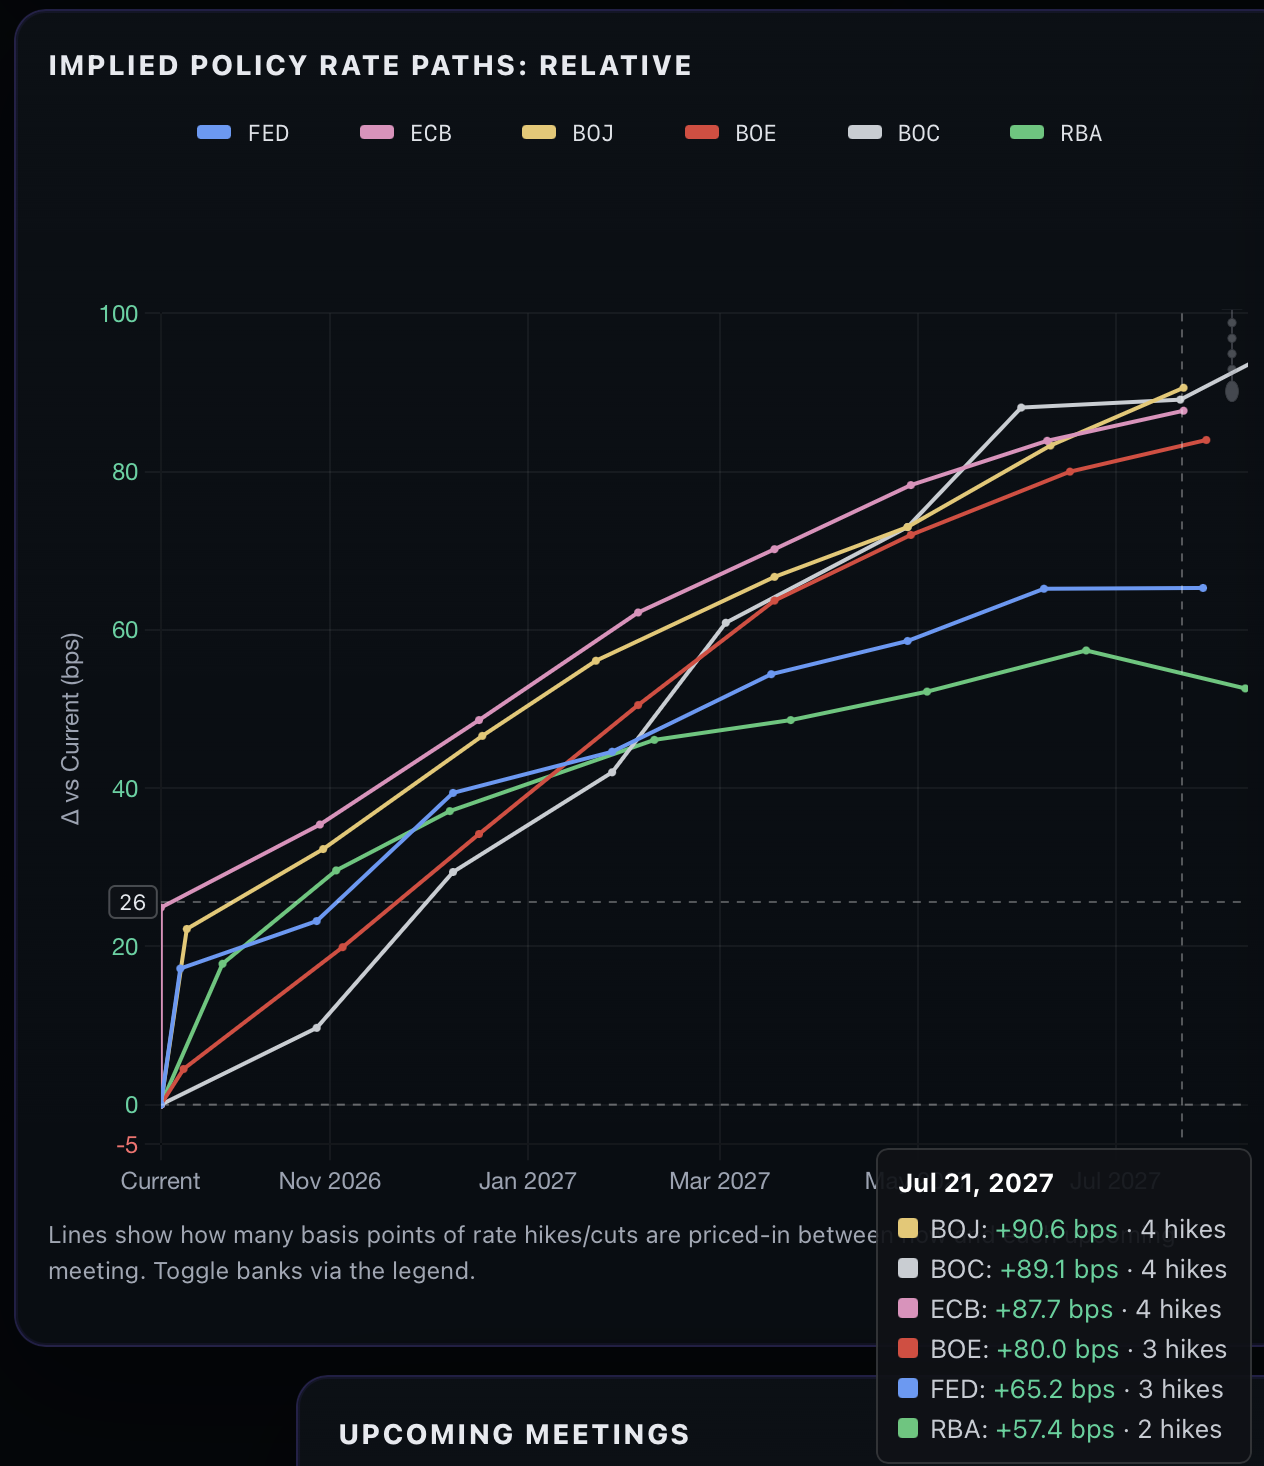
The ECB is virtually guaranteed to hike 25bps this morning and are priced to hike 3 more times during the next 10 months.  I keep wondering how they reconcile a Eurozone economy that is barely growing with hiking rates to reduce demand, and by extension, inflation.  This is where Keynesianism has a really hard time.  In fact, one of the big benefits of Kevin Warsh not having a PhD in economics is that he has never been indoctrinated into that school of thought.

In fact, if you recall Warsh’s first press conference, he lauded the bond market for doing the Fed’s job, raising the cost of funding so the Fed didn’t need to move.  Well, after a lull, the bond market is doing the hard work again.

As an aside, Secretary Bessent’s bond buybacks will take place today and, certainly in no surprise to me, the amount has been increased to $6 billion.  (Remember the ‘at least double’?). In truth, I expect that this program will increase in size each week going forward and ultimately become meaningful with respect to the size of the bond market.  Of course, looking at the bond market’s pricing today, with yields rising another 2bps, the punditry is once again calling out Bessent for not being able to do what he explained.  Funnily, though, they have stopped talking about the yen continuing to decline even though they were quick to dismiss Bessent’s activities there as well.  Personally, I’m going to wait a little longer before I declare the program a success or failure!

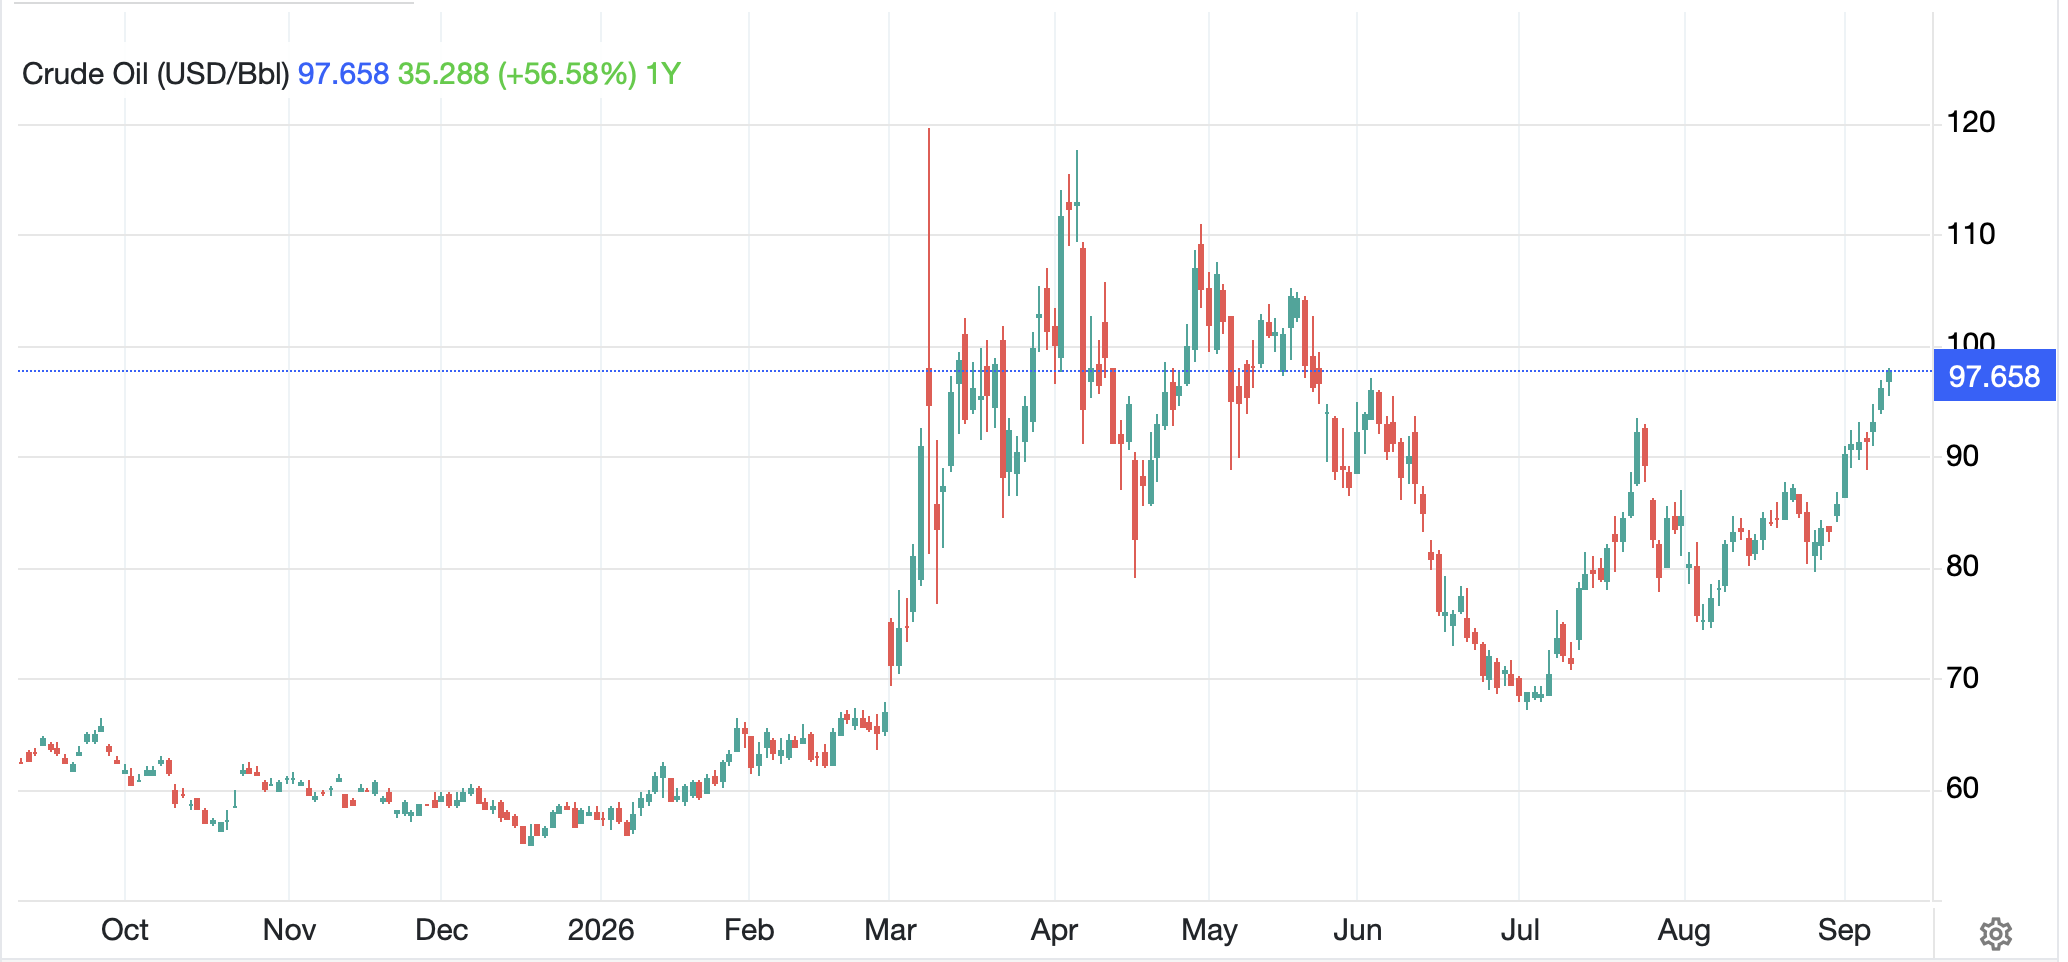
Ok, let’s turn to markets this morning.  Oil (+1.7%) continues to climb as the Iran conflict is showing no signs of cooling off.  It is not hard to see the trend in the chart below, and it is not clear what will alter this trend absent a major change in Iran.
Source: tradingeconomics.com

At the same time, the metals markets are under pressure this morning, with copper (-4.75%) leading the way lower and taking gold (-0.3%) and silver (-2.2%) down as well.  I don’t believe anything has changed with respect to the long-term prospects of metals, but they are quite volatile and always have been.  Copper has been subject to tariffs and the LME – COMEX spread and arbitrage is a key part of the price action there, dwarfing fundamentals right now.

But higher energy prices have weighed on risk appetite everywhere with equity markets struggling in most places around the world.  Yesterday’s US weakness was followed by a general decline throughout Asia (China -0.5%, HK -1.3%, Australia -1.0%, Taiwan -0.5%, Indonesia -1.3%) with only Tokyo (+0.2%) bucking the trend.  The only real news came from Down Under where two RBA members were explicitly hawkish, essentially promising a rate hike at the end of this month and the market has priced in two more going forward, a tightening of expectations.

In Europe, though, despite (because of?) the imminent rate action by the ECB today, equity markets are mixed with some gainers (Italy +0.4%, Spain +0.3%) and some laggards, (UK -0.4%) with Germany essentially unchanged.  There has been no data to alter any views, but I guess we will need to hear what Madame Lagarde has to say later this morning.

Quickly, European sovereign yields are little changed this morning but broadly continue to follow Treasury yields higher and JGB yields (+3bps) bounced after their recent dip.  Recall, I mentioned this pattern yesterday.

Finally, the dollar remains generally quiet, although in the last few hours, we have started to see a bit of dollar strength.  JPY (-0.4%) is edging lower as are NOK (-0.7%) despite rising oil prices and ZAR (-0.45%) because of declining metals prices.  However, most other currencies remain +/-0.1% from yesterday’s closing levels.

On the data front, we get a bunch today.

Initial Claims205K
Continuing Claims1780K
PPI0.4% (5.3% Y/Y)
Core PPI0.3% (4.6% Y/Y)
Existing Home Sales3.98M

Source: tradingeconomics.com

We also see the EIA oil inventory data with a slight draw expected.  I suspect that the ECB is likely to be a nonevent and that PPI, unless it is dramatically different than forecasts, will also have a limited impact.  Oil prices are back in the driver’s seat so we will have to see if this rally continues, or it is, like we have seen in both bonds and yen, speculative driven.

Good luck

Adf
Rumors Imply

Did the BOJ
Intervene? Rumors imply
Lifers it the bid

Twenty-five? Fifty?
Do they really want yen strength?
Can they live with that?

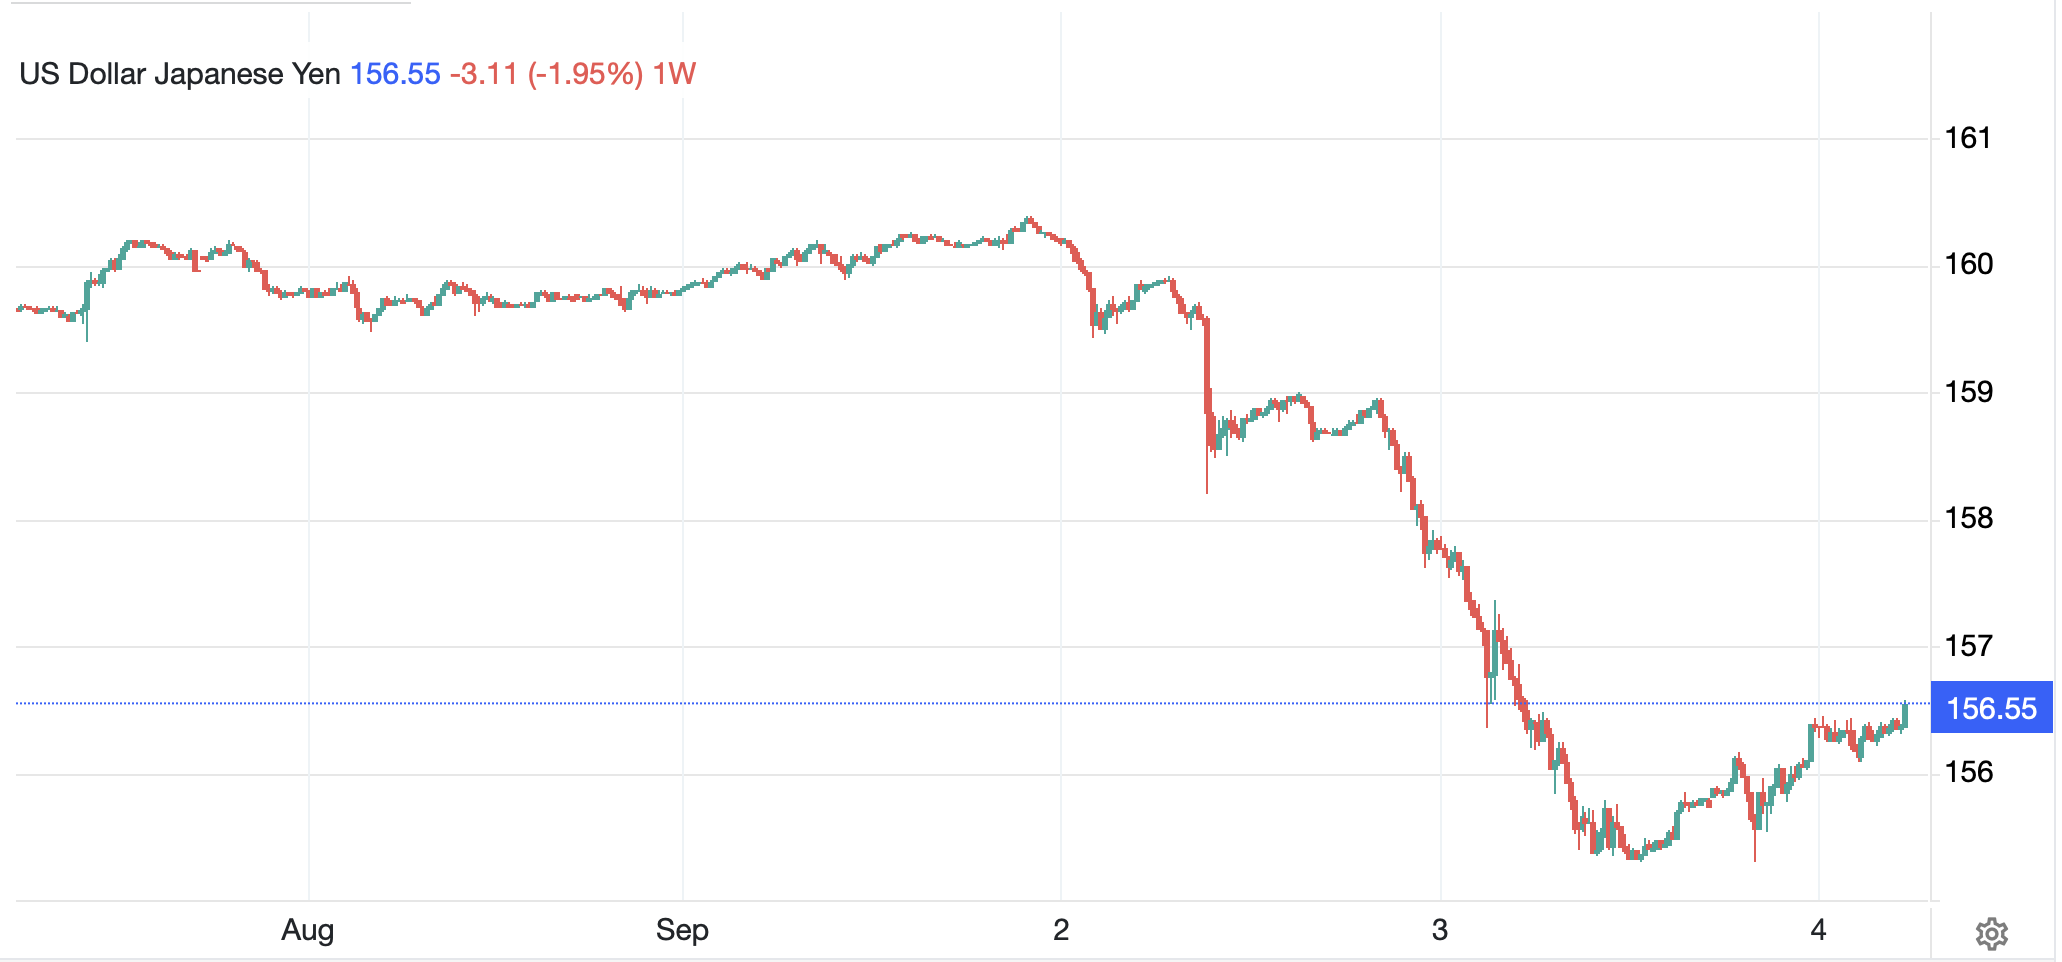
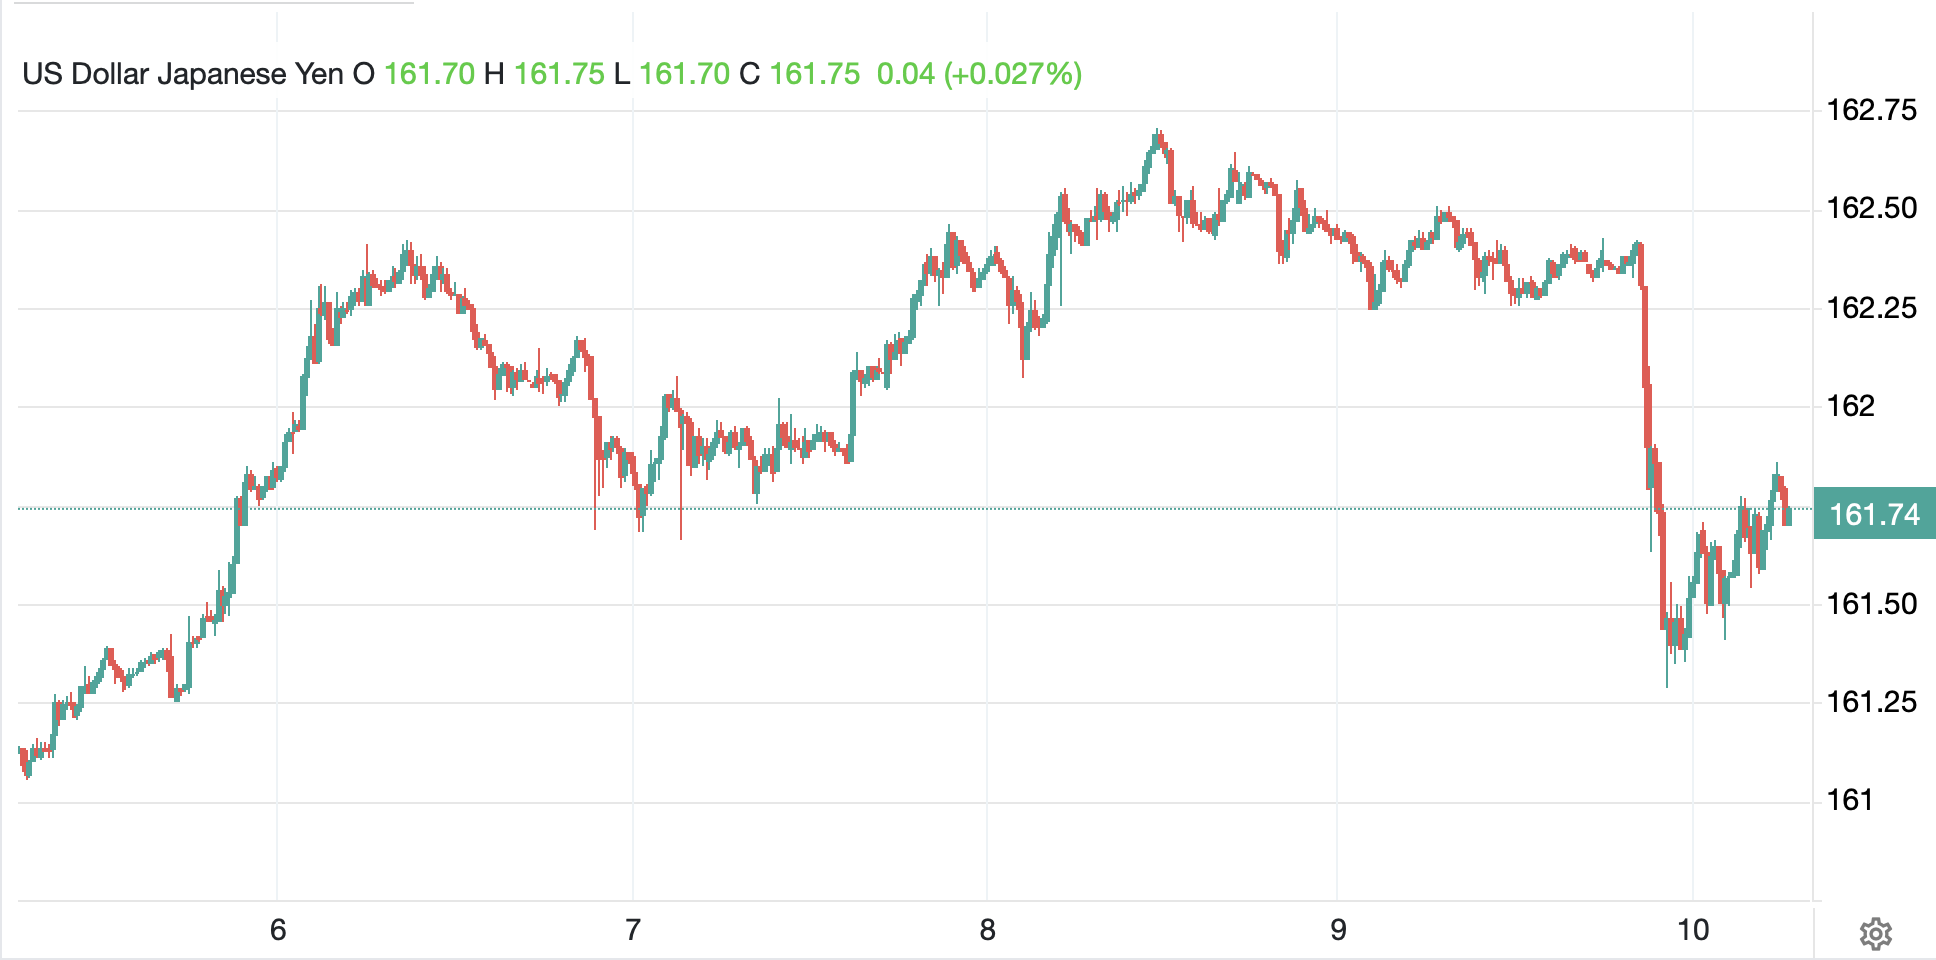
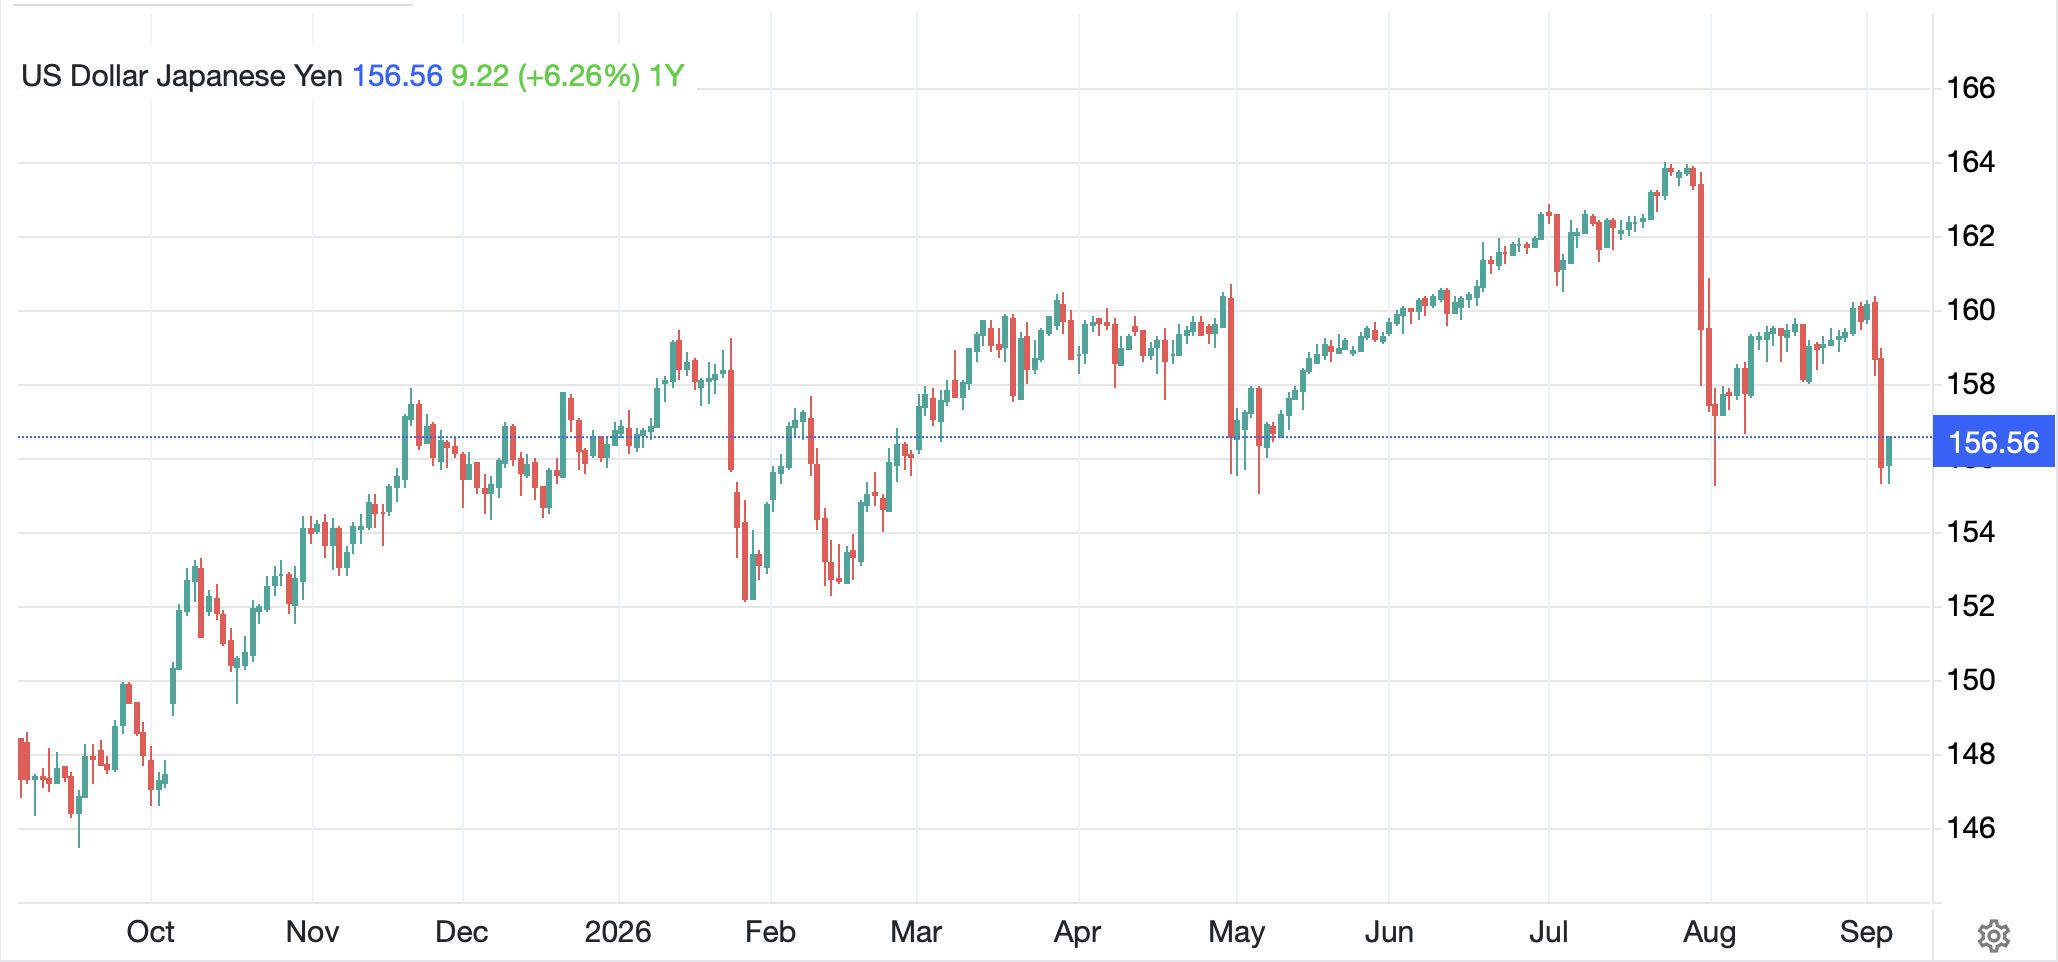
When looking at charts, as I frequently indicate, the timeline of the chart matters a great deal.  For instance, if we look at this 1-year chart with daily candles of USDJPY after the yen jumped 1.8% yesterday, it would be easy to conclude there was another bout of intervention.  After all, the price action certainly seems to indicate a virtual gap move lower, just like the other interventions that we have seen during the past year.

Source: tradingeconomics.com

However, if we look at the chart with much shorter time increments, for instance 15-minute candles, we see that while there was significant selling pressure all day yesterday, and actually from the night before, there are really no gaps on the way down.  This is indicative of a large sell order that is relatively price insensitive meeting a market that is on edge, but absent a clearer signal of intervention, a market that is still willing to make prices.

Source: tradingeconomics.com

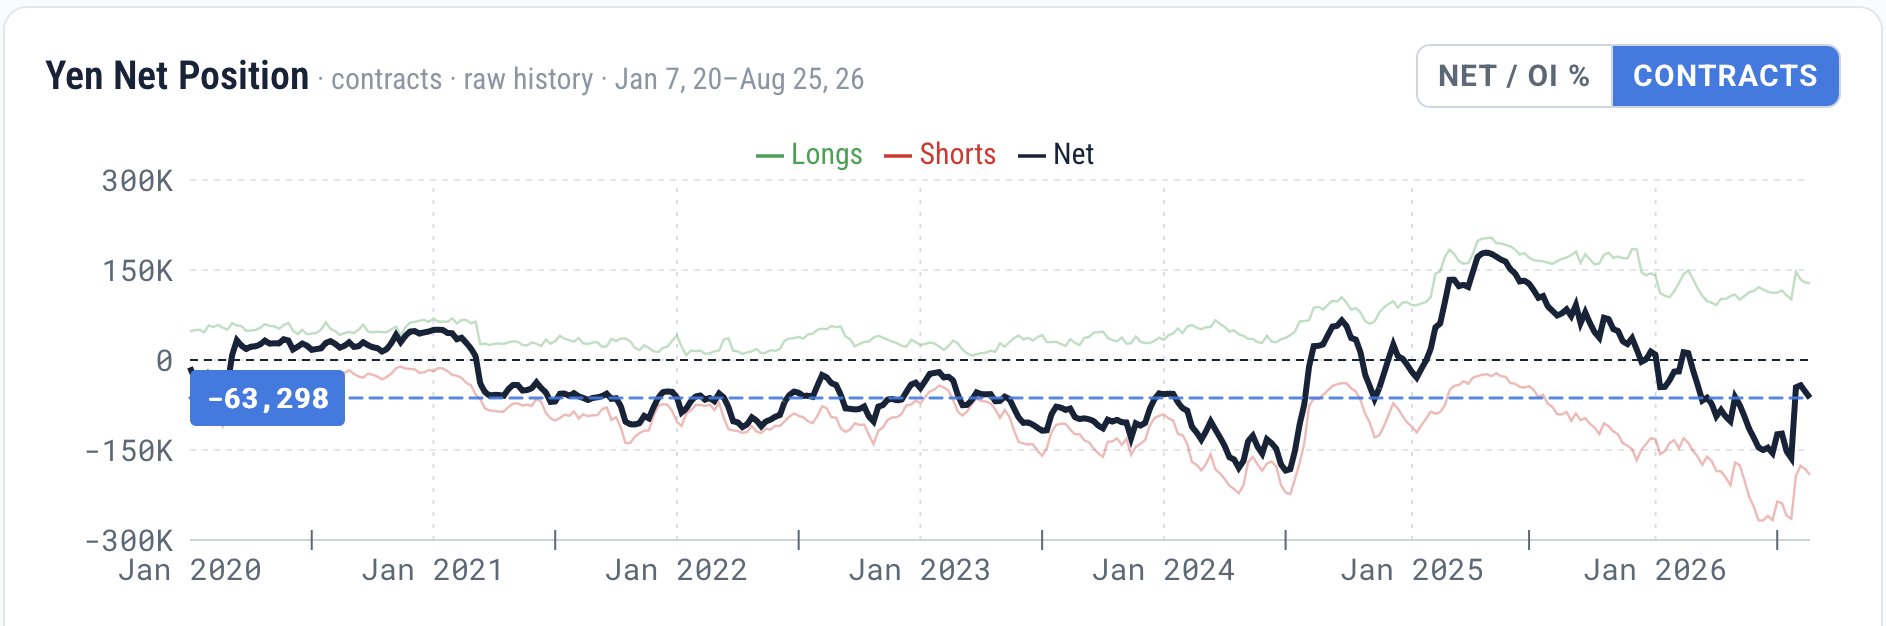
As it happens, from what I understand the market rumor was that the GPIF was moving funds out of dollars, something that had been mooted several weeks ago after Japanese FinMin Katayama discussed it in a news conference, but there was no sign of the BOJ.  And, of course, this morning JPY (-0.5%), has reversed some of that move.  Remember, the BOJ meets in two weeks’ time and as I mentioned on Wednesday, while a 25bp rate hike seems to be baked in the cake, there is increasing talk of 50bps.  Right now, the market is not pricing 50bps, in fact they are at 21bps, so not quite a full hike.  If Ueda-san really wants the yen to strengthen, 50bps will do the trick as it would really hurt the massive JPY shorts that are still rampant.  (see below chart from cotsignal.com). 

Now, over the past month, that net short position, at least in the futures markets, has been reduced, but there are still many short positions in various forms OTC.  A 50bp hike would definitely hurt them and a move to, and possibly through, 150 would be viable then.

Of course, none of that even considers things like this morning’s NFP or next week’s CPI.  There is still plenty of fun to be had!

The other big story today
Is whether a rate hike's in play
If NFP's strong
One could come along
If weak, there will be a delay

Which takes us to the NFP release this morning.  here are the current median estimates by the economist community

Nonfarm Payrolls56K
Private Payrolls45K
Manufacturing Payrolls5K
Unemployment Rate4.1%
Average Hourly Earnings0.3% (3.0% Y/Y)
Average Weekly Hours34.3
Participation Rate61.4%

Source: tradingeconomics.com

Now, ADP Employment was slightly weaker than expected on Wednesday at 38K, but again, this begs the question of how many jobs are necessary in the US economy to continue to maintain full employment and economic growth.  Remember, too, last month’s NFP was surprisingly weak at -23K.  If we were to see another zero to negative outcome, the Fed funds futures market would completely reverse its recent hawkishness, which moved from a ~35% probability of a hike before the Warsh Jackson Hole Speech to a ~65% probability afterwards, but has since drifted back to basically 50:50 after hearing Fed Governor Waller indicate he is a hold as long as data keeps pointing toward declining inflation.  Any weakness today, and especially in next Friday’s CPI reading will likely reverse that period of hawkishness.

At this point, a hike is still fully priced in by the end of this year, although if they hold now, it would be a surprise to see a move one week before the midterm elections.  Arguably, the biggest problem regarding inflation in the US right now is diesel fuel, which as you can see in the below chart has more than doubled in price since December.

Source: barchart.com

Diesel filters into the prices of virtually all goods as transportation for delivery costs rise, and the one thing we all know is that once a company raises prices because of a fuel surcharge, that surcharge never goes away, it is simply absorbed into the price at some point in the future.  In fact, this may well be the single most concerning issue regarding future inflation, at least until the military action in both Iran and Ukraine/Russia ends.  Of course, the Fed cannot print diesel, but do they really want to go down the route of demand destruction?  That is a tough call.  I guess we shall all learn more in two weeks’ time as the quiet period is beginning today.

Which takes us to market activity.  Yesterday’s strong US equity performance was followed by a mixed picture in Asia, although there was far more strength (Tokyo +1.3%, HK +1.7%, Korea +1.6%, India +0.5%, Taiwan +1.5%) than weakness (China -0.1%, Australia -0.2%, Malaysia -0.4%, Indonesia -0.5%) with the rest of the bloc stronger rather than weaker.  In Europe, though, markets are essentially unchanged this morning ahead of the NFP number and US futures are also little changed at this hour (6:55).

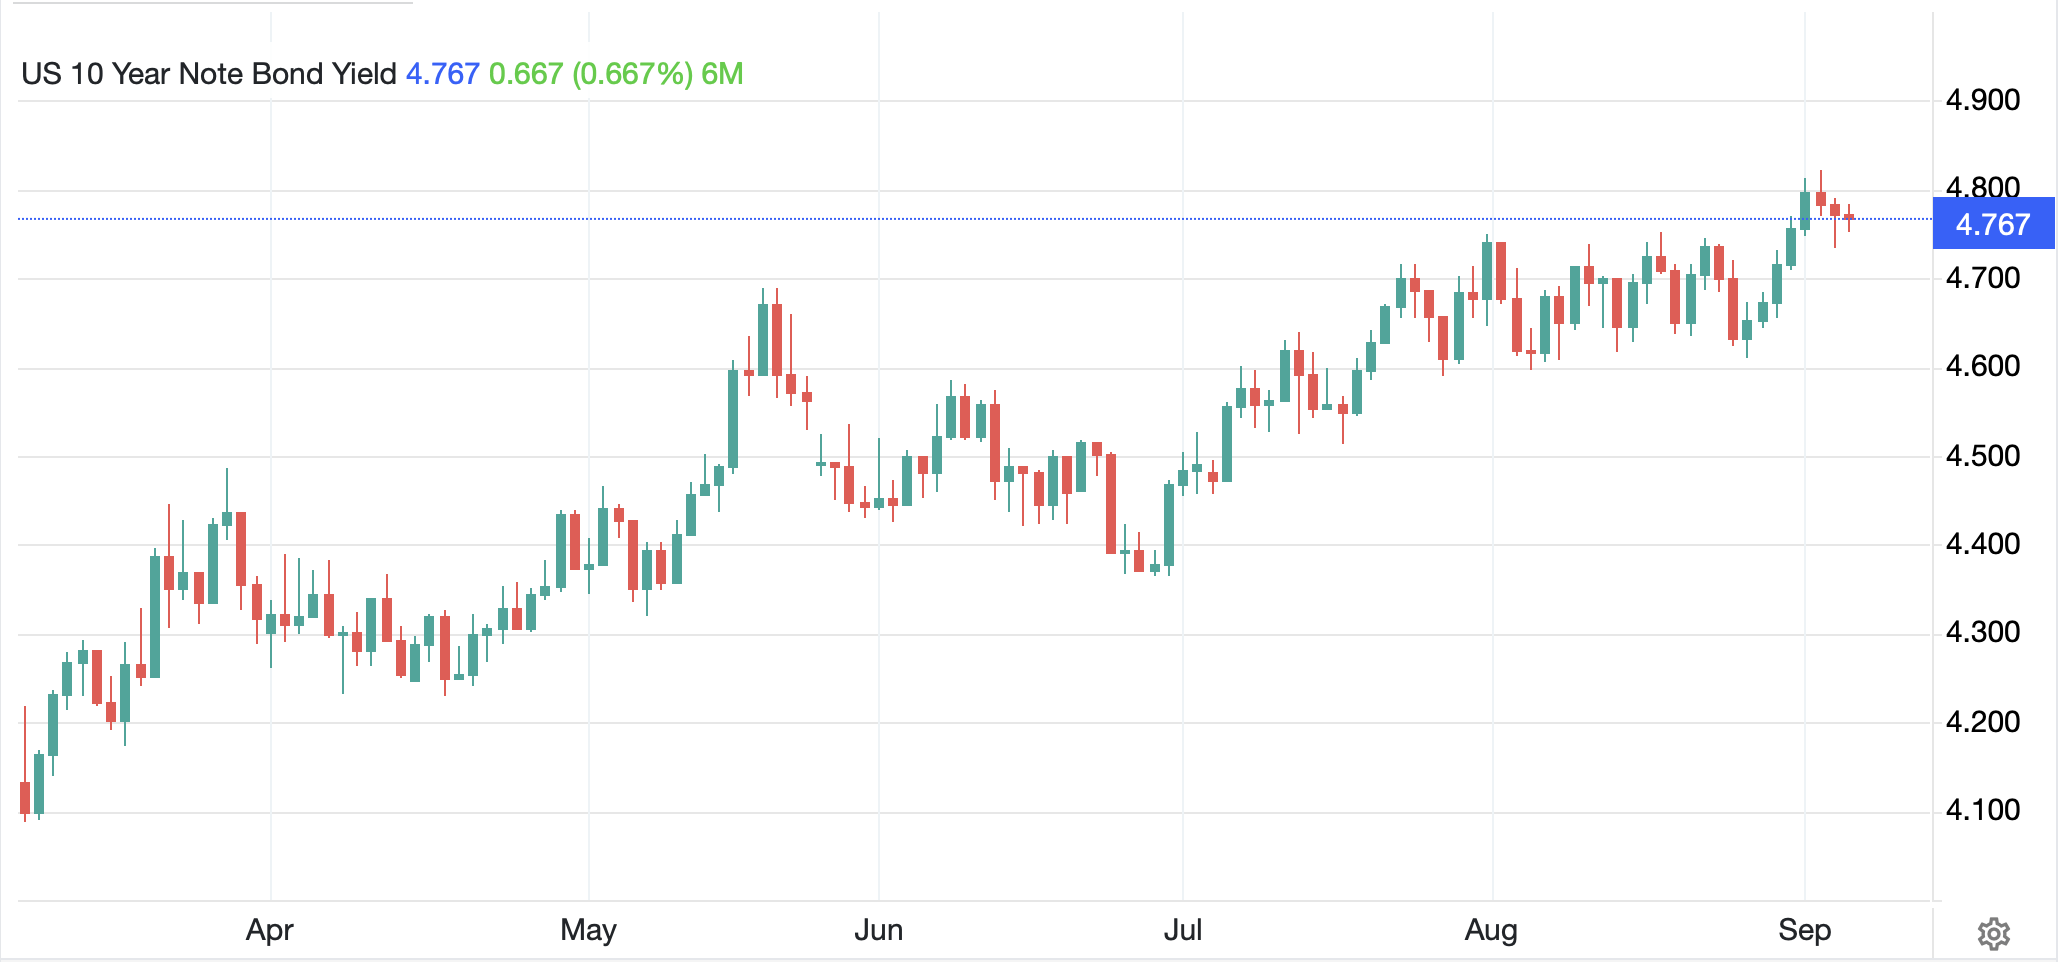
In the bond market, Treasury yields (-1bp) have stopped climbing for now although remain at the upper end of their recent range as you can see in the below tradingeconomics.com chart

European sovereign yields have edged higher by 1bp across the board this morning and JGB yields, perhaps on the alleged buying by GPIF which led to USD sales in the FX market yesterday, have slipped by -4bps.  That is, of course, exactly what FinMin Katayama wants to see.

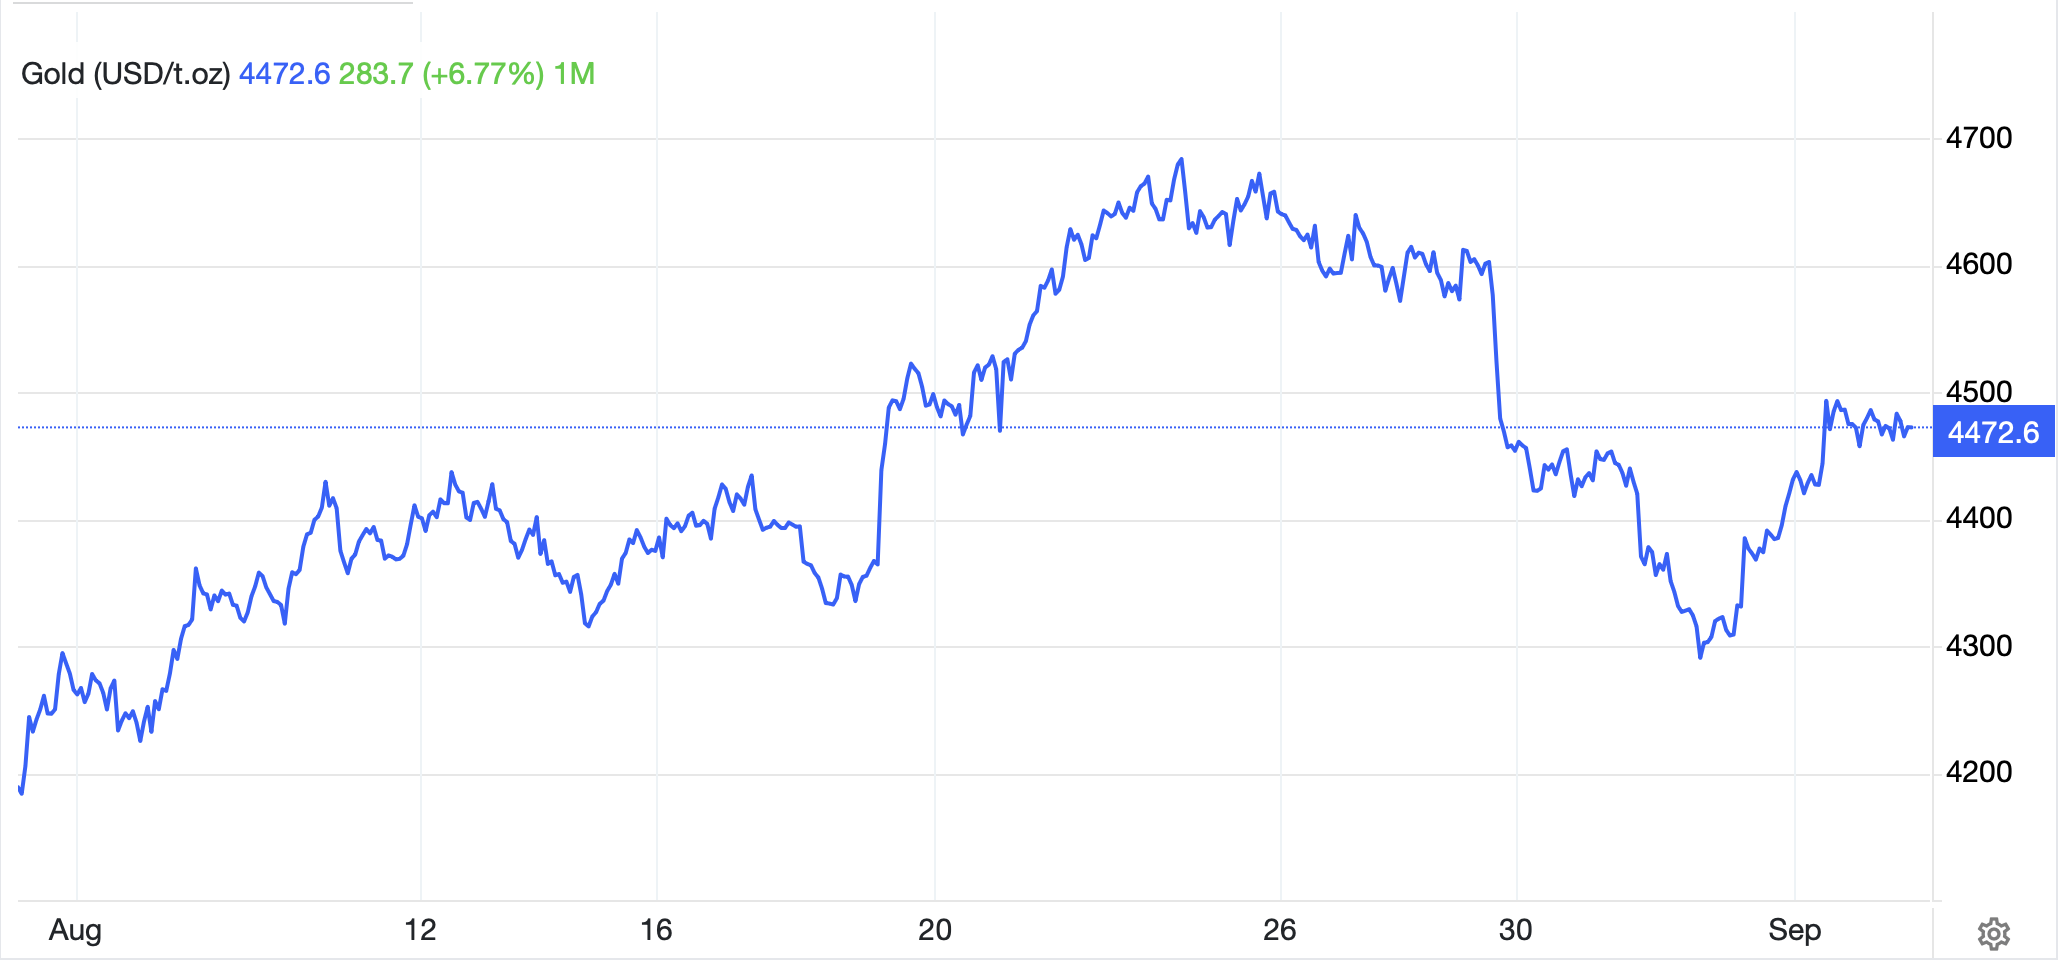
In the commodity markets, oil (-1.0%) is trading just above $90/bbl as the escalation of fighting in the Gulf has not had many headlines lately, although I think it continues.  Many have made the point, though, it is the products that are the driver, so diesel, jet fuel and gasoline are what matter to both measured inflation and the national zeitgeist.  In the metals markets, this morning prices are very little changed although as you can see in the chart below, gold’s recent sharp decline has been reversed to the tune of about 50% of the move.

Source: tradingeconomics.com

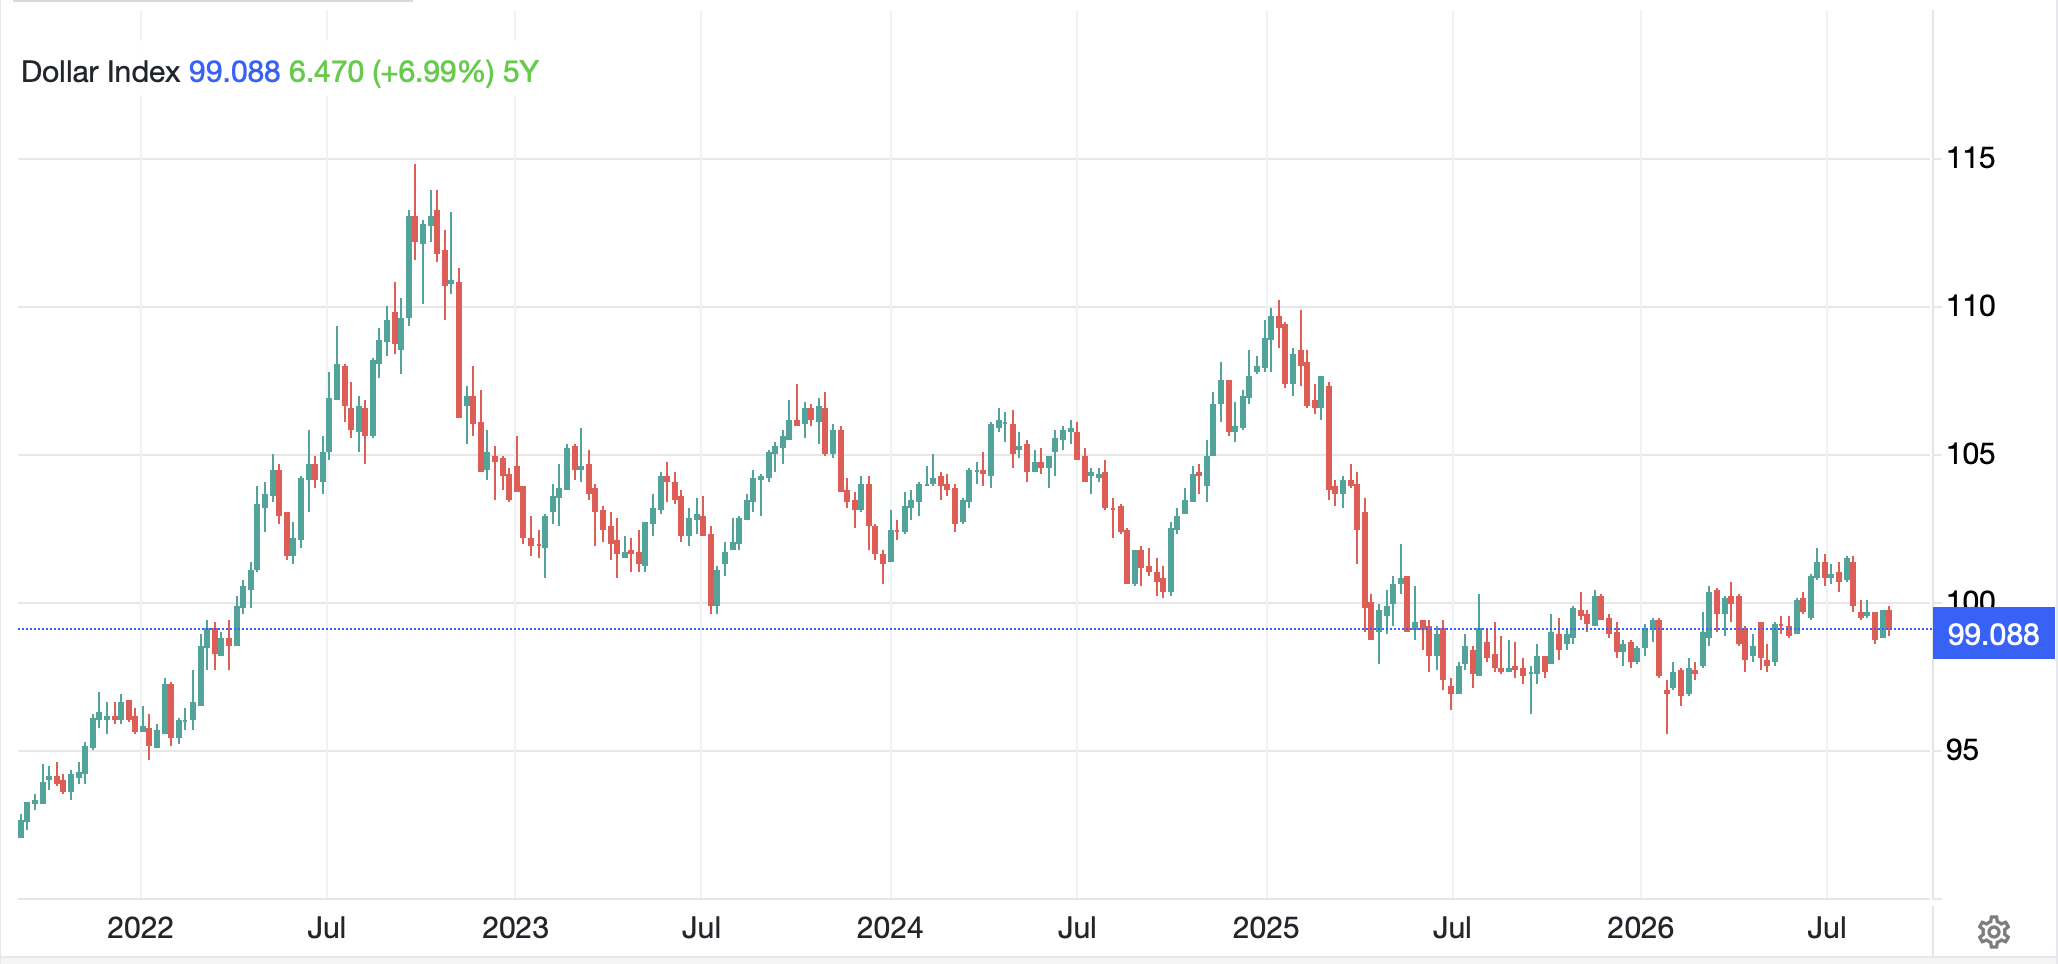
And finally, the dollar, away from the yen, is also largely holding its breath for the NFP report this morning.  KRW (+0.45%) continues to be the big winner over the past several months as capital continues to flow into Korea and its tech industry and tech stocks.  But if we look at the DXY, it is trading just above 99.0 this morning and frankly, if we step back and take a longer-term view of the dollar, away from the histrionics that many pundits try to add, it hasn’t gone anywhere since April 2025 as you can see below.  You may recall the gnashing teeth describing the dollar’s 15% decline in the first six months of 2025 as being ‘unprecedented’, but one need only look at the chart below to see a larger decline in the second half of 2023.  That was much ado about nothing.  But since then, 99 +/- 3 cents has been home.

Source: tradingeconomics.com

And that’s all there is today.  We simply await the data before the next move.

I want to thank all of you who mentioned Marvel, he showed beautifully yesterday but we did not get picked for an award.  We have two big shows this weekend and then the Nationals are the first weekend of October. 

Good luck and good Labor Day weekend

adf

Hike!

Said Kevin, well, not really much
And pundits, their pearls, they did clutch
The haters all said
He's over his head
While others admired his touch

The hawks, meanwhile, think he said "Hike!"
And two-year yields promptly did spike
The dollar exploded
And gold just eroded
Though stocks drifted somewhat dreamlike

I must have listened to a different Kevin Warsh speech than most in the market on Friday morning, as the extreme hawkishness that seems to be the consensus outcome was completely lost on me.  Perhaps this is simply another Warshach Test.  He certainly repeated that the Fed is going to be successful at achieving their 2% target, although I clearly missed the part where he said they would be hiking in September.  But I must be the only one.  Futures traders clearly heard a hike was coming as the probability for a hike has risen to 62%, from about 32% prior to Warsh’s comments as you can see below.

In addition, a second hike in January seems highly probable and the chance of another one next summer has risen to 25%.  

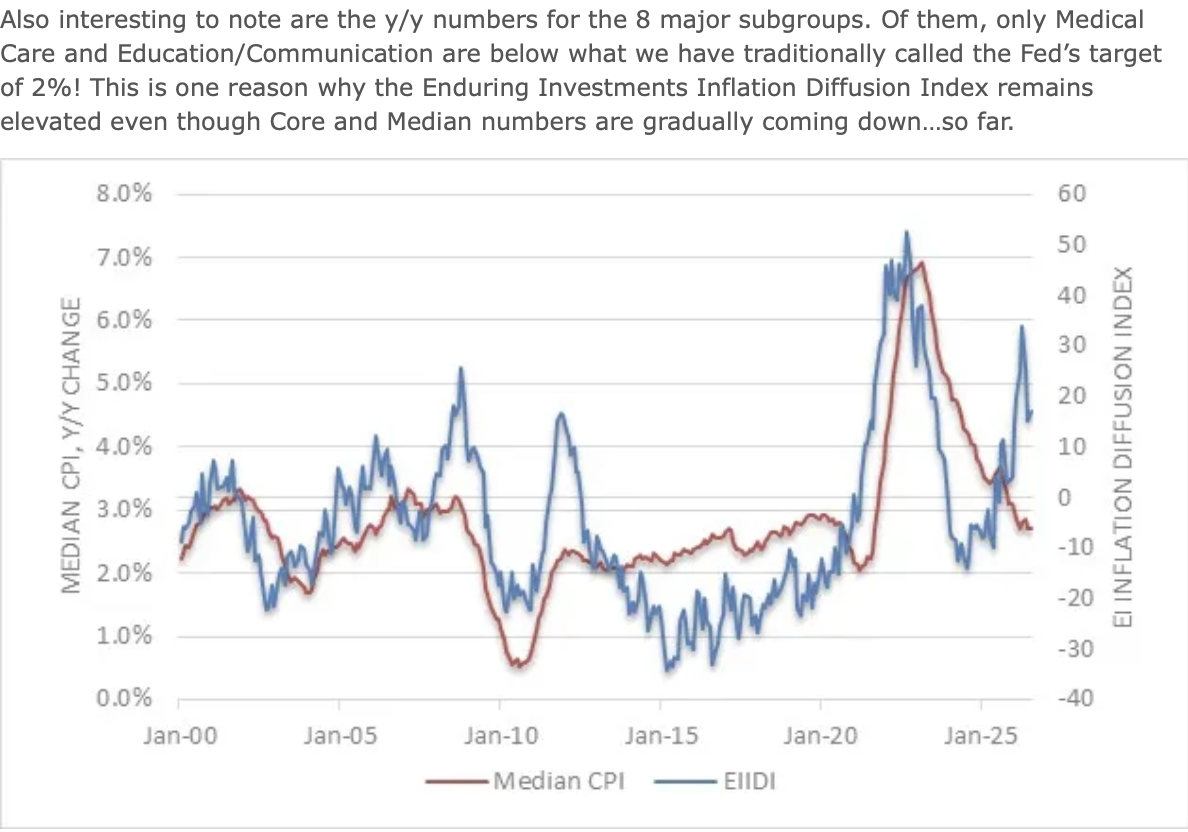
Personally, I thought the most interesting, and encouraging, feature of the speech was his willingness to discuss the details of how PCE is created, a combination of 199 subcategories.  This is akin to the way my favorite inflation analyst, @inflation_guy, Mike Ashton, views the CPI data, and he has created a diffusion index to follow just how many categories are rising rapidly and how many are either falling or rising less rapidly than the overall rate.  Here is his discussion of the July data, released in August.  And here is a chart from that note (which you all should read and subscribe to as it’s free) showing his diffusion index and why inflation is not likely to subside quickly.

But clearly, the market is not interested in my spin, nor in the spin of anyone who disagrees that a hike is on the way.  The behavior of the Treasury market was quite interesting with 2yr yields jumping 12bps while 10yr yields rose 4bps and 30yr yields rose only 1bp.  This was a classic bear flattening of the curve, and it was the driver behind the dollar’s strength (+0.55%) and more impressively, the 3+% decline in the price of gold and silver.  If yields are going up, there is no reason to own gold, apparently.  That seems at odds with all last week’s talk about the resurrection of the debasement trade, but then, I’m just a poet.

One last thing.  After rereading the speech several times (talk about a boring life) my interpretation of the following comment within his Key Principles seems to be very different than the rest of the Street.  

Fifth, short-term interest rates are the predominant tool to achieve the dual mandate. Unconventional policies to spur economic activity may suit genuine crises but should otherwise be used sparingly, if at all.”

I read this as he wants to reduce the balance sheet to reduce the Fed’s market impact and use interest rates as their policy tool and that currently, reducing the balance sheet will result in tighter policy with the same Fed funds rate.  But it appears the first part of my view, which is something Warsh has explained numerous times, is being ignored by the trading community.  Of course, it will take a change of the ‘ample reserves’ framework to get the Fed to reduce its balance sheet, and that will need the imprimatur of the balance sheet task force as well as time for the rest of the committee to get on board.

Regardless of my views, though, the market is now increasingly convinced the Fed is going to hike next month absent much weaker than expected NFP and CPI releases.

It wasn't all that long ago
When war in the Gulf ran the show
When fighting expanded
The market demanded
More havens as risk was the foe

But now, when the fighting gets hot
Most traders don't give it a thought
We're back to the Fed
And all that they've said
As key to what's sold or what's bought

Apparently, there was further military action in the Persian Gulf and the Strait of Hormuz yesterday as the US struck missile launchers on a small island there, claiming the IRGC was planning to launch more naval mines.  Iran said there will be great consequences, but the missile volleys they sent at US bases in Jordan were intercepted which prompted one of the funniest responses on X that I have seen.

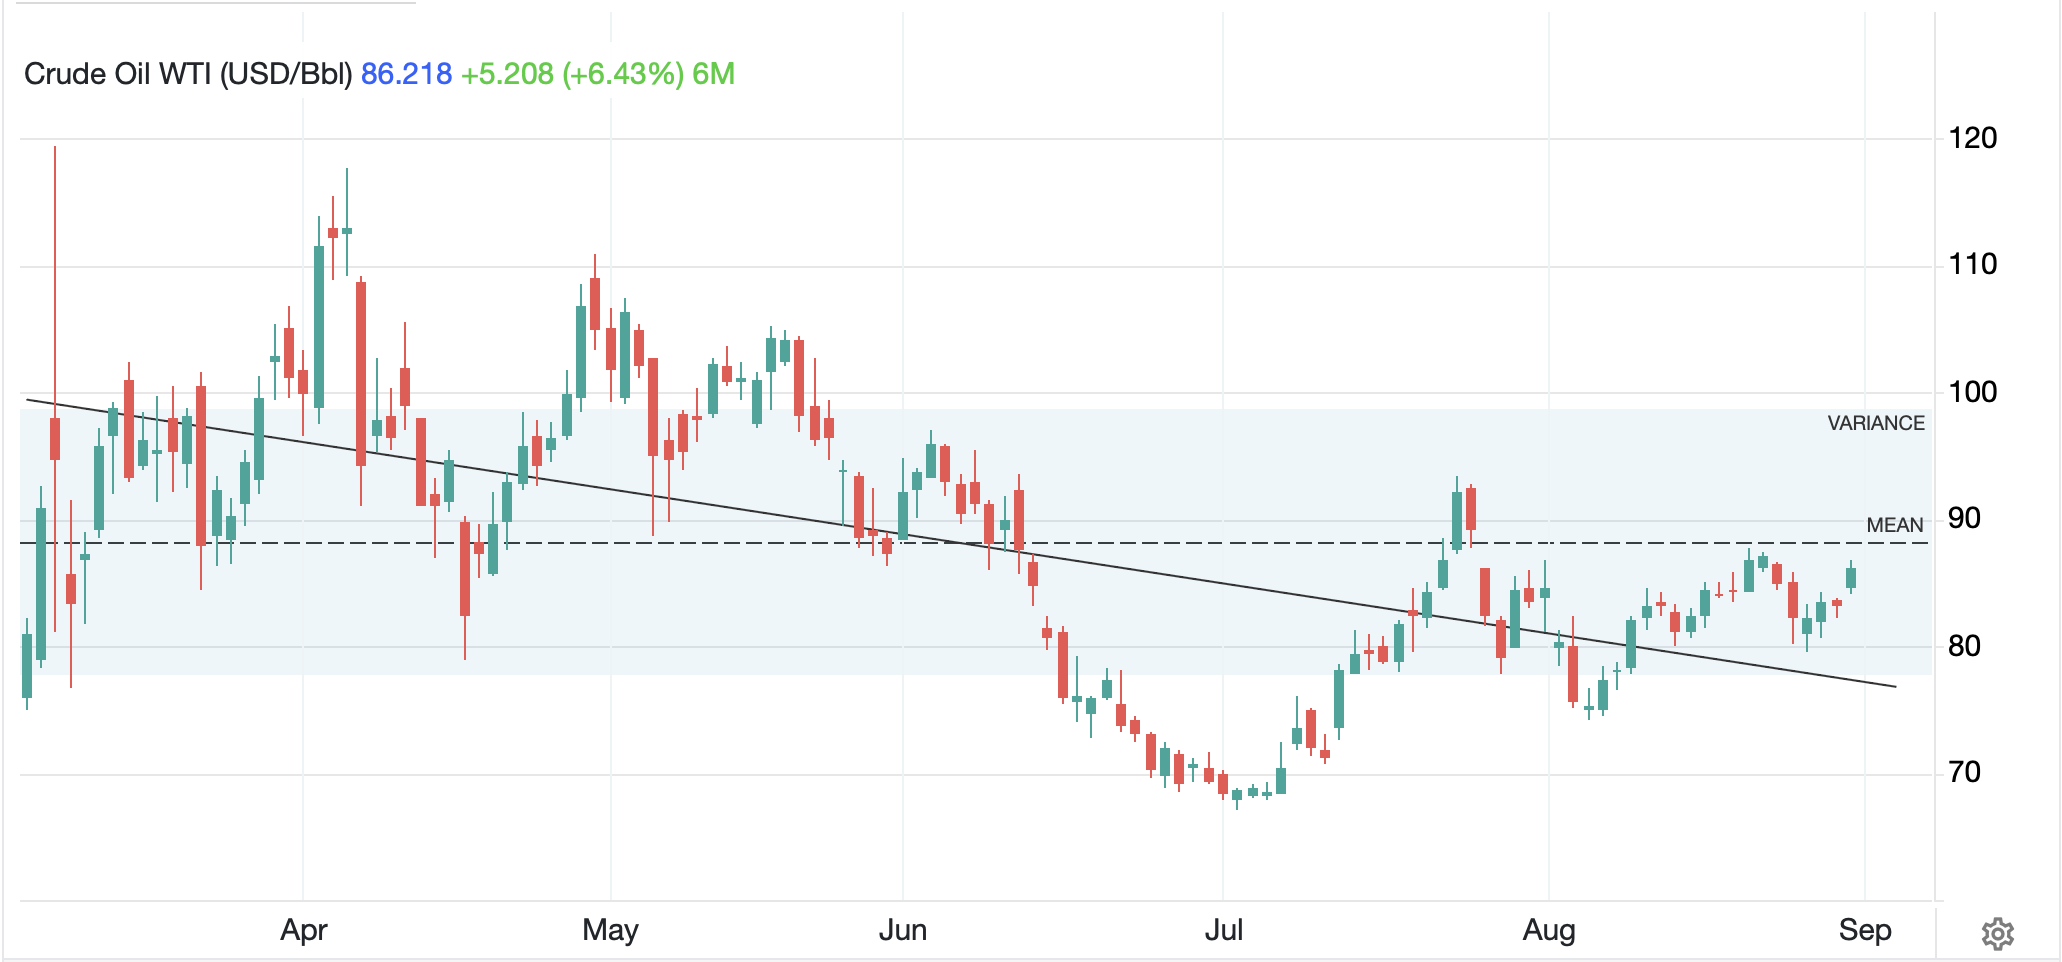
Meanwhile, oil (+3.3%) prices have risen in response, but it has not generated nearly the excitement that we have seen in the past.  And I cannot help but look at the price action in oil over the past six months, since the war began, and remain unconcerned about the future.  Certainly, there has been volatility, but as I have highlighted in other markets, volatile markets are anti-fragile, and that is worth a lot.

Source: tradingeconomics.com

As to the metals markets, after Friday’s washout across the board, this morning gold is unchanged, silver (+1.7%) has rebounded more than $1/oz and copper (+0.4%) has basically recouped its much smaller decline from Friday.  Nothing has changed my view that all metals remain in uptrends.

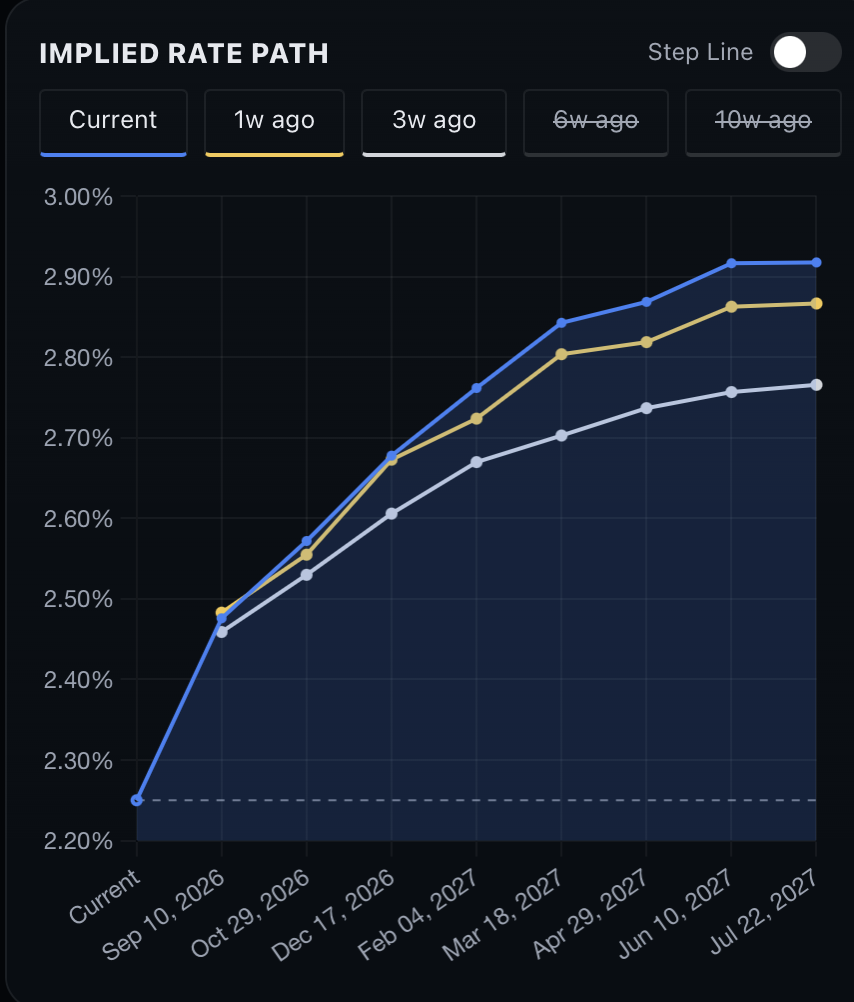
Perhaps the most interesting reaction to the Warsh speech was the equity market on Friday, where the main indices only fell by very modest amounts.  There was no indication from that price action that there is concern about a major tightening cycle.  Turning overseas, the picture was mixed last night in Asia (Tokyo -0.15%, China +0.35%, HK -0.1%, Korea +0.5%, India -0.4%) and is mixed this morning in Europe (Germany -0.8%, France 0.0%, Spain +0.1%) with Germany the obvious outlier.  I might argue that is a response to higher-than-expected inflation readings there and concerns that it might drive the ECB tighter.  I guess if you look at the curve below from rateprobability.com it does imply slightly tighter policy over time, but that’s really at the margin.

As to US futures, at this hour (7:10) they are pointing slightly softer, -0.2% or so.

Of course, Friday was much more exciting for the bond market but this morning Treasury yields are unchanged from the Friday close.  Europe, however, has seen yields climb higher with continental sovereigns all higher by 3bps.

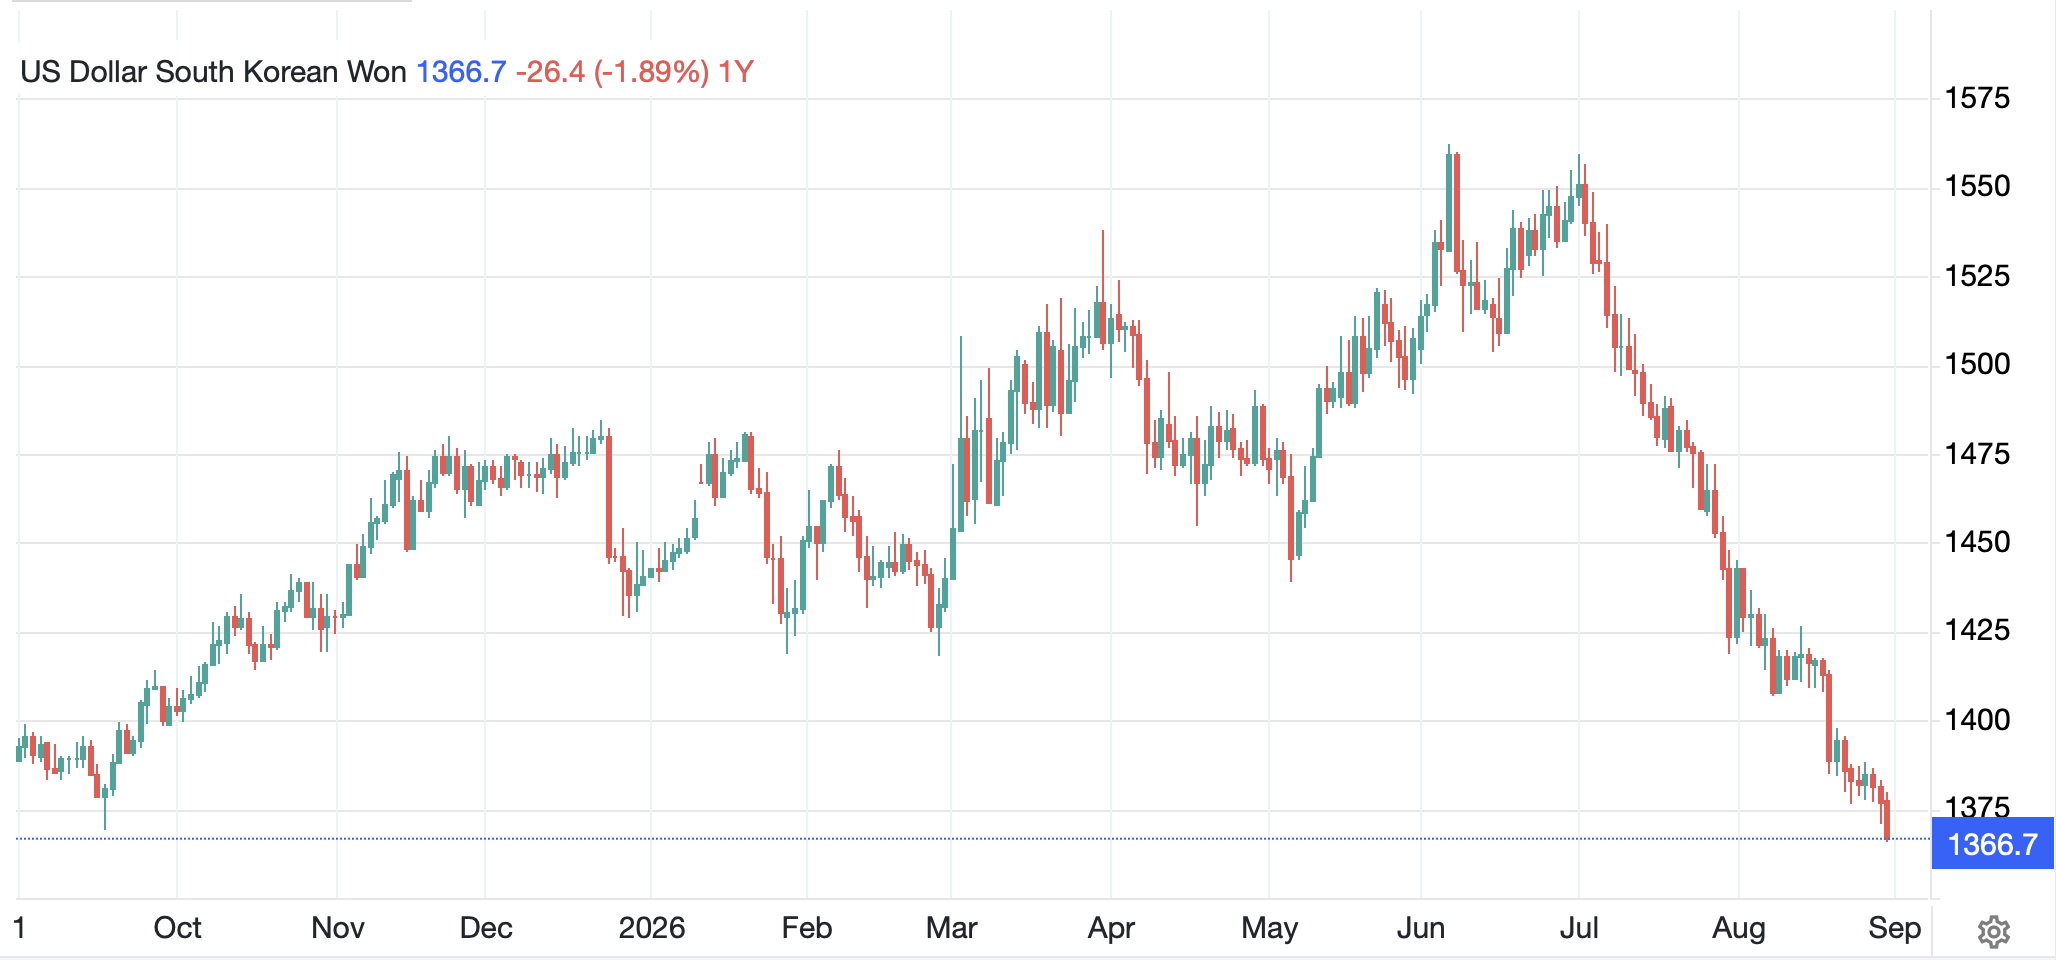
Finally, the dollar, which rallied sharply on Friday is giving back some of those gains with USDJPY back below 160, having closed above that level on Friday, while the bulk of the G10 currencies have gained between 0.1% and 0.2%.  The one exception here has been KRW (+0.7%) which has been on a remarkable roll over the past two months.  Between efforts to internationalize the currency and repatriation by the big semiconductor producers, the won has risen ~12% in the past two months, largely in a straight line.

Source: tradingeconomics.com

On the data front, there is nothing today but there is a big week coming culminating in NFP on Friday.

TuesdayISM Manufacturing55.2
 ISM Prices Paid72.0
 JOLTs Job Openings7.3M
WednesdayADP Employment47K
 Factory Orders0.6%
 -ex Transport0.2%
 Fed’s Beige Book 
ThursdayTrade Balance-$90.0B
 Initial Claims205K
 Continuing Claims1816K
 Nonfarm Productivity1.4%
 Unit Labor Costs1.3%
 ISM Services54.3
FridayNonfarm Payrolls58K
 Private Payrolls58K
 Manufacturing Payrolls5K
 Unemployment Rate4.1%
 Average Hourly Earnings0.3% (3.0% Y/Y)
 Average Weekly Hours34.4
 Participation Rate61.4%

Source: tradingeconomics.com

In addition to this, we hear from three Fed speakers.  The data we have seen of late indicates that the economy remains quite resilient in the face of higher energy prices.  Corporate earnings remain on fire and that continues to underpin risk assets overall.  However, all eyes will be on Friday’s NFP as that will serve to reconfirm prior opinions or perhaps change them.  The hawks will have a hard time making their case if the number is weak, and similarly, the doves if it is strong.  One little noticed thing from Friday was the NFP revisions for the 12 months from April 2025 through March 2026, which were revised lower by ‘just’ 79K.  Last year, the revision was -911K, so if nothing else, the BLS counted better!  But this begs the question, if the population is not growing, or even shrinking after all the deportations, and Baby boomers are retiring, thus reducing headcount, how many jobs are needed to maintain strong economic output?  

It makes a great deal of sense that Chairman Warsh wants to rethink the data because it does feel like the current data is outdated when it arrives, and that does not help forward looking policy decisions.  As to today’s session, it is hard to get too excited about anything right now, certainly in the FX markets.

Good luck

Adf
Monet’ry Bleating

Today it is all about Kevin
And whether, bond markets, he'll leaven
But what if his talk
Does naught to unlock
His views? For bond bears t'will be heaven

Remember, the them of this meeting
Is payments, not monet'ry bleating
Well, if that's the case
There will be a race
In which, only short, are competing

Markets have remained quiet for the past several sessions as investors, traders and algorithms all turn their focus to Jackson Hole, Wyoming this morning awaiting the sage comments of Fed Chair Kevin Warsh.  The market punditry seems convinced he will lay out things like his reaction function to data and his views on where monetary policy is headed.  Of course, I think they are talking their book as they are desperate to write about that.  We know this because all they have written about lately is how awful Warsh is for not telling them all that stuff.

But I have a sneaking suspicion that any discussion of monetary policy will be fleeting, at best, as the title of the symposium is “Financial Innovation: Implications for Payments and Policy.”  Frankly, this sounds like an opportunity for Warsh to wax poetic on the future of money and stablecoins and how the Fed will deal with these new vehicles and their impact on monetary policy.  I have already discussed the idea that stablecoins are going to be inflationary in their own right, and here is an article that describes the situation better than I can.  But in this context, and with the potentially major ramifications of the US government’s embrace of stablecoins, it would not be a surprise for Chairman Warsh to essentially ignore the current interest rate structure and focus entirely on the balance sheet.

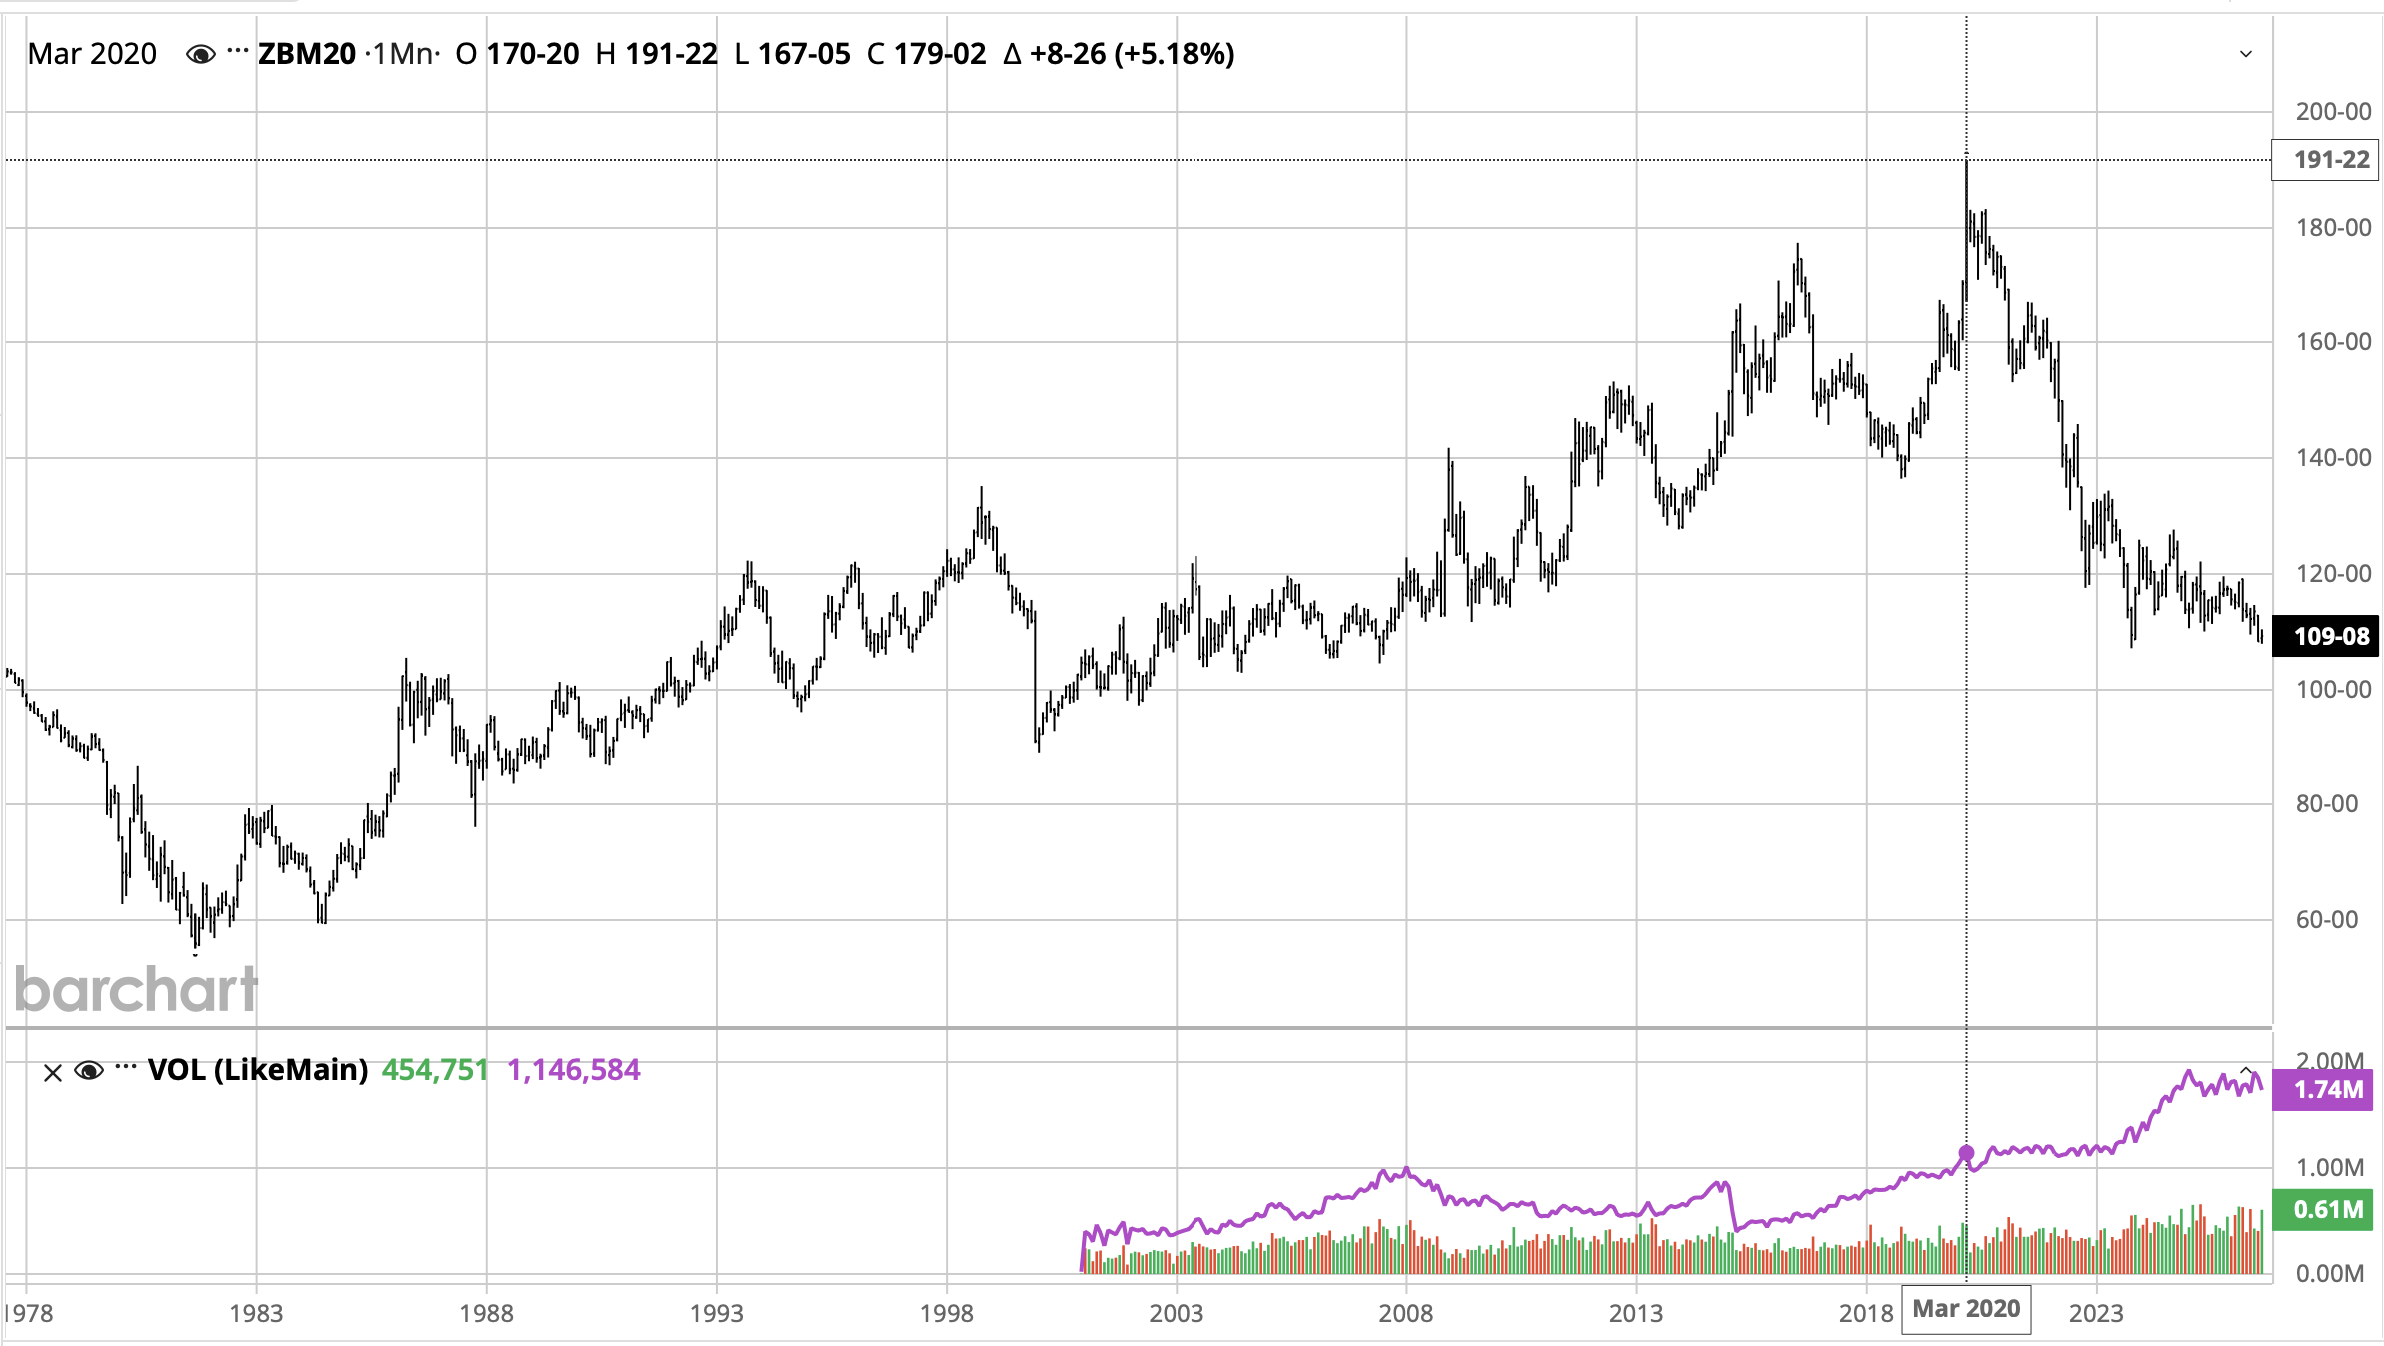
If that is the direction of his speech, I expect that the bond bears will look to double down and really hit the futures market hard, driving yields higher extending the recent move seen in the chart below.

Source: barchart.com

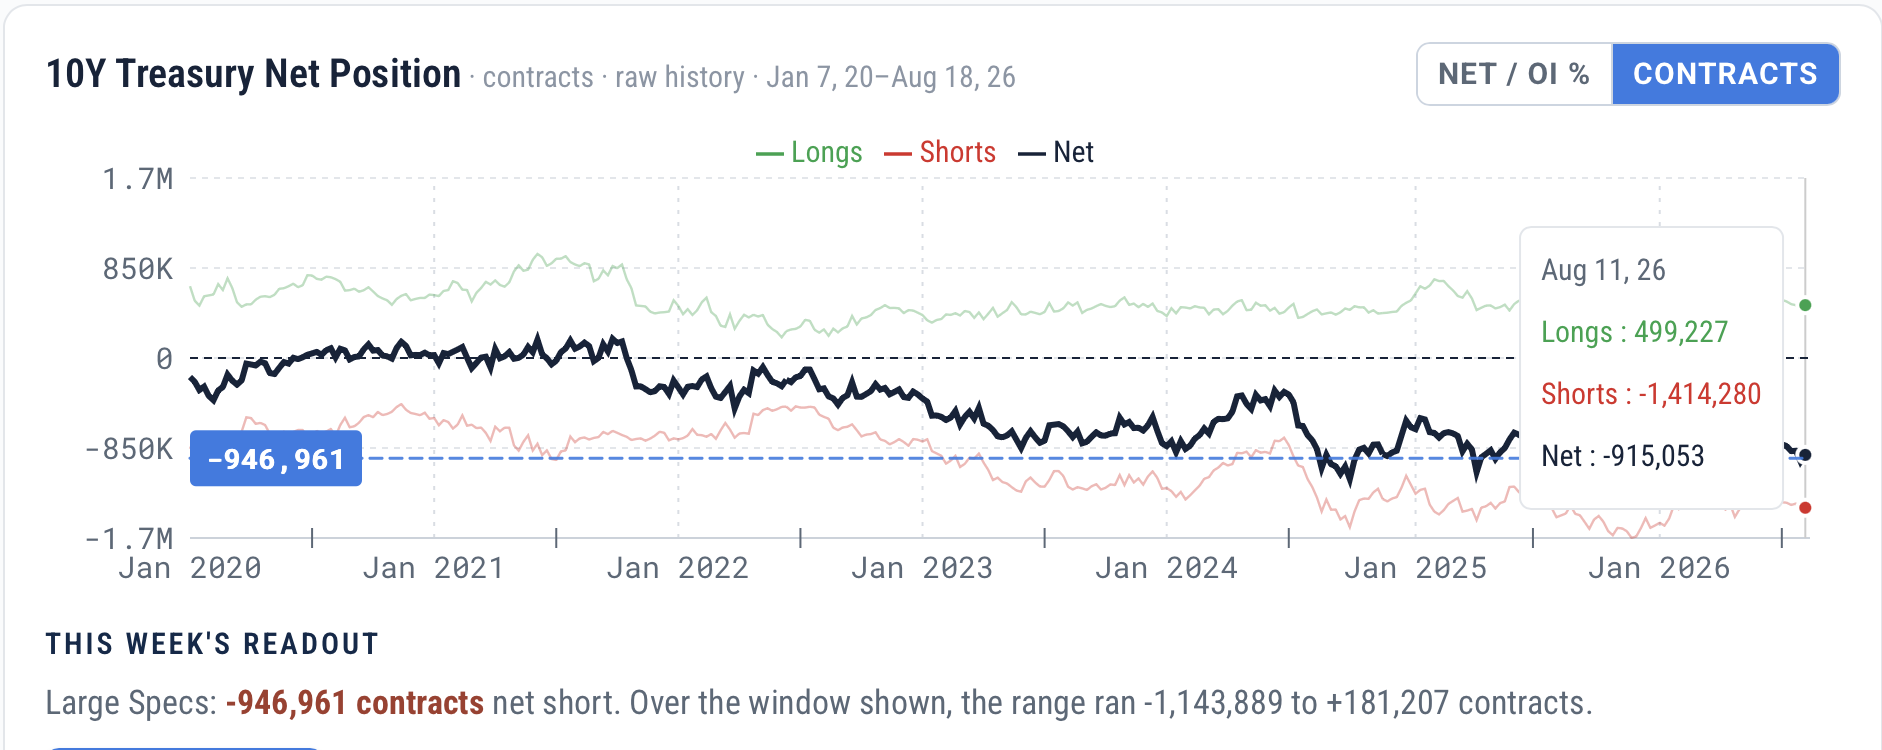
But I also do not rule out Secretary Bessent taking advantage of that and buying them aggressively.  Would it really be a surprise if Bessent, a former hedge fund trader who understands both bond math and the way markets work extremely well, used his ‘at least’ $4 billion of buying power to purchase futures, utilizing leverage to expand the impact significantly?  At current margin levels, that $4 billion could purchase at least $60 billion equivalent in futures or 600,000 contracts in the first week of activity alone.  I think that could drive a pretty good short squeeze, exactly what Bessent wants to see.  Below is a chart of the Commitment of Traders report for 10-year note futures showing a net short of ~915k.  What kind of impact would buying 600k futures have?

Source: cotsignal.com

My take is there would be quite a few hedge fund traders whose bonuses would be negatively impacted!

This is all speculation, obviously, but from what I have read around, the market is really looking for something I sense Warsh is not going to give them.  Prepare for more volatility ahead after several weeks of limited movement.  Just sayin’.

In the meantime, let’s run down market movements overnight, although there was not a lot of excitement.  Yesterday’s US rally was followed by broad-based, albeit not excessive, strength throughout most of Asia (Japan +0.4%, HK +0.1%, Australia +0.6%, Taiwan +0.8%) although both China (-0.4%) and Korea (-1.8%) did not partake.  Given the Nvidiphoria, Korea is a surprising outcome, but volatility in that market has been extreme as I have shown in the past.  

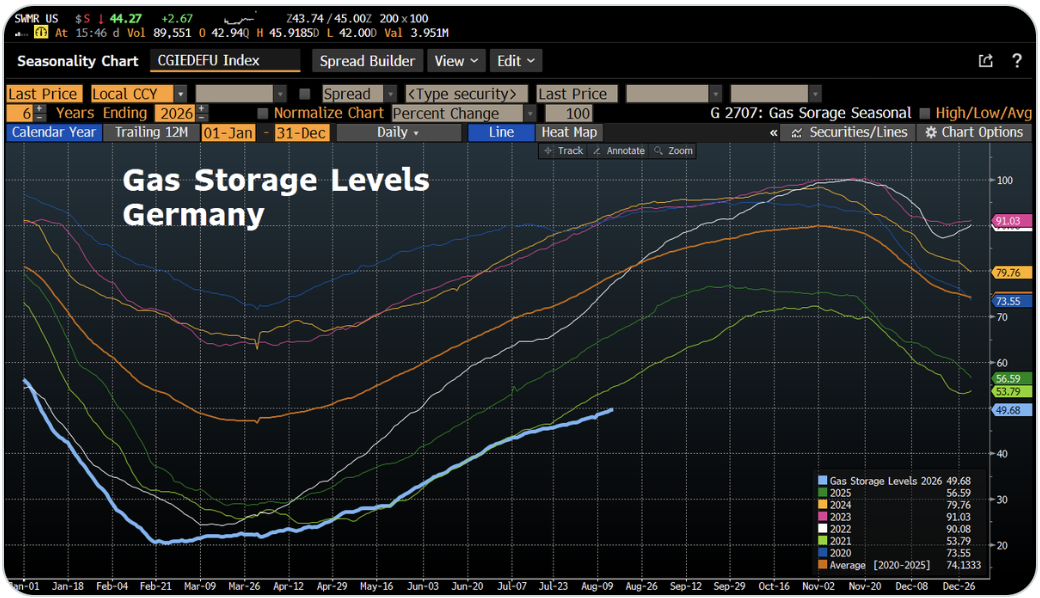
European bourses are also higher this morning (France +0.9%, Spain +0.5%, German +0.5%) after data showed improved business confidence throughout the continent although GDP continues to be lackluster (e.g., France 0.7% Y/Y in Q2).  But sentiment indicators are picking up there slightly and, after all, equity markets are supposed to be forward looking.  Maybe things will get better in Europe, although given their energy policies and the fact that they are behaving far more like grasshoppers than ants these days with respect to Natural gas storage (see chart below), things may get tougher if they are wrong about global warming.

As to US futures, at this hour (7:15) while NASDAQ futures are softer (-0.6%) the other two major indices are essentially unchanged ahead of Mr Warsh.

In the bond market, yields continue to creep back higher with Treasury yields (+1bp) the best performer after JGB yields (+4bps) rose overnight and European sovereign yields have climbed between 2bps and 3bps this morning.  As I highlighted yesterday, or more accurately, the WSJ did the work for me, European yields have been climbing more rapidly than US yields lately as European nations have demonstrated no ability to rein in spending, and in fact, are planning the guns AND butter approach as they build out their defense capabilities while maintaining their nanny states.  What can possibly go wrong? 🙃

In the commodity space, we continue to hear that the Strait of Hormuz is either open or closed depending on the source, although the fact that oil continues to flow has me leaning toward more open than closed.  This morning WTI (-0.6%) is slipping a bit, although it rallied a bit yesterday.  There was a very interesting article in Bloomberg yesterday regarding the shale drillers’ ability to increase production dramatically by using more surfactants (soap) to help the oil flow, gains of 20% or more in a well, which simply reminds us of the amazing technology that exists in that sector.  There is no shortage of oil folks, and likely never will be.  As to the metals markets, gold is flat this morning and silver (+1.3%) is rising again, back above $70/oz.  Copper (+0.6%), too, is having a solid session.  Nothing has changed my views on the metals going higher over time.

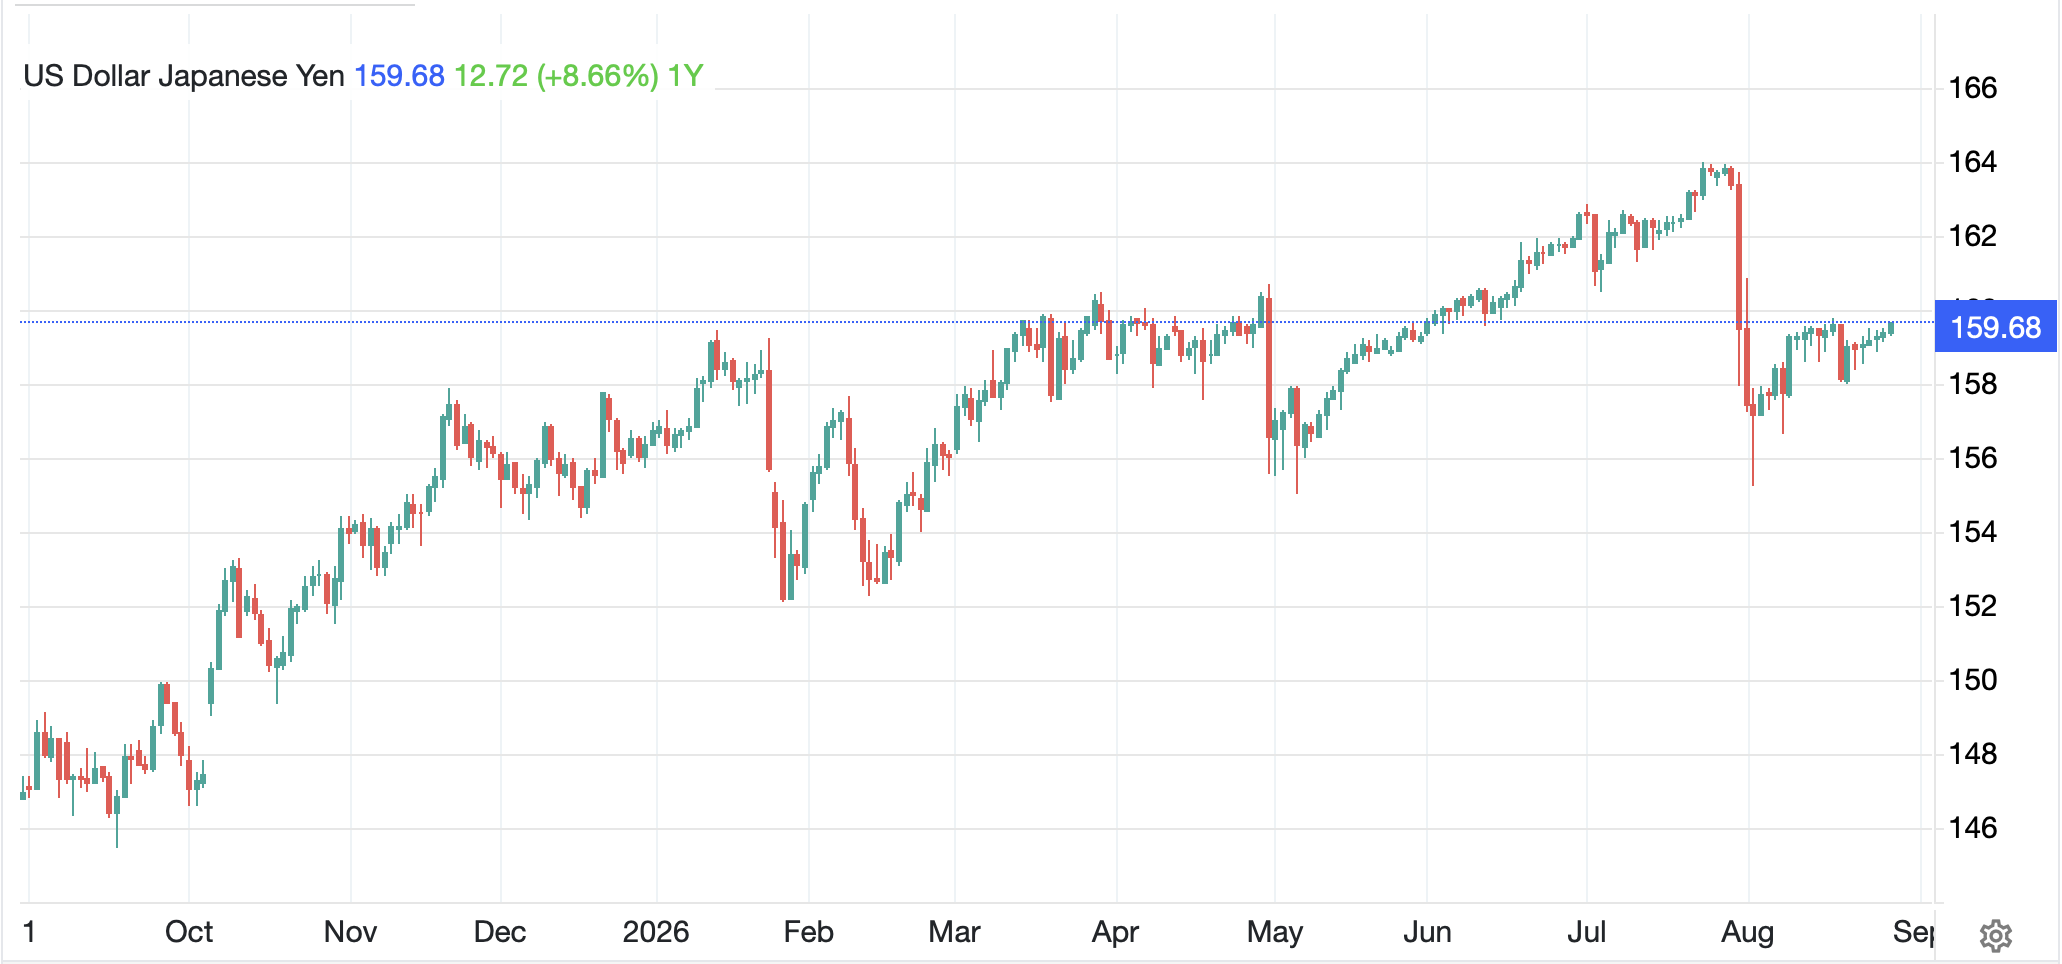
Finally, the dollar has been stuck in neutral as we await Chairman Warsh with the DXY still hovering right above 99.00.  We have not discussed the yen (-0.2%) much lately as it has not been noteworthy, but now that it has been one month since the major intervention, I thought it worthwhile to take a peek at the chart and see how its doing.

Source: tradingeconomcis.com

I challenge you to explain the difference to me between the price action after the last interventions and this one.  The intervention in May took about 6 weeks to unwind and the yen continued lower for another 6 weeks before they stepped in again alongside the US.  Pretty much the only thing I can see that really stops this move is if I am right about Bessent squeezing the shorts and driving yields sharply lower.  In that case, USDJPY would fall sharply without intervention.  Otherwise, it’s hard to get excited about anything in the FX markets right now.

And that’s really it for today.  At 8:30 Canadian GDP (exp 3.4%) is released and then we see Chicago PMI (57.0) and Michigan Confidence (51.0) when Warsh starts to speak.  We also get the annual NFP revision although I have not seen any estimates for that.  But as I have said all week, it’s all about Kevin.  Now we wait and see.

Good luck and good weekend

Adf

Feeling Quite Fraught

The data of late offers nought
To help decide what should be bought
Or sold, so we wait
For CPI’s rate
With risk takers feeling quite fraught

Despite NFP being weak
Some Fed members, when they do speak
Are pining to hike
Into the crude spike
I fear much more havoc they’ll wreak

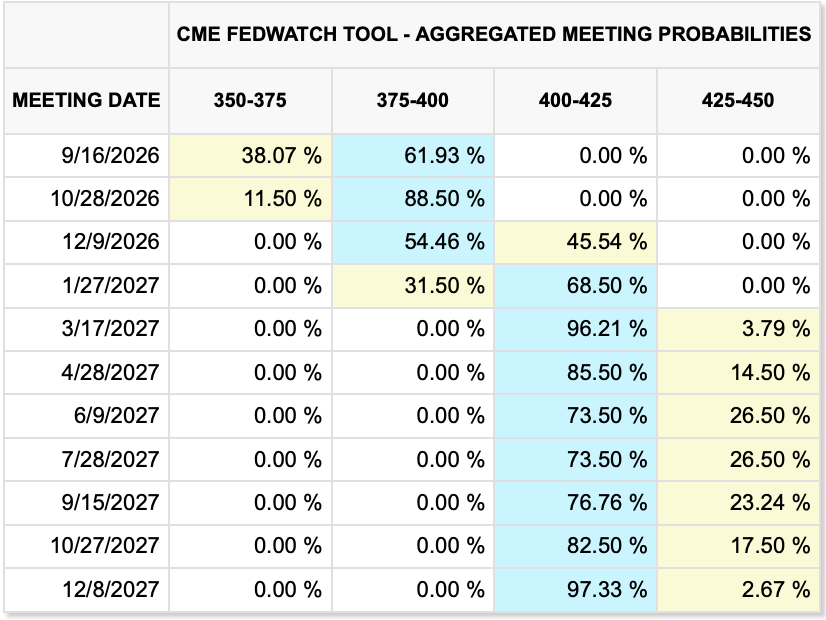
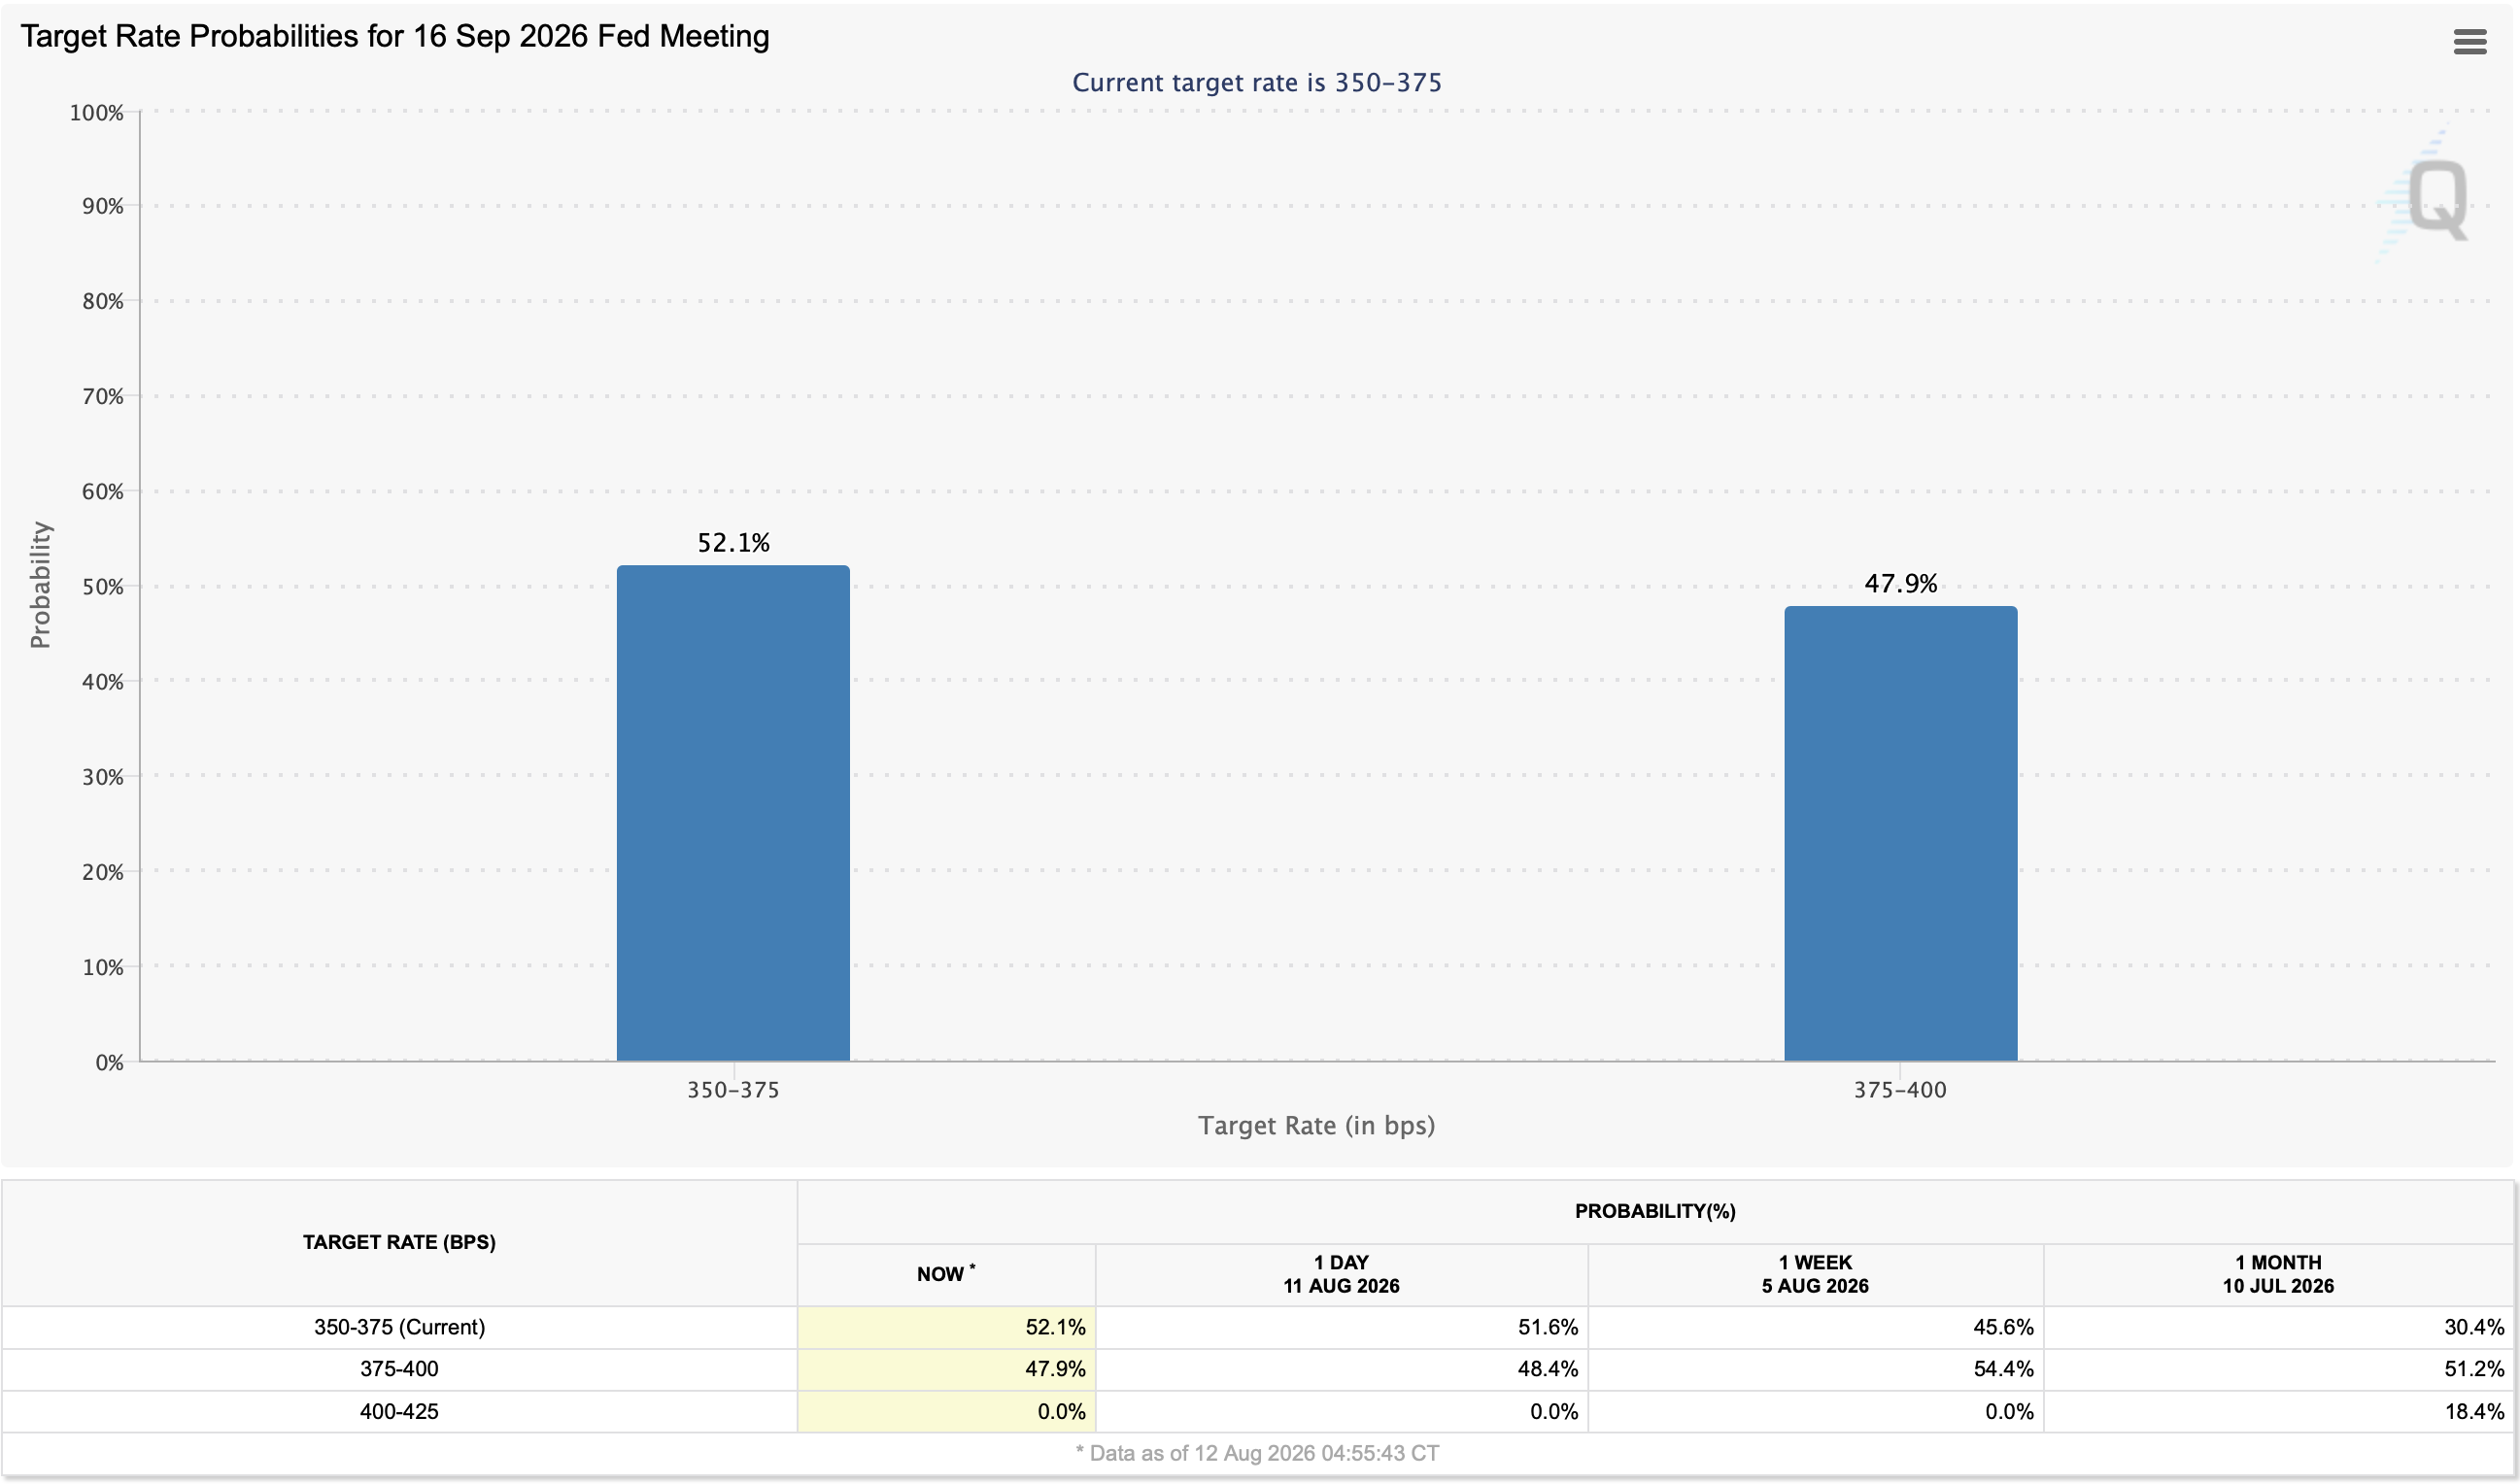
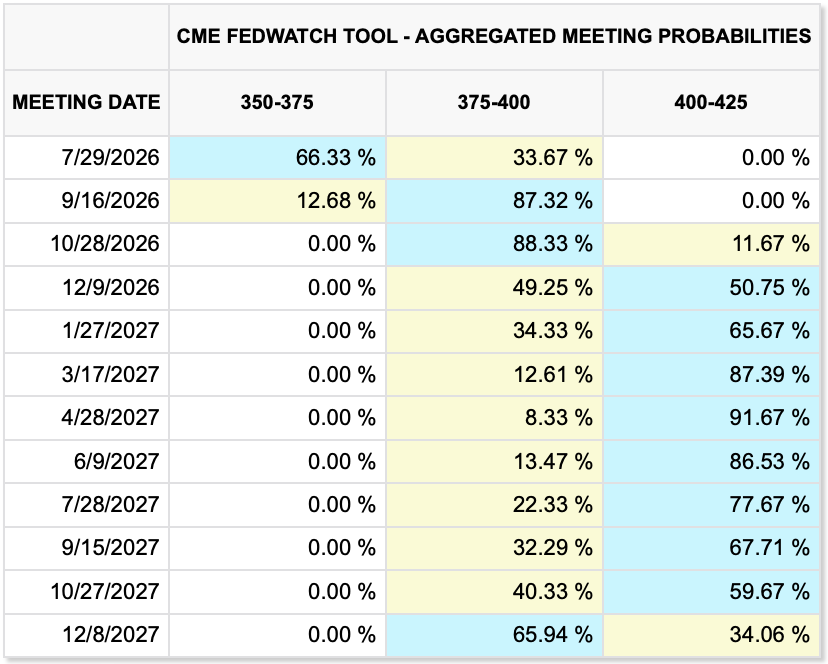
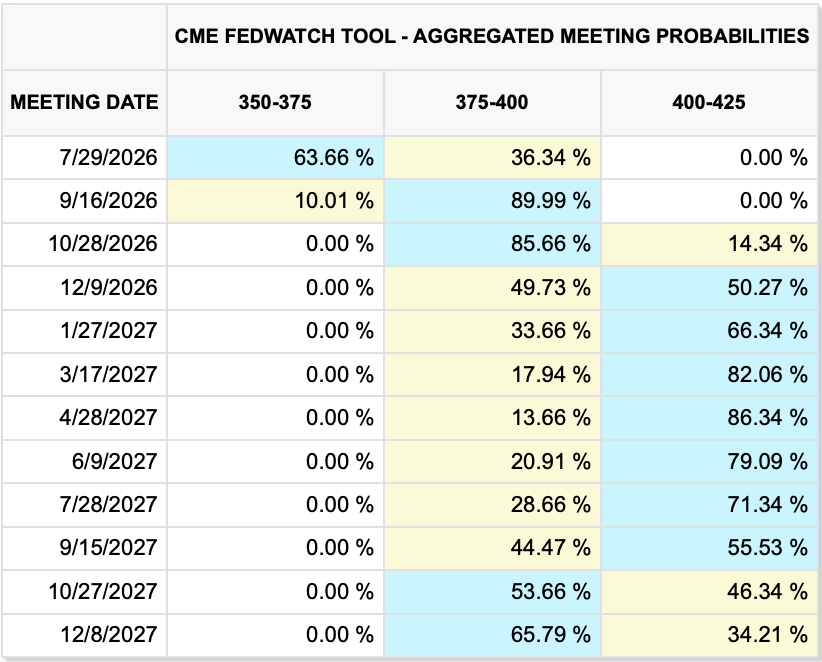
The below chart from cmegroup.com describing Fed fund futures probability pricing for a rate hike at the September meeting is an excellent description of many markets right now, nobody knows nothin’.  It has been pretty rare of late, really in the past 15 years, that market participants were so uncertain about the future path of short-term interest rates.  And frankly, I think this is exactly what Chairman Warsh wants to see.  If uncertainty is high, then risk-taking recedes and that offers a more robust market framework.

If pressed, I think he would be happy if this were the situation going into every meeting, although obviously, there is no meeting imminent, this is a response to today’s CPI data.  

Current consensus expectations are as follows:

  • CPI M/M: 0.1%
  • CPI Y/Y: 3.4%
  • Core CPI M/M: 0.2%
  • Core CPI Y/Y 2.5%

I have no model nor framework to anticipate whether the outcome will be seen as either hot or cold, but since this is for July, we can look at the price of gasoline during the month and see how much it changed.  I apologize for the chart below but it is the only way I could determine how to show the movement from month end to month end where on June 30, RBOB futures closed at $2.8949/gal and on July 31 they closed at $3.1142/gal so a gain of 7.5%, but if you look at the chart, it does seem like it spent a lot more time above the month end close than below it.  In fact, my best estimate of the average price during the month is ~$3.18/gal, higher still, so energy prices were certainly firmer during the month.

Source: tradingeconomics.com

Of course, the question the market is asking is, will this change the Fed’s generic viewpoint on inflation?  The current downside of Chairman Warsh’s attempts to adjust the way the Fed works is that neither traders nor analysts have a good idea of their current reaction function when it comes to data.  We know that there are a group of FOMC members who are itching to hike, but with a relatively soft NFP report last week, if today’s number is also soft, will that change attitudes?  It is this conundrum that neatly defines why the analyst community is so up in arms, since they seem no longer able to think for themselves, they don’t know what to think!

But that’s where we stand for now, a major data release upcoming and a market that has, arguably, pulled in its risk-taking wings to make sure they can fly afterwards.  As this is the biggest story for the day, let’s take a twirl around markets overnight to see what they did in anticipation of the release.

While yesterday’s US session was lackluster, with all three major indices slipping a bit, overnight saw more winners than losers.  So, Tokyo (+0.8%), China (+0.6%), Korea (+3.7%) and Taiwan (+0.9%) all continue to perform well on the back of the tech story although HK (-0.8%) and Australia (-0.5%) lagged.  As to the smaller, regional exchanges, it was a mixed picture, although certainly not an extremely negative one.  It appears that risk appetite remains reasonable if not gigantic.  Certainly, if we look at the Fear & Greed Index, it demonstrates that point exactly.

Meanwhile, in Europe, equity markets are generally a bit firmer led by the DAX (+0.5%) and Spain’s IBEX (+0.2%) while both France and the UK are essentially unchanged although there has been no data to drive things in either direction.  It appears like these markets are awaiting the CPI data just like US markets.  Speaking of which, futures at this hour (7:10) are pointing slightly higher with the NASDAQ (+0.5%) leading the charge.

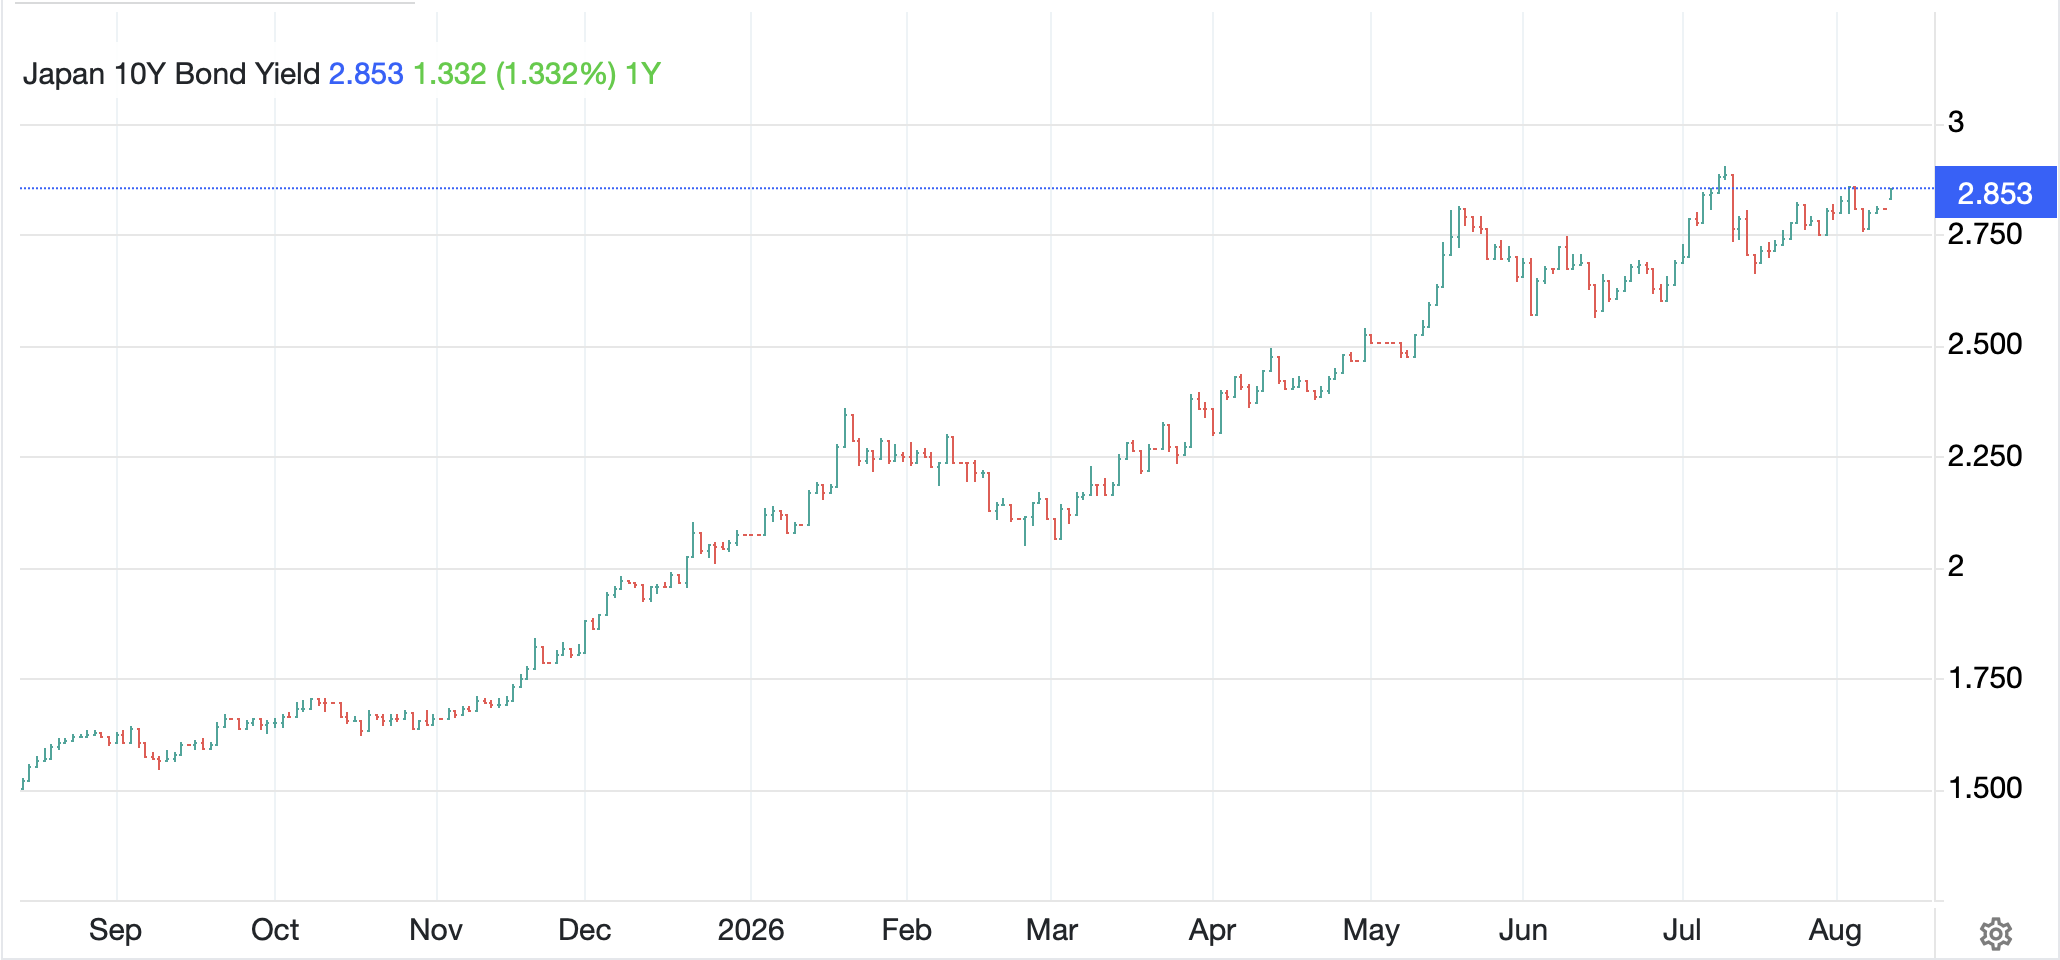
In the bond market, despite all the angst, Treasury yields are lower by -2bps this morning and this is dragging the entire bond market down with European sovereign yields all lower between -2bps and -3bps as well.  Is that an indication that a soft number is expected?  The outlier here is Japan where JGB yields (+4bps) rose last night and are now just 5bps below the recent 30-year high level reached in early July.  

Source: tradingeconomics.com

Bloomberg had numerous articles this morning about Japan and the issues they have with the yen, their monetary policy, their relationship with the US and were generally of the opinion that Japan is making all the wrong moves, hence the weakness in the currency.

In the commodity markets, oil (+0.3%) is back above $83/bbl now having gained 11% in the past week.  The ongoing tit for tat comments from both Iran and President Trump have become just background noise to most of the market these days.  Later this morning we get the EIA inventory data with a small draw expected, although that was expected last week and there was a build in inventories.  It has been nearly 6 months since the war started and the Strait became compromised and there is still seemingly plenty of oil and products available to users.  As to the metals markets, this morning they are quite shiny (Au +0.9%, Ag +2.4%, Cu +0.7%).

Finally, the dollar is…well nobody seems to care much about it these days.  It is virtually unchanged vs. almost all its G10 counterparts with NZD (-0.3%) the lone exception.  The best explanation I can see is that employment data last week may be weighing on the belief the RBNZ is going to hike rates at their next meeting, but that is fishing.  It is quite likely there was an order that went through to drive the price.

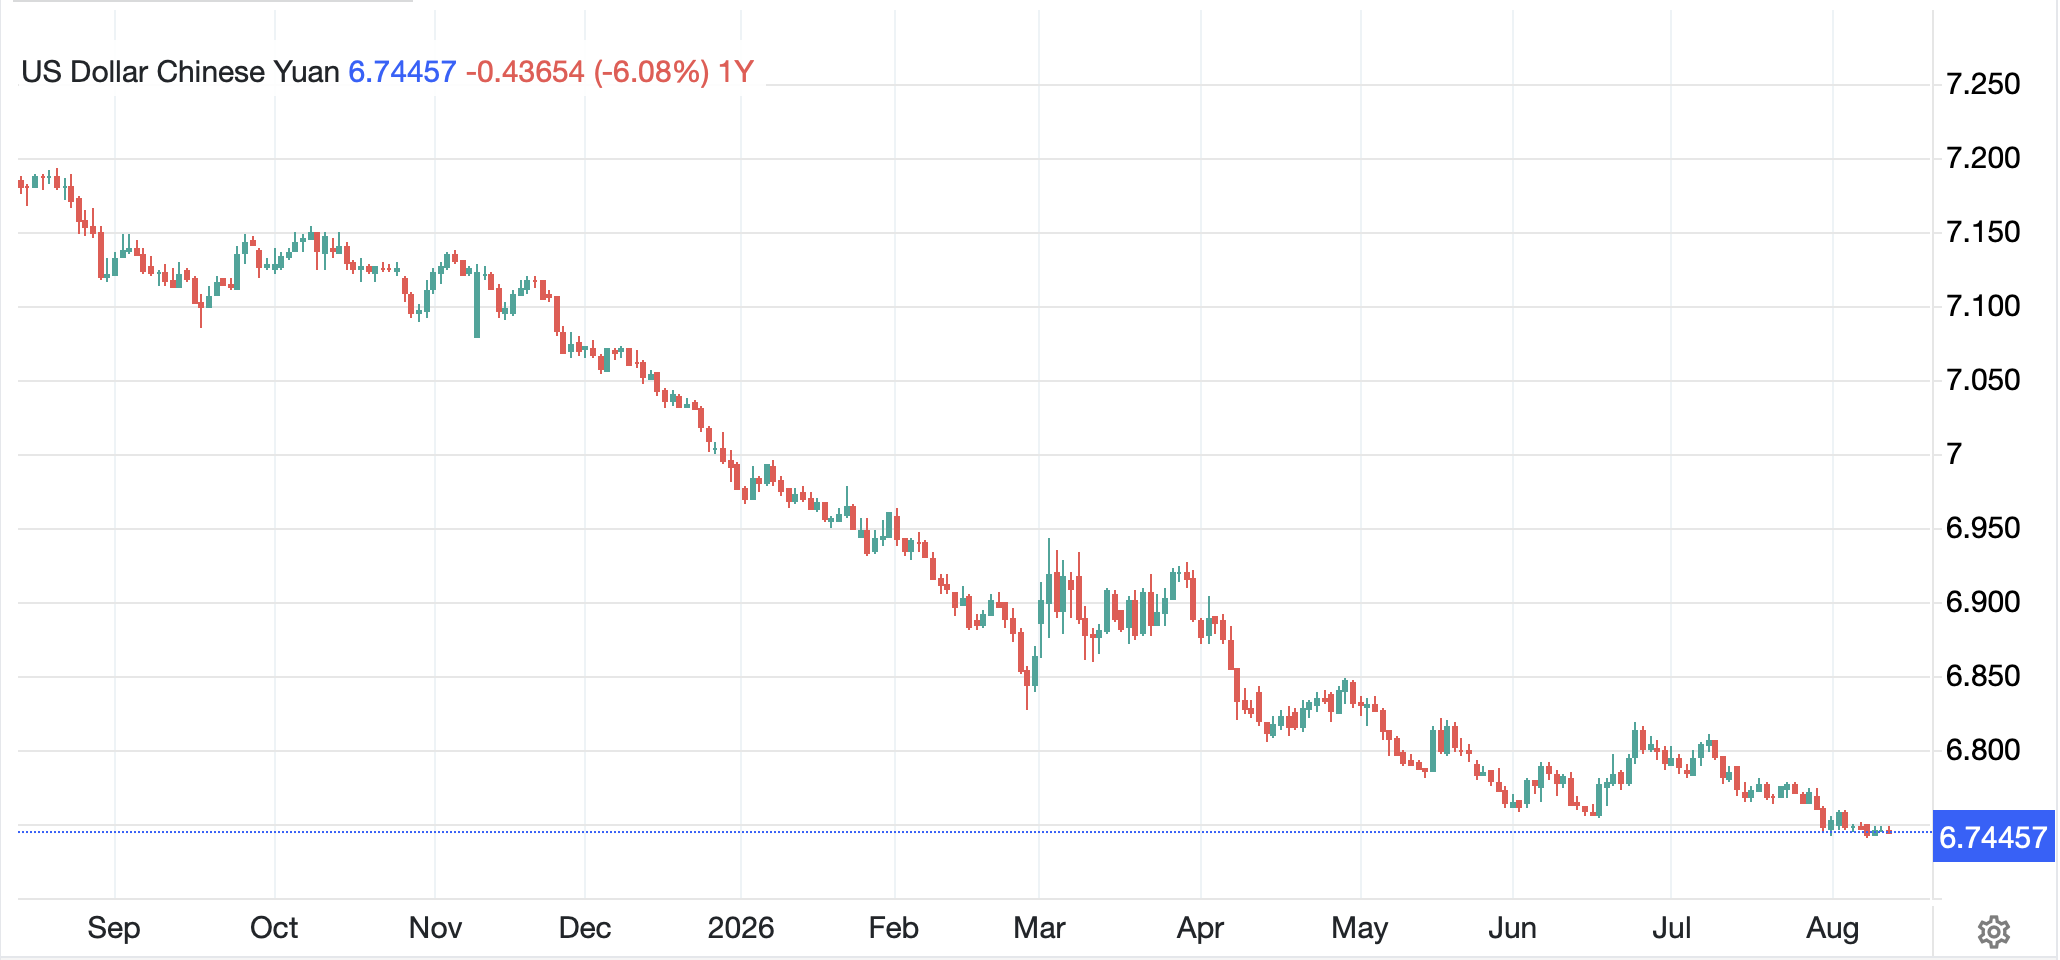
In the EMG bloc, there is also little to discuss overall as FX markets are generally quiet.  But I want to mention CNY as I read something this morning about which I was unaware.  Mike Nicoletos, a very solid analyst, made the point that banks in China are paying up for USD deposits there, as high as 4% vs. 1% for CNY deposits.  This has been occurring despite the fact that the renminbi has been strengthening steadily all year as per the chart below.

Source: tradingeconomics.com

Now, the renminbi is arguably at least 30% undervalued, even after its recent relative strength, which is one reason that China’s exports continue to grow.  The undervalued currency is a key reason China finds itself the subject of tariffs and trade restrictions all around the world.  But recall, there is a narrative that nobody wants dollars and China is de-dollarizing as they try to move to more local currency trade and settlement.  The very fact that banks in China are paying up so much for USD deposits may tell a different story.  Perhaps there is a significant need for dollars, even in China, and banks have no funding.  Remember, there is no Fed swap line with the PBOC so they have to source their dollars the old-fashioned way, pay up for them.  It is interesting that the renminbi continues to strengthen despite this dollar demand, but I suspect this will continue for a while.  Maybe the de-dollarization narrative has some flaws in it after all.

And that’s really it for today.  A hot CPI number will probably see higher yields and some dollar strength and equity weakness with the opposite true for a soft number.  We shall see.

Good luck

Adf
Sense of Foreboding

Well, three little piggies said, whoa!
We think Fed funds rates are too low
But nine said, no way
We think they’re OK
And if hikes come, we should go slow

As well, pundit angst is exploding
Because they are now stuck decoding
The sparse words Warsh tenders
And so, story vendors
Now all have a sense of foreboding

It is truly remarkable to me how much angst was generated because Chairman Warsh refuses to offer any guidance whatsoever on what the Fed may do going forward.  The same people who have railed at the Fed for being the underlying cause of economic problems, are now furious that he is trying to change their operating process.  This tells me that much of that previous concern was theater as those same folks were either making a lot of money in the previous system or had a level of comfort that their positions were protected by the Fed put.

One of the biggest impacts the Fed has had in our society has been Ben Bernanke’s “portfolio-balance channel”, better known as trickle-down economics.  His idea that buying Treasuries and forcing investors out the risk curve was a major driver of the current wealth and income inequalities that exist in today’s K-shaped economy.  In fact, I would contend that we are seeing the results of that monetary experiment lately with the rise of the DSA in politics and the growing belief by many in the younger generations that they cannot get ahead regardless of their effort, so YOLO and socialism are a better fit.

The Fed is more than a century old and has had unchecked power during that entire period.  Paul Volcker was the last Fed chair to be able to ignore (or withstand) the politics in order to do the right thing and address inflation.  Everybody else has been captured by the organization.  My take is currently the other 18 members of the FOMC all despise Warsh because they all hate President Trump, and Warsh is Trump’s man.  Powell was Trump’s man too, but the Fed culture captured and converted him.  Their biggest problem is Bessent and Warsh are besties and so Warsh has political cover. But they won’t go down without a fight.

My strong view is that ending the ample reserves framework and shrinking the balance sheet is the best thing the Fed can do for the economy and to fight inflation.  It will take time, but that is clearly his goal.  We shall see if he’s successful.  But in the meantime, it appears that all the analysts who got paid a lot of money by Wall Street to do very little are now going to start having to earn their keep and think and figure out things on their own.   And that is a really good outcome.  As I continue to write, less certainty may bring more short-term volatility, but it will reduce the opportunity for excess leverage and reduce market fragility.  And that is something to be sought.

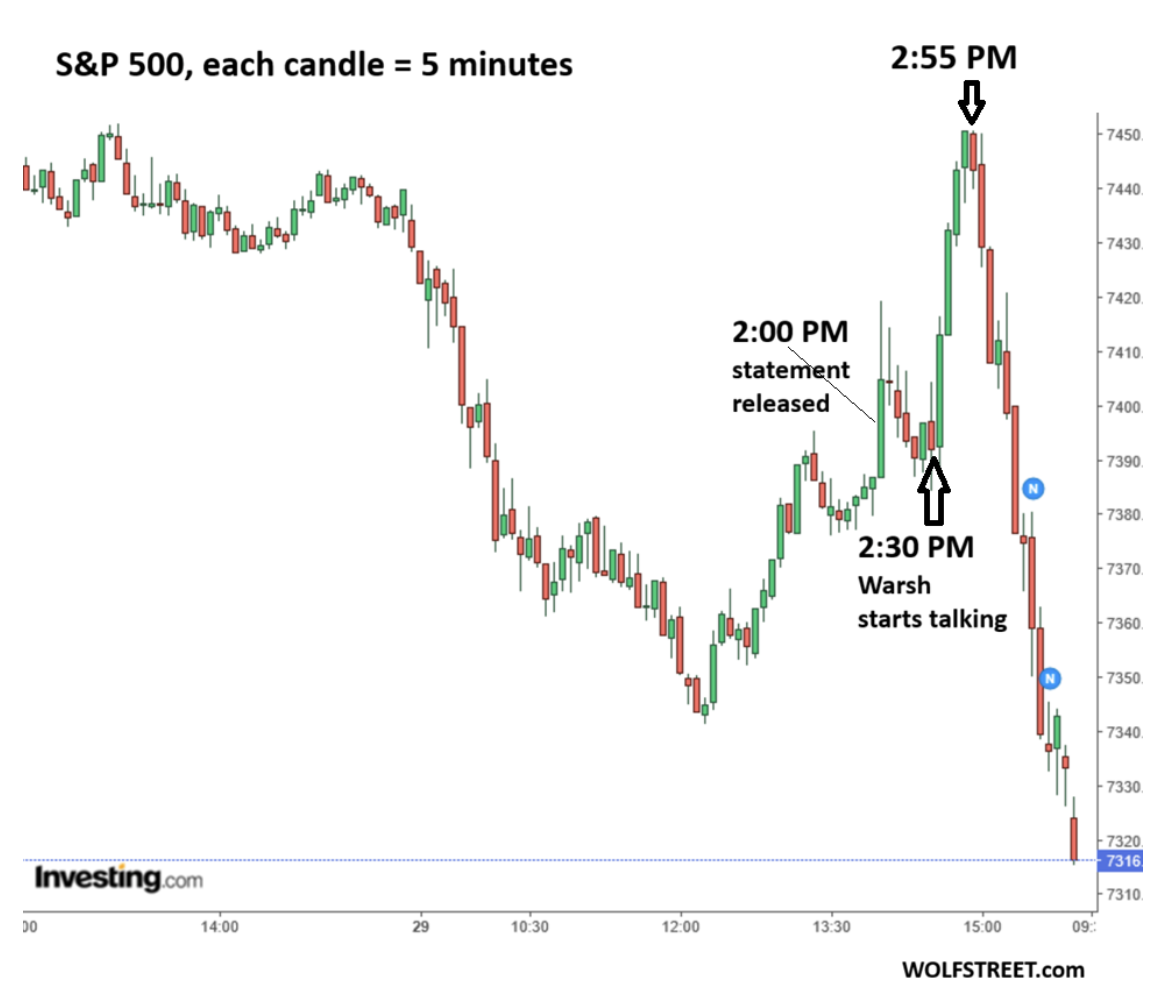
So, how did the market respond?  This chart from wolfstreet.com is annotated beautifully.

The equity market decided they didn’t like uncertainty and are growing increasingly scared there may not be a Fed put anymore.  And so, we saw weakness across the Americas yesterday with US and Canadian indices falling sharply into the close.  Is this the end of the world?  I don’t think so although you might be confused by reading some of the commentary. Overnight, though, things were more mixed with some laggards (China -1.1%, Korea -1.2%, Australia -0.8%, New Zealand -1.5%) and some gainers (Tokyo +0.7%, HK +0.2%, India +0.3%, Indonesia +1.6%).  The continued fighting in Iran (the US launched another series of strikes last night) as well as concerns over the tech sector valuation remains a generic equity market issue right now. 

Europe, though, is in the green this morning (Spain +1.4%, France +0.9%) with Germany and the UK unchanged, as generally better than expected, albeit still soft, GDP data was released this morning as per below:

CountryActualPreviousExpected
France Q/Q0.2%-0.1%0.2%
France Y/Y0.7%0.8%0.8%
Spain Q/Q0.7%0.6%0.6%
Spain Y/Y2.7%2.7%2.5%
Netherlands Q/Q0.4%0.3%0.2%
Netherlands Y/Y1.3%1.4%1.2%
Germany Q/Q0.2%0.4%0.1%
Germany Y/Y0.9%0.7%0.6%
Italy Q/Q0.2%0.3%0.1%
Italy Y/Y1.0%0.8%0.7%
Eurozone Q/Q0.4%0.0%0.2%
Eurozone Y/Y1.0%0.5%0.5%

Source: tradingeconomics.com

Hardly the stuff to quicken your pulse, but better than it could have been.  As to US futures, at this hour (7:15), they are in the green with the NASDAQ (+1.25%) leading the way after MSFT reported excellent numbers last night which has been enough to offset META’s miss.

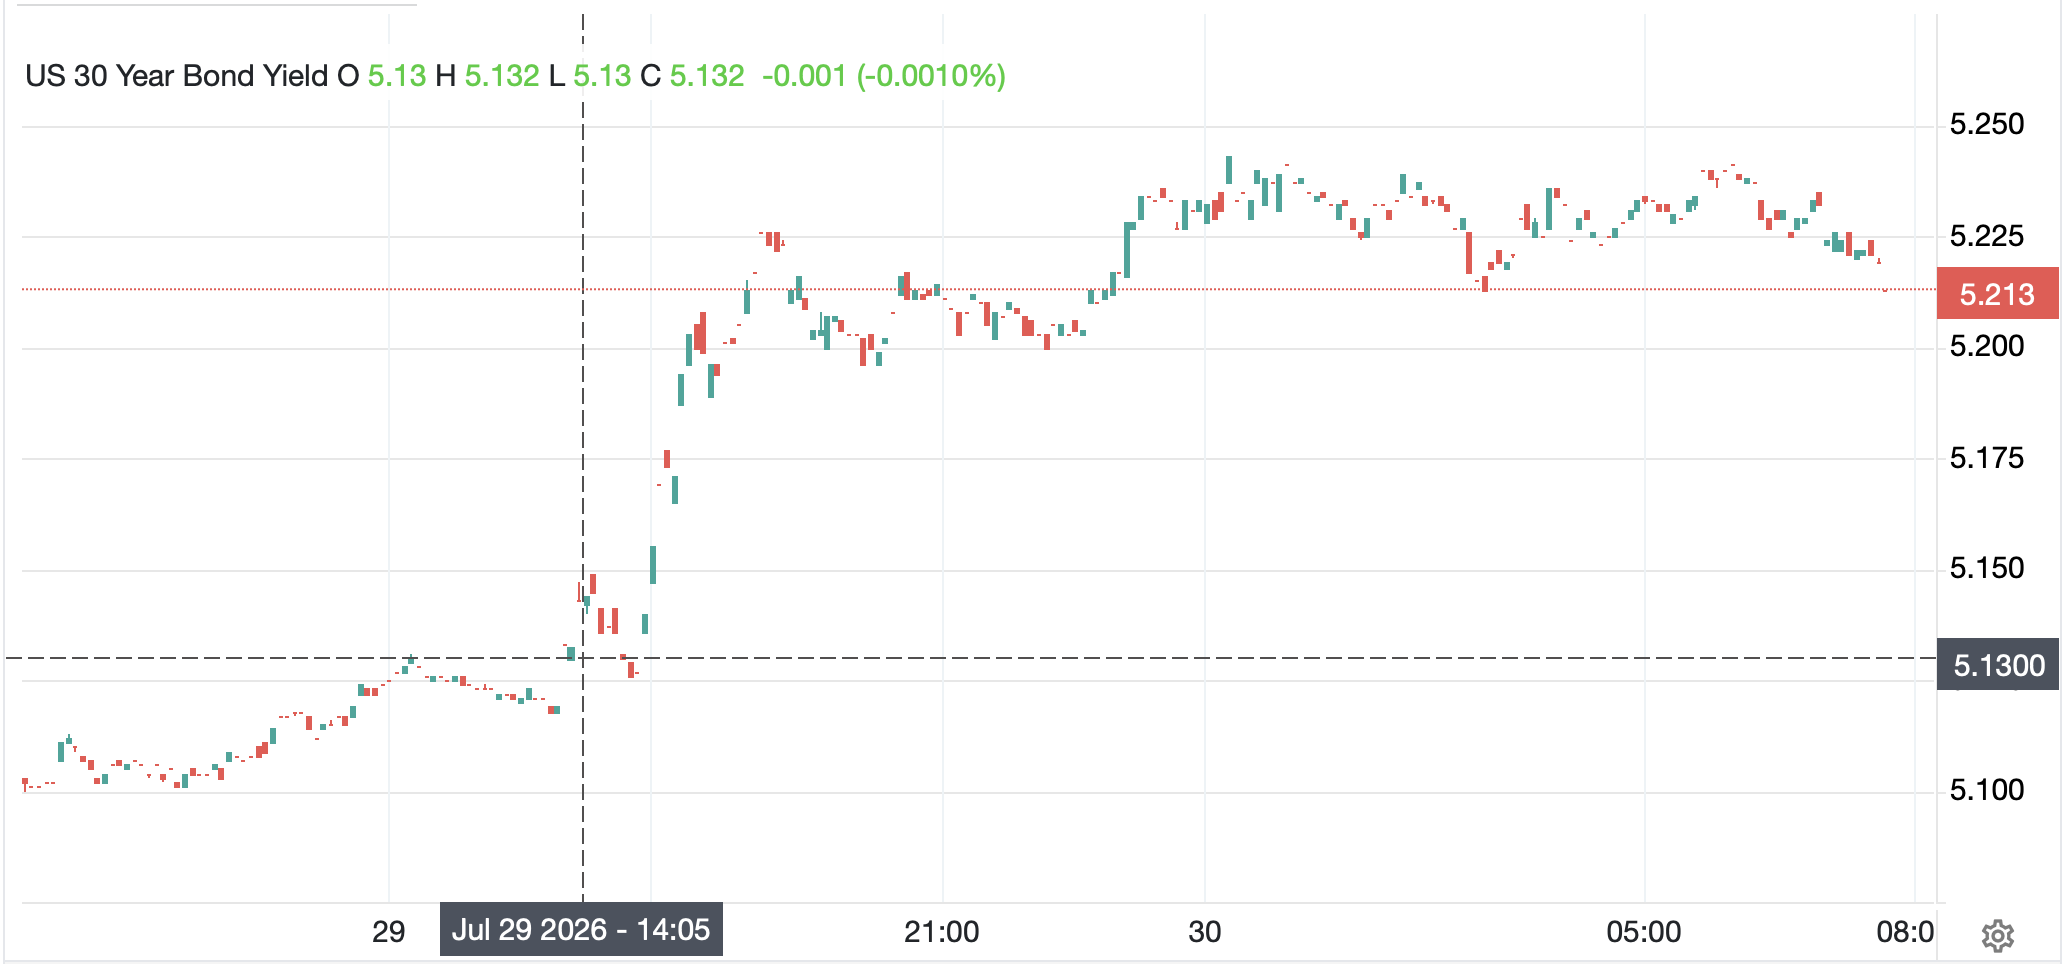
As to the bond market, after the FOMC, the yield curve steepened significantly with 10-year yields climbing 9bps and 30-year yields rising 11bps at their peak.  the chart below of the 30-year shows it well.  In addition, we continue to hear that the 30-year yield is now its highest since 2008.  Again, I would ask all those complaining, you hated what the Fed did before, what did you expect would happen if it changed?

Source: tradingeconomics.com

European sovereign yields also rose yesterday, albeit not as far, more in the 5bp range, and JGB yields rose 6bps overnight.  The BOE left rates on hold, as expected today with 3 votes to raise rates and 6 to stand pat.  Overnight, JGB yields rose 6bps and other Asian yields rose further.  As usual, the Treasury curve is the leader here.

However, it is interesting to note that 2yr Treasury notes actually fell -5bps yesterday as the market continues to adjust its views of what is going to happen going forward.  Chairman Warsh was explicit in saying that he welcomed market movement doing the Fed’s work for them, and if inflation remains a concern, and it does, yields should rise.  In fact, if the Fed starts to shrink its balance sheet (and remember it is still buying T-bills), I expect the curve to steepen and the front-end rates to decline.

In the commodity market, remarkably despite further US attacks on IRGC military sites, oil (-1.3%) is slipping this morning.  This is another market where things are not necessarily following the previous narrative.  As to metals, they are firmer this morning with gold (+0.3%), silver (+0.9%) and copper (+2.2%) all starting the day in good shape.

Finally, the dollar is softer this morning as the DXY (-0.2%) slips back toward its breakout level of 100.50 once again.

Source: tradingeconomics.com

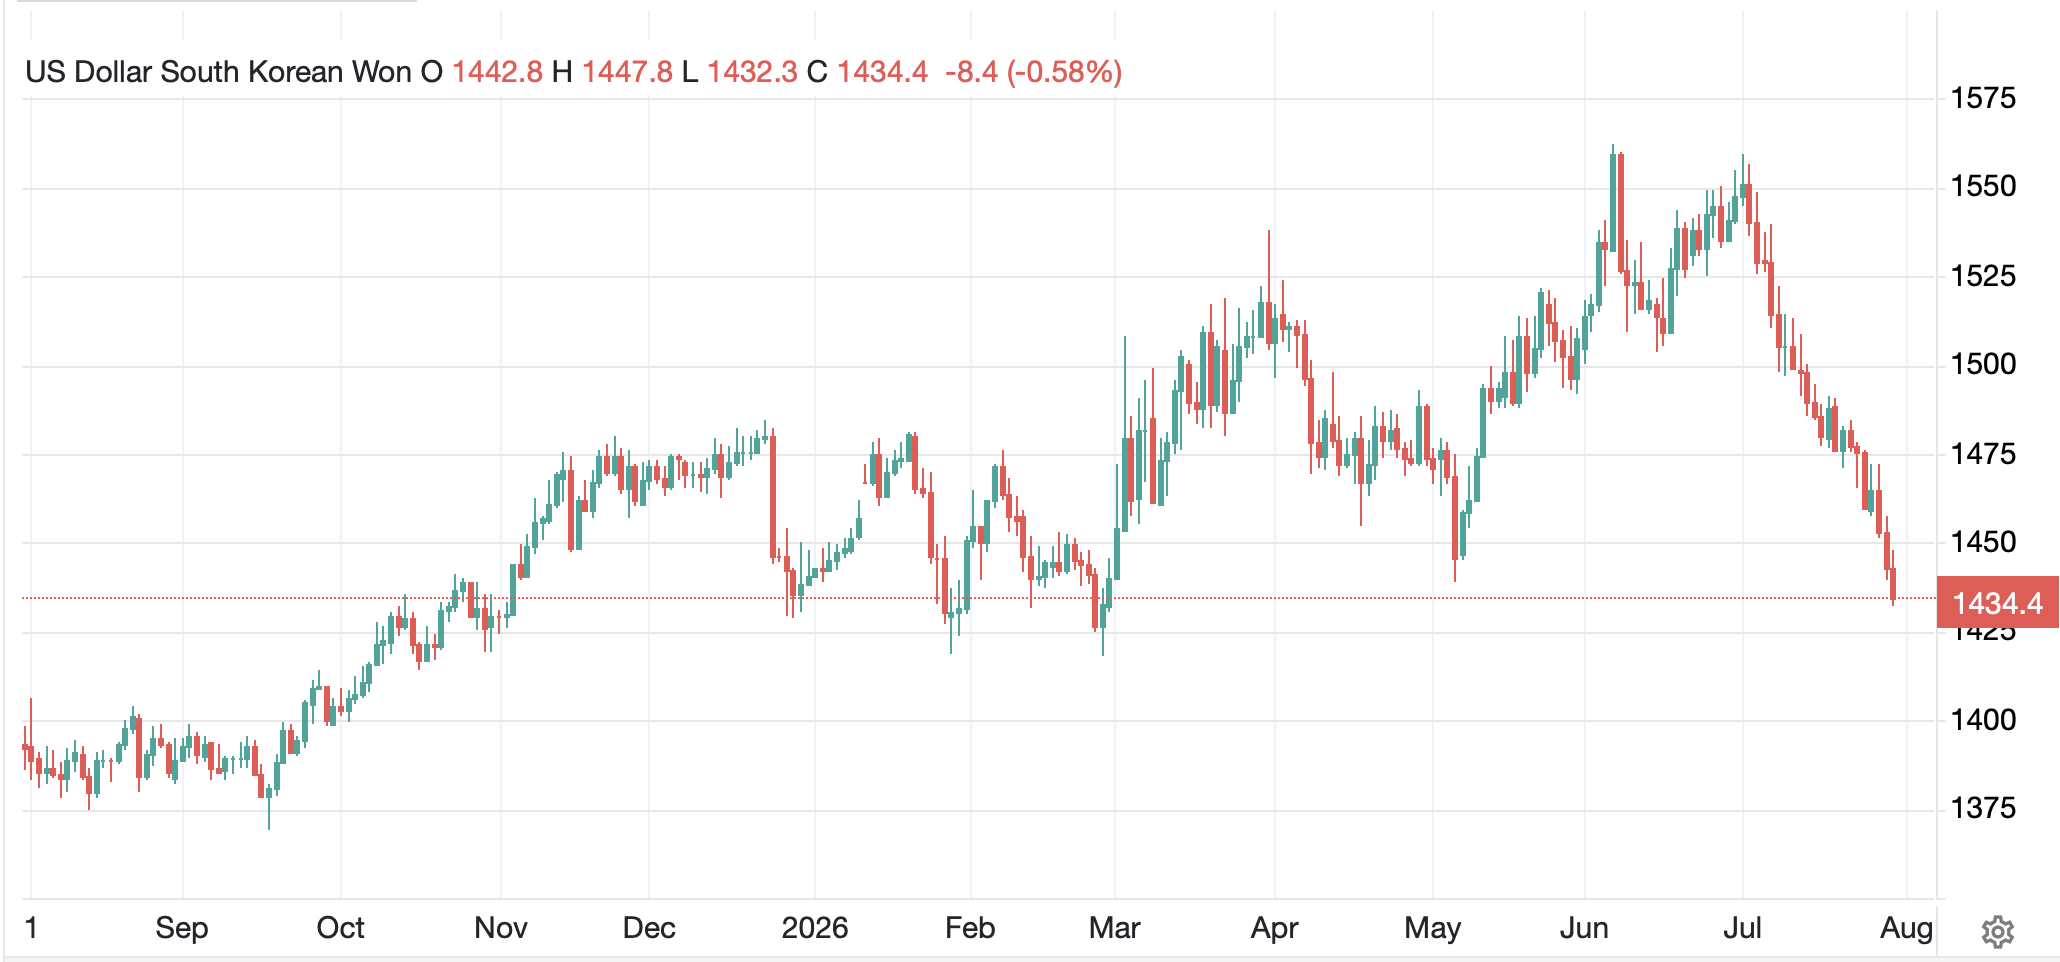
Somebody on Twitter made the point that if the dollar can’t rally amid rising yields, that is a problem.  But my observation, and I believe the numbers back me up, is that the dollar tends to follow short-term yields, like the 2-year, rather than the 30-year bond.  The yen (+0.3%) is having a good day and has backed below 163.00 for the moment taking some pressure off the MOF and the intervention watch.  KRW (+0.6%) continues its remarkable rally which appears to be built on a combination of repatriation of earnings by SK Hynix and Samsung as well as the proceeds from the SK Hynix US IPO, and the strong economic activity plus the BOK’s efforts to internationalize the won.

Source: tradingeconomics.com

But overall, the dollar is under pressure this morning.  and remember, this is not something that the Trump administration worries about, rather they embrace it for its trade benefits.

On the data front, we get a bunch of stuff today as follows:

Initial Claims200K
Continuing Claims1800K
PCE-0.1% (3.7% Y/Y)
Core PCE0.2% (3.3% y/Y)
Q2 GDP (second look)2.1%
Personal Income0.3%
Personal Spending0.3%

Source: tradingeconomics.com

It’s funny, now that Chairman Warsh seems to be de-emphasizing PCE, will it be as important going forward?  Probably still today where a hot number raises the probability of a September hike which currently sits at 63.4%.

Mercifully, there are no Fed speakers today or tomorrow so perhaps we can let the data guide the markets.  Overall, oil still matters a lot, headlines still matter a lot, while the dollar could well slip back into its previous trading range, especially on a soft PCE reading.

Good luck

Adf
Much Hotter

This weekend both wars got much hotter
Iran attacked ships on the water
Ukraine sent its drones
Across three time zones
And struck inside Vlad’s magna mater

Thus, oil has risen a bit
While gold and stocks both trade like sh*t
And soon, CPI
Will prove or deny
That views at the Fed are now split

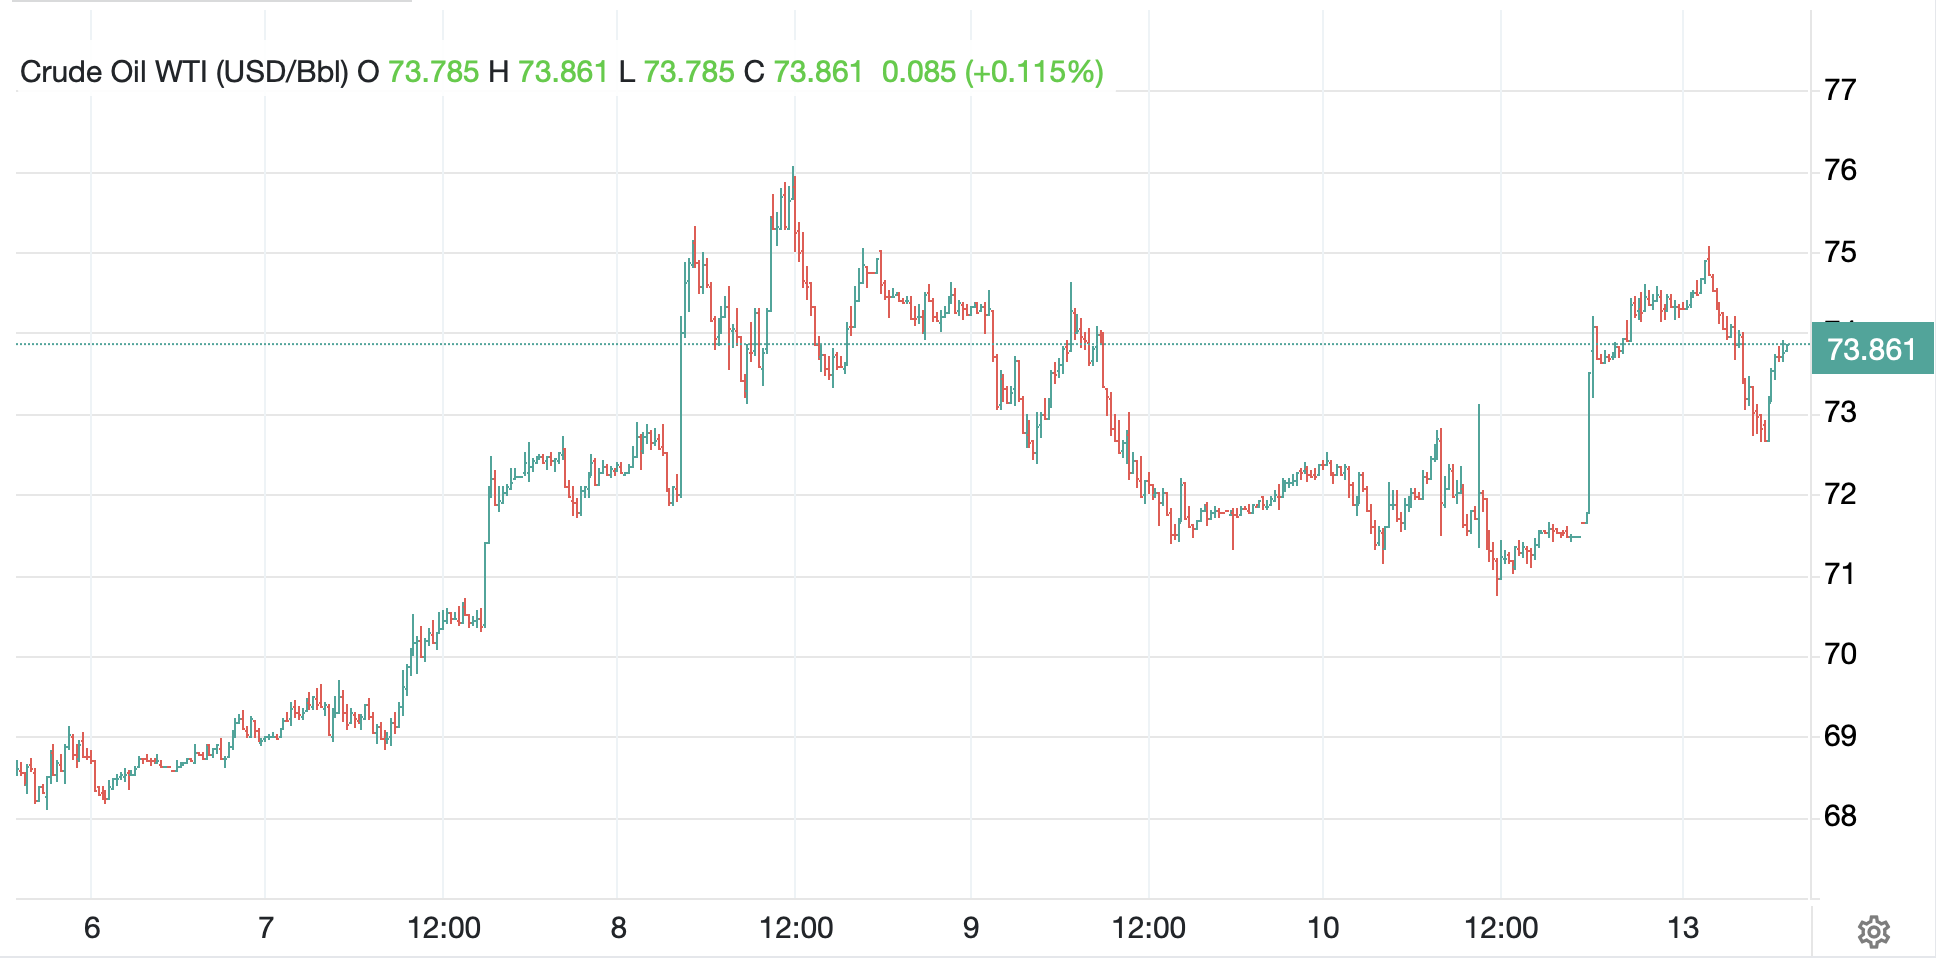
By now, of course, you know that there has been more military activity in the Strait of Hormuz with the IRGC attacking commercial ships and the US retaliating with significant strikes of military sites along the Strait.  From what I can see, there are factions within the IRGC that do not want to end the conflict and whatever government exists within Iran has no control over them.  As such, it is no surprise that the price of oil (+3.5%) has risen, but even in this scenario, it is well off its overnight highs.

Source: tradingeconomics.com

At this point, I believe the trading community will need far greater proof that there is a shortage of oil before responding with significantly higher prices.  Of course, one way that could come about is if Ukraine continues its success with attacks on Russian oil infrastructure as there has been an uptick in that activity with several refineries having been hit in the past several days and Russia imposing an export ban on diesel.  Net, things in the oil space remain precarious, but for all the analysts who continue to promulgate the idea that the end is nigh, markets continue to disagree.  As always, I vote with markets here.

And, not surprisingly, other markets have responded in a similar fashion to their recent trends with higher oil prices leading to pressure on both stocks and bonds, as well as precious metals while the dollar finds some support.  The thing is, my take is the strength of these correlations has been waning somewhat.  Frankly, and remarkably, it appears as though an increase in military activity in the Strait of Hormuz has become somewhat normalized to traders and they are looking for other, fresher signals as to their next move.

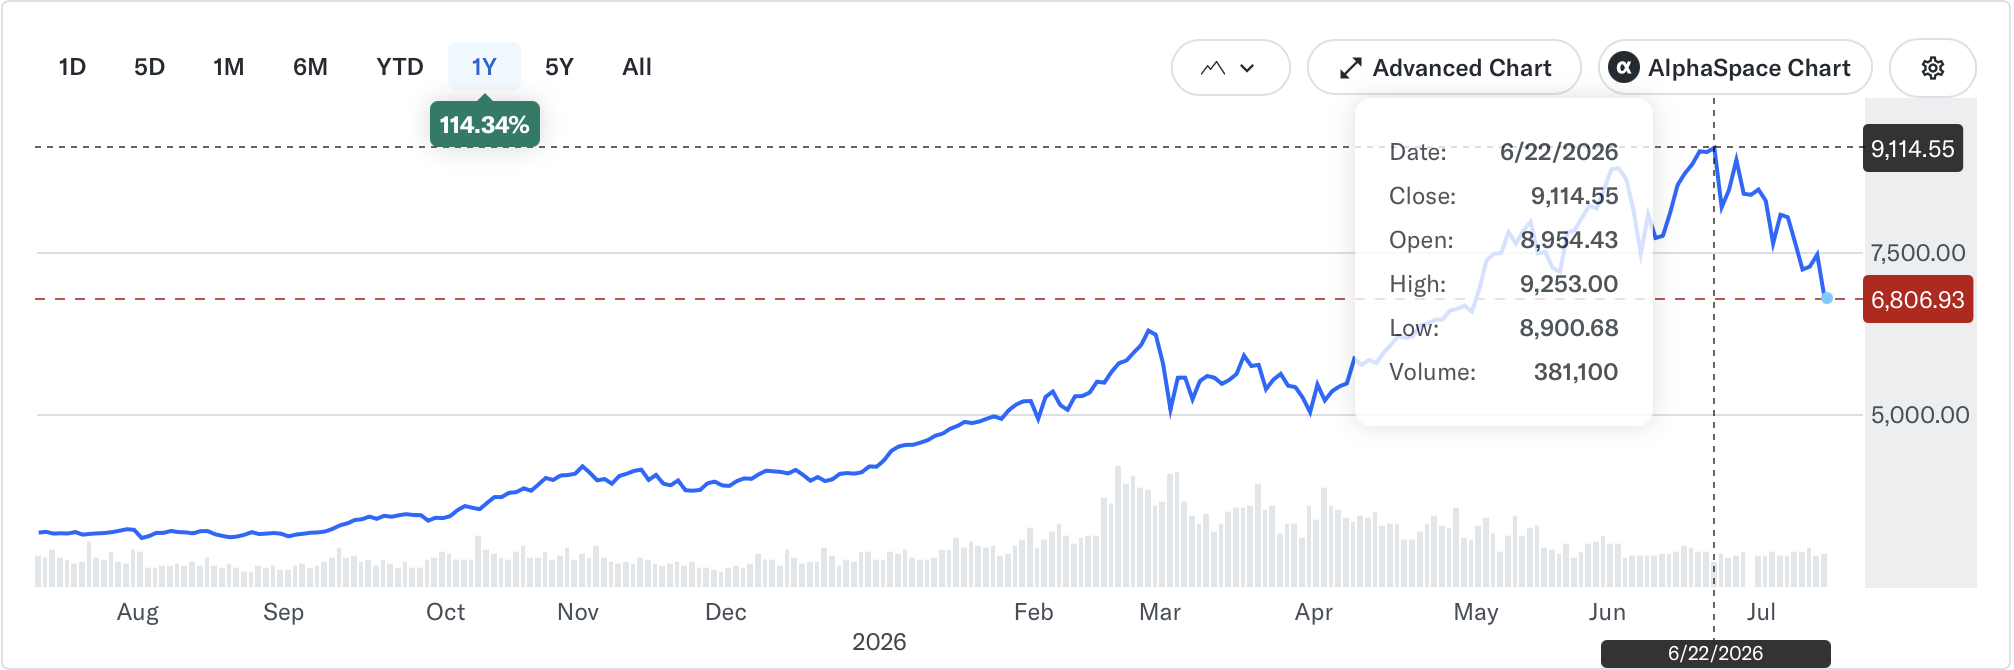
What might those other signals be?  Well, much was made of SK Hynix’s IPO in the US on Friday, which many pundits are now calling the top as the stock fell sharply in Korea overnight, down -15.4% dragging the KOSPI down -9.0% and tech stocks, in general much lower.  Of course, the KOSPI had risen dramatically over the past year, as you can see below, and is still higher by more than 100%  in the past year despite the recent decline of more than 25% since its peak on June 22.

Source: finance.yahoo.com

The problem with calling the top in stocks is that the earnings data, which starts in earnest this week, has been pretty good so far.  If companies continue to earn real profits, investors will continue to purchase stocks.

So, where else can we turn for new information?  Tomorrow brings the latest CPI report (exp 3.8% headline, 2.9% core), and you know that will be heavily scrutinized as the punditry tries to determine the FOMC’s reaction function and if it has changed with the new Chairman.  At this point, I do believe the Fed’s reaction function has changed, and more importantly, I don’t think anybody knows what it will be like, the Fed included.  The previous Fed whisperer, Nick Timiraos at the WSJ put out an article overnight discussing the idea that Chairman Warsh needs to decide whether to undo the most recent rate cuts.  However, there is no evidence that Warsh speaks to Timiraos and based on everything Warsh has said, he is not likely to tip his hand.  Chairman Warsh does testify to Congress this week, but I expect he will deflect all questions about the future path of monetary policy, and let’s face it, with the likes of Maxine Waters on the House committee, they won’t understand anything he says anyway.

And really, those are the only things that I think matter for now, so let’s review the overnight activity in markets.  As mentioned above, stocks are generally under pressure, but not universally so.  For instance, in Asia, Tokyo (-1.9%), China (-1.8%) and the aforementioned South Korea all had rough sessions, but HK, Taiwan, India and Australia were all basically flat on the day.  The big surprise is Taiwan as given the semiconductor weakness; I would have thought that market would have been significantly impacted.  But I guess not.  Meanwhile, European investors appear to be completely focused on tomorrow’s France-Spain World Cup semifinal as equity indices there are virtually unchanged this morning.  As to US futures, at this hour (7:30) NASDAQ futures are weaker by -1.2%, but the other markets are little changed.

Bond yields are higher this morning, but not hugely so.  Treasury yields have edged up by 1bp, and European sovereign yields are higher by 2bps across the board with UK Gilts (+4bps) the real laggard there.  Overnight, JGB yields backed up 4bps as well, but that story has more to do with the GPIF than anything else.

Remember Friday?
Japan was bringing home yen
They were just kidding

Think back to Friday.  Japanese FinMin Katayama mentioned that the GPIF and other Japanese pension funds ought to consider investing more money in Japan and less abroad.  That got tongues wagging about a major policy change coming that would serve to support the yen, and the JGB market while undermining Treasuries as the idea was the GPIF would sell their US Treasuries and buy JGBs instead.  Well, it turns out that is not actually the case.  The GPIF reevaluates its policy annually but has expressed no urgency to change things now despite the FinMin’s comments, at least according to Reuters.  The upshot is that JGBs sold off as did the yen (-0.3%) as per the below chart.

Source: tradingeconomics.com

Perhaps more surprisingly, though, the dollar is mixed on the day, not higher across the board as might have been expected given the uptick in oil and military activity.  So, we have seen weakness in GBP (-0.1%), AUD (-0.2%) and INR (-0.5%) while EUR (+0.1%), NZD (+0.2%), NOK (+0.3%) and KRW (+0.4%) have all had decent sessions.  Net, the DXY is essentially unchanged this morning.

Finally, and quickly, both gold (-1.5%) and silver (-2.0%) are under pressure with the higher oil price although copper (+0.6%) continues to find support and remains well above $6.00/lb.

In addition to the CPI data, it is a pretty busy week as follows:

TuesdayNFIB Small Biz Optimism95.6
 CPI-0.1% (3.8% y/Y)
 -ex food & energy0.2% (2.9% Y/Y)
 Warsh Testimony 
WednesdayPPI-0.1% (6.2% Y/Y)
 -ex food & energy0.3% (5.2% Y/Y)
 Empire State Mfg8.9
 Warsh Testimony 
 Fed’s Beige Book 
ThursdayInitial Claims218K
 Continuing Claims1811K
 Retail Sales0.2%
 -ex Autos-0.1%
 Philly Fed13.5
FridayHousing Starts1.30M
 Building Permits1.40M
 IP0.2%
 Capacity Utilization76.2%
 Michigan Sentiment51.5

Source: tradingeconomics.com

We also hear from 9 other Fed speakers (it almost seems like they didn’t get the memo about reducing communication) but with Warsh on the stand both Tuesday and Wednesday, I don’t think the others will matter that much.  Of course, it will be interesting to hear the other speeches if CPI comes in softer than expected as it may put a crimp in the hawks’ views.

In the end, not that much has really changed I would argue.  The war is an exogenous variable, and the market has learned to largely ignore it.  The Fed is still too uncertain in its new construction for many views to have changed, but I think the one thing we can conclude is that the old models of their reaction function are no longer viable.  My take is the beauty of the task forces for Chairman Warsh is they won’t report for at least 3 months, and probably more like 6 months, so until they report, absent a massive spike in measured inflation, the Fed is not going to do anything.  The Fed funds futures market is now pricing a one-third probability of a hike at the end of this month and certainty of one and 50% probability of two by the end of the year.  I would fade those trades.

Good luck

Adf
Young Turks? Or Warhorses?

Stories about yen
Have multiplied like rabbits
Is it really news?

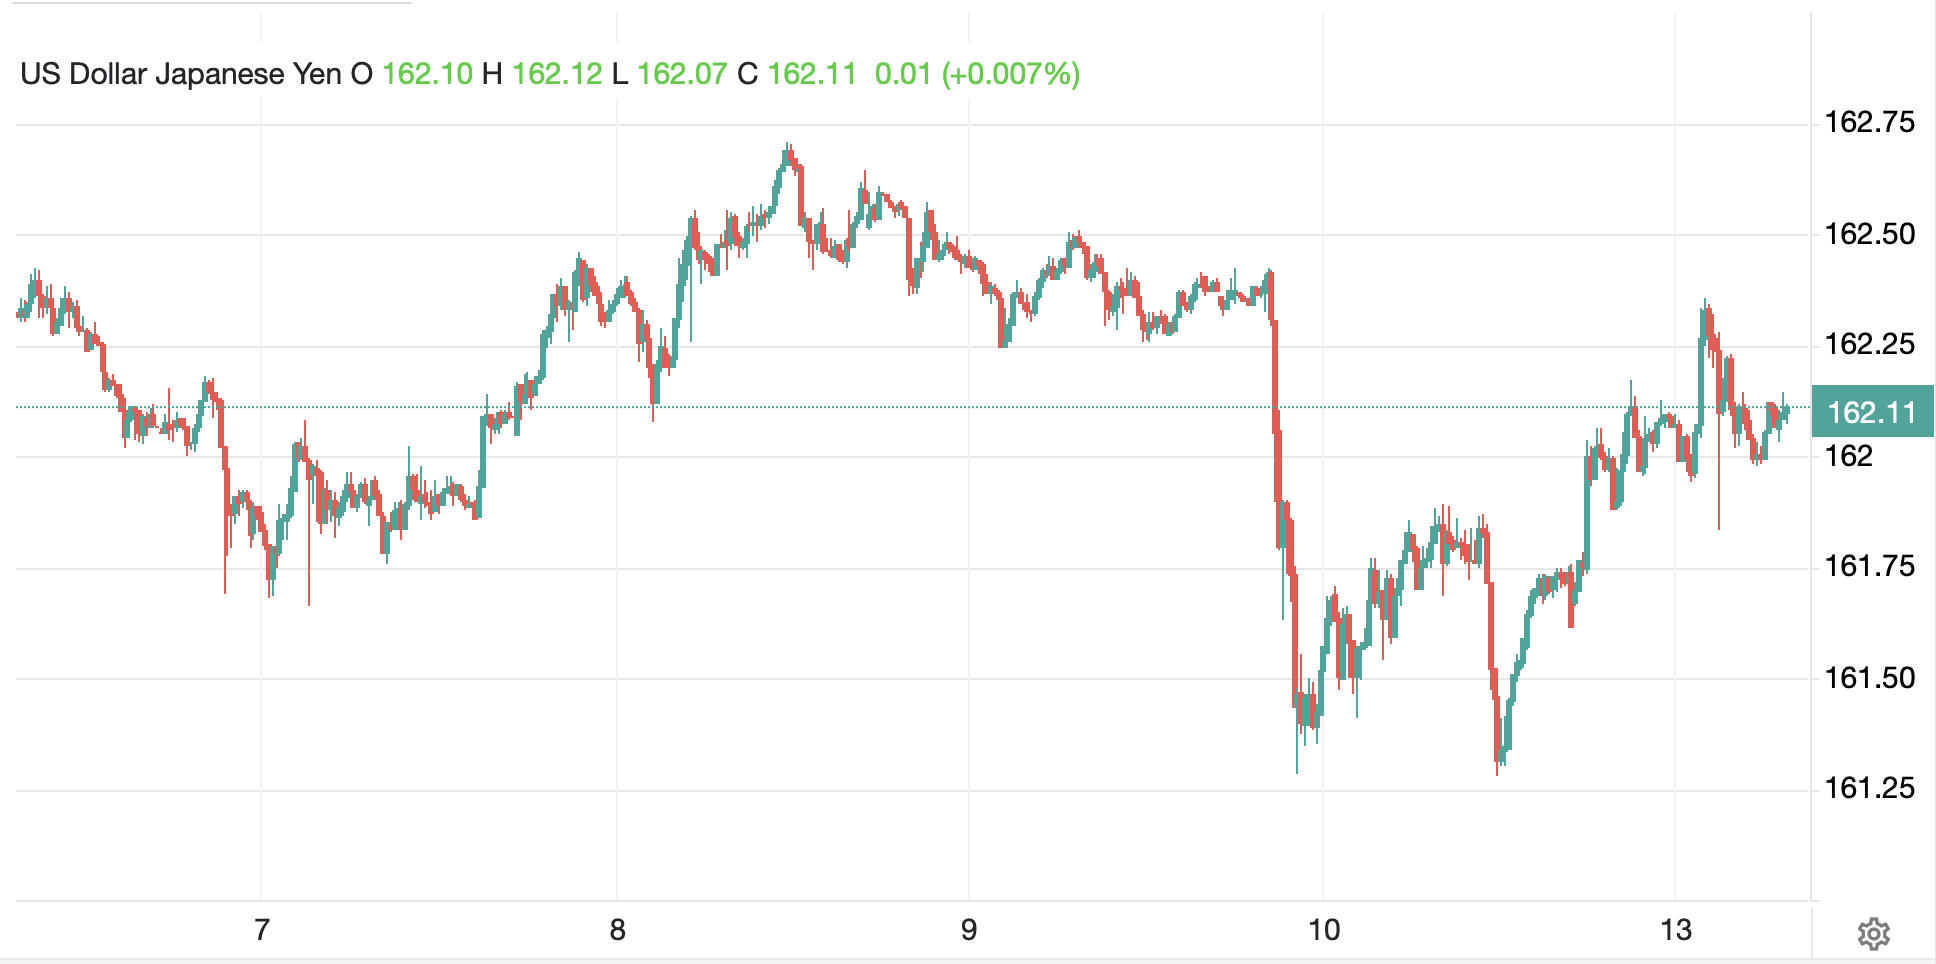
You know it has been a slow session when the yen’s movement, as seen in the chart below, was enough to draw 4 headline stories in Bloomberg.

Source: tradingeconomics.com

And here is a screenshot of the 4 headlines on Bloomberg.com

While it may look dramatic on the screen, that almost one yen move represents less than 0.6%, and as you can see, about half of it has already retraced.  The underlying premise is that FinMin Katayama, in a regular speech about general things, suggested that the GPIF (Japan’s national pension fund) ought to consider investing more assets in Japan and JGBs rather than internationally.  The idea is that if the GPIF changes its investment mix, so will many other Japanese institutional funds, and they do have a lot of money there, upwards of $2 trillion equivalent.  This is not to say that they are going to invest all their money back home, just that the mix could change somewhat.

Now, if they were to do this, it would certainly have an impact on both the FX and global bond markets, with the yen likely to strengthen along with JGB prices (hence JGB yields declining) and potentially Treasury yields rising as a key buyer of US debt would reduce its appetite.  

But this is just a suggestion, and one that has been made numerous times in the past with no further action.  At the same time, yesterday’s US 30-year Treasury auction was extremely well-received with more than 77% indirect bidders.  That statistic is generally seen as foreign investors and central banks.  With the yield coming at 5.058%, it is not surprising that foreign bidders, especially the Japanese, would have significant interest.  After all, their currency continues under pressure, so if the GPIF holds Treasuries, in yen terms they look better almost every day.

The other spate of stories this morning was about the carry trade, and how Goldman Sachs has just explained to its clients that the carry trade, notably shorting yen to hold dollars, amongst other things, is an excellent risk reward trade right now.  I’m guessing Katayama-san didn’t really want to hear that.

My larger point, though, is that despite the yen (+0.4%) having moved a relatively modest amount, it certainly garnered a lot of attention.  In other words, there’s not much else to discuss.

Since Warsh and his minions last met
The question was who they would vet
To lead the task forces
Young Turks? Or warhorses?
Alas, tis the latter quintet

The other moment of excitement yesterday came from the Fed when they released the names of the leaders of each of Chairman Warsh’s five task forces.  The list is linked here.  It certainly did engender a lot of discussion with different analysts taking different views, and while I have some opinions, mine are no more useful than anybody else’s as they are not going to change things.  My observation, though, is that there is an awful lot of old school thinking represented by the list, which is somewhat disappointing for those of us who were looking for a new direction from the Fed.  As an example, Mervyn King, ex-BOE governor, and active participant in forward guidance, seems unlikely to offer many new views on communications.  But that is what we have.  Hopefully some new thinking will come about.

And that’s all there is regarding news, I think so let’s turn to market activity.  Under the theme, you can’t keep tech stocks down, yesterday’s US equity rally was followed by more strength (Tokyo +1.2%, HK +0.6%, Korea +2.5%, India +1.1% and Australia +0.5%) than weakness (China -2.0%, Taiwan -0.8%) in Asia.  The rest of the smaller regional exchanges were largely higher as well.  Arguably, the fact that whatever is happening in the Strait of Hormuz, oil prices have no strong bid, is part of that investment thesis.  As to Europe, other than Spain (+0.5%), the rest of the continent and the UK are all +/-0.1%.  And US futures at this hour (7:15) are showing softness in the NASDAQ (-0.5%) but otherwise not much movement.

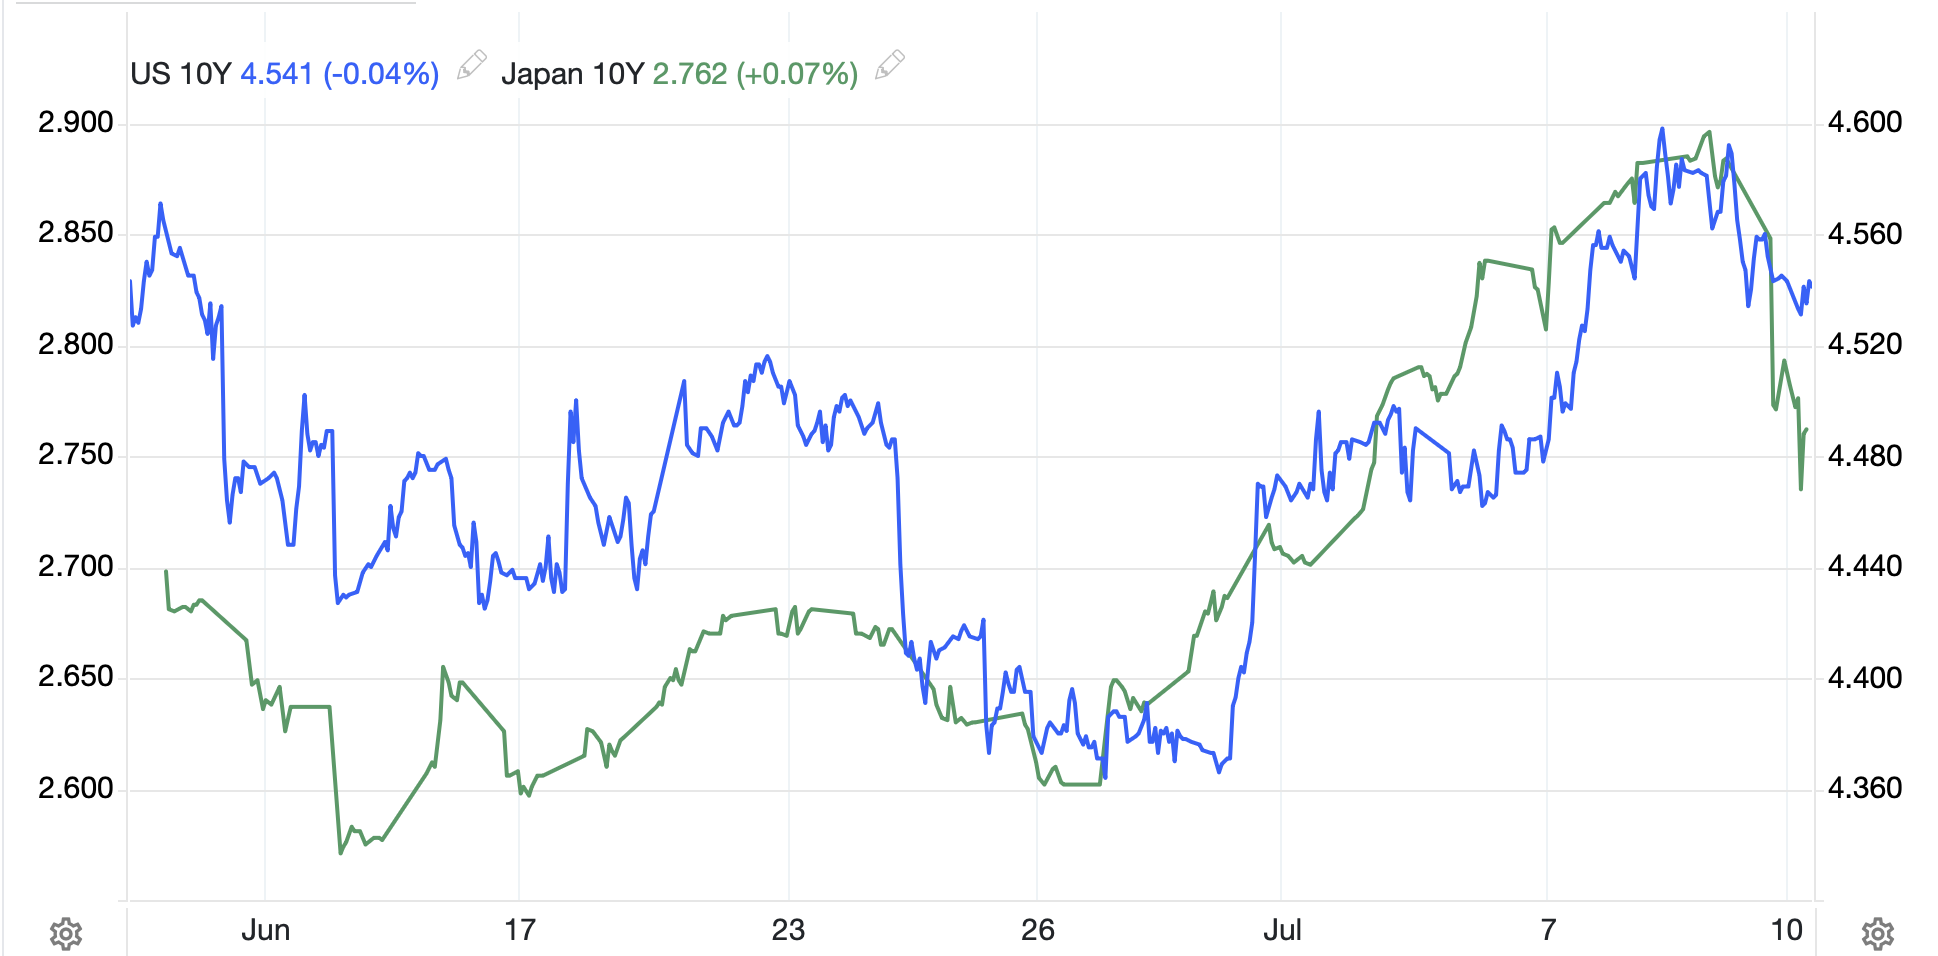
Bond yields, though, are uniformly lower, backing off their recent test of 4.60% in 10-year Treasuries, as now that the auctions have passed, I think a lot of the short positioning into those auctions has been covered.  If oil continues to trade either side of $70/bbl, it is hard to make the case inflation will be running away.  So, Treasuries (-2bps) continue to back off while European sovereign yields have slipped by a similar amount.  The outlier was the JGB market (-13bps) which as you can see in the below chart has really changed vs. its following of Treasury yields, entirely on the GPIF story.

Source: tradingeconomics.com

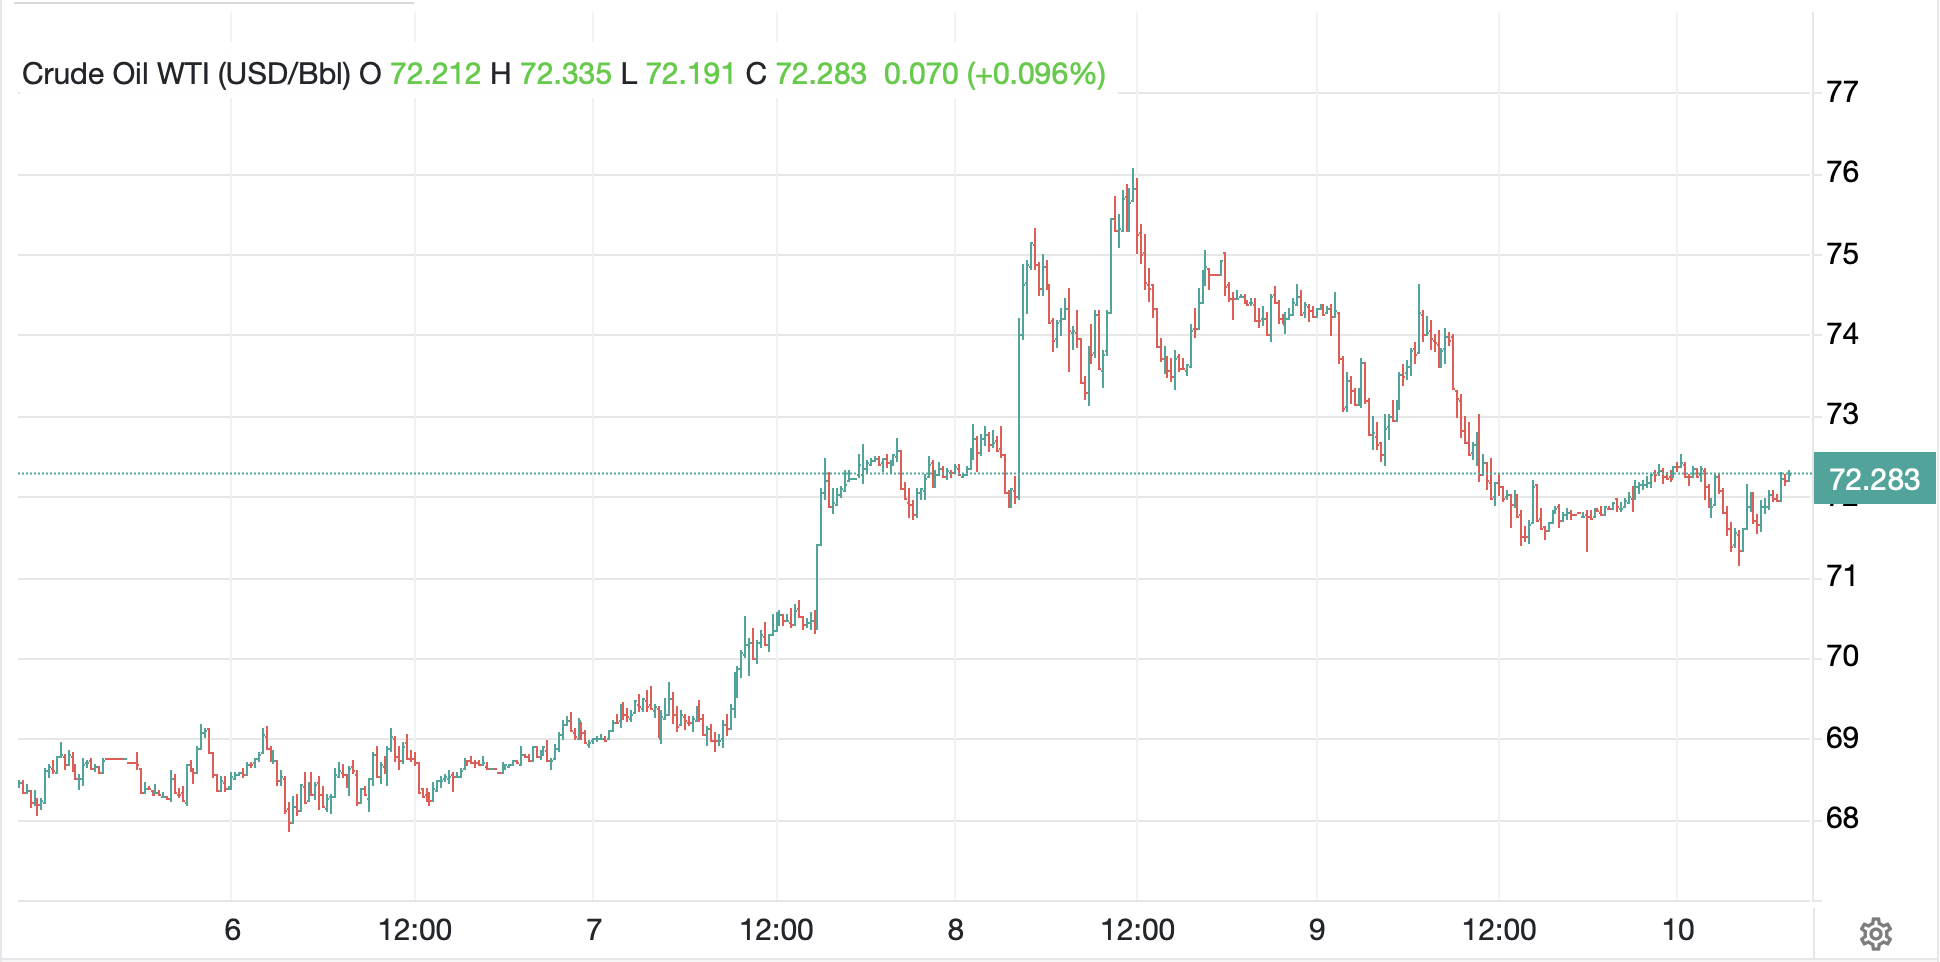
In the commodity space, oil (+0.3%) continues to erase the gains seen Tuesday after the increase in military activity in the Strait.  Even though that seems to be ongoing, the markets just don’t care.

Source: tradingeconomics.com

As to the metals, yesterday’s gains are being moderated with both gold (-0.4%) and silver (-0.7%) slightly softer while copper is unchanged on the day.

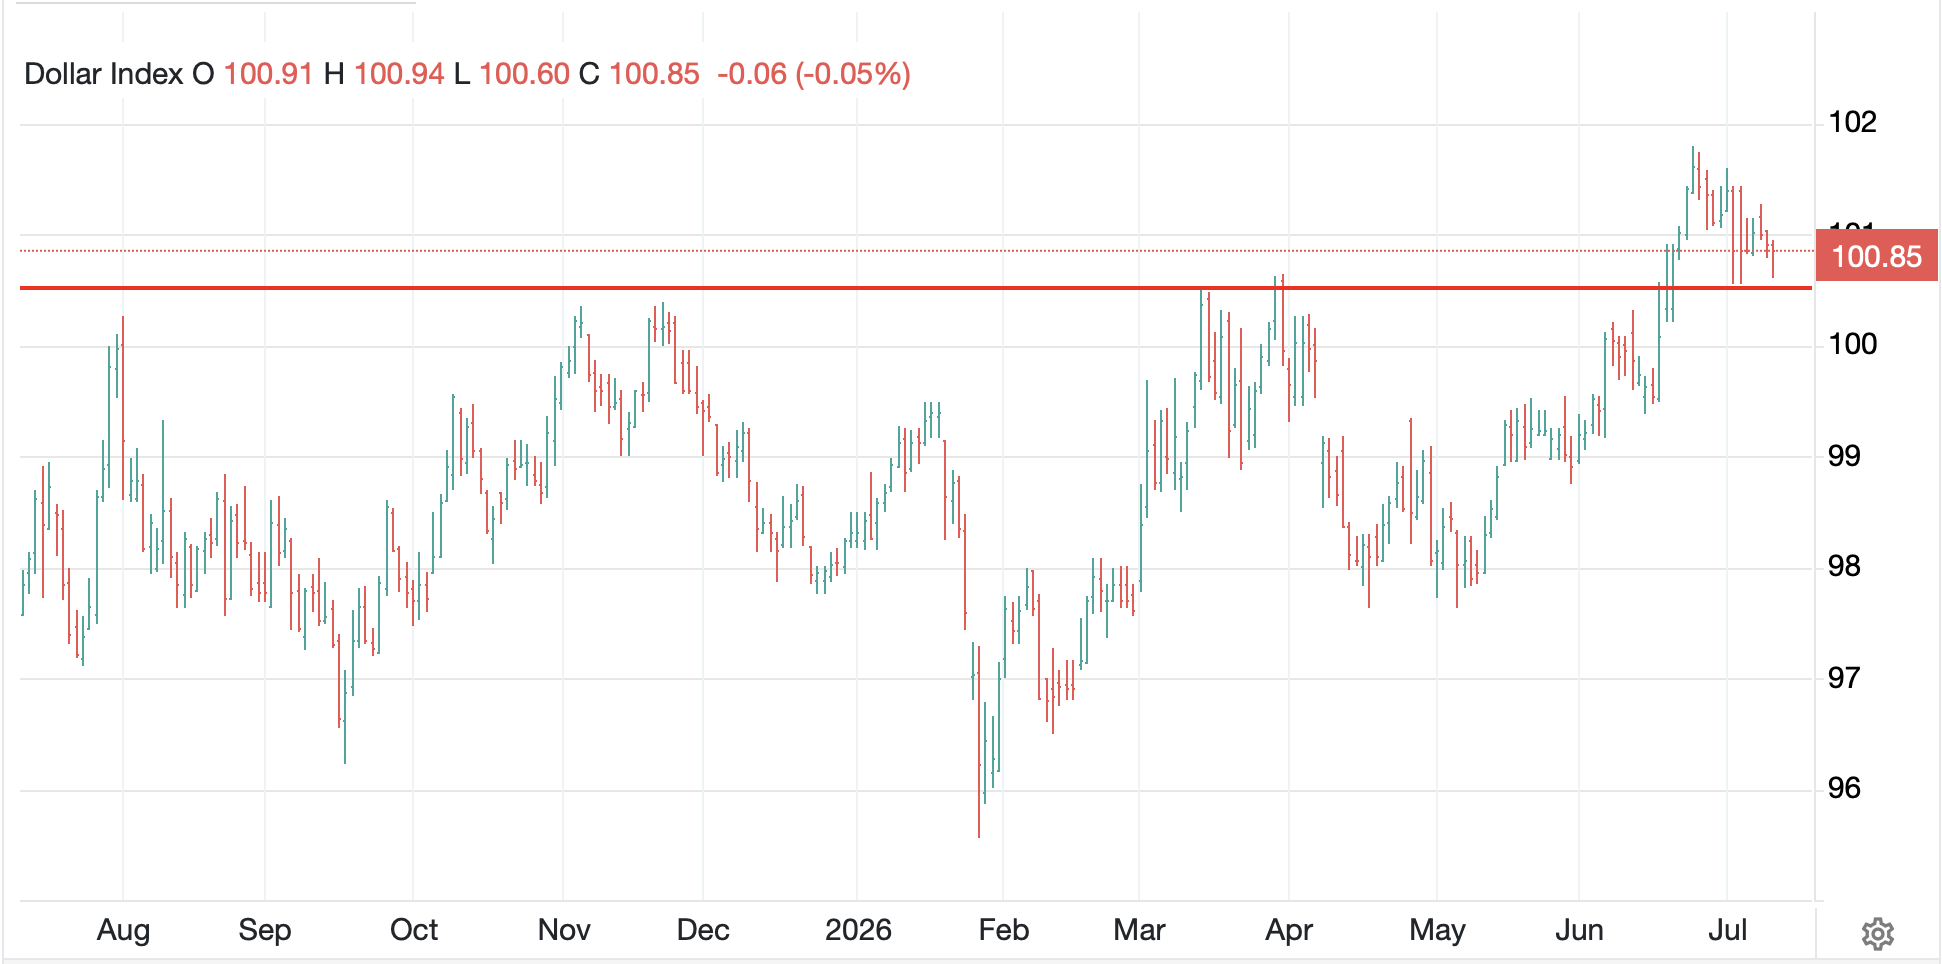
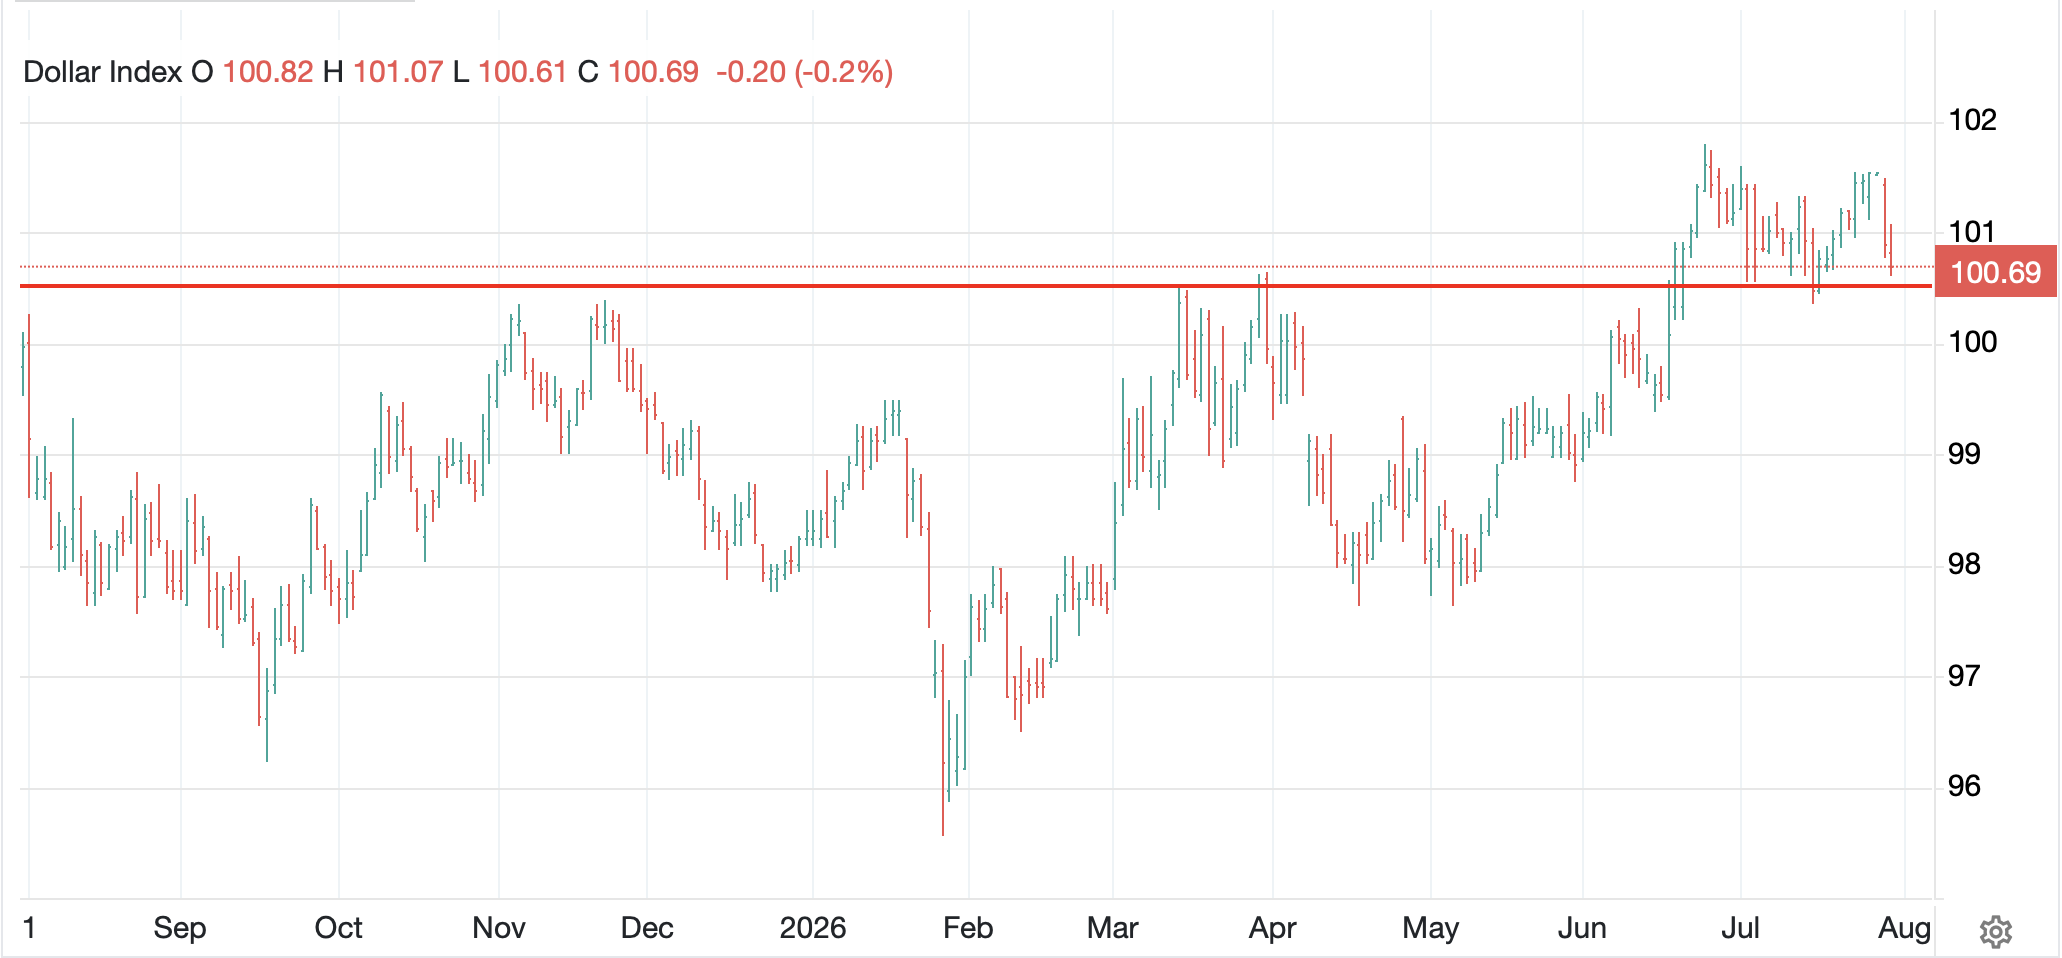
Finally, the FX market, away from the yen, remains generally uninteresting.  Three weeks ago, much was made of the DXY’s break higher from a longer-term range as it traded through 100.50, almost reaching 102.00.  but as you can see in the chart below, for now, that excitement seems to be fading with a nice little downtrend developing since June 24th.

Source: tradingeconomics.com

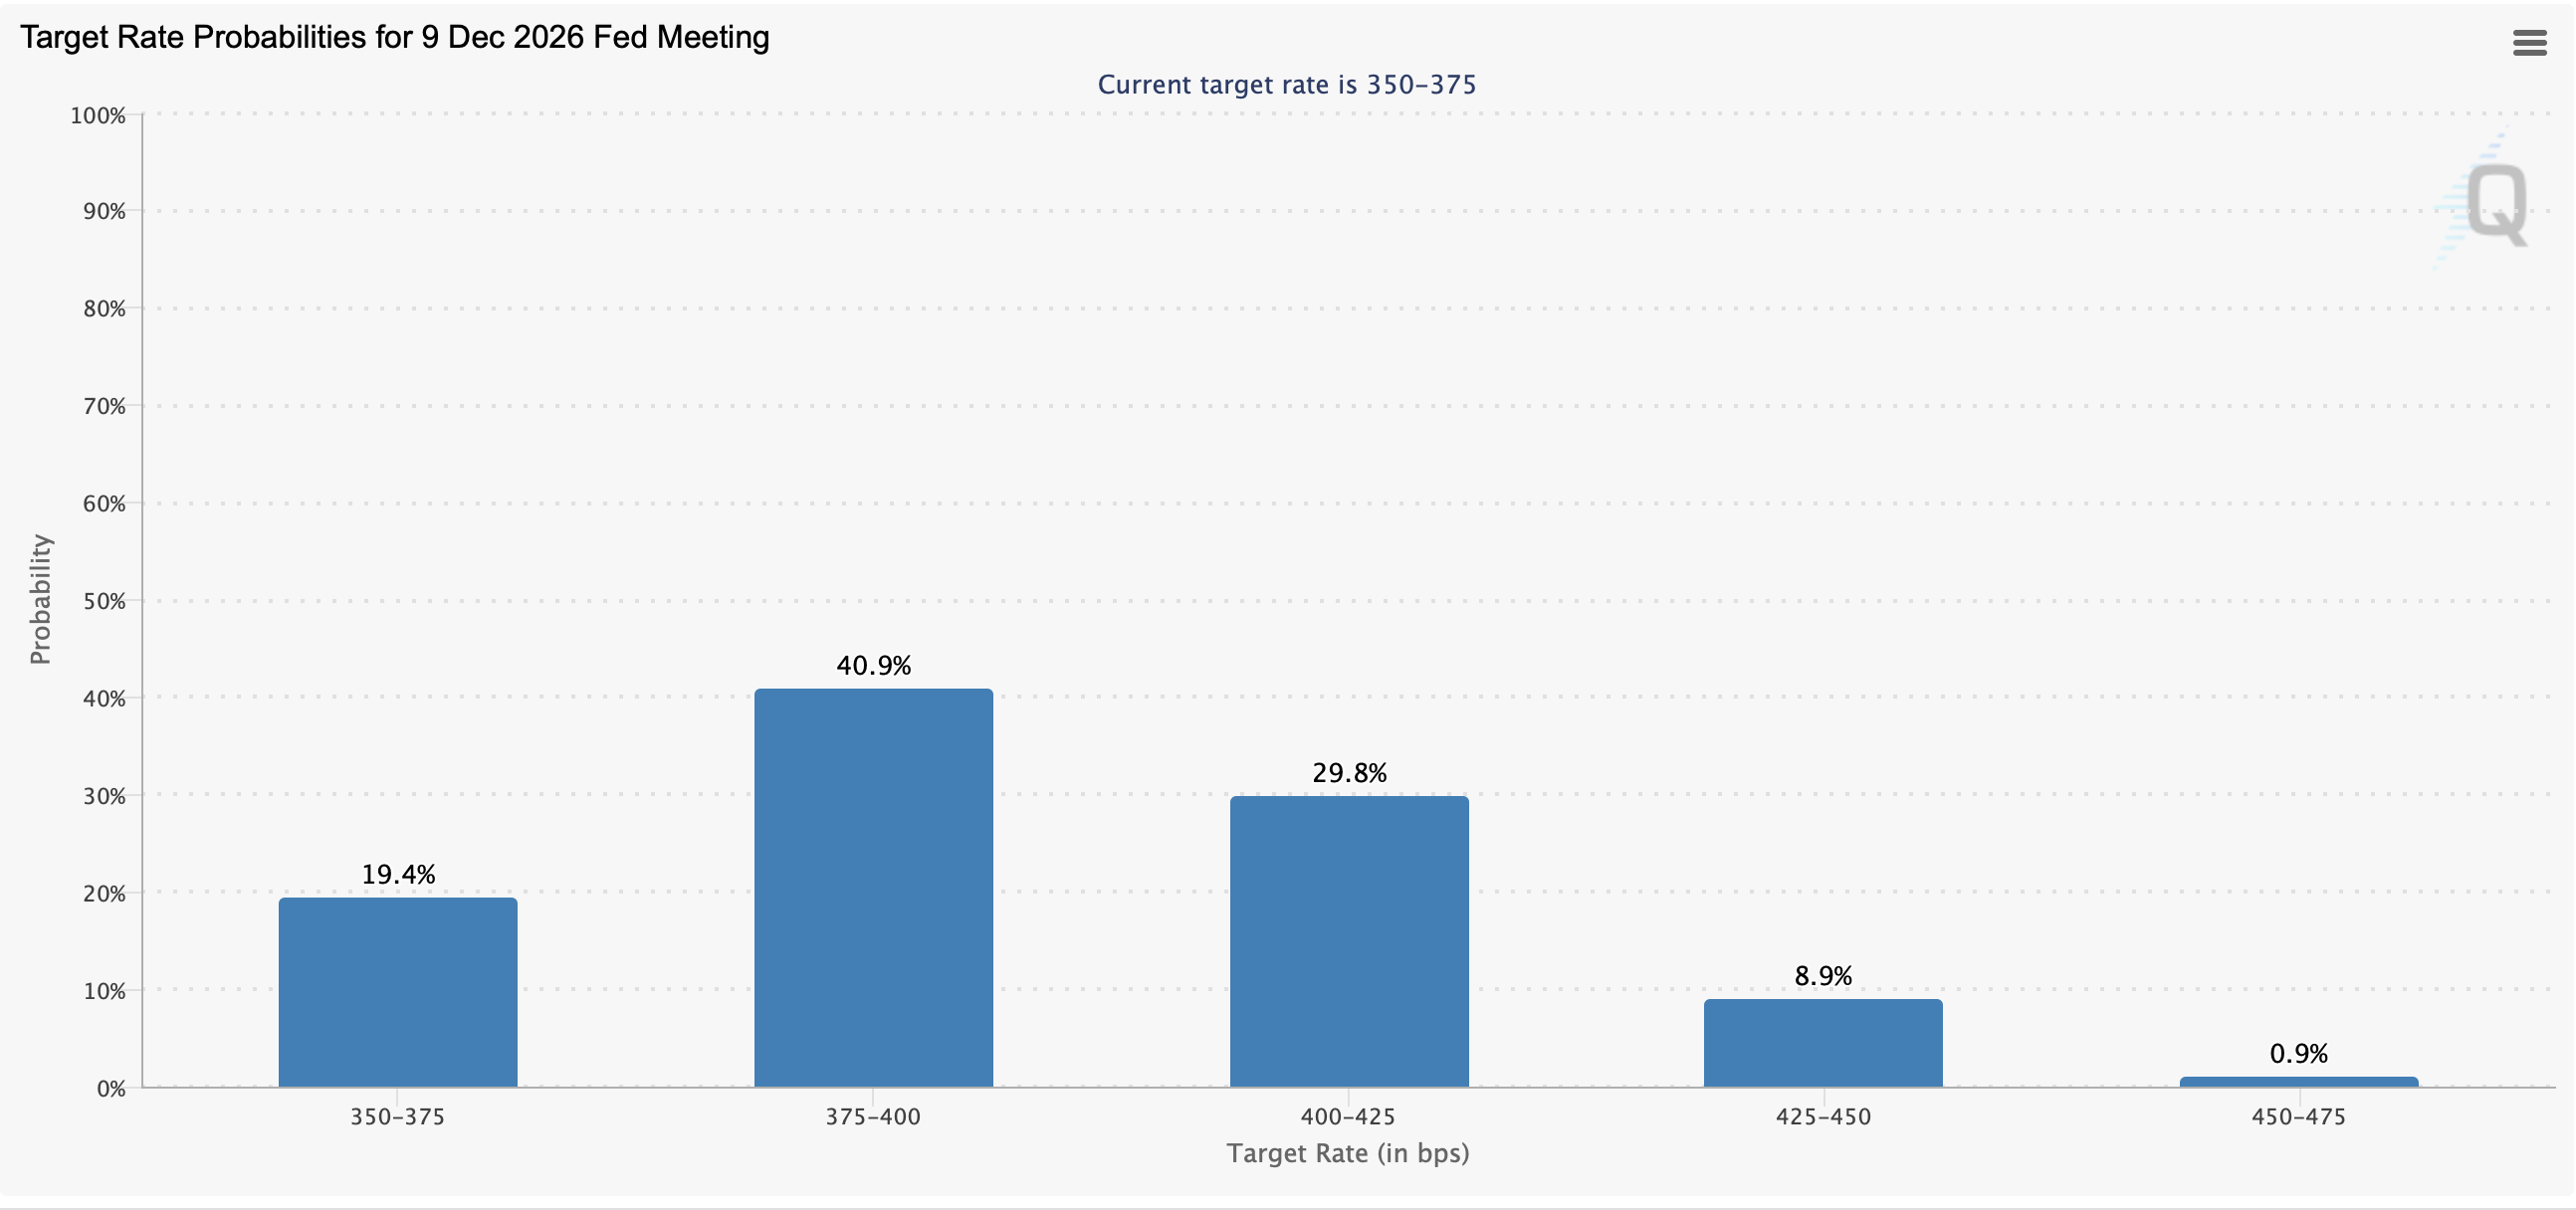
In these dog days of summer, it is hard to get too excited.  Generically, while I remain in the camp that the Fed will not adjust rates this year, and so the market will need to reduce the current 33bps of rate hikes priced into the Fed funds futures curve as you can see below, I also think that ongoing inward investment into the US is going to underpin the dollar over the medium term.

There is no data to be released today, and yesterday’s numbers saw a marginally better Initial Claims number (215K vs 218K expected) and a slightly worse than forecast Existing Home Sales number.  As well, we heard from NY Fed president Williams who said his new main concern is that demand for AI infrastructure is going to drive inflation higher and he is wary of that.  Of course, that is exactly at odds with Chairman Warsh’s view that AI is going to reduce inflationary pressures.  Next week, Chairman Warsh will be testifying to Congress and there are four other Fed speakers, but my take is that over time, we will hear less and less from the rest of the Committee. (Or maybe that is just wishful thinking on my part!)

At any rate, it is shaping up to be a quiet one, so close up early and take a long weekend, you’ve earned it!

Good luck and good weekend

Adf

Rise Like the Sea

So, let’s take a sec to discuss
Inflation, and why it’s a plus
At least for some folks.
In gentle broad strokes,
Though most of us see it and cuss

For those who hate Trump it’s a key
To help destroy his legacy
For Congress, they need
Inflation to plead
That taxes must rise like the sea

And what of the Fed and their role
To keep it in check, on the whole
Now, if they’re successful
T’would truly be stressful
For everyone on their payroll

If you were a government and wanted to design the perfect process by which to extract more money from your citizens allowing you to spend more money on the things you wanted, whatever their views, all while explaining that their lying eyes were deceiving them when they complained, it would be hard to come up with a better process than the official inflation figures.  Of course, today we get more of those figures with PCE and its variants set to be released at 8:30.  While I am here, these are the current market median estimates: PCE (0.5%, 4.1% Y/Y), Core PCE (0.3%, 3.4% Y/Y) although I see no forecast for the Dallas Fed Trimmed Mean reading, the one that Chair Warsh says he wants to focus on.  Too, it is key to remember that they are May numbers.  How many of you can remember what happened in May?

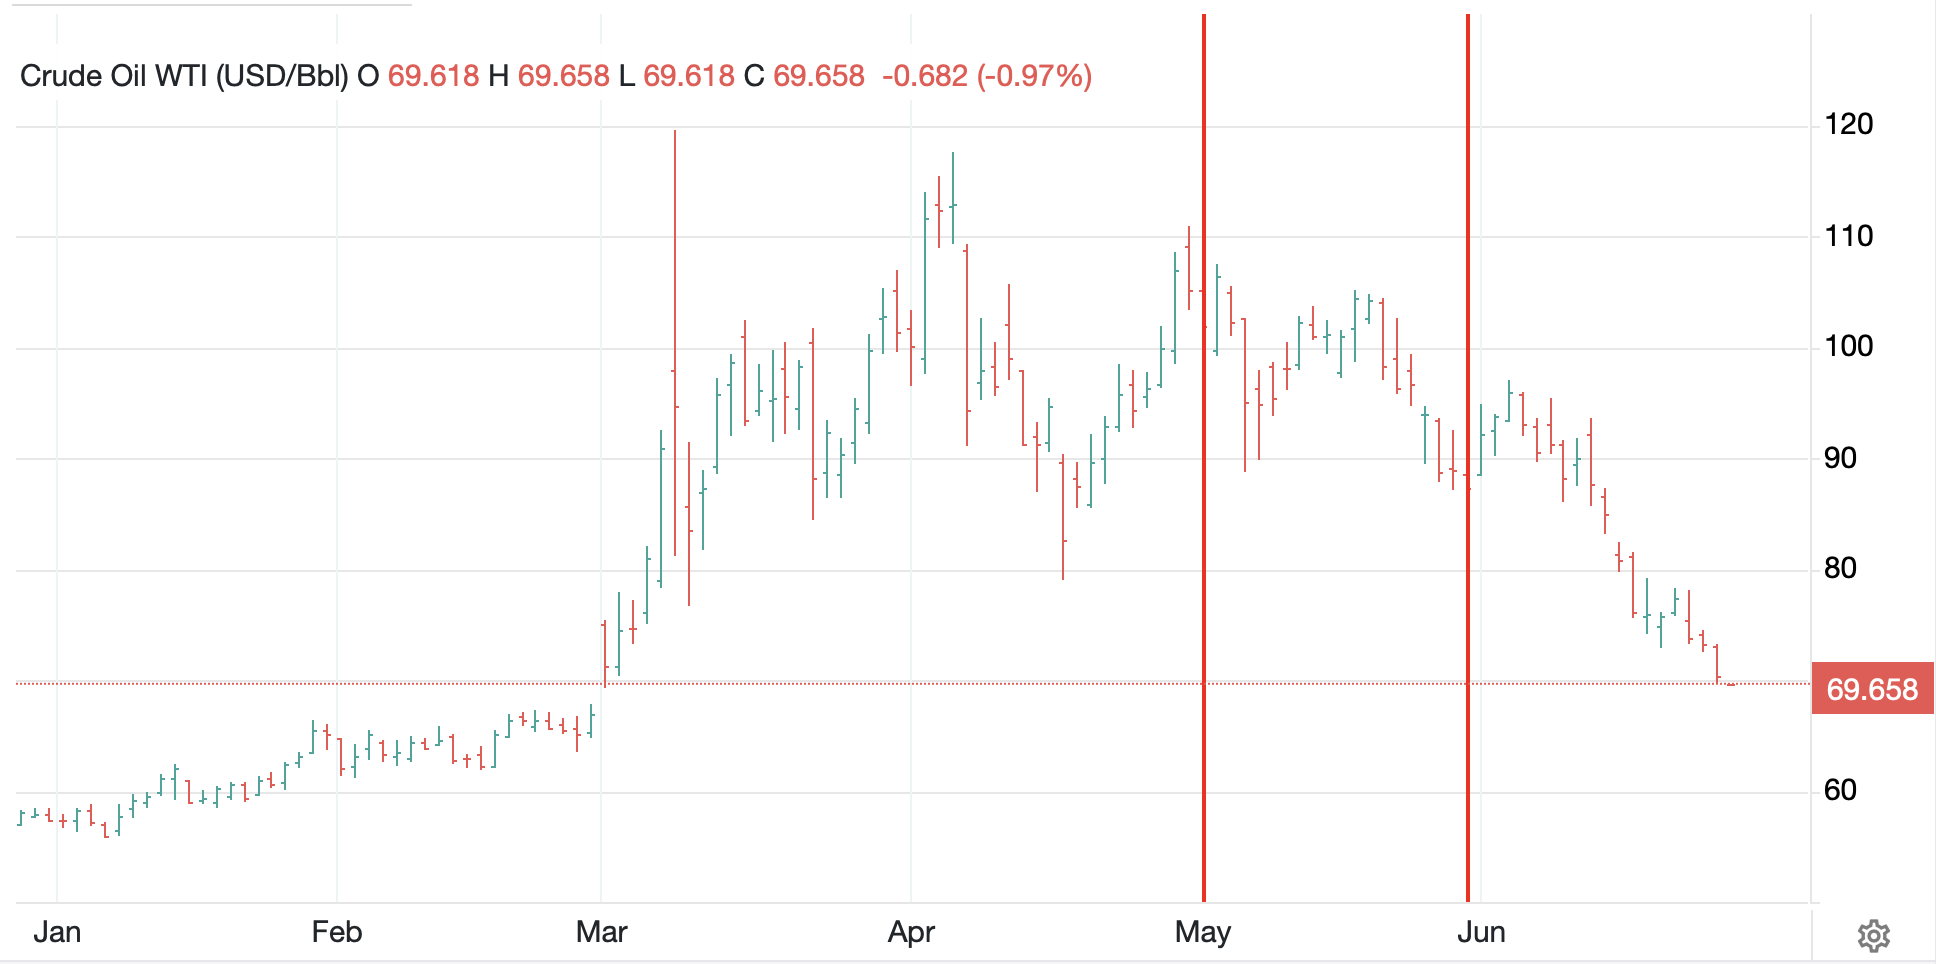
For instance, looking at the easiest one, oil (-1.0% today), as per the below chart, you can see that WTI ranged between 86.50 and 106.50 during May, mostly sliding, bur arguably averaging in the low 90’s.

Source: tradingeconomics.com

This morning, it is trading below $70/bbl, back to the price on March 2nd, the first market day of the Iran conflict.  The BLS indicated that upwards of 60% of the rise in CPI was driven by the rise in energy prices, which tells me that whatever today’s numbers are, they are ancient history and next month’s are going to be lower.  I don’t know about you, but I am quite happy that energy prices are falling back to pre-war levels as, a) it makes life more affordable, and b) cheap and abundant energy leads to significant economic output, something good for us all.

But here’s the thing, with energy prices declining, those who benefit from high inflation need a new story, and there is none better than semiconductors.  The top headline in the WSJ this morning is The Data-Center Boom Is Sparking a Third Wave of Inflation, right on time for the next big inflation scare.  The big winner, at least today, Micron Technology, which had blowout earnings last night and jump-started a serious Techquity™ rally overnight with Tokyo (+4.6%), China (+1.6%) and Korea (+5.4%) leading the way.  HK (-1.4%) lagged and the rest of Asia was mixed, but that gives you an idea.

But the point of the article was that we all need to be prepared and accept that higher inflation is coming because the massive resource demands to build AI are coming along before the productivity gains can moderate the price impact.  And I have no doubt that the resource demands are going to support prices.  I remain uncertain over how quickly AI’s impact will be deflationary, even disinflationary.

And here’s the thing, my lived experience, plus my frequent conversations with The Inflation Guy, Mike Ashton, have me in the camp that CPI is going to live in the mid to high threes for a while to come, regardless of the metrics the Fed uses to measure things.

But I have begun to discern that there is a large community that benefits from rising inflation because it helps them achieve their goals.  After all, we know that governments love inflation as it devalues the real value of their outstanding debt, so a steady depreciation is their best friend.  As well, Congress’s baseline budgeting ruse, which starts each year from the previous year’s expenditures, not from zero, is a huge beneficiary of inflation.  I understand that since about 1980, the BLS has adjusted the CPI calculation somewhere between 30 and 40 times and you can guess the direction of most of those adjustments.  Of course, companies that sell products are a big fan as well, as they tend to adjust prices to both include new costs, and increase margins.  And they have a natural scapegoat; CPI is out of their hands.

All I’m saying is that while there appears to be a strong effort to fight inflation, I’m not a believer.  (And here I should highlight that I use the term ‘inflation’ in the manner it has become understood, rising prices, and not in its classical form of an increase in the money supply, which is 100% the Fed’s doing.)

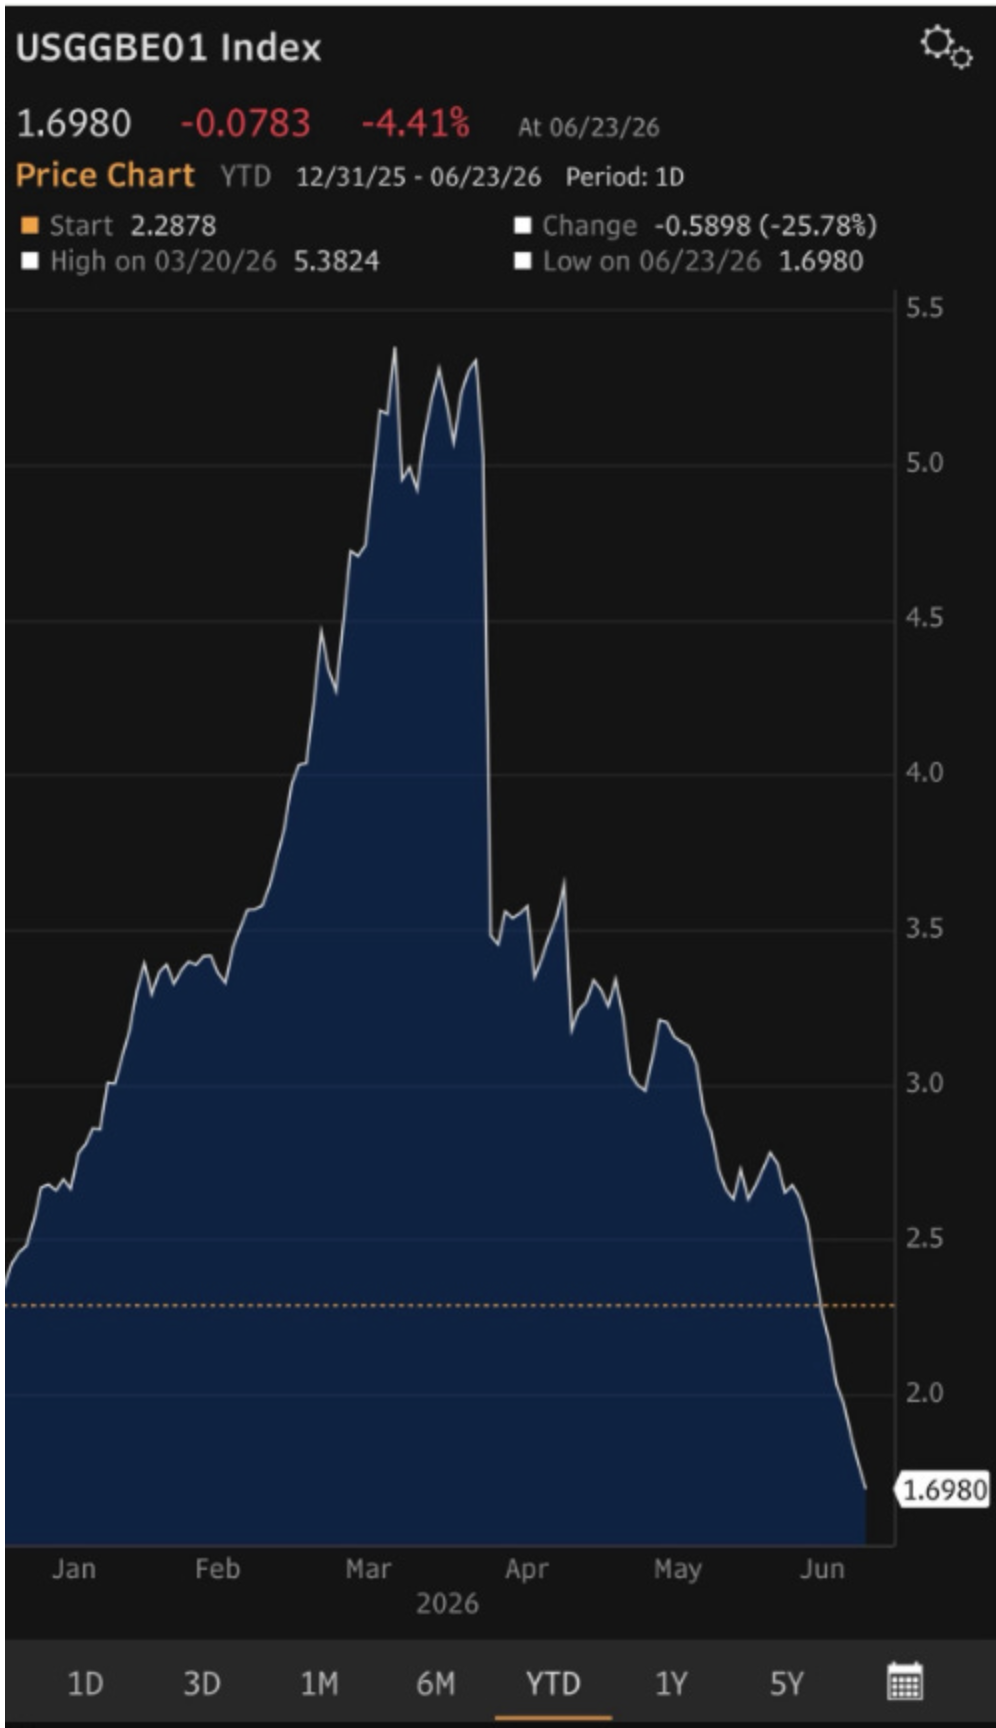
One other thing.  My friend JJ who writes Market Vibes, posted a chart of 1yr breakevens as of yesterday and I reproduce it below.

This is not a signal that the market expects prices to rise, but rather is following the decline in oil prices pretty well.  Once again, I will ask, please explain given market signals, why everyone is so sure the Fed is going to hike.  I maintain my one cut by year end view which is at least 50bps below the current Fed funds futures market pricing.  Ask yourself how the FOMC ‘hawks’, and I use that term loosely, will be able to argue for higher rates if oil continues its trajectory and inflation readings decline.  Precautionary?  How about they will simply say, we want to screw Trump, at least they would be honest then.

Ok, on to other markets overnight.  European bourses are all higher this morning, but since none of them have any real tech exposure, they are not running away.  Rather, 0.3% to 0.7% encompasses the magnitude of movement we have seen.  As to US futures, at this hour (7:25), NASDAQ (+2.0%) is leading the way, but the whole group is higher.

In the bond market, yesterday saw yields decline about -8bps in the 10-year Treasury and -6bps in the 2-year.  this morning they are little changed, consolidating those price gains.  As to European sovereigns, yields there also slipped yesterday, but not as dramatically, about -4bps, and this morning they are largely unchanged.  Overnight, JGB yields fell -3bps as declining oil prices are feeding through to inflation expectations.

The precious metals complex continues to get hurt, with gold (-0.6%) and silver (-0.5%) still under pressure and at new lows for the year, but copper (+1.25%) seems to have found a short-term floor at $6.00/lb.

And finally, the dollar, which has been en fuego lately, rising for the past six consecutive sessions, as per the below chart, is consolidating for now.

Source: tradingeconomics.com

Nothing has changed the yen story, where the dollar creeps ever so slightly higher each day, now just below 162.00 but overall, today’s movement has been quite muted, about +0.15% in the dollar against most currencies, as the focus turns to inflation, at least for today.

On the data front, in addition to the PCE data we get a bunch more as follows:

Initial Claims225K
Continuing Claims1800K
GDP Q1 Final1.6%
Personal Income0.4%
Personal Spending0.6%
Durable Goods-4.5%
-ex Transport0.6%
Chicago Fed National Activity0.12

Source: tradingeconomics.com

Will anyone care about this data?  I doubt it, Core PCE is THE thing today, so we will watch and see how that comes out. But mark my words, if it is soft, the hawkish Fed narrative is going to come under real pressure as stocks rally and yields and the dollar slip.

Good luck

Adf
‘Pocalypse Dreams

Though many have preached the buck’s dead
The greenback keeps moving ahead
And right now, it seems
Their ‘pocalypse dreams
Are still all confined to their head(s)

But narrative writers ignore
Whatever they said from before
Right now, it’s the buck
That’s causing bad luck
As rate hike bets all start to soar

In a fairly rare set of circumstances, the dollar has drawn the spotlight in markets for the past few sessions.  While it always matters to some extent, it is rarely seen as the cause of many other market movements, just a coincident one.  But right now, I read more about how the strong dollar is driving equity weakness and commodity weakness as more and more bets get placed on the Fed hiking rates aggressively to address inflation by the end of the year.
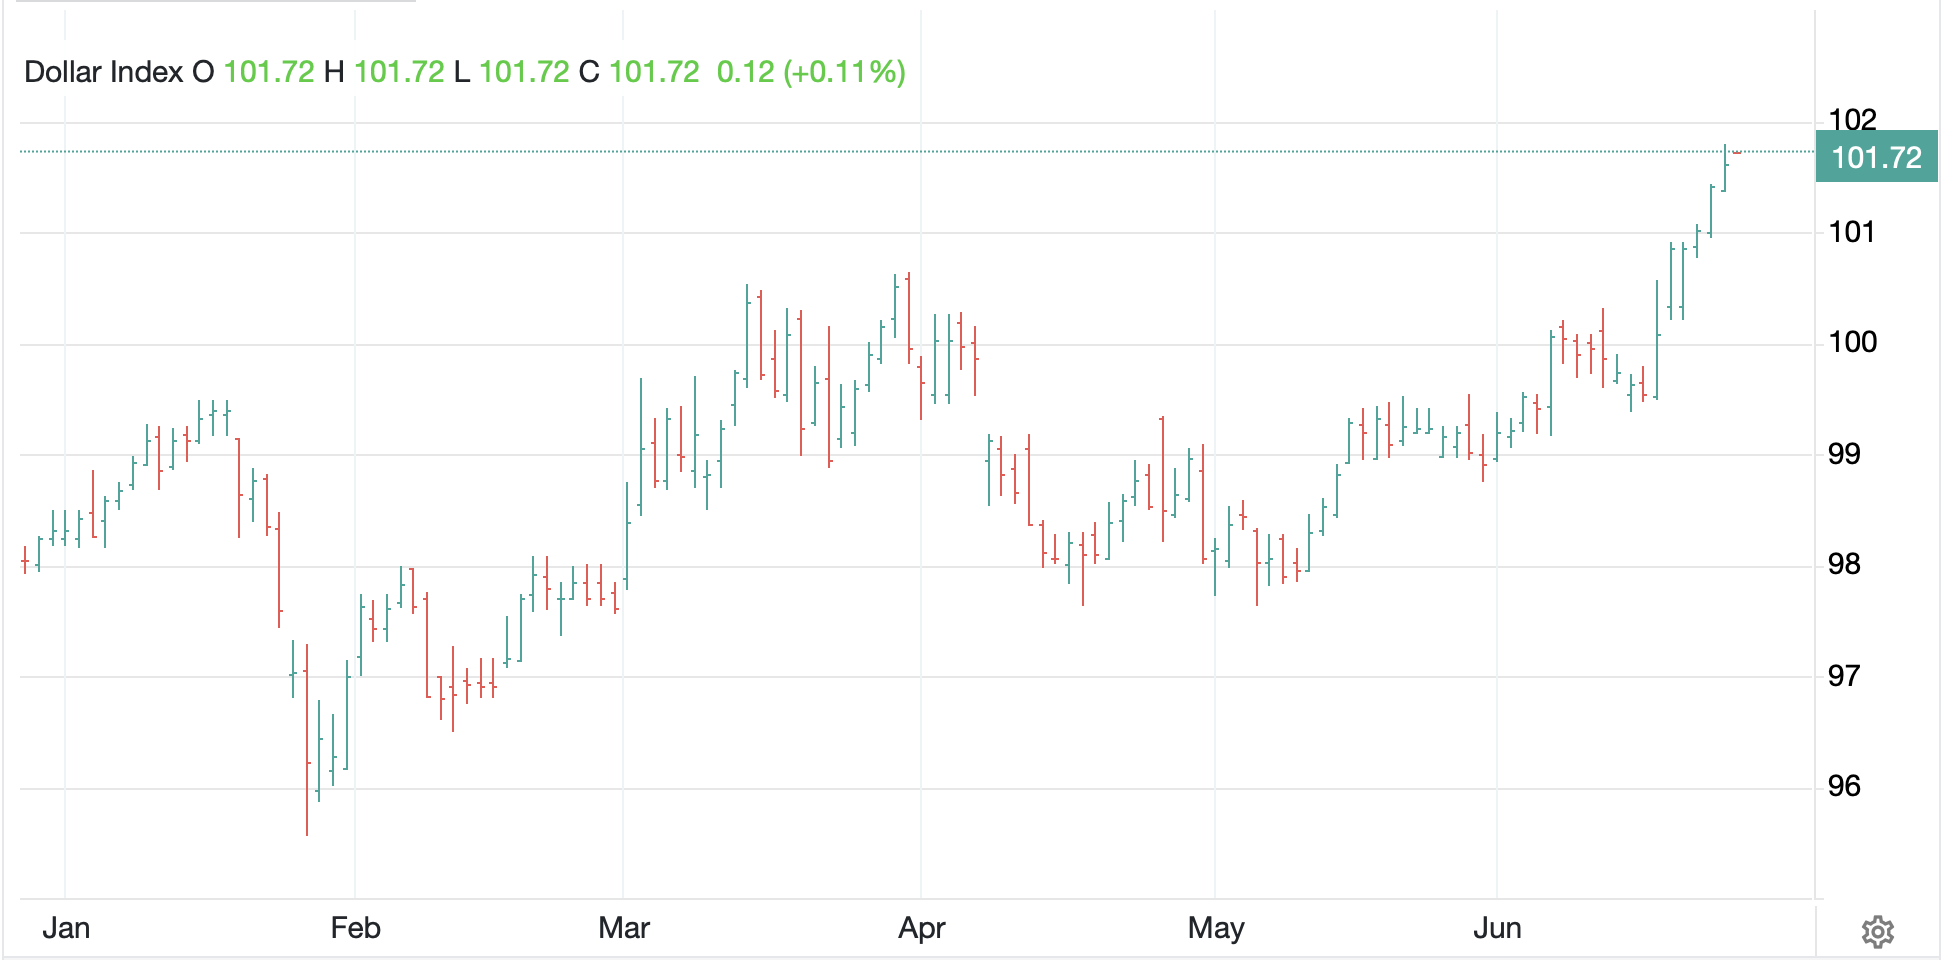
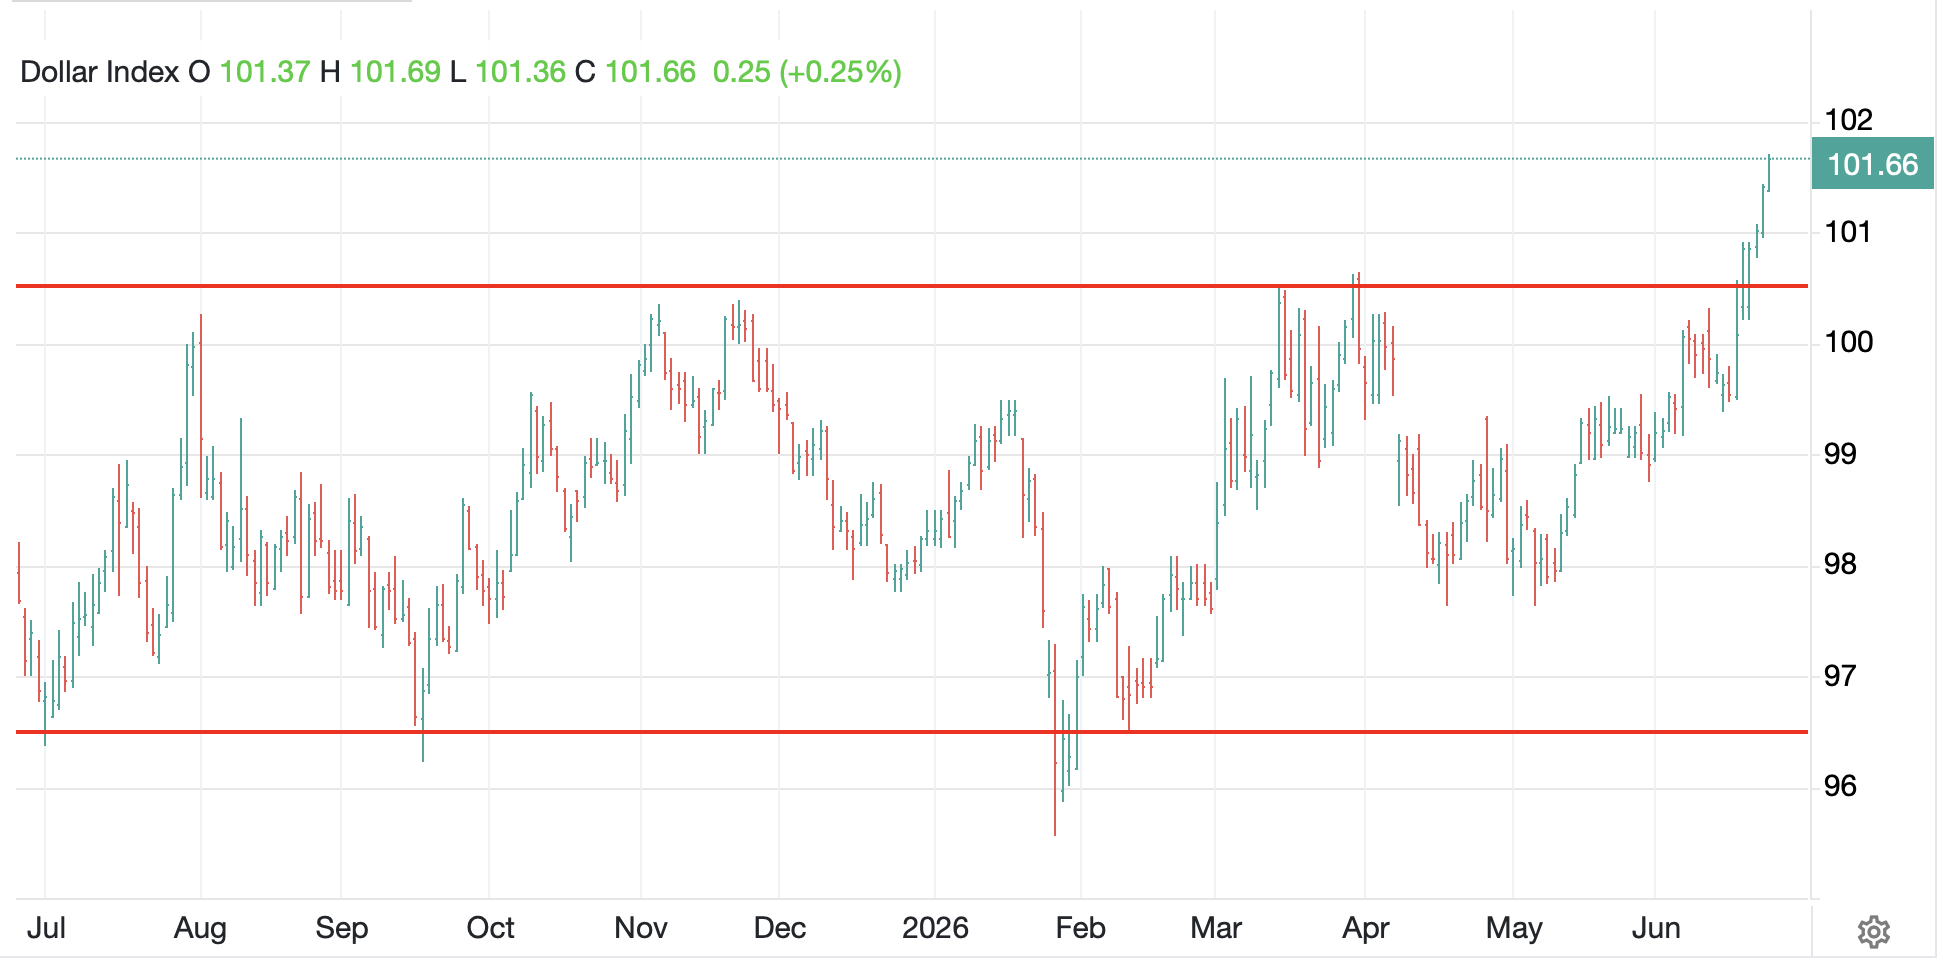
Using the DXY as proxy, the first chart is the one everybody wants you to focus on, showing the last year and how we have had a clear break above the trading range top of 100.50 and now people are creating targets for just how high it can go.

Source: tradingeconomics.com

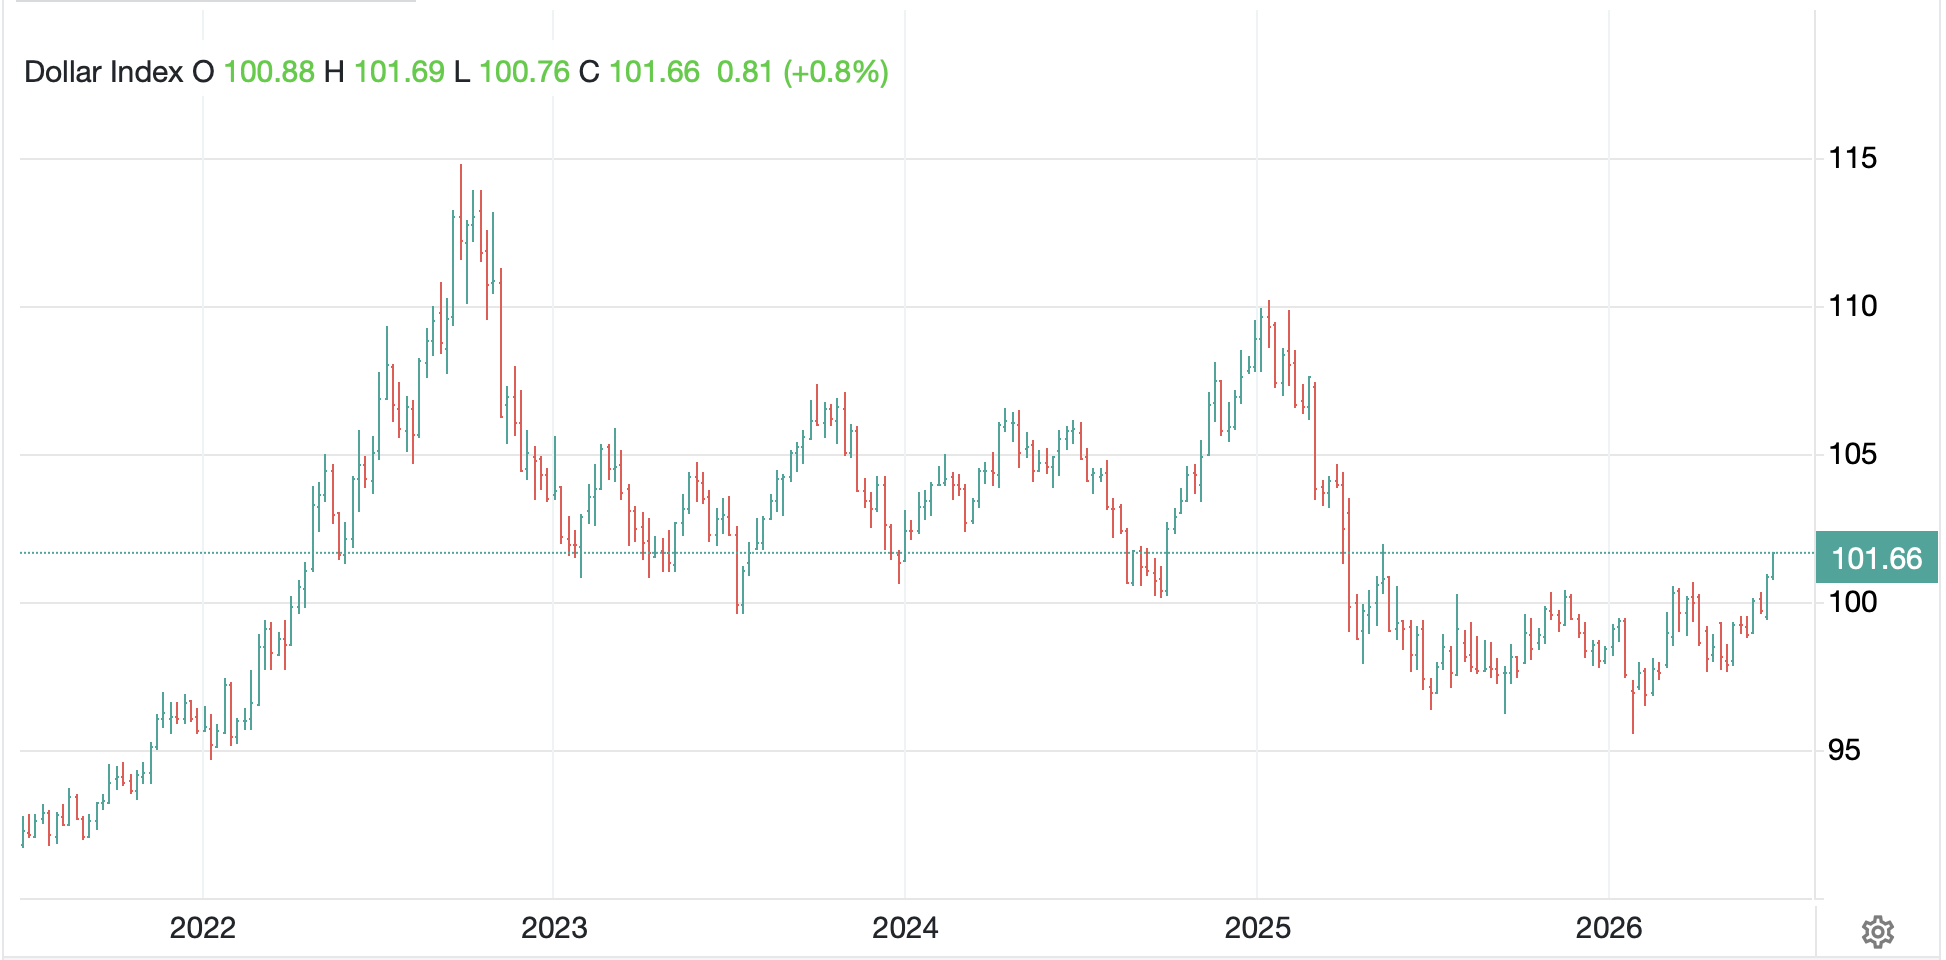
And it certainly can go higher, as a quick step back to get some more perspective shows where the dollar has been during the past 5 years. It seems to me I could create a narrative that the dollar has been massively undervalued over the past 18 months, and this move is simply returning it closer to its longer-term fair value.  In fact, just eyeballing, it seems quite reasonable to think the 5yr average of the DXY is somewhere around 103-104 (subsequently confirmed with Grok), still a few percent higher than current levels.  Reversion to the mean anyone?

Source: tradingeconomics.com

All of this, though, begs the question, are rate hikes really on the near-term horizon?  I remain firmly in the camp that is not the case.  Fortunately, someone on my side is super smart, Bob Elliott, former hedge fund manager at Bridgewater.

On the rate hike front, the below CME probability table has barely changed from yesterday as the narrative is strong that rate hikes are coming.  

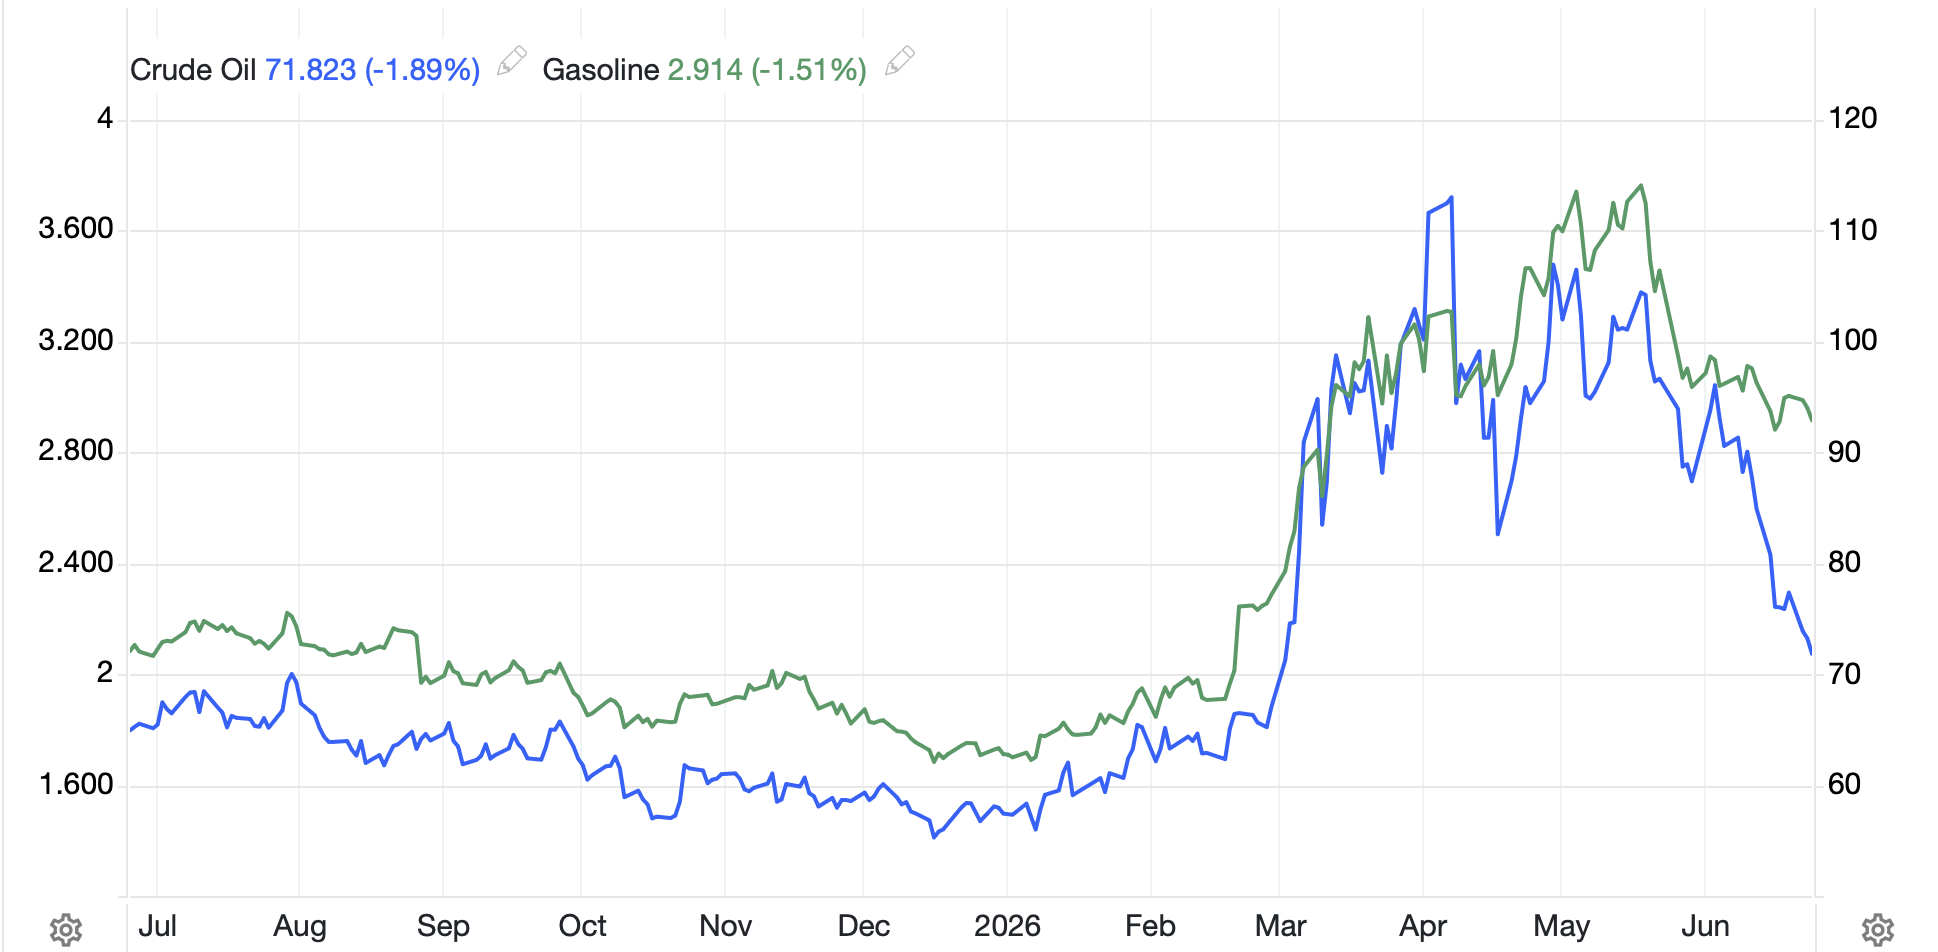
I cannot really understand why this is suddenly the belief set given the fact that the key driver of recent higher inflation data has been the price of oil, and that price continues to fall, down a further -2.0% this morning.  I understand that gasoline prices have not fallen quite as dramatically, but nothing about the chemistry has changed and I remain highly confident that those prices will be falling as well, catching down to oil.

Source: tradingeconomics.com

So, I remain confused as to why everybody seems to believe the Fed, which despite a new Chair remains the same institution that observed inflation run higher for years during Covid and calling it transitory, has become the reincarnation of the Bundesbank.  In fact, the only rationale I see is that other than Waller, Warsh and Bowman, who were all appointed by Trump, everybody else in that room has TDS and is terrified that things will work out such that by the time the election rolls around, the economy is ticking over nicely with inflation a historical issue.  And frankly, I think most of them do share that affliction.

But other than Powell, and Cook to some extent, none of them have really felt the force of the critiques that come with upsetting President Trump, and frankly he didn’t care about Cook per se, she was just a convenient target to get ousted so he could put his man in there.  And in fairness, Cook is a massive dove, and should agree with Trump on this policy, but I’m sure she doesn’t because…Trump.  I am confident none of them signed up for being in that spotlight.

Apparently, BOA is calling for 3 rate hikes this year in the final four meetings.  I think that’s nuts, but futures are pricing a 2/3 chance of a hike at the end of July, which I also think is nuts.

The recent hiccup in stocks, and the steadier downturn in commodities has been blamed on dollar strength which is being driven by expectations of rate hikes coming soon.  While I like the dollar in the long-term, that is because I believe investment flows into the US will drive it, not financial arbitrage flows.  As things evolve, I expect the market to understand the Fed will not be hiking rates and narratives will need to find a new bogeyman.

Ok, let’s tour markets quickly.  Yesterday’s equity market selloff in the US, following the tech selloff in Asia closed well off the lows and futures this morning are pointing slightly higher.  Asia was mixed overnight with Korea (+3.3%) rebounding sharply although there was weakness in Japan (-0.9%), Taiwan (-2.25%), Indonesia (-3.6%) and the Philippines (-2.2%).  But on the flip side, China (+0.5%), HK (+0.3%) and India (+1.0%) all followed Korea while other regional exchanges had much more limited movement.  It appears that people are trying to figure out what to do for now.

In Europe, Germany (-1.0%) is the laggard after Germany cancelled its plans for a new warship and Rheinmetall, the company set to win biggest there, got crushed.  But elsewhere +/-0.3% or less is the norm with little new information as traders await the next shoe to drop.

In the bond market, interest is low as 10-year Treasury yields continue to track around the 4.5% level and movement has been 1bp or so lower across all of Europe.  Nothing to see here for now.  Just wait until views start to change on rate hikes though!

Metals markets continue to get hammered with gold (-1.7%), silver (-2.9%) and copper (-1.6%) all still falling as the opening narrative about higher rates and a stronger dollar play out.  The thing is, I think the fundamentals remain positive for metals markets as there continues to be central bank demand for gold as well as industrial interest in silver and copper and long-term shortages of supply.  But right now, none of that matters.

Finally, looking beyond the DXY, it is no surprise the euro (-0.35%) and pound (-0.35%) are lower given the DXY’s continued rise, but the yen (-0.1% and at a new low (dollar high) for the move) continues to slide and there is weakness pretty much across the board in both the G10 and EMG blocs.  KRW (-1.0%) is today’s laggard while INR (+0.2%) is the lone currency holding its own.  This continues to be a dollar focused story so when the rates story changes, so will the dollar.

On the data front, we see New Home Sales (exp 640K) and then EIA Oil inventories with yet another large draw expected.  And that’s it for today.  As long as this rate hike narrative remains primary, look for weaker risk appetite and a strong dollar.  But I think it is a short-term phenomenon.

Good luck

Adf