Risk assets are feeling the heat
As equity markets retreat
And gold is a mess
While most bonds feel stress
And crude hurts the man on the street

It seems that the drumbeats of war
Are louder than they’d been before
Now rumors abound
The US will pound
Iran with munitions galore
Risk is under pressure this morning as equity markets worldwide retreat, gold is falling and the only asset rising are US Treasuries. Well, that and oil prices which seem to be the proximate cause of the whole story.
I guess we should start with oil (+2.0%) which is rebounding from yesterday’s decline as the story gaining traction is the US and Israel are going to resume military action in Iran shortly. In fact, President Trump commented in questions yesterday that something would happen “pretty soon”. This is of a piece with my expectation that in the wake of the mid-terms in two weeks, Trump would feel he had a free hand to go after Iran again, and I have seen this story from several generally reliable sources on X this morning. I also read that another aircraft carrier group was heading to the Persian Gulf area, further supporting the idea.
This story coincides with the WSJ headline, “Iran’s Fleet of Shadow Tankers Has Run Out of Oil After Monthslong US Blockade” which is a serious problem for the mullahs as, according to the article, some 40% of Iranian government revenue comes from oil sales (I wonder where the rest comes from, pistachios?) and so renewed US/Israeli attacks will be far harder to absorb. With this driving the narrative, it is not surprising that oil prices are higher and uncertainty has risen.
This has manifest itself in the following ways. In equity markets, the below tradingeconomics.com screenshot at 7:08 this morning shows pretty clear evidence of what the mood is today and how things felt overnight (notice Shanghai, Hong Kong and Australia).
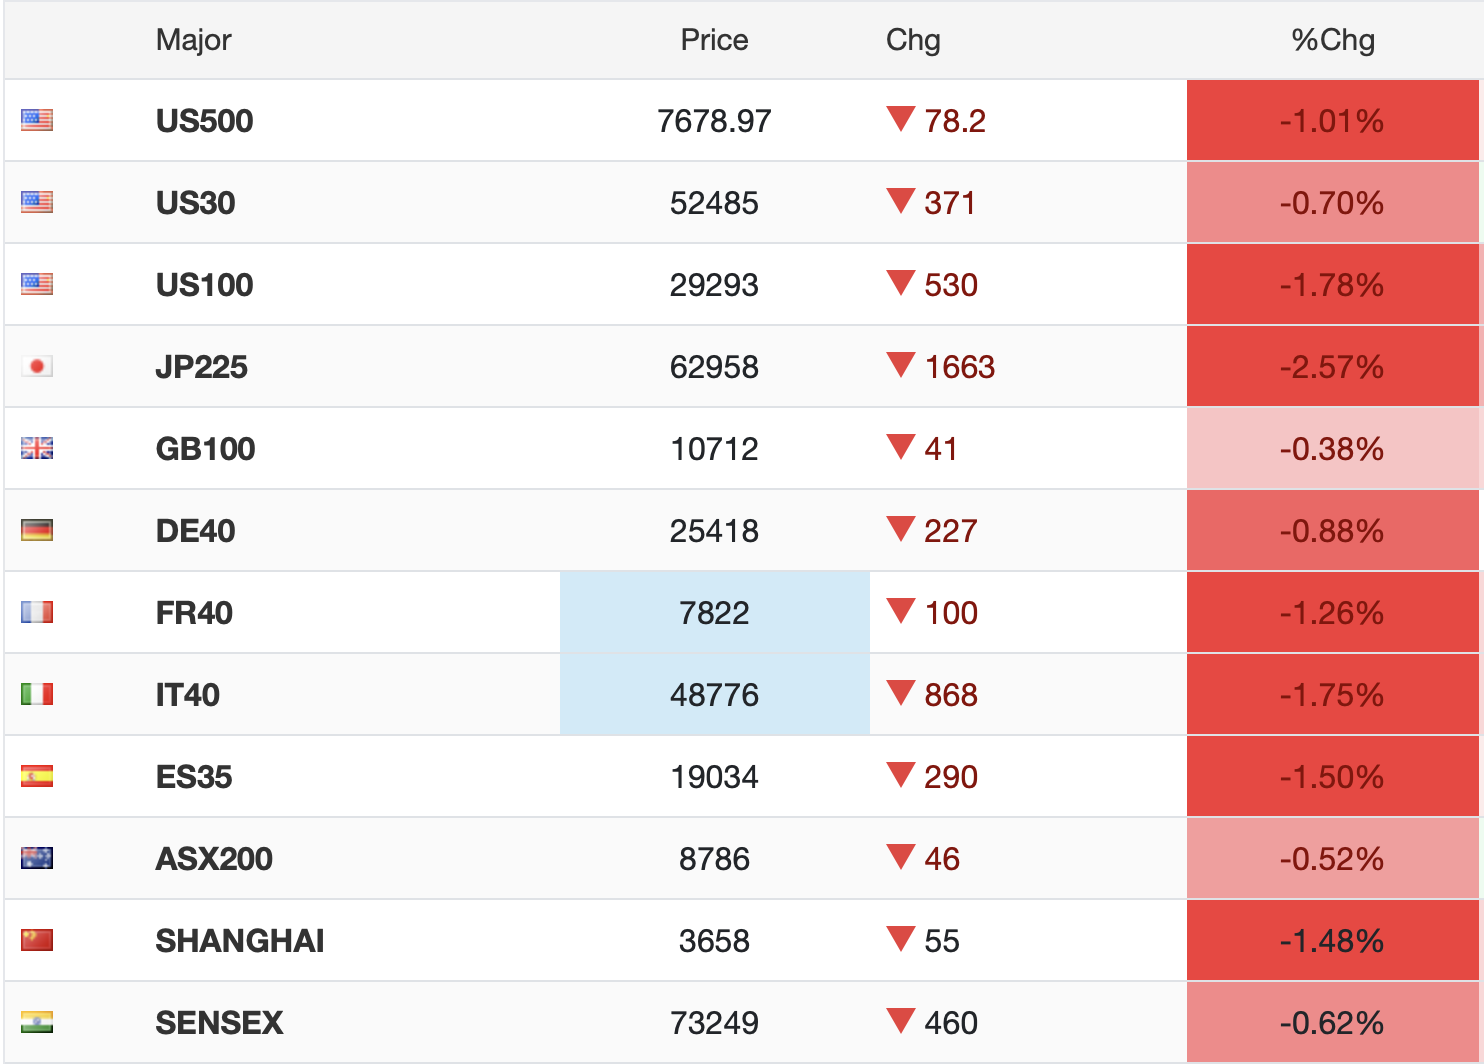
Investors are clearly getting a bit nervous everywhere around the world right now. We can see that in bond markets as well where those nations who are still perceived as safe havens, US, Canada, Germany, Netherlands, Japan) have seen that flight to safety. Even UK gilts have managed to rally, but the story on the continent is a far more concerning one. Looking at the below Bloomberg.com screenshot, you can see that the problems in France are really starting to hurt.
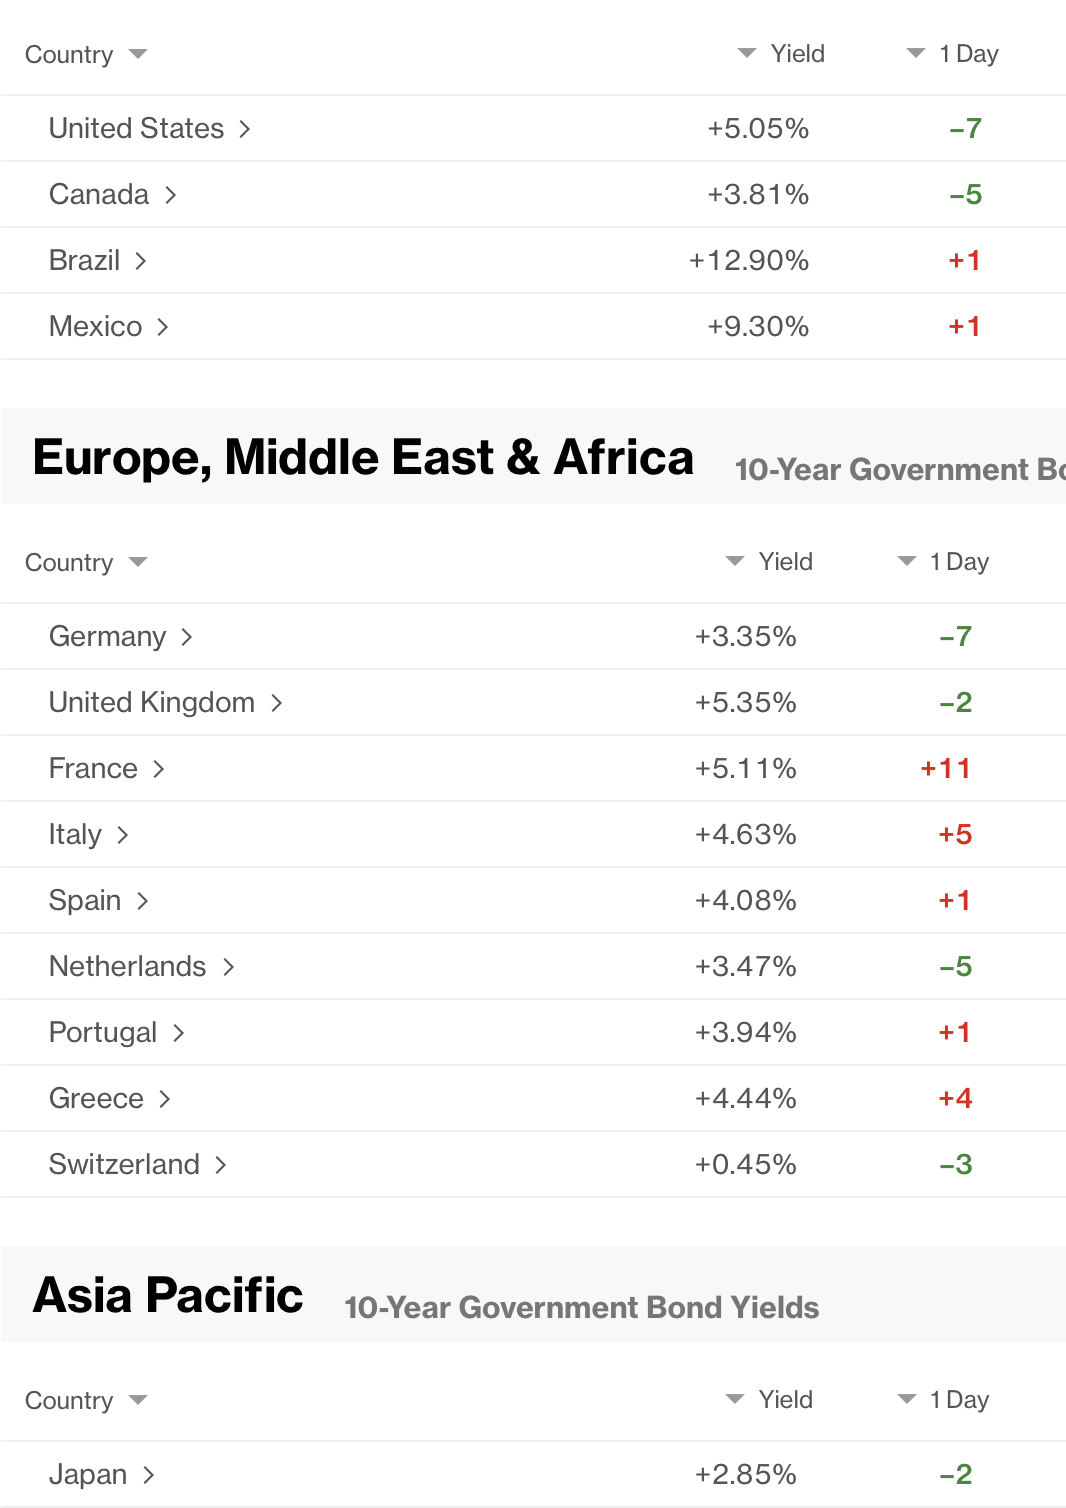
It’s funny, I saw an argument(?), maybe a discussion, on X this morning where one person said traders are treating the situation in France as though the ECB is not going to step in and save the day by bailing out the French, and the response was that the only way for the ECB to do that was if the market behaved in just that manner. The ECB will only jump if the situation looks untenable, at which point they will create yet another program with another acronym, something like European Activity Security Event (EASE) which will instruct central banks to purchase OATs, and possibly BTPs. Now that the Bund-OAT spread is >175bps, it is a virtual guarantee that this will happen.
The other odd thing is that US Treasuries appear to be in demand. It was not that long ago that the bond market narrative was that with US debt climbing above $40 trillion and showing no signs of slowing down, it would soon be worthless. Foreign nations were selling their holdings and the end was nigh. And yet, according to TIC data, the August records (latest available) show that foreign ownership of Treasuries rose ~$83.3 billion. In fact, here is a table to consider.
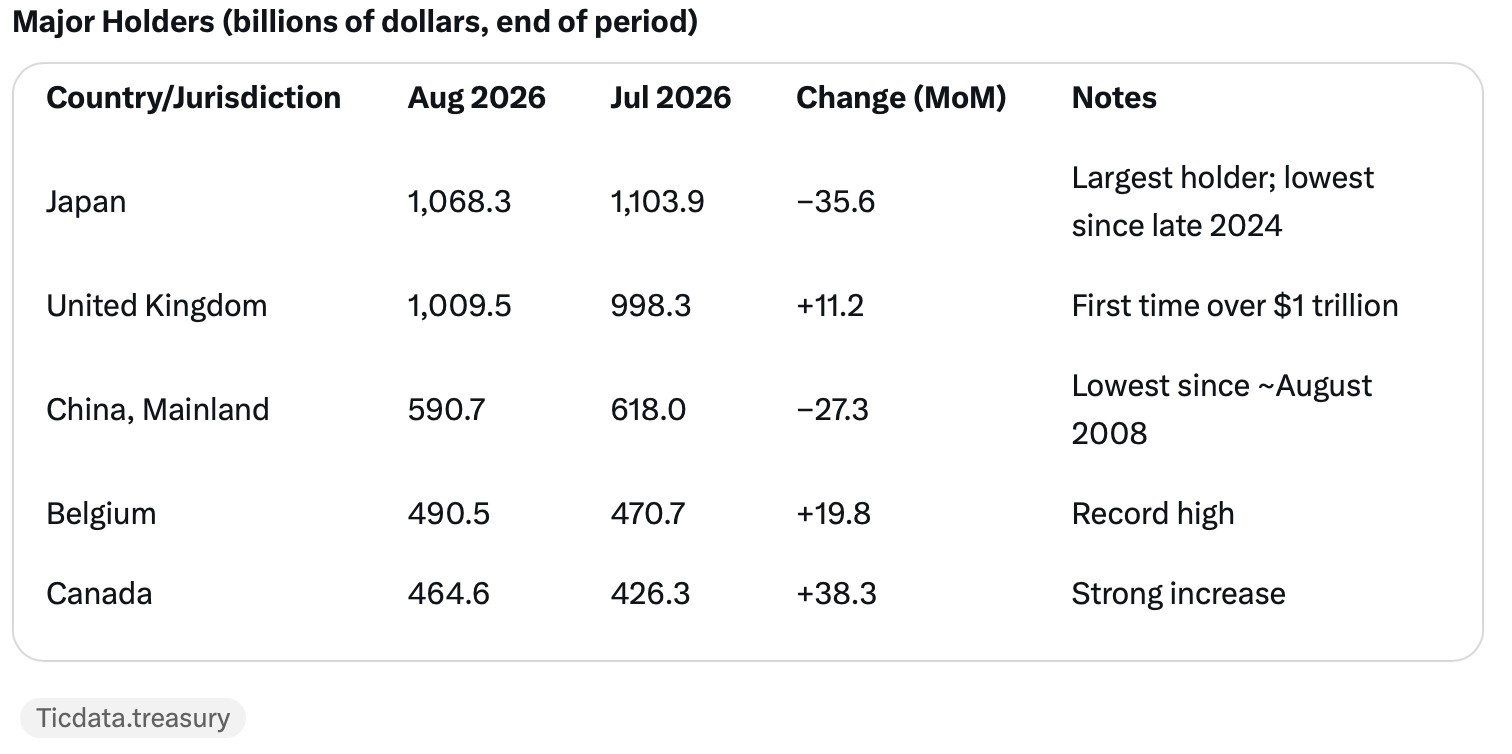
It is true that both the UK and Belgium are clearinghouses, so it is not certain who is the ultimate owner of those bonds, but Canada is far more interesting, and I have read, although it is unsubstantiated, that China has been holding Treasuries there. It is certainly believable that is the case given their ongoing trade surpluses and the need to put the dollars somewhere. In the end, I wouldn’t write off the bond quite yet!
As to other markets, the rout in metals continues, which given the decline in most yields seems odd to me especially as the rationale had been given that higher yields were driving a replacement of gold with bonds. Given its long history as a haven, I have trouble understanding the rationale to sell gold, and my sense is this could be short selling in an environment where risk assets are declining. But I have written before that this is a very new paradigm through which we are living, and it appears this is a new response. My personal view is that this is a short-term phenomenon and the precious metals will regain their luster again, but it may be a while yet. So, gold (-1.9%), silver (-3.8%) and copper (-2.5%) are all on the schneid this morning.
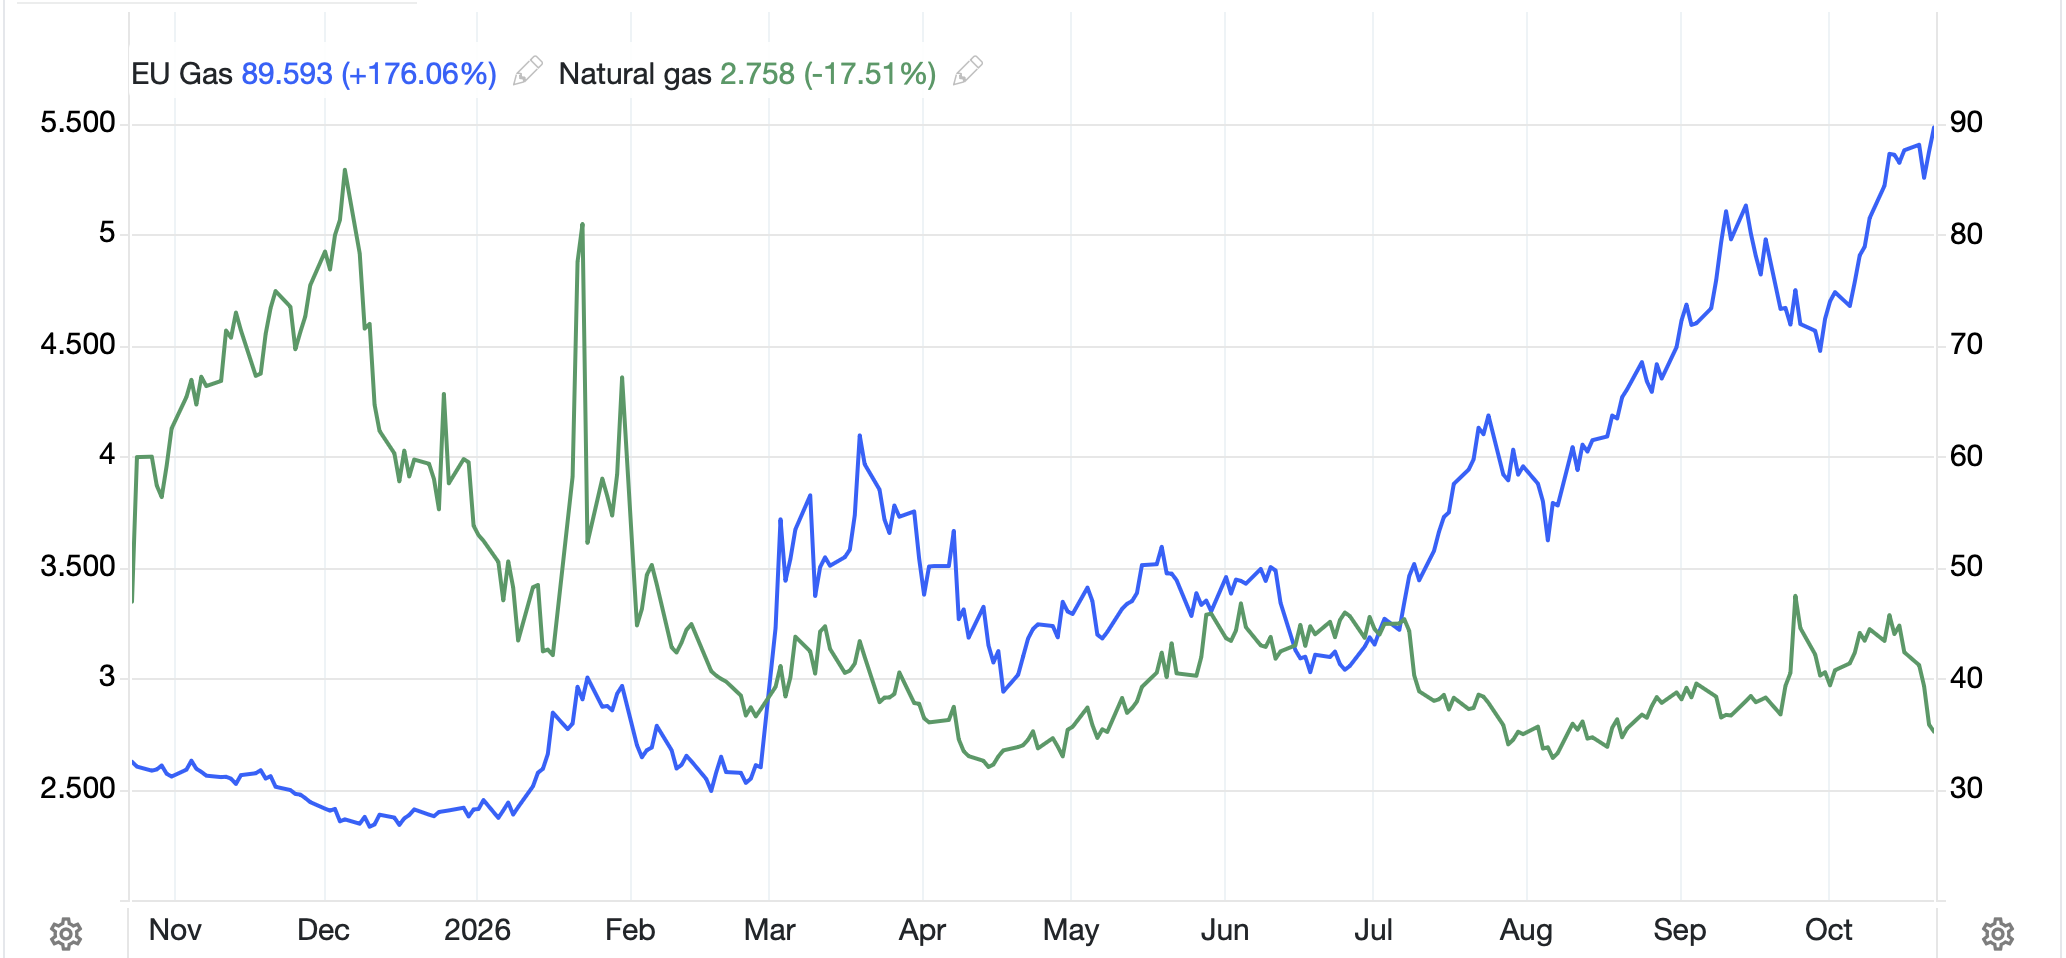
I think it is also worth discussing natural gas, which has been falling sharply over the past several weeks, at least in the US. In fact, the below chart shows a comparison of US and European natural gas prices. If you were wondering what kind of problems Europe is in for this winter, as I have written elsewhere, I hope they have lots of warm sweaters!
Source: tradingeconomics.com
Finally, the dollar, which spent much of the evening doing nothing, has rallied as NY walks in the door, a reasonable response to a haven driven market. But that rise is far more evident vs. EMG currencies than G10 as the DXY futures are essentially unchanged on the day, caught between modest EUR weakness (-0.3%) and more impressive JPY strength (+0.7%). But, in the emerging markets, ZAR (-1.1%), MXN (-0.8%), INR -0.8%), CLP (-1.0%) and PLN (-0.6%) are all under more severe pressure, as overall risk concerns along with declining commodities prices are the drivers.
As it is Thursday, this morning we see Initial (exp 200K) and Continuing (1720K) Claims along with Leading Indicators (-0.1%). And that’s really it.
Under the heading, I’d rather be lucky than good, yesterday afternoon I bought some SPY puts set to expire after the election as a portfolio hedge. My concern is that while I believe the Republicans will do far better than currently forecast, I could easily be wrong and based on the stated policy objectives of the Democratic party, equity markets seem likely to fall if they are elected. I truly hope my puts expire worthless, but for today, they are doing their job. (THIS IS NOT INVESTMENT ADVICE!)
It is certainly reasonable to expect the dollar to test its recent highs, but there doesn’t appear to be enough momentum to break those in any meaningful way, at least absent a major equity market dislocation.
Good luck
Adf

