Screed After Screed

Seems I just can’t leave you alone
Lest havoc and fear you’ll have sown
So, now that I’m back
Let’s try to change tack
And work on a positive tone

But seriously, what I read
Is doomsters in screed after screed
All preening and bragging
That all their chin-wagging
Was right while the markets recede

All I can say is, it’s so good to be home.  While the past three weeks have been enjoyable and traveling across half the country by car offers a great perspective on just how amazing this nation really is, I’m sure all of you will agree that there is nothing more comfortable than sleeping in your own bed.  And this is just as true for Marvel, as it is for the rest of us.
But seriously, I appreciate your patience as it is tough to keep up while driving 10 hours a day.  But now that I’m back, I think it is worthwhile to take a look at how things have moved since I first left back in late September.  Between closing on Friday, September 25 and last night at 9:00pm, these are the moves across major markets that I discuss.
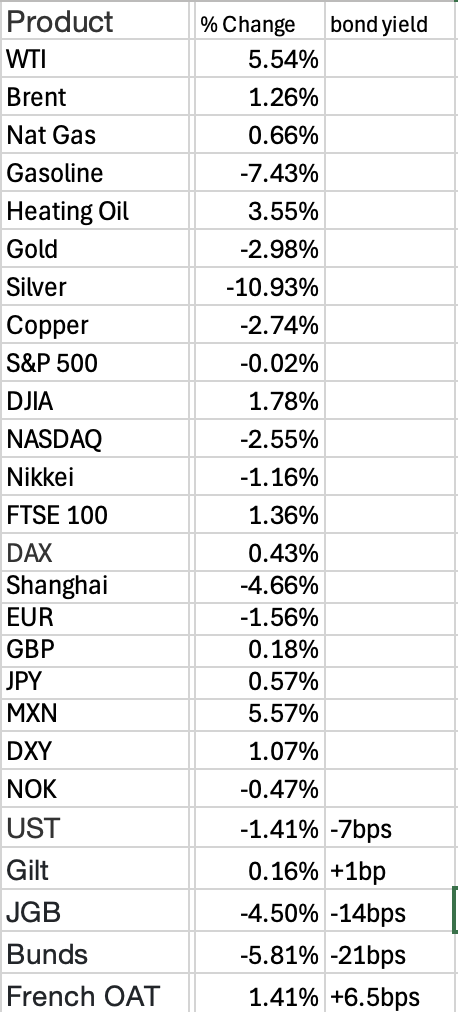
Frankly, it is hard to look at this and conclude that the world is ending.  In fact, despite constant discussion about how the AI (or is it SI?) trade is imploding, the NASDAQ has fallen just -2.5% over the past three weeks and is less than 5% from its all-time highs.  I don’t see the reason for all the excitement.  In fact, the biggest mover, by far, has been silver, which is the least liquid and least important of all these markets.  Despite the end of days discussion about Treasuries, yields have slipped, as have JGB and Bund yields.  One other thing to note is the decline in gasoline prices given the political implications.  I’m confident the White House would like to see them fall further, but there is no indication there is a supply issue there.

I’m just trying to level set here.  I’m sorry if I’m not breathlessly describing the apocalypse, but I just don’t see it. Perhaps I’m simply blind.  But the data continues to lean toward economic growth, not weakness, at least based on the Retail Sales and Initial Claims data we saw yesterday, as well as the ISM and other numbers.  And inflation, to the extent that growth is a driver of that, remains well above the Fed’s 2% target, although based on its causes (read the Inflation Guy’s blog to really understand it), hiking rates is not going to be the solution to inflation, although it certainly has the opportunity to impede growth.

Anyway…

The rules of the road used to be
That nothing defied gravity
But Elon replied
We oughtn’t be tied
To earth, and his car, he set free!

I am sure there is a parable in the contrast between the doom and gloom that consistently dominates the discussion, the vibe as it were, and the fact that the richest man in the world continues to build extraordinary things.  I’m sure you have all seen the video clip of the new Tesla roadster that actually flies, but if not, it’s right there.  No matter your view of the man, you cannot dismiss his extraordinary genius when it comes to building things.  I guess the question is, will the flying car be a metaphor for the economy?  The markets? Or will it crash a burn?

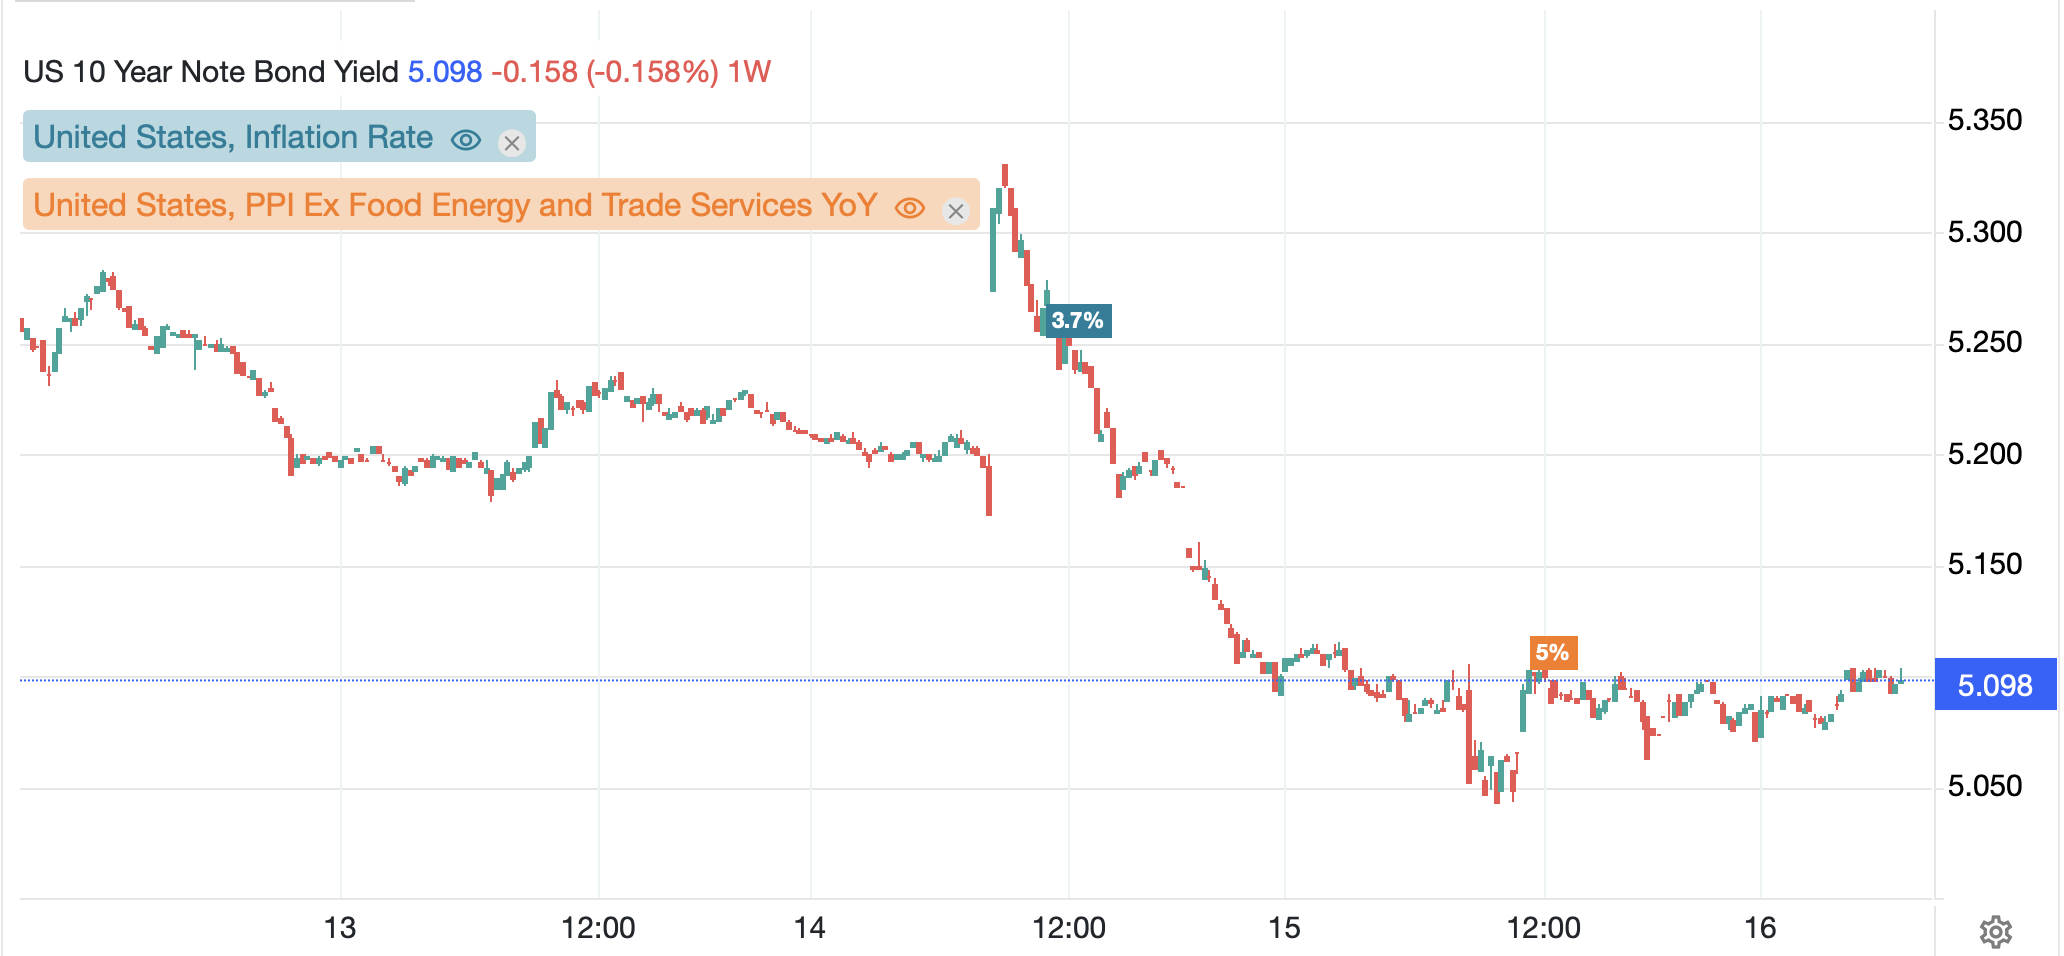
So, now let’s turn to the markets, and I feel like bonds are the right place to start.  The below chart of the 10-year over the past week is remarkable given the CPI, PPI and Retail Sales data released.
Source: tradingeconomics.com

The huge gap was the immediate response to Wednesday’s CPI release which came in a tick hotter than forecast.  Yet much higher-than-expected PPI and Retail Sales data saw yields decline sharply.  Ostensibly, I continue to read about a flight to safety trade, but that seems at odds with the idea that Treasury debt is going to implode because there is so much of it.  I wish the punditry would get their stories straight.  No matter the cause, yesterday saw a complete reversal of the yield rally from Wednesday.  Maybe, and I’m just spit balling here, the punditry doesn’t have any idea about the way things work but simply try to drive a preferred narrative.  And given the underlying visceral hatred of the US administration, specifically President Trump, are very keen to do all in their power to make things worse for him.

Regardless, it appears that despite the higher-than-expected inflation data, yields at current levels represent an attractive opportunity to some investors.  While this morning, 10-year yields have bounced 4bps from yesterday’s closing levels, as I showed above, they are still lower on the month.  And it is no surprise that European sovereign yields have also rebounded this morning, although more on the order of 2bps across the board.  Frankly, it seems to me there is far more risk in owning Bunds or OATs or BTPs than in owning Treasuries.  At least the US is growing pretty well compared to the utter lack of growth in Europe.  Exactly how are the French going to repay their debt, or maybe more importantly service their debt, if growth remains <1%?

As to equities, they, too, have stopped tumbling for now with markets higher yesterday in the US and almost the entirety of Asia and Europe this morning with the one glaring exception of Indonesia (-10.8%) which suffered from MSCI explaining they could downgrade the country to standalone market status (a decisive negative outcome regarding the lack of transparency and liquidity) offering the potential for significant capital outflows.  I understand that there are AI names that have had problems and the banking sector, despite mostly strong earnings, has underperformed, but the end has not shown itself yet.

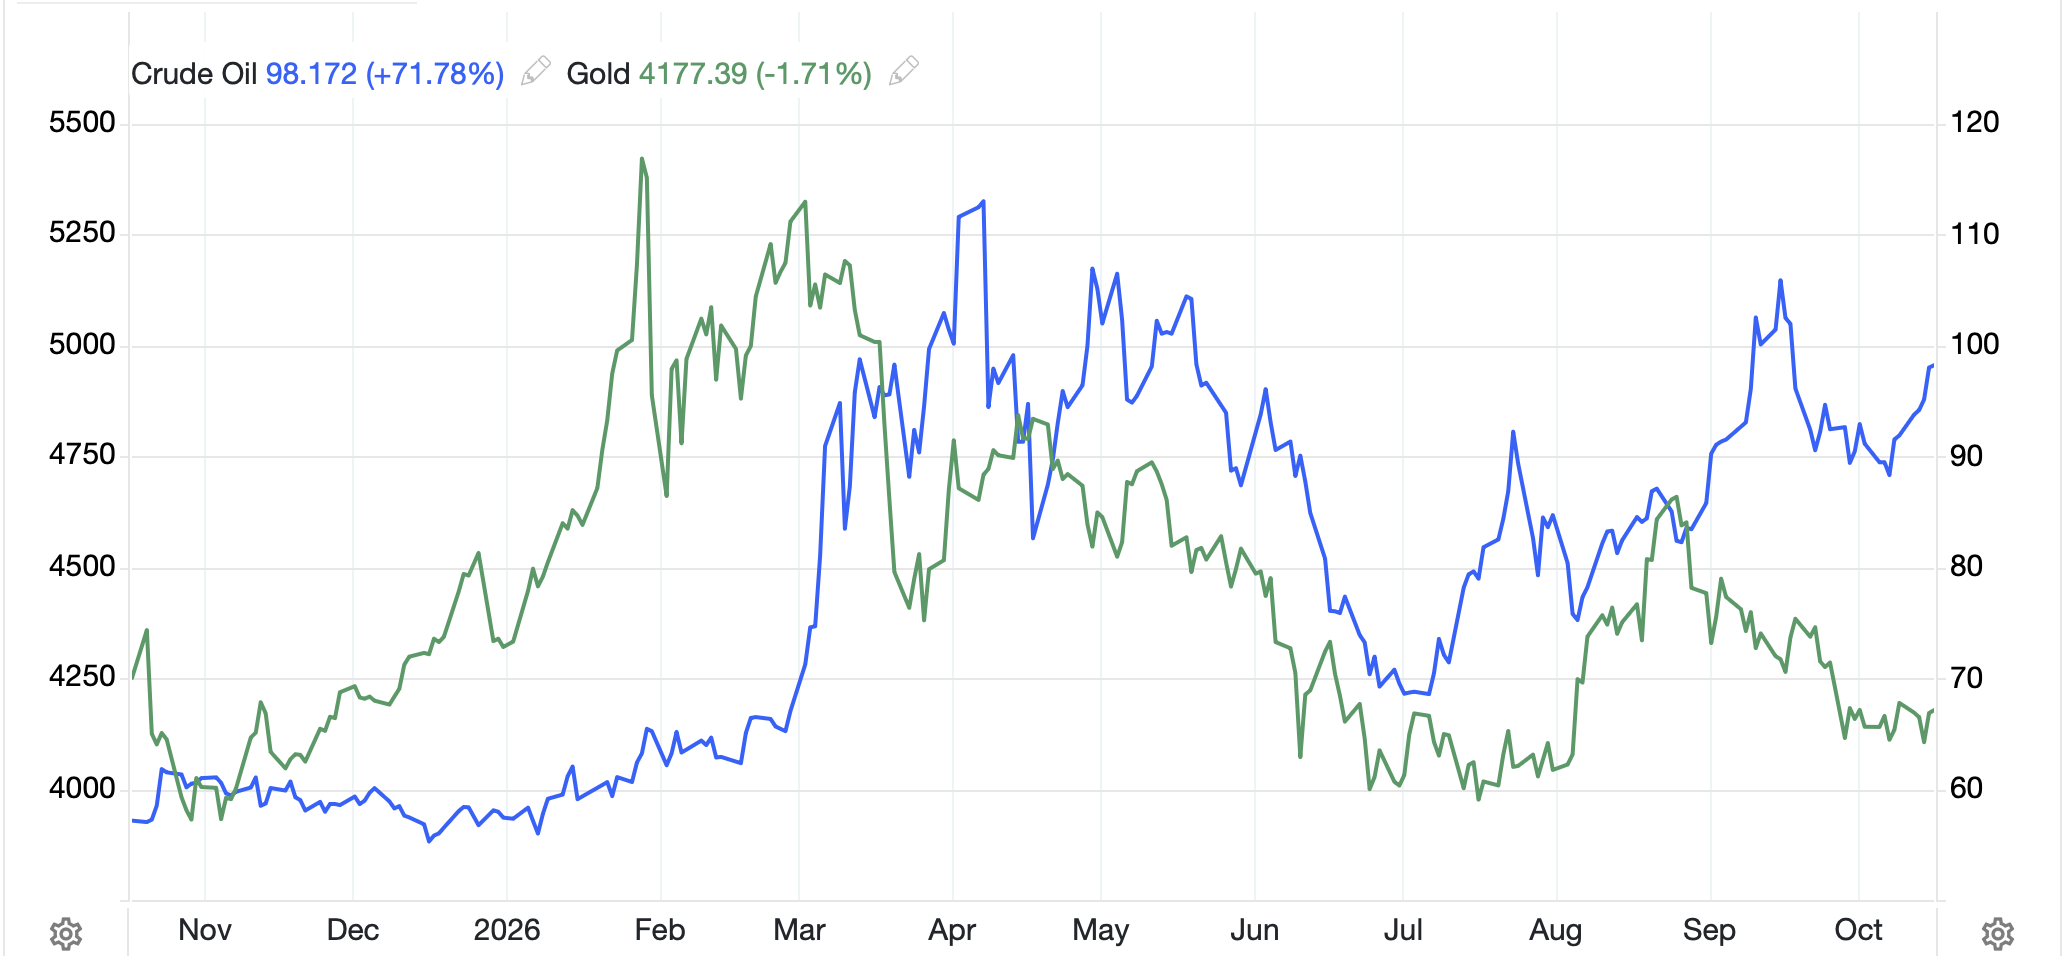
Gold (+0.2%) is another market that seems confused, or at least the trading of it seems so, as its relationship with oil (+0.1%), which had a very clear negative correlation for quite a while, arguably since the beginning of the Iran war, (although according to Grok, the numbers show that correlation to be -0.1% to -0.15% over the past year, hardly a strong relationship), are both higher this morning.  But looking at the chart below, the direction of travail since the summer has been largely opposite directions.
Source: tradingeconomics.com

Obviously, oil is a far more important commodity than gold, which can be seen as a sentiment indicator more than anything else.  But despite the recent rebound in oil prices, economies around the world seem to be figuring out how to cope.  Now, the recent uptick in Iranian and Houthi attacks on ships in Hormuz and Saudi infrastructure are having a clear impact and given the fact that the IRGC literally wrote an open letter to the US to elect Democrats to try to impede President Trump’s ongoing campaign, I have to believe things are getting a lot tougher over there.  It is not impossible to believe that after the election, especially if the Republicans hold both Houses of Congress, that the Iran conflict may end soon.  It does seem that the blockade has starved Iran of the one thing they need, capital, and that is running out quickly.

As to the FX market, I find it interesting that even though yields are rising around the world, the dollar has been the main beneficiary here.  In the wake of the CPI and PPI data, the probability of a rate hike at the end of the month has jumped to 85%, as per the below cmegroup.com table.
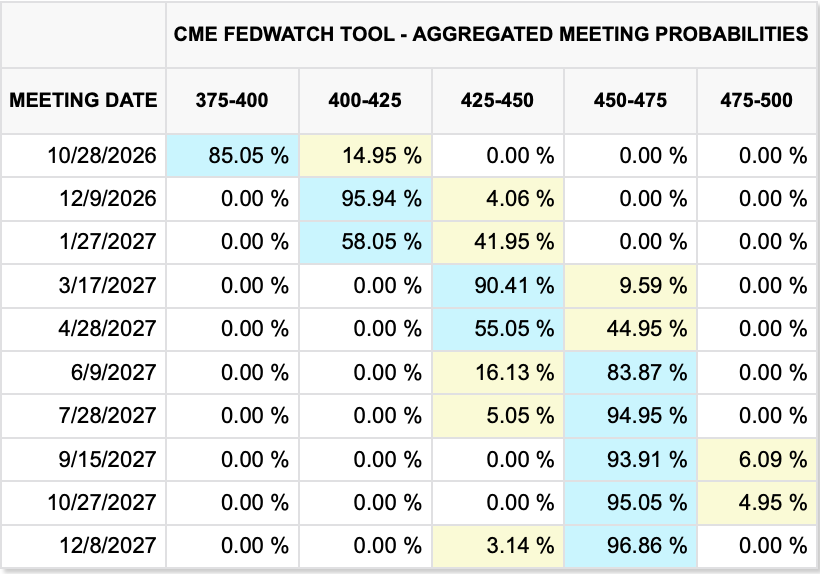
At the same time, Chairman Warsh spoke last night at the IMF meeting in Bangkok but once again, refused to discuss potential Fed moves going forward. “I don’t prejudge meetings. I don’t believe in saying now what I might do at the meetings we have in the balance of this year. It’s a new chapter at the Fed, and we’re not in that business anymore.” While virtually every other member of the FOMC likes the fame/notoriety they get by speaking, Warsh has remained true to his initial comments.  I guess the question is, has the data been sufficient to drive another hike?  It all depends on the membership’s view of economic activity.  If they see strength, I imagine that is what we will get despite the fact it is unlikely to do anything positive for the economy.

Back to the dollar, while it has backed off a bit this morning, with the DXY (-0.85%) the leading decliner despite the fact its components haven’t moved nearly that much (EUR -0.35, JPY unchanged), I guess broadly it is following the 10-year yield.  It is worth noting that while most currencies have not done very much in my absence, (MXN +0.1% today, -5.6% since Sept 25) has suffered on expectations that Banxico is going to cut rates further, thus reducing one of its key supports, the carry trade.

On the data front, this morning we see IP (exp 0.4%) and Capacity Utilization (76.5%).  Those tend not to be market movers so as is frequently the case, the FX market will take its cues from equities and bonds.  Right now, equity futures are essentially unchanged, so if the positivity we saw yesterday fades, perhaps the dollar will rally back some on that flight to safety trade.

Good luck and good weekend

Adf
Growth Outlives Politics

As much as the pundits keep trying
To tell us that nobody’s buying
The Dow hasn’t crumbled
And though bonds have stumbled
There’s no sign that they’re really dying

But negative stories get clicks
And that’s how the punditry ticks
Though there are concerns
‘Bout short-term returns
O’er time growth outlives politics

Over the past several sessions, basically until yesterday afternoon, the vibe was distinctly negative.  Oil prices had rebounded, bond yields continued to rise and there was red all over the equity market screens.  It’s funny, the dollar was rallying and one explanation was investors were fleeing to the dollar for safety, but if they were, it wasn’t clear what they were buying with those dollars.  It wasn’t stocks, bonds or gold, so I guess they were holding cash.  That seems odd in this day and age, but maybe.

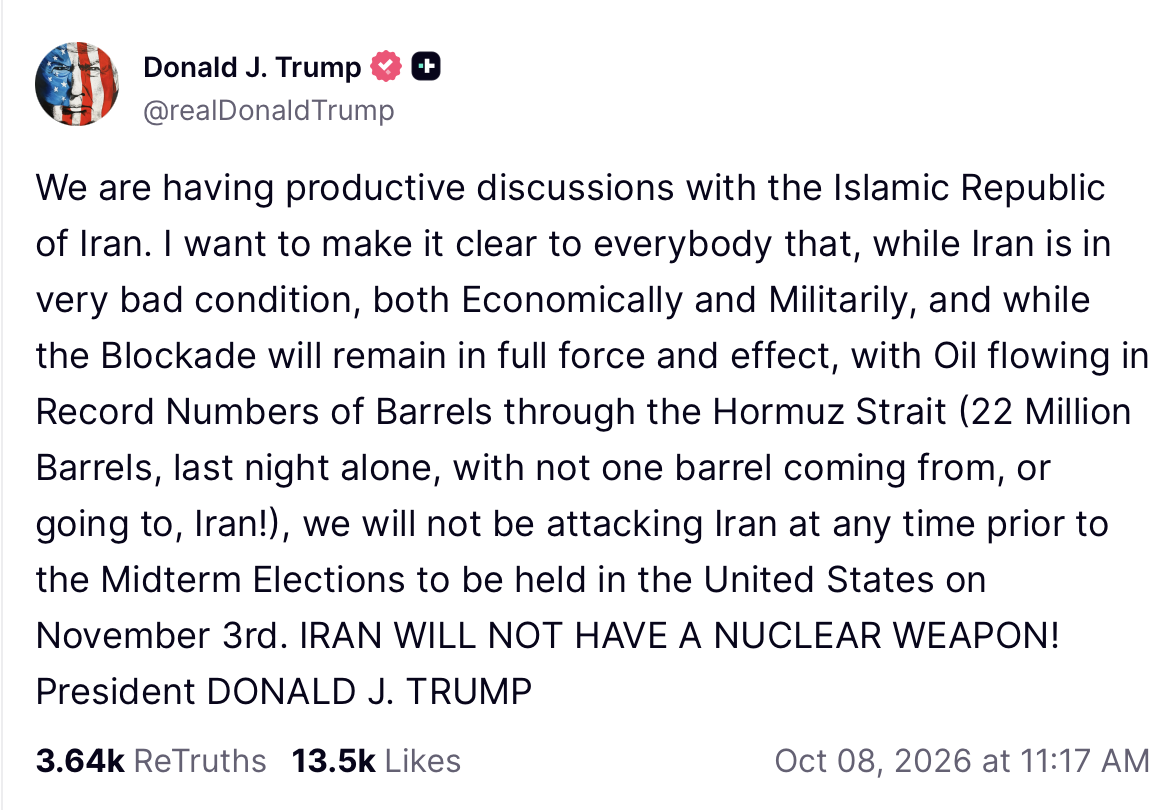
The punditry was in its glory, though, explaining how everything that every government was doing, especially the Trump administration, was destined to fail and that we all must be very afraid.  And then it stopped.  Certainly, a key catalyst to this reversal of fortune was President Trump’s tweet late yesterday morning as per the below:

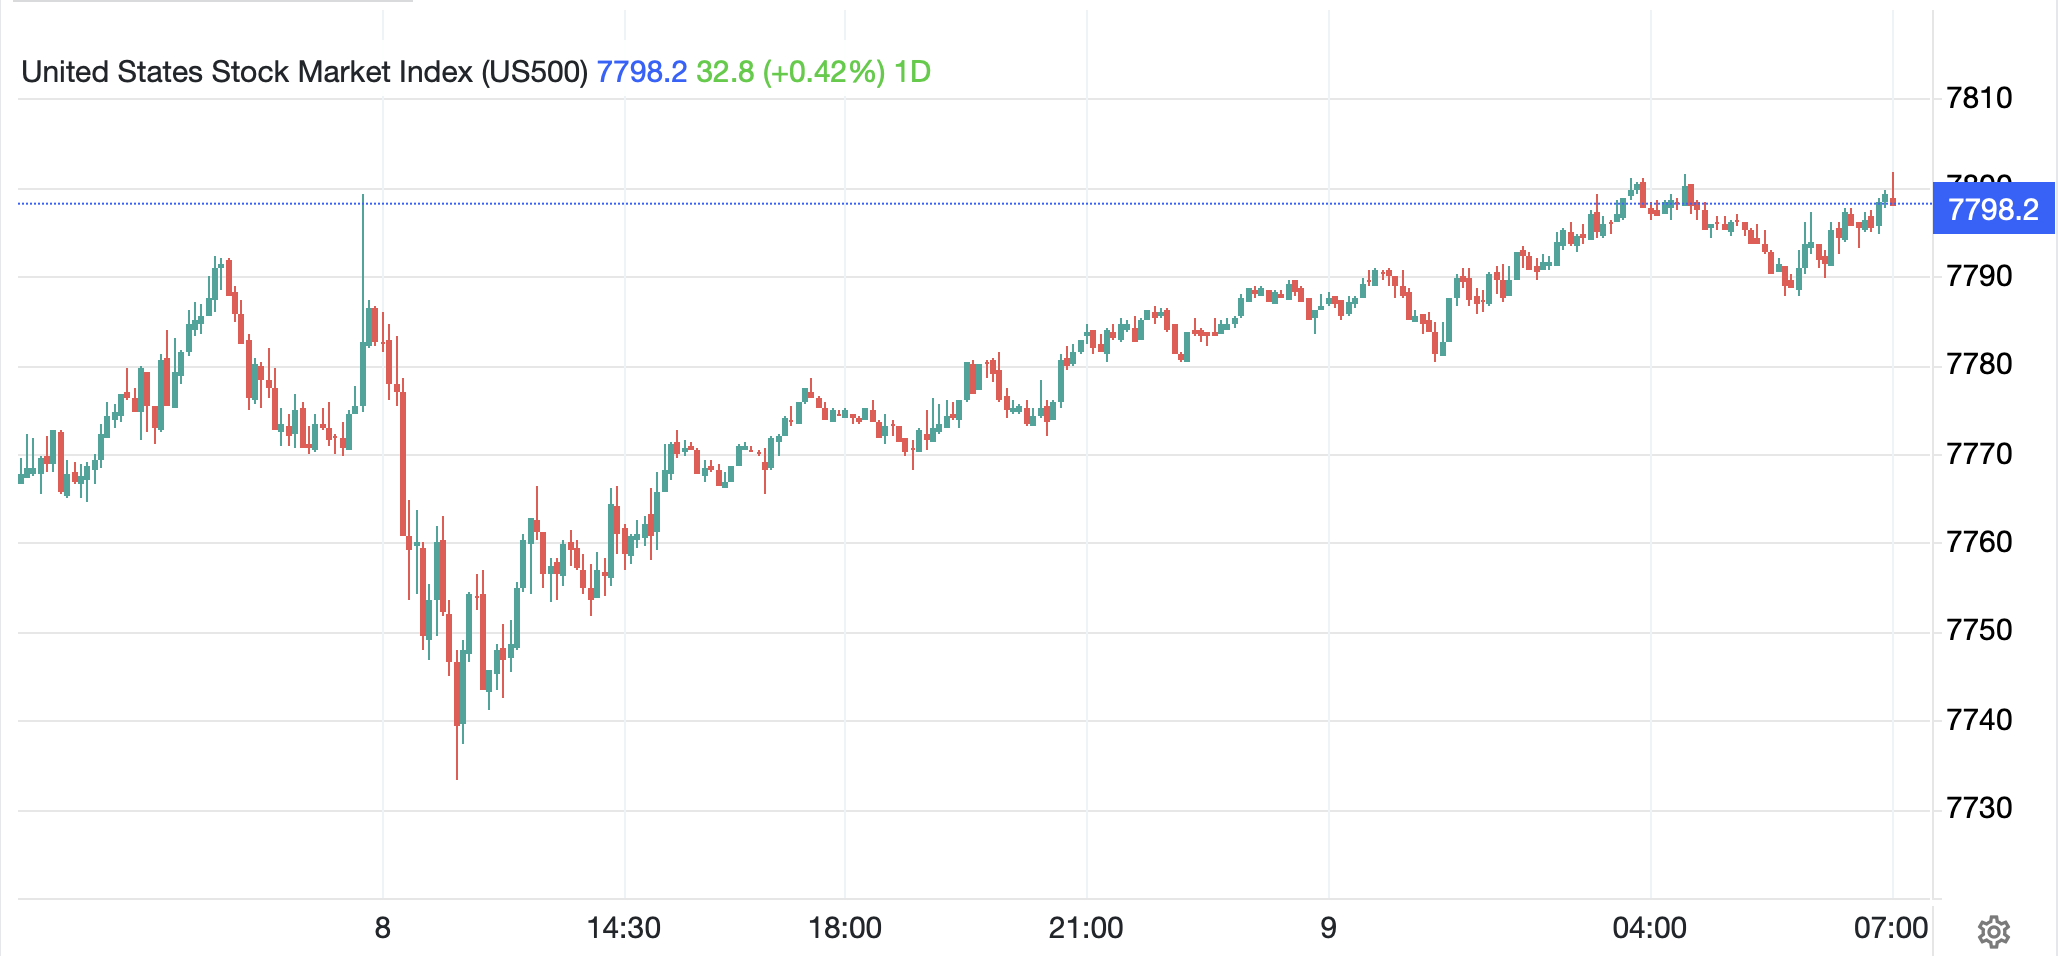
However, while there was an initial spike on the news, risk sold off further for the next hour, as you can see in the below chart, until the Iranians confirmed discussions were ongoing.  It seems that while neither Trump nor Iran is believed by themselves, markets are willing to take a flyer on the two of them saying the same thing.

Source: tradingeconomics.com

And that’s basically where we are this morning.  All the doom and gloom has been put on hold for the moment because, once again, hopes have been raised that there will be a conclusive outcome to the ongoing conflict in Iran and energy markets will be able to get back to a more normal functioning process.  Of course, the Russia/Ukraine war continues and that is also having a significant impact, maybe more than Iran, as Ukraine continues to destroy Russian refining capacity. But the punditry will wait until Iran is settled before they refocus there for their next negative stories.

But as I type this morning, that’s really all there is.  The election remains background noise so far, at least from a market perspective, and likely won’t have a direct market impact until the results are in on November 4th.  The dearth of data this week meant there were no economic fundamentals on which to define a view, so the old trend, which had turned negative, was the default position.  Now, if things really do settle down in Iran, I suspect that will drive renewed interest in both stocks and bonds while the dollar drifts lower.  But we shall see.

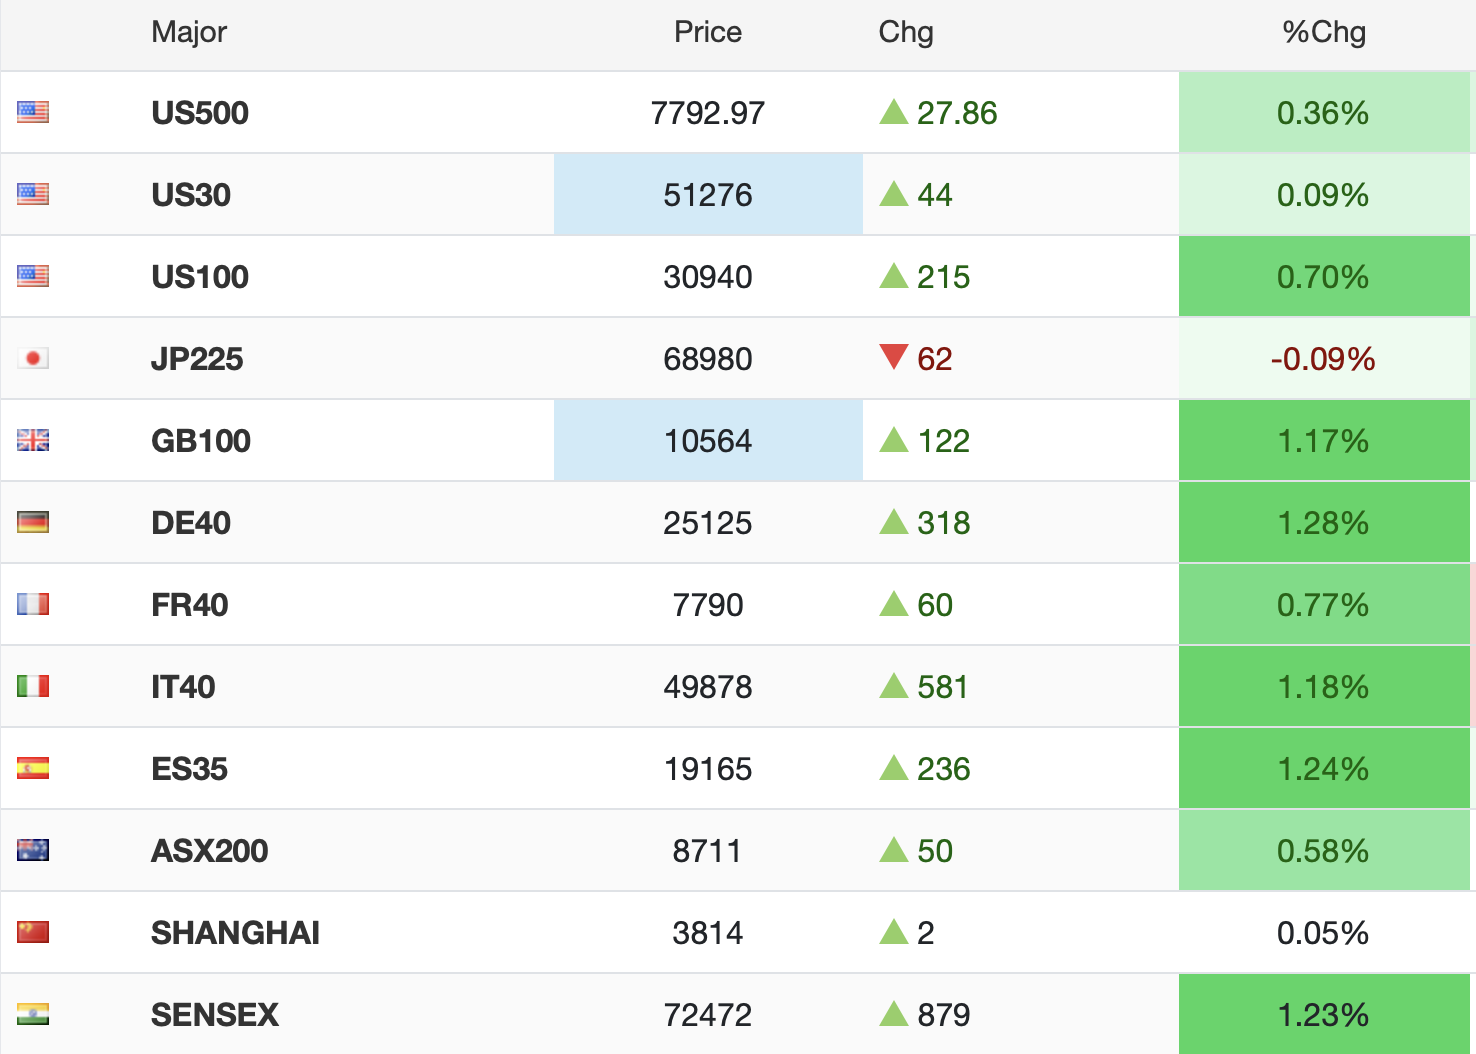
In the meantime, let’s tour how markets have responded to the change in tone.  Equity markets are looking much better this morning as per the below screenshot from tradingeconomics.com.  Other than the Nikkei, which was basically unchanged, green is this morning’s color.  And while the Nikkei slipped ever so slightly, every other index in Japan rose.

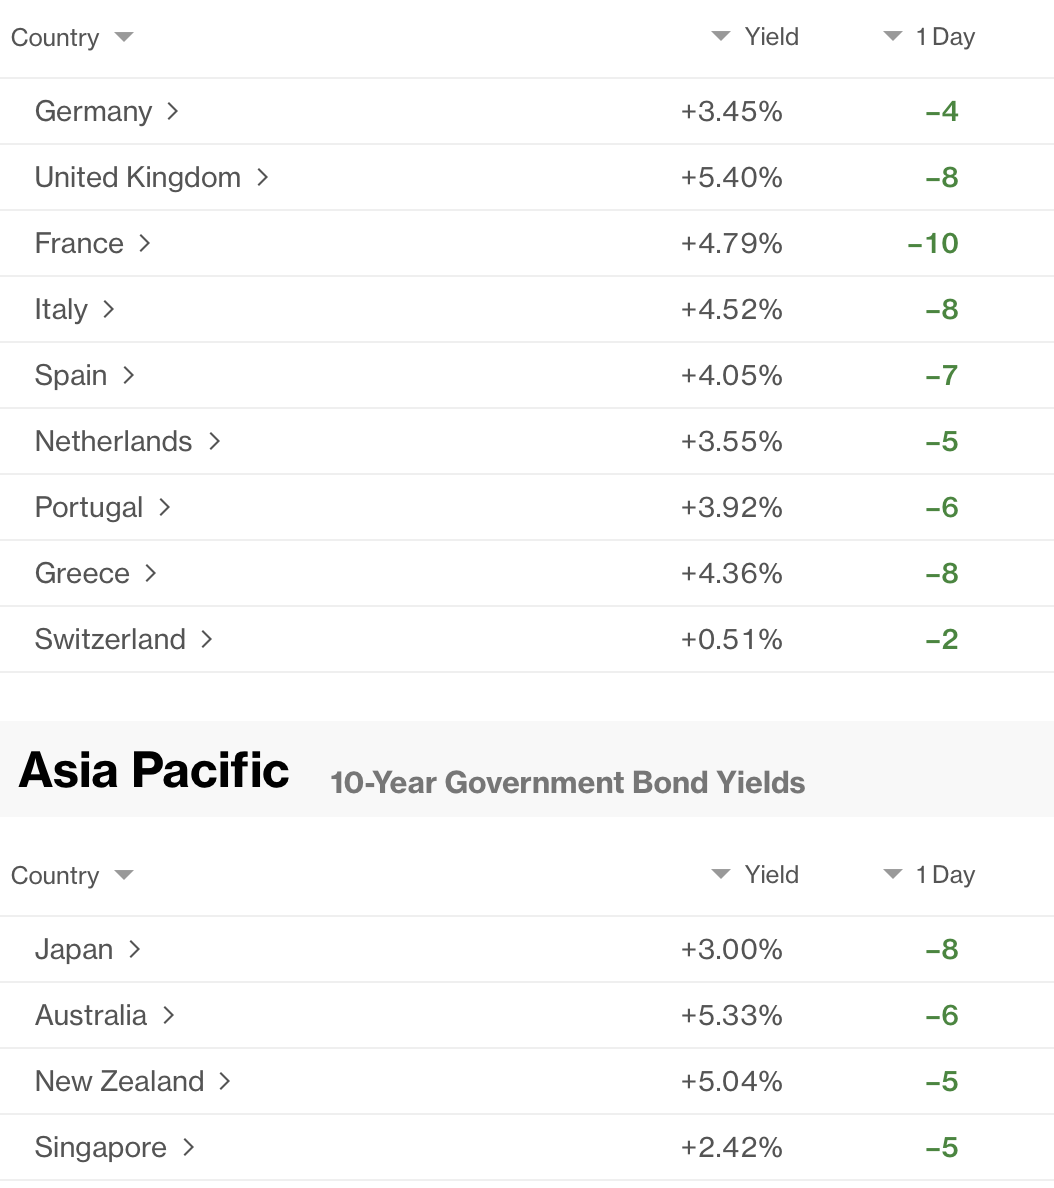
Maybe we are not all doomed after all.  In the bond markets, yesterday afternoon in the US saw yields back off sharply from their recent highs, falling -7bps on the day although they are unchanged this morning.  But that price action has been the driver around the world as you can see in the below Bloomberg screenshot.

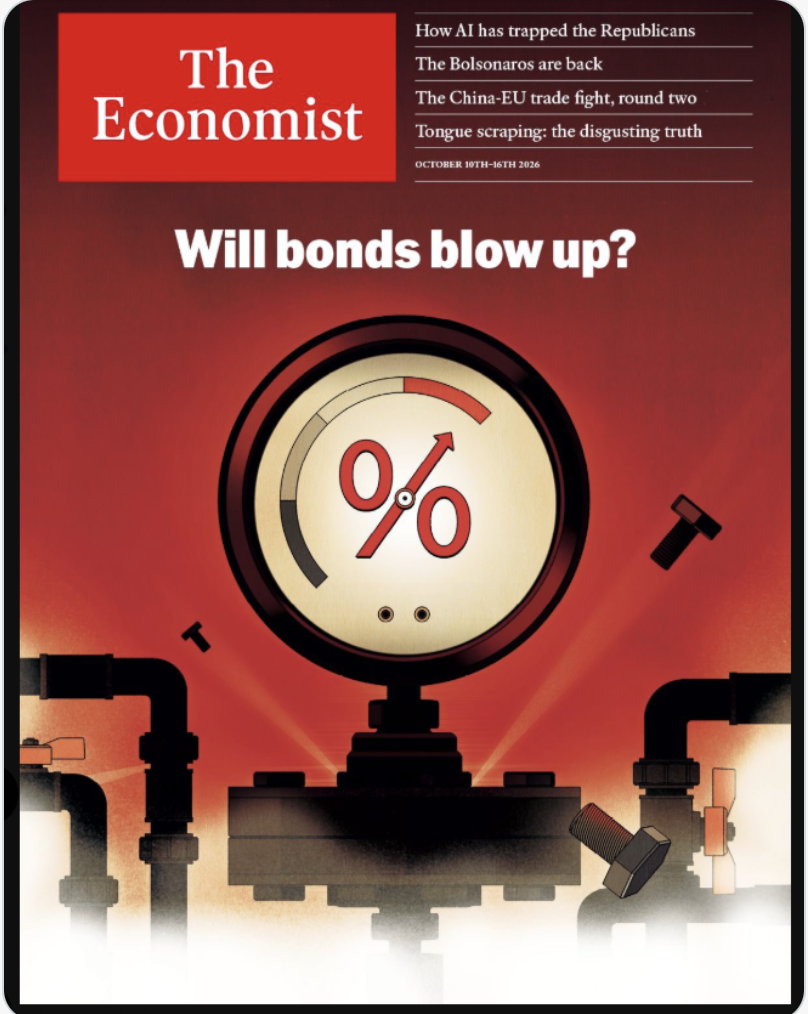
This is not to imply that everything is better around the world, clearly there are still manifest fiscal and monetary issues as well as little things like riots on the streets of France, Belgium and Spain, but those are not yet impacting markets, I believe.  (Of course, if I were Emmanuel Macron, I would be making sure I have an escape route given the outcome of the leadership during the last French Revolution!)  But it seems that at current levels, investors are getting comfortable with the idea of owning bonds.  And the other positive for the bond market is The Economist’s cover this week, a near perfect negative indicator, looks like this:

In the commodity markets, oil (-0.9%) is continuing yesterday afternoon’s slide and sitting right on $90/bbl.  Not surprisingly, between the slide in oil and the fall in interest rates, precious metals markets have rebounded nicely (Au +1.25%, Ag +2.25%, Cu +2.0%).  Certainly, this price action is consistent with what we have seen of late.

Finally, turning to the dollar, it is the one thing breaking the trend as it is marginally higher this morning vs. most of its G10 counterparts.  Recent price action would have you think it should sell off with oil falling and gold rallying, but maybe the stories about fleeing to dollars is correct.  The two outliers here are BRL (+0.5%) and ZAR (+0.5%) with the former seemingly anticipating a Bolsonaro electoral victory and a move toward more conservative fiscal policies while the latter is simply responding to both oil’s decline and gold’s rise.  I continue to have a hard time getting excited about a significant move in the dollar for now although also believe that modest strength over time is the way forward.

On the data front, yesterday’s Initial Claims came in low, just 197K, which continues to point to a labor market that is not under huge stress.  I wonder, too, how quickly the impact of the administration’s crackdown on H1-B visas is going to be seen in the data as the numbers I read this morning, 700K US workers were laid off in the tech space and the same number of H1_B visa’ed immigrants were hired in their place could portend another step lower in this series.  As to this morning, Michigan Sentiment (exp 47.6) is the only thing on the docket.  However, I wonder how much of that particular indicator is a political statement vs. how much as an economic outlook.

The weekend is upon us, and I see no reason for this morning’s positive vibe to dissipate.  I know all the arguments about the lack of breadth in the market and the massive dichotomy between the tech space and the rest of the economy, but following the numbers, there is no indication to me that the end is nigh.  While I disagree with much of Keynesian monetary philosophies, (I lean Austrian there) he was certainly correct when he told us that ‘markets can remain irrational longer than you can remain solvent.’  I’m not betting against a continuation of the equity rally, and am long bonds as a trade, thinking yields have peaked, at least for a while.

Good luck and good weekend

adf

On the Boil

The Minutes were pretty benign
As everyone toed the hike line
But this was old news
And Payrolls did bruise
The view Funds would soon rise and shine

As well, Bessent sold 10-year debt
And yields, buyers’ hunger, did whet
It seems there are some
Who think it’s not dumb
To grab these real yields they can get

And lastly, this morning’s ‘bout oil
Whose price is now up on the boil
The Strait of Hormuz
Is not safe to cruise
And this, major markets, did roil

Starting at the top, the FOMC Minutes were released yesterday and it’s not clear to me how much we learned.  The unanimous vote to raise rates was accompanied by commentary that prices were an ongoing concern while the labor market seemed ‘balanced’.  Of course, that was prior to the release of last week’s NFP report which showed that the balance may be tipping toward the downside, but that was just one report.  The weekly claims data (exp today at 200K) hardly speaks to a serious problem there.  As I type this morning, the probability of a hike at the end of this month is ~20% and has been so since last Friday’s release.  Frankly, I don’t think we learned a great deal here.

Turning to yesterday’s 10-year Treasury auction, though, things were a bit more interesting.  You may recall before my hiatus that there was a 5-year auction that had a relatively long tail, meaning that the final yield was 3.1 basis points higher than the when-issued price at the time of the release.  That was seen as a very negative sign for the bond market.  Well, yesterday, the 10-year auction saw a 1.7 basis point improvement on the when-issued price, a sign there was much more demand than anticipated.  In fact, dealers took down only 2.5% of the auction with the rest going to investors of all kinds.  That type of price action is quite positive and certainly puts paid to any discussion that investors don’t want to own Treasuries.  It seems that at 5.3%, with a real yield of 2.5% or so, investors feel quite comfortable owning Treasuries, despite all the talk of too much debt leading to a calamity.

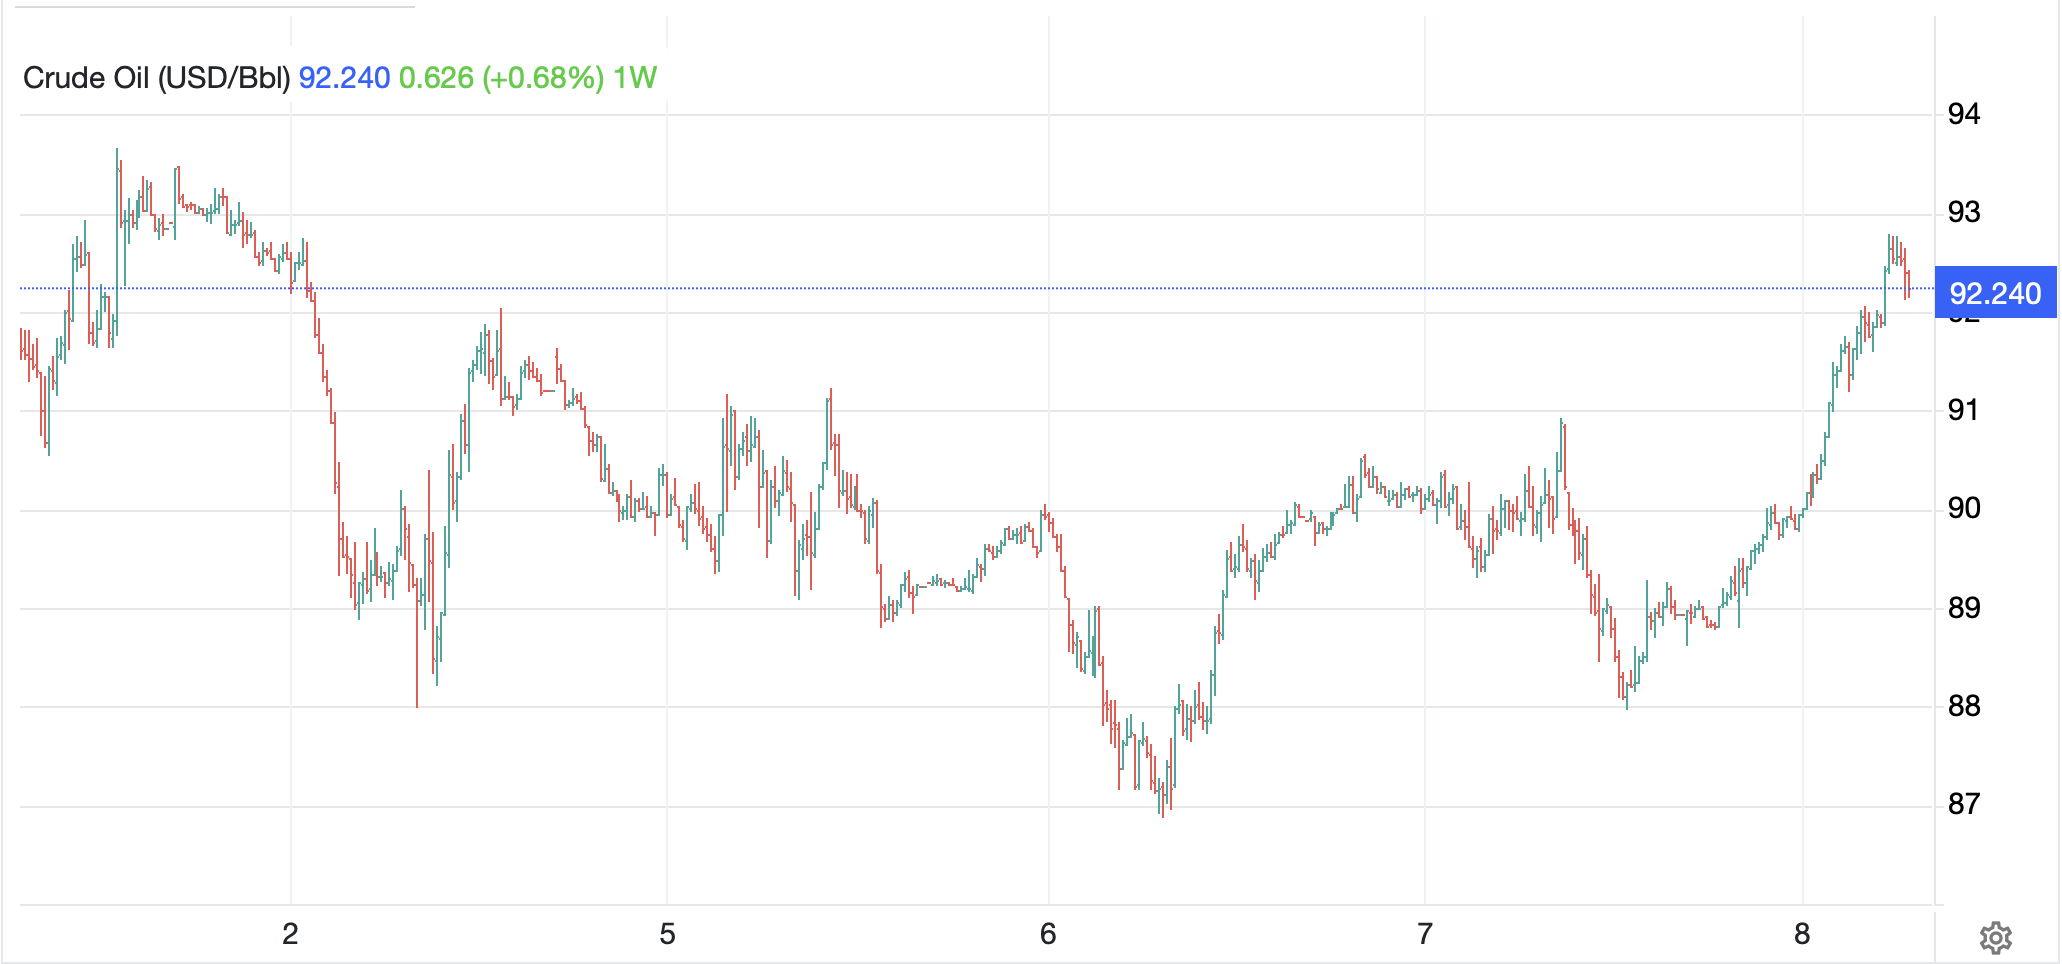
But today is all about oil (+4.5%) and the recent increase in attacks on ships through Hormuz.  While last week, data showed that the flows had resumed to nearly pre-war levels, that has changed.  Add to that the news that President Trump has ostensibly asked the Pentagon for updated plans for renewed military action soon, and nerves are jangling across markets.  The below chart of WTI shows the reversal of price declines, but we are only back to levels seen last week.  This is not extraordinary, especially given the volatility we have seen in this market.  In fact, as you can see in the chart, the 1 week move shows oil higher by just 0.7%.

Source: tradingeconomics.com

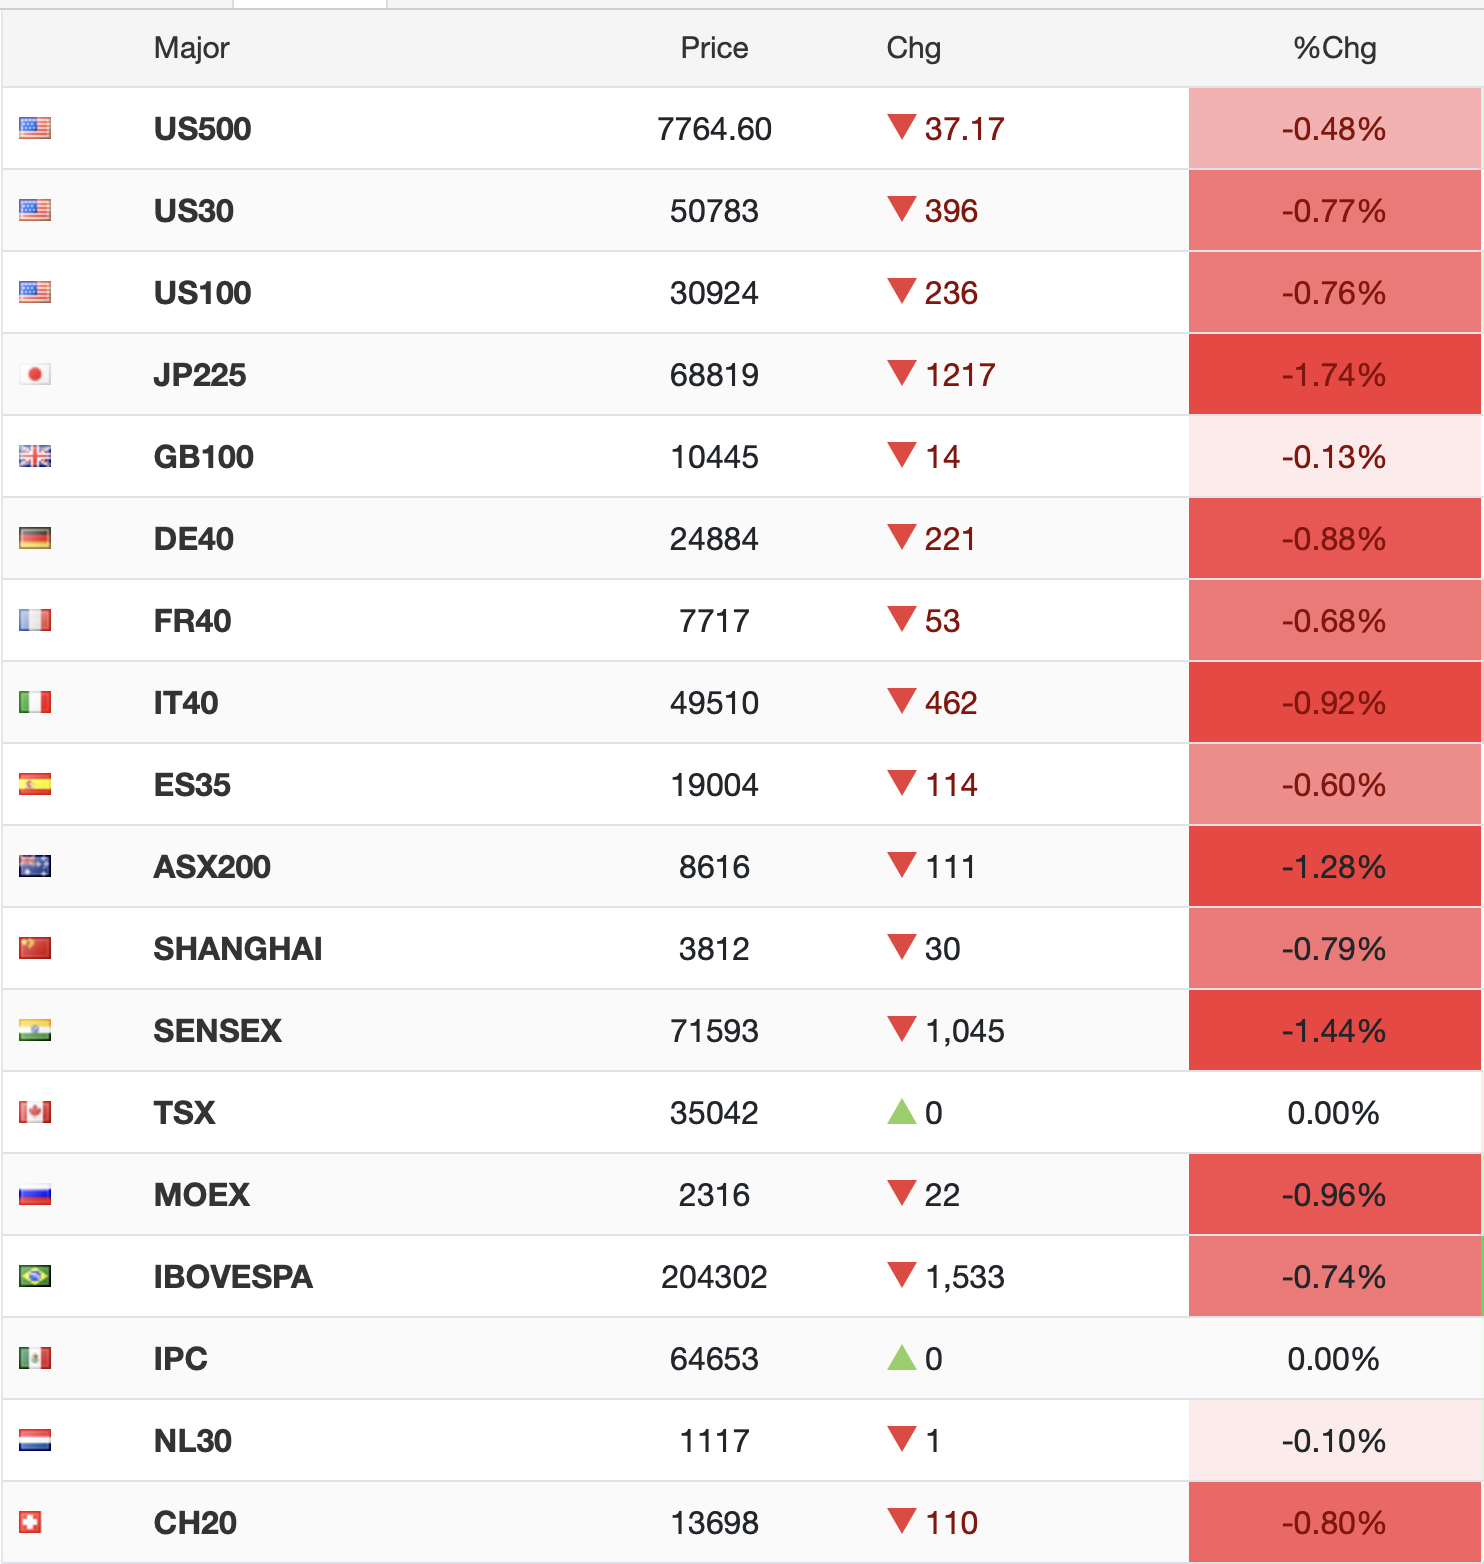
But every day is a new one, and today’s markets are being driven by the oil situation.  You can see that clearly in the equity markets via the screenshot from tradingeconomics.com showing every market that is open (Toronto and Mexico are still closed) lower on the day by a pretty substantial amount.

Adding to the woes in the oil market is that the first hurricane of the season, Isaias, has formed in the Gulf of America and has forced the shut-in of about 25% of drilling activity there.  Of course, that will be gone by Sunday and those rigs restarted, but for now, no bueno.

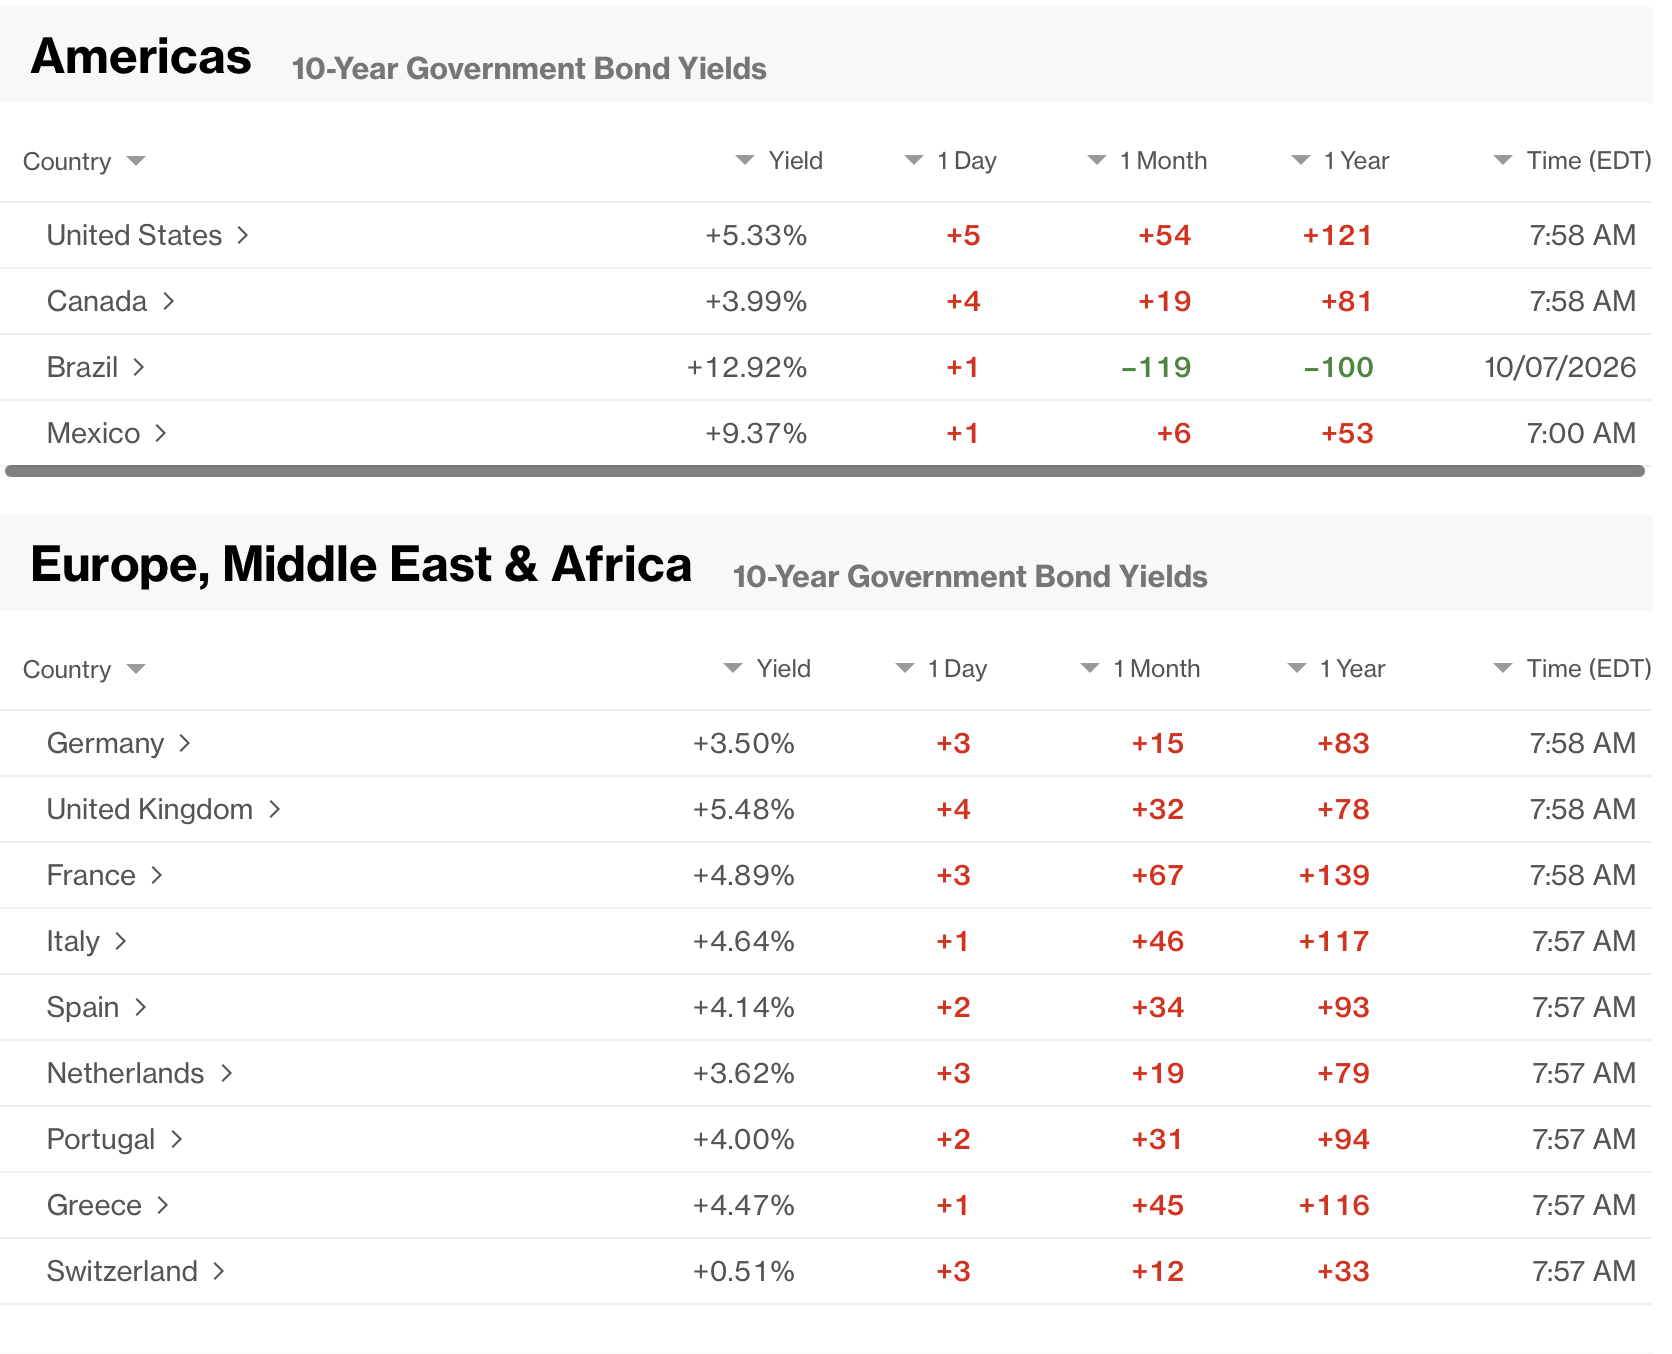
If we head back to the bond market, despite the strong auction results, this morning we are seeing yields rise everywhere in the world, albeit not as dramatically as yesterday.

Source: Bloomberg.com

One thing to note is that the spread between German and French debt has widened to its greatest gap since the Eurozone bond crisis in 2011 as concerns over French fiscal policies are really starting to bite.  The protests in the street there are not helping, and investors are looking forward to the presidential election next spring where both the leading candidates are talking about lowering the retirement age to 60 from the current 62.  I assure you, that will not help the fiscal situation either.

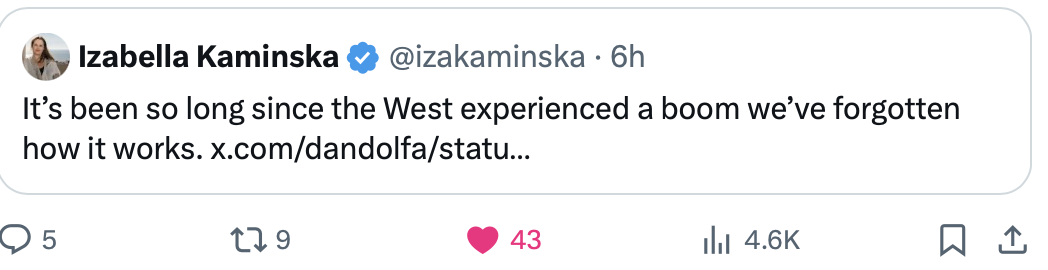
But let us consider this for a moment, why yields are rising.  Is it entirely inflation concerns or is it something else?  Earlier this week I discussed the fact that inflation breakevens remain pretty well anchored in the 2.3% to 2.5% range, indicating inflation is not the main concern.  Rather, it appears to me that the factors driving yields higher are far more positive, namely stronger growth as currently symbolized by the hyperscalers borrowing massive amounts of money for their AI efforts, but arguably a reflection of the fact that the US economy is growing strongly.  Izabella Kaminska (@izakaminska on X), former financial editor at the FT, made a very good point this morning on this subject.

In essence, running it hot means stronger private sector growth pushing demand for financing higher.  However, it should also push up tax revenues reducing requirements for government borrowing.  It can work out so they offset, but that will be tough, so there are going to be bumps.  But, with Kevin Warsh not signaling great concern over the higher yields in the bond market, rather than financial repression (President Trump’s favored strategy), perhaps we just get back to a functioning economy and market with less interference from the government…well, one can always hope!

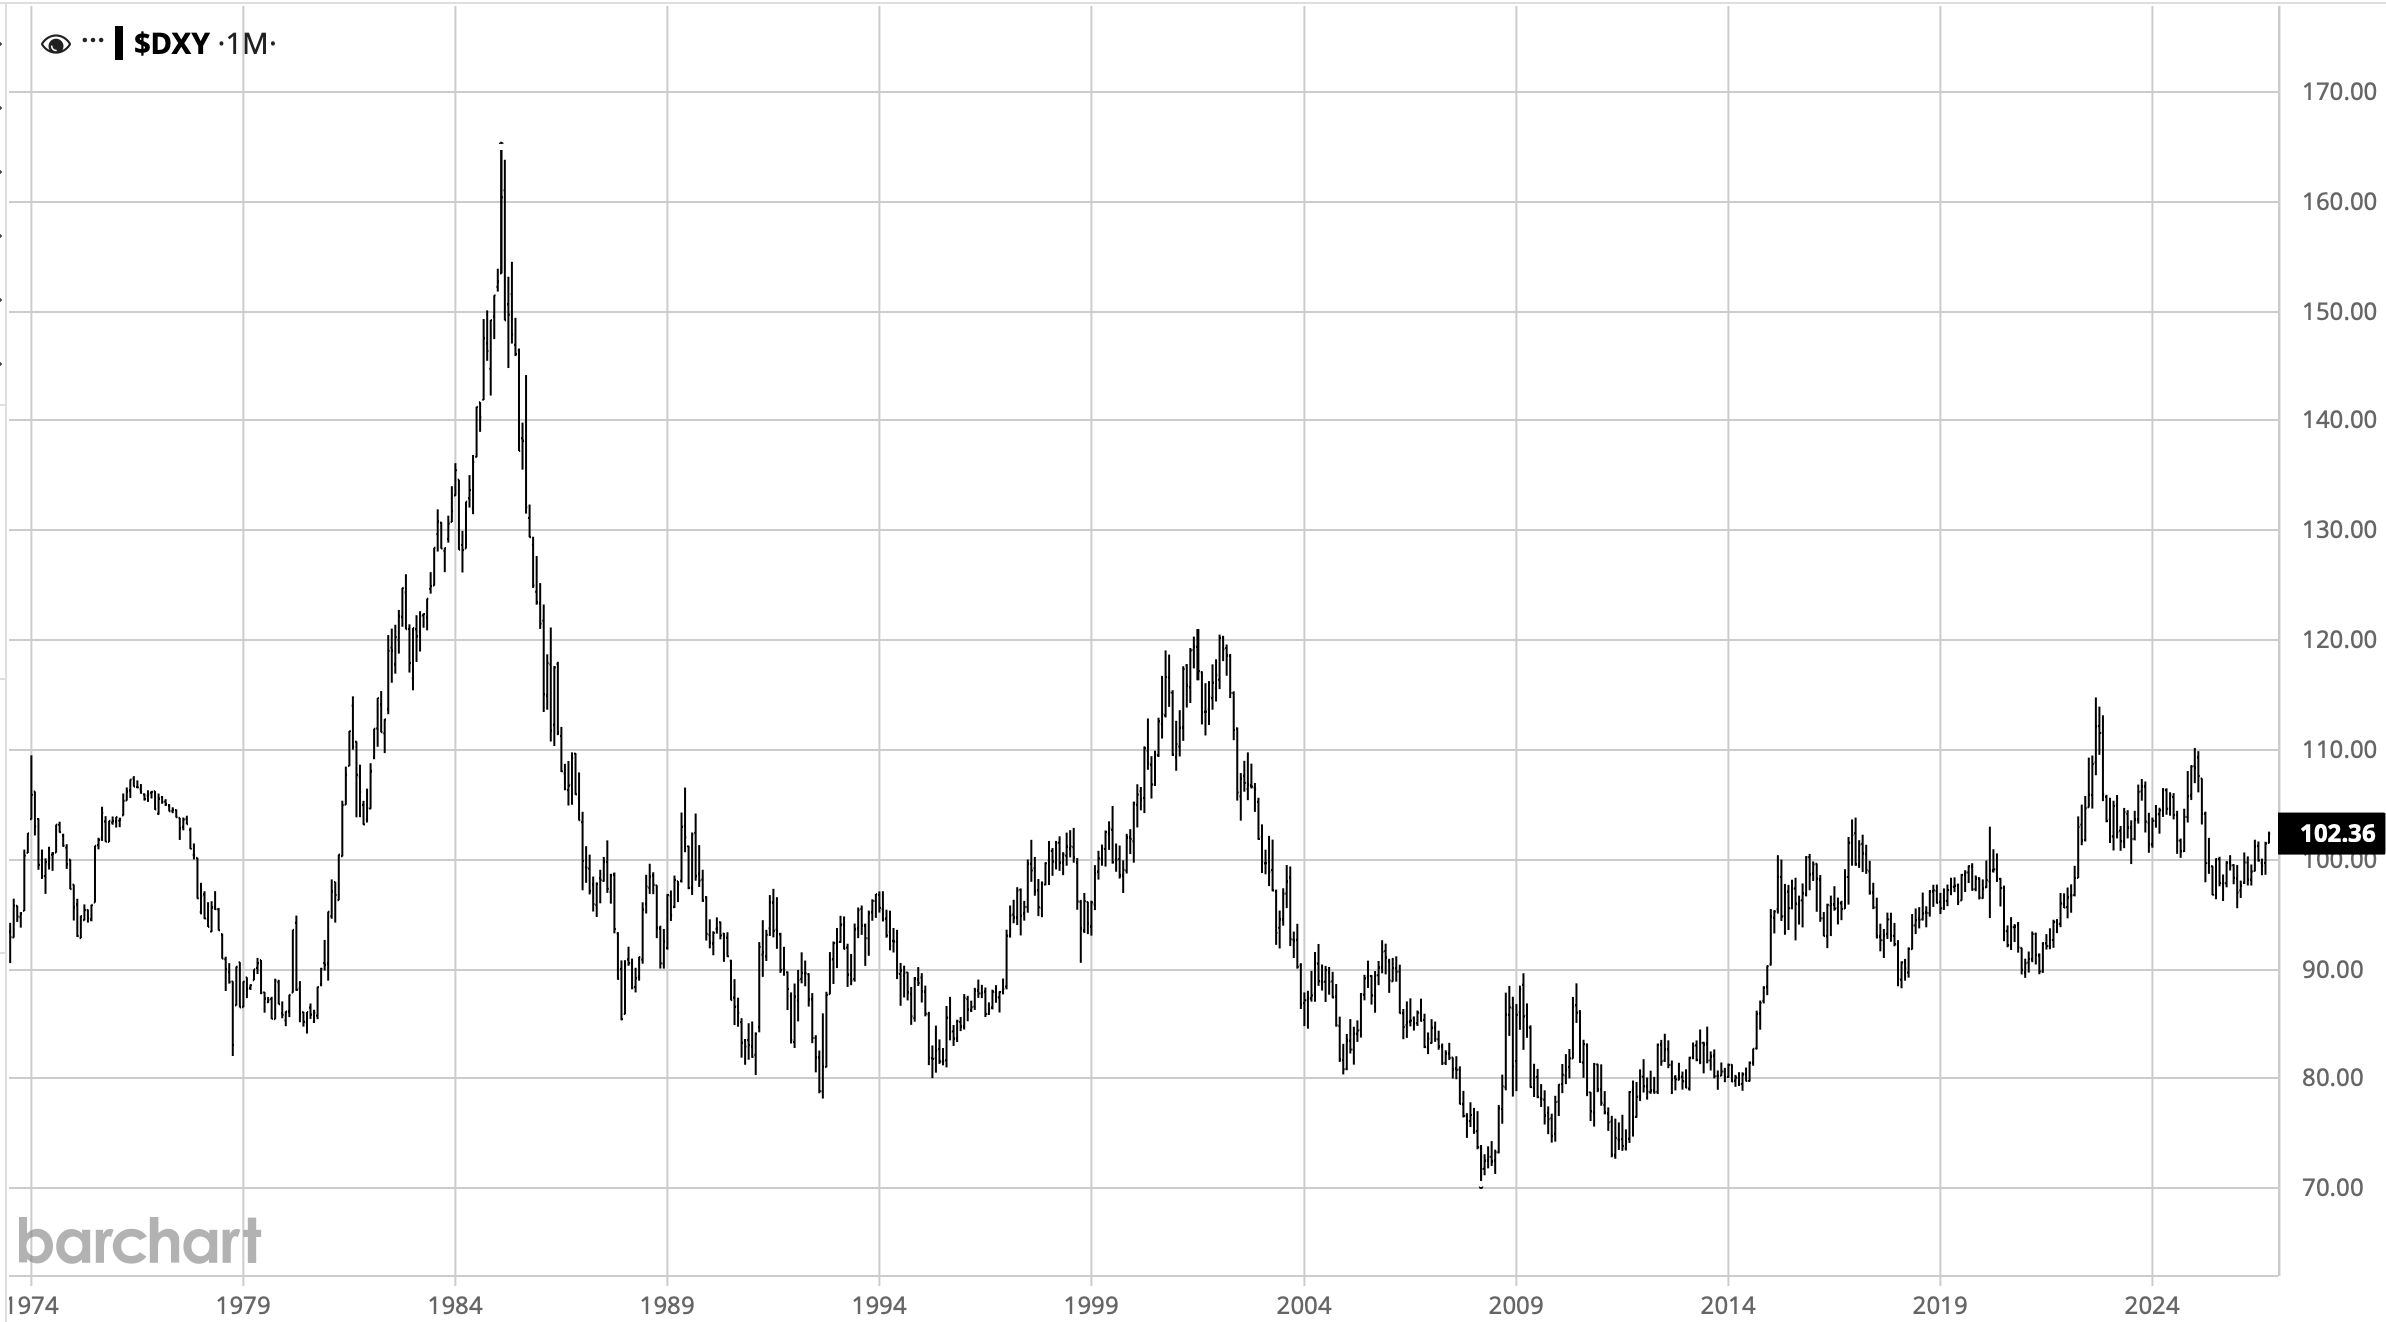
It should not be a surprise, then, that the dollar remains a major beneficiary of the current state of affairs.  This morning it is higher yet again, albeit not dramatically so, only 0.1% against most major currencies.  But let’s talk about the strength of the dollar.  Is it really that strong?  You all know how much I love to take a longer-term view on these things and this is no different.  So, look at this chart of the DXY from barchart.com from its inception in 1974, and tell me if you think the dollar looks “strong”.

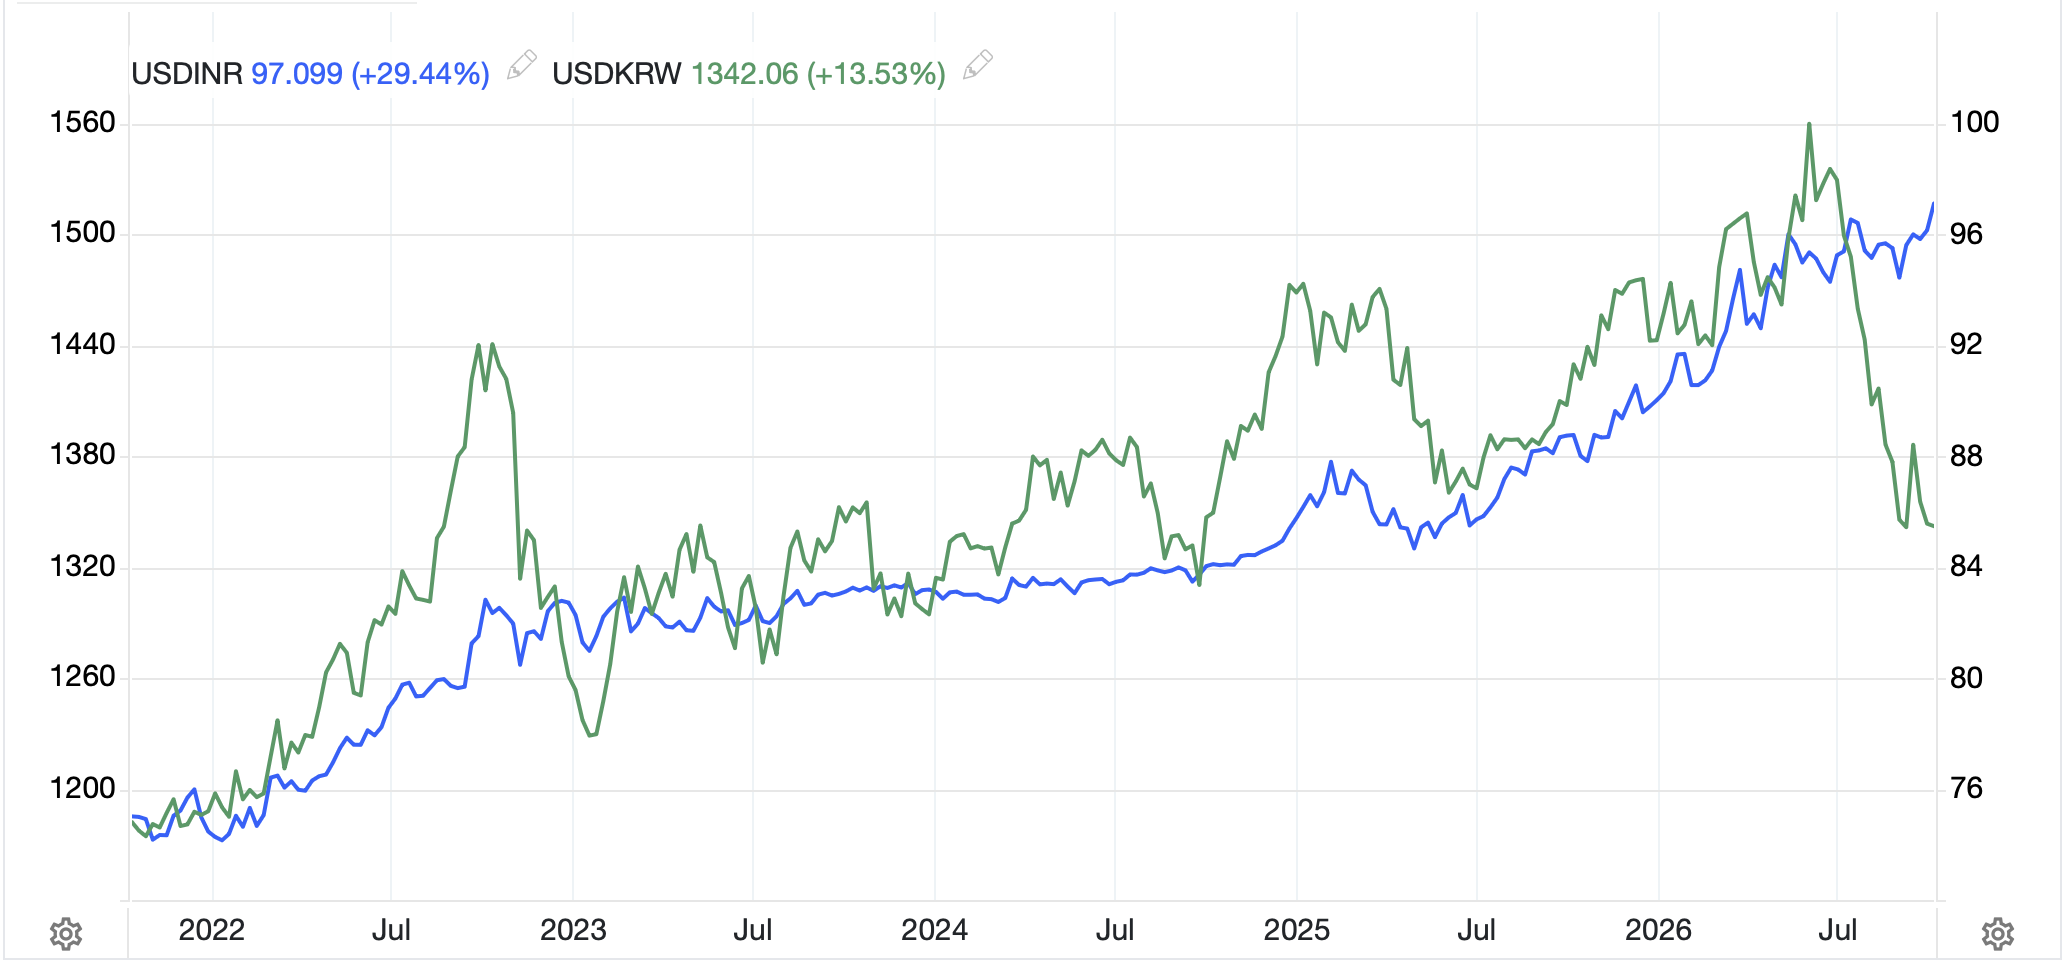
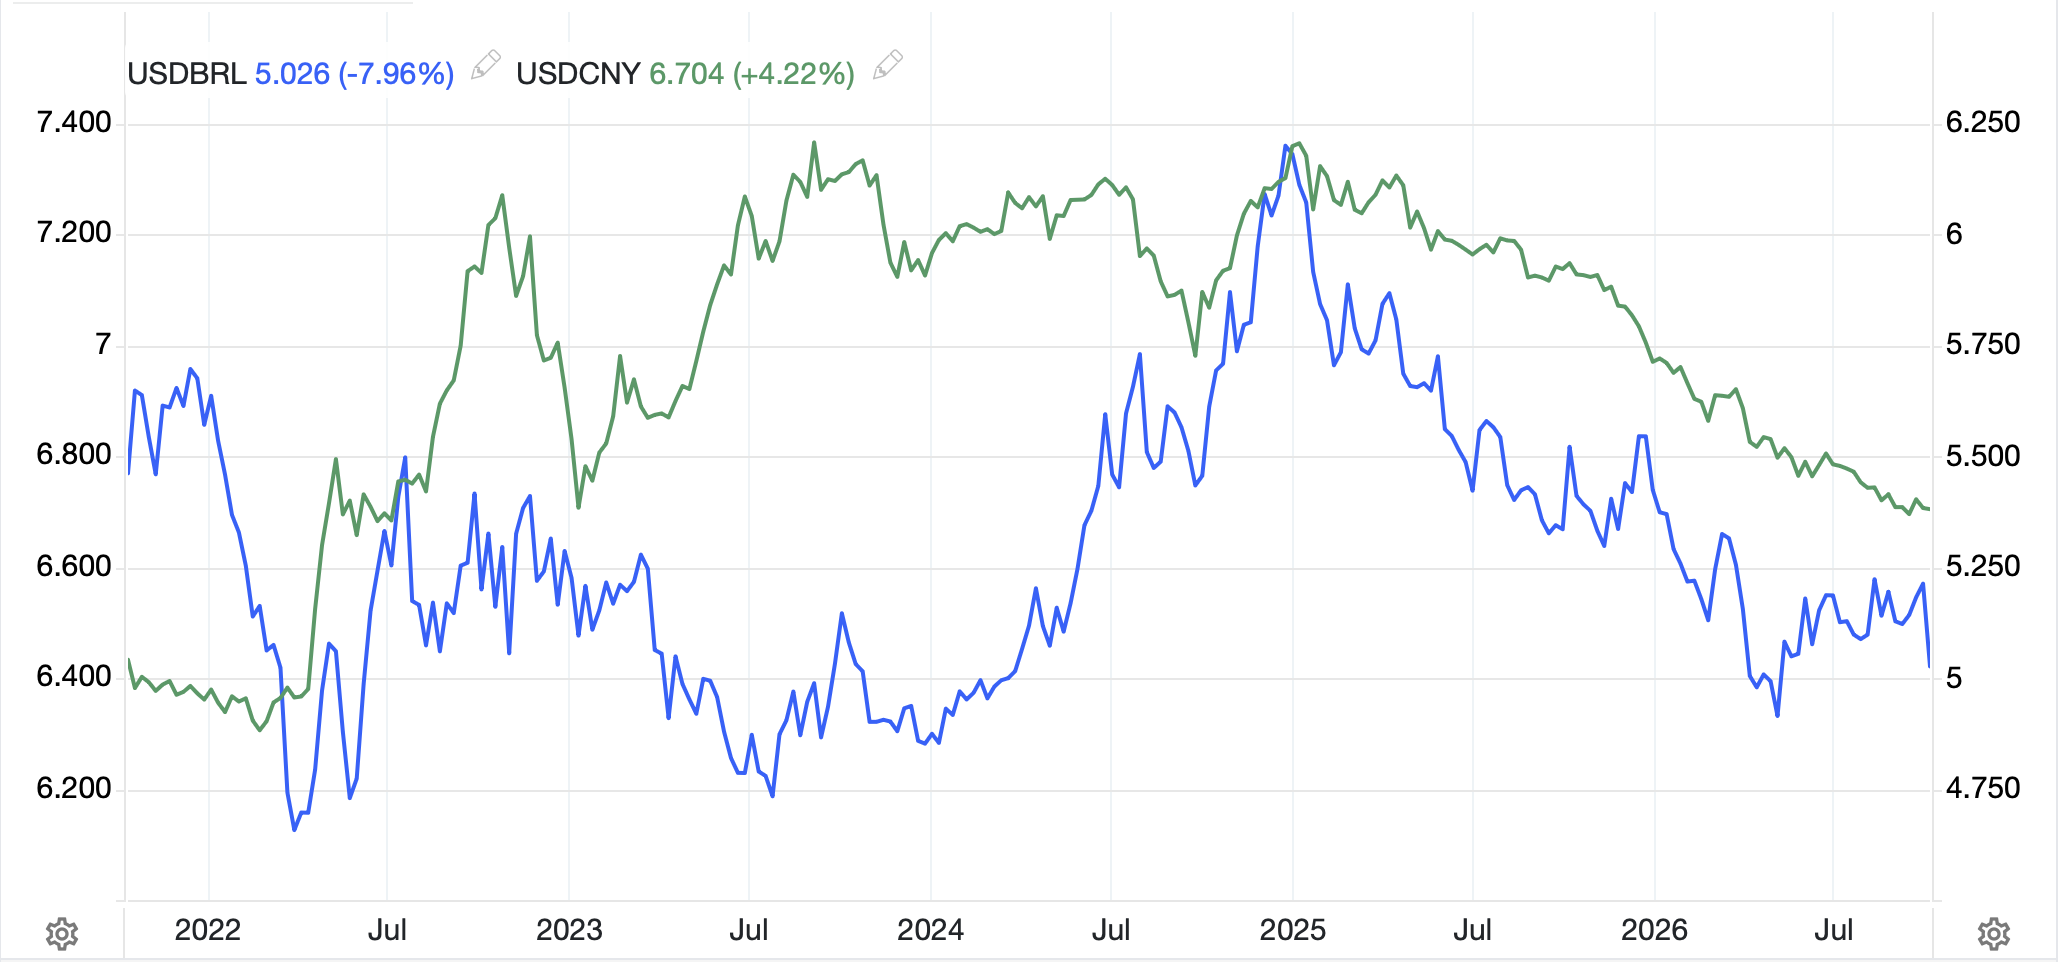
I remember getting the data and the average of the DXY is around 104.00, so we are not even there.  In fact, the greenback is in a very ordinary place.  Now, the DXY is representative of G10 currencies but not necessarily EMG currencies.  However, that story has been quite divergent depending on the currency in question.  For instance, if we look at the next two charts, we can see that movement across key currencies in this bloc have been very different.

Source: tradingeconomics.com

You can see INR and KRW, until very recently, have weakened substantially, while below, BRL and CNY have both shown real strength over the past 18 months, although had been more mixed prior to that.

Source: tradingeconomics.com

My point is, aside from the rupee, which is at long-term historic lows, we have seen all these prices before.  There is no reason to panic about the dollar collapsing or becoming “too” strong.

We get our only real data of the week this morning with Initial (exp 200K) and Continuing (1710K) Claims and Wholesale Inventories (+0.7%), although nobody pays any attention to that.  There is no doubt that market participants are nervous about a lot of things and that is why risk assets are under pressure.  If the Iran conflict escalates, I expect we will see that play out for a longer time, but I have no opinion on whether that will be the case or not.  To me, I take heart in the fact that economic activity appears to be moving along well, and ultimately, that is a huge positive for the country, and by extension, will support the dollar.

Good luck

Adf

It’s Been Hell

Despite all the angst ‘round the earth
The one thing of which there’s no dearth
Is risk appetite
As both left and right
All want to increase their net worth

However, at times it’s been hell
To choose what to buy or to sell
The dollar is strong
So, best to be long
But what if yields here quickly fell

And what about stocks, can they rise
From their now historic new highs?
And let’s not forget
The government debt
Or ‘bout a November surprise

It is very confusing these days, as if you read or listen to the news, the sky is falling.  But if you look at market prices of so many assets, things look pretty good.  Now, I understand the iron rule of media is, if it bleeds, it leads, and so in a world where getting clicks is far more important that recounting a coherent story about what is happening in the world, there is little, if any, effort to produce the latter.  Alas, while sentiment is clearly an important part of all markets, I remain enough of a curmudgeon to continue to believe that the fundamentals still matter.

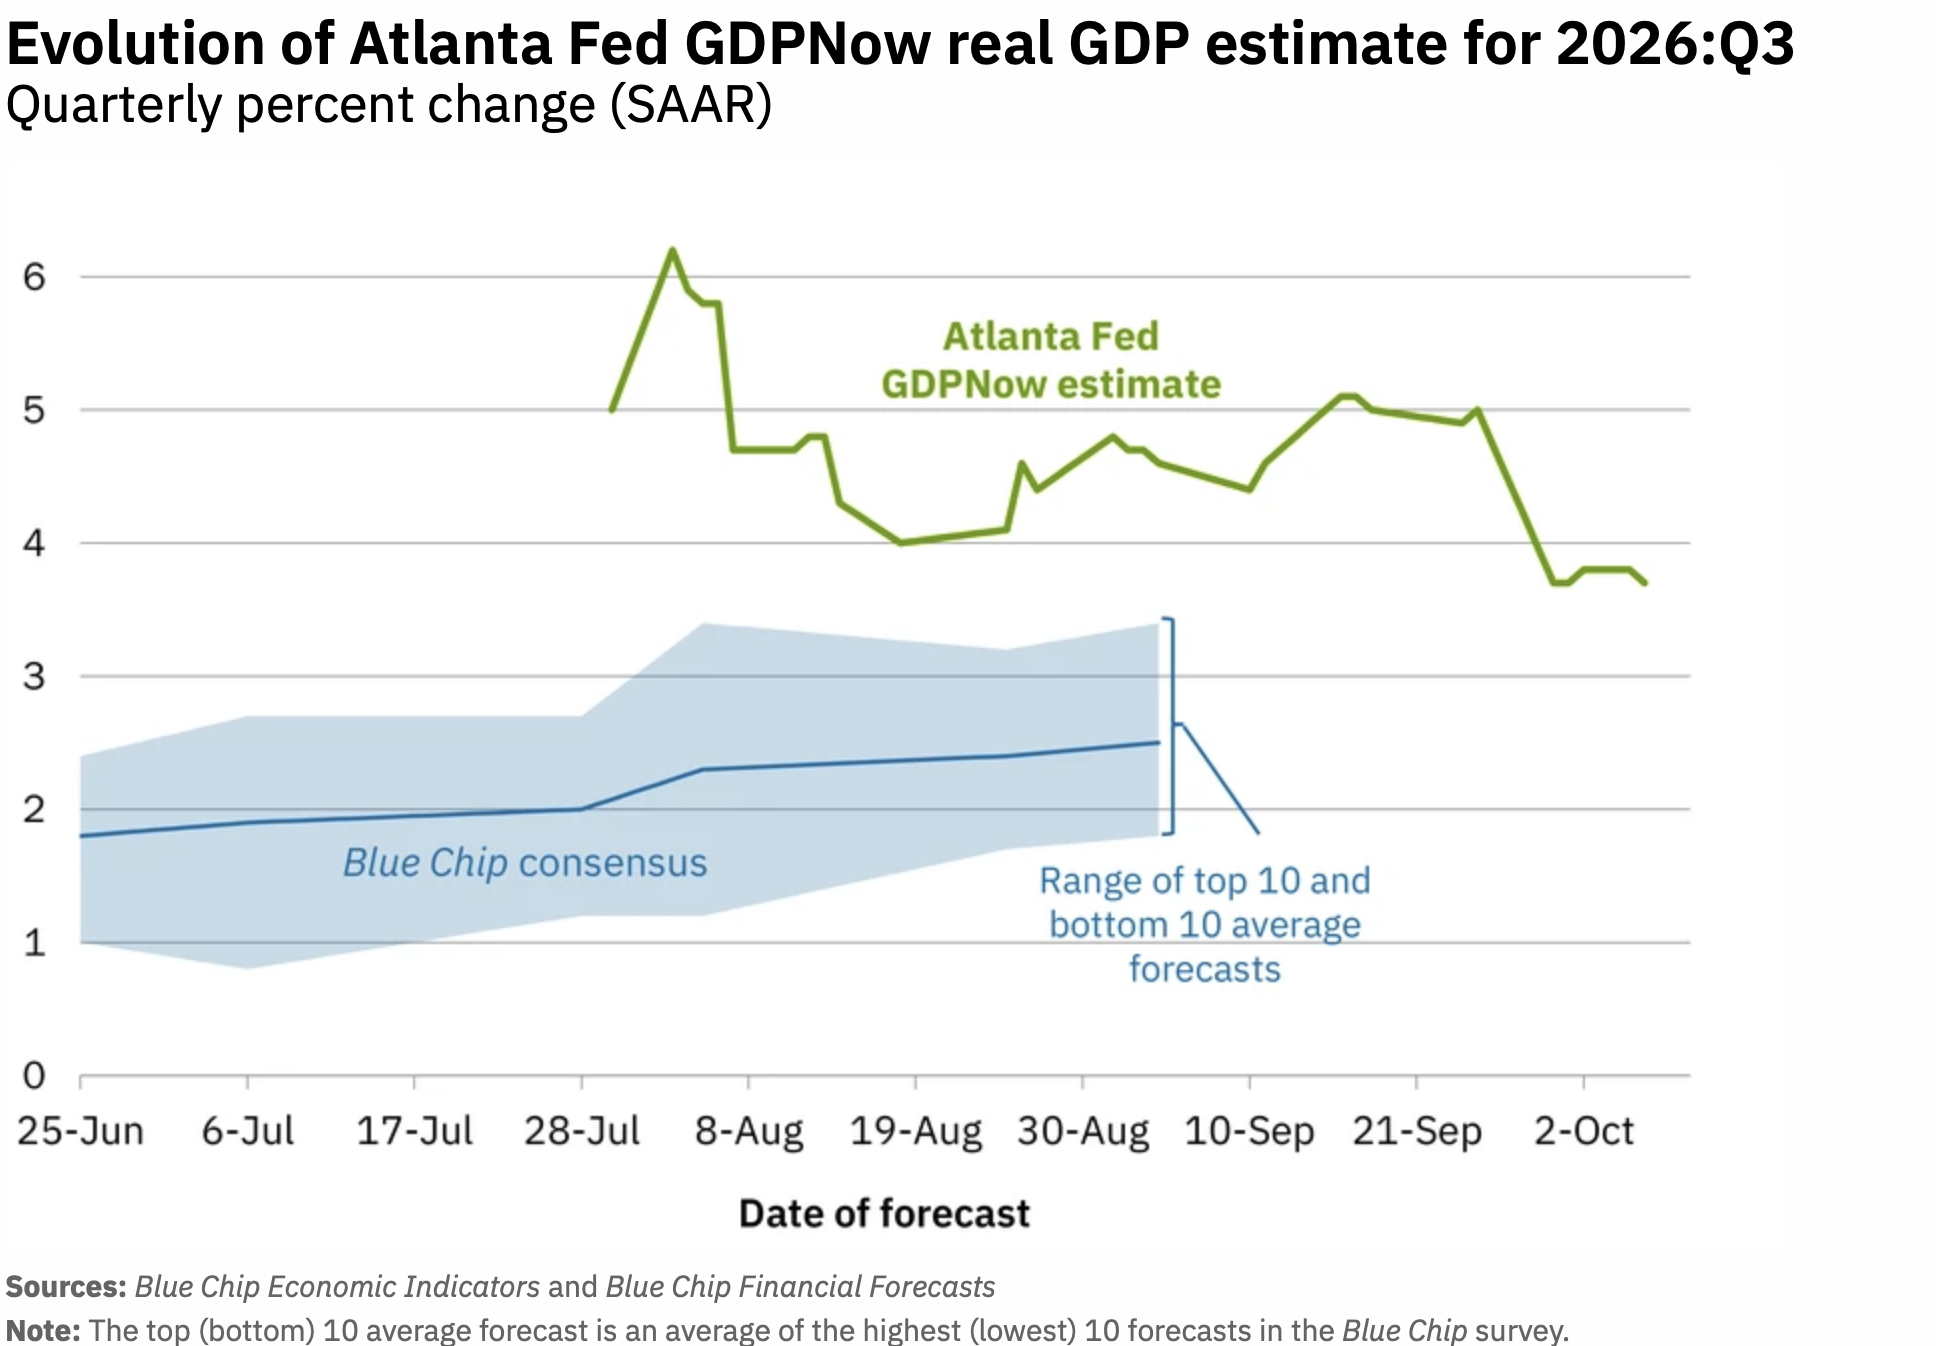
So, what are those fundamentals?  Well, if we look at the economy writ large, even after a weak payroll report last week, the Atlanta Fed’s GDPNow estimate remains at 3.7% for Q3 as per the below chart.

And interestingly, despite all the positive data, notably things like the ISM Surveys, Retail Sales and Personal Spending, we continue to read headlines about problems in the economy.  A great example was yesterday’s Trade deficit which printed at a higher than expected -$105.6B, which was the worst reading since the month before President Trump’s tariffs were inaugurated last year.  But ask yourself, why is our trade deficit growing?  The answer is because the US is growing far faster than other nations and so not only are we sucking in more imports, but export markets are weak.  As it has been said before, if you want to close the trade gap, send the country into a depression, then we won’t buy any imports, although that seems like an extreme solution.

But that US economic strength shows itself in various ways.  For instance, Treasury yields continue to rise, up 5bps this morning, although that is dwarfed by moves in Europe (France +16bps, Italy +13bps, Greece +12bps, UK +10bps).  The question to ask here is, why are yields rising?  While the most recent generation of traders and economists continue to believe this is a sign of fears over inflation, or perhaps excess government debt, given the lack of movement in TIPS breakevens, it very much appears this is all about higher real rates.  Demand for capital in a growing economy seems to be driving yields higher.  Again, I harken back to my youth in markets when the strong belief was that 10-year yields should trade right around nominal GDP growth.  At 5.33%, we remain far below that level.

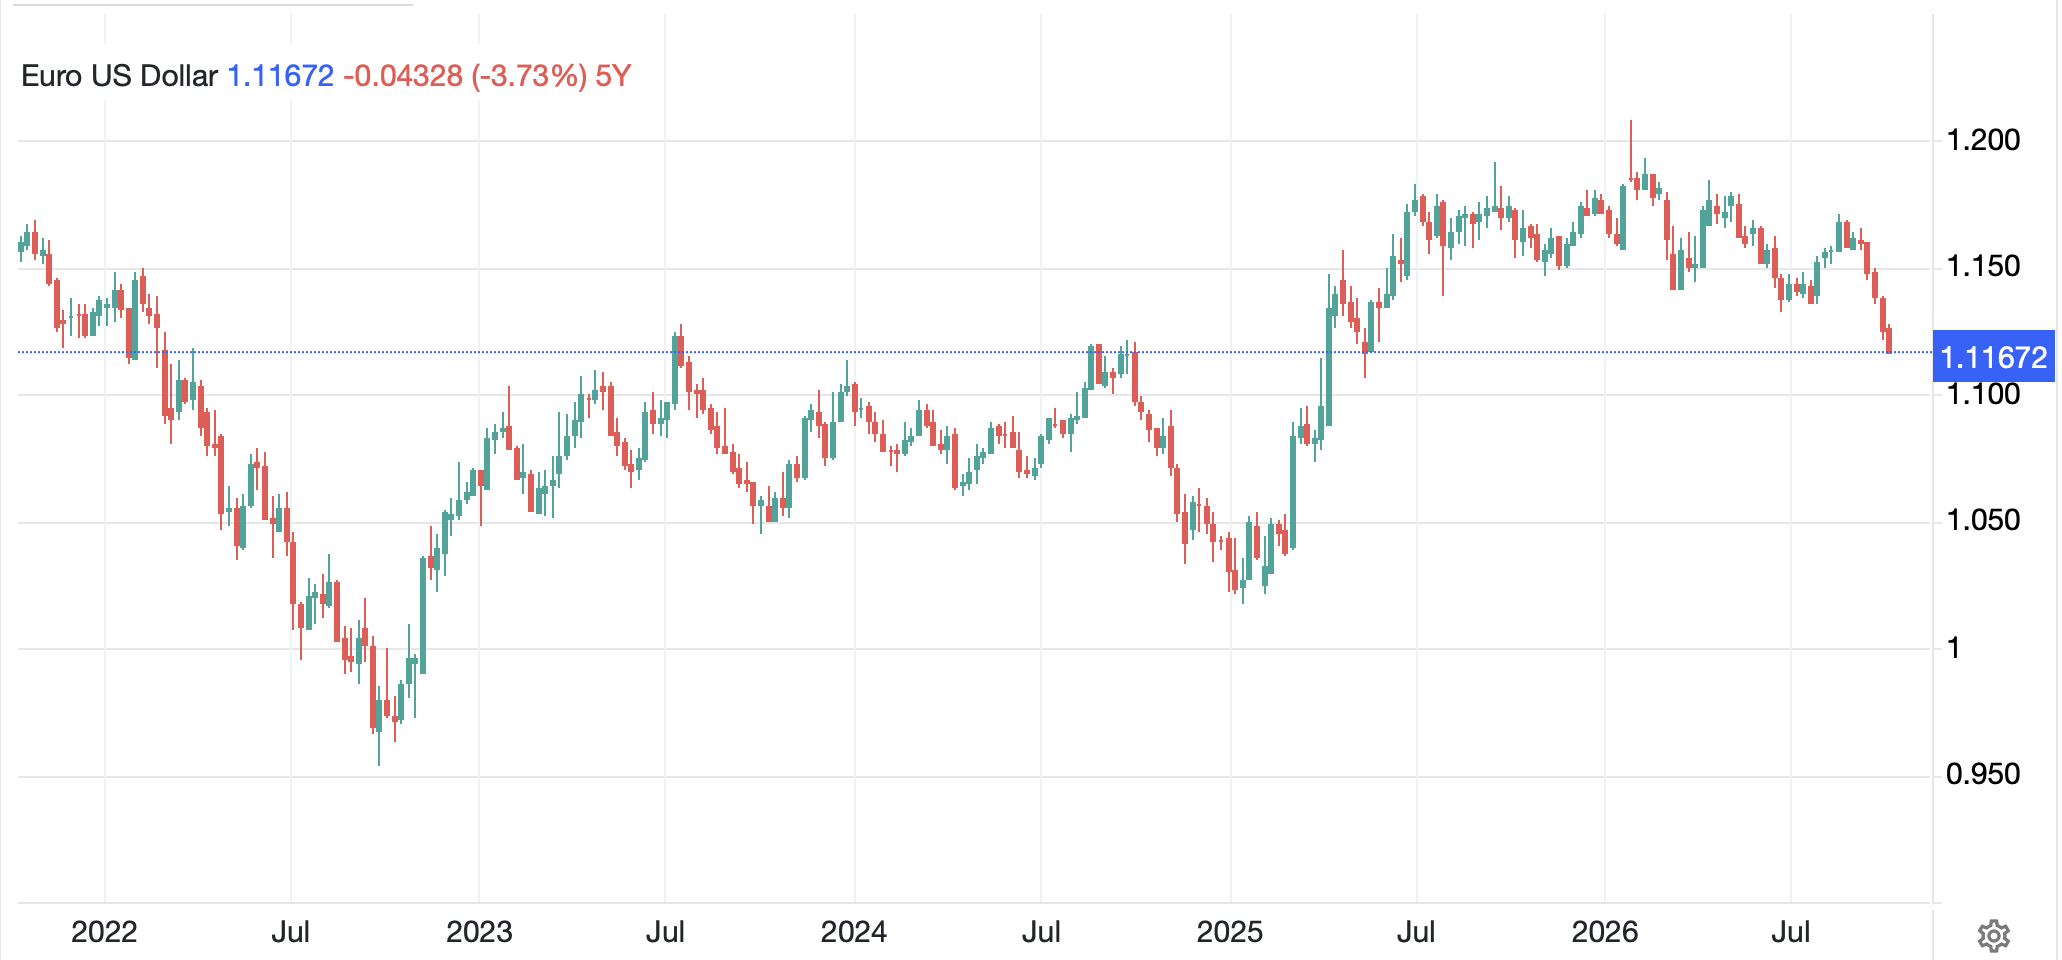
Investors are buying the US writ large.  You can see that in the dollar, where the euro (-0.8%) has fallen to its lowest level since May 2025 as per the below chart.

Source: tradingeconomics.com

But look at this chart.  The euro is nowhere near its lows of the past 2 years, let alone historic lows, so the idea that the dollar is overly strong remains laughable.  In fact, if the US continues to grow its economy the way it has been doing, and if investment keeps flowing into the US like it has been, the dollar can get much stronger.  While the yen has been depreciating for a long time, the same has not been the case with the euro or other G10 currencies, and I see no appetite for any official action to stem the dollar’s strength here.  If I consider the insanity of European energy policy leading to its ongoing deindustrialization, I see no reason that parity in the euro is not a real target.  Not right away, but by sometime next year for sure.  And this is especially so if the Republicans hold the House and Senate next month.

In fact, there are only two currencies that have shown any strength vs. the dollar, the BRL, which I discussed yesterday and is rallying on the back of a positive view of a Bolsonaro presidential victory in two weeks’ time, and the KRW, which has been the beneficiary of consistent inflows for investment into its semiconductor sector.  And while the euro has been the worst performer today in the G10, virtually every currency is weaker vs. the dollar this morning as the news flow continues to point to problems overseas rather than in the US.

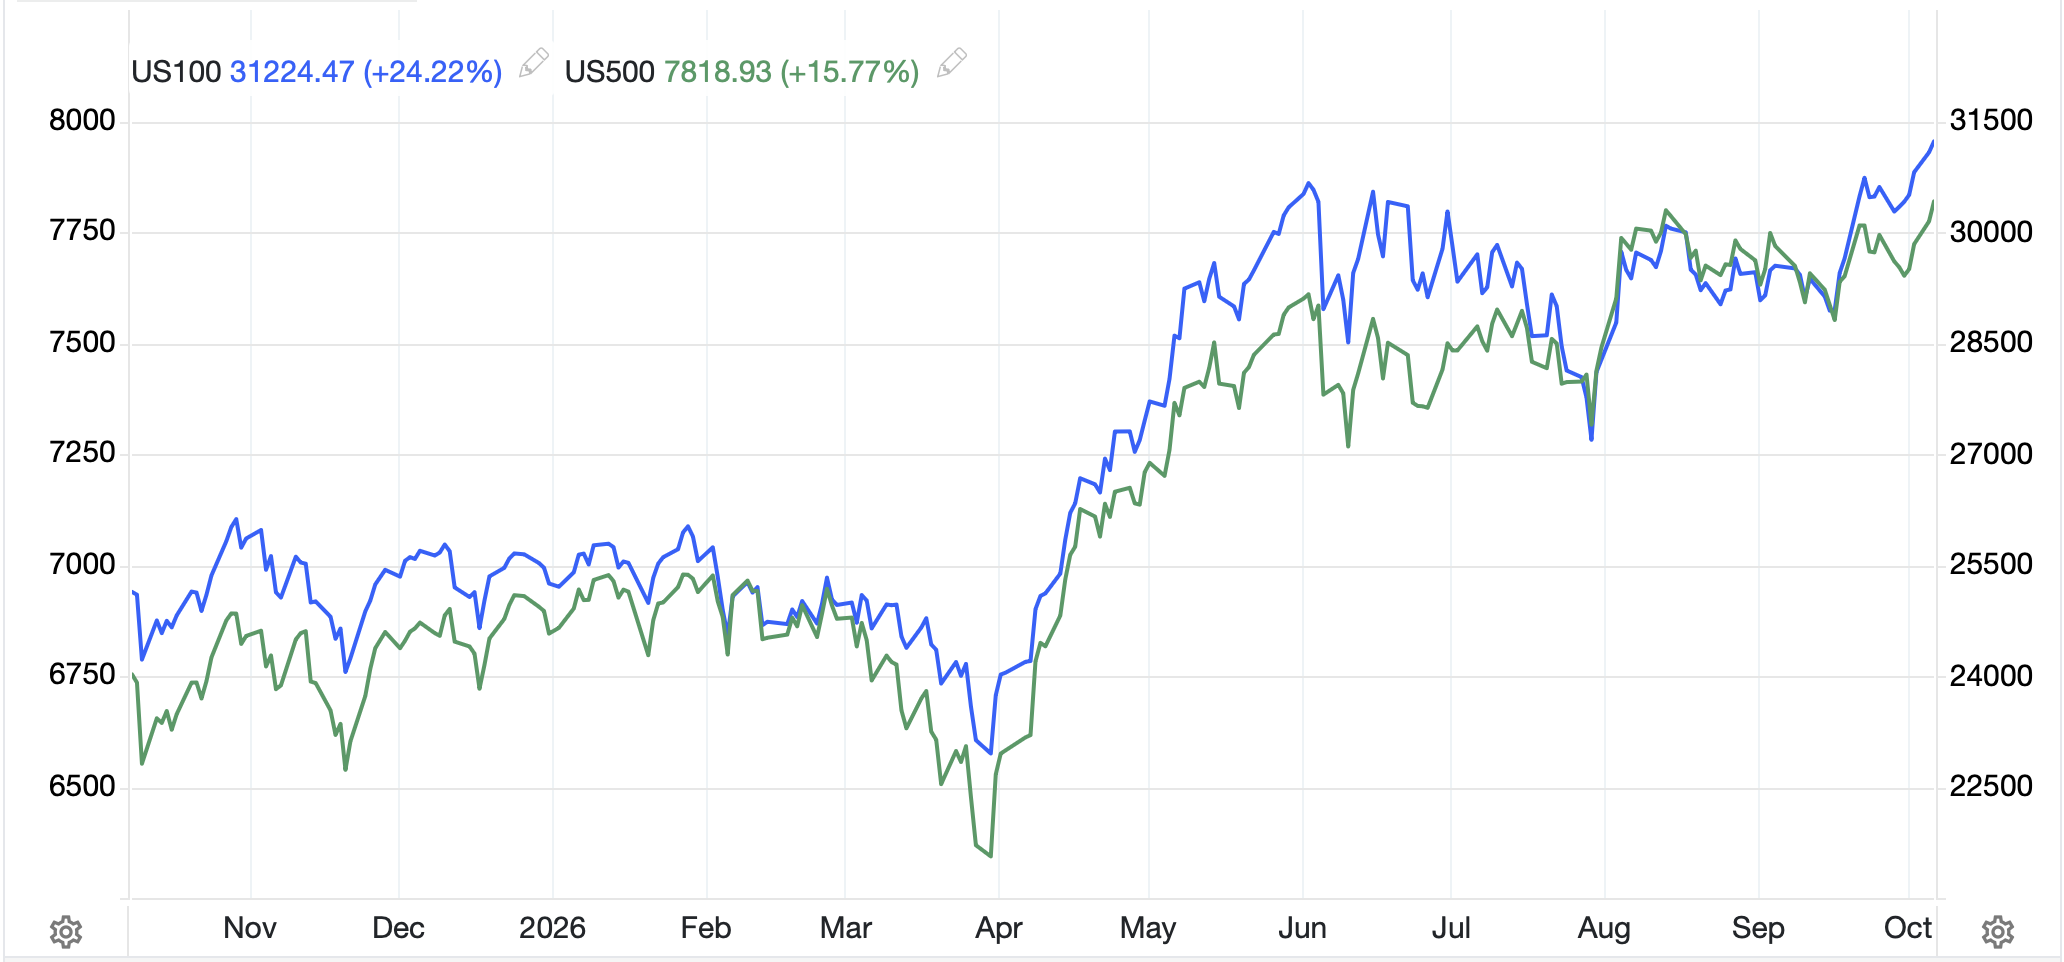
Which takes us to equity markets and the fact that both the S&P 500 and NASDAQ made new all-time highs yesterday, although futures this morning are pointing a bit lower.  

Source: tradingeconomics.com

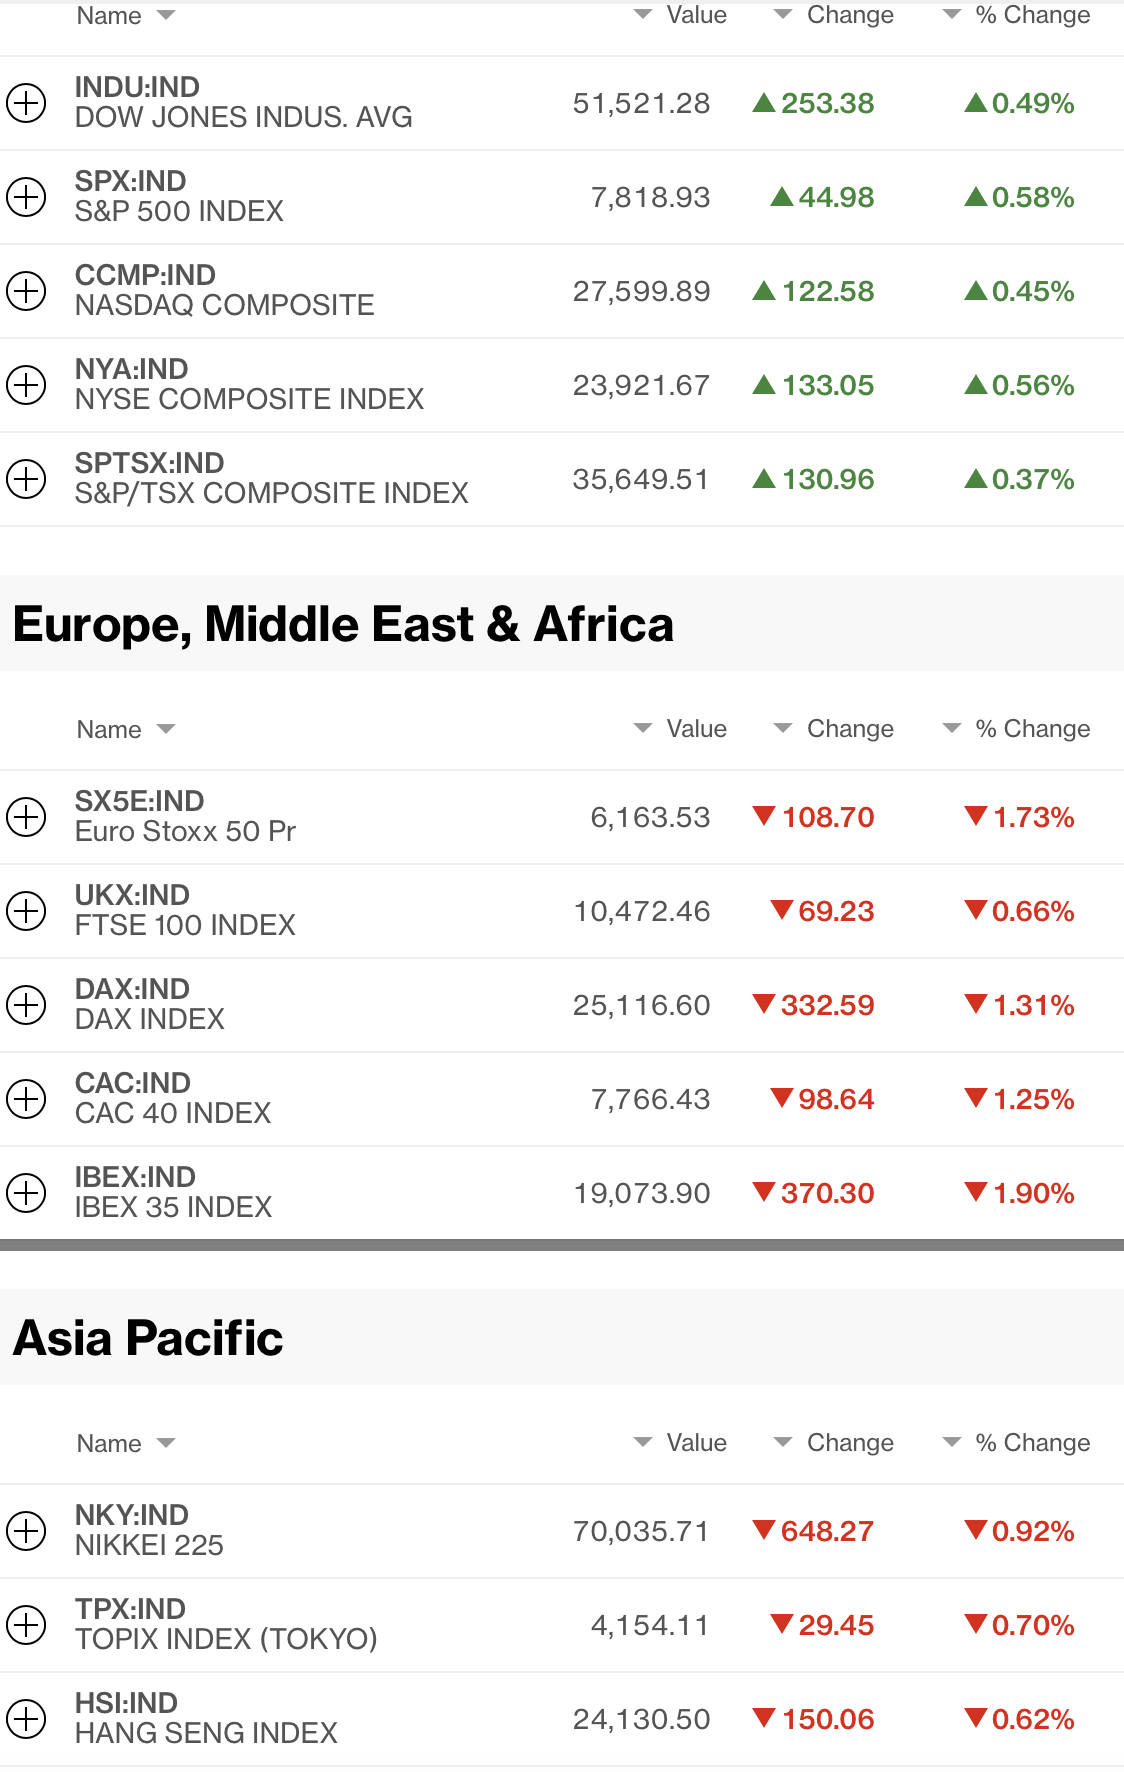
In fact, I think we can look at the US performance relative to that in Europe and Asia and learn the same lesson, capital continues to flow into the US.  A look at the below Bloomberg screenshot tells the story well.

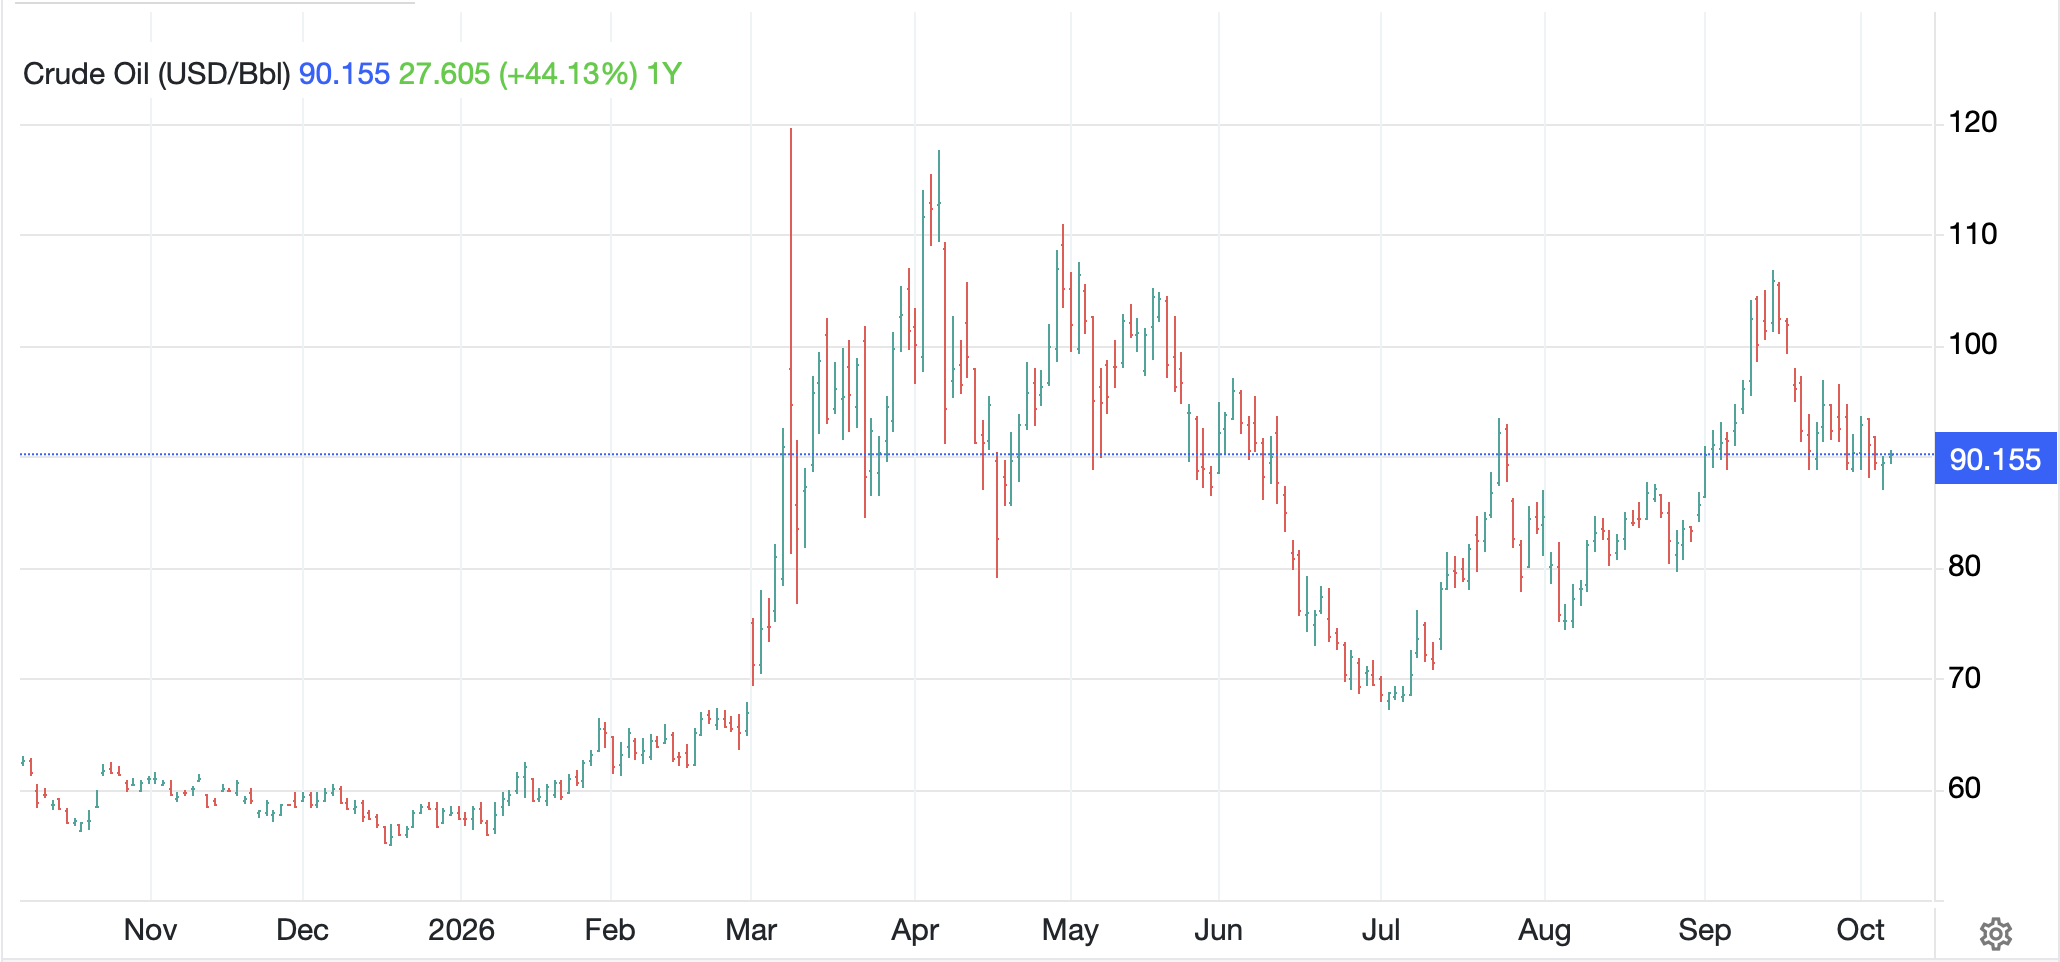
Which takes us to commodity markets.  While oil is off its recent lows, it remains well below the 
$100/bbl level that sets hair on fire as you can see below.

Source: tradingeconomics.com

In fact, I couldn’t help but notice the announcement from the IRGC that they would be closing the “illegal” routes through the Strait of Hormuz shortly, of course implying the Strait is, in fact, basically open.  While President Trump has been saying this for several weeks, the media doesn’t like that outcome so has tried to refute it.  I wonder what they will say now.  Meanwhile, gold (-2.2%) continues in its funk and has been dragging silver (-3.5%) down with it.  Frankly, with real yields at 2.9%ish in the 10-year and 3.5% in the 30-year, those are pretty attractive alternatives to the barbarous relic.  While I still think they have room to rise (metals, that is) I guess now is not the time.  Copper (-0.3%) however, continues to hover just below its recent all-time highs on ongoing fundamental demand in the growing US economy.

In the end, the world is not ending, and in fact I’m positive going forward.  But then, I’m just a poet.  On the data front, on the calendar today we see EIA oil inventories with a small build expected and the FOMC Minutes at 2:00pm.  I imagine a lot of effort will go into parsing those Minutes, but the market has already decided there is no hike coming this month although they still see December as quite likely.  A backing off from equity highs is no surprise, and I do not see this as the beginning of a new trend lower.  In fact, until the election results, I think we are more likely to rally risk assets then sell them.

Good luck

Adf

Back to his Pen

The poet is back to his pen
And thinking ‘bout euros and yen
And oil and gold
As bonds all get sold
While indices rise yet again

Remarkably, o’er the past week
Though headlines, to havoc, did speak
The movement of note
Showed oil got smote
While dollars have reached a new peak

I have not been keeping close tabs on markets overall during my road trip, although am back to focusing again.  But first, the news from Topeka was that, while Marvel showed beautifully, we did not get placed amid very stiff competition.

Plus, as in every judged event, there is a measure of politics involved, and I am just not politically correct!

One other issue is that today is the first day I’ve had viable Wi-Fi to work with as the previous places I stayed just didn’t have it.

So, with all that in mind, I will be brief this morning.  Prior to leaving, I left myself records of where markets closed on September 25th so I could see how much things changed.  And the truth is, not all that much, at least on net since I last wrote.

In the equity markets, while the NASDAQ made new all-time highs, it is just 2% higher than when I left.  The S&P managed a much smaller gain, 0.7% and the DJIA actually slipped a bit during the period.   Elsewhere in the equity space, Japan (+7%) was the big winner while France (-2.5%) cannot keep up as the student riots and the fiscal problems, which are bad enough to garner a top WSJ story this morning, are obviously weighing on things there.  

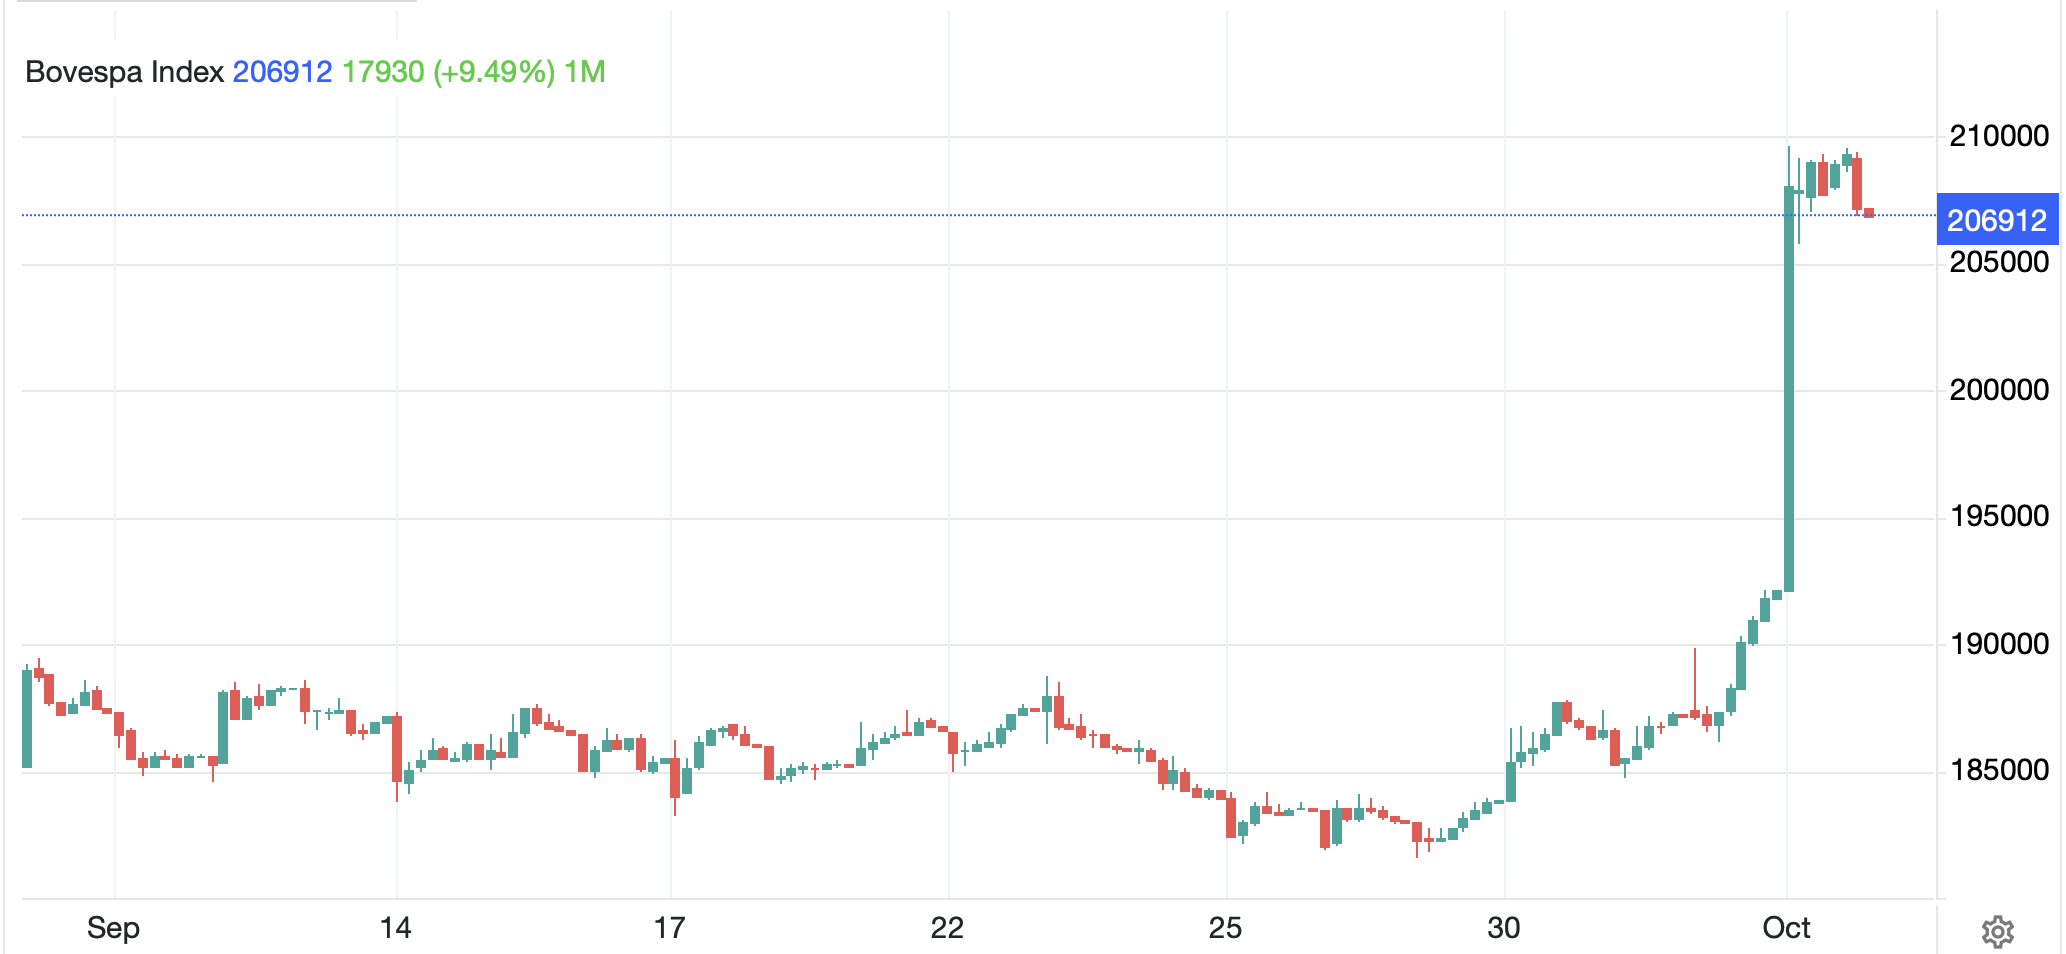
Of course, all the equity moves are happening within the context of the bond market, which continues to see yields climb around the world.  US yields (+11bps) are the talk of the market, but Japanese yields (+3bps and up to yet more 30+nyear highs) are also still climbing.  But arguably, the biggest news is Brazil, which in the wake of the surprising first round lead in the presidential election by Flavio Bolsonaro (son of previous president Jair Bolsonaro) where we have seen Brazilian yields collapse (-115bps) while the Brazilian stock market rocketed 7.7% in the wake of the election results

Source: tradingeconomics.com

Elsewhere, both oil (-5.1%) and gold (-2.9%) have slipped as the former continues to seesaw based on comments about the amount of oil coming out of the Strait of Hormuz, although it is clear product prices are not falling, while the latter has just lost its appeal.  Gold is a funny thing, it is a wonderful long-term store of value and has been so for millennia, but it cares not a whit about day-to-day movements in prices.  Arguably, gold has done its job as that store of value as many holders have utilized their reserves to shore up their own financial situation, thus selling the barbarous relic.  However, it remains difficult for me to look at the fiscal policies extant around the world and think that fiat currencies are going to be embraced.  

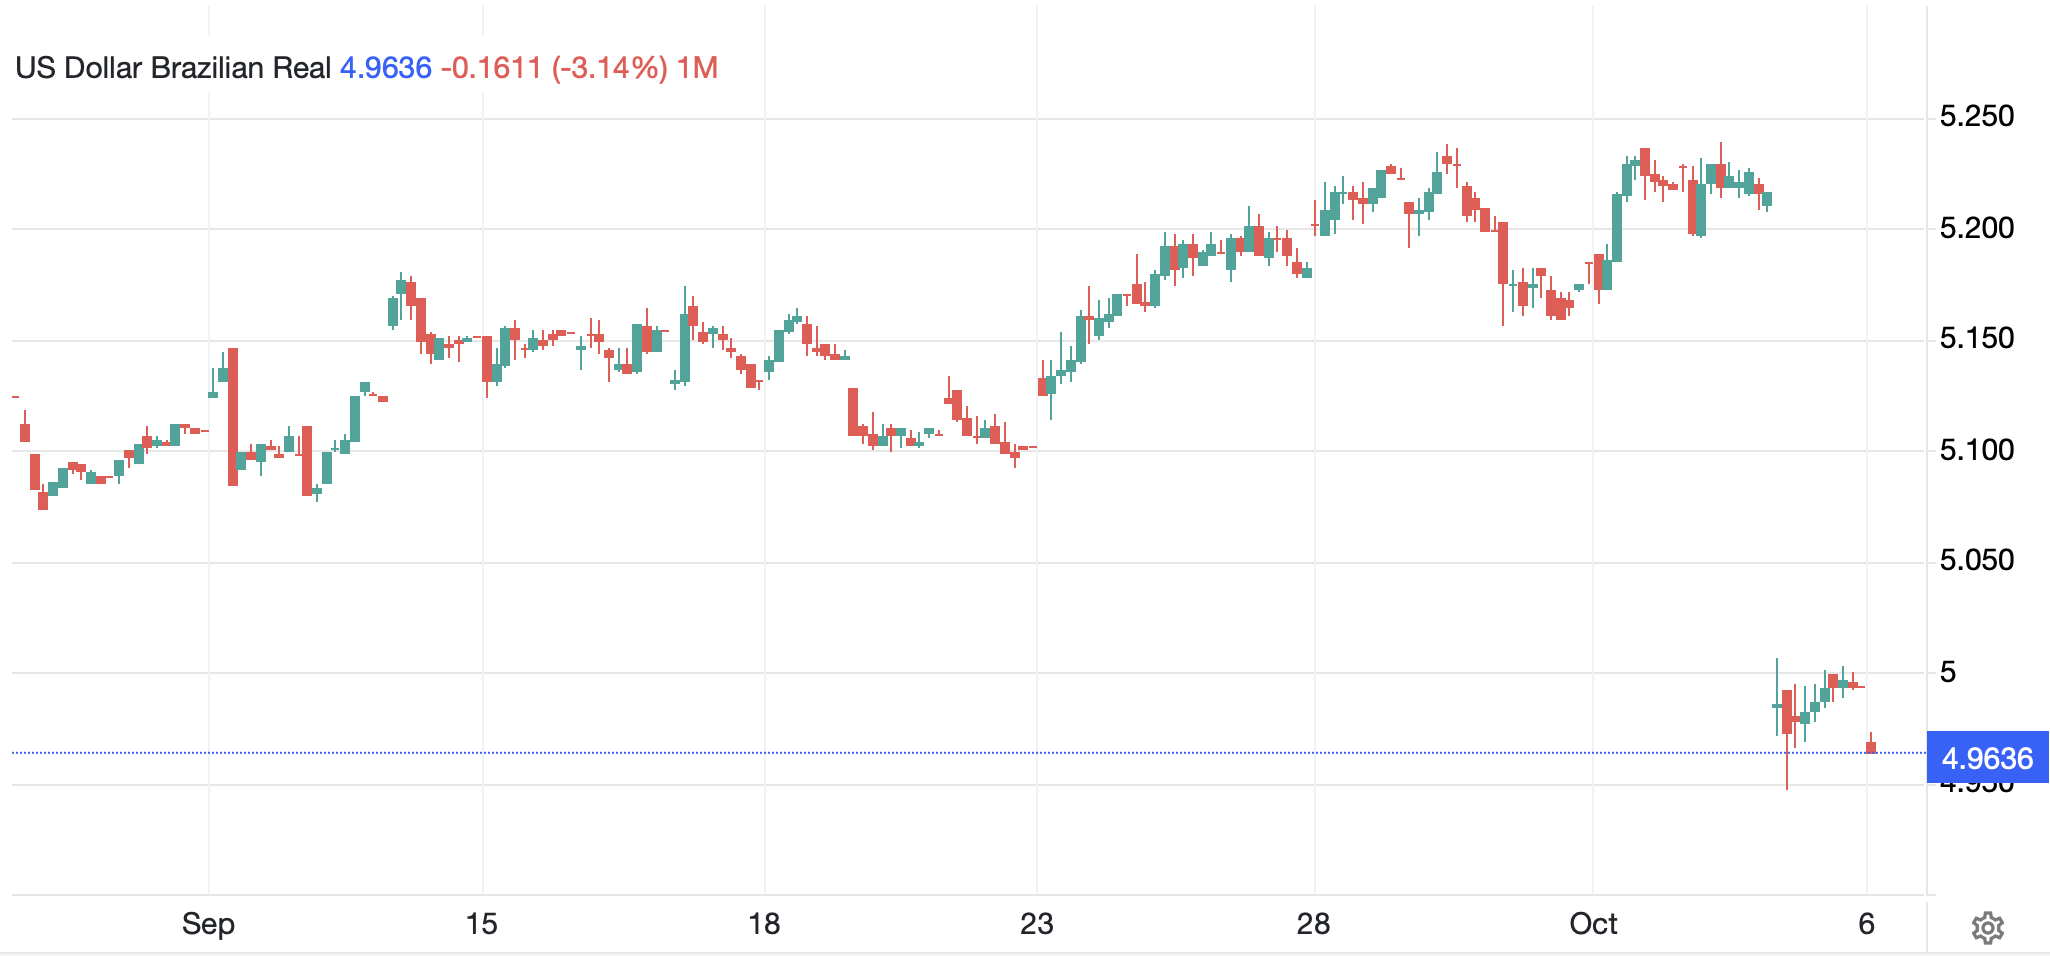
Speaking of fiat currencies, while the dollar is just that, fiat, it is also the currency of the strongest current economy around, so despite all its flaws, and all the questions about the Fed and whether they will be hiking again and what that means, and despite all the angst over the selloff in Treasuries, the dollar continues to be the safest play around.  For instance, the euro, saddled with French misery and Germany fiscal and energy incompetence (as well As Spanish insanity regarding housing policy) has slipped -1.3% over the past week while the DXY has rallied a similar amount.  Despite the Nikkei’s rally, the yen (-0.6%) has slipped as well.  In fact, the only currency of note that has performed well is, not surprisingly, BRL (+3.5%) as money is flowing to the country in anticipation of a Bolsonaro win in the runoff election at the end of the month.  That, my friends, is a serious gap opening!

Source: tradingeconomics.com 

And that’s really all I have this morning, but I will be back going forward, most days, I believe.

On the calendar, there is not a ton this week after last week’s disappointing payroll report.

TodayTrade Balance-$102B
ThursdayInitial Claims200K
 Continuing Claims1710K
FridayMichigan Sentiment47.6

Source: tradingeconomics.com

The payroll report served to reduce the probability of a Fed hike this month dramatically and it is now down to 21% from above 60% when I left.  I still don’t think they need to hike more, although the market remains convinced they will do so in December.  But December is a long time from now and much can happen in the interim.  As to the dollar, it remains the cleanest dirty shirt around.

Good luck

Adf