The data on Friday was strong
With bulls happy they were all long
And so far, today
Things still seem that way
And yet, it feels something is wrong

No matter the truth on the ground
The narrative seeks to confound
All news that is good
With blatant falsehood
Lest media ratings fall down
Humans are an odd species. Positive outcomes are positively loathed by so many, or at least so many whose role is to disseminate information. I have to believe that is a natural outcome as while that group may be a minority, they have realized if they get to write the narrative, even if it is completely false, they can instill their misery on the large majority of people who are pretty happy to go about their lives and see the good that exists. This is not to say that bad things don’t happen, they clearly do. It is also not to say that there are no bad people, or that only bad people go into media, but it certainly appears that there is a larger than statistical aggregation of doomsayers in the media business.
I highlight this because if one looks at Friday’s data objectively, assuming one can do so, it was unambiguously positive as a description of the economy. The payroll data was much stronger than expected with NFP printing at 165K, 100K more than forecast, while the Unemployment Rate fell to 4.1%. As well, Michigan Sentiment rose to 51.0, still lousy, but higher than last month and the forecast, although as you can see from the below chart, the trend remains lower ever since Covid.
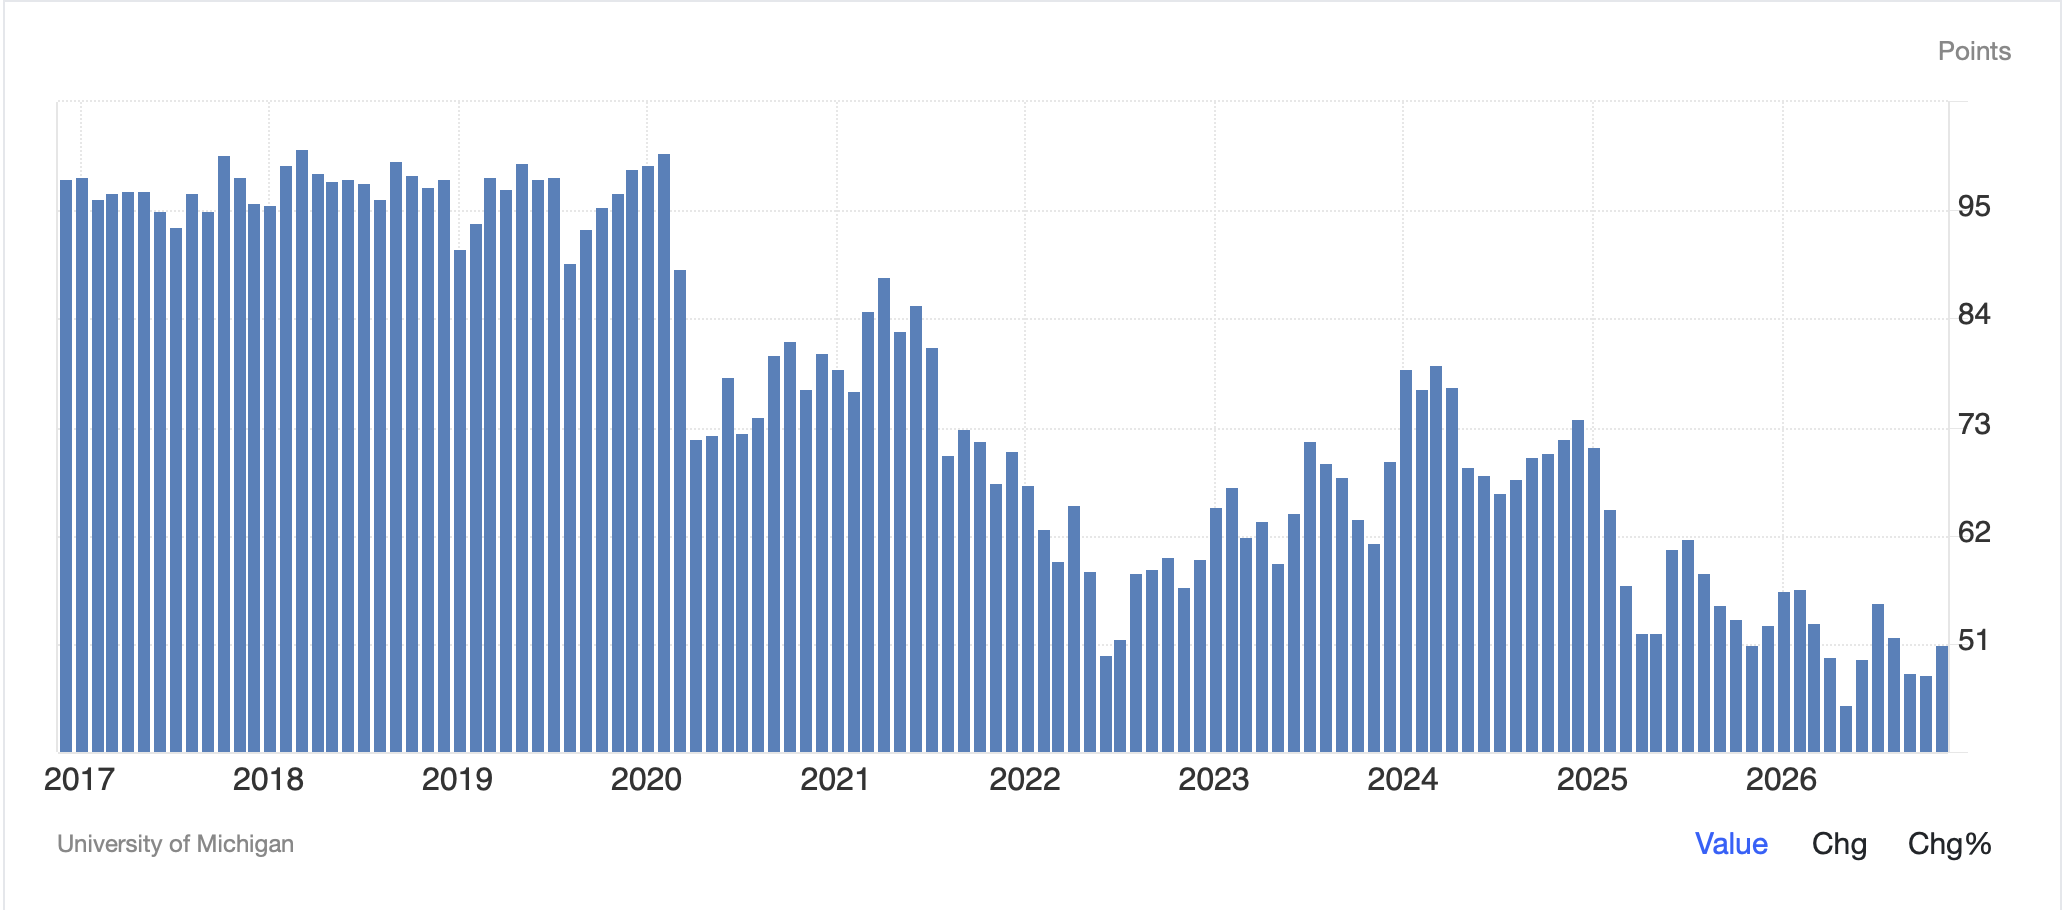
Source: tradingeconomics.com
Not only that, equity markets had a generally positive day on Friday, stabilizing from Thursday’s dramatic decline, and actually rising slightly, as per the below chart.
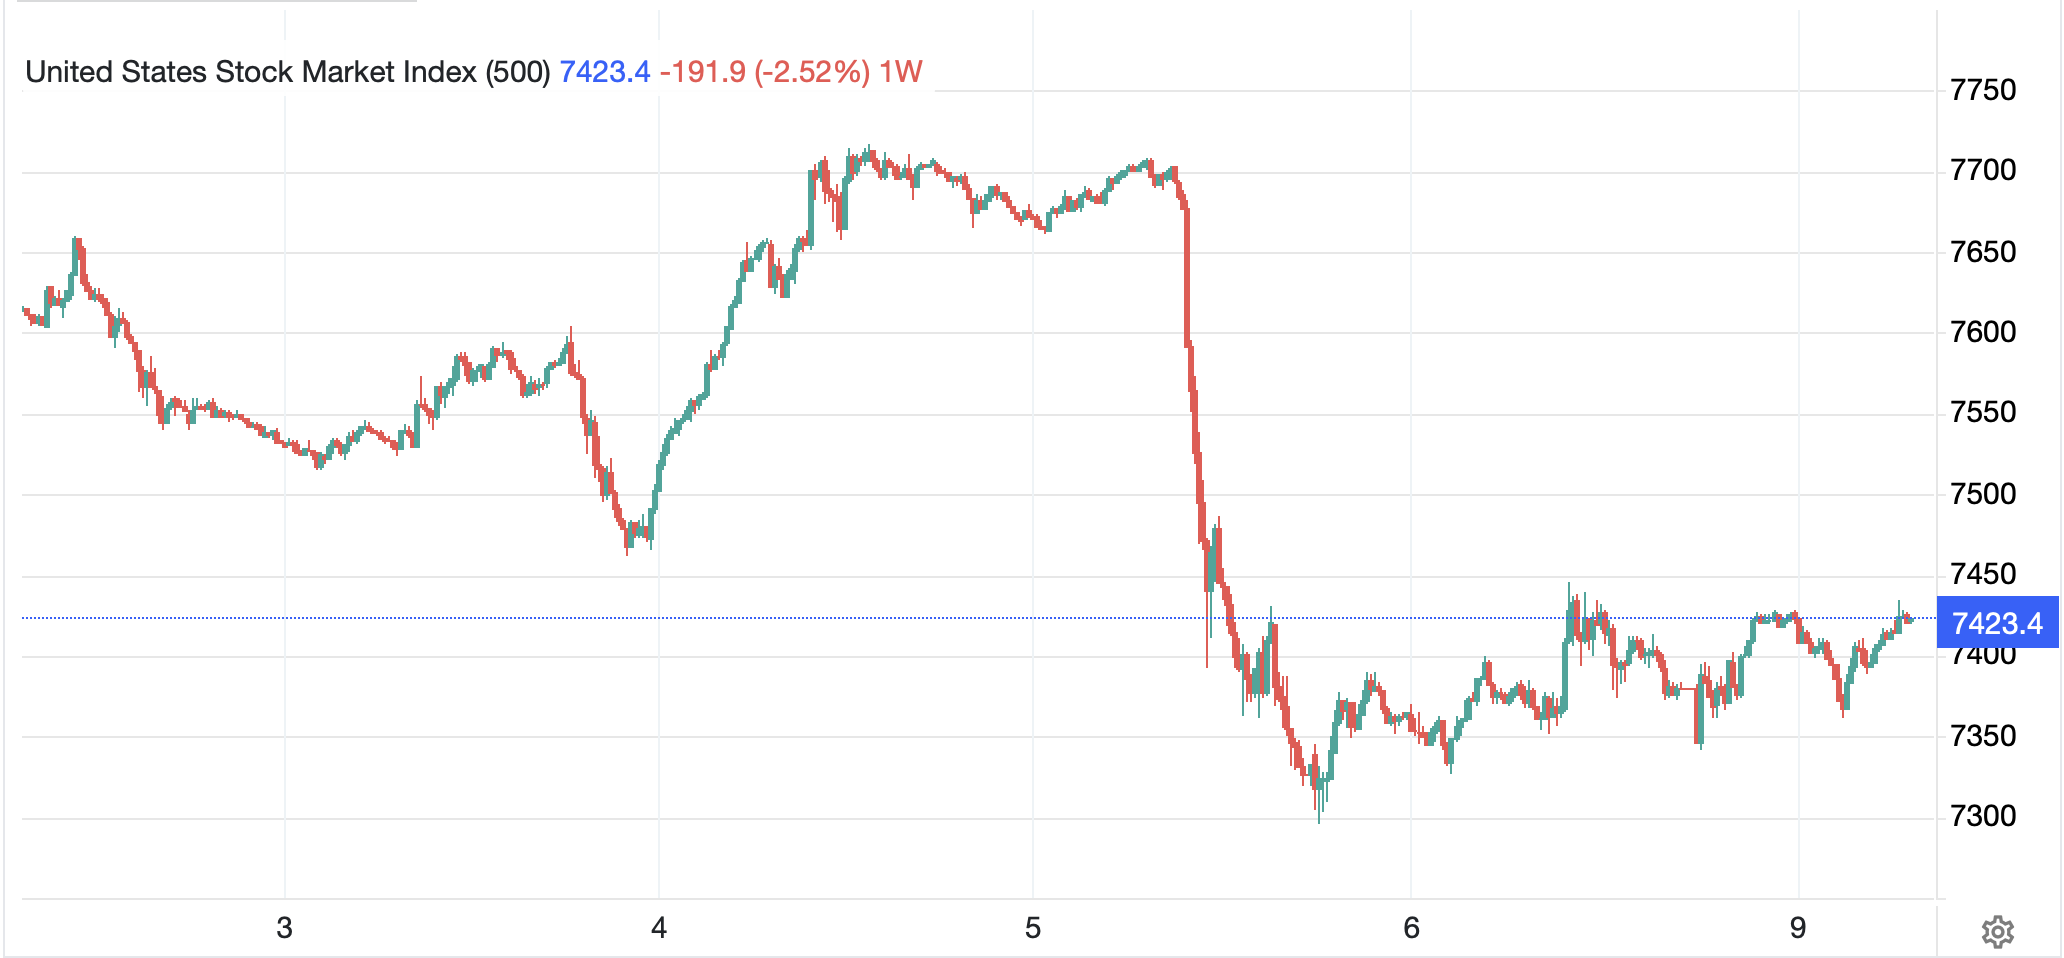
Source: tradingeconomics.com
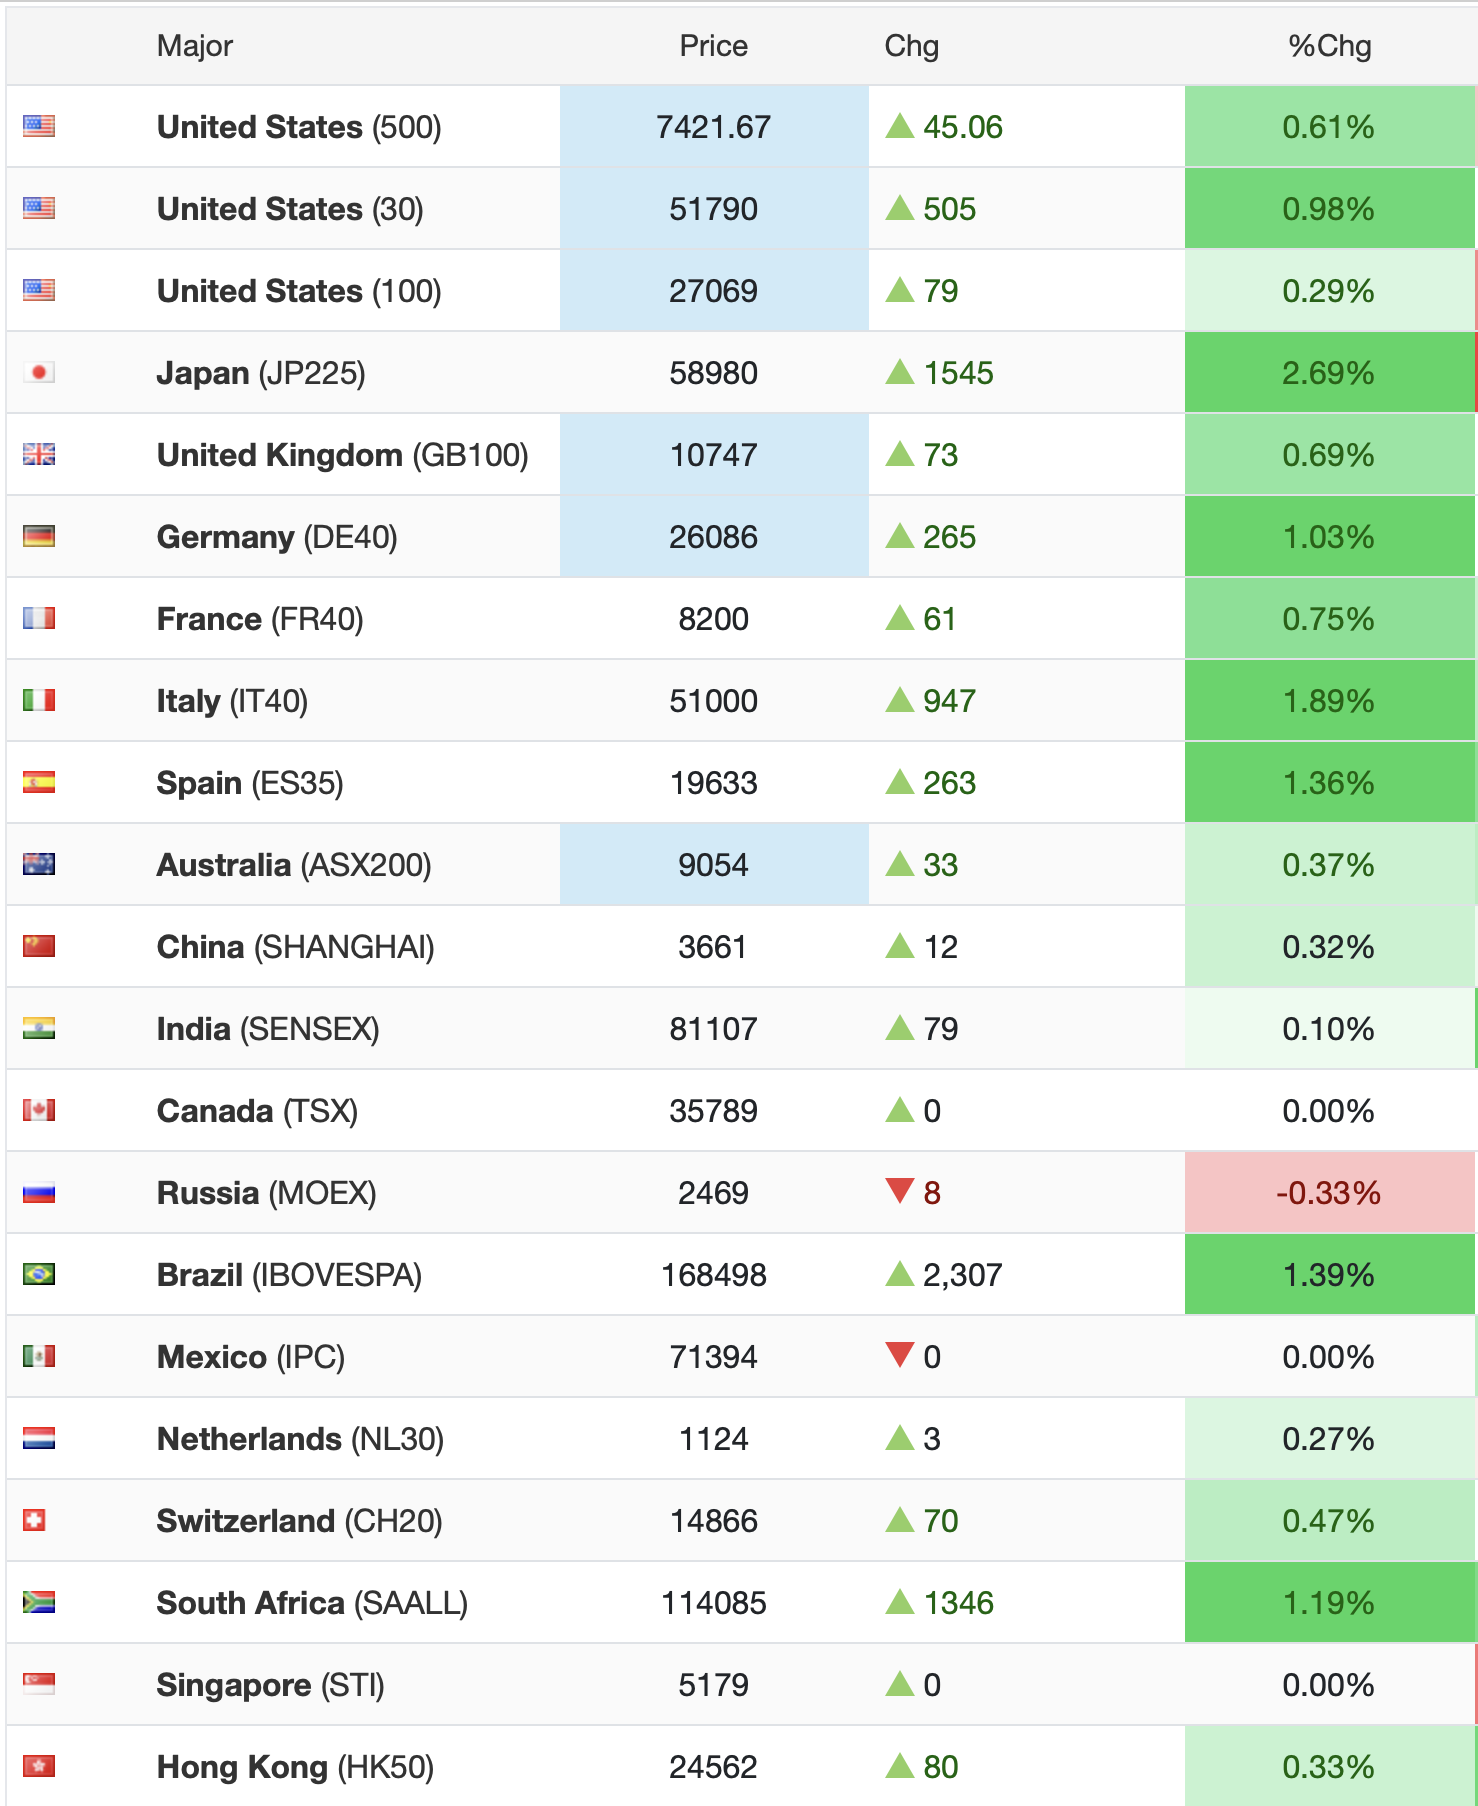
And this morning, US futures are higher across the board, with the DJIA +1.0% as I type at 7:07am with the other two major indices showing lesser gains. Europe is universally higher and Asia had a pretty good session led by Taiwan (+5.0%) after their plunge protection team entered the market. You can see all this in the screenshot from tradingeconomics.com.
I highlight this because I did not see one positive story this morning in the press about anything of note. There is still a significant amount of discussion regarding Thursday’s declines and what that means and if it portends the beginning of the end of the major rally. And this morning’s new fixation is on Jensen Huang’s girlfriend and whether or not she is/was a Chinese spy, with the Nvidia board opening an investigation and the shares lower by -6.4% this morning. This is all in accord with the media theme, ‘if it bleeds, it leads’. So, the amateur psychologist in me is wondering why so many people want to see bad things happen to others and lap up stories about those things, whether they are real or fake and whether they are history or forecast. This is the doom porn I mention all the time. I guess winning and having good outcomes is just not as satisfying for some and I fear their number is growing.
And ultimately, this is my greatest fear, that the negativity that permeates social media, and my experience is that is the majority of stuff, will lead to worse actual outcomes. One need only look at the recent elections and wonder how even though affordability was the single biggest concern according to polls, the party elected to power has NEVER in history been able to address that in an adequate manner. We are already hearing about price freezes being implemented along with moratoria on economic activity like data center construction, and I assure you, all that will do is result in shortages of stuff with two coincident outcomes, black markets and long wait times, both of which are simply inflation in another guise. As Friedrich Hayek noted, “if socialists understood economics, they wouldn’t be socialists.” (as an aside, if you have never seen this video, it is so well done!)
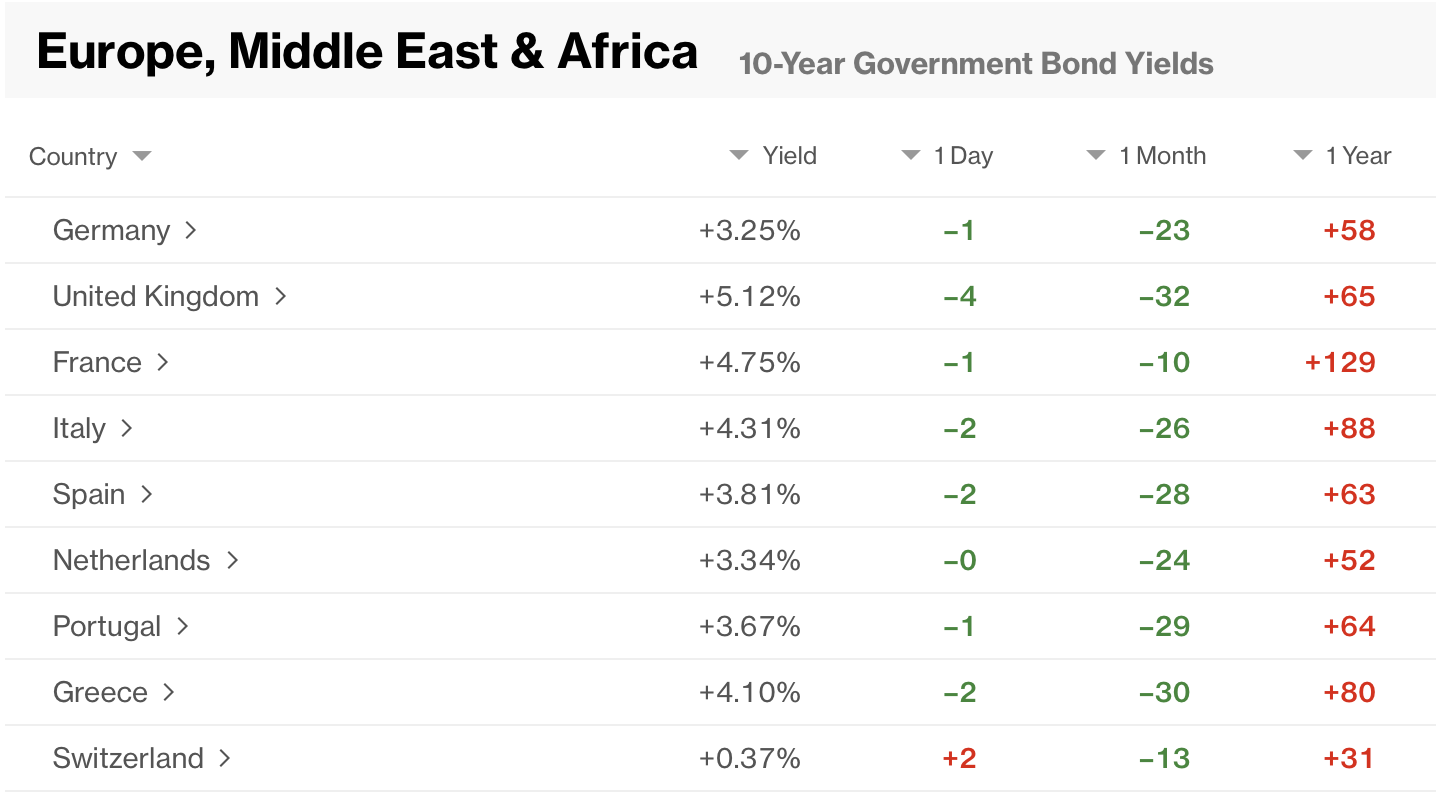
And that is enough philosophizing for this morning, let’s look at the other markets around. Bonds are pretty sleepy this morning with treasury yields unchanged although European sovereign yields are slipping a few basis points as the session progresses as you can see in the below Bloomberg.com screenshot. While yields remain higher over the past year, they have generally retreated recently.
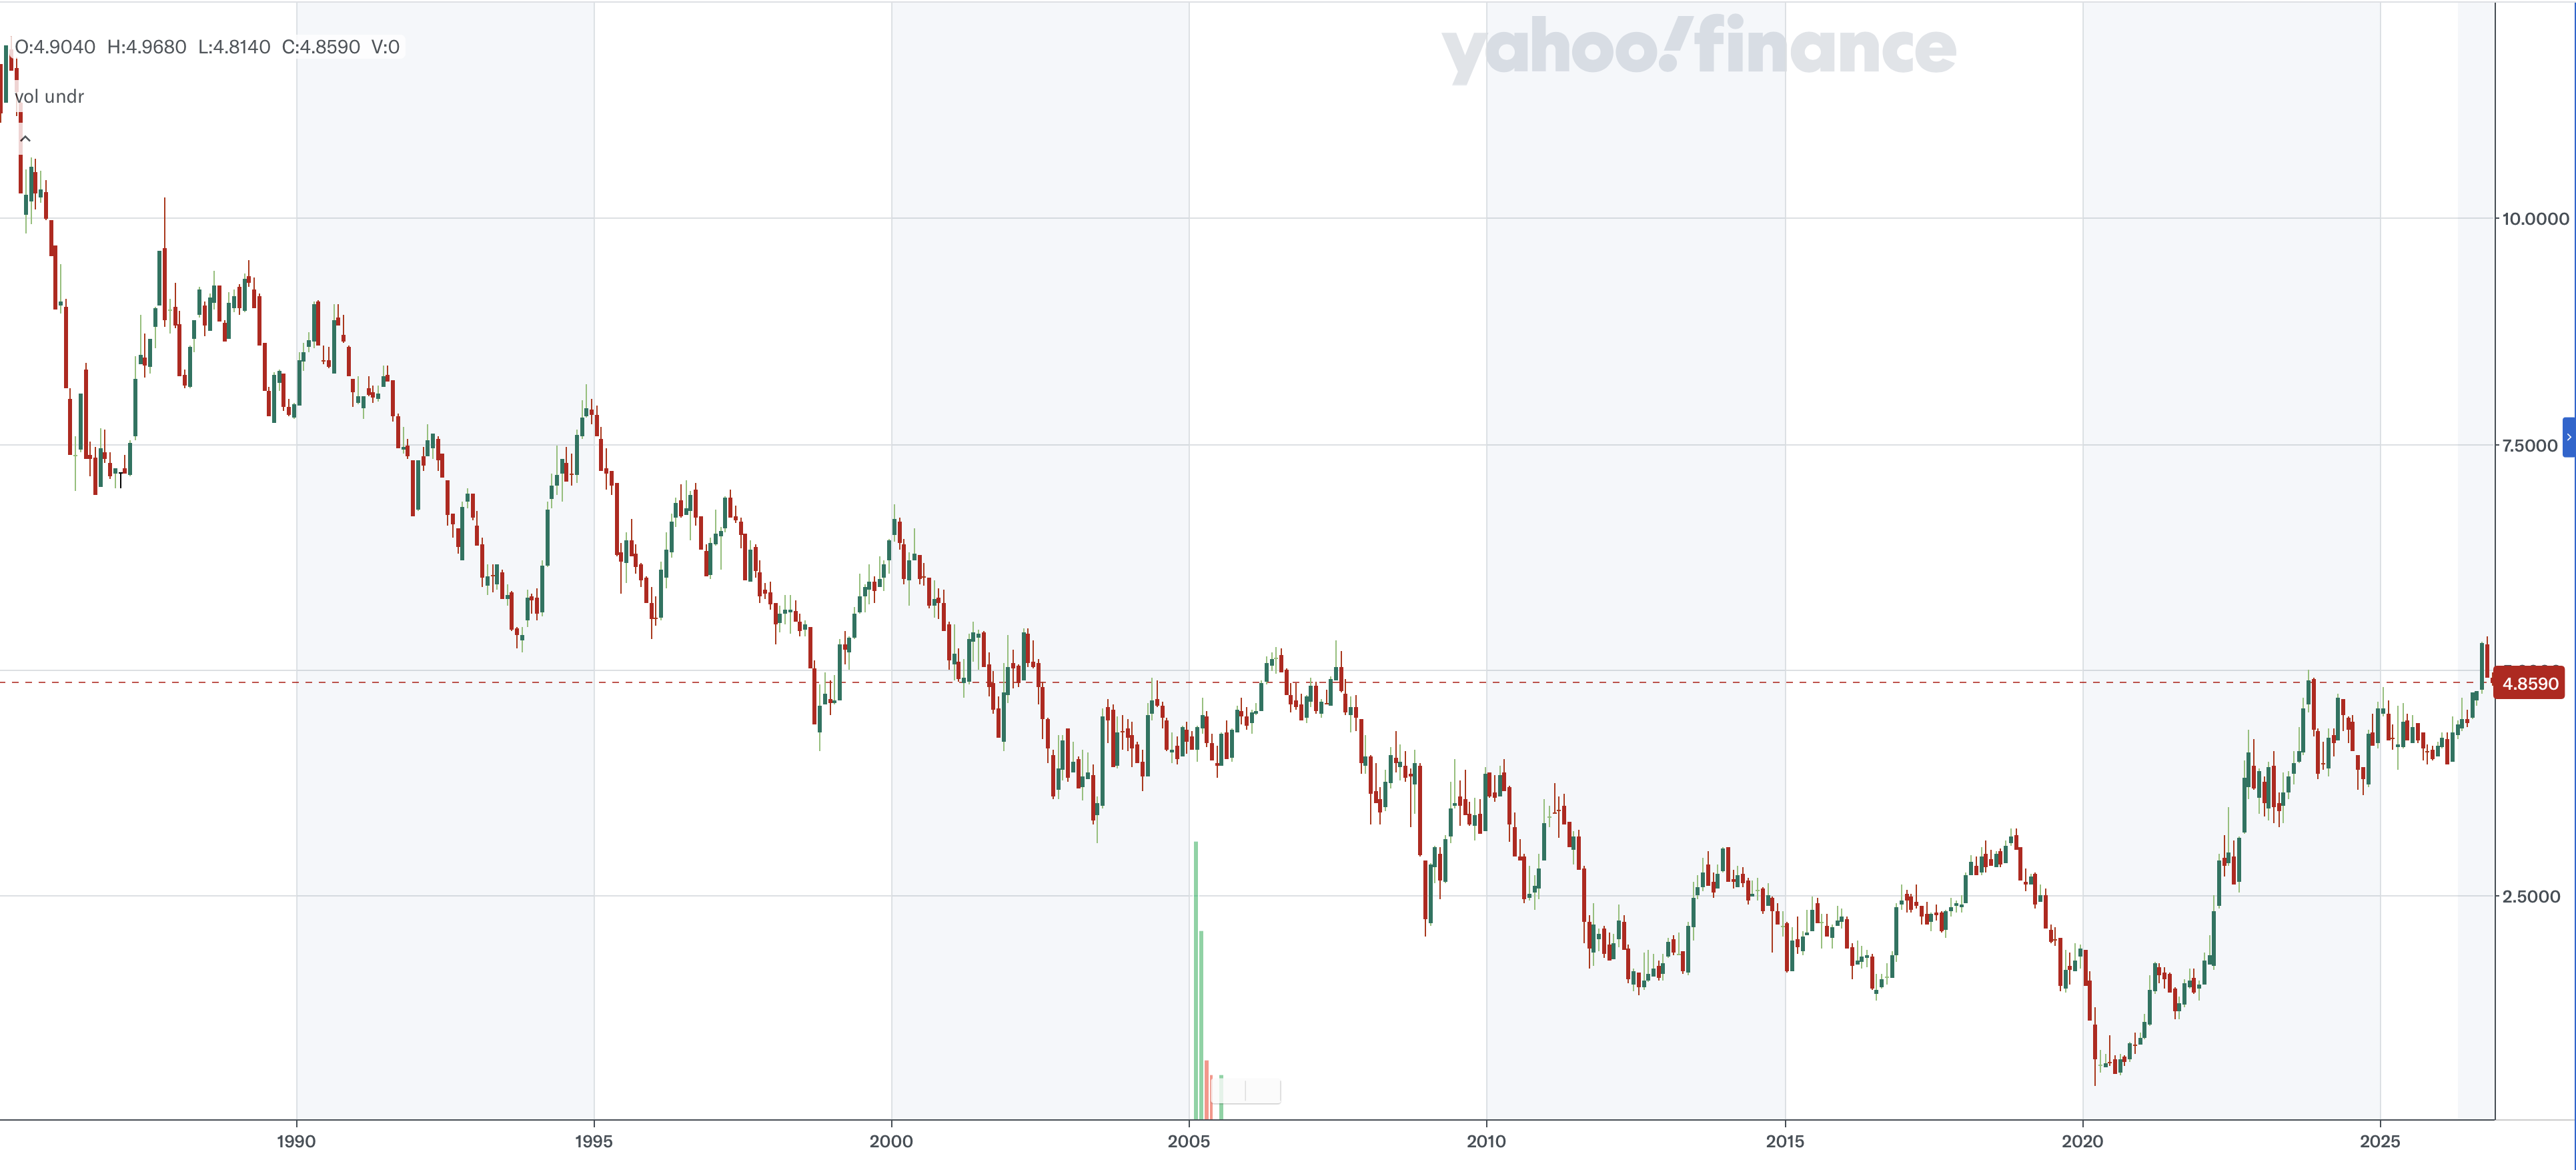
Here’s the thing about bonds, though, while their recent performance has been far better than many expected just a month ago, we cannot lose sight of the longer-term trend which turned at the end of Covid and has been trending with higher yields for the past 5 years at least. Just look at the chart below from yahoo finance. A 40-year trend of lower interest rates ended and seems to have reversed pretty clearly. We will need to see yields slide quite a bit further to break this new trend. My point is bond strength (lower yields) may not be a long-term position here, just a good trade.
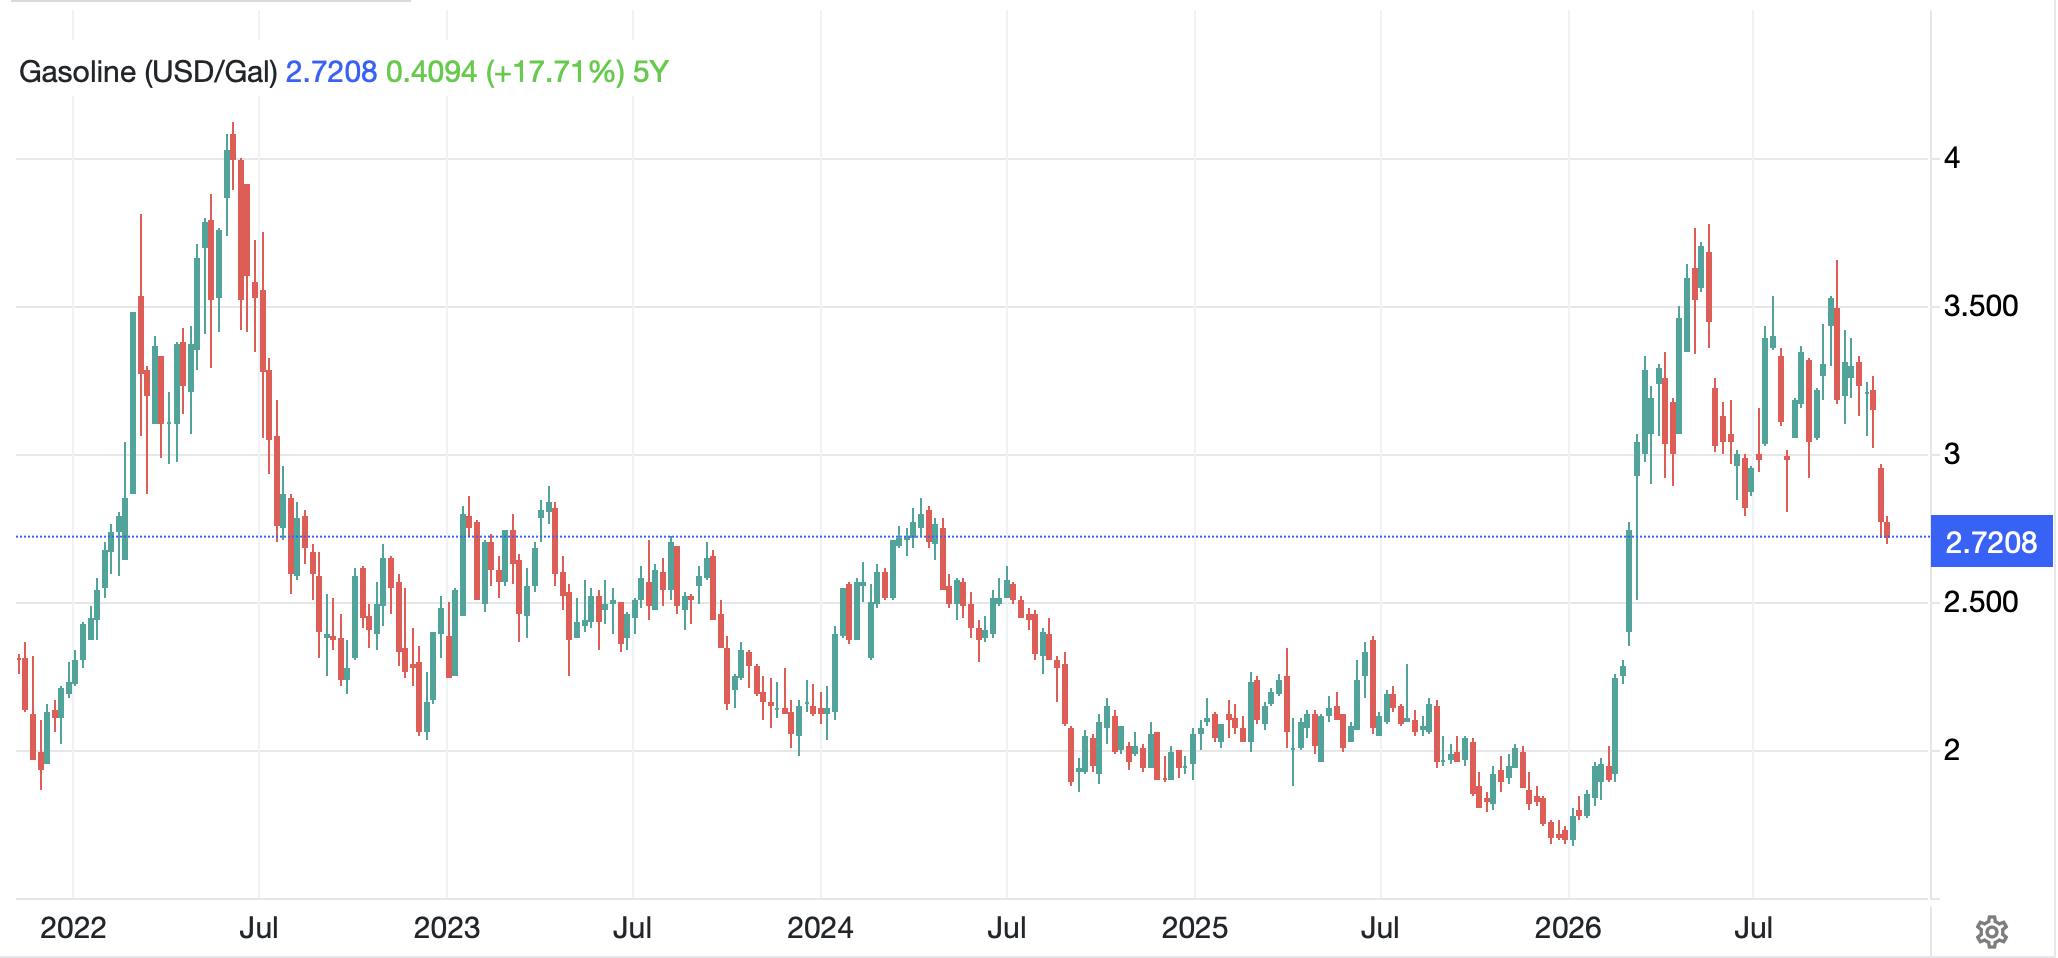
In the commodity space, oil (-2.8%) is falling once again this morning and taking products (gasoline -2.0%) along with it. It remains difficult for anybody not directly involved with the ostensible Iran negotiations to know if there are negotiations and what is happening. One thing I read this weekend was that the recent ‘defensive’ attacks on Qeshm Island and others in the area are part of a systematic US campaign to degrade what’s left of Iranian missile command along the Strait to help maintain traffic volumes there. But frankly, it is almost as though the Iran war is becoming extraneous to the oil market. Clearly there remains plenty of oil around and now, nine months into this campaign, the only shortages, diesel, are largely a result of Ukraine’s attacks on Russian refineries.
It is worth noting that today’s RBOB futures price is right where we spent virtually the entire post Covid Bidenflation years, as per the below chart, with lower prices only achieved at the beginning of President Trump’s second term with his drill, baby, drill policies.
Source: tradingeconomics.com
Given the relationship between gold and oil, it should be no surprise that the precious metals complex is stronger this morning (Au +1.1%, Ag +1.5%). The best case for owning these metals remains the fact that M2 continues to climb rapidly in the US, and regardless of where interest rates go, inflation will be hard to control with that outcome.
Finally, the dollar is on its back foot this morning, down roughly 0.5% +/- a bit across the board. The biggest gainer was NZD (+1.25%) after their national election left the ruling center-right National Party in power, easing concerns over worse economic policies (they have enough bad ones already), and we also saw KRW (+1.3%) rebound after a rough week as corporate repatriation of dollars helped support the won. But really, since the beginning of October, the dollar has been a nonevent in markets, and I continue to believe it is separating itself from the narrative, at least for a while.
On the data front, this is inflation week and here’s what we have coming.
| Tuesday | NFIB Small Biz Optimism | 97.7 |
| CPI | 0.3% (3.9% Y/Y) | |
| -ex food & energy | 0.2% (2.8% Y/Y) | |
| Thursday | Initial Claims | 195K |
| Continuing Claims | 1720K | |
| Existing Home Sales | 3.98M | |
| Friday | PPI | 0.4% (6.6% Y/Y) |
| -ex food & energy | 0.3% (5.0% Y/Y) |
Source: tradingeconomics.com
As well, we have the 3-year, 10-year and 30-year auctions this week, and we hear from 11 Fed speakers over 18 different venues! That’s just too much. It will be interesting to see how this plays out now. After all, consider that my thesis is the hawkishness has been driven by, or at least abetted by, the idea that most FOMC members dislike President Trump and want to hurt him, but now that the Democrats will be in charge of both houses of Congress, do they want to raise rates? Seems like the Fed has found itself in a difficult position where hawkishness will hurt their favored partners. Perhaps the most enjoyable thing this morning was the WSJ article by the former Fed (Powell) whisperer, Nick Timiraos, basically admitting that politics is going to drive the Fed going forward despite all the claims that the Fed is apolitical.
So, that’s the week. Wednesday is Veteran’s Day and markets will be closed. For now, regardless of the politics, markets are showing optimism with oil falling and equities rising. I have a feeling things will remain choppy for a while and there is still a chance of some negative outcomes especially if Congress tries to implement some of the craziest themes. I assure you that Medicare for all will be a massive economic, and market, disaster, although I don’t believe that is on the near horizon.
Good luck
Adf

