The Chairman’s idea is to shrink
Two things, but one’s not what you think
The balance sheet? Sure
But here’s the allure
A calendar showing less ink

So next year they’re planning to cut
One meeting, as eight is a glut
The following year
The Chairman made clear
Six meetings will be the what’s what
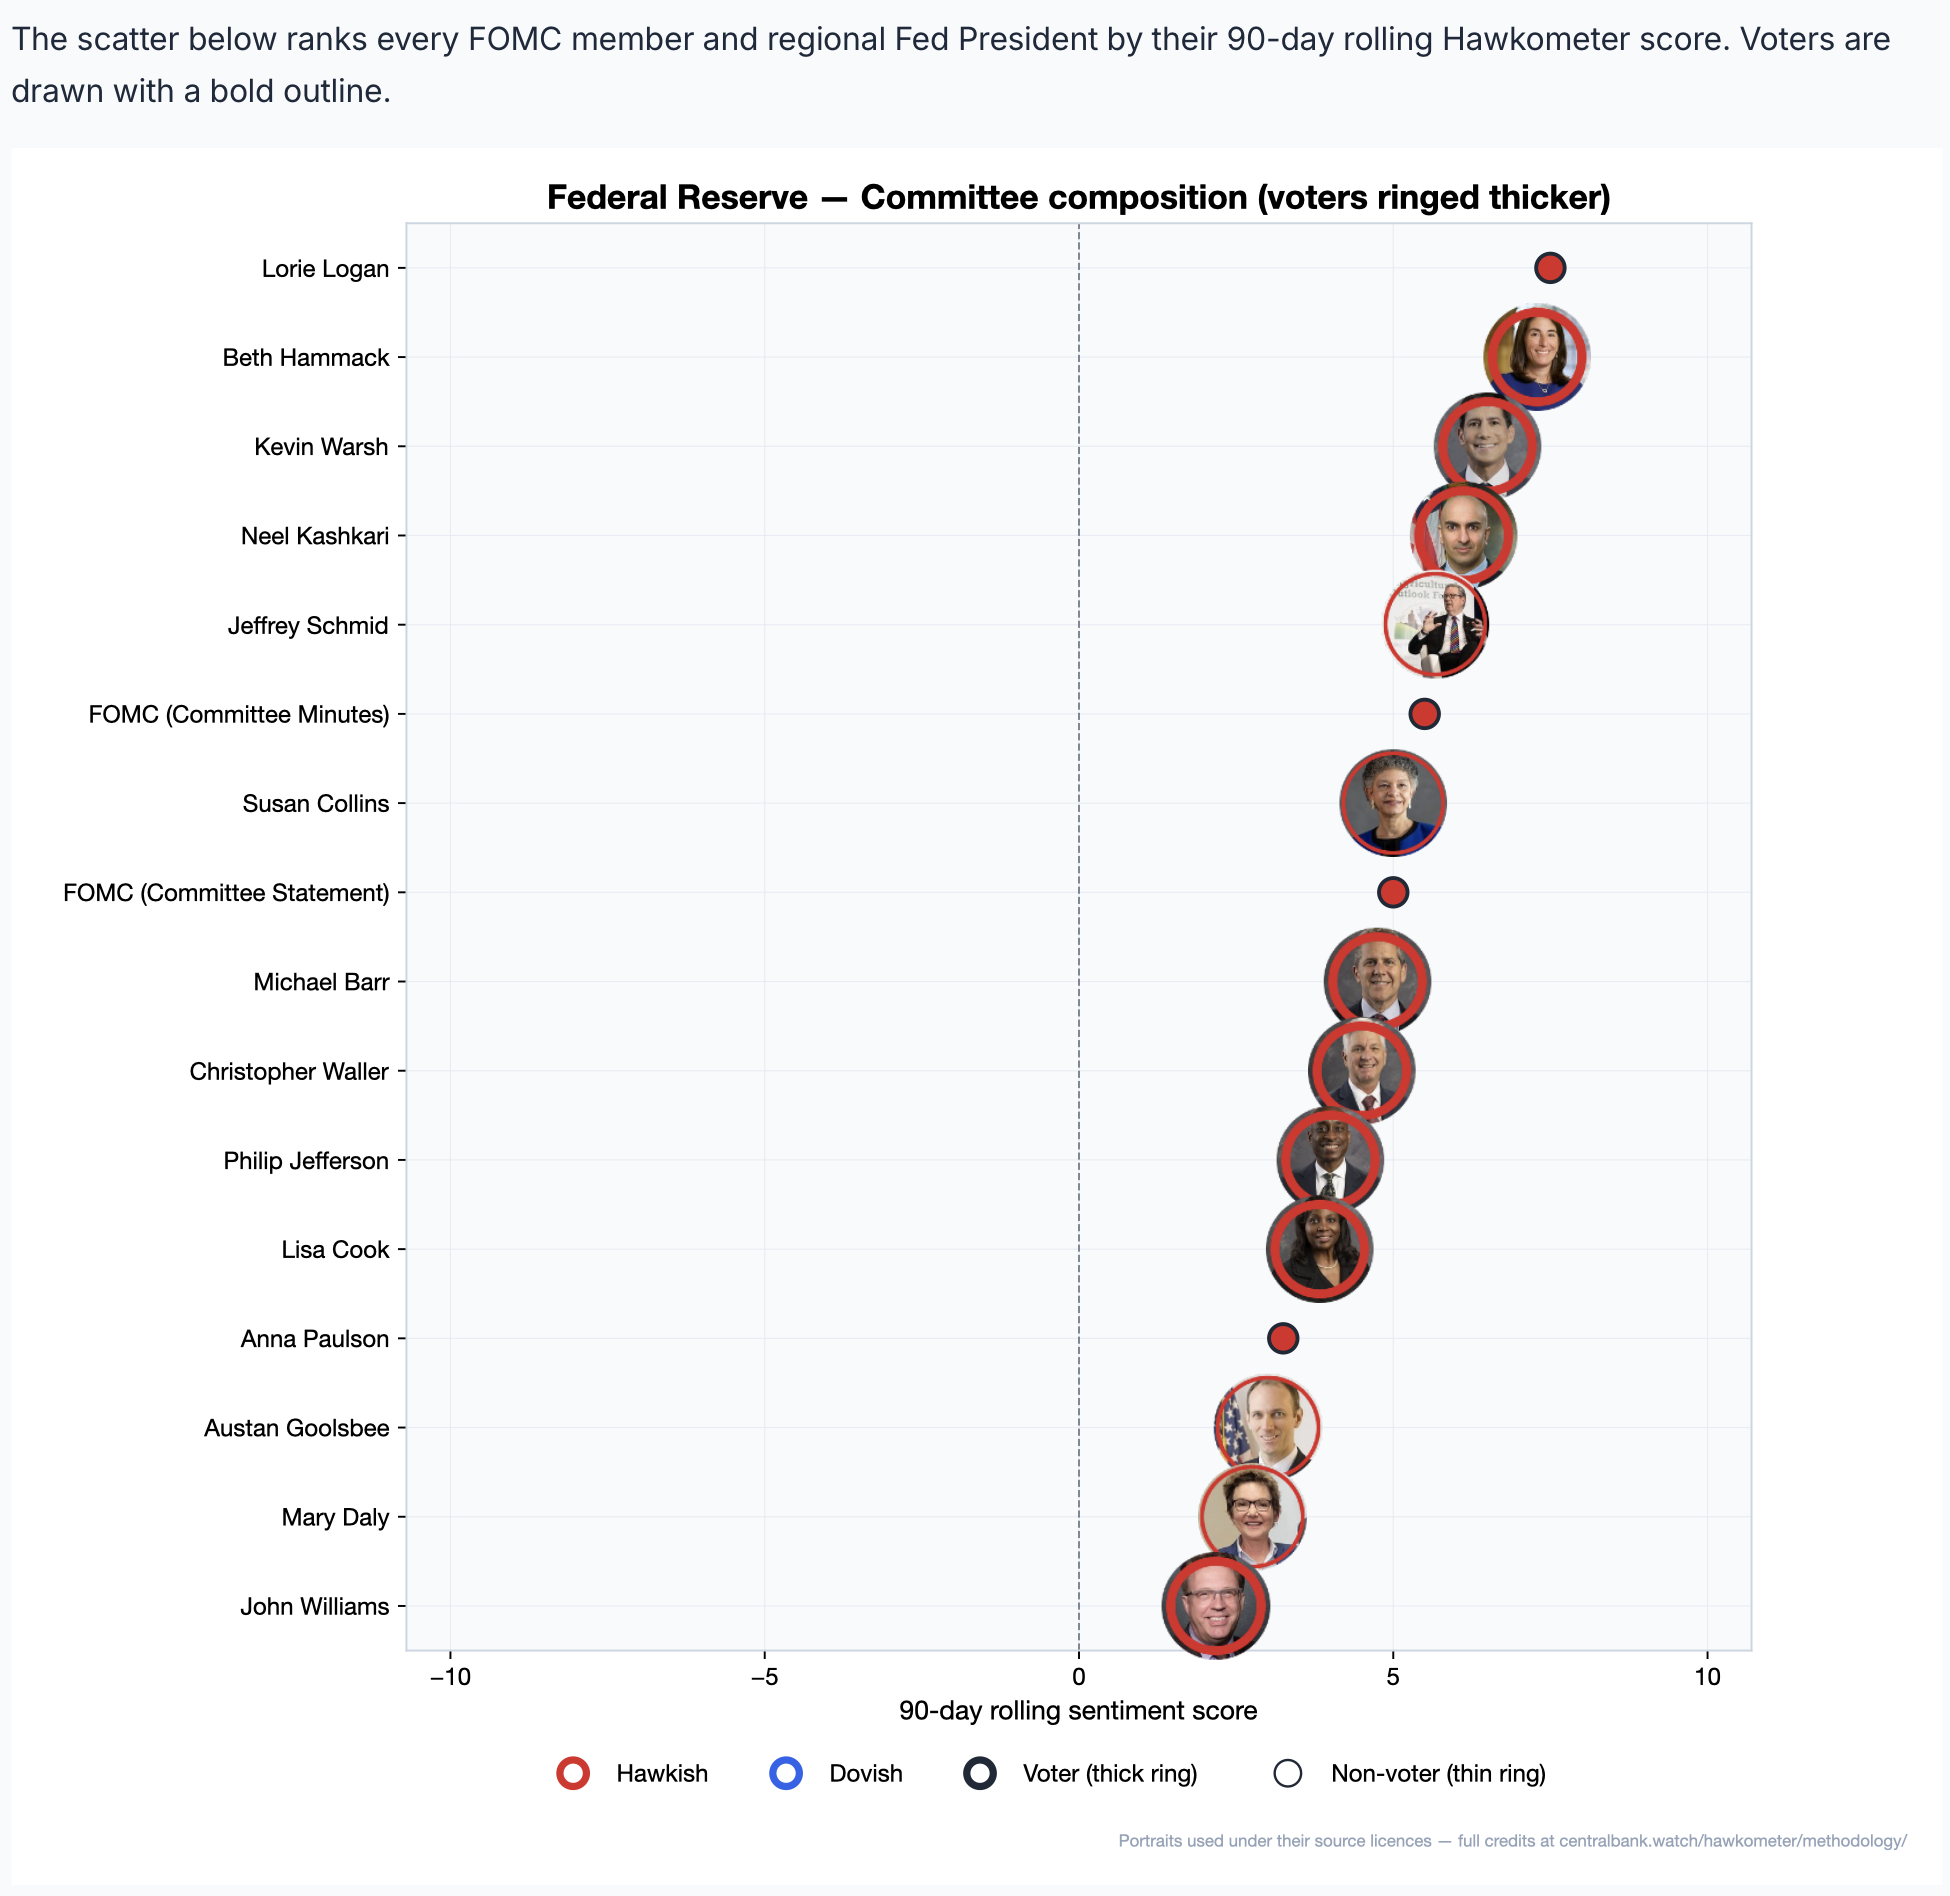
To absolutely nobody’s surprise, the Fed left policy on hold today, with the only possible wrinkle that the vote was 10-2 with Governor Cook and Cleveland President Hammack voting for a hike. Now, Hammack has been a vocal hawk for a while, so no real surprise there but Cook? Below is an interesting graphic from centralbank.watch which shows their estimate of the relative hawkishness or dovishness of the different FOMC members. Up at the (hawkish) top you see Ms. Hammack. But Governor Cook, who was put on the FOMC as a reliable dove and to the extent she has ever had serious thoughts about monetary policy has always been dovish is suddenly a hawk. My best estimate is that given the ongoing legal issues she is having with the administration as they continue to try to get her removed for mortgage fraud, this was a purely political vote with the idea that since President Trump wants rates to fall, she wants them to go higher to hurt him. I’m open to other explanations, but if Neel Kashkari, who dissented in August didn’t want a hike, explain the Cook vote otherwise.
But that’s not the interesting thing about this meeting. Rather, Chairman Warsh has indicated that they will be reducing the number of rate decision meetings to seven next year and then down to six in 2028, with no statements released and the committee simply getting together to discuss the economy and the situation. You will not be surprised that I believe this is a step in the right direction as the Chairman continues to try to wean markets from focusing on the Fed and forcing them to focus on the economy. But it is a process. He also indicated that he expected the task force reports to be submitted by year end, mostly, but then there would be time taken to discuss the results and see how they proceed going forward.
I continue to have great respect for him and his ability to navigate a clearly hostile environment as he is attacking the workings of an institution that has become hidebound and needing to get the agreement of the institution itself to change things.
As to the market response to the Statement and press conference…stocks did nothing, the yield curve steepened a bit with 2yr yields falling while 10yr yields edged higher as you can see below

And the dollar fell slightly as per the DXY chart below:
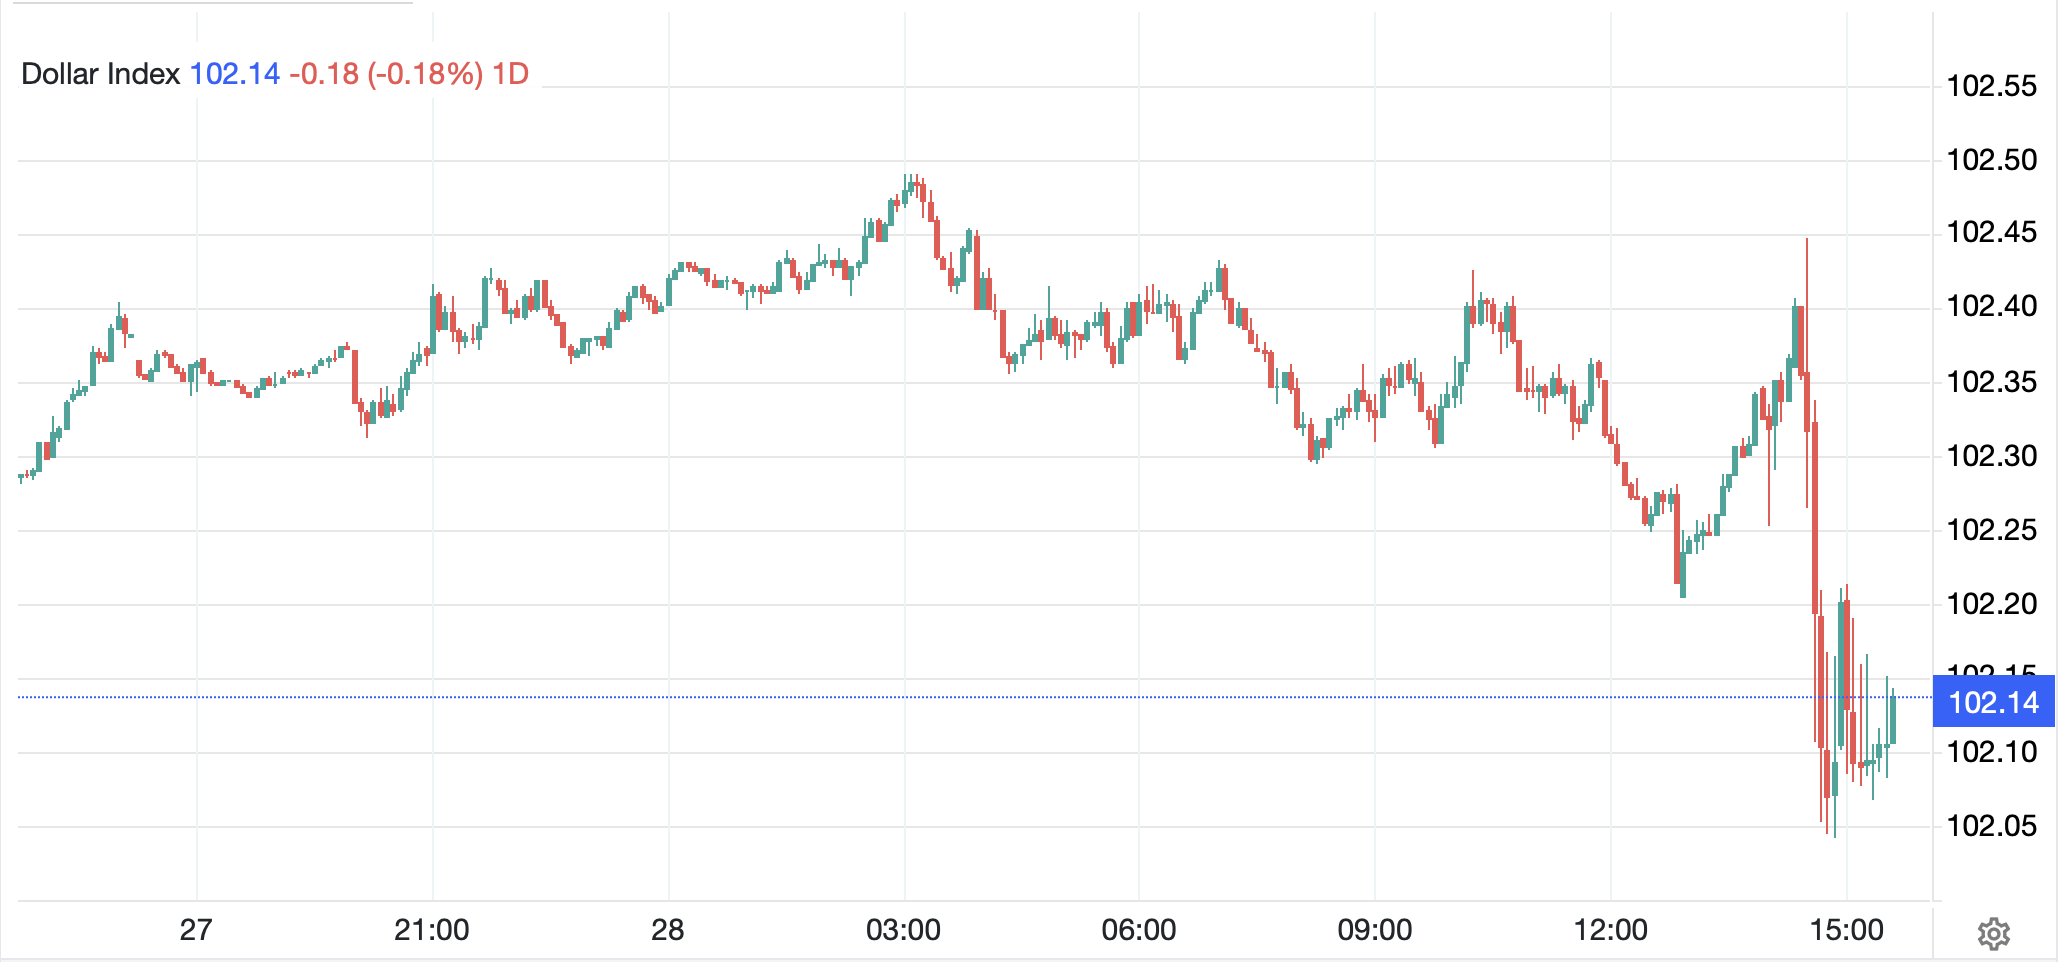
Source: tradingeconomics.com
These were my first thoughts on the FOMC and frankly, nothing has changed in my view this morning. However, I am always amused at the definitive tone taken by some regarding events like the Fed press conference and what was intended beyond what was said. This was my favorite this morning. I don’t know James Thorne, and he is probably an excellent analyst in a position of importance, but to put his opinion out there like a fact, as though Warsh confided in him, is remarkable!
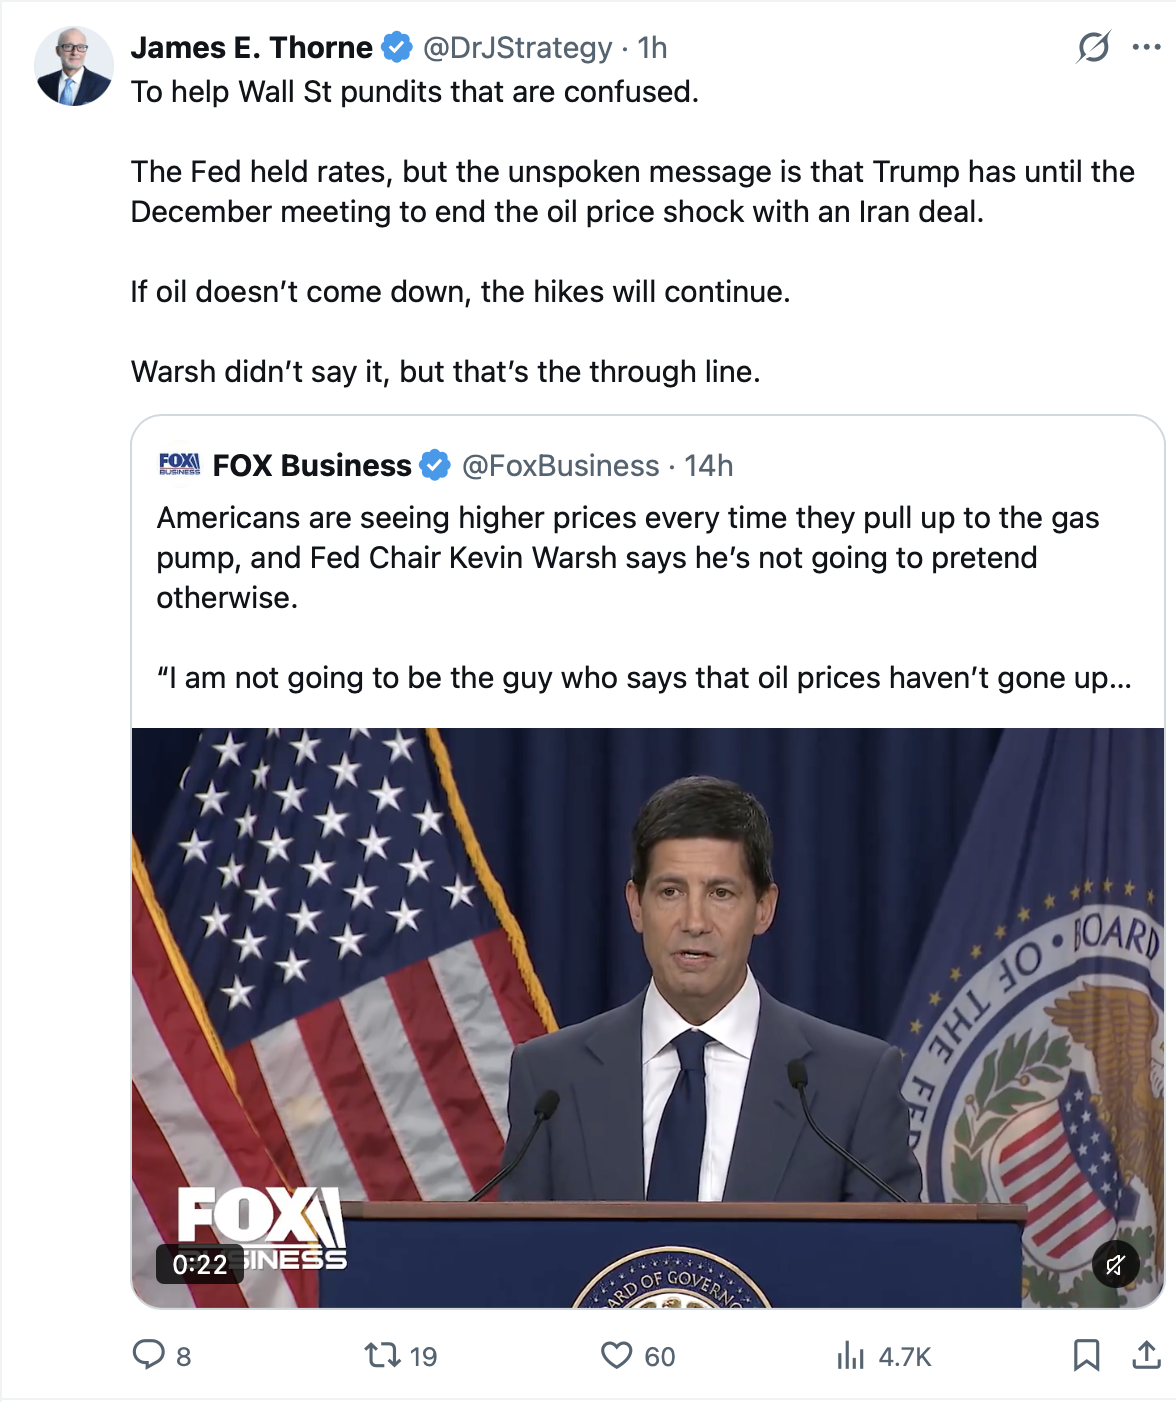
Perhaps he is correct, but my take is between now and the December meeting, there is an awful lot more information coming our way, starting with today’s PCE and GDP data. Remember, too, Chairman Warsh was explicit in his view that stronger economic growth does not necessarily lead to inflation, it is only when there is an imbalance between the supply and demand sides when inflation arises.
Ok, let’s turn to market behavior in the wake of the FOMC as well as the two big earnings reports last night where Alphabet missed estimates and called into question the AI trade while Microsoft beat estimates demonstrating the AI trade is alive and well.
The Asian equity markets were mixed overall. China (-1.0%), HK (-0.6%), Korea (-1.2%) and Taiwan (-1.4%) all followed Google, sinking amid concerns that the AI trade was hurting. Tokyo (+0.15%) and India (+1.2%) saw no such problems nor did Australia (+0.5%) or the Philippines (+0.9%). The Australian outcome was interesting as there has been further very hawkish talk from the RBA after inflation Down Under refuses to fall. And our favorite whipping boy, Indonesia (-3.5%) continues to see significant outflows as international investors flee the market while losing hope the securities regulators can address the MSCI concerns about liquidity and market transparency.
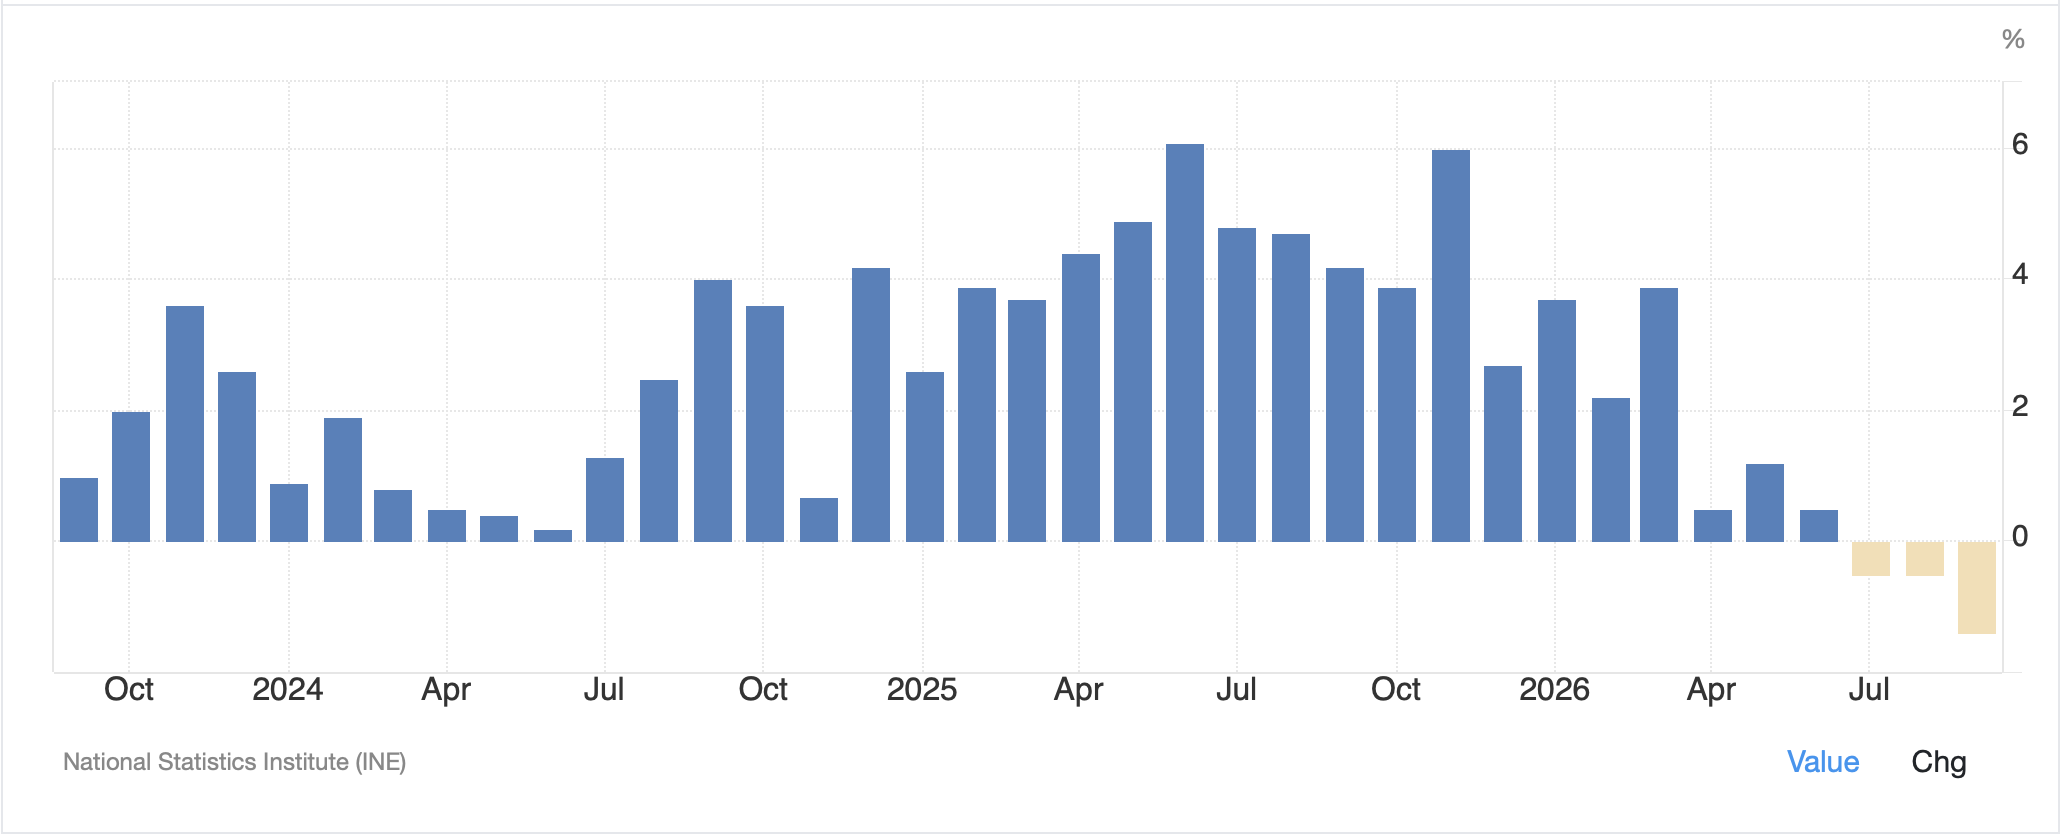
In Europe, it is a mixed picture with Germany (+0.8%) and France (+0.9%) both having solid sessions while Spain (-0.9%) suffers again. My initial thought on Spain was a response to the tragic train crash yesterday, but I think it is more a reflection of the weak Retail Sales data released this morning. if you look at the recent trend in Retail Sales there, as per the below chart, the trend is not very positive!
Source: tradingeconomics.com
Meanwhile, US futures at this hour (7:00) are generally pointing lower led by the NASDAQ (-0.9%) with the Alphabet news obviously more important than the Microsoft news. However, the other two indices are little changed.
The Madame is leaving her Chair
Next year, now those nations prepare
To choose someone new
Ere LePen can screw
Their choice with her typical flair
In the bond market, Treasury yields (-2bps) have edged lower this morning and continue to trade right at the 5.0% level. European sovereign yields, which had been lower earlier in the day, have backed up to unchanged, perhaps on the news that Madame Lagarde has announced she will step down from the role of ECB president as of February 7 next year. This is not that surprising to me, although I admit I thought she would be leaving for a different reason. My take, now, is that she wants to step aside to allow Macron to be part of the decision process since it appears that Marine LePen is going to be the next French president and her views do not align with Lagarde’s at all. My previous thought was she was going to step down early to run for French president, but that seems to be off the table for now, although I do not rule it out!
Turning to the commodity markets, oil prices (-1.5%) are falling this morning as there are sporadic stories about talks starting up again between the US and Iran, but weirdly, metals are also under pressure this morning (Au -0.7%, Ag -1.6%, Cu -1.1%), a break with the more recent negative correlatoin of oil up, metals down and vice versa.
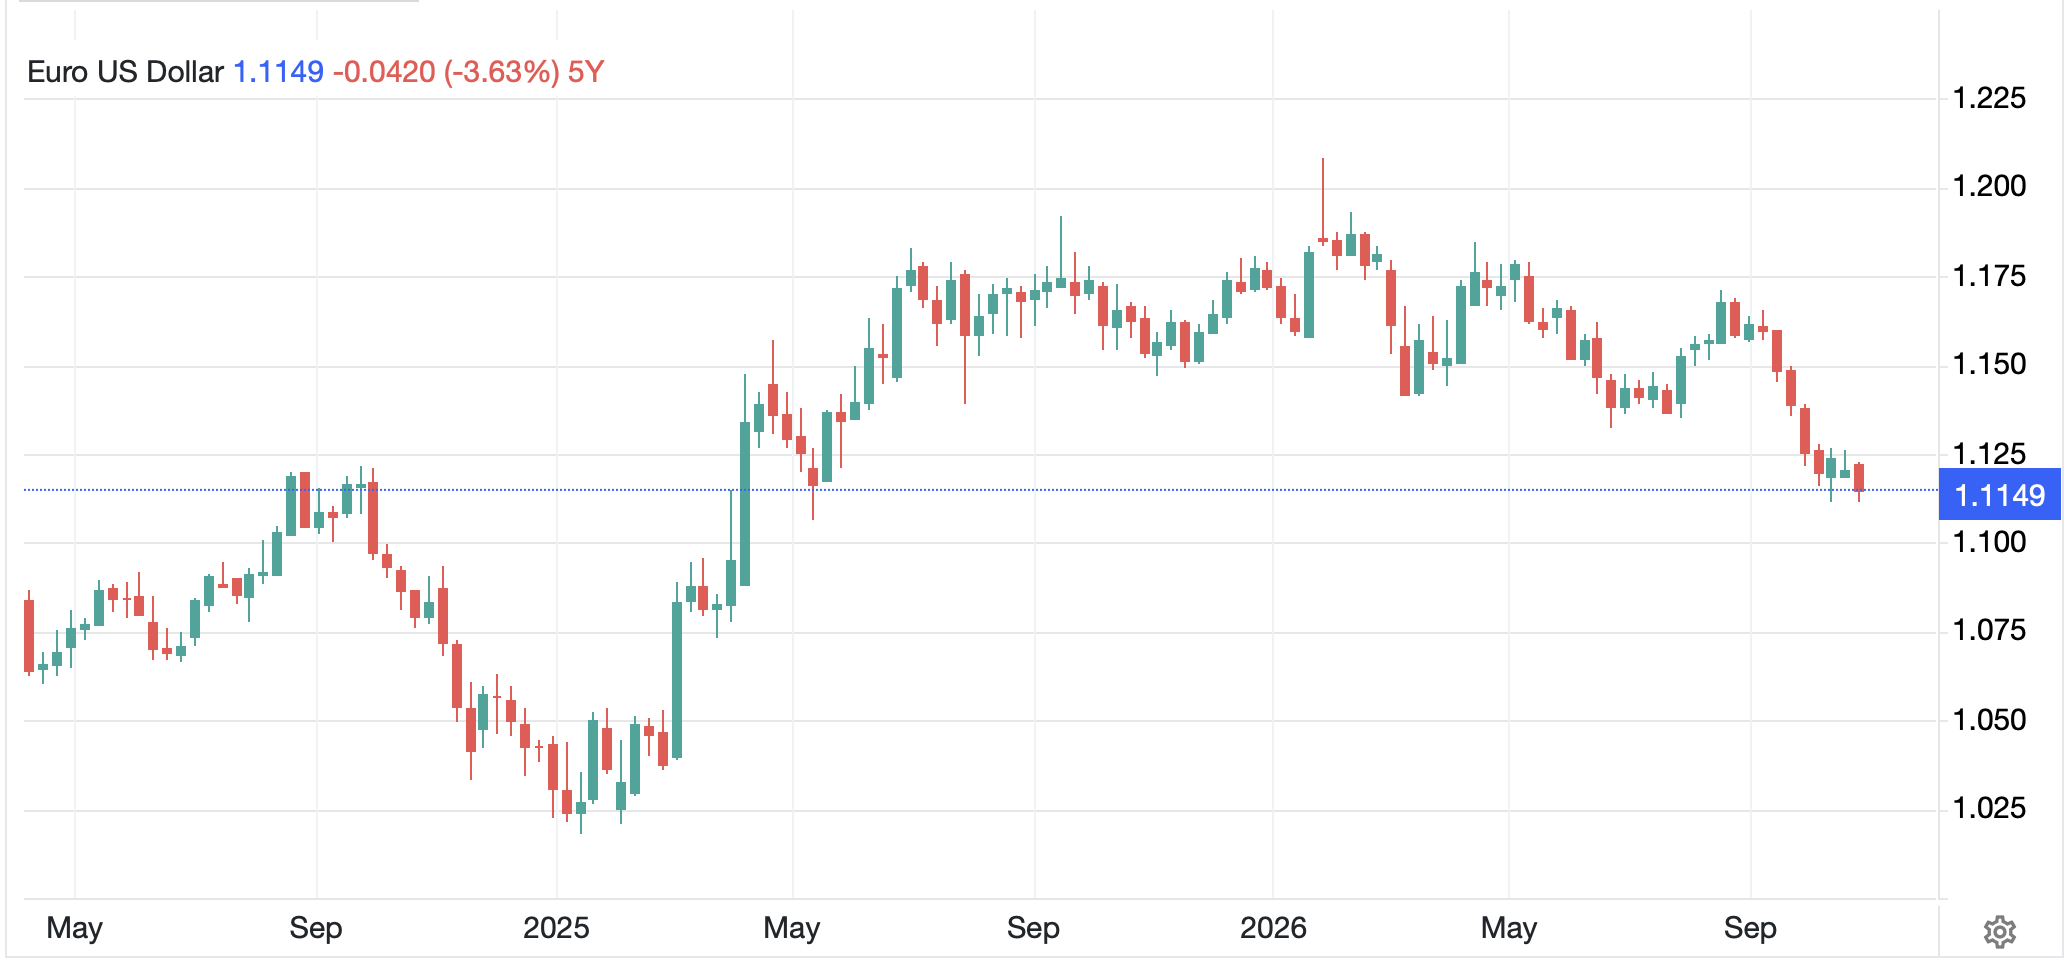
Finally, the dollar is ever so slightly higher on the day as the euro (-0.1%) slips toward its lowest level in nearly 18 months as per the below chart.
Source: tradingeconomics.com
You may remember the beginning of last year when the dollar slid about 10% over the course of 6 months and the punditry was breathlessly explaining the end was nigh as this was an unprecedented move. Of course that was all BS, it was merely a quirk of the calendar, but those were the headlines. At any rate, the euro is back to levels not seen since the end of that run. Here’s the thing, there are so many problems extant in the Eurozone, it is hard to make a positive case for the single currency, at least for me to do so. There is a distinct lack of leadership, a growing energy crisis and ongoing rioting as at least some folks there are displaying their anger more aggressively. More worryingly, there is nothing obvious that is going to change these issues, and if they follow through and cut off LNG imports from Russia at the end of this year, I fear the entire experiment can disintegrate.
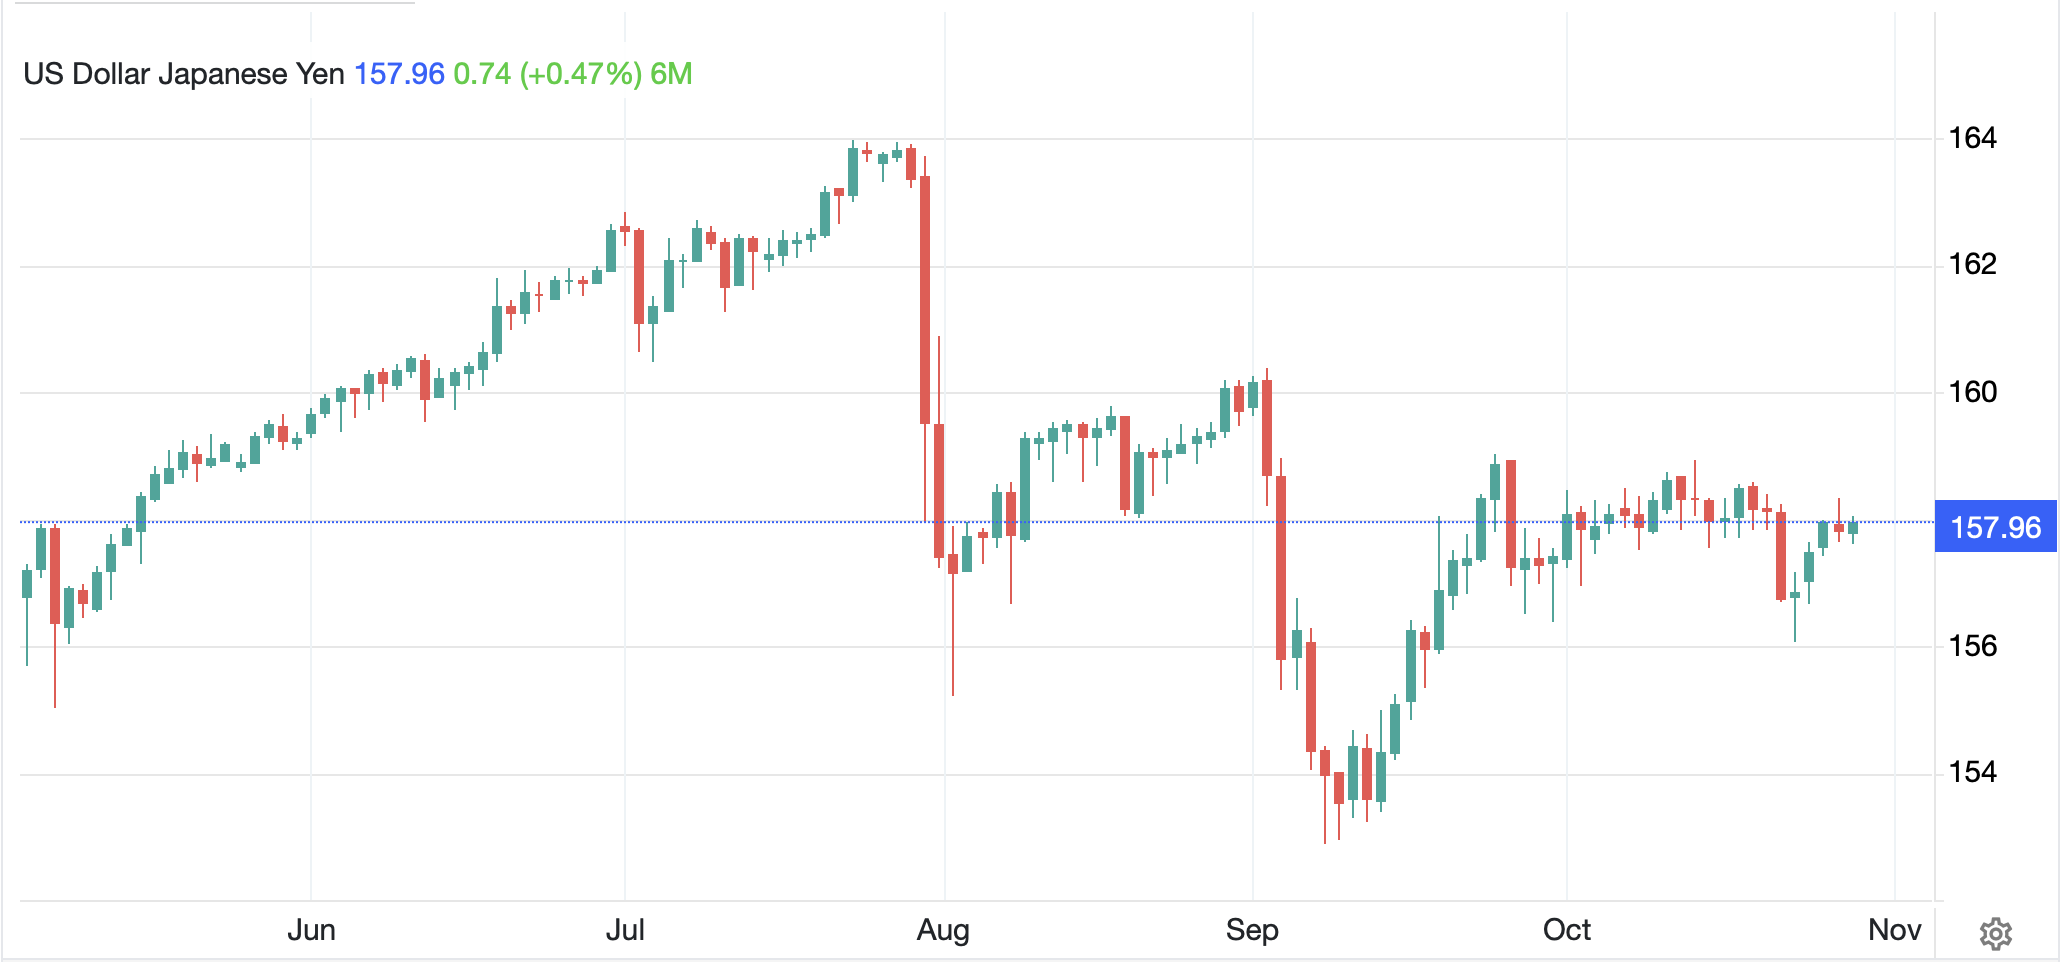
Elsewhere, remember when there was all that angst about the yen, and whether it was going to collapse, or whether the interventions would be effective? Me neither! Basically, as you can see in the below chart, we remain exactly where we were the day after the intervention. There has been no massive repatriation of yen by Japanese investors and for now, it is hard to get excited in either direction. So far, Secretary Bessent’s actions in both the FX and bond markets are holding up despite initial criticism.
Source: tradingeconomics.com
Otherwise, FX remains dull with nothing to discuss.
On the data front, we do get a bunch of stuff this morning as follows:
| Initial Claims | 199K |
| Continuing Claims | 1720K |
| Q3 GDP (1st look) | 3.2% |
| Personal Income | 0.3% |
| Personal Spending | 0.6% |
| PCE | 0.5% (3.6% Y/Y) |
| Core PCE | 0.35 (3.1% Y/Y) |
Source: tradingeconmics.com
We also hear from the ECB at 9:15 this morning but no change is expected. I imagine all the excitement from the ECB is already out there with Lagarde’s announcement.
Did the Fed change anything? I don’t think so, and as I have maintained for a while, I think we need to get through the election before we can make a definitive move in any of these markets.
Good luck
Adf

