Said Trump at the UN, ‘I’m great
And all of you should really fete
The things I have done
So, we’re number one
And you all are now second rate’

Meanwhile, it’s the market for crude
That shows if we’re OK or screwed
Right now, things seem fine
But there’s no red line
Here’s hoping that peace is pursued
I was reading a new novel, prepublication, and I realized what it is I like about poetry so much, especially something like a limerick or haiku. It is the economy of words used to tell a story. Each of those forms of poetry have strict syllabic counts, so if an author is to get his point across, he often must work hard to fit the ideas into the correct syllable count as well as rhyme and meter. Of course, the greater irony is I recognize that in the rest of my morning discussion, I talk too much and often add too much flourish, but that is the way I write. Sorry.
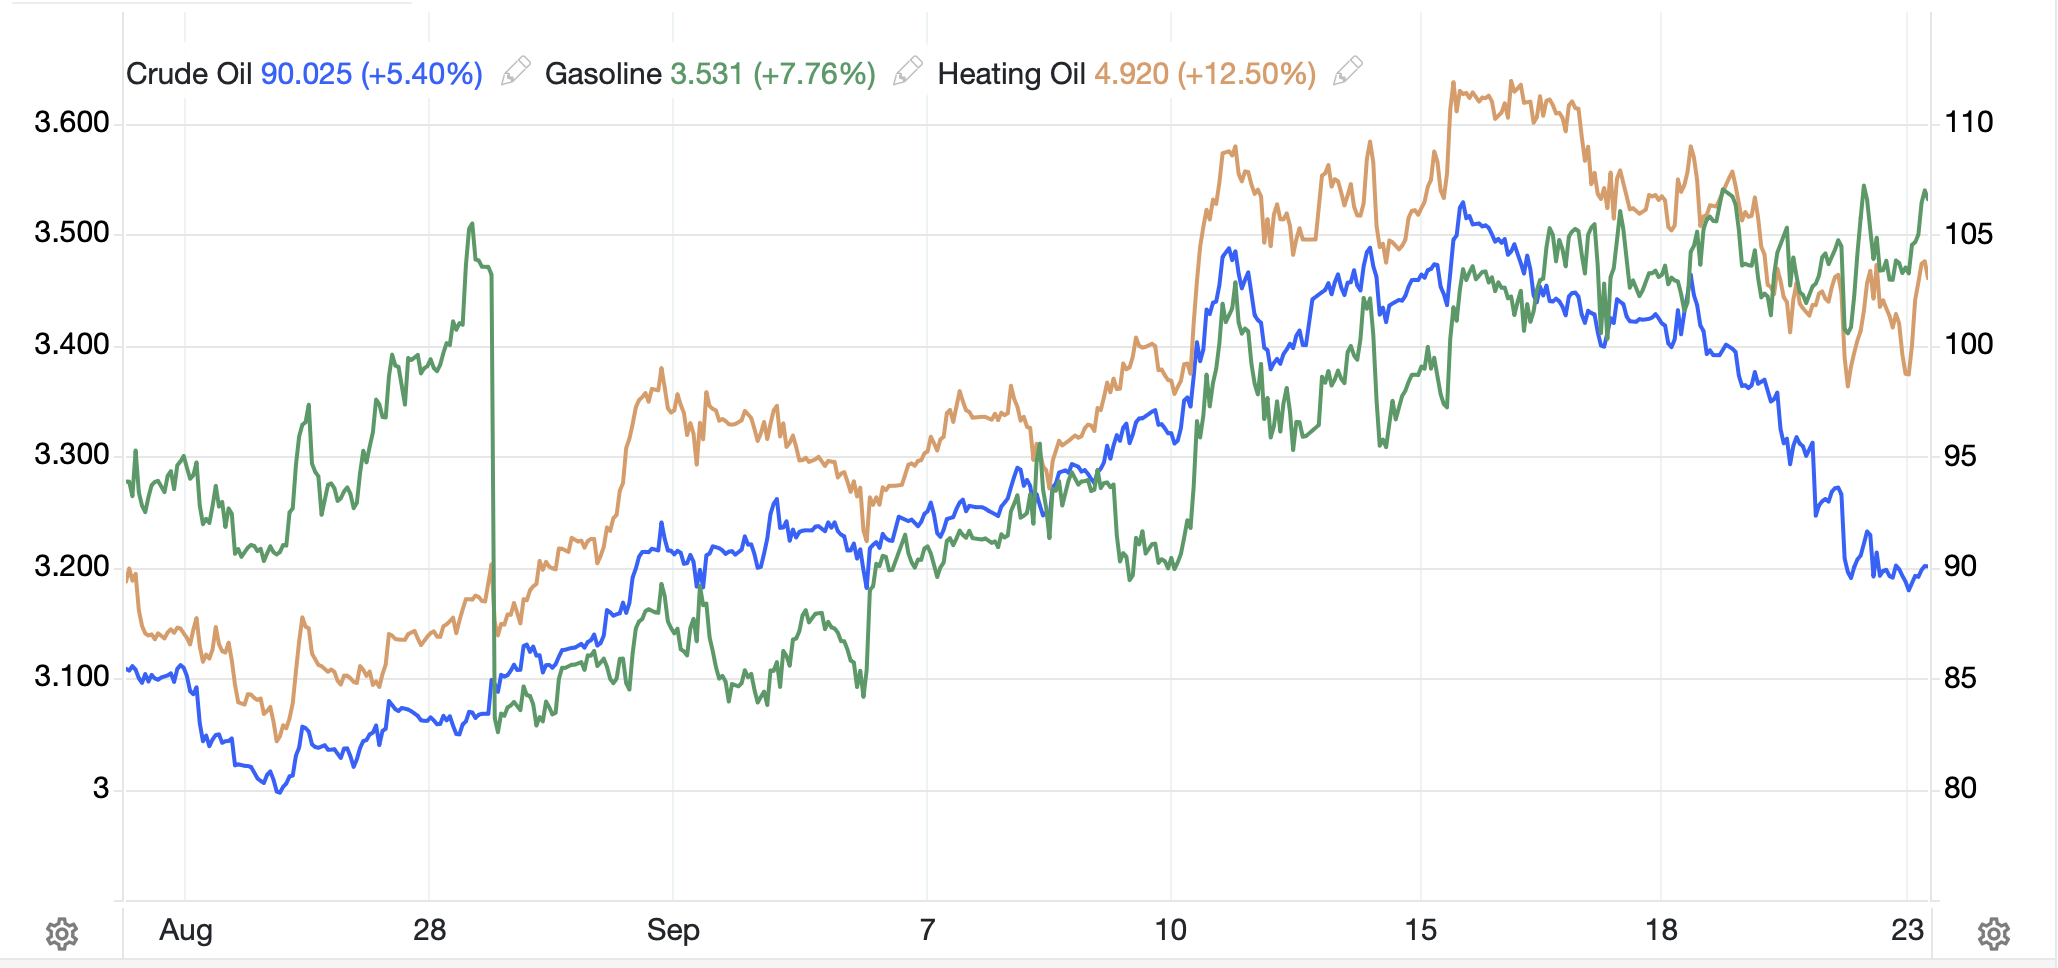
Anyway, getting on to the stories of the day, arguably, President Trump’s speech at the UN was the most noteworthy thing, although it didn’t really move markets. Once again, he offered a choice, negotiate an end to the Iran conflict or obliterate them. In the end, I suspect it will come down to negotiations, but I won’t rule out a step up in destruction there. Oil markets, though, are clearly not fretting about that this morning as WTI (-0.7%) continues its recent decline. Of course, the problem is the price of products, specifically diesel, which is getting all the press as it hits record highs despite the decline in crude prices. Apparently, Ukraine’s attacks on Russia’s refineries are being felt most acutely in diesel. The below chart shows how crude (blue line) has been separating from products over the past week, especially.
Source: tradingeconomics.com
But in truth, away from that story, and the recent backdrop of the hysteria about AI’s ability to kill us all, there is not much happening. Equity markets were mixed yesterday, bond markets barely moved and the dollar continues to edge higher. Discussion about the Fed and what they are going to do at the next several meetings is back page news with the probability of a move at the October meeting right at 50/50 so not driving the discussion at all. There is an increasing focus on the midterm elections, but they are still about 6 weeks away, so not quite imminent. Even X is relatively quiet these days with a distinct lack of anxiety about any specific thing.
So, until there is more excitement somewhere, I’ll just recap markets. After yesterday’s mixed US session, mixed also describes Asia well. Japan was closed again last night, third night running as they had to fit in Old Age Day alongside Autumnal Equinox Day, but while China (-0.6%) and HK (-1.0%) both slipped, Korea (+0.9%) and India (+0.5%) rallied along with Taiwan (+0.75%) and Indonesia (+1.6%). It seems yesterday’s strong US tech performance carried over into Korea and Taiwan and Indonesia responded to the central bank leaving rates on hold in a bit of a surprise. The narrative regarding HK/China is anxiousness ahead of tomorrow’s Trump-Xi meeting for whatever that is worth, which in my opinion is not much, as sometimes markets just go lower.
Turning to Europe, equity markets there are under modest pressure (Germany -0.5%, Spain -0.3%, France -0.2%) despite what I would have called better than expected Flash PMI data released this morning. Or perhaps that is the driver as there might be a growing concern the ECB will feel the need to hike further. That was the view of Joachim Nagel from the Bundesbank, as he indicated the ECB may need to move to “mild restrictive territory” from the current neutral stance. However, the probability of a rate hike at the next meeting is also 50/50 there. As to US futures, at this hour (7:10) they are basically unchanged.
In the bond market, it appears the entire market is following Japan’s lead and doing absolutely nothing with yields within 1bp of yesterday’s levels in Treasuries and across all of Europe. Nothing to see here.
Metals markets appear to be responding to the dollar’s ongoing strength, which I will discuss momentarily. But this morning gold (-1.1%), silver (-2.7%) and copper (-0.3%) are all under pressure, although the copper shortage story seems to still have some legs.
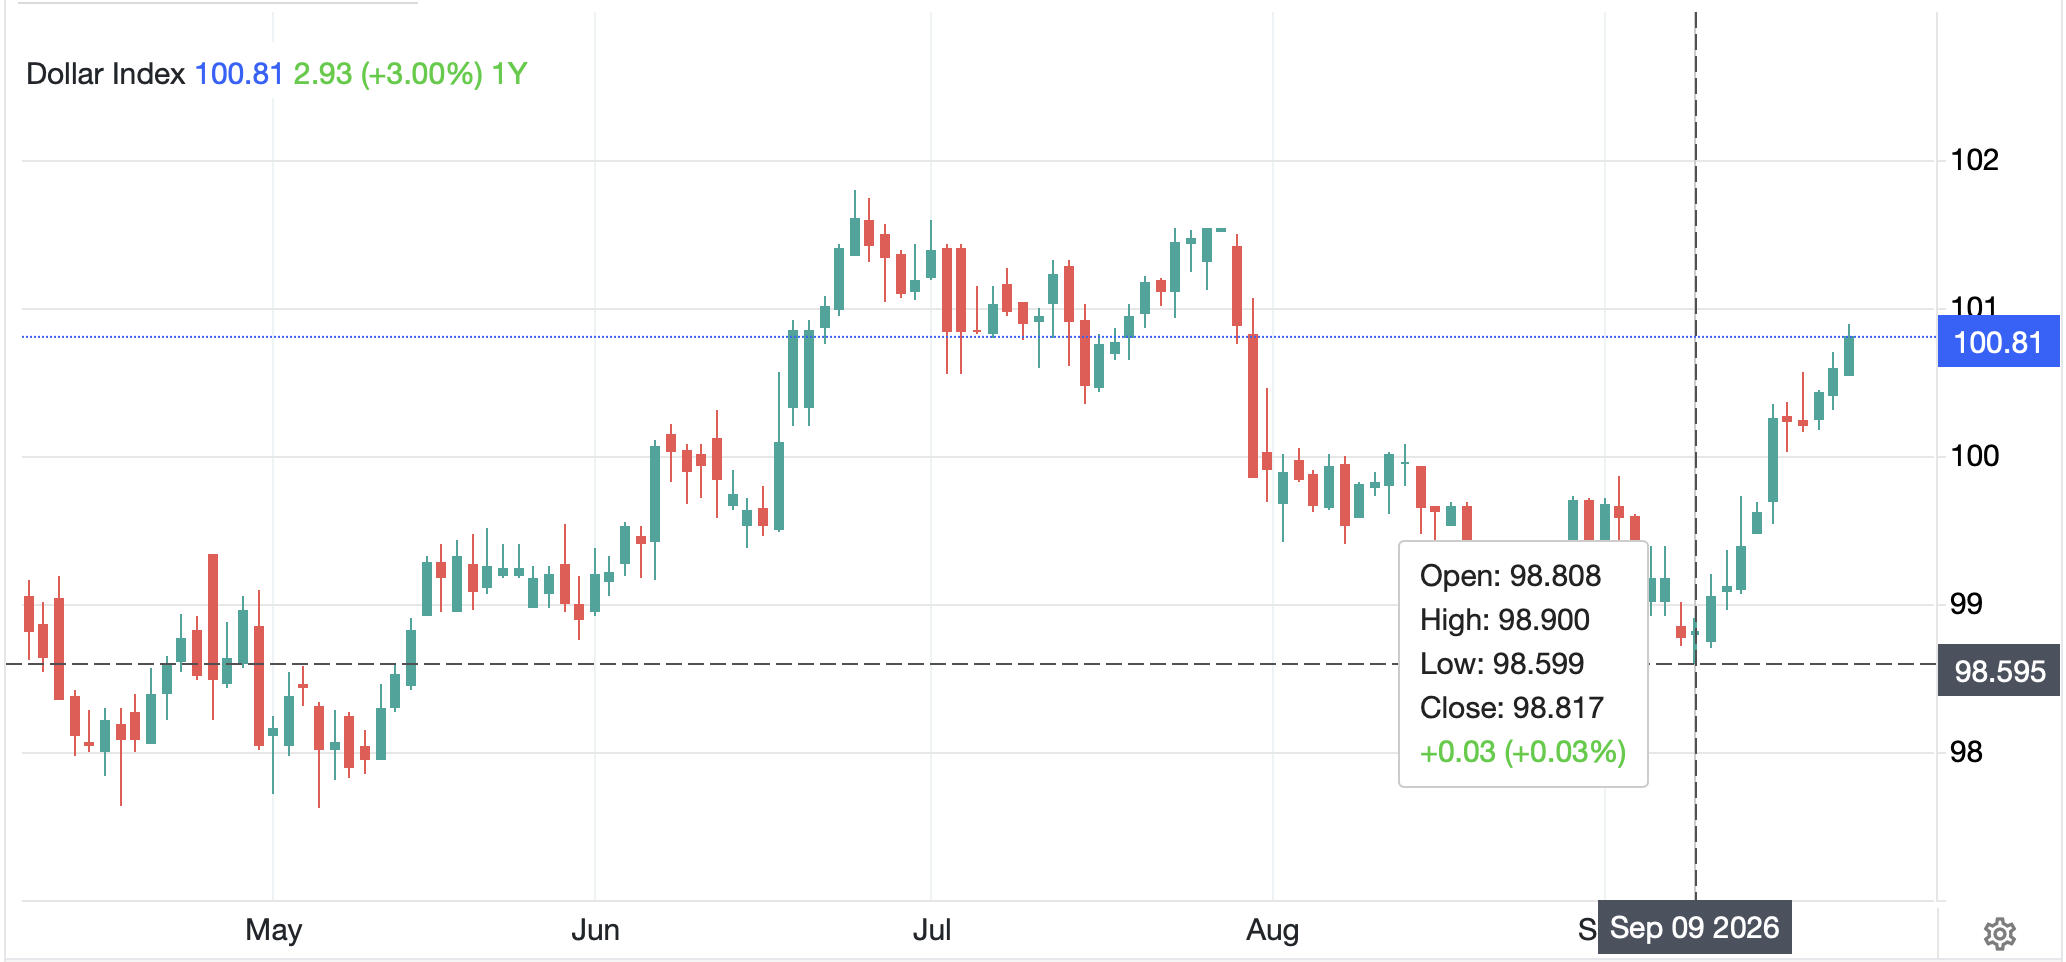
Finally, you can’t keep a good dollar down. I have been using the DXY as proxy and as you can see from the below chart, for the past two weeks this has basically been a one way trade, with the greenback rising more than 2%.
Source: tradingeconomics.com
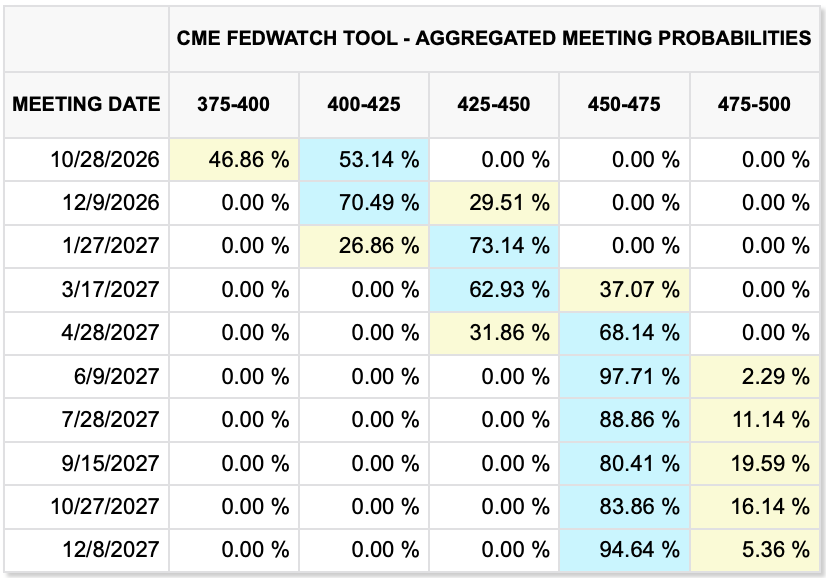
The narrative appears to be that the market is pricing in more FOMC tightening than ECB tightening, although in the short-term, both are priced at a coin toss to hike next month. The thing that still confuses me is the discrepancy between the futures market, where traders are pricing three more hikes by next June as per the below table from cmegroup.com
And the Fed’s dot plot, which, as you can see below, prices in one more hike and then a steady decline thereafter.
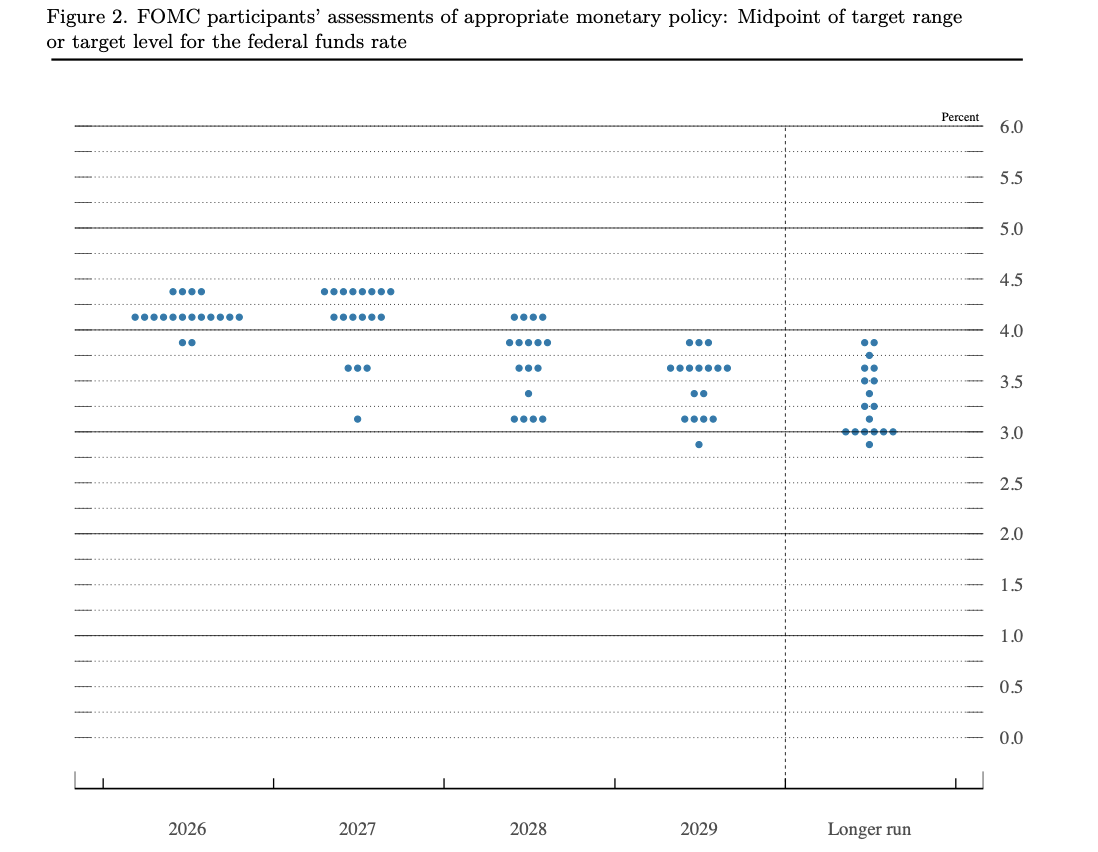
One of these two is wrong, but as of now, we have no way of knowing which one. I will say this, the longer that there is pressure on the products markets, the more likely we see persistent inflationary pressures as diesel costs do feed into virtually everything. If that is the future, then I lean toward the CME. Perhaps, despite President Trump’s well known desire for lower interest rates (he is a real estate guy after all, and they always think rates should be lower), the fact that the US economy continues to show resilience and strength may well lead to tighter policy. Certainly, that is the Keynesian view.
But back to the FX markets where the dollar is firmer across the board, and this morning by some pretty substantial amounts. In the G10, AUD (-0.7%) and NZD (-0.65%) are the laggards but the pound (-0.5%) and euro (-0.4%) are also under pressure. In the EMG bloc, KRW (-0.8%), MXN (-0.9%) and PLN (-0.9%) show just how widespread dollar strength is today. Is this the beginning of a serious move higher in the dollar? While you can never rule anything out, I suspect that is not the case. But can we get back to the top of the DXY range we saw during the summer, so another 1.5%? Sure, easy peasy and nothing fundamental has to change for that to happen.
On the data front, Flash PMI’s are on the calendar (exp Mfg 53.6, Services 56.0) as well as the EIA Oil inventories where a small draw is expected. South Africa’s SARB is expected to raise its base rate to 7.25% this morning and we hear from Fed Governor Barr later this morning as well. It is interesting to me that despite the talk about Fed funds, I rarely hear or see much about what Fed speakers have to say. Perhaps the narratives are already written and if they don’t match up, they are ignored!
I still wouldn’t bet against the dollar here.
Good luck
Adf

