
In what cannot be a surprise
The Fed funds rate surely did rise
But look at the Dots
My read is those spots
Do not portend hikes called king-size

The funny thing is the new mood
Is Warsh is now one hawkish dude
Most pundits agree
That what we’ll now see
Is hikes of a great amplitude

But when I look at the dot plot
One more hike is all that they’ve got
Then, as time progresses
The best of their guesses
Is rates will be falling a lot
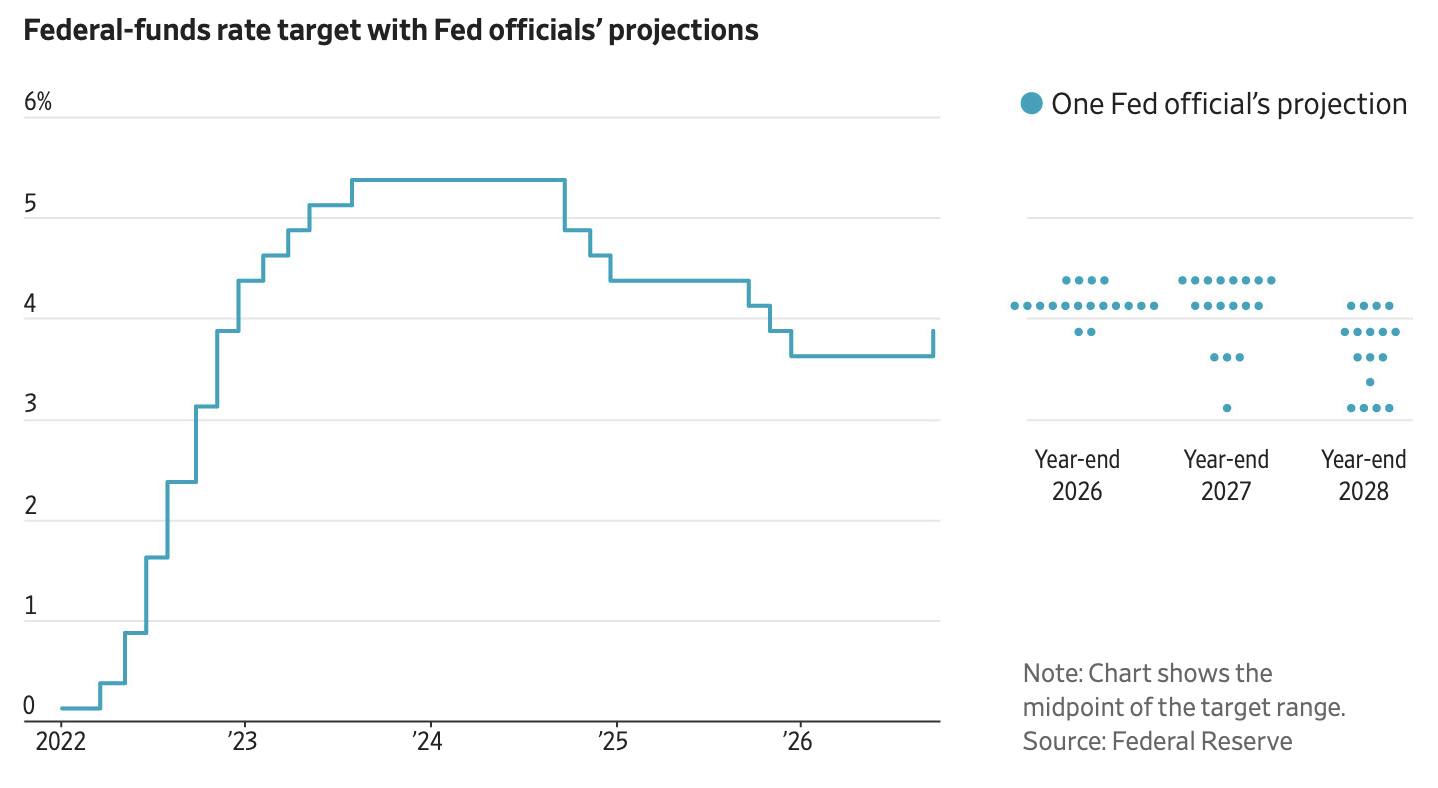
I feel very out of touch with the punditry this morning as the virtually unanimous view was that Chairman Warsh was quite hawkish in his press conference and from what I have read this morning, the Fed is embarking on a series of rate hikes to address inflation. However, that is not what I took away from yesterday’s events. In fact, if you look at the below chart which was published in the WSJ this morning and is truly quite helpful in showing the dot plot and the Fed funds rate next to each other and on the same scale, the median view is for one more rate hike this year and then a hold and decline going forward.
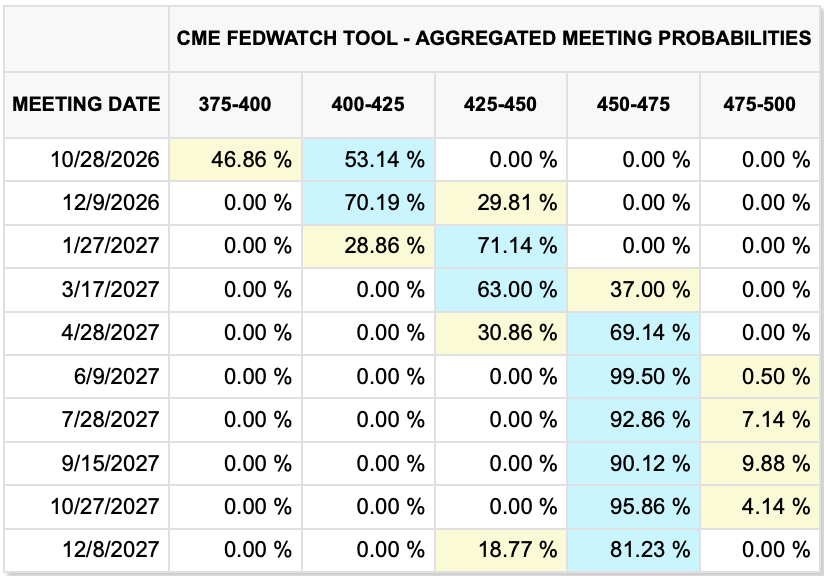
However, my view is clearly a minority one right now. As you can see in the cmegroup.com table below, futures are pricing about a 50% probability of a hike in October and the certainty of one, plus a chance for more, by December with two more coming next year.
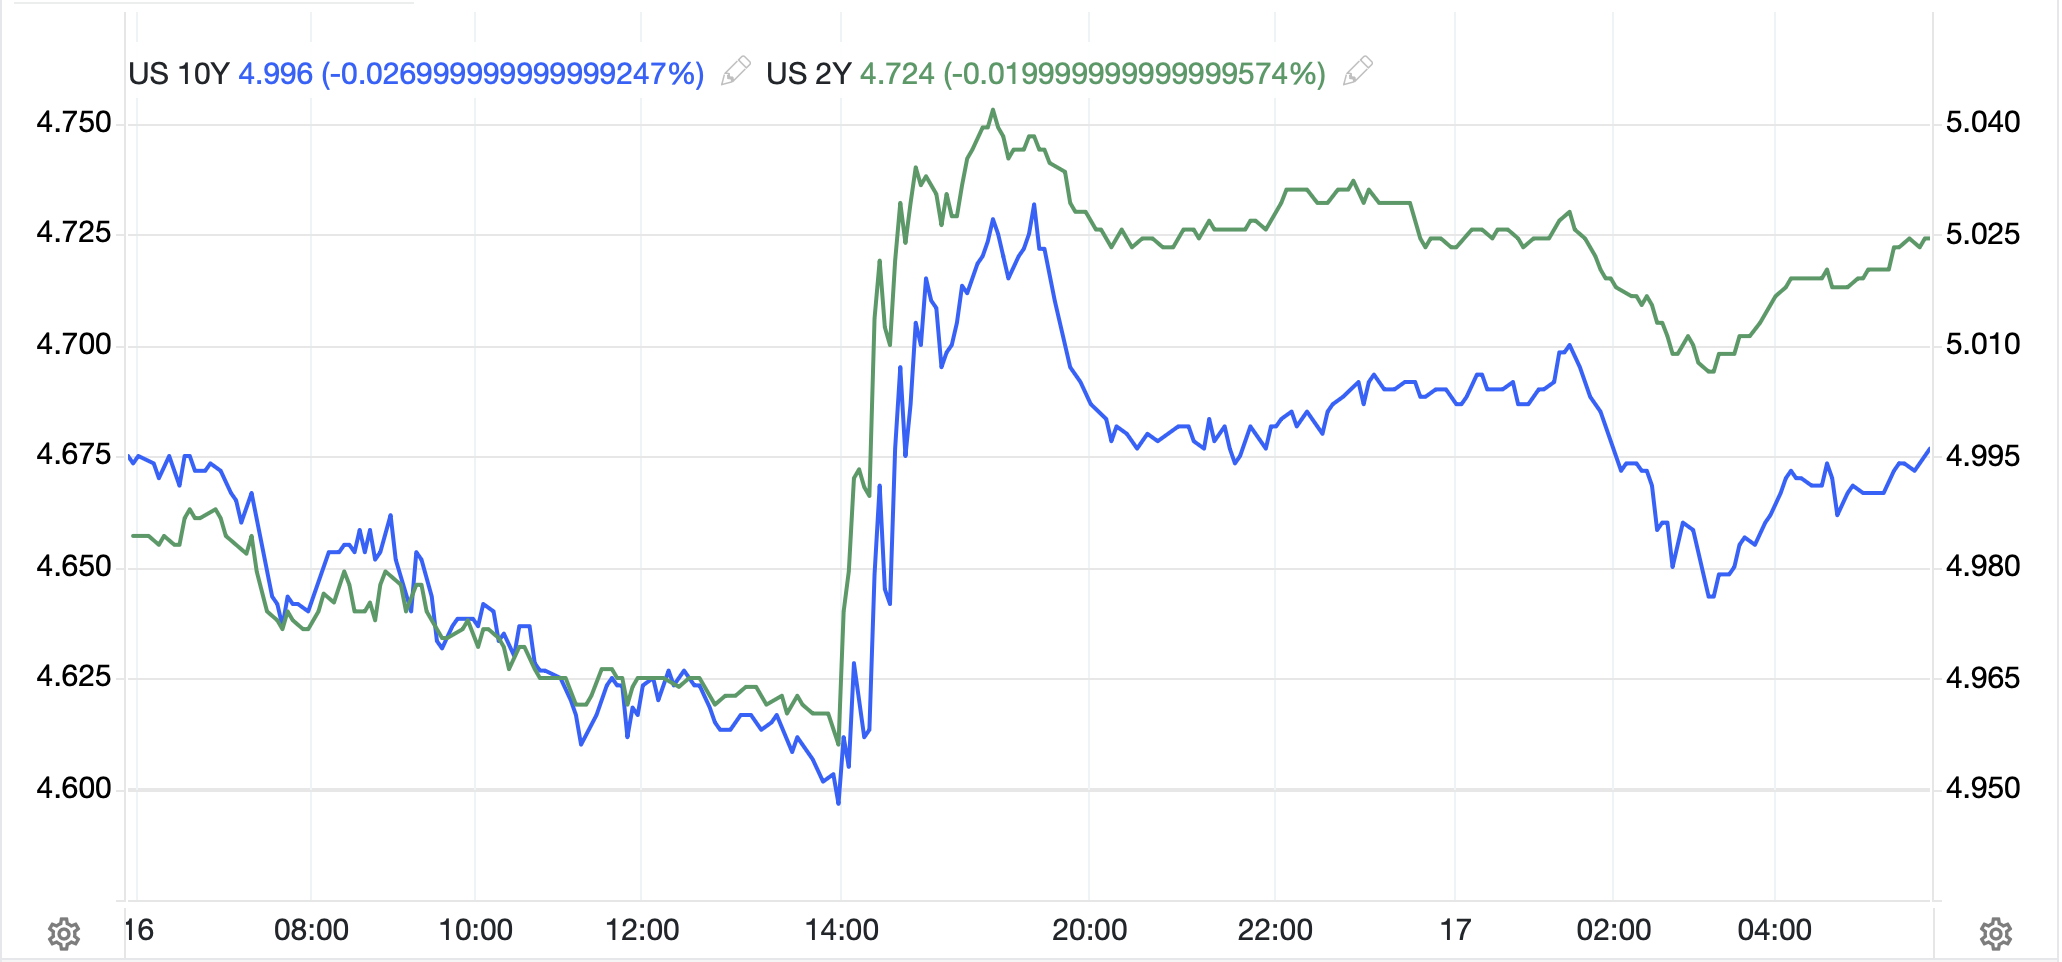
Again, that is far different than the dots and not what I heard, but then, I am just a poet. So, let us turn to how markets responded to the event. Below is a chart of both the 2yr (in green, LHS) and the 10yr (in blue, RHS) over the past 24 hours. While both curves show a similar shape, be sure you look at the Y-axes as the increments are wider for the 2yr than the 10yr.
Source: tradingeconomics.com
As of this morning, the 10-year is essentially unchanged while the 2yr yield has climbed about 6bps, implying the cash bond market, too, is looking for more hikes sooner rather than later. We have discussed the logic behind hiking rates at this time, but oftentimes logic does not matter, at least not for a while.
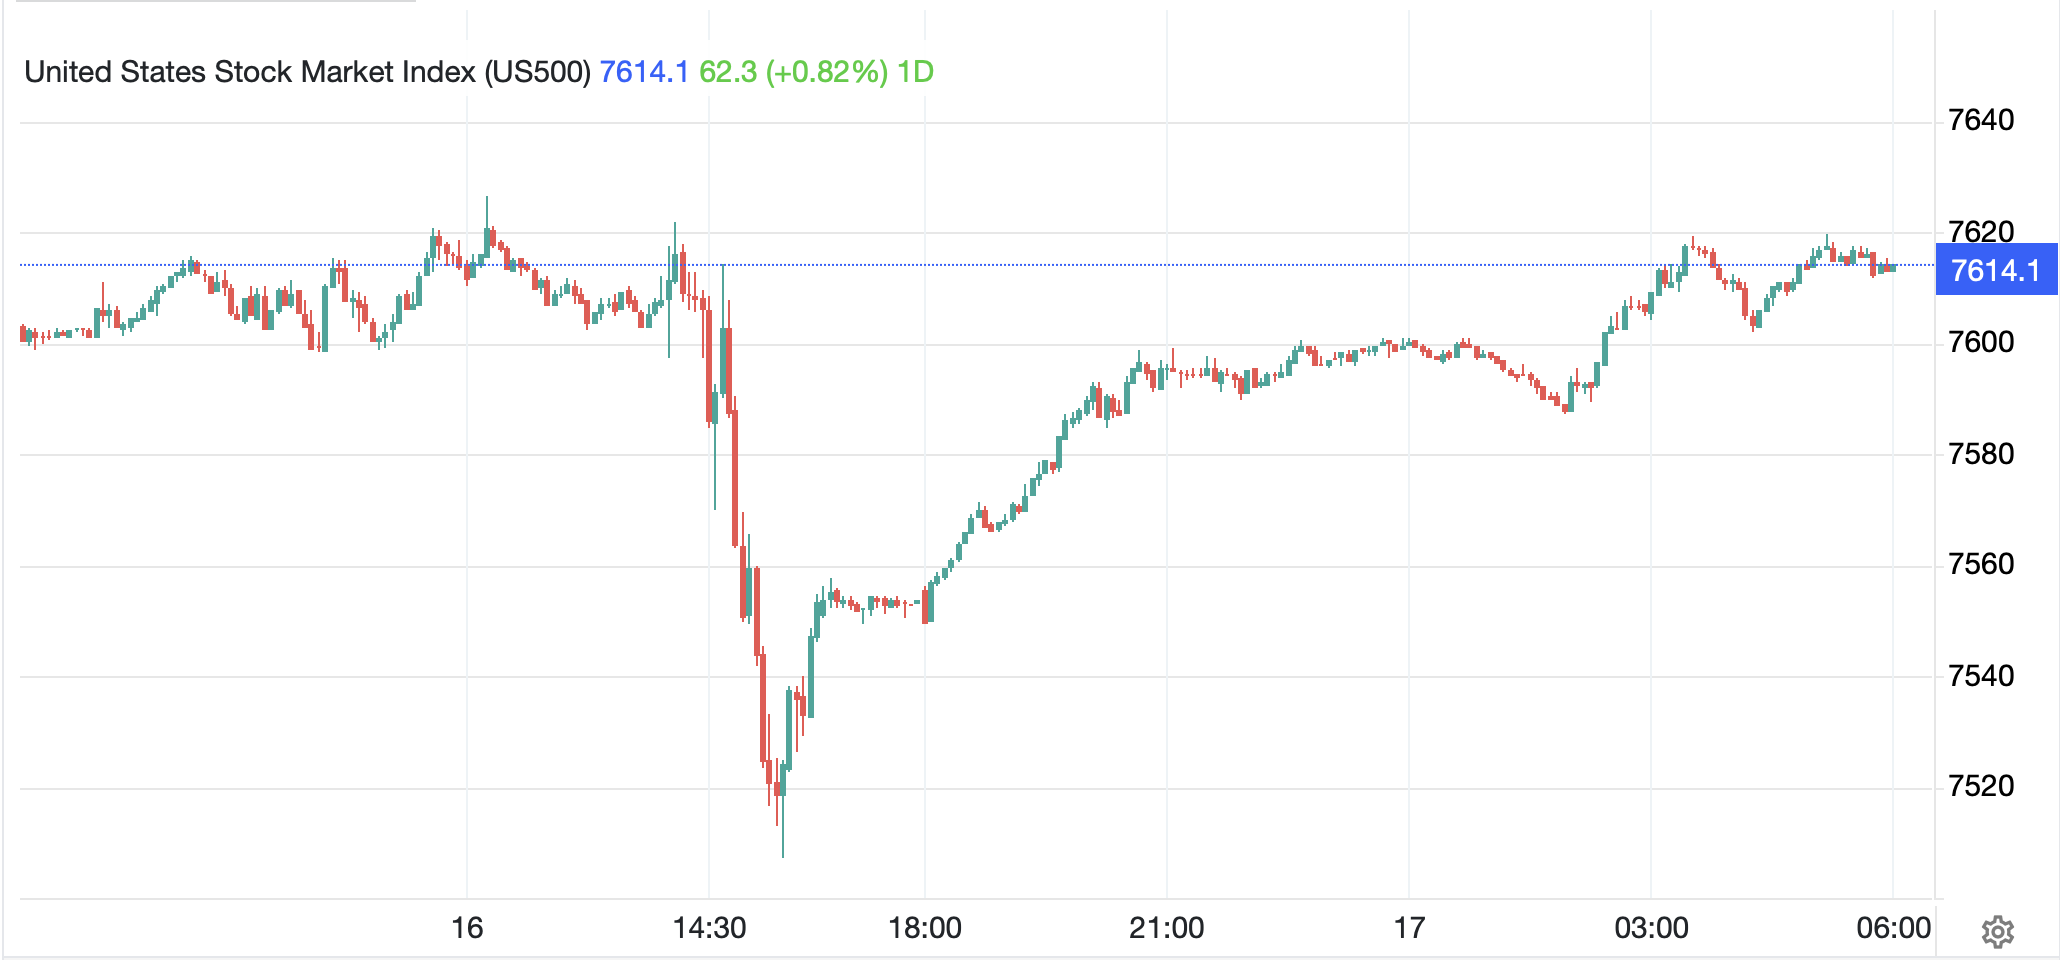
As to equity markets, while both the DJIA and SPX closed lower yesterday, the NASDAQ was unchanged by the end of the day, as you can see from the chart below, those losses have also been recouped.
Source: tradingeconomics.com
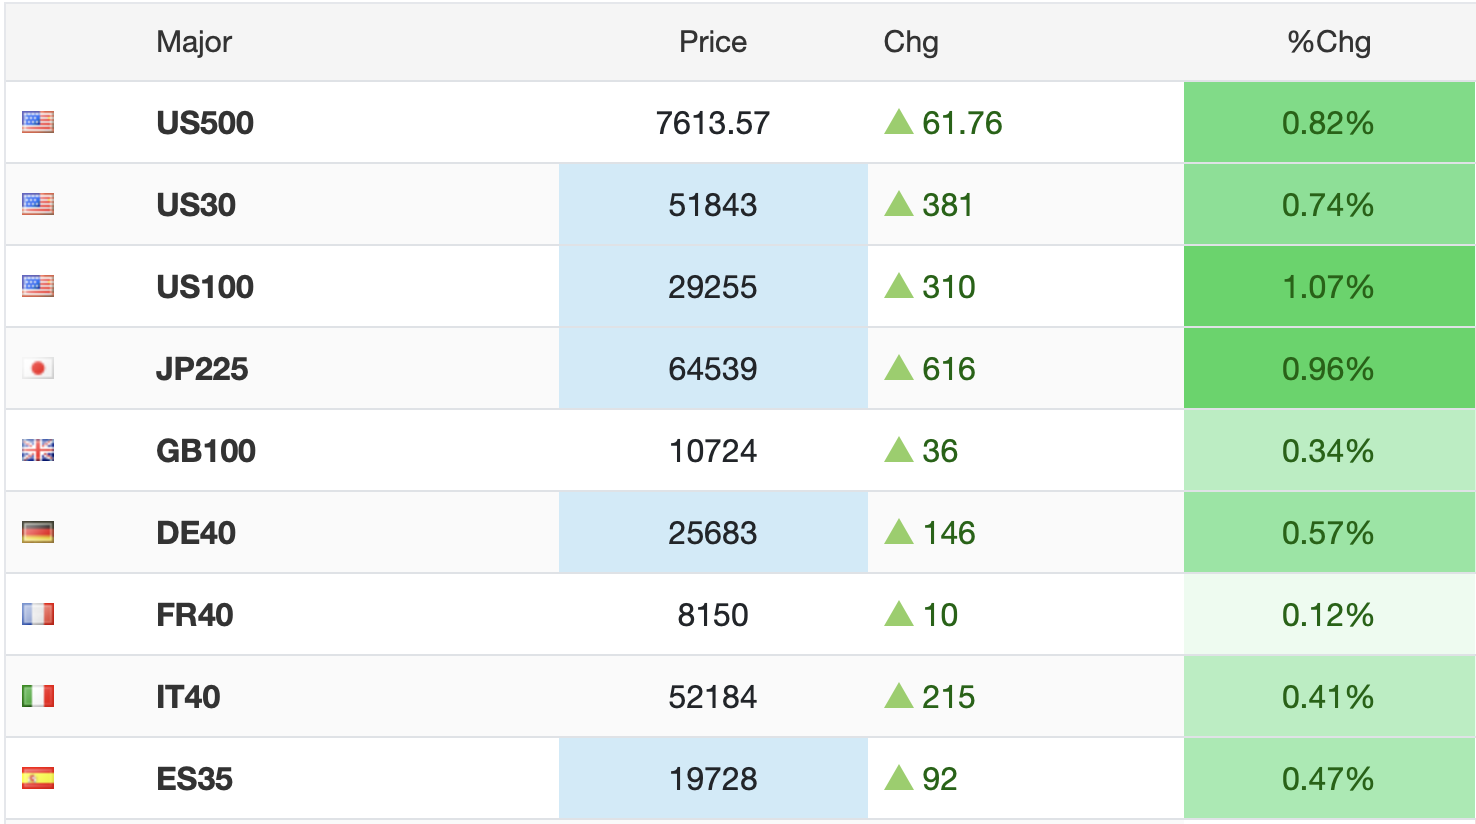
In fact, green is this morning’s color with all of Europe and US futures all higher as I type at 6:00.
Source: tradingeconomics.com
Although, in fairness, China (-0.5%) and HK (-0.4%) didn’t have as much fun, much of Asia also was higher overnight. It appears that the idea that central banks are set to fight inflation more aggressively, as confirmed by the Fed’s hike yesterday, has equity investors feeling better about themselves.
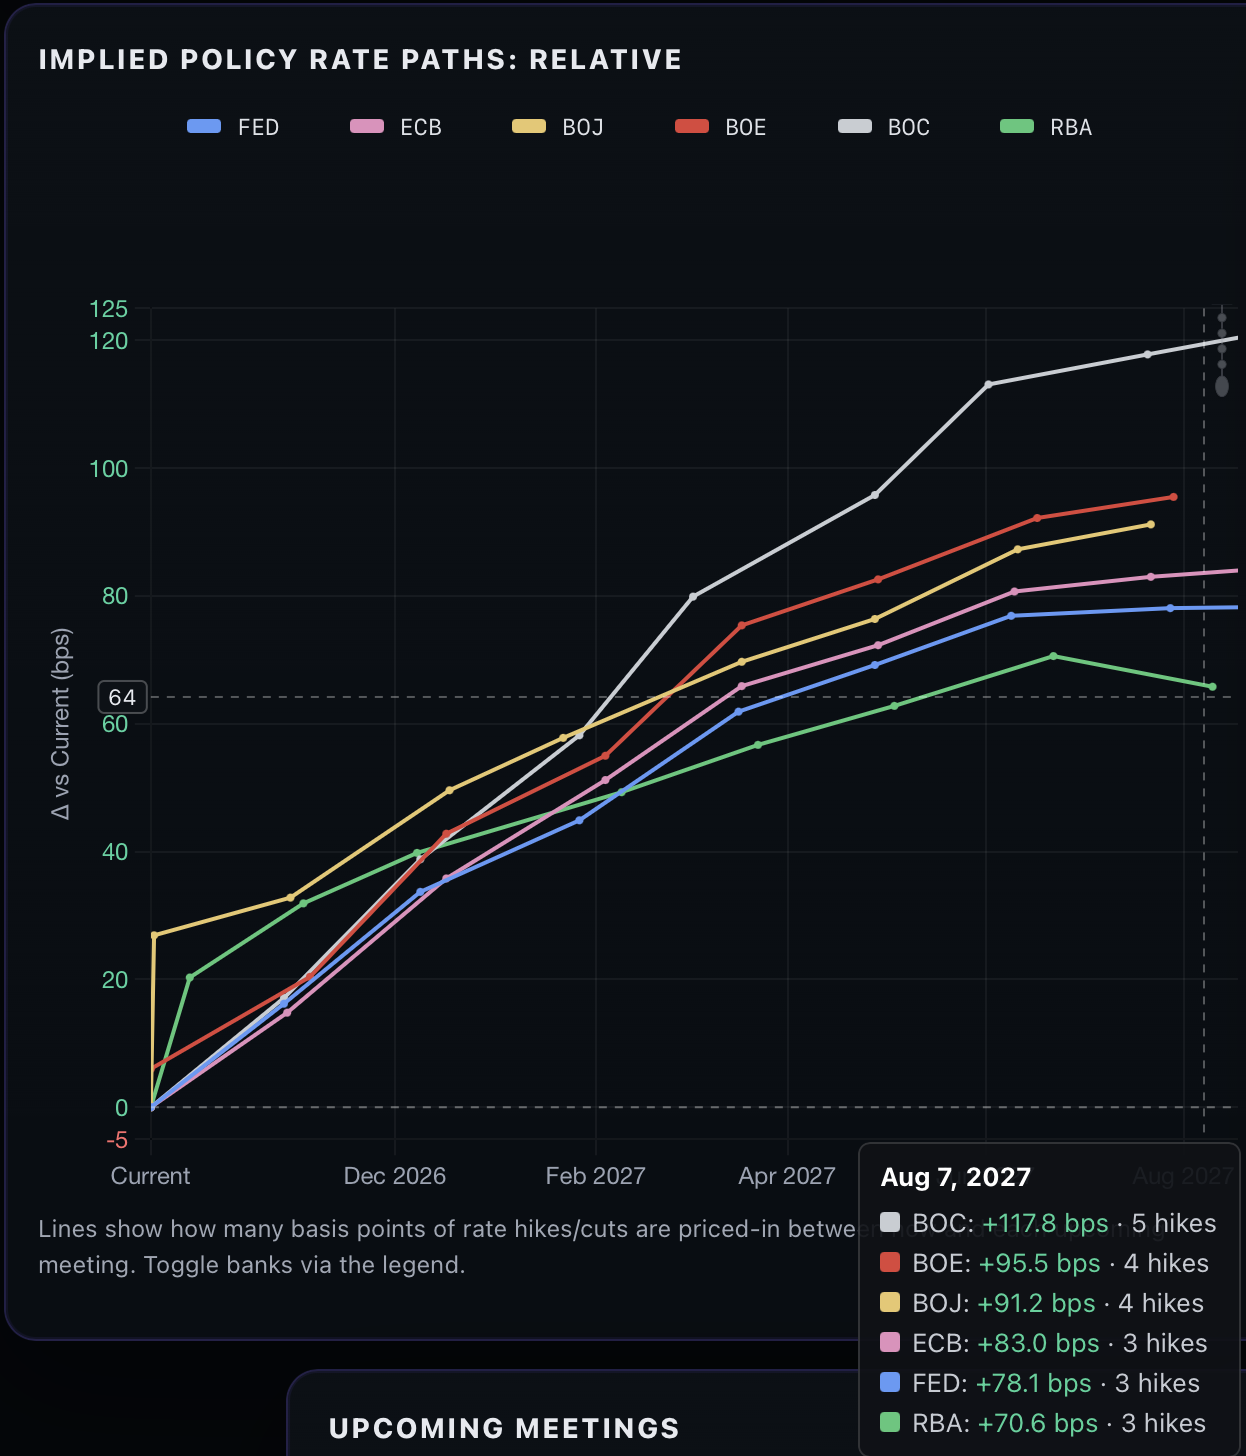
And that idea remains cemented in traders’ collective views as my new favorite website on the topic, rateprobability.com, continues to show plenty of hikes in the pipeline. Interestingly, though, this morning’s BOE meeting is only showing a 24% probability as of 6:40am, 20 minutes before the release.
But now let’s turn away from the central banks and see what else is happening. Oil prices (-1.8%) are slipping again as it appears the latest attacks on Saudi infrastructure have stopped and the Saudis claim they will have restored the bulk of the flow to Yanbu in the Red Sea within weeks. At the same time, inventory data from the US continues to show plenty of oil around, as well as gasoline, although distillates are not as prevalent. And of course, with oil lower, we cannot be surprised that the metals complex is higher (Au +1.25%, Ag +1.2%, Cu +1.3%).
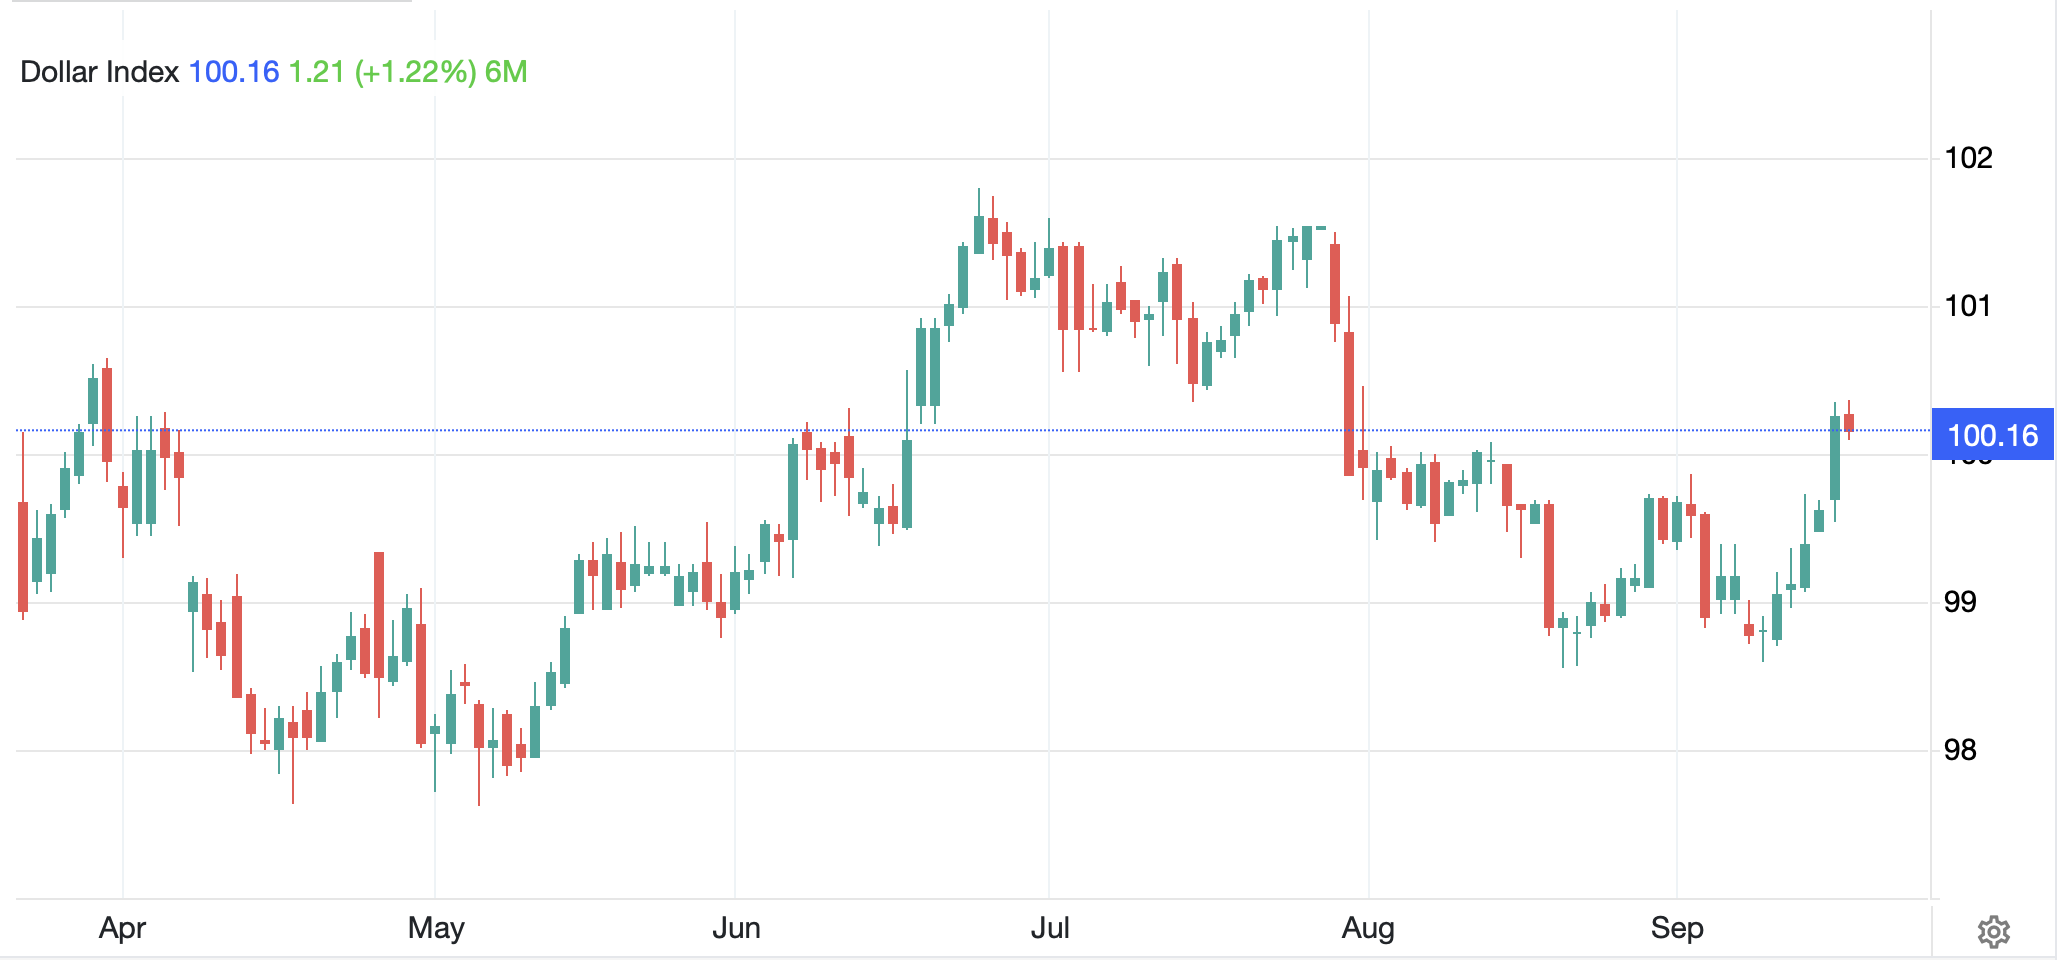
Finally, the dollar, after a 6-day run higher, is consolidating with the DXY now slightly above 100.00. However, as I have been saying for quite a while, the reality is the dollar is doing very little overall, having traded both sides of 100 regularly and not trending in any direction.
Source: tradingeconomics.com
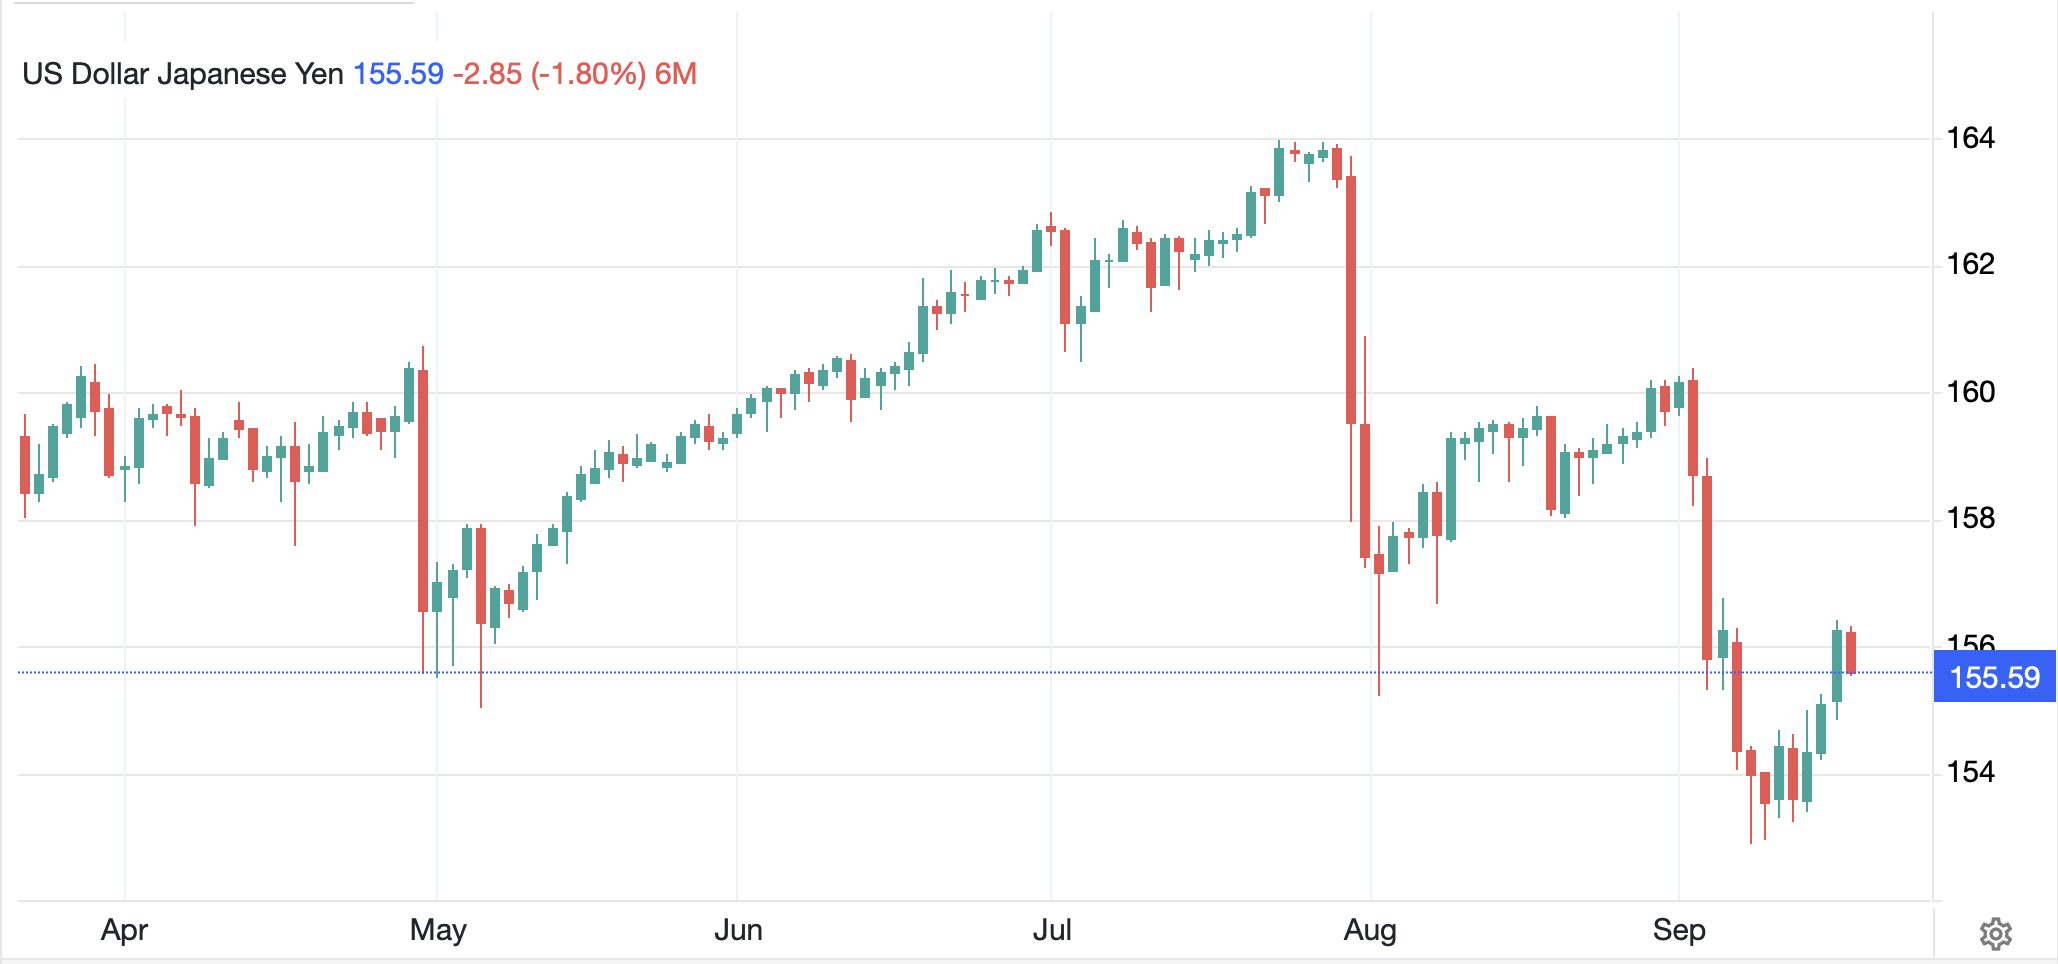
Now, USDJPY (-0.4%) has bounced from its recent lows (yen highs) although remains below the levels of the initial intervention from the end of July as per the below chart. And with the BOJ set to hike rates tonight, absent a massively hawkish message from Ueda-san, I think 154-156 is going to be the new home for a while.
Source: tradingeconomics.com
Looking across the rest of the currency universe, there are several moves today in line with the yen strength as ZAR (+0.55%), SEK (+0.4%), and NZD (+0.4%) are all having solid sessions with the rest of the lot +/-0.15% or less. Again, I ascribe this more as a reaction to recent price moves than to anything new in the world.
And that’s really it in the markets this morning. Fortunately, AI has not yet killed us all, although we continue to hear from various players that it is a civilizational threat. The biggest problem those people have is that we have recently seen several civilizational threats that just didn’t come true, whether Covid, the reelection of Donald Trump or the strong showing by AfD in Germany. Climate change is certainly biding its time if it is going to kill us all, and to my knowledge, CO2 is still exhaled by everyone who has informed us that CO2, if it reaches 0.045% of the atmosphere, will end life. Perhaps that is what AI will do. Perhaps it will take control of all the oil drilling and coal mining around the earth, expand it, combust it and drive that CO2 number up high enough to do the job!
On the data front, the UK left rates on hold, as largely expected, but I guess that means they will be hiking next time. In the US, we get the weekly Initial (exp 208K) and Continuing (1780K) Claims data as well as Housing Starts (1.31M), Building Permits (1.41M) and Philly Fed (30.5) all at 8:30. And that’s it. The BOJ will be hiking rates tonight and there are no Fed speakers on the calendar today, although we will hear from Governor Michelle Bowman tomorrow morning.
The hawks are certain that Chairman Warsh has joined their club. Personally, I think he is biding his time until the task forces report so that he can start to make the changes that are necessary at the Fed since it clearly has not done its job properly for many years.
As to the dollar, there is nothing exciting on the horizon overall, although I guess a surprise from Tokyo tonight could change a few views.
Good luck
Adf
 fxpoetry
