
The market’s now certain this week
On Wednesday, when Warsh gets to speak
That he’ll have raised rates
And tossed to the fates
Just how much more havoc he’ll wreak

But ask yourself, what would you do
As Fed chair, midst this ballyhoo
A rate hike don’t drill
Instead, it might kill
The growth impulse we’re living through
I guess it’s a done deal, at least in the market’s collective mind, that the FOMC is going to hike rates on Wednesday. This is according to the Fed funds futures market as you can see below. In addition, you can see that the futures market is now pricing essentially 4 hikes over the course of the next year.
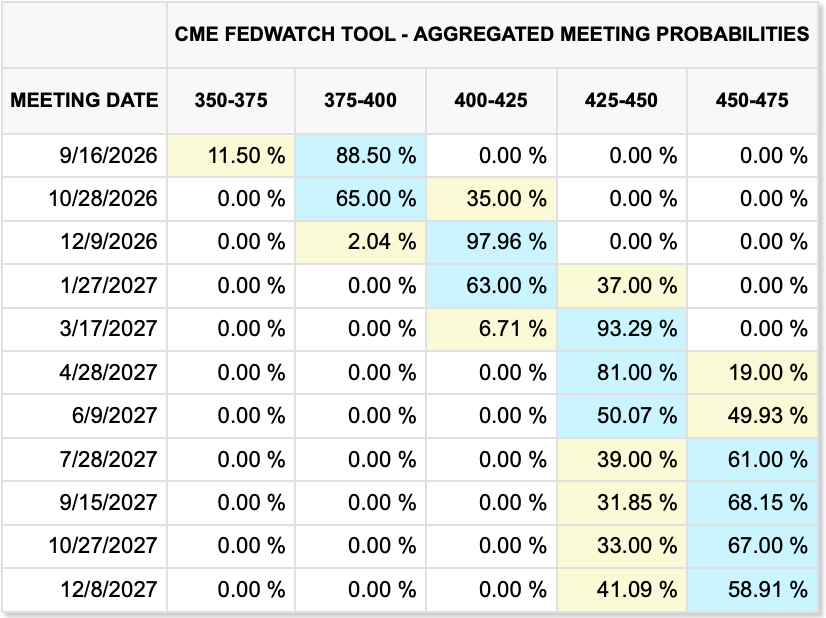
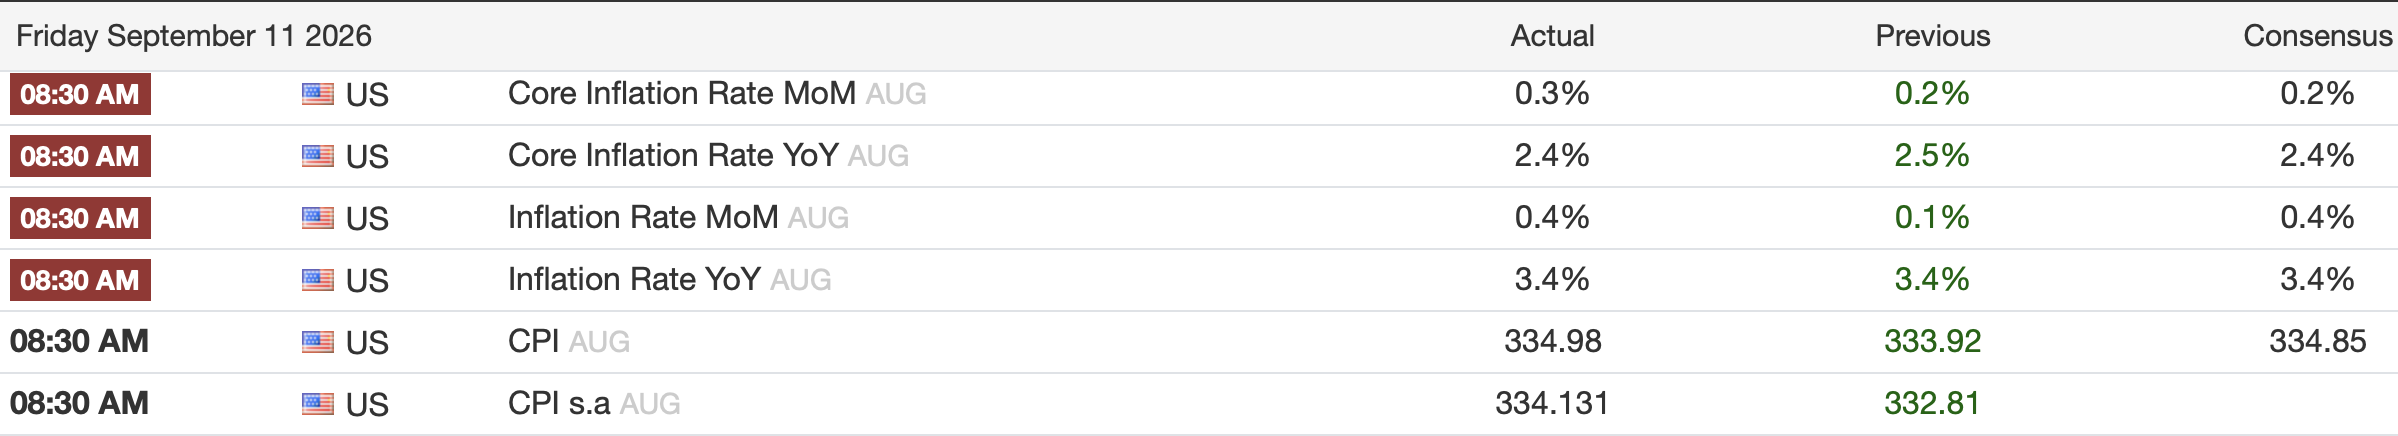
So, why the change of heart? Apparently, the ‘hot’ CPI data from Friday combined with higher oil prices this morning has sealed the deal. Let’s take the two in order. Below are the reported CPI figures from Friday:
Source: tradingeconomics.com
It seems the fact that the M/M Core result was 0.3% instead of the 0.2% forecast, despite the fact that the Y/Y number was as expected at 2.4%, has been the catalyst for the increased certainty of a hike. You may recall that Friday before the CPI release the futures market had priced in about a 60% probability of a hike, i.e., still a lot of uncertainty. Of course, oil prices (+2.6%) are higher this morning as well after the Saudis cut movement through their East-West pipeline once it had been attacked, which has further reduced the flow of oil from the Middle East. And certainly, if oil prices continue to rise, that will feed into inflation pretty quickly as we saw at the beginning of the summer.
However, just for a moment, let us consider the rationale behind raising interest rates to address inflation. The main central bank thesis is that higher interest rates will reduce demand and therefore it will reduce price pressures. This process takes some time, the so-called long and variable lags of Fedspeak, but this is what it boils down to, reduce demand to reduce prices. As an aside, history has shown that every economic boom has been ended by the central bank squashing it with higher interest rates.
But now let us consider the current situation. Higher oil prices are certainly driving up some portion of the overall consumption basket, and that is responsible for the bulk of the rise in measured inflation. Higher oil prices are also acting as a dampener of demand as money that may have gone toward other things is now being used to pay up for gasoline and diesel. The natural result is those other things, whether goods or services, have seen demand slip somewhat and the purveyors of those things have limited ability to raise prices, at least those not getting paid directly by governments like healthcare providers. In other words, higher oil prices are already reducing the demand that the Fed will be trying to address via a rate hike.
If the Fed decides to hike rates this week, they will be reducing demand further and could well push the economy off its current solid growth path to something less positive where companies see further reductions in demand and begin to reduce headcount. Again, history has shown that central bank rate hikes to address energy price shocks (or really any exogenous price shocks) have been categorical mistakes. I fear this is where we could be headed. And the worst part is that if they hike rates, it won’t change oil prices at all.
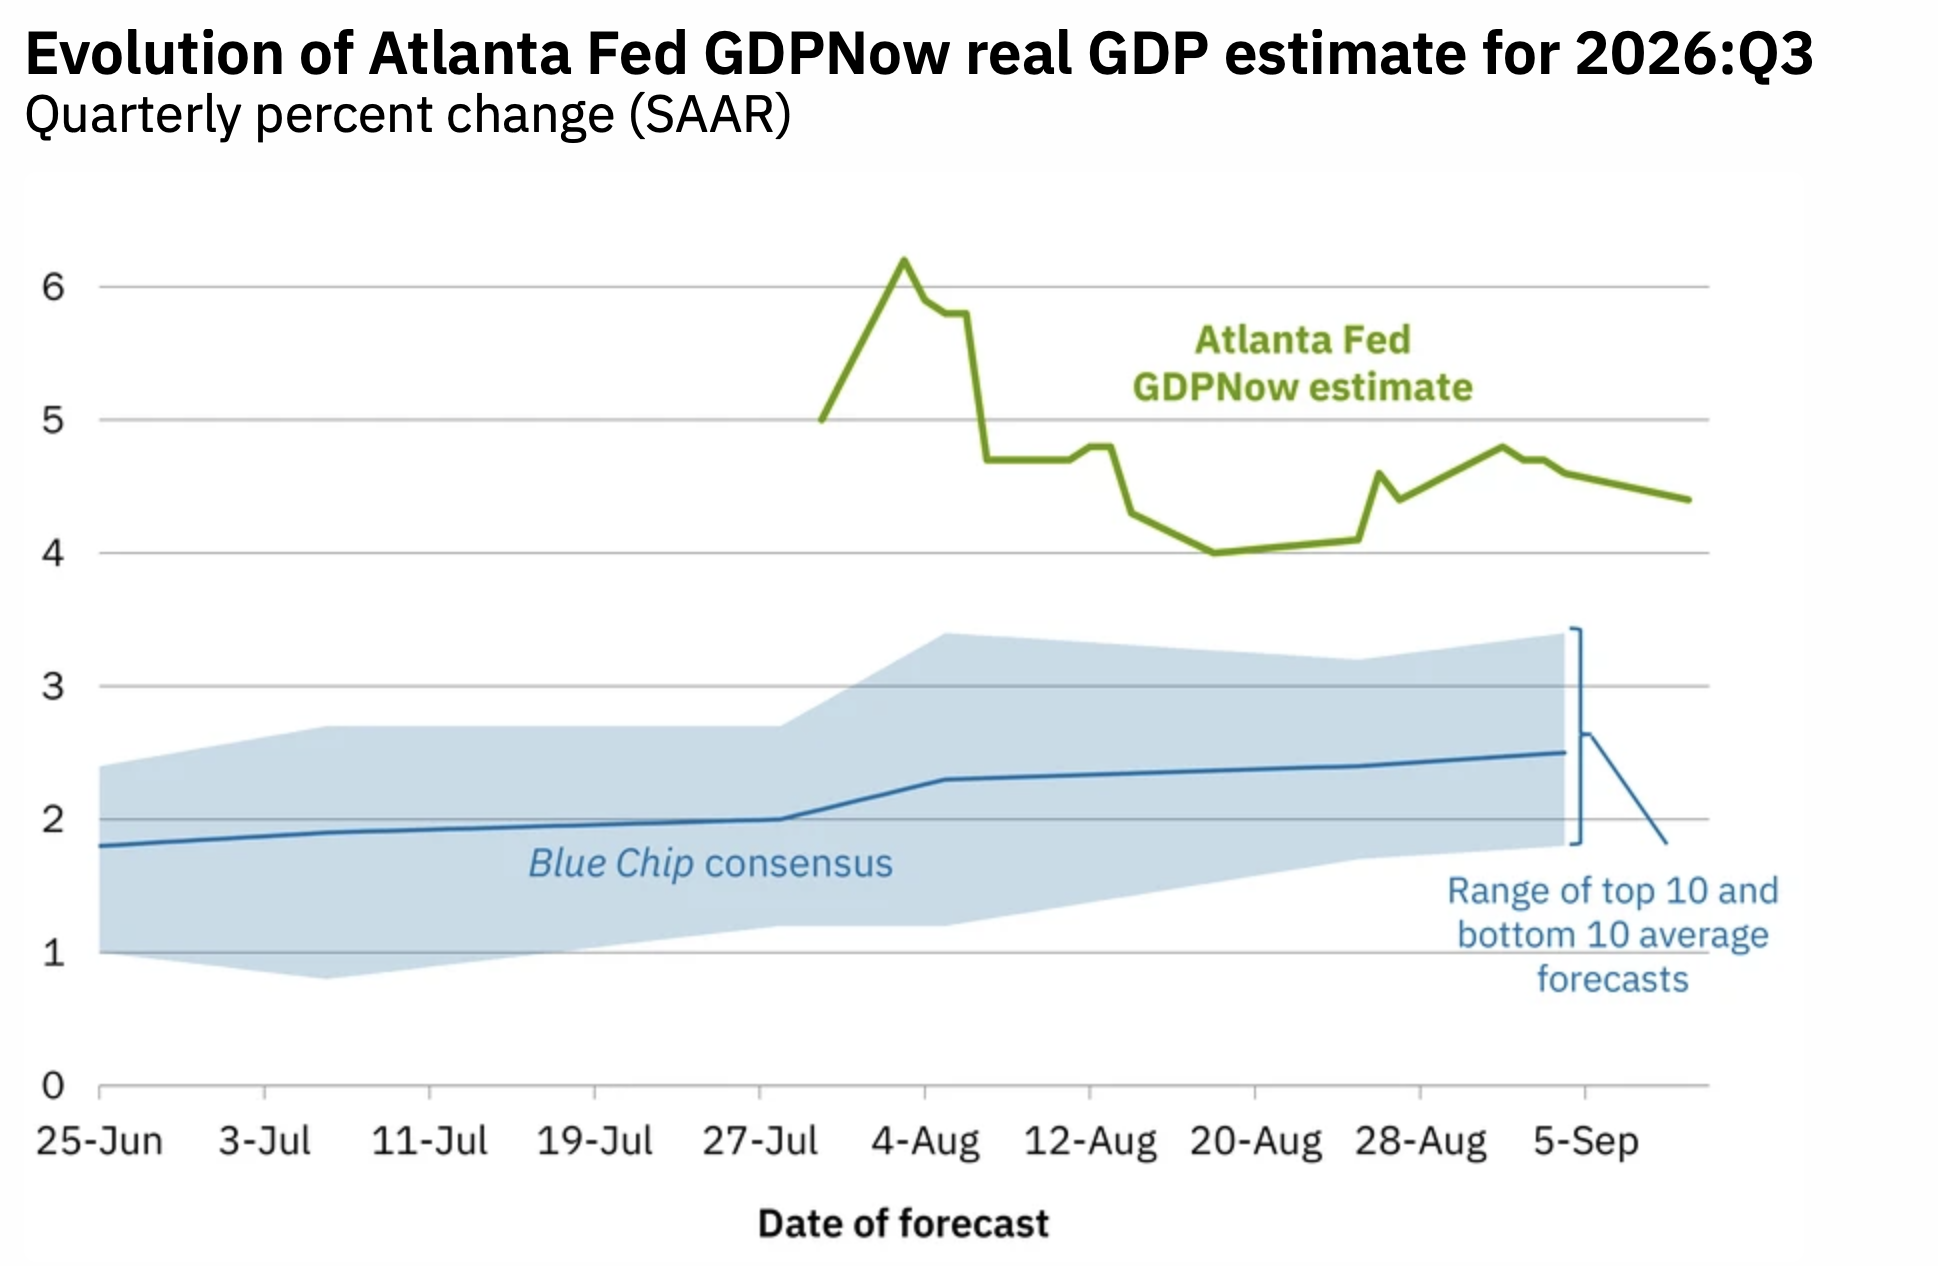
As a reminder, a quick look at the Atlanta Fed’s GDPNow Q3 GDP estimate shows things are looking pretty good at 4.4%.
Perhaps this discussion is the reason that I am most positive about Kevin Warsh as chairman. I don’t know if they will hike or not this week, but the entire idea of the five task forces is to try to change the way the Fed looks at the world. Their neo-Keynesian view has become destructive, in my mind, given the complexities that have arisen in the economy with globalization dramatically reduced and trade policies no longer moving toward free trade. As well, the changing demographics of the US, both via an aging population and a reduction in immigration in addition to actual deportations is having a significant impact on the economy and does not appear to have been taken into account in the current Fed models.
Away from this discussion, the other main topic is AI and whether it will, indeed, kill us all, or whether it is simply a very powerful tool that if used well can enhance productivity. Like most issues these days there doesn’t appear to be any middle ground here. For me, I have a hard time overcoming the perspective that there is a well-orchestrated campaign now to demonize AI in an effort to get the government, at both state and federal levels, to regulate it more strictly, although I don’t know who benefits from this most so I’m not sure who is funding it. It’s almost as though the demonization of data centers has been unable to slow the train enough, so they had to up the ante and explain AI is Skynet.
Ok, let’s see how all this new news is impacting markets. Since commodities seem to be the primary driver right now, if we look beyond oil, we see NatGas (+2.3%) rising this morning but it remains extremely well behaved and substantially cheaper than in Europe and the UK as per the below chart from tradingeconomics.com
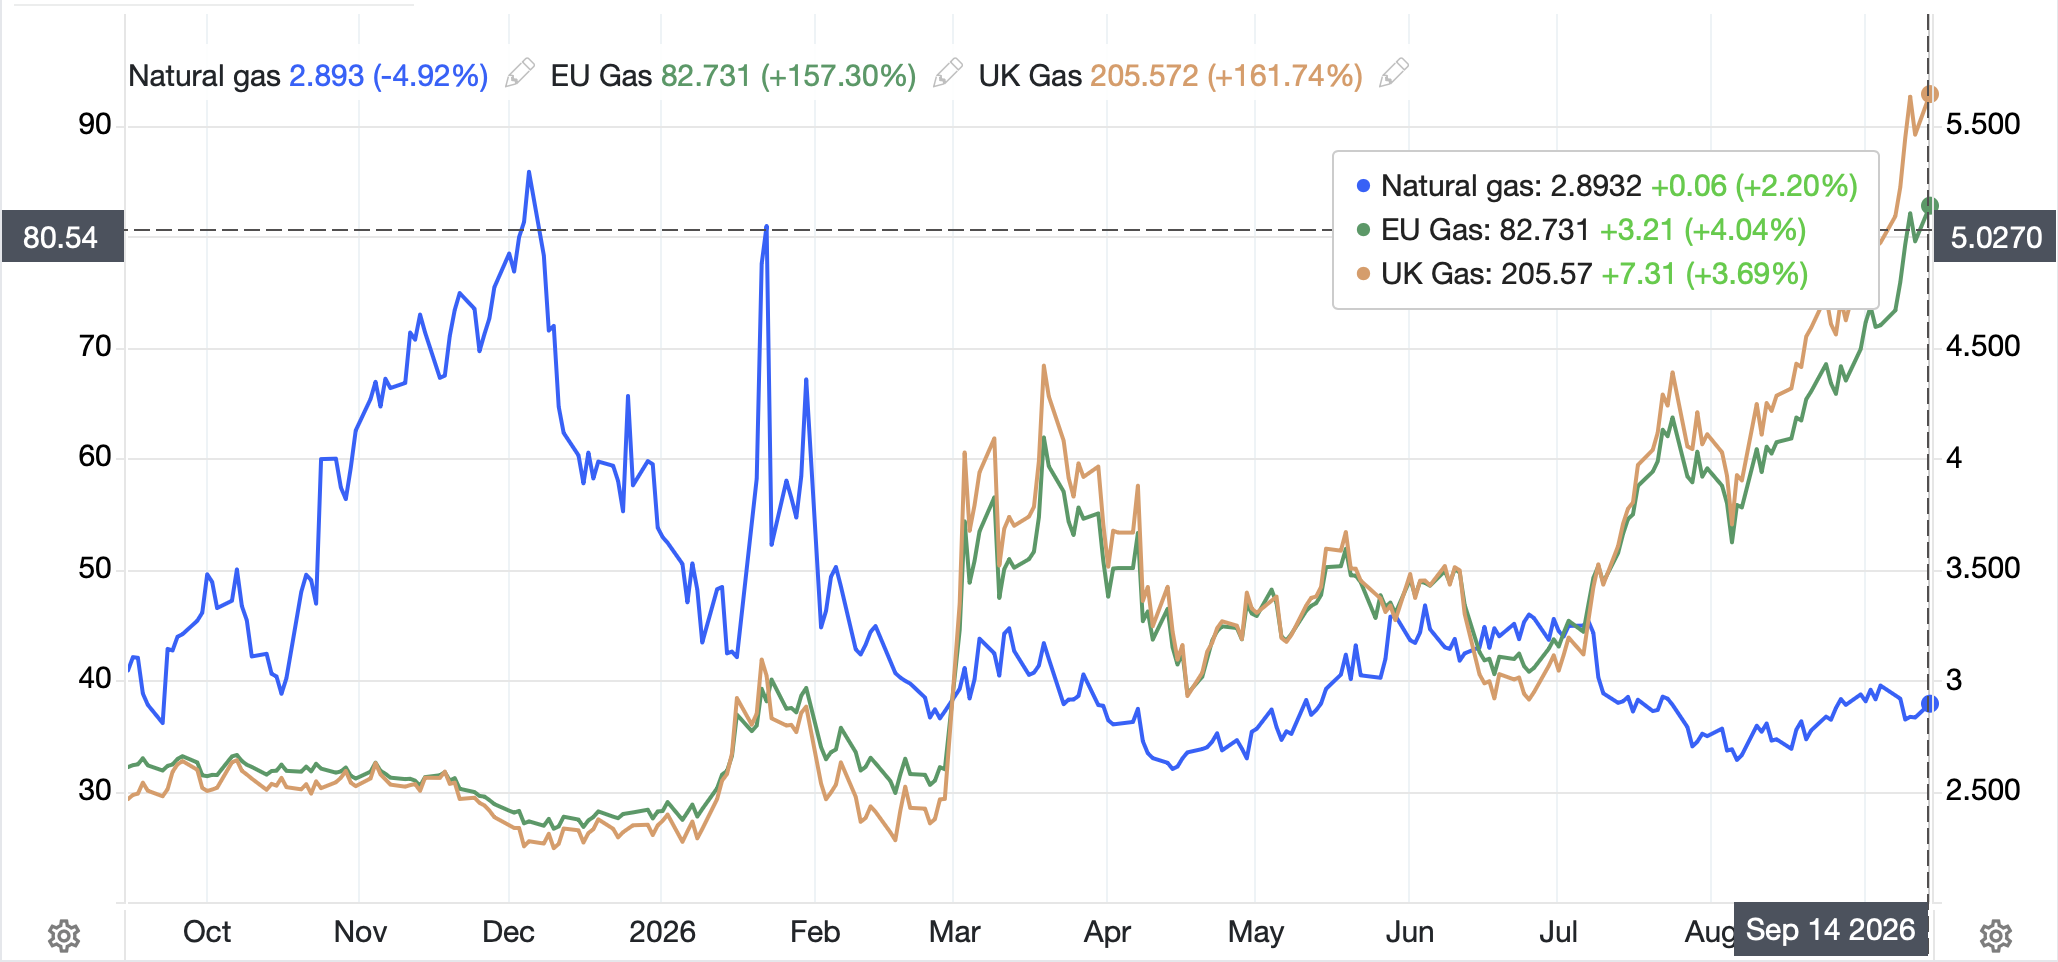
In fact, putting all three prices into $/MMBtu, the US is at $2.89, the UK is at ~$27.75 and the EU is at ~$27.99. In other words, Europe and the UK are paying nearly 10X what we pay for NatGas. They have serious problems there. As to the precious metals, they are not that precious this morning as the negative correlation with oil continues (Au -1.3%, Ag -2.1%, Cu -1.9%).
Turning to bonds, this is the other key discussion point as 10-year yields approach 5.0% in the US. This morning, Treasury yields are unchanged, although they have climbed 31bps in the past month. European sovereign yields are all a touch higher with Italy (+4bps) in the worst shape but the rest of the continent seeing yields climb between 1bp and 3bps. And JGBs, ahead of the BOJ meeting on Friday, have edged higher by 1bp.
In the equity markets, Friday’s US rally (which given all the hype on the Fed tightening seems strange, although oil prices did slide then, has been followed by a mixed picture in both Asia and Europe. In Asia, the Nikkei (-0.8%) suffered although the broader TOPIX (+0.75%) did not. HK (+0.5%) rallied as did some of the smaller regional markets (Australia, Singapore, Malaysia) but there was more substantial weakness amongst Korea (-3.25%) and China (-0.7%). Mixed describes it well. in Europe, there is far more red (Italy -1.1%, Spain -0.85, France -0.7%, Germany -0.3%) than green (UK +0.7%) with the latter benefitting as oil stocks (BP and Shell) both rallied on the back of oil price rises and that has been sufficient to counter the other negativity. As to US futures, they are all lower this morning with the NASDAQ (-1.5%), leading the way with the others lower by -0.5% or so.
Finally, the dollar is rocking this morning, with DXY (+0.4%) a pretty good indicator of things. EUR, AUD, NZD, JPY are all lower by about that amount, as is NOK (-0.4%) despite the rise in oil prices. SEK (-0.8%) is the G10 laggard but it has company with ZAR (-0.8%) on weaker gold prices and CE3 (PLN -0.9%, CZK -0.75%, HUF -0.8%) all demonstrating their high beta to the euro. In LATAM, MXN (-0.6%) and CLP (-0.6%) are both under pressure on metals weakness and even KRW (-0.3%), which has been on a tear, is softer this morning. Higher US rates and the prospect for even higher ones seems to be driving market activity.
On the data front, obviously, this week is all about the Fed, but here is the other stuff:
| Tuesday | Empire State Manufacturing | 14.75 |
| Wednesday | Retail Sales | 0.9% |
| -ex Autos | 0.6% | |
| FOMC Decision | 4.0% (current 3.75%) | |
| Brazil Interest Rate Decision | 13.75% (current 14.0%) | |
| Thursday | Initial Claims | 205K |
| Continuing Claims | 1775K | |
| Housing Starts | 1.31M | |
| Building Permits | 1.41M | |
| Philly Fed | 32.5 | |
| Friday | BOJ Interest Rate Decision | 1.25% (current 1.00%) |
| IP | 0.3% | |
| Capacity Utilization | 76.4% | |
| Leading Indicators | 0.1% |
Source: tradingeconomics.com
So, it all comes down to, will they hike or not. While I don’t believe it is the right thing to do, the market certainly believes that to be the case. I wouldn’t be surprised, however, if they do hike, to see a counter reaction, like a buy the rumor, sell the news outcome, especially in the FX markets.
Good luck
Adf
 fxpoetry
