
The 10-year yield hit Five Percent
And somehow, despite this event
The nation’s still here
And growth’s still in gear
Perhaps all that doom was misspent

It’s not to say things are all great
And many, til Wednesday will wait
To see if the Fed
And chief talking head,
Chair Warsh, will then bless a new rate
I’m going to let pictures do much of the talking to start this morning as we are seeing significant moves across the board in various classes. To start with government bonds, here is this morning’s view from a Bloomberg screenshot.
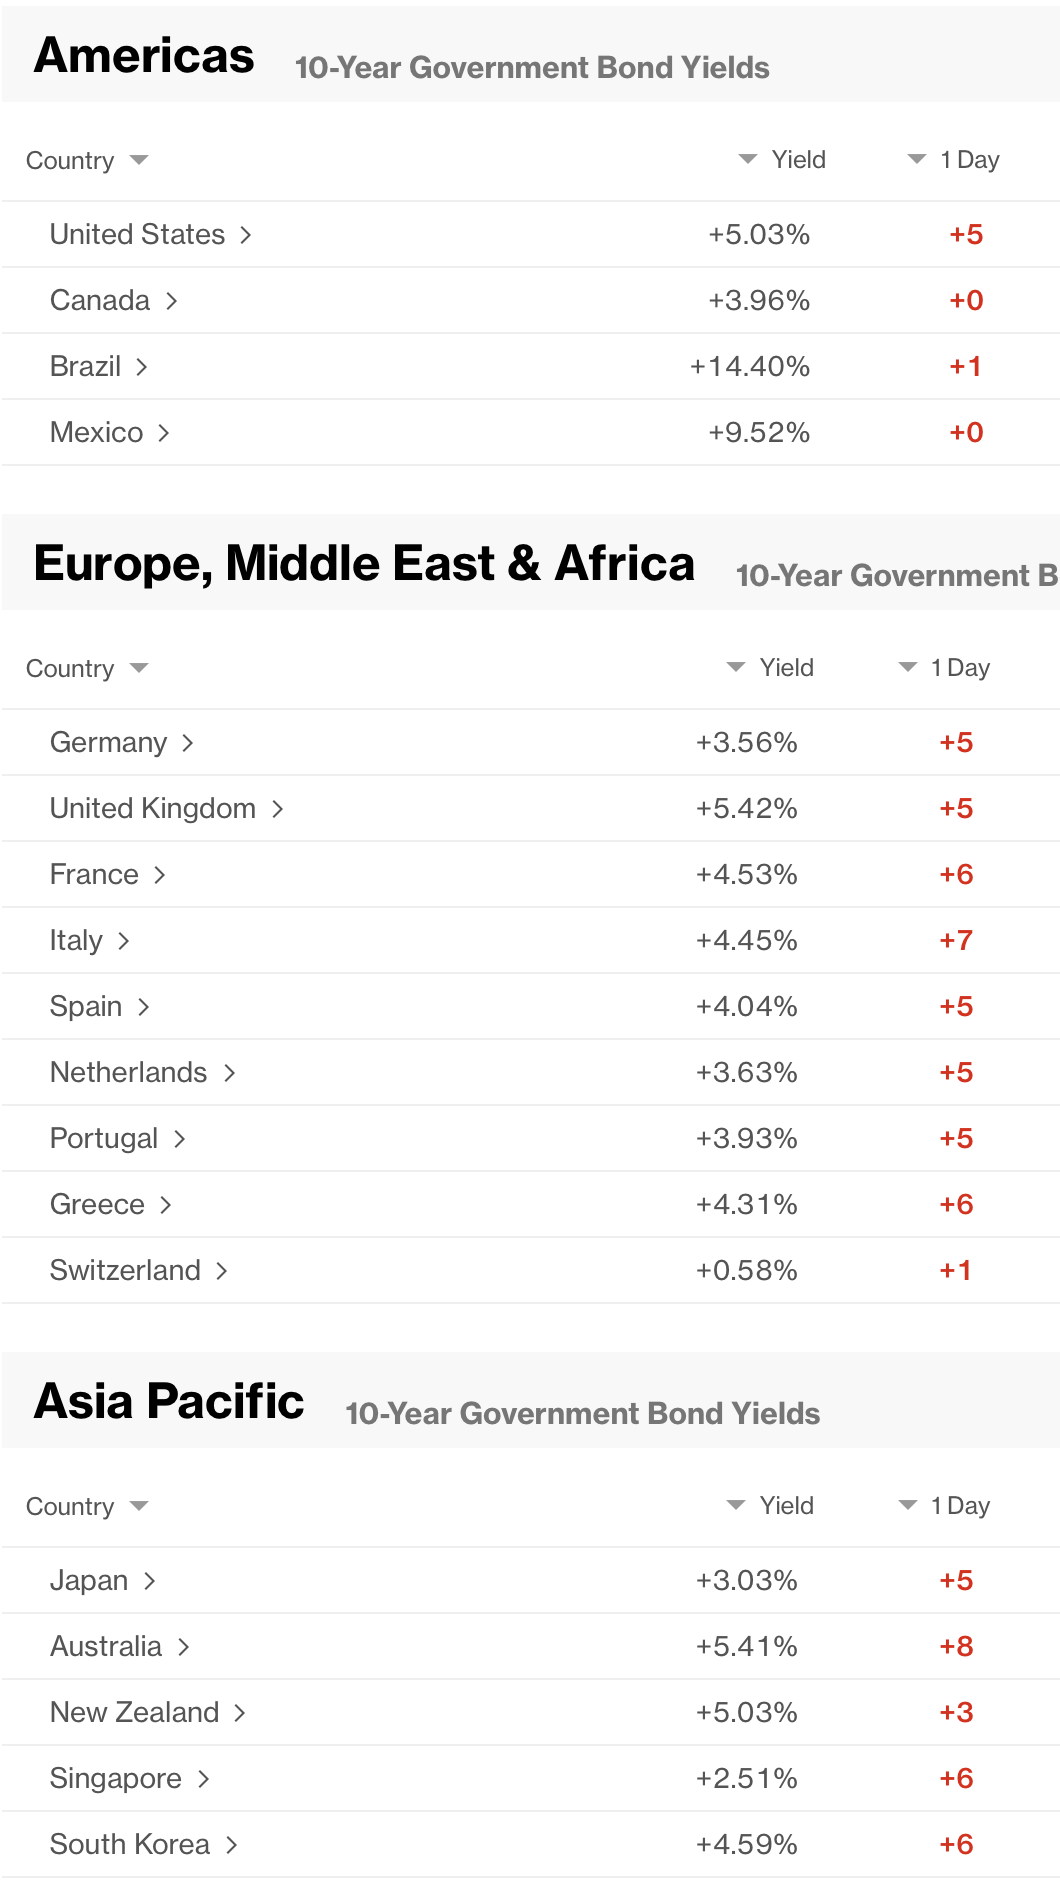
As you can see, yields have jumped with most nations seeing them climb around 5bps or more. (Canada, Brazil and Mexico are not yet open, hence the lack of movement). Prior to touching, and now breaking the 5.0% level, the punditry had spilled a great deal of ink regarding how devastating this was going to be for both risk assets and for the US economy. On the first count, if we look at equity markets around the world this morning, they were correct, selling is the name of the game as you can see in the below screenshot from tradingeconomics.com
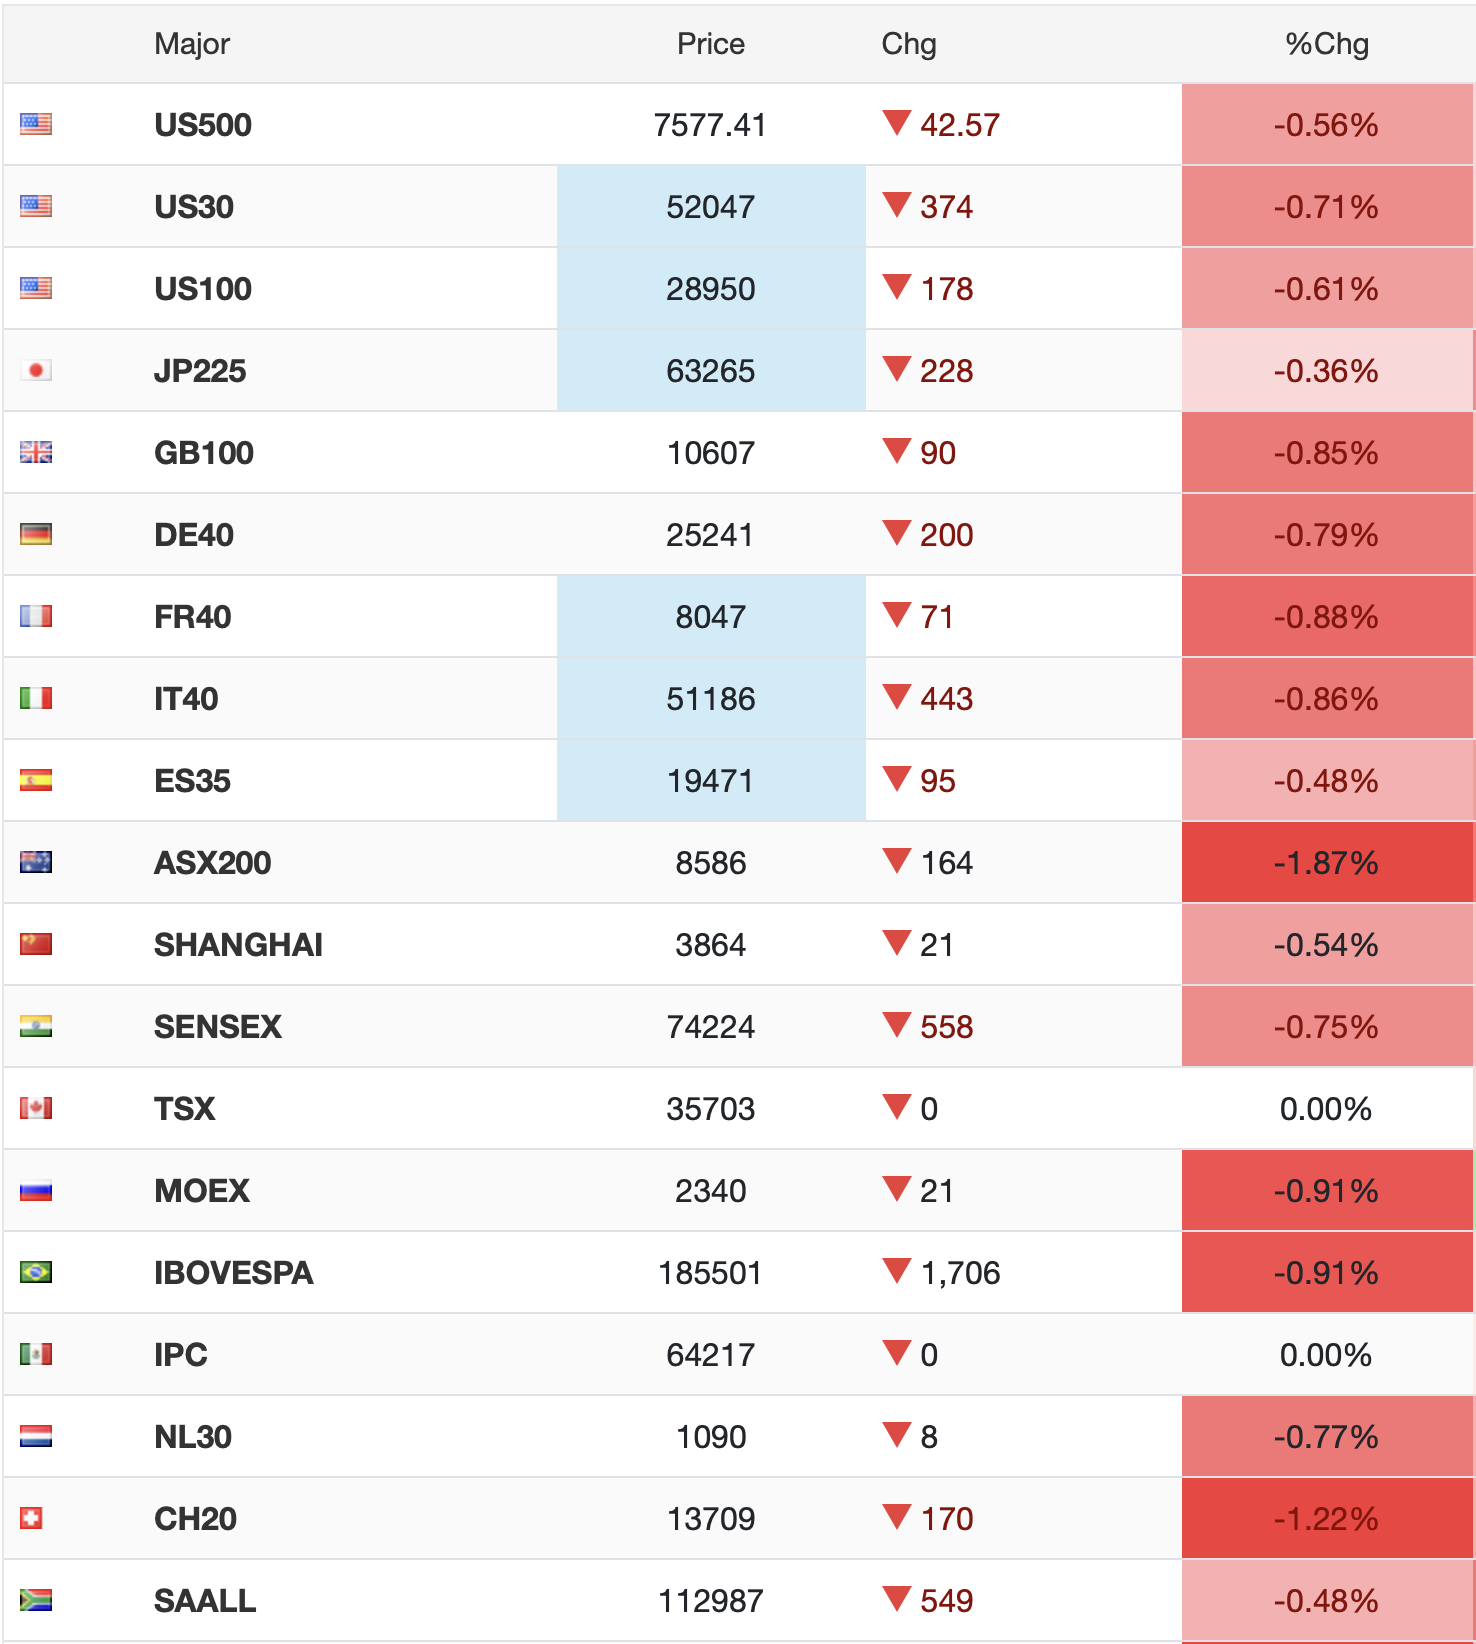
There are not many happy equity investors this morning, although energy shares are holding their own better than most other things. (Again, Canada and Mexico are closed.) But as to the second point, it remains to be seen how devastating 5.0% yields on the 10-year Treasury are going to be. And of course, we still have the FOMC meeting starting today with the policy announcement and press conference coming out tomorrow afternoon.
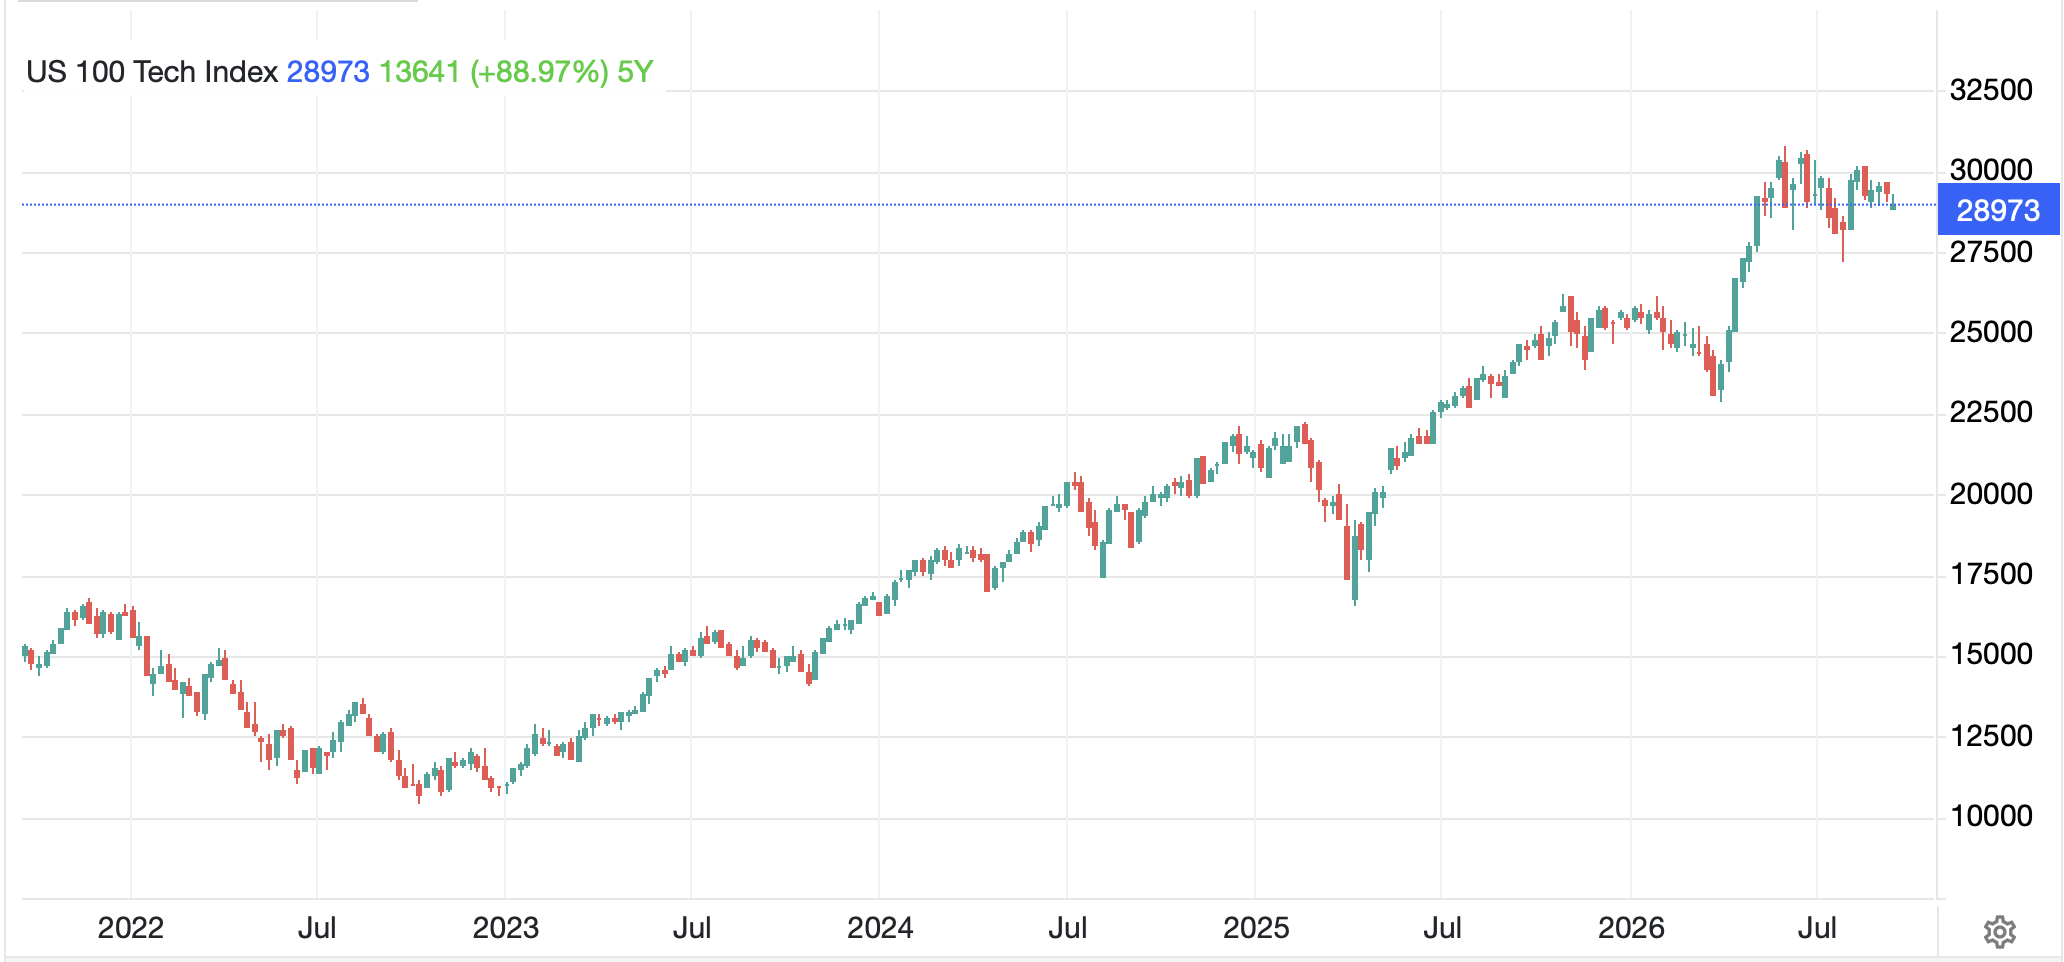
But here’s the thing to remember about the equity markets, even the NASDAQ, which has had the most discussion as the tech sector has been rerating lower, is only lower by 6.3% from its all-time high seen in early June. While nobody ever likes to see their portfolios decline in value, prices remain dramatically higher over the past several years and all three major indices are still higher by 10% or more so far in 2026. It is hard to call the below chart of the NASDAQ bearish!
Source: tradingeconomics.com
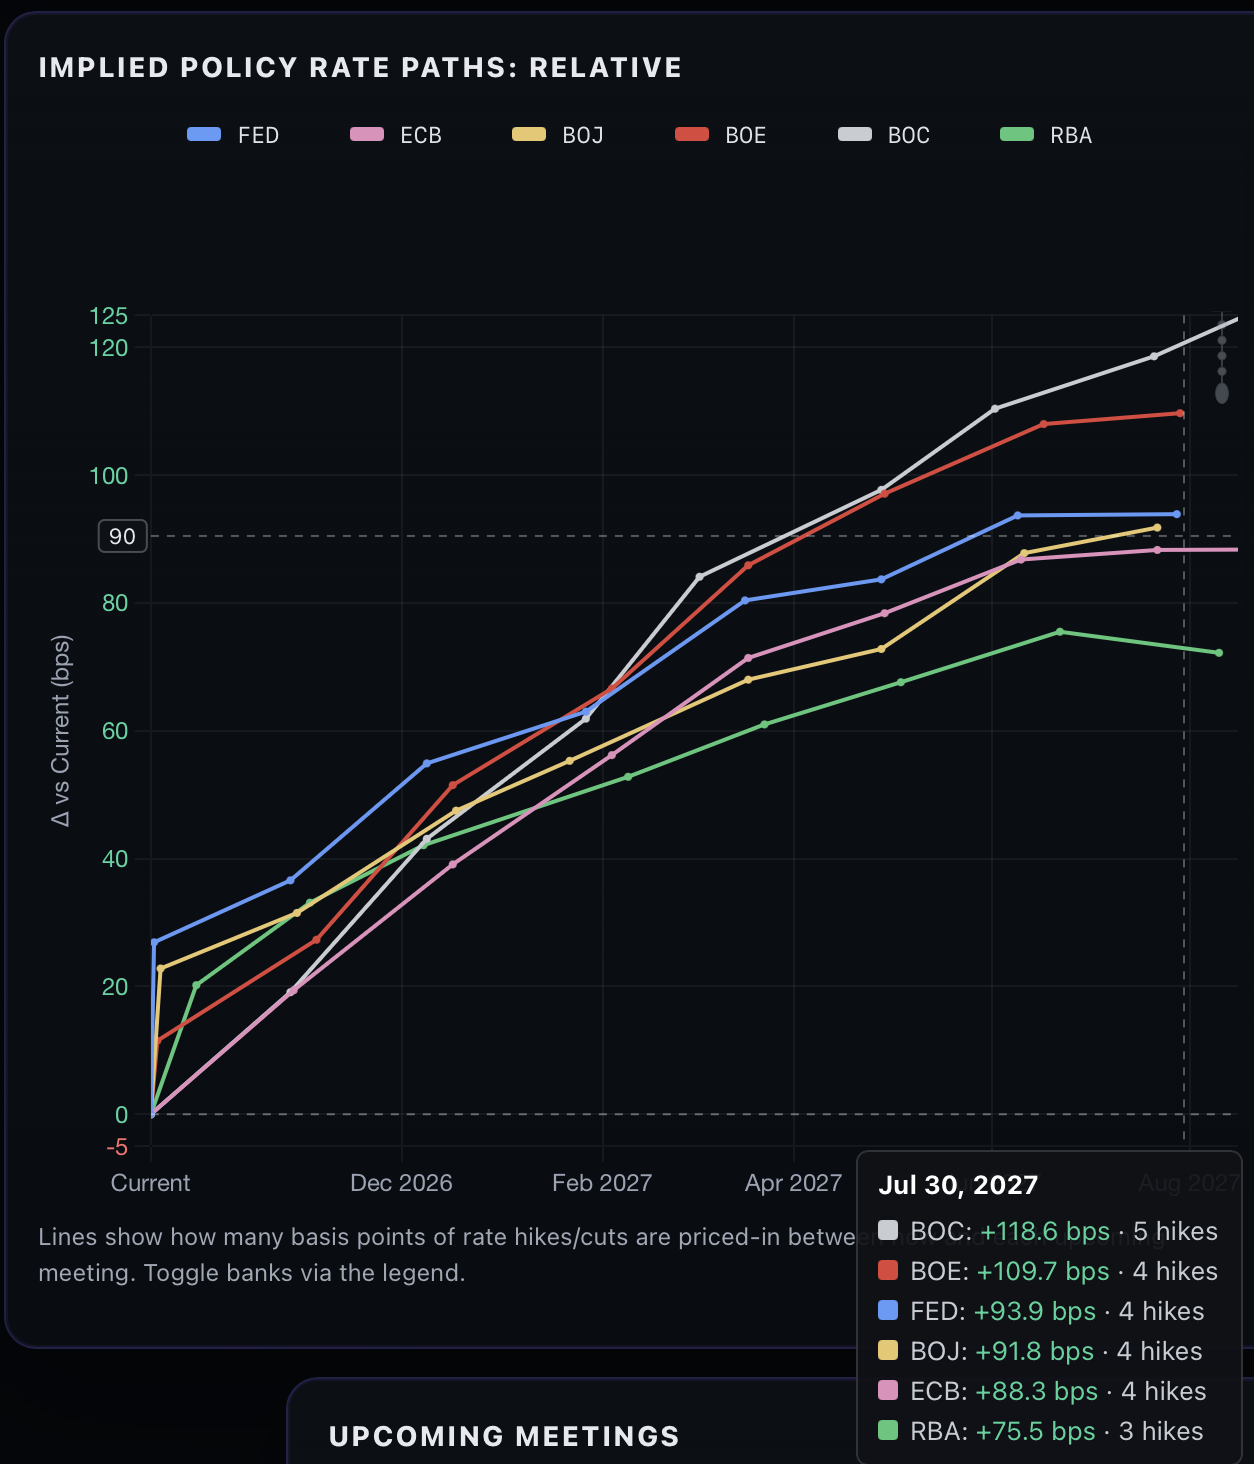
Which, I guess, takes us to the Fed and the ongoing discussion about what they will do. Depending on where you look, the probability priced into markets for the Fed to hike rates tomorrow is 92% (CME futures) or 100% (rateprobability.com). Looking at the latter’s most recent chart of the six major G10 central banks, market expectations are for interest rates to rise over the next year by at least 100bps across the board. (Australia just hiked rates last week so that was their first 25bps).
Now, I often make the case that market pricing ought to be the key feature to watch when considering a situation, but I have to admit, when it comes to the Fed funds rate, there is a bit more to the story, namely the politics involved.
Let me start by repeating my view that I believe a rate hike would be a mistake. While headline inflation is running above target, it remains largely an energy story, and we all understand that is outside the Fed’s control. But if you dig deeper into the inflation statistics, things are not great, but not calamitous either. It is ironic, if Congress were truly worried about inflation, they would cut spending to balance the budget at which point I am highly confident inflation would no longer be a concern. Martin Armstrong (@StrongEconomics) made an excellent point this morning on X worth repeating here relative to the FOMC meeting.
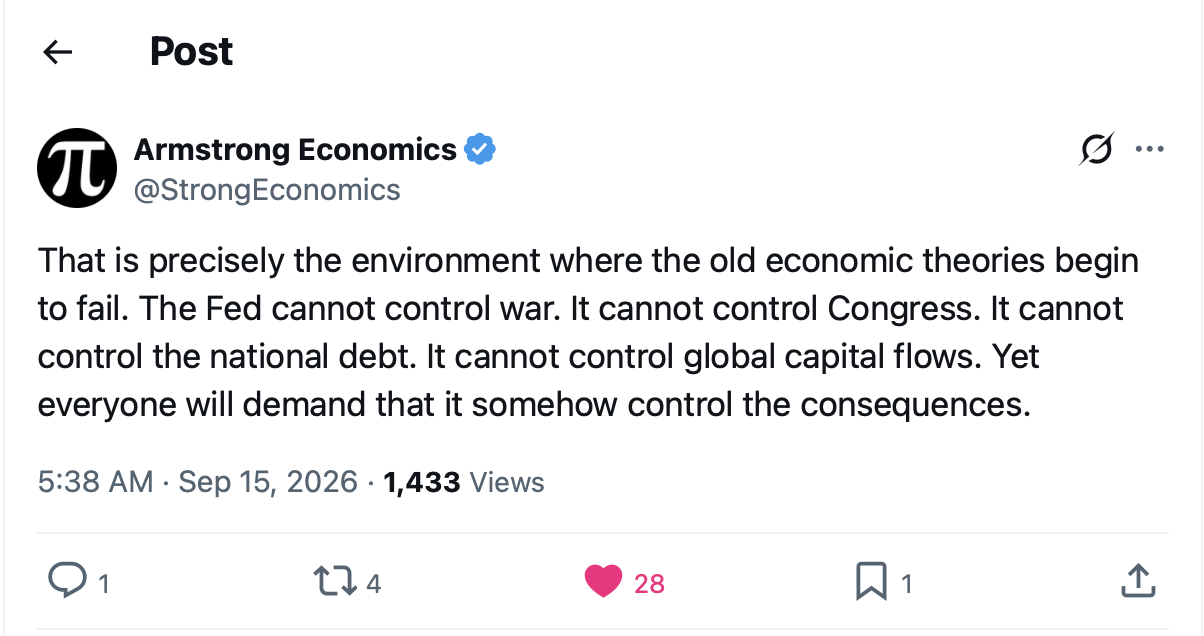
As to Chairman Warsh, I think he still must be frustrated that the discussion revolves around what the FOMC is going to do but I presume he will take the information of higher yields in the back end into account regarding this decision. Remember, too, it is not just his decision, 7 voters need to vote for a hike, and while we know there are three that believe it is proper, are there four more? I guess we will find out tomorrow afternoon.
It’s interesting, even though oil and energy prices remain the key driver of market activity, they get remarkably little press compared to the stock and bond markets. Sure, there are still stories about how the real energy crisis is about to come, and market pricing is certainly indicating more concern now than several months ago, but the price of Nvidia or Meta or the 10-year is the top story these days. At any rate, oil (+1.25%) is higher this morning but has stalled just above $100/bbl for now. Interestingly, NatGas (-0.6%) is softer and the same is true across Europe and the UK. I find that quite interesting, especially in the latter places, as there is no indication that more supply is forthcoming. And, not surprisingly, gold (-0.4%) and silver (-0.1%) are slightly softer with the ongoing rally in oil prices.
Finally, the dollar, which had a very strong session yesterday, is continuing to rally this morning. it seems that even though interest rates are rising around the world, those higher rates only help the dollar. Perhaps this is one reason that despite all the hate the dollar absorbs from a certain part of the financial community, it remains the haven of choice. Open capital markets are worth an awful lot to international investors, and none are more open than those in the US.
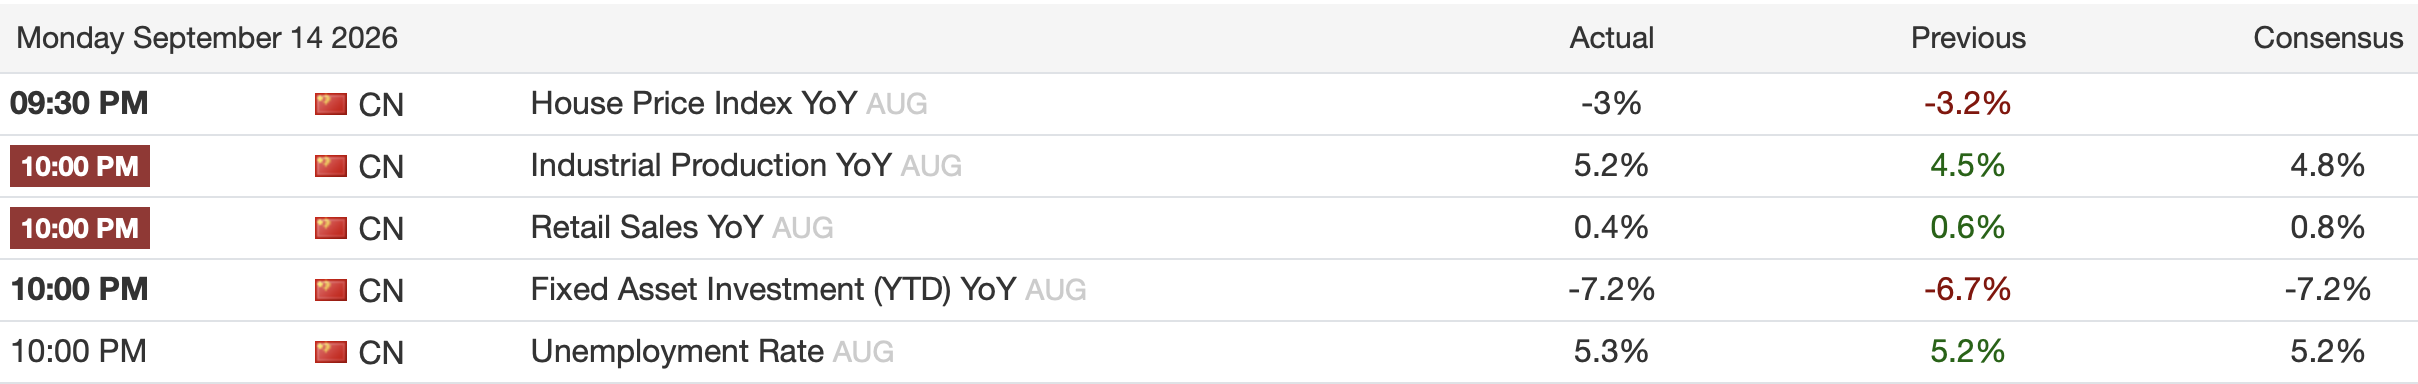
Perhaps this is a good time to discuss China, a land of closed capital markets, and what is happening there. Last night they released some of their key economic statistics and, the idea that domestic demand is being supported is a joke.
Source: tradingeconomics.com
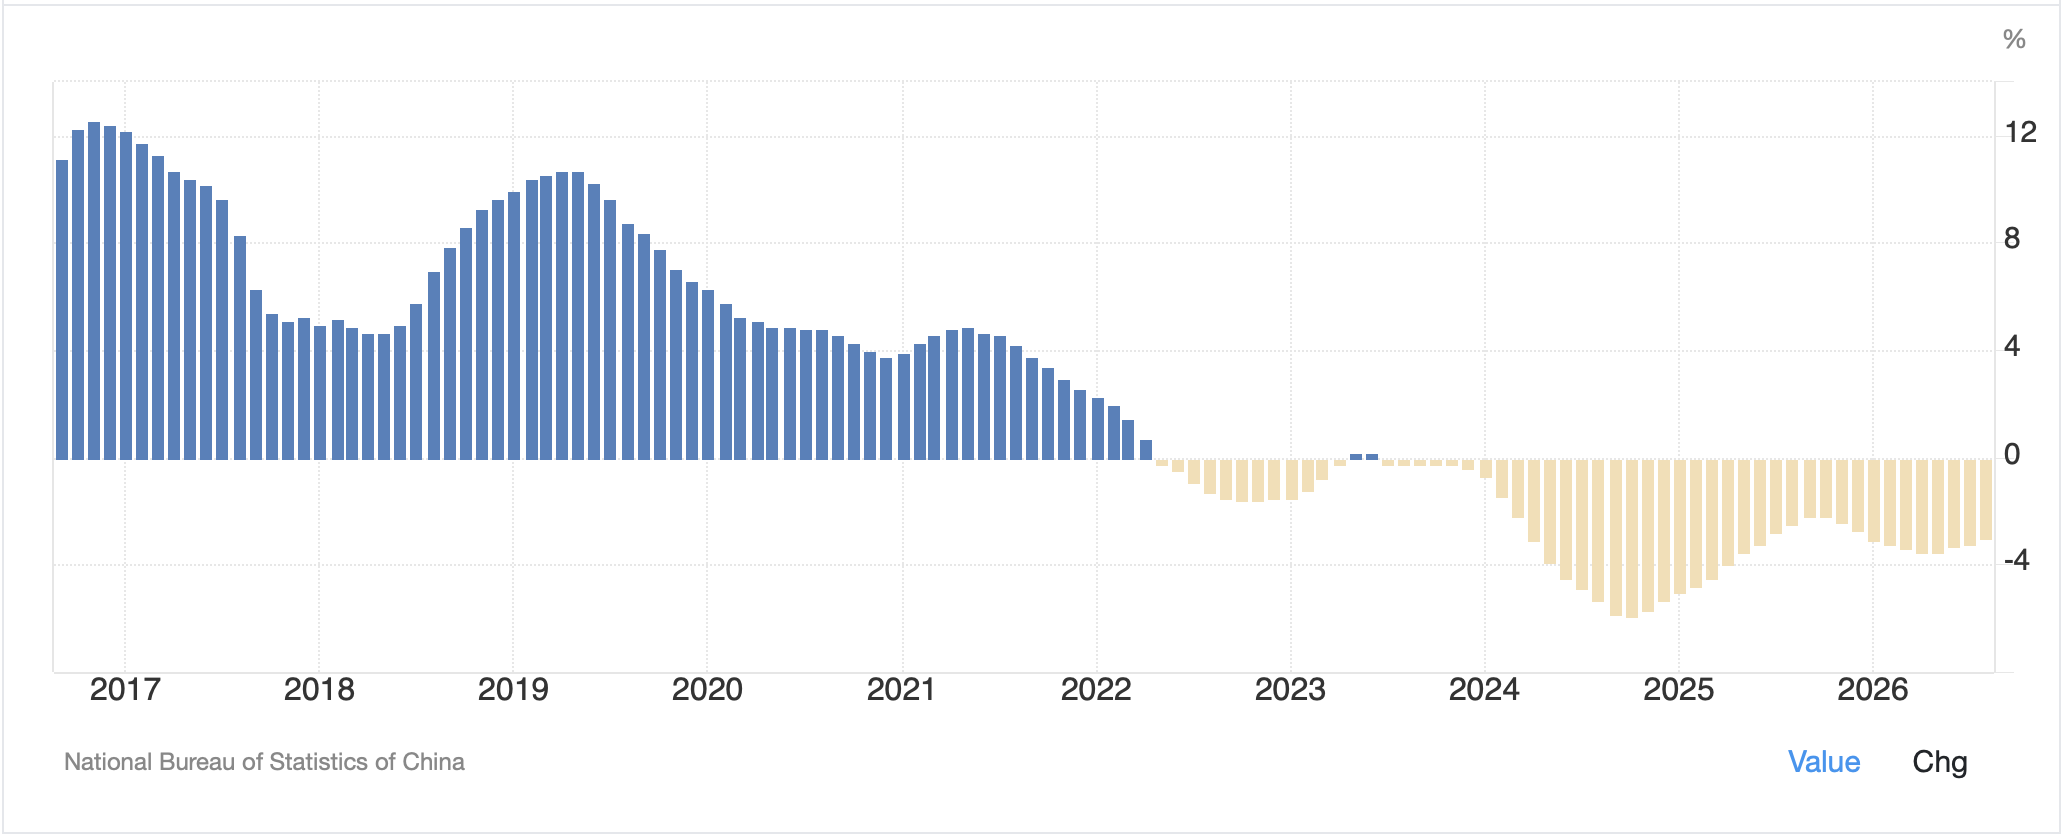
It is very difficult to look at these numbers and think things are going gangbusters there. For instance, the housing market, which has been a key destination for private savings has been declining for five years and has been negative for more than four.
Source: tradingeconomics.com
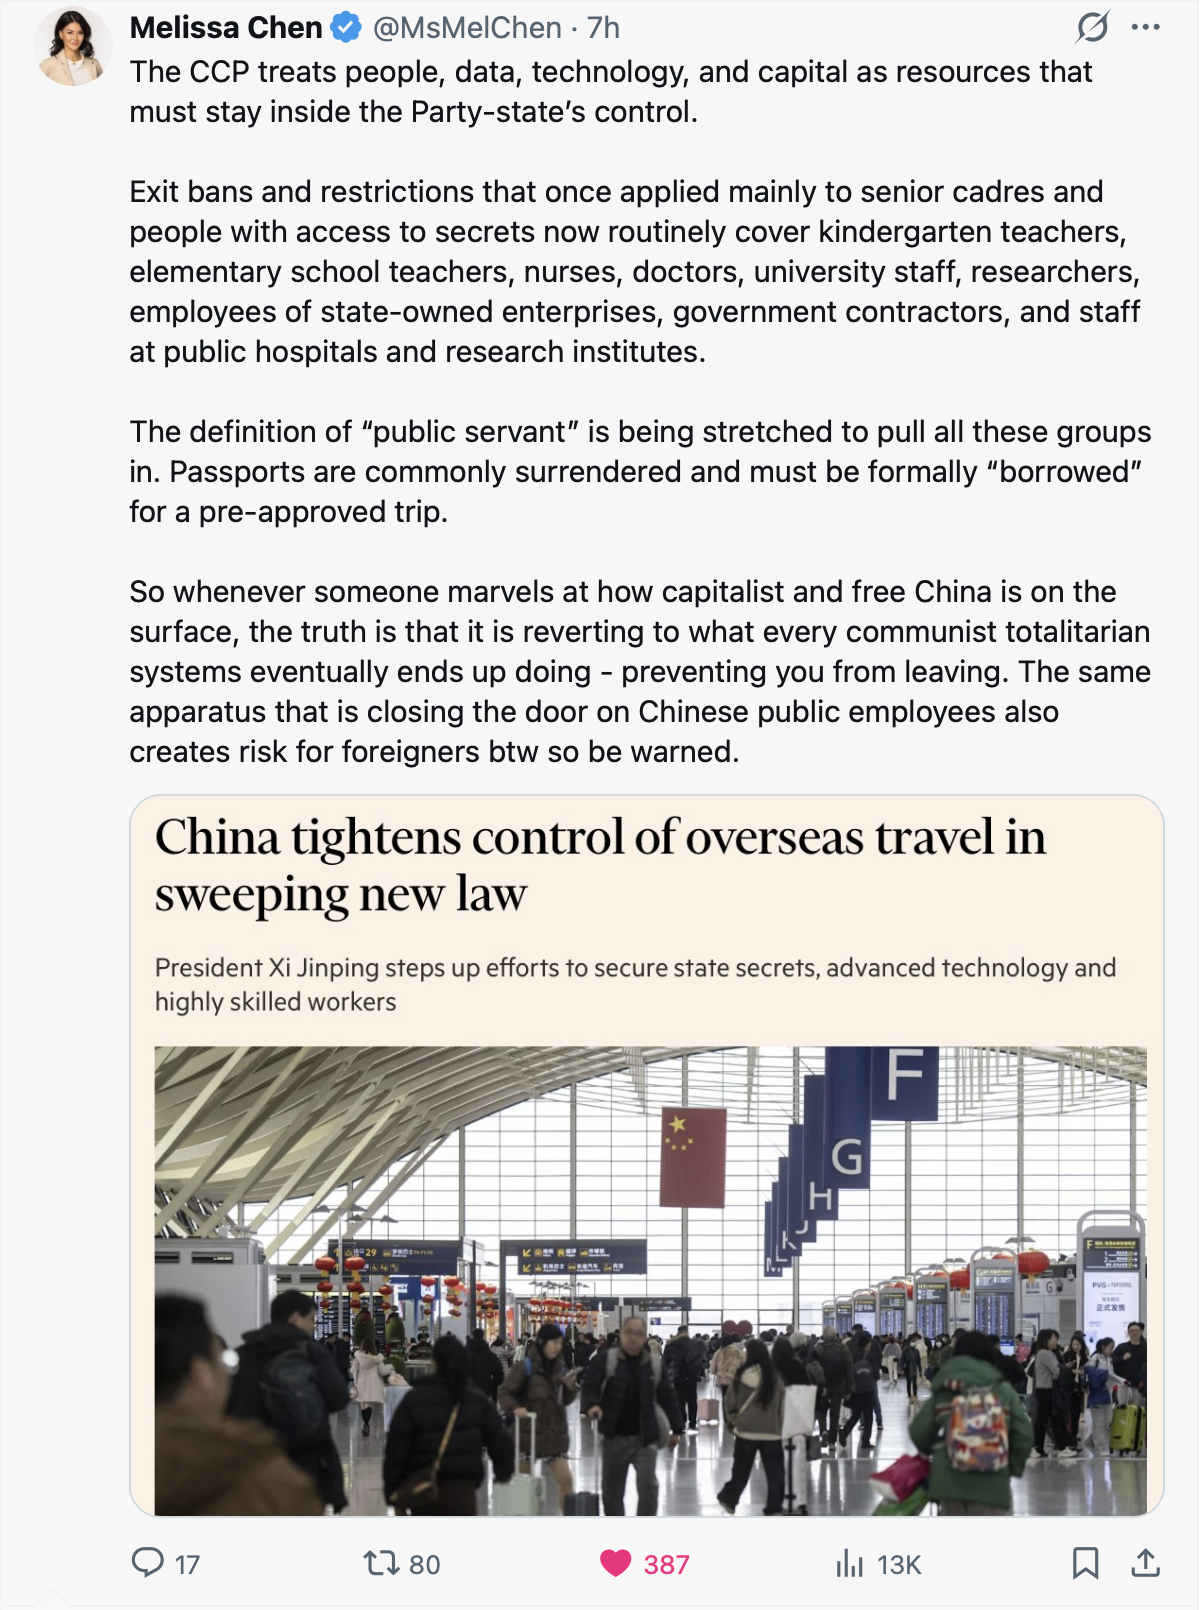
But more tellingly to me was the new regulations that were imposed starting today regarding the ability of people in China to simply leave the country on holiday. The below tweet from journalist Melissa Chen from The Spectator is a telling sign that there is growing stress in that nation.
Again, my point is that as many problems as exist in the US, and we have plenty, it is not as though other nations are killing it. Rather, they, too, are being killed. Now, has this impacted the CNY? Not at all. It is a completely controlled currency and the PBOC is slowly driving it higher although it remains massively undervalued. As to the rest of the FX market, the dollar is stronger by somewhere between 0.1% and 0.3% nearly across the board with only KRW (-0.9%) outside that window, but remember, the won has been flying over the past two months, so a little pullback is no surprise.
On the data front, this morning brings Empire State Manufacturing (exp 14.75) and that’s it. It is also worth mentioning that the German ZEW Sentiment Index was released at a weaker than expected 34.7, just showing that there is a bit of despair all around the world.
I have a feeling today is going to be relatively quiet as all eyes look to the Marriner Eccles Building and Chairman Warsh tomorrow afternoon.
Good luck
Adf
 fxpoetry
