
While everyone waits for the Fed
A story that’s come to its head
Is Canada speaking
To Europe while seeking
A road where the two can now tread

Meanwhile in the markets we see
A rate hike’s a fait accompli
But what will Warsh say
Some hours away?
Not much based on his history
I have to start with the news about the EU looking to make Canada an honorary associate member of the bloc since they all hate President Trump so much. Now, maybe this will work out very well for them, after all, Canada is rich with natural resources and Europe is desperate for a friendly source. But then, Europe has gone out of their way to hamstring themselves by banning fracking and new drilling for oil in the North Sea, so I wonder why they will be so happy to buy Canadian oil and gas. Oh, and there are no effective ways to move that energy from Alberta, where most of it sits, to Europe as there is no pipeline network across Canada. But I am certain they will make many impressive speeches on the topic and will feel really good about themselves. It’s funny, I always thought politics was about the possible, but apparently in Europe it is more about the good feelings of moral superiority. As the continent, writ large, is very likely going to be deficient in natural gas come January, I hope they all have warm sweaters and blankets.
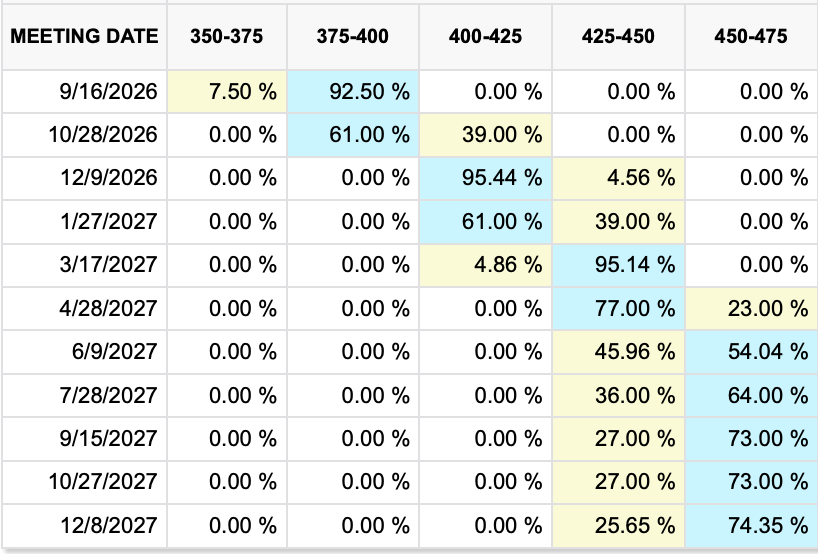
Which takes us to today’s biggest story, the FOMC meeting and the interest rate decision. The futures market is pricing a 92.5% probability of a hike and another three over the course of the next year as per the below table from cmegroup.com.
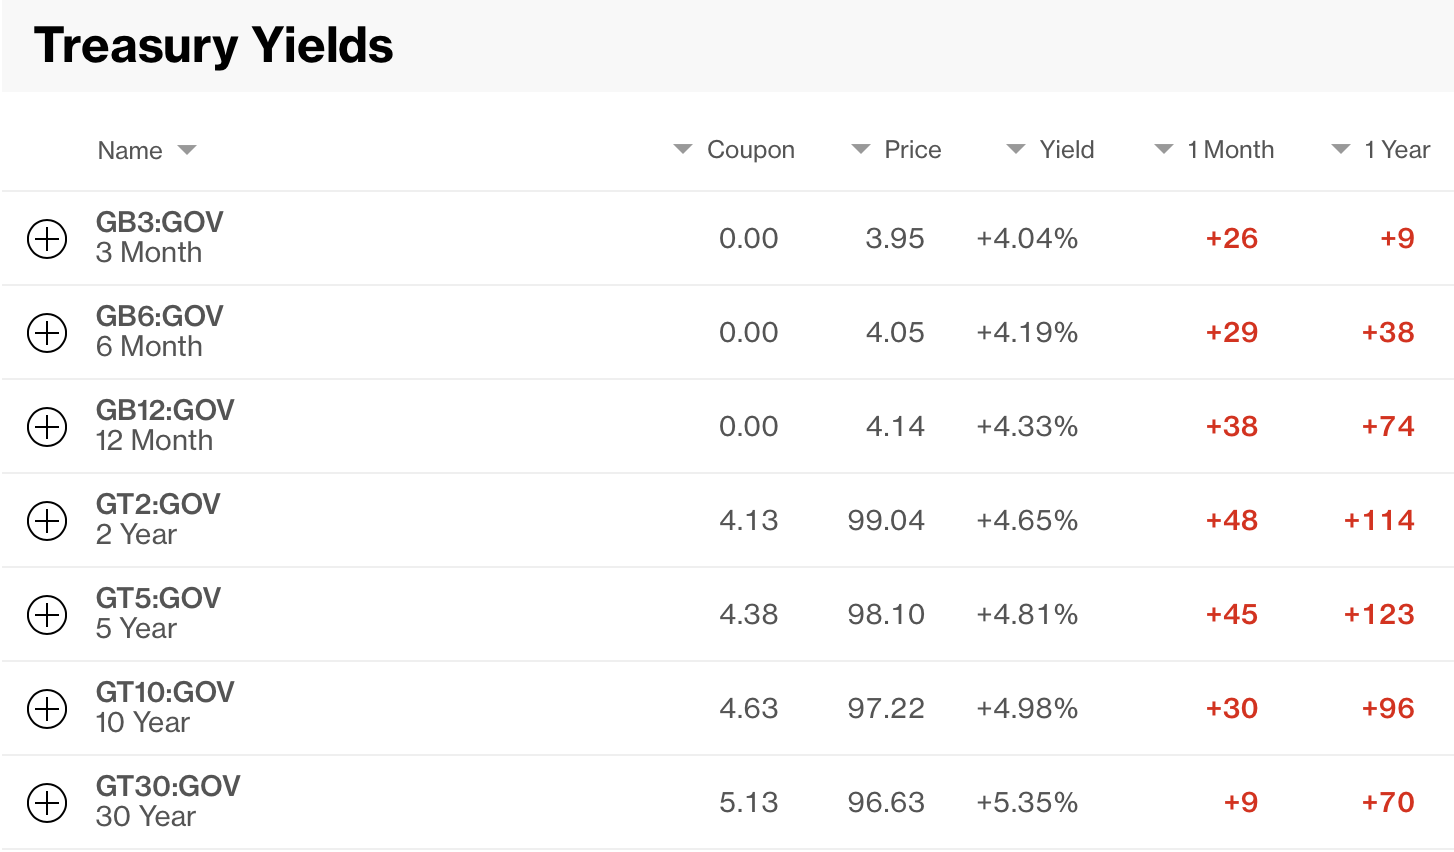
At the same time, yields continue to rise in the US across the board as you can see from the below Bloomberg screenshot, although this morning, the 10-year yield has slipped back -2bps.
There is a strong thesis that if the Fed hikes and sounds hawkish that the bond market will reverse course as investors gain comfort that the Fed is going to be addressing inflationary pressures. Yet, I don’t understand why that would be the case since raising the Fed funds rate is not only not going to produce more oil or open the Strait of Hormuz, but it is going to make drilling for oil more expensive. However, that is the discussion that I have seen on X as well as the WSJ this morning.
At this point, you are aware of my view that the Fed has no reason to hike, and, in fact, I fear it would be counterproductive. It would not surprise me if the vote, whichever way it goes, winds up 7-5 as I think despite the market pricing, there is real skepticism on the committee. We shall see later today.
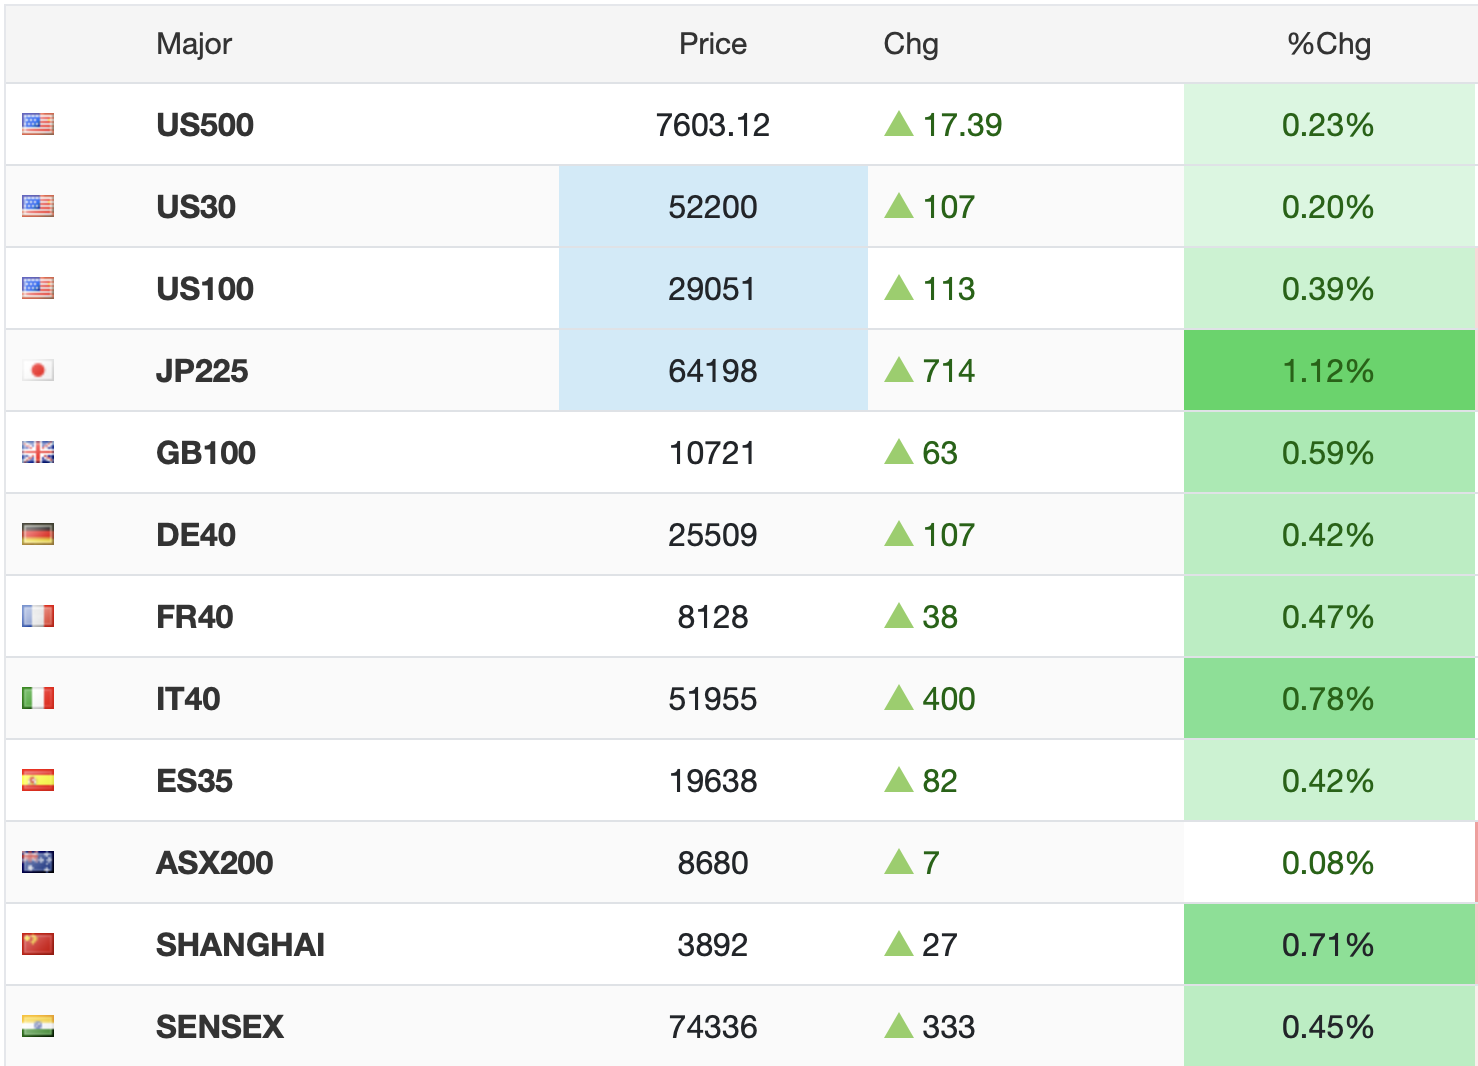
And with that in mind, let’s look at how other markets are behaving this morning. There has definitely been an air of negativity around markets lately, with much more discussion regarding the bad things that can happen rather than any potential good ones. Whether it is the energy crisis finally arriving, or the ‘AI is going to kill us all’ story or higher rates are going to force the stock market to implode, the bears have ample opportunity to make their case. And yet, as I type this morning, screens are green in equity markets around the world.
Source: tradingeconomics.com
So, Asia saw strength in Tokyo, Shanghai and Mumbai, Europe is seeing it across the board and US futures are all pointing slightly higher. Too, it is important to remember that while share prices were lower yesterday in the US, it was not a rout, all three major indices were lower by about -0.5% to -0.6%. I would not panic at this price action.
While above I noted how much US yields have moved over the course of the last month and year, the overnight movement is a touch lower, -2bps, and that is consistent with European sovereigns, all of which have seen their yields slip -1bp or -2bps this morning. In fact, the UK (-6bps) is the outlier here after inflation data this morning was less concerning than expected. And overnight we saw Asian bond markets, led by JGBs (-5bps) all see yields slide a bit.
There are still many analysts and pundits who are looking at the US fiscal situation, as well as fiscal situations elsewhere in the world (all of them are bad) and calling for much higher US yields with the 10-year set to go to 6% or 7% or 10% even in the extreme cases. But I think that is so much clickbait and not serious analysis. Consider, for many years it was assumed that Japanese yields had to climb dramatically as the debt/GDP ratio there rose to 250% and growth was stagnant, yet they maintained that situation for more than two decades! However bad the situation is in the US, and I’m not saying things are great fiscally, it can go on for a much longer time.
In the commodity markets, this morning oil (-2.4%) is backing off a bit but remains well above $100/bbl. It appears that the Saudis have shut the East-West pipeline after attacks recently and that could reduce supply by 4mm bpd, a significant hit, especially for Europe and Asia. While timing is everything in life, and the fact that drilling and setting up production takes time, nothing has changed my view that there is essentially infinite oil available around the world that will come online and replace those flows. Consider that Venezuela is now pumping 1.2mm bpd (according to OPEC via Grok) far more than before the events last January, and far more than the pundits had said could be pumped in such a short period of time. There is plenty of oil around, it is more a question of getting it from where it is to where it needs to be, and that infrastructure is still being built out.
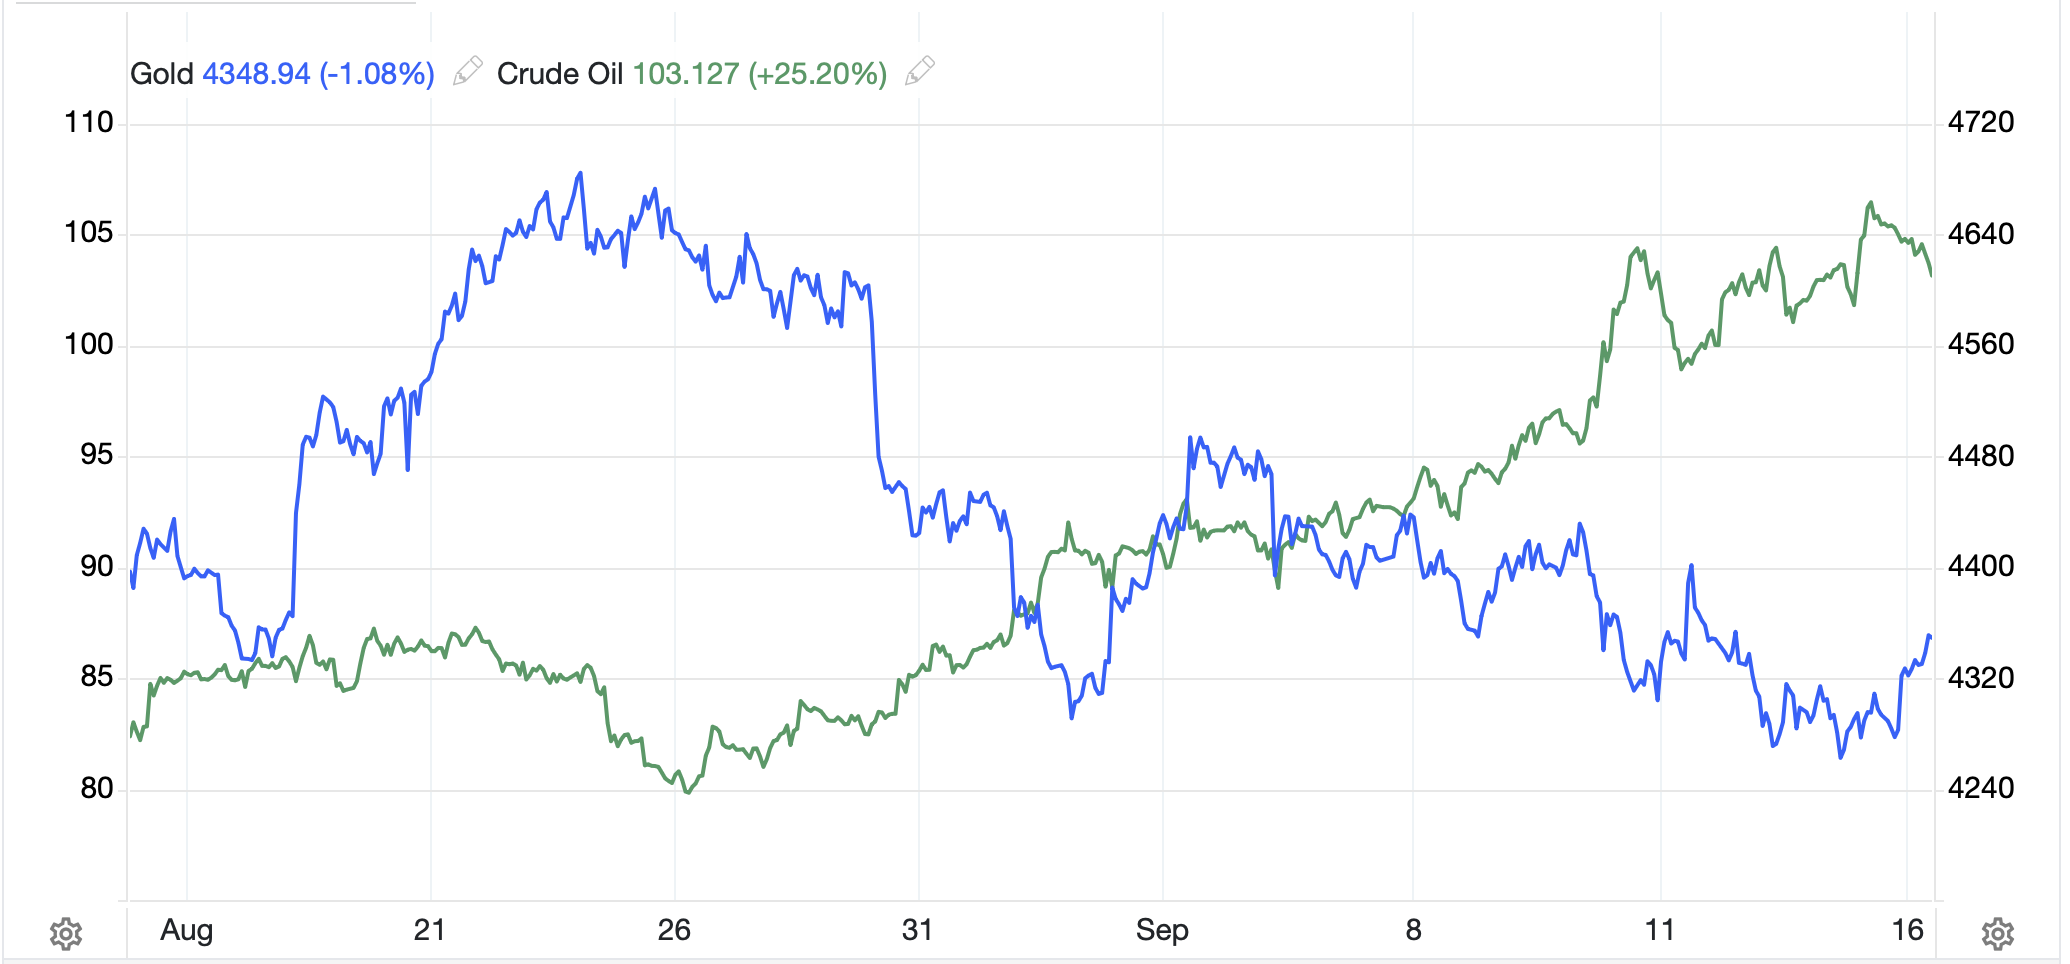
As to the metals markets, with oil lower, it is no surprise they are higher (Au +1.35, Ag +1.9%, Cu +1.1%). Certainly, as you can see in the below chart, there has been a very strong negative correlation between oil and gold over the past month, at least.
Source: tradingeconomics.com
Finally, the dollar continues to find support. No matter how much people want to hate the dollar and explain it is going to collapse, it just won’t die. This morning, the dollar’s gains are minimal, 0.05% to 0.15% largely across the board, but this feels more like consolidation than reversal. I suppose traders are trying to run ahead of the FOMC news (boy if they don’t hike, I suspect the dollar really could fall sharply, but once again, I posit that no matter how bad things are in the US, they are generally worse everywhere else.
On the data front, this morning brings Retail Sales (exp 0.8%, 0.5% ex autos) and the EIA oil inventory data with a small draw expected. Then, of course, the FOMC at 2:00 and the press conference at 2:30. My sense is people hold their collective breath until then.
Good luck
Adf
 fxpoetry
