As awful as things seemed last week
On Monday we got a sneak peek
Of how things might play
When we see the day
The mullahs and Trump finally speak

At this point, it’s not very clear
If talks have brought settlement near
But I have a sense
That there’s no pretense
And things will be settled this year
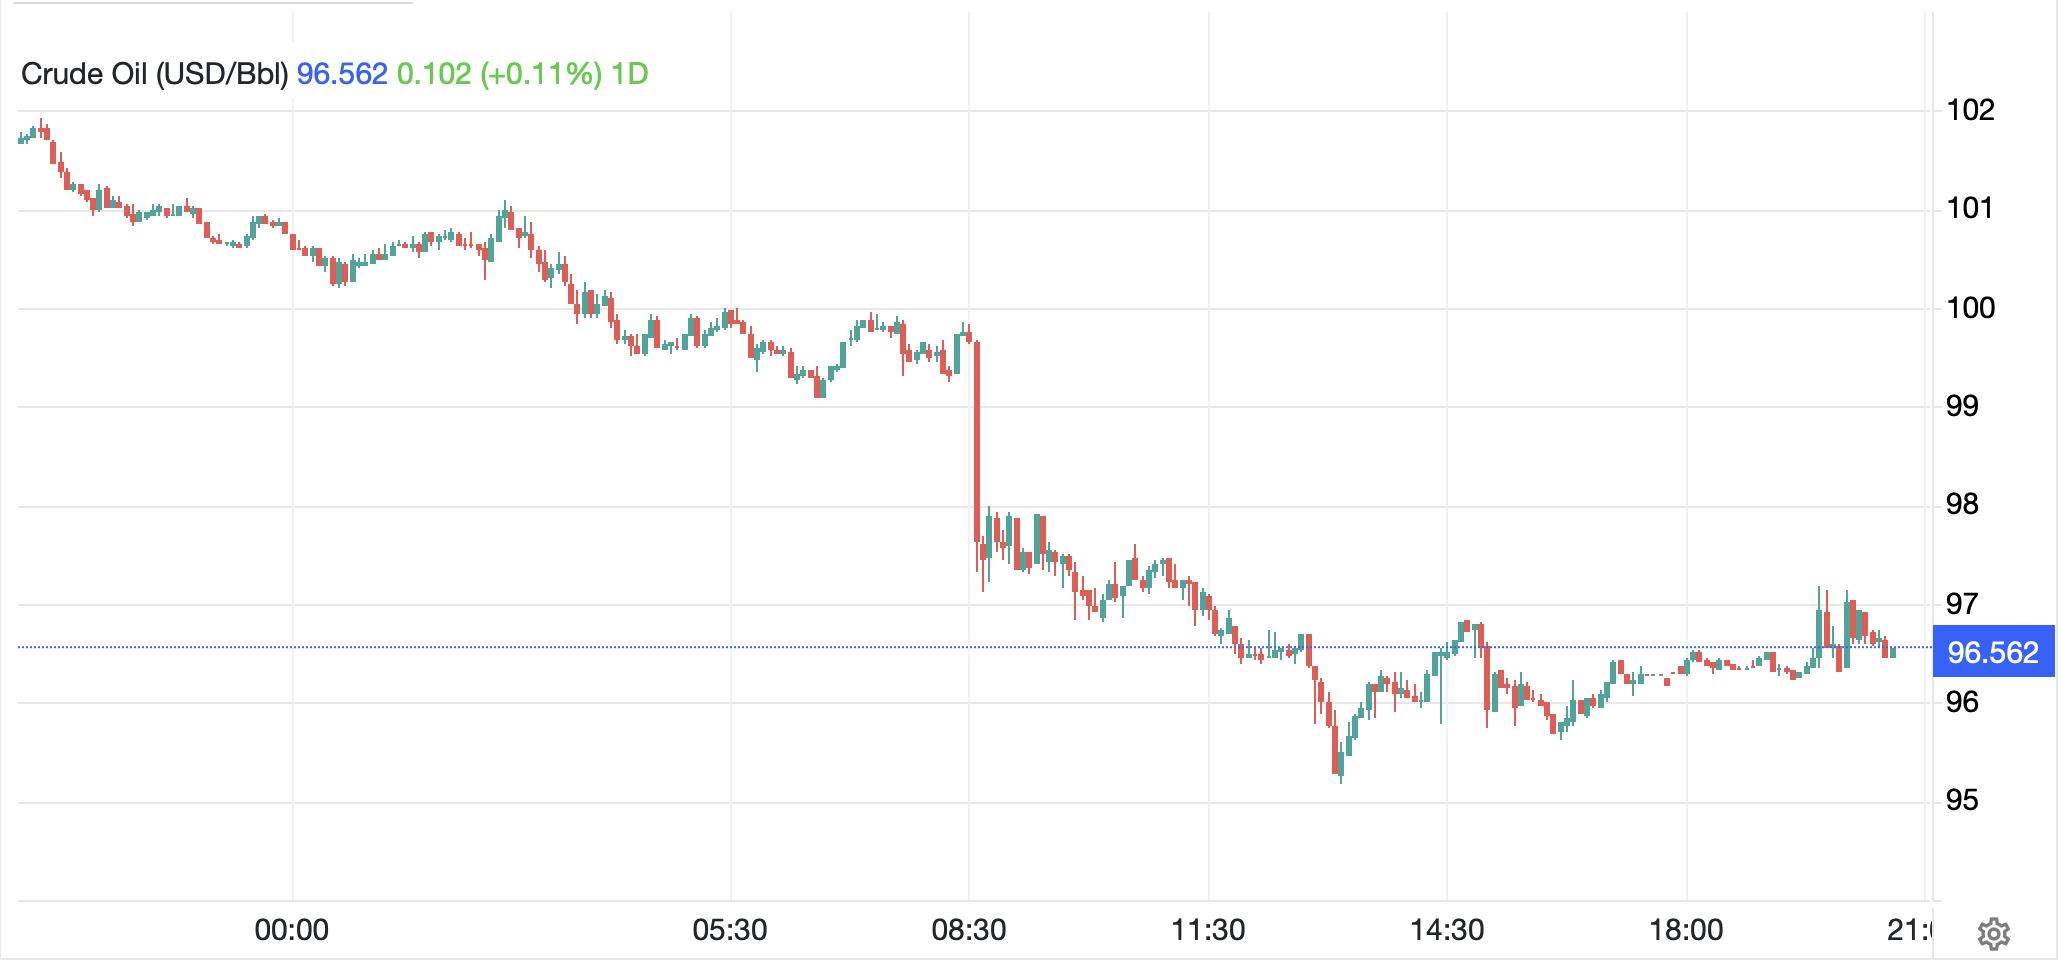
When I wrote yesterday morning, oil had only moved half of its ultimate decline as stories about more successful peace talks regarding Iran made the rounds as per the below chart.
Source: tradingeconomics.com
You can see the large red candle shortly after 8:30 yesterday morning when positive news about the Ayatollah expanding negotiating room for the civilian government came out. One of the noteworthy market moves was the fact that prompt prices for physical delivery, which had been trading as much as $30/bbl above the futures prices we see, collapsed back to a di minimis premium. That indicates a belief that oil is going to flow again through the Strait, and soon. Word is Iran has offered to reopen the Strait if the US ends the blockade. This tells me the blockade has been extremely effective and that Iran is really running out of cash. After all, why would they consider a deal ahead of the election? Of course, they may believe their heartfelt endorsement for Democrats has done its job and they will win today. The only thing I know about today is I cannot wait for the political ads to end on TV!
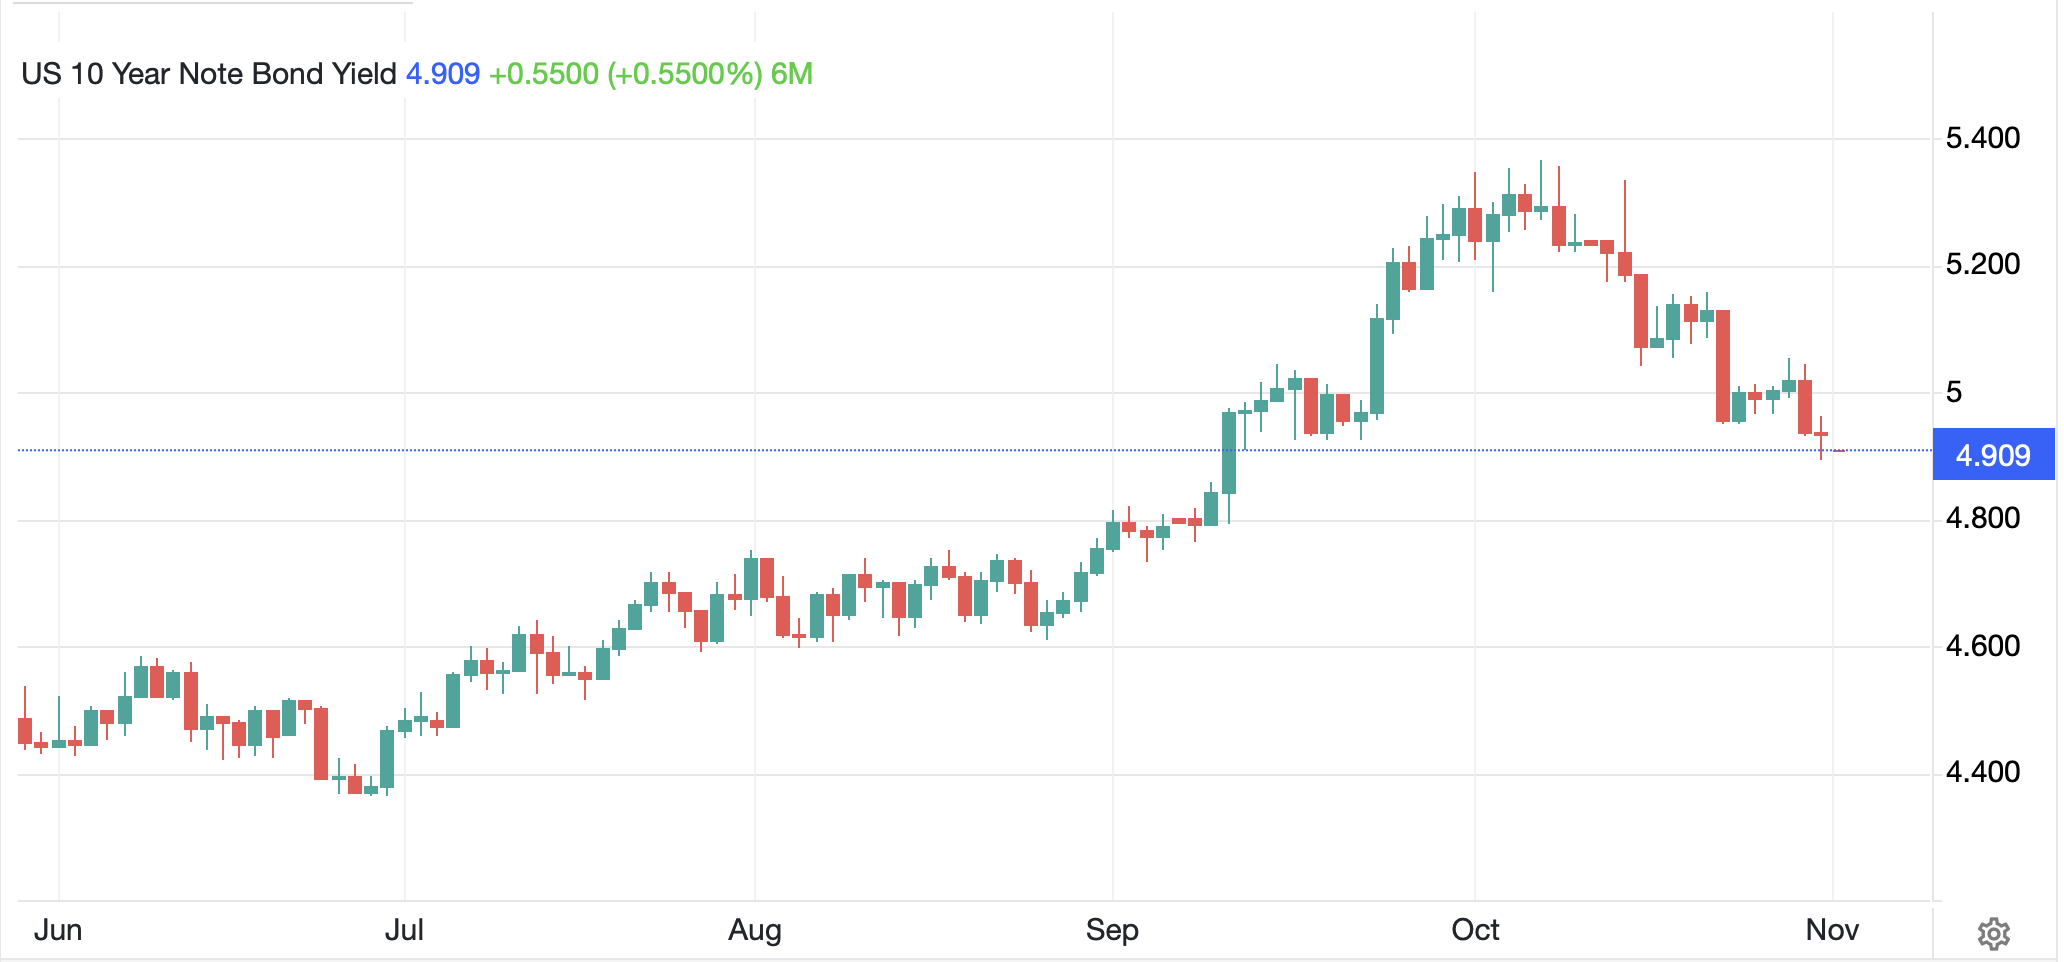
But it was not just oil that moved, we saw bond yields slip another -2bps yesterday, now down to their lowest level since mid-September.
Source: tradingeconomics.com
The Treasury’s borrowing estimates were within effective pennies of expectations, and I don’t think will have a major impact. Of more importance is the refunding estimates to see how much Secretary Bessent will be borrowing in longer dates going forward. There is talk of eliminating the 20-year bond, which never seemed to find a home, and a reduction in 30-year bond issuance, both of which would serve to reduce supply and support prices/reduce yields. We shall see on Wednesday.
Precious metals soared on the decline in yields, the slipping of the probability of a Fed hike in December, now down to 73%, and the slipping dollar. But stocks, which started the morning in a great mood, did give back a bunch on the tech side. And that was yesterday.
The booths open early this morning
And both sides, the other, are scorning
Meanwhile, China tweaks
And wartime still wreaks
More havoc, it should be a warning
Which brings us to this morning and the beginning of Election Day. You already know my views and that I am well outside the mainstream of opinion. We shall learn more this evening and I suspect that the question of control of both Houses will be determined before we go to bed, certainly that will be the case in the Senate.
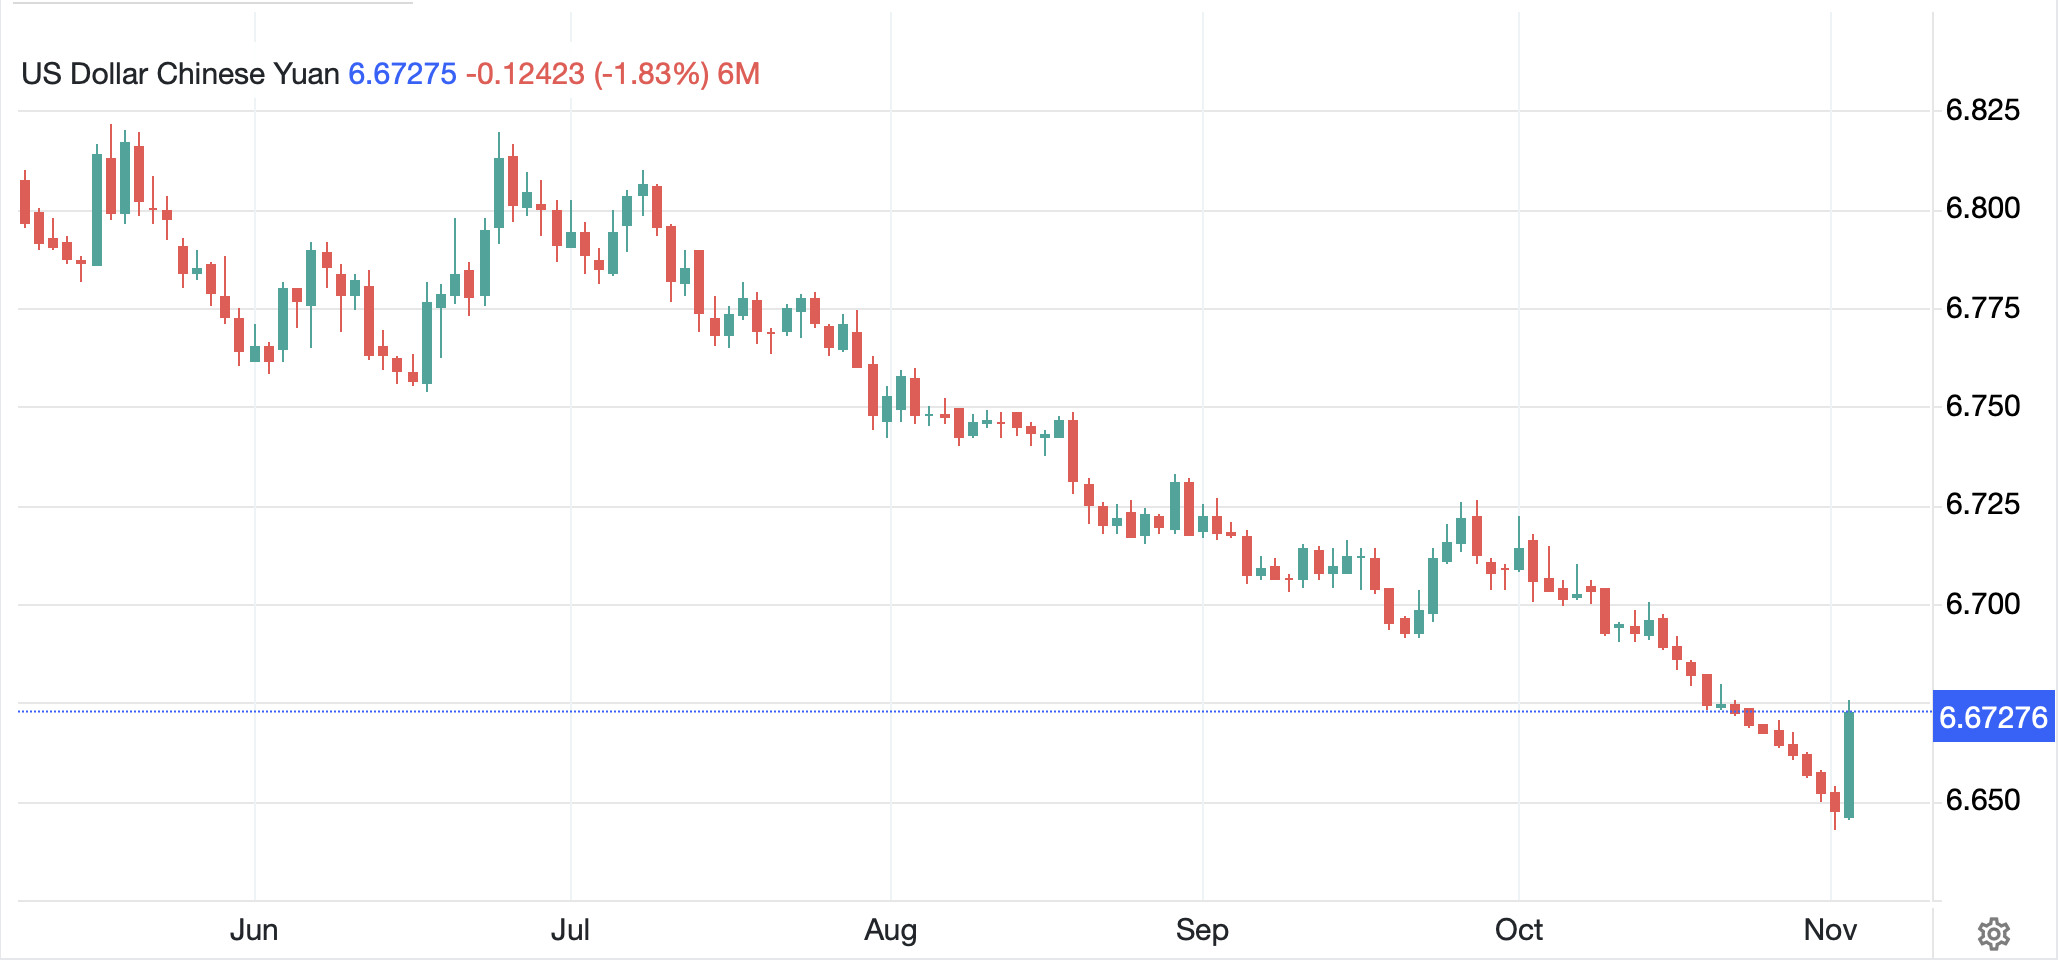
Elsewhere, the PBOC adjusted the RRR for foreign exchange at local banks, increasing the ratio from 4% to 6% to slow the too rapid strengthening of the renminbi. We have discussed here before that CNY remains significantly weaker than its fundamentals and that is a policy stance China maintains to support its export-led mercantilist economy. But under significant pressure from around the world, the renminbi had been appreciating steadily. However, it seems that the PBOC decided the pace was too quick, which is odd given they were the ones in charge, but nonetheless, the change yesterday resulted in a sharp reversal in CNY (-0.4%) which while not extreme, counts as sharp in that currency.
Source: tradingeconomics.com
I am confident that CNY will resume its appreciation over time, but perhaps at a much slower pace.
The other noteworthy news item this morning was the report that there was limited military activity on Qeshm Island in the mouth of the Strait of Hormuz. The report is the Iranians fired a surface-to-air missile at a US fighter jet and the US responded by attacking the missile installation. Ostensibly this has not derailed the alleged ongoing negotiations although oil (+2.1%) has rebounded off the lows seen yesterday. A not surprising consequence of the move in oil is that metals prices have sold off aggressively again (Au -1.0%, Ag -3.2%, Cu -3.0%) as that relationship remains fully intact. Reading about the metals markets, the best explanation I have seen regarding their recent price declines has been a discussion of the reduction in overall liquidity that is available amid ongoing expansion of debt issuance by both public and private sectors. Consider, the more debt that is sold to investors, the less they have to buy other things, with commodities being the first thing tossed aside.
In this vein, the most likely event to change this ongoing situation will be the resumption of QE as central banks will eventually be forced to, once again, buy sovereign debt to support their own debt markets. I know this is diametrically opposed to what Chairman Warsh has indicated he would like to do, but I struggle to find an alternative solution to a lack of funds available for investors. We are already seeing specific sectors of the economy feel that strain, notably the worst credits as CCC credit spreads have exploded relative to the rest of the risk curve. Rotation in the equity markets does not solve this problem, so metals, which have had a tremendous run over the past several years, remain the current asset to unload.
As to the rest of the markets, Treasury yields have backed up 2bps this morning while European sovereign yields are higher by between 4bps (Germany, Netherlands) and 7bps (Italy) amid growing concern over both the rebound in oil prices and the ongoing fiscal profligacy that is evident throughout Europe. While US yields have fallen back sharply from their October highs, European yields remain much closer to those levels as debt/GDP ratios remain a major concern for investors there.
In the stock market, Asian markets were mixed as the Nikkei (-2.2%), China (-1.4%) and HK (-0.7%) all suffered on the ongoing angst over tech stocks and the rotation out of that sector although Korea (+4.6%) which is the poster child for tech stock dominance, had a remarkably strong session. Taiwan (-2.5%) was in the gutter as was Indonesia (-2.0%), which continues to suffer from concerns over transparency and its potential removal from the MSCI frontier markets category. Other regional bourses moved far less, with a mix of gainers and laggards.
European markets, though, are all under pressure this morning, with all but Paris (-0.25%) down by -0.6% or more. There has been no data released this morning here except Swiss Inflation which rose to 1.5%! Maybe that’s why there is rioting in Zurich. As to US futures, they are mixed this morning with the DJIA (-0.9%) suffering while the other two major markets are either side of unchanged at this hour (7:15).
Finally, the dollar is broadly firmer this morning with one glaring exception, NOK (+0.8%) which is obviously responding to the bounce in oil prices. BRL (-1.1%) is a currency we haven’t discussed much lately but as you can see from the below chart, there has been no recovery, whatsoever, from the electoral surprise last weekend. Too, you can see the BOVESPA stock market also remains under pressure.
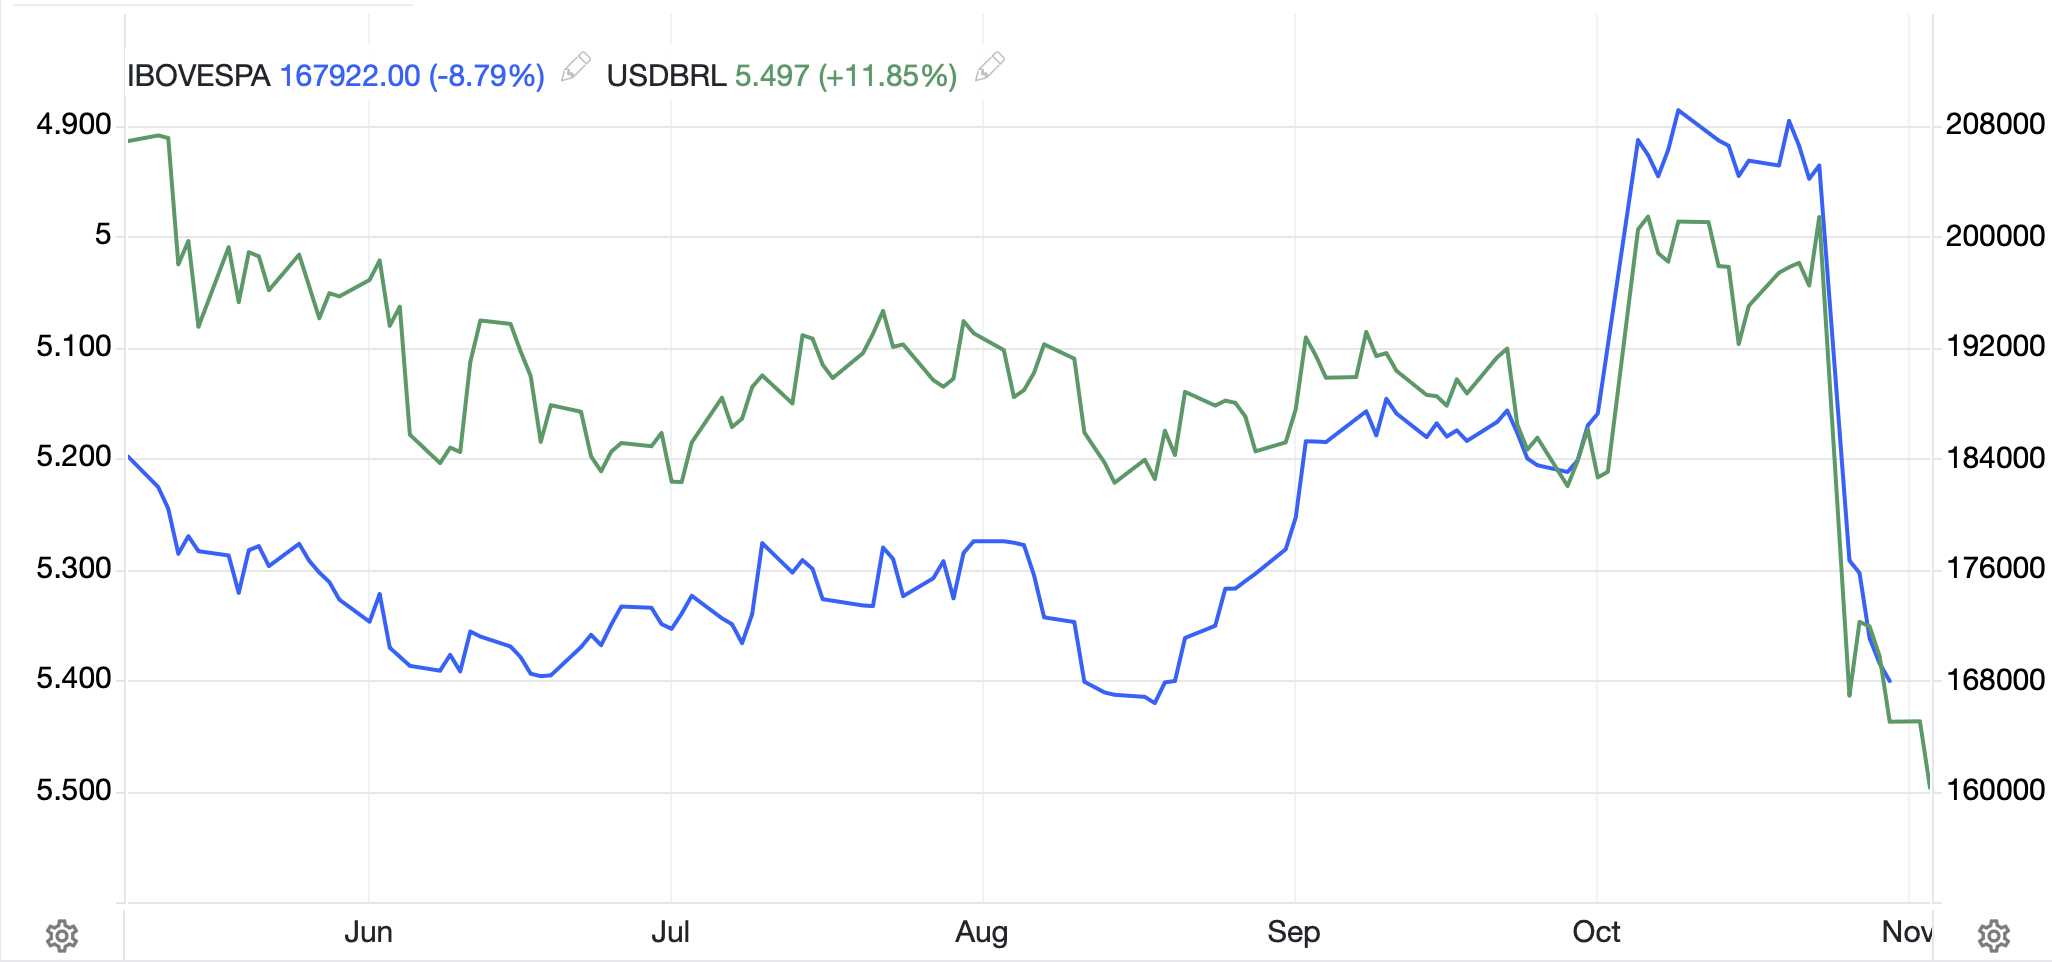
Source: tradingeconomics.com
But the major currencies aren’t doing much today, perhaps biding their time for election results. In fact, I suspect that will be much of the story during today’s session although I would be careful of early announcements from exit polls declaring victories on either side.
On the data front, yesterday’s ISM data was strong, 55.5, with Prices Paid softer than expected at 75.2. This morning we see the JOLTs Job Openings data (exp 7.10M) and Factory Orders (1.2%) but neither will matter to markets today. Last night, the RBA hiked their base rate by 25bps, as expected, although the decision was split and AUD (-0.3%) lost a little luster as expectations of future hikes were reduced.
Unless the Iran situation comes completely unstuck today, it is all about the elections and for that, we need to wait until this evening at the earliest. Hedged and close to the vest remains the way, I believe.
Good luck
Adf

