On Friday, it certainly seemed,
As equity markets got creamed,
The end of the world
Had slowly unfurled
Just like the bears worldwide had dreamed

This morning, though, screens are all green
‘Cept crude whose price has lost its sheen
But Europe’s still burning
And that’s quite concerning
So, what, from this mess, can we glean?
I am going to stop listening to podcasts on my weekend morning walks with Marvel as they have become increasingly apocalyptic and, frankly, if the world is going to end, perhaps it’s better not to know ahead of time, it will save so much angst! One of the podcasts that I periodically listen to is Palisades Radio, which this week had an interview with Simon Hunt, a pretty well-known macroeconomist and analyst. I have the link above, but I can only recommend listening if you are seeking a reason to commit suicide as he basically explained that the world we know is over, specifically that the House of Saud was going to collapse, the US was going to lose in Iran and with that China and Russia would become the new global hegemons. Now, maybe that is exactly what is going to happen, I certainly don’t know. But that feels like an outlier position to me. Of course, Simon sounds so intellectual with his gravelly British accent, that it gets a great deal of respect.
However, I constantly go back to the idea that predictions are hard, especially about the future. The other thing about pronouncements like this are they are impossible to verify given his timeline is measured in years, so in 2032 or 2034, if what he forecasts doesn’t pan out, nobody will remember, but if it does, he will be screaming it from the hills. Of course, if it does pan out, no matter how loud he screams, nobody will be listening as the new global hegemons will not be interested in economic analysis.
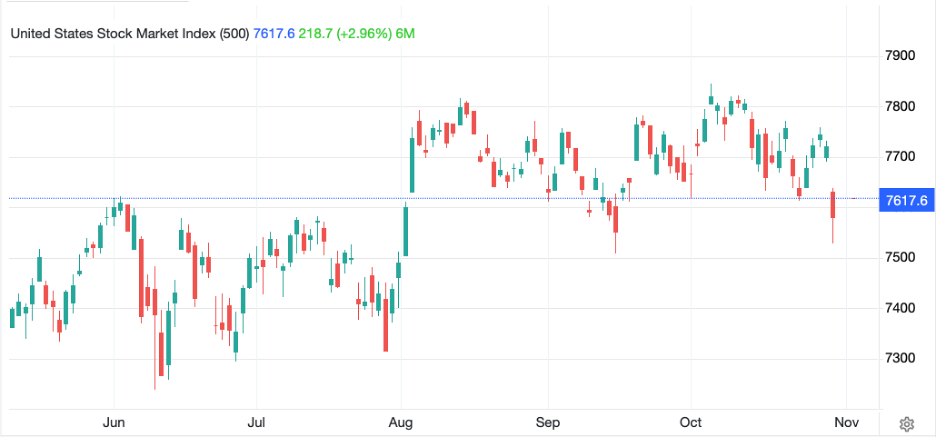
My weekend perambulations aside, Friday certainly had an apocalyptic tone to it as earnings releases during the week mostly failed to meet expectations and equity markets fell sharply. Meanwhile, the number of articles discussing the increasing likelihood that the US was going to resume its military campaign in Iran when the election was over, egged on by President Trump himself, grew and there was an overall negative vibe. This was clearly expressed in the equity markets as you can see in the below chart with Friday’s large red candle portending doom and gloom.
Source: tradingeconomics.com
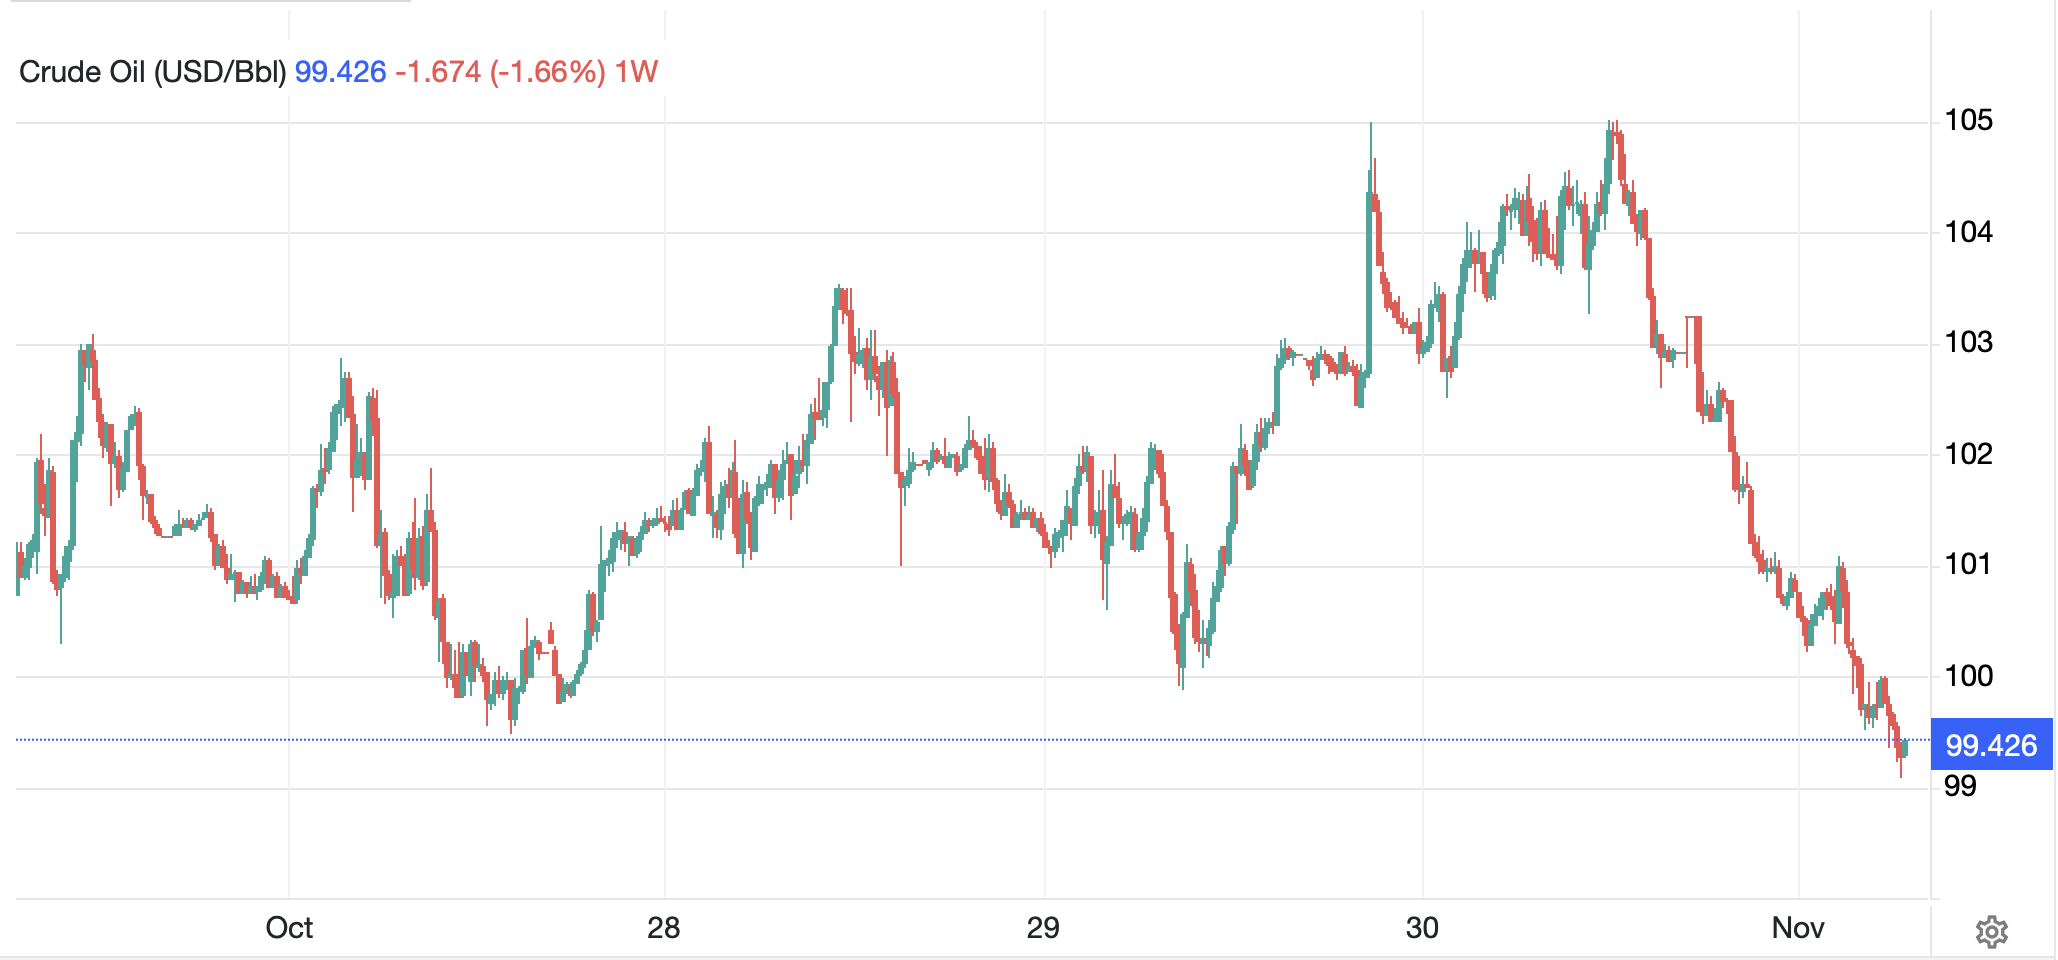
Of course, there is another potential explanation for Friday’s price action, it was month end, and there could well have been rebalancing flows driving the trade. And this morning, the entire vibe in the US, at least, has changed. It starts with oil, as most markets do these days, and as you can see in the below chart, WTI has fallen sharply today, down -4.5% on news that a diplomatic solution to Iran may be coming together.
Source: tradingeconomics.com
Now, I have no idea if that is true or not, and I suspect neither does anybody else, but it does appear that there has been an increase in diplomatic efforts by the Qataris, Turks and Omanis as the election comes near. And despite Iran’s claims they are prepared for anything and will inflict significant damage if they are attacked, I imagine they really don’t want to sustain another intense wave of bombing.
But it’s not just the Iran situation that is on the markets’ collective mind, but US elections. Now, I am on record as forecasting the Republicans maintain both houses of Congress, but I am in the minority. However, the surprise endorsement of Republican Mike Rogers by Democrat Haley Stevens, the woman who lost the Democratic primary to Abdul El-Sayed, has certainly gotten tongues wagging and it appears there is a growing sentiment that some of the Senate Races that the MSM had confidently called for Democratic victories may not be so sure after all, notably Texas and Michigan. If I am correct in my political prognostications, I believe much equity market angst will dissipate quickly.
Turning to Europe, there was a coup in Poland, or not, I am not sure what is going on, and based on the articles I have read, I don’t think anybody is sure. Perhaps the most surprising thing I saw was that there are riots in Zurich and Basel. Of all the places on the planet, perhaps only Antarctica would be a less likely spot for a riot than Zurich. But one must question what would cause the people of Zurich to riot. The idea that Europe is burning spontaneously is suspect.
If we sum it all up, what do we know? The universal truth in media is, if it bleeds, it leads. Given that as well as the fact that media has evolved into a 24/7/365 festival (nightmare?) on social media, perhaps we should not be surprised that every terrible event is highlighted and anything positive is dismissed because it doesn’t get enough engagement. My experience over time, though, is that rarely do we see either the best or worst cases come about, but some middle ground instead. I expect that is what we are going to see ahead as well. Companies are still doing business and earning profits, people are still going to work, earning and spending money and living their lives, and that is the majority of activity. We need to be careful as to how much of the news we consume as gospel given the potential for excessive pessimism, mostly, to become entrenched.
Enough life lessons. Let’s review markets. As I said, equities are having a better day than Friday with more strength (China +0.8%, HK +0.4%, Korea +2.2%, India +1.7%) than weakness (Tokyo -0.3%, Australia -0.6%, Taiwan -0.6%) in Asia as word from China was that they would be increasing their support for stock markets there as per this X summary. As to Europe, while Spain (+0.9%) is having a solid session, the rest of the major bourses are +/-0.2% or less after PMI Manufacturing data was pretty decent (weak in France and Italy, not surprisingly) but Retail sales data was soft in both Germany and Switzerland. (I guess if the rioters are going to steal stuff, they won’t be buying much.) US futures, though, are firmer at this hour (7:30), up by 0.5% or so across the board.
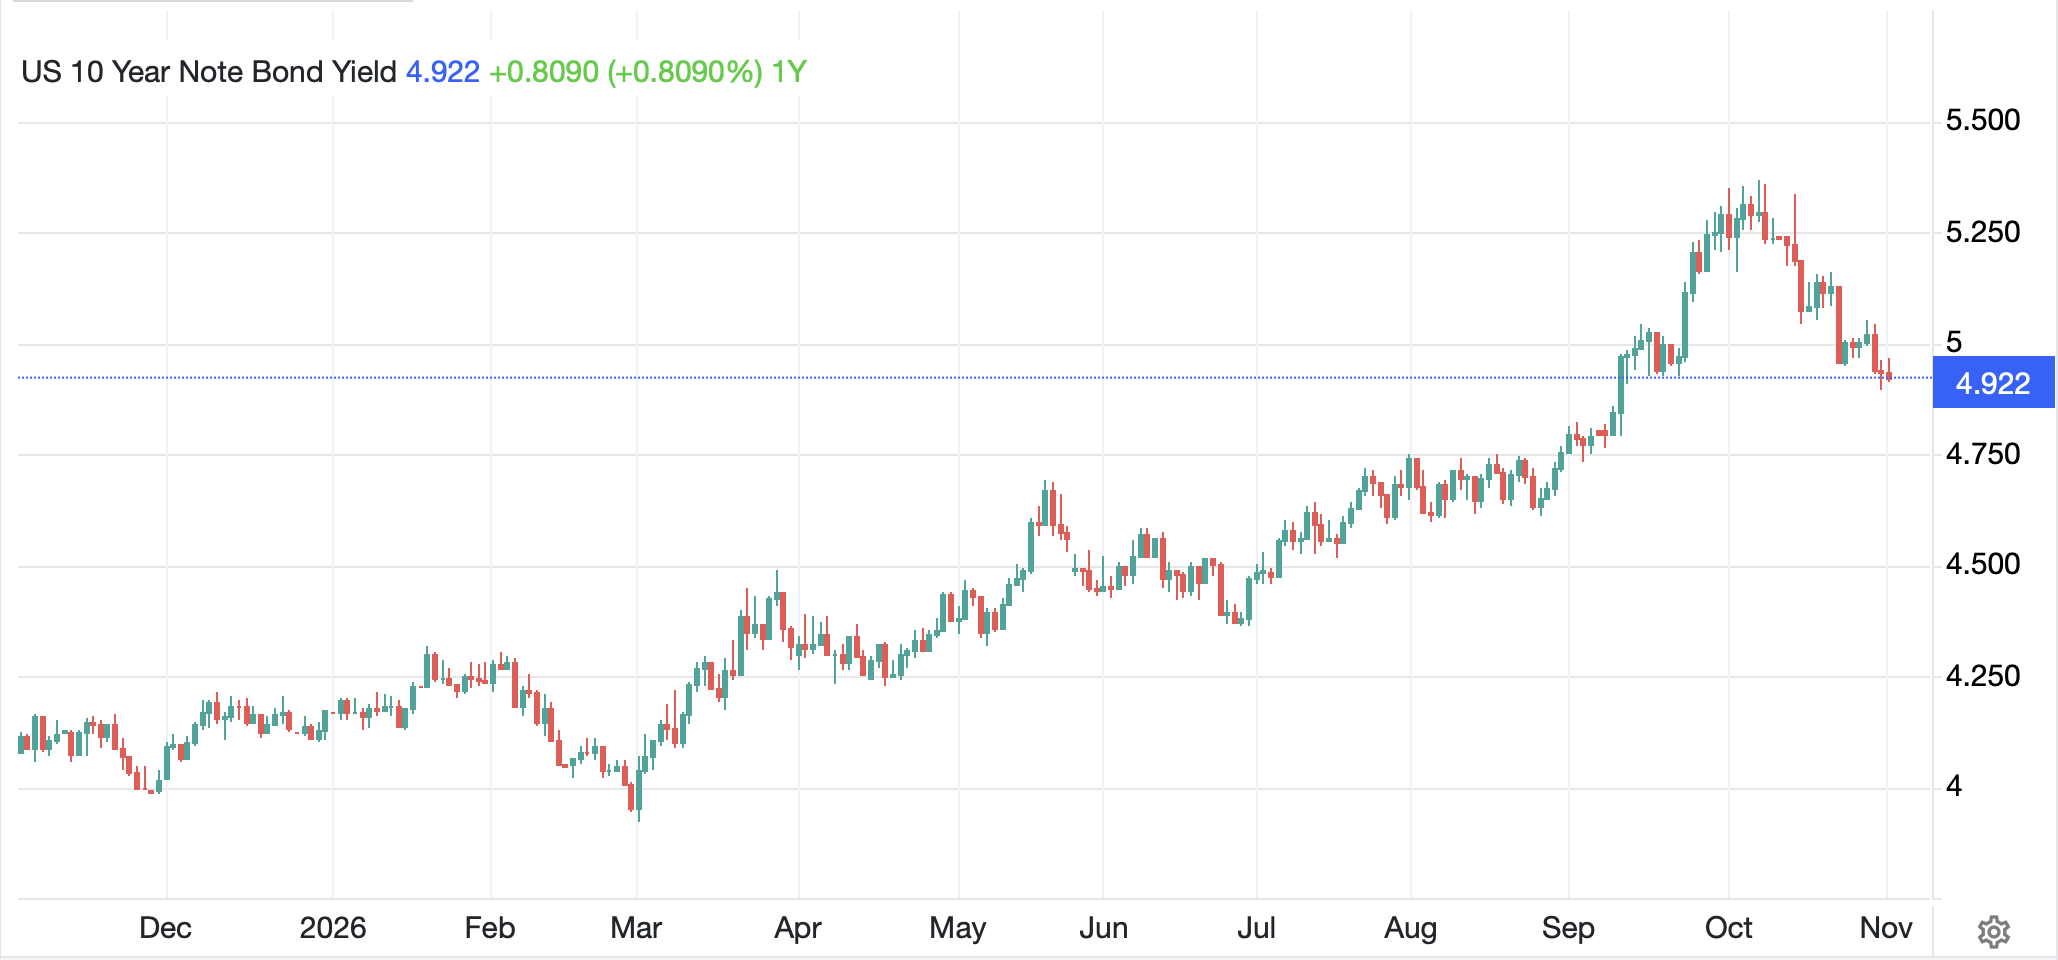
In the bond market, Treasury yields (-2bps) continue to slide and are dragging European sovereign yields down as well. I think it is worth remembering that less than a month ago, 10-year yields were 45bps higher than today and the consensus view was that owning bonds was a disastrous idea as the government would never close the deficit and other central banks would stop buying Treasuries. But markets are funny like that, and the chart below shows just how big this reversal has been. Are yields low? Absolutely not, but for now, at least, fears of the bond market collapsing have gone away.
Source: tradingeconomics.com
This week also brings the Treasury refunding announcement for next quarter and there is some intrigue over how Secretary Bessent is going to present things and his strategy to reduce yields. Of course, you remember when he talked about repurchasing off-the-run bonds at a discount it was all poo-poohed as a waste of time with no impact, and yet here we are 45bps lower. Maybe he really is ‘The House’!
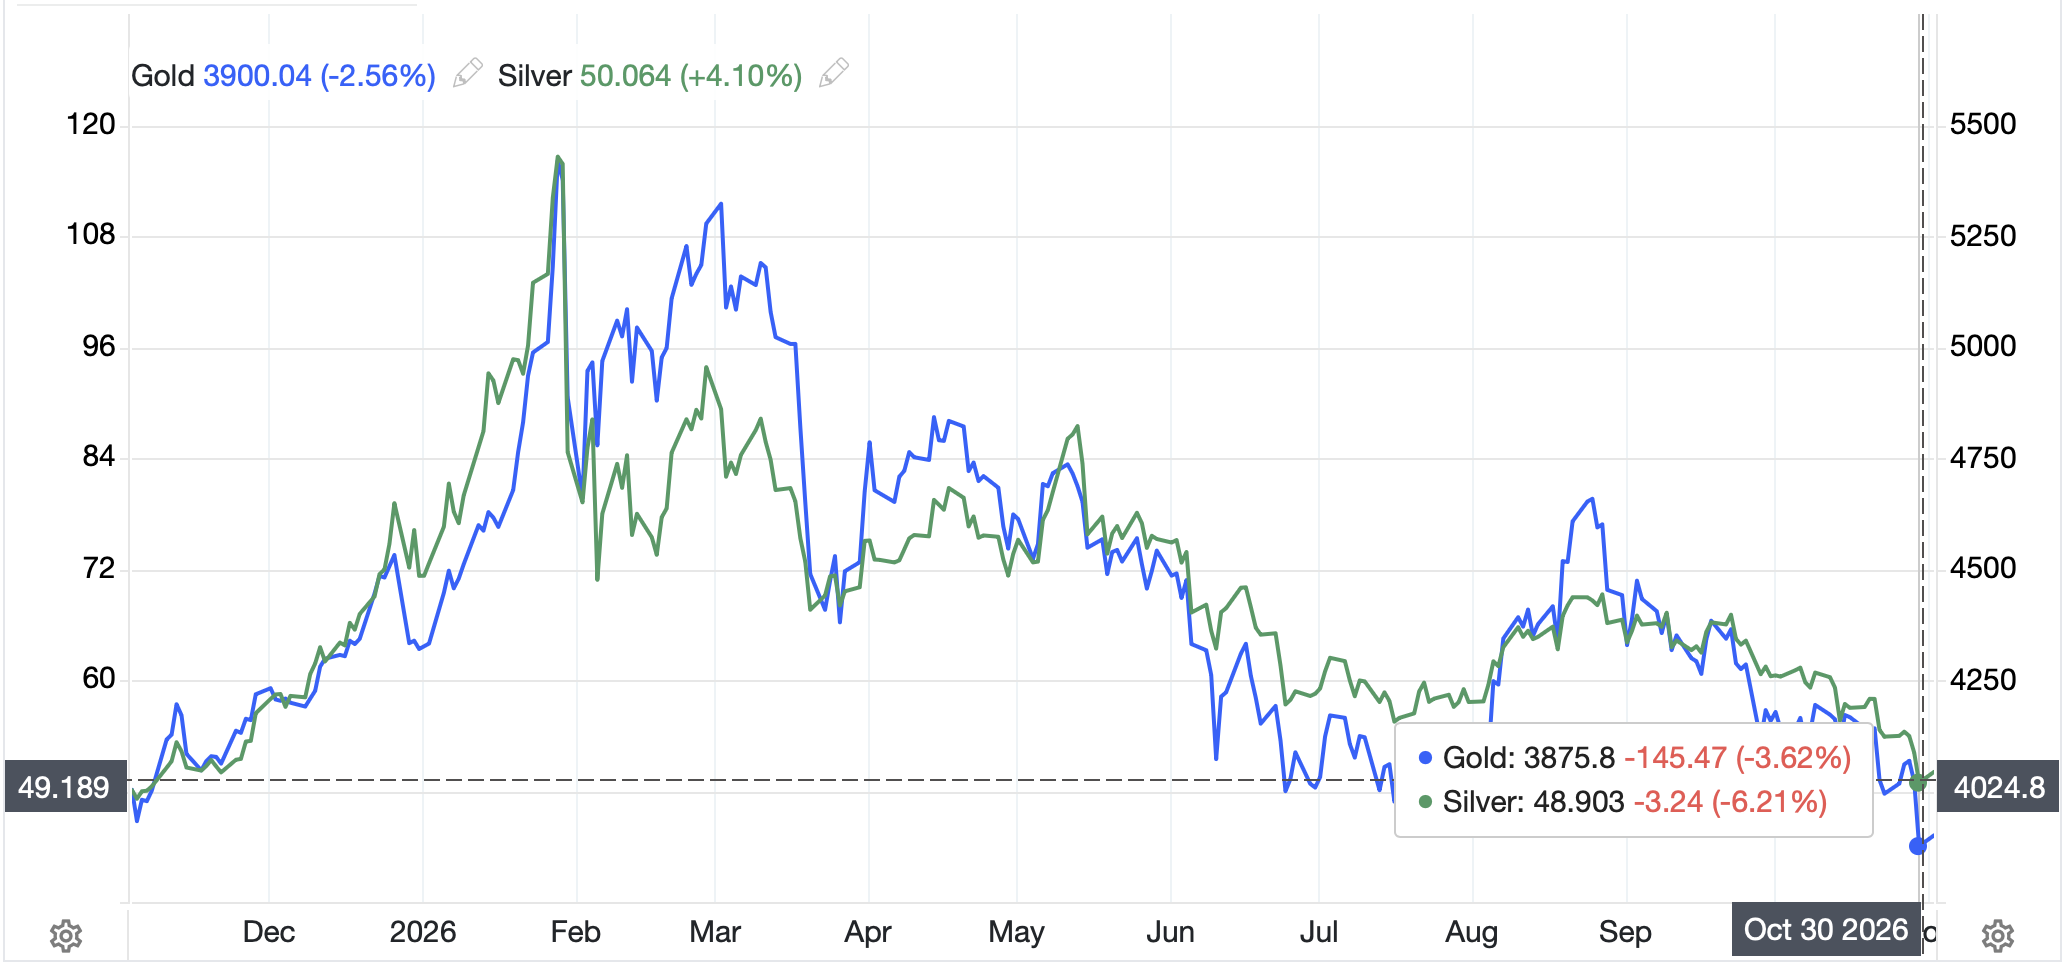
We cannot be surprised that metals markets have rebounded with the sharp decline in oil, so gold (+0.6%), silver (+2.3%) and copper (+0.4%) are all higher on the day. However, that said, Friday’s declines were sharp enough to take gold below $4000/oz and silver below $50/oz, levels that had been seen as key supports for the long-term bulls.
Source: tradingeconomics.com
Finally, the dollar is softer this morning, notably against the euro (+0.5%) and Swiss franc (+0.7%) although given the ongoing rioting in both places I am a bit confused by the price action. Too, the economic data was not encouraging, but the best I can distill is traders are forecasting a Democratic sweep in tomorrow’s elections. The yen (-0.2%) is not partaking, neither is Aussie (-0.3%) although we have seen real strength in CZK (+1.0%) and HUF (+1.0). Weirdly, PLN (+0.1%) is not doing very much despite both the wide range of today’s trading and the news about the coup/not coup.
As this is the first week of the month, there is a lot to see.
| Today | ISM Manufacturing | 54.6 |
| ISM Prices Paid | 77.0 | |
| RBA Interest Rate Decision | 4.85% (+25bps) | |
| Tuesday | JOLTs Job Openings | 7.13M |
| Factory Orders | 1.2% | |
| Wednesday | ADP Employment | 65K |
| Trade Balance | -$108.0B | |
| ISM Services | 54.8 | |
| Thursday | BOE Interest Rate Decision | 4.0% (+25bps) |
| Initial Claims | 195K | |
| Continuing Claims | 1710K | |
| Unit Labor Costs | 0.6% | |
| Friday | Nonfarm Payrolls | 65K |
| Private Payrolls | 58K | |
| Manufacturing Payrolls | 4K | |
| Unemployment Rate | 4.2% | |
| Average Hourly Earnings | 0.3% (2.9% Y/Y) | |
| Average Weekly Hours | 34.4 | |
| Participation Rate | 61.9% | |
| Michigan Sentiment | 48.2 | |
| Consumer Credit | $11.8B |
Source: tradingeconomics.com
So, plenty to digest along with the election results. Certainly, too much to describe at once. As I have been saying, I think the elections are the fulcrum and once we see how they play out, we will have a better chance to make sense of other things as depending on who wins, different things may be important. In the meantime, close to the vest and hedged remains the best thing you can be.
Good luck
Adf

