Fervor and Joy

The talk of the Street is the Fed,
While quiet this week, will soon shed
The higher for longer
Idea, with words stronger
That cuts are directly ahead
 
So, bonds are the new favorite toy
Of every hedge fund girl and boy
Since growth is now slowing
Investors are going
To buy bonds with fervor and joy


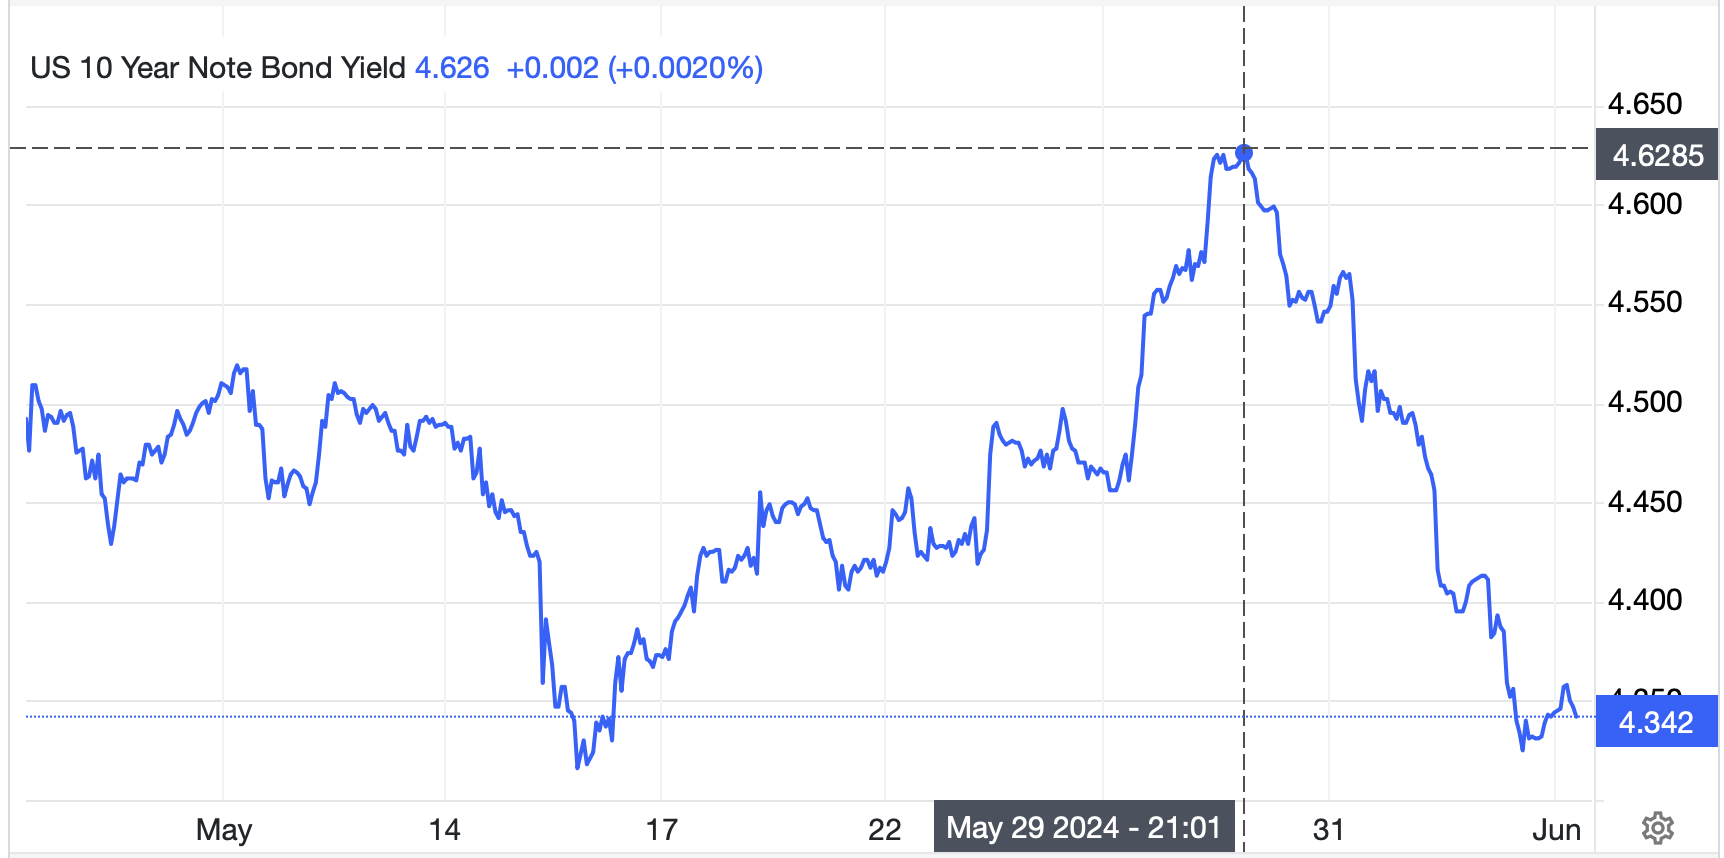
The amazing thing about markets is just how quickly they can shift their focus and reverse course if they find the right catalyst. Consider that just one week ago, 10-year Treasury yields were trading at 4.63%, having risen nearly 30 basis points in the prior two weeks on the strength of hawkish commentary from FOMC speakers, a much more hawkish than expected FOMC Minutes release, and economic data that indicated economic growth was still solid.
Source: tradingeconomics.com

And yet, in the past seven days, that entire move has been reversed and now the commentary is pointing to weakening economic activity, declining inflation, a looser jobs market and the inevitability of the Fed cutting rates before the election!  So, what happened?

Well, first, a little perspective is in order.  While a 30 basis point move in 10-year yields is a nice sized move, it is hardly unprecedented.  Consider that if we look at a chart of yields over just the past year, rather than the past month as above, the most recent dip does not stand out as particularly impressive.

Source: tradingeconomics.com

But second, the economic data in the US is starting to align more clearly in a negative fashion.  Yesterday I showed the Citi Surprise economic indicator index, which demonstrated that data is failing to keep up with forecasts.  Then yesterday, the JOLTS Job Openings data was released at a much diminished 8.059M, more than 300K jobs less than both anticipated and than last month.  In fact, despite this data point really looking backward (yesterday’s print was for April data), the recent trend, as seen below is very clearly lower.  
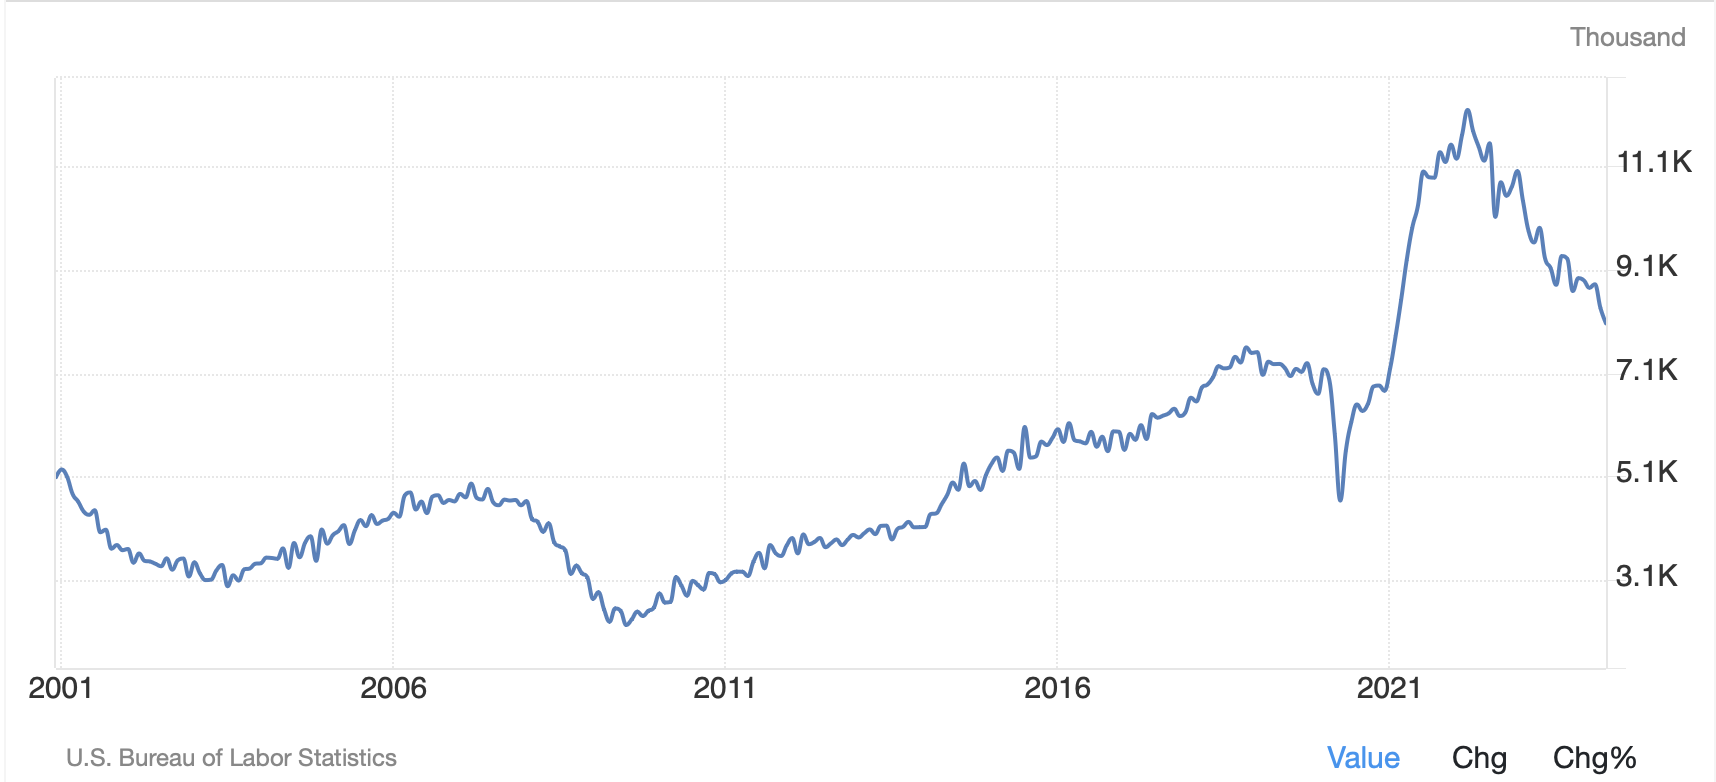
Source: tradingeconomics.com

This is an indication that the jobs market is much looser than the Fed had been worried about with regards to inflation, but of course is a problem for their maximum employment mandate.  In any event, the weaker data continues to pile up and the natural response of investors is to start to price in a more traditional weak growth scenario.  This includes declining bond yields on the assumption the Fed is going to ease policy, declining commodity prices on lessening demand, and a declining dollar on the back of those lower interest rates.  And that is exactly what we have seen.  

You will notice I left out the equity response to these events as I would contend it is far less clear.  Initially, I expect that equity investors will be excited by the prospects of rate cuts, and we could see stocks rally, but if growth is really slowing, then that is going to negatively impact earnings which should undermine equity prices.  Historically, when the Fed is cutting rates, it is in response to a slowing economy and equity prices have not fared well in this scenario.  You can see in the chart below, that the Fed tends to cut rates (orange line) during recessions (grey areas), and those declines are coincident with equity market (S&P 500 – blue line) declines.
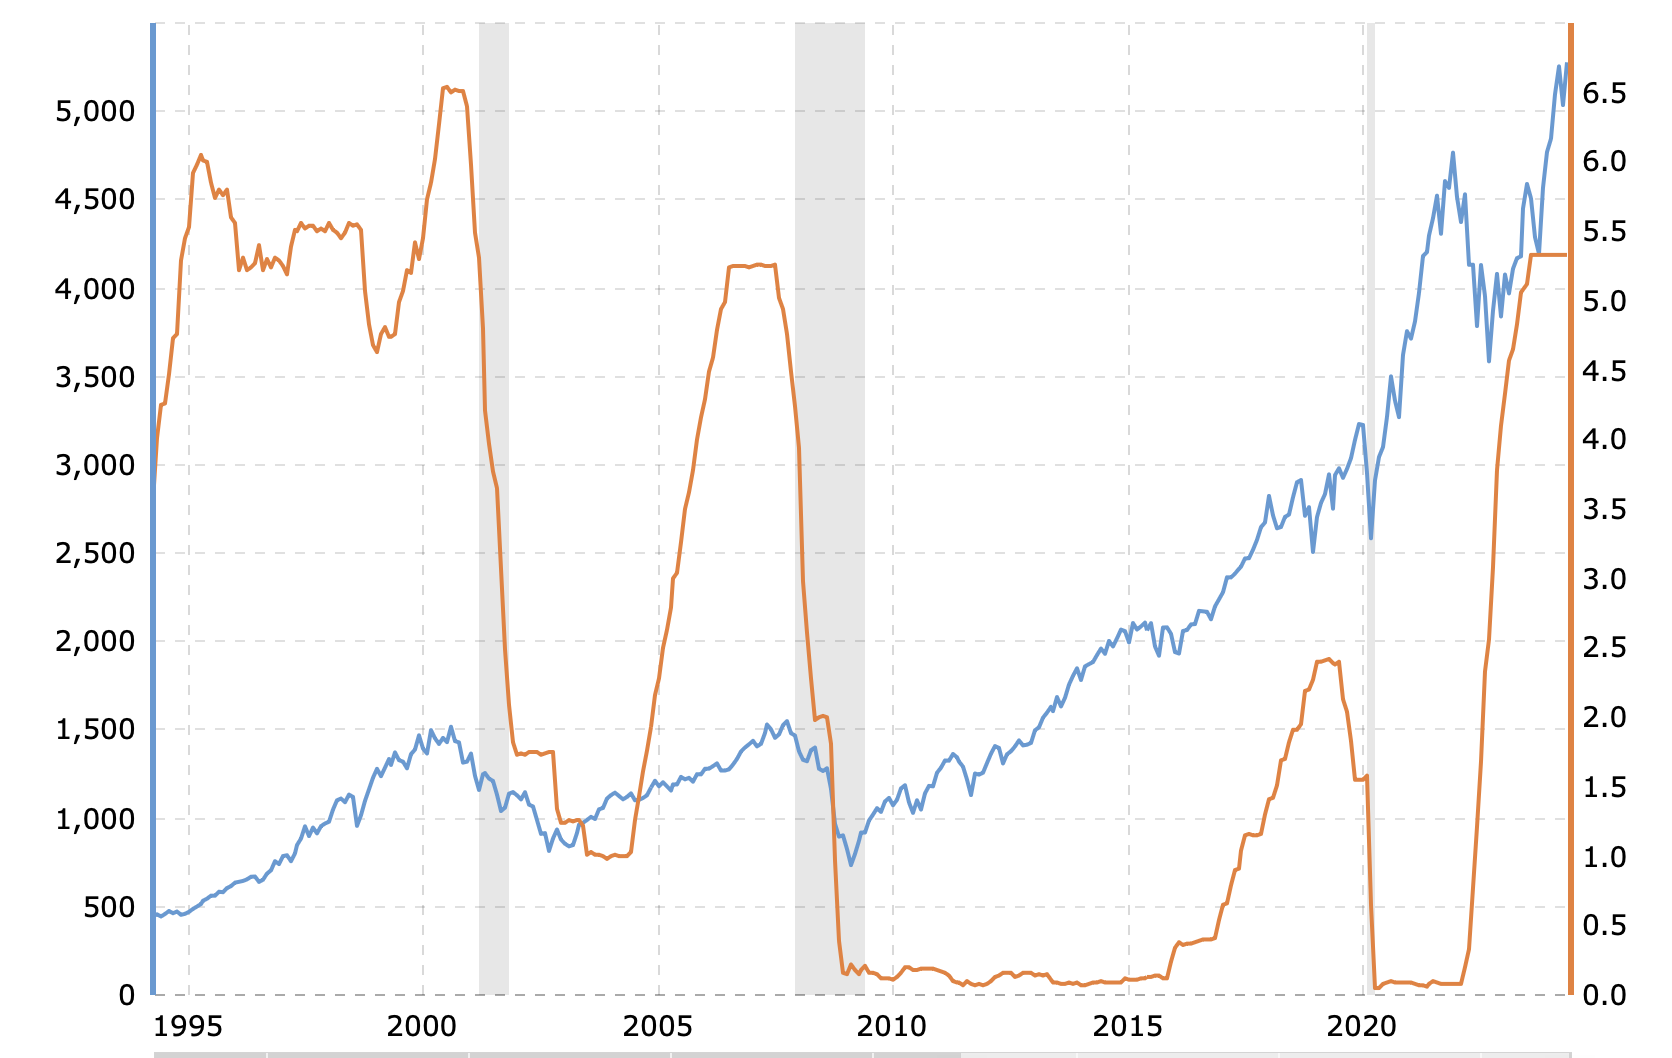
Source: macrotrends.net

So, has the economy turned down for real now?  I would contend there are more indicators that are widely followed which indicate that is the case.  Several months ago, one really needed to dig into the secondary parts of major releases to conclude things were rolling over.  Today, it seems a bit clearer.  But remember, too, Treasury Secretary Yellen has > $700 billion in the TGA to spend leading up to the election in an effort to prevent that outcome, and you can be certain she will do all in her power to do so.  Will it be enough?  I guess we will find out.  

One last thought, though, is that my take is the current sticky inflation may well remain sticky despite an economic slowdown.  Remember, there is a humongous amount of money around, and the response of every government will be to print even more if things slow, so the idea of stagflation remains very real and cannot be dismissed at this time.

Ok, let’s look at the overnight session to see how things have fared.  After yesterday’s late equity rally resulted in very minor gains in the US, Asia had a mixed session with both Japan (-0.9%) and China (-0.6%) lower, although there were gains throughout the region led by India (+3.6%) rebounding from the initial election news there.  PM Modi will continue ruling, but in a coalition, so with much reduced power.  But Korea, Australia and Taiwan all performed well.  In Europe this morning, equity markets are having a good day with gains on the continent around 0.9% across the board although UK stocks are only higher by a bit (0.3%).  PMI Services data was released, and it was generally a touch better than forecasts (France excepted) but certainly not significant enough to change the view that the ECB is going to cut rates tomorrow.  Meanwhile, US futures are picking up at this hour (8:00), rising 0.3% across the board.

We discussed bonds earlier but not the fact that Treasury yields fell 7bps yesterday after the softer data, dragging European yields down as well.  This morning, Treasuries are another 1bp softer with Europe sliding by between 1bp and 4bps.  Overnight, yields also fell, with JGB’s down 2bps and now right back at 1.00%, while other bonds in Asia saw yields fall more sharply.  It seems pretty clear that the market is starting to price in a global slowdown in the economy.

In the commodity sector, after a week of routs, things have settled this morning with oil (+0.5%) bouncing slightly, although still lower by -7% in the past week.  Gold (+0.25%) too, is a bit firmer, although that was not the metal that fell most sharply.  Both silver and copper are unchanged this morning as the bullish long-term story mongers (present company included) are all licking their wounds, but absent more weak data, there is no incentive to sell things aggressively here right now.  However, if the data keeps softening, so will these prices.

Finally, the dollar, which had fallen earlier in the week, has edged up a touch this morning.  JPY (-0.6%) is giving back some of its recent haven inspired gains, and we have also seen both MXN (+0.9%) and INR (+0.25%) recoup a small amount of their election related losses.  ZAR (-1.0%), however, is still under pressure as the weakened state of the government combined with the weakness in metals prices is clearly a major weight on the rand.  All eyes today will be on CAD (unchanged) as the BOC meets and will be announcing their rate decision at 10:30. There is a 60% probability of a rate cut priced into the market, as recent data softness is getting traders excited that Governor Macklem will ignore his recent comments about needing “months of data” to confirm the situation.  After all, inflation up there is within the BOC’s range, and I suspect a cut is coming.

On the data front, ADP Employment was just released at a slightly softer than forecast 152K (exp 170K) and then we see ISM Services (50.8) at 10:00am.  As of yet, there has been no real response to the ADP data.  At this point, the narrative is swinging quickly to the idea that softer economic activity will lead the Fed to cut sooner than previously expected.  The Fed funds futures market has moved the probability of the September cut up to nearly two-thirds.  For now, that is going to drive things, and as such, I believe the dollar will remain under pressure overall.  Absent a very strong NFP report Friday, perhaps we have seen some near-term tops in yields and the dollar.

Good luck

Adf

Kind of a Mess

The narrative which had been forming
Was prices were constantly warming
While job growth was strong
The bears were all wrong
And buyers of stocks were now swarming
 
But Friday the data was less
Impressive, and kind of a mess
At first, NFP
Was weak, all agree
Then ISM caused more distress


It is remarkable how quickly a narrative can change, that’s all I can say!  One week ago, the story was all about how the economy continued to perform well overall, that inflation remained sticky at levels higher than targeted and that the Fed would stick with higher for longer with a chance of a rate hike on the table.  This morning, in the wake of a clearly dovish Powell press conference and softer than expected ISM and employment data, the narrative appears to be coalescing around the idea that cuts are back on the table while a recession can no longer be ruled out.

The table below, courtesy of the Chicago Mercantile Exchange, shows the current probabilities for Fed funds based on futures pricing for the December 2024 contract as well as how they have evolved over the past week and month.

Source: CME

When calculating how much is priced into the market, one simply multiplies the size of the cut by its stated probability and voila, the answer appears.  To save you the trouble of doing the math, the current market pricing shows that as of this morning, the market is pricing in 47.6bps of cuts by year-end, so essentially two cuts.  One week ago, that number was 34.8bps while one month ago it was 65.7bps.  in other words, we have seen a bit of movement in this sentiment indicator.  And really, that’s exactly what this is, a measure of the market’s sentiment and expectations of how Fed funds are going to evolve over time.  

What should we make of this information?  Well, anecdotally, for the past several weeks I have not been reading about recession at all.  The no-landing scenario seemed to be the favorite as the soft-landing idea ebbed amid too high inflation readings.  But this morning, in concert with the Fed funds futures market, I have seen several stories discussing that a recession is on the horizon now and coming into view.  The ISM data was clearly a problem as both the Manufacturing (49.2) and Services (49.4) numbers slipped below the 50.0 boom/bust line while the Chicago PMI release was abysmal at 37.9.  Even worse, the Prices paid data for both Manufacturing (60.9) and Services (59.2) rose sharply, exactly what Chair Powell did not want to see.  In fact, this data rhymes with the Q1 GDP data which showed the mix of activity was turning toward less growth (1.6%) and more inflation (3.7%) for a given amount of activity.

Now, Powell was very clear that he saw neither the ‘stag’ nor the ‘flation’ sides of the idea that the US was slipping into stagflation, and certainly compared to the situation in the 1970’s, we are nowhere near that type of situation.  But there is a bit of whistling past the graveyard here, I believe, as slowing real growth and rising prices are not the combination that any central bank wants to have to fight.  When Mr Volcker took over the role as Fed Chair in 1979, he pretty quickly decided that it was more important to fight inflation first, and deal with any recession later, hence the double-dip recessions of 1980 and 1982.  But that set the stage for structurally lower interest rates for two generations.

Based on Powell’s press conference comments as well as the tone of many of the mainstream media stories that are currently in print regarding the economic situation, it appears to this poet as though Mr Powell may be far more willing to allow inflation to run hotter than target for longer as he tries to prevent a sharp recession, especially ahead of the presidential election.  With rate hikes no longer an option, any semblance of higher inflation will be met with words alone, and that will not do the trick.  I have maintained for a long time that if the Fed eased policy before inflation was squashed, it would be bad for bonds, bad for the dollar and good for commodities and stocks.  I am now coming to believe that we are entering this environment, and that while the initial move in bonds may be higher (lower yields) as it becomes clear that inflation remains with us, bond investors will quickly decide that the risk/reward in an inflationary environment is quite poor, and we will see the back end of the curve sell off.

After those cheery thoughts for a Monday morning, let’s look at how markets have behaved overnight.  Friday’s rip-roaring rally in the US was mostly followed by strength throughout Asia where markets were open (Japan and South Korea were closed) with China, Hong Kong, Australia, and Taiwan all having good sessions, up between 0.75% and 1.25%.  It should also be no surprise that European bourses are all in the green this morning as rate pressures eased and adding to the happiness were PMI Services reports that were generally on target or slightly better than the flash numbers.  In other words, all is right with the world!  Finally, US futures are also firmer by a bit this morning, up 0.2% or so with the main talk still about Apple’s massive stock repurchase program as well as the Berkshire Hathaway AGM this past weekend.

Of course, bonds were the big mover on Friday, with yields plummeting in the wake of the softer than expected NFP data, where not only were claims lower, but so was earnings data and the Unemployment Rate ticked up to 3.9%.  The initial move was a 9bp decline in the 10yr and and 10bps in the 2yr although by Friday’s close, both markets had retraced half of those declines.  This morning, though, yields are sliding again with 10yr Treasuries down 3bps and all European sovereigns following suit, falling 4bps.  (As an aside, on Friday, the European yields followed Treasuries tick for tick.). With Japan closed, there was no JGB movement overnight.

In the commodity markets, crude oil (+1.0%) is bouncing today from yet another weak performance on Friday as the weaker economic data is weighing on the demand story there.  However, regarding geopolitics and the middle east, this morning’s headlines regarding Israel telling Palestinians to leave Rafah has the market on edge.  But metals markets are back on fire this morning with both precious (Au +0.7%, Ag +2.1%) and industrial (Cu +2.0%, Al +1.1%) rallying on the lower interest rate, higher inflation story that is percolating through markets.

Finally, the dollar, too, is under pressure this morning continuing its trend from last week, although it is not collapsing by any stretch with the DXY still trading just above 105.00.  There is a great deal of discussion as to whether the BOJ/MOF have been successful in their efforts to stem the yen’s decline permanently.  It is clear that their two bouts of intervention (neither officially admitted) has done a good job in the short run.  The story here, though, is all about interest rates.  If, and this is a big if, the Fed is truly turning their sights on cutting rates with any help at all from inflation showing signs of ebbing again, then the higher dollar thesis is going to run into real trouble.  I have made no bones about the idea that the dollar’s strength was entirely reliant on the fact that the Fed was the most hawkish of all the main central banks.  If that is no longer the case, then the dollar is going to come under universal pressure and the yen probably has the most to recover.

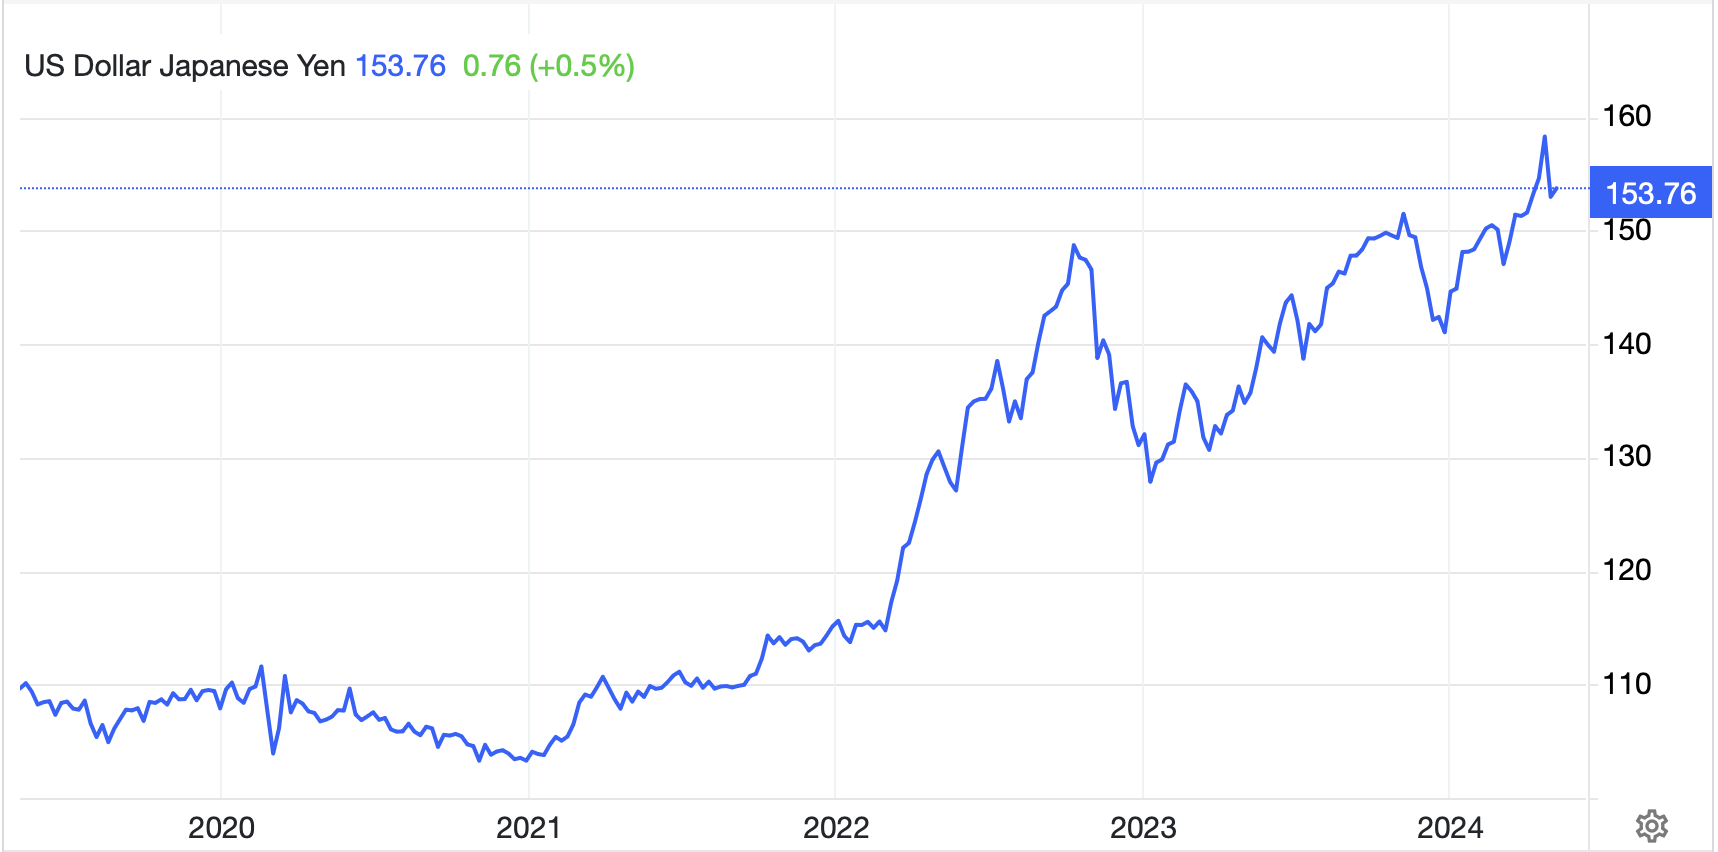
**This is really critical for JPY asset and receivables hedgers.  There is no better time to consider using purchased options or zero premium collars than right now.  If the recent movement is a head fake, and the inflation story in the US grows such that the Fed puts hikes back on the table, then you will have put hedges in place.  But…if this is the beginning of a truly new narrative, where US rates are going to decline, USDJPY can fall a very long way in a very short time.  Look at the 5-year chart of USDJPY below.  It was in 2022 when USDJPY was trading at 115 and that had been the level for several years.  we can go back there in a hurry, believe me!**

Source: tradingeconomics.com

As to the rest of the currencies out there, you will not be surprised that ZAR (+0.5%) is top of the heap this morning although a thought must be given to CLP’s 2.25% gain on Friday (market not open yet) as it rallied alongside copper’s rally.  Ironically, the one currency that is under pressure this morning is JPY (-0.5%), but remember, it has risen 4% from the levels when the BOJ first intervened, so a little bounce is no surprise.

Turning to the data this week, it is an incredibly light week, with CPI not coming until next week.

TuesdayConsumer Credit$15B
ThursdayInitial Claims212K
 Continuing Claims1895K
FridayMichigan Sentiment77.0
Source: tradingeconomics.com

As well, we have eight Fed speakers including NY president Williams and vice-Chair Jefferson.  It will be very interesting to hear how they play the apparent pivot.  While I expect that the governors are all on board, the regional presidents will have more leeway to speak their mind I believe.

And that’s what we have for today.  I believe that things have changed and that the Fed is now very clearly far more willing to allow inflation to run hotter.  Be very wary of your bond positions and watch for the dollar to remain under pressure until something else changes.

Good luck

Adf

‘Voiding a Crisis

There once was a fellow named Jay
Whose job, as it works out today
Is managing prices
And ‘voiding a crisis
A mandate from which he can’t stray
 
The problem he has, as it stands
Is others are tying his hands
So, prices keep rising
And he’s now realizing
He’s no longer giving commands

Friday’s PCE data was not as hot as some had feared, but certainly showed no signs of cooling.  To recap, the M/M numbers for both headline and core were 0.3%, as expected, although at the second decimal they must have been higher because both Y/Y numbers were higher than expected at 2.7% headline and 2.8% core.  As can be seen in the chart below from tradingeconomics.com, both the core (blue line) and headline (gray line) have the appearance of having bottomed.

While things certainly could have been worse, especially based on the price deflator data we saw in the GDP report, this cannot have helped Chair Powell’s attitude.  Remember, too, that 0.3% rises annualize to a bit more than 3.6%, far higher than the ostensible target.  The inflation fight has not yet been won by the Fed although I expect that we are going to hear a lot of commentary going forward that it has.  Wednesday brings the FOMC meeting, something on which we will touch tomorrow, and obviously a critical aspect of the discussion.  One other thing, given the data was not as hot as feared, it took until yesterday for the Fed whisperer to write his article, which was focused on the long-term neutral rate rather than inflation per se.

Did they sell or not?
Looking at charts, possibly
But they’ll never say

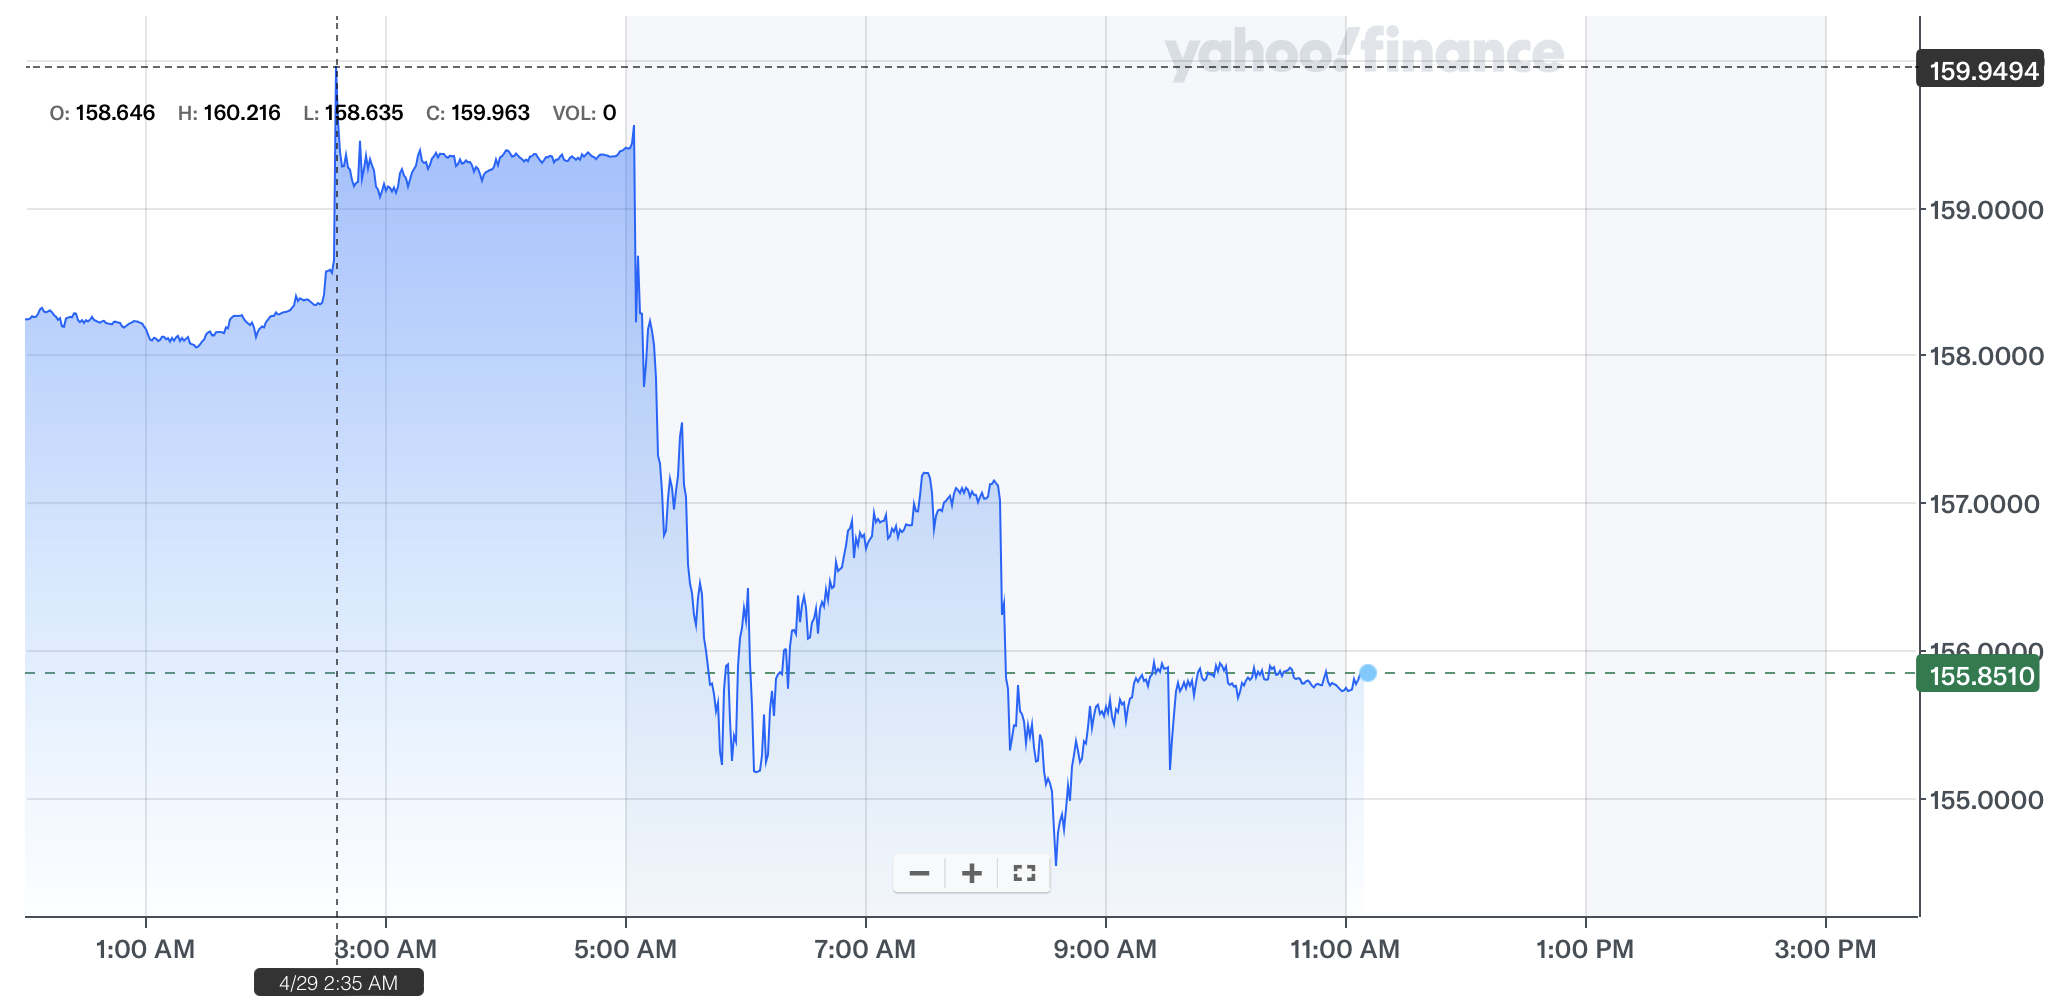
The next story of note was the fact that USDJPY trade above 160 last night, during the early hours of the session.  As can be seen from the below chart from yahoo finance, it seemed to have touched 160.216 before slipping back to the mid-159’s and then collapsing a few hours later, back to its current state just below 156.

Something to remember is that it is golden week in Japan, with the nation on holiday yesterday so banks were, at most, running skeleton staffs of junior traders and market liquidity was significantly impaired.  But the question today is, did the BOJ intervene on behalf of the MOF.  From what I have been able to glean, there was significant selling by the big three Japanese banks, certainly a sign that intervention was possible.  Of course, the chart shows how sudden the decline was, also an indication that it could have been intervention.  The best explanation I have heard for the initial move above 160 was it was some bank(s) running stop-losses at the level, as well as triggering barriers there in the options market.  At this hour (6:15), the yen has appreciated by 1.6% from Friday’s closing levels.  However, I sincerely doubt that we have seen the end of the weakness in the yen.  This is especially true if Chair Powell comes across as more hawkish on Wednesday, something that is clearly quite possible.

The last thing to note for today
Is Yellen and her QRA
How much will she borrow?
And Wednesday, not ’morrow
We’ll learn if more bonds are in play

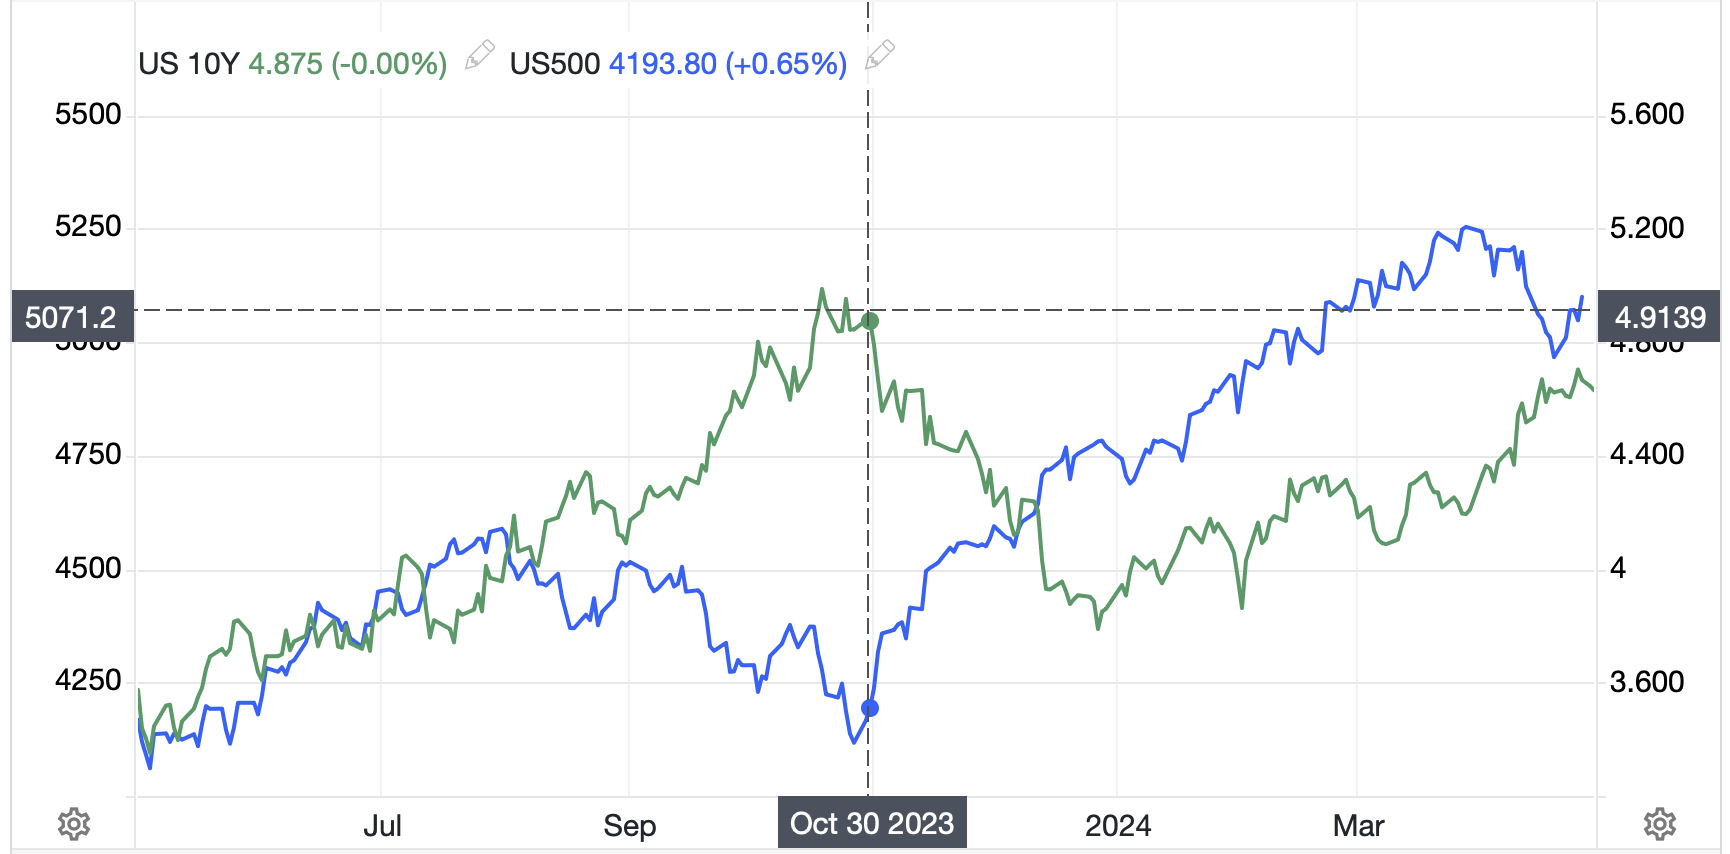
This brings us to the Quarterly Refunding Announcement (QRA) to be released at 3:00 this afternoon.  While historically, the only people who cared about this report were bond market geeks, it has gained a significant amount of status since the October 31st announcement where the Treasury indicated it would be issuing less debt than had been expected.  That led directly to the massive bond market rally at the end of last year as well as the concomitant stock market rally.  Looking at the below chart from tradingeconomics.com, it is pretty clear when things turned around, and it was right when the QRA came about.

Once we know the borrowing plans from this afternoon, we will learn on Wednesday the mix of borrowing that will be coming, and whether Secretary Yellen will continue to issue a more significant amount of debt in T-bills, or if she will try her hand at notes and bonds again.  Given that yields have been climbing lately, I suspect there will be more T-Bill issuance than is the historic norm, which has been about 20% of total borrowing, but perhaps not the 80% she issued last quarter.  Ultimately, the real concern today is that the estimated borrowing numbers could be larger than current forecasts, and perhaps just as importantly, the question of just how much was borrowed last quarter.  The sustainability of this process is starting to be called into question although I don’t expect anything to happen quite yet.  

Ok, that’s enough for one day!  A quick recap of the overnight session shows that Chinese shares rallied on the back of news from Beijing that the government was relaxing some regulations in the property sector.  In fact, that was sufficient to help all Asian equity markets higher on the order of 0.5% – 1.0%.  Meanwhile, European bourses are mixed this morning with both the DAX and CAC little changed, the FTSE 100 edging higher by 0.5%, but other continental exchanges under pressure.   As to US futures, they are very modestly higher this morning after Friday’s rally.

In the bond market, after modestly higher yields on Friday, this morning is seeing Treasury yields slip 4bps and European sovereigns fall between 5bps and 7bps.  Clearly, there is not much concern that the QRA is going to indicate massive new borrowing, but I guess we will know this afternoon.  

Commodity prices are on the quiet side this morning with oil basically unchanged, as is gold as both hold onto last week’s gains.  However, copper (+0.5%) continues to rally and is now just $0.30/pound below its all-time highs of $4.89.  There are many stories regarding the copper market with some discussing hoarding by the Chinese and others focused on the needs of the ongoing ‘energy transition’ which will need significant amounts of the red metal to electrify everything.  While it has run up quite quickly of late, I must admit the long-term view remains positive in my mind between the absence of new mines and the needs of the transition although a pullback would not be a surprise.

Finally, the dollar, aside from vs. the yen, is generally lower across the board.  While it remains in the upper end of its recent trading range, it appears the sharp decline in USDJPY has had knock-on effects elsewhere. The financial currencies, like EUR (+0.3%), GBP (+0.4%) and CHF (+0.3%) are all firmer as are the commodity bloc (NOK +0.3%, ZAR +0.45%, AUD+0.5%).  In fact, I am hard-pressed to find a currency that is underperforming the greenback.  Positioning in dollars has been quite long lately so ahead of this week’s FOMC meeting as well as the NFP on Friday, it is quite likely that we are seeing a little reduction in those positions.  However, we will need to see a change in the data to change the longer-term view.

Obviously, there is a ton of stuff coming out this week.

TodayQRA 
TuesdayEmployment Cost Index1.0%
 Case Shiller Home Prices6.7%
 Chicago PMI44.9
 Consumer Confidence104.0
WednesdayADP Employment 179K
 ISM Manufacturing50.1
 JOLTS Job Openings8.68M
 FOMC Rate Decision5.50% (unchanged)
ThursdayInitial Claims212K
 Continuing Claims1782K
 Nonfarm Productivity0.8%
 Unit Labor Costs3.2%
 Factory Orders1.6%
FridayNonfarm Payrolls243K
 Private Payrolls180K
 Manufacturing Payrolls7K
 Unemployment Rate3.8%
 Average Hourly Earnings0.3% (4.1% Y/Y)
 Average Weekly Hours34.4
 Participation Rate62.7%
 ISM Services52.0

Source: tradingeconomics.com

In addition to all this, on Friday we will hear from two Fed speakers, Williams and Goolsbee, and I imagine if they are unhappy with the market response to their messaging on Wednesday, we will hear from more.

Ultimately, this is an important week to help us understand how things are going in the economy and how the Fed is thinking about everything.  As long as payrolls continue to hang in there, any chance of Fed dovishness seems to diminish by the day.  But stranger things have happened.  As to the dollar, today’s position adjustments make sense and I suspect there will be a few more before the big news hits on Wednesday and Friday.  Til then, I think all we can do is watch and wait.

Good luck

Adf

Debased

Said Powell, the path is still clear
For cutting three times all this year
Though data’s been hot
We’ve certainly not
Decided no rate cuts are near

This was, of course, warmly embraced
By traders who bought shares post-haste
But do not forget
The very real threat
The dollar will, thus, be debased

Chairman Powell regaled us once again and yesterday he sounded far more like the December Powell than the March Powell.  Notice in his comments that he has essentially dismissed the recent hotter than expected inflation data and instead insists they are on the right road to achieve their goal.  He explained [emphasis added], “The recent data do not…materially change the overall picture, which continues to be one of solid growth, a strong but rebalancing labor market, and inflation moving down to 2% on a sometimes bumpy path.” And maybe he is correct.  Maybe the January and February data points are the outliers, and the rate of inflation is going to reverse back lower.

But he has to know that when he coos like a dove, risk assets are going to rally sharply.  The difference today is that the bond market is beginning to ignore all the Fed talk as we see despite these dovish tones, yields remain at their highest level (4.36%) since November, with no downward movement at all.  In fact, perhaps the real concern that the Fed should have is that gold continues to rise strongly almost every day, trading to $2300/oz and showing no signs of slowing down.

I have been consistent in my view that if the Fed cuts despite the ongoing better than expected data the result would be a sharp decline in the dollar, a sharp decline in bond prices (rise in yields) and a sharp rise in commodity prices.  I have also indicated that, at least initially, I expected equities to rally, but their medium-term outlook was more suspect.  Well, yesterday, that was exactly how the market behaved with metals markets screaming higher, stocks trading well and bonds lacking any bids.

Yesterday’s data showed the ADP Employment number jumping 184K, well above expectations of 148K, but the ISM Services data was a bit soft at 51.4 (exp 52.7) and more importantly, the Prices sub-index fell to 53.4 down 5 points from last month.  That was the set-up for Powell’s comments, and he jumped on board.  It remains abundantly clear that the Fed is desperate to cut rates almost regardless of the economics.  My take is the reason has more to do with the debt situation than the presidential election although there is a third possible explanation as well, a too-strong dollar.

Consider the following: the dollar remains the world’s reserve currency and the currency most widely used in trade and financing activity.  Because of this, a large majority of the world’s total outstanding debt of approximately $350 trillion is denominated in dollars despite the fact that most companies and countries are not USD functional.  The result of this situation is that all those non-USD functional debtors need to buy dollars in order to service and repay that debt.  If you were looking for an underlying reason as to the dollar’s broad strength, this is another candidate in the mix.

As such, it is entirely realistic that Chairman Powell is feeling intense pressure from the international community to cut interest rates to weaken the dollar.  While I don’t expect that a Plaza Accord type agreement is in the offing, it is possible that Powell sees this as an achievable outcome and one that would not result in global chaos.  However, whatever the reason, as we watch commodities rally, while the dollar and bond market sell off, we are watching Fed credibility dissipate.

Ok, let’s peruse the overnight session to see how markets have responded to the dovish version of Powell. While US equities sold off late in the day yesterday, minimizing gains, the same was not true overseas.  Though Chinese markets were closed for the Ching Ming Festival, pretty much everywhere else in Asia saw equity rallies of substance with the Nikkei’s 0.8% rise a good proxy for all.  Meanwhile, in Europe the screens are all green as well, although not quite as impressively, more on the order of 0.25% – 0.5%.  This performance is in accord with Services PMI data that was released this morning showing broadly better than expected outcomes across all the major nations as well as the Eurozone as a whole.  Finally, US futures at this hour (6:45) are firmer across the board by 0.25%.

In the bond market, Treasury investors do not see the benefits of Powell’s dovish turn amid still high inflation.  The ADP data is certainly a concern as all eyes turn toward tomorrow’s NFP report.  In fact, what we are seeing is a bit of a curve steepening (less inversion) with the 10yr-2yr inversion now down to -31bps from its -40bp level that had been steady for the past several weeks.  However, European sovereign yields are all a touch lower this morning, down between 2bps (Germany) and 6bps (Italy) as comments from Robert Holtzmann, Austrian central bank chief and the most hawkish ECB member finally conceded that a cut in June could be appropriate.  Of course, now there is talk of a cut at the end of this month weighing on yields.  Meanwhile, JGB yields crept higher by 1bp, but remain at 0.75%, showing no signs of running away higher.

Oil prices (-0.3%) are consolidating this morning after yet another positive session yesterday with WTI now trading above $85/bbl and Brent crude just below $90/bbl.  OPEC reconfirmed that production would remain at current levels and two nations, Iraq and Kazakhstan have promised to cut back to bring their numbers back in line with quotas.  As well, EIA data showed a build in crude but a much larger draw in gasoline stocks (which is why prices are rising at the pump) adding support to the market.  Gold (-0.1%), too, is consolidating this morning but the trend remains strongly higher.  At the same time, copper (+0.5% today, +5.75% this week) is continuing its rapid rise and is back to levels last touched in January of last year.  It appears the broader growth story remains a driver here, especially with the idea that the Fed may be cutting rates and goosing it further.

Finally, the dollar is under a bit more pressure this morning after Powell’s dovish stance, sliding against most of its counterparts in both the G10 and EMG blocs.  AUD (+0.65%) and SEK (+0.65%) are the leaders in the G10 space with most of the rest of the bloc following higher.  One exception is CHF (-0.4%) which has fallen after CPI there fell to 1.0% Y/Y (0.0% M/M) and encouraged traders to bet on faster rate cuts from the SNB.  The yen (-0.1%) too, is not following suit, which perhaps indicates we are seeing a reversion to the classic risk-on stance (higher stocks and commodities, weaker dollar and havens), at least for today.  In the emerging markets, most currencies are firmer led by (CLP +0.6% on copper strength) and HUF (+0.4%) which is simply demonstrating its higher beta relative to the euro, although there are key currencies that are little changed like MXN, BRL and CNY.

On the data front, this morning brings the weekly Initial (exp 214K) and Continuing (1822K) Claims data as well as the Trade Balance (-$67.3B).  As well we hear from five more Fed speakers (Barkin, Goolsbee, Mester, Musalem, and Kugler) to add to yesterday’s comments.  The question I would ask is, even if some of them sound more hawkish, given what we just heard from Powell, will it matter?  For instance, yesterday, Atlanta’s Raphael Bostic reiterated his stance that one cut was likely all that was necessary this year and nobody heard him speak, effectively.  We would need to hear every one of them vociferously defend the current stance and call for zero cuts to have an impact.  And that ain’t happening!

With Powell showing his dovish feathers, the dollar is going to remain under pressure while asset prices perform.  I think that’s the most likely outcome ahead of tomorrow’s data, where a particularly hot number could change things.  But we will discuss that then.

Good luck
Adf

Cooed Like Doves

Well, Jay and the Fed cooed like doves
And treated the bulls with kid gloves
But under the hood
Was it quite so good?
It’s clear number up’s what he loves!
 
The upshot is stocks really soared
As everyone’s sure Jay’s on board
To cut first in June
And thrice when Cold Moon
Is seen, near the birth of our Lord


Whatever the pundits thought about the hottish inflation readings in January and February, they clearly did not read the room properly, at least not the room in the Eccles Building.  Despite raising their 2024 forecasts for GDP growth (2.1% from 1.4%) and Core PCE (2.6% from 2.4%), as well as maintaining their forecast for the Unemployment Rate to remain quiescent (4.0% to 4.1%), they are hell-bent on cutting rates this year, with June still the most likely starting point.  I created a little table to show, however, that perhaps the consensus is not quite what the headlines would have you believe.

 DecMar
 MedianAvgMedianAvg
20244.6254.7044.6254.809
20253.6253.6123.8753.783
20262.8752.9473.1253.066
Longer Term2.5002.5862.6252.813

Source: Data FRB, calculations @fx_poet

The highlighted points show that while the median for 2024 remained the same, the average was nearly a full cut less.  In fact, if one more member had adjusted their forecast higher, the median would have come out for just 2 cuts this year.  But as I wrote yesterday, perhaps of more importance is the Longer Term view, where not only did the median rise by 12.5bps, but the average is substantially higher, a full 25bps higher than the December views.  

However, the market has ignored this wonkish number crunching and accepted the numbers at face value; three cuts this year and three more next year helping drive equity prices to yet another set of new all-time highs.

Regarding the tapering of the balance sheet, Powell explained at the press conference that they had, indeed, discussed the topic as they were trying to determine the best way to continue the process without any untoward events, but that is not the issue.  The issue is…BUY STONKS!!!

I would estimate that Chairman Powell is pretty happy with the outcome and am certain that Secretary Yellen is very happy with the outcome.  After all, the equity rally continued while bond yields managed to drift lower by a couple of basis points.  But the really happy campers are the holders of gold which rallied more than 1% and traded above $2200/oz for the first time ever.  The market has reviewed this outcome and decided that the biggest risk going forward is a further devaluation of the dollar vs. stuff, although vs. other fiat currencies it is likely to hold its own.  In other words, inflation ain’t dead.  I expect the bond market to determine this is the case over the next several weeks and see yields rising further, especially if the PCE data next week is hot again.

While Jay may have had the most press
In Switzerland, Tom did aggress
He cut twenty-five
In order to drive
Their growth with a bit more largesse


This morning, we have seen three more G10 central banks and the only surprise comes from Switzerland, where soon-to-retire President, Thomas Jordan, cut their base rate by 25bps to 1.50%.  While there were several analysts who had suggested this might be the case (including this poet on Monday), the bulk of the market was in the no change camp.  However, cut they did, and the result was an immediate 1.1% decline in the Swiss franc, arguably a key part of their goal.  In the statement, they explained that inflation had been well within their target range, and they would have the tool of further currency intervention if they felt the franc was weakening too much.

One theory on the surprise cut is that the SNB wanted to get ahead of the pack as they only meet 4 times each year and their next meeting is after the June Fed and ECB meetings.  As well, many pundits are now saying this is the “proof” that the Fed and ECB are going to cut in June.  My take is that while I agree the ECB is a done deal come June, I think the Fed may have a tougher time as there is still no evidence that inflation is heading back to their 2% target.  We have two more CPI and PCE reports before the June meeting, and if the recent price activity continues (and given energy prices remain buoyant I expect they will), it will be very difficult for Chair Powell to explain the need to cut rates unless Unemployment is surging.  Perhaps that will be the case, but right now, the data does not indicate things are collapsing.  The next three months should be quite interesting.

Ok, let’s see how other markets have responded to Powell and the SNB surprise.  Equity markets are in a happy place right now after records fell in the US yesterday.  The Nikkei (+2.0%) also set a new record and the Hang Seng (+1.9%) continued its recent rebound.  In fact, only mainland Chinese stocks couldn’t muster a rally last night, with every other nation in APAC in the green, often by more than 1%.  In Europe, though, the picture is a bit more mixed with more gainers than losers, but still several nations seeing modest pressure on their equity indices.  It should be no surprise that Swiss stock markets are higher, but France and Denmark are suffering somewhat today.  The best performer is the UK (+0.9%) which seems to be benefitting from a solid uptick in its Flash Manufacturing PMI (49.9, exp 47.8).  Lastly, in what should not be a surprise at all, US futures are pointing higher across the board.

In the bond market, all is right with the world this morning as there are bids everywhere with yields declining correspondingly.  Treasury yields slipped another 4bps overnight and throughout Europe, we are seeing declines between 3bps and 5bps with Swiss bonds lower by 7bps.  In fact, Asia is where things were modestly different as JGB’s remain unchanged (tighter policy remains an idea not a reality yet) and Australian yields rose after much stronger than expected employment data was released last night.

In the commodity space, oil (-0.25%) is a touch softer after a decline of more than 1% during yesterday’s session.  With all the focus on the Fed, there was not a lot of news driving things here specifically.  But the real winner in the commodity space is gold (+1.0%) as the market appears to be calling BS on the Fed’s inflation and QT forecasts.  The thing to remember about gold is it is not so much a good hedge for consumer inflation, but it is a very good hedge for monetary inflation (i.e. the excess printing of money).  While those two inflations tend to be correlated, they are not tick for tick, so gold seems to be amiss at times.  But the very idea that despite ongoing inflationary pressures, and the continued supplying of liquidity by the global central banking cast, is the right time to cut interest rates is a step too far for gold markets.  I believe this has room to run higher.  As well, copper (+0.7%) is also rebounding, and I expect that we will see most commodities continue to perform well going forward in this environment.

Finally, the dollar is under some pressure this morning, adding to yesterday’s declines in the wake of the Fed meeting.  Recall, the dollar had rallied the first half of the week as the punditry was looking for the Fed to seem more hawkish.  But that was not to be and this morning it is broadly, though not universally lower.  AUD (+0.3%) and JPY (+0.2%) are the biggest gainers in the G10 while CHF (-0.65%) is the laggard after the rate cut, although has rebounded from its worst levels.  In the EMG space, PHP (+0.4%), MYR (+0.5%) and IDR (+0.4%) are the leading gainers although we are seeing weakness in EEMEA with ZAR (-0.3%) and CZK (-0.3%) lagging.  

On the data front, as it is Thursday, we see Initial (exp 215K) and Continuing (1815K) Claims as well as the Current Account deficit (-$209B) and Philly Fed (-2.3) all at 8:30.  Then as the morning progresses, we see the Flash PMI data (51.7 Manufacturing, 52.0 Services), Existing Home Sales (3.94M) and Leading Indicators (-0.2%).  As well, we get our first Fed speaker post the meeting, vice-chairman for regulation Michael Barr, this afternoon, but given my assessment that the Fed is happy with the market response, I don’t imagine he will say anything new.

Overall, the bulls and doves are walking hand in hand (what a terrible metaphor, sorry) and that means that risk assets are likely to continue to perform well for now and the dollar seems likely to come under a bit more pressure.  I maintain that the bond market is going to figure out the inflation story is not great and react, but that is not today’s story.

Good luck

Adf

Not Very Far

Said Jay, we are not very far
From when we can all wave au revoir
To higher for longer
With confidence, stronger,
Inflation will reach our lodestar
 
“We’re waiting to become more confident that inflation is moving sustainably at 2%.  When we do get that confidence — and we’re not far from it — it’ll be appropriate to begin to dial back the level of restriction.”  So said Chairman Powell yesterday in front of the Senate Banking Committee in response to some of the questions he received.  Nuff said!  Regardless of the fact that there has been limited indication of slowing economic activity (although this morning’s payroll report will be critical), it seems quite clear that Powell is under a great deal of pressure to reduce rates.  One must assume this pressure comes from the White House as in last night’s SOTU speech, President Biden even mentioned that mortgage rates were too high, and he was going to push them down.  Clearly, the only tool that Biden has is to lean on Powell to cut rates.
 
But despite what had appeared to be a concerted effort by every Fed speaker to push back against the proximity of the first interest rate cut for this cycle, it appears that Powell is blinking.  Interestingly, while the Fed funds futures markets didn’t really adjust very much, we did see the 2yr Treasury yield fall back 5bps and this morning it sits slightly below 4.50%, its first time back to this level since the surprising CPI print last month.  Of course, equity markets love the message, and we continue to see new highs on a daily basis.  But we are also continuing to see new highs in the anti-fiat monies, gold and bitcoin.  The world is not without risk.
 
An angry old fella named Joe
Last night tried explaining our woe
Was not his, to blame
Though he wouldn’t name
The culprit, throughout the whole show
 
While I try to leave politics out of this missive, the status of the SOTU is such that I don’t believe it can be completely ignored.  My takeaway from last night’s speech was that President Biden, in an attempt to show vigor, came across as the angry old man shaking his fist and yelling at the clouds.  He had a laundry list of things he claims to want to accomplish, all of which will cost trillions of dollars, and none of which are likely to be enacted before the election.  Many pundits pointed out this seemed more like a campaign speech than a SOTU and I think there is merit in that view.  In the end, while we understand where the pressure on Powell is coming from, I don’t believe this is going to change anything, certainly not from a market perspective.
 
And finally, it’s time to turn
To data for which we all yearn
The Payroll report
Which, if it falls short
Will likely give hawks great heartburn

Looking ahead, this morning brings the monthly payroll report.  Current median expectations are as follows:

Nonfarm Payrolls200K
Private Payrolls160K
Manufacturing Payrolls10K
Unemployment Rate3.7%
Average Hourly Earnings0.3% (4.4% Y/Y)
Average Weekly Hours34.3
Participation Rate62.6%

Source: tradingeconomics.com

Recall, last month’s number was massively higher than anticipated at 353K and had higher revisions as well.  The revisions were almost more surprising than the headline number as the trend for the entire previous year had been for revisions to be to softer data.  There will certainly be revisions to the January data as well, so there is a great deal of uncertainty.  My sense is, though, that the market really wants to see a softer number with downward revisions as that will work toward cementing the case for the Fed to cut rates even sooner.  Sub 150K and look for a bond and stock rally.  Above 250K and bonds will sell off, although stocks have a life of their own.  At least that’s one man’s view.

Ok, let’s look at how things played out overnight ahead of this key data.  Asian markets followed the US rally with green across the screen.  The Hang Seng, which is seen as the tech proxy in Asia, rallied most, 0.75%. Europe, on the other hand, is having a tougher day with most markets slightly softer although the FTSE 100 is down -0.5%, the clear laggard this morning.   Apparently, Madame Lagarde’s comments did nothing to support the hopes that rate cuts were coming soon as ostensibly, rate cuts were not even discussed in the meeting and all signs point to June as the first time by which they will have confidence in the inflation story, if it is to come.  Meanwhile, US futures are pointing a bit lower, -0.3%, at this hour (8:00).

In the bond markets, Treasuries have edged lower another 1bp this morning and we are seeing yields across the board in Europe decline by between 2bps and 4bps.  I can’t tell if that is confidence in the ECB (doubtful) or belief that the ongoing decline in economic activity (Eurozone GDP in Q4 was confirmed at 0.0% Q/Q and 0.1% Y/Y) has simply encouraged investors that rates are going to fall with no chance of a backup.  Meanwhile, JGB yields were unchanged overnight despite the ongoing excitement(?) that the BOJ may raise rates a week from Monday.

Oil prices have retreated a bit (-0.6%) but are essentially range trading and have been for the past month.  However, the star of the commodity space continues to be the barbarous relic, with gold rallying another 0.3% this morning to yet another new all-time high.  As to the base metals, copper is unchanged this morning, but has been on a roll lately while aluminum is higher by 0.65%.  Metals investors are gaining confidence that not only is there going to be no landing in the US, but that China is going to stimulate more.

Finally, the dollar remains under pressure overall as yields continue to decline.  While the euro is a touch softer this morning, virtually every other G10 currency is firmer with JPY (+0.55%) leading the way.  Remember, too, that with FY end approaching for Japan, we will begin to see Japanese corporates repatriating funds which typically sees further yen strength.  Combine that seasonal activity with the relatively new BOJ hawkishness/Fed dovishness combination and the yen could rally a lot more.  After all, it has fallen a lot in the past two years!  But, while the G10 currencies are generally having a good day, the picture in the EMG bloc is far more mixed with BRL (-0.6%) the laggard after total credit in Brazil was shown to have fallen in January for the first time since the pandemic.  On the flipside, CLP (+1.0%) is rallying after a higher-than-expected CPI report (4.5%) has traders looking for tighter monetary policy than previously anticipated.

Aside from the payroll report, there is no other data to be released and there are no Fed speakers on the calendar.  Yesterday we did hear Cleveland Fed president Mester sound more hawkish, becoming the third FOMC member to discuss only 2 cuts this year, and I maintain that when the dot plot comes out, that could be the median view.  But for now, markets and investors remain euphoric about the apparent Powell dovishness, so that will be the driver absent a huge NFP this morning.  For the dollar, that will be bad news.

Good luck and good weekend

Adf

No Confidence

So far, we’ve no confidence that
Inflation is down on the mat
Thus, rates won’t be sinking
Til prices are shrinking
Said Jay in his Wednesday House chat

But also, it seemed clear to all
No rate hikes were likely on call
With that set aside
He then did confide
That Basel III cap rules may fall

It can be no surprise that Chairman Powell’s testimony yesterday explained that the Fed is still not yet confident that inflation is going to achieve their 2% target on a sustainable basis.  While he was clear that most of them thought that would eventually be the case, the proof is not nearly conclusive at this stage.  Of course, this is exactly what he told us last month and essentially what every Fed speaker since has repeated.  He did appear to rule out any further rate hikes at this time, but quite frankly, if inflation readings start to head higher, you cannot take those off the table.  At the very least, the current Fed funds futures pricing for cuts (3% in March, 20% for May and 87% for June show the market has really decided the first cut is a summer event.  Remember, though, between now and the June 12 meeting, we will see three more CPI and PCE reports as well as three more NFP reports.  It would not be impossible for these ideas to change between now and then.

One other thing to note is we have heard several FOMC members now discuss needing only two rate cuts this year.  Do not be surprised if the March dot plot has that as the median forecast and that would be a significant change to market perceptions.

The essence of the questions by the Congressmen and women revolved around two things; the fact that high rates were hurting people trying to buy houses and how proposed capital increases due to the Basel III regulations were going to kill the banking community.  While Powell empathized with the housing issue, he reminded them all that inflation hurts everyone.  But the big surprise was Jay indicated that he may overrule Regulation vice-chair Barr and look to reduce some of those capital requirements.  Not surprisingly, the GSIB bank stocks rallied on the news!

And in fact, so did the overall stock market.  The combination of what seemed to be a promise to avoid further rate hikes and relaxing capital requirements was just what the doctor ordered to alleviate Tuesday’s pain.

Is the table set
For a March policy change?
A new wind’s blowing

The yen (+1.1%) is on the move this morning after a combination of news that Rengo, the Japanese Trade Union Confederation, is asking for wage increases of 5.8% this year, the highest request in 30 years.  While they will likely not get the full amount, certainly wages are set to rise more substantially than in a long time there.  This is music to PM Kishida-san’s ears as he wants to see more spending, and apparently, this is AOK with Ueda-san who now believes that their 2% price target has a greater chance of being sustainable.  Alongside the yen’s rally, the OIS market has bumped up the probability of a March rate hike to above 50% and several analysts in Tokyo are making that their new call.

Thinking about the situation here, the BOJ meets a week from Monday, 2 days prior to the FOMC.  It strikes me that we have the opportunity for some real volatility as if Ueda-san does raise their base rate to 0.00%, I expect the market will be looking at this being the beginning of a series of hikes and start to move the entire Japanese interest rate curve higher.  That will be bullish for the yen.  But…if the Fed’s dot plot comes in at only 2 cuts, or possibly even 1 cut this year, that is also quite hawkish for the US rate situation, will likely see the yield curve back up and should support the dollar.  The reason we hedge is to prevent movement of this nature from having too great an impact on results.  Keep that in mind.

Interestingly, I believe those two stories are far more important to markets than the ECB meeting this morning.  There is virtually no chance of any policy change, so the real question is how the statement addresses the situation for the first rate cut and its potential timing.  The commentary that we have heard to date, at least to my ears, has been a split between April and June, with a slight nod toward the latter.  One key clue will be the updated economic and inflation forecasts with some analysts looking for lower outcomes there.  If that is the case, I expect that April will get a lot more press.

But ahead of the meeting, I would argue that the narrative is shifting as follows:  the Fed has indicated that the peak has been reached and it’s simply a matter of time before they start to cut rates while the ECB has been trying to hold out their hawkish bona fides.  As such, it should be no surprise that the dollar is under some pressure and the euro has rebounded to 1.09 for the first time since mid-January.  However, there is still a lot of new information on the horizon, specifically tomorrow’s NFP and next week’s CPI which can quickly alter the Fed narrative and with it, the dollar narrative.  Be careful.

Ok, let’s look at the overnight session where, not surprisingly, the Nikkei (-1.2%) fell on the back of the hawkish sentiment and stronger yen.  It has fallen back below the 40K level, so it remains to be seen if this is temporary or if, after 40 years, the new top was just barely above the old one.  Chinese shares were also weak despite a very strong Trade Balance, although the rest of Asia followed the US higher.  In Europe this morning, Spain’s IBEX (+0.6%) is once again leading the way higher although the major markets, FTSE 100, DAX and CAC are all little changed on the day.  Finally, at this hour (7:15), US futures are edging higher by about 0.25%.

In the bond market, yesterday saw Treasury yields fall 4bps and they are down a further 1bp this morning.  Market participants are going all-in on the idea that Fed funds are going to get cut soon.  I am not comfortable with that viewpoint at all.  As to European sovereigns, they too, have seen yields slide a bit, down 2bps-3bps this morning.  All this is in contrast to JGB yields, which backed up 2bps overnight on the new hawkish take.

In the commodity markets, oil (-0.75%) is softer this morning, unwinding yesterday’s modest rally.  For now, there has been much less focus on energy than on the interest rate story although I suspect that will change again going forward.  Gold (+0.4%) continues to be the absolute star of the commodity space, rallying for the 7th consecutive session and extending its all-time high levels.  My take is there is much more room on the upside here as it is not a widely held trade and if it continues, the momentum guys are going to want to get in.  But we are also seeing strength in the base metals with both copper (+1.3%) and aluminum (+0.9%) having strong sessions.  As long as the narrative is looking for US rate cuts, these metals have further to climb.

Finally, the dollar is under pressure everywhere, not just in Japan.  Both Aussie (+0.65%) and Kiwi (+0.5%) are strong on the back of commodity strength, and we are even seeing NOK (+0.2%) rise despite oil’s decline.  If you needed proof this is a broad dollar selling environment, that’s it.  Interestingly, in the EMG bloc, while almost every currency is firmer, the movement has been quite small, with nothing more than +0.2%.  So, this seems to be a comment on the ostensibly dovish Powell testimony that has bolstered the US stock market.

On the data front today, after the ECB leaves rates on hold at 4.5% we see Initial (exp 215K) and Continuing (1889K) Claims leading the way as they do every Thursday.  We also see the Trade Balance (-$63.5B), Nonfarm Productivity (3.1%) and Unit Labor Costs (0.6%) at 8:30.  Powell starts up again in front of the Senate at 10:00 and then this afternoon, Consumer Credit ($9.25B) is released.  In addition to Powell, we hear from Loretta Mester of the Cleveland Fed.  It will be quite interesting if she hints at only two cuts this year, following Goolsbee and Barkin.  I have a feeling that is the current direction and that is not in the pricing right now.

For now, the dollar remains under pressure, so unless Powell is perceived to be more hawkish this morning, I suspect the dollar can slide a bit more before it’s all over.

Good luck
Adf

The Really Good Stuff

While yesterday’s markets were tough
Today starts the really good stuff
It’s ADP first
Then Jay’s well-rehearsed
Defense the Fed’s doing enough


As I suggested in yesterday’s note, markets had a little further to fall prior to the beginning of the information onslaught that is coming today and continues for the rest of the week.  Apparently, this was the worst session since sometime in October, but in the broad scheme of things, a 1.0% – 1.5% decline doesn’t seem that dramatic.  After all, even after yesterday’s declines, the NASDAQ 100 is higher by 8.1%, the S&P 500 by 7.1% and the Dow Jones by 2.3% so far this year.

This morning, however, I think we need to look ahead to what is on the near horizon as I believe today’s information may be the most important of the week.  Before we get into the US story, a quick note on Europe and the UK.  Many of you will recall that during the Brexit drama in 2016, the Remainers claimed that the UK economy would collapse if they left the EU.  I cannot help but notice how it is the continent which is suffering the worst effects of the current economic situation with the UK faring quite a bit better.  

One need only look at the PMI data as evidence that while things in the UK may not be great, the Eurozone is in much worse condition.  Today’s Construction PMIs are a perfect encapsulation with the UK printing 49.7, not great, but miles ahead of Germany (39.1), France (41.9), and the Eurozone as a whole (42.9).  And this has been the pattern of data we have seen consistently for the past several years.  While the UK may have suffered somewhat, Europe is in far worse shape.  Looking at the data, it is easy to see why expectations for the ECB to cut rates first are rising.  They need to do something to support the Eurozone economy.

But anyway, let’s turn to this morning’s activity which starts with the ADP Employment number (exp 150K).  The relationship between this and the NFP data seems to have broken down a bit lately, but it remains a key early look at the US employment situation.  While 150K does not indicate remarkable strength, it would be the second highest print in the past six months, a time when the economy has grown at a > 3.0% clip.  I feel like the market will pay attention to a big miss in either direction, especially a weak number as that will be seen as a harbinger of rate cuts coming sooner.

The next thing we get is the Bank of Canada rate decision, where the universal expectation is for no adjustment in the current 5.0% rate.  Here, the issue will be much more about the tone of the statement and commentary.  Recent inflation data in Canada has been softer than expected, slipping below 3.0%, but growth data continues to motor along well.  There are many in the markets who believe that the BOC will lead the way in policy changes, and if they indicate a cut is coming soon, the Fed will follow.  Personally, I don’t buy that, but then, I remain unconvinced the Fed is going to cut at all.

Which takes us to Chairman Powell’s Senate testimony starting at 10:00am.  If I were to guess on the nature of his opening statement it will be something along the lines of; things are going well as growth is solid, unemployment remains low and inflation seems to be trending lower, however, inflation remains job #1 and we are not yet convinced it will sustainably reach our goal of 2%.  He will then get a series of bizarre and idiotic questions from Senators who have virtually no understanding of the economy, and only care about grandstanding on TV for their constituents.

But this is where the most opportunity for a market moving event will take place.  If Powell offers anything other than the above recap, look for markets to react quickly.  Any hint that they are closer to a cut, and we will see equities fly and the Fed funds futures markets rally sharply (remember the December pivot?).  Any hint that cuts seem unnecessary given the overall economic strength and continued low unemployment rate and look out below.

And that’s how the day is shaping up.  However, it would not be complete if I didn’t mention perhaps the most important inflation indicator I have seen to date, and perhaps a harbinger of the future.  Of course, I am referring to the Average Tooth Fairy payout as seen below.

I found this on the Morning Hark, a terrific Substack that does a great job of aggregating information published all around the world every day, and one I cannot recommend highly enough.  But let’s face it, if the tooth fairy is cutting back her (his? Its?) payout, inflation must be dead!

Ok, it’s time to review the overnight activity.  Following yesterday’s declines in the US, Asia had a mixes session with the big winner being the Hang Seng (+1.7%) on the strength of a strong earnings report from JD.com as well as a rebound from the prior session’s sharp declines.  But elsewhere, things were mixed with limited movement overall.  In Europe, the screen is green, but only Spain’s IBEX (+1.15%) is showing any real life, with the other bourses just barely above flat.  You will be happy to know, though, that US futures are all pointing higher at this hour (7:30) by between 0.25% and 0.75%.

In the bond market, things are stable although yields have drifted a bit lower over the past several sessions.  This morning, Treasury yields are down just 1bp while we are seeing a mixed view in Europe with different nations seeing moves of + or – 1 bp.  But in general, not much to note here.  As to Asia, yields fell overnight, following the US lead of late, with JGB’s the lone exception, creeping higher 1bp.  Arguably, the fact that the bulk of the movement has been 1 basis point tells us nothing is going on!

In the commodity market, oil is rebounding slightly this morning, up 0.9%, which reverses earlier losses this week.  The star here continues to be gold (+0.3%) which has risen 5% to new all-time highs this week and looks like it is not going to stop in the near future.  Alongside the sharp rally in Bitcoin, a case can be made that investors are seeking out non-monetary alternatives given the massive debt issuance that is ongoing in the US, as well as elsewhere in the world.  For instance, yesterday China mentioned they were going to be issuing an additional CNY 1 trillion of ultra-long-term bonds to finance some stimulus.  It is not unreasonable for investors to seek non-monetary stores of value when concerns arise over non-stop issuance of paper.

Finally, this morning the dollar is a bit softer against virtually all its counterparts.  While the movement has not been large, the breadth of the decline could be indicative of a view that Chairman Powell is going to be cooing like a dove today.  This is especially so if one has a political view as after yesterday’s Super Tuesday primary results, the presidential race has been cemented as a rematch of 2020.  Many make the case that Powell does not like Trump, especially given Trump has said he will not reappoint Powell.  But I don’t think that Powell cares about that as much as about trying to get things right.  He is independently wealthy and can retire with his head held high if he can get inflation back to target.  

We’ve already discussed the data although I left out the JOLTS Job Openings (exp 8.9M) at 10:00, and then the Beige Book is released at 2:00.  We also hear from Minneapolis Fed president Kashkari, but will anybody really care what he says having just heard from Powell himself?  I think not.

So, today is all about early data and more importantly Powell’s comments.  I continue to believe that the Fed does not need to cut rates at all given the economic backdrop and despite the Tooth Fairy, inflation will remain sticky and above the Fed’s target.  As the market prices out Fed rate cuts, the dollar should benefit, but that will take more time.

Good luck

Adf

Ain’t Hunky-Dory

For President Xi it appears
The stock market’s shed enough tears
So, he’s set to meet
The finance elite
And likely to box all their ears

As such, I expect we shall see
The Hang Seng will start on a spree
With New Year’s approaching
A little more coaching
By Xi, for a rally, is key

The big news overnight was that Chinese equity markets rebounded sharply (Hang Seng +4.0%, CSI 300 +3.5% CSI 1000 +7.0%) after the news that President Xi Jinping would be meeting with market regulators to find out what is going on there.  Banning short sales has not yet been effective nor has increased purchases by specific state funds.  According to Morgan Stanley, foreign investors sold $2.4 billion in Chinese equities in January, arguably a key driver of the market’s recent weakness there.  But the fact that Xi is getting involved directly has traders believing that more support from the government is on its way, hence today’s big rally.

While that is all fine and well for equity investors, the far more important question for the rest of us is will this stock market support help the Chinese economy as well?  Or will that continue to meander along at a weak growth pace?  Of course, it is far too early to know the answer to this question but given that the preponderance of Chinese individual wealth is tied up in real estate, not equities, I expect that this will have far less impact on the economy there than is hoped by both Xi and the traders.  After all, one of the key reasons so many in the US care about the stock market is that so much of our 401K investments are in equities, a rally shows up in our accounts daily.  But in China, that same situation does not hold.  Will a rally in stocks, if it even comes, be enough to sway the average person’s thinking there that things are getting better?  I have my doubts.

A turn to the interest rate story
Shows things there just ain’t hunky-dory
Yields just won’t stop rising
And that’s neutralizing
The thought rate cuts are mandatory

Friday morning, 10-year Treasury yields traded as low as 3.82% prior to the release of the NFP report.  This morning, they are trading at 4.16%, 34 basis points higher and the largest two-day yield rally since the covid volatility in March 2020.  Prior to that, it was 1981 when yields moved that far that fast.  Adding to Friday’s NFP story, yesterday’s ISM Services report was not only stronger than expected at 53.4, but the Prices index jumped to 64.0, its highest in a year and hardly a comforting thought for Chairman Powell and his fight against inflation.

At this point, the Fed funds futures market has lowered the March rate cut probability to 16.5%, and some of the punditry, although not yet any Fed speakers, have raised the question if another hike might be in order if things continue on their recent trajectory.  I assure you that the equity market has not priced in the possibility of a rate hike anywhere in the next 2 years at least.  Let’s just say that next week’s CPI report is going to be quite closely watched by everyone as if what I have seen as recent stickiness continues to exert itself, and with the economy seeming to be ticking over quite nicely, then the narrative could well change.  It is not impossible for the Fedspeak to turn even more hawkish if we were to see CPI rise 0.4%, a rate that is far too high for Fed comfort.  And that, my friends, would likely not be well-received by the equity market or risk assets overall.  While I have no special insight into how this data is going to evolve, I think the reaction function is clear.

Ok, let’s look at the overnight session beyond Chinese stocks.  In what cannot be that surprising after US equities struggled and given its recent negative correlation to Chinese stocks, the Nikkei fell -0.5% while the rest of Asia was mixed with some gainers (India, Taiwan) and some laggards (Korea, Australia).  However, the story in Europe is a little brighter with gains most everywhere except Germany, which is flat on the day after mixed data, with a blowout Factory Orders result of +8.9%, but the Construction PMI falling to 36.3.  Contradictory data leading to no movement.  As to US futures, at this hour (7:45) they are essentially unchanged on the day.

In the bond market, it seems traders are sitting on the sidelines after the bloodbath described above as 10-year Treasury yields are unchanged on the day and in Europe, the sovereign bonds are higher by a mere 1bp-2bps across the board.  We saw a similar lack of movement in Asia as well, despite the fact that the RBA, at their meeting last night, sounded somewhat hawkish although left policy rates on hold as universally expected.  As the treasury market is clearly leading the way globally, we will need to get some new information here, I think, before we see any substantive movement again.  Since the next big piece of data is CPI in one week’s time, it could be a quiet week for bonds.

In the commodity market, oil (+0.6%) is bouncing slightly this morning although it remains far lower than levels seen last week.  Gold (+0.1%) is also edging higher along with the industrial metals although there has been no strong catalyst here today given the lack of substantive rate movement.  Perhaps there is some optimism from the Chinese stimulus story, but that feels quite premature.

Finally, the dollar is a touch softer this morning, although only just.  While the euro has been unable to bounce, we have seen some modest gains in the pound (+0.25%) and Aussie dollar (+0.25%) as well as the renminbi (+0.3%).  In addition, the LATAM bloc is very modestly firmer this morning but generally, most of the movement is of that 0.25% magnitude or less.  This feels very much like a trading response to a powerful rally over the past two days.

There is no hard data to be released today but we do hear from three more Fed speakers, Kashkari, Collins and Mester, all this afternoon.  Yesterday, Chicago Fed president Goolsbee strayed from the Powell message, indicating he still believed a cut in March was possible, but he is not a voter this year and nobody really paid any attention.  After yesterday’s data, it would be hard to believe that any of these three would sound dovish, but you never know.

Overall, when looking at the dollar, as long as the inflation story has reawakened and is driving yields in the US, it is hard to see coming weakness.  This is especially true given the economic weakness we continue to see elsewhere in the world.  Today feels like a reaction, not a trend in the making, and I expect that the dollar has better days ahead for as long as inflation is once again the driving force.

Good luck
Adf

Seems Like a Crisis

The Chinese have not finished yet
Their efforts to counter the threat
Of weaker stock prices
Which seems like a crisis
So new triple R rates were set

But one thing I don’t understand
Is while CCP’s in command
Just why do they care
‘Bout stocks anywhere
Perhaps communism ain’t grand

Yesterday, the Chinese government announced that there would be up to CNY 2 trillion of support for Chinese equity markets in their latest effort to stanch the 3-year bear market.  But apparently, that was not enough as last night Pan Gongsheng, the PBOC governor, announced they were reducing the Reserve Requirement Ratio (RRR or triple R) in order to free up additional loan capacity for the banks.  The move, a 0.50% cut in the ratio will ostensibly release another CNY 1 trillion into the economy.

There are two issues I’d like to address here.  First, given the property market in China remains under significant pressure as activity still seems to be lethargic, at best, and the economy overall is not really expanding at a significant pace, why do they think that allowing more loans will encourage people to take more loans.  After all, last week, they left the Loan Prime Rates unchanged, so were not trying to encourage more activity, and it is not clear that loan capacity has been a constraint in any manner during the past several years.  As global growth remains slow overall, it is entirely possible, if not likely, that there is just reduced demand for Chinese manufactures around the world right now.

The second issue is a bigger picture question, why does the Chinese Communist Party care at all about the stock market?  After all, a reading of Das Kapital would explain that there is no place for private ownership at all in a communist system and by extension, no place for shareholders.  The state is supposed to own everything.  My conclusion is that Xi, and the entire CCP, are full of s*it regarding their belief in communism.  In fact, I would contend that is true for every communist regime on the planet.  Rather, those in charge in communist regimes merely see it as the most effective way to command all the power and wealth personally and could care less about the concepts Marx espoused.  In the end, I would argue that the human condition is one where acquiring as much power and wealth as possible is the driving goal for most people.  While many people have much smaller ambitions, the sociopaths who rise to leadership roles in politics know no bounds as to what they believe is their due.  Just sayin!

Regardless of the underlying rationale, though, the PBOC had the desired impact as both the Hang Seng (+3.6%) and the CSI 300 (+1.4%) rallied sharply on the news.  As well, the Nikkei (-0.8%) slid a bit further as it seems there had been a growing position by CTAs and hedge funds in the long Japan/short China trade which I illustrated yesterday.  If China is rebounding, I expect that Japanese shares will have further to slide in the near-term.  As well, after another day with some record high closings in the US yesterday, European bourses are all in the green nicely this morning with the DAX (+1.3%) leading the way although the other main indices are also higher by about 1%.  The laggard here is the UK (+0.4%) and I attribute this movement to the Flash PMI data which was released this morning showing that continental growth continues to slide, hence increasing the chance of a rate cut sooner, while UK data was a bit better than expected, and well above 50 across the board, implying the BOE will lag any rate cuts going forward.  And happily, as I type at 8:00, US futures are all nicely in the green as well.

In the bond market, Treasury yields are a touch softer this morning, down 2bps, but still hanging right around the 4.10% level which has been a pivot for the past week.  European sovereigns have seen yields decline about 3bps across the board after that soft PMI data, while UK Gilts have moved the other direction on the stronger data there.  Of more interest, I think, is that JGB yields have jumped 5bps overnight and are now back above 0.70%.  It seems that there is an evolution in thinking regarding Ueda-san’s comments after the BOJ meeting Monday night, and the belief that they will be exiting NIRP in April is growing stronger.  We shall see.

Commodity prices are higher across the board this morning with oil (+0.3%) continuing to find support, arguably from the troubles in the Middle East, although some short-term issues like the shuttering of a Russian export terminal after a Ukrainian attack have also had an impact.  But metals markets are universally higher this morning as well, with gold (+0.25%) far less impressive than copper (+2.0%) or aluminum (+0.9%) as positivity from the Chinese RRR cut and the potential for stronger growth on the mainland feed through the markets.

Finally, the dollar is under pressure this morning across the board.  This is true in the G10 bloc with the euro and pound both firmer by 0.5%, while the yen (+0.8%) and CHF (+0.8%) are having even better days.  Similarly, the EMG bloc has seen gains across the board with the leader ZAR (+1.1%) on the back of those metals gains, but strength in PLN (+0.8%), CZK (+0.7%) and HUF (+0.65%) showing their high beta with respect to the euro, and gains in APAC currencies (KRW +0.4%, SGD +0.3%, CNY +0.3%) and LATAM currencies (MXN +0.6%, BRL +0.8%) as it is unanimous regarding the dollar’s weakness.

On the data front, today brings only the Flash PMI data (exp 47.9 manufacturing, 51.0 services) and the EIA oil inventories.  There are no Fed speakers due to the quiet period, so I foresee market activity focused on equity earnings releases although none of the big names are due today.  Right now, the dollar is under pressure amid ongoing belief that the Fed is going to cut ahead of other central banks.  Until that story changes, I expect that we could see a bit more dollar weakness.  But in the end, tomorrow’s GDP and Friday’s PCE data are going to really drive views.  Look for a quiet one today.

Good luck
Adf