Memories Morose

A score and five years now have passed
Since evil, near home, struck so close
And I will ne’er forget that blast
Though it brings back memories morose

While I have worked to block it out
We lived through a great deal of stress
And recent events leave no doubt
New York City is still quite the mess

I understand you weren’t there
But absence remains no excuse
To disregard those thoughts and prayers
Of folks who feel torment, profuse

No other day that I recall
Impacted our lives with such woe
And to this day, its darkened pall
Still hides much of life’s radiant glow

On this somber day, remembering the events of that bright and sunny morning, I sincerely hope none of you ever forget what happened.  From my vantage point, a single block away, the devastation was remarkable.  Unfortunately, I lost many friends that day, and they are all in my thoughts this morning.  If ever you wondered how important the markets are, they pale in comparison to the realities of life…and death.

And while I try to keep politics out of this missive, this morning, it pains me greatly that New York City mayor Mamdani, with a history of supporting the very people who perpetrated this heinous crime, will have anything to do with the commemorative ceremony.

Now back to our regularly scheduled programming.

The punditry’s near salivating
As Treasury yields keep inflating
The glee they express
O’er bond market stress
Can fairly be called fascinating

Elsewhere, there’s a new boogeyman
Replacing the war in Iran
AI is Skynet
Much worse than huge debt
As it will destroy all it can

The primary market discussion this morning revolves around government bond yields after yesterday’s dramatic rise virtually across the board.  If you look at the chart below, it shows the yields for US, UK and German 10-year bonds and how they have all risen dramatically in the past week (18bps, 20bps and 15bps respectively) with the bulk of that coming yesterday.  

Source: tradingeconomics.com

There have been many theories as to why things broke yesterday with some pointing to oil’s dramatic rise, some pointing to President Trump’s $5k bonus payment and others pointing to Secretary Bessent’s bond repurchases where he was only able to buy $5.1 billion of the $6.0 billion they tendered for.  As is often the case, all of these likely had some impact, and you can throw in some views of yesterday’s PPI data, which while released at expectations did nothing to cool inflationary ardor.  

If we look at Fed funds futures in the table below from the CME, we can see that the probability of a rate hike next week has risen to 67%, but more interestingly, there is now pricing for a total of 100bps of hikes over the course of the next year.

In fact, if we look across the globe, the number of rate hikes has grown since yesterday.  Compare this morning’s chart from rateprobability.com to the one I published yesterday, and you can see that expectations have risen between 15bps and 25bps across all the major central banks.

Today’s chart.

Yesterday’s chart.

At this point, we are highly confident that Japan is going to raise rates at their meeting later this month because Nikkei News reported it last night, and their track record here is, literally, perfect, never having missed a call.  Of course, the ECB raised rates yesterday, and it appears quite likely that rate hikes are the new normal.  I wonder what will happen, though, if today’s CPI (exp 0.4% Headline, 0.2% Core) comes in cool.  Frankly, I think the market is so convinced that it won’t matter at all.

Ok, before I run down markets, I must comment on the increased chatter regarding AI.  Let me start by saying, I am not an expert on AI, although I have a pretty good feel for human behavior.  The recent comments from the Anthropic scientist who left and explained that AI was going to kill us all were remarkable.  But what is more remarkable is the call for ‘government experts’ to oversee AI’s ongoing evolution. Every time I hear of government experts I hearken back to the end of “Raiders of the Lost Ark” when Indiana Jones tells the army intelligence men that the Ark needs to be studied, and they reply it is being studied.  When queried ‘by who?’ they reply, top…men.

My point is there are likely zero AI experts who work in the government as all of them are working for companies building AI.  Congress has proven itself to be uniquely incompetent across virtually every sphere of thought and action, so having Bernie Sanders or Hakeem Jeffries or Josh Hawley say they need to be involved does not inspire confidence.  Here’s the thing, we have heard this before.  After all, wasn’t global warming or climate change or Covid going to kill us all if we didn’t do exactly what government said?  It is almost as if they are running the same playbook on AI and it is becoming pretty tiresome.  Perhaps AI is developing into Skynet, but like virtually everything else, early hysteria is regularly misplaced.

Which takes us to markets.  Oil (-3.2%) may have been a tad overdone yesterday during its $6.50 rally.  Threats and counter threats between the US and Iran continue to be the backdrop, and Saudi Arabia did announce they produced their least amount of oil since 1991, but the US is producing record amounts, and Venezuela is coming back faster than expected and there still appears to be a surfeit of the stuff around.  While EIA oil stocks had a very modest draw of 390K, gasoline stocks rose > 1mm barrels and there is no indication supplies are gone.  However, while refinery runs in the US are consistently near 98% of capacity, the lack of refining in Russia and the Gulf continue to drive prices.  I guess the question is how long can the IRGC withstand the very clear economic pressure the blockade and newer sanctions have imposed?  I have no answers.

As to metals, yesterday saw sharp declines across the board as both interest rates and oil prices rallied, but this morning they are rebounding a bit (gold +0.5%, silver +0.5%) although copper is still under some pressure (-0.25%).

In the equity markets, in truth, despite all apocalyptic talk, the major US indices were only lower by about -0.6% across the board, not great but not devastating.  Asia, however, had a rougher go of things with Tokyo (-1.9%), China (-0.8%) and HK (-0.6%) leading the way with most of the rest of the region also in the red (Korea -1.8%, Taiwan -1.6%, Australia -0.9%, etc.). But at some point overnight, things turned brighter as European bourses are higher by between 0.6% and 0.7% across the board with the only data release UK GDP and Production data, all coming in stronger than expected.  Perhaps the idea is that if the UK can grow despite extraordinarily bad economic and energy policies, so can the rest of Europe!  As to US futures, at this hour (7:30) they are higher by 0.6% across the board.

As we’ve already discussed bonds at length, it leaves us to the FX markets which continue to garner limited interest from the trading community.  While the dollar is a touch firmer this morning, DXY +0.1%, if we use that as the proxy, over the past month, as you can see from the below chart, it has traded within a 1.5% range (98.50 – 100.00) and that is with a key piece of the index, JPY having shown a substantial move.

Source: tradingeconomics.com

Someone on X this morning was claiming that this market is setting up for a big move lower with many attendant impacts if that is to be the case, but while he is a very smart guy (Tavi Costa) whose views I respect, he is looking at a VERY long-term chart.  Perhaps he is right, and I guess if we see major destruction in the bond market with yields exploding higher, that could be correct, but it is so hard to get excited about FX right now.  It continues to be a background event.

In addition to the CPI data, we also see the preliminary Michigan Sentiment (exp 51.0) Survey but that’s it.  My take on CPI is if the data is cool, it will have very limited impact, but if it comes in hot, we will see another wave of selling in bonds, and probably stocks, so an asymmetric outlook in my view.

Good luck and good weekend

Adf

Falling Fast

His swords were words he wielded well
He spoke his truths, but would not yell
His followers enrapt
His enemies then snapped
And undeservedly he fell
 
RIP Charlie Kirk
 
A score plus four of years have passed
Since thousands died, we were aghast
No logic could be found
For those at, zero, ground
Society is falling fast


A generation after the horrific events of September 11, 2001, it appears that memories have faded.  Personally, having observed those events from one block away, it is indelibly imprinted on my brain.  But now, in the course of a week we have seen several senseless murders make the news as whatever decorum may have existed at the turn of the century is long gone.  Messrs. Howe and Strauss were always quite clear that the 4thTurning involved chaos and the destruction of institutions.  I fear the process is accelerating.  I also fear that it must play out to get through to the other side.  Civil war feels excessive as a description, but as I have forecast for the past year or two, one of the major political parties was likely to explode.  Right now, it feels like the Democrats are on that path.  I don’t know what will replace it, but something must, and it would behoove us all if there is some coherence in their policies when it appears.  I remain confident that Socialists are not the answer, nor will they be embraced across the nation. 
 
The reason I discuss this, which seems outside the bounds of my market perspective, is that it is going to impact markets even more than it already has.  The ongoing politicization of the media, businesses and entertainment does not lead to kumbaya, but rather volatility and distress.  If you wonder why gold continues to perform well, look no further.  Whatever the data, whatever the Fed does, whatever Trump and his administration do, or what Congress tries to do, gold has a history of maintaining value for the past 5 millennia.  Everything else is new and prices are all relative to gold.  Remember that as you approach your day job and your investments, whether you hedge for a living, or simply are trying to make a living.
 
There are now two things on the docket
That could lead risk assets to rocket
First, CPI comes
The Jay and his bums
Decide what gets put in our pocket

Considering these very serious issues, it seems almost ridiculous to discuss markets, but they will continue to trade and the ability to keep your eye on that particular ball is still critical to financial outcomes.  So, let us turn to the two stories (well, maybe two and a half stories) that have the potential to change some viewpoints.  The first is today’s CPI, then next week’s FOMC meeting with a half nod given to today’s ECB meeting.

Regarding the least important, the ECB is almost certainly going to leave policy unchanged.  The only opportunity for anything new will come from Madame Lagarde’s press conference and if she displays a new tone, whether hawkish (I doubt) or perhaps more dovish as European data continues to ebb.

But let’s move on to CPI.  After yesterday’s much lower than expected PPI data, where the M/M numbers for both headline and core were -0.1% compared to +0.3% expected, there has been some talk on the margins that we could see much softer CPI data.  However, it is worth knowing that for the inflation cognoscenti (e.g., @inflation_guy) PPI data is seen as a random number generator with very little direct impact on the consumer data.  (In fact, after my look at NFP data, aren’t all the data points random?)  With that in mind, current median expectations remain as they were earlier in the week (0.3% M/M for both headline and Core with the Y/Y numbers expected at 2.9% and 3.1% respectively).  

Given the market is currently pricing a full 25bp cut with an 8% probability of 50bps, my take is the only way to change things would be for CPI to also print like the PPI data as negative numbers.  If that were to be the case, and I do not anticipate that outcome by any stretch, it would give Chairman Powell ample opportunity to cut 50bps with the market welcoming the outcome along with President Trump.  On the flip side, I don’t think CPI can print a high enough number to remove the 25bp cut.  As a reminder, below are the cumulative probabilities for future Fed funds rates based on the CME’s futures contract.  A total of 75bps remains the default view for the rest of 2025.

We will learn about the outcome at 8:30 this morning and I have no particular insight into whether those median forecasts are high, low or on the money.  This is a wait and see situation.

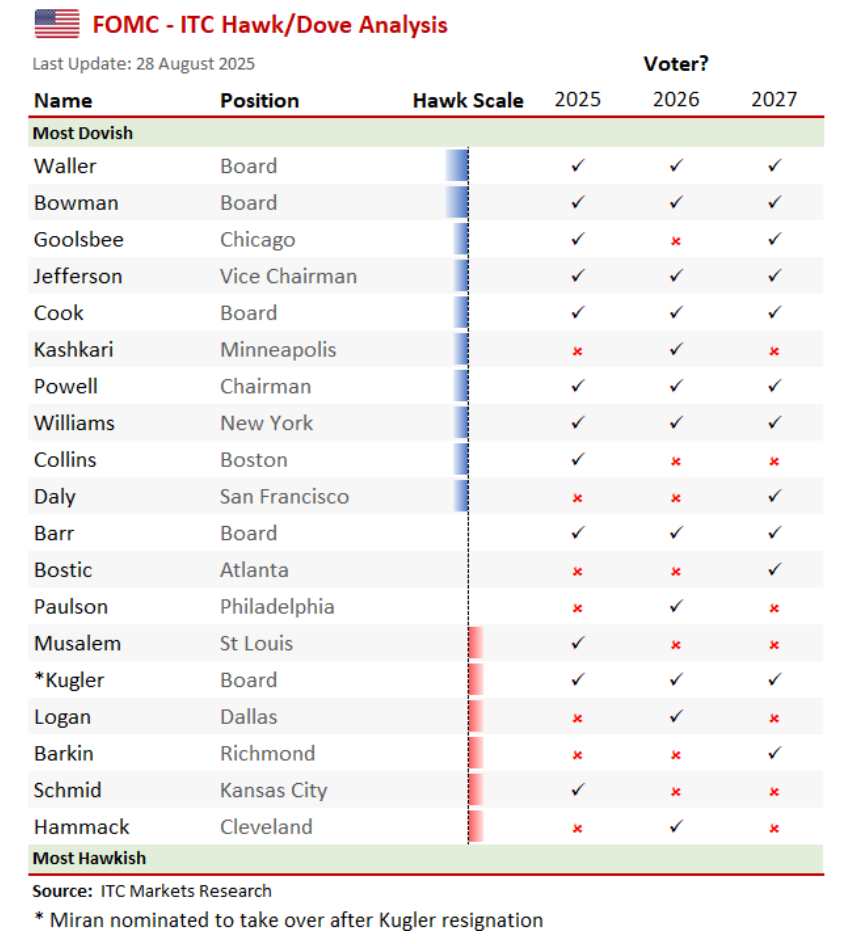
As to the FOMC meeting, it has the opportunity to be far more impactful.  While 25bps is currently baked in the cake, I remain of the opinion that 50bps is a very viable outcome.  Recall, the most recent Fed discussions were about the importance of the employment portion of their mandate as opposed to the inflation portion.  With the newly revised reduction in NFP over the past twelve months, characterizing the employment situation as solid or strong seems unreasonable.  Weakening would seem a more apt description and should have the discussion be between 25bps or 50bps.  We already know there are at least two governors, Bowman and Waller, who wanted to start cutting last time, and it appears that Stephen Miran, Trump’s current head of the CEA, is going to get approved by the Senate in time to sit in the meeting next week.  One would assume that is a vote for easier policy.   

ITC Markets has a very nice table on the perceived hawkishness/dovishness of FOMC members, and it shows that the governors, as a whole, live in the dovish camp with only a few regional presidents as known hawks.  In fact, one of the remarkable things about the entire Lisa Cook affair is that she was always one of the more dovish members of the board and the fact that she was not pushing for cuts never made any sense.  At least based on her background and history.  However, if you take politics into account, and the idea that she didn’t want to cut because President Trump wanted a cut, it begins to become clearer.  At any rate, it strikes me that based on this table, which feels reasonable, 50bps is in play.

With all that in mind, let’s take a quick turn around the markets to see what is happening ahead of this morning’s data.  As seemingly always, equity markets rallied in the US yesterday, well mostly.  The DJIA slipped, but the other indices managed to continue their hot streaks.  It is very hard to link economic activity to equity market outcome these days, at least to my eyes.

But on to Asia, where Japan (+1.2%) had a solid session on the back of the remarkable rise in Oracle shares and the idea that Japanese tech companies will benefit.  China (+2.3%) was the beneficiary of the story that President Xi is now looking to have banks prop up local governments that have stopped paying contractors now that their property sale gravy train has derailed.  It seems that they have figured out if you don’t pay people, they don’t consume anything.  So, upwards of CNY 1 trillion will be injected into local government coffers specifically to pay these late bills and try to kickstart consumption.  But, as I look through the rest of the region, it was a much more mixed picture with some gainers (Korea, Indonesia, Thailand), some laggards (HK, Malaysia, Australia) and many markets that barely moved.

In Europe, all the major markets are green this morning led by the CAC (+0.85%) and UK (+0.5%) with the others showing much smaller gains (DAX +0.2%, IBEX +0.25%).  There is no obvious reason for the gains as expectations for the ECB remain static and there has been no data of note released.  Meanwhile, US futures are higher by 0.25% at this hour (7:30).

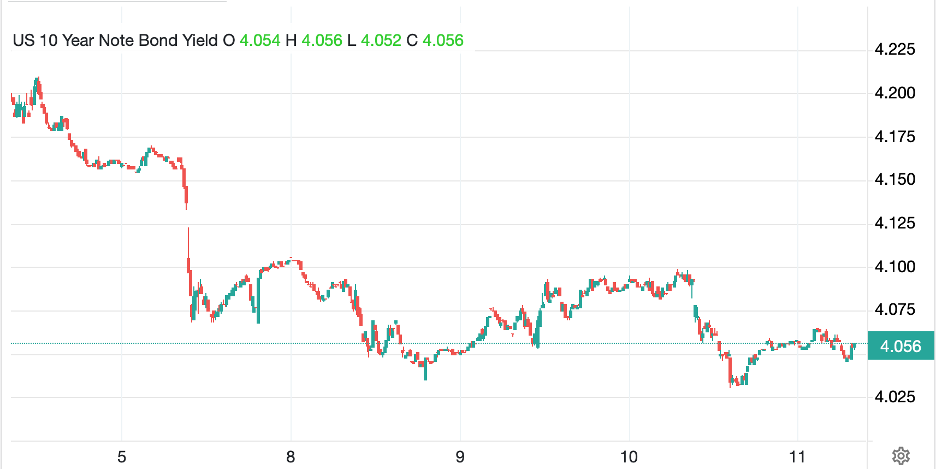
Bond markets remain frozen as Treasury yields have edged higher by just 1bp and European sovereign yields are +/-1bp from yesterday’s close.  As you can see from the chart below, the range on 10-year Treasuries has been fairly narrow for the past week.  Perhaps today’s CPI will shake things up.

Source: tradingeconomics.com

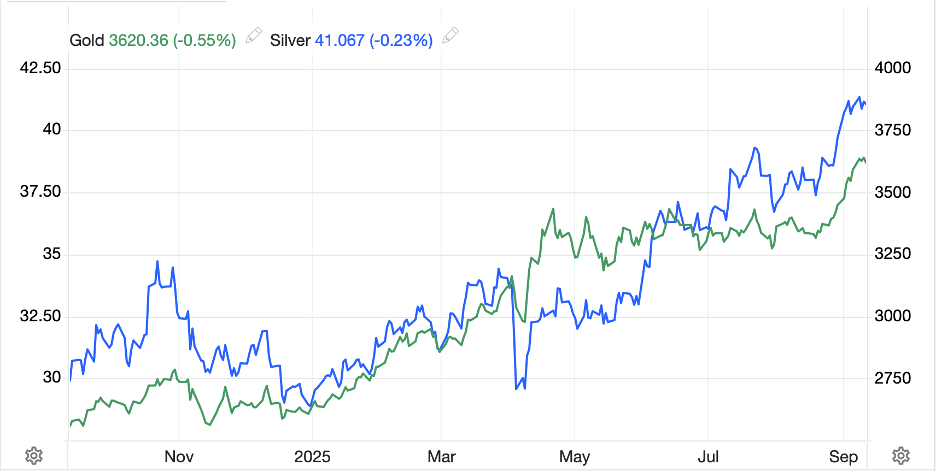
In the commodity space, oil (-1.25%) is giving back the gains it saw earlier in the week but basically remains unchanged overall.  If fears grow that a recession is upon us, I could see a rationale for oil to decline, but it is hard to get excited about the market right now.  Gold (-0.6%) is backing off its most recent all-time high, but is still firmly above $3600/oz.  Given the recent run, it is no surprise it takes a breather here and there is no reason to believe that precious metals are topping out.  In fact, a look at the charts tells me that there is plenty of upside left across the space.

Source: tradingeconomics.com

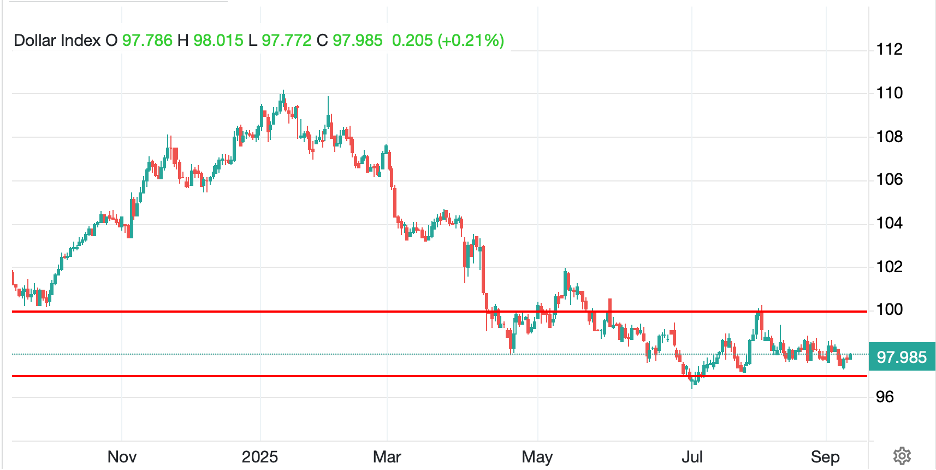
Finally, the dollar is a bit firmer this morning, probably one reason the precious metals are under some pressure, but here too, if we use the DXY as our proxy, the range is pretty clear.

Source: tradingeconomics.com

JPY, INR and ZAR are the largest movers this morning, each declining -0.4%, while the rest of the world is mostly softer by -0.1% to -0.2%.  Broad based dollar strength but no depth whatsoever.  We shall see how things behave after the CPI release.

And that’s really it.  For now, the big picture remains the same, where the prospects of an easier Fed will weigh on the dollar and support commodities.  Equities will like that for now, at least until inflation picks back up, and bonds feel subject to manipulation so I’m just not sure.

Good luck

Adf