Impuissance

The world now awaits the response
Of Israel, which at the nonce
Has traders concerned
Restraint will be spurned
While mullahs pray for impuissance

Thus, oil continues to rise
And it oughtn’t be a surprise
The talk that inflation
Achieved its cessation
Has slowed while concerns crystalize

The most important market story this morning, I would contend, is the potential response by Israel after Iran’s missile attacks yesterday.  While only a handful of the approximately 180 missiles breached the Israeli aerial defenses, some damage was inflicted.  Israel has promised a response at their leisure and history has shown they have been effective in inflicting greater damage than they receive.

The major market concern is that Israel will attack Iran’s oil production capability, something which would certainly drive oil prices, which have spiked more than 8% in the past two sessions, higher still.  Currently, Iran is producing about 3.27 mm barrels/day, a solid 3% of global production and consumption.  Given the highly inelastic nature of the oil price, any attack there would have a substantial impact, at least in the short term.  Remember, though, that the Saudis have something along the lines of 3mm barrels/day of production shut in as OPEC+ has tried to support the price.  I expect that they would be able to bring that online quite quickly, so any price move would be short-lived.  The downside, though, is that it would use up the available spare capacity so any other event, say another hurricane which shuts in Gulf of Mexico production, would have an outsized impact.  Net, a response of that nature may only have a short-term impact on the price but would lead to more fragility overall.

As well, I am confident that the Biden administration is really working to convince Israel to leave the oil assets alone as during the campaign, a spike in oil, and by extension gasoline, prices will not be a welcome turn of events.  However, from Israel’s point of view, the destruction of Iran’s oil production capacity would result in a much weaker Iran, one that would have far more difficulty promoting their attacks on Israel.  At this point, we can only wait and see.

Away from that news, yesterday saw the PMI and ISM data releases which simply confirmed that global manufacturing activity remains in a slump.  The US report, printing at a weaker than expected 47.2, the 22ndmonth in the last 23 that the reading has been below the boom/bust line of 50.0, continues to drive concerns about economic weakness in the US.  Of course, manufacturing represents less than 25% of the economy directly, although many service jobs are dependent on the manufacturing sector.

Arguably, the perception of economic weakness that remains prevalent in the US stems from this situation, where manufacturing remains weak, and the ancillary activity typically driven by it remains weak as well.  These are the traditional blue-collar jobs, and it is those people who seem to be feeling the current economic malaise most severely.  In fact, this is as good an explanation as I can find for why despite some decent top line economic data, there are still so many people in the US who are highly stressed and living paycheck to paycheck.  While this is a macroeconomic discussion, it is also a key political discussion as it will highly likely be an important driver of voters come November.

As to the other topic that has traders engaged, central bank policy, the plethora of Fed speakers yesterday did nothing to alter any views on their next steps.  Currently, the Fed funds futures market is pricing a 35% probability of a 50bp cut in November, but still pricing an 85% probability that there will be 75bps of cuts by year end.  Now, this is less cutting than had been priced just a week ago, but that move was driven by Powell on Monday.  Given the amount of data that we will be receiving between now and the November meeting, including two NFP reports as well as a CPI and PCE report this month, and the first look at Q3 GDP, many views can change.

And that’s kind of it this morning.  Last night’s VP debate had no market impact, nor would I have expected it to do so.  Worries about the Middle East and questions about central bank policy are the current market drivers.

With that in mind, let’s see how things played out overnight after yesterday’s weak showing in US markets.  In Japan, the Nikkei (-2.2%) gave back Tuesday’s gains as the market tries to determine exactly how new PM Ishiba is viewing the economy and central bank.  In a statement, he indicated the government would work with the BOJ to achieve joint goals, and his initial hawkish perception has been walked back.  In fact, it is odd that Japanese stocks fell given JGB yields (-2bps) also declined alongside the yen (-0.7%) on those comments.  As to the rest of Asia, the Hang Seng (+6.2%) rocketed higher on the Chinese stimulus story (mainland markets are still closed for their holiday), but the other Asian markets that were open, including Korea, Malaysia and Indonesia, all saw selling pressure with declines on the order of -1.0%.

In Europe, continental bourses are all lower led by the DAX (-0.6%) and IBEX (-0.6%) although the FTSE 100 (+0.2%) has managed a small gain.  The UK move has been driven by energy stocks rallying on the Middle East story while the lack of energy stocks on the continent seems to be the key to losses as investors turn cautious.  As to US futures, at this hour (7:30), they are lower by between -0.2% and -0.4%.

Bond yields are lower this morning with Treasuries down -2bps while European sovereign yields have all fallen between -5bps and -6bps.  The weak PMI data there has increased the discussion about more aggressive policy ease from the central bank and the likelihood that inflation stays quiescent.

We have already discussed oil but a look at the metals markets shows that after a 1% rally yesterday, gold (-0.3%) is consolidating near its all-time highs, while both silver (+0.3%) and copper (+0.8%) continue to move higher.  For the latter two, everything I read is about how both metals are critical for building out the energy transition infrastructure and both metals are in structural shortage with stockpiles being utilized as mining output lags demand and getting new mines up and running is a decade long affair.  My take is both have further to rise.

Finally, the dollar is net little changed this morning after a very solid two-day rally.  Remember it was just Monday that I was discussing key technical levels in the DXY (100.00), EUR (1.1200) and GBP (1.3500).  Well, we have moved well away from all those levels as the dollar weakness story takes a break.  When Chairman Powell explained he was in no hurry to cut rates rapidly, that part of the narrative needed to change quickly…and it did.  So, this morning, aside from the yen’s weakness mentioned above, the other large mover is NOK (+0.7%) which is simply responding to the oil rally.  In fact, the commodity currencies are doing exactly what they are supposed to be doing with CLP (+0.5%) tracking copper and MXN (+0.4%) tracking both silver and oil.  ZAR (unchanged) is actually the surprise here although it has been rallying steadily since April on a combination of the strong metals markets and continued belief in a better economic situation based on the new government’s business friendly policies.

On the data front, this morning brings only ADP Employment (exp 120K) and the EIA oil inventories where further inventory drawdowns are anticipated.  We also hear from four more Fed speakers although given Powell’s lack of concern regarding the speed of cuts, it will be hard for these speakers to change the market perception in my view.  This leaves us with the big picture.  Right now, employment remains the most important data for the Fed and their policy views.  As such, this morning’s ADP is likely to have more importance than it ordinarily would, despite the limited correlation between this data and the NFP to be released on Friday.

It seems that there are some subtle changes in central bank views with market perceptions of FX moves impacted.  The Fed is now seen as not quite as dovish, while the BOJ and ECB are seen as a touch more dovish, hence the dollar’s gains against both the yen and euro.  However, I think the central bankers realize they are still feeling their way in the dark and will be slow to respond to outlier data, so this vibe seems likely to hold in the near term.

Good luck
Adf

Not in a Hurry

The committee is not in a hurry
Said Jay, but the bulls needn’t worry
‘Cause Jay knows what’s what
And he can still cut
Quite quickly and watch the bears scurry
 
Meanwhile, at all ports in the east
The longshoremen’s working has ceased
With them now on strike
We could see a hike
In costs soon with ‘flation increased


“Overall, the economy is in solid shape; we intend to use our tools to keep it there. This is not a committee that feels like it’s in a hurry to cut rates quickly.  Ultimately, we will be guided by the incoming data. And if the economy slows more than we expect, then we can cut faster. If it slows less than we expect, we can cut slower.”

These were the key comments by Chairman Powell yesterday at the National Association for Business Economics annual meeting in Nashville.  They were the very essence of the two-handed economist who explains both sides of an issue without drawing a conclusion.  However, it appears what the market heard was ‘the Fed’s only going to cut 25bps at a clip going forward’.  This was made evident by the fact that when he began speaking, we saw equity markets dip right away as per the chart below of the S&P 500, although as he continued, and made clear that they expected to continue to cut rates and support the economy, traders (and algorithms) decided things were fine.  

Source: Bloomberg.com

We also heard from two other Fed members, Atlanta Fed president Bostic and Chicago Fed president Goolsbee, who both explained 50bps could well be the appropriate next move if things don’t follow their current script perfectly.  Naturally, equity markets heard that news and were soothed, hence the result that all three major indices closed slightly higher on the day.

The other major story this morning is that the International Longshoreman’s Association, the union for dockworkers along the entire East Coast and Gulf of Mexico, have gone on strike as of midnight.  They are demanding a 77% increase in wages over the next 6 years as well as promises about the speed with which further automation will occur in order to save jobs.  While the Taft-Hartley act could be invoked by the president to force both sides back to the bargaining table and require the workers to get back on the job for the next 80 days, President Biden has chosen not to do so in an effort to polish his political bona fides with unions.

The ultimate impact of the strike will depend entirely on its length.  This was not a surprise and many retailers and other importers pre-ordered inventory to tide them over as the holiday shopping season gets going.  However, estimates range up to an economic cost of $5 billion per day for each day of the strike, and the longer it goes on, the bigger the problem because rescheduling once things are settled will be that much more complex.  Regardless of the timing, though, one can be pretty certain that this will pressure prices higher as either shortages of certain items develop, or the wage gains result in higher shipping costs which will almost certainly be passed through the value chain.  

Remember, while headline PCE fell to 2.2% last month, core remained at 2.7%.  In the CPI readings, headline is still 2.5% with core at 3.2%, and perhaps more disconcertingly, median CPI at 4.2%.  Powell’s decision to cut rates 50bps last month with GDP still growing at 3%, the Unemployment Rate at a still historically low level of 4.2% and inflation, whether measured as PCE or CPI well above 2.0% was quite aggressive.  If this strike lasts a while, more than one week, expect to see price pressures begin to build again and that is going to put the Fed in a very difficult position.

One last thing to consider is the fact that virtually every major central bank around the world is in easing mode now that the Fed has begun to cut despite the fact that growth remains in decent shape in most places (Germany excepted).  This morning’s Eurozone CPI data (1.8%, 2.7% core) was even softer than expected virtually guaranteeing more aggressive action by the ECB and of course the PBOC was hyperaggressive last week in their easing actions.  Yesterday, Banxico indicated they may begin to cut more aggressively after having started their easing stance with 25bp cuts, as inflation in Mexico continues to decelerate to their target level of 3% +/- 1%.  The point is that policy worldwide is easing, or even in the few places where it is not, e.g. Japan and Australia, they are not tightening at any great pace.  The upshot is there is greater scope for a rebound in inflation while the dollar and other currencies continue to devalue vs. real items like commodities and real estate.  That is another way of saying that prices in those two asset classes should continue to climb.  As to the fiat currency world, relative values will depend on the pace with which individual nations ease, but they will all sink over time.

So, how have markets responded to the latest news?  After the modest US gains yesterday, and remember China is closed all week, Japan (+1.9%) regained about half of Monday’s declines after Ishiba-san was officially named PM and he appointed and Abenomics veteran, Katsunobu Kato, as his FinMin, helping encourage the idea that the BOJ may not be quite as aggressive as previously thought.  The rest of Asia saw more gainers than laggards with Taiwan (+0.75%) the next best performer and a mix otherwise.  In Europe, the picture is mixed with some gainers (FTSE 100 +0.4%, DAX +0.3%) and some laggards (IBEX -0.6%, CAC -0.2%) after Manufacturing PMI data across the continent continued to show lackluster results with Germany falling even further to a reading of 40.6 although Spain’s reading jumped to 53.0.  I must admit the stock market outcomes seem backward although I can understand the German view that the ECB will be more aggressive, thus supporting stocks, but why that is not helping Spain is a mystery.  As to US futures, at this hour (7:20) only the DJIA (-0.35%) is showing any discernible movement.

In the bond market, after yields backed up 5bps yesterday over concerns that the Fed’s more aggressive stance would lead to inflation and the port strike would not help that situation, they are sliding this morning.  Treasury yields, after touching 3.80% during yesterday’s session are down to 3.74% this morning and European sovereign yields have fallen even more sharply, between -7bps (Germany) and -12bps (France) as traders and investors become convinced that the ECB is going to become more aggressive in their easing.  JGB yields also slid 1bp last night after Kato-san’s appointment.

It should be no surprise that metals prices are rebounding this morning given the decline in yields as well as the growing concerns over inflation.  So, gold (+0.5%) is leading the way higher but the entire group is higher on the session.  However, oil (-0.8%) remains under pressure as news of Israel’s ground incursion into Lebanon to root out Hezbollah seem to be ignored while news that Libya is getting set to restart production after a political settlement was reached there adds to the supply picture.  

Finally, the real surprise is the dollar, which based on yields and metals would have been expected to continue sliding, but instead has rebounded sharply.  In fact, yesterday, the DXY rallied virtually all day and that has continued this morning with the index now above 101.00.  You may recall I highlighted that it was testing the 100 level which is seen as a key support.  I guess there is no break coming today.  This morning, the dollar’s move is universal, rising versus both the euro (-0.5%) and pound (-0.5%) as well as the rest of the G10 save the yen which is unchanged on the day.  In fact, 0.5% is the magnitude of that move virtually all the other currencies in the bloc.  As to the EMG bloc, these currencies have also suffered by -0.5% or so regardless of the region with the CE4 the worst performers, averaging -0.7%, while Asian currencies were down more on the order of -0.3% and LATAM -0.5%.

On the data front, ISM Manufacturing (exp 47.5) and JOLTS Job Openings (7.655M) are the main features and we hear from four more Fed speakers (Bostic, Cook, Barkin and Collins) before the day is done.

It is hard for me to look at the current situation without growing concern that the Fed is in the process of making a catastrophic error by easing policy into the base of an inflation cycle that just got more impetus from a key labor situation.  In the end, it is not clear to me how the dollar will behave against other currencies in the short run, but I see only upside for commodity prices.  If things do get ugly, the dollar will be seen as the best of a bad lot, and as commodity demand grows, so will demand for the greenback in order to buy those commodities, but this is not a positive story.

Good luck

Adf

More Money to Mint

As an eagle soars
So too did the yen after
Ishiba-san won


Political change in Japan is far less bombastic and exciting than here in the US as evidenced by the election of Shigeru Ishiba as the new leader of the Liberal Democratic Party (LDP) last night.  Given the LDP’s large majority in the Diet (Japan’s parliament), as the new leader, Ishiba-san is now all but certain to be the new Prime Minister. This will likely be confirmed by a vote as early as next Tuesday, but sometime very soon regardless.

Ishiba’s background, a party veteran and former defense minister, seems to have been the right focus at the right time as strains with China have recently increased and the electorate (LDP members, not the general population) are clearly hearing about security concerns more than other issues.  The implication is that economic issues were not the driving force here, but in that vein, Ishiba’s views appear to be to allow the BOJ and Governor Ueda to continue their normalization process, finally ending the decade plus of Abenomics that worked to raise inflation.  

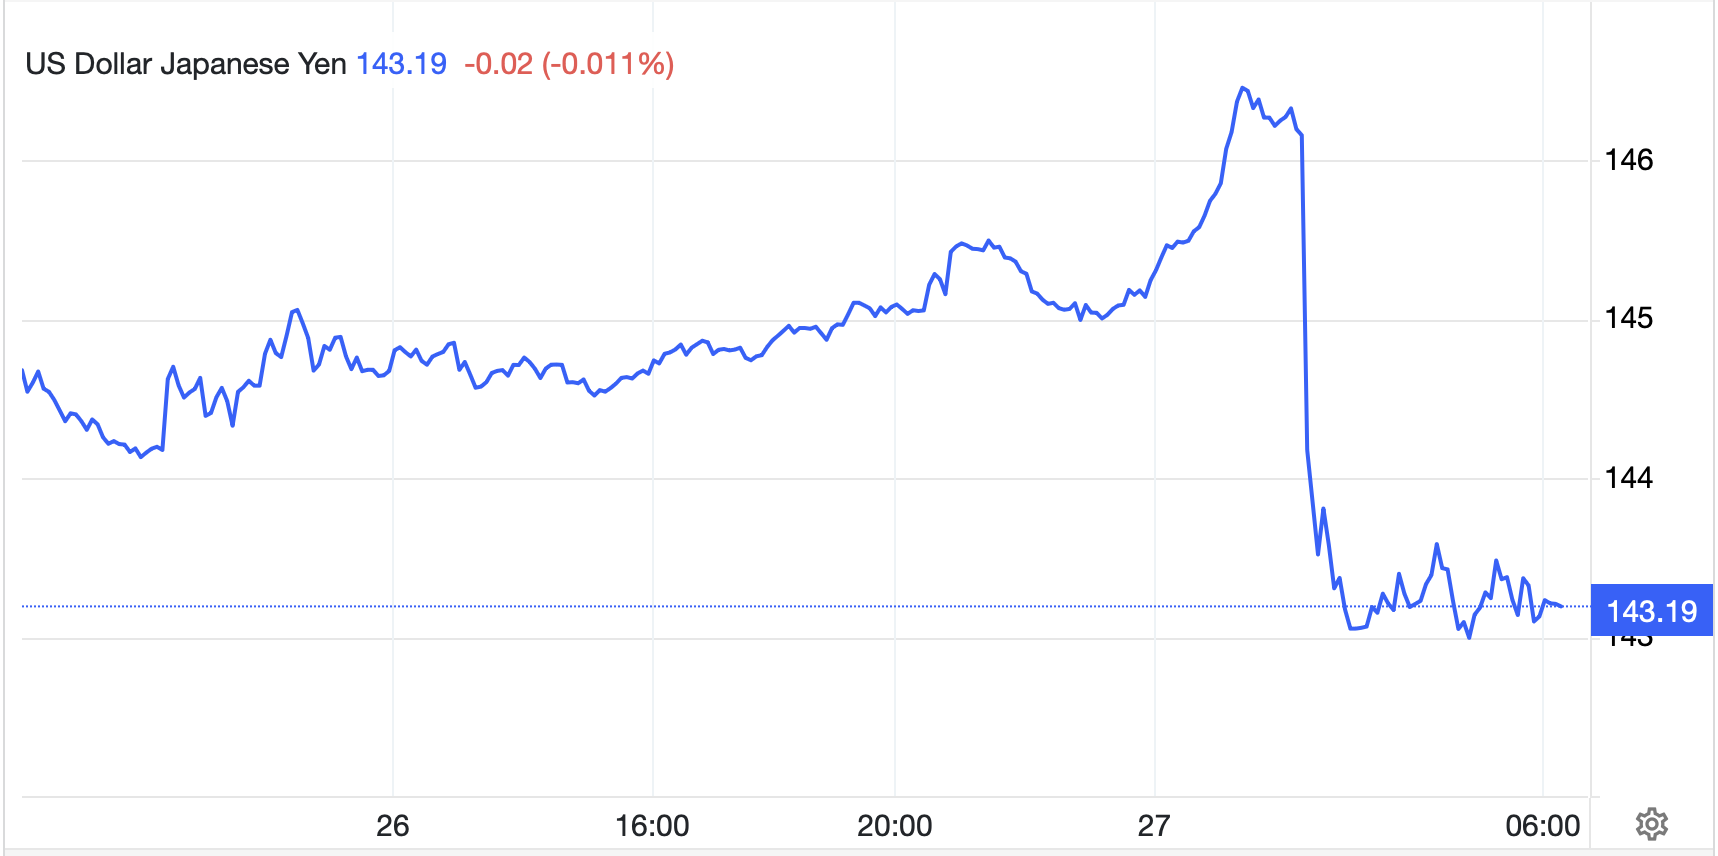
Now, as it happens, last night Tokyo inflation was released with the headline falling to 2.2% and the core falling to 2.0%, as expected.  It also appears that one of his key opponents, Sanae Takaichi, had been an advocate of pressuring the BOJ to slow its policy normalization, so with the results, market participants reacted swiftly, and the yen rallied sharply on the news as per the below chart while the Nikkei after an initial sharp decline, rebounded and closed higher by 2.3%.

Source: tradingeconomics.com

Going forward, it seems unlikely that the yen is going to be a focus of the new Ishiba administration.  Rather, he is clearly focused on defense strategy so Ueda-san will be able to continue his normalization efforts at his own pace.  As evidence, JGB yields stopped their recent slide and backed up 2bps overnight.  I suspect that we will see a very gradual move higher here with key drivers to be purely economic issues rather than political ones, at least for a while.

This morning, the PCE print
Will help give another key hint
To whether the Fed
When looking ahead
Will soon start, more money, to mint

The other story for the day is the PCE report to be released at 8:30. Current expectations are for a 0.1% M/M, 2.3% Y/Y rise in the headline number and a 0.2% M/M, 2.7% Y/Y rise in the ex-food & energy reading.  If these are the realized outcomes, the trend lower in inflation will remain on track and all the Fed speakers will feel vindicated that the 50bp cut last week was appropriate.  But I think it is worthwhile to take a quick look at a chart of how this number (core PCE) has evolved over time to help us better understand where things are in relation to the pre-pandemic economy. 

Source: tradingeconomics.com

Now, while there is no doubt that we are well below the highest levels seen two years ago, it is not difficult to look at this chart and see a potential basing formation, well above the pre-pandemic levels.  In fact, today’s expectations on the core reading are for a bounce higher of 0.1% which would only reinforce the idea that we have seen the bottom in this reading.  Of course, any one month’s data is not definitive as everything is subject to revisions, and simply looking at the chart, it is easy to see both ebbs and flows in the data well before the pandemic.  But I continue to be concerned that the Fed’s very clear ‘mission accomplished’ attitude on inflation is a big mistake that will come back to haunt us all sooner than you think.

Ahead of the data, a look at the overnight session shows that the ongoing rally in risk assets that started with the Fed and has been goosed by China’s efforts this week, remains the dominant theme.  In fact, Chinese shares had another gargantuan session last night (CSI 300 +4.5%, Hang Seng +3.6%) as hedge funds who had been quite short the Chinese stock market prior to the announcements this week continue to scramble to cover those shorts as well as get long for the rest of the expected ride.  But away from China and Japan, the rest of Asia was far less excited with declines seen in India, Korea and Australia leading most indices lower there.  As to European bourses, they are firmer this morning led by the DAX (+0.8%) but green everywhere after preliminary inflation data for September from France and Spain saw declines well below expectations to 1.5% and investors increased the probability of an October ECB rate cut substantially.  While some ECB members remain concerned over the stickiness of services prices, which continue to hover above 4%, if the headline numbers are falling below 2%, I think it will be very difficult for Madame Lagarde to push back against another cut next month.  Meanwhile, ahead of the data, US futures are unchanged.

In the bond market, Treasury yields have edged lower by 1bp while European sovereign yields have moved a similar amount except for French OATs which have slipped 3bps.  The story about French debt yielding more than Spain, one of the original PIGS has gotten a lot of press and it seems deeper thinkers disagree with the idea and are buying ‘undervalued’ French OATs.  

In the commodity markets, oil (+0.15%) has finally stopped falling, at least for the moment, although the recent trend is anything but encouraging for oil bulls.  Crude is lower by -4.5% in the past week and -9.0% in the past month, clearly helping the headline inflation readings.  As to the metals markets, after another strong day yesterday, they are consolidating with very modest declines (Au -0.2%, Ag -0.1%, Cu -0.4%) although the trend in all three remains firmly higher.

Finally, the dollar, after several sessions under a lot of pressure, is also bouncing slightly, at least against most of its counterparts.  We have already discussed the yen’s gains, but vs. the rest of the G10, it is firmer by roughly 0.15% or so while vs. its EMG counterparts some are seeing losses  (CE4 -0.3% to -0.4%) while there are others with modest gains (ZAR +0.3%, MXN +0.4%).  For now, the trend remains for a lower dollar, and if we see a soft PCE reading this morning, I expect that to reassert itself as thus far, today’s price action appears more like a trading response to the recent weakness.

In addition to the PCE data, we also see Personal Income (exp 0.4%), Personal Spending (0.3%), the Goods Trade Balance (-$99.4B) and Michigan Sentiment (69.3).  Mercifully, on the Fed front, only Governor Bowman speaks, she of the dissent at the last meeting, although yesterday’s plethora of Fed speakers taught us nothing new at all.  

I don’t have a strong opinion as to how this data will play out, but I would caution that if PCE is firmer than expected, look for a hiccup in the recent euphoria over stocks and bonds, while the dollar consolidates its support.  However, if we see a softer print than forecast, watch out for a much bigger rally in stocks and a much weaker dollar.

Good luck and good weekend

Adf