Right On Humming

So, CPI didn’t decline
And may not be quite so benign
As Jay and the Fed
Consistently said
When hinting more rate cuts are fine
 
However, that will not deter
Chair Powell, next month, to confer
Another rate cut
Though it is somewhat
Unclear if his colleagues concur


Despite the fact the narrative is pushing Unemployment as the primary focus of the FOMC, yesterday’s CPI report, which seemingly refuses to decline to the Fed’s preferred levels, had Fed speakers beginning to hedge their bets regarding just how quickly rates would be coming down from here. [Emphasis added.]

St. Louis Fed President Alberto Musalem explained, “The strength of the economy is likely to provide the space for there to be a gradual easing of policy with little urgency to try and find where the neutral rate may be.”

Dallas Fed President Lorrie Logan commented (using a series of maritime metaphors for some reason) “After a voyage through rough waters, we’re in sight of the shore: the FOMC’s Congressionally mandated goals of maximum employment and stable prices, but we haven’t tied up yet, and risks remain that could push us back out to sea or slam the economy into the dock too hard.”  

Finally, Kansas City Fed President Jeff Schmid told us, “While now is the time to begin dialing back the restrictiveness of monetary policy, it remains to be seen how much further interest rates will decline or where they might eventually settle.”  

If we ignore the oddity of the maritime metaphor, my takeaway is that the Fed is still looking to cut rates further as directed by Chairman Powell, but the speed with which they will act seems to be slowing down.  As I have maintained in the past, given the current data readings, it still doesn’t make that much sense to me that they are cutting rates at all, but arguably, that’s just another reason I am not a member of the FOMC.  Certainly, the market is on board as futures pricing increased the probability of that cut from 62% before the release to 82% this morning.  There is still a long way to go before the next meeting, with another NFP, PCE and CPI report each to be released, as well as updates on GDP and Retail Sales and all the monthly figures, so this story is subject to change.  But for now, a rate cut seems likely.

One other thing, I couldn’t help but notice a headline that may pour a little sand into the gears of the rate cutting apparatus at the Eccles Building.  This is on Bloomberg this morning: Manhattan Apartment Rents Rise to Highest Level Since July.  Again, the desperation to cut rates seems misplaced.

Despite the fact rate cuts are coming
The dollar just keeps right on humming
This morning it’s rising
Which ain’t that surprising
As more depths, the euro is plumbing

Turning our attention to the continent, European GDP figures were released this morning, and they remain disheartening, to say the least.  While the quarterly number rose to 0.4%, as you can see from the chart below, it has been several years since the continent showed any real growth, and that was really just the rebound from the Covid lockdowns.  Prior to Covid, growth was still lackluster.
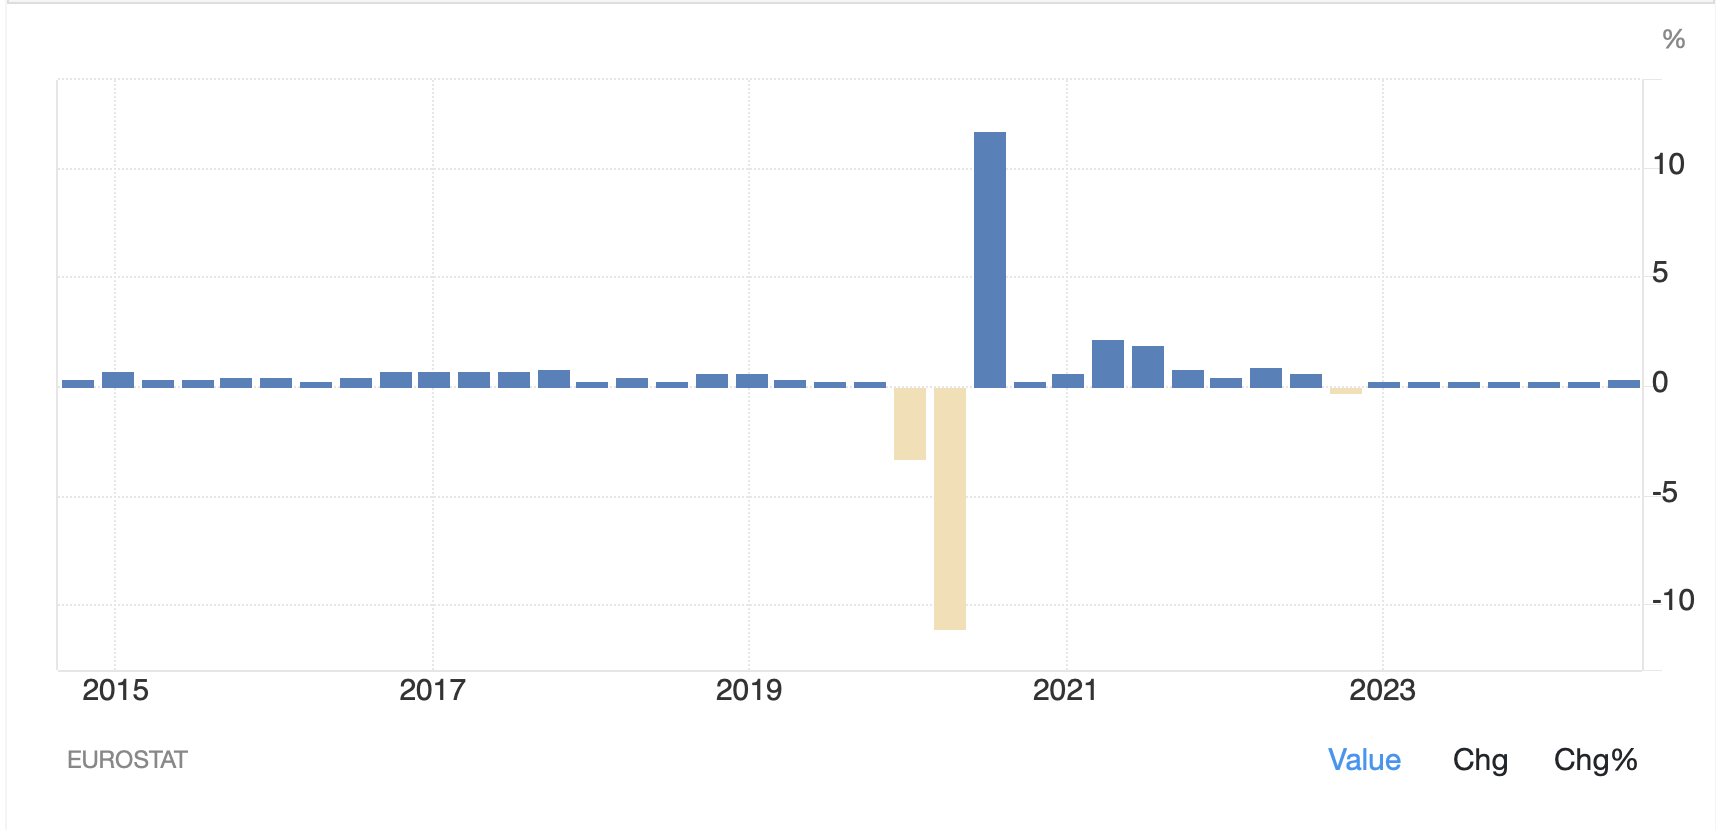
Source: tradingeconomics.com

While these are the quarterly numbers, when looking at the Y/Y results, real GDP grew less than 1% in Q3 for the past 6 quarters and, in truth, shows little sign of improving.  After all, virtually every nation in the Eurozone is keen to continue their economic suicide via energy policy and regulation.  This thread on X (formerly Twitter)is a worthwhile read to get an understanding of the situation on the continent.  I show it because this morning, the euro has fallen yet further, and is touching the 1.05 level, seemingly on its way to parity and below.  It highlights that since just before the GFC, the Eurozone economy has fallen from virtually the same size as the US economy, to just 60% as large, and explains the key reasons.  Read it and you will be hard-pressed to consider the euro as a safe store of value, at least relative to the dollar.  And remember, the dollar has its own issues, but at least the US economy remains dynamic.

But the dollar is king, again, this morning, rising against virtually all its counterparts on the session.  Versus the G10, the average movement is on the order of 0.3% or so, but it is uniform.  USDJPY is now pushing 156.00, the pound seems headed for 1.2600 and Aussie is below 0.65.  My point is concerns about the dollar and its status in the world seem misplaced in the current environment.  If we look at the EMG bloc, the dollar is stronger nearly across the board as well, with similar gains as the G10.  MXN (-0.5%), ZAR (-0.4%) and CNY (-0.2%) describe the situation which has been a steady climb of the greenback since at least the Fed rate cut, and for many of these currencies, for the past 6 months.  Nothing about President-elect Trump’s expected policies seems likely to change this status for now.

If we look at equity markets, yesterday’s US outcomes were essentially little changed on the day.  However, when Asia opened, with the dollar soaring, we saw a lot more weakness than strength, notably in China with the CSI 300 (-1.7%) and Hang Seng (-2.0%) leading the way lower although the Nikkei (-0.5%) also lagged along with most other Asian markets.  While there were some modest gainers (Australia +0.4%, Singapore +0.5%) red was the predominant color on screens.  In Europe, however, investors are scooping up shares with the DAX (+1.2%) leading the way although all the major bourses are higher on the session.  It seems that there is a growing consensus that the ECB is going to cut 25bps in December and then another 25bps in January, which has some folks excited.  US futures, meanwhile, are slightly firmer at this hour (7:00).

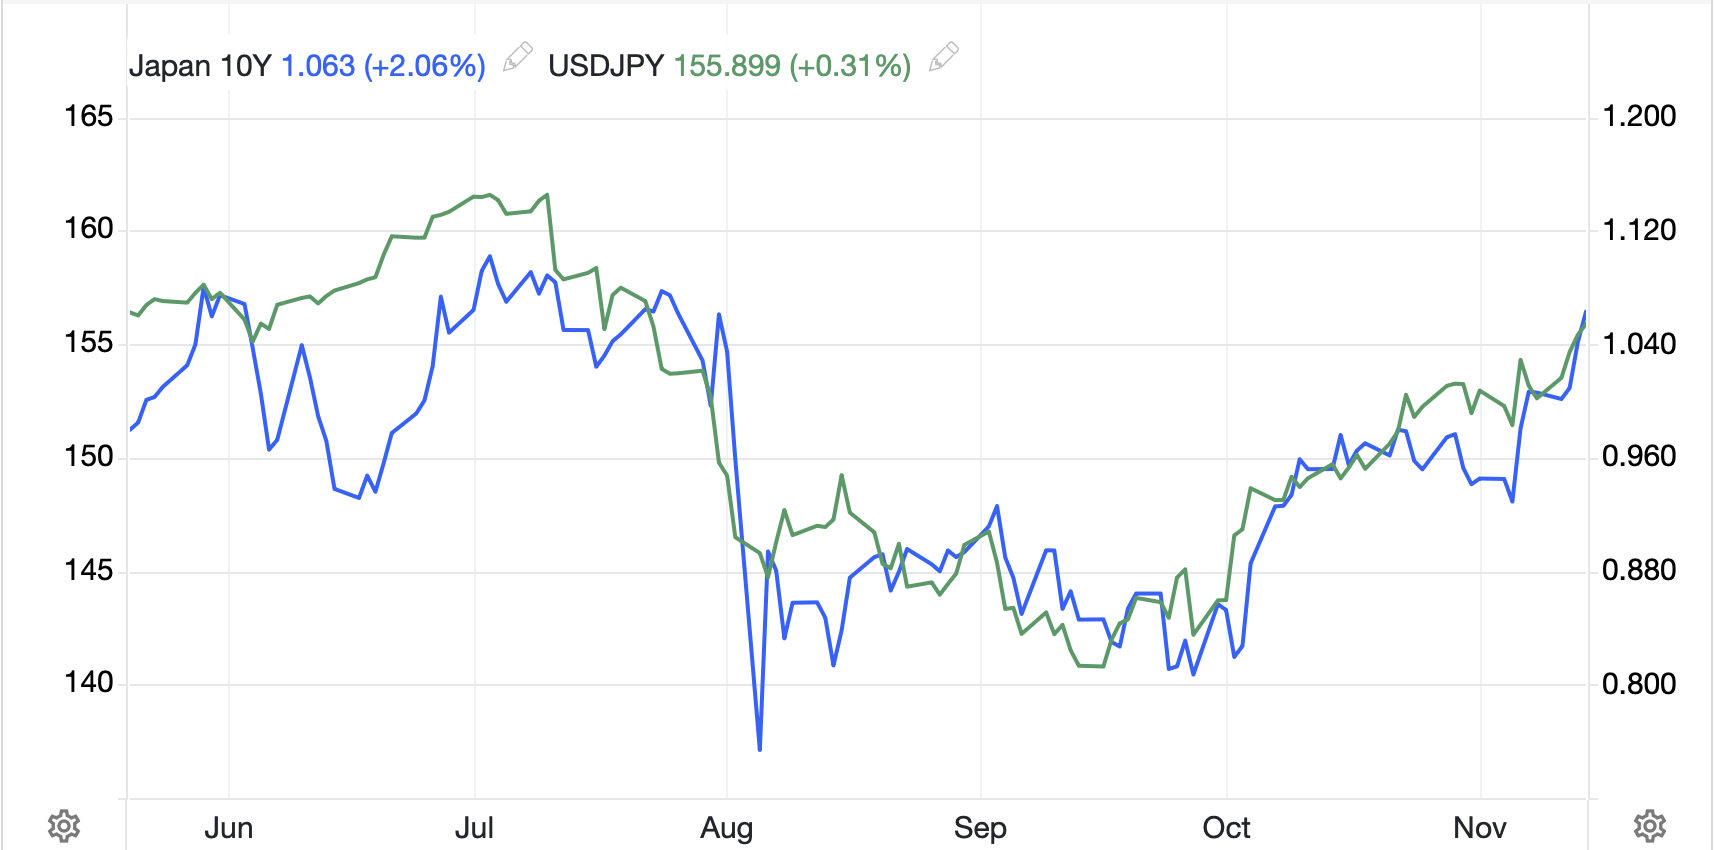
All this is happening against a backdrop of a continued climb in yields around the world.  Yesterday, again, yields rose with 10yr Treasuries trading as high as 4.48%, their highest level since May, and that helped drag most European yields higher as well.  This morning, we are seeing some consolidation with Treasury yields backing off 1bp and European sovereign yields lower by -2bps across the board.  The one place not following is Japan, where JGB yields edged higher by 1bp and now sit at 1.05%.    Consider, though, that despite those rising yields, the yen continues to slide.  In fact, that is the correlation that exists, weaker JPY alongside higher JGB yields as you can see in the below chart.
Source: tradingeconomics.com

While it is open to question which leads and which follows, my money is on Japanese investors searching for higher yields, selling JGB’s and buying dollars to buy Treasuries.

Finally, the commodity space continues to get blitzed, or at least the metals markets continue that way as once again both precious and industrial metals are all lower this morning.  In fact, in the past week, gold (-5.7%), silver (-6.4%) and copper (-9.1%) have all retraced a substantial portion of their YTD gains.  It is unclear to me whether this is a lot of latecomers to the trade getting stopped out or a fundamental change in thinking.  My view is it is the former, as if the Trump administration is able to support growth, I expect that will reveal the potential shortages that exist in the metals space.  Oil (+0.4%) is a different story as it continues to consolidate, but here I think the odds are we see lower prices going forward as more US drilling brings supply onto the market.

On the data front, this morning brings the weekly Initial (exp 223K) and Continuing (1880K) Claims data along with PPI (0.2%, 2.3% Y/Y) and core PPI (0.3%, 3.0% Y/Y).  In addition, the weekly EIA oil data is released with modest inventory builds expected and then we hear from Chair Powell at 3:00pm this afternoon.  Arguably, that is the event of the day as all await to see if the trajectory of rate cuts is going to flatten out or not.

I cannot look at the data and conclude that the Fed will be very aggressive cutting rates going forward.  The futures market is now pricing in about 75bps of cuts, total, by the end of 2025.  That is a 50bp reduction in that view during the past month and one of the reasons the dollar remains strong.  I would not be surprised if there are even fewer cuts.  Right now, everything points to the dollar continuing to outperform virtually every other currency.

Good luck

Adf
Lickspittle

The Fed has a banker named Jay
Who last week was quick to betray
His fervent belief
He can’t come to grief
If Trump wants to force him away
 
This morning his Journal lickspittle
Wrote glowingly ‘bout Jay’s committal
To stand strong and firm
And finish his term
No matter how much he’s belittled


First, on this Veteran’s Day holiday, let us all pause a minute and remember those veterans who gave their lives for our nation.

The reverberations of Donald Trump’s re-election last week continue to be felt around the world with comments from virtually every walk of life explaining their joy/distress at the outcome and trying to prognosticate what will play out in the future.  I will tell you that I have no idea how things will evolve, although I am hopeful that his administration will be able to reduce the size of the federal government as that can only be a benefit.

But one of the things that we learn about people during times of change, especially people who believe they are crucially important to the world, is just how much they believe they are crucially important to the world.  Nothing highlights this quite like the lead article in this morning’s WSJ titled, If Trump Tries to Fire Powell, Fed Chair Is Ready for a Legal Fight.  This is not to say that Powell doesn’t have an important role, he certainly does.  But this pre-emption of the entire question is a testimony of just how important he thinks he is.  

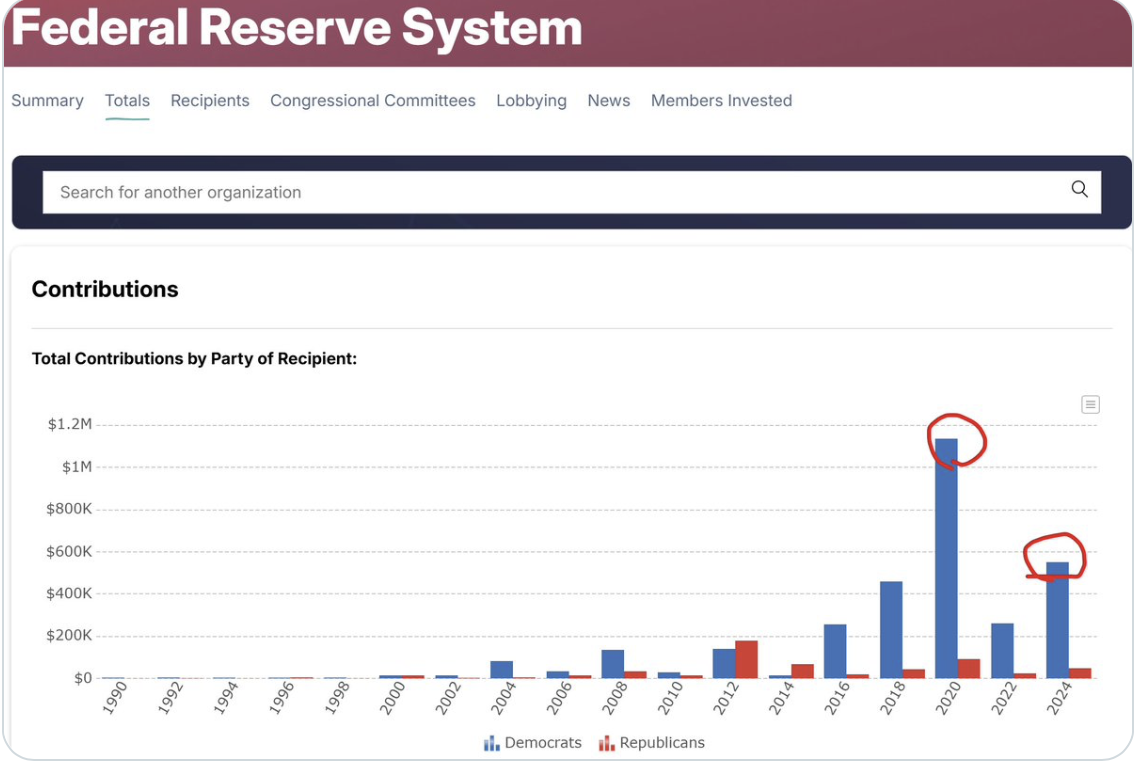
My one observation on this is that despite all the discussion that the Fed isn’t political, it is clearly a very political institution.  Nothing highlights that better than this Tweet from Joseph Wang (aka @FedGuy12), a commentator who spent a dozen years at the Fed and understands its inner workings quite well.  Under the rubric that a picture is worth 1000 words, take a look at Federal Reserve political contributions below and then ask yourself if the Fed is not only political, but partisan.  

Source: X @FedGuy12

It is important to recognize this as it also may help explain why the Fed is cutting interest rates despite GDP (currently 2.8%) and Core PCE (currently 2.7%) running far above their long-term expectations and Unemployment (currently 4.1%) running below their long-term expectations as per the below SEP from the September FOMC meeting.  If anything, I might argue they should be raising interest rates!

Source: fedreserve.gov

At any rate, the ramifications of this election outcome are likely to drive the market narrative for a while yet.

But overnight, there just wasn’t that much of interest, at least not that much new.  So, let’s take a look at overnight market activity.  After Friday’s latest record high closes in the US, the picture in Asia was less robust with Japanese equities basically unchanged on the day after Shigeru Ishiba was elected PM to run a minority government, while Hong Kong (-1.5%) and mainland Chinese (+0.7%) shares went in opposite directions.  Chinese financing data was released that was mildly disappointing, but there are several stories about how the government is going to reacquire land that is currently in private hands but not being used and repurpose it for benefit.  The rest of the region had many more laggards than gainers, perhaps on concerns that Trump will be imposing tariffs throughout the region.  As to Europe, despite all the pearl clutching by the leadership there, equity investors are excited with gains seen across the board (DAX +1.3%, CAC +1.2%, FTSE 100 +0.8%).  US futures at this hour (7:30) are continuing their ride higher, up 0.4%.

In the bond market, Treasuries aren’t really trading today with banks closed.  In Europe, sovereign yields have edged down between 1bp and 2bps, perhaps feeling a little of that equity euphoria, as there was precious little in the way of news or commentary to drive things.

In the commodity space, oil (-1.7%) is under further pressure as broadly slower global growth undermines demand while prospects of the Trump administration fostering significant additional drilling opportunities helps build the supply side.  However, NatGas (+7.0%) is soaring this morning as Europe, notably Germany, is suffering from dunkelflaute (maybe the best word I have ever heard) which means ‘a period of low wind and solar power generation because it is cloudy, foggy and still’, and so they need to buy a lot more NatGas to power the economy.  In fact, NatGas is higher by nearly 15% in the past month although remains substantially cheaper in the US than in Europe and Asia.  My take is this discrepancy cannot last forever.  As to the metals markets, they are under pressure again this morning with both precious (Au -0.9%, Ag -0.3%) and industrial (Cu -0.5%, Al-1.4%) feeling the pain.  

A key driver in the metals space is the dollar, which is rallying against all its counterparts this morning quite robustly.  The euro (-0.6%) is back to levels last briefly touched in April, but where it spent more time a year ago, as it seems to be heading to 1.05 and below.  Meanwhile, JPY (-0.8%) is also feeling the heat while NOK (-0.7%) is pressured by both the dollar’s general strength and the oil weakness.  In the EMG bloc, MXN (-1.3%) is having a rough go as the tariff talk heats up, but we have also seen weakness in EEMEA with ZAR (-1.4%), PLN (-1.0%) and HUF (-1.2%) all under pressure this morning.  Not to be outdone, Asian currencies, too, are selling off with CNY (-0.3%) back above 7.20 for the first time since August while THB (-0.9%), MYR (-0.7%) and SGD (-0.6%) demonstrate the breadth of the move.

With the holiday, there is no data to be released today, but this week brings CPI amongst other things.

TuesdayNFIB Small Biz Optimism91.9
WednesdayCPI0.2% (2.6% Y/Y)
 Ex food & energy0.3% (3.3% Y/Y)
ThursdayPPI0.2% (2.3% Y/Y)
 Ex food & energy0.3% (2.9% Y/Y)
 Initial Claims224K
 Continuing Claims1895K
FridayRetail Sales0.3%
 -ex autos0.3%
 Empire State Mfg-1.4
 IP-0.3%
 Capacity Utilization77.2%

Source: tradingeconomics.com

In addition to this data, we hear from 11 different Fed speakers this week, including Chairman Powell again at 3:00pm on Thursday afternoon.  It is difficult to believe that the message from last week is going to change, but you never know.  However, I expect that every one of them is going to be explaining that things are good, but they are cutting rates to ensure things remain that way as they consistently congratulate themselves on having slain inflation.  I hope they are right…I fear they are not.

For now, though, the US economy remains the strongest in the world (7% budget deficits will help prop up growth after all) and capital continues to flow in this direction.  I see no reason for the dollar to fall anytime soon.  Whatever problems lie ahead, I believe they are over the metaphorical horizon and other than a few doomporn purveyors, not in the market’s view.

Good luck

Adf

Clueless

The risks to our mandates appear
More balanced so let us be clear
We’re still cutting rates
Which just demonstrates
We’re clueless and shaking with fear


To absolutely nobody’s surprise, the Fed cut the Fed funds rate by 25bps yesterday.  The accompanying statement explained, “The Committee judges that the risks to achieving its employment and inflation goals are roughly in balance.”  The implication is that they remain confident that inflation is slowly heading to their 2.0% target, and they are keeping a close eye on the Unemployment Rate, especially after the terrible number last week.  Of course, the combination of the Boeing strike and the impact of the two major hurricanes, Helene and Milton, were likely responsible for a significant portion of that underperformance, so we will need to see how the November report, published on December 6th plays out.  There is a lot of time between now and then so the narrative could easily change prior to the release.  Be vigilant.

The press conference consisted of a lot of self-congratulatory comments about how they have done a good job “recalibrating” policy and continuing to insist inflation is dying, although not quite dead yet.  The market response was to continue the US equity rally, with the NASDAQ (+1.5%) leading the way higher and to reverse some of yesterday’s bond losses with 10-year yields slipping -8bps.  In the commodity markets, yesterday saw all of them rebound, recouping roughly half of their losses from Wednesday and the dollar gave back some of those initial gains as well.

At this stage, the market is pricing a two-thirds probability of another 25bp cut at the December meeting, and all eyes are now going to turn to Trump and whatever policy prescriptions he starts to tout.  The early indication is that people expect more growth in the US from his policies as the no-landing scenario seems to be the favorite.  We shall see.

Investors had high hopes that Xi
Would give away more renminbi
Instead, in a flop
They’ve spurred a debt swap
While stimulus, no one can see

The other story of note overnight was the final statement of the Standing Committee in China, where many had expected hoped the elusive Chinese Bazooka would be fired.  It was not.  Instead, they gave more details on an effective debt swap that they will permit for local governments.  

A brief tutorial: Chinese cities and regions had typically financed infrastructure investment via local government funding vehicles (LGFV) which issued debt to investors that was backed by the government entity, but not officially on their balance sheet.  This model evolved because there were restrictions on how much debt these cities/regions were allowed to issue.  These entities would then sell land to developers to service and pay off the debt.  It all worked great while the property bubble in China was inflating and nobody was the wiser.  But now that property prices have been falling for 3 years, it is a major problem because the cities/regions aren’t generating the property sales and revenues needed to repay the debt.  

The solution that Xi came up with is to allow the cities/regions to issue debt on the balance sheet, upwards of CNY 10 trillion over the next 5 years, and replace the off-balance sheet stuff from the LGFVs.  And that’s it!  A debt swap that will likely lower interest rates slightly and save somewhere along the lines of CNY 600 billion over 5 years.  While the central government claims there is only a total of CNY 14.3 trillion in these LGFVs, most analysts put the number at around CNY 60 trillion.  This is not really that stimulative, will not help Chinese consumers nor factories in any way, and is very likely to have only a tiny impact. 

Cagily, the Standing Committee didn’t announce this until after local markets closed for the weekend, so the fact that stocks on the mainland and in Hong Kong only fell -1.0% does not represent the totality of the disappointment.  I expect we will see further declines next week.  President Xi has some tough sledding ahead for his economy.

And that was really the news of note.  Literally everything else you can read is a post-mortem of the election.  So, let’s look at how markets behaved overnight.  Away from the Chinese share declines, there were more winners than losers in Asia, with those nations that seem to have closer ties to the US benefitting (Taiwan, Australia, Singapore, New Zealand) while others which are more neutral or in China’s sphere of influence under pressure (India, Thailand, Vietnam).  The other noteworthy news was that the Chinese Current Account hit its second highest surplus ever last month, but with most people expecting significant tariff implementation when Trump takes office in January, I suspect those numbers will decline.  

Meanwhile, European bourses are almost entirely under water this morning with most lower by -0.9% although Spain’s IBEX is unchanged on the day.  There hasn’t been much in the way of new data, and I sense that investors are starting to price in more difficult relations with the US now that it seems clear the Republicans will win the House as well, giving Trump the ability to implement his vision.  Meanwhile, at this hour (6:50) US futures are little changed, consolidating ahead of the weekend.

In the bond market, yields which backed off in the wake of the FOMC meeting yesterday have edged 2bps lower this morning and are now sitting at 4.30%. This is the level, when first reached a week ago, set hair on fire as to the dichotomy between the Fed cutting rates and longer-term yields rising.  My view continues to be that yields have higher to climb over time as the Fed’s inflation fight is not won, and it will become evident that is the case going forward.  As to European sovereign yields, they are all lower by -4bps this morning as they are simply following Treasury yields but had to catch up given the FOMC meeting occurred after their close yesterday.

In the commodity markets, it appears that nobody wants to own ‘stuff’ anymore as they are back under real pressure.  Oil (-1.4%) is sliding although that makes sense as a Trump administration is very likely to support as much production as possible thus increasing supply.  But metals prices are also under pressure (Au -0.5%, Ag -1.5%, Cu -2.2%) which makes less sense as if economic expansion is the view, I would expect these to perform well.  Of course, it is possible that this is a reaction to the damp squib from China last night, but I expect these items to gradually regain lost ground.

Finally, the dollar is gaining some strength this morning, rising against most of its G10 counterparts with AUD (-0.6%) the worst performer, although JPY (+0.5%) and CHF (+0.2%) have managed to climb.  It’s almost as if this is a classic risk-off scenario in the FX markets.  Certainly, EMG currencies are under pressure this morning with ZAR (-1.1%) the laggard, but declines across the board, notably CNY (-0.3%) and pushing back toward the 7.20 level.  But the dollar is strong everywhere in this bloc.  

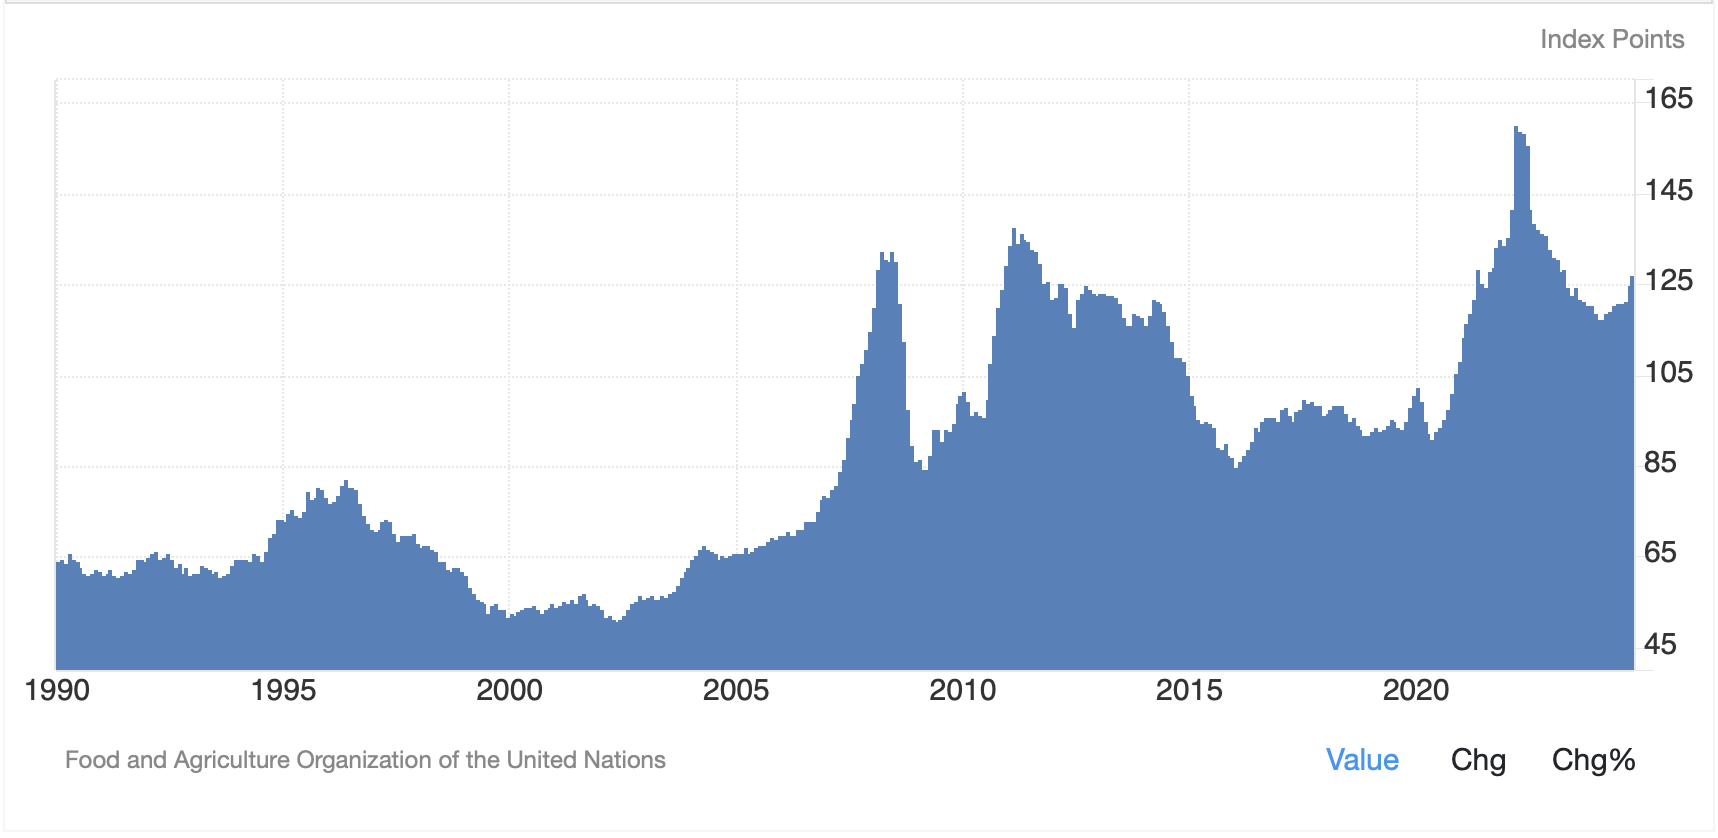
On the data front, Michigan Sentiment (exp 71.0) is all we get this morning although we also get our first Fed speaker, Governor Bowman, who has been one of the more hawkish voices.  One other thing to note is that the FAO’s Food Price Index was released this morning, climbing 2% to 127.4.  as you can see from the chart below, while this is not as high as prices reached in the immediate aftermath of the Russian invasion of Ukraine, this level is still in the upper echelons of where things have been over the past thirty-four years.

Source: tradingeconomics.com

It is worth remembering that the Arab Spring in 2011 was partially driven by rising food prices with large scale protests upending several governments.  Given how unhappy people around the world have been with their leadership, as evidenced by the number of governments that have been kicked out of office in recent elections and given that rising food prices have been a constant complaint, this needs to be kept in mind for how events unfold in the future.  To me, the market implication is that more volatile politics around the world will feed into more volatile financial markets as uncertainty grows.  In times of stress, the dollar remains the haven of choice, so this is just another reason to keep looking for the dollar to outperform in the medium term.

Good luck and good weekend

Adf

Pulling All-Nighters

As Harris and Trump try persuading
The voters, the markets keep trading
So, narrative writers
Are pulling all-nighters
To pump up the side that is fading
 
The latest attack is on Trump
Who’s blamed for the bond market slump
But what of the Fed
Whose rate cuts have spread
The fear that inflation will jump?


It appears we have reached the point in time when macroeconomic data is taking a backseat to the political situation.  Almost every story you can read in any of the mainstream media right now is about how the election is going to affect whatever subject an article is about.  The latest discussion, which I have seen across numerous sources like Bloomberg, the WSJ and Reuters, just to name a few, is that the bond markets recent decline is entirely Trump’s fault.  The logic is that as Trump’s election prospects improve, and those of fellow Republicans in both the House and Senate alongside him, the market is suddenly concerned that the government is going to spend a lot of money and run a large deficit.  You can’t make this up!

The federal government deficit under the current administration is pegged to be just shy of $2 trillion this fiscal year, and you have all heard about the fact that interest payments on the government’s nearly $36 trillion of debt have grown to be more than $1 trillion.  But that is not the driver according to the narrative.  The driver is the idea that the Republicans could sweep and that would mean large deficits because…Trump.

Now, I realize I am only an FX guy (FX poet I guess), but my rudimentary understanding of economics is that when economic activity is strong (like the current data implies) and the central bank then adds more liquidity to the system to goose demand, say by cutting interest rates in the front end of the curve, then demand can outstrip supply and prices will rise.  As such, bond investors, when they see a dovish Fed entering an easing cycle while economic activity continues to move along and the government is already running a large fiscal deficit, are concerned over higher inflation ahead and so demand higher yields to own Treasury securities.  Of course, that view doesn’t necessarily suit the narrative so desperately pushed by the mainstream media that Trump is the root of all evil, but it does seem to make more sense.

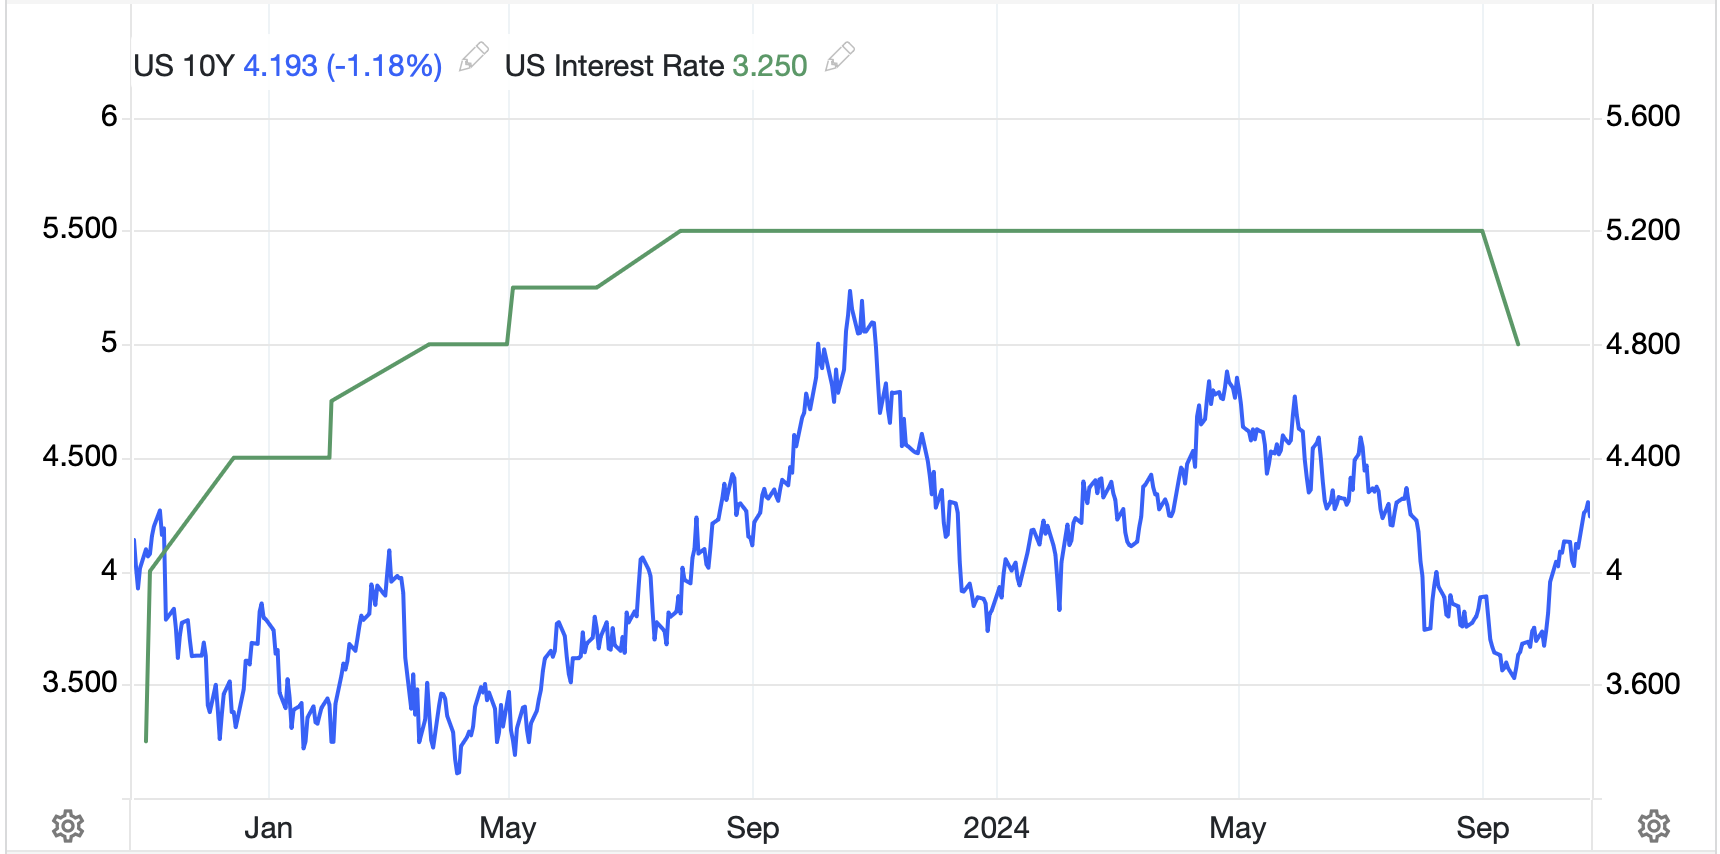
At any rate, for the next two weeks at least, and likely four years if Trump wins, I can assure you that every negative day in any financial market will be blamed on Trump and his policies, despite the fact that the Fed seems to be the one with far more direct impact on short-term economic outcomes.  A look at the below chart, showing 10yr Treasury yields and the Fed funds rate cannot help but show that it was the Fed’s rate cut that is coincident with the recent sharp rise in yields, and this took place long before the odds of a Trump victory improved.  Look through the narrative and instead at the data and Fed activities for the most important clues as to what is actually happening.  I would argue that this is a bond market that is concerned about returning inflation as the Fed’s policy prescription no longer matches the reality on the ground.

Source: tradingeconomics.com

One other thing.  If the Fed does continue to cut rates while US economic data continues to demonstrate solid growth, look for commodity prices to continue their ongoing rally, likely equity markets to continue to perform well, but the dollar is more nuanced as rising inflation ought to undermine the greenback, but given we are seeing more aggressive rate cuts elsewhere in the world (Bank of Canada just cut 50bps this week and the ECB and BOE are going to be cutting again next month), it is entirely possible the dollar holds its own despite macroeconomic fundamentals that should point to weakness.

Ok, let’s see what happened overnight.  Yesterday’s US sell-off, the third consecutive day of broad market weakness, seems to have been sufficient to wash out some of the froth in the market as US futures are pointing higher this morning, especially after Tesla’s better than expected earnings report.  But overnight, the trend from yesterday’s US session was intact with most Asian markets under pressure (Hang Seng -1.3%, CSI 300 -1.1%, KOSPI -0.7%) with only Japan (Nikkei +0.1%) bucking the trend.  In Europe, however, this morning’s color is green with all the major bourses showing life (CAC +0.75%, DAX +0.7%, FTSE 100 +0.5%). Now, there was data released in Europe with the Flash PMI readings out this morning.  The funny thing is that they did not paint a great picture, with continued softness almost everywhere.  My take is Europe is going through a ‘bad news is good’ phase where the weak PMI data implies there will be more aggressive rate cuts by the ECB going forward.  Certainly, Eurozone economic activity, led by Germany’s virtual stagnation, is lackluster at best.

In the bond markets, after several sessions of rising yields, Treasuries have seen yields slip back 5bps this morning with similar declines across the board in European sovereign markets.  Part of this is the weak PMI data I believe, but part of it is a simple trading response to a market that is likely somewhat oversold.  After all, for the past month, bonds have been under significant pressure so a bounce can be no surprise.

In the commodity markets, after yesterday’s rout, where there seemed to be a lot of profit taking of the recent rally, this morning the march higher continues.  Oil (+1.0%) is leading the energy complex higher and the entire metals complex (Au +0.5%, Ag +0.7%, Cu +0.5%, Al +0.9%) is back in gear as all the underlying drivers (rising inflation, solid demand, and for gold, ongoing geopolitical concerns) remain in place.

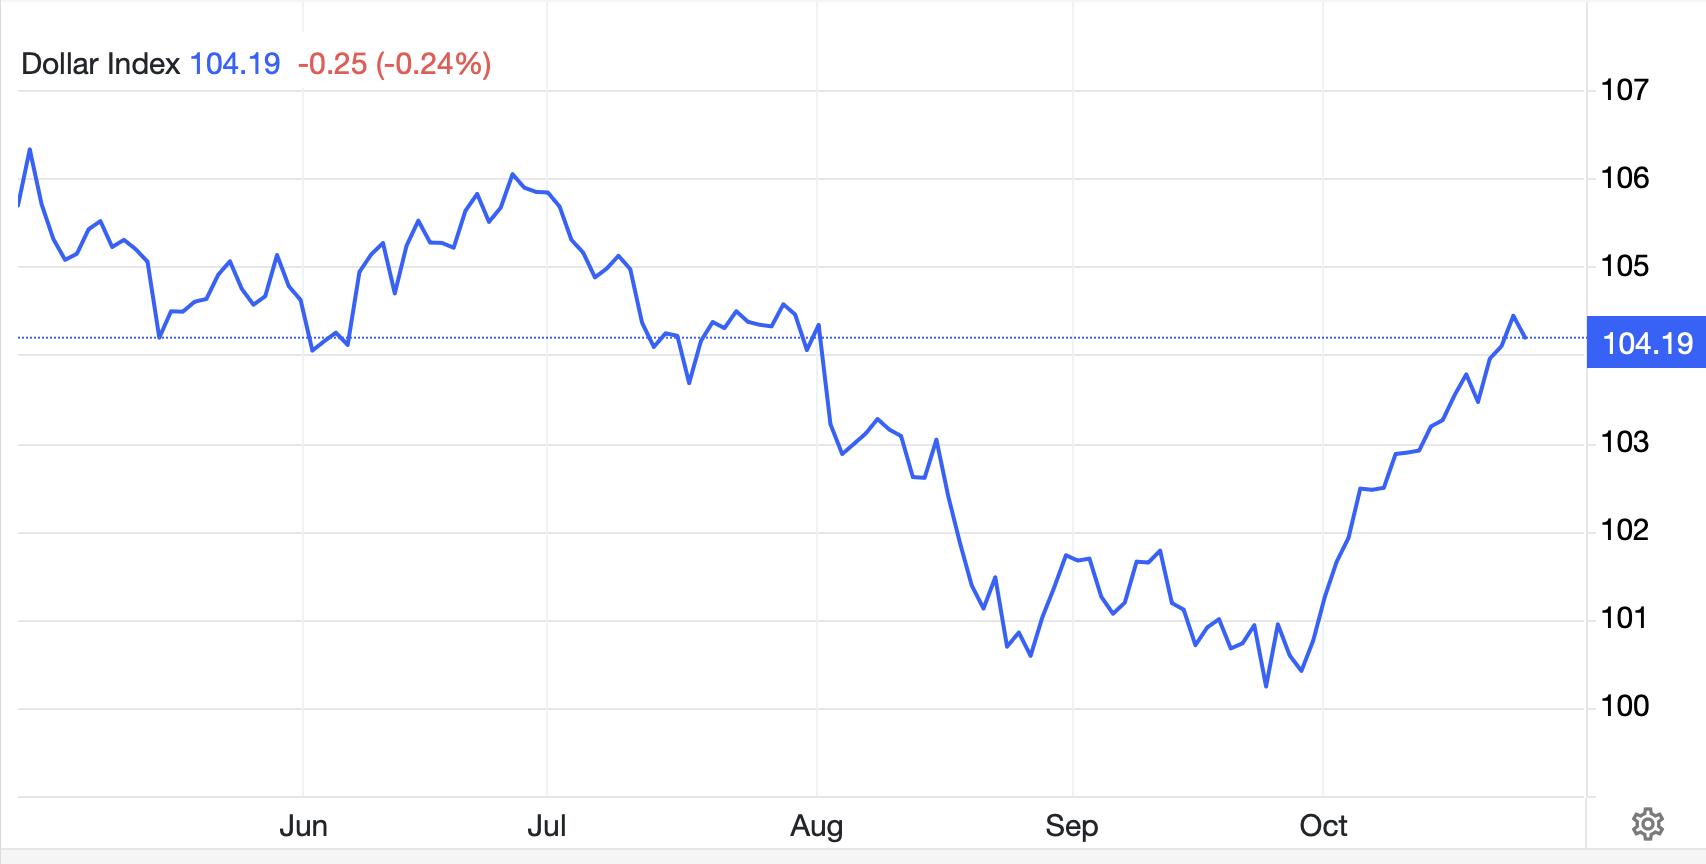
Finally, the dollar is a bit softer this morning, but this too seems like a response to what has been a strong rally.  Once again, using DXY as a proxy (see chart below) for the broad dollar, the rally over the past month has been quite strong, so a day of backing off is to be expected.  As I mentioned above, the future of the dollar is nuanced because while the macro indicators point to potential weakness, if the rest of the world eases monetary policy more aggressively, the dollar will still rally.

Source: tradingeconomics.com

As to today’s movement, currency gains have been between 0.2% and 0.5% with the commodity bloc the biggest beneficiary (ZAR +0.5%, NOK +0.4%, AUD +0.3%) and we have also seen the yen (+0.5%) regain a little of its footing amid declining US yields, although it remains far above the 150 level.  There are those who are looking for another bout of intervention, but I am not in that camp, at least not in the near-term.

On the data front, this morning brings the Chicago Fed National Activity Index (exp 0.2), Initial Claims (242K), Continuing Claims (1880K), Flash PMI (Mfg 47.5, Services 55.0) and New Home Sales (720K).  Yesterday’s Existing Home Sales data was weaker than expected at 3.84M, arguably a testament to the fact that mortgage rates have followed Treasury yields higher and are back above 7.0% again.  On the Fed front, we hear from new Cleveland Fed president Beth Hammack, but it feels like Fed speak is losing some momentum.  Nobody believes that they are going to stop cutting rates, and fewer and fewer analysts think they should continue amid strong growth.  The futures market is now pricing a 95% probability of a November cut but only a 71% probability of a December cut to follow.  I remain in the camp that they pause in December, especially in the event of a Trump victory.

While the dollar is under pressure today, I continue to believe it retains the ‘cleanest shirt in the dirty laundry’ appeal and will ultimately continue to rally.  

Good luck

Adf

Nothing But Fearporn

Said Logan, right now things are cool
With loads of reserves in the pool
And if I’m correct
The likely effect
Is rates will remain our key tool
 
As such, talk of balance sheet woes
Is nothing but fearporn, God knows
We’ll let bonds mature
Though we are unsure
Of how many we need dispose


“If the economy evolves as I currently expect, a strategy of gradually lowering the policy rate toward a more normal or neutral level can help manage the risks and achieve our goals,” explained Dallas Fed President Lorrie Logan on Monday. “However, any number of shocks could influence what that path to normal will look like, how fast policy should move and where rates should settle.”

In other words, we want to keep up appearances but we have no real idea how things are going to play out and so whatever we think our policies are going to be right now, they are subject to changes at any time.  It shouldn’t be surprising that the Fed doesn’t really know where things are going to go, after all, predicting the future is very hard.  But for some reason, many folks, both market focused and politicians, seem to believe they should be able to forecast well and control the outcomes.

Based on the market reaction to Logan’s comments, market participants, at least, are losing some of that confidence.  Treasury yields jumped 11bps in the 10-year dragging the entire yield curve higher along with all of Europe.  And perhaps more ominously for the Fed’s wish list, mortgage rates also rocketed to their highest level since July.  I might suggest market participants are losing their belief that the Fed is going to continue to cut interest rates as many had believed.  Fed funds futures have reduced their cut probabilities by nearly 10 points compared to yesterday as the latest example of this issue.  

And you know what else continues to benefit as those interest rates refuse to decline?  That’s right, the dollar continues to rally steadily against all comers.  Using the DXY as a proxy, the greenback has rebounded 3% from its levels around the time of the last Fed meeting as per the below chart.  I assure you, if I am correct that the Fed cuts 25bps in November and then doesn’t cut in December, the dollar will be much higher still.  Something to watch for!  

Source: tradingeconomics.com

In fact, there were four Fed speakers yesterday and three of them, including Logan, sounded more cautionary in their view of the future path of rates.  However, uber dove Mary Daly from the SF Fed is still all-in for many more cuts to come.  And this is the current situation at the Fed, I believe.  There are FOMC members who remain in the “we must cut rates at all costs” camp, who despite the evidence of the data they supposedly track remaining stronger than expected want lower rates, and there are those who are willing to reduce the pace of cuts, but still want lower rates.  This tells me that the Fed is going to continue to cut rates regardless, and so the bond market is going to become the arbiter of financial conditions.  Recent bond market movements seem more likely to be a harbinger of the future than an aberration, at least unless/until the economy weakens substantially.  In fact, you can see that the relation between bond yields and the dollar is quite strong now, something I suspect will remain true for a while going forward.

And that was really all that we had as the overnight session brought us virtually nothing new.  So, a quick recap of the overnight shows that after a lackluster session in the US on low volumes, Asia had more laggards than leaders with Tokyo (-1.4%) and Australia (-1.7%) dominating the story although China (CSI 300 +0.6%, Hang Seng +0.1%) managed to buck the trend.  The latter two, though, seemed like reactionary bounces from recent declines.  In Europe, bourses are all red this morning led lower by Spain’s IBEX (-1.1%) but seeing weakness everywhere (CAC -0.7%, FTSE 100 -0.7%, DAX -0.25%).  And, at this hour (7:45), US futures are lower by -0.5% or so.

After yesterday’s dramatic rise in yields in the US, we are seeing a continuation this morning with Treasuries edging higher by 1bp but European sovereigns all higher b between 4bps and 5bps.  That seems to be catching up to the last of the afternoon Treasury move yesterday.  As I mention above, I see the trend for yields in the US to be higher, and that should impact yields everywhere.

In the commodity markets, once again, demand is increasing and we are seeing gains in oil (+1.1%), gold (+0.6% and new all-time highs), silver (+1.7%) and copper (+0.9%).  The financial narrative is turning more and more to inflation concerns and the fact that commodities remain an undervalued and important segment in which to have exposure.  I am personally long throughout this space and believe there is much further to run here.

Finally, after the dollar’s blockbuster day yesterday, it has paused for a rest with the noteworthy gainers today all in the commodity bloc (AUD +0.5%, NZD +0.55%, MXN +0.2%, ZAR +0.2%, NOK +0.4%) with most other currencies actually a bit softer vs. the buck.  Keep an eye on JPY (-0.2%) which is now firmly above the 150 level and is likely to begin to see more discussion about potential intervention soon.

There is no data of note this morning although we do hear from Philly Fed president Harker.  It will be interesting to hear if he is in the dovish or uber dovish camp, as there appear to be no hawks left on the FOMC. 

Until the election in two weeks, I suspect that volumes will remain low but trends will remain intact, so higher yields and a higher dollar seem most likely to be in our future.

Good luck

Adf

Not Persuaded

In China, Xi’s still not persuaded
The actions he’s taken have aided
The ‘conomy’s course
The outcome, perforce
Is access to money’s upgraded


In an otherwise very uninteresting session, the biggest news comes from China where the PBOC cut both the 1yr and 5yr Loan Prime Rates by a more than expected 25bps last night.  While PBOC chief Pan Gongsheng did indicate that more cuts were coming, the speed and size of this move are indicative of the fact that worries are growing about the nation’s ability to achieve their “around 5%” GDP growth target.  At least the people who will be blamed if they don’t achieve it are starting to get worried!

The interesting thing about this move is the singular lack of impact it had on Chinese markets with the CSI 300 rising a scant 0.25% for the session.  Although, perhaps it had more impact than that as the Hang Seng (-1.6%) seemed to express more concern over the need for the move than embrace any potential benefits.

Ultimately, the issue for Xi is that the breakdown of economic activity in China remains unbalanced in a manner that is no longer effective for current global politics.  China’s rapid growth since its accession to the WTO in 2001 has been based on, perhaps, the most remarkable mercantile effort in the world’s history.  But now, that mercantilist model is no longer politically acceptable to their main markets as the rest of the world has seen a significant political shift toward populism.  Populists tend not to be welcoming to foreign made goods (or people for that matter), and so Xi must now recalculate how to continue the growth miracle.

Economists have long explained that China needs to see domestic consumption, currently ~53%, rise closer to Western levels of 65% – 70% in order to stabilize their economy.  However, that has been too tall an order thus far.  It is far easier in a command economy to command businesses to produce certain amounts of stuff, than it is to command the citizens to consume a certain amount of stuff, especially if the citizens remain shell-shocked over the destruction of their personal wealth as a result of the imploding property bubble.  As much as Xi wants to change this equation, it seems clear he doesn’t feel he has the time to wait for the gradual adjustment required, as that might result in much weaker GDP growth.  Given that the most important promise he has made, at least tacitly, to his people is that by taking more power he will increase their prosperity, he cannot afford any indication that is not the path on which they are traveling.

My take is that we are going to continue to see more efforts by the Chinese to prop up the economy, but it remains unclear if the fiscal ‘bazooka’ that many in markets have anticipated will ever be fired.  History has shown the Chinese are much more comfortable with slow and steady progress, rather than massive changes in policy, at least absent an actual revolution!  Ultimately, nothing has changed my view that the ultimate relief valve is for the renminbi to depreciate over time.  Xi is fighting that for geopolitical reasons, not for economic ones, but unless or until the domestic situation there changes, I believe that will be the destiny.

Away from the China story, though, there is precious little else of note ongoing, at least in the financial markets.  As this is not a political discourse, I will not discuss the election until afterwards as only then will we have an idea of what will actually happen fiscally and economically.  Meanwhile, everything else seems status quo.  

So, let’s look at the overnight markets.  Aside from China and Hong Kong, and following Friday’s very modest rally in the US, the rest of Asia had no broad theme attached.  There were gainers (Korea, Australia, New Zealand) and laggards (India, Japan, Singapore) with movements of between 0.5% and 0.75% while the rest of the region saw much lesser activities.  In Europe, the mood is dourer with red the only color on the screen ranging from the UK (-0.2%) to virtually all the large continental bourses (CAC, DAX, IBEX) at -0.8%.  There has been no data of note to drive this decline except perhaps the fact that the dollar continues to rise, a situation typical of a risk-off environment.

In the bond markets, yields are climbing across the board this morning, a very risk-on perspective.  (This is simply more proof that the traditional views of asset performance for big picture risk on or off movements is no longer valid.)  At any rate, Treasury yields have risen 4bps while European sovereign bonds have all seen yields jump between 7bps and 8bps.  It appears that bond investors are growing somewhat concerned that central banks are going to allow inflation to run hotter than targeted over time as they are desperate to prevent any significant economic downturn.  As well, given the Treasury market leads all other bond markets, and US economic data continues to perform, that is a key global yield driver as well.

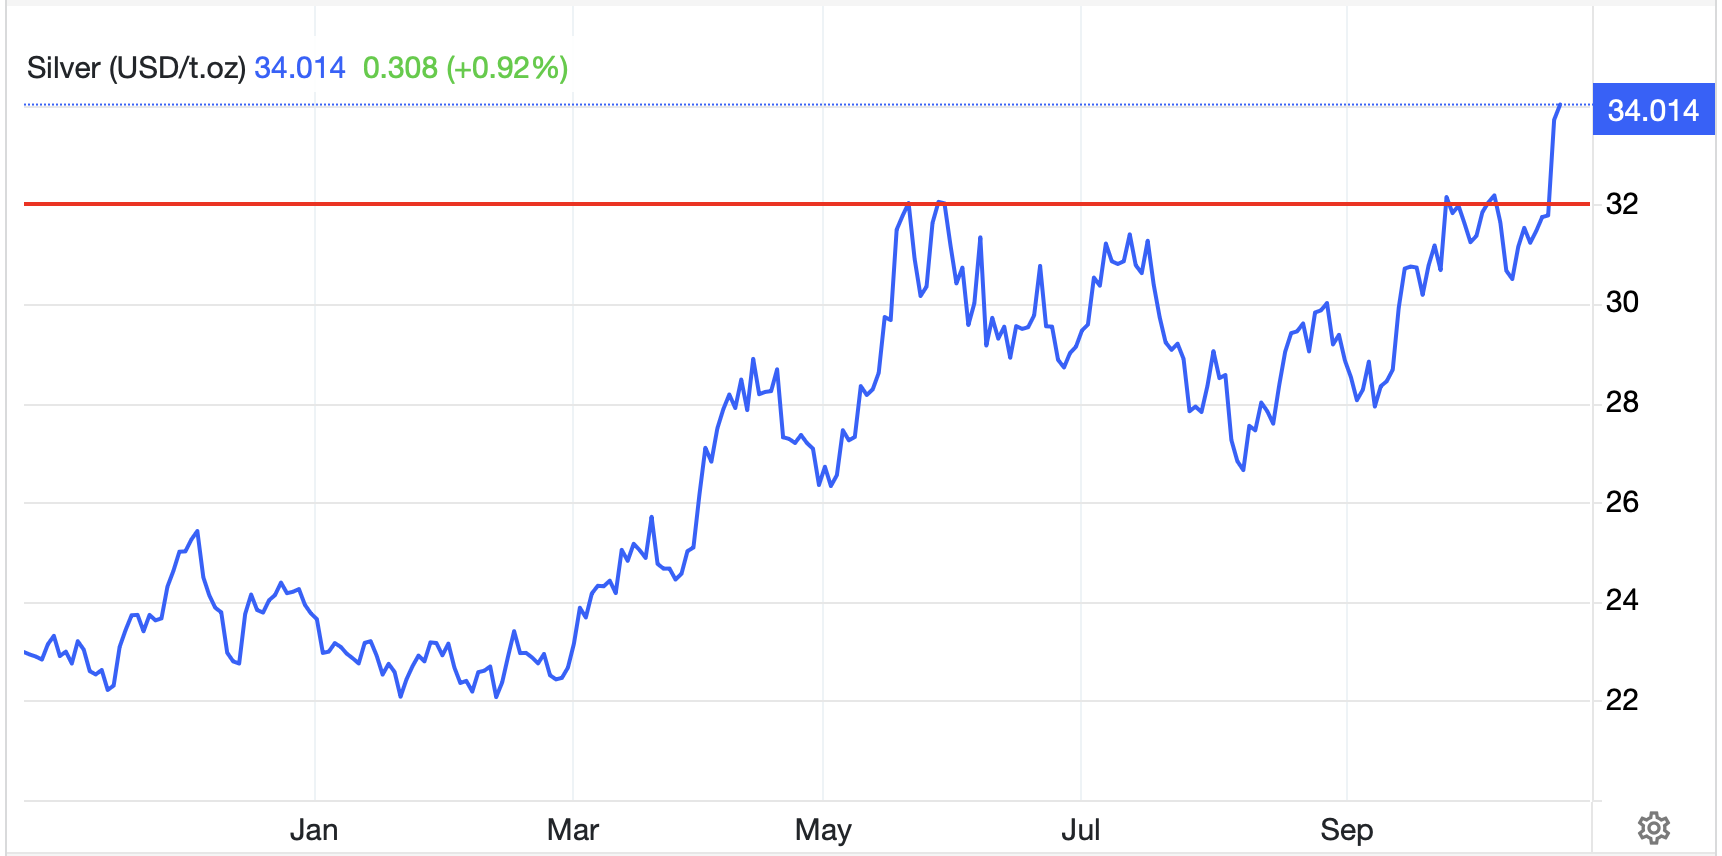
Arguably, the biggest story in markets continues to be the commodities space, specifically metals markets, as once again, and despite today’s dollar strength, we see gold (+0.5%), silver (+1.0%) and copper (+1.1%) rallying with the barbarous relic making yet another set of new all-time highs while silver has broken above a key technical resistance level at $32.00/oz as seen in the chart below.

Source: tradingeconomics.com

One of the reasons I focus on commodities so much is I believe they are telling an important story about the state of the global economy.  We have seen a decade of underinvestment in the production of stuff, especially metals, but also energy, as this has been sacrificed on the altar of ESG policies.  But the world marches on regardless, and that stuff is necessary to build all the things that people want and are willing to pay for.  As they say, the cure for high prices is high prices, meaning high prices are required to increase supply.  That is what we are witnessing, I believe, the beginning of high enough prices to encourage the investment required to increase the supply of these critical inputs to the economy.  However, given the often decade-long process to get from discovery to production of things like metals, look for these prices to continue to rise as a signal that demand is growing ahead of supply.  

As to oil prices, they too, have found legs this morning with a significant bounce (+2.2%) and back above $70/bbl.  On the energy front, we are also seeing NatGas rally sharply with gains in both the US and Europe of > 2%.

Finally, the dollar, as I mentioned, is stronger this morning with only NOK (+0.1%) outperforming the greenback in the G10 space as the dollar benefits from rising yields and continued strong growth, at least as measured by the major data points.  In the EMG bloc, it is universal with the dollar higher against all comers and the worst performers (KRW -0.75%, HUF -0.7%, MXN -0.3%) in each region continuing their recent trend declines.  Until we see a substantive change in the US economic situation, I see no reason for the dollar to fall very far at all.

On the data front, this week brings a lot more Fedspeak than hard data, but this is what we have.

TodayLeading Indicators-0.3%
WednesdayExisting Home Sales3.9M
ThursdayChicago Fed Nat’l Index0.2
 Initial Claims247K
 Continuing Claims1865K
 Flash PMI Manufacturing47.5
 Flash PMI Services55.0
 New Home Sales720K
FridayDurable Goods-0.9%
 -ex Transport-0.1%
 Michigan Sentiment69.3

 Source: tradingeconomics.com

None of this is all that exciting or likely market moving, but we will be regaled with speeches from seven more FOMC members, both governors and regional presidents.  While ordinarily I feel like these comments have limited impact, my take is the market is starting to adjust its views of future Fed actions.  After all, the rationale to cut rates is hard to understand if the economic data continues to rise alongside inflation.  As of this morning, the market is pricing in a 93% probability of a November cut and a 73% probability of a December one as well.  While I agree November is a necessity for them to save face, I think December is a much longer shot than that based on recent data.

With the last two weeks ahead of the election upon us, things are heating up further and most focus will be there.  Given the secondary nature of this week’s data, my suspicion is that absent a massive surprise, or a really consistent theme amongst the Fed speakers that rates are going to go a lot lower soon, the dollar is going to continue its recent rebound.

Good luck

Adf

Panic Attack

The FX Poet will be in Nashville at the AFP Conference October 21-22, speaking about effective ways to use FX options in a hedging program.  Please come to the presentation on Monday at 1:45 in Grand Ballroom C1 if you are there.  I would love to meet and speak.
 
Said Madame Lagarde, we’re “on track”
To make sure inflation gets back
Below two percent
So, we can prevent
A government panic attack
 
The subsequent news from the East
Is Chinese growth, once more, decreased
Their five-percent goal
Ain’t on cruise control
So, Xi needs more skids to be greased


See if you can find the conundrum in the ECB statement issued yesterday after they cut interest rates 25bps, as expected, taking the Deposit Rate down to 3.25%,. [emphasis added]

“The incoming information on inflation shows that the disinflationary process is well on track. The inflation outlook is also affected by recent downside surprises in indicators of economic activity. Meanwhile, financing conditions remain restrictive.

Inflation is expected to rise in the coming months, before declining to target in the course of next year. Domestic inflation remains high, as wages are still rising at an elevated pace. At the same time, labour cost pressures are set to continue easing gradually, with profits partially buffering their impact on inflation.”

While I realize that I am just an FX guy, and that my education at MIT was far more focused on numbers than words, I cannot help but read the highlighted phrases and be confused how the conclusion of high domestic inflation and expectations for it to rise means the disinflationary process is “well on track.”  Of course, it is important to remember that Madame Lagarde is a politician, not an economist nor banker nor any other background familiar with numbers, so perhaps she is the one that doesn’t understand.  Either that or as with every politician she is simply lying.

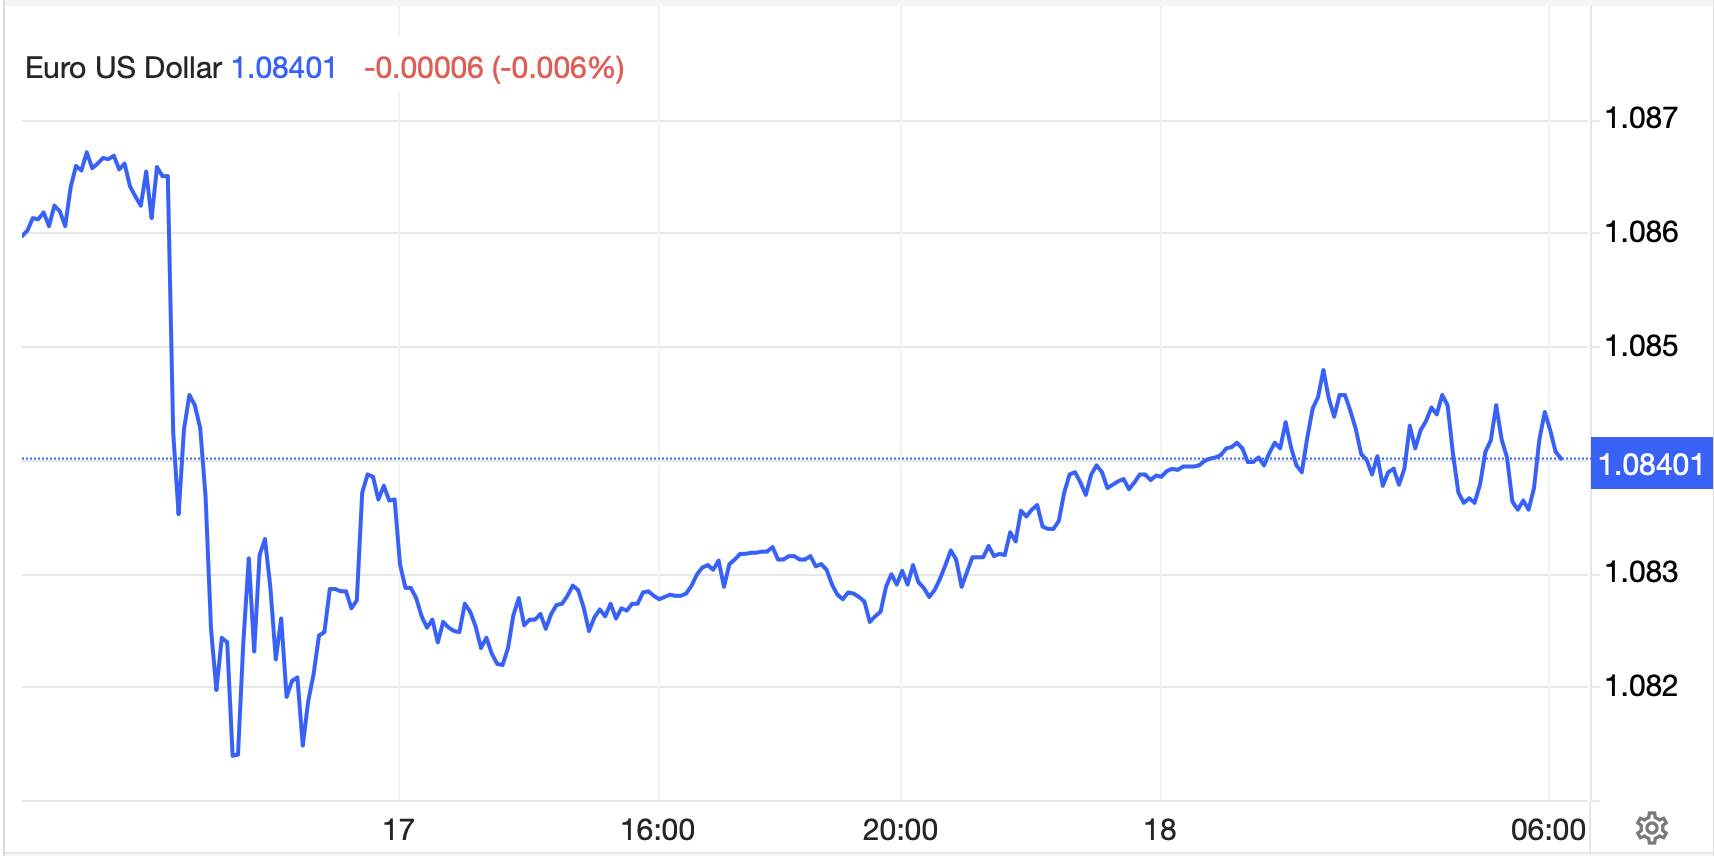
Regardless, as you can see in the chart below, the market response in the wake of the announcement was to sell the euro as interest rate traders priced in a December rate cut as well.

Source: tradingeconomics.com

The juxtaposition of US and Eurozone data remains the key here and as yesterday’s US numbers showed, the long-awaited recession continues to be postponed.  It becomes ever more difficult to see how the Fed will justify easing policy in any substantive manner if every economic print beats expectations.  (To clarify, Retail Sales printed at 0.4%, 0.5% ex-autos vs. expectations of 0.3% and 0.1% respectively. Philly Fed printed at 10.3 vs. expectations of 3.0 and Initial Claims fell to 241K despite the hurricanes, vs expectations of 260K). 

In the end, all this simply reinforces my view that the euro has further to decline going forward.  I still like the 1.05 – 1.06 level as a target by year end.

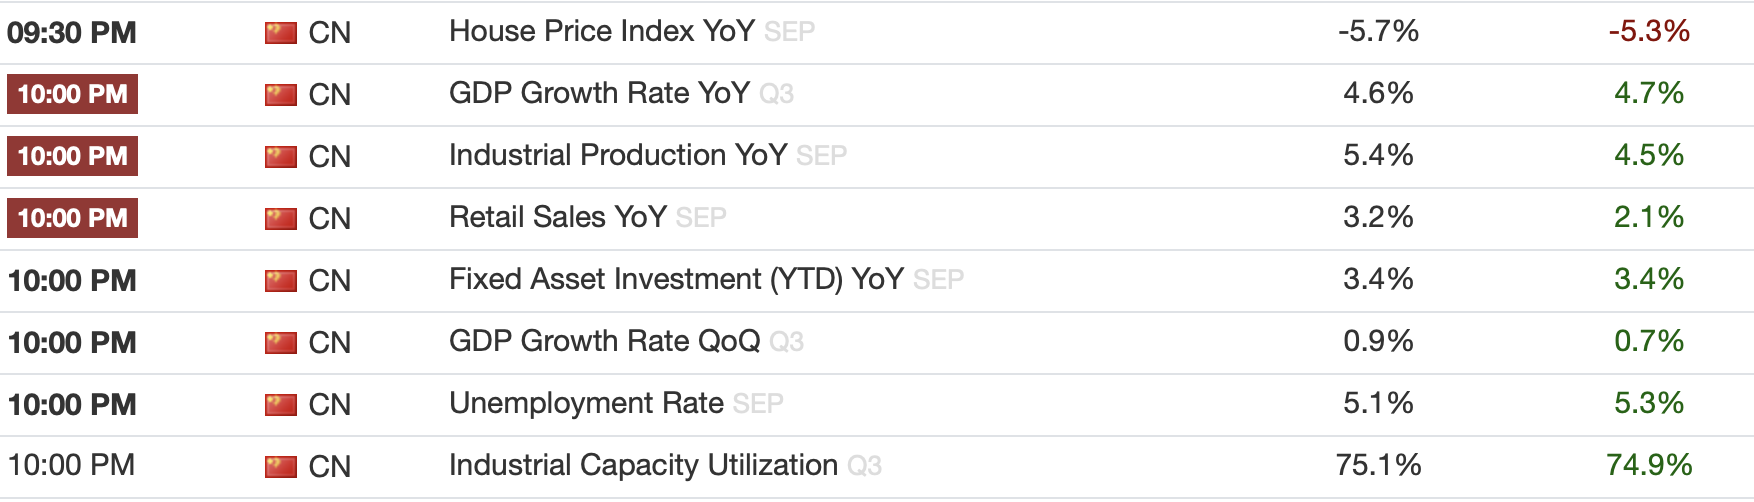
Turning to China, last night they had their monthly data dump and the numbers there continue to point to an economy struggling to gain momentum. (The first, black, number is the September data, the second, green or red, number is the August data.)

Source: tradingeconomics.com

Xi’s 5% target, or even if you use their recent “around 5%’ concept, is getting strained.  While Retail Sales there was a positive, the ongoing disintegration of the housing/property market is a major problem.  Now, all this data represents activity before the plethora of stimulus measures that have been announced.  However, recent equity market performance there, if using as an indicator of the belief that the stimulus was going to be effective, had shown a substantial decline from the early sugar highs back in September immediately following the first stimulus announcements.

With that in mind, PBOC Governor Pan Gongsheng strongly hinted that there would be another interest rate cut next week, as the government struggles to not only convince investors that they have things under control, but to also implement the measures already described.  Now, last night, after Pan hinted at the rate cuts, along with other comments regarding the funds allocated to help companies buy back shares, Chinese equity markets rose sharply in the afternoon session, as per the below chart, rising 3.6% on the day.

Source: Bloomberg.com

Once again, I will highlight the irony of the Chinese Communist Party focusing on the epitome of capitalism, the equity market, as a key means of economic improvement and a key signal that they are on the right track.

That was really all the big news since I last wrote.  Let’s look at the overall market activity.  After yesterday’ lackluster US session, Japanese shares (+0.2%) managed to edge a bit higher and Hong Kong (+3.6%) mirrored Chinese mainland shares.  The other beneficiary of the Chinese stimulus discussion was Taiwan (+1.9%) but Australia (-0.9%), Korea (-0.6%) and a host of other regional exchanges did not seem to appreciate the effort.  In Europe, only the UK (-0.3%) is really under any pressure although the gains on the continent are not terribly impressive with the CAC (+0.5%) the leader at this point.  Most other markets there are little changed to slightly higher.  As to US futures, at this hour (7:20), they are higher by about 0.25%.

In the bond market, after yesterday’s much stronger than expected US data, Treasury yields jumped 7bps and this morning have edged higher by another 1bp to get back to 4.10%.  However, on the continent, sovereign yields this morning are lower by between -2bps and -4bps after yesterday’s ECB action and comments.  The one exception here is the UK, where gilt yields are higher by 2bps after UK Retail Sales data printed much stronger than expected at +0.3% in September, vs. -0.3% expected.

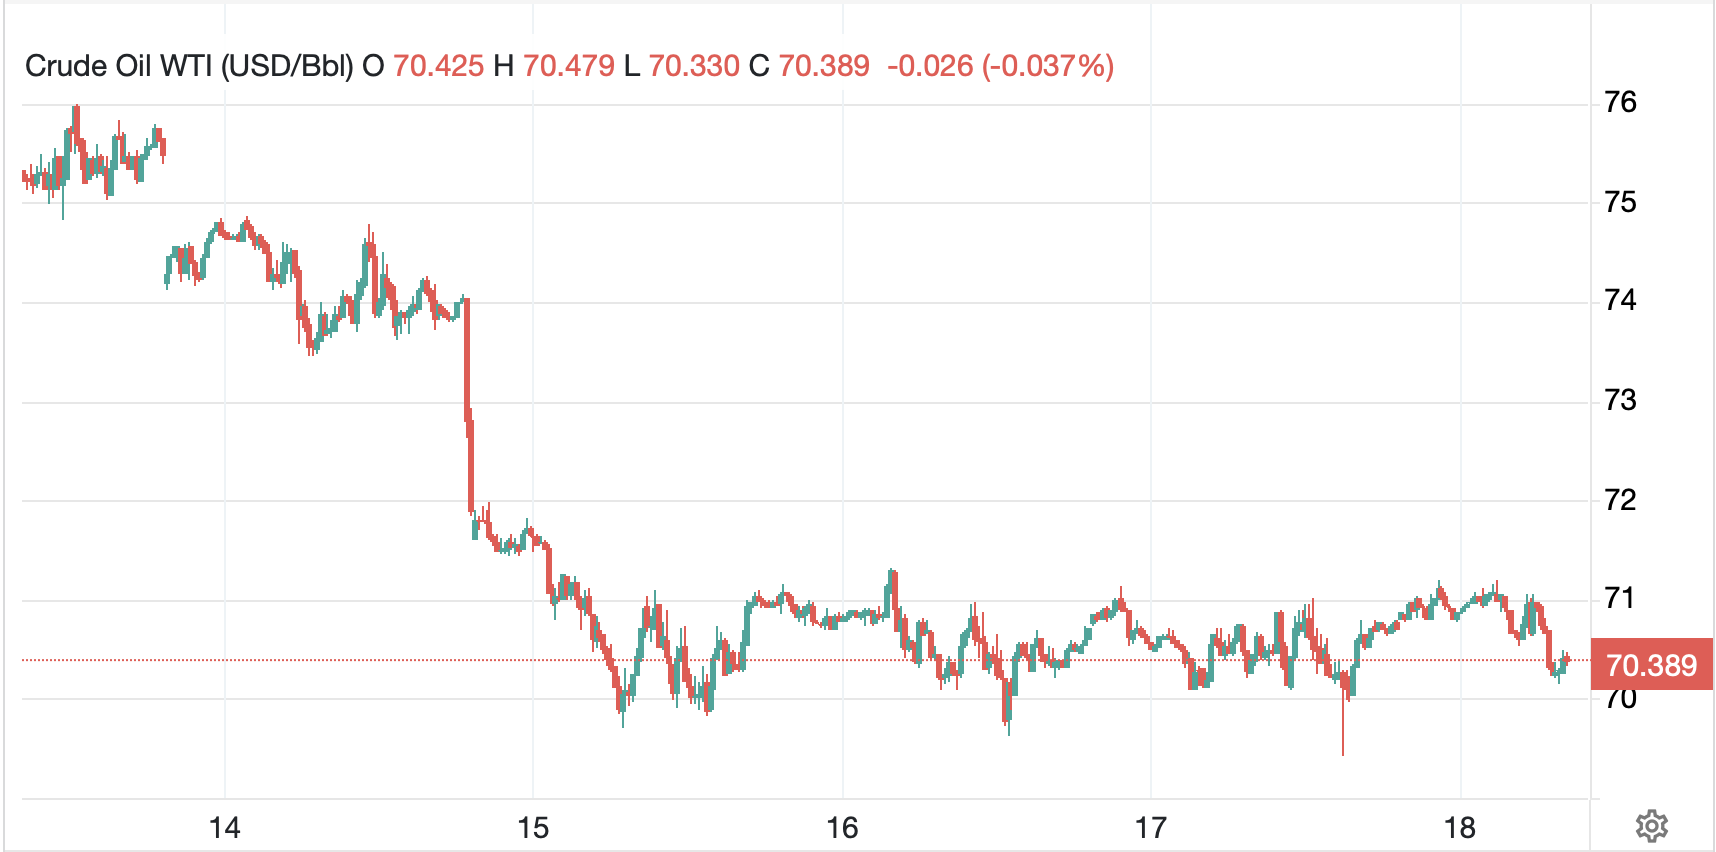
In the commodity markets, oil (-0.4%) is modestly lower this morning but really going nowhere for now as evidenced by the chart below.  Once the word had come that Israel was not going to target Iranian oil infrastructure and the price fell, it has basically been flat.

Source: tradingeconomics.com

As to the metals complex, gold (+0.6%) continues its ongoing rally and is at yet another new all-time high, above $2700/oz this morning, as demand continues to be present from all segments.  However, this morning, all the metals are rallying with silver (+1.0%) and copper (+1.5%) showing even better performance.  The combination of continued solid data from the US and hopes for a return to Chinese demand seem to be the drivers.

Finally, the dollar is closing the week on a down note, as traders reduce positions and take profits ahead of the weekend.  During the week, the dollar rose against virtually every one of its main counterparts in both the G10 and EMG blocs.  Again, the big picture here is that for the dollar, good US economic data is going to continue to benefit the greenback, and we will need to see not just one bad number, but a series of them before the dollar truly suffers.

On the data front, we see Housing Starts (exp 1.35M) and Building Permits (1.46M) at 8:30 this morning and then we hear from three more Fed speakers (Bostic, Kashkari and Waller) with Bostic making two appearances.  At this stage, despite the strong data, the Fed funds futures market is pricing in a 92% probability of a 25bp cut next month and then a 75% probability of another one in December.  I know that Powell seems desperate to cut rates, but if the data continues to show strength, the case to do so is going to be much harder to make.  That doesn’t mean he won’t do it, but if he continues down that path, it just means that inflation will return that much sooner.  

Good luck and good weekend and reach out if you are in Nashville at the AFP!

Adf

Nearly Obscene

The FX Poet will be in Nashville at the AFP Conference October 21-22, speaking about effective ways to use FX options in a hedging program.  Please come to the presentation on Monday at 1:45 in Grand Ballroom C1 if you are there.  I would love to meet and speak.
 
While here in the States we have seen
Inflation that’s nearly obscene
In Europe, inflation
In ‘bout every nation
Has fallen much more than foreseen
 
The narrative there has adjusted
As all of their models seem busted
So, cuts with more speed
We’ll soon see proceed
Though central banks still aren’t trusted

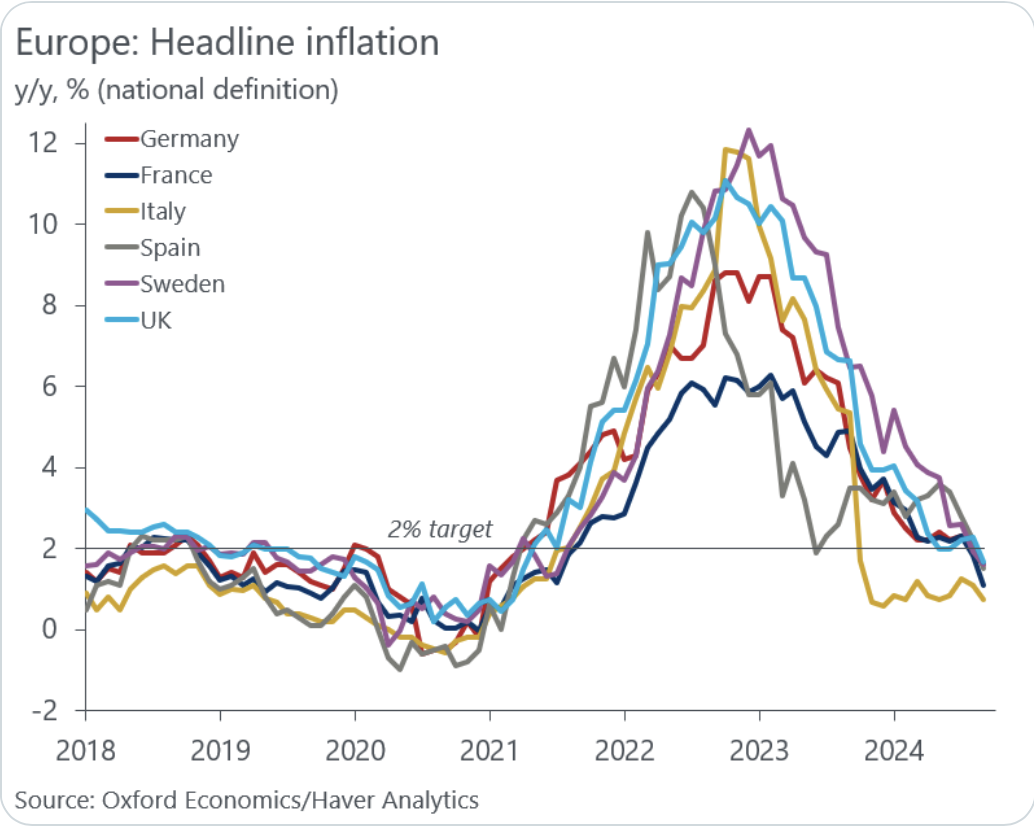
While Fed speakers are trying to claim victory over inflation, whether or not that is reality, the situation in Europe is a bit different.  In fact, headline inflation has fallen quite dramatically virtually across the board as evidenced by the below chart.

Now, a critical piece of this decline is the fact that energy prices have fallen dramatically in the past year with Brent Crude (-16.5%) and TTF NatGas (-18.9%) leading the way lower.  In fact, core inflation data, for the few nations that show it, remains above that 2% target with the UK (Core 3.2% Y/Y) the latest to report this morning.  One other thing to remember is that in the wake of the Covid pandemic, no nation printed and spent nearly as much money as the US on a relative basis, let alone an absolute basis, so there was less fiscal largesse elsewhere.

Yet, the fact remains that headline inflation throughout Europe and the UK has fallen below the 2% targets and so the narrative has now shifted to see more aggressive rate cuts by the central banks everywhere.  This will be part of the discussion tomorrow at the ECB, where most analysts are looking for a 25bp cut although some are calling for 50bps, and the market is pricing more than 40bps at this point.

You know what else is pricing a larger rate cut by the ECB?  The FX market.  Yesterday, the euro fell below the 1.09 level for the first time in more than two months (remember that chart of the double top formation from Monday?) and the single currency has fallen more than 2% in the past month.  Similarly, the pound, after today’s softer than expected CPI readings, has fallen -0.35% this morning, the worst performer in the G10, and is now lower by nearly -1.5% in the past month and looking like it has reversed the uptrend that existed through the summer and early autumn.

Ultimately, my point is that the narrative about rate cuts is shifting to a more accelerated mode in Europe and the UK (where talk of a 50bp cut is making the rounds as well) while here in the States, a 25bp cut is not fully priced in even after yesterdays’ much weaker than expected Empire State Manufacturing Index (-11.9 vs. exp 3.8 and last month’s +11.5).  If you want a reason to explain the dollar’s resilience, you could do worse than the fact that economies elsewhere in the world are lagging the performance here.

Speaking of the Fed, yesterday’s surprise Fedspeak came from Raphael Bostic, Atlanta Fed president, when he explained that he only foresees one more rate cut in 2024.  That is quite a different story than we have been hearing from the rest of the FOMC speakers, who seem completely on board with at least 50bps of cuts and seemingly could be persuaded to head toward 75bps.  There is still much to learn between now and the next FOMC meeting the day after the election here, but despite Bostic’s comments, I believe the minimum we will see before the end of the year will be 50bps.

Ok, that was really all the action overnight.  Yesterday’s disappointing US equity performance, with all three major indices lower by at least -0.75% (I thought that was outlawed 🤣) was followed by similarly weak performance in Asia with the Nikkei (-1.8%) leading the way lower as tech shares underperformed, but further weakness in China (-0.6%) as Godot seems more likely to arrive than the Chinese stimulus.  Throughout the region, only Thailand (+1.2%) managed any gains after the central bank there cut rates 25bps in a surprise move seeking to foster a better growth situation.  In Europe, only the UK (+0.6%) is rallying on the strength of the idea that lower inflation will encourage a 50bp cut from the BOE when they meet the day after the Fed. But otherwise, red is the color of the day in Europe with losses ranging from -0.1% (Spain) to -0.6% (France).  Meanwhile, US futures are a touch firmer at this hour (7:15), by just 0.2%.

In the bond market, yields are lower across the board after that weak Empire State number encouraged the slowing economy narrative and the lower inflation prints in Europe and the UK have weighed on yields there this morning.  So, Treasury yields (-2bps) are lagging most of Europe (Bunds -3bps, OATs -3bps) and UK Gilts (-8bps) are all about the data this morning.  Even JGB yields (-1bp) got into the act.

In the commodity space, oil (-0.5%) is continuing its recent decline, although yesterday it managed to bounce a bit and close above the $70/bbl level where it still sits, barely.  But the metals complex is having another good day with gold (+0.6%) pushing to new all-time highs as western investors are finally following Chinese and Indian investors as well as global central banks.  The lower interest rates certainly help here.  Similarly, we are seeing gains in the other metals (Ag +1.2%, Cu +1.1%) as stories regarding shortages for both metals in the long-term resurface given the lack of new mining activity and increased demand driven by the idea of increased solar and electricity needs respectively.

Finally, the dollar, overall, is little changed, holding onto its recent gains although with a mixed performance this morning.  ZAR (+0.5%) is this morning’s leader on the back of the metals market gains, and we have seen strength in KRW (+0.3%) as well.  However, elsewhere, movement is small and favoring the dollar (HUF -0.2%, CZK -0.2%) and we’ve already discussed the euro and pound.  Interestingly, the THB (+0.45%) rallied after the rate cut on the back of equity inflows.

There is no major data set to be released this morning and no Fed speakers on the current calendar, although as always, I suspect we will still hear from some of them.  Madame Lagarde speaks this afternoon, and given the ECB meeting tomorrow, there will be many interested listeners.

Overall, the themes seem to be that Eurozone inflation is sinking and rate cuts are coming.  That should keep some downward pressure on European currencies vs. the dollar, at least until we see or hear something that describes a more aggressively dovish Fed.  The one truly consistent feature of these markets has been the rally in gold which seems to benefit from fear, inflation and lower rates, all of which appear to be in our future.

Good luck

Adf

Open and Shut

The FX Poet will be in Nashville at the AFP Conference October 21-22, speaking about effective ways to use FX options in a hedging program.  Please come to the presentation on Monday at 1:45 in Grand Ballroom C2 if you are there.  I would love to meet and speak.
 
The great thing about recent data
Is nobody thinks it will matta
It’s open and shut
The Fed’s gonna cut
As ‘flation ambitions they shatta
 
In Jay’s mind, the risk tradeoff’s clear
As stocks work to find a new gear
However, for debt
They’re making the bet
The problems won’t hit til next year

On this Columbus Day holiday, US cash markets are closed although futures are trading, so no stock or bond market activity today.  The FX market will be open, as always, although I suspect liquidity will be less than usual, especially once Europe goes home at noon so hopefully, you don’t have much to do today in the way of hedging.

As it happens, there was not a lot of news overnight to discuss, although China did manage to once again disappoint with respect to their fiscal support announcement on Saturday, not offering up even a big picture number, let alone specific programs, that they are considering.  Interestingly, this did not deter the new China stock bulls, with the CSI 300 (+1.9%) rallying sharply, but this is becoming a sentiment story, not a data driven one.  Someone on X asked the question about why Xi was not doing more, and my view has become that he recognizes to truly get the economy going again he will need to cede some of the power he has spent the past 10 years amassing.  I sincerely doubt he is willing to do that, and since his life won’t change regardless of the amount of stimulus, in the end, holding power is far more important to him.

But let’s go back to the data driven approach and its pluses and minuses.  This morning’s WSJ had an articleby James Mackintosh titled, “The Fed Has a Dependency Problem That Needs Fixing”, and it is his view that data dependence is the current Achilles Heel for Powell and friends.  Now, I won’t dispute that the market’s tendency to extrapolate one data point out to infinity can have market consequences, but I think the point Mr Mackintosh misses is that this is a problem entirely of the Fed’s own making.  Nobody instructed them to offer their views, other than the semi-annual testimony before Congress.  Nobody is forcing FOMC members to be out blathering virtually every day (in fact, two of them, Waller and Kashkari, will be speaking today despite markets being closed).  Forward Guidance was Benny the Beard’s brainstorm, it is not a Congressional mandate, it is not in the Fed’s charter, it is entirely their own.

So, if too much forward guidance is a problem, the Fed can simply stop it.  There is no doubt the recent data releases have been somewhat confusing, with more strength than most economists and analysts have forecast, and there is no doubt that any given month’s data point is subject to certain random fluctuations and revisions.  However, consider if the Fed was not trying to guide the market to whatever their preferred outcome may be.

If there was no Forward Guidance, then each individual investor would have to analyze the current situation themselves, get their best estimate of how they anticipated the future to evolve, and position themselves accordingly.  In today’s world, there is a lot of data pointing in different directions.  Absent the Fed trying to sway opinion, position sizes would be greatly reduced, and the large reversals in markets like we saw in the wake of the recent rate cut and subsequent NFP and CPI releases, would likely be far less significant.  

When the Fed explains that they are going to keep rates lower for longer (as they did in the wake of the GFC and again post covid) that is a clear signal to investors to load up on assets that perform well in a low-rate environment (i.e. stocks).  When they change that view…oops!  That is what we saw in 2022 when they flipped the script and went from transitory inflation to persistent inflation.  Everybody who was long both stocks and bonds suffered.  

But let’s run a thought experiment.  If the Fed gave no Forward Guidance, and merely adjusted rates as they saw fit, investors would have had significantly less confidence that regardless of what had clearly become an inflation problem, the Fed was going to maintain low interest rates.  There would have been a much more gradual move out of risk assets as investors determined inflation was a problem, and the Fed wouldn’t have had all that egg on their face when they had to admit they made a mistake about inflation.

In the end, I disagree with Mackintosh that the Fed should essentially ignore the data, but I agree that they shouldn’t talk about it at all.  In fact, I think we would all be far better off if none of them ever said a word!

Enough of my diatribe.  Let’s see how the rest of the world’s markets behaved overnight.  While mainland Chinese stocks performed well, Hong Kong (-0.75%) did not.  Japan was closed for National Sports Day, although the broad Asia look was that markets there followed Friday’s US rally as well.  However, this morning in Europe, the picture is mixed with some gainers (DAX, IBEX) and some laggards (CAC, FTSE 100) and none of the moves more than 0.3%.  The only data overnight was Chinese Trade (reduced Trade surplus of $81.7B) and Chinese financing which was modestly disappointing despite the recent efforts at goosing things there.  US futures are trading this morning and at this hour (7:00) they are mixed with modest gains and losses of ~0.25%.

With Japan closed along with the US, it should be no surprise that bond market activity is extremely limited with yields essentially unchanged this morning from where they were at Friday’s close.  However, remember that 10-year Treasury yields are higher by nearly 50bps since the day before the FOMC meeting.  This is an important signal that market participants are far more concerned about inflation than the Fed.  On this subject, I think the market is correct.

In the commodity markets, oil (-2.4%) continues its recent decline as the long awaited and feared Israeli response to Iran’s missile attacks seems to have been postponed further.  The absence of that supply concern alongside the lack of Chinese stimulus, and by extension demand, has weighed heavily on the market.  Gold is unchanged this morning although we are seeing some softness in the industrial metals with both silver and copper softer today.

Part of that metals weakness is due to the fact that the dollar continues to rise against all forecasts.  This weekend there was a meeting of the old Soviet nations, the CIS (absent Ukraine of course) and they pledged to stop using dollars in their trade.  This is in the lead-up to the BRICS conference to be held next week in Kazan, Russia, where once again many claim that this group of nations will create their own currency in their efforts to get away from the dollar’s hegemony.  Whether or not they formally do so, I have yet to see a path that includes a cogent rationale for anyone to use this currency, especially if it is backed by a series of nonconvertible currencies like the CNY, BRL and INR.  But it does generate clicks in the doomporn sphere.  

But back in the real world, the dollar is just grinding higher vs everything this morning with NOK (-0.8%) suffering on oil’s weakness and AUD (-0.5%) and NZD (-0.5%) under pressure because of metals weakness and lack of Chinese stimulus.  ZAR (-0.8%) is also feeling the metals weakness but JPY (-0.4%) and CNY (-0.35%) are all softer this morning.  In other words, it is business as usual.  In fact, for those of you with a market technical bias, a quick look at the euro chart seems to define the concept of a double top.

Source: tradingeconomics.com

On the data front, aside from loads more Fedspeak this week, and the ECB monetary meeting on Thursday, the big data print in the US is Retail Sales, also on Thursday.

TuesdayEmpire State Manufacturing2.3
ThursdayECB Rate Decision3.25% (current 3.5%)
 Initial Claims255K
 Continuing Claims1870K
 Retail Sales0.3%
 -ex Autos0.2%
 Philly Fed3.0
 IP-0.1%
 Capacity Utilization77.8%
FridayHousing Starts1.35M
 Building Permits1.45M

Source: tradingeconomics.com

Adding to today’s Fedspeak, we hear from eight more speakers this week. With the Fed funds futures market pricing a 14% probability of no cut at all in November, which would be remarkable given the 50bp cut they made last month, it strikes me that there will be very little new from the speakers.  Rather, if the data this week comes in hotter than forecast, that is going to be the market driver.  I think it is fair to say the Fed has made a hash of things lately.  As long as the data continues to look good, though, I have to believe that fears of renewed inflation and higher rates are going to support the dollar.

Good luck

Adf

A Trumpian Size

A question on analysts’ lips
Is whether Jay can come to grips
With job growth expanding
While he was demanding
A rate cut of fifty whole bips
 
Concerns are beginning to rise
That voters will soon recognize
Inflation’s returning
And they will be yearning
For change of a Trumpian size


By now, I am guessing you are aware that the payroll report on Friday was significantly better than expected.  Nonfarm Payrolls rose 254K, much higher than the 140K expected, and adding to the gains were revisions higher for the previous three months of 55K.  The Unemployment Rate fell to 4.051%, rounding to 4.1%, lower than expected and another encouraging sign for the economy.  You may remember the discussion of the Sahm Rule, which claims that if the 3-month average Unemployment Rate rises 0.5% from its low in the previous 12 months, history has shown the US is already in recession at that point.  Well, ostensibly that rule was triggered two months ago, and the Unemployment Rate has now fallen 0.25% since then with a gain of over 400K jobs since then.  Those are not recessionary sounding numbers.

The upshot is that the market got busy adjusting its views with the dollar continuing to rebound against most currencies, equity markets rejoicing in the renewed growth story and bond markets getting hammered with 10-year yields rising sharply in the US (10bps Friday and 4bps more this morning) with moves higher everywhere else in the world.  In fact, this morning, European sovereign yields are also higher by between 3bps and 5bps and we saw JGB yields jump 5bps overnight.  The end of inflation story is having a tough time.

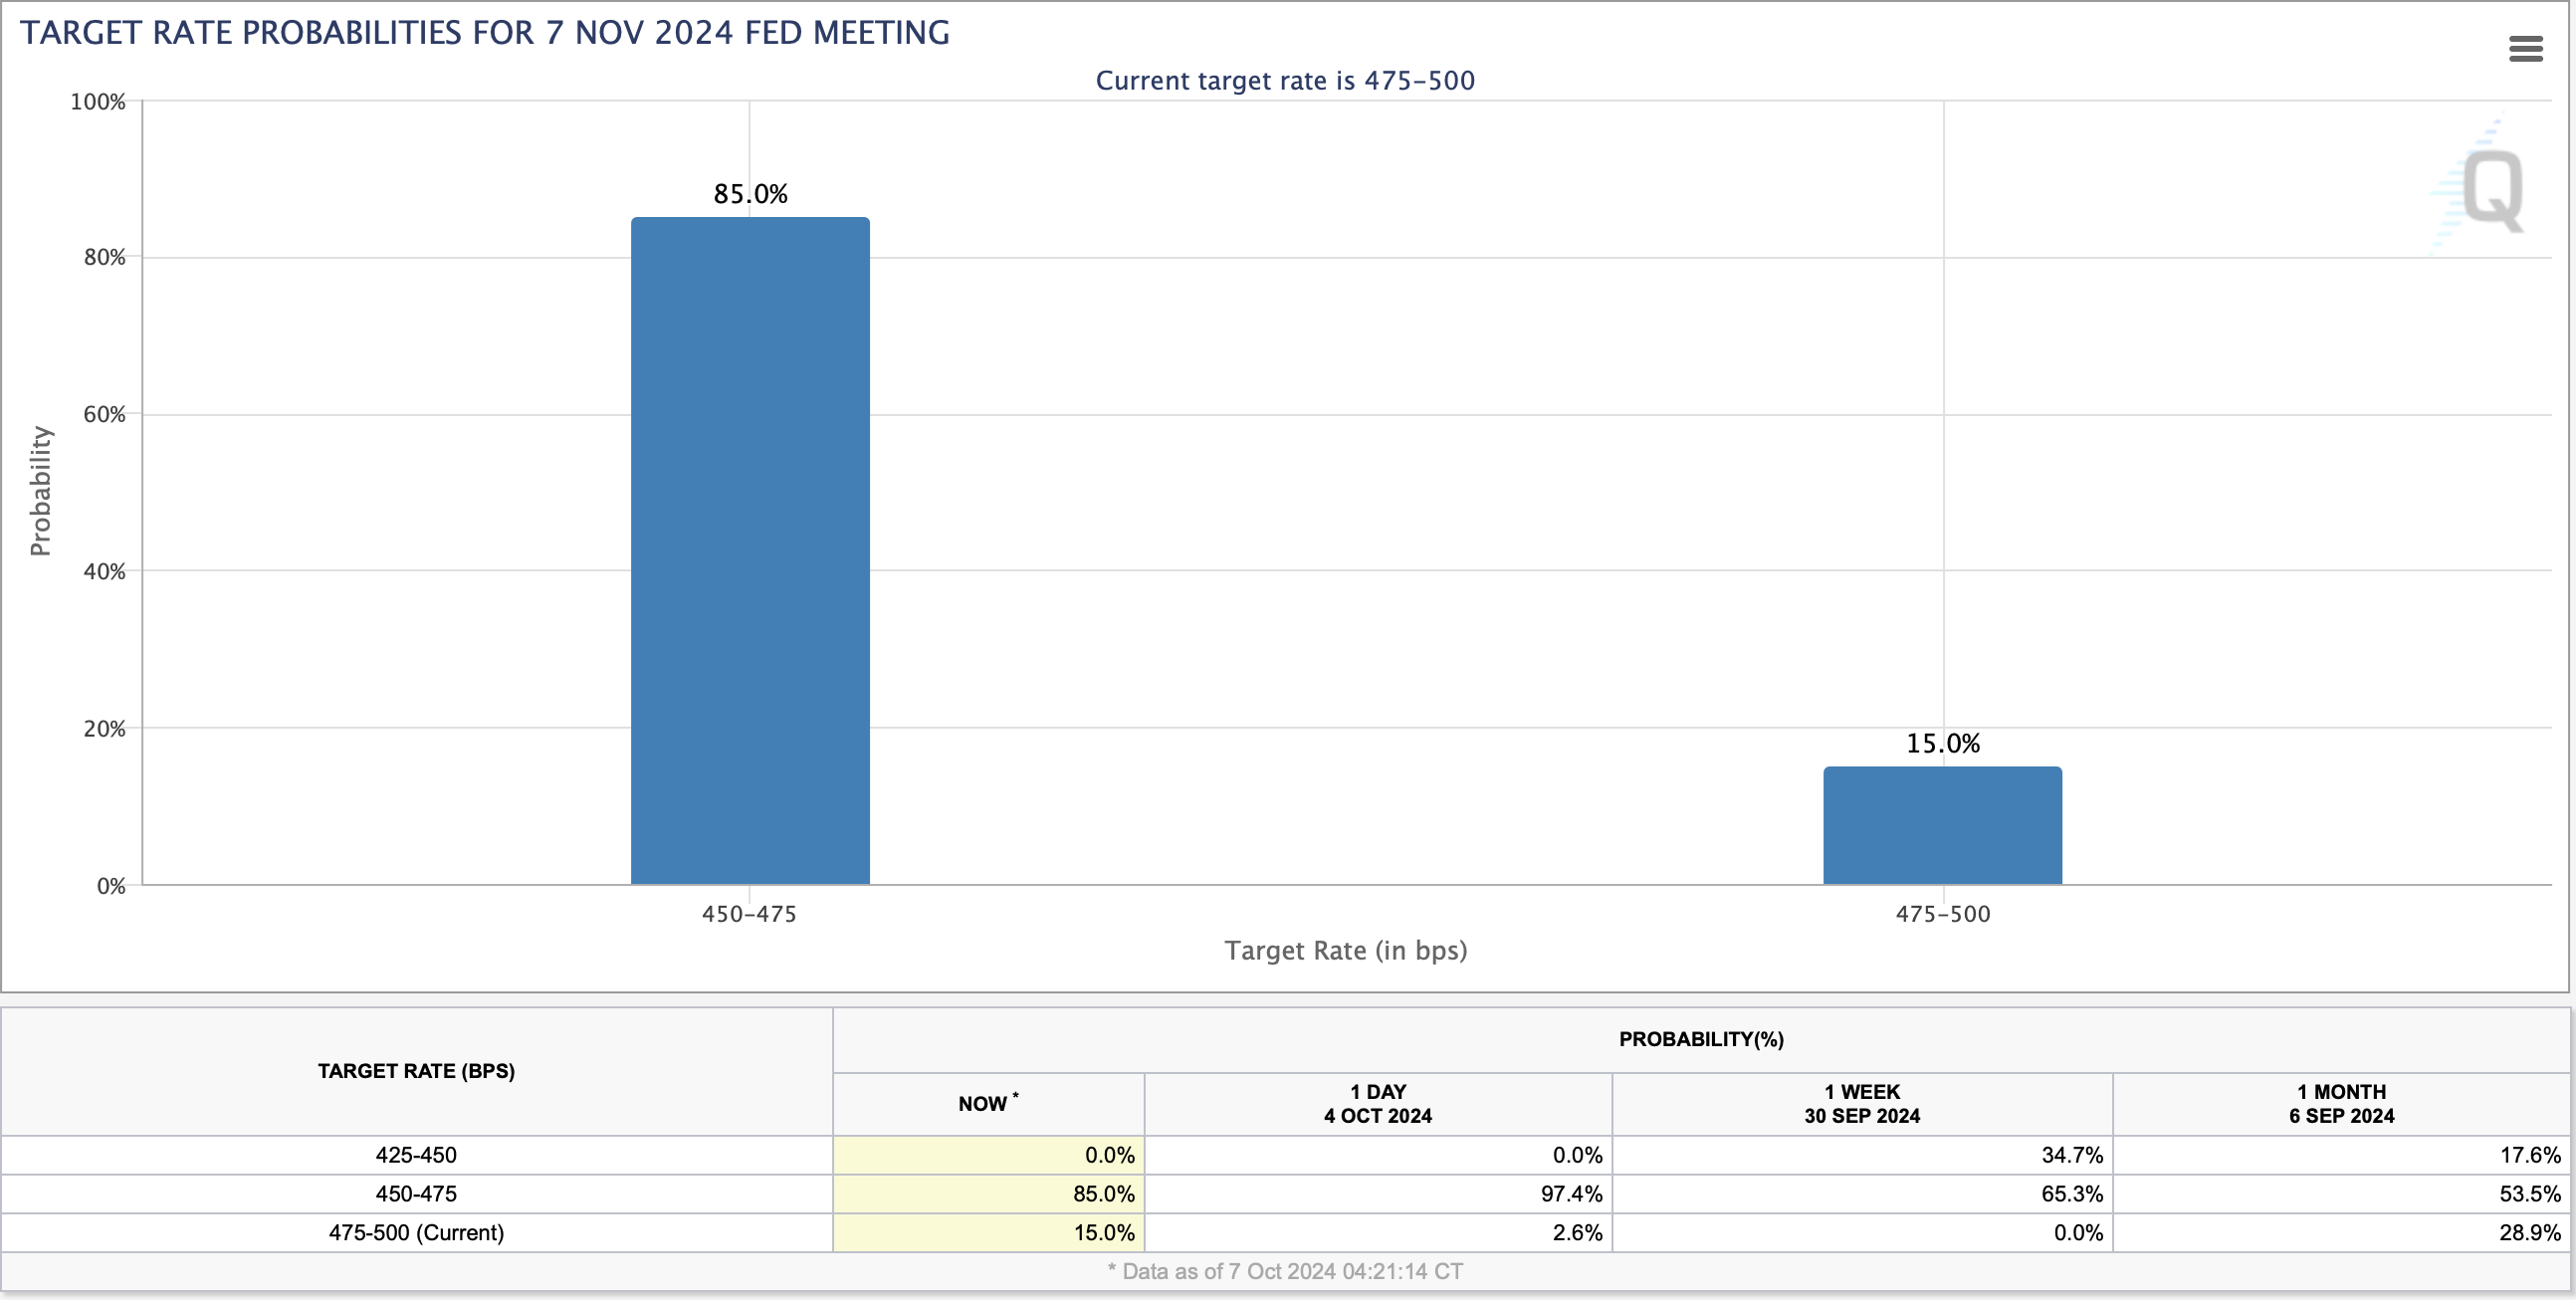
Perhaps the best depiction of things comes from the Fed funds futures markets where now there is only an 85% probability priced for a 25bp cut and a 15% probability of no cut at all.  Look at the table below the bar chart to show how much things have changed in the past week.  Jumbo rate cuts are no longer a consideration.  It will be very interesting to see how the Fed speakers adjust their tone going forward as there were many who seemed all-in on another 50bp cut as soon as next month.

Source: cmegroup.com

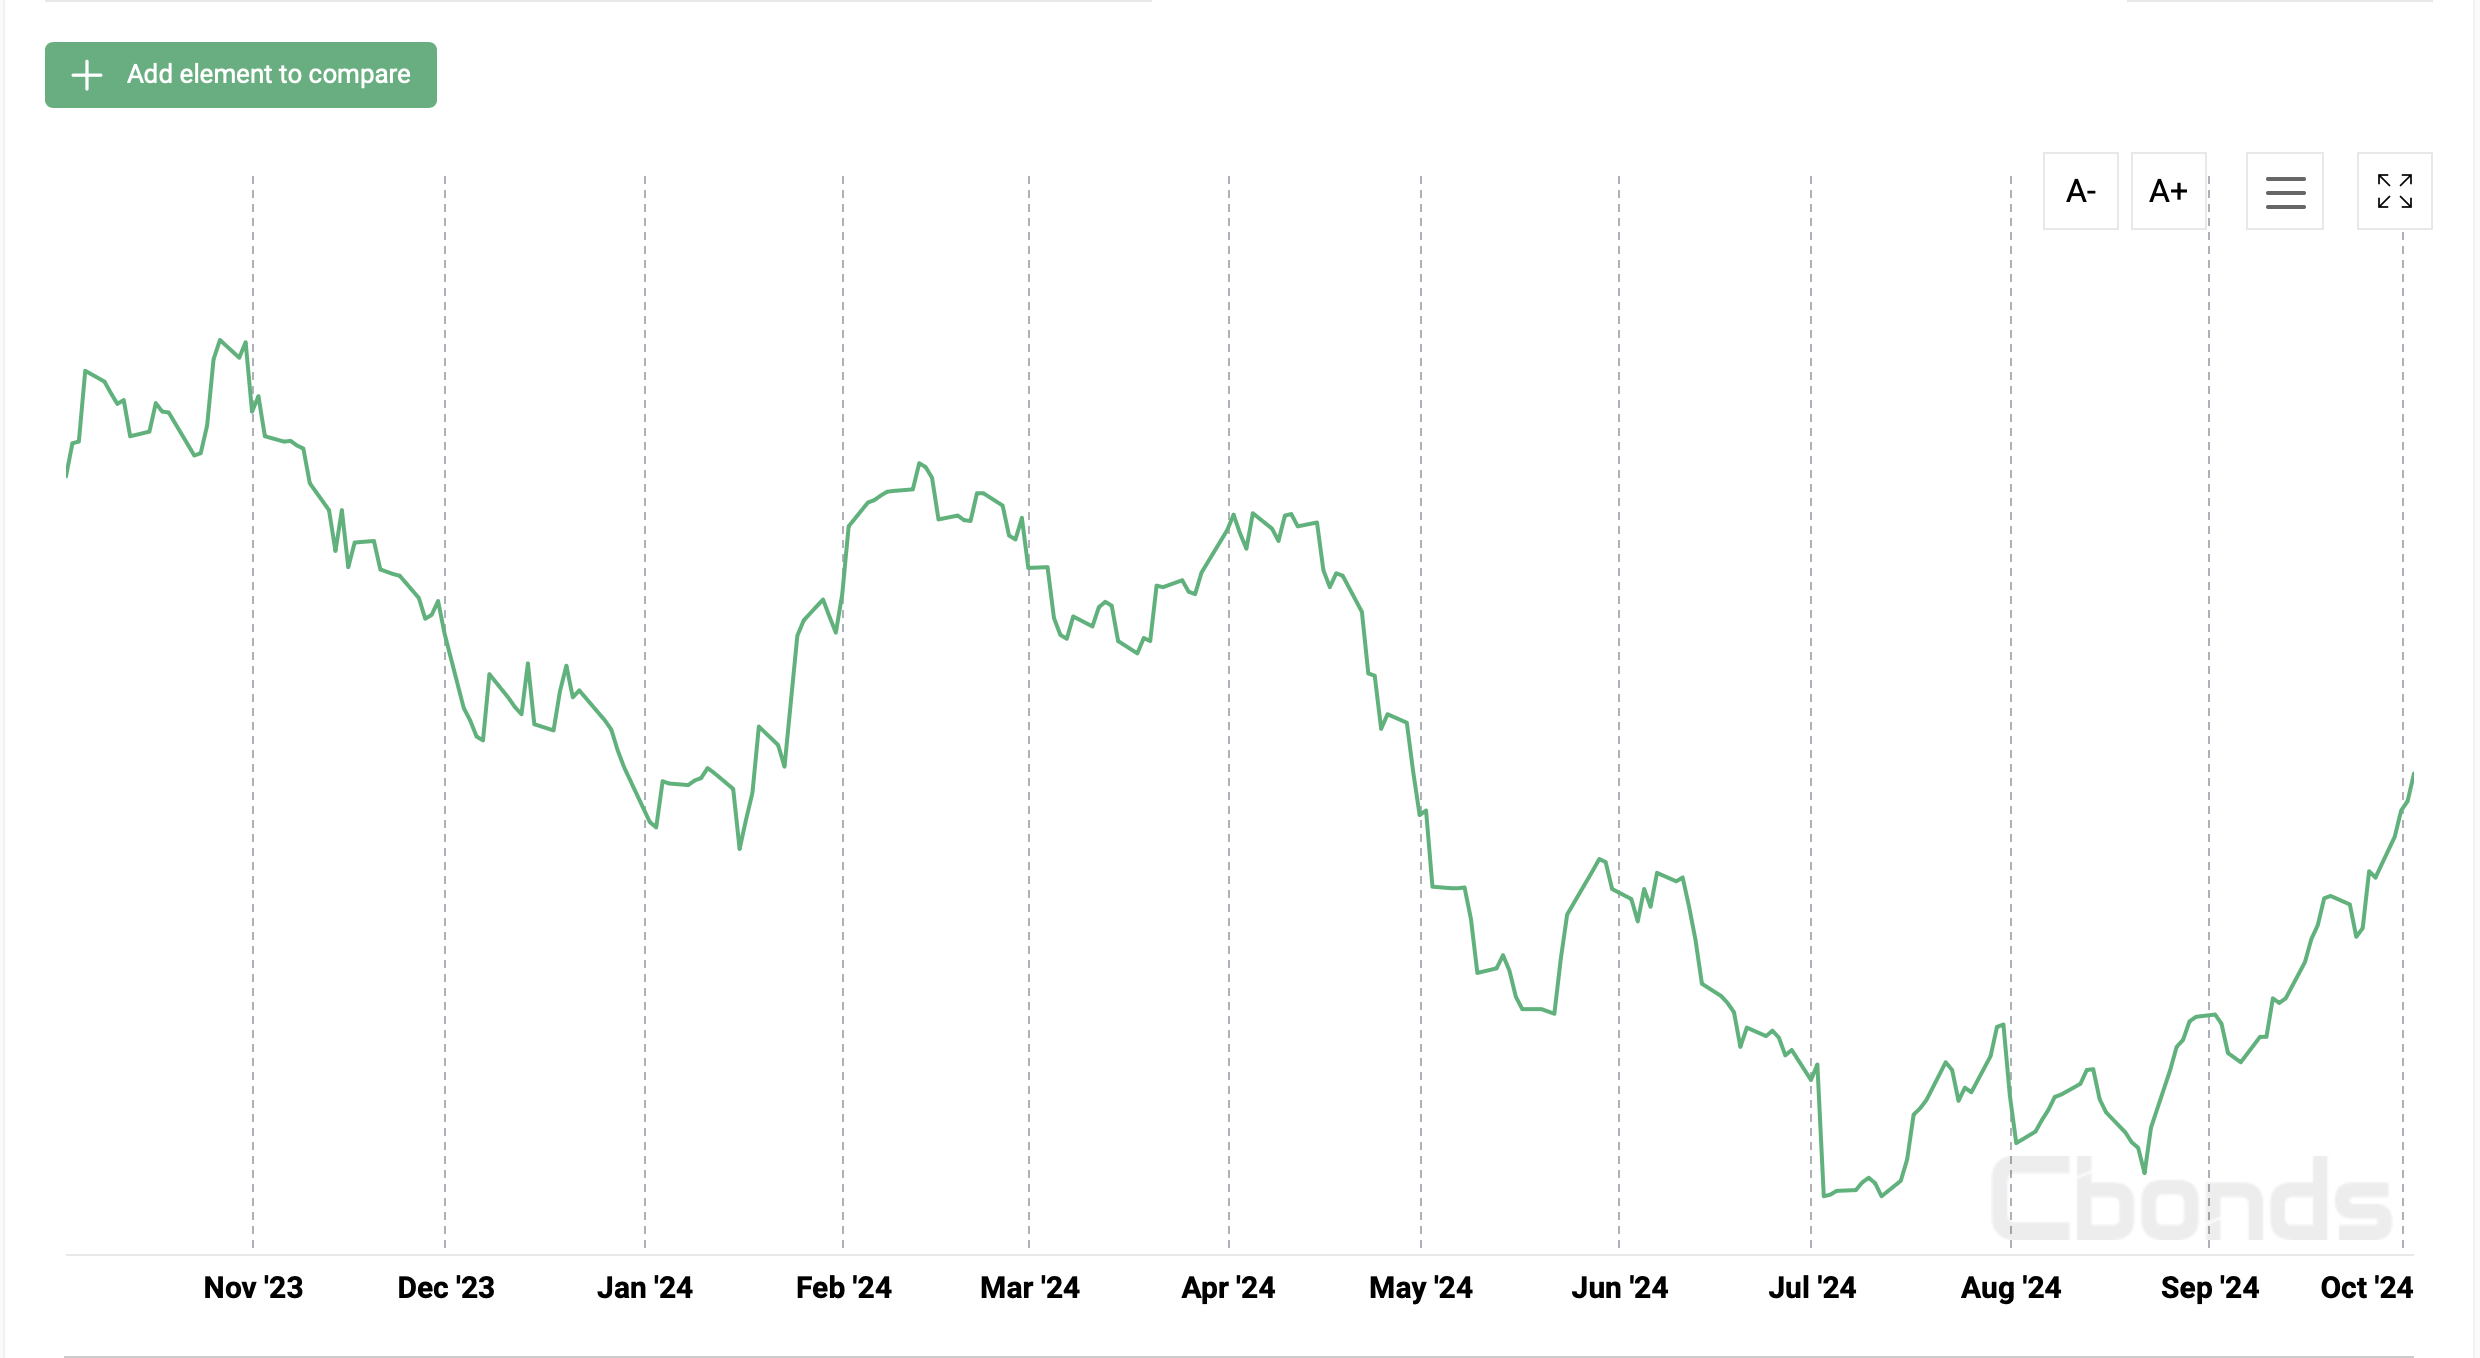
So, is this the new reality?  Recession is out and another up-cycle is with us?  Certainly, recent data has been quite positive as evidenced by the Citi Surprise Index, seen below courtesy of cbonds.com, which has shown a positive trend since early July.

This index is a measure of the actual data releases compared to consensus market forecasts ahead of the release.  When it is rising, the implication is that the economy is outperforming expectations and therefore is growing more rapidly than previously priced by markets.  Again, the point is the recessionistas are having a hard time making their case.  However, for the inflationistas, it is a different story.  With the employment situation improving greatly and last week’s Services ISM data showing real strength, the inflation narrative is regaining momentum.  Recall, the Fed’s rationale for cutting 50bps was that they had beaten inflation and were much more concerned about the employment situation where things seemed to be cooling.  That line of reasoning has now been called into question and the market is awaiting Powell’s answers.

Remember the time
The yen carry trade was dead?
Nobody else does!

While it may seem like this is ancient history, it was less than a month ago when the market was convinced that the yen carry trade (shorting yen to go long higher yielding assets) was dead, killed by the combination of a dovish Fed and a hawkish BOJ.  Oops!  It turns out that story may not have been completely accurate, although it was a wonderful discussion at the time.  As you can see from the chart below, the yen peaked two days ahead of the FOMC meeting, as those assumptions about both central banks reached their apex and has been steadily weakening ever since.  In fact, late last week I saw an article somewhere discussing how the carry trade was back!  The thing to understand is the carry trade never left.  It has been a popular hedge fund positioning strategy for a decade, made even more popular by the Fed’s aggressive rate hiking cycle.  While latecomers to the trade may have been forced out in the past several months, I am confident the position remains widely held.  And, based on the recent price action in USDJPY, it is growing again.

Source: tradingeconomics.com

And I believe those are the key drivers of markets this morning.  Fortunately, the Middle East situation does not appear to have gotten worse although oil (+2.6%) is trading like something is about to blow up.  The rest of the noteworthy news shows that Germany remains in a funk with Factory Orders falling sharply, -5.8%, just another indication that growth on the continent is going to struggle going forward.

Ok, let’s tour the markets we have not yet touched upon.  While Chinese markets remain closed (the holiday ended today and markets there reopen tomorrow), the Nikkei (+1.8%) continues to rebound alongside USDJPY and amid stories that new PM Ishiba has dramatically moderated his hawkish views ahead of the snap election called for the end of the month.  The Hang Seng (+1.6%) also had a strong session, with rumors of still more Chinese stimulus to be announced tonight. The combination of positive US growth news and the Chinese stimulus news helped virtually every market in Asia save India (-0.8%), which has been singing a different tune consistently.  In Europe, it should be no surprise the DAX (-0.3%) is softer, although there are some gainers on the continent (Spain +0.4%, Hungary (+0.4%) and other laggards (Norway -0.7%, Netherlands (-0.3%).  Overall, it is hard to get excited about the European scene this morning.  Alas, US futures are pointing lower this morning, down -0.5% at this hour (6:30).

We’ve already discussed the bond market and oil, but metals markets show a split this morning with gold (+0.2%) seeming to find haven support while both silver (-0.7%) and copper (-0.3%) are under modest pressure.  Remember, though, if the economic growth story is real, these metals should climb further.

Finally, the dollar is continuing its climb alongside US rates with the pound (-0.4%) the G10 laggard of note.  Most other G10 currencies are softer by a lesser amount although the yen (+0.1%) and NOK (+0.1%) are pushing slightly the other way, the former on a haven trade with the latter following oil.  The EMG bloc is more mixed with ZAR (+0.5%) actually the biggest mover as investors continue to flock toward the stock market there on the back of positivity of a change in the trajectory of the economy from the new government.

On the data front, the biggest number this week is CPI, but of real note are the 13(!) Fed speakers over 20 different venues this week.  I don’t know if I’ve ever seen that many on the calendar for such a short period.  It strikes me that they understand they need to tweak their message after the recent data.  It will be very interesting to see if they fight the data and stay the course for another cut in November or whether they walk it back completely. After all, they claim to be data dependent, and if the data points to growth, why cut?

Here is the rest of the data:

TodayConsumer Credit$12B
TuesdayNFIB Small Biz Optimism91.7
 Trade Balance-$70.4B
WednesdayFOMC Minutes 
ThursdayInitial Claims230K
 Continuing Claims1829K
 CPI0.1% (2.3% Y/Y)
 -ex food & energy0.2% (3.2% Y/Y)
FridayPPI0.1% (1.6% y/Y)
 -ex food & energy0.2% (2.7% Y/Y)
 Michigan Sentiment71.0

Source: tradingeconomics.com

And that’s how we start the week.  Whatever your personal view of the economy, the recent data certainly points to more strength than had been anticipated previously and markets are responding to that news.  For equities and the dollar, good news is good, but there seems to be a lot of time between now and Thursday’s CPI reading for attitudes to change.

Good luck

Adf