A Fifth Wheel

Confusion is clearly what reigns
As even the punditry strains
To understand whether
Investors will tether
Their future to stocks or take gains


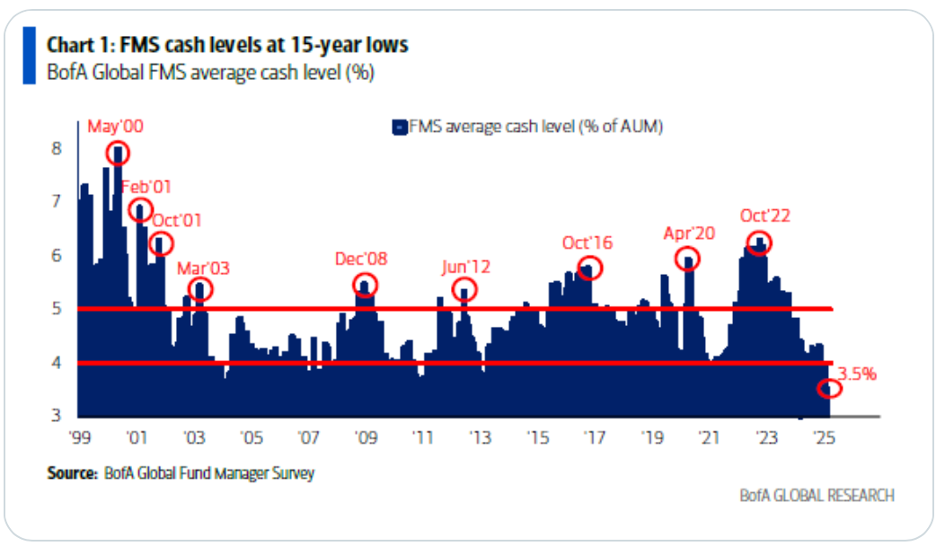
As there was no activity in the US financial markets yesterday, it seems there was time for analysts to consider the current situation and make pronouncements as to investor behavior.  Ironically, we saw completely opposite conclusions from two major players.  On the one hand, BofA posted the following chart showing that investors’ cash holdings are at 15-year lows, implying they remain fully invested and quite bullish.
Meanwhile, the WSJ this morning has a lead article on how bearish investors are, claiming they are the most bearish since November 2023 according to the American Association of Individual Investors.  Apparently, 47.3% of investors surveyed believe stock prices will fall over the next 6 months.
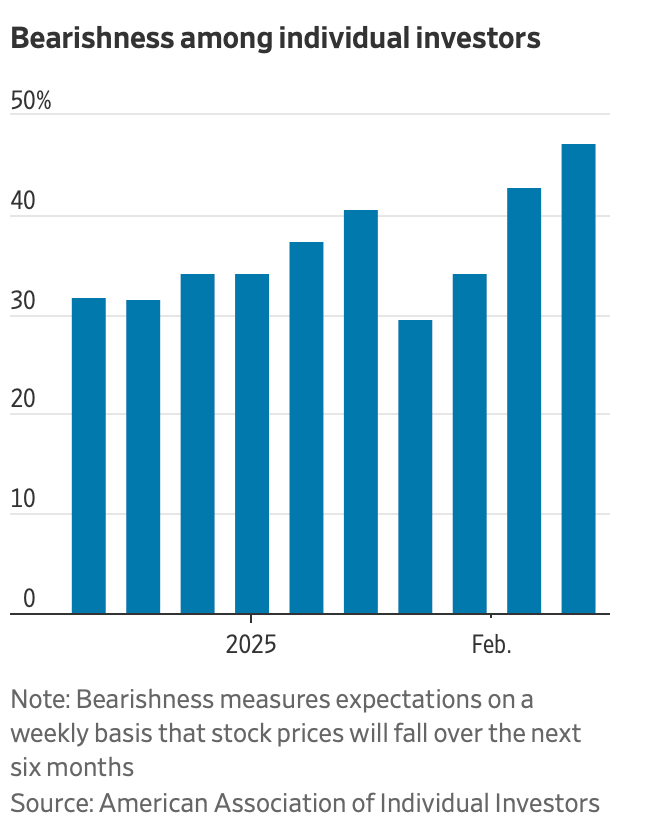
So, which is it?  Are investors bullish or bearish?  To me this is a perfect description of the current situation.  Everyone is overloaded with information, much of which is contradictory, and so having a coherent view has become extremely difficult.  This is part and parcel of my view that the only thing we can clearly expect going forward is an increase in volatility.  In fact, someone said that Donald Trump is the avatar of volatility, and I think that is such an apt description.  Wherever he goes, mayhem follows.  Now, I also believe that people knew what they were voting for as change was in demand.  But for those of us who pay close attention to financial markets, it will take quite the effort to keep up with all the twists and turns.

Fed speakers are starting to feel
Like they have become a fifth wheel
So, let’s get prepared
For Fed speaking squared
As they work, their views, to reveal

Away from the conundrum above, the other noteworthy thing is that FOMC members are starting to feel left out of the conversation.  Prior to President Trump’s inauguration, market practitioners hung on their every word, and they apparently loved the power that came with that setting.  However, now virtually every story is about the President and his policies with monetary policy falling to a distant issue on almost all scorecards.  Clearly, for a group that had grown accustomed to moving markets with their words, this situation has been deemed unacceptable.  The solution, naturally, is to speak even more frequently, and I fear believe this is what we are going to see (or hear) going forward.  

Yesterday was a perfect example, where not only, on a holiday, did we have multiple speakers, but they actually proffered different messages.  From the hawkish side of the spectrum, Governor Michelle Bowman, the lone dissenter to the initial 50bp rate cut back in September, explained caution was the watchword when it comes to acting alongside President Trump’s mooted tariff and other policies, “It will be very important to have a better sense of these policies, how they will be implemented, and establish greater confidence about how the economy will respond in the coming weeks and months.”  That does not sound like someone ready to cut rates anytime soon.

Interestingly, from the dovish side of the spectrum, Governor Christopher Waller, an erstwhile hawk, explained in a speech in Australia (on the day the RBA cut rates by 25bps for their first cut of the cycle and ending an 18 month period of stable rates) that, “If this wintertime lull in progress [on inflation] is temporary, as it was last year, then further policy easing will be appropriate.”  I find it quite interesting that Governor Waller suddenly sounds so dovish as many had ascribed to him the intellectual heft amongst the governors.  This is especially so given that is not the message that Chairman Powell articulated either after the last meeting or at his Humphrey-Hawkins testimony recently.  

So, which is it?  Is the Fed staying hawkish or are they set for a turn?  That will be the crux of many decision-making processes going forward, not just in markets but also in businesses.  We will keep tabs going forward.

Ok, on to the market’s overnight performances.  Lacking a US equity market to follow, everybody was on their own last night which showed with the mixed results.  Japan (+0.25%) showed modest gains while the Hang Seng (+1.6%) rocketed higher on the belief that President Xi is going to be helping the economy, notably the tech firms in China, many of which are listed in Hong Kong.  Alas, the CSI 300 (-0.9%) didn’t get that memo with investors apparently still concerned over the Trump tariff situation.  Elsewhere in the region, Korea and Taiwan rallied while Australia lagged despite the rate cut.  In Europe, unchanged is the story of the day with most bourses just +/-0.1% different than yesterday’s close.  Right now, in Europe, the politicians are trying to figure out how to respond to the recent indication that the US is far less interested in Europe than in the past, and not paying close attention to financial issues.  As to the US, futures at this hour (7:25) are pointing higher with the NASDAQ leading the way, +0.5%.

In the bond market, yields are climbing led by Treasuries (+4bps) with most of Europe seeing yields edge higher by 1bp or 2bps as well.  Remember, yesterday European sovereign yields rose smartly across the board.  Also, I must note JGB yields (+4bps) which have made further new highs for the move and continue to rise.  It appears last night’s catalyst was a former BOJ member, Hiroshi Nakaso, explained he felt more rate hikes were coming with the terminal rate likely to be well above 1.0%.  While I believe the Fed will be cautious going forward, I still think they are focused on rate cuts for now.  With that in mind and the ongoing change in Japanese policy, I am increasingly comfortable with my new stance on the yen.

In the commodity markets, last Friday’s sell-off in the metals markets is just a bad memory with gold (+0.5%) rallying again and up more than 1% since Friday’s close.  I continue to believe those moves were positional and not fundamental.  Too, we are seeing gains in silver (+0.2%) and copper (+0.6%) to complete the triad.  Meanwhile, oil (-0.25%) continues to lag, holding above its recent lows but having a great deal of difficulty finding any buying impulse.  Whether that is due to a potential peace in Ukraine and the end of sanctions on Russian oil, or concerns over demand growth going forward is not clear to me, but the trend, as seen in the chart below, is clearly downward and has been so for the past year.
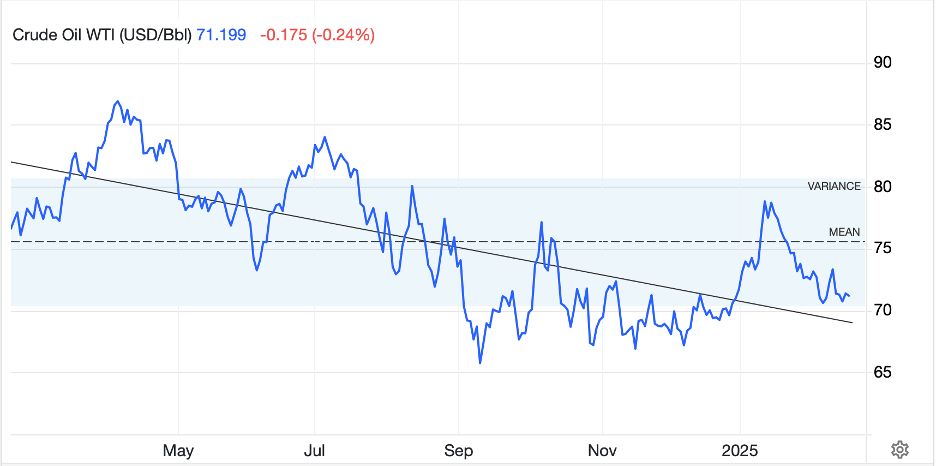
Source: tradingeconomics.com

Finally, in the FX markets, the dollar is firmer this morning rising against all its G10 counterparts with NZD (-0.6%) the laggard.  But losses of -0.2% are the norm this morning.  In the EMG bloc, we are seeing similar price behavior in most markets although MXN (+0.2%) is bucking the trend, seemingly benefitting from what appears to be a hawkish stance by Banxico and the still highly elevated interest rate differential in the peso’s favor.

On the data front, Empire State Manufacturing (exp -1.0) is the only data point although we will hear from two more Fed speakers, Daly and Barr.  I cannot believe that they have really changed their tune and expect that caution will remain their guiding principle for now, although I expect to hear that repeated ad nauseum as they try to regain their place in the spotlight.

Aside from my yen view, I still find it hard to be excited about many other currencies for now.  There is still no indication the Fed is going to move anytime soon, and other central banks are clearly in easing mode.  That bodes well for the dollar going forward.

Good luck

Adf
Eclipse

This morning, the question on lips
Is where did DeepSeek get their chips
As well, there’s concern
That China will learn
Our secrets, and so, us, eclipse


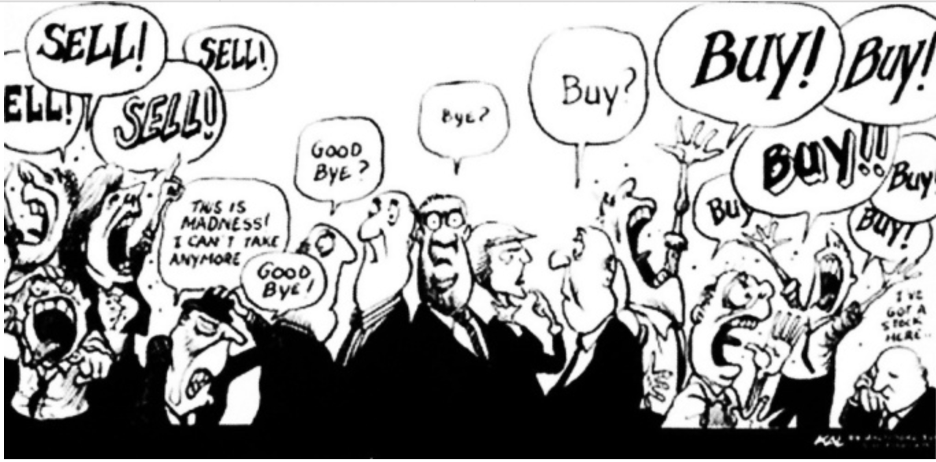
Narratives are funny things.  They seemingly evolve from nowhere, with no centralization, but somehow, they quickly become the only thing people discuss.  I’ve always been partial to the below comic as a perfect representation of how narratives evolve for no apparent reason.

Of course, yesterday’s narrative was that the Chinese LLM, DeepSeek, was built by a hedge fund manager with older NVDA chips and for far less money than the other announced models from OpenAI or Google and performed just as well if not better.  While equity traders were not going to wait around to determine if this was true or not, hence the remarkable selling on the open of all things AI, a little time has resulted in some very interesting questions being raised about the veracity of how DeepSeek was built, what type of chips they use and who actually built it.

For instance, a quick look at NVDA’s 10Q shows that, remarkably, Singapore is a major source of revenue, and it has been growing dramatically.

Source: SEC.gov

Now, it is entirely possible that Singapore is a hotbed of AI development, but from what I have read, that is not the case.  In fact, there is basically one lab there that has resources on the order of just $70mm.  But despite that lack of local investment, at least reported local investment, Nvidia shows that chip sales in Singapore nearly quadrupled in the last year.  Far be it from me to suggest that the narrative may change again, but who is buying those chips, more than $17 billion worth?  The idea that they have been trans shipped to China is quite plausible and they may well be what underpins DeepSeek.

Again, I have no first-hand knowledge of the situation but it is not beyond the pale to make the connection that China has been effectively circumventing US export controls through Singapore, have built their own LLM model using the exact same chips as OpenAI and others, but propagated a narrative that they have built something better for much less in order to undermine the US tech sector equity performance and call into question some underlying beliefs in the US market and economy.  Now, maybe this Chinese hedge fund manager did what he said.  But the one thing we know about China is, it is opaque in everything it does, so perhaps we need to take this story and dig deeper.  I am sure others will do so, and more information will be forthcoming, but it highlights that narratives continue to drive markets, but can also, at times, be constructed rather than simply evolve.

The thing is, this is still the only story of note in the market.  Scott Bessent was confirmed as Treasury Secretary yesterday, and indicated he was a fan of gradual tariff increases, perhaps 2.5% per month, rather than large initial tariffs, but that does not seem all that exciting.  And while Trump has not slowed down one iota, his focus has been on things like browbeating California into allowing reconstruction of LA rather than international issues, at least for the past twenty-four hours.  The upshot is that markets, which even yesterday closed far above their worst levels from the opening, are rebounding further today with many of yesterday’s moves reversing, at least to some extent.

Starting in the equity markets, despite the weakness in the tech sector, US market closes were far higher than the opens with the DJIA actually gaining 0.65% on the session.  However, while Japanese shares (-1.4%) definitely felt the pain of the tech sector, the rest of Asia saw some decent performance (Korea +0.85%, India +0.7%, Taiwan +1.0%) although Chinese shares (-0.4%) struggled.  Of course, one reason for that may be that the largest Chinese property company, Vanke, reported humongous losses and both the Chairman and CEO stepped down.

In Europe, though, all is well with every major exchange in the green led by Spain’s IBEX (+1.0%) although gains of 0.5% – 0.7% are the norm.  Now, remember, there is effectively no tech sector in Europe to be negatively impacted by the AI story, and it should be no surprise that these shares have followed the DJIA higher.  And this morning in the US futures market, at this hour (6:50), we are seeing gains on the order of 0.4% across the board.

In the bond market, yesterday’s early rally in prices (decline in yields) backed off as stocks bounced from their lows although Treasury yields still fell 10bps on the day.  This morning, the bounce in yields continues with Treasury yields higher by another 3bps and European sovereign yields rising between 1bp and 2bps on the session.  It will be very interesting to watch the bond market now that Bessent has been confirmed as Treasury Secretary given his goal to extend the maturity of the US debt outstanding.  Arguably, that should push up back-end yields, so we will see how effective he can be in reaching that goal.  

Turning to commodities, yesterday saw a rout there as well with both oil and the metals markets suffering greatly.  However, this morning, like many other markets, things are reversing course.  Oil (+0.75%) has bounced off its lows from yesterday, and despite a pretty rough past two weeks, is still higher than it was at the beginning of the year.  Gold and silver are unchanged from yesterday’s closing levels, and while off their recent highs, remain much higher in the past month.  Copper, too, is bouncing slightly and still much higher this month.  Perhaps yesterday’s price action was a catalyst for lightening up positions rather than changing views.

Finally, the dollar has rebounded vs. the G10 this morning, rising alongside US yields with the euro (-0.7%) and AUD (-0.8%) lagging the field, although dollar gains of 0.5% are the norm across the entire G10 this morning.  In the EMG bloc, the CE4 are all tracking the euro lower, with all down around -0.6% to -0.8%, but yesterday’s biggest laggards, MXN, COP and BRL are little changed this morning, not rebounding, but not falling further.  With the Fed expected to remain on hold while both the BOC tomorrow and ECB on Thursday are set to cut rates, perhaps the FX market is reverting to its more fundamental interest rate drivers than the hysteria of AI models.  If that is the case, then we are likely to turn our attention to Chairman Powell’s press conference as the next critical piece of news.

On the data front this morning, we see Durable Goods (exp 0.8%, 0.4% -ex Transport), Case Shiller Home Prices (+4.3%) and Consumer Confidence (105.6).  Yesterday saw New Home Sales rise more than expected but still resulted in the smallest number of sales for the year since 1995 when the population was far smaller.  

Once again, depending on where you look, you can find data that supports either economic strength or weakness.  It strikes me that today’s data will be of little consequence as traders will be focused on the equity market to see if the rebound has legs, as well as further news regarding DeepSeek.  Tomorrow, however, the Fed will take center stage.

Good luckAdf

Much Havoc

Colombia tried to prevent
Deportees, who homeward were sent
But Trump’s strong response
Meant that in a nonce
Gustavo, his knee quickly bent
 
Meanwhile, all the talk of AI
This weekend has pundits awry
The Chinese DeepSeek
Could very well wreak
Much havoc in stocks priced sky-high


If there was any doubt that things were going to be different under a Trump administration than virtually any previous administration, even his first term, they were dispelled this weekend.  By now you will all have heard the story of the Colombian president, Gustavo Petro (he of the 26% local approval rating) and his refusal to allow two US C-17 military transports filled with Colombian deportees, land in Bogota.  Apparently, when Trump was informed while playing golf, after birdieing the 3rd hole, he tweeted that the US would immediately impose 25% tariffs on everything Colombia exports to the US, rising to 50% in one week if this policy was not changed.  By the time he finished the 6th hole, President Petro reversed his policy and even offered the Colombian presidential plane to come and pick up the deportees.

While the golf portion of the story is amusing, the lesson to the rest of the world is that President Trump is very serious about his electoral promises, and he will utilize the entire might of the US government to achieve his goals.  For smaller nations with little power and leverage, it means that toeing the line is the only solution.  For larger nations, it certainly is a wakeup call to the idea that the US attitude toward international relations has dramatically changed.  As Machiavelli explained, it is better to be feared than loved, and it seems abundantly clear that President Trump understands that.

Perhaps the biggest takeaway from this situation, though, is that the US government is no longer the slow-moving behemoth to which it had evolved over the past decades.  The rest of the world is going to find itself needing to respond very quickly to things that in the past were sent to committees for study and review but now are decided instantly.  If you want to understand why I believe volatility is set to increase across all asset classes, this is the crux of the issue.

Turning to the tech world, the buzz is all about DeepSeek, which is a Chinese AI model that allegedly outperforms OpenAI’s top model, or performs just as well, although it costs a fraction of what OpenAI and others (Microsoft, Google, etc.) spent to train the model and it uses far less advanced chips which are also much less expensive and less power hungry.  Because this is all a new story, it remains unclear if DeepSeek will be an effective replacement for the others, or if it excels in only one or two areas and still lags elsewhere.  

But the market impact has been instantaneous and dramatic.  At this hour (6:00am), the NASDAQ (-4.5%) is leading US equity markets lower with the S&P (-2.4%) along for the ride.  Nvidia (-10.6% in premarket trading) is leading the way, but I suspect that this news will be negative for the entire US tech sector.  After all, it was certainly priced at premium levels.  

Source: tradingeconomics.com

In the short term, I expect we are going to hear a lot more analysis of why this is a game changing event and how the future that was so clear just last week is now cloudy.  However, while this will almost certainly take the shine off the megacap tech companies for a while, I think it would be a mistake to dismiss their futures because of this.  Two things in their favor are they still have virtually infinite resources, and they have dramatically large installed networks which means that changing things will be very difficult.  While their equity prices can decline a lot, it doesn’t mean their businesses are going to collapse.

PS, spare a thought for the impact on the energy sector here as well.  One of the narratives that has been fed lately is that all this AI will require gobs of power that will need a lot more power production.  It was a key feature of the Uranium story as nuclear is seen as one of the few sources capable of delivering the reliable power necessary.  I suspect that this part of the narrative will need to adjust as well if the AI story has actually changed.  But keep in mind that with efficiency comes more demand, so perhaps this is just a temporary downdraft.  Again, volatility is the name of the game.

Ok, let’s see how these stories have impacted the rest of the world.  With all the news over the weekend, you may not recall that US equity markets edged lower on Friday.  Well, Asian markets were mixed overnight with the Nikkei (-0.9%) following the US, although also reacting to the fact that the yen (+1.3%) rallied sharply as well.  Meanwhile, Hong Kong (+0.7%) managed to gain while mainland Chinese shares (-0.4%) certainly showed no benefit from the changing attitudes in tech.  Elsewhere in the region, Korea (+0.9%) and Taiwan (+1.0%) rallied while India (-1.1%) and Indonesia (-0.9%) fell and the rest of the region batted back and forth. In Europe, red is the dominant color, likely on the generally weak US performance although there are no European tech companies of note (perhaps ASML).  But the DAX (-1.2%) is leading the way down followed by the CAC (-0.9%) and the bulk of the rest of the continent and the UK.  Let’s just say that equities are not in favor this morning.

However, what we are seeing is a major bond market rally as Treasury yields (-12bps) tumble as risk is very definitely off.  European sovereign yields are also lower, by between -5bps and -7bps, and JGB yields (-2bps) also slipped, although relative to the rest of the world, they held up pretty well.  Interestingly, with all the talk about DeepSeek and the impact on the tech community, there has been virtually no discussion about the myriad central bank meetings this week, including, of course, the Fed on Wednesday where the market still sees no chance of a rate cut.

Commodity markets are relatively calm this morning as oil (-0.6%) is a touch lower although there has been no news of note.  The background story is that President Trump and Saudi Arabia’s Mohammed bin Salman are talking about increasing production to drive oil prices lower, but that remains more rumor than anything else.  As the polar vortex has passed, and forecasts are for warmer weather, NatGas (-6.2%) is sliding.  In the metals markets, very little movement is ongoing as traders try to determine what all the new news means.

Finally, the dollar is under some pressure this morning despite the risk off attitude that prevails.  I suppose it is because one of the recent drivers of the dollar’s strength has been the insatiable demand for the megacap tech stocks.  It seems that for now, that demand has been satiated.  So, the yen is behaving in its traditional safe haven role, as is the CHF (+0.85%) but the euro (+0.15%) and pound (+0.15%) are both a touch higher.  That said, we are definitely seeing emerging market currencies under pressure as they have nothing to do with tech and everything to do with the very obvious change in attitude regarding how the US is going to deal with smaller nations that don’t accede to US demands, especially regarding immigration.  So, MXN (-1.0%), COP (-1.1%), ZAR (-1.4%) and BRL (-0.6%) are all under significant pressure.  CE4 currencies, though, are not in the line of fire, so are little changed this morning.  

On the data front, remarkably, it almost seems an afterthought given what we just saw this weekend, but along with the Fed, BOC and ECB, we get PCE on Friday.

TodayNew Home Sales670K
TuesdayConsumer Confidence106.0
WednesdayBank of Canada Rate Decision3.0% (current 3.25%)
 FOMC Rate Decision4..5% (current 4.5%)
ThursdayECB Rate Decision2.75% (current 3.0%)
 Initial Claims220K
 Continuing Claims1885K
 Q4 GDP2.8%
FridayPersonal Income0.4%
 Personal Spending0.5%
 PCE0.3% (2.6% Y/Y)
 Core PCE0.2% (2.8% Y/Y)
 Chicago PMI40.0

Source: tradingeconomics.com

At this point, the central bank story is background noise, not the major theme, but by Wednesday I expect that all eyes will be on Chairman Powell as he describes the Fed’s thoughts at the press conference.  Of course, that assumes that there are no other political earthquakes, which may not be a very good assumption these days.  I think we are in a seismic zone for now.  

As to the dollar, if DeepSeek really is an Nvidia killer, then it is not hard to derive a scenario that says, US equity markets are going to decline, along with growth expectations.  The Fed will cut more aggressively, and the dollar will start to really fall as well.  I’m not forecasting that, just highlighting a possible, if not likely, scenario in the event the world believes the AI story is not going to be as expensive and profitable for the Mag7 as they thought last week.  Once again, the key is to hedge your risks, because as you learned this weekend, things change, and they can change quickly!

Good luck

Adf

More Than a Tweet

In Davos, the global elite
Were treated to more than a Tweet
The president spoke
And in one broad stroke
Explained that he won’t be discreet
 
For oil, he wants prices falling
For Europe, he said it’s appalling
That nations don’t pay
Enough to defray
The costs of the war they’re forestalling


If, prior to yesterday, European leaders weren’t sure how things were going to play out now that Mr Trump is back in office, they have a whole lot better understanding now.  I imagine that all their fears were realized when Trump spoke via video at the WEF meeting in Davos, Switzerland.  It’s funny, Argentine president Javier Milei has been calling out the globalist agenda since his election last year and Europe didn’t care and didn’t change their behavior.  I guess that makes sense because the European press would never allow the narrative to change for a minor player like that.  Alas, for the European narrative now, the US, one of their largest trading partners and the nation that insures their safety via NATO membership, is calling them out for their behaviors, whether it is the rarely discussed tariffs they impose on US imports, or the lack of funding for a war they claim is critical to continue in Ukraine, and they are suddenly aware they better reconsider their positions. 

It will be very interesting to watch if things change in Europe (I think they will) and how quickly these changes will come (that could take more time).  Arguably, the biggest problem the current  European leaders have is that there are already large segments of their populations that are unhappy and have been voting accordingly, whether for AfD in Germany, or the RN in France to name two.  Trump’s comments are going to only foment more support for those positions.  I suspect the elections upcoming in Europe are going to see a further rightward swing, or perhaps simply a further swing against the incumbents given what appears to be a significant amount of dissatisfaction amongst the electorate.  No matter your view of Trump’s policies, we all must recognize he is a remarkable political force!

Fifty basis points
Is now Japan’s new baseline
Can it go higher?

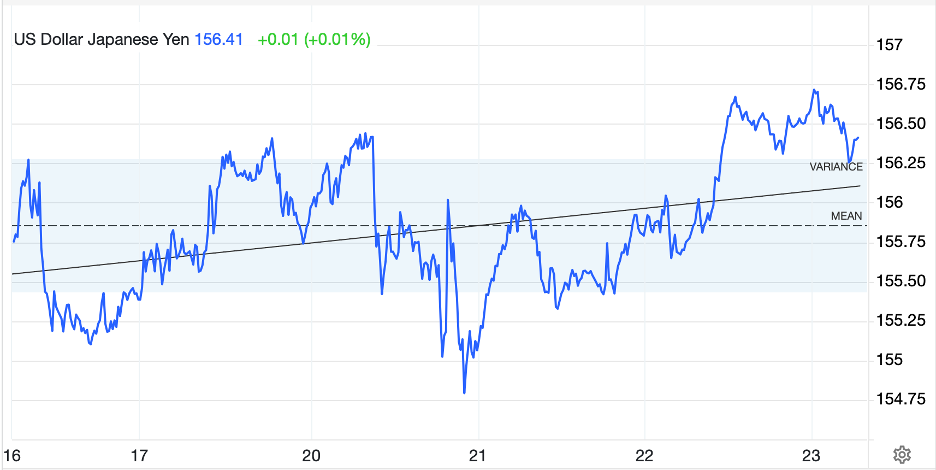
As widely expected, the BOJ hiked its base rate by 25bps last night to 0.50%, the highest levels since October 2008.  The immediate market response, as you can see in the chart below, was for the yen to rally (dollar decline) almost one full percent despite interest rate markets having fully priced in the hike.  However, as you can also see, the yen has given back virtually all those gains in the wake of Ueda-san’s press conference where he explained the BOJ was not “seriously behind the curve” which was taken as meaning that it will be a while before they move again.  

Source: tradingeconomics.com

While JGB yields did perk up 2bps on the session, it hardly seems like the start of a rout.  And, as I highlighted yesterday, the interest rate differential does not seem likely to have changed enough to alter investor plans. Going forward, I expect the yen to be entirely beholden to the dollar’s broad movement.  If, as I suspect, the market starts to price in a more hawkish Fed, USDJPY is likely to go back and test its highs from last summer.

Ok, let’s move on to the overnight market action.  Once again, US equities rallied yesterday, although at this hour (7:10), futures are essentially unchanged.  In Asia, Japanese shares shed early gains after the BOJ rate hike and Ueda presser and closed unchanged on the day.  However, both Hong Kong (+1.9%) and China (+0.8%) rallied on the news that Trump and Xi had a “friendly” conversation as traders and investors took that to mean that tariffs on Chinese goods were not coming right away.  As to the rest of Asia, once again there were both gainers (Korea, Taiwan, Australia) and laggards (India, Indonesia, Philippines) with the rest showing little net movement.  

In Europe, the picture is also mixed as the CAC (+0.9%) is leading the way higher as investors want to believe that Trump’s call for lower interest rates as well as lower oil prices will help the European economy, especially the luxury sector in France.  But elsewhere in Europe we see Germany (+0.3%) a bit higher while Spain (-0.4%) and the UK (-0.4%) are lagging with the former suffering from rising energy prices while the ongoing political mess in the UK has investors steering clear of the Kingdom for now.

In the bond market, Treasury yields are unchanged this morning, holding the recent 10bp bounce from the lows seen last week.  European sovereign yields are higher by 1bp to 2bps across the board, with activity quiet and we’ve already discussed JGBs.  

Ironically, after Trump’s call for lower oil prices, they are firmer this morning, up 0.6%, although in the broad scheme of things, relative to the recent price action, that is tantamount to unchanged.  Here is something to consider though, which is a little bit outside the box.  The Biden EO that cited the OCSLA of 1953 prohibited drilling across a series of areas including the Atlantic and Pacific Oceans as well as the Gulf of Mexico.  Now, what is one of the first things that Trump said?  He is renaming the Gulf of Mexico to the Gulf of America.  Does that nullify the EO?  (h/t Alyosha).  I’m sure that is a legal battle to be had, but it would be right in line with Trump’s MO.  It would also allow drilling to continue unabated there, which to my understanding, has the most fruitful potential new sites.

Meanwhile, in the metals markets, they are all rallying nicely this morning with gold (+0.85%) now just about 1% below the all-time high seen in October of $2826/oz.  There are many market technicians (and gold bugs) calling for a breakout to new highs, but there is a case to be made this remains a technical short squeeze into NY delivery next week.  However, gold has dragged both silver (+0.9%) and copper (+0.9%) along for the ride.

Finally, the dollar is under pressure this morning with the DXY (-0.5%) falling to its lowest level since mid-December.  Ironically, while the G10 weakness is widespread (EUR +0.7%, GBP +0.5%, AUD +0.5%) the yen, after the rate hike, is the massive underperformer.  In the EMG bloc, one of the biggest movers is CNY (+0.5%) which is clearly benefitting from that phone call, while SGD (+0.5%) is benefitting despite the MAS having eased monetary policy.  This is an indication of just how much of a dollar selling move this is this morning.  In fact, other than the yen’s modest decline, every other major counterpart currency is higher vs. the dollar today. 

On the data front, Flash PMI (exp 49.6 Manufacturing, 56.5 Services) leads off at 9:45 then at 10:00 we see Existing Home Sales (4.19M) and Michigan Sentiment (73.2).  With the Fed meeting next Tuesday and Wednesday, there are still no speakers.  Perhaps of more interest is the fact that we have not seen a single article from the Fed whisperer lately.  As the data is third tier this morning, I wouldn’t expect anything today either.  Too, next week there is limited data of note before the meeting so unless we see a narrative shift of substance, I imagine the Fed will do nothing next week and Powell will dodge any questions regarding the future.

For now, it is all Trump and his actions, comments and EOs.  And you can’t plan how to trade those.  Once again, this is why hedging is so important.

Good luck and good weekend

Adf

Trump’s Whirlwind

Markets have embraced
Trump’s whirlwind. Thus, Ueda
Is free to hike rates


Tonight, the BOJ is apparently set to hike rates by 25bps.  The market probability is essentially 100% and the key clue is that the Nikkei news organization wrote an article about it that was published after the first day of the BOJ’s two-day meeting.  At the December BOJ meeting, Ueda-san explained that if inflation remained at or above their 2.0% target (it has) and if there were no major ructions in markets after President Trump’s inauguration (there haven’t been), then the BOJ was likely to continue to move their policy rate toward what they believe is a neutral stance.  Currently, that neutral stance is mooted at 1.00%, so a 25bp hike tonight takes the overnight rate to 0.50%, somewhat closer.

With all this widely anticipated and markets pricing in the result, the key question is how what Ueda-san will say during his press conference that follows the meeting.  There are many who are looking for a so-called ‘dovish’ hike, where there is no indication of the timing of any further rate hikes and a benign view of the future.  Certainly, a look at the FX market, where the yen (unchanged today, -0.8% in the past week) doesn’t indicate a great deal of fear over a much tighter policy.

Source: tradingeconomics.com

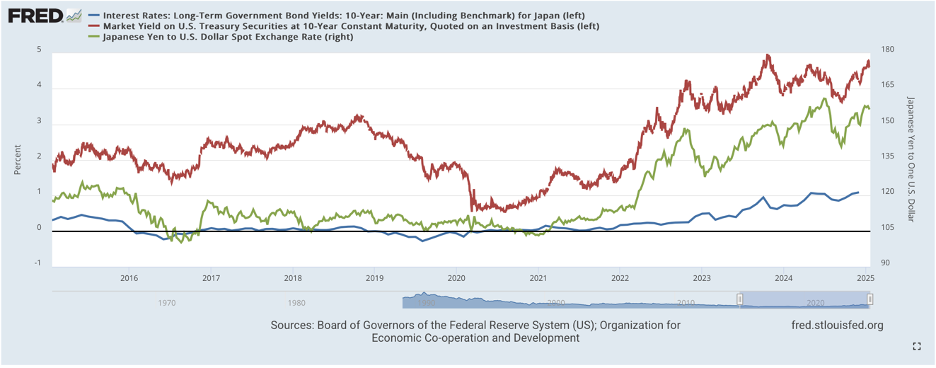
There has been a background narrative that explains the BOJ’s ongoing tightening is going to reach a point where Japanese investors are going to repatriate much of their overseas investment, driving a forceful upward move in the yen and having major negative impacts on risk assets around the world as liquidity retreats.  This is based on the idea that the Japanese are the largest exporters of capital in the world which is one of the key reasons equity markets are rallying everywhere, so if they bring that money home, that means they will sell their foreign equity holdings and buy yen.  While I believe this is a neatly wrapped idea, I would contend Japanese investment prospects are not yet near the same as in the US, so this idea may be premature.  In fact, a look at the chart below showing 10-year US Treasury and JGB yields overlaid with USDJPY indicates that the rate differential is nowhere near where it might need to be in order to encourage that type of behavior.  My take is absent some type of multilateral agreement to weaken the dollar, this will not happen organically.

Source: FRED database

In China, though communists rule
They favor the capital tool
Of equity bourses
And so, Xi endorses
A government stock buying pool

Elsewhere in the world, as we try to get outside the maelstrom that is Donald Trump, I couldn’t help but notice that, once again, Xi Jinping has called on his finance minions to do something, anything, to support the stock market.  And I cannot help but be struck by the irony of the Chinese Communist Party being so concerned about the situation in the most capitalistic institution of all.  The WSJ had an article discussing the latest measures that are on the board, including forcing encouraging insurance companies to increase the local equity portion of their portfolios and utilizing 30% of premium income to buy stocks.  This is on top of the PBOC reducing interest rates last year for companies that want to repurchase shares.

It continues to be very difficult for me to accept the idea that the Chinese are playing 4-D chess with long-term goals in mind while the US is playing checkers.  If that is the case, then the Chinese, or at least President Xi, is a really bad player.  His economy is under dramatic pressure because the property bubble he inflated has been shrinking for the past three years, undermining both the population’s wealth (property was their store of value) and confidence, while he ramps up more beggar thy neighbor trade policies at the same time the US has just elected a president whose middle name is Tariff.  Their population is shrinking because of the ‘foresight’ of their leadership to impose a one-child policy for two generations and while millions of people will risk their lives to immigrate to the US, people are looking to leave China.  Once again, I cannot look at this situation and conclude anything other than the CNY (-0.15%) is going to gradually decline all year long, and maybe not so gradually if pressure really builds.

Ok, let’s take a look at how markets are handling the latest set of Trumpian pronouncements and reactions by targets of his ire.  After yet another rally in the US, albeit on declining volumes so not as exciting as it might otherwise have been, Japanese shares rallied (+0.8%) as investors seem to believe that the interest rate hike tonight will be accompanied by a more dovish stance at the press conference.  Mainland Chinese shares (CSI 300 +0.2%) eked out a gain after the latest news discussed above, although Hong Kong shares (-0.4%) did not follow suit.  After all, the focus is on mainland shares.  The rest of the region was widely dispersed with gainers (Taiwan, Singapore, Philippines) and laggards (Korea, Australia, Thailand), many of these moves in excess of 1%.  It appears investors don’t know which way to turn yet given the speed of changes emanating from Washington.

In Europe, most bourses are modestly firmer (DAX +0.3%, CAC +0.5%) as we continue to hear more from ECB speakers that not only are rates going to be cut, but they are increasingly certain that they will achieve their inflation target.  Maybe they will.  As to US futures, at this hour (7:00) they are mixed to slightly softer with the NASDAQ (-0.4%) the laggard.

In the bond market, the decline in yields appears to be over, at least for now, as Treasuries (+3bps) continue to bounce from their recent lows at 4.54%.  As is almost always the case, this has carried European sovereign yields higher as well, by between 1bp and 3bps across the continent and UK and we saw JGB yields gain 1bp overnight.  I would contend there is still a great deal of uncertainty as to how the Trump administration is going to handle the conundrum of reducing inflation while expanding growth.  Outside of declining energy prices, which may be coming, it will be a tall task, and inquiring minds want to know.

Speaking of energy prices, oil (+0.35%) is edging higher after a lackluster session yesterday.  As with most markets, uncertainty is rife right now although this is clearly an area where Mr Trump is focused on expanding output.  NatGas (-0.3%) is a touch softer as forecasts for the end of the current Polar Vortex keep getting moved up. Metals markets are under some pressure this morning, with gold (-0.3%) backing away from that all-time high level and both silver and copper fading as well.  However, volumes remain light here implying not much interest overall.

Finally, the dollar is a touch stronger this morning, but there are few large movers in either the G10 or EMG blocs.  In fact, every G10 currency is within 0.2% of yesterday’s closing levels and none of them are at extremes.  The biggest loser today is ZAR (-0.6%) which seems to be responding to the precious metals complex backing off a bit overnight.  It remains very difficult to get a read on the dollar with all the other things ongoing.  As it happens, this is one market that has not received any Trumpian attention at all…yet.

We finally have a smattering of data this morning with the weekly Initial (exp 220K) and Continuing (1860K) Claims to be followed by the EIA’s oil inventory data where it appears a modest net build across products is forecast.  With the Fed quiet, and very little focus on Powell and company right now, today looks to be shaping up as another equity focused day with the dollar likely taking its cues there.  While we never know what will hit the tape these days, absent a new surprise vector, there is no reason to look for significant movement today at all.

Good luck

Adf

Trump 2.0

Today begins Trump 2.0
And pundits are trying to show
Their ideas are sound
As how he’ll redound
On policies he will bestow
 
But this poet can’t comprehend
How anyone thinks what they’ve penned
Is likely to be,
To any degree,
Correct. ‘Stead, let’s look at the trend


As Donald Trump prepares to take the oath of office today, there has been a non-stop barrage of pundits putting forth their views as to how policy proposals that were made during the campaign, and even since the election, are going to impact the economy as well as equity, bond and FX markets.  But I would take exception to all these as, if we learned nothing else from Trump’s first term in office, we have no idea how he may try to do the things he says he is going to do.  Are tariffs a funding process?  Are they negotiating tactics?  Are they punishment?  Since we have no idea at this point (all three of those ideas have been floated by “insiders” and pundits), how can we meaningfully forecast the impact tariffs may have going forward?  So, I won’t even try.

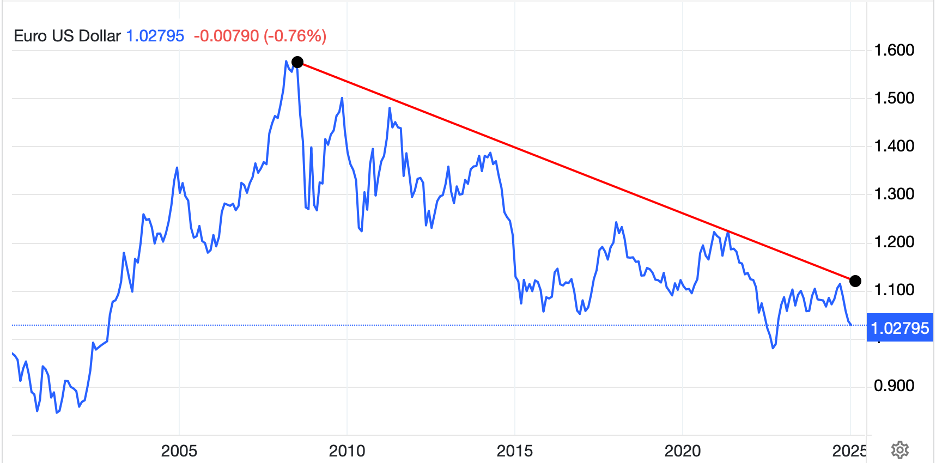
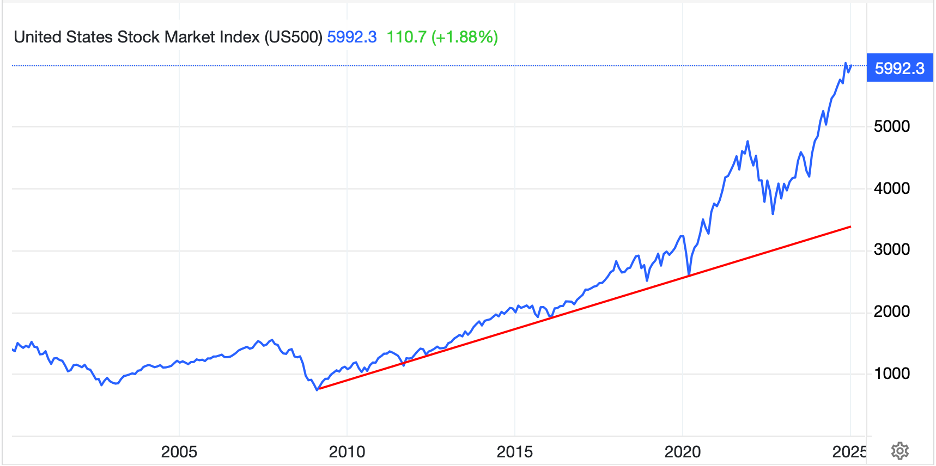
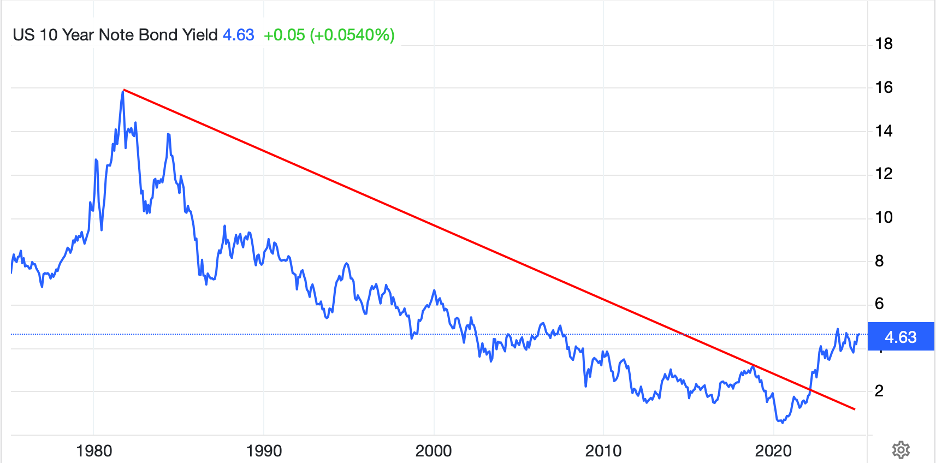
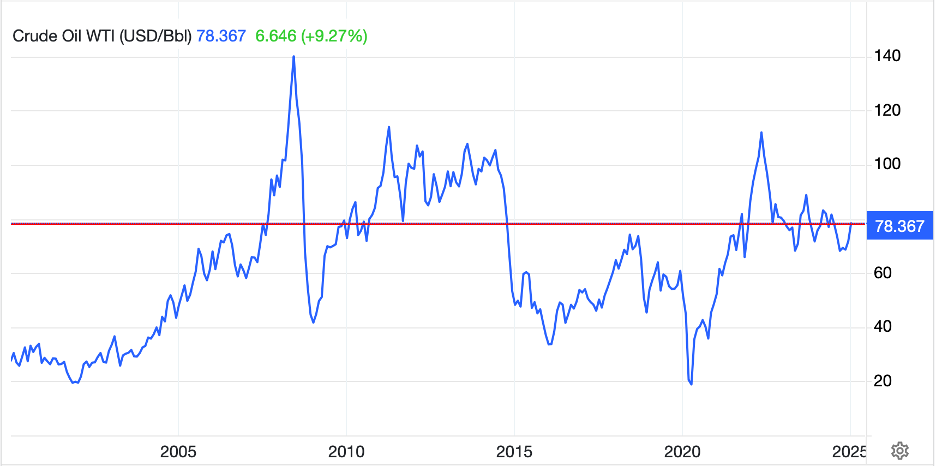
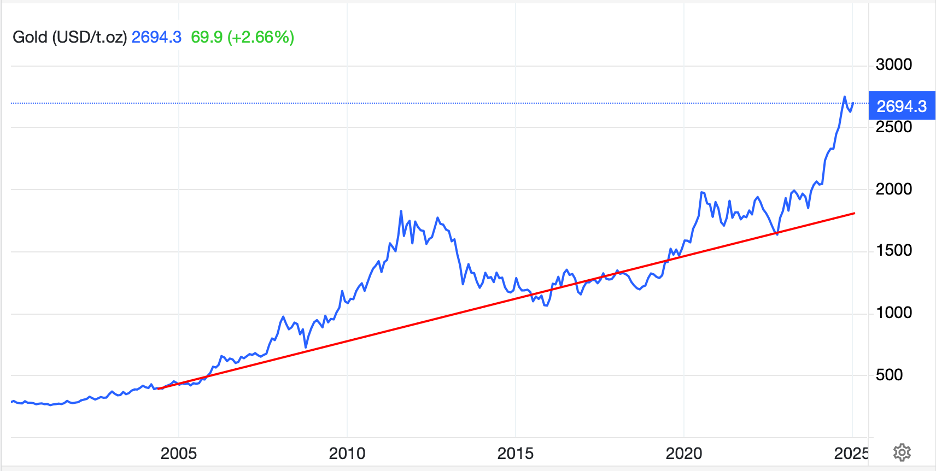
Rather, I think there is much to be learned from looking at the long-term trends in markets and perhaps trying to come up with reasons that these trends may be changing, or not, going forward.  As such, take a look at the charts below, all from tradingeconomics.com, where I have tried to highlight the long-term trend in the dollar (EURUSD), the S&P 500, 10-Year Treasury Notes, oil and gold.

My first observation is that over the past twenty-five years, oil has traded both higher and lower with no discernible direction.  Certainly, we are higher now than 25 years ago, but we have been both much higher and lower in the interim.  Now, if Trump is successful at freeing up more drilling opportunities, removing the offshore drilling ban that Biden imposed last week, and reducing the regulatory structure such that the cost of drilling declines, my take is increased supply will result in some downward pressure.  As well, if he is successful at bringing an end to the Ukraine war, it seems probable that Russian oil may no longer be sanctioned, and that, too, would pressure prices lower.  But will he impose tariffs on Canada, a key source of sour crude used to refine diesel?  That could easily pressure prices higher.  And what of Venezuela?  As I said, no way to know.  In the end, my take is that the most likely outcome is that oil will continue to demonstrate its inherent price volatility given its price inelasticity.  I think you can equally make the case for $50 oil as well as $100 oil based on many idiosyncratic issues that have nothing to do with Trump.

The only noteworthy change we have seen is in 10-Year Treasury yields, which after a 40-year downtrend following the back-to-back recessions in 1980-1982 and Fed Chair Volcker’s policy tightening, look very clearly to have reversed course.  I am not the first to notice this but believe that it is an important feature of markets going forward.  There are virtually two generations of traders and investors who have only ever seen interest rates decline and have created their mental investment models on that underlying thesis.  If the future is going to bring about higher interest rates over time (and given my view that inflation is not going to disappear and that will be a key driving force), then investment models in a higher inflation, higher yield environment are going to be different than what we have seen up through 2022.  

One of the keys is that the idea behind the 60/40 portfolio, where declines in stock prices were offset by rises in bond prices, turns out to only really be true in a low inflation environment, sub 2.5%.  If inflation is going to run at 3.5% – 4.5% going forward, then all the strategies that incorporated that 60/40 basis are going to have an awfully difficult time, again, regardless of what Trump does.  The one caveat here is if he is successful in driving inflation back to that <2.0% level, but that seems highly unlikely in the near term given how sticky inflation has proven to be even without any new policies.

Now, if we look at the dollar, that trend has been very consistent and remains in place with the dollar seemingly set to continue to appreciate.  Given Trump’s stated desire to reshore American manufacturing and reduce the trade deficit, he almost certainly would like to see the dollar decline.  However, at this point, it’s not clear what policies are going to drive that.  Historically, loose monetary and tight fiscal policy will weaken a currency, and that could well be what we see, except that is likely to create a burst of inflation before the tight fiscal policy reins that in.  And you know as well as I that Trump will be very displeased with that outcome.

It is certainly possible that the Treasury could intervene to weaken the dollar, but that is also something that is exceedingly rare in this country.  Perhaps the most likely situation here would be a Mar-a Lago (?) Accord, or something like that akin to the Plaza Accord of 1985, where the G7 at the time all agreed that the dollar needed to decline.  Now, on the one hand, given the weakness in the other G10 economies currently when compared to the US, my take is those nations are pretty happy to have weak currencies to help support their domestic industries.  On the other hand, I suspect the EMG bloc who have funded themselves in USD are really interested in seeing a weaker dollar to help them get easier access to dollars to service and repay their debt.  My take is that until there is a definitive policy pronouncement, and this will require something like that as quiet policy adjustments are likely to be missed by the FX market, this trend will remain intact.

Finally, a look at both equities and gold shows basically the same chart, with both showing accelerating price increases and both now significantly above their long-term trend lines.  The question, of course, is can this continue?  Keynes was reputed to have told us that markets can remain irrational longer than you can remain solvent, implying just because market pricing doesn’t make fundamental sense doesn’t mean it cannot continue further.  But in the end, trees don’t grow to the sky, and corrections in these markets seem somewhat overdue.  Consider the S&P 500 chart, where we see the sharp decline in 2022.  Many remember that as the worst market since the GFC crash, and yet on the chart, it looks like a modest correction.  Consider also, that if the market were to decline to the trend line I have drawn, it would be nearly a 50% correction, and that just puts it back on trend!  Again, volatility seems the watchword going forward, but until we see something that is going to change opinions, the trend in both stocks and gold seems higher.

OK, as we await the official change in presidency here, let’s review the overnight price action, which was generally positive following Friday’s US equity rally.  Remember, too, it is MLK Day, and markets are closed in the US.

Asian markets saw broad gains with the Nikkei (+1.2%) and Hang Seng (+1.75%) leading the way while mainland shares (+0.45%) lagged but were still in the green.  Away from the major markets, there were far more gainers than laggards, but the biggest moves were on the order of 0.4%, nothing of real note.  Positive Japanese data was the driver in Tokyo (Machinery Orders +3.4%) while HK and Chinese shares benefitted from the news that Presidents Trump and Xi spoke, hopefully in a prelude to less tension.  In Europe, markets are essentially unchanged across the board this morning as it seems investors cannot discern whether Mr Trump will be beneficial for the continent or not.  Certainly, I continue to read about a number of European leaders who are unhappy at the prospects of a Trump presidency (specifically PM Starmer who has ostensibly said the US-UK relationship is destined to diminish).  While that may be true, my take is it will not help the UK very much.  And, while US markets are closed today, US futures are pointing modestly higher this morning.

In the bond market, yields are edging higher in Europe, up between 1bp and 2bps on the continent while UK Gilt yields are higher by 3bps.  Overnight saw JGB yields slip 1bp and, of course, with banks closed in the US, Treasury yields are unchanged in the cash market.  However, bond futures are pointing to a 1bp rise as well.

In the commodity markets, oil is little changed on the day while NatGas (-4.4% after a -6.0% decline on Friday) is falling on news that weather models, which had been calling for another cold spell in February, have changed and are now saying temperatures will be milder then.  In the metals markets, gold (+0.3%) is edging higher while both silver (-0.3%) and copper (-0.4%) are slipping a touch, but given their inherent volatility, arguably these are unchanged on the day.

Finally, the dollar is under some pressure this morning with then euro (+0.5%) leading the G10 higher although similar sized gains are seen across the board with only JPY (0.0%) failing to go along for the ride.  EMG currencies are also picking up led by HUF (+2.0%) as it seems there is excitement in Hungary regarding the inauguration as PM Orban seems to share many of President Trump’s views on various geopolitical issues.  But CZK (+0.9%) and PLN (+0.6%) are also rallying alongside KRW (+0.5%), although MXN (-0.3%) seems to be showing concerns regarding how that relationship will evolve.  Certainly, as I mentioned above, President Trump will not be unhappy to see the dollar slide a little, but I don’t see this as the beginning of a new trend.

With no data today, and a light week in general, and given how long this missive has already become, I will lay out the data releases tomorrow.  Today, all eyes will be on the ~200 Executive Orders President Trump will sign and I expect it will take a little time to digest it all, so we will see how things really begin tomorrow.

Good luck

Adf

Falling Further

Like a stone toward earth
The yen keeps falling further
Beware Kato-san


While we have not discussed the yen much lately, its recent weakness, in concert with the dollar’s broad strength, has begun to cause some discomfort in Japan.  Last night, Japanese FinMin Katsunobu Kato explained, “We will take appropriate action if there are excessive movements in the currency market.”  He went on that he is “deeply concerned” by the recent weakness, especially moves driven by those evil pesky speculators.

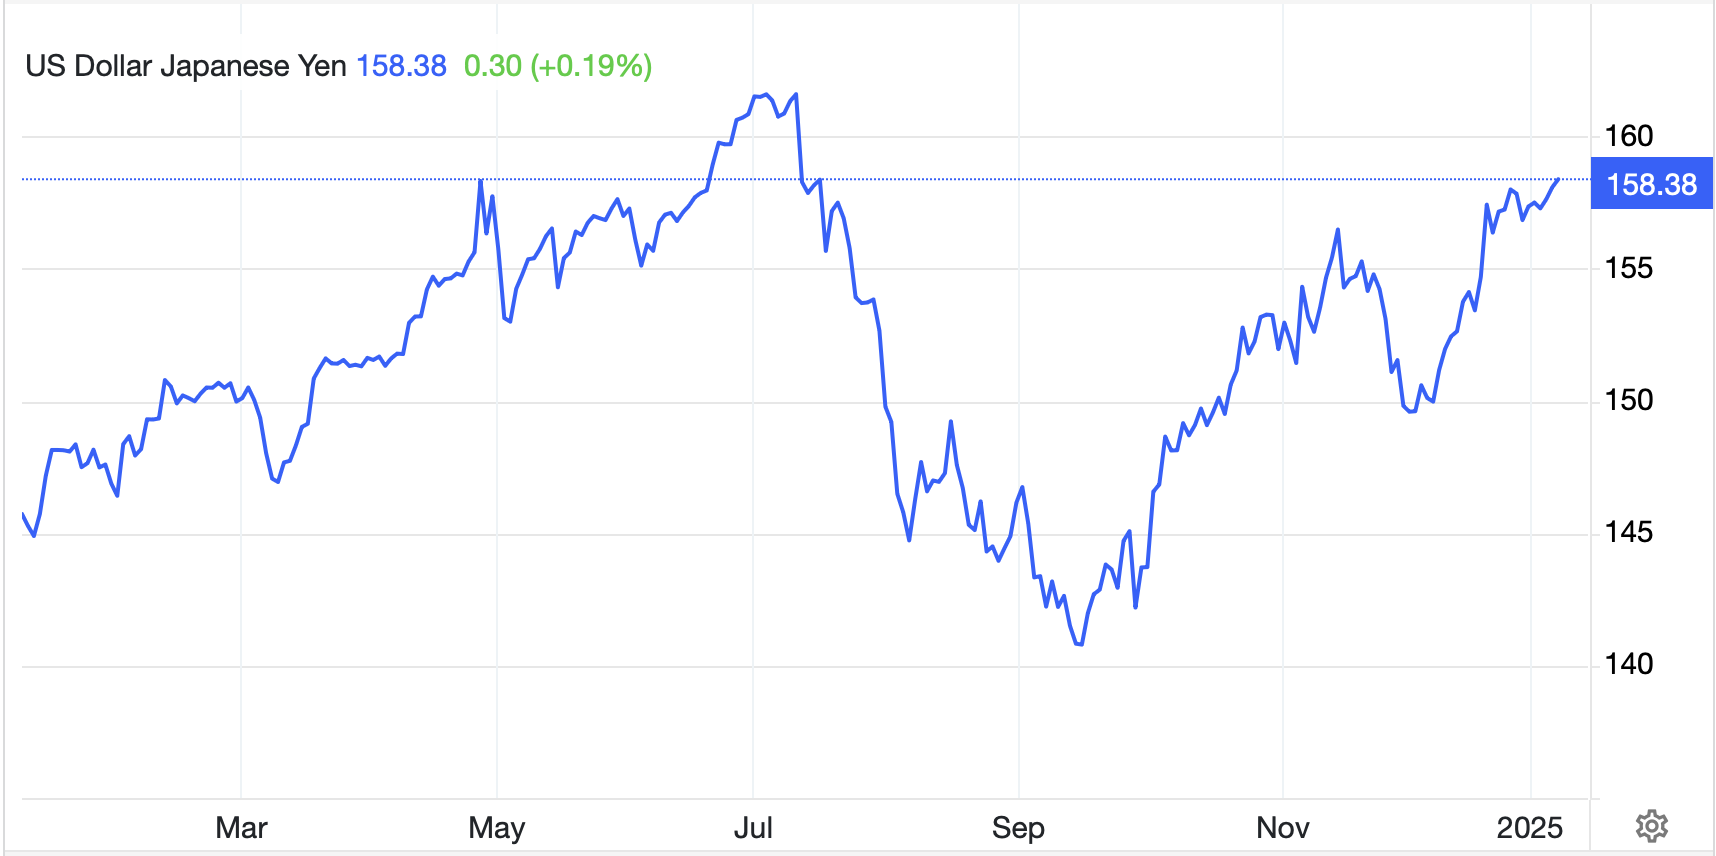
The problem, of course, is that all those expectations that the BOJ would be tightening policy to fight domestic inflation while the Fed would continue to ease policy since they “beat” inflation, with the result being the yen would regain its footing, have proven to be false hope.  Instead, as you can see from the below chart, since the Fed first cut rates back in September, the yen has tumbled nearly 13% and very much looks like it is going to test the previous four-decade highs seen last summer.

Source: tradingeconomics.com

Last year, the MOF/BOJ spent about $100 billion in their efforts to stem the yen’s weakness.  They still have ample FX reserves to continue with that process, but ultimately, history has shown that maintaining a cap on a currency that is weakening for fundamental reasons is nigh on impossible.  If a weak yen is truly seen as existential in Tokyo, then Ueda-san needs to be far more aggressive in tightening monetary policy.  This is especially so given the Fed continues to back away from earlier expectations that it would be aggressively loosening policy.  Now, while JGB yields have moved higher over the past several sessions, trading now at 1.18%, which is their highest level since April 2011, that is not going to be enough to stem this tide.  From what I read, inflation is an issue, but not the same as it was in the US in 2022, so Ueda-san is not getting the same pressure to address it as Powell did back then.  My read is the BOJ remains on hold this month and hikes rates in March while the yen continues its decline.  Look for another bout of intervention when we test the 162 level, but that will not stop the rot.  Nothing has changed my view of 170 or higher in USDJPY by year end.

Though Treasury yields have been rising
Most credit spreads have been downsizing
So, corporate supply
Is ever so high
An outcome that’s somewhat surprising

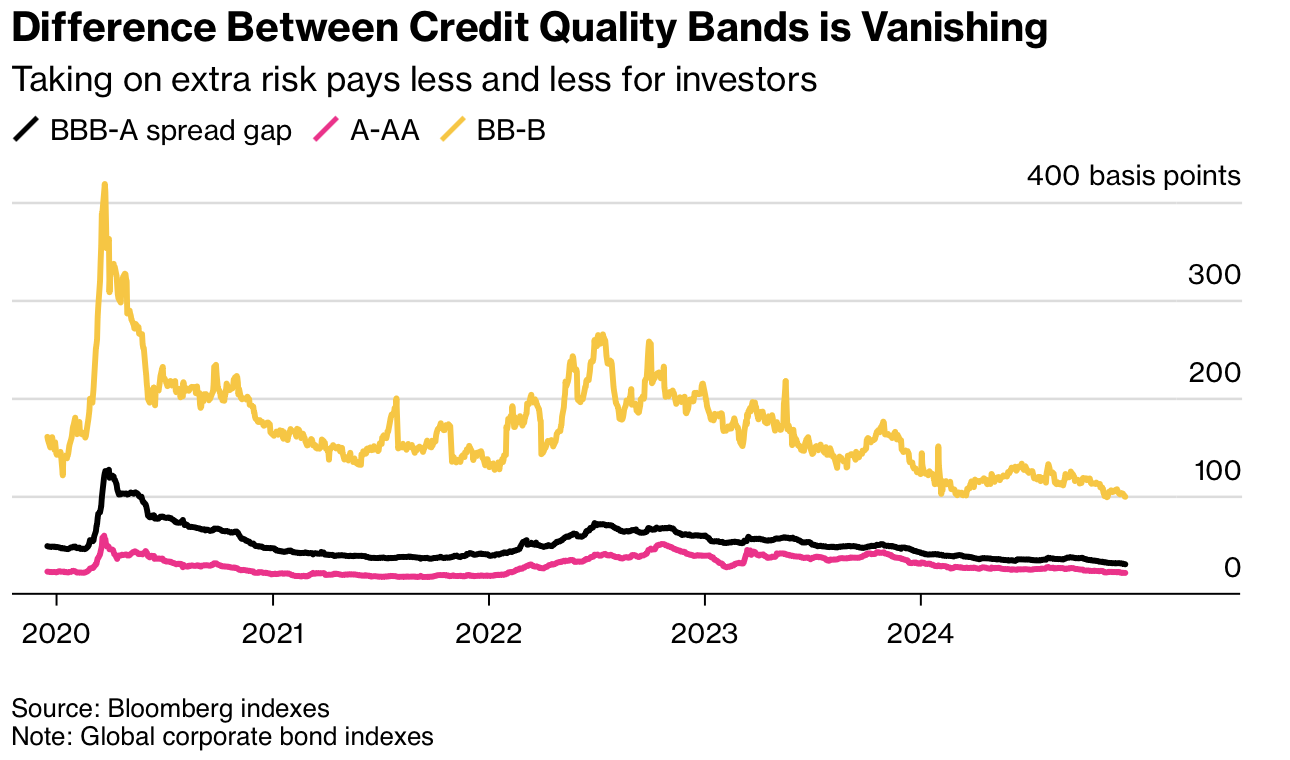
In the bond market, government bond yields continue to rise around the world (China excepted) as investors increase their demands in order to hold the never-ending supply of new bonds.  Ironically, despite this ongoing rout in government bonds across the board, corporate debt issuance looks as though it will set new records this month.  One thing to remember here is that corporates have a lot of debt coming due over the next two years as all that issuance during the ZIRP period needs to be rolled over.  But the other thing to recognize is that corporate credit spreads, the amount of yield investors require to own risky corporate bonds vis-à-vis “safe” government bonds, has fallen to its lowest levels in years, and as can be seen in the chart below, the extra yield available for high-yield investors is shrinking faster than for investment grades.

Potentially, one reason for this is the dramatic increase in the amount of Private Credit, the latest investment fad where weaker credits go directly to funds designed to lend money rather than to their banks, and investors ostensibly remove one of the middlemen from the process.  As such, there is less of this debt around than there otherwise might be, hence increasing demand and reducing that credit spread.  But the other reason is that there continues to be a significant amount of investable assets looking for a home, and with global yields near the highest they have been in a decade or more, and with the equity market dividend yield down to just 1.27% or so, a record low, there are lots of investors who are comfortable with clipping 5% or 5.5% coupons on BBB corporate bonds.

The question I would ask is, if government bond yields continue to climb, and I see no reason for that to stop given the trend in inflation and necessary issuance, at what point are investors going to get scared?  We are likely still a long way from that point, but beware if the new Treasury Secretary, Scott Bessent, follows through with his hinted views of reducing T-bill issuance and increasing coupon issuance, yields could go much higher absent the Fed implementing QE.  That would cause some serious market ructions!

Ok, let’s see how things look around markets this morning after yesterday’s sell-off in the US equity markets.  It seems Japanese stocks were caught between the weaker yen (generally a stock positive) and the tech sell-off (generally a stock negative) with the Nikkei closing lower by -0.25% on the session.  Meanwhile, the Hang Seng (-0.9%) suffered a bit more on the tech move, although Mainland shares (-0.2%) were not as badly affected.  An interesting story here is that the chief economist at state-owned SDIC Securities made comments at an international forum run by the Peterson Institute that really pissed off President Xi.  Gao Shanwen said the quiet part out loud when he claimed that actual GDP growth in China for the past several years has likely been much closer to 2% than the 5% published.  That story has been widespread in the West, although has never been given official credence.  And for Xi, 2% growth is not going to get it done, what with the property bubble still imploding and consumption declining despite promises of more stimulus.  Stay tuned to this story to see if we start to see more Western analysts reduce their expectations.  Elsewhere in Asia, the picture was mixed with gainers (Korea, Australia, Singapore) and laggards (Taiwan, Malaysia, Philippines).

In Europe, red is today’s color, led by the CAC (-1.0%) although we are seeing losses across the board. Eurozone data showed declining Consumer Confidence, Economic Sentiment and Industrial Sentiment all while inflation expectations remain stubbornly high.  That stagflationary hint is typically not an equity market benefit so these declines should be expected.  The story on the continent is not a positive one and I maintain that the ECB is going to have to cut rates more aggressively than their inflation mandate would suggest.  That might support equities a bit, but it will be hell on the euro!  Finally, US futures are a touch softer (-0.2%) at this hour (7:05) although they were higher most of the overnight session before this.

As mentioned above, bond yields are higher with Gilts (+9bps) leading the way as not only is the economy suffering from some very poor policy decisions by the Starmer government, but it seems that the ongoing political crisis regarding grooming gangs has investors shying away.  But yields continue to rise across the board with continental yields up between 3bps and 6bps, Treasury yields higher by another 1bp this morning after a 10bp rise in the previous two sessions, and JGB yields, as mentioned, higher by 5bps.  This trend is very clear!

In the commodity markets, oil (+0.5%) keeps on keeping on, as API data showed a greater than 4mm barrel draw on inventories, far more than expected and indicating a reduced supply around.  Cold temperatures are keeping NatGas (+5.0%) firm as well.  In the metals markets, both precious and base are under a touch of pressure this morning, down less than -0.2%, largely in response to the dollar’s rebound.

Speaking of the dollar, it is higher against all its counterparts this morning with the pound (-1.2%) the G10 laggard although weakness on the order of 0.5% is pretty common this morning.  In the EMG bloc, ZAR (-1.5%) is the worst performer, after weaker than expected PMI data called into question the economic path forward.  But here, too, we are seeing weakness like MXN (-0.9%), CLP (-0.8%), PLN (-0.8%) and KRW (-0.5%).  I would be remiss to ignore CNY (-0.25%), which is trading below (dollar above) 7.3600 in the offshore market, and is now 2.4% weaker than last night’s fixing rate.  This is also the weakest the renminbi has been since it touched this level back in September and then November 2007 prior to that.  Those Chinese problems are coming home to roost for President Xi.

On the data front, ADP Employment (exp 140K) leads the day followed by Initial (218K) and Continuing (1870K) Claims.  These are being released this morning because of tomorrow’s quasi holiday regarding the late President Carter, when US markets will be closed.  This afternoon, the FOMC Minutes arrive and will be scrutinized closely to see just how hawkish they have become.  We also hear from Governor Waller this morning with caution being the watchword from virtually every Fed speaker of late.

It is all playing out like I anticipated, with the ISM data showing strength yesterday, not just in the headline number, but also in the Prices Paid number.  The Fed will have no chance to cut rates again, and I look for the dollar to continue to rise.

Good luck

Adf

Active De-Bonding

Up north is a nation quite vast
Whose money, of late’s been, out, cast
But word that Trudeau
Is soon set to go
Has seen Loonies quickly amassed
 

One of the biggest stories over the weekend has been the sudden upsurge in articles and discussion regarding the remaining tenure for Canadian PM Justin Trudeau.  For the past several weeks, since his FinMin Krystia Freeland resigned and published a scathing resignation letter, pressure on Trudeau has increased dramatically.  It appears that it is coming to a head with articles from both Canadian and international sources indicating he may step down as soon as this week.  As well, his main political rival, conservative party leader Pierre Poilievre, is touted, according to the betting websites, as an 89% probability to be the next PM.
 
Now, we all know the dollar has been strong in its own right lately, and I suspect that while there will be bumps along the road, it will get stronger still over the year absent some major Fed rate cutting.  As such, USDCAD is higher along with everything else.  However, you can see in the chart below (the green line rising faster than the blue line since December) that it has been an underperformer for the past month, since that Freeland resignation, as investors have been shying away from Canada, given the combination of concerns over the incoming Trump administration imposing tariffs and no political leadership to address these issues.


Source: tradingeconomics.com

While no sitting politician is ever willing to cede power easily, and there are indications that Trudeau is going to go down kicking and screaming, ultimately, I expect that Poilievre will be the PM and will develop a strong relationship with the US.  As that becomes clearer, I expect to see the CAD appreciate modestly vs. the dollar, but much more so against other G10 currencies.

Once more, what the Chinese have said
Is stimulus is straight ahead
But so far, its talk
They ain’t walked the walk
So, bulls need take care where they tread

Another tidbit this morning comes from Beijing, where the economic planning agency there has indicated that they will expand subsidies for consumer purchases of electronic goods like cellphones, tablets and smart watches, as President Xi continues to watch his nation’s economy grind along far more slowly than he really needs to happen.  There was an excellent thread on X this morning by Michael Pettis, one of the best China analysts around, describing the fundamental problem that Xi has and why the slow motion collapse of the property market portends weakness for a long time going forward.  As is almost always the case, while tearing the proverbial band aid off quickly can hurt more at the instant, the pain dissipates more quickly.  President Xi believes he cannot afford to inflict that much pain, so their problems, which stem from decades of malinvestment in property that inflated a massive bubble, are going to last for a long time.  While CNY (+0.4%) is modestly firmer this morning, that is only because the dollar is weaker across the board, and in fact, it is significantly underperforming.

This week, the US Treasury’s Yellen
Much debt, will look forward to sellin’
The market’s responding
By active “de-bonding”
With dollars and bonds both rebellin’

The last big story of the day is clearly the upcoming Treasury auctions this week, where the US is set to sell $119 billion of debt, starting with $58 billions of 3-year notes today.  Arguably, market participants have been aware that this was going to be a necessary outcome given the massive deficits that continue to be run by the US.  Adding to the broad concept of deficits, the Biden administration appears to be trying to spend every appropriated dollar in the last two weeks in office and that requires actual cash, hence the auctions to raise that cash.  In addition, the debt ceiling comes back into force shortly, so they want to get this done before that serves to prevent further issuance.

Now, the yield curve has reverted back to a normal slope with the 2yr-10-yr spread at 34bps and 30yr bonds trading another 22bps higher than 10yr at 4.81% and bringing 5% into view.  Here’s the thing about the relationship between the dollar and yields; the dollar is typically far more correlated to short-term yield differentials, not long-term yields.  So rising 30yr bond yields is not likely to be a dollar benefit.  In fact, just the opposite as international investors will not want to suffer the pain of those bonds declining in price rapidly.  

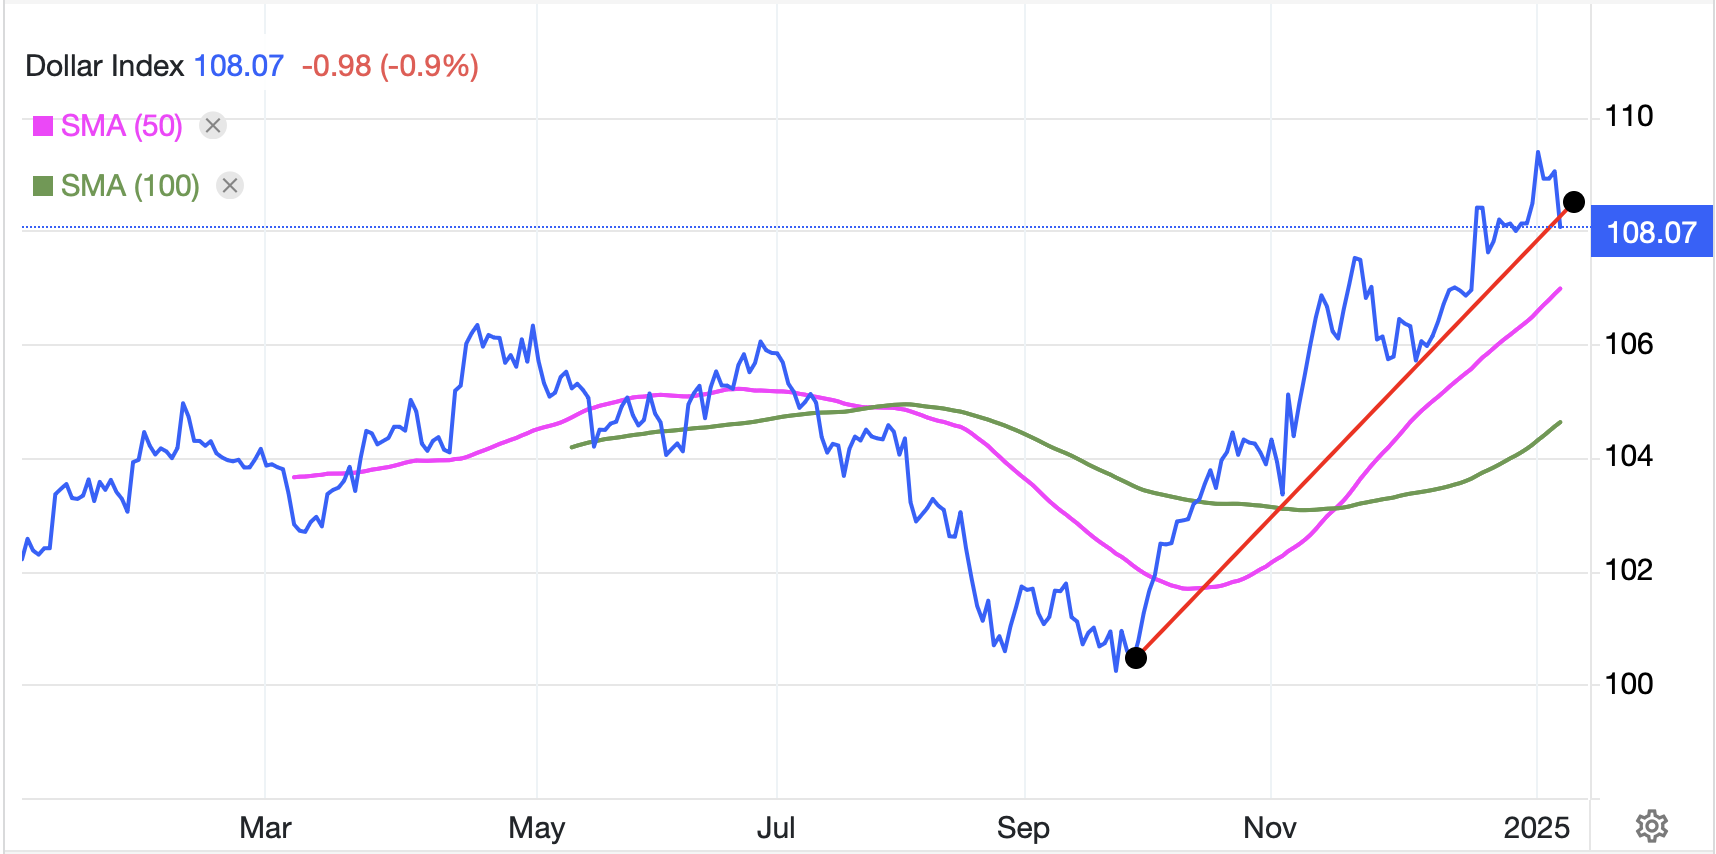
And this is what we are witnessing this morning as the dollar, which rallied sharply at the end of last week, is correcting in a hurry today.  As mentioned above, CNY is the laggard with the euro, pound, Aussie, Kiwi and Loonie all firmer by 1% or more this morning and similar gains seen across the emerging markets, with some extending those gains as far as 1.35% or so.  Is this the end of the dollar?  I would argue absolutely not.  However, that doesn’t mean that we won’t see a further decline in the buck before it heads higher again.  A quick look at the chart below, which shows the Dollar Index, while it has just touched the steep trend line higher, it remains far above its 50-day and 100-day moving averages.  Howe er, it seems that the big story here comes from a report from the Washington Post that Trump is considering much less widespread tariff impositions with only some critical imports to be addressed.  As such, given the tariffs = higher dollar consensus, if this is true, you can understand the dollar’s retreat.

Source: tradingeconomics.com

However, today’s story is that of a weak dollar and strong equity markets, well at least in some places. Friday’s US equity rally was not followed by similar enthusiasm in Asia with the Nikkei (-1.5%) leading the way lower while both the Hang Seng (-0.4%) and China (-0.2%) also lagged.  Perhaps the mooted China stimulus helped those markets on a relative basis.  Europe, however, is in fine fettle (CAC +2.3%, DAX +1.4%, IBEX +0.9%) as PMI data released this morning was solid, if not spectacular, and the weaker dollar seems to be having a net positive impact.  US futures are also firmer, with NASDAQ (+1.1%) leading the way.

In the bond market, the big movement was in Asia overnight as JGBs (+4bps) sold off alongside virtually every other Asian bond market except China, which saw yields edge lower by 1bp to a new record low of 1.59%.  In Europe, there has been very little movement with yields +/- 1bp at most and Treasury yields, which had been firmer earlier in the overnight session, have actually slipped back at this hour and are lower by 2bps to 4.58%.

In the commodity markets, the weak dollar has helped support prices here with oil (+1.0%) continuing its rally (+9% in the past month) as the combination of Chinese stimulus hopes and cold weather seem to be providing support.  Speaking of cold weather, NatGas (+7.4%) is also in demand this morning as winter storm Barrie makes its way across the country.  In the metals markets, gold (+0.3%) is the laggard this morning with both silver (+2.3%) and copper (+2.4%) really taking advantage of the dollar’s weakness.

On the data front, there is a ton of stuff this week, culminating in NFP on Friday.

TodayPMI Services58.5
 PMI composite56.6
 Factory Orders-0.3%
TuesdayTrade Balance-$78.0B
 ISM Services53.0
 JOLTS Job Openings7.70M
WednesdayADP Employment139K
 Initial Claims217K
 Continuing Claims1848K
 Consumer Credit$12.0B
 FOMC Minutes 
FridayNonfarm Payrolls160K
 Private Payrolls134K
 Manufacturing Payrolls10K
 Unemployment Rate4.2%
 Average Hourly Earnings0.3% (4.0% Y/Y0
 Average Weekly Hours34.3
 Participation Rate62.8%
 Michigan Sentiment73.9

Source: tradingeconomics.com

In addition to all this, we hear from six more Fed speakers over seven venues with Governor Waller likely the most impactful.  Over the weekend, we heard from Governor Kugler and SF President Daly, both explaining that they needed to see more progress on inflation before becoming comfortable that things were ok.

Clearly, the tariff story is the current market driver in the dollar.  As I never saw tariffs as the medium-term driver of dollar strength, I don’t think it has as much importance.  Plus, this is a report from the Washington Post.  There are still two weeks before inauguration and many things can happen between now and then.  Nothing has changed my longer-term view that the dollar will be supported as the Fed, which is not tipped to cut rates this month and is seen only to be cutting about 40bps all year will ultimately raise rates as inflation proves far more stubborn than desired.  But that is the future.  Today, pick spots to establish dollar buys and leave orders.

Good luck

Adf

Boom and Bust

According to people we “trust”
The past which involved boom and bust
Will stay in the past
And now, at long last
The owning of stocks is a must
 
So, whether today’s NFP
Is weak or strong, what we foresee
Can best be expressed
By buying the best
That BlackRock will sell for a fee


Is it different this time?  Have stocks reached a “permanently high plateau”?  Has the global economy exited the cycle of ‘boom and bust’ which has existed since the beginning?  These questions are relevant today after the release of BlackRock’s 2025 Global Outlook which explained that “Historical trends are being permanently broken in real time as mega forces, like the rise of artificial intelligence (AI), transform economies.”

BlackRock’s claim is simply the latest by a well-known investor that stock prices will never retreat again, and the future is unbelievably bright.  “This time is different” has been said about virtually every bull market top, whether the real estate bubble, the tech bubble, the Japanese bubble, the Chinese real estate bubble or even the South Seas bubble hundreds of years ago.  In fact, in order to inflate a bubble, the narrative must be, this time is different.

That permanently high plateau comment came from Irving Fisher, who while a very well-respected economist for his work on debt deflation (which came after the Depression started), famously made that comment on October 21, 1929, just days before the crash that led to the Great Depression.

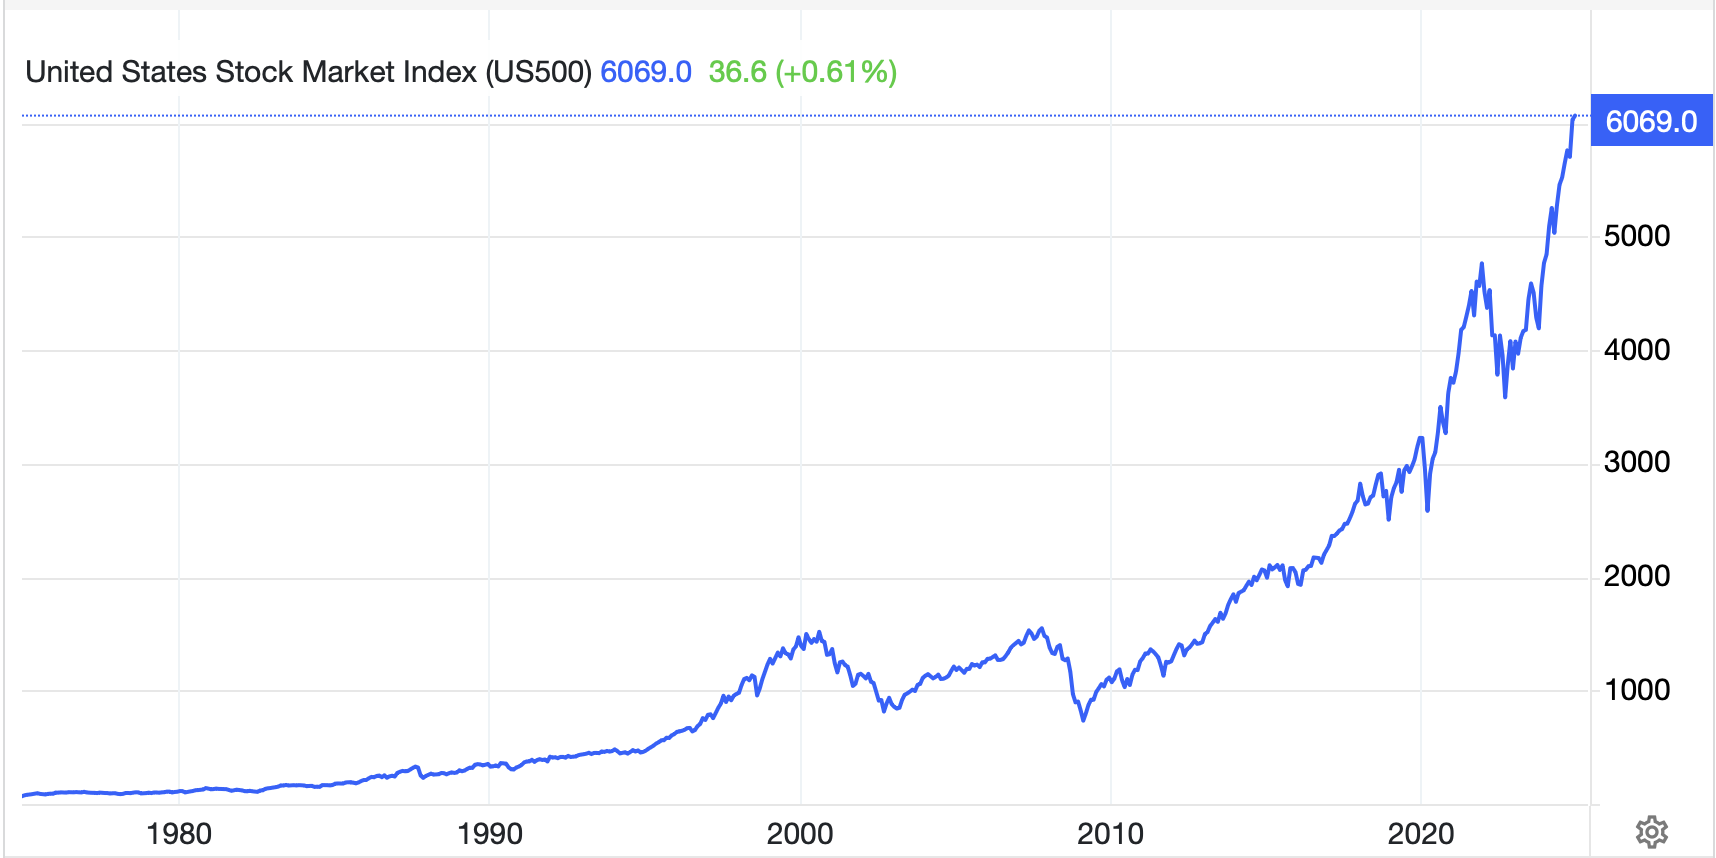
So, the question is, has BlackRock defined the top in equity markets this time?  I think it is worthwhile to take a longer-term perspective on market performance to try to answer that question, and more importantly, figure out what to do if this is the top.  A look at the chart below, the last 50 years of the S&P 500, shows that every one of the major downturns we have seen, at least in my lifetime, has been nothing more than a blip.

Source: tradingeconmics.com

For instance, the tech bubble was an anthill around 2000 on this chart, and the GFC crash, while described as the worst recession since the Great Depression, seems to be a pretty modest dip.  Covid in 2020 was almost nothing and the biggest was really 2022, which saw the index slide 25% through the first 9 months of the year.  Of course, part of this is the number itself.  A 25% decline now would be ~1500 S&P points (or 11,000 Dow points), the type of thing that would freak out nearly everybody.  

Is this possible?  Certainly, it is, 25% declines have occurred pretty regularly through the history of the market.  Is it likely?  This is a much tougher question.  BlackRock’s thesis is that this time is different; that AI is the game changer, and the future will be finally filled with flying cars and robots doing all our chores on the basis of unlimited free energy for everyone.  Ok, that may be a slight exaggeration, but they are extremely optimistic that technology will continue to move forward and solve what currently appear to be intractable problems.

The one thing working in their favor, I think, is that governments and central banks around the world have essentially lost their tolerance for market corrections, whether that is in equity or fixed income markets, and so will do whatever they can to prevent any small slide from becoming a large one.  Of course, the only thing they can do is print money to buy those assets that are falling in price.  If that is the plan of action, then the future will be highly inflationary, that is the only clear outcome.

I have no idea how things will turn out.  Perhaps BlackRock is correct, and we are about to embark on an entirely new segment of economic and financial history.  Perhaps Elon will successfully help restructure the US government so it is efficient and focused on a more limited role, and that process will inspire other nations to follow suit.  Perhaps pigs can fly as well.  I hate to be a curmudgeon, but trees still don’t grow to the sky, whether they are created by AI or nature.  Gravity remains undefeated.  But I am wary when I read reports claiming this time is different.  Forty plus years in the markets has taught me that is never the case.  Tools may change, timelines may change, but ultimate outcomes remain the same.

Ok, as we await this morning’s NFP report, let’s see what happened overnight.  Yesterday’s very modest declines in the US equity markets were followed by a slide in Japan (Nikkei -0.8%) and one in Australia (-0.6%) although this was predicated on weaker than expected GDP data, while Chinese shares (Hang Seng +1.6%, CSI 300 +1.3%) rallied on hopes that the economic conference next week is going to finally fire that long awaited Chinese bazooka!  In Europe, the most interesting aspect is the CAC (+1.4%) is having a wonderful day after the French government fell and prospects for managing the economy there remain extremely uncertain.  Perhaps that represents the idea that if the government is not interfering, French corporates can get on with the business of business unhindered and make more money.  Or perhaps it is an assumption that the ECB will ease more forcefully to prevent a major mishap.  After all, Madame Lagarde is French, so is likely not unbiased in the matter.  As to US futures, at this hour (7:15) they are lower by -0.1% across the board as we await the data.

In the bond market, there is nothing going on at all. Treasury yields are unchanged on the day which is true of virtually every European sovereign with one exception, French OATs which have seen more buying and have slipped 2bps lower in the session.  Here, too, it almost seems as though the market has decided the lack of a working government is better for France’s finances than when there is someone in power.  One other thing to note is that JGB yields have edged lower by 1bp this morning and have fallen 4bps this week as USDJPY has traded higher over the same period.  The most noteworthy thing here is that Toyoaki Nakamura, one of the most dovish BOJ members, explained that he was not against hiking rates, per se, and market participants took that as an opening for the BOJ to do just that and perhaps take a more pronounced stance against the ongoing inflation there.  I’ll believe it when I see it.

In the commodity markets, apparently nobody needs oil (-0.8%) anymore as it continues to sell off.  Remember just a few days ago we breached $70/bbl on the upside.  Well, this morning we are below $68/bbl amid fears(?) that peace is breaking out in the Middle East with talk that Hamas is willing to release the hostages to achieve a cease fire.  Arguably, a bigger issue is that much of the world (mostly China and Europe) have seen slowing economic activity and so demand estimates continue to decline along with the price.  As to the metals markets, they have been bouncing around lately, not making any headway in either direction as it appears traders are waiting for more concrete clues about demand here as well.  Gold (+0.2%) is the exception here, with demand not in question, just the timing of the next wave of central bank purchases.

Finally, the dollar is somewhat stronger overall this morning, notably vs. both AUD (-0.5%) and NZD (-0.4%) on the back of that weak GDP data.  Away from that, the rest of the G10 is mostly a bit softer, but not seeing large moves with NOK (-0.4%) excepted on the weak oil prices.  In the EMG bloc, declines are pretty consistent around the -0.2% range, but nothing really of note.

Now to the NFP data.  Here’s what is forecast:

Nonfarm Payrolls200K
Private Payrolls200K
Manufacturing Payrolls28K
Unemployment Rate4.2%
Average Hourly Earnings0.3% (3.9% y/Y)
Average Weekly Hours34.3
Participation Rate62.6%
Michigan Sentiment73.0

Source: tradingeconomics.com

In addition, we hear from four more Fed speakers (Bowman, Goolsbee, Hammack and Daly) so it will be interesting to see how they perceive the amount of caution that is appropriate going forward.  As a marker, this morning the Fed funds futures market is pricing a 70% probability of a December rate cut, down 4 points.

The big picture remains that the economy continues to outperform the naysayers, at least according to the official data.  The fact that performance is spread unevenly does not matter to markets at this time.  As such, it remains difficult for me to create the scenario where the dollar gives up substantial ground.  If the Fed does cut in two weeks, I think it will be the last for a while unless we start to see some major revisions lower in the data.  Maybe that starts this morning, but until then, you have to like the buck.

Good luck and good weekend

Adf

Three-Three-Three

Apparently, everyone’s sure
Scott Bessent is wholesome and pure
As well, he will fix
The Treasury’s mix
Of policies for more allure
 
He’s focused on three, three and three
His shorthand for what we will see
The budget he’ll cut
Build up an oil glut
And push up the real GDP


President-elect Trump has named hedge fund manager Scott Bessent to be Treasury Secretary.  This appears to be one of his less controversial selections and has been widely approved by both the punditry and the markets, at least as evidenced by the fact that equity futures are rallying while Treasury yields are sliding.  An article in the WSJ this morning lays out his stated priorities which can be abbreviated as 3-3-3.  The 3’s represent the following:

  • Reduce the budget deficit to 3%
  • Pump an additional 3 million barrels/day of oil
  • Grow GDP at 3% on a real basis

The target is to have these three processes in place by the end of Trump’s term in 2028.  I certainly hope he is successful!  However, while 3-3-3 is a catchy way to define things, it is a heavy lift to achieve these goals.  In the article, he also explains that he will be seeking to make permanent the original Trump tax cuts from 2017 as well as uphold Trump’s promises of no tax on tips, overtime or Social Security.  

Now, the naysayers will claim this is impossible, especially the idea of cutting taxes and reducing the budget deficit, but then, naysayers make their living by saying such things.  While nothing about this will be easy, the one overriding rule, I believe, is that increasing the pace of real GDP growth is the only way to achieve any long-term sustainability.  It is in this space where I believe the synergies between Treasury and the newly created DOGE of Musk and Ramaswamy will be most critical.  Improved government efficiency (I know, that is truly an oxymoron) and reduced regulatory red tape will be what allows the real economy to perform above its currently believed potential growth rate.  And in truth, if Trump and his government are successful at that, the chances of overall success are quite high.  Yes, that’s a big ‘if’ but it’s all we’ve got right now.

And truthfully, this has been the only story of note overnight as the punditry churns out stories about what can be good or why he will fail.  While there was a note that a ceasefire in Lebanon may be close, I don’t believe that has been a major part of the market narrative regarding oil prices for a while.  After all, Lebanon doesn’t have any oil infrastructure and while Iran clearly funds Hezbollah, it doesn’t appear they have been willing to lay it all on the line for Hezbollah’s success.

So, market participants are very busy trying to determine the best investments in the new Trump administration and based on all we have seen so far, it appears that Bitcoin is at the top of the list followed by equities, especially value and small-cap and then the rest of the equity universe.  US markets remain more attractive than foreign markets while commodities, especially haven assets like precious metals, have lost their allure in this shiny new world.  At this point, the big Investment banks are busy increasing their equity market targets for 2025 and beyond with S&P 500 forecasts of 6700 and more already being put in place.

Oh yeah, one other thing is the dollar, which had been on a tear for the past two months, has at the very least paused and some are calling that it has topped.  While it is certainly softer this morning, calling a top may be a bit premature.  At any rate, let’s see how markets around the world have behaved in the wake of the newest US news.

Some are saying that Friday’s US equity rally was in anticipation of the Bessent pick, and certainly his name was on the short-list, but that’s a tough case to make in my eyes.  Nonetheless, rally it did and that was followed by strength in Japan (+1.3%) overnight as well as most of Asia (Korea +1.4%, India +1.25%, Australia +0.3%) although both China (-0.5%) and Hong Kong (-0.4%) lost ground as Bessent is very clear that tariffs are an important part of his strategy.  Meanwhile, in Europe, there are modest gains (DAX +0.1%, FTSE 100 +0.2%, IBEX +0.6%) although the DAX (-0.1%) is softer after weaker than forecast IFO data.  Europe remains stuck in a difficult situation as their energy policy is hamstringing the economy while services inflation remains stickier than they would like to see, thus potentially hindering more aggressive ECB policy.  In the end, though, prospects on the continent are just not as bright as in the US right now.  US futures are quite happy with the Bessent choice, rising 0.5% at this hour (7:30).

In the bond market, investors are also of the belief that Bessent will be able to solve some of the US’s problems and Treasury yields have slipped -4bps this morning, although remain near 4.40%.  However, European sovereign yields are all creeping higher, between 1bp and 3bps, as the prospects there seem less positive.  I would say that investors are willing to give Bessent a chance to try to improve the US fiscal situation and that should help encourage bond buying.

Commodity markets, though, are under pressure generally, although not completely. For instance, oil prices fell $1/bbl upon the Bessent news but have since regained the bulk of that as it appears the growth story is starting to take over.  Nat Gas (+4.8%) is continuing to rally strongly, especially in Europe as cold weather forces rapid inventory drawdowns and supplies remain a political, not market question.  Interestingly, upon inauguration, one of the first things Trump has promised is to take the pause off the LNG terminals which should raise demand in the US as exports increase and potentially reduce prices in Europe.  

However, as mentioned above, precious metals are under pressure (Au -1.2%, Ag -1.9%) as investors believe that a combination of less warmongering and an attack on the fiscal deficit will both reduce the need for a safe haven.  As well, given Trump’s well-known disdain for the climate change hysteria, it seems likely support for wind and solar will be reduced, if not eliminated, and silver is a critical need for solar panels.  

Finally, the dollar is under pressure this morning, lower versus almost all its counterparts, notably the euro (+0.6%), although also seeing losses (currency gains) against the entire G10, more on the order of 0.25% or so.  In the EMG bloc, CLP (+0.9%) is the leader as copper (+0.6%) is the outlier in the metals group gaining on the positive economic story.  But we are seeing strength in MXN (+0.45%), PLN (+0.8%) and CNY (+0.15%) as long dollar positions are reduced.  

On the data front this week, with the Thanksgiving holiday on Thursday, everything is crammed into the beginning of the week as follows:

TodayChicago Fed National Activity-0.15
TuesdayCase-Shiller Home Prices4.9%
 Consumer Confidence111.6
 New Home Sales730K
 FOMC Minutes 
WednesdayPCE0.2% (2.3% Y/Y)
 Core PCE0.3% (2.8% Y/Y)
 GDP2.8%
 Personal Income0.3%
 Personal Spending0.3%
 Durable Goods0.5%
 -ex transports0.2%
 Initial Claims217K
 Continuing Claims1910K
 Real Consumer Spending3.7%
 Chicago PMI44.7

 Source: tradingeconomics.com

Mercifully, the Fed seems to be taking the week off with no scheduled speakers although I suppose if something surprising happens, we will likely hear from someone.  

I guess the question is, does Scott Bessent really change everything by that much?  Obviously, we have no way of knowing until he is in the chair, and that is probably two months away at minimum and then it will take some months before anything of substance actually happens.

But, when I consider my long-term thesis which was that inflation is going to be with us for a while which will result in a steeper yield curve, especially if the Fed continues to cut rates, that would have helped both the dollar and gold while hurting both equities and bonds.  This morning, though, the probability of a December rate cut has fallen to 52%, and I imagine it will continue to decline, especially if the PCE data remains hotter than the Fed keeps expecting.  As well, questions about the Fed’s political bias will be raised again as the rationale for cutting rates 75bps given the headline data remained strong has always been unclear.  So, if the Fed is done cutting, that means the dollar is far more likely to rally from here than fall further, commodity prices will struggle (except maybe NatGas) and bond markets may not anticipate nearly as much future inflation with a tighter Fed and a new administration focused on more fiscal rectitude.  In that situation, equities certainly hold much more appeal, although pricing remains steep no matter how you slice it.

Good luck

Adf