Many Ructions

Just two days before Halloween
When Jay and his minions convene
With great joie de vivre
Investors believe
A quarter-point cut will be seen
 
But what if the model that Jay
Consults might have led him astray
Then Fed fund reductions
May cause many ructions
In markets, and too, the beltway


But I am just a poet and my voice is not so loud in financial markets.  However, John Mauldin is someone with much greater reach and his letter this week highlighted that exact issue. (For those of you who are not familiar with John, his weekly letter, “Thoughts from the Frontline” is usually an excellent read and completely free, you should sign up.)  At any rate, he reprinted a chart originally in the WSJ that I think does an excellent job of demonstrating the flaws in models developed pre-Covid.
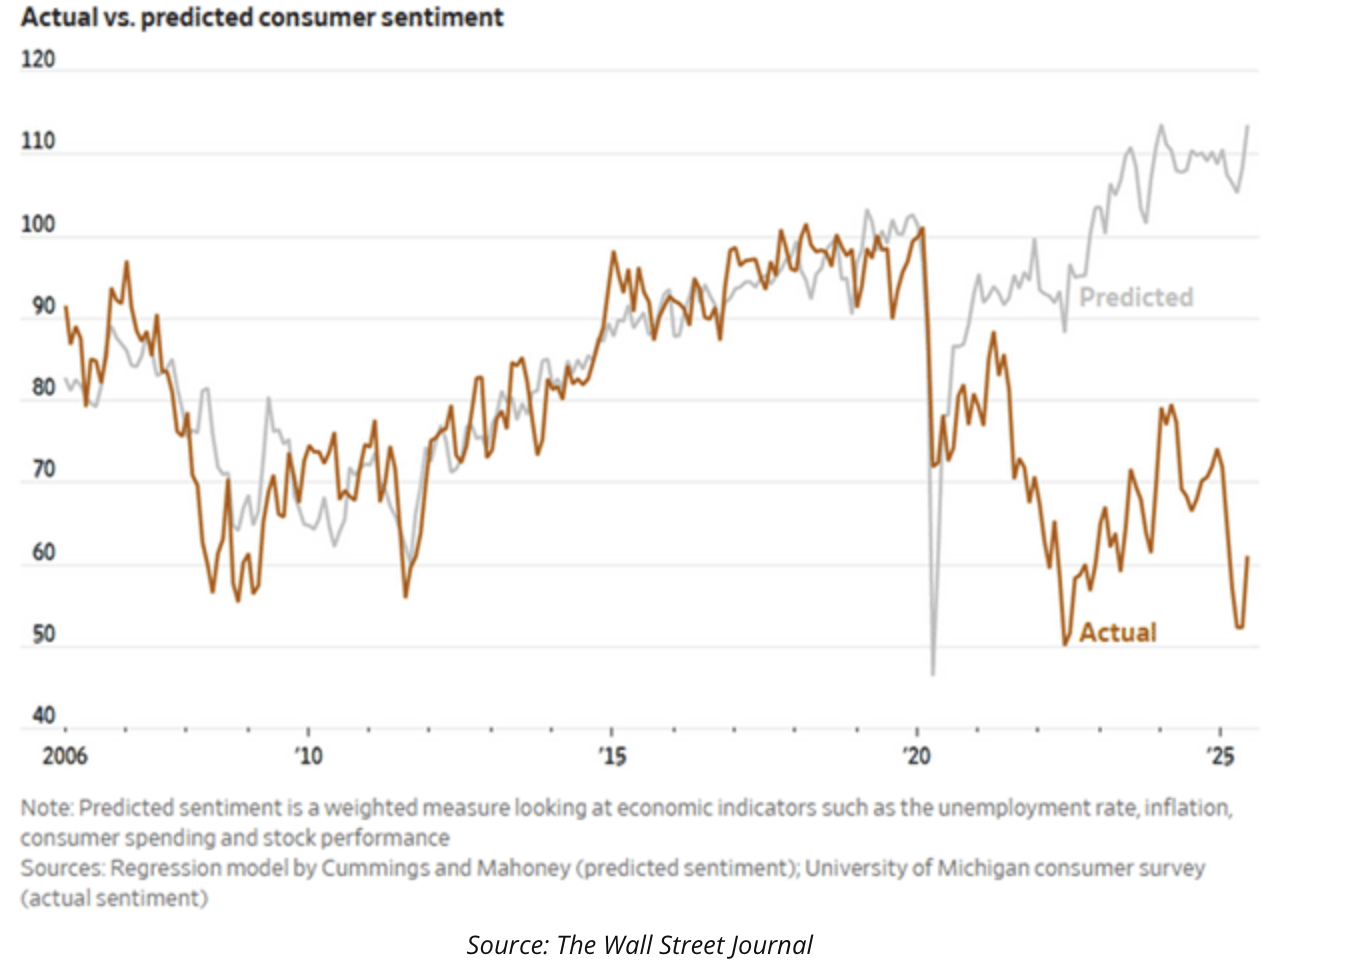
It is quite apparent how this particular model, which appears to use the type of inputs that most econometric models utilize, had done a pretty good job, even throughout the GFC, of anticipating changes in consumer sentiment right up until Covid.  However, it is also clear that since then, it has a terrible track record.  

And this is the problem.  I would wager that every one of the models built by the hundreds of PhD’s at the Fed has a similar problem, things that used to drive economic decision making no longer do.  I guess when people get used to the government supporting them completely, many are willing to sit back and do nothing.  And when that support stops, it appears that people aren’t very happy about that situation.  Go figure!

The bigger picture here is that I believe it is time for the Fed to question its own modeling prowess.  Consider the situation that with interest rates at their current levels of 4% +/- a bit depending on the tenor, many people, especially retirees, were quite content to clip coupons and were spending those funds supporting the economy.  At the same time, interest expense for small companies never really fell that far, so current rates are not deathly. 

But you know who benefits from low interest rates?  The government and large corporations who have access to capital markets and pay the lowest rates.  And even there, companies like Apple, Google and Microsoft have so much cash on hand that they are net earning interest with higher rates.

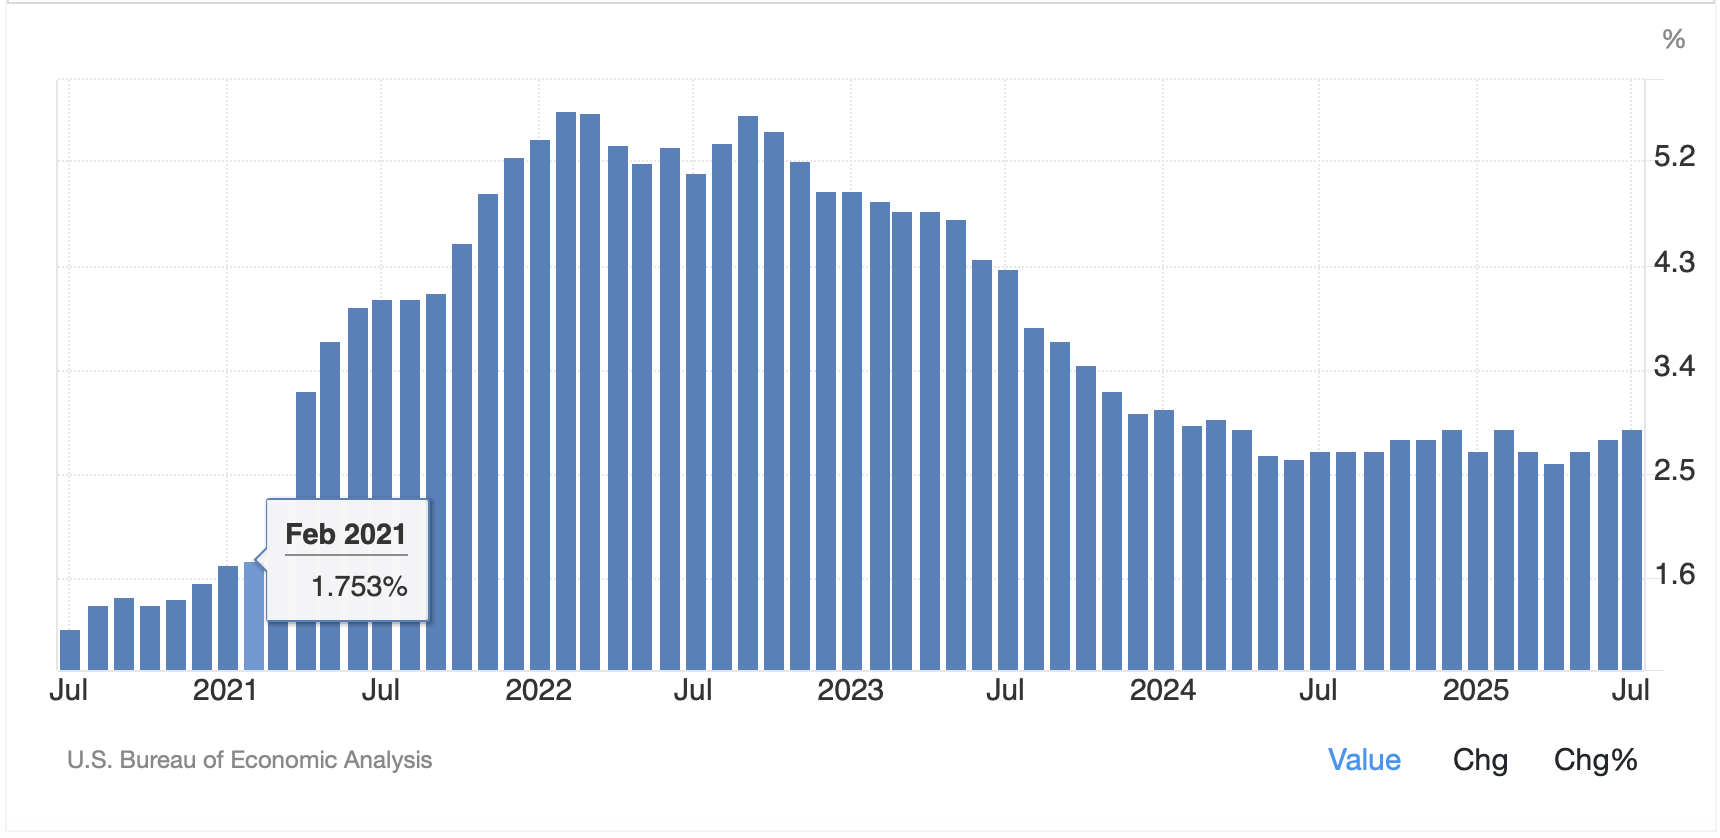
All this begs the question, what is the purpose of the Fed cutting rates?  A key risk is that inflation will return with a vengeance.  It has been 55 months since core PCE was at or below the Fed’s target level of 2.0% as you can see in the below chart, and I feel confident in saying that when the data is released this Friday, it will not be changing that trend.
Source: tradingeconomics.com

So, savers will suffer as their income will be reduced, the risk of rising inflation will increase as easier monetary policy typically precedes that type of movement, and long-term yields, which have rebounded recently, run the risk of starting higher again.  Remember what happened last year when the Fed cut, 10-year Treasury yields rose 100bps. (see chart below)

Source: tradingeconomics.com

It is far too early to claim the outcome will be the same this time, but it is a real risk.  After all, bond yields have a strong relationship with inflation, running at a long-term correlation of 0.36 and as can be seen in the chart below I prepared from FRED data.

Concluding, the current batch of economic models utilized by analysts and the Fed appear to have limited ability to describe the economy, whether it is because of the asynchronous nature of the current state of the world, or because the unprecedented government responses around the world to the Covid pandemic have changed the way everything works.  The market is pricing a 93% probability of another rate cut in October, and it appears Chairman Powell believes that to be the case.  But is it the right move at this time?  I feel like that is not the question being asked, but it needs to be by people more powerful than this poet.

Ok, I’ll step down from my soapbox to survey the market activity overnight.  Friday’s US closes at yet more all-time highs were followed by a more mixed session in Asia.  While Japanese investors got the joke, with the Nikkei rising 1.0%, Hong Kong (-0.8%) and India (-0.6%) were both under pressure with the former suffering from a strengthening currency and concern about a major typhoon about to hit the island nation, while India is suffering from the backlash of the Trump policy change on H1-b visas, now charging $100,000 for them.  It turns out Indian firms were the largest user of those visas and there is concern over a serious economic impact there.  Otherwise, the region saw a mixture of green (China, Taiwan, Australia, Malaysia) and red (New Zealand, Indonesia, Singapore, Thailand).

European bourses, though, are having a tougher time this morning with the continental exchanges all under pressure (DAX -0.7%, CAC -0.3%, IBEX -1.0%, FTSE MIB -1.0%) as concerns rise over the Flash PMI data to be released tomorrow and the idea it may show a much weaker economy than previously considered.  As well, USD futures are softer at this hour (6:40), with all three major indices showing declines on the order of -0.25%.  However, we must keep in mind that the trend in equity markets has been strongly higher so a modest pullback would not be a surprise and perhaps should be welcomed.

In the bond market, yields having moved higher on Friday, are quite stable this morning with Treasury yields unchanged and most of Europe seeing a -1bp decline.  The only outlier here is Japan, where JGB yields topped 1.65%, a new high for the move and the highest level since 2008 as per the below chart from marketwatch.com.  Ueda-san has to start getting worried soon, I think.

In the commodity space, oil (-0.7%) is continuing its recent decline but remains within the trading range and doesn’t appear to have much impetus in the short term in either direction.  However, I continue to look for an eventual decline here.  As to gold (+1.15%) and silver (+1.6%), nothing is going to stop this train.  Well, certainly there is no indication that policy changes are coming anywhere in the world that would force investors to rethink the idea of continuous depreciation of fiat currencies, and let’s face it, that’s all this represents.  I continue to see analysts raise their target price for the barbarous relic and I agree there is plenty of room to run as interest has been modest, at best, by Western investors.

Finally, the dollar is a touch softer this morning with both the euro (+0.25%) and pound (+0.25%) leading the way in the G10, although the yen is basically unchanged.  There was an interesting story in Bloombergdiscussing how volatility in the FX markets has been declining rapidly with many attributing this to the rise of algorithmic trading.  As well, all over X this morning are stories about how the dollar’s decline this year (about -14% vs. the euro) is unprecedented.  It’s not at all which is one of the reasons you need be careful about what people put up there.  It seems that some analysts are putting undue emphasis on the starting point being January 1st, rather than when the market tops.  But saying the dollar is declining in an unprecedented manner is absurd and picayune.  Meanwhile, EMG currencies are all over the place with gainers (KRW +0.4%, ZAR +0.4%) and laggards (MXN -0.5%, INR -0.25%) and everything in between.  

On the data front, PCE is Friday’s offering, but before then there is some stuff and more interestingly, there is lots of Fed speak.

TodayChicago Fed National Activity-0.17
TuesdayFlash Manufacturing PMI52.0
 Flash Services PMI53.9
WednesdayNew Home Sales650K
ThursdayDurable Goods-0.5%
 -ex transport-0.2%
 GDP (Q2)3.3%
 Initial Claims235K
 Continuing Claims1930K
 Existing Home Sales3.96M
FridayPCE0.3% (2.7% Y/Y)
 Core PCE0.2% (2.9% Y/Y)
 Personal Income0.3%
 Personal Spending0.5%
 Michigan Sentiment55.4

Source: tradingeconomics.com

On top of the data, we hear from…wait for it…ten different Fed speakers, including Chair Powell tomorrow, across 16 different events.  I expected to hear from a lot as there is clearly no real consensus at this point in time there.

People love to hate the dollar, and if the Fed is going to ease more aggressively, I understand that, but longer term, I think the story is different.  Just be careful.

Good luck

Adf

A Third Fed Mandate

As Jay and his minions convene
A new man is making the scene
Now, Stephen Miran
A man with a plan
Will help restart Jay’s cash machine
 
But something that’s happened of late
Is talk of a third Fed mandate
Yes, jobs and inflation
Have been the fixation
But long-term yields need be sedate


As the FOMC begins their six-weekly meeting this morning, most market participants focus on the so-called ‘dual mandate’ of promoting the goals maximum employment and stable prices.  This, of course, is why everybody focuses on the tension between the inflation and unemployment rates and why the recent revisions to the NFP numbers have convinced one and all that a rate cut is coming tomorrow with the only question being its size.  But there is a third mandate as is clear from the below text of the Federal Reserve Act, which I have copied directly from federalreserve.gov [emphasis added]:

“Section 2A. Monetary policy objectives

The Board of Governors of the Federal Reserve System and the Federal Open Market Committee shall maintain long run growth of the monetary and credit aggregates commensurate with the economy’s long run potential to increase production, so as to promote effectively the goals of maximum employment, stable prices, and moderate long-term interest rates.

[12 USC 225a. As added by act of November 16, 1977 (91 Stat. 1387) and amended by acts of October 27, 1978 (92 Stat. 1897); Aug. 23, 1988 (102 Stat. 1375); and Dec. 27, 2000 (114 Stat. 3028).]”

One of the things we have heard consistently from Treasury Secretary Bessent is that he is highly focused on ensuring that longer-term yields do not get too high.  Lately, the market has been working to his advantage with both 10-year, and 30-year yields having declined by more than 25bps in the past month.  And more than 40bps since mid-July.  (Look at the yields listed on the top of the chart below to see their recent peaks, not just the line.)

Source: tradingeconomics.com

Now, with President Trump’s head of the CEA, Stephen Miran getting voted onto the board to fill the seat that had been held by Governor Adriana Kugler, but heretofore vacant, one would think that the tone of the conversation is going to turn more dovish.  What makes this so odd is that, by their nature, central bankers are doves and seemingly love to print money, so there should be no hesitation to cut rates further.  But…that third mandate opens an entirely different can of worms and brings into play the idea of yield curve control as a way to ensure the Fed “promote(s)…moderate long-term interest rates.”

It was Ben Bernanke, as Chair, who instigated QE during the GFC although he indicated it was an emergency measure.  It was Janet Yellen, as Chair, who normalized QE as one of the tools in the toolbox for the Fed to address its dual mandate.  I believe the case can be made that newly appointed Governor Miran will begin to bang the drum for the Fed to act to ensure moderate long-term interest rates, and there is no better policy to do that than QE/YCC.  Actually, there is a better policy, reduced government spending and less regulation that allows productivity to increase and balances the production-consumption equation, but that is out of the Fed’s hands.

At any rate, we cannot ignore that there could be a subtle change in focus to the statement and perhaps Chairman Powell will discuss this at the press conference.  If this has any validity, a big IF, the market impacts would be significant.  The dollar would start another leg lower, equities would rise sharply, and commodity prices would rise as well.  Bonds, of course, would be held in check regardless of the inflationary consequences.  Just something to keep on your bingo card!

Ok, let’s check out the overnight activity.  While it was quiet in the US yesterday, we did manage to make more new highs in the S&P 500 as all three major indices were higher.  As to Asia, Tokyo (+0.3%) had the same type of session, with modest gains as it takes aim at a new big, round number of 45,000.  China (-0.2%) and HK (0.0%) did little although there was a lot of positivity elsewhere in the region with Korea (+1.2%), India, (+0.7%) and Taiwan (+1.1%) leading the way amidst almost all markets, large and small, showing gains.  Europe, though, is a different story with red today’s color of the day, as Spain (-0.8%) and Germany (-0.6%) leading the down move despite better-than-expected German ZEW data (37.3 vs. 26.3 expected).  One of the things I read this morning was that German auto manufacturers have laid off 125,000 workers in the past 6 weeks.  That is a devastating number and bodes ill for German economic activity in the future.  As to other European bourses, -0.1% to -0.4% covers the lot.  US futures, though, continue to point higher, up 0.3% at this hour (7:30).

In the bond market, Treasury yields are unchanged this morning while European sovereign yields have edged higher by between 1bp and 2bps.  It doesn’t feel like investors there are thinking of better growth, but we did hear from several ECB members that while cuts are not impossible during the rest of the year, they are not certain.

In the commodity space, oil (+0.7%) is back in a modest upswing but still has shown no inclination to move outside that trading range of $60/$65.  It has been more than a month since that range has been broken and absent a major change in the Russia sanctions situation, where Europe actually stops buying Russian oil (as if!) I see no short-term catalyst on the horizon to change this situation.  Clearly, producers are happy enough to produce and sell at this level and demand remains robust.

Turning to the metals markets, I discuss gold (+0.4%) a lot, and given it is making historic highs, that makes sense, but silver (+0.4%) has been outperforming gold for the past month and looks ever more like it is going to make a run for its all-time highs of $49.95 set back in January 1980.  The more recent peak, set in 2011, of $48.50 looks like it is just days away based on the recent rate of climb.

Source: finance.yahoo.com

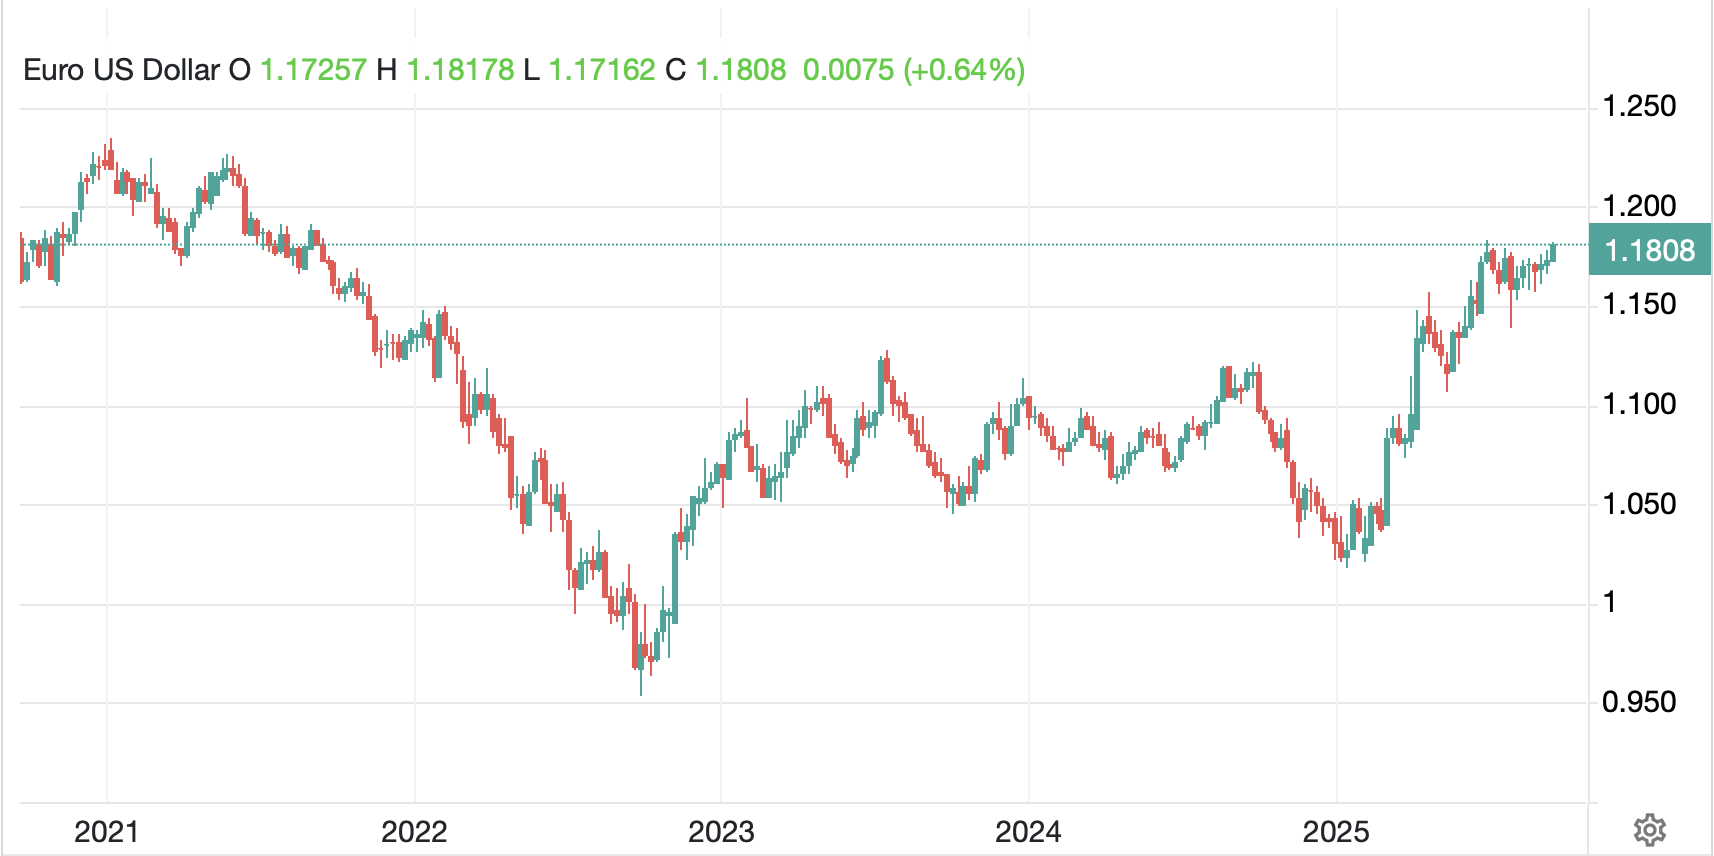
Finally, the dollar is under pressure this morning, with the euro (+0.4%) trading above 1.18 again for the first time since July 1st and there is a great deal of discussion as to how it is going to trade back to, and through, 1.20 soon, a level not seen since 2021.  

Source: tradingeconomics.com

The narrative is now that the Fed is set to begin cutting rates and the ECB is going to stand pat, the euro will rise.  This is true for GBP (+0.3%) as wel, with the Sterling chart largely the same as the euro one above.  Here’s the thing.  I understand the weak dollar thesis if the Fed gets aggressive, I discussed it above. However, if German manufacturing is contracting that aggressively, and the layoffs numbers are eye opening, can the ECB really stand pat?  Similarly, PM Starmer is under enormous, and growing, pressure to resign with the Labour party in the throes of looking to oust him for numerous reasons, not least of which is the economy is struggling.  So, please tell me why investors will flock to those currencies.  I see the dollar declining, just not as far as most.

Data this morning brings Retail Sales (exp 0.2%, 0.4% -ex autos) along with IP (-0.1%) and Capacity Utilization (77.4%).  However, it is not clear to me that markets will give this data much consideration given the imminence of the FOMC outcome tomorrow.  The current futures pricing has just a 4% probability of a 50bp cut.  I am waiting for the Timiraos article to see if that changes.  Look for it this afternoon.

Good luck

Adf

More Insane

Though debt round the world keeps on growing
The equity run isn’t slowing
But what’s more insane
Is yields slowly wane
Despite signs inflation ain’t slowing
 
The French are the latest to hear
Their credit’s somewhat less sincere
But CBs this week
Seem likely to tweak
Rates lower, and markets will cheer


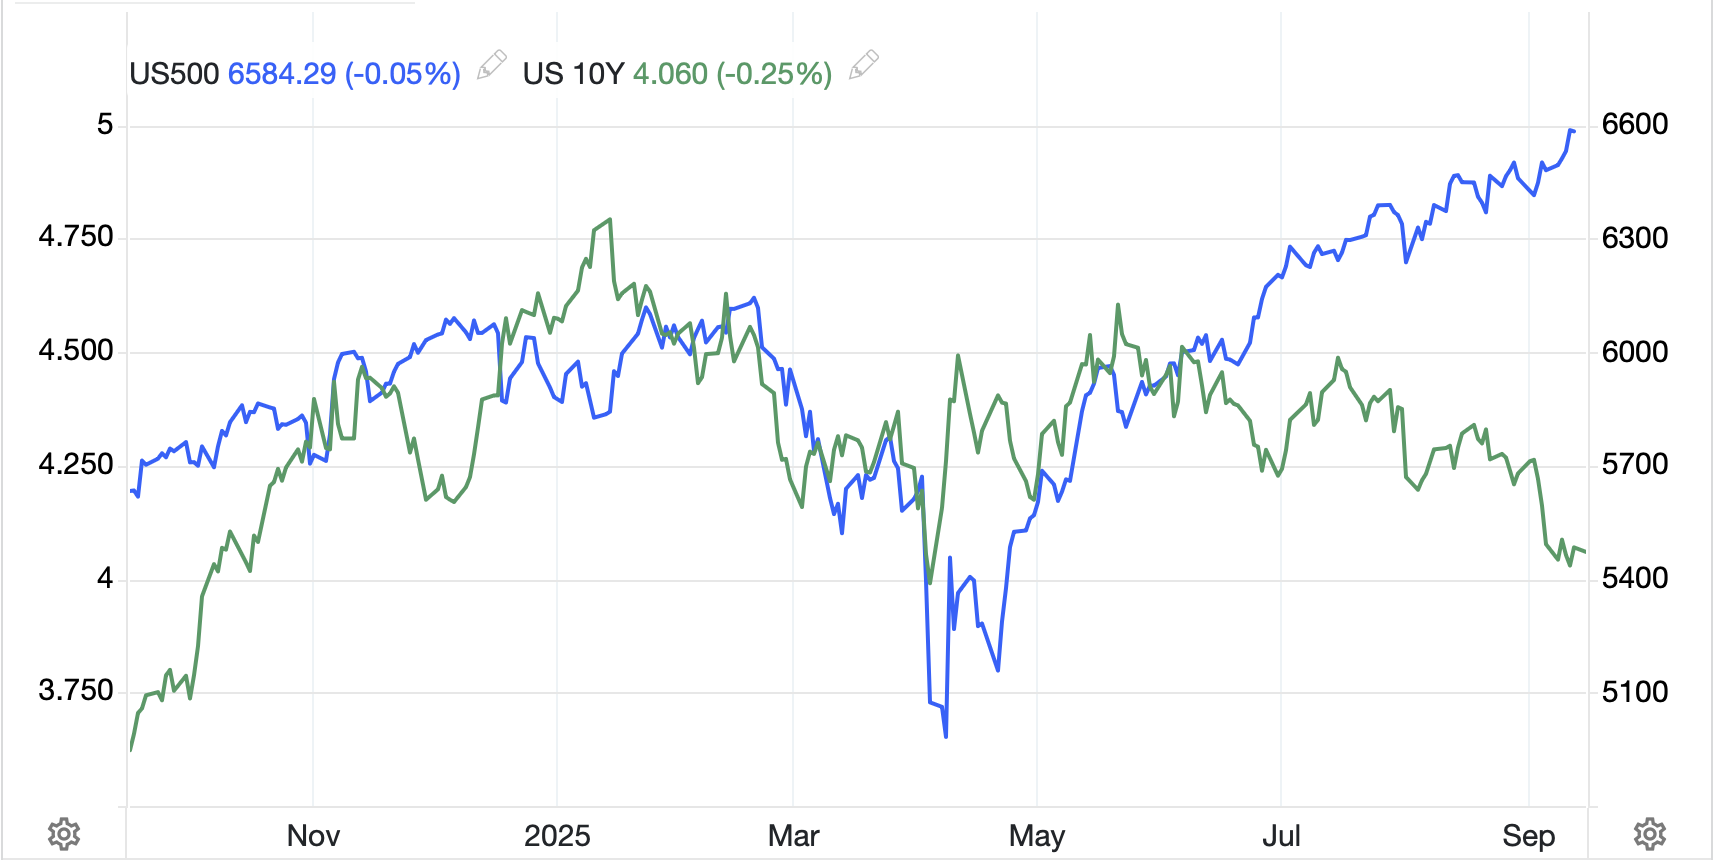
Something is rotten in the state of financial markets, or at least that is the conclusion this poet has drawn (and please do not think I am trying to compare myself to Shakespeare).  No matter what my personal view of the economy may be, I cannot help but look at the recent performance of the equity market and the bond market and be extremely confused.  The chart below shows the past year’s price action in the S&P 500 (blue line) and US 10-year yields (green line). 

Source: tradingeconomics.com

Since early June, the two price series, which have historically had a pretty decent correlation, have gone in completely opposite directions.  Equity markets continue to trade to new highs on a regular basis as earnings multiples continue their expansion.  Typically, multiples only expand when growth expectations are rising, and the economy is in an uptrend.  Ergo, if multiples are high and rising, it seems equity investors believe that is the case.  I understand that view as there are strong indications the administration is going to continue to ‘run the economy hot’ meaning do all it can to increase economic activity and allow inflation to rise as well, counting on the fast growth to offset the pain.

However, 10-year Treasury yields have been sliding steadily for the past three months despite the equity market belief in running it hot.  Bond yields have historically been far more sensitive to inflationary pressures and the fact that yields have been declining, down >40bps since early June, would lead to a very different conclusion about the economy, that it is going to see much slower growth and by consequence, reduced inflationary pressures.

I have discussed the asynchronous economy in the past and I believe this is more proof of that thesis.  The equity markets are still being largely driven by the AI/Tech sector and while that is a huge portion of the equity market, its size within the overall economy is pretty small.  Given the capital weightings of both the S&P 500 and NASDAQ, strength in that sector has clearly been sufficient to drive stock indices higher.  However, much of the rest of the economy is not seeing the same benefits, and in fact, there is a portion suffering as AI takes over roles that had been filled by people thus increasing unemployment.  That segment of the economy is much larger, and it seems there is a growing probability that a recession may be coming there.  

Or not, if the administration is able to run it hot.  Ultimately, the thing the makes the least sense to me is that there is no indication that inflation is slowing anywhere back toward the Fed’s alleged 2% target.  Rather CPI looks far more likely to coalesce around the 3.5%-4.0% level which means that PCE, even on a core basis, is going to be hanging around 3.0%.  If the Fed is getting set to cut rates, and by all indication they are going to cut at least 25bps on Wednesday, I think it is clear that 3.0% is the new 2.0%.

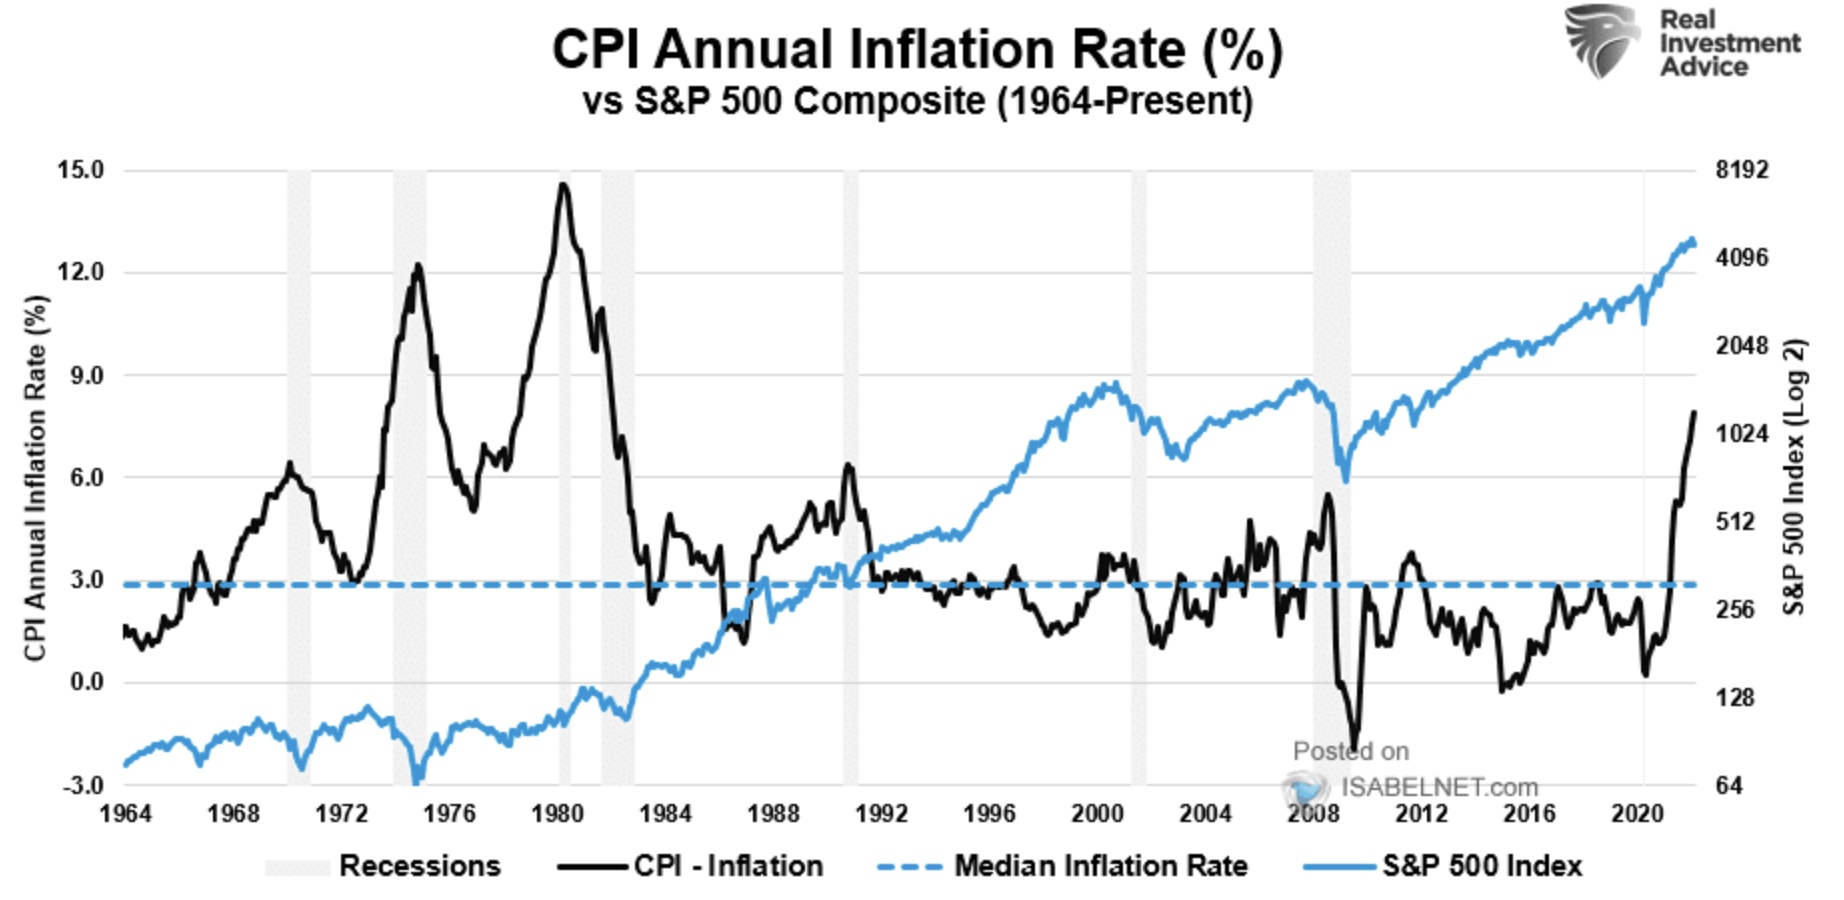
And here’s the problem with that. When inflation is low, 2% or less, equities have historically been negatively correlated with bond prices, so if stocks fell, bonds rallied and the 60:40 portfolio had an internal hedge.  But when inflation is higher, and it doesn’t need to be 10%, 4% is enough to change the relationship, equity prices and bond prices tend to move in sync.  This means, if stock prices fall because of a recession, so do bond prices with yields rising.  In that situation, the 60:40 portfolio suffers greatly.  Just think back to 2022 when both equities and bonds fell -30% or so.  Where was inflation?  Right, we were in the throes of the Fed’s last mistake regarding the word transitory.  The below chart is the best I could find to show how things behaved in the 60’s and 70’s with inflation running hot and then how things changed after Mr Volcker began to squash inflation.

Original source: Isabelnet.com

And what of the dollar you may ask?  Well, theoretically, rising inflation should undermine the currency, but rising rates, when central banks fight inflation, should help support it.  However, this time, with rising inflation and the Fed set to cut, it seems the dollar may have some trouble, although as other central banks follow suit, and they will, the dollar will find support.

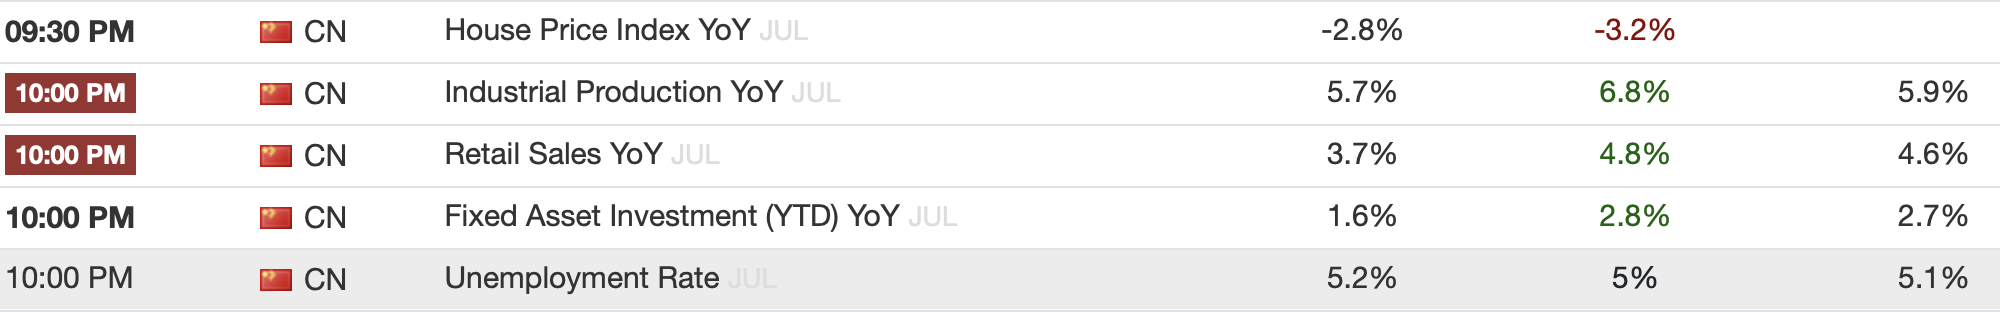
Ok, let’s see how things behaved overnight.  While Friday’s US session was mixed with only the NASDAQ managing to gain, there was more green in Asia and Europe.  The Japanese celebrated Respect for the Aged Day, so markets there were closed.  However, both HK (+0.2%) and China (+0.25%) managed modest gains despite (because of?) weaker than expected Chinese economic data.  Every aspect of the data, IP, Retail Sales, Investment and Unemployment, printed worse than forecasts and has now encouraged investors to look for further Chinese government stimulus to support the economy.  That theory helped Korea, Malaysia and Indonesia, all showing solid gains, but did nothing for the rest of the region, perhaps most surprisingly Taiwan.

In Europe, Fitch cut France’s credit rating to A+ from AA- based on fiscal deficits and political turmoil (aka no government), yet equity investors saw that as a buy signal with the CAC (+1.15%) leading European shares higher.  The DAX (+0.4%) and IBEX (+0.6%) are also doing well although the FTSE 100 (0.0%) is just treading water.  There has been no data of note, so it appears investors there are anticipating good things from the US where futures are higher by 0.2% at this hour (7:30).

Bond yields in the US are unchanged this morning, but European sovereign yields have slipped -2bps across the board, despite France’s downgrade.  I am really at a loss these days to understand the mind of bond investors.  I guess there is a growing belief that central bank rate cuts are going to help!

In the commodity sector, oil (+0.4%) has edged higher this morning but remains firmly in the middle of its 3-month trading range and is showing no desire to move in either direction.  Metals markets, meanwhile, are basically unchanged this morning, simply sitting at their recent highs with the latest contest on Wall Street being who can forecast the highest price for gold in 2026.  Goldman just explained that $5000/oz is reasonable if just 1% of risk assets move into the relic.

As to the dollar, while it did little most of the evening, as NY is walking in, it is slipping a bit, with the euro (+0.25%) and pound (+0.5%) leading the way higher in the G10, and truthfully across the board as the largest EMG moves are KRW (+0.4%) and HUF (+0.4%) while the rest have moved on the order of 0.1% to 0.2%.  There has been growing chatter that China is now going to allow the renminbi to start to strengthen more steadily (in fairness, it has been strengthening modestly since the beginning of 2025, up about 3% since then), and that this is part of the trade negotiations ongoing with the US currently taking place in Madrid.  But remember, while CNY has been creeping higher this year, a quick look at the chart below shows it has fallen substantially since 2022, having declined more than 17% between 2022 and the beginning of this year.

Source: tradingeconomics.com

On the data front, in addition to the FOMC, there are several other central bank meetings and some important data as follows:

TodayEmpire State Manufacturing5.0
TuesdayRetail Sales0.3%
 -ex autos0.4%
 Control Group0.4%
 IP-0.1%
 Capacity Utilization77.4%
WednesdayIndonesia Rate Decision5.0% (Unchanged)
 Housing Starts1.37M
 Building Permits1.37M
 Bank of Canada Rate Decision2.5% (-0.25%)
 FOMC Decision4.25% (-0.25%)
 Brazil Rate Decision15.0% (unchanged)
ThursdayBOE Rate Decision4.0% (unchanged)
 Initial Claims240K
 Continuing Claims1950K
 Philly Fed2.3
 South Africa Rate Decision7.0% (unchanged)
 Leading Indicators-0.1%
 BOJ Rate Decision0.5% (unchanged)

Source: tradingeconomics.com

So, while Retail Sales may give us some more color on the strength of the economy, it is really a week filled with central bank policy decisions and the ensuing discussions they have to spin things as they desire.  I imagine we will be getting an article from Nickileaks this afternoon or tomorrow to get Powell’s message out, but it remains to be seen if we are watching bond traders buy the rumor and they are set to sell bonds on the news, especially if the Fed goes 50bps, something that remains a real possibility in my mind, though the futures market is pricing just a 4% chance of that as of this morning.

A 50bp cut will undermine the dollar in the short run and may put pressure on the BOE to cut more rather than hold.  Until then, though, I suspect there will be little net movement in either direction.

Good luck

Adf
Seek the Abyss

As so often has been the case
The market is in Trump’s embrace
Will he make a deal
And sell it with zeal
Or will Putin spit in his face
 
Because of the focus on this
Though PPI data did miss
Most markets held tight
With highs still in sight
As naysayers seek the abyss


Based on the fact that equity markets in the US were all essentially unchanged yesterday, I think it is reasonable to assume that investors are waiting to see the outcome of today’s Trump-Putin meeting in Alaska.  I have no opinion on how things will work out, although I am certainly rooting for a result that includes a ceasefire and the next steps toward a lasting peace.  From a direct market perspective, arguably oil (-0.75% this morning) is the one place where the outcome will have an impact.  Any type of deal that results in the promised end to sanctions on Russian oil seem likely to push prices lower.  In this vein, we continue to see the IEA and EIA reduce their demand forecasts (although some of this is because they keep expecting BEVs to replace ICE engines and that is not happening at the pace they would like to see). However, away from oil, I expect that this will be much more important to overall sentiment than anything else.

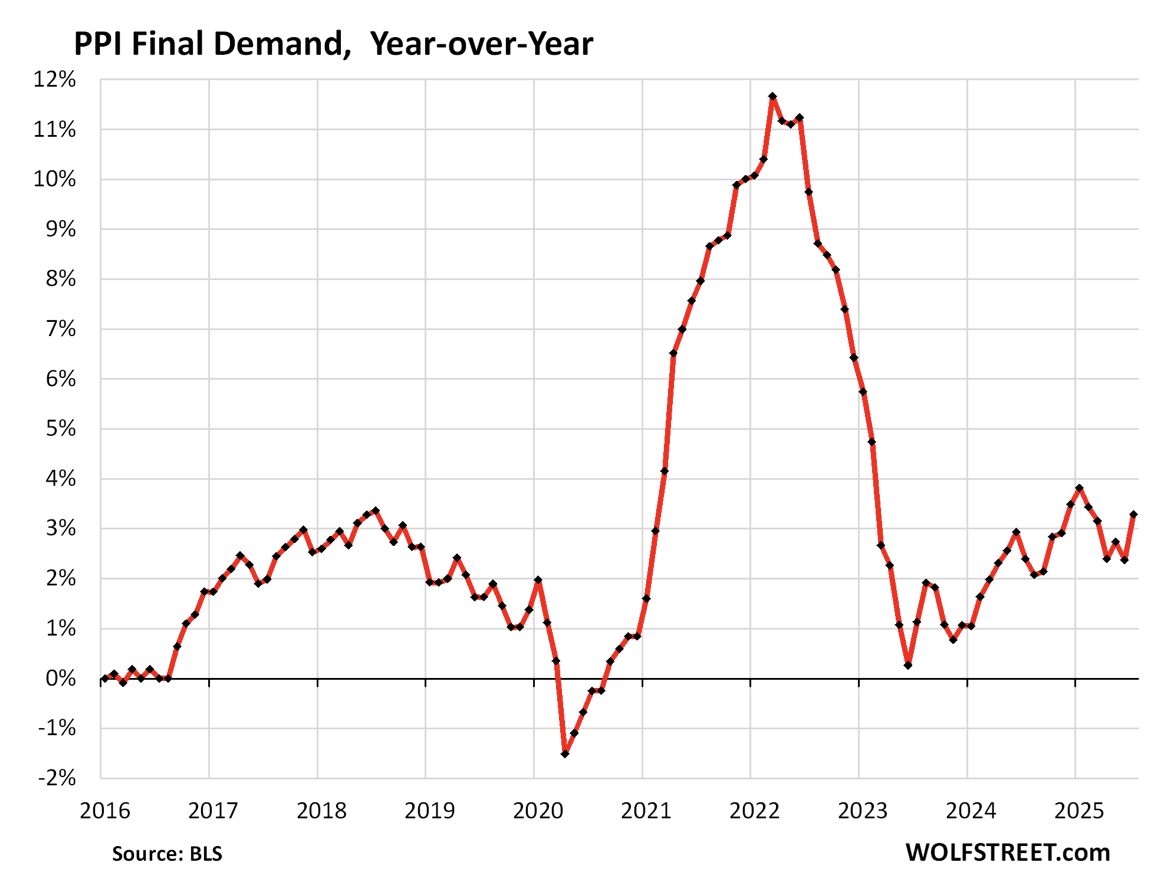
But sentiment matters a lot.  As does the attention span of traders, which as we already know, approximates the life of a fruit fly.  For instance, yesterday’s PPI data was unambiguously hotter than expected, with both headline and core monthly jumps of 0.9%.  Surprisingly for many economists, it was not goods prices that rose so much, but rather the price of services.  For the narrative, it is much harder to blame service price hikes on tariffs, than goods price hikes, but not to worry, economists are working hard to make that case.  As well, the near universal claim is that CPI is going to rise much more quickly going forward as evidenced by this rise in PPI.  A quick look at the chart below of annualized PPI shows that we are starting to rise above levels last seen in 2018, but if you recall, CPI then was very low, sub 2.0%. The relationship between the two, CPI and PPI, is not as strong as you might expect.

The contra argument here is that corporations, which were able to raise prices rapidly during the pandemic response are finding it more difficult to do so now.  We have discussed several times how corporate profit margins remain extremely high relative to history and what we may be seeing is the beginnings of those margins starting to compress as companies absorb more of the costs, be they tariffs or labor.  I also couldn’t help but notice the article in the WSJ this morning working to explain why tariffs haven’t boosted inflation as much as many economists expected.  Their answer at least according to this research, is that the many exemptions have resulted in tariffs being collected on only about half of imports, which despite all the headlines touting tariffs are now, on average, somewhere near 18%, makes the effective rate below 10%, higher than in the past, but not devastatingly so.  And remember, imports represent about 14% of GDP.  Let’s do that math.  If half of imports are excluded and the average tariff is more like 9%, we’re looking at 60 basis points of price increases, of which corporates are absorbing a great deal.  

One other thing in the article was how it highlighted the exact result that President Trump is seeking when explaining that more companies are searching for alternative sources of goods in the US.

The tariffs, are however, impacting other nations with China last night reporting a much weaker batch of data as per the below:

                                                                                                              Actual          Previous            Forecast

The property market there continues to drag on the economy, but government efforts to prop up consumption seem to be failing and clearly tariffs are impacting IP as less orders from the US result in less production.  Arguably, though, President Xi’s greatest worry is the rise in Unemployment as the one thing he REALLY doesn’t want is a lot of unemployed young males as that is what foments a revolution.  The interesting thing about the market response here is that while the Hang Seng (-1.0%) fell sharply, the CSI 300 (+0.7%) rallied, seemingly on hopes of additional stimulus being necessary and implemented.  One other thing to note about Chinese markets is that yesterday, 40-year Chinese government yields fell below 30-year Japanese yields for the first time ever, a sign that expectations of future Chinese activity are waning.  With this in mind, even though the renminbi has been gradually appreciating this year (even if we ignore the April Liberation Day spike), the Chinese playbook remains mercantilist at its heart.  I would look for a weaker CNY going forward, although the overnight move was just -0.1%.

Source: tradingeconomics.com

Ok, let’s look at the rest of markets ahead of the Alaska summit and today’s data.  Tokyo (+1.7%) had a strong session as GDP data from Japan was stronger than expected allaying worries that the tariffs would crush the economy there and bringing rate hikes back onto the table.  Australia (+0.7%), too, had a good session on solid corporate and bank earnings but the rest of the region was pretty nondescript with marginal moves in both directions.  In Europe, gains are the order of the day on the continent (DAX +0.3%, CAC 0.65%, IBEX +0.35%, FTSE MIB +1.1%) as hopes for a formalized trade deal being finalized grow.  However, UK stocks are unchanged on the session as investors here seem to be biding their time ahead of the Trump-Putin summit.  US futures are higher led by DJIA (+0.7%) although that appears to be on news that Berkshire Hathaway has taken a stake in United Health after the stock’s recent beatdown.

In the bond markets, Treasury yields are unchanged this morning although they reversed course yesterday, closing higher by 5bps rather than the -3bp opening, pre-PPI, levels.  But that rebound in yields has been seen throughout Europe where sovereigns on the continent are higher by between 3bps and 4bps and JGB yields (+2bps) rose overnight after the stronger than expected GDP data.

Away from oil, metals markets are doing very little this morning as it appears much of the activity has to do with option expirations in the ETFs SLV and GLD, so price action is likely to be choppy, but not instructive.

Finally, the dollar is softer this morning despite the higher Treasury yields.  One of the interesting things is that despite the hotter PPI data, the probability for a September cut, while falling from a chance of 50bps, to a 92.6% probability of a 25bp cut, is still pricing in an almost certain cut.  Remember, we are still a month away from that meeting and we have Jackson Hole in between as well as another NFP and CPI report so lots of potential drivers to change views.  And there is still a lot of talk of a 50bp cut, although for the life of me, I don’t understand the economic rationale there.  But softer the dollar is, falling against all its G10 brethren, on the order of 0.25% or so, and most EMG counterparts, with many having gained 0.4% or so.  But this is a dollar story today.

On the data front, ahead of the summit, which I believe starts at 2:30pm Eastern time, we see Retail Sales (exp 0.5%, 0.3% -ex autos, 0.4% Control Group) and Empire State Mfg (0.0) at 8:30, as well as IP (0.0%), Capacity Utilization (77.5%) at 9:15 and then Michigan Sentiment (62.0) at 10:00.  Retail Sales should matter most as a strong number there will encourage the equity bulls while a weak number will surely bring out the naysayers.  I still have a bad feeling about markets here, but that is my gut, not based on the data right now.  As to the dollar, there are still huge short positions out there and if rate cuts become further priced in, it can certainly decline further.

Good luck and good weekend

Adf

Lest ‘Flation Has Spice

The market absorbed CPI
And equities started to fly
Though Core prices rose
T’was Headline, I s’pose
Encouraged investors to buy
 
As well, Fed funds futures now price
The Fed will cut rates this year thrice
The upshot’s the buck
Is down on its luck
Beware though, lest ‘flation has spice


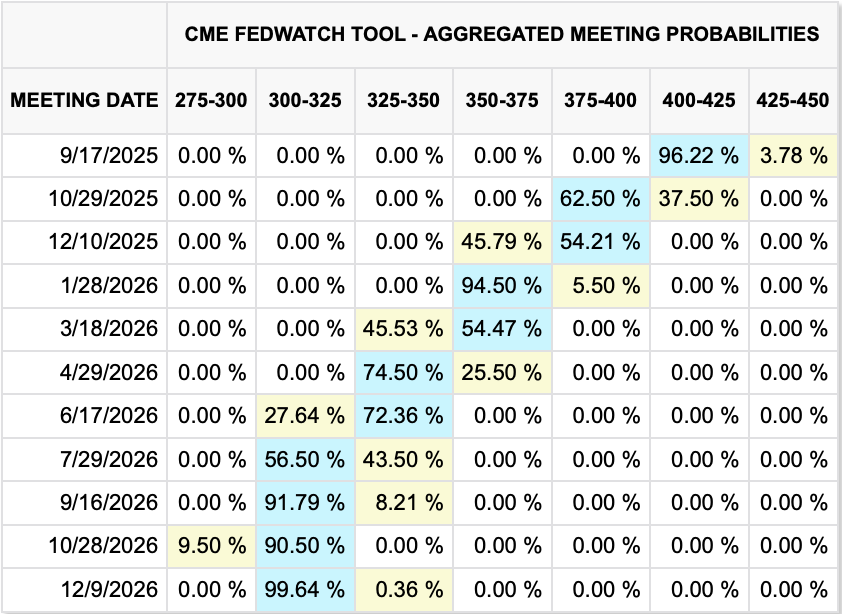
Core prices rose a bit more than forecast in yesterday’s CPI report although the headline numbers were a touch softer.  The problem for the Fed, if they are truly concerned about the rate of inflation, is that the strength of the numbers came from core services less shelter, so-called Supercore, a number unimpeded by tariffs, and one that has begun to rise again.  As The Inflation Guy™ makes clear in his analysis yesterday, it is very difficult to look at the data and determine that 2% inflation is coming anytime soon.  I know the market is now virtually certain the Fed is going to cut in September, but despite President Trump’s constant hectoring, I must admit the case for doing so seems unpersuasive to me.

Here are the latest aggregated probabilities from the CME and before you say anything, I recognize the third cut is priced in January, but you need to allow me a little poetic license!

However, since I am just a poet and neither institutions nor algorithms listen to my views, the reality on the ground was that the lower headline CPI number appeared to be the driver yesterday and into today with equities around the world rallying in anticipation of Fed cuts.  As well, the dollar is under more severe pressure this morning on the same basis.  However, it remains difficult for me to look at the situation in nations around the world and conclude that the US economy is going to underperform in any meaningful way over time.  

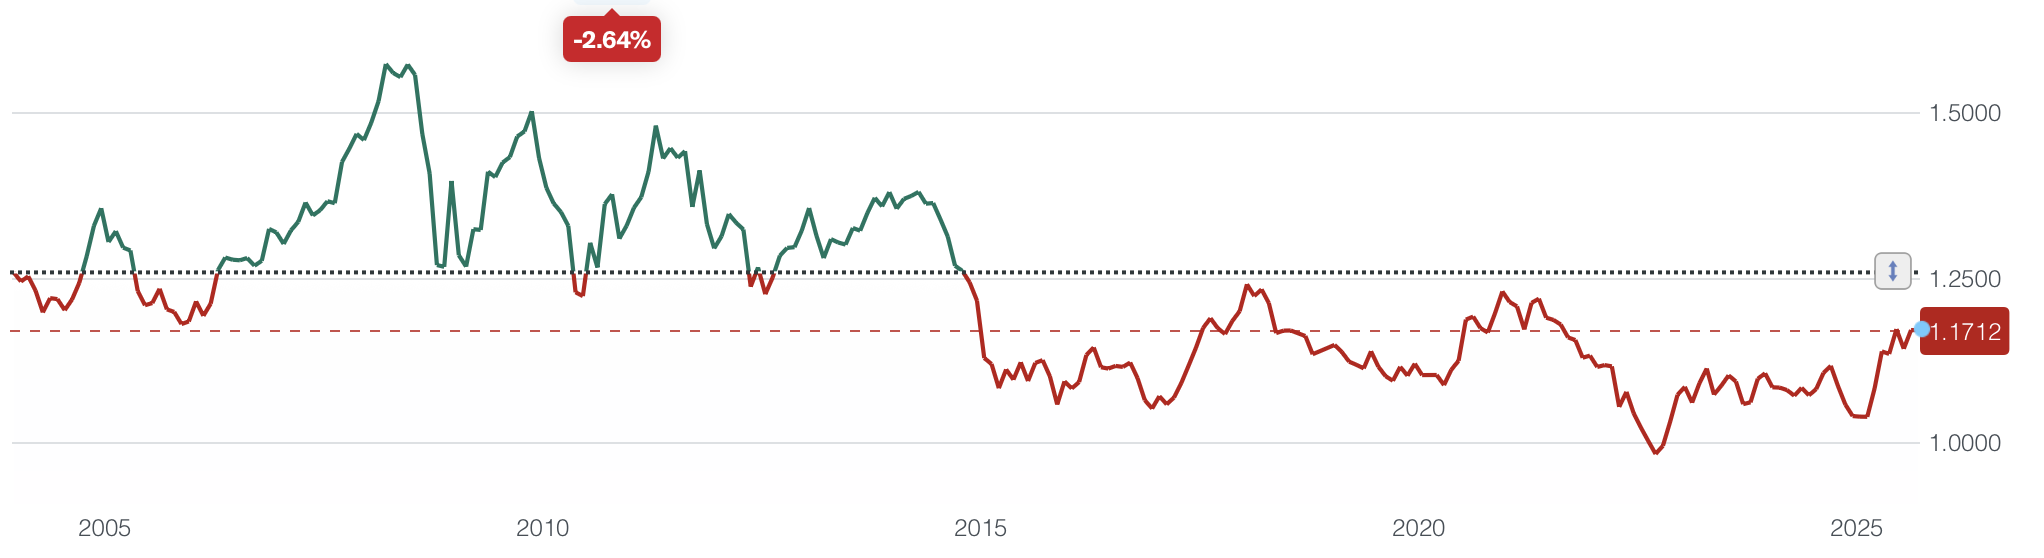
So, to the extent that a currency’s relative value is based on long-term economic fundamentals, it is difficult to accept that the dollar’s relative fiat value will decline substantially, and permanently, over time.  I use the euro as a proxy for the dollar, which is far better than the DXY in my opinion as the Dollar Index is a geometric average of 6 currencies (EUR, JPY, GBP, CAD, SEK and CHF) with the euro representing 57.6% of the basket.  And I assure you that in the FX markets, nobody pays any attention to the DXY.  Either the euro or the yen is seen as the proxy for the “dollar” and its relative value.  At any rate, if we look at a long-term chart of the euro below, we see that the twenty-year average is above the current value which pundits want to explain as a weak dollar.  Too, understand that back in 1999, when the euro made its debut, it started trading at about 1.17 or so, remarkably right where it is now!

Source: finance.yahoo.com

My point is that the dollar remains the anchor of the global financial system, and given the current trends regarding both economic activity and the likely ensuing central bank policies, as well as the ongoing performance of US assets on a financial basis, while short-term negativity on the dollar can be fine, I would be wary of expecting it to lose its overall place in the world.

Speaking of short-term views, especially regarding central bank activities, it appears clear that the market is adjusting the dollar’s value on this new idea of the Fed cutting more aggressively.  If that is, in fact, what occurs, I accept the dollar can decline relative to other currencies, but I really would be concerned about its value relative to things like commodities.  And that has been my view all along, if the Fed does cut rates, gold is going to be the big beneficiary.

Ok, let’s review how markets have absorbed the US data, as well as other data, overnight.  Yesterday’s record high closings on US exchanges were followed by strength in Tokyo (+1.3%), Hong Kong (+2.6%), China (+0.8%) despite the weakest domestic lending numbers in the history of the series back to 2005.  In fact, other than Australia (-0.6%) every market in Asia rallied.  The Australian story was driven by bank valuations which some feel are getting extreme despite the RBA promising further rate cuts, or perhaps because of that and the pressure it will put on their margins.  Europe, too, is rocking this morning with gains across the board led by Spain (+1.1%) although both Germany (+0.9%) and France (+0.6%) are doing fine.  And yes, US futures are still rising from their highs with gains on the order of 0.3% at this hour (7:45).

In the bond market, Treasury yields have slipped -3bps this morning, with investors and traders fully buying into the lower rate idea.  European sovereigns are also rallying with yields declining between -4bps and -5bps at this hour.  JGBs are the exception with yields there edging higher by 2bps, though sitting right at their recent “home” of 1.50%.  as you can see from the chart below, 1.50% appears to be the market’s true comfort level.

Source: tradingeconomics.com

In the commodity space, oil (-0.6%) continues to slide as hopes for an end to the Russia-Ukraine war rise ahead of the big Trump-Putin meeting on Friday in Alaska.  Nothing has changed my view that the trend here remains lower for the time being as there is plenty of supply to support any increased demand.

Source: tradingeconomics.com

Metals, meanwhile, are all firmer this morning with copper (+2.6%) leading the way although both gold (+0.4%) and silver (+1.7%) are responding to the dollar’s decline on the day.

Speaking of the dollar more broadly, its decline is pretty consistent today, sliding between -0.2% and -0.4% vs. almost all its counterparts, both G10 and EMG.  This is clearly a session where the dollar is the driver, not any particular story elsewhere.

On the data front, there is no primary data coming out although we will see the weekly EIA oil inventory numbers later this morning with analysts looking for a modest drawdown.  We hear from three Fed speakers, Bostic, Goolsbee and Barkin, with the latter explaining yesterday that basically, he has no idea what is going on and no strong views about cutting or leaving rates on hold.  If you ever wanted to read some weasel words from someone who has an important role and doesn’t know what to do, the following quote is perfect: “We may well see pressure on inflation, and we may also see pressure on unemployment, but the balance between the two is still unclear.  As the visibility continues to improve, we are well positioned to adjust our policy stance as needed.”  

And that’s all there is today.  The dollar has few friends this morning and I see no reason for any to materialize today.  But longer term, I do not believe a dollar weakening trend can last.

Good luck

Adf

Not Crashing

The data was pretty darn good
And so, it must be understood
The world is not crashing
Though some things are flashing
Red signs, where recession’s a ‘could’


A review of yesterday’s economic data shows that Retail Sales were stronger than expected on every metric and subcomponent, Import Prices rose a scant 0.1%, the Philly Fed Index was much stronger than expected and Jobless Claims fell on both an Initial and Continuing basis.  In truth, it was a sweep of positive economic news.  As such, we cannot be surprised that equity markets responded positively, as did the dollar, while bonds held their ground, given the lack of inflationary signals.  But if we look at the movements in markets, they remain very modest overall.  Sure, the S&P 500 made a new high, by 2 points, but if you look at the chart below, since July 3rd, the rally has been 26 points, or 0.4%.  This is hardly the stuff of excitement.

Source: tradingecononmics.com

Of course, this did not stop the pundits who are calling for recession to highlight any negative subtext, nor did it prevent Fed Governor Waller from claiming that a rate cut in July was appropriate because the labor market is on the edge.  But the naysayers find themselves with diminishing attention these days as market price action has been quite positive.  In fact, most markets have shown similar behavior.  Whether gold or oil or other equity indices or bonds, we have been in a narrow range for a while now and it is not clear what it will take to break us out.  But here’s one thought…

On Sunday, Japan
Will vote for their Upper House
Is there change afoot?

While market insiders will discuss today’s options’ expirations as the key driver of things in the short-term, I think we need turn our eyes Eastward to Japan’s Upper House elections this Sunday.  PM Ishiba’s LDP-Komeito coalition is already in a minority status in the more powerful Lower House, a key reason why so little has been accomplished there.  But at least he had a majority in the Upper House to rubber stamp anything that was enacted.  However, signs are pointing to the LDP losing their majority in the Upper House which could well lead to Ishiba getting forced out.

Now, why does this matter to the rest of us?  There is a case to be made that flows in the JGB market are an important driver of global bond flows, including Treasuries.  For instance, Japan is the second largest net creditor nation with about $3.73 trillion invested abroad (according to Grok), much of which is Japanese insurance companies searching for higher yields than have been available there for the past decades. You may remember back in May, when there was a spike in long-dated JGB yields as all maturities from 20 years on out reached new historic highs (see below chart), well above 3.0%. 

Source: tradingeconomics.com’

Now, consider if you were a Japanese life insurer looking to match your assets to your liabilities.  Historically, buying Treasury bonds, with their much higher yield, was the place to be, especially over the past several years when the yen weakened, adding to your JPY gains.  However, that is still a risky trade, and hedging the FX risk is expensive given the yield differential between the US and Japan.  (Hedgers need to sell USD forward and the FX points reduce the effective exchange rate and by extension the benefits of the higher bond yields.)

But now, for the first time ever, JGB yields are above 3.0%, and that can be earned by a Japanese life insurer with zero FX risk, a very attractive proposition.  In fact, Bloomberg has an article this morning discussing just such a situation with one of the larger insurers, Fukoku Life.

Circling back to the election, it appears that the key issues are the rising cost of living and what the government is going to do about it.  Apparently, there are two approaches; the LDP is talking about giving out cash bribes grants of ¥20,000 to individuals while the opposition is talking about reducing consumption taxes on necessities like food.  However, in either case, the reality is that fiscal policy would loosen further with the MOF needing to issue yet more JGBs to make up for either the increased outlays or reduced income.  Add to that the uncertainty over future Japanese policy if the LDP loses its majority, and the pressure from the US regarding tariff negotiations and suddenly, it makes a lot more sense that the knock-on effects of this election can be substantial, at least with respect to the global bond markets and the USDJPY exchange rate.  (It must be said that Japanese inflation data last night actually fell to 3.3%, but that was due entirely to declining oil prices as fresh food prices, the big issue there, continue to rise.)

An election outcome that weakens PM Ishiba, potentially leading to a fall of his government and new elections in the Lower House, would be a distinct negative for the yen, and likely for the JGB market.  The impact would be felt in global bond markets as yields in the back end would almost certainly rise everywhere around the world.  This is not to imply that yields would rise by 100bps or more, but rather that the current trend of rising long-dated yields would continue for the foreseeable future.  And that will make things tough on every government.

Ok, sorry, I went on a bit long there.  A quick turn through markets shows that other than Japan (-0.2%) Asian equity indices were mostly nicely in the green following the US lead with the biggest winners Australia (+1.4%), Hong Kong (+1.3%) and Taiwan (+1.2%).  Meanwhile, in Europe this morning, while green is the color, the movement has been miniscule, averaging about 0.1% gains.  And US futures are also modestly higher at this hour (7:00) about 0.15% across the board.

In the bond market, Treasury yields have edged lower by -2bps but European sovereign yields are all higher by 2bps across the board.  The talk in Europe is over concerns regarding the conclusion of a trade deal with the US, where concerns are growing nothing will be achieved by the end of the month.

In the commodity markets, oil (+1.3%) is continuing its rebound, perhaps on the beginnings of a belief that the economy is not going to crater in the US.  Certainly, yesterday’s data was positive.  As to the metals markets, they are in fine fettle this morning with both gold (+0.4%) and silver (+0.4%) trading back to the middle of their trading ranges and copper (+1.3%) pushing back toward its recent all-time highs.

Finally, the dollar is under pressure this morning, sliding against the euro (+0.25%), pound (+0.2%) and AUD (+0.4%).  But the real movement has been in the commodity space where NOK (+0.8%) and ZAR (+0.7%) are both having solid days.  There continues to be a great deal of discussion regarding President Trump’s desire to fire Chairman Powell with a multitude of articles describing how that would be the end of the world as we know it because the Fed cherishes their “independence”.  Let’s not have that discussion.

On the data front, this morning brings Housing Starts (exp 1.3M) and Building Permits (1.39M) and then Michigan Sentiment (61.5) at 10:00.  There are no Fed speakers on the slate for today although Governor Kugler, not surprisingly, explained that waiting was the right call for the Fed when she spoke yesterday.  

It is a Friday in the summer with relatively unimportant data.  Absent another surprise from the White House Bingo card, I expect a quiet session overall as most traders and investors leave the office early for the weekend.  The dollar’s biggest risk is the Fed does cut early, but if the data keeps cooperating, it will be much harder for dollar bears, especially since so many are already short, to sell it aggressively from here.

Good luck and good weekend

Adf

Widely Abhorred

Most traders this summer are bored
Thus, markets are being ignored
Attention, instead
Is on a man, dead
For years, but still widely abhorred
 
So, even though President Trump
More tariffs on copper did pump
The outrage is such
That nothing else much
Is noticed, not gains nor a slump


This is not a political discussion piece but the only story getting any press today, overwhelming the terrible tragedy in Texas from the weekend, is the closing of the Jeffrey Epstein case by the Trump administration.  I will not go into the details here as they are not relevant to our focus, but it certainly has many people irate, although I imagine there are a small number who are relieved.  On the surface, though, it certainly doesn’t seem to be in accord with Trump’s remarkable transparency in all other facets of his governance.  I will leave it at that.

Regarding market issues, while there continue to be ongoing tariff negotiations with numerous countries, nothing new has been completed in that realm in the past several days.  The one new thing is copper, where the president mooted 50% tariffs on the red metal yesterday during a wide-ranging press conference.  See if you can determine when he mentioned this.

Source: tradingeconomics.com

The result is that copper is now trading at new all-time highs, although in fairness, this morning it has slipped back -2.6% from the peak it reached yesterday.  This move has also weighed on gold (-0.3%) and silver (-0.5%), although both those metals remain in longer term uptrends as well.

Away from those stories, perhaps the biggest news is that the Supreme Court overturned a lower court injunction against a Trump executive order from February that was designed to reduce the size of the government.  His cabinet secretaries now have the ability to reduce headcounts as they deem appropriate with estimates of several hundred thousand expected to be let go.  (If I recall correctly, immediately upon entering office Trump offered a buyout for government employees with a generous severance.  I suspect those laid off will not receive the same benefits now).  

I make the connection here as a reduced headcount seems likely to help reduce government spending at the margin, something that has been a key focus of everyone concerned about both inflation and the general growth of government.  Also consider, given the remarkable inefficiency of government processes, any other job these laid off employees take will almost certainly add more value to the economy than they are currently adding.

Otherwise, I’ve got nothing.  Things are just not very interesting right now.  So, let’s recap the overnight session.  Yesterday’s US session was the epitome of dull, with the DJIA the worst performer at just -0.4% and the other two essentially unchanged.  Asian markets saw a modest gain in Tokyo (+0.3%) as investors get used to the new tariffs.  Elsewhere in the region there was no consistency at all with gainers (Korea, Taiwan, Indonesia and Singapore) and laggards (China, Hong Kong, India and Australia).  In other words, there is no pattern here to note.  In Europe, however, gains are universal (DAX +1.0%, CAC +1.15%, IBEX +0.85%) as it appears trade talks are getting close to some sort of agreement.  Again, given the amount of time it has historically taken to reach agreement, the speed with which things are occurring right now is remarkable.  I guess sometimes a stick is needed rather than a carrot.  Lastly in the equity world, US futures at this hour (7:10) are slightly higher, 0.2% or so.

In the bond market, yields, which I pointed out yesterday have risen 20bps in the past week, are on hold this morning with Treasury yields (+1bp) edging higher ahead of today’s 10-year auction.  In Europe, sovereign yields are lower by -1bp across the board which appears to be a simple trading reaction to the recent rise.  JGB yields are also edged higher by 1bp overnight as Japan closes in on its election and comments from a BOJ member indicated they are not likely to hike rates again until March!  Remember, inflation in Japan is 3.6%!

Oil prices continue to edge higher, up 0.5% this morning despite the increased OPEC+ production and the alleged global slowdown in economic activity.  Something about this price action is out of kilter with the narrative and either we are going to see production numbers decline dramatically or the economic data is going to start to show that things are much better than the bears would have you believe.

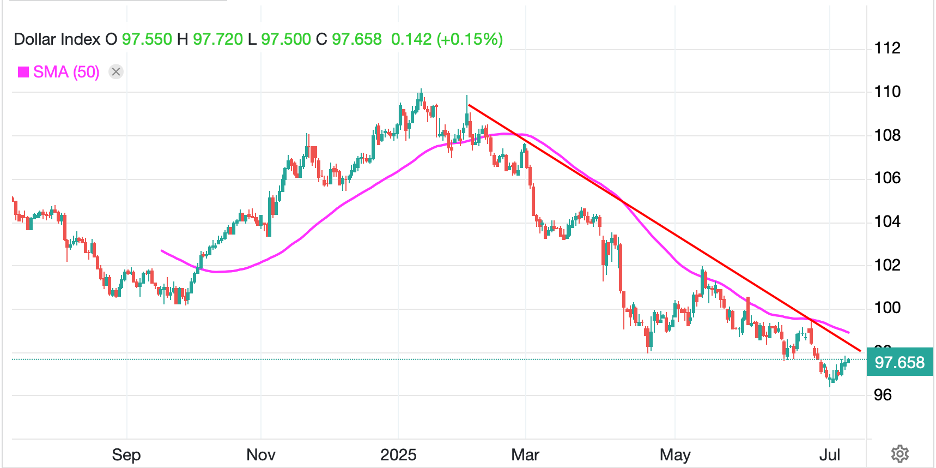
Finally, the dollar is slightly firmer this morning, +0.2% on the DXY, but continues to trade well below its 50-day moving average and bump up against a very clear trendline lower as per the picture below.

Source: tradingeconomics.com

I am no technician as is obvious by my efforts on the chart, but the general thesis remains intact.  Right now, lower seems to be the direction of least resistance although positioning in the market remains quite net short dollars.  But looking at individual currencies this morning, KRW (-0.5%) is the biggest mover, as concerns over more tariffs on semiconductors undermined investor sentiment there, but other than that, you are hard pressed to find a currency move of 0.2% in either direction.  In essence, like every other market, there is just nothing going on right now.

On the data front, today brings only the EIA oil inventory data where a small draw is expected and the FOMC Minutes at 2:00, although my take is they are pretty stale at this point.  Yesterday saw a surprising decline in Consumer Inflation expectations to 3.0%, despite all the tariff talk, and a decline in Consumer Credit to $5.1B, not a good sign for spending.

As per the above chart, the dollar’s trend remains lower for now.  We will need to see some major changes in policy to alter that trajectory I think, and for now, that seems unlikely.  Everything continues to revolve around what the President says and where he focuses.  If you can anticipate that, good for you.  But this poet hasn’t a clue on the next target.  Stay hedged and nimble.

Good luck

Adf

Over the Hump

It’s beautiful and it’s quite big
Though more complicated than trig
But President Trump
Got over the hump
Though sans views that he is a Whig
 
As well, Friday’s Canada rift
Has ended, boy that was sure swift
Now, this week we’ll learn
If there’s still concern
‘Bout jobs, or if there’s been a shift


The weekend news revolves around the fact that the Senate has passed the BBB with a 51-49 vote, and it now moves to committee so both Houses of Congress can agree the final details before it gets to President Trump’s desk for signature and enactment.  This is another victory for the President, adding to last week’s wins and remarkably there have been several others as well.  The Supreme Court ended the ability of a single district court judge to injunct the entire nation based on a single case, a move that will prevent judges who disagree with the president from stopping his policy efforts.  Then, Canada announced they were going to impose a tax on US technology companies (the one that the Europeans just killed) and after Mr Trump ended the trade dialog quite vociferously, Canada backed down from that stance and is back at the negotiating table.

I mention this not to be political but as a backdrop to what is helping to drive the improved sentiment in US markets for both equities and bonds.  While a quick look at YTD performances of US equity indices vs. Europeans shows the US still lags, that gap is narrowing as the news cycle continues to point to positive things happening in the US.  Certainly, my understanding of the BBB is that it is quite stimulative, although it is changing priorities from the previous administration.

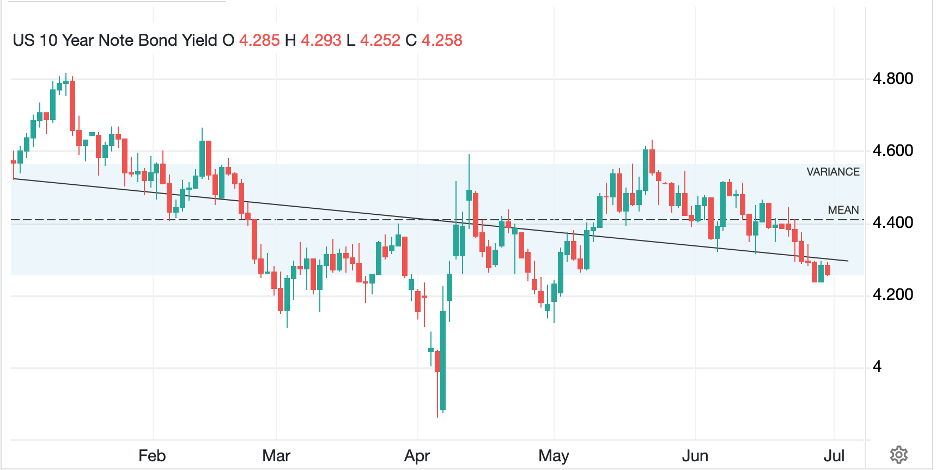
More interestingly, the Treasury market, which has been the subject of many slings and arrows lately from the part of the analyst community that continues to worry about refinancing the growing US debt pile, continues to behave remarkably well.  A quick look at the chart below shows that 10-year yields have been trending lower for the past 6 months, at least, and this morning are continuing that trend, slipping another -3bps.

Source: tradingeconomics.com

My point is that despite relentless doom porn regarding the economy, the big picture continues to point to ongoing growth in economic activity.  There are many anecdotes regarding the impending weakness, (the latest I saw was the increase in the number of credit card purchases that have been rejected is rising rapidly) and yet, the main data has yet to crack and roll over to point to a clear sign of significant slowing.  Perhaps this week when the NFP report is released on Thursday (Friday is July 4th holiday), we will see that long-awaited decline.  However, as of this morning, the Fed funds futures market continues to price just a 21% probability of a July rate cut as forecasts for NFP show the median to be 110K. 

While I completely understand the concerns that the doomers recite, I have come to understand that the idea of a recession is a policy choice, not a natural phenomenon.  While in the past, the business cycle was more powerful than the government, that is no longer the case.  Rather, what we have observed over the past 15 years at least, since the GFC and the onset of QE, is that the government has become a large enough part of the total economy to drive it at the margin.  And I assure you, if a recession is a policy choice, there is not a politician that is going to choose one.  Perhaps we will reach a point where the imbalances get beyond the control of the central banks and their finance ministries, but we are not there yet.

Ok, let’s take a peek at the overnight price action.  Despite all the spending promises by governments around the world, yields have slipped everywhere with all European sovereigns taking their lead from the US and lower this morning by -2bps to -3bps.  Even JGB yields (-1bp) have managed to decline slightly.  If inflation fears are building, they are not obvious this morning.

In the equity markets, Friday’s US rally was followed by most Asian bourses rising (Nikkei +0.8%, Australia +0.3%, China +0.4%) although HK (-0.9%) slipped after Chinese PMI data was released that indicated things weren’t collapsing, but that future monetary stimulus may not be coming after all.  The worst of both worlds for stocks.  Meanwhile, European exchanges are mostly a touch softer, but only on the order of -0.2%, so really very little changed amid light volume overall.  Interestingly, US futures are solidly higher at this hour (7:00), rising by 0.55% across the board.

In the commodity markets, oil (-0.35%) is slipping a bit, but is basically hanging around near its recent lows as the market remains unconcerned about an escalation of fighting between Iran and Israel and any possible closure of the Strait of Hormuz.  Meanwhile, gold (+0.4%) is bouncing from a weak performance Friday which appears to have been a bit oversold, although copper and silver are not following suit this morning with the former (Cu -0.7%) the laggard.  However, all the metals remain sharply higher this year and in strong up trends.

Finally, the dollar is modestly softer again this morning with KRW (+0.9%) the biggest mover, by far, while the entire G10 complex is showing gains on the order of 0.1% to 0.2%.  This trend lower in the dollar remains strong (see chart below), but as I continue to remind everyone, we are nowhere near an extreme valuation in the dollar.  If, and it’s a big if, we see substantial weakening in the employment data, I think the Fed could decide to act and that would increase the speed of the downtrend (as well as goose inflation higher), but absent that, I do not see a sharp decline, rather a slow descent.  Remember, this is exactly what Trump and Bessent want, a more competitive dollar for the manufacturing sector.

Source: tradingeconomics.com

As it is the first week of the month, there is plenty of data to digest.

TodayChicago PMI43.0
TuesdayISM Manufacturing48.8
 ISM Prices Paid69.0
 JOLTs Job Openings7.3M
WednesdayADP Employment 85K
ThursdayNonfarm Payrolls110K
 Private Payrolls110K
 Manufacturing Payrolls-6K
 Unemployment Rate4.3%
 Average Hourly Earnings0.3% (3.9% y/Y)
 Average Weekly Hours34.3
 Participation Rate62.3%
 Initial Claims240K
 Continuing Claims1960K
 ISM Services50.5
 Factory Orders8.0%
 -ex Transport0.9%

Source: tradingeconomics.com

In addition to the payrolls, we hear from Chairman Powell again on Tuesday and Atlanta Fed president Bostic twice.  I guess the rest of the FOMC took a long holiday week(end).

As it’s a holiday week, I expect that activity will be light, although headline bingo remains a key part of the markets today.  I feel like the trends are well entrenched though, with the dollar slipping, equities and commodities rallying and bonds currently leaning toward lower yields, although that seems out of sync with the other markets.  But in the summer, with less liquidity and activity, anomalies can continue for a while.

Good luck

Adf

Full Schmooze

The temperature’s starting to fall
With Israel and Iran’s brawl
On hold for the moment
Though either could foment
Resumption, and break protocol
 
But that truce combined with the news
That Trump’s team are pushing full schmooze
On trade, has the markets
Increasing their bull bets
While skeptics are singing the blues


President Trump is having a pretty remarkable week.  The successful attack and destruction of Iran’s nuclear enrichment facilities combined with the news that the US and China have agreed the details of the trade framework that was outlined in Geneva and followed up in London has market participants feeling a lot better about the world this morning.  Add to that the news that a particularly onerous part of the BBB, Section 899, which was nicknamed the Revenge clause for its tax targeting anybody from nations that imposed excess taxes on US companies internationally, being stripped after negotiations with European leaders, and the fact that NATO has gone all-in on increasing their spending, and Mr Trump must be feeling pretty good this morning.  Certainly, most markets are feeling that, except those that thrive on chaos and fear, like precious metals.

In fact, this morning it seems that the entire discussion is a rehash of what has occurred all week with very little new added to the mix.  Data from the US yesterday was mixed, with Claims a bit softer and Durable Goods quite strong while the third look at Q1 GDP was revised lower on more trade data showing imports were greater than first measured while Consumer Spending and Final Sales were a bit weaker than expected.  Net, there was not enough to push a view of either substantial strength or weakness in the economy, so investors and their algorithms continue to buy shares.

The other story that continues to get airplay is the pressure on Chairman Powell and questions about whether at the July meeting Fed governors are going to vote against the Chairman.  Apparently, it has been 32 years since that has occurred (and you thought they were actual votes!) and the punditry is ascribing the dissent to politics, not economics.  It should, of course, be no surprise that there is a political angle as there is a political angle to every story these days, but the press is particularly keen to point out that the two most vocal Fed governors discussing rate cuts were appointed by Trump.

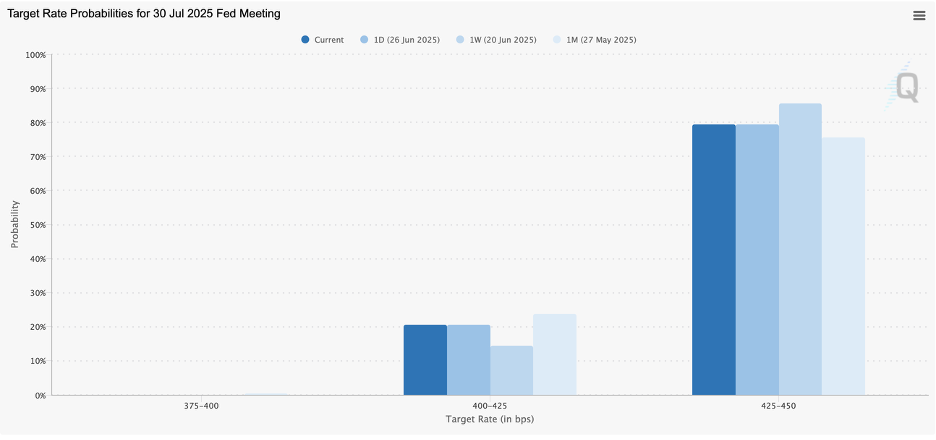
However, despite all the talk, the futures market does not appear to have adjusted its opinion all that much as evidenced by the CME chart of probabilities below.  In fact, over the past month, the probability of a cut has declined slightly.  Rather, I would contend that on a slow news Friday, the punditry is looking for a story to get clicks.

The last story of note is about the dollar and its ongoing weakness.  This is an extension of the Fed story as there is alleged concern that if the Fed is perceived to lose some of its independence, that will be a negative for the dollar in its own right, as well as the fact that the loss of independence would be confirmed by a rate cut when one is not necessary (sort of like last autumn prior to the election.  Interestingly, I don’t recall much discussion about the Fed’s loss of independence then.)

But, in fairness, the dollar has continued to decline with the euro trading to its highest level, above 1.17, in nearly four years.  It is hard to look at the story in Europe and think, damn, what a place to invest with high energy costs and massive regulatory impediments, so it is reasonable to accept that what had been a very long dollar position is getting unwound.  But look at the next two charts (source: tradingeconomics.com) of the euro, showing price action for one year and for five years, and more importantly notice the trend lines that the system has drawn.  There is no doubt the dollar is under pressure right now, but I am not in the camp that believes this is the beginning of the end of the dollar’s global status.  Remember, too, that President Trump would like to see the dollar soften to help the export competitiveness of the US, and so I would not expect to hear anything from the Treasury on the matter.

However, while these medium and long-term trends are clear, the overnight session was far less exciting with the largest move in any major currency the ZAR (+0.5%) which is despite the decline in gold and platinum prices.  Otherwise, today’s movement is basically +/- 0.2% across both G10 and EMG currencies.

Speaking of the metals, though, they are taking it on the chin this morning as we approach month end and futures roll action.  Gold (-1.3%), silver (-1.7%), copper (-0.9%) and platinum (-4.4%) are all under pressure, although all remain significantly higher YTD.  However, to the extent that they represent a haven and the fact that havens seem a little less necessary this morning seems to be the narrative driver adding to the month end positioning.  Meanwhile, oil (+0.5%) continues to bounce ever so slowly off the lows seen immediately in the wake of the bombing attacks.

Circling back to equity markets, after a nice day in the US yesterday, with gains across the board approaching 1% and the S&P 500 pushing to within points of a new all-time high, Japan (+1.4%) followed suit as did much of the region (India, Taiwan, New Zealand, Indonesia) but China (-0.6%) and Hong Kong (-0.2%) didn’t play along.  Europe, though, is having a positive session with gains ranging from 0.65% (DAX) to 1.3% (CAC) and everything in between.  It seems that the NATO spending news continues to support European arms manufacturers and the cooling of tensions in the Middle East has lessened energy concerns.  US futures are also bright this morning, up about 0.5% at this hour (7:40).

Finally, bond markets are selling off slightly after a further rally yesterday and yields since the close have risen basically 3bps in both Treasury and European sovereign markets.  There is still no indication that any government is going to stop spending, rather more increases are on the horizon, but there is also no indication that central banks are going to stop supporting this action.  No central bank is going to allow their nation’s bond market to become unglued, regardless of the theories of what they can do and what they control.  Ultimately, they control the entire yield curve.

On the data front, this morning brings Personal Income (exp 0.3%), Personal Spending (0.1%) the PCE data (Core 0.1%, 2.6% Y/Y; Headline 0.1%, 2.3% Y/Y) and at 10:00 Michigan Consumer Sentiment (60.5) and Inflation Expectations (1yr 5.1%, 5yr 4.1%).  There are several more Fed speakers, including Governor Cook, a Biden appointee who is a very clear dove, but has not yet agreed that rate cuts make sense.  It will be interesting to see what she has to say.

It is a summer Friday toward the end of the month.  Unless the data is dramatically different than forecast, I expect that the dollar will continue to slide slowly for now, although I do expect the metals complex to find a bottom and turn.  As to equities, apparently there is no reason not to buy them!

Good luck and good weekend

Adf

He’s the Worst

The talking points have been disbursed
With narrative writers well-versed
The dollar is falling
‘Cause Trump is now calling
For Powell to leave, “He’s the worst!”
 
The idea is Trump will soon name
The next Fed Chair, turning Jay lame
This shadow Fed Chair
Will have to beware
Since he’ll, for bad outcomes, get blame


The dollar is weaker this morning and if we use the Dollar Index as a proxy, it has fallen to its lowest level since February 2022.  

Source: tradingeconomics.com

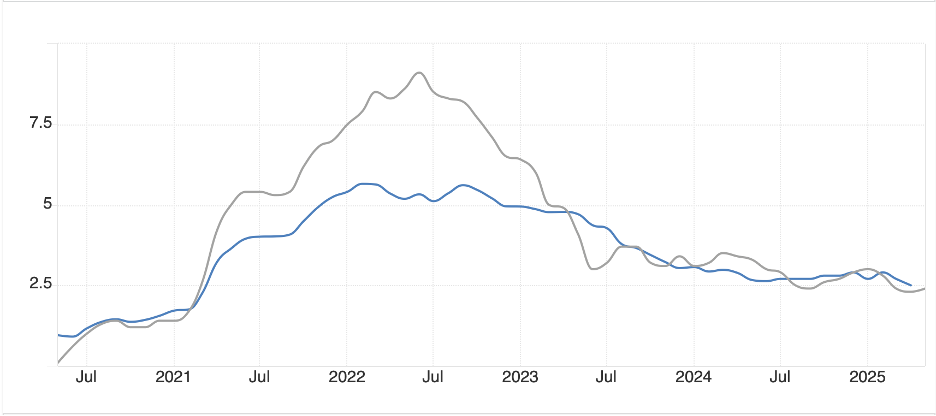
While certainly a part of this movement has been the fact that US yields continue to slide lately, it also seems there is a new narrative that has been distributed to journalists, the dollar is falling because President Trump is considering naming a new Fed Chair much earlier than usual in an effort to undermine Chairman Powell.  We have all heard about the rants the President has had regarding Powell’s unwillingness to cut rates even though inflation readings have been declining for the past two months, and are, on a Y/Y basis back to their lowest level since March 2021 whether measured as CPI (grey line) or Core PCE (blue line).

Source: tradingeconomics.com

But in an exclusive (!) article in the WSJ, which was repeated in Bloomberg, that is the story du jour.  While Bloomberg’s take cannot be a surprise given Mayor Mike’s intense hatred of Trump (after all Trump is the NY billionaire that became president, not Bloomberg), and editorial direction clearly comes from the top, it is more interesting that the Journal is pushing this theme.  Of course, given the Fed whisperer is the article’s writer, it is more than possible that he is simply airing Powell’s views and trying to explain how any move like this would result in chaos, so it’s not Powell’s fault if things go pear-shaped.

Nonetheless, that is today’s story.  In concert with this story, though is another, somewhat more interesting feature, where a really smart analyst, Marko Papic, has broken down the dollar’s movements across different time zones during 2025.  The chart below shows that the dollar selling has been emanating from Asia mostly with Europe having a lesser impact and no substantive change in the NY session.  The implication is that Asian holders of dollars, which tend to be sovereigns rather than other users like investors or corporates, are the ones bailing out.

This activity first became noticeable in early April, right around “Liberation Day” and does fit with the idea that higher US tariffs will result in a smaller US trade deficit.  But as I consider that concept, it strikes me that a smaller US trade deficit will result in fewer dollars around the rest of the world, a reduction in supply, and that would arguably increase the dollar’s value ceteris paribus.  Perhaps this reflects investors selling US assets and converting them to Europe, which has been another theme this year as European companies are set to benefit from a major increase in defense spending by NATO.  However, that doesn’t really sync with the fact that US equities continue to trade near all-time highs.  At this point, I think this is an interesting observation, but am not sure of its meaning.  I’m open to suggestions.

Ok, while that is the narrative this morning, let’s look at how markets are behaving.  Yesterday’s lackluster activity in the US, with the S&P 500 almost exactly unchanged and the other two main indices +/- 0.3% was followed by a burst higher in Tokyo (Nikkei +1.6%) but lagging activity in HK (-0.6%) and China (-0.4%).  The rest of the region couldn’t decide on much with a couple of solid performances (India, Indonesia) and one laggard of note (South Korea).  In Europe, Germany (+0.6%) is leading the way higher across the board, as NATO countries have promised to spend upward of 5% of GDP on total defense (including nonlethal investments), with as much as possible going to European based companies.  That is a lot of money, well over $1.5 trillion.  Meanwhile, US futures are all higher at this hour (7:15), up by about 0.4% or so.

In the bond market, Treasury yields (-2bps) continue to slip and are now back to their lowest level since early May.  Perhaps more interestingly, European sovereign yields are sliding today as well, led by Italian BTPs (-4bps) but lower across the board.  This is interesting given the promises of more borrowing based on the NATO announcement.  But net, bond yields have not really done very much lately at all.

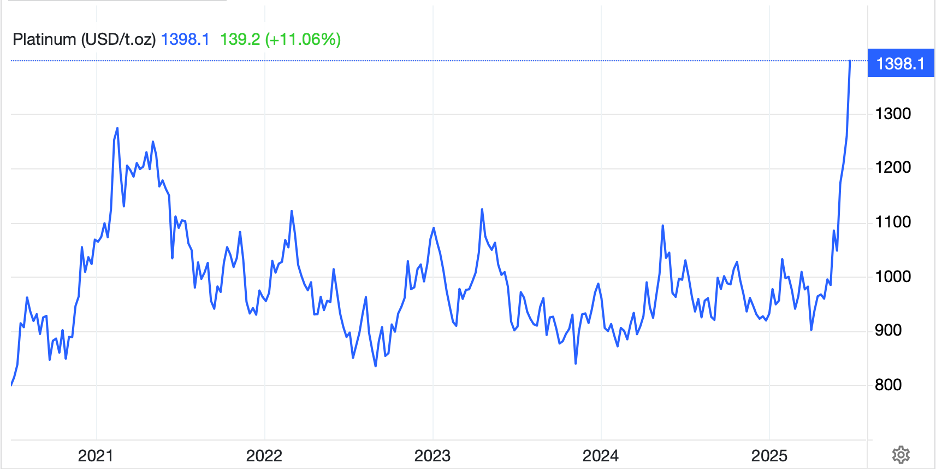
In the commodity markets, oil (+0.5%) is continuing to slowly bounce from the initial lows in the wake of the Iran/Israel ceasefire.  This market still feels quite heavy to me and absent a major change on the ground in the Middle East, if war were to resume and oil facilities be attacked, I still think lower is the way.  In the metals markets, gold (+0.25%) which tried to sell off yesterday continues to find bids below the market, likely central bank support.  But silver (+0.9%) and copper (+2.3% and above $5.00/lb) are looking good although nowhere near as impressive as platinum (+3.4%) which has now risen above $!400/oz and is going parabolic here.  There is much talk here about a supply shortage (it is used for catalytic converters) and significant Chinese demand.

Source: tradingeconomics.com

Finally, the dollar, as mentioned, is under pressure across the board, although the magnitude of this morning’s movement has not been that large.  The largest movement has been in Asia with IDR (+0.6%), JPY (+0.4%) and KRW (+0.35%) while European and LATAM movements have been generally 0.2% or less.  So, the direction is clear, but it has not been impressive.

On the data front, there is plenty today starting with the weekly Initial (exp 245K) and Continuing (1950K) Claims, the Chicago Fed National Activity Index (-0.1), the last look at Q1 GDP (-0.2%), and Durable Goods (8.5%, 0.0% ex-Transports).  We also hear from four more Fed speakers, but Powell just repeated yesterday that they are happy where they are and unlikely to move soon unless something really changes rapidly.  However, despite Powell’s claims of nothing to come, the Fed funds futures market is pricing a 25% probability of a cut at the July 30 meeting.  There is a lot of time between now and then for that to change.

I keep trying to figure out what actually matters to markets anymore as responses to different potential catalysts seem confused.  People do seem to be coalescing around the dollar is falling theme, something I have believed for a while, and if the Fed does lean to a cut next month, I do believe there is further for it to fall.  One thing to remember, though, is with Mr Trump as president, things are still a tweet away from a dramatic change.  If I were in charge of hedging risk, I would adhere to guidelines closely.  There is too great an opportunity for a sudden major reversal in the current environment.

Good luck

Adf