Clearly Explained

The warmups in Davos for Trump
With Howard and Scott on the stump
Quite clearly explained,
While WEFers complained,
The US was, no more, the chump
 
The globalist world that existed
Is no longer to be assisted
Instead, US goals
Align with Trump’s polls
No matter the words WEF has twisted


As we await President Trump’s address in Davos this morning, it is worth recapping the highlights from yesterday’s US speakers, Commerce Secretary Howard Lutnick and Treasury Secretary Scott Bessent.   Starting with Lutnick, he explained the White House view as follows; “The Trump Administration and I are here to make a very clear point—globalization has failed the West and the United States of America. It’s a failed policy… and it has left America behind.”  The video is linked above in his name.  It is hard to misunderstand what he is saying, and that is very clearly US policy.

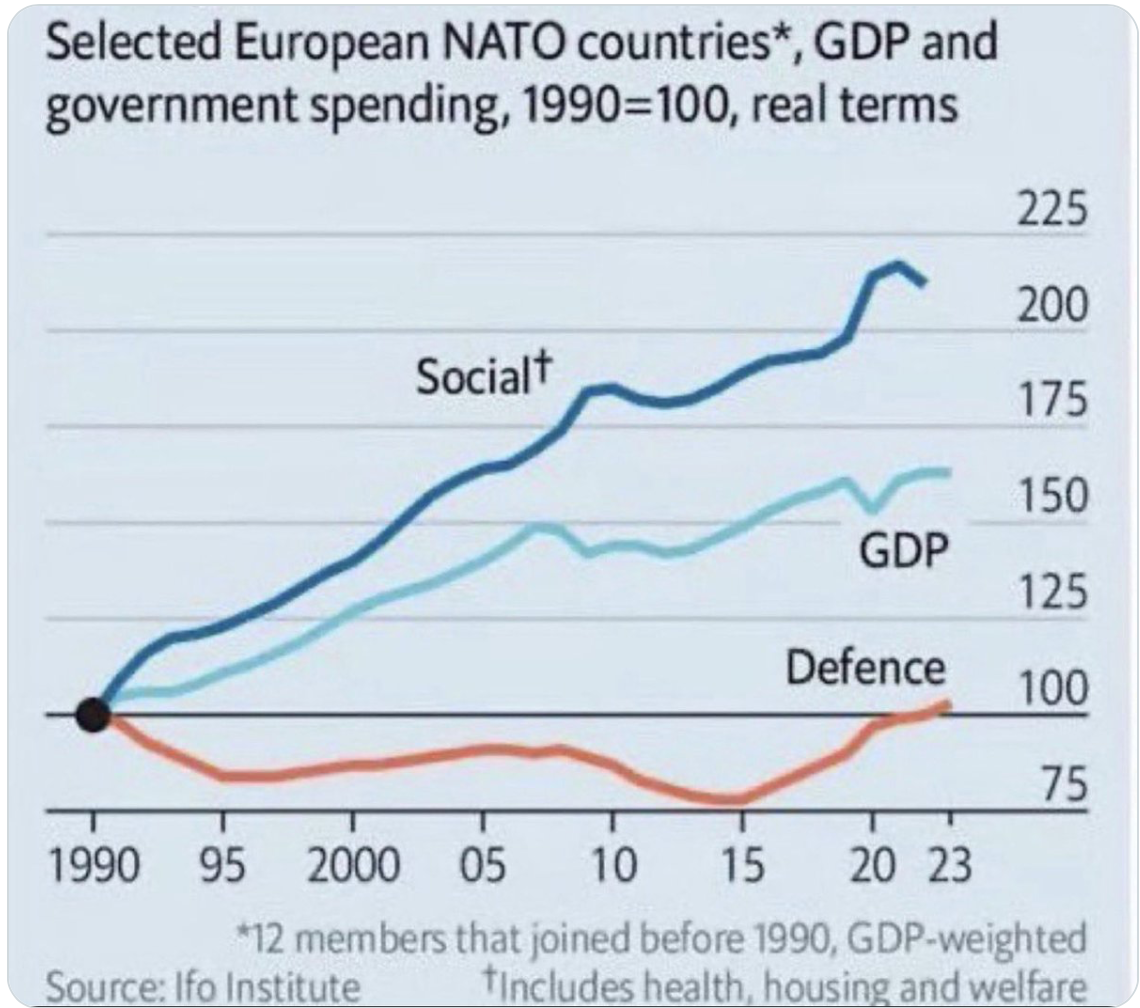
Turning to Secretary Bessent, he explained that the US has spent $22 trillion more than the rest of NATO since 1980 on defense while Europe and Canada created their welfare states.  “The Europeans have been spending the money on social welfare, on roads, on education, and it’s time for them to pay more, which they’ve agreed to do.”  The video clip is linked to his name in the first stanza.  The below graph is telling:
At the same time, Europe continues to buy Russian oil, funding Russia’s war against Europe.

Needless to say, Europeans were unhappy with the commentary as they appeared to be coming under attack from the US.  The market narrative quickly framed around President Trump going too far and how it was going to destroy the US as nobody will want to invest in the US. That is the explanation for yesterday’s decline in US equities (although they fell around the world), the dollar and Treasury bonds (although bonds, too, fell everywhere, notably in Japan).  

Yesterday I sought to disabuse you of the notion that Europe is going to sell all their Treasuries to hurt the US as the results would likely be either irrelevant or horrific for Europe.  So, the narrative pivoted to Trump is bad and destroying the US.  

And yet, remarkably, the world did not end either yesterday or last night, despite what many have explained is inevitable.  This morning markets are somewhat less catastrophic.  It makes sense that markets are going to remain volatile as the underlying theses for international relations adjust to the new reality of power politics and economic statecraft from the previous “Rules Based Order”.  And at this stage, there is no way to know which outcomes are most likely.  The only thing of which I am confident is that we have not seen the end of this play out.  

I must admit, that while I don’t think President Trump cares much about France and President Macron’s comments seeking more Chinese investment in that nation, I suspect that PM Carney’s efforts to cozy up to President Xi will be less welcome based on the Donroe Doctrine of US dominance in the Western Hemisphere.  But I also believe that the power structure between the US and Canada is such that it will ultimately bend to the US’s will.

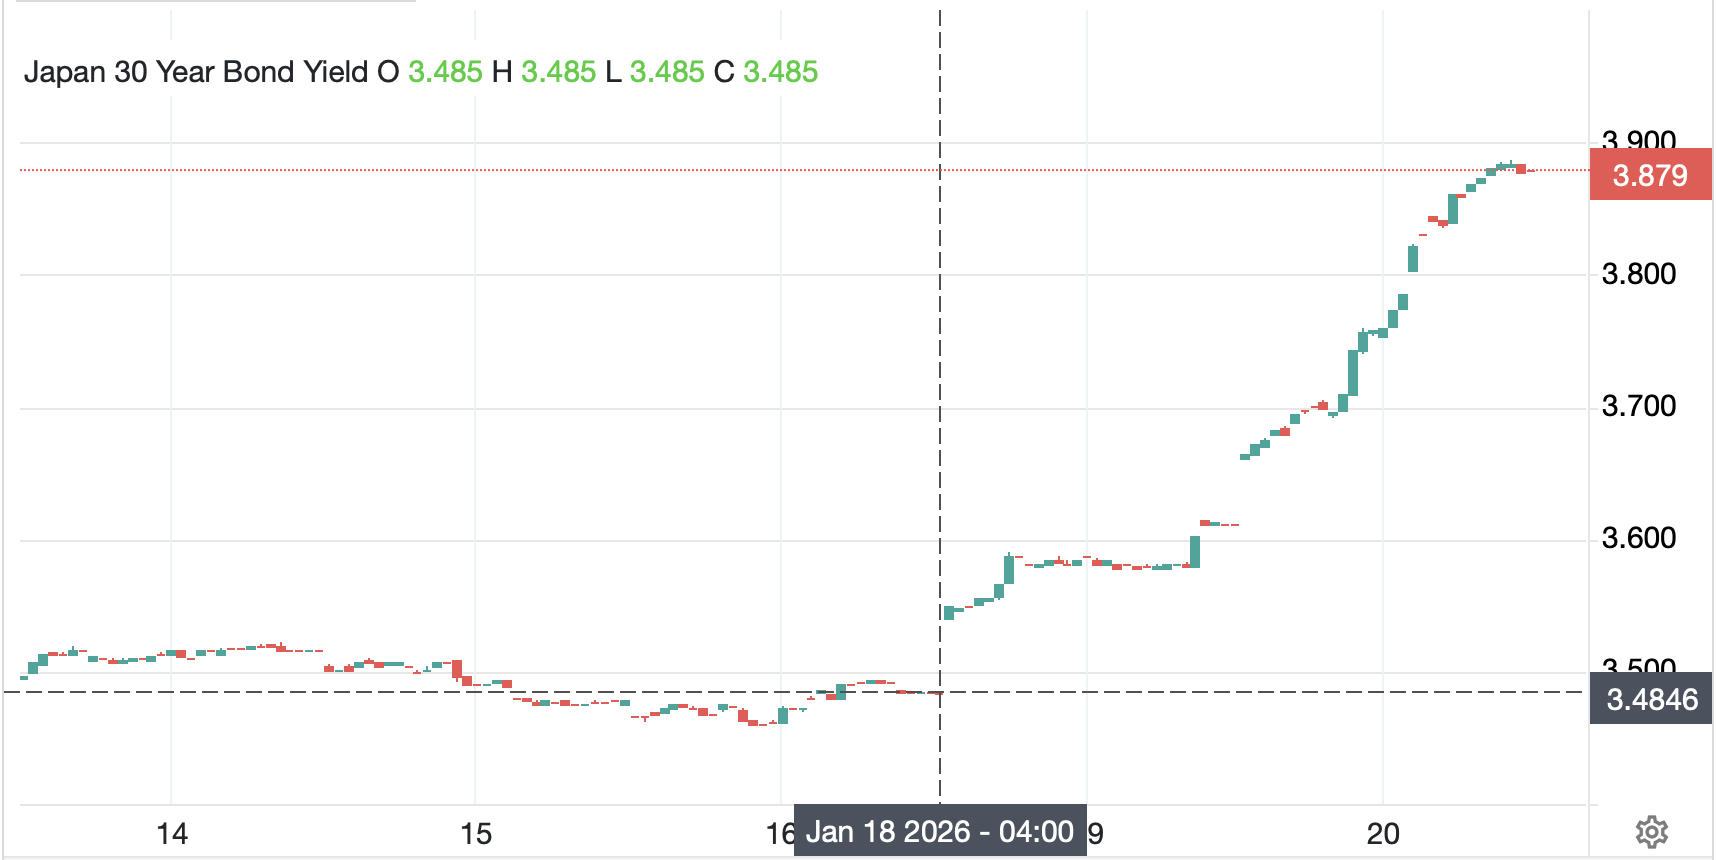
So, let’s review market activity overnight as we await President Trump’s comments, which I understand have been delayed until 11:30 EST this morning.  Yesterday’s sharp declines around the world have been followed by less dramatic activity last night and so far today.  In Asia, Tokyo (-0.4%) slipped a bit further, but hardly dramatically, as FinMin Katayama focused on the JGB market in comments made in Davos.  “Since last October, our fiscal policy has consistently been responsible and sustainable, not expansionary, and the numbers clearly demonstrate that.  I’d like everyone in the market to calm down.”  I’m sure she would.  And it worked with JGB yields slipping -8bps and 30yr yields falling -17bps.  Elsewhere in Asia, China was flat, HK (+0.4%) rallied a bit along with Korea (+0.5%) while Taiwan (-1.6%) led the way lower across numerous other regional markets.  

In Europe, red is today’s color led by Germany (-0.7%) and Spain (-0.5%) although France and the UK have both only ceded -0.1% so far during the session.  The discussion here continues to revolve around President Trump, the trade deal, and potential new tariffs on nations that try to prevent the US from its Greenland desires.  As to US futures markets, at this hour (6:45) they are slightly firmer, +0.1%, so not yet, at least, indicating the end of the American investment thesis.

As to the rest of the bond market, away from Japan, yields are basically -1bp lower across Treasuries and European sovereigns as investors await Mr Trump’s comments.  Again, the mooted collapse in the US bond market has yet to appear.  However, there is a popular meme about the Danish pension fund, Akademikerpension, which has announced that it will sell all its US Treasuries by the end of the month, a total of $100 million, due to its perception of increased credit risk.  This has been fodder, though, for those who continue to believe that Europe is going to ditch their Treasuries, and many are calling it a signal.  While certainly a trendy decision, I see it as noise, not signal.

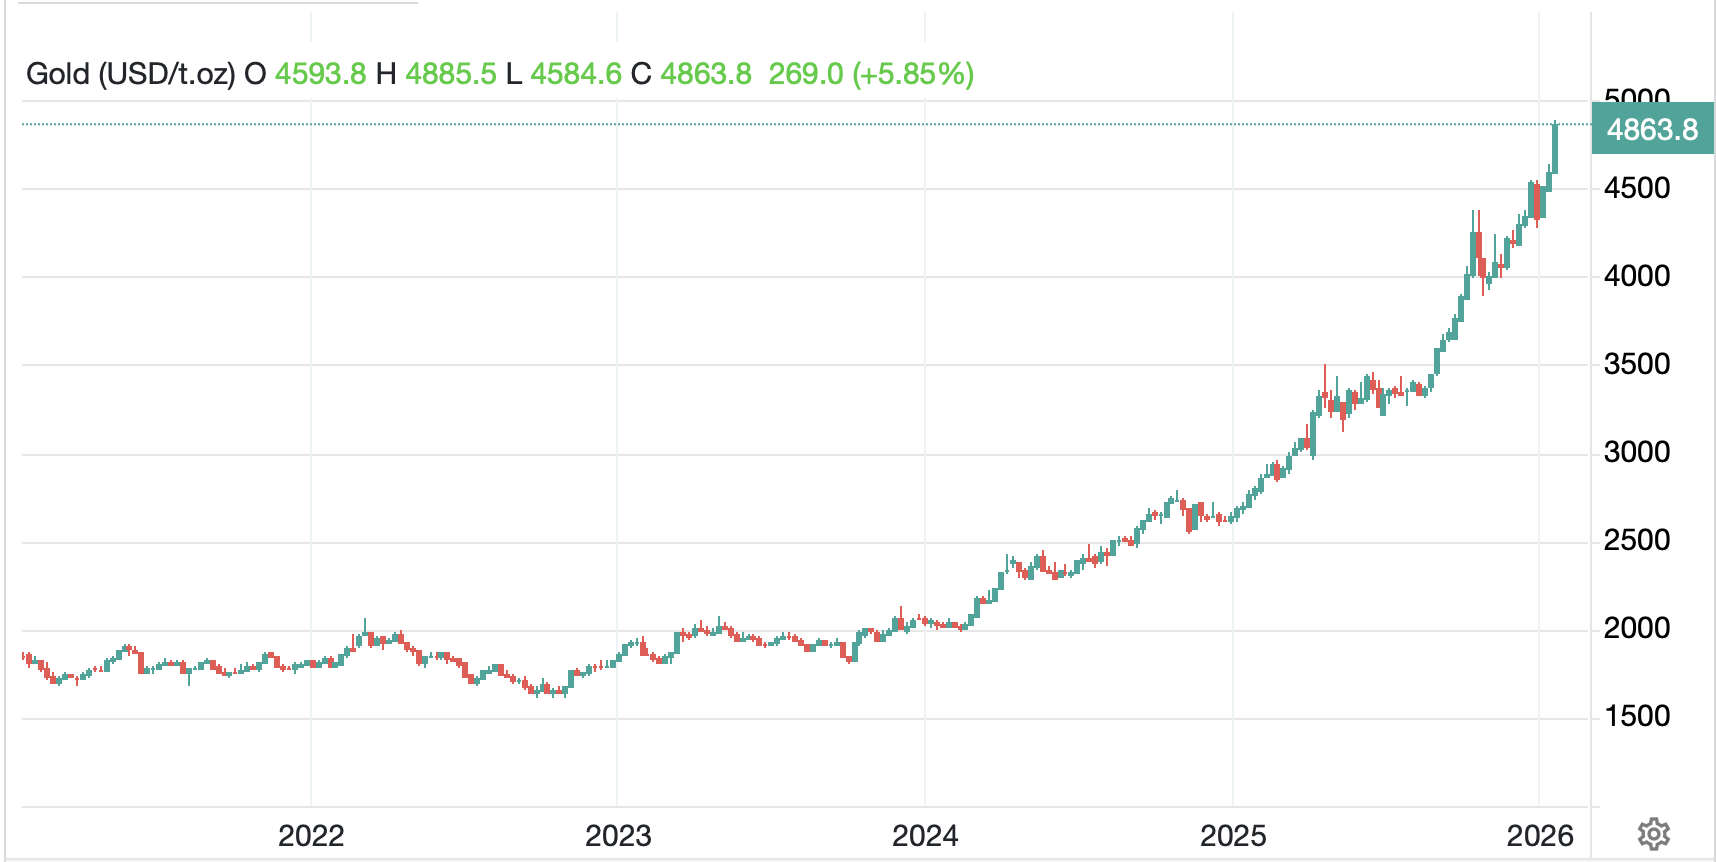
Turning to commodities, one cannot be but impressed with gold’s consistency of late.  It has risen another 2.1% this morning and is now nearing $4900/oz.  I guess $5000/oz is right around the corner.  Looking at the long-term chart below, we have seen a monster rally for the past two years.  
Source: tradingeconomics.com

FWIW, which may not be much, I continue to see this as a commentary on all fiat currencies, not the dollar per se as evidenced by the table I created from data on goldbroker.com.  While you can see that the dollar has definitely underperformed during the past year (which we already knew given the early year 10% decline vs. the euro and pound, over time, it is hard to make the case that other currencies are any better.  In fact, I find it particularly surprising that the rand has performed so poorly given its seeming benefits when gold rallies.  And of course, it is no surprise that the yen which has been having a really tough time, is the worst of the lot.

 Historical Returns of Gold 
Currency1 Month1Year5 Year10 Year
EUR9.54%54.22%164.28%300.85%
JPY10.02%76.45%288.91%481.02%
USD9.62%73.45%154.49%331.44%
GBP9.13%59.31%160.26%357.37%
MXN7.04%47.93%127.14%305.03%
ZAR7.35%53.89%179.88%327.69%

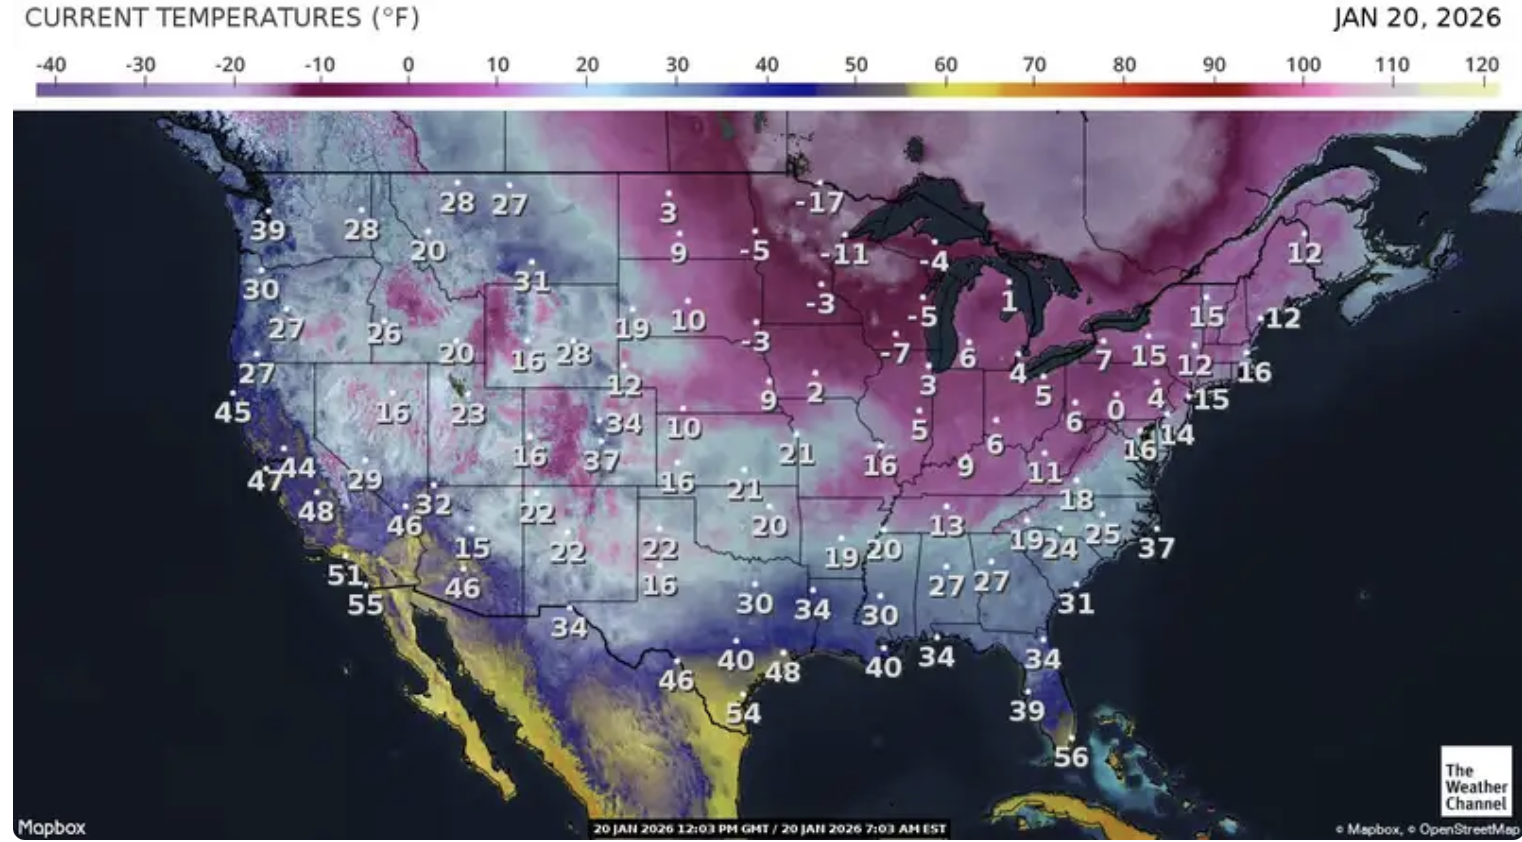
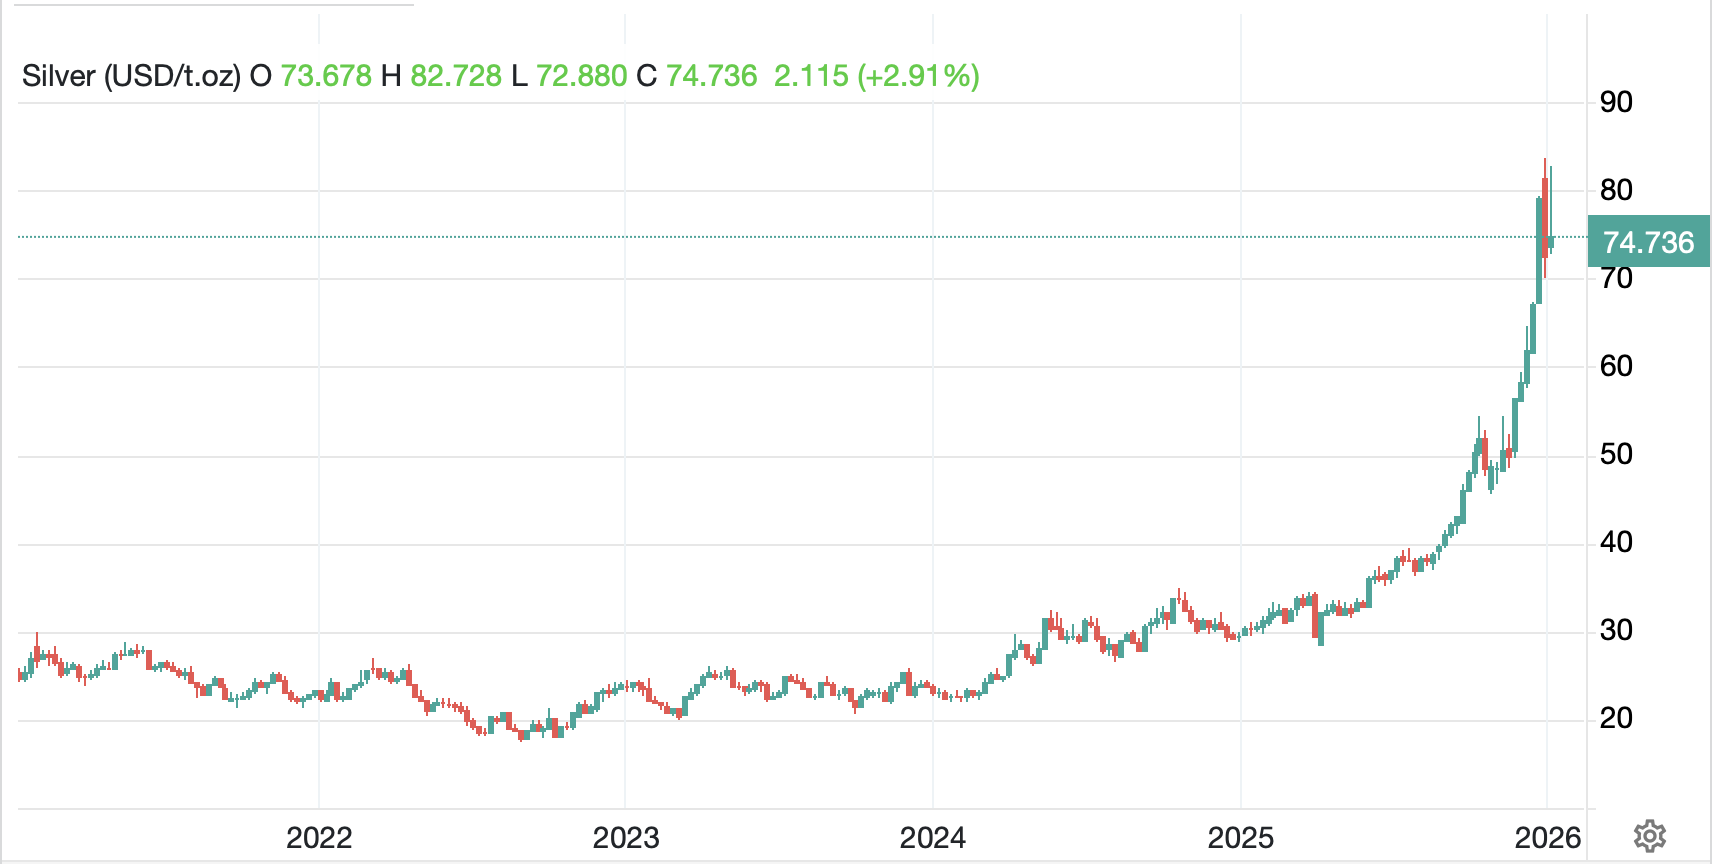
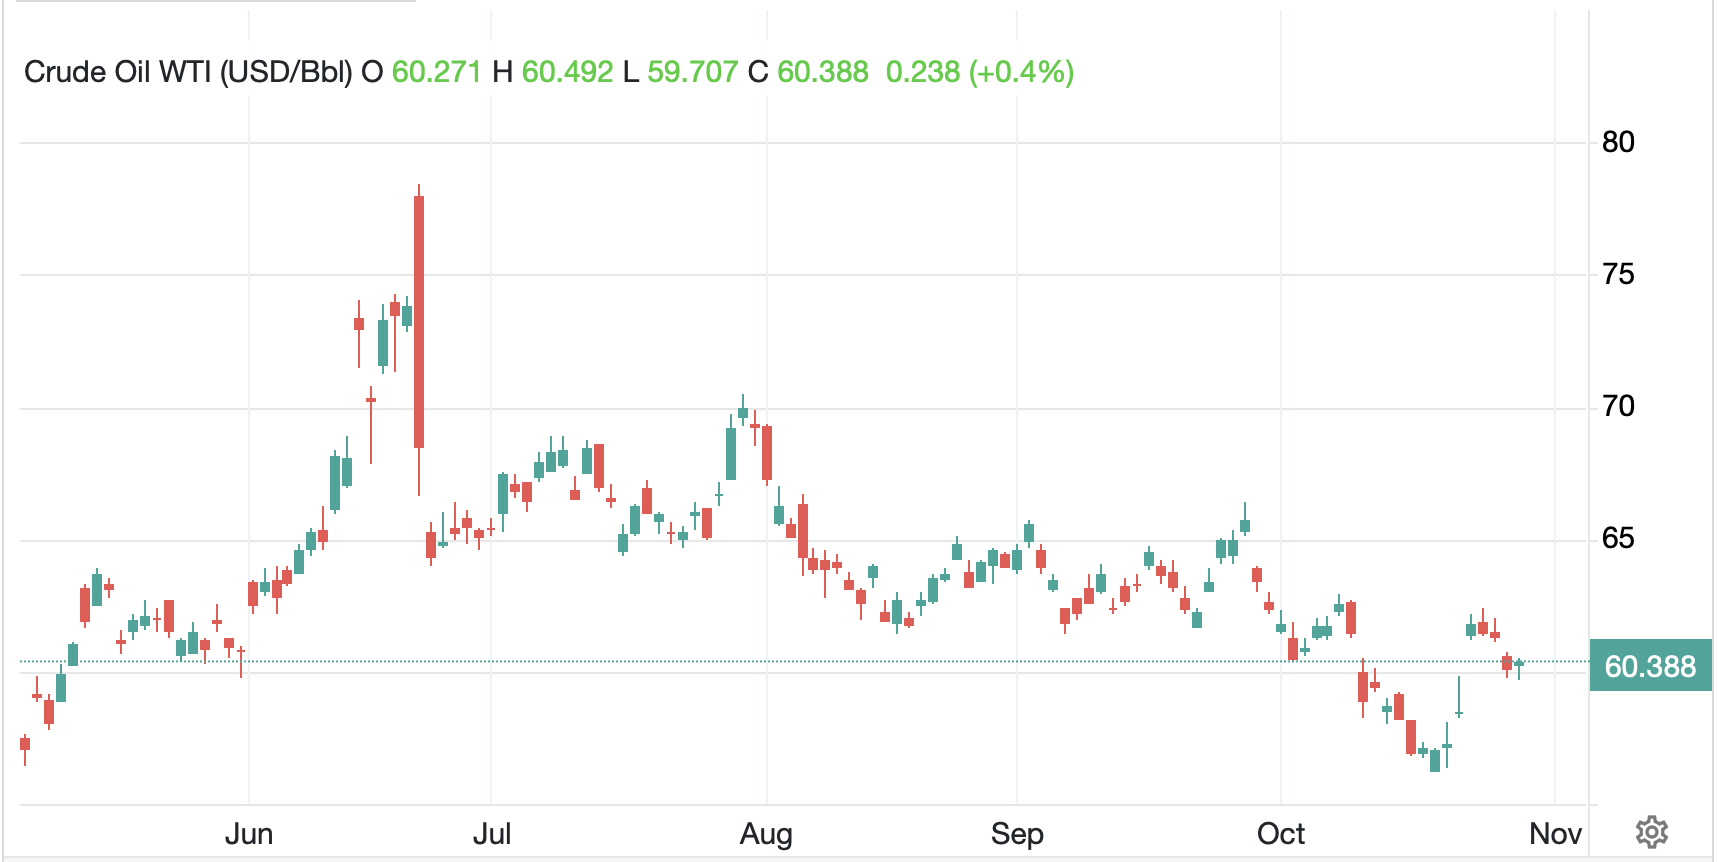
As to the other metals, silver (0.0%) seems to be getting tired after its move and has done little over the past several sessions.  Platinum (+1.0%) seems to still have life as does copper (+0.75%).  Turning to energy markets, oil (+0.3%) is trying to figure out whether the geopolitics is going to blow up or fade away and remains right around $60/bbl.  But given the temperature here in New Jersey is 1° this morning, we cannot be surprised that NatGas (+21.5%) has exploded (no pun intended) higher.

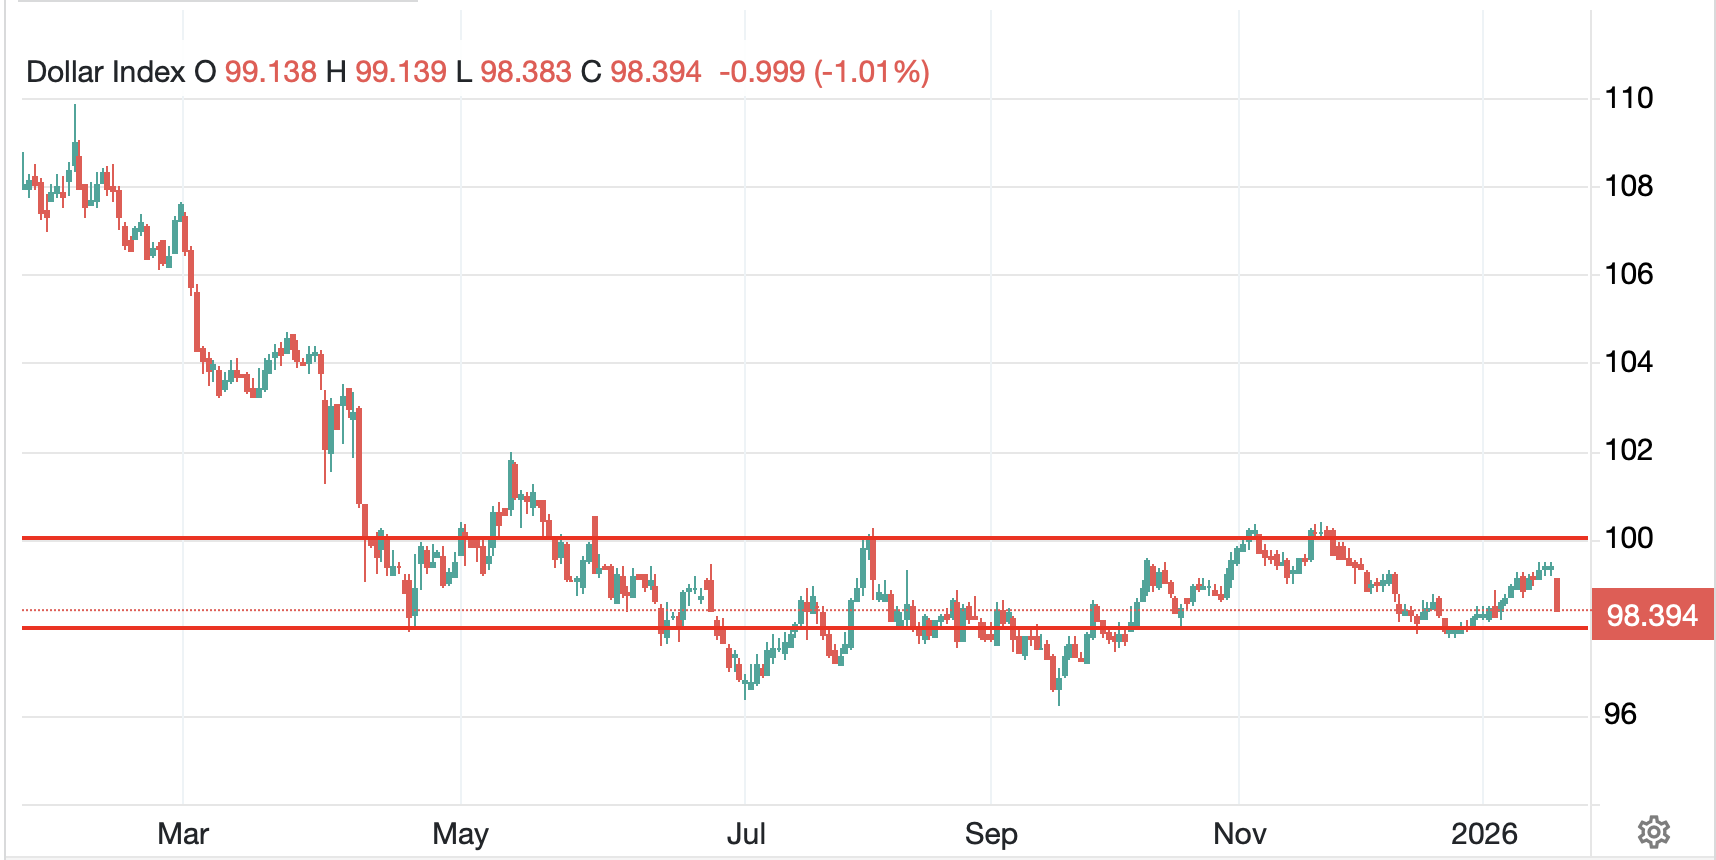
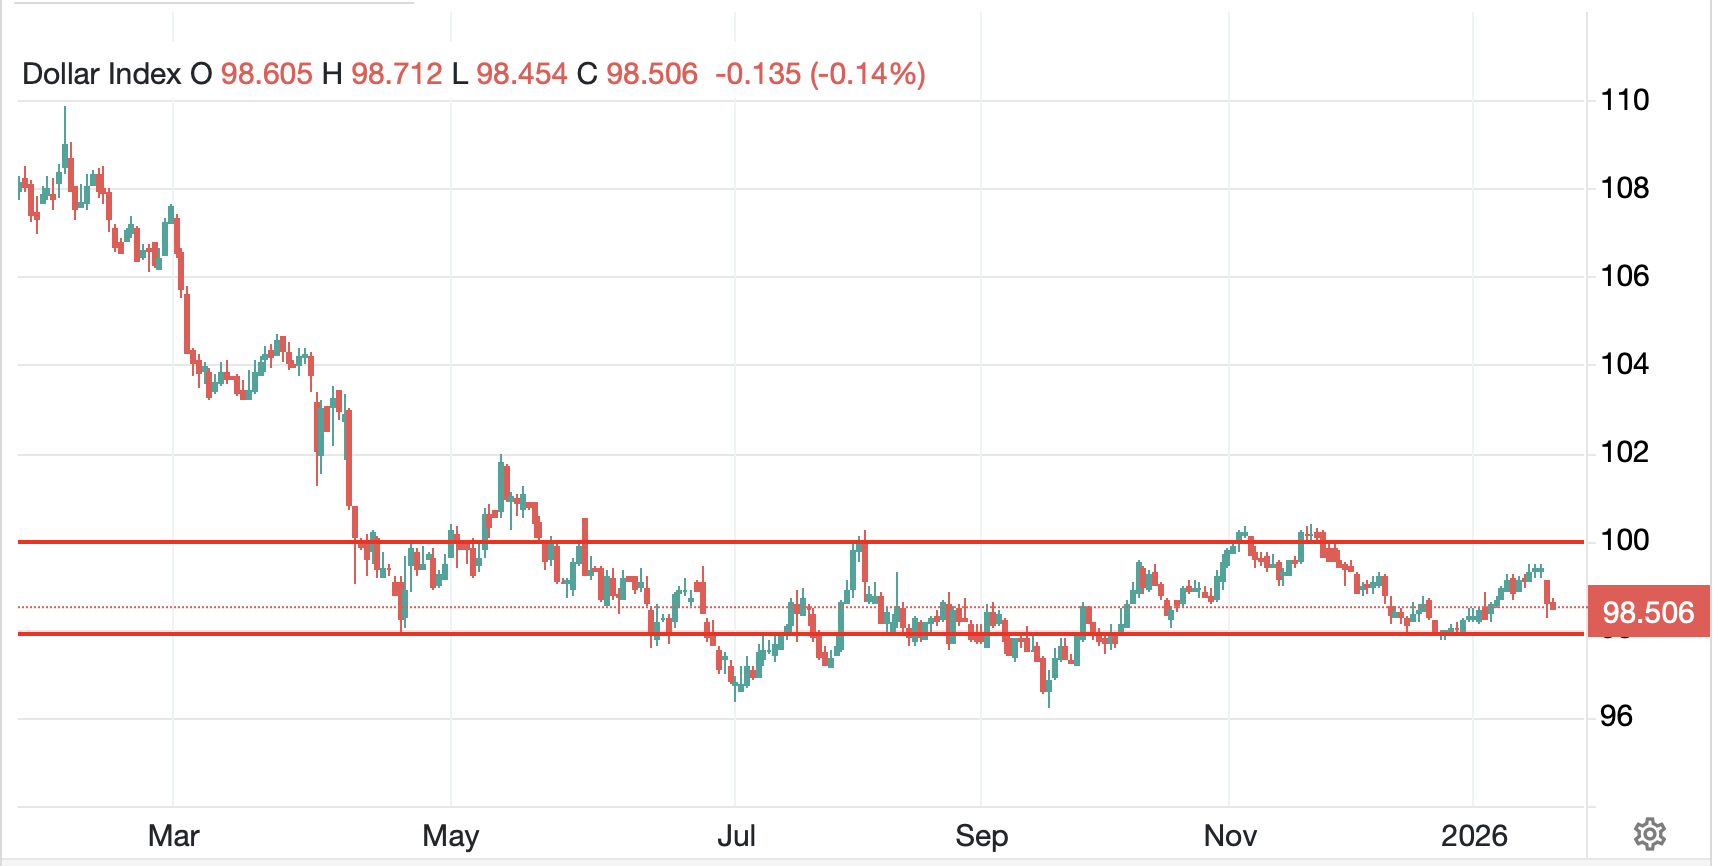
Finally, the dollar is a touch softer this morning, but not very much.  The euro is unchanged, and the pound, after some lousy inflation data, has fallen -0.2%.  But JPY (+0.2%) is offsetting that, arguably responding to FinMin Katayama’s comments, although elsewhere, KRW (+1.1%) rebounded after comments from President Lee Jae Myung sought to sooth investors and explain that the government would continue to work to boost economic growth with new policies.   But once again, my recent favorite chart of the DXY shows that this is not a USD story.
Source: tradingeconomics.com

On the data front, aside from the President’s speech today, nothing but tomorrow brings the real data.

ThursdayQ3 GDP4.3%
 Q3 Price Index3.7%
 Initial Claims212K
 Continuing Claims1880K
 Personal Spending (Nov)0.5%
 Personal Income (Nov)0.4%
 PCE (Nov)0.2% (2.8% Y/Y)
 Core PCE (Nov)0.2% (2.8% Y/Y)
FridayFlash PMI Manufacturing52.1
 Flash PMI Services52.8
 Michigan Sentiment54.0

Source: tradingeconomics.com

Don’t forget that next week the FOMC meets, but on the Fed story, today Governor Cook’s case about dismissal will be heard at the Supreme Court, which is, potentially, a much bigger deal.  If the Fed is not protected from Presidential authority, that will certainly change many views on the future, and likely initially, see the dollar and bond markets decline while stocks rally.  But that decision won’t come for months, and remember, we are still awaiting the tariff decision.

There is much we don’t know and volatility remains the most likely outcome.  Be careful out there.

Good luck

Adf
Most Enthralling

Some fractures are starting to show
In markets, as Trump’s blow by blow
Attack on the Danes
And friends, really strains
The view ‘Twenty-Six will lack woe
 
So, equities worldwide are falling
While bond yields, much higher, are crawling
The buck’s in a rut
While oil’s a glut
Thus, gold is the thing, most enthralling


Something is rotten in the state of Denmark.”  So said Marcellus, when Shakespeare introduced him to the world in 1603(ish) in one of his most brilliant works, Hamlet, and it seems true today, 423 years later.  By now, you are likely aware that President Trump has imposed 10% tariffs, to begin on February 1st, on Denmark, Norway, Sweden, France, Germany, Finland, the Netherlands and the UK as he presses his case for US ownership of Greenland.  This is not the venue to discuss the relative merits or pitfalls of the strategy, so I won’t bore you with my views on the subject.  

Rather, this is a venue to discuss the market impacts and how they may evolve, in one poet’s eyes, going forward given the new starting condition.  As I type this morning, investors around the world are extremely unhappy, at least holding paper claims on either assets or governments.  However, holding real assets, notably gold (+1.15% and at new all-time highs), silver (+0.9% and at new all-time highs) and platinum (+1.45%, not quite at new highs yet) are feeling much better.

It is interesting to me that the WEF is meeting this week, and likely no coincidence that President Trump escalated things ahead of the meeting where he is scheduled to speak tomorrow.  It seems that the protagonists in this latest drama are set to meet while in Davos as well, so all these views are subject to change at a moment’s notice.  But for now, since there really is no other story that matters, let’s look at how markets have (mis)behaved since we last saw them here in the US on Friday.

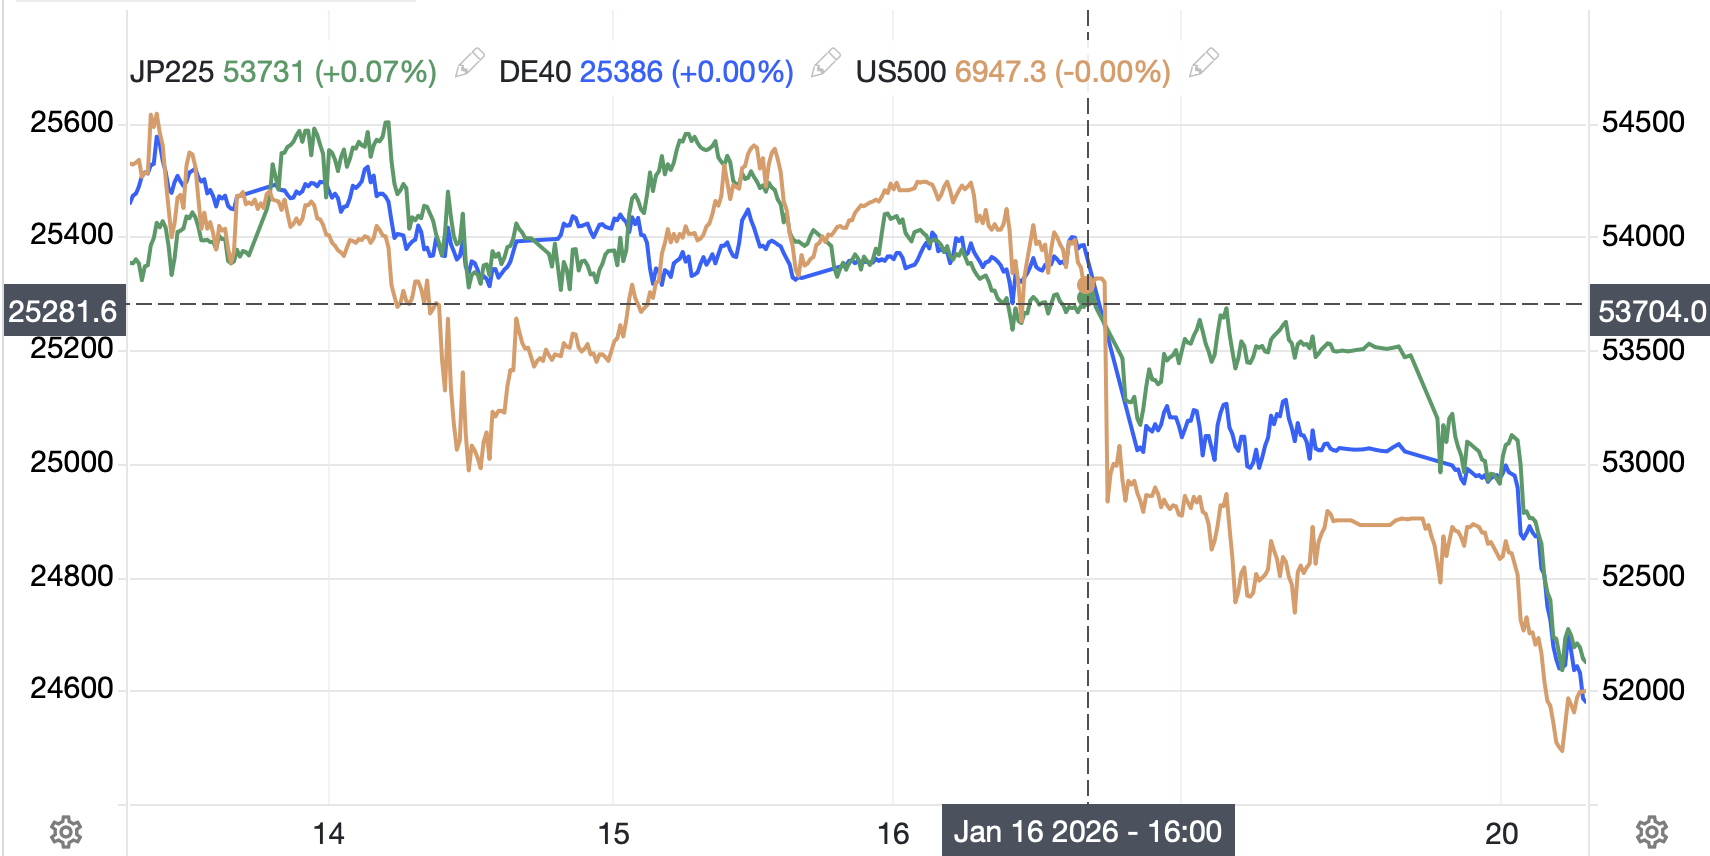
As you can see from the chart below combining the Nikkei 225, the DAX and the S&P 500 futures, the move has been consistent since the close in NY on Friday, with all three main indices lower by between -1.75% (Japan) and -3.1% (Germany), with the US (-2.1%) in the middle.  

Source: tradingeconomics.com

In fact, that price action has been widespread across the rest of the G10 markets and many EMG markets as well. Only China (-0.2% since Friday) has bucked the trend and remains little changed.  Of course, that makes sense given this spat has nothing to do with China, on the surface.  At this point, I expect that all equity markets are going to remain under pressure until there is some resolution.  While Europe has threatened to invoke its Anti-Coercion Instrument on the US if those tariffs come into being, one must wonder will that do more damage to the US or Europe?  FWIW, I expect some type of resolution to be achieved before the Feb 1 deadline but could easily be wrong about that.  One last thing about tariffs; remember last week when expectations were high that the Supreme Court was going to rule on the legality of the ones already imposed?  That has suddenly gone very quiet.  My take there is the longer we don’t hear anything, the more likely they are not going to stop them.

Perhaps, though, the bond market is the more interesting place to look this morning with government bonds around the world getting sold aggressively.  While all eyes have been focused on the US (+6bps and well above the top of the previous range) and Europe (Germany +5bps, UK +7bps, France +6bps) perhaps the real activity is happening in Japan (+9bps).  In fact, Japanese 30yr yields have exploded higher by 40 basis points since Friday’s close, and I’m confident that has nothing to do with Greenland!

Source: tradingeconomics.com

In fact, it appears that JGB holders are getting increasingly concerned that PM Takaichi is going to really run it hot, with more unfunded fiscal stimulus and are responding accordingly.  The latest Takaichi proposal for the upcoming election is that they are going to remove the GST (VAT tax) on food for 2 years to help alleviate inflation problems.  I certainly like that better than capping prices, but fiscally, it’s a tough road to follow.  

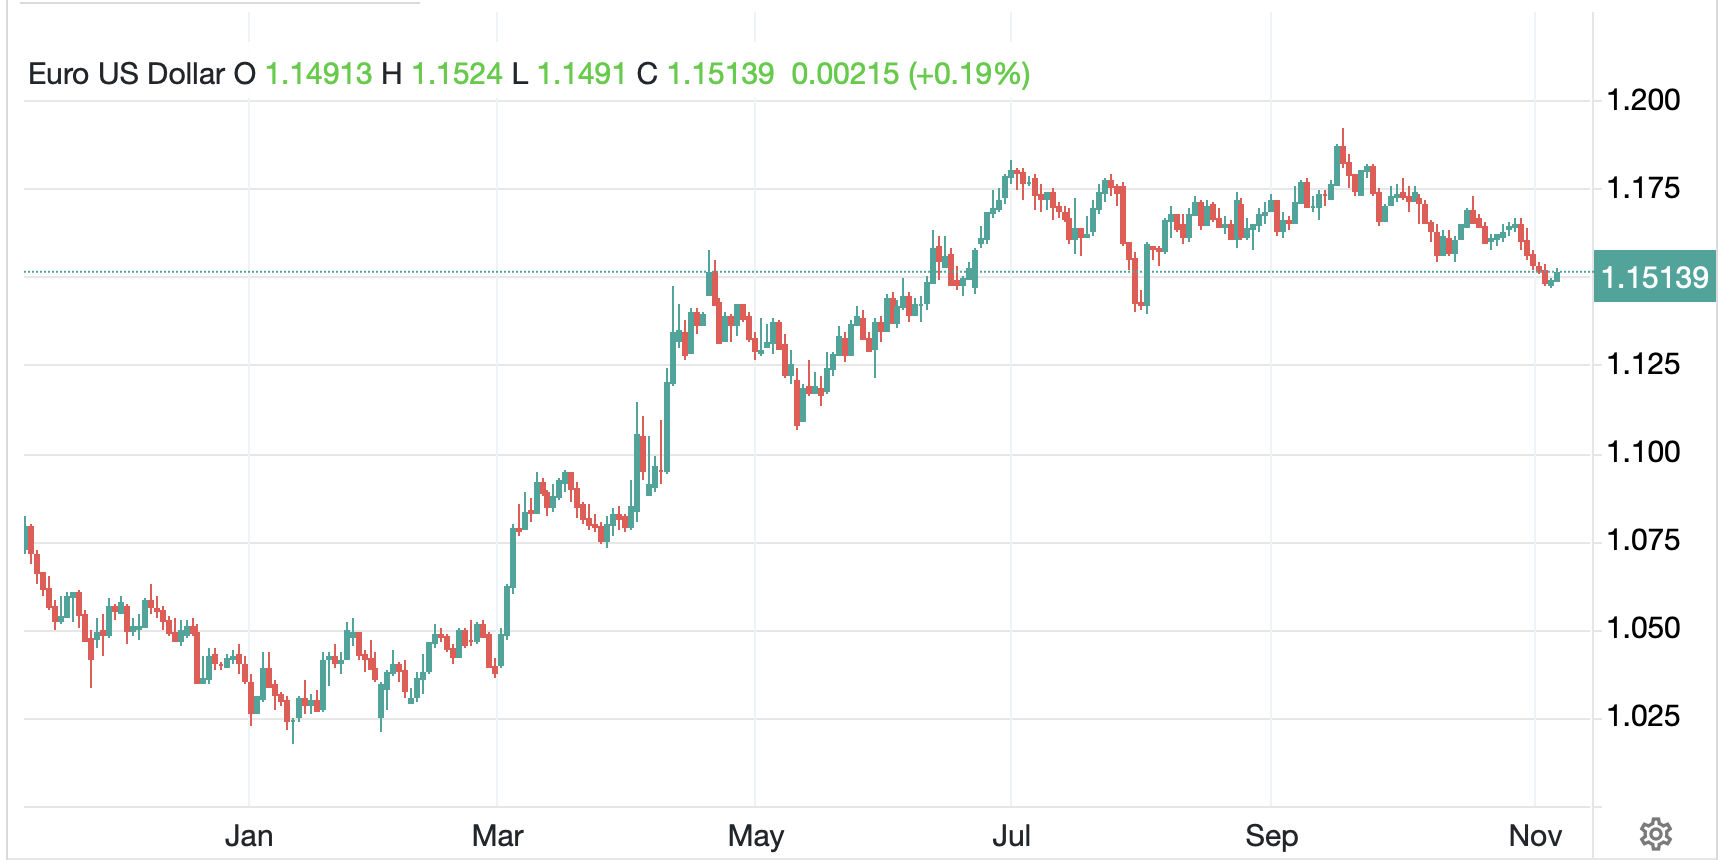
One other bond market story that is making the rounds is the idea that Europeans would attack the US by simultaneously unloading their US Treasury holdings.  We have heard this story before with respect to China, and if you look across all of Europe, between central banks and private investors, there are likely upwards of $2 trillion held there.  But the question I ask every time I hear something of this nature is…what will they do with the proceeds if they were somehow able to coordinate the sales?  First, in the worst case, the Fed would buy them to prevent the market from collapsing.  And second, now they would have a whole lot of dollars that need to be invested elsewhere.  Which markets can absorb that amount of flow?  US equities?  Sure, but would that achieve their goals?  I think not.  If they converted them into euros, a one-way flow of $2 trillion into euros in short order would pretty much render all European manufacturing uncompetitive right away as the euro rose to 1.50 or 1.60 or higher.  Gold?  Think $10k/oz or higher.  Ain’t gonna happen.

Let’s hit the dollar next, which is under pressure across the board.  As I type (7:20), the DXY has fallen -1.0% this morning, a very large move for that index, but remains within the trading range that we have seen since October.

Source: tradingeconomics.com

The sell-off in the dollar is almost universal, although interestingly, ZAR (-0.5%), MXN (-0.3%) and CLP (-0.3%) are all bucking that trend.  I understand the nervousness, but it strikes me that none of this conversation is a positive for Europe, excepting the idea they sell all their Treasuries and convert the dollars into euros and pounds, an idea I tried to squash above.  

Finally, let’s look at commodities where the metals, as discussed above are soaring while oil (+0.8%) is picking back up off its end of week lows and currently sits just below $60/bbl.  The Iran situation remains murky, at best, and my sense is we have not heard the last of the situation there, although from what I have seen on X, the rioting has been quelled to some extent.  However, I think there is still enormous pressure on the government there and would not be surprised to see some type of US intrusion. 

But I’m confident the one thing almost all of you are feeling this morning is the bitter cold that has enveloped most of the US as per the weather.com map below.

Given natural gas is the most common fuel for heating homes, we cannot be surprised that its price has skyrocketed today, jumping 24% in the session so far, although it is now simply back to where it was this time last year.  however, a key issue in this market is Europe, which since they virtually shut off Russian gas, is now highly reliant on US LNG to heat their homes.  It turns out that their storage has fallen to slightly less than 50% of capacity, well below their average storage level for this date of 60% – 65%.  European TTF gas, on a like for like basis, currently costs ~$12.25/MMBtu compared to $3.85/MMBtu in the US, even after the massive jump.  Again, Europe has some issues going forward.

On the data front, there is really nothing today or tomorrow of note although Thursday brings GDP amongst other things.  I will review them tomorrow because, after all, markets right now are far more beholden to President Trump and Europe than to data.

Fear is growing more widespread and will likely continue to do so until there is some type of resolution over Greenland.  But then, it will dissipate quickly as consider, two weeks ago we were all Venezuela experts and today, nobody even cares about that nation anymore!

As to the dollar, I expect that when the resolution arrives, the dollar will make up lost ground, but given we are in the midst of a White House bingo game, one needs to play things close to the vest.  Hedges are crucial here.

Good luck

Adf
Too Potent a Force

The headline today’s NFP
As pundits will try to agree
On whether the Fed
When looking ahead
Will like what it is that they see
 
But, too, the Supreme Court is due
To rule whether tariffs imbue
Too potent a force
For Trump, to endorse
Or whether they’ll let them go through


As the session begins in NY, markets have been relatively quiet as traders and algorithms await the NFP data this morning.  Recall, Wednesday’s ADP number was a touch softer than forecast, but still, at 41K, back to a positive reading.  Forecasts this morning are as follows:

Nonfarm Payrolls60K
Private Payrolls64K
Manufacturing Payrolls-5K
Unemployment Rate4.5%
Average Hourly Earnings0.3% (3.6% y/Y)
Average Weekly Hours34.3
Participation Rate62.6%
Housing Starts1.33M
Building Permits 1.35M
Michigan Sentiment53.5

Source: trading economics.com

Regarding this data point, there are two things to remember.  First, last month Chairman Powell explained that he and the Fed were coming to the belief that the official data was overstating reality by upwards of 60K jobs due to concerns over the birth/death portion of the model.  That is the factor the BLS includes to estimate the number of new businesses started vs. old ones closed in any given month.  Historically, at economic inflection points, it tends to overstate things when the economy is starting to slow and understate when it is turning up.  

The second thing is that given the changes in the population from the administration’s immigration policy, with net immigration having fallen to zero recently, the number of new jobs required to maintain solid economic growth is much lower than what we have all become used to, which in the past was seen as 150K – 200K.  So, 60K, or even 40K, may be plenty of new jobs to absorb the growth in the labor market, which will come from people re-entering the market who had previously quit looking for a job.

The ancillary data, like ADP and the employment pieces of ISM were both stronger in December than November, so my take is, the estimates are probably reasonable.  I have no strong insight into why it would be dramatically different at this point.  The question is, how will markets respond?  My take is this could well be a ‘good news is bad’ situation where a strong print will see pressure on bonds and stocks as the market reduces its probability of a Fed rate cut (currently 14% for January, 45% for March) even further.  The dollar would benefit, as would oil on the demand story, but I think metals will do little as that story is not growth oriented.  A weak number would see the opposite.

Of course, the other big potential news today is the Supreme Court ruling on the legality of Trump’s tariffs.  The odds markets are at ~70% they will overturn them, but there is the question of whether it will require the government to repay the tariffs or simply stop them.  As well, most of them will be able to be reimposed via different current laws, so net, while a blow to the administration I don’t believe it will have a major long-term impact with repayment the biggest concern.  This particular issue is far too esoteric for a simple poet to prognosticate.

And those are the market stories of note, although we cannot ignore the growing protests in Iran as videos show buildings burning in Tehran and there is word that the Mullahs are at the airport, which if true tells me that the regime is on the edge.  While this would be a great victory for the people of Iran, it would also have a dramatic impact on oil markets and specifically on China.  While sanctions could well be lifted, thus depressing the price as more comes to market, China currently benefits from buying sanctioned oil at a massive discount, and that discount would disappear.

As we await all the news, let’s review the overnight activity.  A mixed US session was followed by strength in Tokyo (+1.6%) as the Japanese government surprised one and all by reporting a stronger 30-year JGB auction than anticipated as well as an uptick in spending by households.  Too, nominal GDP growth has been outpacing deficit growth driving the net debt ratio lower, exactly what the US is seeking to do.  As to the rest of the region, both China (+0.45%) and HK (+0.3%) managed gains, as did Korea and Malaysia but India (-0.7%) continues to lag as it has all year.  Data from China showed inflation fell less than expected, although the Y/Y number remains at just 0.8%.

In Europe, gains are also the norm with France (+0.9%) leading the way with both the UK (+0.55%) and Germany (+0.4%) having solid sessions.  Retail Sales data from the Eurozone was firmer than expected at 2.3%, a rare positive outcome, but showing some support.  As to the US futures market, at this hour (7:30) all three major indices are higher by about 0.15%.

In the bond market, while yields have edged higher by 2bps this morning, as you can see from the chart below, they remain within, albeit at the top, of the recent 4.0% – 4.2% trading range.  

Source: tradingeconomics.com

The most interesting data point from yesterday was the dramatic decline in the Trade deficit, which fell to -$29B, its lowest level since 2009.  Recall that a long-time issue has been the twin deficits, with the budget and trade deficits linked closely.  I wonder, are we going to see Trump’s efforts at reducing government’s size and reach result in a smaller budget deficit?  Most pundits dismiss this idea, but I’m not so sure.  As to the rest of the world, European sovereigns are essentially unchanged this morning as investors everywhere await the US data and tariff ruling.

In the commodity markets, oil (+0.9%) is creeping higher but remains in its downward trend.

Source: tradingeconomics.com

Wednesday, we saw a large draw in crude inventories abut a massive build in both gasoline and distillates which feels mildly bearish.  The narrative is the Iran story is getting people nervous for potential short-term disruption, but I remain overall bearish for now.  As to the metals markets, gold (-0.3%) is slipping after having recovered early morning losses yesterday and finishing higher, while silver (+0.6%) is still bouncing along with copper (+1.8%) and platinum (+0.4%). Metals are in demand and supply is short.  Price here have further to rise I believe.

Finally, the dollar continues to rebound off its recent lows with the DXY back to 99 again this morning.  it has rallied in 11 of the past 13 sessions, not typical price action for a trading vehicle that is in decline.

Source: tradingeconomics.com

In fact, the greenback is firmer against virtually all its G10 and EMG counterparts this morning with the largest declines seen in JPY (-0.5%), KRW (-0.5%) and NZD (-0.5%) with others typically sliding between -0.1% and -0.3%.  again, it is hard to watch recent price action and see impending weakness.  We will need to see much weaker US data to change my view.  And along those lines, the Atlanta Fed’s GDPNow number just jumped to 5.4% for Q4 after the Trade data yesterday, again, atypical of further weakness in this sector.

And that’s really all as we covered data up top.  To me, the wild cards are Iran and the USSC.  While I do believe the regime will fall in Iran (they just shut down the internet to try to prevent a further uprising) my take on the Supremes is they may stop further tariffs but will not force repayment.  Net, that won’t change much at all and given the prediction markets are pricing a 70% probability of an end to tariffs, if it happens, it’s already in the price!

Good luck and good weekend

adf

Spinning More Heads

The speed of the change underway
In global relations today
Is spinning more heads
And tearing more threads
Than ever before, one might say
 
For markets, the question of note
Is how will investors all vote
Are bulls still in charge
Or bears now at large
Who seek, excess profits, to smote


It is becoming increasingly difficult to focus only on market activity given the extraordinary breadth of important, non-market activities that are ongoing.  When I think back to previous periods of significant market volatility and uncertainty, it was almost always driven by something endogenous to finance and the economy.  Going back to Black Monday in 1987, or the Thai baht crisis in 1997 or the Russia Default in 1998, the dot-com crash in 2000, and the GFC in the wake of the housing bubble (blown by the Fed) in 2008-09, all these periods of significant market volatility were inward looking.

But not today.  Trump 47 has become the most significant presidency since Ronald Reagan with respect to changing both domestic and international realities.  The key difference is that Mr Reagan worked within the then consensus view of international relations, merely pushing them to the limit while Mr Trump sees those views as constrictions needing to be removed.

In fairness, the world was a very different place in the 1980’s, notably for the fact that China was not a major player in any sphere of economic activity and was essentially ignored.  That is no longer the situation, and the entry of another power player has complicated things.  Arguably, this is why the president sees the old rules as obsolete, they were built for a different time with a different cast of characters.  Regardless, for those of us paying attention to markets, it is imperative to widen our view to include international relations as well as international finance.

With that as preamble, a look at today’s headlines reminds us that keeping up with the news is not for the faint of heart.  Starting with Venezuela and the impact on oil (+1.6%), news sources are littered with articles explaining why the US acted as we did and the potential implications for energy markets and energy producing countries.  From what I can tell, Venezuela recognizes that they are completely beholden to US demands at this point with respect to their oil industry (mining as well I presume although that gets less press).  And you can be sure that means they will be expected to pump more, with US corporate help, and direct their sales to the US, as opposed to Cuba, China and Iran.

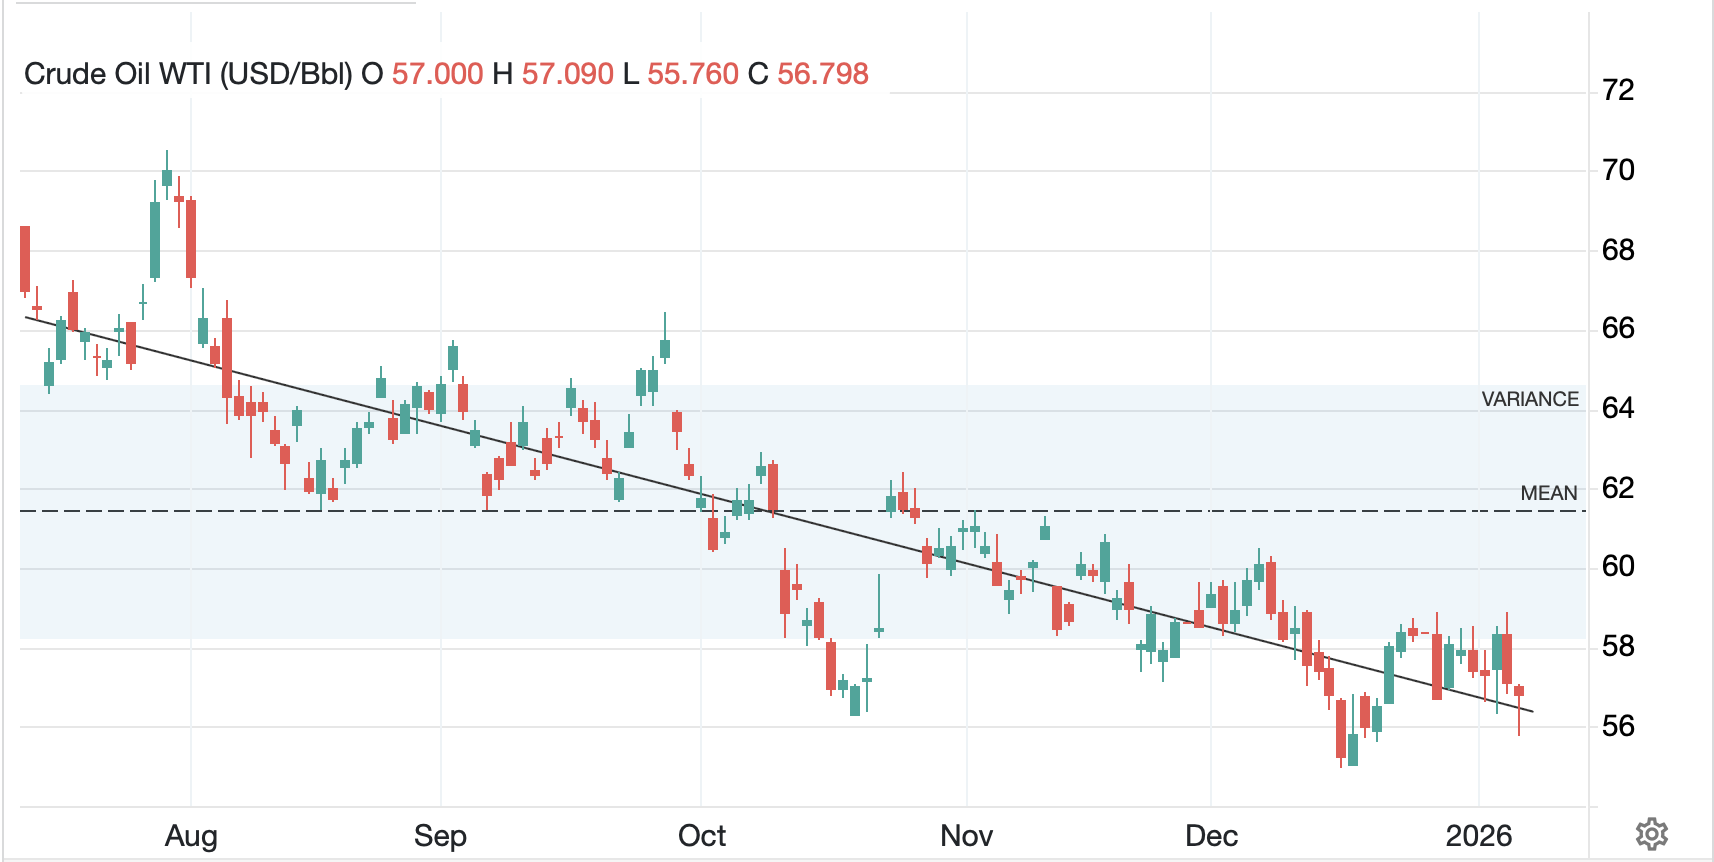
Despite today’s rally, it remains my strong opinion that the price of oil has further to decline.  The trend continues to be sharply lower, as per the below chart, and the domestic political demand of reducing gasoline prices is going to keep this particular trend intact, I believe.

Source: tradingeconomics.com

News overnight indicated that two more shadow fleet tankers have been apprehended which is simply all part of the same plan, bring Venezuela back online legitimately with a focus to sell to the US.  The other global issue that is going to weigh on the price of oil are the ongoing protests in Iran which if ultimately successful at overthrowing the Ayatollah’s theocracy, will almost certainly bring Iran back into the brotherhood of nations, and see the end of sanctions on Iranian oil.  While that is bad news for China (and India) who buy a lot of cheap sanctioned oil, it will increase production and weigh on market prices.

The other sector of the commodity markets, metals, have been their own roller coaster of late, with far more volatility than any other product, cryptocurrencies included.  It cannot be a surprise that we are seeing prices retrace after the extraordinary price action over the past several months.  The silver (-4.4%) chart below is the very definition of a parabolic move and history has shown that moves of this nature tend to see, at the very least, short-term sharp reversals, even if the ultimate trend is going to continue.  

Source: tradingeconomics.com

The underlying features in these markets remain supply shortages, meaning that there is more industrial demand for utilization than there is new supply that comes to market each year.  In silver, the number apparently is ~100 million ounces, and deliveries of physical metal remain the norm these days.  That is a telling feature of the market as historically, cash settlement was sufficient.  Given the recent run, it is no surprise that gold (-0.8%) and platinum (-6.5%) are also declining sharply, but nothing has changed my view that these will trend higher this year.  One last thing about silver (h/t Alyosha), the Bloomberg commodity index (BCOM) is rebalancing next week and given the huge moves in precious metals, along with the lack of change in percentage allocation, there will be significant selling over the course of the next week, upwards of 70 million ounces of silver, which will go a long way to satisfying the shortage this year.  It will be interesting to see if demand remains intact. 

If we turn to the dollar, rumors of its death remain exaggerated.  Certainly, the price action thus far this year, and even over the past six months, points to gradual strength (see chart below from tradingeconomics.com).

Again, I have a hard time understanding the argument that the dollar will decline this year based on the fact that the US economy continues to outperform the rest of the G10, there are substantial inward investment promises that are beginning to be seen (shipbuilding, semiconductors, steel) and the US interest rate structure remains higher than the rest of the G10.  While I understand markets look forward, it is becoming increasingly difficult for me to see the benefits of European monetary policy as a driver for owning the euro, and given their industrial/energy policies are disastrous, I don’t see the rationale.  The same can be said for the pound, I believe.

In today’s session, while the movement is mostly marginal (EUR 0.0%, GBP -0.1%, SEK -0.3%, AUD -0.4%), the trend remains intact and the movement is broad with almost all G10 and EMG currencies slipping a bit further.  Money goes where it is best treated, and I am hard pressed to find other nations that treat money better.  Although…

The equity markets are a bit shakier this morning after two presidential tweets yesterday regarding institutional ownership of housing (he wants to end that for single family homes) and defense company spending priorities (he wants defense companies to end stock buybacks and dividends and invest in R&D and production).  It is not clear to me whether he can successfully force these actions, but his bully pulpit is significant.  These resulted in sharp declines in directly impacted companies, but regarding defense, he also came out of a meeting with Congressional leaders and said he wants to budget there to grow to $1.5 trillion.  

The upshot is confusion here which was evidenced by more weakness than strength in the US session and similarly, declines in Asia (Japan -1.6%, China -0.8%, HK -1.2%).  Elsewhere in the region, India (-0.9%) continues to be the laggard, but there was more red than green overall.  In Europe, red is also today’s color, albeit not as bright as in Asia.  The DAX (-0.2%), CAC (-0.25%) and FTSE 100 (-0.3%) are emblematic of the situation as investors dismissed better than expected German Factory Order data (+5.6%) although the rest of the data released was mostly at expectations.  I guess the question is does Europe treat money better than the US?  I would argue not, but that’s just my view.  Meanwhile, at this hour (7:55), US futures are down slightly, about -0.1% across the board.

Finally, the bond market remains an afterthought almost everywhere.  Perhaps the most amazing thing President Trump has accomplished is to remove the focus on the latest tick in the 10-year bond as a key metric for the economy.  So, this morning, its 1bp rise just leaves it right in that 4.0% – 4.2% range that has existed for months.  Most European sovereign yields edged higher by about 3bps with Germany (+7bps) the outlier here after that strong Factory Orders data.  Also worth noting is that JGB yields slipped -5bps overnight as the market prepares for the first 30-year JGB auction of the year.  Recent 10-year auctions have been received quite well, hence the anticipation of something good here.

On the data front, Initial (exp 210K) and Continuing (1900K) Claims lead the way along with the Trade Balance (-$58.9B) and then Consumer Credit ($10.0B) this afternoon.  Yesterday’s ADP data was a touch softer than expected but the JOLTS data was much worse, showing a decline in job openings of 300K and falling well short of expectations of 7.6M.  At this point, though, to the extent that people are paying attention to the data, tomorrow’s NFP is of far more import I believe.  

The hardest thing about these markets is the White House bingo card and its surprises that can change working assumptions.  Absent something new there, I see the dollar drifting higher helped by both its recent trend and the short-term pullback in metals.  

Good luck

Adf

The Doctrine, Donroe

There once was a time in the past
When Vene-zu-ela was cast
As queen of the ball
With Maduro’s fall
But life around Trump moves so fast
 
He’s already moved to expand
His target to Denmark’s Greenland
The EU’s gone crazy
And called Trump fugazy
While claiming that they’ll take a stand
 
But really, the Doctrine, Donroe
Explains that the US most grow
Its regional strength
And keep at arm’s length
It’s foes from Beijing to Moscow


It is truly difficult to keep up with all the things that are ongoing in the world these days as so much is happening so quickly.  It is very easy to understand Lenin’s quote, “there are decades where nothing happens; and there are weeks where decades happen” given recent events.  This is clearly one of the latter weeks.

So, Trump, after successfully taking down Maduro has turned his sights on Greenland, something he has discussed from Day 1 of this administration, but apparently now, there seems to be a willingness to discuss things on the other side.  At the same time, from what I read on X, the city of Abadan in Iran has basically ‘fallen’, at least with respect to the Iranian regime’s control as the police are marching with the protestors now.  The rumors are that the Ayatollah has already made escape plans to Moscow.

From a geopolitical perspective, if Iran sees a regime change, which appears increasingly likely, and if the US throws its support behind the replacement regime, it would appear to be a significant power play against China.  After all, if sanctioned Iranian and Venezuelan oil was no longer being sold on the cheap to China, two places where they receive a significant amount of their daily requirements, (between 20% – 25% according to Grok) it would be a major blow.  

But from our lens in markets, if the Iranian regime falls and sanctions are lifted, suddenly there is much more unsanctioned oil available, and its price is likely to decline further.  This morning, oil (-0.6%) is slipping further after a sharp decline yesterday with Monday’s rally a wispy memory.  I have maintained the trend here remains lower, and that was without government changes in sanctioned nations.  As you can see from the chart below, nothing about this story has changed.

Source: tradingeconomics.com

In the meantime, be prepared for all those who had just shown their new bona fides about Venezuela to be explaining the Greenland story from their newly acquired “deep” knowledge.  This poet certainly doesn’t know enough about Greenland to make any prognostications, but it would not surprise me if within a matter of weeks, we reach an accord with the territory where the US plays a much greater role in its activities while increasing its military presence on the island.  

And to think, we are just finishing the first week of 2026.  Do not be surprised if, as the year progresses, there are more government changes in Europe as the current leadership there has been shown to be weak and ineffective, and an increasing number of people are unhappy with the situation.  While fears over the fall of NATO are rife now, if Germany, France and the UK wind up having snap elections, a distinct possibility at this point, and the new regimes are AfD, RN and Reform UK led, there could well be much greater agreement on the way forward for the alliance.

However, like most of you, I am neither a politician nor geopolitical analyst, I’m just a poet who watches the world and tries to make sense of how it impacts markets.  So, let’s go down that road.

After another strong equity session in the US, where both the DJIA and S&P 500 made new all-time highs, the story in Asia seemed to be one of some early profit-taking after strong rallies.  So, Japan (-1.1%), China (-0.3%) and HK (-0.9%) all slipped during the session with generally less excitement seen overnight than earlier in the week.  India (-0.1%) continues to lag, and while Korea (+0.6%) managed to maintain its upward momentum, the rest of the region was relegated to +/- 0.4% or less in their movement.  

As to Europe, only the DAX (+0.6%) is showing any positivity this morning, mostly on defense names still performing well, while the UK (-0.6%) is lagging after weaker than expected Construction PMI data (40.1 vs. 42.5 exp) and the rest of the continental bourses are little changed overall.  Eurozone inflation was confirmed at 2.0%, cementing the idea that the ECB will remain on hold, so I suspect opportunities here will rely on global trends.  As to US futures, at this hour (7:10) they are mixed, but with movement less than 0.2% in either direction.

In the bond market, yields are sliding around the world, perhaps on the understanding that oil prices are likely to slide given the potential for new, unsanctioned supply hitting the market.  Certainly, there is no indication that government spending anywhere in the world is going to slow down, so that avenue is still closed.  But, recapping, Treasury yields (-3bps) are not declining as much as most of Europe (-4bps to -5bps) or the UK (-8bps after the weak data).  I continue to believe that this year is going to be extremely dull in bond land as central bank support is going to offset additional issuance.

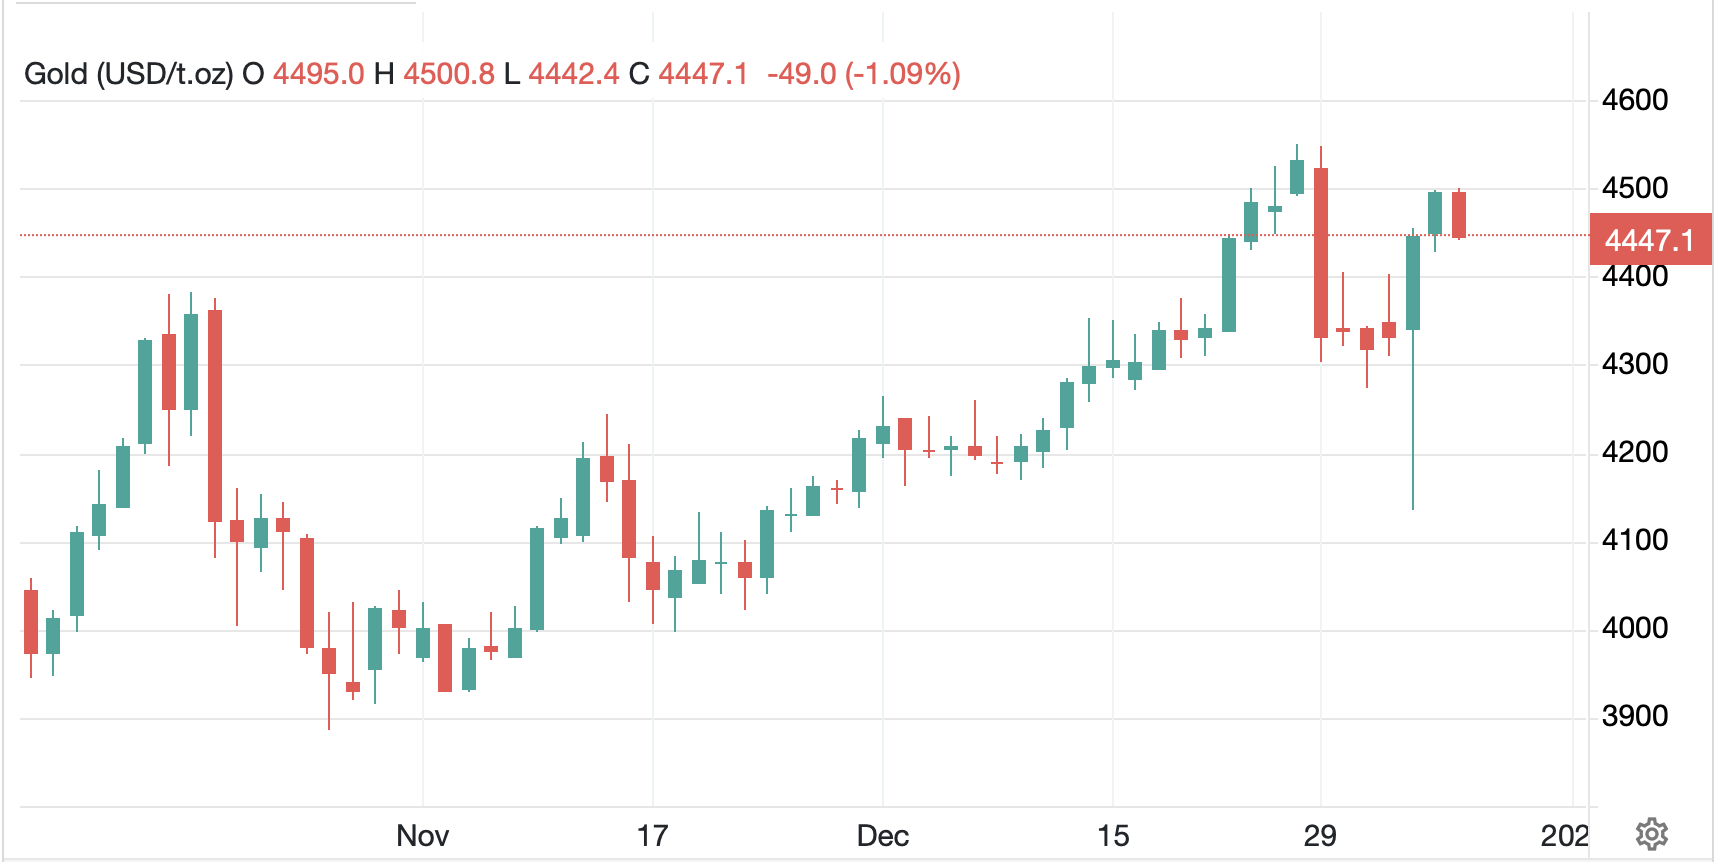
We’ve already discussed oil, but metals, which is where the real action has been, are all lower this morning, very clearly on profit taking activity.  Consider that gold (chart below from tradingeconomics.com) has been the least remarkable and still rallied 4% since the beginning of the year, so slipping -1.2% this morning can be no surprise.

Meanwhile platinum (-6.1%) which is the least liquid of all the precious metals, saw a nearly 20% gain this week prior to today’s decline.  The chart below is not for the faint of heart!

Source: tradingeconmics.com

Silver (-3.1%) is somewhere in between these two, but the story has not changed at all.  There continues to be significant demand for physical metals with paper futures no longer able to control the price action.  One way to follow this is to look at the price on the Shanghai Futures Exchange where it is all delivery settlement and where the price trades at a substantial premium to the COMEX, on the order of $3-$4/oz.

Finally, the dollar is still there, and vs. most of its counterparts, doing very little this morning.  the outlier today is ZAR (-0.5%) which is obviously hurting on the back of gold and platinum’s weakness.  In fact, it is worth looking at the relationship between ZAR and gold, as per the below chart, to help you understand just how closely tied is the price action between the two.

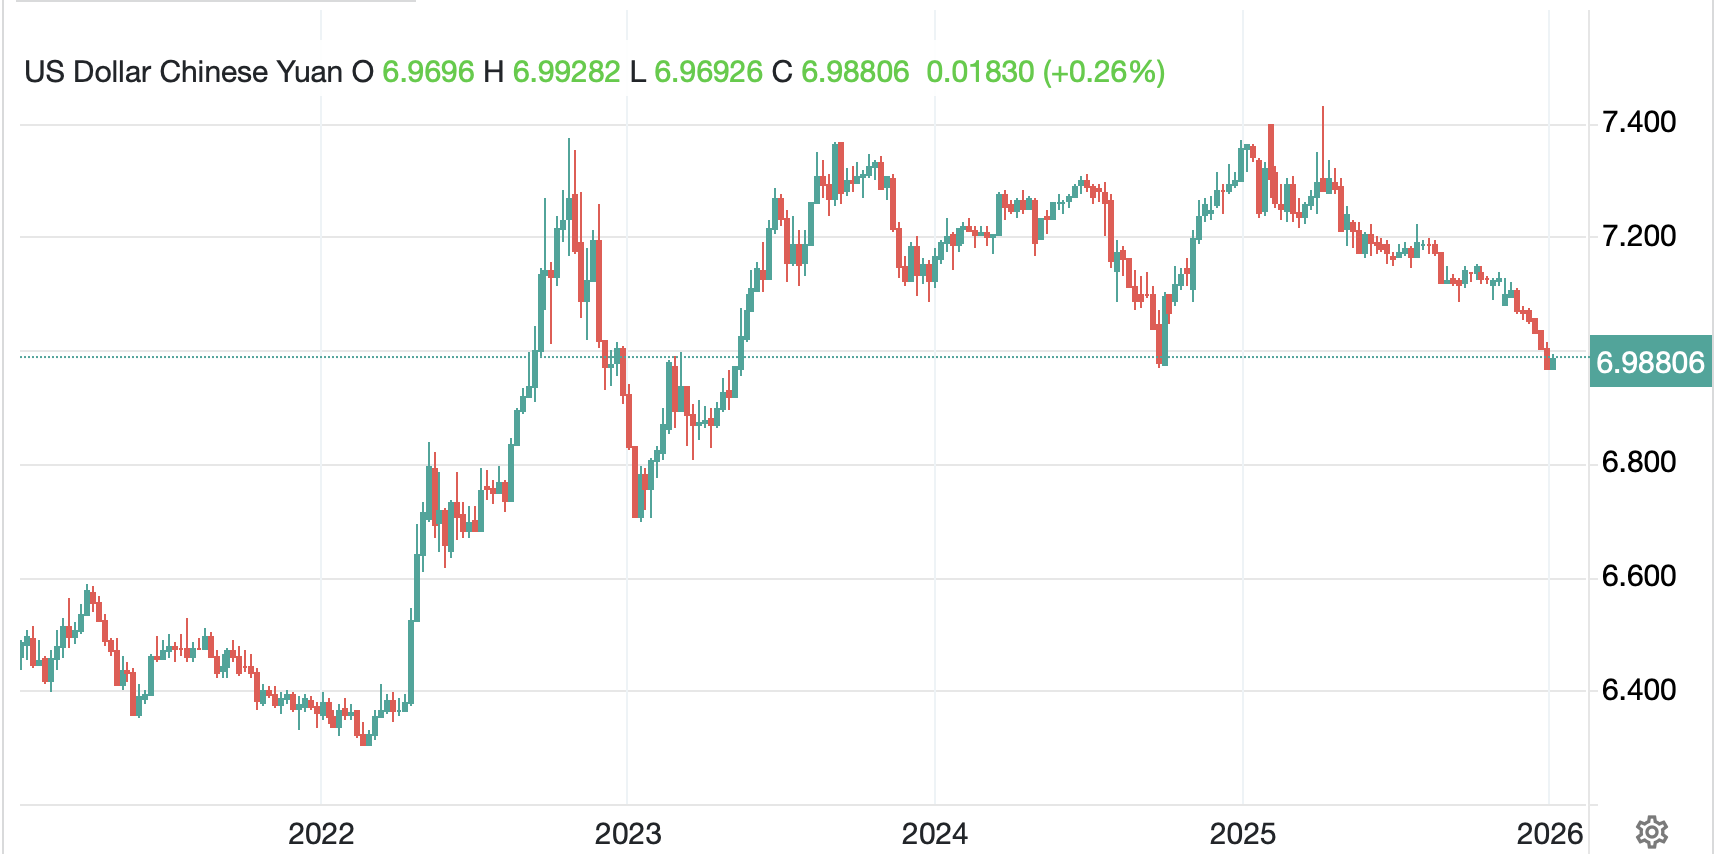
The other currency that has been trending steadily is CNY, with it breaching the 7.00 level at the end of 2025 for the first time since September 2024.  While this trend has been steady for the past year, a look at the longer-term chart shows the renminbi is nowhere near an extreme in either direction. 

Source: tradingeconomics.com

I maintain my view that if China really does create domestic demand for its products, the renminbi will continue this rally and strengthen further.  But we have heard this same story of Chinese government support for the domestic economy for at least a decade, and it hasn’t shown up yet.

On the data front, ADP Employment (exp 47K), JOLTs Job Openings (7.6M), ISM Services (52.3) and Factory Orders (-1.2%, -0.3% ex Transport) are the key releases this morning.  we also get EIA oil inventory data with expectations for a decent build.  There is only one Fed speaker, Governor Bowman, but the Fed just doesn’t seem as important this year as last.

The dollar is not the focus right now, neither are bonds.  Metals remain top of mind with oil a close second.  While recent price action in the former has been extremely volatile, nothing has changed my view that the long-term trend remains higher there.  Similarly for oil, the long-term trend remains lower with recent events simply adding to the weight.

Good luck

Adf

First Black Swan

‘Ought Twenty-Six barely got started
And Trump has already departed
From previous norms
Of post-Cold War forms
Now socialists are broken-hearted
 
Their man in Caracas is gone
With outrage from Beijing to Bonn
But folks on the street
Believe it’s a treat
Please welcome this year’s first black swan


I certainly didn’t have the exfiltration of Venezuelan strongman Nicholas Maduro from his palace in the middle of the night on my bingo card, did you?  But that is what we all woke up to Saturday morning.  In a way, we cannot be surprised as President Trump indicated several weeks ago that he spoke with Maduro, told him if he left, he could have safe passage, and be left alone, but ostensibly Maduro turned him down.  I’m guessing old Nick is questioning that decision right now.

As this all took place Saturday morning, no financial markets, other than cryptocurrencies, are open and based on Bitcoin’s movement of 0.1% as I type, it appears the issue is not seen as a major concern.  There is much discussion regarding what will happen to the price of oil, as unquestionably, Venezuelan oil was part of the decision equation.  But the Venezuelans have been producing less than 1 million bpd, far below their pre-socialist levels, and given they sit on the largest known oil reserves on the planet, far below what their ultimate capabilities can be.  If you’re Chevron’s CEO, you must be thrilled this morning, as they are already operating in country there.

Too, remember that Venezuelan crude is heavy and sour, which is what most Gulf Coast refineries are tuned to utilise to distill diesel, gasoline and other products.  It is too early to know what will happen to oil prices in the short run, but I would suggest that the longer-term view has to be lower prices going forward.  Consider that the US already is the largest producer of oil and oil equivalents (about 20mm bpd) in the world.  I would expect that Venezuela will be exiting OPEC under a new administration there, and with US oil expertise, will be seeking to expand that sector as rapidly as possible.  In fact, achieving 10mm bpd within a few years does not seem unrealistic. 

Now consider that by the end of the decade, the Western hemisphere could well be producing half the world’s oil supply, as already, despite degradation of capabilities in both Venezuela and Mexico, it produces more than one-third of the oil pumped.  That would certainly put a crimp in Russia’s war machine as the price seems far more likely to head toward $50/bbl than $80/bbl or higher, and by all accounts, that would be hard on Russia’s budget.

Too, consider the geopolitical ramifications if China were suddenly paying full price rather than whatever discounts they currently get for sanctioned oil purchases.  As well, what does a lower price do to the Iranian regime’s finances?  Probably not very helpful.

It is way too early to know how things will evolve, but between growth in production in Guyana and Argentina, and the prospects for significant growth in Venezuela going forward, it should become cheaper to fill up your tank going forward.

We will see how markets open Sunday night, and I would not be surprised to see oil rally at the start, but I would contend the politics points to lower prices not higher ones.  

Source: visualcapitalist.com

Note that neither Venezuela nor Argentina make this list individually.   I would wager that by 2027, both will be prominent producers, along with Guyana.

Welcome to 2026!  It is going to be an interesting year.

Good luck

Adf

Buy or Go Short?

The question on tariffs today
Is what will the Court, Supreme, say
Will they agree Trump
Has power to pump
Up taxes with no Senate sway?
 
Or otherwise, will the top court
Decide to, Trump’s tariffs, abort?
And if they decide
That Trump is offside
Is it time to buy or go short?


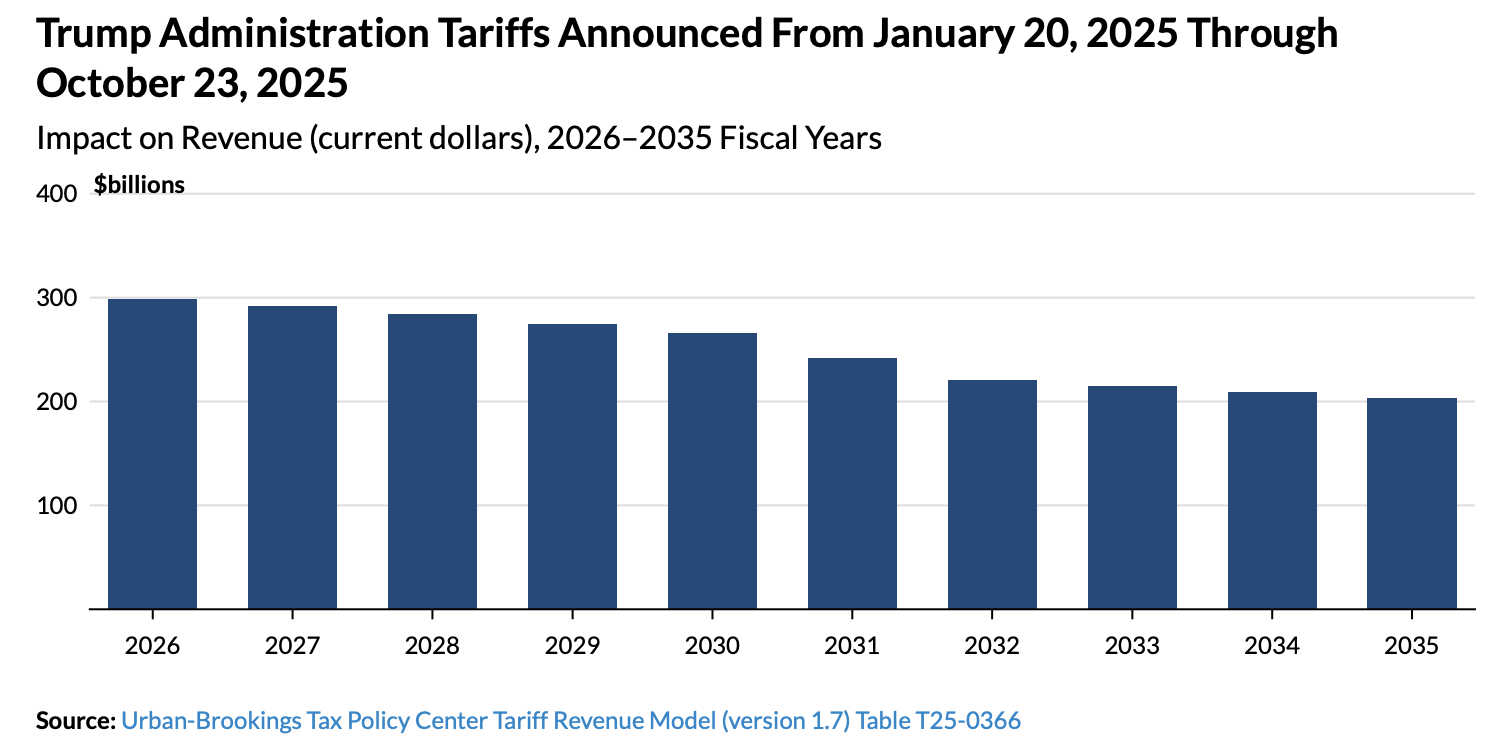
As testament to the idea that no matter the shock to a system, if it is a dynamic system, it will manage to adapt to the new reality, today’s existential question is, what happens if the Supreme Court decides that President Trump’s tariffs are unconstitutional?  Let’s forget for a moment, the fact that they have generated approximately $200 billion in government revenue since their imposition and are forecast to generate upwards of $300 billion next year and $2.5 trillion in the next decade, at least according to the Tax Policy Center (see chart below from taxpolicycenter.org).  Obviously, this is a good chunk of change for a government that has been running $2 trillion annual deficits.

Rather, let us consider the features that have accompanied the tariff negotiations, notably the promised inward investment to the United States.  Although there are several figures that have been mooted, with President Trump claiming $10 trillion, it appears that a fair estimate of the number is half that, so $5 trillion, to be invested in the US, notably in manufacturing capabilities, over time.  That, my friends, is a lot of money.

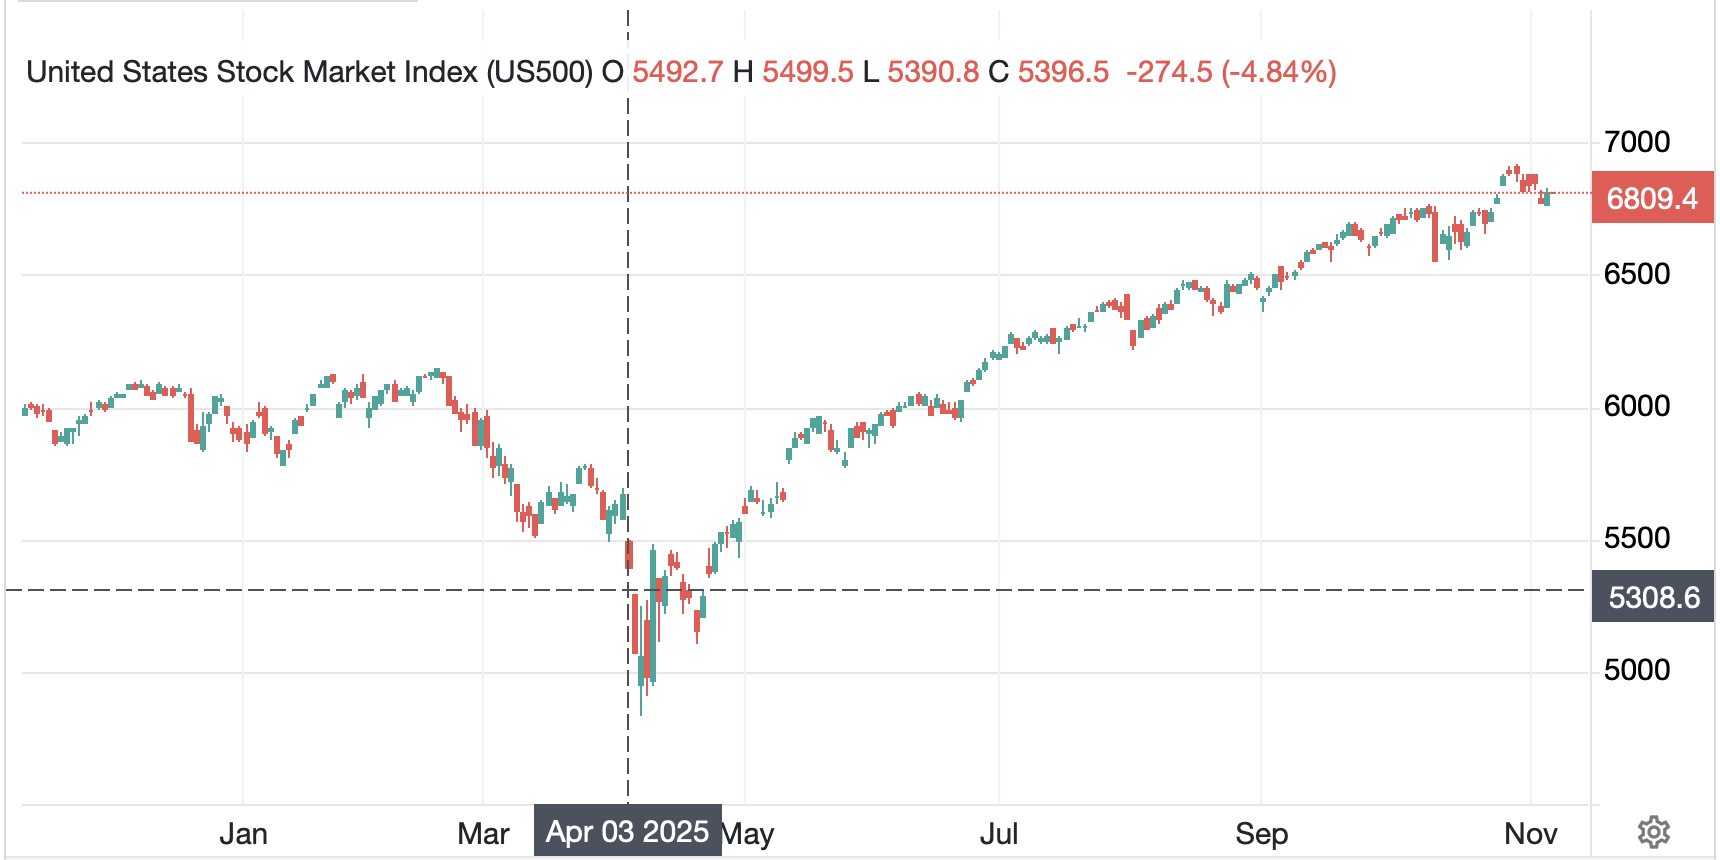
Now, we all remember what happened when Mr Trump announced those tariffs on Liberation Day back in April, but here is a chart of the S&P 500 to remind us of the size of the initial decline in equity markets.

Source: tradingeconomics.com

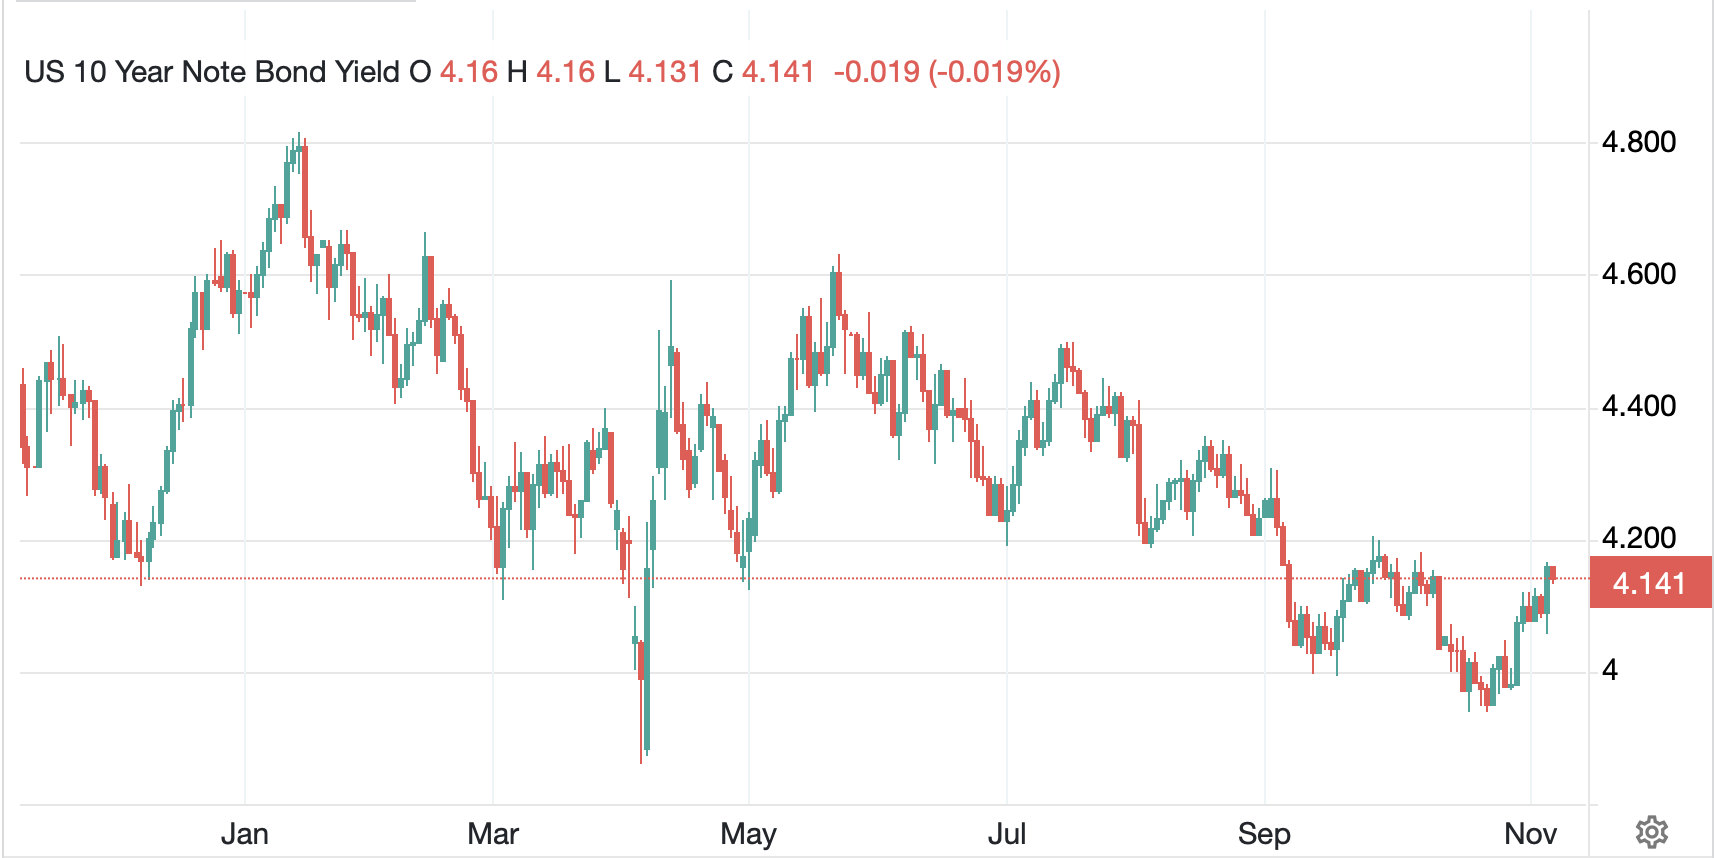
The decline from the close on April 2nd to the low on April 7th was ~12%, at which point, things were put on hold for 90 days and a series of furious negotiations began.  But we saw similar dramatic moves across all markets.  For instance, 10-year Treasury yields fell 33bps during that time, before rebounding sharply.

Source: tradingeconomics.com

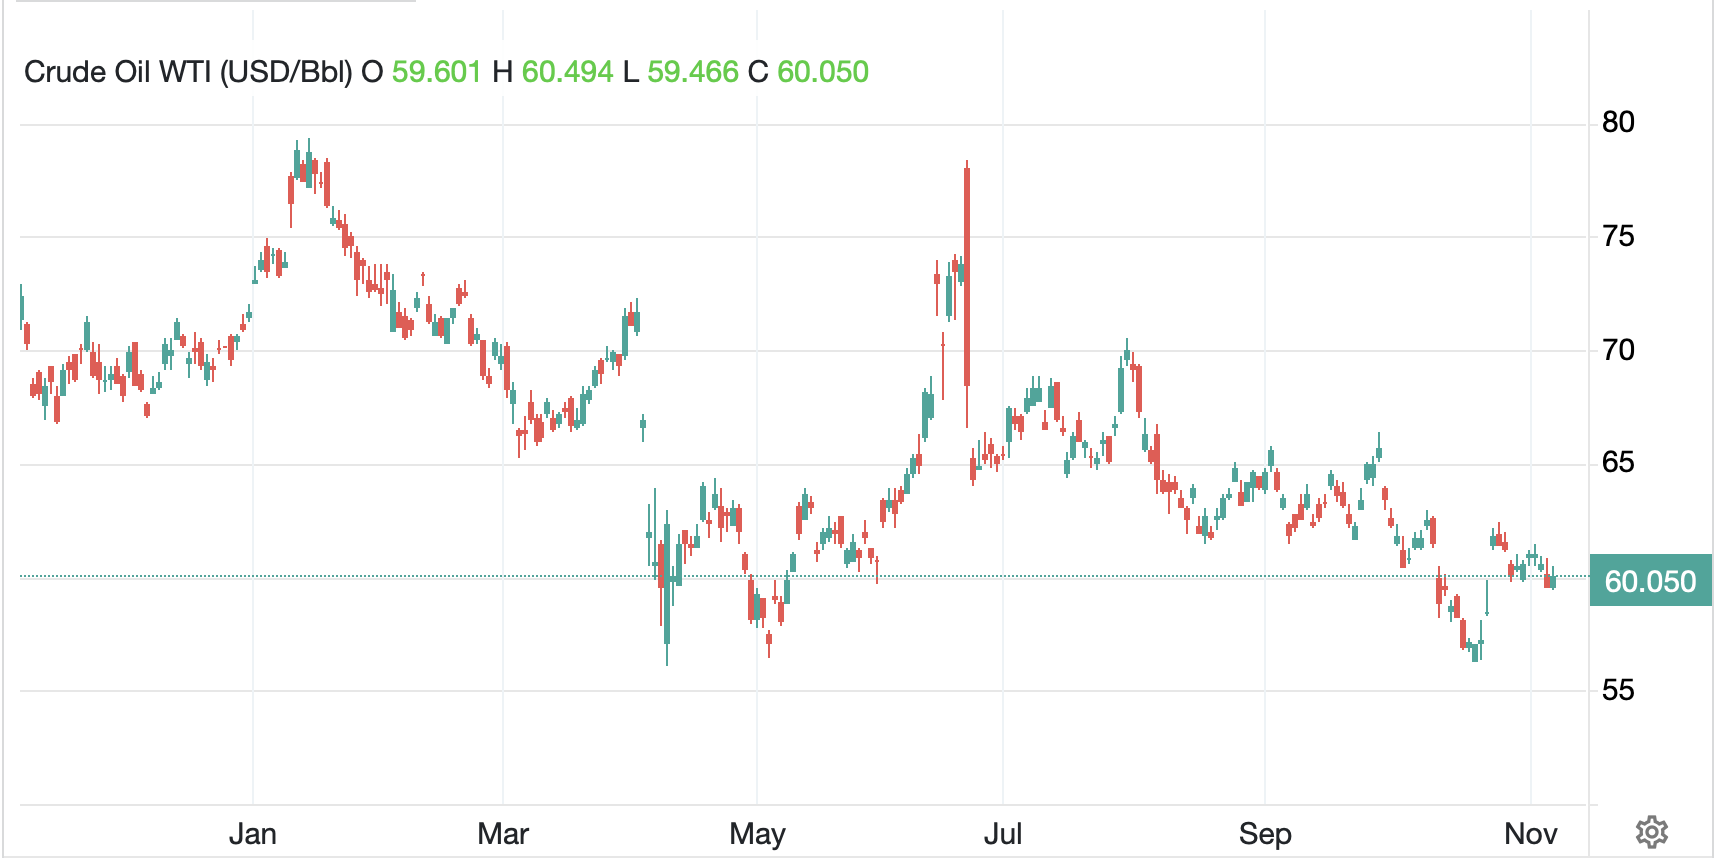
Oil also collapsed on the news, falling from nearly $72/bbl to $56/bbl in that stretch as the announcement shook up virtually all financial markets around the world.

Source: tradingeconomics.com

Perhaps the most surprising outcome was that the dollar actually fell about 3% during that period despite every economist and every textbook explaining that the impact of tariffs on currency markets would be that those countries whose goods were tariffed would see their currencies decline while the one imposing the tariffs would see strength.  (Yet another reason to pay little heed to economists and their theories which sound great but rarely seem to describe reality.)

Source: tradingeconomics.com

I highlight all this movement because the market behavior since then has been nothing but positive.  Equity markets have decided that things are great and rallied dramatically.  Bond markets have absorbed the information and decided it doesn’t matter that much or perhaps priced in the new revenue model as part of finding a new equilibrium around 4%.  Oil markets have other things about which to worry, with the current theme the alleged glut of oil that is around, and the dollar, while it continued to decline a bit further over the ensuing three months, has now seemingly found a bottom, and if anything looks like it is preparing to climb.

But…what if the tariffs must go?  And what if the government must repay those already collected?  If you recall, the narrative about tariffs back in April was that they were the end of the US economy and a disaster.  Obviously, that has not turned out to be the case.  Is the new narrative that the end of tariffs will be a disaster?  That feels like a pretty big reversal of opinion.    

To my thinking, one of the keys to the recent optimism for the US economy, at least for those who are optimistic, is that the inward investment is going to have very positive medium- and long-term impacts on the economy.  They are going to be critical in the reshoring of American manufacturing, whether Japanese investment into US Steel, or Korean investment into shipbuilding or Taiwanese investment into semiconductor manufacturing.  All these things are unalloyed positives for the nation and its future.  But if the tariffs are revoked, will the investments disappear?  That is the $5 trillion question, and one that I believe would be incredibly detrimental to both the nation and its financial markets.  Stocks would fall sharply and so would bonds as growth prospects would shrink and the fiscal imbalance likely grow even further.  The dollar would suffer between the capital outflows, and the fiscal problems and oil would likely fall amid a dramatic reduction in US demand.  Arguably, the only thing that would prosper would be gold, the historic safe haven.  

Which brings the question back to the Supremes (not these Supremes, although the sentiment is right!), will they unleash that chaos?  Or will they find a way to avoid it?  

With so much to consider, let’s do a brief twirl around the world overnight.  Yesterday saw a solid US equity rally across the board which was followed by strength throughout most of Asia (Nikkei +1.3%, Hang Seng +2.1%, CSI 300 +1.4%) with generally lesser gains elsewhere in the region.  Europe, though, is on its back foot with modest declines (UK -0.4%, Germany -0.1%, France -0.4%) after weaker than expected Construction PMI data across the board.  As to US futures, at this hour (7:00) they are very slightly firmer across the board, 0.1% or so.

In the bond market, yesterday saw US yields climb about 6bps after the ADP Employment data was released at a stronger than expected 42K with modest revisions higher to the previous months.  Remember, last month’s revisions lower were for an entire year, not specifically the past two months, so it appears that job growth is still decent, just not quite as strong as last year.  That data helped push yields up around the world, notably with JGB yields higher by 3bps.  But this morning, yields have backed off -3bps in the US and are unchanged across the entire continent and UK.  As to the UK, they left rates on hold at 4.0%, as expected, but the vote was 5 – 4 with 4 votes looking for a cut, so a more dovish signal.

In the commodity markets, oil (+0.8%) is rebounding after a decline yesterday based on a much larger than expected build in EIA inventories while NatGas also climbed on forecasts for colder weather and increased LNG demand in Europe and Asia.  Gold (+0.9%) and silver (+1.4%) continue their rebound from recent lows and seem like they are getting comfortable in their new “homes” of $4000 and $48.00 respectively.

Finally, the dollar is under modest pressure this morning, with the DXY slipping barely below the 100.00 level (currently 99.94) while the euro (+0.25%) and pound (+0.2%) both edge higher.  It appears that the dollar’s recent strength is on hold for today, although my take is it will resume shortly.  While a negative Supreme Court ruling on tariffs is likely to really undercut the greenback, I don’t see anything else in the near term to do the job.

There is no data of note to be released today, but we have an onslaught of Fed speakers, six in total starting at 11:00 this morning.  The Fed funds futures contract is now pricing just a 65% probability of a rate cut next month, as the ADP number encouraged some folks to change their views.  My take is we are going to hear a lot about caution given the absence of data, but I might contend the market is already somewhat cautious, at least the bond market is.

The thing about the tariff issue is it won’t be decided for at least several weeks, if not months, so may hang over the market like the Sword of Damocles.  I have no idea how they will rule, and the commentary from observers of the hearing gave different views based on their political biases, so it is hard to know.  But it is going to matter a lot.  In the meantime, I expect the recent trends to remain in place, so equity strength, little bond movement, little oil movement and dollar strength.

Good luck

Adf
Curses and Squeals

Though data is scarce on the ground
This week has the chance to astound
Four central banks meet
And when it’s complete
Two cuts and two stays ought abound
 
Meanwhile, Mr Trump’s signing deals
In Asia, an act that reveals
His fervent desire
To drive markets higher
As foes let out curses and squeals


Some days, there’s very little to note, with the news cycle a rehash of stories that have been festering for weeks.  This is especially true in the political sphere, but also on the economic front.  As well, given the ongoing government shutdown and the lack of government data being released, a key market focus is missing.  But not today!

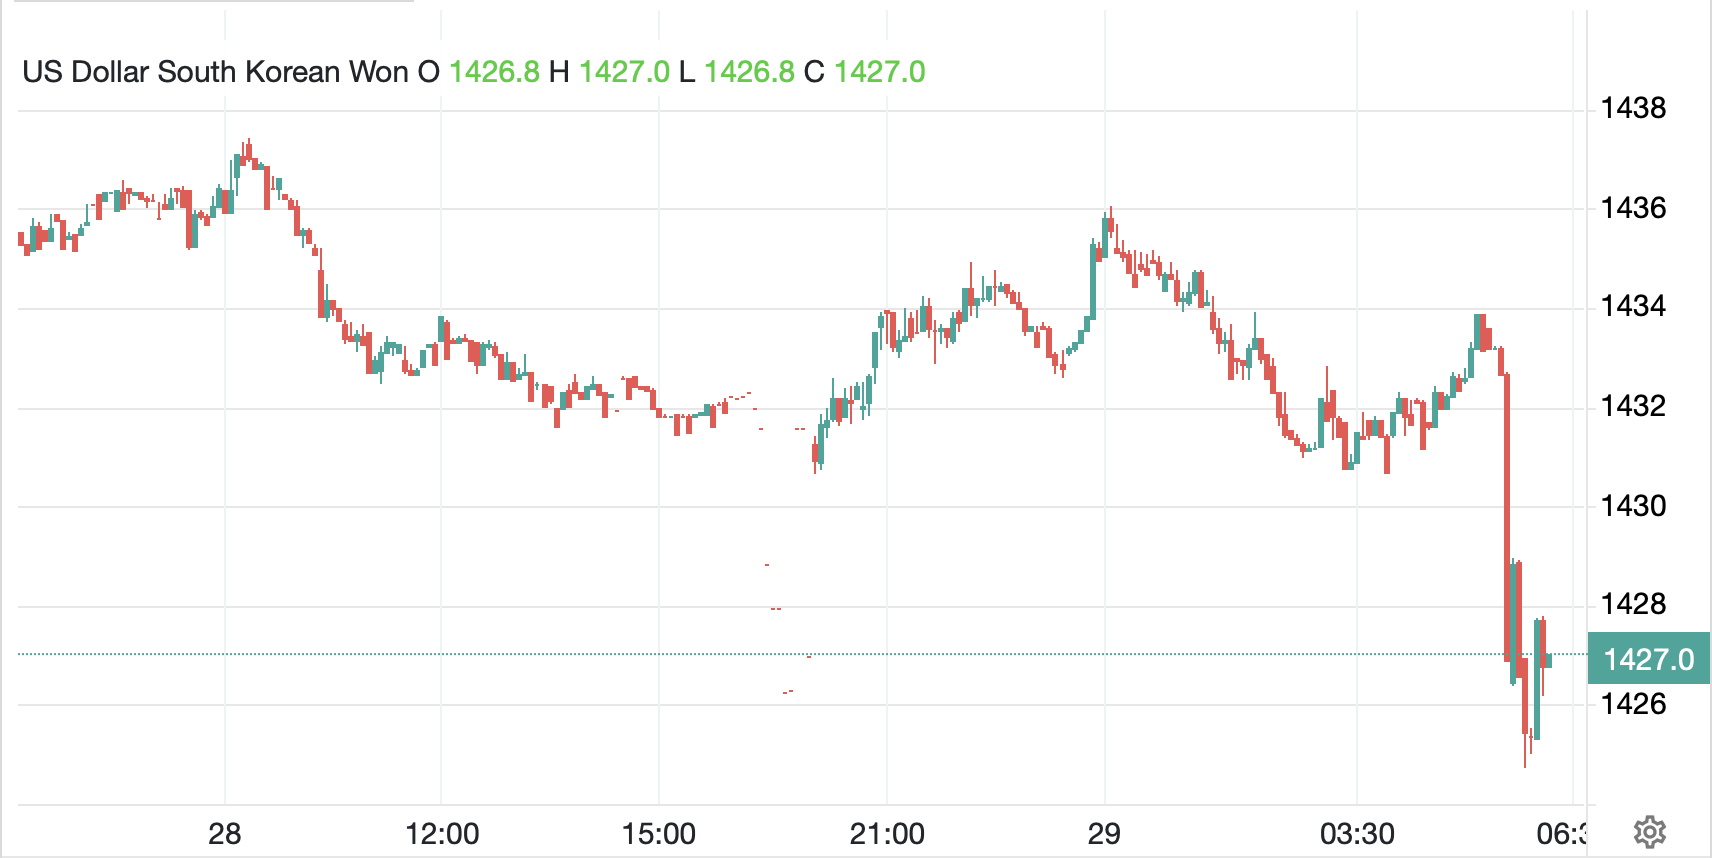
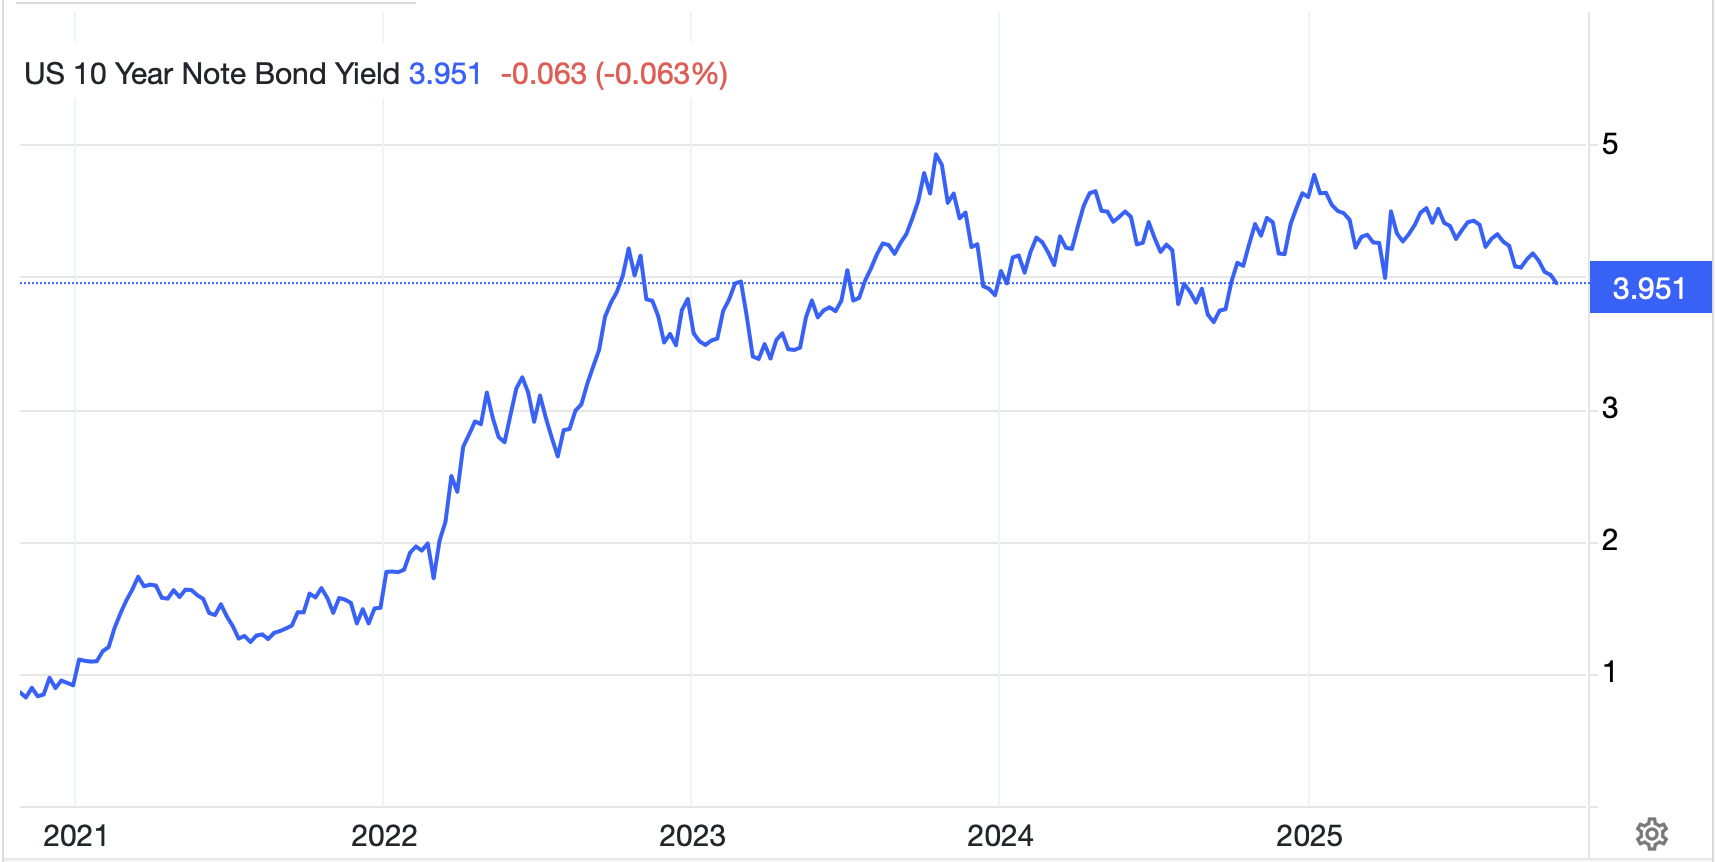
News across the tape moments ago is that President Trump has agreed a trade deal with South Korea, although the details of the deal are yet to be revealed.  When it comes to Trump and trade deals, it is always difficult to get through the hype to determine if things will actually improve, but if we use the KRW as a proxy for market sentiment, as you can see in the chart below, the announcement was seen as a benefit to the won.

Source: tradingeconomics.com

This is hardly definitive, and the nature of a trade deal is that it takes time to be able to determine its benefits for both sides, but for now, it appears markets are giving it the benefit of the doubt.  As well, it continues to be reported that Presidents Trump and Xi will be sitting down tomorrow (tonight actually) and that a trade framework has been agreed by Secretary Bessent and Chinese Vice Commerce Minister Li Chenggang which includes reduced tariffs, fentanyl, soybeans, semiconductors and rare earth minerals as key pieces of the puzzle.  

The ongoing competition between the US and China is not about to end with this deal, but perhaps it will be able to revert to a background issue rather than a headline one, and that is likely a positive for all.  Certainly, equity markets continue to believe that this dialog is a benefit as evidenced by their daily trips to new highs.

Which takes us to the other key discussion point in markets, central banks.  Over the next twenty-seven hours (it is 6:30am as I type) we are going to hear four major central banks explain their latest policy steps starting with the Bank of Canada (expected 25bps cut) at 9:45 this morning, then the FOMC at 2:00 this afternoon with their 25bps cut.  This evening at 11:00, NY time, the BOJ is expected to leave rates on hold, although there are those who believe a 25bps hike is possible, and then tomorrow morning at 9:15 EDT, the ECB will also leave rates on hold.  

While this is certainly a lot of new information, the question is, will it have any market impact?  Given the market pricing of these events, if any of the central banks do something different, you can be sure its markets will respond.  If I had to assess what might be different, both the BOC and FOMC could cut more than 25bps, and the ECB could cut 25bps rather than standing pat.  In all those cases, the currency would likely weaken sharply at first, although if all those things happened, I suppose it would simply create a new equilibrium.  But understand, I don’t think any of that WILL happen.

Regarding the Fed, though, there is another question and that is, what is going to happen to QT and the balance sheet.  Lately, there has been a great deal of discussion regarding how much longer the Fed will allow the balance sheet to shrink.  Last week I discussed the difference between ample and abundant reserves, but in numeric terms, the signals are coming from the SOFR (Secure Overnight Financing Rate) market, the one that replaced LIBOR.  It seems that there is increasing concern over the recent rise in the rate.  This is seen by numerous pundits, as well as by some in the Fed, as a signal that the reserve situation is getting tighter, thus offsetting the Fed’s attempts at ease. 

The below chart from the NY Fed shows the daily wiggles, but also, it is pretty clear that the recent trend has been higher.  You can see the September Fed funds cut in the sharp drop, and the first peak after that was September 30th, the quarter-end when banks typically look to spruce up their balance sheets, so borrow more aggressively.  But since then, this rate has been edging higher, an indication that there may not be sufficient reserves available for the banking system.

This begs the question; will the Fed end QT today?  Or wait until December?  My money is on today as they are growing concerned about the employment situation with the uptick in recent layoff announcements, and the pressure on SOFR is the best indicator they have that things have reached the point where their balance sheet no longer needs to shrink.  One other thing to keep in mind, at some point, it seems likely that the Fed is going to need to find more buyers of Treasuries as the market may develop indigestion given the amount being issued.  That pivot back to QE, whatever it is called, is easier if they are not simultaneously reducing their own balance sheet.

And one final point on the Fed.  Apparently, when they cut today, it will be the twenty-second time the Fed will have cut with stock indices at all-time highs, and of those previous twenty-one, twenty-one times equity markets were higher one year later.  Let’s keep that party rolling!

Ok, let’s look at how things have gone overnight.  Tokyo (+2.2%) was basking in the glow of all the love between President Trump and PM Takaichi, as it, too, traded to new all-time highs.  China (+1.2%) gained on the news of the trade framework, but interestingly, HK (-0.3%) did not follow suit.  And it should be no surprise that Korea (+2.1%) rallied on that trade news with India and Taiwan rising as well.  Australia (-1.0%) though, had a rougher go after a higher than forecast inflation print (3.5%) put paid to the idea that the RBA would be cutting rates again soon.

In Europe, Spain (+0.65%) is rallying on solid GDP data (1.1% Q/Q) although the rest of the continent is doing very little with virtually no change there.  In the UK, the FTSE 100 (+0.6%) is rallying on stronger corporate earnings from miners (metals are higher) and pharma companies.  As to US futures, at this hour (7:30) they are all nicely in the green, about 0.35% or so.

In the bond market, Treasury yields have backed up 2bps, but are still just below the 4.00% level, hardly signaling major concern right now.  European sovereign yields are all essentially unchanged this morning and overnight, only Australia (+5bps) moved after that CPI data Down Under.

Turning to commodities, oil (+0.5%) is bouncing after a couple of weak sessions, but net, we are right back to the $60 level which appears to be a comfortable level for both buyers and sellers.  It is also a high enough price to encourage continued exploration, so my take is we are likely to trade either side of this level for quite a while going forward.  My previous bearish views are being somewhat tempered, although I don’t foresee a major rally of any note.  

Source: tradingeconomics.com

In the metals markets, gold (+1.7%) is bouncing off its recent trading low and currently back above $4000/oz.  A look at the chart for the past month shows just how large the movements have been as the parabolic blow-off to near $4400 was seen through the middle of the month, and after a second try, the rejection was severe.  I don’t believe the long-term story in the precious metals has changed at all, the idea that fiat currencies are going to maintain their current status as reserve assets is going to be more and more difficult to defend with gold the natural replacement.  But in a market with a history of manipulation, don’t be surprised to see many more sharp moves ahead.

Source: tradingeconomics.com

As to the rest of the metals, they are all higher this morning with silver (+2.1%) leading the way and copper (+0.6%) and platinum (+1.6%) following in its wake.

Turning to those fiat currencies, the dollar is broadly firmer this morning, with only AUD (+0.15%) managing any gains against the greenback after that inflation print got traders thinking about higher rates Down Under.  But otherwise, in the G10, the dollar is ascendant.  In the EMG bloc, we already discussed KRW, but ZAR (+0.2%) is also gaining today on the back of the metals bounce.  Elsewhere, though, modest dollar strength is the rule.  What makes this interesting is the dollar is back to rallying alongside precious metals.

Ahead of the Fed, we only see EIA oil inventories with a small draw expected.  In theory, with President Trump in South Korea, one would expect him to be sleeping throughout most of today’s session, but apparently the man rarely sleeps.

The big picture is that run it hot remains the play, and that means equities should benefit, bonds should have a bit more trouble, but the dollar and commodities should do well.  I see no reason for that to change soon.

Good luck

Adf

Has, Now, the Bell Tolled?

The pundits are still talking gold
But what is the reason it sold?
Liquidity drying
Means selling, not buying
Of havens. Has, now, the bell tolled?


One of the great things about FinX (FKA FinTwit) is that there are still a remarkable number of very smart folks who post things that help us better understand market gyrations.  The recent parabolic rise and this week’s reversal in the price of the barbarous relic seem unrelated to any concept of fundamentals one might have.  After all, perhaps the only fundamental that impacts gold is the rate of inflation, and since we haven’t seen a reading there in a month, it seems unlikely that had anything to do with this price action.  However, there is a far more likely explanation for the move lower, which has been very impressive in any context.  First, look at the chart below from tradingeconomics.com which shows the daily bars for the past 6 months.  The rise since early September has been nothing short of remarkable.

This begs two questions; first, why did it rise so far so fast, and second, what the heck happened on Friday to turn it around so dramatically?

The first question has several pieces to its answer including ongoing concerns over fiat currencies in general (the debasement trade that became popular), increased central bank buying and a recent change in financial advisors’ collective thought process about the merits of holding gold in an investment portfolio.  In fact, I think it was Bank of America (but I could be wrong) that recently suggested that the 60:40 portfolio should really be 60:20:20 with the final 20% being gold!  Given the human condition of jumping on bandwagons, it is no surprise that this type of ‘analysis’ has become more popular lately.  Whatever the driver, or combination of drivers, the price action was remarkable and clearly overdone.  After all, compare the current price, even after the recent sharp decline, to the 50-day moving average (the blue line on the chart) as an indicator of the extreme aspect of the price action.

But let’s focus on the last few days and the sharp reversal, which takes me back to X.  There is an account there (@_The_Prophet_) who put out an excellent step by step rationale of what led up to yesterday’s dramatic decline and why it is important.  I cannot recommend it highly enough as a short read.

In sum, his point is, and I fully subscribe to this idea, that when things get tough, investors/traders/speculators sell what they can sell, not what they want to sell.  If liquidity is drying up for the funding of speculative assets that are highly leveraged, then when margin and collateral calls come, and they always do, those owners sell whatever they have that they can liquidate.  In this case, given the massive run up in the price of gold, there was a significant amount of value to be drawn down and utilized to satisfy those margin calls.  

History has shown this to be the case time and again.  I would point to the Long-Term Capital Management fiasco back in 1998 where the Nobel Prize winning fund managers quickly found out that liquidity was much more important than ideas and they were forced to sell out their Treasury holdings rather than their leveraged positions because the former had prices and the latter didn’t.  This ultimately led to the liquidation of their fund along with some $5 billion in capital.

There has been much discussion as to the nature of the recent rise in asset prices with many pundits calling it the everything bubble.  Bubbles are created when central banks pump significant liquidity into the system and this is no different.  We know the Fed has allegedly (look at the graph of M2 below to see how much they have been increasing money supply during their tightening) been trying to reduce its balance sheet (i.e. liquidity) but this could well be a sign that phase is over.  Typically, the next step is QE in some form, so beware.  And when that comes, you can be sure that gold will rally sharply once again!

Of course, while the gold move has been the most spectacular, we have seen a lot more market volatility in the past several sessions, so let’s look at how things behaved overnight.  Yesterday’s mixed US session was followed by more laggards than leaders in Asia with Japan essentially unchanged, while HK (-0.9%) and China (-0.3%) both slid a bit.  Recent comments by President Trump that he may not sit down with President Xi next week have investors and traders there nervous.  Elsewhere, Korea (+1.5%) and Thailand (+1.1%) had solid sessions while the rest of the region (Indonesia -1.0%, Malaysia -0.9%, Australia -0.7%) all lagged.

In Europe, the UK (+0.9%) is benefitting this morning from softer than expected inflation readings (3.8% vs 4.0% expected) which has tongues wagging that the BOE will now be cutting rates.  The market priced probability has risen to 60% for a cut this year, up from 40% yesterday, before this morning’s data release.  However, on the continent, only Spain (+0.6%) is showing any life on local earnings performance while the rest of the markets are all lower by varying degrees between -0.1% and -0.5%.  As to US futures, at this hour (7:20) they are unchanged.

Bond markets continue to see yields slide lower with Treasuries (-1bp) now nicely below 4.00% and trading at their lowest level in more than a year (see below)

Source: tradingeconomics.com

European sovereign yields have seen similar movement, edging lower by -1bp except for UK gilts, which have fallen -10bps this morning after that inflation report.  Perhaps more interesting is the fact that despite Takaichi-san becoming PM, with her platform of increased fiscal spending, JGB yields are 2bps lower this morning.

Turning to the rest of the commodity space, oil (+2.1%) is rising on the news that the US has started to refill the SPR.  While the initial bid is only for 1 million barrels, this is seen as the beginning of the process with the administration taking advantage of the recent low prices.  Arguably, given they want to see more drilling as well, it is very possible that $55/bbl is as low as they really want it to go.  As to the metals beyond gold (-2.4% this morning), silver (-1.6%) is still getting dragged along but copper (+0.6%) and platinum (+0.9%) seem to be consolidating after sharp declines in both.  My sense is gold remains the liquidity asset of choice given its far larger market value.  (One other thing to note is that there was much discussion how gold has replaced Treasuries as the most widely held central bank reserve asset.  That was entirely a valuation story, not a purchase story.  In other words, the dramatic rise in the price of gold increased the value of its holdings relative to other assets on central bank balance sheets.)  

Finally, the dollar is doing just fine.  It continues within its recent trading range and basically hasn’t gone anywhere in the past six months.  In fact, of you look at the DXY chart below from Yahoo Finance, it is arguably in the upper quintiles of its long-term price action.  It is very difficult for me to listen to all the reasons that the dollar is going to be replaced by some other reserve currency and take it very seriously.

As to specific currency moves today, the pound (-0.3%) is slipping on the increased belief in a rate cut coming soon and ZAR (-0.5%) is suffering on the ongoing gold price decline but away from those two, +/-0.1% is the story of the day.

EIA Crude Oil inventories are the only data of the day with a modest build expected.  Yesterday, Governor Waller discussed payment systems and cryptocurrencies never straying into monetary policy so we will need to wait for CPI on Friday, the FOMC next Wednesday and whenever the government reopens, which I sense is coming sooner rather than later as the Democrats have been completely unsuccessful in making the case this is President Trump’s fault.  

It appears the cracks in the leverage that has accompanied the recent rally in asset prices are beginning to appear.  If things get worse, and they probably will, look for the Fed to respond and haven assets to be in demand.  Amongst those will be the dollar.

Good luck

Adf

Rare Earths No More

Said Xi, we’ll sell rare earths no more
Said Trump, well that means we’re at war
The stock market puked
As traders got spooked
And Trump imposed tariffs galore
 
The question is just why would Xi
Get feisty when things seemed to be
Improved for both sides
With fewer divides
Did Mideast peace kill his esprit?


Let’s talk about markets for a moment.  Sometimes they go down and go down fast when you’re not expecting it.  That is their very nature, so it is important to understand that Friday’s price action, while dramatic relative to what we have seen over the past 6 months, is not that uncommon at all over time.  It appears the proximate cause of the market decline was the word from China that they would stop selling and exporting rare earth minerals. 

It can be no surprise that President Trump immediately responded by threatening an additional 100% tariffs on all Chinese exports and new controls on software, all to be implemented on November 1st.  There is a lot of tit-for-tat in the dueling messages from China and the Trump administration and it is hard to tell what is real and what isn’t.  However, equity markets clearly weren’t prepared for a break in the previous expectations that the US and China were closing in on a more lasting trade stance.

But weekends are a long time for markets as so much can happen while they are closed.  This weekend was a perfect example.  After the carnage on Friday, we cannot be that surprised that both sides of this new tiff modified their responses.

First we saw this on Truth Social:

Then China backed off clarified that what they are really doing is require licensing for all rare earth minerals and products that contain them in exports.  China claims that applications that meet regulations will be approved although the regulations have not yet been defined. Ostensibly this is for national security reasons, and it is unclear exactly who will receive licenses, but this is clearly not the same as ending exports.  

And just like that, many of the fears that were fomented on Friday have been alleviated as evidenced by this morning’s equity market moves in the futures markets.

Source: tradingeconomics.com

But why did Xi make this move in the first place?  I have no idea, nor does anyone but Xi, although here are two completely different thought processes, one very conspiratorial and one rooted in the broader escalation of geopolitical affairs.

As to the first, (Beware, you will need your tinfoil hat here!) consider if the Israel-Gaza peace settlement, (with the hostages returned as of the time I am writing this morning at 5:30) does not serve China’s interest.  First, the one Middle East nation that will be on the outside is their ally, Iran.  Second, the ongoing problems there were always a distraction for the US, something that clearly suits Xi and China.  After all, if the US is focused there, they will have more difficulty paying attention to things Xi cares about like Taiwan and the South China Sea.  If the peace in Israel-Gaza holds, and the Abraham Accords extend to the bulk of the rest of the region, Xi loses a major distraction that cost him virtually nothing.  Plus, this opens the door for tightening sanctions on Iran even further, which could negatively impact China’s oil flows.  

The second is much more esoteric and I read about it this weekend from Dr Pippa Malmgren, someone who has a deep insight into global politics from her time as a presidential advisor as well as from her father, Harold Malmgren, who advised four presidents.  In her most recent Substack post she explained the importance of Helium-3 (3He), a rare isotope of helium that has major energy and military implications and where the largest deposit of the stuff known to man is on the moon.  Her claim is this is the foundation of the recent acceleration in the space race between the US and China and without rare earth minerals, the US ability to achieve its goals and obtain this element would be greatly hampered opening the door for China to get ahead.

Are either of these correct?  It is not clear, but I would contend each contains some logic.  In the end, though, as evidenced by the quick retreat on both sides, I suspect that the trade situation between the US and China will move forward in a positive manner, although there could well be a few more hiccups along the way.  And those hiccups could easily see equity markets decline such that there is a real correction of 15% to 20%.  Just not today.

So, what is happening today?  Let’s look.  First, I would be remiss if I didn’t highlight the following Bloomberg headline: ‘Buy the Dip’ Call Grows Louder as China Selloff Seen Containedas it perfectly encapsulates the ongoing mindset in equity markets.  At least in US equities.  Asia had a much rougher session despite the backtracking with HK (-1.5%) and China (-0.5%) under pressure and weakness virtually universal in the time zone (Korea -0.7%, India -0.2%, Taiwan -1.4%, Australia -0.8%). Tokyo was closed.  It appears there are either still concerns over the trade situation, or perhaps the fact that globally, markets have had long rallies has led to some profit taking amid rising uncertainties.  

European bourses, though are all in the green, with the continent seeing gains of 0.5% or so across the board although the UK is lagging with a miniscule 0.05% gain at this hour (6:30).  As to US futures, as seen above, gains range from 1.0% (DJIA) to 2.0% (NASDAQ).

Meanwhile, bond yields also saw a dramatic move on Friday, tumbling -8bps and back to their lowest level seen in a month as per the below chart from tradingeconomics.com

This morning, those yields are unchanged.  European sovereign yields, which followed Treasury yields lower on Friday are also little changed at this hour, down another -1bp as concerns begin to arise that economic growth is going to be impaired by the escalation in trade tension between the US and China.  

I would argue that commodities are the one area where the back and forth is raising the most concern.  At least that is true in metals markets, with gold, which rallied 1% Friday amid the equity carnage, higher by another 1.6% this morning, to more new highs and we are seeing silver (+1.6%), copper (+4.2%) and Platinum (+3.6%) all in sync.  To me, this is the clearest indicator that there is an underlying fear pervading markets.  Oil (+1.8%) has rebounded from Friday’s rout as the easing of trade tensions appears to have calmed the market somewhat, although WTI remains just below $60/bbl at this point.  

Finally, the dollar is firmer again this morning as, although it softened slightly Friday, it has since regained most of those losses and is back on its recent uptrend as you can see below.

Source: tradingeconomics.com

While Tokyo was closed overnight, we did see further JPY weakness as the yen retraced most of its Friday gains like the rest of the market.  The biggest G10 mover was CHF (-0.9%) followed by AUD (-0.7%) and JPY (-0.7%) with other currencies less impacted and NOK (+0.2%) benefitting from the oil rally.  However, the EMG bloc has seen a much wider dispersion with MXN (+0.5%), ZAR (+1.1%) and CLP (+0.8%) all rallying sharply on the metals rally while PLN (-0.5%) and CZK (-0.4%) lag as they follow the euro lower.

And that’s enough for today.  With the government still on hiatus, no official statistics will be released although we do get a little bit of stuff as follows:

TuesdayNFIB Small Business Index100.5
WednesdayEmpire State Manufacturing-1.8
 Fed’s Beige Book 
ThursdayPhilly Fed Manufacturing9.1

Source: tradingeconomics.com

But, with the lack of data, it appears Chairman Powell has instructed his minions to flood the airwaves with a virtual cacophony of speeches this week, I count 18 on the calendar including the big man himself on Tuesday afternoon.  It seems difficult to believe that their opinions on the economy will have changed very much given the lack of new data.  The market is still pricing a 98% chance of a cut at the end of this month and another 91% chance of a cut in December.  With the increased trade tension, there is much more discussion regarding a slower economic course ahead, which would play into further rate cuts.  However, while that would clearly help precious metals as it ends any ideas of an inflation fight, it is not clear it will weaken the dollar very much as everybody else will almost certainly follow along.

Good luck

Adf