The Tariff Watusi

Undoubtedly, most are confused
And many portfolios bruised
The problem I fear
Is throughout this year
Both bulls and bears will be contused


Right now, it’s the tariff Watusi
With rules that seem quite loosey-goosey
So, traders are scared
While pundits declared
The president’s just too obtuse-y


But will volatility reign
All year with the requisite pain?
Or will, as Trump said
When looking ahead
The outcome be growth once again?

(Before I start, “Ball of Confusion” is brilliant and timeless.  But isn’t Billy Joel’s “We Didn’t Start the Fire” covered and updated by Fall Out Boy, really the same song for a different generation?) Now, back to our regular programming.

  • Tariffs are a tax.  So, say seemingly all the most credentialed analysts and economists around.  
  • Tariffs are inflationary.  So, say many of these same analysts and economists.  
  • Ergo, taxes are inflationary.  So, say…well none of the credentialed analysts and economists.  (H/T to Alyosha for highlighting this idea last week.)  

But it is important to recognize this dichotomy as we listen to the many pundits and analysts who are now telling us that a recession is coming, if not already here, and the world is ending.  It seems to me if you cannot recognize this connection then your views may be colored by something other than strict logic.

We are experiencing a complete regime change in both financial markets and economic outcomes around the world and as old as I am, the last time something like this occurred was long before I was born.  I am very wary of any analyst who demonstrates any certitude in their views at this point.  Frankly, I am more inclined to listen to historians than economists, as they have potentially studied previous regime changes.  Alas, I have not so I am reliant on those who I read.

The current confusion remains over tariffs, their implementation and their impact.  To me, the key point that is missing in most of the tariff discussions is the elasticity of demand for any given product.  If something is highly inelastic and tariffs are added, then the price of that item is very likely to rise.  However, if something has very elastic demand, then a tariff will do one of two things, either the producer will absorb the cost or the volume of sales will drop dramatically, but any price rise will be constrained.

I highlight this because the weekend’s ostensible pause in tariffs on electronic goods from China is the latest discussion point.  It strikes me that under the thesis tariffs are inflationary, then inflation forecasts and expectations should now be declining.  But I haven’t seen that yet.  In the end, though, I don’t believe anybody really knows how things will evolve from here, although I believe the end goal is becoming clearer.  

It appears that President Trump’s goal is seeking to isolate China from much of the developed world.  He wants to create a situation where nations declare they are either with the US or against the US when it comes to economic relations.  I read this morning that 75 nations are in negotiations with the US regarding tariff reductions.  Given that, by themselves, the G10 represent nearly 50% of global GDP, even not knowing which nations are negotiating, the group almost certainly represents upwards of 70% or more of the global economy.  

I would contend it is still very early days with respect to the results of President Trump’s actions.  There is no question he has unleashed a certain amount of chaos in the government and in markets, but I don’t believe he is greatly concerned by that, and in fact he may welcome the process.  Regime changes are always messy, and this one is no different.  Be nimble.

Ok, let’s look at how things behaved overnight.  Friday’s US equity rally was followed by strength throughout most of Asia (Japan +1.2%, Hong Kong +2.4%, China +0.2%, Korea +1.0%, India +1.8%) with Taiwan (-0.1%) the true laggard in the region.  Clearly the tariff reprieve, even if temporary, was welcomed.  In Europe, too, the gains are strong and widespread with the DAX (+2.3%) leading the way but the rest of the Continent and the UK all up at least 1.8%.  And at this hour (6:30) US futures are higher by around 1.0% as well.

But let’s keep things in perspective.  The below chart of the S&P 500 over the past 20 years can help you understand the magnitude (or lack thereof) of the recent decline.  Yes, the index is lower by about 12% from the all-time highs set in February, and yes, uncertainty is rife.  But if you ever wanted to understand what has happened since the Fed’s response to the GFC led to the financialization of the entire economy, the latest minor dip is being described as catastrophic by the punditry.  It’s not!
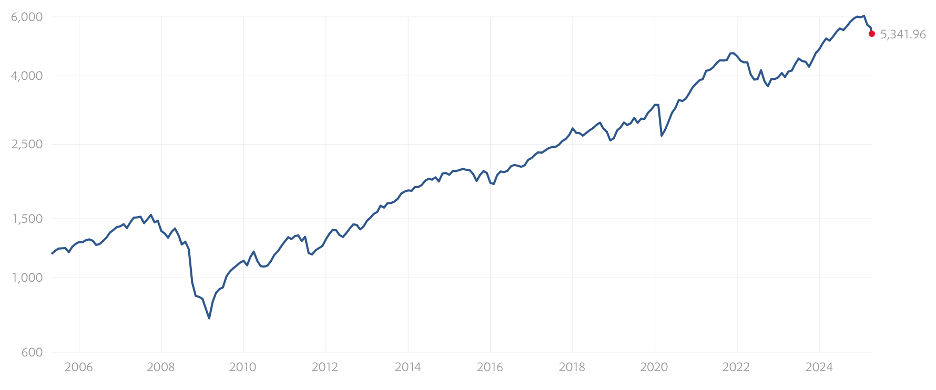
Source: multpl.com

Next, the Treasury bond market has been the focus of a great deal of angst lately.  Once again, these same analysts and economists claim the world is ending because yields have risen over the past week.  I grant the movement has been sharp, but my experience tells me that when a market as liquid as 10-year Treasuries moves this sharply, it is a position liquidation that is driving the move.  In fact, both the 10-year and 30-year auctions last week seemed to have gone quite well, with strong demand.  So, I am not of the opinion the bond market is about to collapse, nor do I believe that China is liquidating their Treasury holdings.  Rather, hedge funds carrying significant leverage and being forced to unwind seems the most likely culprit here.  Too, remember that 10-year yields are right in the middle of their range for the past six months at 4.43% (-6bps today).
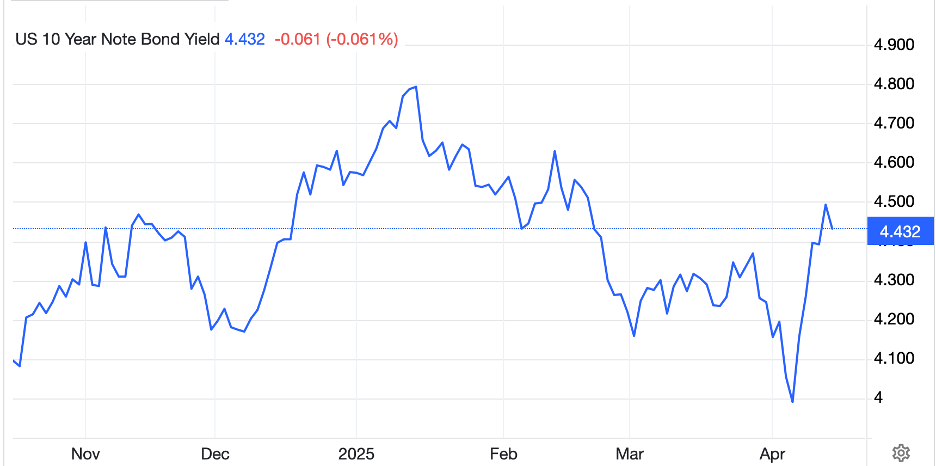
Source: tradingeconomics.com

In fact, European sovereign yields are also retreating this morning led by Italy and Greece (-9bps) with German bunds (-4bps) the laggard of the session.  With equity markets around the world rallying, it doesn’t appear this is safe haven buying.  However, I do believe that there are many investors who are pushing at least some of their equity portfolios into fixed income amidst overall uncertainty.

Turning to commodities, oil (+1.25%) seems to have found a bottom, at least in the short-term, just below $60/bbl.  While a recession doesn’t necessarily drive inflation lower, I am very comfortable with the idea that it reduces demand for energy and oil prices can slip.  Is the recent move a harbinger of recession?  I think there is too much noise to discern the signals the market is giving us right now, although a recession, which has been long awaited by many analysts, certainly seems possible.  

As to the metals markets, while both gold (-0.7%) and silver (-0.3%) are a bit softer this morning, one need only look at their performance in the past week (both higher by more than 7%) to recognize that there is a great deal of growing demand for precious metals.  Dr Copper (+0.9%), like oil today, is not indicating that a recession is coming as it, too, rose 7% last week and is higher by 15% YTD.  Again, there is a lot of noise to get through to find the signal.

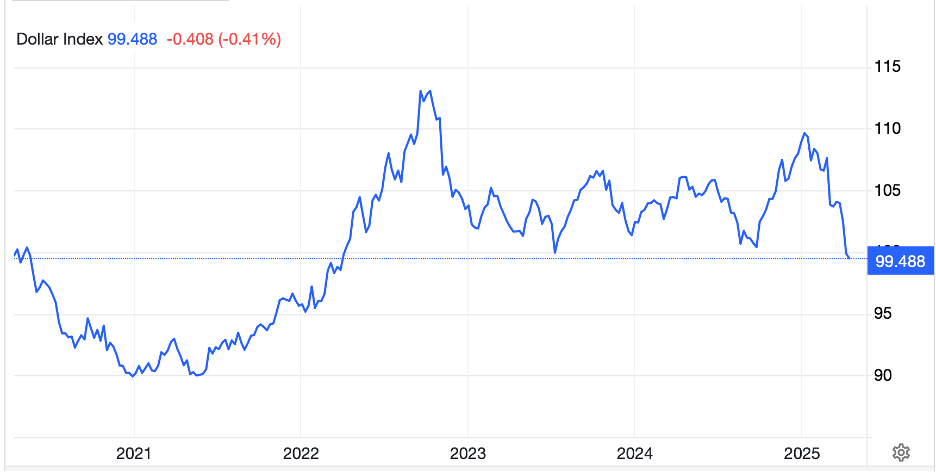
Finally, the dollar, is lower again today and is back at levels last seen…in September 2024.  And before that in July 2023 and March 2022.  In fact, if you look at the chart of the DXY below, I challenge you to show me that this decline was more dramatic than any of the three other major declines we have lived through in the past 3 years.
Source: tradingeconomics.com

Net the dollar has declined by about 10% since its recent peak in February, not insubstantial, but not unprecedented by any stretch.  In fact, over the long-term, the dollar is within spitting distance of its long-term average, which as measured by the DXY is about 104.  Looking at individual currencies, there is a strange grouping of currencies that have fallen vs. the greenback this morning, BRL (-0.85%), TRY (-0.5%), CHF (-0.5%) and CNY (-0.4%).  Given the pause in tariffs on Chinese electronic goods, CNY is confusing, as is CHF, which might imply havens are out of favor (but then why is JPY stronger?).  TRY is its own case and BRL is quite confusing.  Commodity prices have held their own or risen lately, and BRL is nothing, if not a commodity currency.  I need to search further here.  Perhaps we are seeing some carry trades being unwound.

I apologize as once again my Monday missive has grown too long for comfort.  I will highlight the data tomorrow with Retail Sales on Wednesday as the most important data release this week and the BOC and ECB meetings on Wednesday and Thursday respectively with the market looking for no change and a 25bp cut respectively.

The world is a messy place right now, with armed conflict now being joined by economic conflict.  Opinions are hardening along political lines, and I don’t see how this changes in the short run.  If you are managing risk, maintain your hedges, even if they seem expensive.  There are too many opportunities for large movements that can be costly.

Good luck

Adf
Their Own Ego Trip

The talk of the town is the “Pause”
Which led to much market applause
Though naysayers still
Say Trump’s actions will
Result in bad outcomes…because


But yesterday saw markets rip
And all those who did buy the dip
Are feeling quite smart
When viewing the chart
Of prices, their own ego trip


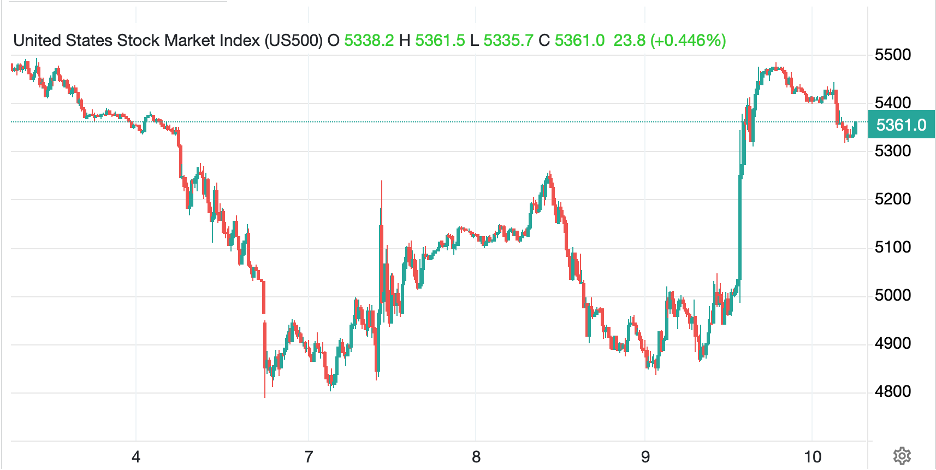
See if you can guess when President Trump posted that there would be a 90-day pause on tariffs for everyone but China.

Source: tradingeconomics.com

By now, you are almost certainly aware that equity markets in the US rebounded massively in the US, with one of the biggest gains on record as the S&P 500 rose 9.5% and the NASDAQ 12.2%.  Of course, that merely retraced the bulk of the losses seen since the beginning of the month.  In fact, the S&P 500 is still lower by about 200 points since then.  Regardless, moods are much brighter today than they were yesterday at this hour.  And those equity gains are global.

I’ve seen several interpretations of the sequence of events and like virtually everything these days, it appears to have a partisan bias to people’s views.  There are those who claim President Trump could not stand the pressure of a declining stock market and “blinked” in the game of chicken he was playing.  There are also those who claim this was part of the strategy all along, essentially moving the Overton Window substantially in his preferred direction and now he is ready to reap the benefits of this move.  

Arguably, there is evidence for both sides of this argument and I suggest we will never really know. Remember, Trump is quite comfortable making outlandish pronouncements as he level sets for a negotiation.  But he is also quite the realist and while I do not believe he was concerned with his personal or family fortune, recognized that the speed of the pain inflicted could be damaging overall.  In the end, it is not clear the rationale matters, the action stands on its own merits.  

But remember this, equity valuations were very high before the decline last week, and were still quite high, although obviously less so, after the decline.  The rebound put them back in very high territory, especially with equity analysts revising profit forecasts lower on the back of the still 10% tariffs being imposed.  A truism is that the biggest rallies in the stock market occur during bear markets.  Keep that in mind as you assess risk going forward.

But let us turn our attention to a player who is not getting much attention these days, the Fed.  Many questioned the Fed’s rate cuts back in Q4 and attributed the moves to a partisan effort to help VP Harris get elected.  Certainly, there is no love lost between Chairman Powell and President Trump.  Of late, though, the commentary has focused on patience regarding any further policy ease as the impacts of Trump’s tariff policies are unknown at this stage.  Yet, it is not hard to read these comments and get a sense that the Fed is going to work at cross purposes to Mr Trump.  

For instance, yesterday, Minneapolis Fed President Neel Kashkari released an essay with the following comments, “Given the paramount importance of keeping long-run inflation expectations anchored and thelikely boost to near-term inflation from tariffs, the bar for cutting rates even in the face of a weakening economyand potentially increased unemployment is higher.  The hurdle to change the federal funds rate one way or theother has increased due to tariffs.”  While the words here don’t appear partisan per se, Mr Kashkari is one of the most dovish FOMC members and dismissed inflation concerns regularly for a long time.  This sudden change is interesting, at the least.  

At any rate, the market, which had been pricing a 50% probability of a rate cut next month just a few days ago and a total of at least 4 cuts this year, is back down to a <20% probability of a cut in May and about 3 cuts this year.  Truly the pause that refreshes.

So, let’s look at how other markets responded to the pause.  Markets everywhere, including China, rallied last night and this morning, with Tokyo (+9.1%) and Taiwan (+9.2%) leading the way in Asia although gains were universal.  Hong Kong (+2.1%) and China (+1.3%) were the laggards with gains between 2.5% and 5.0% the norm.  In Europe, too, equities are flying this morning as the threat of much higher tariffs is removed, at least temporarily, with the UK (+4.6%) the laggard and gains between 5.0% and 6.5% the story there.  Alas, futures this morning, at 7:00am, are pointing lower by -2.0% or so.  Is that profit taking or a harbinger of the day to come?

In the bond market, which has expressly been Trump and Bessent’s main concern, yields are a bit lower this morning, -3bps in 10-year Treasuries.  But the story in Europe is confusing to me, or perhaps not.  German bunds (+6bps) have seen the largest rise while UK Gilts (-10bps) have seen a sharp decline.  Too, Italy (-4bps and Greece (-2bps) have seen yields decline.  Could this be an illustration that bunds are a better safe haven than Treasuries? And now that haven status seems less important today, they are being sold off?  JGB yields (+9bps) are also rising, perhaps on the same notion.  The corroborating evidence is that nobody thinks Gilts are a good investment, so with risk back on, they are in demand given their highest yield in the G10.

In the commodity markets, oil rebounded sharply alongside equities yesterday although it has slipped 2.4% this morning.  I have altered the Y-axis on the chart below to percentages to give an idea of the magnitude of these moves in the past days, especially relative to the past 6 months.  Despite being the most liquid commodity market around (both figuratively and literally), it is far less liquid than bonds or FX or even stocks, so as commodities are wont to do, sometimes the moves are breathtaking.

Source: tradingeconomics.com

As to the metals markets, gold (+1.0%) continues its march higher, recovering more than 5% from the lows Tuesday morning.  I maintain that much of that selling was margin based, with positions liquidated to cover margin calls in other markets.  Now that the panic has passed, demand is likely increased given the new uncertainties.  However, both silver (-0.5%) and copper (-1.3%), which rallied sharply yesterday, have slipped back a bit.  These are different stories.

Finally, the dollar is lower this morning, having yo-yoed like every other market on the tariff news.  CHF (+1.9%) and JPY (+1.4%) are the big gainers in the G10 although the euro (+1.2%) is having a day as well.  However, there are currencies with less pizzazz this morning, notably ZAR (-0.9%), KRW (-0.6%) and MXN (-0.5%), as it remains difficult to know how to proceed going forward.  JPMorgan has a global volatility index which is a useful barometer of how things are going.  As you can see below, it is not surprising that volatility in this space has also risen sharply.

Once again, I return to the idea that President Trump is the avatar of volatility, and you must always remember that volatility can happen in both directions.  While financial assets tend to collapse (yesterday being the exception) when things get out of hand, commodities go the other way as supply interruptions are the big risk. Writ large, volatility simply means a lot of movement.

We finally get some meaningful data this morning with headline CPI (exp 0.1%, 2.6% Y/Y) and Core (0.3%, 3.0% Y/Y) along with the weekly Claims data (Initial 223K, Continuing 1880K).  Given all the focus on the tariffs, though, it is not clear to me what this data will imply on a forward-looking basis.  As we have seen with the Fed getting sidelined by Mr Trump, his tariff policies have also served to overshadow economic data, at least for now.  There are a couple of more Fed speakers and a 30-year bond auction as well.  Interestingly, I expect that auction may be the most important outcome of the day.  Will there be real demand or are investors shying away?

I expect that over the next few months, tariffs will be discussed on a nation-by-nation basis as new deals are struck.  But that will impede any medium-term views on the economy as until we have a much better sense of the end results, it will be difficult to assess things.  The upshot is, we may be entering a period where we chop up and down, but don’t go anywhere until the global trade situation is clearer.  Volatility with no direction is great for traders, less so for investors.  Headline bingo is still the game we are playing.

Good luck and good weekend

Adf

Squealed Like Stuck Pigs

What many just don’t comprehend
Is tariffs are not near the end
Of policy changes
As Trump rearranges
The world into foe and to friend
 
And while Wall Street squealed like stuck pigs
Trump’s boosters just don’t give two figs
They’re willing to try
The Trump calculi
If they see it hurts the bigwigs


I’m old enough to remember when Nonfarm Payrolls were the most important thing to market participants regardless of the asset class.  Ahh, those were the days.  It is remarkable that across major business headlines, I haven’t seen anything discussing the release for later this morning.  Don’t misunderstand me, I’m not upset about that fact, I think there has been far too much focus on that data point for far too long, but I am surprised.  This may be the best indicator that we are in a new regime for finance and economics.  It appears that most of the things the analyst community used to consider important are now merely afterthoughts.

I thought the WSJ had the most consequential article in this morning’s ‘paper’ asking, who is going to buy the $400 billion of stuff that China makes that will no longer be price competitive in the US?  They weren’t mentioned explicitly, but I imagine that Temu and Shein are both going to find their business models significantly impaired.  But will other “free trading’ nations allow all that stuff across their borders tariff free?  The Chinese mercantilist model was built with the idea that if they could produce stuff more cheaply than other nations, whether through subsidy or efficiency, other nations would welcome that stuff.  It remains to be seen how well that model holds up given the changes wrought by President Trump.

On a different note, I have read many comparisons of yesterday’s market declines to the March 2020 Covid panic, but my take is it is far more akin to the September 2008 Lehman Brothers collapse, at least from the tone of the market.  Covid was an exogenous event while Lehman and the tariffs were home-made.  The issue with the GFC and the current time was/is that they are systemic alterations which means that things will be different going forward in finance and economics.  Covid clearly changed our lives based on the government response, but it didn’t change the way markets behaved.  

At this point, there is no indication that President Trump is going to change his tune, and why would he? Again, amongst the key financial market goals he and Secretary Bessent have touted were a reduction in 10-year yields, lower by 75bps since inauguration, (✔️), a reduction in the price of oil, lower by $14/bbl or 18%,  (✔️) and a lower dollar relative to other currencies lower by 6.5%,(✔️).  Ask yourself, do you really think they are unhappy with the current situation?

I have no idea how things will play out from here, and in reality, neither does anybody else.  Reliance on models that were built with past assumptions does not inspire confidence.  As well, we have barely seen the response to these tariffs, although just moments ago China indicated they would be imposing 34% tariffs on all US goods entering their country.  But anybody who believes they know the end game is delusional.  This is the beginning of the change, and there will be much more to come across many different aspects of the economy and markets as the year progresses.  Interesting times indeed.

With that in mind, let’s see how day two of the new world order is playing out (and to think, there were all those conspiracy theories about a new world order before, but this was not what they had in mind.)  Green is a hard color to find on screens again today as after yesterday’s rout in US markets, the follow-through in Asia was almost complete.  Indonesia (+0.6%) managed a gain somehow, but every other major market declined, some quite substantially.  Singapore (-3.0%), Thailand (-3.6%) and Tokyo (-3.1%) were the biggest losers, but shares everywhere fell with most declining more than -1.0% on the session.  Interestingly, European shares are having a much worse session today than yesterday with Italy’s FTSE MIB (-7.1%) leading the way although Spain’s IBEX (-5.5%), the DAX (-4.5%), CAC (-3.8%) and FTSE 100 (-3.5%) are not exactly loving life today either.  As to US futures, they are pointing much lower again today, -3.0% or so for all the major indices.

Bonds, however, are in great demand with yields virtually collapsing as investors seek anyplace that is not equities to find shelter from this storm.  Treasury yields have fallen a further 15bps this morning and you can see in the chart below, just how large this decline has been.  In fact, yields have almost retraced to the level just before the Fed started cutting rates last September!

Source: tradingeconomics.com

But bonds everywhere in the world are in demand with yields on European sovereigns lower by between -7bps (Italy and Greece) and -15bps (Germany) as credit quality has also entered the picture there.  Finally, JGB yields have also tumbled, down -18bps overnight, as Japanese investors flee global markets and bring their money home.

Arguably, though, the biggest move has been in oil (-6.9%) which is now down to levels not seen since it was rebounding from Covid inspired lows back in 2022.

Source: tradingeconomics.com

I would contend this is almost entirely a recession fear, lack of forward demand story, although I believe OPEC+ is still planning on reducing its production cuts as the year progresses.  I imagine the latter is subject to change based on the economic outcomes.  In the metals markets, gold (+0.15%) after a sell-off yesterday, is consolidating for now.  Given the amount of leverage that abounds and given that when margin calls come, folks sell what they can, not what they want to, I suspect much of gold’s selling yesterday was forced rather than based on fear.  Rather, I suspect gold will outperform as it maintains its ultimate haven status.  The same, though, is not true for other metals with silver (-1.5%) and copper (-4.2%) both sharply lower this morning.  Certainly, in copper’s case, given the increased recession fears, it can be no surprise that its price is declining.

Finally, turning to the dollar, after a sharp decline yesterday, largely across the board, this morning the picture is a bit more mixed with a rebound against some currencies (AUD -3.0%, NZD -2.5%, SEK -1.7%, NOK (-2.1% although also inspired by oil’s precipitous decline.). However, both the yen (+1.0%) and Swiss franc (+1.25%) are continuing to display their haven attributes, while the euro (-0.1%) seems caught in the middle.  In the EMG bloc, though, the dollar is quite solid this morning with MXN (-1.9%), ZAR (-1.7%) and CLP (-1.0%) all falling.  Of note, CNY (0.0%) has barely moved throughout the entire process.

As I mentioned above, today we do see the NFP report, although my take is a strong report will be ignored as old regime, while a weak report will be ‘proof positive’ a recession is near.  Here are the expectations as of this morning:

Nonfarm Payrolls135K
Private Payrolls127K
Manufacturing Payrolls4K
Unemployment Rate4.1%
Average Hourly Earnings0.3% (3.9% Y/Y)
Average Weekly Hours34.2
Participation Rate62.4%

Source: tradingeconomics.com

Will the data really matter?  I don’t think so, at least not to policy makers as they realize (I hope) the world today is different than when this data was collected.  At this point, the market is now pricing in a full 75bps of rate cuts by year end from the Fed with a ~30% probability of a cut early next month.  But Powell and company don’t have any idea how this will play out either.  I fear that we are in a market situation where volatility is the dominant theme, in both directions.  Remember, Donald Trump is best thought of as the avatar of volatility.  He has earned that nickname.  This is why I harp on maintaining hedges, the world is a tricky place.

Good luck and good weekend

Adf

Stress and Dismay

The only discussion today
Is how badly tariffs will weigh
On stocks and on growth
As certainly both
Will feel some more stress and dismay
 
But hopefully, once they’re in force
It will change the pundits’ discourse
‘Cause I’m sick and tired
That it’s now required
We all, tariffs, hate or endorse


A funny thing happened on the way to the market collapsing yesterday, especially given the early morning portents, and that is the market didn’t collapse at all.  Equities opened lower and rallied all day with the Dow even having a quite respectable 1% gain when all was said and done.  I think the lesson that needs to be taken from this is markets have a tendency to get ahead of the news and reversals are pretty frequent.  In fact, this is a perfect example of ordinary market behavior, a sharp move in one direction is suddenly reversed for no obvious reason.  Certainly, there was nothing said or done yesterday that seemed a specific catalyst for a short-term rebound.  That, my friends, is simply how markets work.

However, for now, with tomorrow being President Trump’s “liberation day” when tariffs will be announced, they remain the major story across both financial markets and political narratives.  As I sit here in the cheap seats, observing the back and forth, what has become abundantly clear is that the politicization of economic actions is the true reality.  Yesterday I highlighted the difference between Democrat and Republican views on future inflation.  Reading through the commentary on X, as well as stories in Bloomberg and the WSJ, I think this is the same situation, with Democrats certain tariffs will be the downfall of the economy and lead to rampant inflation, while Republicans believe they will help the nation recapture lost manufacturing capacity.  Personally, I’m just looking forward to moving on to a different story as we have been discussing tariffs for more than two months straight and it is tiresome.

Here’s the one thing of which I am confident, however, and that is nobody has any idea what the impacts will ultimately be on either markets or the economy.  I maintain that pretty much every model that has been in use for the past two decades, all of which were developed based on data during a period of low inflation and declining interest rates as well as significant increases in central bank provided liquidity, no longer work.  After all, those underlying conditions no longer exist.  Inflation remains much higher than during the pre-pandemic decades;

Source: tradingeconomics.com

Interest rates are much higher;

Source: fred.stlouisfed.org

And central banks have been reducing net liquidity for some time now (think QT). 

Source: tradingeconomics.com

So, if all the underlying conditions have changed, it seems unlikely that the models based on those conditions will add much value.  After all, nobody really knows how elastic prices are for any given goods directly, nor how willing companies will be to sacrifice margin to maintain sales.  As such, forecasting short-term movements is a mugs’ game here.  In fact, yesterday’s price action is a perfect example of how things are not necessarily how they appear.

With that in mind, let’s see how yesterday’s risk reversal in US equity markets fed into the rest of the world.  Asian equities saw a wide range of price action overnight.  While Japan, Hong Kong and China were all tantamount to unchanged, Korea (+1.6%) and Taiwan (+2.8%) saw significant bounces while India (-1.8%) fell after concerns that President Trump’s mooted additional sanctions on any nation that buys Russian oil hit home as India buys, I read, 44% of their oil from Russia.  Meanwhile, in Europe, screens are green this morning with gains across the board of between 0.7% and 1.0%.  This is despite weaker PMI data, with every nation in Europe reporting a sub 50 manufacturing number.  However, inflation fell a tick more than expected with Core falling to 2.4% and headline down to 2.2% and this has encouraged traders to believe that the ECB will be cutting again later this month despite some commentary to the contrary from several ECB members.  As to US futures, at this hour (7:15) they are pointing lower by about -0.4% across the board.  

In the bond market, 10-year yields continue to slide around the world with Treasuries (-5bps) falling back to their lowest level in a month and prior to that since early December.  Too, European sovereigns are seeing yields fall sharply, with declines of between -6bps and -10bps as the combination of slowing inflation and weak PMI data has overwhelmed the previous concerns about German defense spending.  In fact, that is a story we have not heard in a while, eh?  Last week, that was the end of European bond markets, today it is ancient history!

Turning to commodities, oil (+0.1%) is consolidating after a sharp $2/bbl rise yesterday that was fomented by Trump’s threats to both Russia and Iran (he threatened to bomb them if they didn’t renounce their nuclear ambitions).  The thing about oil’s price action is since late 2022, it has remained in a trading range of $65/$80 more or less, so despite the large move yesterday, I would argue no new ground has been covered.  Certainly Trump’s efforts to open up more area for drilling is likely to weigh on prices over time, but over what timeframe remains to be seen.  As it is a day ending in “y”, gold is higher again, this morning by 0.3%, but there is no indication this trend is running out of steam.  The remarkable thing is the steadiness of the move.  However, the other two major metals, silver (-0.35%) and copper (-0.3%) have slipped a bit this morning.

Finally, the dollar remains confused.  Versus the euro (-0.25%) it is stronger, but versus the CHF (+0.25%) and JPY (+0.5%) it is weaker.  Now, you might say that is a sign of a risk-off trade, but equity markets are rallying in Europe along with bonds.  So, is this a move to havens or risk?  The biggest mover this morning is CLP (-0.9%) but it has been one of the biggest gainers YTD, so with copper soft, this looks a lot like some profit taking.  Otherwise, movements of +/- 0.2% are the order of the day.

Here’s a crazy theory, perhaps President Trump is seeking to drive the economy weaker in order to force the Fed to cut rates.  After all, that appears to be the Fed’s bias, but recent inflation data has made them uncomfortable to do so.  If Trump can drive up Unemployment, maybe it does the trick!

Ok, let’s see the data the rest of the week as yesterday’s Chicago PMI (47.6) while modestly better than expected really didn’t seem to matter that much.

TodayISM Manufacturing49.5
 ISM Prices Paid65.0
 JOLTS Job Openings7.63M
WednesdayADP Employment105K
 Factory Orders0.5%
 -ex Transport0.7%
ThursdayInitial Claims225K
 Continuing Claims1860K
 Trade Balance-$123.0B
 ISM Services53.0
FridayNonfarm Payrolls128K
 Private Payrolls110K
 Manufacturing Payrolls1K
 Unemployment Rate4.2%
 Average Hourly Earnings0.3% (3.9% Y/Y)
 Average Weekly Hours34.2
 Participation Rate62.4%

Source: tradingeconomics.com

In addition to all this, we hear from six Fed speakers including Chairman Powell Friday morning at 11:30am.  For today and tomorrow, tariffs will be the primary story, although it is not clear it is the primary driver.  However, once they are announced, I expect we will move onto the next big thing, although I have no idea what that will be.  But the one thing on which we can count regarding President Trump is there will be another big thing.  Stay hedged is all the advice I can give because uncertainty is extremely high.

Good luck

Adf

Nobody Knows

The punditry’s now out in force
As they hope, their views, we’ll endorse
When tariffs arrive
On Wednesday they’ll strive
To claim they were right, but of course
 
The problem is nobody knows
Exactly what Trump will propose
So, models will fail
While Trump haters wail
More chaos is all that he sows


Well, folks, it’s month and quarter end today and many are decrying that President Trump’s policies have derailed the bull market in risk assets.  And they are almost certainly correct.  Yet, at the same time, there has been a broad recognition across a wide spectrum of analysts and politicians that the situation he inherited was unsustainable.  Whether the 7% budget deficits, the $36+ trillion in government debt or the ongoing inflationary pressures, the only people who were happy were those who saw their equity portfolios rise against all odds.  (I guess the gold holders have been pretty happy too, in fairness.)

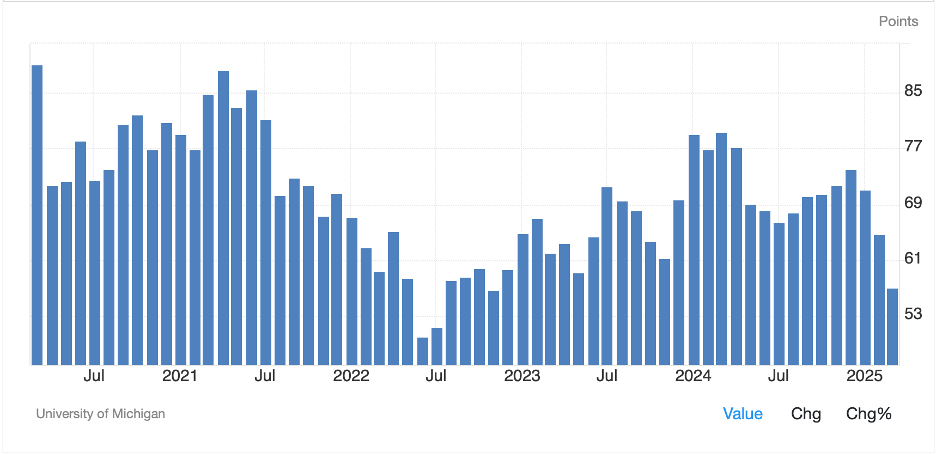
However, the underlying reality of a situation is rarely enough to alter a good story, or a story that somebody wants to tell.  For instance, the Michigan Consumer Survey was released on Friday, and it fell more than expected to a reading of 57.0, its lowest reading since July 2022, when inflation was peaking.

Source: tradingeconomics.com

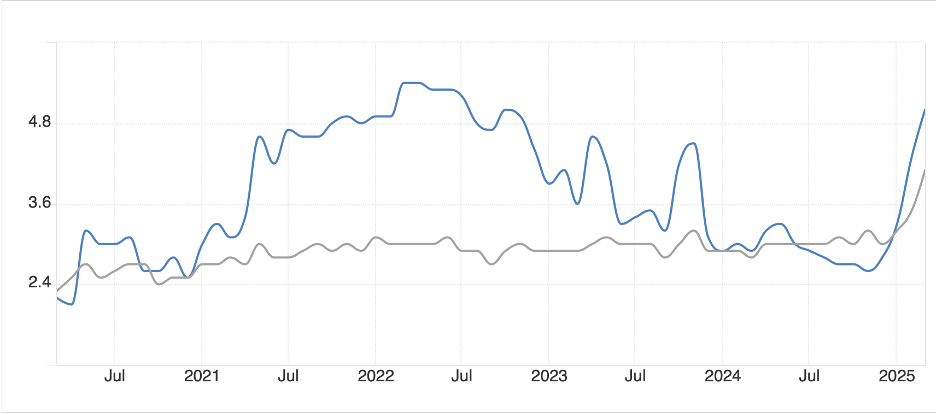
But the story that has been getting all the press is the extraordinary rise in inflation expectations.  As you can see below, both 1-year (blue line) and 5-year (grey line) have risen sharply in 2025.  Conveniently for the mainstream media this has been blamed on President Trump’s policies given their efforts to discredit everything the president does.

However, the Michigan Survey, while having a long pedigree, isn’t that large a survey.  As such, it is possible that non-economic factors may be impacting the results.  For instance, when the survey is taken, the respondents’ political leanings are asked as well.  Now, take a look at the data when split by political views as per the below.  Perhaps, we need to take this survey with a grain or two of salt as it appears the question may be seen as a way to express one’s opinion about the current administration rather than unbiased views of future inflation.

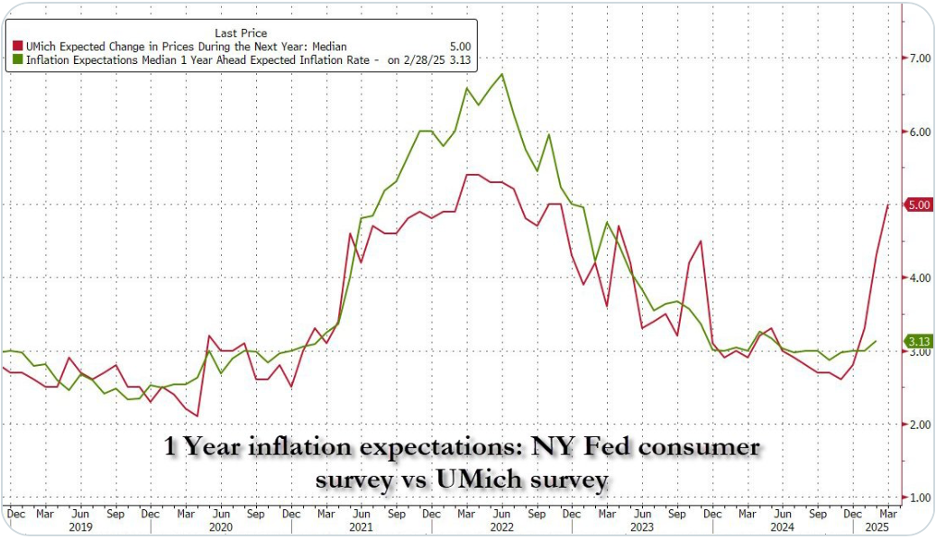
This is especially true when we look at other measures of expected inflation, like the NY Fed’s Consumer inflation survey shown below with the green line compared to that Michigan survey in red.

Source: zerohedge.com

My point is, we need to be careful to notice the non-economic factors that enter into things like expectations surveys.  As well, the idea that inflation expectations are a critical driver of future inflation, although a staple of current central bank thinking, does not have much empirical backing.  For instance, my friend Mike Ashton, the Inflation Guy™, explained in this article way back in 2015, that inflation expectations do not have much empirical proof of effectively forecasting future inflation.  But perhaps, if you don’t believe him, you will consider a scholarly paper by a Fed economist, Jeremy Rudd, written in 2021 that is pretty damning with respect to the idea that the Fed relies on this data as part of their policy toolkit.  

In the end, the one truism of which I am highly confident is that pretty much all the models that have been utilized for the past twenty plus years are no longer reflective of the reality on the ground today.  Not just for inflation, but for growth and trade and every other aspect.  President Trump has not merely upset the applecart; he has broken it into pieces and burned them all to cinders.  All the fiscal problems mentioned above are still extant, but President Trump appears set on changing them in the direction desired by almost all mainstream economists.  They don’t like his methods, but it’s not clear how changes of this magnitude can be made smoothly.  So, perhaps the proper question is just how rough things are going to be.  If the overnight session is any indication, they could get pretty rough.

The dominant feature today
Is fear is what’s now holding sway
As markets decline
More pundits consign
The blame on Trumps tariff pathway

Investors have risk indigestion this morning, as their appetite to own equities anywhere in the world has significantly diminished.  After a rough week ending session on Friday in the US, equity markets in Asia have almost universally declined led by Tokyo (-4.05%) but with sharp declines seen in Korea (-3.0%), Taiwan (-4.2%), Australia (-1.75%), Malaysia (-1.45%) and Thailand (-1.5%).  Chinese (-0.7%) and Hong Kong (-1.3%) shares also fell, although perhaps not quite as far as others.  The entire conversation today is about President trump’s promise to impose tariffs around the world on Wednesday, with many analysts trying to estimate what damage will occur despite no clarity on the size and breadth of the tariffs.  But investors have decided that havens are a better place to hide for now.

European bourses are also sharply lower, although more in the -1.7% to -2.0% range, with every major index in Germany, France, Spain and Italy down by those amounts.  There continues to be a great deal of discussion amongst the European leadership about how they will respond to the mooted tariffs, but of course, like everybody else, they have no idea exactly what they will be.  As to US futures, at this hour (6:45) the picture is grim with declines between -0.6% (DJIA) and -1.3% (NASDAQ).  Right now, the only people who are happy are those holding puts.

Of course, in this risk-off environment, it should be no surprise that bond yields have slipped a bit as, at the margin, investors are flocking to own Treasuries (-5bps) and European sovereigns (Bunds -3bps, OATs -2bps, Gilts -4bps).  Even JGBs (-5bps) saw yields decline last night with any thoughts of the BOJ hiking rates in the near term fading away completely.  

On the other hand, commodities are finding a lot more interest this morning with gold (+1.15%) leading the way higher and proving itself to continue to be one of the most consistent safe havens available.  Interestingly, oil (+0.5%) is rallying this morning despite a number of Wall Street analysts upping their estimate of the probability of a US recession.  However, offsetting the potential future demand weakness is the news that President Trump is “pissed off” at Vladimir Putin for his ongoing aggression in Ukraine and seeming unwillingness to move to a ceasefire.  This has raised the specter of further sanctions on Russian oil output, potentially reducing supply.  As well, the Trump administration continues to tighten the noose on both Iranian and Venezuelan oil sales, so potentially reducing supply even further.  I guess this morning, the supply story is bigger than the demand story.

Finally, as we turn to the currency markets, the dollar is generally firmer this morning, although by widely varying amounts depending on the currency.  For instance, in the G10, NOK (-0.75%) is the laggard despite oil’s gains, followed by AUD (-0.6%) and NZD (-0.55%), with all three of these being major commodity producers at a time when commodities are doing well.  As to the rest of this bloc, JPY (+0.35%) is off its best levels, but behaving as a haven, and the others are just marginally changed from Friday’s closing levels.  In the EMG bloc, ZAR (+0.25%) is the exception this morning, clearly benefitting from gold’s ongoing run to new all-time high prices, but otherwise, most of these currencies are modestly softer (MXN -0.2%, PLN -0.2%, KRW -0.25%).

Speaking of currencies, though, there is an article on this morning’s Bloomberg website that is worth reading, I believe, for everyone involved in the FX market.  The gist of the article is something that I have been discussing for the past several years, the fact that market liquidity here, despite the extraordinary volumes that trade on average each day (currently estimated by the BIS at $7.5 trillion across all FX products) is not nearly as deep as might be anticipated.  

My observation from my time on bank desks was that while there was a great deal of electronic flow, likely driven by HFT firms seeking to extract the last tenth of a pip out of thousands of transactions, when a real client, generally a corporate, had a need to do something specific to address a business need, and that amounted to more than $100 million equivalent, the liquidity situation was far more suspect. 

My personal theory was as follows: bank consolidation reduced the net amount of risk-taking appetite as larger banks did not increase their risk-taking commensurate with the reduction that occurred by small banks being gobbled up.  Combining this with the introduction of high-frequency trading firms in the business, who had no underlying client base to whom they owed a price, and therefore, could turn off their machines in a difficult market, further reducing liquidity, led to a situation where liquidity was a mile wide and an inch deep.  My point is for all the corporates out there who have significant transactions to execute, you must carefully consider the best way to approach the situation to avoid a potentially significant increase in execution costs.

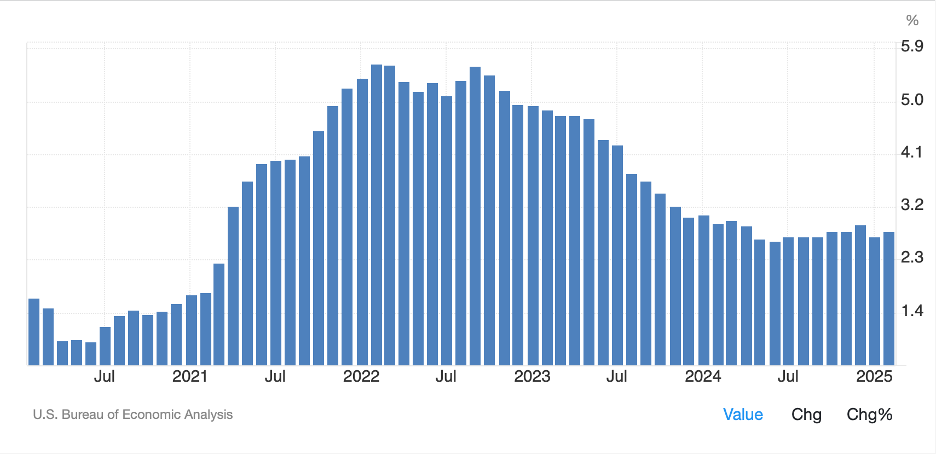
Turning to the data, before we look at this week, which ends with NFP, a quick word on Friday’s core PCE data, which came in at a hotter than expected 0.4% taking the YY number to 2.8%.  The Fed cannot be happy with this outcome as a quick look at the recent readings makes it hard to accept inflation is continuing its decline from the 2022 highs.  Rather a look at the below chart, at least to my eye, shows me a stability in Core PCE of somewhere between 2.5% and 3.0%, well above the Fed’s target range, and hardly a cause to cut rates further.

Source: tradingeconomics.com

As this note has already gotten a bit longer than I like, I will list the week’s data tomorrow but note that Chicago PMI (exp 45.4) is the only noteworthy data point to be released today.  

Absent a complete reversal of Trump’s tariff plans, I see nothing positive on the horizon for risk assets, and expect that equities will maintain, and probably extend the overnight losses while gold and bonds both rally, at least for now.  As to the dollar, my take is it will not benefit universally in this risk-off scenario, although there are currencies that will clearly suffer.  Remarkably, despite the performance of Aussie and Kiwi overnight, I do believe the commodity bloc has the best prospects for now.

Good luck

Adf

Tripping Off Tongues

Recession is tripping off tongues
And pundits ain’t twiddling their thumbs
Political shades
Are driving tirades
And screams at the top of their lungs
 
But are we that likely to see
A minus in our ‘conomy?
We certainly could
And probably should
But life doesn’t always agree


The major discussion point over the weekend has been recession, and how likely we are to see one in the US in the coming months.  Of course, this matters to the punditry not because of any concern over the negative impacts a recession has on the population, but ‘more importantly’ because recessions tend to result in sharp declines in equity values.  And let’s face it, do you honestly believe that the editors of the New York Times or the Wall Street Journal are remotely interested in the condition of the majority of the population?  Me neither. 

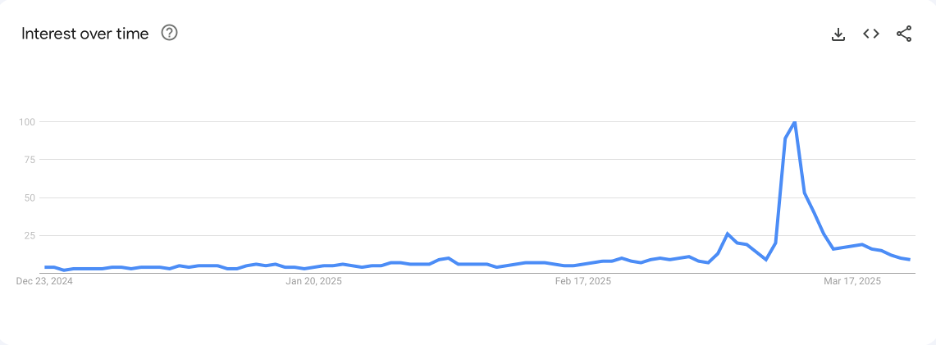
However, if they can call out something that they believe can impede President Trump, or detract from his current high ratings, they will play that over and over and over.  Funnily enough, when I went to Google Trends, I looked up “recession” over the past 90 days with the result below:

That peak was on March 11 although there was no data of note that day compared to a reading of 9 today. Looking at the news of that day, even CNN had a hard time finding bad news with the four top stories being 1) the Continuing Resolution vote in the House being passed, 2) the Department of Education announcing a 50% RIF, 3) 25% tariffs on steel and aluminum being imposed and 4) Ukraine accepting terms for a 30-day ceasefire.  From an economic perspective, the tariffs clearly will have an impact, but it seems a leap that the average American can go from 25% tariffs on imported steel and aluminum to recession in one step.  And based on the positive responses that continue to be seen regarding President Trump’s efforts to reduce the size of government, I doubt the DOE cuts were seen as the beginning of the end of the economy.  

And yet, recession was the talk of the punditry this weekend.  To try to better understand why this is the case, I created the following table of several major economic indicators and their evolution since December, prior to President Trump’s inauguration.

Key indicatorsDecJanFeb
NFP323125151
Unemployment Rate4.10%4.00%4.10%
CPI2.90%3.00%2.80%
Core CPI3.20%3.30%3.10%
PCE2.60%2.50% 
Core PCE2.90%2.60% 
IP1.10%0.30%0.70%
Capacity Utilization77.60%77.70%78.10%
ISM Mfg49.250.950.3
ISM Services5452.853.5
Retail Sales0.70%-1.20%0.20%

Source: tradingeconomics.com

Once again, while I am certainly no PhD economist, this table doesn’t strike me as one demonstrating a clear trend in worsening data, certainly not on an across-the-board basis.  Rather, while you might say January was soft, the February data has largely rebounded.  My point is that despite ABC, NBC, Bloomberg, the BBC and CNN all publishing articles or interviews on the topic this weekend, I’m not yet convinced that is the obvious outcome.

My good friend the Inflation Guy™, Mike Ashton, made an excellent point in a recent podcast of his that is very well worth remembering.   The breadth of the US economy is extraordinarily wide and covers areas from manufacturing to agriculture to finance to energy and technology along with the necessary housing markets as well as the entire population consuming both goods and services.  Added to the private sector, the government sector is also huge, although President Trump and Elon Musk are trying hard to shrink it.  But the point is that it is not merely possible, but likely, that while some areas of the economy may go through weak patches, that doesn’t mean the entire economy is going to sink into the abyss.

If we think back to the last two recessions, the most recent was Covid inspired, which resulted from the government literally shutting down the economy for a period of several months, while giving out money.  Net, things weakened, but even then, there were stronger parts and weaker parts.  Go back to the GFC and the housing bubble popped and dragged banks along with it.  That was the problem because banking weakness inhibits the free flow of money and that will impact everyone.

The question to be asked now, I would suggest is, are we likely to see another catalyst that will have such widespread impacts?  Higher tariffs are not going to do the trick.  Shrinking government, although I believe it is critical for a better long-term trajectory for the economy, will have a short-term impact, but it is not clear to me that it will negatively impact the economy writ large.  Certainly, the Washington DC area, but will it impact the Rocky Mountain area?  Or Texas and Florida?  

Now, a recession could well be on the way.  Running 7% budget deficits was capable of papering over many holes in the economy and pumping lots of liquidity into it as well.  If those deficits shrink, meaning spending shrinks, the pace of activity will slow.  But negative?  It seems a stretch to me, at least based on what we have seen so far.  One last thing here, is how might this potential weakening economic growth impact inflation? Now, we all ‘know’ that a recession causes inflation to decline, don’t we?  Hmmm. While that makes intuitive sense, and we hear it a lot, perhaps the Inflation Guy™ can help here as well.  Back in February he wrote a very good explanation about how that is not really the case at all, at least based on the macroeconomic data.  The truth is economic growth and inflation have very little correlation at all.

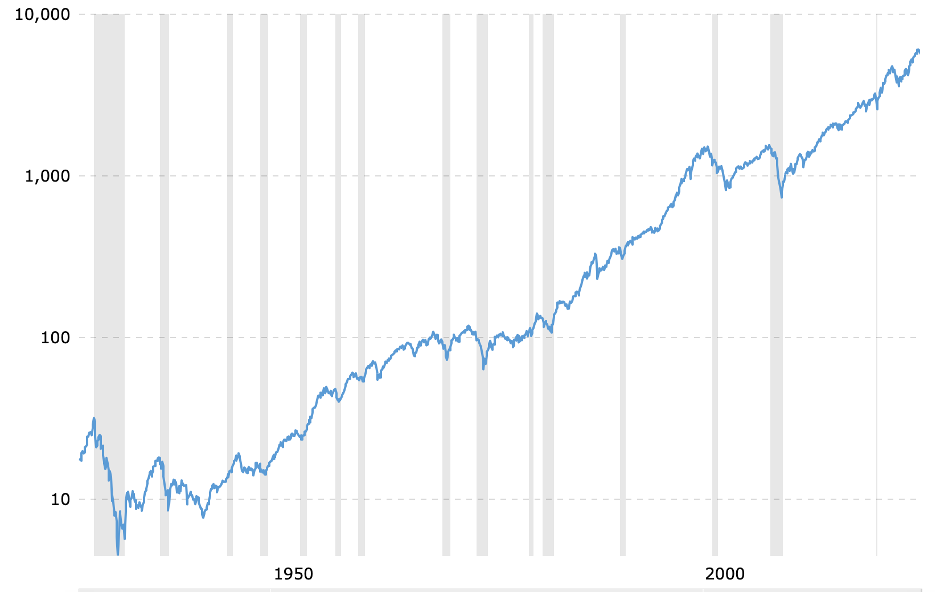
Of course, perhaps the most critical issue for the punditry is, will a recession drive stock prices lower?  Here the news is far less sanguine if you are a shareholder and believe there is going to be a recession.  As you can see from the below chart of the S&P 500, pretty much every recession for the last 100 years has resulted in a decline in stock market indices.

Source: macrotrends.net

This is a log chart so some of those dips don’t seem that large, but the average downturn during a recession is about 30%, although that number can vary widely.  To sum it up, while the data doesn’t scream recession to me, it cannot be ruled out.  As well, both President Trump and Secretary Bessent have indicated that weakness is likely going to be a result of their early actions, although the idea is to pave the way for a more stable economic performance ahead.  As I have written repeatedly, volatility is likely the only thing of which we can be certain as all these changes occur.  Hedge your exposures!

Ok, let’s look at the overnight activity.

The rumor is Trump may delay
His tariffs as he tries to weigh
How much he should charge
And how much, writ large,
These nations are going to pay

Equity futures in the US are higher this morning as the big story is that President Trump is considering narrowing the scope of nations who will have tariffs imposed on April 2nd.  Apparently, his administration has identified the “dirty fifteen” nations with the largest bilateral imbalances and they will be first addressed.  The telling comment in the WSJ article I read was when Trump said, “Once you give exemptions for one company, you have to do that for all. The word flexibility is an important word. Sometimes there’s flexibility, there’ll be flexibility.”  To my ear, the final plans are not in place, but my sense is he will impose then remove tariffs, rather than avoid them initially.  Interestingly, that story was written last night, yet Asian equity markets were not that ebullient.  Japan (-0.2%) saw no benefit although Chinese shares (HK +0.9%, CSI 300 +0.5%) fared better. Things elsewhere in the region were mixed with both gainers (India, Thailand) and laggards (Korea, Taiwan, Indonesia) with many bourses little changed overall.

In Europe, green is the predominant color this morning but movement is modest with Spain’s IBEX (+0.4%) the leader and lesser gains elsewhere.  While US futures are all higher by about 1% or more at this hour (6:45) apparently the Europeans aren’t as excited at the tariff delay process.

In the bond market, yields have backed up virtually across the board with Treasuries (+4bps) leading the way higher and most European sovereigns showing yields rising by 1bp or 2bps.  It’s interesting, while there has been much discussion regarding German yields having traded substantially higher in the wake of the effective end of the debt brake and anticipation of much further issuance, a look at the chart below tells me that after that gap higher on the news, concerns over German finances have not deteriorated at all.  And after all, the difference is about 25bps higher, hardly the end of the world.

Source: tradingeconomics.com

In the commodity markets, oil (+0.7%) is continuing its gradual rebound from the lows seen on, ironically, March 11th.  Arguably, what this tells us is that despite the weekend barrage of recession focused articles, the market doesn’t really see that outcome.  In the metals, strength is the word, again, with copper (+1.25%) making new all-time highs on the back of China’s stated goals of growing its strategic stockpile.  Not surprisingly, both gold (+0.2%) and silver (+0.6%) are also climbing this morning alongside copper as commodities remain in greater demand than a recession would indicate.

Finally, the dollar is a bit softer despite rising Treasury yields with both the euro (+0.3%) and pound (+0.4%) bouncing after last week’s modest declines.  And this is despite lackluster Flash PMI readings this morning out of Europe.  The biggest winner is NOK (+0.6%) which given the dollar’s broad weakness and oil’s rebound makes perfect sense.  Otherwise, while the dollar’s weakness is broad, it is no deeper than the aforementioned currencies.

Given the length of this note already (my apologies) and the dearth of data to be released, with only the Chicago Fed National Activity Index (exp +0.08), I will cover data tomorrow as we do end the week with GDP and PCE data.

Headline bingo remains the key concern for all market participants, but ultimately, my altered view of a softer dollar and higher commodities remains intact.

Good luck

Adf

No Retreating

The virtue of patience remains
The key to our policy gains
Though tariffs and trade
May one day, soon, fade
It’s still ‘nuff to scramble our brains


In a bit of a surprise, Chairman Powell resurrected the term ‘transitory’ in his press conference yesterday with respect to the potential impact on prices from President Trump’s tariff policies.  He explained, “We now have inflation coming in from an exogenous source, but the underlying inflationary picture before that was basically 2½% inflation, 2% growth and 4% unemployment.”  In addition, he said, “It’s still the truth if there’s an inflationary impulse that’s going to go away on its own, it’s not the right policy to tighten policy because by the time you have your effect, you’re in effect, by design, you are lowering economic activity and employment.”  It is this mindset that returned ‘transitory’ to the discussion.  Now, while mainstream economics would agree to that characterization, with the idea being it is a one-off price rise, not the beginning of a trend, given the Fed’s history of using the word to describe the impact of monetary and fiscal policies in the wake of the pandemic, it caught most observers off guard.

But in the end, the Fed’s only policy change was a reduction in the pace of runoff of Treasuries from the Balance Sheet on a temporary basis.  Previously, they had been allowing $25B per month to run off without being replaced and starting April 1, that will be reduced to $5B per month.  The runoff of Mortgage-backed assets will continue as before.  This has been a widely discussed idea as the Fed approaches their target of “ample” reserves on the balance sheet, an amount they still characterize as “abundant”.

As to changes in the dot plot and SEP forecasts, they were, at the margin, modest, with the median dot plot ‘forecast’ continuing to call for 2 rate cuts this year.  Fed fund futures are now pricing in 65bps of cuts, so marginally tighter than the 75bps seen last week.  The SEP also showed slightly different forecasts for growth, inflation and unemployment, but just a tick or two different, hardly enough about which to get excited.  

Certainly, Mr Powell said nothing to upset equity markets as the response was a continuation of the modest rally that began in the morning.  As well, bond yields slid almost 9bps from their level just before the Statement was released.  Net, I expect the only people who are unhappy with the Fed’s performance are the hundreds of millions of Americans who have seen the inflation rate remain above the 2.0% target for the past 48 months (see chart below), but then Powell doesn’t really respond to them directly, now does he?

Source: tradingeconomics.com

Oh yeah, President Trump also published a little note on Truth Social that Powell should cut rates, but I don’t think that had any impact at all.  For now, Trump’s attention is elsewhere, and if 10-year yields continue to slide, I suspect he will be fine, certainly Secretary Bessent will be.

In Europe, the leaders are meeting
Again, as they keep on repeating
They need to spend more
To maintain the war
In Ukraine, ‘cause there’s no retreating

Back in the real world, the diverging points of view between President Trump, and his attempts to end the Ukraine War, and the EU, which seems hell-bent on continuing it ad infinitum were highlighted again today as yet another summit meeting is being held in Brussels to discuss the process and progress on rearming the continent as well as how they envision the future of Ukraine.  This matters to markets as the continuous calls for more fiscal military spending is going to be a driver of equity prices in Europe, and given it is going to be funded by issuing more debt, on both a national and supranational basis, yields are likely to rise as well over time.  

There has been much talk lately of the end of US exceptionalism, and certainly there has been a shift of investment into European shares, especially defense firms, and out of US tech shares.  This has helped support the single currency, which while it has slipped the past two days, remains higher by 4.5% since the beginning of the month.  Ex ante, there is no way to know how this situation will evolve, but if history is a guide at all, the US continues to hold all the defense cards in the deck, and so even with European protests, I suspect the war will come to an end.

But here’s a thought, perhaps even if the war ends, the pre-war energy flows may not resume.  This would not be because Europe doesn’t want cheap Russian gas, but perhaps because Russia doesn’t want to sell it to those who will use it to build armaments that can be used against Russia.  The world has moved to a different place both politically and economically, than where it was pre-Covid.  My sense is many old models may no longer work as proxies for reality, which takes me back to my favorite theme, the one thing on which we can count is more volatility!

Ok, let’s take a turn through markets overnight.  After the US rally, Asia was far more mixed with the Nikkei (-0.25%) slipping a bit and both China (-0.9%) and Hong Kong (-2.2%) falling more substantially on fears that US tariffs could slow growth there more than previously feared.  But elsewhere in the region there were far more gains (Korea, Australia, India, Taiwan) than losses (Malaysia, Thailand). 

Europe, though, is having a tougher session with losses across the board.  The continent is particularly hard hit (Germany -1.7%, France -1.2%, Spain -1.2%) although the UK (-0.3%) is holding up better after decent employment data was released.  We did see the Swiss National Bank cut its base rate by 25bps, as expected, while Sweden’s Riksbank left rates on hold, also as expected.  In fairness, European stocks have had quite a good run, so a pullback should not be a surprise, but it is disappointing, nonetheless.  As to US futures, at this hour (7:10), they are pointing lower by -0.5% or so.

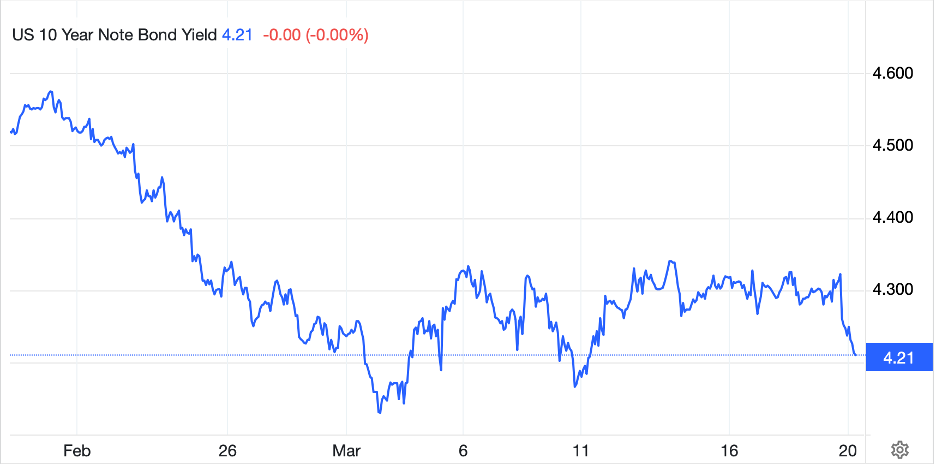
In the bond market, Treasury yields are lower by a further -4bps this morning and down to 4.20%, still well within the recent trading range (see chart below).  As to European sovereigns, they too are lower by between -3bps and -5bps, as despite concerns over potential new issuance, fear seems to be today’s theme.  Oh yeah, JGB yields are still pegged at 1.50%.

Source: tradingeconomics.com

In the commodity bloc, oil is little changed this morning, and net, on the week little changed as well.  It is difficult to see short-term drivers although I continue to believe we will see it drift lower over time as supply continues apace while demand, especially in a slowing growth scenario, is likely to ebb.  Gold (-0.6%) is having its worst day in more than a week, but the trend remains strongly higher.  Arguably a bit of profit taking is visible today.  This is dragging silver (-1.8%) along for the ride although copper (+0.1%) is sitting this move out.

Finally, the dollar is firmer again this morning, higher by 0.5% according to the DXY, with the biggest currency laggards the AUD (-1.1%), SEK (-0.8%) and ZAR (-0.75%).  But the dollar’s strength is universal this morning.  One possibility is that traders have decided Powell is not going to cut rates, hence more pressure on US equities, and more support for the dollar.  I don’t agree with that thesis, as I believe Powell really wants to cut rates, but for now, the other argument has the votes.

On the data front, we get the weekly Initial (exp 224K) and Continuing (1890K) Claims as well as the Philly Fed (8.5) all at 8:30.  Then at 10:00 we see Existing Home Sales (3.95M) and Leading Indicators (-0.2%).  Also, at 8:00 we will get the BOE rate decision, with no change expected.  However, as I have been explaining, central bank stories are just not that important, I believe.  Investors in the UK are far more worried about the Starmer fiscal disaster than the BOE.

There are no Fed speakers on the schedule today, so, I suspect it will be headline bingo.  While the dollar has outperformed for the past two sessions, I continue to believe the trend is lower for the buck and higher for commodities.  Perhaps today is a good day to take advantage of some dollar strength for payables hedgers.

Good luck

Adf

Just a Mistake

It wasn’t all that long ago
That folks really wanted to know
What Jay and the Fed
Implied was ahead
And if more cuts were apropos
 
But later today when they break
Their words are unlikely to shake
The narrative theme
That whate’er they deem
Important, is just a mistake


Presidents Trump and Putin spoke at length yesterday, but no solution was achieved so the Ukraine War will continue unabated for now. While talks are better than not, certainly this is a disappointment to some.  As well, the astronauts who have been stranded in space for the past 8 months are safely back on earth.  I mention these things because they are seemingly far more important than central banks these days, and today, that is all we have to discuss regarding financial markets.

To begin, last night the BOJ left rates on hold as universally anticipated.  The initial market response was for the yen to weaken through 150 briefly, but then Ueda-san spoke and discussed the expected wage increases and how the economy was doing fine, and the new market assessment is that the BOJ will hike rates by 25bps in May at their next meeting.  The market response was to buy back the yen, at least for a little while, although right now, USDJPY seems to be attracted to the 150 level overall.  

Source: tradingeconomics.com

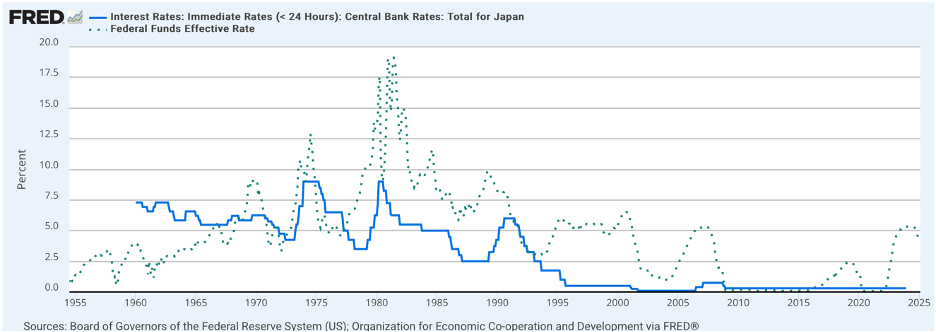
It is worth understanding, though, that the last time short-term interest rates were that high in Japan was back in July 2008.  And they have not been above that level since August 1995.  The below chart from FRED database speaks volumes about just how low interest rates have been in Japan over time, and as an adjunct, just how long the opportunity for shorting JPY on the carry trade has been around.  That dotted line is the Fed funds rate compared to the Japanese overnight rate.  

Along the central bank thesis, Bank Indonesia, too, met last night and left policy on hold with their policy rate at 5.75%.  Governor Warjiyo explained that he felt falling inflation and improving growth would help prevent rupiah weakness despite the fact that the currency has been the worst performing Asian currency this year and is trading at historic lows.

But on to the FOMC meeting which will conclude at 2:00 this afternoon with the policy statement (no change expected although some tweaking of the verbiage is likely) and the release of the latest dot plot.  You have probably forgotten that at the December meeting, the FOMC reduced the median expectation of rate cuts for 2025 from 4 prior to the election to just 2.  In the interim we have seen Fed funds futures trade to where barely one rate cut was priced in, although we are now back to three cuts, seemingly on the idea that tariffs will cause significant economic weakness, and the Fed will need to respond.  At least that’s what the punditry maintains.

Here is the last dot plot for information purposes and it will be interesting to see just how much things have changed.  will longer run rates continue to move higher?  Will 2 rate cuts still be the median outcome for 2025?  All this we get to learn at 2:00.

Source: federalreserve.gov

But arguably, of far more import will be Chairman Powell’s press conference beginning at 2:30.  Prior to the Fed’s quiet period, the broad assessment was that patience in future rate moves was appropriate and they were happy with the current situation.  However, I am confident there will be numerous questions regarding the potential impact of tariffs on monetary policy responses, as well as other things like DOGE and an audit of the Fed.  Will any of it matter?  Maybe at the margin, but for most markets, I suspect that fiscal issues will remain dominant.  The one exception is the FX market, where unalloyed hawkishness could change views on the dollar’s recent weakness (although it is firmer this morning) while a dovish tone will almost certainly undermine the greenback.  So, with no other data of note to be released beforehand, it is clearly the day’s major event.

Ahead of that event, let’s see how markets have behaved overnight.  Following a weak session in the US, where all three major indices were lower by about -1.0% on average, Asia had a mixed picture.  The Nikkei (-0.25%) found no love from Ueda-san and drifted lower.  Both Hong Kong (+0.1%) and China (+0.1%) edged higher but continue to doubt the benefits of the mooted Chinese stimulus program while the rest of the region was mixed with some gainers (Indonesia, Korea, India) and some laggards (Taiwan, Australia, Malaysia).  In Europe, too, the picture is mixed with the DAX (-0.4%) lagging while the CAC (+0.5%) is gaining.  In Germany, the historic breech of the debt brake is not having the positive impact anticipated, or perhaps this is just selling the news.  Overall, though, shares in Europe seem to be awaiting the Fed’s actions, or comments, rather than focusing on anything else.  As to US futures, at this hour (7:30), they are pointing slightly higher, about 0.25% across the board.

In the bond market, Treasury yields have edged up 1bp this morning but continue to hang around 4.30%.  European sovereign debt has seen yields slip -1bp to -2bps, arguably on the Eurozone inflation data released 0.1% lower than forecast at 2.3%.  This continues the idea that the ECB will be cutting rates again at their next meeting.  As to JGBs, they are unchanged yet again, seemingly affixed at 1.50%.

Commodity prices show oil (-0.2%) continuing yesterday’s decline.  From the time I wrote to the end of the session, WTI fell $2/bbl, perhaps on the idea that the Putin/Trump phone call was bringing the war closer to an end.  Regardless, if economic activity is slowing, that will lessen demand everywhere, a clear price negative.  As to gold (+0.25%) it continues to trade higher undaunted by any news on any front.  While silver is little changed this morning, copper (+0.7%) has now crested $5.00/lb and is pushing to the all-time highs seen back in May 2024.

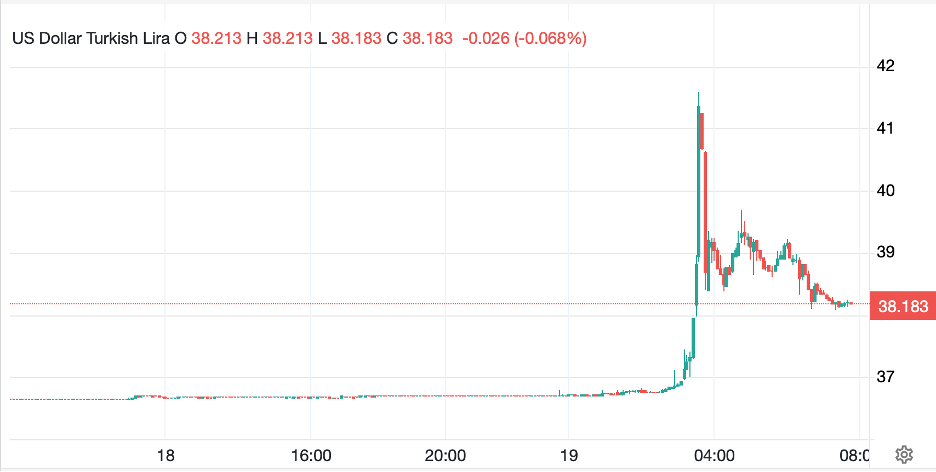
Finally, the dollar is rallying this morning, higher against all its G10 counterparts by between 0.2% and 0.4%.  This looks to me like a trading correction, not a new trend.  The same price action is true in the EMG bloc with one real outlier, TRY (-4.2%) which actually traded down by as much as -10% earlier in the session (see chart below) on the news that President Erdogan had his key political rival, Istanbul mayor Ekrem Imamoglu, arrested on charges of fraud and terror, while his university diploma was revoked, seemingly in an effort to prevent him from running for president in the future.  Thank goodness we never have things like that happen in this country!

Source: tradingeconomics.com

There is no data released today other than EIA oil inventories where a modest net build across products is currently expected.  So, until the Fed, I would anticipate very little net movement.  After that, it all depends.  However, Powell will need to by extremely hawkish to shake any of my view that the dollar is headed lower overall.

Good luck

Adf

Not Fraught

The Retail Sales data did nought
To clarify anyone’s thought
‘Bout growth or inflation
While anticipation
Of Jay, for a change, is not fraught
 
Meanwhile, tariffs are, once again
A question of how much, not when
Just two weeks from now
The president’s vow
For more, has disturbed market zen


In a remarkable situation, at least these days, there is precious little new news impacting financial markets.  Perhaps that is why equities around the world are rallying, the absence of bad news is seen as good.  Here in the States, the biggest story continues to be the controversy over the deportation of several hundred Venezuelan and Salvadorean gang members that some claim ignored a judge’s order.  I’m confident this will get top billing for at least another day, but after that, we will move on.  However, market related stories are sparser.

For instance, we can look at yesterday’s Retail Sales data, which was not terrible, but not great, as the headline number rose a less than expected 0.2%, but that still translated into 3.1% growth Y/Y.  One of the things weighing on the data was the fact that gasoline prices fell, thus despite modest growth in volume, total dollar sales declined.  The same was true with autos, where allegedly prices declined though volumes remained solid.  (Remember, Retail Sales measures the dollar value of sales, not the quantity of items sold.). At any rate, investors absorbed the data and decided that the recent market declines, to the extent they are a reflection of concerns over rapidly slowing economic activity, were overdone.  The result, happily, is that equities rallied most of the day yesterday and that has followed through around the world overnight.

Alas, the other string of stories in headlines today is the Trump administration’s efforts to determine exactly how they want to implement the promised reciprocal tariffs which are due to be put in place on April 2.  It seems the fact the US trades with over 180 nations, each with their own tariff schedules, makes the details of the proposal difficult to shape and implement.  However, my take is, absent some major shifts by other nations, these tariffs will be imposed.

Ultimately, given the US is the ‘buyer of last resort’ for pretty much every other nation on earth with regards to any of their exports, I expect that there will be a number of nations that choose to adjust their own schedules rather than have diminished access to the US market.  But ex ante, there is no way to determine which nations will blink.

As a testament to just how much things have changed in the market, and just as importantly, the market narrative, the fact that three major central banks are meeting this week with the potential to adjust policy, is basically a footnote.  The FOMC starts their meeting today and tomorrow afternoon they will announce rates are unchanged.  Some attention will be paid to the dot plot, to try to see if the recent discussions of patience translate into higher long-term rate expectations, but quite frankly, it is not clear to me that Chairman Powell can say anything that is going to move markets absent a surprise rate adjustment.  The Fed funds futures market continues to price in basically one rate cut each quarter for the rest of the year at this point.

But before that, this evening the BOJ will announce their latest policy updates and, not surprisingly, there is no anticipation of a move there either.  While there has been much discussion in Japan of how companies will be, on average, increasing pay by 5.46% this year, that has not resulted in any expectations for the BOJ to adjust policy in response.  And in fairness to Ueda-san and his crew, the fact that the yen (-0.3% today) has been relatively stable of late, having rebounded from its dramatic lows last summer and held a good portion of those gains, concerns over a much weaker yen have diminished.

Source: tradingeconomics.com

Looking at the chart above, while I am no market technician, there seem to be several overhead resistance levels starting with that recent trend line.  The absence of concern over a declining yen (rising dollar) will leave the BOJ on hold for a while I think.

And let us not forget Thursday morning, where the BOE will convene, also with no policy changes expected. While GDP remains desultory there, printing at 1.0% Y/Y last week for Q4, inflation refuses to fall to their 2% target and so Governor Bailey is caught between that proverbial rock and hard place.  In such a scenario, no action is the most likely outcome.

Ok, let’s turn to the overnight market activity, which has all investors excited given the fact that markets everywhere are embracing risk today.  A solid day in the US was followed by strong gains throughout Asia (Nikkei +1.2%, Hang Seng +2.5%, CSI 300 +0.3%) with the mainland a little disappointing.  There has been more discussion recently that despite some splashy headlines about more Chinese stimulus, it is less than meets the eye.  That is a view with which I agree.  The exception to this rule was Indonesia (-3.9%) which fell after concerns over slowing growth and a widening budget deficit spooked foreign investors.  In Europe, things are also bright with all markets firmly higher led by Germany (+1.2%) as continued belief in the end of the debt brake has investors anxious to take advantage of all the government spending set to come.  We shall see how that works out, but if the US is the template, it probably has some room to run.  However, all these bourses are higher this morning in a general risk-on mood.  The crimp in the story is US indices are all slightly softer this morning ahead of Housing data.

In the bond market, yields are climbing with Treasury yields up by 1bp and European sovereign yields all higher by 3bps.  Again, this seems to be focused on the mooted extra government spending which is coming down the pike, although yields have backed off the levels seen after the initial announcements as per the below.  In fact, I read a forecast this morning about German bund yields rising to 4% by the end of next year after all the borrowing.

Source: tradingeconomics.com

In the commodity bloc, gold (+0.9%) is unstoppable for now, and taking silver (+1.1%) and copper (+0.4%) along for the ride.  Whatever else is ongoing, it appears that more and more investors have decided that having some portion of their portfolios in the barbarous relic is the right trade. After all, it is higher by more than 15% just since the beginning of the year and more than 40% over the past twelve months.  Oil (+1.1%) is also managing to hold above its recent lows but continues to run into resistance below $70/bbl.  The biggest news today is that Saudi Aramco has seen its stock price falling to 5-year lows, down 50% from its highs of 2022 after cutting dividends earlier this month.

Finally, the dollar is little changed at this hour (7:45), rebounding from modest weakness earlier in the session.  The euro and pound are unchanged, and the yen remains slightly softer.  However, MXN (-0.5%) and KRW (-0.5%) are both feeling the heat of the tariff story.  In the opposite camp, CL (+0.6%) continues to benefit from the rally in copper prices.  The big picture here remains unchanged, with the dollar likely to remain on its back foot as capital flows toward Europe’s government spending bonanza and away from the US, which appears to be pushing for fiscal tightness. 

On the data front, this morning we see Housing Starts (exp 1.38M) and Building Permits (1.45M) at 8:30 then at 9:15 we get IP (0.2%) and Capacity Utilization (77.8%).  With the Fed meeting ongoing, the only headlines will come from the White House, and those are virtually random these days.  Tight fiscal and loose monetary policy tends to weaken a currency and given that is the best description of the US these days, it remains my default position.

Good luck

Adf

Not Worried

‘Bout markets, Scott Bessent’s not worried
As favor with specs can’t be curried
Instead, what he seeks
Is policy tweaks
To help growth, though folks want that hurried
 
Meanwhile, Chairman Jay and his team
Continue their policy theme
Inflation’s still falling
Although they are calling
For patience, as bulls start to scream


“I’ve been in the investment business for 35 years, and I can tell you that corrections are healthy, they are normal,” Bessent said Sunday on NBC’s Meet The Press. “I‘m not worried about the markets. Over the long term, if we put good tax policy in place, deregulation and energy security, the markets will do great.”

The above comments from Treasury Secretary Scott Bessent yesterday morning (quote courtesy of Bloomberg.com) have garnered a remarkable amount of commentary amidst both the political and market punditry.  My first comment is I must be much older than Mr Bessent, since I have been in the investment business for 43 years.  However, as I have written numerous times over the course of the past years, the market has not cleared for a very long time.  Since the 1987 stock market crash, when then Fed Chair Greenspan started pumping liquidity into the financial markets to stabilize things, and realized he could do that to prevent serious downturns, we have seen two significant downdrafts, the tech bubble and the housing market crash, both of which were immediately met with massive liquidity injections, extremely low interest rates and for the latter, the advent of QE.

All of that liquidity has resulted in market excesses across many markets and has been a key driver in the stock market’s exceptional rise since the Covid blip.  Adding to that was the massive fiscal spending (remember those 7% budget deficits?) which has helped to insure that not only did markets rise, but so did retail prices.

Now, along comes a Treasury Secretary who hasn’t married himself to higher stock markets on a day-to-day basis and instead is focused on the long-term.  What I find most interesting is that the same pundits who are screaming about Bessent and Trump destroying the economy, were all-in on the discussion of how the US debt was going to ultimately cause a collapse.  Yet as the administration explicitly tries to address that issue (you may disagree with their methods, but that is their clear goal) suddenly, the fact that stock prices are falling is a tragedy of biblical proportions.  Here’s the thing, the worst performer, the NASDAQ, is down about -12% since its peak last month as per the below chart.  I might argue that is hardly a collapse.  In fact, a healthy correction doesn’t seem to be a bad description.

Source: tradingeconomics.com

There is no doubt that uncertainty about the near-term direction of the economy has grown, and there is no doubt that President Trump’s mercurial tendencies make long-term planning difficult.  However, I would contend we are a long way from the apocalypse or even a stockopalypse.  But once again, I highlight that volatility remains the key metric for now, and that hedging exposures remains very important.

With that as backdrop, the FOMC meets on Wednesday and while there is no expectation of any rate move, the market continues to price three rate cuts for the rest of the year, pretty much one each quarter.  A key unknown is just how hawkish or dovish Fed members currently find themselves given the recent market gyrations.  As well, while inflation had seemingly been the primary focus, with all the concern over a significant slowdown in the US economy, there are now many who believe we will see a rising Unemployment Rate despite a lack of evidence from the weekly Claims data.  These same pundits are also certain that Trump’s tariff policy will lead to rising inflation, really putting the Fed in a bind with a stagflationary outcome.  And maybe that is what will happen.

But I would contend it is far too early to assume that is our future.  First off, on the inflationary front, energy prices have fallen, a key inflation component, and as far as the tariffs are concerned, if they reduce demand, that is likely to cap prices. If on the other hand, demand is not reduced, I don’t see slowing growth as the likely outcome.  

In the end, if the economy is adjusting from one with far more government spending support, to one with more organic private sector economic activity, the transition may be bumpy, but the outcome will be far stronger.  We shall see if that is how things evolve.

In the meantime, let’s look at how the world has responded to the latest stories.  Friday’s US equity rebound was welcomed everywhere, although the key narrative remains the end of American exceptionalism, at least as regards equity markets.  Friday also saw the exiting German Bundestag agree to eliminate the debt brake for infrastructure and defense, with Chancellor-to-be Merz agreeing to waste spend €100 billion on climate related projects to convince the Green Party, which is out of the new government, to vote in the rule change before the new government is seated.  It is not clear to me how spending that money on net-zero ideas will defend Germany, but then I am just a poet, not a German policymaker.

As to Asian markets, other than mainland China (-0.25%) green was the predominant color on screens overnight with Japan (+0.9%), Australia (+0.8%) and Hong Kong (+0.8%) all following the US.  One of the remarkable things, though, is that Chinese data overnight showing IP (5.9%), Retail Sales (4.0%) and Fixed Asset Investment (4.1%) was generally solid.  Of course, Unemployment (5.4%) rose 2 ticks, an unwelcome outcome, and House prices (-4.8%) continue to decline, albeit at a slowing rate, but neither of those speak to a rebound in the Chinese economy.  The end of the Chinese NPC offered more platitudes about supporting the consumer, but it is not clear where the money is coming from.  And recall, more than 60% of Chinese household wealth remains tied up in housing investment, which continues to decline in value.  The Chinese have a long way to go in my view.

Quickly, European bourses are all modestly higher this morning, on the order of 0.3% or so, as hope springs eternal that the rearming of Europe will drive profit margins higher.  Unfortunately, at this hour (7:15), US futures are pointing lower, about -0.25% across the board, although that is up from earlier session lows.

In the bond market, Treasury yields have slipped -2bps this morning, but are really just trading around in their new trading range of 4.20% to 4.35% as investors try to get a handle on which of the big themes are going to drive markets going forward.  European sovereigns are all seeing rallies, with yields slipping -5bps to -6ps which seems out of step with the news about the end of the German debt brake.  Perhaps bond investors don’t believe the legislation will pass, or perhaps that they won’t spend the money after all.  As to JGB yields, the edged lower by -1bp in the 10yr, although longer dated paper has seen yields rise with 40-year bonds touching 3.0% for the first time in their relatively short history.

In the commodity markets, oil (+1.4%) is continuing to bounce of its lows from last week but remains well below levels seen at the beginning of the month.  The US attack on the Houthis is being called the beginning of an escalation in the Middle East by some, and perhaps that has traders concerned.  On the flip side, ostensibly, Presidents Trump and Putin are to speak tomorrow in an effort to get peace talks moving along, potentially a bearish oil signal.  In the metals markets, gold (+0.6%) remains in great demand having crested the $3000/oz level last week and rising from there.  This has helped both silver and copper, with the latter, despite concerns over slowing economic activity, pushing closer to $5.00/lb.  There is much talk of shortages in the market driving the price action.

Finally, the dollar is under pressure this morning with every G10 currency firmer led by NZD (+0.6%) and AUD (+0.4%) although gains elsewhere are on the order of +0.25%.  This story seems to go hand-in-hand with the German defense spending and the end of US exceptionalism.  As to the EMG bloc, most of these currencies are also stronger this morning, but the magnitude of these moves is generally less than the G10 bloc.  Recall, Trump wants a lower dollar, and my default is that is where we are headed at this point.

On the data front, we have an action-packed week ahead starting this morning.

TodayRetail Sales0.6%
 -ex autos0.4%
 Empire State Manufacturing-0.75
TuesdayHousing Starts1.375M
 Building Permits1.45M
 IP0.2%
 Capacity Utilization77.8%
WednesdayFOMC Rate Decision4.50% (unchanged)
ThursdayInitial Claims224K
 Continuing Claims1880K
 Philly Fed12.1
 Existing Home Sales3.92M
 Leading Indicators-0.2%

Source: tradingeconomics.com

As we have seen over the past many months, I suspect that this week’s data will be likely to give analysts on both sides of the economy is stronger/weaker argument new fodder.  While the Fed won’t be doing anything, and despite their relative decline in importance, I suspect that Chairman Powell’s press conference will still get a lot of attention.

While we don’t know what the future will bring for sure, I remain convinced that the dollar will slide, and commodities will rally.  As to stocks and bonds, well your guess is as good as mine.

Good luck

Adf