Change Their World View

The markets are trading like peace
Has come, hence the stock price increase
While crude prices fall
And risk, overall
Is favored like summer in Greece

But can we trust this time it’s true?
Or will, once again, this fall through?
I guess time will tell
If this will compel
The doomers to change their world view

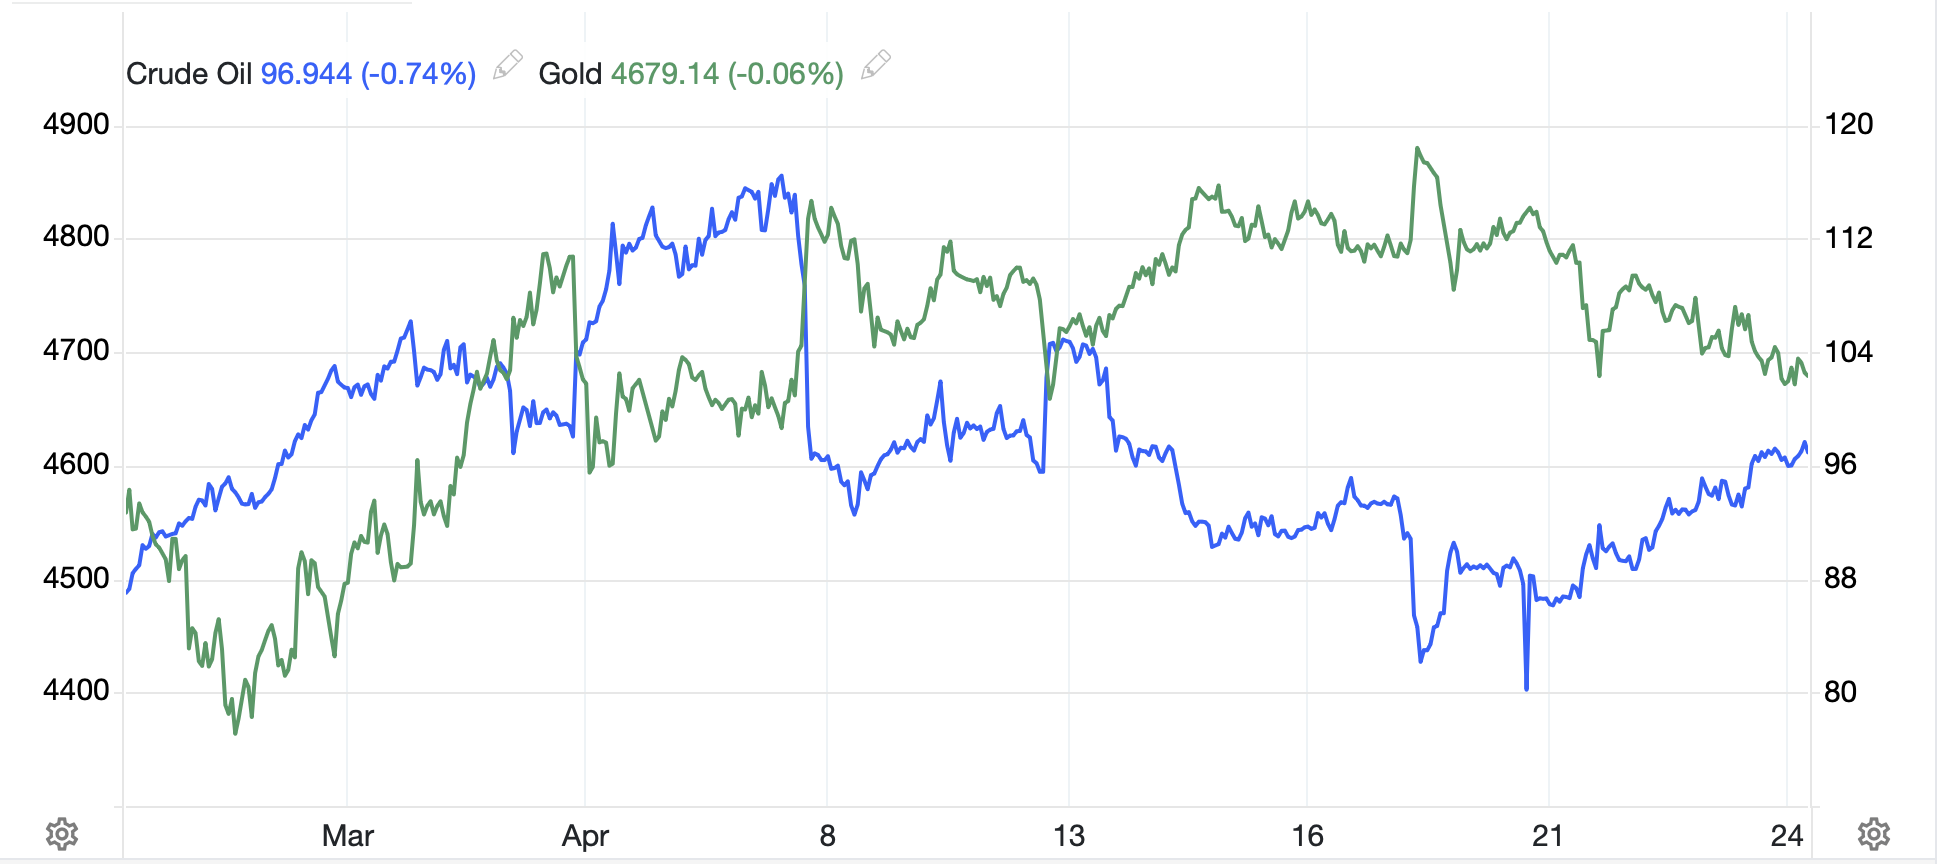
It is certainly a hopeful morning today as risk rallies around the world while oil prices tumble.  At $84.72/bbl, down -3.4% on the session, oil is trading at its lowest level since April 17.  
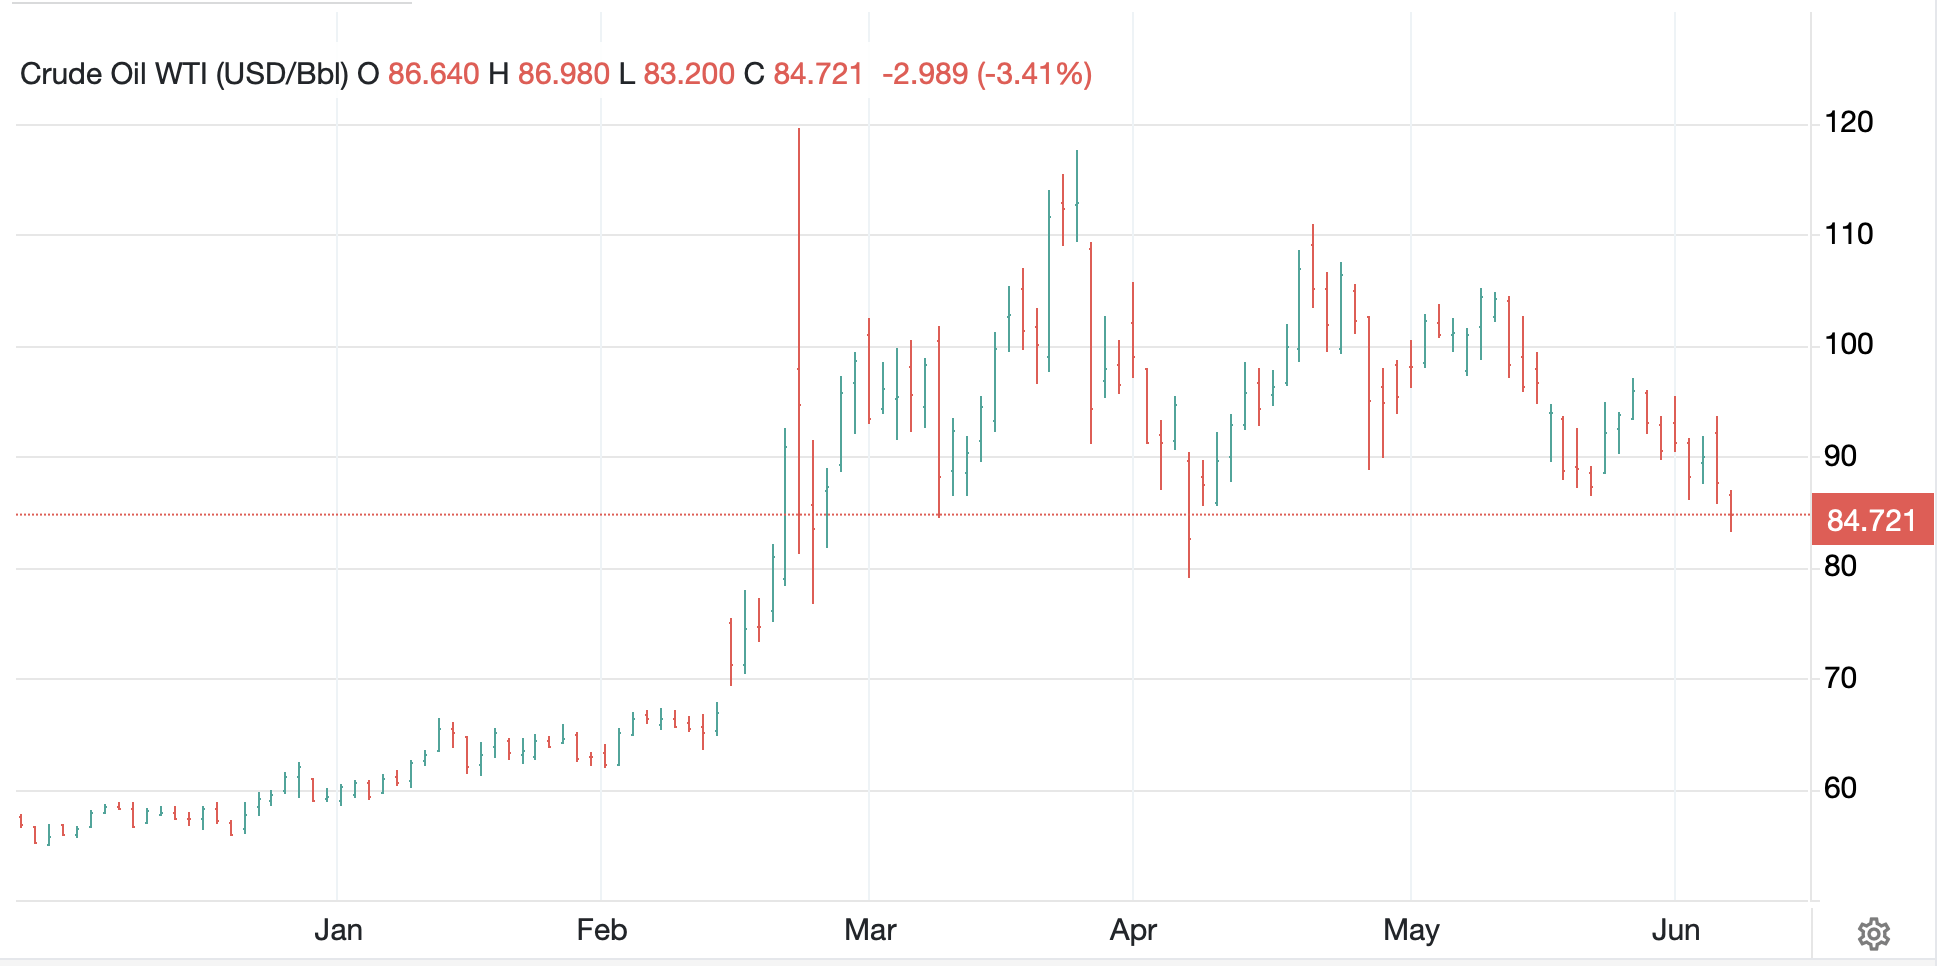
Source: tradingeconomics.com

While President Trump had once again threatened to destroy Iran’s oil infrastructure, shortly thereafter he reversed that call with news that Iran was back at the table with both sides closing in on a peace deal.  Frankly, despite the absolute certitude that so many pundits seem to have, the reality is nobody really knows if this time is the charm or not.  In fact, I would argue that the Iranians themselves, as well as President Trump, are not certain, as though I’m confident both sides would like to stop this, there are many political calculations that go into the process, and the punditry is simply not party to those conversations.  We shall see.

Of course, markets trade the rumor, not the news, or at least they initiate positioning on the rumor, so with that story making the rounds, it is also no surprise that equity markets have shaken off their early week blues and rallied strongly pretty much everywhere around the world.  The below chart of futures markets shows just how widespread the gains are with only Russia’s MOEX under pressure (is that really even a market still?) and although Toronto, Mexico and Brazil have not yet opened, all rallied yesterday alongside the US.
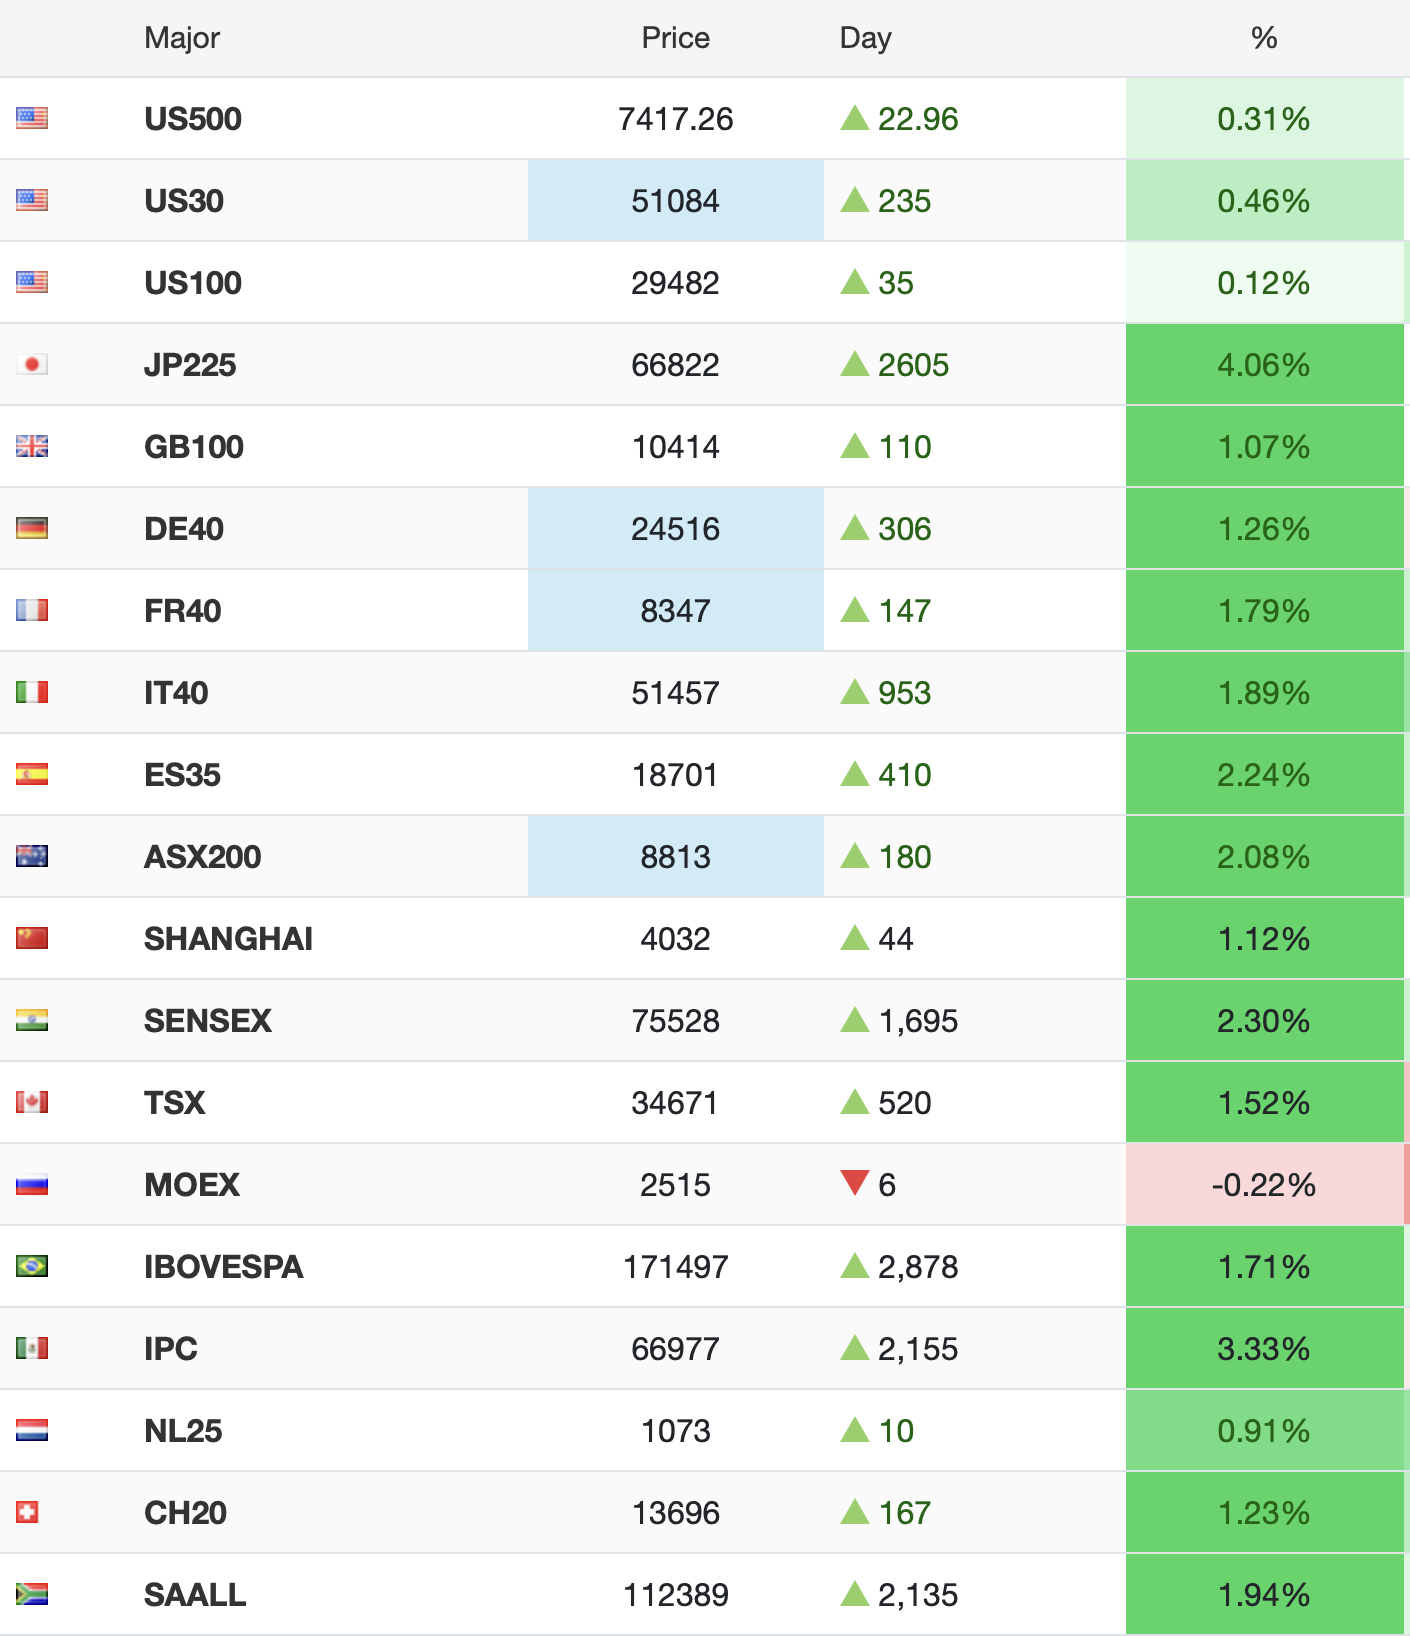
Source: tradingeconomics.com

Of course, there is another equity story and that is SpaceX, which IPO’d last night at a price of $135/share, and which, like so many things these days, has a seen a huge disparity between the pros and the cons.  Many analyses have been performed showing that the company is not “worth” anywhere near the $1.8 trillion market cap at which it is starting.  But those same folks have consistently explained that Tesla is not worth the $1.5 trillion, and yet there Tesla sits.  There was a huge amount of interest with more than $75 billion of retail orders to buy the IPO.  My observation is that Elon Musk is somebody who gets things done, and usually better than anyone else.  But markets are, as I always say, perverse, so this will be an interesting ride.

Other than the end of the war and the SpaceX IPO, the two stories that made a brief appearance were yesterday’s PPI data, which depending on the analyst were either hot or cold, and the fact that Madame Lagarde and the ECB raised their base rate by 25bps yesterday, right as energy prices started falling dramatically.  This is not the first time the ECB has made a mistake of this nature, one need only look back to the beginning of the GFC when then-president Jean Claude Trichet controversially raised interest rates in July 2008 and reversed course 3 months later after Lehman Brothers failed.

And that’s what the setting is as we head into the last trading session of the week.  So, let’s see how other markets are behaving.

It should be no surprise that bond yields are falling.  While Treasury yields are unchanged this morning, they fell about -7bps across the board yesterday.  But the Iran news was after the European close so sovereign yields are lower by between -4bps and -7bps this morning.  I presume some investors are happy that the ECB is fighting inflation, but I think most are responding to the idea that the end of the war means lower oil prices and therefore a significant reduction in inflation pressures.  Last night in Asia, we also saw yields fall sharply across the board with JGBs down -6bps and every other market (Australia, Singapore, Korea) slide by a similar or even greater amount.

In the metals markets, while gold (-0.1%) is little changed this morning, it did manage to rally more than $100/oz yesterday, or more than 2%.  Silver (-0.5%) is also slipping a bit today but that is after a 6% rally yesterday.  My take is these are short term profit taking trades.

Finally, the dollar is, overall, little changed this morning.  it was very modestly weaker during yesterday’s session with the DXY slipping back below 100 (currently 99.75), but USDJPY remains above 160, still in a danger zone although there has been precious little discussion on the topic for the past several sessions.  You will not be surprised that NOK (-0.5%) is under pressure as it is probably the currency that tracks most closely to oil prices.  But other than that, not much to say in this market either.

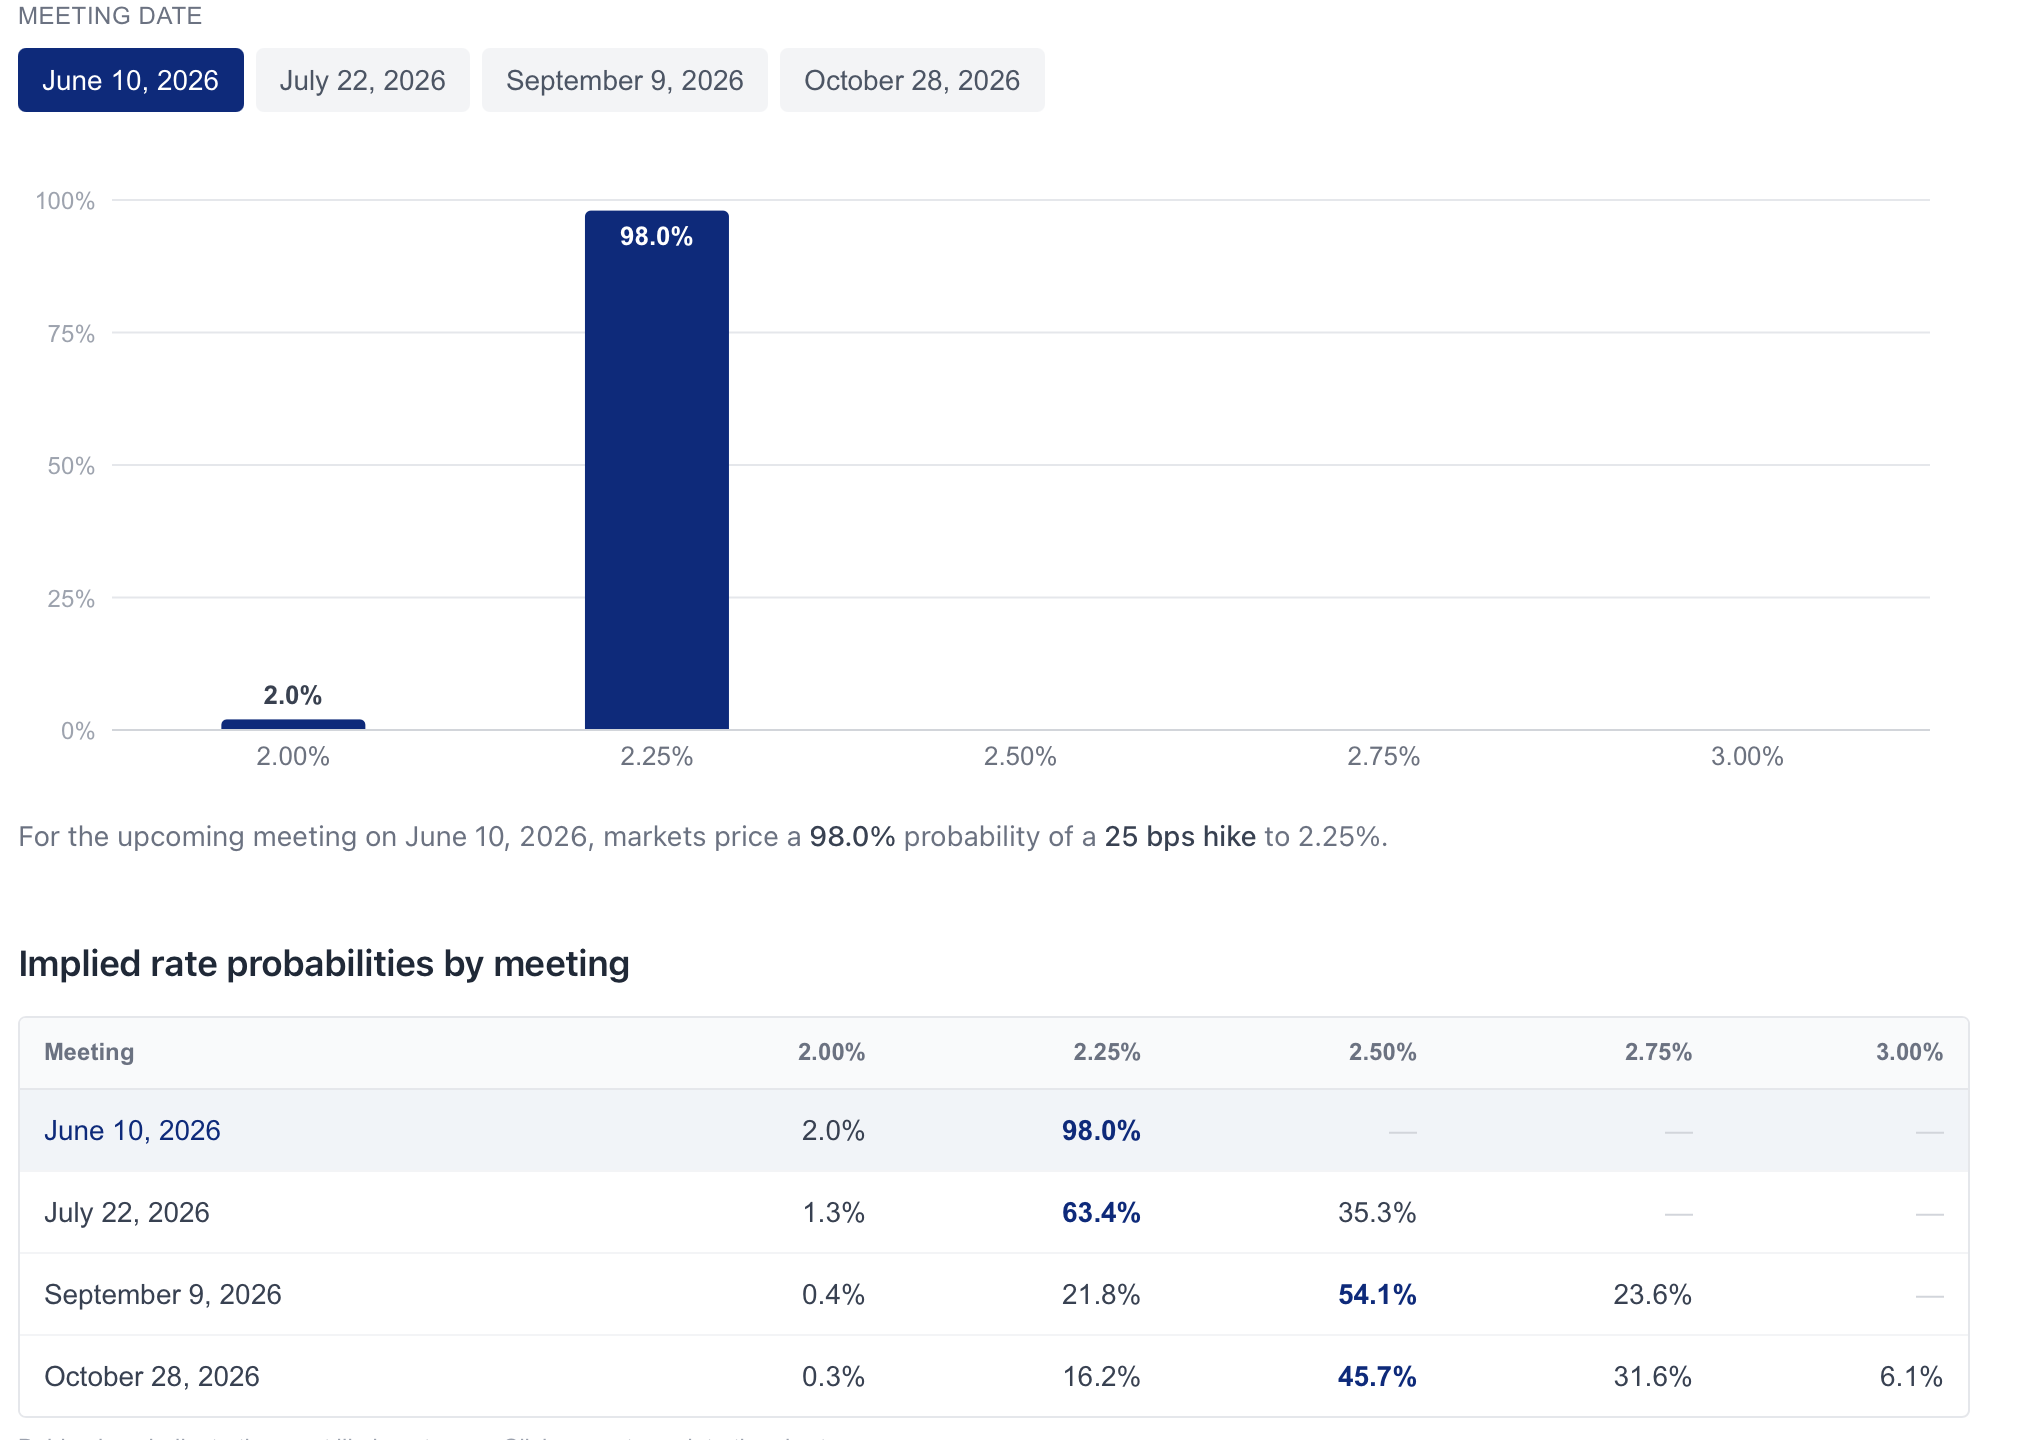
On the data front, this morning brings only Michigan Sentiment (exp 46.0), which continues to hug the lows of the series as a contradiction to the highs in equity markets.  But now, with CPI/PPI out of the way, all eyes will turn to next week’s FOMC meeting.  If we look at the Fed funds futures curve, it is still forecasting a rate hike by the end of this year.
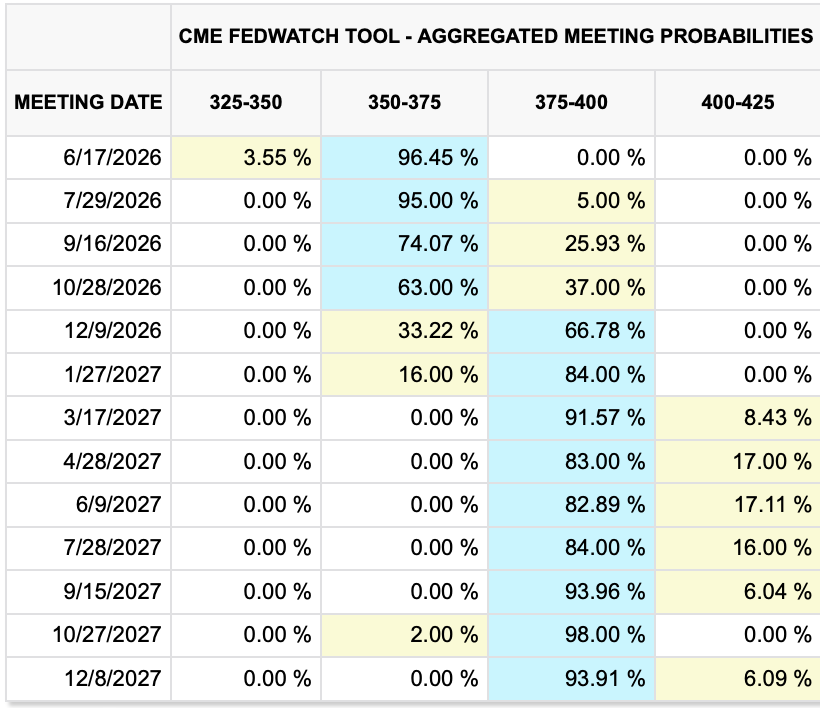
Source: cmegroup.com

But I have to wonder, if the fighting stops and a deal is reached such that the Strait is reopened and the blockade is lifted, the one certainty is that oil prices will fall much lower, probably below the levels seen prior to the war began.  Given all the talk about secondary effects of high oil prices, I would expect that talk to disappear.  History has shown that every shortage of a commodity is followed by a glut.  Will economists be explaining why persistently low energy prices in the future are going to undermine inflationary expectations?

Markets are still beholden to the headlines so if this deal falls apart, you need to expect all these moves to reverse course with oil higher alongside yields and the dollar while stocks and precious metals fall.  But if this is the end of the Iranian engagement, I suspect that risk is going to be in vogue for quite a while, investment will be flowing into the US and the dollar will hold its own, even as yields decline.  (Going back to my flows as a key driver, not just interest rates.)

Good luck and good weekend

Adf
In Secret, Would Toil

Since March, traders focused on oil
Where every explosion could roil
The bulls and the bears
In bonds and in shares
While data, in secret, would toil

Today, though, the payroll report
Is taking bows on center court
For those who are long
The buck, they need strong
Results, while a weak one helps short(s)

For a change of pace today, the market truly seems to be looking at the data release rather than the latest zig or zag in Iran.  It has been at least four months, since before the first bombs dropped in March, that this data point has had any real import for the narrative, so it is a welcome return to what we used to consider normal.  With that in mind, let’s look at what the current expectations are:

Nonfarm Payrolls85K
Private Payrolls85K
Manufacturing Payrolls2K
Unemployment Rate4.3%
Average Hourly Earnings0.3% (3.4% Y/Y)
Average Weekly Hours34.3
Participation Rate61.7%

Source: tradingeconomics.com

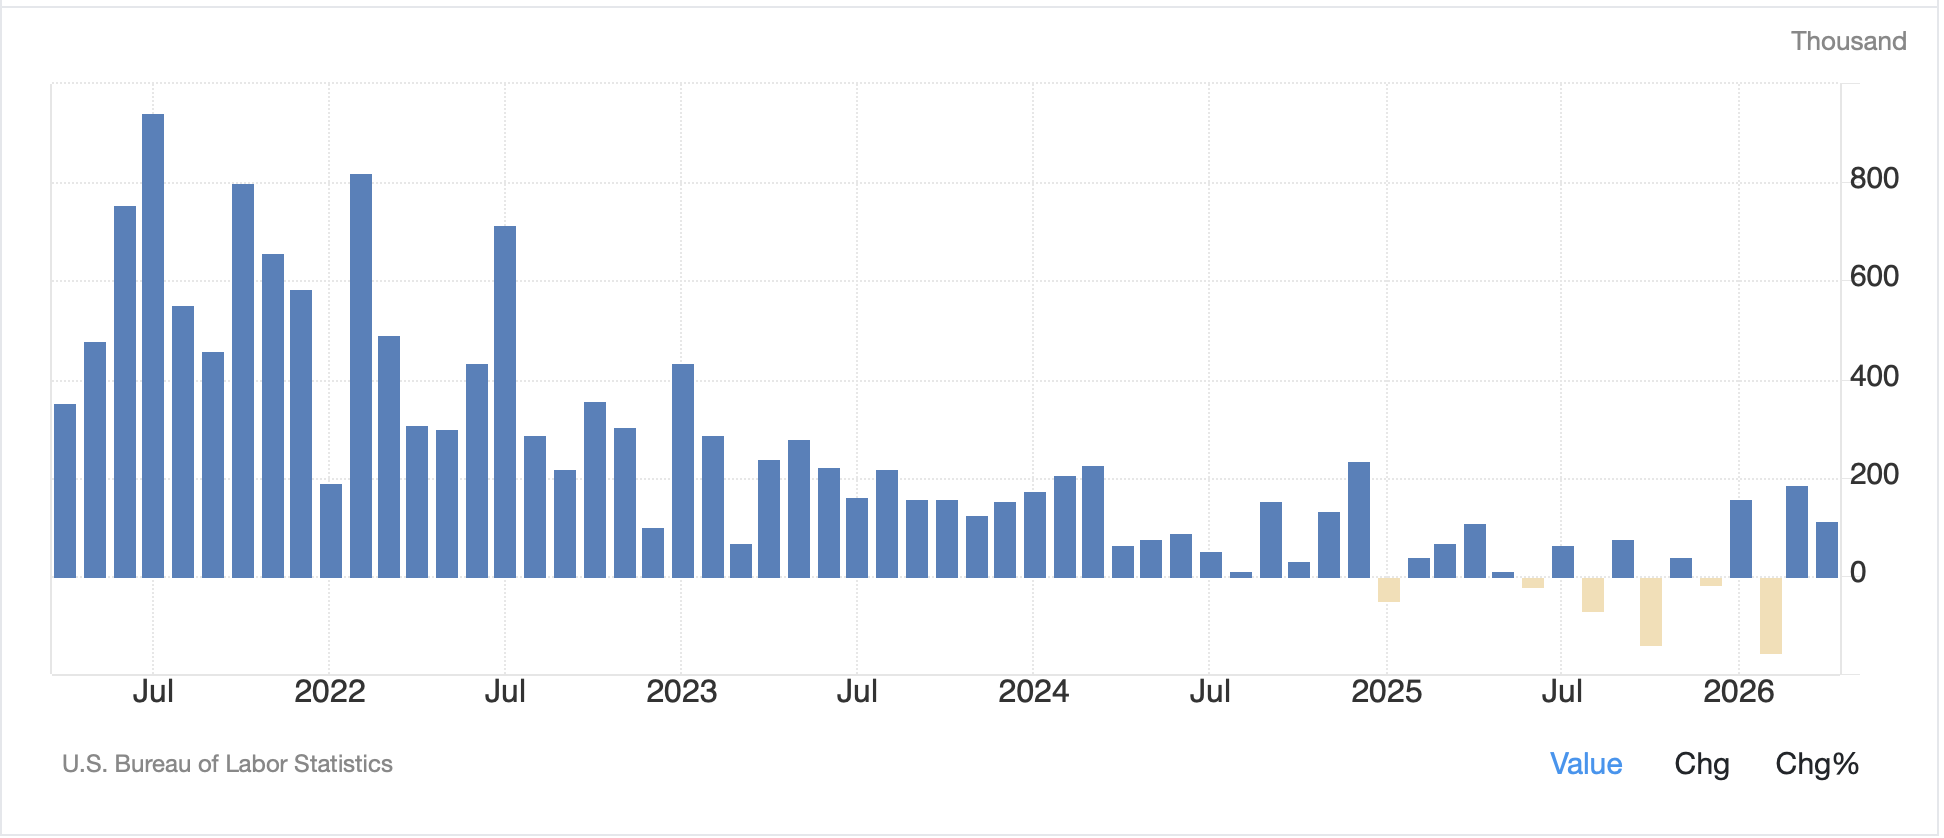
While 85K is much lower than the pre-Trump 2.0 level deemed necessary to maintain a strong labor market, it is abundantly clear that between the closure of the borders and the deportations, that is no longer the situation.  Estimates I have seen to achieve labor stability have been between 0 and 50K, and that includes comments from former Fed Chair Powell.  While an outturn at the forecast level would be lower than last month, it would still indicate the labor market is in decent condition.  Of course, one of the hardest things is to see through the revision noise as the BLS birth/death model describing new companies is clearly not representative of the current economy.  Below is a look at the past five years of monthly reports which is showing a clear trend lower, but as per the above, that may not be a problem.

Source: tradingeconomics.com

However, the other data we have seen lately, notably the strong ADP number, the solid employment subindices from the ISM data and the fact that claims data, although a touch higher yesterday, remains very contained, tells me that we are going to see a better number than forecast, something around 115K like last month.

Perhaps the real question is why this matters now.  Well, as the war fades into the background, and remarkably that is what is happening, investors are back to looking for clues as to how the economy is performing and how the Fed is likely to behave going forward.  Several times this week I have highlighted the importance of capital flows, and a key part of that story is central bank liquidity being available to flow.  Thus, if the Fed sees this data and leans more toward tightening, that is likely to have a negative impact on those markets that require easy money like stocks, high-yield debt and private markets.  Interestingly, if bond traders sense that the Fed is going to pay closer attention to inflation, that should help the long end of the bond market, and we could see a bull flattener result.  Nothing has changed in the Fed funds futures market, but that is something that could really move on an outlier number here.  We will learn soon enough.

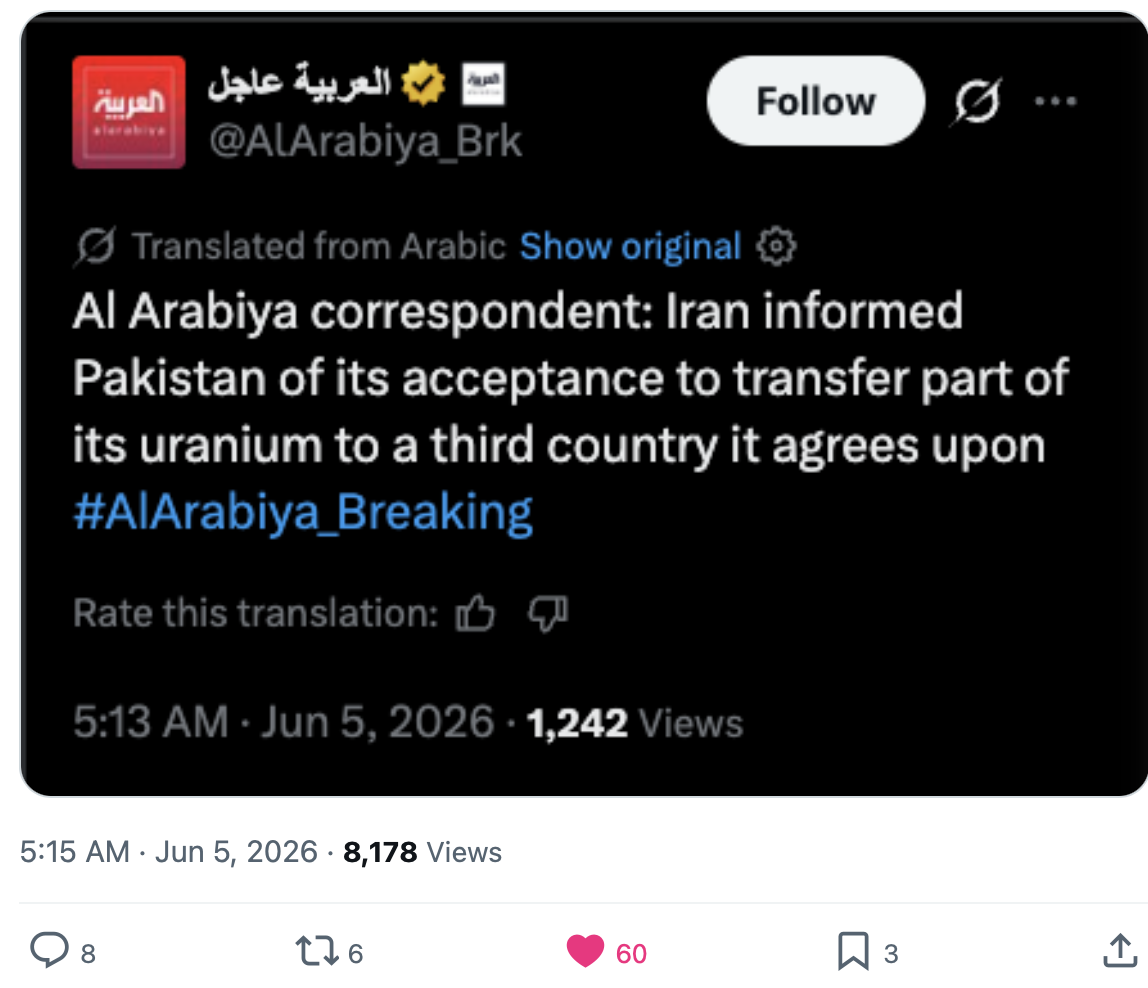
Away from that, though, the most interesting thing I have seen is the below tweet although the commentary was strongly of the opinion that this is fake news.  If it is real, that is a major breakthrough in leading to the end of the war, however, based on the fact that oil prices are essentially unchanged (-0.15%), the market does not appear to believe the story.

Ok, let’s see what else is happening in other markets.  Not surprisingly, gold (-0.25%) is also not doing much but both silver (-1.7%) and copper (-1.6%) are softer despite the fact oil’s little changed.  Metals appear to have lost some of their luster for now, but I do believe that their long-term prospects remain strong.

In the stock markets, yesterday saw the DJIA take the lead for a change, rallying to a new all-time high although the NASDAQ went nowhere as questions about the AI story are beginning to be raised.  Too, semiconductor stocks, which have been extraordinarily strong, are beginning to be questioned given the highly cyclical nature of that business.  Yesterday Harris Kupperman wrote a very interesting piece on semiconductors which I think is worth reading.

In the meantime, Asian markets followed the tech lead from NASDAQ and were virtually all lower, some extremely so.  The worst case was Korea (-5.5%) followed by Indonesia (-4.2%) but the major indices all fell as well (Tokyo -1.3%, HK -1.15%, China -1.8%).  Tech took a beating.  Of course, for Europe, since they basically have no tech, markets are having a much better day with Spain (+1.1%) leading the way followed by France (+0.5%), the UK (+0.4%) and Germany (+0.2%).  Perhaps the fact that Eurozone GDP for Q1 was revised down to -0.2% Q/Q and +0.3% Y/Y has some thinking the ECB may not (stupidly) raise rates due to the oil shock.  But if that’s the case, you cannot tell by the interest rate markets which show the current probabilities as per the ECB itself.

At this hour (7:40) US futures are mixed with the NASDAQ (-0.9%) still suffering while the DJIA (+0.2%) continues to smile.

Apparently, global bond markets are collectively holding their breath ahead of the data point as yields are essentially unchanged in the US, Europe and were unchanged last night in Asia.

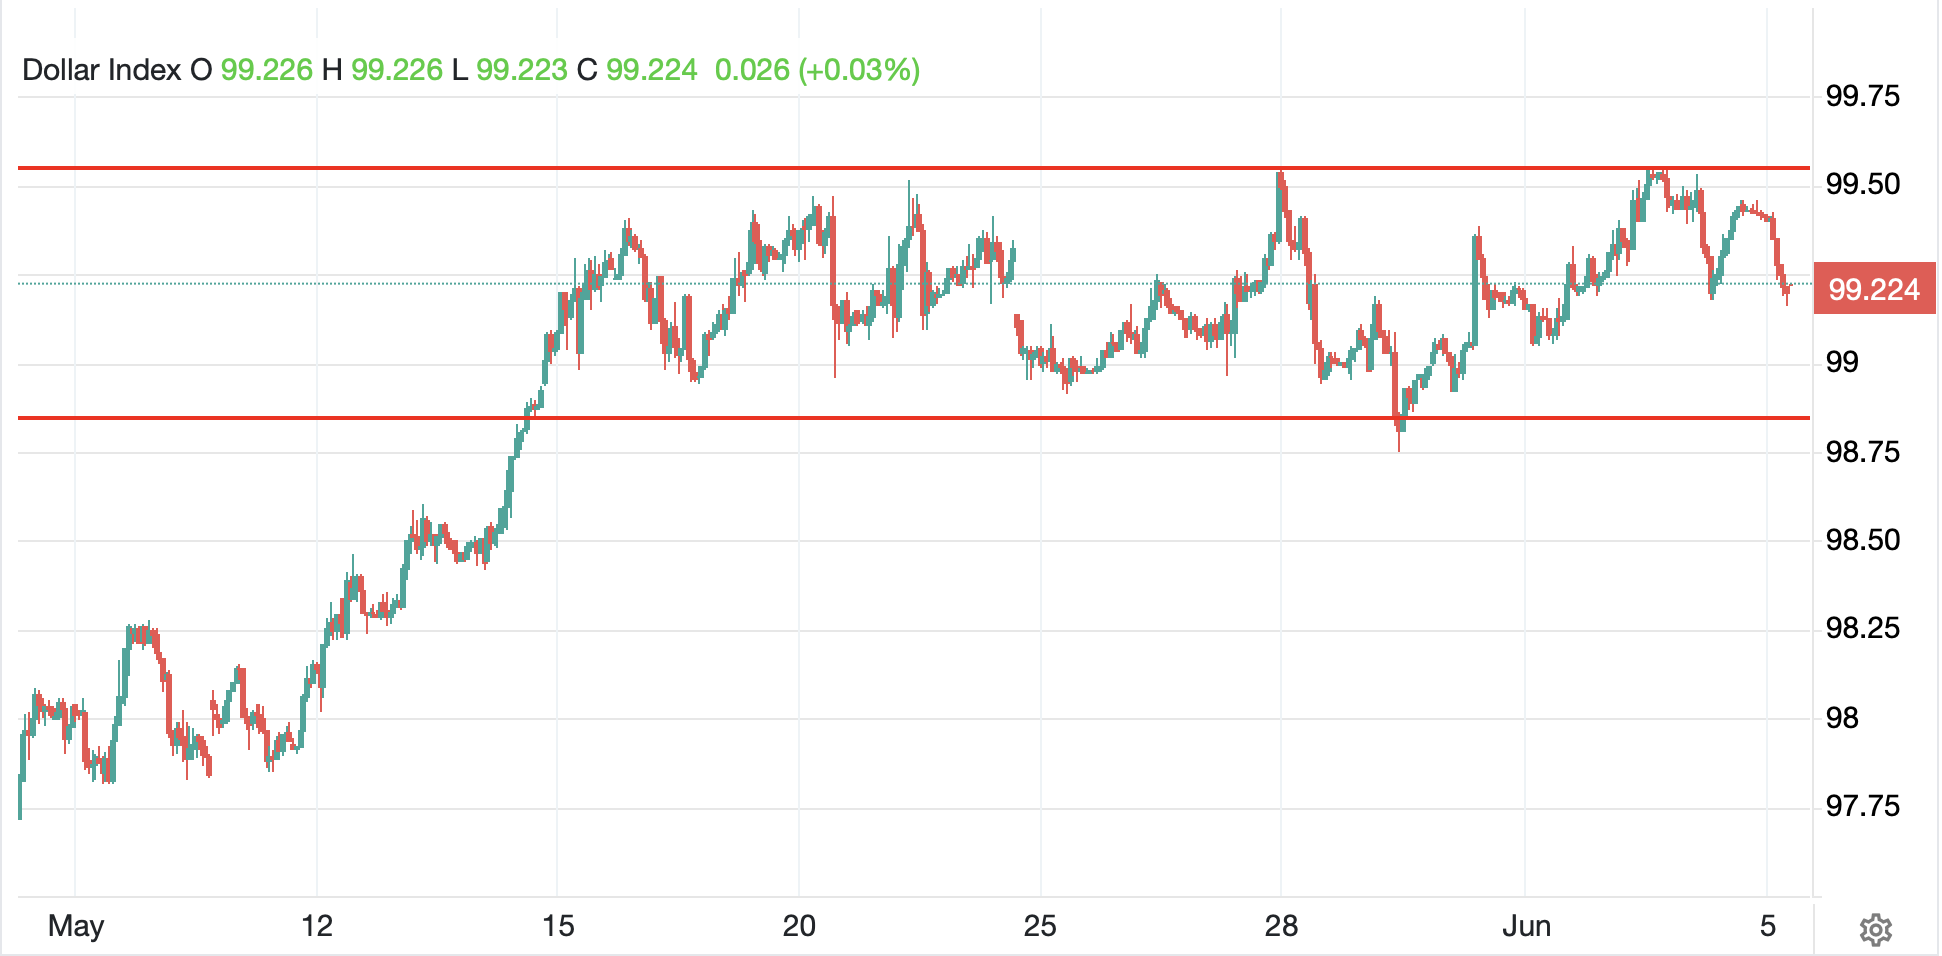
Finally, the dollar is slightly softer this morning, although remains above 99 on the DXY and is merely chopping back and forth within the extremely tight range of the past 3 weeks I show, once again, below.

Source: tradingeconomics.com

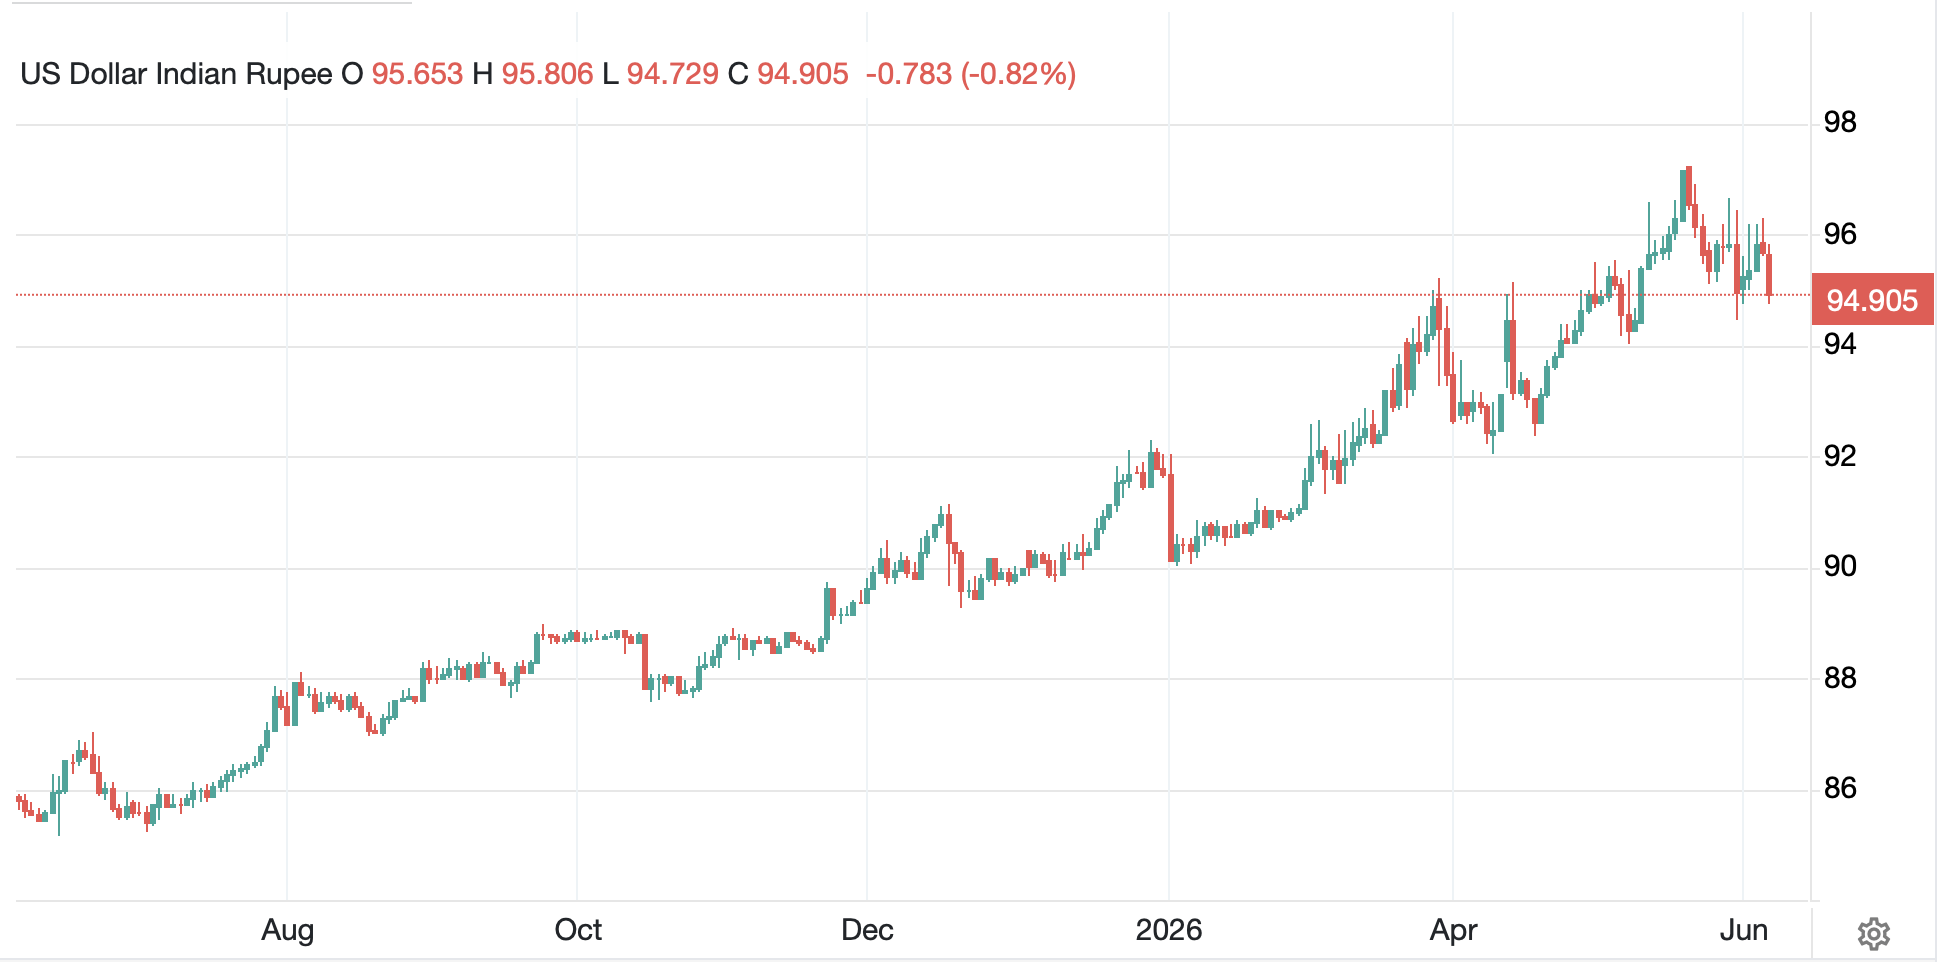
Most movement today across both the G10 and EMG blocs is +/-0.25% or less, hardly the sign of a trend.  The one exception is INR (+0.8%) after the RBI left rates on hold, as expected, but instituted several measures to try to attract foreign capital such as easing investment rules for foreigners.  We shall see if that has a long-term benefit, but at least the rupee has put a little space between the current level and the bottom (dollar top) seen two weeks ago.

Source: tradingeconomics.com

And that’s really all for today.  So, absent news about real movement toward the end of the Iran conflict, it’s payrolls then a summer Friday where many will be seeking to leave early.  If I am correct and we see a stronger number, I see the dollar benefitting which should hurt the metals, although oil is independent of this news.  Since this would imply more chance of a Fed rate hike, I expect stocks would not be pleased, nor will bonds.  We shall see.

Good luck and good weekend

Adf
There’ll Be Chagrin

Since April, the story has been
The stock market’s yang with no yin
But yesterday’s fall
Reminds one and all
Be wary or there’ll be chagrin

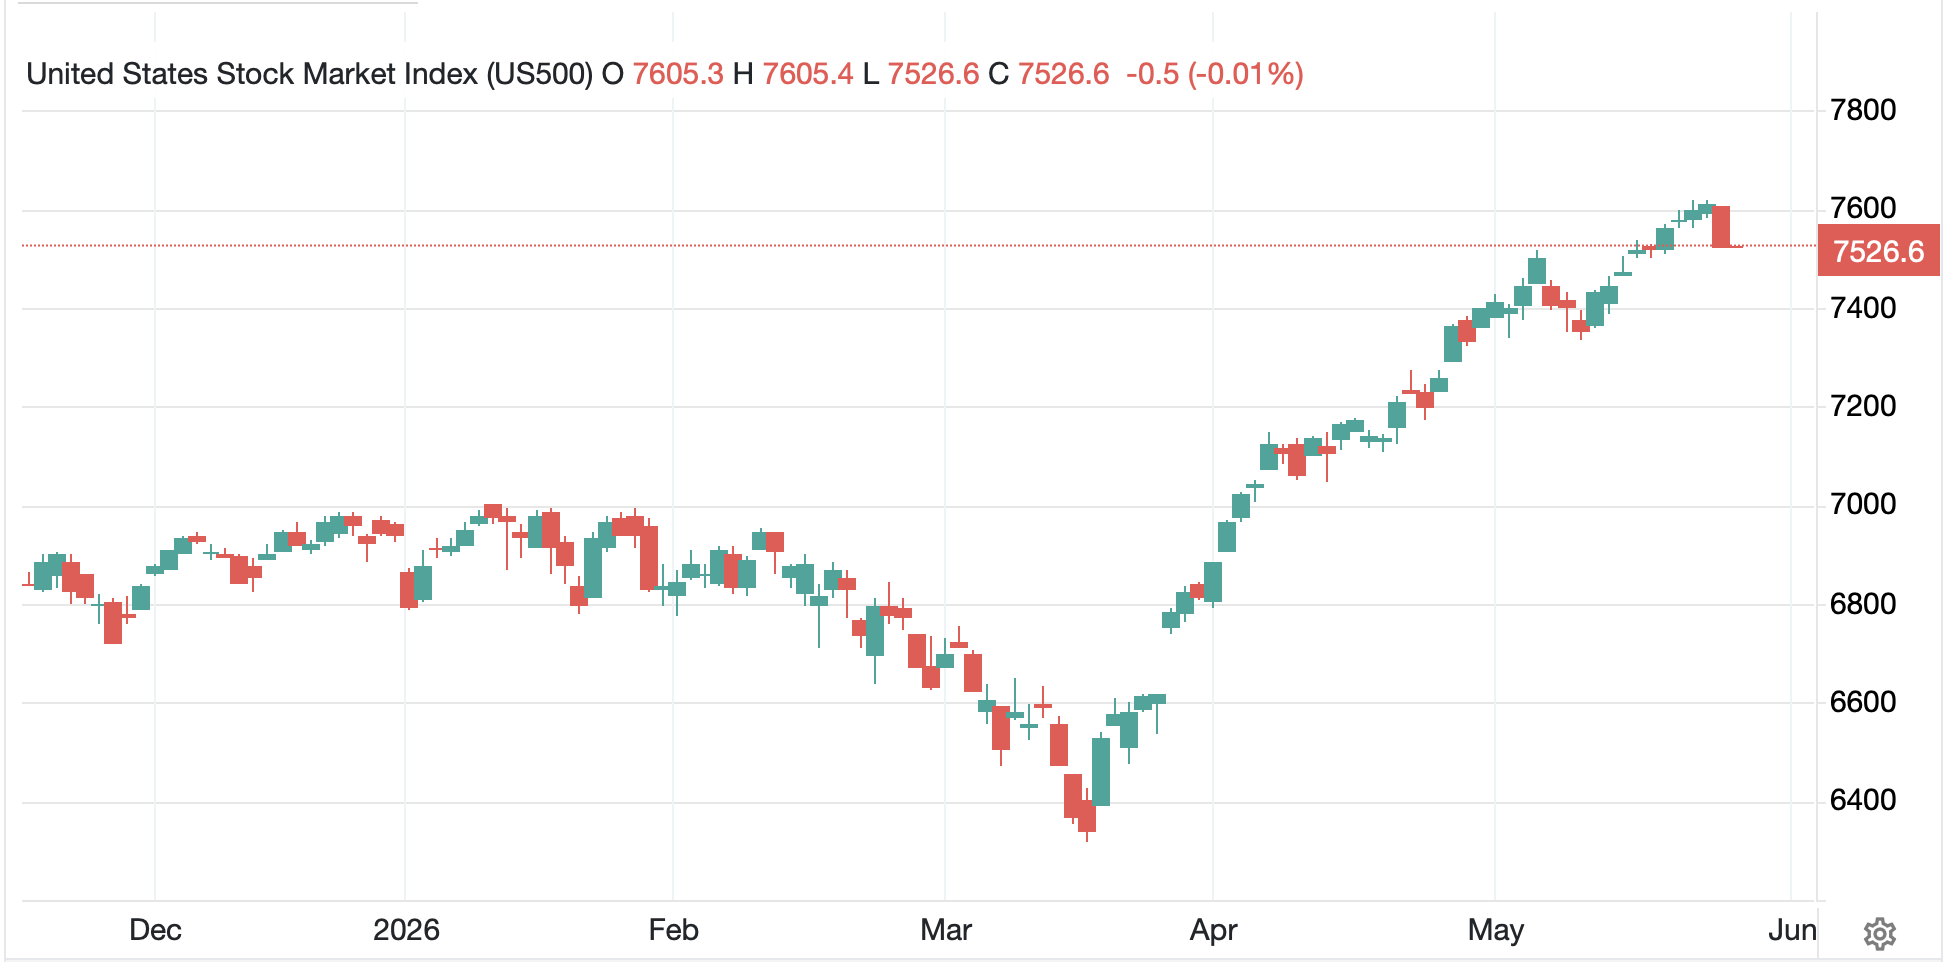
Since the beginning of April, as you can see in the below chart of the S&P 500, stocks have risen sharply (~18%) as up days outnumbered down days 33 to 12, including yesterday’s drop.  That’s a pretty good definition of a raging bull market.

Source: tradingeconomics.com

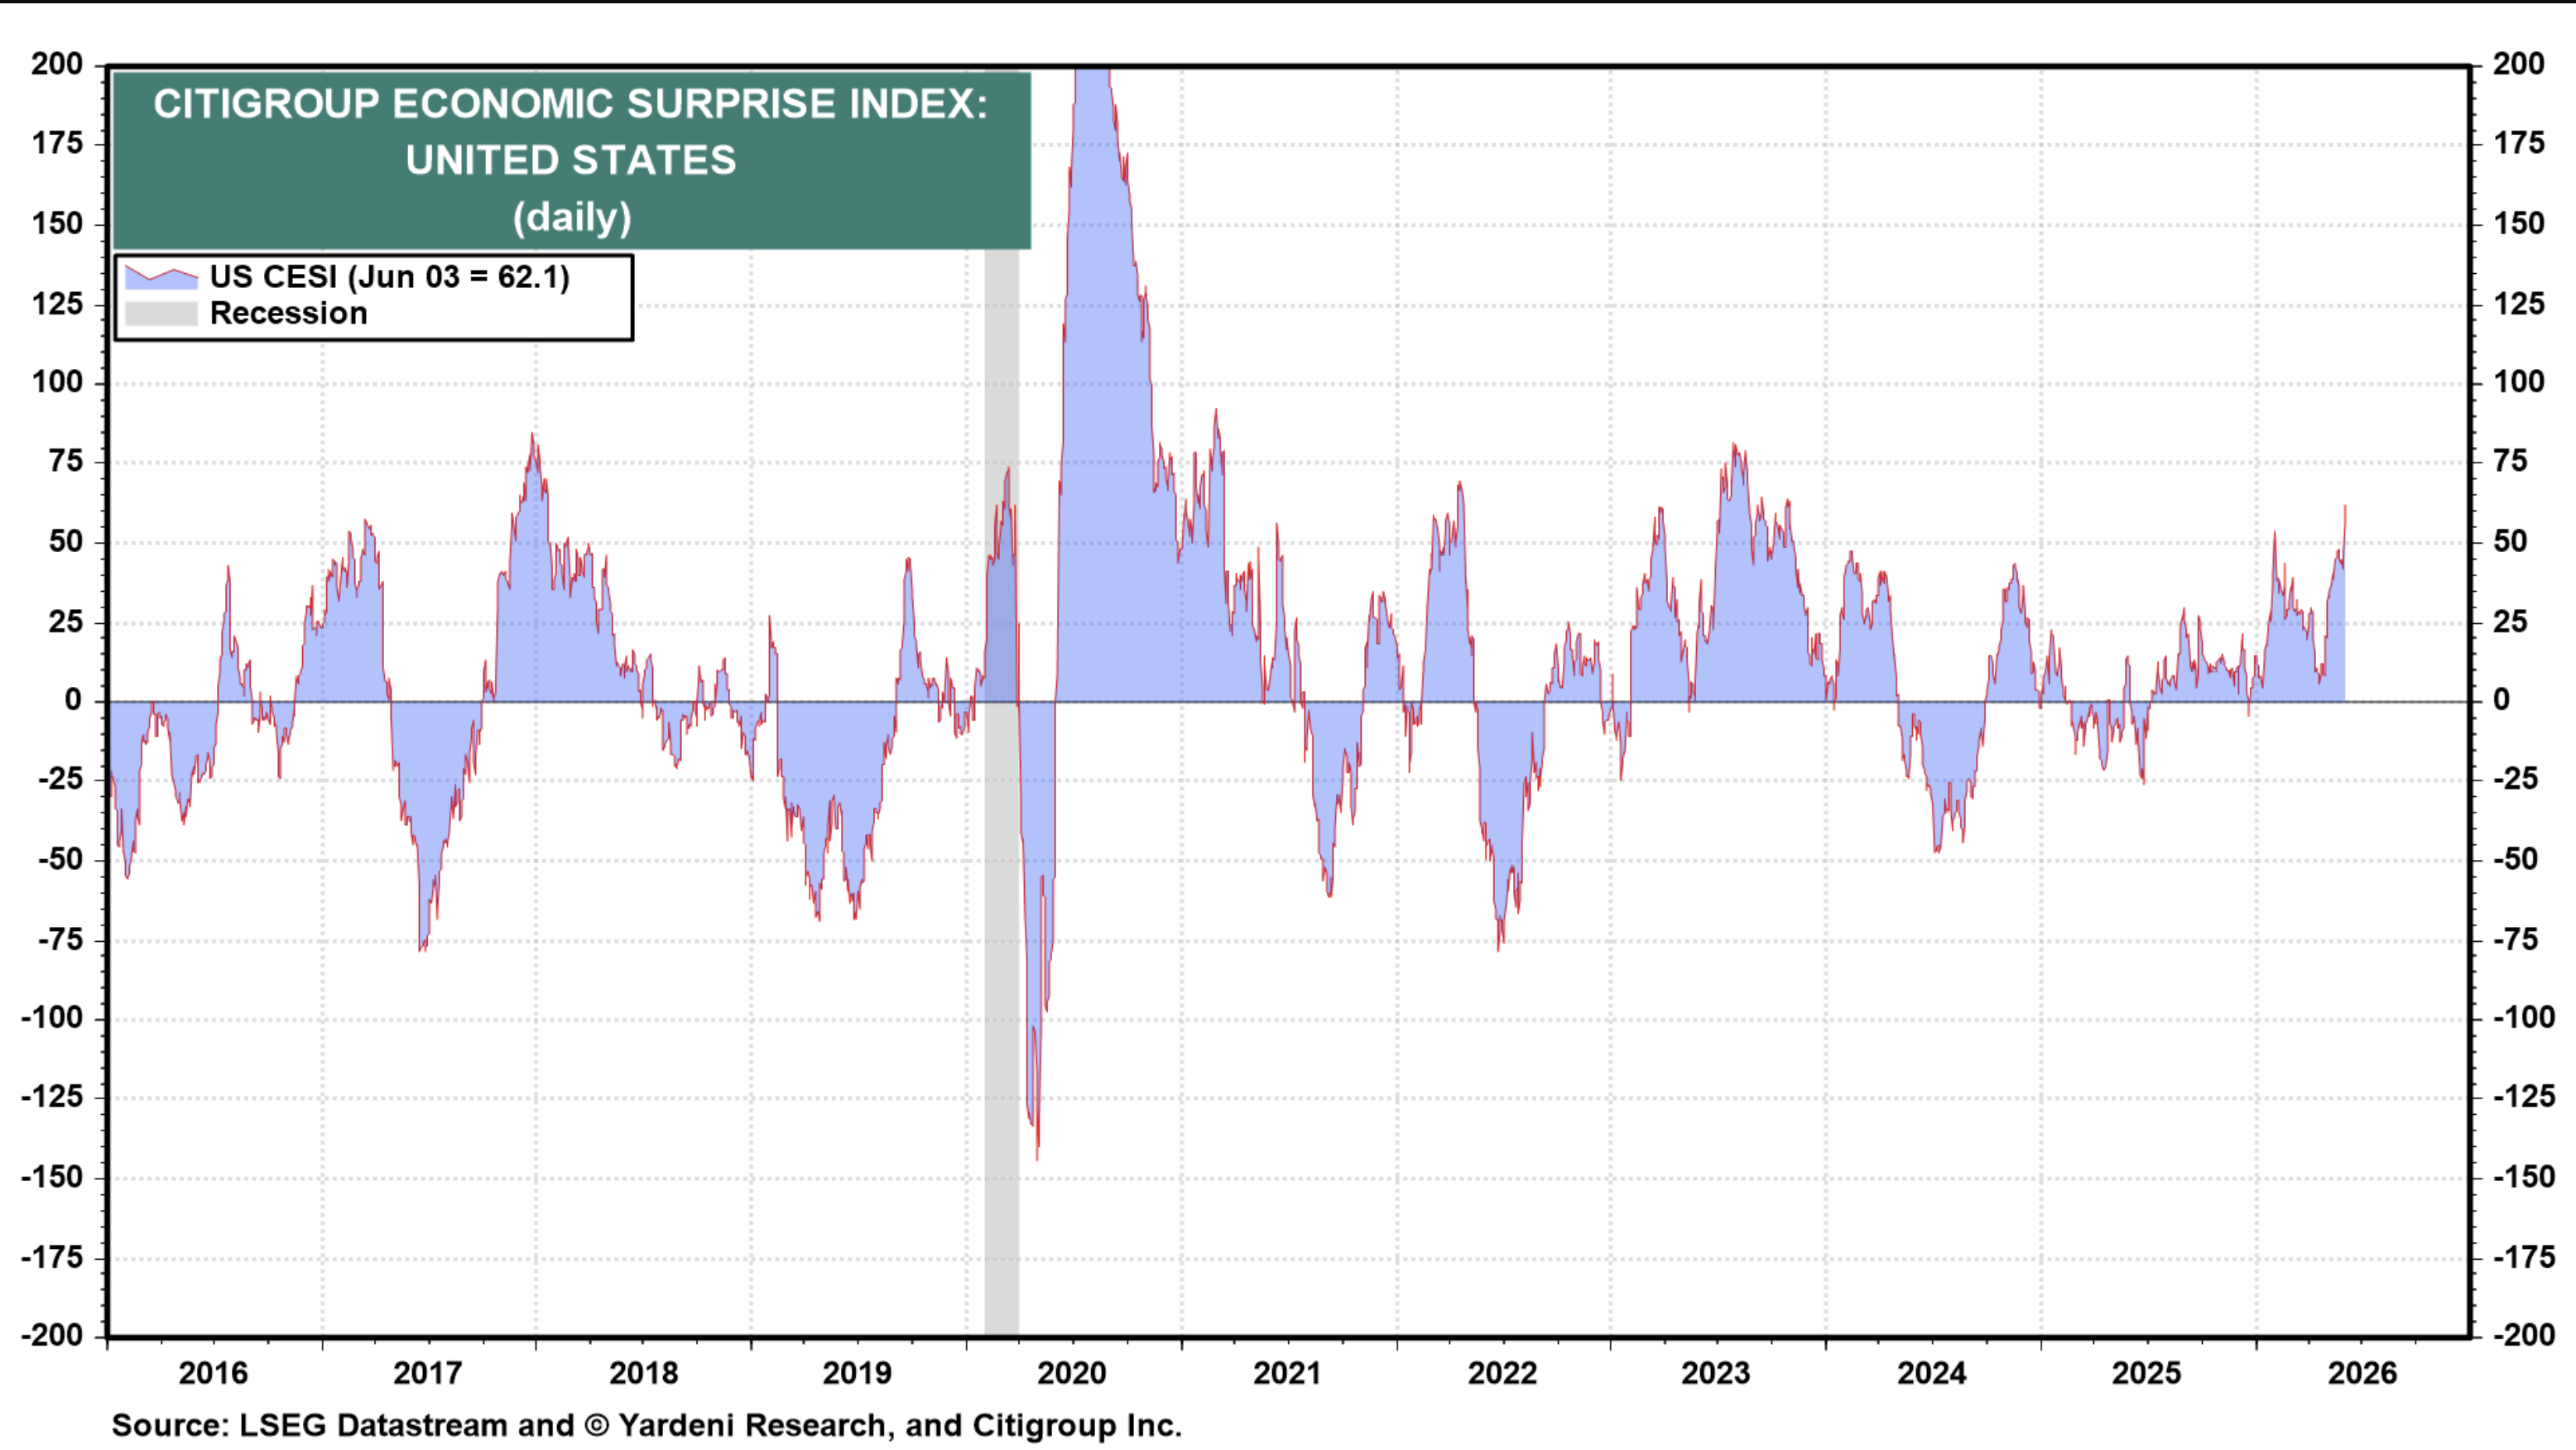
Here’s the thing; nothing really changed yesterday.  Certainly, there has been no change in the status with the Iran conflict, and therefore no change in the prospects for oil prices going forward.  If anything, the data we have been getting has been demonstrating that the US economy is performing better than expected with yesterday’s ISM and Factory Orders data stronger than forecast as was the ADP Employment Report.  If you add that to the JOLTs data from Tuesday, it appears that the overall jobs situation in the US is diverging from the narrative that AI is going to take all the jobs and there is nothing left for people to do.  In fact, a look at the Citi Surprise Index, designed to show the difference between actual economic releases and the forecasts ahead of those releases shows it has risen to its highest level since mid-2023 as per the below chart.

This is a strong signal that the economy, despite a lot of negative talk, is doing pretty well.  Of course, by now we have all learned that the stock market and the economy are very different things.  While historically, the relationship between equity markets and the economy was clearer, with equity markets a reasonable estimator of future economic activities, with somewhere between a 6 month and 1 year lag, ever since the GFC and the financialization of the economy, that relationship has lost much of its luster.  Rather, akin to my discussion of the yen being dependent on capital flows, not economic activity, that is also the story of stocks right now.

This brings us to the story that really seems to be percolating around the market, and that is the imminent IPO’s of SpaceX, Anthropic and OpenAI, as well as Google’s $80 billion share sale.  For the last 30ish years, between share repurchases by companies and the growth of Private Equity which gobbled up public companies, the number of publicly listed company equities has been shrinking, with the number falling roughly in half during that period.  According to Grok, at the end of 2025 there were just 3,657 domestic companies listed on US exchanges, not even enough to fill out the Russell 5000!  With that in mind, and remembering the laws of supply and demand, it ought not be a surprise that prices rose while supply fell.

But is that getting set to change?  While headline companies like SpaceX will get all the press, it seems likely that PE firms are going to be looking to IPO many of their holdings given current overall valuations.  Remember, many of these companies were bought during the era of ZIRP, so debt financing made lots of sense, but once the Fed tightened policy, it has been a problem.  Retail investors have been hoovering up equities for a while now, and I suspect we are going to see a lot more equities come available to meet that demand.  In fact, this is the best story I have heard about what can halt the rally.

But this can also highlight the difference between the economy and the stock market.  Consider the ramifications of the mega names issuing stock and using the funding to continue to build out the AI infrastructure including data centers, power production, turbines, semiconductor fabs, etc., that is all going to result in significant economic activity as people get hired to do the work and all the benefits that accrue from investment lead to real growth in GDP.  We could easily see equity markets stall, or stumble while the economy powers ahead.  Something to consider for the medium-term view here.

But in the short-term, let’s turn to markets and see how yesterday’s US declines played out overnight.  Asia had a generally miserable session with every major and most other regional exchanges sliding.  This included Tokyo (-1.4%), HK (-1.5%), China (-0.7%), Korea (1.8%), Taiwan (-1.7%) and Australia (-1.1%).  And the smaller markets were no better as India (0.0%) was the top performer.  In Europe, though, the picture is not so dire as only the UK (-0.9%) is under real pressure with the continent (France +0.6%, Germany +0.35% and Spain +0.25%) all managing small gains.  Perhaps the driver here has been inflation data which showed that it has not risen as fast as feared and therefore there is a bit less concern about more aggressive ECB tightening.  As to US futures, they are mixed this morning with NASDAQ (-1.35%) falling sharply on poor Broadcomm earnings although the DJIA (+0.7%) are rebounding from yesterday’s losses as investors rotate a bit from tech to industrials while oil prices have slipped aiding things.

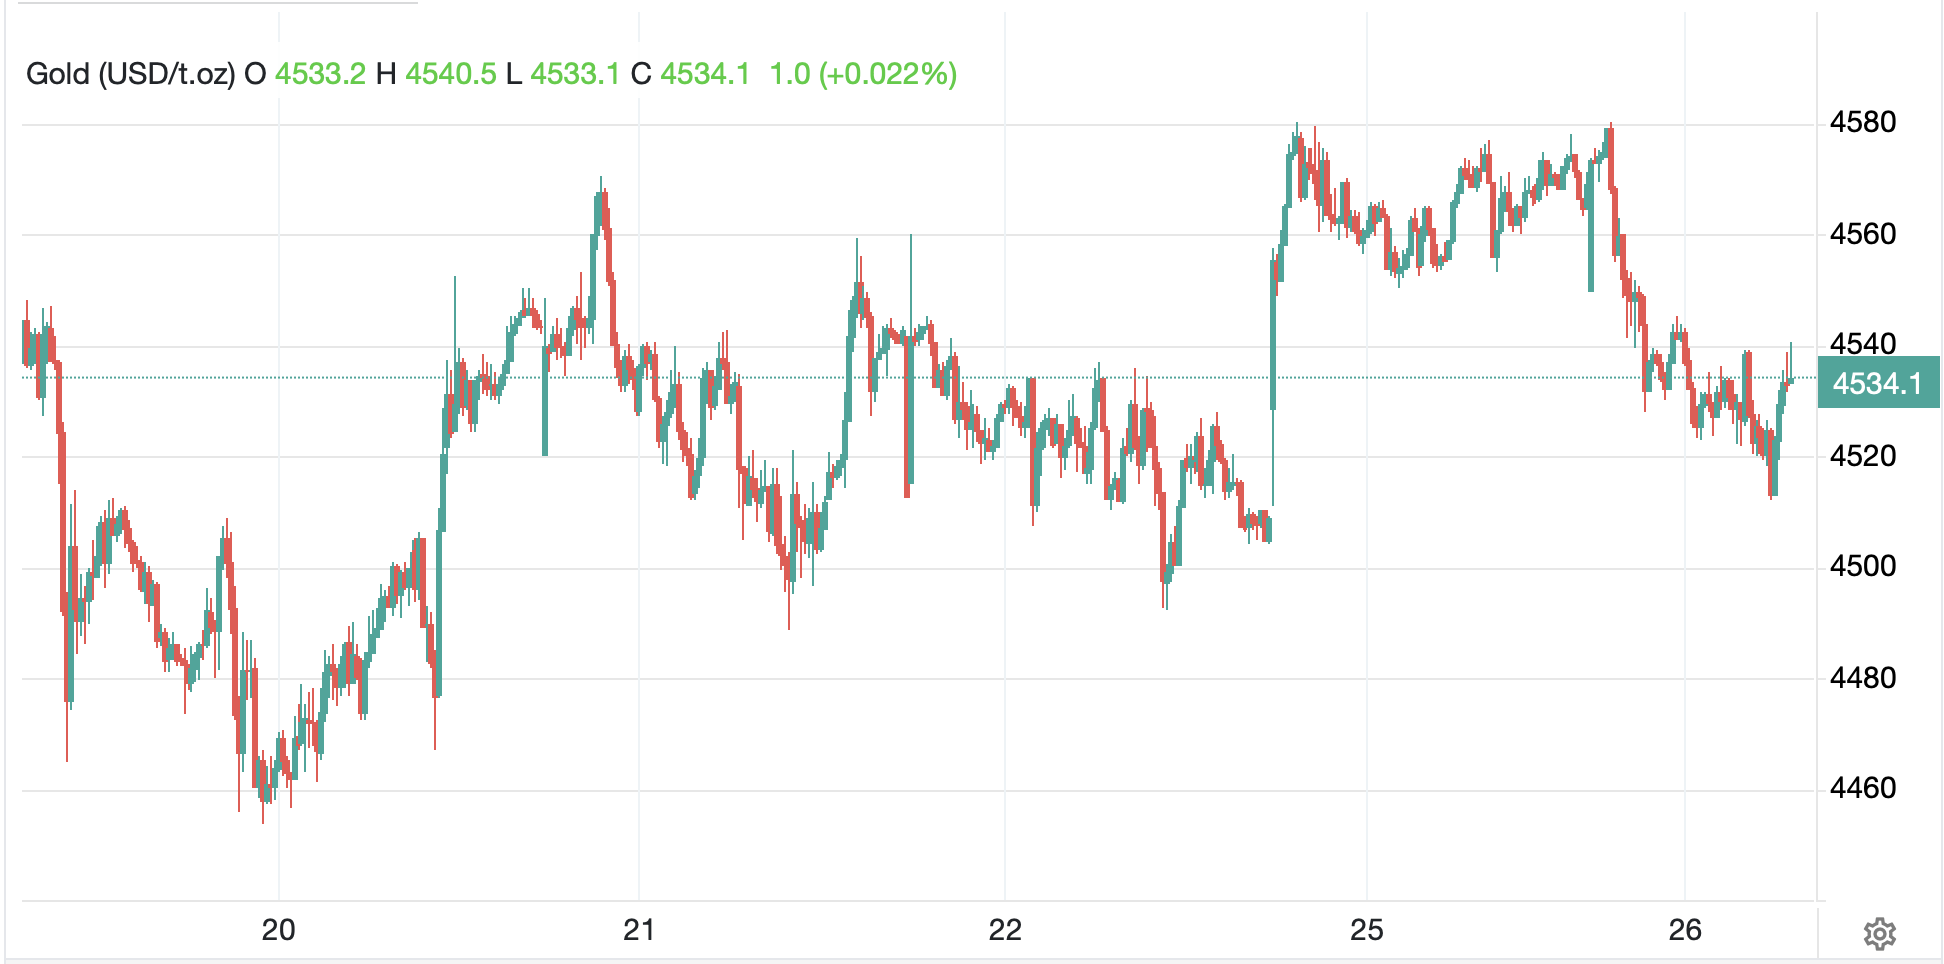
Speaking of oil (-2.3%), it appears to be responding to comments that the US will not resume an all-out war absent the death of US troops.  At least that’s one rationale, although the idea of the price heading back to its recent average is viable as well.  However, this has helped metals markets (Au +1.25%, Ag +1.8%, Cu +0.5%) as that relationship remains quite solid.

In the bond market, yields are also responding as would be expected with Treasuries (-3bps) leading the way as European sovereign yields all slip between -1bp and -2bps.

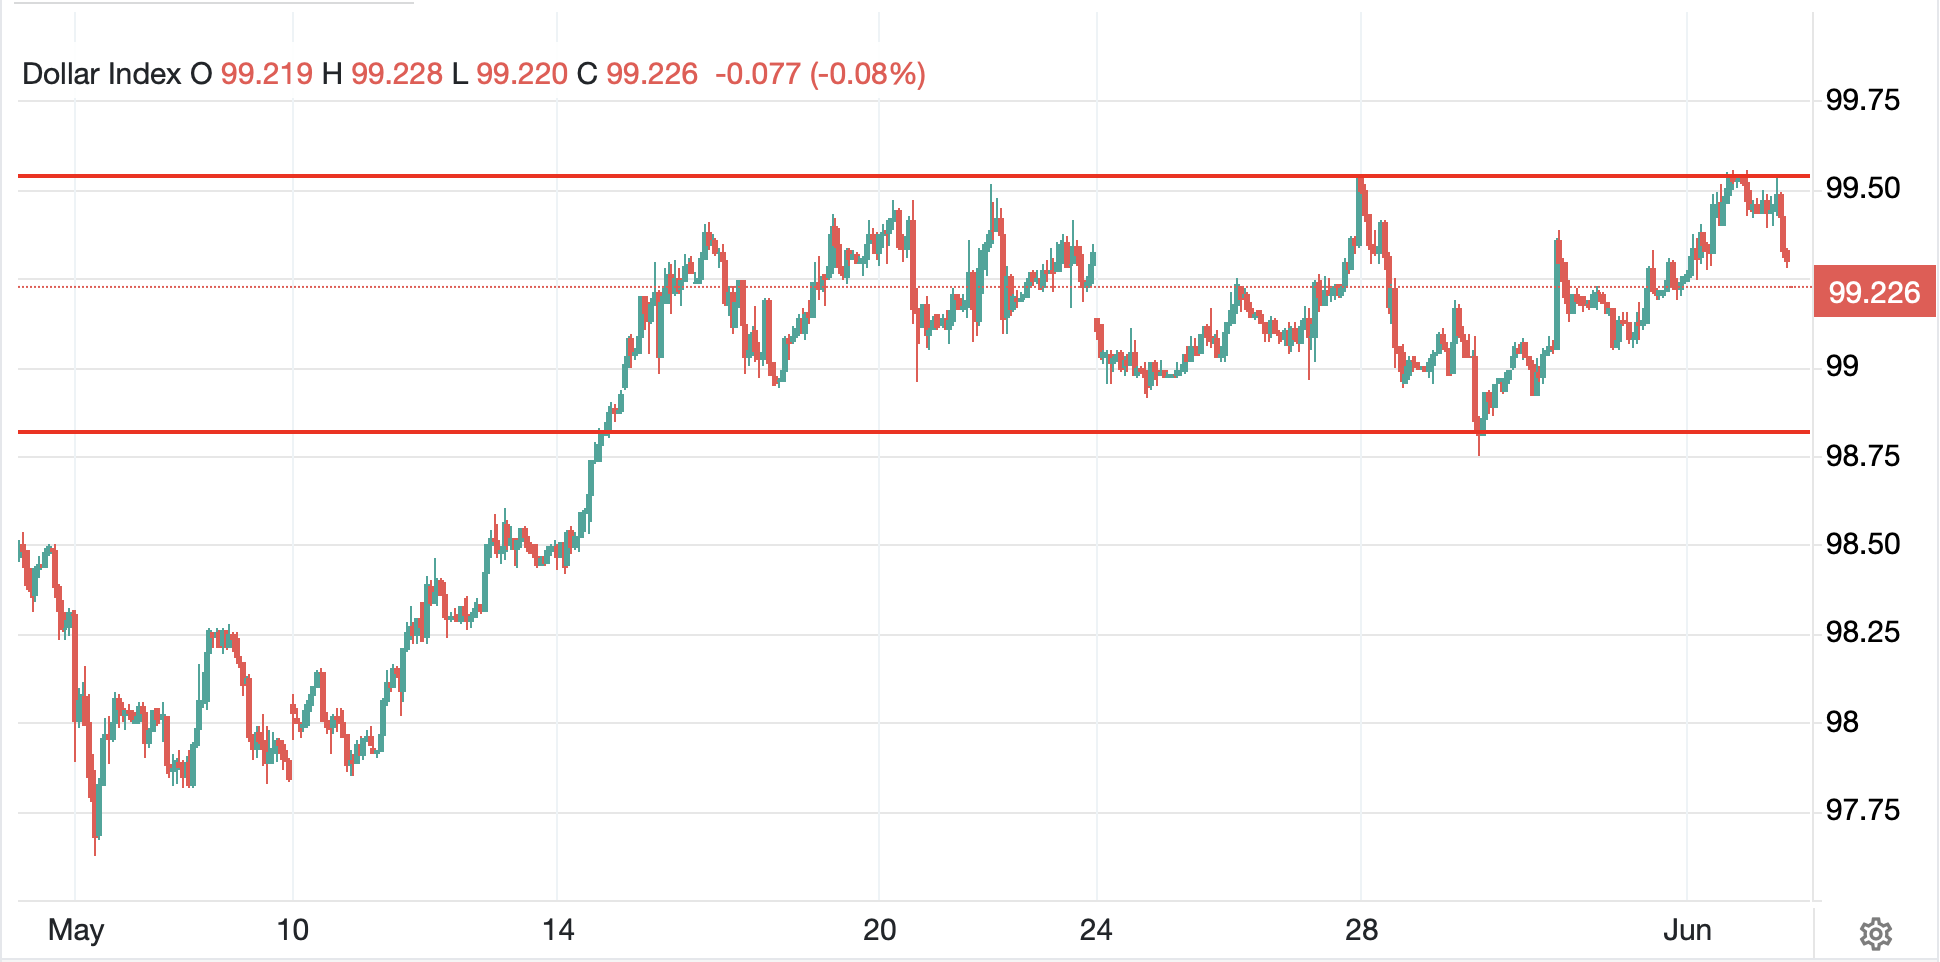
Finally, the dollar is giving up some of its recent gains but as you can see in the chart below for the DXY, during the past 3 weeks, the index has traded between 98.85 and 99.55, a very tight range and indicative of the general lack of movement in the dollar.

Source: tradingeconomics.com

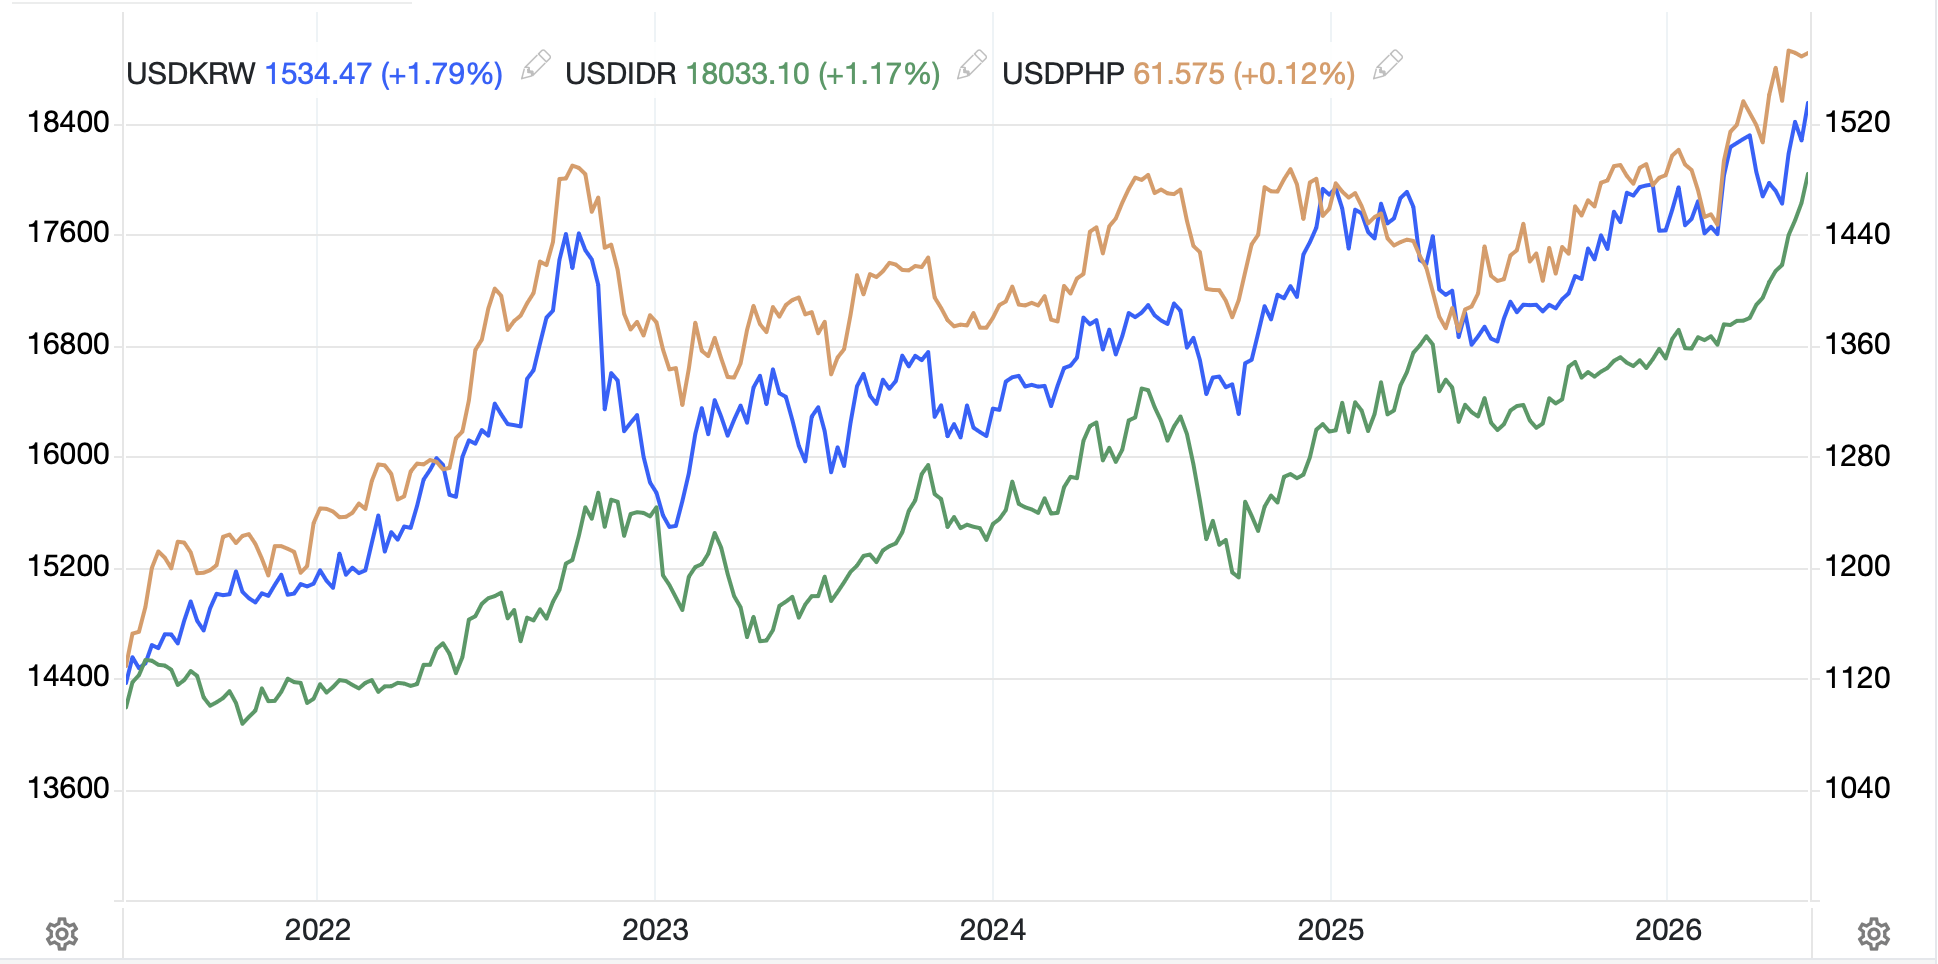
However, that is the dollar writ large vs. major currencies.  Against several Asian currencies, the story is not the same.  The below chart shows the Korean won, Indonesian rupiah and Philippine peso, all of which are trading at their lowest levels since the GFC as the pressure from higher oil prices and reduced supplies has really impacted their economies and currencies by extension.

Source: tradingeconomics.com

As to the JPY, it managed to trade through 160.00 yesterday, but only just, and this morning sits just below that level with no sign of the BOJ/MOF.  The Japan story remains the same, but the changes required there will be politically fraught.  However, for the smaller Asian nations, much is out of their hands, and my sense is that while they will all seek to mitigate the pace of decline, there is very little they can do to stop it on their own.  That will require the Iran situation to end and oil prices to head back lower with supplies rebuilding.

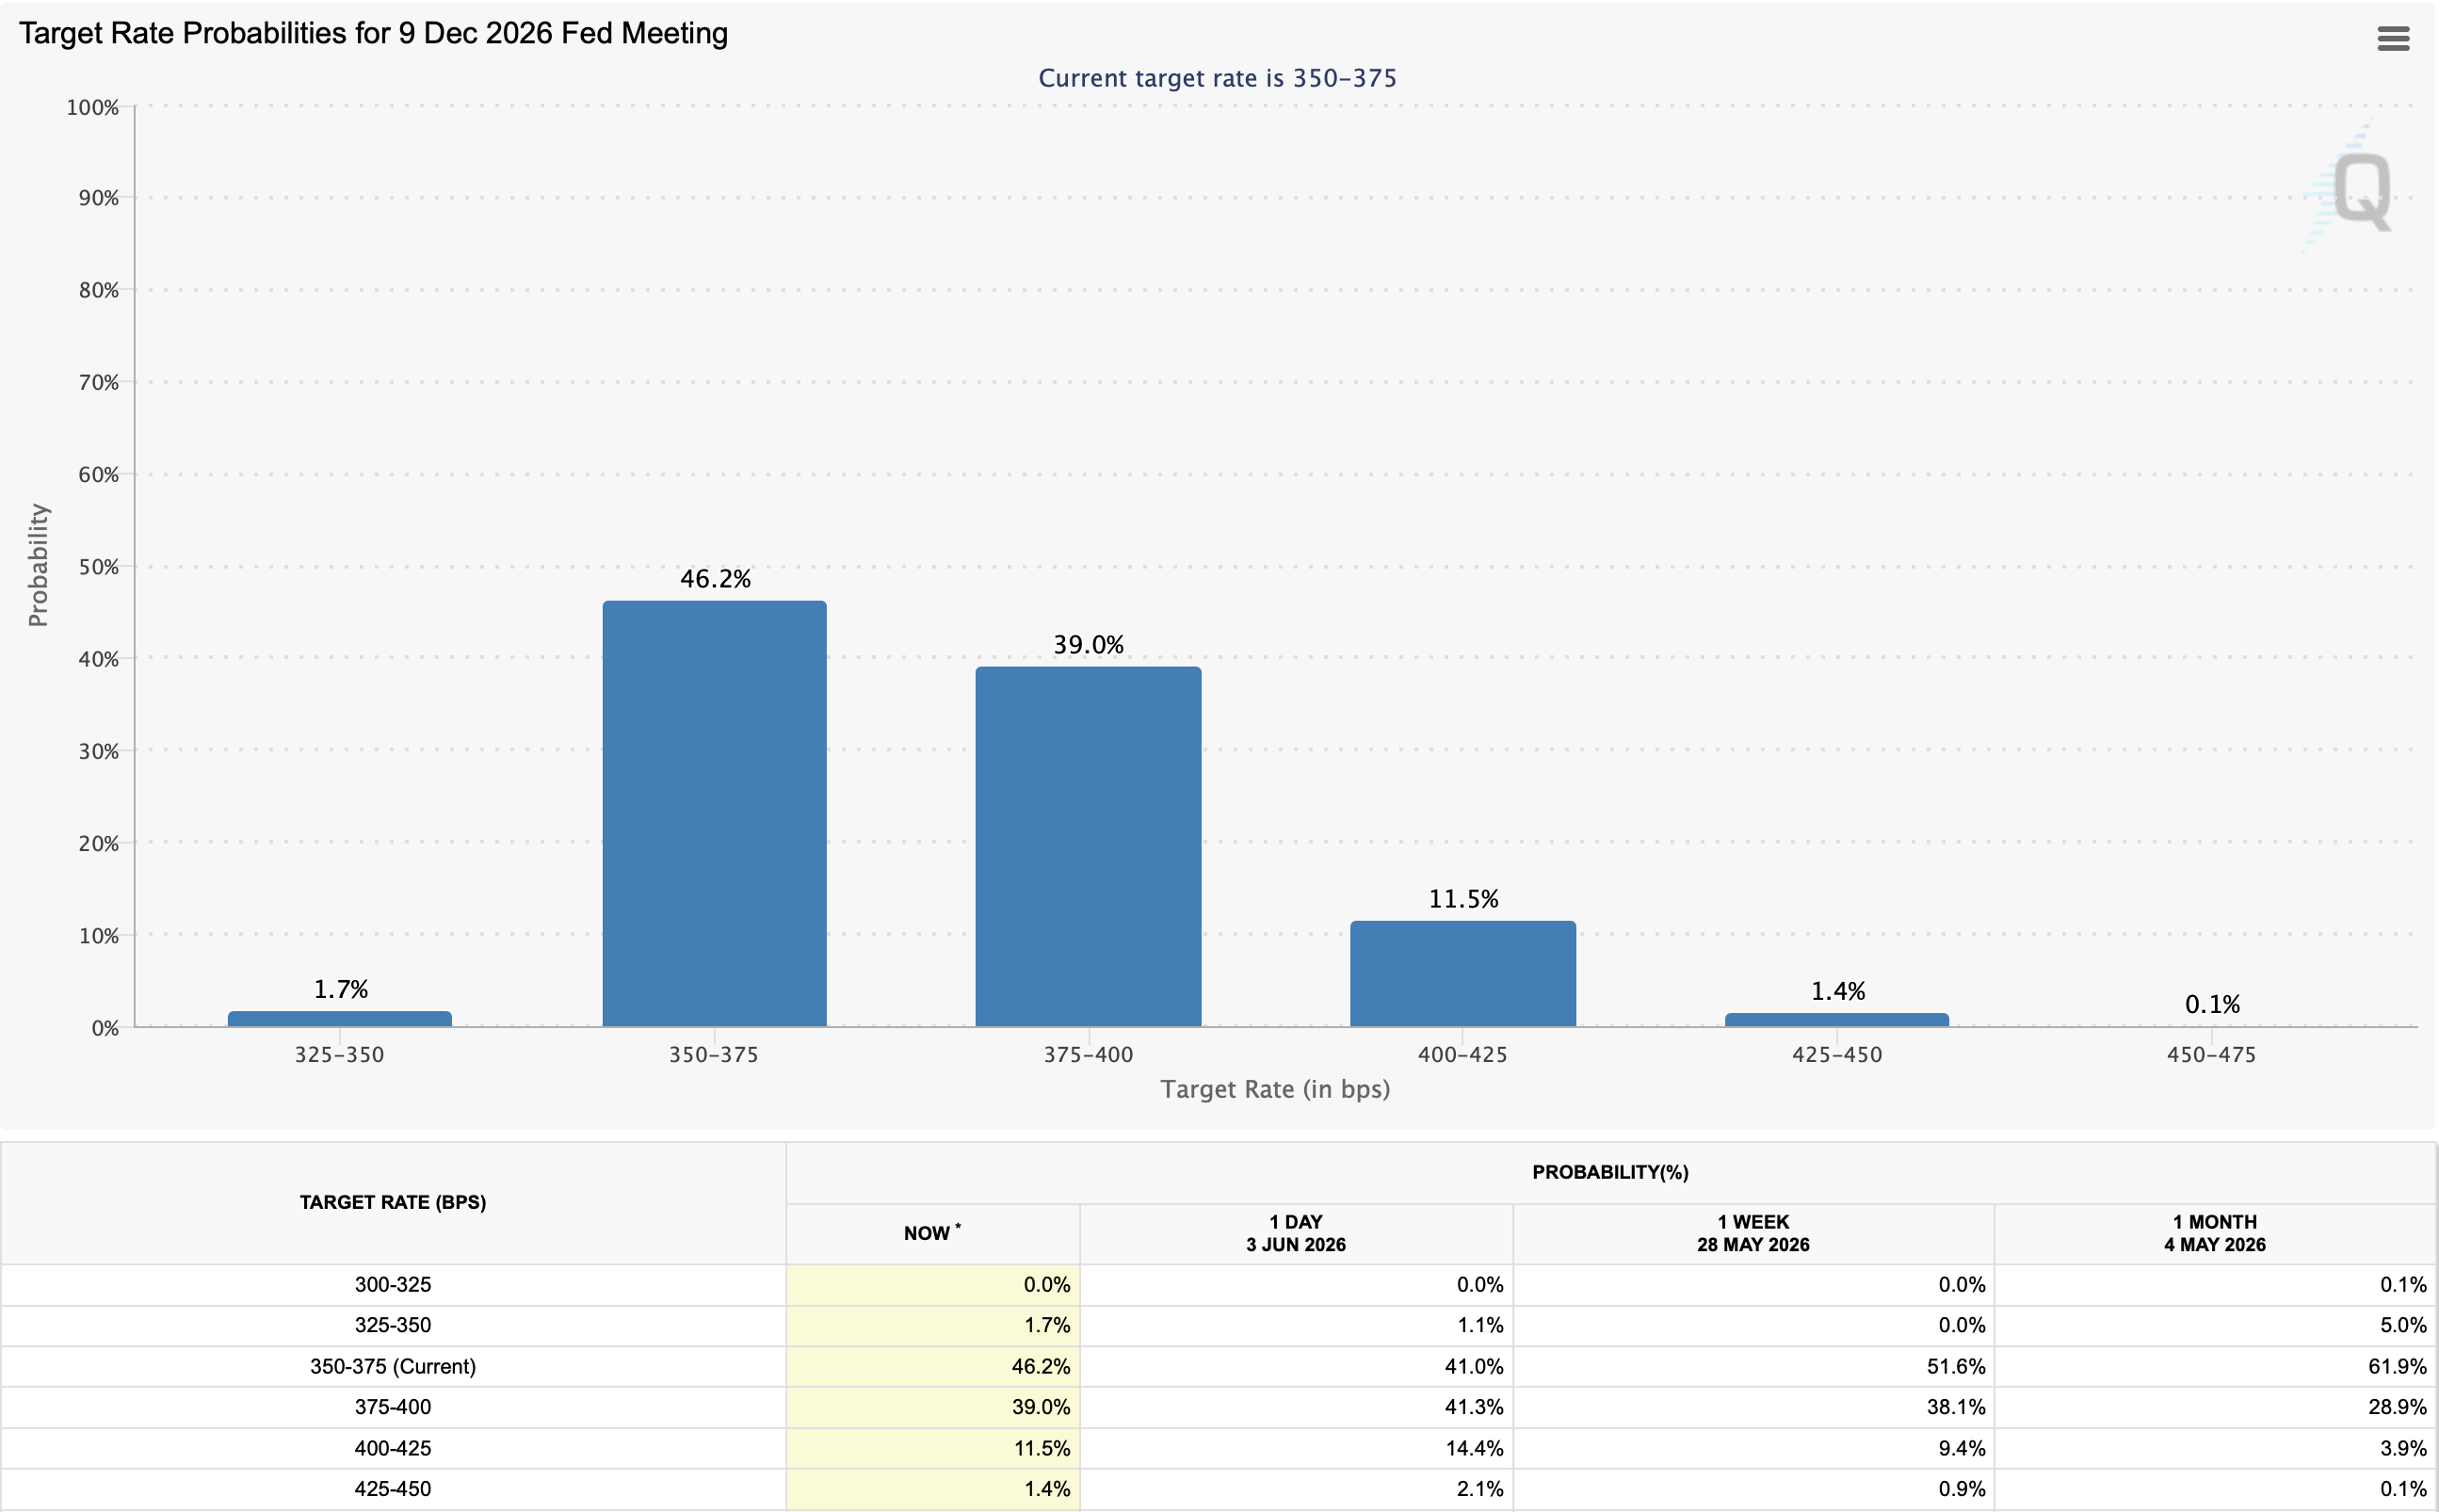
On the data front, this morning brings the weekly Initial (exp 213K) and Continuing (1780K) Claims data as well as Nonfarm Productivity (0.5%) and Unit Labor Costs (2.5%.  Too, we hear from several more Fed speakers but given all the other things that are ongoing, their words don’t seem to move markets.  For instance, yesterday Dallas Fed president Logan said she thought inflation pressures indicated rates may need to rise.  But she is a known hawk, one of the hawkish dissents at the last meeting, and thus this is not new news.  Below is the CME’s futures probability page for the December meeting which shows a slightly more than 50% chance of a hike by then.  However, if you look at the table at the bottom, you can see that the probability has been creeping higher in the past month, although that is just as likely on the back of the better data than any Fedspeak.  Certainly, next week’s first Warsh chaired meeting will get a great deal of attention.

And that’s really it for the day.  In the FX market, as well as bonds frankly, I don’t expect anything of note.  Oil looks to be drifting lower while metals drift higher and the real wild card is equities, which have been showing inordinate strength.  My thoughts above reflect my views for potential later in the year, not today.

Good luck

Adf

Actively Chided

Ostensibly, talks are ongoing
However, some fighting is sowing
The seeds of more doubt
That they’ll work it out
Ere Tehran’s surroundings are glowing

But markets have clearly decided
An outcome will soon be provided
Thus, risk is embraced
And stocks, higher, chased
While bond bears are actively chided

I hope everyone had a nice Memorial Day weekend, although until Monday afternoon, I must admit the weather here in NJ was less than we might have hoped.  Of course, a few raindrops are nothing compared to the “defensive” attacks executed by US forces, sinking two Iranian boats while they were trying to lay mines in the Strait.  Apparently, Iran’s response, several volleys of surface-to-air missiles was met with the destruction of those launchers as well.  

There is nothing better, though, than the language Iran uses in situations like this.  According to the WSJ, the head of the national security committee of Iran’s parliament, Ebrahim Azizi, explained that any attacks on the country’s armed forces would be met with “a decisive, crushing and regrettable response.”  It certainly sounds impressive, but it is not clear they can back up those words that effectively.  I guess we shall see.

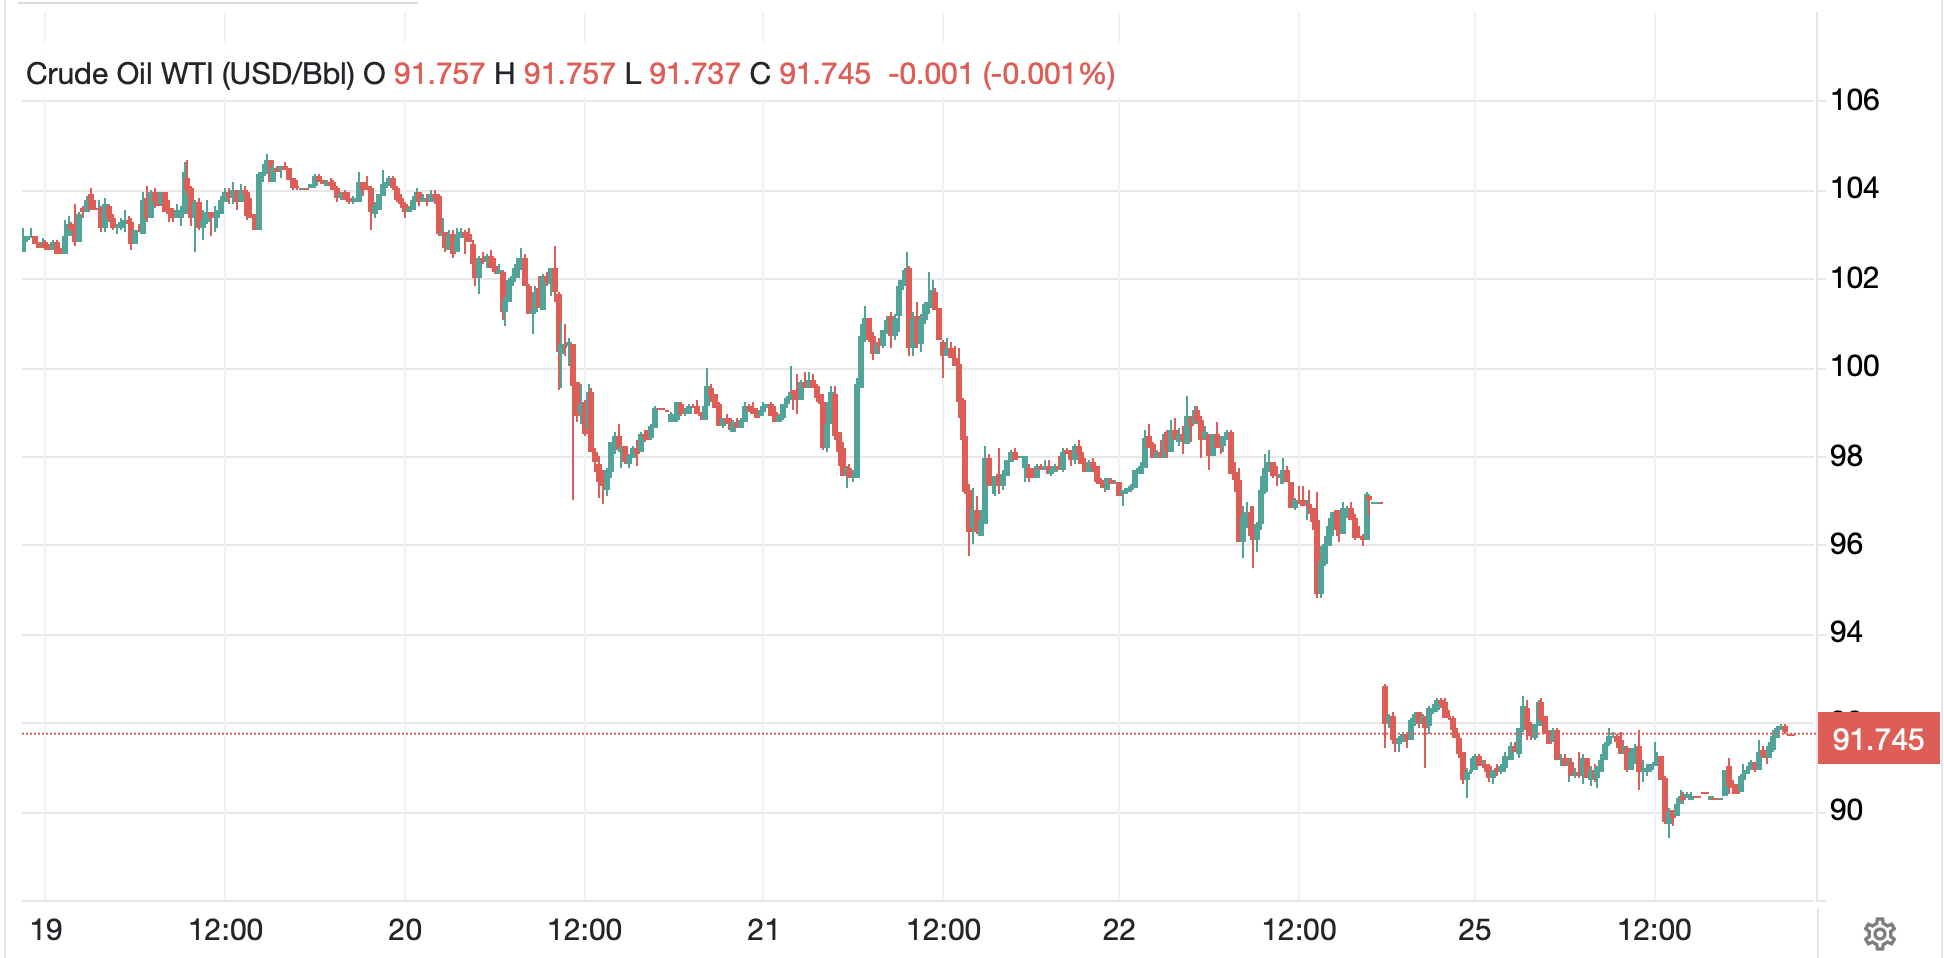
In the meantime, the other newsworthy item from the weekend was that the Supreme Leader, Mojtaba Hussein, was killed in a military strike and yet talks appear to be continuing.  President Trump explained that the framework for a deal was getting close and that was enough for traders to don their rose-colored glasses as oil gapped lower by more than $5/bbl when futures markets opened Sunday night and despite the recent “defensive” strikes mentioned above, remains far below levels seen last week.

Source: tradingecomomics.com

Not surprisingly, as Monday night trading in Asia gets underway, risk is back on with equities and metals higher, and bond yields lower.  

And as we awaken Tuesday morning, very little new has occurred.  The market continues to believe in the idea that the war is over in all but the details, at least the Iran war.  Ukraine continues, alas.  

On Friday, the latest Fed Chair
A man with a full head of hair
Was sworn to uphold
The idea that gold
To dollars, must never, compare

Before the weekend began, Kevin Warsh was sworn in as the new Fed Chair and the man has a tough job, that is for sure.  As another indication that the Fed is not an apolitical institution (as if any institution based in Washington DC could be apolitical), he hadn’t even gotten the keys to the office before two Fed governors were out opposing his very existence. The WSJ editorial page had a nice summation here which explained that Michael Barr, the erstwhile Vice Chair for Supervision who oversaw the collapse of Silicon Valley Bank (perhaps not the best credentials) was adamant that shrinking the balance sheet would lead to problems, as though he could foresee them!  Then Chris Waller, who was in the hunt for the Chairman’s seat, reversed his recent views on interest rates, explaining hikes were likely in order.  I’m sure there are no sour grapes there!

From this poet’s perspective, the financialization of the economy has been one of the biggest long-term problems we have seen and part and parcel of that financialization has been the Fed bloating expanding its balance sheet from <$1 trillion prior to the GFC to nearly $9 trillion at the height of the Covid madness and still well above $6 trillion today.  It is much harder to financialize things if there is less money around.  I fully support the idea that shrinking the Fed’s balance sheet would be a good thing.  Alas, that will be a tough road to hoe for Mr Warsh.  Good luck to him.

And with that, there are few other stories of note, so let’s look at the market response to the latest peace initiatives.  While we’ve already discussed oil above, gold saw the initial move you would have expected, jumping sharply, but has since given back much of those gains, as per the below chart, and is now about 0.5% higher than Friday’s close.

Source: tradingeconomics.com

Silver has seen similar price action as has copper.  Certainly, if a deal is signed, I believe we can expect oil to head back toward $75 – $80 per barrel and gold and silver to rebound sharply as well.  

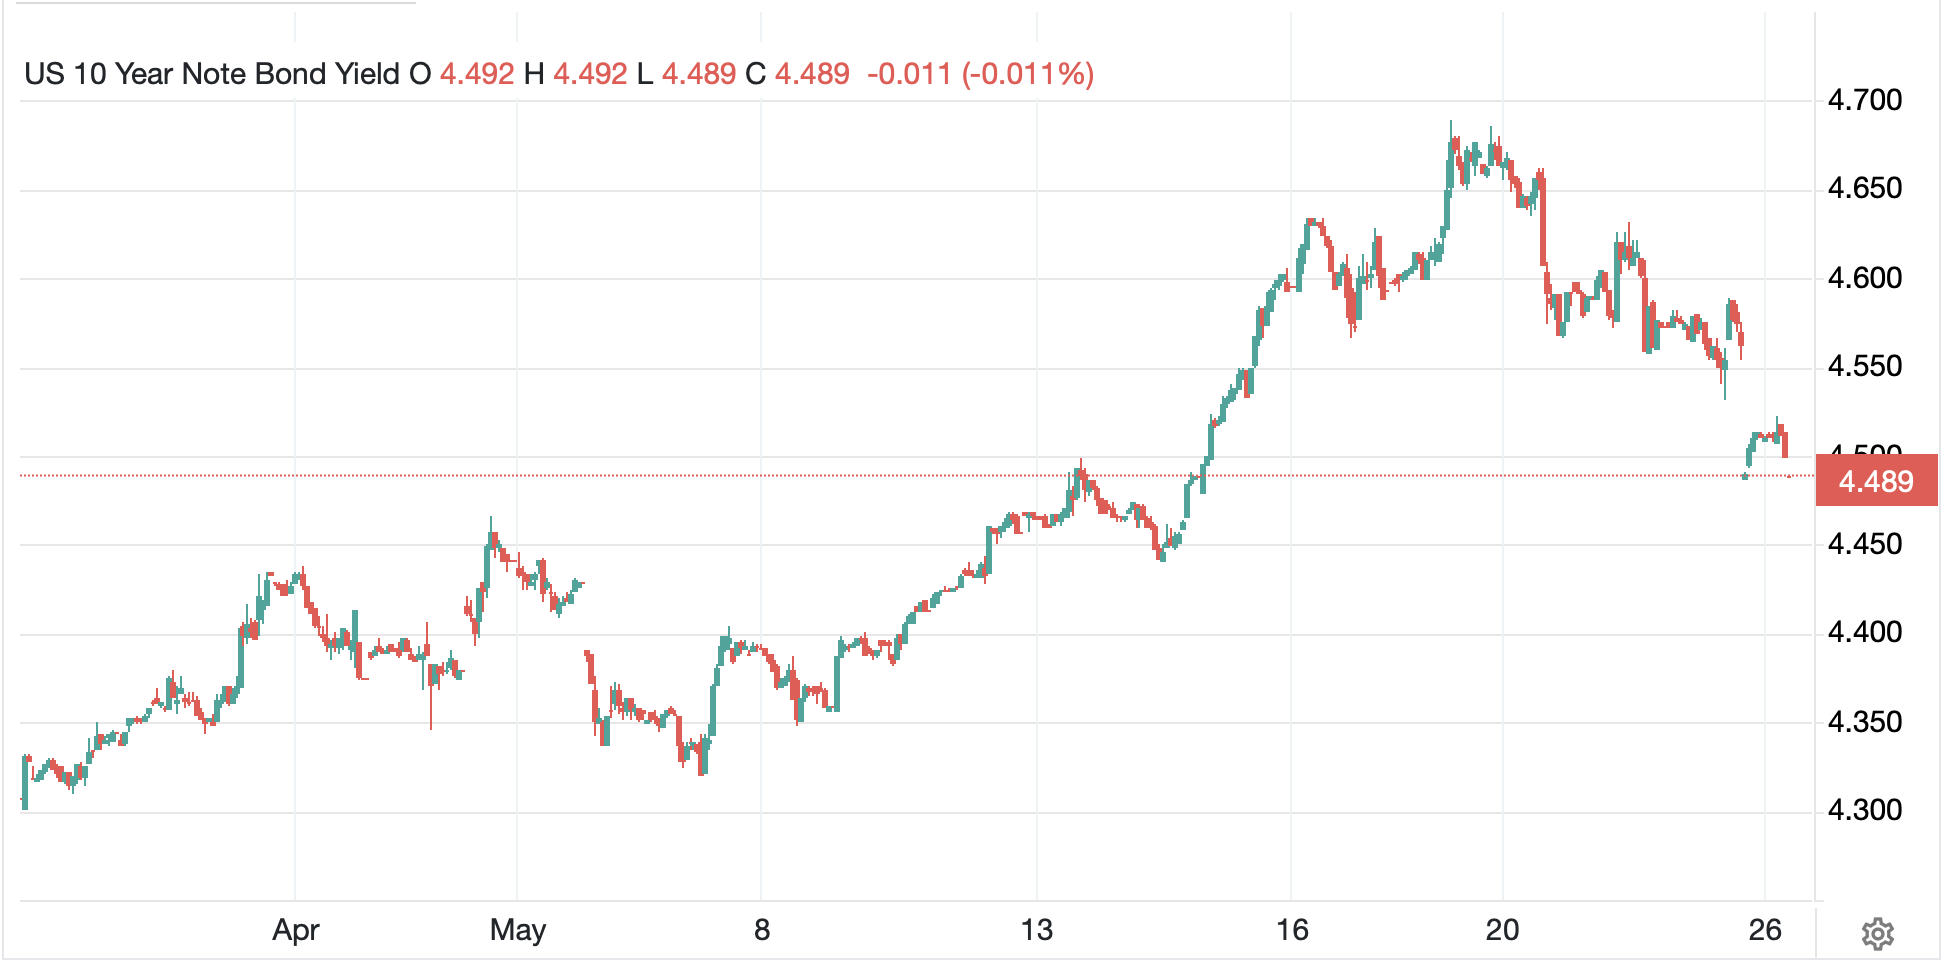
The other noteworthy mover was the bond market, which saw yields fall sharply on the news of the deal framework getting close.  You may recall the apocalyptic prognostications just last week when 10-year Treasury yields climbed near 4.70% with many discussions regarding the steepening of the yield curve and the trouble ahead for the economy.  But as I type this morning at 7:00am, the 10-year yield has dipped back below 4.50% in sync with the oil move lower as some of those inflation fears seem to be mitigating.

Source; tradingeconomics.com

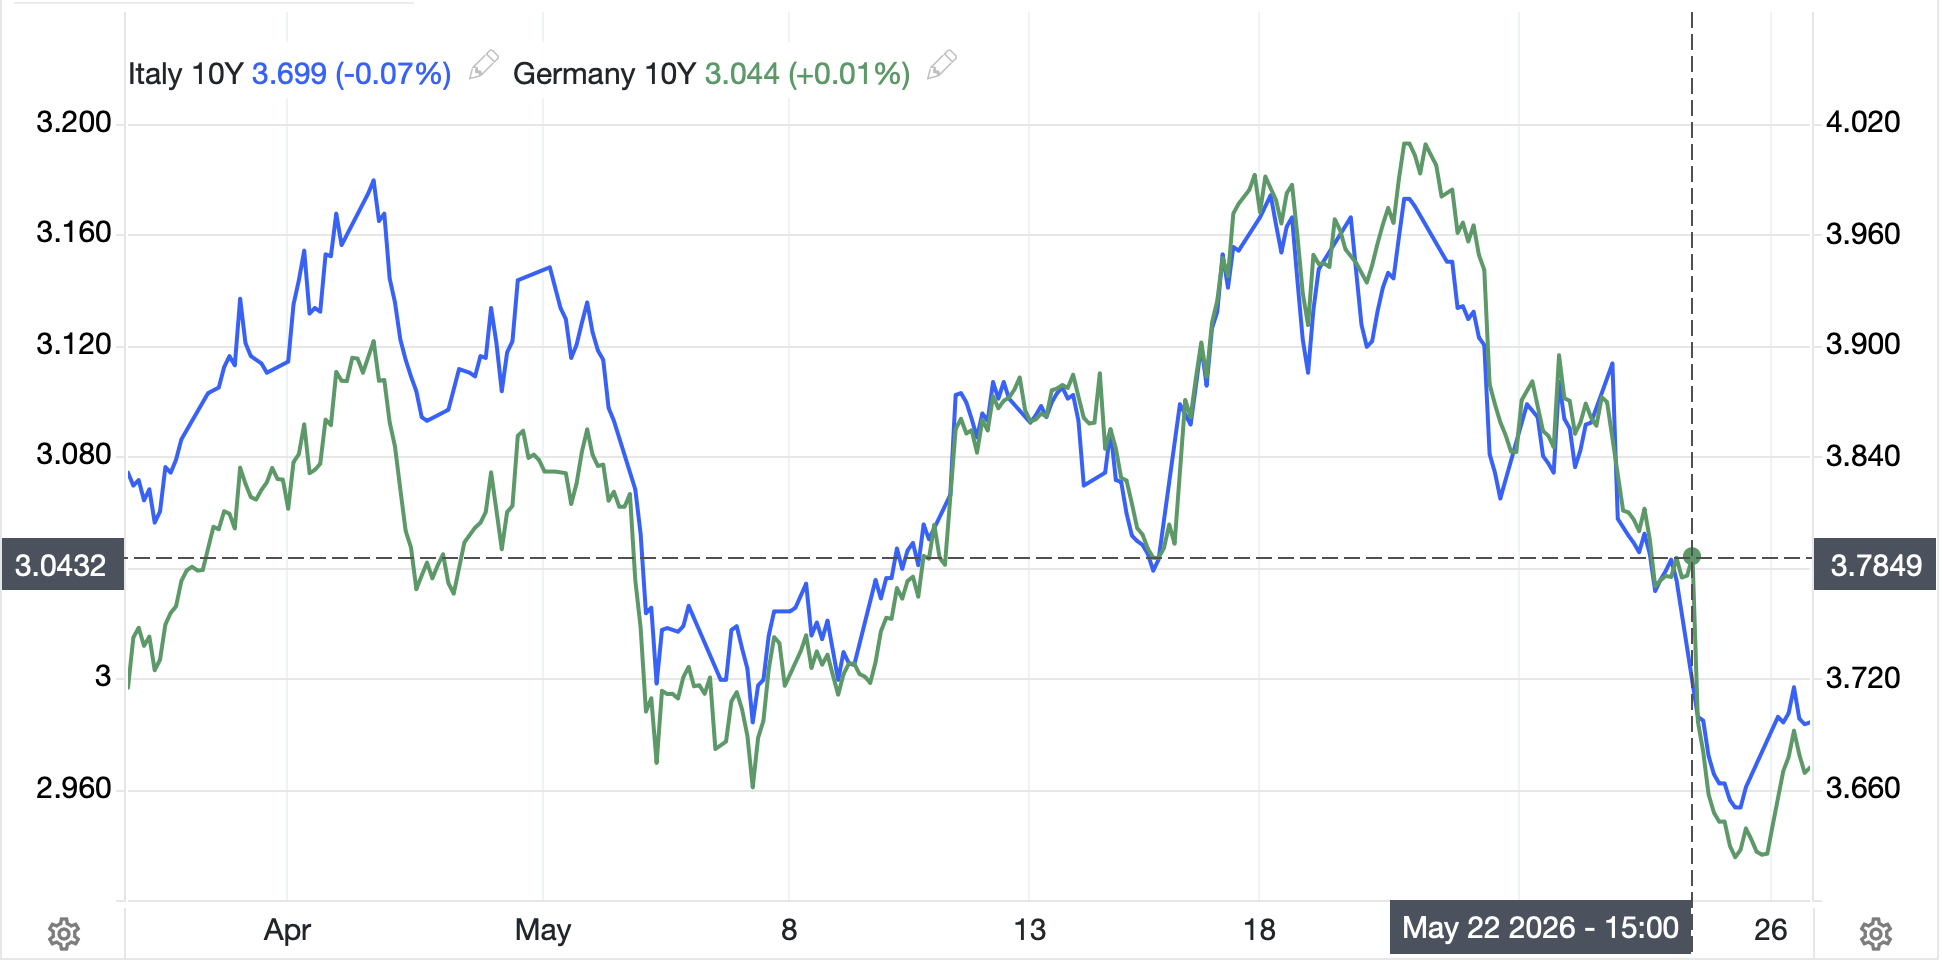
Now, as I look across European sovereign markets, they all show modest rises in yields this morning, but that is because yesterday, they fell so sharply.  Net, over the two days, yields are lower across the board.  As an example, the chart below shows both German and Italian 10-year yields and I highlighted Friday’s closing levels.  As you can see, both fell sharply yesterday and bounce a bit this morning but remain much lower.

Source: tradingeconomics.com

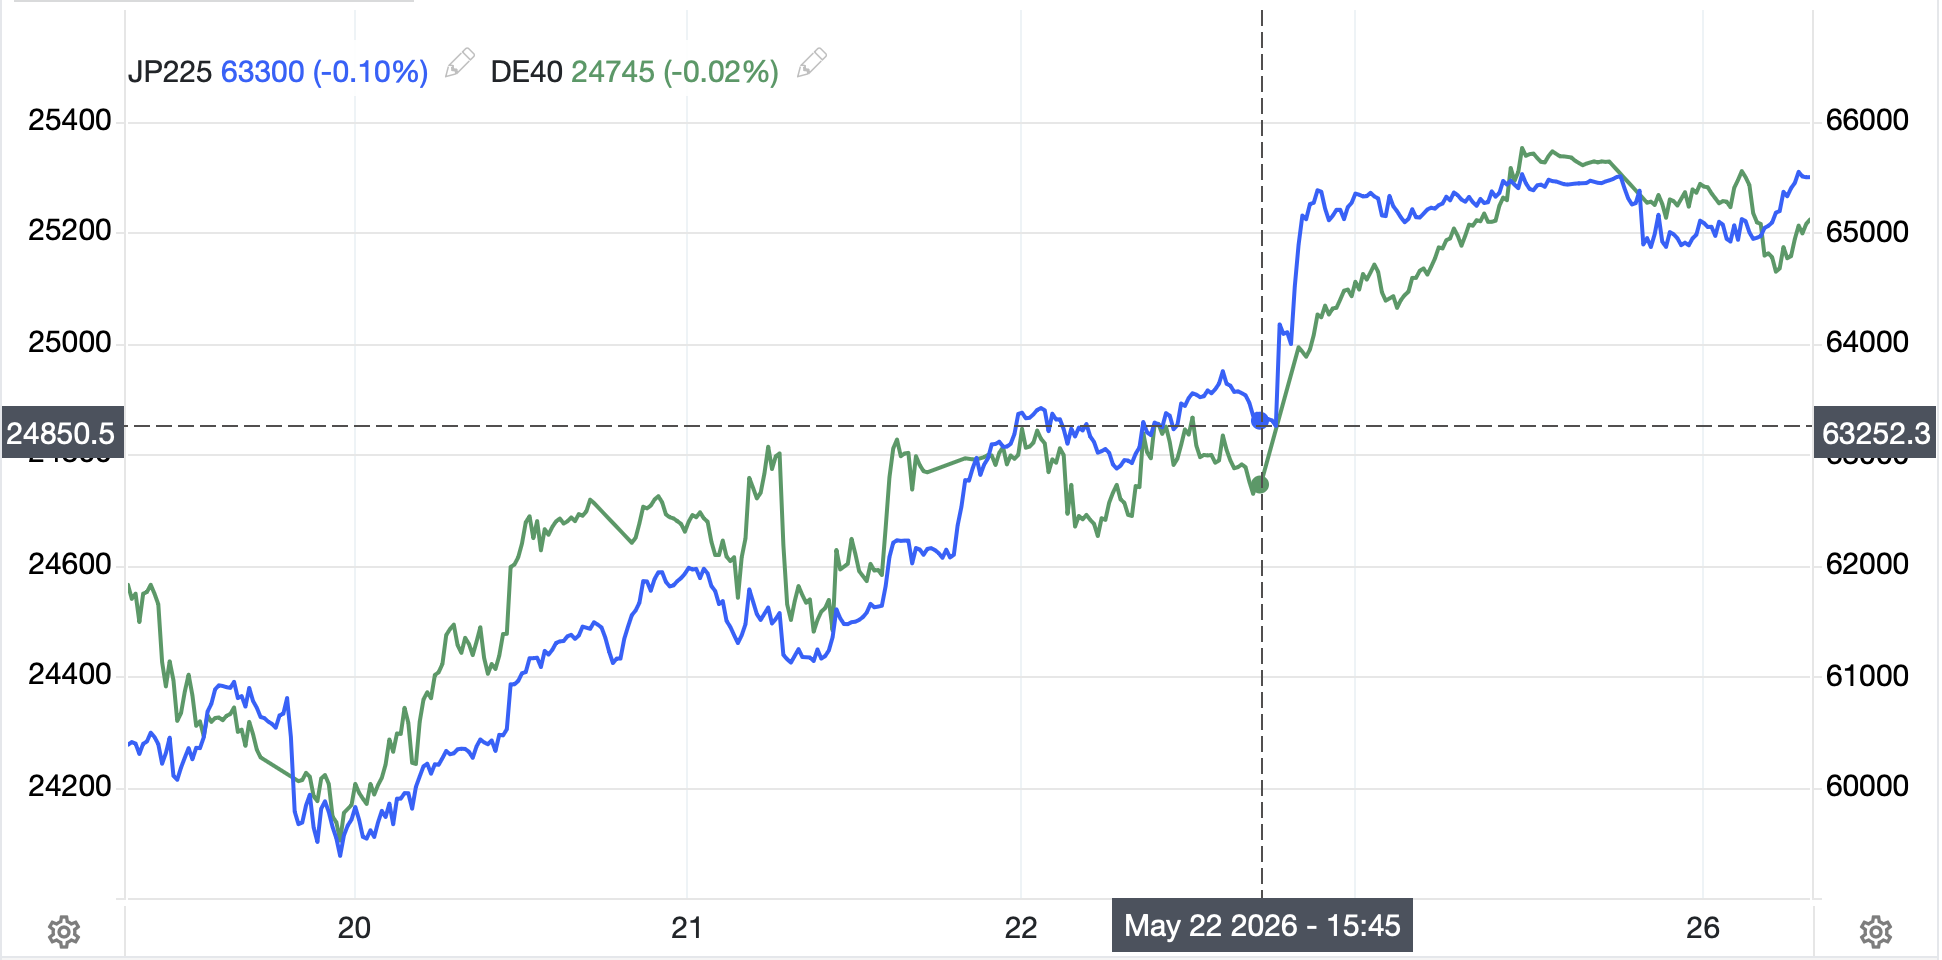
Moving on to equity markets, we have observed the same phenomena there, where there was a gap opening higher on Sunday night in futures markets which continued in cash markets while the US markets were closed for Memorial Day.  So, while last night, the Nikkei (-0.25%) slipped, that was after a more than 3% rally on Sunday night/Monday.  Ultimately, given the US holiday and the news cycle over the weekend, we need to look at the movement since Friday to get a sense of things.  So, below is a chart of both the Nikkei and the German DAX showing the rally from Friday’s late trading.  Again, risk is back baby!!

Source: tradingeconomics.com

Finally, the dollar is, well, it is all over the place this morning.  I look at tradingeconomics.com as my source for currency prices as they are all in one place.  One of the weird things this morning is that the EUR (-0.1%), GBP (-0.2%), JPY (-0.15%), CAD (0.0%), CHF (-0.2%) and SEK (-0.2%), the components of the DXY, are all flat to weaker this morning, the DXY itself is also weaker.  I have no explanation for that.  Generally, I would say the dollar is a bit firmer overall this morning with one notable exception, KRW (+0.7%) which saw demand alongside the sharp rally in the KOSPI overnight.  but otherwise, the dollar is modestly higher against most of its counterparts.  Lastly there has been a lot more noise than signal here.

On the data front, the short week does bring some important information.

TodayChicago Fed National Activity-0.3
 Case-Shiller Home Prices1.0%
 Consumer Confidence92.0
ThursdayInitial Claims211K
 Continuing Claims1780K
 Durable Goods3.5%
 -ex Transport0.5%
 Personal Income0.4%
 Personal Spending0.5%
 GDP Q12.0%
 PCE0.5% (3.8% Y/Y)
 Core PCE0.3% (3.3% Y/Y)
 New Home Sales670K
FridayGoods Trade Balance-$87.0B
 Chicago PMI49.7

Source: tradingeconmics.com

Now, with PCE coming, we are going to have to get a new line there as Chairman Warsh likes trimmed-mean PCE, which not surprisingly, has been lower of late, as the key metric for the Fed to follow.  I assume that will become the newest thing to watch.  Of course, it is far too early to have any sense of anything at the Fed now, other than the fact that there will be lots of politicking going on.

So, what have we learned?  Markets are still hopeful that the Iran conflict will end soon with a satisfactory (meaning no SOH problems) conclusion.  In that circumstance, risk will be the ongoing preferred stance, and I expect the dollar will come under pressure in that scenario, at least for a time.

Good luck

Adf

Greatly Vexed

For weeks it appeared that the war
Was something we all could ignore
As equities rallied
And most people tallied
Their gains as those prices did soar

But yesterday, things took a turn
And suddenly, stocks, folks, did spurn
While oil went higher
As missiles did fire
And UAE oil did burn

The question today is what’s next?
Will Hormuz soon wind up annexed?
Or will Iran’s forces
Back up their discourses
And keep Mr Trump greatly vexed?

For nearly two weeks, it appeared that the market was completely willing to accept the narrative that the Iranians were on their last legs and that the Strait would be reopened soon, thus relieving the pressure on the oil markets, and global markets in general.  After all, US equity markets, as well as those in Korea and Taiwan, were making new all-time highs regularly despite the ongoing stress in Iran.  

But yesterday, those happy thoughts were called into question as evidenced by the equity markets’ collective sharp decline throughout Europe and the US.  Of course, most of Asia was closed on Monday, but the few markets that were open performed well then.  Alas, last night was a different story with more losers (HK, India, Australia, New Zealan, Singapore) than gainers (Malaysia, Indonesia).  Even if markets don’t decline much further, there has been a distinct change in sentiment about things, at least in my view.

The timing of the progress in potential negotiations and the question of potential escalation of fighting again are suddenly weighing more heavily on investor perceptions than they had for the last several weeks.

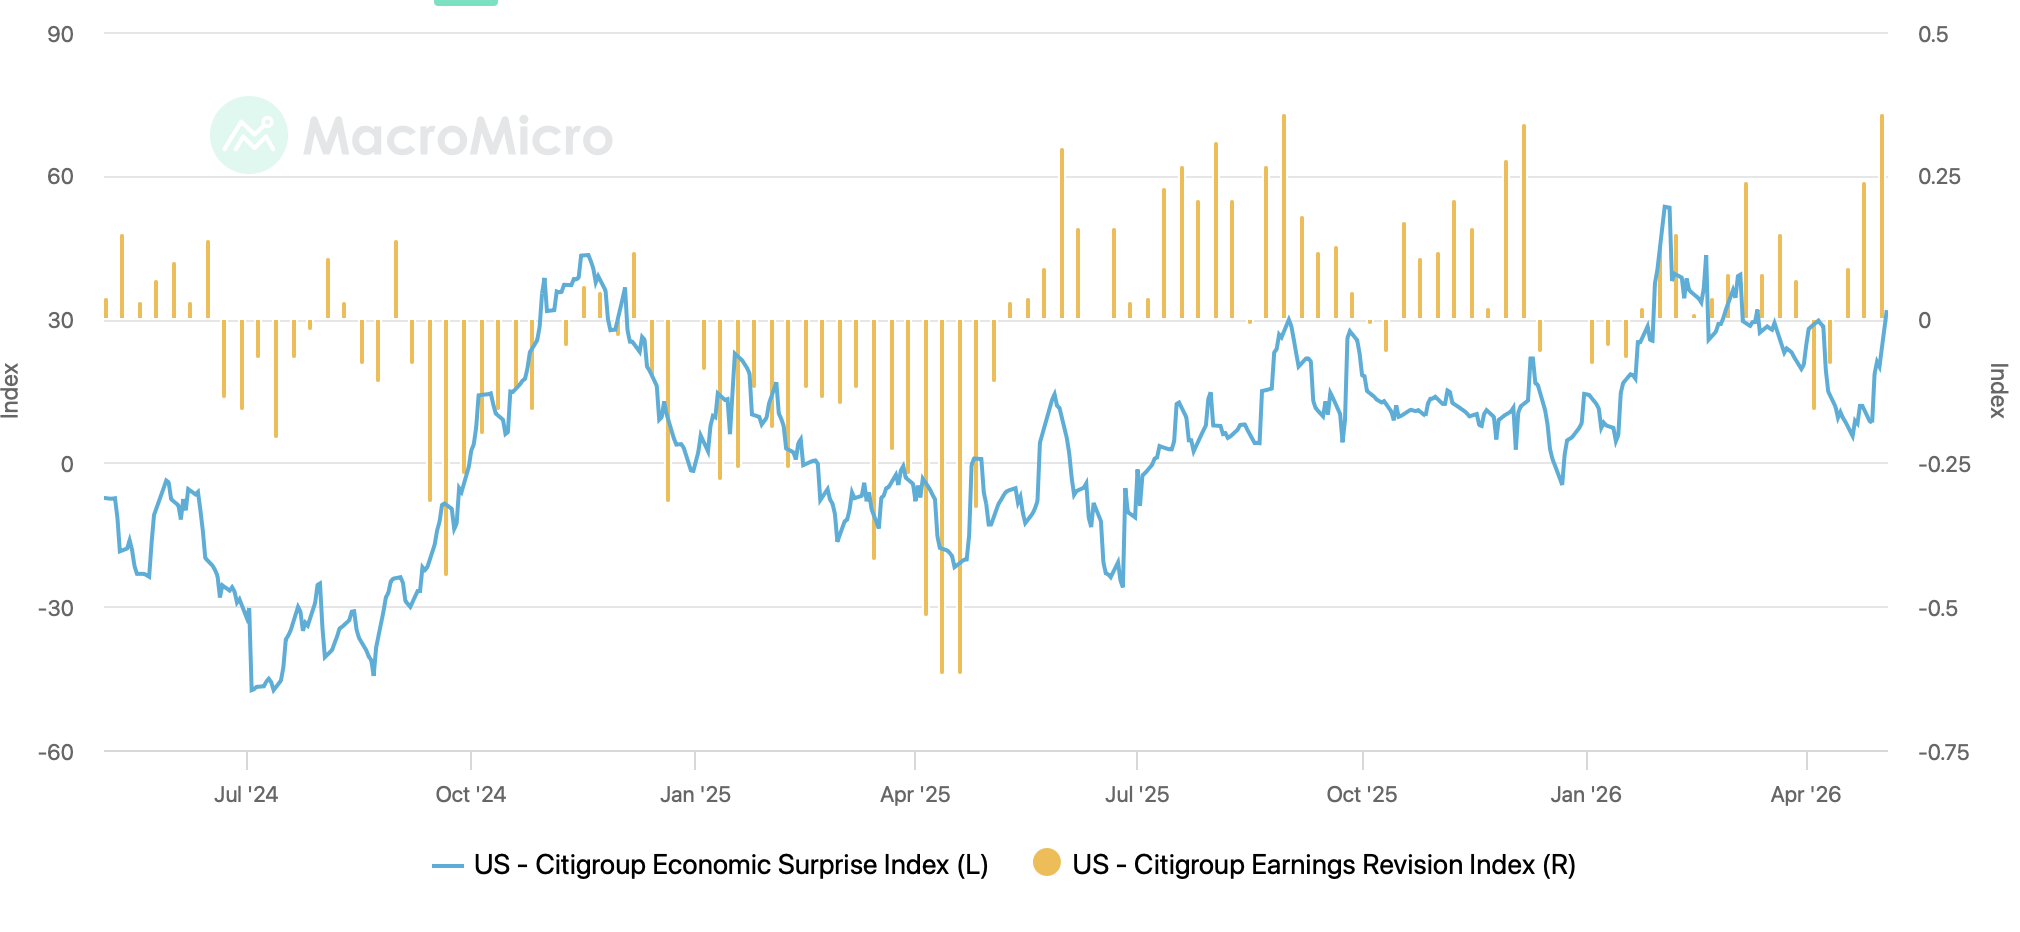
In the meantime, if we turn our attention to economic data, yesterday’s Factory Orders came in much stronger than expected, just the latest in a line of “surprisingly” strong data points from the US.  If we look at the chart below from macromicro.me, showing the Citi Surprise Index and their earnings index, we can see that both the economic indicators and US corporate earnings results are moving higher.  This seems at odds with the narrative of imminent collapse that is still making the rounds but is likely the cause of the equity market’s resilience.

In fact, this morning, markets are once again pointing in a more favorable direction as yesterday’s skirmishes in the Gulf have been quickly forgotten, it seems, and European bourses are all higher (Germany +1.0%, France + 0.6%, Spain +1.1%) recouping yesterday’s losses although UK equities (-1.0%) are suffering on a combination of yesterday’s concerns as well as a surprisingly negative HSBC earnings report.  And US futures are also higher at this hour (5:45) by about 0.4% across the board.  It is difficult to get markets downbeat for very long these days, which is remarkable given the sentiment indicators which have consistently been reading quite poorly.

This dichotomy is quite interesting to me as I am currently reading “Narrative Economics” by Robert Shiller, where he describes how social narratives have, throughout history, led to economic outcomes, whether positive or negative.  His implication is that the data tends to follow the current zeitgeist, and then almost regardless of any government efforts to change that narrative, the zeitgeist is what drives the economy.  For those of us who have been observing markets for any extended length of time, I don’t think this is a surprising revelation, although Shiller does a great job highlighting all the different times the narrative drove the bus.  

And that is what makes the current situation so remarkable, the narrative is that things are terrible with the nation dramatically split politically while gasoline prices have risen so much and inflation is a major problem.  You can see that in the Michigan Sentiment Survey and the political polls.  Yet Retail Sales remain firm and we just saw those strong Factory Orders, two things which one would expect to soften given the current narrative.

Perhaps what we have seen is the impact of social media and ‘influencers’ whose goal is to show the good life and why/how you should live it.  Given they only maintain their followers if they show an ideal situation, there will be no shaming for ostentatious consumption, that is their stock in trade.  So, while during the Great Depression, social pressures were such that buying anything new, like cars or houses, was seen as inappropriate, today, buying new cars is seen as a requirement, the more expensive the better.  Or going on an expensive holiday, or some other extravagance.  I wonder if the gloomy narrative will end up overcoming the influencers.  I suppose much will depend on just how much longer the war in Iran continues, as a clear end soon would almost certainly see a major sentiment change and another wave higher in risk assets while the longer it drags on, the more likely negativity overwhelms.

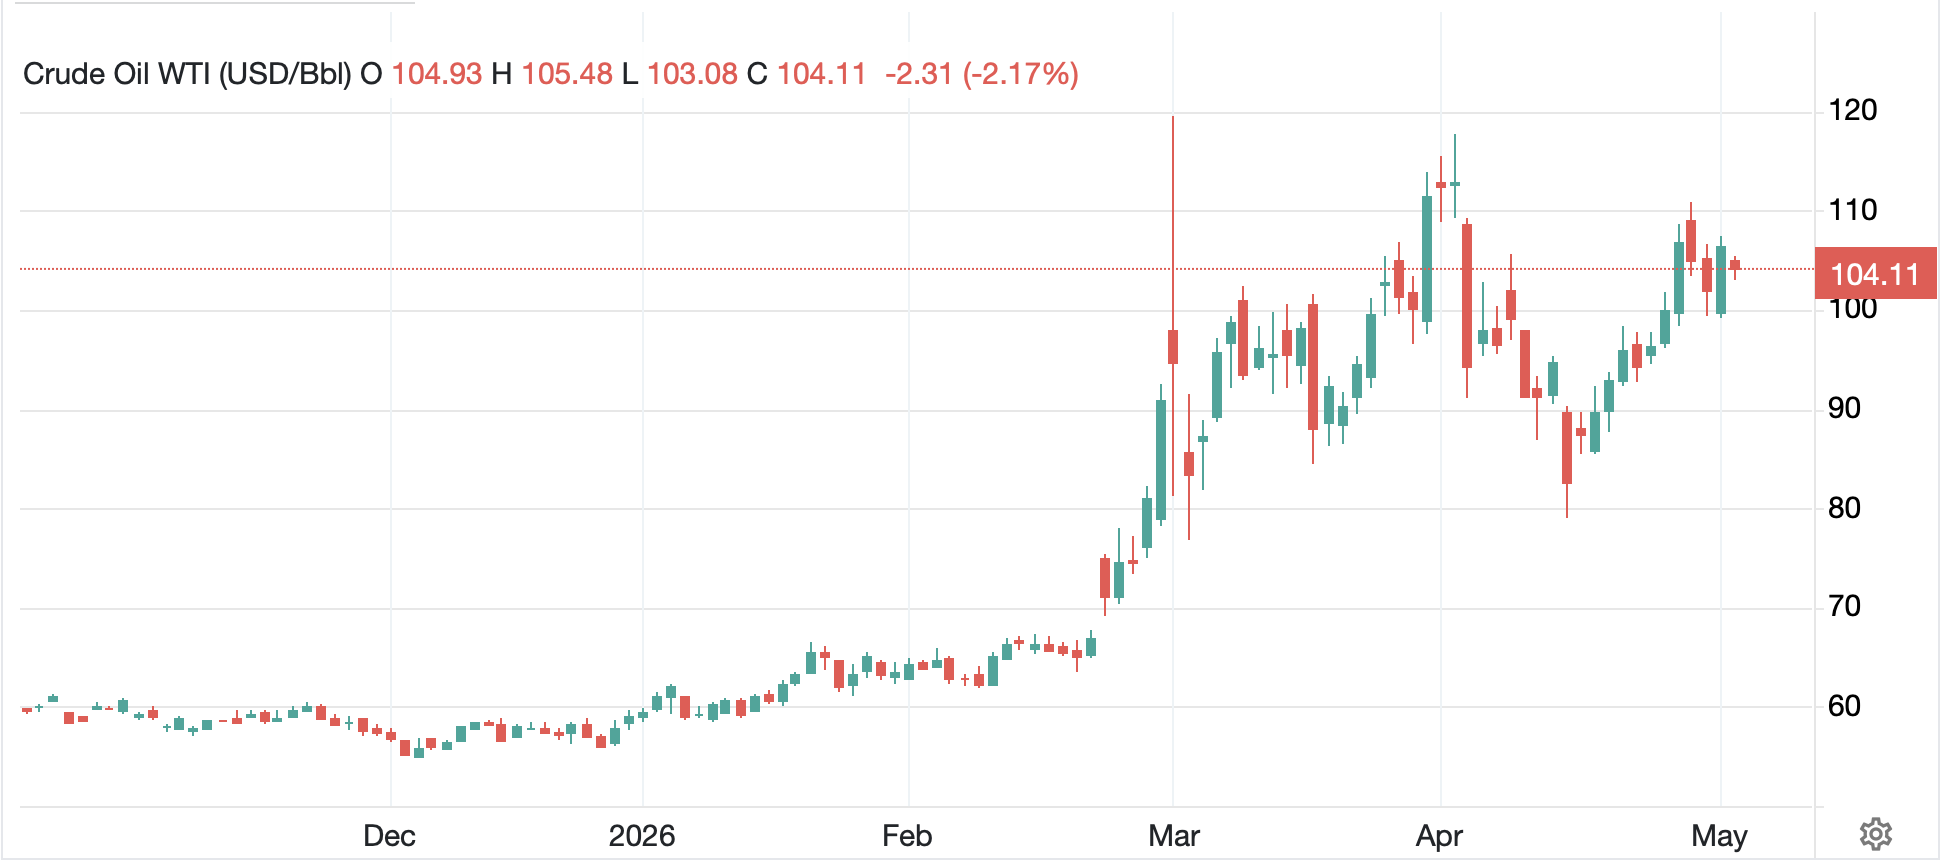
But this morning, having already looked at equity markets, we see a key piece of that story is oil (-2.0%) having slipped back.  Perhaps the fact that there have been no new skirmishes has people back to a brighter outlook.  Or perhaps, as the conspiracy theorists would explain, governments are in manipulating the price lower again.  As I look at the chart, though, it remains remarkable to me that despite the Strait having been closed for two months now, oil prices have not risen further.

Source: tradingeconomics.com

The question at this point is how quickly things can return to any semblance of normal when the hostilities end.  From what I have read, and I am not an expert, it almost seems like every day the Strait remains closed will require one and a half days more before things get back to the pre-war situation.  Of course, even if that is the case, if the war ends, the zeitgeist will change far faster and that will likely be overlooked.

Meanwhile, given the current gold/oil relationship, we cannot be surprised that gold (+0.6%) and silver (+1.3%) are higher this morning.

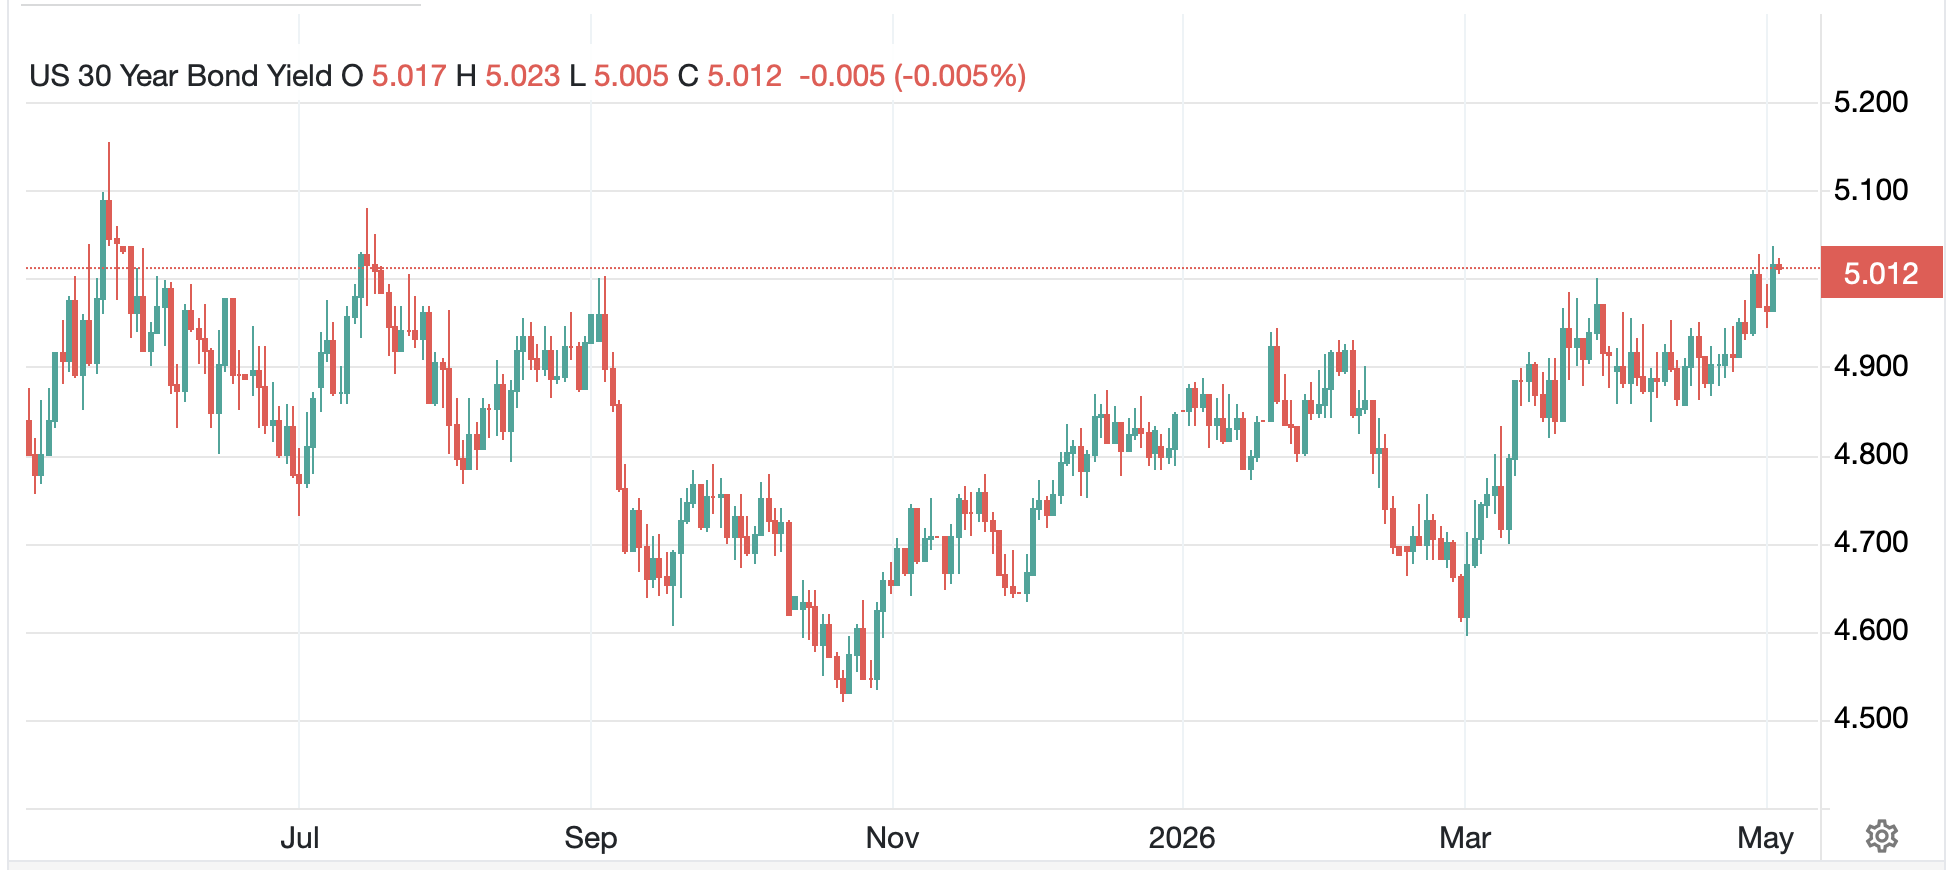
In the bond market, after yields rose sharply yesterday (Treasuries +8bps), this morning, things are less dramatic with 10-year Treasury yields slipping -1bp and European sovereign yields all softer with Greece and Italy (-5bps) seeing the largest declines although German bunds (-1bp) were more in line with Treasuries.  There has been much discussion lately about 30-year Treasuries and how they have traded back above 5.0% again, indicating it is a sign of the apocalypse.  However, if you look at the chart below, you can see we have been at or above that level several times in just the past year.  I understand 5.0% is a big round number, but I don’t see this as an imminent disaster because of the move. (Don’t misunderstand, the US fiscal situation is a major problem with many potential problems going forward, I just don’t think this is the final straw.)

Source: tradingeconomics.com

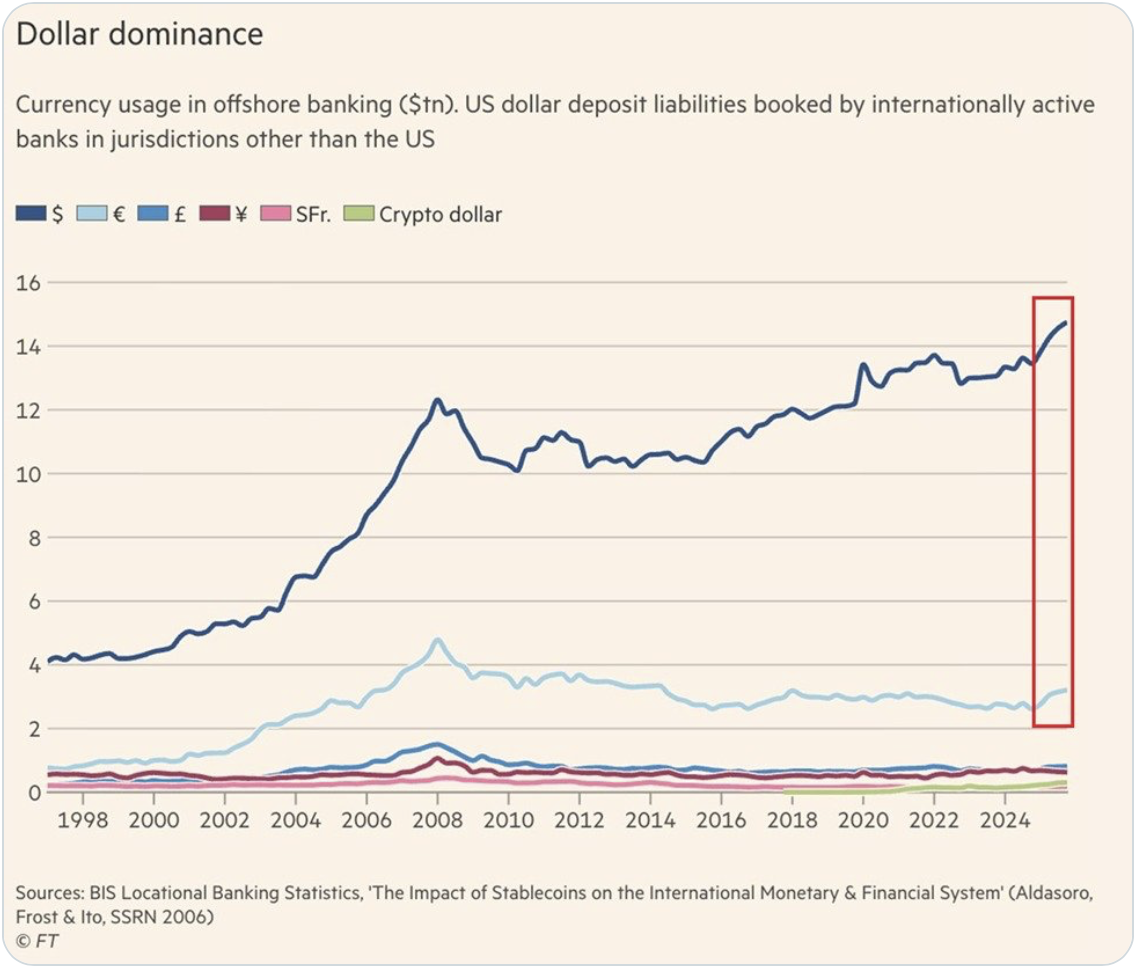
Finally, turning to the dollar, after modest gains yesterday, it is little changed this morning.  The RBA raised rates by 25bps, as expected and AUD is unchanged, as are the euro and pound.  With the BOJ on holiday, JPY (-0.2%) is slipping slightly, but not showing any major activity.  However, we have seen several EMG currencies improve with MXN (+0.3%) and BRL (+0.4%) both benefitting from the increased risk appetite we are seeing in overall markets.  The thing about the dollar is it has not been interesting for quite some time, trading within a fairly narrow range.  However, while we continue to hear many pundits describe the dollar’s ultimate demise, there is an interesting story in the FT about the dollar’s dominance in global markets as can be seen in the chart below from Kobeissi on X.

This is not a demonstration of the world shunning dollars, just sayin!

On the data front, this morning brings the Trade Balance (exp -$60.5B) along with ISM Services (53.7) and JOLTs Job Openings (6.83M).  We also see New Home Sales (668K) and hear from two Fed governors, Bowman and Barr.

But it is all still about the war and oil, and until something definitively changes there, I expect we will chop with every headline.

Good luck

Adf

A Bad Bet

While nothing is terribly clear
It seems there’s more worry and fear
The war’s gonna start
To blow things apart
Once more, thus risk gets a Bronx cheer

At this point the navy is set
With carriers, three, as the threat
Meanwhile, Iran’s leaders
Are fighting seceders
It could be they made a bad bet

As the week draws to a close, there is no clarity regarding the potential for a peace deal to end the war as both sides continue to claim the other is the problem with respect to getting to talks.  There continues to be a massive amount of propaganda from both sides and maritime traffic remains at a standstill in the Strait of Hormuz.  Arguably the most noteworthy occurrence was that the USS George H.W. Bush has arrived in theater, bringing the navy armada up to 19 ships, I believe.  That is an enormous amount of firepower.  In fact, there is a theory that the entire purpose of the ceasefire was to allow the US to move all its assets into theater to ensure that the next action completes the process.  

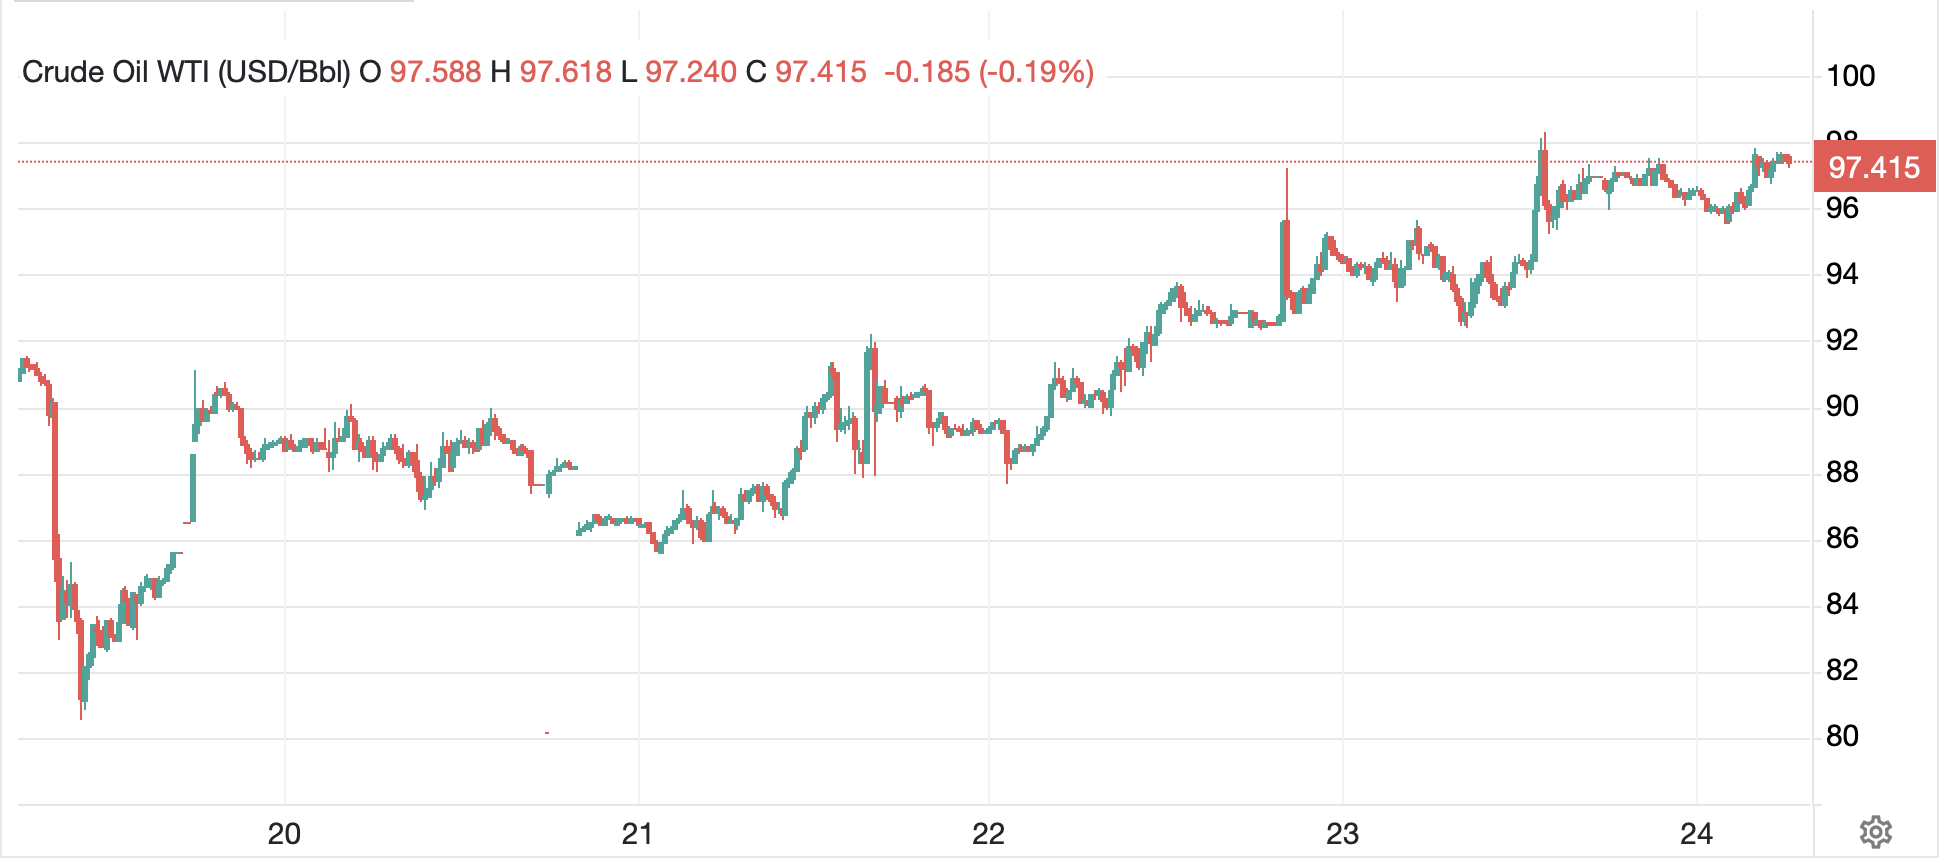
But there has been a change amongst the views of market participants about how things are going to proceed as evidenced by the price of oil.  Arguably, there is no better barometer of the situation than that price and as you can see from the below chart, crude oil’s price (+1.6%) has traded higher consistently all week.

Source: tradingeconomics.com

Too, the fact that we are approaching the weekend has me thinking that the next step in this war is about to kick off.  President Trump has shown that he favors military action when markets are closed and I am pretty certain that view hasn’t changed.  So, keep alert for the news when you wake up tomorrow morning.

However, until such time that the situation on the ground there changes, we are left with a great deal of pontification (present company included, although I try to simply focus on the markets and how their price action offers indications of current events).  Beyond the war, there is precious little new news of market import, though, right now.  Data continues to be a secondary consideration for traders and investors as everything is being distorted by the sudden impacts of the sharp rise in energy prices.  Politics is always a long-term phenomenon, with the daily machinations rarely having a market impact.  Which leaves us with speculative activity, which never rests!

With that in mind, let’s look at the markets and see what they are telling us (or me at least).  Having already highlighted the fact that oil has been creeping higher all week, which I reiterate, implies to me that market participants have begun to believe further military action is imminent, we cannot be surprised that gold (-0.4%) and silver (-0.7%) are slipping as the correlation between the metals and oil has turned negative since the war began about 2 months ago.  Historically, this had almost always been a positive correlation, but right now, that relationship has clearly inverted as you can see in the below chart.

Source: tradingeconomics.com

It certainly remains an enigma that what many perceive to be the ultimate safe haven, gold, is performing so relatively poorly during the greatest strife we have seen in a number of years.  But there you go.

Of course, for risk appetite, the most consistent place to look is the equity market.  Yesterday saw US markets slip a bit, about -0.5% or so across the board, but they remain within spitting distance of their all-time highs.  Certainly, no panic yet.  And this morning, as I type (7:05), the futures markets show the NASDAQ firmer by nearly 1.0% while the DJIA is lagging, -0.2% and the SP500 is in between (+0.3%).  Last night, Tokyo (+1.0%) had a strong session after inflation data was released right at expectations and has not yet shown signs of running away higher.  At the same time, market participants are increasingly certain the BOJ will remain on hold next week, although there is now a 60% probability priced for a 25bp rate hike at the June meeting.  The rest of the region was mixed with China (-0.35%), India (-1.3%) and Indonesia (-3.4%!) all under pressure, the latter suffering after 4 major banks there were downgraded by Fitch, while Taiwan (+3.2%) soared after positive earnings data and economic data showing IP exploding higher by 28.7% in March.

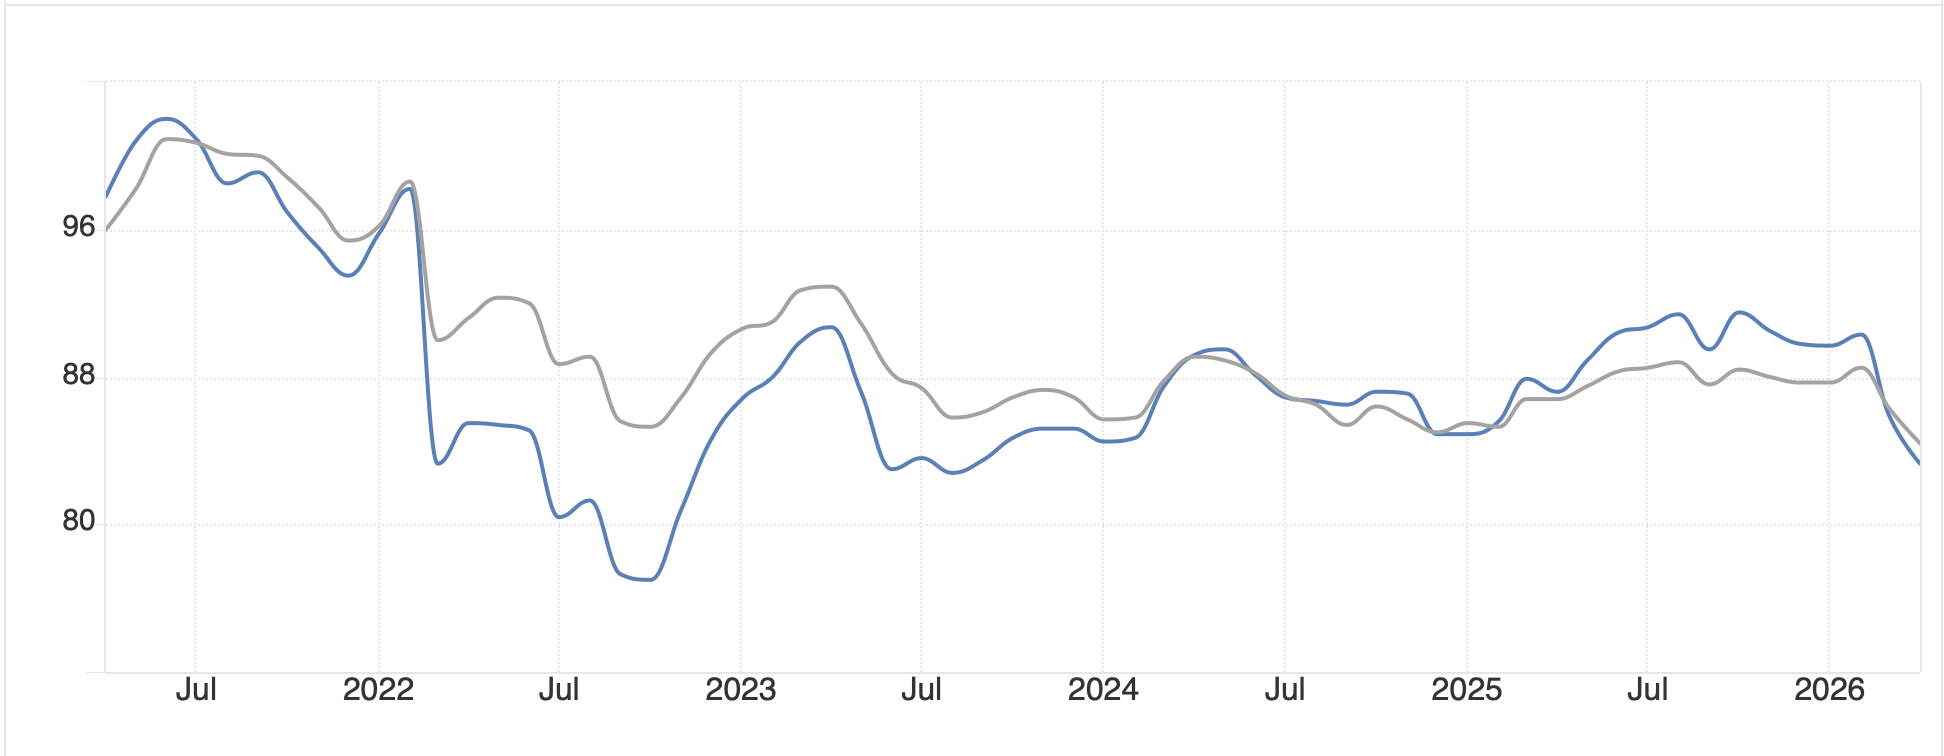
In Europe, though, there are no happy faces with Spain’s IBEX (-1.4%) leading the way lower for the entire continent (CAC -1.1%, DAX -0.4%, FTSE 100 -0.6%).  It is a bit surprising as the only data of note was German Ifo Business Climate (84.4 and the grey line) and Expectations (83.3 and the blue line), both of which printed at their lowest levels since August 2023 and are both clearly trending lower.

Source: tradingeconomics.com

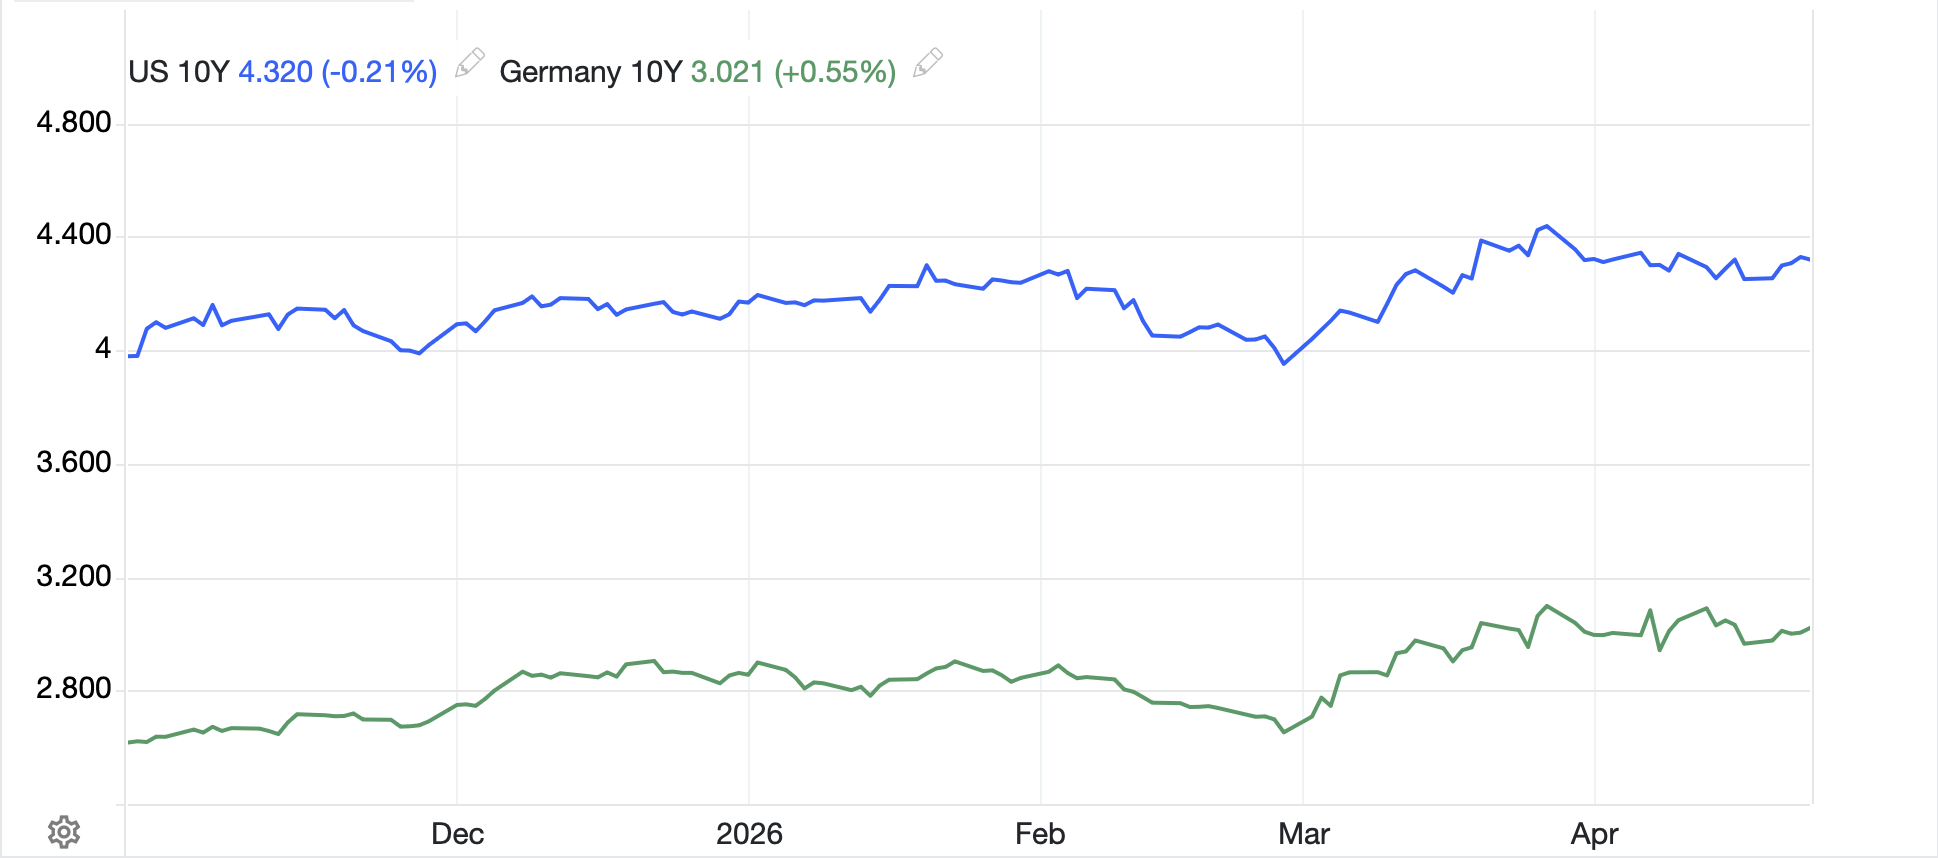
Bond yields are doing very little this morning, with Treasury yields lower by -1bp while European sovereign yields are all higher by between 1bp and 2bps.  Bond investors remain quite concerned about energy driven inflation but are also looking at the negative impacts on economic activity and so remain uncertain which way to go.  One thing to remember is that yields have really done very little over the past 6 months, at least, and that Treasury yields continue to be the global driver.  You can see the similarity in the shape of the price curves for both Treasuries and Bunds below, and both lines are pretty flat to my eye with one blip higher at the beginning of the war.

Source: tradingeconomics.com

Finally, the dollar is softer this morning, which is not in accord with its usual relationships to other assets.  Although it turns out that in the course of the hour I have been writing, things have changed and I cannot see a reason.  So, oil is now lower by -1.6%, gold is higher by 0.2%, and the dollar is softer across the board by 0.2% or so.  For me, I’m happy the relationships still hold, but I would love to be able to offer a catalyst for the change in sentiment.  And yes, US futures are higher across the board now.

Regarding the dollar, though, I couldn’t help but notice the Bloomberg article regarding the carry trade and how it has come back into favor as implied volatilies have fallen over the past month.  What this tells me is that there are no long-term views in the FX market despite all the dollar is going to collapse pap that comes from the FinTwit (FinX?) community.  Shorting yen remains the favored funding vehicle and the discussion is how BRL, MXN and TRY are the asserts favored to be held.  The thing about the carry trade is, it is great until it isn’t, but they don’t ring a bell before things change.  It is also a very different thing to short JPY and be long USD against it, with the USDJPY market amongst the most liquid markets in the world.  But if you are long BRL and short JPY, be prepared for a pretty wide spread on a forced exit because things have changed.  And if that is TRY or ZAR, the spread will be even wider!  Just sayin’.

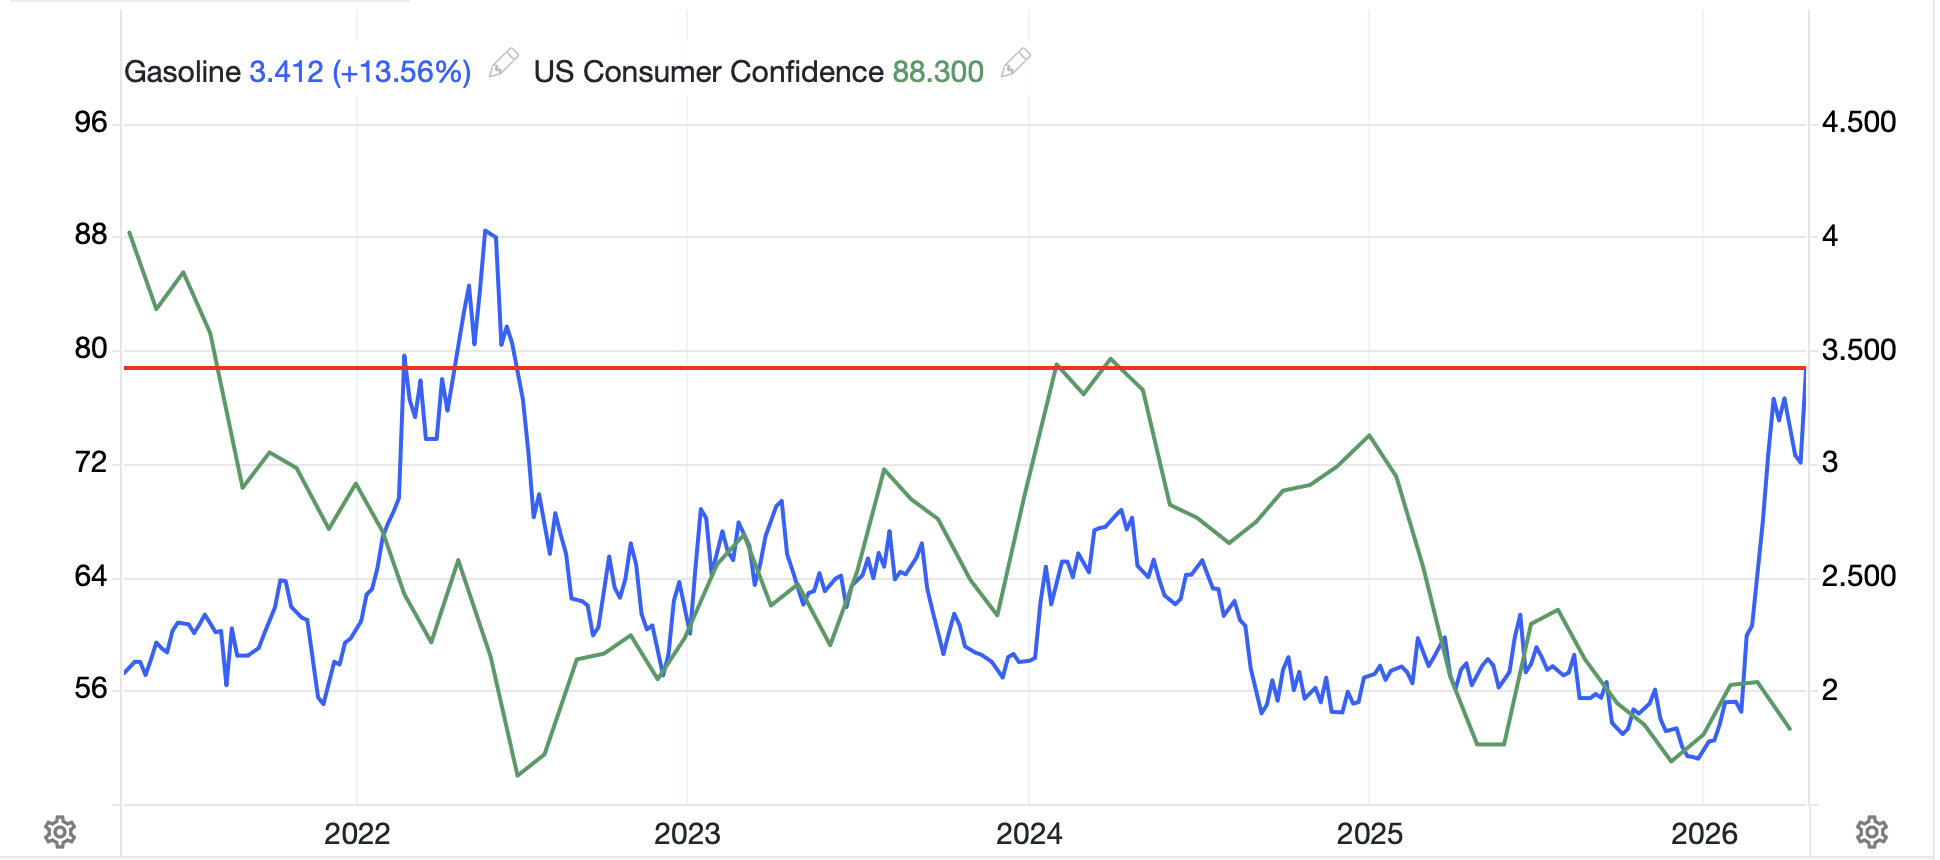
On the data front, this morning brings Michigan Sentiment (exp 47.6) unchanged from the preliminary reading which was the lowest in the 84-year history of the series.  Are things really that bad?  Maybe, but that certainly doesn’t jibe with the Retail Sales and PMI data.  The problem with survey data is there is an element of politics that distorts the reading and President Trump is such a polarizing figure, it exacerbates the situation.  Nobody likes high gasoline prices, but it is hard to reconcile gasoline prices, which by the way, remain lower than what we saw in the immediate wake of Russia’s invasion of Ukraine as per the chart below, with such a dramatic decline in confidence, hence my view of the political angle.

Source: tradingeconomics.com

Personally, I am on the lookout for the next military incursion or a deal this weekend, with diametrically opposed market impacts on Monday morning.  Once again, my advice is risk mitigation is the way you stick around to play again next week.

Good luck and good weekend

Adf
Dire Straits

Said Jay, I will not be ignored
And so, I ain’t leaving the board
When my time as Chair
Is up, and I swear
I will see the president gored

So first off, we ain’t cutting rates
‘Cause here in the United States
Inflation’s a worry
And I’m in no hurry
To help Trump escape dire straits

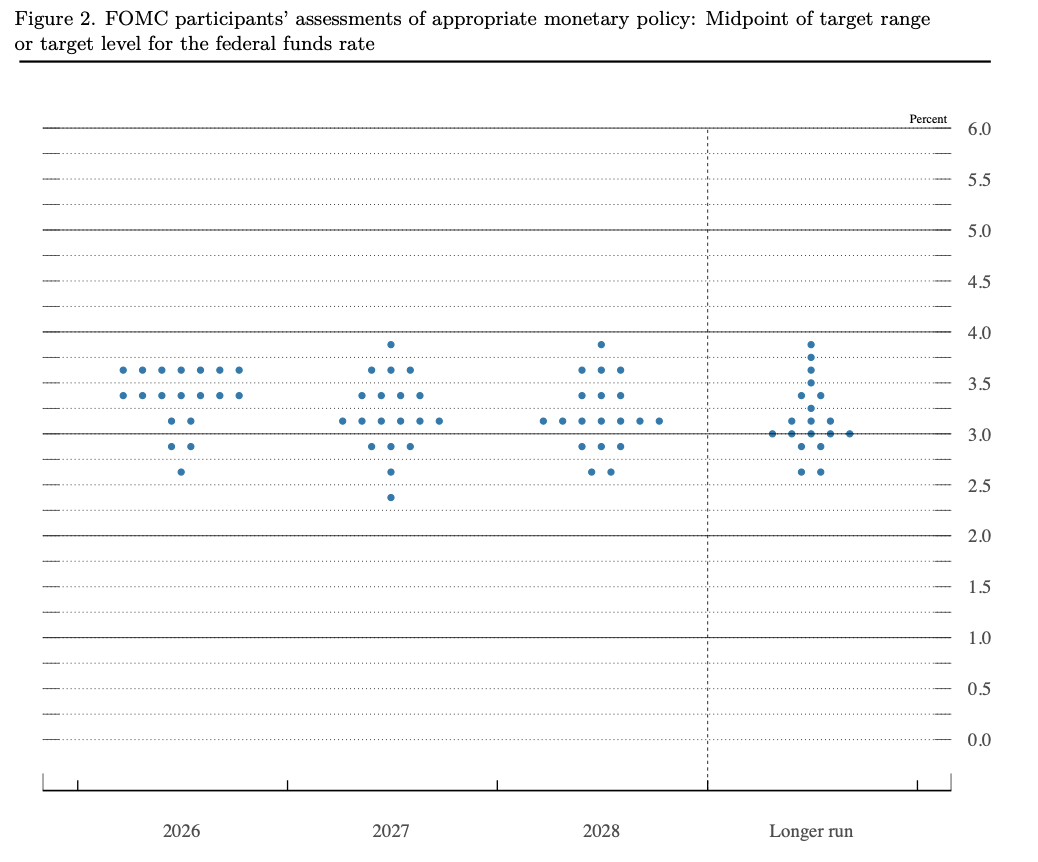
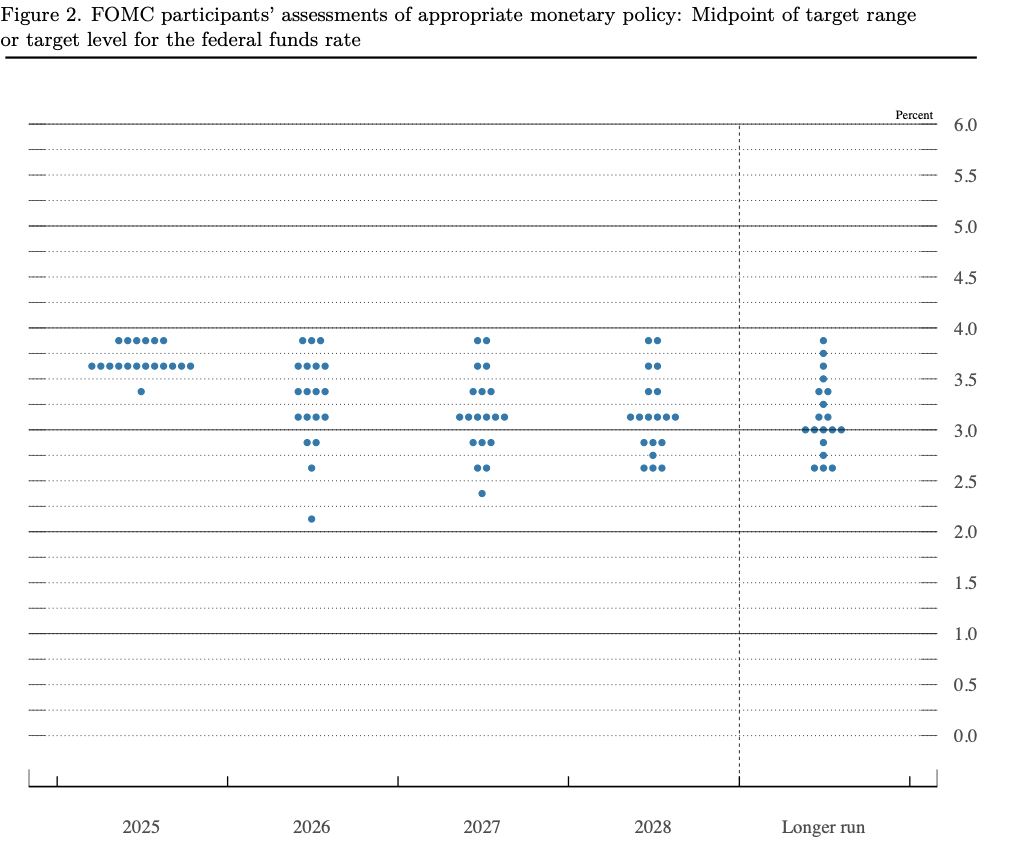
I guess we cannot be surprised that Chairman Powell was combative during his press conference yesterday after the Fed left rates on hold, as expected.  There was only one dissent this month, Governor Miran, still looking to cut rates.  However, while standing pat given the high level of uncertainty that exists from the war situation makes sense, compare the dot plot from this meeting to the December meeting below it.  The dispersion of views on the committee has really tightened up a lot.  While the median for 2026 continues to point to one cut, it appears that the Fed now believes we are near r*, although they didn’t say that exactly.

March 2026 dot plot

December 2025 dot plot

The other noteworthy comment from the Chair was when he explained he had “no intention of leaving” the Fed until the Justice Department investigation is completed.  And, if Kevin Warsh is not confirmed by the Senate by the end of Powell’s term as Chair on May 15th, he will remain as Chairman pro tempore, the same situation as his previous nomination when the Senate delayed his confirmation.  

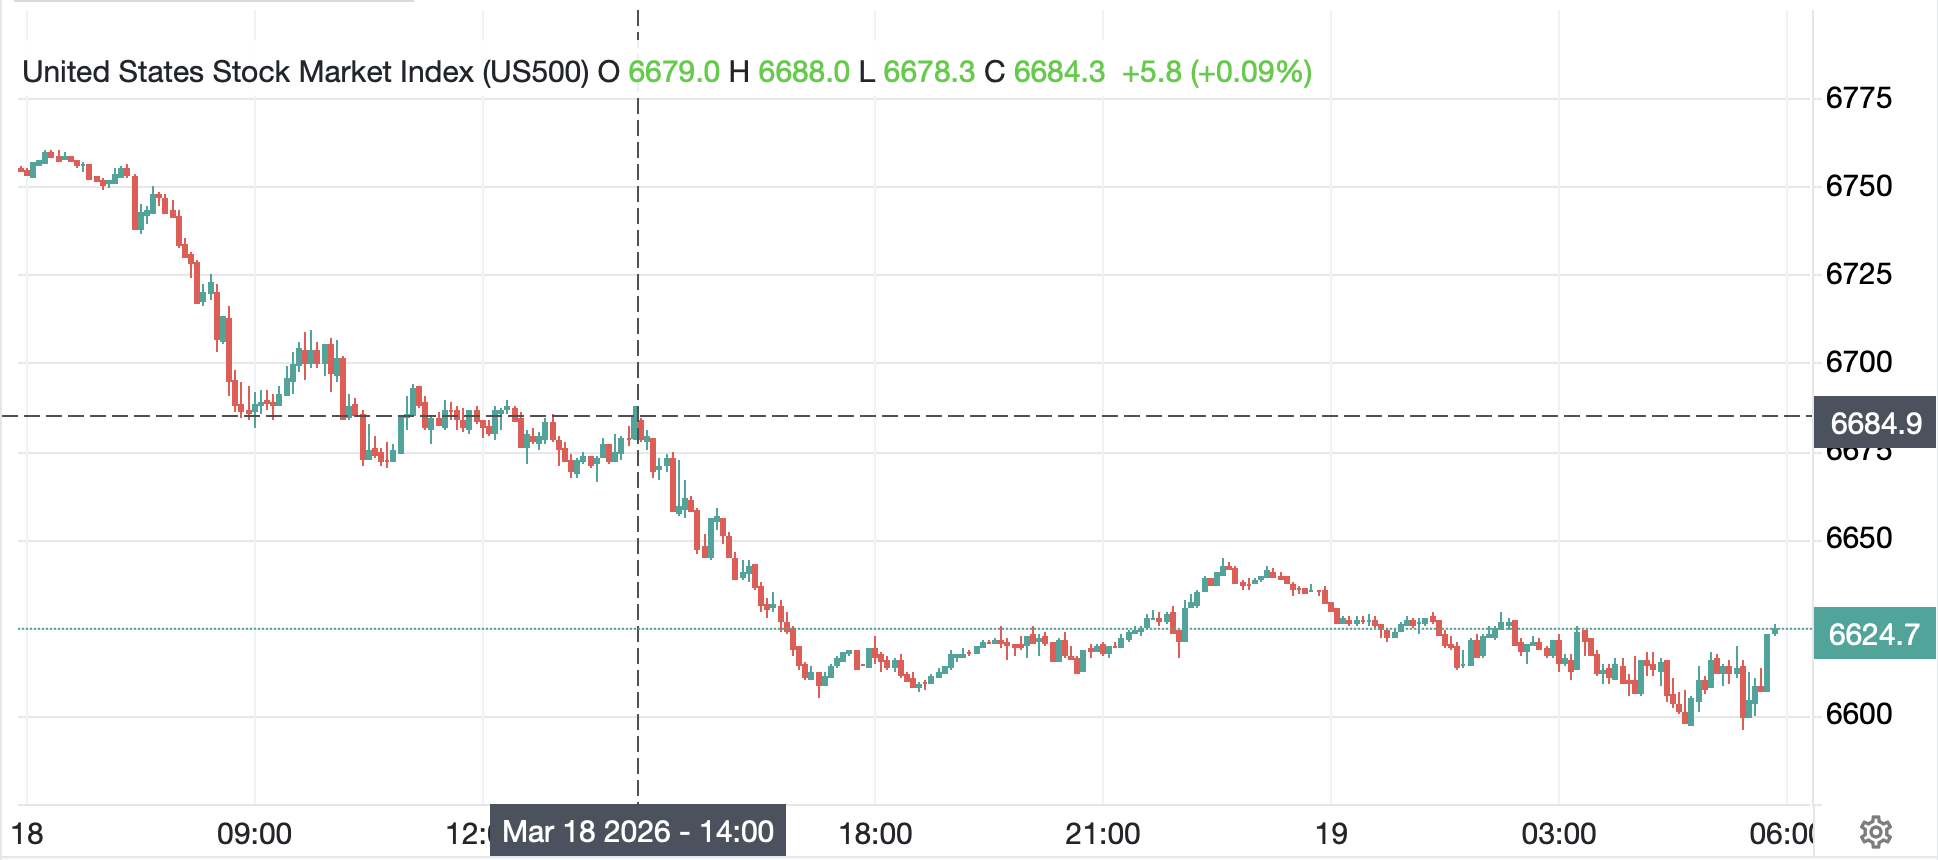
The market response to both the combative tone and the hawkish rhetoric overall was a further 1% decline in the S&P 500 from an already weak place as per the below chart where I highlighted the time of the Statement release.  You can see how things behaved thereafter.

Source: tradingeconomics.com

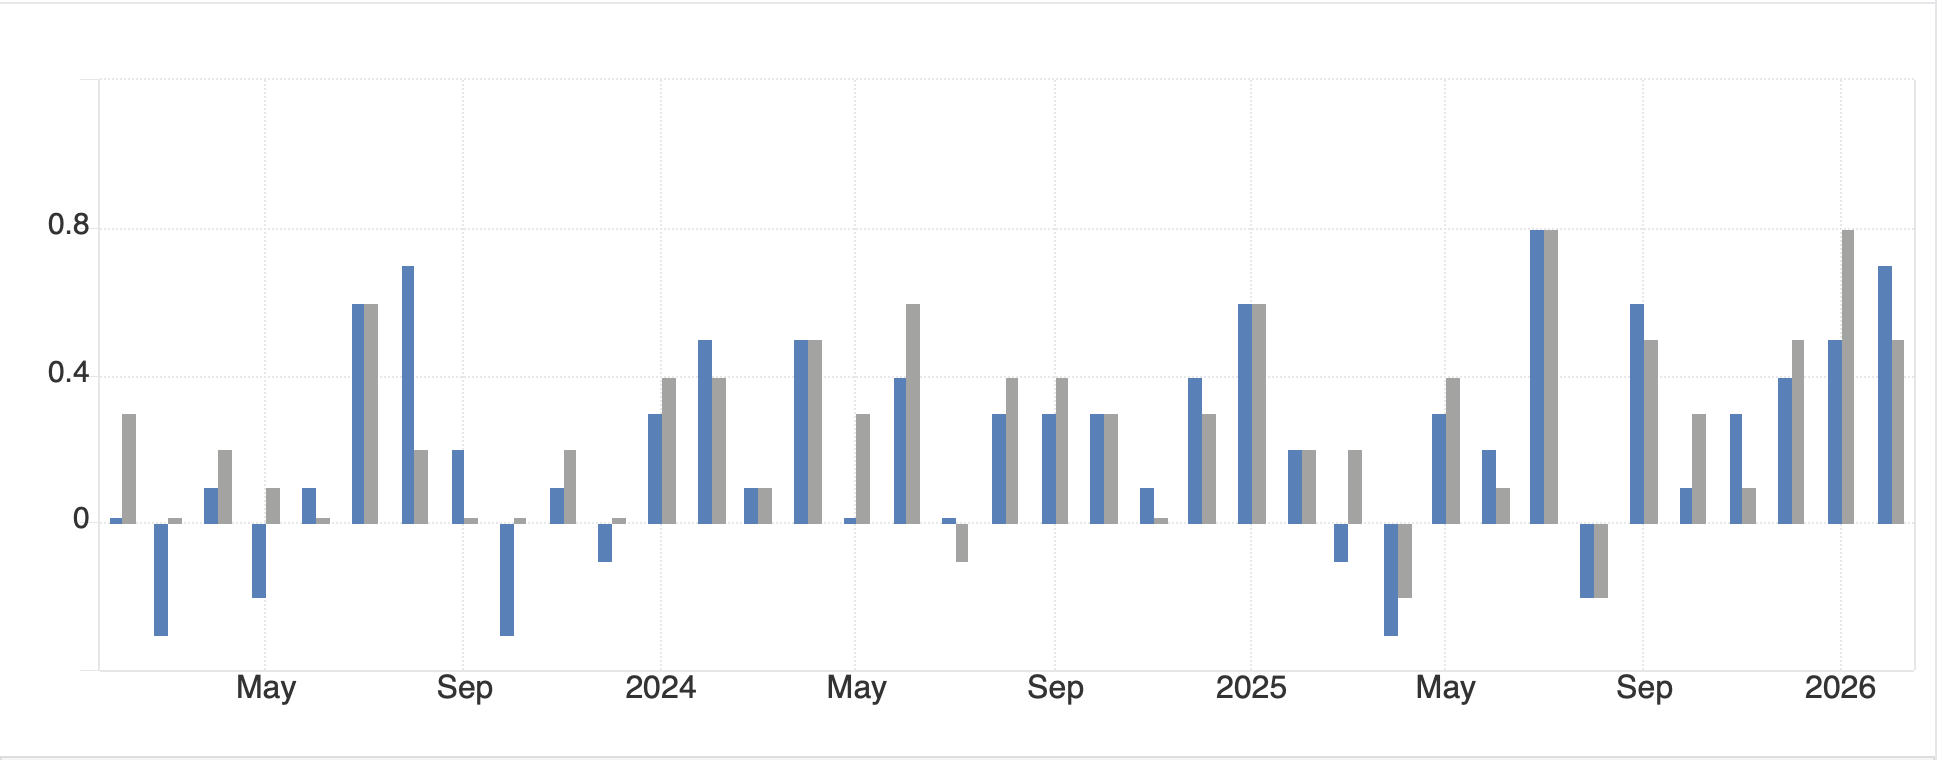
But that wasn’t all that happened yesterday, PPI came out MUCH hotter than forecast with headline at 0.7% (3.4% Y/Y) and core at 0.5% (3.9% Y/Y) as inflation concerns rose to the fore.  If you look at the PPI chart below showing both headline (blue bars) and core (gray bars), it is very difficult to discern a pattern of declining producer prices.

Source: tradingeconomics.com

In fact, it is hard to look at this data and reconcile it with the Fed’s SEP forecasts describing the view that inflation, even their measure of core PCE, is going to smoothly return to their 2% target over any particular timeline.  

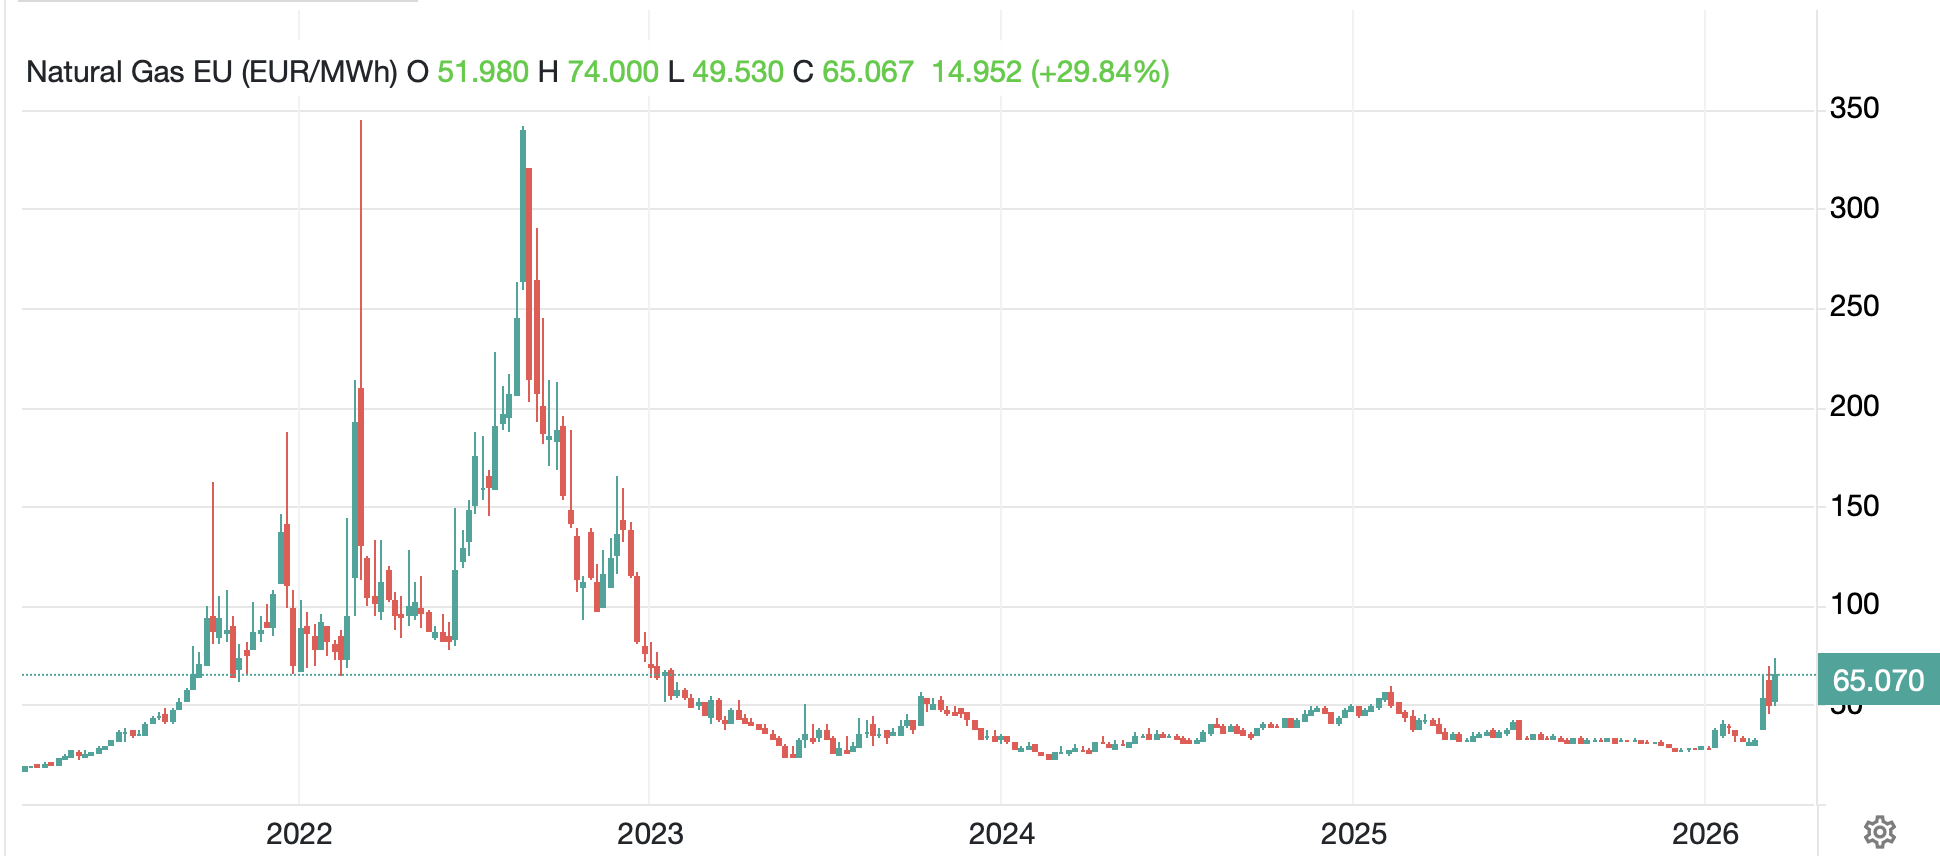
One last event of note was the Iranian response to an attack on its main Natural Gas field, South Pars, where they inflicted serious damage to the Ras Laffan LNG facility in Qatar, which happens to be the largest in the world and is on the wrong side of the Strait of Hormuz to boot.  The result has been a significant rise in the price of European (and UK) natural gas, with both soaring more than 20% this morning while, Brent crude has jumped 7.2% as opposed to WTI’s unchanged status today.  This has taken European NatGas to ~$22.MMBtu compared with the US price of $3.15.  Ask yourself how long Europe can afford to pay 7x US prices for NatGas and maintain any competitive ability to manufacture anything.  (As an aside, this remains a key reason that I see long-term prospects for the euro so dimly.)  But if we look at the longer-term chart of European NatGas, despite the dramatic increase since the Iran conflict began, it is nothing compared to what we saw in the wake of Russia’s invasion of Ukraine.

Source: tradingeconomics.com

Summarizing yesterday’s session in one word, I would say, Aaaaaaggggghhhhhh!

I assume I have depressed you enough with yesterday’s activities, but I will run through market responses overnight.  You won’t be surprised to learn they have not been positive.

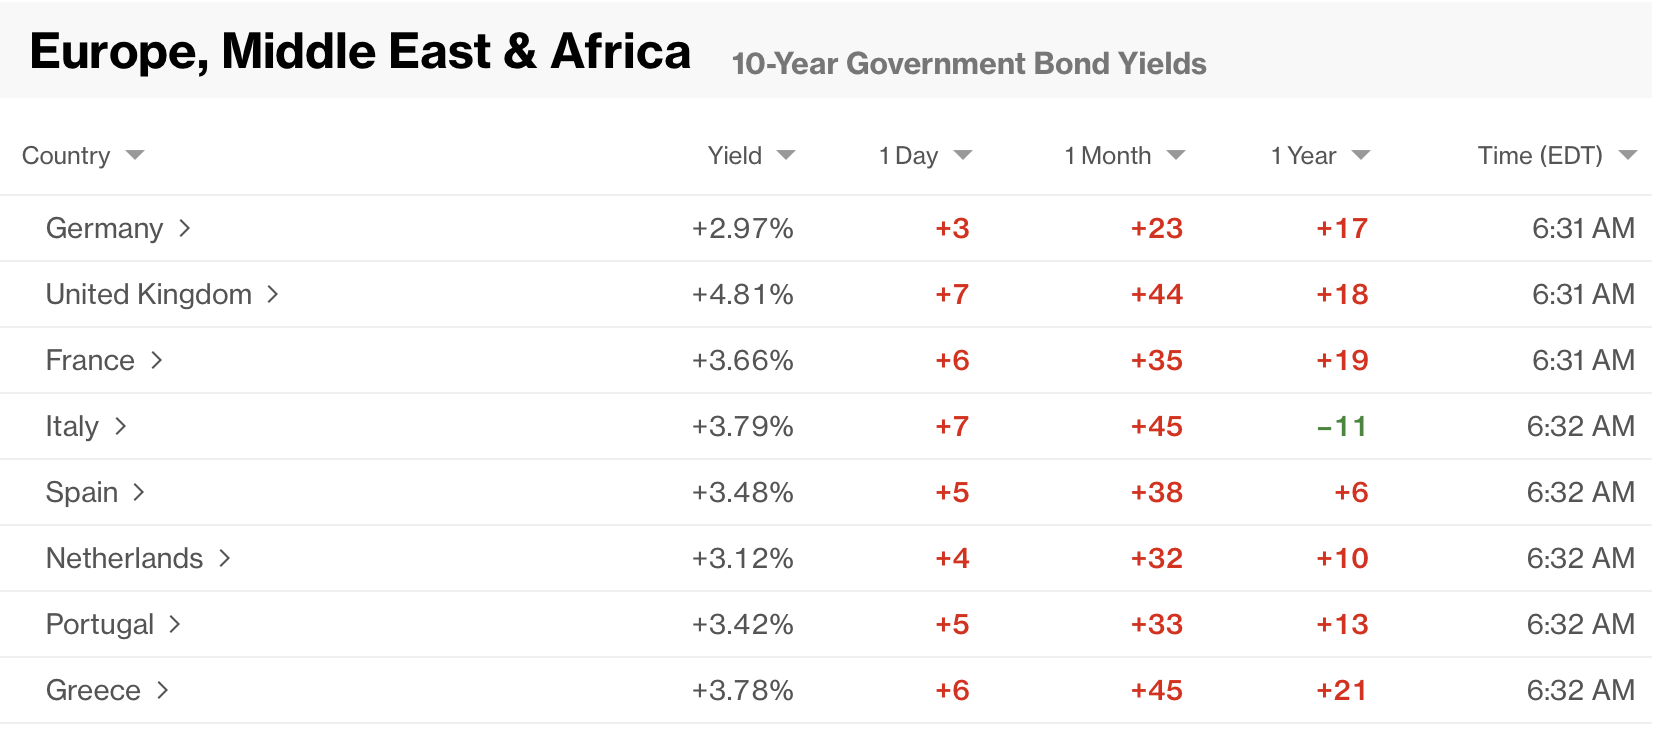
In fact, I guess I will start with bonds this morning, which I didn’t discuss above, but not surprisingly given the high PPI readings and the sharp rise in oil and gas prices, have suffered a lot.  Yesterday, Treasury yields reversed their early declines and closed higher on the day by 6bps.  They have edged up another 1bp this morning and are back above that 4.20% range I have focused on.  Meanwhile, European sovereign markets were all closed when the FOMC meeting concluded, which added to the pressure on bond yields which started with the US PPI data.  Net, yesterday, German bunds rose 4bps and this morning they are higher by a further 3bps.  But as you can see from the below Bloomberg screenshot, they are the champs in Europe today.

JGB yields also rose sharply, up 6bps and we saw similar rises throughout Asian bonds.  Right now, it is very clear that inflation is a bondholder’s concern, not recession.

As to equity markets, you will not be surprised to know that every market in Asia declined, most by more than -1.0% with the Nikkei (-3.4%) the worst performer followed closely by India’s Sensex (-3.1%), but there was no place to hide in Asia.  In Europe, the damage is equally broad, although there is one outlier, Norway (+0.5%) which is obviously benefitting from the sharp rise in oil prices.  But otherwise, -1.5% to -2.5% is today’s story across the board there.  Interestingly, at this hour (6:45) US futures are little changed to slightly lower, just -0.1%.  Perhaps this is a sign that all is not lost.  Or maybe the algorithms just haven’t started their day yet.  One noteworthy decline is South African shares (-4.0%) which is suffering from gold getting sold off yet again yesterday and today.

Since we already touched on energy, a quick trip through metals markets sees a major rout ongoing with gold (-2.75%) and silver (-5.2%) both suffering greatly, as is copper (-2.5%) and platinum (-6.1%).  I continue to believe that gold is being liquidated to pay for other losses as the primary attraction of the barbarous relic remains.  One thesis is that Middle Eastern central banks are liquidating their holdings as, given the dramatic decline in their oil revenues, they need money for continuing operations, and arguably, that’s what the gold is for.  Essentially, gold is the rainy-day fund.  As to the other three metals, those hint more at slowing economic activity rather than forced liquidation.  After all, there was a lot of euphoria on the way up, so if the narrative is changing, as that dissipates, so will demand.

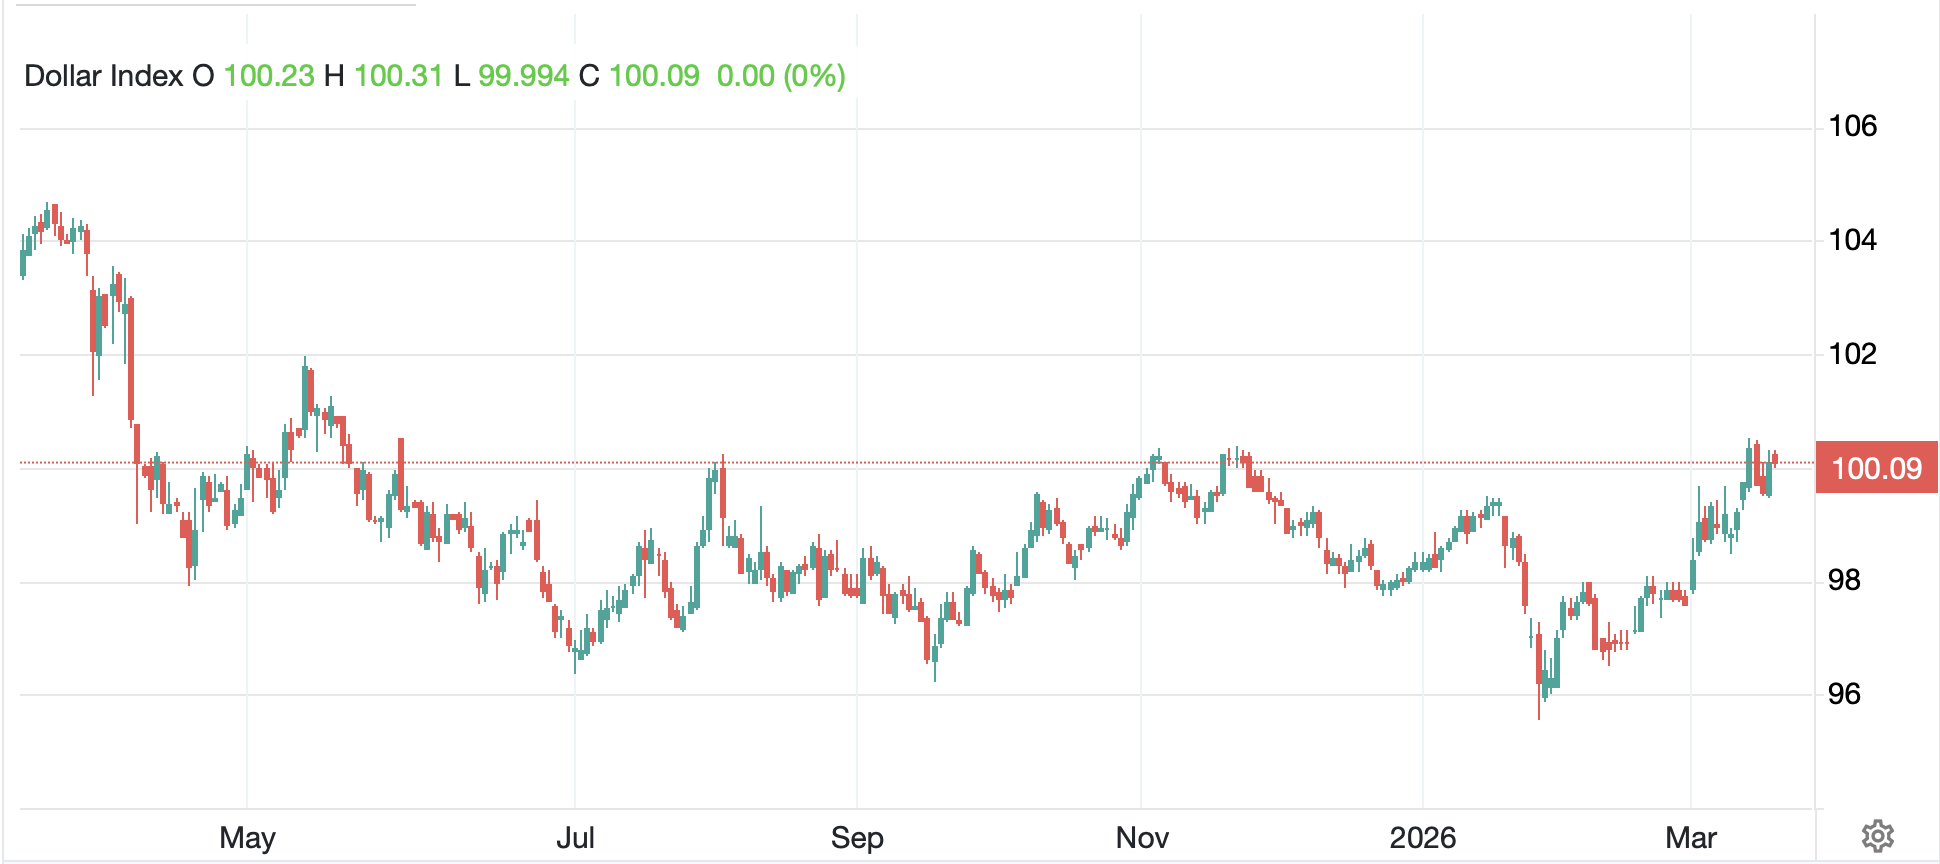
Finally, the dollar has given back a small portion of yesterday’s solid gains but remains at the top of its 96.00 / 100.00 trading range as defined by the DXY and shown in the chart below.

Source: tradingeconomics.com

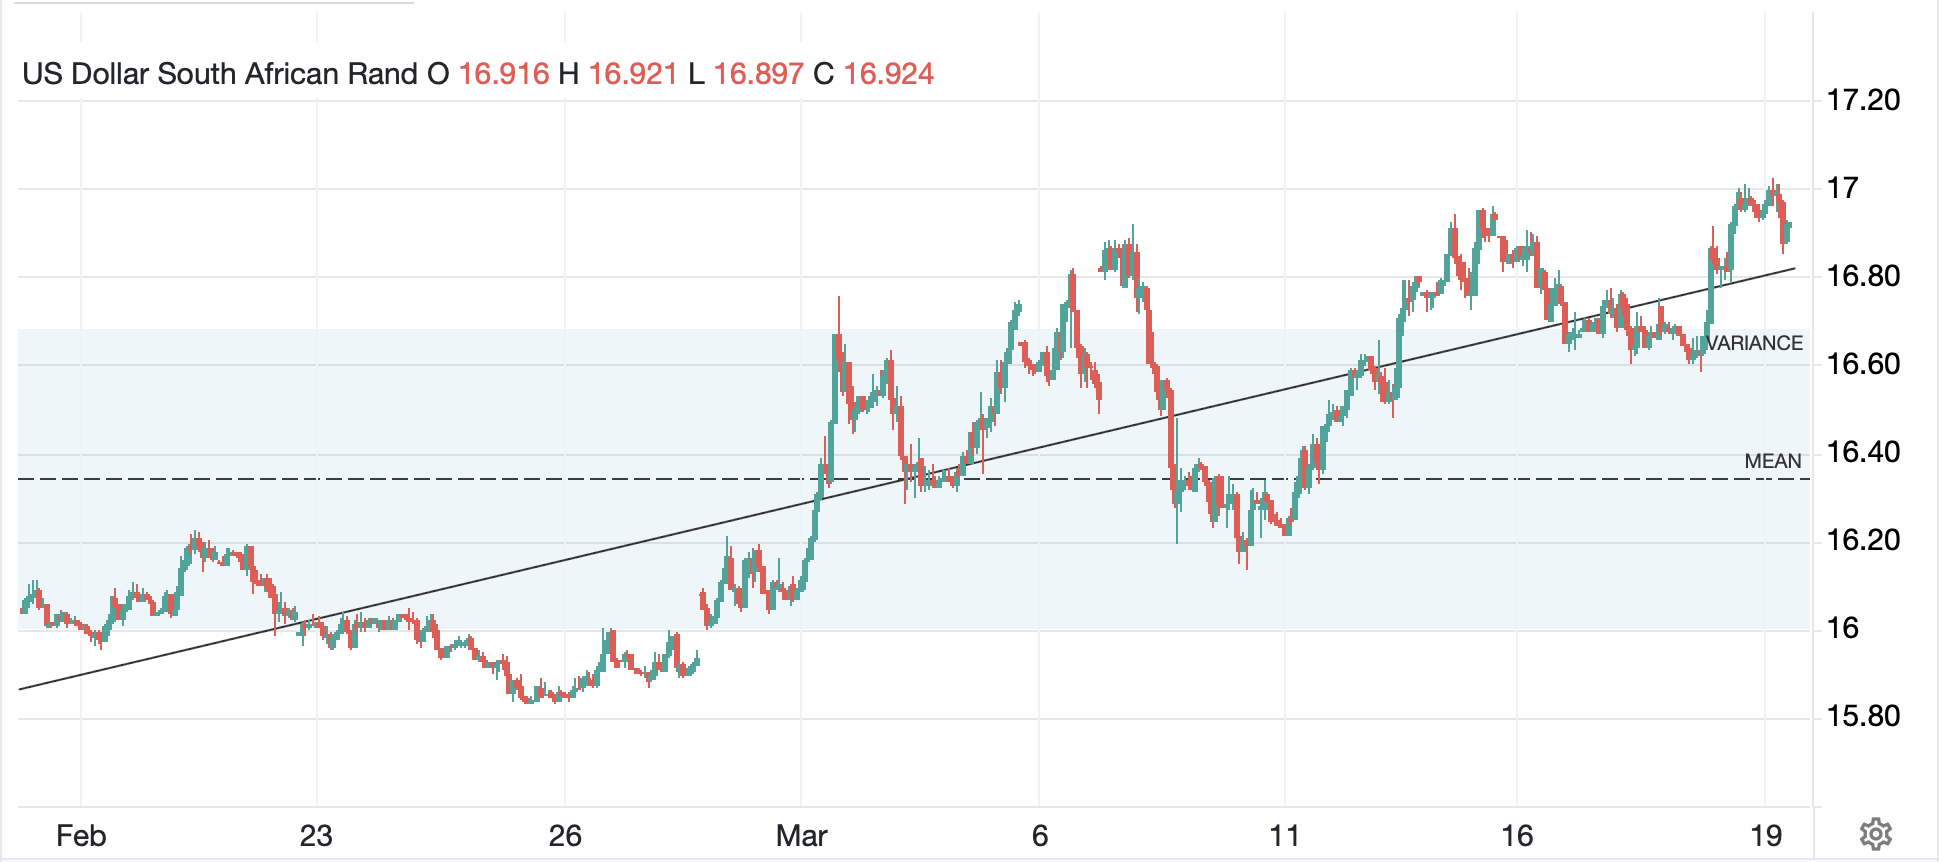
Again, considering energy policies and availability around the world, the US, which is the largest energy producer in the world and a net exporter of energy products, seems better positioned than any of its competitors to weather the current economic gyrations.  However, if we look across specific currency pairs this morning, we see relative strength elsewhere on the order of 0.2% to 0.3%.  Frankly, it is a bit surprising to see ZAR (+0.4%) rally given what is happening in both gold and the South African equity market, but stepping back slightly, given the rand’s weakness since the end of January, I guess we cannot be that surprised that there is consolidation.  Certainly, there is nothing about the chart for the last month that indicates the rand is about to reverse course and strengthen dramatically.

Source: tradingeconomics.com

The big picture here remains, in my view, that the US has more pluses than minuses vs almost all its counterparts.

On the data front, I didn’t even mention last night’s BOJ meeting, where they left policy on hold, as it didn’t seem to have a major impact.  Perhaps, Ueda’s mildly hawkish comments have helped the yen a bit this morning.  As well, the Swedish Riksbank left policy on hold and in a short while we expect both the BOE and ECB to leave policy rates on hold.  The one which might move is the UK, where last time they voted 7/2 to leave policy unchanged but analysts think 4 members could vote for a cut.  However, my sense is that cutting rates at this time, before there is evidence that the economy is truly suffering from the war, would be a surprise.  Otherwise, we get the weekly Initial (exp 215K) and Continuing (1850K) Claims as well as the Philly Fed (10.0) and then at 10:00 we see New Home Sales (720K).  One other thing to note is that yesterday’s EIA data showed a substantial build in crude inventories, but a large draw in gasoline and distillates.  It is this activity that helps explain the rise in crack spreads, and why the refiners should be having a very good quarter.

And that’s it for today.  Quite frankly, that’s enough for me.  As it happens, there will be no poetry tomorrow, so I will get to recap today and tomorrow on Monday and see what has changed in the Persian Gulf as well as any other new news.

Good luck and good weekend

Adf
Doesn’t Make Sense

There’s something that doesn’t make sense
As stock market rallies commence
While word from the Strait
Just doesn’t look great
And politics worldwide is tense

Can every investor ignore
The risk of a much longer war?
Or will, sometime soon
They sing a new tune
And sell stocks whose risks they abhor?

One must be impressed with the way markets, in general, have handled the disruption caused by the ongoing conflict in Iran and the Persian Gulf.  The insouciance with which it appears most investors are treating the situation is remarkable.  There seem to be endless ways in which this can result in much greater damage to the global economy, mostly related to the impact on energy and food production going forward.  You’ve all heard the numbers, I’m sure, about the 20% of daily oil and LNG that traversed the Strait of Hormuz prior to the war.  Less well known was the amount of sulfur (~44% according to Grok) and nitrogen fertilizer (~30%-35% according to Grok) that regularly transited the Strait and has now been stopped.

The latter two matter greatly for global food production, but also for mining as sulfuric acid is a key part of almost all metals mining operations.  Too, one-third of global helium supplies went through the Strait, and that is critical in semiconductor manufacturing.

The point is, if the conflict continues for too much longer, it is quite possible, if not probable, that parts of the global economy could be impaired for a much longer term with real negative consequences for economic activity.  And while this may be a tail risk, the fact that the potential impact could be so large leads me to believe the market is underpricing potential damage from the war, at least economically.  Last night, Alyosha posted a very interesting piece regarding potential consequences for the Gulf region as a whole as well as oil markets.  His conclusion was that if things don’t end soon, there may be irreversible damage to the Gulf oil industry as well as the Gulf nations themselves as their cashflows are being completely starved for now.

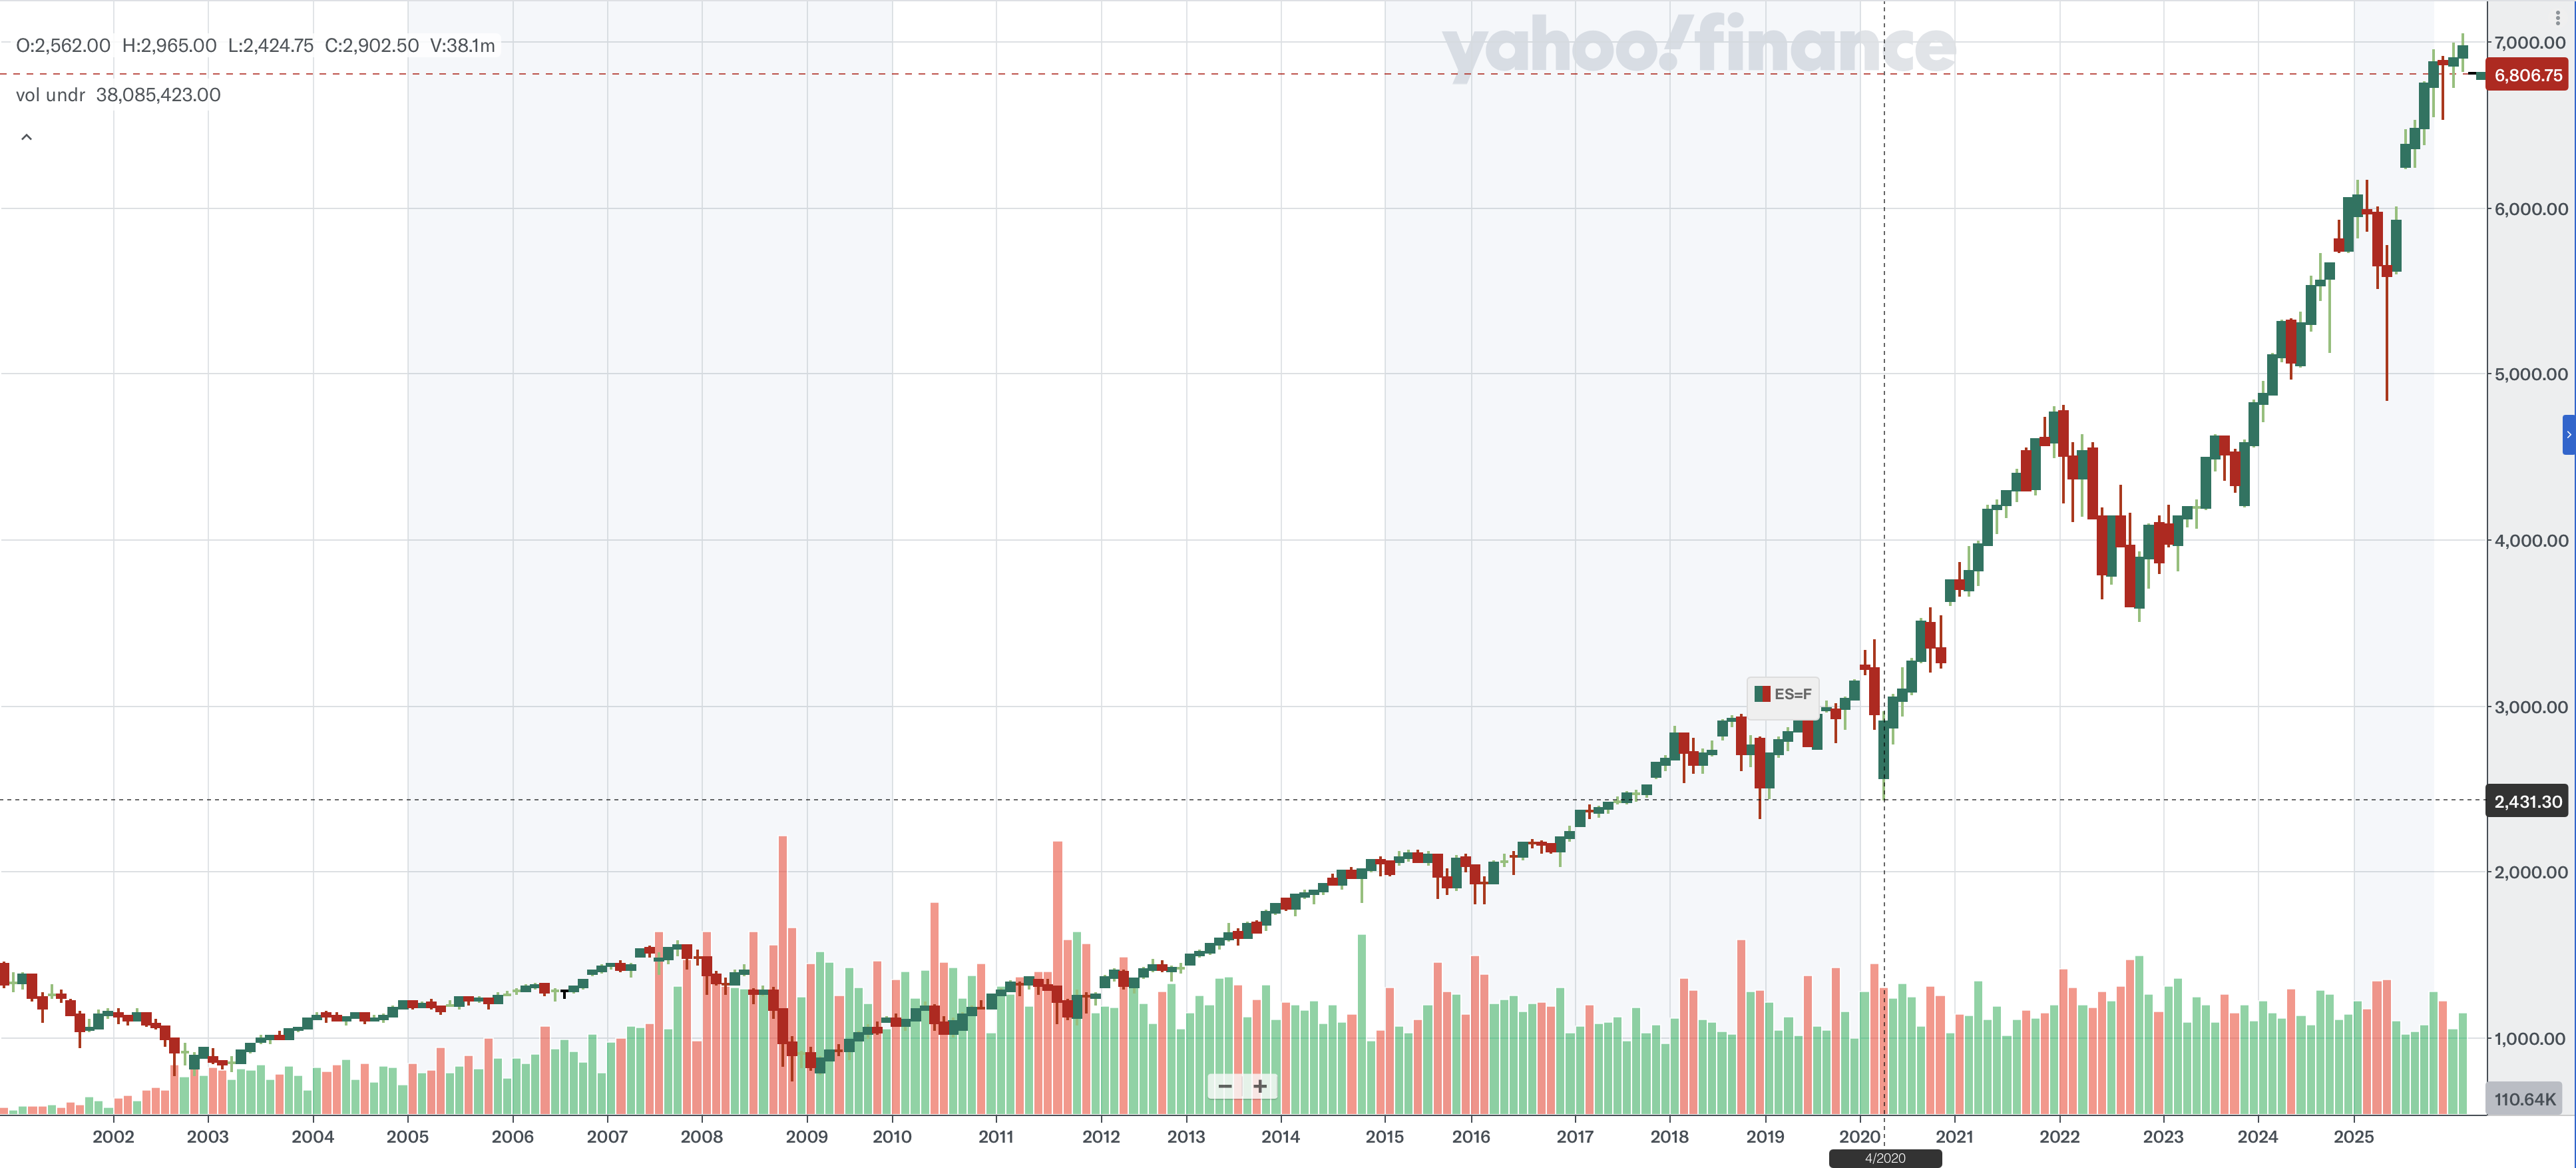
I know that doomsaying is a losing proposition with equity markets over the long run, as the century long trend shows human innovation continues to advance economic prospects and outcomes.  But in the shorter term, interruptions of that trend are common and can be quite painful for those investing when they occur.  Recall how you felt when Covid shutdowns resulted in a 30% decline in two months in early 2020, as per the below chart.  How about the similar drawdown, along with the selloff in bonds, during 2022’s inflation led declines?

Source: finance.yahoo.com

All I’m saying is that markets can ignore things for a long time before suddenly repricing an outcome and I have a feeling that is what we are witnessing right now.  So, as we head into today’s FOMC meeting, which seems unlikely to have any impact whatsoever, I would play things close to the vest and am doing just that myself.

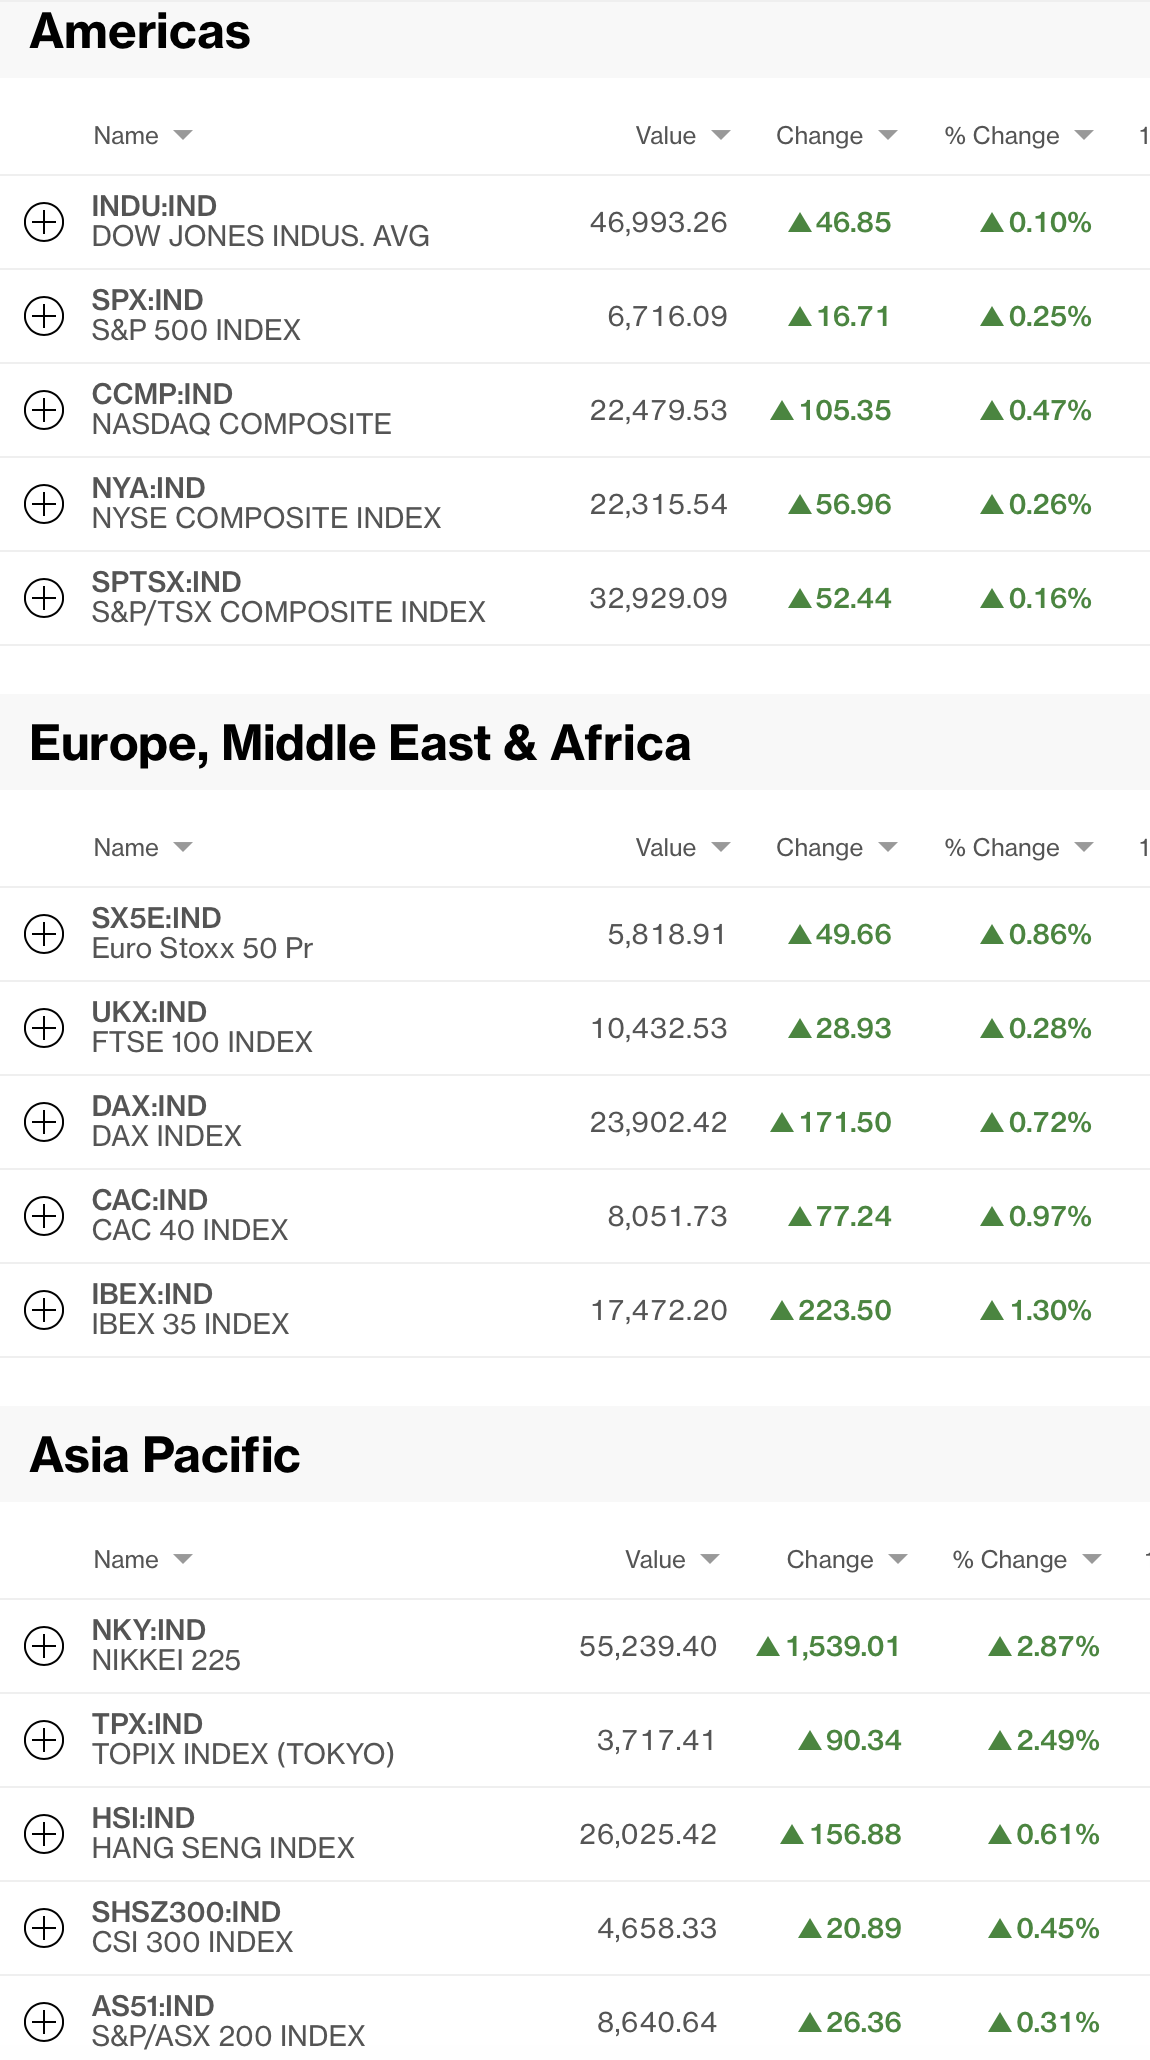
Ok, let’s tour the euphoria in markets, which remains puzzling to me.  You have to search far and wide to find an equity index that fell in the past twenty-four hours and here is a Bloomberg snapshot of major indices at 7:10 this morning,

Literally, every market in Asia rallied, some excessively so, Korea (+5.0%) and I could only find two markets in Europe that are down this morning, Denmark and South Africa, both of which have slipped about -0.3%.  Otherwise, it’s all green as prospects are, apparently, great. US futures are also higher as I type, up about +0.6% or so.  Certainly, there is little concern about potential long-term consequences of this war.

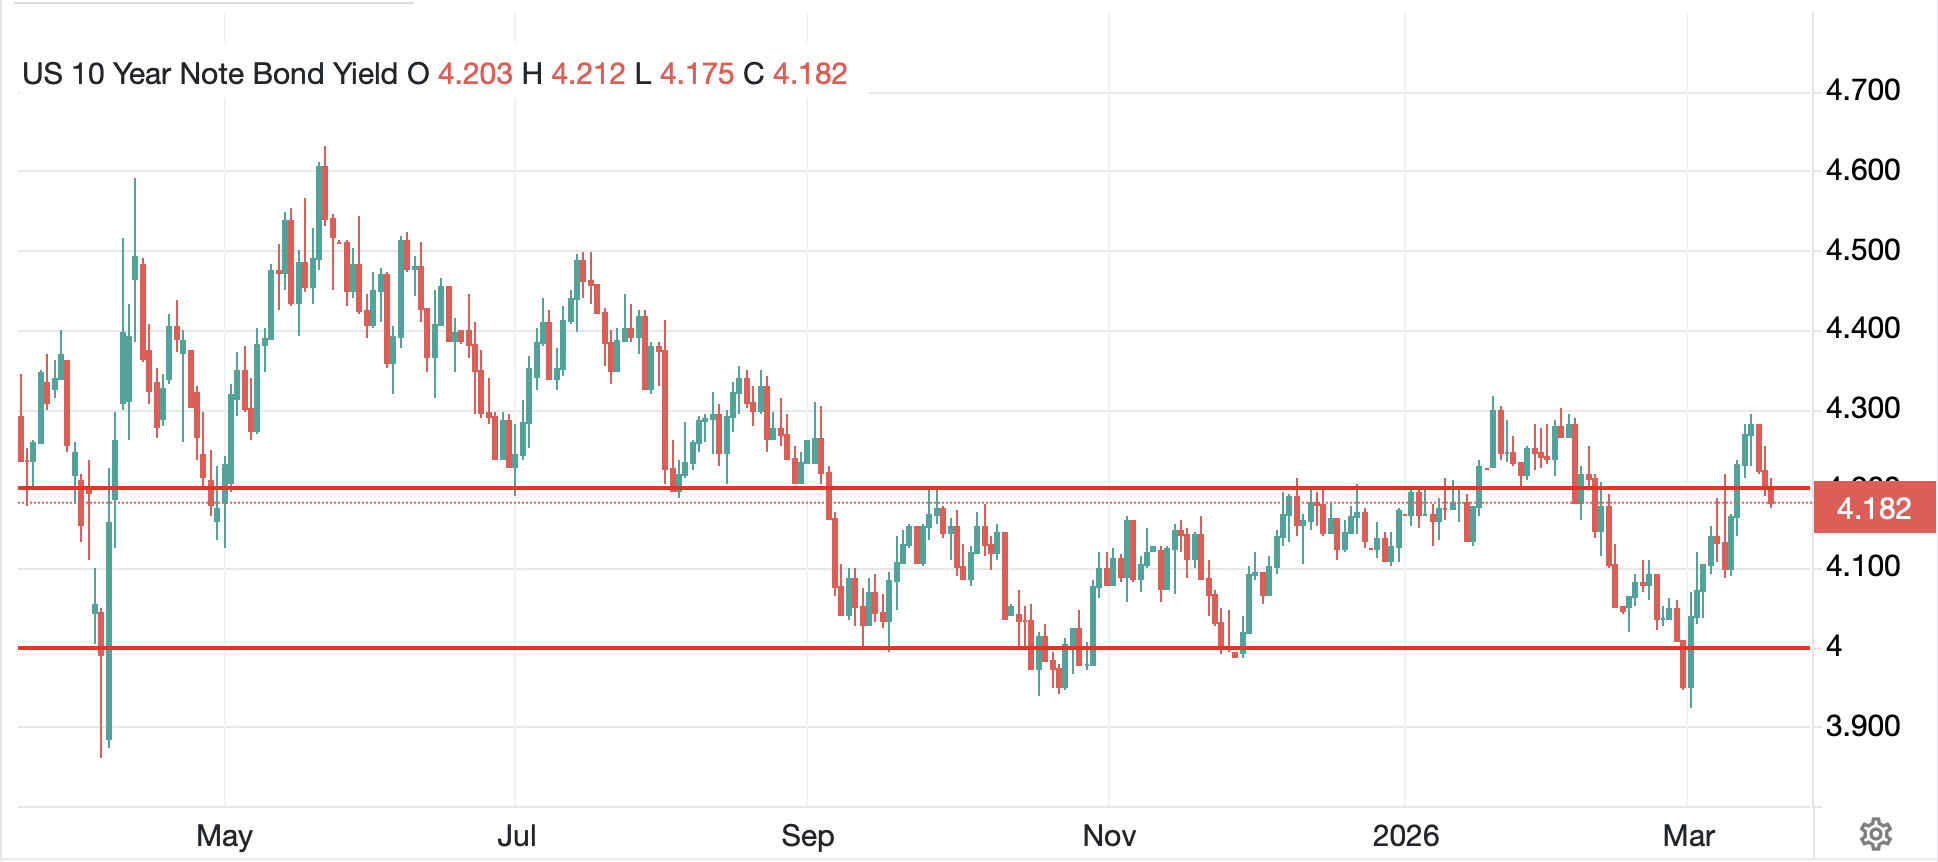
In the bond market, yields everywhere are slipping again with Treasuries (-2bps) falling back into that longer term range, while European sovereign yields are lower between -2bps and -3bps and JGB yields fell -5bps.  As per the below chart from tradingeconomics.com, we spent 5 days above the top of the trading range.  

Perhaps the market is starting to price in a recession and much weaker growth, although with oil prices firmly above $95/bbl, inflation is coming, at least in the near future.  Of course, the Fed response is going to be critical here, and while they will almost certainly make no policy changes today, all eyes will be on their forecasts via the dot plot and SEP.  We shall find out at 2:00pm.

Speaking of oil (-1.7%), perhaps its new home is $95/bbl, not $100/bbl like I mentioned yesterday, but for now, there doesn’t seem to be urgency in either direction.  The futures market remains in steep backwardation although in the US, there are ample supplies.  So, while gasoline prices at the pump are up substantially, there is no rationing here in the US, nor I suspect, will there be given we are pretty self-sufficient on that front.  But demand destruction can be real, as even though the short-term elasticity of demand for oil is limited, over time, substitutes will be found.  In fact, this is the biggest risk for the Gulf nations, the idea that substitutes can be found and their key resource loses value.  I don’t believe that is going to happen on any visible timeline, but stranger things have happened.  

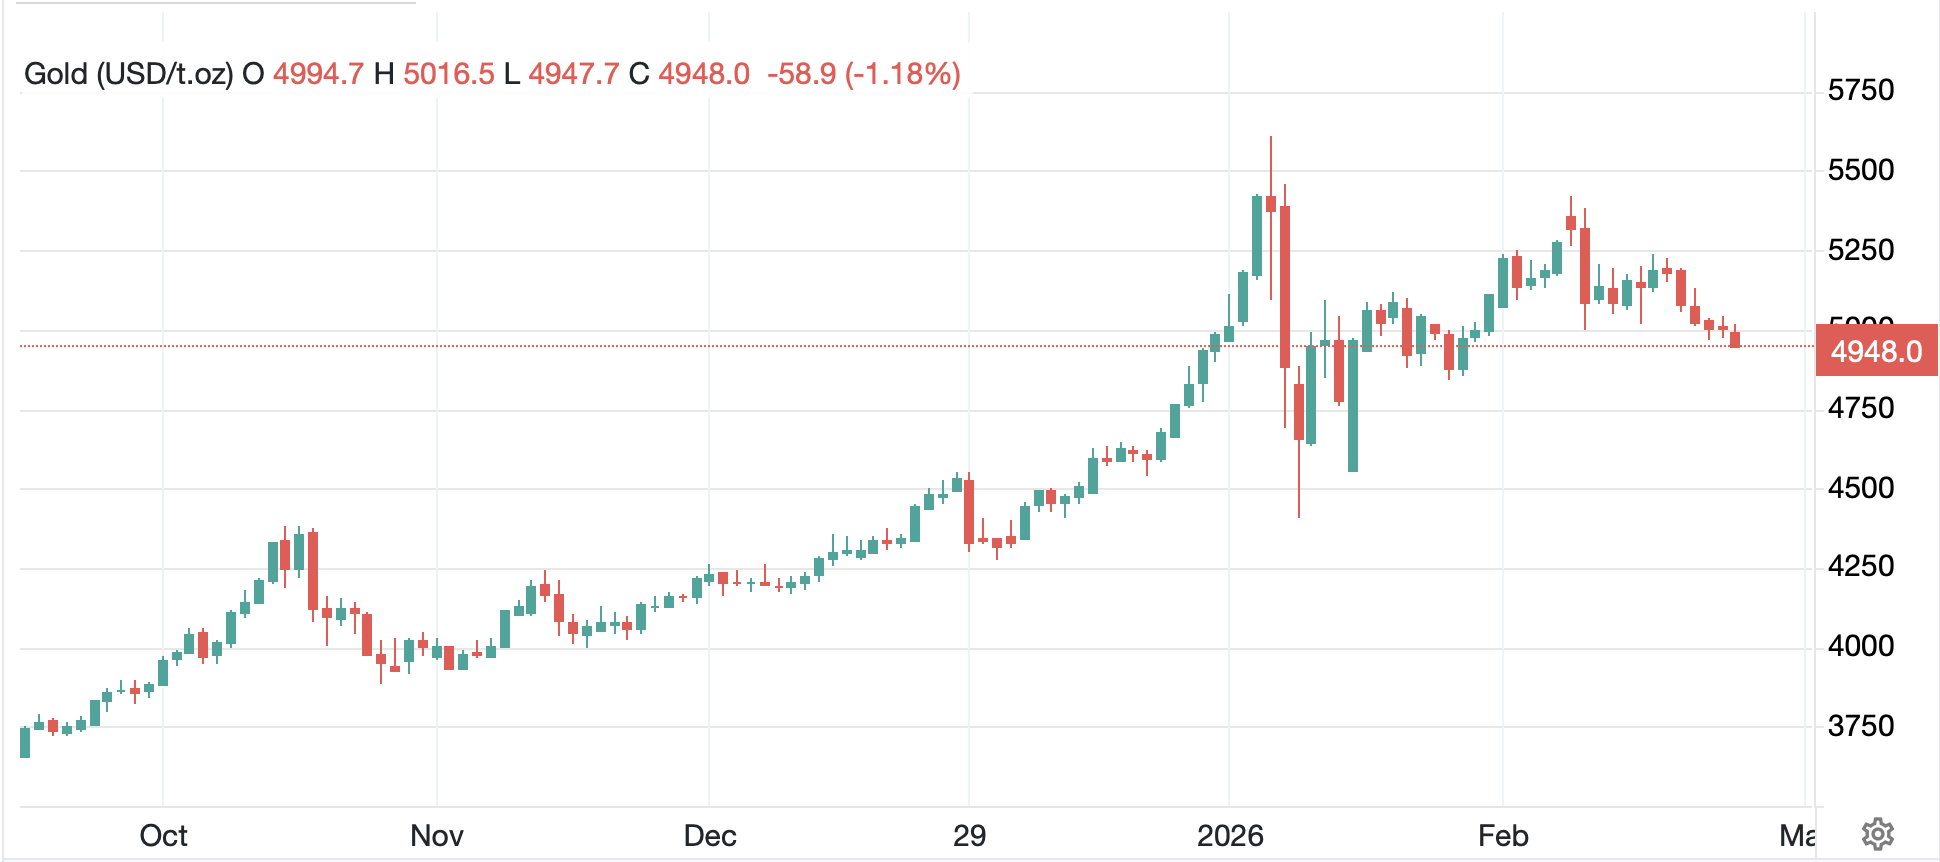
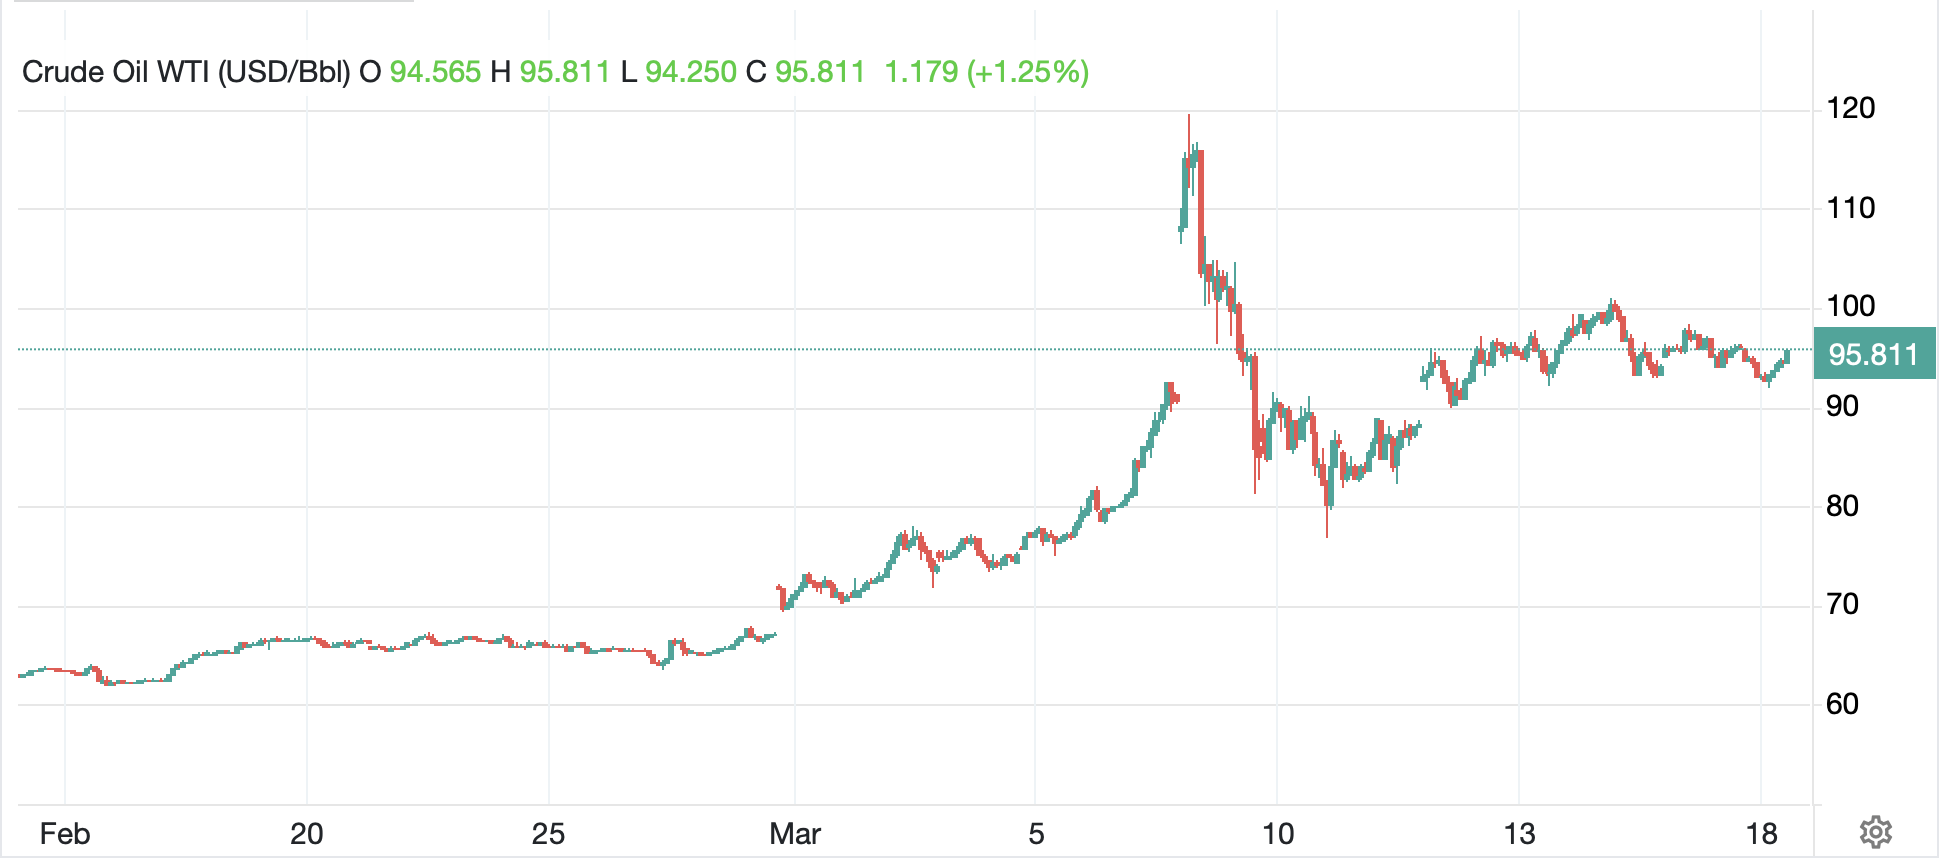
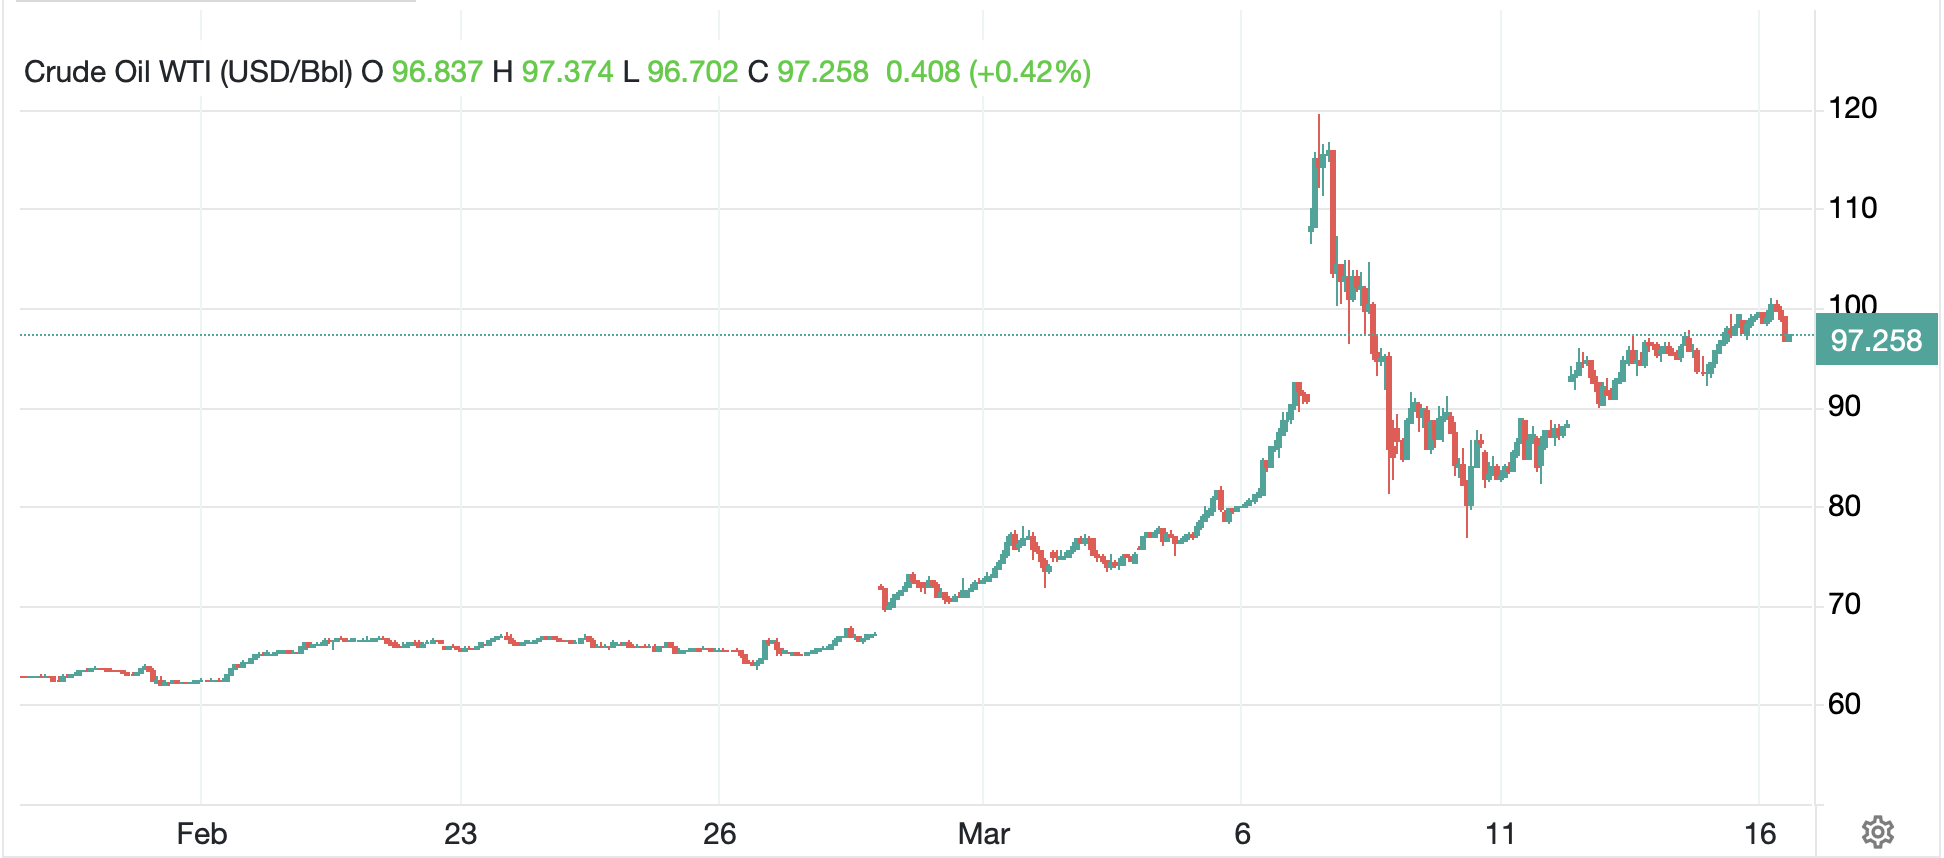
In the metals markets, gold (-0.9%) is slipping this morning, but remains right near that $5000/oz level and silver is unchanged, just below $80/oz.  The price action in both precious metals and oil is remarkably similar, if offset by one month as metals spiked and dropped first, then found a new home in the middle of those extremes, and oil has done the same thing.  You can see the similarities in the two following charts:

Source: tradingeconomics.com

Source: tradingeconomics.com

Finally, whatever people are doing in financial markets, FX is not part of today’s equation.  The dollar is virtually unchanged vs. the euro, pound, yen, CAD or CHF.  In the EMG bloc, +/- 0.2% pretty much defines the range of movement.  There’s really no story here right now.

On the data front, we see PPI (exp 0.3%, 2.9% Y/Y headline and 0.3%, 3.7% Y/Y core) as well as Factory Orders (0.1%). The Bank of Canada will leave rates on hold this morning, and of course the Fed will do the same this afternoon.  We also see the EIA oil inventory data with a small draw expected in gasoline and distillates but a crude oil build.  Yesterday’s API oil data showed a 6.6-million-barrel build.  As I said above, there is no shortage of the stuff in the US.

The uncertainties of war remain the market drivers, but as we frequently see, markets have relatively short attention spans.  Absent a significant increase negative news from the Gulf (e.g. more Iranian destruction of other gulf assets) I’m not sure what will change this sentiment.  And if something happens that reduces the conflict, the initial view will be extremely bullish I believe.

Good luck

Adf
Keep Up the Fighting

The Strait of Hormuz remains closed
And right now, both sides seem disposed
To keep up the fighting
While pundits keep writing
That Trump will soon find himself hosed

Meanwhile, this week central banks meet
And none are expected to treat
The oil price spike
With any rate hike
Though keep eyes on each balance sheet

Nothing seems to have changed dramatically in Iran with US bombing attacks continuing and Iranian missile and drone attacks continuing.  It remains a daunting challenge to discern reality on the ground there as every news source spins any information to their political viewpoint, and I, for one, have been unable to pull much signal from the noise.  This is truly the fog of war.

With that in mind, it does appear that different markets are taking very different cues from the situation, with some (oil and the dollar) continuing to hew to a strong risk-off viewpoint while others, equities and bonds, remain unconvinced that the world is about to end.

As such, perhaps we should take a few moments to consider the fact that this week, we are going to see interest rate decisions from every major Western central bank in the following order: RBA, BoC, FOMC, ECB, BOE, BOJ, SNB, starting tonight and concluding on Thursday.

Of all these banks, only the RBA is expected to move, raising its base rate by 25bps to 4.10%, although that was baked in prior to the events in Iran beginning.  I would contend this is not a response to the oil price.  In fact, one must assume that central bankers are aware of the history of responses to exogenous price shocks, like an oil spike, and that any attempt to offset the inflationary consequences in the past has led to major economic pain.  It is not hard to understand that a sharp rise in oil prices, and the concurrent rise in gasoline and diesel, acts as a “tax” on the economy which tends to reduce economic activity.  Hiking rates into that scenario would very likely result, and historically has resulted, in a recession in short order.

Remember, the reason central banks, in general, look to core inflation, is because they know they cannot impact the prices of food or energy via interest rate policy.  While the ultimate impact of this oil price spike will only be known many months from now, if the conflict ends in the next several weeks, it is likely that any structural price issues will be avoided.  Of course, we have no idea how long things will last right now, so as investors and hedgers, reduced exposure to financial markets is likely the best advice for almost everyone.

Which means, it’s time to look at the markets and see what they are telling us.  After Friday’s soft close in the US, Asia saw a mix of outcomes.  Tokyo (-0.1%) did little overall, and we saw some weakness in Australia (-0.4%), New Zealand (-0.3%) and the Philippines (-0.9%) with Indonesia (-1.6%) the regional laggard.  However, there were numerous markets who ignored the oil price and rallied including Hong Kong (+1.5%), Korea (+1.1%), India (+1.3%) and Singapore (+0.6%) with mainland China essentially unchanged in the session.  China released a raft of data showing that the economy there continues to have property troubles (House Prices -3.2%), but the rest of things were largely in line with their reduced GDP expectations excepting Unemployment, which rose to 5.3%.  

Europe, too, is seeing a mixed picture this morning with some gainers (Germany, UK) and some laggards (Spain, France, Italy) although none of the movement is very significant, < 0.3% in every case.  US futures at this hour (7:10) are all pointing nicely higher, in fact, by 0.5% to 0.8%.

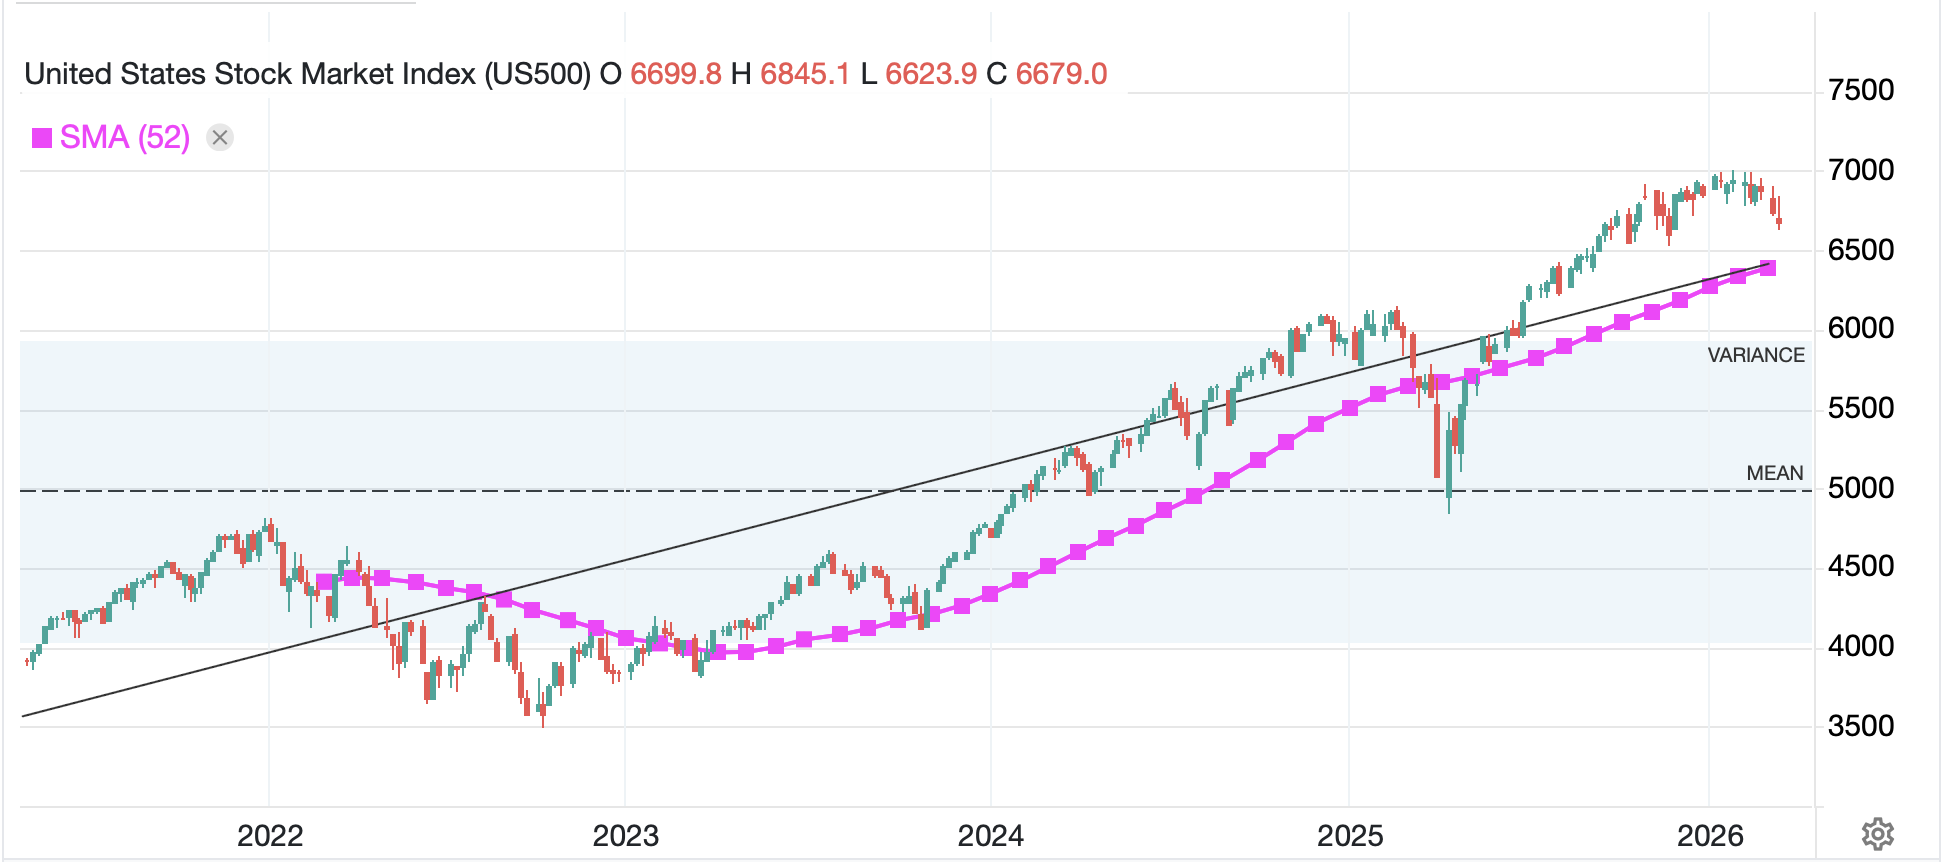
My point is that despite fears of the death of the equity rally, as I type this morning, the S&P 500 is just 4.5% from its all-time high made at the end of January.  I am no technician, but the chart below shows both the long-term direction and the 52-week moving average, and the current price is well above both of these indicators.  This is not to say the market cannot decline from here, just that the broader trend remains higher.  It does not feel very apocalyptic to me at this point.

Source: tradingeconomics.com

Turning to the bond market, yields are lower across the board this morning with Treasuries (-3bps) backing off the highest levels seen last week, and currently at 4.25%.  While that rate is clearly above the lows, it hardly smacks of panic nor of a bond-buying strike.  Of course, historically, when uncertainty rises, Treasuries have been a primary safe haven, and that has not been the case this time either.  It appears to me that investors are caught between fears of rising inflation and fears of economic contraction so don’t know whether they want to hold their bonds or sell them.  As to European sovereigns, all are in fine fettle this morning with yields slipping between -2bps (Germany) and -6bps (UK).  Again, this does not smack of inflation fears today.

Which takes us to the key driver of almost everything, oil.  Right now, WTI is trading lower by -1.5% and is back below the $100/bbl level.  While, of course, the recent trend is higher, that is entirely on the back of the Iran situation.  If/when that is resolved, I expect the price to retreat sharply right away, although probably not to its prewar levels for another few months.  But if it traded back to $70/bbl, that would remove virtually all the inflation talk and investors would need to look elsewhere for cues.

Source: tradingeconomics.com

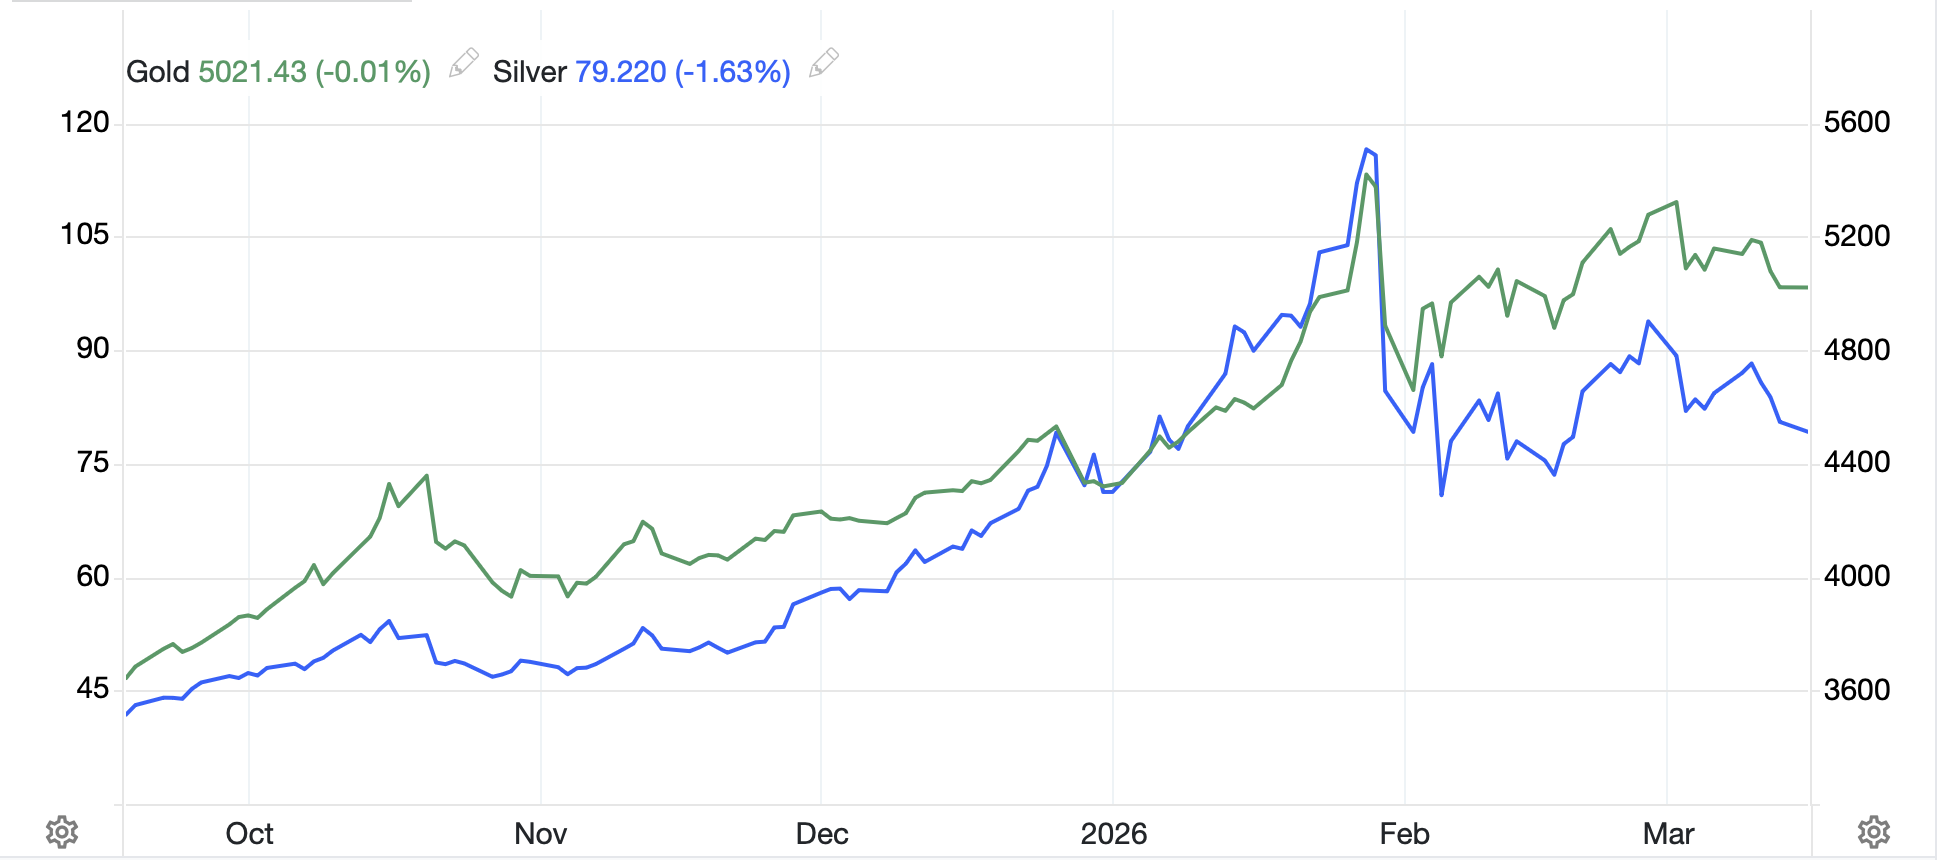
In the metals markets, gold (0.0%) is trading just above $5000/oz and silver (-1.6%) just below $80/oz, and neither has responded as would have been expected prior to the Iran conflict.  Recall, both peaked at the end of January, just before the Kevin Warsh as Fed chair announcement, and as you can see below, both have largely gone nowhere, albeit with a lot of daily volatility attached to that lack of movement.

Source: tradingeconomics.com

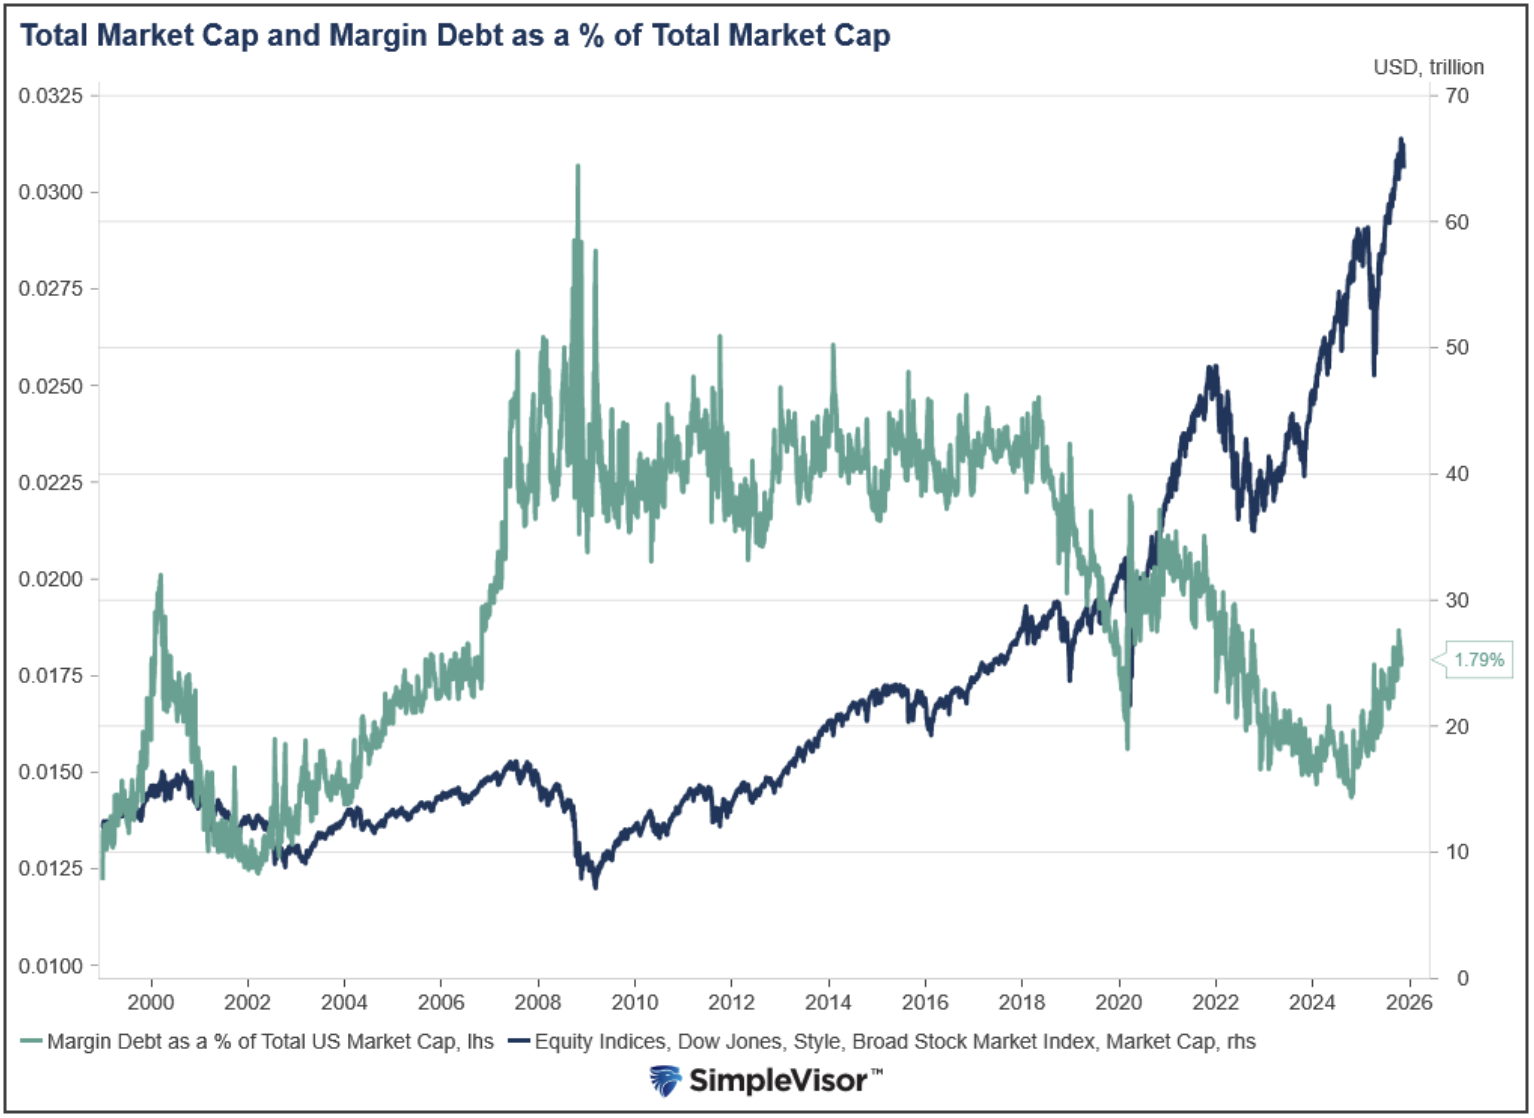
It makes no sense to me that after a 5000-year history as the ultimate monetary safe haven, gold has suddenly lost its allure in that capacity.  As such, I continue to believe that the lack of follow-through higher during this war is a result of leveraged investors needing to raise cash to cover margin calls and given the gains that were available in their gold positions, and the liquidity in the market, gold was the most convenient way to manage positions.  Remember, leverage has been a key part of the story of recent market moves, with margin debt at all-time highs, > $1.1 trillion, although it represents just 1.9% of outstanding market capitalization, less than the all-time high percentages seen ahead of the financial crisis.

Source: investing.com

Nothing has changed my take on the underlying demand for precious metals at this point.

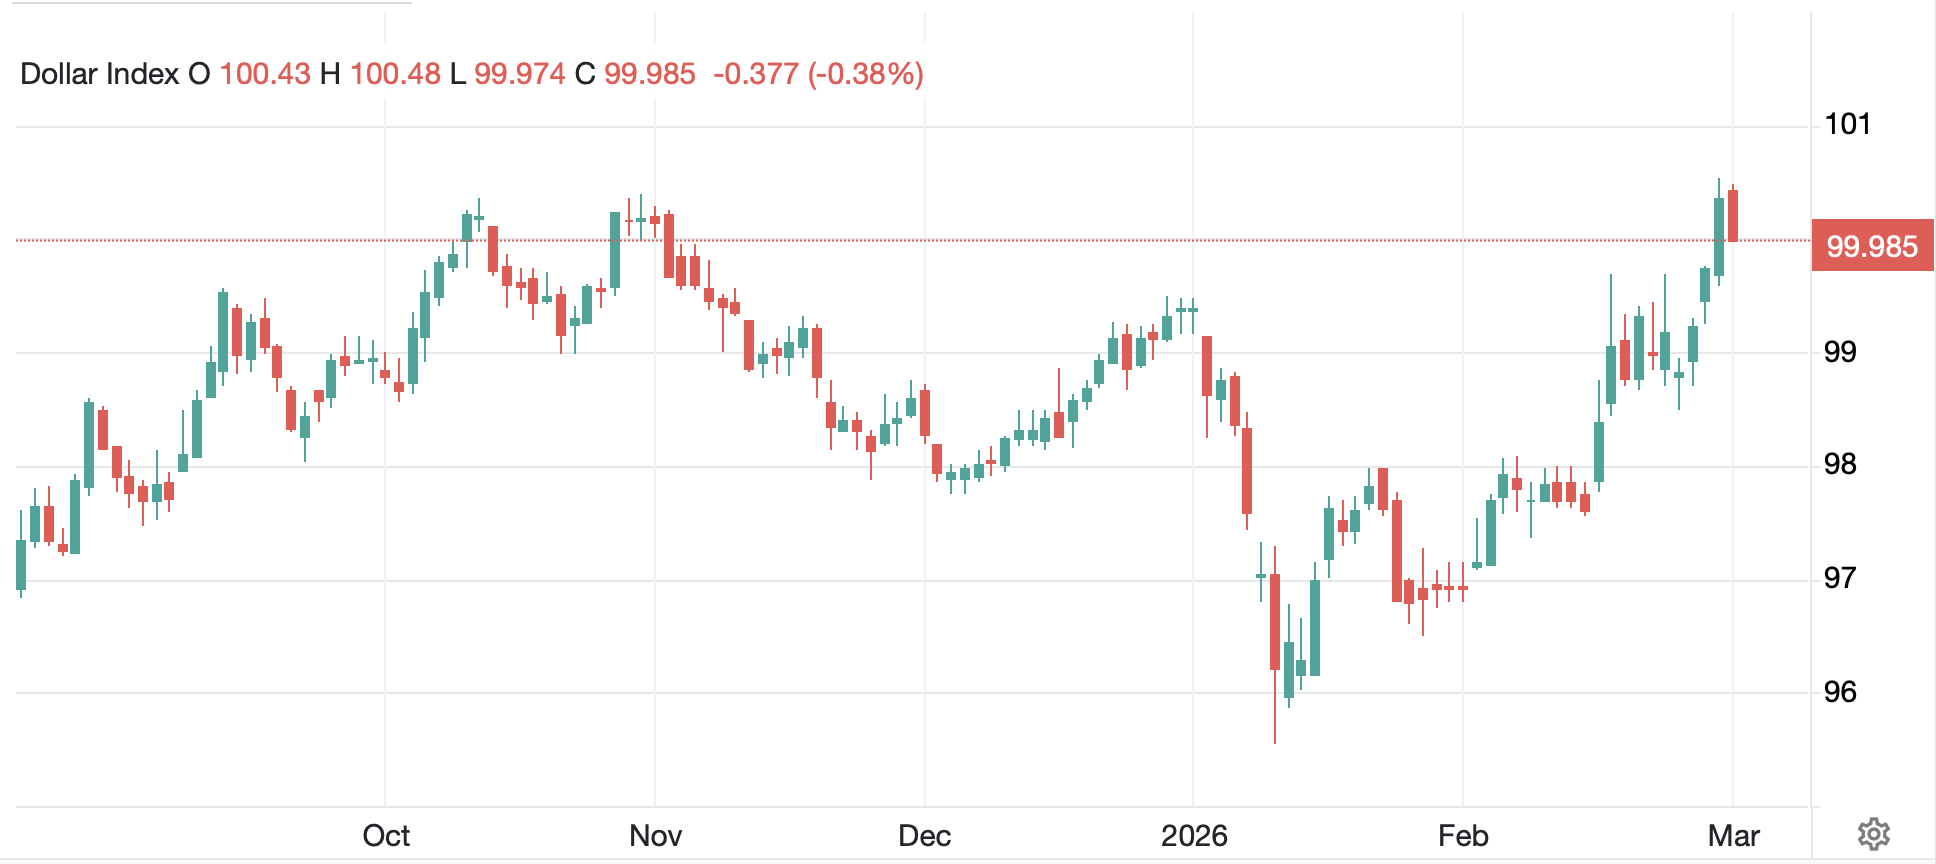
Finally, the dollar is a bit softer this morning but has retained most of its gains from this move.  However, as a descriptor of today’s lack of fear, the dollar’s pull back is as clear a signal as any.  So, the euro (+0.5%) is rebounding away from the 1.1400 level seen Friday, while the yen (+0.4%) is backing away from the 160 level.    AUD (+1.0%) seems like it is preparing for this evenings’ RBA rate hike, but the dollar is lower across the board after a solid run ever since the Warsh announcement.  Looking at the DXY (-0.35%) below, you can see that today’s move is modest in the scheme of things, and we will need to see a lot more dollar selling before this trend changes.

Source: tradingeconomics.com

EMG currencies are having a very strong day, almost like the war is over.  CZK (+1.8%), HUF (+1.7%), PLN (+1.1%), ZAR (+1.0%), MXN (+0.9%) and KRW (+0.9%) are representative of today’s price action.  I’m wondering if I missed the news that the war ended!

On to the data this week, which in addition to all those central bank meetings includes a large array of generally secondary data, although PPI is part of the mix.

TodayEmpire State Manufacturing3.2
 IP0.1%
 Capacity Utilization76.2%
WednesdayPPI0.3% (2.9% Y/Y)
 -ex Food & Energy0.3% (3.7% Y/Y)
 Factory Orders0.2%
 FOMC Rate DecisionUnchanged
ThursdayInitial Claims215K
 Continuing Claims1855K
 Philly Fed9.0
 New Home Sales720K

Source: tradingeconomics.com

I imagine that folks will look at the PPI data to see if they can glean anything about inflation going forward, but it, too, is a February number, so will not have anything from the war.  It will also be interesting to see what Chairman Powell says in his press conference, but I can’t imagine much new information will flow there either.  After all, with the war, they are kind of stuck for now.

So, it continues to come down to market interpretations of commentary regarding the war.  As I said, this morning, investors don’t seem that worried things will get worse.  The Greed and Fear index is at 22, not great, but we have seen worse just recently.  Again, lighter positions are the way to go in my view.

Good luck

Adf
Bonds are a Flop

The war has now widened in scope
And though all of us truly hope
It won’t last too long
We could, there, be wrong
As such we must all learn to cope
 
So, oil, right now, knows no top
While havens like bonds are a flop
There’s no place to hide
Thus, you must decide
If trading makes sense or should stop

Carl von Clausewitz, the 19th century Prussian military strategist, is credited with describing the fog of war in his 1832 book, On War.  “…three quarters of the factors on which action in war is based are wrapped in a fog of greater or lesser uncertainty.”  This is quite an apt description of things, even now with cameras literally everywhere in the world.  Context remains difficult to understand, and, of course, there is an enormous amount of propaganda from both sides of any conflict as the protagonists attempt to sway both their own populations and those of their opponents.

I highlight this because I continue to be amazed at the certitude with which some analysts proclaim to “know” how things will turn out.  As I have written elsewhere, nobody knows nuthin right now.  With that in mind, I would highlight the IMF’s statement yesterday which added exactly zero to the conversation, “It is too early to assess the economic impact on the region and the global economy. That impact will depend on the extent and duration of the conflict.”  Now, don’t you feel educated after that pronouncement?

At any rate, with more than a full day’s trading in financial markets, perhaps we can try to assess how things are going.  The first thing to note is that many alleged haven assets are not performing up to snuff, notably Treasury bonds, Japanese yen, Swiss francs and gold.  In fact, as of this morning, the only traditional haven that is performing as expected is the dollar.

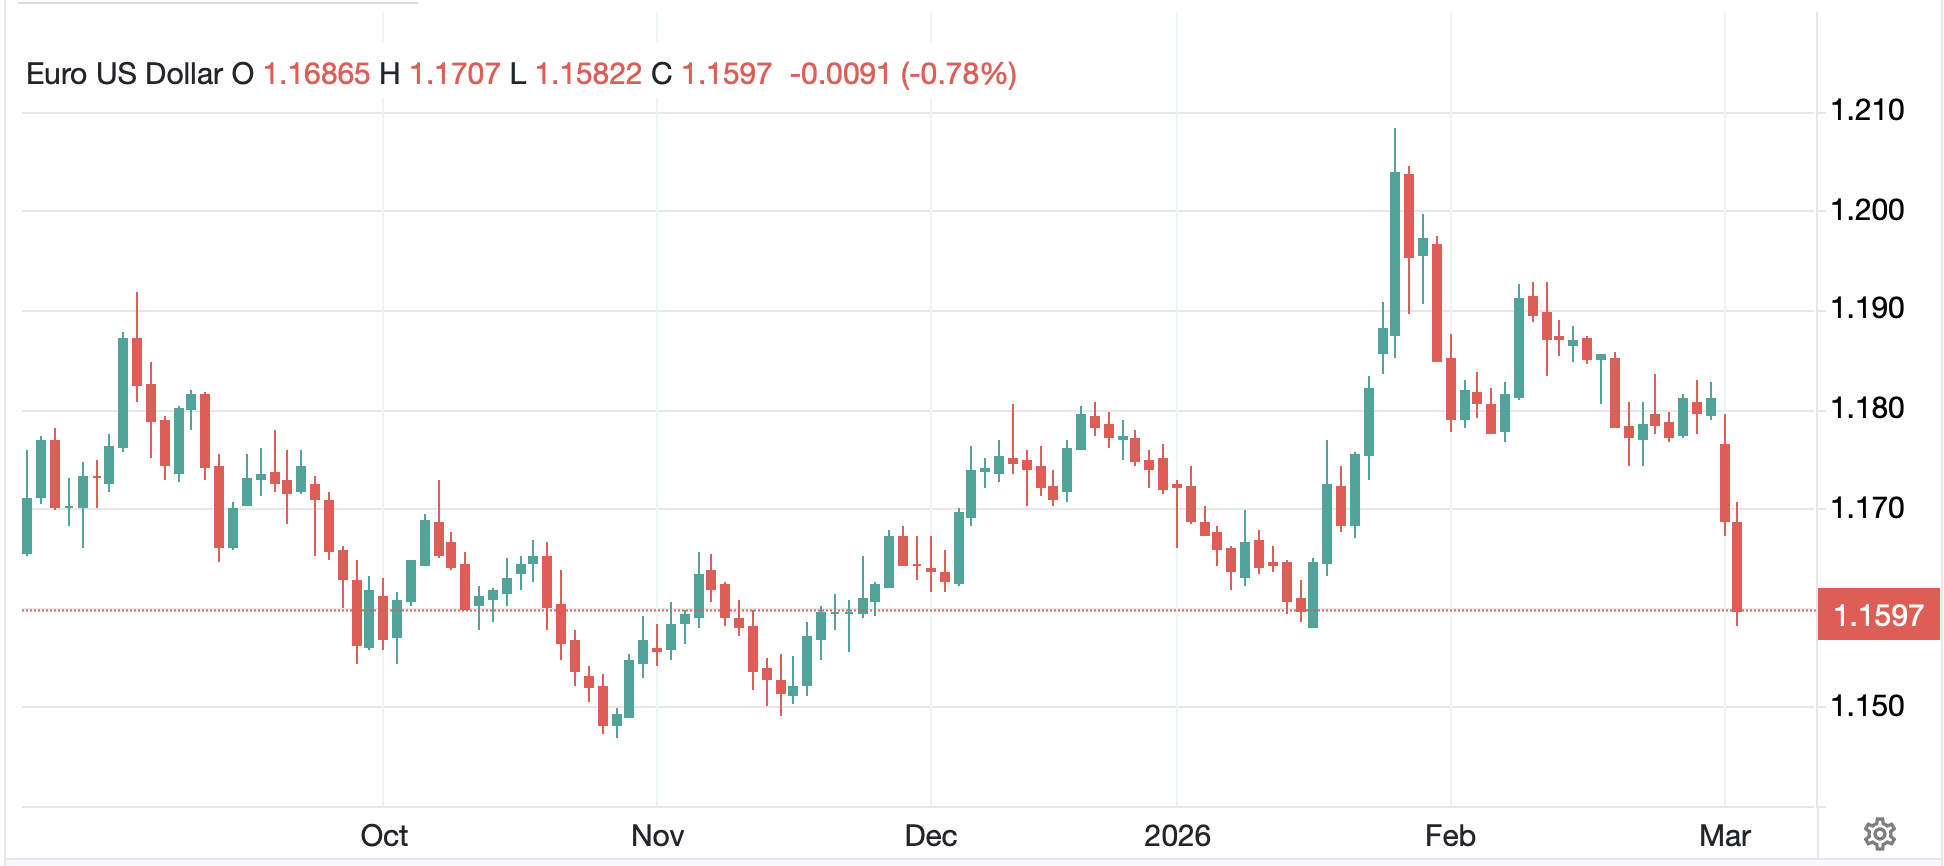
It was just over a month ago when the cognoscenti were explaining that the euro above 1.20 was indicative of the dollar’s long decline into the depths of history.  I recall someone in my LinkedIn feed asking how soon the euro would trade through 1.25 and beyond.  I would argue that timeline has been extended somewhat, if you still believe that is likely to be the case.  Rather, as you can see in the below chart, the single currency (-0.8%) is now back below 1.1600.

Source: tradingeconomics.com

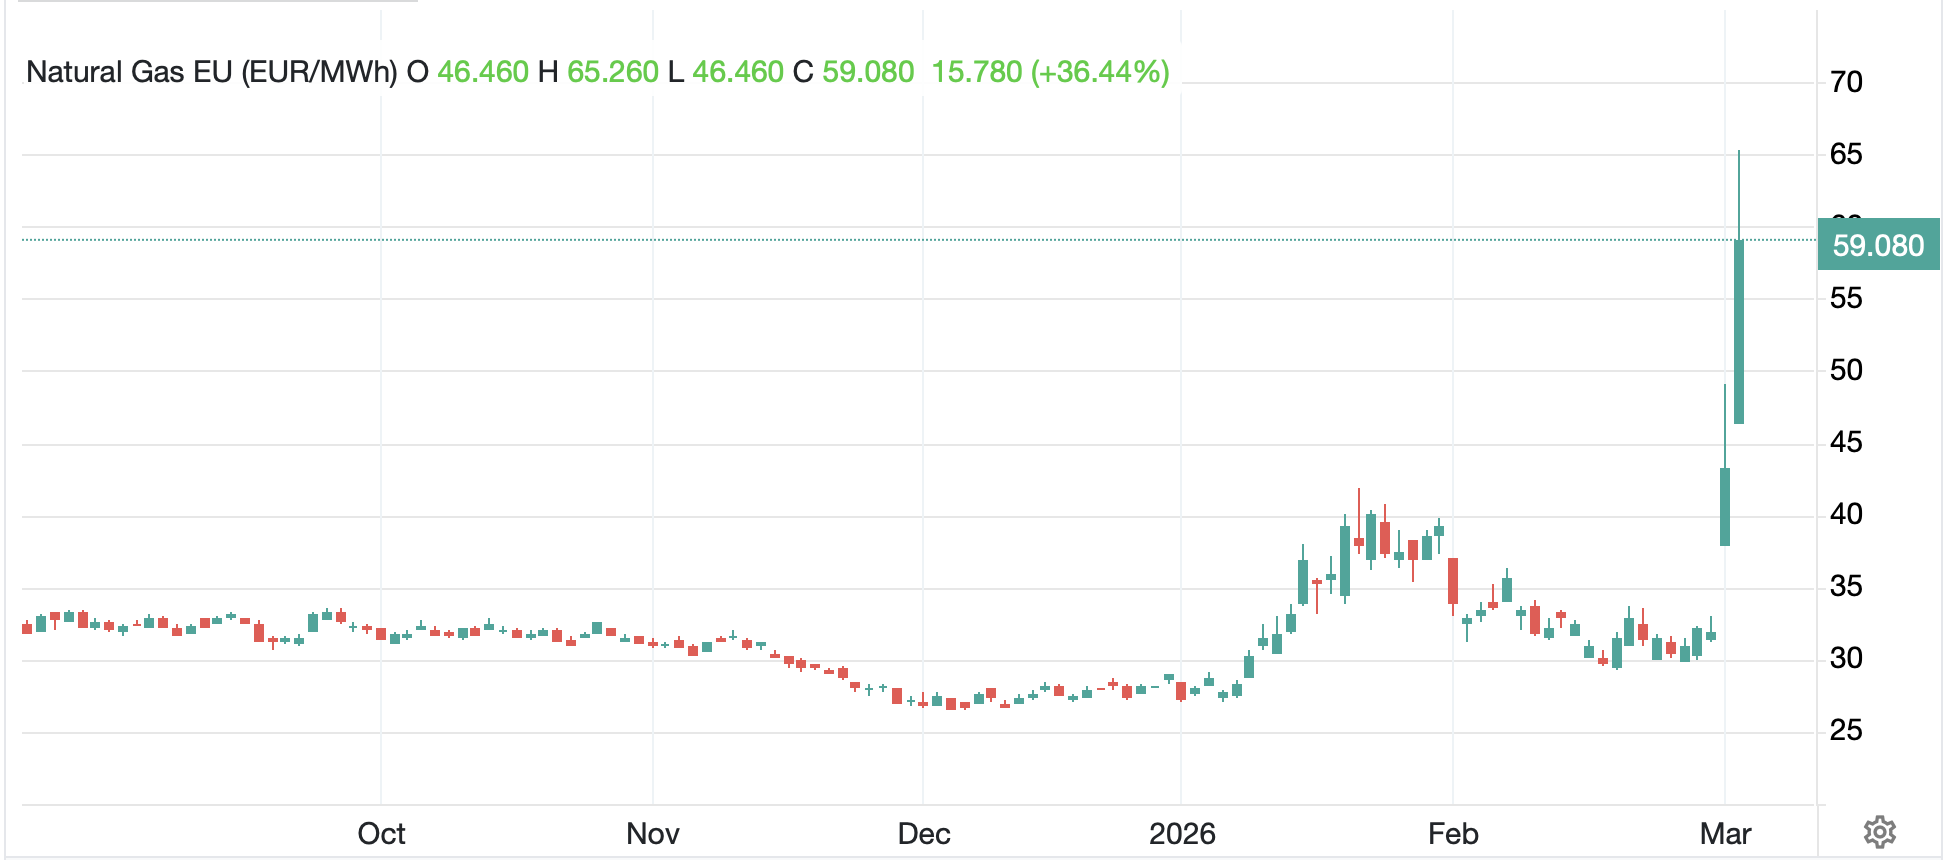
There are several things weighing on the euro right now.  First is the fact that they are energy price takers for every form of energy, so not only are higher oil prices hurting the continent, but NatGas there has exploded higher as per the below chart, rising 37% today and nearly 95% since the weekend.

Source: tradingeconomics.com

Recall, Europe has been trying to wean themselves off Russian gas, have been huge buyers of US LNG but also huge buyers of Qatari LNG, and with the Strait of Hormuz effectively closed (shipowners cannot get insurance so nobody transits the Strait), this is a problem.  Adding to the European problem is the fact that their storage levels of NatGas are extremely low for this time of year, about 30%, when typical levels in early March are near 50%.  We cannot be surprised at this price action.  So, while US NatGas (+6.3% this morning, 10% this week) has risen, it is currently trading at $3.14/MMBtu.  The comparable Eurozone price is $20.28/MMBtu.  Perhaps a weaker euro is not that surprising after all.  (As an aside, one of the reasons I find it difficult to accept the weak dollar story is that the US controls its own energy destiny and given energy is life and the economy, we are fundamentally in better position to perform going forward.)

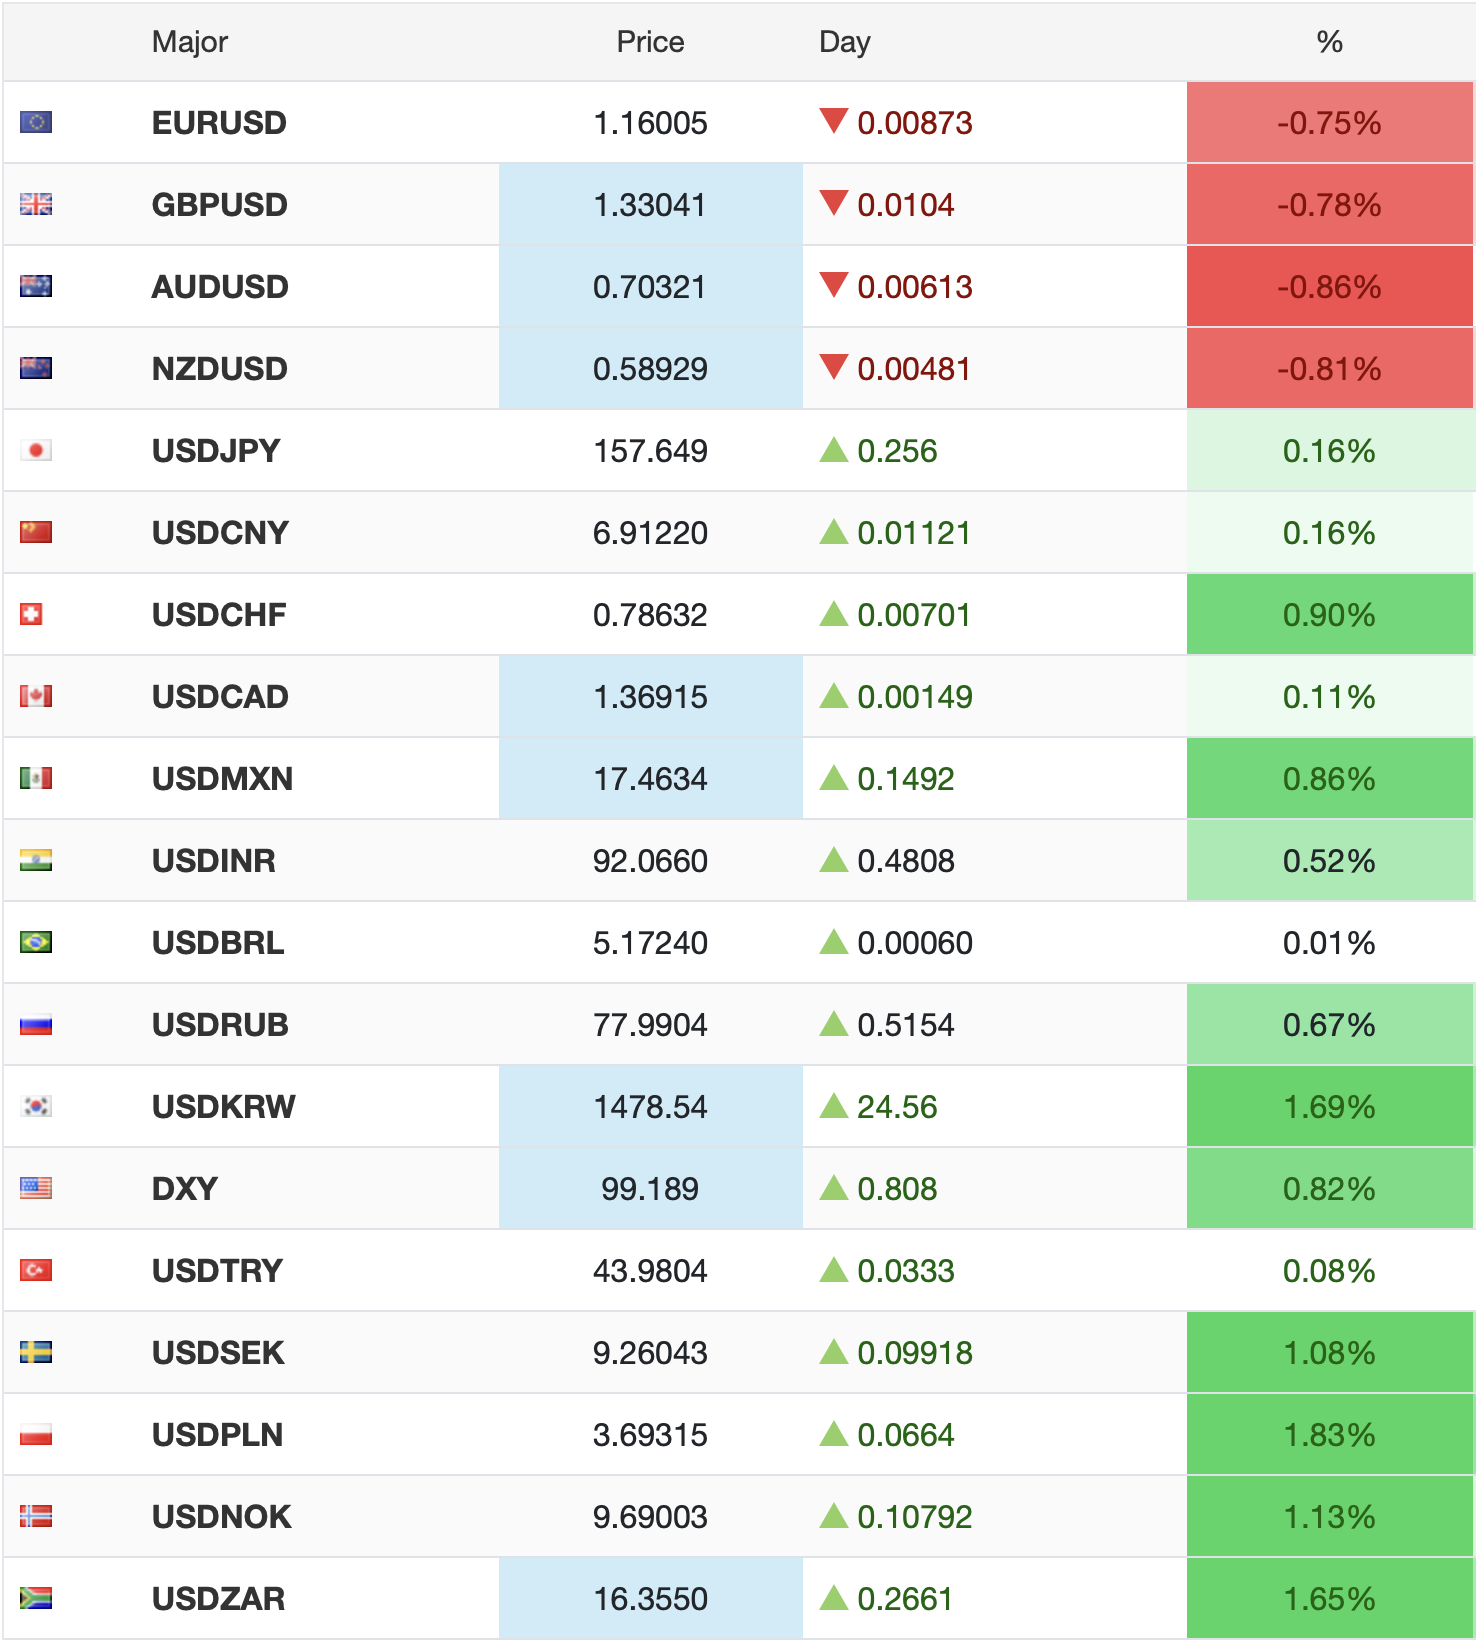
But the dollar is strong against all comers again today as per the below table from 7:10 this morning.  Will this continue?  While nobody knows, my take is there is still ample room for further strength in the buck, probably another 3%-5% before it starts to impact other things significantly.

Source: tradingeconomics.com

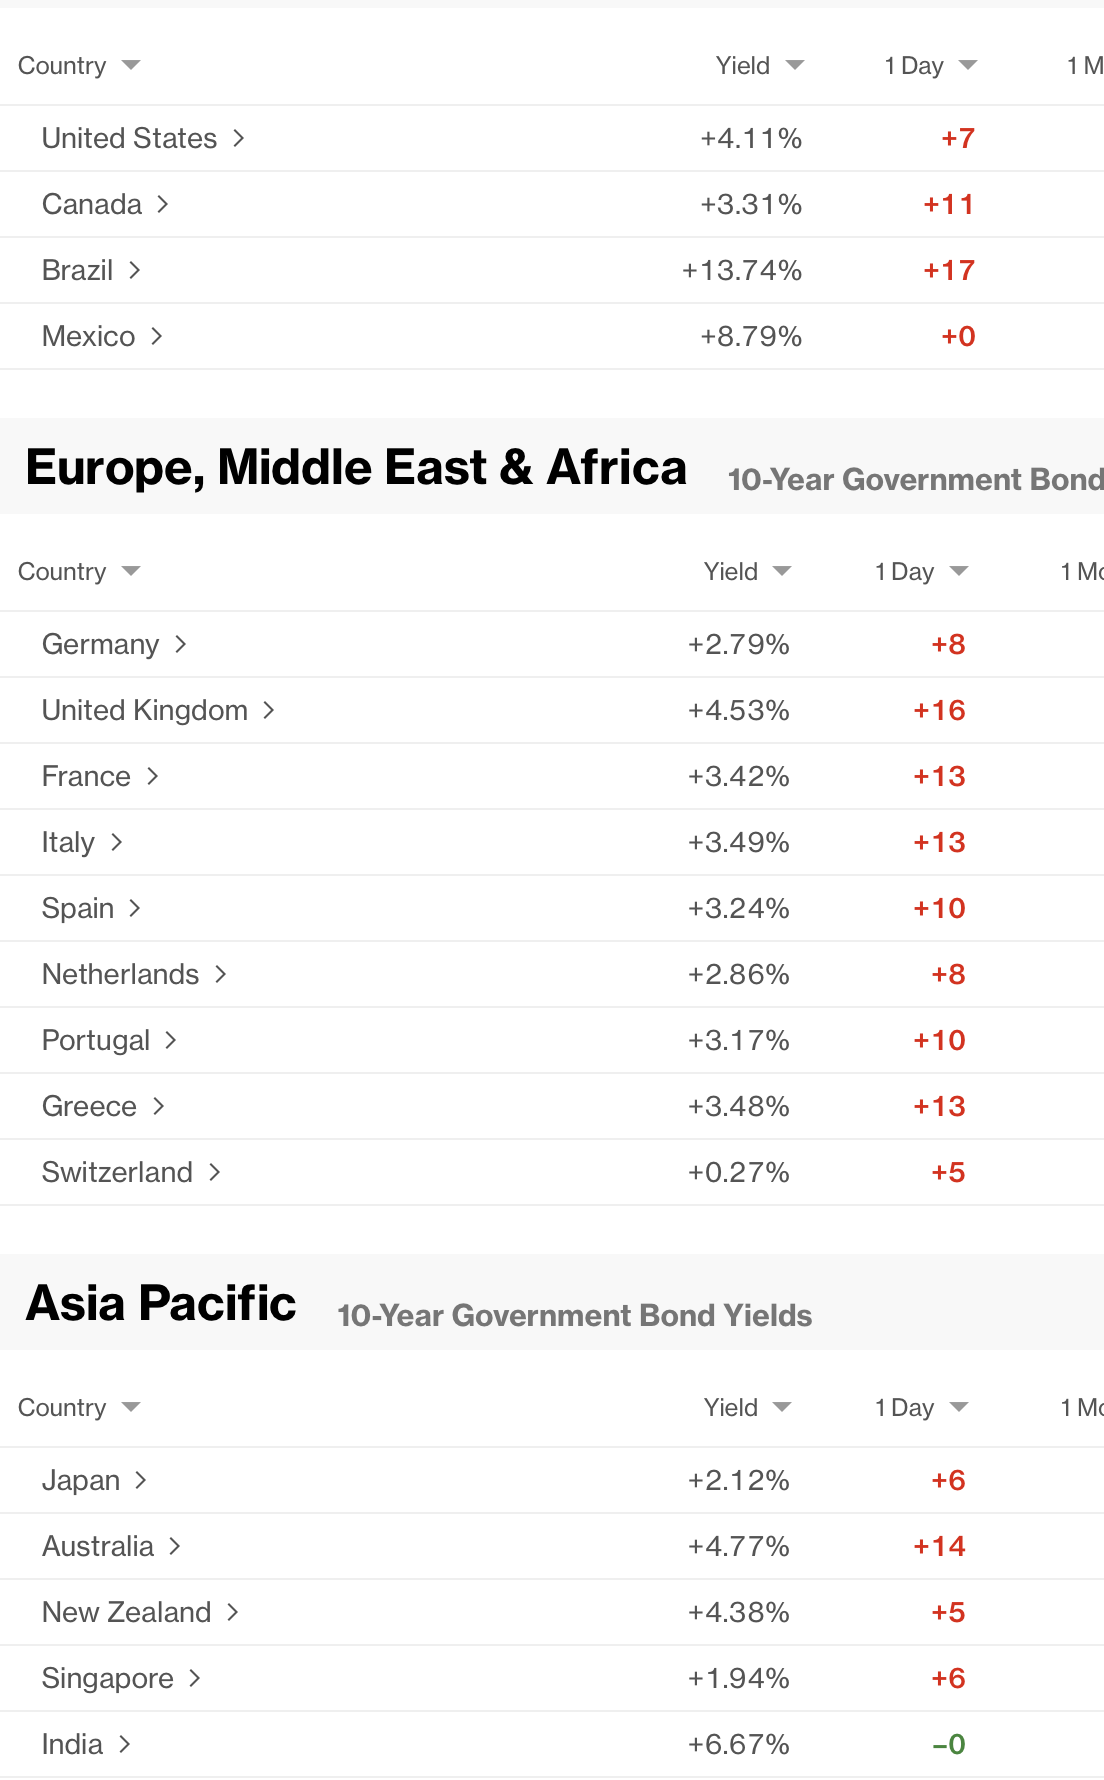
I think the biggest surprise for most of us is the incredibly poor performance of the bond market, which has always been seen as a safe haven.  However, this morning, that is not the case at all as you can see from the Bloomberg table below.

My take is that there is only one thing we truly know about war, it is inflationary.  While the early signs are for energy prices to rise, war is a major consumer of resources that will never be recycled and therefore will require new baseline production.  As well, governments don’t fight war on an austerity budget, so you can be sure that there will be plenty of money around.  All that leads to higher prices and that is why bond markets are feeling pain around the world this morning.  If, as President Trump has indicated, this war ends in the next 4 weeks or so, we will be able to re-evaluate the inflationary and other impacts, but while I had thought bonds were going to perform well, clearly that is not the case right now.

Turning to commodities, oil (+6.75%) continues to rise and I expect will remain well bid until the fighting stops.  The prospects for higher prices from here remain dependent on whether Iran tries to destroy other Middle East production facilities and if they are successful.  Meanwhile, in the Western hemisphere, the US, Canada, and all of Latin America are going to be pumping at full strength for now.  So, while prices may tick higher, it is unlikely we will see any supply issues here.

Metals are another surprising trade this morning with gold (-2.65), silver (-7.8%) and copper (-2.3%) all sharply lower.  Given the sharp decline in equity prices I will discuss below and given the amount of leverage that is rampant in the equity markets, I think gold is a victim of ‘sell what you can, not what you want to.’  Arguably, there is some of that with bonds as well.  In a way, though, I am more surprised about silver and copper given their criticality in fighting the war.  Both are being consumed rapidly via weapons being deployed so this is more baffling to me.  However, I do not believe the longer-term thesis in either of these metals has changed, there is a supply shortage relative to industrial usage for both with no new supply on the horizon.  As such, I do see prices here rallying over time.

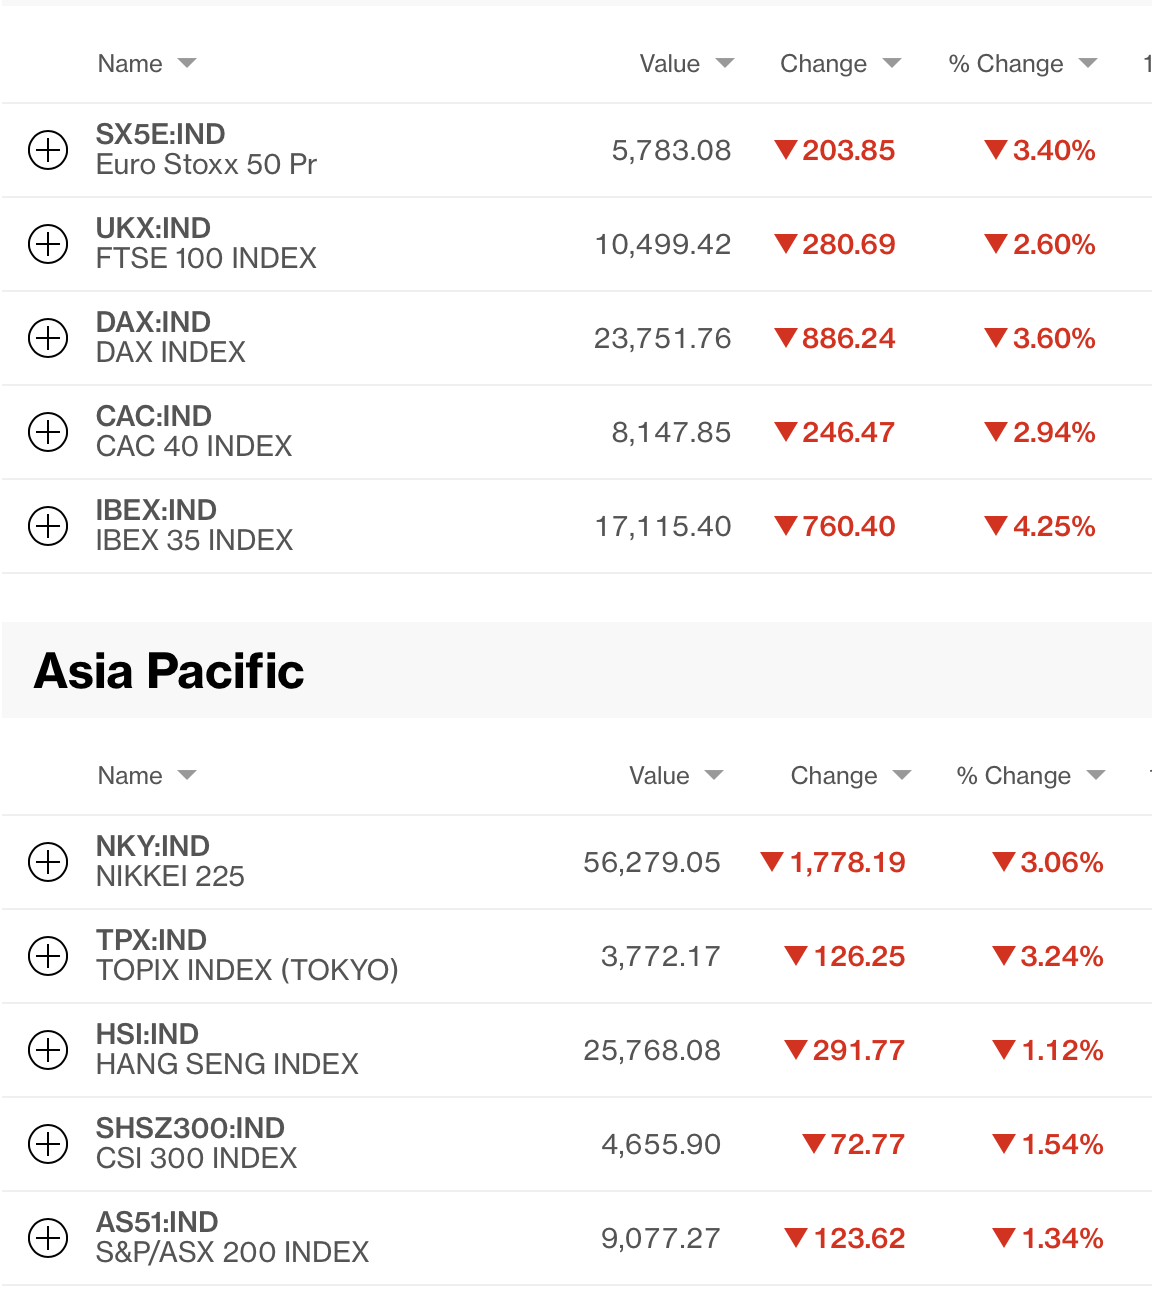
Finally, the equity markets are sharply lower almost everywhere.  The below Bloomberg table shows how major markets in Asia performed overnight and how Europe stacks up at 7:30 this morning.

What it doesn’t show is that the KOSPI in Korea fell -7.25%, nor that there were sharp declines in India (-1.3%), Taiwan (-2.2%) and Thailand (-4.0%).  You will also not be surprised that US futures are pointing much lower this morning, -1.5% across the board.  Yesterday’s performance was quite the surprise, I think, but today is much more in line with what we expected.

And that’s where things stand this morning.  obviously, the war is the only story that matters, so data releases are going to be secondary for now, even Friday’s payroll report.  At some point, I expect that traditional havens will play their role, but as leveraged positions continue to get unwound, it may take a few more sessions before we see that.  If you’re trading, smaller sizes make sense.  If you’re hedging, stick to longer term fundamentals I think.

Good luck

Adf