Forked Tongue

The major discussion today
Is tariffs and if they’re in play
While Trump thinks they’re great
Economists hate
Their impact and watch with dismay
 
Meanwhile it has not been a week
And questions are rife ‘bout DeepSeek
The most recent questions
Are making suggestions
That China, with forked tongue, did speak


President Trump has promised to impose 25% tariffs tomorrow on all Canadian and Mexican exports to the US if those nations do not agree to further efforts to tighten border security regarding the movement of both immigrants and drugs across the borders.  Even within his administration, there are many who do not want to see them imposed given the potential disruption they would cause in supply chains throughout the nation.  And of course, economists abhor tariffs as a pure deadweight loss to the economy.  But Trump sees the world through very different eyes, that much is clear, and as evidenced by the very short-term row with Colombia last weekend, believes they can be useful tools to achieve strategic, non-economic outcomes.

This poet is not fool enough to try to anticipate what will actually happen as the mercurial nature of President Trump’s actions is far beyond my ability to forecast.  However, if history is any guide, we will see both Mexico and Canada make some additional concessions and an announcement that because of that, the tariffs will be delayed until negotiations can be completed by some new deadline.  (Well, maybe I am fool enough 🤣)

From our perspective observing market reactions, the only consistent view is that US tariffs will drive the dollar higher, or more accurately, other currencies lower, as the FX market adjusts to compensate for the tariffs.  If we look back at Trump’s first term, the first tariffs were imposed on China in early 2018 on solar panels and washing machines and a few other things.  A look at the chart below shows that the yuan (the green line) did, in fact, weaken substantially following those tariffs, with the dollar rising from 6.25 to 6.95 over the course of the ensuing six months.  However, if we broaden our horizons beyond the renminbi to the dollar writ large, as seen by the Dollar Index (the blue line), which rose from 88 to 96 over the same period, the renminbi’s price action was directly in line with the dollar overall.  There was only limited additional impact to CNY.  Remember, too, that in 2018, the US equity market was performing quite well, and funds were flowing into the US, thus driving the dollar higher, not dissimilar to what we have seen over the past year.  The point is that while the tariffs may have some impact, it is also likely that the dollar will move based on its traditional drivers of interest rate differentials and capital flows regardless.

Source: tradingeconomics.com

Away from the tariff talk, though, there is precious little other market related news, at least on a macro basis.  Yesterday’s data showed that GDP grew a tick less than anticipated at 2.3% in Q4, but Real Consumer Spending, which is a critical part of the economic picture, rose at 4.2%, a very solid performance and an indication that things in the economy are still ticking along just fine.  (The difference between that number and the GDP number is due to inventory adjustments, which are seen to wash out over time.). In fact, arguably, that solid growth was a key reason that the equity markets in the US had another strong session yesterday, with gains across the board.

Well, there is one other thing on many people’s minds, and that is the veracity of the claims about DeepSeek.  You may recall I highlighted the question of all those Nvidia sales to Singapore earlier in the week as somewhat strange.  Well, I was not the only one asking that question and this morning in Bloomberg, there is an exclusive story about a US government investigation into whether China actually got the most advanced H100 chips via Singapore after all.  If that is the case, then perhaps the DeepSeek claims are not as impressive as they were initially made out.  I suspect if this turns out to be the case, that worries over the need for AI to no longer utilize the most advanced chips will dissipate and the tech rally will regain momentum.

So, let’s look at markets now.  China and Hong Kong remain closed for their New Year celebrations.  Japan (+0.15%) had a modest gain and the truth is that only two Asian bourses had strong sessions, Singapore (+1.45%) and India (+1.0%) with the rest of the region mostly a touch firmer.  In Europe, all markets are slightly stronger this morning, on the order of 0.3% or so, as the combination of yesterday’s ECB rate cut and hints at future cuts by Madame Lagarde, seem to be underpinning the markets.  Certainly, today’s Eurozone data, showing German Unemployment climbing a tick to 6.2% while Retail Sales there fell -1.6% in December don’t seem like a rationale to buy equities.  In the US futures market, though, we are seeing solid performance, 0.5% or more, as I believe many are jumping back on the AI bandwagon.

In the bond market, Treasury yields have edged higher by 1bp, and remain just north of 4.50% as the tension between solid growth and slowing inflation dreams keeps the market quiet.  In Europe, though, yields are continuing their decline from yesterday, with sovereign yields down by between -3bps and -4bps as investors look for further easing from the ECB as the Eurozone sinks slowly toward recession.  However, in Japan, JGB yields rose 3bps as data overnight showed inflation remains above target and expectations for another rate hike in the first half of the year rise.

In the commodity markets, oil (-0.35%) continues to chop around in the middle of its trading range with no strong directional impulse (see chart below).

Source: tradingeconomics.com

It is very difficult to know how to view this market in the short run given the potential for disruptions by tariffs and even more sanctions, but nothing has changed my long-term view that there is plenty of oil around and prices will remain here or decline.  In the metals markets, both gold and silver are little changed on the morning although both have been in the midst of a strong rally with gold making new all-time highs in the cash market yesterday.  Copper (-0.7%) is offered this morning but is still much higher than at the beginning of the month/year.

As to the dollar, it is modestly firmer this morning rallying against most of its G10 counterparts, but not by very much, 0.3% (JPY) at most.  Versus its EMG counterparts, though, there is more strength with PLN (-0.6%) and ZAR (-0.4%) both under a bit of pressure.  The latter is responding to ESKOM, the national electrical utility, announcing that they may need to impose rolling blackouts to help repair parts of the grid.

On the data front, this morning brings Personal Income (exp 0.4%) and Spending (0.5%) but of more importance it brings PCE (0.3%, 2.6% Y/Y) and core PCE (0.2%, 2.8% Y/Y) along with the Chicago PMI (40.0) release at 9:45.  We also hear our first post-meeting Fed speaker, Governor Bowman, this morning but it would be shocking if she said anything other than they are going to be patient to watch inflation slowly move toward their target, almost as if by magic.

Once again, tape bombs are the biggest risk, as they will be for the next four years, but I imagine all eyes will be on Trump and the tariffs as the key driver.  For now, nothing has dissuaded me from my view the dollar is more likely to rise than fall, but we need to see how things evolve.

Good luck and good weekend

Adf

Stardom is Fleeting

Remarkably few people care
That Jay and the Fed will soon share
Their latest impressions
On growth and recessions
An outcome, of late, that’s quite rare
 
Does this mean that ere the next meeting
There will be an increase in bleating
By every Fed speaker
Each one a fame seeker
As they realize stardom is fleeting?


I wonder how the atmosphere in the meeting room at the Marriner Eccles building has changed today vs. what it has been for the past decade at least.  Usually, the FOMC meets, and financial markets are riveted by the potential and then everything comes to a virtual standstill as traders and investors await the wisdom of the Fed Chair to help determine where markets are likely to go.  I am reminded of the crop report scene in Trading Places, where the entire pit stops to watch the news and then springs back into action. 

One of the consequences of this evolution is that every member of the FOMC feels it is their duty to reiterate their views as frequently as possible, whether they are changing or not, because they are trying to increase their profile to ensure a lucrative future gig want to make sure that the American people understand just how much the Fed is doing to help them and the nation.  This is why for the first four weeks after a Fed meeting, virtually every day we have at least one if not two or three FOMC members repeating themselves ad nauseum.

But suddenly, they have real competition for airtime.  President Trump, no shrinking violet he, is incredibly adept at forcing all the world’s attention on himself, to the exclusion of formerly important voices like Alberto Musalem or Lisa Cook.  Now, the fact that you can probably not remember who those two people are is exactly my point.  FOMC members speak constantly, but it is the office, not the voice, to which people are listening.  And right now, fewer and fewer people are listening to the Fed because President Trump is commanding all the attention.  In fact, to the extent the Fed is discussed, it is generally in relation to how they are going to respond to Trump’s next moves.

But, in an effort to maintain our focus on markets and not politics, to the extent that is possible right now, the Fed still has a role to play in both expectations of how things are going to evolve as well as actual pricing.  A quick summation of where we have been with Powell and friends is that last year, starting in September they cut rates for the first time in nearly two years and have since reduced the Fed funds rate by 100bps.  A key issue here is the fact that the economy is showing no signs of slowing down, unemployment remains modest at best, and inflation has been, at best, bottoming well above their 2.0% target, if not rising again.  Hence, there have been many questions as to why they cut rates at all.

At this point, though, the Fed’s narrative prior to the quiet period, was one of increased caution that further rate cuts may not be necessary, or certainly not imminent, given the ongoing positivity in the economic situation.  As such, there is no expectation for a rate cut today, and according to the Fed funds futures market, only a 30% probability of a March cut, with basically two full cuts priced in for all of 2025.  I would argue that based on the data we have seen, it is not clear why there would be any further cuts, and, in fact, believe that by mid-year, we are likely to start to hear talk of a rate hike before the end of the year.  This will be dependent on the data, but if inflation continues to remain sticky (see chart of Core PCE below), the bar for cuts will move higher still.  Certainly, to my non-PhD trained eye, it doesn’t really look like their key metric is declining anymore.

Source: tradingeconomics.com

Perhaps the most remarkable thing about this Fed meeting is that I have seen virtually nothing regarding expectations of how the statement may change or forecasts may change.  FWIW, which is probably not much, my take is the statement will be virtually identical given no real changes in the data trends, and that Chairman Powell will go out of his way to say absolutely nothing at the presser, especially when asked about President Trump and his policies.  Of course, this will not prevent the cacophony of Fedspeak that will come between now and the next meeting, but there may be fewer folks paying attention.

Ok, let’s turn to markets.  While Monday was a tech stock rout, yesterday was the reverse with the NASDAQ shaking off the DeepSeek fears or actually embracing them based on Jevon’s Paradox (the idea that the more efficient something becomes, the greater the need/desire for it and therefore the increase in its price) leading to the new narrative that Nvidia’s chips will be in more demand.  But regardless, everybody was happier!  Asian markets responded with the Nikkei (+1.0%) regaining some luster on the tech story as well as the weaker JPY, which saw the dollar rally a full yen on the session, although it is little changed overnight.  While not universal, there was a lot more green than red in Asia, although Chinese shares (-0.4%) did not participate.

In Europe, most bourses are showing gains this morning although the CAC (-0.3%) is lagging after luxury goods makers saw weaker growth than expected.  But the DAX (+0.75%) and IBEX (+1.0%) are both stronger as is the FTSE 100 (+0.3%) as Chancellor Reeves continues to try to explain that growth is Labour’s goal despite all their policies that seem to point in the other direction.  As to US futures, at this hour (7:30) they are higher led by the NASDAQ (+0.5%).

In the bond market, the fear from Monday is gone although the bounce in yields was modest yesterday and this morning Treasury yields are unchanged on the session.  I suspect that there is some waiting for the Fed involved here.  European sovereign yields, though, are all a bit lower, down between -2bps and -3bps, as investors anticipate tomorrow’s ECB rate cut and are looking for a dovish message going forward.

In the commodity space, yesterday modest rebound in oil (-0.6%) is being reversed this morning while NatGas (0.0%) is consolidating after a dramatic decline in the past week of more than 20% given the latest weather models are now calling for much warmer temperatures in the northern hemisphere.  In the metals markets, gold (-0.2%) is consolidating yesterday’s gains as is silver (+0.2%) and copper (-0.1%).  For now, these are not all that interesting.

Finally, in the FX markets, the dollar continues to regain momentum higher with the euro (-0.3%) sliding back below 1.04 this morning and the DXY (+0.2%) back above 108.00.  However, looking across both the G10 and EMG blocs, while the dollar’s strength is widespread, it is not dramatic, with AUD (-0.5%) and PLN (-0.5%) the biggest movers of the session.  It should be no surprise that there is confusion here given the uncertainty sown by President Trump and his tariff discussions.

On the data front, the only numbers today, aside from the FOMC meeting and the BOC meeting (expected 25bp cut) is the Goods Trade Balance (exp -$105.4B).  We also get the EIA oil data with inventory builds anticipated.  But really, despite the seeming lack of interest leading up to today’s FOMC meeting, it is the only game in town.  To me, the risk is something more dovish as that part of the narrative seems to be ebbing lately, so will be a real surprise.  If that is the case, then I suspect the dollar will suffer somewhat.

Good luck

Adf

Much Havoc

Colombia tried to prevent
Deportees, who homeward were sent
But Trump’s strong response
Meant that in a nonce
Gustavo, his knee quickly bent
 
Meanwhile, all the talk of AI
This weekend has pundits awry
The Chinese DeepSeek
Could very well wreak
Much havoc in stocks priced sky-high


If there was any doubt that things were going to be different under a Trump administration than virtually any previous administration, even his first term, they were dispelled this weekend.  By now you will all have heard the story of the Colombian president, Gustavo Petro (he of the 26% local approval rating) and his refusal to allow two US C-17 military transports filled with Colombian deportees, land in Bogota.  Apparently, when Trump was informed while playing golf, after birdieing the 3rd hole, he tweeted that the US would immediately impose 25% tariffs on everything Colombia exports to the US, rising to 50% in one week if this policy was not changed.  By the time he finished the 6th hole, President Petro reversed his policy and even offered the Colombian presidential plane to come and pick up the deportees.

While the golf portion of the story is amusing, the lesson to the rest of the world is that President Trump is very serious about his electoral promises, and he will utilize the entire might of the US government to achieve his goals.  For smaller nations with little power and leverage, it means that toeing the line is the only solution.  For larger nations, it certainly is a wakeup call to the idea that the US attitude toward international relations has dramatically changed.  As Machiavelli explained, it is better to be feared than loved, and it seems abundantly clear that President Trump understands that.

Perhaps the biggest takeaway from this situation, though, is that the US government is no longer the slow-moving behemoth to which it had evolved over the past decades.  The rest of the world is going to find itself needing to respond very quickly to things that in the past were sent to committees for study and review but now are decided instantly.  If you want to understand why I believe volatility is set to increase across all asset classes, this is the crux of the issue.

Turning to the tech world, the buzz is all about DeepSeek, which is a Chinese AI model that allegedly outperforms OpenAI’s top model, or performs just as well, although it costs a fraction of what OpenAI and others (Microsoft, Google, etc.) spent to train the model and it uses far less advanced chips which are also much less expensive and less power hungry.  Because this is all a new story, it remains unclear if DeepSeek will be an effective replacement for the others, or if it excels in only one or two areas and still lags elsewhere.  

But the market impact has been instantaneous and dramatic.  At this hour (6:00am), the NASDAQ (-4.5%) is leading US equity markets lower with the S&P (-2.4%) along for the ride.  Nvidia (-10.6% in premarket trading) is leading the way, but I suspect that this news will be negative for the entire US tech sector.  After all, it was certainly priced at premium levels.  

Source: tradingeconomics.com

In the short term, I expect we are going to hear a lot more analysis of why this is a game changing event and how the future that was so clear just last week is now cloudy.  However, while this will almost certainly take the shine off the megacap tech companies for a while, I think it would be a mistake to dismiss their futures because of this.  Two things in their favor are they still have virtually infinite resources, and they have dramatically large installed networks which means that changing things will be very difficult.  While their equity prices can decline a lot, it doesn’t mean their businesses are going to collapse.

PS, spare a thought for the impact on the energy sector here as well.  One of the narratives that has been fed lately is that all this AI will require gobs of power that will need a lot more power production.  It was a key feature of the Uranium story as nuclear is seen as one of the few sources capable of delivering the reliable power necessary.  I suspect that this part of the narrative will need to adjust as well if the AI story has actually changed.  But keep in mind that with efficiency comes more demand, so perhaps this is just a temporary downdraft.  Again, volatility is the name of the game.

Ok, let’s see how these stories have impacted the rest of the world.  With all the news over the weekend, you may not recall that US equity markets edged lower on Friday.  Well, Asian markets were mixed overnight with the Nikkei (-0.9%) following the US, although also reacting to the fact that the yen (+1.3%) rallied sharply as well.  Meanwhile, Hong Kong (+0.7%) managed to gain while mainland Chinese shares (-0.4%) certainly showed no benefit from the changing attitudes in tech.  Elsewhere in the region, Korea (+0.9%) and Taiwan (+1.0%) rallied while India (-1.1%) and Indonesia (-0.9%) fell and the rest of the region batted back and forth. In Europe, red is the dominant color, likely on the generally weak US performance although there are no European tech companies of note (perhaps ASML).  But the DAX (-1.2%) is leading the way down followed by the CAC (-0.9%) and the bulk of the rest of the continent and the UK.  Let’s just say that equities are not in favor this morning.

However, what we are seeing is a major bond market rally as Treasury yields (-12bps) tumble as risk is very definitely off.  European sovereign yields are also lower, by between -5bps and -7bps, and JGB yields (-2bps) also slipped, although relative to the rest of the world, they held up pretty well.  Interestingly, with all the talk about DeepSeek and the impact on the tech community, there has been virtually no discussion about the myriad central bank meetings this week, including, of course, the Fed on Wednesday where the market still sees no chance of a rate cut.

Commodity markets are relatively calm this morning as oil (-0.6%) is a touch lower although there has been no news of note.  The background story is that President Trump and Saudi Arabia’s Mohammed bin Salman are talking about increasing production to drive oil prices lower, but that remains more rumor than anything else.  As the polar vortex has passed, and forecasts are for warmer weather, NatGas (-6.2%) is sliding.  In the metals markets, very little movement is ongoing as traders try to determine what all the new news means.

Finally, the dollar is under some pressure this morning despite the risk off attitude that prevails.  I suppose it is because one of the recent drivers of the dollar’s strength has been the insatiable demand for the megacap tech stocks.  It seems that for now, that demand has been satiated.  So, the yen is behaving in its traditional safe haven role, as is the CHF (+0.85%) but the euro (+0.15%) and pound (+0.15%) are both a touch higher.  That said, we are definitely seeing emerging market currencies under pressure as they have nothing to do with tech and everything to do with the very obvious change in attitude regarding how the US is going to deal with smaller nations that don’t accede to US demands, especially regarding immigration.  So, MXN (-1.0%), COP (-1.1%), ZAR (-1.4%) and BRL (-0.6%) are all under significant pressure.  CE4 currencies, though, are not in the line of fire, so are little changed this morning.  

On the data front, remarkably, it almost seems an afterthought given what we just saw this weekend, but along with the Fed, BOC and ECB, we get PCE on Friday.

TodayNew Home Sales670K
TuesdayConsumer Confidence106.0
WednesdayBank of Canada Rate Decision3.0% (current 3.25%)
 FOMC Rate Decision4..5% (current 4.5%)
ThursdayECB Rate Decision2.75% (current 3.0%)
 Initial Claims220K
 Continuing Claims1885K
 Q4 GDP2.8%
FridayPersonal Income0.4%
 Personal Spending0.5%
 PCE0.3% (2.6% Y/Y)
 Core PCE0.2% (2.8% Y/Y)
 Chicago PMI40.0

Source: tradingeconomics.com

At this point, the central bank story is background noise, not the major theme, but by Wednesday I expect that all eyes will be on Chairman Powell as he describes the Fed’s thoughts at the press conference.  Of course, that assumes that there are no other political earthquakes, which may not be a very good assumption these days.  I think we are in a seismic zone for now.  

As to the dollar, if DeepSeek really is an Nvidia killer, then it is not hard to derive a scenario that says, US equity markets are going to decline, along with growth expectations.  The Fed will cut more aggressively, and the dollar will start to really fall as well.  I’m not forecasting that, just highlighting a possible, if not likely, scenario in the event the world believes the AI story is not going to be as expensive and profitable for the Mag7 as they thought last week.  Once again, the key is to hedge your risks, because as you learned this weekend, things change, and they can change quickly!

Good luck

Adf

More Than a Tweet

In Davos, the global elite
Were treated to more than a Tweet
The president spoke
And in one broad stroke
Explained that he won’t be discreet
 
For oil, he wants prices falling
For Europe, he said it’s appalling
That nations don’t pay
Enough to defray
The costs of the war they’re forestalling


If, prior to yesterday, European leaders weren’t sure how things were going to play out now that Mr Trump is back in office, they have a whole lot better understanding now.  I imagine that all their fears were realized when Trump spoke via video at the WEF meeting in Davos, Switzerland.  It’s funny, Argentine president Javier Milei has been calling out the globalist agenda since his election last year and Europe didn’t care and didn’t change their behavior.  I guess that makes sense because the European press would never allow the narrative to change for a minor player like that.  Alas, for the European narrative now, the US, one of their largest trading partners and the nation that insures their safety via NATO membership, is calling them out for their behaviors, whether it is the rarely discussed tariffs they impose on US imports, or the lack of funding for a war they claim is critical to continue in Ukraine, and they are suddenly aware they better reconsider their positions. 

It will be very interesting to watch if things change in Europe (I think they will) and how quickly these changes will come (that could take more time).  Arguably, the biggest problem the current  European leaders have is that there are already large segments of their populations that are unhappy and have been voting accordingly, whether for AfD in Germany, or the RN in France to name two.  Trump’s comments are going to only foment more support for those positions.  I suspect the elections upcoming in Europe are going to see a further rightward swing, or perhaps simply a further swing against the incumbents given what appears to be a significant amount of dissatisfaction amongst the electorate.  No matter your view of Trump’s policies, we all must recognize he is a remarkable political force!

Fifty basis points
Is now Japan’s new baseline
Can it go higher?

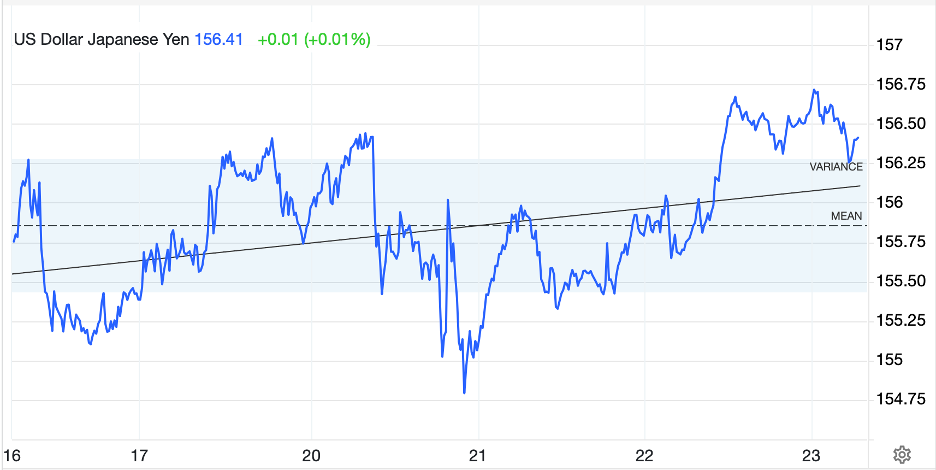
As widely expected, the BOJ hiked its base rate by 25bps last night to 0.50%, the highest levels since October 2008.  The immediate market response, as you can see in the chart below, was for the yen to rally (dollar decline) almost one full percent despite interest rate markets having fully priced in the hike.  However, as you can also see, the yen has given back virtually all those gains in the wake of Ueda-san’s press conference where he explained the BOJ was not “seriously behind the curve” which was taken as meaning that it will be a while before they move again.  

Source: tradingeconomics.com

While JGB yields did perk up 2bps on the session, it hardly seems like the start of a rout.  And, as I highlighted yesterday, the interest rate differential does not seem likely to have changed enough to alter investor plans. Going forward, I expect the yen to be entirely beholden to the dollar’s broad movement.  If, as I suspect, the market starts to price in a more hawkish Fed, USDJPY is likely to go back and test its highs from last summer.

Ok, let’s move on to the overnight market action.  Once again, US equities rallied yesterday, although at this hour (7:10), futures are essentially unchanged.  In Asia, Japanese shares shed early gains after the BOJ rate hike and Ueda presser and closed unchanged on the day.  However, both Hong Kong (+1.9%) and China (+0.8%) rallied on the news that Trump and Xi had a “friendly” conversation as traders and investors took that to mean that tariffs on Chinese goods were not coming right away.  As to the rest of Asia, once again there were both gainers (Korea, Taiwan, Australia) and laggards (India, Indonesia, Philippines) with the rest showing little net movement.  

In Europe, the picture is also mixed as the CAC (+0.9%) is leading the way higher as investors want to believe that Trump’s call for lower interest rates as well as lower oil prices will help the European economy, especially the luxury sector in France.  But elsewhere in Europe we see Germany (+0.3%) a bit higher while Spain (-0.4%) and the UK (-0.4%) are lagging with the former suffering from rising energy prices while the ongoing political mess in the UK has investors steering clear of the Kingdom for now.

In the bond market, Treasury yields are unchanged this morning, holding the recent 10bp bounce from the lows seen last week.  European sovereign yields are higher by 1bp to 2bps across the board, with activity quiet and we’ve already discussed JGBs.  

Ironically, after Trump’s call for lower oil prices, they are firmer this morning, up 0.6%, although in the broad scheme of things, relative to the recent price action, that is tantamount to unchanged.  Here is something to consider though, which is a little bit outside the box.  The Biden EO that cited the OCSLA of 1953 prohibited drilling across a series of areas including the Atlantic and Pacific Oceans as well as the Gulf of Mexico.  Now, what is one of the first things that Trump said?  He is renaming the Gulf of Mexico to the Gulf of America.  Does that nullify the EO?  (h/t Alyosha).  I’m sure that is a legal battle to be had, but it would be right in line with Trump’s MO.  It would also allow drilling to continue unabated there, which to my understanding, has the most fruitful potential new sites.

Meanwhile, in the metals markets, they are all rallying nicely this morning with gold (+0.85%) now just about 1% below the all-time high seen in October of $2826/oz.  There are many market technicians (and gold bugs) calling for a breakout to new highs, but there is a case to be made this remains a technical short squeeze into NY delivery next week.  However, gold has dragged both silver (+0.9%) and copper (+0.9%) along for the ride.

Finally, the dollar is under pressure this morning with the DXY (-0.5%) falling to its lowest level since mid-December.  Ironically, while the G10 weakness is widespread (EUR +0.7%, GBP +0.5%, AUD +0.5%) the yen, after the rate hike, is the massive underperformer.  In the EMG bloc, one of the biggest movers is CNY (+0.5%) which is clearly benefitting from that phone call, while SGD (+0.5%) is benefitting despite the MAS having eased monetary policy.  This is an indication of just how much of a dollar selling move this is this morning.  In fact, other than the yen’s modest decline, every other major counterpart currency is higher vs. the dollar today. 

On the data front, Flash PMI (exp 49.6 Manufacturing, 56.5 Services) leads off at 9:45 then at 10:00 we see Existing Home Sales (4.19M) and Michigan Sentiment (73.2).  With the Fed meeting next Tuesday and Wednesday, there are still no speakers.  Perhaps of more interest is the fact that we have not seen a single article from the Fed whisperer lately.  As the data is third tier this morning, I wouldn’t expect anything today either.  Too, next week there is limited data of note before the meeting so unless we see a narrative shift of substance, I imagine the Fed will do nothing next week and Powell will dodge any questions regarding the future.

For now, it is all Trump and his actions, comments and EOs.  And you can’t plan how to trade those.  Once again, this is why hedging is so important.

Good luck and good weekend

Adf
Trump’s Whirlwind

Markets have embraced
Trump’s whirlwind. Thus, Ueda
Is free to hike rates


Tonight, the BOJ is apparently set to hike rates by 25bps.  The market probability is essentially 100% and the key clue is that the Nikkei news organization wrote an article about it that was published after the first day of the BOJ’s two-day meeting.  At the December BOJ meeting, Ueda-san explained that if inflation remained at or above their 2.0% target (it has) and if there were no major ructions in markets after President Trump’s inauguration (there haven’t been), then the BOJ was likely to continue to move their policy rate toward what they believe is a neutral stance.  Currently, that neutral stance is mooted at 1.00%, so a 25bp hike tonight takes the overnight rate to 0.50%, somewhat closer.

With all this widely anticipated and markets pricing in the result, the key question is how what Ueda-san will say during his press conference that follows the meeting.  There are many who are looking for a so-called ‘dovish’ hike, where there is no indication of the timing of any further rate hikes and a benign view of the future.  Certainly, a look at the FX market, where the yen (unchanged today, -0.8% in the past week) doesn’t indicate a great deal of fear over a much tighter policy.

Source: tradingeconomics.com

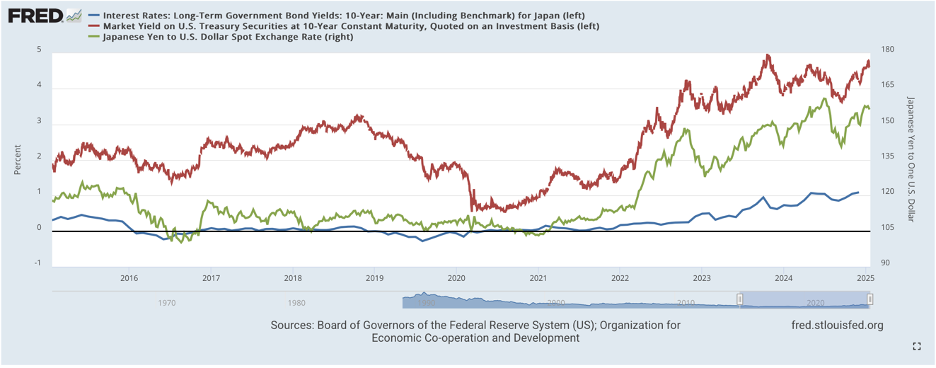
There has been a background narrative that explains the BOJ’s ongoing tightening is going to reach a point where Japanese investors are going to repatriate much of their overseas investment, driving a forceful upward move in the yen and having major negative impacts on risk assets around the world as liquidity retreats.  This is based on the idea that the Japanese are the largest exporters of capital in the world which is one of the key reasons equity markets are rallying everywhere, so if they bring that money home, that means they will sell their foreign equity holdings and buy yen.  While I believe this is a neatly wrapped idea, I would contend Japanese investment prospects are not yet near the same as in the US, so this idea may be premature.  In fact, a look at the chart below showing 10-year US Treasury and JGB yields overlaid with USDJPY indicates that the rate differential is nowhere near where it might need to be in order to encourage that type of behavior.  My take is absent some type of multilateral agreement to weaken the dollar, this will not happen organically.

Source: FRED database

In China, though communists rule
They favor the capital tool
Of equity bourses
And so, Xi endorses
A government stock buying pool

Elsewhere in the world, as we try to get outside the maelstrom that is Donald Trump, I couldn’t help but notice that, once again, Xi Jinping has called on his finance minions to do something, anything, to support the stock market.  And I cannot help but be struck by the irony of the Chinese Communist Party being so concerned about the situation in the most capitalistic institution of all.  The WSJ had an article discussing the latest measures that are on the board, including forcing encouraging insurance companies to increase the local equity portion of their portfolios and utilizing 30% of premium income to buy stocks.  This is on top of the PBOC reducing interest rates last year for companies that want to repurchase shares.

It continues to be very difficult for me to accept the idea that the Chinese are playing 4-D chess with long-term goals in mind while the US is playing checkers.  If that is the case, then the Chinese, or at least President Xi, is a really bad player.  His economy is under dramatic pressure because the property bubble he inflated has been shrinking for the past three years, undermining both the population’s wealth (property was their store of value) and confidence, while he ramps up more beggar thy neighbor trade policies at the same time the US has just elected a president whose middle name is Tariff.  Their population is shrinking because of the ‘foresight’ of their leadership to impose a one-child policy for two generations and while millions of people will risk their lives to immigrate to the US, people are looking to leave China.  Once again, I cannot look at this situation and conclude anything other than the CNY (-0.15%) is going to gradually decline all year long, and maybe not so gradually if pressure really builds.

Ok, let’s take a look at how markets are handling the latest set of Trumpian pronouncements and reactions by targets of his ire.  After yet another rally in the US, albeit on declining volumes so not as exciting as it might otherwise have been, Japanese shares rallied (+0.8%) as investors seem to believe that the interest rate hike tonight will be accompanied by a more dovish stance at the press conference.  Mainland Chinese shares (CSI 300 +0.2%) eked out a gain after the latest news discussed above, although Hong Kong shares (-0.4%) did not follow suit.  After all, the focus is on mainland shares.  The rest of the region was widely dispersed with gainers (Taiwan, Singapore, Philippines) and laggards (Korea, Australia, Thailand), many of these moves in excess of 1%.  It appears investors don’t know which way to turn yet given the speed of changes emanating from Washington.

In Europe, most bourses are modestly firmer (DAX +0.3%, CAC +0.5%) as we continue to hear more from ECB speakers that not only are rates going to be cut, but they are increasingly certain that they will achieve their inflation target.  Maybe they will.  As to US futures, at this hour (7:00) they are mixed to slightly softer with the NASDAQ (-0.4%) the laggard.

In the bond market, the decline in yields appears to be over, at least for now, as Treasuries (+3bps) continue to bounce from their recent lows at 4.54%.  As is almost always the case, this has carried European sovereign yields higher as well, by between 1bp and 3bps across the continent and UK and we saw JGB yields gain 1bp overnight.  I would contend there is still a great deal of uncertainty as to how the Trump administration is going to handle the conundrum of reducing inflation while expanding growth.  Outside of declining energy prices, which may be coming, it will be a tall task, and inquiring minds want to know.

Speaking of energy prices, oil (+0.35%) is edging higher after a lackluster session yesterday.  As with most markets, uncertainty is rife right now although this is clearly an area where Mr Trump is focused on expanding output.  NatGas (-0.3%) is a touch softer as forecasts for the end of the current Polar Vortex keep getting moved up. Metals markets are under some pressure this morning, with gold (-0.3%) backing away from that all-time high level and both silver and copper fading as well.  However, volumes remain light here implying not much interest overall.

Finally, the dollar is a touch stronger this morning, but there are few large movers in either the G10 or EMG blocs.  In fact, every G10 currency is within 0.2% of yesterday’s closing levels and none of them are at extremes.  The biggest loser today is ZAR (-0.6%) which seems to be responding to the precious metals complex backing off a bit overnight.  It remains very difficult to get a read on the dollar with all the other things ongoing.  As it happens, this is one market that has not received any Trumpian attention at all…yet.

We finally have a smattering of data this morning with the weekly Initial (exp 220K) and Continuing (1860K) Claims to be followed by the EIA’s oil inventory data where it appears a modest net build across products is forecast.  With the Fed quiet, and very little focus on Powell and company right now, today looks to be shaping up as another equity focused day with the dollar likely taking its cues there.  While we never know what will hit the tape these days, absent a new surprise vector, there is no reason to look for significant movement today at all.

Good luck

Adf

Cha-Ching

It wasn’t all that long ago
When data would headline the show
As traders would wait
For each release date
And then recount trades blow-by-blow
 
But now there is only one thing
That matters, Trump’s latest cha-ching
He speaks off the cuff
Which makes it quite tough
To plan from Berlin to Beijing


As the morning of the third day of President Trump’s second term dawns, it is nigh on impossible to keep up with all the things he is doing and their actual and potential impacts on markets going forward.  Arguably, the main FX market driver continues to be the tariff discussion and the question of if, and when, he may be imposing said tariffs. You will recall that on Monday, the mere absence of his reaffirmation that tariffs were coming resulted in a major dollar decline, which was subsequently reversed when he finally mentioned them in the evening.

Of course, those were aimed at Canada and Mexico with China, significantly, left out of the mix.  Last night he remedied that situation declaring that China and Europe were also in his sights for tariffs, although he mooted a 10% initial level, far below the 60% he discussed during the election campaign.  Once again, I would argue it is not possible at this point to make any serious market prognostications based on the lack of information as to the products to be impacted, the exact timing and what he is seeking in return for a reduction or elimination of those threats. 

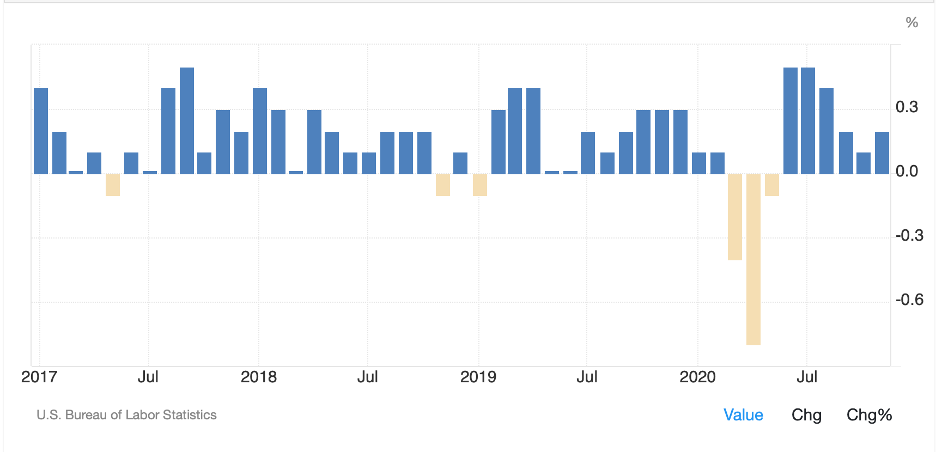
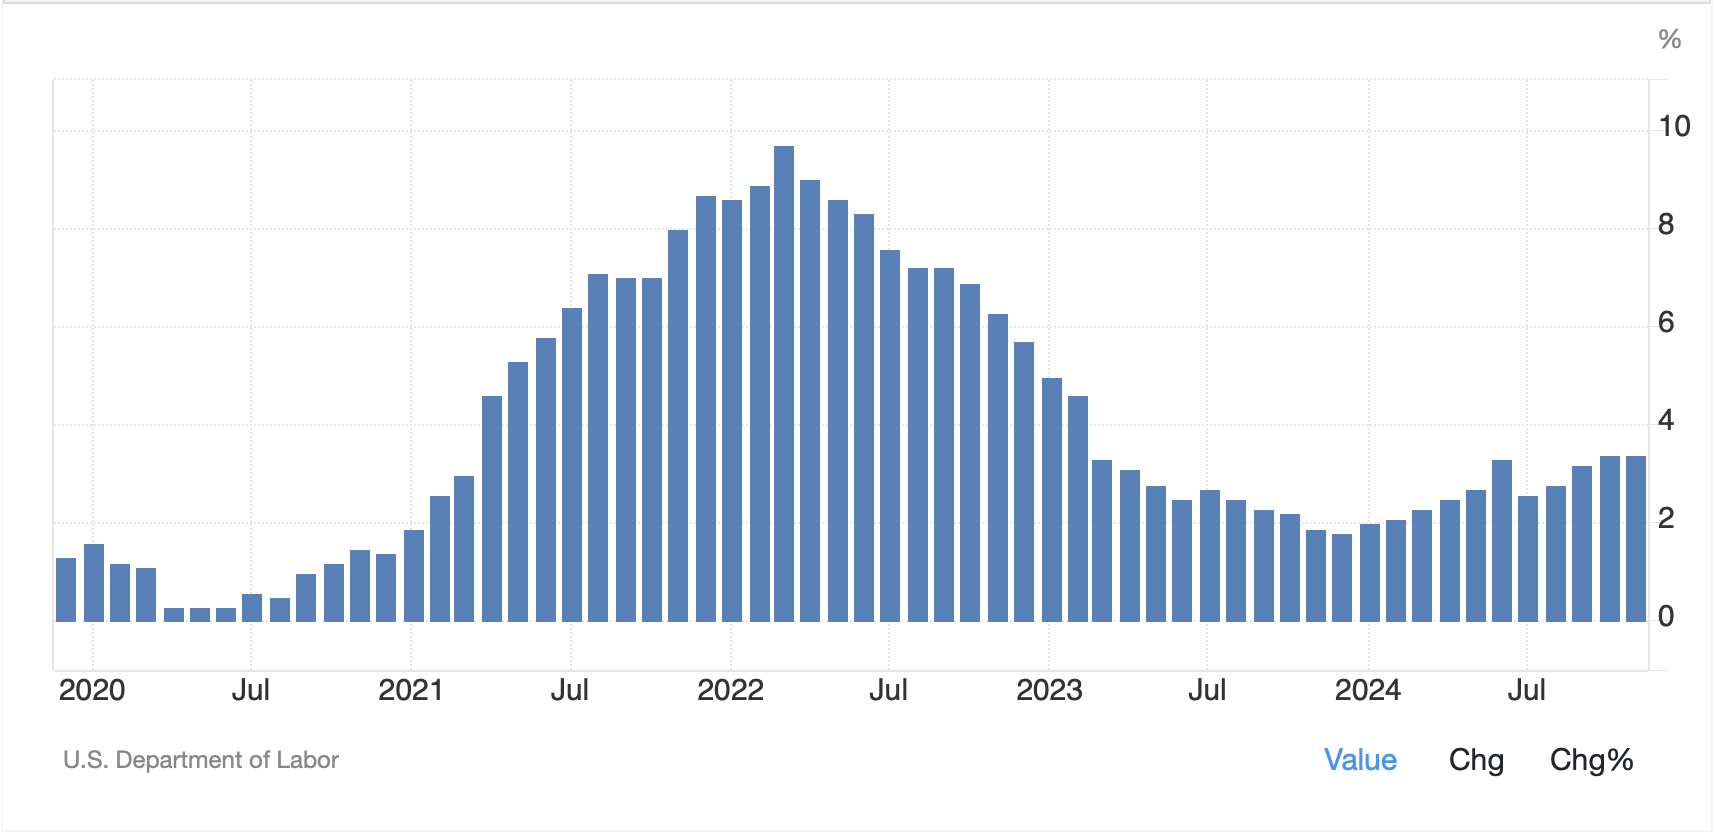
At the same time, I find the strait-laced approach that ‘tariffs are bad and a tax on Americans which will lead to inflation’ which continues to be promulgated by orthodox academic economists, typically from a left-leaning lens, to be almost comical at this point.  We all should remember that during his first term, he imposed many tariffs, especially on China, and yet inflation was quiescent, with CPI averaging 1.9% during the entire term.  This is not to say things will be identical in 2024 and beyond, just that in fairness, his record demonstrates that tariffs are not necessarily inflationary.  Below is a chart of the monthly readings showing only 8 of the 48 months he was in office that headline CPI rose more than 0.3%, implying the rest of the time it was at or below that level.  Those were the days.

Source: tradingeconomics.com

Beyond the tariff discussion, the bulk of his time currently seems to be focused on the size of the government workforce, which is certainly due to shrink, and the border and immigration.  What will market impacts of these issues be like?  For the former, I would suggest that less government employees will lead to less government interference in the workplace, and arguably, be beneficial for productivity if nothing else.  As to the latter, it is a much more difficult problem to solve as there will likely be reductions in both labor supply but also demand for services like housing.  It seems quite possible that there will be a reordering of the economy, although it is unclear if that will lead to a net positive or negative from an overall growth perspective, or at least an inflation perspective.  Growth, of course, is the product of the size of the workforce * productivity, so a smaller workforce, if that is the outcome, will weigh on topline GDP, but not necessarily on per capita GDP.  As I mentioned above, there are far more unknowns than knowns at this time, so forecasting the future is a mug’s game.

As we keep in mind that nobody knows anything about the future, let’s take a look at what happened overnight amid all the knee-jerk reactions to the latest Trump comments.

Yesterday saw US equity markets continue in their winning ways seemingly trying to achieve new highs.  In Asia, the follow on was broad with Japan (+1.6%), Korea (+1.2%) and India (+0.75%) all nicely higher although Chinese shares suffered.  This should be no surprise now that Trump has squarely put China on the tariff map again, but there are other things happening here as well.  Perhaps the most confusing is the word that financial workers would be seeing pay cuts of up to 50% as President Xi no longer sees them as critical workers for the nation.  I’m sure this will help rebalance the consumption-production equation…not!  So, it should be no real surprise that both mainland (-0.9%) and Hong Kong (-1.6%) shares were under pressure.

Not so the case in Europe where the DAX (+1.2%) is leading the way higher although gains are universal, after comments from several ECB bankers that rate cuts were coming next week and likely will continue during the year.  While inflation remains the sole ECB mandate, the weak economic situation plus the threat of tariffs certainly has Madame Lagarde under pressure to do something to support the economy there.  Finally, it should be no surprise that US futures are nicely higher this morning with the NASDAQ (+0.9%) leading the way at this hour (7:15).

In the bond market, yields have stabilized after their recent 20bp decline in the past week and have edged higher by 1bp this morning.  The same price action has been seen in Europe where sovereign yields are little changed to higher by 2bps across the continent.  As to JGB yields, they, too, were unchanged on the session despite an increase in chatter that the BOJ is set to hike rates on Friday.

In the commodity space, gold continues to rally and is now within 1% of its all-time highs set back in late October.  This has dragged silver along for the ride, and copper, in truth, although today copper is ceding -0.6%.  however, a look at the price movement over the past month shows all three metals nicely higher (Au +5.3%, Ag +3.7%, Cu +6.2%).  Oil (0.0%) is flat today as it consolidates its recent retracement.  Recall, for the first two weeks of the year, it rallied sharply, up nearly $10/bbl, although it seems that may have been more of a short squeeze than a fundamental shift in thinking.  Since then, it has given back about $4/bbl as market participants try to decide if the theorized Trumpian demand increase will offset the supply increase of drill, baby, drill.

Finally, the dollar is little changed this morning overall.  That said, net over the past week, it has given back about 1.5% although that was from recent highs.  This price movement feels far more like consolidation than a change in view especially given that the tariff story remains front and center.  Now, it is possible that the market pushed the dollar higher ahead of the inauguration on a ‘buy the rumor’ idea and is now selling the news, but it remains difficult to see what has changed in the US economy relative to its counterparts that would encourage a change in rate expectations.  As to today’s movement, there are more gainers than laggards vs. the dollar, but nothing of any real significance.

On the data front, the only US data is the Leading Indicators (exp 0.0%) so traders will continue to look at corporate earnings and listen to the president for the next pronouncement.  I assure you; I have no idea what that will entail.  Once again, I am a strong proponent of being hedged because the one thing we have learned lately is that markets can turn on a dime.

Good luck

adf

A Trump Trope

For one day the markets expected
That tariffs were roundly rejected
But late yesterday
Trump said the delay
Was short with two nations affected
 
The upshot is all of that hope
That saw the buck slide down a slope
Has largely reversed
As dollar shorts cursed
That tariffs are not a Trump trope


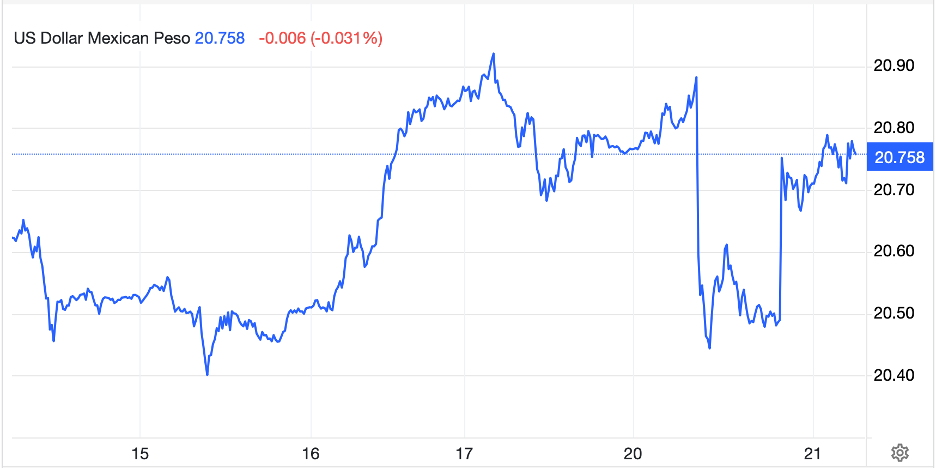
This poet feels vindicated in not trying to anticipate what President Trump is going to do that might impact markets after yesterday’s events.  Early in the day there was a story that tariffs would be delayed and were seen as negotiating tools, not punishment.  FX traders (mis)read the room and sold the dollar aggressively, with the greenback suffering declines of more than 1% against some currencies, notably MXN.  Then, Mr Trump was inaugurated, made a speech, where he promised to make many changes within the operating system of the US, signed a load of Executive Orders and mentioned in a press conference much later in the evening that 25% tariffs on Mexico and Canada would be coming on February 1st.  The chart of USDMXN below shows the price action with the peso having given back the bulk of yesterday’s gains.

Source: tradingeconomics.com

Once again, if we learned nothing from Trump’s first term, it is that anticipation of his moves is a very fraught and dangerous way to manage market risk.  Now, will those tariffs actually be implemented?  Will they be universal if they are?  Or does he anticipate changes from behavior by both nations in the next 10 days?  The answer is, nobody knows, probably not even Trump.  The upshot is if you have financial market risk, hedging is critical to maintaining acceptable outcomes.  And, oh by the way, look for implied volatility of all financial products to rise as market makers also have no idea what is going to happen so will require hedgers to pay up for protection.

In Davos, the world’s glitterati
Are meeting, and though they are haughty
They’re losing their splendor
And edicts they render
Are sinking in value like zloty

While there is a great deal more that President Trump has promised to do immediately, the bulk of it seems likely to only have potential longer-term impacts on financial markets.  Meanwhile, in Davos, the World Economic Forum is under way and the main message that I can discern from what I’ve read is that, the members really liked it when everybody listened to what they said and are now really unhappy that President Trump is essentially raining on their parade and devaluing their views and comments.  With Trump withdrawing from the Paris Climate Accords and the WHO, key global initiatives are severely hamstrung, which means the WEF is less important.  And all their pronouncements regarding the need free trade and global cooperation has far less impact if the US has decided to focus on itself rather than the world at large.  My forecast is that by the end of Mr Trump’s term, the WEF will be a sideshow, not a headline event.

And really, at this point, that is pretty much what is happening.  Yes, UK Unemployment rose to 4.4% while wages rose 5.6%, but this has simply put the BOE in a tougher spot.  The Old Lady has only an inflation mandate, but if Unemployment is rising, they cannot ignore that, and the market is now far more convinced (82% probability) that they will be cutting the base rate by 25bps at their meeting the first week of February.  While the pound (-0.8%) is lower this morning, that seems much more about the dollar’s overall strength than this weaker than expected data point as since the release, the pound has fallen only another 0.2%.

So, let’s look around the world and see how markets responded to Trump 2.0.  Equity markets in Asia were largely in the green as neither Japan nor China were mentioned on the immediate tariff list, although the late-night proclamation regarding Canada and Mexico implies that this story has not yet been completed.  Nonetheless, gains in Japan (+0.3%), Hong Kong (+0.9%) and China (+0.1%) showed the way for most of the region with only India (-1.6%) really suffering during the session on a variety of fears regarding tariffs and interest rates despite no mentions by Trump.  In Europe, only Spain’s IBEX (-0.5%) is showing any movement of note and that appears to be specific to some slightly softer than expected corporate earnings results.  Surprisingly, Germany and the rest of the continent are little changed, as is the UK.  As to US futures, at this hour (7:10) they are pointing higher by about 0.4% in anticipation of more earnings reports today and a generally positive attitude from the new president.

In the bond market, Treasury yields have fallen 5bps overnight, seemingly on the idea that because Trump announced the government would do all it can to reduce prices, and therefore inflation, it would magically work.  While I am optimistic things will get better, that is a heavy lift in my opinion and the Fed will need to be far more emphatic on its inflation fighting actions to see this through.  In Europe, yields are basically unchanged across the board and similarly, there was no movement in Asia overnight.  Once again, the world is looking toward the US for directional cues.

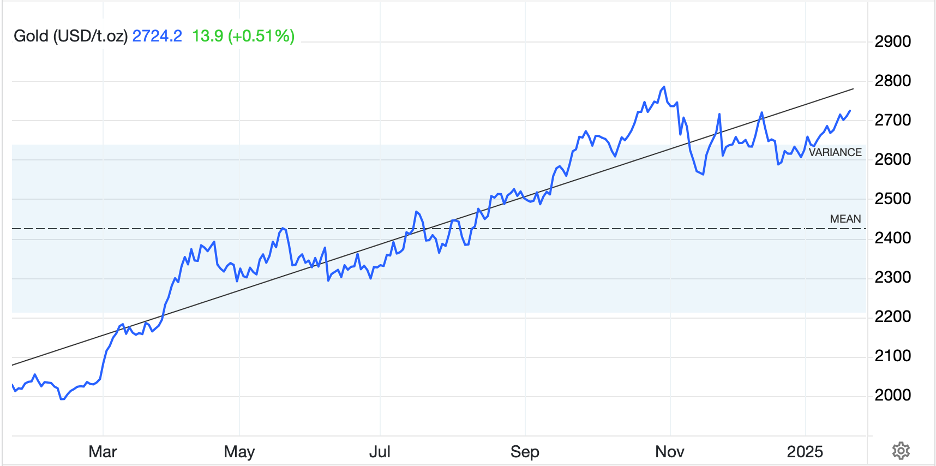
In the commodity markets, oil (-1.3%) is sliding back as Trump’s promise to open up more drilling spaces on federal land as well as his overall encouragement of ‘drill, baby, drill’ has traders concerned that supply is going to come around more quickly than demand.  Last January I wrote about my view that there is plenty of oil and it is merely political will that prevents it from being accessed.  I have a feeling that is what we are going to begin to see, a change in that political will which means potentially lower prices and increased demand accordingly.  In the metals markets, gold (+0.5%) is continuing to climb as we approach month end.  There are many in this market who believe the technical picture (see chart below) is pointing to a break to new all-time highs soon.  However another, and perhaps more accurate narrative, is that there is an arbitrage between the NY, London and Shanghai exchanges for physical metal and metal is flowing into NY for delivery which begins next Friday. (H/T Alyosha)

Source: tradingeconomics.com

As to the other metals, they are little changed this morning.

Finally, as mentioned at the top, the dollar is much firmer across the board this morning with the peso and NOK (-1.0%) leading the way lower although most currencies seem to be down by at least -0.5%.  (Yes, PLN is weaker by -0.6%).  This is all dollar-driven with no other idiosyncrasies of note right now.  We shall see how this evolves over time.

On the data front, the rest of the week looks like the following:

WednesdayLeading Indicators0.0%
ThursdayInitial Claims218K
 Continuing Claims1860K
FridayFlash Manufacturing PMI49.6
 Flash Services PMI56.6
 Existing Home Sales4.16M
 Michigan Sentiment73.2

Source: tradingeconomics.com

The Fed is in its quiet period so with the lack of data, I suspect that markets will have heightened awareness to every Trump pronouncement with volatility the new normal.  Remember, consistency is not his strong suit, at least when it comes to commentary about how he may respond to things.

From the market’s perspective, as long as tariffs are still seen as the likely outcome, look for the dollar to remain well bid while equities will see a mixed performance depending on the nature of the company/industry with importers likely suffering.  

Good luck

Adf

Trump 2.0

Today begins Trump 2.0
And pundits are trying to show
Their ideas are sound
As how he’ll redound
On policies he will bestow
 
But this poet can’t comprehend
How anyone thinks what they’ve penned
Is likely to be,
To any degree,
Correct. ‘Stead, let’s look at the trend


As Donald Trump prepares to take the oath of office today, there has been a non-stop barrage of pundits putting forth their views as to how policy proposals that were made during the campaign, and even since the election, are going to impact the economy as well as equity, bond and FX markets.  But I would take exception to all these as, if we learned nothing else from Trump’s first term in office, we have no idea how he may try to do the things he says he is going to do.  Are tariffs a funding process?  Are they negotiating tactics?  Are they punishment?  Since we have no idea at this point (all three of those ideas have been floated by “insiders” and pundits), how can we meaningfully forecast the impact tariffs may have going forward?  So, I won’t even try.

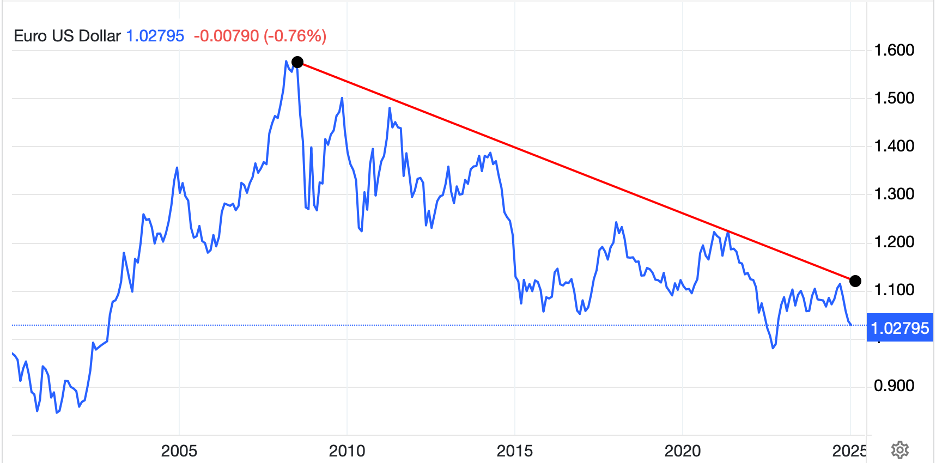
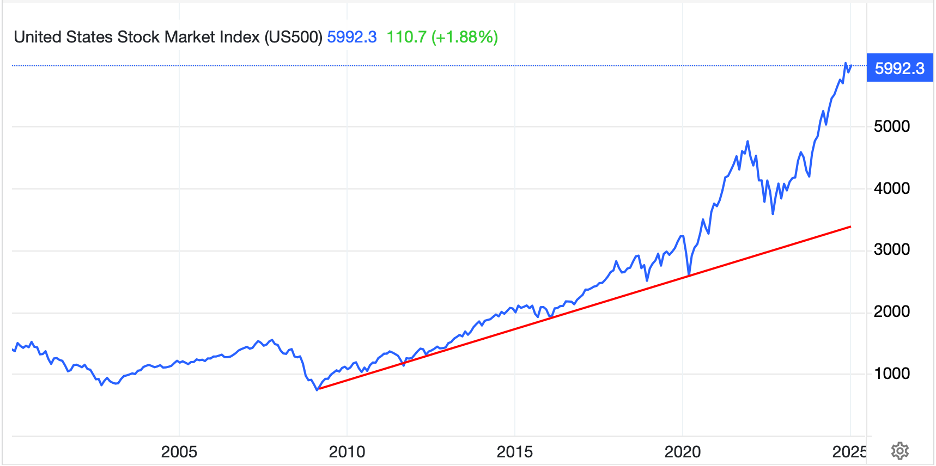
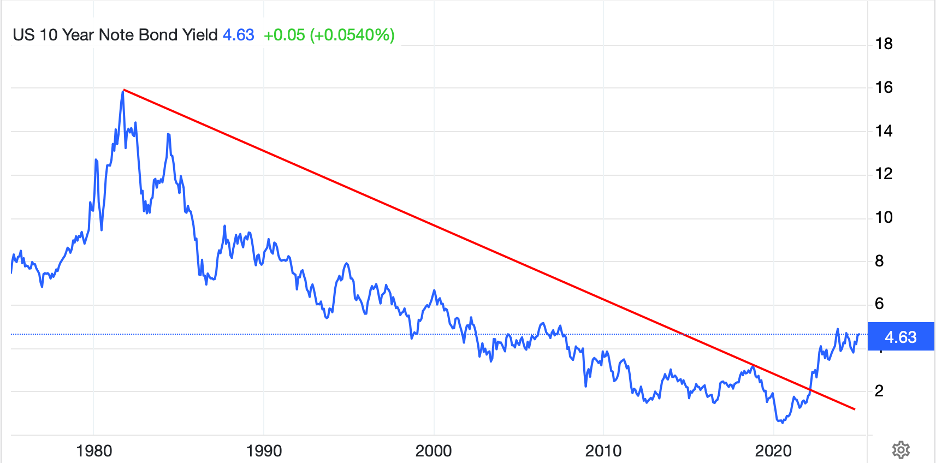
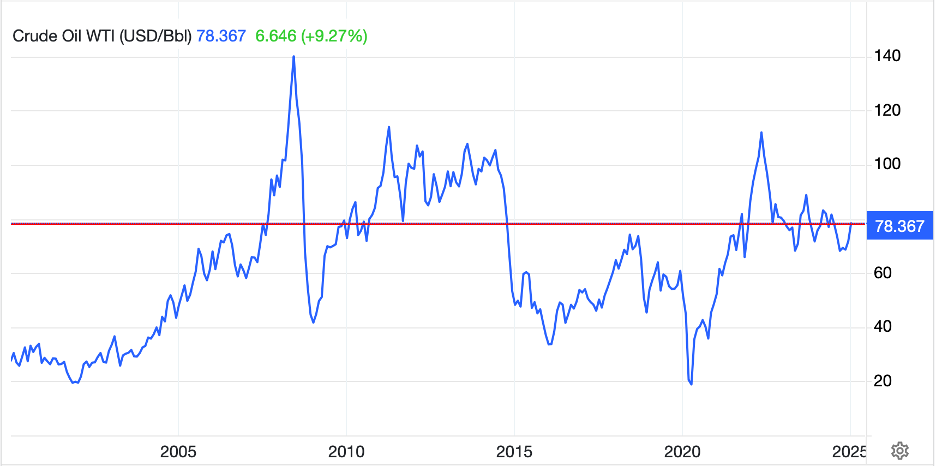
Rather, I think there is much to be learned from looking at the long-term trends in markets and perhaps trying to come up with reasons that these trends may be changing, or not, going forward.  As such, take a look at the charts below, all from tradingeconomics.com, where I have tried to highlight the long-term trend in the dollar (EURUSD), the S&P 500, 10-Year Treasury Notes, oil and gold.

My first observation is that over the past twenty-five years, oil has traded both higher and lower with no discernible direction.  Certainly, we are higher now than 25 years ago, but we have been both much higher and lower in the interim.  Now, if Trump is successful at freeing up more drilling opportunities, removing the offshore drilling ban that Biden imposed last week, and reducing the regulatory structure such that the cost of drilling declines, my take is increased supply will result in some downward pressure.  As well, if he is successful at bringing an end to the Ukraine war, it seems probable that Russian oil may no longer be sanctioned, and that, too, would pressure prices lower.  But will he impose tariffs on Canada, a key source of sour crude used to refine diesel?  That could easily pressure prices higher.  And what of Venezuela?  As I said, no way to know.  In the end, my take is that the most likely outcome is that oil will continue to demonstrate its inherent price volatility given its price inelasticity.  I think you can equally make the case for $50 oil as well as $100 oil based on many idiosyncratic issues that have nothing to do with Trump.

The only noteworthy change we have seen is in 10-Year Treasury yields, which after a 40-year downtrend following the back-to-back recessions in 1980-1982 and Fed Chair Volcker’s policy tightening, look very clearly to have reversed course.  I am not the first to notice this but believe that it is an important feature of markets going forward.  There are virtually two generations of traders and investors who have only ever seen interest rates decline and have created their mental investment models on that underlying thesis.  If the future is going to bring about higher interest rates over time (and given my view that inflation is not going to disappear and that will be a key driving force), then investment models in a higher inflation, higher yield environment are going to be different than what we have seen up through 2022.  

One of the keys is that the idea behind the 60/40 portfolio, where declines in stock prices were offset by rises in bond prices, turns out to only really be true in a low inflation environment, sub 2.5%.  If inflation is going to run at 3.5% – 4.5% going forward, then all the strategies that incorporated that 60/40 basis are going to have an awfully difficult time, again, regardless of what Trump does.  The one caveat here is if he is successful in driving inflation back to that <2.0% level, but that seems highly unlikely in the near term given how sticky inflation has proven to be even without any new policies.

Now, if we look at the dollar, that trend has been very consistent and remains in place with the dollar seemingly set to continue to appreciate.  Given Trump’s stated desire to reshore American manufacturing and reduce the trade deficit, he almost certainly would like to see the dollar decline.  However, at this point, it’s not clear what policies are going to drive that.  Historically, loose monetary and tight fiscal policy will weaken a currency, and that could well be what we see, except that is likely to create a burst of inflation before the tight fiscal policy reins that in.  And you know as well as I that Trump will be very displeased with that outcome.

It is certainly possible that the Treasury could intervene to weaken the dollar, but that is also something that is exceedingly rare in this country.  Perhaps the most likely situation here would be a Mar-a Lago (?) Accord, or something like that akin to the Plaza Accord of 1985, where the G7 at the time all agreed that the dollar needed to decline.  Now, on the one hand, given the weakness in the other G10 economies currently when compared to the US, my take is those nations are pretty happy to have weak currencies to help support their domestic industries.  On the other hand, I suspect the EMG bloc who have funded themselves in USD are really interested in seeing a weaker dollar to help them get easier access to dollars to service and repay their debt.  My take is that until there is a definitive policy pronouncement, and this will require something like that as quiet policy adjustments are likely to be missed by the FX market, this trend will remain intact.

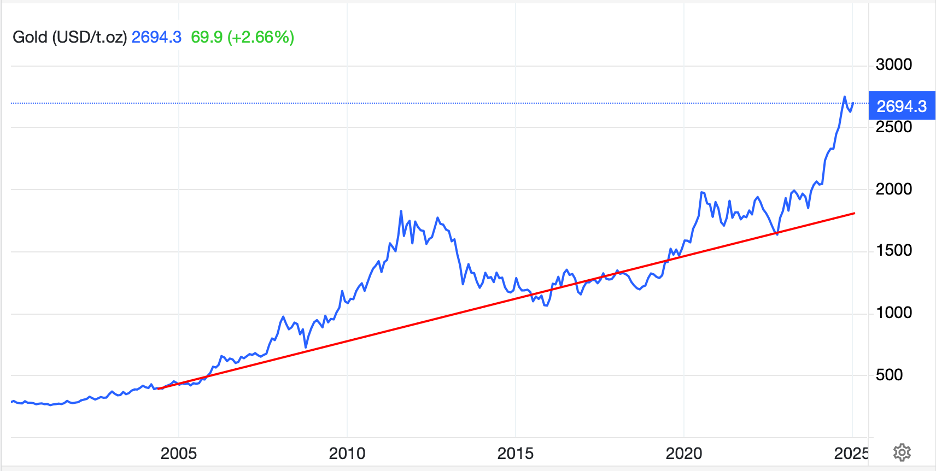
Finally, a look at both equities and gold shows basically the same chart, with both showing accelerating price increases and both now significantly above their long-term trend lines.  The question, of course, is can this continue?  Keynes was reputed to have told us that markets can remain irrational longer than you can remain solvent, implying just because market pricing doesn’t make fundamental sense doesn’t mean it cannot continue further.  But in the end, trees don’t grow to the sky, and corrections in these markets seem somewhat overdue.  Consider the S&P 500 chart, where we see the sharp decline in 2022.  Many remember that as the worst market since the GFC crash, and yet on the chart, it looks like a modest correction.  Consider also, that if the market were to decline to the trend line I have drawn, it would be nearly a 50% correction, and that just puts it back on trend!  Again, volatility seems the watchword going forward, but until we see something that is going to change opinions, the trend in both stocks and gold seems higher.

OK, as we await the official change in presidency here, let’s review the overnight price action, which was generally positive following Friday’s US equity rally.  Remember, too, it is MLK Day, and markets are closed in the US.

Asian markets saw broad gains with the Nikkei (+1.2%) and Hang Seng (+1.75%) leading the way while mainland shares (+0.45%) lagged but were still in the green.  Away from the major markets, there were far more gainers than laggards, but the biggest moves were on the order of 0.4%, nothing of real note.  Positive Japanese data was the driver in Tokyo (Machinery Orders +3.4%) while HK and Chinese shares benefitted from the news that Presidents Trump and Xi spoke, hopefully in a prelude to less tension.  In Europe, markets are essentially unchanged across the board this morning as it seems investors cannot discern whether Mr Trump will be beneficial for the continent or not.  Certainly, I continue to read about a number of European leaders who are unhappy at the prospects of a Trump presidency (specifically PM Starmer who has ostensibly said the US-UK relationship is destined to diminish).  While that may be true, my take is it will not help the UK very much.  And, while US markets are closed today, US futures are pointing modestly higher this morning.

In the bond market, yields are edging higher in Europe, up between 1bp and 2bps on the continent while UK Gilt yields are higher by 3bps.  Overnight saw JGB yields slip 1bp and, of course, with banks closed in the US, Treasury yields are unchanged in the cash market.  However, bond futures are pointing to a 1bp rise as well.

In the commodity markets, oil is little changed on the day while NatGas (-4.4% after a -6.0% decline on Friday) is falling on news that weather models, which had been calling for another cold spell in February, have changed and are now saying temperatures will be milder then.  In the metals markets, gold (+0.3%) is edging higher while both silver (-0.3%) and copper (-0.4%) are slipping a touch, but given their inherent volatility, arguably these are unchanged on the day.

Finally, the dollar is under some pressure this morning with then euro (+0.5%) leading the G10 higher although similar sized gains are seen across the board with only JPY (0.0%) failing to go along for the ride.  EMG currencies are also picking up led by HUF (+2.0%) as it seems there is excitement in Hungary regarding the inauguration as PM Orban seems to share many of President Trump’s views on various geopolitical issues.  But CZK (+0.9%) and PLN (+0.6%) are also rallying alongside KRW (+0.5%), although MXN (-0.3%) seems to be showing concerns regarding how that relationship will evolve.  Certainly, as I mentioned above, President Trump will not be unhappy to see the dollar slide a little, but I don’t see this as the beginning of a new trend.

With no data today, and a light week in general, and given how long this missive has already become, I will lay out the data releases tomorrow.  Today, all eyes will be on the ~200 Executive Orders President Trump will sign and I expect it will take a little time to digest it all, so we will see how things really begin tomorrow.

Good luck

Adf

In the “Know”

According to those in the “know”
It’s certain that tariffs will grow
But now some are saying
The timing is straying
From instant to something more slow


In what has been a generally quiet evening in the markets, the story that President-elect Trump is considering imposing all those tariffs on a gradual basis, rather than instantaneously when he is inaugurated, was taken as a bullish sign by investors.  This seems to have been the driving force behind yesterday afternoon’s modest rebound in equity markets as the current market narrative is tariffs = bad, no tariffs = good.  From what I can determine, these are anonymous comments not directly attributed to Trump or his incoming economics team and, in fact, Trump denied that possibility.

But the market impact was real as not only did equity markets rebound a bit, but the dollar, which had soared yesterday, has given back some of those gains and is modestly lower this morning.  If we learned nothing else from President Trump’s first term, it should be clear that there is frequently a great deal of bombast emanating from the White House and responding to each and every comment is a recipe for exhaustion and disaster. While this cannot be ruled out, if one were to ascribe a Trumpian gospel it would be that tariffs are beautiful so slow-rolling them doesn’t really accord with that view.  I guess we will all find out more next week.

Now, turning to data releases
This week its inflation showpieces
Today’s PPI
Is tipped to be high
While Wednesday the core rate increases

Away from that story, though, there has been little else of note overnight.  As such, let’s focus on the PPI data this morning and CPI tomorrow as they ought to help inform our views on the Fed’s actions going forward. Expectations are for headline to rise to 3.4% Y/Y while core jumps to 3.8% Y/Y.  It is difficult to look at a chart of these readings and not conclude that the bottom is in and the trend is higher.

Source: tradingeconomics.com

This is not to say that we are going to see price rises like we did back in 2022 as the waves of Covid spending washed through the economy, but the Fed’s mantra that inflation is going to head back to 2.0% over time is not obvious either.  In fact, if I were a betting man, I would estimate that we are likely to continue to see inflation run between 3.5% and 4.5% for the foreseeable future.  There is just nothing around to prevent that in the short run.  Now, if we do see significant productivity enhancements, those numbers will decline, but my take is the best opportunity for that, more effective and widespread use of AI, is still several years away.

Remember, too, that the government writ large, whether headed by R’s or D’s is all-in on inflation as it is the only opportunity they have to reduce the real value of the outstanding government debt.  Perhaps the Trump administration will take a different tack, but it is not clear they will be able to do so.  The only time inflation is a concern is when it becomes a political liability.  For the two decades leading up to Covid, it was not a daily concern of the population and central banks around the world were terrified of deflation!  In fact, there are so many comments by folks like Yellen, Bernanke and other Fed governors and presidents decrying the fact that their key regret was not getting inflation high enough, it is difficult to count them.  But as evidenced by the chart below of CPI, we no longer live in that world.

Source: tradingeconomics.com

Summing up, the current situation is that inflation has likely bottomed, the government continues to run massive fiscal deficits and given the $36 trillion in debt outstanding, the government needs to reduce the interest rate they pay on their debt.  If pressed, I would expect that we will see synthetic yield curve control (YCC) enabled by regulatory changes requiring banks and insurance companies to own a greater percentage of Treasury notes and bonds in their portfolios to ensure there is sufficient demand for issuance.  That can have the effect of turning long-term real yields negative, exactly the outcome the government wants. Remember, from 1944-1951, the Fed enacted YCC directly and it worked wonders in reducing the debt/GDP ratio.  They know this tool and will not be afraid to use it.

Ok, let’s take a look at what little action there was overnight.  After yesterday’s late rebound resulted in a mixed close with the NASDAQ still lower but the other two indices closing in the green, Asian equity markets also had a mixed picture.  The Nikkei (-1.8%) was the laggard, seemingly following last week’s US market movement after reopening from a holiday weekend.  However, Chinese shares (Hang Seng +1.8%, CSI 300 +2.6%) rallied sharply on the latest news that more Chinese stimulus was coming soon.  This time the Ministry of Commerce claimed they would be looking to boost consumption this year, but neglected to mention how they will do so.  Regardless, investors liked the story and when added to the gradual tariff story, it was all green.

European bourses are also in fine fettle this morning with gains across the board (CAC +1.2%, DAX +0.8%, IBEX +0.6%) and even the FTSE 100 (+0.1%) has managed to rally a bit.  This price movement, and that of the rest of Asia where gains were seen, seems all to be a piece with the slower tariff story discussed above.  As to US futures markets, at this hour (6:40), they are pointing modestly higher, 0.45%.

In the bond market, the only place where yields have moved significantly today is in Japan, where JGB yields have jumped 5bps and are now at their highest point since February 2011.  This followed comments from Deputy Governor Himino that the board was likely to debate a rate hike at their meeting next week and market pricing has a 60% probability priced in for the move.  There is much talk of wage increases in Japan, and Himino-san also raised questions about what the Trump administration will do and how it will impact yields.  Interestingly, despite the more hawkish rhetoric, the yen (-0.25%) actually declined today, not necessarily what you would expect.  As to the rest of the bond market, everything is within 1bp of Monday’s closing levels.

In the commodity markets, oil (-0.3%), which has been rocking lately on the increased Russia sanctions, is consolidating this morning although remains higher by nearly 6% this week and 12% in the past month. (As an aside, I don’t understand the Biden theory that sanctions driving up prices is going to be a detriment to Putin as he will make up for the loss of volume with higher prices, but then, I’m not a politician.). Meanwhile, NatGas (-3.2%) has backed off its recent highs as storage concerns ebb, although the ongoing cold weather appears to have the opportunity to push prices higher again.  As well, the latest dunkelflaute throughout Europe is driving demand for LNG.  In the metals markets, yesterday’s declines have been arrested, and we are basically unchanged this morning.

Finally, the dollar is mixed this morning, edging higher against some G10 counterparts (GBP -0.3%, JPY -0.4%) but sliding against others (NZD +0.6%).  Versus the EMG bloc, again the picture is mixed today with gainers (ZAR +0.4%, KRW +0.3%) and laggards (CZK -0.2%) although overall, I would argue the dollar is a touch softer on the back of the gradual tariff story.

On the data front, this morning’s PPI data (exp 0.3% M/M, 3.4% Y/Y) headline and (0.3% M/M, 3.8% Y/Y) core is the extent of what is to come.  Interestingly, the NFIB Index jumped to 105.1, the highest print since October 2018, as small businesses are clearly excited about the prospects of a Trump administration and the promised regulatory cuts.

Right now, both the dollar and Treasury yields are pushing to levels that have caused market problems in the past.  If these trends continue, be prepared for some more significant price action.  That could manifest as a sharp decline in equity markets, or some surprising Fed activity as they try to address any potential market structural problems that may arise.  But there is nothing due to stop the trends right now.

Good luck

Adf

No Reprieve

The scuttlebutt had it correct
Trudeau hit the button, eject
But he’s yet to leave
And there’s no reprieve
His legacy will be neglect


Those reports from yesterday morning were spot on as around 11:00am, PM Trudeau announced that he would, in fact, be stepping down.  There is a somewhat convoluted process involved which sees the Canadian Parliament prorogued until late March, while the ruling Liberal party seeks a new leader.  At that point, Parliament will be called back into session, and it seems likely a vote of no confidence will be held.  Assuming that vote goes against the new leader, an election will be called.  No matter how long the Liberals delay this process, and you can bet they will hang on for as long as possible, by October, an election is required.  As well, currently all things point to the Conservative party led by Pierre Poilievre winning that election and taking power with a significant majority.  Obviously, Poilievre would like the election to happen sooner, rather than later, but it seems hard to believe now, regardless of the new Liberal leader, that the Conservatives will fail to win.

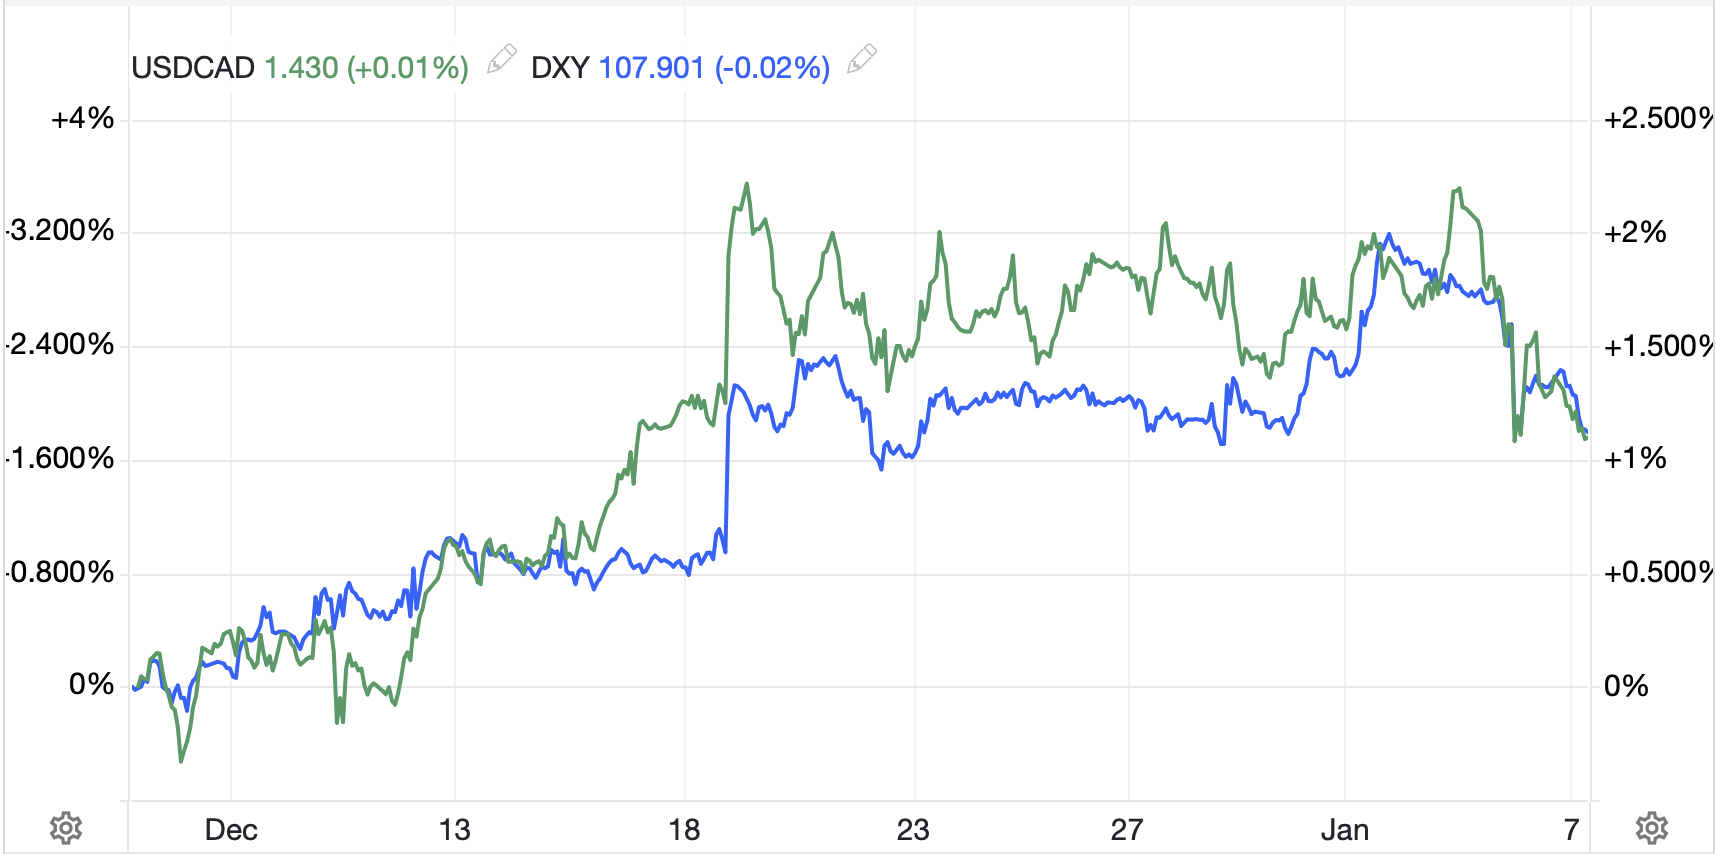
The market impact of this news needs to be separated from the broader drivers, but as I showed yesterday, CAD had been weakening more quickly than the dollar writ large, and now it seems to be moving back into line with the general movement as per the below chart showing the movements between the DXY and USDCAD right on top of each other. 

Source: tradingeconomics.com

My sense is that Canada has now had its day in the sun and will soon retreat to the background of most market consciousness going forward.  After all, despite it being our largest trading counterparty, it has a small population and small economy with limited impact on the global situation.

Certification’s complete
And Trump, in two weeks, takes his seat
Between now and then
Again and again
Prepare for a surfeit of Tweet(s)

In truth, aside from the Canadian story, the bulk of the discussion in both financial and political circles is focused on exactly what President Trump will do when he is inaugurated on the 20th.  The biggest financial discussion revolves around tariffs and exactly how he plans to utilize them going forward.  For the surface thinkers, tariffs are an unadulterated bad policy with significant negative consequences.  As well, the idea that tariffs = higher dollar is axiomatic to these people.  In fact, yesterday’s reversal in the dollar’s recent substantial gains was based entirely on a story that despite some campaign rhetoric of large tariffs imposed on Day 1 of the new Trump administration, in fact things would be far more nuanced.

While I understand the economic case behind tariffs driving the dollar higher (nations hit with tariffs will devalue their currency sufficiently to offset the tariff and allow their exports to remain competitive in the US), I have always been suspect of that theory and logic.  First, we can look at Trump’s first term and see how things played out.  The chart below of USDMXN, a tariff target, shows that, in fact, initially the peso strengthened upon Trump’s inauguration and range traded for the bulk of his term, only weakening substantially during the Covid market dislocations.

Source: tradingeconomics.com

We can look at USDCNY as well and see that over Trump’s first term, there were several large ebbs and flows in the yuan but that, in fact, CNY was stronger vs. the dollar at the end of his term than at the beginning.  Again, this assumption the dollar will appreciate strongly because of tariffs is a talking point, not an empirical reality.

Source: tradingeconomics.com

The other thing to remember about Trump (although it is not clear how you can forget it) is that he is a businessman, not a politician.  He is very transactional and wants to make deals.  I am a strong proponent of the idea that Trump sees tariffs as a negotiating tool and while he is a man of great bluster in his public pronouncements, his ultimate goal remains clearly to achieve his sense of fairness in trade relations.  If his belief is that a nation is maintaining a weak currency to enhance its mercantilist model, Trump will respond aggressively.  Ultimately, I believe a large part of the angst that is evident in governments around the world is that Trump will not behave in a diplomatic manner and will call out all the problems he sees or believes.  And other governments are uncomfortable with their own dirty laundry left to air dry.  While I continue to believe that inflation remains far stickier than the Fed is willing to admit now, nothing has changed my view that the Fed will not cut again and may be forced to raise rates before the year ends.  And that will support the dollar!

Ok, let’s turn to the overnight session.  After a mixed Wall Street performance, where the Mag7 continue to shine, but not so much else, we saw the Nikkei (+2.0%) rally sharply as well, following the NASDAQ.  Chinese shares (CSI 300 +0.7%, Hang Seng -1.2%) were split with the former benefitting from the reduced tariff story while the Hang Seng suffered largely on the back of Tencent Holdings being named a military contractor by the US DOD with its shares tumbling 8% in the US and HK.  Elsewhere in the region, there were both gainers and laggards but nothing of any note in either direction.  In Europe, UK shares (-0.3%) are under pressure as 30yr Gilt yields have risen to their highest level since 1998, an indication that investors are becoming concerned over the UK’s future path.  For context, current levels are 50bps above those which triggered the October 2022 gilt crisis and spelled the end of PM Liz Truss’s time in office.  Meanwhile, continental bourses are modestly higher led by the CAC (+0.6%) which seems to be benefitting from both the lower tariff story as well as hopes that Chinese stimulus will support the luxury goods sector.  As to US futures, at this hour (7:05) they are essentially unchanged.

In the bond market, yields are continuing to edge higher everywhere with Treasuries up 1bp and European sovereign yields higher by between 2bps and 4bps across the board.  Asian government bond markets continue to sell off as well, with yields there climbing in Japan and Australia and even Chinese 10yr yields edging higher by 1bp.  As long as central banks around the world insist that rate cuts are the future (and most of them do) look for bond yields to continue to climb.

In the commodity space, oil (+0.8%) continues to hold its own as trading activity remains modest and hopes are pinned on Chinese stimulus.  NatGas (-3.2%) is backing off its highs as the winter storm has passed (although it is still really cold here!) while the metals markets are performing well.  Gold (+0.5%) continues to trade either side of $2650/oz as speculators await the next major leg.  However, silver (+1.1%) and copper (+0.5%) have both bounced nicely from recent lows as specs look for another breakout higher.

Finally, the dollar is under modest pressure this morning compared to yesterday’s closing levels but is actually slightly firmer than when I wrote yesterday morning.  My point is that while it has been selling off from its peak late last week, there is no collapse coming and all eyes will be turning toward the data later this week to see if the Fed will have room to ease further, or if the NFP report will once again show strength and push any further rate cuts off in time.  The leading gainer in the G10 is NZD (+0.65%) which is benefitting from a combination of higher commodity prices, hopes for more Chinese stim and the tariff reduction story.  But for the rest of the market, 0.2% gains are the norm with only JPY (-0.15%) bucking the trend.

On the data front, this morning brings the Trade Balance (exp -$78.0B) as well as ISM Services (53.3) and JOLTS Job Openings (7.70M).  Yesterday’s PMI data while solid was softer than forecast and Factory Orders, too, were a tick lower than expected at -0.4%.  First thing this morning we will hear from Richmond Fed president Barkin who has been on the more hawkish side lately.  After the weekend chorus that cuts needed to be deliberate, I expect more of the same here.

For now, the broad themes remain unchanged, higher US yields on the back of inflation concerns forcing the Fed to reverse course this year.  But on a day-to-day basis, it would not be surprising to see the dollar continue to give back some of its recent gains given the significant size and speed with which they were attained.  I still like hedgers picking levels and leaving orders to buy dollars a bit cheaper from here.

Good luck

Adf