They Mostly Confuse

We’re back to the Strait of Hormuz
As driver to all traders’ views
Both Trump and Iran
Have proffered a plan
But really, they mostly confuse

The, otherwise, story of note
Is coming as CPI’s quote
If hot, Chairman Warsh
Will field comments, harsh
If cool, he’ll be able to gloat

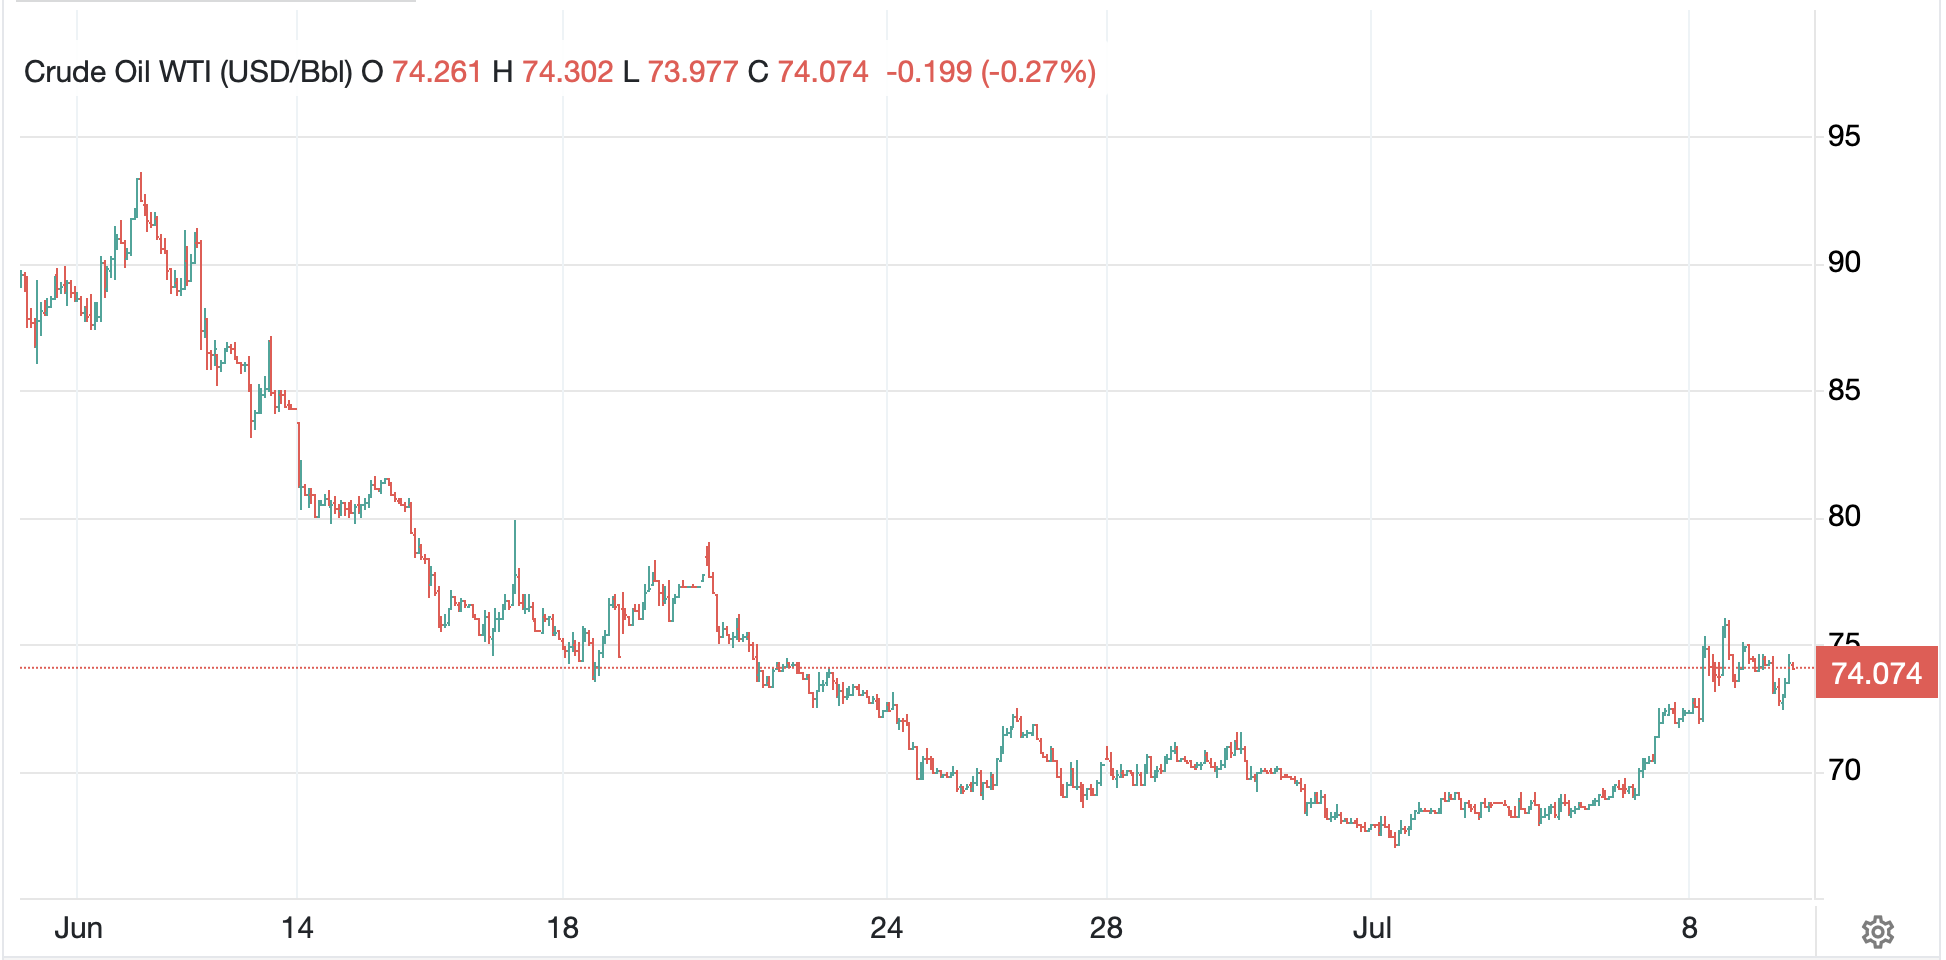
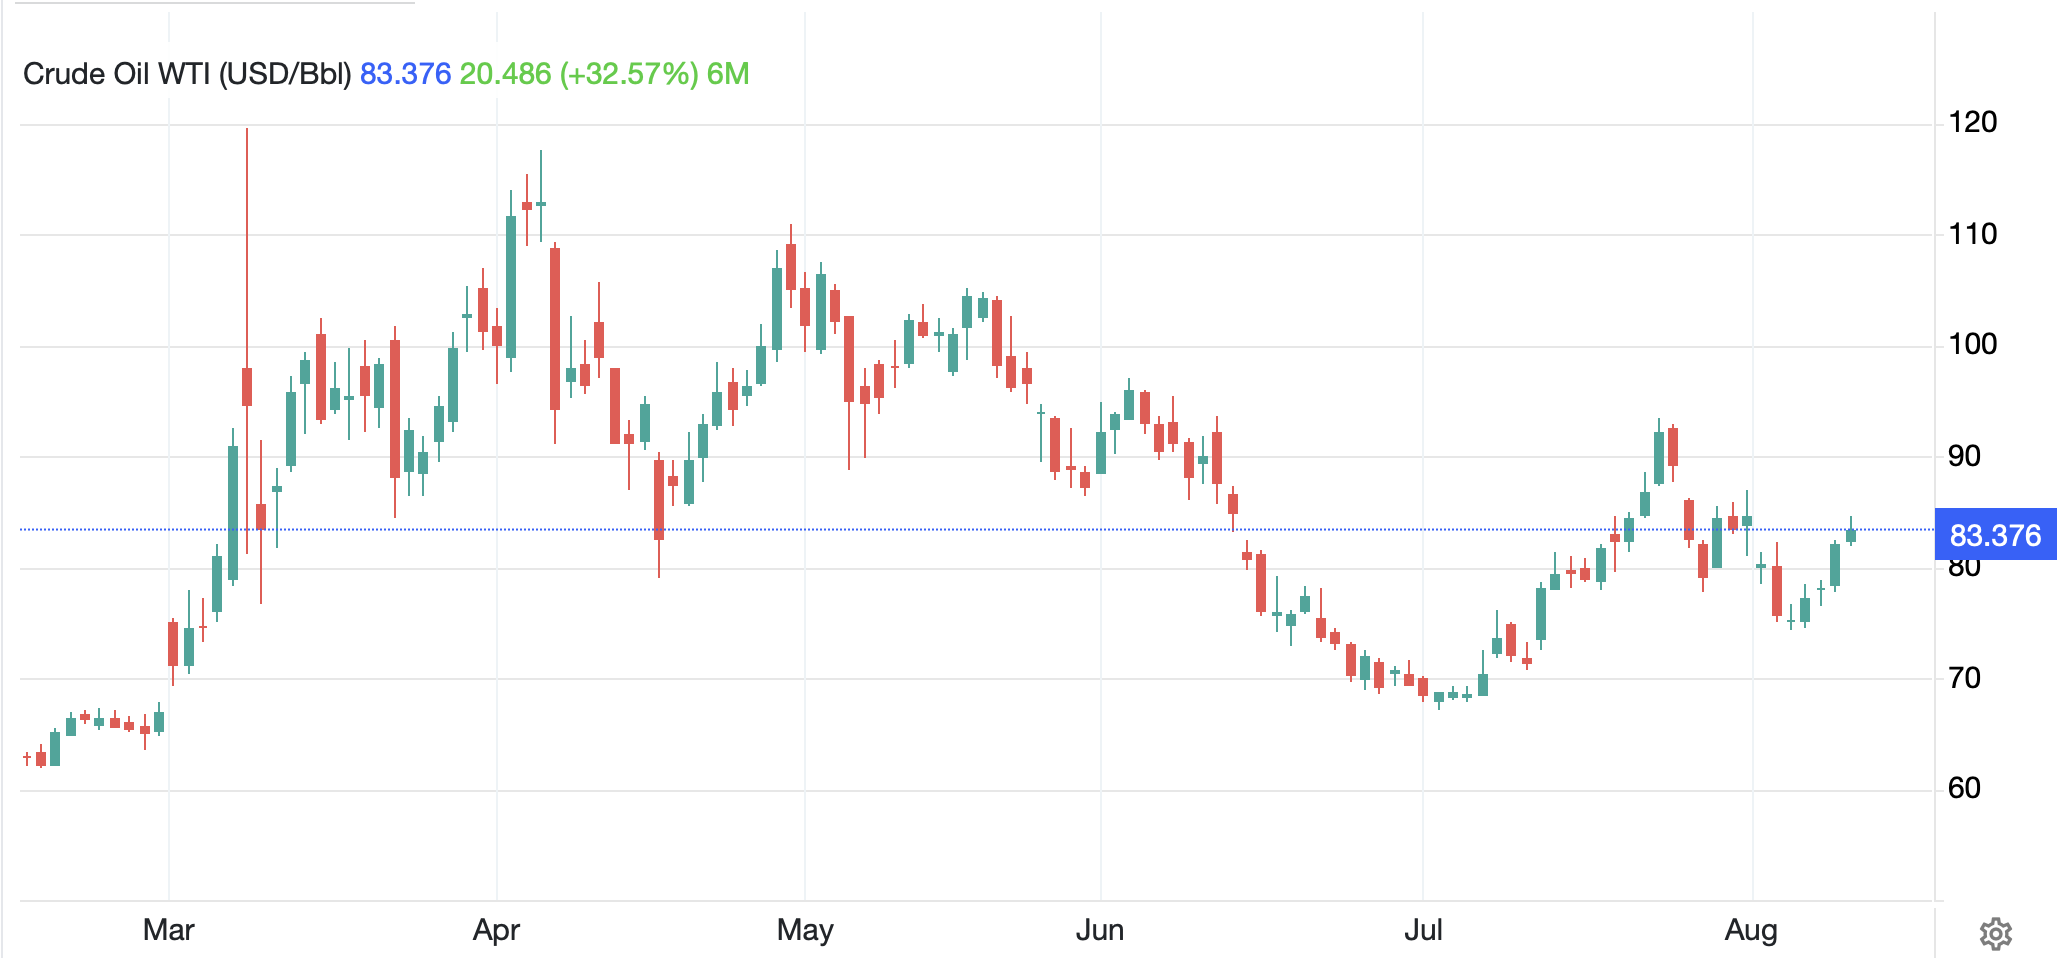
Oil prices (+1.5%) are higher again this morning and have now been up five consecutive sessions, rising 10% in that run as you can see in the chart below.
Source: tradingeconomics.com

There is a theory that the rhetoric in Iran increases when they have oil to sell so need higher prices, but once those cargoes have been sold, they talk peace again.  I don’t think you can rule out that hypothesis although I certainly have no corroborating evidence it’s true.  The one thing I did note yesterday is an Iranian comment that as long as sanctions remain, diplomacy cannot happen which tells me that economic sanctions are biting harder.  Whatever, the situation on the ground (or water) is over there, I have no insight per se. 

Much has been made over the fact that the SPR is at its lowest level since 1983 and has fallen below 300 million barrels with all the attendant pearl clutching while simply ignoring the fact that the SPR releases have been oil swaps with the back ends starting to come back in the next several months in greater amounts than have been released.  Maybe the end is nigh regarding oil, and the doomsters will get their $200/bbl outcome, but I would still take the under there.

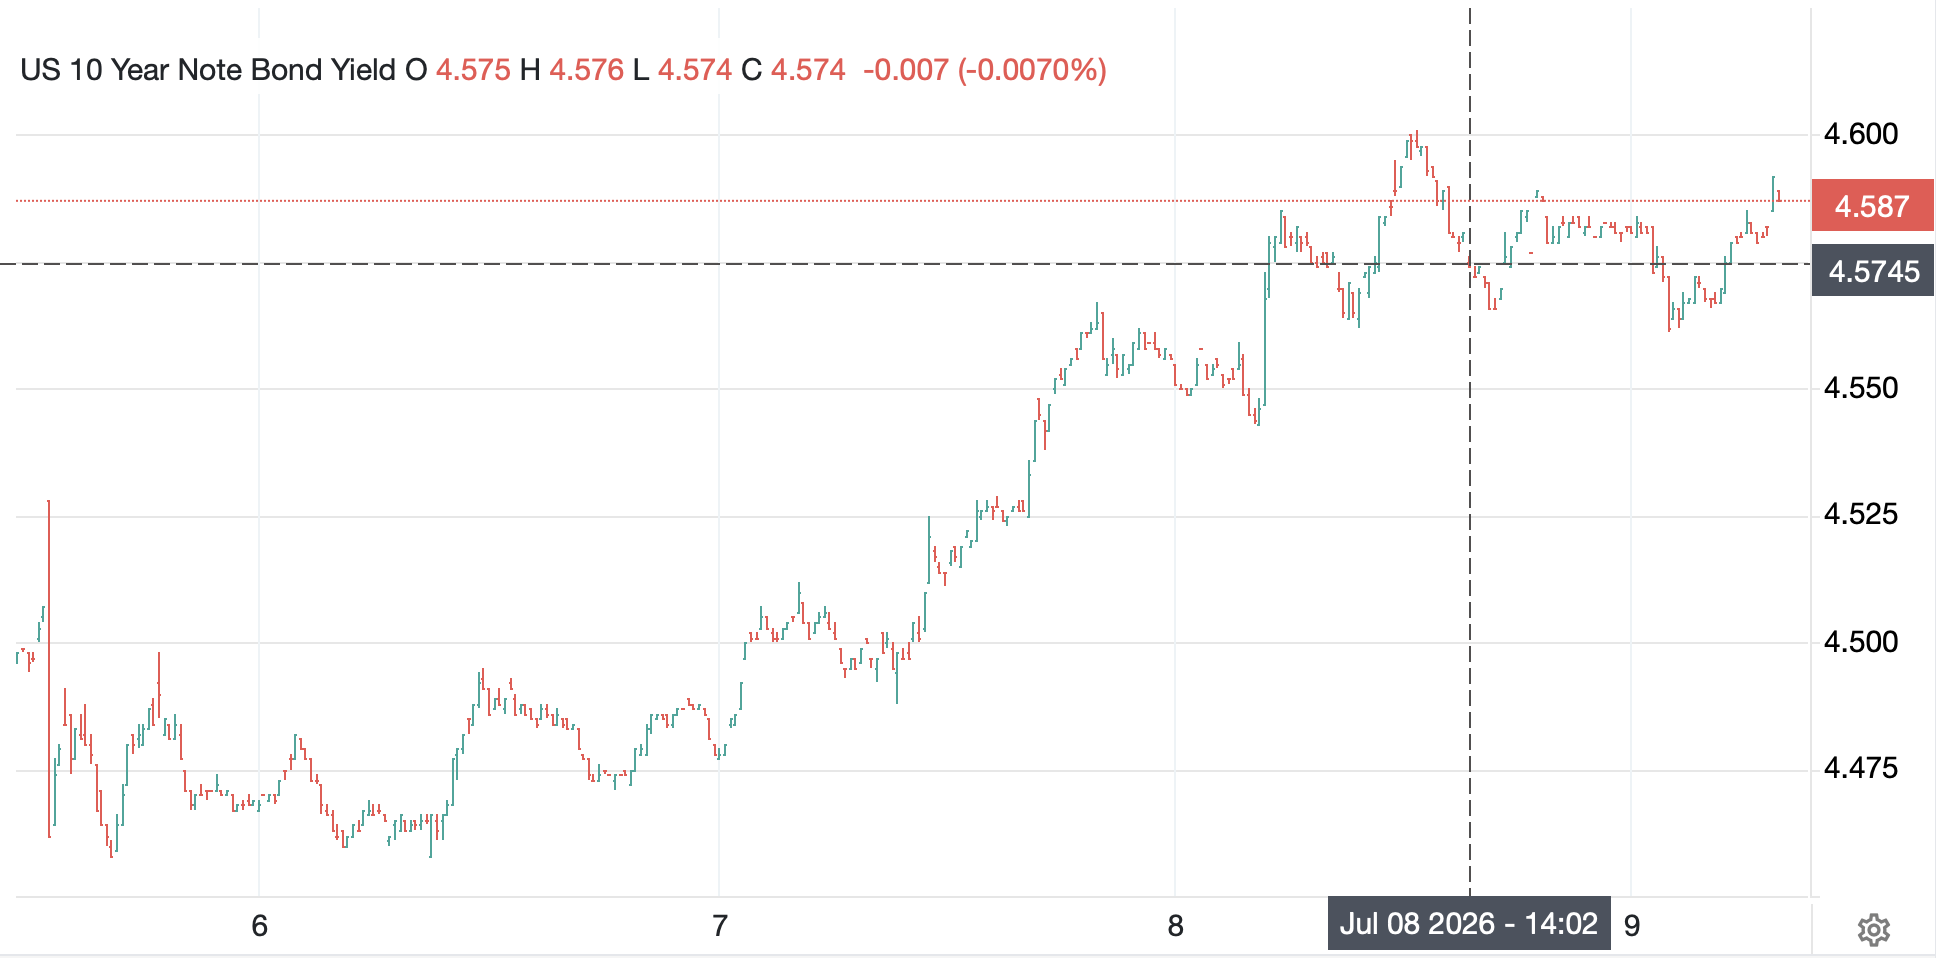
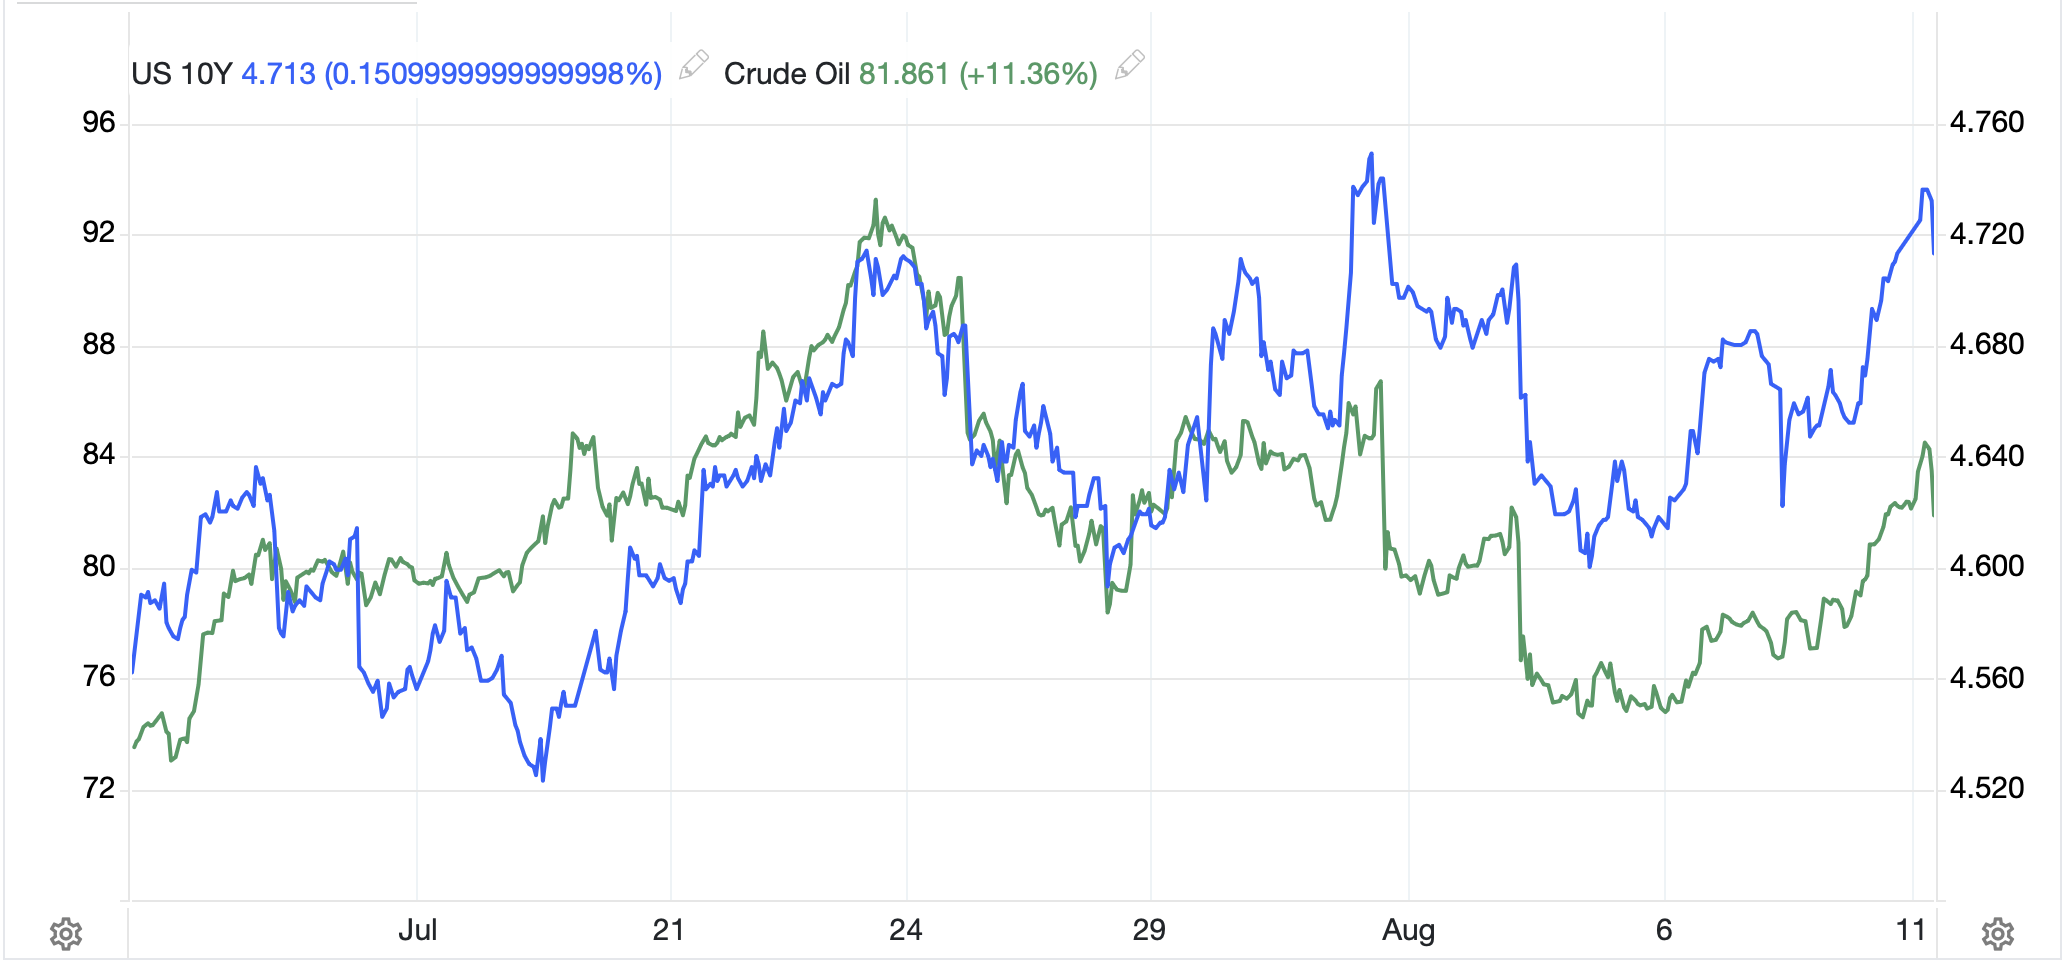
In sync with the oil price rise we have seen yields rise, as well (see chart below), around the world.  But here, it appears that Chairman Warsh is the favored scapegoat for all the world’s inflation problems.  To hear his critics explain, if only he would give us forward guidance, everything would be fantastic.  Hedge funds could load up on leverage and increase their profits, real money investors would be comfortable that future real returns would be acceptable and, most importantly, the punditry would be able to explain all this to us plebes and burnish their beliefs in their own brilliance.
Source: tradingeconomics.com

But I wonder if there is not another explanation for rising yields that has nothing to do with the Fed, the idea that debt issuance, from both government and private sources, is growing dramatically and all that supply is weighing on prices, hence driving up yields.  We already know that governments around the world continue to issue debt willy-nilly, so there is nothing to discuss there.  But now the AI hyper scalers are issuing massive amounts of debt to pay for all the GPUs and data centers and power as the race to “win” in AI continues at an increasing pace.  

It is, of course, this last issue which has many pundits explaining that QE will soon reemerge as the only viable way for all that debt to get bought.  If central banks buy government debt that will leave funds for private investors to buy AI related debt.  And maybe that is the way it will work out although Chairman Warsh has thus far only discussed shrinking the balance sheet, not expanding it.

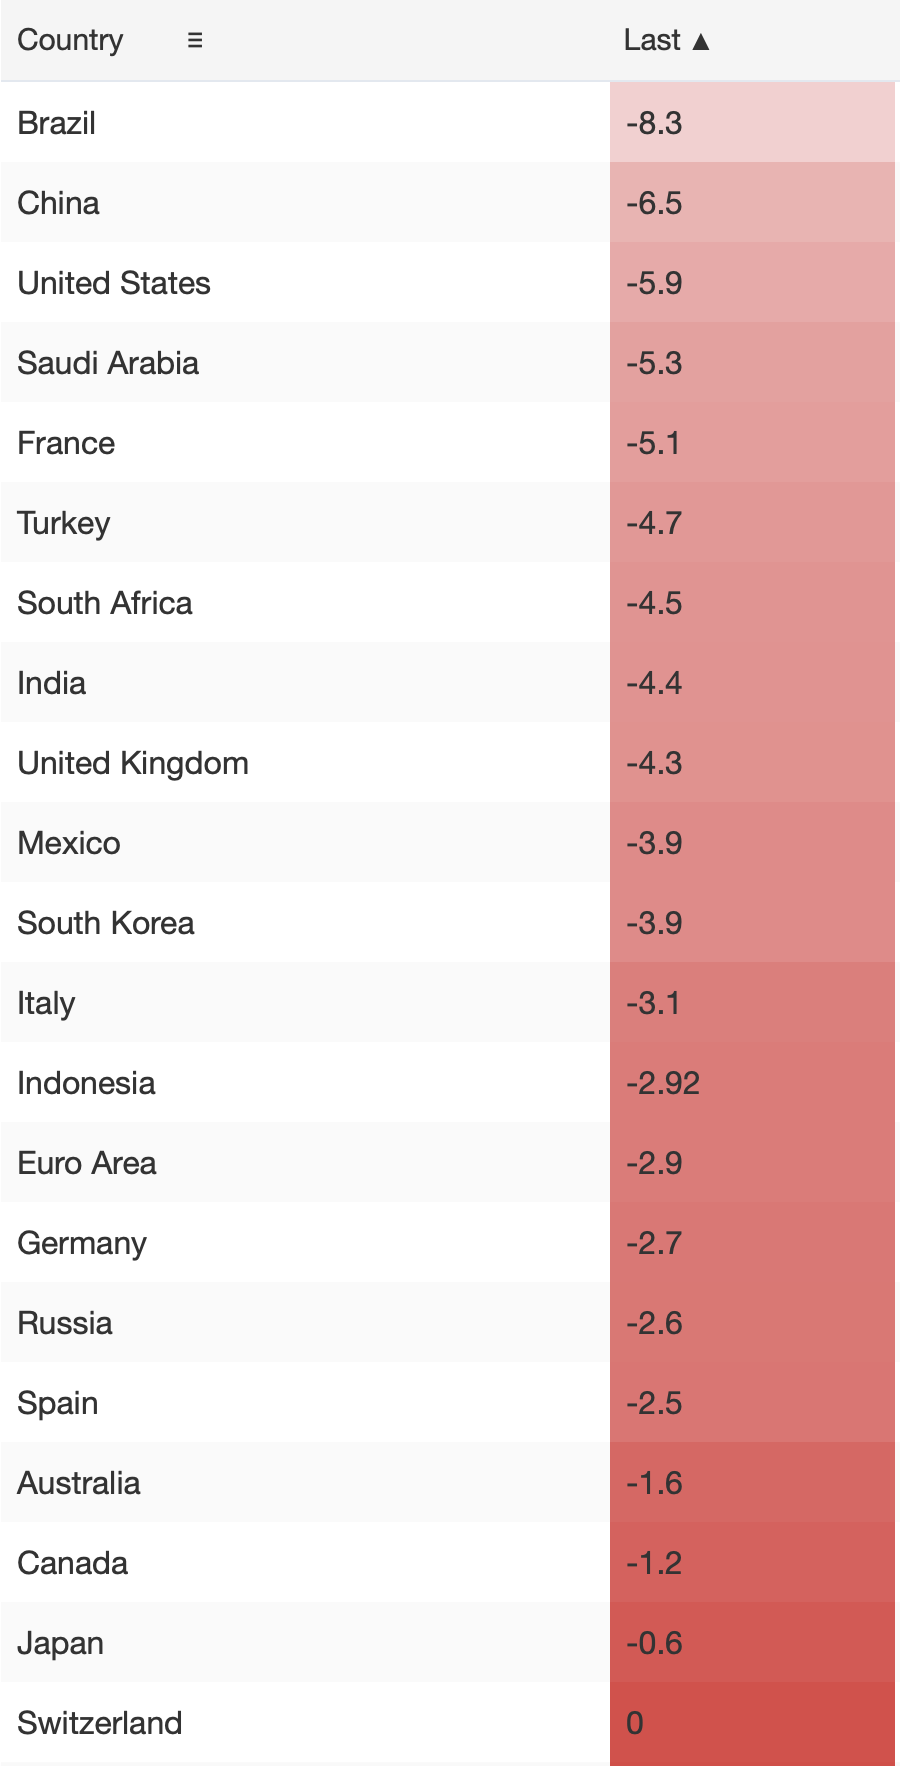
Please understand I am not ignoring the many serious problems that exist within the current fiscal and monetary frameworks around the world.  Government spending remains excessive as evidenced by the fact that virtually every nation in the world is running significant budget deficits as per the below table from tradingeconmics.com (notice China, a country that seems to get a pass on this score from the punditry).
All I am saying is that the idea that all of this is going to fall apart quickly is highly improbable.  As much as purists would like for there to be consequences for bad policy decisions, governments everywhere have an enormous number of tools to delay the pain, and they use them all the time.  Whether that is subsidies or tax cuts or regulations prohibiting competition, all these things substitute short-term gains for long-term problems.  But they will still be used regularly.

So, to recap, increasingly hawkish rhetoric on the Iran situation has driven oil prices higher which is increasing inflation concerns.  Adding to that is the ongoing fiscal profligacy of virtually every major government which is also weighing on bond prices and driving yields higher in sync.  And basically, the punditry has decided it’s all Kevin Warsh’s fault.  Too much will be made of tomorrow’s CPI report, whether it is hot or cool, that is the one things of which I am certain.

Ok, yesterday’s lackluster US session with all three major indices slipping a bit was followed by weakness in China (-0.8%) and HK (-1.1%) but elsewhere in Asia, things were mixed with Korea (+0.7%) gaining and the other regional bourses generally +/-0.5% or so.  Tokyo was closed for Mountain Day and the only other news of note from the region was the RBA left rates on hold at 4.35%, as expected, but expressed concerns about both slowing growth and future inflation.  Interestingly, Australian stocks were slightly higher despite that news, +0.2%.

In Europe, Spanish stocks (+0.5%) are the leader on the strength of Banco Santander’s share repurchase announcement while the rest of the continent and the UK are little changed.  As to US futures, at this hour (7:35) they are little changed.

While we have broadly discussed bond yields rising, and yesterday they were higher by 4bps-5bps in the US and Europe, this morning they are unchanged across the board.  Now, they were higher again this morning when I started to write, but it seems there was just a comment from Pakistan that the US and Iran are close to an agreement which has turned things around.  Oil prices, too have slipped back to unchanged on the day from an hour ago.

In the metals markets, gold (-0.2%) and silver (-0.9%) are backing off solid sessions yesterday and copper (+0.8%) continues to march higher.

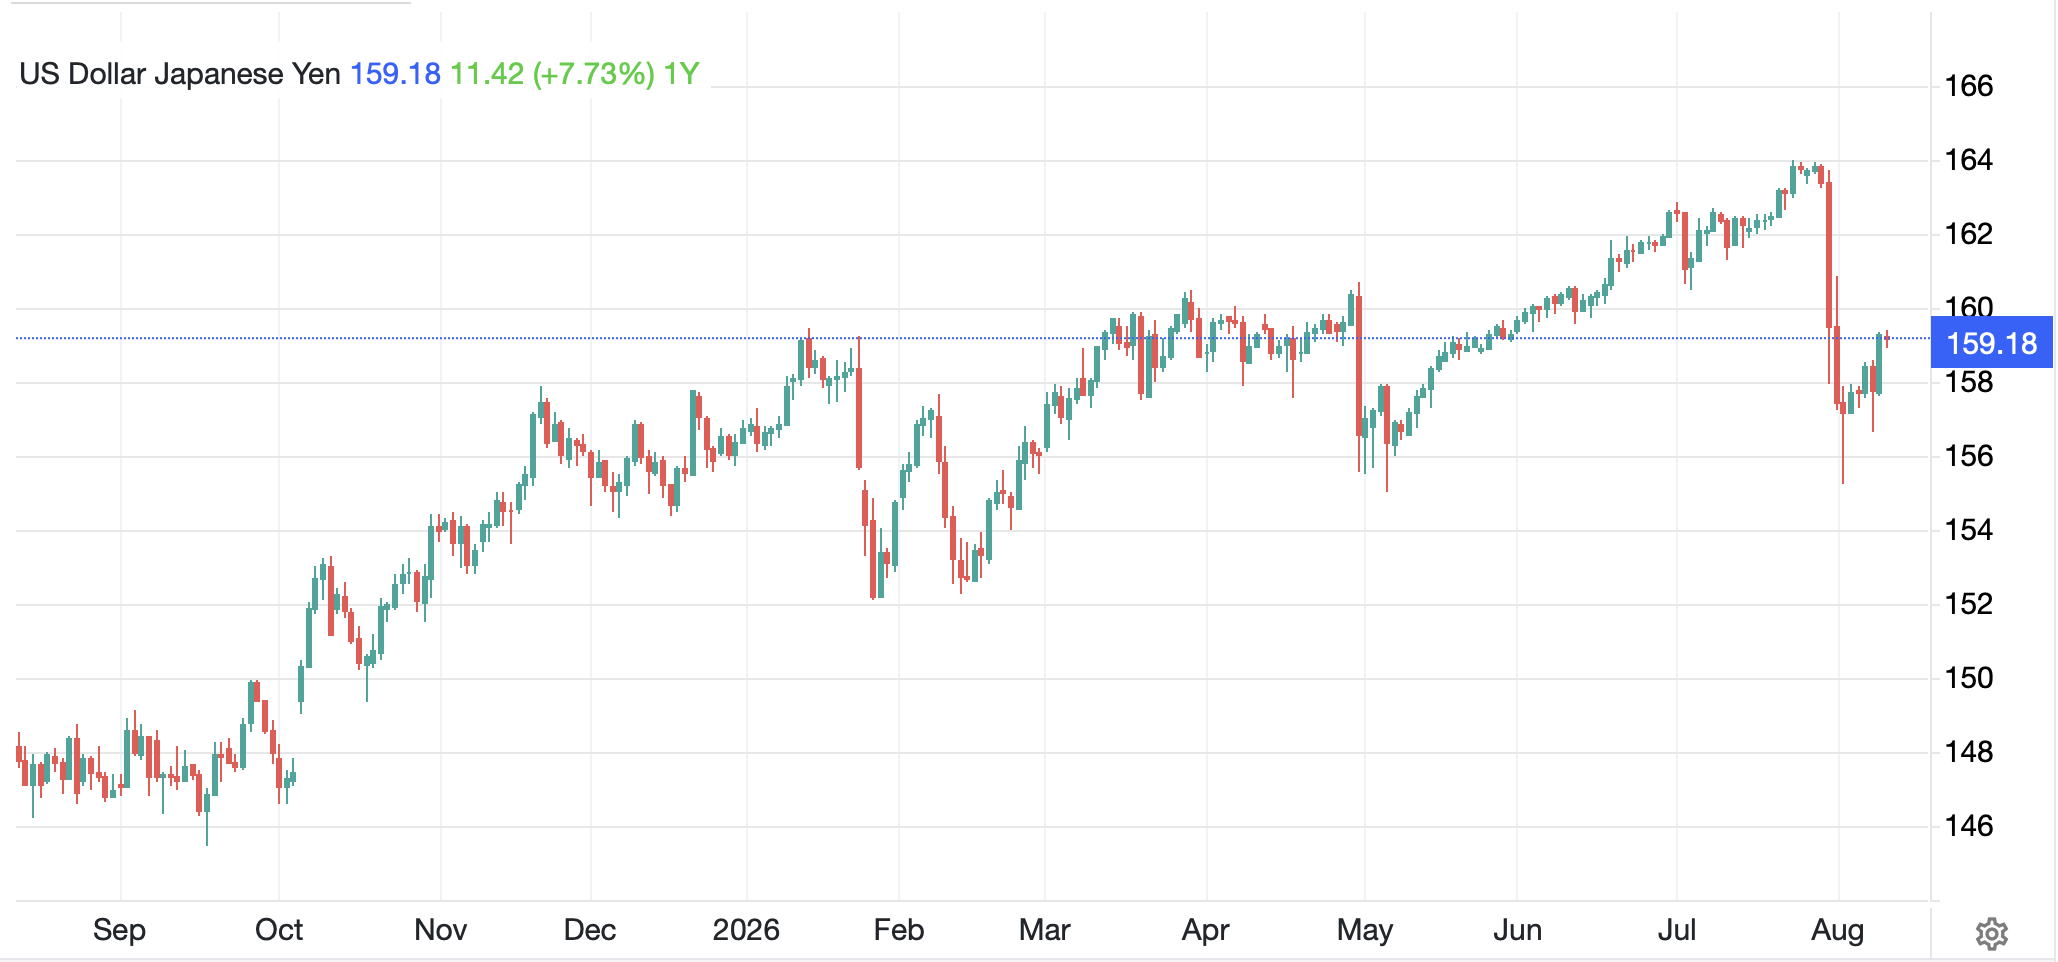
Finally, the dollar is, net, little changed this morning, although we cannot ignore the fact that the yen fell -1.0% during yesterday’s session.  In fact, a look at the yen chart continues to show the market response to intervention, an immediate rally and a gradual decline resuming.
Source: tradingeconomics.com

As to the rest of the space, KRW (+0.3%) is the actual largest mover today, and that is not enough of a move to spin any story.  The DXY remains just below 100 and firmly within its yearlong trading range and some pundits are saying the fact that it is not rallying during the current conditions, with yields rising and fear all about, is an indication that the dollar is losing its status.  However, I am confident if you offered those same pundits payment in dollars, they would grab them as greedily as possible!

On the data front, this is inflation week plus a few more things as follows:

TodayExisting Home Sales4.05M
WednesdayCPI0.1% (3.4% Y/Y)
 Ex food & energy0.2% (2.5% y/Y)
ThursdayInitial Claims202K
 Continuing Claims1800K
 PPI0.2% (4.9% Y/Y)
 Ex food & energy0.3% (4.2% Y/Y)
FridayRetail Sales0.1%
 -ex autos0.2%
 Michigan Sentiment54.5

Source: tradingeconomics.com

Obviously, all eyes will be on CPI tomorrow as investors and analysts look for clues as to how the Fed may behave going forward.  Speaking of the Fed, Cleveland Fed president Hammack said in an interview yesterday that she thought the Fed needed to raise rates more than 25bps to get inflation under control.  But as I think about the Fed and its dual mandate, of maximum employment and stable prices, I cannot help but wonder what they consider maximum employment.  While they have defined stable prices (incorrectly in my view) as Core PCE rising 2.0% per annum, they have never tied themselves to a number on employment.  So, here’s a thought.  Look at the Labor Force participation rate, which as per the data last Friday fell to 61.4%, that is the lowest level since 1975 (excepting Covid) as per the below chart from FRED.
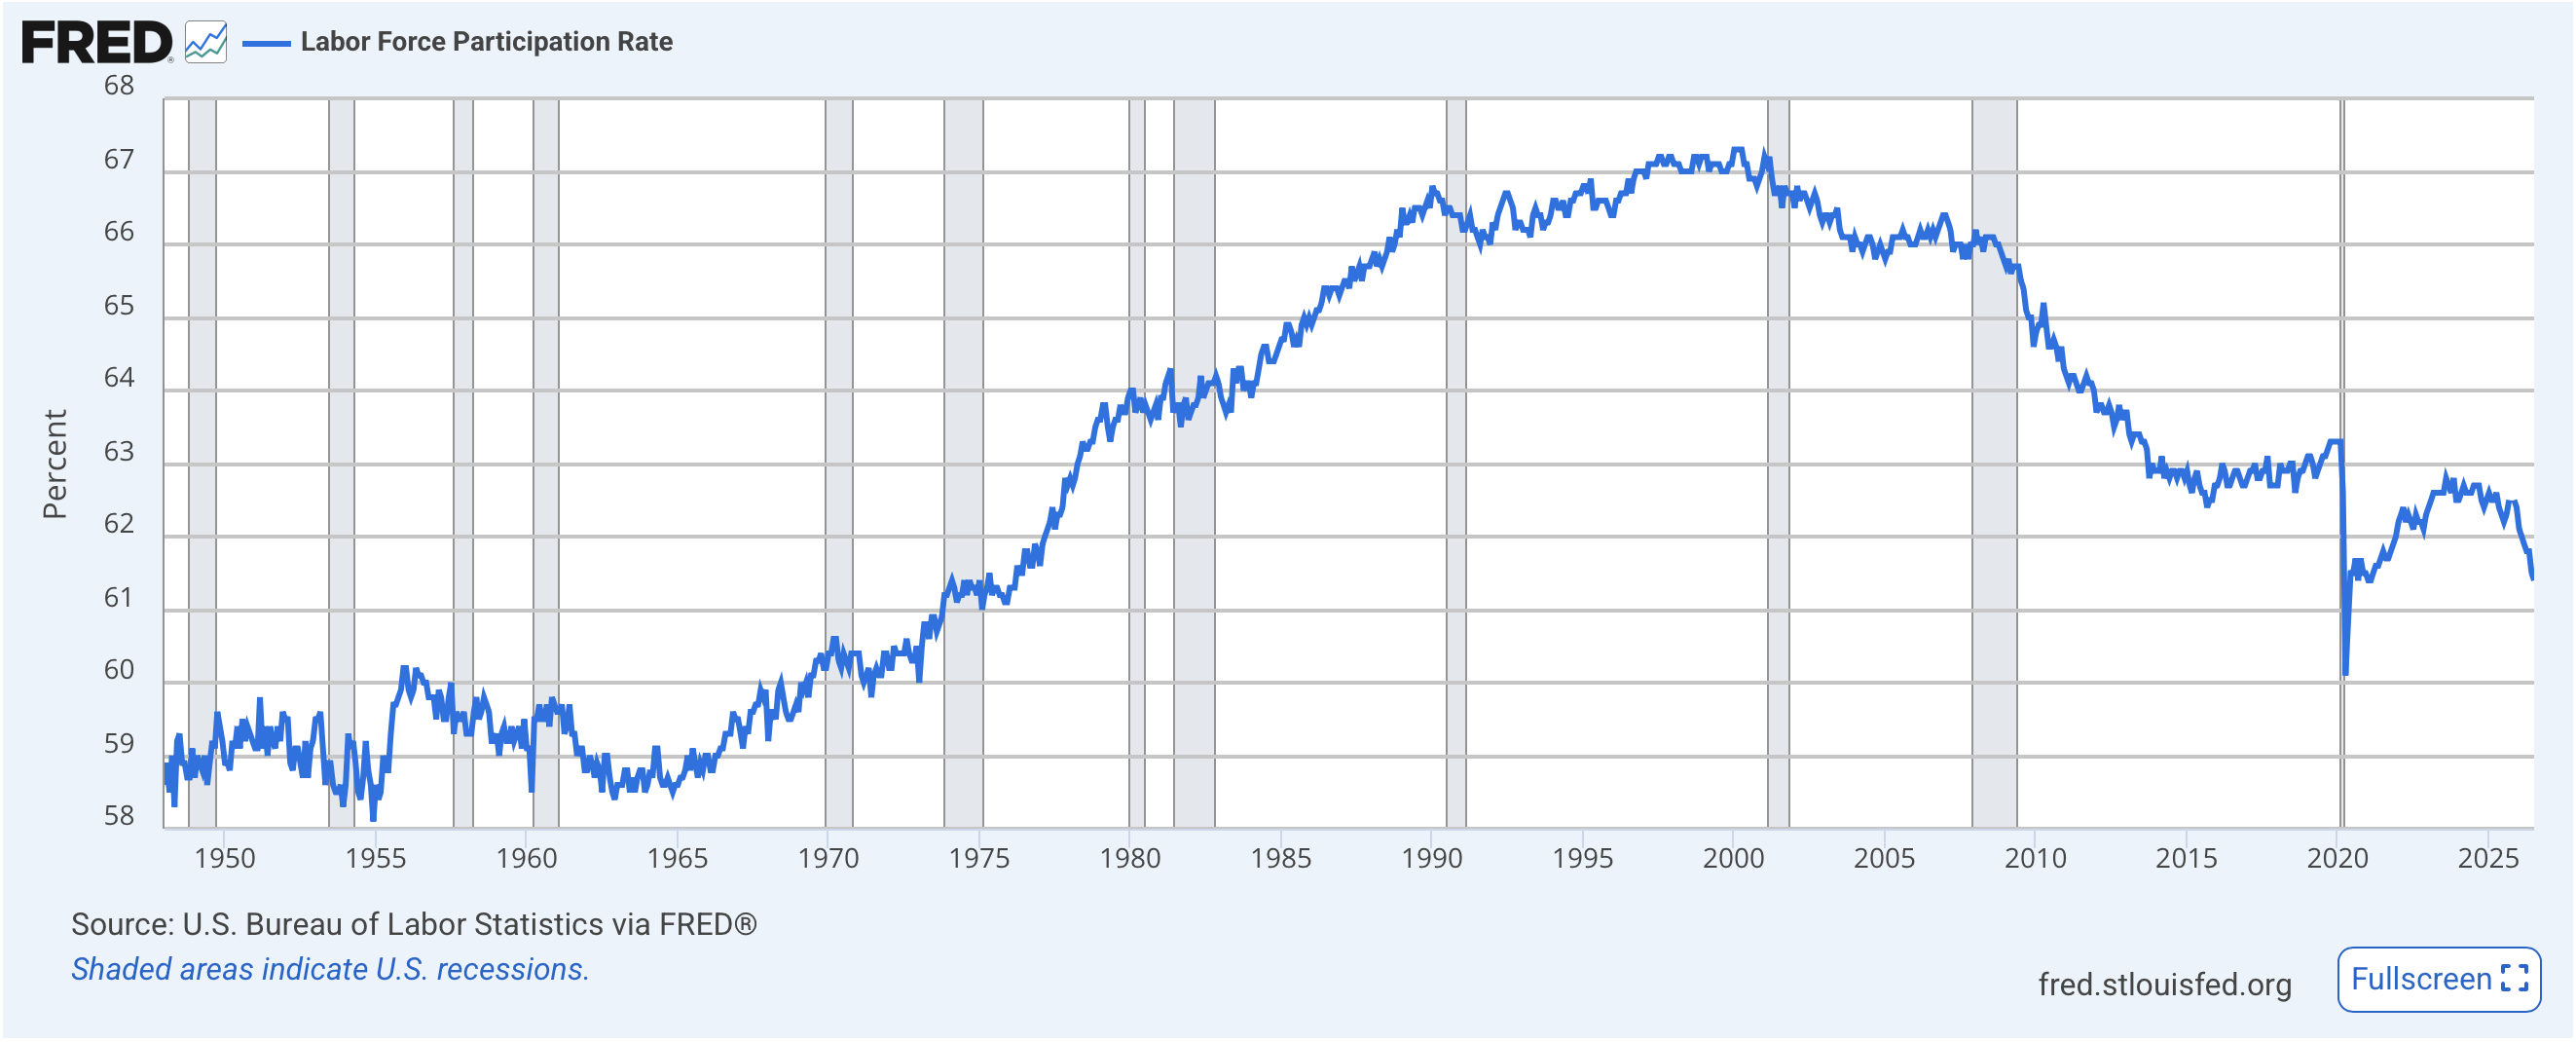
That hardly seems maximal, but then, I’m just an FX guy, not a Fed PhD.  After all, if we take the plain meaning of the word maximum, as per the American Heritage Dictionary, I cannot look at the chart above and conclude they have achieved that part of their mandate either.
But that’s just me.  Anyway, if there is going to be movement on the Iran story, that will drive the immediate market movements, but you can be sure that in the current environment, it will all come back to the Fed and whatever they may do going forward.

Good luck

Adf
The Score

Hormuz is blockaded once more
The latest response in the war
So, crude prices rose
While both sides expose
Their relative views of the score

Now after a month of some peace
Seems tensions are set to increase
So, what about stocks?
The sales are in blocks
While buyers, few bids will release

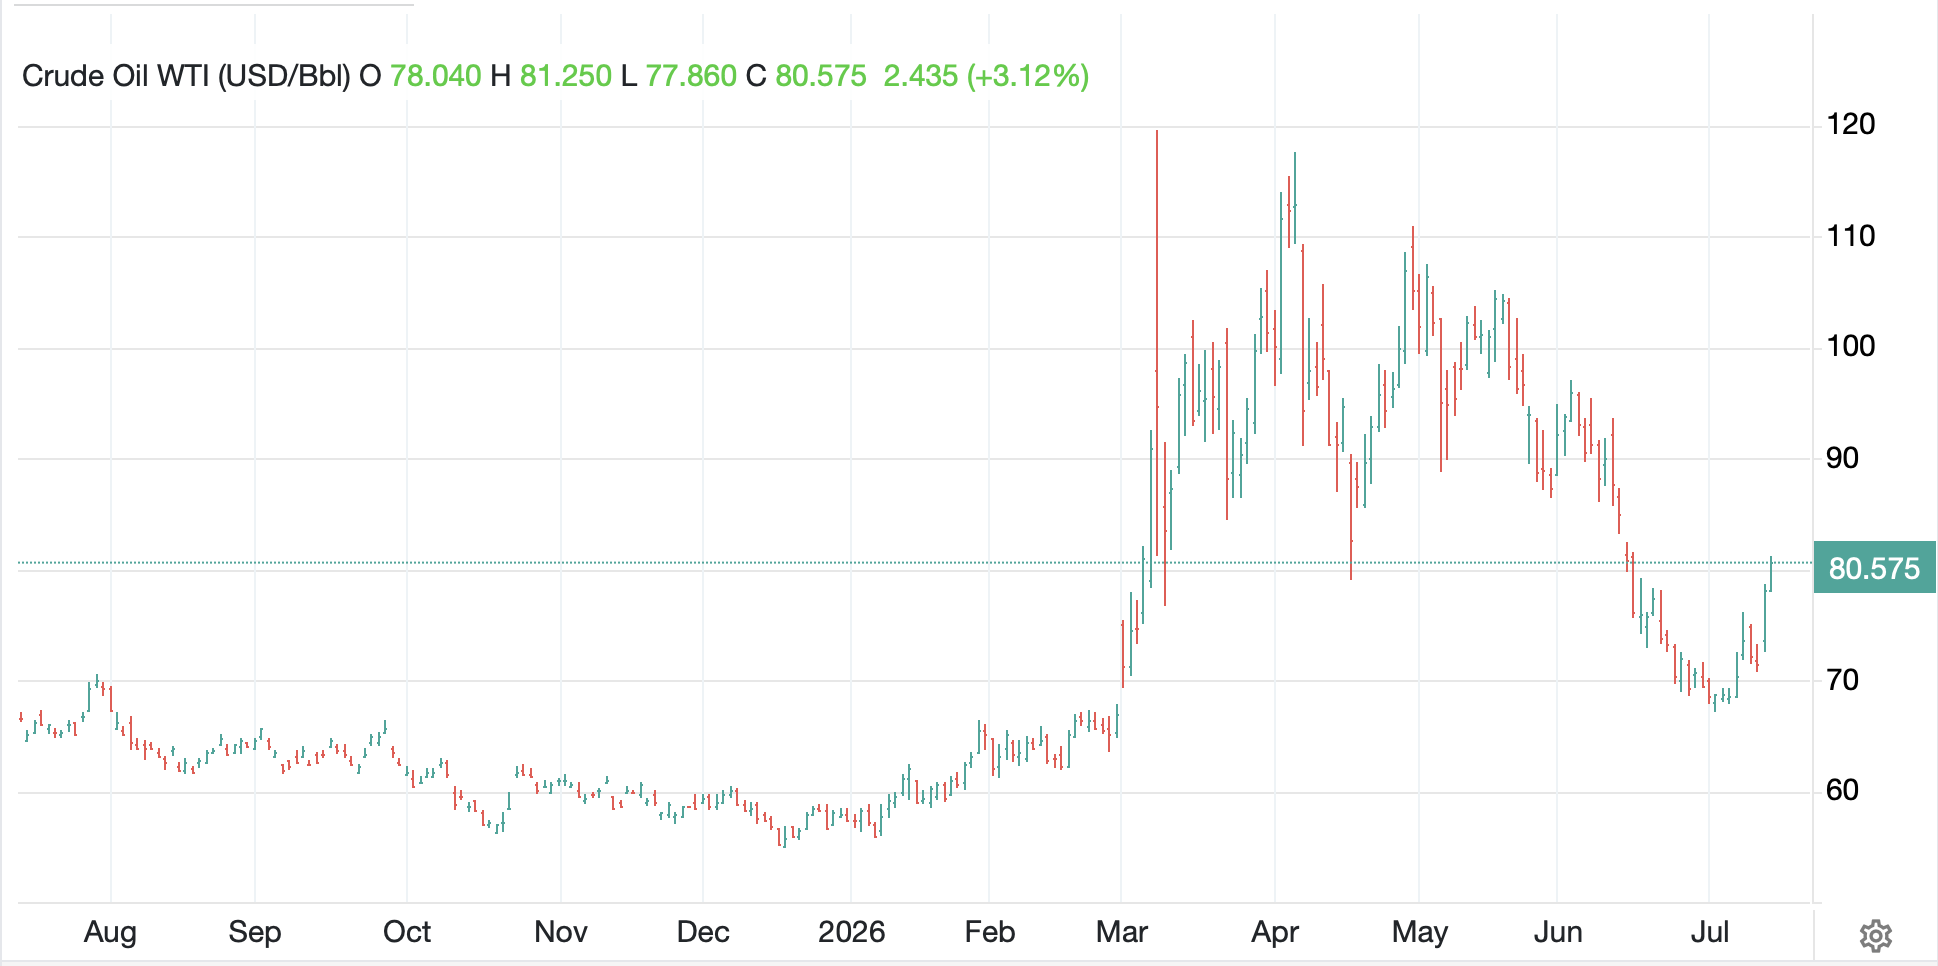
After a brief respite for markets, where oil had seemed to be drifting out of the headlines, the events of the past weekend plus the US reimposition of the blockade of the Strait of Hormuz has changed the narrative dramatically, and rightly so.  The benign attitude of an eventual conclusion to this situation has been tossed aside and the oil bulls and war hawks are both back in the ascendancy.  Yesterday ultimately saw oil prices rise 9.4% and this morning they are a further 3.2% higher, and perhaps more importantly, back above the psychological level of $80/bbl.

Source: tradingeconomics.com

There doesn’t seem to be any short-term solution to this situation.  There are clearly enough hard-liners still with power in Iran to prevent any move toward a negotiated solution.  As long as this maintains, the outlook for oil will tilt higher.  However, as I have written before, and is very clear now, the effort to reroute oil shipments from the Gulf nations away from the Strait is intensifying and will continue to do so.  As well, alternative sources of supply including additional US production, Brazil, Argentina, Guyana, Venezuela and Canada are satisfying demand.  While uncertainty remains high, especially in the short run, by the end of next year, my take is less than 8% – 10% of the world’s oil will need to transit the Strait.  However, in the meantime, given that everybody who was long oil as the war initially ramped up has sold out, there are few sellers left to cap the price.  I imagine a move toward $90/bbl is quite possible in the next weeks.

As well as the story on crude
Two other themes will be pursued
First CPI’s print
Will offer a hint
Then Warsh will discuss why he’s screwed

If we turn our attention away from the oil market now, the two main events today are the CPI release at 8:30 this morning followed by Chairman Warsh testifying to the House Financial Services committee in his semi-annual trip to Congress.  Starting with CPI, expectations are for a decline from last month as headline (exp -0.1% M/M, 3.8% Y/Y) and core (0.2% M/M, 2.8% Y/Y) are due.  From what I can tell, there are a number of analysts who are calling for a relatively hotter number, although I’m not sure on what basis they believe that.  Certainly, oil prices, and energy prices across the board, declined significantly in June and that will be reflected in the reading.  Looking at the home price data, that doesn’t appear to have risen dramatically, and other commodity prices have also slipped.  I don’t’ rule out any outcome, but on the surface, expectations seem reasonable.  

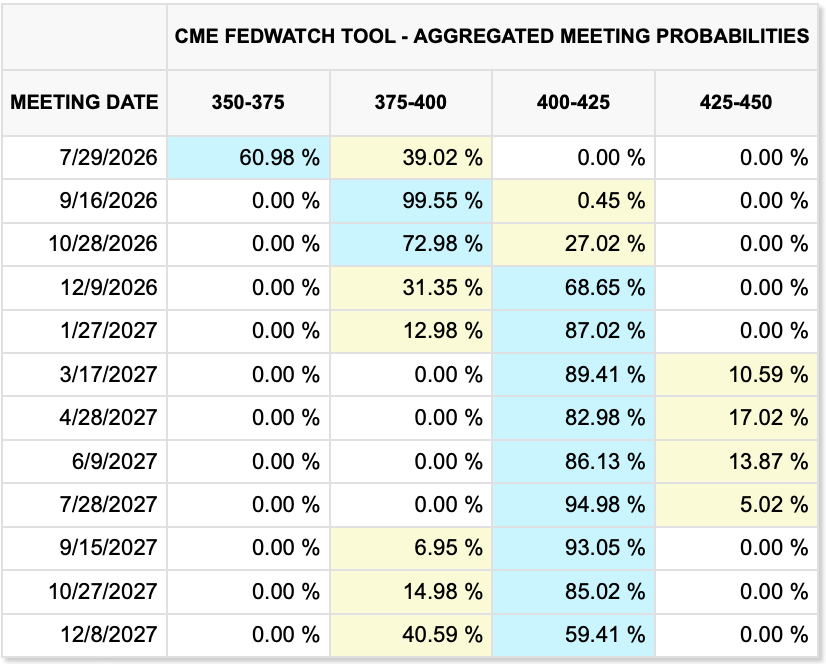
Of course, with oil prices rising, talk of more rate hikes is all the rage and according to the Fed funds futures market, as per the below CME table, you can see that expectations have risen to a 40% probability of a hike this month and a two-thirds probability of two hikes before the end of the year.  My personal view, FWIW, remains that there will be no hikes this year, although with the resumption of hostilities in the Gulf, I think a cut is off the table as well.  Remember, too, that if oil prices remain elevated that will negatively impact economic activity, so hiking rates into that scenario doesn’t seem to make much sense.  But then, I’m not on the FOMC.

Now, I have long maintained that FOMC members should shut up, but it seems Mr Warsh will have a hard time getting them to do so.  I’m not sure if they think they are helping, or they are just enamored with their own voices.  But yesterday, Governor Waller spoke and explained that if the CPI data was hot, a rate hike would be an appropriate response.  And remember, we hear from another 7 or 8 of these folks just this week, four today!  

While I expect that Warsh’s testimony will be dry, and that most of the questioning will be either long-winded preening by some idiot member, or an attempt at a gotcha question, I am confident that Chairman Warsh will continue to avoid discussing his views of where policy should go and reiterate forcefully that the Fed’s goal is to reduce inflation, full stop.  I am also confident that he will not be dragged into any discussions of other issues like global warming or DEI and simply repeat that ending inflation is the only job he has.  We shall all find out shortly.

On to the markets.  It should be no surprise that equity markets were under pressure yesterday in the US with the jump in oil prices.  This added to the chorus of those who believe the AI bubble is popping as the NASDAQ led the way lower, falling -1.5%.  But a funny thing happened in Asia.  Despite the jump in oil prices and declines in US equity markets, Tokyo (+0.75%), HK (+0.5%) and China (+2.15%) all rallied nicely last night.  In fact, so did Korea (+0.7%) and Malaysia (+1.3%) although we did see declines in India (-0.7%) and Taiwan (-1.4%) with the rest of the region moving far less.  This is a surprising outcome to me, especially as Asia is the region most negatively impacted by rising oil prices.

Europe though is trading true to form with declines across the board ranging from Spain (-1.1%) to the UK (-0.4%) and everywhere in between.  There has been precious little data overnight to drive things, and this appears to be entirely oil related.  Of course, Europe’s suicidal energy policy, notably the UK’s ban on drilling for oil in the North Sea, remains one of the key reasons that the area will continue to struggle.  As to US futures, this morning DJIA futures are lower (-0.8%) but the other two major markets are little changed at this hour (7:25).

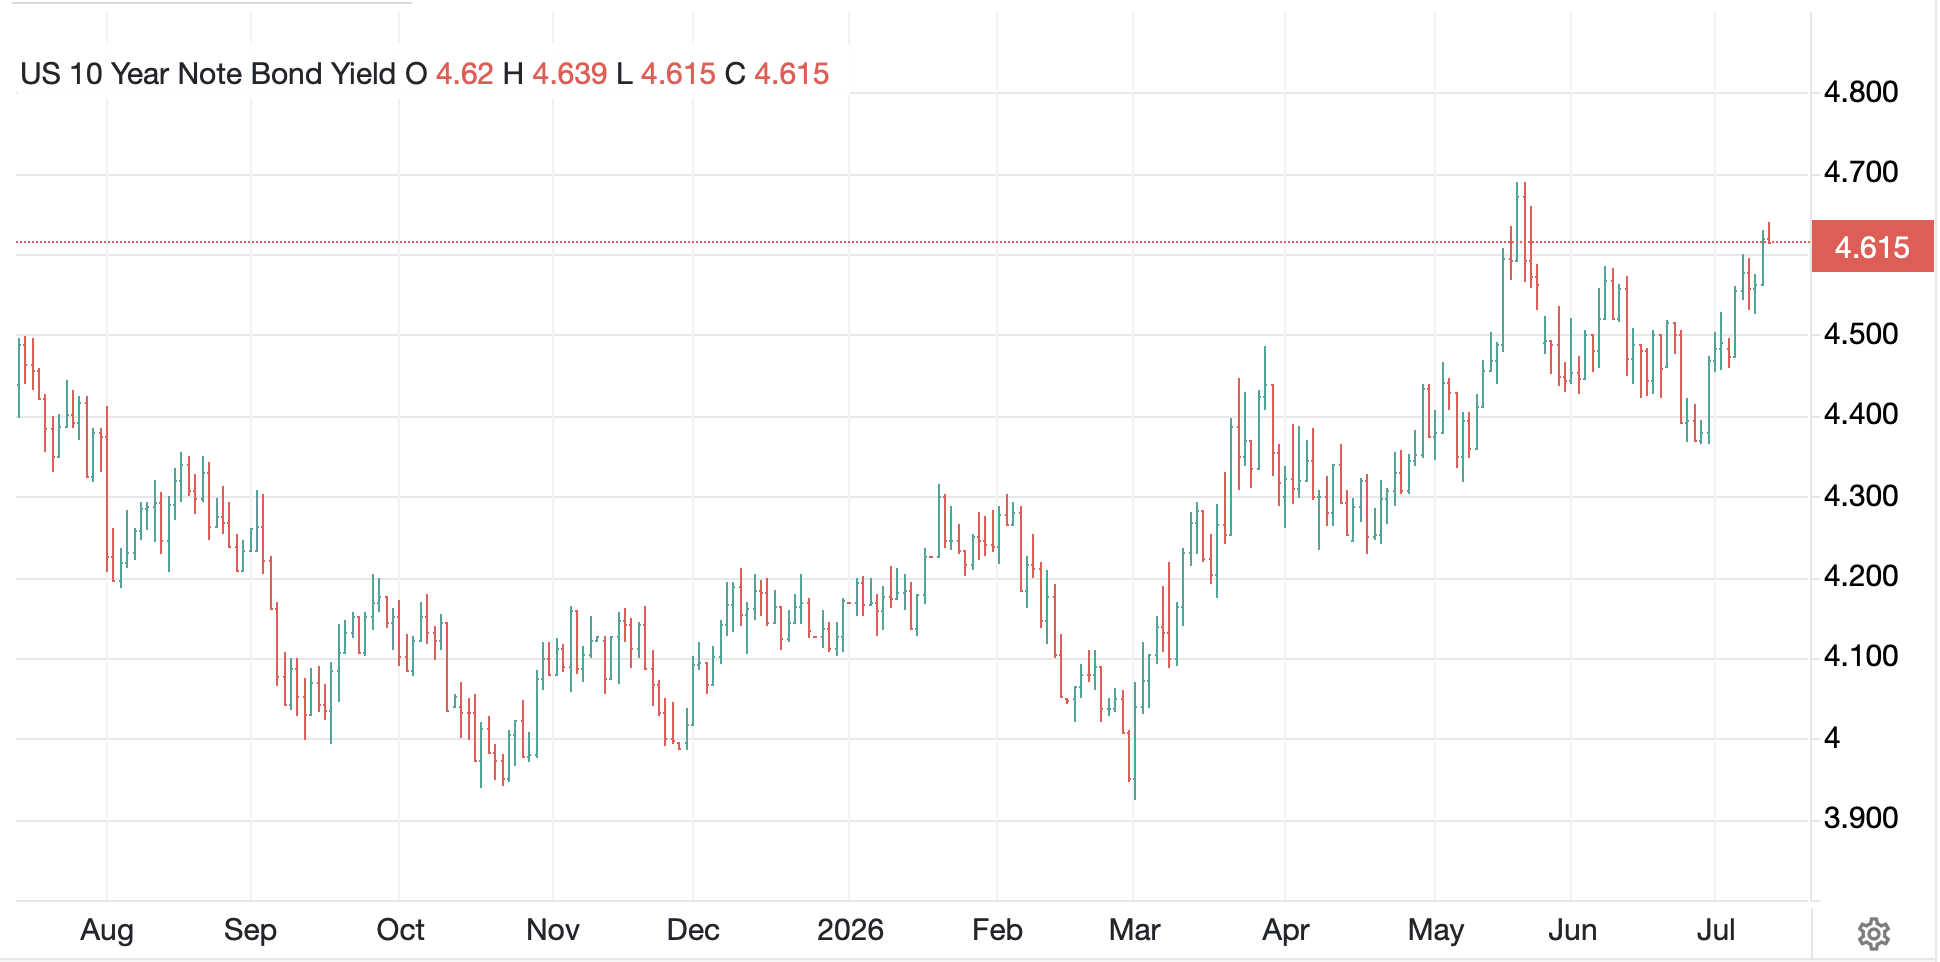
In the bond market, 10-year Treasury yields jumped 6bps yesterday although are little changed this morning.  However, as you can see from the chart below, they are pushing back up toward the highs seen in late May.

Source: tradingeconomics.com

There is a lot of talk about how Warsh should hike rates aggressively this month to gain bond market credibility in his fight against inflation, but I sense that is a lot of people talking their books.  I continue to believe that there will be no Fed action ahead of task force reports.  As to other nations, yields are generally firmer in Europe today, ranging between +1bp (Germany) and +3bps (Italy) with the UK worst of all (+4bps) as 10-year Gilts now yield more than 5.0% again, also pushing back to late-May highs.  The one exception is Japan (JGBs -5bps) where the latest ploy by Katayama-san is to propose JGBs be allowed to be invested in tax-free accounts for individuals in Japan.  Given the long history of zero rates there, a tax-free return of 2.7% with no currency risk could well be quite attractive, I think.

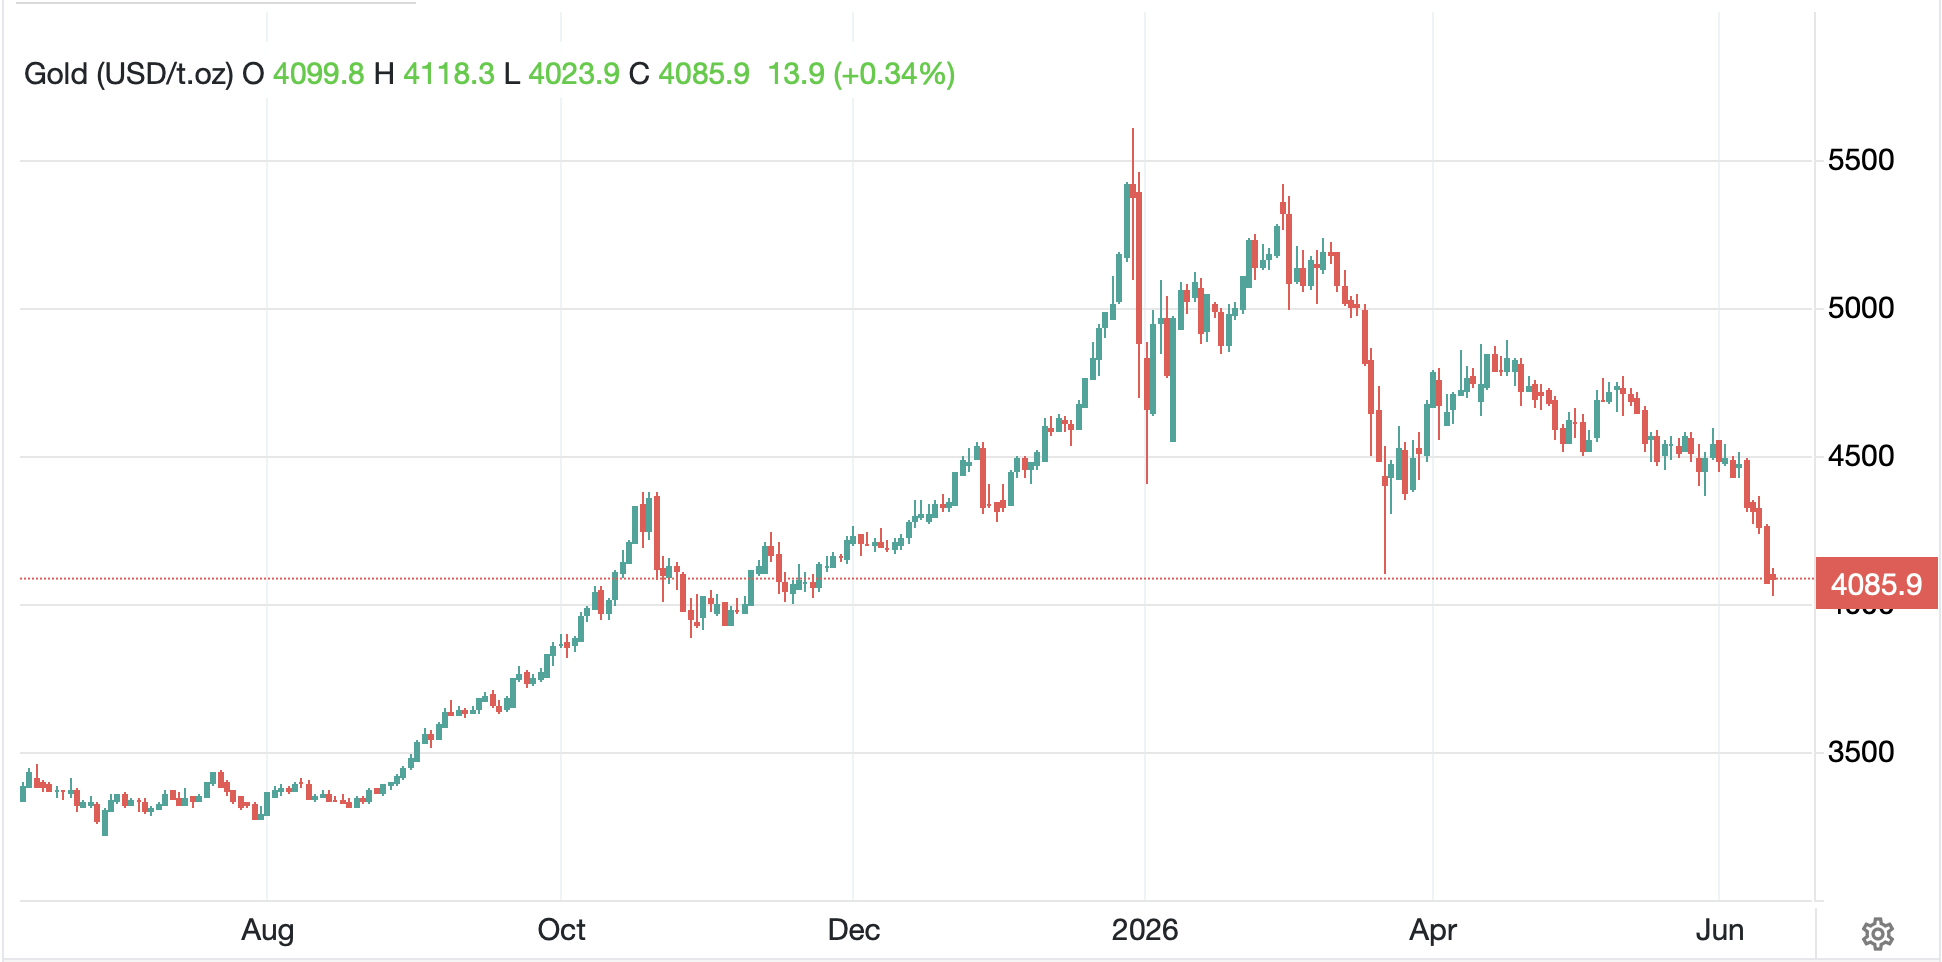
In the metals markets, it is no surprise that both gold and silver fell yesterday with the jump in oil prices, but despite oil’s continued rally this morning, both gold (+0.7%) and silver (+0.7%) are finding support, with gold seeming to hold the $4000/oz level for now.  Copper (+1.6%) is also holding up well, but its relation to the precious sector seems to be waning.  Perhaps the precious metals story is less about oil and more about the dollar.

Turning to the dollar, yesterday it put in a strong performance with the DXY rallying about 0.3% from Friday’s closing levels as you can see in the chart below.

Source: tradingeconomics.com

However, as you can also see in the chart, this morning the greenback is under pressure despite the rise in oil prices and yesterday’s increase in yields.  The biggest outlier is NZD (+0.9%) as the RBNZ continues to make hawkish statements about the need for further rate hikes.  And of course, NOK (+0.7%) is benefitting from the oil price rise.  But the rest of the G10 are all firmer, and so is most of the EMG bloc with only INR (-0.5%) standing out as underperforming.  That story appears to be based on higher oil prices and concerns, or thoughts at least, that the RBI will not be aggressively hiking rates to protect the rupee.  Otherwise, most currencies have moved higher vs. the dollar on the order of +0.15% to +0.25%.

And that’s really it today with CPI the only data release other than the already released NFIB Small Business Optimism index (97.4, exp 95.8), but that predates the change in the Gulf.  Chairman Warsh has his work cut out for him to get his colleagues to shut up.  I wonder if he can fine them if they speak.

We are in a narrative transition right now, but longer term, I remain bullish the US and the dollar.  

Good luck

Adf

A Warshach Test

While narrative writers obsessed
For some this was a Warshach test
The doves and the hawks
Each messaged their flocks
That Warsh, to their views, acquiesced

Meanwhile, in Iran bombs are falling
And President Trump is name calling
However, despite
The restarting fight
Risk assets keep on, higher, crawling

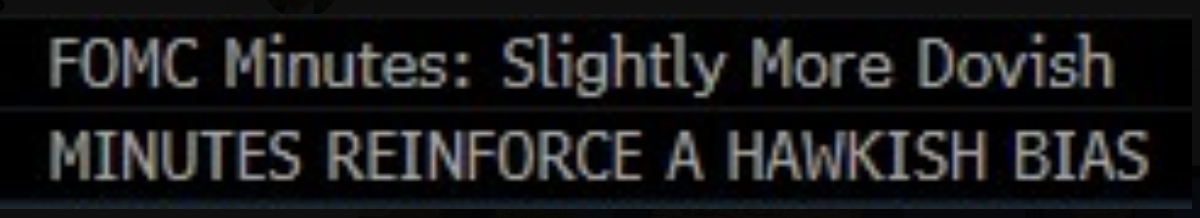
So, the FOMC Minutes were released, and they were hawkish dovish irrelevant.  The best expression of this came from Bloomberg’s Joe Weisenthal when he posted this on X,

Two simultaneous takes on the release that he received.  And I confess, I read those Minutes and didn’t learn anything at all.  It seems that the decision to leave rates on hold was unanimous although several committee members would have voted for a hike as well.

What does this say about the state of things?  I am very hopeful that we are on our way to a Fed that is less intrusive in market activities, both by reducing its balance sheet size, something that Chairman Warsh has expressly indicated as a goal, and by hearing less from committee members.  As @inflation_guy, Mike Ashton explains here, if forward guidance is dead, then why do we need to hear from any FOMC members about anything?  All those speeches were simply each member’s way to get their opinion out there and try to influence markets.  As I have frequently written, we would be much better off if the Fed were opaquer in their decision making as it would reduce risk and leverage and that would enhance financial market stability.  For everyone who wants Warsh to be Volcker redux, remember, back then, there were probably fewer than 10 people on Wall Street, let alone anywhere else, who could name a single member of the FOMC other than Mr Volcker himself.  That is an aspirational goal!

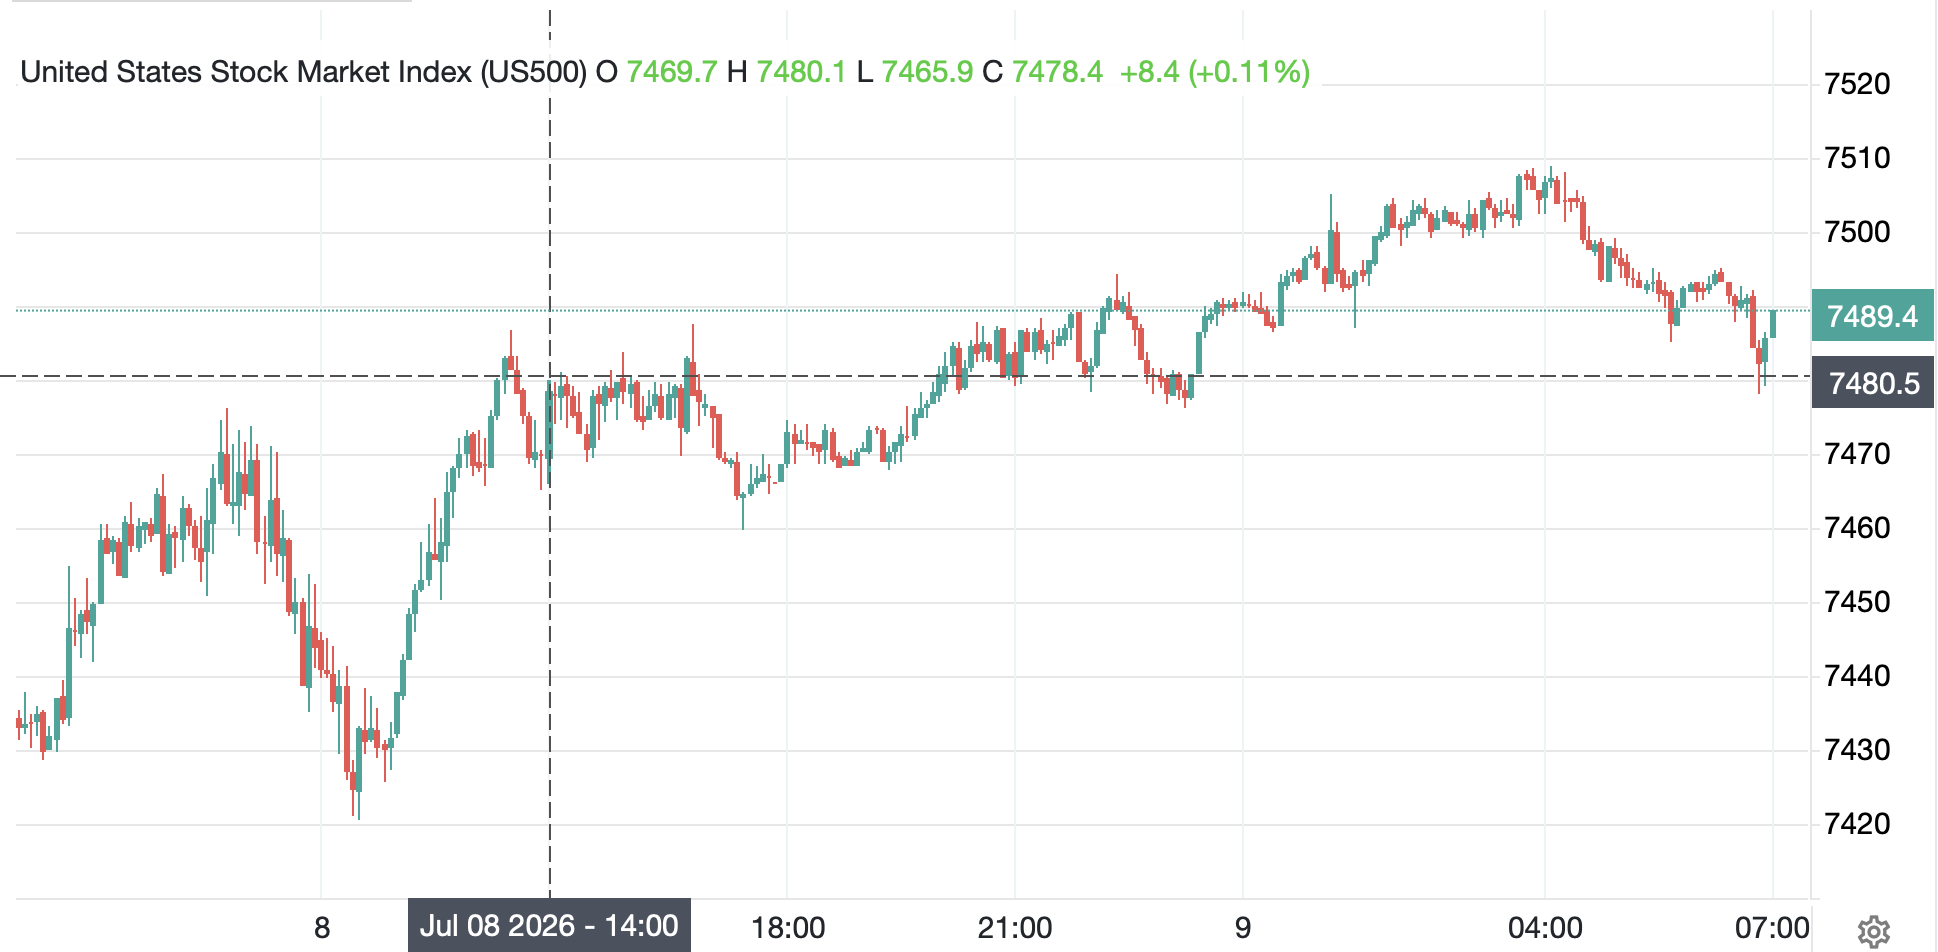
How did the market respond to the Minutes?  They basically ignored them.  Equity markets, which had opened much lower, were already in the process of reclaiming those losses when the Minutes were released and edged higher from there, with no meaningful change in trajectory as you can see in the below chart of the S&P 500.

Source: tradingeconomics.com

How about bonds?  Well, here is the 10-year chart and you tell me if the Minutes had an impact.

Source: tradingeconomics.com

I guess the real question is will the rest of the world’s central banks follow Mr Warsh’s lead and seek to end forward guidance and simply go about their job of managing inflation?  One can always hope.

Which takes us to the other story of note, the apparent end of the ceasefire in Iran and the question of what is now happening in the Strait of Hormuz.  First, let’s be clear, nobody really knows as the fog of war remains thick.  Obviously, yesterday saw a sharp rise in the price of oil as concerns over future transits of the Strait rose dramatically.  However, as of this morning, while WTI (+0.6%) has edged slightly higher from yesterday’s closing levels, as you can see from the chart below, it seems to have found a new short-term home here around $74/bbl.

Source: tradingeconomics.com

Scrolling through X this morning, the $200/bbl analysts were back at it, explaining that this time, with all those inventories having already been used up, we are going to see much higher prices.  But weirdly, yesterday’s EIA data showed an inventory build of 3 million barrels.  I keep seeing charts of the US SPR and how it is at its lowest level since 1982 implying that we are on the cusp of running out like this one from Bob Elliott.  Now, Bob Elliott is a really smart guy, but I feel like the piece of the puzzle that is missing in these analyses is that right now, the US is producing just under 14 million bpd of oil, plus another ~7.5 million bpd of natural gas liquids and 110 billion cubic feet/day of dry natural gas.  In fact, we are a massive exporter of oil and products, so perhaps a better question is, why do we need an SPR anymore?  After all, it was created when we were at the mercy of the Middle East and producing just 8.6 million bpd.  That is no longer the case.

My take is the world can run perfectly well on $75/bbl oil and there is plenty of supply at that level.  In addition, we have seen numerous announcements of how Gulf oil producers are building new methods of transport away from the Strait, and over time, that will no longer be a choke point with any meaning.  War is exciting to market participants for about two weeks, at which point they get bored and move on to the next big thing.  After all, the Ukraine war has been ongoing for 4 years and it doesn’t get a mention in market commentary.  Next week we start to see earnings releases for Q2 and that will be much more interesting for equity, and likely all other, markets.

In the meantime, let’s see what happened overnight.  Based on the mix of information, we cannot be surprised that there were mixed outcomes in equity markets around the world.  Yesterday’s US split (DJIA -1.1%, NASDAQ +0.2%) was followed by gains in Tokyo (+1.4%), China (+2.5%), Korea (+0.6%) and India (+0.3%) while HK (-0.7%), Taiwan (-0.8%) and the Philippines (-0.8%) all slid a bit.  There was no rhyme or reason here.  The only data of note overnight was Chinese inflation data where CPI fell to +1.0%, while PPI rose to +4.1%.  It strikes me that Chinese companies will continue to see pressure on their margins.

In Europe, things are also mixed with Spain (+0.8%), Italy (+0.7%) and France (+0.3%) all higher while the UK (-0.6%) is slipping and Germany is little changed.  As to US futures, they are leaning higher at this hour (7:50).

Bond markets seem to have stopped selling off as yields this morning are little changed (Treasury +1bp, Bunds +1bp, Gilts -3bps, OATs -3bps).  JGBs were unchanged overnight.  The 10-year auction yesterday went pretty well with a bid-to-cover ratio of 2.59, although with yields at 4.58%, it is not that surprising there was real demand.  I will say this, bonds, too, are a market with some smart folks with diametrically opposed views of the future outcome.  Both 3% and 6% are seen as the next major destination depending on the analyst.

Interestingly, metals markets are showing some life this morning with gold (+0.8%), silver (+1.4%) and copper (+2.2%) all bouncing off recent lows.  This is a bit out of character compared to recent price action relative to oil, but maybe we are putting in some bottoms here.

Finally, the dollar is, net, little changed this morning.  In the G10, NZD (+0.65%) is the big mover, which continues on the back of their rate hike from yesterday.  But otherwise, +/-0.1% is the norm here.  In the EMG bloc, KRW (-0.5%) is giving back some of its recent gains but continues to hover near multi-decade lows.  The recent gains have been on the back of a record current account surplus, but it remains an interesting conundrum that despite the massive gains in the Korean stock market, the currency has not attracted more buying interest.  Otherwise, modest EMG gains on the order of +0.1% are today’s story.

On the data front, we see Initial (218K) and Continuing (1820K) Claims as well as Existing Home Sales (4.20M) today.  In addition, there are two Fed speakers as I imagine getting them to shut up will take some time.  However, I wonder, will they really add to the discussion?

Oil continues to be the driving force in markets, but right now, my sense is eyes are turning to upcoming earnings releases.  Of course, we also get CPI next week, which will be a critical number for markets, at least for now.  

Good luck

Adf

Rise Like the Sea

So, let’s take a sec to discuss
Inflation, and why it’s a plus
At least for some folks.
In gentle broad strokes,
Though most of us see it and cuss

For those who hate Trump it’s a key
To help destroy his legacy
For Congress, they need
Inflation to plead
That taxes must rise like the sea

And what of the Fed and their role
To keep it in check, on the whole
Now, if they’re successful
T’would truly be stressful
For everyone on their payroll

If you were a government and wanted to design the perfect process by which to extract more money from your citizens allowing you to spend more money on the things you wanted, whatever their views, all while explaining that their lying eyes were deceiving them when they complained, it would be hard to come up with a better process than the official inflation figures.  Of course, today we get more of those figures with PCE and its variants set to be released at 8:30.  While I am here, these are the current market median estimates: PCE (0.5%, 4.1% Y/Y), Core PCE (0.3%, 3.4% Y/Y) although I see no forecast for the Dallas Fed Trimmed Mean reading, the one that Chair Warsh says he wants to focus on.  Too, it is key to remember that they are May numbers.  How many of you can remember what happened in May?

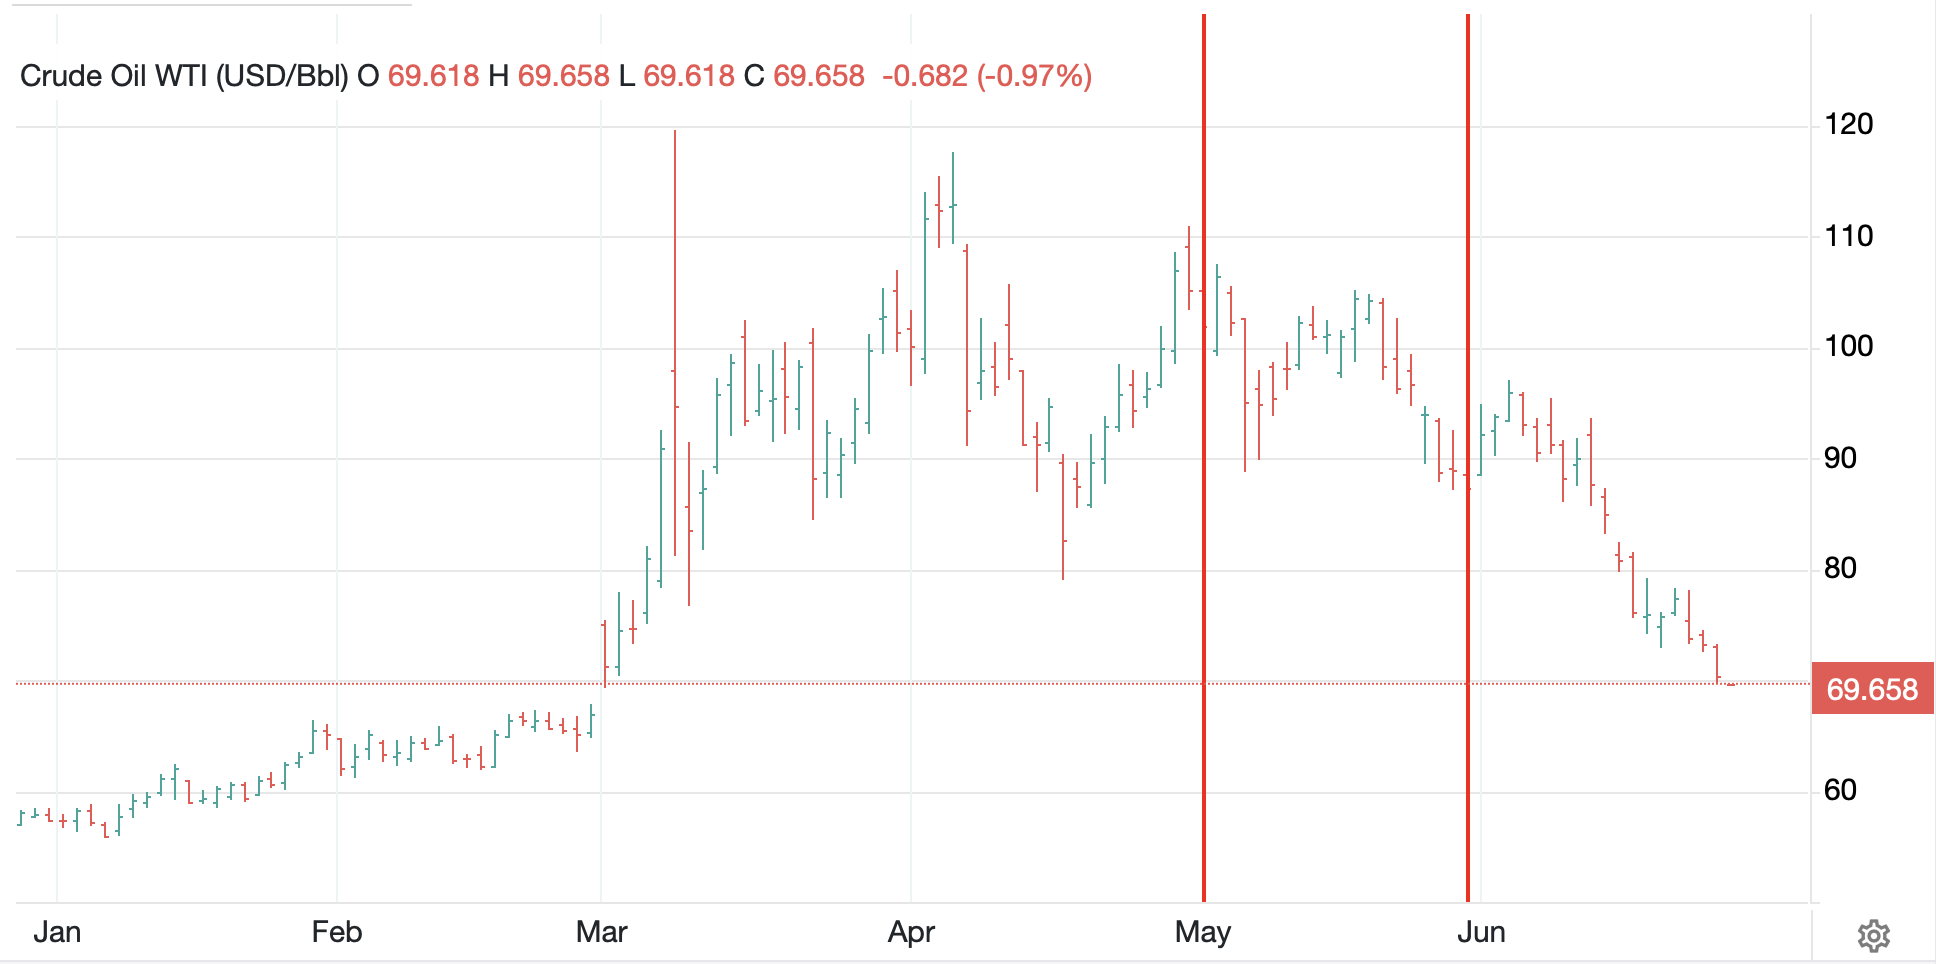
For instance, looking at the easiest one, oil (-1.0% today), as per the below chart, you can see that WTI ranged between 86.50 and 106.50 during May, mostly sliding, bur arguably averaging in the low 90’s.

Source: tradingeconomics.com

This morning, it is trading below $70/bbl, back to the price on March 2nd, the first market day of the Iran conflict.  The BLS indicated that upwards of 60% of the rise in CPI was driven by the rise in energy prices, which tells me that whatever today’s numbers are, they are ancient history and next month’s are going to be lower.  I don’t know about you, but I am quite happy that energy prices are falling back to pre-war levels as, a) it makes life more affordable, and b) cheap and abundant energy leads to significant economic output, something good for us all.

But here’s the thing, with energy prices declining, those who benefit from high inflation need a new story, and there is none better than semiconductors.  The top headline in the WSJ this morning is The Data-Center Boom Is Sparking a Third Wave of Inflation, right on time for the next big inflation scare.  The big winner, at least today, Micron Technology, which had blowout earnings last night and jump-started a serious Techquity™ rally overnight with Tokyo (+4.6%), China (+1.6%) and Korea (+5.4%) leading the way.  HK (-1.4%) lagged and the rest of Asia was mixed, but that gives you an idea.

But the point of the article was that we all need to be prepared and accept that higher inflation is coming because the massive resource demands to build AI are coming along before the productivity gains can moderate the price impact.  And I have no doubt that the resource demands are going to support prices.  I remain uncertain over how quickly AI’s impact will be deflationary, even disinflationary.

And here’s the thing, my lived experience, plus my frequent conversations with The Inflation Guy, Mike Ashton, have me in the camp that CPI is going to live in the mid to high threes for a while to come, regardless of the metrics the Fed uses to measure things.

But I have begun to discern that there is a large community that benefits from rising inflation because it helps them achieve their goals.  After all, we know that governments love inflation as it devalues the real value of their outstanding debt, so a steady depreciation is their best friend.  As well, Congress’s baseline budgeting ruse, which starts each year from the previous year’s expenditures, not from zero, is a huge beneficiary of inflation.  I understand that since about 1980, the BLS has adjusted the CPI calculation somewhere between 30 and 40 times and you can guess the direction of most of those adjustments.  Of course, companies that sell products are a big fan as well, as they tend to adjust prices to both include new costs, and increase margins.  And they have a natural scapegoat; CPI is out of their hands.

All I’m saying is that while there appears to be a strong effort to fight inflation, I’m not a believer.  (And here I should highlight that I use the term ‘inflation’ in the manner it has become understood, rising prices, and not in its classical form of an increase in the money supply, which is 100% the Fed’s doing.)

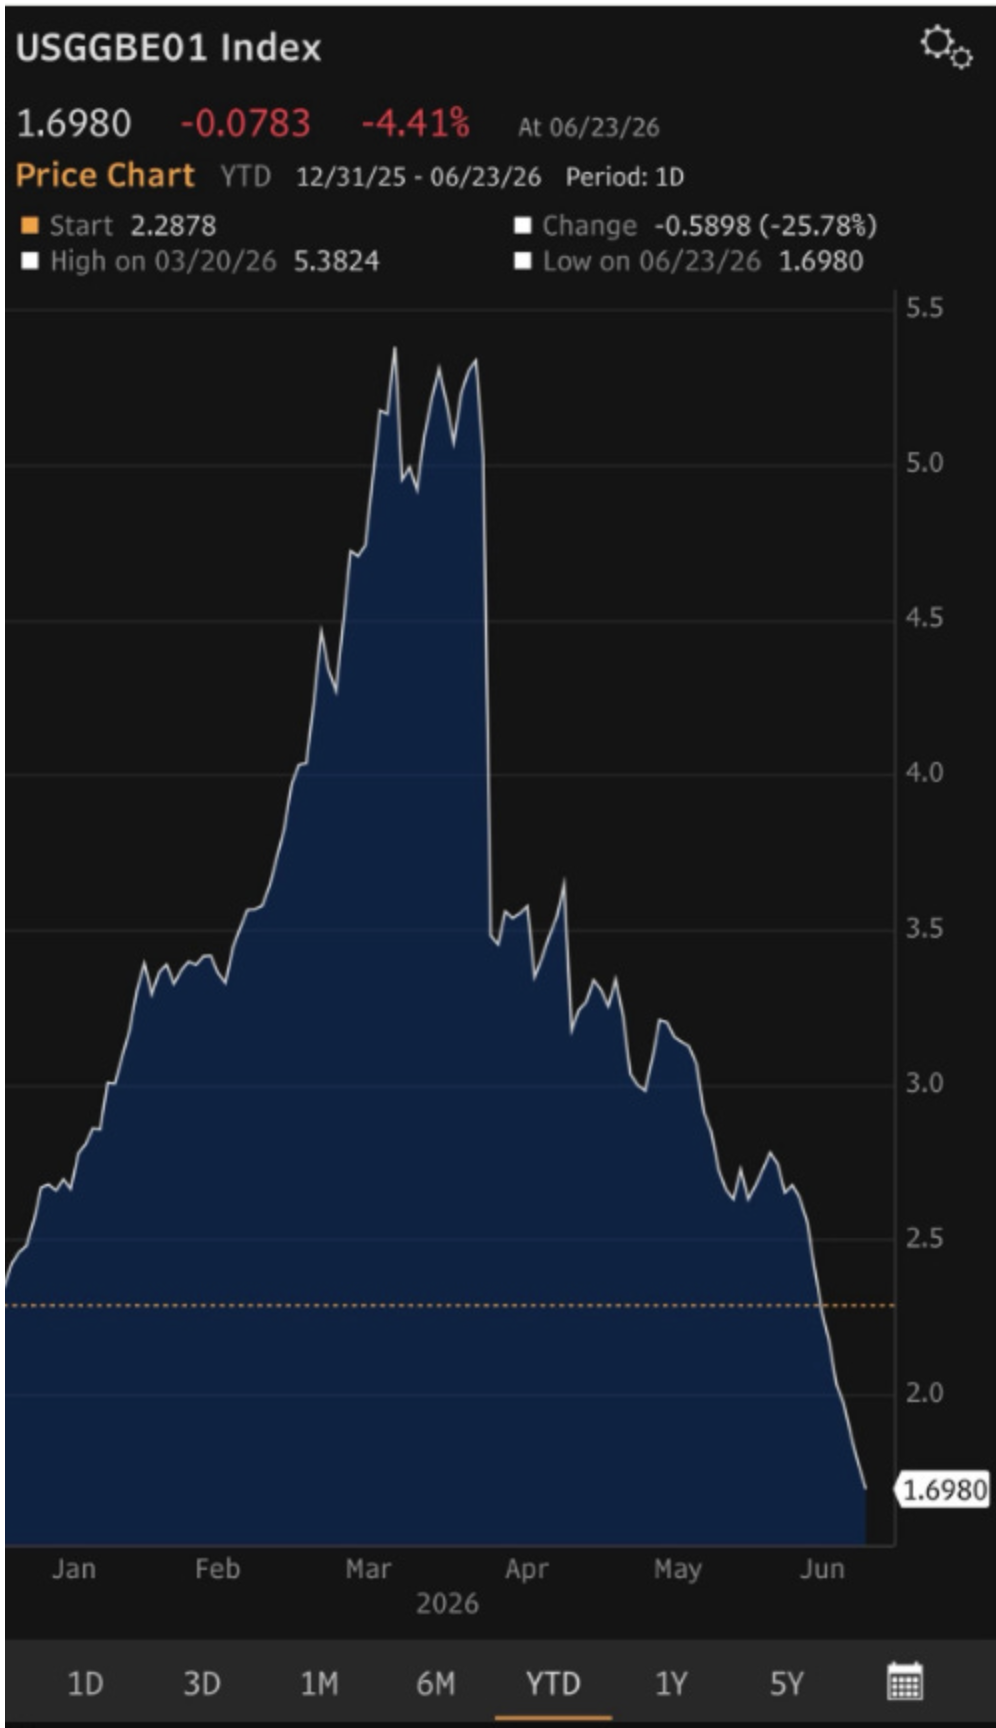
One other thing.  My friend JJ who writes Market Vibes, posted a chart of 1yr breakevens as of yesterday and I reproduce it below.

This is not a signal that the market expects prices to rise, but rather is following the decline in oil prices pretty well.  Once again, I will ask, please explain given market signals, why everyone is so sure the Fed is going to hike.  I maintain my one cut by year end view which is at least 50bps below the current Fed funds futures market pricing.  Ask yourself how the FOMC ‘hawks’, and I use that term loosely, will be able to argue for higher rates if oil continues its trajectory and inflation readings decline.  Precautionary?  How about they will simply say, we want to screw Trump, at least they would be honest then.

Ok, on to other markets overnight.  European bourses are all higher this morning, but since none of them have any real tech exposure, they are not running away.  Rather, 0.3% to 0.7% encompasses the magnitude of movement we have seen.  As to US futures, at this hour (7:25), NASDAQ (+2.0%) is leading the way, but the whole group is higher.

In the bond market, yesterday saw yields decline about -8bps in the 10-year Treasury and -6bps in the 2-year.  this morning they are little changed, consolidating those price gains.  As to European sovereigns, yields there also slipped yesterday, but not as dramatically, about -4bps, and this morning they are largely unchanged.  Overnight, JGB yields fell -3bps as declining oil prices are feeding through to inflation expectations.

The precious metals complex continues to get hurt, with gold (-0.6%) and silver (-0.5%) still under pressure and at new lows for the year, but copper (+1.25%) seems to have found a short-term floor at $6.00/lb.

And finally, the dollar, which has been en fuego lately, rising for the past six consecutive sessions, as per the below chart, is consolidating for now.

Source: tradingeconomics.com

Nothing has changed the yen story, where the dollar creeps ever so slightly higher each day, now just below 162.00 but overall, today’s movement has been quite muted, about +0.15% in the dollar against most currencies, as the focus turns to inflation, at least for today.

On the data front, in addition to the PCE data we get a bunch more as follows:

Initial Claims225K
Continuing Claims1800K
GDP Q1 Final1.6%
Personal Income0.4%
Personal Spending0.6%
Durable Goods-4.5%
-ex Transport0.6%
Chicago Fed National Activity0.12

Source: tradingeconomics.com

Will anyone care about this data?  I doubt it, Core PCE is THE thing today, so we will watch and see how that comes out. But mark my words, if it is soft, the hawkish Fed narrative is going to come under real pressure as stocks rally and yields and the dollar slip.

Good luck

Adf

Frankly, Outré

The rate of inflation expanded
Though core came out more evenhanded
The war in Iran
Ain’t going to plan
But oil’s not over demanded

However, the story today
Is SpaceX shares soon on their way
To stock market listing
Though some are insisting
Its value is, frankly, outré

It’s a funny thing lately, there has been quite a bit of market activity, but the narrative storylines are changing so quickly that they don’t seem to have a real impact.  So, every day there is some new thesis as to why prices are behaving in whatever manner they are.  It is almost as if the market is trying on different stories to see which one fits best.

As I am wont to do, I always like to step back and take a longer-term view on things as regardless of the daily wiggles, my experience is that those very big picture issues are what drive markets over time.  So, let’s review what I see as the key long-term drivers;

  • FX – ultimately, the combination of monetary and fiscal policies is critical in this space with a good rule of thumb being tight monetary and loose fiscal policy strengthen a currency while the opposite settings tend to weaken them.  When both policies are on the same setting, it is far less clear, although I would err on the side of monetary policy being the driver.  Key to this is that monetary policy tends to drive short-term flows.
  • Equities – earnings are still the ultimate issue here as, remember, shares represent ownership in a company (although the recent gamification of markets has certainly obscured that view).  Too, equities tend to be forward-looking, anticipating how future earnings are going to evolve.  The biggest change in this space has been the steady growth of passive investing, though, which represents more than 50% of the market now.  Passive investing simply means that as money flows into funds, like 401K’s, the funds buy stocks with the S&P 500 the most popular destination regardless of earnings and prospects.  So, flows are the other critical issue, just like in FX.
  • Bonds – despite much recent angst, Treasuries remain a haven asset and benefit from that status.  However, especially as you move out the maturity ladder, inflation expectations are the primary driver in an unencumbered market.  While much hay has been made regarding the extraordinary size of the US outstanding debt, now approaching $40 trillion, I do not believe we have reached a point where anyone believes they will not get their money back, albeit money that has been devalued by inflation.
  • Commodities – this is the space where supply and demand remain paramount, and really, it’s current supply and demand.  As such, the fact that oil is back below $90/bbl this morning tells us that a combination of increased non-OPEC supply plus some measure of demand destruction has found a new equilibrium level.  This remains far below the levels anticipated by many after the closure of the Strait of Hormuz, and there are still many analysts calling for a sharp move higher when all the mitigating factors that have prevented a much bigger move run out. This morning, Javier Blas at Bloomberg had an excellent piece describing his view of why oil prices aren’t higher despite the war.

Every narrative is an attempt to either describe or hide the longer-term issue, with much more hiding than describing in my experience.  But I stand by these concepts.

Which takes us to today’s narratives.  CPI yesterday was largely as expected, actually the core number at 0.2% M/M came in a bit light, but that stopped mattering about 2 minutes after the release.  Inflation has become a favorite subject about which to bitch, but very few do anything about it.  (if you want to do something, go to www.usdicoin.com and you can buy some USDi which is a fully backed inflation tracking cryptocurrency).  

There was a short resumption of military activity in the Gulf after a US helicopter was shot down by Iran and the US retaliated.  Frankly, I didn’t even read the details as they just don’t matter to the big picture.  It is unclear whether negotiations are ongoing, but the stalemate continues.

And finally, the truly big story, the SpaceX IPO this evening.  It is the one thing that has the most tongues wagging in the markets and if you read X, it appears there are many more analysts who believe the price is absurdly high than that it represents value.  I have no opinion on the deal but anecdotally, I did speak with someone last evening who just put money into a Fidelity VC fund that has stakes in all the big names (SpaceX, Anthropic, OpenAI) and a 10-year lockup and is very excited.  

So that’s where I see things this morning.  Yesterday’s US equity declines were followed by more weakness (China, HK, India, Australia, New Zealand) than strength (Korea, Singapore) in Asia.  Tokyo was essentially unchanged.  However, in Europe this morning things are much brighter with solid gains across the board.  US futures, too, are higher this morning by about 0.7% across the board as I type at 7:15.

In the bond market, yields have edged back down with Treasuries (-3bps) leading the way and European sovereigns right there with them.  Whatever longer term concerns about inflation exist are not showing up aggressively at this point.

In the commodity markets, oil (-1.1%) continues to underperform all the calls for catastrophe and another anecdote, I saw diesel below $5.00/gallon yesterday for the first time in several months.  Products are available.  As to the metals, they are uniformly hated although this morning both gold (+0.4%) and silver (+0.6%) have edged a touch higher.  However, the trend here in gold (and silver) is clearly back down for now. 

Source: tradingeconomics.com

Nothing has changed my longer-term concerns over fiat debasement, but for now, gold is not the play.

Finally, the dollar is somnolent this morning, with the euro, pound and yen all basically unchanged but sticking near recent dollar highs.  No matter how I slice it, I cannot come up with a significant dollar down story despite many having that view.  The US economy, by most measures, continues to drive global growth and I suspect that will remain the case for a while yet.

On the data front, this morning brings the weekly Initial (exp 219K) and Continuing (1780K) Claims data as well as PPI (0.7% M/M, 6.4% Y/Y) and core (0.5% M/M, 5.4% Y/Y).  We also hear from the ECB shortly, with a near universal belief that they will be hiking 25bps in order to drill for more oil push back against the recent energy induced price rises.  The beginnings of a major error in my view.

And that’s really it.  It has been getting more difficult to find interesting things to discuss, that’s for sure, and as we head deeper into the summer, the doldrums have a history of keeping things dull.

Good luck

Adf

Stoke Some More Fear

The word of the day is inflation
As data from many a nation
Appears, still, to show
It has room to grow
With fears this is no aberration

But are things as bad as we hear
From media outlets who cheer
More pain, as they make
Their case Trump will break
The nation, and stoke some more fear

It’s CPI day here in the US and similarly, we got readings from various nations around the world overnight.  To level set, expectations for this morning’s numbers are:

  • Headline – 0.5% M/M, 4.2% Y/Y
  • Core – 0.3% M/M, 2.9% Y/Y

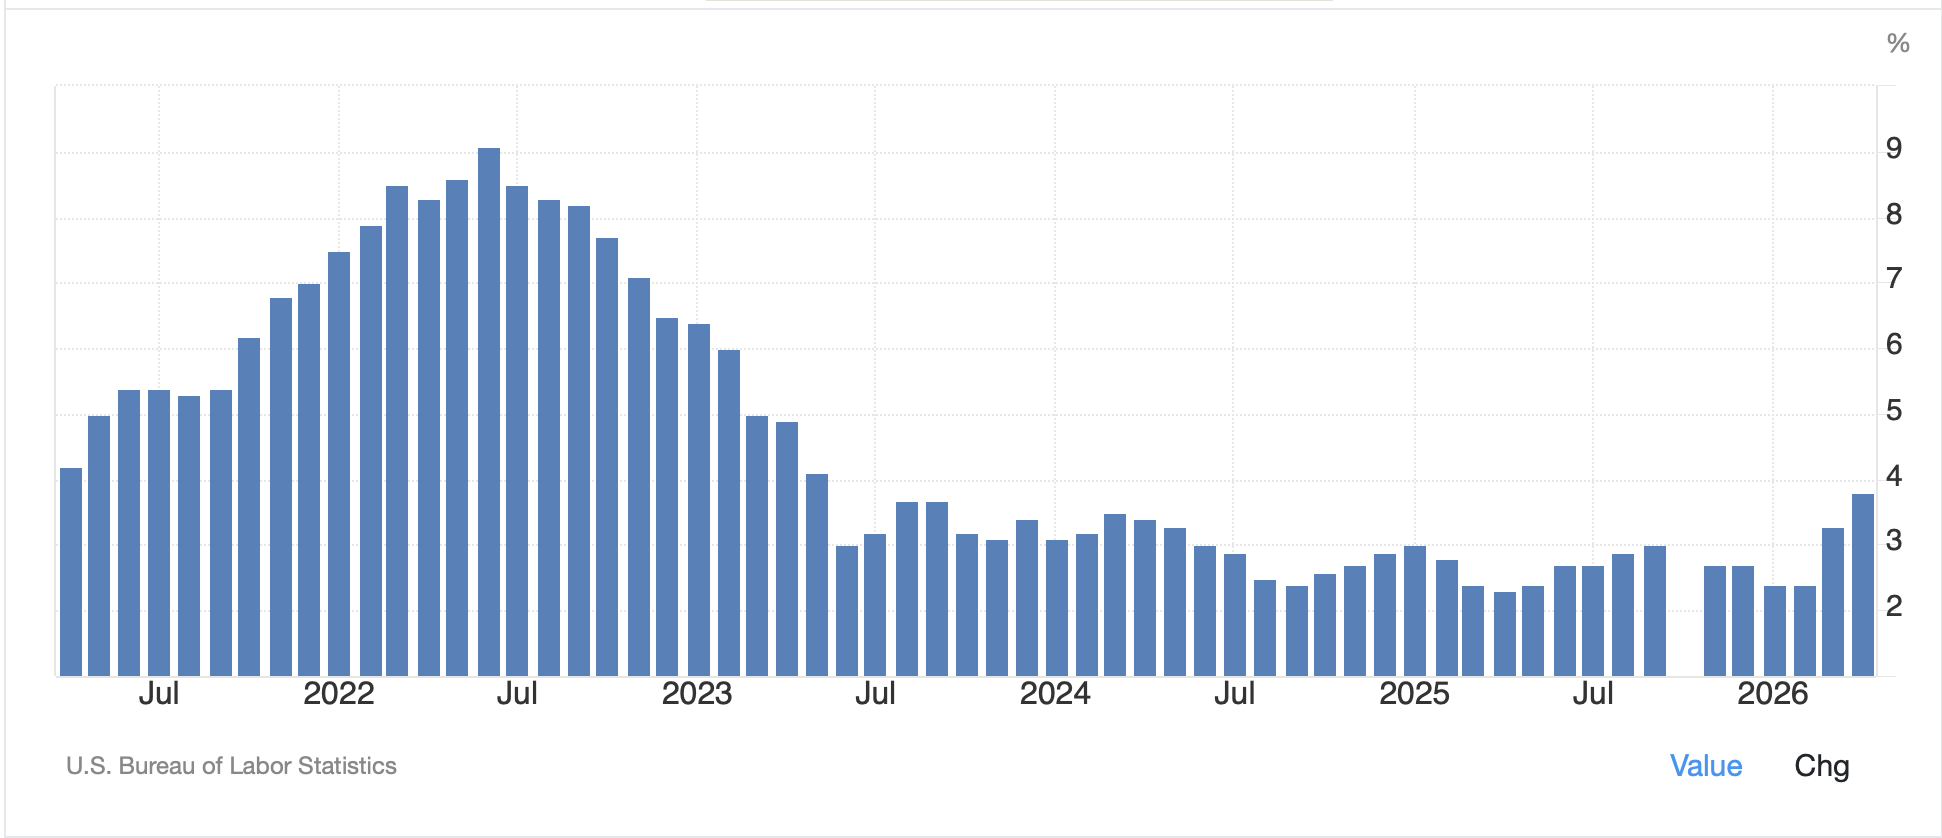
On an annual basis, as you can see in the below chart from tradingeconomics.com, 4.2%, while much higher than some recent data and much higher than we would like, was seen as recently as April 2023 during the “transitory” phase from the Covid years.

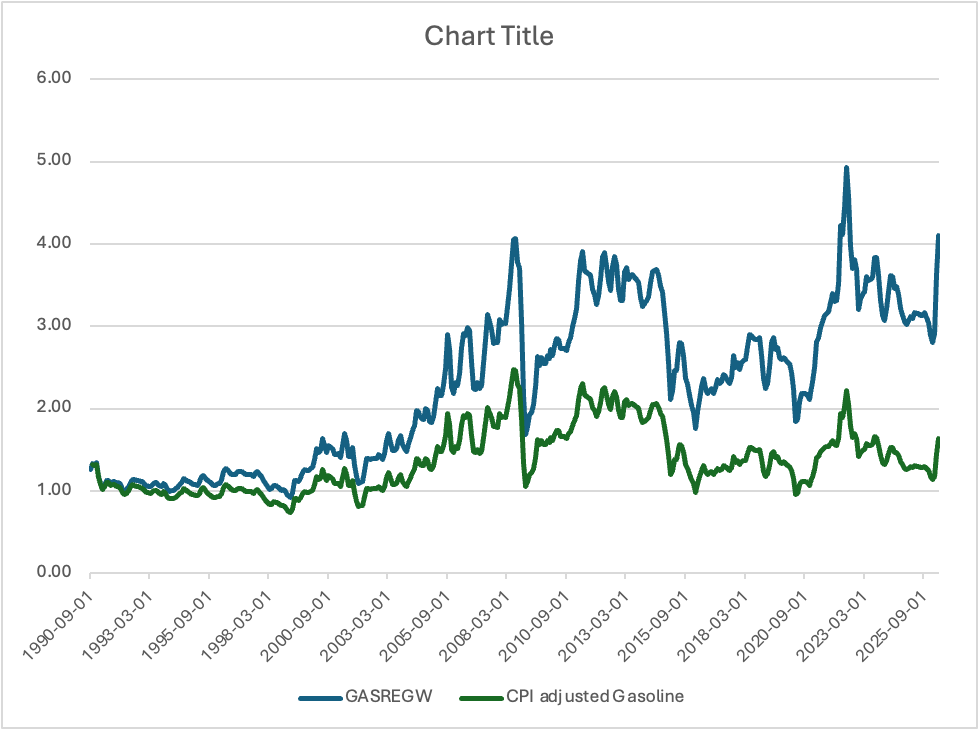
And don’t get me wrong, I am as sensitive to inflation as all of you as I go to the supermarket or Costco and see prices and fill up my car’s gas tank as well.  In fact, speaking of gasoline, there is no question it is much higher than it was prior to the beginning of the Iran conflict.  Looking at the chart I drew from FRED data below shows that, nominally, it is back at levels from the immediate aftermath of Russia’s invasion of Ukraine in 2022.  But look at the other line on the chart, that is the price of a gallon of unleaded adjusted for CPI starting back in 1990.  It is remarkable that the latest reading, while still obviously higher than a few months ago, is just $1.635/gallon in real terms.

Somebody else pointed out that gasoline is one of the few things that seems rarely to be described in real terms, arguably because it hasn’t really risen all that much over time and those who describe things in real terms are frequently trying to make the point that inflation is far too high.  Arguably, though, this is further proof of famed economist Julian Simon’s thesis that commodity prices all head lower over time as the ability to produce them in abundance, and their relative abundance in the earth, drive those prices lower.

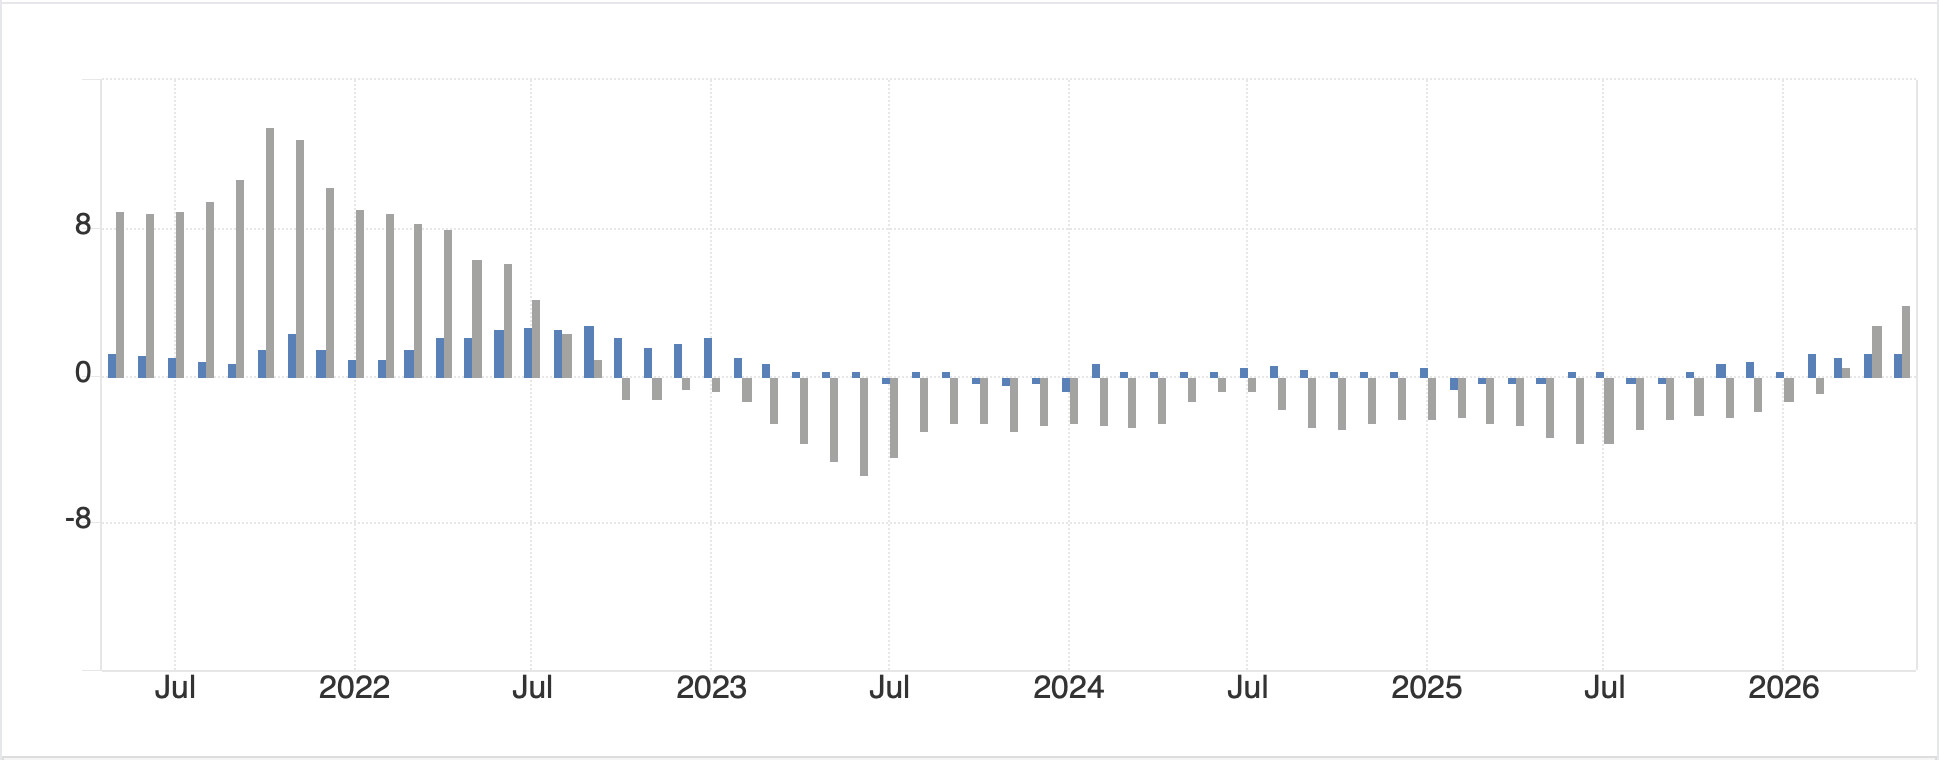
As to elsewhere in the world, last night China reported that CPI (blue bars) remained at 1.2% but PPI, which may be a better indication of price activity there, rose to 3.9%.  This implies that Chinese corporate profits are under increasing pressure.  It also represents a sea change in China as can be seen in the below chart where PPI (grey bars) was negative for the 3 years prior to April.  

Source: tradingeconomics.com

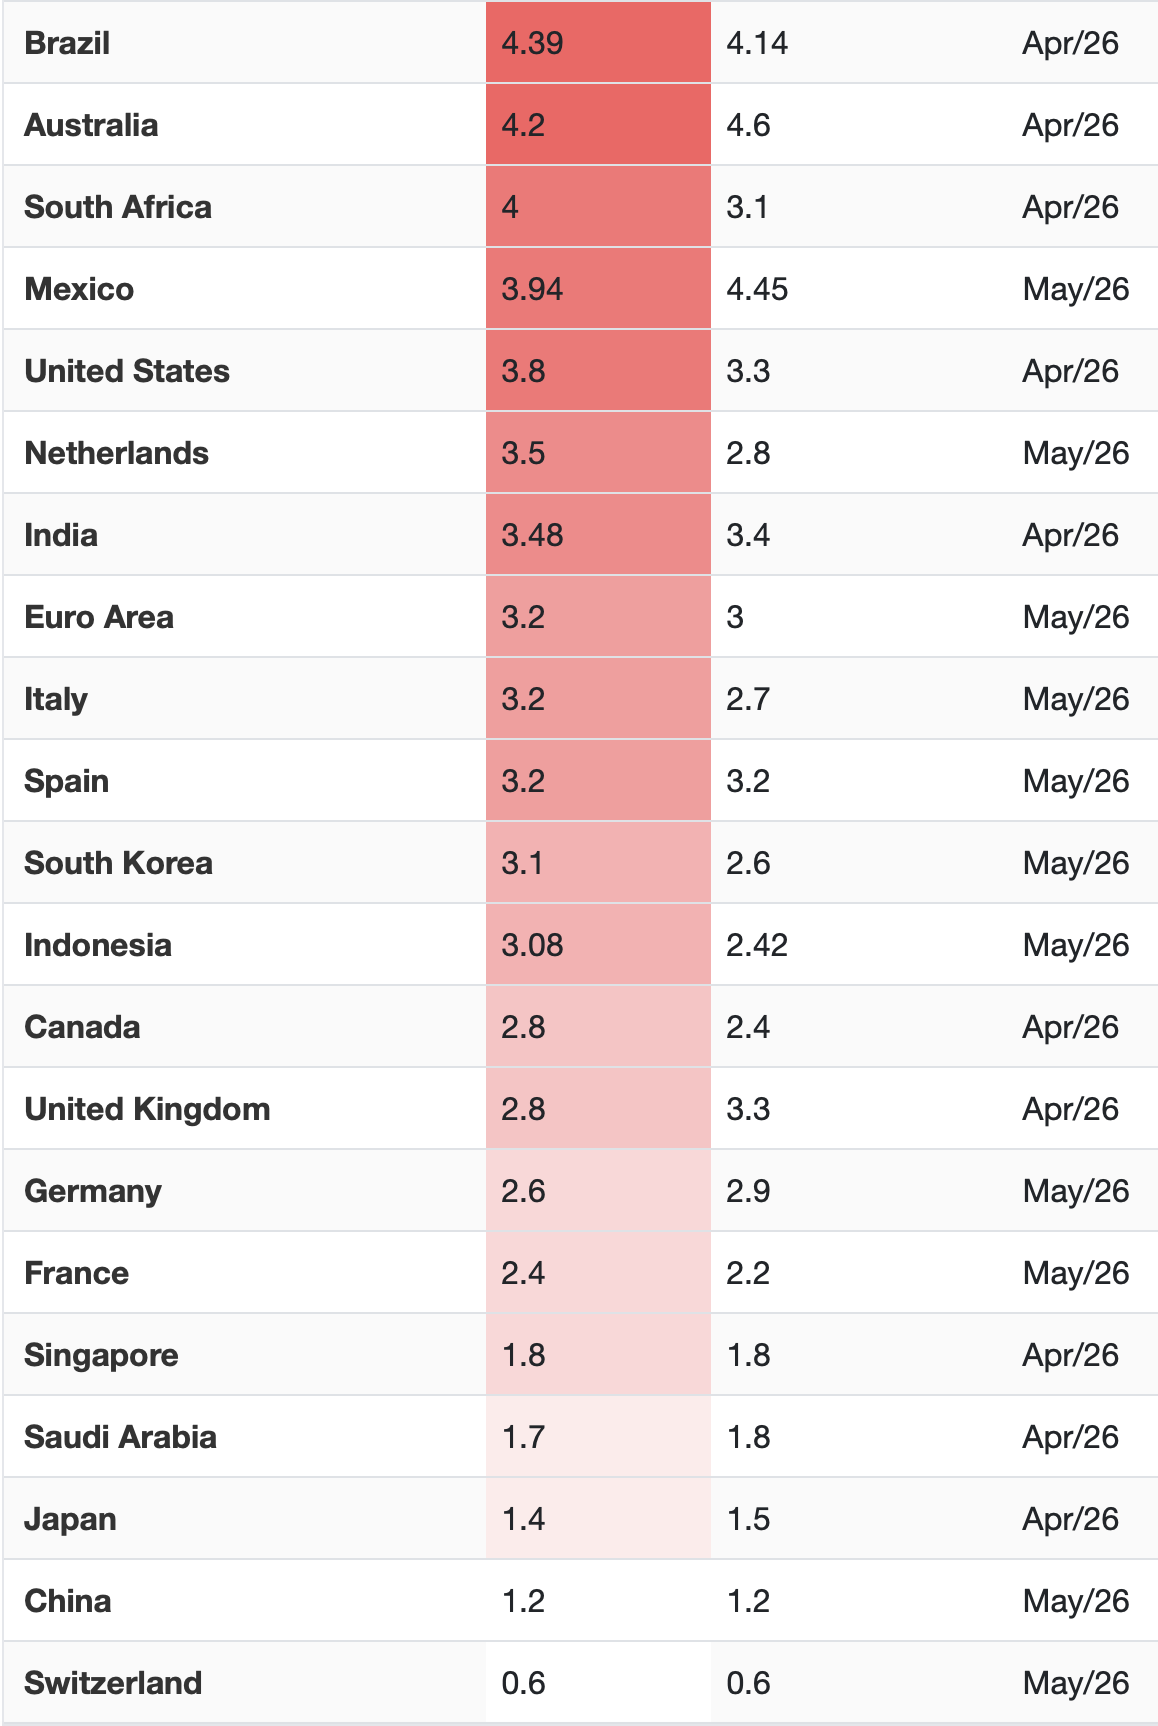
As with all inflation analysis, the real question is who absorbs the price pressures.  In the US, the recent experience from Covid, when the government helicoptered $5 trillion into the economy so people had money to spend, businesses raised prices and continue to believe they can do so.  Apparently in China, that is not the case.  To finish the discussion, below is a chart of 17 of the G20 nations and their most recent headline CPI readings (I left out Argentina, Turkey and Russia as I couldn’t fit them all on the screenshot).  Interestingly, only 11 of these 17 nations have seen CPI rise in the past month.  I wonder, is inflation the global phenomenon that some make it out to be.

Country Last. Previous Date

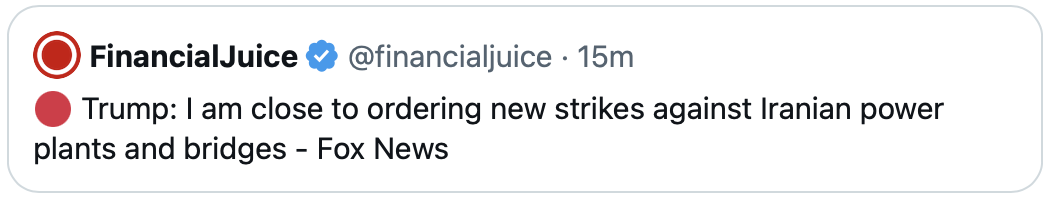
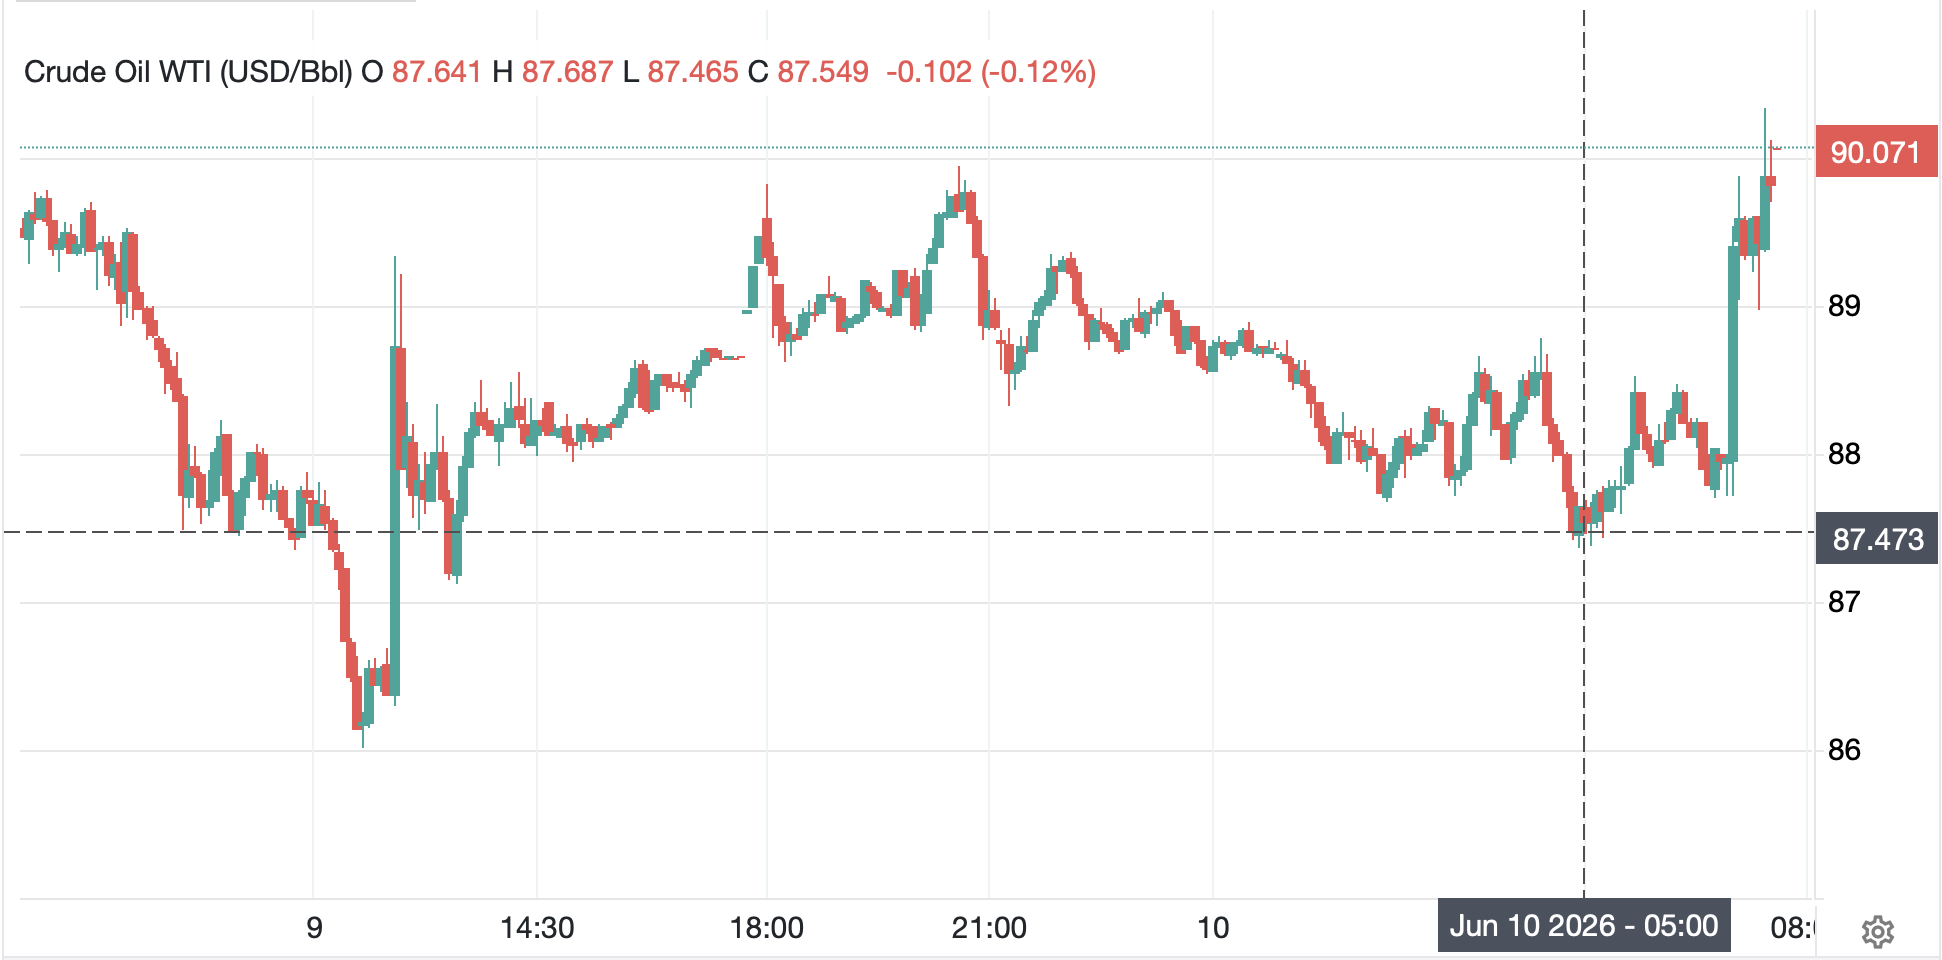
Ok enough on that.  Let’s move on to market activity.  For the past several days, the oil story did not seem quite as important as despite a few random missiles being fired, it appeared that the Iran conflict was quieting down.  This allowed the focus to turn to important things like AI and the SpaceX IPO coming tomorrow after the close.  For example, when I sat down this morning around 5:00, oil was around $87.50/bbl and had slipped slightly lower compared to yesterday’s close.  However, in the interim, President Trump tweeted out the following:

But despite these comments, while oil has jumped as per the below chart, it is just barely at $90/bbl, hardly a sign the market believes something dramatic is on its way.

Source: tradingeconomics.com

In the meantime, there continue to be multiple articles that we are heading to the cliff for oil inventories and prices will skyrocket soon.  You know my opinion on those as I take the market’s side things are not as dire as some believe.

But if things heat up in Iran and the Gulf, I expect that we will see a downdraft in equities and bonds while the dollar moves higher.  And that is what we are currently seeing.  Below is a screenshot of equity futures markets as of 7:45 this morning.

source: tradingeconomics.com
Not a lot of happy faces there.  As well, overnight saw weakness throughout most of Asia after yesterday’s modest US declines.

In the bond market, Treasury yields are backing up 3bps and European sovereign yields are also higher this morning, between 3bps and 5bps across the entire continent.  So despite my statements above that inflation may not be as big a deal as some explain, bond investors are at least a bit uncomfortable this morning.

As to the metals markets, that break below the 200-day moving average in gold is seeing real follow through as old long positions and new short momentum plays pile on with the barbarous relic (-2.5%) tumbling as well as silver (-1.9%) and copper (-1.2%).  The key here is that whatever the short-term price action is, I think the one unalloyed truth is that fiat currencies will continue to get printed like there is no tomorrow and precious metals will regain their form.  But it could take a while.  In that vein, there was a Bloomberg article this morning explaining that more government bonds have been sold at this point in the year, ~$504 billion, than the first half of 2020 with Covid.  If my short-term inflation thesis is wrong, this is the reason why.

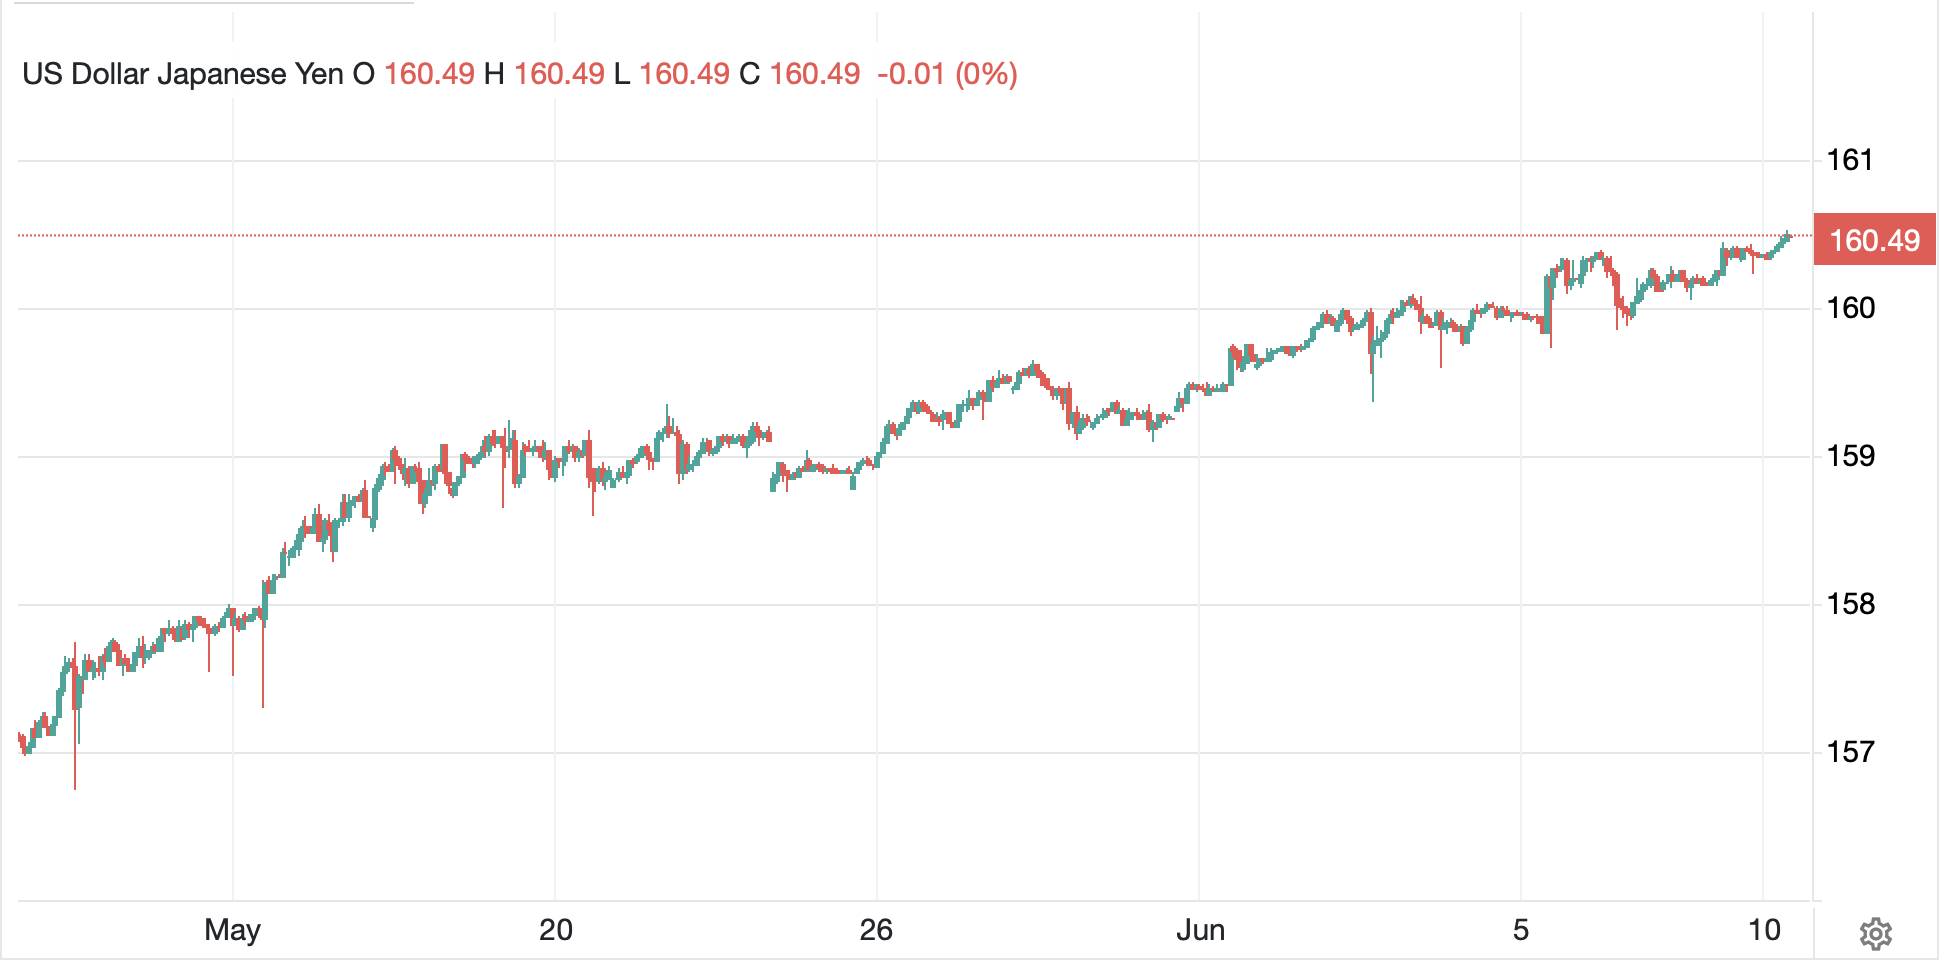
Finally, the dollar has edged higher this morning but is generally little changed.  The noteworthy thing is that USDJPY is at 160.50, above the supposed line-in-the-sand for the MOF, but as you can see from the below chart, the movement has been extremely gradual, with very little volatility.  Remember, one of the things the MOF focuses on is that volatility, so if the dollar continues to creep higher, they are likely to hold off for a while before feeling the need to intervene.

Source: tradingeconomics.com
But otherwise, most currency movement has been modest overnight.

Aside from CPI, and the oil inventory data, we do hear from the Bank of Canada, which is likely to leave policy rates on hold.

It feels like the market is getting increasingly concerned over an uptick in activities in the Gulf, which will have a negative impact on financial assets but support the dollar.  We shall see.

Good luck

Adf

His Denouement

In England and Scotland and Wales
Without getting into details
The PM has lost
Support, and will be tossed
But Labour, so far’s, moved like snails

Until the time comes when he’s gone
And Keir reaches his denouement
Both gilts and the pound
Will fall toward the ground
But they’ve no one to settle on

While the stalemate in the Gulf continues, although there is clearly less optimism that things are going to end quickly according to the oil market (+3.0% and back to $101/bbl), there are a few other things that are ongoing in the world that are impacting markets.  This morning, the most obvious is in the UK, where PM Keir Starmer, he of the <20% approval rating, is seeing his grip on power slip away, but like most politicians, he will hold on as tightly as possible for as long as possible regardless of the negative impact that has on his constituency, which in this case is the entire nation.

For instance, a quick look at the gilt market shows that yields there, this morning, have jumped 12bps in the 10-year, up to their highest level, at 5.11%, since April 2008, as per the below chart from marketwatch.com.

Perhaps, of more concern for the UK Treasury and the BOE is the fact that the spread between US Treasuries and UK Gilts has jumped 9bps this morning and, at 67bps, is now pushing back toward its upper quartile, also not seen since 2008 as per the below chart from worldgovernmentbonds.com.

The pound (-0.5%) is faring no better this morning, lagging the rest of the G10 while UK stocks suffer alongside with the FTSE 100 (-0.6%) adding to the overall pressure on Starmer. 

Now, in fairness to poor Keir, he has failed in essentially every aspect of government, notably as to his promises when elected, so this cannot be a surprise.  The question becomes; how much longer will he try to fight this very clear outcome to the detriment of his nation?  From a fiscal perspective, I imagine he will be seeking to offer money to specific constituencies in an effort to buy more time, but my take is the die is cast here.  For now, I expect UK assets and the pound are going to underperform and likely will until he is gone, regardless of his replacement.

However, aside from the war in Iran, where there is nothing new of note today, the next biggest stories are that President Trump is on his way to Beijing to meet with President Xi and this morning’s CPI report.  Since I can offer nothing of note on the summit meeting, let’s turn to inflation.

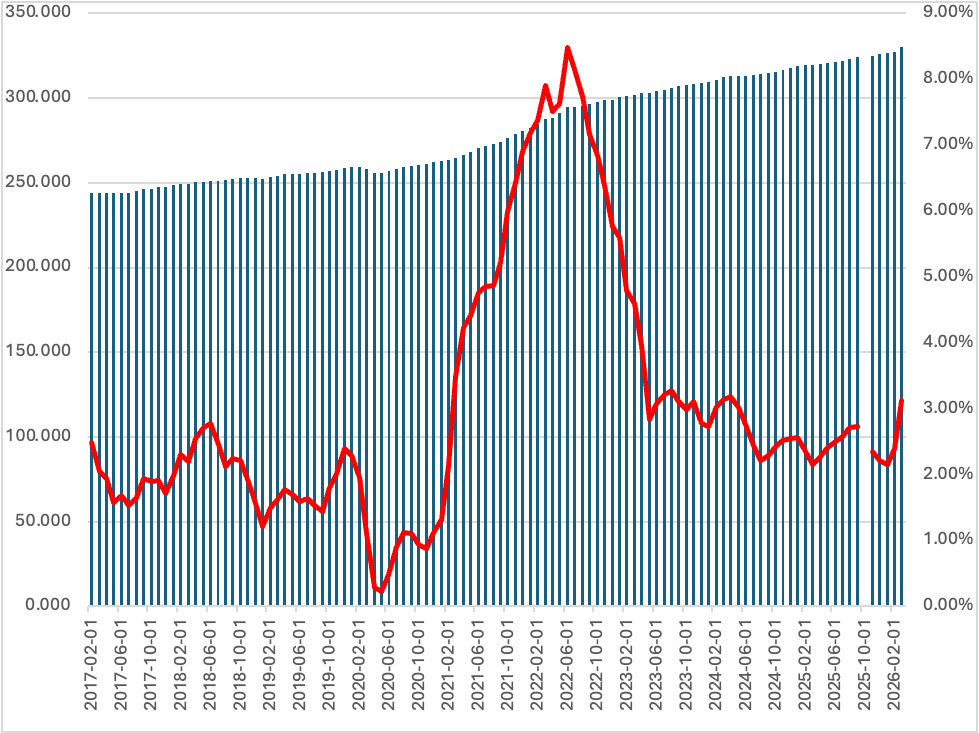
Expectations this morning are for the headline number to print 0.6% M/M and 3.7% Y/Y while the core (ex-food & energy) number is expected at 0.3% M/M and 2.7% Y/Y.  Below is a chart showing headline CPI for the past 10 years, which I believe is informative of the national mood.  In it, you can see both the annual rate of inflation (the red line, RH axis) and the steady growth of the underlying CPI index published by the BLS (blue bars, LH axis).  To get the full sense of things, though, make sure you look at the index level on the left, which has grown, in aggregate, 38.7% over the past 10 years.  It is this feature which drives the nation’s unhappiness with prices, I would contend, not the monthly data, but the cumulative nature of the problem.

Data: Fred, graphics: @fx_poet

All of us remember the peak inflation in the immediate post-Covid years.  In addition, I’m sure we all remember the government shutdown and the missing data point because of the inability to collect data and the known assumption that if data were not collected, it would be assumed to be 0.0%.  Well, not only is the Iran war having a direct impact on inflation, but that missing data is starting to leave the calculations, so the red line is going to continue to head higher.  I must admit, that if I were to guess how things arise this morning, I would suspect the estimates to be on the low side, but we shall see in a few hours.  The question here is; will the markets respond to this or are they focused on other issues?  I also suspect that this depends on the outcome.  If CPI is higher than forecast, it does not bode well for Treasury prices, nor likely stocks.  But, if it is softer than forecast, I would look for the equity rally to continue.

Ok, let’s see how markets are behaving as we await the data.  Yesterday’s nondescript and modest US rally was followed by a lot of nondescript trading in Asia (Tokyo +0.5%, HK -0.2%, China -0.1%), although both Korea (-2.3%) and India (-1.9%) had a bit more action with the former seeming a reaction to its recent moonshot rise while the latter continues to try to deal with a steadily weakening currency and the government’s efforts to address that without raising interest rates.  Otherwise, in the region there were both winners and laggards but nothing else noteworthy.

In Europe, though, red is the only color I see with the DAX (-1.1%) leading the way down despite a better than expected, although still negative, ZEW report of -10.7.  But Spain (-0.9%), Italy (-0.8%) and France (-0.6%) are all under pressure with only Norway (+0.6%) showing any life as its energy-centric market performs well with oil prices back up again this morning.  As to US futures, they, too, are red with the NASDAQ (-1.1%) the worst of them at this hour (7:10).

We’ve already discussed Gilt yields but yields around the world are higher this morning with US Treasuries (+2bps) adding to yesterday’s 5bp rise.  In Europe, and in Japan, yields are higher by 4bps to 5bps across the board.  This appears to be a combination of concerns over both increased supply as nations spend more than they tax and rising inflation.  It’s a pretty toxic combination for bonds.

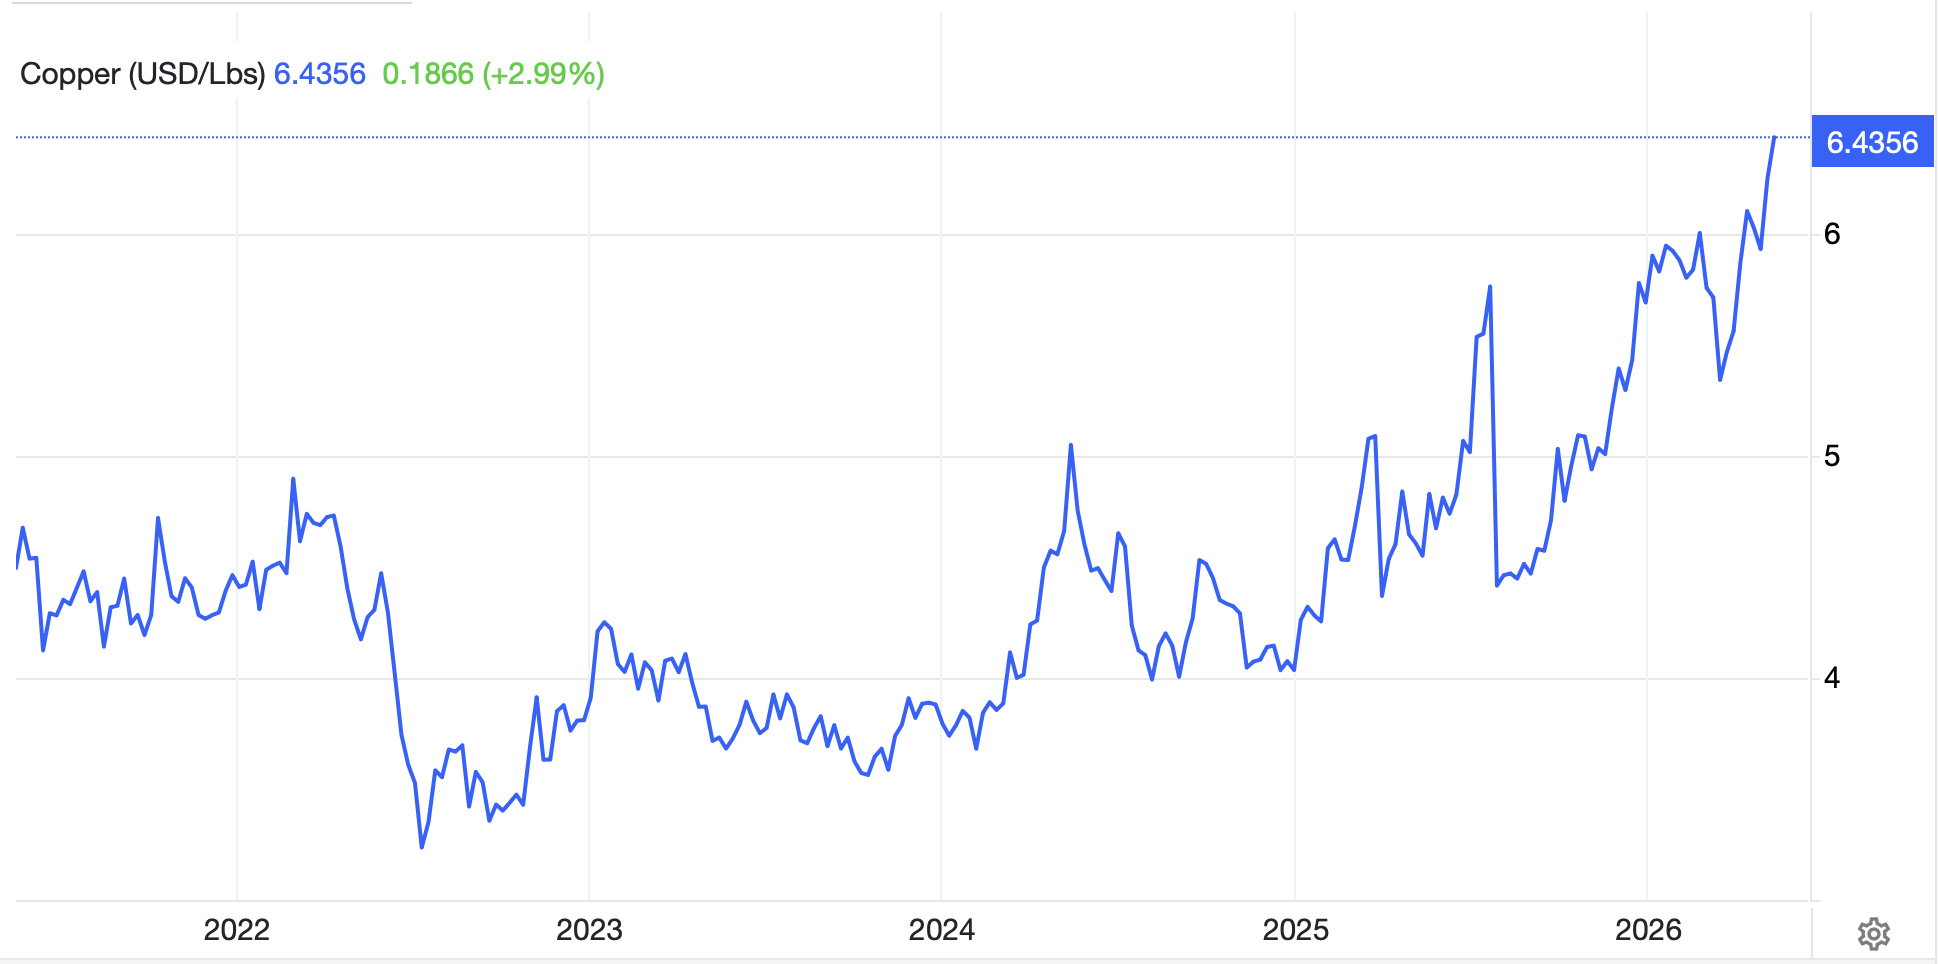
Yesterday was a bit of an anomaly in the precious metals markets as despite the rise in oil prices we saw, gold, silver and copper all rally as well.  Recently, we would have expected the metals to trade lower in that circumstance.  And this morning, with oil (+3.0%) higher again, they are with gold (-0.9%) and silver (-3.3%) both under pressure although copper (+0.4%) continues to rise to new records.  It turns out, the electrification of everything, and the massive power requirements for data centers along with rebuilding aging electricity grid infrastructure will require a lot of copper, likely more than will be mined at the current prices.  It feels like this chart will continue to go higher.

Source: tradingeconomics.com
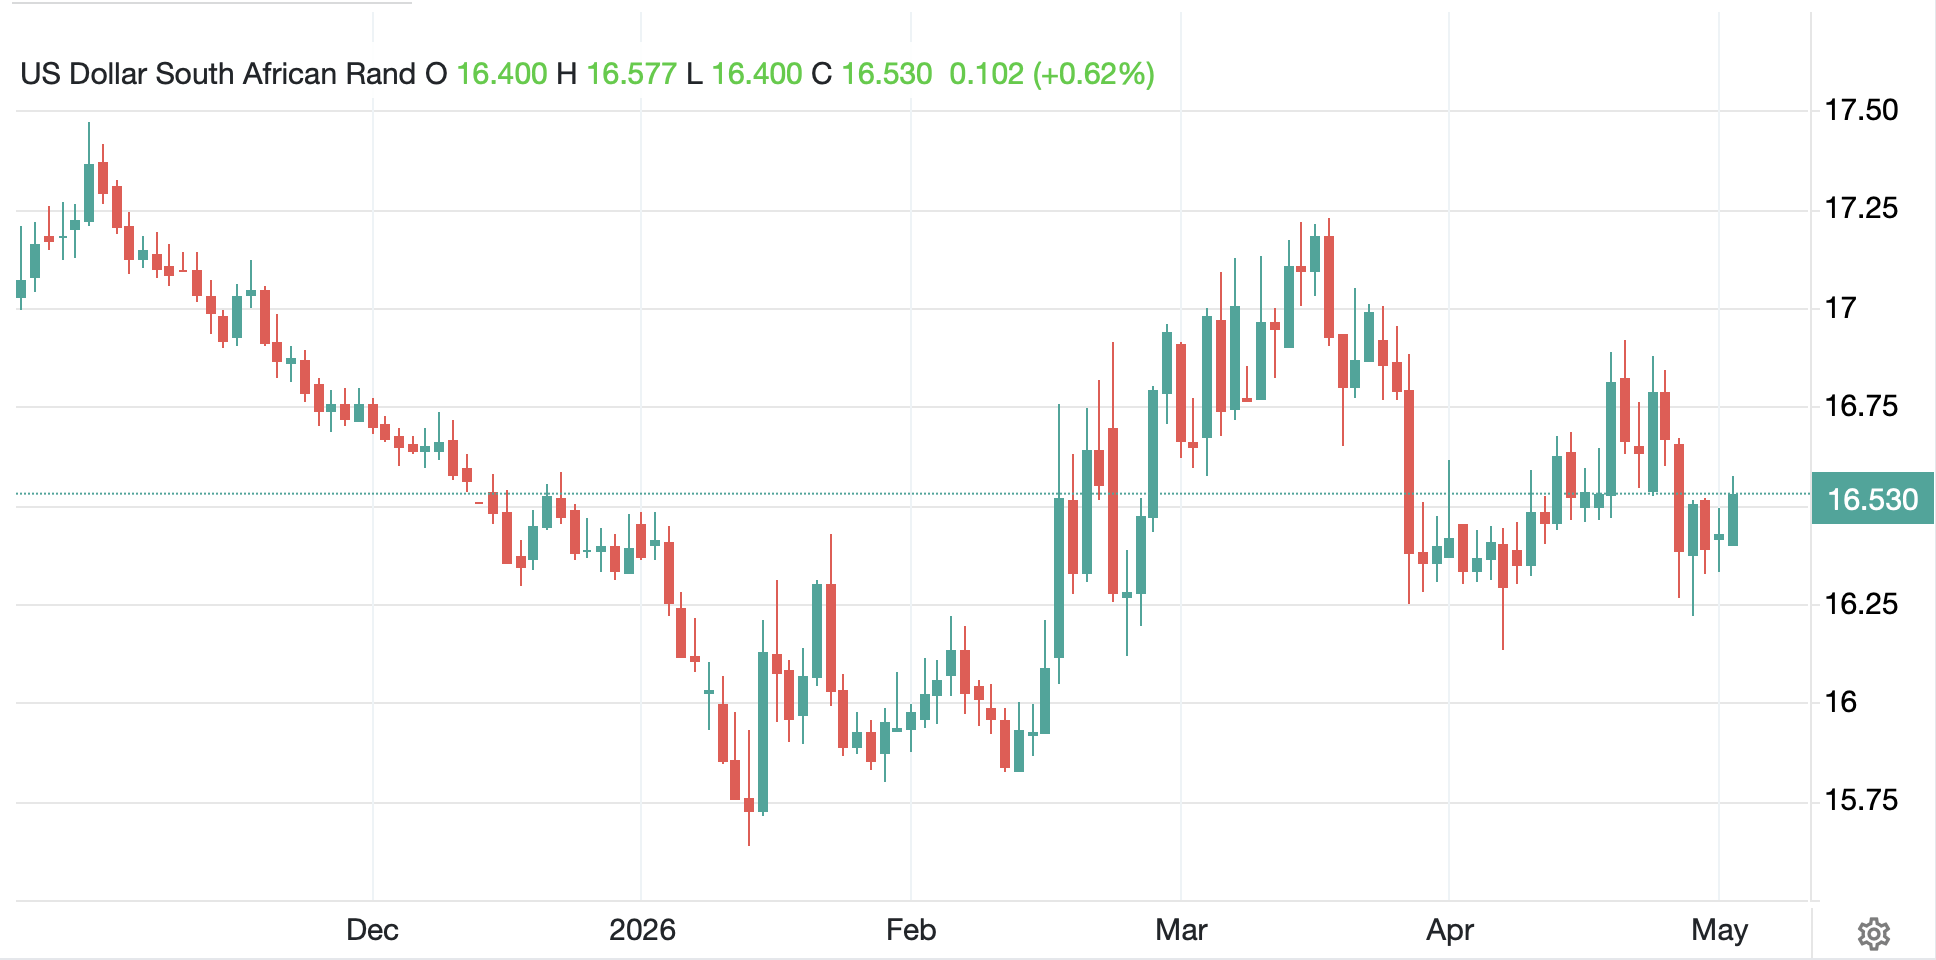
Finally, the dollar is back in form this morning against virtually all its counterparts in both the G10 and EMG blocs.  In fact, it is easier to discuss the outliers which are NOK (+0.3%) and BRL (+0.4%) both benefitting from rising oil prices (as is the dollar!) while the rest of the world collectively suffers.  The DXY (+0.35%) continues to ignore all the calls for its collapse and today’s weakest performers are KRW (-1.0%) and ZAR (-0.6%).  The latter continues to be buffeted by the combination of higher oil and lower gold prices, although remains well above the lows (below dollar highs) seen at the beginning of the war that started this price action as per the below chart.

Source: tradingeconomics.com
KRW, though, is a bit more confusing to me as while weakness overnight alongside the KOSPI, makes sense, it has, in truth, performed terribly compared to the KOSPI’s remarkable rally.  It would have made a great deal of sense to see significant foreign inflows to the won as investors jumped on that bandwagon, but I guess not.

There is nothing other than the CPI data released in the US this morning so that will be the driver for now.  I would be remiss if I didn’t highlight, again, that the best way to manage inflation risk for us all is to own USDi, the fully backed, inflation-tracking cryptocurrency that is returning 12.588% annualized this month and depending on the exact CPI print this morning, set to return something on the order of 8% or so in June.  Remember, Treasury bills return 3.6% annualized, so this is a way to keep up with prices.  Check out www.usdicoin.com for more information and the ability to mint your own!

Good luck

Adf

Disconcerting

The third time, it wasn’t a charm
As thankfully, Trump saw no harm
But it’s disconcerting
The left keeps on flirting
With killing Trump by firearm

But absent more news on the war
Investors, most stocks, still adore
And there’s still a call
The dollar should fall
Though so far, they’re down on that score

It is certainly disconcerting that there have been three bona fide assassination attempts on President Trump in the past two years, something I fear speaks loudly about his opponents.  Fortunately, this one also failed.  Interestingly, as this occurred at the White House Correspondents Dinner, the entire Washington press corps, who largely detest the man, were there.  I wonder if this experience will alter their rhetoric, which I would argue has been the key driving force behind these attempts.  Alas, I fear that will not be the case, at least not for more than a few days at best.  

But that was a far more exciting weekend than anybody imagined as there is no new news regarding the Iran war with potential talks never occurring over the weekend.  Neither have the marines moved in on Kharg Island, so the status quo, a US naval blockade, remains the primary situation.  This leads to two questions; first, how long can Iran withstand the lack of revenue with the government, or more accurately the military, still operating effectively? And second, how long before Iran’s oil wells need to be shut in, which is likely a death sentence on those wells, and by extension, on Iran’s long-term revenue stream?

Frankly, that’s what the weekend brought, so let’s turn to markets.  While the DJIA lagged on Friday, both the NASDAQ and S&P 500 rallied to yet further new all-time highs as US corporate earnings remain robust and the market looks ahead to this week where 5 (MSFT, GOOG, AMZN, META, AAPL) of the Mag7 report earnings this week on Wednesday and Thursday.  As well, Wednesday brings the FOMC decision, with no change expected.  As to US futures this morning, as I type (6:50), they are essentially unchanged.

Overnight, Asia’s session was mixed with Japan (+1.4%) putting in a nice performance along with Korea (+2.15%), India (+0.8%) and Taiwan (+1.8%) although there were laggards (HK, Australia, Indonesia, Singapore) as well, with much smaller declines.  China was basically unchanged.  Perhaps the biggest news was that an oil tanker from the US arrived in Japan for the first time, although certainly not the last time.  European bourses are all a bit firmer this morning, seemingly responding to decent earnings throughout many nations there.  Thus, Germany (+0.6%) is leading while Spain, France and Italy (+0.5% each) lag slightly and the UK (+0.1%) brings up the rear as King Charles prepares to visit President Trump and the US starting today, ostensibly trying to resurrect the once special relationship that has deteriorated over time.

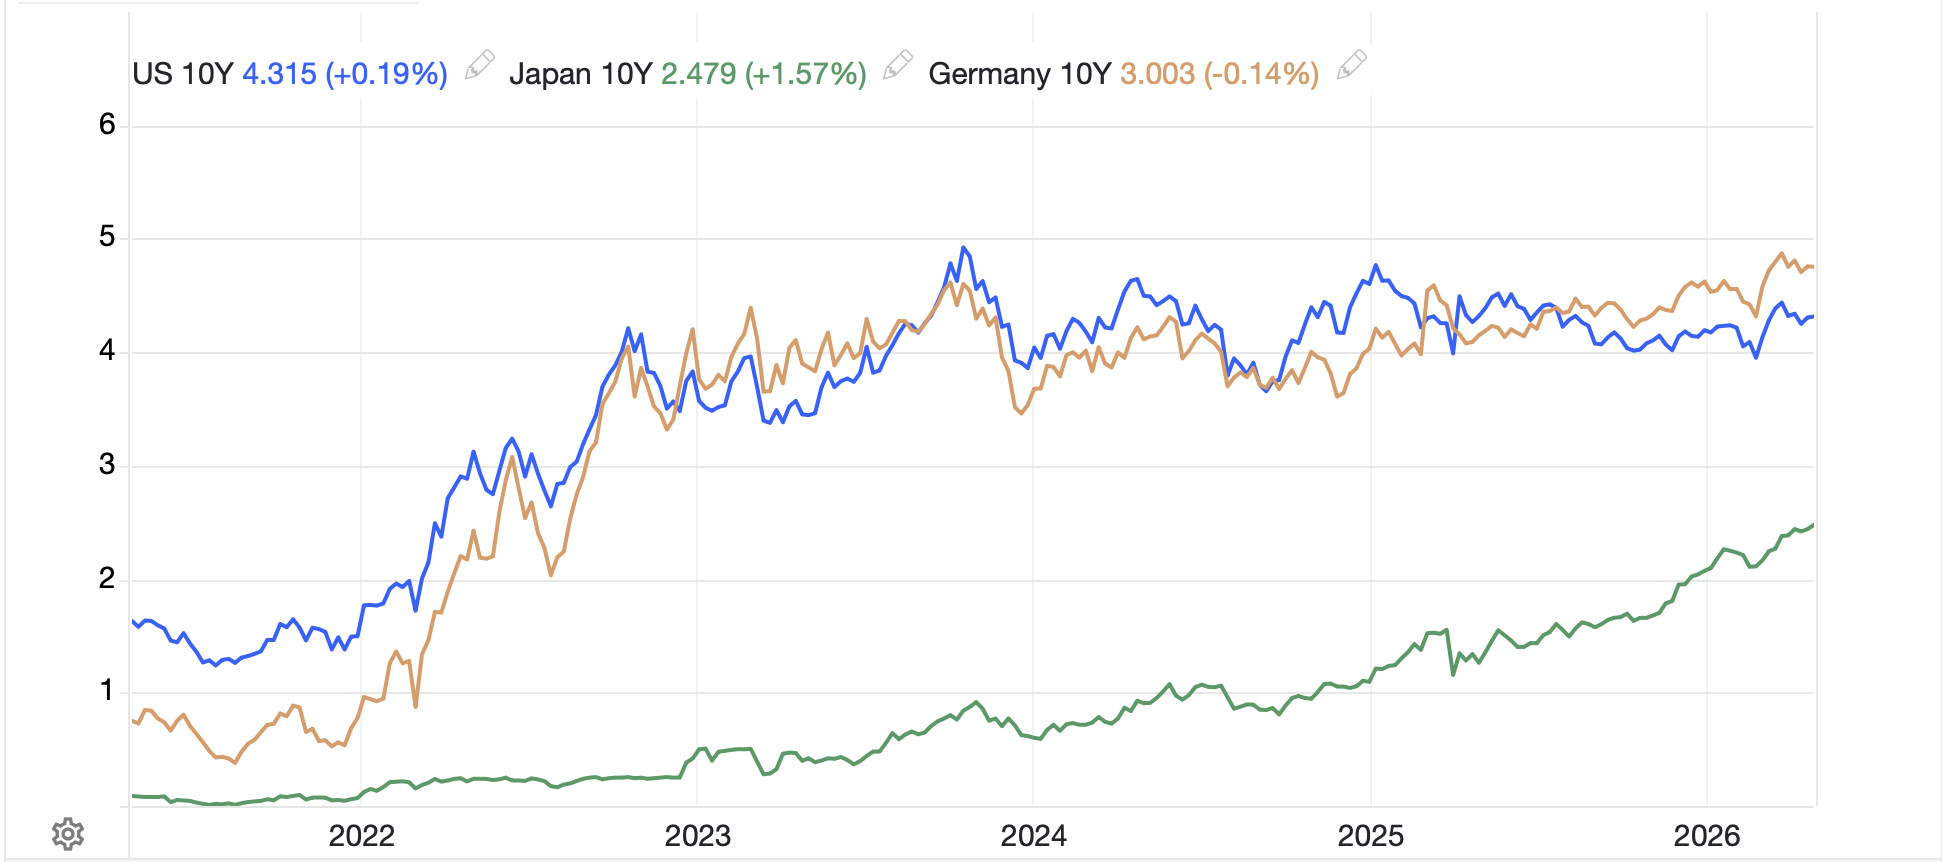
In the bond market, nothing continues to happen with Treasury yields higher by 1bp this morning and similar price action across all of Europe.  JGB yields (+4bps) were the big mover as market participants await three key central bank meetings this week, the Fed, ECB and BOJ.  But here’s the thing, of all the major economies around, Japan’s is the only one where the bond market is offering any real signal.  The below chart from tradingeconomics.com shows US (blue line), German (tan line) and Japan (green line) 10-year yields over the past 5 years.

While we all remember the pain in markets when the Fed, and then all other central banks, figured out that the Covid policy inflation wasn’t going to be as transitory as they hoped and pushed rates up at a historically fast pace in 2022, since then, it is pretty easy to make the case that neither US nor Germany (and by extension the rest of Europe) have seen any substantive change in their bond markets.  I am speaking in a big picture reference here, not the day-to-day noise that we see.  Meanwhile, Japan has finally begun to feel the pressure of a massive debt/GDP ratio and rising inflation.

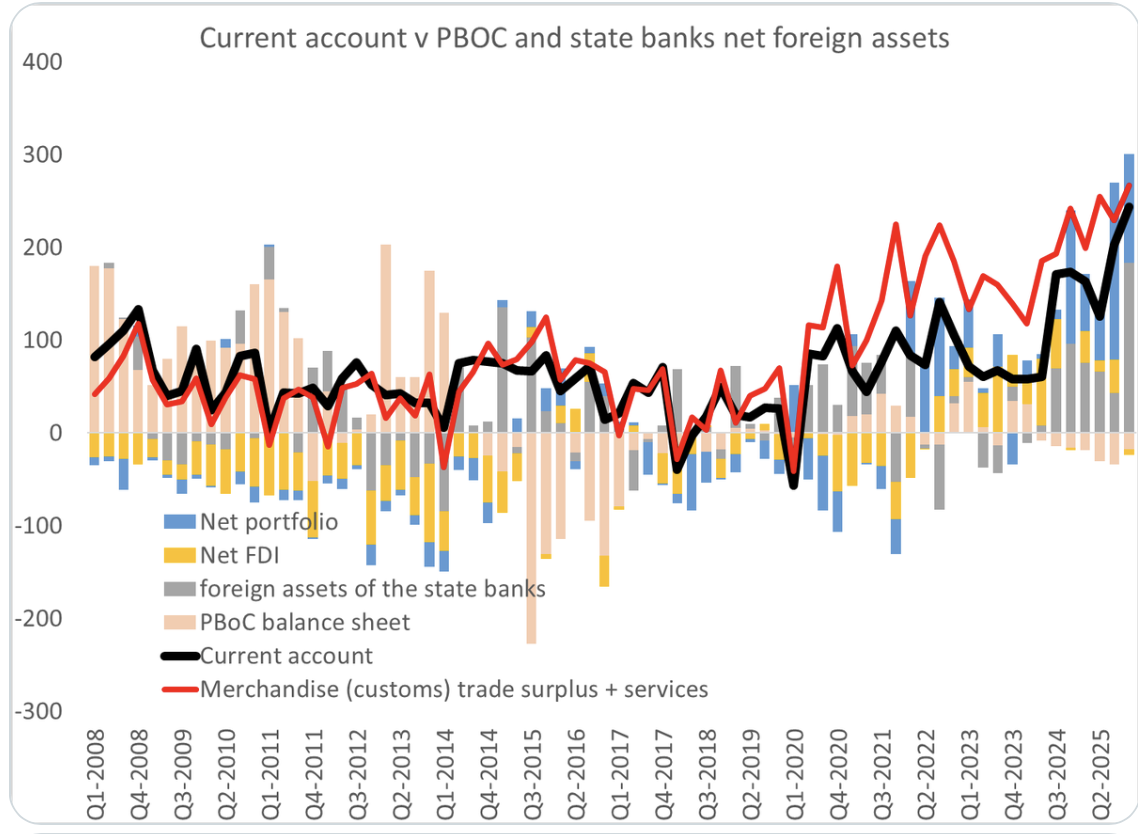
Contrary to popular belief, Treasury bonds remain the reserve asset of choice around the world as every nation needs to hold a certain amount of USD simply to function in the world today (which is why there is so much recent discussion regarding USD swap lines for numerous countries).  While it sounds great for the panican set to discuss how Chinese “official” holdings of Treasuries have collapsed and that is a signal they are selling bonds, the reality is they have switched their custodians from the Fed to Clearstream and Euroclear in Brussels and Luxembourg while many of those assets are now held in large Chinese ‘private’ banks rather than on the PBOC’s balance sheet.

Source: @Brad_Setser

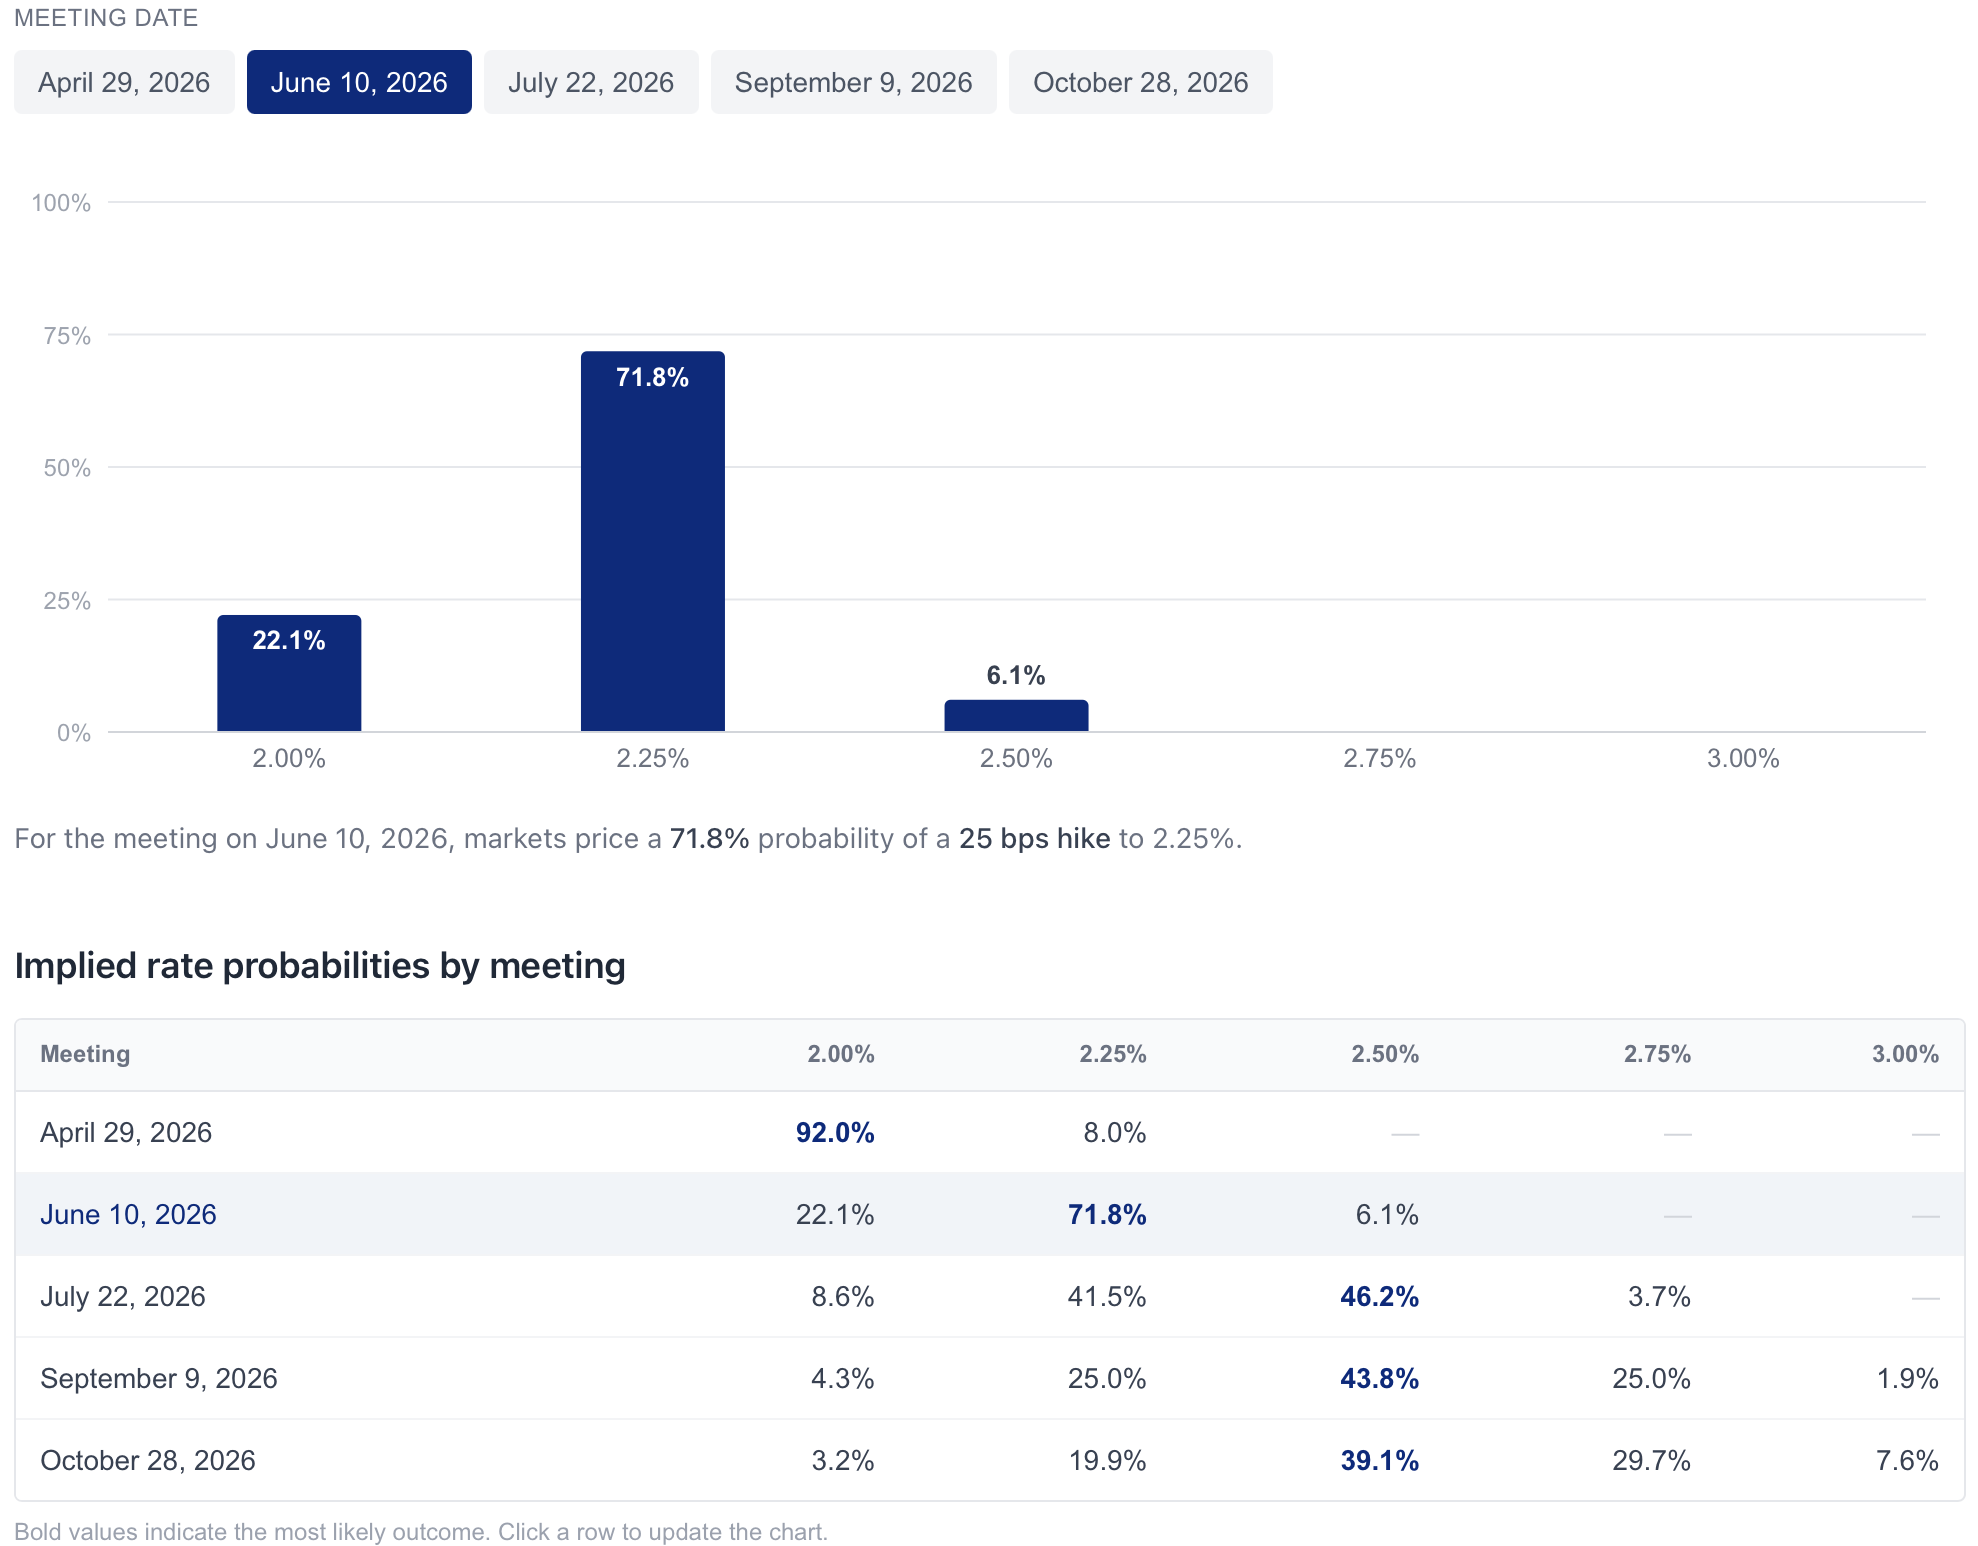
Notice the large grey bar at the right, foreign assets of the state banks.  Which brings us to the central bank meetings this week where no major central bank is expected to change policy.  Japan seems the diciest call, but the word was put out last week that June is the likely date. As well, the ECB’s own market watching website is now looking at June as a probable rate hike as per the below from ecb-watch.eu.

For the FOMC, no change today and now that the DOJ has referred the cost overrun investigation to the IG at the Fed, the hold on Kevin Warsh by Senator Tillis has been lifted.  I expect he will be confirmed in time for Powell to leave on his scheduled date.  It remains to be seen if Powell will stay on the FOMC (his term technically runs until January 2028), but historically, once a Fed chair leaves that role, they step away completely.  Ultimately, until the markets begin to understand that inflation is going to be structurally higher than in the past, I suspect bond yields are going to remain range bound.

In the commodity space, oil (+0.7%) is a touch higher as the market seems to be becoming increasingly concerned that the impacts of the closure of the Strait of Hormuz are going to be longer lasting than previously assumed.  However, the futures curve remains steeply backwardated as per the below chart form tradingview.com.

Personally, I see this as confirmation of my own view that oil prices are likely to decline over time as more and more supply becomes available with new projects.  If anything, this war has accelerated that process.  Meanwhile, metals prices are essentially unchanged this morning, biding their time for the next big piece of news.

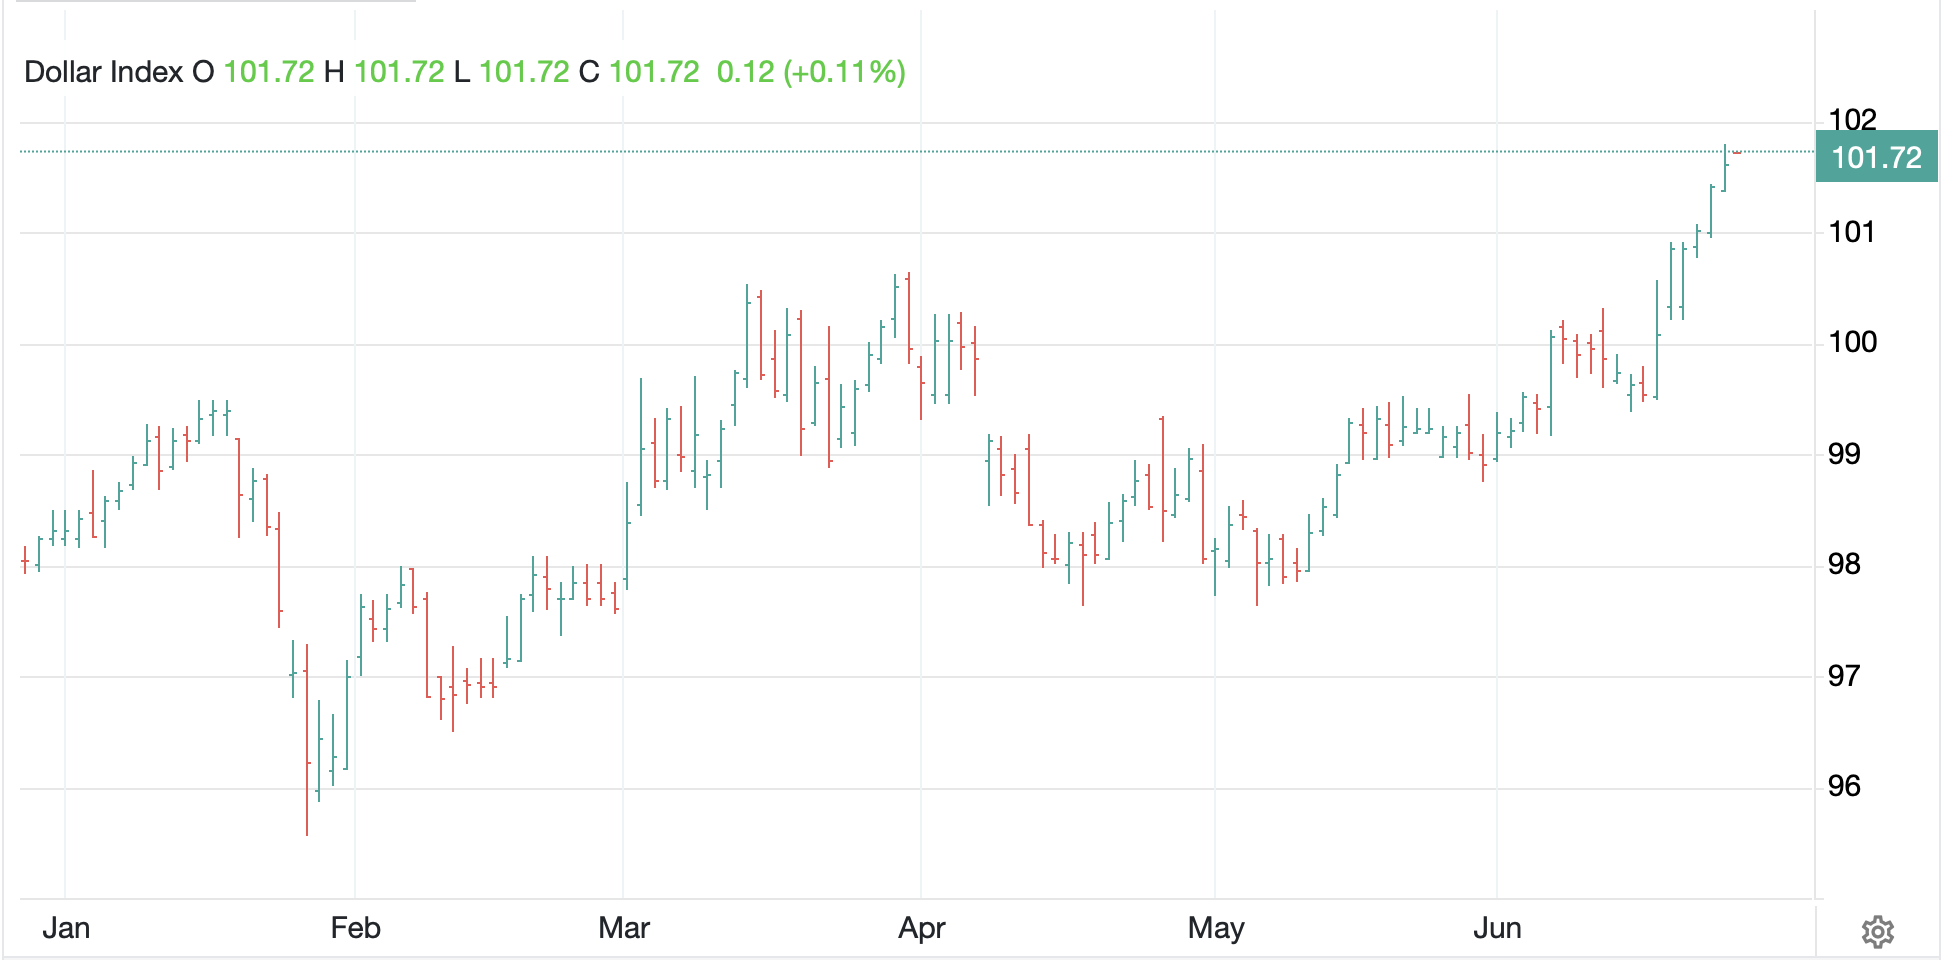
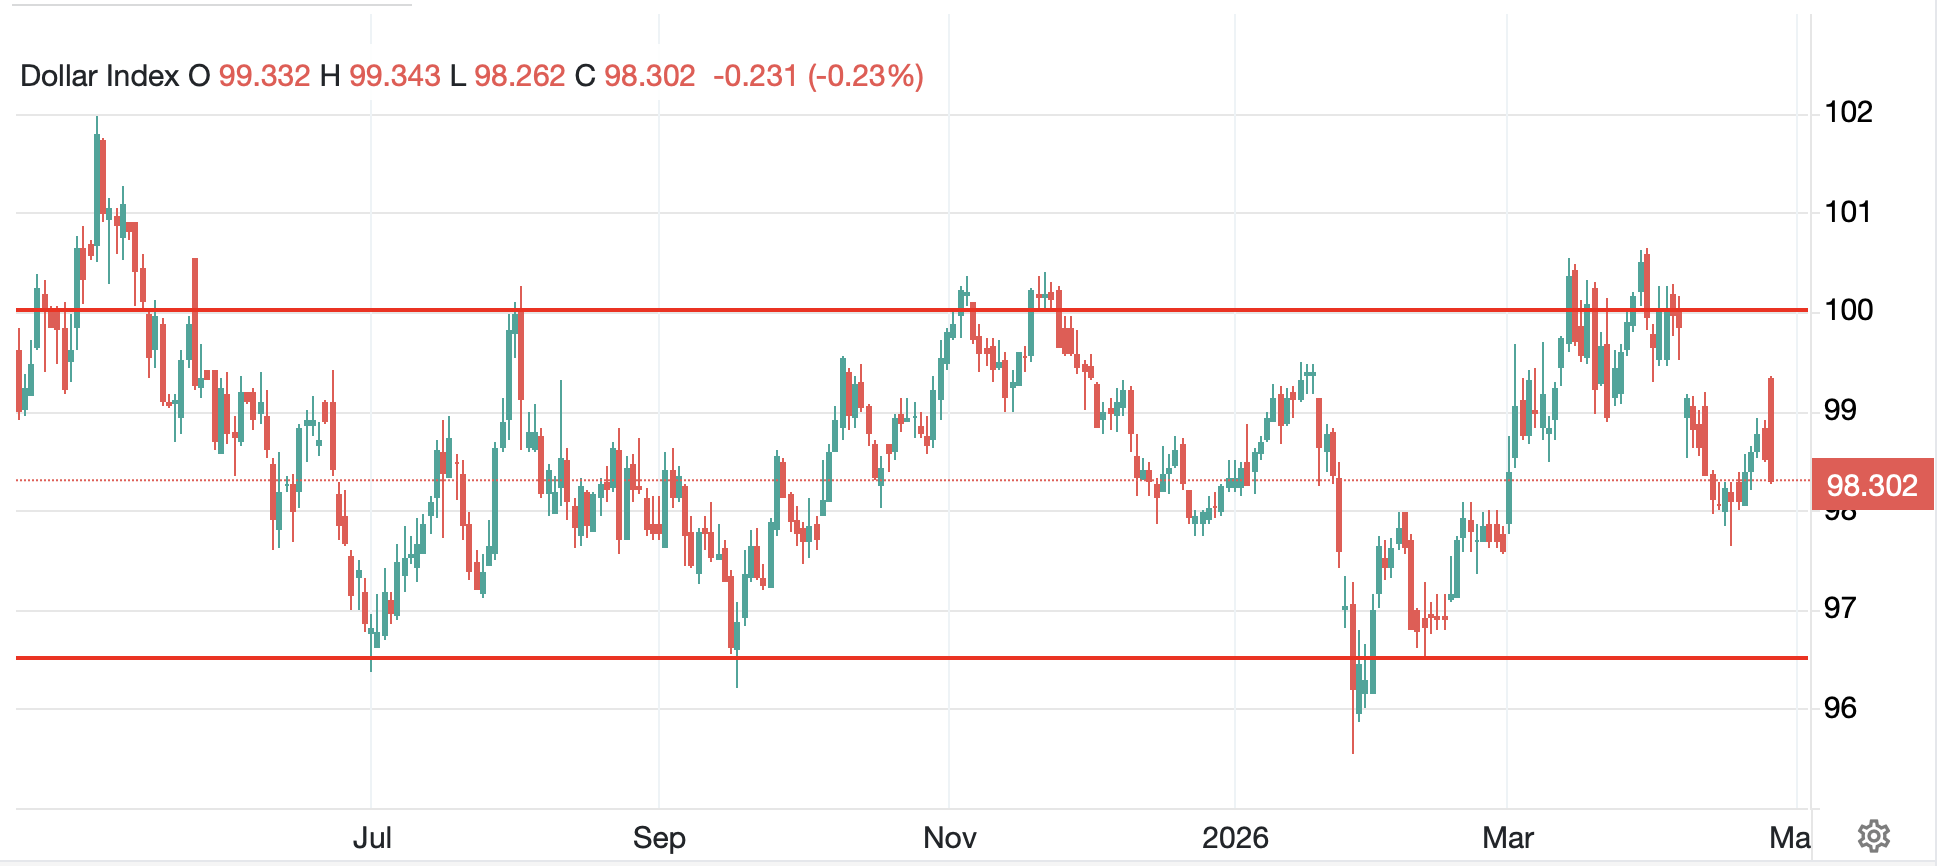
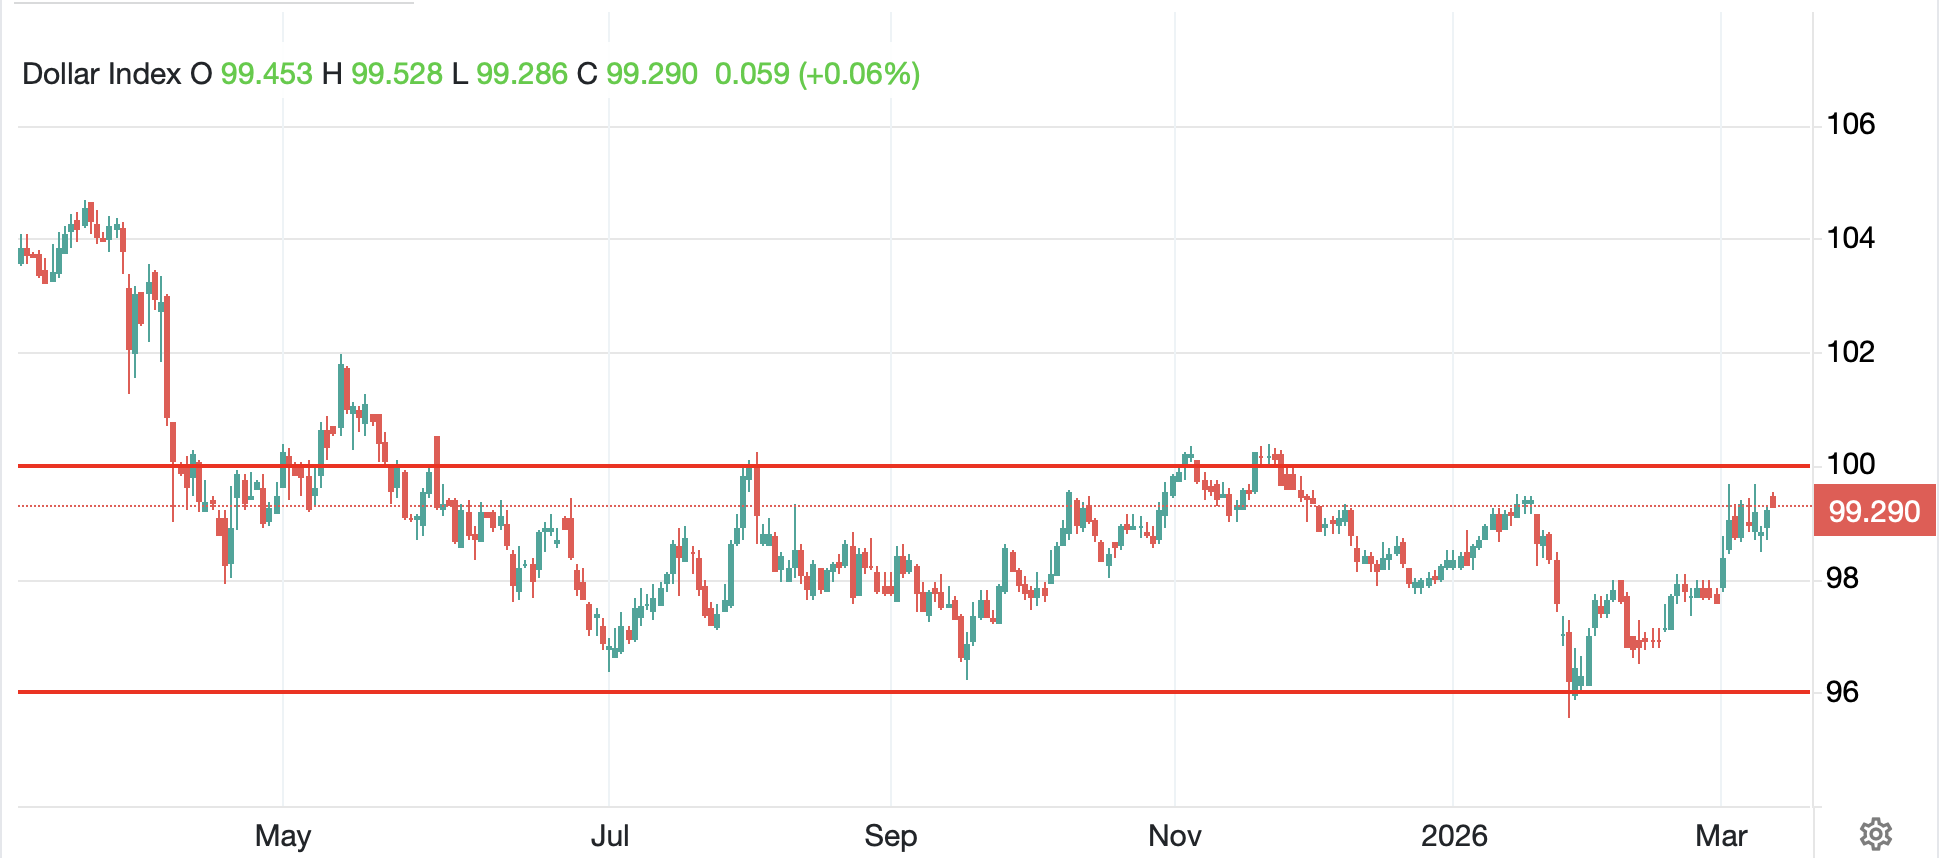
Finally, the dollar is under modest pressure this morning, down about -0.2% across the board as risk appetites continue to build with the war receding in traders’ collective mindset.  But here, too, just like in the bond market, it is difficult to make the case that anything of note has happened to the dollar, writ large, over the past year.  I know I show this chart frequently, but it is simply to hammer home the idea that the dollar is not collapsing.  It has basically had a 3.5% range 96.50 – 100.00 for the past twelve months.  I’m sorry, that is not a death omen!

Source: tradingeconomics.com
On the data front, there are a total of 5 central bank meetings with no changes expected anywhere, and then PCE data later on.

TonightBOJ Rate Decision0.75% (unchanged)
TuesdayCase-Shiller Home Prices1.1%
 Consumer Confidence89.2
WednesdayHousing Starts1.4M
 Building Permits1.39M
 Durable Goods0.5%
 -ex Transport0.4%
 Goods Trade balance -$86.0B
 BOC Rate Decision2.25% (unchanged)
 FOMC Rate Decision3.75% (unchanged)
ThursdayBOE Rate Decision3.75% (unchanged)
 ECB Rate Decision2.0% (unchanged)
 Q1 GDP2.2%
 Personal Income0.3%
 Personal Spending0.9%
 Initial Claims215K
 Continuing Claims1820K
 PCE0.7% (3.5% Y/Y)
 Core PCE0.3% (3.2% Y/Y)
 Chicago PMI53.0
 Leading Indicators-0.1%
FridayISM Manufacturing53.0
 ISM Prices Paid80.0

Source: tradingeconomics.com
It remains difficult to get too excited about the data, though, as war stories remain top of mind.  Until something changes there, I suspect we will see equities continue to rally on earnings data with the rest of the markets doing very little overall, data be damned.

Good luck

Adf

Humbling

The ceasefire seemed to be crumbling
And stocks all around started tumbling
Then late in the morning
Trump issued a warning
To Bibi that clearly was humbling

So, Lebanese fighting decreased
Though, so far, it has not yet ceased
The door’s now ajar
For peace near Qatar
Thus, risk appetite rose like yeast

Which takes us to data today
With March CPI on the way
It surely will show
That prices did grow
But how long will increases stay?

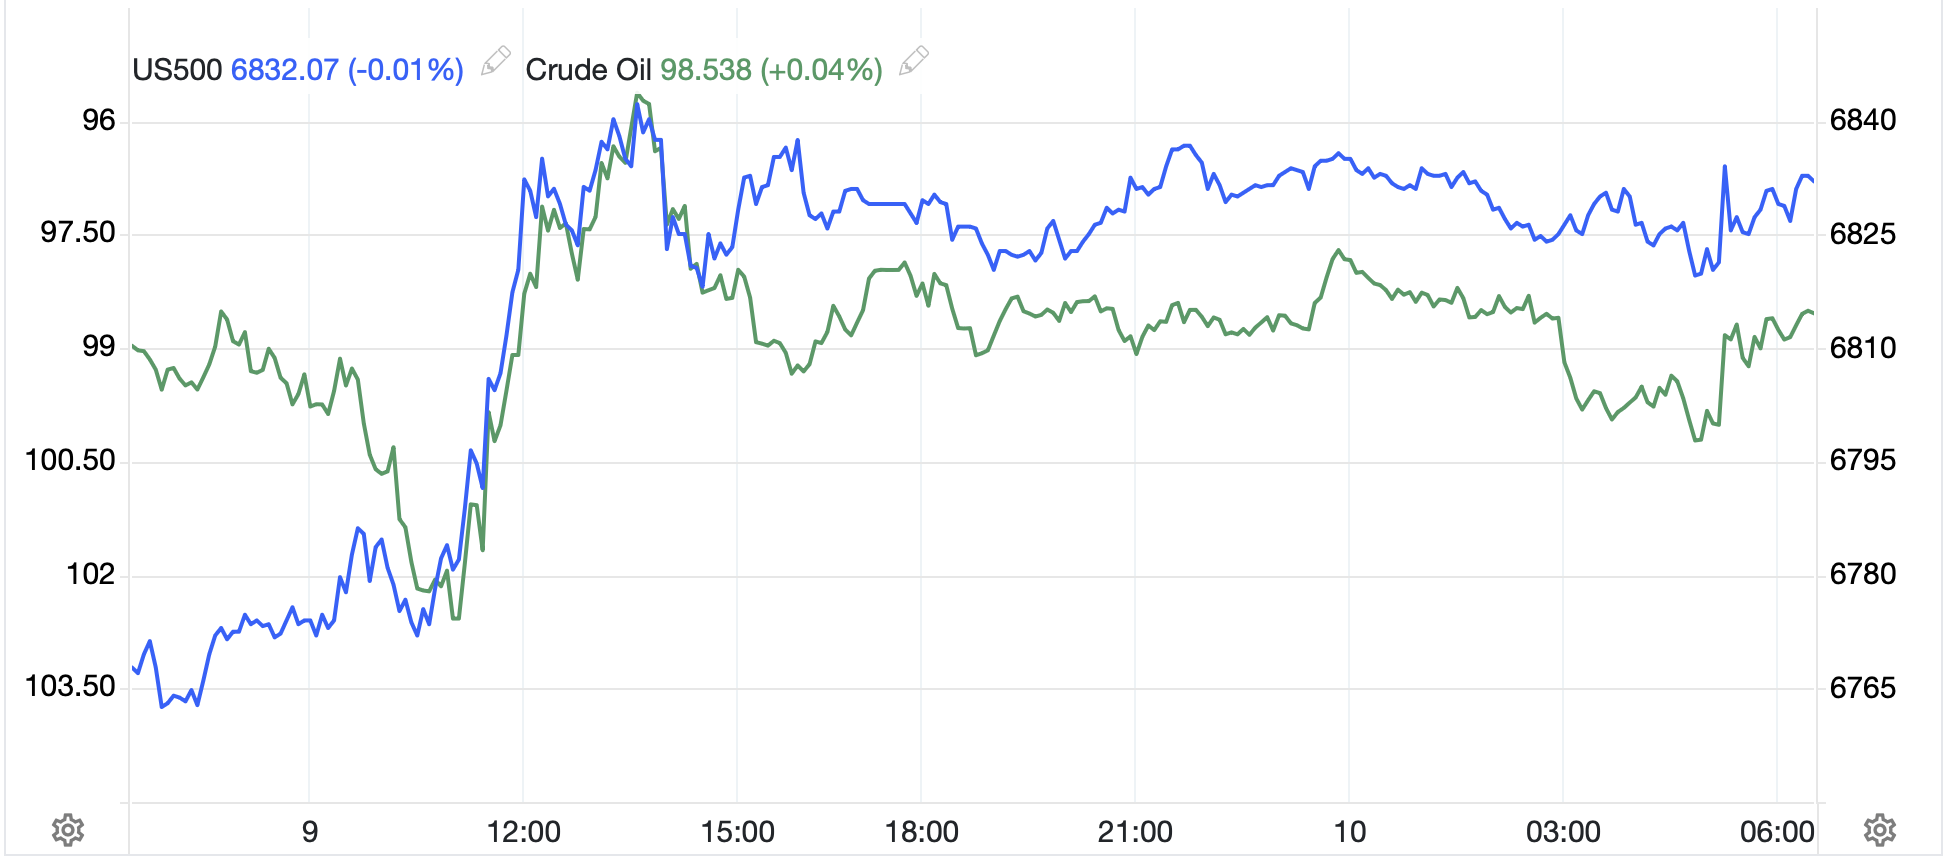
As you can see from the below chart showing oil (inverted) and the S&P 500, about 11:00 yesterday morning, the news hit that Israel was going to stop its ongoing fighting against Hezbollah in Lebanon, which the Iranians claimed was a violation of the ceasefire and had undermined general, and market, belief that the ceasefire would hold at all.  The impact was instant with a substantial rally in the S&P, 1% within an hour, while oil prices tumbled about 6% in the same span (given oil’s volatility is so much higher, that discrepancy is not surprising at all.)

Source: tradingeconomics.com
This is the lead-in to the first face-to-face talks between the US and Iran that are due to occur today in Karachi, Pakistan.  Hopefully, they will lead to a lasting peace with the upshot that Iran will no longer be a sponsor of terrorism, but I must admit, I’m not holding my breath for that outcome.  The overnight market reaction was pretty much exactly what you would have expected with a generally positive view of risk almost everywhere in the world.  Obviously, if the talks lead to a peace and a reopening of the Strait of Hormuz, the strong belief is that things will eventually revert to the prewar stance, at least from an energy and economic perspective.  We shall see.

Which takes us to the other piece of news that markets are going to need to absorb this morning, the March CPI data.  Yesterday we saw the February PCE data and while it was released at expected levels, those levels (2.8% Headline, 3.0% Core) are already far above the Fed’s 2.0% target.  In fact, as you can see from the chart below, it has been a full five years since Core PCE was at or below their target.

Source: tradingeconomics.com
And now, we get March CPI this morning which will include a substantial rise in oil prices as the average in February was $64.51/bbl vs. March’s $93.58/bbl.  Obviously, that is going to have a major impact on headline CPI, but the question is just how much of an impact will it have on core?  Expectations are for Headline to rise 0.9% M/M and 3.3% Y/Y, while the Core rises just 0.3% M/M and 2.7% Y/Y.  Now, we are coming halfway through April and oil prices have not retreated yet, so we are likely going to see continued upward pressure on core prices going forward as those high oil prices feed their way into other things.  But that is for the future.  For today, all eyes are on the data to see if it will be enough to concern central bankers.

In fact, next week is World Bank / IMF week in Washington DC and Kristalina Georgieva, the IMF’s Managing Director, expressed concern that the global economy is going to slow down because of the impact of higher oil prices, but implored central bankers around the world to be patient and not hike rates right away, while asking governments not to subsidize fuels and increase demand.  It is, of course, much easier for her to make these comments as she doesn’t face an electorate that is angry about rising prices.

At any rate, other than the virtually infinite number of takes on the Iran war and the CPI data, there’s not much else to discuss, so let’s see how markets have responded to the latest and where they sit ahead of the data.

Yesterday’s early declines in the US were reversed, as per the chart at the top with all three major indices rallying more than 0.6%.  in Asia, weirdly just Australia (-0.15%) and New Zealand (-0.7%) were the outliers on the downside with the rest of the region all in the green, some substantially so.  Tokyo (+1.8%), China (+1.5%), Korea (+1.4%), Taiwan (+1.6%) and India (+1.2%) all had very strong sessions.  Arguably, the weakness Down Under may be a reflection of their energy policies heading into the Iran war as neither nation has a substantial reserve (fossil fuels were deemed bad so their governments didn’t want to buy them) and both economies could suffer far worse than anyone else because of those decisions.  

In Europe, markets are higher across the board although the gains are far more muted with France (+0.5%) the leader followed by Germany (+0.4%) and Italy (+0.4%) then the UK (+0.2%).  While, certainly better than losses, they are hardly inspirational.  As to US futures, at this hour (7:15), they are also pointing slightly higher, about 0.2% or so.

In the bond market, yields are backing up this morning with Treasuries (+2bps) the least impacted while European sovereign yields are higher between 5bps (Germany) and 8bps (Italy) with the rest of the continent somewhere in between.  It is difficult to ascribe a particular story here other than rising concerns about general inflation being higher due to elevated energy costs.  The market is pricing about 59bps of rate hikes by the ECB this year, perhaps a sign that investors don’t believe energy prices in Europe are going to decline as much as they will elsewhere.  Given the continent-wide energy policies they have in place, I believe they are correct.

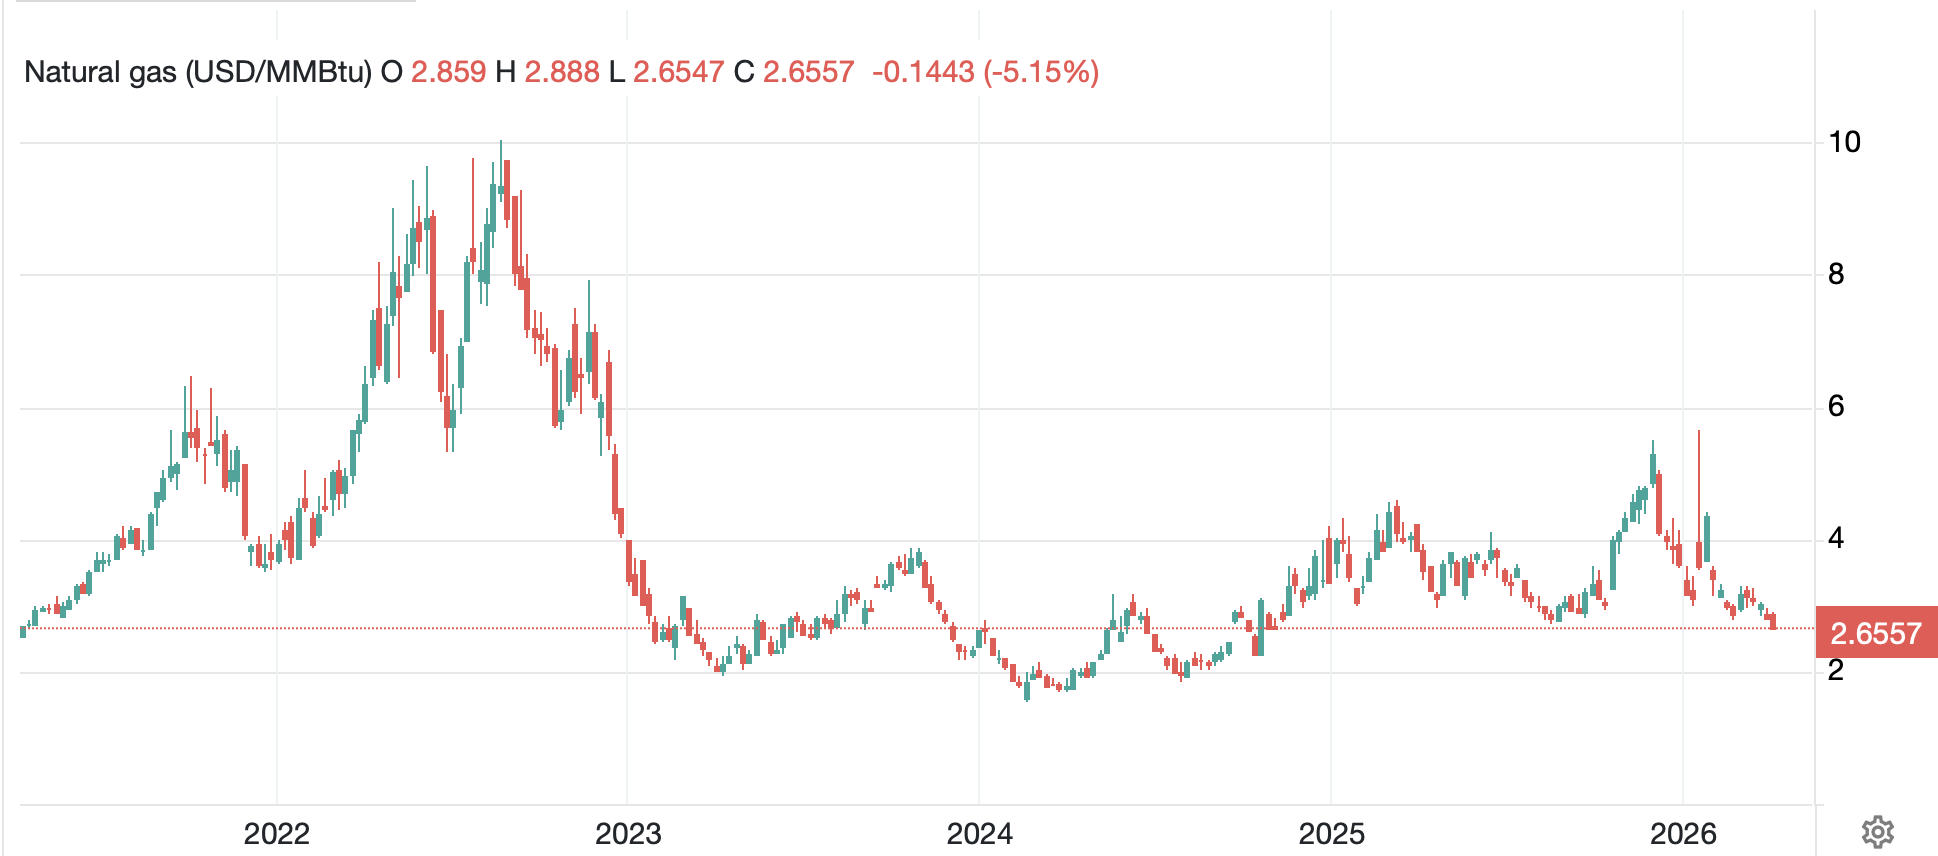
Turning to commodities, oil (0.0%) is unchanged this morning after sliding on the Lebanon news yesterday morning.  The truly interesting thing is to watch NatGas (-0.6%) which continues to slide. Back toward its multi-year lows as it continues to be produced as an associated product alongside all the oil drilling that is ongoing.  

Source: tradingeconomics.com
I cannot look at the above chart and reconcile the massive energy advantage the US has with basically the rest of the world and conclude that the US economy is going to be at any disadvantage with other economies going forward, and hence the dollar seems very likely to remain in good stead going forward.  Meanwhile, metals, too, are little changed this morning (gold 0.0%, silver +0.4%, copper +1.3%) with the latter a bit of a surprise after Argentina just passed legislation that will allow for more drilling in the Andes where Chile’s major copper deposits lie.  That is a long-term prospect though, I must admit.

Finally, the dollar is mixed this morning, with very few significant movers in either direction.  In the G10, +/-0.2% is the name of the game with the most noteworthy thing, I think, the yen (-0.25%) which is back above 159 this morning, although not yet threatening the perceived line in the sand of 160.  In the EMG bloc, KRW (-0.6%) and ZAR (-0.4%) are the laggards although it is hard to ascribe specific news to either move.  Rather, looking at the recent trading action, where both currencies have been rebounding sharply, these moves look like position squaring ahead of the weekend.

In addition to CPI, we also see Michigan Sentiment (exp 52.0) and Factory Orders (-0.2%) at 10:00.  There are no Fed speakers so today is shaping up to be data dependent unless we hear something from the talks in Pakistan.  However, it seems far too early for anything of substance there.  I imagine if core CPI is firm, that could be an equity negative as that would encourage more thought of the Fed hiking, but I have a feeling that despite the broader importance of the number, markets are not going to do much today.

Good luck

Adf

Rise and Shine

Though CPI’s print was benign
It’s clear that it didn’t enshrine
The impact of war
That caused crude to soar
Thus, yields round the world rise and shine

But other than yields heading higher
And prospects for peace looking dire
Most markets lack motion
Which leads to the notion
That not very much may transpire

It seems incongruous but despite the war, and a remarkable cacophony from the press, markets are not really doing very much at all.  Certainly, at the margin, there is some movement, and, of course, this does not include oil prices which have been all over the map, but generally, if you look at the charts below, it is hard to get too excited.

Starting with the dollar, as per the DXY, it has traded in a 4% range for basically the past year, touching both top and bottom three times each.  The current rebound looks almost identical to the October rally.  But 4% is just not that much of a move, certainly not one that implies a regime change.  Overnight, the largest move was PLN (-0.4%) with virtually every other counterpart, whether G10 or EMG, +/-0.25% or less.

Source: trading economics.com

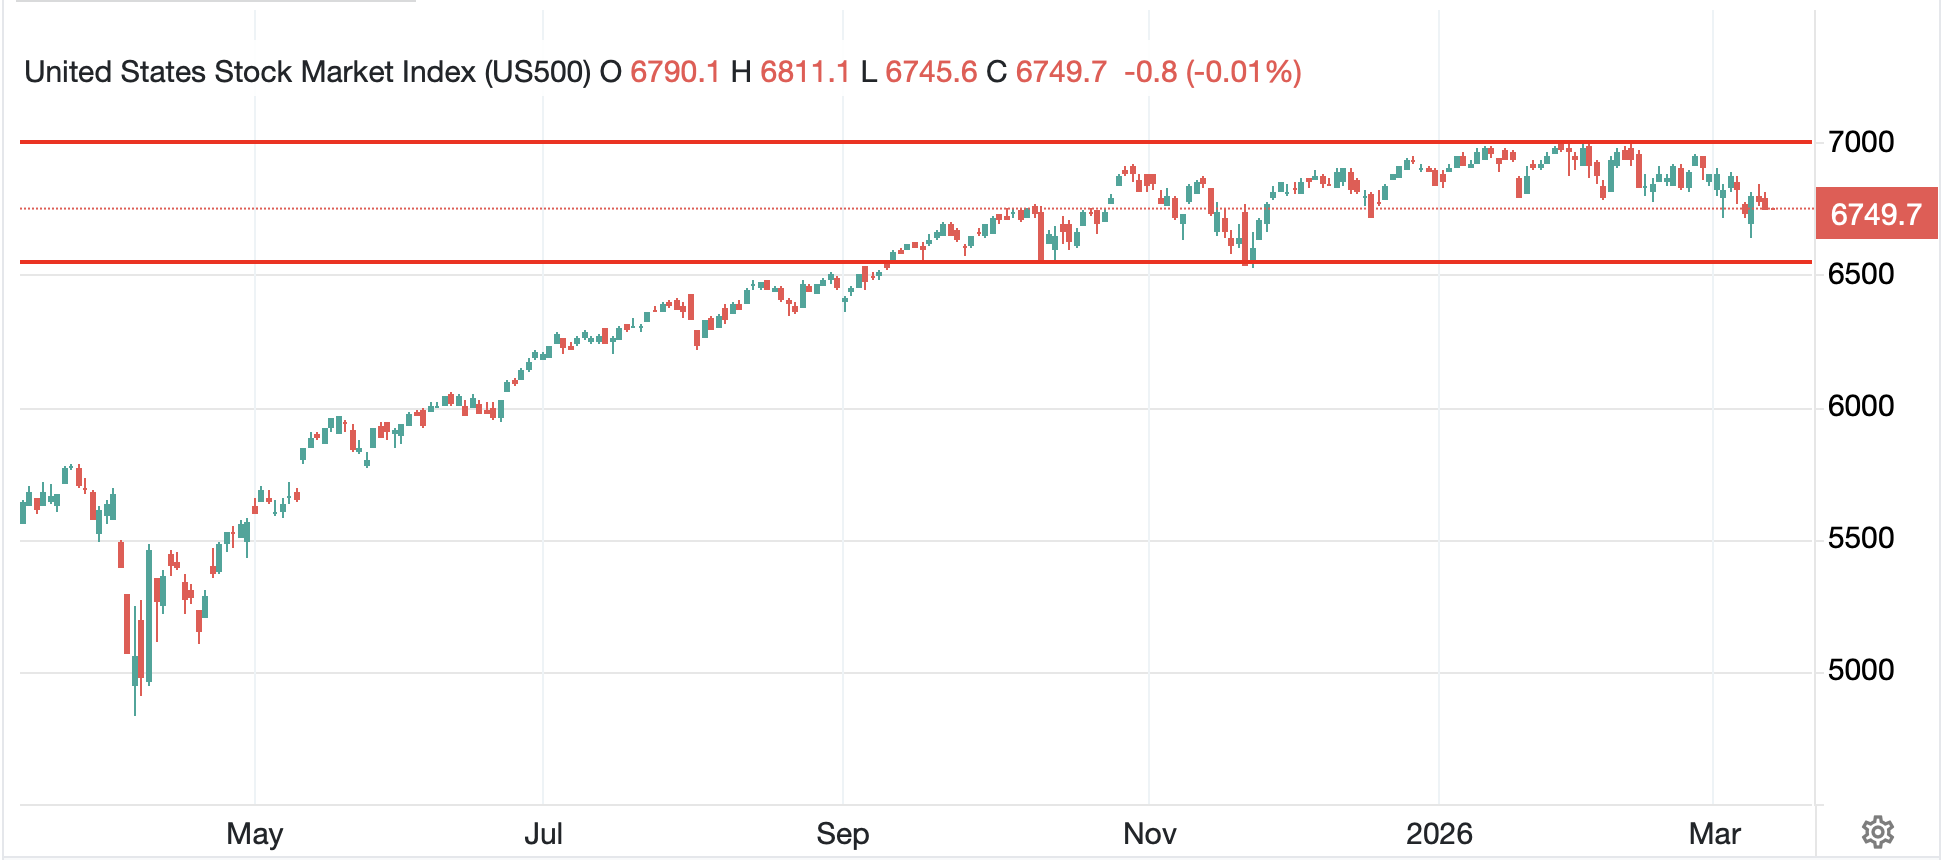
Turning to stocks, it is difficult to look at the below chart of the S&P 500 and come away with the conclusion that it is either rallying or declining in any meaningful measure.  For the past 6 months, the range has been about 450 S&P points, which, given the level, works out to less than 7%.  It is no surprise that equity volatility is a bit higher than currency volatility, but this chart does not instill fear of either collapse or breakout to my eyes.

Source: tradingeconomics.com
Yes, this morning there is rising concern and equity markets around the world had a weak session overall, but nothing indicating a collapse.  Consider in Asia we saw the following movement:

  • Tokyo -1.0%
  • Hong Kong -0.7%
  • China -0.4%
  • Korea -0.5%
  • Taiwan -1.6%
  • India -1.0%
  • Australia -1.3%

A weak performance?  Absolutely.  Unprecedented declines?  Not even close.  The same is true in Europe, but even less so, with Spain (-0.7%) the worst offender by far while France (-0.3%), the UK (-0.3%) and Germany (0.0%) all tread water.  Again, where is the fear?  US futures, at this hour (6:50) are lower by just -0.4%, again, soft but not catastrophic.

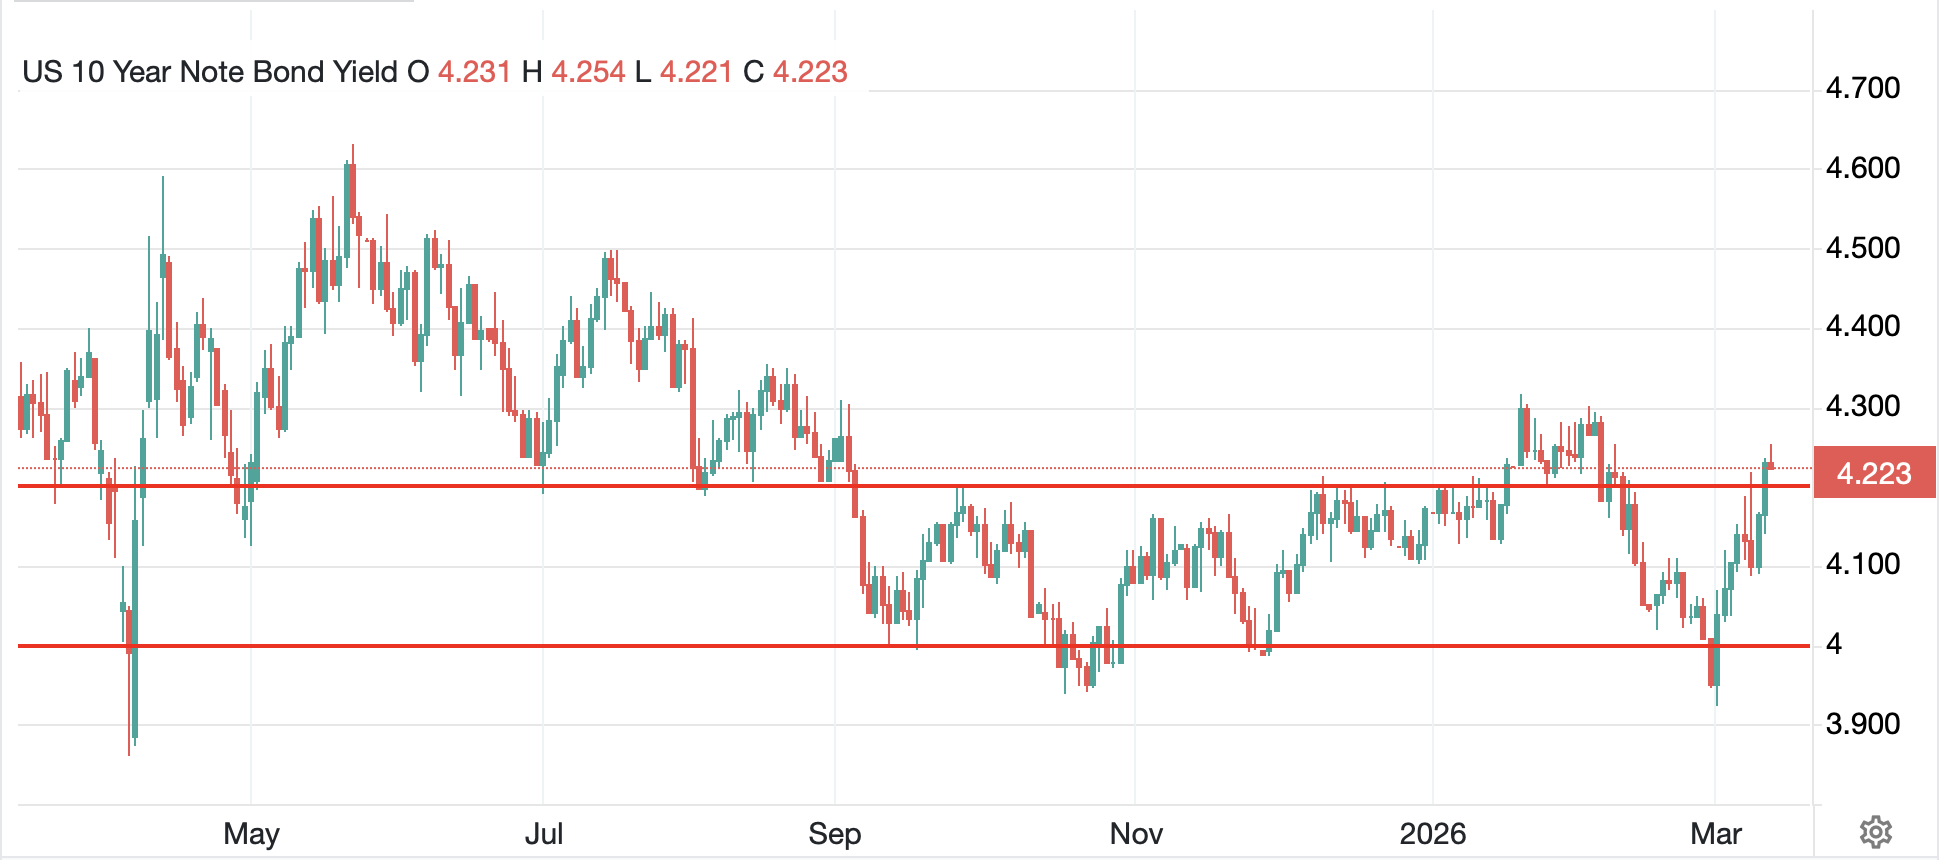
Turning to bonds, while Treasury yields climbed 7bps yesterday, and have been rising since the beginning of the month, they are just now at the top (and slightly through) the range of the past 6 months.  Now, the recent rise is understandable as we all know that yesterday’s benign CPI reading didn’t include any of the oil price movement since the Iran war began.  My understanding is that the rule of thumb for headline CPI is that every $10/bbl rise translates to 0.2% higher CPI.  So, with this morning’s WTI price at $91.50/bbl, compared with $65/bbl prior to the first attacks, that is about 0.5% higher CPI ceteris paribus.  Now, ceteris is never paribus, so we don’t know how things will actually play out, but it seems a fair bet headline inflation will be higher next month.  (This is the point where I will highlight the best way to take advantage of the rising CPI is through USDi, the fully-backed CPI tracking currency.  We already know that CPI next month is going to be higher because of the catch up from the October government shut down.  Add to that the oil price moves and we are looking at annualized returns in the coin of 4.5+% over the next quarter, well above T-bills!)

Back to the bond market, a look at the chart shows the chopping action described above, just like the dollar’s price action.

Source: tradingeconomics.com
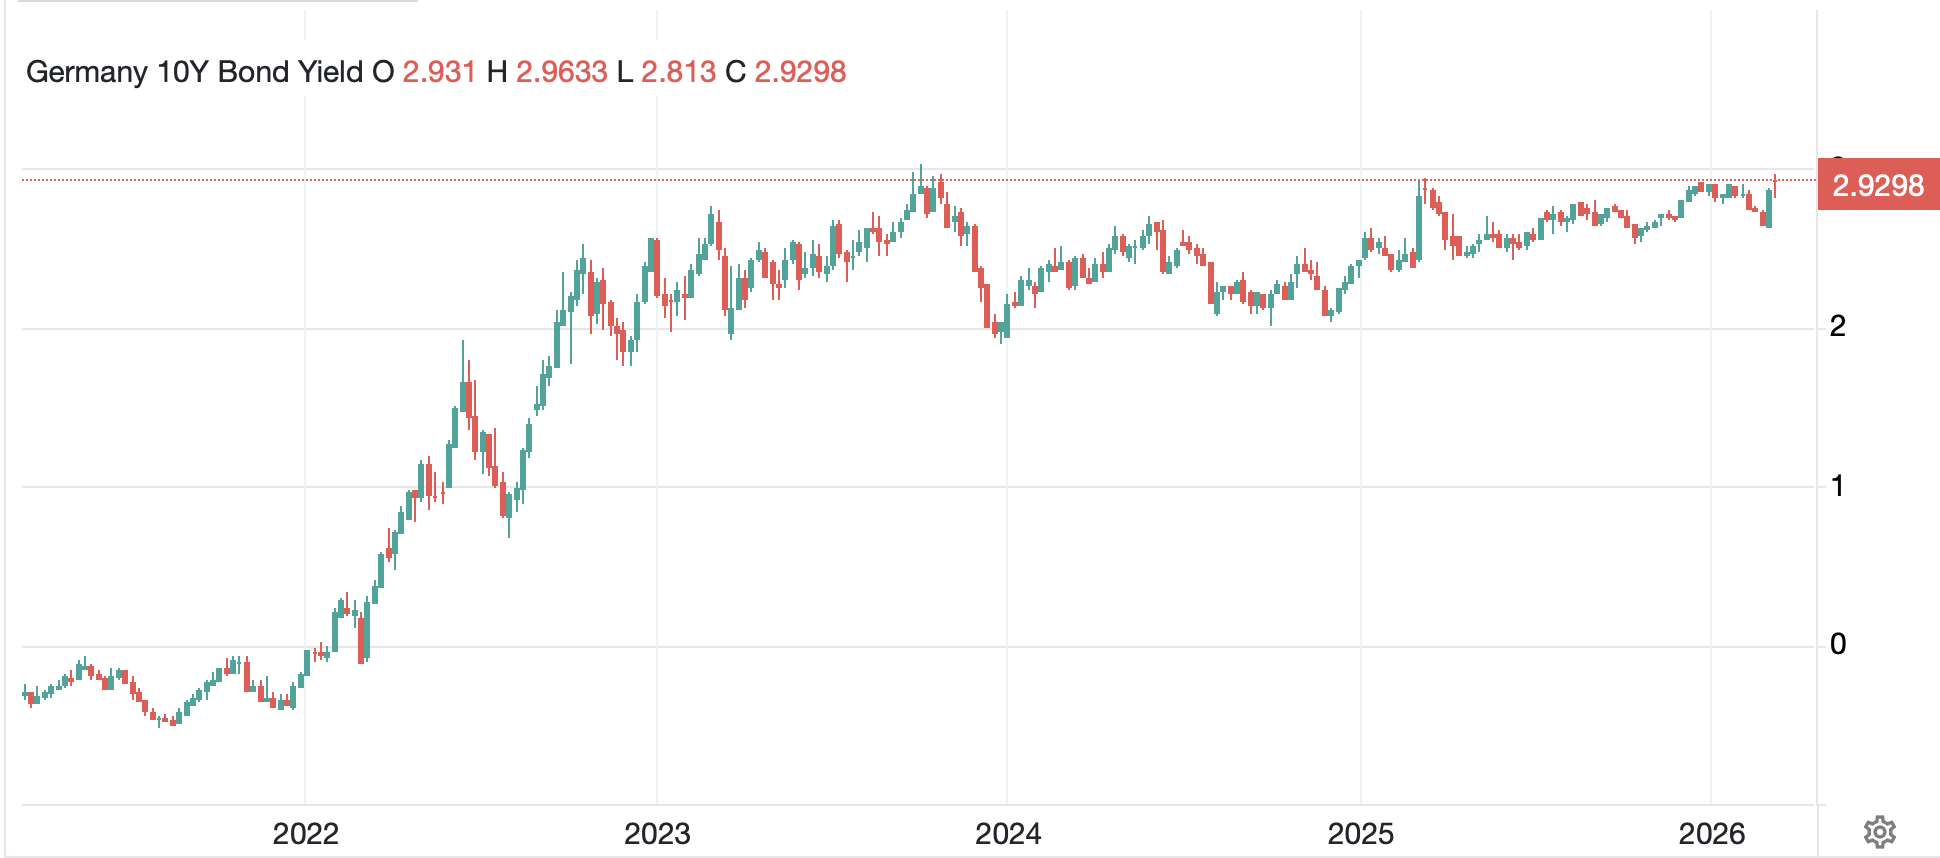
This is the Treasury story.  Elsewhere around the world, things have not been quite as benign.  For instance, German bund yields have, this morning, traded to their highest level since October 2023 as per the below chart, although, in fairness, the rise has been gradual.

Source: tradingeconomics.com

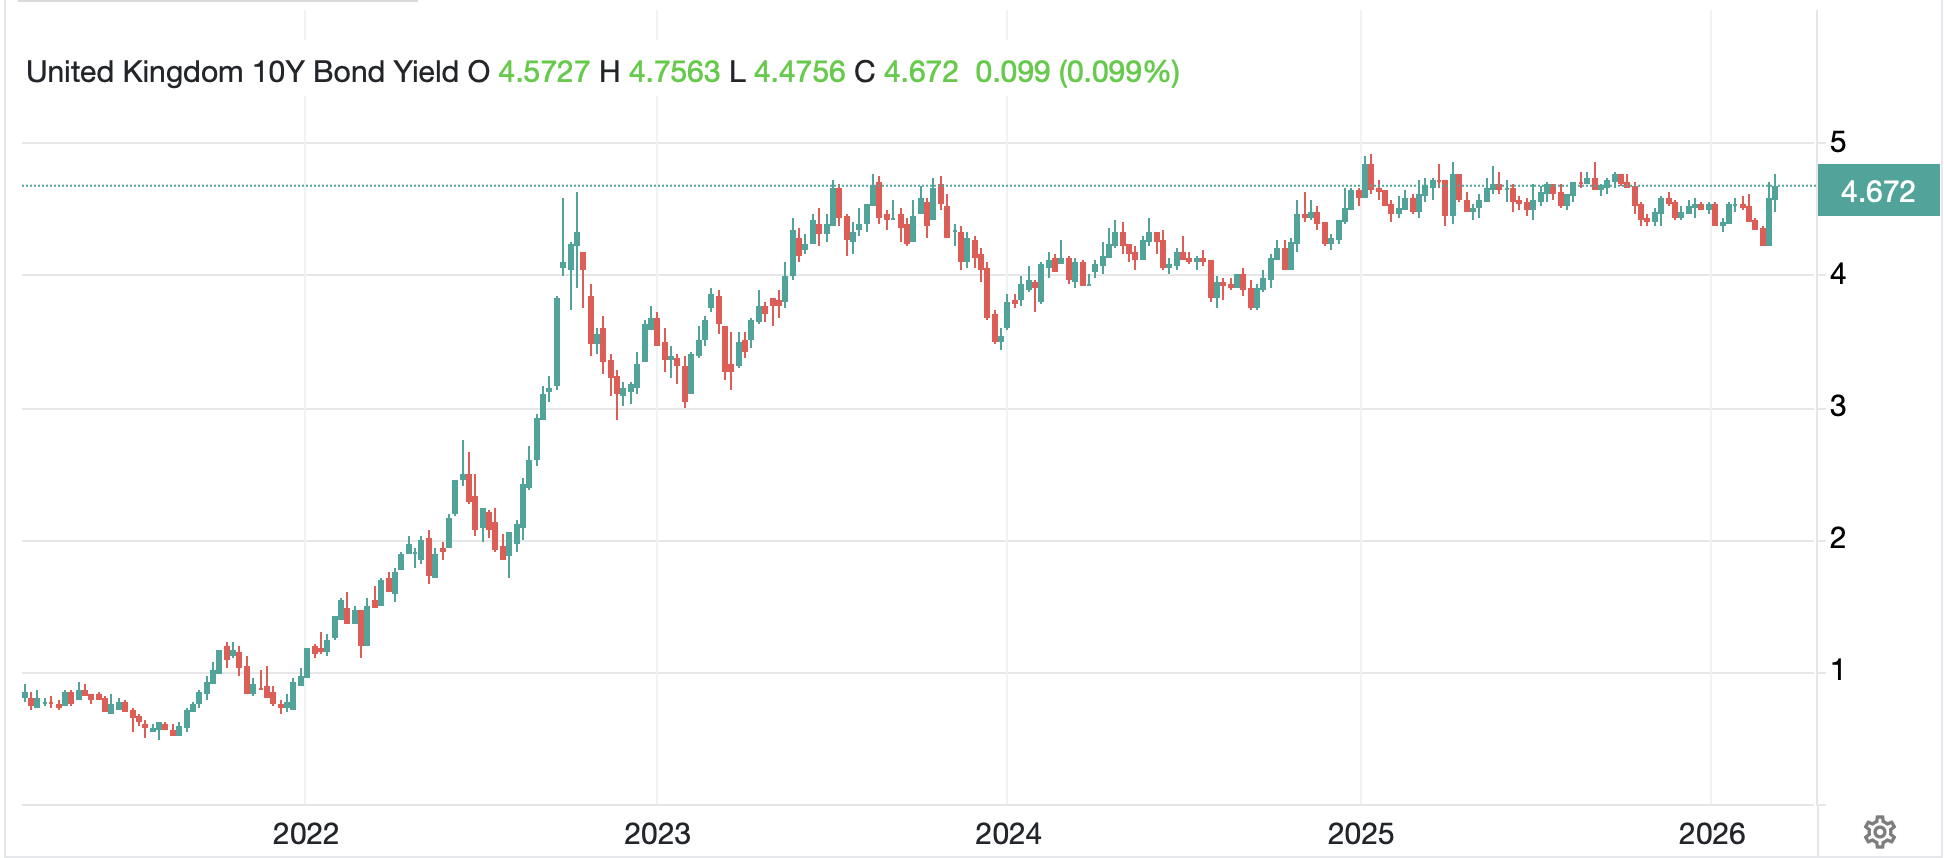
UK gilts, on the other hand, have been somewhat more volatile, although I suspect that has a great deal to do with UK domestic economic policy as the nation continues its effort at suicide by insisting that Net Zero CO2 output is the way of the future, thus crushing economic output while suffering through remarkably higher energy prices, and the corresponding inflation that comes with that.  But even here, while the price action has been choppier, the result so far has been similar, a sharp rise in the post Covid recovery reaching a plateau.  

Source: tradingeconomics.com

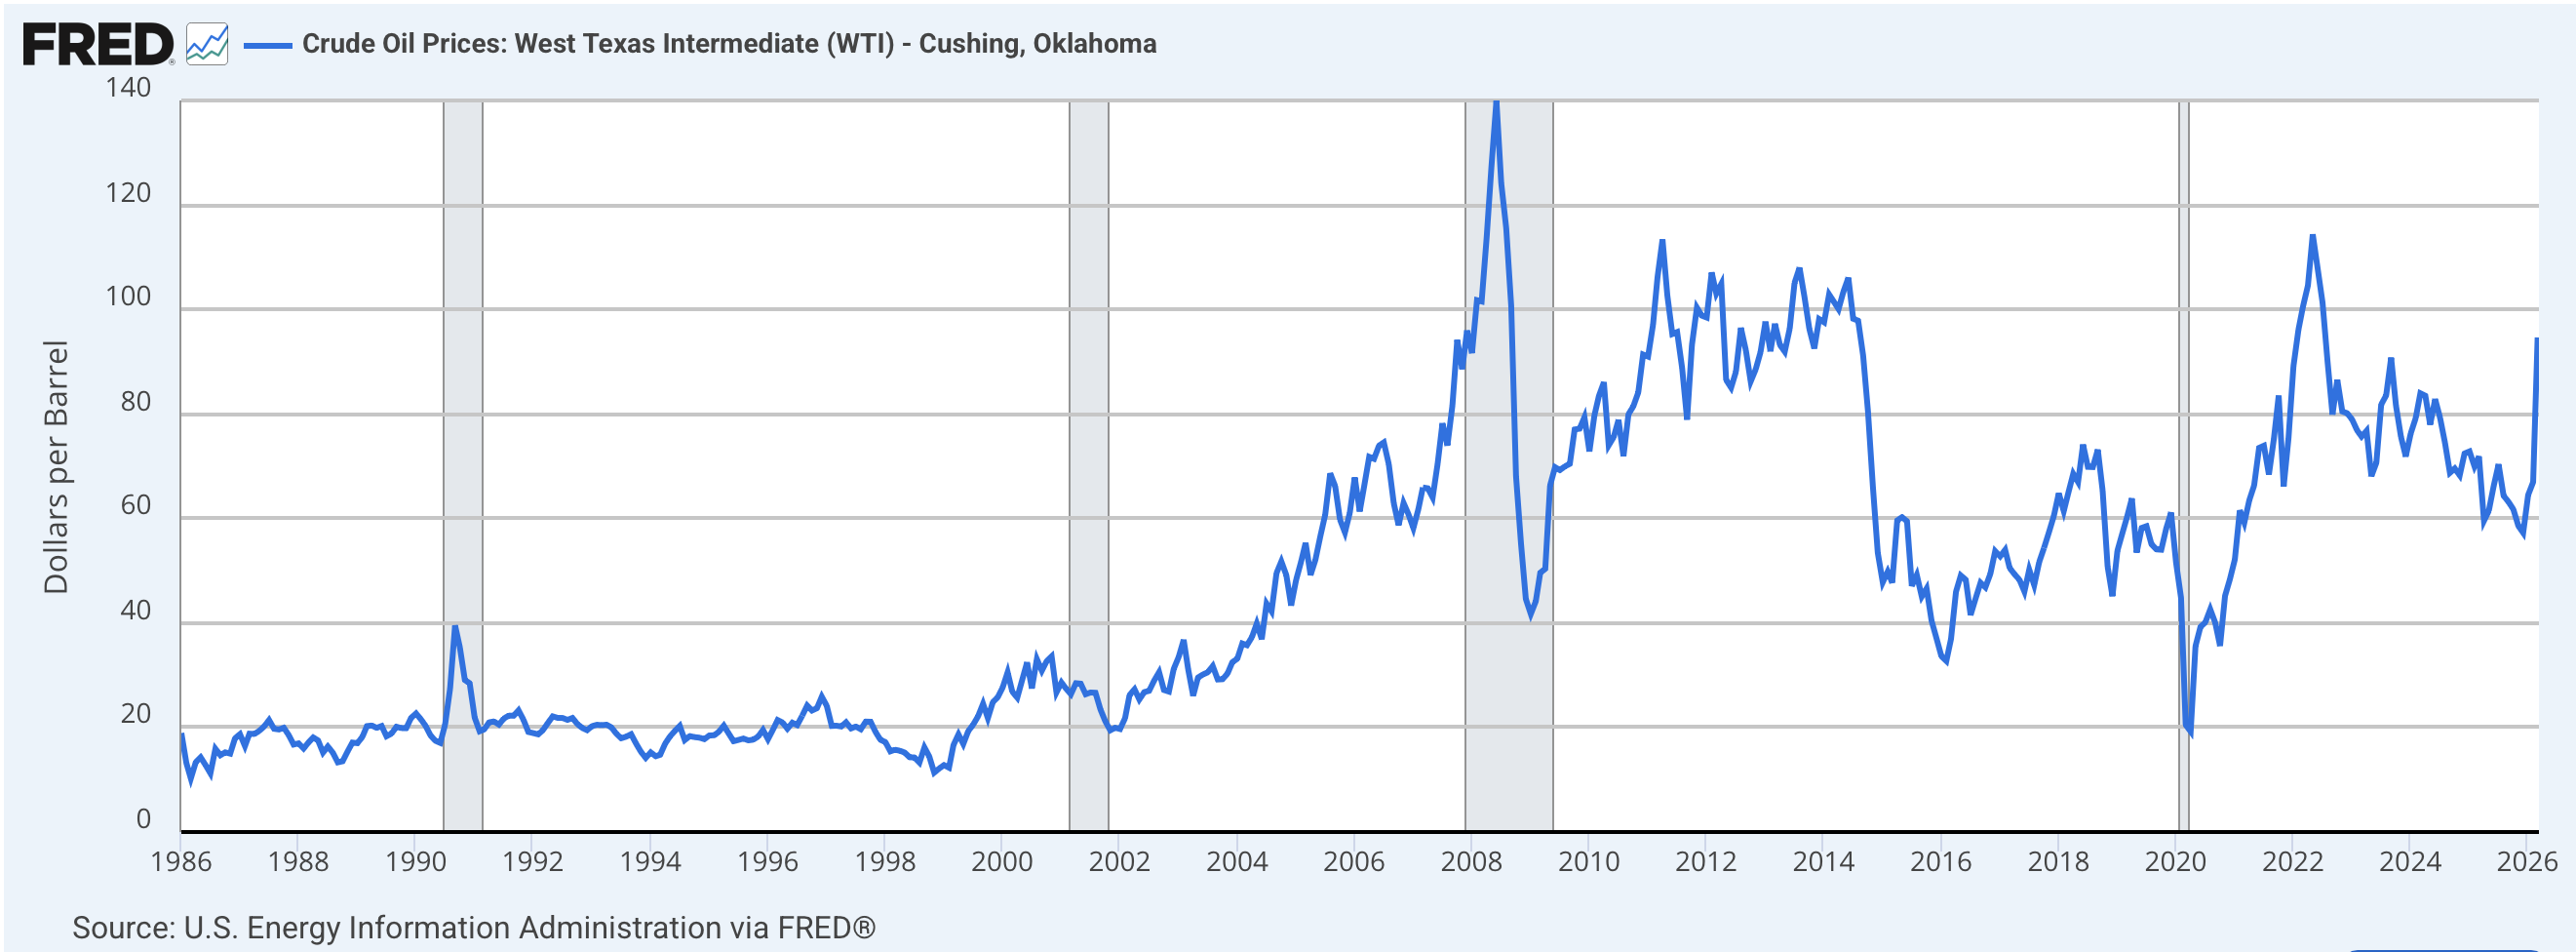
The fear here, and across all bond markets, is that the Iran war lasts much longer, that oil prices continue to rise, perhaps back to the post Ukraine invasion levels of $120 or higher, and that inflation reignites.  History has shown that every time oil prices rise swiftly and remain there for any length of time, it leads to a recession or at least coincides with one as per the below chart from the FRED database.

Remember, recessions are called after the fact, so my take is the NBER goes back to include the spike.  But it is not a hopeful chart.

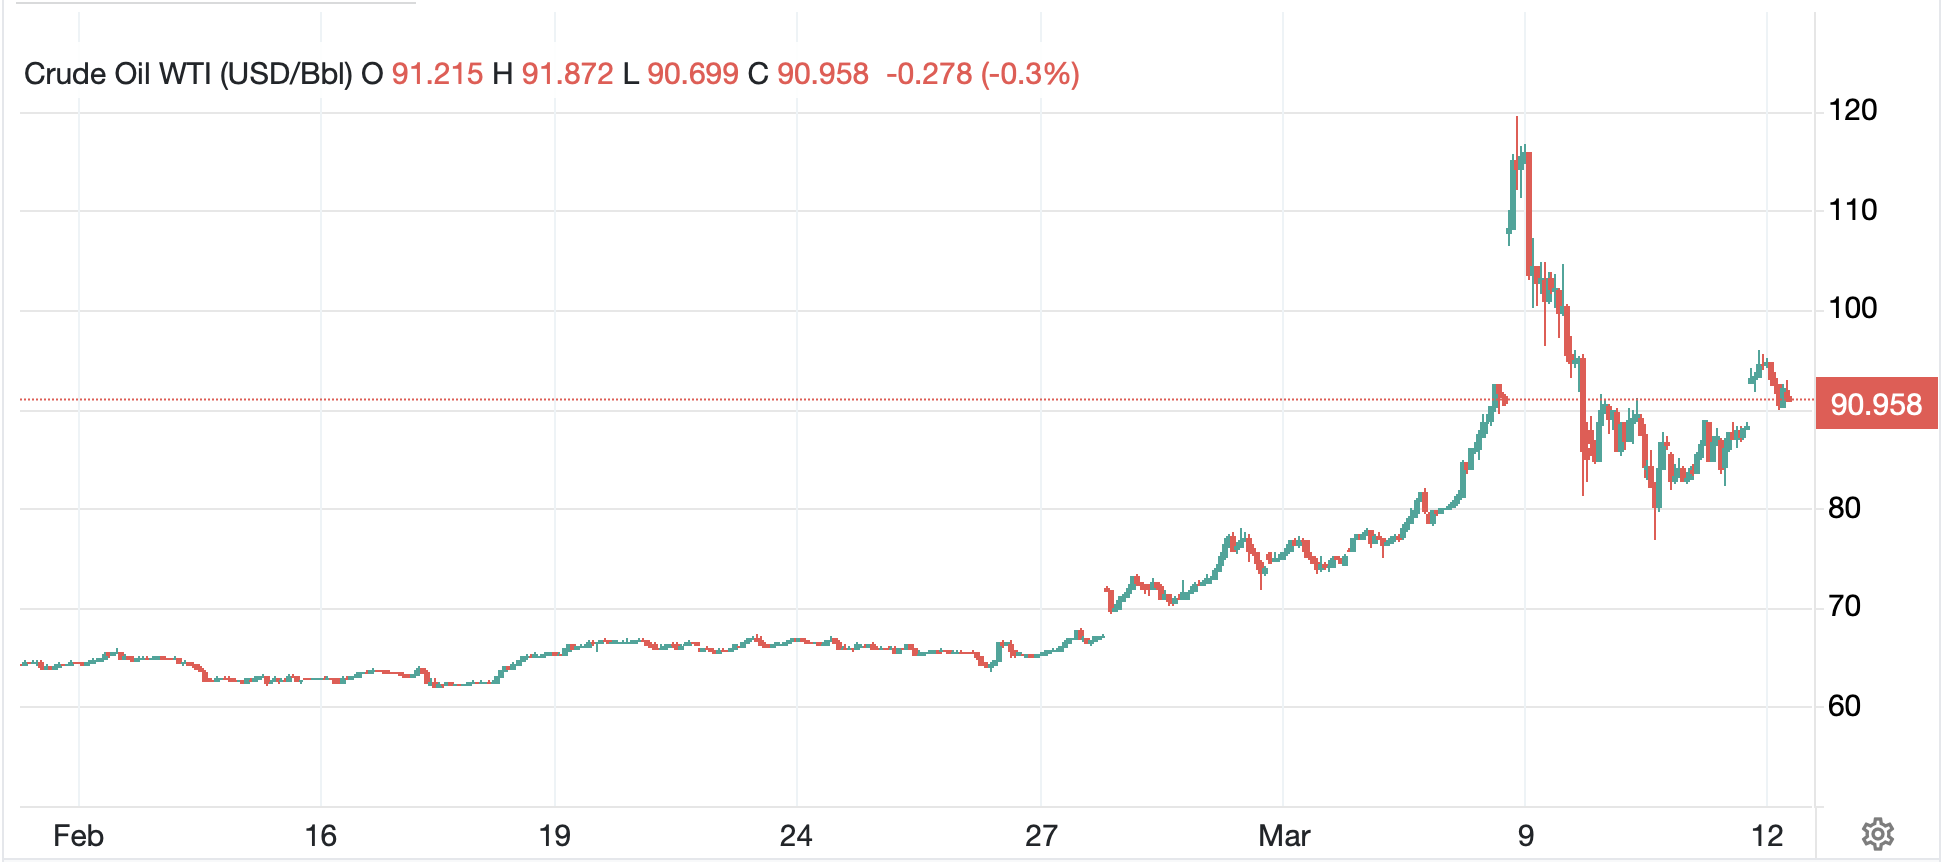
On the subject of oil, this morning it is higher by 4.2% as news that Iran has begun to mine the Strait of Hormuz has the narrative updating to explain that the Strait will be closed for an extended length of time and so some 20% of global oil supplies will be off the market.  Now, this is not strictly true as Iran is still transiting the Strait and sending those cargos to China, and I read that India is trying to negotiate for oil heading there to get through as well.  Nonetheless, there is a significant backup there and production is starting to get shut in, which is never a good sign.  While we remain far below the Sunday night panic peak, there is nothing to say we cannot climb back there if things deteriorate in Iran.

Source: tradingeconomics.com

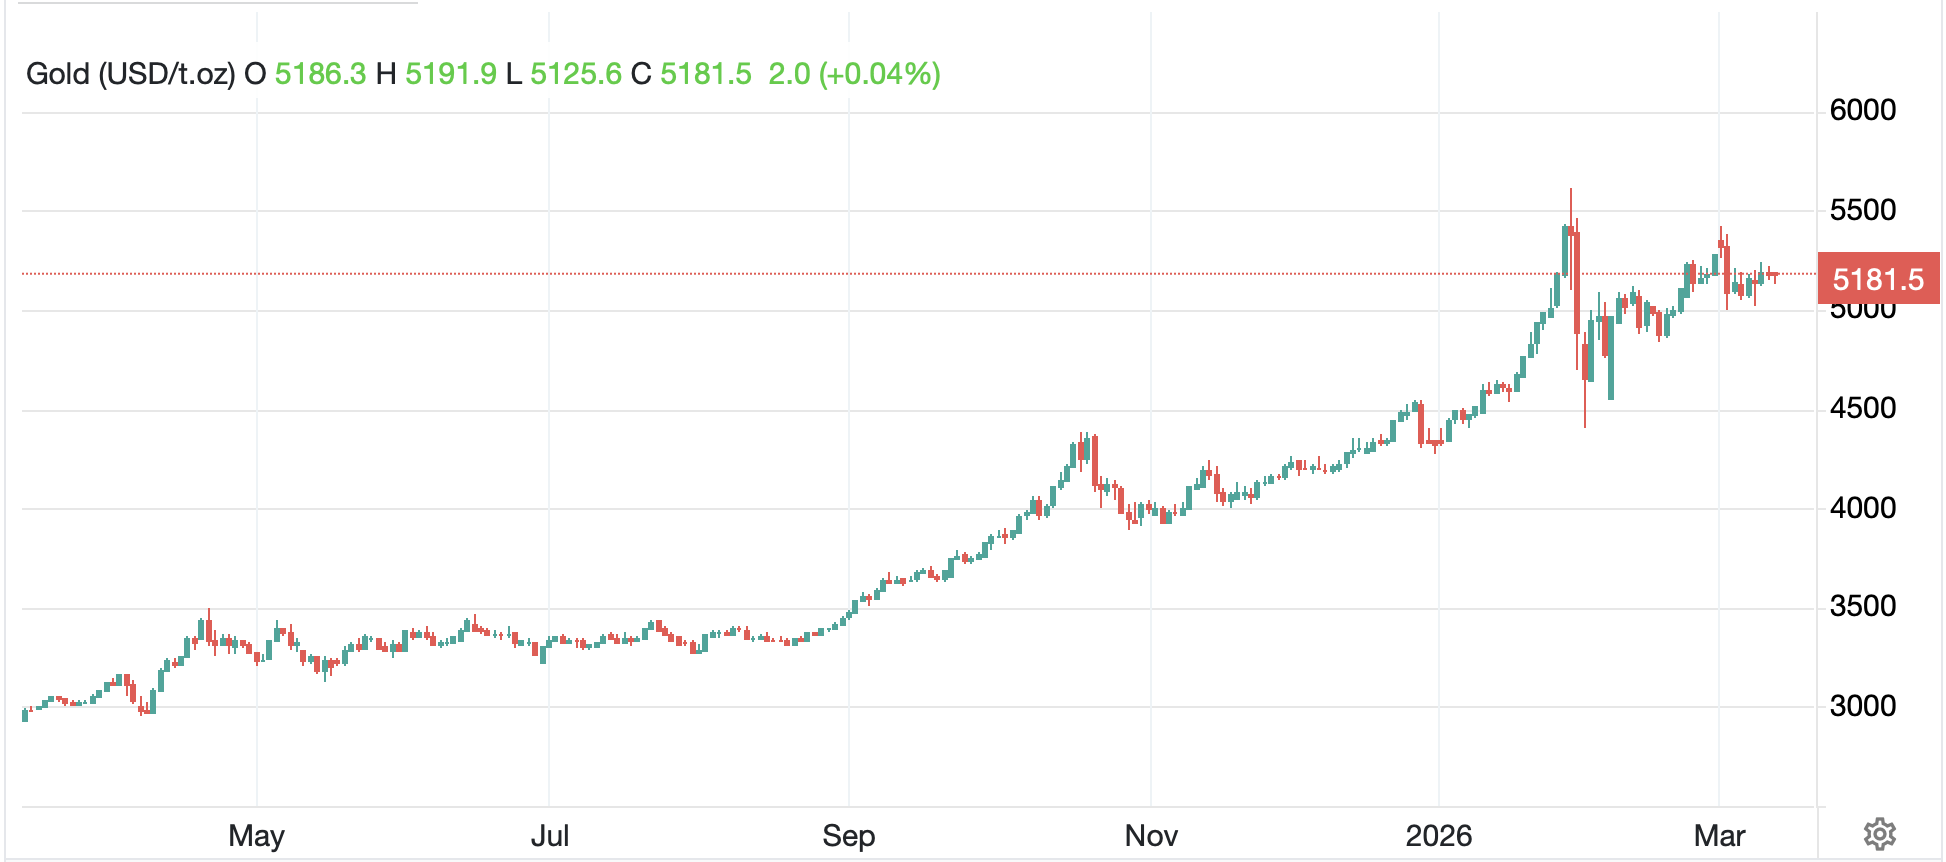
Which takes us to the metals markets.  After a remarkable run over the past two years, gold (0.0%) appears to be settling into a new trading range, as does silver (+1.75%).  

Source: tradingeconomics.com

The funny thing about this is that gold has historically been seen as an inflation hedge, so with inflation almost guaranteed to be higher for the next several months, at least, one might expect gold to rally more aggressively.  One consideration is that with inflation rising, expectations are for rising interest rates which, correspondingly, are negative for gold, so there is no buying. (H/T Alyosha for that narrative.). But perhaps the explanation is that gold has historically been a hedge for monetary inflation, meaning the printing of more currency.  If inflation is caused by a spike in energy prices, gold typically sits on the sidelines. 

Which takes us to the Fed.  If Powell and friends look at inflation and decide that they need to raise rates to address it, that would be a double negative for gold in my view as not only would interest rates be higher, but it would almost certainly trigger a recession.  Initially, that would not be a gold positive, although their response to the ensuing recession, which would be significant policy ease, would definitely send the barbarous relic soaring again.  

So, that’s how I see things this morning.  some market chop, but nothing really changing.  I suppose that we will need to see a conclusion of some sort in Iran to change opinions because, if things drag on, just like they did in Ukraine, investors forget about it after a while.  For instance, how many of you remember Venezuela, which was just 2 months ago.  Attention spans these days are very short.

On the data front, Initial (exp 215K) and Continuing (1850K) Claims lead this morning alongside the Trade Balance (-$66.6B) and Housing Starts (1.35M) and Building Permits (1.41M).  There is also a 30-year auction today, although nobody has been discussing auctions at all lately.  

You will not be surprised that I am not excited by the current market situation, and in fact, my take is the bigger risk for a large move is a sudden end to the Iran conflict, rather than anything else.  In the meantime, I am hunkering down.

Good luck

Adf