Center of Blame

It's not just the 'economy's heat
Why we're at the edge of our seat
But also, Iran
Where this all began
That's left traders feeling downbeat

Thus, crude oil's back in the game
As being the center of blame
How high can crude rise
Til bonds paralyze
Activity, snuffing that flame

Bond yields remain topic A this morning as they continue to climb around the world.  There are many opinions as to why that is happening but I think it boils down to either 1) increasing deficit spending by governments around the world resulting in significant increases in supply thus driving yields higher, or 2) rising oil prices after the US-Iran conflict has seen an increase in military action on both sides thus driving the inflation narrative further.  Arguably, it is a combination of both these things.

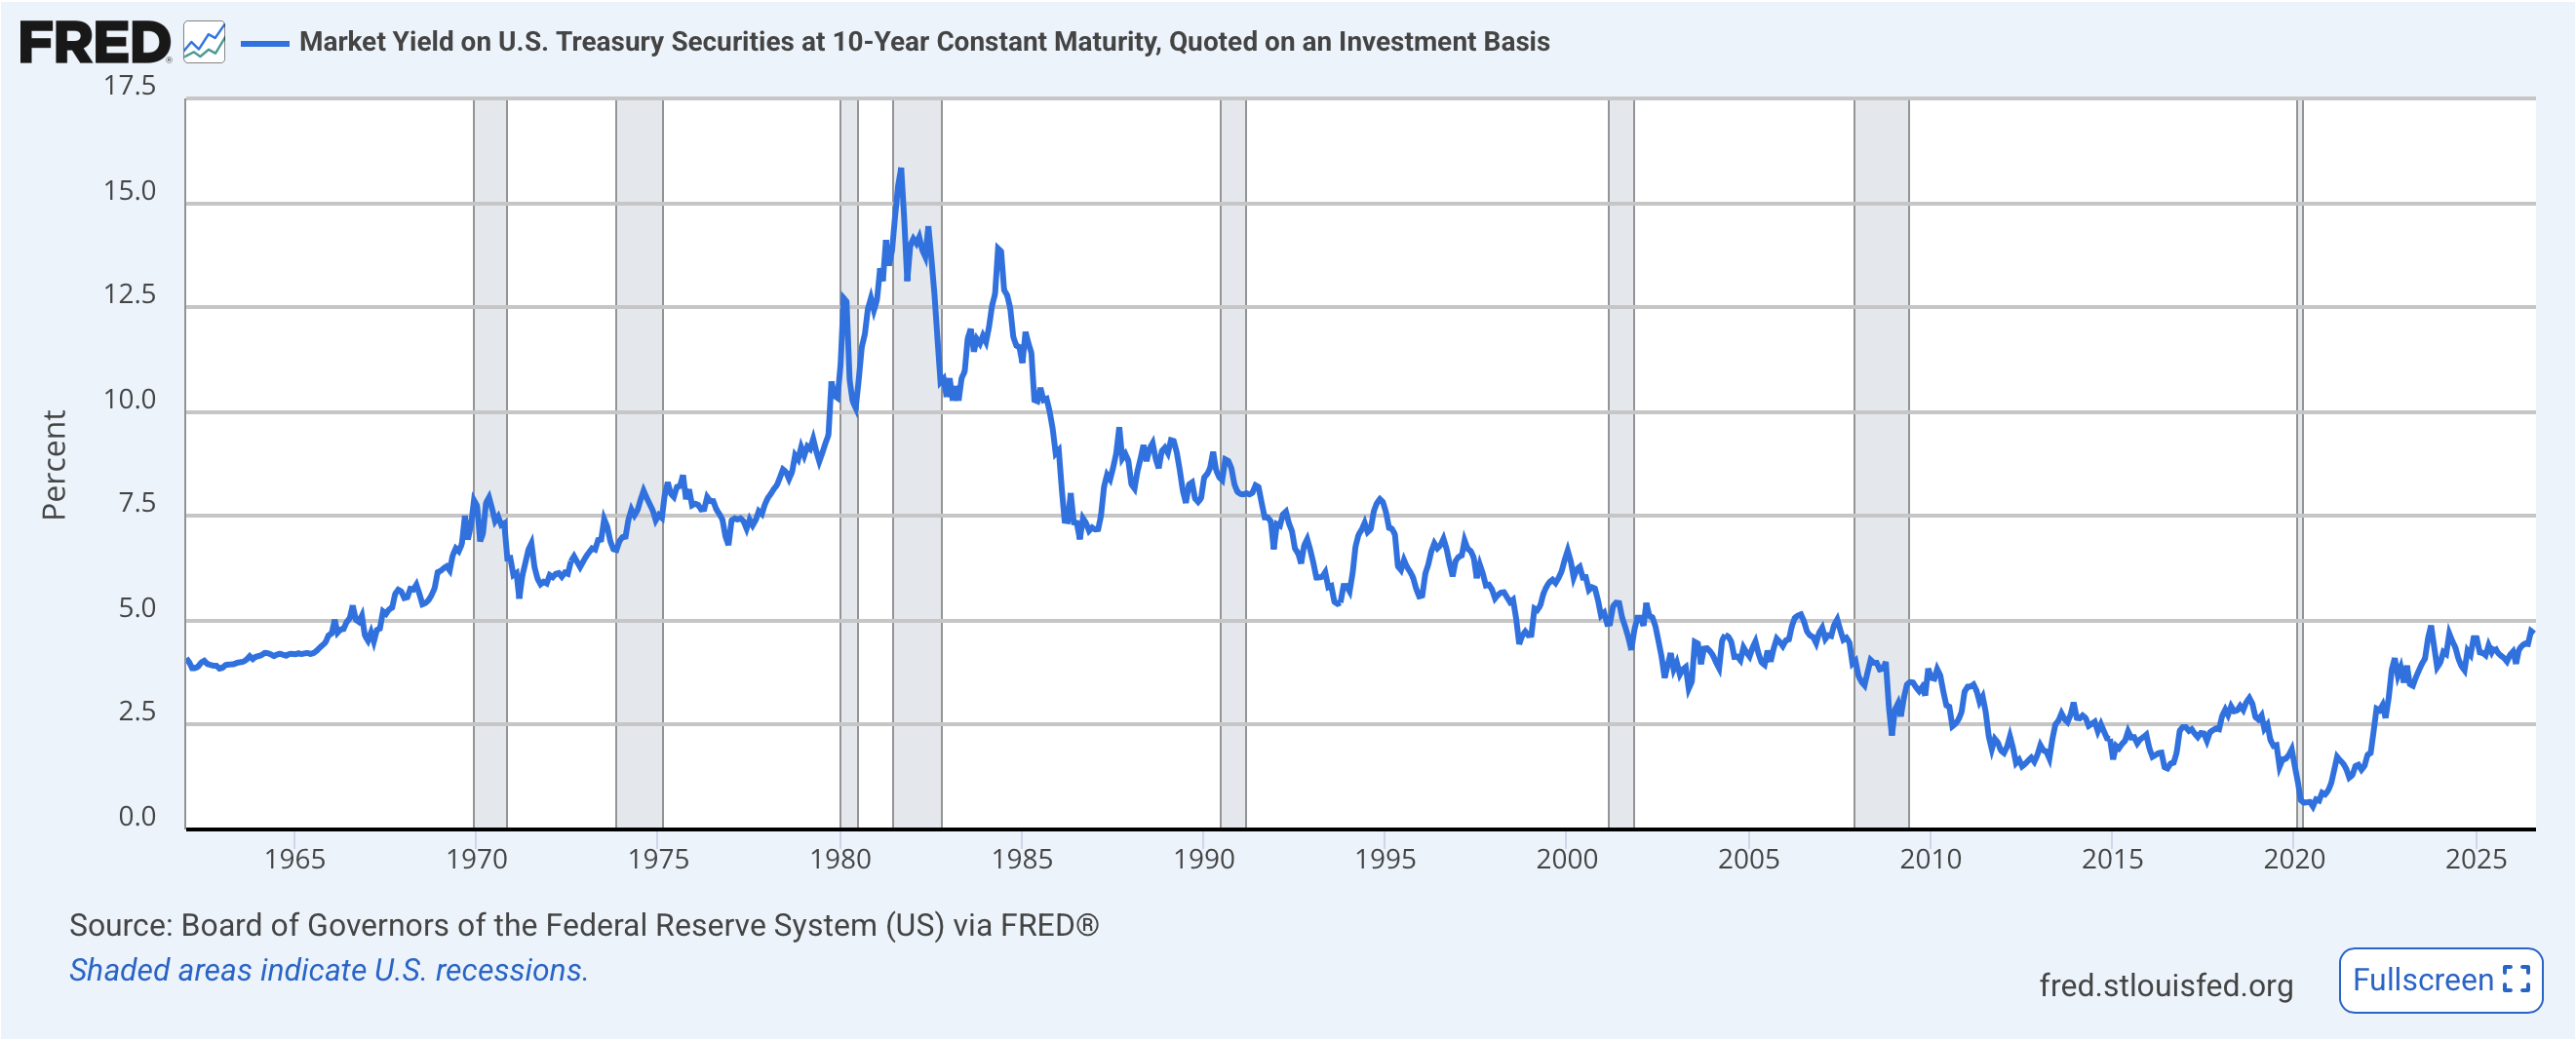
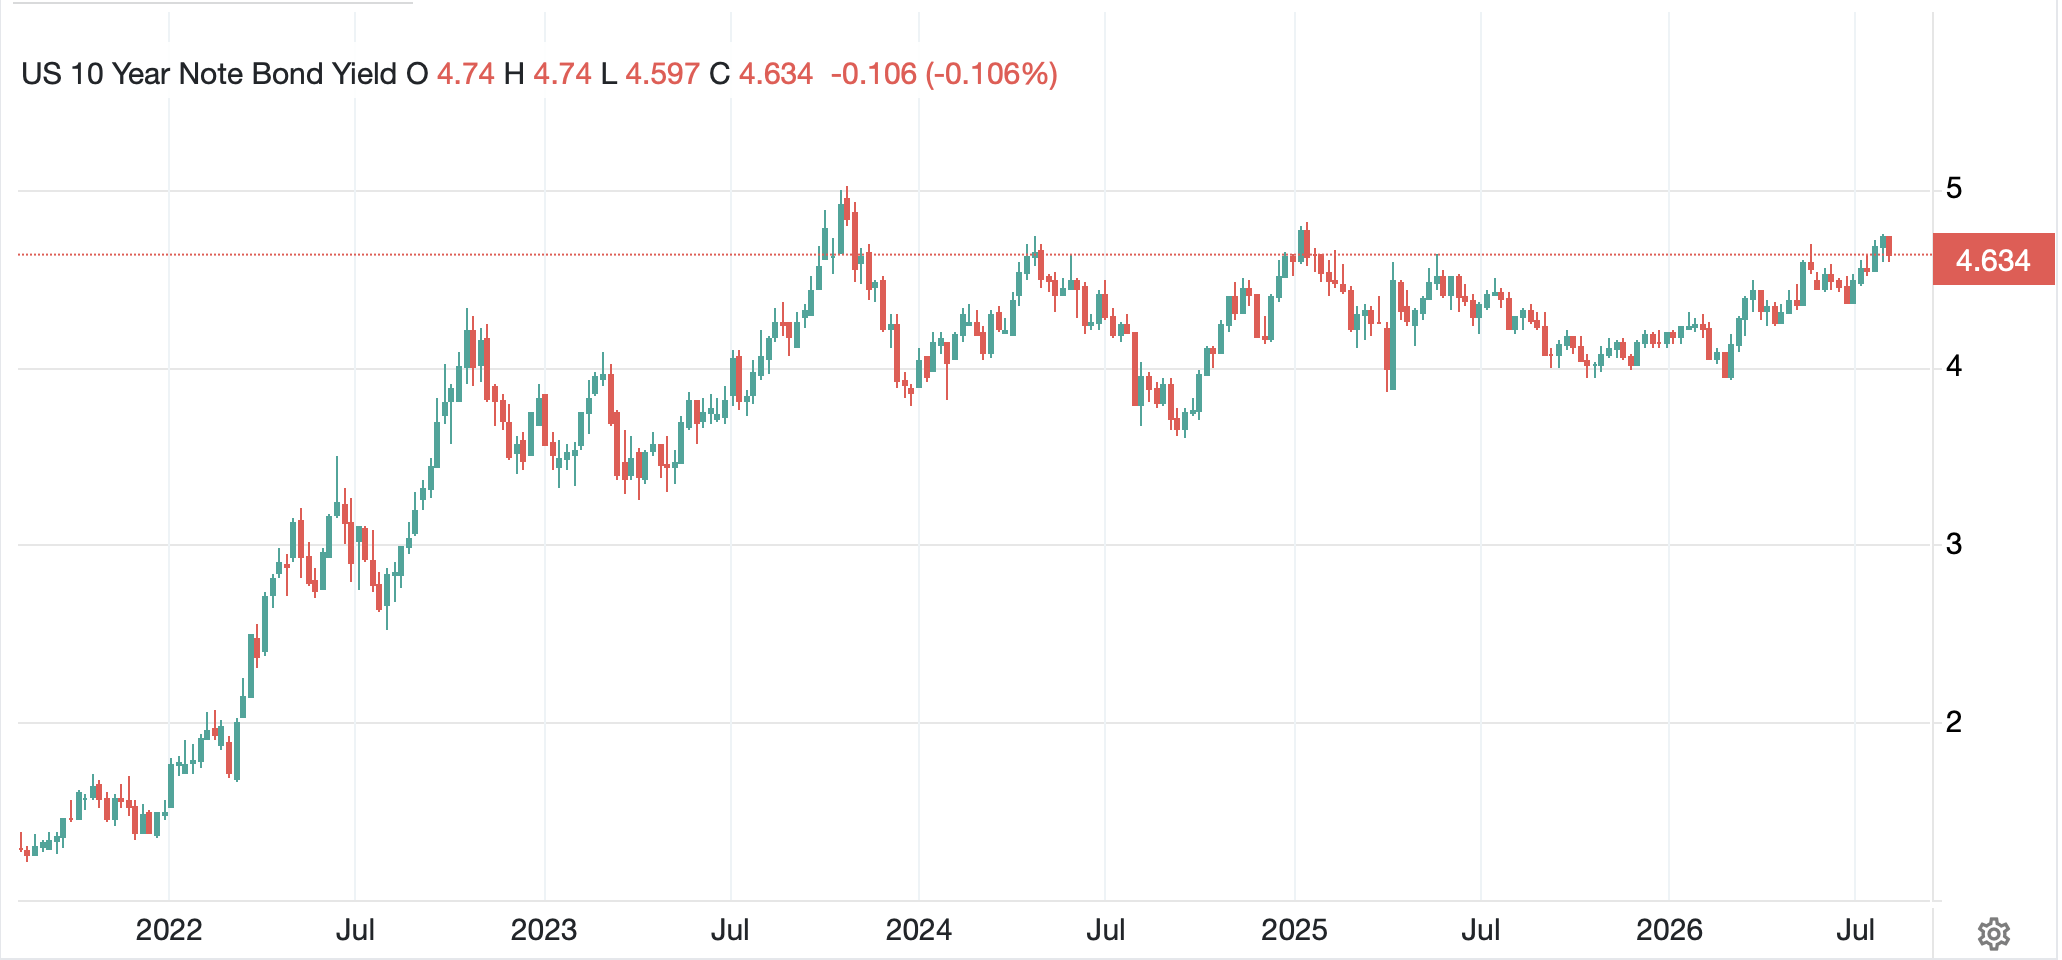
Much has been written that these are the highest yields since 2011 or 2008 (or 1996 in Japan’s case) and how that makes them, somehow, more dangerous.  Or at least that is the implication.  When it comes to bond yields though, I always like to maintain perspective by looking at the long-term history of 10-year yields.  If you look at the chart below from FRED, I think it fair to ask the question, what is the aberration, current yields at 4.8% or yields at 2.5% or lower seen post the GFC?
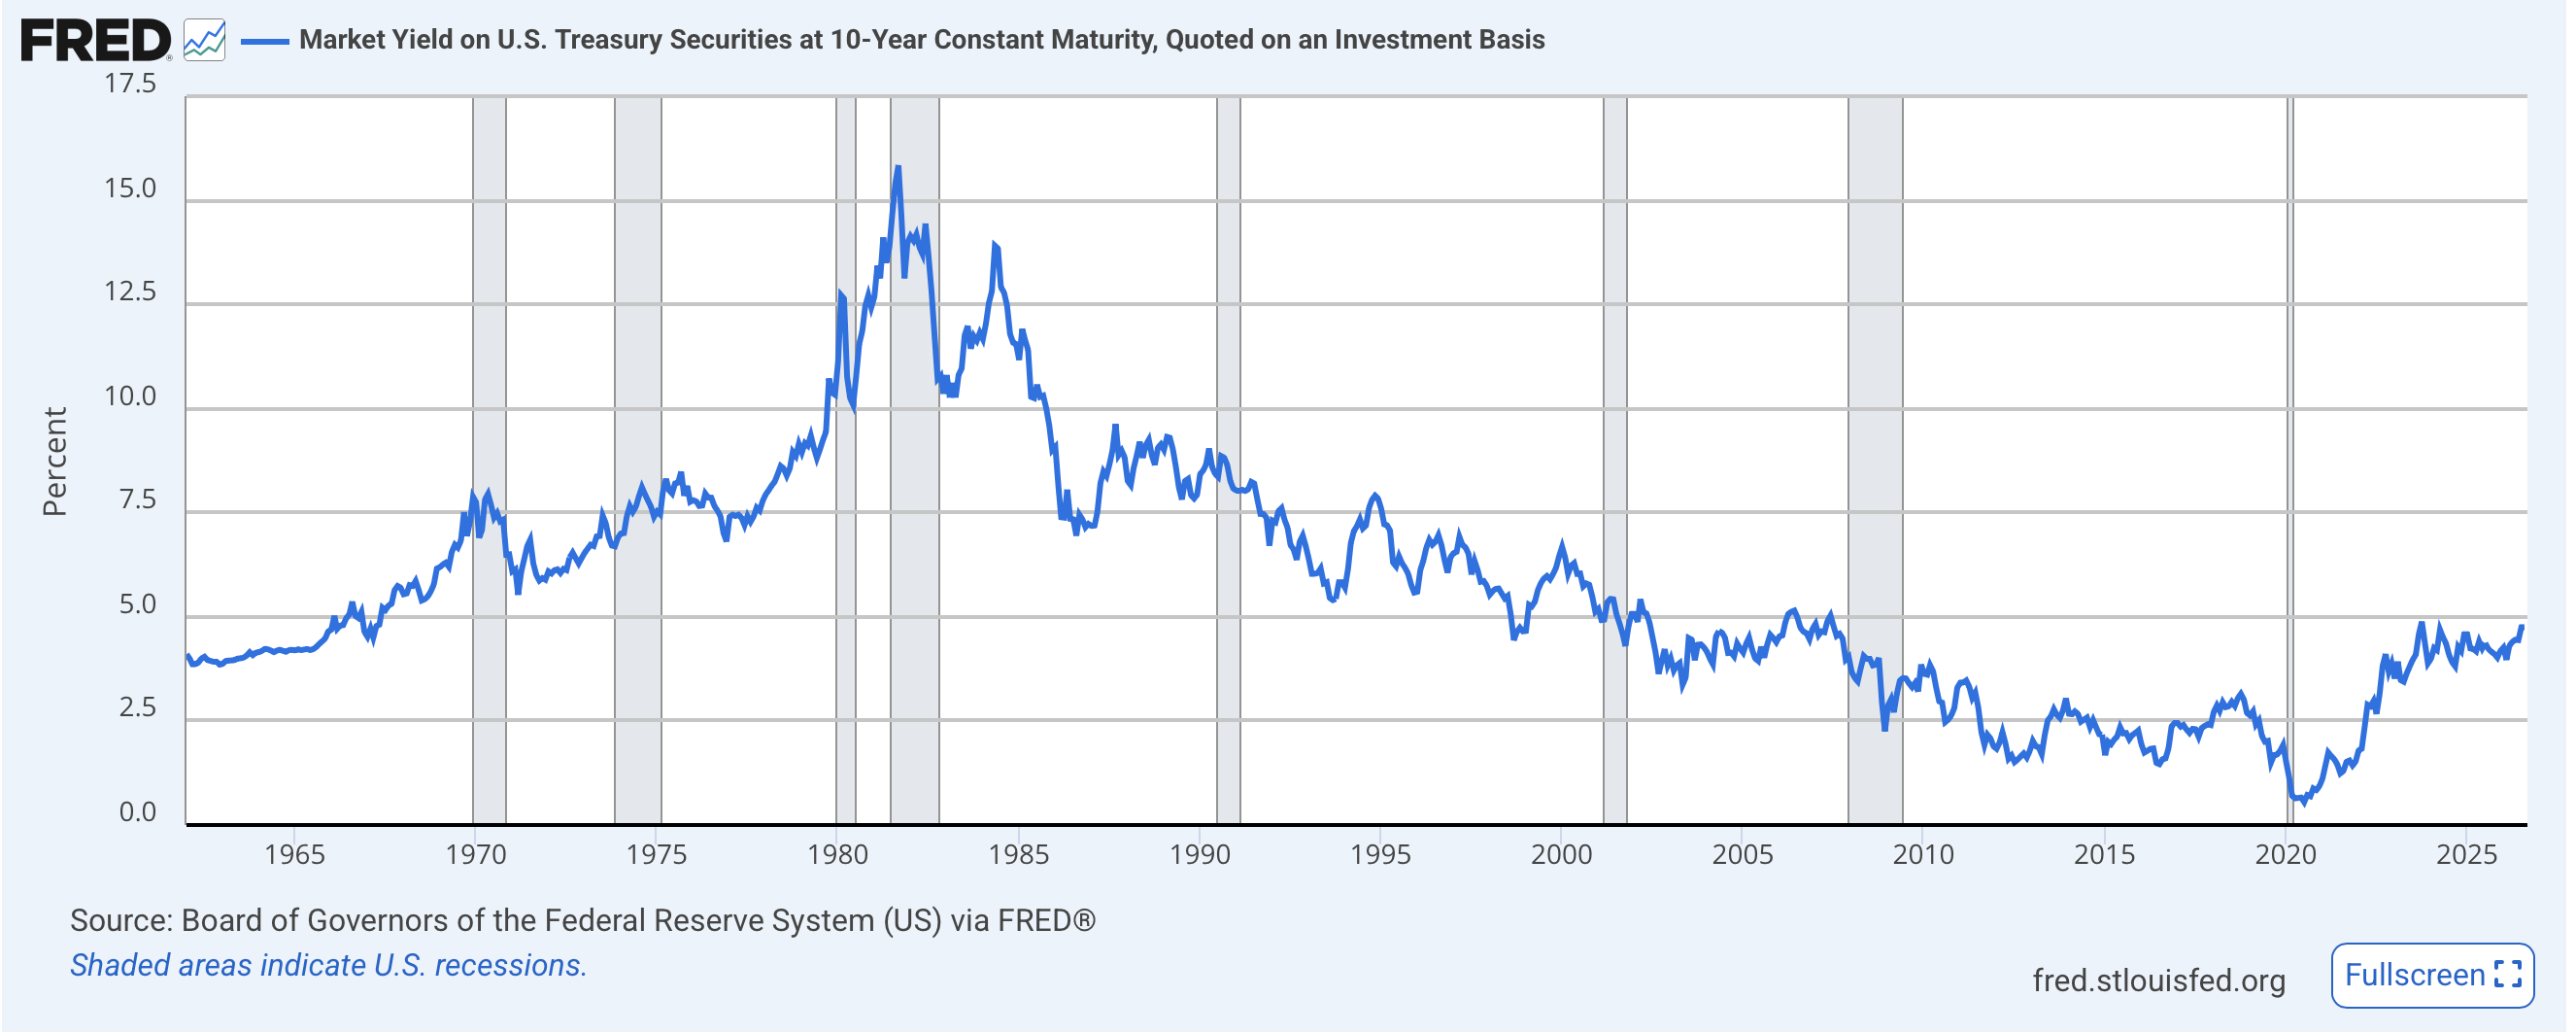
As I have written before, the average 10-year yield over the past 60 years is 5.81%, still 100bps higher than current levels.  I understand that debt outstanding has grown dramatically over the years, but it’s not like it wasn’t growing during Covid.  In fact, it was exploding higher then too.  Ultimately, the original sin is excess government spending relative to the economy’s overall size and, unfortunately, the underlying thesis of RIH is that is not going to change.  To me the question becomes, how does one prepare for the impacts of this policy.  And remember, this is not a US only policy, it is now the default policy of every government in the world, save perhaps Switzerland.

How can it get fixed?  That is the $64 trillion question and there is no easy answer.  If governments around the world reduced their spending, especially on things that add no true economic value (subsidies for green energy are huge and immediately come to mind), it would help but not solve the problem.  Entitlement spending is the major expense everywhere in the G10 and as those nations age demographically, that will only get worse. 

I haven’t discussed the 4th Turning in a while, but this is all of a piece with that scenario, massive institutional changes as old institutions, be they corporations, central banks, government structures or educational organizations, will be redesigned for the new age.  Perhaps that is the promise of AI, a “voice” that can analyze history and help guide future decisions.  Alas, mankind is mankind, and I don’t foresee that changing so whatever comes out on the other side, it, too, will only have four generations of life!

Was it hint or threat?
Could Ueda hike fifty?
No breath holding, please

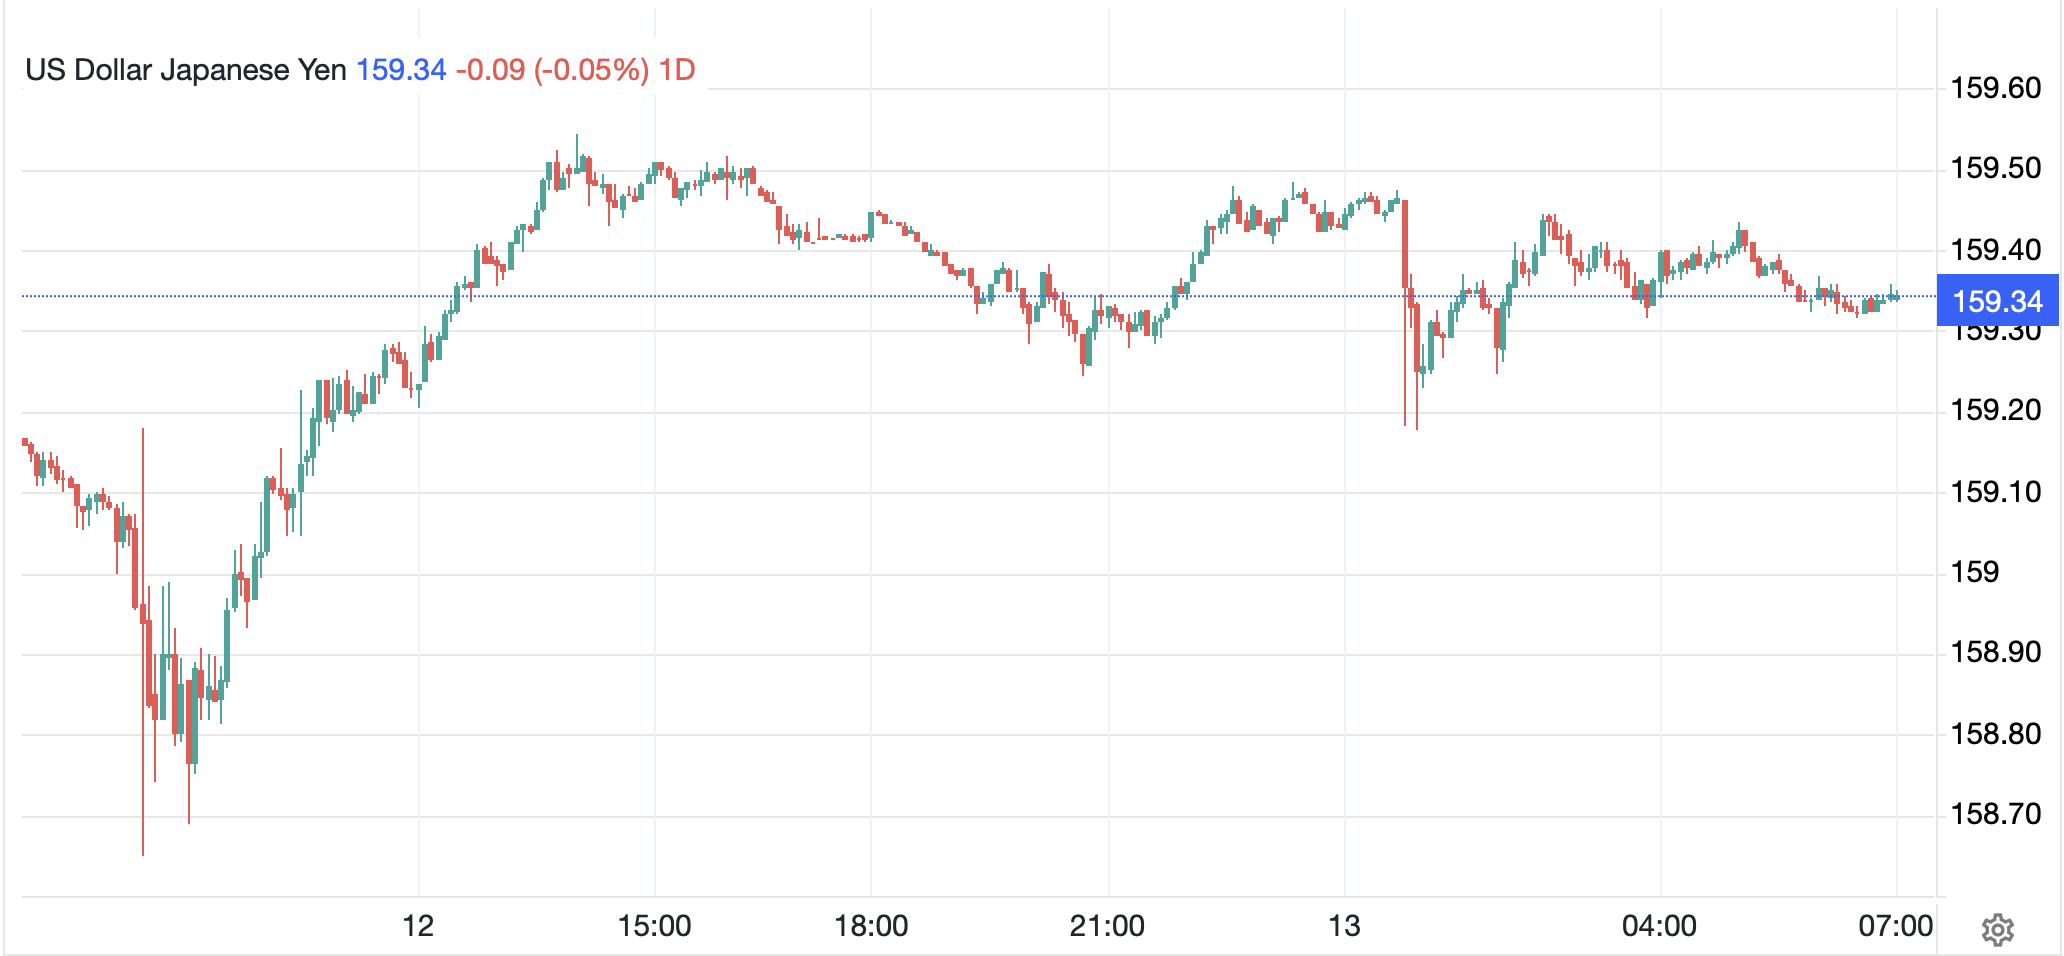
The other story of note this morning was that BOJ Board Member Takata, a known hawk, gave a speech and indicated that the BOJ could surprise with a 50bp hike this month, or perhaps hike two months in a row rather than their current once every six months cadence.  Bloomberg’s article was succinct.  This story did have a modest impact on the yen (+0.25%) as you can see in the chart below.
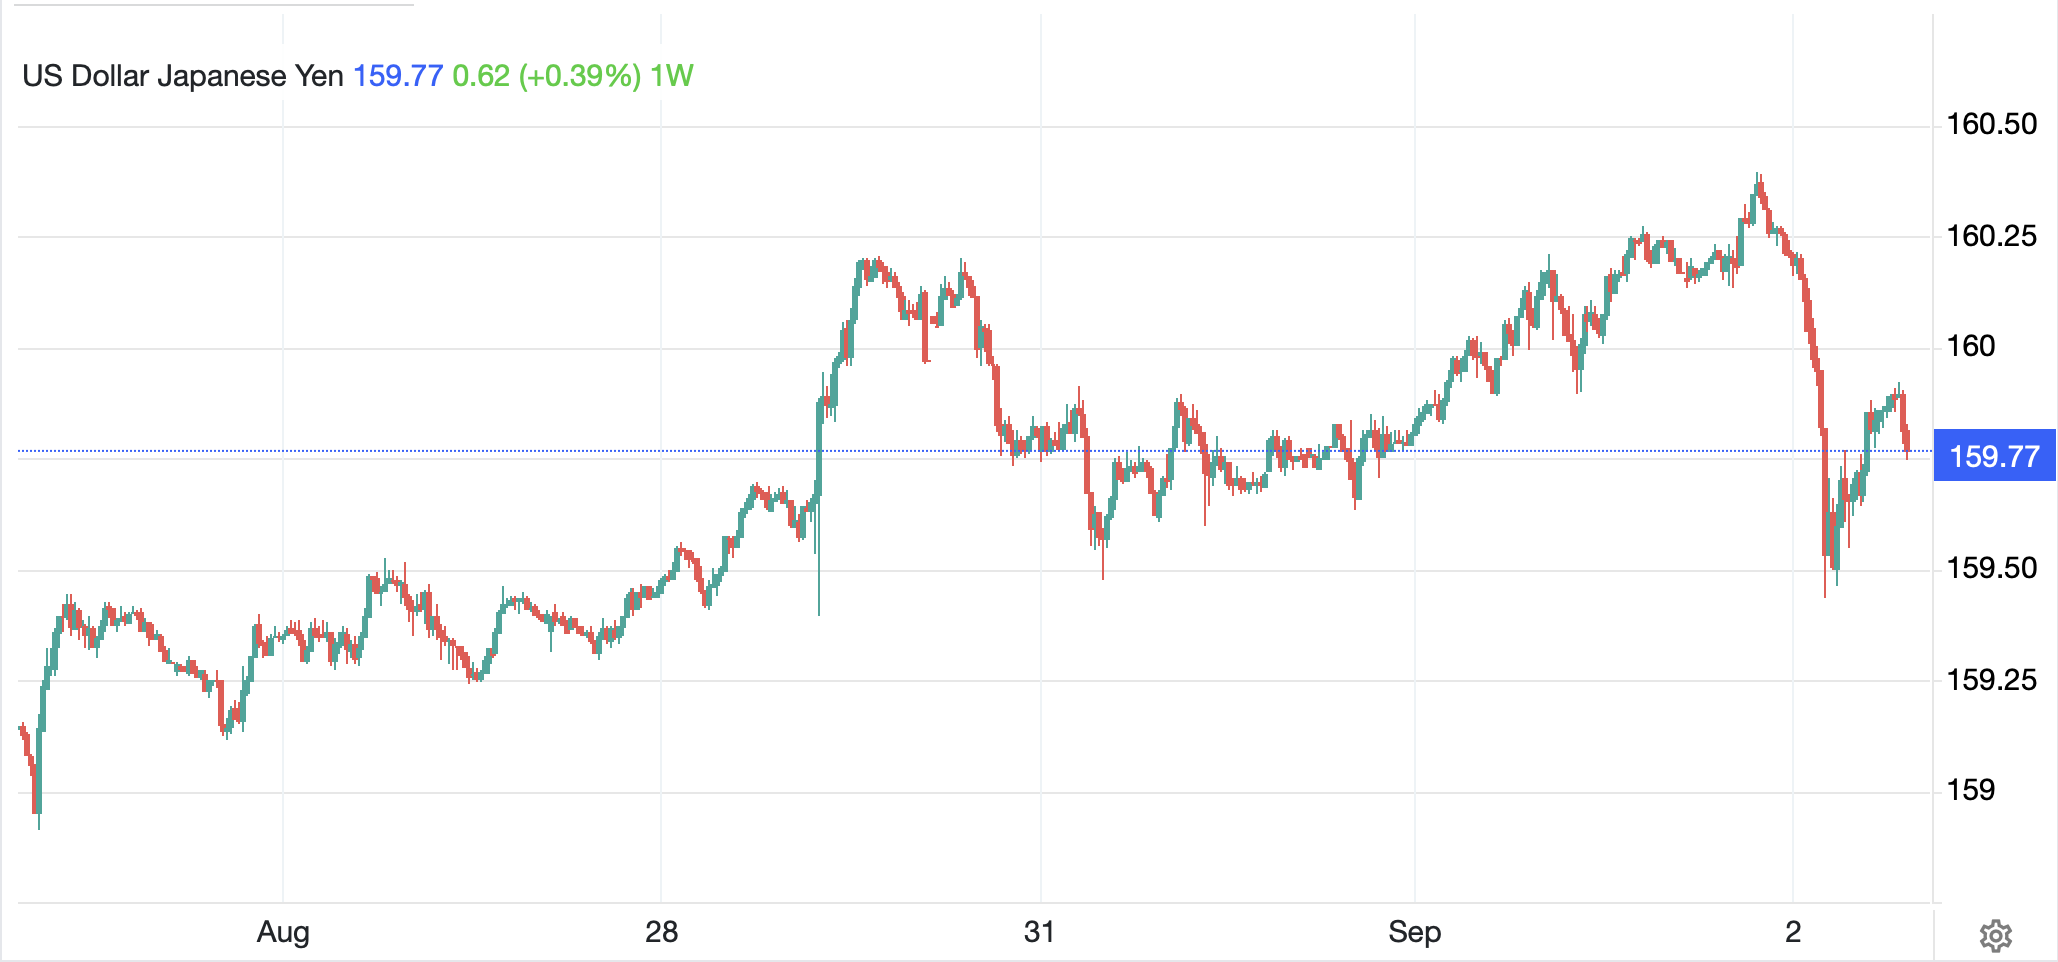
Source: tradingeconomics.com

But if we step back from the 1-week view above to the movement over the past year, as per the below chart, it doesn’t appear to have had a significant impact.
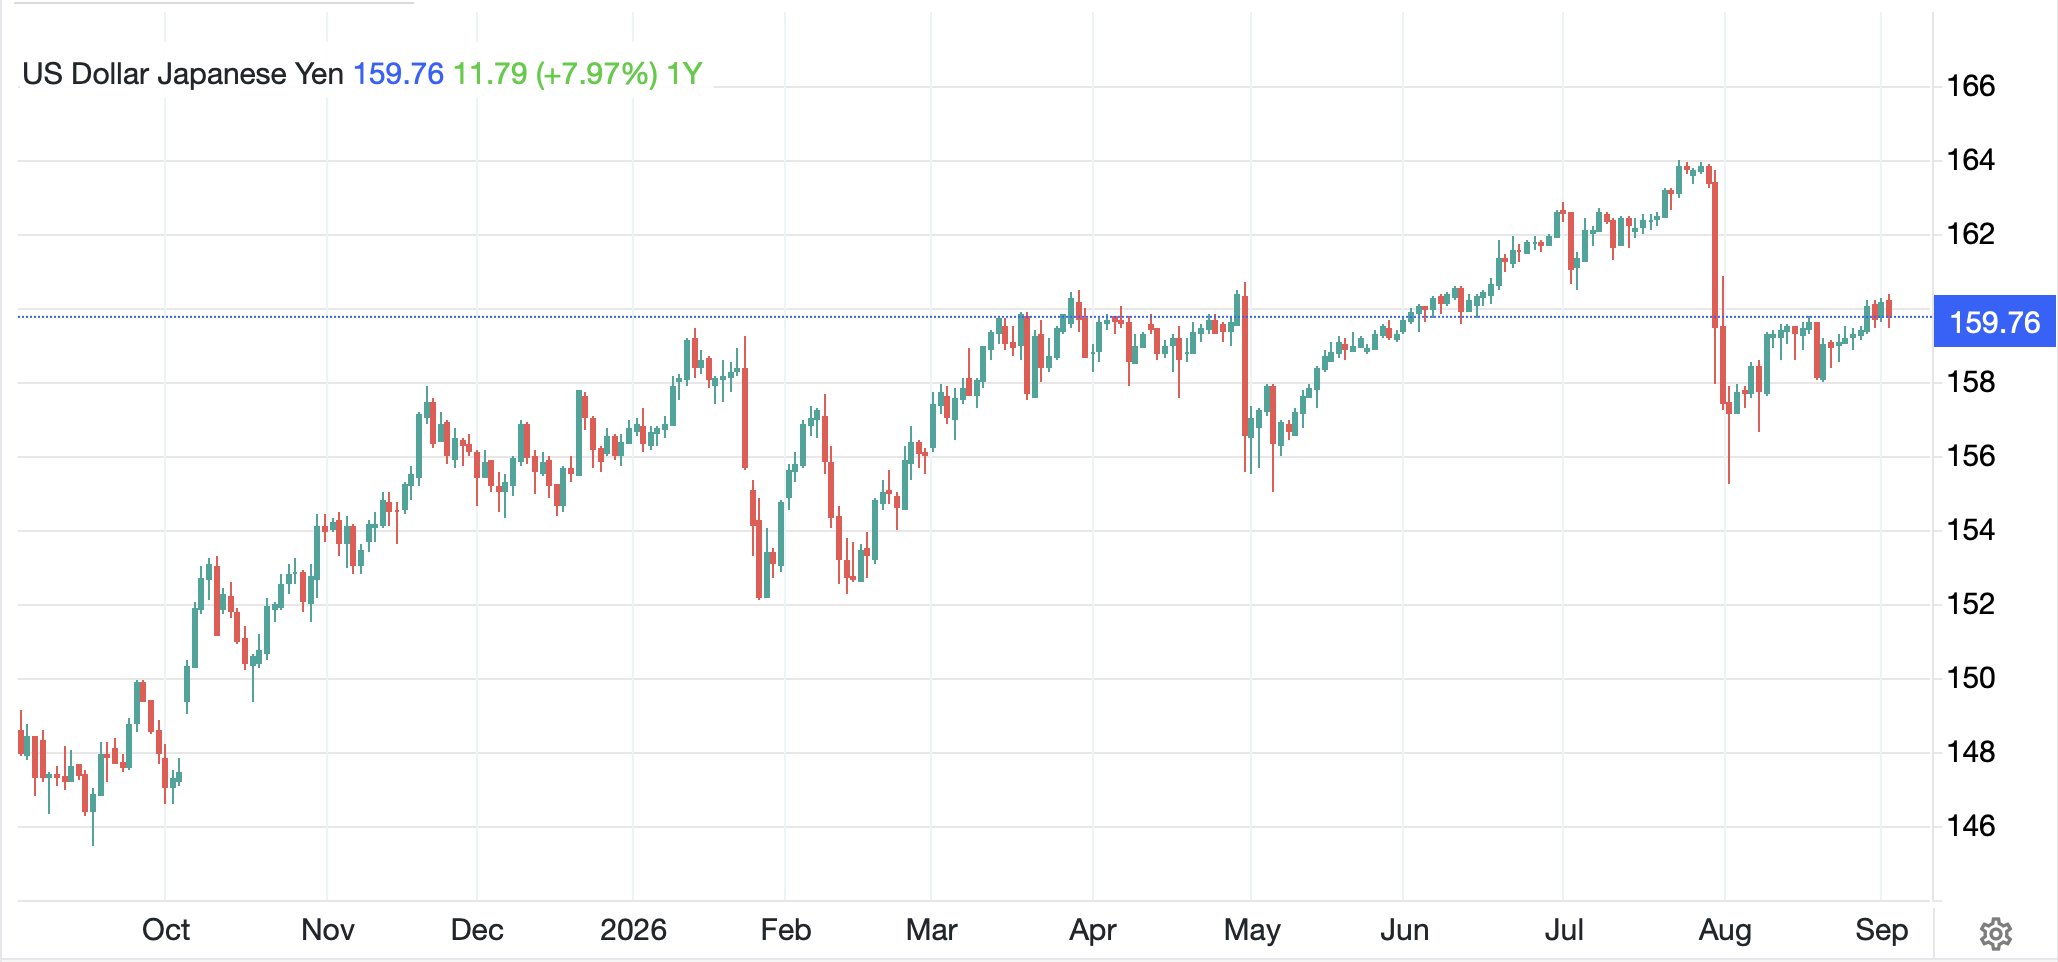
Source: tradingeconomics.com

The post-intervention pattern remains perfectly intact.  However, it did help increase the probability of further rate hikes by the BOJ as you can see in the rateprobability.com chart below.  The blue line is the current market compared to previous readings, with the market now expecting a total of 100bps of hikes during the next year. 
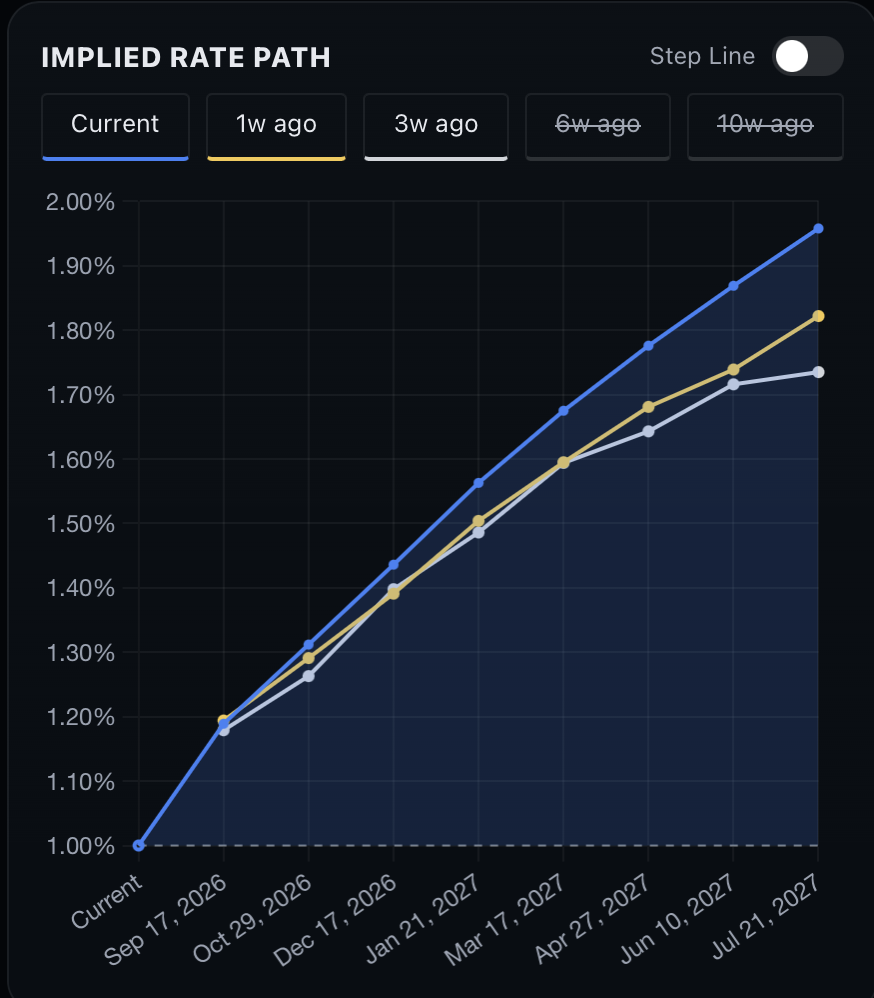
Alas, that did not help the JGB market, where yields remain at the 3.0% level, although they did not rise further last night.  Speaking of bonds, Treasury yields, which climbed 3bps yesterday, are unchanged this morning but European sovereign yields are all higher by between 3bps and 5bps, with France the worst case.

Looking at equity markets, red is the color of the day as every major market either declined last night or is in the process of doing so as I type as per the below Bloomberg screenshot.
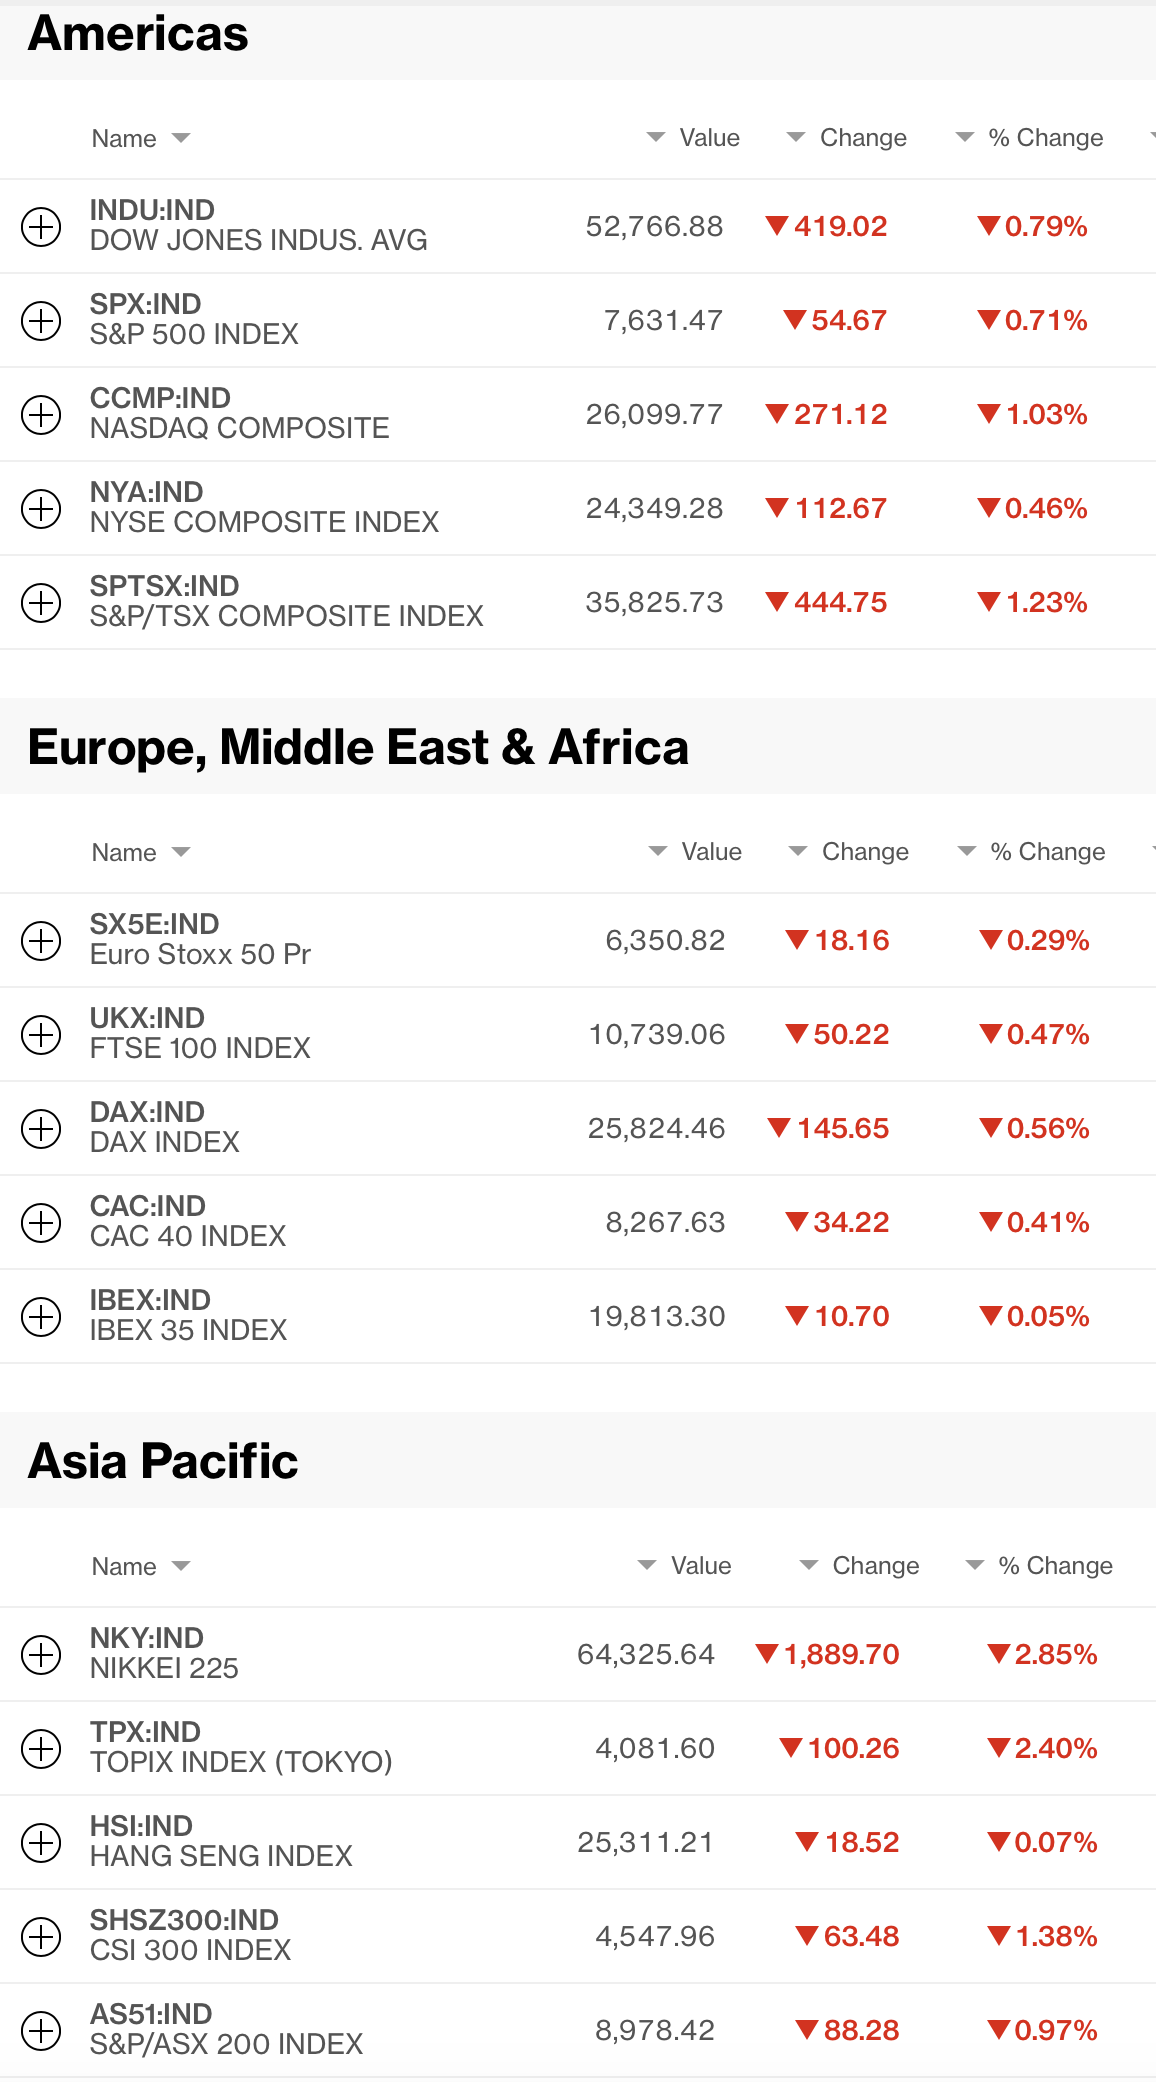
Certainly, there is a great deal of angst in equity markets right now, but when I looked at the S&P 500, it is still just 2.5% off its all-time highs from the middle of August.  And this morning, while the NASDAQ futures are lower by -0.7%, the other two indices are unchanged as we await this morning’s ADP data (exp 47K) and this afternoon’s Beige Book.  Higher yields are always a struggle for equity markets, but there is no collapse yet, that’s for sure.

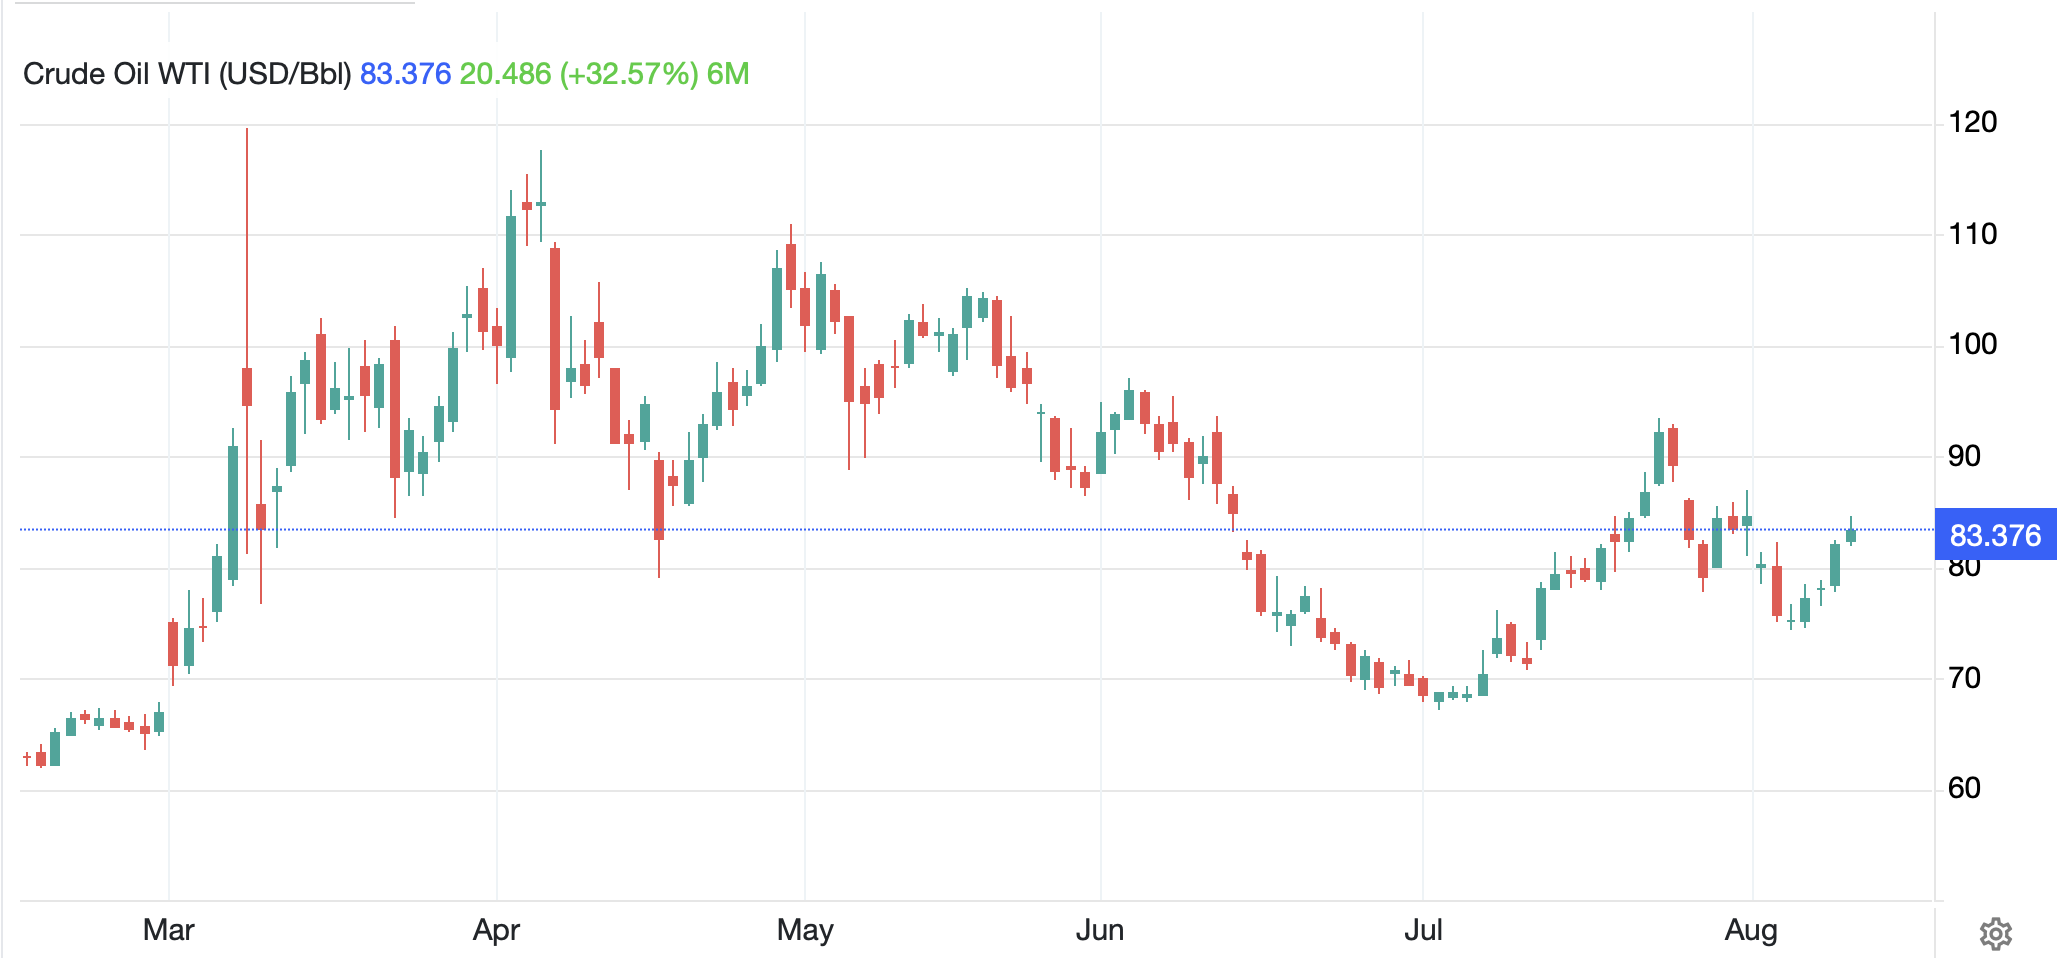
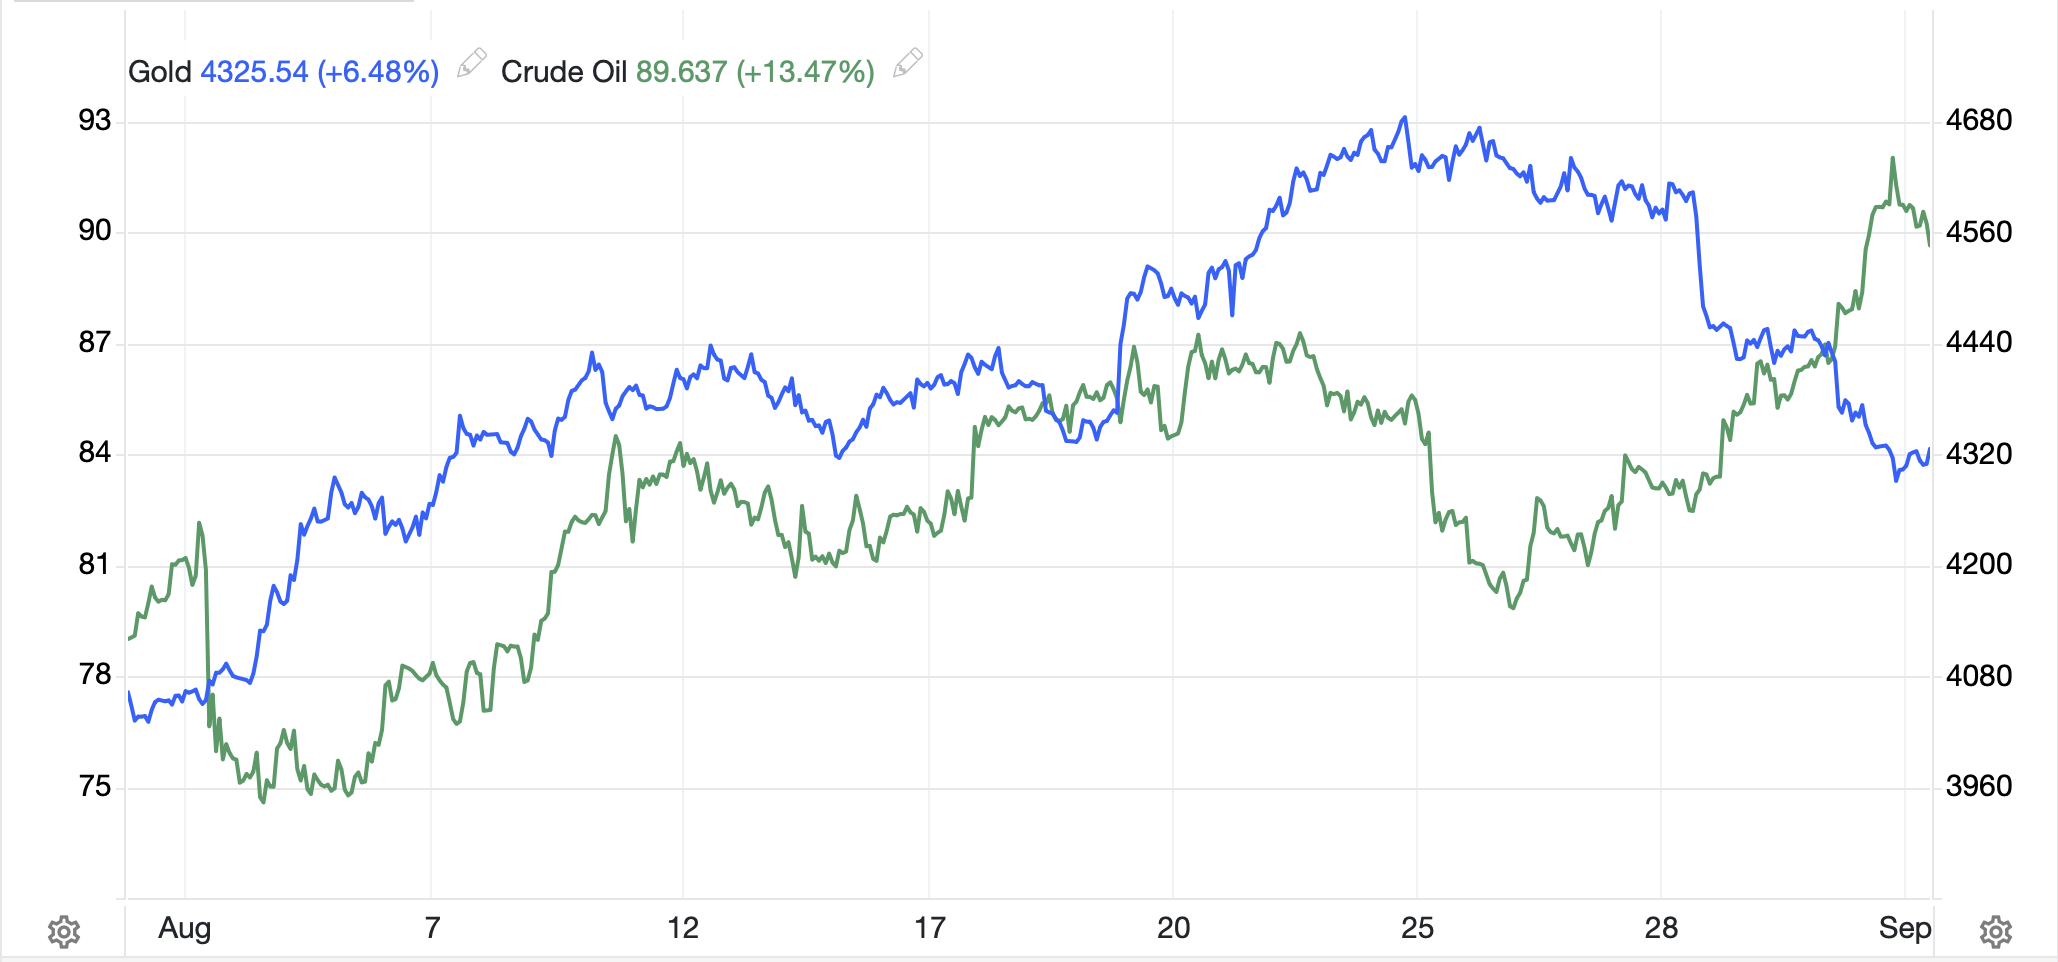
In the commodity markets, oil (-0.7%) has backed off the highs from yesterday and has traded back below $90/bbl, although that remains far higher than just a few weeks ago.  The escalation of fighting has certainly got traders nervous.  As to the metals markets, while they have been getting crushed the last few days, this morning they are essentially unchanged, perhaps consolidating after that rough ride.  You may remember there had been a strong negative correlation between oil and gold for a while which seemed to dissipate during the summer when things in the Gulf settled down.  Well, as you can see in the chart below, that negative correlation is back in spades for the past two weeks.  We will have to see how long that lasts, as historically, the two traded together more often than not.
Source: tradingeconomics.com

Finally, the dollar is creeping higher again this morning with the DXY (+0.1%) a pretty good proxy of the entire market with just a few exceptions.  We already noted the yen but NZD (-1.2%) fell sharply after the RBNZ raised rates by 25bps, as expected, but sounded more dovish in their comments afterwards.  As it happens, that helped the NZ stock market buck the negative trend as well.  The other outlier was KRW (+0.8%) which continues to rally strongly on positive inflows and positive economic news.  Last night, inflation data was better than expected, which helped the currency, rather than set it up for a rate hike.

And that’s really it today.  We also get Factory Orders (0.6%, 0.2% ex Transport) and the EIA oil inventories.  ADP could be interesting, but all eyes remain on Friday’s NFP on the data front.  And of course, who knows what will happen in the Gulf.

There will be no poetry tomorrow as we show GCH Nubia’s Take Your Breath Away on the road to the Nationals next month.
Good luck

Adf
Markets This Hated

No matter the nation you view
Its bondholders now see to rue
Their previous buys
And under that guise
Won't buy and bonds that are new

So, yields have been rising with haste
Though currencies have not debased
But markets this hated
Have often created
Reversals, which many then chased

Global Bond Yields Surge as Oil Prices Fuel Inflation Worries

The above article in the WSJ this morning captures the current zeitgeist in markets and seeks to explain why everything has turned bad.  Certainly, the rebound in oil prices (+2.5%) is putting pressure on economies around the world, but so, too, are the unrestricted spending plans seen throughout the G10, and frankly across most of the planet.  My take is that ‘run it hot’ (RIH) has become the economic strategy around the world.  Perhaps the only outlier here is China, but even that is not really true, they are just running it hot differently.  While most governments are responsive to their peoplevoters, Xi Jinping has demonstrated time and again he doesn’t really care about that.  Rather he has his strategic goals of global domination and is pushing his economy to achieve that.

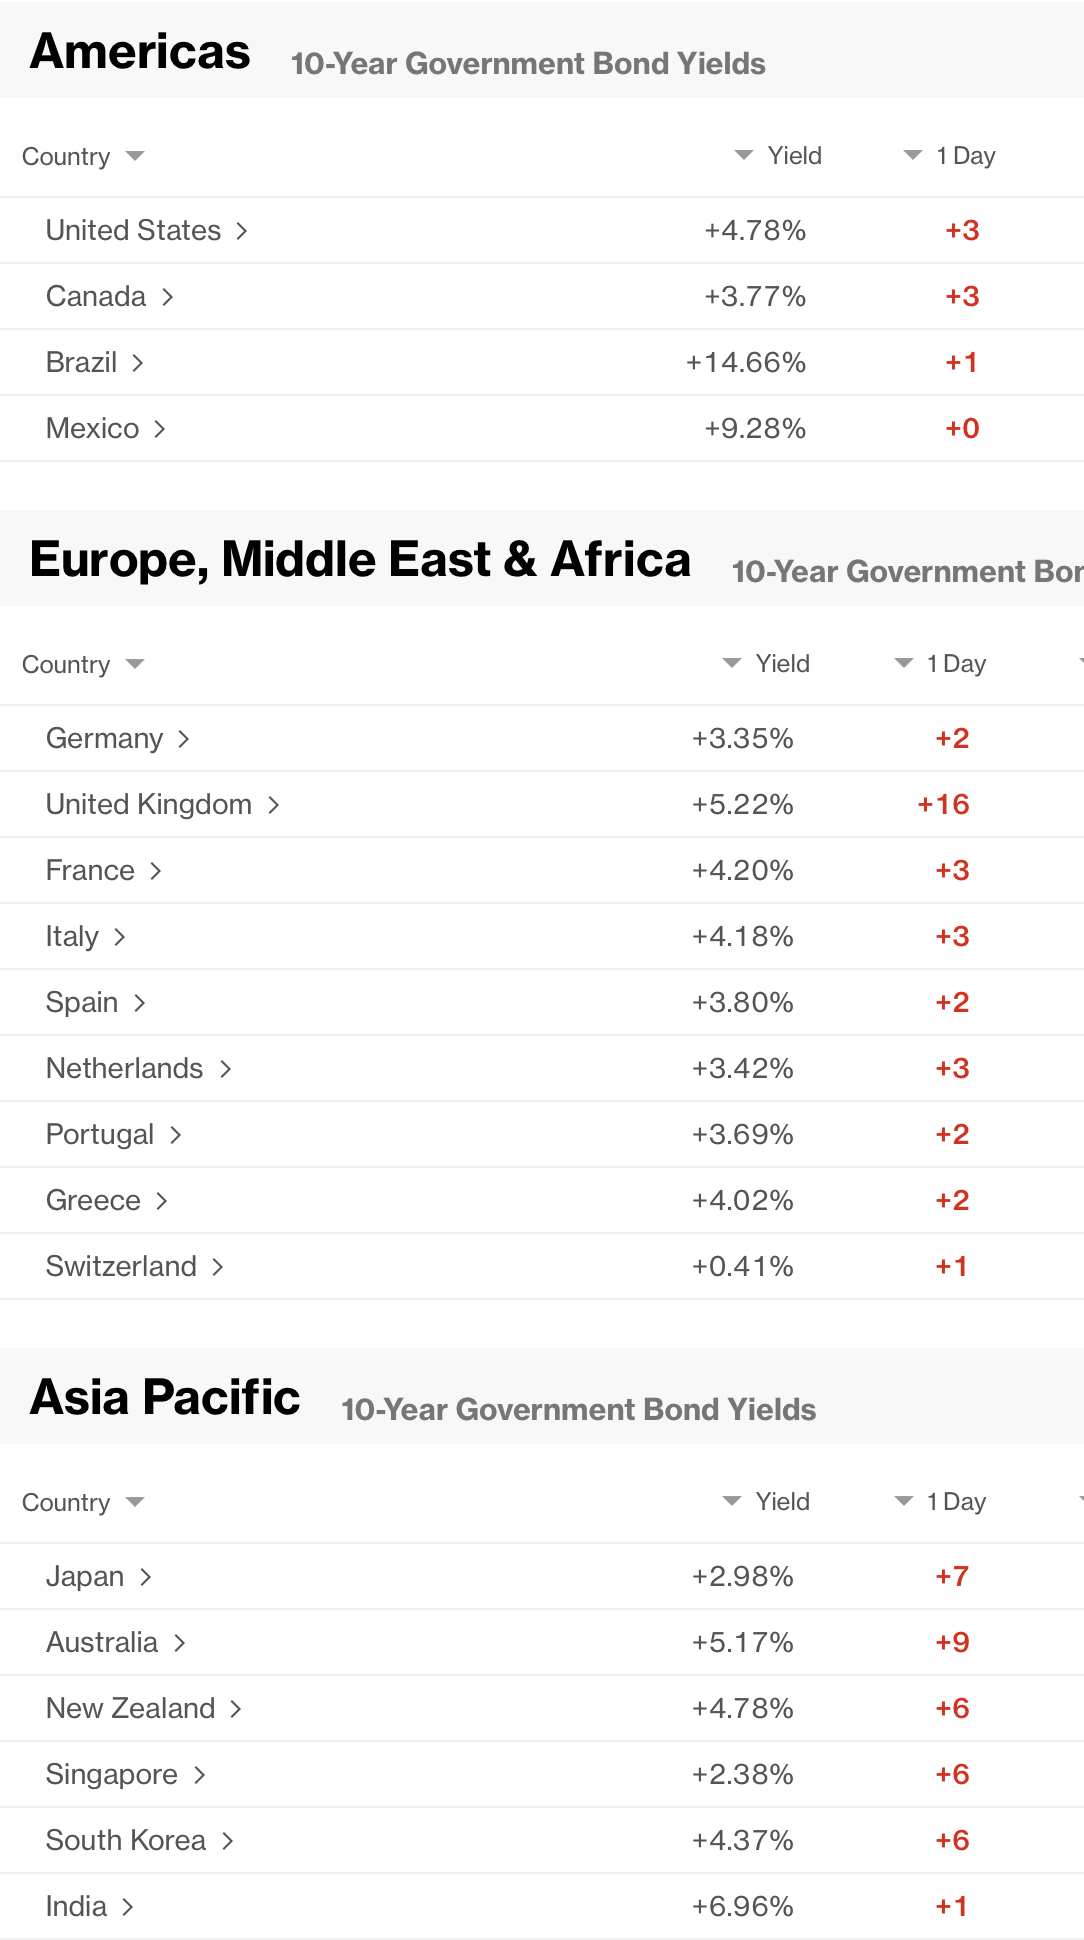
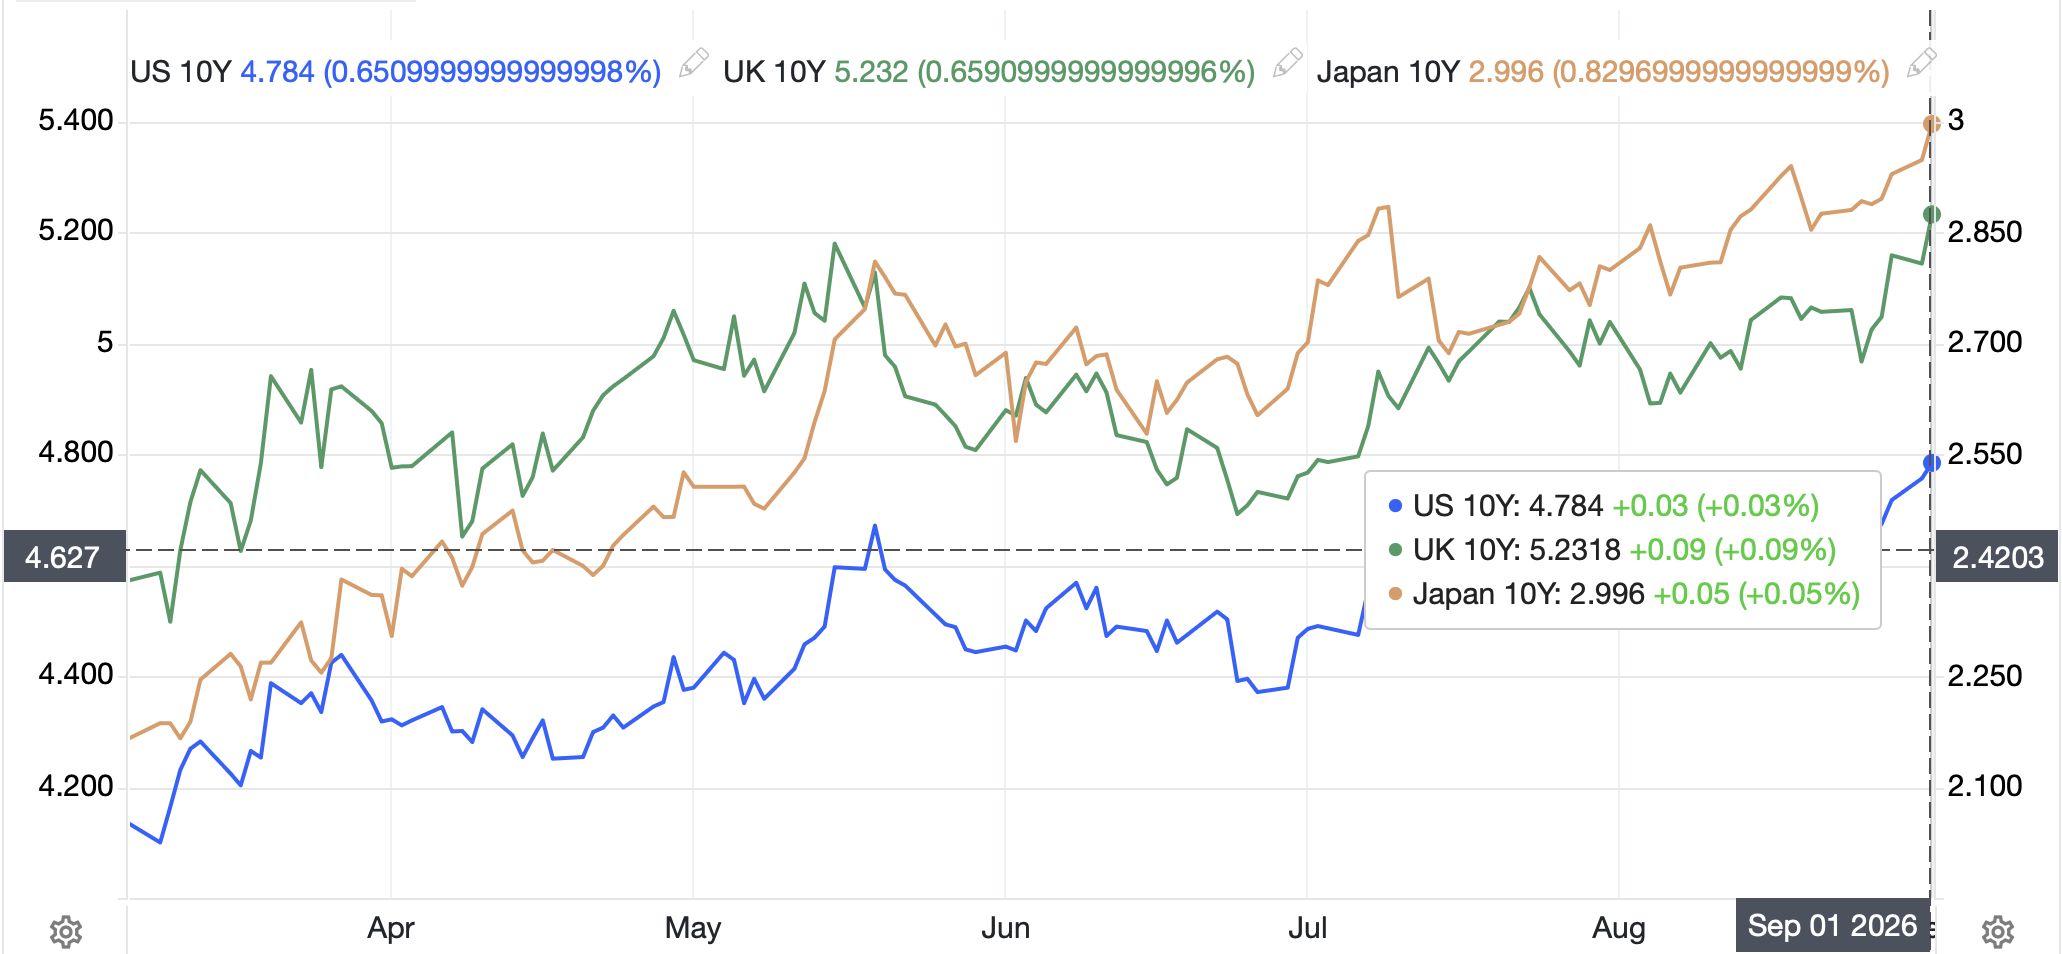
The upshot is that bond yields are rising and as you can see in the chart below, it is uniform, this is not just a US phenomenon.  In fact, much ink has spilled that 10-year JGB yields have traded to 3.0%, their highest level in 30 years.

Source: tradingeconomics.com

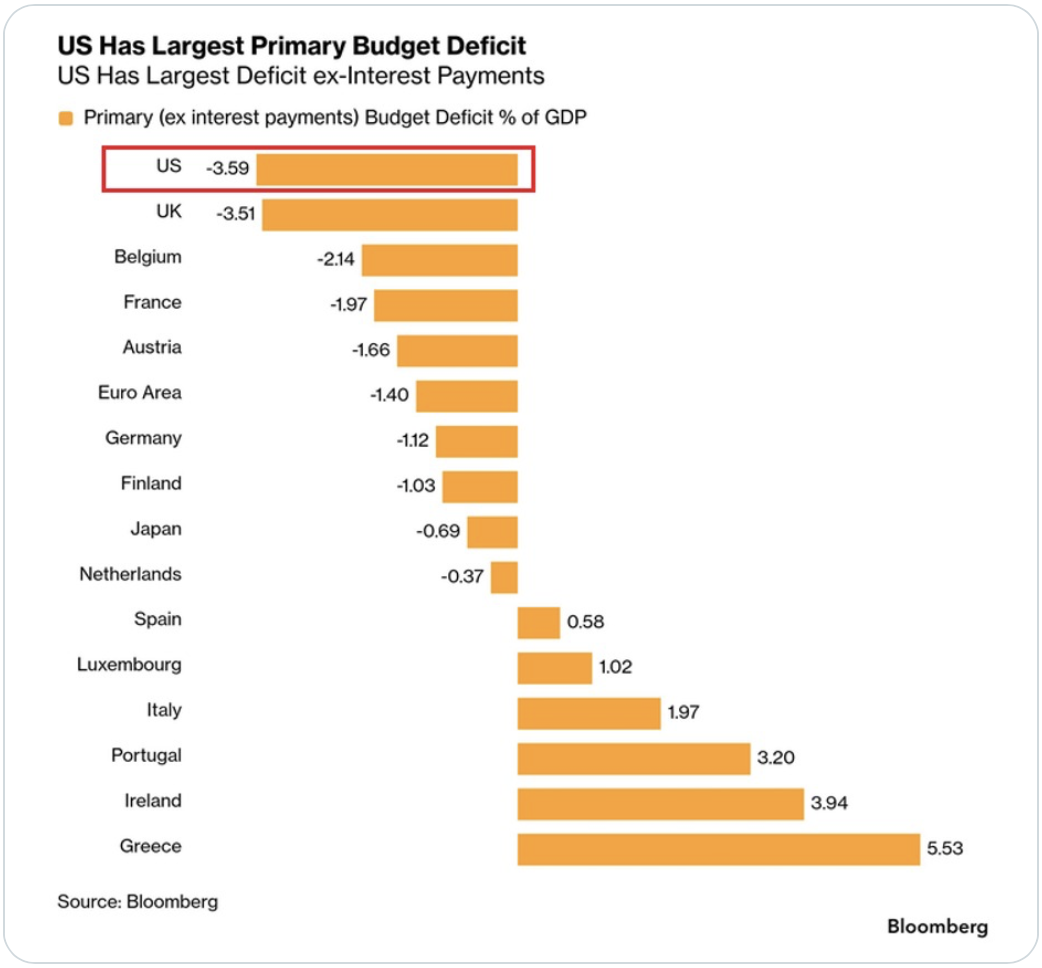
Now, as I said at the top, oil prices are clearly one of the pressure points as there are fears it will feed into higher inflation, thus investors are demanding higher yields.  And the other big story, which in my view is more concerning, is that governments are running increasingly larger budget deficits as the guns AND butter approach has become de rigueur in polite circles, or at least political ones.  In fact, the concern is that governments are increasingly running primary budget deficits (spending less interest payments) which is why debt loads are growing so rapidly.

Source: @KobeissiLetter

And this leads to the RIH theory.  If a country can grow its nominal GDP fast enough, then the denominator in the debt/GDP ratio will rise more quickly than the numerator thus reducing that ratio and implying a healthier fiscal outlook.  Now, nominal GDP is the sum of real GDP, the number that is reported, plus inflation and that sum can be any combination.  For instance, a nominal GDP growth of 7% could easily be 2% real GDP and 5% inflation, or vice versa.  In the RIH scenario the typical outcome is that wages rise, corporate earnings rise, stock market values rise…and prices rise.  The last point being the key political question.

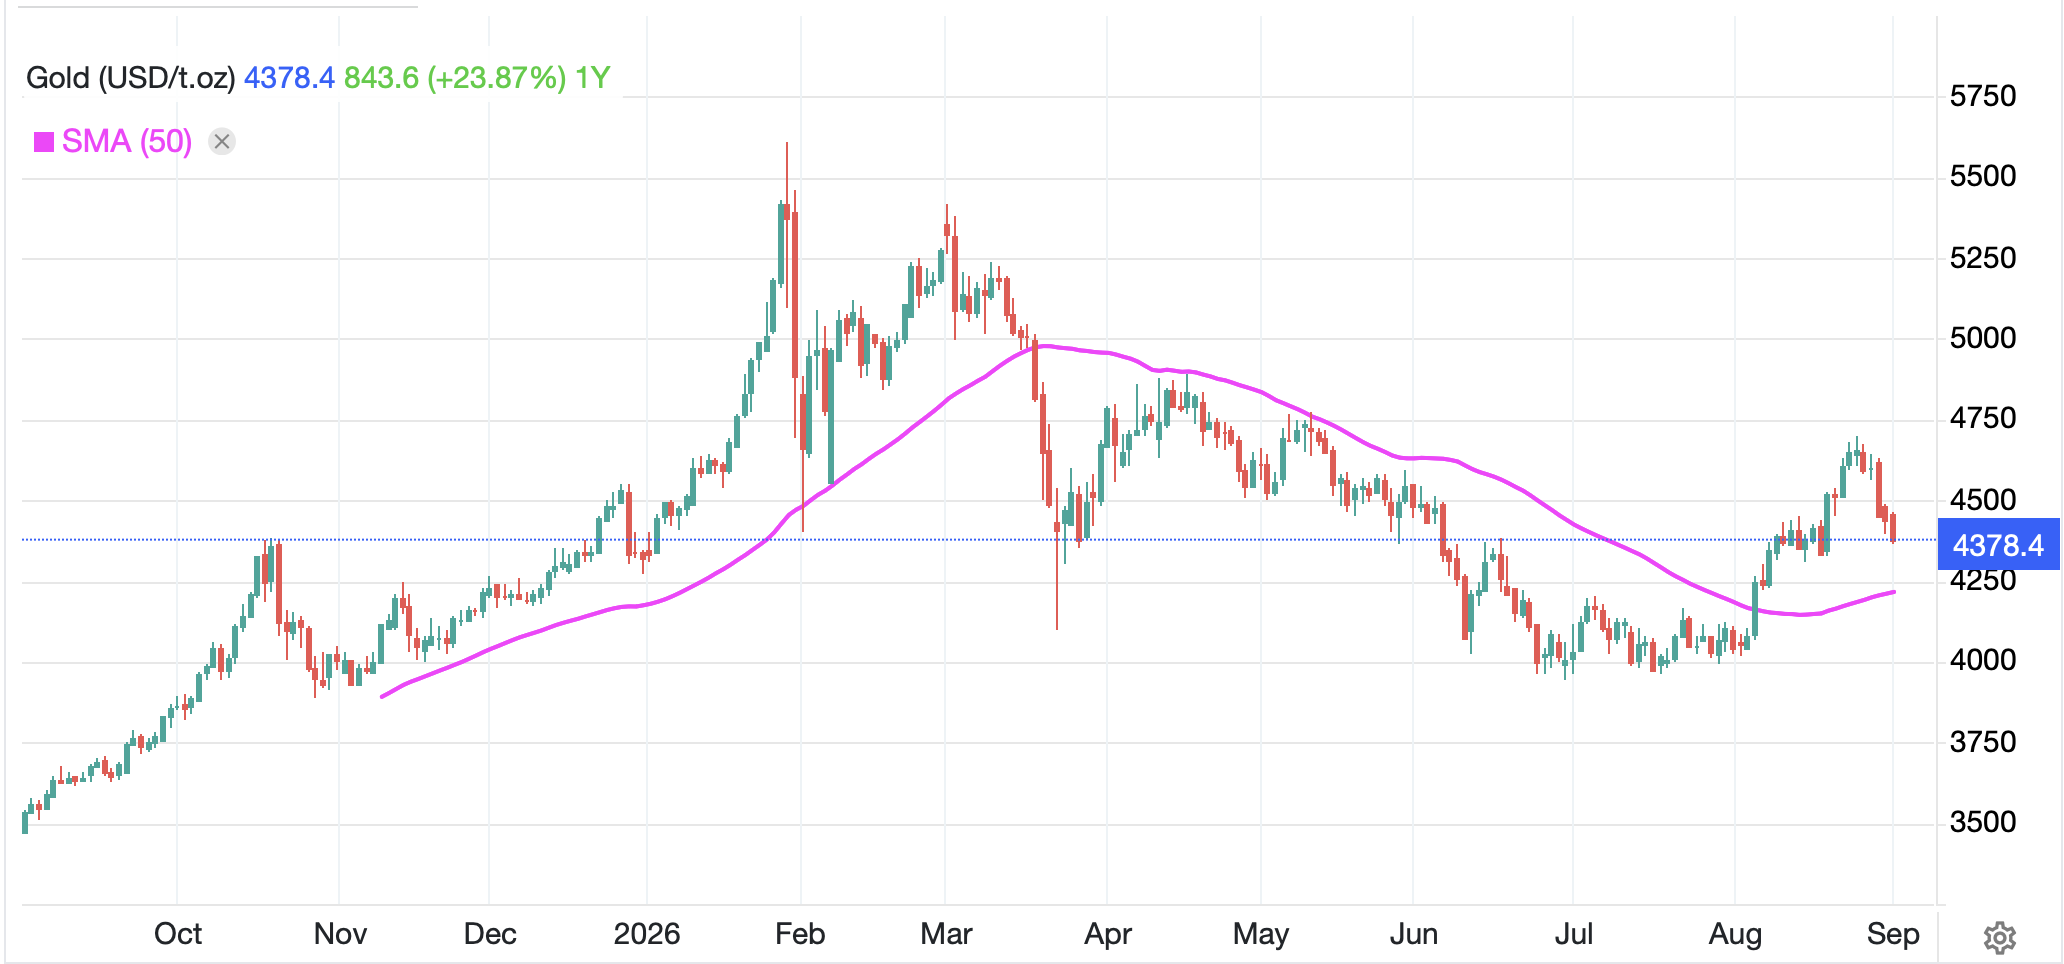
Which takes us back to the bond market and a few questions I have.  First an observation.  In the old days (Greenspan era) a rule of thumb in the bond market was the 10-year yield should approximate nominal GDP growth as a stable base.  I mention that because I am confused by the bond market reaction given the near universal view of Chairman Warsh’s speech on Friday was that he was hawkish and that rate hikes were coming.  But if that is the case, and the Fed is going to more aggressively address inflation, then why are bonds selling off?  Second, regarding the debasement trade, if bonds are selling off because of concerns over massive debt issuance and the assumed result that the dollar, and all currencies, are going to lose purchasing power, why is gold (-1.4%) selling off so aggressively?  It strikes me that gold should be flying higher on the view that inflation is going to rise, but then, I’m just a poet.  I guess one could make the technical argument that it is merely correcting its recent strong rally and it remains far above its 50-day moving average as per the below chart.

Source: tradingeconomics.com

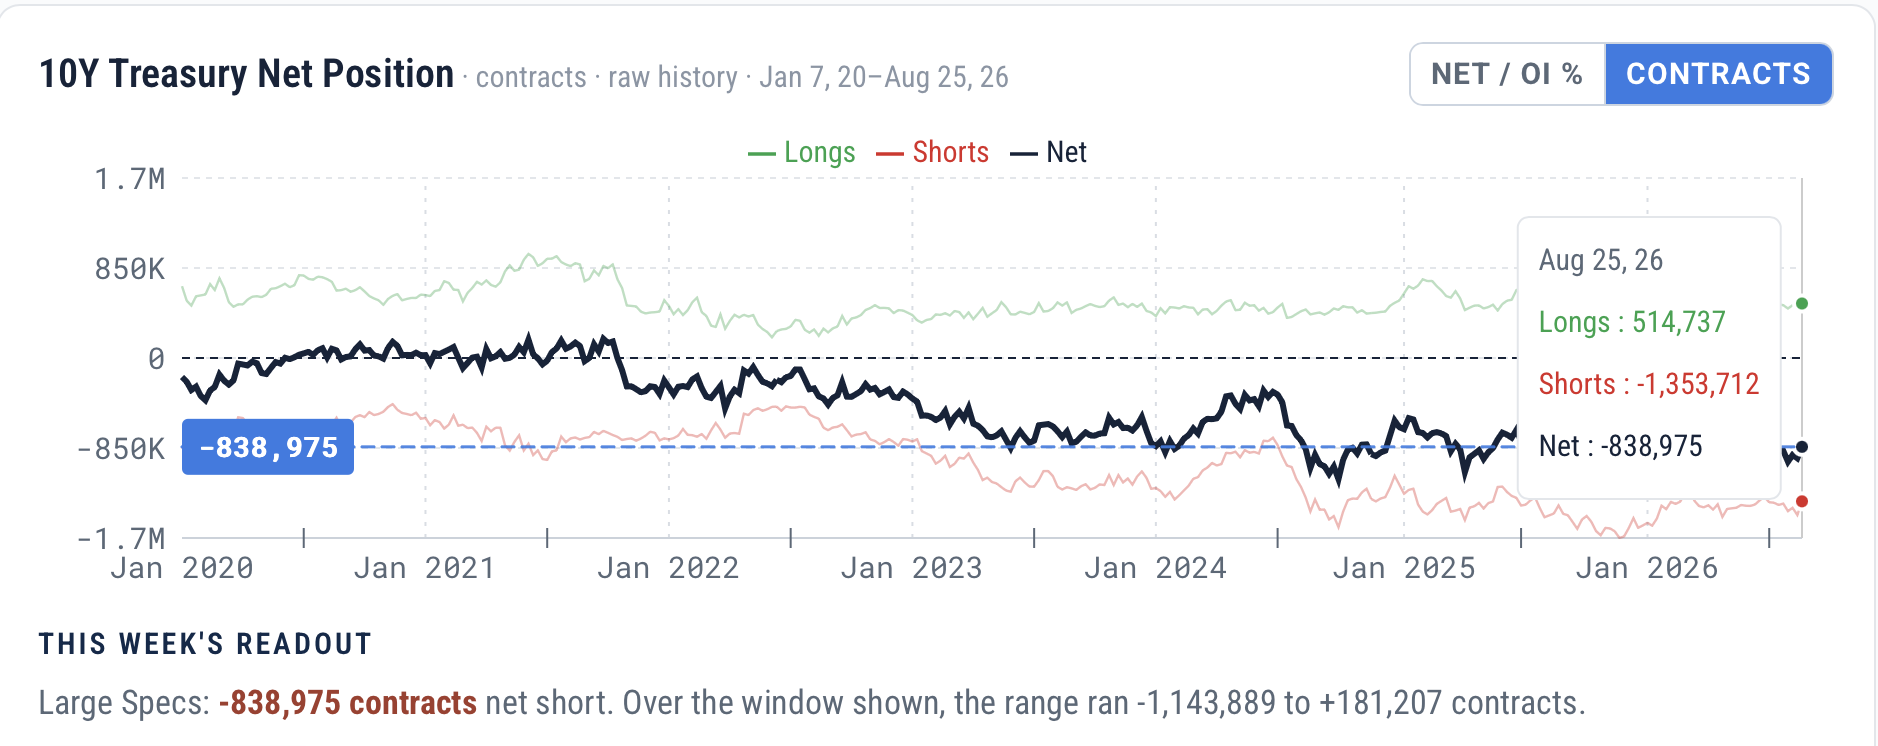
I wish I had the answers here, but I don’t.  However, something is amiss.  If the Fed was so hawkish, the bond market would not be aggressively selling off.  If the Fed was not hawkish, then the sell-off makes sense, but 90% of the punditry was wrong in their analysis of Warsh’s speech.  (My guess is they see that as a bigger problem.) One thing I do know, though, is that the bond market is quite bearish right now with nary a positive word to be found.  There is still a huge net short position in the bond futures market, as per the below chart.

Source: cotsignal.com

Here’s the thing about markets, at least in my experience.  Markets tend to seek out the ‘pain’ trade, the trade that will hurt the most participants most significantly.  As well, bull markets begin when all investors express uniform hatred of a product, like bonds right now.  Combining those two things leads me to believe that we could well be setting up for a significant bond market rally.  Just beware.

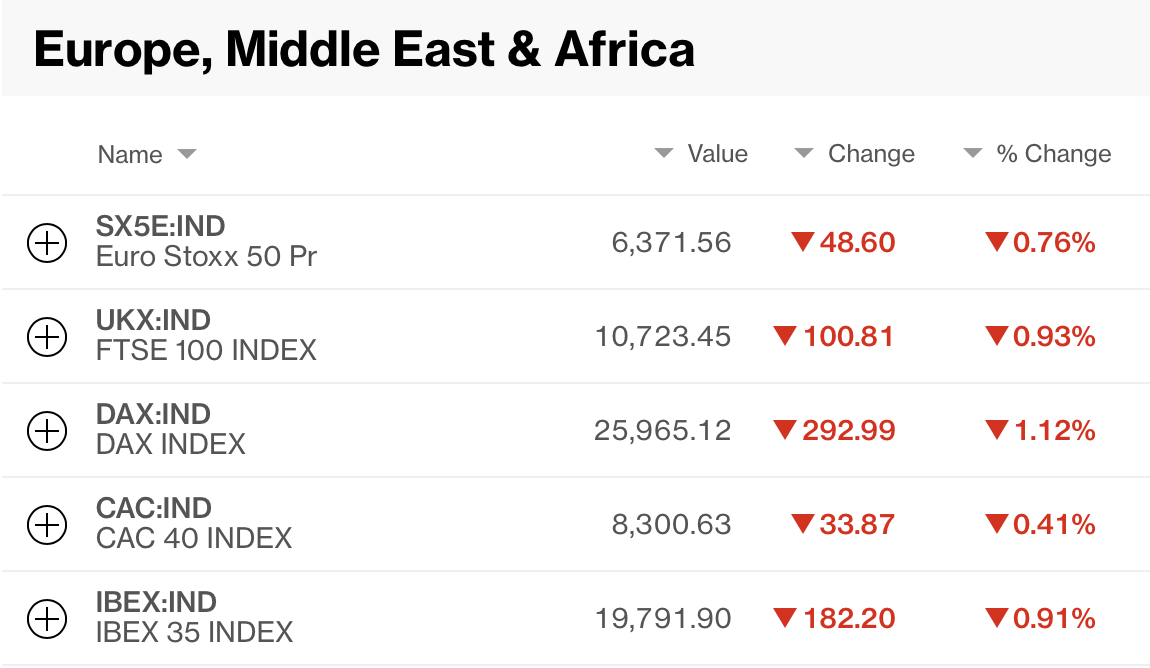
In the meantime, a quick tour of markets overnight shows negativity everywhere.  After yesterday’s declines in the US session, Asia saw mostly red numbers (Tokyo -0.15%, China -0.3%, HK -0.9%, Malaysia -1.5%, Singapore -0.8%) although Taiwan (+1.8%) and Korea (+0.25%) bucked the trend on some tech support which is also why the NASDAQ fell the least yesterday.  As to Europe, as you can see in the below screenshot from Bloomberg, it is universally red.

Lastly, US futures are under the gun this morning, down -0.5% except for the NASDAQ which is reversing yesterday’s outperformance and lower by -1.3% at this hour (7:20)

We’ve already discussed bonds, but this Bloomberg screenshot is worthwhile, I think.

Of course, the outlier here is the UK, which was closed yesterday so had a lot of catching up (down?) to do.

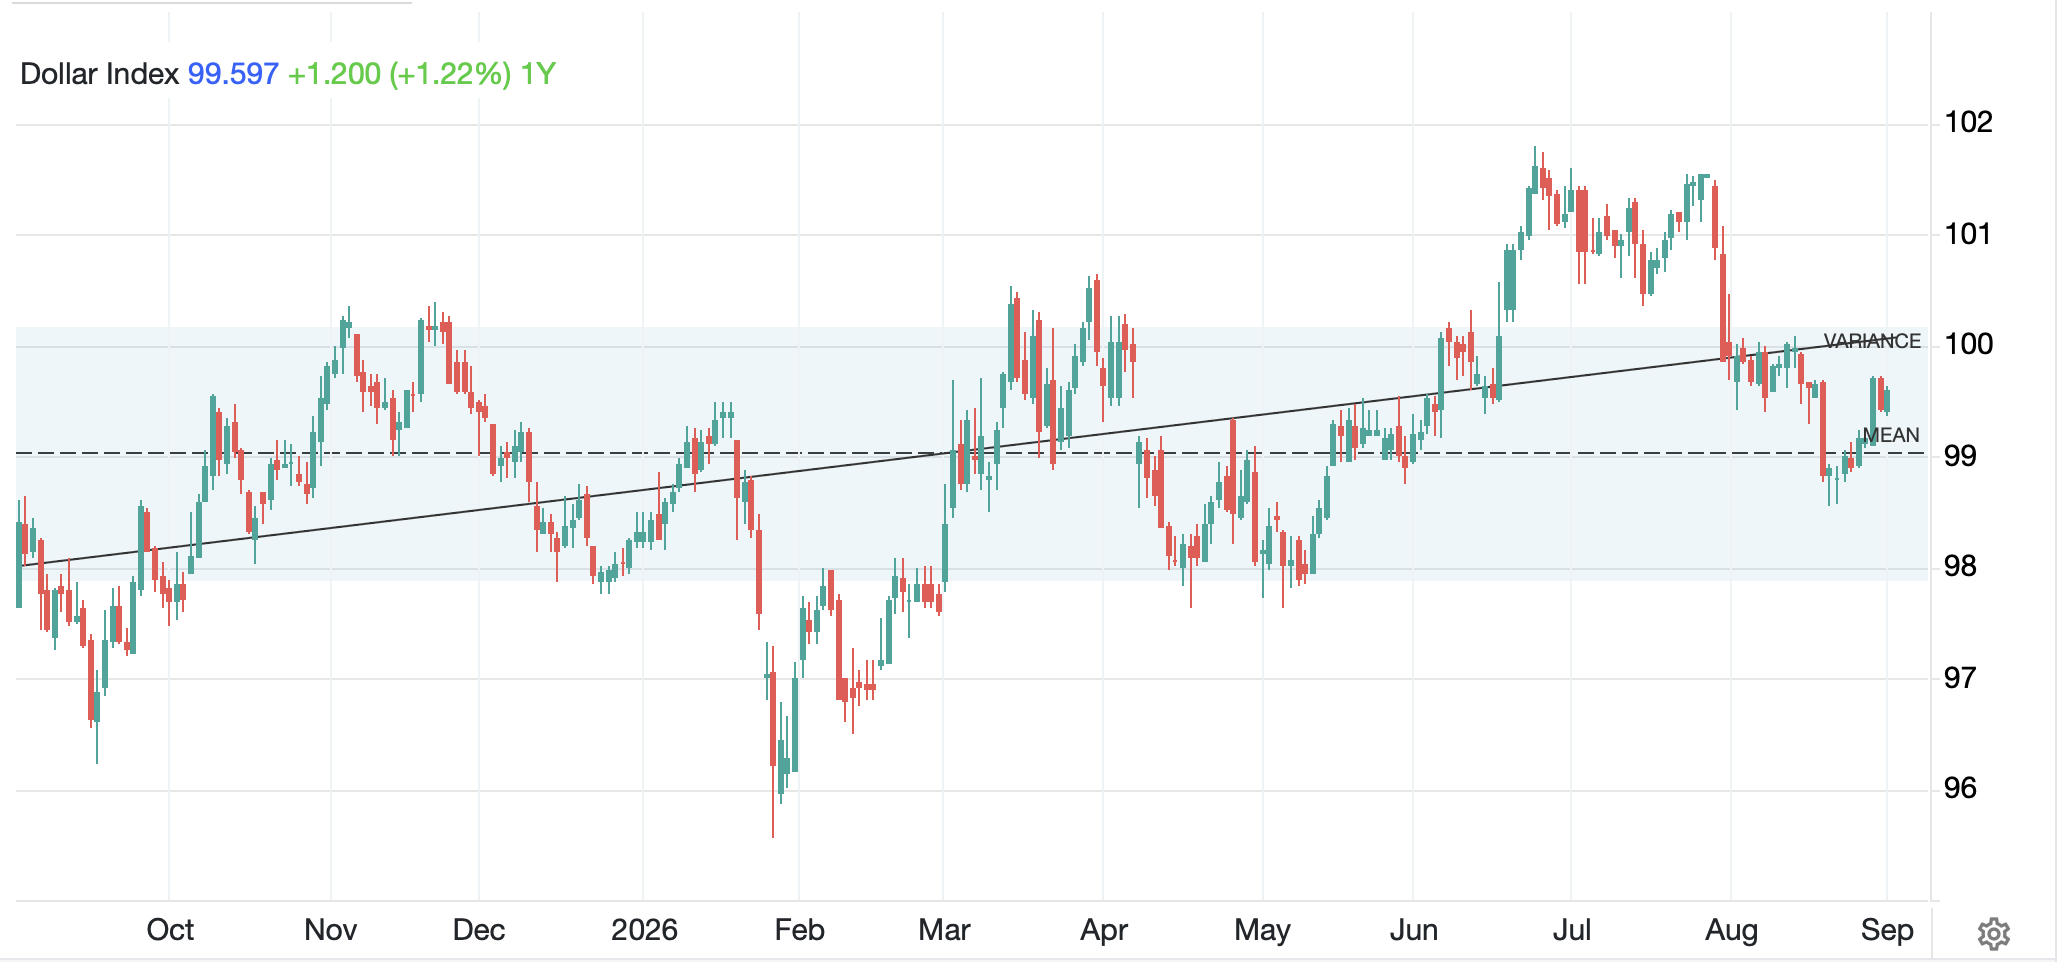
We’ve already discussed commodities which brings us to the dollar, which is rising despite yields rising everywhere.  Now, the DXY is at 99.60, hardly new territory although the trend over the past year is marginally higher as per the below chart.

Source: tradingeconomics.com

If we look at individual currencies, JPY (-0.2%) has seen the dollar rise back above 160 as the post intervention price action remains consistent with every previous effort.  Perhaps the most surprising outcome today is ZAR (-0.1%) which is holding up quite well despite much higher oil prices and much weaker gold prices, the two key issues in that economy.  But net, as much as people worry about the debasement of the dollar, it appears they are more worried about the debasement of other currencies more rapidly.

On the data front, this morning brings ISM Manufacturing (exp 55.2) and Prices Paid (72.0) as well as the JOLTs Job Openings report (7.3M). Fed Governor Barr speaks before the data at 9:00 this morning so I wonder if he will reaffirm the hawkish vibe, and if he does, shouldn’t that help the bond market?  I am still focused on Friday’s NFP as the next truly important piece of news, but there is an awful lot that can happen between now and then, especially with this President.

Good luck

Adf
Hike!

Said Kevin, well, not really much
And pundits, their pearls, they did clutch
The haters all said
He's over his head
While others admired his touch

The hawks, meanwhile, think he said "Hike!"
And two-year yields promptly did spike
The dollar exploded
And gold just eroded
Though stocks drifted somewhat dreamlike

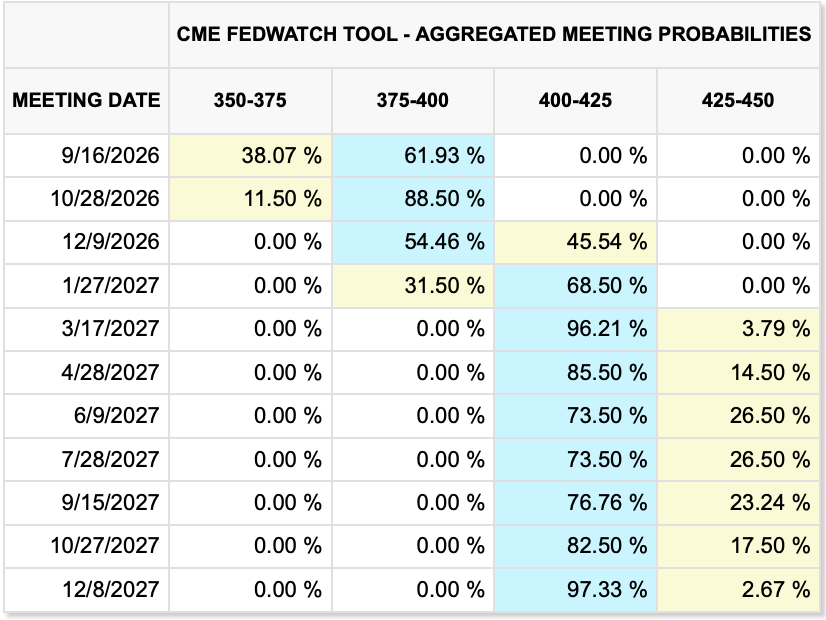
I must have listened to a different Kevin Warsh speech than most in the market on Friday morning, as the extreme hawkishness that seems to be the consensus outcome was completely lost on me.  Perhaps this is simply another Warshach Test.  He certainly repeated that the Fed is going to be successful at achieving their 2% target, although I clearly missed the part where he said they would be hiking in September.  But I must be the only one.  Futures traders clearly heard a hike was coming as the probability for a hike has risen to 62%, from about 32% prior to Warsh’s comments as you can see below.

In addition, a second hike in January seems highly probable and the chance of another one next summer has risen to 25%.  

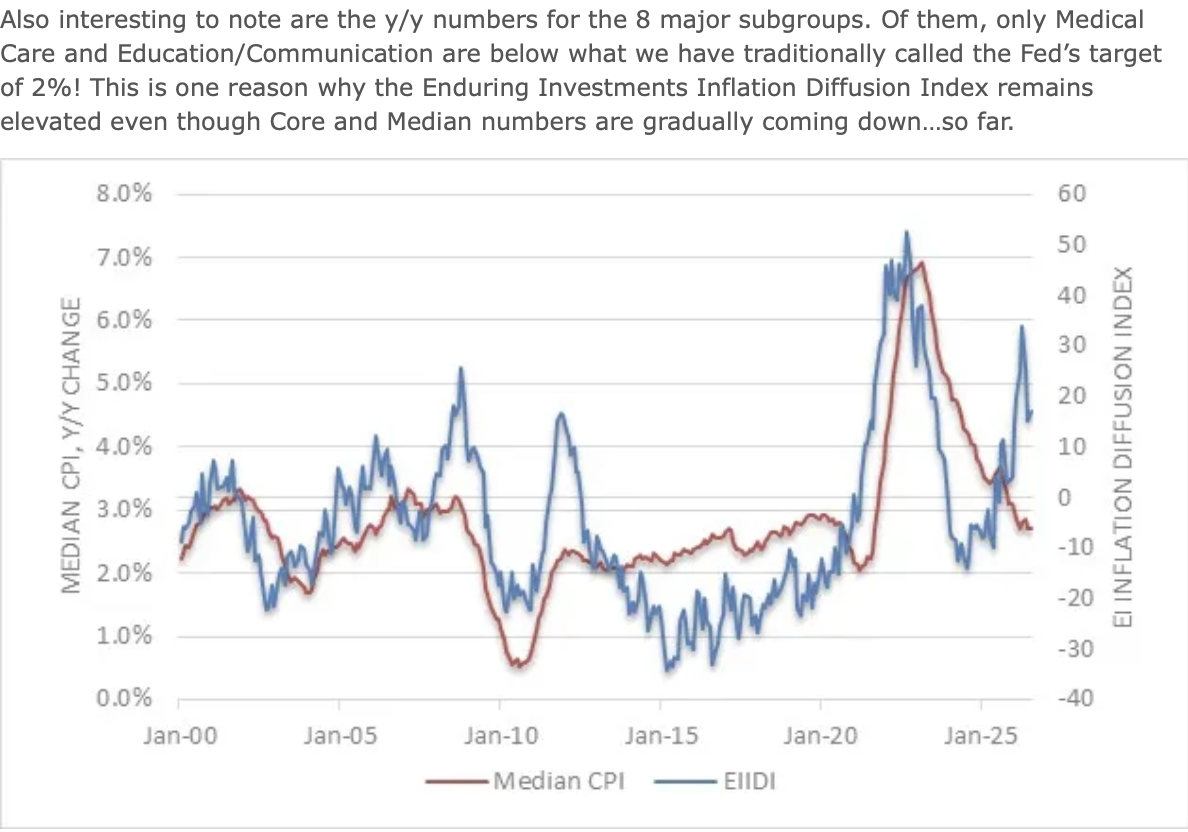
Personally, I thought the most interesting, and encouraging, feature of the speech was his willingness to discuss the details of how PCE is created, a combination of 199 subcategories.  This is akin to the way my favorite inflation analyst, @inflation_guy, Mike Ashton, views the CPI data, and he has created a diffusion index to follow just how many categories are rising rapidly and how many are either falling or rising less rapidly than the overall rate.  Here is his discussion of the July data, released in August.  And here is a chart from that note (which you all should read and subscribe to as it’s free) showing his diffusion index and why inflation is not likely to subside quickly.

But clearly, the market is not interested in my spin, nor in the spin of anyone who disagrees that a hike is on the way.  The behavior of the Treasury market was quite interesting with 2yr yields jumping 12bps while 10yr yields rose 4bps and 30yr yields rose only 1bp.  This was a classic bear flattening of the curve, and it was the driver behind the dollar’s strength (+0.55%) and more impressively, the 3+% decline in the price of gold and silver.  If yields are going up, there is no reason to own gold, apparently.  That seems at odds with all last week’s talk about the resurrection of the debasement trade, but then, I’m just a poet.

One last thing.  After rereading the speech several times (talk about a boring life) my interpretation of the following comment within his Key Principles seems to be very different than the rest of the Street.  

“Fifth, short-term interest rates are the predominant tool to achieve the dual mandate. Unconventional policies to spur economic activity may suit genuine crises but should otherwise be used sparingly, if at all.”

I read this as he wants to reduce the balance sheet to reduce the Fed’s market impact and use interest rates as their policy tool and that currently, reducing the balance sheet will result in tighter policy with the same Fed funds rate.  But it appears the first part of my view, which is something Warsh has explained numerous times, is being ignored by the trading community.  Of course, it will take a change of the ‘ample reserves’ framework to get the Fed to reduce its balance sheet, and that will need the imprimatur of the balance sheet task force as well as time for the rest of the committee to get on board.

Regardless of my views, though, the market is now increasingly convinced the Fed is going to hike next month absent much weaker than expected NFP and CPI releases.

It wasn't all that long ago
When war in the Gulf ran the show
When fighting expanded
The market demanded
More havens as risk was the foe

But now, when the fighting gets hot
Most traders don't give it a thought
We're back to the Fed
And all that they've said
As key to what's sold or what's bought

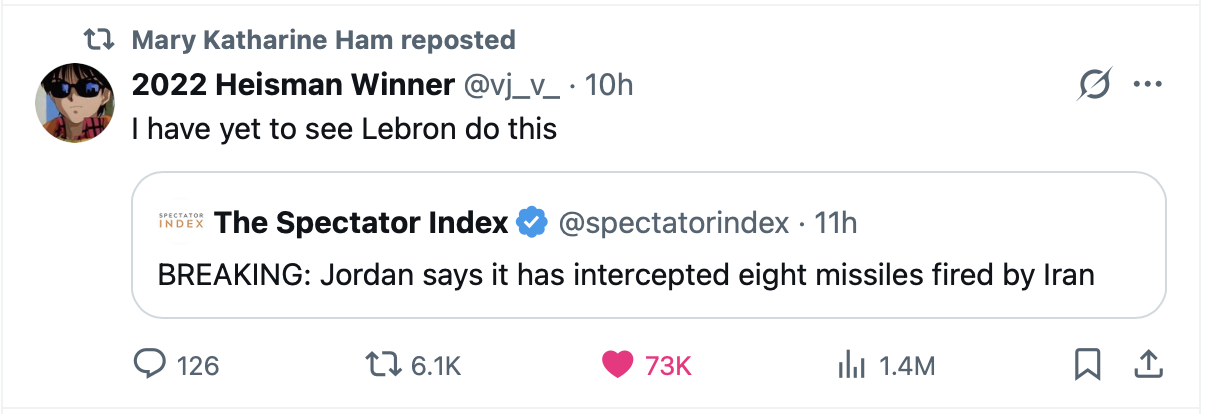
Apparently, there was further military action in the Persian Gulf and the Strait of Hormuz yesterday as the US struck missile launchers on a small island there, claiming the IRGC was planning to launch more naval mines.  Iran said there will be great consequences, but the missile volleys they sent at US bases in Jordan were intercepted which prompted one of the funniest responses on X that I have seen.

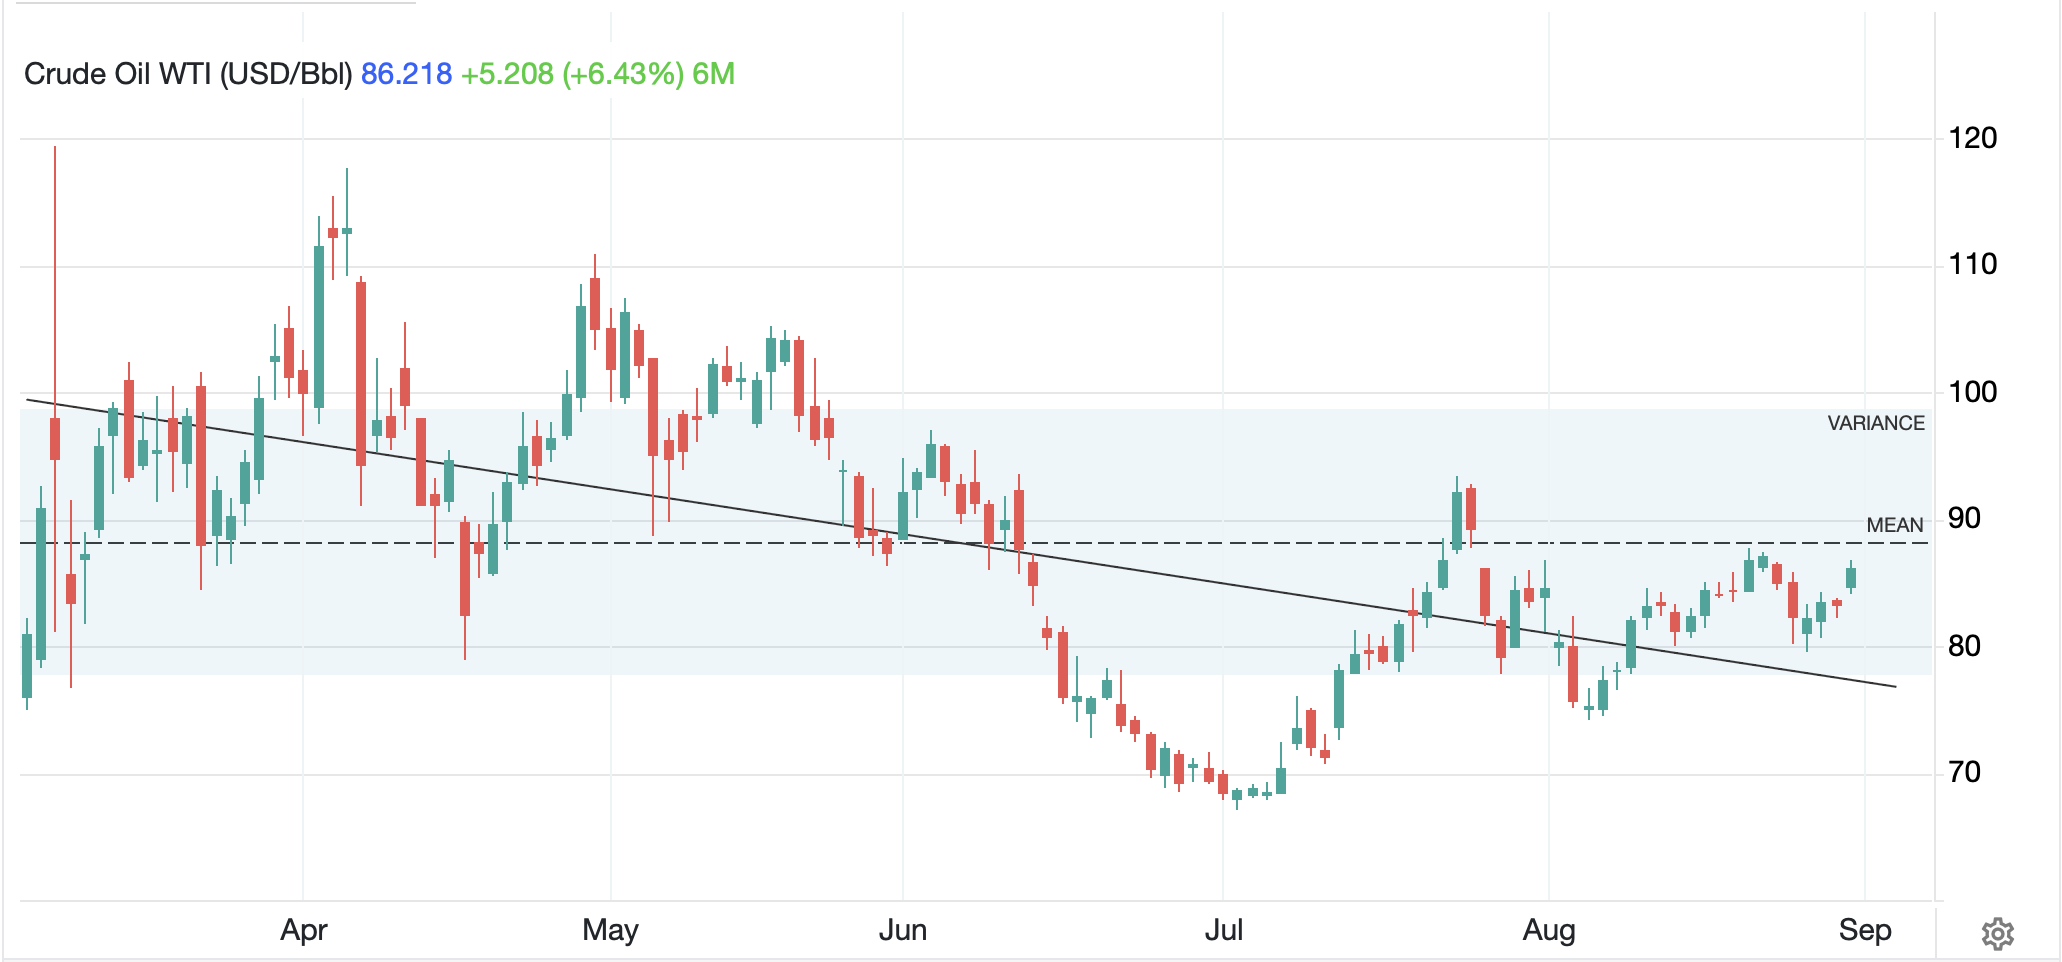
Meanwhile, oil (+3.3%) prices have risen in response, but it has not generated nearly the excitement that we have seen in the past.  And I cannot help but look at the price action in oil over the past six months, since the war began, and remain unconcerned about the future.  Certainly, there has been volatility, but as I have highlighted in other markets, volatile markets are anti-fragile, and that is worth a lot.

Source: tradingeconomics.com

As to the metals markets, after Friday’s washout across the board, this morning gold is unchanged, silver (+1.7%) has rebounded more than $1/oz and copper (+0.4%) has basically recouped its much smaller decline from Friday.  Nothing has changed my view that all metals remain in uptrends.

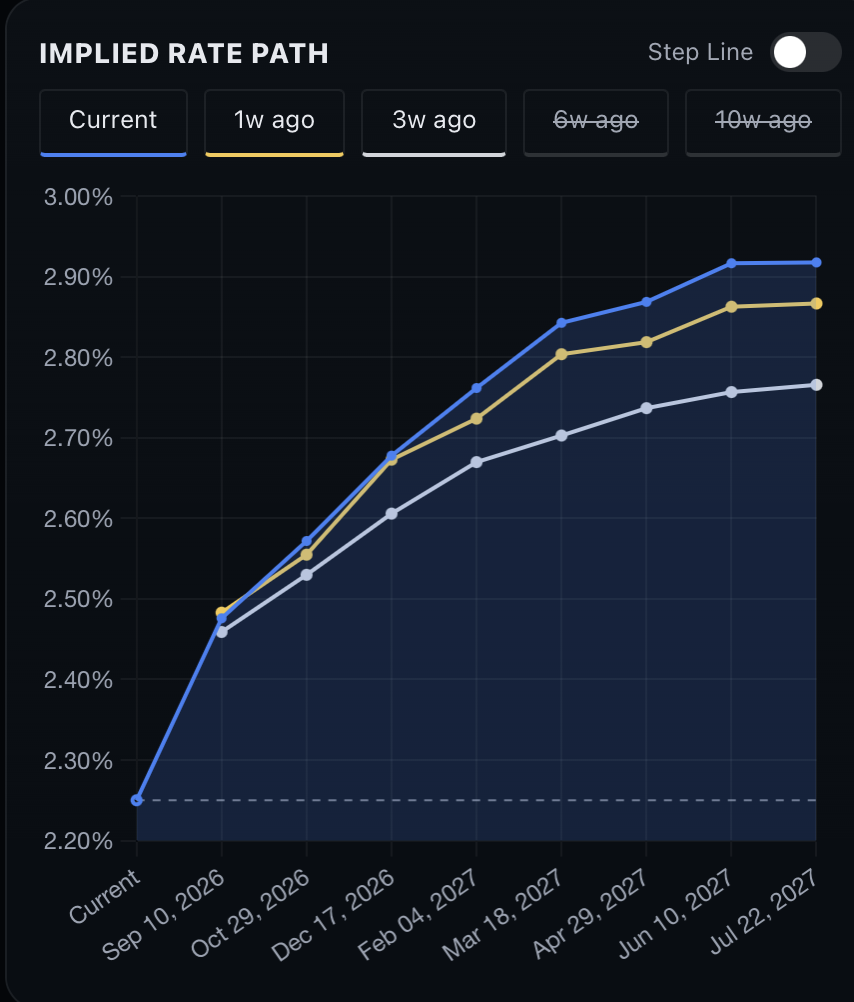
Perhaps the most interesting reaction to the Warsh speech was the equity market on Friday, where the main indices only fell by very modest amounts.  There was no indication from that price action that there is concern about a major tightening cycle.  Turning overseas, the picture was mixed last night in Asia (Tokyo -0.15%, China +0.35%, HK -0.1%, Korea +0.5%, India -0.4%) and is mixed this morning in Europe (Germany -0.8%, France 0.0%, Spain +0.1%) with Germany the obvious outlier.  I might argue that is a response to higher-than-expected inflation readings there and concerns that it might drive the ECB tighter.  I guess if you look at the curve below from rateprobability.com it does imply slightly tighter policy over time, but that’s really at the margin.

As to US futures, at this hour (7:10) they are pointing slightly softer, -0.2% or so.

Of course, Friday was much more exciting for the bond market but this morning Treasury yields are unchanged from the Friday close.  Europe, however, has seen yields climb higher with continental sovereigns all higher by 3bps.

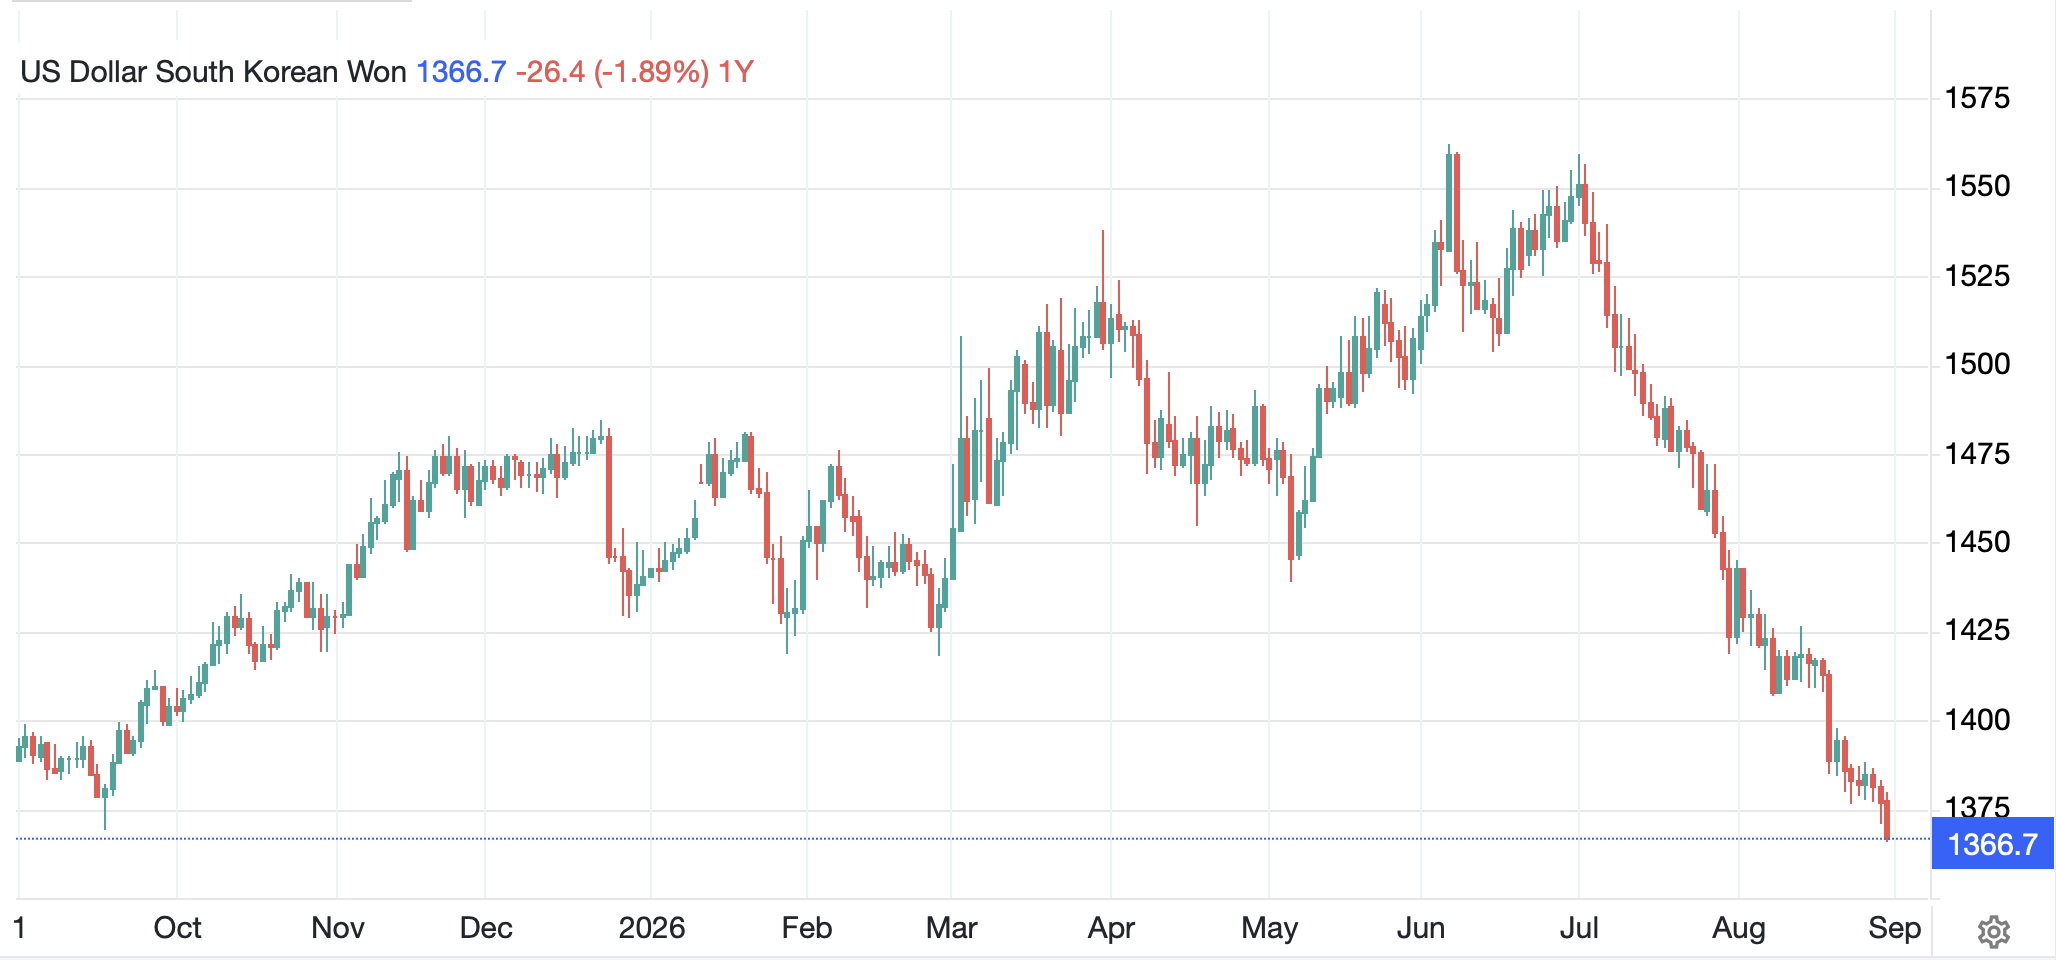
Finally, the dollar, which rallied sharply on Friday is giving back some of those gains with USDJPY back below 160, having closed above that level on Friday, while the bulk of the G10 currencies have gained between 0.1% and 0.2%.  The one exception here has been KRW (+0.7%) which has been on a remarkable roll over the past two months.  Between efforts to internationalize the currency and repatriation by the big semiconductor producers, the won has risen ~12% in the past two months, largely in a straight line.

Source: tradingeconomics.com

On the data front, there is nothing today but there is a big week coming culminating in NFP on Friday.

TuesdayISM Manufacturing55.2
 ISM Prices Paid72.0
 JOLTs Job Openings7.3M
WednesdayADP Employment47K
 Factory Orders0.6%
 -ex Transport0.2%
 Fed’s Beige Book 
ThursdayTrade Balance-$90.0B
 Initial Claims205K
 Continuing Claims1816K
 Nonfarm Productivity1.4%
 Unit Labor Costs1.3%
 ISM Services54.3
FridayNonfarm Payrolls58K
 Private Payrolls58K
 Manufacturing Payrolls5K
 Unemployment Rate4.1%
 Average Hourly Earnings0.3% (3.0% Y/Y)
 Average Weekly Hours34.4
 Participation Rate61.4%

Source: tradingeconomics.com

In addition to this, we hear from three Fed speakers.  The data we have seen of late indicates that the economy remains quite resilient in the face of higher energy prices.  Corporate earnings remain on fire and that continues to underpin risk assets overall.  However, all eyes will be on Friday’s NFP as that will serve to reconfirm prior opinions or perhaps change them.  The hawks will have a hard time making their case if the number is weak, and similarly, the doves if it is strong.  One little noticed thing from Friday was the NFP revisions for the 12 months from April 2025 through March 2026, which were revised lower by ‘just’ 79K.  Last year, the revision was -911K, so if nothing else, the BLS counted better!  But this begs the question, if the population is not growing, or even shrinking after all the deportations, and Baby boomers are retiring, thus reducing headcount, how many jobs are needed to maintain strong economic output?  

It makes a great deal of sense that Chairman Warsh wants to rethink the data because it does feel like the current data is outdated when it arrives, and that does not help forward looking policy decisions.  As to today’s session, it is hard to get too excited about anything right now, certainly in the FX markets.

Good luck

Adf
Monet’ry Bleating

Today it is all about Kevin
And whether, bond markets, he'll leaven
But what if his talk
Does naught to unlock
His views? For bond bears t'will be heaven

Remember, the them of this meeting
Is payments, not monet'ry bleating
Well, if that's the case
There will be a race
In which, only short, are competing

Markets have remained quiet for the past several sessions as investors, traders and algorithms all turn their focus to Jackson Hole, Wyoming this morning awaiting the sage comments of Fed Chair Kevin Warsh.  The market punditry seems convinced he will lay out things like his reaction function to data and his views on where monetary policy is headed.  Of course, I think they are talking their book as they are desperate to write about that.  We know this because all they have written about lately is how awful Warsh is for not telling them all that stuff.

But I have a sneaking suspicion that any discussion of monetary policy will be fleeting, at best, as the title of the symposium is “Financial Innovation: Implications for Payments and Policy.”  Frankly, this sounds like an opportunity for Warsh to wax poetic on the future of money and stablecoins and how the Fed will deal with these new vehicles and their impact on monetary policy.  I have already discussed the idea that stablecoins are going to be inflationary in their own right, and here is an article that describes the situation better than I can.  But in this context, and with the potentially major ramifications of the US government’s embrace of stablecoins, it would not be a surprise for Chairman Warsh to essentially ignore the current interest rate structure and focus entirely on the balance sheet.

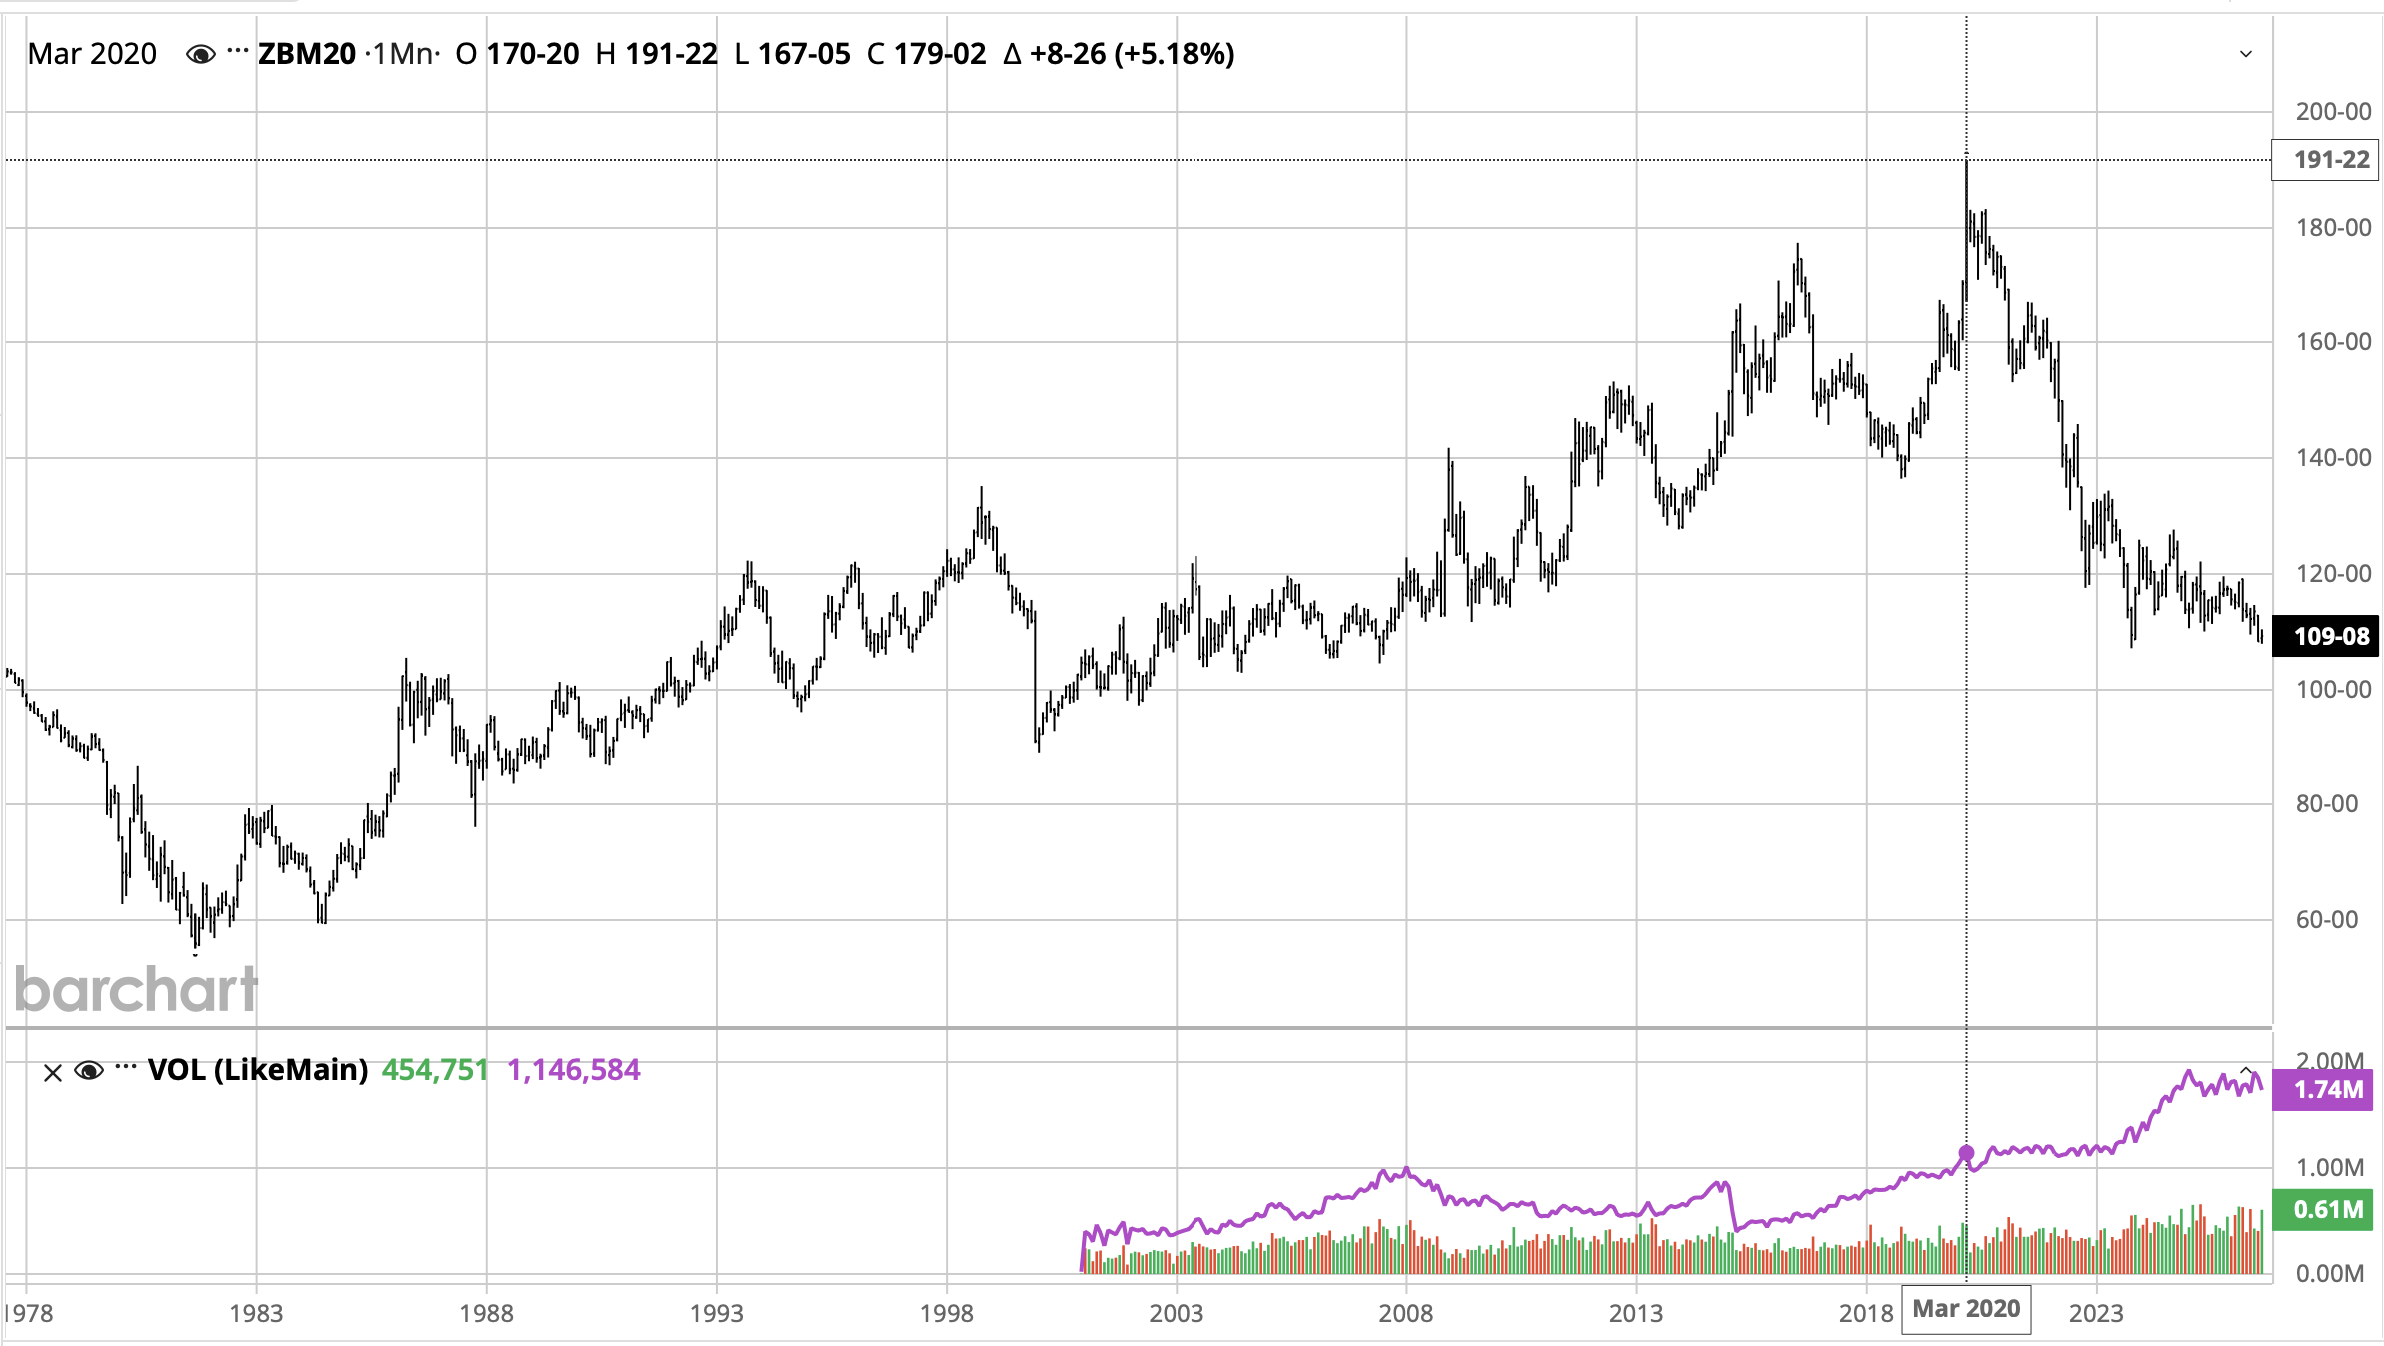
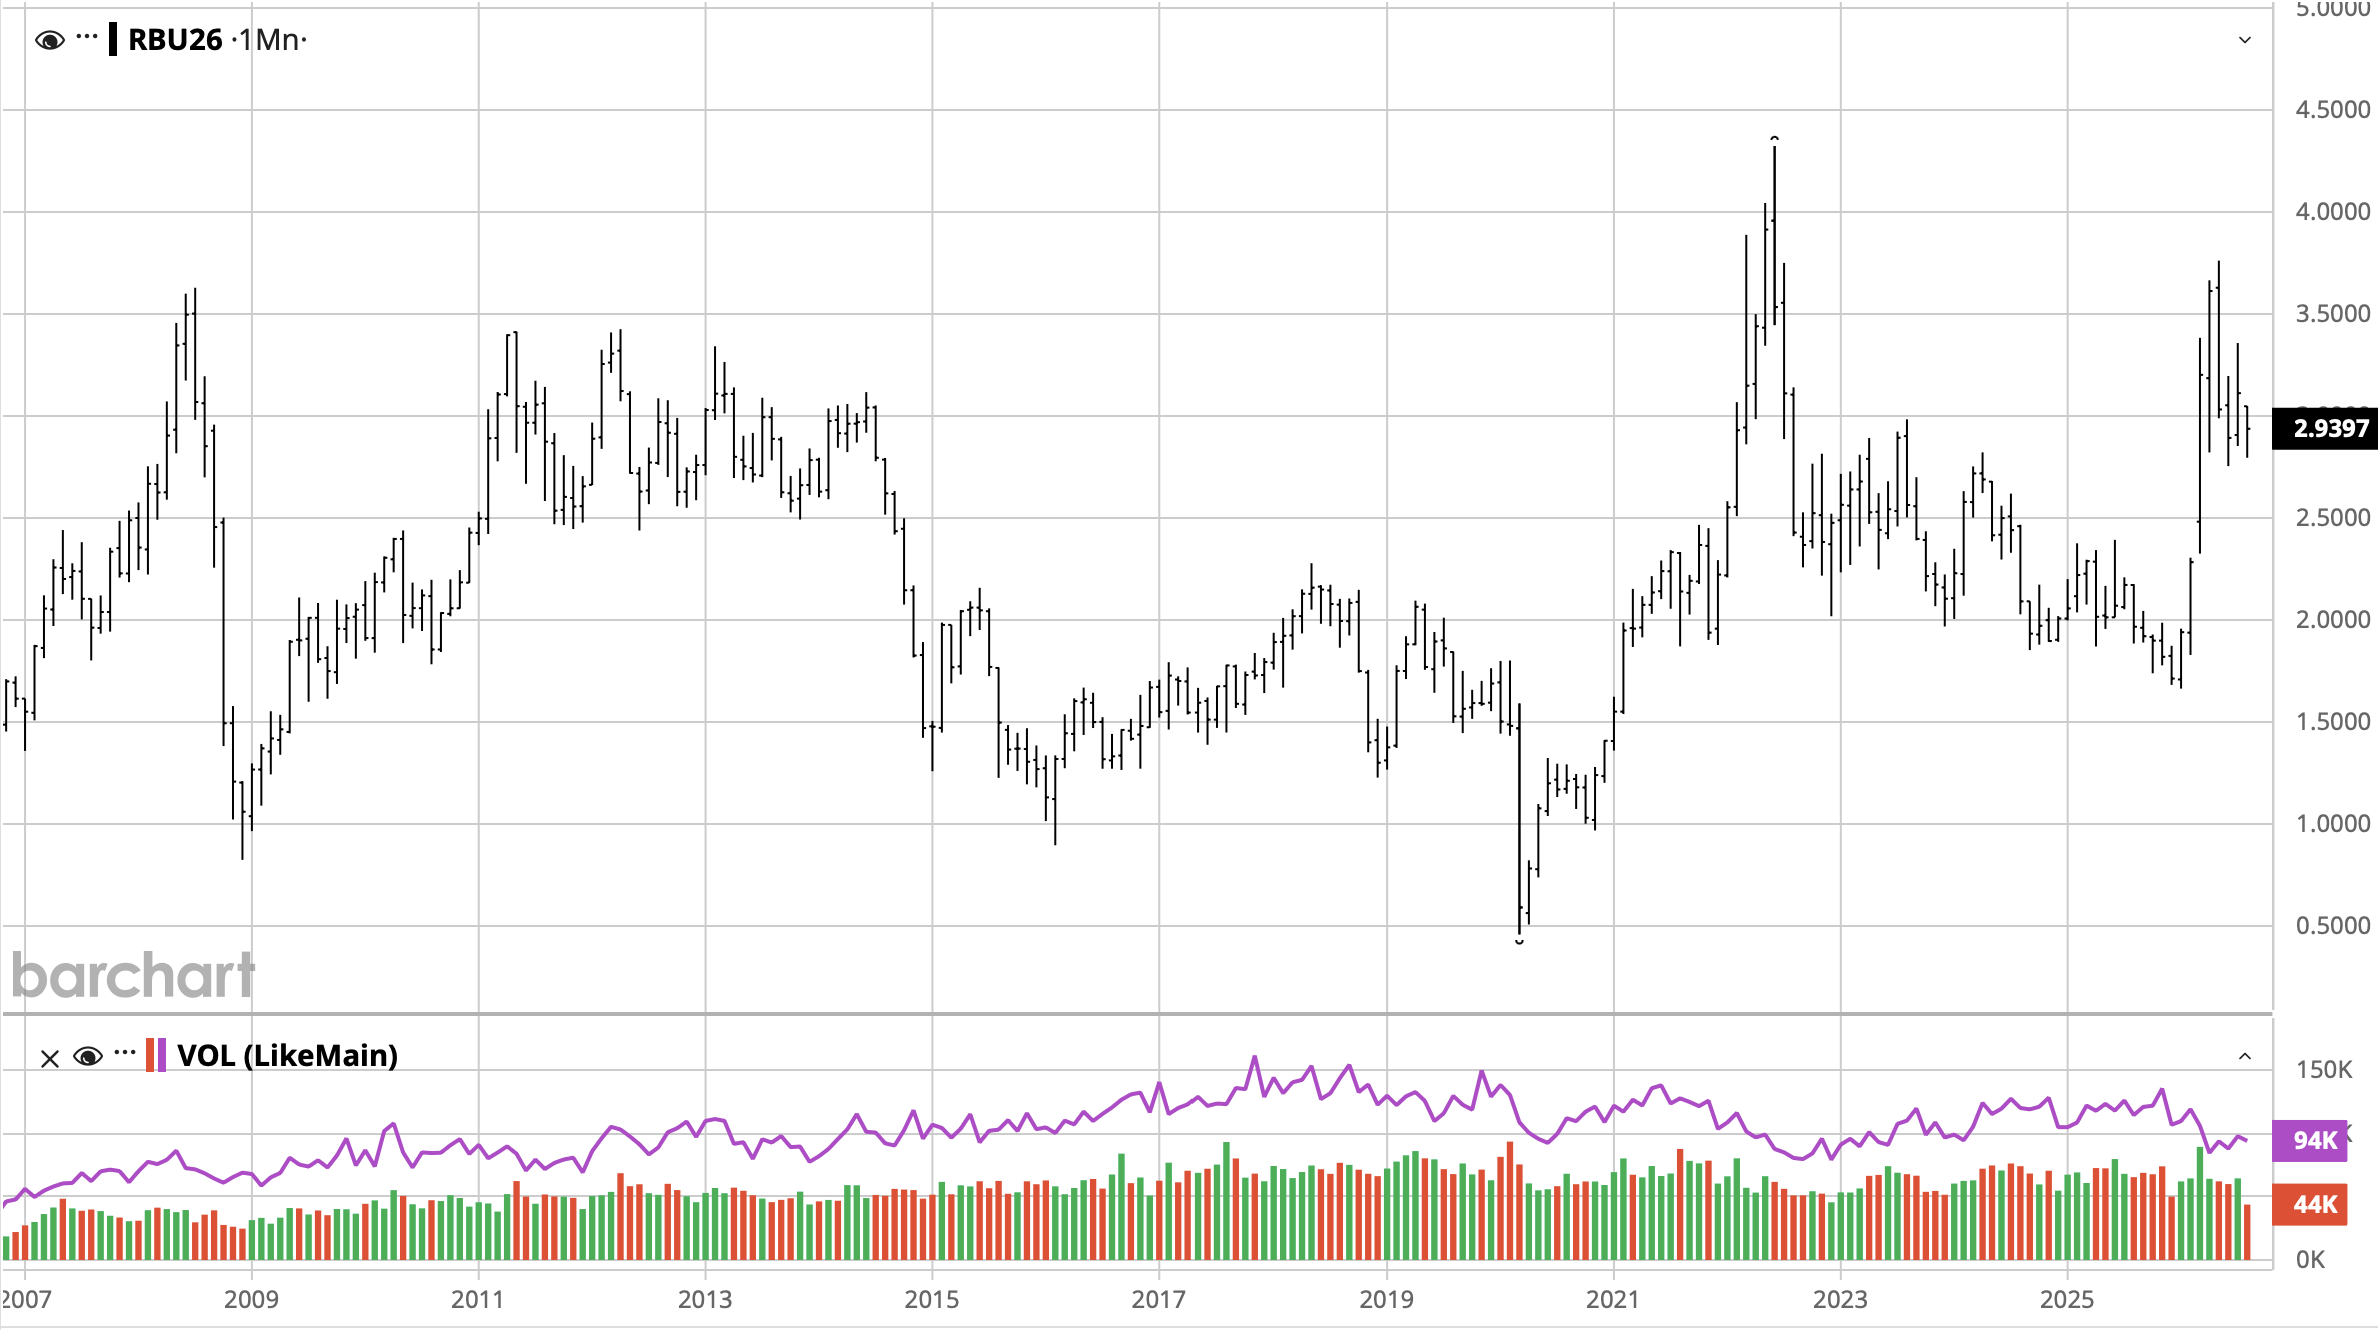
If that is the direction of his speech, I expect that the bond bears will look to double down and really hit the futures market hard, driving yields higher extending the recent move seen in the chart below.

Source: barchart.com

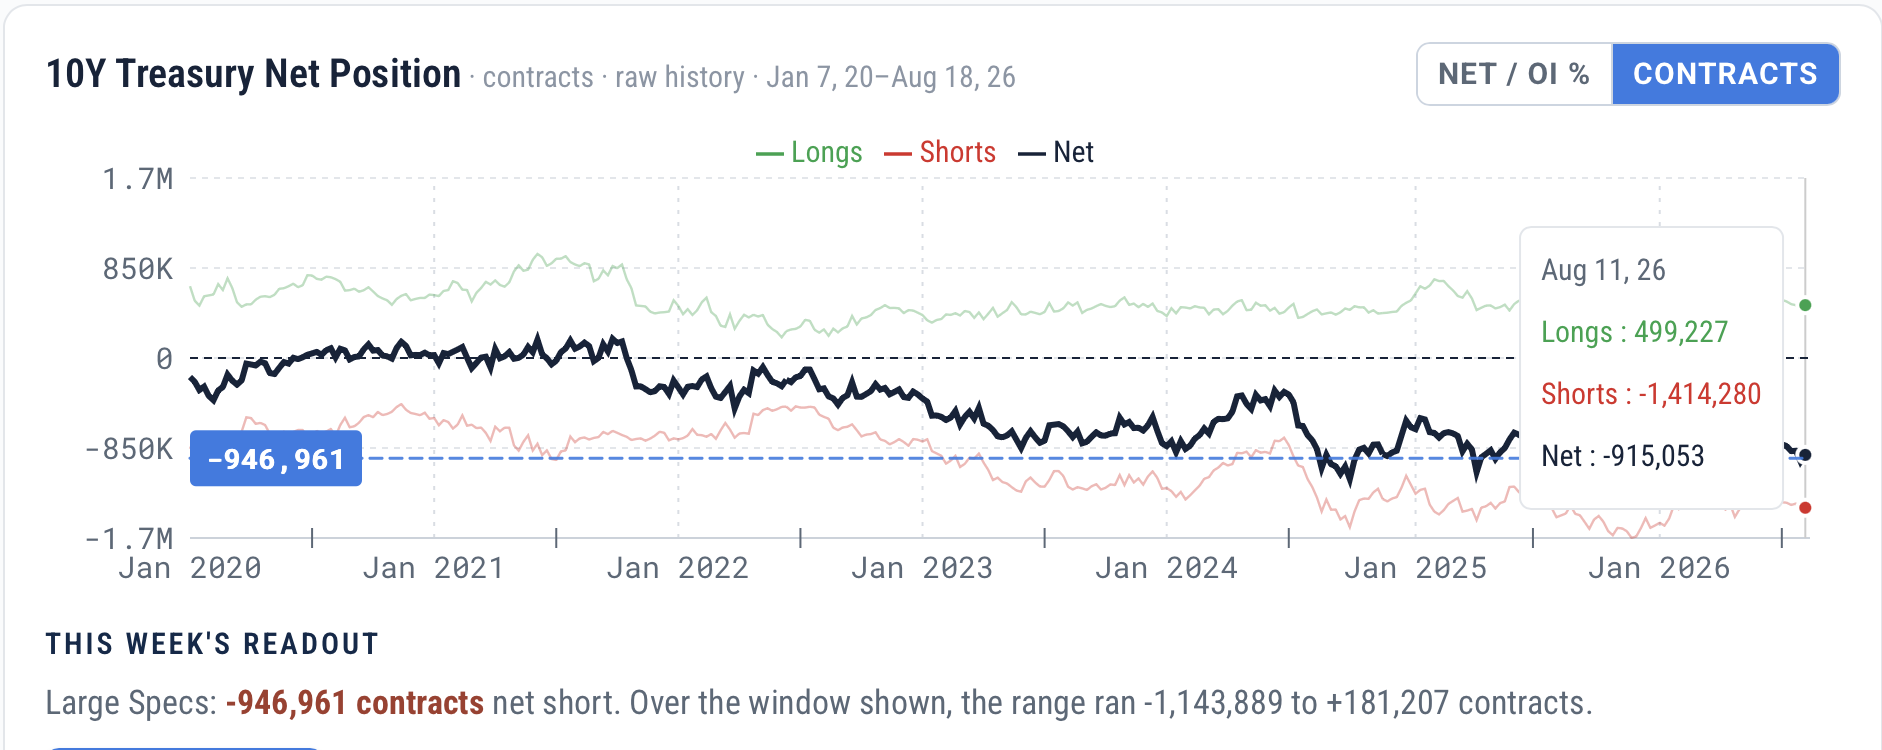
But I also do not rule out Secretary Bessent taking advantage of that and buying them aggressively.  Would it really be a surprise if Bessent, a former hedge fund trader who understands both bond math and the way markets work extremely well, used his ‘at least’ $4 billion of buying power to purchase futures, utilizing leverage to expand the impact significantly?  At current margin levels, that $4 billion could purchase at least $60 billion equivalent in futures or 600,000 contracts in the first week of activity alone.  I think that could drive a pretty good short squeeze, exactly what Bessent wants to see.  Below is a chart of the Commitment of Traders report for 10-year note futures showing a net short of ~915k.  What kind of impact would buying 600k futures have?

Source: cotsignal.com

My take is there would be quite a few hedge fund traders whose bonuses would be negatively impacted!

This is all speculation, obviously, but from what I have read around, the market is really looking for something I sense Warsh is not going to give them.  Prepare for more volatility ahead after several weeks of limited movement.  Just sayin’.

In the meantime, let’s run down market movements overnight, although there was not a lot of excitement.  Yesterday’s US rally was followed by broad-based, albeit not excessive, strength throughout most of Asia (Japan +0.4%, HK +0.1%, Australia +0.6%, Taiwan +0.8%) although both China (-0.4%) and Korea (-1.8%) did not partake.  Given the Nvidiphoria, Korea is a surprising outcome, but volatility in that market has been extreme as I have shown in the past.  

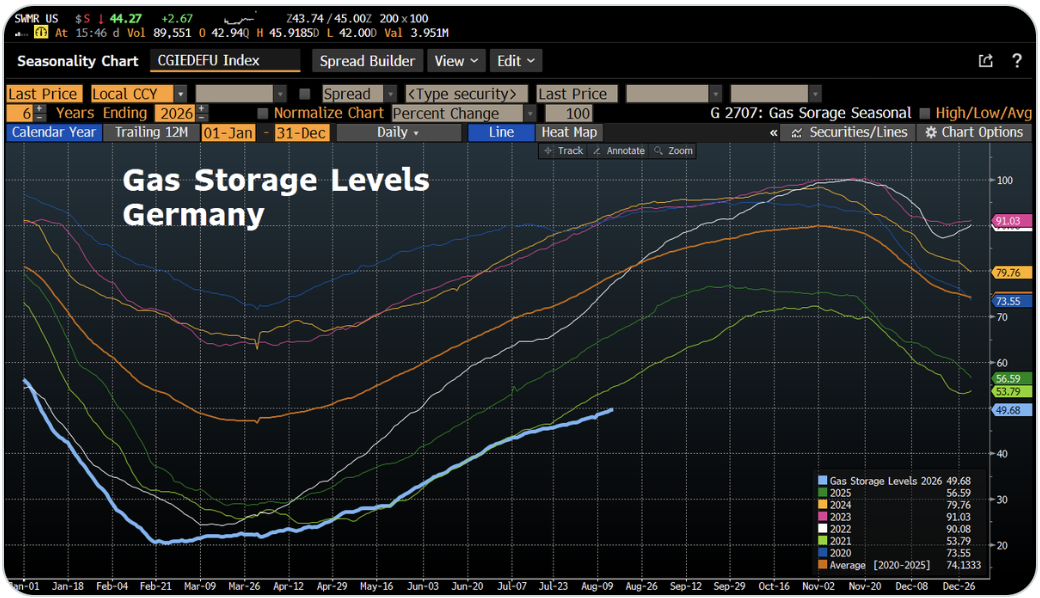
European bourses are also higher this morning (France +0.9%, Spain +0.5%, German +0.5%) after data showed improved business confidence throughout the continent although GDP continues to be lackluster (e.g., France 0.7% Y/Y in Q2).  But sentiment indicators are picking up there slightly and, after all, equity markets are supposed to be forward looking.  Maybe things will get better in Europe, although given their energy policies and the fact that they are behaving far more like grasshoppers than ants these days with respect to Natural gas storage (see chart below), things may get tougher if they are wrong about global warming.

As to US futures, at this hour (7:15) while NASDAQ futures are softer (-0.6%) the other two major indices are essentially unchanged ahead of Mr Warsh.

In the bond market, yields continue to creep back higher with Treasury yields (+1bp) the best performer after JGB yields (+4bps) rose overnight and European sovereign yields have climbed between 2bps and 3bps this morning.  As I highlighted yesterday, or more accurately, the WSJ did the work for me, European yields have been climbing more rapidly than US yields lately as European nations have demonstrated no ability to rein in spending, and in fact, are planning the guns AND butter approach as they build out their defense capabilities while maintaining their nanny states.  What can possibly go wrong? 🙃

In the commodity space, we continue to hear that the Strait of Hormuz is either open or closed depending on the source, although the fact that oil continues to flow has me leaning toward more open than closed.  This morning WTI (-0.6%) is slipping a bit, although it rallied a bit yesterday.  There was a very interesting article in Bloomberg yesterday regarding the shale drillers’ ability to increase production dramatically by using more surfactants (soap) to help the oil flow, gains of 20% or more in a well, which simply reminds us of the amazing technology that exists in that sector.  There is no shortage of oil folks, and likely never will be.  As to the metals markets, gold is flat this morning and silver (+1.3%) is rising again, back above $70/oz.  Copper (+0.6%), too, is having a solid session.  Nothing has changed my views on the metals going higher over time.

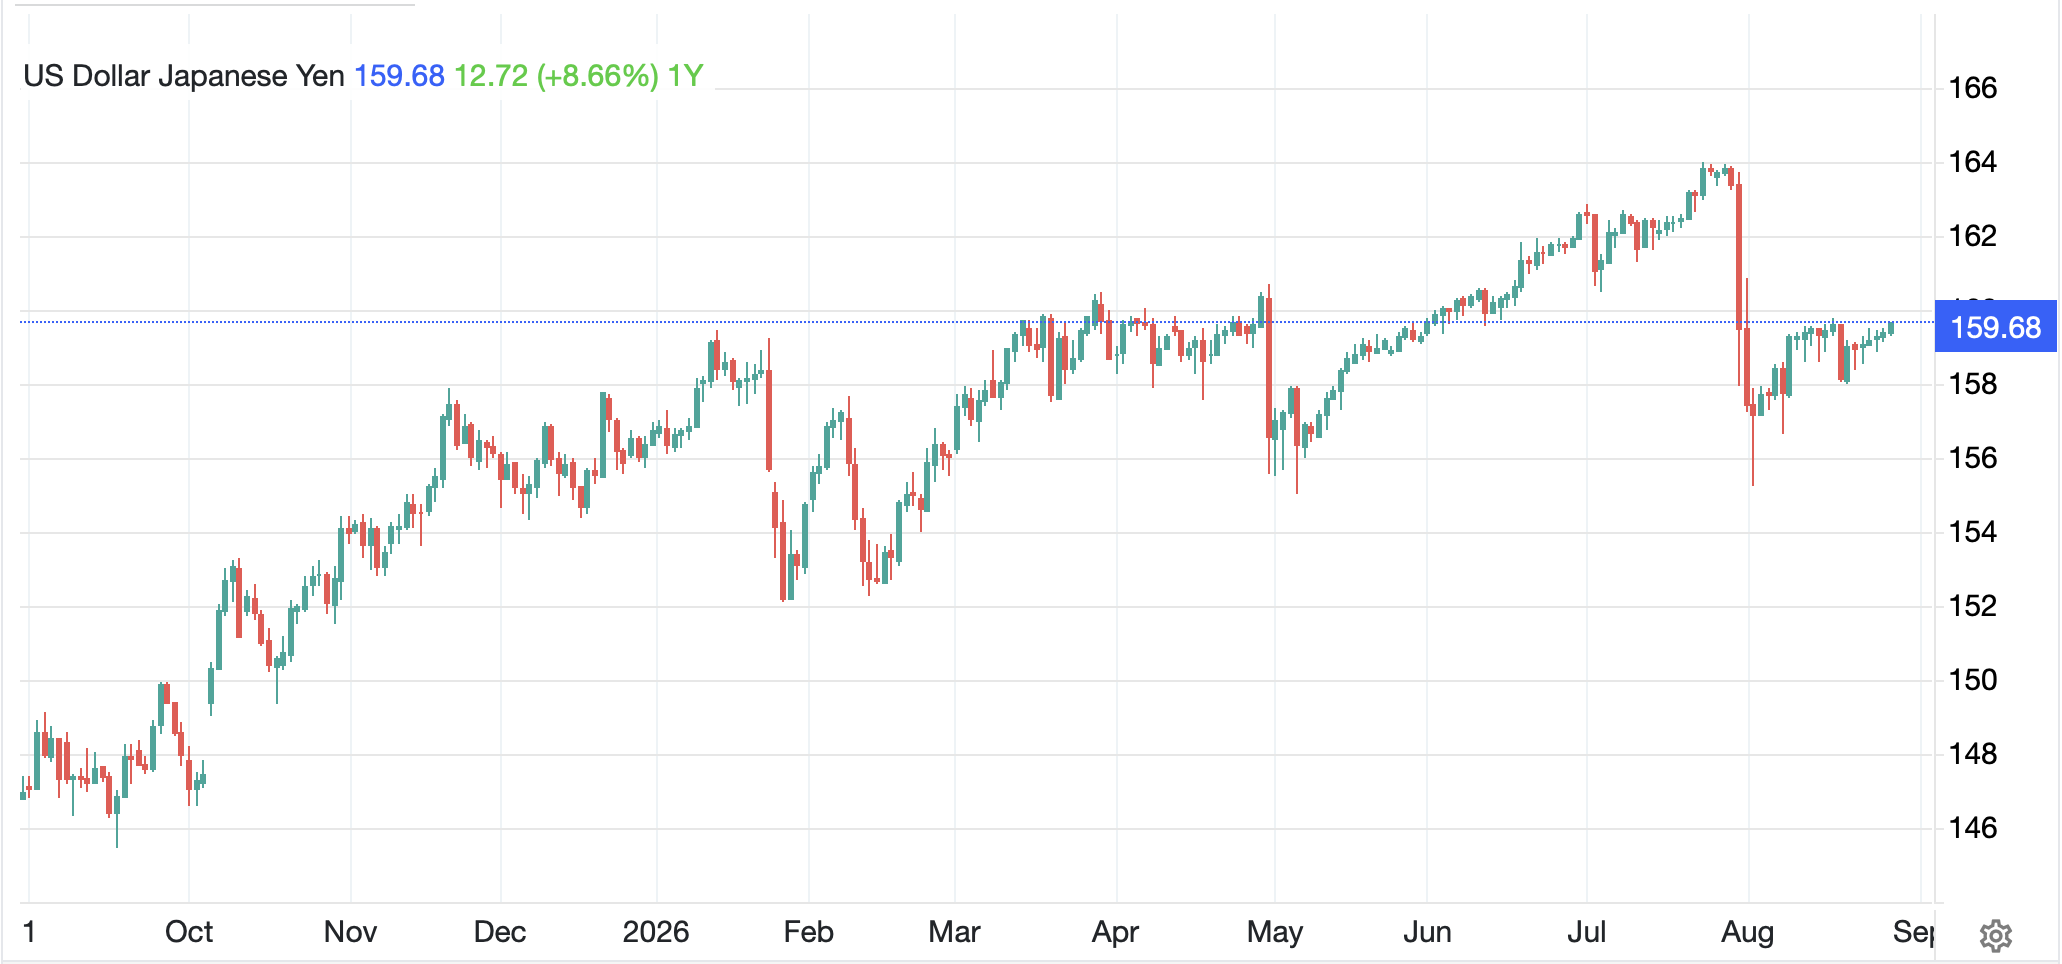
Finally, the dollar has been stuck in neutral as we await Chairman Warsh with the DXY still hovering right above 99.00.  We have not discussed the yen (-0.2%) much lately as it has not been noteworthy, but now that it has been one month since the major intervention, I thought it worthwhile to take a peek at the chart and see how its doing.

Source: tradingeconomcis.com

I challenge you to explain the difference to me between the price action after the last interventions and this one.  The intervention in May took about 6 weeks to unwind and the yen continued lower for another 6 weeks before they stepped in again alongside the US.  Pretty much the only thing I can see that really stops this move is if I am right about Bessent squeezing the shorts and driving yields sharply lower.  In that case, USDJPY would fall sharply without intervention.  Otherwise, it’s hard to get excited about anything in the FX markets right now.

And that’s really it for today.  At 8:30 Canadian GDP (exp 3.4%) is released and then we see Chicago PMI (57.0) and Michigan Confidence (51.0) when Warsh starts to speak.  We also get the annual NFP revision although I have not seen any estimates for that.  But as I have said all week, it’s all about Kevin.  Now we wait and see.

Good luck and good weekend

Adf

A Desperate Act

A key market story yesterday was that the Treasury buyback operations, you know the ones that would be “at least” doubled to $4 billion per event, could grow much larger as secretary Bessent would tap the Treasury General Account (TGA) for this purpose.  Now the TGA is the federal government’s checking account.  It is where your taxes get paid into, along with the receipts from bond sales and tariffs.  It is also the account that pays all the federal government’s obligations like salaries and purchases of defense and other equipment.  The current balance (a/o Aug 21st) is about $936 billion according to the Treasury website.  Obviously, that is a huge amount of money, but then the federal government has a huge amount of payment obligations.  I bet it is a hard checking account to balance!

Now, technically, I presume that all their operations are paid by the TGA.  The mechanics would work that Treasury would issue T-bills, receive the cash in the TGA and use that cash to buy back bonds.  But the implication was that he would just spend the money that was already there.  Personally, I doubt that will be the outcome, and frankly, it almost sounded more like a threat than a future course of action.  But it did get tongues wagging.  

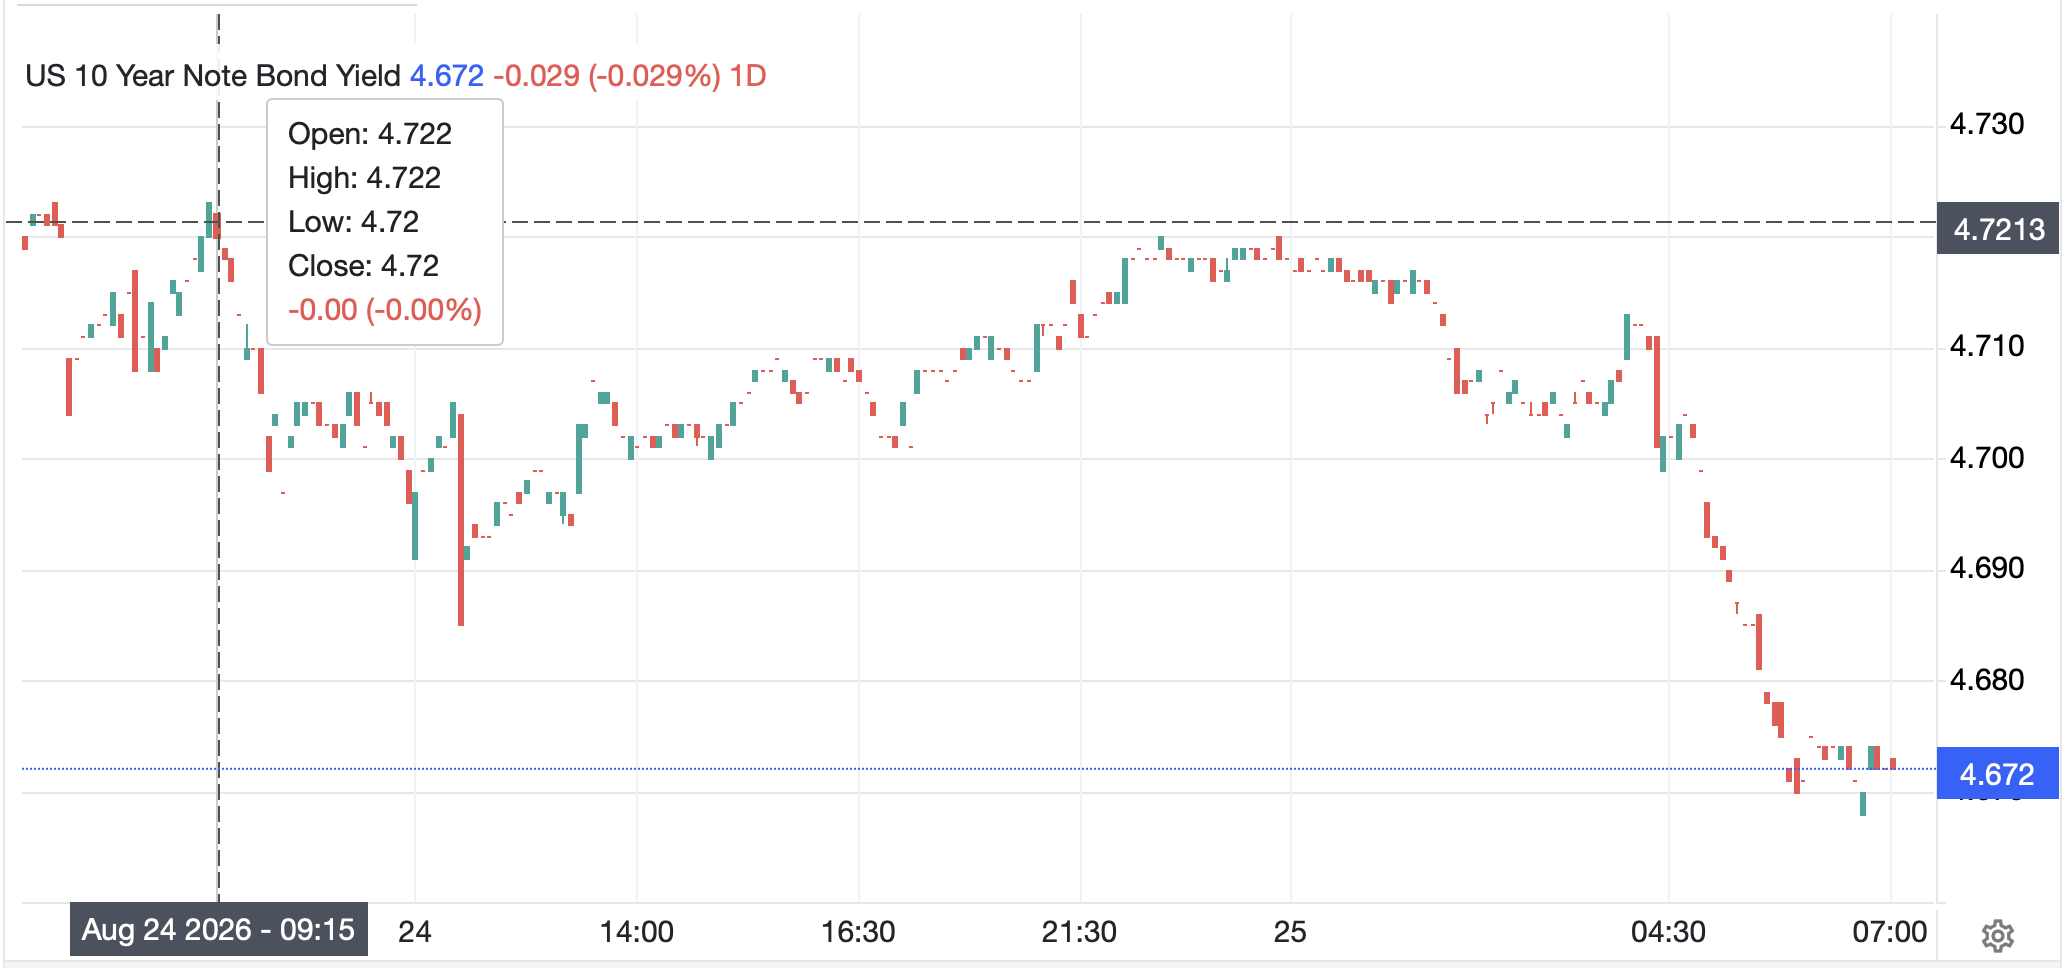
According to Grok, these comments came in an interview on CNBC at a bit after 9:00 yesterday morning.  The chart below shows the bond market price action from that point onward, which tells me that while there was a modest initial response, it completely disappeared until another catalyst (lower oil prices I believe) helped push yields down early this morning.

Source: tradingeconomics.com

But this clearly struck a nerve as in this morning’s WSJ, Stan Druckenmiller, Bessent’s mentor at the old Soros hedge fund, wrote an op/ed decrying the move.  As I survey all that I have learned thus far, it seems clear that Bessent is looking to remove duration from the market in an effort to drive longer dated yields lower.  But his tools are limited compared to the Fed’s abilities and, at least right now, it does not appear the Fed is going to cooperate.  The first operations aren’t scheduled until September 7th, so until then, it is all just speculation, and I’m not even going to try.

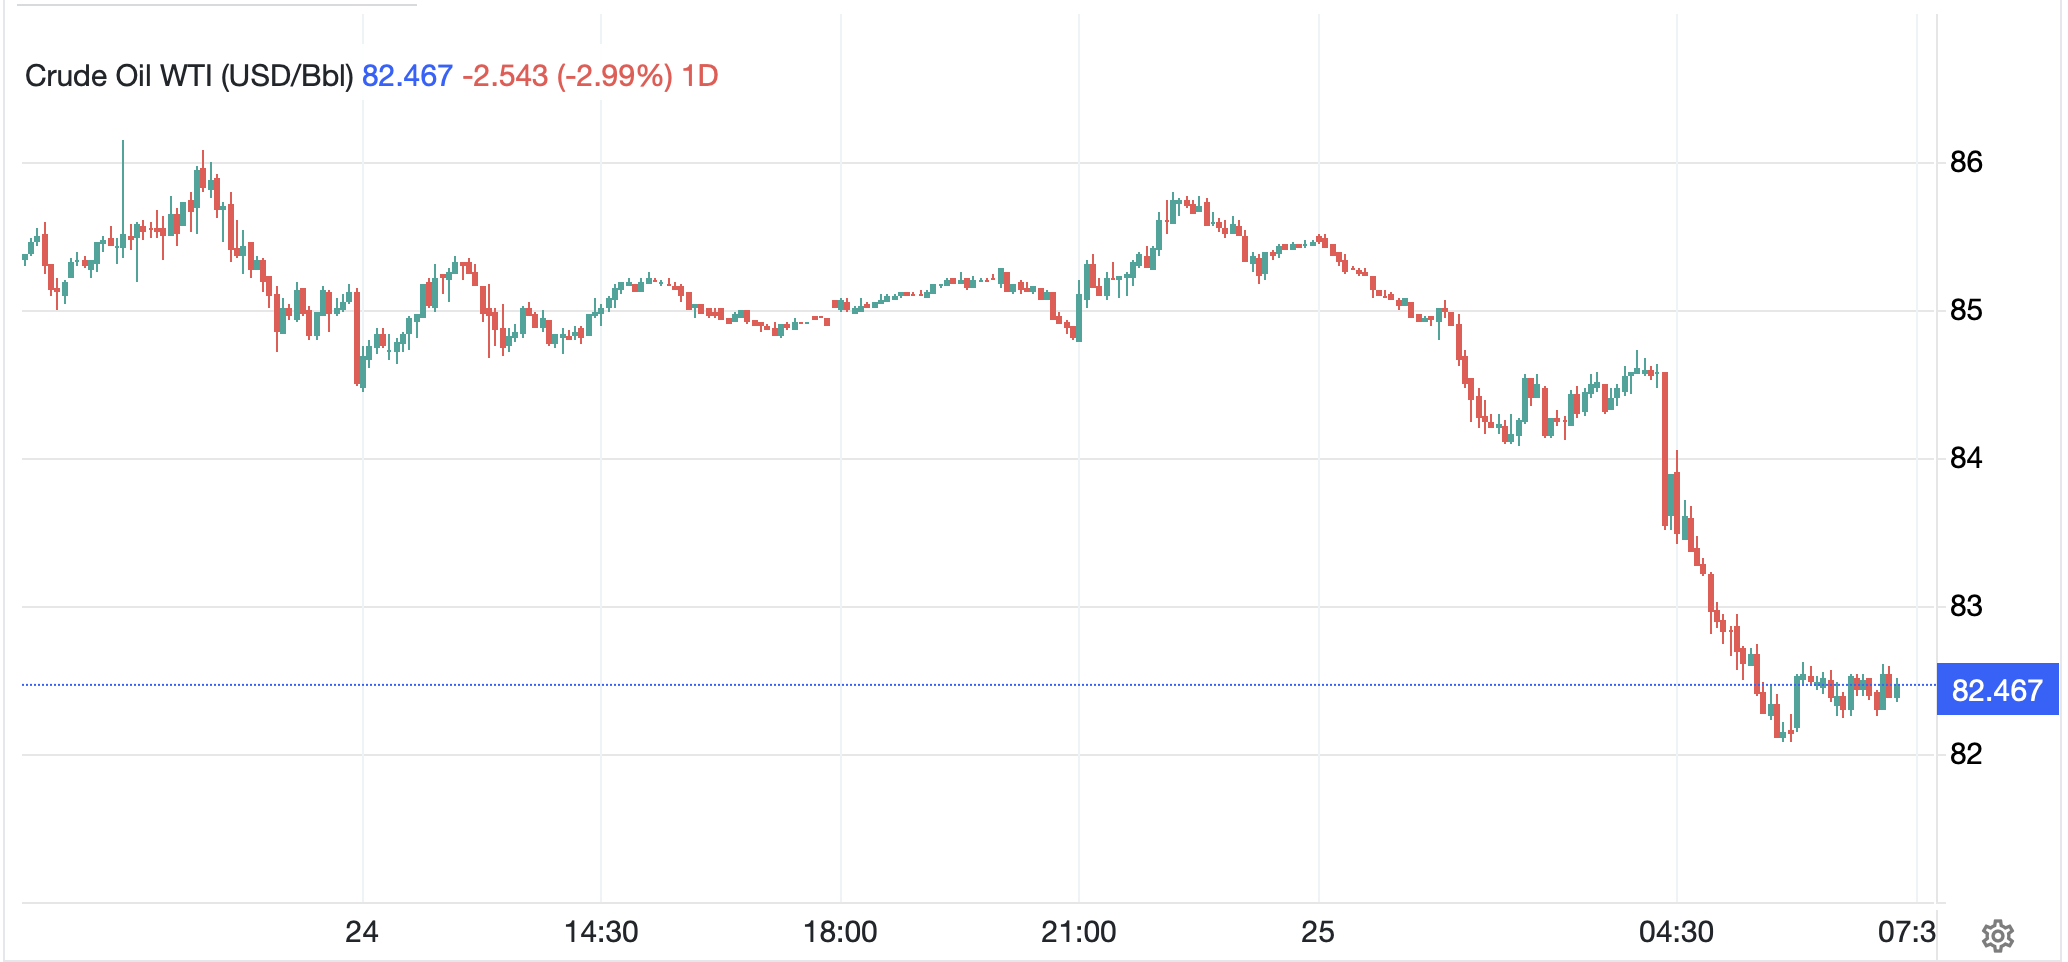
The other thing that Secretary Bessent did yesterday, that may have a larger impact on things, was announce sweeping new sanctions on Iran and countries that do any residual business with Iran in an effort to add further pressure on the regime.  It is possible, but not clear to me, that this is part of the rationale for this morning’s decline in the price of oil (-3.0%).  However, if you look at the chart of oil for the past 24 hours, it is remarkably similar to that of the 10-year Treasury above.

Source: tradingeconomics.com

Ostensibly, the news here, which of course would impact bond yields, is that the Pakistani army chief was intermediating between the US and Iran in an effort to find a solution and reduce tensions in the Gulf.  That would certainly be a welcome outcome for all, but I’m not holding my breath.  However, this price action has set the tone for risk markets this morning, so let’s take a look.

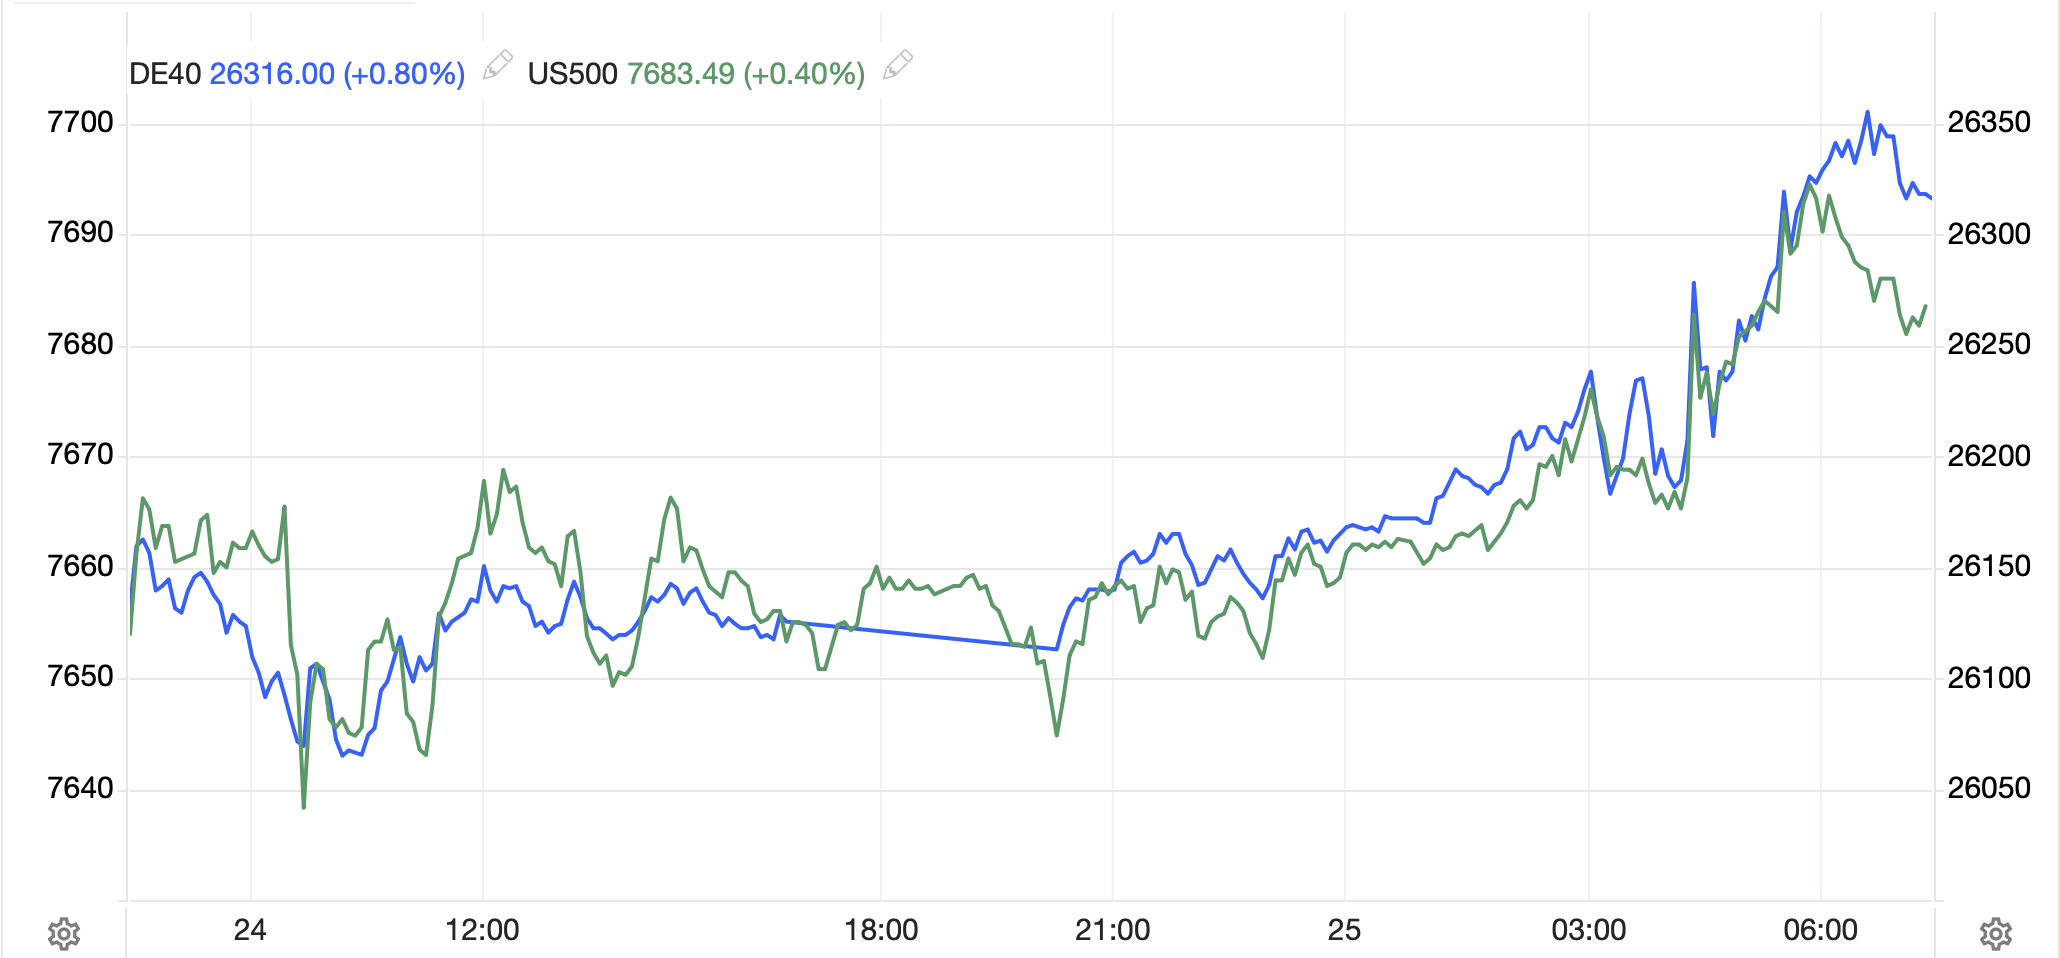
While Asia was mixed overnight (Tokyo +0.5%, China -0.3%, HK 0.0%) following the mixed US session, with pressure still evident on the tech sector, Europe is firmer this morning across the board (Germany +0.8%, Spain +0.4%, France +0.4%, UK +0.25%) with all those rallies timed almost exactly alongside the oil and bond moves.  As you can see in the chart below, the same is true in the US where futures at this hour (7:25) are also higher and moved right alongside other equity markets.  As to specific stories here, I think there is a great deal of breath holding for the Nvidia earnings report tomorrow after the close.

Source: tradingeconomics.com

In the bond market, as mentioned above, yields are lower across both Treasuries (-3bps) and all European sovereigns with the entire bloc seeing yields decline by between -3bps and -4bps.  It appears this all revolves on the same story driving oil and equities.

In the metals markets, gold (-0.2%) is edging lower but basically consolidating another strong day yesterday.  It is reasonable to conclude that market participants are growing cautious regarding US debt given there is no indication of spending restraint.  But the reality is that markets are growing cautious of all G10 debt given that statement regarding spending restraint is universally true in that bloc.  I continue to believe we are going to see governments around the world try to ‘run it hot’ with nominal GDP growth rising faster than government spending, thus reducing the real burden.  However, running it hot generally means higher inflation, and that is something that is a political problem.  As to the other metals, silver (-1.2%) is under pressure, although still far higher over the past week and month, while copper (+0.5%) is a bit firmer this morning.

Finally, the dollar is still sleeping this morning, virtually unchanged on the DXY at 99.00 and virtually unchanged vs. almost every major counterpart.  The biggest mover is INR (+0.35%) a major beneficiary of lower oil prices and not surprisingly, NOK (-0.2%) is suffering on the same catalyst.  But otherwise, everything is +/- 0.1% from yesterday’s close.

On the data front, there is not a ton this week, although PCE comes tomorrow, but really all eyes remain on Chairman Warsh’s speech Friday morning.

TodayCase-Shiller Home Prices1.7%
 New Home Sales620K
 Consumer Confidence90.2
WednesdayPCE0.1% (3.7% Y/Y)
 Core PCE0.2% )3.3% Y/Y)
 Q2 GDP1.5%
 Durable Goods0.7%
 -ex Transport0.5%
 Personal Income0.3%
 Personal Spending0.2%
ThursdayGoods Trade Balance-$99.0B
 Initial Claims208K
 Continuing Claims1811K
FridayChicago PMI57.0
 Warsh Speech 
 Michigan Sentiment51.0

Source: tradingeconomics.com

In addition, the EIA oil inventories are expected to see another build as there remains ample supply, at least so it seems.  While PCE is important, I think it will be less so given the pending Warsh comments.  To me, tomorrow’s Nvidia earnings and then Warsh are the keys for the rest of the week, absent a major change in Iran, and alas, I don’t see that.

The bond brouhaha is much ado about nothing I believe as it will not change the trajectory of Federal spending, and that is what is necessary to have a long-term impact.  Unfortunately, that usually takes a crisis, and those are unpleasant.  They also take a VERY long time to develop, after all Argentina imploded for nearly 100 years before electing Javier Milei who promised to do something about it.  It has only been 25 years here since we last ran a budget surplus.  I fear it could be much longer before things really change.

Good luck

Adf
Things Are Bleak

The one thing on which you can rely is that there is a large segment of the punditry who will complain about every action taken by financial authorities, often offering ad hominem comments to make their case while demonstrating their own ignorance.  The benefit you have here is that I know there are many things I don’t know and don’t pretend otherwise.

Of course, I am referring to the Treasury Secretary’s recent announcement to ‘at least’ double the activity in their bond purchase program.  Once again, let me remind everyone that Secretary Bessent did not unilaterally pass laws to enact spending, that was Congress’s doing and the dramatic increase in spending has been ongoing for at least 25 years.  Just like every treasurer in every company, Bessent’s primary job is to ensure there is sufficient funding, and that is what he is doing.  Machinations as to the tenor of the debt are left to his discretion and fortunately, he is a man with an extraordinarily broad and deep understanding of financial markets.

The claims that he is panicking now are ridiculous, although I’m sure he isn’t thrilled with the situation.  But he inherited the situation, he didn’t create it.  For every doomster out there explaining the bond market is going to collapse, or the government is going to be forced to change their ways, my response is, don’t hold your breath.  

While yields have certainly risen over the past several years, that was from the extremes of Covid policy.  If you take a longer look, as per the chart below from FRED, the current level of 10-year yields is hardly dramatic, and actually, as I have written before, remains well below the long-term average.

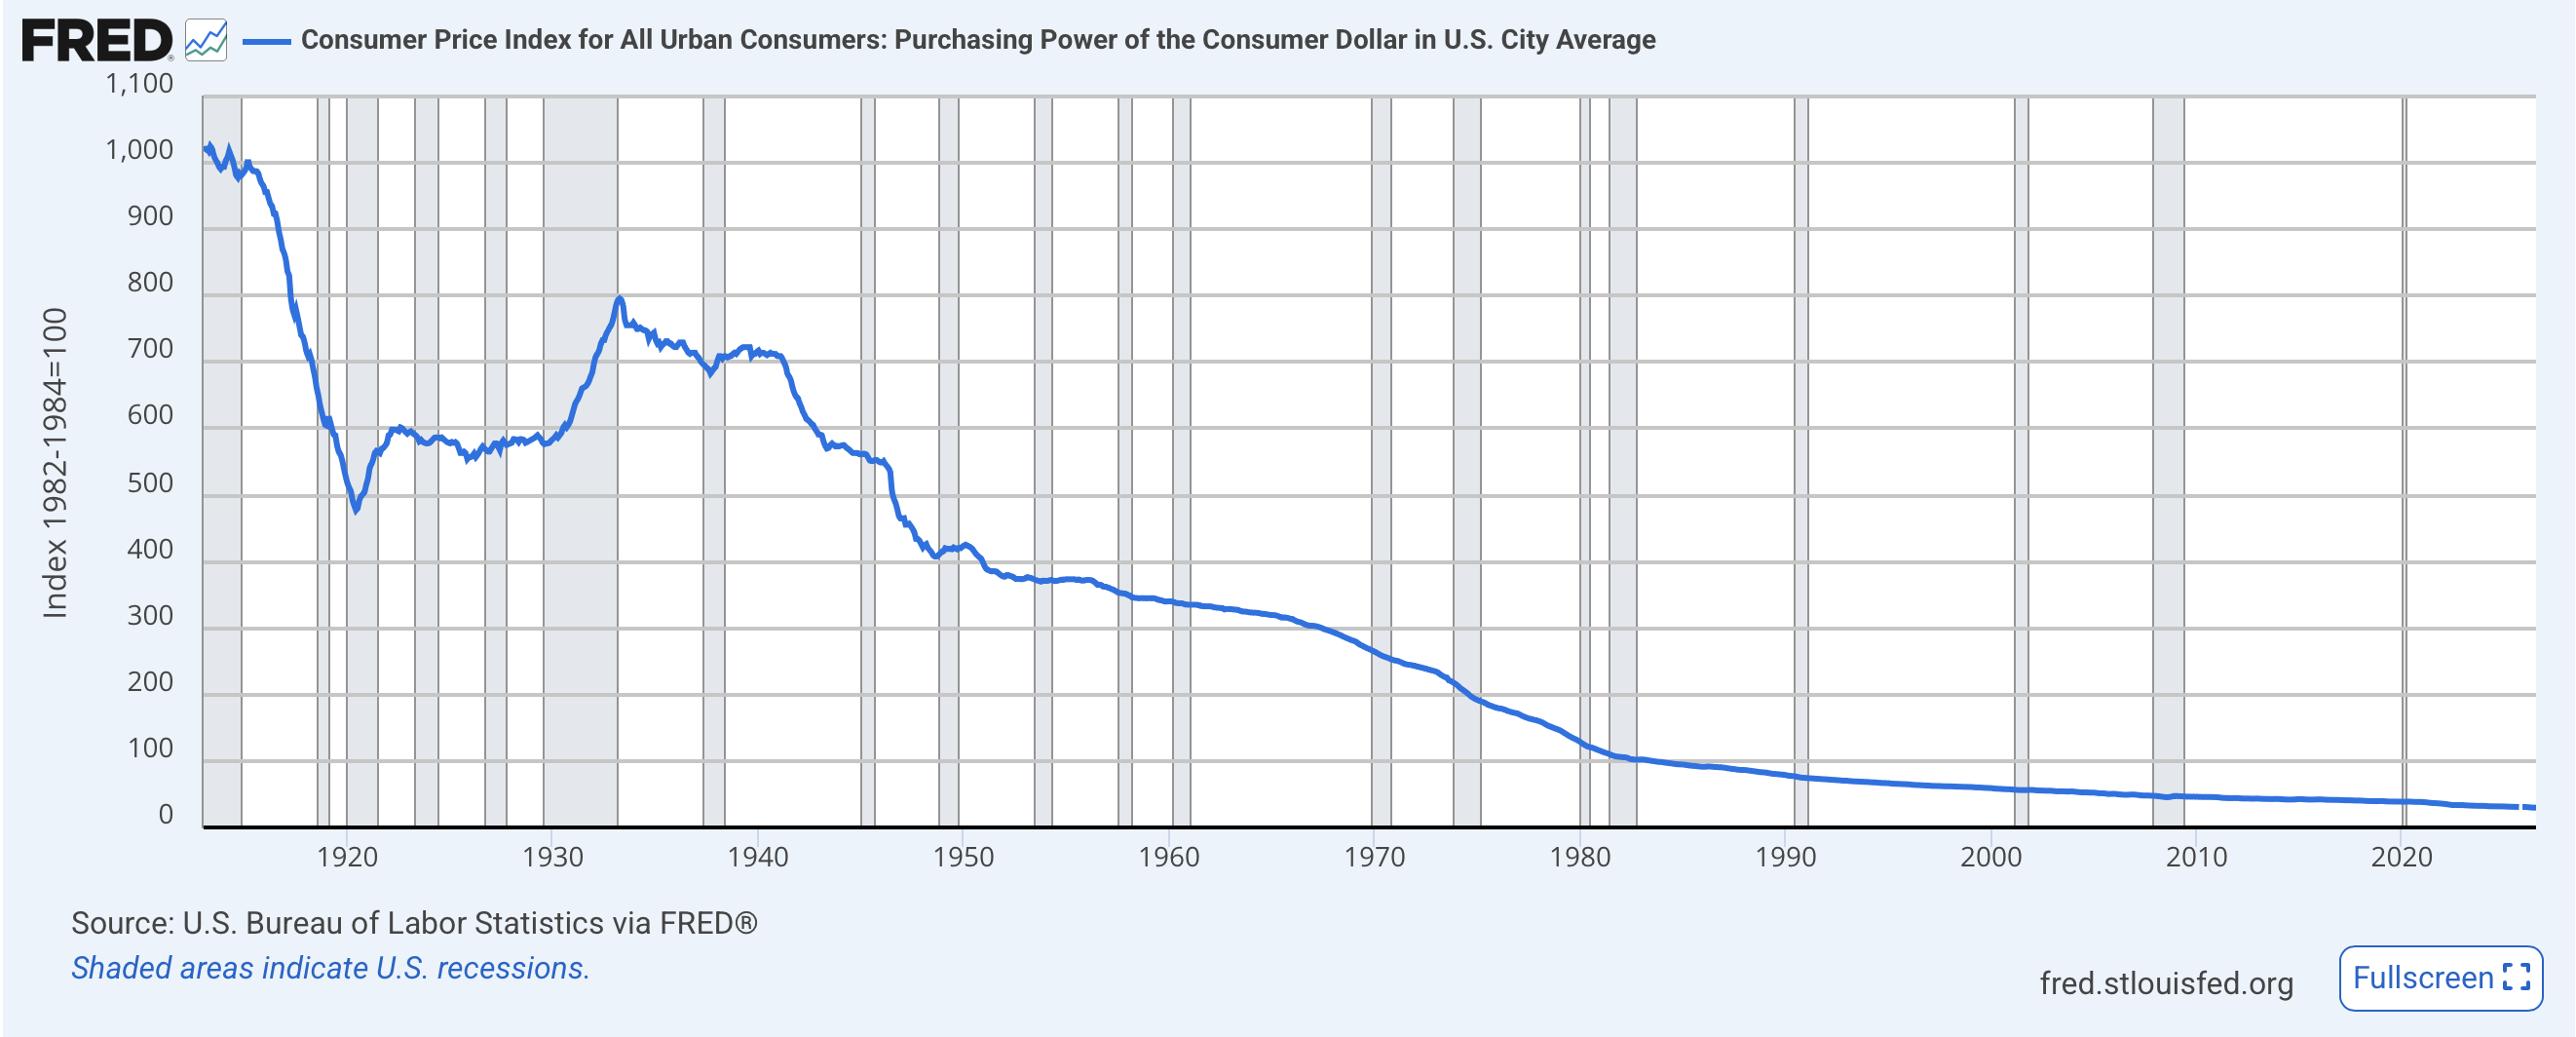
Now, I understand that the amount of debt outstanding is much larger, on both an absolute and relative to GDP basis, but I also know that there is literally a 0.0% probability that the US will not repay that debt.  The question is what the real value of the dollars you receive will be when they are returned, and there, the picture is less bright.  Of course, as you can see from the below chart, also from FRED, this is hardly a new concept either.  In fact, ever since the Federal Reserve was created in 1913, the value of the dollar has declined by about 97%.  This is not a new phenomenon.

Which brings us to Chairman Warsh.  I find it interesting that the punditry believes that Bessent’s activities were completely independent of Warsh.  The two are BFF’s for god’s sake, and speak every week, if not every day.  Each has a job to do, and each is working to achieve it.  Inherently, Warsh’s job is made more difficult because of the US fiscal situation, not because Bessent is tweaking the Treasury’s maturity ladder.

And here’s the thing, both men are working to make institutional changes in hidebound institutions that are fighting things tooth and nail.  Frankly, I sincerely hope both are successful.  Back to Warsh.  Friday, he will speak at the KC Fed’s annual Jackson Hole Symposium, this year titled “Financial Innovation: Implications for Payments and Policy.”  Now, that is a bit afield from the details of monetary policy, as I suspect the policy part of the title refers more to the stablecoin question rather than the size of the Fed’s balance sheet.  But I am confident he will discuss current monetary policy in some manner.  I am also confident he will not offer suggestions as to the next rate move.  

The current narrative has morphed into, the problem for markets/analysts is not the lack of forward guidance, it is those people don’t understand the Fed’s reaction function.  This, too, is disingenuous in my mind as Chairman Warsh has made clear, his function is to reduce inflation to the 2% target, and he has clear ideas how to do that.  The problem is his ideas are different than the neo-Keynesian views that dominate the Fed (and every other central bank), and so are making people uncomfortable.  He has made very clear he is happy to allow the bond market to do the Fed’s work, tightening policy.  He is also very politically astute and clearly understands Bessent’s actions.  I would contend that of all the dysfunction in the government, the least concern should be afforded to the Fed/Treasury nexus.

And finally, it appears that the latest trade talks with Canada have broken down and both sides will be imposing tariffs on the other side.  My personal view is this is a mistake, only because there is no predatory relationship between the two nations, but politics is politics and PM Carney has called on national pride as his rationale.  The thing for the US is, it isn’t going to matter that much. According to Grok, Canadian imports represent ~10% of total US imports and ~1.5% of GDP, so higher tariffs on that relatively small amount is not going to change much.  For Canada, though, exports to the US represent ~20% of GDP, so interruption there is going to hurt a lot more.  Something tells me we will get a deal here pretty soon though as both sides will benefit.

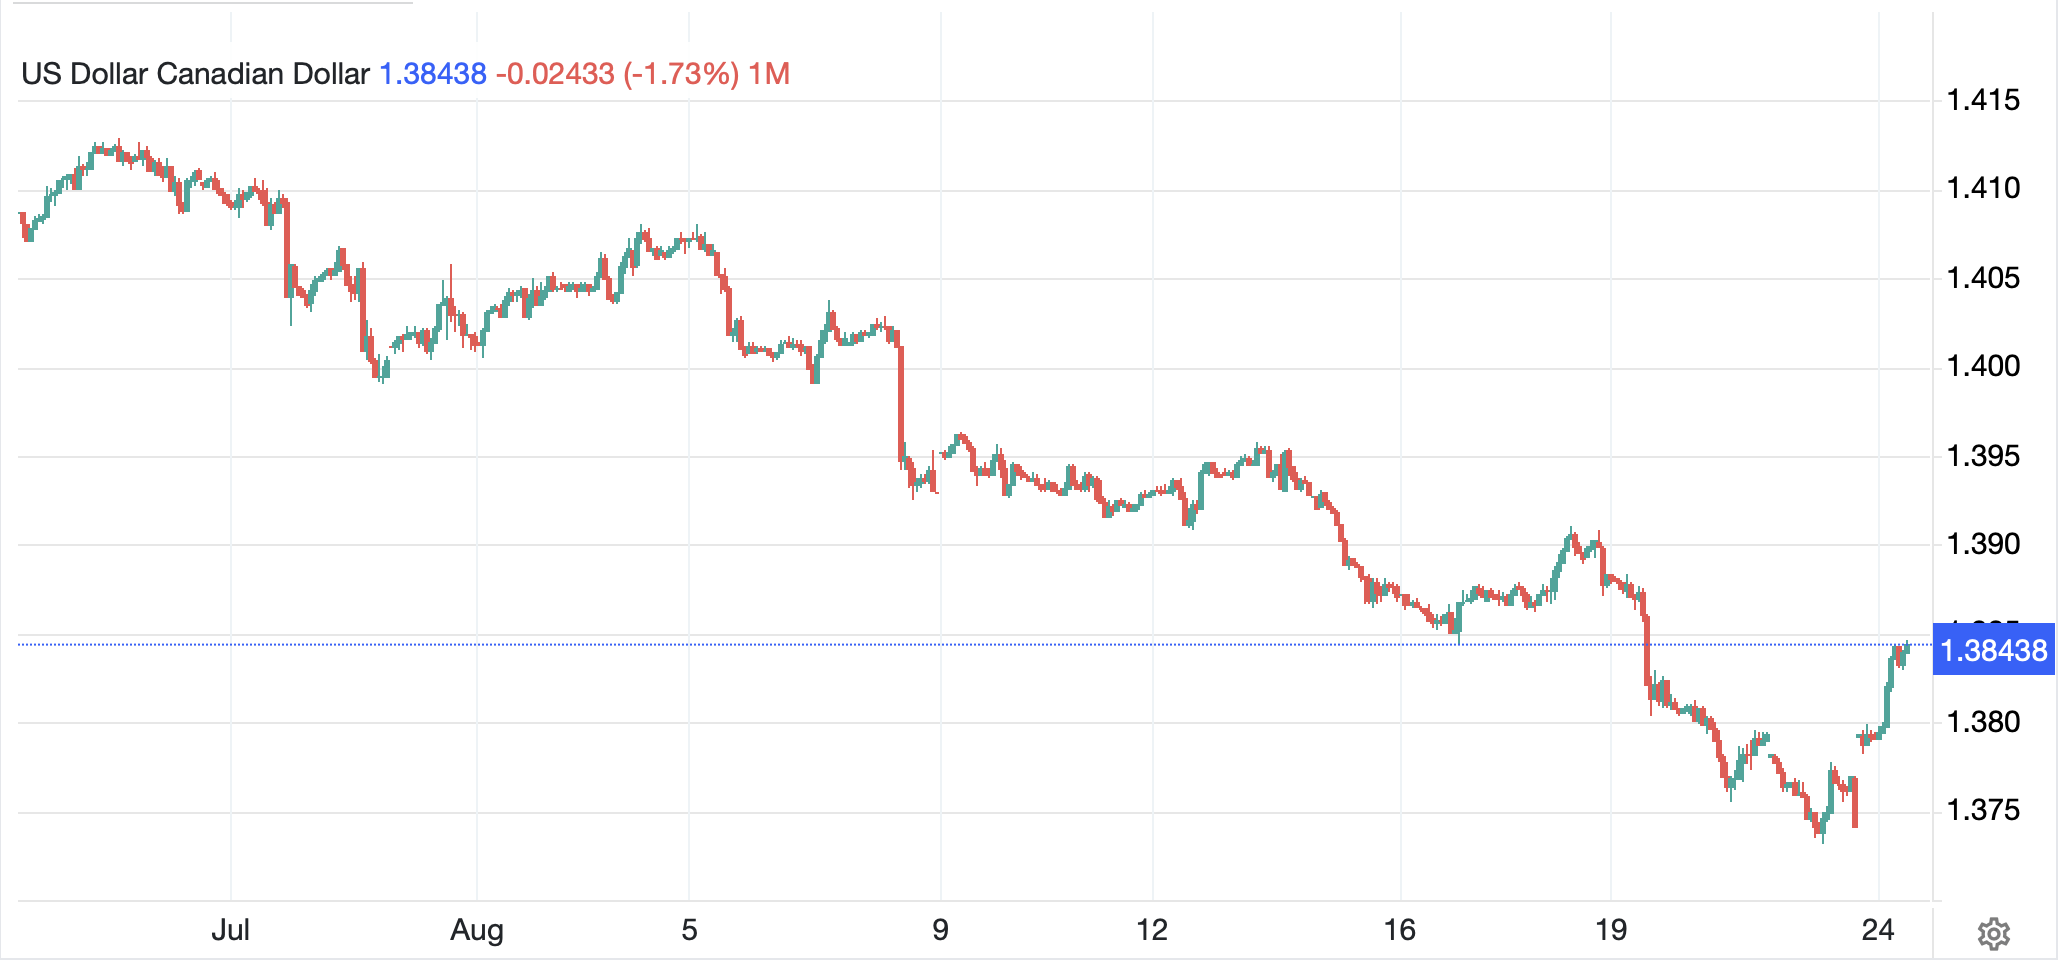
The market’s initial reaction in USDCAD was a slight hit to the Loonie (-0.6%) as you can see in the chart below.  But the CAD has been appreciating over the past month like every other currency vs. the dollar, and this move is hardly breathtaking.  My take is USDCAD remains far more beholden to the broad dollar story with this simply a blip.

Source: tradingeconomics.com

Sticking with the currency theme, the dollar more broadly is a touch higher this morning, with the DXY up 0.2% and modest gains vs. most of its G10 and EMG counterparts.  With the dollar back in the middle of its broader long-term range, it is hard to get excited in either direction at this point.  Certainly, a case can be made that we will see a significant decline going forward if the worst-case scenarios play out, but that is not my base case.  Rather, I have a sense that we are going to remain somnolent in the dollar for a while to come, at least until policies are clearer and that is anybody’s guess as to the timing.

Looking at commodity markets, oil (-2.2%) which spent most of last week rising on increased concerns over Iran and the situation there, has reversed course this morning on two stories.  First, it appears that flows through the Strait of Hormuz have been picking up again as per this article, although it remains very uncertain as to the full amounts.  However, oil is moving.  The second story is the latest set of sanctions that the US is set to impose on Iran and secondary nations that trade with Iran as a means to effectively starve the regime there.  Regardless, lower oil prices are certainly better than higher from a global perspective.

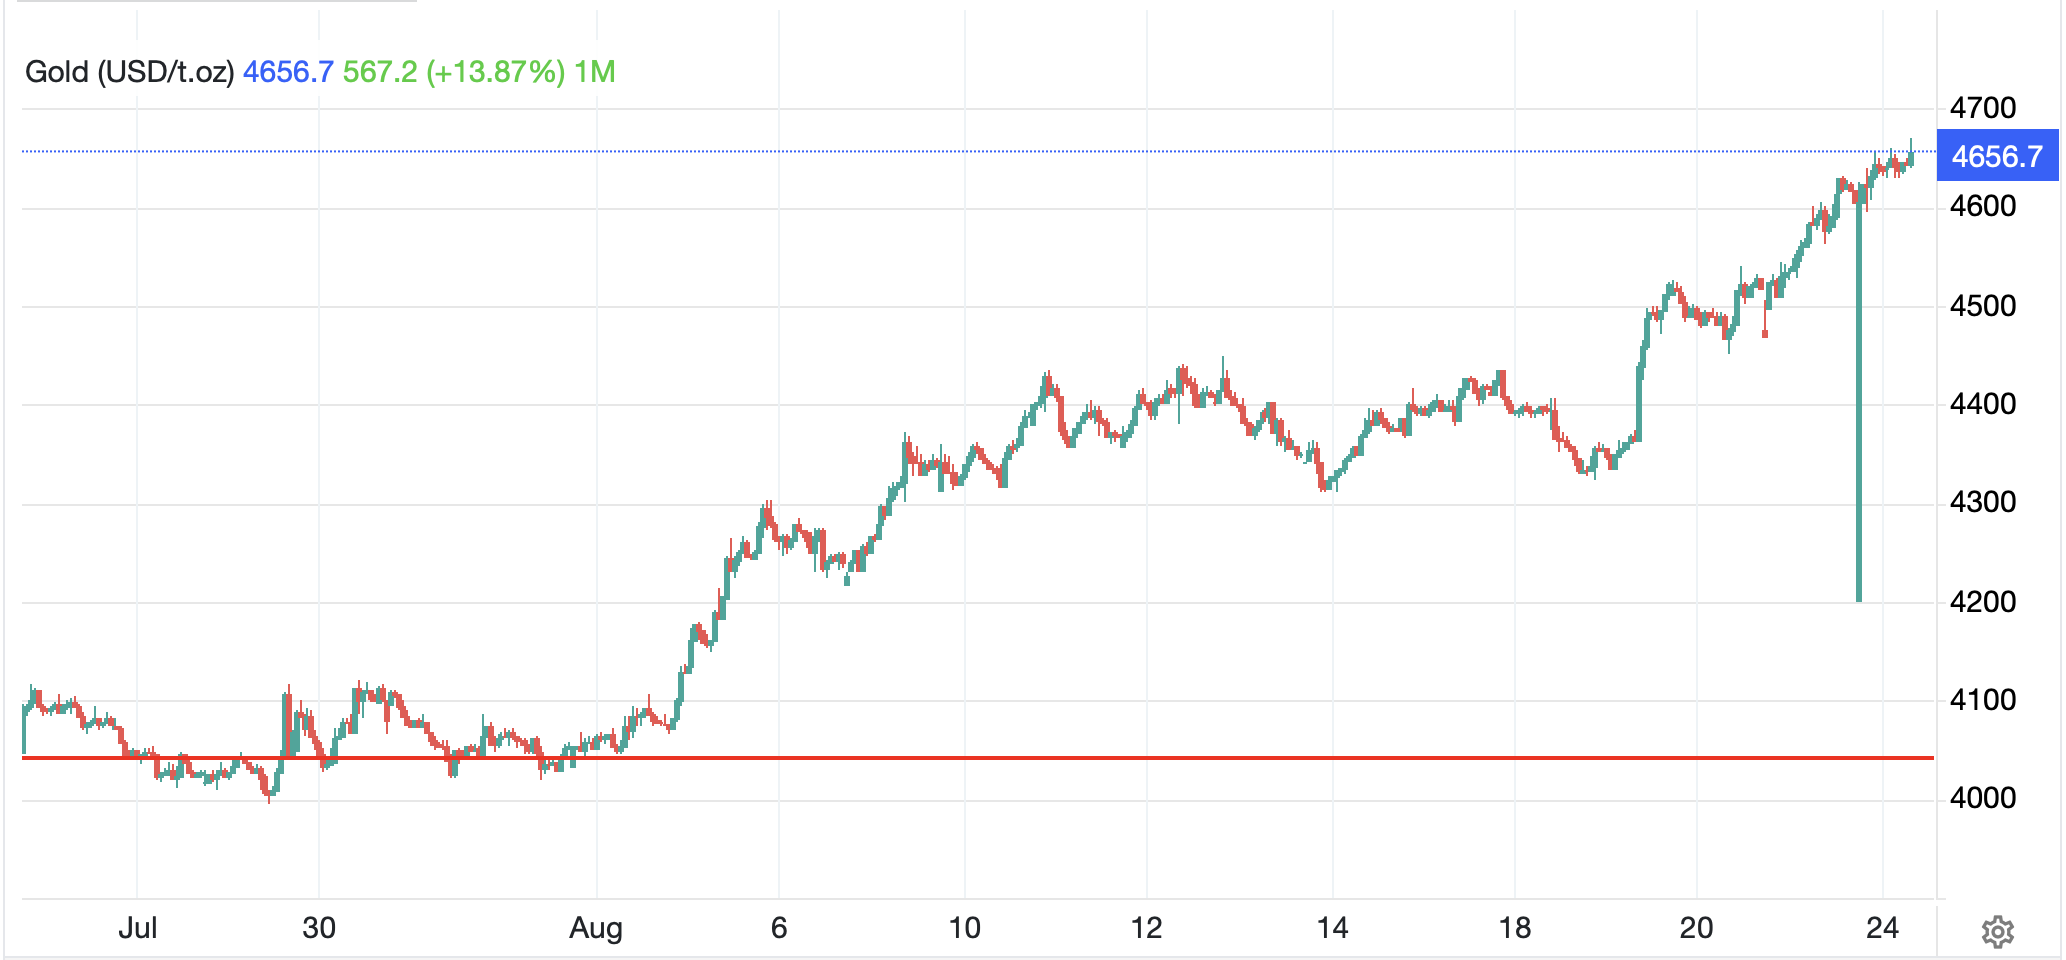
Meanwhile, despite the dollar’s modest strength this morning, the barbarous relic (+1.1%) is higher by 15% since the beginning of August and really appears to be building strength in the move.  Is this related to concerns over fiat currency debasement in the US and elsewhere?  Probably as that 5000-year history of holding value in all times is starting to seem quite attractive.  Not surprisingly, this has helped silver (+0.5%) and copper (+0.1%).

Source: tradingeconomics.com (that green bar on the right appears to be a misprint)

In the bond market, yields are edging lower this morning with Treasuries (-3bps) leading the way and most European sovereigns, as well as JGBs seeing -1bp declines.  Nothing has changed the big picture here with too much government debt being issued around the world, but I have a feeling everyone is waiting for Chairman Warsh on Friday before taking their next steps.

Finally, equity markets which had a decent session in the US on Friday, are more mixed.  In Asia, the big markets all fell (Tokyo (-0.75%, HK -1.9%, China -1.2%, Korea -3.1%, Taiwan -1.0%) with only Australia (+0.5%) bucking the trend on stronger commodity prices.  In Europe, it has been a very quiet session, no surprise at the end of August, with bourses there within 0.2% of Friday’s close.  US futures, though, are being dragged down by tech and the NASDAQ (-0.8%) at this hour (8:05) although the other indices are only marginally softer.

As I’ve run on too long as it is, I will cover data this week tomorrow given there is nothing to be released today.  The oil story and anecdotes about tech are the keys for now absent a major White House surprise, something you can never rule out.

Good luck

Adf
Beguiled

It turns out, inflation of late
Did not start to accelerate
Instead, it was mild
With doves now beguiled
But not yet declaring checkmate

The odds of a hike keep on sliding
But ere the Committee’s deciding
In two weeks, we’ll hear
Chair Warsh try to steer
The narrative with gentle (?) chiding

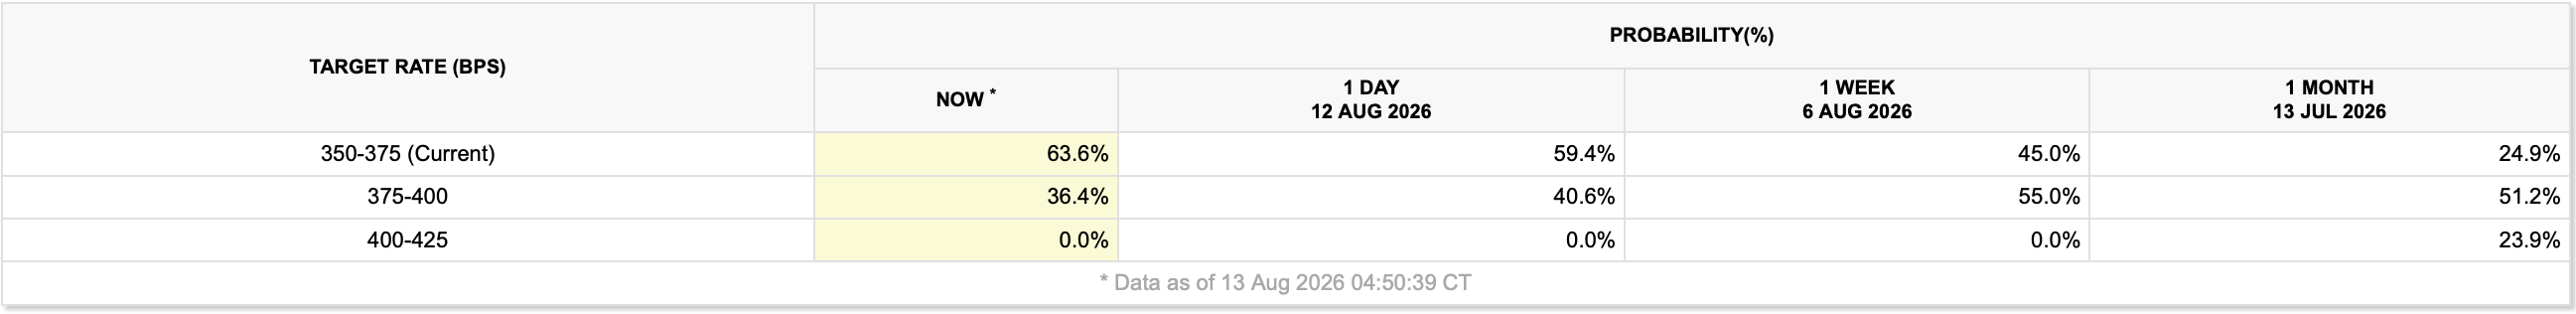
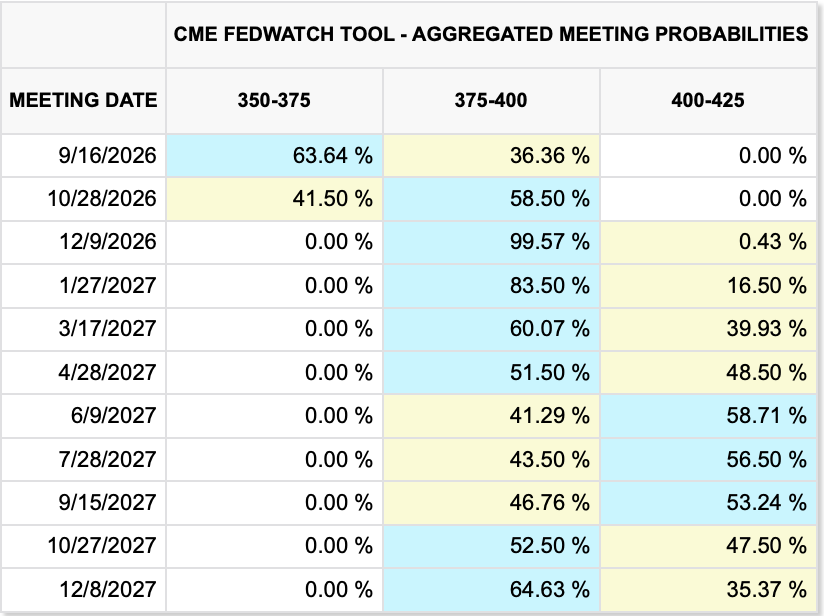
The fears over rising inflation have been allayed for the moment after yesterday’s CPI data was released right on expectations with monthly increases of 0.1% headline and 0.2% core and Y/Y results of 3.4% and 2.5% respectively.  For all those who have been pining for that rate hike ASAP, this was unwelcome news.  The below table from cmegroup.com shows how things have changed over the past month.

On July 13, markets were pricing a 75% probability of a hike in September with thoughts of a 50bp hike a reality.  This morning, the probability of that September rate hike has fallen to just 36%.  You may recall that I have been consistent in my views that there would be no rate hikes this year, and that continues to be my view.  If we look at the entire Fed funds futures curve, as per the next table, we now have one hike priced for December only, compared with two plus hikes several months ago.

This is not to say I believe that inflation is dead, just that it is not accelerating away.  As my friend The Inflation Guy points out in his piece on yesterday’s CPI, the data was boring, “Boring, right on expectations. The bad news is that it is boring and right on expectations…at 3%.”  This is still a far cry from the Fed’s self-defined 2% target, but fears of “Amerizuela” type outcomes are vastly overblown.  (However, you still want to protect you purchasing power and one effective way to do that is via USDi, the only inflation tracking cryptocurrency.)

Now, we still have a bunch more data before the next FOMC meeting, including today’s PPI, PCE at the end of the month and another NFP and CPI reading in September.  As well, we cannot forget that Chairman Warsh will have the opportunity to clarify his thinking at the Jackson Hole soiree on Friday morning, August 28th.

So, has anything really changed that much after the CPI report?  While the reality hasn’t shifted, it does appear that market participants are beginning to adjust their views a bit.  One number does not a trend make, nor will it have bolstered Warsh’s credibility, assuming that is in question, either.  This is a saga that will continue to play out over time.  It seems to me that if the Fed really wanted to fight inflation effectively, they would be digging much deeper into why they continue to hold >$1.9 trillion in MBS on their balance sheet and run an ample reserves framework.  Going back to scarce reserves allows the market to drive interest rates, something clearly on Chairman Warsh’s wish list.  But that will have to wait for the task force reports.

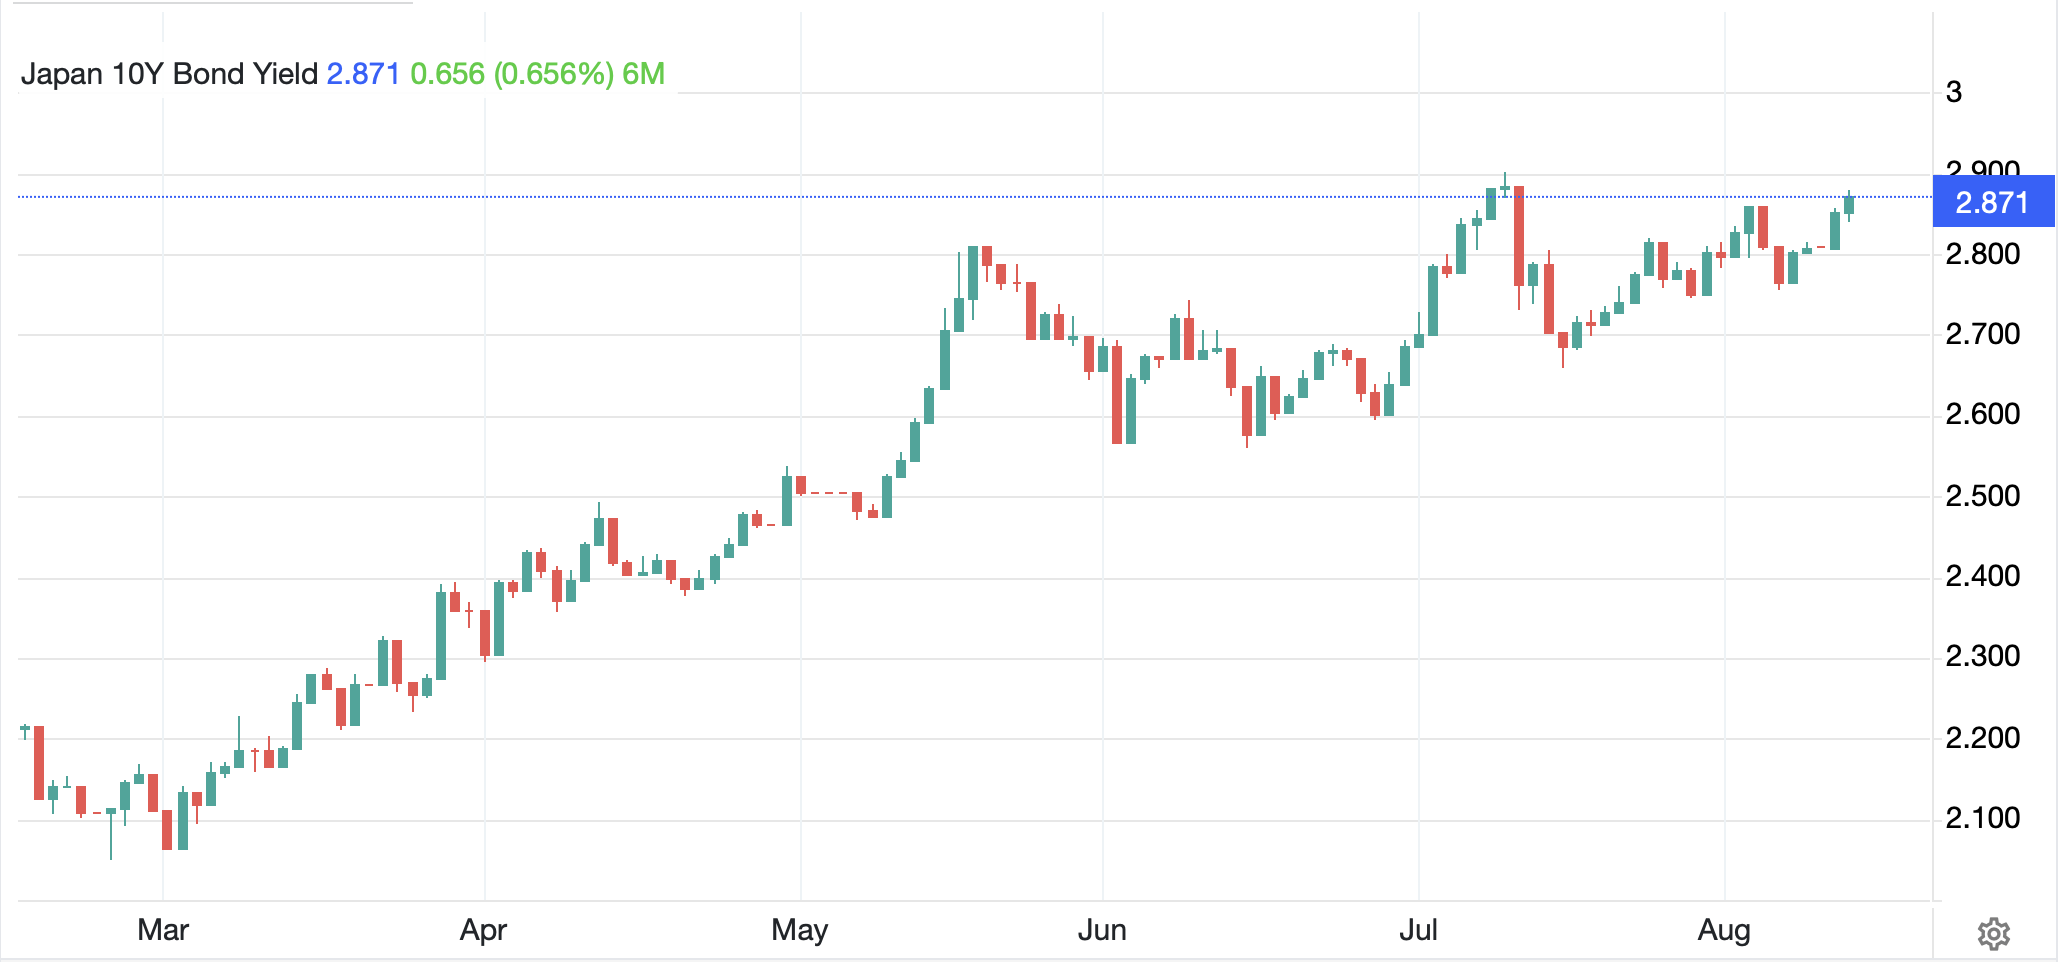
Ok, let’s see how markets other than Fed funds have responded to this news and data.  Since we are on the rates subject, let’s start there this morning with bonds which have seen yields slip -2bps in Treasuries and between -1bp and -3bps in Europe.  Oil prices (-2.1%) are slipping this morning so that appears to be the proximate cause of the yield move, a bit less concern over inflation.  Yesterday, after the CPI data, we also saw Treasury yields drop -2bps, so for now, fears of an imminent test of 5.0% on 10-year Treasuries seem overblown.  JGB yields, though, continue to creep higher, another 2bps overnight and are now just 3bps below their multi-decade high of 2.90% as per the chart below.

Source: tradingeconomics.com

Speaking of Japanese rates, Bloomberg has an article this morning explaining that the Takaichi administration is ok with the BOJ raising rates sooner, a change in the market’s perspective if not an outright change of view there.  Alas for those looking for a stronger yen and the end of the carry trade, the impact of the report was essentially nil as you can see in the chart below.  The three large, red candles just to the right of center represent the immediate aftermath of the release of the report.  Net, USDJPY is virtually unchanged on the day and the trend since the intervention remains for the dollar to move higher.  My sense is perceptions of Fed rate activity is going to have a bigger impact than the BOJ for now.

Source: tradingeconomics.com

As to the rest of the FX market, +/- 0.2% covers the gamut for both G10 and EMG blocs.  It wasn’t just the CPI report that was boring, so are FX markets overall.

Turning to equities, yesterday’s US market response was benign with only the NASDAQ showing much life, gaining 0.5%.  In Asia, though we did see Tokyo (+1.1%) rise despite talk of the BOJ being more aggressive.  Of course, the real price action remains in Korea (+3.6%), which is redefining what equity index volatility actually means.  Otherwise, there were some gainers (Taiwan, New Zealand, India) and more laggards (China, HK, Australia, Malaysia, Indonesia) but none of these moves topped 1% in either direction.  

European bourses, however, are feeling a bit better this morning led by Spain (+0.7%) and Germany (+0.5%) as earnings seem to be the driver here helping Spanish shares despite the tick higher in inflation there.  UK shares (-0.2%) are lagging after GDP and production data was on the disappointing side while the Trade Deficit expanded further.  And at this hour (7:30) US futures are little changed to slightly higher.

Finally, turning to commodities, oil’s decline seems to be attributable to the IEA reducing its global oil demand outlook (although they have been wrong about this for several years as they try to push a peak oil, transition to wind/solar narrative that is just not happening) as well as the fact that yesterday’s EIA data showed a 17+mm barrel build, a far cry from the slight draw expected and another blow to the tank bottoms story.  As to the precious metals, the luster is gone (Au -0.5%, Ag -0.6%, Cu -0.5%) although copper remains quite close to its all-time highs, and both gold and silver remain in short-term uptrends after seemingly having bottomed back in July.

On the data front, this morning brings the weekly Initial (exp 202K) and Continuing (1800K) Claims data along with PPI (0.2%, 4.9% Y/Y) and core PPI (0.3%, 4.2% Y/Y).  It strikes me that neither of these releases are going to be major market movers.

It is summer, and I assure you trading desk vacation schedules are far more important than secondary economic data releases.  I suspect another boring day overall here.  In fact, I suspect that until Warsh speaks in two weeks, we may see very little activity across most markets.

Good luck

Adf
They Mostly Confuse

We’re back to the Strait of Hormuz
As driver to all traders’ views
Both Trump and Iran
Have proffered a plan
But really, they mostly confuse

The, otherwise, story of note
Is coming as CPI’s quote
If hot, Chairman Warsh
Will field comments, harsh
If cool, he’ll be able to gloat

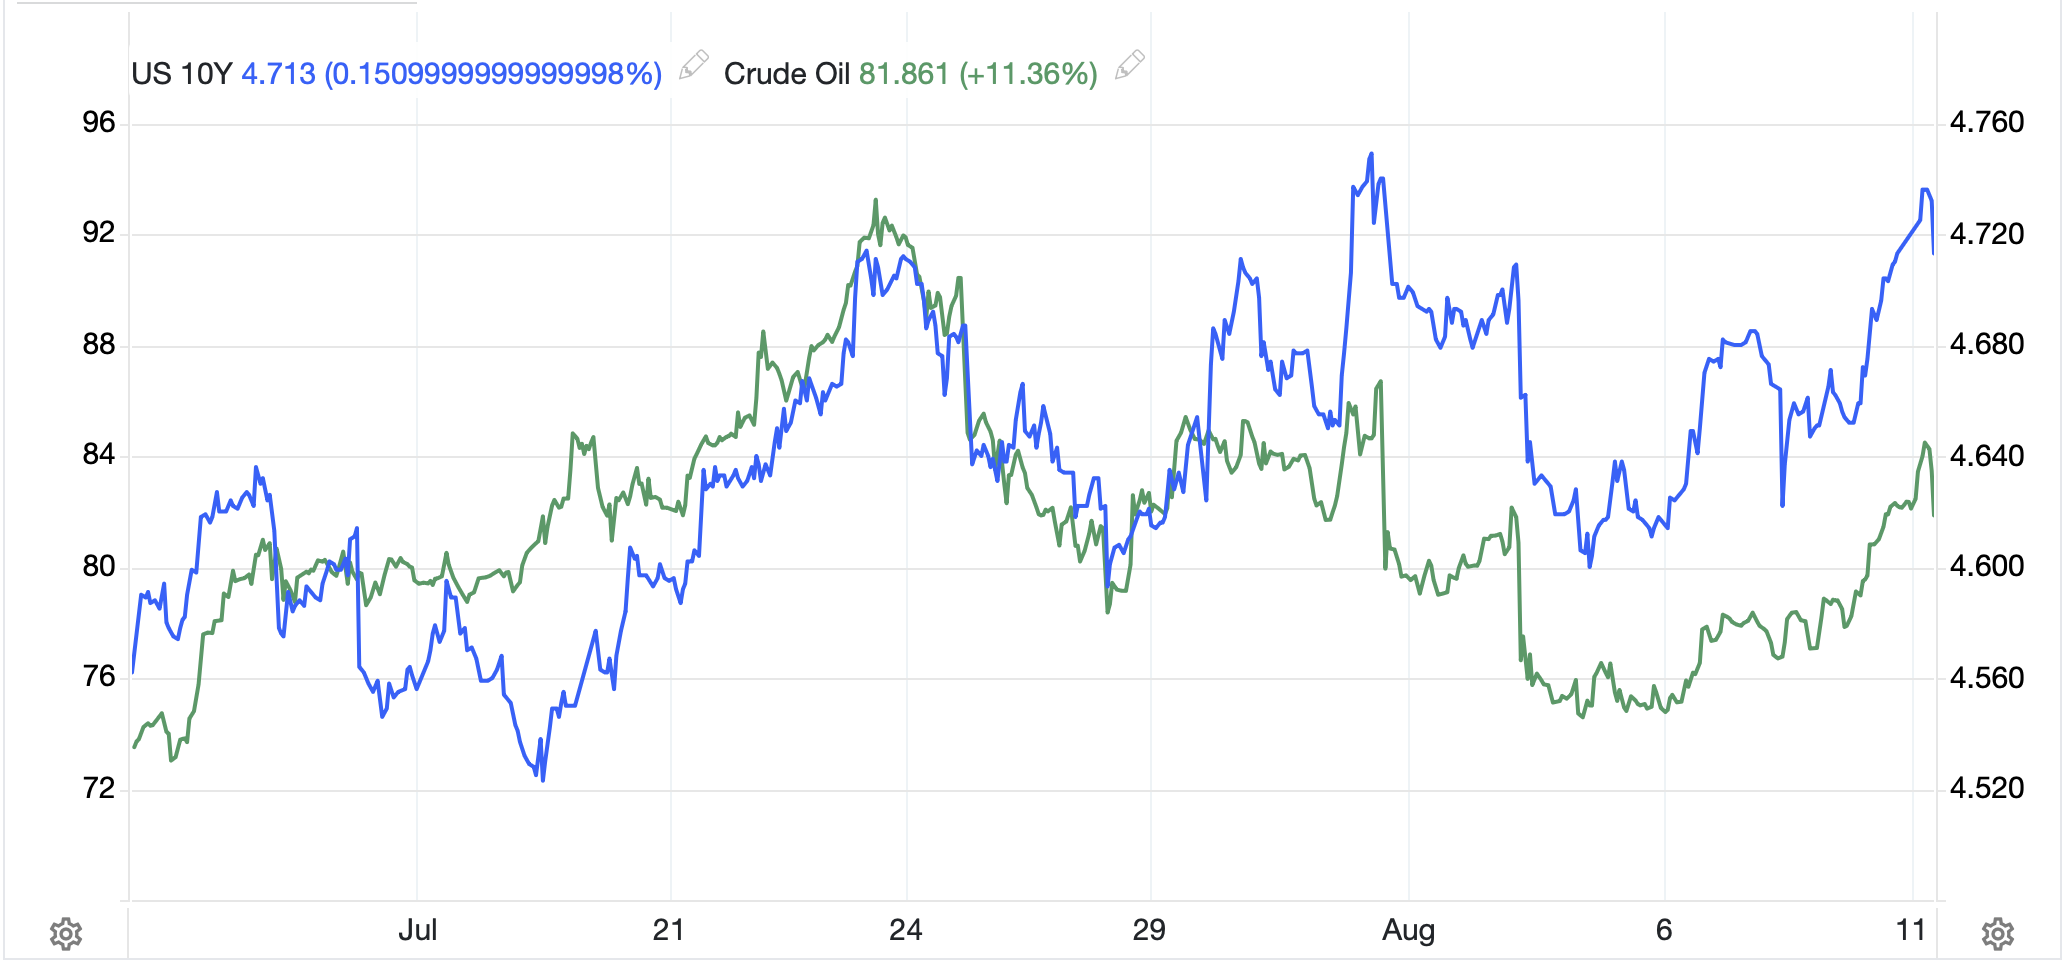
Oil prices (+1.5%) are higher again this morning and have now been up five consecutive sessions, rising 10% in that run as you can see in the chart below.

Source: tradingeconomics.com

There is a theory that the rhetoric in Iran increases when they have oil to sell so need higher prices, but once those cargoes have been sold, they talk peace again.  I don’t think you can rule out that hypothesis although I certainly have no corroborating evidence it’s true.  The one thing I did note yesterday is an Iranian comment that as long as sanctions remain, diplomacy cannot happen which tells me that economic sanctions are biting harder.  Whatever, the situation on the ground (or water) is over there, I have no insight per se. 

Much has been made over the fact that the SPR is at its lowest level since 1983 and has fallen below 300 million barrels with all the attendant pearl clutching while simply ignoring the fact that the SPR releases have been oil swaps with the back ends starting to come back in the next several months in greater amounts than have been released.  Maybe the end is nigh regarding oil, and the doomsters will get their $200/bbl outcome, but I would still take the under there.

In sync with the oil price rise we have seen yields rise, as well (see chart below), around the world.  But here, it appears that Chairman Warsh is the favored scapegoat for all the world’s inflation problems.  To hear his critics explain, if only he would give us forward guidance, everything would be fantastic.  Hedge funds could load up on leverage and increase their profits, real money investors would be comfortable that future real returns would be acceptable and, most importantly, the punditry would be able to explain all this to us plebes and burnish their beliefs in their own brilliance.

Source: tradingeconomics.com

But I wonder if there is not another explanation for rising yields that has nothing to do with the Fed, the idea that debt issuance, from both government and private sources, is growing dramatically and all that supply is weighing on prices, hence driving up yields.  We already know that governments around the world continue to issue debt willy-nilly, so there is nothing to discuss there.  But now the AI hyper scalers are issuing massive amounts of debt to pay for all the GPUs and data centers and power as the race to “win” in AI continues at an increasing pace.  

It is, of course, this last issue which has many pundits explaining that QE will soon reemerge as the only viable way for all that debt to get bought.  If central banks buy government debt that will leave funds for private investors to buy AI related debt.  And maybe that is the way it will work out although Chairman Warsh has thus far only discussed shrinking the balance sheet, not expanding it.

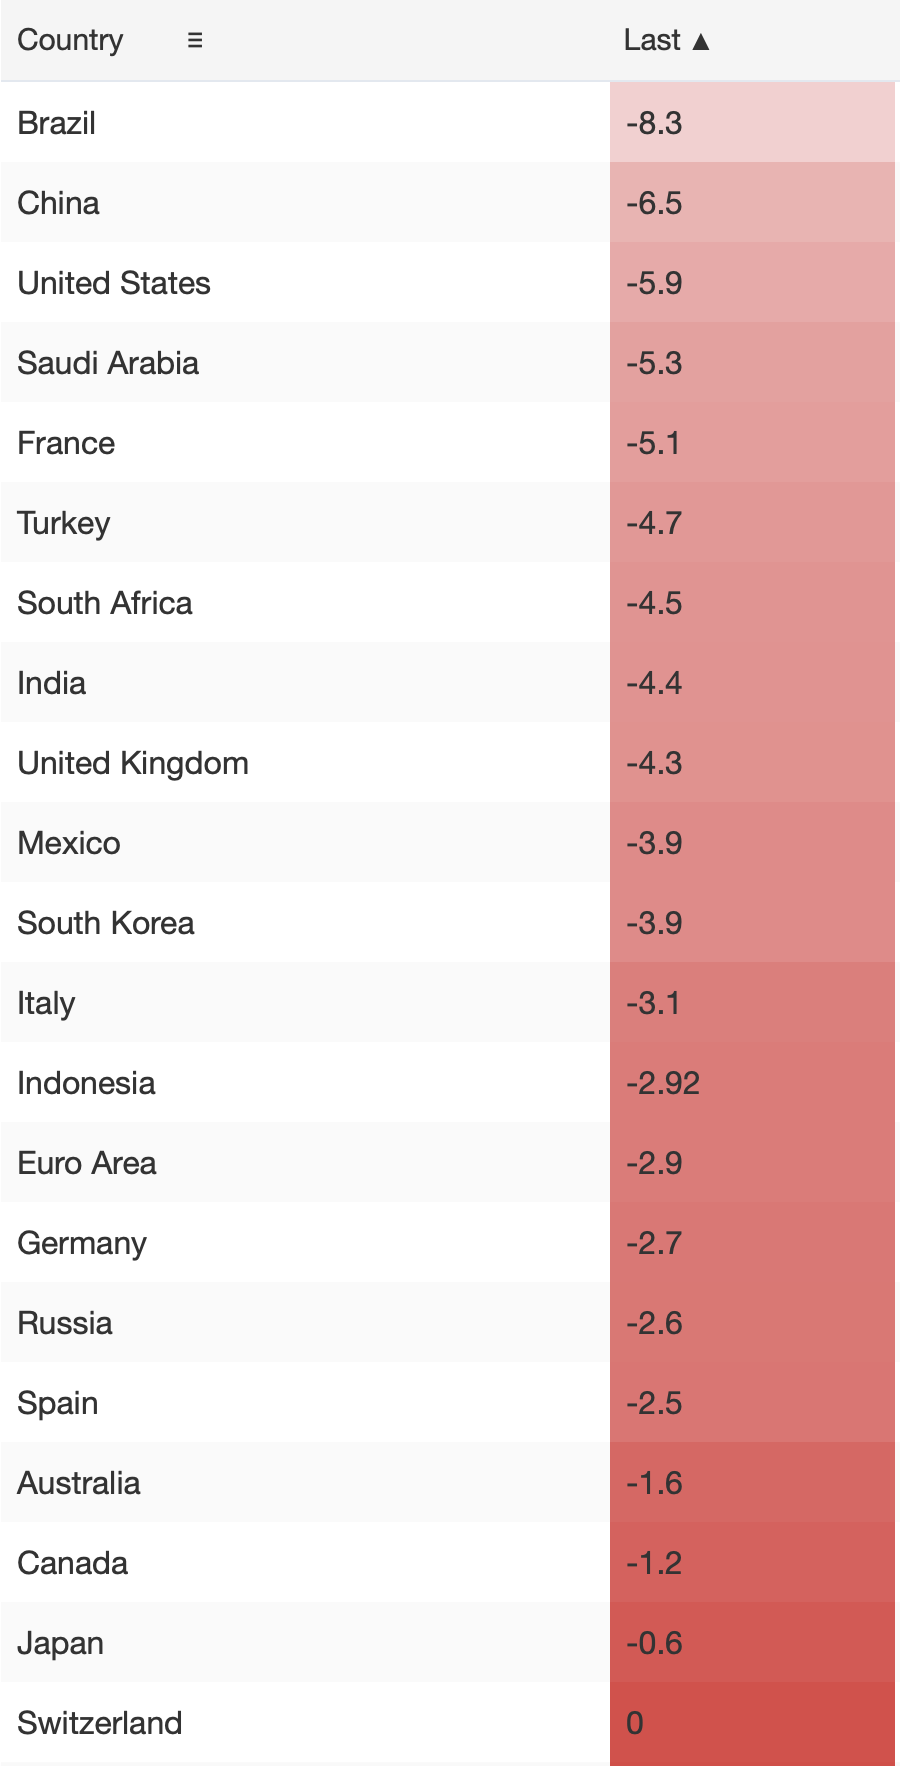
Please understand I am not ignoring the many serious problems that exist within the current fiscal and monetary frameworks around the world.  Government spending remains excessive as evidenced by the fact that virtually every nation in the world is running significant budget deficits as per the below table from tradingeconmics.com (notice China, a country that seems to get a pass on this score from the punditry).

All I am saying is that the idea that all of this is going to fall apart quickly is highly improbable.  As much as purists would like for there to be consequences for bad policy decisions, governments everywhere have an enormous number of tools to delay the pain, and they use them all the time.  Whether that is subsidies or tax cuts or regulations prohibiting competition, all these things substitute short-term gains for long-term problems.  But they will still be used regularly.

So, to recap, increasingly hawkish rhetoric on the Iran situation has driven oil prices higher which is increasing inflation concerns.  Adding to that is the ongoing fiscal profligacy of virtually every major government which is also weighing on bond prices and driving yields higher in sync.  And basically, the punditry has decided it’s all Kevin Warsh’s fault.  Too much will be made of tomorrow’s CPI report, whether it is hot or cool, that is the one things of which I am certain.

Ok, yesterday’s lackluster US session with all three major indices slipping a bit was followed by weakness in China (-0.8%) and HK (-1.1%) but elsewhere in Asia, things were mixed with Korea (+0.7%) gaining and the other regional bourses generally +/-0.5% or so.  Tokyo was closed for Mountain Day and the only other news of note from the region was the RBA left rates on hold at 4.35%, as expected, but expressed concerns about both slowing growth and future inflation.  Interestingly, Australian stocks were slightly higher despite that news, +0.2%.

In Europe, Spanish stocks (+0.5%) are the leader on the strength of Banco Santander’s share repurchase announcement while the rest of the continent and the UK are little changed.  As to US futures, at this hour (7:35) they are little changed.

While we have broadly discussed bond yields rising, and yesterday they were higher by 4bps-5bps in the US and Europe, this morning they are unchanged across the board.  Now, they were higher again this morning when I started to write, but it seems there was just a comment from Pakistan that the US and Iran are close to an agreement which has turned things around.  Oil prices, too have slipped back to unchanged on the day from an hour ago.

In the metals markets, gold (-0.2%) and silver (-0.9%) are backing off solid sessions yesterday and copper (+0.8%) continues to march higher.

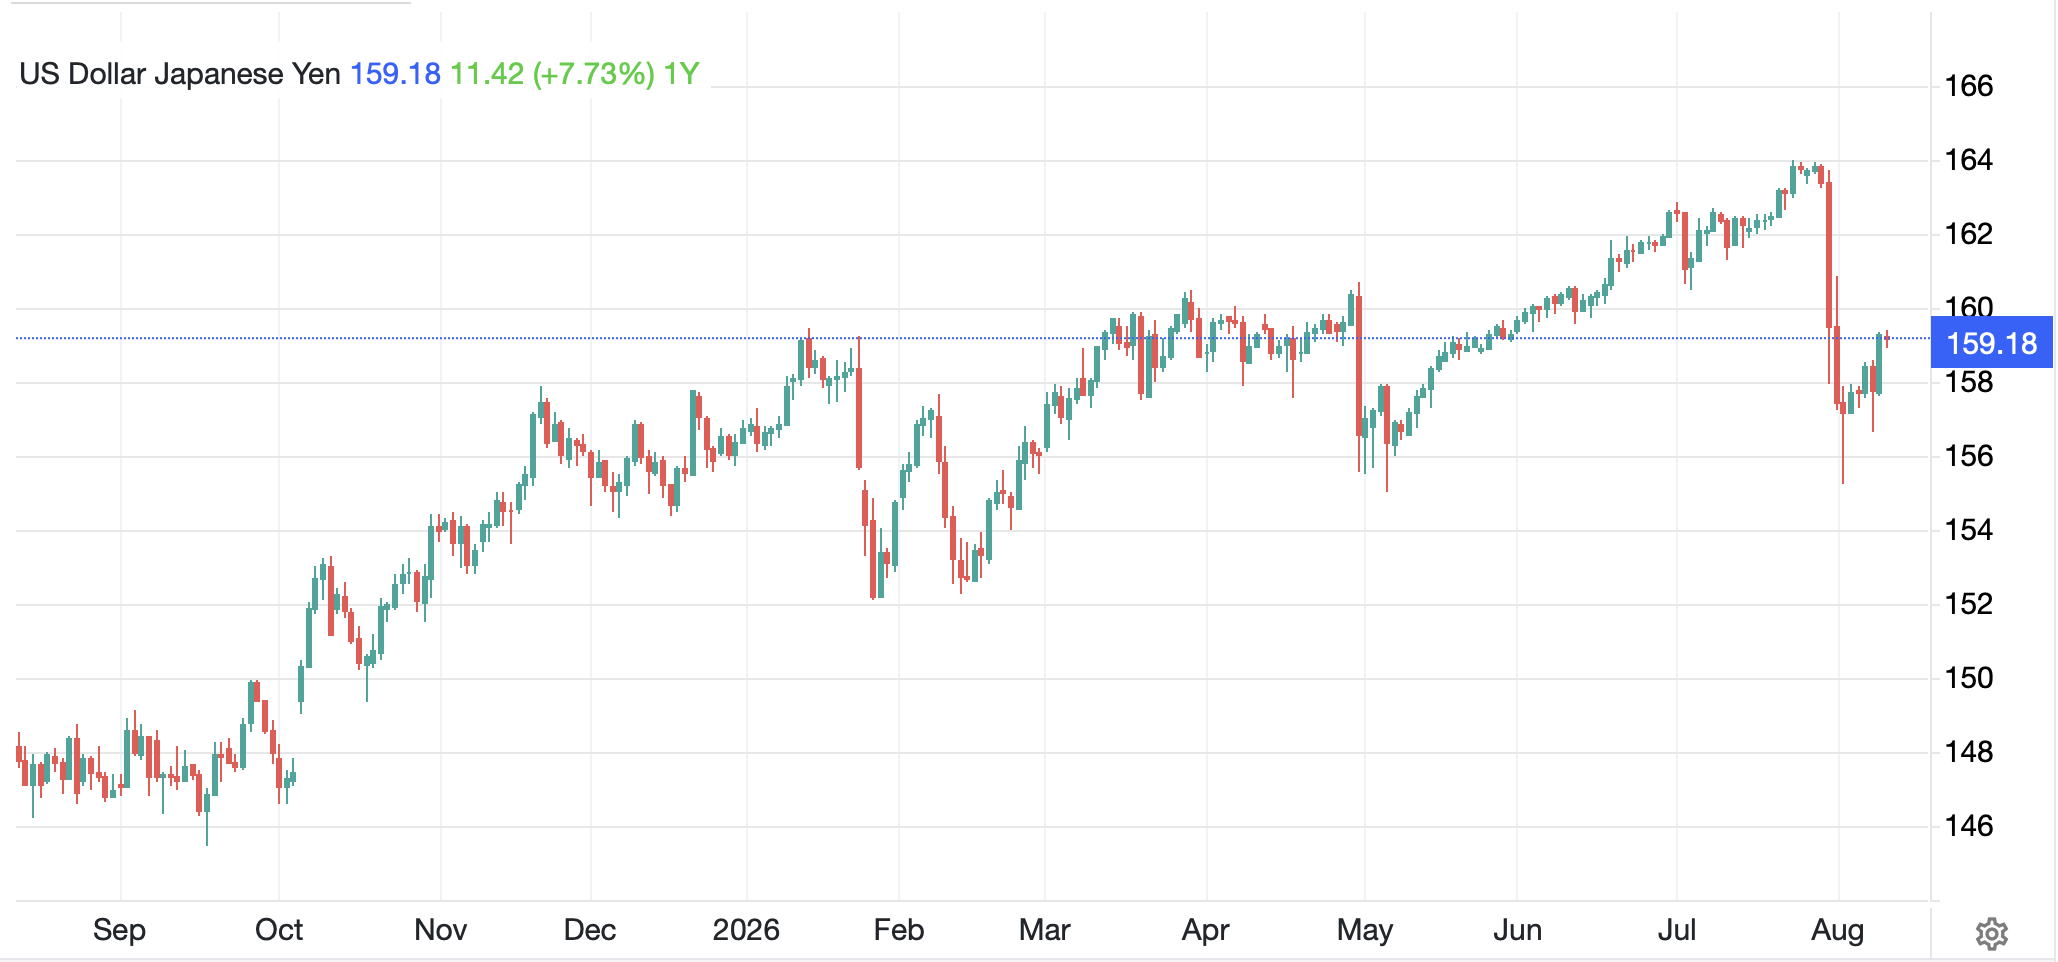
Finally, the dollar is, net, little changed this morning, although we cannot ignore the fact that the yen fell -1.0% during yesterday’s session.  In fact, a look at the yen chart continues to show the market response to intervention, an immediate rally and a gradual decline resuming.

Source: tradingeconomics.com

As to the rest of the space, KRW (+0.3%) is the actual largest mover today, and that is not enough of a move to spin any story.  The DXY remains just below 100 and firmly within its yearlong trading range and some pundits are saying the fact that it is not rallying during the current conditions, with yields rising and fear all about, is an indication that the dollar is losing its status.  However, I am confident if you offered those same pundits payment in dollars, they would grab them as greedily as possible!

On the data front, this is inflation week plus a few more things as follows:

TodayExisting Home Sales4.05M
WednesdayCPI0.1% (3.4% Y/Y)
 Ex food & energy0.2% (2.5% y/Y)
ThursdayInitial Claims202K
 Continuing Claims1800K
 PPI0.2% (4.9% Y/Y)
 Ex food & energy0.3% (4.2% Y/Y)
FridayRetail Sales0.1%
 -ex autos0.2%
 Michigan Sentiment54.5

Source: tradingeconomics.com

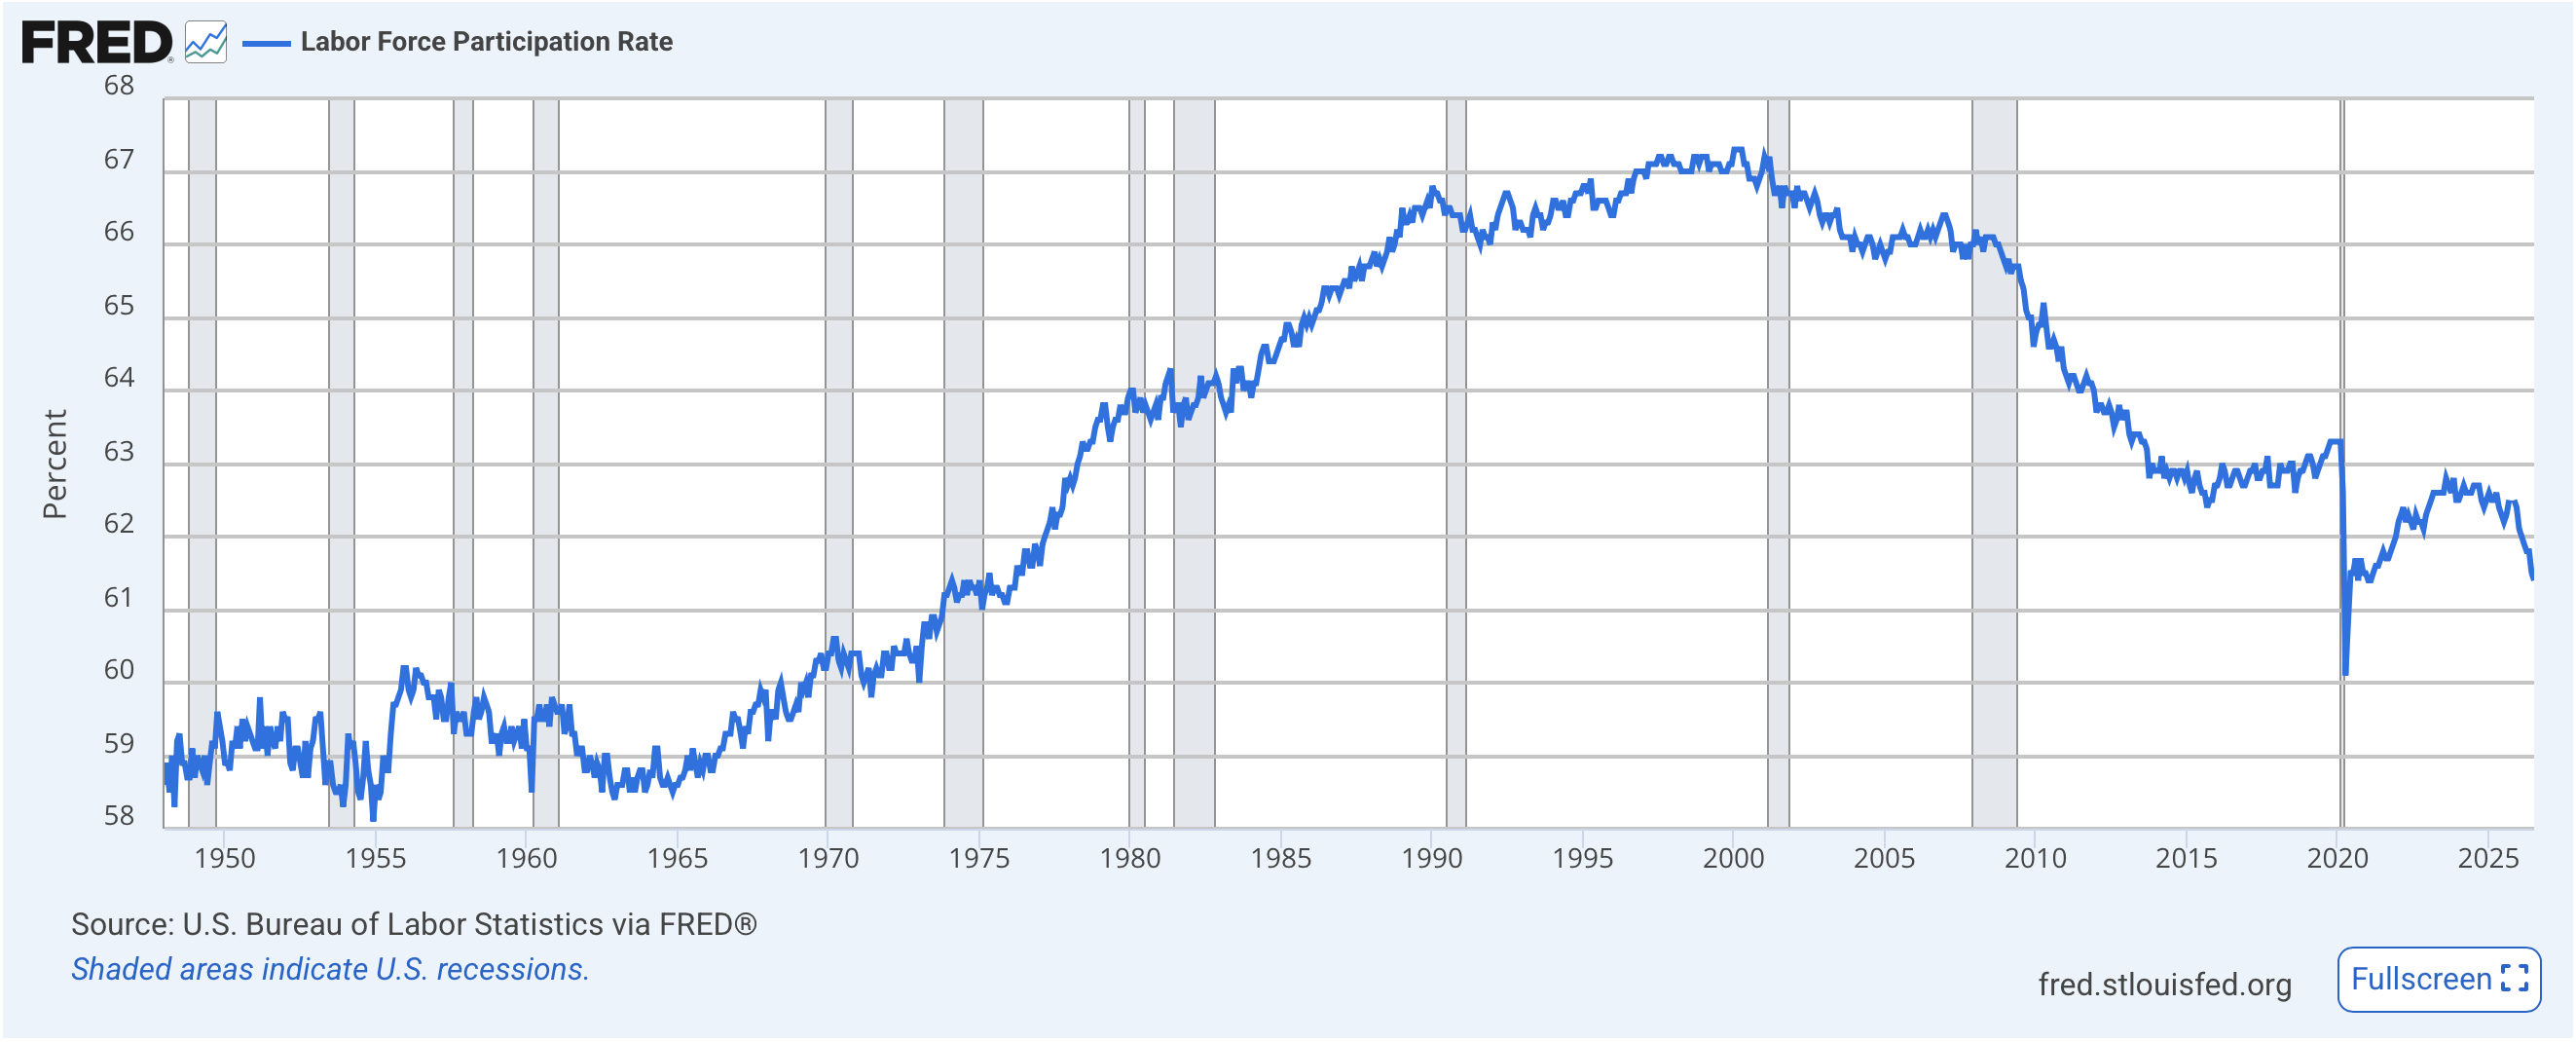
Obviously, all eyes will be on CPI tomorrow as investors and analysts look for clues as to how the Fed may behave going forward.  Speaking of the Fed, Cleveland Fed president Hammack said in an interview yesterday that she thought the Fed needed to raise rates more than 25bps to get inflation under control.  But as I think about the Fed and its dual mandate, of maximum employment and stable prices, I cannot help but wonder what they consider maximum employment.  While they have defined stable prices (incorrectly in my view) as Core PCE rising 2.0% per annum, they have never tied themselves to a number on employment.  So, here’s a thought.  Look at the Labor Force participation rate, which as per the data last Friday fell to 61.4%, that is the lowest level since 1975 (excepting Covid) as per the below chart from FRED.

That hardly seems maximal, but then, I’m just an FX guy, not a Fed PhD.  After all, if we take the plain meaning of the word maximum, as per the American Heritage Dictionary, I cannot look at the chart above and conclude they have achieved that part of their mandate either.

But that’s just me.  Anyway, if there is going to be movement on the Iran story, that will drive the immediate market movements, but you can be sure that in the current environment, it will all come back to the Fed and whatever they may do going forward.

Good luck

Adf
Investors Are Troth

The doom mongers are up in arms
As though they raise many alarms
Investors don’t care
And add risk with flair
Ignoring the much-mooted harms

So, war is no longer concerning
And though hyperscalers are burning
Through all of their cash
Amid much backlash
Investors, their shares, are still yearning

And what about data and growth?
Investors care naught about both
Concerns about yen?
Not that trope again!
To stocks most investors are troth

As I read through my X feeds in the morning, as well as the WSJ and Bloomberg, the overriding theme appears to be the end is nigh.  Whether discussing Iran and the oil price and the future of the Strait of Hormuz, AI and the bubble or the potential for massive job losses and the creation of Skynet, the economic data and the incipient recession coming because people cannot afford to continue their consumption habits, or the idea that we are on the precipice of a Treasury bond market collapse because the Japanese yen is weak, the dominant theme is disaster is around the corner.  It is really tiresome, I have to say.

Now, you might say that I simply follow the wrong people, and that may be true, but my feed hasn’t changed, and I never look at the algorithm’s selections for me, I only look at my followings.  So, I cannot tell if people have become that much more bearish on the overall situation, or if they simply write these things because they believe they will get more engagement.  I fear it is the latter, but that simply devalues anything useful they may have to say.  Mostly, it’s frustrating to try to get an unbiased sense of what is happening in the world these days.  After all, while I understand that governments put out propaganda constantly, I thought the idea behind X and Substack was you could avoid that.  I think I am going to go back to reading books!

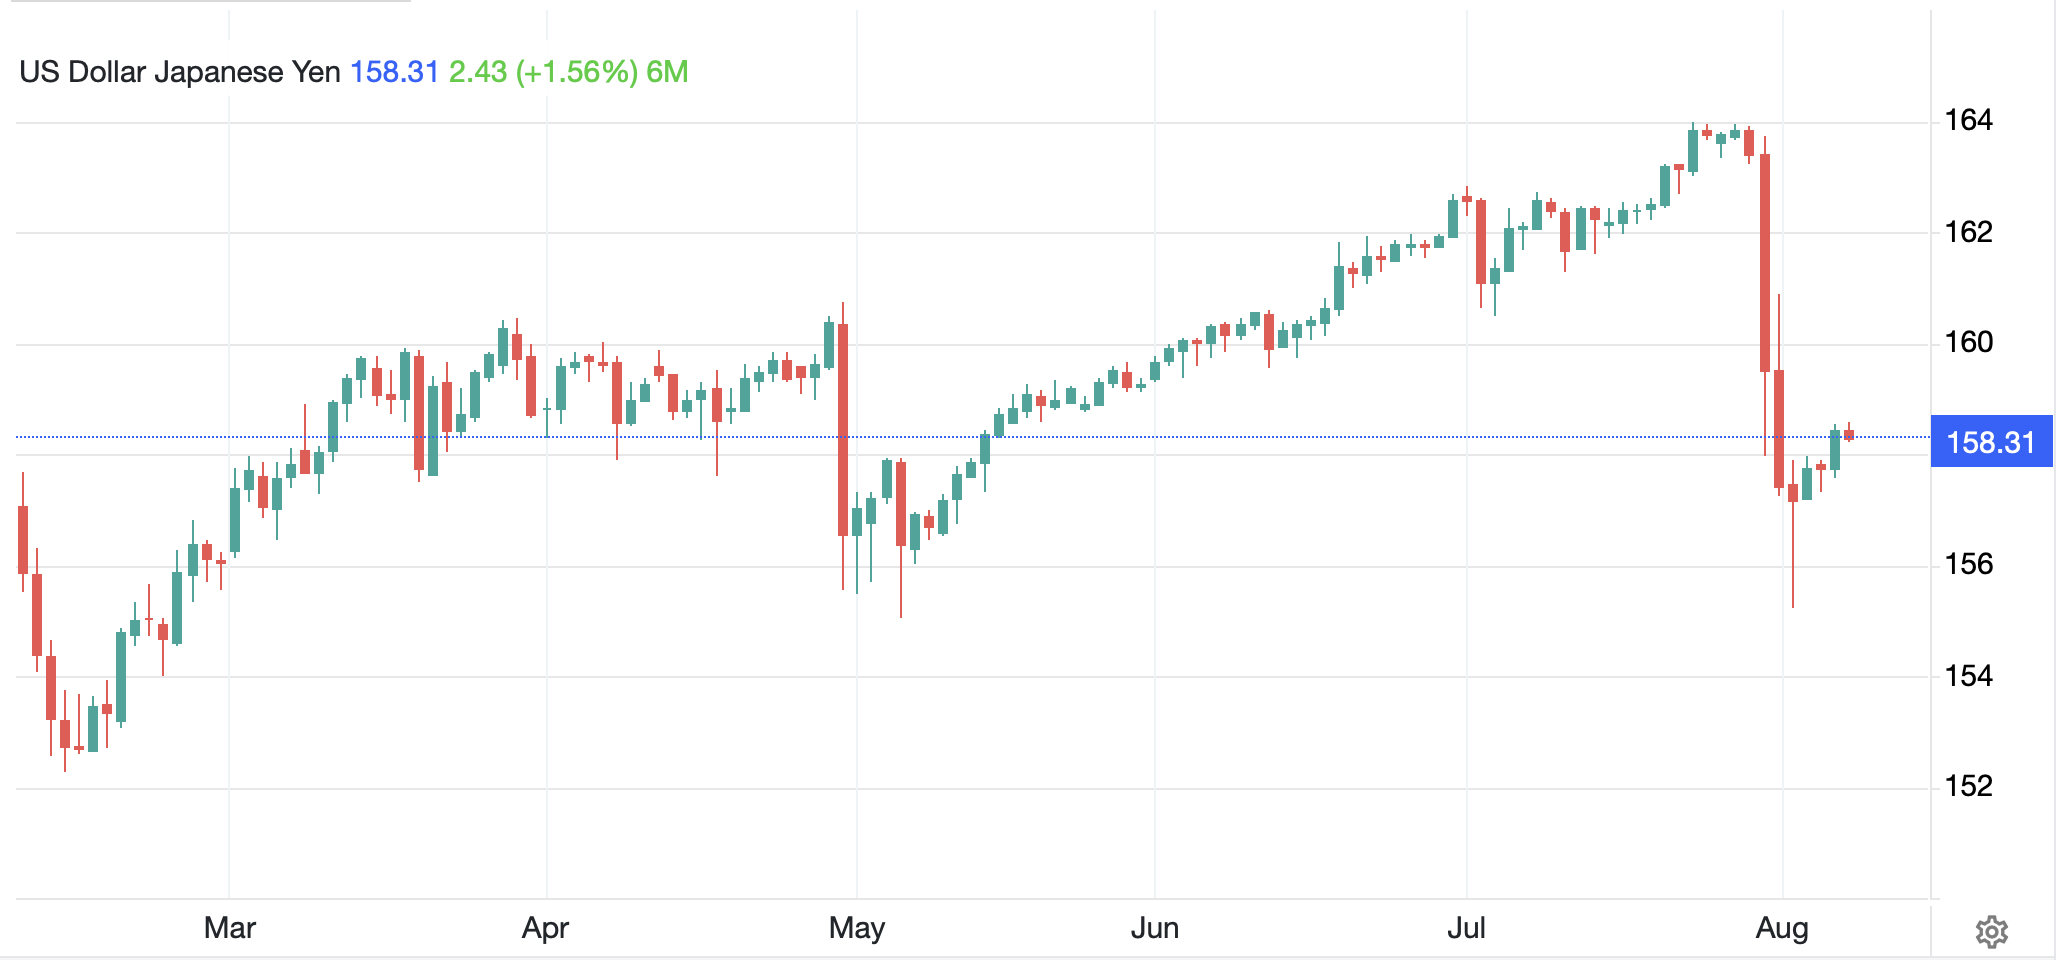
So, as we await this morning’s payroll report, I’ll try to touch on the key issues I believe matter.  Starting with the yen, which continues to garner attention, or more accurately, the joint intervention garners attention, I first have to laugh at the following Bloomberg headline, “Yen Surrenders Nearly Half Its Gains From US-Japan Intervention”.  This was written by Mia Glass, and I don’t know anything about her except her grasp of arithmetic is tenuous.  Here is the chart of USDJPY and while the yen has been weakening steadily since the intervention last week, half?  Even taking the spike low into account, we are nowhere near a 50% retracement and on a closing basis, it is a ridiculous claim.

Source: tradingeconomics.com

There continues to be much fodder made about Secretary Bessent trying to prevent a meltdown in the Treasury market but Occam’s Razor tells me that it is far more likely that a too-weak yen is bad for Japan because of its inflationary impact and the US because it impedes US exports so joint intervention made sense.  And as I have maintained all along, unless underlying fiscal and monetary policies change, the yen is going to continue to weaken.

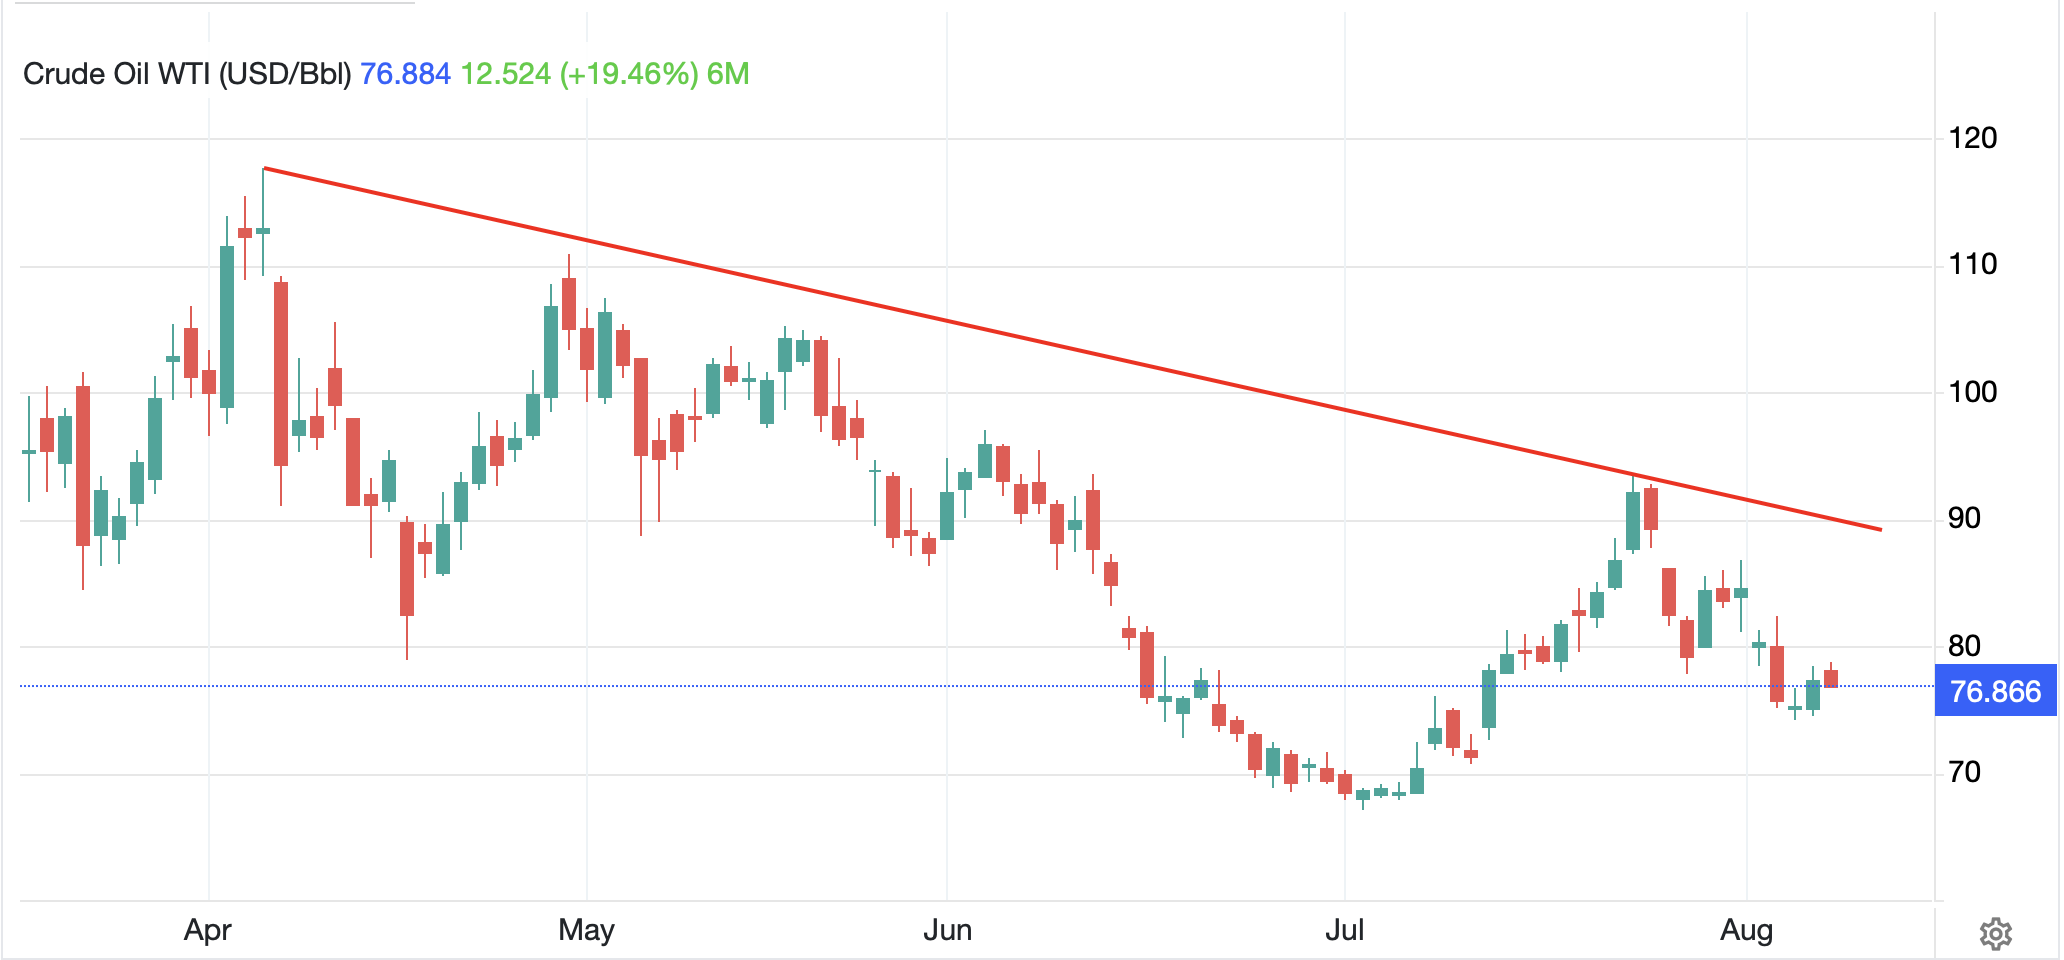
Turning to Hormuz, the press continues to write with glee about President Trump’s miscalculation and the US losing the war and whether Iran and Oman are going to come to some agreement on the Strait, but oil prices, while they rallied a bit yesterday, are lower this morning by -0.6% and -9.25% in the past week.  Looking at the chart below, despite all the discussion of inventory depletion, which are real, but obviously not as important to the price as many previously believed, the trend remains downward and we are well below the trend.  Frankly, at $75/bbl, it appears the world works fairly well.

Source: tradingeconomics.com

Look, I would rather pay less for my diesel, and I know you would all like to pay less for your gasoline, but here’s a 20-year history of the RBOB (NYMEX gasoline) contract.  We are hardly in unprecedented territory having spent a lot of time around here from 2011 through 2015 as well as the beginning of the Russia/Ukraine war.

I have no idea how things will end up in Iran, nor does any other commentator.  I know I am happier if Iran does not have a nuclear weapon and ballistic missiles that can reach Europe, let alone the US.  But I would say the market has almost lost interest in the war.

As to the hyperscalers and the AI bubble, in truth, it seems much of the animosity has been turned toward SpaceX as everyone loves to hate Elon almost as much as they love to hate Trump.  But it appears by many metrics that equity markets continue to benefit across the board from strong earnings results, with ~85% of companies (depending on your source) beating estimates which is well above the average of 77%.  So, the economy continues to grow pretty strongly, and companies continue to make money, and investors continue to want to buy shares.  The hyperscalers aren’t leading the pack anymore, but they have not collapsed either.  There are many who continue to explain this cannot go on forever and there will be a reckoning, and they may well be correct, but in this case, being early and being wrong are the same thing.

Ok, enough of that.  Let’s see if anything noteworthy has happened overnight.  The truth is, not especially.  Asian shares were mixed with Chinese shares doing well after solid trade data, but the rest of the region drifted lower.  European shares are firmer across the board after broadly positive data (German IP and Trade, French Trade) although the French Unemployment Rate ticked higher to 8.3%.  And US futures are higher this morning as well ahead of the NFP report.  Despite the doom and gloom, equity markets are doing fine.

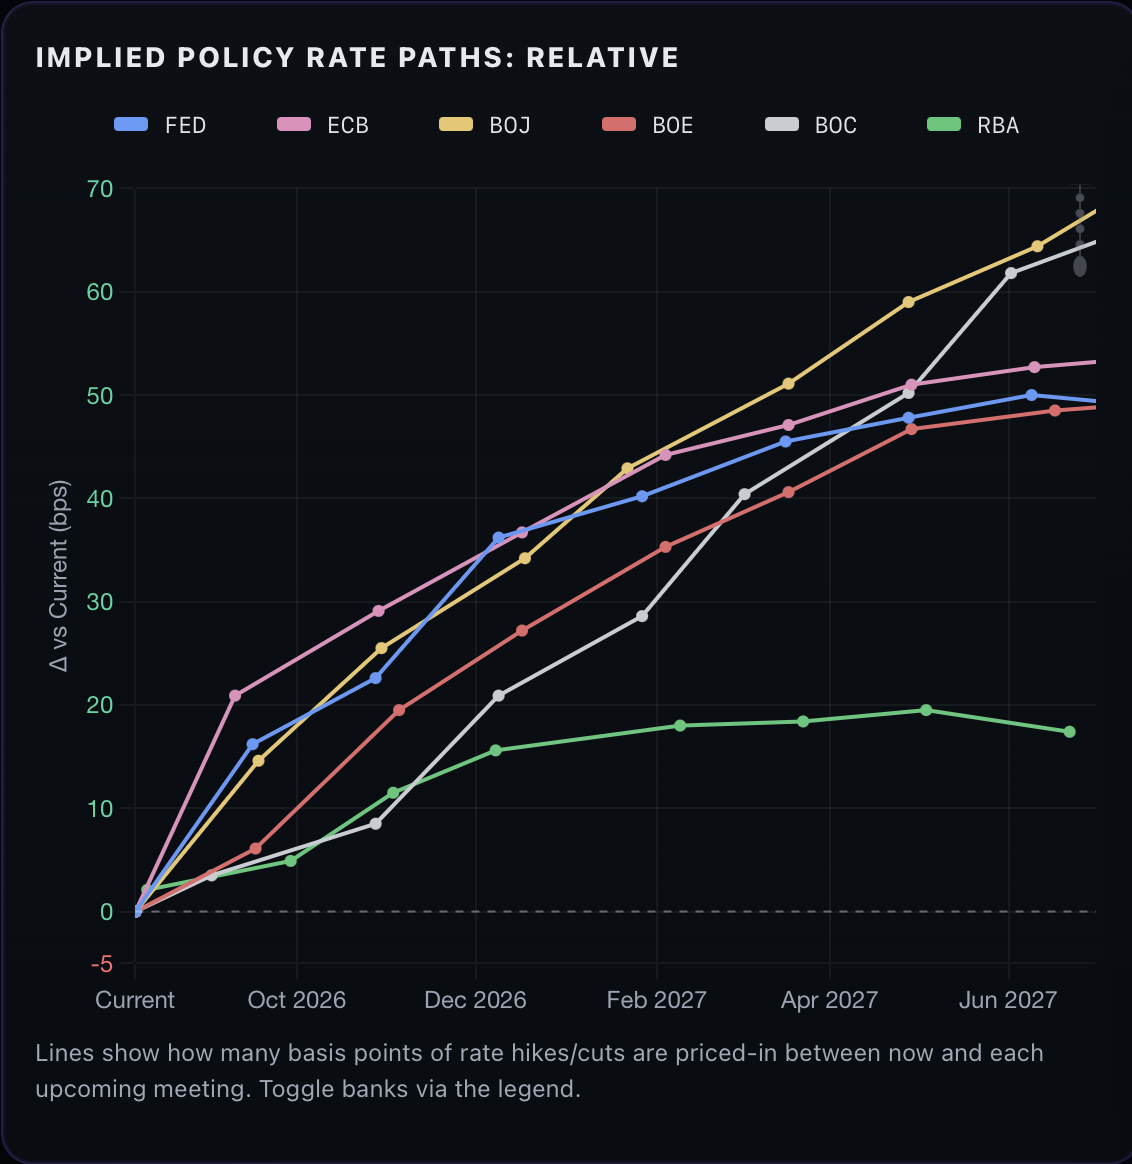
Bond markets have barely moved overnight, although we did see Treasury yields back up 5bps yesterday.  That appears to have been on the back of the oil price rise, although as I look at probabilities of central bank rate hikes, there is a growing belief that the Fed, ECB and BOJ are all going to raise rates next month as hiking rates into an energy shock seems to be their MO.

Source: rateprobability.com

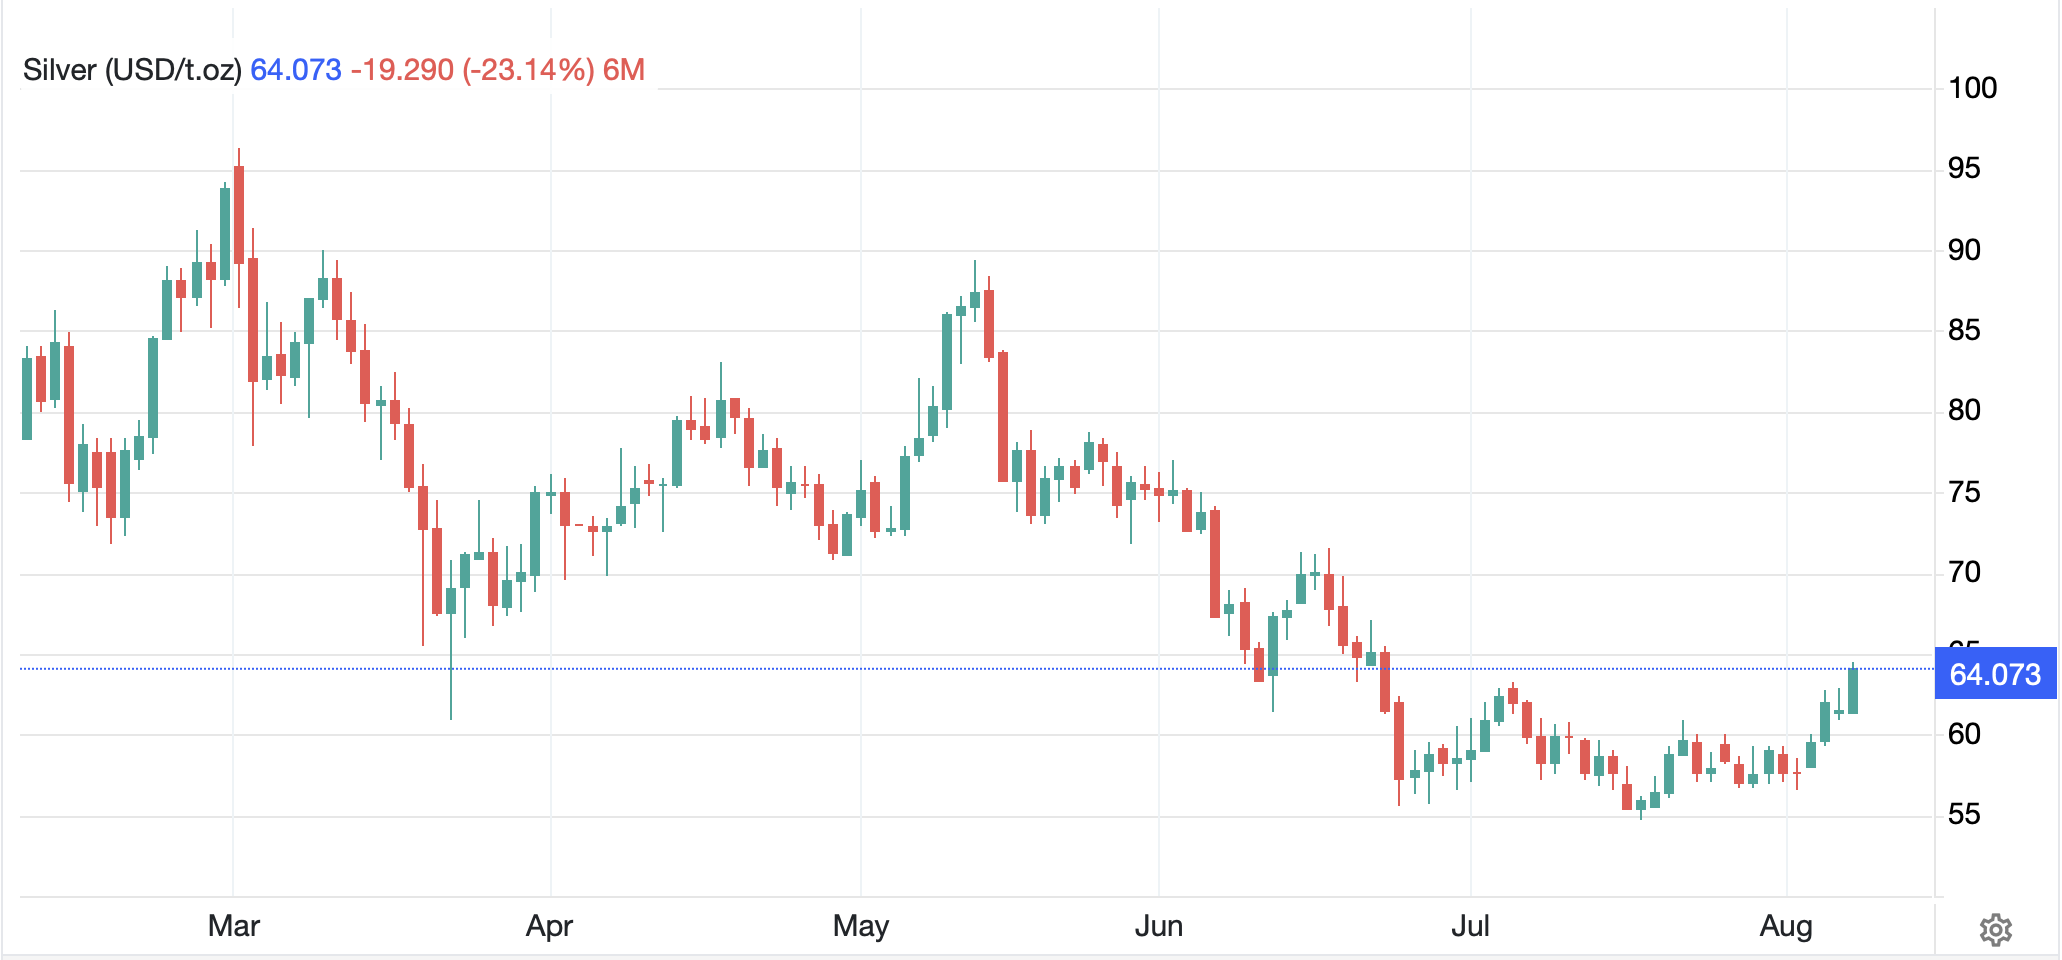
We discussed oil but gold (+2.0%) and silver (+4.1%) are the real story in commodities as both are extending their recent rallies from the consolidation lows.  For instance, silver is higher by 11% this week and $9/oz since July 17th.

Source: tradingeconomics.com

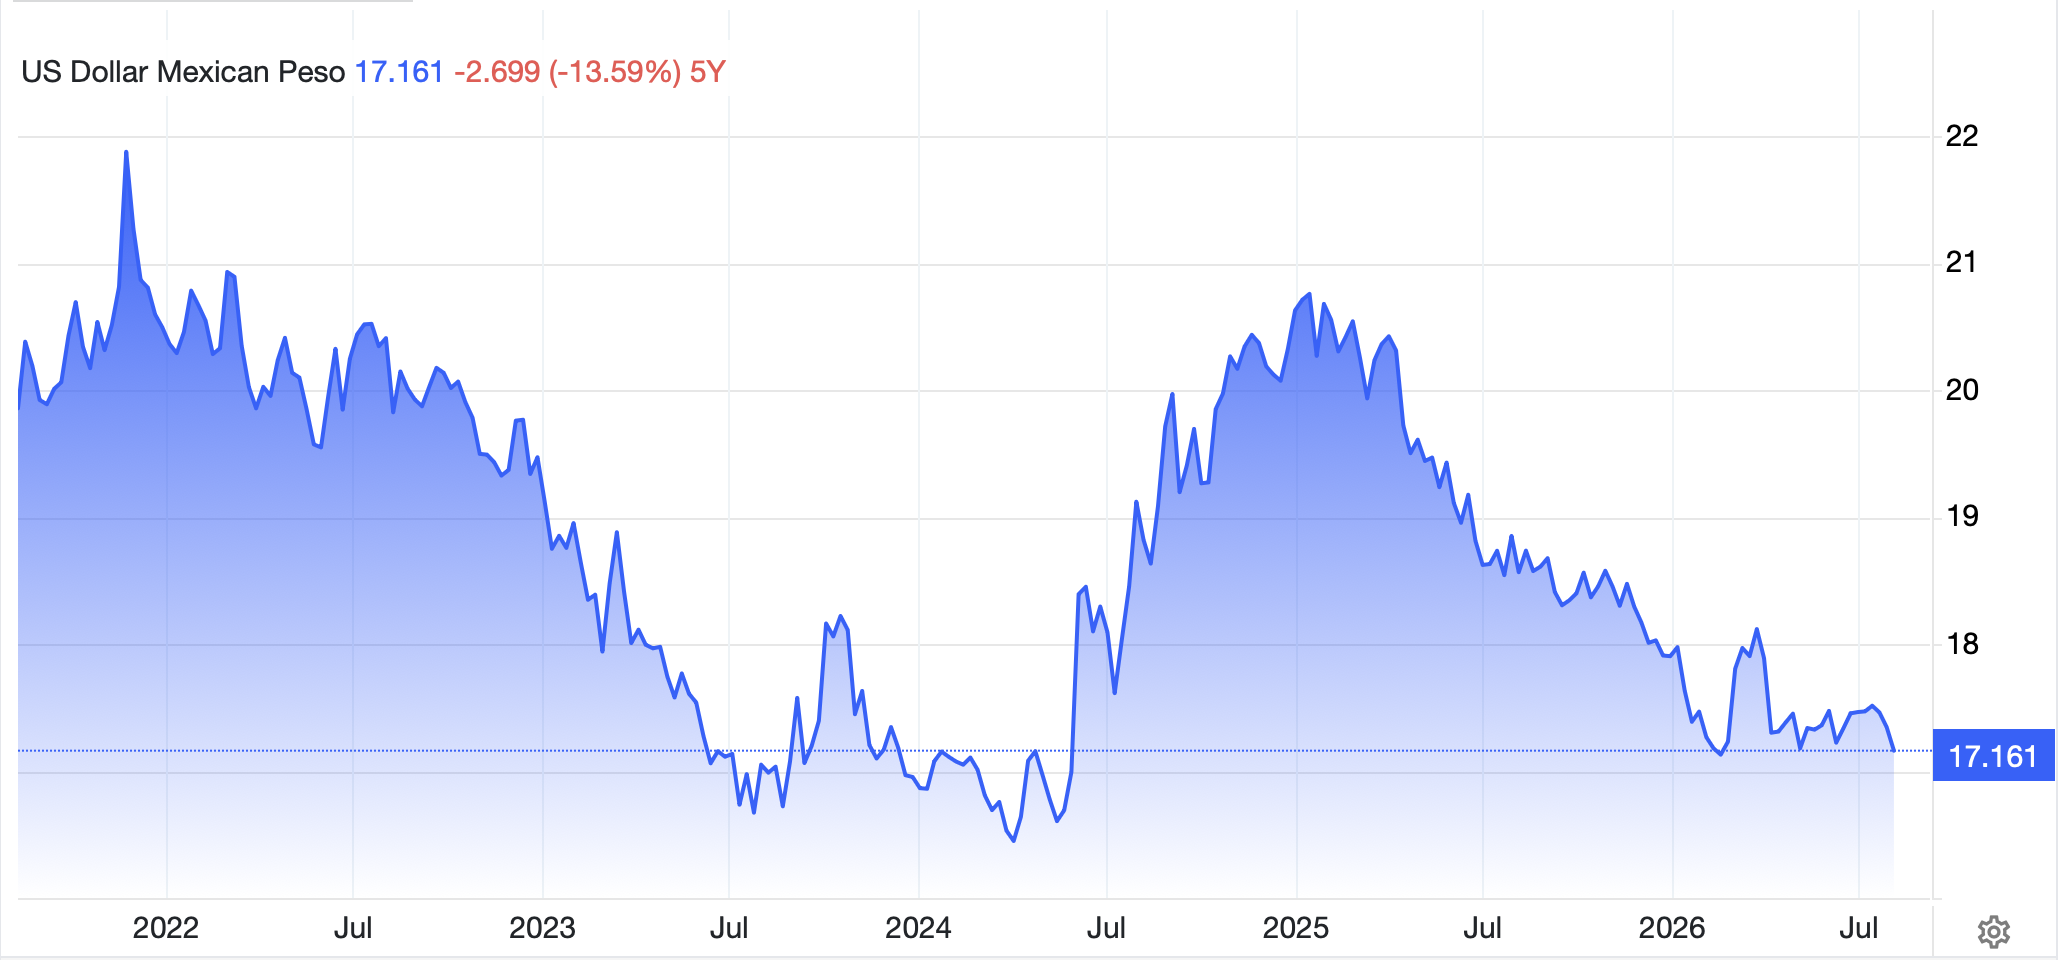
Finally, the dollar, despite all the anxiety about the yen, remains quiet overall.  The DXY is below 100, back in its range and showing no inclination to move in either direction.  This morning ZAR (+0.7%) is the king of the hill on the rally in gold while MXN (+0.3%) is a touch higher after Banxico left rates on hold.  But remember, peso rates are still high and economic growth continues apace so investment opportunities abound.  The peso has strengthened more than 17% since the beginning of 2025, shaking off any tariff concerns easily.

Source: tradingeconomics.com

As to the data, here are consensus forecasts:

Nonfarm Payrolls80K
Private Payrolls78K
Manufacturing Payrolls4K
Unemployment Rate4.2%
Average Hourly Earnings 0.3% (3.5% Y/Y)
Average Weekly Hours34.3
Participation Rate61.6%

Source: tradingeconomics.com

We also see Canadian employment data (exp 6.5% Unemployment Rate) and hear from Thomas Barkin, the Richmond Fed president.  But it is a summer Friday and typically, about an hour after the NFP release, traders are gone for the weekend so don’t expect too much today.

The world is not ending, the dollar is not collapsing, the Treasury market is not collapsing, and equity markets are not about to implode.  My take is the big stories from the past months have lost their luster and I suspect after a lull, we are going to start to focus on the politics of the midterm elections in November.  But until then, have a cold one and relax.

Good luck and good weekend

Adf
Does It Matter?

Much ink has been spilled
Describing intervention
But does it matter?

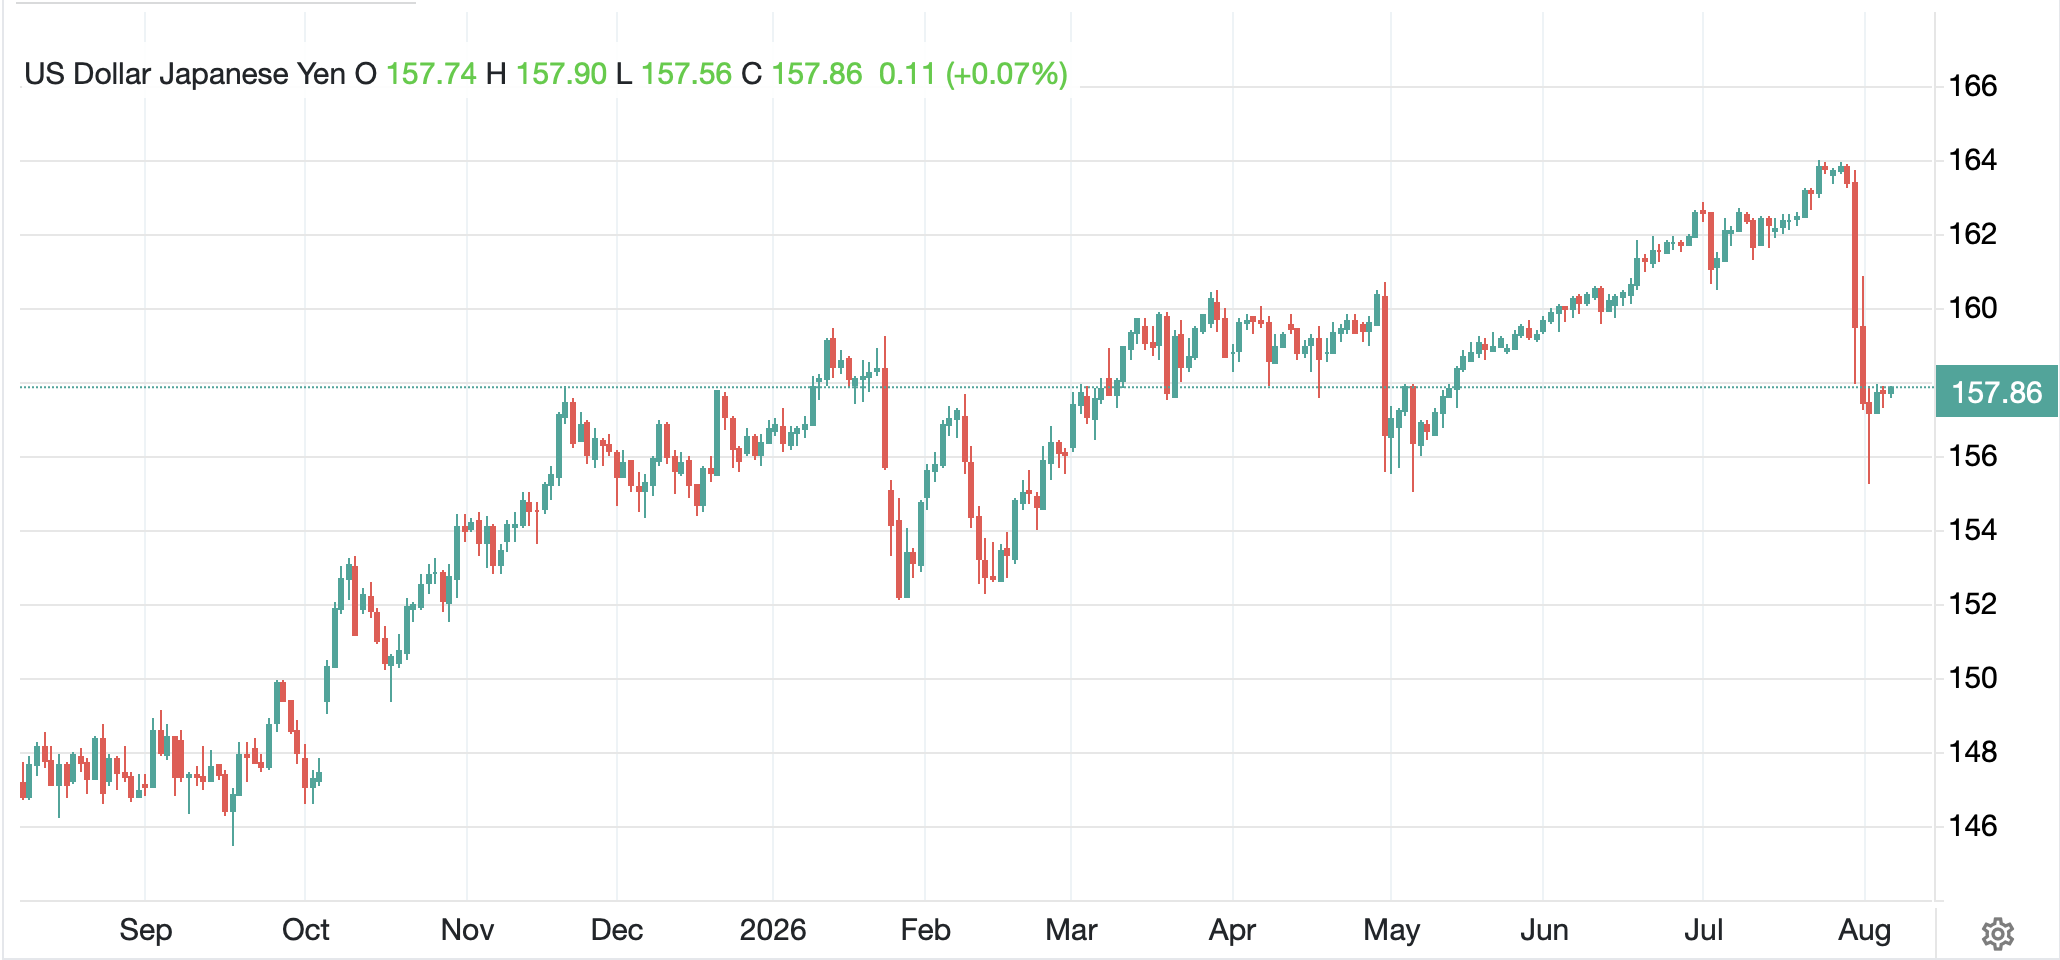
It is still early days since the joint intervention in USDJPY by the US and Japan, and we know they spent a lot of money, but the question at this point is, has it really changed anything?  It is pretty easy to look at the chart below and see the pattern following previous interventions repeating already.  Major dollar decline followed by very gradual dollar strength.
Source: tradingeconomics.com

But as I said it is early days.  Now, I have made the point that unless more fundamental changes are made in Japan, whether that is reining in spending (which seems highly unlikely) to reduce the budget deficit and ongoing increases in debt issuance, or tightening monetary policy by raising interest rates more aggressively, it strikes me that despite all the headlines, this won’t change the situation that much.  

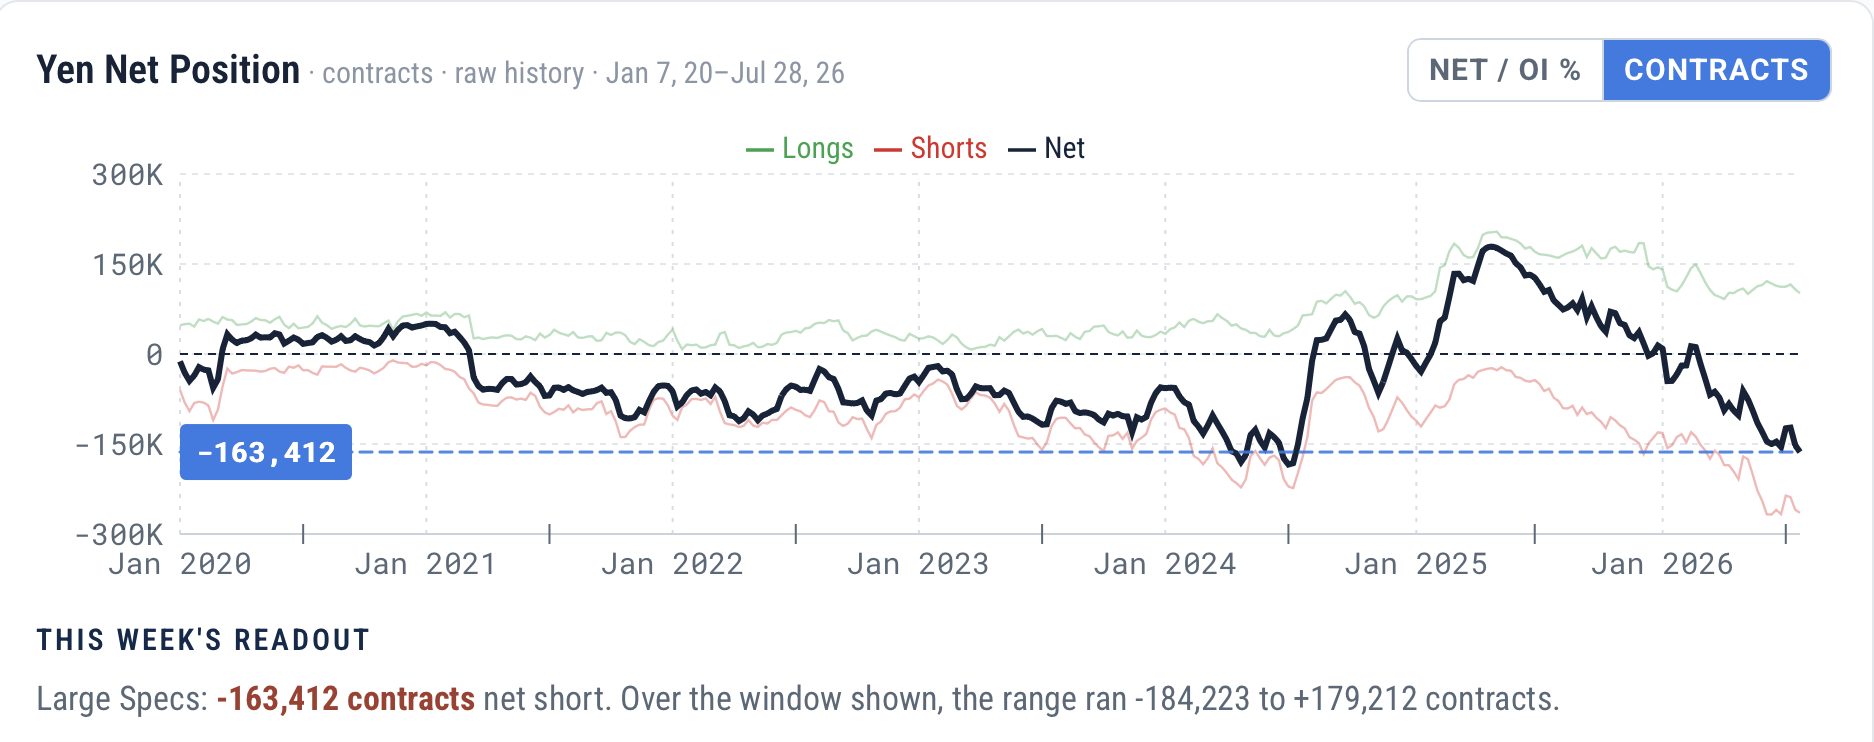
If we use CME JPY futures positions as a proxy for the carry trade, as you can see in the below chart from cotsignal.com, that while we are not at record short positions in the large spec community, we are awfully close.

In fact, it is difficult to see at this point, although the data to be released tomorrow could well show it, much change in the short JPY positioning amongst the speculative set.  In fact, I would expect that would be the case to some extent.  And yet, as in the first chart, the yen appears to have begun to grind lower again.

Much has been made of the potential ramifications of the fact that the Foreign and International Monetary Authority (FIMA) swap lines were used to fund this intervention rather than Japan simply selling some of its Treasury holdings (remember, it holds some $1.13 trillion), and what it means.  Some analysts are claiming Secretary Bessent is concerned over the reaction in the Treasury market if the Japanese sell their bonds and so was trying to prevent any additional pressure there.  And perhaps that is correct.  We will never really know as Bessent will certainly never admit that.  

But let me offer a different, simpler explanation.  The BOJ didn’t want to take the losses on their bonds which are probably quite large given where US yields have been.  Remember Silicon Valley Bank?  So, if the BOJ used a repo facility, they get the cash and don’t take the loss.  After all, that is not really a new idea.  Yet I haven’t heard a single analyst mention it.  I guess it’s not sexy enough.  Time will tell if things have really changed, but to my eyes, not yet.

Let’s turn now to Friday’s release
Of Payrolls, where there’s an increase
Expected and if
It comes, folks will sniff
A hike ere the summer does cease

On a subject that has not gotten a lot of press so far this week, tomorrow brings the NFP report where a solid growth in NFP is expected (80K) although yesterday’s ADP Employment number disappointed at just 44K.  Remember, since the change in immigration policy and the deportation of several million foreigners, it is becoming dogma that a stable Unemployment Rate can be achieved by simply not losing jobs as opposed to having to keep creating new ones. 

In this light, 80K indicates a still solid labor situation.  Now, the question at hand is how the market will absorb the data.  We continue to see equity market participants focused entirely on the earnings data being released, with macro concerns a distant third place on their worry list.  (I imagine oil is second). But for the fixed income market and the newly created Fed watchers, this is a critical piece of information.  

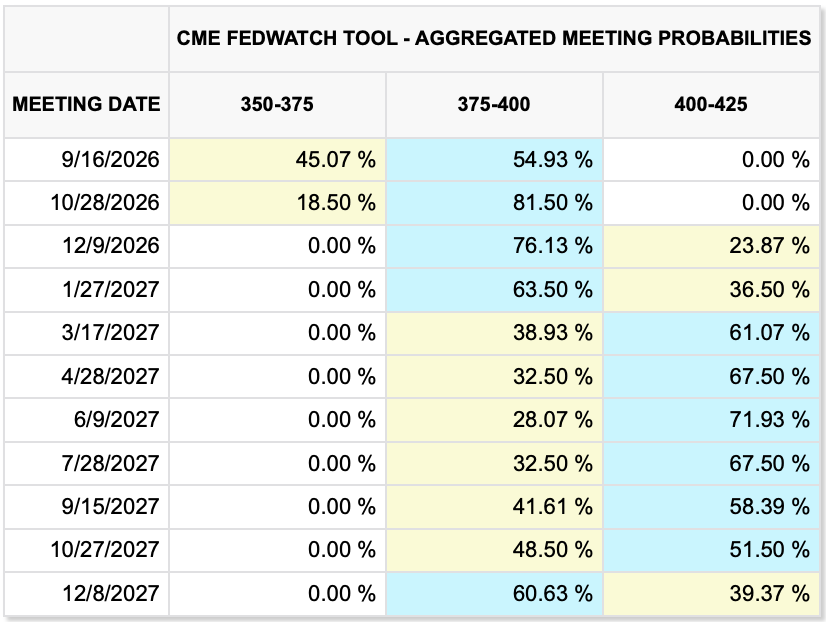
The few Fed speakers we have heard this week have all discussed how they are now very focused on inflation (where were they in 2022?) and may need to raise rates if it continues to rise although a look at the Fed funds futures market shows that the probability of a rate hike next month has declined to 55% from two-thirds earlier this week.  And while a second hike is still priced in the curve, it has been delayed until next spring from the earlier January expectations.

I find this quite interesting as all the Fed commentary has been hawkish and the data we have seen, notably ISM, continues to show economic strength.  So, too, does the corporate earnings data and forecasts, with strength as far as the eye can see.  I have no explanation for this change, and, in fairness, it is a bit subtle, but the futures market appears to be pricing in a different outcome than the punditry or at least starting to.  We will need to watch this carefully as it may be a harbinger for more substantive changes in the narrative and future price action.

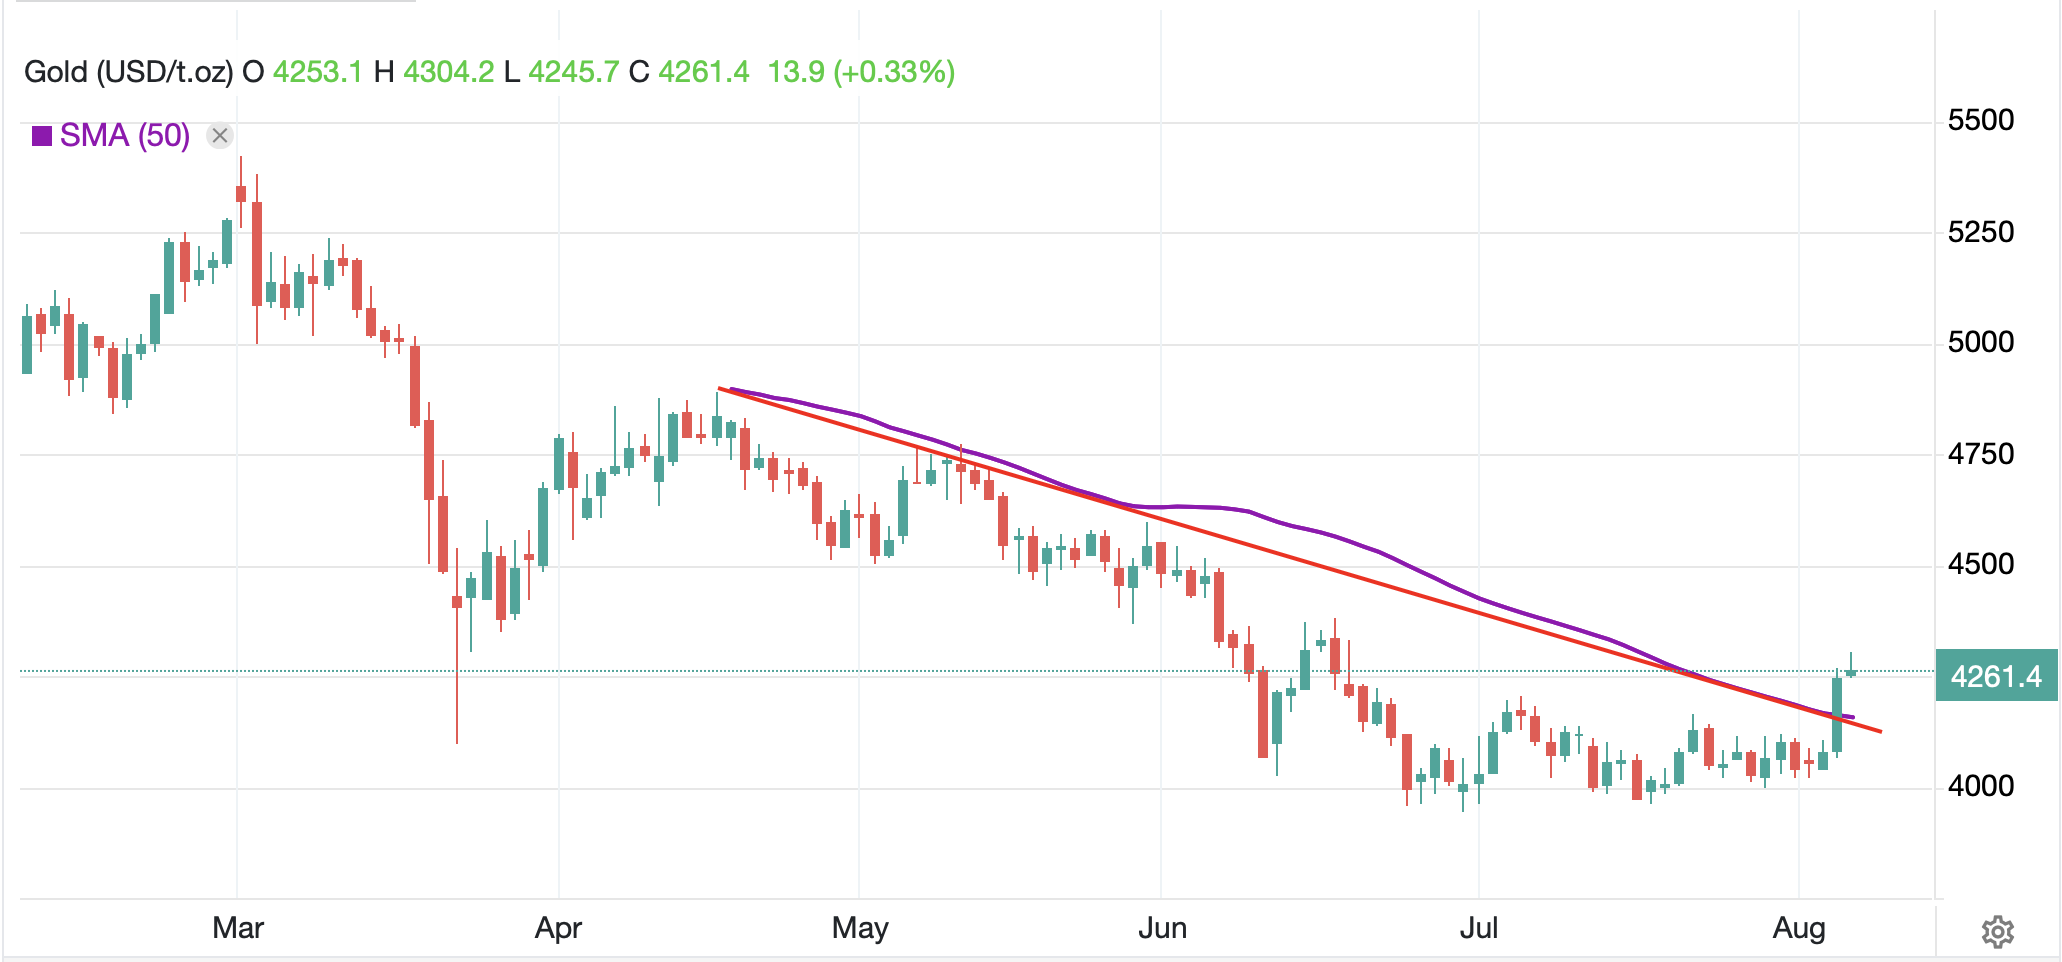
Ok, let’s quickly look at markets.  The outstanding performer yesterday was clearly the precious metals space with gold (+4.1% yesterday, +0.3% this morning) having its largest gain since the late March bounce.  Whether I draw a trend line or look at the 50-day moving average, it seems like a clear break higher after six weeks of consolidation around the $4000/oz level.

Source: tradingeconomics.com

Silver (-0.5%) had a similar move yesterday while copper (+0.9%) is in the process of making yet more new highs this morning although this move has been far steadier.  I’ve seen explanations about how yesterday, the market suddenly realized that inflation was a problem or other such nonsense, but my experience tells me this is more likely a positioning event with new money entering after the markets demonstrated a more certain bottom.  In other words, since it couldn’t go down despite bad news, the only direction left was up.

Oil (+1.0%) is almost an afterthought these days, remarkably.  There is a lot of discussion about an imminent deal between Oman and Iran on the Strait of Hormuz, but my impression is that the market has pretty much moved beyond that story.  EIA inventories rose, inventories at Cushing rose and there is no evidence of shortages anywhere in the West.  

In the equity markets, yesterday’s mixed US session was followed by a generally weaker one in Asia (Japan -0.9%, China -0.2%, HK -1.5%, Korea -4.6%) although there were some gainers as well (India +0.5%, Australia +0.5%, Singapore +1.0%, Thailand +0.7%).  The tech story continues to be the driver and yesterday was a clear demonstration of tech concerns compared to basic materials bullishness.  Europe, though, is firmer this morning led by Spain (+1.1%) and France (+0.6%) after some positive data was released (Spanish IP, French Construction PMI, German Factory Orders) although the DAX (+0.25%) is lagging the group.  As to US futures, at this hour (7:40) while the NASDAQ (-0.4%) is lower, the other two indices are firmer by 0.2%.

In the bond market, yields are edging higher this morning with Treasuries (+2bps) leading the way and most European sovereign yields higher by 1bp.  While yields across the board are at the high end of their recent ranges (see chart below), they do not appear to be breaking out  Although for now, the trend across the board does seem to be modestly higher.

Source: tradingeconmics.com

Finally, the dollar is a bit firmer this morning, but only just.  In fact, there is really no currency movement of note to discuss.  Brazil cut its SELIC rate to 14.0% as expected and the BRL (+0.3%) is a touch firmer, but really, other than that, 0.1% is today’s story and that is not much of a story.

Today’s data releases include Initial (exp 202K) and Continuing (1790K) Claims as well as Nonfarm Productivity (0.6%) and Unit Labor Costs (2.1%) and that’s really it.  There is another speech by St Louis Fed president Alberto Musalem, but we already know he is a hawk, so there will be nothing new there.

While we need to keep our eye on how things play out in the yen, there seem to be fewer stories of interest right now, at least marketwise.  Perhaps we are finally in the summer doldrums.

Good luck

Adf