Things Are Bleak

The one thing on which you can rely is that there is a large segment of the punditry who will complain about every action taken by financial authorities, often offering ad hominem comments to make their case while demonstrating their own ignorance.  The benefit you have here is that I know there are many things I don’t know and don’t pretend otherwise.

Of course, I am referring to the Treasury Secretary’s recent announcement to ‘at least’ double the activity in their bond purchase program.  Once again, let me remind everyone that Secretary Bessent did not unilaterally pass laws to enact spending, that was Congress’s doing and the dramatic increase in spending has been ongoing for at least 25 years.  Just like every treasurer in every company, Bessent’s primary job is to ensure there is sufficient funding, and that is what he is doing.  Machinations as to the tenor of the debt are left to his discretion and fortunately, he is a man with an extraordinarily broad and deep understanding of financial markets.

The claims that he is panicking now are ridiculous, although I’m sure he isn’t thrilled with the situation.  But he inherited the situation, he didn’t create it.  For every doomster out there explaining the bond market is going to collapse, or the government is going to be forced to change their ways, my response is, don’t hold your breath.  

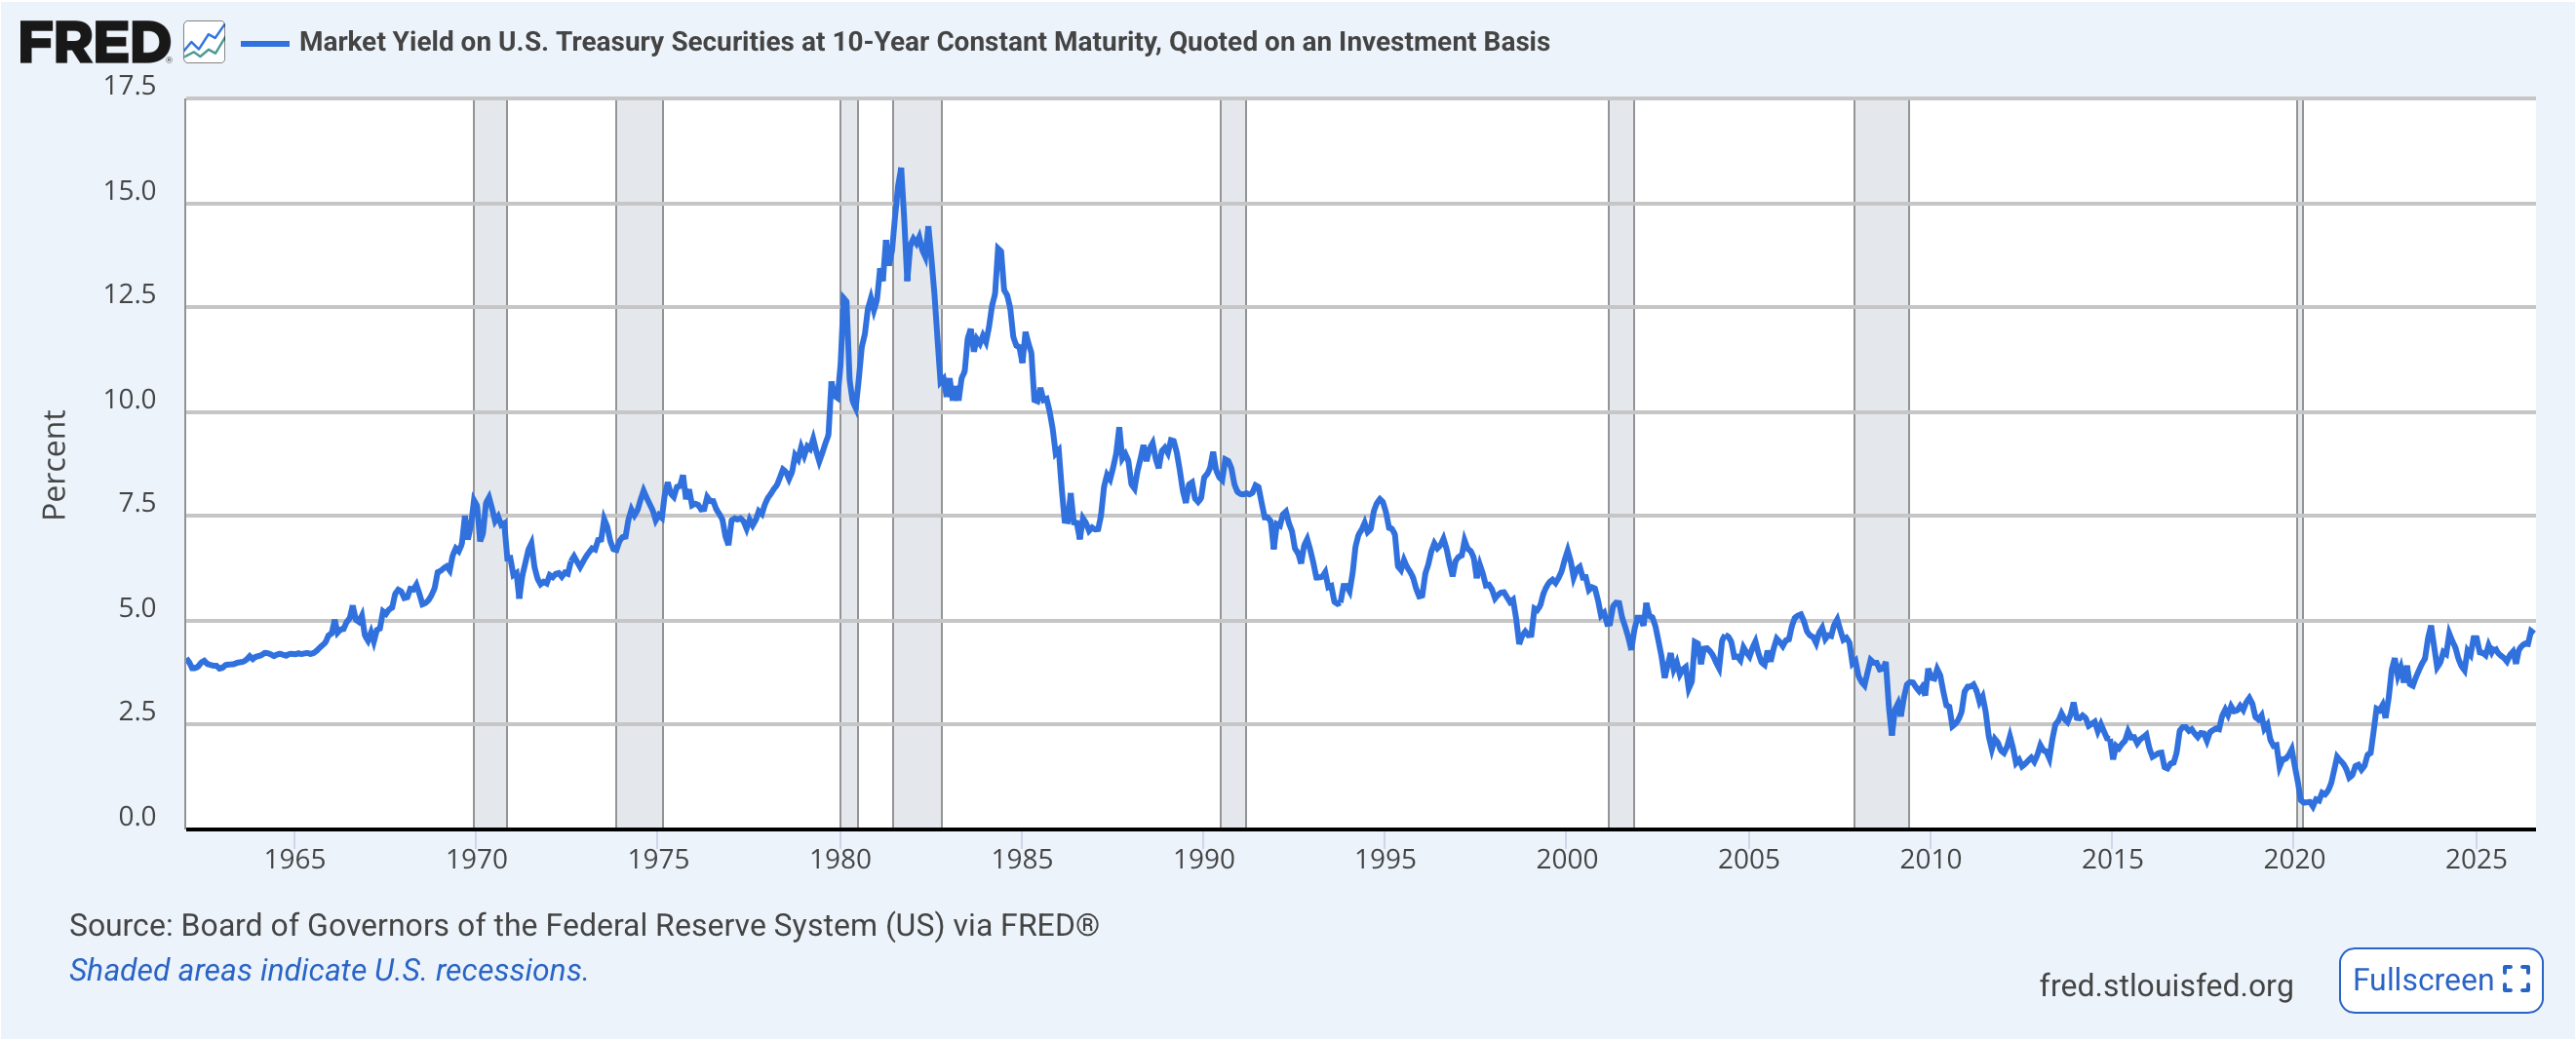
While yields have certainly risen over the past several years, that was from the extremes of Covid policy.  If you take a longer look, as per the chart below from FRED, the current level of 10-year yields is hardly dramatic, and actually, as I have written before, remains well below the long-term average.
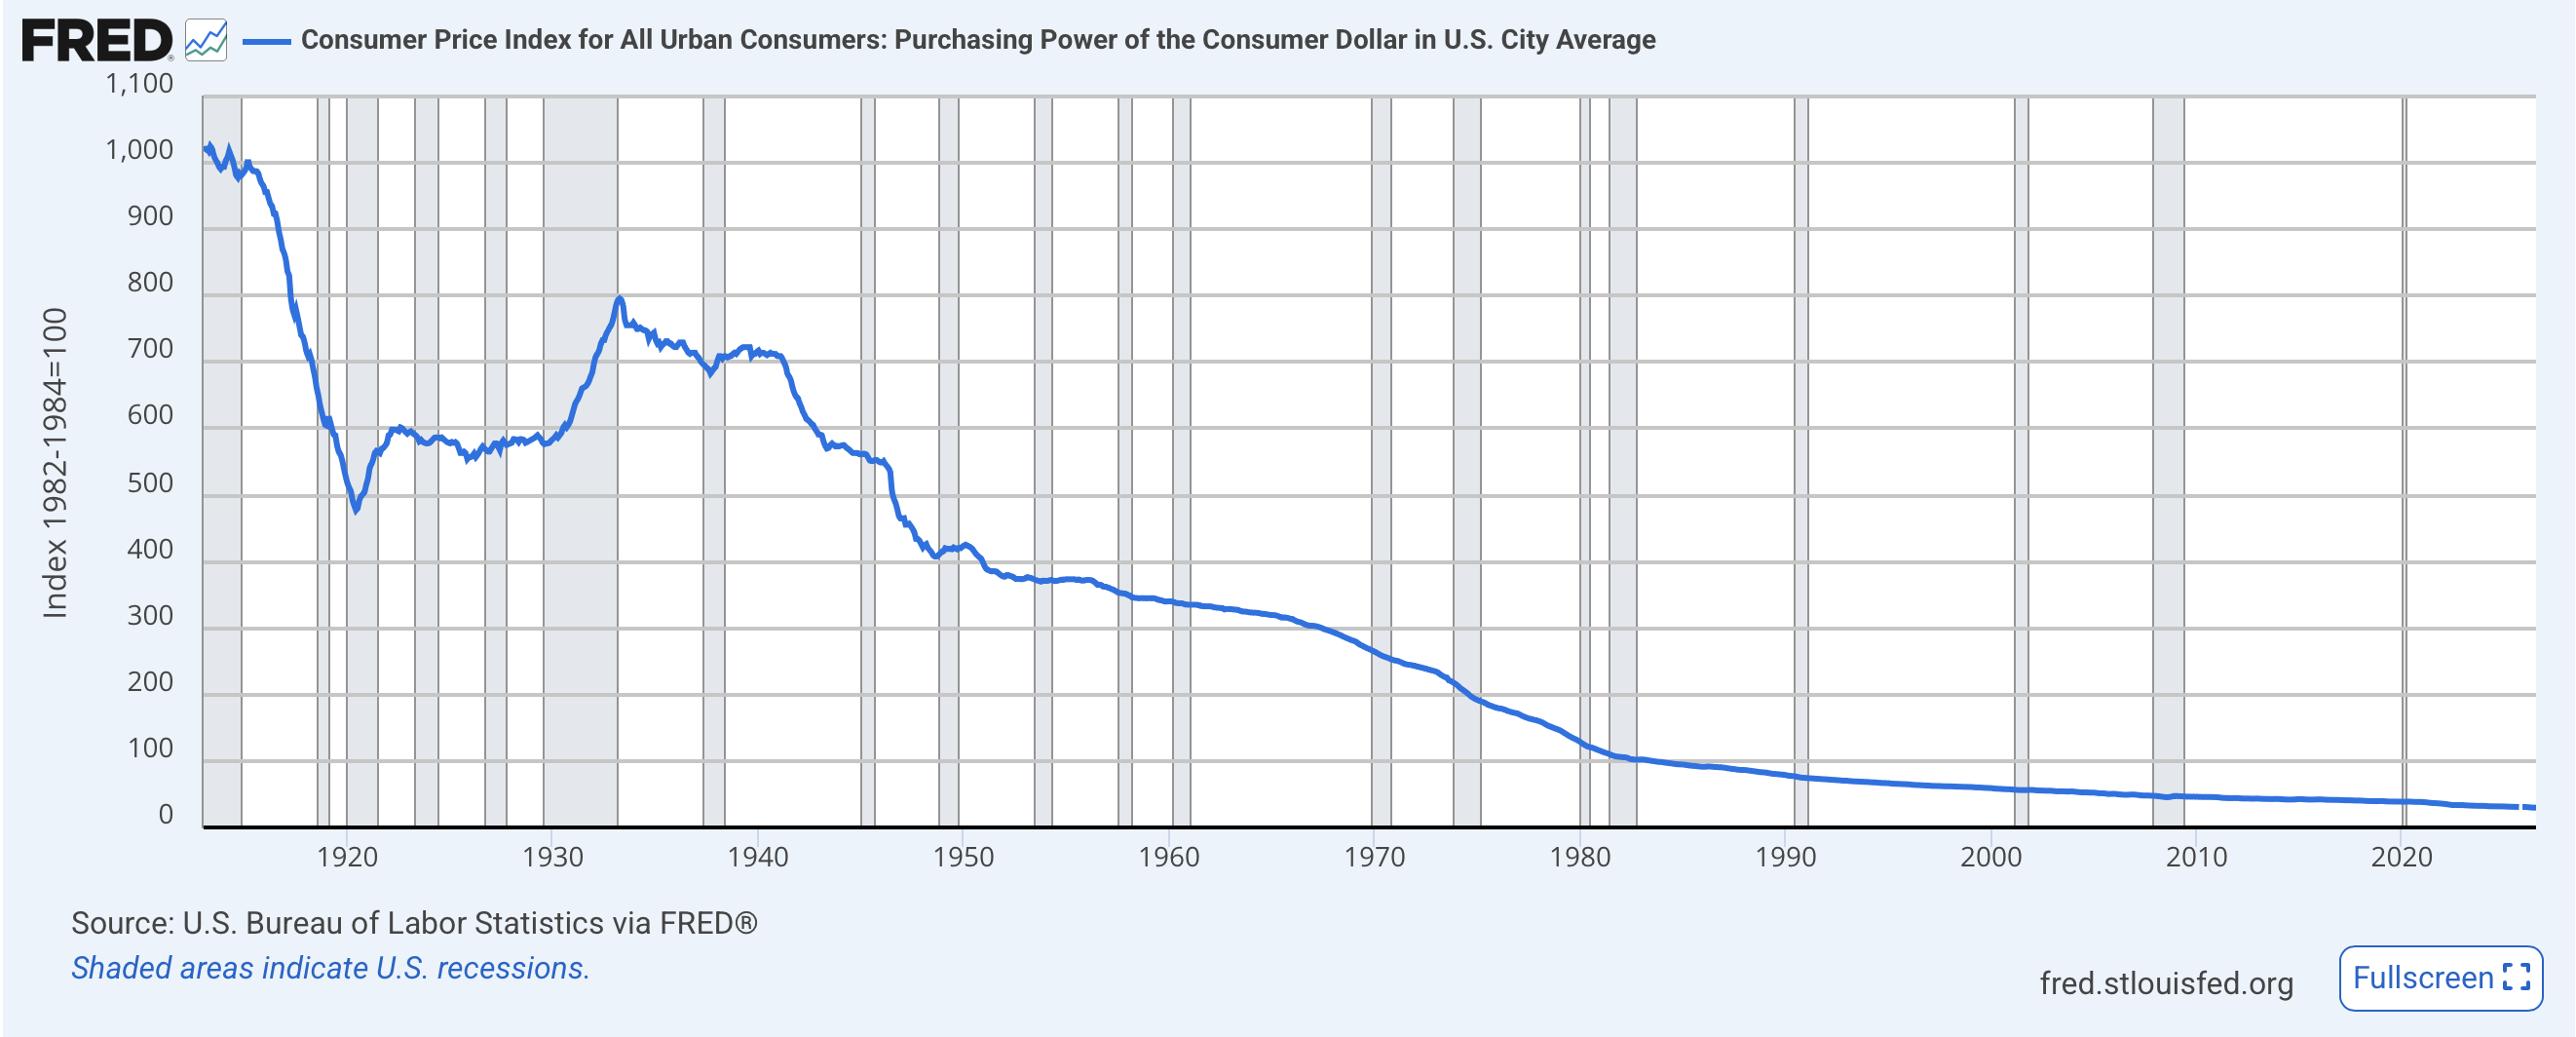
Now, I understand that the amount of debt outstanding is much larger, on both an absolute and relative to GDP basis, but I also know that there is literally a 0.0% probability that the US will not repay that debt.  The question is what the real value of the dollars you receive will be when they are returned, and there, the picture is less bright.  Of course, as you can see from the below chart, also from FRED, this is hardly a new concept either.  In fact, ever since the Federal Reserve was created in 1913, the value of the dollar has declined by about 97%.  This is not a new phenomenon.
Which brings us to Chairman Warsh.  I find it interesting that the punditry believes that Bessent’s activities were completely independent of Warsh.  The two are BFF’s for god’s sake, and speak every week, if not every day.  Each has a job to do, and each is working to achieve it.  Inherently, Warsh’s job is made more difficult because of the US fiscal situation, not because Bessent is tweaking the Treasury’s maturity ladder.

And here’s the thing, both men are working to make institutional changes in hidebound institutions that are fighting things tooth and nail.  Frankly, I sincerely hope both are successful.  Back to Warsh.  Friday, he will speak at the KC Fed’s annual Jackson Hole Symposium, this year titled “Financial Innovation: Implications for Payments and Policy.”  Now, that is a bit afield from the details of monetary policy, as I suspect the policy part of the title refers more to the stablecoin question rather than the size of the Fed’s balance sheet.  But I am confident he will discuss current monetary policy in some manner.  I am also confident he will not offer suggestions as to the next rate move.  

The current narrative has morphed into, the problem for markets/analysts is not the lack of forward guidance, it is those people don’t understand the Fed’s reaction function.  This, too, is disingenuous in my mind as Chairman Warsh has made clear, his function is to reduce inflation to the 2% target, and he has clear ideas how to do that.  The problem is his ideas are different than the neo-Keynesian views that dominate the Fed (and every other central bank), and so are making people uncomfortable.  He has made very clear he is happy to allow the bond market to do the Fed’s work, tightening policy.  He is also very politically astute and clearly understands Bessent’s actions.  I would contend that of all the dysfunction in the government, the least concern should be afforded to the Fed/Treasury nexus.

And finally, it appears that the latest trade talks with Canada have broken down and both sides will be imposing tariffs on the other side.  My personal view is this is a mistake, only because there is no predatory relationship between the two nations, but politics is politics and PM Carney has called on national pride as his rationale.  The thing for the US is, it isn’t going to matter that much. According to Grok, Canadian imports represent ~10% of total US imports and ~1.5% of GDP, so higher tariffs on that relatively small amount is not going to change much.  For Canada, though, exports to the US represent ~20% of GDP, so interruption there is going to hurt a lot more.  Something tells me we will get a deal here pretty soon though as both sides will benefit.

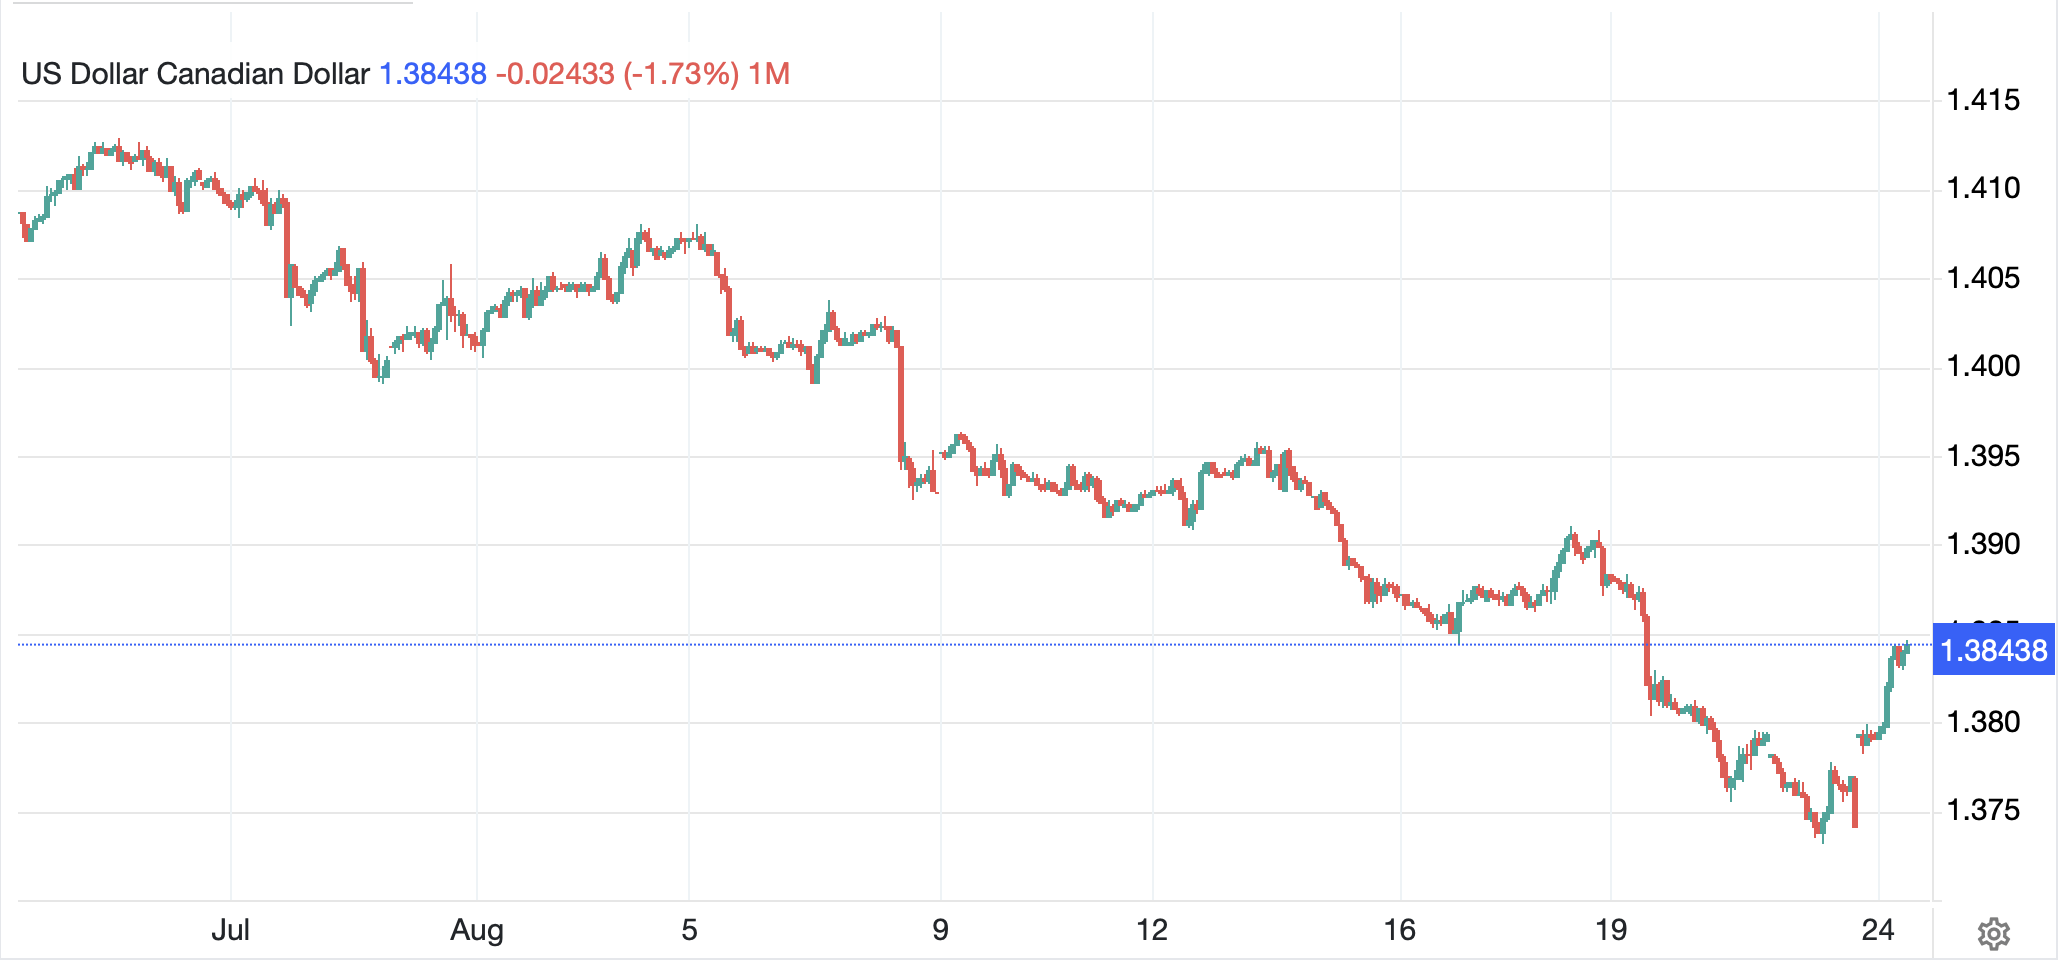
The market’s initial reaction in USDCAD was a slight hit to the Loonie (-0.6%) as you can see in the chart below.  But the CAD has been appreciating over the past month like every other currency vs. the dollar, and this move is hardly breathtaking.  My take is USDCAD remains far more beholden to the broad dollar story with this simply a blip.
Source: tradingeconomics.com

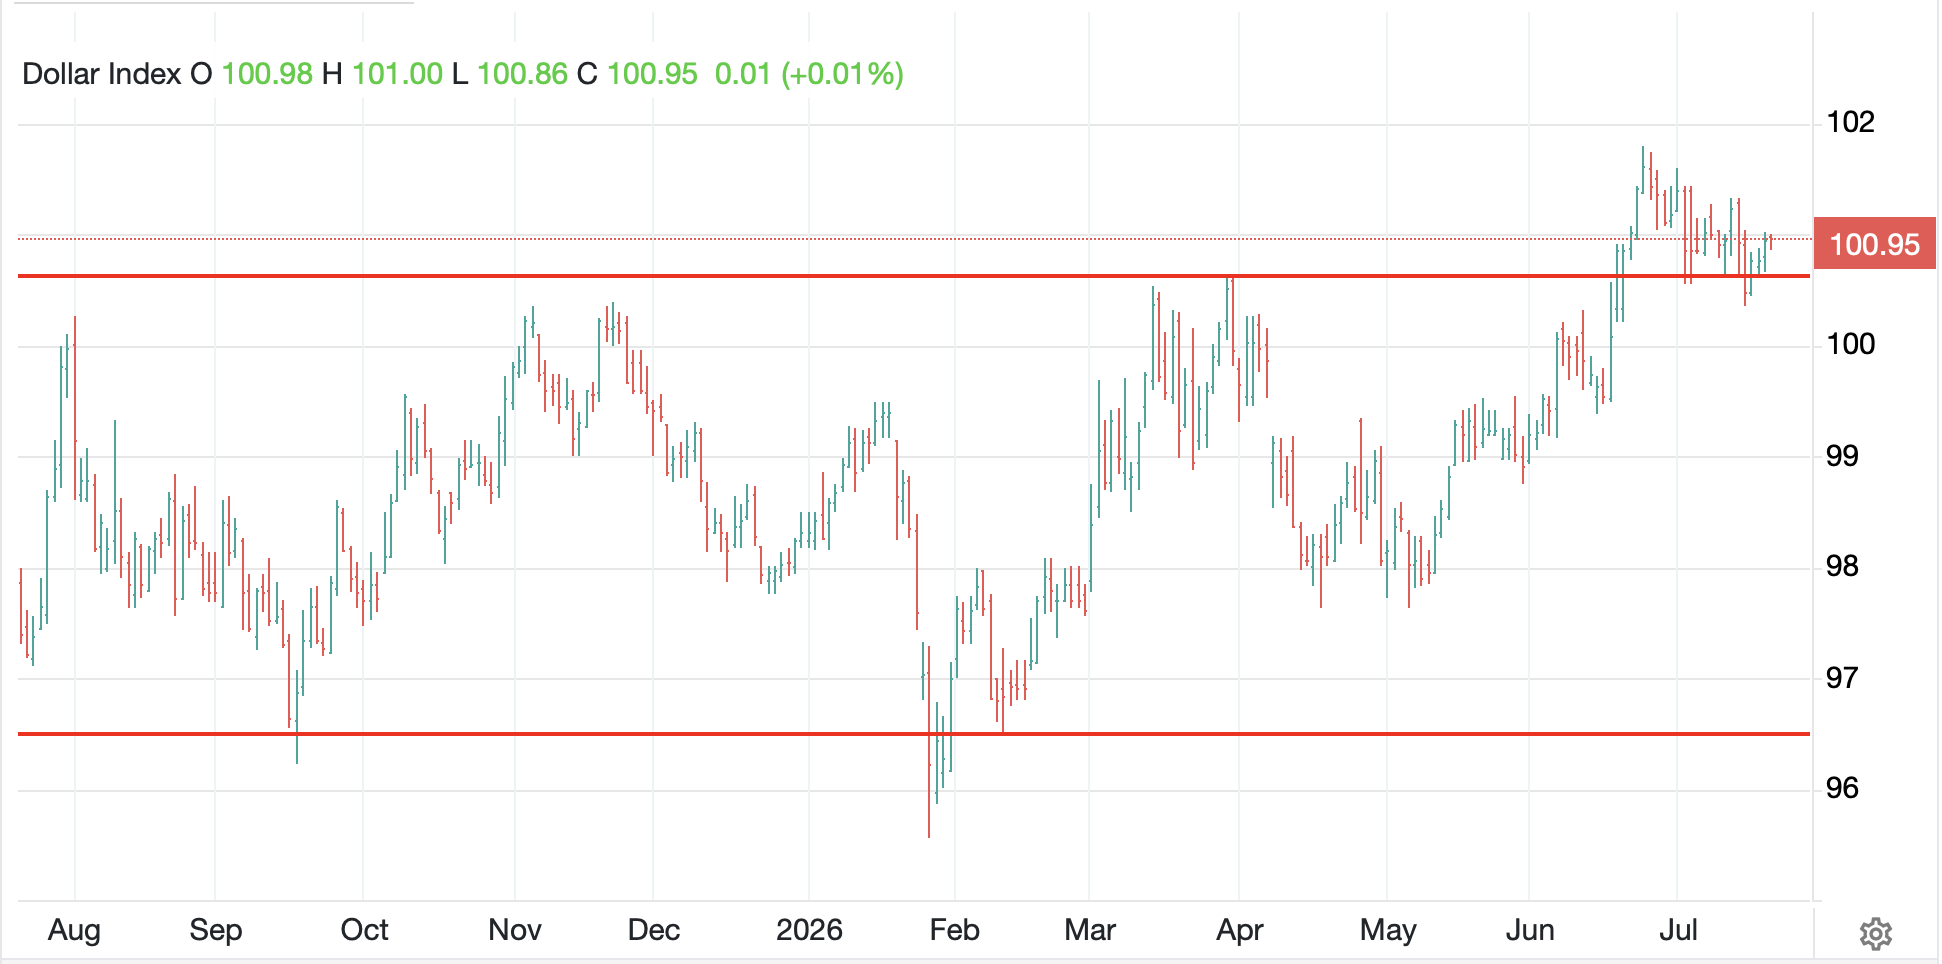
Sticking with the currency theme, the dollar more broadly is a touch higher this morning, with the DXY up 0.2% and modest gains vs. most of its G10 and EMG counterparts.  With the dollar back in the middle of its broader long-term range, it is hard to get excited in either direction at this point.  Certainly, a case can be made that we will see a significant decline going forward if the worst-case scenarios play out, but that is not my base case.  Rather, I have a sense that we are going to remain somnolent in the dollar for a while to come, at least until policies are clearer and that is anybody’s guess as to the timing.

Looking at commodity markets, oil (-2.2%) which spent most of last week rising on increased concerns over Iran and the situation there, has reversed course this morning on two stories.  First, it appears that flows through the Strait of Hormuz have been picking up again as per this article, although it remains very uncertain as to the full amounts.  However, oil is moving.  The second story is the latest set of sanctions that the US is set to impose on Iran and secondary nations that trade with Iran as a means to effectively starve the regime there.  Regardless, lower oil prices are certainly better than higher from a global perspective.

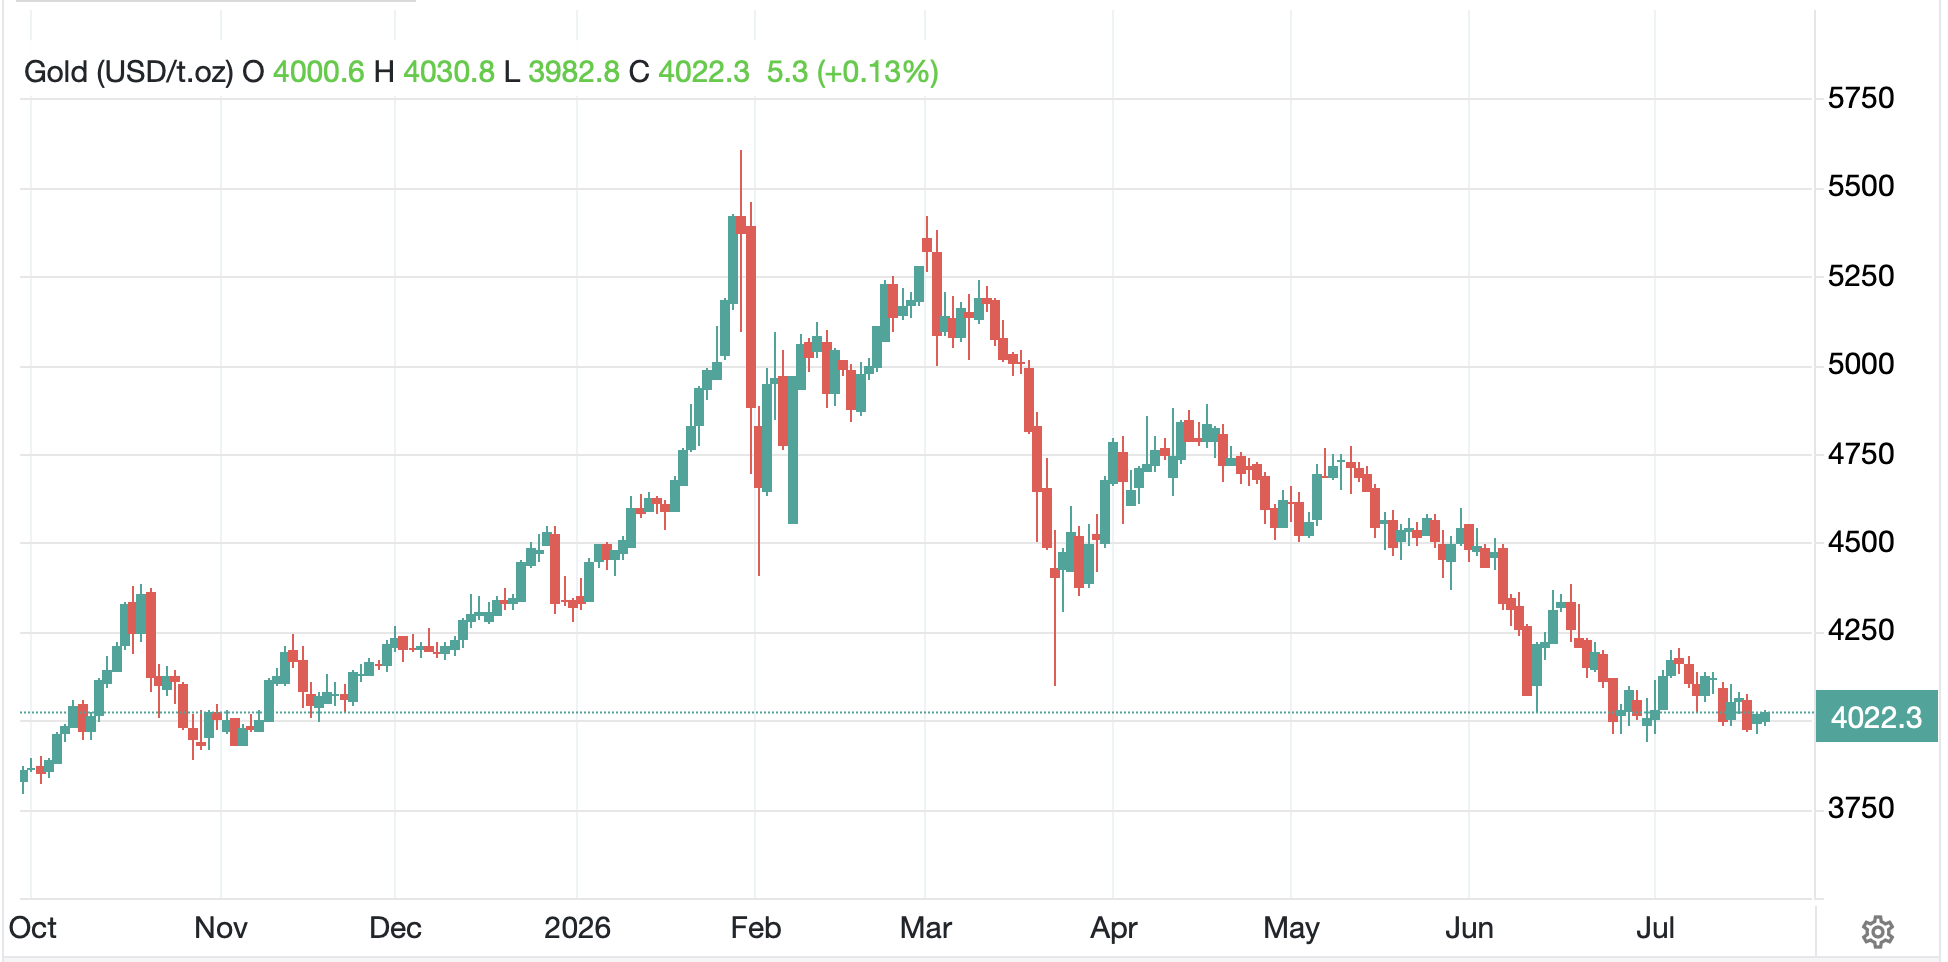
Meanwhile, despite the dollar’s modest strength this morning, the barbarous relic (+1.1%) is higher by 15% since the beginning of August and really appears to be building strength in the move.  Is this related to concerns over fiat currency debasement in the US and elsewhere?  Probably as that 5000-year history of holding value in all times is starting to seem quite attractive.  Not surprisingly, this has helped silver (+0.5%) and copper (+0.1%).
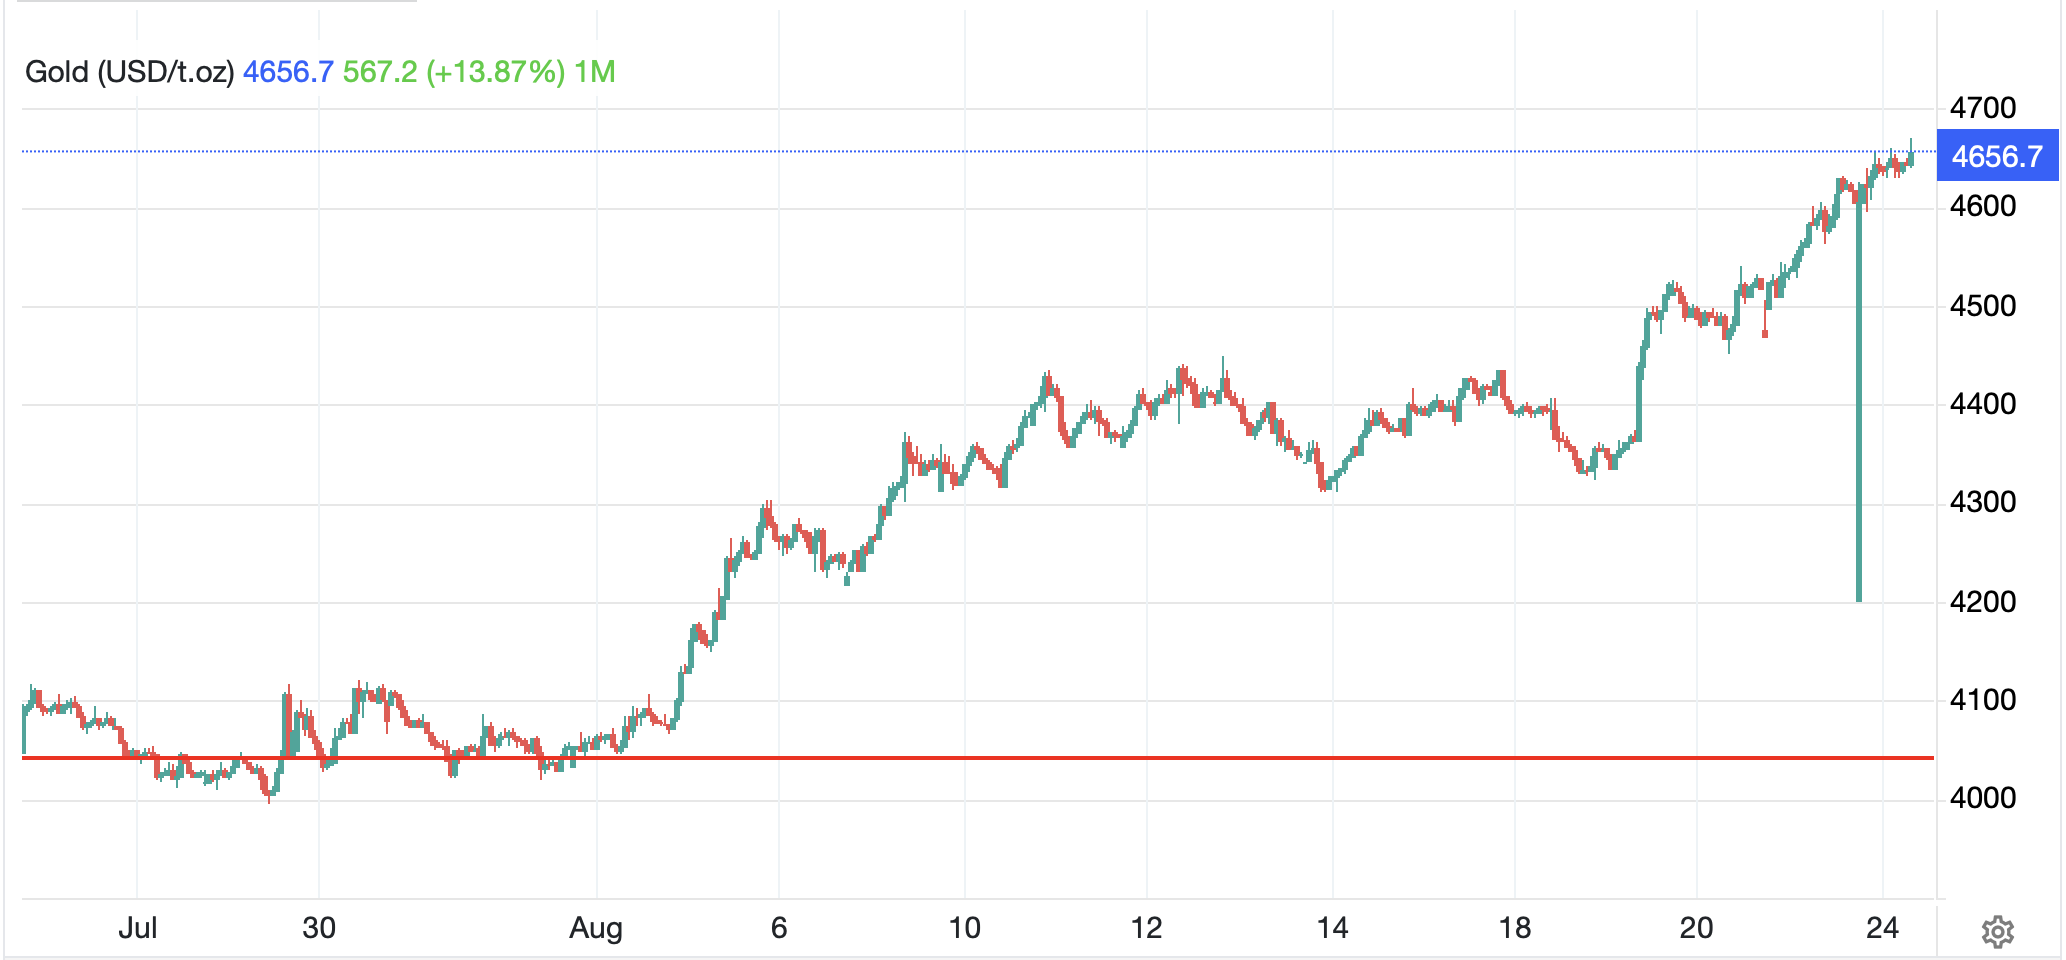
Source: tradingeconomics.com (that green bar on the right appears to be a misprint)

In the bond market, yields are edging lower this morning with Treasuries (-3bps) leading the way and most European sovereigns, as well as JGBs seeing -1bp declines.  Nothing has changed the big picture here with too much government debt being issued around the world, but I have a feeling everyone is waiting for Chairman Warsh on Friday before taking their next steps.

Finally, equity markets which had a decent session in the US on Friday, are more mixed.  In Asia, the big markets all fell (Tokyo (-0.75%, HK -1.9%, China -1.2%, Korea -3.1%, Taiwan -1.0%) with only Australia (+0.5%) bucking the trend on stronger commodity prices.  In Europe, it has been a very quiet session, no surprise at the end of August, with bourses there within 0.2% of Friday’s close.  US futures, though, are being dragged down by tech and the NASDAQ (-0.8%) at this hour (8:05) although the other indices are only marginally softer.

As I’ve run on too long as it is, I will cover data this week tomorrow given there is nothing to be released today.  The oil story and anecdotes about tech are the keys for now absent a major White House surprise, something you can never rule out.

Good luck

Adf
Held At Bay

The doldrums have finally arrived
As interest in markets nosedived
While stocks still creep higher
The marginal buyer
Is sleeping and must be revived

But it seems unlikely today
Is going to show us the way
I think, til Warsh speaks,
And that’s in two weeks,
Excitement will be held at bay

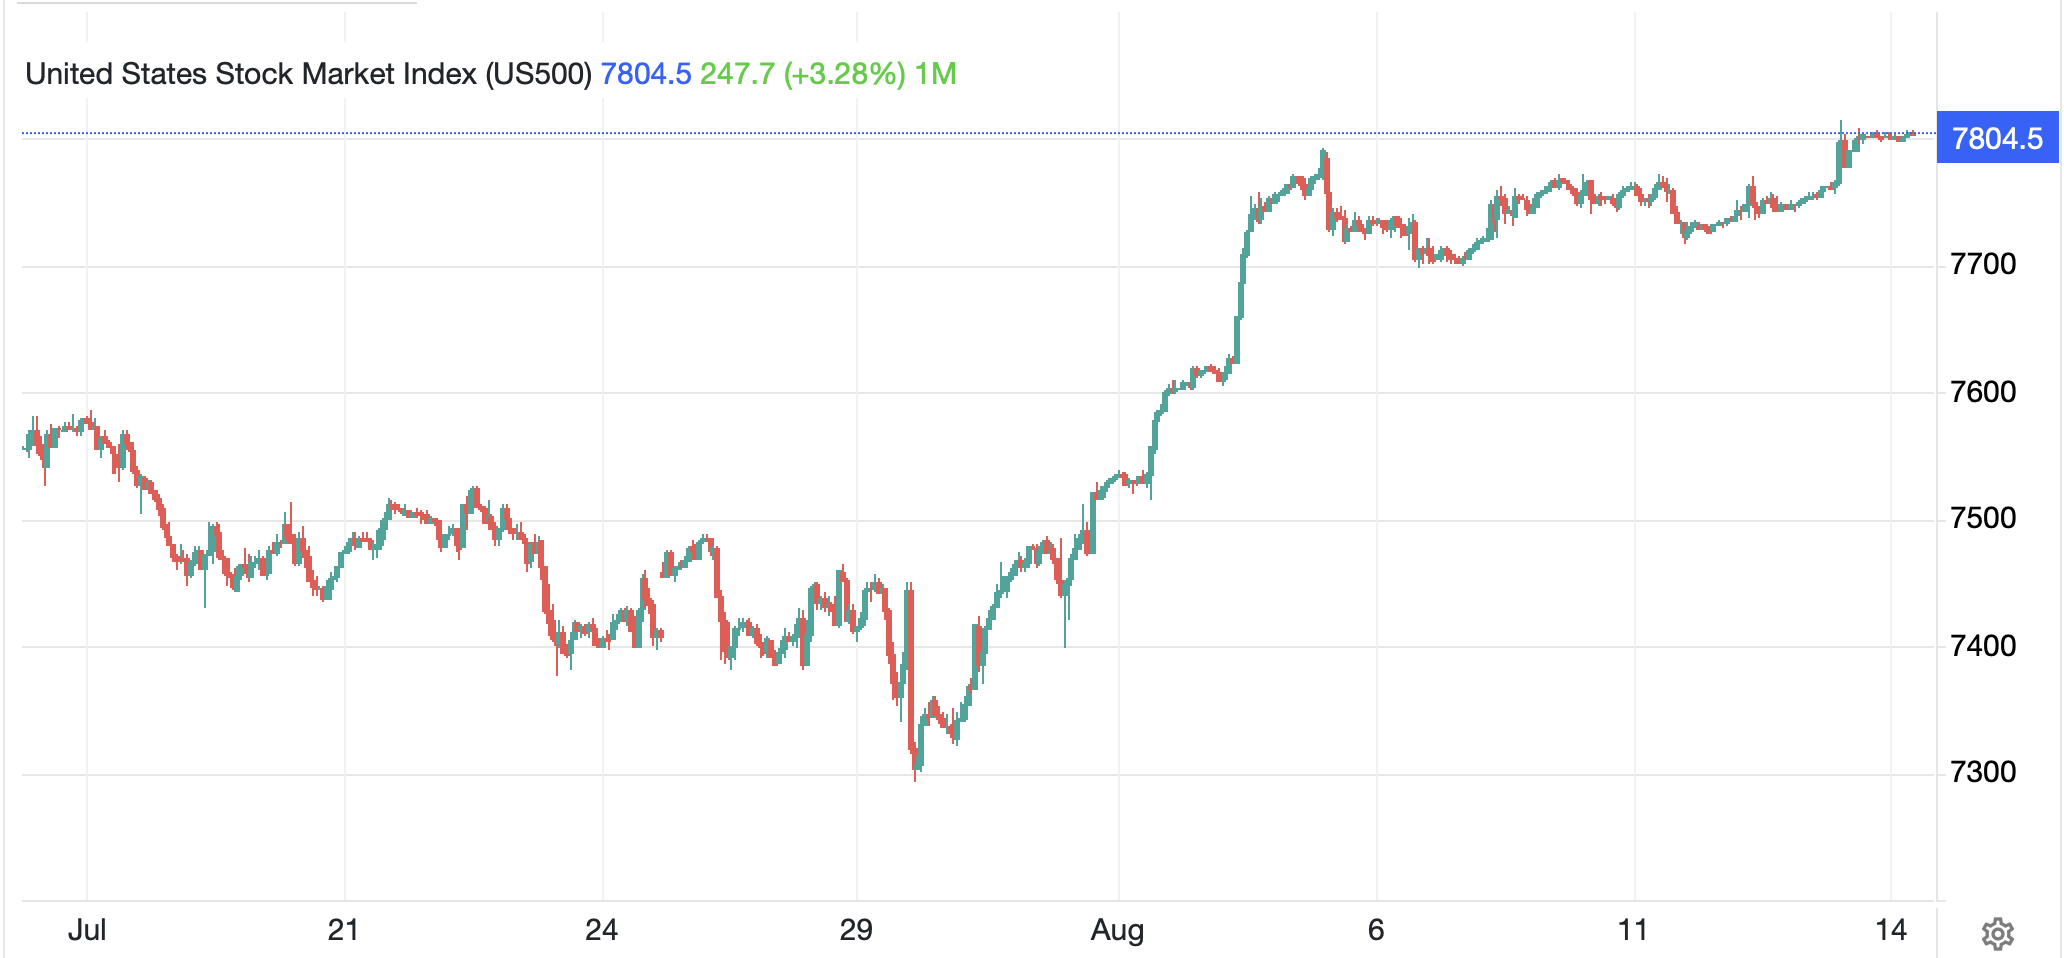
While not every market is completely stagnating, for the past seven sessions, despite NFP, CPI and many stories about oil and war, market price action has been extremely dull.  Whether we look at stocks:

Source: tradingeconomics.com

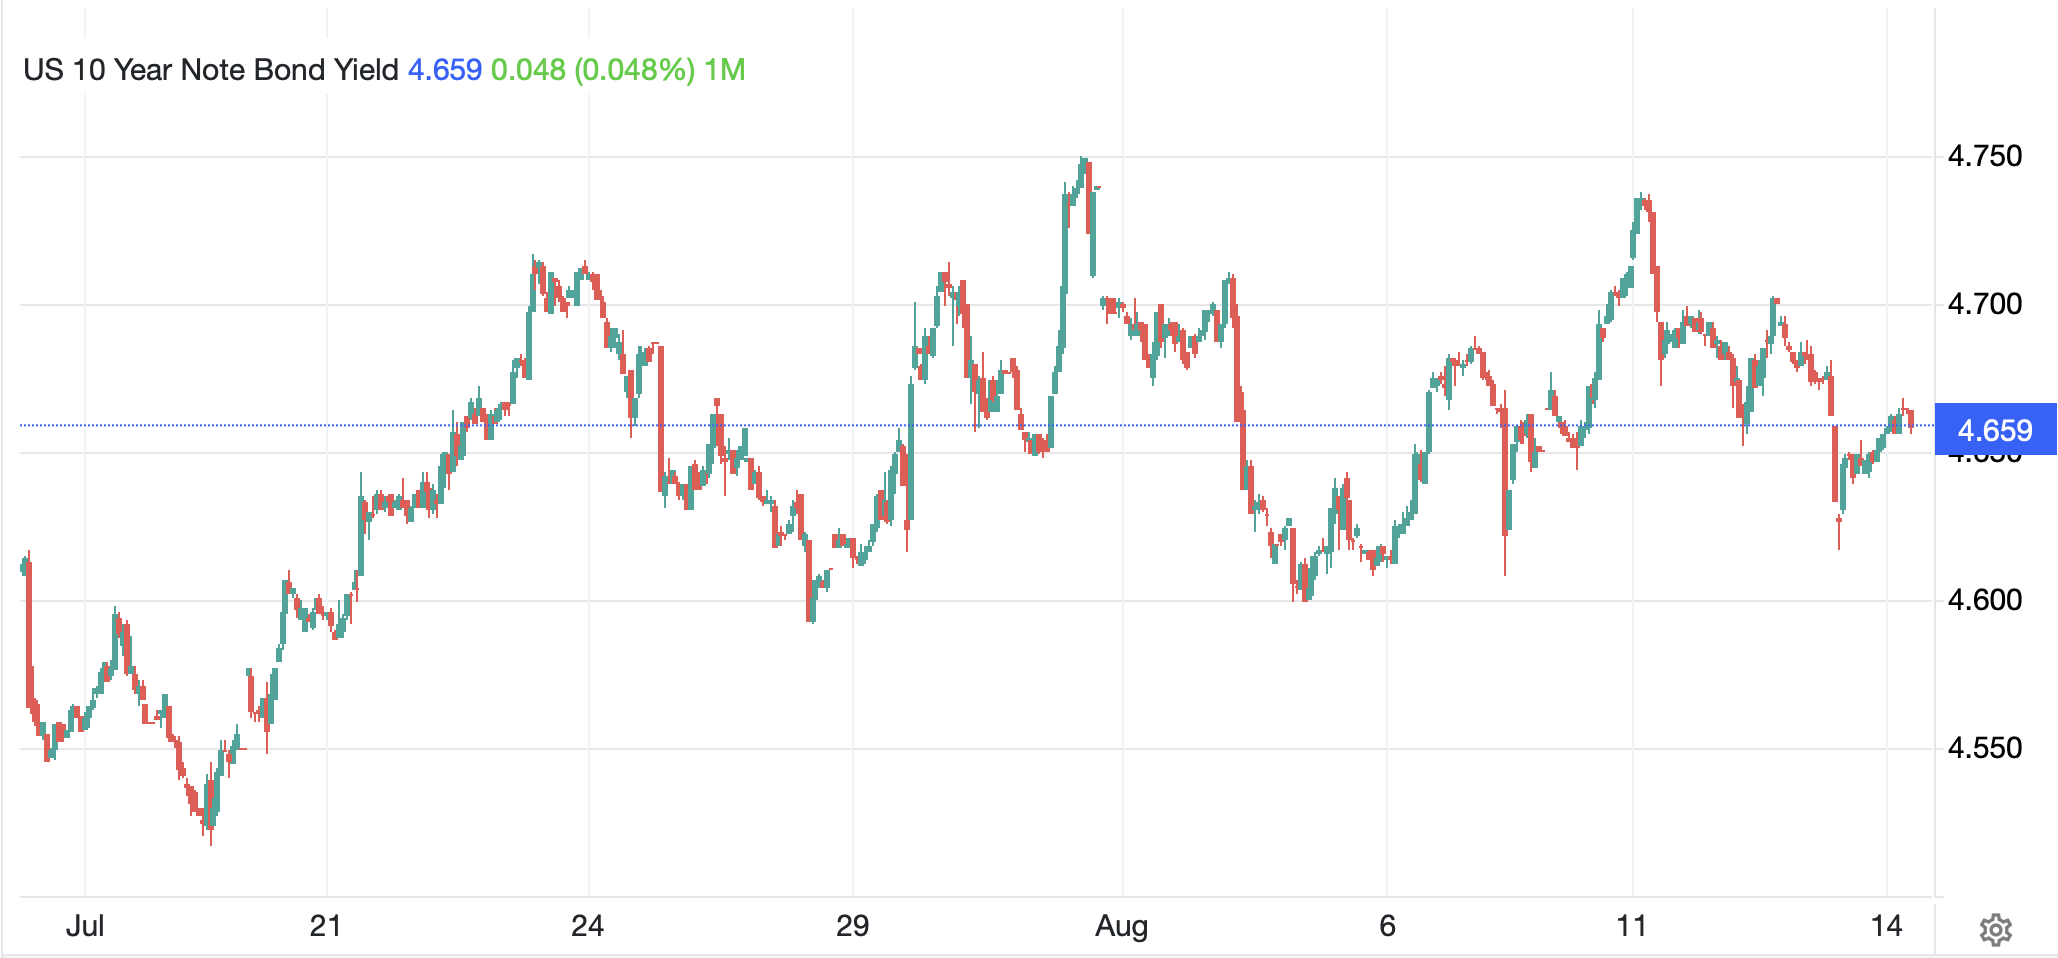
Or bonds, which in fairness have been a little choppier but still gone nowhere:

Source: tradingeconomics.com

The dollar:

Source: tradingeconomics.com

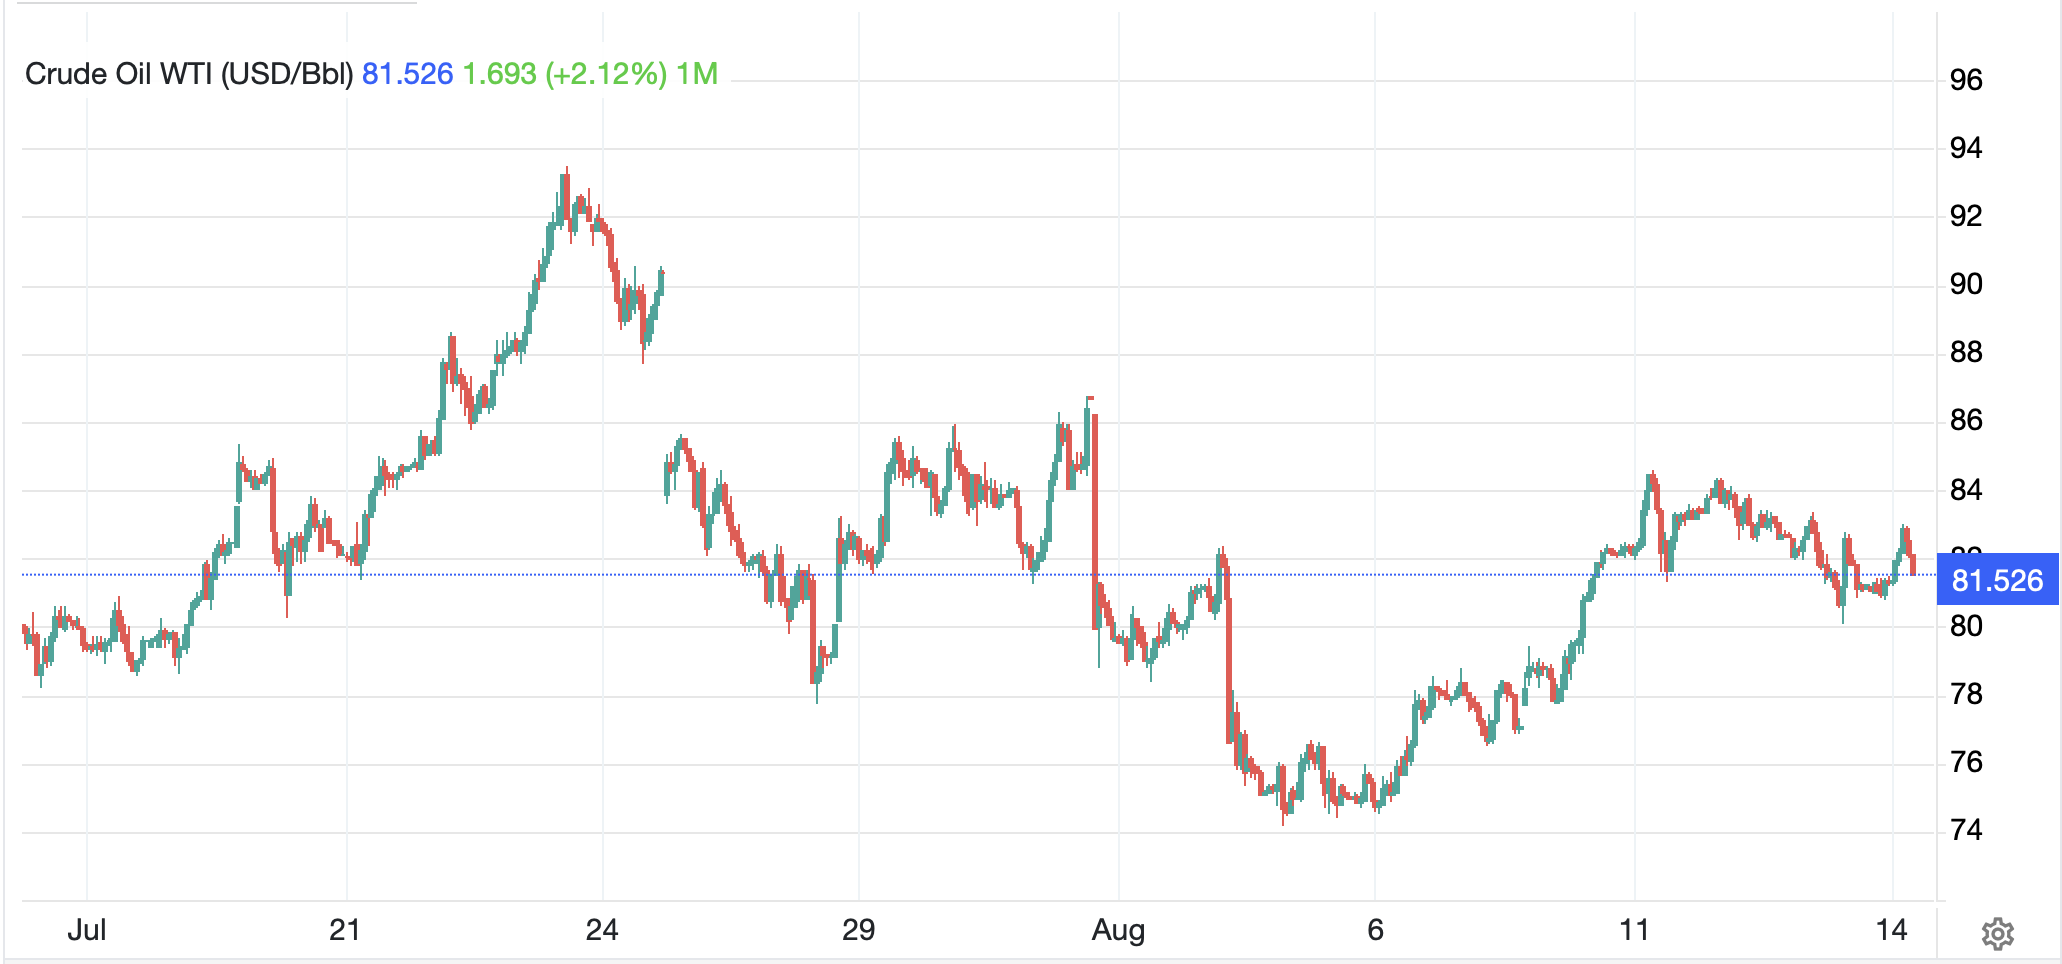
Or even oil, which in the past week has barely moved on net:

Source: tradingeconomics.com

We are very clearly in the summer doldrums.  I think even the narrative writers have gone on summer holiday as there is precious little to discuss.  Yes, we’ve seen a soft NFP report and softer than expected CPI and PPI data, but that has not generated much excitement.  While the Iran situation can always find something for people to discuss, certainly based on the recent EIA oil inventory data, the ‘running out of oil’ story has been put to bed.

Frankly, there is very little to discuss, and I have a feeling it is going to stay that way until we hear from Chairman Warsh at the Jackson Hole summer confab in exactly two weeks.  As it’s August, we already knew that Europe was on vacation, but other than some primary elections in the US, where the effort to generate excitement ahead of the midterms in November has not yet gained traction, what is really new?  Arguably, the most interesting story is Enes Kanter Freedom, the ex-NBA player declaring for the WNBA draft as the WNBA cannot seem to figure out how to define a woman.

So, to keep things brief, I will give a quick rundown now and send you on your way.  Yesterday’s modest gains in US equities were followed by a mixed session in Asia with Tokyo (+0.6%), Korea (+2.4%, which these days is a modest movement here) and Indonesia (+1.6%) all gaining while China was flat and HK (-1.1%), Australia (-0.8%) and Taiwan (-0.5%) all slipped a little.  It is hard to tell a story about this outcome.  

In Europe, only Germany (+0.7%) is showing any life, reaching another record high on the back of some more strong earnings reports, mostly from German defense manufacturers.  But the rest of the continent is little changed, +/- 0.1%.  And at this hour (7:10), US futures are also +/-0.1%, in other words flat.

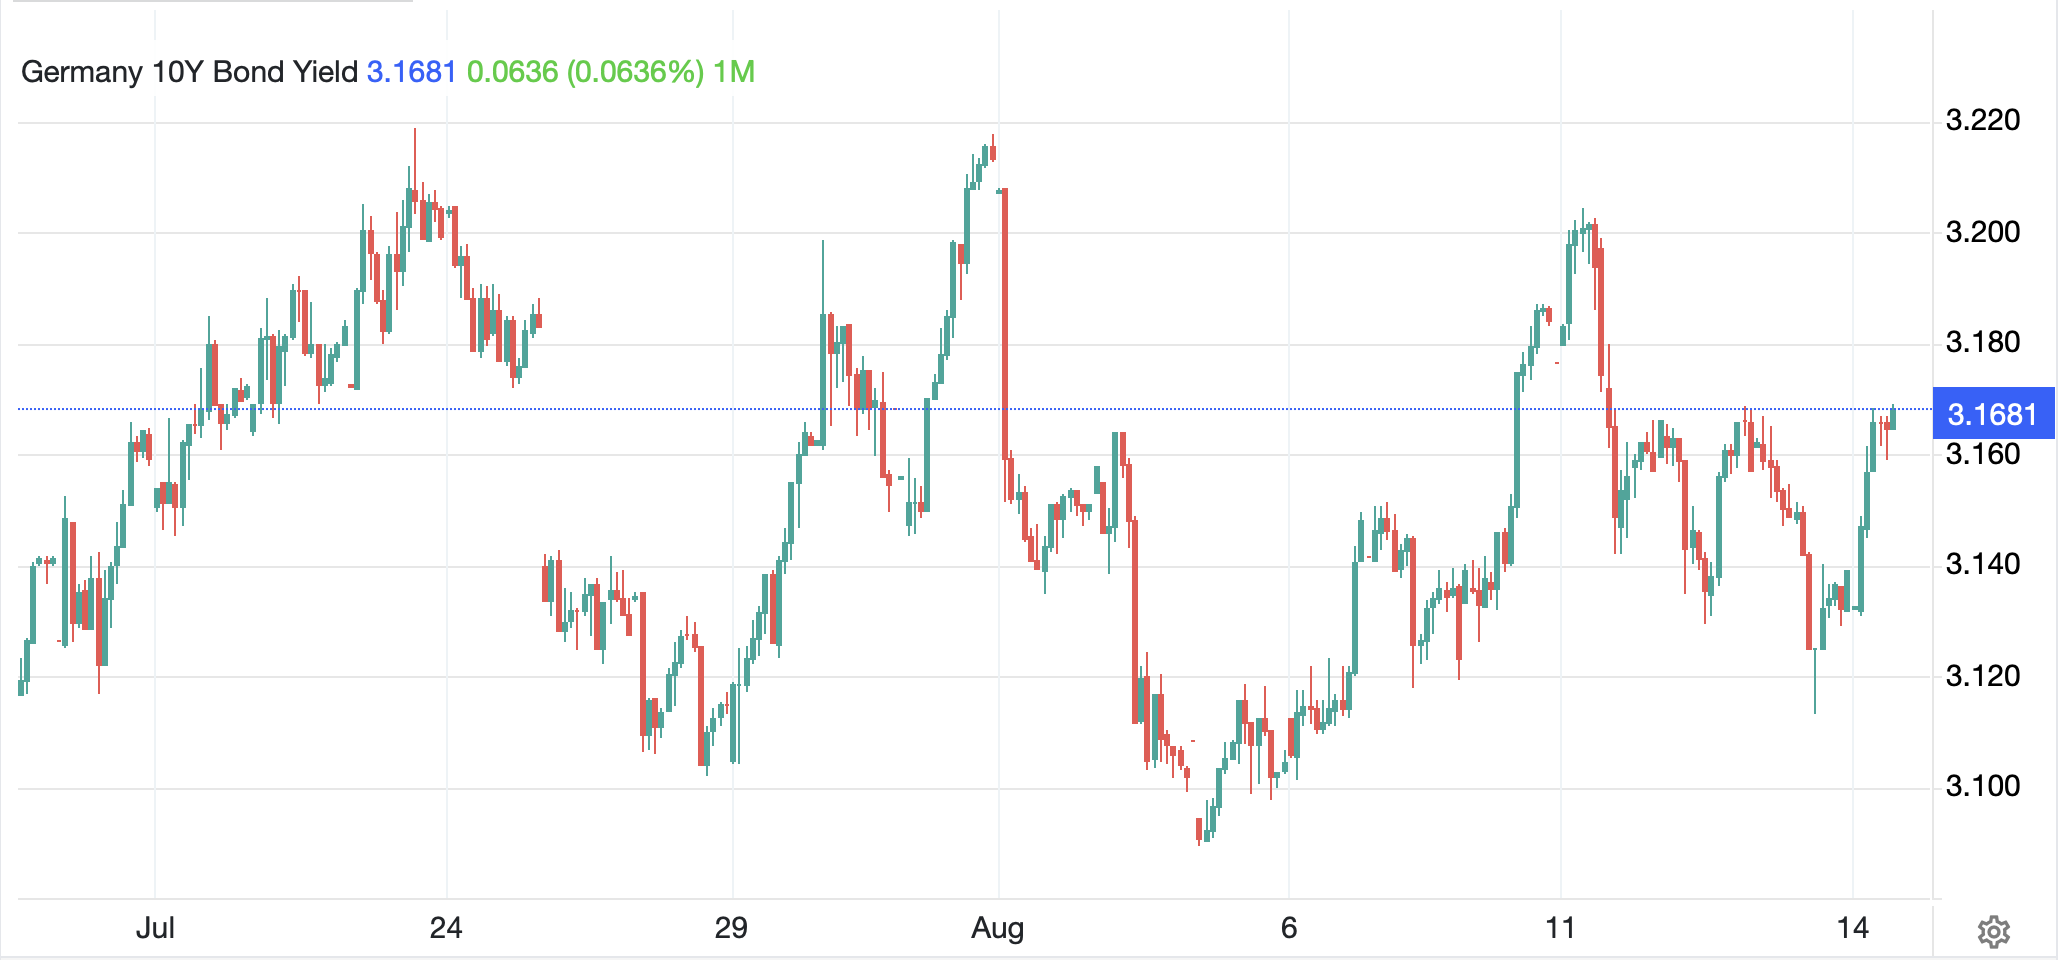
In the bond market, Treasury yields, which slipped -5bps yesterday as both PPI and oil prices were softer, have edged higher by 1bp.  However, European sovereign yields are all higher by between 3bps and 4bps this morning, although it is not clear what is driving this movement.  In truth, if I use bunds as my example, while like Treasuries, the price action has been choppy, as you can see in the below chart from tradingeconomics.com, we haven’t gone anywhere in weeks.

As to JGB yields, this morning they are unchanged, hanging on just below the recently achieved multi-decade highs.  

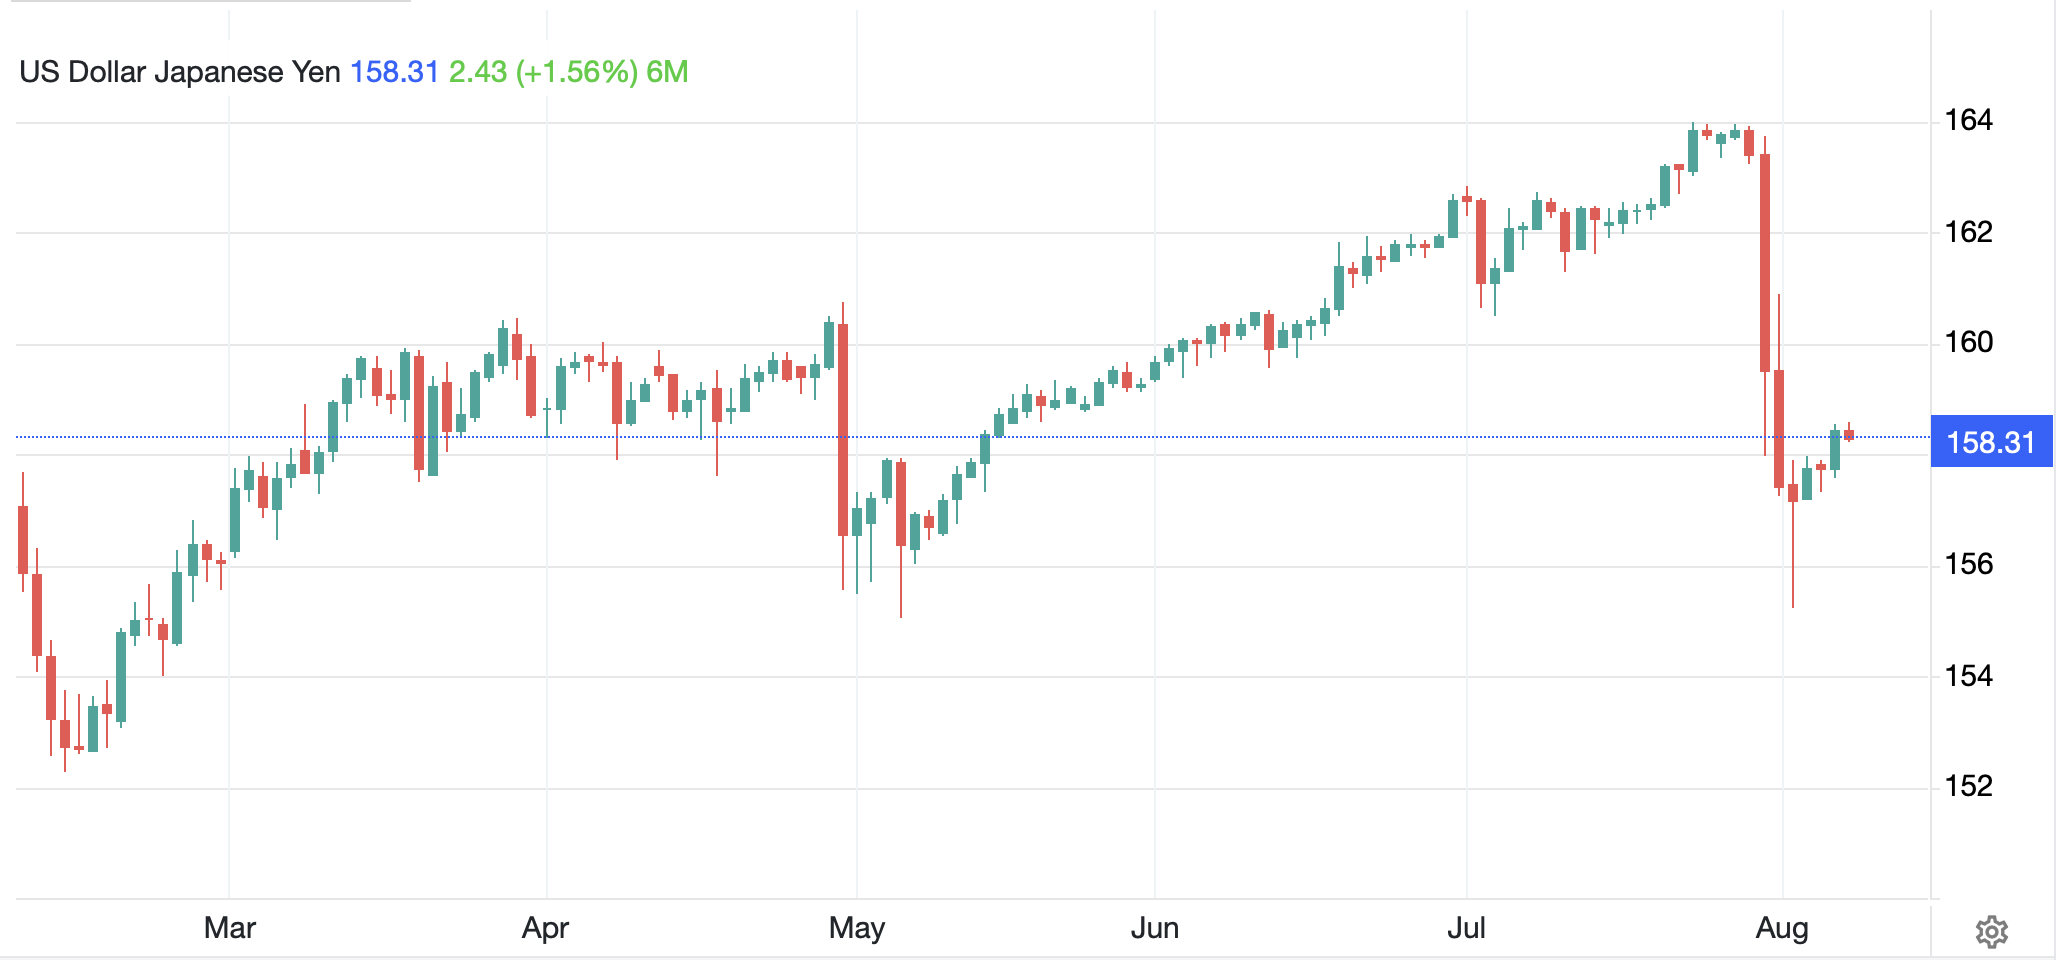
But speaking of Japan, while the yen (+0.2%) is slightly stronger this morning, as you can see in the chart below, the post intervention pattern remains in force.  In fact, Bloomberg had an article about how speculators used the intervention to reload on short JPY positions.  But the more interesting thing I saw this morning was the following Tweet:

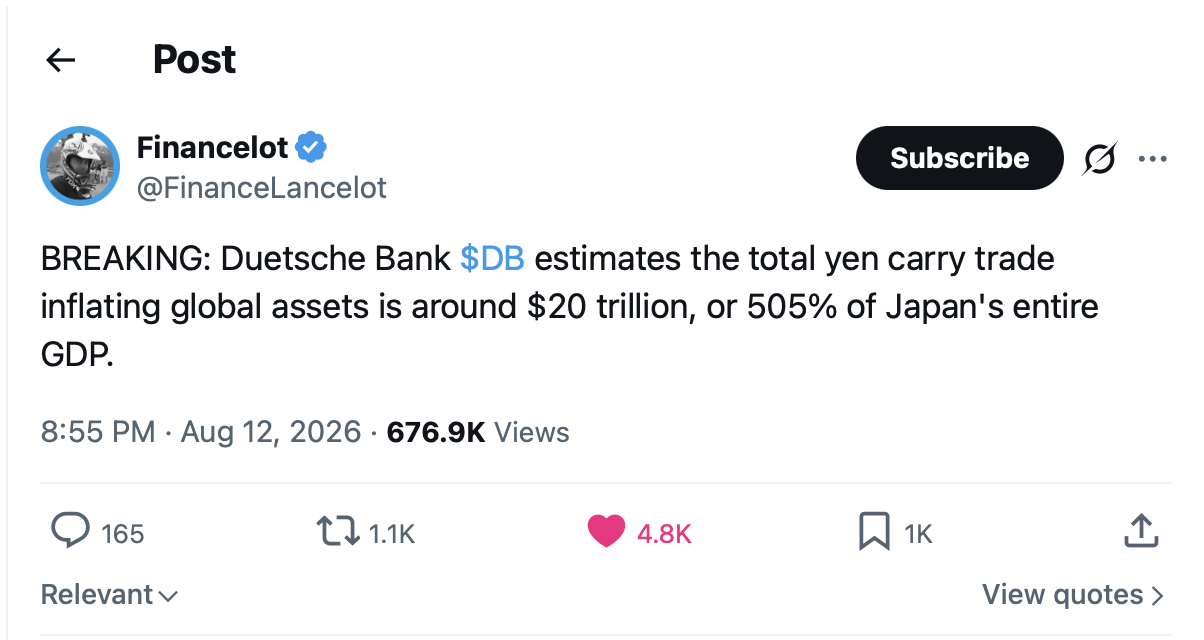
Now, I don’t know how they arrived at that number, and while I always thought the trade was in excess of $3 trillion, $20 trillion is much larger than I expected, but if this is true, it certainly adds a certain stress level to the global economy.  I have maintained that outward Japanese investment in financial products, so purchases of non-Japanese bonds and stocks buy Japanese institutions is a part of this process and adds to the number.  I assume that is part of the calculation Deutsche has made, but I could be wrong, I have not seen the actual report.  But along those lines, in the most recent week, Japanese investors purchased >¥1.6 trillion (~$10 billion) in foreign bonds, keeping up the flow.

If we look at just the G-SIB banks, the major players in international finance, according to Grok, their total combined balance sheets summed to about $78.4 trillion at the end of 2025.  Of course, assuming the carry trade makes heavy use of derivatives for financing, much of that alleged $20 trillion may not show up on their balance sheets, but perhaps it represents as much as 15% of bank assets.  This is quite a concern, especially as, again according to Grok, those same banks have only ~$4.7 trillion in Tier 1 capital.  

So, if these numbers are even in the ballpark, it tells a tale of a highly leveraged banking system that is subject to major convulsions if a certain series of events unfold, notably, the carry trade loses its luster.  (if you ever wondered why goldbugs are goldbugs, this is exhibit A).  The thing to remember is it has taken decades for this trade to accumulate, and it will not decumulate in weeks, or even months, but will take years to do so.  As well, if things start to turn, you can be certain that central banks will do their best to prevent a runaway train, and they have enormous power, specifically the power to print money, to slow things down.  But that doesn’t mean things won’t get ugly if this is the future.  I hark back to my comments regarding the end of forward guidance and how that will enhance markets’ collective anti-fragility.  It feels like the global financial system, if this is true, is seriously fragile!

Ok, let’s wrap up.  In FX, the dollar is softer this morning across the board, with the DXY (-0.4%) quite representative of the movement across both G10 and EMG currencies.  However, the thing to remember here is that we are still rangebound overall for the past year in G10 currencies, although we have seen broad based strength in a number of EMG currencies like MXN, BRL and ZAR , all of which have much higher real rates than the US.

Lastly, oil (+0.3%) is a touch higher, while metals prices (Au +0.3%, Ag +0.8%) are also firming up on the softer dollar.  But there is little to discuss here.  News that the US is sending another aircraft carrier to the Persian Gulf area got oil to rise earlier, but that is fading already.

On the data front, this morning brings Retails Sales (+0.1%, +0.2% -ex autos) and then Michigan Sentiment (54.5) at 10:00.  There is one Fed speaker, an Atlanta Fed VP and acting President as they seek a new President.  However, given her acting status and the fact Atlanta is not a voter, I don’t think anybody will even listen!

So, absent a seriously strong Retail Sales report, the die is cast for another slow day in my view. 

Good luck and good weekend

Adf

Investors Are Troth

The doom mongers are up in arms
As though they raise many alarms
Investors don’t care
And add risk with flair
Ignoring the much-mooted harms

So, war is no longer concerning
And though hyperscalers are burning
Through all of their cash
Amid much backlash
Investors, their shares, are still yearning

And what about data and growth?
Investors care naught about both
Concerns about yen?
Not that trope again!
To stocks most investors are troth

As I read through my X feeds in the morning, as well as the WSJ and Bloomberg, the overriding theme appears to be the end is nigh.  Whether discussing Iran and the oil price and the future of the Strait of Hormuz, AI and the bubble or the potential for massive job losses and the creation of Skynet, the economic data and the incipient recession coming because people cannot afford to continue their consumption habits, or the idea that we are on the precipice of a Treasury bond market collapse because the Japanese yen is weak, the dominant theme is disaster is around the corner.  It is really tiresome, I have to say.

Now, you might say that I simply follow the wrong people, and that may be true, but my feed hasn’t changed, and I never look at the algorithm’s selections for me, I only look at my followings.  So, I cannot tell if people have become that much more bearish on the overall situation, or if they simply write these things because they believe they will get more engagement.  I fear it is the latter, but that simply devalues anything useful they may have to say.  Mostly, it’s frustrating to try to get an unbiased sense of what is happening in the world these days.  After all, while I understand that governments put out propaganda constantly, I thought the idea behind X and Substack was you could avoid that.  I think I am going to go back to reading books!

So, as we await this morning’s payroll report, I’ll try to touch on the key issues I believe matter.  Starting with the yen, which continues to garner attention, or more accurately, the joint intervention garners attention, I first have to laugh at the following Bloomberg headline, “Yen Surrenders Nearly Half Its Gains From US-Japan Intervention”.  This was written by Mia Glass, and I don’t know anything about her except her grasp of arithmetic is tenuous.  Here is the chart of USDJPY and while the yen has been weakening steadily since the intervention last week, half?  Even taking the spike low into account, we are nowhere near a 50% retracement and on a closing basis, it is a ridiculous claim.

Source: tradingeconomics.com

There continues to be much fodder made about Secretary Bessent trying to prevent a meltdown in the Treasury market but Occam’s Razor tells me that it is far more likely that a too-weak yen is bad for Japan because of its inflationary impact and the US because it impedes US exports so joint intervention made sense.  And as I have maintained all along, unless underlying fiscal and monetary policies change, the yen is going to continue to weaken.

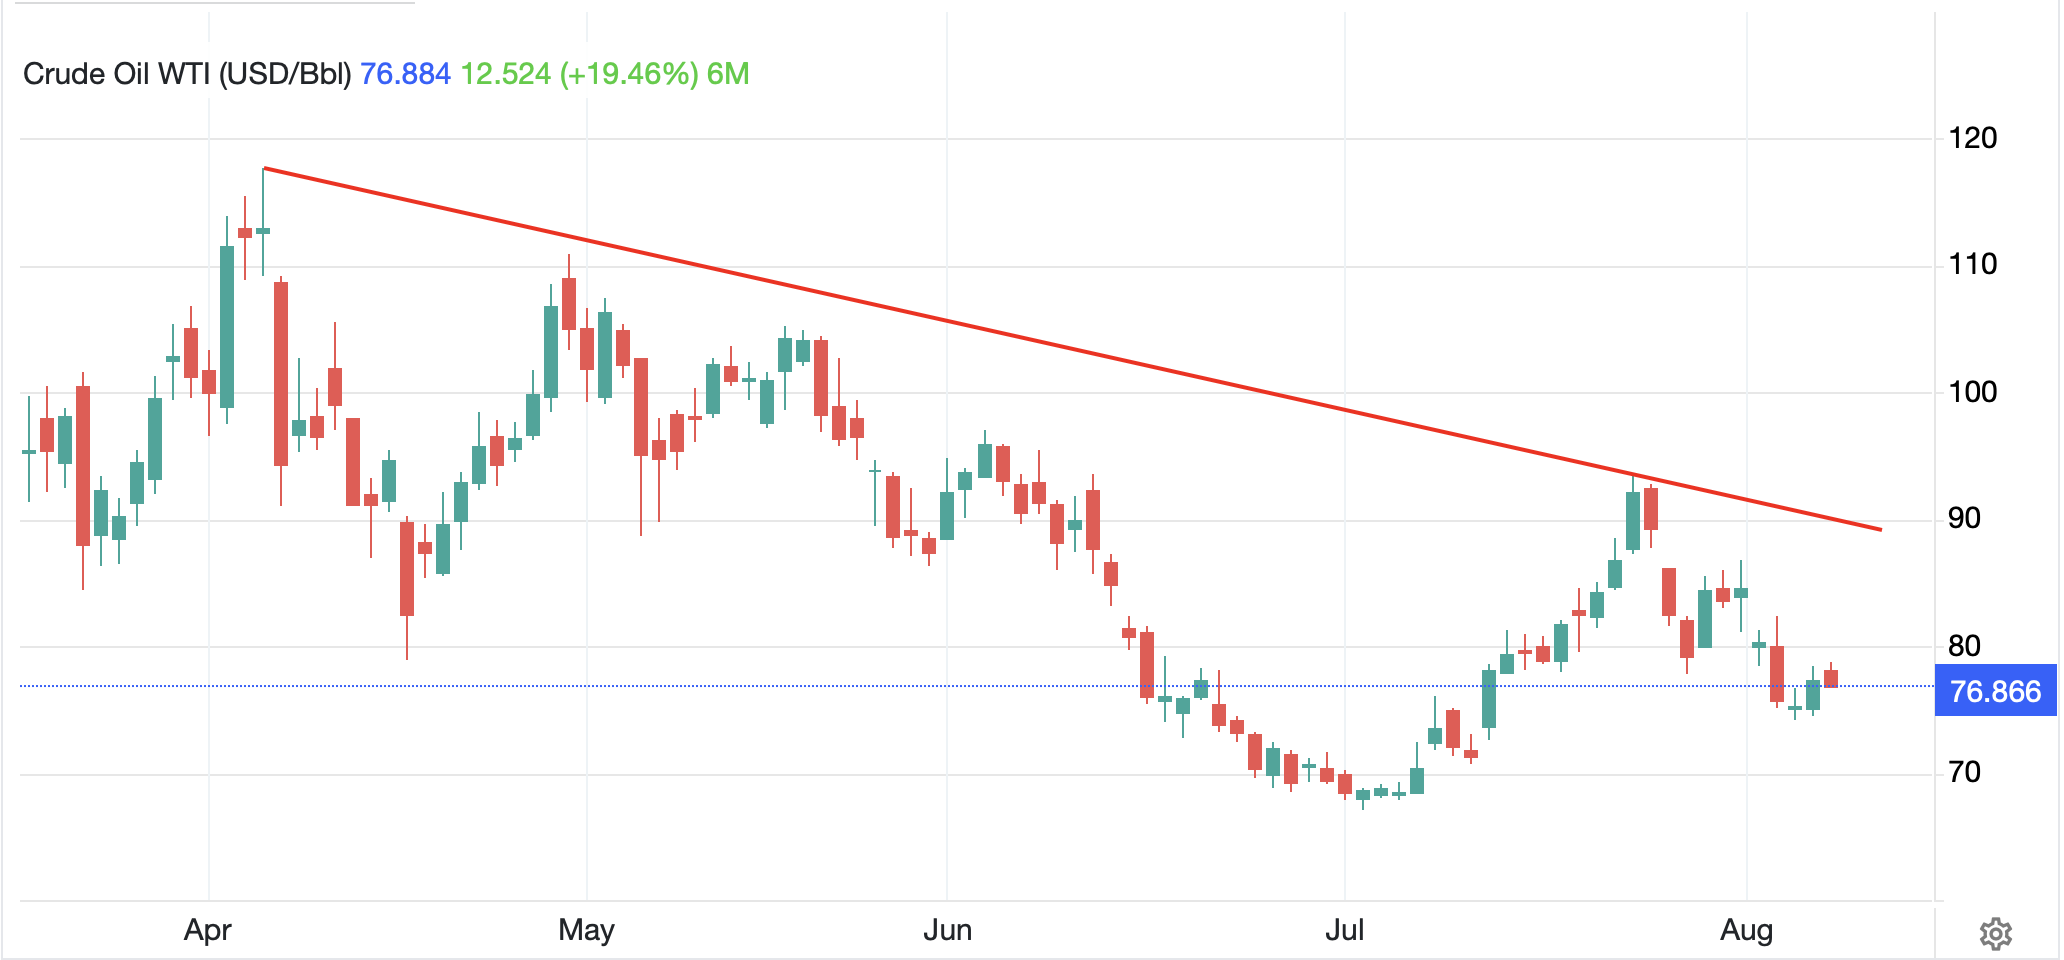
Turning to Hormuz, the press continues to write with glee about President Trump’s miscalculation and the US losing the war and whether Iran and Oman are going to come to some agreement on the Strait, but oil prices, while they rallied a bit yesterday, are lower this morning by -0.6% and -9.25% in the past week.  Looking at the chart below, despite all the discussion of inventory depletion, which are real, but obviously not as important to the price as many previously believed, the trend remains downward and we are well below the trend.  Frankly, at $75/bbl, it appears the world works fairly well.

Source: tradingeconomics.com

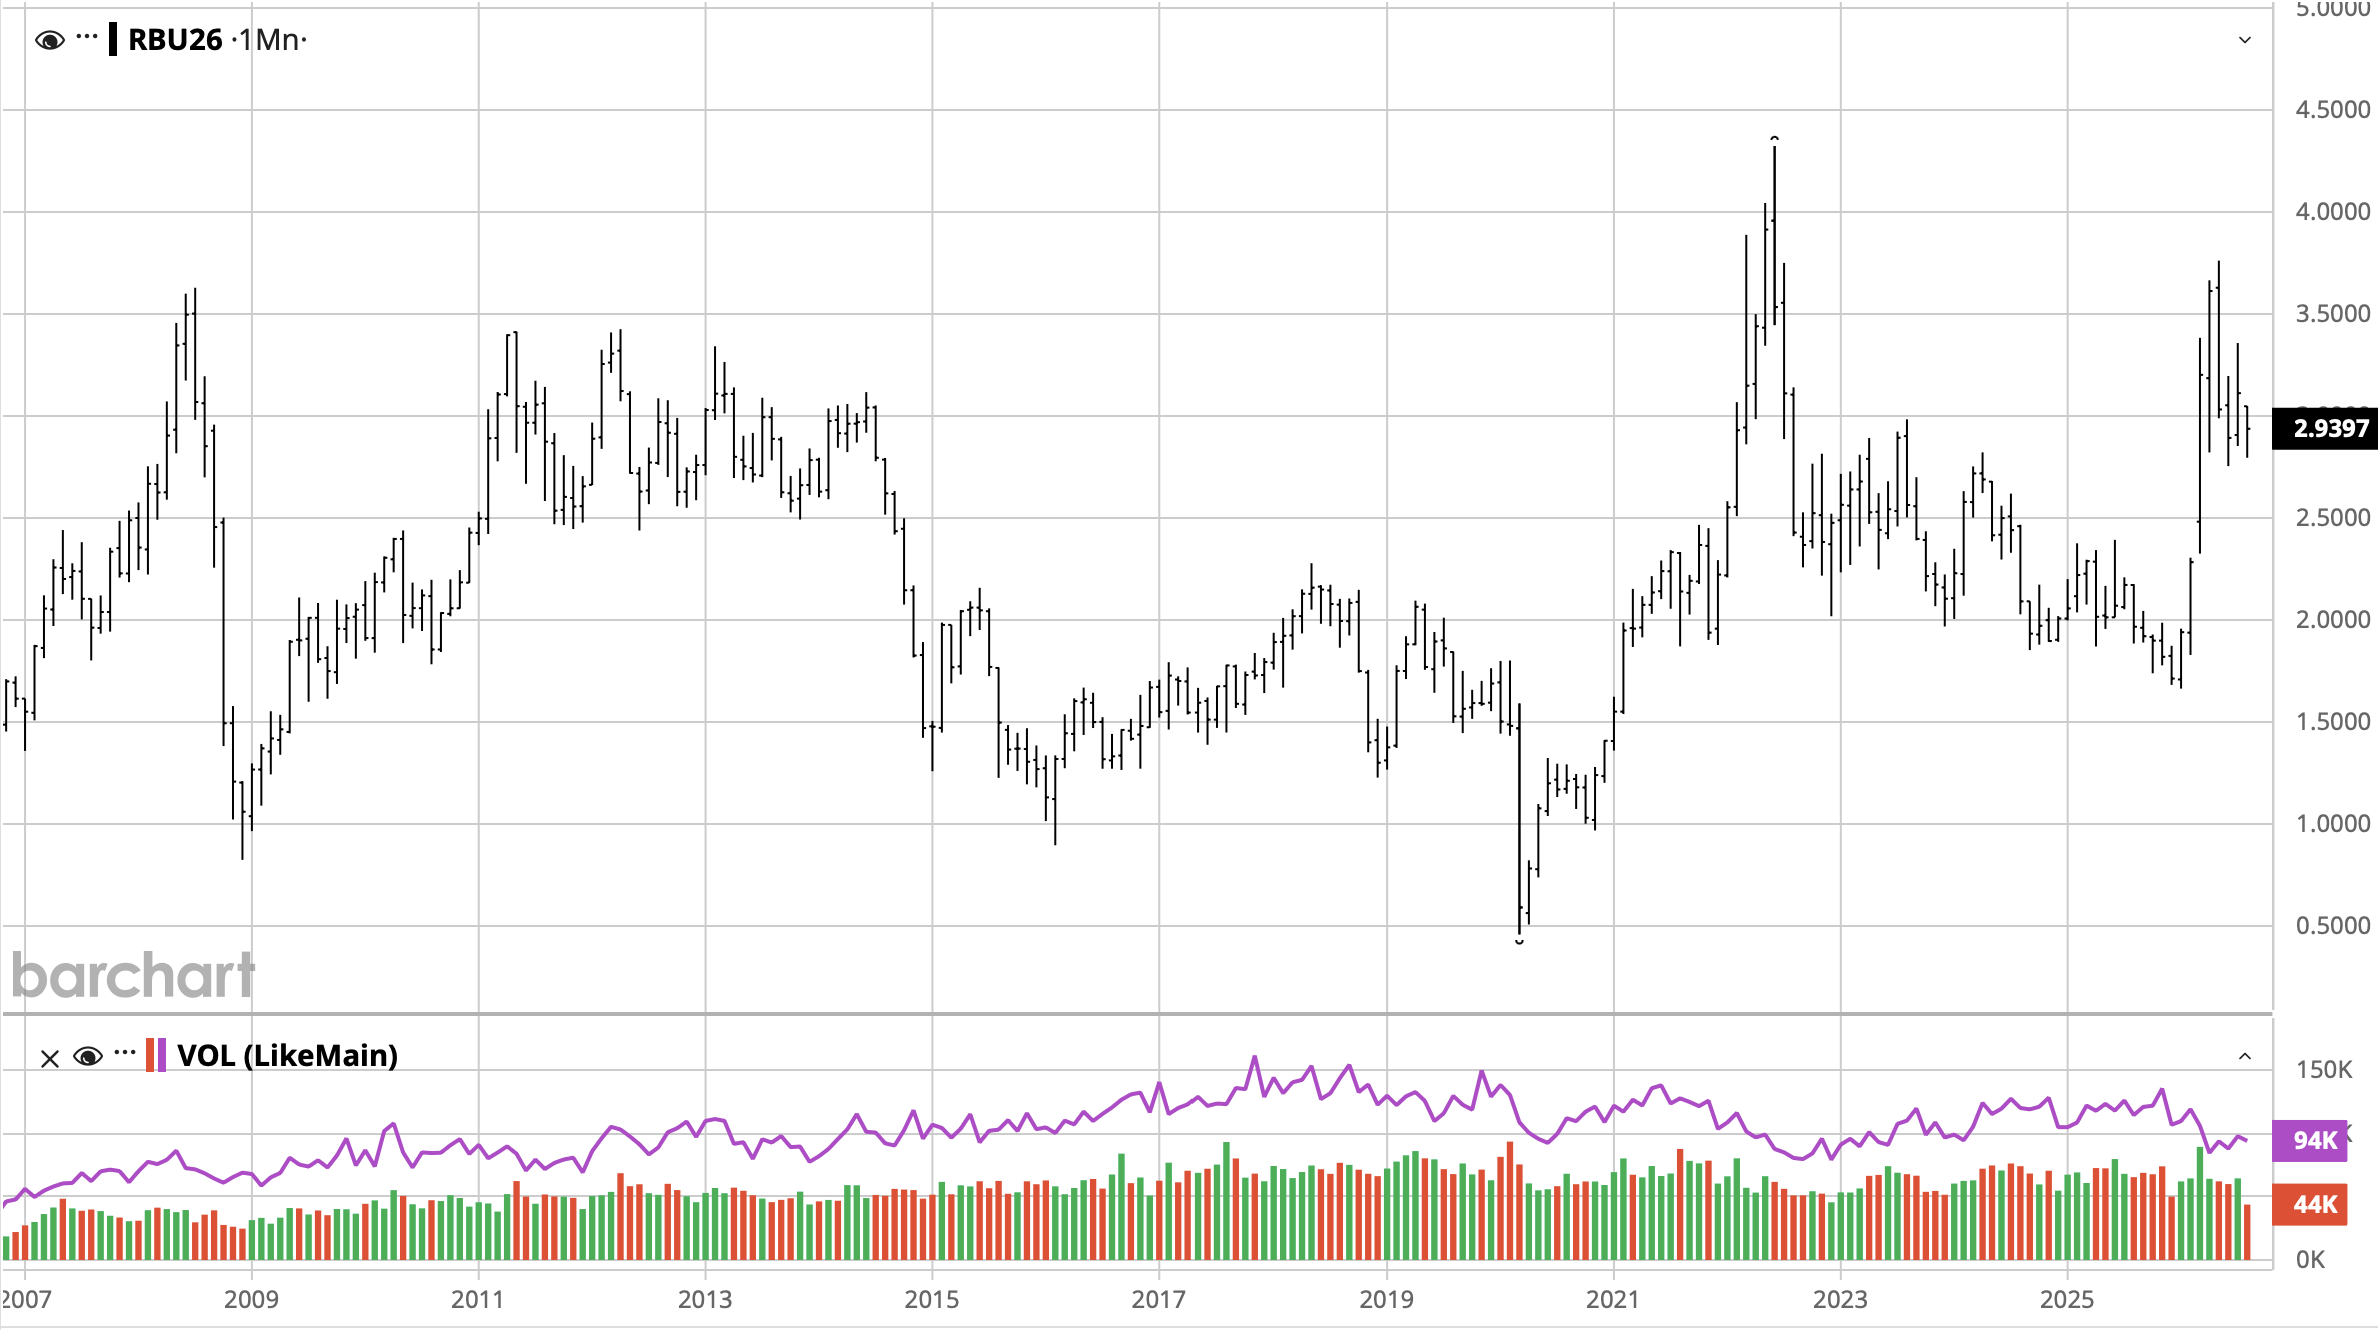
Look, I would rather pay less for my diesel, and I know you would all like to pay less for your gasoline, but here’s a 20-year history of the RBOB (NYMEX gasoline) contract.  We are hardly in unprecedented territory having spent a lot of time around here from 2011 through 2015 as well as the beginning of the Russia/Ukraine war.

I have no idea how things will end up in Iran, nor does any other commentator.  I know I am happier if Iran does not have a nuclear weapon and ballistic missiles that can reach Europe, let alone the US.  But I would say the market has almost lost interest in the war.

As to the hyperscalers and the AI bubble, in truth, it seems much of the animosity has been turned toward SpaceX as everyone loves to hate Elon almost as much as they love to hate Trump.  But it appears by many metrics that equity markets continue to benefit across the board from strong earnings results, with ~85% of companies (depending on your source) beating estimates which is well above the average of 77%.  So, the economy continues to grow pretty strongly, and companies continue to make money, and investors continue to want to buy shares.  The hyperscalers aren’t leading the pack anymore, but they have not collapsed either.  There are many who continue to explain this cannot go on forever and there will be a reckoning, and they may well be correct, but in this case, being early and being wrong are the same thing.

Ok, enough of that.  Let’s see if anything noteworthy has happened overnight.  The truth is, not especially.  Asian shares were mixed with Chinese shares doing well after solid trade data, but the rest of the region drifted lower.  European shares are firmer across the board after broadly positive data (German IP and Trade, French Trade) although the French Unemployment Rate ticked higher to 8.3%.  And US futures are higher this morning as well ahead of the NFP report.  Despite the doom and gloom, equity markets are doing fine.

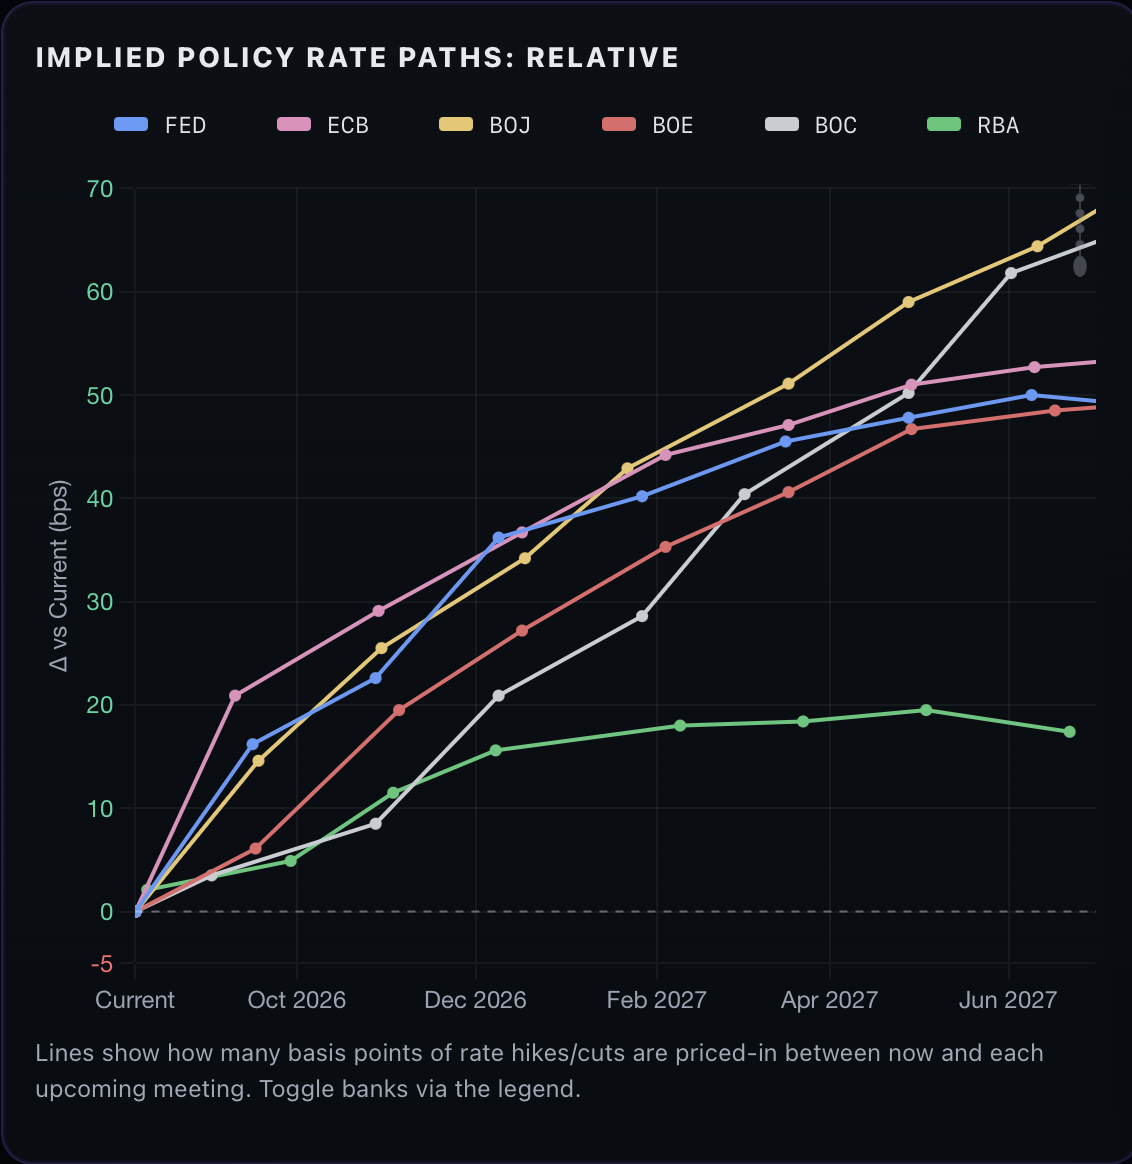
Bond markets have barely moved overnight, although we did see Treasury yields back up 5bps yesterday.  That appears to have been on the back of the oil price rise, although as I look at probabilities of central bank rate hikes, there is a growing belief that the Fed, ECB and BOJ are all going to raise rates next month as hiking rates into an energy shock seems to be their MO.

Source: rateprobability.com

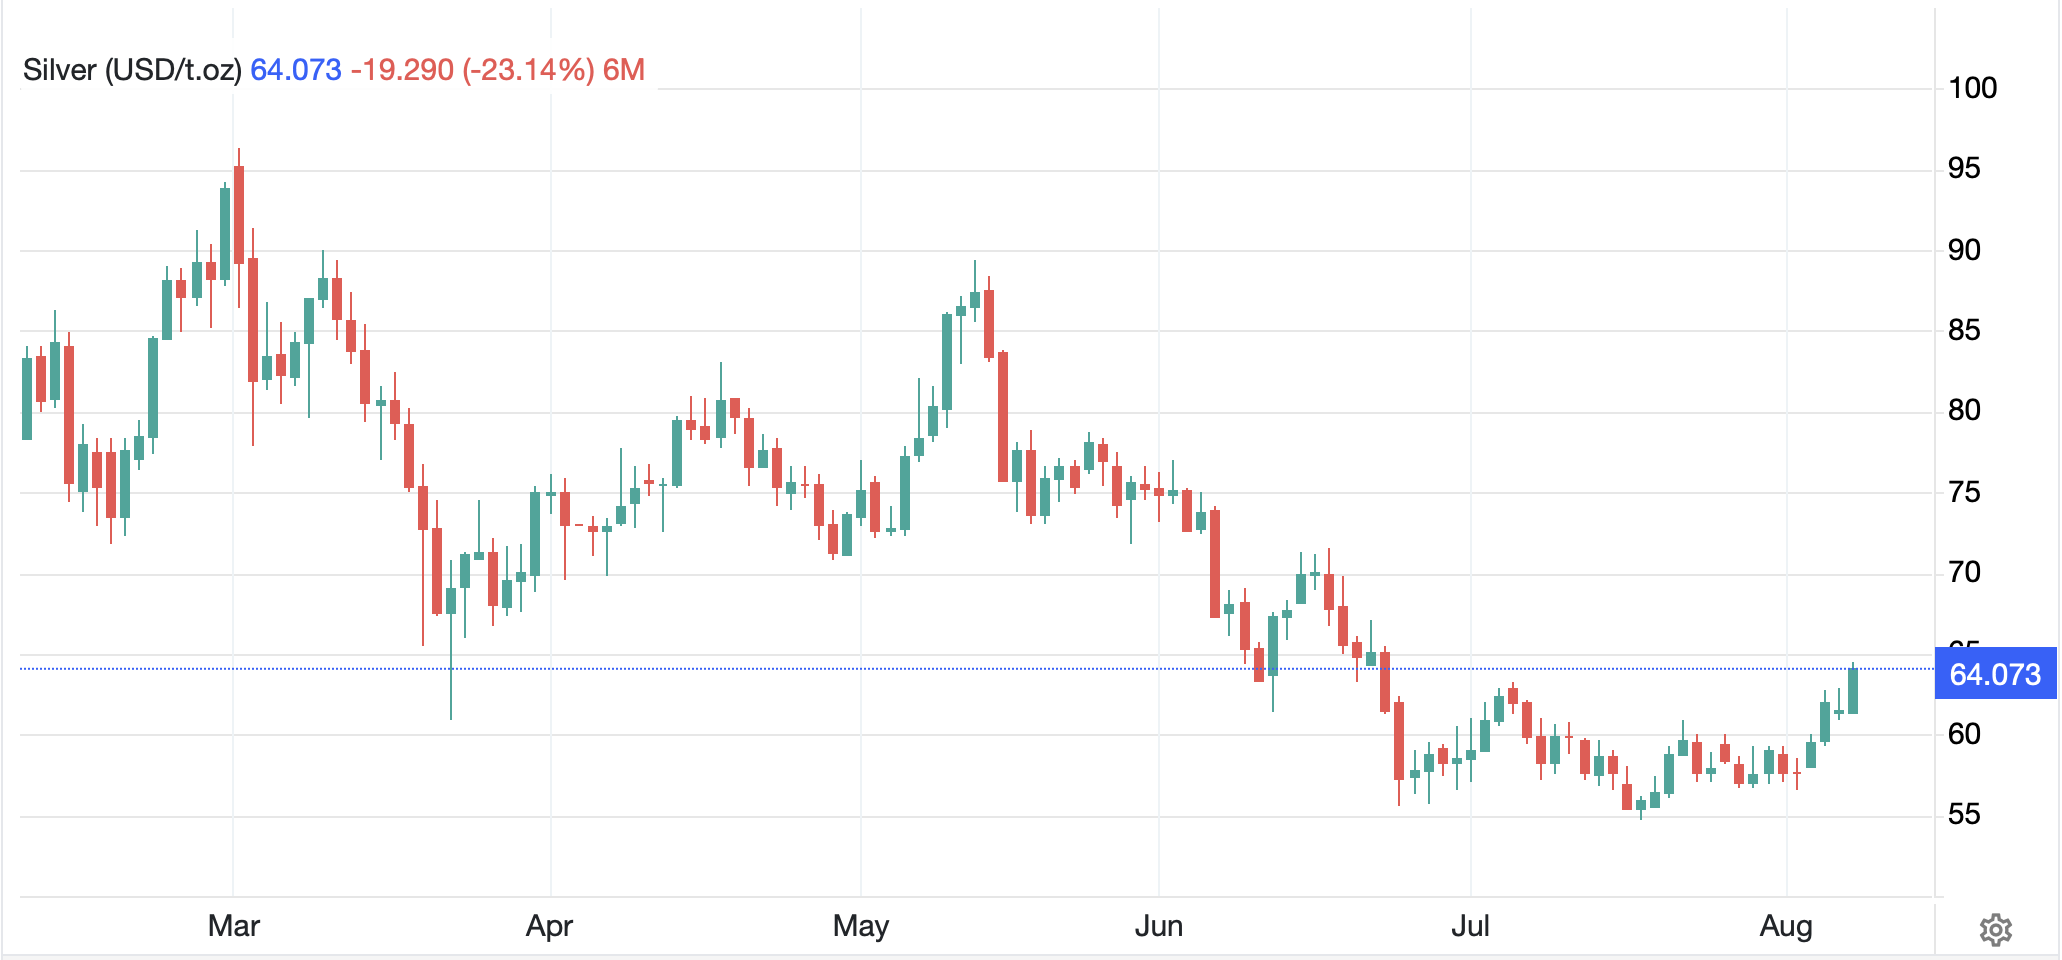
We discussed oil but gold (+2.0%) and silver (+4.1%) are the real story in commodities as both are extending their recent rallies from the consolidation lows.  For instance, silver is higher by 11% this week and $9/oz since July 17th.

Source: tradingeconomics.com

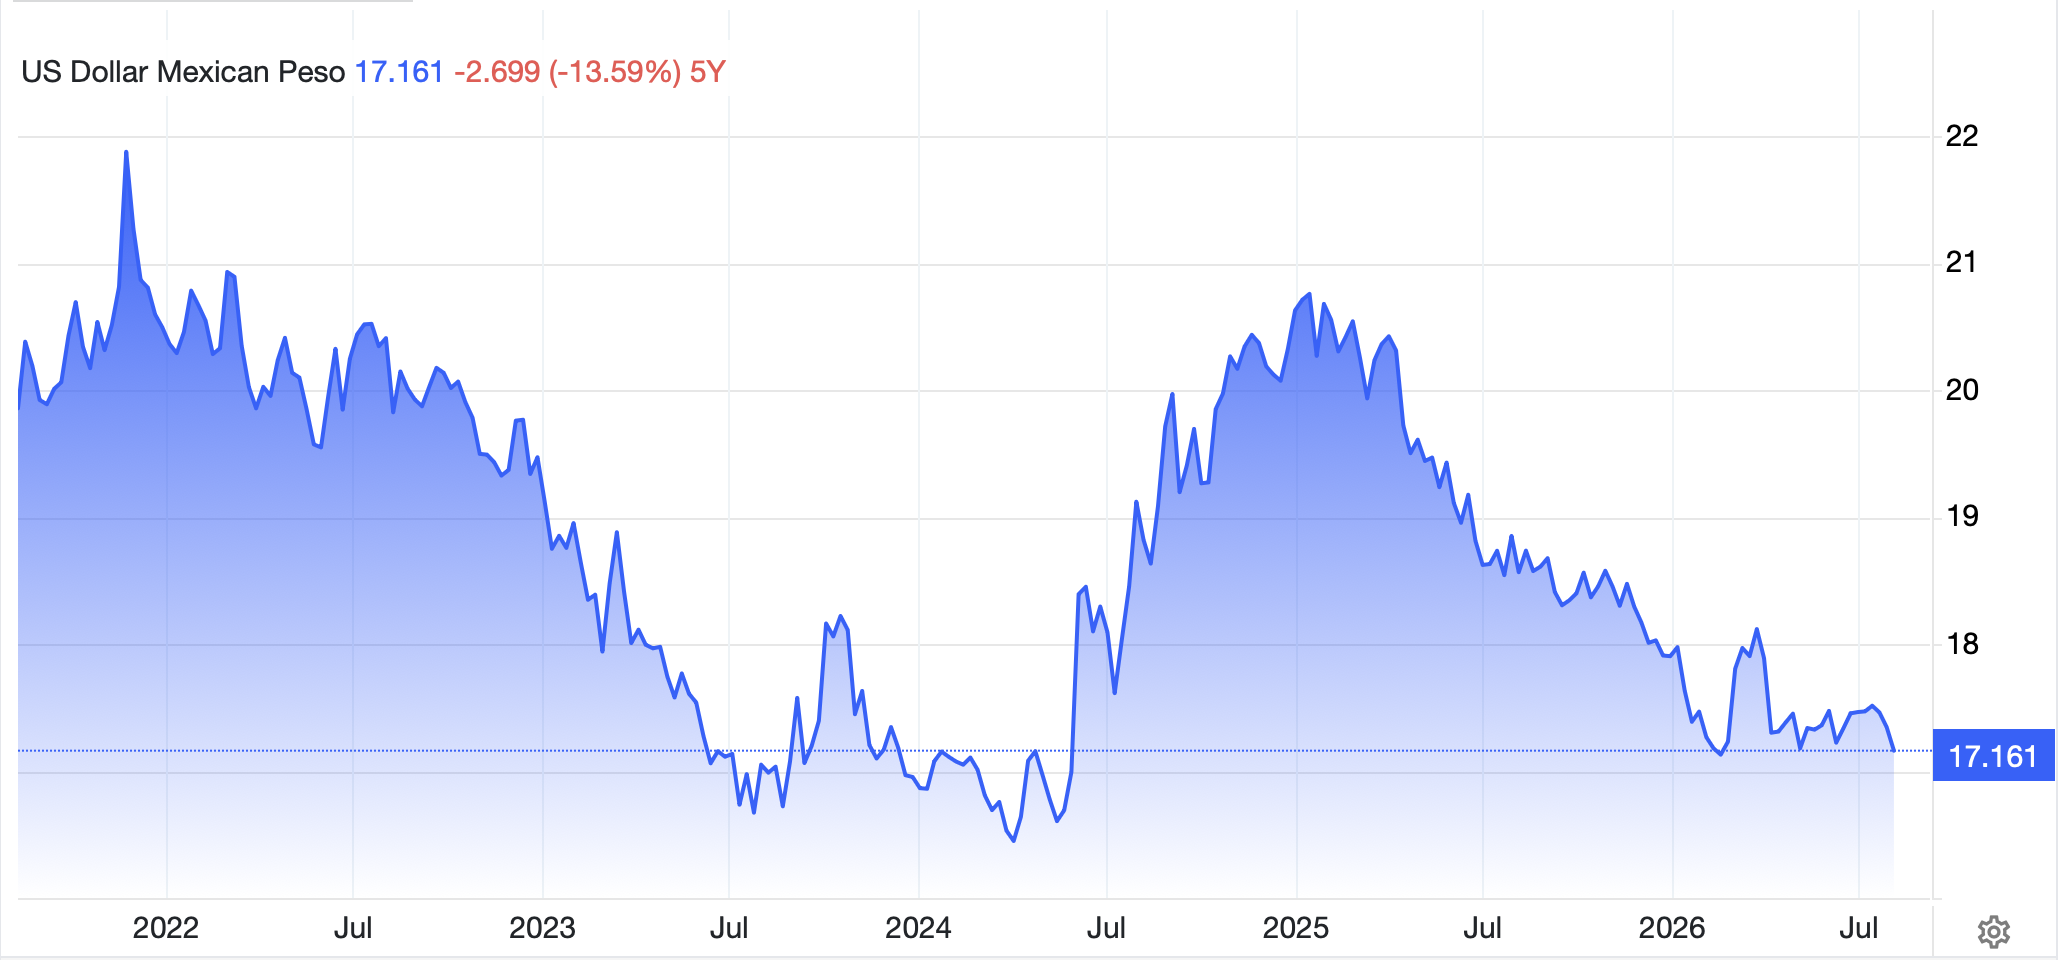
Finally, the dollar, despite all the anxiety about the yen, remains quiet overall.  The DXY is below 100, back in its range and showing no inclination to move in either direction.  This morning ZAR (+0.7%) is the king of the hill on the rally in gold while MXN (+0.3%) is a touch higher after Banxico left rates on hold.  But remember, peso rates are still high and economic growth continues apace so investment opportunities abound.  The peso has strengthened more than 17% since the beginning of 2025, shaking off any tariff concerns easily.

Source: tradingeconomics.com

As to the data, here are consensus forecasts:

Nonfarm Payrolls80K
Private Payrolls78K
Manufacturing Payrolls4K
Unemployment Rate4.2%
Average Hourly Earnings 0.3% (3.5% Y/Y)
Average Weekly Hours34.3
Participation Rate61.6%

Source: tradingeconomics.com

We also see Canadian employment data (exp 6.5% Unemployment Rate) and hear from Thomas Barkin, the Richmond Fed president.  But it is a summer Friday and typically, about an hour after the NFP release, traders are gone for the weekend so don’t expect too much today.

The world is not ending, the dollar is not collapsing, the Treasury market is not collapsing, and equity markets are not about to implode.  My take is the big stories from the past months have lost their luster and I suspect after a lull, we are going to start to focus on the politics of the midterm elections in November.  But until then, have a cold one and relax.

Good luck and good weekend

Adf

A Bad Taste

For weeks, things appeared to get better
As yields slipped and helped every debtor
But we’ve seen some changes
With yields breaking ranges
And oil back to the pacesetter

So, stocks are not really embraced
While bonds have left all a bad taste
The dollar’s moved higher
While gold’s back to dire
With analysts worldwide disgraced

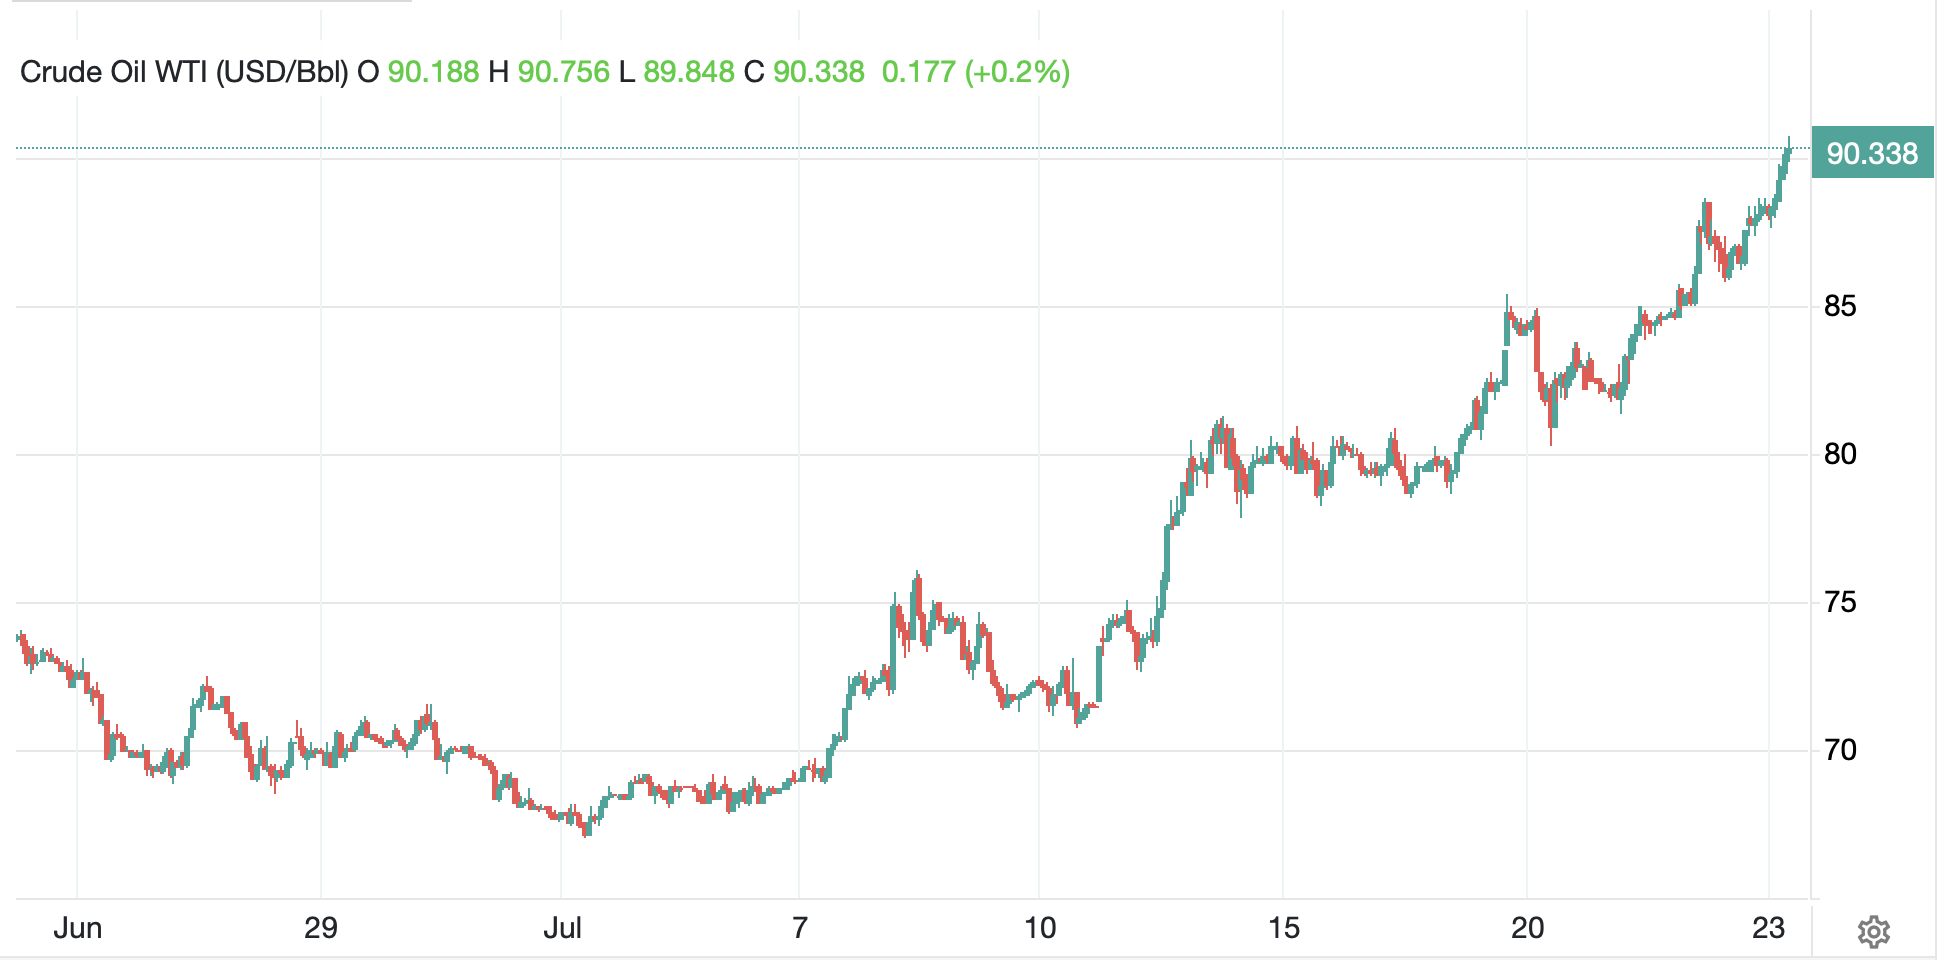
Investors are not as happy this morning as they had been for the past several weeks as the situation in Iran and the Middle East appears to be deteriorating again.  The US continues to attack Iranian missile launchers and fortifications on a daily basis while Iran continues to fire missiles at targets throughout the Gulf region.  As well, the Houthis are back at it in the Red Sea restricting oil flows through there as well.  Arguably the chart below of oil (+4.0%) is the most descriptive view of what is driving everything.

Source: tradingeconomics.com

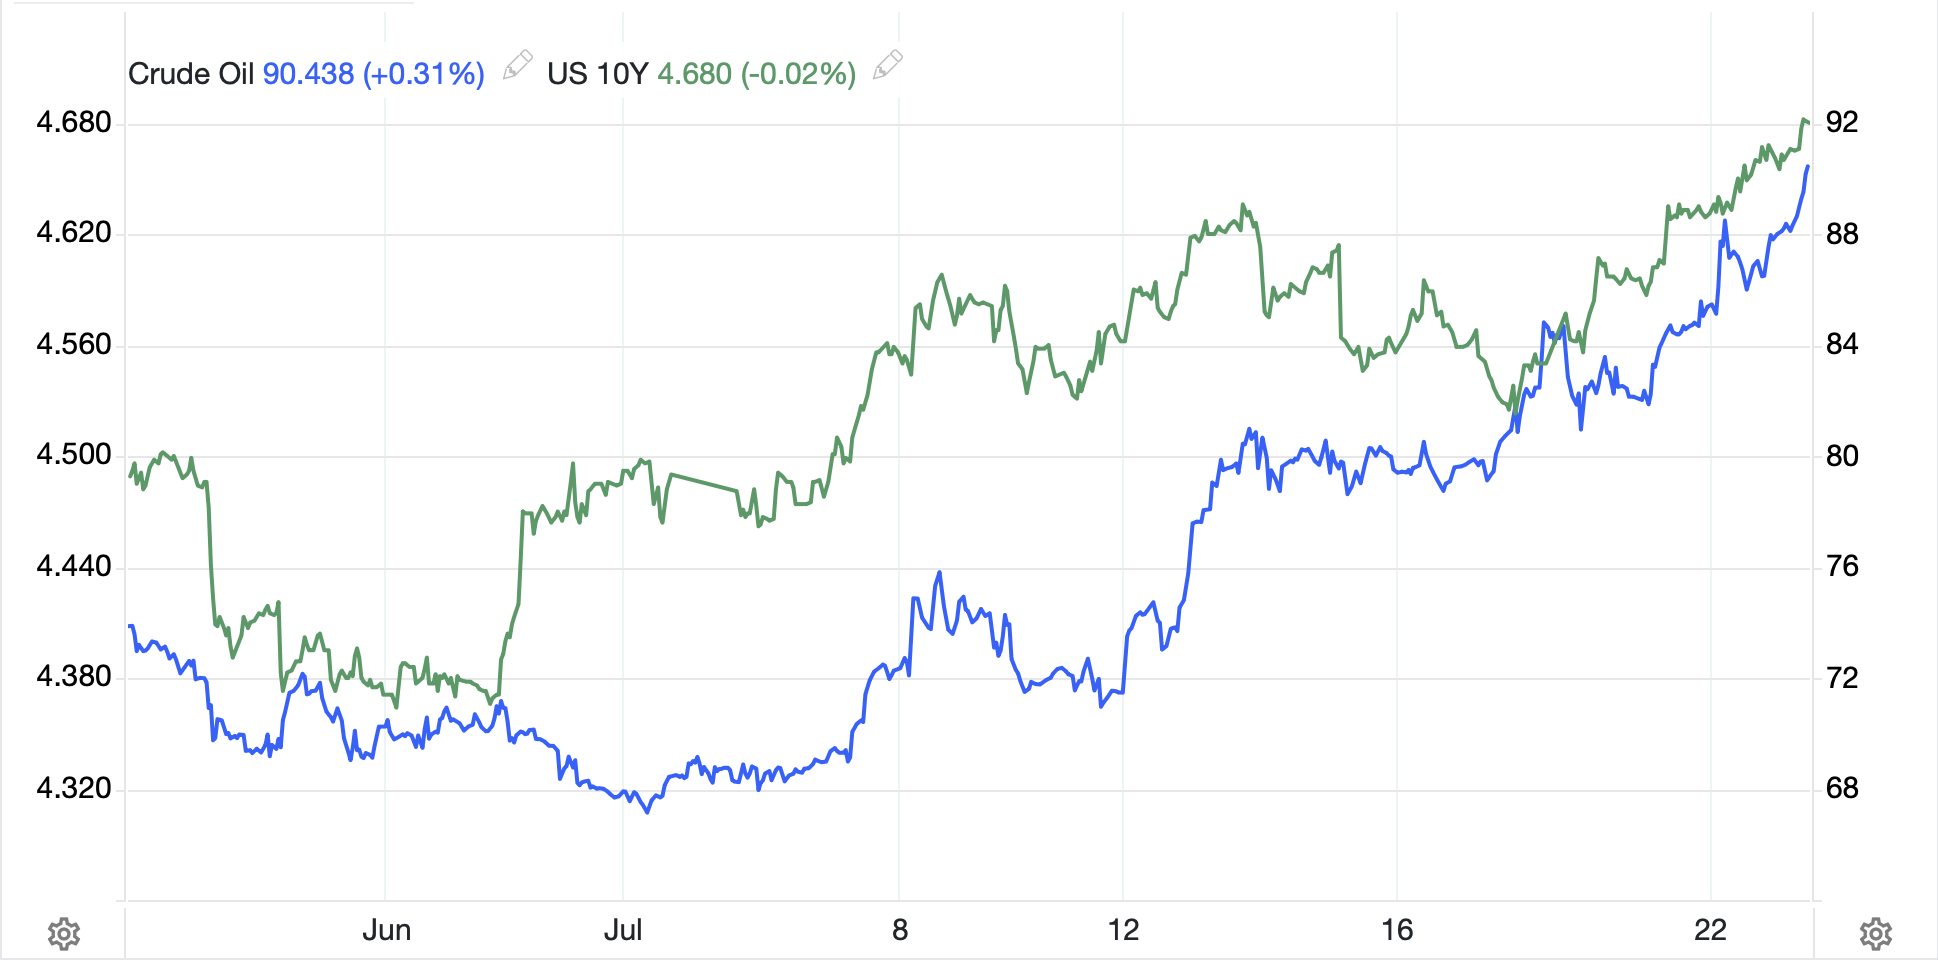
Crude is higher by 29% in the past month and back above $90/bbl.  This makes things tough on everybody but the oil companies.  Does this mean we are running out of oil?  I don’t think that is the case.  Rather, the short-term impediments to shipping it are driving the price.  But the price is rising nonetheless and that is impacting everything else.  If you recall when things kicked off in this war back in March, the oil price was the primary catalyst for movement in every market. As things seemed to settle down and it appeared there was an opportunity for a resolution, focus turned back to things like earnings for equities and interest rate differentials for currencies with oil in the background.  But it appears we are back to, as oil goes, so goes every other market.

For instance, here is a chart of oil and 10-year Treasury yields over the past month.  As you can see, the trajectory, especially over the past several sessions, is quite similar.

Source: tradingeconomics.com

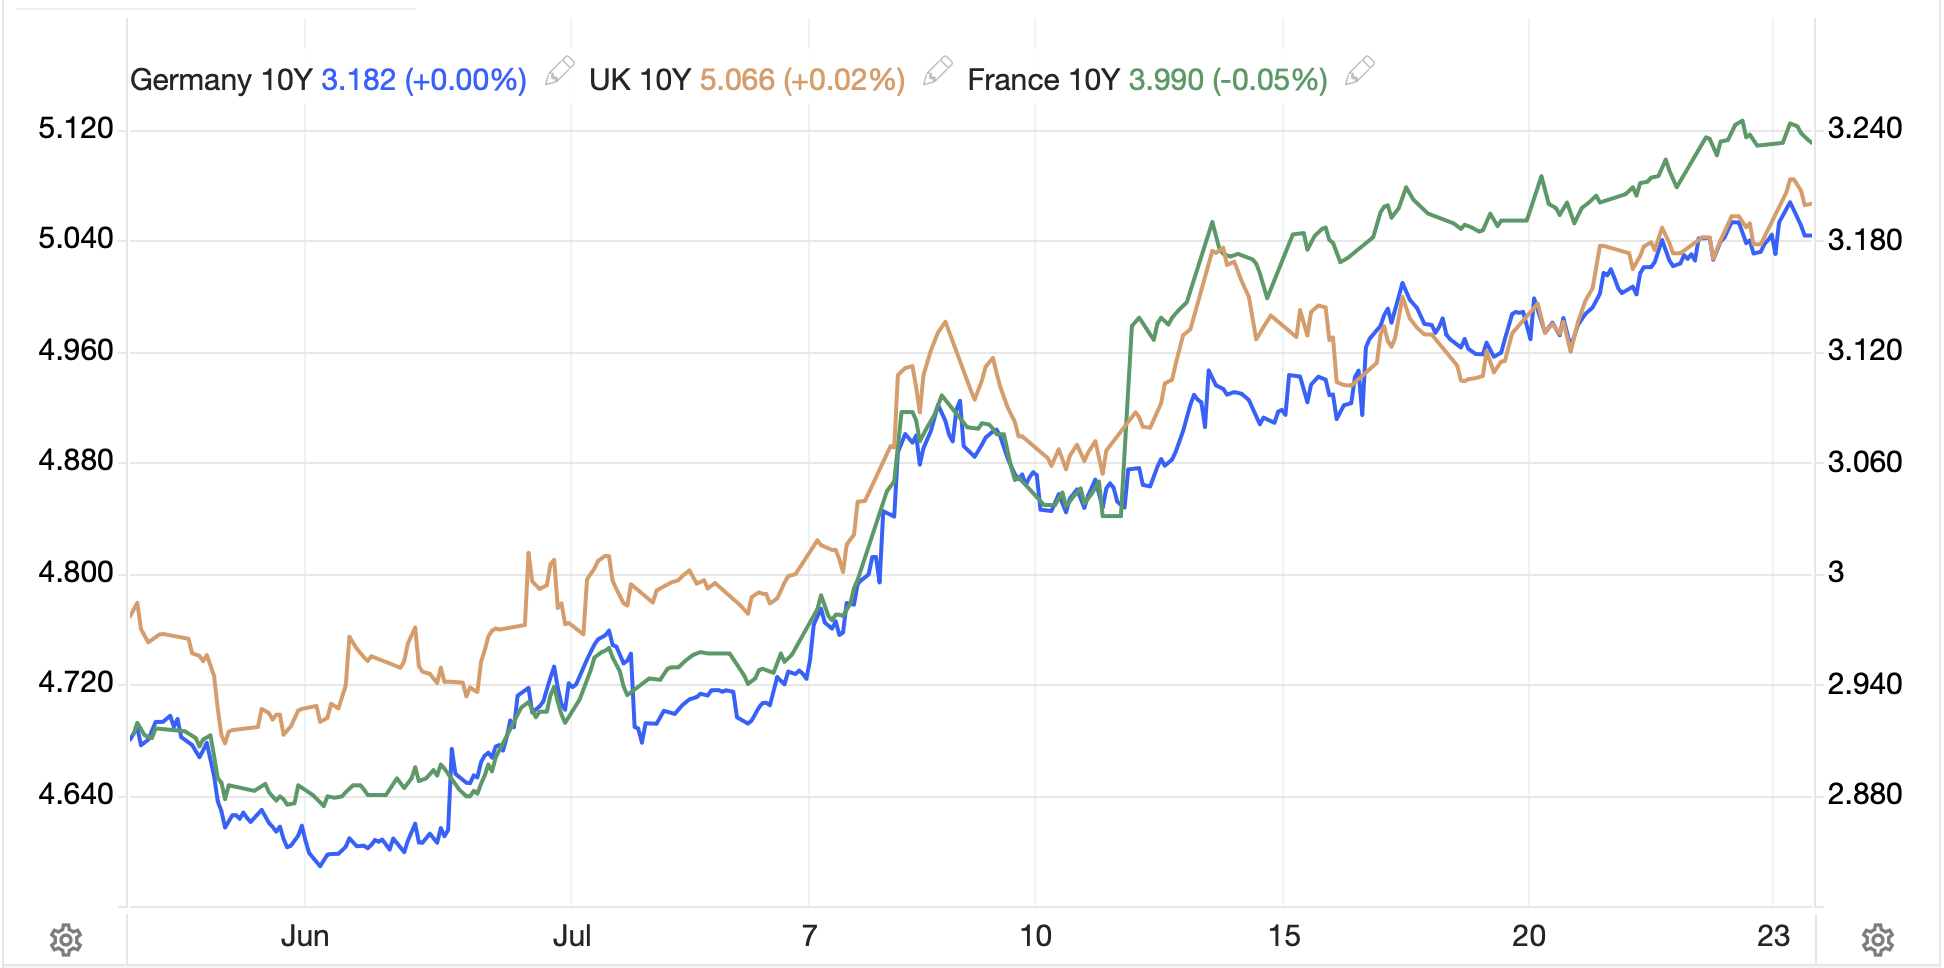
But if we look at 10-year yields across Europe, we can see that they are all climbing in sync as well.

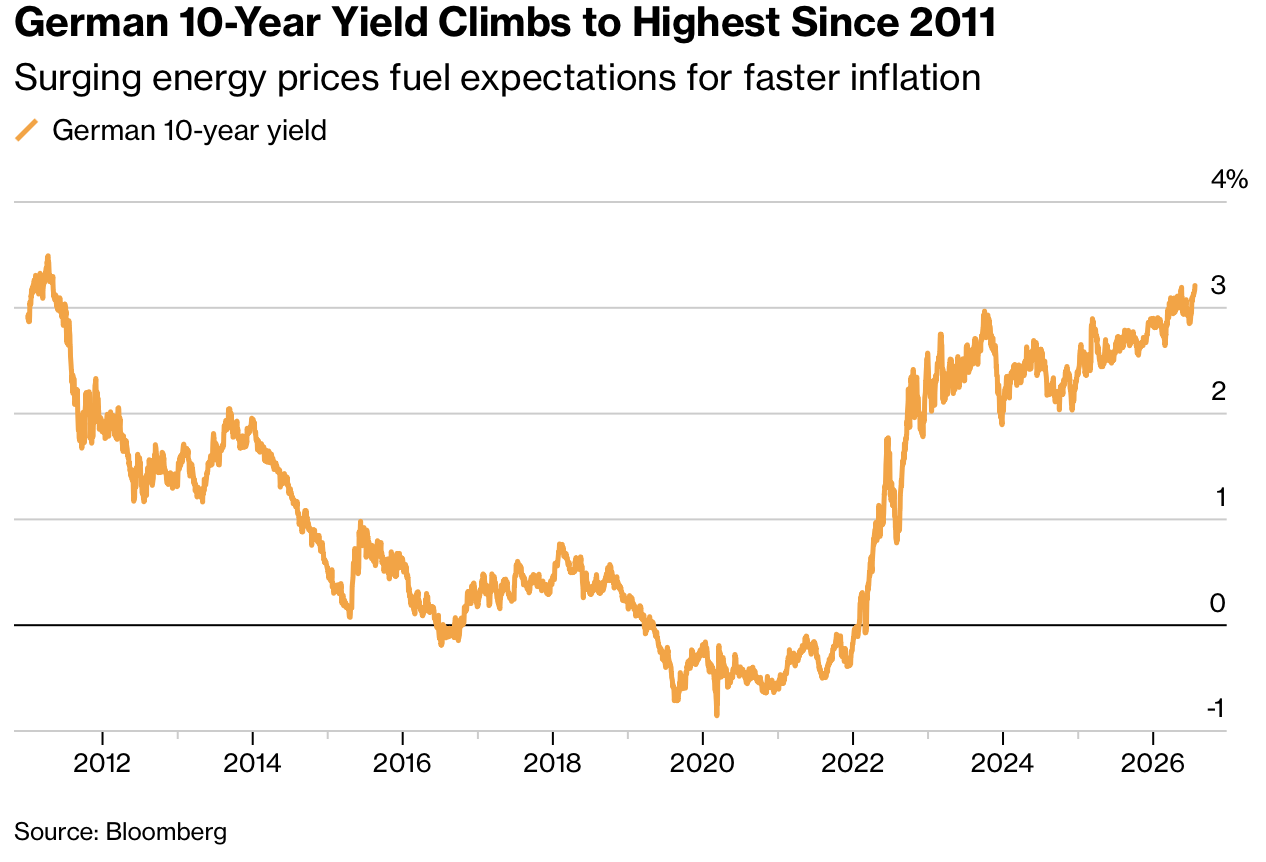
German yields have reached their highest level in 15 years according to Bloomberg.

The entire moderation story is falling apart.  So, now instead of conversations discussing the relative merits of AI and whether it will be a boon for mankind or end it, we are discussing the probability that the world will end soon.  I guess it’s no surprise that risk is under pressure.  Of course, the latter conversation doesn’t seem that coherent to me as if there is concern over the end of the world, I would have thought gold would have a better bid!

At any rate, oil is the main story and the driver of every market.  It underpins the question of whether the ECB will hike rates today (they won’t) or whether the FOMC will do so next week (also, they won’t) but the probabilities for those moves have risen.  It has also detracted from the earnings stories, or perhaps exacerbated the negatives, or perceived negatives.

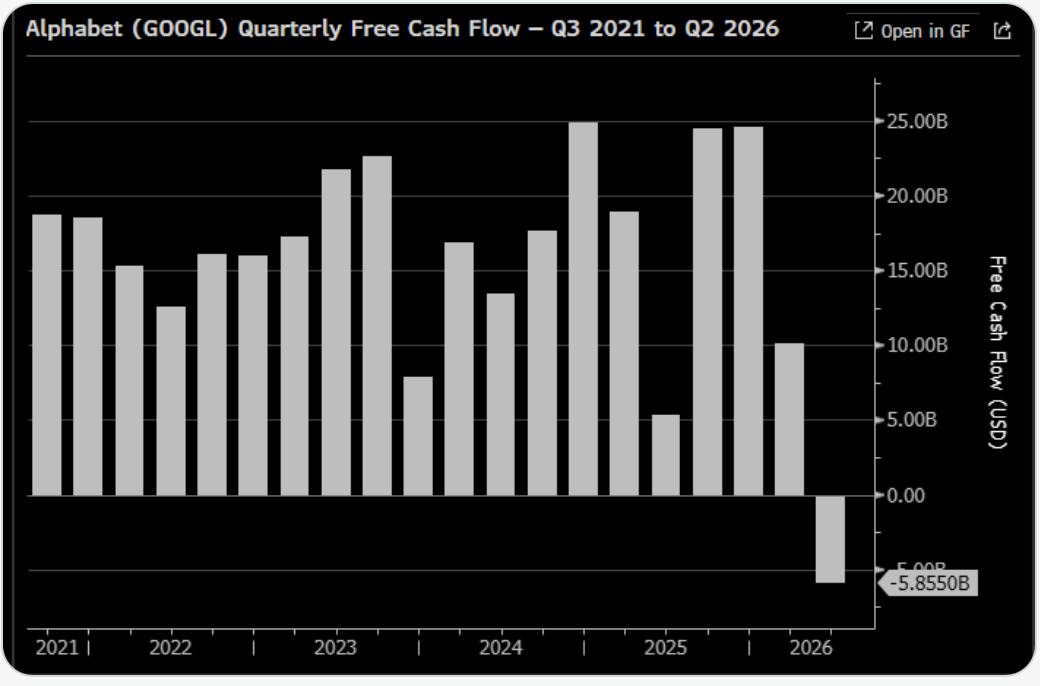
For instance, Alphabet reported last night and Q2 revenues beat estimates coming in at $119.8 billion.  But all the talk is of free cash flow, which in this Bloomberg chart shows how much they are spending on the AI buildout.

Here’s my question, is it bad that Alphabet is spending its money to improve its future?  If it recognizes the criticality of AI to the future of its own existence, it seems like a reasonable move.  Of course, the naysayers claim that spending all that cash is a waste.  I don’t know the answer, and I suspect nobody does yet, but companies spending their cash flow on improving their business seems to be the whole idea behind having companies in the first place.  

It begs the question, on what did investors base the value of Alphabet before AI?  If it was seen as only a cash cow, it certainly traded at a very high multiple for a boring business.  But today, it will be tarred with the oil brush along with all stocks.

Ok, I have gone far afield here, let’s get back to markets overnight.  Yesterday’s lackluster US session was followed by strength throughout most of Asia.  Tokyo (+0.5%), China (+0.25%), HK (+1.3%) and Korea (+4.4%) all had solid sessions with Korea continuing to define what volatility means in equity markets.  Look at the expansion in the daily ranges in this barchart.com chart of the KOSPI over the past month.  It’s remarkable!

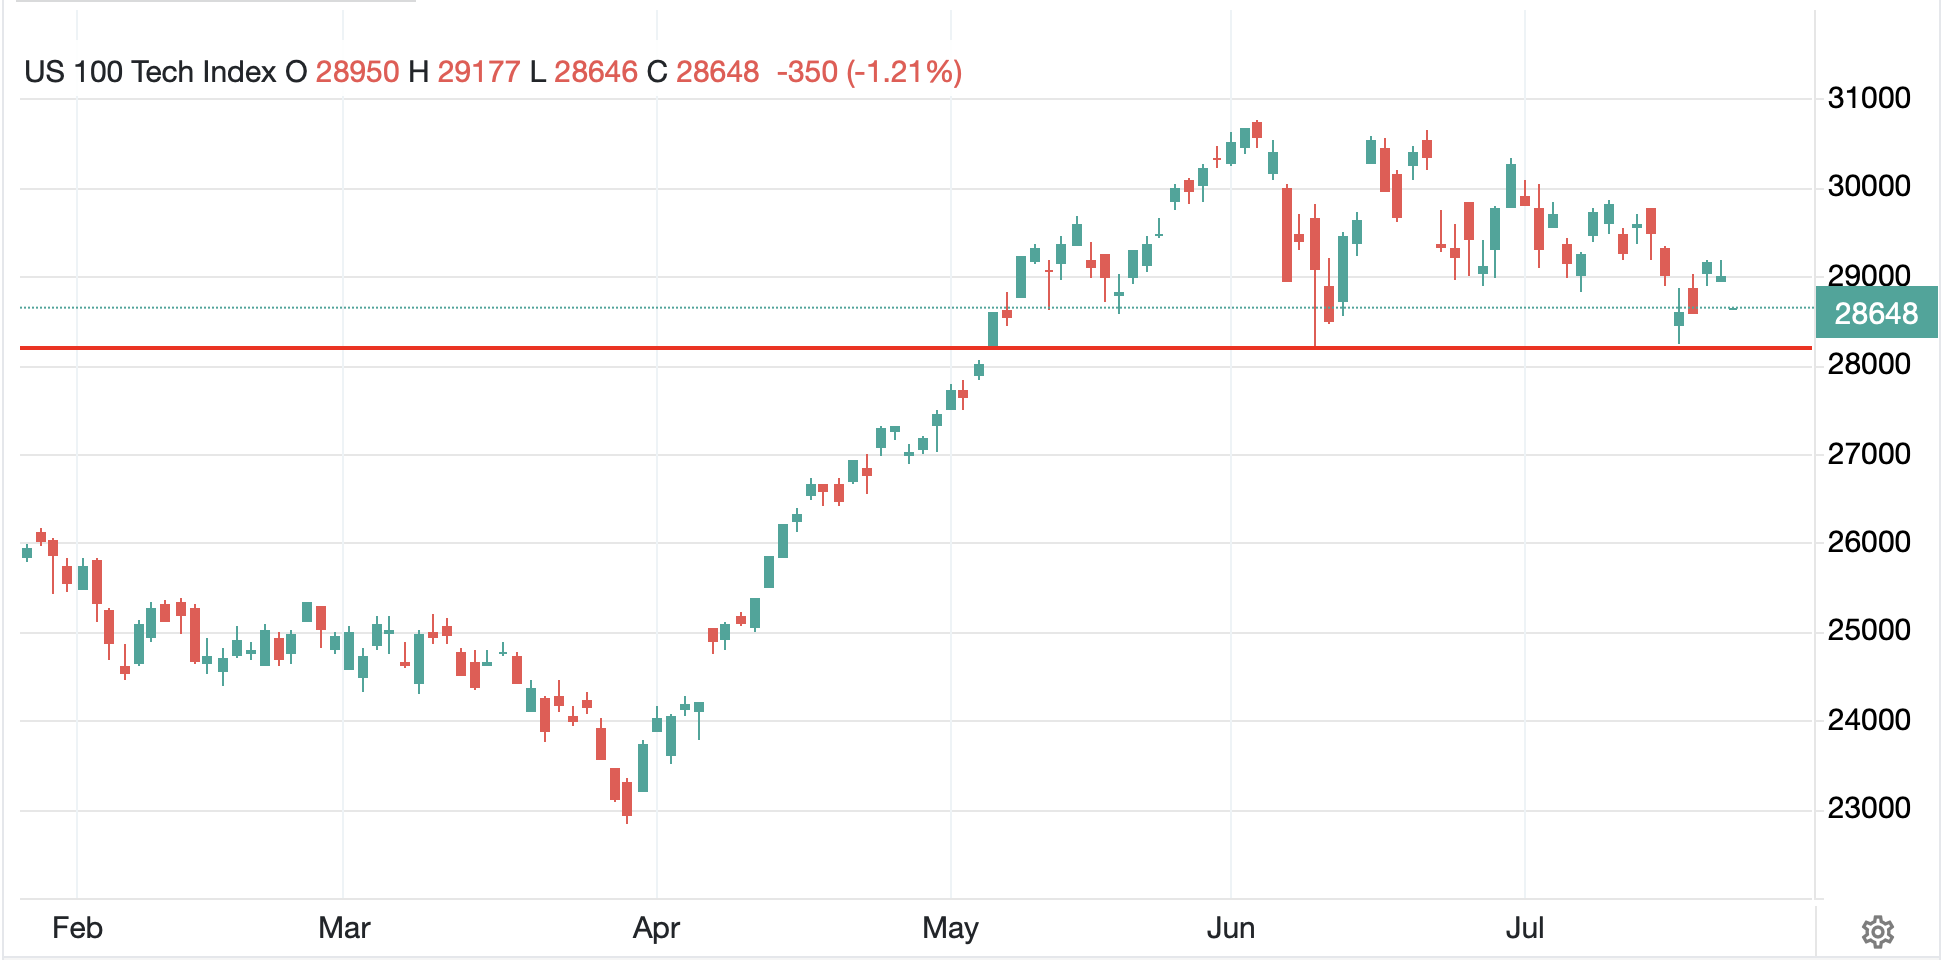
European bourses, though, are having a much rougher go of things this morning as Brent crude approaches $100/bbl.  France (-1.1%), Italy (-1.9%), Spain (-0.6%) and Germany (-0.6%) are under real pressure this morning as earnings numbers there have been lackluster and the broader macro picture deteriorates all the while.  As to US futures, right now (7:40), they are pointing lower led by the NASDAQ (-1.2%) although it has not yet breached that critical support level as per the below chart.

Source: tradingeconomics.com

We’ve already discussed bond markets, with yields higher this morning by between 2bps and 3bps across Treasuries and all European sovereign markets.  Turning to the metals, while we had a couple of days where they rallied alongside oil, this morning they have reversed course with gold (-1.3%), silver (-2.6%) and copper (-0.7%) all under pressure.  It seems the interest rate story is today’s discussion as higher yields are the topic du jour.

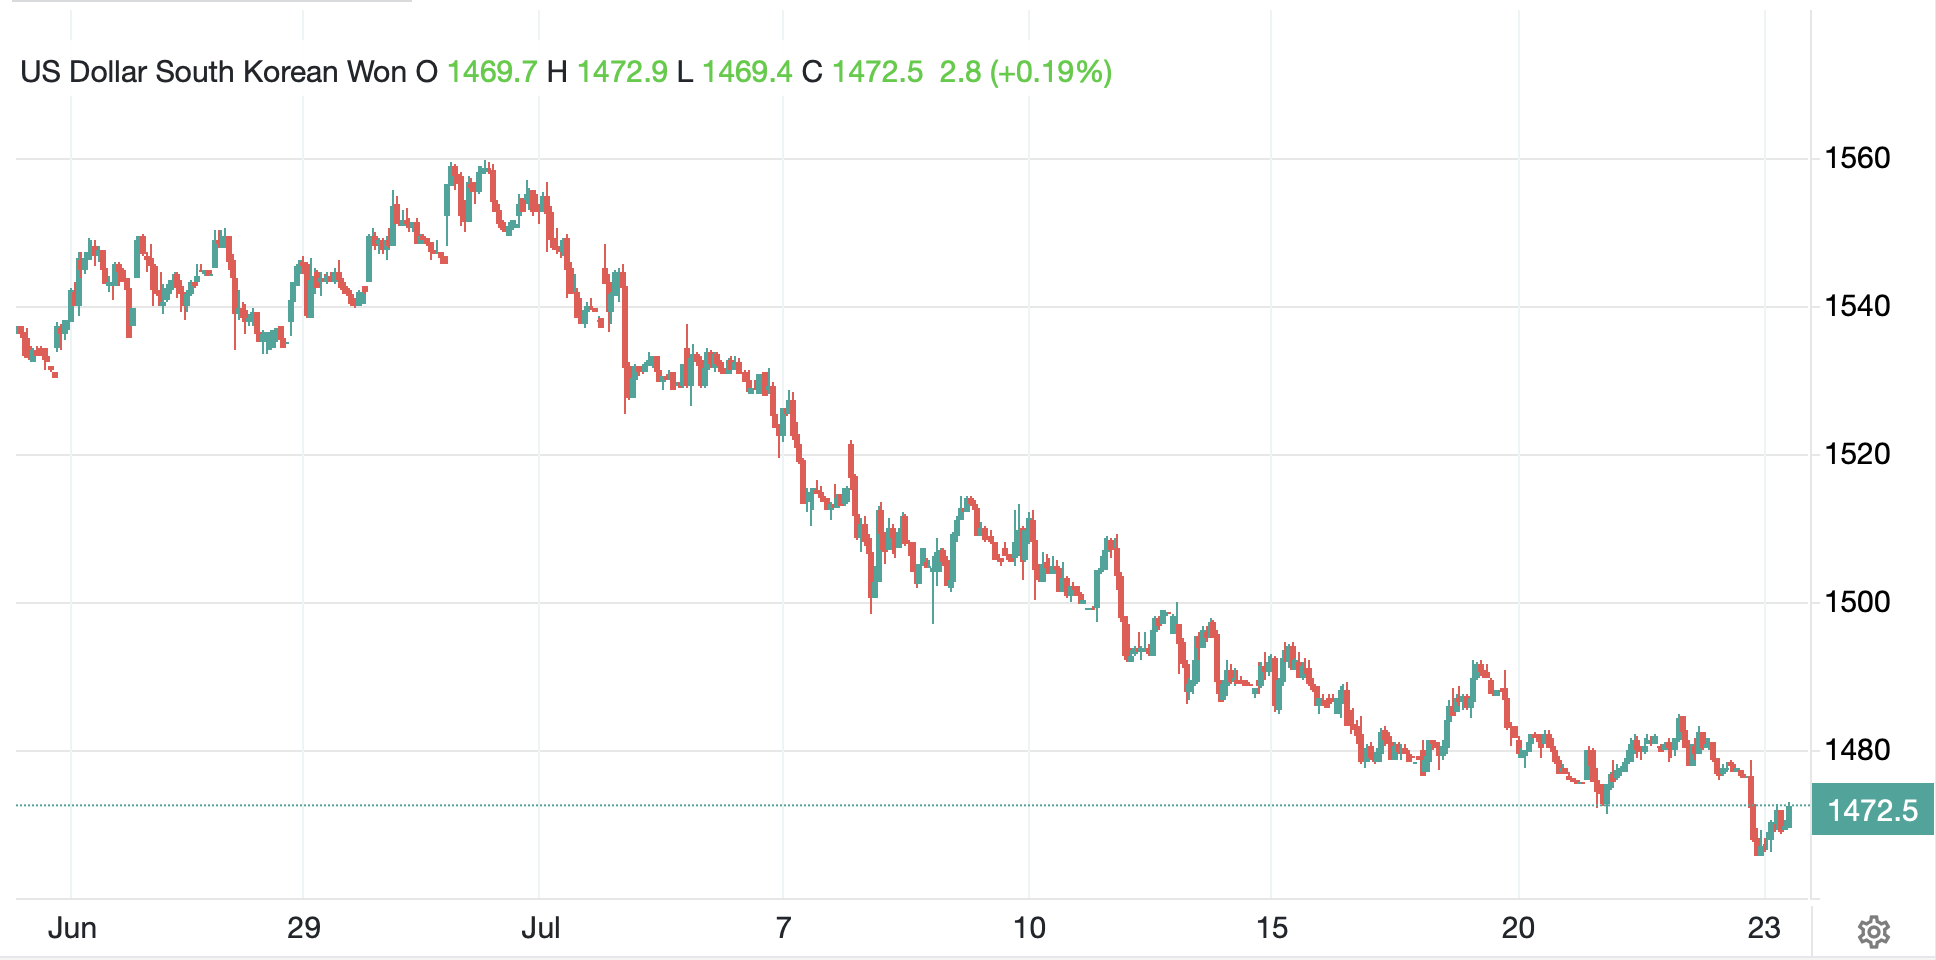
Finally, the dollar is stronger across the board this morning, although most of this strength just materialized over the past few hours with the Asia session broadly unchanged.  But no matter how you slice it, the dollar is firmer vs. all its G10 counterparts by about 0.25% and almost all of its EMG counterparts by a similar amount.  The exceptions this morning are BRL (+0.25%) and KRW (+0.3%).  Regarding Brazil, you must remember they are an oil exporter, so benefit from high oil prices and have amongst the highest real interest rates around, so draw capital for that as well in the carry trade.  The real has appreciated about 8.5% during the past year, so this is nothing new.  As to KRW, the government’s efforts at internationalization continue to be paying off and a look at the chart below shows that this trend is quite strong right now.

Source: tradingeconomics.com

There was an interesting article in Bloomberg this morning explaining how the dollar’s weakness vs. LATAM currencies has begun to bite for local companies but I find it quite interesting when it comes to discussions about the dollar; some find it too strong and are looking for it to tumble while others complain it is too weak!  Seems nobody is ever happy here!

On the data front we see Chicago Fed National Activity (exp 0.14) as well as Initial (212K) and Continuing (1809K) Claims.  Of course, we have the ECB announcement shortly, although no change is expected.  Something getting very little press is the fact that Crude Oil stocks rose in the US last week, but I guess that doesn’t suit the narrative!

This market is entirely focused on oil, and as it moves, so will everything else.  If oil keeps climbing, look for stocks and gold to fall while yields and the dollar rise.  If oil reverses, so with those moves.

Good luck

Adf
Decidedly Iffy

Though war in Iran keeps on going
The impact is not really showing
Risk assets seem fine
And oil’s benign
So, bubbles still need some more blowing

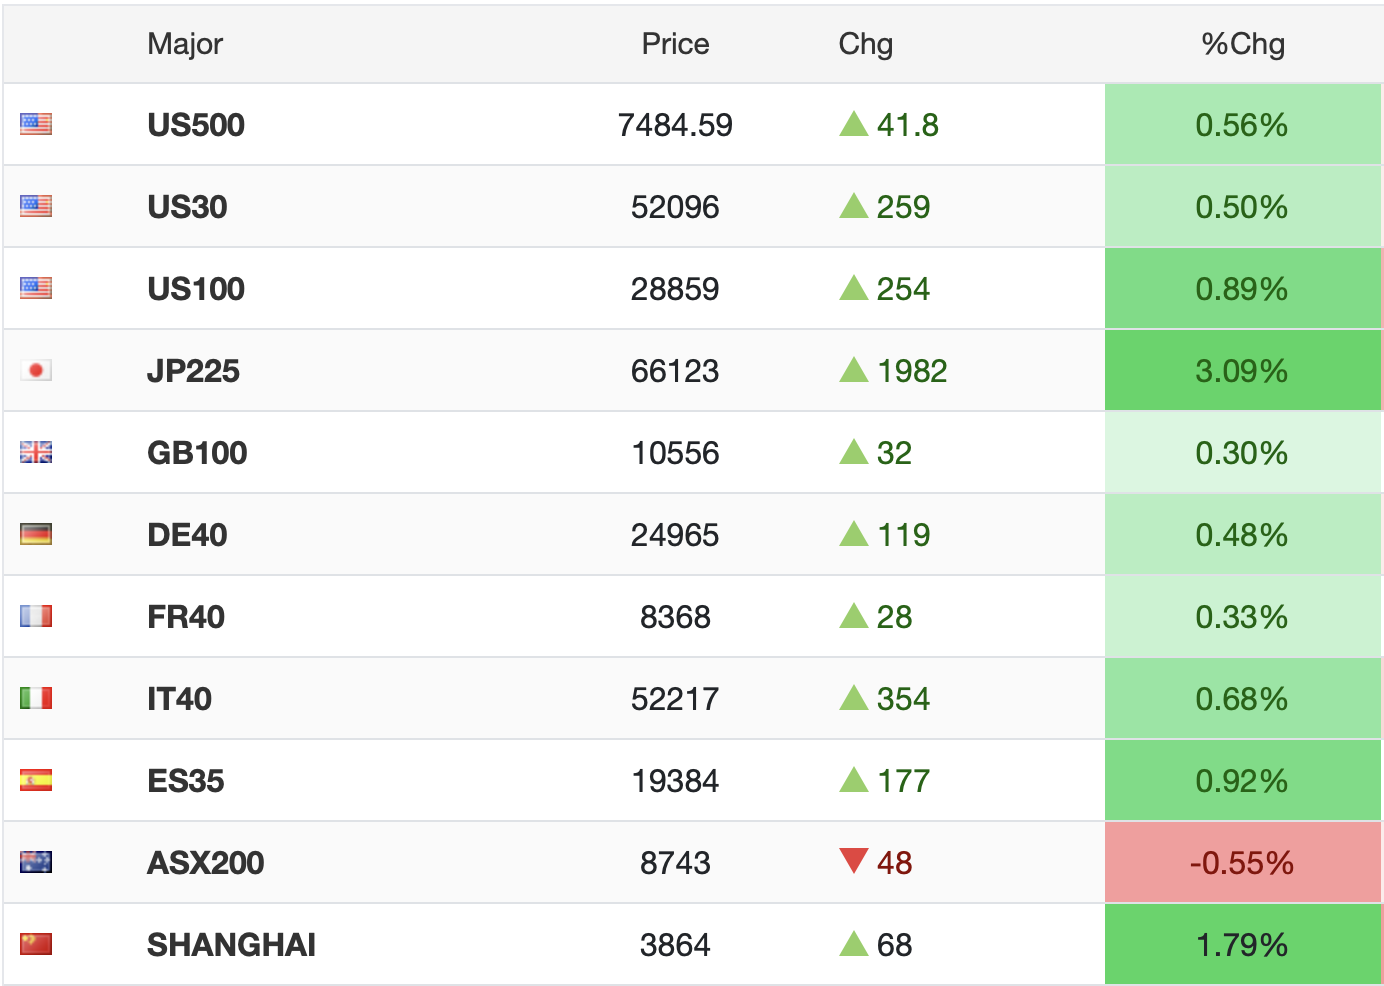
As I often say, markets are perverse and recent price action is a perfect example of this reality. As the US struck Iranian targets for the 10th consecutive day, and risk appetite during yesterday’s US session clearly waned such that all three major indices closed slightly in the red after solid openings, it was easy to expect a continuation of a risk-off attitude this morning.  But as you can see from the tradingeconomics.com screenshot below at 6:45 this morning, only Australia last night did not get the memo.

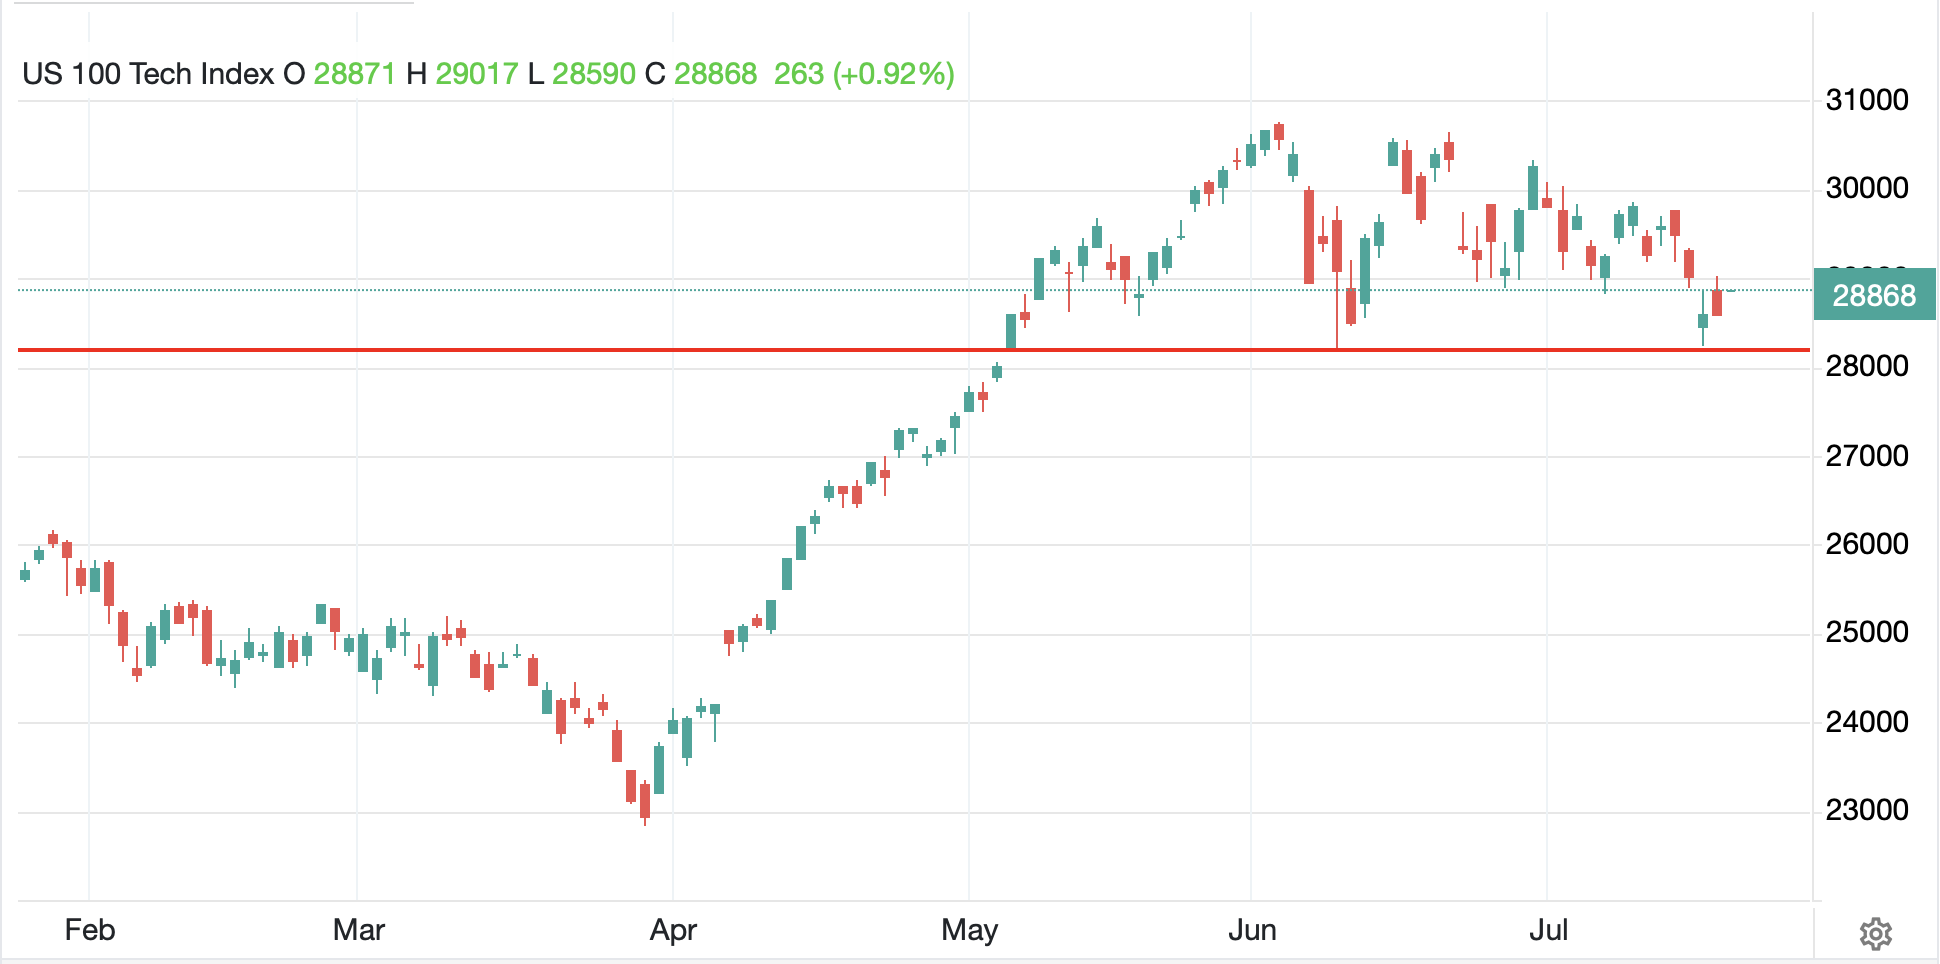
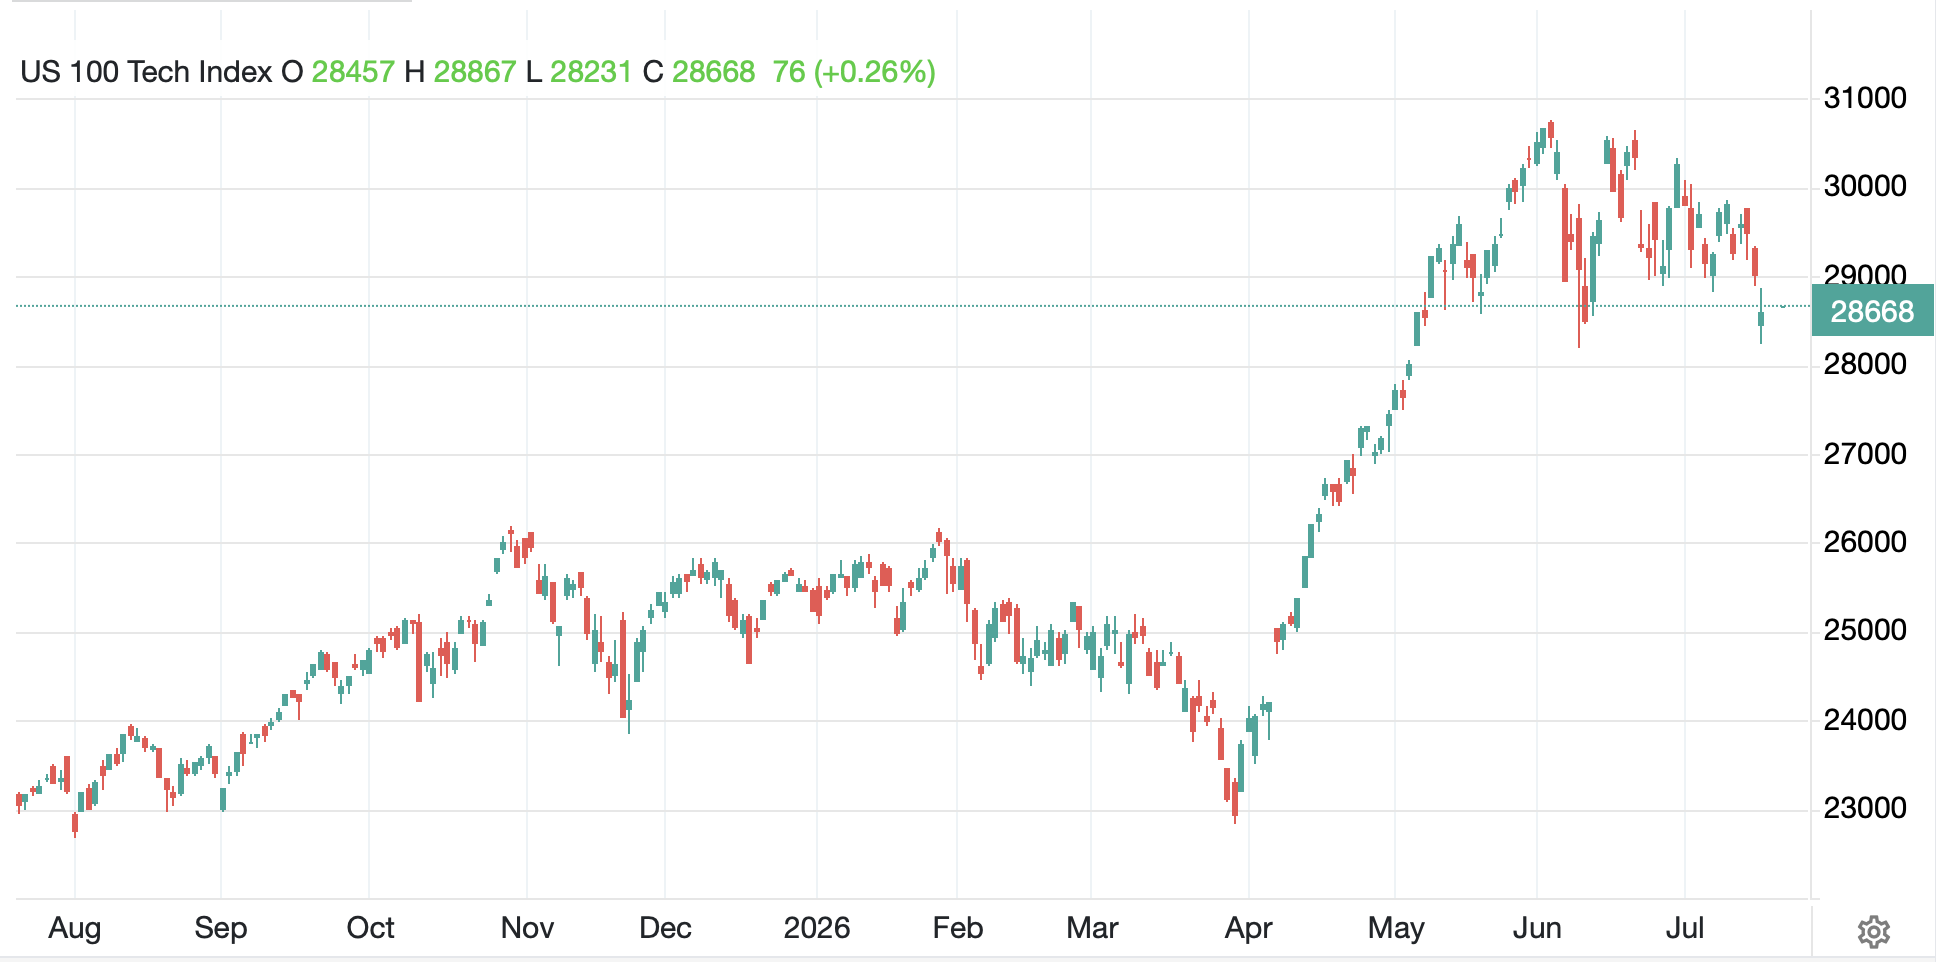
So, for now, it appears that everything is just fine.  The big banks all reported blow-out earnings last week and next week we are looking forward to the big tech names’ earnings reports.  Now, recent price action has shown that companies that miss their estimates are punished severely, so there is ample opportunity for more fireworks this week.  But so far, a look at the chart of the NASDAQ below shows the line in the sand that must hold in many market technicians’ eyes to keep the party going, and it continues to hold.

Source: tradingeconomics.com

It’s funny, yesterday afternoon I was considering buying some QQQ puts as my concern was that we were about to break down and a 5%-8% correction would be quite reasonable.  My read on the sentiment was turning decidedly negative, although I didn’t pull the trigger, deciding to wait for the actual break before acting.  And last night I wrote the following limericks, expressing my sense of things.

The mood is decidedly iffy
With stock market bulls getting miffy
And now we’ve heard calls
For much further falls
With bears’ attitudes, oh so sniffy

So, two things have risk-takers tense
The first is the increasing sense
That war in Iran
Has no master plan
And may cause, more problems, immense

The second is whether AI
Has peaked, or has further to fly
If we’ve seen the top
The ensuing drop
Will bring a Wall Street hue and cry

In fact, I think it is instructive to help understand just how quickly sentiment can change without any obvious catalyst.  For the life of me, reading through the headlines this morning, there is nothing I have seen that would cause me to believe things are so much better today than at the close yesterday.  But perhaps this is a case of less market activity allowing a bit more volatility in markets.  After all, it is summer and there are many market participants on vacation on any given day.  According to Grok, in the past 5 trading sessions, average volume for NASDAQ shares was about 7.6 billion, but as large as that is, it is well below the YTD average of around 9.0 billion.  In reduced volume markets (no matter how large they are) there can be large, unexplained moves based on individual flows.  I’m grasping at straws here!

Regardless, this is where we stand this morning.  There are headlines dueling between further military action and further efforts at peace talks, with markets clearly preferring the latter rather than the former.  Oil prices (+0.9%) remain within their recent range although are creeping higher this morning.  Is this a prelude to a move back to $100/bbl?  

Source: tradingeconomics.com

The problem with that story is that there continues to be a massive supply of crude oil around.  And Ukraine’s success in attacking Russian refineries has actually brought more crude to market as the Russians can no longer refine their own in the same volumes thus are shipping it to anyone who will buy it. 

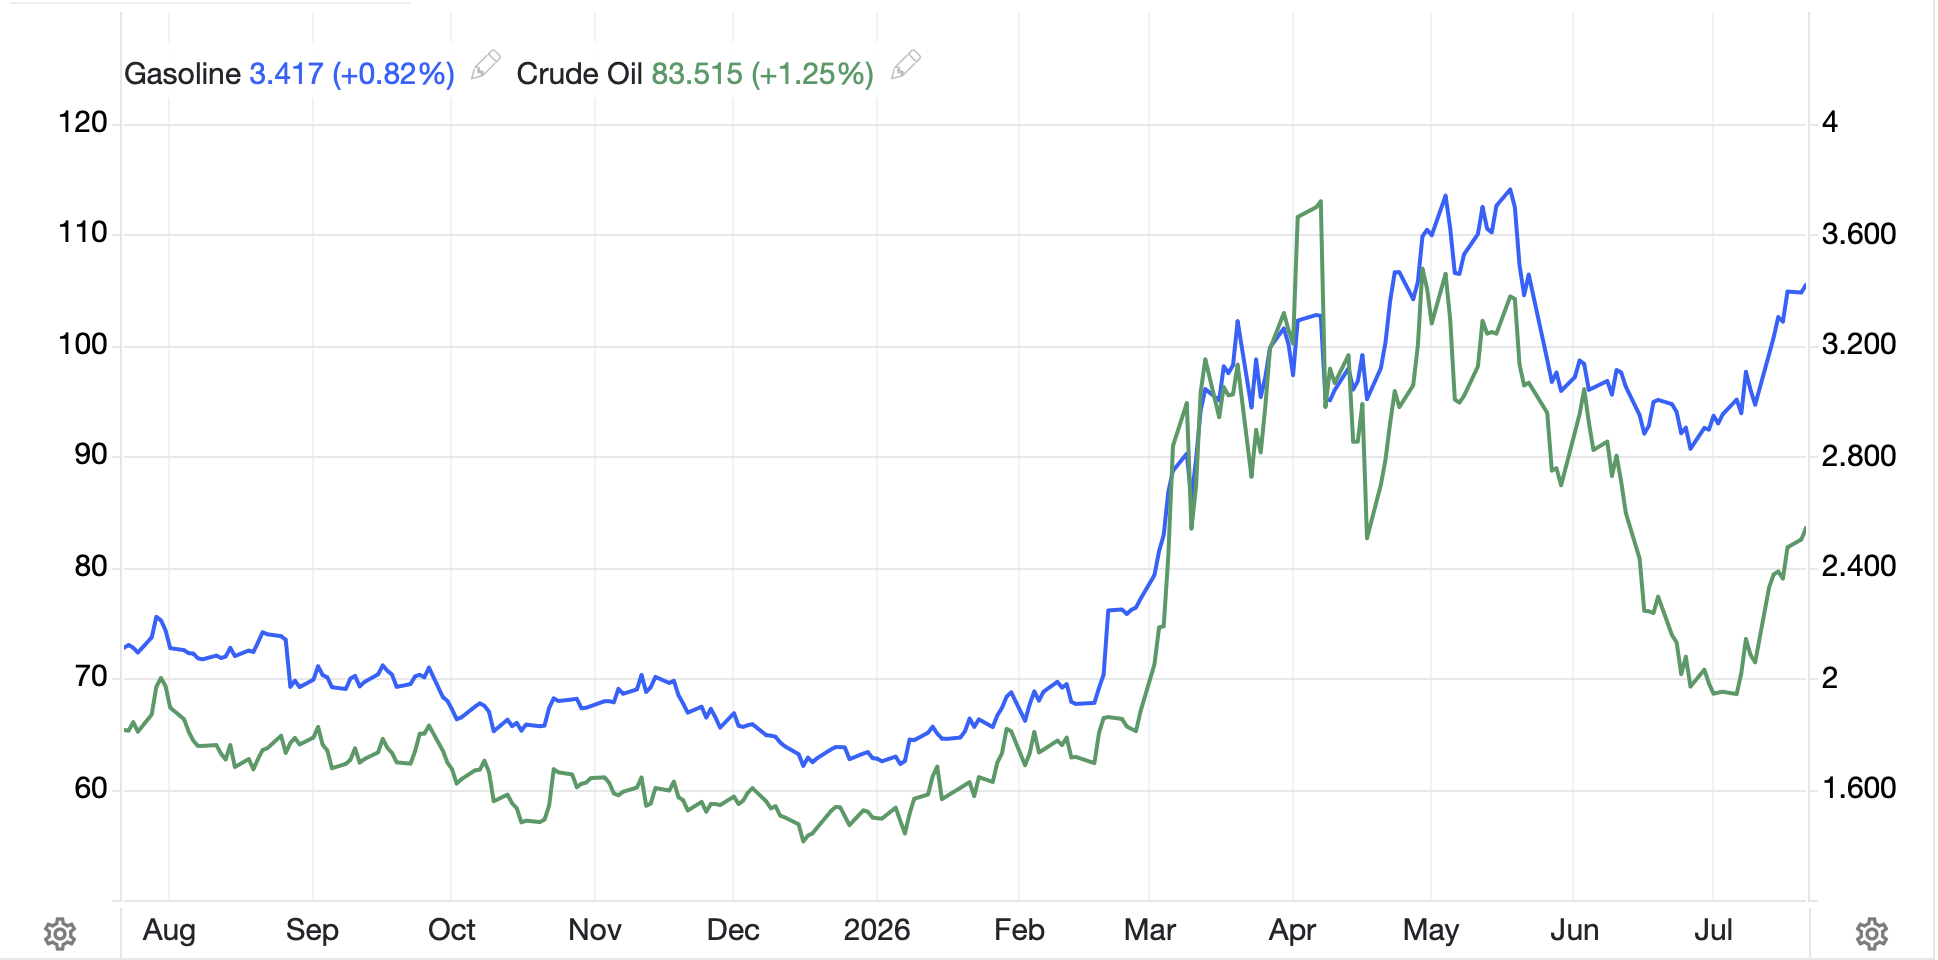
Products, though, are a different story as the lack of refining capacity (US refiners are running at about 98% capacity) has led to record high crack spreads.  (The crack spread is the value of the products created from crude; gasoline, jet fuel and diesel largely, compared to the price of a barrel of crude.  The higher that spread the more profitable the business is for refiners, and the more we pay at the pump). Referring back to the chart above, the blue line is gasoline futures in NY, which as you can see are much closer to their early war highs despite the more dramatic decline in oil (green line).

In fact, this chart may be the best metaphor for the current sentiment in the US with the population suffering from rising gasoline prices while the government touts the decline in crude prices.

Net, I am having trouble finding a single coherent narrative that is widely believed.  So, let’s look at how other markets behaved overnight, having already seen equities and oil.  Bond yields rose yesterday with Treasury yields higher by 5bps and a further tick up this morning.  Similar price action was seen in Europe although more of these markets are +2bps this morning, rather than the +1bp in Treasuries.  And JGB yields rose 3bps overnight.  

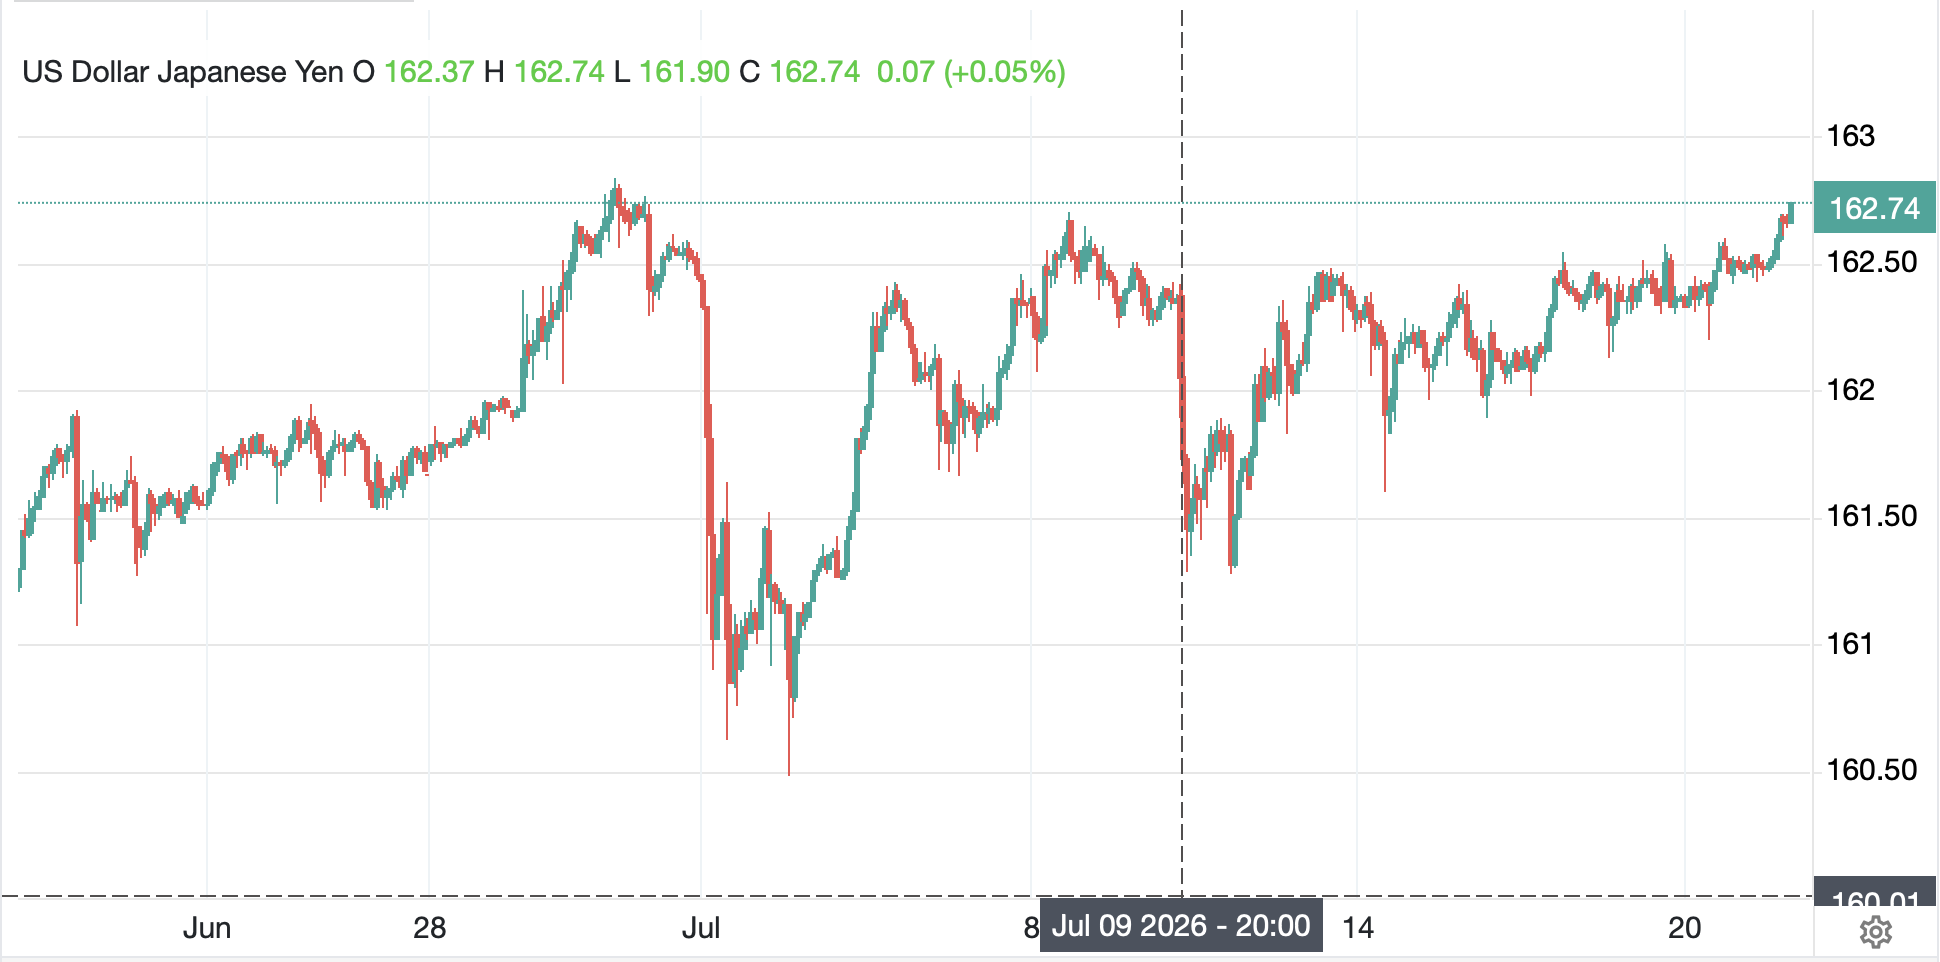
Speaking of Japan, you may recall the story from about two weeks ago where Japanese FinMin Katayama expressed the idea that Japanese pension funds should consider investing more domestically, bringing home some of their massive $3+ trillion in assets.  The market got quite excited about that and as you can see in the below chart, the yen immediately rallied.  

Source: tradingeconomics.com

Well, that was sooooo two weeks ago!  This morning, the yen is just 5 pips, as I write, from breeching the peak seen before the last intervention scare.  As you can see in the chart, the move is extremely gradual, but in this case, the tortoise is being played by the yen.  I saw more discussion on this pension story this morning but while I think it is highly probable to play out over time, I think the timeline is better measured in years, not weeks, or even months.  As such, the gradual depreciation of the yen seems likely to continue.  Elsewhere, it remains very hard to get excited about the dollar vs. any currency right now.  Sure, NOK (+0.6%) is rallying on the oil rally, and perhaps the real surprise today is ZAR (+0.5%) which despite higher oil has seen higher gold prices help sustain it.  But if we look at the dollar writ large, the ‘breakout’ from its year-long range seen back in mid-June has been a damp squib as per the below chart of the DXY.

Source: tradingeconomics.com

Perhaps the big surprise this morning is the metals (Au +1.2%, Ag +4.2%, Cu +3.1%) are all higher despite the rise in oil prices and yields.  While I remain long term constructive on the metals sector, it is very difficult to understand what is driving today’s price action at this point.

And that’s really it today.  There are no frontline data points to be released so I expect that oil sentiment will continue to lead markets although there will certainly be excitement about equities if they can maintain the rally today.  As to the dollar, nobody seems to care.

Good luck

Adf
Iran’s Bases, to Stress

For nine days and nights the US
Has sought, Iran’s bases, to stress
So, ships through the Strait
Will now have to wait
Until Trump has made more progress

The upshot is prices for crude
Have risen a fifth and are skewed
Right now, to go higher
As three key suppliers
All find their production subdued

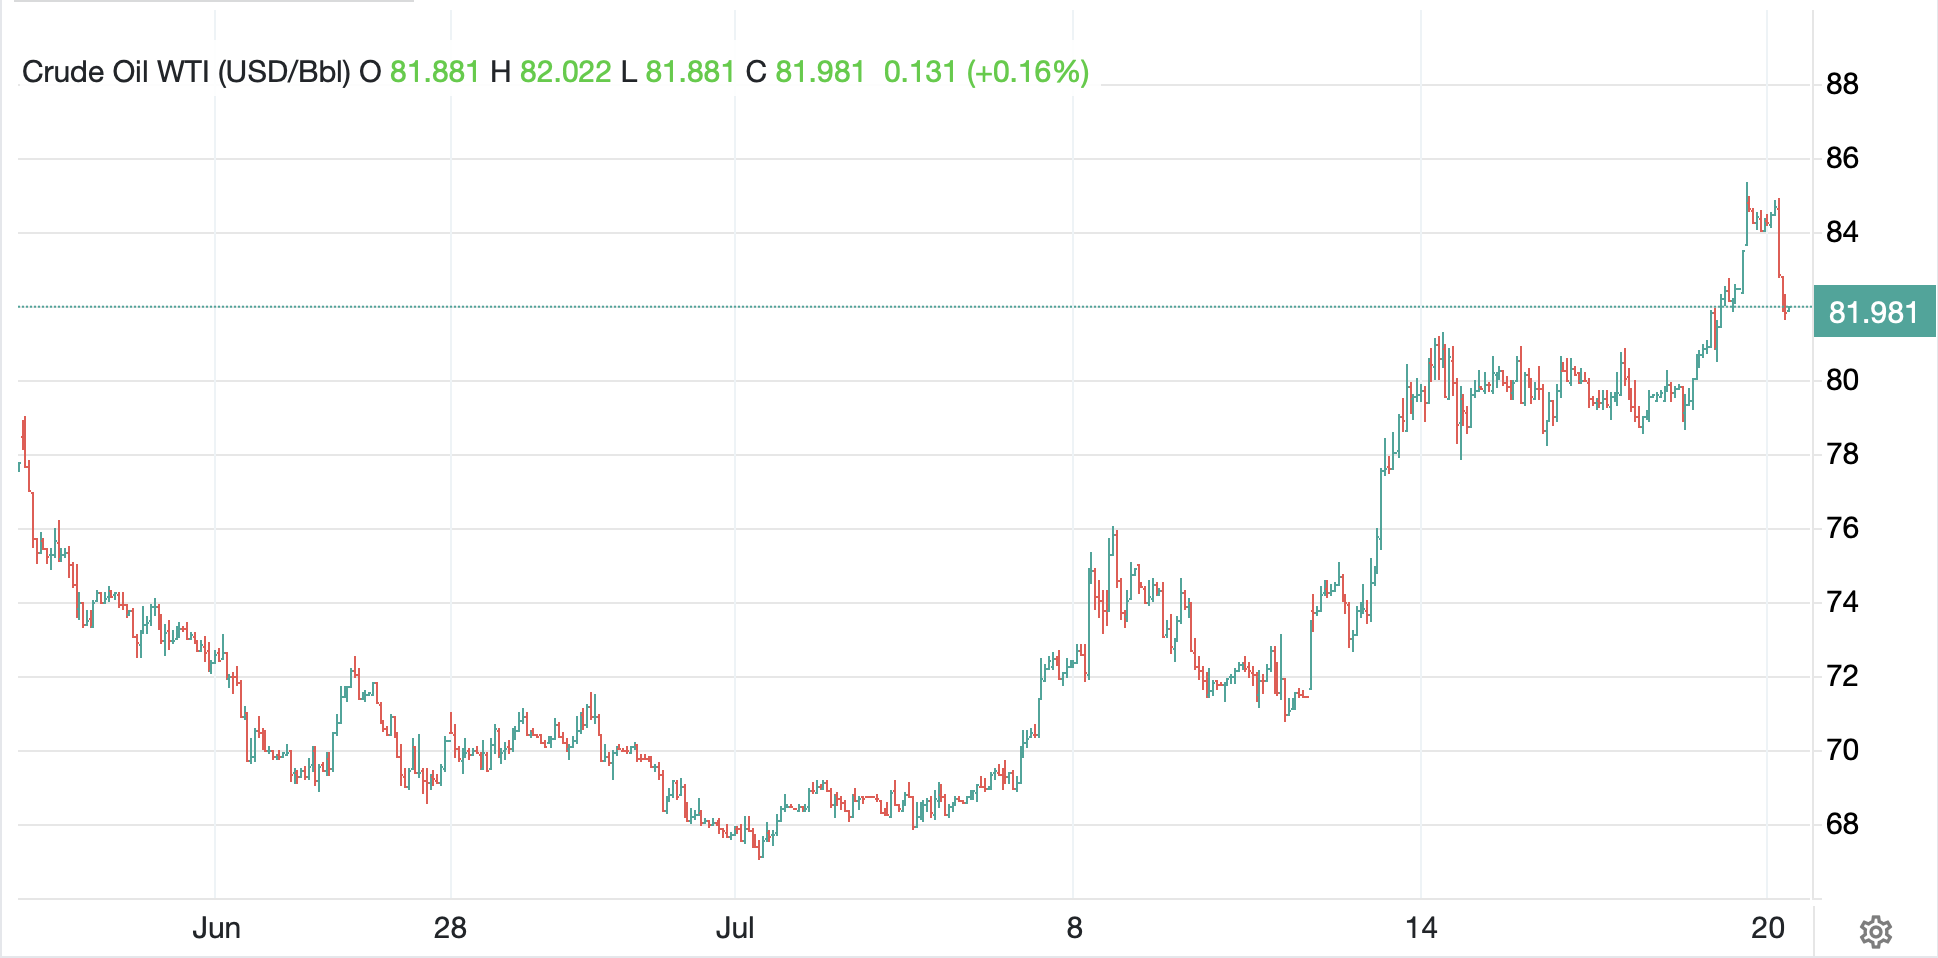
Oil (-0.7%) started the overnight session more than 2% higher after nine consecutive days of US military strikes on Iranian ports and missile sites amid more threatening rhetoric on both sides.  It certainly seemed like things were rapidly deteriorating.  Iran struck targets in Jordan as well as Kuwait, Qatar and Bahrain as the conflict escalates.  As such, we cannot be surprised that there has been a steady rise in the price of oil during this period.  Since the increase in fighting, WTI prices have risen about 20%. However, a quick look at the chart below shows that things reversed overnight.  

Source: tradingeconomics.com

The proximate cause for this reversal was commentary from Secretary Rubio that Iran has signaled an interest in resuming negotiations.  Additionally, there is another story about other Gulf intermediaries, although unnamed, who are trying to bring proposals toward the same end.  Now, the one thing I know is that both sides in this conflict (and any conflict really) put out reams of propaganda, especially about the conflict.  With that in mind, we have no way of knowing whether negotiations are going to restart or not.  However, it appears market participants are willing to believe that is the case.  

What does this mean for markets?  If we have learned nothing else throughout this conflict, it is that many old relationships are no longer operating the way they had in the past.  Consider gold for a moment.  Prior to this conflict it was considered the ultimate safe haven, the thing you wanted to own if things got really bad and there was an escalating war.  And yet, here we are with gold having fallen some 25% since the US first bombed Iran as you can see below.

Source: tradingeconomics.com

Now, two things about this are that first, that followed a remarkable rally for the previous twelve months, so a correction wasn’t crazy and second, it seems that one of the key drivers in the price decline was selling of gold by sovereigns that needed the money including Russia and Turkey.  After all, that is why those reserves exist, for a rainy day, and it was certainly raining hard.  Nonetheless, that narrative theme, owning gold in case of war, has not played out at all as expected.  

Or we can look at the equity markets, especially tech stocks.  It is hard to look at the chart of the NASDAQ below and conclude that the Iran conflict was anything but beneficial for them.  This, too, runs counter to the general narrative prior to the war that risk assets would suffer during a war.

Source: tradingeconomics.com

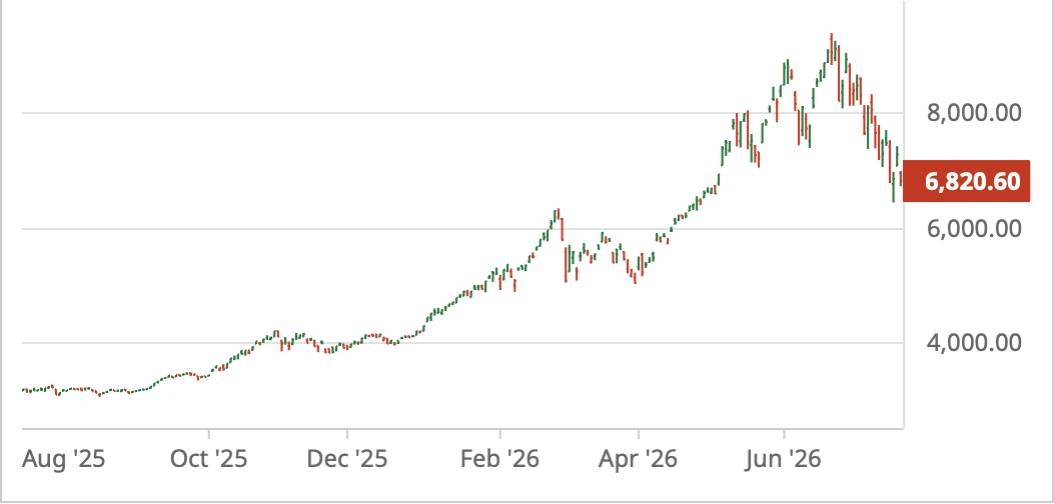
Now, if we widen our lens a bit to include other nations’ equity markets, Korea in this case, the story is not so sanguine.  As you can see from the below chart of the KOSPI, it has fallen 29% since it peaked about one month ago.

Source: Bloomberg.com

But is that war related?  Or is that the air coming out of what appears to have been a massive bubble in semiconductor stocks.  Recall, about 40% of the value of the KOSPI is made up of just two companies, SK Hynix and Samsung, and both have mooned because they build semiconductors that are in huge demand due to the AI race around the world.  

Now, one of the few truisms in markets is that every shortage is followed by a glut as the high prices from the shortage lead to massive overinvestment in whatever is lacking.  So, consider this comment from someone I believe is quite reliable.

There will be a comeuppance in tech sector shares, I believe, although I would not dare to guess when.  Semiconductors are historically a cyclical industry, and I don’t think anything has changed about that, except perhaps the amplitude of this cycle.  But there will be a downwave and likely one that wipes out many of the gains seen.

And how has the escalation/de-escalation played out elsewhere?  Well, Chinese shares rallied (+1.5%, HK +2.3%) although that was because the Chinese plunge protection team was in the market buying shares, and they told us so.  Tokyo was closed for Marine Day and otherwise, Friday’s weak US performance was followed by general declines, although far less than Korea’s -4.5%.  As to Europe, there is very little ongoing this morning with virtually no data, no commentary and limited market movement.  Arguably, the only story of note was the official resignation of Kier Starmer as PM and the installation of Andy Burnham, although that has resulted in the FTSE 100 selling off -0.5%, the laggard in Europe.  And given his history, including a lack of experience and stated preferences for far-left policies, I think there could be more to come there.  As to US futures, at this hour (7:30) they are slightly higher across the board, +0.3% or so.

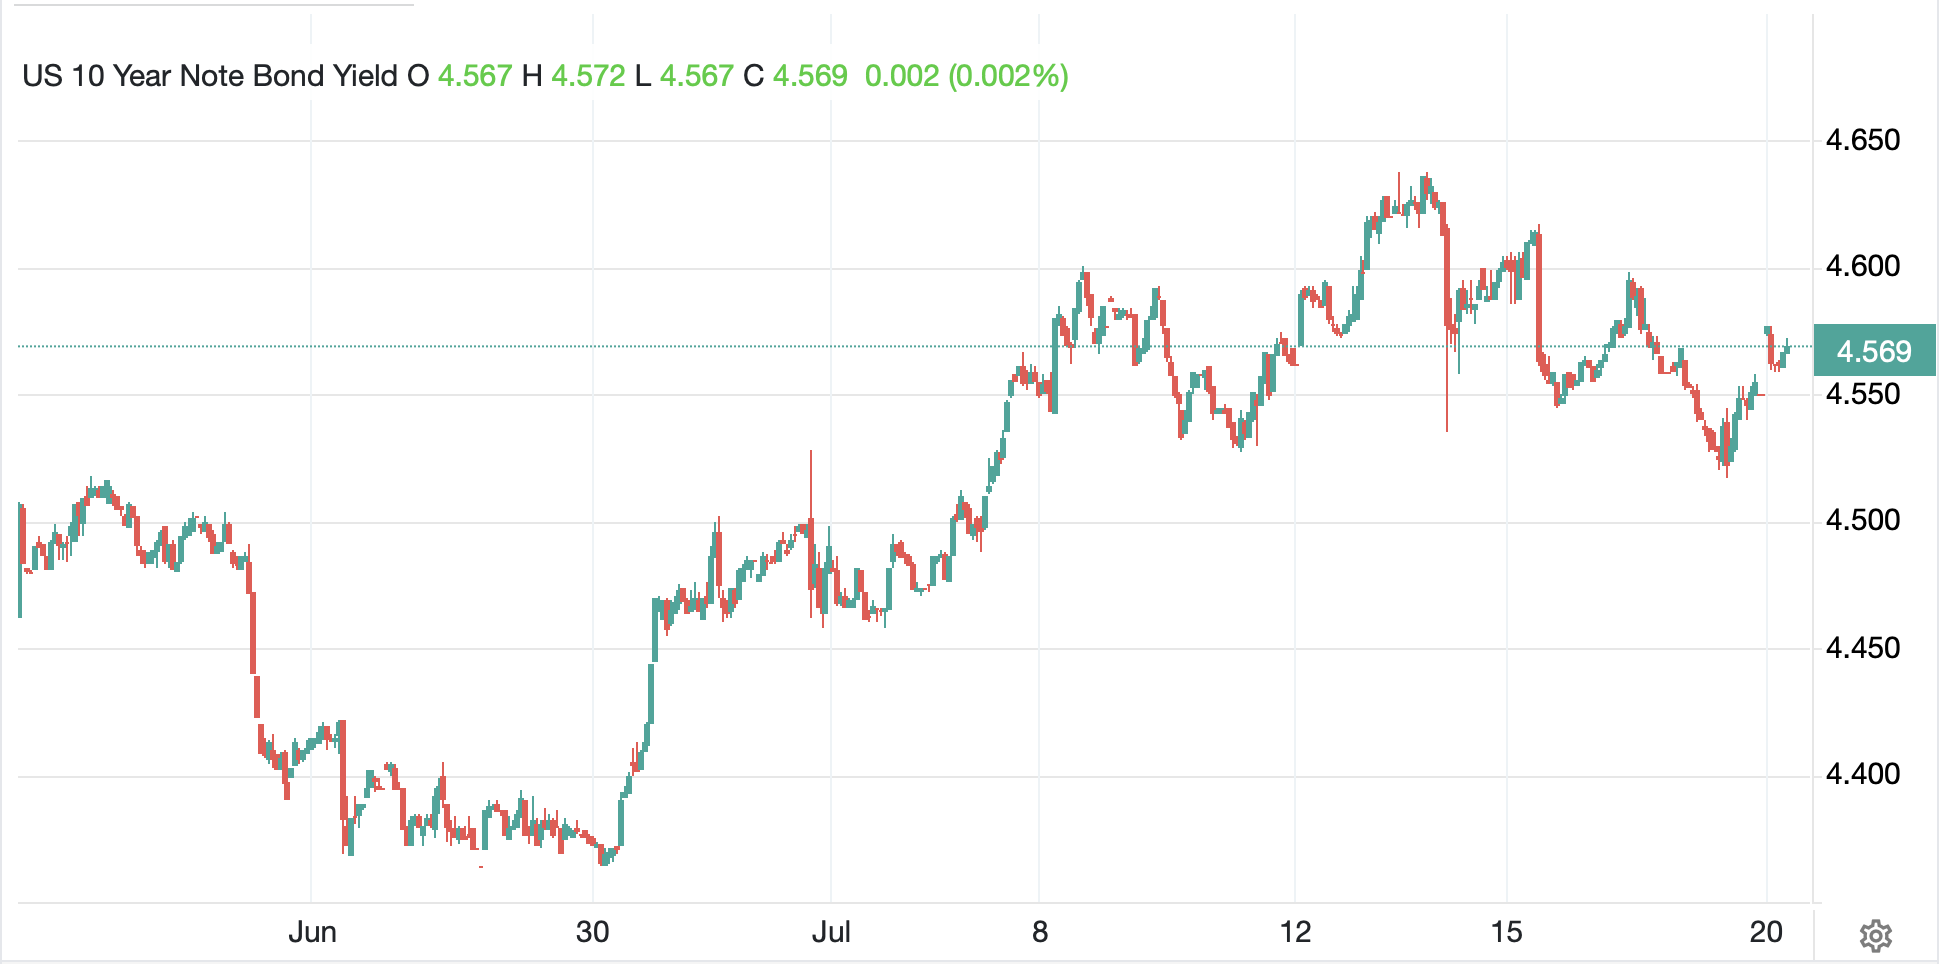
Treasury yields have edged higher by 2bps, and European sovereign yields are higher by 1bp across the board with only UK gilts (+3bps) doing worse.  But it remains difficult to look at 10-year yields and get overly excited about anything.  I grant that there has been some choppiness, but in the big scheme of things, a 20bp range on a 4.5% handle over the course of the past month is not all that shocking, especially given the backdrop of a war and extremely volatile oil prices.

Source: tradingeconomics.com

With oil retreating, the three major metals, gold (+0.4%), silver (+2.4%) and copper (+1.2%) are all firmer this morning.  That relationship has been quite consistent, I will admit.

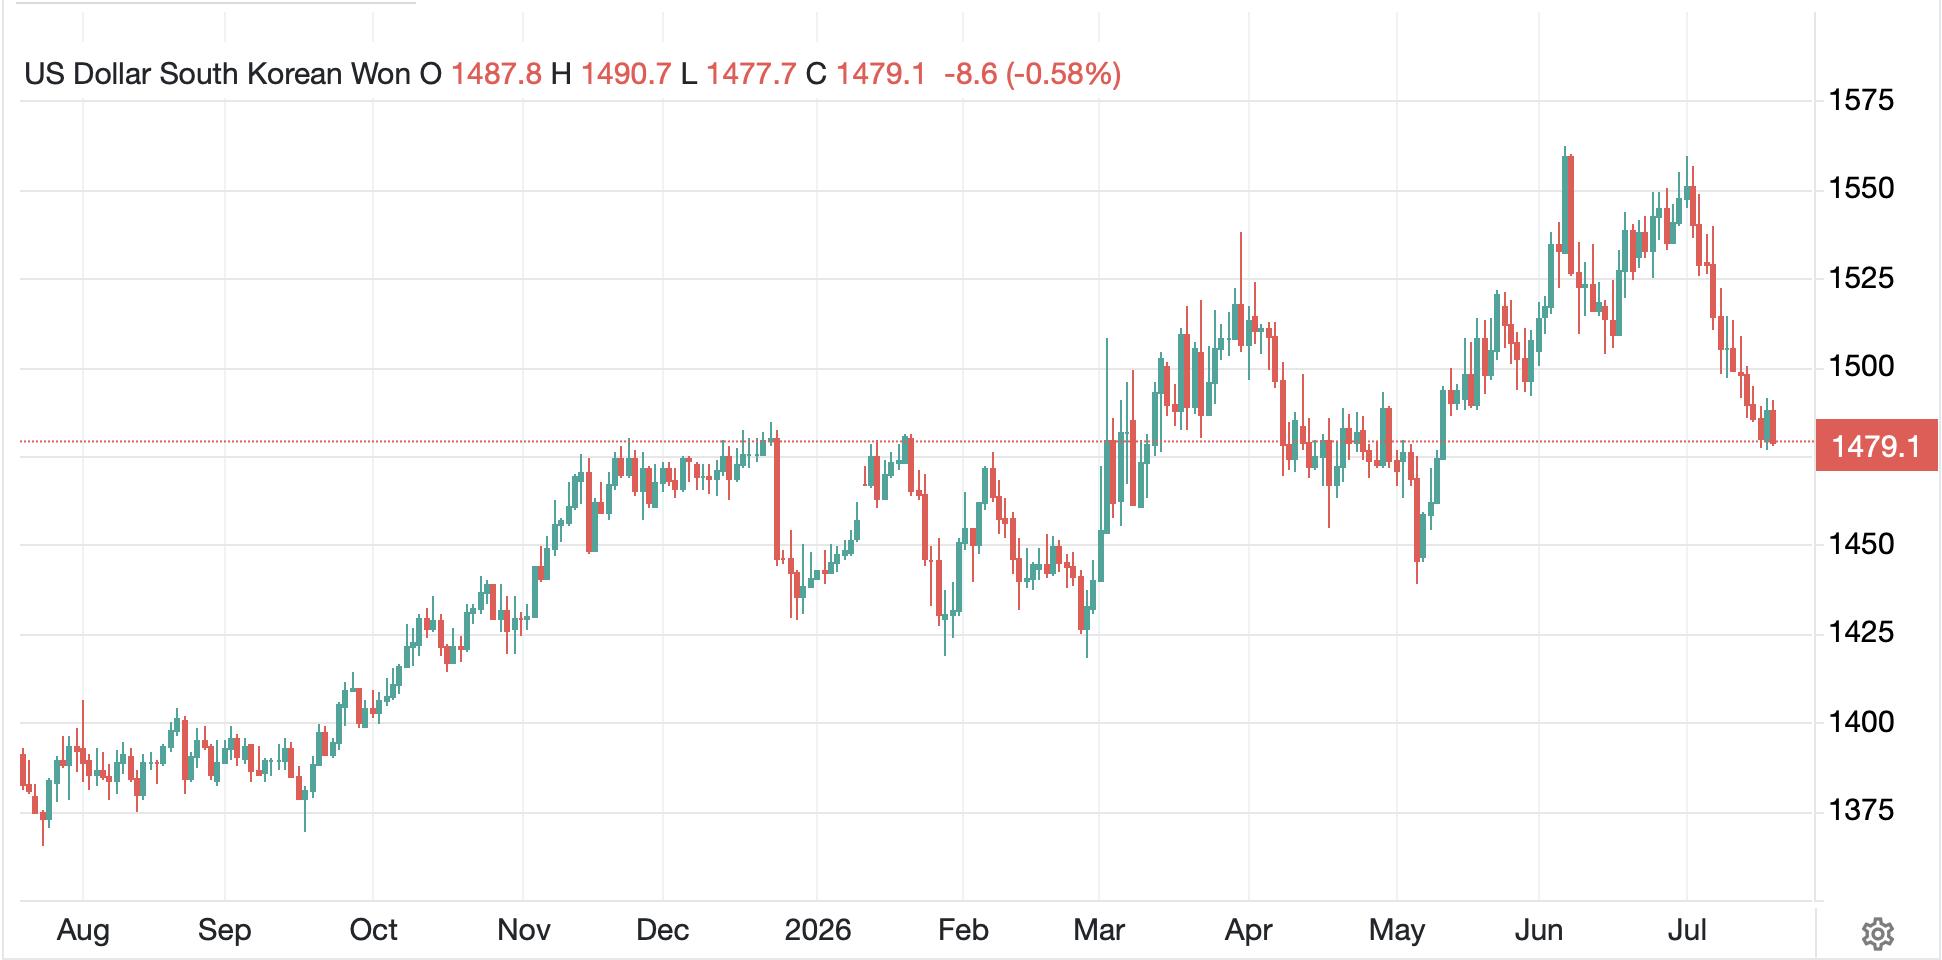
Finally, the dollar remains uninteresting overall with the DXY little changed although there have been two stories of note.  First, KRW (+0.6%) has rallied more than 5% over the past several weeks as the BOK works to change its status from a restricted currency to one that is freely convertible.  They have just announced plans for that to become the reality starting in January 2027 and I expect that it will help the won going forward.

Source: tradingeconomics.com

While the downside of convertibility is a potential increase in volatility, one need only look at the chart above to see it was already reasonably volatile.  But the positive is that KRW can become a viable asset for international utilization, opening up investment to a much wider community and that is inherently strengthening.

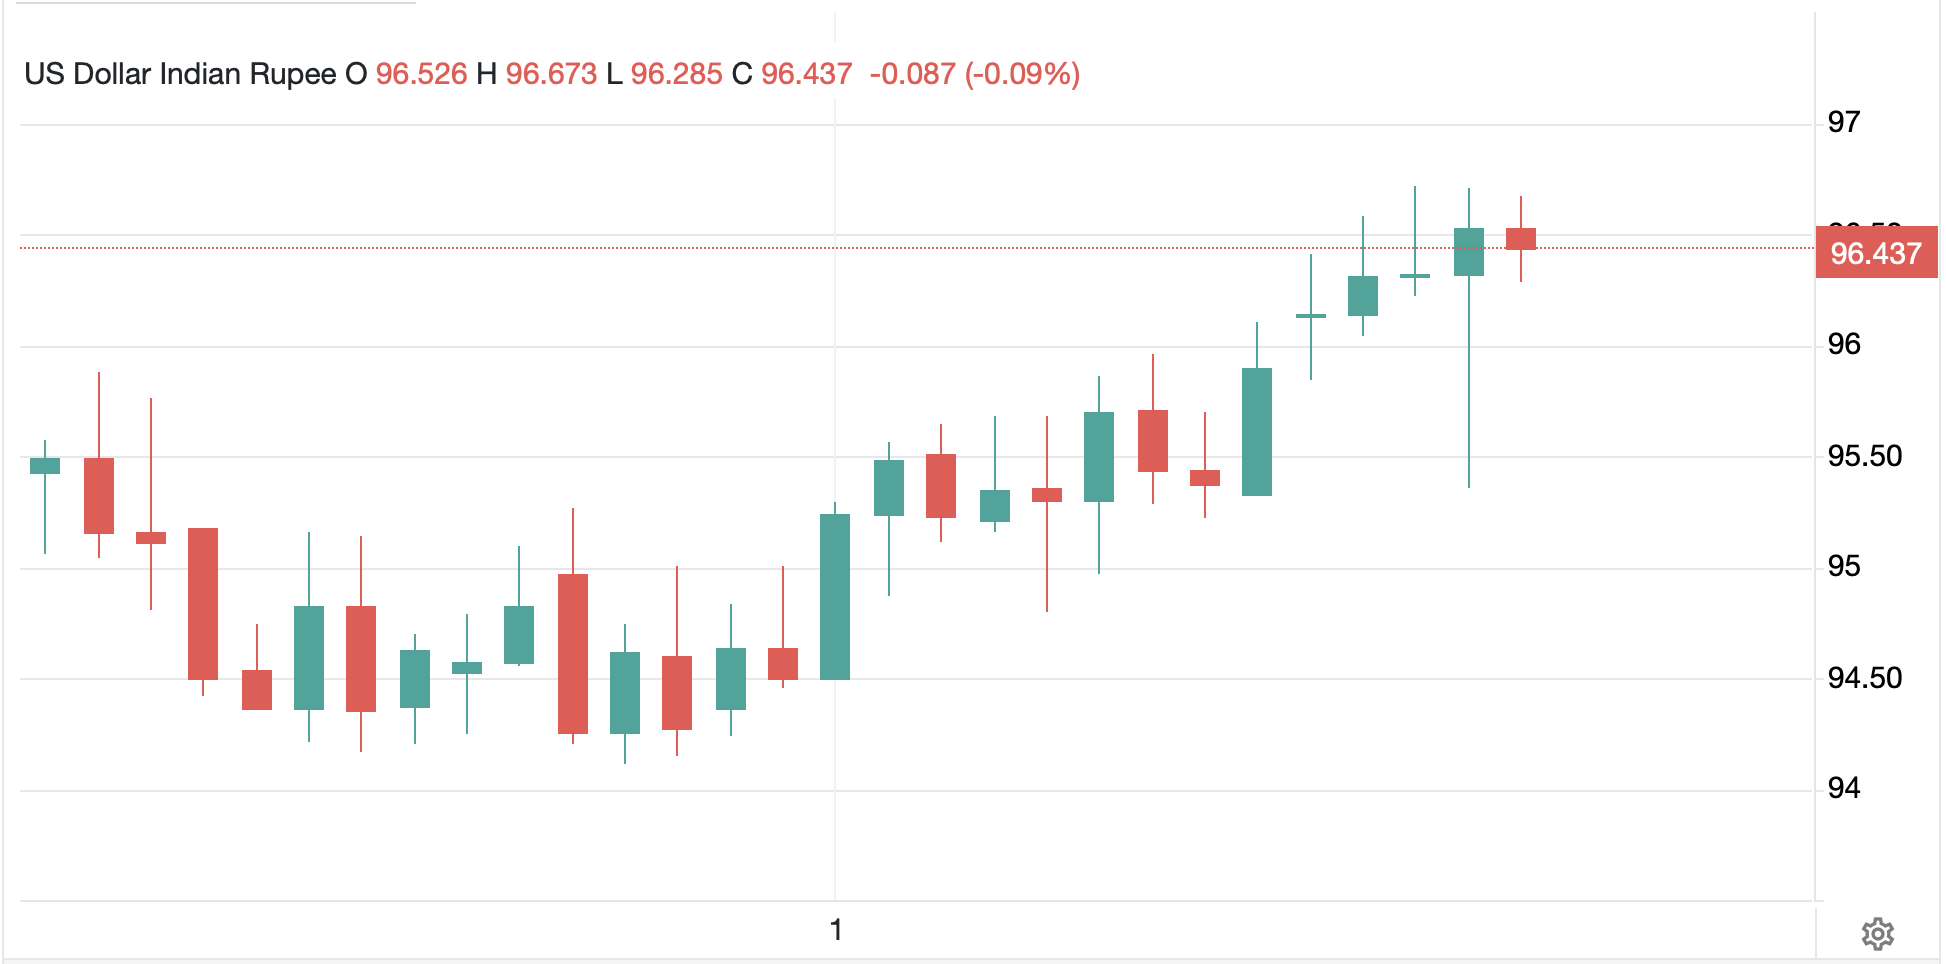
The other story is INR (0.0%) which while little changed this morning, saw another bout of central bank intervention on Friday as you can see on the chart below (the long green spike downward on the second candle from the right).

Source: tradingeconomics.com

Alas, the 1.4% gain was very short-lived and merely wasted some more of the RBI’s reserves.  The rupee is likely to remain under pressure until the Iran conflict ends as higher oil prices are a severe impediment to the Indian economy.  I cannot help but think that we are going to test 100.00 at some point before the end of 2026, although I also imagine we will see some more substantial changes from India going forward to help mitigate the impact.  But other currencies are doing little overall.

On the data front, it is an extremely quiet week with the ECB meeting (no change expected) arguably the highlight on Thursday.

TodayLeading Indicators-0.1%
ThursdayECB Rate Decision2.25% (unchanged)
 Chicago Fed Index0.14
 Initial Claims212K
 Continuing Claims1809K
FridayNew Home Sales610K
 Flash PMI Manufacturing54.5
 Flash PMI Services51.5

Source: tradingeconomics.com

As we are in the quiet period, there will be no Fedspeak until, at least, the FOMC meeting next week.  So, the war remains the story to watch, and who knows how that will go this week.

Good luck

Adf
Risk-Taking Cracks

The president told us elections
Were filled with some lethal infections
He’s unclassified
More docs to help guide
The courts to start making corrections

Meanwhile in Iran more attacks
Has led to some risk-taking cracks
Thus, oil is higher
While semis look dire
Have we seen the market climax?

A few words on the president’s speech last night as it was widely touted.  In it, he explained he declassified a trove of documents offering proof that there have been many election irregularities over the past six years, naming China as a major player in the process.  These documents are available online for all to see and ostensibly refute (I have not read them, nor am I likely to do so) that our elections have been secure in the US.  In fact, the same government analysts that have declared there to have been no issues are the ones who these documents purport to show were interfering.  My only observation, especially on this topic, is that no matter the proof available, minds have long been made up, and this will not change opinions, at least until arrests are made and trials are held.

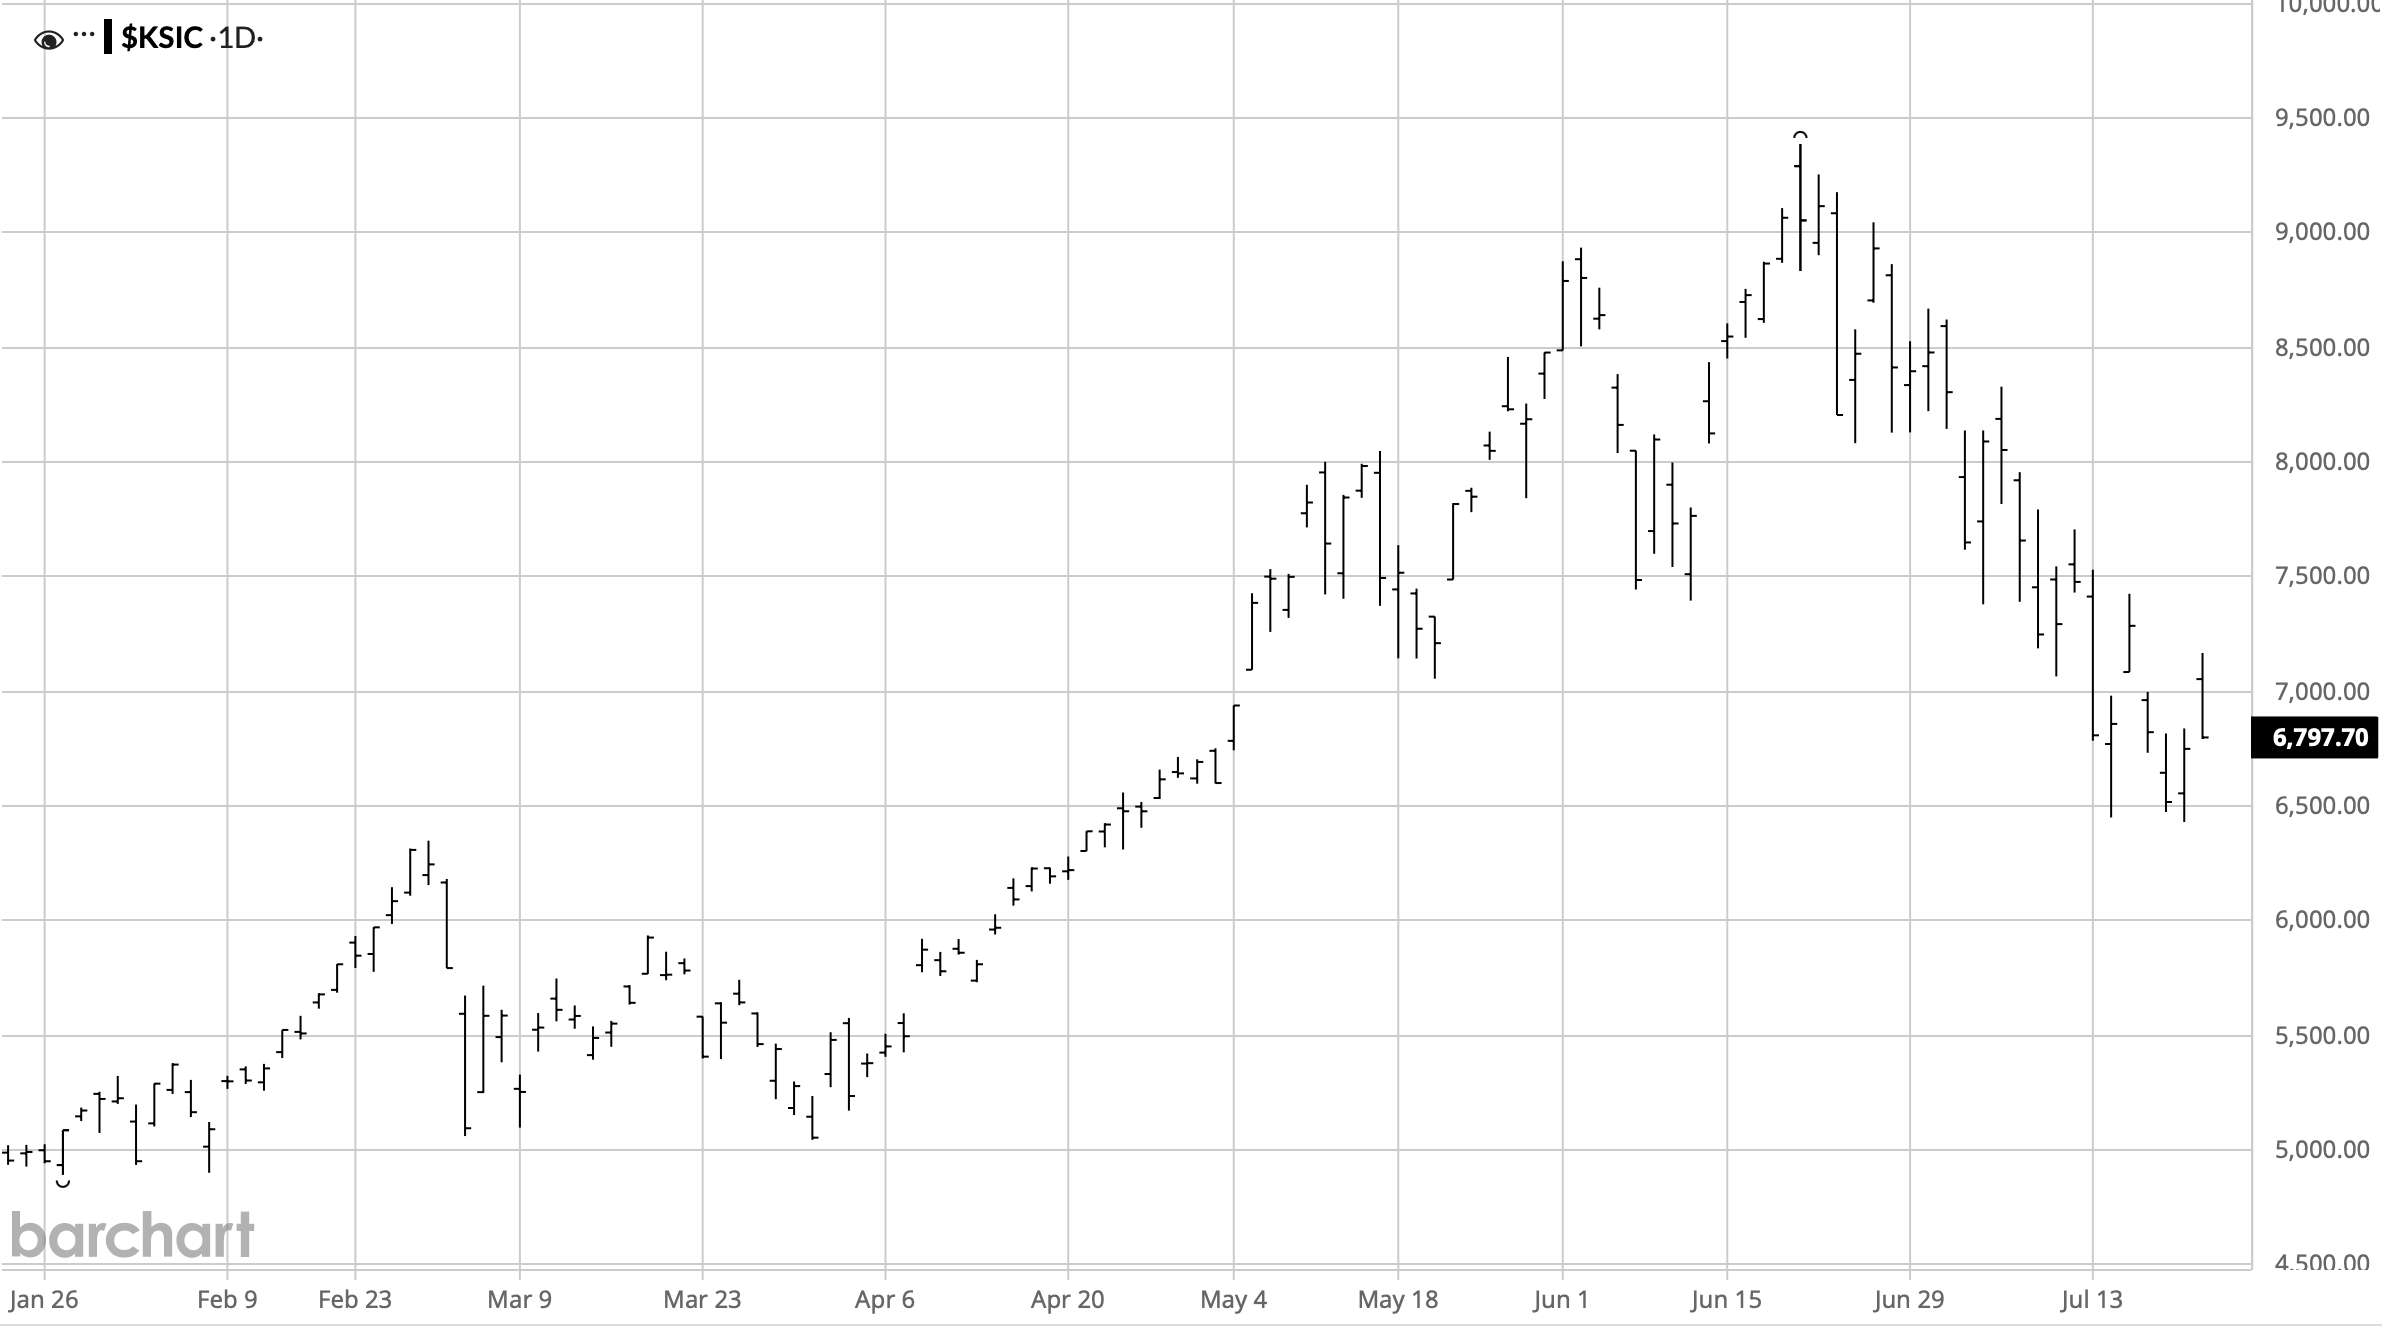
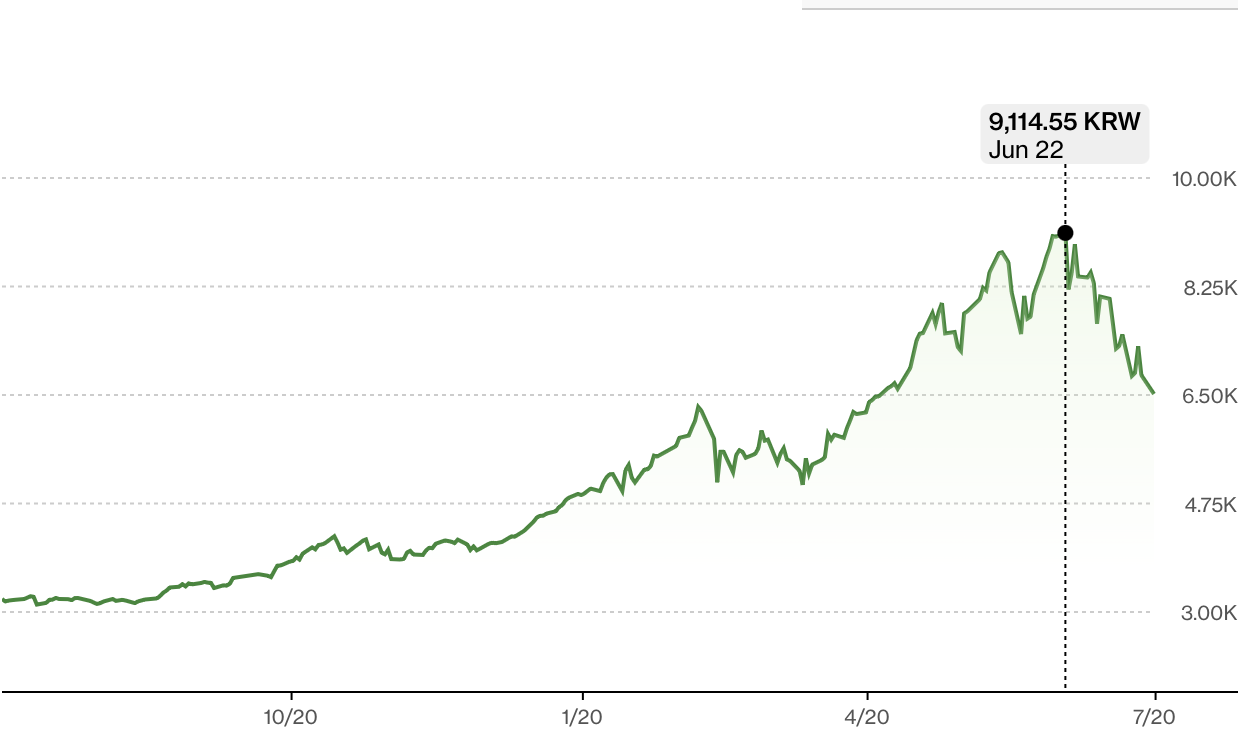
Which takes us to more relevant market issues.  Arguably, the poster child for semiconductor stocks is the Korean KOSPI (-6.4%), where just two companies, both major players, Samsung and SK Hynix, represent some 40% of the index value.  As you can see from the below chart, it has been tough sledding for the past month, with that market closing lower by nearly 28% from its highs on June 22nd.

Source: barchart.com

And while that may be extreme, if we look across major markets in Asia, there was some rough times last night almost everywhere.  Tokyo (-4.0%), HK (-1.8%), China (-3.6%) and Taiwan (-6.5%) all had serious dislocations downward.  And, of course, the thread running through them all is the tech exposure.  There has been much discussion of a rotation out of tech and AI stocks into other areas, with financials and energy amongst the beneficiaries, and certainly, last night’s price action supports that thesis.  Interestingly, India (+1.25%) completely bucked that trend, but then, India is perceived to be a major loser from the AI story, so if that is unwinding, I guess it’s no surprise that India benefits.  Elsewhere in the region, things were far less volatile.

As to Europe, despite a glaring dearth of technology companies, equity markets there are also under pressure this morning (DAX -0.9%, CAC -0.9%, IBEX -0.5%, FTSE 100 -0.1%) although that is more likely to be a response to the fact that oil prices have picked back up as the US resumes more aggressive military activities against Iran.  As to US futures, at this hour (6:45), they are all lower led by the NASDAQ (-1.8%) although both the SPX and DJIA are down by -0.7%.

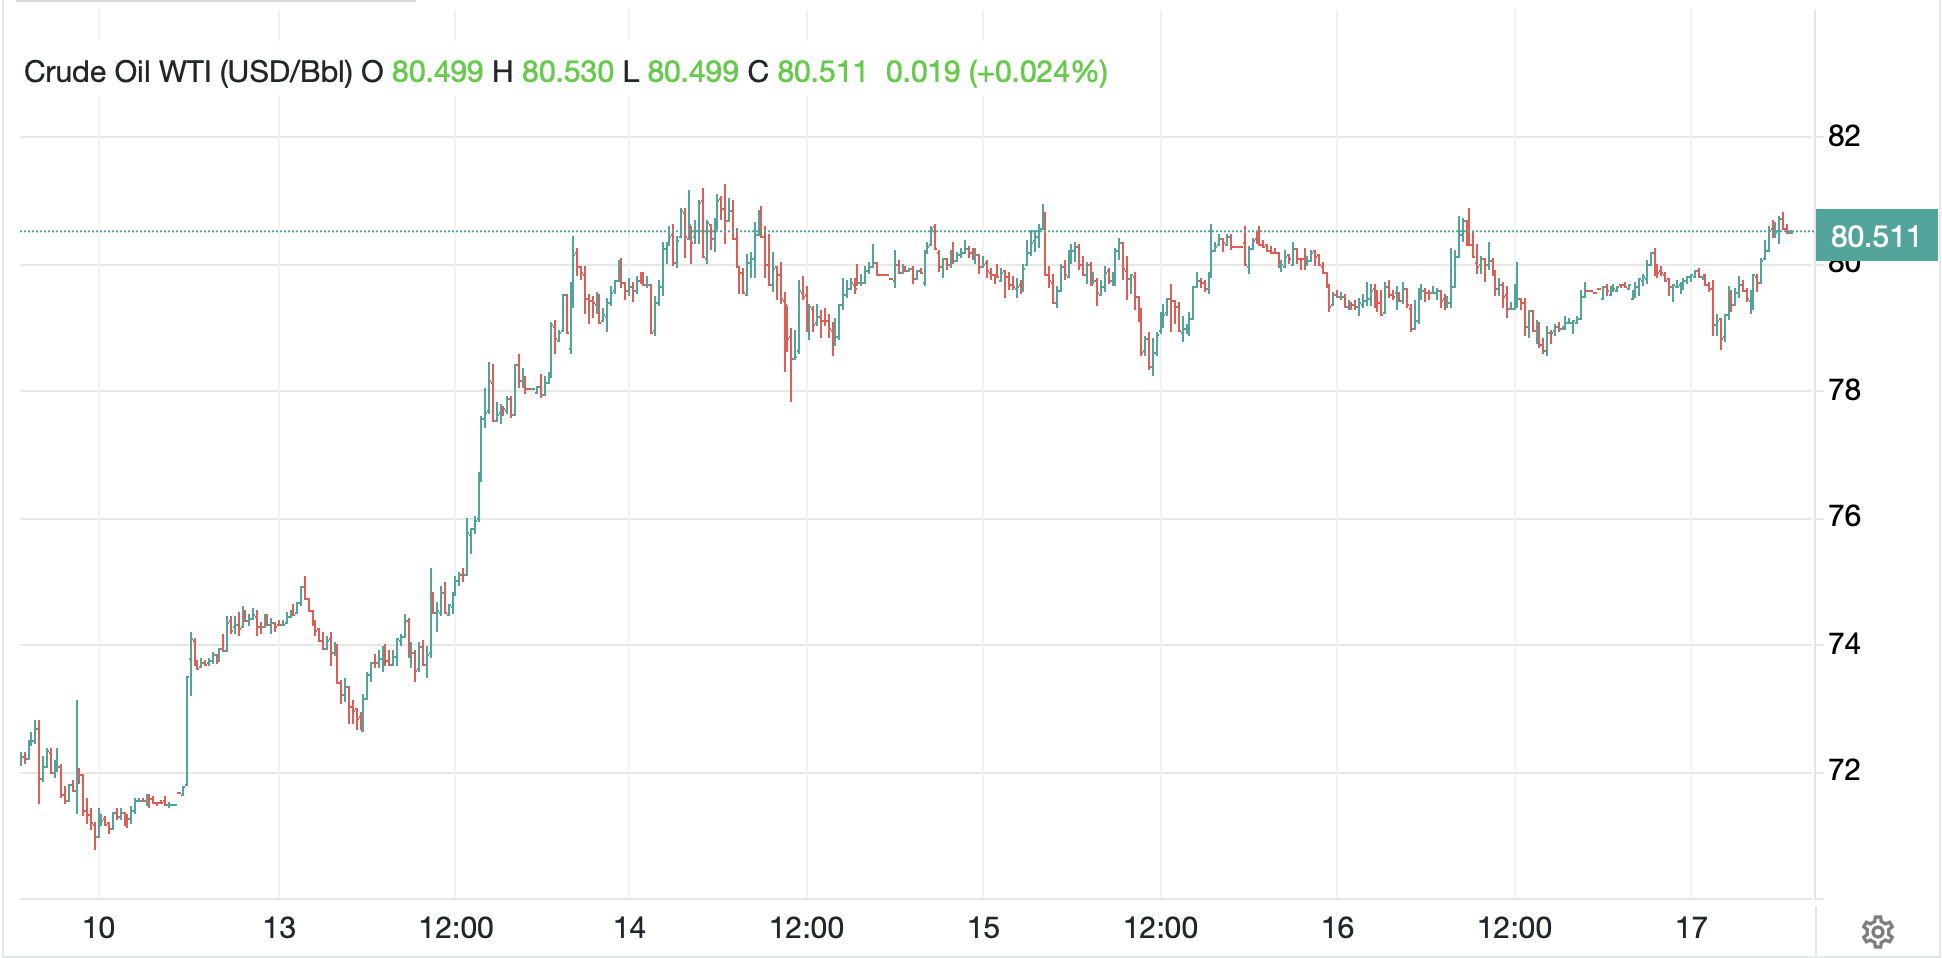
Which takes us to oil.  The black, sticky stuff is higher by 2.0% this morning, although, as you can see from the chart below, it is still hovering right around $80/bbl, the level I described as its new home earlier in the week.  

Source: tradingeconomics.com

The key question here remains just how much of an interruption in economic activity has been caused by the Iran conflict.  Not dissimilar to the election question at the top, it seems the two sides of this argument are dug in and will countenance no discussion that they are misreading the situation.  There are still analysts who discuss tank bottoms and the idea that now that so many reserve inventories have been released, we are quickly approaching a situation where their much mooted $200/bbl is right around the corner.  And yet, despite the tick higher overnight, the market continues to price a relative lack of concern over future supplies.  As always, I go with prices as the best arbiter, but that’s just me.  The massive production increases from the US and Canada, as well as Brazil and Guyana, increases from Venezuela and the workarounds by the Gulf nations to get their oil to market continue to demonstrate that supply is available.  

One wild card that is very difficult to completely understand is China, where things are always opaque, and where their imports have fallen sharply, thus reducing demand.  Was that demand “destroyed” in the sense that it will never return?  Seems unlikely.  Rather, my best guess, and it is just a guess, is that China tapped into their own SPR and has been using that, rather than importing.  Whatever the situation, there appears to be no shortage of oil available.  

One other thing weighing on the price has been Ukraine’s success in attacking Russian refining capacity.  If the Russians cannot refine their oil, they need to sell it as crude rather than products, and that is adding to the inventories available for sale.  It is also part of the explanation as to why products prices and the crack spread remain so high, more oil, less refining.

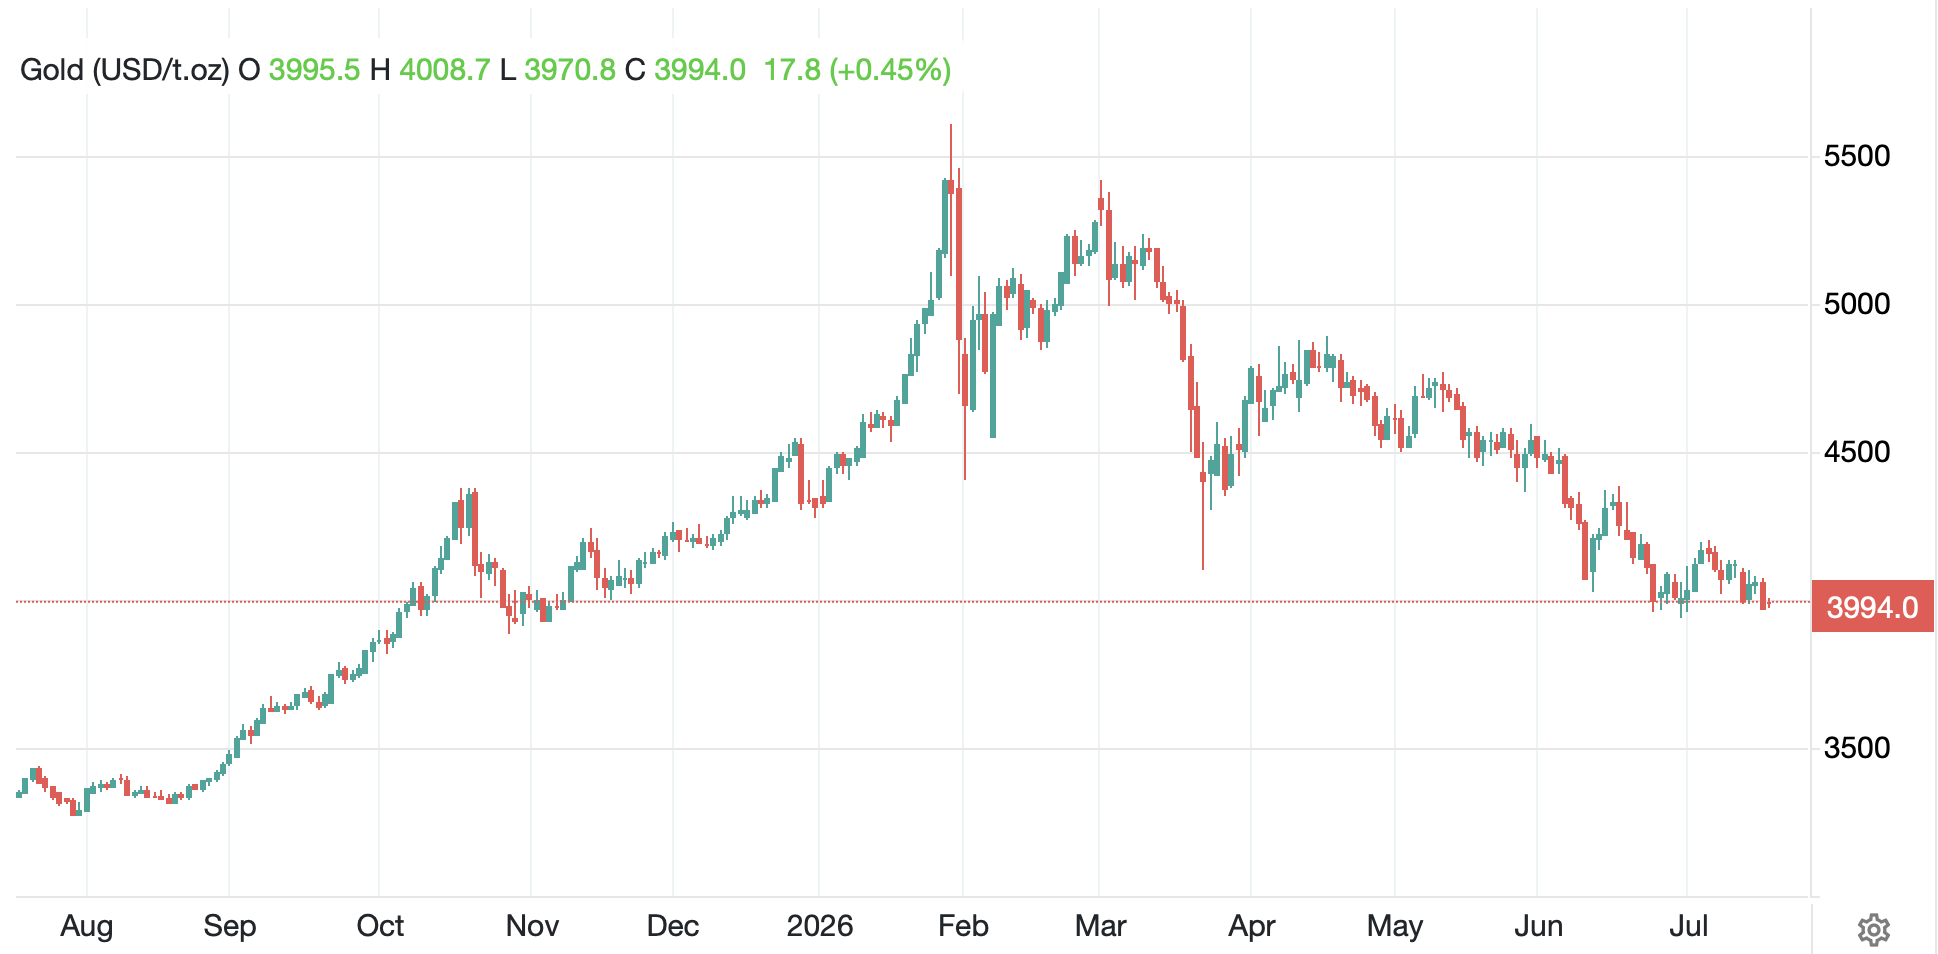
Looking at precious metals, gold (+0.4%) closed below $4000/oz yesterday for the first time since last November as per the below chart.

Source: tradingeconomics.com

Silver (-0.4%) also remains under pressure and this morning copper (-1.9%) is suffering alongside the precious space.  But perhaps a few words on what gold really represents are in order.

As J.P. Morgan said in 1912, before the Federal Reserve was created, “Gold is money, everything else is credit.” Certainly, the second part of the statement is correct as your bank deposits rely on your bank standing behind them, making you a creditor of your bank.  Federal Reserve Notes are paper obligations of the US government, so again, represent purchasing power, but as we have learned, a decreasing amount of it every day.  Meanwhile, gold has a 5000-year history of being accepted as a thing of inherent value.  Now, the widely accepted definition of money these days is it must have three characteristics; it serves as a medium of exchange, a store of value and a unit of account.  Gold historically has served as the first two, although rarely as a unit of account.  Rather, gold holdings were always converted into whatever the unit of account was at the time.

Which takes us to the present, why does gold continue to represent a part of the financial markets, and over the past several years, an increasingly important part.  I would contend this is all of a piece with the broader changes in the global community, notably the end of the Pax Americana, where the US no longer chooses to (or can) guarantee the peace of the post WWII and Cold War worlds.  Instead, we have seen a constant increase in debt by every nation as governments around the world seek to placate their own citizens and are unable to pay for all the goodies they offer, thus borrow the difference.  

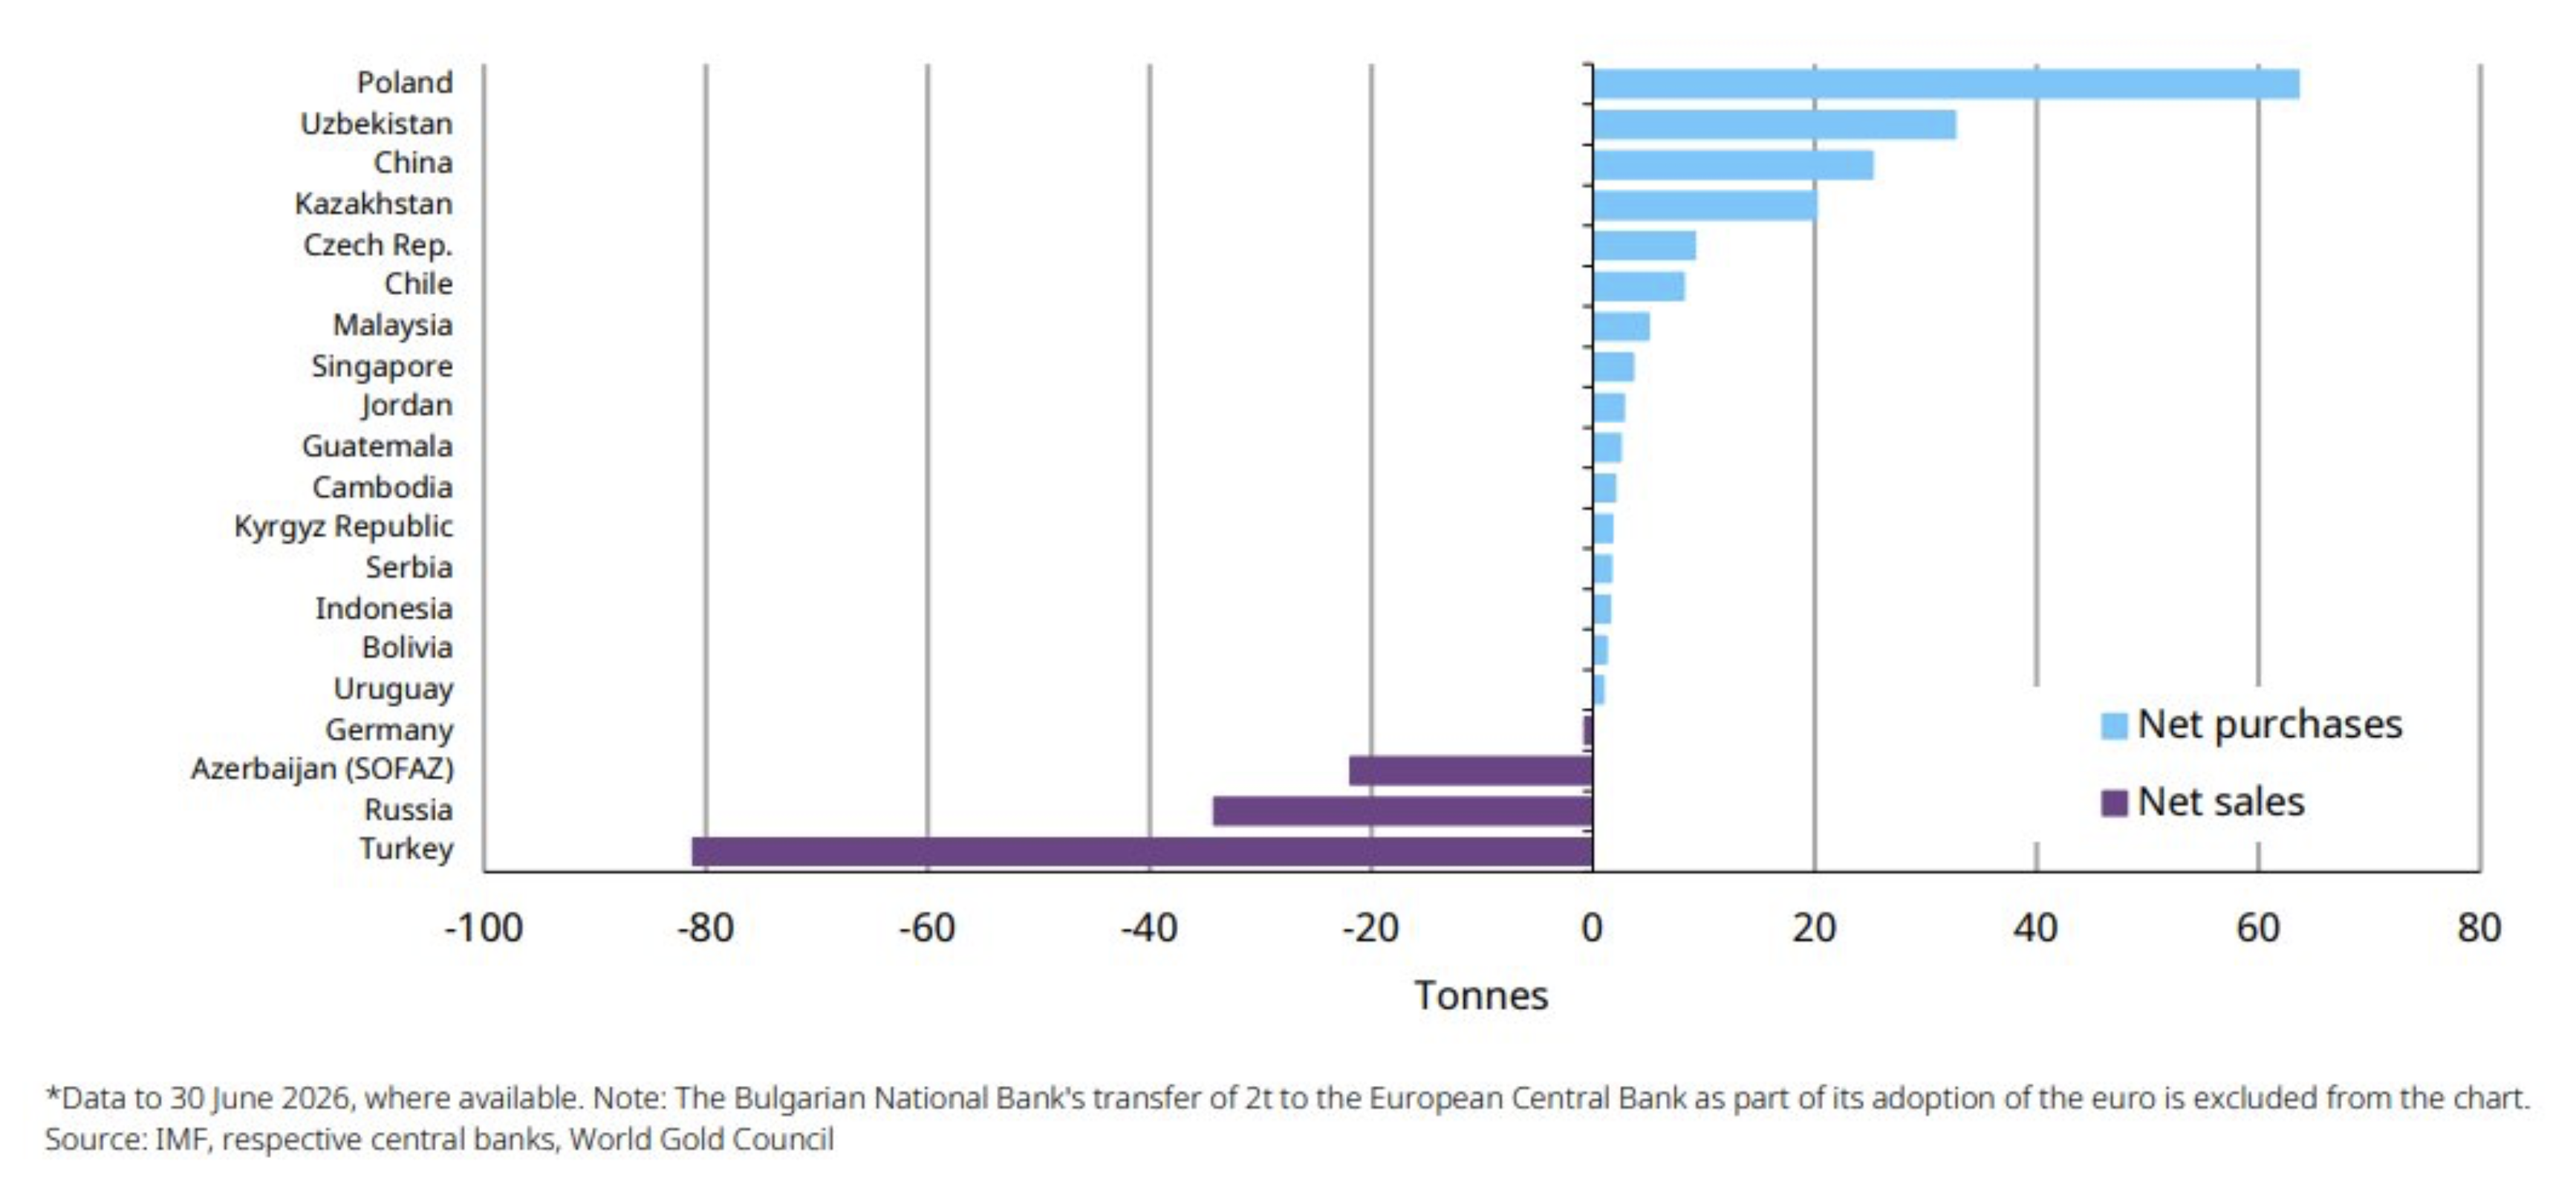
However, the freezing of Russian reserve assets by the West in the wake of the invasion of Ukraine has altered many views about what is safe and represents value, and what is paper and doesn’t represent value and central bankers, charged with maintaining a nation’s wealth, have gone back to gold as the one thing they know will retain value given it is nobody’s liability.  The chart below shows activity in May, which is similar to what has been happening virtually every month, that central banks are relatively price insensitive, buying the stuff as a strategic asset.  And the sellers, were selling because they needed the money!

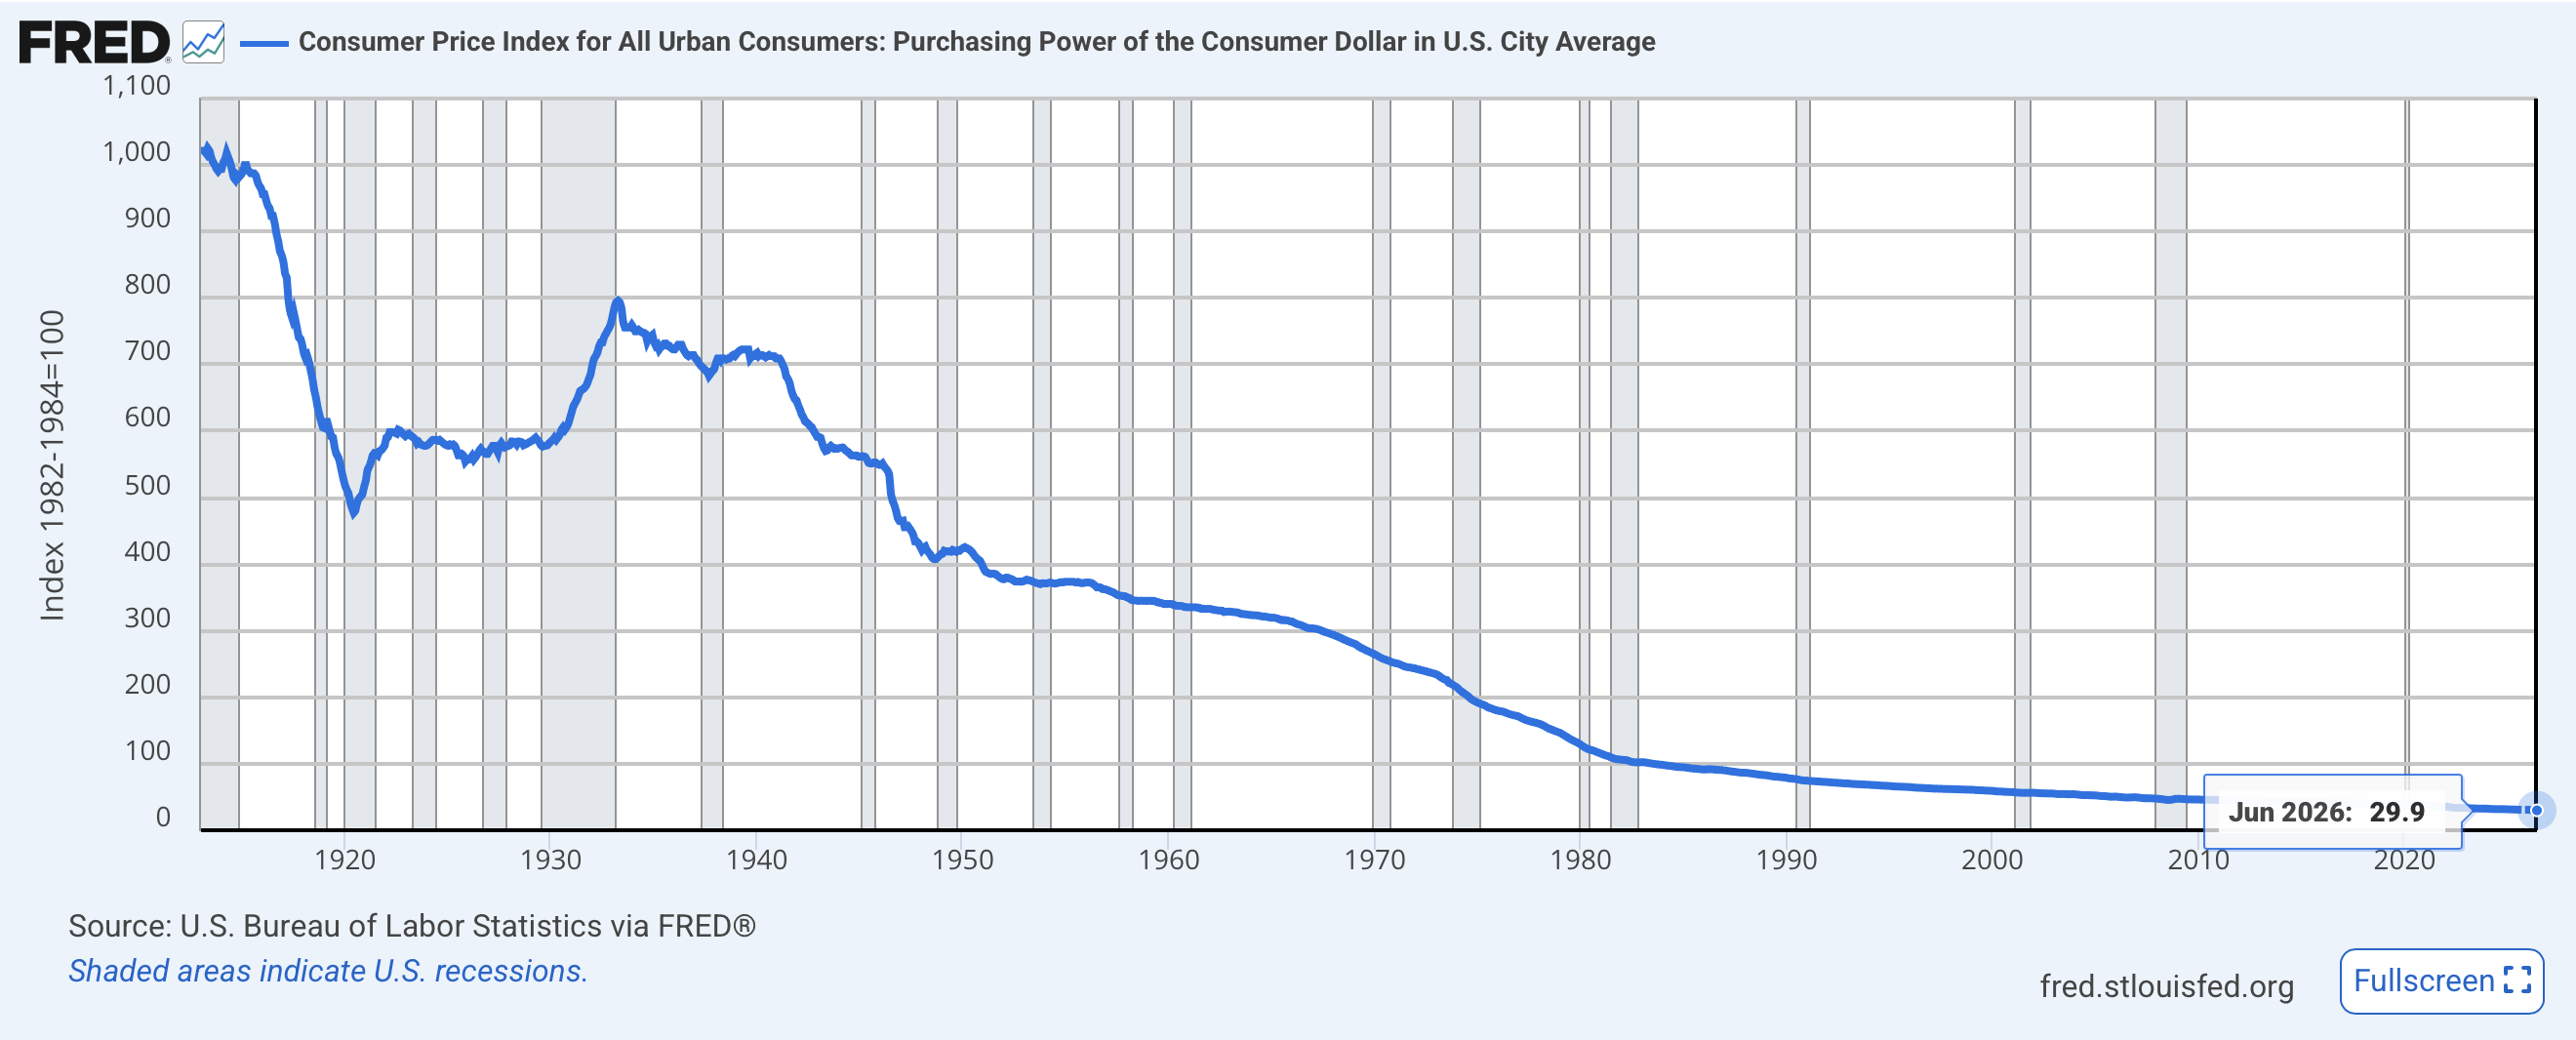
One last chart to make the point about gold and purchasing power.  The below chart from the FRED database demonstrates just how much purchasing power the dollar has lost since the Fed came into existence; i.e. just how much inflation has destroyed the real value of the dollar.  For reference, that opening level is 1021 compared to today’s 29.9, a 97.1% devaluation in 113 years of the Fed.  It can be argued that the Fed has failed catastrophically in their effort to maintain the value of the dollar.

Ok, quickly elsewhere bond yields have edged lower, with Treasuries (-3bps) leading the way and European sovereigns either unchanged or having slipped by -1bp.  JGBs overnight also slid -2bps, but overall, while there is a lot of discussion about yields, they are not moving very far.

Finally, the dollar is a bit firmer this morning with the pound (-0.3%), Aussie (-0.4%) and euro (-0.1%) all slipping although NOK (+0.2%) is benefitting from oil’s move.  In the EMG bloc, though, there is more trouble with KRW (-0.5%), ZAR (-0.6%) and MXN (-0.3%) representative of more anxiety there.  Ultimately, I still have a hard time getting too bearish the dollar in the current world.

On the data front this morning brings Housing Starts (exp 1.31M) and Building Permits (1.40M) as well as IP (0.2%) and Capacity utilization (76.2%).  Finally, at 10:00 we see Michigan Sentiment (51.0).  There are no Fed speakers scheduled, and they are entering their quiet period, so we won’t hear from them until the meeting on the 29th.  (Perhaps we won’t hear from them anymore after that too!). 

Summing up, Iran and oil are still key drivers, equity market rotation is happening, although given how far it has moved, we may be near the end of that process, and yields have no direction.  Regarding yields, we may have reached the point where the issue is not inflation concerns, per se, but rather the sheer volume of debt that is going to be issued going forward, and the fact that private investors want more yield to be persuaded to buy it.  As to the dollar?  Like I said, I just don’t see the bear case over any longer-term horizon.

Good luck and good weekend

Adf

Just Keeping Up

The yen slid further
Is it accelerating?
Or just keeping up?

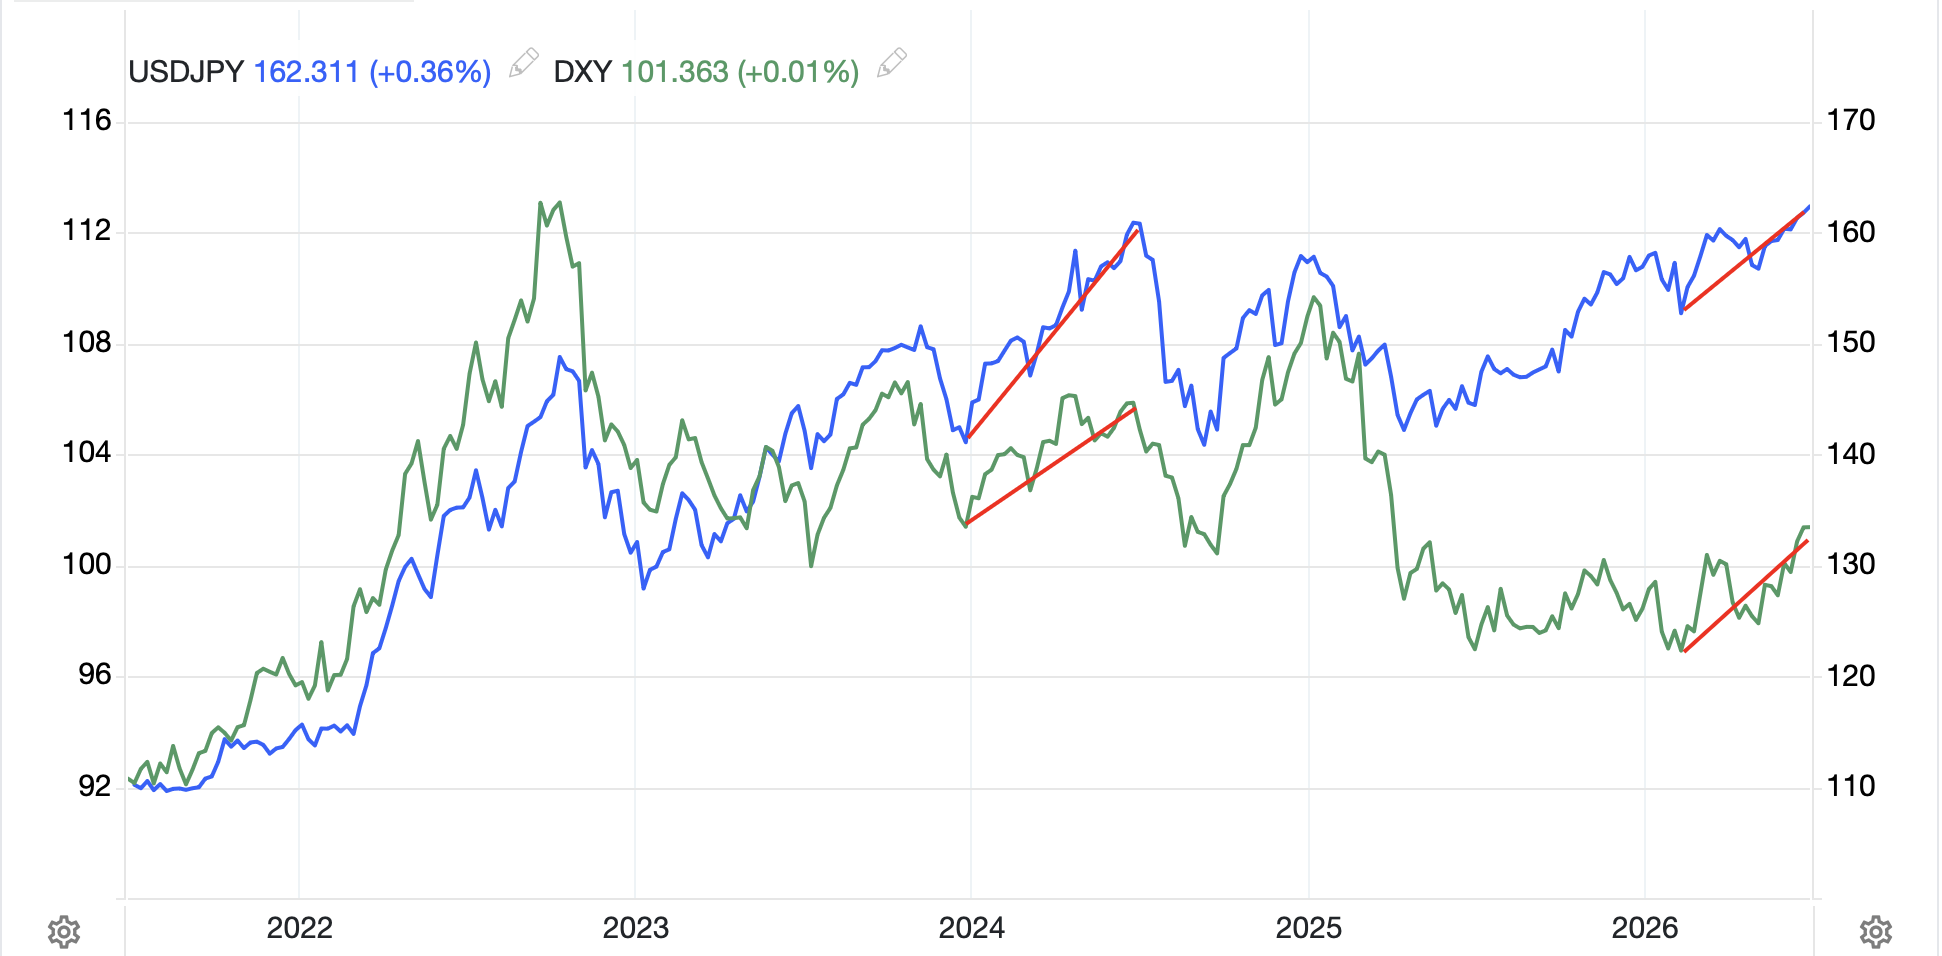
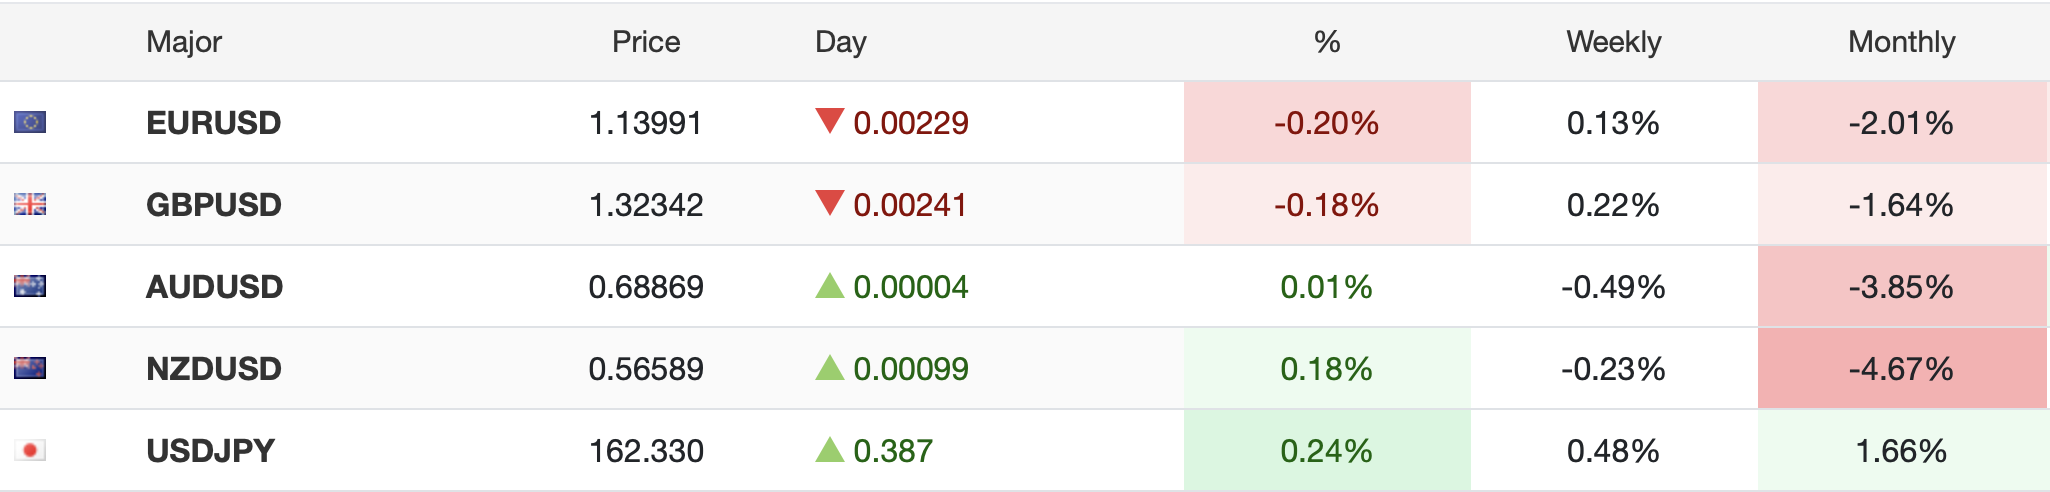
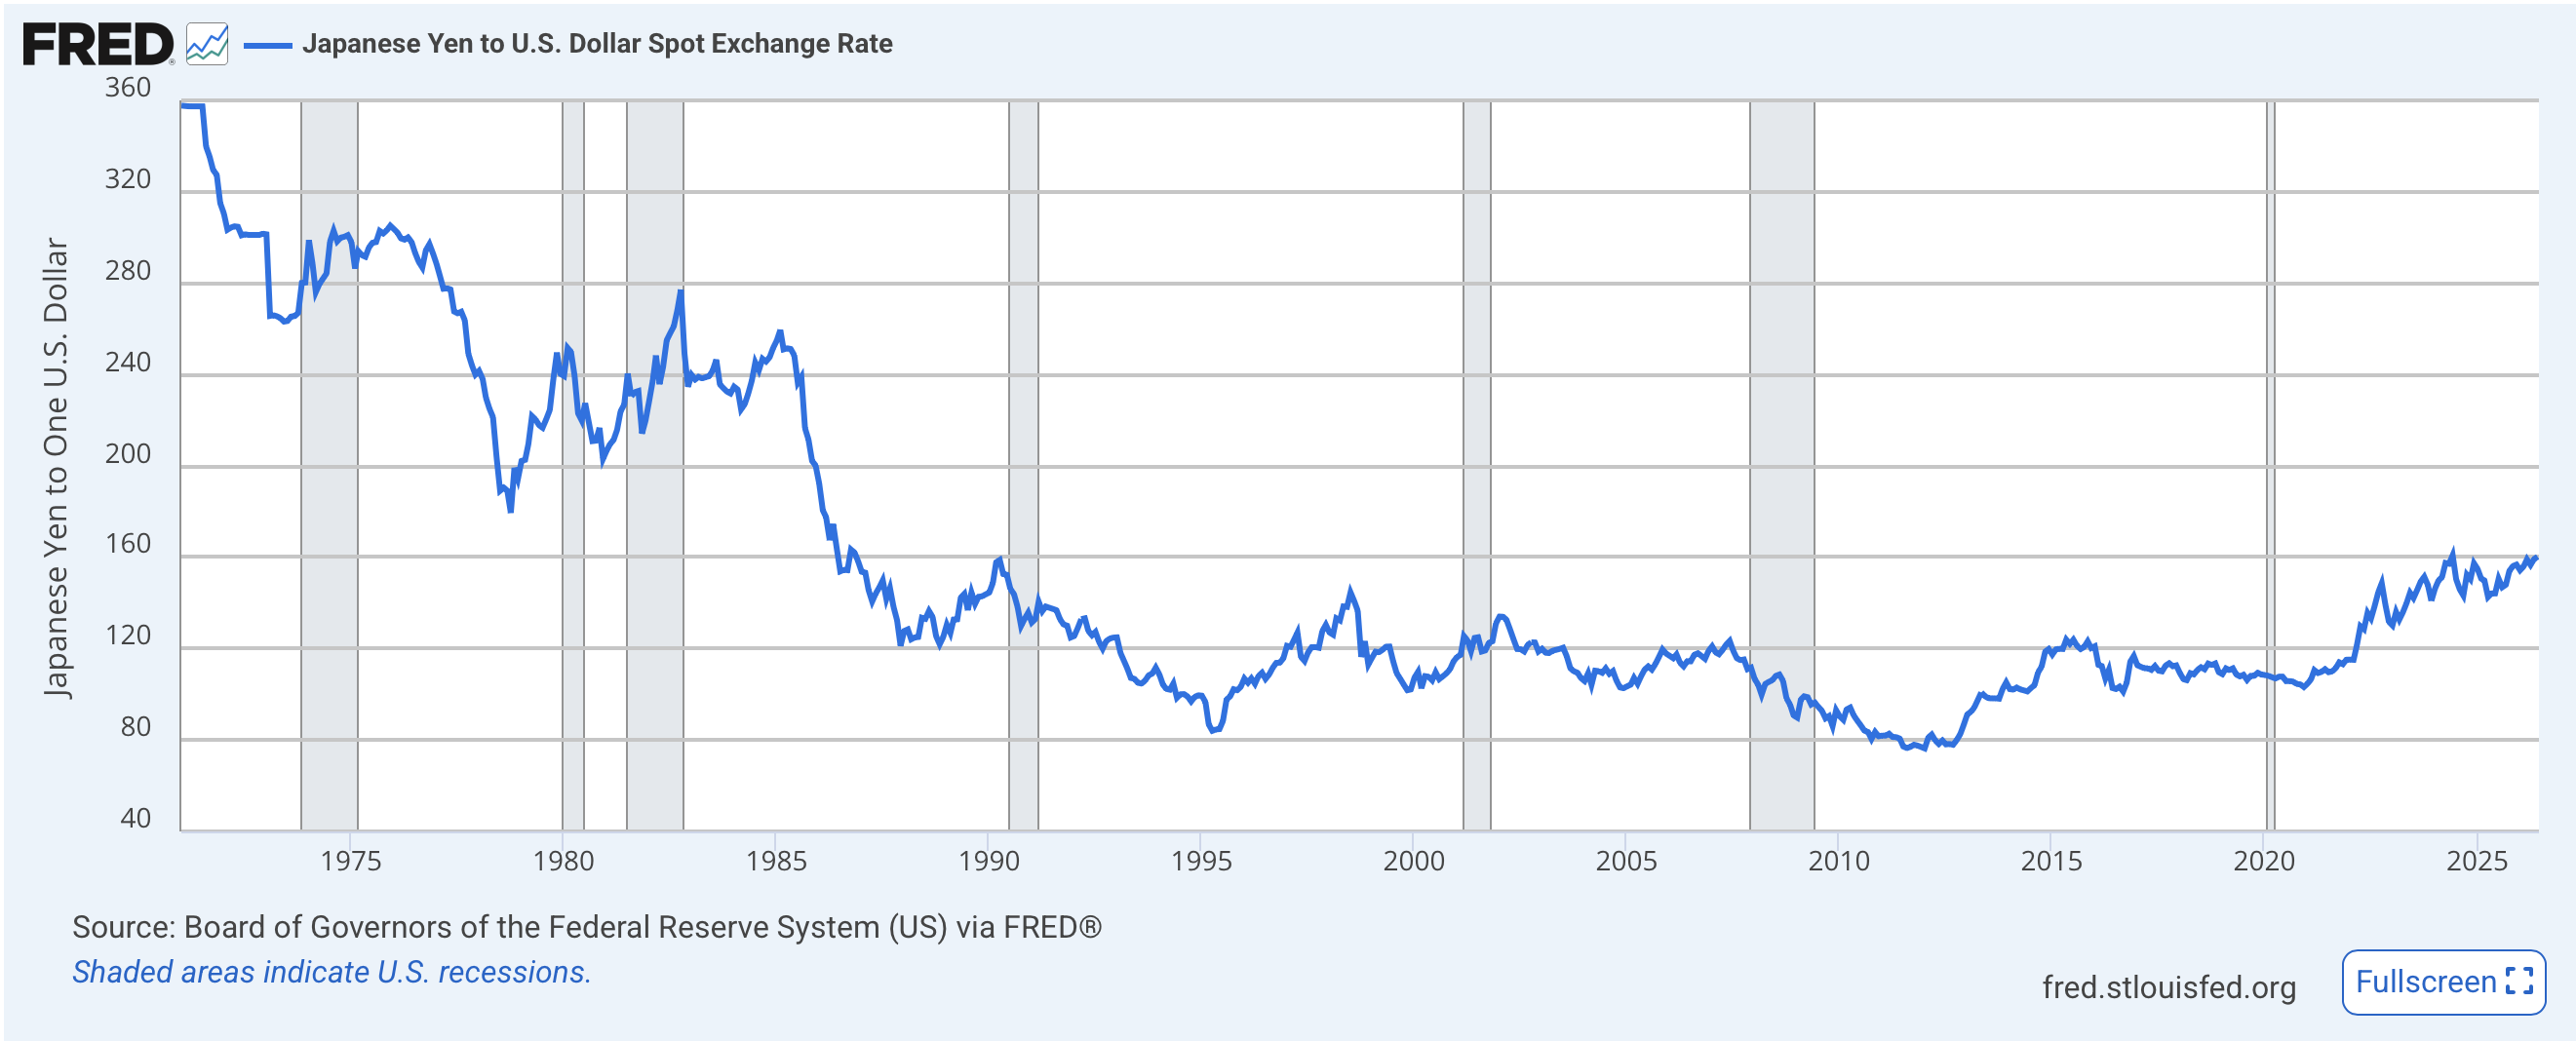
There has been a lot of press this morning regarding the yen (-0.25%) which as you can see has weakened a bit, but hardly an extraordinary move.  Thus, the press is all about the level at which it now trades, 162.30ish which is a new high for the move, although it has yet to break above its 1986 levels.  The nature of the articles has been a question as to when the BOJ is going to be back intervening again which then morphs into a discussion as to whether intervention is effective.  (While I don’t know if they will be back in, I imagine that will be the case at some point, we know it is not effective.)  At any rate, I have created the following chart on tradingeconomics.com so that you can (hopefully) see why they have not yet intervened.

One of the key features of the MOF seven step program to intervention is the pace of the yen’s movement.  A rapid decline is far less tolerable than a gradual movement.  As well, there is the question of whether the yen is declining across the board, or it if is declining specifically, or at least more rapidly, vs. the dollar.  It is no surprise to me that the MOF remains on the sidelines as the dollar is rallying everywhere right now, so yen weakness is really more about dollar strength.  If you look at the chart above, I tried to show the slope of the movement in USDJPY vs. DXY back in the beginning of 2024 which was the previous time the yen started to show serious weakness and the BOJ intervened.  To my eye, the slope of the two lines in 2024 are far different than the slope of the current movement.  In fact, the table below shows that the yen’s weakness over the past week and month is hardly an outlier.  In fact, it has basically held up better than its major counterparts.

My point is much is being made about the yen’s breech of the 162 level, but the movement has been quite gradual, hardly the rapid and volatile movement that has driven intervention decisions in the past.  Frankly, there is little reason to believe that with the dollar strong across the board, the BOJ can do anything other than waste money in an intervention effort.

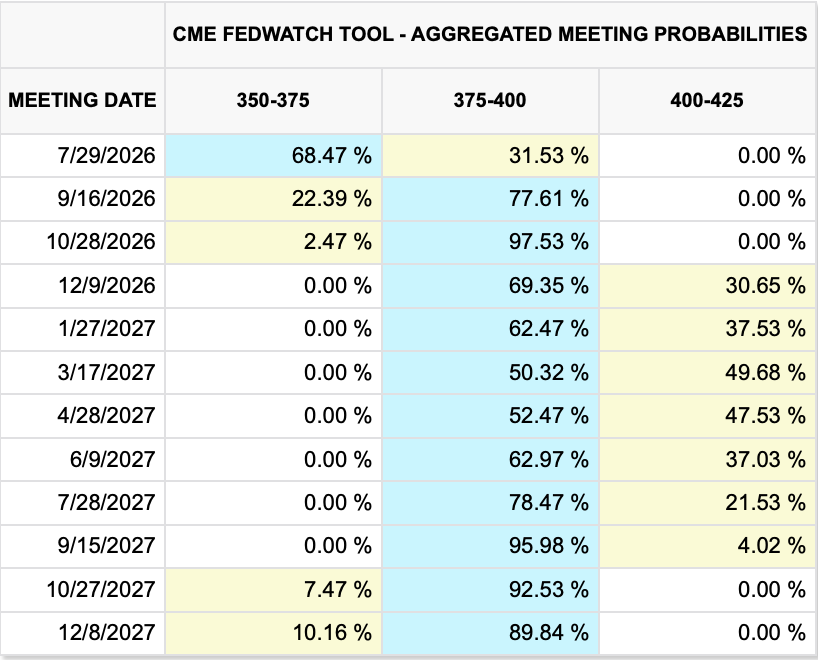
Which begs the question, why is the dollar performing so well?  The pat answer remains that the market is pricing in a suddenly hawkish FOMC with the Fed funds futures market pricing an October rate hike now, with a one-third chance of a second one in December.  See below from the CME.

But I still don’t understand that pricing.  Despite all the ongoing chatter about the imminent shortage of oil/diesel/gasoline/jet fuel that has yet to appear and has now been delayed to H2 of this year, markets continue to price limited further interruption to energy availability.  In addition, one need only look at today’s raft of Eurozone inflation data where France (1.8%), Italy (3.0%) and every German state (between 2.1% and 2.4%) all printed lower than last month, as well as lower than forecast, and recognize that the significant decline in energy prices over the past month is going to push down measured inflation.  Nothing has changed my view that the Fed is on hold for now, and over the next several months the idea of rate cuts will come back into vogue.  At that point, I assume the dollar will give up its recent gains, although I do not foresee a reason for a substantial decline.  After all, investment flows into the US are going to remain robust.

And with that, let’s look at other markets.  As proof positive that nothing is ongoing, oil is unchanged this morning, just above $70/bbl and there has been precious little new news about the situation in the Gulf.  Metals are edging higher (Au +0.4%, Ag +1.3%, Cu +1.3%) but the precious set remain in downtrends although copper is in demand.

You’ve already seen the dollar movement above, at least vs. the bulk of the G10.  But elsewhere, it is not a very interesting picture either.  Perhaps the fact that ZAR (+0.3%) is firmer this morning on the back of both the modest rise in gold and the fact that their fiscal situation looks a bit better (significantly reduced budget deficit in May) is the outlier of note.

Bond markets continue to drift as 10-year Treasury yields slip -1bp and we see similar price action across most of Europe.  The outlier here is Italy (+3bps) which given the better-than-expected inflation data is confusing and I have seen no other cogent explanation.  As well JGB yields (+4bps) overnight reacted to the yen’s weakness as well as to comments by the newest BOJ member, Ayano Sato, who sounded modestly dovish.

Finally, turning to the equity markets, another record setting day in the US was followed by a mixed picture in Asia with both gainers (Tokyo +0.9%, China +1.1%, Korea +1.0%, Taiwan +2.5%) and laggards (HK -0.6%, Australia -0.5%, India -0.3%, Indonesia -3.1%) with the latter a response to a legal verdict of corruption which the market has taken as a major government intrusion into the economy and frightened investors.

Turning to Europe, though, everybody is happy this morning with gains across the board (Germany +1.5%, UK +1.2%, Spain +0.7%, France +0.6%) as those slipping inflation numbers help the overall sentiment.  As to US futures, you will not be surprised that at this hour (7:25) they are marginally higher.  

One must be impressed with the consistency of equity market gains.  It is enough to make you reconsider your prior ideas as to how markets work.  Arguably, the key feature of the recent equity market performance is that earnings data continues to improve.  Now, if you look at the ongoing growth in money supply, both in the US and around the world, it is no surprise that nominal results continue to rise.  It is also not surprising that people are feeling stressed by inflation regardless of the data that is printed as all that money has to find a home somewhere.  And the Cantillon effect tells us that the first folks who get the newly printed money (banks and institutions) are the ones who benefit the most while the rest of us simply watch our cost of living increase.  This is the entire wealth/income inequality story and, arguably, the reason that the idea of socialism is making a comeback.  And socialism does have a perfect record in its economic outcomes; it has failed 100% of the time it has been tried.  But right now, I fear that record is not going to be a problem.  There is much potential trouble ahead.

Today’s data brings Case-Shiller Home Prices (exp 0.9%) as well as Chicago PMI (58.1), JOLTs Job Openings (7.30M) and Consumer Confidence (94.7).  But with Warsh on the tape tomorrow morning and then NFP on Thursday, I don’t see today’s data having much impact.

While the Iran situation is in the background right now, it remains the issue with the biggest potential impact going forward.  A successful conclusion of a deal and resumption of flows of energy through the SOH will put additional downward pressure on energy prices, and by extension general inflation.  In that scenario, central banks will be quick to turn away from rate hikes.  However, if things collapse there, then we will need to be prepared for another major hiccup, that’s for sure.

Good luck

Adf
Peace Was in Sight

The weekend saw missiles in flight
As both sides continued the fight
But just ere the open
The market put hope in
The idea that peace was in sight

So, here we are first thing today
And focus has moved far away
We’re back to AI
And pie in the sky
As stocks, once again, make more hay

Much has been made of the fact that President Trump is hyper aware of financial markets and seeks to ensure that whatever is happening in the world, it happens on weekends so that by the time markets reopen, the situation appears far less dire, hence less need to sell stocks.  This weekend is a perfect example as Friday after the close, it was announced that the US had responded to the several Iranian attacks on ships in the Strait of Hormuz last week with significant force.  The early punditry on Friday night and Saturday was that when markets reopened, the recent decline in oil prices would reverse as that has been predicated on a more lasting peace.  But then, last night shortly before futures markets opened, there were announcements that the US had finished its response and that the peace talks were back on under the guise of the 60-day ceasefire.  

I have to say, though, it almost appears as if Iran is in on the joke.  After all, if not, wouldn’t they try to force Trump’s hand during market hours?  Just asking.  Whatever the case, the situation as we wake up this morning is that oil (+0.8%) has edged back higher near $70/bbl but certainly doesn’t have the feel of breaking out higher.  Meanwhile, equity markets are generally positive and have been overnight while bond yields and the dollar are little changed.  in other words, there’s not much happening this morning.

In reality, it is not that surprising that things are quiet.  It is summer and summer markets are typically somewhat less active.  As well, away from the uncertainties of the Iran conflict, economic activity seems to be ticking along pretty well.  Arguably, the biggest story remains AI and both its potential impact on workers and the economy as well as the questions about its ability to generate sufficient revenue to repay the hundreds of billions of dollars being spent on it.  But those are longer-term stories, not day-to-day.

Which takes us to this morning.  Frankly, I don’t think there is an interesting market related them right now.  Instead, we have much time-biding until the next big thing.

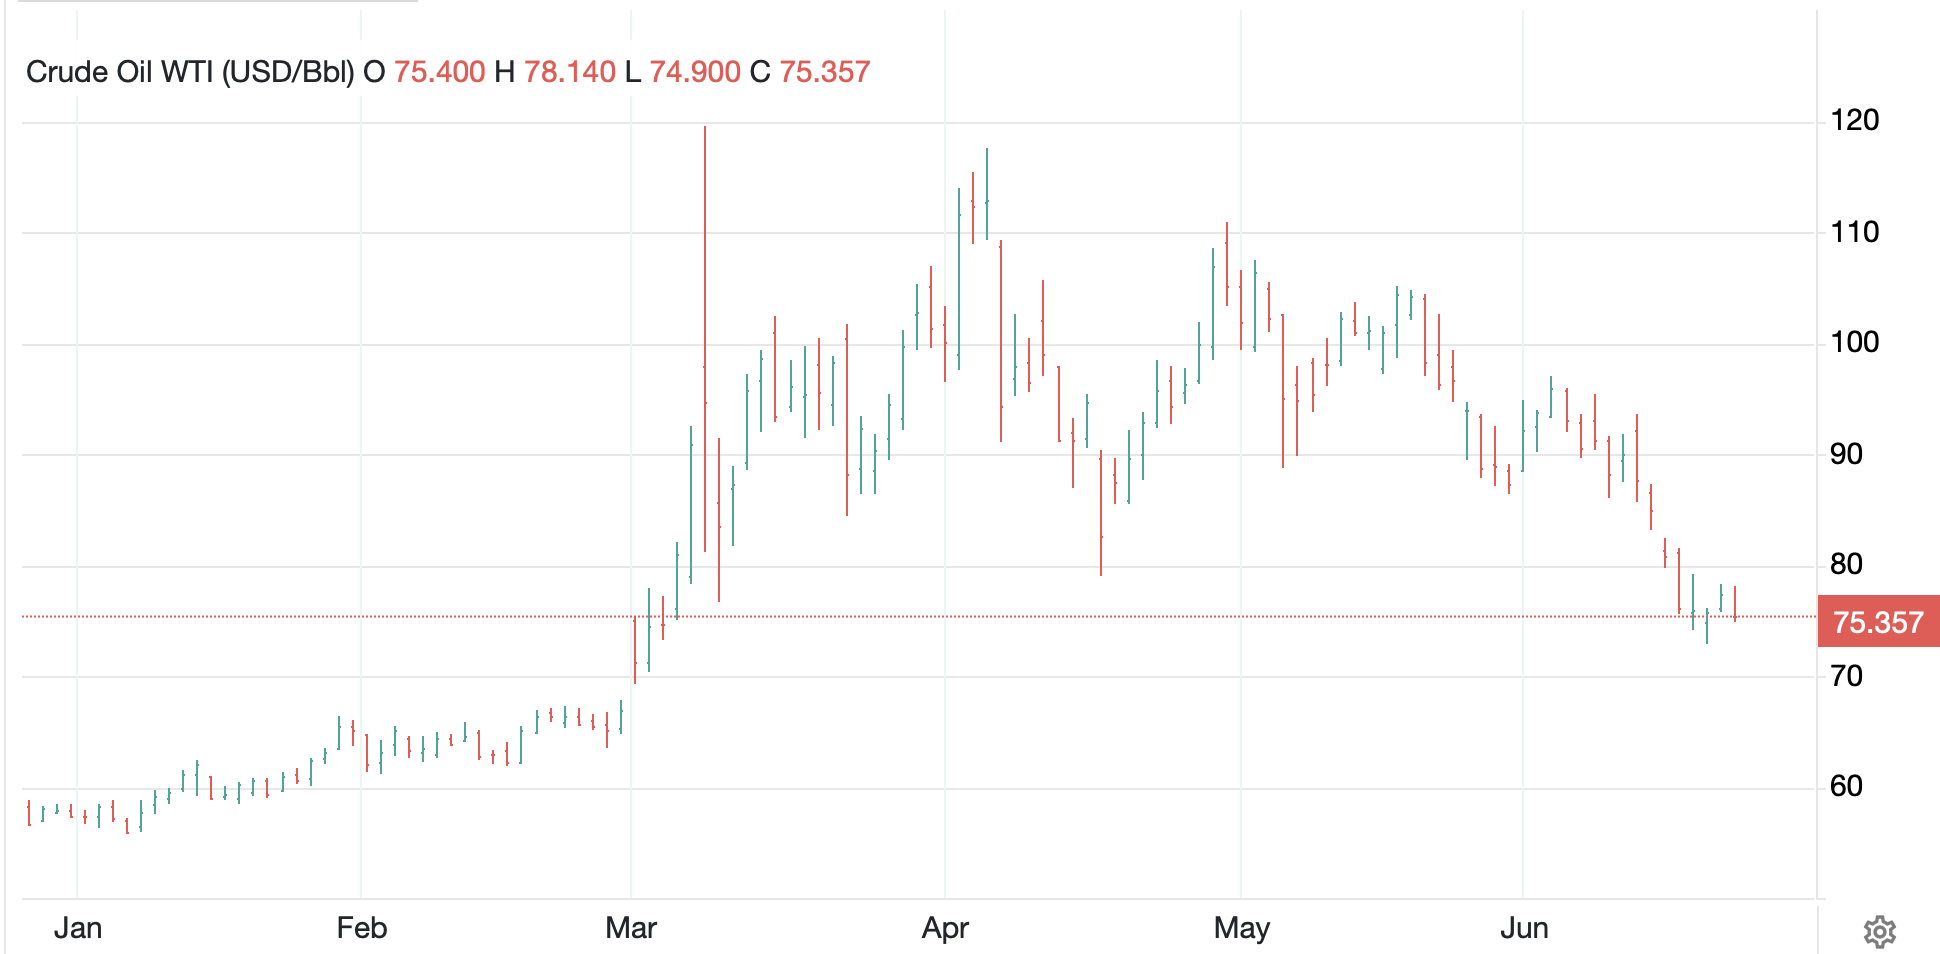
Let’s start with commodities as oil continues its multi-month decline from the early April peak.  it remains very difficult to look at the below daily chart and think, damn, oil is about to run away higher.  At least for me.

Source: tradingeconomics.com

There are still numerous analysts who maintain that the drawdown of reserves is going to come back and haunt the market, driving prices much higher as inventories fall and tank bottoms are reached.  And I am sure they earnestly believe those outcomes are ordained.  But the relative wisdom of market prices disagrees.

Remember back when this all started, there was another point that was made by these same analysts, that fertilizer shortages would be manifest and food prices would rise much higher.  The story was that the closing of the Strait would reduce the ability of Qatar to produce and ship LNG and that was a critical input into the making of Urea.  Let me show you the price chart for Urea.

Source: tradingeconomics.com

While it certainly rose initially, apparently there is sufficient urea around to continue with agriculture as we know it.  Again, much of the initial fear seems to have been misplaced.  I do not know if that is because analysts didn’t really understand the way these markets operated, or because they have models that they have used for years, and those models are no longer fit for purpose.  My observation is that many analysts try to determine the price trends by looking at their understanding of both supply and demand of a given commodity.  But I might argue that the price is what defines both supply and demand, and that at given prices, those two curves adjust to make the system work.  Think of it as price is the independent variable, not supply/demand.

Moving on to the metals markets, they remain under pressure this morning with both gold (-1.3%) and silver (-1.9%) unable to find support, especially the latter.  Copper (-0.3%) is holding up better and I continue to believe that all three will fare well over time, but not right now.

In the equity markets, Friday’s nondescript US markets were followed by more strength (Tokyo +0.15%, HK +1.6%, China +1.2%, Australia +0.7%, Taiwan +1.0%) than weakness (Korea -0.2%, India -0.5%, Indonesia -1.3%) in Asia.  The big news overnight was the South Korean government supporting a massive semiconductor investment by the two big Korean firms, SK Hynix and Samsung, to build four more fabs.  In Europe, though, things are less positive with Germany’s unchanged performance leading the way although the declines elsewhere (UK -0.2%, France -0.3%, Spain -0.4%) are hardly devastating.  We ought not be surprised that US futures are higher this morning as I type (7:25) led by the NASDAQ (+0.9%) as the AI/semiconductor theme continues.

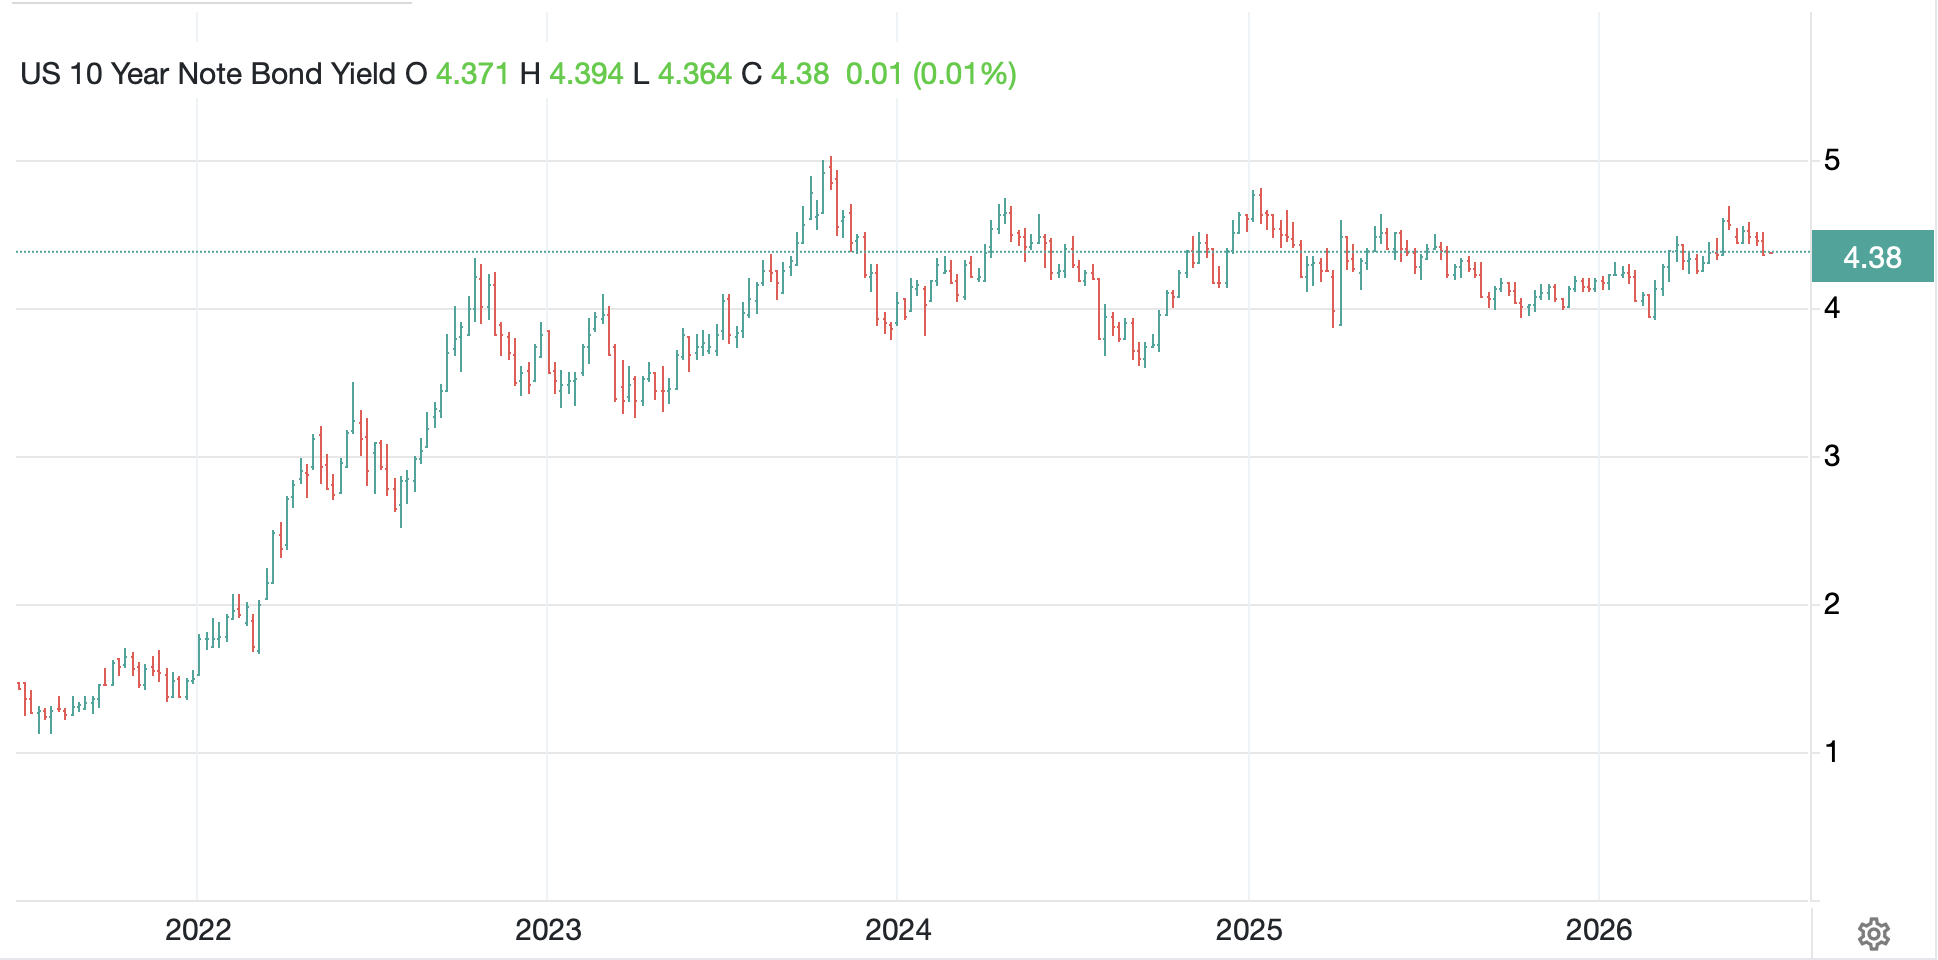
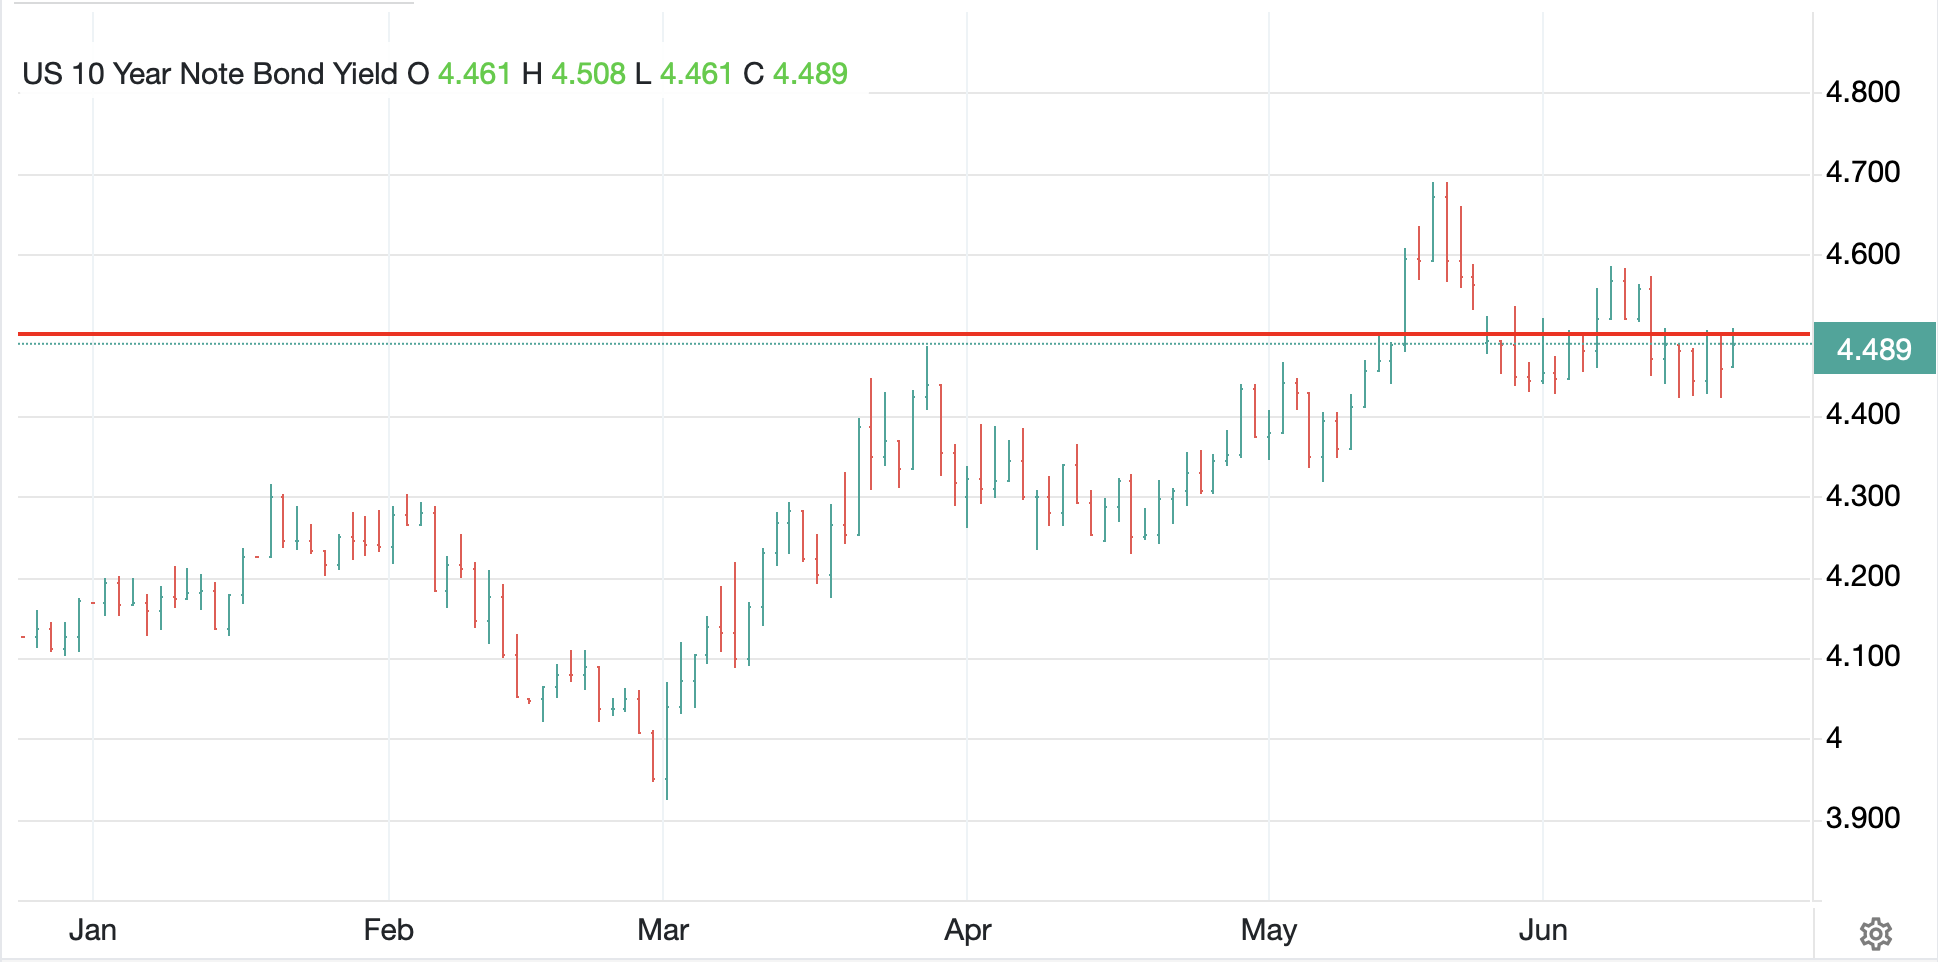
Bond markets continue to do very little with yields essentially unchanged on the day in Europe or the US.  10-year Treasury yields are currently 4.37%, well off the highs seem a month ago near 4.70% when there was much discussion about a breakout higher.  But look at the below longer-term chart of the 10-year Treasury yield and tell me that anything substantive has happened in the past 3+ years.  Since yields rise alongside the 2022 inflation surge, we have seen very little net movement.

Source: tradingeconomics.com

Finally, the dollar is a bit softer this morning but is clearly not the focus today.  I continue to read analyses about Chairman Warsh and what he is going to do and why he will not be able to achieve his goals.  The implication is that either he will need to be ultra hawkish, raise rates quickly and the dollar will soar, or he will wind up with QE 5 or 6 or whatever number we are on, and the dollar will collapse.  My personal view is neither of those scenarios will play out.  As I wrote in the wake of his first meeting, I expect inflation data will ease along with the recent decline in energy prices, and he will be able to do nothing without consequences as he works to change the way things work there.  In the meantime, the dollar will remain supported by real investment flows.

On the data front, even though it is a holiday-shortened week with markets closed Friday for July 4th, we get a lot of data.

TuesdayCase-Shiller Home Prices0.8%
 Chicago PMI60.0
 JOLTS Job Openings7.28M
 Consumer Confidence94.2
WednesdayADP Employment113K
 ISM Manufacturing54.0
 ISM Prices Paid79.0
ThursdayNonfarm Payrolls110K
 Private Payrolls115K
 Manufacturing Payrolls3K
 Unemployment Rate4.3%
 Average Hourly Earnings0.3% (3.5% Y/Y)
 Average Weekly Hours34.3
 Participation Rate61.7%
 Initial Claims220K
 Continuing Claims1825K
 Factory Orders-2.1%
 -ex Transport0.4%

Source: tradingeconomics.com

Obviously, all eyes will be on the payroll data on Thursday.  But Chairman Warsh will be at Europe’s version of Jackson Hole, in Sintra Portugal and speaking at 9am Wednesday morning.  It will certainly be interesting to hear what he has to say there.

It doesn’t seem like there is much about which to get excited today, or tomorrow frankly.  So, Warsh and then NFP will be this week’s story absent another major flareup in the gulf.

Good luck

Adf
No Plan of Action
In England and Scotland and Wales
Kier Starmer has gone off the rails
A buffoon-like clown
He’s set to step down
As from the Brits eyes, fall their scales

But will his replacement gain traction
Or will Burnham be a distraction
From solving their woes
As Lord only knows
They’ve many, and no plan of action

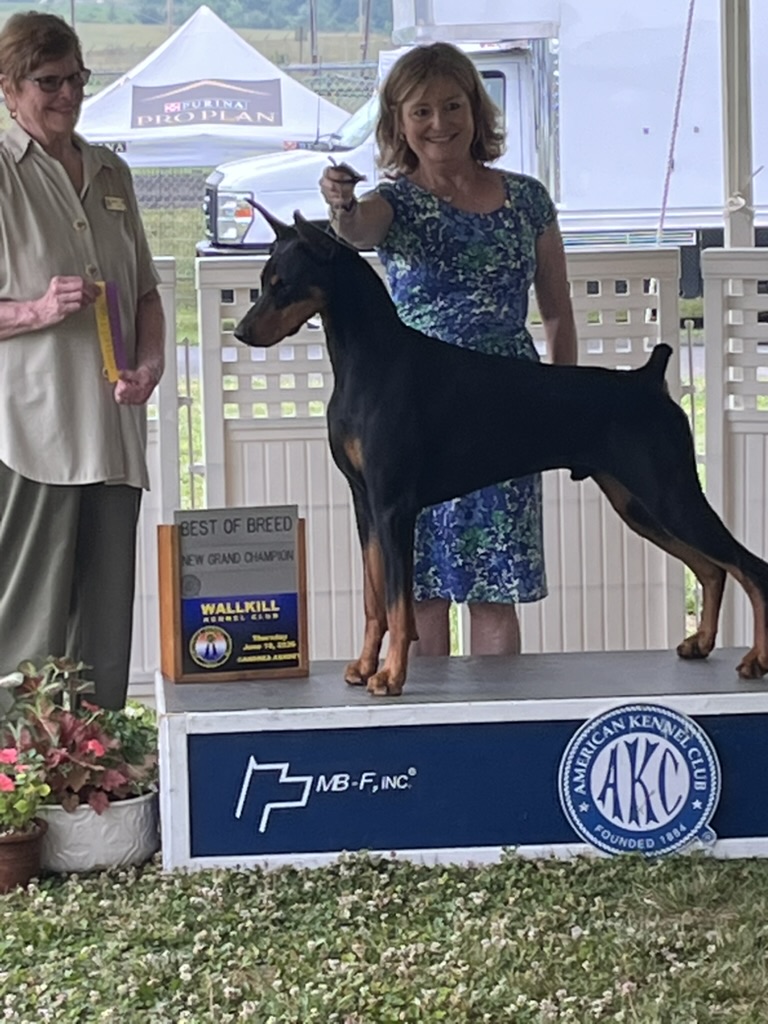
It has been an eventful weekend for me so let me start by telling you that Marvel was Best of Breed in back-to-back shows last Thursday.  We are very proud and happy.

Second, Friday was a more difficult day for me as I wound up having emergency surgery, although everything is fine.  But I am still in recovery mode.  Sometimes, aging is harder than other times.

With that in mind, we can talk about the three things that matter, I believe, the change of PM in the UK, the on-again-off-again peace talks in Iran and the fact that the yen is now weaker than the level that got the MOF to intervene back in April.

Starting with the UK, PM Starmer has promised to step down now that his most likely successor, Andy Burnham, the former mayor of Manchester, is in Parliament and will now become PM sometime in the next several months depending on the actual timing of certain technicalities.  He is described as left-wing, even by the press, which tells you that he must be quite far to the left.  But the UK has serious problems with respect to their economy, slowing growth and high inflation, and the social structure due to massive immigration, both legal and illegal.  As well, the report that just dropped about the Pakistani grooming gangs that were systematically raping young English girls is so damning, it is hard to believe, yet it was all covered up.  The government doesn’t have to go to the national polls until 2029, so Burnham will have time to try to implement policies, but the nation has many troubles ahead.

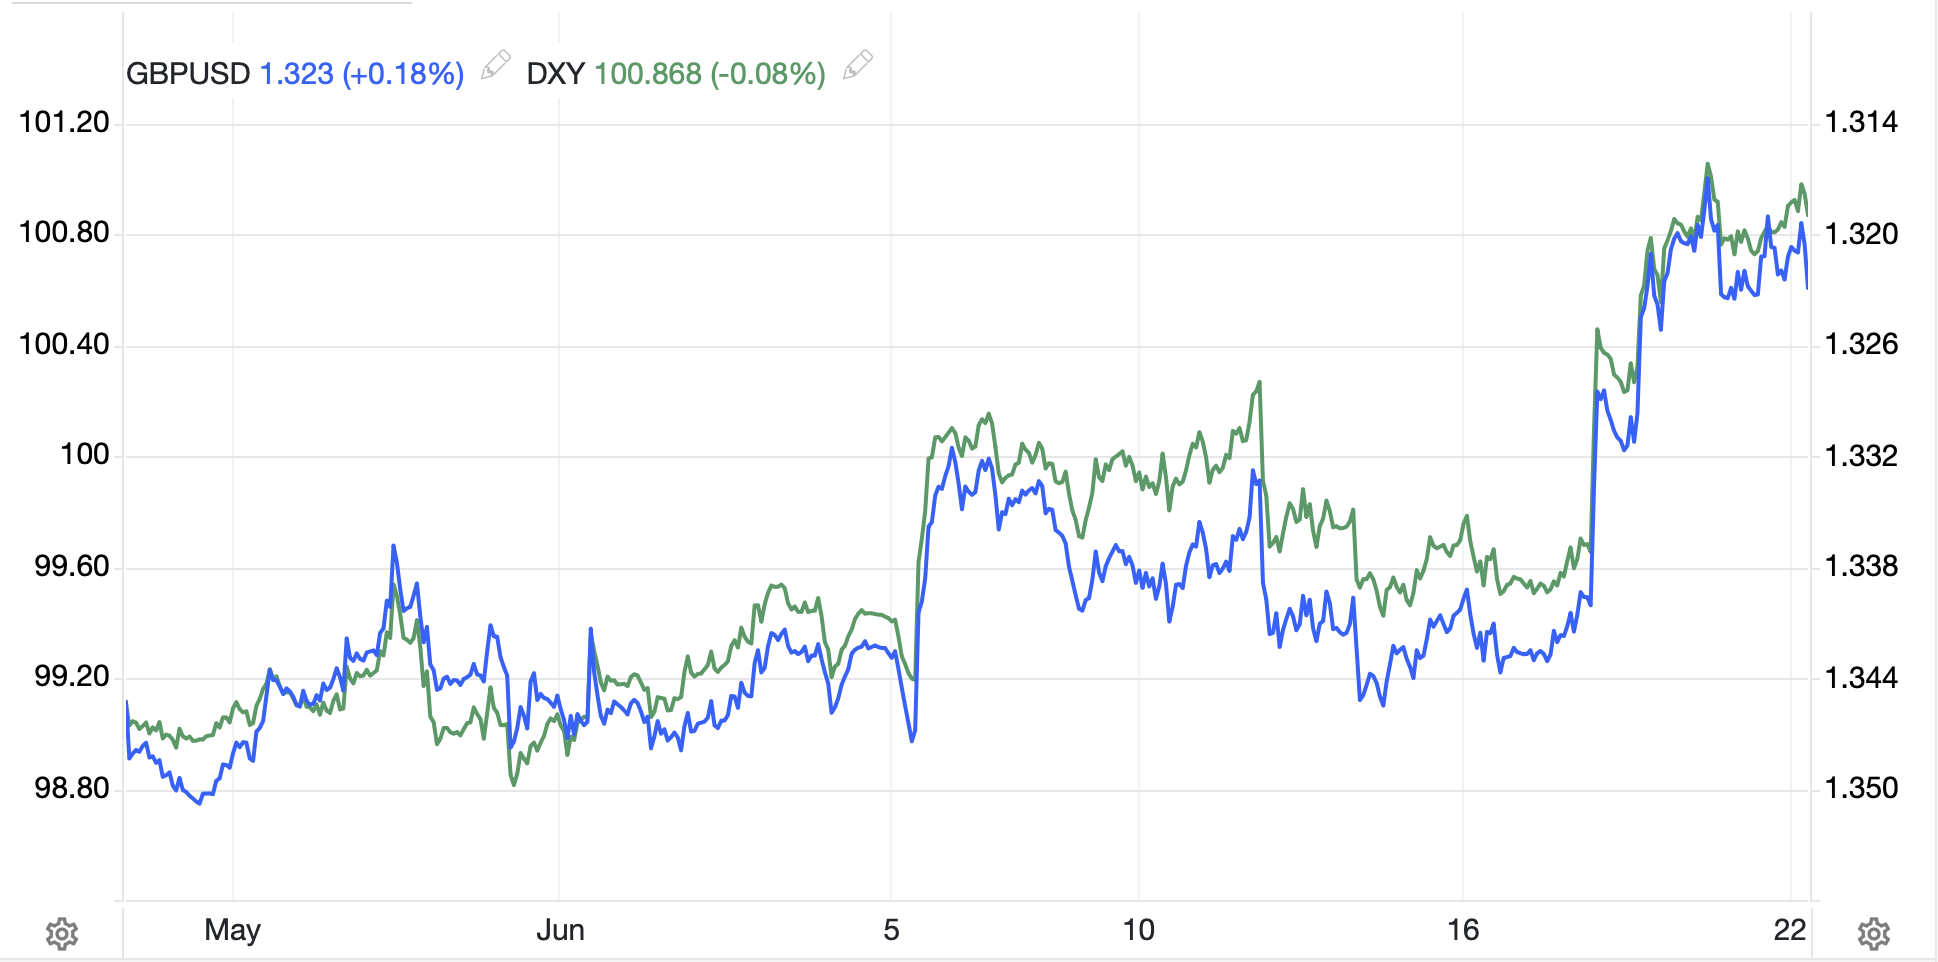
As to UK markets, both the pound and FTSE 100 have been underperformers relative to their peer European counterparts over the past month or so as this process has heated up, but in truth, not by very much.  Much of the pound’s weakness can be attributed to dollar strength (see chart below), where the dollar has broken through key technical resistance in the DXY, while the FTSE is just drifting given the lack of positive news.  Certainly, this story didn’t help either one, as both are unchanged on the day.

Source: tradingeconomics.com

In Switzerland, talks are ongoing
As Trump and the Mullahs try showing
That they are the ones
Who have the most guns
But progress seems like it is growing

It cannot be a great surprise that there is a lot of bluster from both sides of this negotiation between the US and Iran as President Trump tries to end the conflict in Iran.  After all, both sides are famous for their bluster!  And you can read whatever you like from whatever source you want to get your spin, but I’m not smart enough to understand the intricacies of international diplomacy.  However, what I do understand is market price movement, and here we are this morning, with oil prices falling further, down -2.5%, and back to levels last seen in early March, right at the beginning of this conflict.

source tradingeconomics.com

Thus far, every story about tank bottoms being reached and an insufficient amount of oil for the pipeline infrastructure to be effective has proven not to be true.  There is still a large group of analysts who are calling for end of days, but the market signals just don’t agree.  I suspect that the only ones who really want to see oil prices remain high are the oil companies who sell the stuff, but for the rest of the world, lower is clearly better.  Obviously, anything can still happen, but by all appearances, it seems that more and more traffic is flowing through the Strait and we are going to see lower prices going forward.

In the end, from my vantage point thousands of miles away from the action, it appears that Iran was greatly weakened by this conflict on a military basis, but more importantly, every one of its Gulf neighbors realized that they needed alternative routes to get their oil to market, and we are going to see a lot more pipeline infrastructure built to do just that, so as time goes by, this choke point is going to lose its effectiveness.  And that is probably a bigger weakness for Iran, as that was something they held over the world, but now it seems it is not as impressive a strength as it had been made out to be in the past.

It’s no waterfall
But the yen keeps dripping down
Whence the BOJ?

Finally, the yen (-0.3%) is having a tough time right now as it has traded back to its lowest level vs. the dollar since 1986!  That’s right folks, it has been forty years since USDJPY traded above 162.00, and we are pushing that level right now as you can see in the chart below.

The last two times the yen reached these levels, back in April and in July 2024, the BOJ intervened in the markets aggressively.  But so far, crickets.  I think the issue for them is the dollar continues to be quite strong, especially as traders are now pricing in rate hikes by the Fed, and so intervening is going to be a waste of money.  And it’s true, if the dollar is rallying across the board, there is very little Ueda-san can do.  As I have repeatedly said, the only way for the yen to break this slide is for serious fiscal and monetary policy changes, and frankly, that doesn’t look like it is in the cards right now.  While I know there are many who think the dollar is heading to its graveyard, it apparently still has a bit of life left in it.

Which takes us to the overnight activity.  Equity markets have been mixed as all this new information gets digested.  In Asia, Tokyo (+1.6%) and China (+2.4%) both had strong sessions although HK (-0.7%) couldn’t keep up.  Elsewhere in the region, there was slightly more green than red led by Taiwan (+2.75%) while the Philippines (-1.65%) was the biggest laggard.  Uncertainty continues to reign although as the Iran situation slowly resolves, I expect to see things brighten here as Asia was the region hurt most by the entire conflict.

In Europe it is also a mixed picture with the UK (+0.3%) now rallying on the news that Starmer is leaving and Spain (+0.4%) has managed a gain as well while both Germany (-0.3%) and France (-0.7%) are lagging this morning, although there is no news of note in either place.  US futures are basically unchanged at this hour (7:15).

In the bond market, Treasury yields (+3bps) have edged higher this morning, I guess on this new belief in higher Fed funds, although I would have thought the bond market would appreciate a hawkish Fed fighting inflation.  European sovereign yields, though, are lower across the board down about -2bps everywhere.  Bonds remain less interesting now that they are back in their ranges and not breaking out as so many though was occurring back in May as per the below chart.

Source: tradingeconomics.com

With oil prices lower, it should be no surprise that gold (+1.35%) and silver (+2.4%) are both higher this morning.  Many have made the case that with the dollar strengthening, the precious metals complex will remain under pressure, and it is a valid case, but for some reason, I have a feeling it will not be as dramatic as they believe.

Finally, the dollar is firmer across the board this morning, albeit not by very much.  Wednesday and Thursday of last week were the big moving days in the wake of the FOMC meeting and the new hawkish read.  Since then, not much has happened, just a slow drift higher across the board.  FWIW, I don’t think that Chairman Warsh is going to be that hawkish, but I look forward to the structural changes that he makes.  However, for now, that is the market assessment.

On the data front, there is nothing today and really nothing of import until Thursday so I will go through it tomorrow.

That’s how things are shaping up, with the dollar gaining, oil sliding and stocks uncertain what to do next.  I am a fan of uncertainty as it will reduce systemic risk, and that is something we really need to see.

Good luck

Adf