The Score

Hormuz is blockaded once more
The latest response in the war
So, crude prices rose
While both sides expose
Their relative views of the score

Now after a month of some peace
Seems tensions are set to increase
So, what about stocks?
The sales are in blocks
While buyers, few bids will release

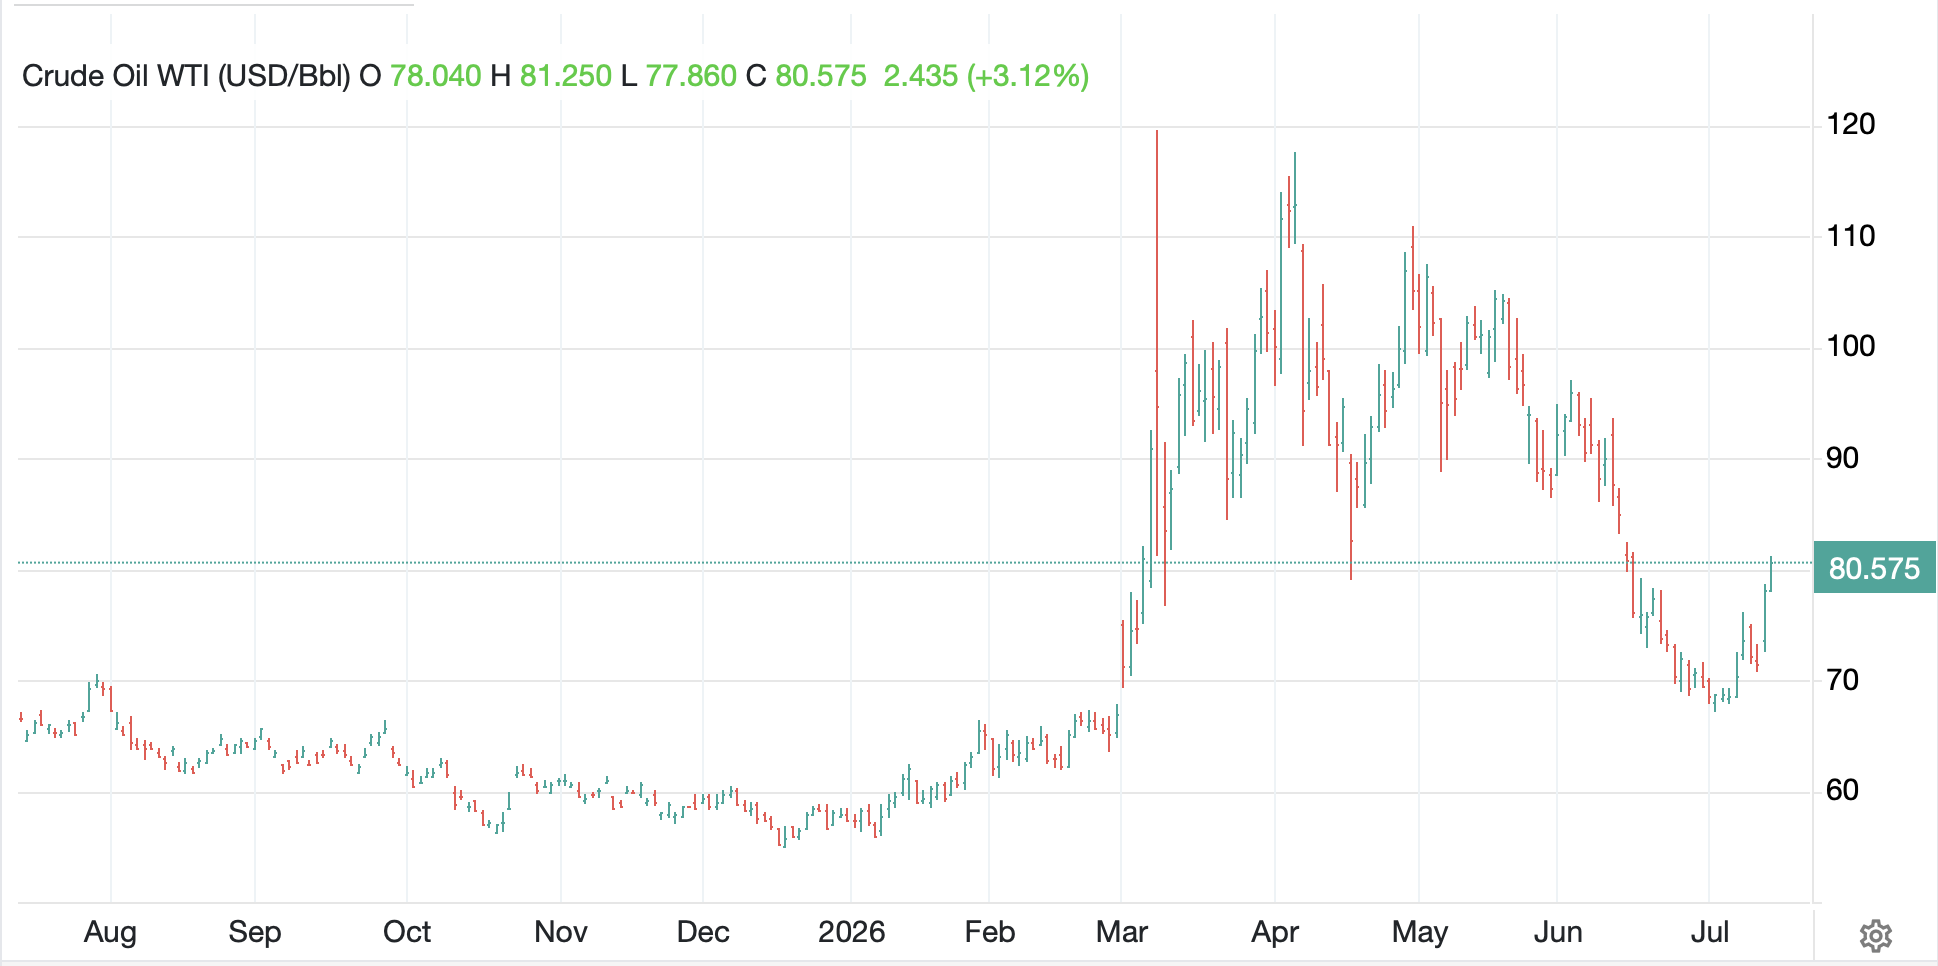
After a brief respite for markets, where oil had seemed to be drifting out of the headlines, the events of the past weekend plus the US reimposition of the blockade of the Strait of Hormuz has changed the narrative dramatically, and rightly so.  The benign attitude of an eventual conclusion to this situation has been tossed aside and the oil bulls and war hawks are both back in the ascendancy.  Yesterday ultimately saw oil prices rise 9.4% and this morning they are a further 3.2% higher, and perhaps more importantly, back above the psychological level of $80/bbl.
Source: tradingeconomics.com

There doesn’t seem to be any short-term solution to this situation.  There are clearly enough hard-liners still with power in Iran to prevent any move toward a negotiated solution.  As long as this maintains, the outlook for oil will tilt higher.  However, as I have written before, and is very clear now, the effort to reroute oil shipments from the Gulf nations away from the Strait is intensifying and will continue to do so.  As well, alternative sources of supply including additional US production, Brazil, Argentina, Guyana, Venezuela and Canada are satisfying demand.  While uncertainty remains high, especially in the short run, by the end of next year, my take is less than 8% – 10% of the world’s oil will need to transit the Strait.  However, in the meantime, given that everybody who was long oil as the war initially ramped up has sold out, there are few sellers left to cap the price.  I imagine a move toward $90/bbl is quite possible in the next weeks.

As well as the story on crude
Two other themes will be pursued
First CPI’s print
Will offer a hint
Then Warsh will discuss why he’s screwed

If we turn our attention away from the oil market now, the two main events today are the CPI release at 8:30 this morning followed by Chairman Warsh testifying to the House Financial Services committee in his semi-annual trip to Congress.  Starting with CPI, expectations are for a decline from last month as headline (exp -0.1% M/M, 3.8% Y/Y) and core (0.2% M/M, 2.8% Y/Y) are due.  From what I can tell, there are a number of analysts who are calling for a relatively hotter number, although I’m not sure on what basis they believe that.  Certainly, oil prices, and energy prices across the board, declined significantly in June and that will be reflected in the reading.  Looking at the home price data, that doesn’t appear to have risen dramatically, and other commodity prices have also slipped.  I don’t’ rule out any outcome, but on the surface, expectations seem reasonable.  

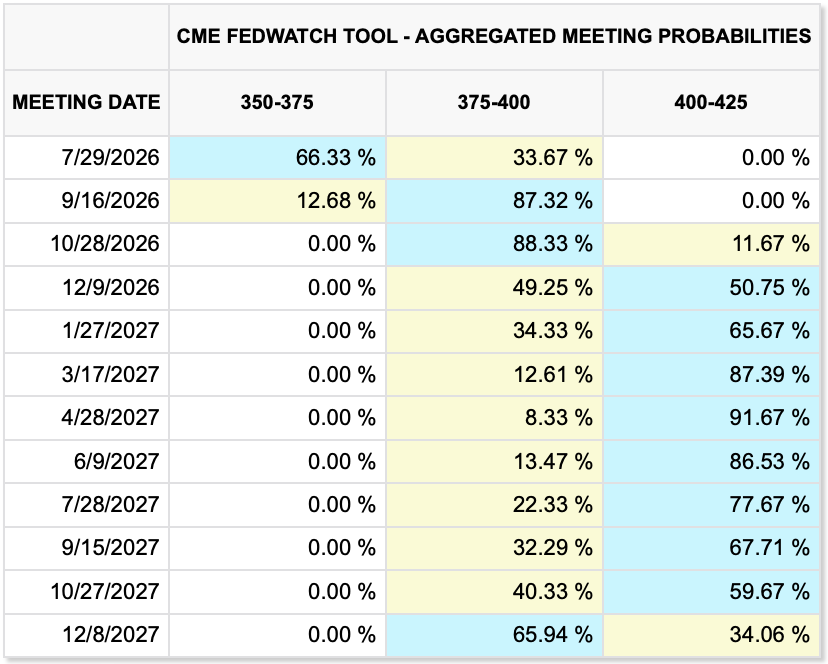
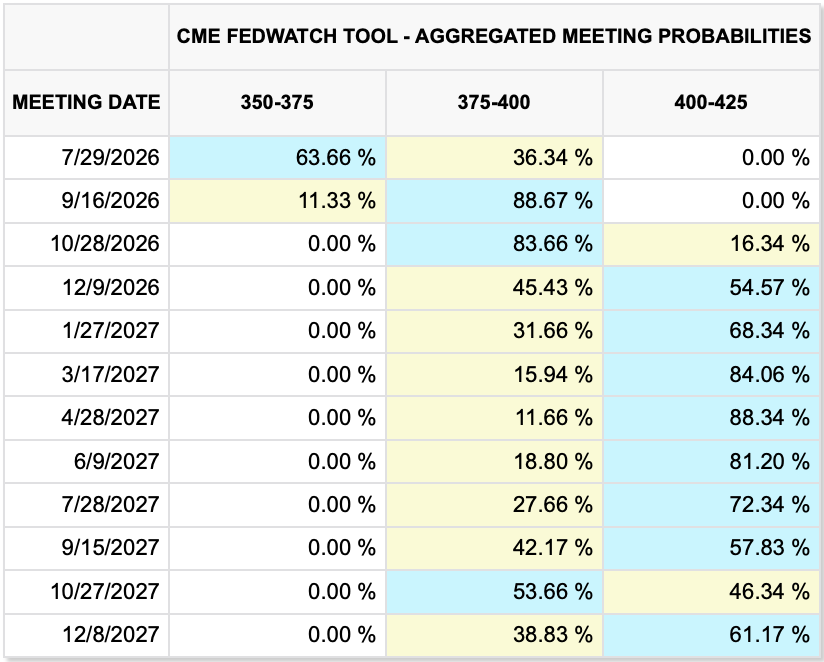
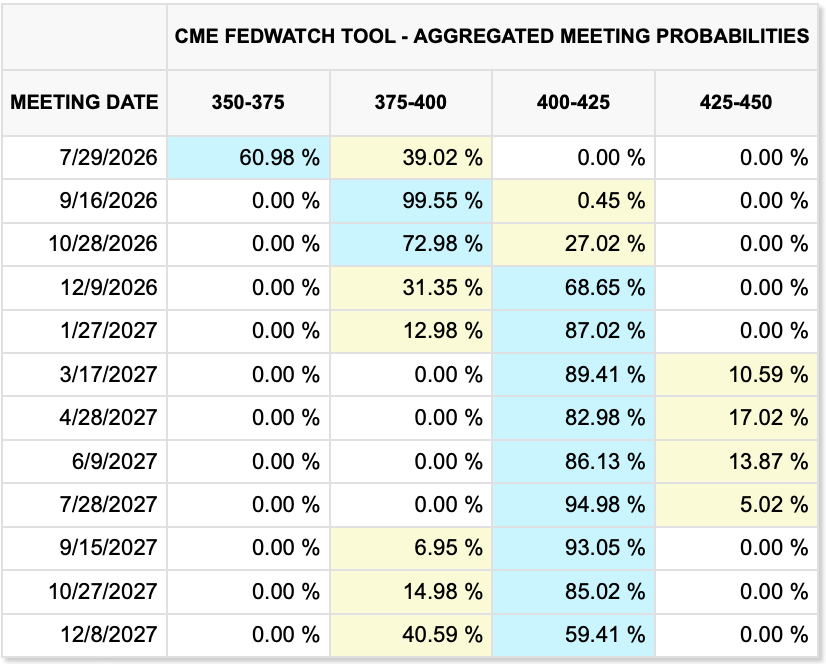
Of course, with oil prices rising, talk of more rate hikes is all the rage and according to the Fed funds futures market, as per the below CME table, you can see that expectations have risen to a 40% probability of a hike this month and a two-thirds probability of two hikes before the end of the year.  My personal view, FWIW, remains that there will be no hikes this year, although with the resumption of hostilities in the Gulf, I think a cut is off the table as well.  Remember, too, that if oil prices remain elevated that will negatively impact economic activity, so hiking rates into that scenario doesn’t seem to make much sense.  But then, I’m not on the FOMC.
Now, I have long maintained that FOMC members should shut up, but it seems Mr Warsh will have a hard time getting them to do so.  I’m not sure if they think they are helping, or they are just enamored with their own voices.  But yesterday, Governor Waller spoke and explained that if the CPI data was hot, a rate hike would be an appropriate response.  And remember, we hear from another 7 or 8 of these folks just this week, four today!  

While I expect that Warsh’s testimony will be dry, and that most of the questioning will be either long-winded preening by some idiot member, or an attempt at a gotcha question, I am confident that Chairman Warsh will continue to avoid discussing his views of where policy should go and reiterate forcefully that the Fed’s goal is to reduce inflation, full stop.  I am also confident that he will not be dragged into any discussions of other issues like global warming or DEI and simply repeat that ending inflation is the only job he has.  We shall all find out shortly.

On to the markets.  It should be no surprise that equity markets were under pressure yesterday in the US with the jump in oil prices.  This added to the chorus of those who believe the AI bubble is popping as the NASDAQ led the way lower, falling -1.5%.  But a funny thing happened in Asia.  Despite the jump in oil prices and declines in US equity markets, Tokyo (+0.75%), HK (+0.5%) and China (+2.15%) all rallied nicely last night.  In fact, so did Korea (+0.7%) and Malaysia (+1.3%) although we did see declines in India (-0.7%) and Taiwan (-1.4%) with the rest of the region moving far less.  This is a surprising outcome to me, especially as Asia is the region most negatively impacted by rising oil prices.

Europe though is trading true to form with declines across the board ranging from Spain (-1.1%) to the UK (-0.4%) and everywhere in between.  There has been precious little data overnight to drive things, and this appears to be entirely oil related.  Of course, Europe’s suicidal energy policy, notably the UK’s ban on drilling for oil in the North Sea, remains one of the key reasons that the area will continue to struggle.  As to US futures, this morning DJIA futures are lower (-0.8%) but the other two major markets are little changed at this hour (7:25).

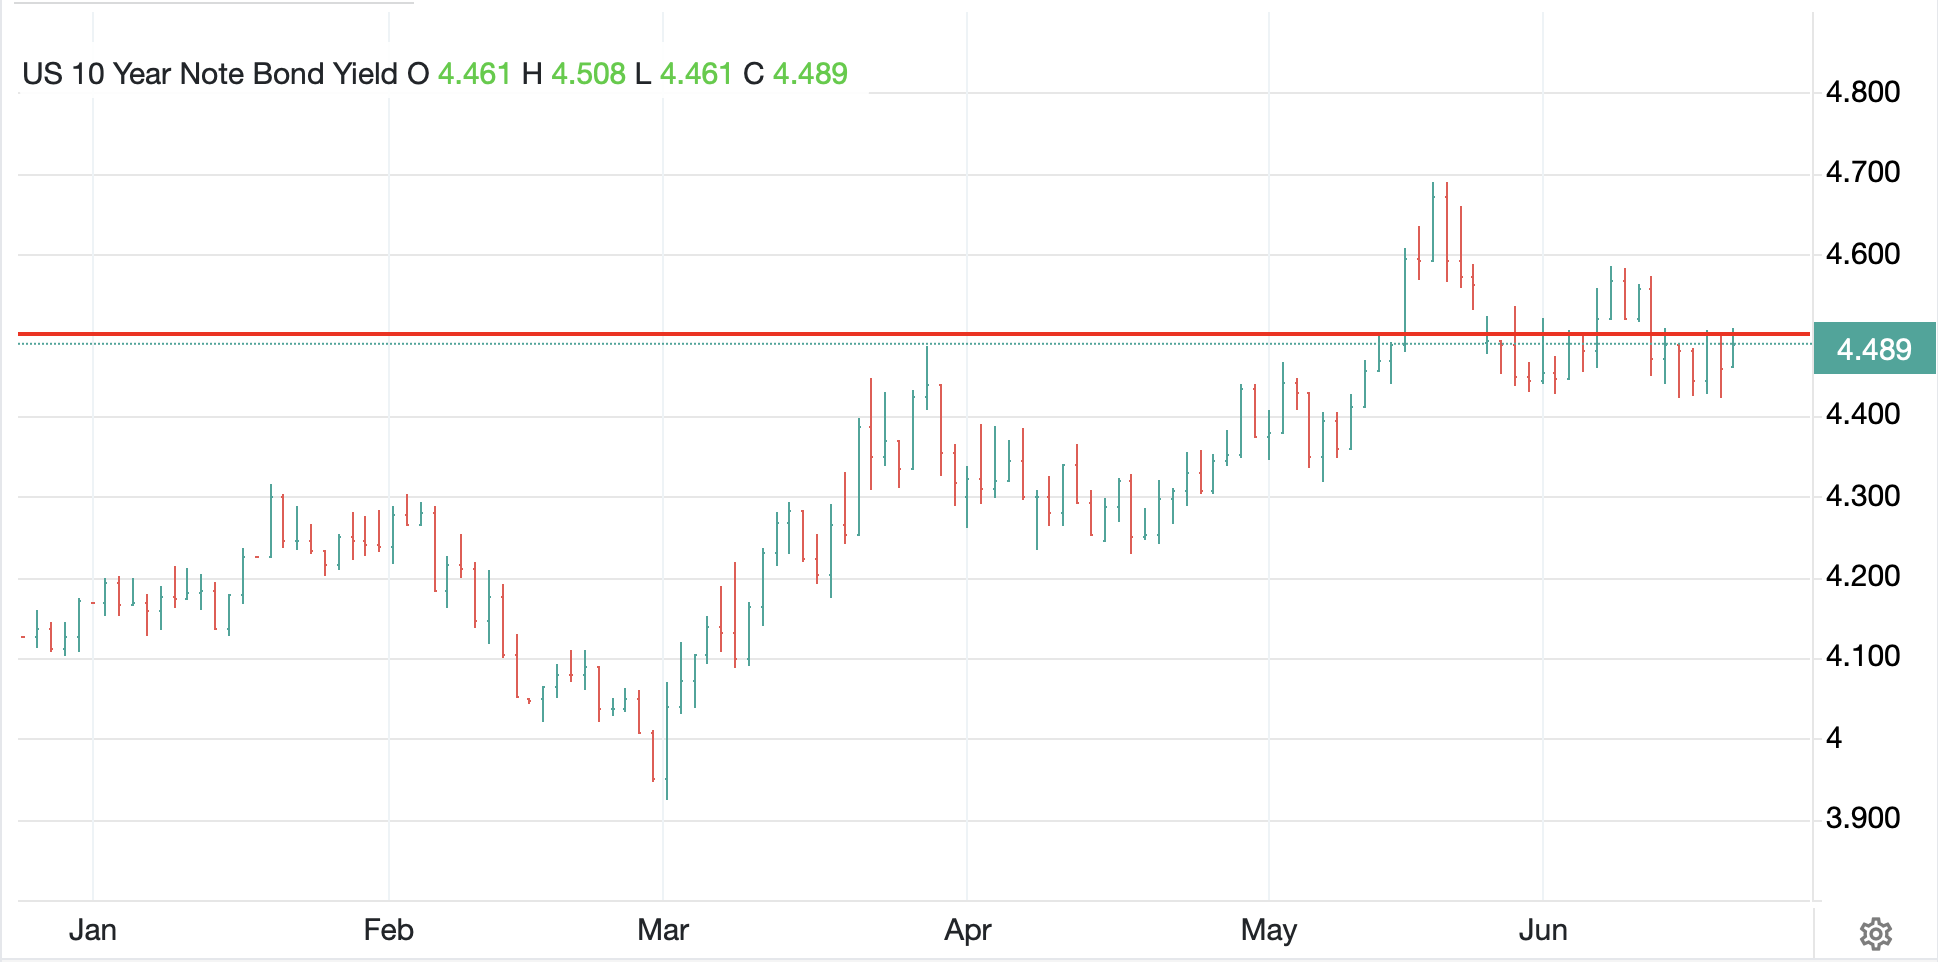
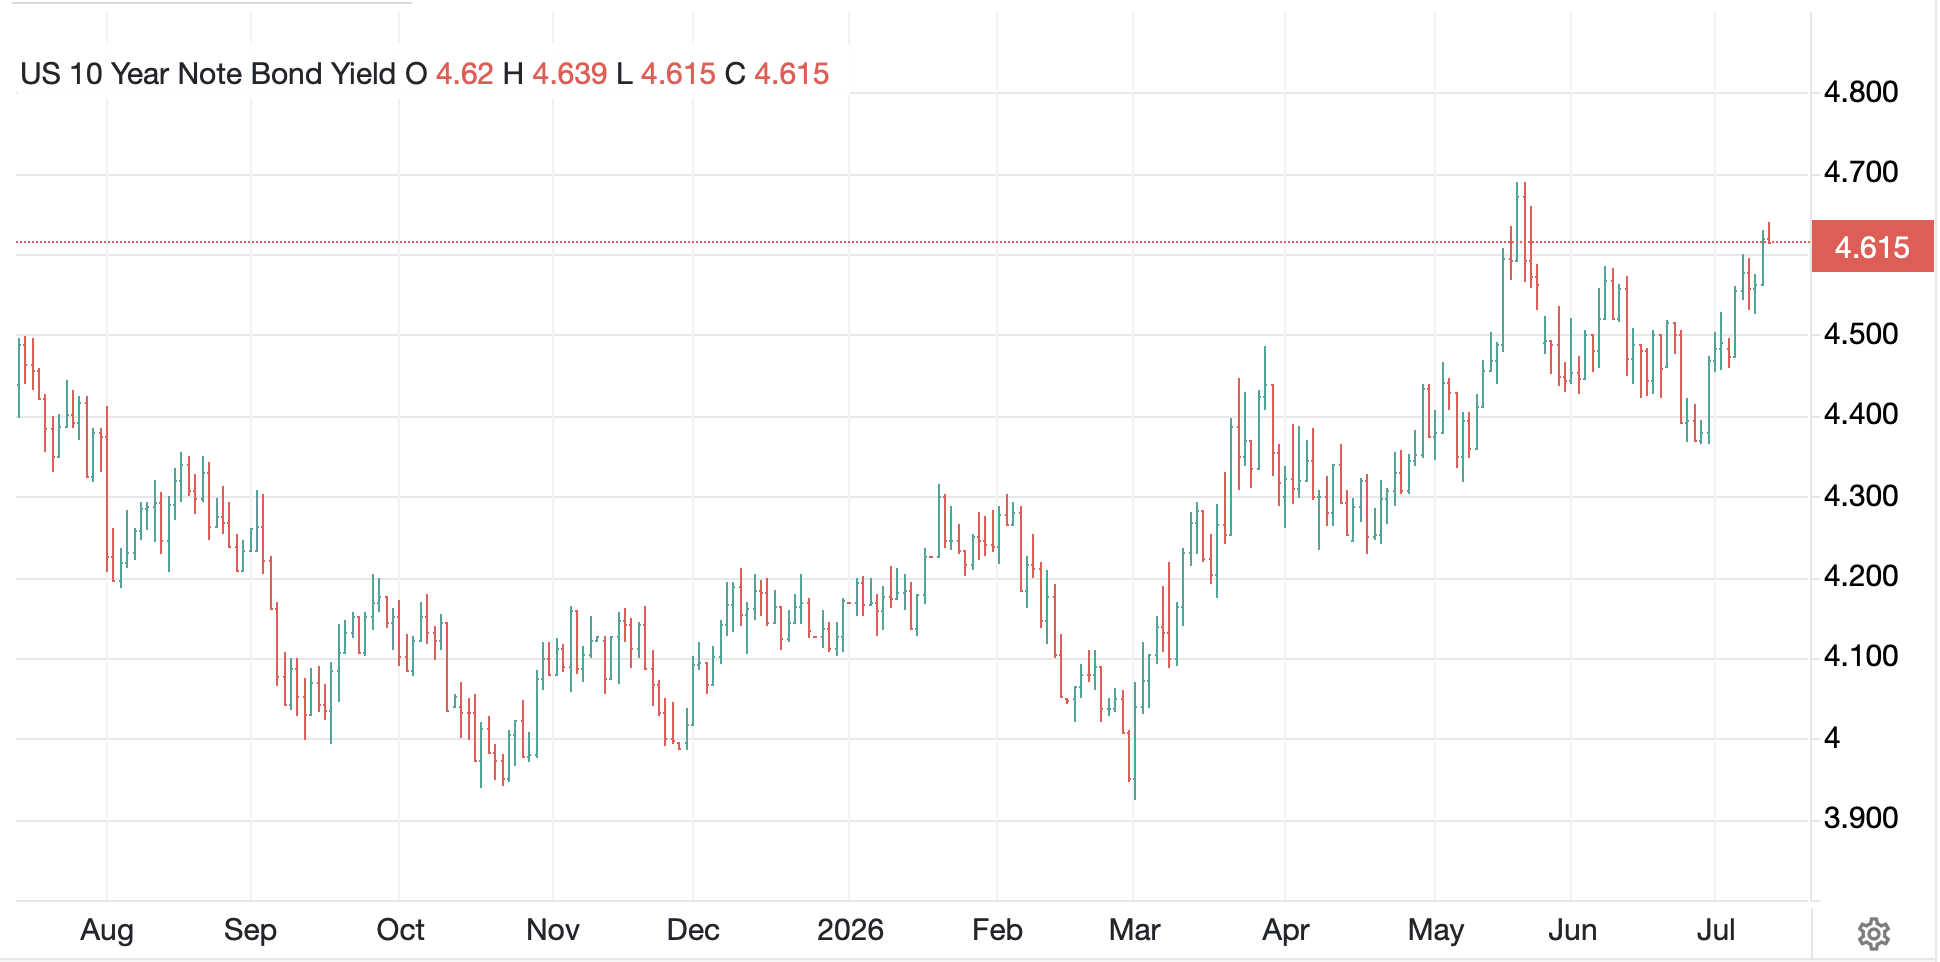
In the bond market, 10-year Treasury yields jumped 6bps yesterday although are little changed this morning.  However, as you can see from the chart below, they are pushing back up toward the highs seen in late May.
Source: tradingeconomics.com

There is a lot of talk about how Warsh should hike rates aggressively this month to gain bond market credibility in his fight against inflation, but I sense that is a lot of people talking their books.  I continue to believe that there will be no Fed action ahead of task force reports.  As to other nations, yields are generally firmer in Europe today, ranging between +1bp (Germany) and +3bps (Italy) with the UK worst of all (+4bps) as 10-year Gilts now yield more than 5.0% again, also pushing back to late-May highs.  The one exception is Japan (JGBs -5bps) where the latest ploy by Katayama-san is to propose JGBs be allowed to be invested in tax-free accounts for individuals in Japan.  Given the long history of zero rates there, a tax-free return of 2.7% with no currency risk could well be quite attractive, I think.

In the metals markets, it is no surprise that both gold and silver fell yesterday with the jump in oil prices, but despite oil’s continued rally this morning, both gold (+0.7%) and silver (+0.7%) are finding support, with gold seeming to hold the $4000/oz level for now.  Copper (+1.6%) is also holding up well, but its relation to the precious sector seems to be waning.  Perhaps the precious metals story is less about oil and more about the dollar.

Turning to the dollar, yesterday it put in a strong performance with the DXY rallying about 0.3% from Friday’s closing levels as you can see in the chart below.

Source: tradingeconomics.com

However, as you can also see in the chart, this morning the greenback is under pressure despite the rise in oil prices and yesterday’s increase in yields.  The biggest outlier is NZD (+0.9%) as the RBNZ continues to make hawkish statements about the need for further rate hikes.  And of course, NOK (+0.7%) is benefitting from the oil price rise.  But the rest of the G10 are all firmer, and so is most of the EMG bloc with only INR (-0.5%) standing out as underperforming.  That story appears to be based on higher oil prices and concerns, or thoughts at least, that the RBI will not be aggressively hiking rates to protect the rupee.  Otherwise, most currencies have moved higher vs. the dollar on the order of +0.15% to +0.25%.

And that’s really it today with CPI the only data release other than the already released NFIB Small Business Optimism index (97.4, exp 95.8), but that predates the change in the Gulf.  Chairman Warsh has his work cut out for him to get his colleagues to shut up.  I wonder if he can fine them if they speak.

We are in a narrative transition right now, but longer term, I remain bullish the US and the dollar.  

Good luck

Adf
Much Hotter

This weekend both wars got much hotter
Iran attacked ships on the water
Ukraine sent its drones
Across three time zones
And struck inside Vlad’s magna mater

Thus, oil has risen a bit
While gold and stocks both trade like sh*t
And soon, CPI
Will prove or deny
That views at the Fed are now split

By now, of course, you know that there has been more military activity in the Strait of Hormuz with the IRGC attacking commercial ships and the US retaliating with significant strikes of military sites along the Strait.  From what I can see, there are factions within the IRGC that do not want to end the conflict and whatever government exists within Iran has no control over them.  As such, it is no surprise that the price of oil (+3.5%) has risen, but even in this scenario, it is well off its overnight highs.

Source: tradingeconomics.com

At this point, I believe the trading community will need far greater proof that there is a shortage of oil before responding with significantly higher prices.  Of course, one way that could come about is if Ukraine continues its success with attacks on Russian oil infrastructure as there has been an uptick in that activity with several refineries having been hit in the past several days and Russia imposing an export ban on diesel.  Net, things in the oil space remain precarious, but for all the analysts who continue to promulgate the idea that the end is nigh, markets continue to disagree.  As always, I vote with markets here.

And, not surprisingly, other markets have responded in a similar fashion to their recent trends with higher oil prices leading to pressure on both stocks and bonds, as well as precious metals while the dollar finds some support.  The thing is, my take is the strength of these correlations has been waning somewhat.  Frankly, and remarkably, it appears as though an increase in military activity in the Strait of Hormuz has become somewhat normalized to traders and they are looking for other, fresher signals as to their next move.

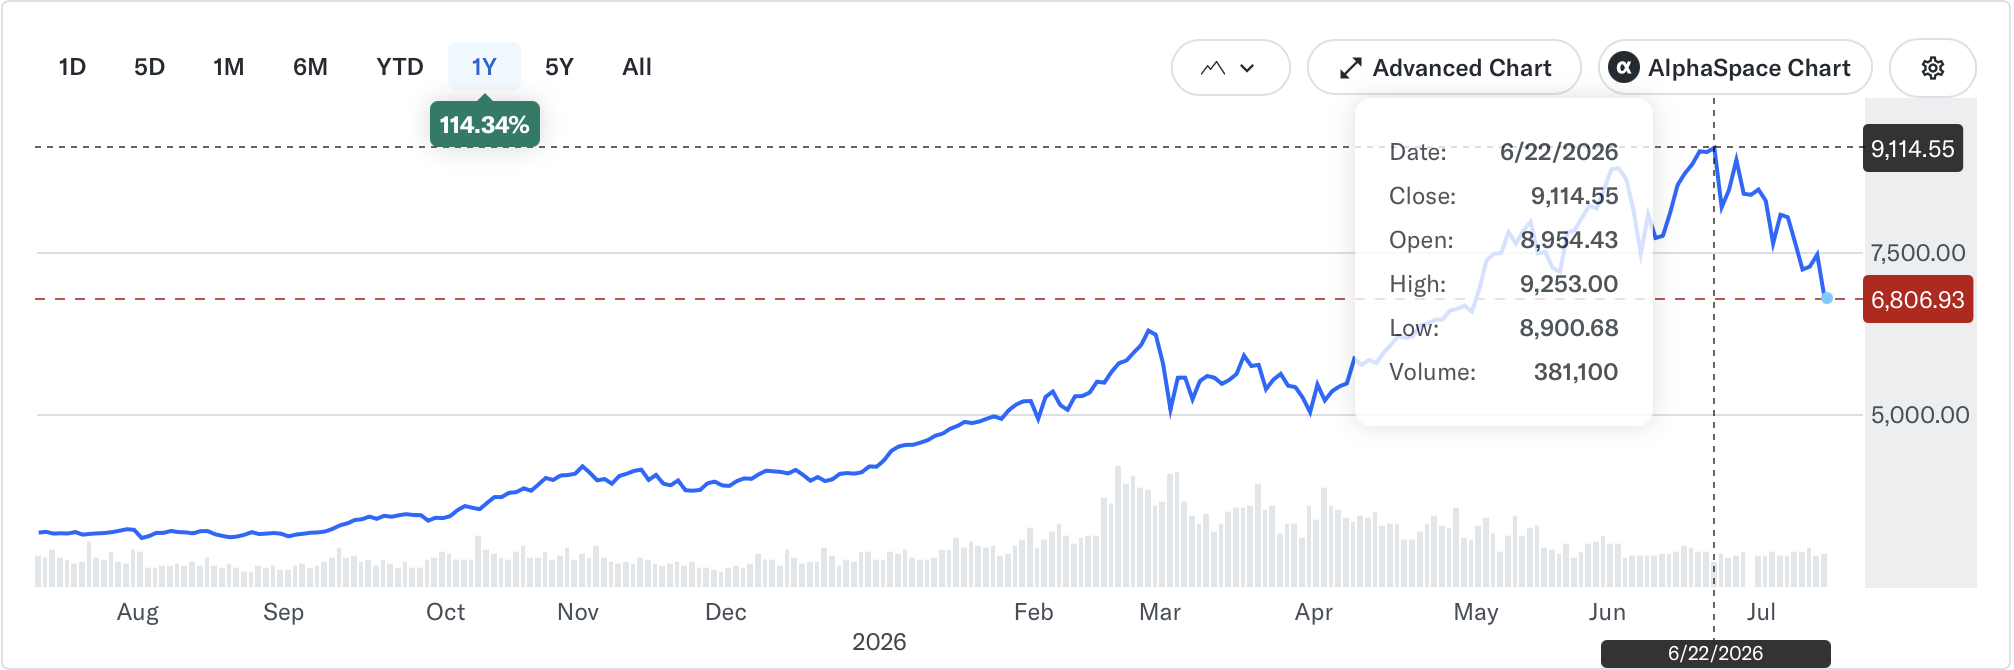
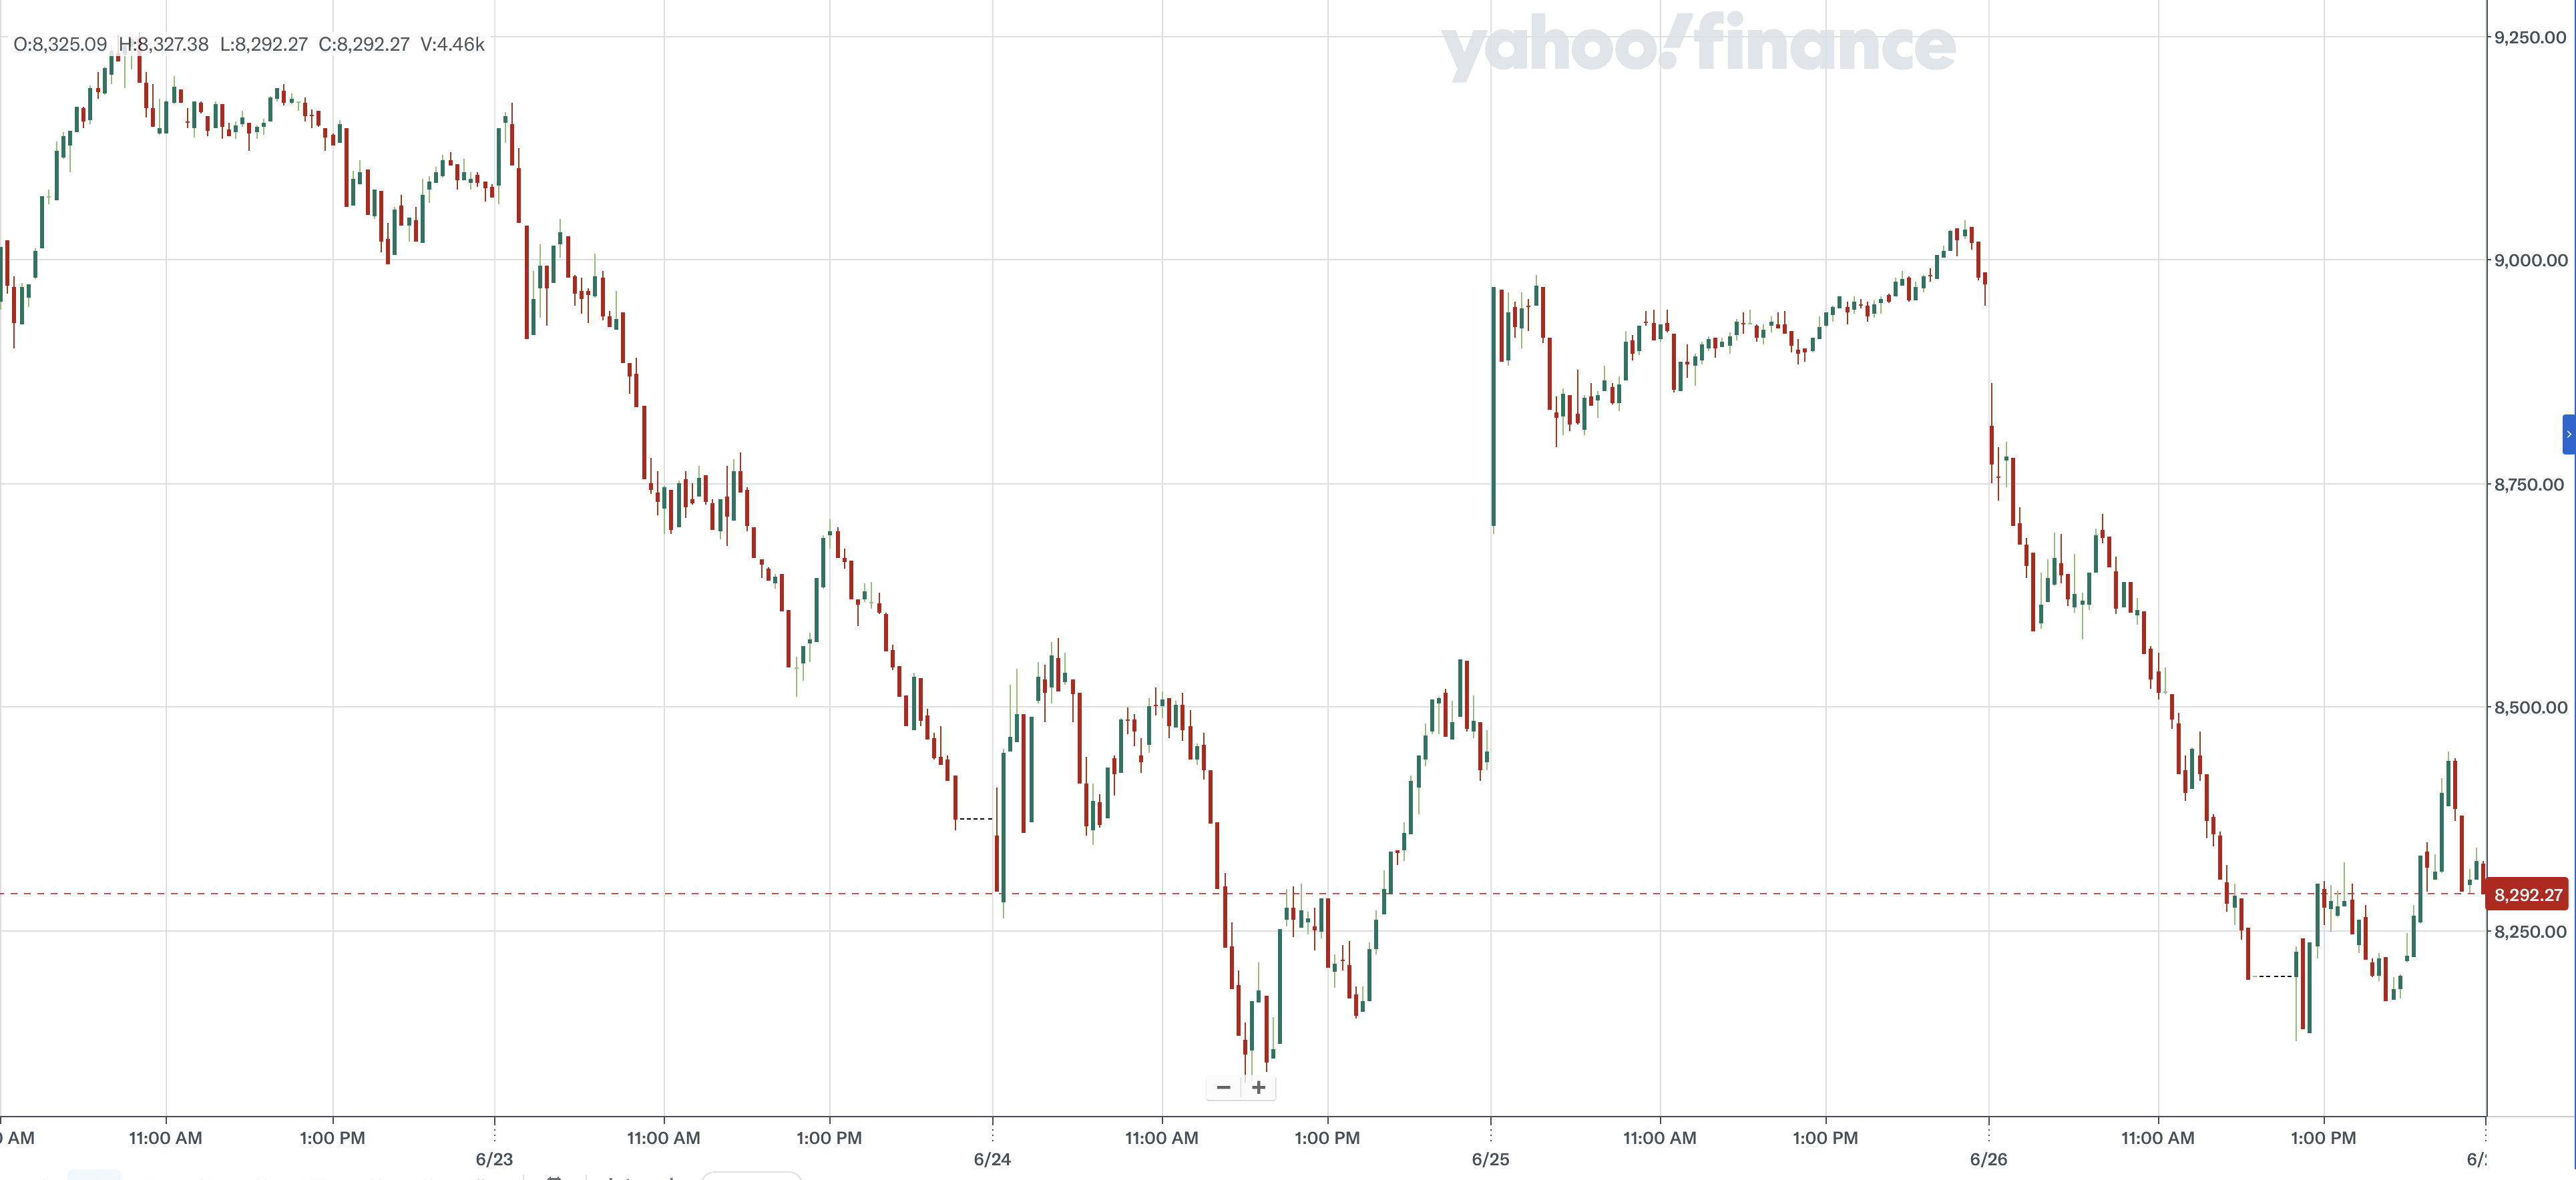
What might those other signals be?  Well, much was made of SK Hynix’s IPO in the US on Friday, which many pundits are now calling the top as the stock fell sharply in Korea overnight, down -15.4% dragging the KOSPI down -9.0% and tech stocks, in general much lower.  Of course, the KOSPI had risen dramatically over the past year, as you can see below, and is still higher by more than 100%  in the past year despite the recent decline of more than 25% since its peak on June 22.

Source: finance.yahoo.com

The problem with calling the top in stocks is that the earnings data, which starts in earnest this week, has been pretty good so far.  If companies continue to earn real profits, investors will continue to purchase stocks.

So, where else can we turn for new information?  Tomorrow brings the latest CPI report (exp 3.8% headline, 2.9% core), and you know that will be heavily scrutinized as the punditry tries to determine the FOMC’s reaction function and if it has changed with the new Chairman.  At this point, I do believe the Fed’s reaction function has changed, and more importantly, I don’t think anybody knows what it will be like, the Fed included.  The previous Fed whisperer, Nick Timiraos at the WSJ put out an article overnight discussing the idea that Chairman Warsh needs to decide whether to undo the most recent rate cuts.  However, there is no evidence that Warsh speaks to Timiraos and based on everything Warsh has said, he is not likely to tip his hand.  Chairman Warsh does testify to Congress this week, but I expect he will deflect all questions about the future path of monetary policy, and let’s face it, with the likes of Maxine Waters on the House committee, they won’t understand anything he says anyway.

And really, those are the only things that I think matter for now, so let’s review the overnight activity in markets.  As mentioned above, stocks are generally under pressure, but not universally so.  For instance, in Asia, Tokyo (-1.9%), China (-1.8%) and the aforementioned South Korea all had rough sessions, but HK, Taiwan, India and Australia were all basically flat on the day.  The big surprise is Taiwan as given the semiconductor weakness; I would have thought that market would have been significantly impacted.  But I guess not.  Meanwhile, European investors appear to be completely focused on tomorrow’s France-Spain World Cup semifinal as equity indices there are virtually unchanged this morning.  As to US futures, at this hour (7:30) NASDAQ futures are weaker by -1.2%, but the other markets are little changed.

Bond yields are higher this morning, but not hugely so.  Treasury yields have edged up by 1bp, and European sovereign yields are higher by 2bps across the board with UK Gilts (+4bps) the real laggard there.  Overnight, JGB yields backed up 4bps as well, but that story has more to do with the GPIF than anything else.

Remember Friday?
Japan was bringing home yen
They were just kidding

Think back to Friday.  Japanese FinMin Katayama mentioned that the GPIF and other Japanese pension funds ought to consider investing more money in Japan and less abroad.  That got tongues wagging about a major policy change coming that would serve to support the yen, and the JGB market while undermining Treasuries as the idea was the GPIF would sell their US Treasuries and buy JGBs instead.  Well, it turns out that is not actually the case.  The GPIF reevaluates its policy annually but has expressed no urgency to change things now despite the FinMin’s comments, at least according to Reuters.  The upshot is that JGBs sold off as did the yen (-0.3%) as per the below chart.

Source: tradingeconomics.com

Perhaps more surprisingly, though, the dollar is mixed on the day, not higher across the board as might have been expected given the uptick in oil and military activity.  So, we have seen weakness in GBP (-0.1%), AUD (-0.2%) and INR (-0.5%) while EUR (+0.1%), NZD (+0.2%), NOK (+0.3%) and KRW (+0.4%) have all had decent sessions.  Net, the DXY is essentially unchanged this morning.

Finally, and quickly, both gold (-1.5%) and silver (-2.0%) are under pressure with the higher oil price although copper (+0.6%) continues to find support and remains well above $6.00/lb.

In addition to the CPI data, it is a pretty busy week as follows:

TuesdayNFIB Small Biz Optimism95.6
 CPI-0.1% (3.8% y/Y)
 -ex food & energy0.2% (2.9% Y/Y)
 Warsh Testimony 
WednesdayPPI-0.1% (6.2% Y/Y)
 -ex food & energy0.3% (5.2% Y/Y)
 Empire State Mfg8.9
 Warsh Testimony 
 Fed’s Beige Book 
ThursdayInitial Claims218K
 Continuing Claims1811K
 Retail Sales0.2%
 -ex Autos-0.1%
 Philly Fed13.5
FridayHousing Starts1.30M
 Building Permits1.40M
 IP0.2%
 Capacity Utilization76.2%
 Michigan Sentiment51.5

Source: tradingeconomics.com

We also hear from 9 other Fed speakers (it almost seems like they didn’t get the memo about reducing communication) but with Warsh on the stand both Tuesday and Wednesday, I don’t think the others will matter that much.  Of course, it will be interesting to hear the other speeches if CPI comes in softer than expected as it may put a crimp in the hawks’ views.

In the end, not that much has really changed I would argue.  The war is an exogenous variable, and the market has learned to largely ignore it.  The Fed is still too uncertain in its new construction for many views to have changed, but I think the one thing we can conclude is that the old models of their reaction function are no longer viable.  My take is the beauty of the task forces for Chairman Warsh is they won’t report for at least 3 months, and probably more like 6 months, so until they report, absent a massive spike in measured inflation, the Fed is not going to do anything.  The Fed funds futures market is now pricing a one-third probability of a hike at the end of this month and certainty of one and 50% probability of two by the end of the year.  I would fade those trades.

Good luck

Adf
A Warshach Test

While narrative writers obsessed
For some this was a Warshach test
The doves and the hawks
Each messaged their flocks
That Warsh, to their views, acquiesced

Meanwhile, in Iran bombs are falling
And President Trump is name calling
However, despite
The restarting fight
Risk assets keep on, higher, crawling

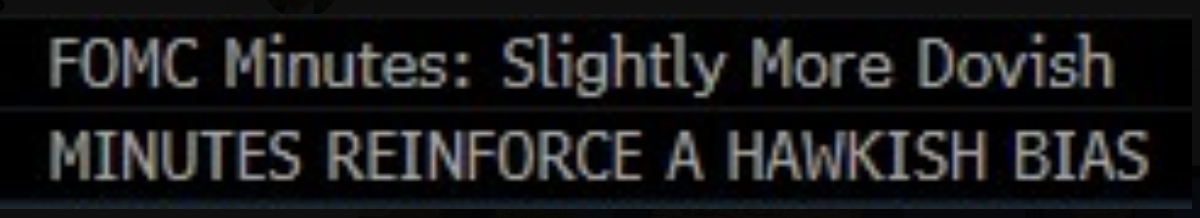
So, the FOMC Minutes were released, and they were hawkish dovish irrelevant.  The best expression of this came from Bloomberg’s Joe Weisenthal when he posted this on X,

Two simultaneous takes on the release that he received.  And I confess, I read those Minutes and didn’t learn anything at all.  It seems that the decision to leave rates on hold was unanimous although several committee members would have voted for a hike as well.

What does this say about the state of things?  I am very hopeful that we are on our way to a Fed that is less intrusive in market activities, both by reducing its balance sheet size, something that Chairman Warsh has expressly indicated as a goal, and by hearing less from committee members.  As @inflation_guy, Mike Ashton explains here, if forward guidance is dead, then why do we need to hear from any FOMC members about anything?  All those speeches were simply each member’s way to get their opinion out there and try to influence markets.  As I have frequently written, we would be much better off if the Fed were opaquer in their decision making as it would reduce risk and leverage and that would enhance financial market stability.  For everyone who wants Warsh to be Volcker redux, remember, back then, there were probably fewer than 10 people on Wall Street, let alone anywhere else, who could name a single member of the FOMC other than Mr Volcker himself.  That is an aspirational goal!

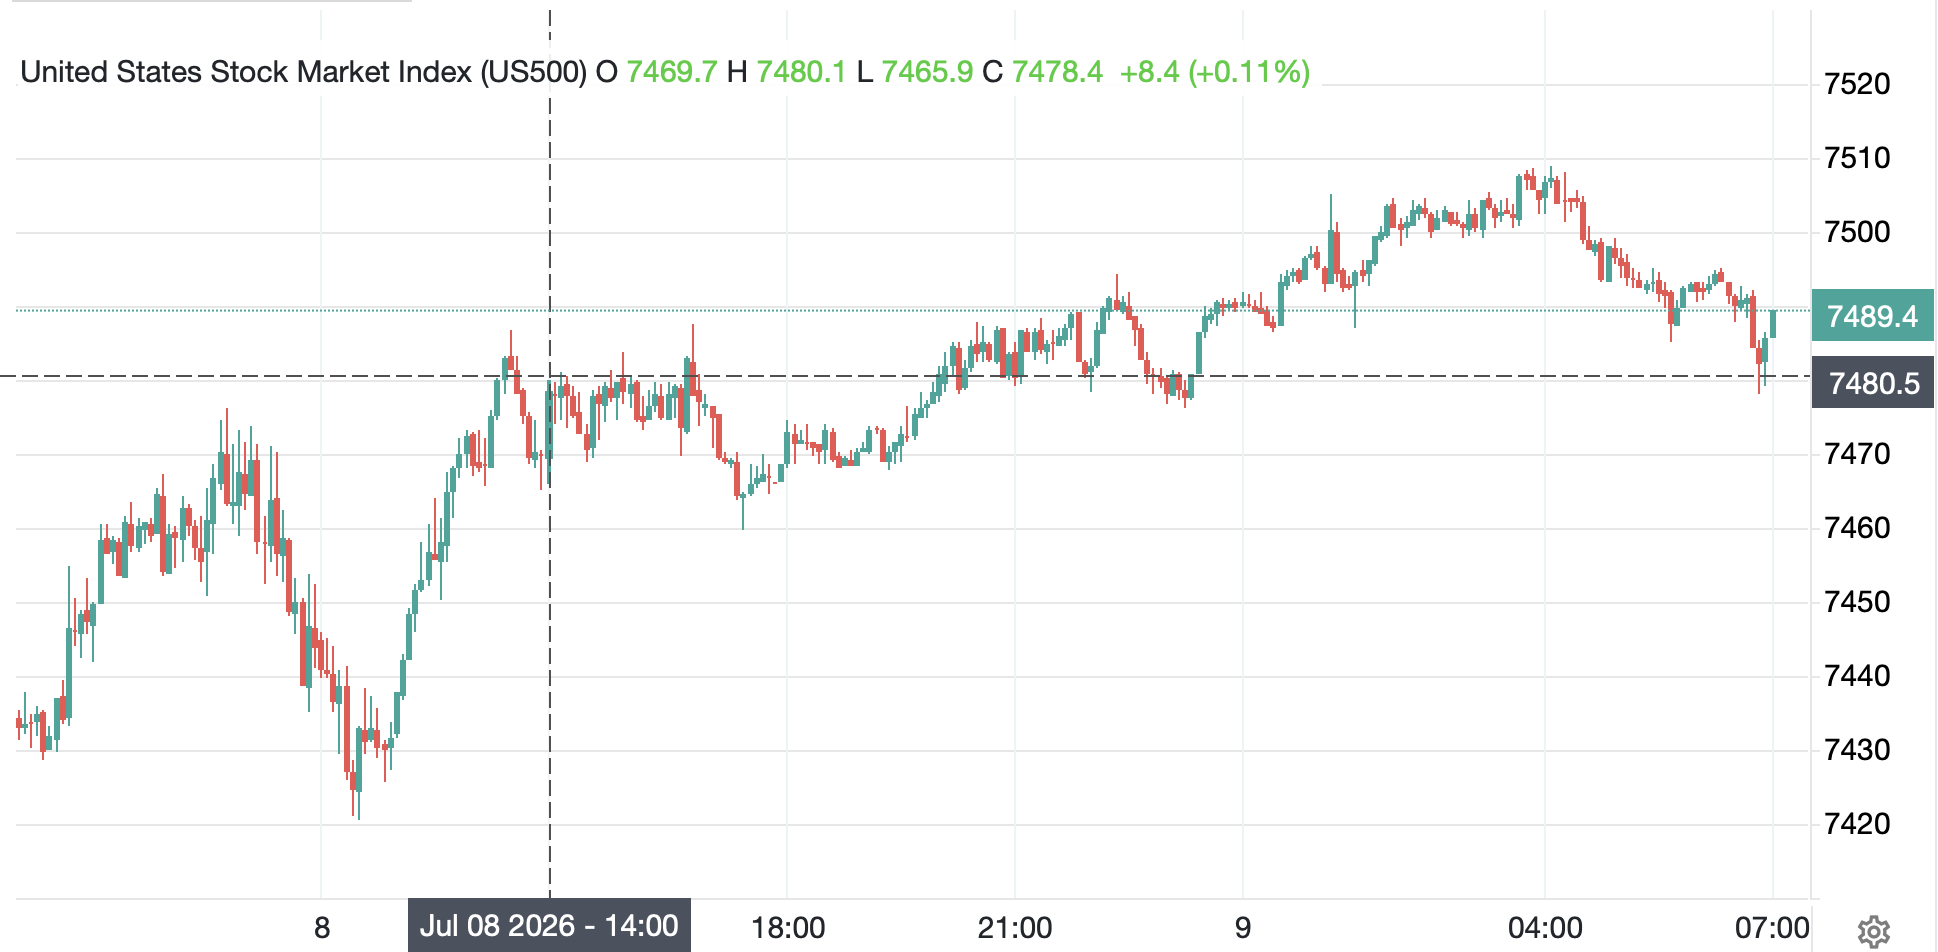
How did the market respond to the Minutes?  They basically ignored them.  Equity markets, which had opened much lower, were already in the process of reclaiming those losses when the Minutes were released and edged higher from there, with no meaningful change in trajectory as you can see in the below chart of the S&P 500.

Source: tradingeconomics.com

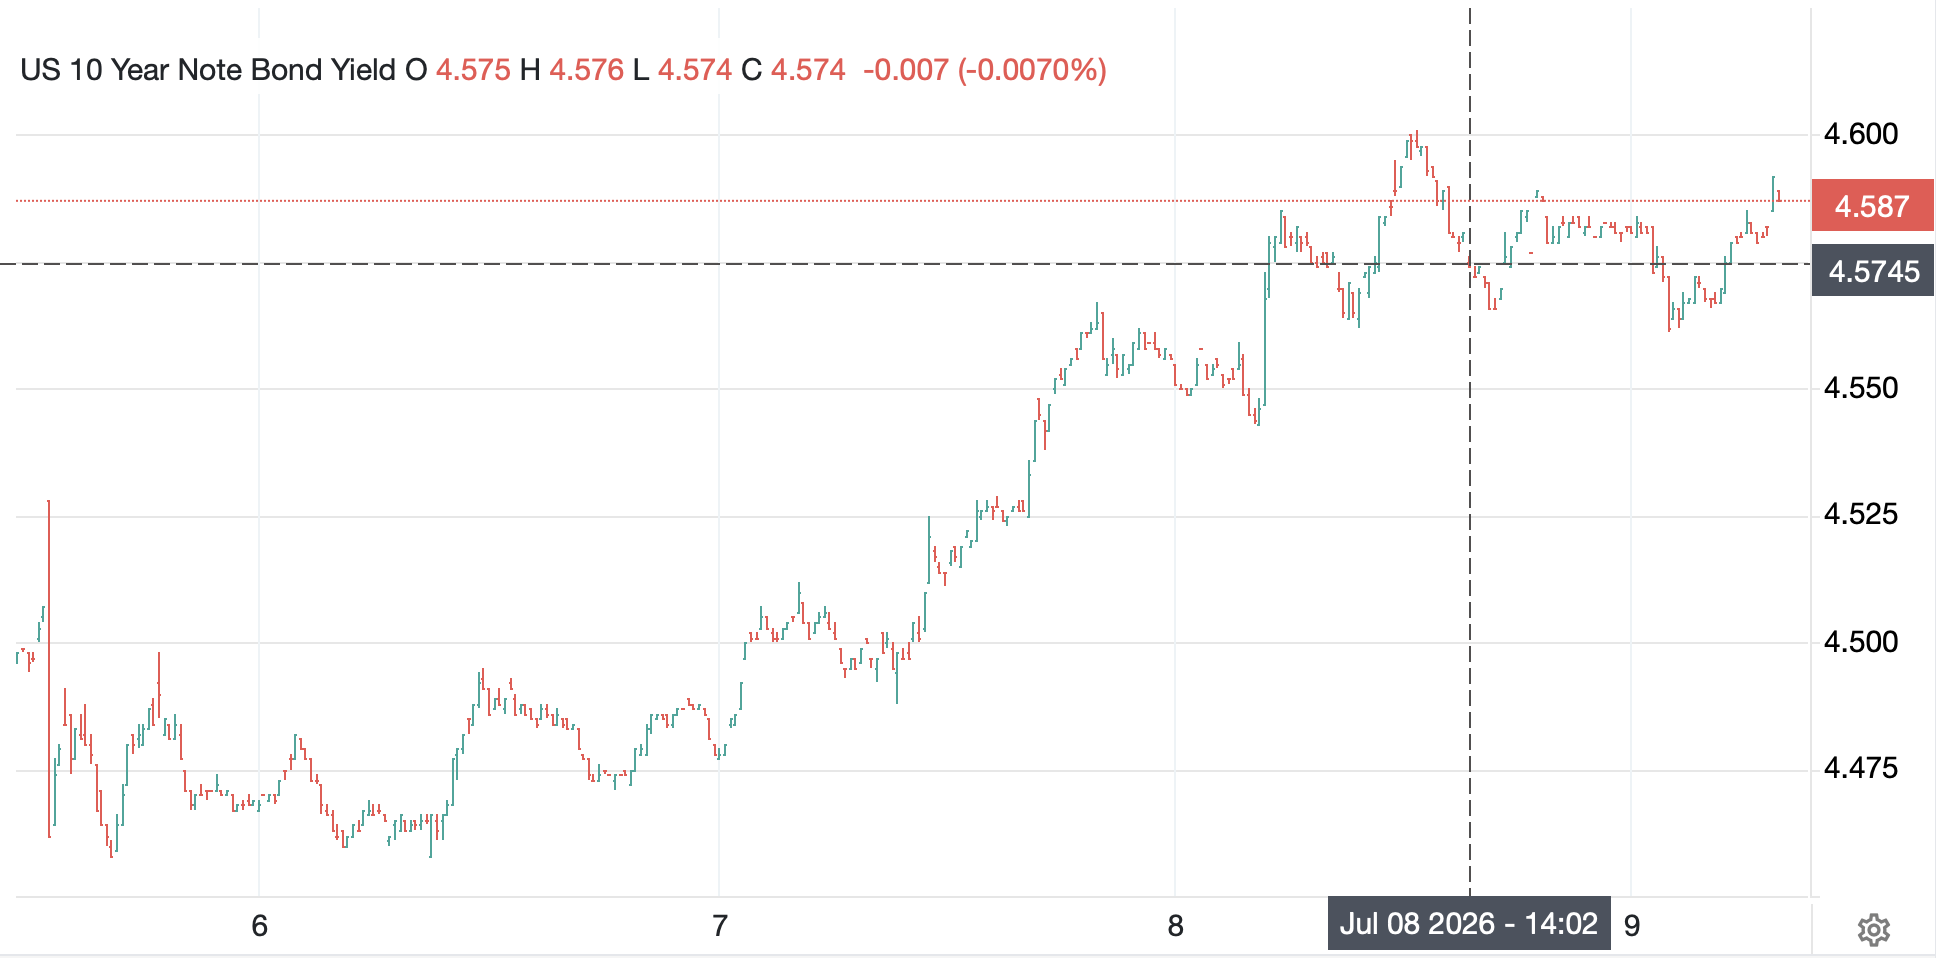
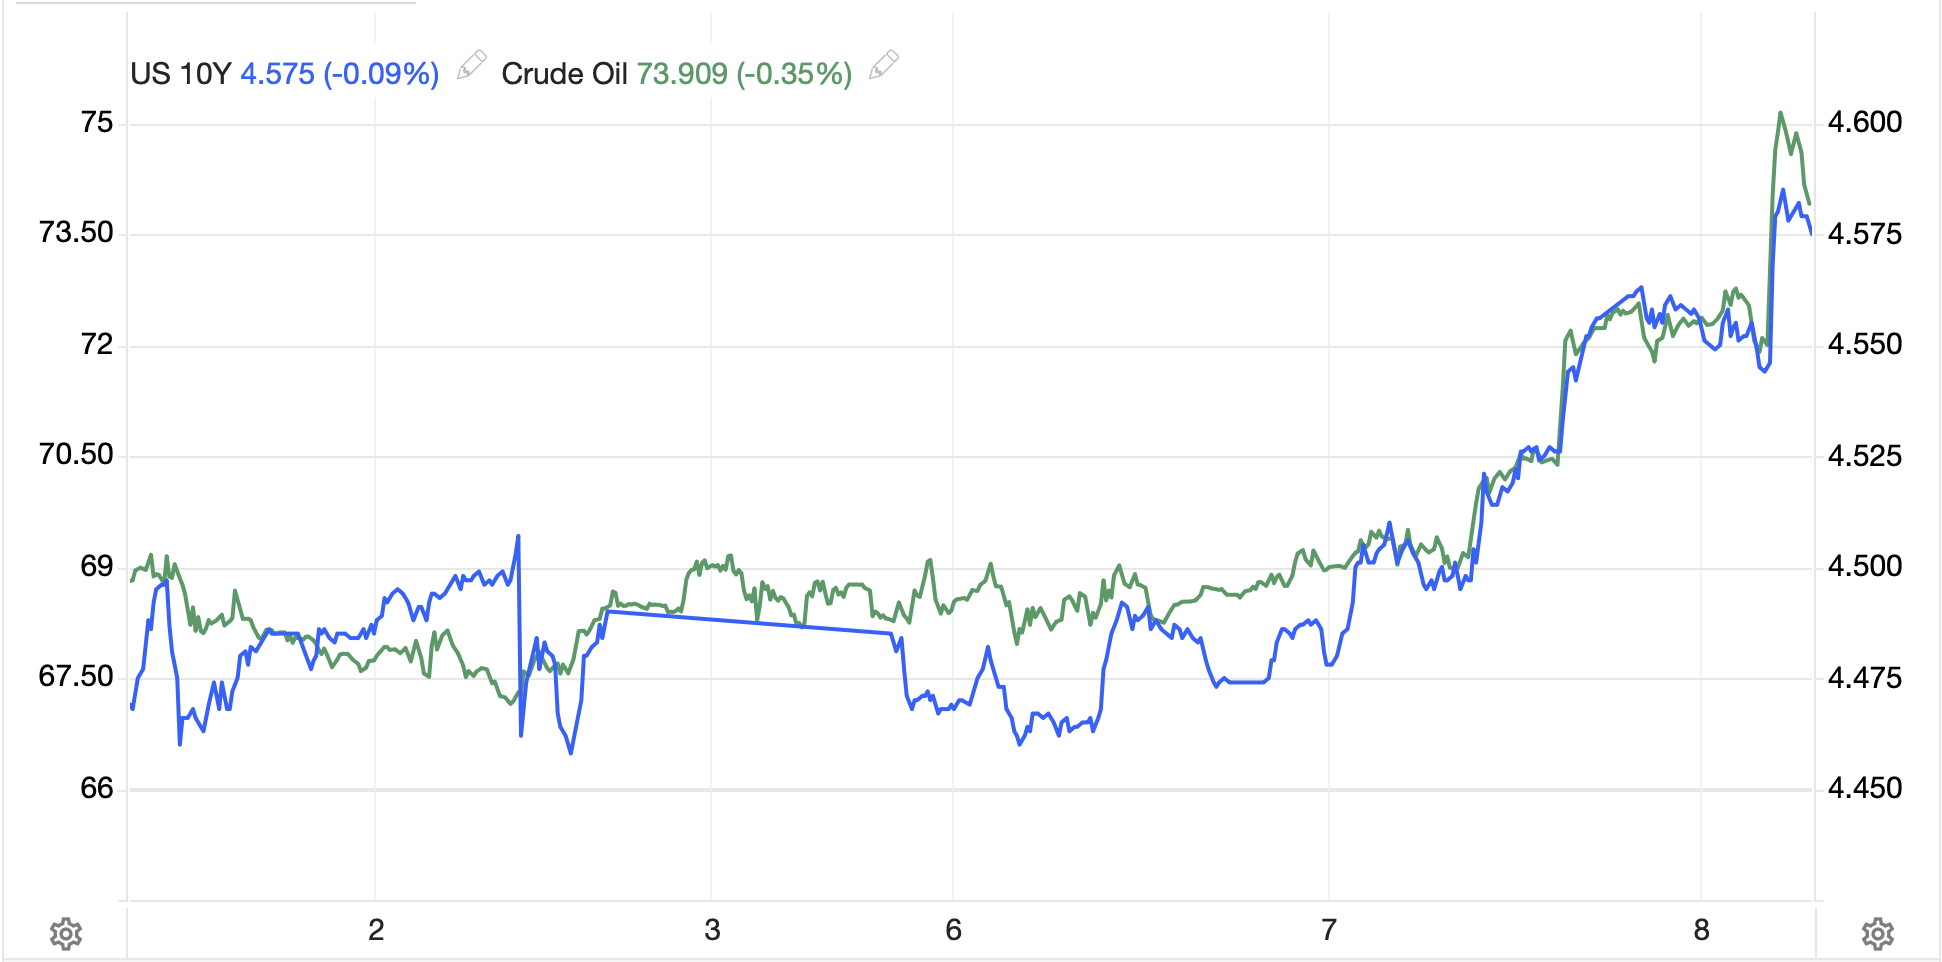
How about bonds?  Well, here is the 10-year chart and you tell me if the Minutes had an impact.

Source: tradingeconomics.com

I guess the real question is will the rest of the world’s central banks follow Mr Warsh’s lead and seek to end forward guidance and simply go about their job of managing inflation?  One can always hope.

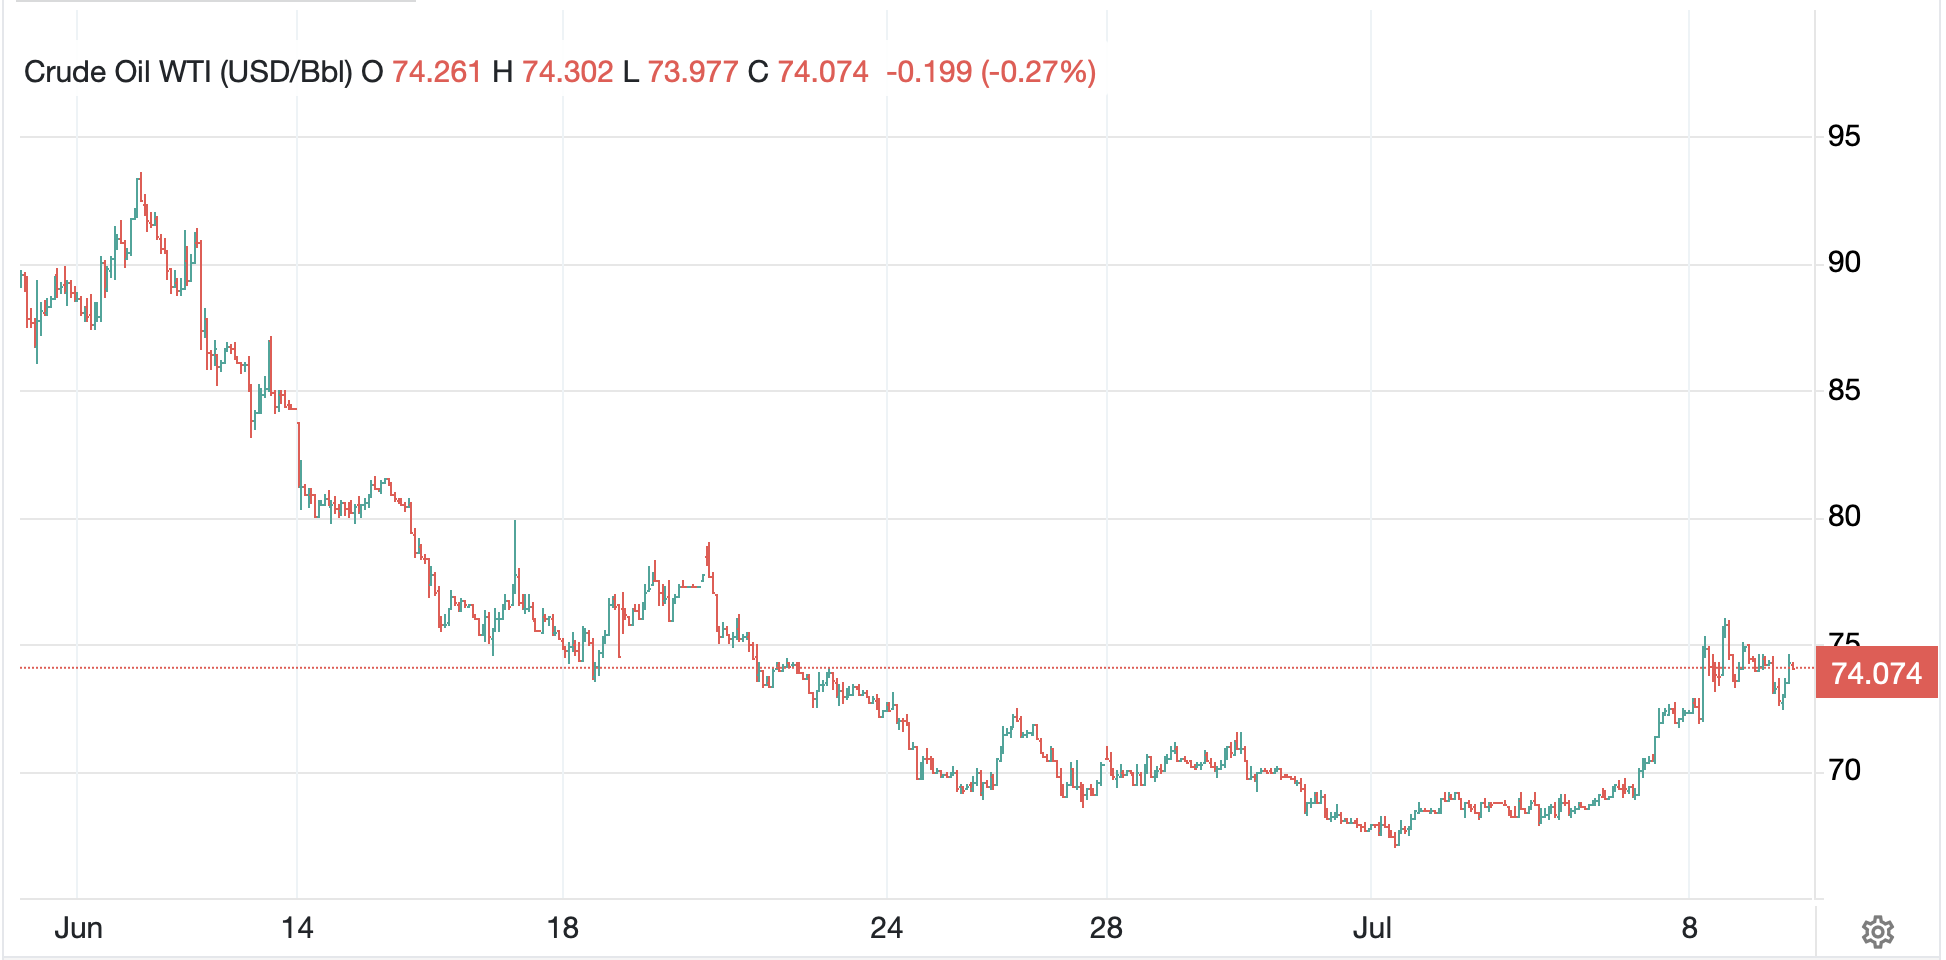
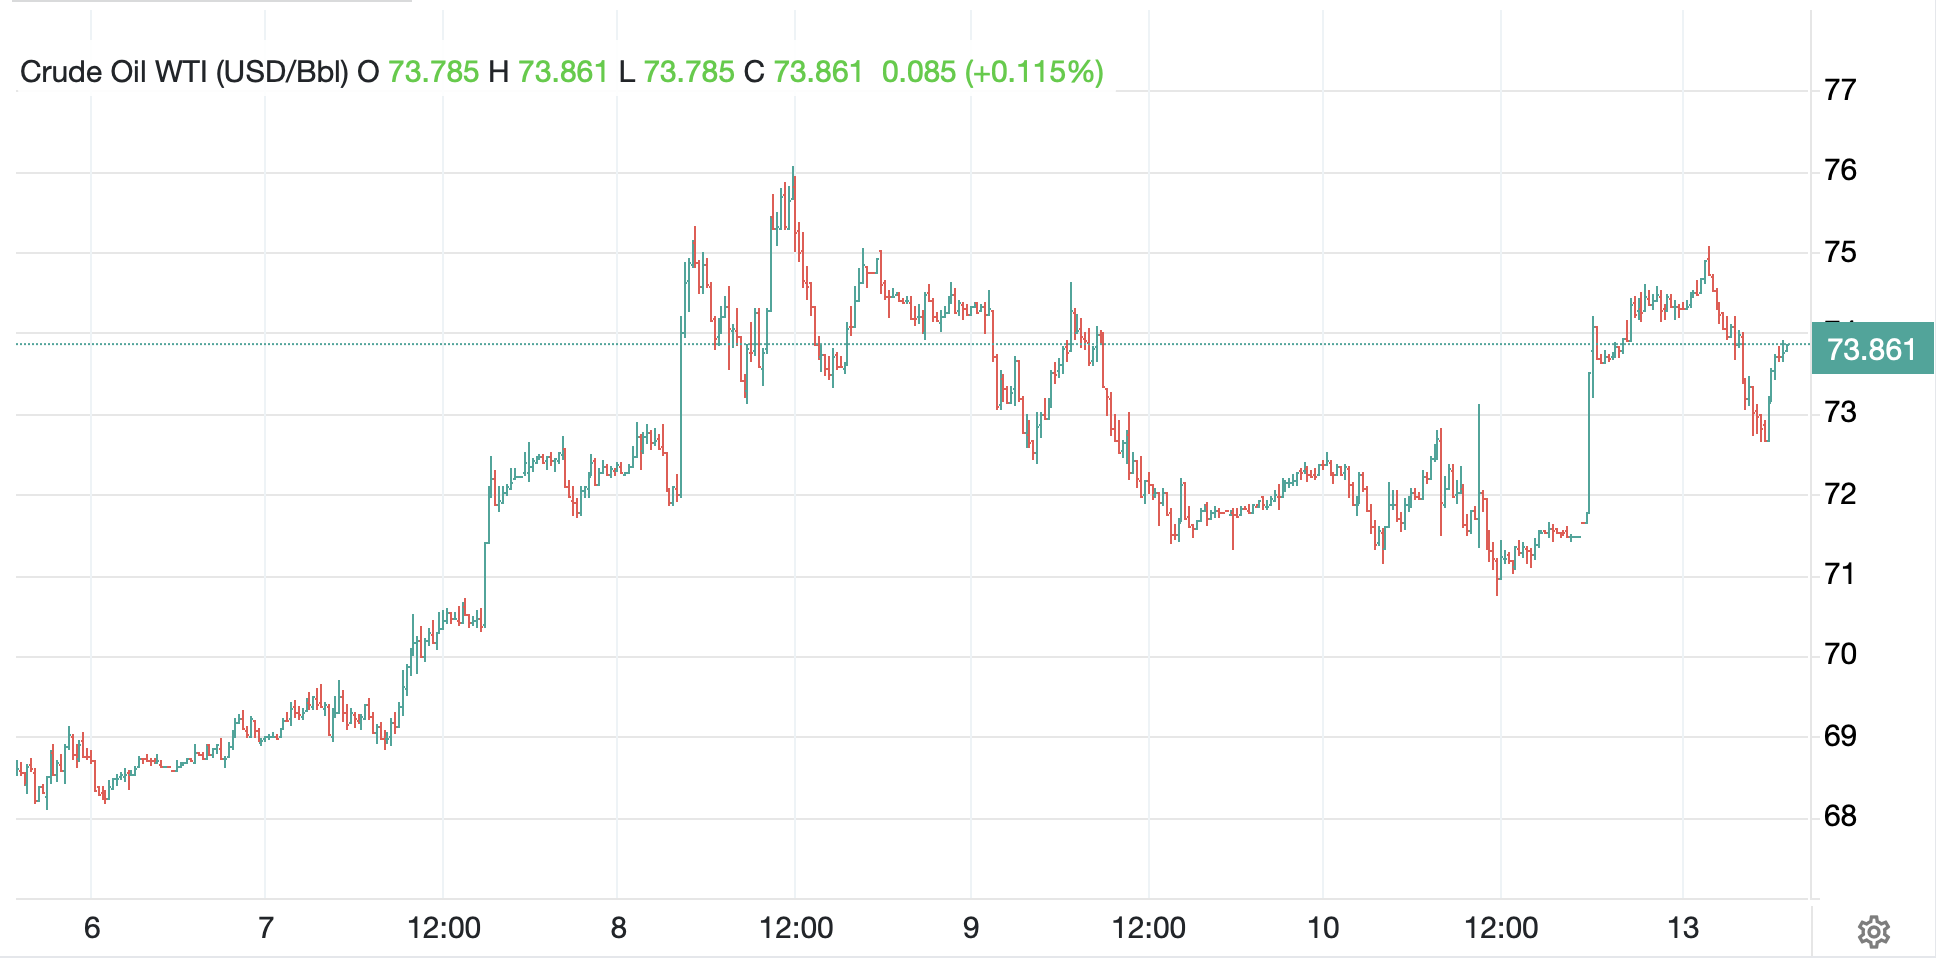
Which takes us to the other story of note, the apparent end of the ceasefire in Iran and the question of what is now happening in the Strait of Hormuz.  First, let’s be clear, nobody really knows as the fog of war remains thick.  Obviously, yesterday saw a sharp rise in the price of oil as concerns over future transits of the Strait rose dramatically.  However, as of this morning, while WTI (+0.6%) has edged slightly higher from yesterday’s closing levels, as you can see from the chart below, it seems to have found a new short-term home here around $74/bbl.

Source: tradingeconomics.com

Scrolling through X this morning, the $200/bbl analysts were back at it, explaining that this time, with all those inventories having already been used up, we are going to see much higher prices.  But weirdly, yesterday’s EIA data showed an inventory build of 3 million barrels.  I keep seeing charts of the US SPR and how it is at its lowest level since 1982 implying that we are on the cusp of running out like this one from Bob Elliott.  Now, Bob Elliott is a really smart guy, but I feel like the piece of the puzzle that is missing in these analyses is that right now, the US is producing just under 14 million bpd of oil, plus another ~7.5 million bpd of natural gas liquids and 110 billion cubic feet/day of dry natural gas.  In fact, we are a massive exporter of oil and products, so perhaps a better question is, why do we need an SPR anymore?  After all, it was created when we were at the mercy of the Middle East and producing just 8.6 million bpd.  That is no longer the case.

My take is the world can run perfectly well on $75/bbl oil and there is plenty of supply at that level.  In addition, we have seen numerous announcements of how Gulf oil producers are building new methods of transport away from the Strait, and over time, that will no longer be a choke point with any meaning.  War is exciting to market participants for about two weeks, at which point they get bored and move on to the next big thing.  After all, the Ukraine war has been ongoing for 4 years and it doesn’t get a mention in market commentary.  Next week we start to see earnings releases for Q2 and that will be much more interesting for equity, and likely all other, markets.

In the meantime, let’s see what happened overnight.  Based on the mix of information, we cannot be surprised that there were mixed outcomes in equity markets around the world.  Yesterday’s US split (DJIA -1.1%, NASDAQ +0.2%) was followed by gains in Tokyo (+1.4%), China (+2.5%), Korea (+0.6%) and India (+0.3%) while HK (-0.7%), Taiwan (-0.8%) and the Philippines (-0.8%) all slid a bit.  There was no rhyme or reason here.  The only data of note overnight was Chinese inflation data where CPI fell to +1.0%, while PPI rose to +4.1%.  It strikes me that Chinese companies will continue to see pressure on their margins.

In Europe, things are also mixed with Spain (+0.8%), Italy (+0.7%) and France (+0.3%) all higher while the UK (-0.6%) is slipping and Germany is little changed.  As to US futures, they are leaning higher at this hour (7:50).

Bond markets seem to have stopped selling off as yields this morning are little changed (Treasury +1bp, Bunds +1bp, Gilts -3bps, OATs -3bps).  JGBs were unchanged overnight.  The 10-year auction yesterday went pretty well with a bid-to-cover ratio of 2.59, although with yields at 4.58%, it is not that surprising there was real demand.  I will say this, bonds, too, are a market with some smart folks with diametrically opposed views of the future outcome.  Both 3% and 6% are seen as the next major destination depending on the analyst.

Interestingly, metals markets are showing some life this morning with gold (+0.8%), silver (+1.4%) and copper (+2.2%) all bouncing off recent lows.  This is a bit out of character compared to recent price action relative to oil, but maybe we are putting in some bottoms here.

Finally, the dollar is, net, little changed this morning.  In the G10, NZD (+0.65%) is the big mover, which continues on the back of their rate hike from yesterday.  But otherwise, +/-0.1% is the norm here.  In the EMG bloc, KRW (-0.5%) is giving back some of its recent gains but continues to hover near multi-decade lows.  The recent gains have been on the back of a record current account surplus, but it remains an interesting conundrum that despite the massive gains in the Korean stock market, the currency has not attracted more buying interest.  Otherwise, modest EMG gains on the order of +0.1% are today’s story.

On the data front, we see Initial (218K) and Continuing (1820K) Claims as well as Existing Home Sales (4.20M) today.  In addition, there are two Fed speakers as I imagine getting them to shut up will take some time.  However, I wonder, will they really add to the discussion?

Oil continues to be the driving force in markets, but right now, my sense is eyes are turning to upcoming earnings releases.  Of course, we also get CPI next week, which will be a critical number for markets, at least for now.  

Good luck

Adf
Theses All Wrecked

There once was a fire that ceased
Which many hoped would lead to peace
But recent attacks
On ships did climax
In poking the milit’ry beast

The market’s response was direct
With oil bears’ theses all wrecked
The dollar, it rose
While risk takers chose
Their stocks and bonds, now, to reject

While we had all become accustomed to the gradual decline in the price of oil as it appeared there was a solid chance that an agreement would be reached between Iran and the US, that all came a cropper yesterday after Iran attacked 3 different ships exiting the Strait and the US responded with attacks on more than 80 targets, including (according to the WSJ) “air-defense systems, command and control networks, antiship missile sites and more than 60 Iranian small boats near the waterway.”  This was a significant uptick in the nature of the response from previous skirmishes and according to President Trump, the ceasefire is over.

“To me, I think it’s over, I don’t want to deal with them anymore,” Trump told reporters at a NATO summit in Ankara on Wednesday. “They’re liars, they’re cheats, they’re sick people.” 

Given the sudden change in the status in the Gulf, we cannot be surprised by the market response.  WTI (+6.0%) rocketed higher as you can see in the chart below.

Source: tradingeconomics.com

And while that is clearly a significant move, and has changed attitudes in the market, I think it is worth stepping back slightly and looking at the price action over the past month, just to remind ourselves that though things may be changing, we have still seen a dramatic decline in price.

Source: tradingeconomics.com

Here’s the thing, right now there is no way to know if we are going back to the situation in early March, where there was substantial fighting, or at least bombing and missile attacks, each day, or if this, too, is going to pass like the previous minor skirmishes.  Certainly, President Trump appears tired of the current situation, but it is not clear what type of further response is in the offing.

In the meantime, given the new military action and the limited prognosis for a quick return to the previous status of ships moving through the Strait, it can be no surprise that investors decided to dump a lot of risk.  So, let’s take a look at how things behaved overnight.

You will not be surprised that equity markets are broadly lower this morning.  Yesterday’s US session was soft on concerns over the tech sector and that was before the resumption of hostilities in Iran.  So, Tokyo (-2.1%), China (-0.8%), Korea (-5.4%) and India (-2.2%) all fell sharply amongst major markets in Asia with most of the smaller exchanges under pressure as well.  The outliers here were HK (+3.0%) and Taiwan (+0.6%) as both saw continued demand for semiconductor and tech shares.  It feels to me that these two markets will have difficulty maintaining this positivity under the current circumstances.

In Europe, it is a bloodbath with all major bourses lower led by Germany (-2.4%) and Spain (-2.7%) while France (-2.2% and the UK (-1.6%) are not far behind.  The NATO meeting ongoing in Ankara is not helping anybody’s views as President Trump continues to add pressure to NATO to pay their own way.  Ultimately, the NATO transition continues, and it is anybody’s guess as to how involved the US will be going forward.  As to US futures, at this hour (6:35) all the major markets are lower by -1.0% or more.

In the bond market, yesterday saw Treasury yields rise 6bps during the session as yields tracked the oil move pretty closely.

Source: tradingeconomics.com

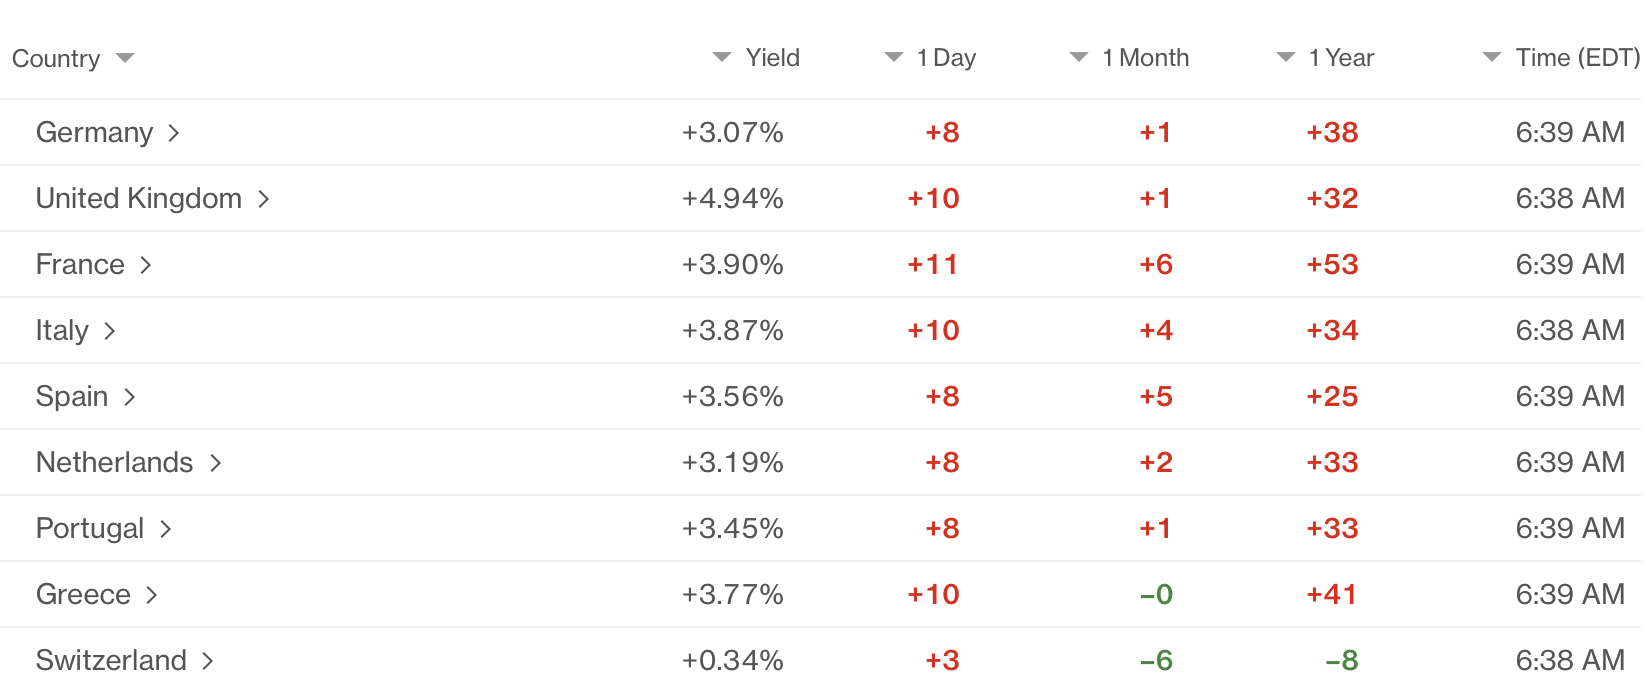
This morning, Treasury yields are higher by 2bps more but that is nothing compared to the European sovereign markets, which as you can see from the below Bloomberg.com screenshot are substantially higher this morning.

All those visions of inflation finally starting to decline were abruptly altered after the renewed activities in the Gulf.  Adding to the pressure on bonds is the concern over the increased spending promises from governments around the world which has seen traders increase short positions in the bond market to near record levels.

We cannot be surprised that gold (-1.2%), silver (-2.2%) and copper (-2.2%) are lower in response to the renewed fighting and rise in oil prices as that relationship has been very consistent.  We also cannot be surprised that the dollar is a bit firmer this morning, although not universally so.  For instance, JPY (-0.2%) is now pushing back to its recent lows (dollar highs) although the pace of movement remains quite modest.  As well ZAR (-0.6%) is also under pressure amid the decline in gold prices and rising oil prices (they are an importer of oil).  On the flip side, though, NOK (+0.4%) is benefitting from oil’s rally as is CAD (+0.25%) while KRW (+0.6%) seems to be benefitting from money flowing home after the recent equity rout there (covering margin calls?).  NZD (+0.4%) strengthened on the back of the RBNZ raising their base rate by 25bps as they continue to have some concern over inflation, but that only takes it back to 2.50%, hardly tight money.  As to the other main currencies, they have not really done that much, although lean slightly lower this morning.

On the data front, we see the EIA oil inventory data with draws still expected, as well as a 10-year Treasury auction, where it will be quite interesting to see if investors are keen on the extra yield now available.  And we get the FOMC Minutes, which despite the Iran situation, will still be keenly watched and read as the analyst community tries to get a better understanding of the way the Fed will be behaving going forward.  What is the new reaction function?  

Looking at the Fed funds futures market, pricing for that first rate hike has moved to September from the previous October timeframe, and a second hike is back in the cards as well.

However, nothing has changed my view about the way things will evolve.  Certainly, the increased hostilities are a negative for markets, but I suspect that this will be a short-lived episode and things will calm down again sooner rather than later.  With that in mind, I have not changed my view about no rate hikes this year with a potential cut.  However, if this fighting does increase and the oil price creeps higher over the next weeks and months, I will be rethinking this stance.

Right now, we are back to being hostage to events on the other side of the world.  All we can do is watch and respond.  

Good luck

Adf
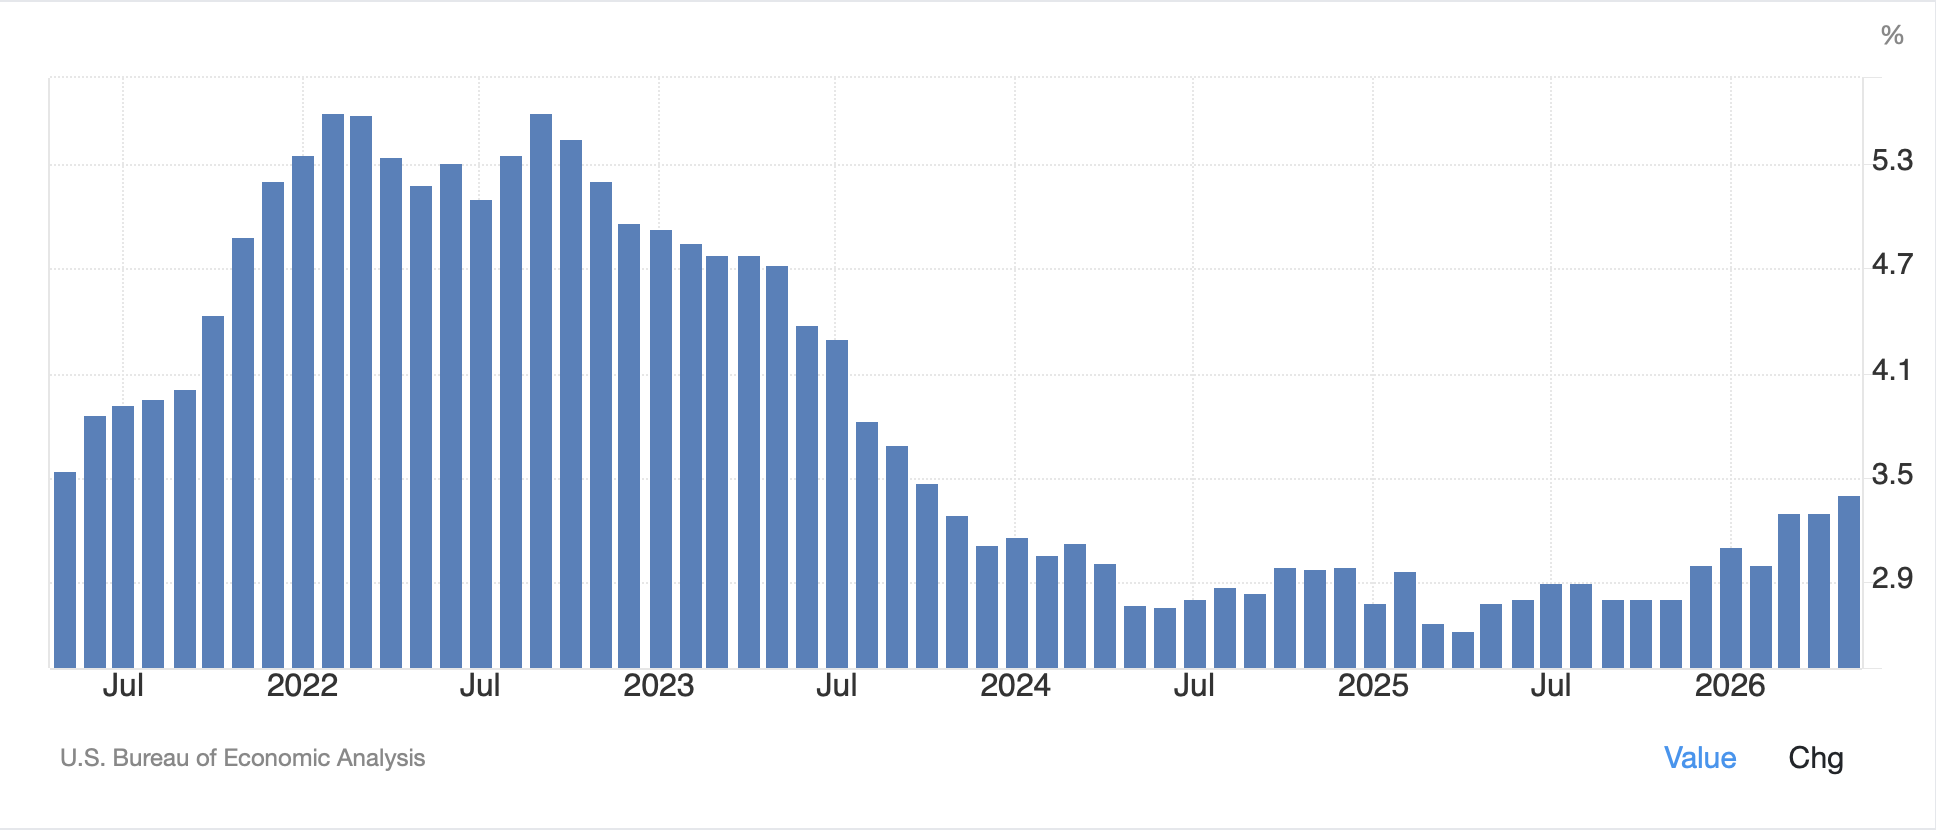
Discussing Their Plight

Now, all eyes will turn to the chat
When Warsh and his minions, they sat
Round oak polished bright
Discussing their plight
‘Bout prices and jobs and all that

But since they met three weeks ago
Chair Warsh very clearly did show
His view that inflation
Was short in duration
And rate hikes were not apropos

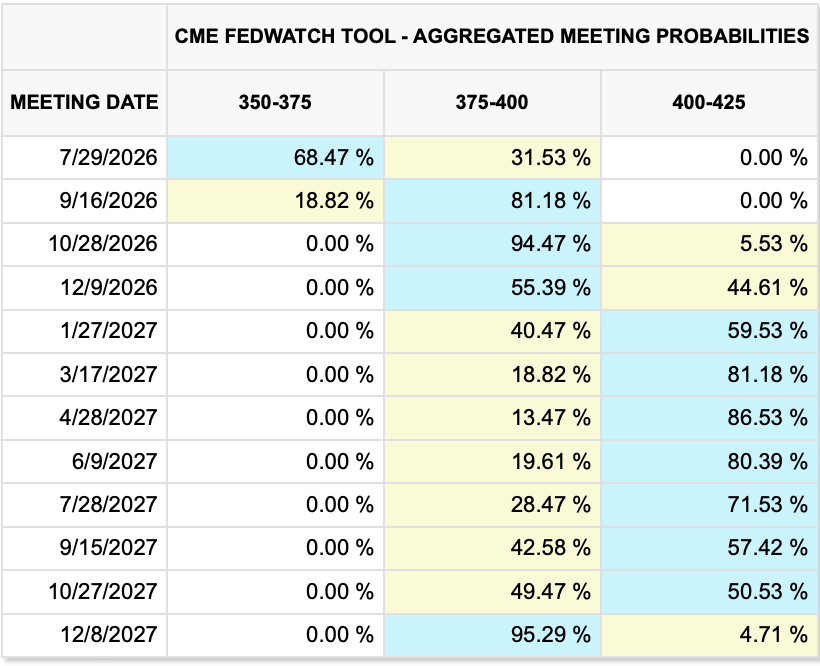
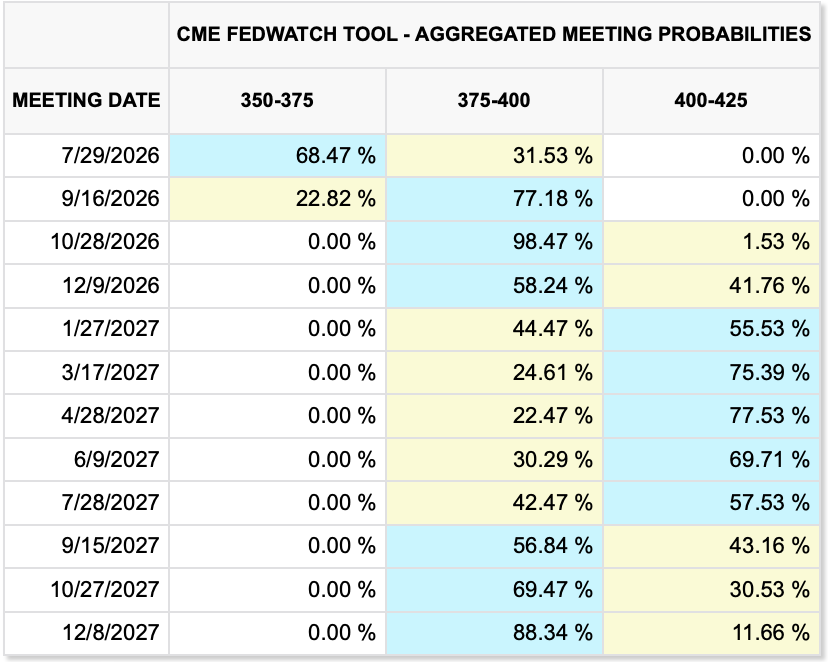
It is getting increasingly difficult to maintain a hawkish Fed view as both the data and the Chairman are working against you.  While we all enjoy the World Cup this week, arguably the biggest market related news will be Wednesday’s release of the Minutes from the last FOMC meeting.  You may recall that in the wake of that meeting, interest rate hawks were in the ascendancy with an October hike fully priced and odds for a second, December, hike priced as well as you can see in the below CME table from June 24th.

Now, in the wake of that meeting and the press conference, the combination of the dot plot showing half the committee expecting a hike this year and the lack of forward guidance along with the succinct statement explaining the Fed would achieve their 2.0% inflation mandate had many analysts expecting a serious tightening cycle upcoming.

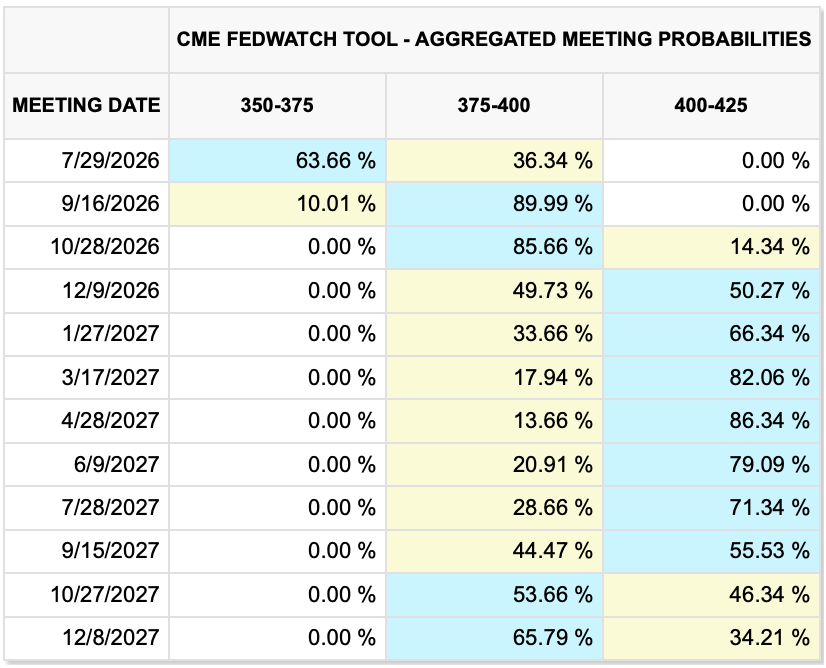
But a funny thing happened on the way to the next FOMC meeting, still three weeks hence, the price of oil, and energy in general, accelerated its decline.  Given how much effort was made to explain that the core inflation readings were heading higher because of the impact that energy has on everything, hence the need to hike rates, this has been an inconvenient outcome for the hawks.  Add to that Chairman Warsh’s comments at Sintra, Portugal last week, regarding the easing of inflationary pressures as energy prices decline (oil -0.9% this morning) and futures traders have been adjusting their views pretty steadily as per this morning’s CME table.

While a hike is still assumed by year end, the second one has fallen by the wayside.  Personally, as we continue to see inflation pressures subside alongside energy prices, I expect that not only will we not see a hike this year at all, but a cut by December is viable.

Adding to the downward bias on Fed funds futures was Thursday’s payroll report, where the headline number was softer than expected, although the Unemployment Rate did slip another tick to 4.2%.  I think a key problem with using the Unemployment report as such a critical signal is the fact that since President Trump’s inauguration and the actual closing of the Southern border, as well as the deportation (by both the government and on a self-basis) of somewhere between 2.5 million and 3.0 million according to Grok, the old econometric models of what type of job growth was necessary to maintain solid economic growth are no longer terribly useful. If we throw in the dramatic changes to the economy on the back of the increase in AI as a tool and infrastructure investment, it becomes increasingly difficult to utilize the old models.  Too, one of the main themes from several months ago was that AI was going to replace hundreds of thousands of jobs and unemployment would skyrocket, while now, those ideas are being rethought with many analysts now expecting AI will support more jobs.  Perhaps, the best thing that can come of this change is that markets will no longer radically adjust based on an outdated statistic.

There is still a long way to go before the next FOMC meeting and I doubt that the many task forces will have come to any conclusions yet, but if energy prices continue to decline, and I couldn’t help but notice this WSJ article discussing the sudden glut of oil driving prices lower, and I am growing increasingly confident in my views.

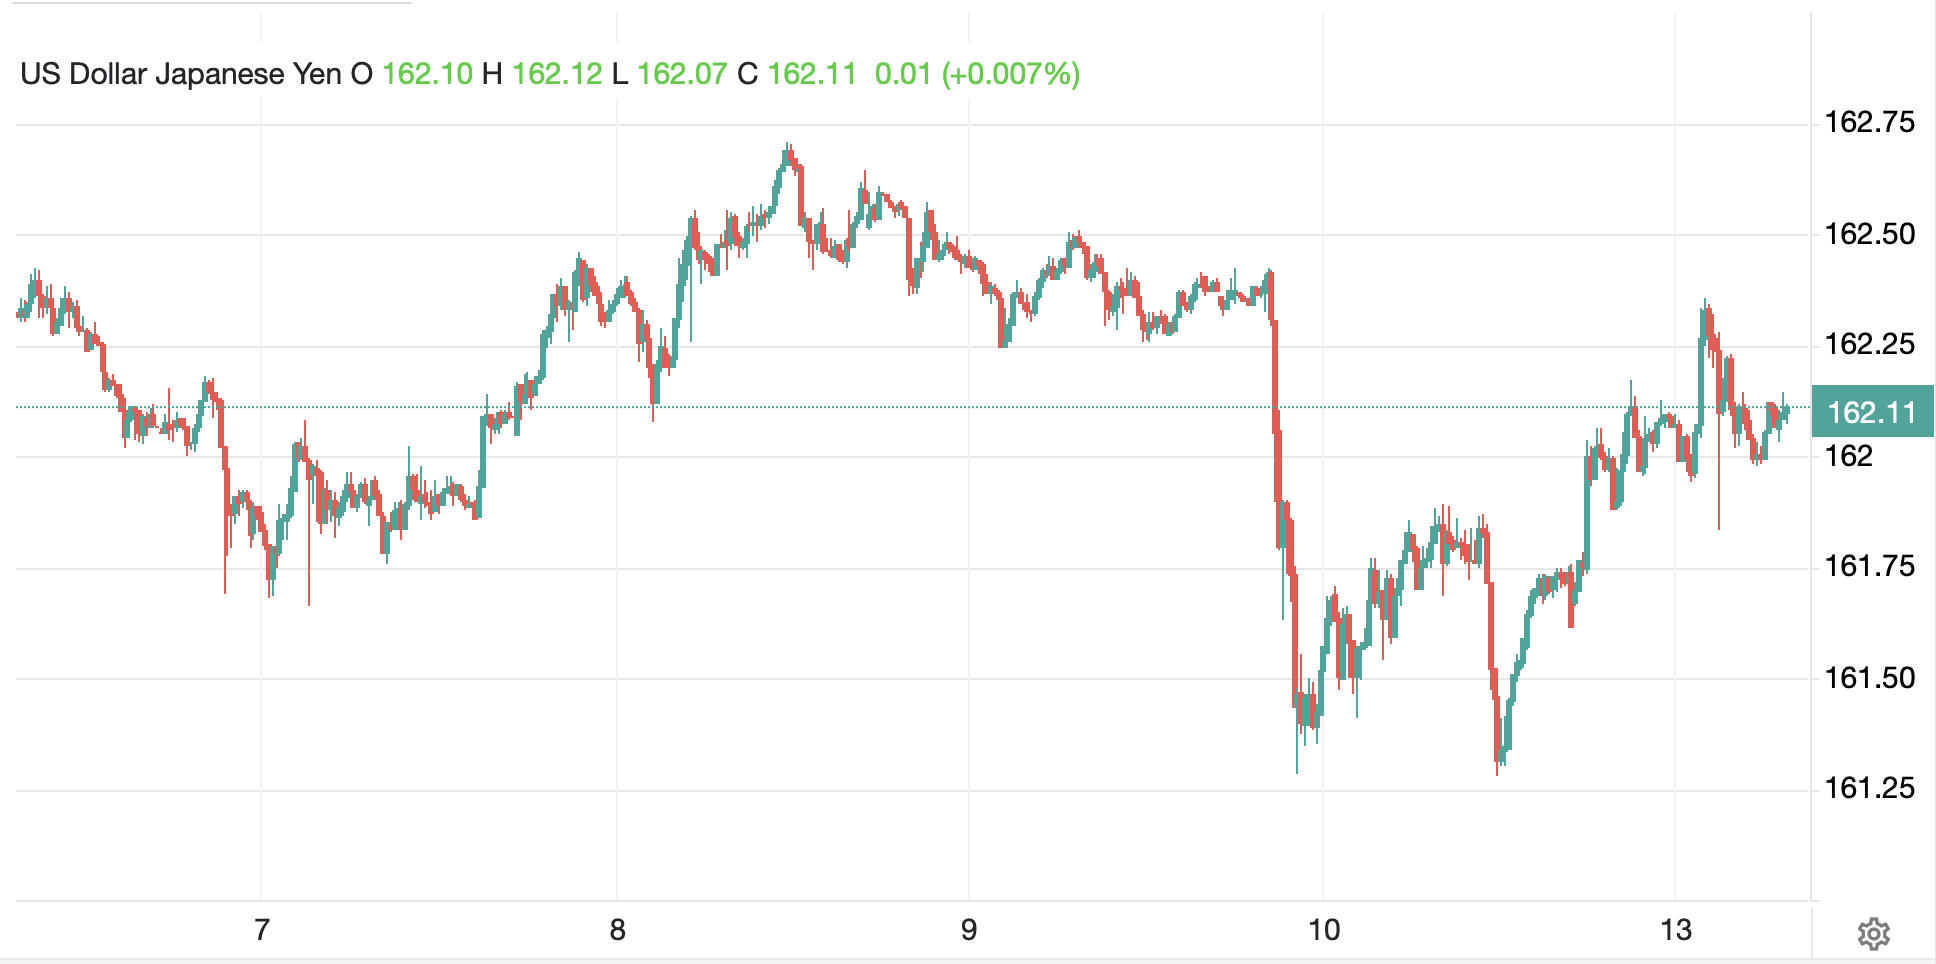
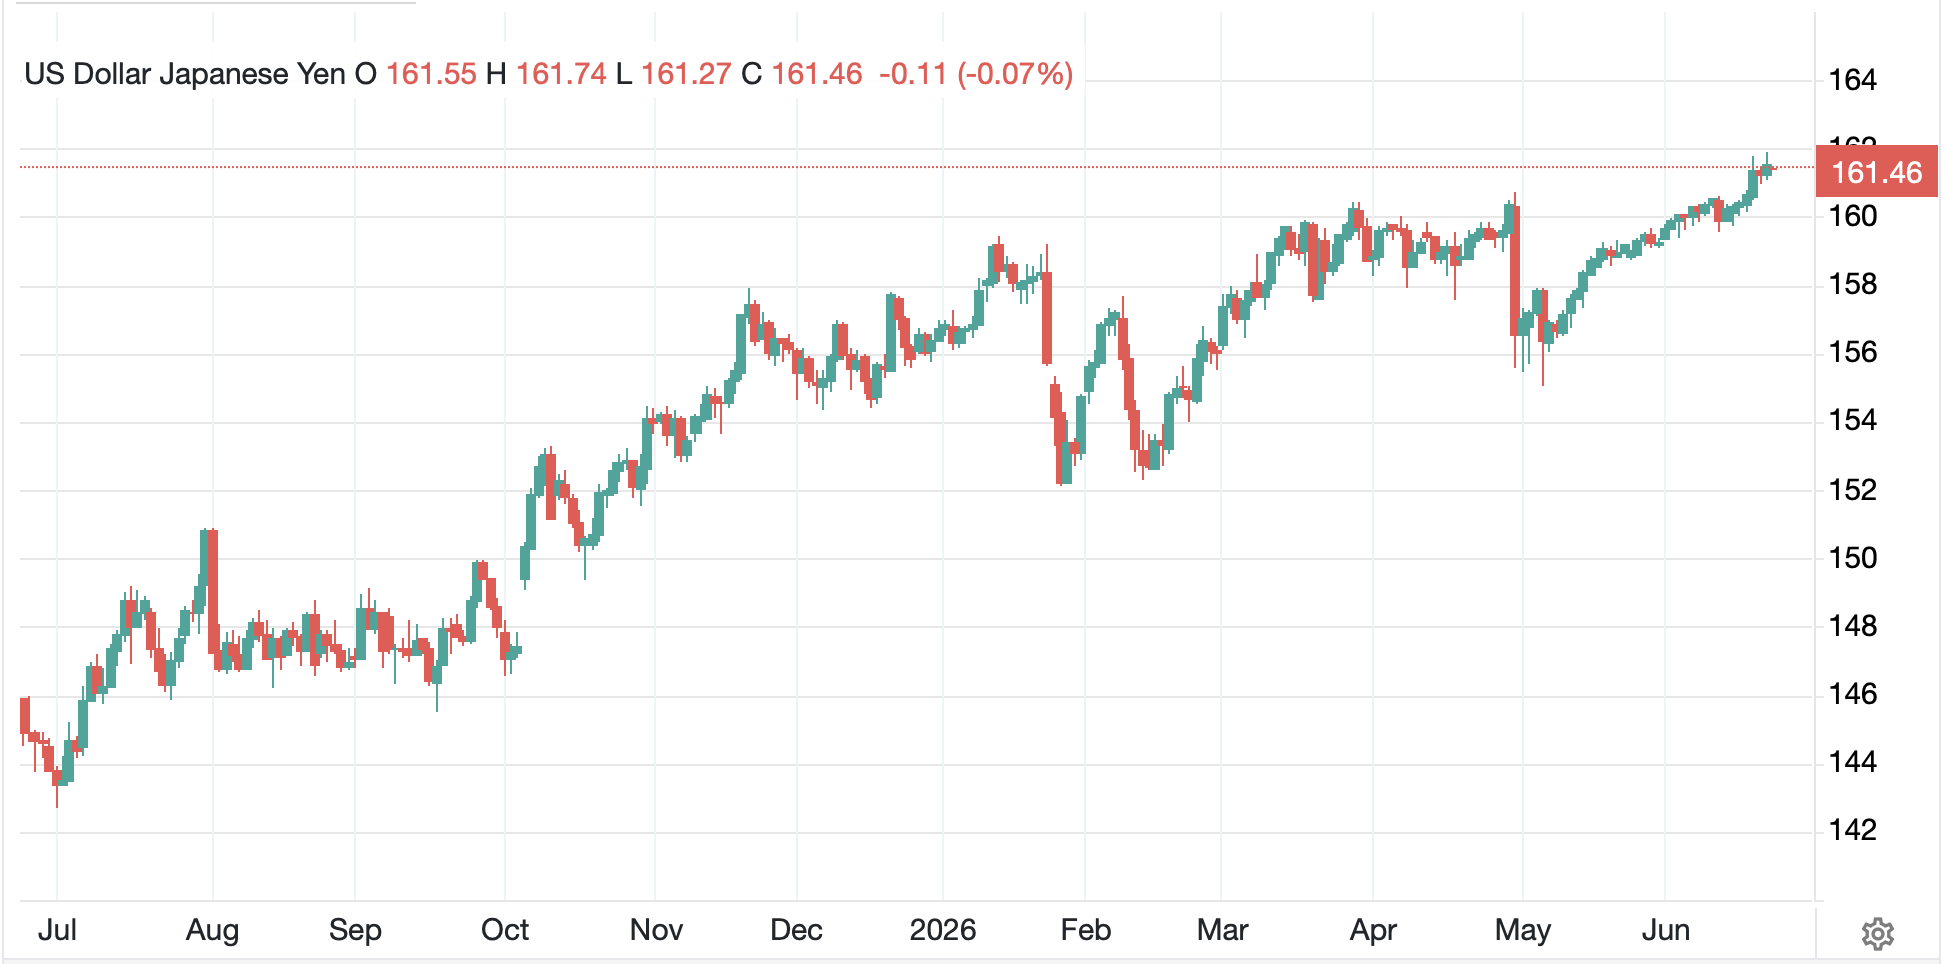
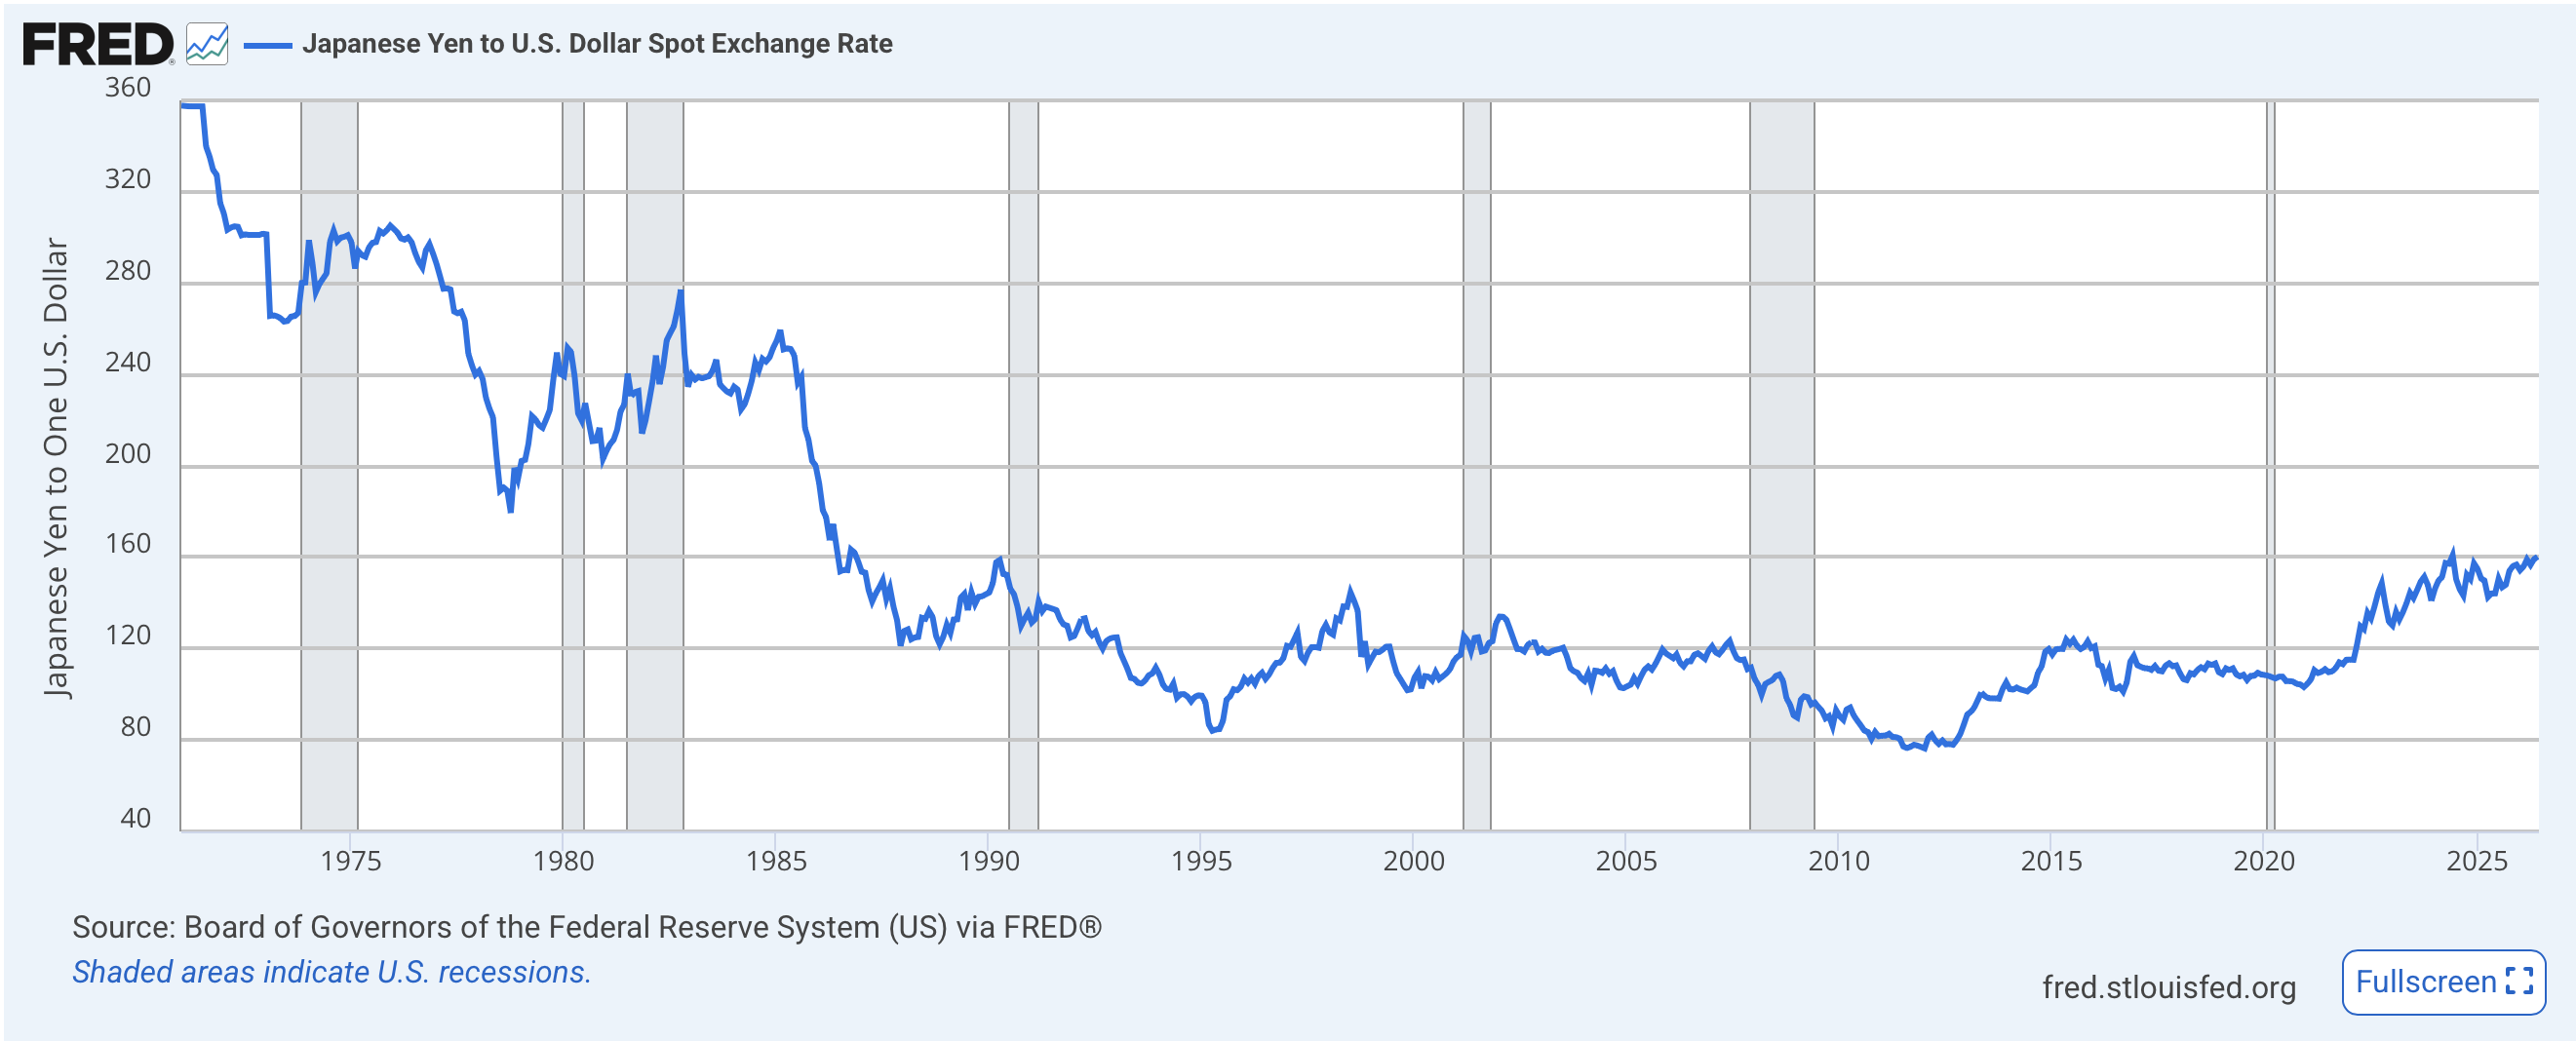
Which takes us to the currency that most needs to see a more dovish FOMC, the yen (-0.6%).  You may remember last week when the yen, after making yet another new low for the move, suddenly reversed course ahead of the July 4thholiday.  While there was no actual intervention, the discussion was that the MOF would no longer discuss their intentions ahead of any intervention and with a holiday weekend seeing reduced liquidity, many anticipated some action.  Well, as you can see from the chart below, that idea has essentially been erased with the yen softening again and pushing back to those lows seen last week.

Source: tradingeconomics.com

Bloomberg ran an article this morning about a former Vice Minister from the MOF explaining his view that the yen was undervalued by 20% or so.  If we look at the yen on a PPP basis, the IMF claims the value should be about 93-95 instead of the current 162+.  The Economist’s Big Mac Index calls for 78.00, and by all accounts, visiting Japan is relatively inexpensive for most foreigners.  In fact, I read that Japan was increasing the visa fees to try to discourage the massive amount of tourism as people around the world see it as a cheap destination.

Ultimately, the problem with the yen, in my view, remains that real interest rates remain deeply negative and the government’s spending plans continue to indicate massive deficits as far as the eye can see.  While reduced energy prices are a boon, the yen was falling sharply long before the Iran conflict began.  Policy changes of substance are required, and they are still uncomfortable for domestic politics.  While the pace of the yen’s decline may slow, I still see it weakening going forward.

So, let’s briefly look at markets overnight before closing.  Regarding the dollar, it is broadly stronger this morning with only BRL (+0.3%) finding any support despite their ignominious defeat to the Norwegians.  But modest slippage across the G10 is the rule, -0.1% to -0.2%, while similar movement has been observed in the rest of the EMG space.  For now, the yen remains the only interesting currency.

In the commodity markets, despite oil’s continuing slide, this morning the metals (Au -0.4%, Ag -0.6%, Cu -0.1%) are also under pressure, but that accords with the dollar’s strength.  As long as the dollar remains bid, it appears the metals markets will have difficulty gaining traction.  But if I am correct regarding the Fed and the market turning toward a more dovish view, I would look for the metals to head higher again.

In the bond market, Treasury yields (-3bps) are slipping as the market reopens after the holiday weekend, arguably following through on the softer payroll data.  European sovereign yields are little changed to lower by -1bp amid a quiet market while JGB yields (+4bps) are the notable outlier, arguably as concerns rise over the weakening yen.

Finally, equity markets remain beholden to the semiconductor and AI trade and with the US having been closed on Friday, there was less information for the rest of the world.  But this morning, NASDAQ futures (+0.9%) look like they are set to resume their march higher, dragging the S&P with them.  But this follows a mixed to lower session in Asia (Tokyo 0.0%, China 0.0%, HK +1.1%, Korea -0.5%, India +0.7%, Taiwan -0.5%) as leadership was lacking.  Not surprisingly, European bourses are also mixed this morning (Spain -0.7%, UK -0.2%), Germany and France both +0.1%) as the question of note is how much defense investment is going to be forthcoming from NATO and European nations and how much of that will be spent in Europe.  Perhaps excitement in the US will help global risk appetite as the day wears on.

On the data front, it is a quiet week for numbers with just the below on the docket:

TodayISM Services54.0
TuesdayTrade Balance-$78.0B
WednesdayFOMC Minutes 
ThursdayInitial Claims220K
 Continuing Claims1810K
 Existing Home Sales4.20M

Source: tradingeconomics.com

As well, we hear from three Fed speakers, Waller, Williams and Logan. Now it will be interesting to see if any of them start to discuss the lower energy prices and how that is likely to moderate their inflation concerns.  If we do hear something like that, I expect the Fed funds table above will reflect that quickly.  We shall see.

It is summer, and there is not much new to discuss.  With the US playing Belgium tonight, all eyes will be there, and my take is we are not looking forward to a terribly exciting session today.

Good luck

Adf
Really Vexed

Said Warsh, when I think of what’s next
For prices, I’m not really vexed
The narrative’s starting,
A new view, imparting
That lower, is what it expects

While futures have yet to adjust
The more this idea gets discussed
The more it’s presumed
The hike story’s doomed
While negative vibes turn to dust

Fed Chair Warsh was in Sintra, Portugal yesterday on a panel with Madame Lagarde, BOE Governor Bailey and BOC Governor Macklem answering questions about monetary policy, forward guidance, and the future of economies as they are impacted by AI.  Now, despite Mr Warsh’s adamant explanation at the last FOMC presser that forward guidance was dead, that didn’t stop the interviewer from asking about the Fed’s likely future moves repeatedly.  This is getting tiresome.  

Nonetheless, here is the comment I believe was most important. “Expectations of future inflation [over the last four weeks] have come down. Inflation risks have come down,” and anyone expecting the Fed would tolerate inflation running above its 2% goal “would be disappointed,” he added.

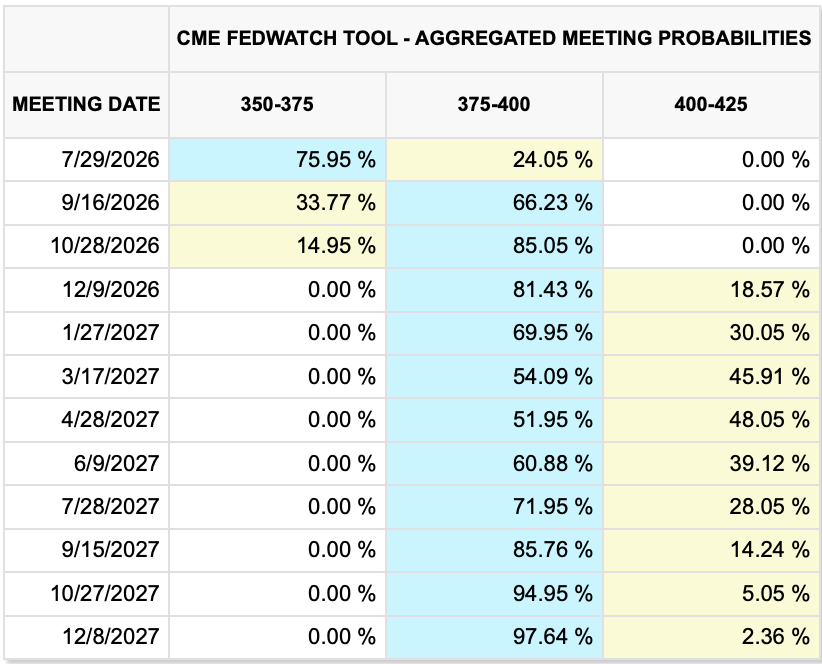
So, the first thing I did was look at the CME’s probability matrix based on its Fed funds futures contract, and there is no evidence to support Warsh’s comments there.  As you can see from the below table, it looks virtually identical to what we have seen over the past week, a hike in October and a 40% chance of a second one in December.

Now, I will cut him some slack because, while I agree with him and expect that we will see lower inflation readings this month, simply on the back of the decline in energy prices, the rate hike narrative has been building for a while and has many adherents.  My take is that the above table will not change very much until we have seen the two key data points this month, today’s NFP and CPI which is due to be released on Bastille Day.

While I’m on the subject, here is the current view of today’s median expectations according to tradingeconomics.com

Nonfarm Payrolls110K
Private Payrolls110K
Manufacturing Payrolls3K
Unemployment Rate4.3%
Average Hourly Earnings0.3% (3.5% Y/Y)
Average Weekly Hours34.3
Participation Rate61.7%
Initial Claims220K
Continuing Claims1810K
Factory Orders-1.8%
-ex Transport0.4%

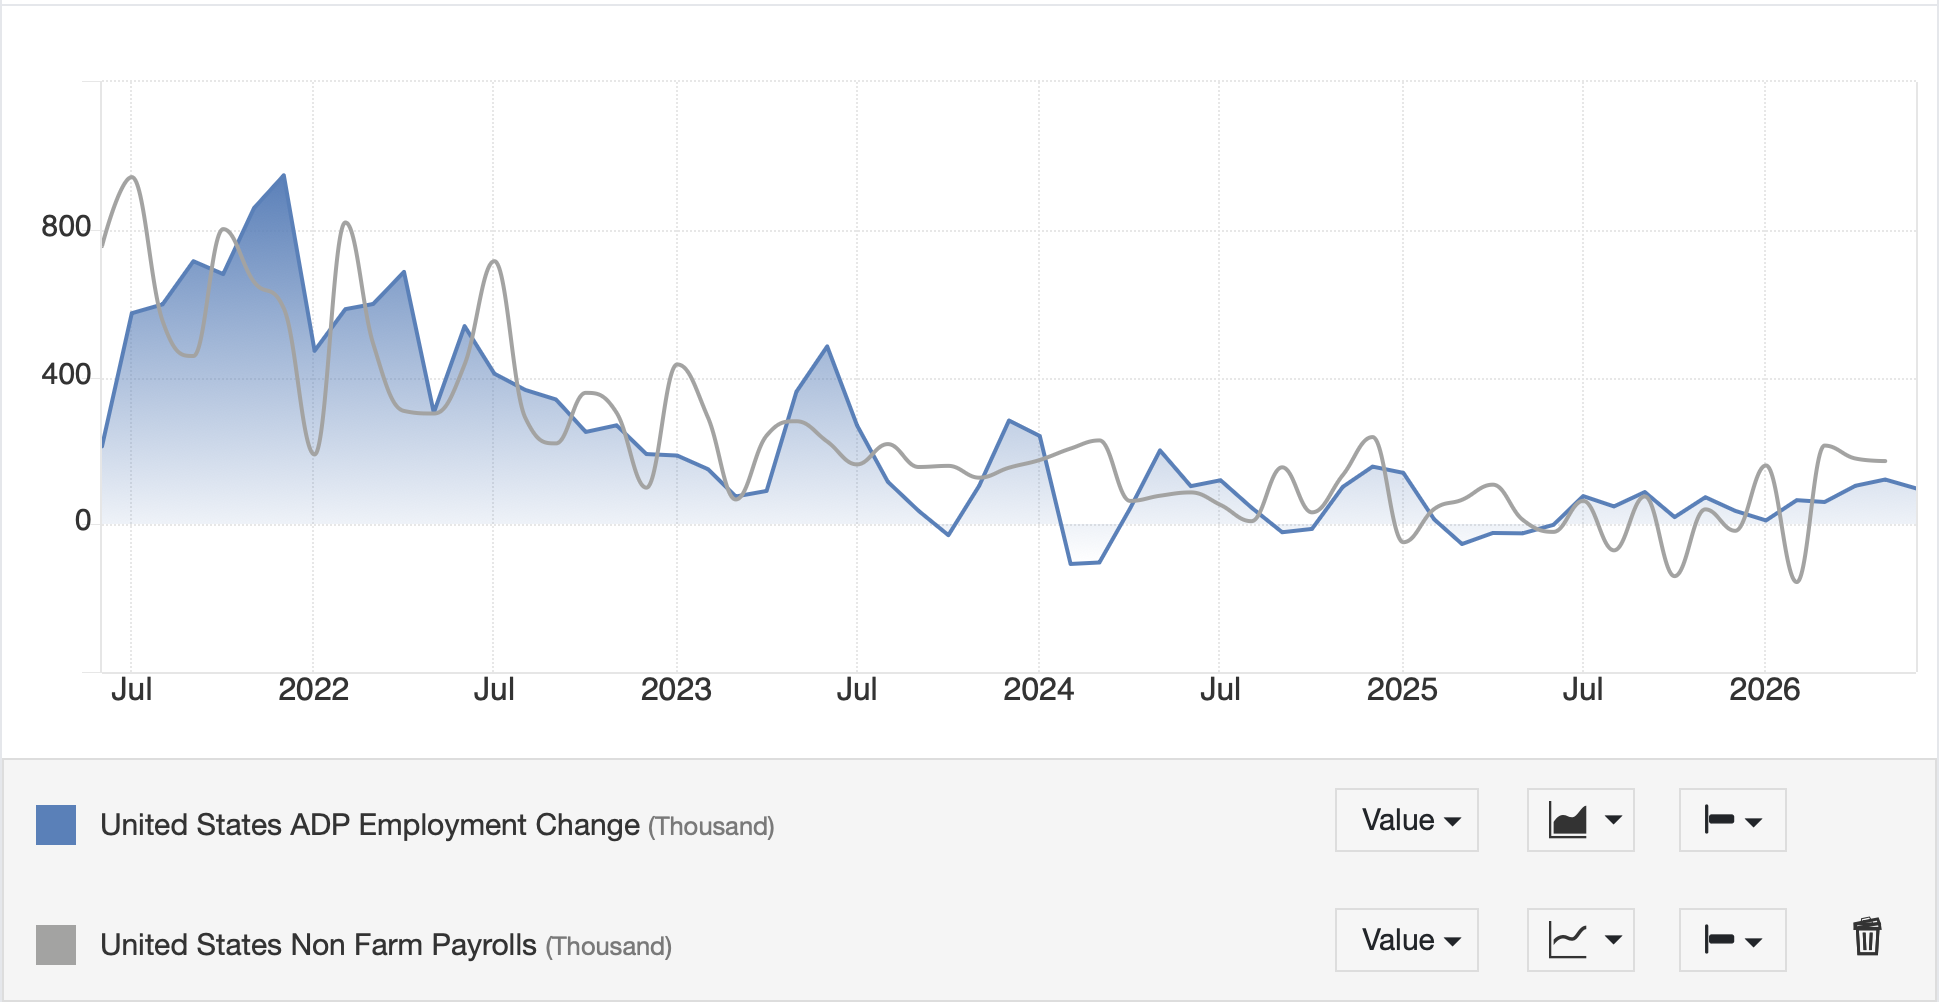
Yesterday saw a slightly softer than expected ADP employment number, 98K vs. the 113K expected and 122K last month, but as you can see from the chart below, comparing ADP to NFP, while the trend remains similar in both, there are an awful lot of wiggles in any given month.

Source: tradingeconomics.com

As things currently stand, the market’s strong Keynesian belief is if NFP is strong, that will be inflationary although it is quite clear that Chairman Warsh does not adhere strictly to that viewpoint (another reason I like him) as he anticipates significant productivity enhancements going forward on the back of AI adoption.  But my point is, if we see a strong print this morning, I would look for the market to price more aggressively for a rate hike.  I guess we’ll find out shortly.

In the meantime, let’s see what happened overnight.  Starting with commodity markets, oil (-1.5%) continues to slide regardless of the group of doomporners who insist that we are about to run out of oil, or that Iran now controls the Strait of Hormuz and will kill the global economy.  In fact, from a technical perspective, we have filled the gap that opened back on March 2nd, the first day markets were open after the conflict began.

Source: tradingeconomics.com

My question for all those who remain certain that we have merely delayed oilmageddon is, how low will prices need to fall before they are willing to admit they misread the reality of the global oil market?  And, with oil sliding, precious metals (Au +0.8%, Ag +1.1%) are finding support.  It seems to me there is a lot of wood left to chop in the PM market, but I maintain my longer-term bullish outlook.

Turning to the bond market, yields rose again yesterday in the US (10-year +6bps) and have edged higher again this morning by 1bp.  My sense is this is based on the idea that Warsh’s final comment from above about tolerating above-target inflation has the hawks all bulled up.  Perhaps, Sintra helped the hawkish case elsewhere as well as European sovereign yields are all higher this morning by between 4bps and 5bps and JGB yields overnight jumped 8bps.

But there is a kink in the narrative now as despite this perceived hawkishness in the bond market, the FX market clearly heard a different tune.  This is clearest in USDJPY, my favorite recent discussion, as you can see in the chart below.  The yen jumped 0.7% ostensibly on the idea that Warsh’s comments about reduced inflation expectations implied a less hawkish Fed, despite the bond market reading the comment about unwillingness to tolerate inflation as a more hawkish Fed.

Source: tradingeconomics.com

But it’s not just the yen.  The dollar is lower vs. virtually all its counterparts in both G10 and EMG spaces.  So, the question you need to ask yourself is, who do you believe?  Bond traders or FX traders?  Historically, observers call bond investors/traders the ‘smart’ money, but they have made plenty of mistakes in the past.  And the thing about FX traders is they seem to be far nimbler.  Of course, you know I am an FX guy, and as it happens, I think this is the market that has it right.

Finally, equity markets had a mixed performance in Asia (Japan -2.5%, China -3.0%, Korea -7.9%) as tech stocks have been feeling some pain, but we did see gains in HK (+0.8%), India (+0.8%) and Singapore (+1.1%) as a counterbalance.  That Korean number was impressive, but mostly what we are seeing there is serious volatility as the KOSPI is even more concentrated than the NASDAQ with just two companies, Samsung and SK Hynix, representing about 40% of the index.  If they have a bad day, the index does as well.

In Europe, though, things are brighter this morning with gains across the board (Germany +0.9%, Spain +0.9%, France +0.8%, UK +0.5%) although there is no obvious catalyst for the move.  There was no data of note (Eurozone Unemployment fell to 6.2% but that seems unlikely to be the driver) so perhaps the very fact there are no tech companies in Europe and tech is what is currently under pressure makes Europe seem a bargain.  As to US futures, ahead of all the data this morning, they are little changed.

And that’s really it for today.  As tomorrow is a holiday, there will be no poetry, so I wish you all a wonderful holiday weekend.  3 Cheers for the USMNT after their Round of 32 victory last night (alas it was on way too late for me to watch, but we will all be cheering on Monday night.

Good luck and good weekend

Adf

Once Again Crumbled

The Techquity rally has stumbled
Though oil has once again crumbled
But pundits don’t care
As they’ll still declare
They’re right. They can never be humbled

Some days are simply less interesting than others, and based on the number of new stories, it seems today is falling into that category.  That’s not to say that some markets haven’t moved, there has been some significant movement, it’s just that the movement is based on the same rehashed story lines we’ve heard for the past several weeks.

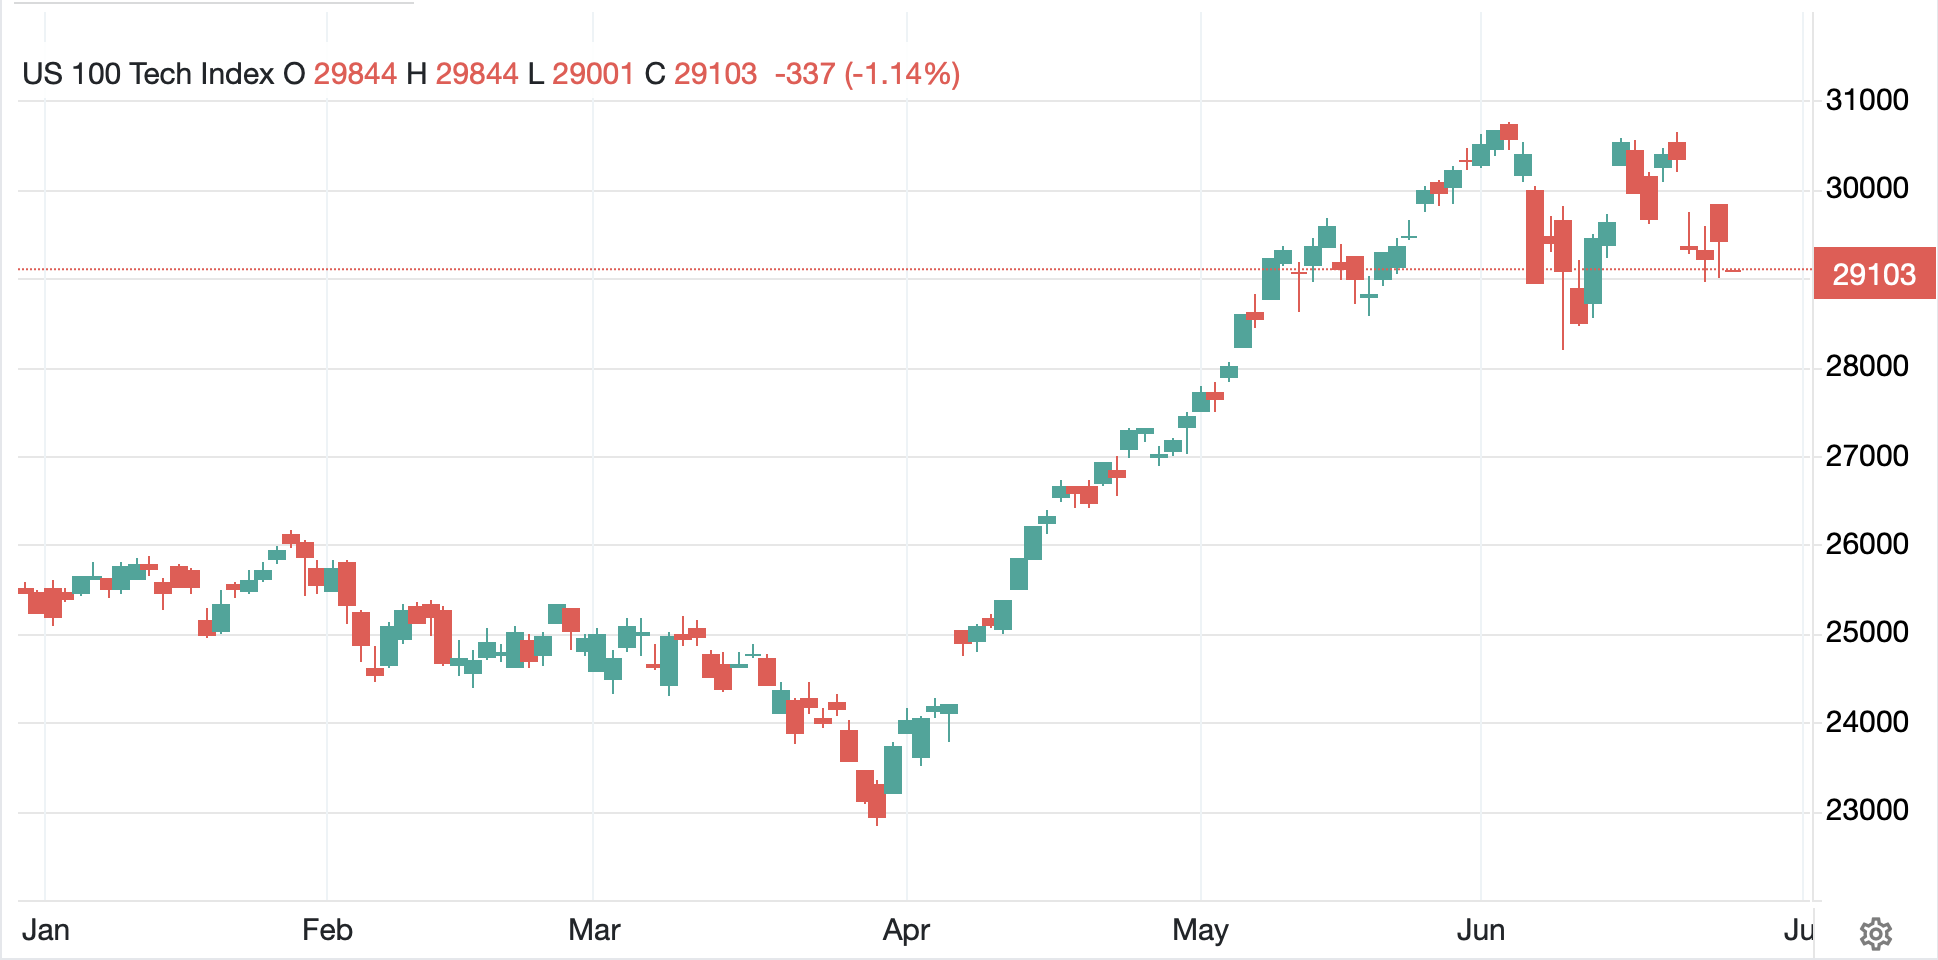
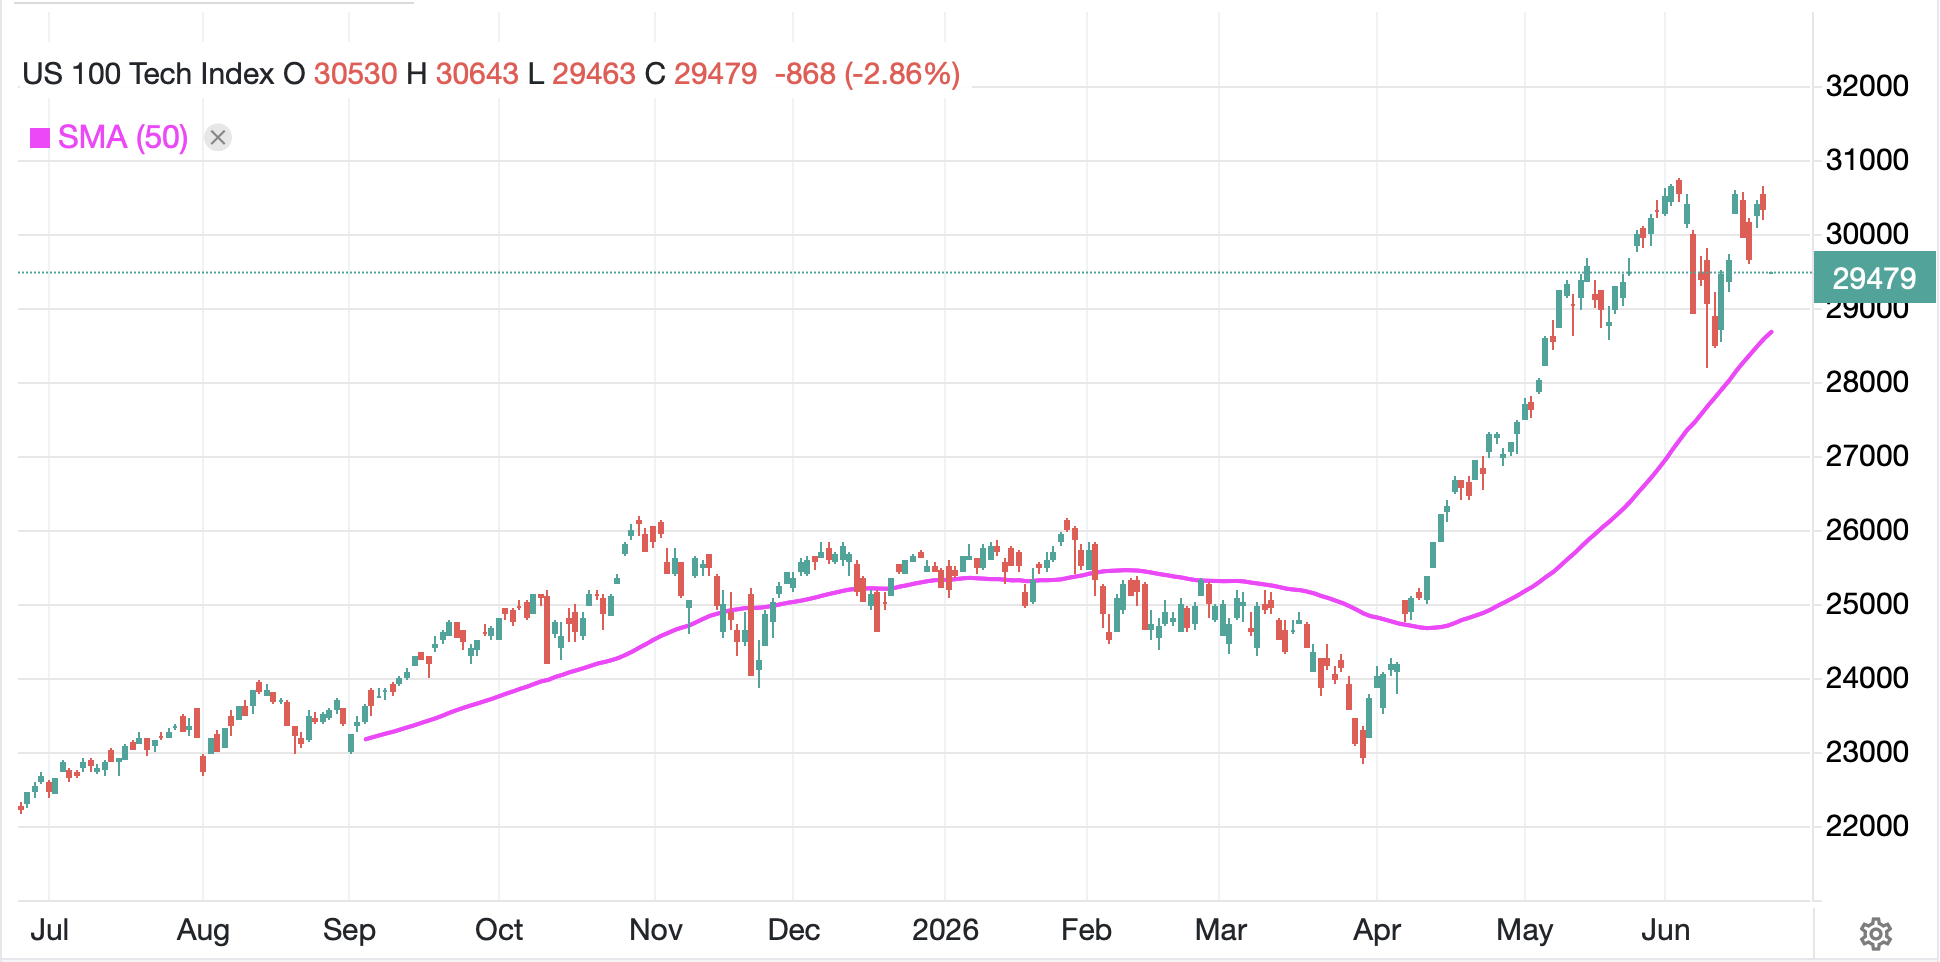
For instance, the below chart of the NASDAQ, with daily candles, shows just how choppy the tech sector has been this month.

Source: tradingeconomics.com

For the market technicians, if you are inherently bearish, this will read as a double top and the next leg is lower, targeting something with a 26000 handle.  However, if you are bullish, you will make the case that this is the end of the “c” wave and we are ready to break to new highs above 31000. 

That’s the thing about market technicals, they remain in the eye of the beholder. If you ask about new news, arguably the Micron Technology earnings were the biggest story of the week, but despite a tremendous outcome, tech stocks could not hold any early gains.  The flipside is that OpenAI has postponed their IPO until next year, a clear sign that they are concerned with sufficient investor capacity.  Again, spin it as you see fit, since there is no right or wrong here, but there are conflicting sentiments.

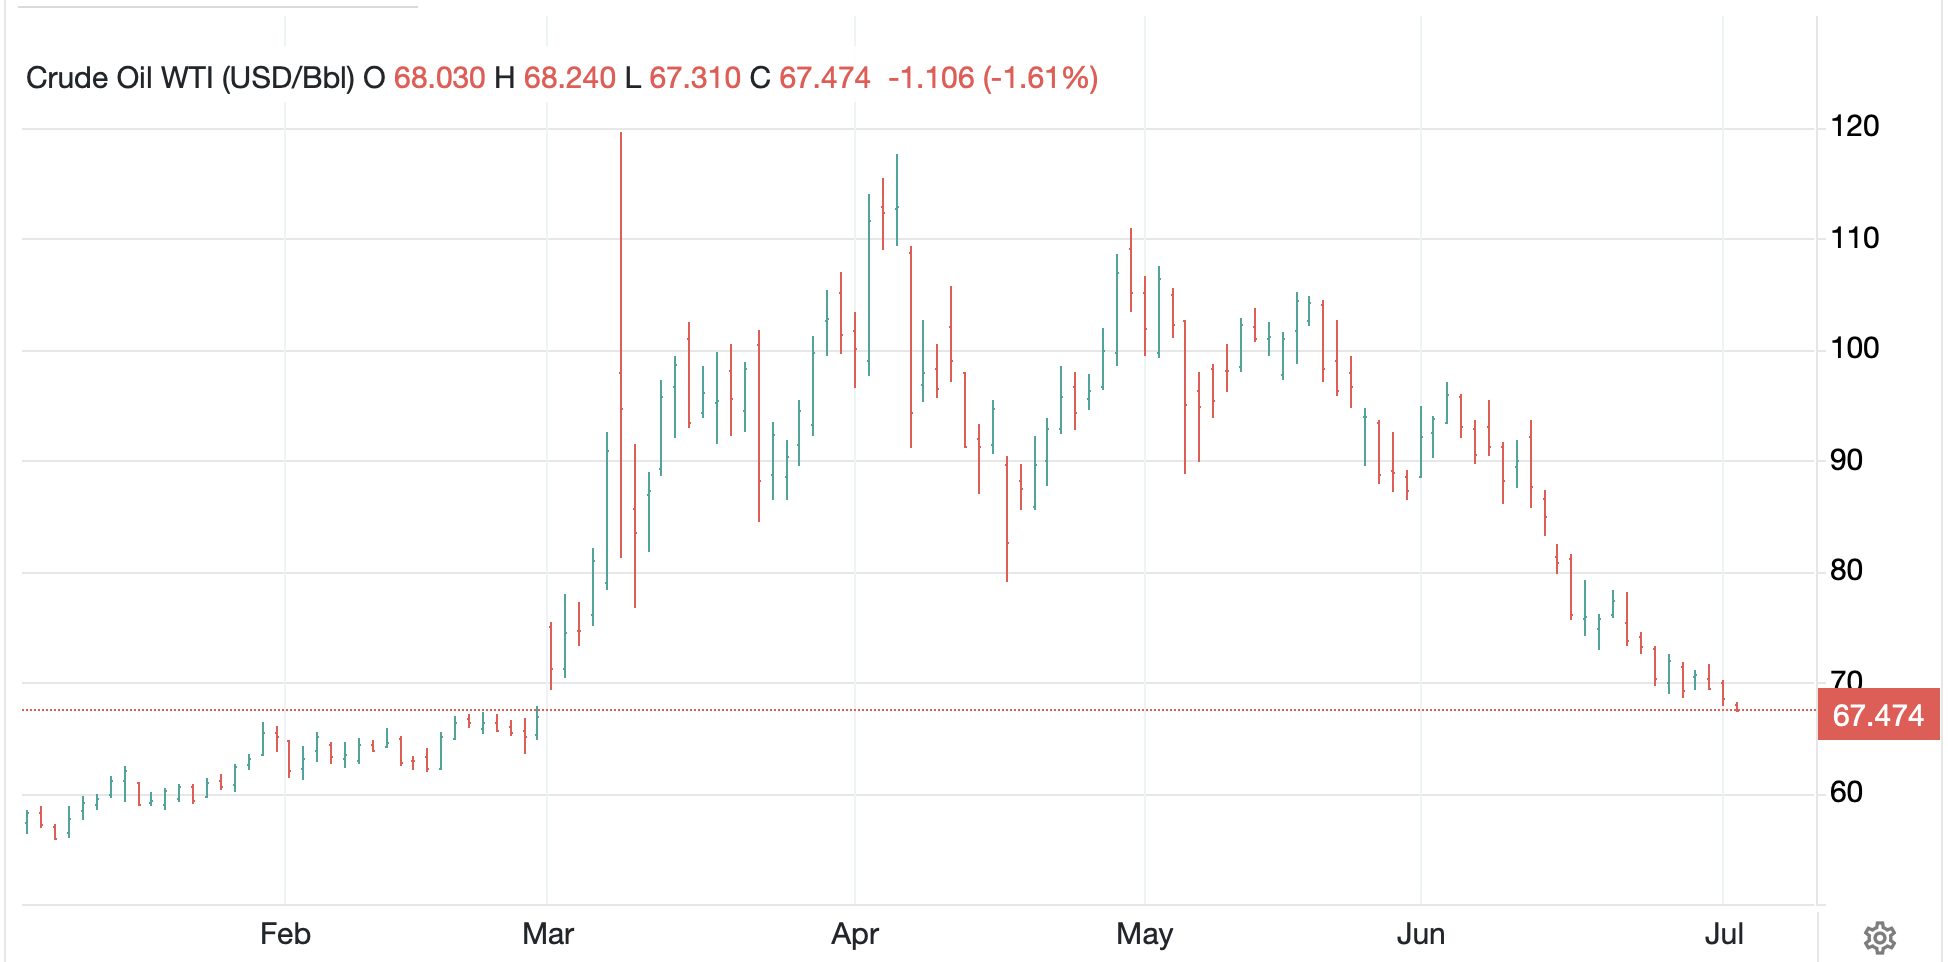
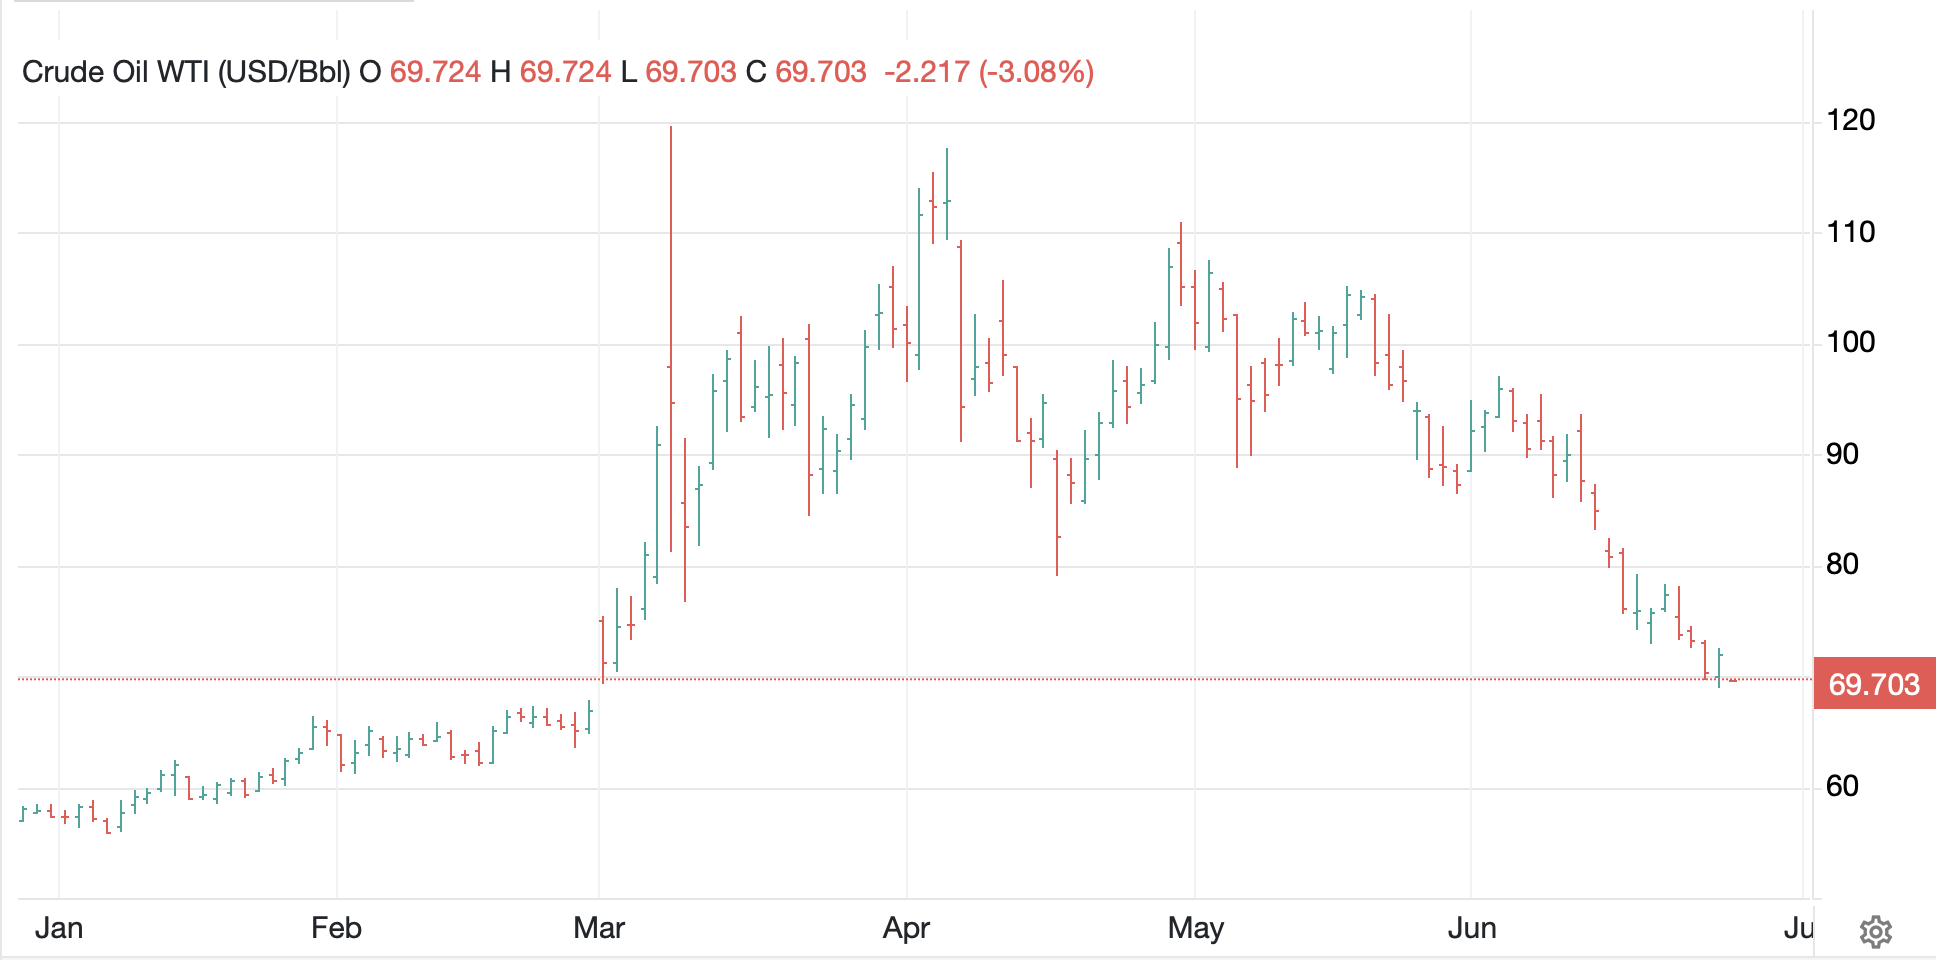
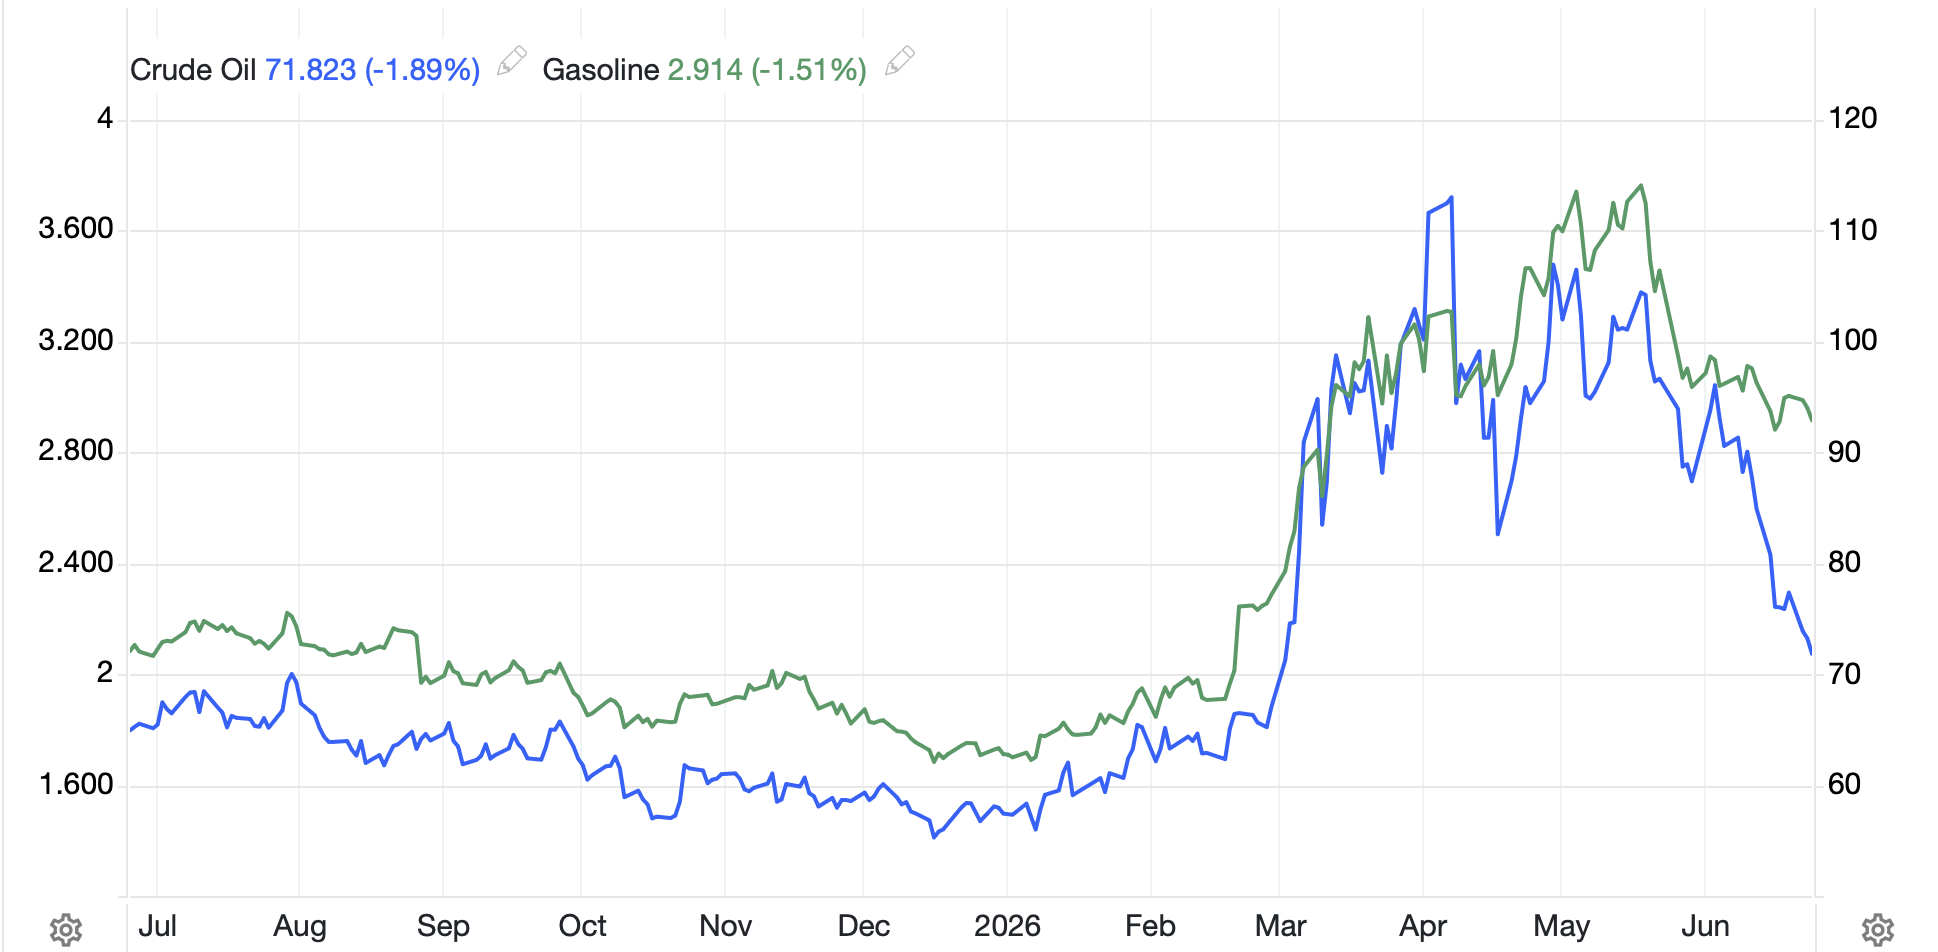
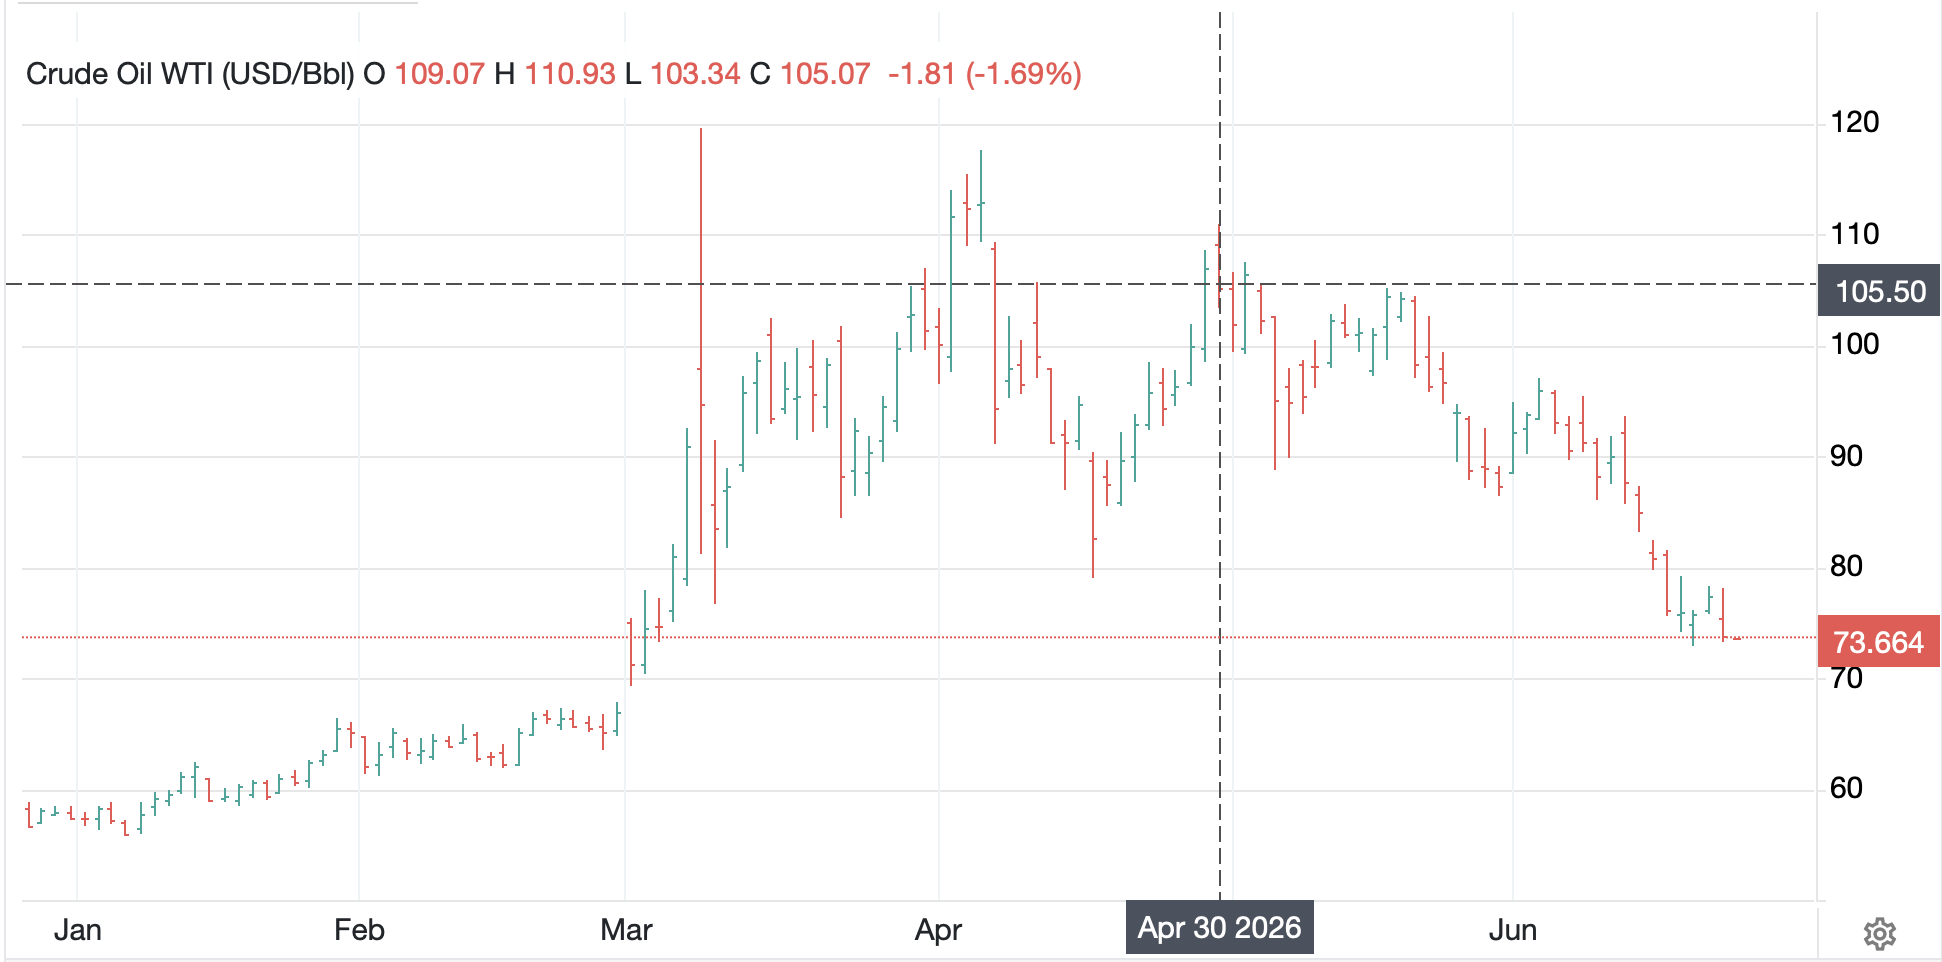
My point is that while there have been headlines, there hasn’t been any news.  Or consider oil (-3.1% this morning), which as you can see from the chart below has fallen back to prewar levels.  

Source: tradingeconomics.com

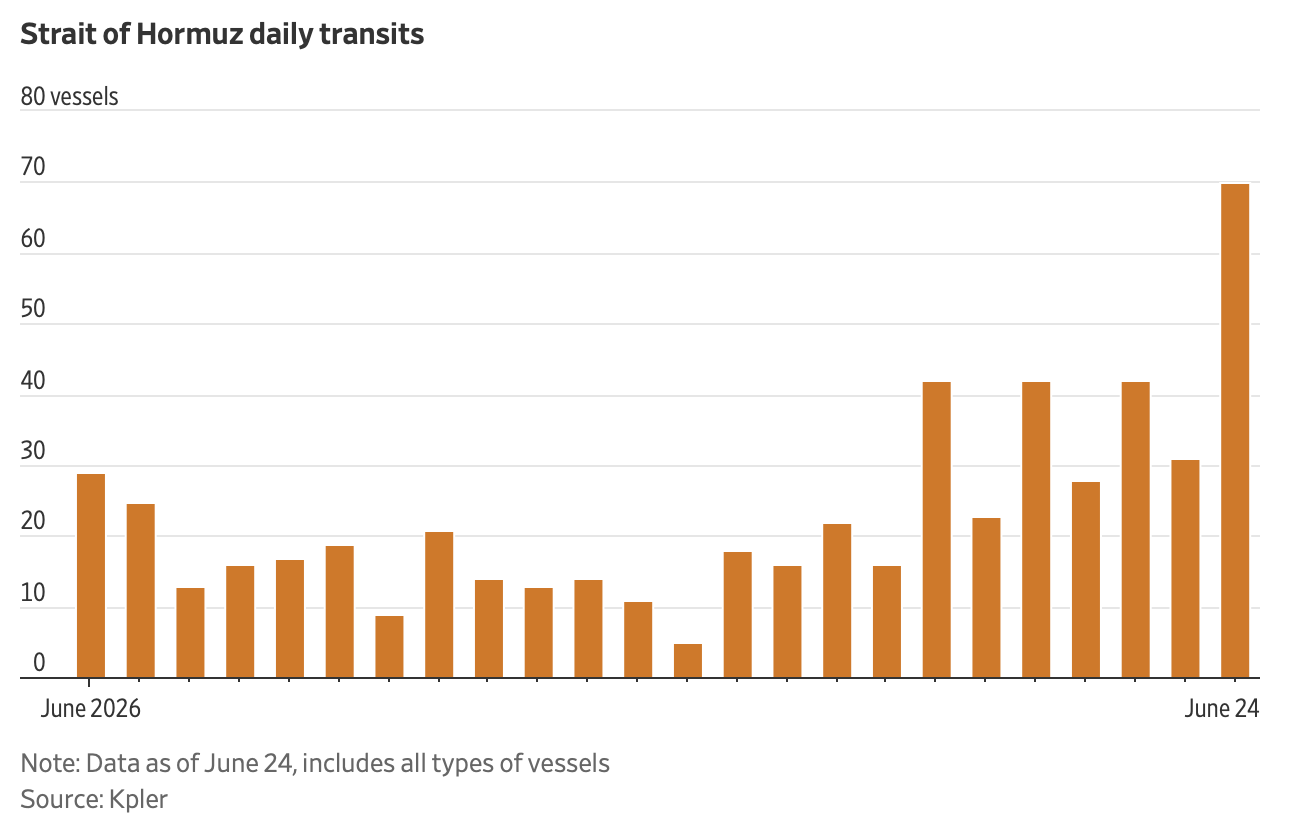
Yes, there was an incident with some freighter being hit by an unidentified object in the SOH, and that jangled a few nerves yesterday, but apparently fully laden VLCCs carrying 2mm barrels of oil, are fleeing the Gulf in ever larger numbers.  I read that 78 ships transited yesterday and as you can see from the chart below from the WSJ this morning, the trend is higher.  

All of the stories about tank bottoms and a sudden spike higher in the price of oil continue to be nothing more than fear porn.  As Alyosha from Market Vibes notes, the likely reason for less inventory is the oil companies are expecting a huge influx of oil from the Gulf and they need some place to put it.  Again, these are warmed over stories and not new news.

By all accounts, we are continuing along the recent path where oil prices continue to normalize while other markets search for the next big thing.  For stocks, the AI debate continues to rage on as to its impact on the future, while resource companies continue to be seen as a place to hang out given the needs of the economy as it grows, and that is a global comment.  For bonds, is inflation fading or persistent and setting to move higher?  The recent view is fading, but obviously that is subject to change.  And the dollar?  It’s had a nice rally, but is it about to break to much higher levels or reverse course?  Over time I see it higher, but for now, not so much.

Ok, let’s review the overnight session.  Tech stocks in Asia had a rough go of it, reversing yesterday’s gains as Japan (-4.15%), China (-3.0%), HK (-1.8%), Taiwan (-3.6%) and Korea (-5.8%) all reversed yesterday’s rallies.  The below chart from finance.Yahoo.com of the KOSPI gives an excellent sense for the magnitude of the moves this week.

Elsewhere in the region, there was far more red than green, but those were the standouts.  In Europe, everything is lower this morning as well, with Germany (-1.2%) the laggard, although there is no news that would lead you to believe things are worse there than in the UK (-0.8%), France (-0.7%) or Spain (-0.4%).  It’s a soft day.  US futures are on this same path with NASDAQ (-1.2%) leading the way lower.

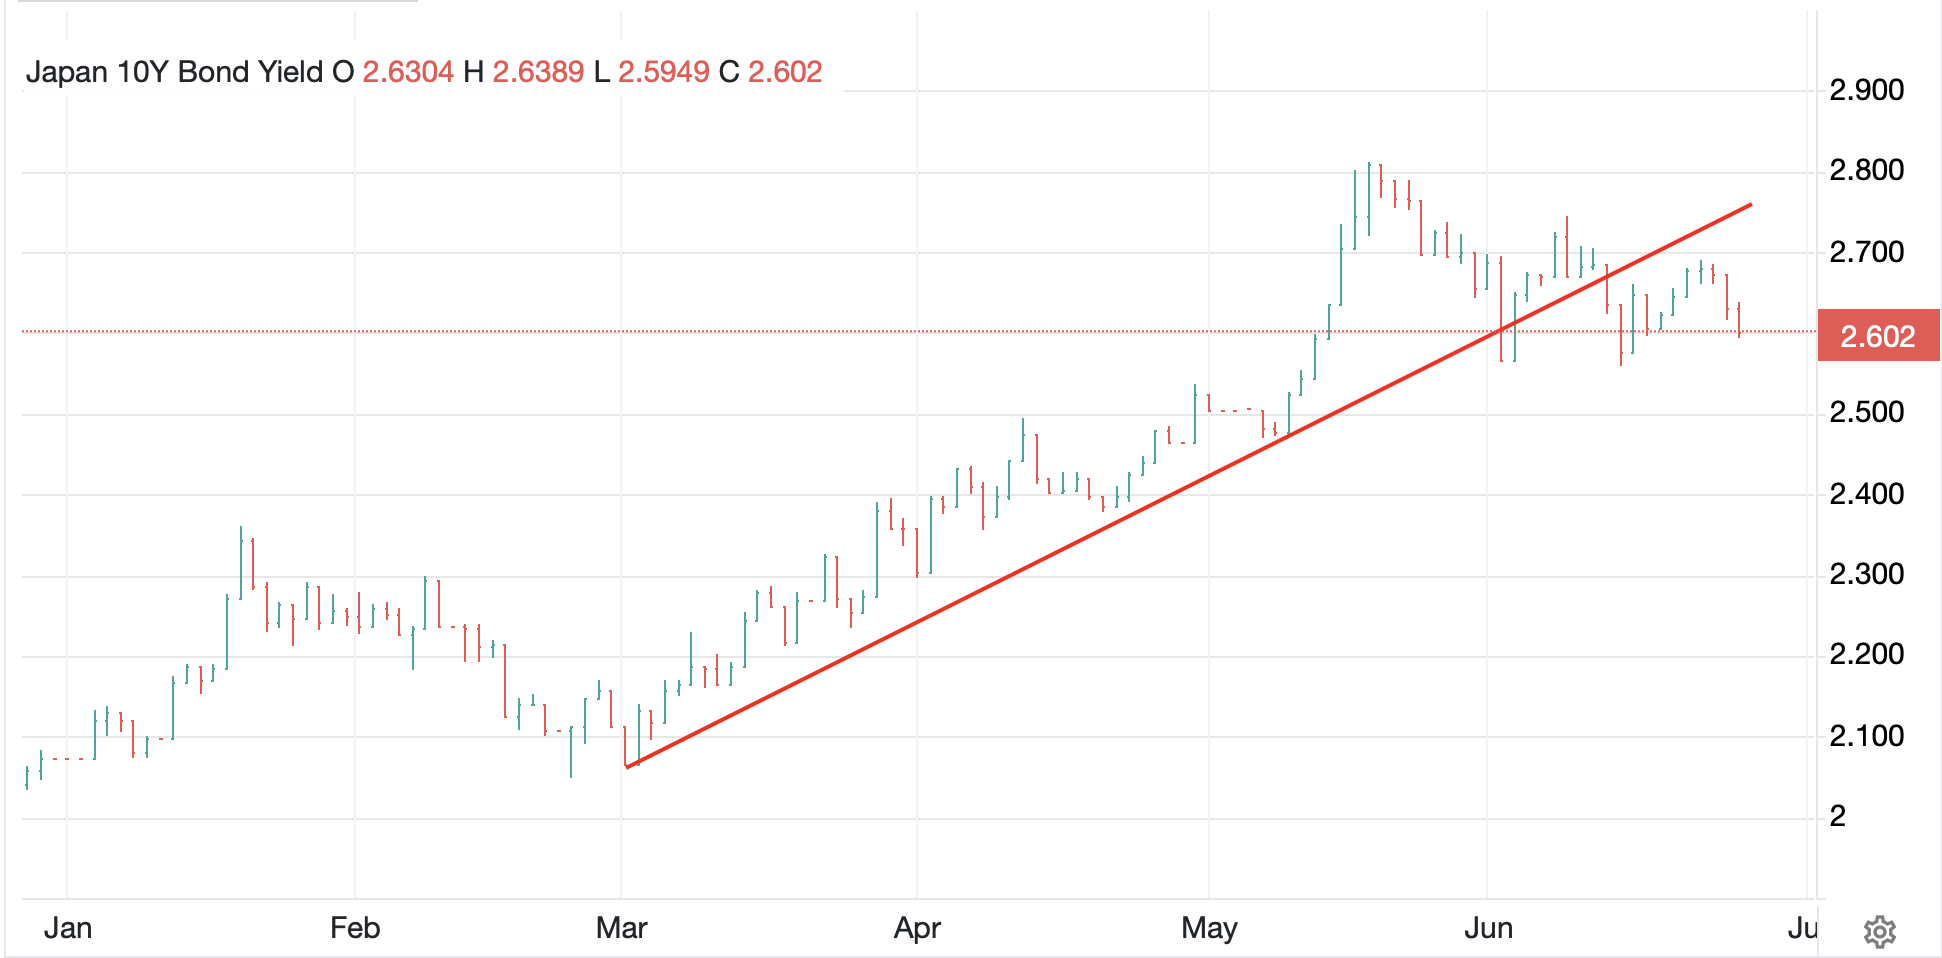
In the bond market, yields are little changed to slightly softer this morning with Treasuries (-2bps) actually leading while European sovereign yields have edged lower by -1bp across the board.  Interestingly, JGB yields (-3bps) are slipping and some pundits are making the case we have seen the highs in 10-year JGBs, at least for quite a while.  Certainly, looking at the chart below, the case that the uptrend has been broken is viable. Last night, Tokyo CPI data was released there at 1.6%, as expected and well below the 2.0% target.  Is it possible that inflation pressure there is abating as well?

Source: tradingeconomics.com

In the metals markets, it appears that the rout is on hold, at least for now, as gold (+0.5%), silver (+0.7%) and copper (+0.6%) all seem to have found recent support with gold holding the $4000/oz level and copper the $6.00/lb level.  We saw a massive bubble in these that has deflated, but real demand remains in place.  China continues to hoover up gold, and the electrification narrative has not disappeared, nor the data center one, both of which require massive amounts of copper.

Finally, the dollar is softer this morning, slipping somewhere between -0.1% and -0.3% vs. almost all its counterparts.  NOK (-0.4%) is an outlier as oil slides but otherwise, it is hard to get excited here at all.  JPY did not make another new low last night, so it has that going for it.

On the data front, this morning brings the Goods Trade Balance (exp -$85.0B) and then Michigan Sentiment (50.0).  Yesterday’s PCE data is a perfect example of the narrative, and how there is a real attempt to write a story from nothing.  While GDP rose more than expected, as did Personal Income and Spending, the PCE data was right on expectations, or even a tick low in the headline monthly number.  So, this was clearly priced into markets.  Yet virtually every headline I saw was how these were the highest prints since 2023, which as you can see in the chart below, is absolutely true, but hardly newsworthy.  But it makes for good headlines if you are trying to tell a story of rampant inflation.

Source: tradingeconomics.com

At any rate, that’s all I’ve got today.  My take is oil is still heading lower although Techquity prices just might follow for now.  However, I’m not in the collapse camp there.  And the dollar?  Softer for a bit, but I have a feeling all we’ve done is widen the range, not really broken out.

Good luck and good weekend

Adf

‘Pocalypse Dreams

Though many have preached the buck’s dead
The greenback keeps moving ahead
And right now, it seems
Their ‘pocalypse dreams
Are still all confined to their head(s)

But narrative writers ignore
Whatever they said from before
Right now, it’s the buck
That’s causing bad luck
As rate hike bets all start to soar

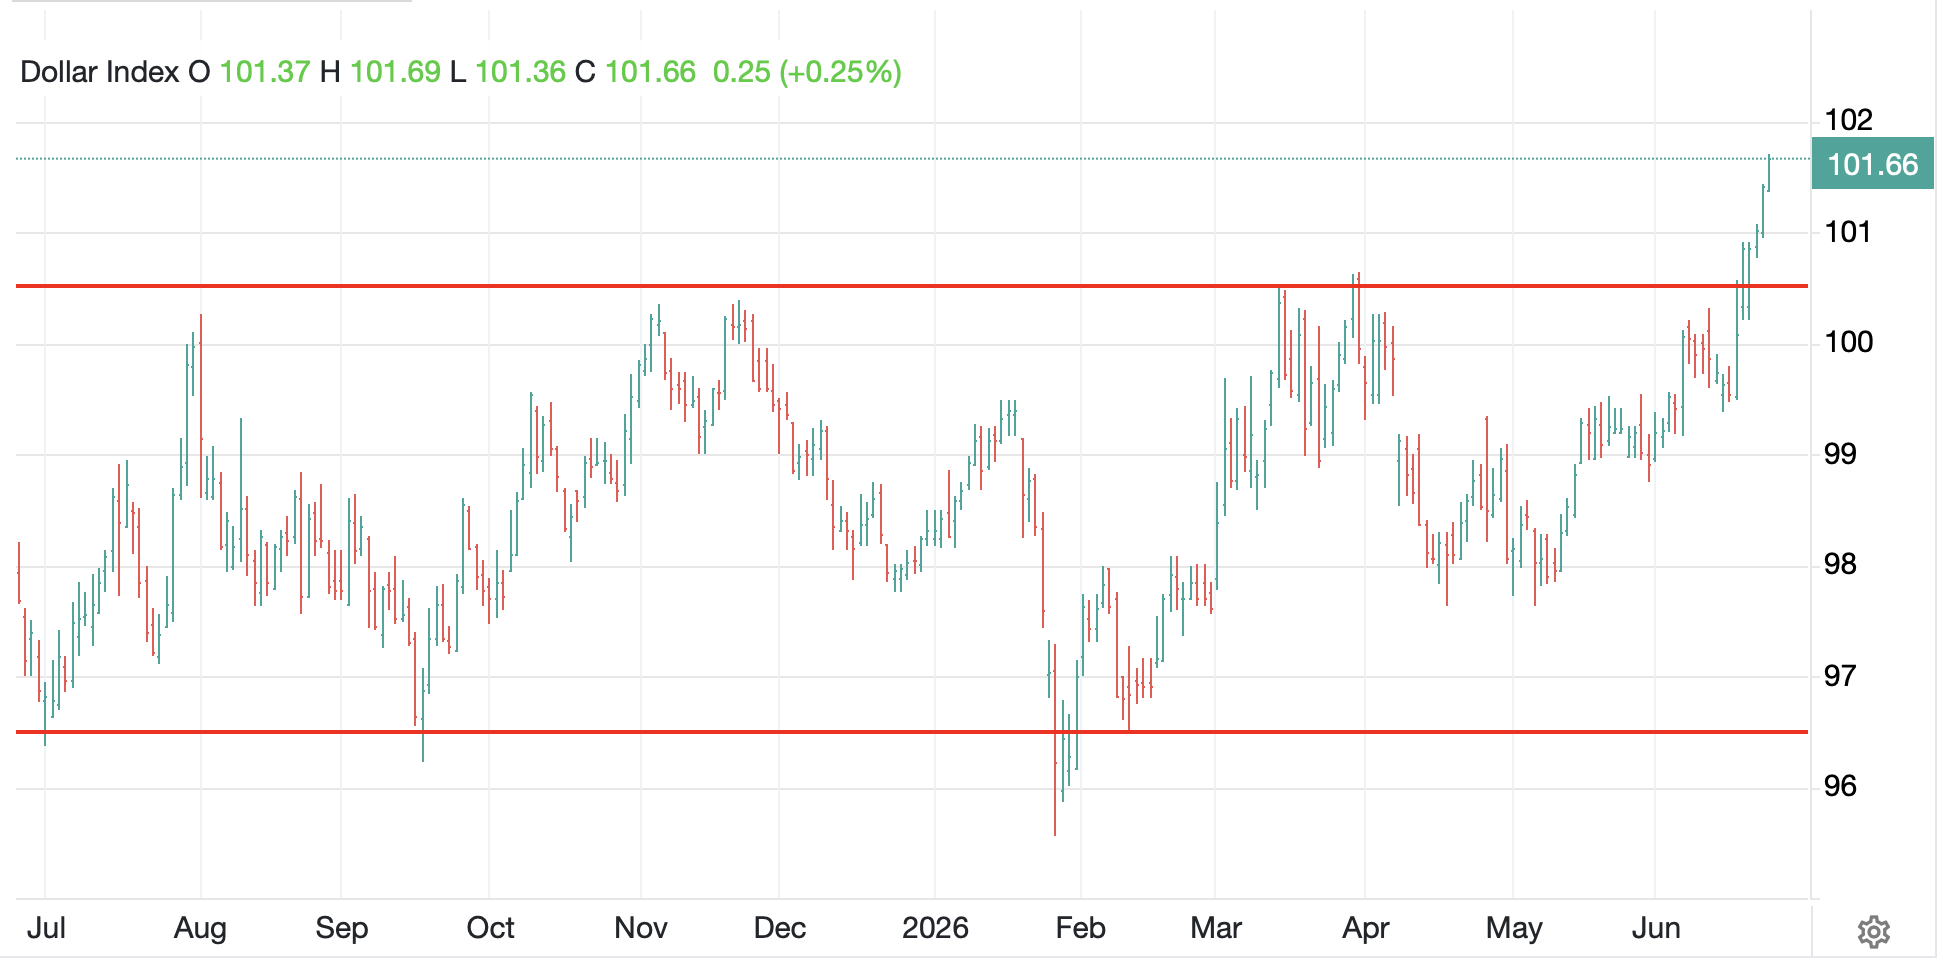
In a fairly rare set of circumstances, the dollar has drawn the spotlight in markets for the past few sessions.  While it always matters to some extent, it is rarely seen as the cause of many other market movements, just a coincident one.  But right now, I read more about how the strong dollar is driving equity weakness and commodity weakness as more and more bets get placed on the Fed hiking rates aggressively to address inflation by the end of the year.

Using the DXY as proxy, the first chart is the one everybody wants you to focus on, showing the last year and how we have had a clear break above the trading range top of 100.50 and now people are creating targets for just how high it can go.

Source: tradingeconomics.com

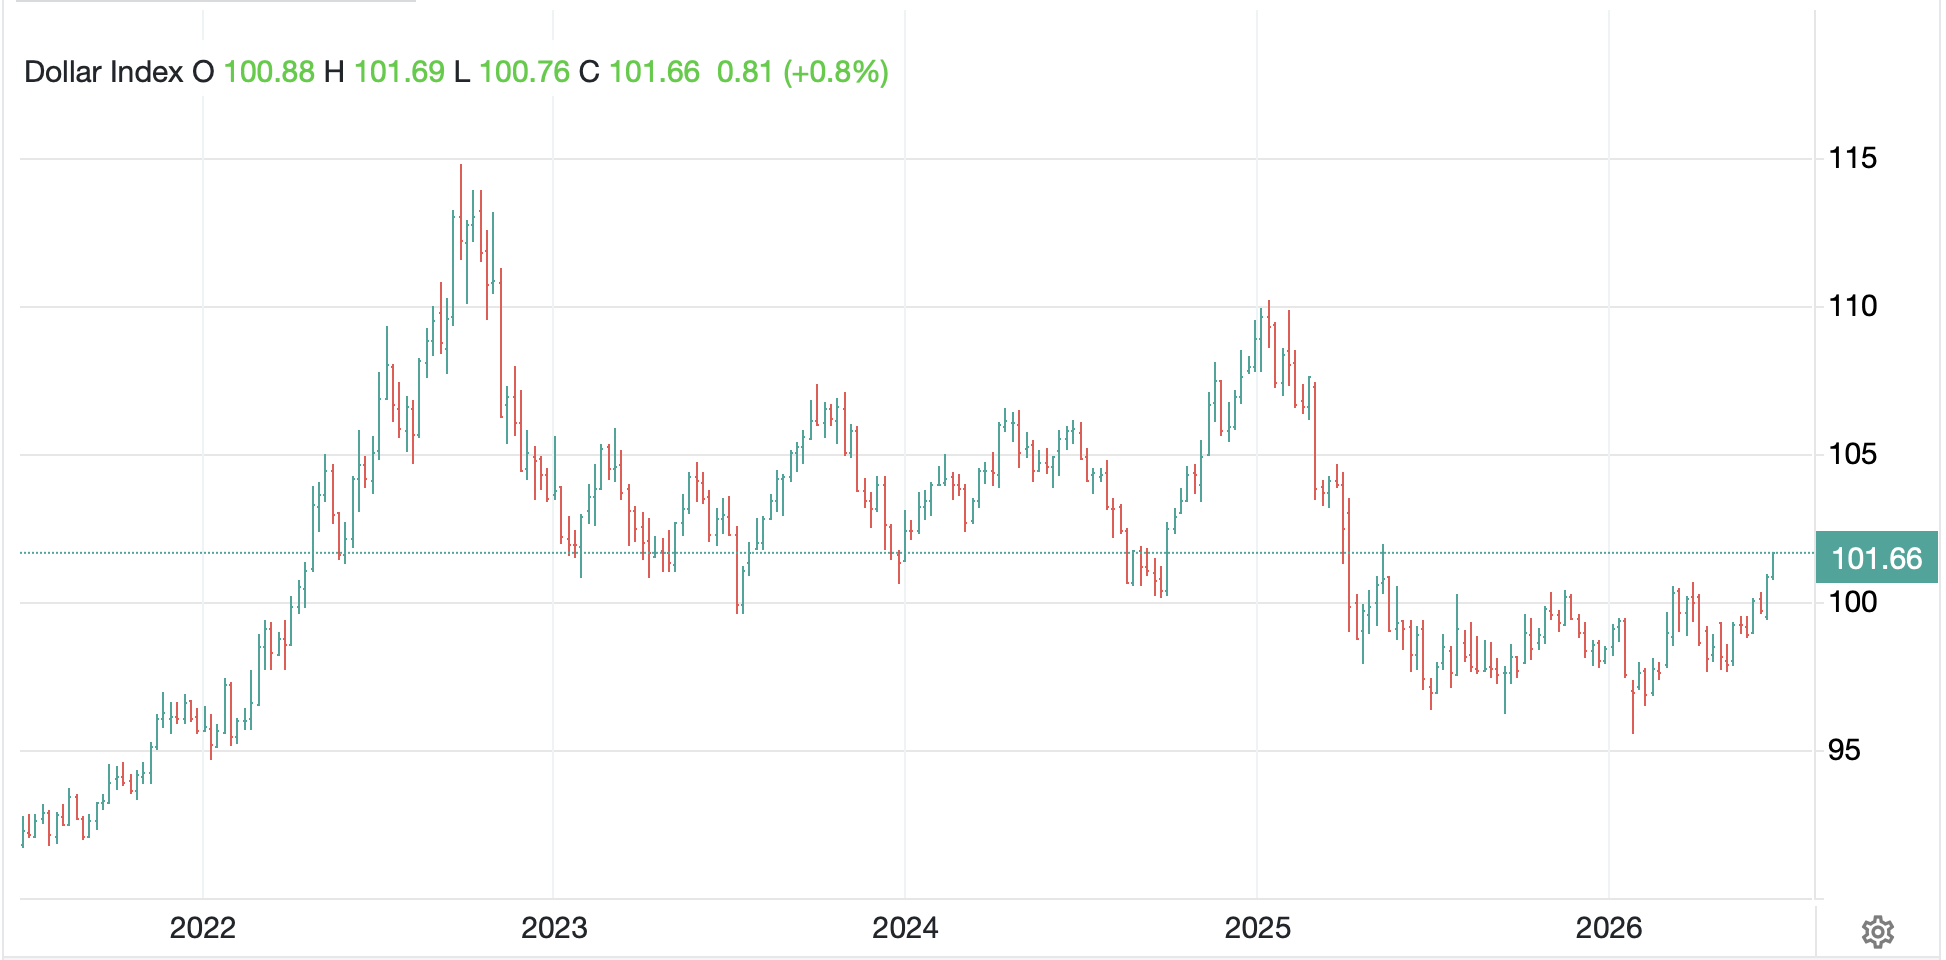
And it certainly can go higher, as a quick step back to get some more perspective shows where the dollar has been during the past 5 years. It seems to me I could create a narrative that the dollar has been massively undervalued over the past 18 months, and this move is simply returning it closer to its longer-term fair value.  In fact, just eyeballing, it seems quite reasonable to think the 5yr average of the DXY is somewhere around 103-104 (subsequently confirmed with Grok), still a few percent higher than current levels.  Reversion to the mean anyone?

Source: tradingeconomics.com

All of this, though, begs the question, are rate hikes really on the near-term horizon?  I remain firmly in the camp that is not the case.  Fortunately, someone on my side is super smart, Bob Elliott, former hedge fund manager at Bridgewater.

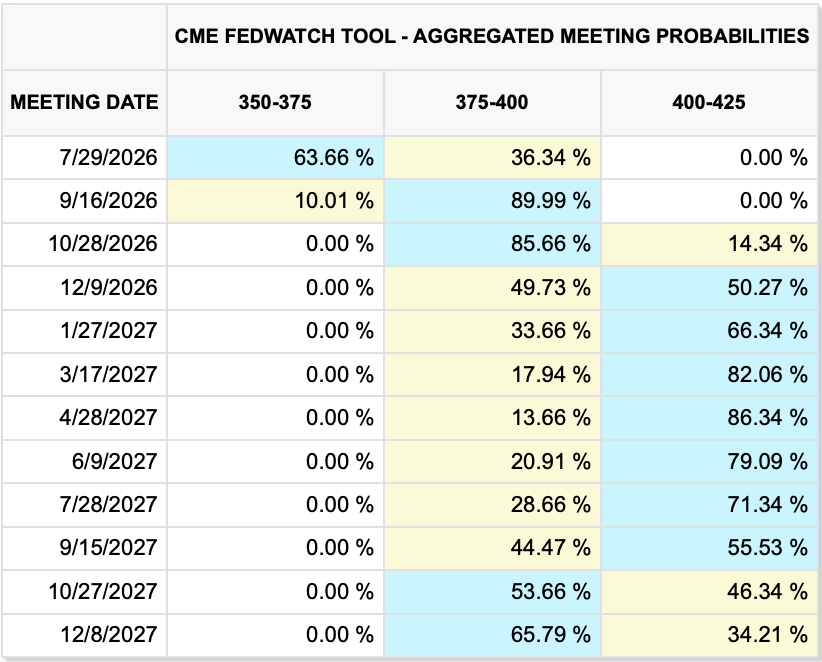
On the rate hike front, the below CME probability table has barely changed from yesterday as the narrative is strong that rate hikes are coming.  

I cannot really understand why this is suddenly the belief set given the fact that the key driver of recent higher inflation data has been the price of oil, and that price continues to fall, down a further -2.0% this morning.  I understand that gasoline prices have not fallen quite as dramatically, but nothing about the chemistry has changed and I remain highly confident that those prices will be falling as well, catching down to oil.

Source: tradingeconomics.com

So, I remain confused as to why everybody seems to believe the Fed, which despite a new Chair remains the same institution that observed inflation run higher for years during Covid and calling it transitory, has become the reincarnation of the Bundesbank.  In fact, the only rationale I see is that other than Waller, Warsh and Bowman, who were all appointed by Trump, everybody else in that room has TDS and is terrified that things will work out such that by the time the election rolls around, the economy is ticking over nicely with inflation a historical issue.  And frankly, I think most of them do share that affliction.

But other than Powell, and Cook to some extent, none of them have really felt the force of the critiques that come with upsetting President Trump, and frankly he didn’t care about Cook per se, she was just a convenient target to get ousted so he could put his man in there.  And in fairness, Cook is a massive dove, and should agree with Trump on this policy, but I’m sure she doesn’t because…Trump.  I am confident none of them signed up for being in that spotlight.

Apparently, BOA is calling for 3 rate hikes this year in the final four meetings.  I think that’s nuts, but futures are pricing a 2/3 chance of a hike at the end of July, which I also think is nuts.

The recent hiccup in stocks, and the steadier downturn in commodities has been blamed on dollar strength which is being driven by expectations of rate hikes coming soon.  While I like the dollar in the long-term, that is because I believe investment flows into the US will drive it, not financial arbitrage flows.  As things evolve, I expect the market to understand the Fed will not be hiking rates and narratives will need to find a new bogeyman.

Ok, let’s tour markets quickly.  Yesterday’s equity market selloff in the US, following the tech selloff in Asia closed well off the lows and futures this morning are pointing slightly higher.  Asia was mixed overnight with Korea (+3.3%) rebounding sharply although there was weakness in Japan (-0.9%), Taiwan (-2.25%), Indonesia (-3.6%) and the Philippines (-2.2%).  But on the flip side, China (+0.5%), HK (+0.3%) and India (+1.0%) all followed Korea while other regional exchanges had much more limited movement.  It appears that people are trying to figure out what to do for now.

In Europe, Germany (-1.0%) is the laggard after Germany cancelled its plans for a new warship and Rheinmetall, the company set to win biggest there, got crushed.  But elsewhere +/-0.3% or less is the norm with little new information as traders await the next shoe to drop.

In the bond market, interest is low as 10-year Treasury yields continue to track around the 4.5% level and movement has been 1bp or so lower across all of Europe.  Nothing to see here for now.  Just wait until views start to change on rate hikes though!

Metals markets continue to get hammered with gold (-1.7%), silver (-2.9%) and copper (-1.6%) all still falling as the opening narrative about higher rates and a stronger dollar play out.  The thing is, I think the fundamentals remain positive for metals markets as there continues to be central bank demand for gold as well as industrial interest in silver and copper and long-term shortages of supply.  But right now, none of that matters.

Finally, looking beyond the DXY, it is no surprise the euro (-0.35%) and pound (-0.35%) are lower given the DXY’s continued rise, but the yen (-0.1% and at a new low (dollar high) for the move) continues to slide and there is weakness pretty much across the board in both the G10 and EMG blocs.  KRW (-1.0%) is today’s laggard while INR (+0.2%) is the lone currency holding its own.  This continues to be a dollar focused story so when the rates story changes, so will the dollar.

On the data front, we see New Home Sales (exp 640K) and then EIA Oil inventories with yet another large draw expected.  And that’s it for today.  As long as this rate hike narrative remains primary, look for weaker risk appetite and a strong dollar.  But I think it is a short-term phenomenon.

Good luck

Adf
What’s Next To Be Feared?

For Holmes, when the dog didn’t bark
He recognized that was the spark
To solving the case
And so, we must brace
For narrative changes quite stark

This morning, no headline appeared
Regarding Iran, which is weird
Have markets moved past
This problem, at last?
And if so, what’s next to be feared?

So, perusing the WSJ on-line this morning, the notable absence was any story on Iran and the current situation regarding the ongoing peace talks.  There was a throwaway article about Trump and what he has said about Iran, but nothing of substance.  Part of me is amazed that this is the case as the conflict would still seem to be the most important issue in the markets given the impact on oil prices and inflation, as well as its general geopolitical impact.  But part of me cannot be surprised at all.  It’s not just traders who have the attention span of a fruit fly, apparently so does the general public.

I made the point several weeks ago that this conflict would fade into history quickly when it was ending based on the fact that the Venezuela incursion, back in January, fell from headlines within about three days.  Given the generic MO for most publications of, if it bleeds, it leads, the fact that bombs are no longer falling, and peace talks are ongoing is no longer that interesting.  Add to that the generic TDS of most of the media, where they loved to play up rising oil prices as a major policy failure for Trump, now that those prices have been falling for the past 11 weeks and have slipped >30% in that period, and quite frankly, have further to fall, most editors have moved on.  If they cannot tar Trump with a policy failure, they would rather not discuss the subject at all.

Source: tradingeconomics.com

So, here we are this morning with the market now turning its focus to an ostensibly hawkish Fed despite the recent analysis by the BLS indicating that more than 60% of the recent uptick in inflation was driven by the rise in energy costs.  So, with energy costs reversing course dramatically, what does that say about their impact on inflation and exactly how hawkish does the Fed need to be in that case.

Right now, equity markets are under some pressure as some of the euphoria associated with the rising tech sector’s stock prices and the ongoing AI mania, is wearing a little thin.  And let’s face it, things certainly seemed a bit bubblicious.  But the combination of ongoing fiscal support from the OBBB and tax cuts and declining energy prices is likely to help support things going forward.  No matter the timeline you observe, we have seen a remarkable rally in tech stocks, as evidenced by the NASDAQ’s chart below.  A correction to the 50-day moving average would hardly be surprising, nor would it be damaging to the overall market structure, I think, although it would almost certainly result in ‘end of days’ headlines!

Source: tradingeconomics.com

So, while futures this morning are lower across the board (NASDAQ -2.9%, SPX -1.4%, DJIA -0.6%) as of 6:40am, and we could easily see some weakness for a few more days/weeks as positions shake out, I am not in the camp of things are about to collapse.

Speaking of equity markets, the overnight session was filled with red ink led by the KOSPI (-10.0%) in South Korea, although there was weakness pretty much everywhere (Nikkei -3.6%, CSI 300 -2.8%, Hang Seng -1.8%) with India and Taiwan also slipping more than -1.0% although Australia, NZ and Singapore had more muted declines.  Tech was clearly under pressure.  Of course, we cannot be surprised that European shares are also lower in a generally weak risk scenario, but given the lack of tech companies headquartered there, the declines have been far less significant (DAX -1.0%, CAC -0.6%, IBEX -0.2%, FTSE 100 -0.2%) although the Netherlands (-1.3%) home to ASML, the only tech name of note on the continent, is underperforming as well.

Meanwhile, the bond market has peeked at the oil market and decided, perhaps inflation is not a chronic condition, or at least not as bad as previously feared.  Yields are lower across the board with Treasuries (-3bps) leading the way while European sovereigns are all lower by between -3bps and -4bps.  Overnight, though, JGB yields could make no headway lower as the yen continues to be under enormous pressure.

Speaking of the yen, it continues to slowly weaken despite prominent statements by Japanese FinMin Katayama about her discussions with Treasury Secretary Bessent and their agreement to have the US coordinate with Japan in the event it is decided something needs to be done in the markets.  But so far, no signs of actual intervention.  A look at the chart below shows a very slow and steady climb in the dollar, and frankly, I do not see what will change this trajectory.

Source: tradingeconomics.com

While interest rates aren’t the only driver, they still have a key impact, and they are the one thing that can be changed quickly.  In fact, the best hope for the yen, in my view, is the fact that at some point soon, the market is going to understand the Fed is not about to raise rates again, and the next move will likely be lower, albeit not until later in the year.  but that change in tone will change a lot of opinions on how the yen should behave, and a move back toward 155 amid modest overall dollar weakness could easily be seen.  But right now, everybody is of the opinion that the FOMC is going to hike this year, and Japan cannot afford to be aggressive in that context, hence the yen’s weakness.

Here is a forecast I do not make lightly, Fed funds will finish the year lower than they are now, probably 3.25%-3.50%.  And the current Fed funds futures market has bottomed (rates peaked) as per the CME table below.

As to the rest of the FX world, the dollar reigns supreme this morning as the euro (-0.3%) is below 1.1400 this morning, its weakest in more than a year as the Flash PMI data did it no favors, but the new hawkish Fed, higher US rates strong dollar narrative has been the driver.  We have seen the same type of movement elsewhere, except where the dollar has moved further, with AUD (-0.8%) the worst performer in the G10 although HUF (-1.0%) is actually the biggest laggard.  However, given the overall decline in commodity prices, those currencies that benefit from rising commodities are also under pressure (NOK (-0.7%, ZAR -0.5%, SEK -0.8%, MXN -0.7%) and we already discussed AUD.

Lastly, the metals markets are also under serious pressure with gold (-1.6%), silver (-4.5%) and copper (-3.3%) all tumbling on the same new view of higher rates and a stronger dollar.  The thing about the commodities story is the fundamentals still seem positive to my eyes, and this seems like the last of the fluff getting taken out.

On the data front, Thursday’s PCE data is the big day and here’s what we have overall:

TodayFlash Manufacturing PMI54.8
 Flash Services PMI51.0
WednesdayNew Home Sales640K
ThursdayInitial Claims225K
 Continuing Claims1800K
 Q1 GDP Final1.6%
 Personal Income0.4%
 Personal Spending0.6%
 PCE0.5% (4.0% Y/Y)
 Core PCE0.3% (3.4% Y/Y)
 Durable Goods-4.3%
 -ex Transport0.7%
FridayMichigan Sentiment50.3

Source: tradingeconomics.com

In addition to the data, we start to hear from some of the FOMC members, although I am confident Chairman Warsh won’t be out and about.  Some analysts claim that Warsh’s view of less communication is going to weaken him as others will get to make their point and he won’t be able to counter it.  But I think that Warsh has a plan, and if we continue to see oil prices decline, which seems the likely outcome, then all the inflation fears are going to dissipate and by the time the next meeting rolls around, it will be far harder to make the case that tighter policy is necessary.  Historically, hiking into an energy price shock has been a central banking mistake, and I think Warsh knows this and is keen not to repeat it.

Net, for now, everybody loves the dollar and hates risk on this new hawkish Fed narrative.  But going forward, I like the dollar on the back of a better economy and better investments and expect that the hawkish Fed narrative is going to fade away.  But I’m just an FX poet.

Good luck

Adf
No Plan of Action
In England and Scotland and Wales
Kier Starmer has gone off the rails
A buffoon-like clown
He’s set to step down
As from the Brits eyes, fall their scales

But will his replacement gain traction
Or will Burnham be a distraction
From solving their woes
As Lord only knows
They’ve many, and no plan of action

It has been an eventful weekend for me so let me start by telling you that Marvel was Best of Breed in back-to-back shows last Thursday.  We are very proud and happy.

Second, Friday was a more difficult day for me as I wound up having emergency surgery, although everything is fine.  But I am still in recovery mode.  Sometimes, aging is harder than other times.

With that in mind, we can talk about the three things that matter, I believe, the change of PM in the UK, the on-again-off-again peace talks in Iran and the fact that the yen is now weaker than the level that got the MOF to intervene back in April.

Starting with the UK, PM Starmer has promised to step down now that his most likely successor, Andy Burnham, the former mayor of Manchester, is in Parliament and will now become PM sometime in the next several months depending on the actual timing of certain technicalities.  He is described as left-wing, even by the press, which tells you that he must be quite far to the left.  But the UK has serious problems with respect to their economy, slowing growth and high inflation, and the social structure due to massive immigration, both legal and illegal.  As well, the report that just dropped about the Pakistani grooming gangs that were systematically raping young English girls is so damning, it is hard to believe, yet it was all covered up.  The government doesn’t have to go to the national polls until 2029, so Burnham will have time to try to implement policies, but the nation has many troubles ahead.

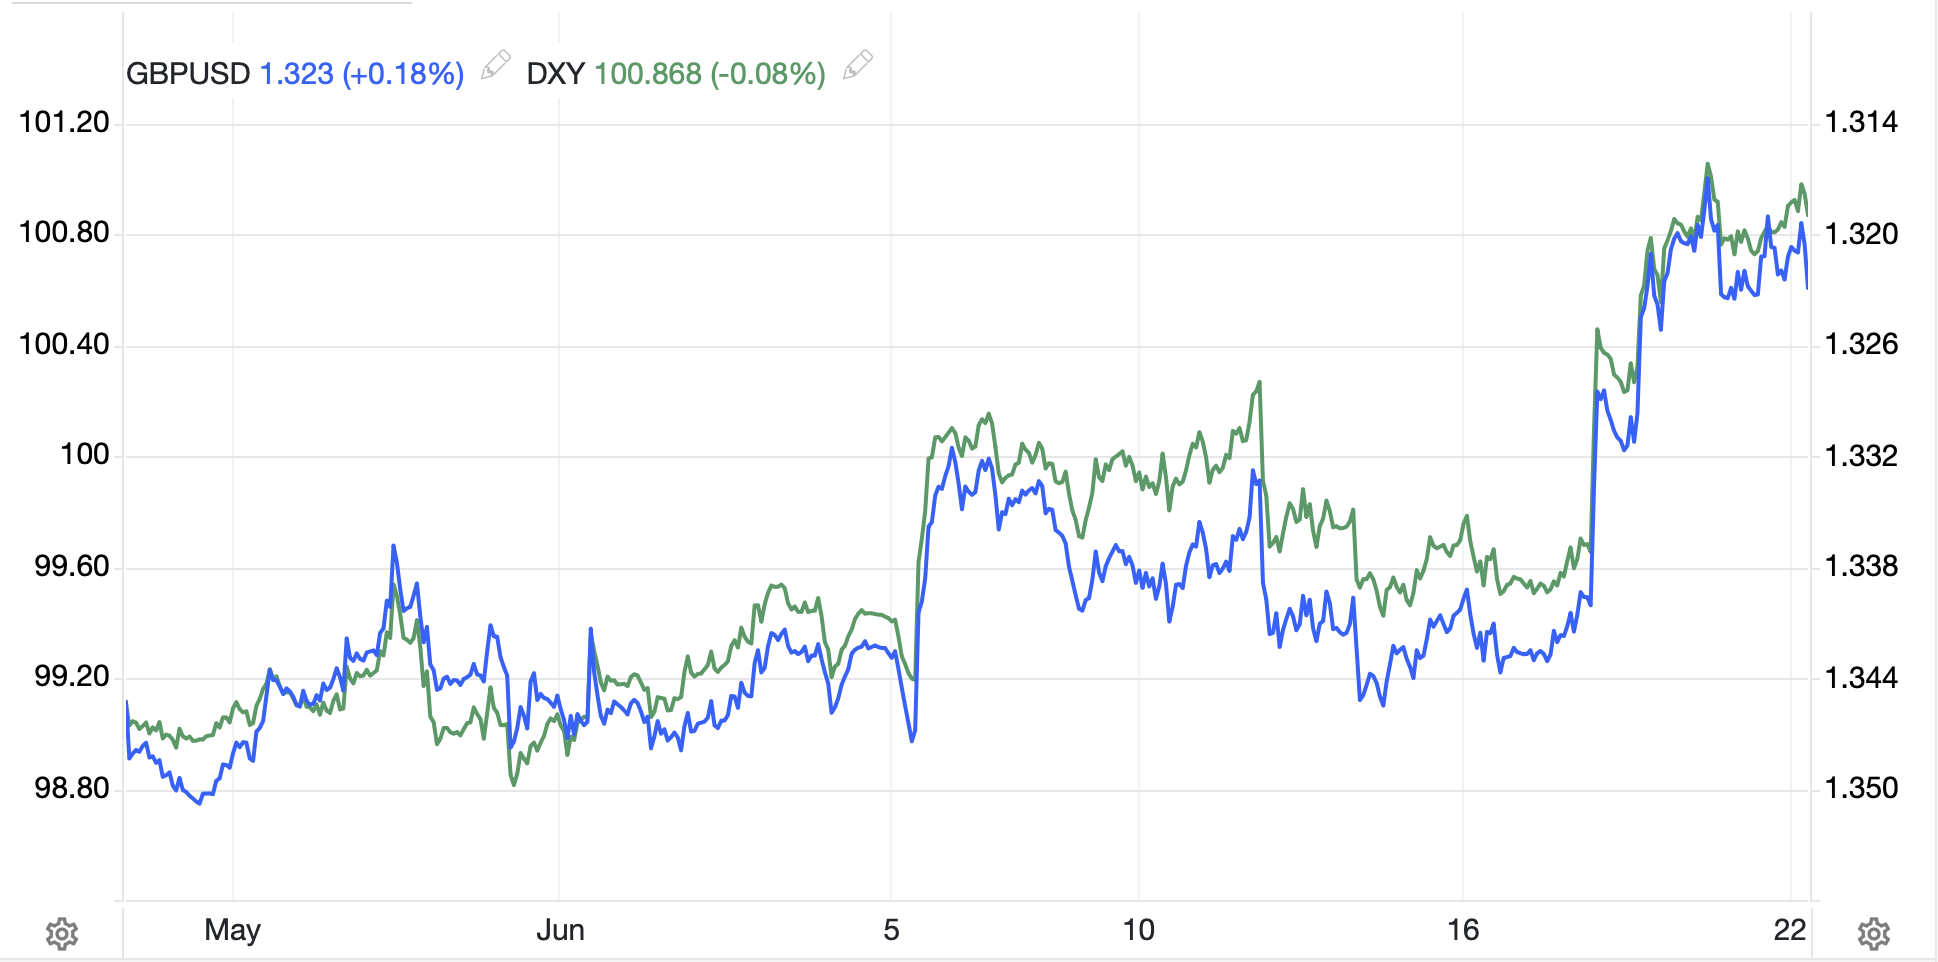
As to UK markets, both the pound and FTSE 100 have been underperformers relative to their peer European counterparts over the past month or so as this process has heated up, but in truth, not by very much.  Much of the pound’s weakness can be attributed to dollar strength (see chart below), where the dollar has broken through key technical resistance in the DXY, while the FTSE is just drifting given the lack of positive news.  Certainly, this story didn’t help either one, as both are unchanged on the day.

Source: tradingeconomics.com

In Switzerland, talks are ongoing
As Trump and the Mullahs try showing
That they are the ones
Who have the most guns
But progress seems like it is growing

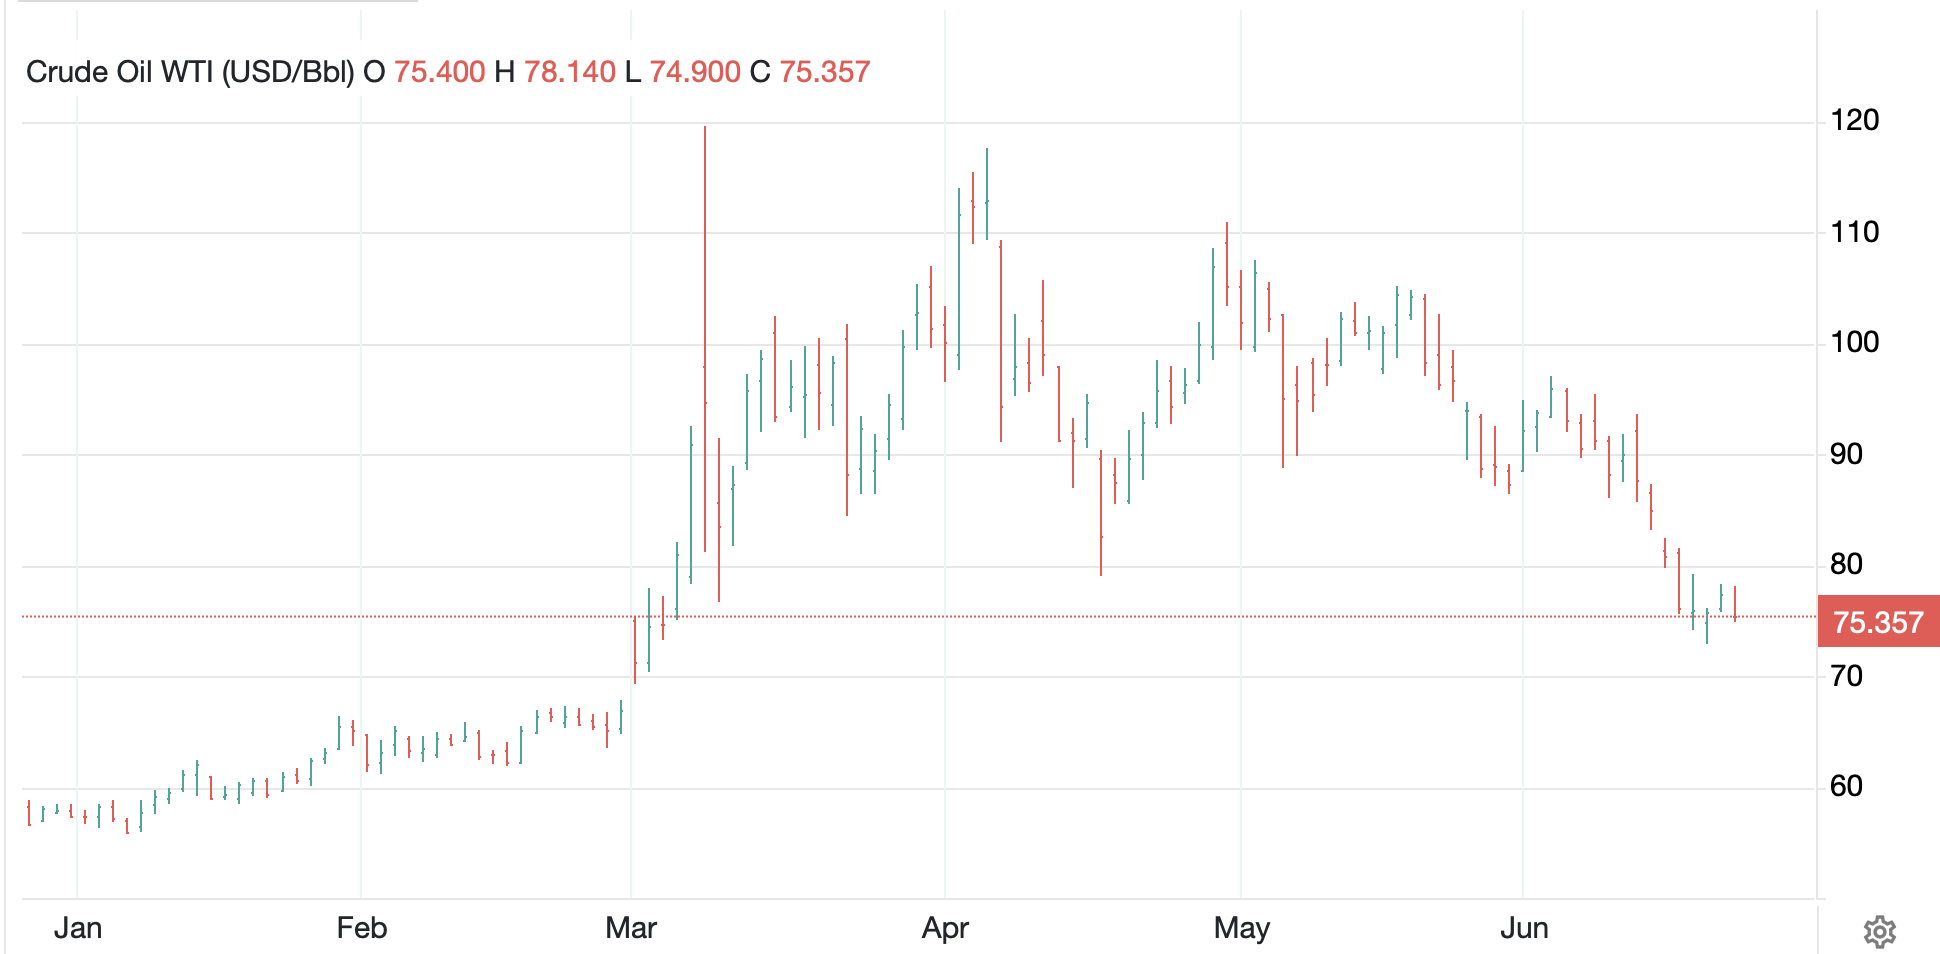
It cannot be a great surprise that there is a lot of bluster from both sides of this negotiation between the US and Iran as President Trump tries to end the conflict in Iran.  After all, both sides are famous for their bluster!  And you can read whatever you like from whatever source you want to get your spin, but I’m not smart enough to understand the intricacies of international diplomacy.  However, what I do understand is market price movement, and here we are this morning, with oil prices falling further, down -2.5%, and back to levels last seen in early March, right at the beginning of this conflict.

source tradingeconomics.com

Thus far, every story about tank bottoms being reached and an insufficient amount of oil for the pipeline infrastructure to be effective has proven not to be true.  There is still a large group of analysts who are calling for end of days, but the market signals just don’t agree.  I suspect that the only ones who really want to see oil prices remain high are the oil companies who sell the stuff, but for the rest of the world, lower is clearly better.  Obviously, anything can still happen, but by all appearances, it seems that more and more traffic is flowing through the Strait and we are going to see lower prices going forward.

In the end, from my vantage point thousands of miles away from the action, it appears that Iran was greatly weakened by this conflict on a military basis, but more importantly, every one of its Gulf neighbors realized that they needed alternative routes to get their oil to market, and we are going to see a lot more pipeline infrastructure built to do just that, so as time goes by, this choke point is going to lose its effectiveness.  And that is probably a bigger weakness for Iran, as that was something they held over the world, but now it seems it is not as impressive a strength as it had been made out to be in the past.

It’s no waterfall
But the yen keeps dripping down
Whence the BOJ?

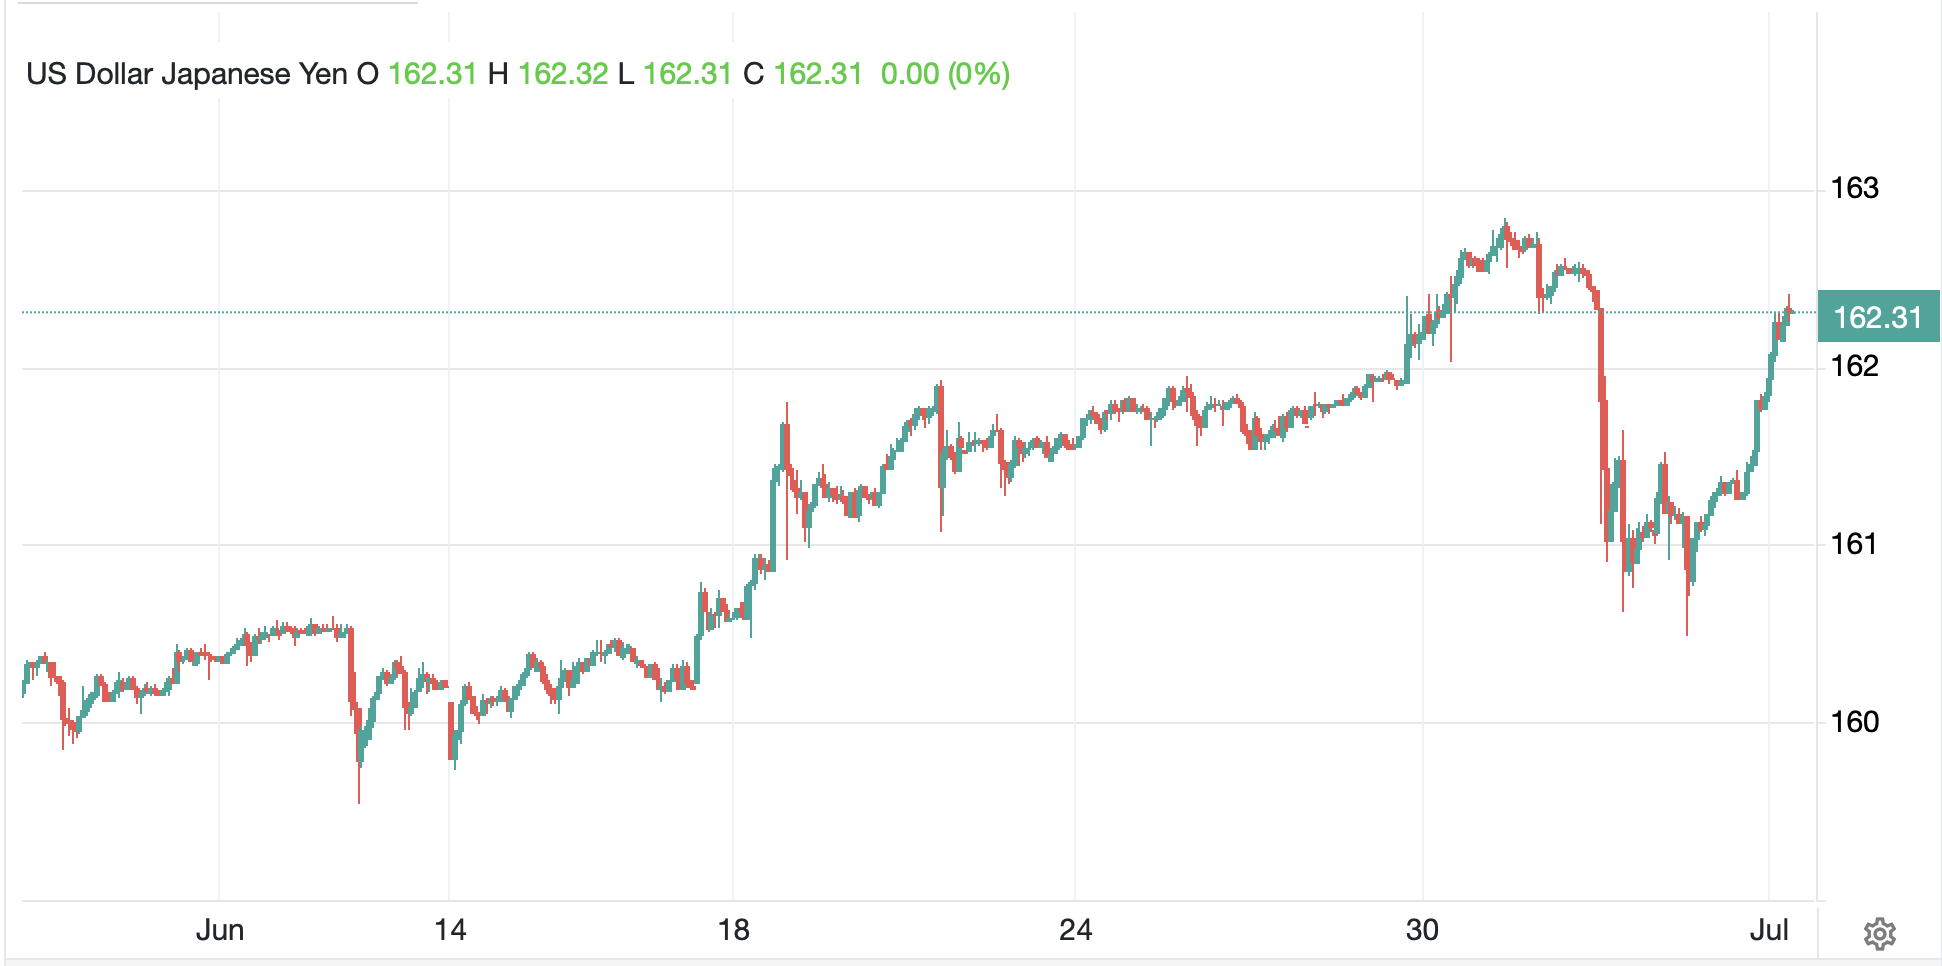
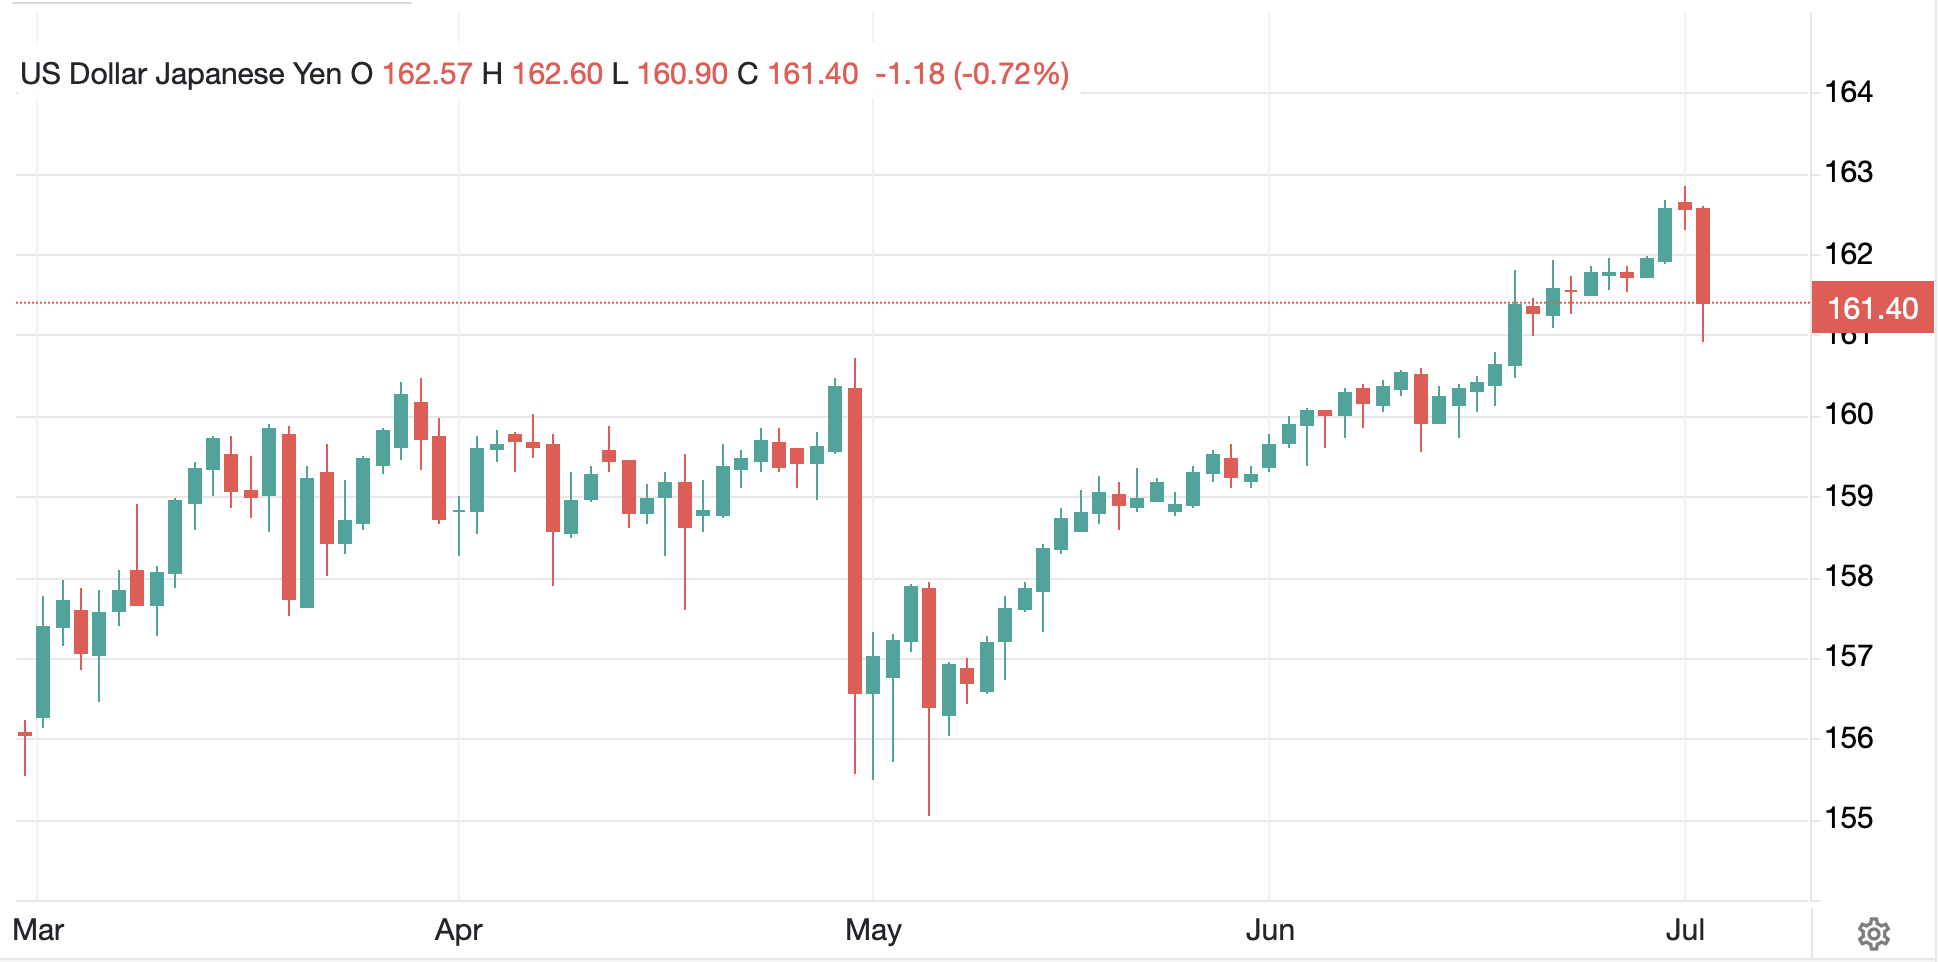
Finally, the yen (-0.3%) is having a tough time right now as it has traded back to its lowest level vs. the dollar since 1986!  That’s right folks, it has been forty years since USDJPY traded above 162.00, and we are pushing that level right now as you can see in the chart below.

The last two times the yen reached these levels, back in April and in July 2024, the BOJ intervened in the markets aggressively.  But so far, crickets.  I think the issue for them is the dollar continues to be quite strong, especially as traders are now pricing in rate hikes by the Fed, and so intervening is going to be a waste of money.  And it’s true, if the dollar is rallying across the board, there is very little Ueda-san can do.  As I have repeatedly said, the only way for the yen to break this slide is for serious fiscal and monetary policy changes, and frankly, that doesn’t look like it is in the cards right now.  While I know there are many who think the dollar is heading to its graveyard, it apparently still has a bit of life left in it.

Which takes us to the overnight activity.  Equity markets have been mixed as all this new information gets digested.  In Asia, Tokyo (+1.6%) and China (+2.4%) both had strong sessions although HK (-0.7%) couldn’t keep up.  Elsewhere in the region, there was slightly more green than red led by Taiwan (+2.75%) while the Philippines (-1.65%) was the biggest laggard.  Uncertainty continues to reign although as the Iran situation slowly resolves, I expect to see things brighten here as Asia was the region hurt most by the entire conflict.

In Europe it is also a mixed picture with the UK (+0.3%) now rallying on the news that Starmer is leaving and Spain (+0.4%) has managed a gain as well while both Germany (-0.3%) and France (-0.7%) are lagging this morning, although there is no news of note in either place.  US futures are basically unchanged at this hour (7:15).

In the bond market, Treasury yields (+3bps) have edged higher this morning, I guess on this new belief in higher Fed funds, although I would have thought the bond market would appreciate a hawkish Fed fighting inflation.  European sovereign yields, though, are lower across the board down about -2bps everywhere.  Bonds remain less interesting now that they are back in their ranges and not breaking out as so many though was occurring back in May as per the below chart.

Source: tradingeconomics.com

With oil prices lower, it should be no surprise that gold (+1.35%) and silver (+2.4%) are both higher this morning.  Many have made the case that with the dollar strengthening, the precious metals complex will remain under pressure, and it is a valid case, but for some reason, I have a feeling it will not be as dramatic as they believe.

Finally, the dollar is firmer across the board this morning, albeit not by very much.  Wednesday and Thursday of last week were the big moving days in the wake of the FOMC meeting and the new hawkish read.  Since then, not much has happened, just a slow drift higher across the board.  FWIW, I don’t think that Chairman Warsh is going to be that hawkish, but I look forward to the structural changes that he makes.  However, for now, that is the market assessment.

On the data front, there is nothing today and really nothing of import until Thursday so I will go through it tomorrow.

That’s how things are shaping up, with the dollar gaining, oil sliding and stocks uncertain what to do next.  I am a fan of uncertainty as it will reduce systemic risk, and that is something we really need to see.

Good luck

Adf