Theses All Wrecked

There once was a fire that ceased
Which many hoped would lead to peace
But recent attacks
On ships did climax
In poking the milit’ry beast

The market’s response was direct
With oil bears’ theses all wrecked
The dollar, it rose
While risk takers chose
Their stocks and bonds, now, to reject

While we had all become accustomed to the gradual decline in the price of oil as it appeared there was a solid chance that an agreement would be reached between Iran and the US, that all came a cropper yesterday after Iran attacked 3 different ships exiting the Strait and the US responded with attacks on more than 80 targets, including (according to the WSJ) “air-defense systems, command and control networks, antiship missile sites and more than 60 Iranian small boats near the waterway.”  This was a significant uptick in the nature of the response from previous skirmishes and according to President Trump, the ceasefire is over.

“To me, I think it’s over, I don’t want to deal with them anymore,” Trump told reporters at a NATO summit in Ankara on Wednesday. “They’re liars, they’re cheats, they’re sick people.” 

Given the sudden change in the status in the Gulf, we cannot be surprised by the market response.  WTI (+6.0%) rocketed higher as you can see in the chart below.

Source: tradingeconomics.com

And while that is clearly a significant move, and has changed attitudes in the market, I think it is worth stepping back slightly and looking at the price action over the past month, just to remind ourselves that though things may be changing, we have still seen a dramatic decline in price.

Source: tradingeconomics.com

Here’s the thing, right now there is no way to know if we are going back to the situation in early March, where there was substantial fighting, or at least bombing and missile attacks, each day, or if this, too, is going to pass like the previous minor skirmishes.  Certainly, President Trump appears tired of the current situation, but it is not clear what type of further response is in the offing.

In the meantime, given the new military action and the limited prognosis for a quick return to the previous status of ships moving through the Strait, it can be no surprise that investors decided to dump a lot of risk.  So, let’s take a look at how things behaved overnight.

You will not be surprised that equity markets are broadly lower this morning.  Yesterday’s US session was soft on concerns over the tech sector and that was before the resumption of hostilities in Iran.  So, Tokyo (-2.1%), China (-0.8%), Korea (-5.4%) and India (-2.2%) all fell sharply amongst major markets in Asia with most of the smaller exchanges under pressure as well.  The outliers here were HK (+3.0%) and Taiwan (+0.6%) as both saw continued demand for semiconductor and tech shares.  It feels to me that these two markets will have difficulty maintaining this positivity under the current circumstances.

In Europe, it is a bloodbath with all major bourses lower led by Germany (-2.4%) and Spain (-2.7%) while France (-2.2% and the UK (-1.6%) are not far behind.  The NATO meeting ongoing in Ankara is not helping anybody’s views as President Trump continues to add pressure to NATO to pay their own way.  Ultimately, the NATO transition continues, and it is anybody’s guess as to how involved the US will be going forward.  As to US futures, at this hour (6:35) all the major markets are lower by -1.0% or more.

In the bond market, yesterday saw Treasury yields rise 6bps during the session as yields tracked the oil move pretty closely.
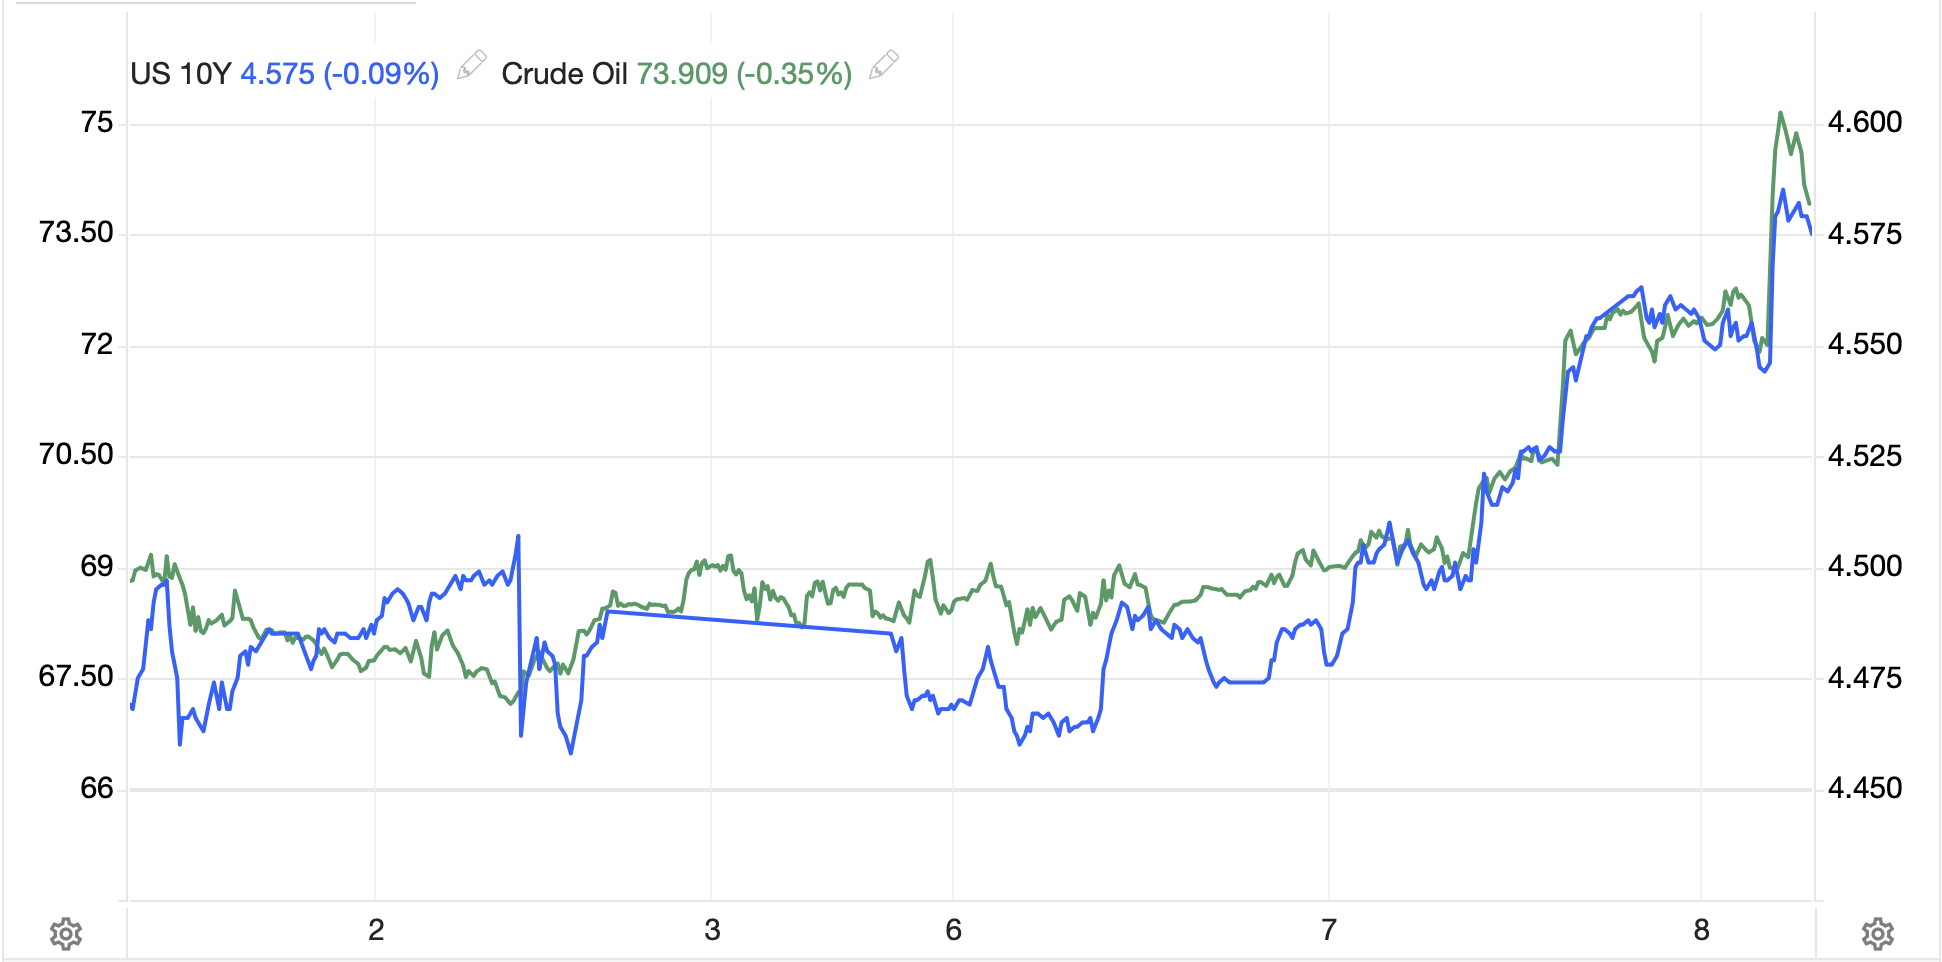
Source: tradingeconomics.com

This morning, Treasury yields are higher by 2bps more but that is nothing compared to the European sovereign markets, which as you can see from the below Bloomberg.com screenshot are substantially higher this morning.
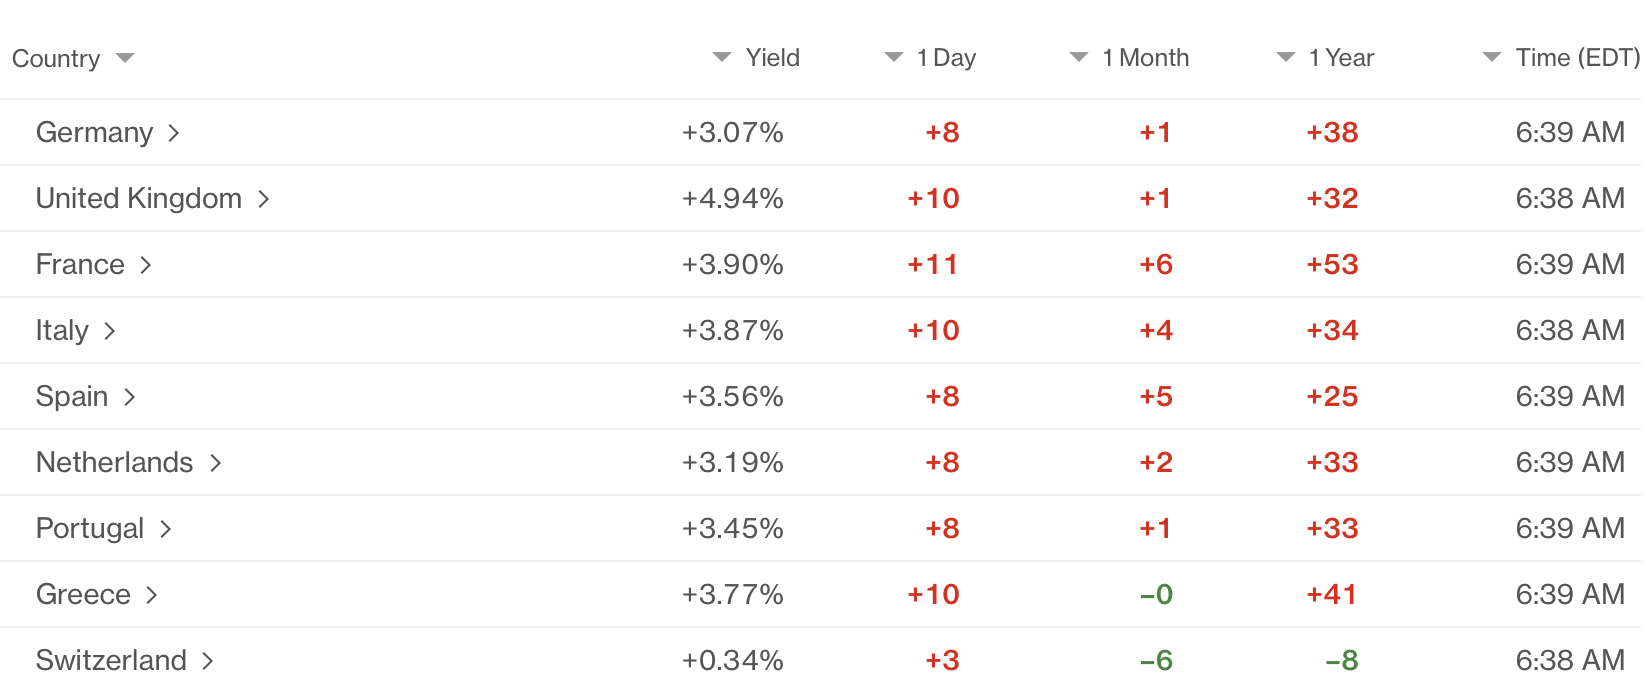
All those visions of inflation finally starting to decline were abruptly altered after the renewed activities in the Gulf.  Adding to the pressure on bonds is the concern over the increased spending promises from governments around the world which has seen traders increase short positions in the bond market to near record levels.

We cannot be surprised that gold (-1.2%), silver (-2.2%) and copper (-2.2%) are lower in response to the renewed fighting and rise in oil prices as that relationship has been very consistent.  We also cannot be surprised that the dollar is a bit firmer this morning, although not universally so.  For instance, JPY (-0.2%) is now pushing back to its recent lows (dollar highs) although the pace of movement remains quite modest.  As well ZAR (-0.6%) is also under pressure amid the decline in gold prices and rising oil prices (they are an importer of oil).  On the flip side, though, NOK (+0.4%) is benefitting from oil’s rally as is CAD (+0.25%) while KRW (+0.6%) seems to be benefitting from money flowing home after the recent equity rout there (covering margin calls?).  NZD (+0.4%) strengthened on the back of the RBNZ raising their base rate by 25bps as they continue to have some concern over inflation, but that only takes it back to 2.50%, hardly tight money.  As to the other main currencies, they have not really done that much, although lean slightly lower this morning.

On the data front, we see the EIA oil inventory data with draws still expected, as well as a 10-year Treasury auction, where it will be quite interesting to see if investors are keen on the extra yield now available.  And we get the FOMC Minutes, which despite the Iran situation, will still be keenly watched and read as the analyst community tries to get a better understanding of the way the Fed will be behaving going forward.  What is the new reaction function?  

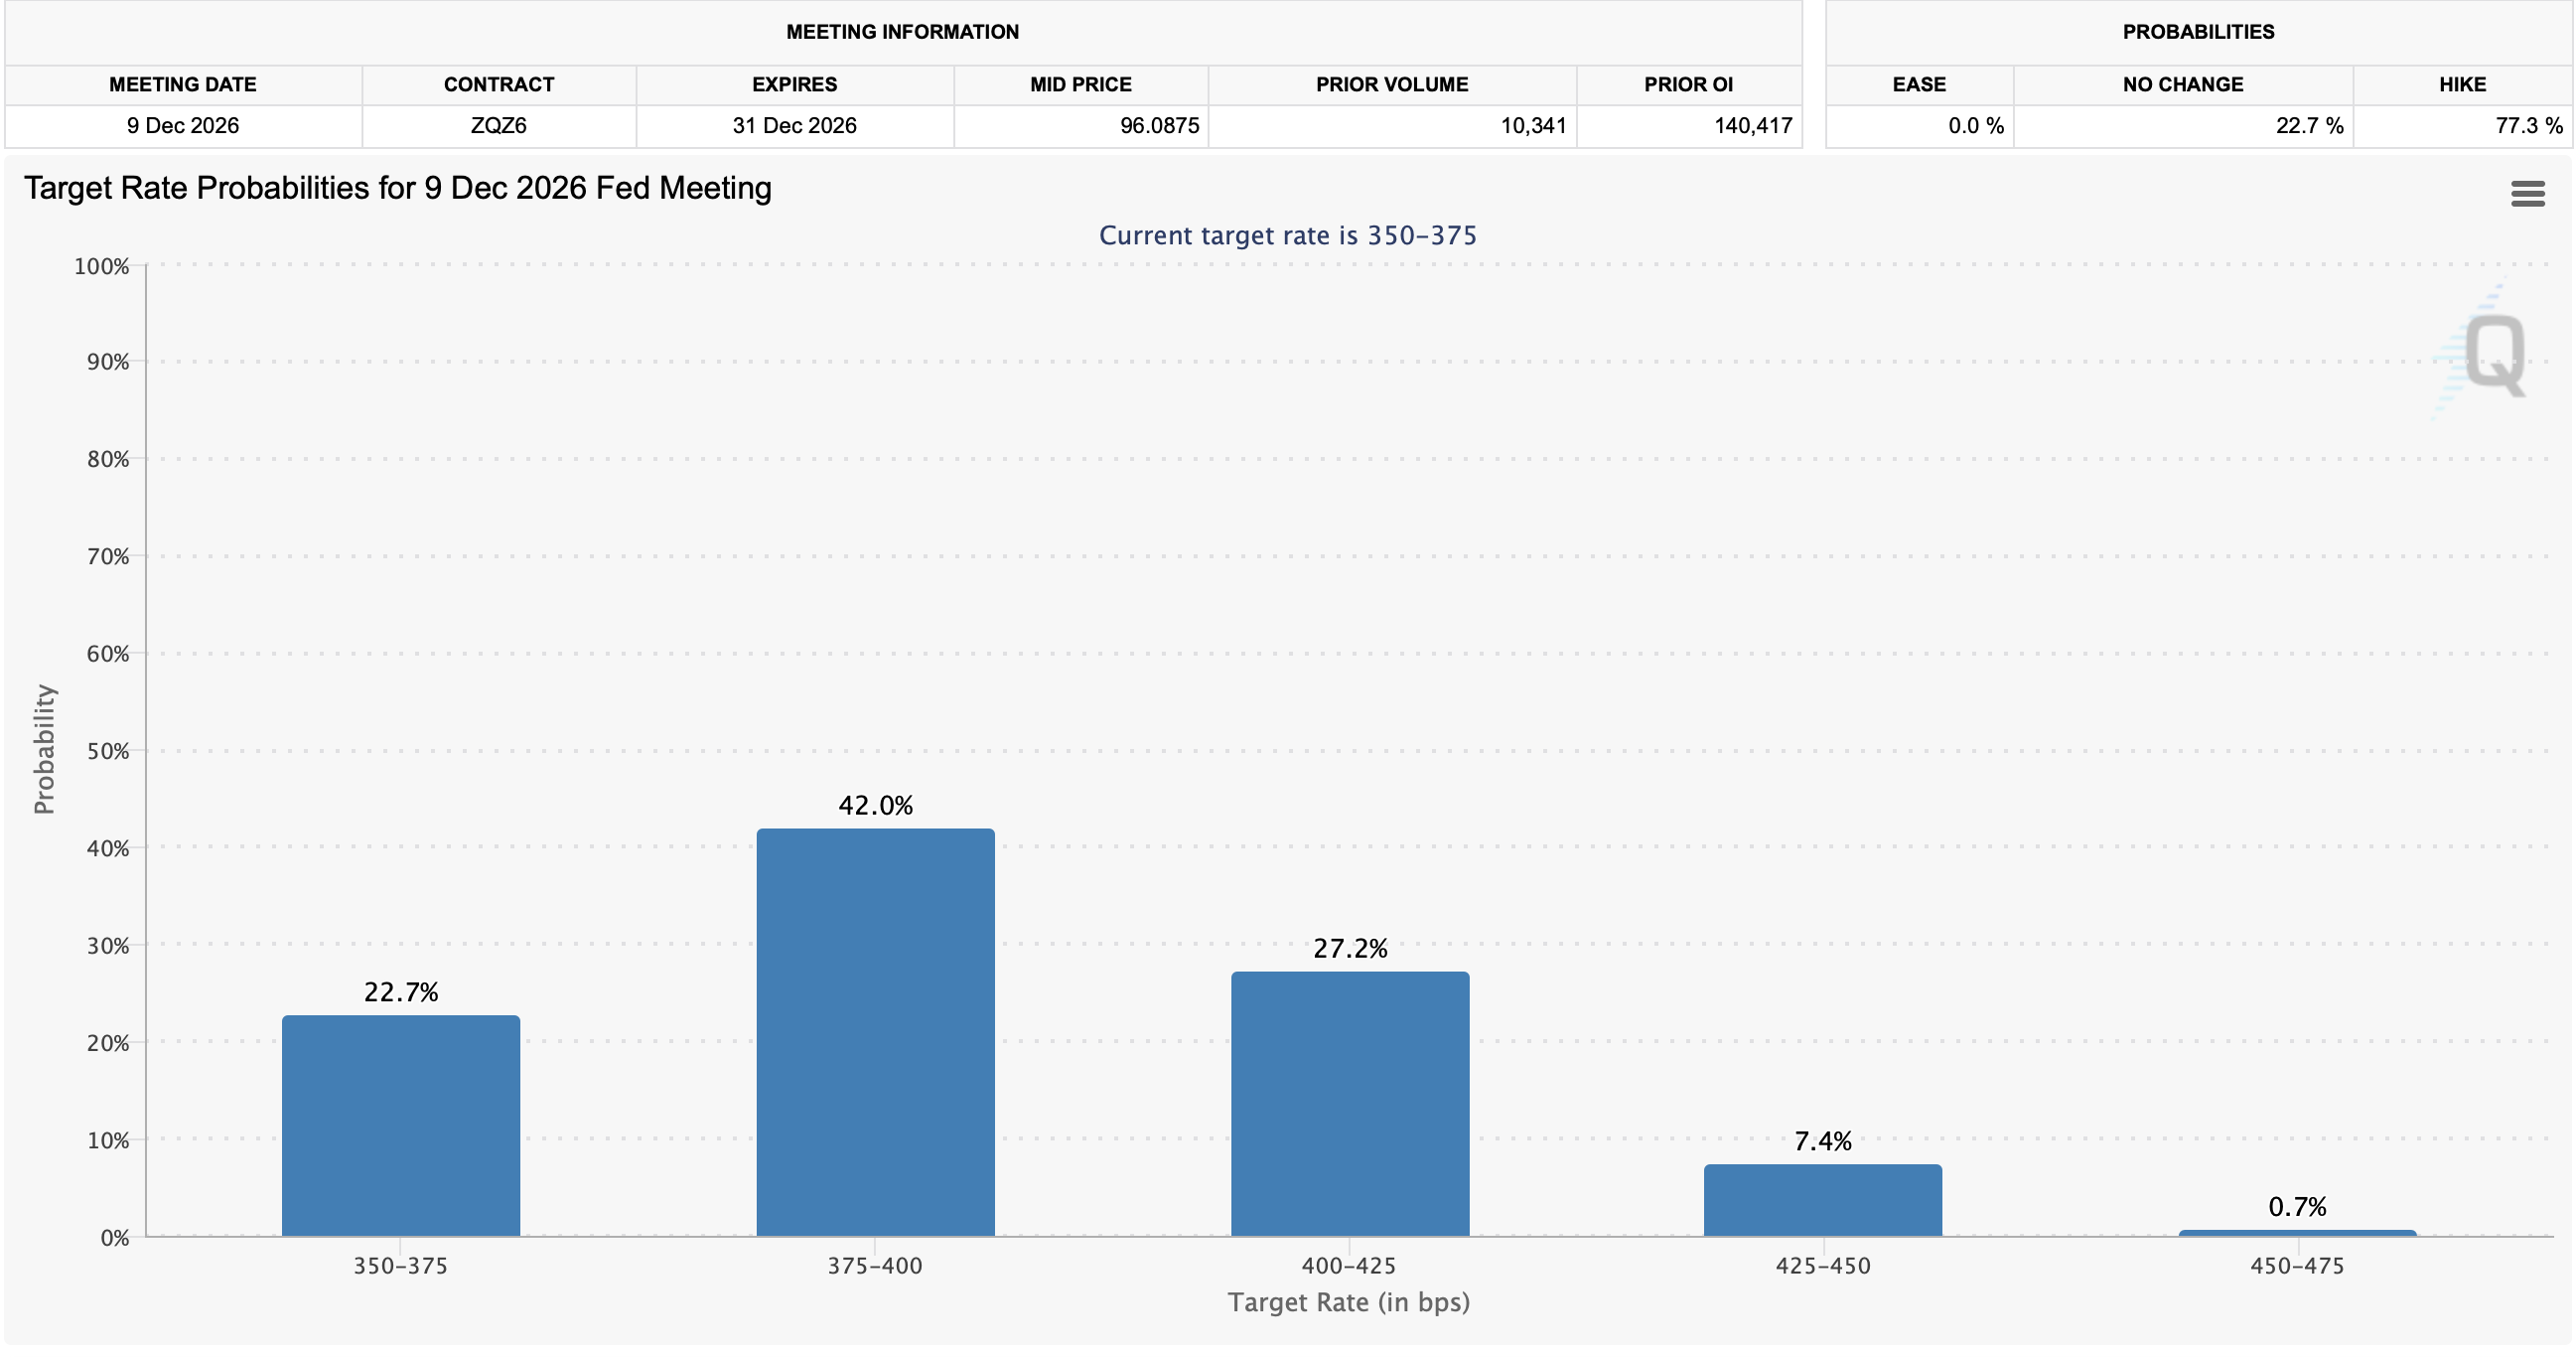
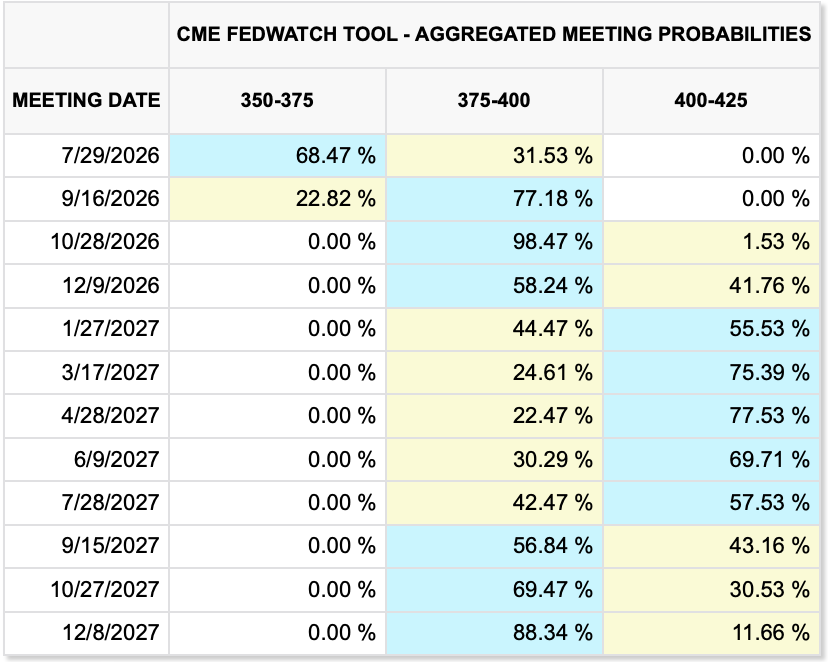
Looking at the Fed funds futures market, pricing for that first rate hike has moved to September from the previous October timeframe, and a second hike is back in the cards as well.
However, nothing has changed my view about the way things will evolve.  Certainly, the increased hostilities are a negative for markets, but I suspect that this will be a short-lived episode and things will calm down again sooner rather than later.  With that in mind, I have not changed my view about no rate hikes this year with a potential cut.  However, if this fighting does increase and the oil price creeps higher over the next weeks and months, I will be rethinking this stance.

Right now, we are back to being hostage to events on the other side of the world.  All we can do is watch and respond.  

Good luck

Adf
Subterfuge

The narrative right now is run
By hawks who think Warsh is the one
To raise short-term rates
Right out of the gates
And so, they’re long bucks by the ton

Thus, futures positions are huge
With no effort at subterfuge
But if they are wrong
About being long
The hawks will have all been the stooge

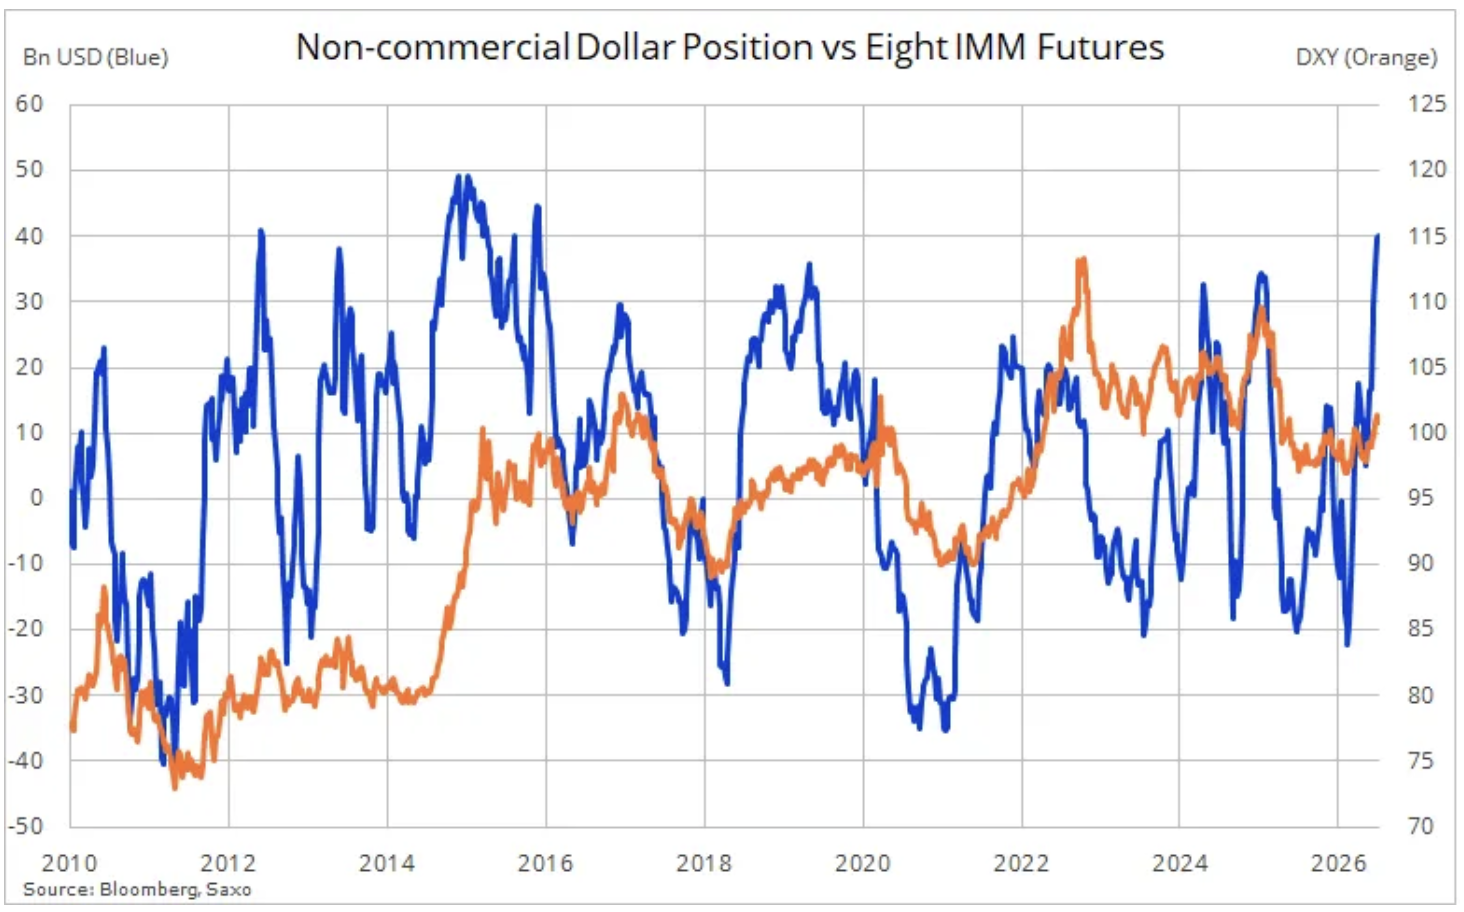
In an otherwise quiet session, this morning I am going to borrow from Ole Sloth Hansen, the futures maven at Saxo Bank.  He publishes a Substack that is well worth reading if you are actively involved in the markets as he breaks down futures positions and offers context.  This morning I am going to juxtapose those positions with my views, which are diametrically opposed to the way the market is currently positioned.

Starting with the FX market, he has created a wonderful chart showing that the net non-commercial long USD position against eight major currencies has reached 10-year highs.  Interestingly, the DXY is not anywhere near those highs, although it appears that is the growing expectation of many traders.

Arguably, this is based on the idea that Chairman Warsh is Paul Volcker redux and will be quite hawkish going forward.  Now, I cannot tell if this is the narrative because, absent forward guidance, narrative writers must now think on their own and are incapable of doing so, or if they truly believe that despite all the talk that rising oil prices were going to feed through to inflation readings, declining oil prices won’t have the same impact on the way down.

But it is not just the FX trading community that is on board with this story, so too is the short-term interest rate trading community.  While LIBOR has been forced out of existence, SOFR (Secured Overnight Funding Rate) is the new benchmark in interest rate markets and, naturally, there is an active futures market there as well.  As you can see from the below chart, also from Mr Hansen, the current positioning is strongly expecting higher short-term interest rates.

This is completely in accord with the Fed funds futures market where the market continues to price a 25% probability of a hike at the end of July and a virtual certainty of a hike by October.  By my calculations, as per the chart from cmegroup.com below, the market is pricing about 30bps of rate hikes by the December meeting.

Or course, by now you know that my view is the Fed will not be hiking rates at all, and as measured inflation slides back (just look around the world and at oil prices) the narrative will belatedly shift to the need willingness to reduce rates on Warsh’s part and all these market positions will adjust.  

My longer-term positive view of the dollar is based on the ongoing investment inflows into the US, for real investment, not merely equity market participation, and nothing has happened to change that view.  In fact, the announcement yesterday by Toyota that they will be expanding their San Antonio truck and SUV plant with a $3.6 billion investment is just the latest in a series of these announcements.  But that is not the carry trade driving things.  In fact, ironically, we could easily see US rates slide a bit as the dollar rallies on natural investment demand rather than financial demand.  As well, if I am correct, the Fed funds futures market is going to head back to pricing no rate hikes, perhaps as soon as next week after the CPI data is released.

I think the lesson is that the narrative writers need to bone up on their understanding of macroeconomics and international finance as the central bank policy driver may not be the future.  Certainly, if Mr Warsh has anything to say about it, and he does, that will likely be the case.

Which takes us to the overnight session. The most excitement overnight was for Belgium as they completely outplayed the USMNT in a 4-1 victory in Seattle.  But otherwise, the story that Iran fired two missiles at ships heading through Hormuz helped support oil prices, but as I type, they are higher by just 0.7% (~50¢/bbl) so not really very much.  The interesting discussion in the oil market this morning is the fact that Iranian oil, which is no longer sanctioned, cannot seem to find any buyers with some 58 million barrels in floating storage and no takers.  Meanwhile, despite ongoing buying by central banks around the world, gold (-0.5%) continues to struggle, although appears to be putting in a base and silver (-1.4%) is suffering as well.  

In the bond market, yields are creeping higher with both Treasuries and European sovereigns all higher by 2bps this morning with a similar move by JGBs overnight.  My take is this is less of an inflation concern than a supply concern.  Certainly, there is no indication that the US, Europe or Japan are about to slow down their fiscal stimulus, with Europe now further ramping up its defense spending as the US pressures NATO further.  To me, this is where the rubber will meet the road as if Warsh really does seek to reduce the Fed’s balance sheet, it is not clear where buyers are going to be found to replace them.  I suspect we will see more regulatory freedom for banks and insurance companies to hold Treasuries without capital penalties, but that is a big hole to fill.  

In the equity markets, yesterday’s US rally was followed by a reversal in Asia with Korea (-4.9%) leading the way lower on the back of weakness in SK Hynix stock despite stellar earnings.  But that dragged down the entire region (Japan -2.1%, China -1.0%, HK -0.5%, Taiwan -2.3%) and various declines everywhere else except Singapore (+1.4%) although I can find no specific catalyst for that outlier move.  In Europe, things are more mixed with Germany (-0.7%) under pressure although there is modest strength in the UK (+0.3%), France (+0.2%) and Spain (+0.1%).  All the talk here is about defense spending, although one would have thought that would help Germany the most.  As to US futures, at this hour (7:55), NASDAQ futures are following Asia lower, -1.3%, but the other indices are little changed.

Finally, the dollar is generally a bit stronger this morning, at least against its G10 counterparts, although JPY (+0.1%) is holding up.  But the dollar’s gains are minimal, about 0.1% to 0.2%, so it is difficult to get too excited.  In the EMG bloc KRW (+1.0%) is the clear leader after the country expanded trading hours in the currency markets, and there has been modest strength in BRL (+0.4%) and INR (+0.4%) although neither has seen any major policy changes.

On the data front, yesterday’s ISM Services data was right on the button at 54.0.  This morning we see the Trade Balance (exp -$78.5B) and that’s it.  The hawkish Fed story continues to be the most popular, and until we see some data that can undermine that story, I expect it will remain in place.  Tomorrow’s FOMC Minutes should be interesting as there was obviously a lot of back and forth at the meeting, but since we have already heard further from Mr Warsh, and it is way too early to hear back from the task forces, I suspect we are in for more quiet markets for now.

Good luck

Adf
Discussing Their Plight

Now, all eyes will turn to the chat
When Warsh and his minions, they sat
Round oak polished bright
Discussing their plight
‘Bout prices and jobs and all that

But since they met three weeks ago
Chair Warsh very clearly did show
His view that inflation
Was short in duration
And rate hikes were not apropos

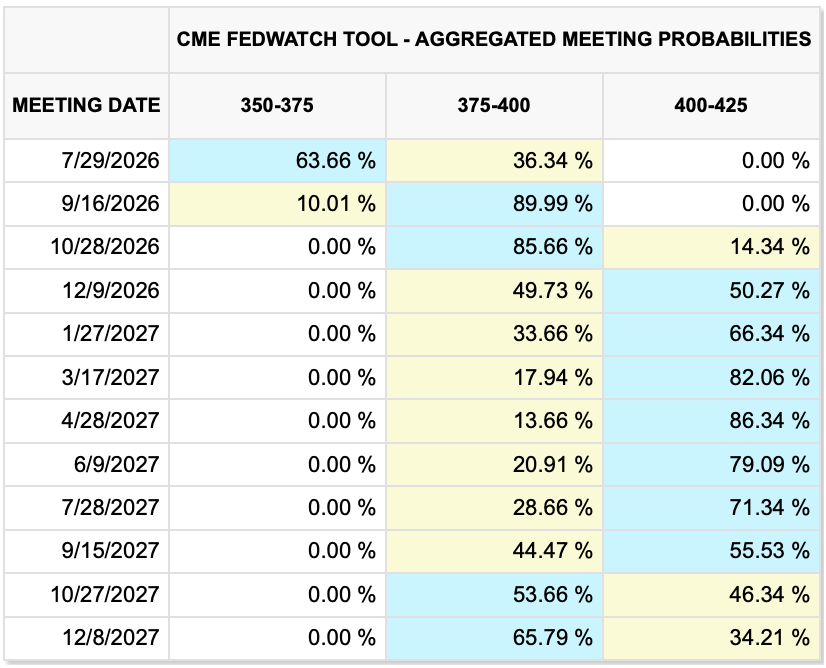
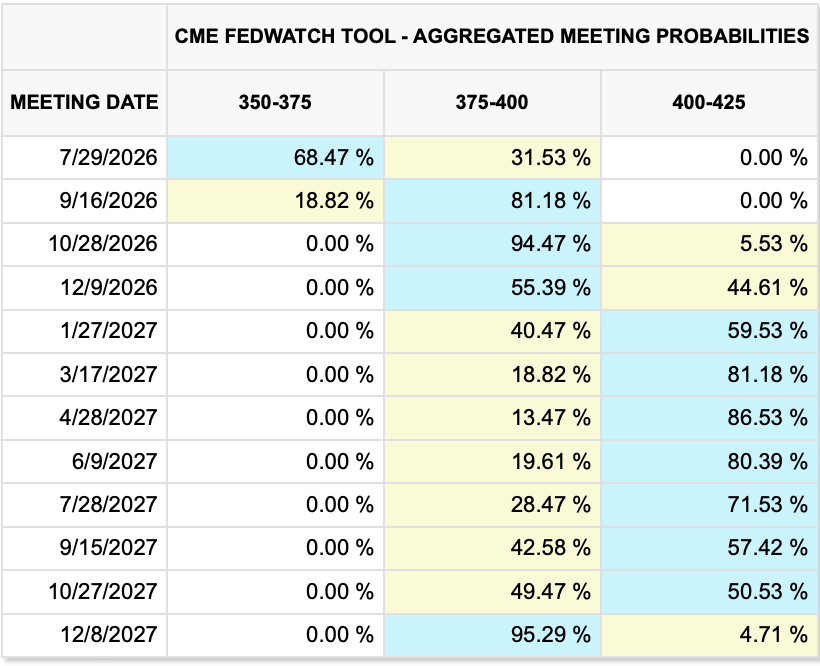
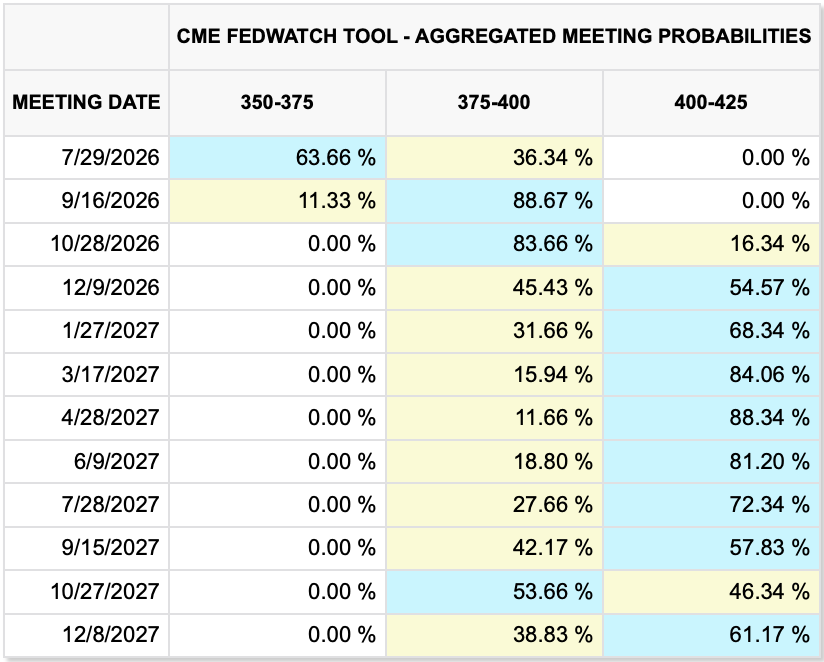
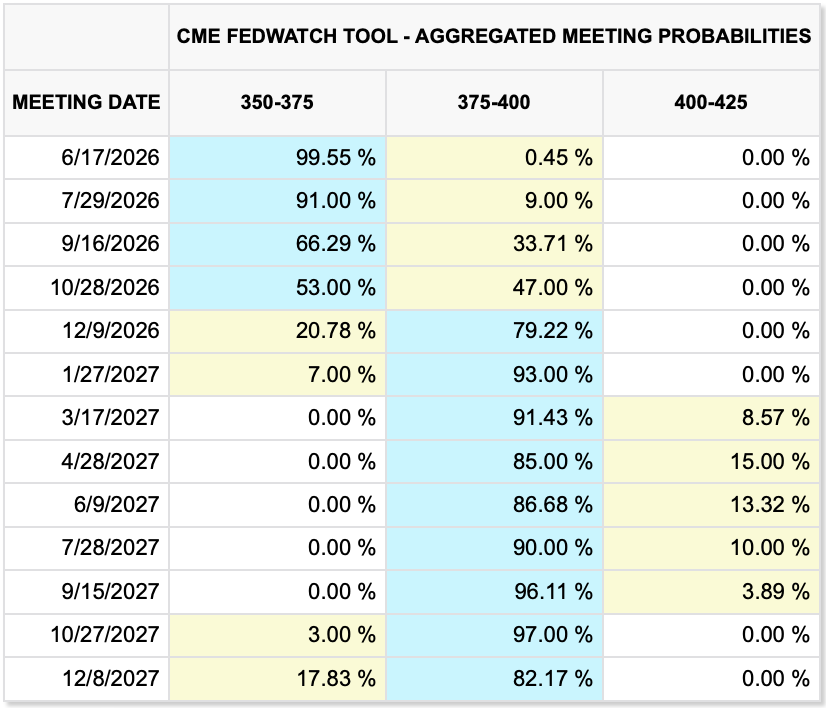
It is getting increasingly difficult to maintain a hawkish Fed view as both the data and the Chairman are working against you.  While we all enjoy the World Cup this week, arguably the biggest market related news will be Wednesday’s release of the Minutes from the last FOMC meeting.  You may recall that in the wake of that meeting, interest rate hawks were in the ascendancy with an October hike fully priced and odds for a second, December, hike priced as well as you can see in the below CME table from June 24th.

Now, in the wake of that meeting and the press conference, the combination of the dot plot showing half the committee expecting a hike this year and the lack of forward guidance along with the succinct statement explaining the Fed would achieve their 2.0% inflation mandate had many analysts expecting a serious tightening cycle upcoming.

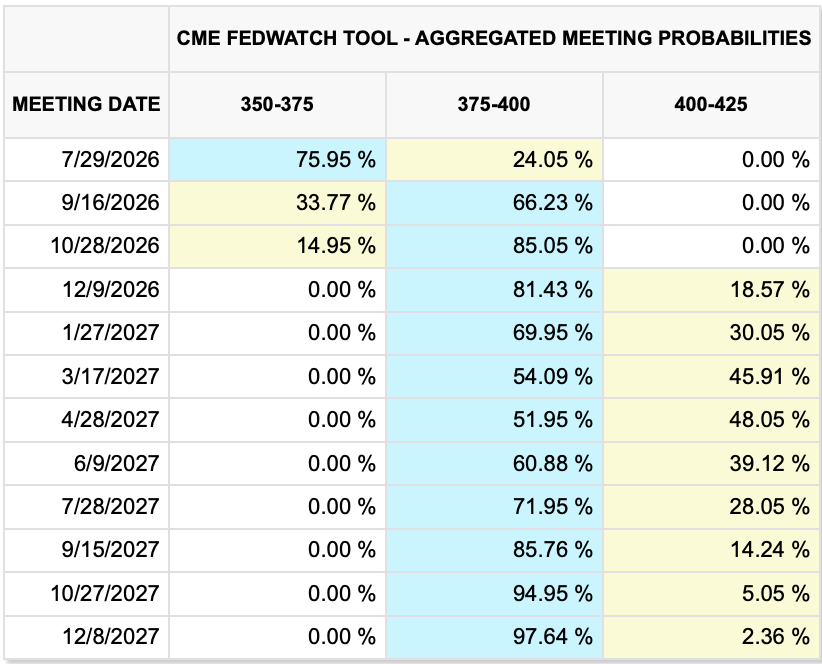
But a funny thing happened on the way to the next FOMC meeting, still three weeks hence, the price of oil, and energy in general, accelerated its decline.  Given how much effort was made to explain that the core inflation readings were heading higher because of the impact that energy has on everything, hence the need to hike rates, this has been an inconvenient outcome for the hawks.  Add to that Chairman Warsh’s comments at Sintra, Portugal last week, regarding the easing of inflationary pressures as energy prices decline (oil -0.9% this morning) and futures traders have been adjusting their views pretty steadily as per this morning’s CME table.

While a hike is still assumed by year end, the second one has fallen by the wayside.  Personally, as we continue to see inflation pressures subside alongside energy prices, I expect that not only will we not see a hike this year at all, but a cut by December is viable.

Adding to the downward bias on Fed funds futures was Thursday’s payroll report, where the headline number was softer than expected, although the Unemployment Rate did slip another tick to 4.2%.  I think a key problem with using the Unemployment report as such a critical signal is the fact that since President Trump’s inauguration and the actual closing of the Southern border, as well as the deportation (by both the government and on a self-basis) of somewhere between 2.5 million and 3.0 million according to Grok, the old econometric models of what type of job growth was necessary to maintain solid economic growth are no longer terribly useful. If we throw in the dramatic changes to the economy on the back of the increase in AI as a tool and infrastructure investment, it becomes increasingly difficult to utilize the old models.  Too, one of the main themes from several months ago was that AI was going to replace hundreds of thousands of jobs and unemployment would skyrocket, while now, those ideas are being rethought with many analysts now expecting AI will support more jobs.  Perhaps, the best thing that can come of this change is that markets will no longer radically adjust based on an outdated statistic.

There is still a long way to go before the next FOMC meeting and I doubt that the many task forces will have come to any conclusions yet, but if energy prices continue to decline, and I couldn’t help but notice this WSJ article discussing the sudden glut of oil driving prices lower, and I am growing increasingly confident in my views.

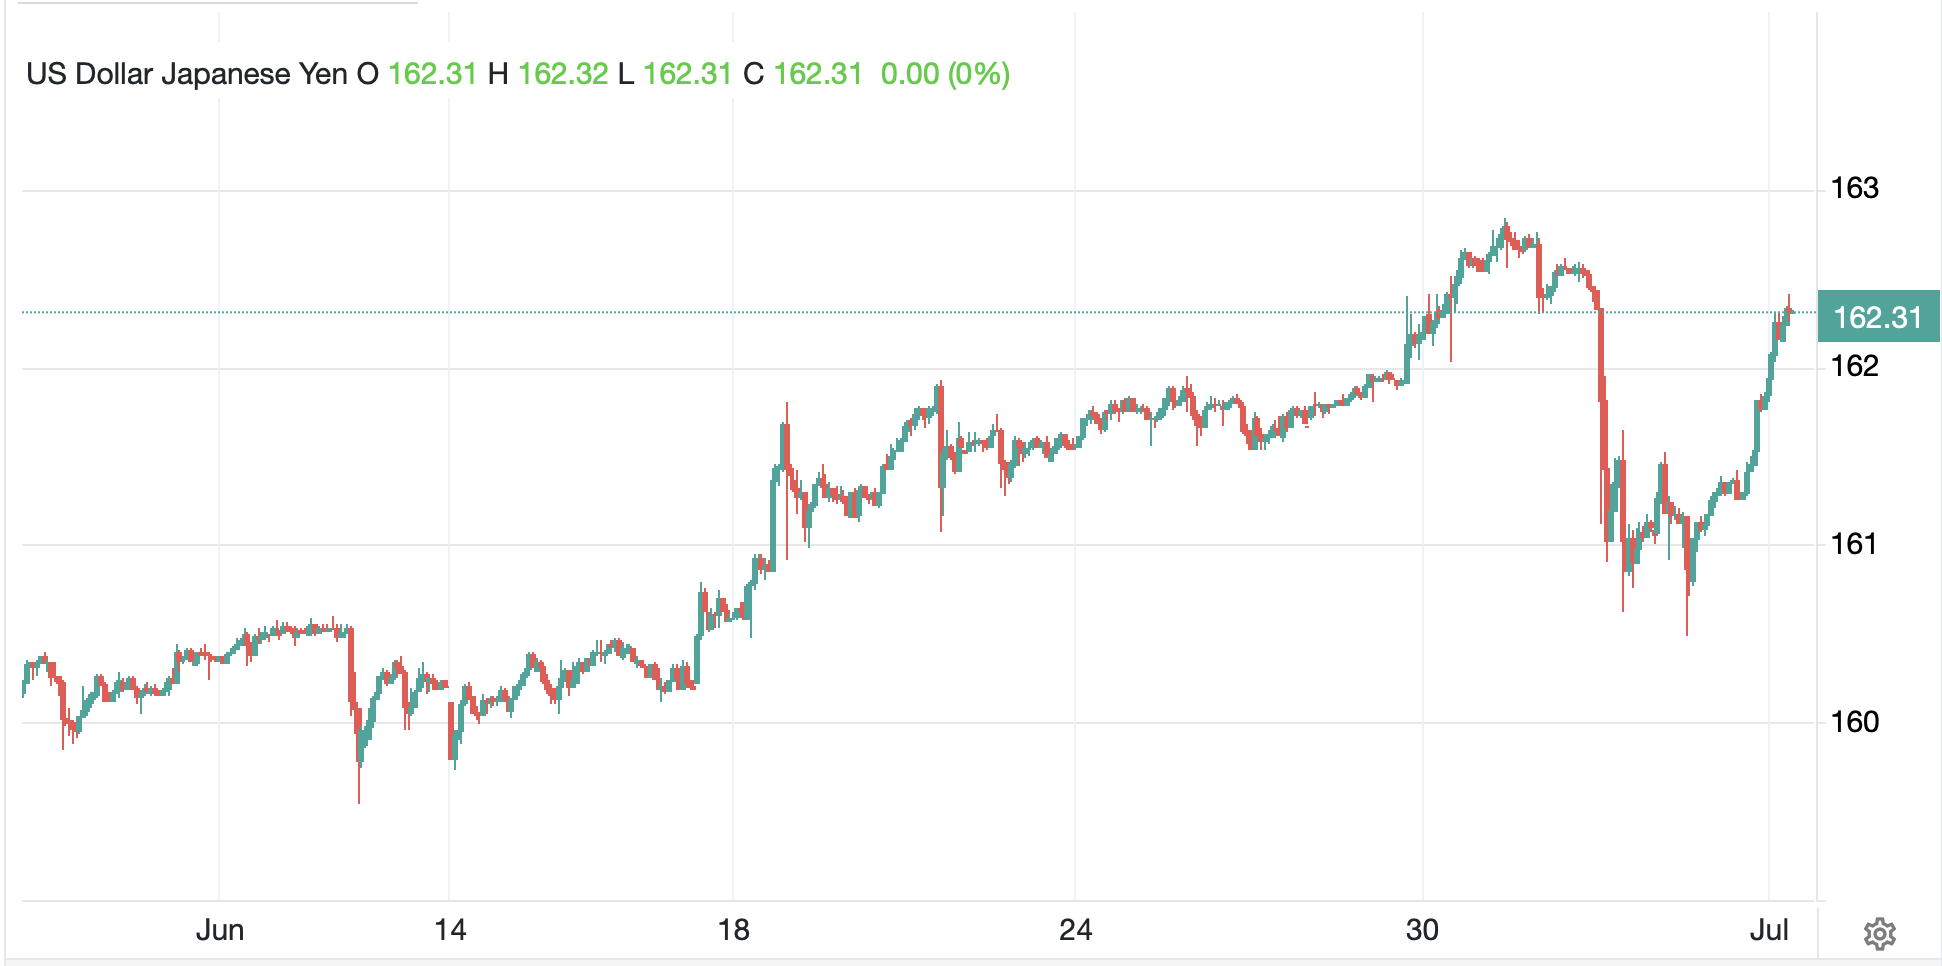
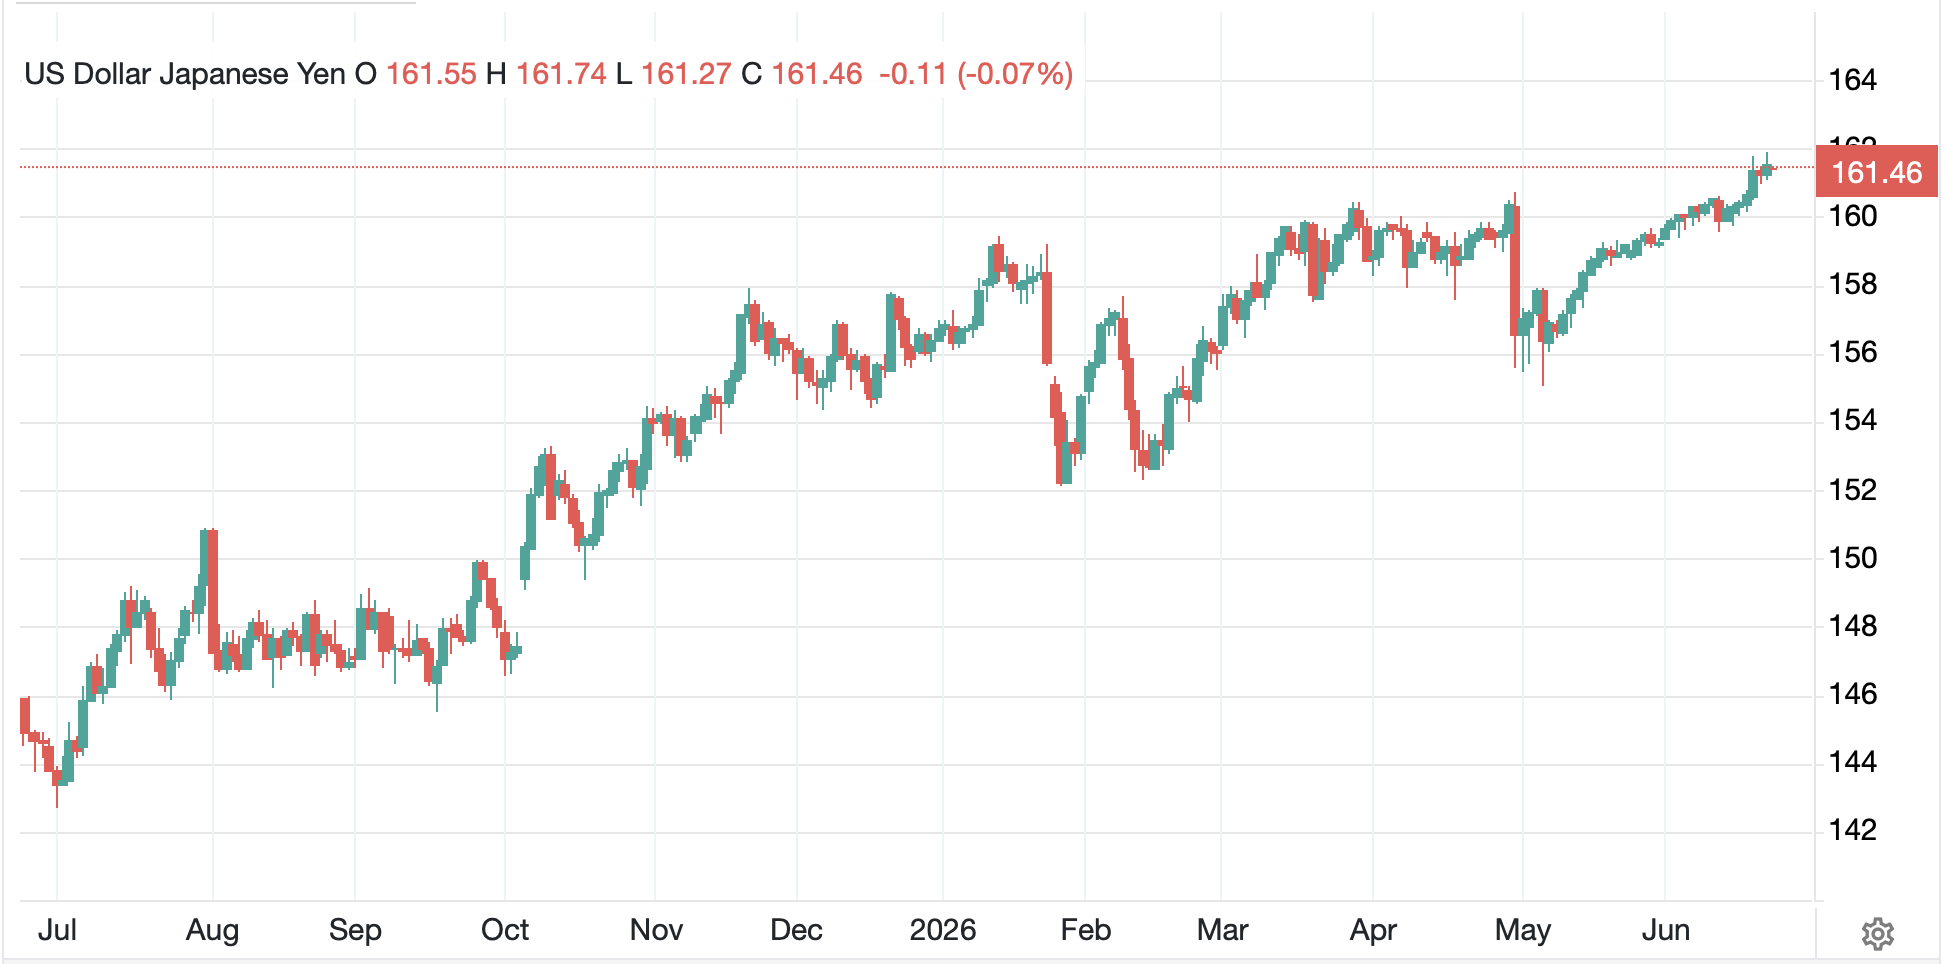
Which takes us to the currency that most needs to see a more dovish FOMC, the yen (-0.6%).  You may remember last week when the yen, after making yet another new low for the move, suddenly reversed course ahead of the July 4thholiday.  While there was no actual intervention, the discussion was that the MOF would no longer discuss their intentions ahead of any intervention and with a holiday weekend seeing reduced liquidity, many anticipated some action.  Well, as you can see from the chart below, that idea has essentially been erased with the yen softening again and pushing back to those lows seen last week.

Source: tradingeconomics.com

Bloomberg ran an article this morning about a former Vice Minister from the MOF explaining his view that the yen was undervalued by 20% or so.  If we look at the yen on a PPP basis, the IMF claims the value should be about 93-95 instead of the current 162+.  The Economist’s Big Mac Index calls for 78.00, and by all accounts, visiting Japan is relatively inexpensive for most foreigners.  In fact, I read that Japan was increasing the visa fees to try to discourage the massive amount of tourism as people around the world see it as a cheap destination.

Ultimately, the problem with the yen, in my view, remains that real interest rates remain deeply negative and the government’s spending plans continue to indicate massive deficits as far as the eye can see.  While reduced energy prices are a boon, the yen was falling sharply long before the Iran conflict began.  Policy changes of substance are required, and they are still uncomfortable for domestic politics.  While the pace of the yen’s decline may slow, I still see it weakening going forward.

So, let’s briefly look at markets overnight before closing.  Regarding the dollar, it is broadly stronger this morning with only BRL (+0.3%) finding any support despite their ignominious defeat to the Norwegians.  But modest slippage across the G10 is the rule, -0.1% to -0.2%, while similar movement has been observed in the rest of the EMG space.  For now, the yen remains the only interesting currency.

In the commodity markets, despite oil’s continuing slide, this morning the metals (Au -0.4%, Ag -0.6%, Cu -0.1%) are also under pressure, but that accords with the dollar’s strength.  As long as the dollar remains bid, it appears the metals markets will have difficulty gaining traction.  But if I am correct regarding the Fed and the market turning toward a more dovish view, I would look for the metals to head higher again.

In the bond market, Treasury yields (-3bps) are slipping as the market reopens after the holiday weekend, arguably following through on the softer payroll data.  European sovereign yields are little changed to lower by -1bp amid a quiet market while JGB yields (+4bps) are the notable outlier, arguably as concerns rise over the weakening yen.

Finally, equity markets remain beholden to the semiconductor and AI trade and with the US having been closed on Friday, there was less information for the rest of the world.  But this morning, NASDAQ futures (+0.9%) look like they are set to resume their march higher, dragging the S&P with them.  But this follows a mixed to lower session in Asia (Tokyo 0.0%, China 0.0%, HK +1.1%, Korea -0.5%, India +0.7%, Taiwan -0.5%) as leadership was lacking.  Not surprisingly, European bourses are also mixed this morning (Spain -0.7%, UK -0.2%), Germany and France both +0.1%) as the question of note is how much defense investment is going to be forthcoming from NATO and European nations and how much of that will be spent in Europe.  Perhaps excitement in the US will help global risk appetite as the day wears on.

On the data front, it is a quiet week for numbers with just the below on the docket:

TodayISM Services54.0
TuesdayTrade Balance-$78.0B
WednesdayFOMC Minutes 
ThursdayInitial Claims220K
 Continuing Claims1810K
 Existing Home Sales4.20M

Source: tradingeconomics.com

As well, we hear from three Fed speakers, Waller, Williams and Logan. Now it will be interesting to see if any of them start to discuss the lower energy prices and how that is likely to moderate their inflation concerns.  If we do hear something like that, I expect the Fed funds table above will reflect that quickly.  We shall see.

It is summer, and there is not much new to discuss.  With the US playing Belgium tonight, all eyes will be there, and my take is we are not looking forward to a terribly exciting session today.

Good luck

Adf
Really Vexed

Said Warsh, when I think of what’s next
For prices, I’m not really vexed
The narrative’s starting,
A new view, imparting
That lower, is what it expects

While futures have yet to adjust
The more this idea gets discussed
The more it’s presumed
The hike story’s doomed
While negative vibes turn to dust

Fed Chair Warsh was in Sintra, Portugal yesterday on a panel with Madame Lagarde, BOE Governor Bailey and BOC Governor Macklem answering questions about monetary policy, forward guidance, and the future of economies as they are impacted by AI.  Now, despite Mr Warsh’s adamant explanation at the last FOMC presser that forward guidance was dead, that didn’t stop the interviewer from asking about the Fed’s likely future moves repeatedly.  This is getting tiresome.  

Nonetheless, here is the comment I believe was most important. “Expectations of future inflation [over the last four weeks] have come down. Inflation risks have come down,” and anyone expecting the Fed would tolerate inflation running above its 2% goal “would be disappointed,” he added.

So, the first thing I did was look at the CME’s probability matrix based on its Fed funds futures contract, and there is no evidence to support Warsh’s comments there.  As you can see from the below table, it looks virtually identical to what we have seen over the past week, a hike in October and a 40% chance of a second one in December.

Now, I will cut him some slack because, while I agree with him and expect that we will see lower inflation readings this month, simply on the back of the decline in energy prices, the rate hike narrative has been building for a while and has many adherents.  My take is that the above table will not change very much until we have seen the two key data points this month, today’s NFP and CPI which is due to be released on Bastille Day.

While I’m on the subject, here is the current view of today’s median expectations according to tradingeconomics.com

Nonfarm Payrolls110K
Private Payrolls110K
Manufacturing Payrolls3K
Unemployment Rate4.3%
Average Hourly Earnings0.3% (3.5% Y/Y)
Average Weekly Hours34.3
Participation Rate61.7%
Initial Claims220K
Continuing Claims1810K
Factory Orders-1.8%
-ex Transport0.4%

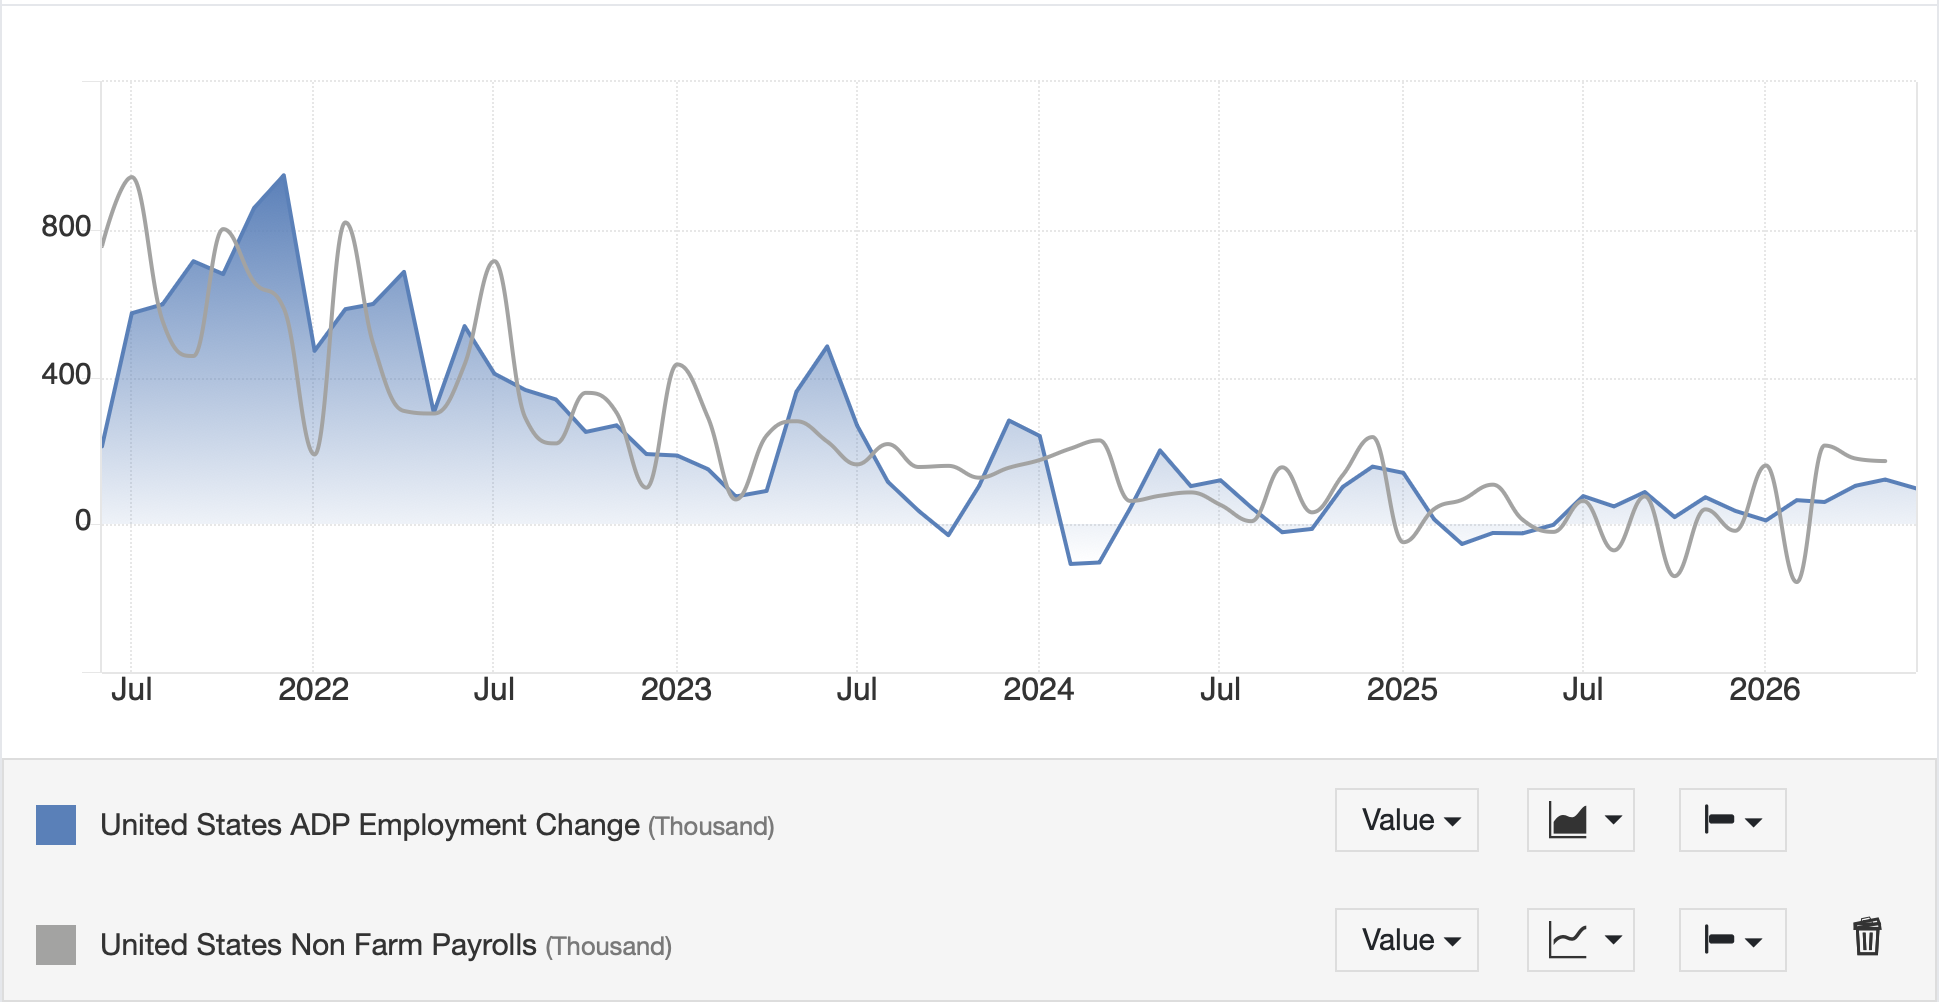
Yesterday saw a slightly softer than expected ADP employment number, 98K vs. the 113K expected and 122K last month, but as you can see from the chart below, comparing ADP to NFP, while the trend remains similar in both, there are an awful lot of wiggles in any given month.

Source: tradingeconomics.com

As things currently stand, the market’s strong Keynesian belief is if NFP is strong, that will be inflationary although it is quite clear that Chairman Warsh does not adhere strictly to that viewpoint (another reason I like him) as he anticipates significant productivity enhancements going forward on the back of AI adoption.  But my point is, if we see a strong print this morning, I would look for the market to price more aggressively for a rate hike.  I guess we’ll find out shortly.

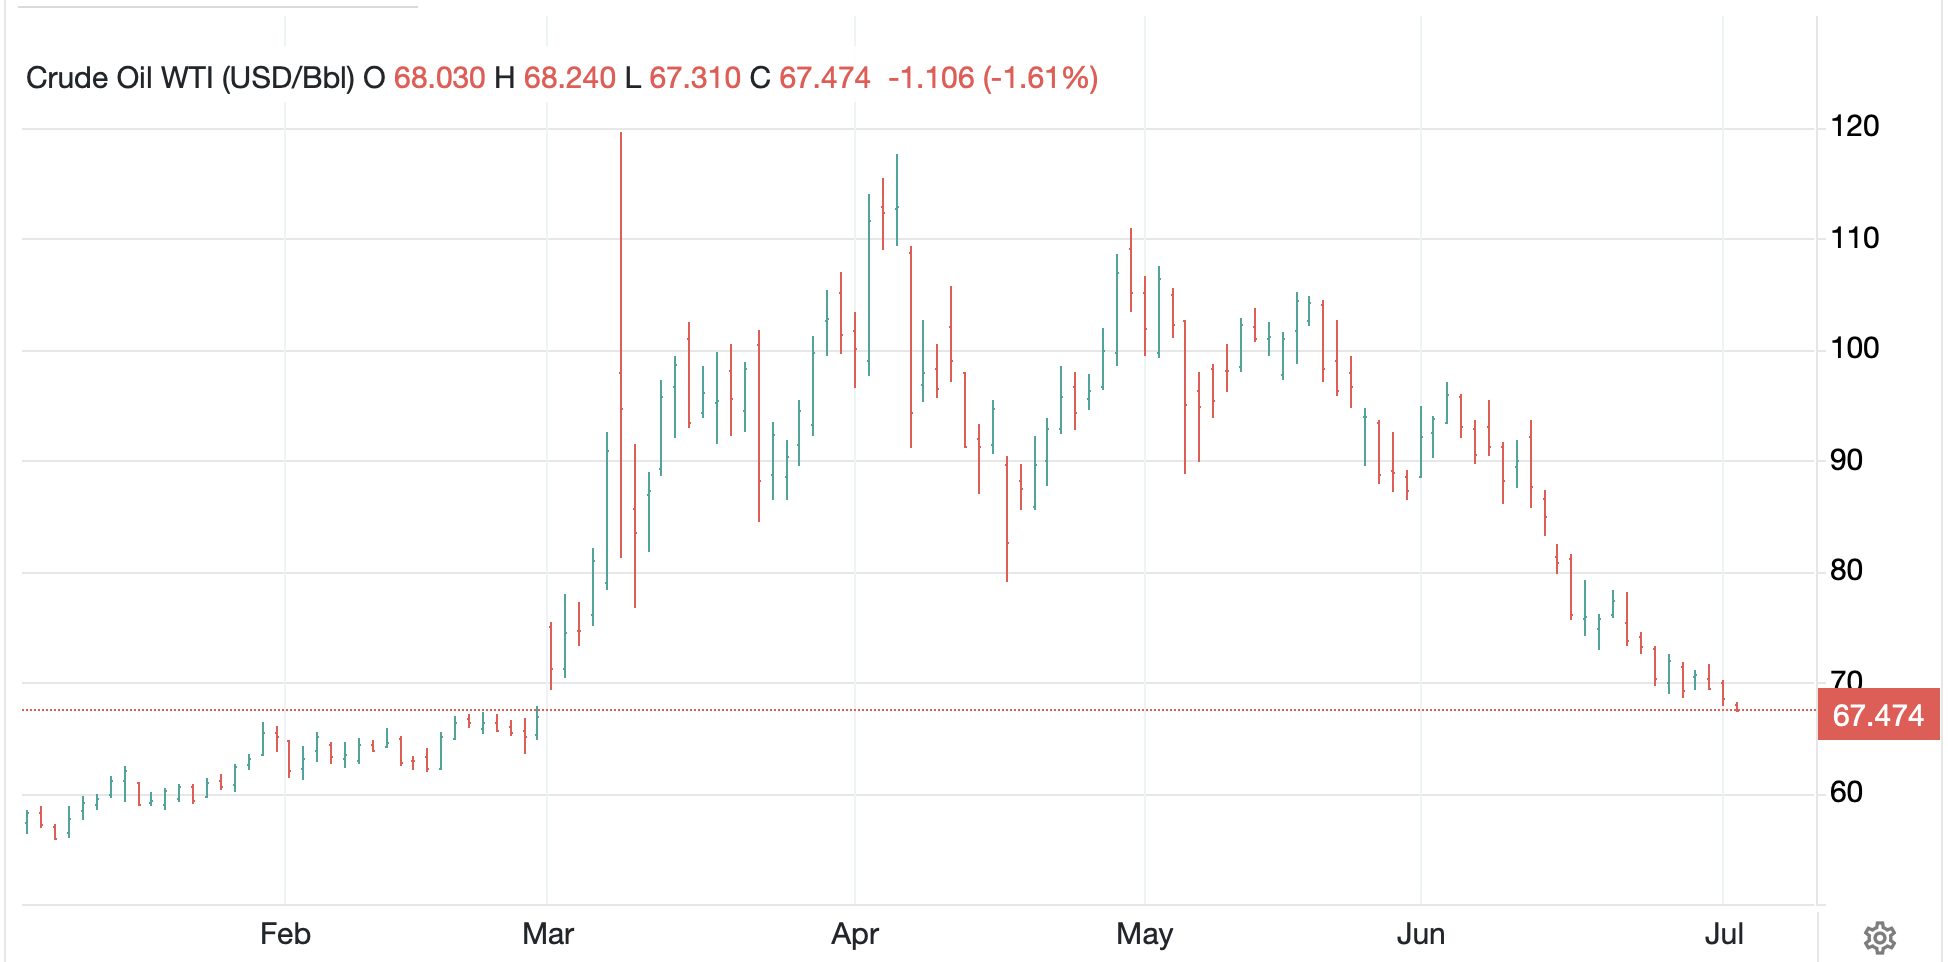
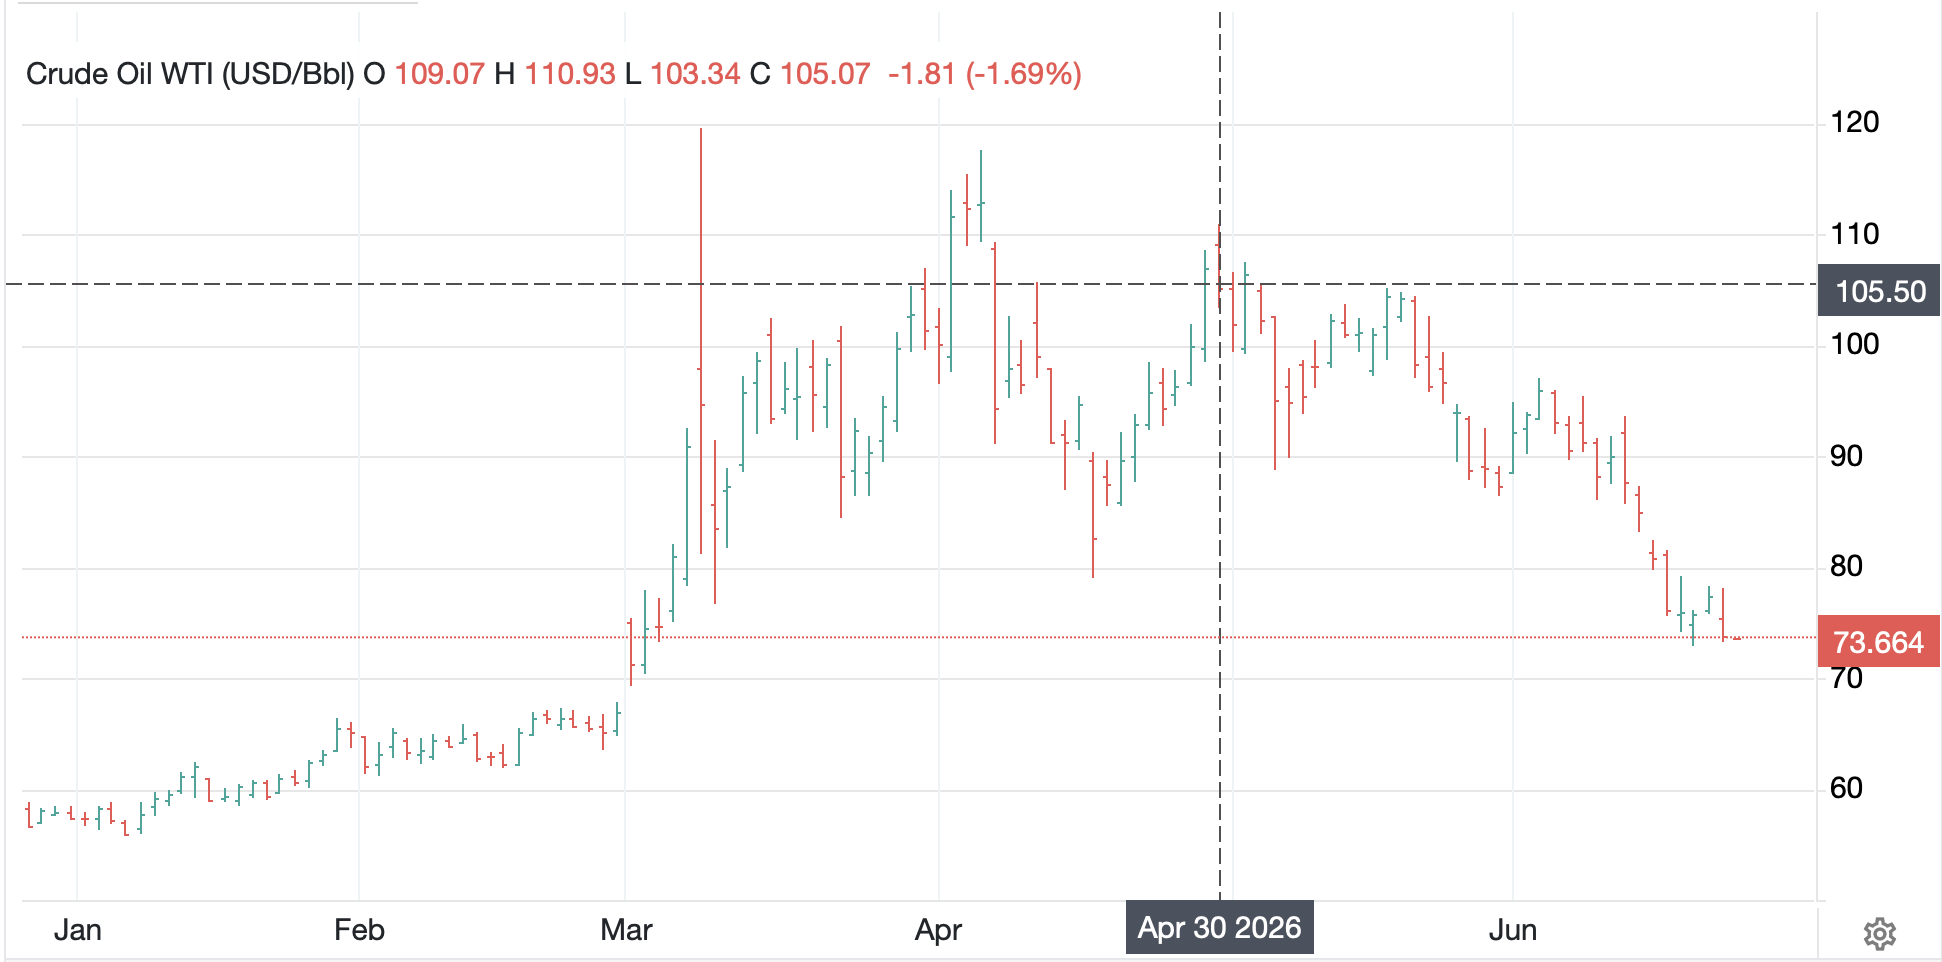
In the meantime, let’s see what happened overnight.  Starting with commodity markets, oil (-1.5%) continues to slide regardless of the group of doomporners who insist that we are about to run out of oil, or that Iran now controls the Strait of Hormuz and will kill the global economy.  In fact, from a technical perspective, we have filled the gap that opened back on March 2nd, the first day markets were open after the conflict began.

Source: tradingeconomics.com

My question for all those who remain certain that we have merely delayed oilmageddon is, how low will prices need to fall before they are willing to admit they misread the reality of the global oil market?  And, with oil sliding, precious metals (Au +0.8%, Ag +1.1%) are finding support.  It seems to me there is a lot of wood left to chop in the PM market, but I maintain my longer-term bullish outlook.

Turning to the bond market, yields rose again yesterday in the US (10-year +6bps) and have edged higher again this morning by 1bp.  My sense is this is based on the idea that Warsh’s final comment from above about tolerating above-target inflation has the hawks all bulled up.  Perhaps, Sintra helped the hawkish case elsewhere as well as European sovereign yields are all higher this morning by between 4bps and 5bps and JGB yields overnight jumped 8bps.

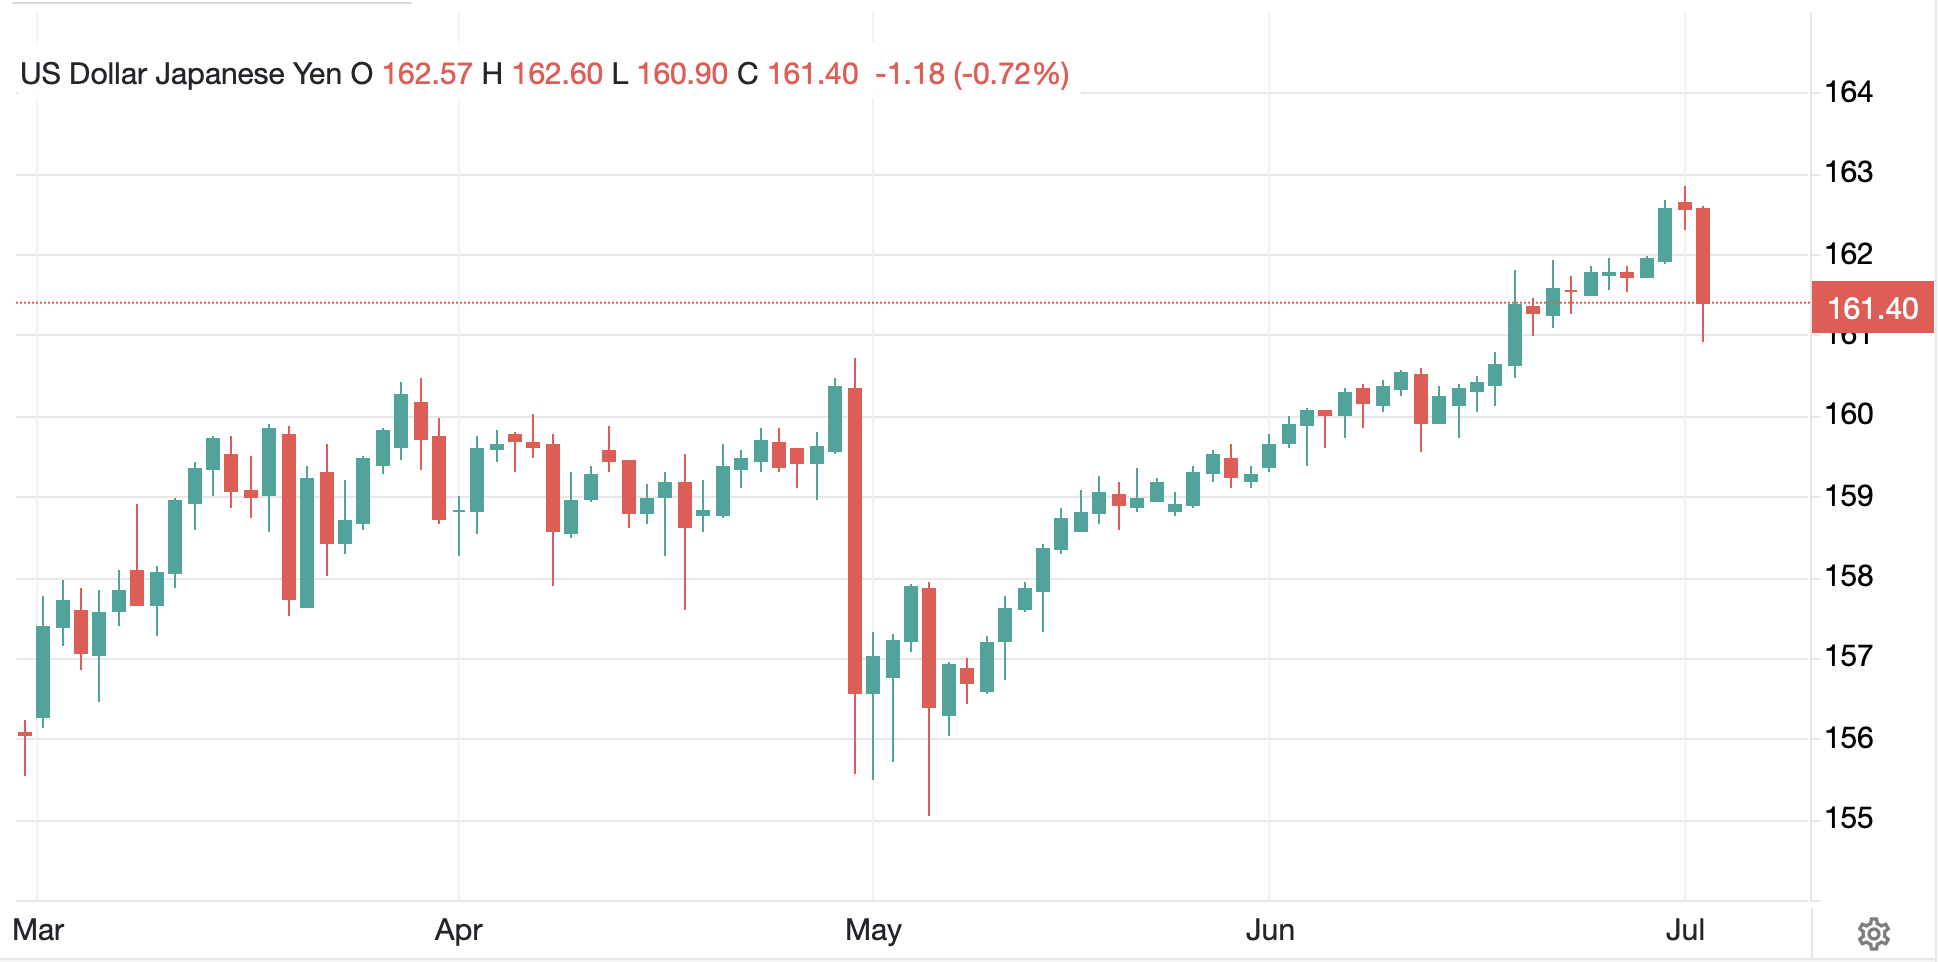
But there is a kink in the narrative now as despite this perceived hawkishness in the bond market, the FX market clearly heard a different tune.  This is clearest in USDJPY, my favorite recent discussion, as you can see in the chart below.  The yen jumped 0.7% ostensibly on the idea that Warsh’s comments about reduced inflation expectations implied a less hawkish Fed, despite the bond market reading the comment about unwillingness to tolerate inflation as a more hawkish Fed.

Source: tradingeconomics.com

But it’s not just the yen.  The dollar is lower vs. virtually all its counterparts in both G10 and EMG spaces.  So, the question you need to ask yourself is, who do you believe?  Bond traders or FX traders?  Historically, observers call bond investors/traders the ‘smart’ money, but they have made plenty of mistakes in the past.  And the thing about FX traders is they seem to be far nimbler.  Of course, you know I am an FX guy, and as it happens, I think this is the market that has it right.

Finally, equity markets had a mixed performance in Asia (Japan -2.5%, China -3.0%, Korea -7.9%) as tech stocks have been feeling some pain, but we did see gains in HK (+0.8%), India (+0.8%) and Singapore (+1.1%) as a counterbalance.  That Korean number was impressive, but mostly what we are seeing there is serious volatility as the KOSPI is even more concentrated than the NASDAQ with just two companies, Samsung and SK Hynix, representing about 40% of the index.  If they have a bad day, the index does as well.

In Europe, though, things are brighter this morning with gains across the board (Germany +0.9%, Spain +0.9%, France +0.8%, UK +0.5%) although there is no obvious catalyst for the move.  There was no data of note (Eurozone Unemployment fell to 6.2% but that seems unlikely to be the driver) so perhaps the very fact there are no tech companies in Europe and tech is what is currently under pressure makes Europe seem a bargain.  As to US futures, ahead of all the data this morning, they are little changed.

And that’s really it for today.  As tomorrow is a holiday, there will be no poetry, so I wish you all a wonderful holiday weekend.  3 Cheers for the USMNT after their Round of 32 victory last night (alas it was on way too late for me to watch, but we will all be cheering on Monday night.

Good luck and good weekend

Adf

Just Keeping Up

The yen slid further
Is it accelerating?
Or just keeping up?

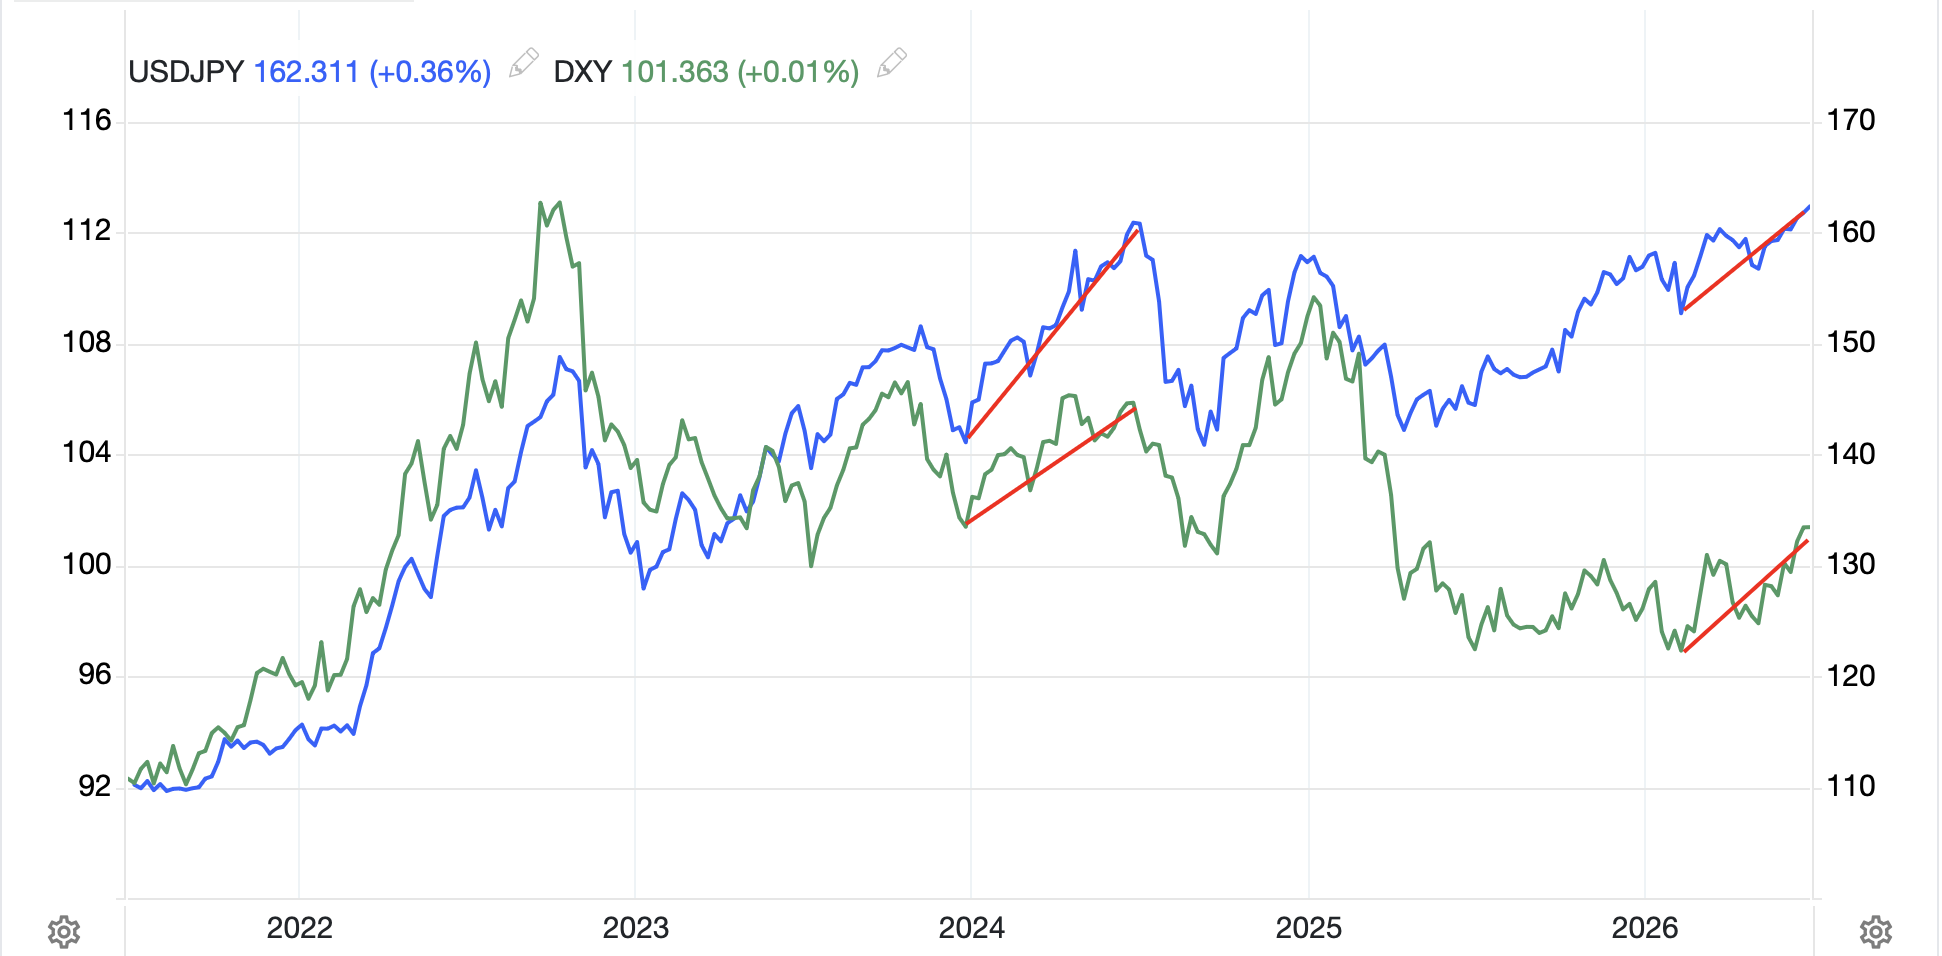
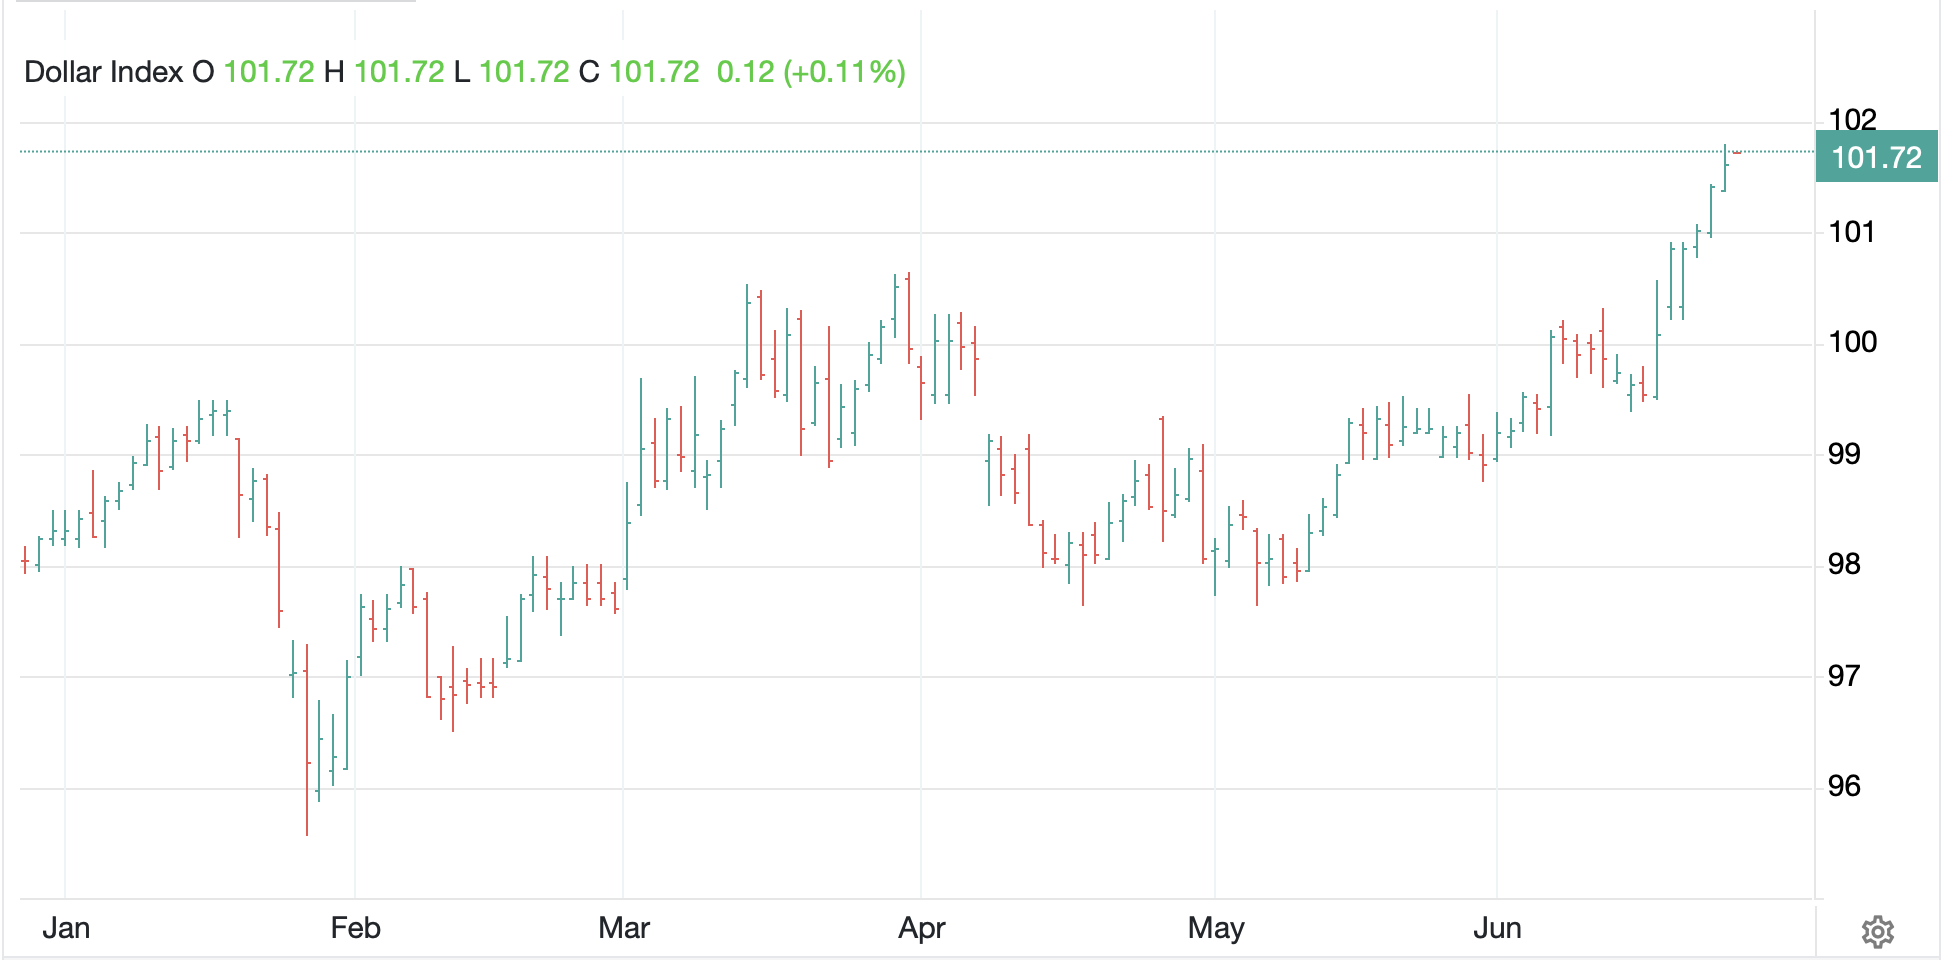
There has been a lot of press this morning regarding the yen (-0.25%) which as you can see has weakened a bit, but hardly an extraordinary move.  Thus, the press is all about the level at which it now trades, 162.30ish which is a new high for the move, although it has yet to break above its 1986 levels.  The nature of the articles has been a question as to when the BOJ is going to be back intervening again which then morphs into a discussion as to whether intervention is effective.  (While I don’t know if they will be back in, I imagine that will be the case at some point, we know it is not effective.)  At any rate, I have created the following chart on tradingeconomics.com so that you can (hopefully) see why they have not yet intervened.

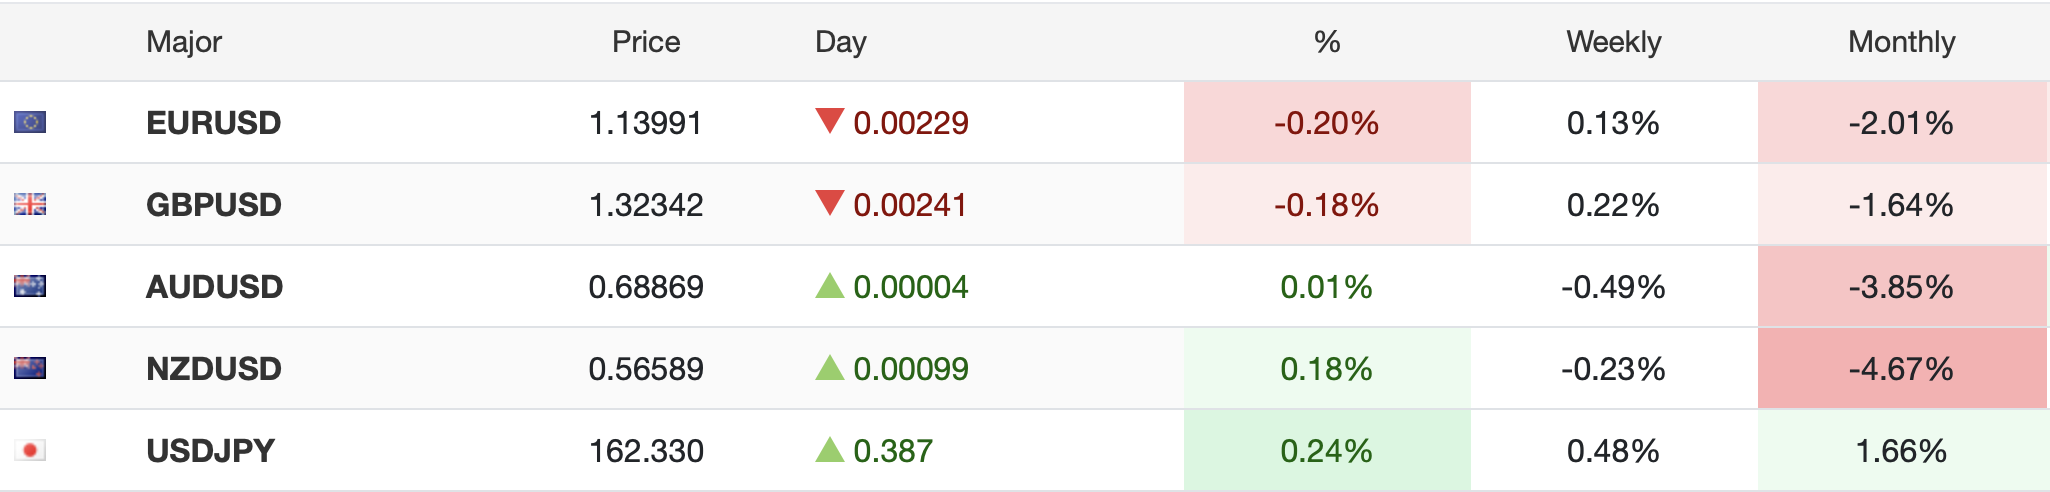
One of the key features of the MOF seven step program to intervention is the pace of the yen’s movement.  A rapid decline is far less tolerable than a gradual movement.  As well, there is the question of whether the yen is declining across the board, or it if is declining specifically, or at least more rapidly, vs. the dollar.  It is no surprise to me that the MOF remains on the sidelines as the dollar is rallying everywhere right now, so yen weakness is really more about dollar strength.  If you look at the chart above, I tried to show the slope of the movement in USDJPY vs. DXY back in the beginning of 2024 which was the previous time the yen started to show serious weakness and the BOJ intervened.  To my eye, the slope of the two lines in 2024 are far different than the slope of the current movement.  In fact, the table below shows that the yen’s weakness over the past week and month is hardly an outlier.  In fact, it has basically held up better than its major counterparts.

My point is much is being made about the yen’s breech of the 162 level, but the movement has been quite gradual, hardly the rapid and volatile movement that has driven intervention decisions in the past.  Frankly, there is little reason to believe that with the dollar strong across the board, the BOJ can do anything other than waste money in an intervention effort.

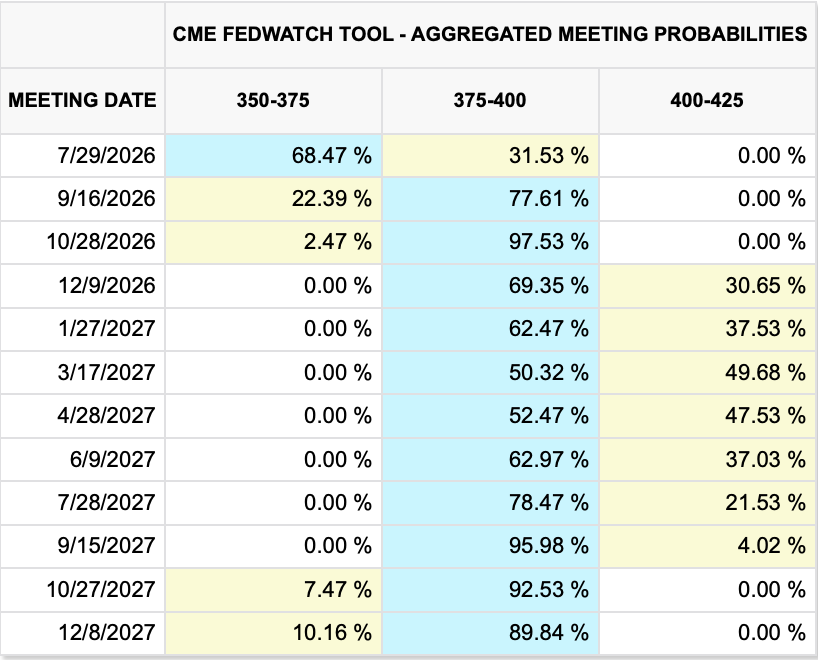
Which begs the question, why is the dollar performing so well?  The pat answer remains that the market is pricing in a suddenly hawkish FOMC with the Fed funds futures market pricing an October rate hike now, with a one-third chance of a second one in December.  See below from the CME.

But I still don’t understand that pricing.  Despite all the ongoing chatter about the imminent shortage of oil/diesel/gasoline/jet fuel that has yet to appear and has now been delayed to H2 of this year, markets continue to price limited further interruption to energy availability.  In addition, one need only look at today’s raft of Eurozone inflation data where France (1.8%), Italy (3.0%) and every German state (between 2.1% and 2.4%) all printed lower than last month, as well as lower than forecast, and recognize that the significant decline in energy prices over the past month is going to push down measured inflation.  Nothing has changed my view that the Fed is on hold for now, and over the next several months the idea of rate cuts will come back into vogue.  At that point, I assume the dollar will give up its recent gains, although I do not foresee a reason for a substantial decline.  After all, investment flows into the US are going to remain robust.

And with that, let’s look at other markets.  As proof positive that nothing is ongoing, oil is unchanged this morning, just above $70/bbl and there has been precious little new news about the situation in the Gulf.  Metals are edging higher (Au +0.4%, Ag +1.3%, Cu +1.3%) but the precious set remain in downtrends although copper is in demand.

You’ve already seen the dollar movement above, at least vs. the bulk of the G10.  But elsewhere, it is not a very interesting picture either.  Perhaps the fact that ZAR (+0.3%) is firmer this morning on the back of both the modest rise in gold and the fact that their fiscal situation looks a bit better (significantly reduced budget deficit in May) is the outlier of note.

Bond markets continue to drift as 10-year Treasury yields slip -1bp and we see similar price action across most of Europe.  The outlier here is Italy (+3bps) which given the better-than-expected inflation data is confusing and I have seen no other cogent explanation.  As well JGB yields (+4bps) overnight reacted to the yen’s weakness as well as to comments by the newest BOJ member, Ayano Sato, who sounded modestly dovish.

Finally, turning to the equity markets, another record setting day in the US was followed by a mixed picture in Asia with both gainers (Tokyo +0.9%, China +1.1%, Korea +1.0%, Taiwan +2.5%) and laggards (HK -0.6%, Australia -0.5%, India -0.3%, Indonesia -3.1%) with the latter a response to a legal verdict of corruption which the market has taken as a major government intrusion into the economy and frightened investors.

Turning to Europe, though, everybody is happy this morning with gains across the board (Germany +1.5%, UK +1.2%, Spain +0.7%, France +0.6%) as those slipping inflation numbers help the overall sentiment.  As to US futures, you will not be surprised that at this hour (7:25) they are marginally higher.  

One must be impressed with the consistency of equity market gains.  It is enough to make you reconsider your prior ideas as to how markets work.  Arguably, the key feature of the recent equity market performance is that earnings data continues to improve.  Now, if you look at the ongoing growth in money supply, both in the US and around the world, it is no surprise that nominal results continue to rise.  It is also not surprising that people are feeling stressed by inflation regardless of the data that is printed as all that money has to find a home somewhere.  And the Cantillon effect tells us that the first folks who get the newly printed money (banks and institutions) are the ones who benefit the most while the rest of us simply watch our cost of living increase.  This is the entire wealth/income inequality story and, arguably, the reason that the idea of socialism is making a comeback.  And socialism does have a perfect record in its economic outcomes; it has failed 100% of the time it has been tried.  But right now, I fear that record is not going to be a problem.  There is much potential trouble ahead.

Today’s data brings Case-Shiller Home Prices (exp 0.9%) as well as Chicago PMI (58.1), JOLTs Job Openings (7.30M) and Consumer Confidence (94.7).  But with Warsh on the tape tomorrow morning and then NFP on Thursday, I don’t see today’s data having much impact.

While the Iran situation is in the background right now, it remains the issue with the biggest potential impact going forward.  A successful conclusion of a deal and resumption of flows of energy through the SOH will put additional downward pressure on energy prices, and by extension general inflation.  In that scenario, central banks will be quick to turn away from rate hikes.  However, if things collapse there, then we will need to be prepared for another major hiccup, that’s for sure.

Good luck

Adf
Peace Was in Sight

The weekend saw missiles in flight
As both sides continued the fight
But just ere the open
The market put hope in
The idea that peace was in sight

So, here we are first thing today
And focus has moved far away
We’re back to AI
And pie in the sky
As stocks, once again, make more hay

Much has been made of the fact that President Trump is hyper aware of financial markets and seeks to ensure that whatever is happening in the world, it happens on weekends so that by the time markets reopen, the situation appears far less dire, hence less need to sell stocks.  This weekend is a perfect example as Friday after the close, it was announced that the US had responded to the several Iranian attacks on ships in the Strait of Hormuz last week with significant force.  The early punditry on Friday night and Saturday was that when markets reopened, the recent decline in oil prices would reverse as that has been predicated on a more lasting peace.  But then, last night shortly before futures markets opened, there were announcements that the US had finished its response and that the peace talks were back on under the guise of the 60-day ceasefire.  

I have to say, though, it almost appears as if Iran is in on the joke.  After all, if not, wouldn’t they try to force Trump’s hand during market hours?  Just asking.  Whatever the case, the situation as we wake up this morning is that oil (+0.8%) has edged back higher near $70/bbl but certainly doesn’t have the feel of breaking out higher.  Meanwhile, equity markets are generally positive and have been overnight while bond yields and the dollar are little changed.  in other words, there’s not much happening this morning.

In reality, it is not that surprising that things are quiet.  It is summer and summer markets are typically somewhat less active.  As well, away from the uncertainties of the Iran conflict, economic activity seems to be ticking along pretty well.  Arguably, the biggest story remains AI and both its potential impact on workers and the economy as well as the questions about its ability to generate sufficient revenue to repay the hundreds of billions of dollars being spent on it.  But those are longer-term stories, not day-to-day.

Which takes us to this morning.  Frankly, I don’t think there is an interesting market related them right now.  Instead, we have much time-biding until the next big thing.

Let’s start with commodities as oil continues its multi-month decline from the early April peak.  it remains very difficult to look at the below daily chart and think, damn, oil is about to run away higher.  At least for me.

Source: tradingeconomics.com

There are still numerous analysts who maintain that the drawdown of reserves is going to come back and haunt the market, driving prices much higher as inventories fall and tank bottoms are reached.  And I am sure they earnestly believe those outcomes are ordained.  But the relative wisdom of market prices disagrees.

Remember back when this all started, there was another point that was made by these same analysts, that fertilizer shortages would be manifest and food prices would rise much higher.  The story was that the closing of the Strait would reduce the ability of Qatar to produce and ship LNG and that was a critical input into the making of Urea.  Let me show you the price chart for Urea.

Source: tradingeconomics.com

While it certainly rose initially, apparently there is sufficient urea around to continue with agriculture as we know it.  Again, much of the initial fear seems to have been misplaced.  I do not know if that is because analysts didn’t really understand the way these markets operated, or because they have models that they have used for years, and those models are no longer fit for purpose.  My observation is that many analysts try to determine the price trends by looking at their understanding of both supply and demand of a given commodity.  But I might argue that the price is what defines both supply and demand, and that at given prices, those two curves adjust to make the system work.  Think of it as price is the independent variable, not supply/demand.

Moving on to the metals markets, they remain under pressure this morning with both gold (-1.3%) and silver (-1.9%) unable to find support, especially the latter.  Copper (-0.3%) is holding up better and I continue to believe that all three will fare well over time, but not right now.

In the equity markets, Friday’s nondescript US markets were followed by more strength (Tokyo +0.15%, HK +1.6%, China +1.2%, Australia +0.7%, Taiwan +1.0%) than weakness (Korea -0.2%, India -0.5%, Indonesia -1.3%) in Asia.  The big news overnight was the South Korean government supporting a massive semiconductor investment by the two big Korean firms, SK Hynix and Samsung, to build four more fabs.  In Europe, though, things are less positive with Germany’s unchanged performance leading the way although the declines elsewhere (UK -0.2%, France -0.3%, Spain -0.4%) are hardly devastating.  We ought not be surprised that US futures are higher this morning as I type (7:25) led by the NASDAQ (+0.9%) as the AI/semiconductor theme continues.

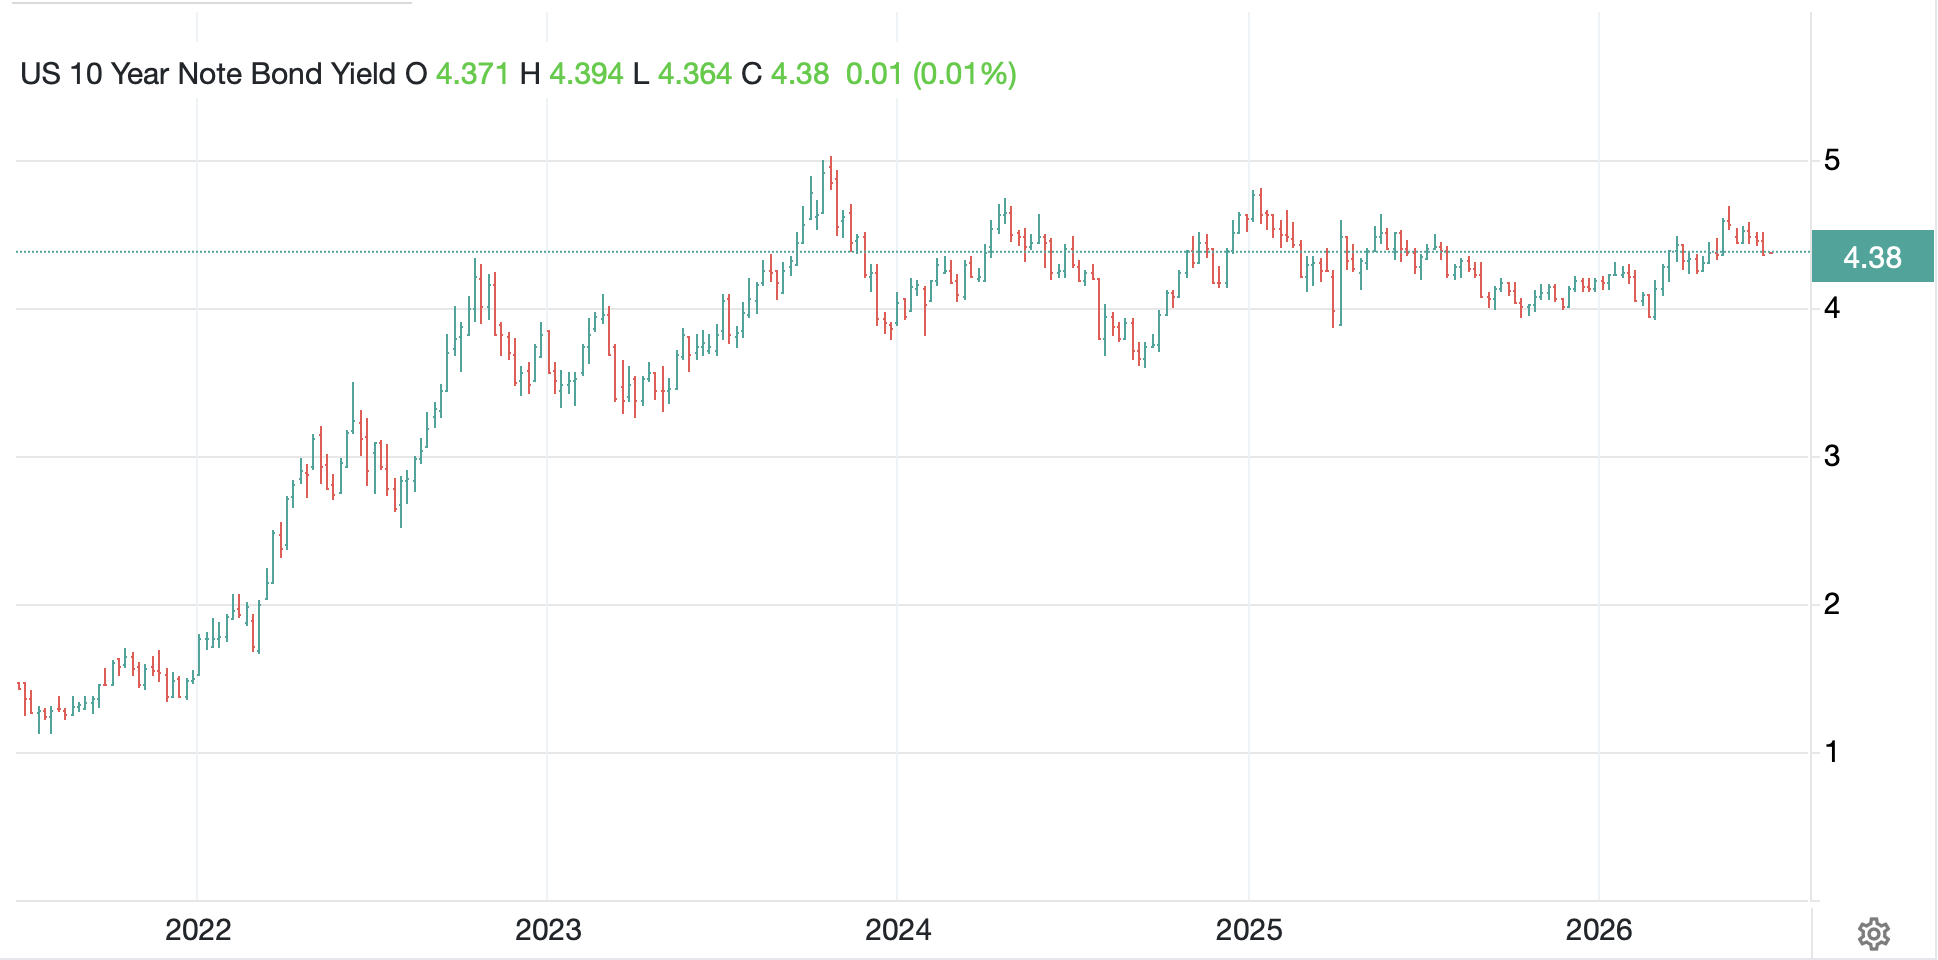
Bond markets continue to do very little with yields essentially unchanged on the day in Europe or the US.  10-year Treasury yields are currently 4.37%, well off the highs seem a month ago near 4.70% when there was much discussion about a breakout higher.  But look at the below longer-term chart of the 10-year Treasury yield and tell me that anything substantive has happened in the past 3+ years.  Since yields rise alongside the 2022 inflation surge, we have seen very little net movement.

Source: tradingeconomics.com

Finally, the dollar is a bit softer this morning but is clearly not the focus today.  I continue to read analyses about Chairman Warsh and what he is going to do and why he will not be able to achieve his goals.  The implication is that either he will need to be ultra hawkish, raise rates quickly and the dollar will soar, or he will wind up with QE 5 or 6 or whatever number we are on, and the dollar will collapse.  My personal view is neither of those scenarios will play out.  As I wrote in the wake of his first meeting, I expect inflation data will ease along with the recent decline in energy prices, and he will be able to do nothing without consequences as he works to change the way things work there.  In the meantime, the dollar will remain supported by real investment flows.

On the data front, even though it is a holiday-shortened week with markets closed Friday for July 4th, we get a lot of data.

TuesdayCase-Shiller Home Prices0.8%
 Chicago PMI60.0
 JOLTS Job Openings7.28M
 Consumer Confidence94.2
WednesdayADP Employment113K
 ISM Manufacturing54.0
 ISM Prices Paid79.0
ThursdayNonfarm Payrolls110K
 Private Payrolls115K
 Manufacturing Payrolls3K
 Unemployment Rate4.3%
 Average Hourly Earnings0.3% (3.5% Y/Y)
 Average Weekly Hours34.3
 Participation Rate61.7%
 Initial Claims220K
 Continuing Claims1825K
 Factory Orders-2.1%
 -ex Transport0.4%

Source: tradingeconomics.com

Obviously, all eyes will be on the payroll data on Thursday.  But Chairman Warsh will be at Europe’s version of Jackson Hole, in Sintra Portugal and speaking at 9am Wednesday morning.  It will certainly be interesting to hear what he has to say there.

It doesn’t seem like there is much about which to get excited today, or tomorrow frankly.  So, Warsh and then NFP will be this week’s story absent another major flareup in the gulf.

Good luck

Adf
Once Again Crumbled

The Techquity rally has stumbled
Though oil has once again crumbled
But pundits don’t care
As they’ll still declare
They’re right. They can never be humbled

Some days are simply less interesting than others, and based on the number of new stories, it seems today is falling into that category.  That’s not to say that some markets haven’t moved, there has been some significant movement, it’s just that the movement is based on the same rehashed story lines we’ve heard for the past several weeks.

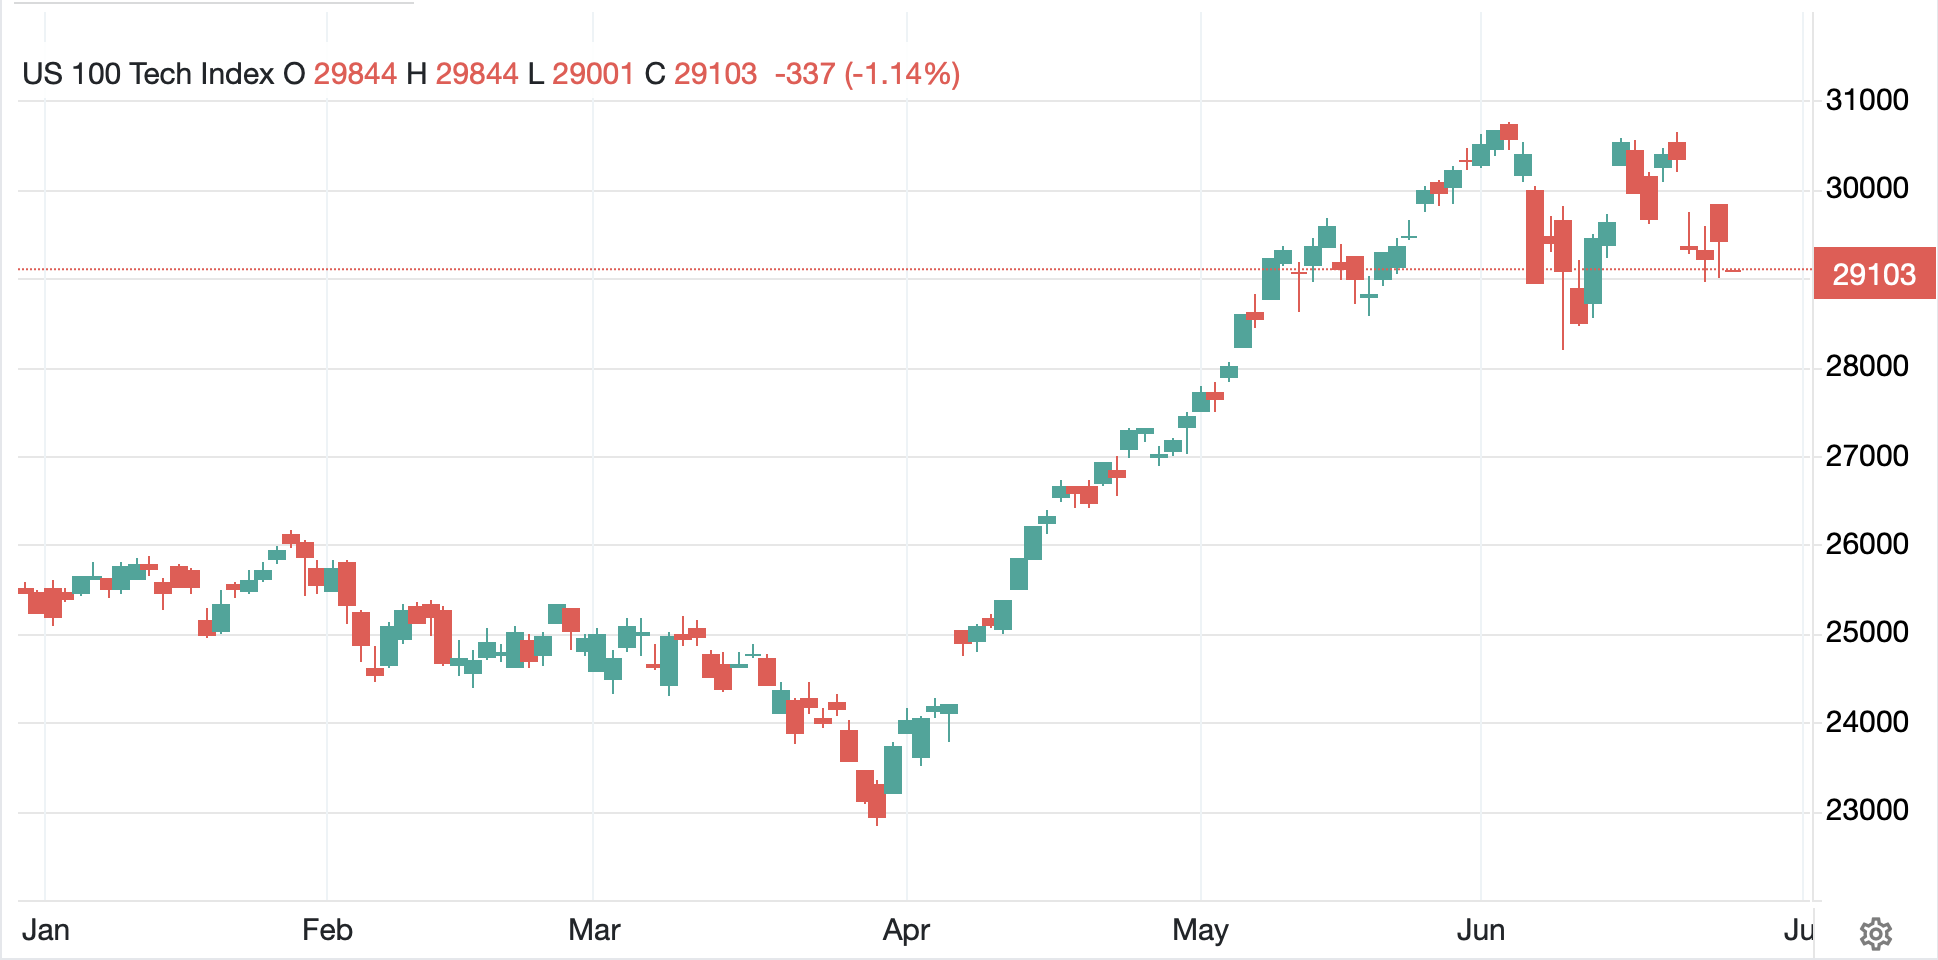
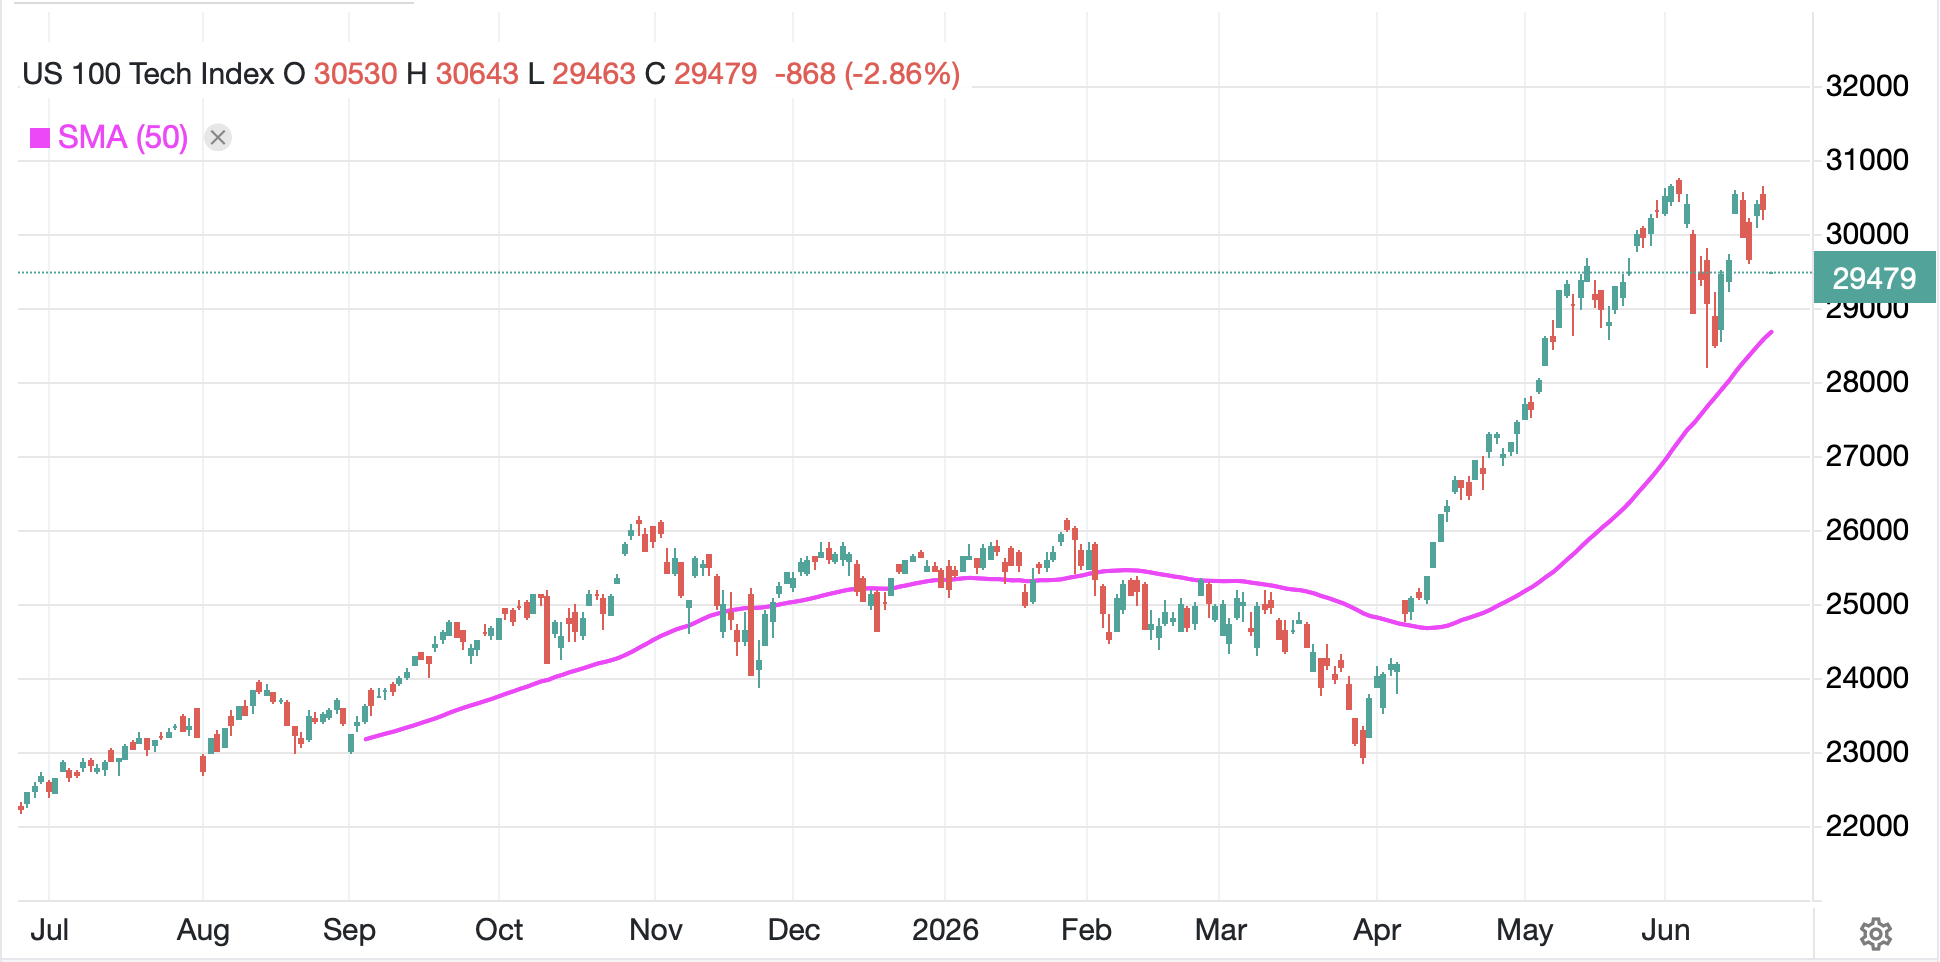
For instance, the below chart of the NASDAQ, with daily candles, shows just how choppy the tech sector has been this month.

Source: tradingeconomics.com

For the market technicians, if you are inherently bearish, this will read as a double top and the next leg is lower, targeting something with a 26000 handle.  However, if you are bullish, you will make the case that this is the end of the “c” wave and we are ready to break to new highs above 31000. 

That’s the thing about market technicals, they remain in the eye of the beholder. If you ask about new news, arguably the Micron Technology earnings were the biggest story of the week, but despite a tremendous outcome, tech stocks could not hold any early gains.  The flipside is that OpenAI has postponed their IPO until next year, a clear sign that they are concerned with sufficient investor capacity.  Again, spin it as you see fit, since there is no right or wrong here, but there are conflicting sentiments.

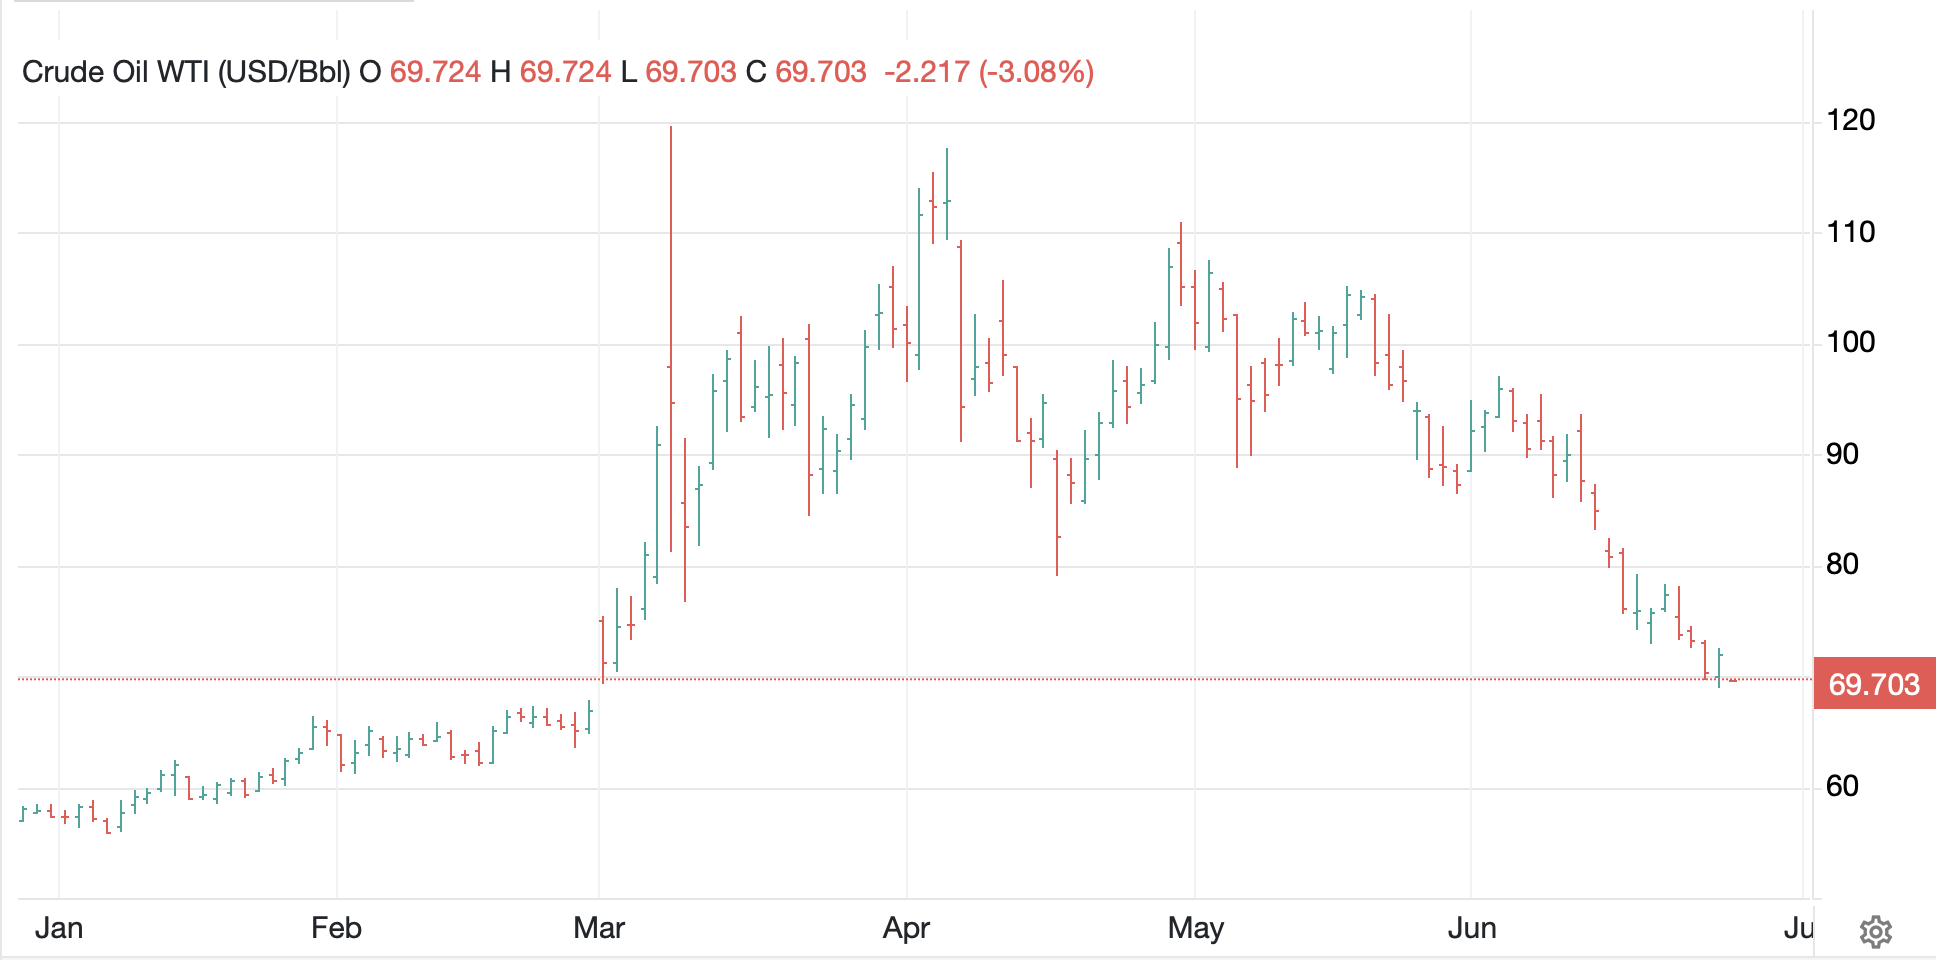
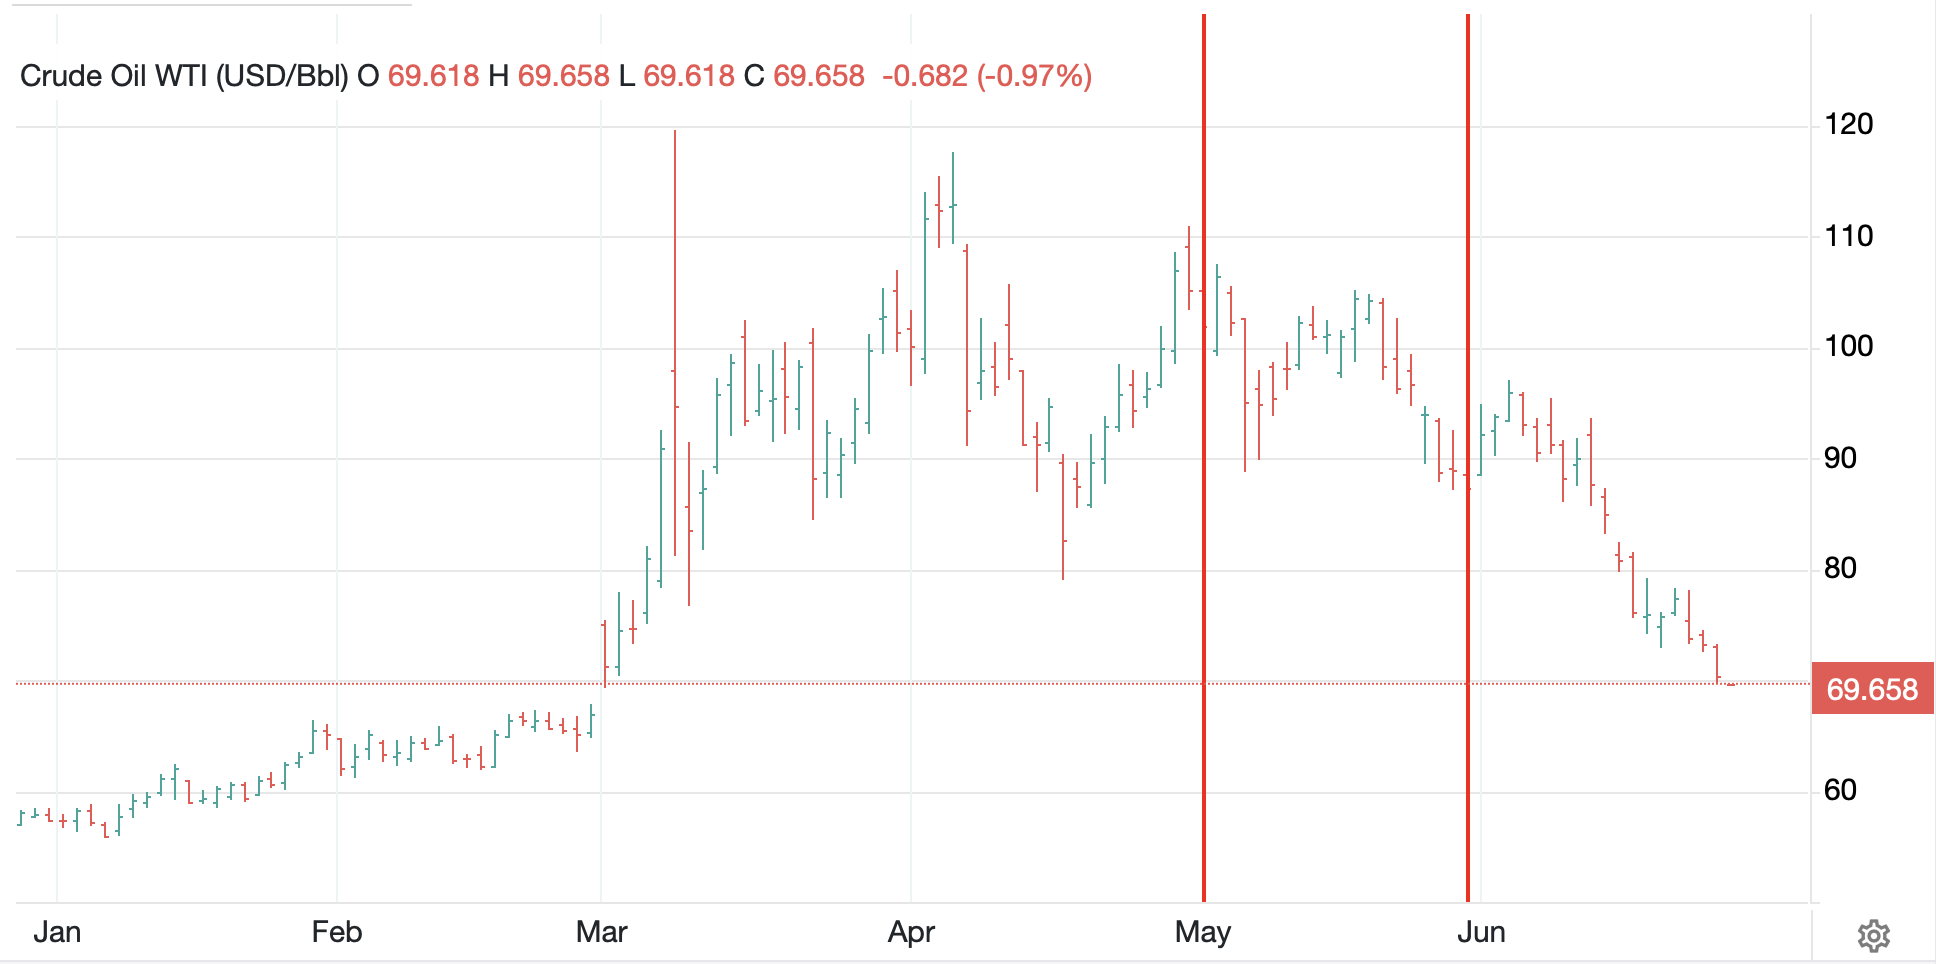
My point is that while there have been headlines, there hasn’t been any news.  Or consider oil (-3.1% this morning), which as you can see from the chart below has fallen back to prewar levels.  

Source: tradingeconomics.com

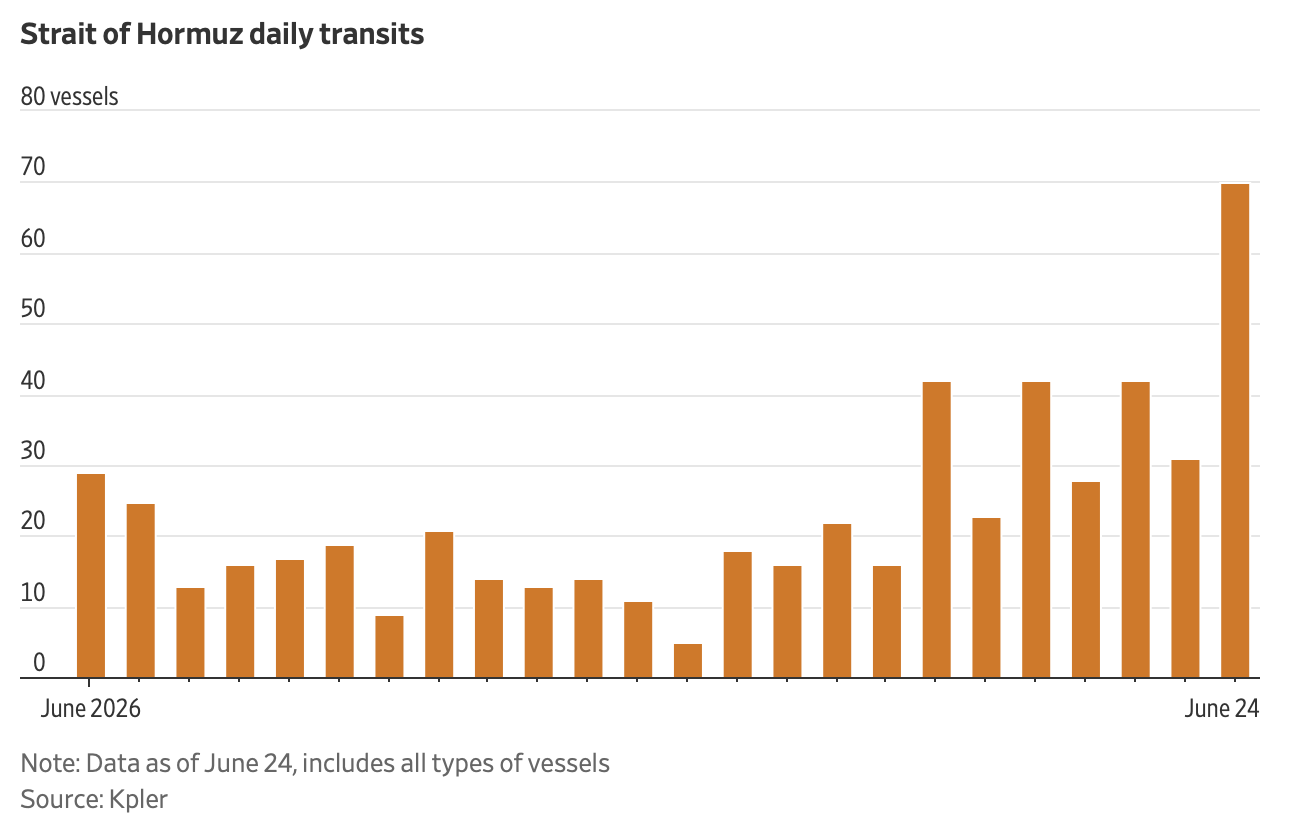
Yes, there was an incident with some freighter being hit by an unidentified object in the SOH, and that jangled a few nerves yesterday, but apparently fully laden VLCCs carrying 2mm barrels of oil, are fleeing the Gulf in ever larger numbers.  I read that 78 ships transited yesterday and as you can see from the chart below from the WSJ this morning, the trend is higher.  

All of the stories about tank bottoms and a sudden spike higher in the price of oil continue to be nothing more than fear porn.  As Alyosha from Market Vibes notes, the likely reason for less inventory is the oil companies are expecting a huge influx of oil from the Gulf and they need some place to put it.  Again, these are warmed over stories and not new news.

By all accounts, we are continuing along the recent path where oil prices continue to normalize while other markets search for the next big thing.  For stocks, the AI debate continues to rage on as to its impact on the future, while resource companies continue to be seen as a place to hang out given the needs of the economy as it grows, and that is a global comment.  For bonds, is inflation fading or persistent and setting to move higher?  The recent view is fading, but obviously that is subject to change.  And the dollar?  It’s had a nice rally, but is it about to break to much higher levels or reverse course?  Over time I see it higher, but for now, not so much.

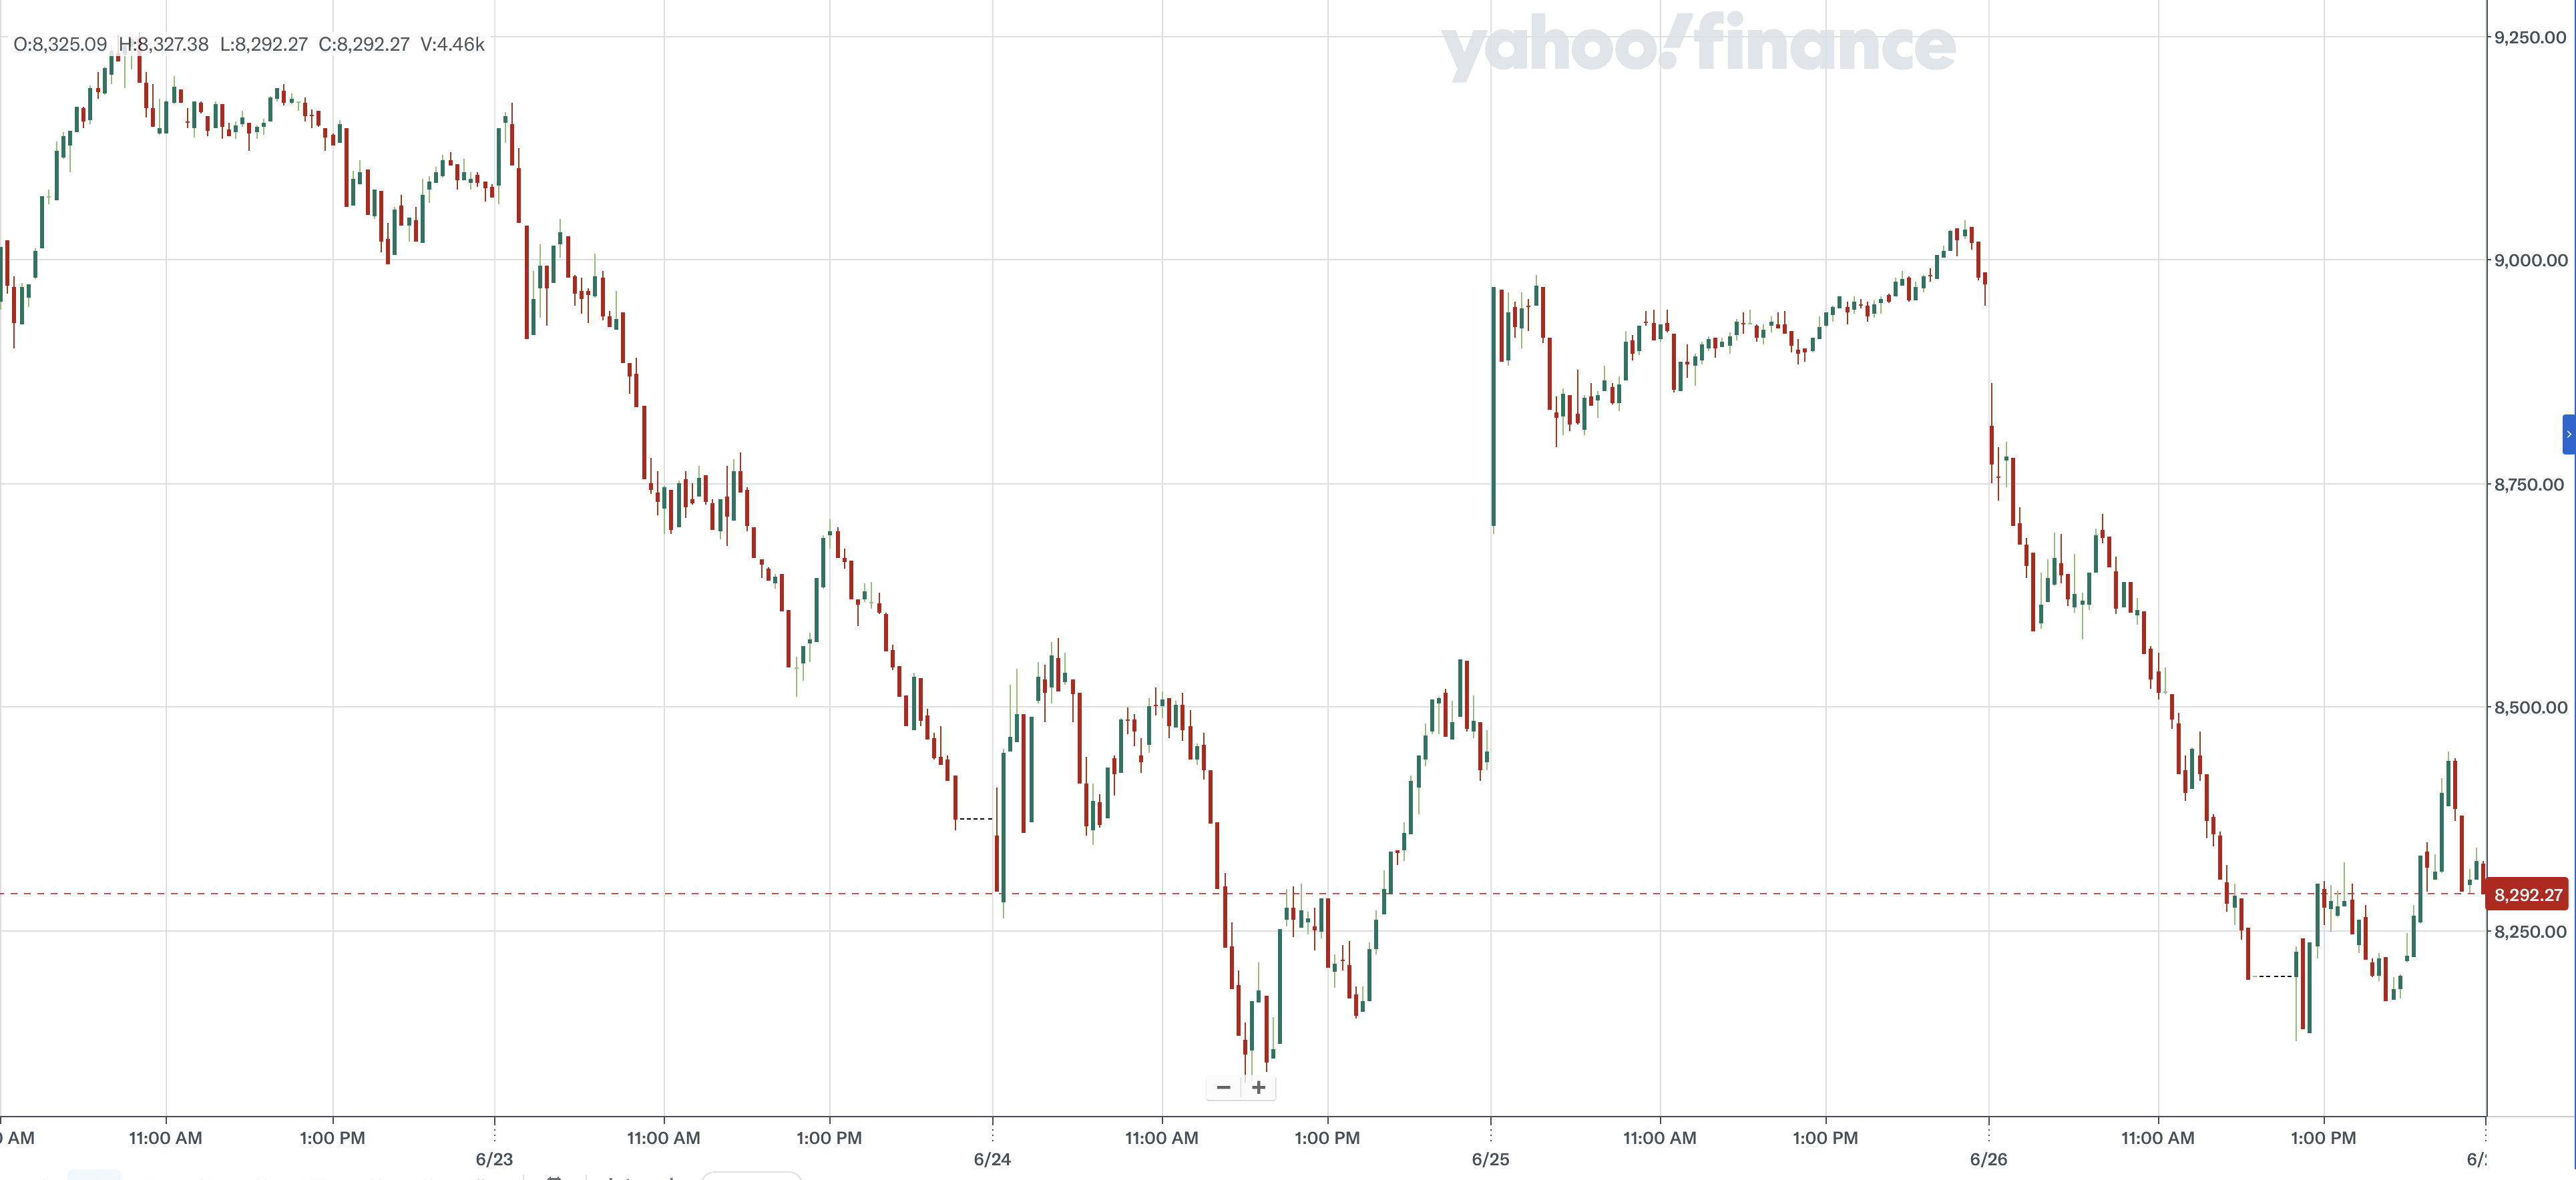
Ok, let’s review the overnight session.  Tech stocks in Asia had a rough go of it, reversing yesterday’s gains as Japan (-4.15%), China (-3.0%), HK (-1.8%), Taiwan (-3.6%) and Korea (-5.8%) all reversed yesterday’s rallies.  The below chart from finance.Yahoo.com of the KOSPI gives an excellent sense for the magnitude of the moves this week.

Elsewhere in the region, there was far more red than green, but those were the standouts.  In Europe, everything is lower this morning as well, with Germany (-1.2%) the laggard, although there is no news that would lead you to believe things are worse there than in the UK (-0.8%), France (-0.7%) or Spain (-0.4%).  It’s a soft day.  US futures are on this same path with NASDAQ (-1.2%) leading the way lower.

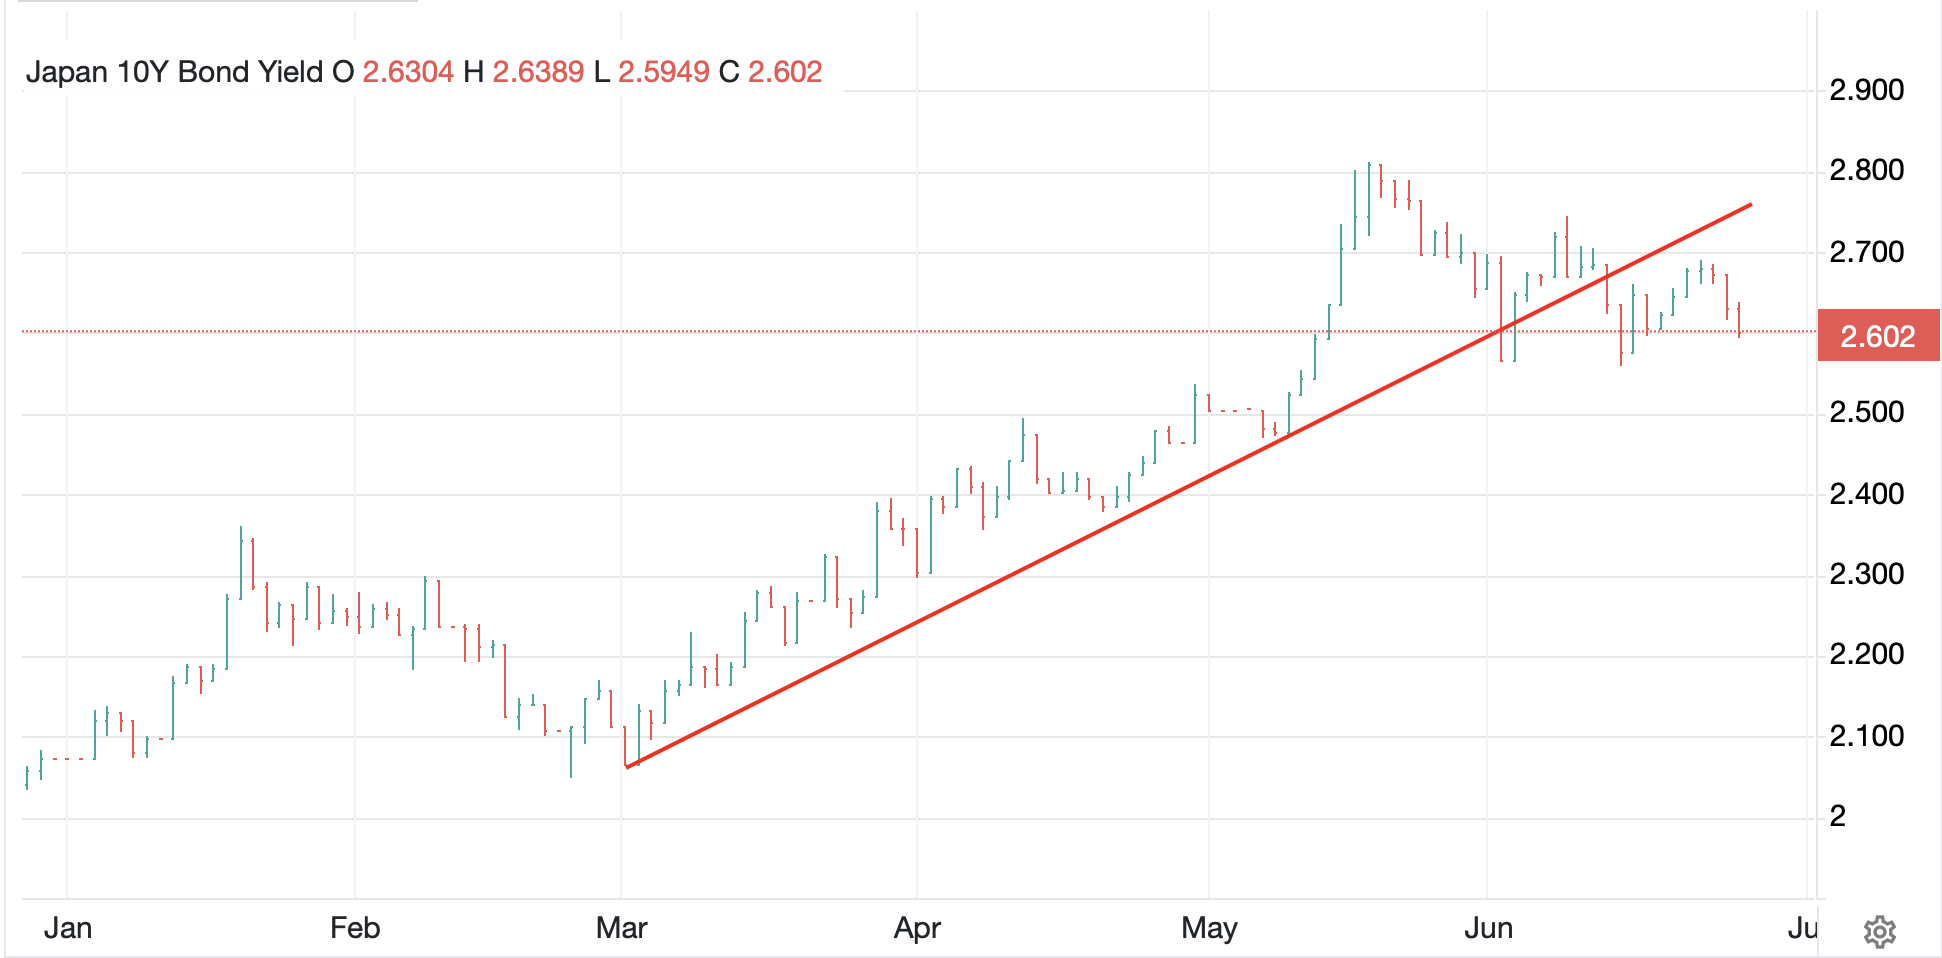
In the bond market, yields are little changed to slightly softer this morning with Treasuries (-2bps) actually leading while European sovereign yields have edged lower by -1bp across the board.  Interestingly, JGB yields (-3bps) are slipping and some pundits are making the case we have seen the highs in 10-year JGBs, at least for quite a while.  Certainly, looking at the chart below, the case that the uptrend has been broken is viable. Last night, Tokyo CPI data was released there at 1.6%, as expected and well below the 2.0% target.  Is it possible that inflation pressure there is abating as well?

Source: tradingeconomics.com

In the metals markets, it appears that the rout is on hold, at least for now, as gold (+0.5%), silver (+0.7%) and copper (+0.6%) all seem to have found recent support with gold holding the $4000/oz level and copper the $6.00/lb level.  We saw a massive bubble in these that has deflated, but real demand remains in place.  China continues to hoover up gold, and the electrification narrative has not disappeared, nor the data center one, both of which require massive amounts of copper.

Finally, the dollar is softer this morning, slipping somewhere between -0.1% and -0.3% vs. almost all its counterparts.  NOK (-0.4%) is an outlier as oil slides but otherwise, it is hard to get excited here at all.  JPY did not make another new low last night, so it has that going for it.

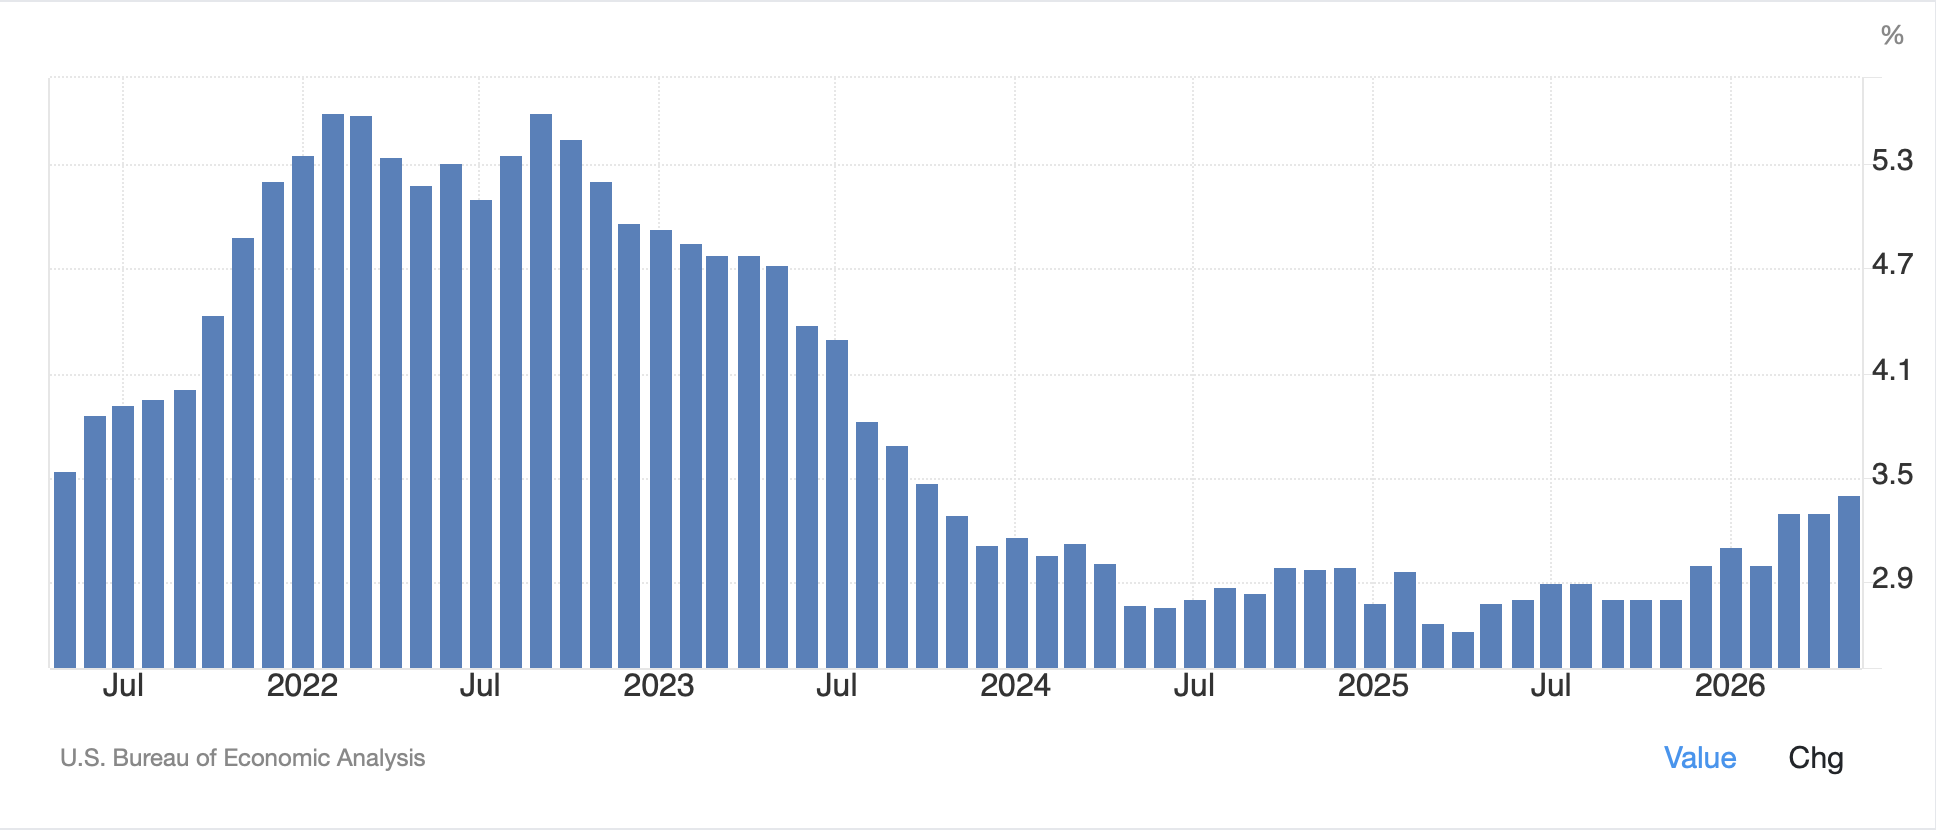
On the data front, this morning brings the Goods Trade Balance (exp -$85.0B) and then Michigan Sentiment (50.0).  Yesterday’s PCE data is a perfect example of the narrative, and how there is a real attempt to write a story from nothing.  While GDP rose more than expected, as did Personal Income and Spending, the PCE data was right on expectations, or even a tick low in the headline monthly number.  So, this was clearly priced into markets.  Yet virtually every headline I saw was how these were the highest prints since 2023, which as you can see in the chart below, is absolutely true, but hardly newsworthy.  But it makes for good headlines if you are trying to tell a story of rampant inflation.

Source: tradingeconomics.com

At any rate, that’s all I’ve got today.  My take is oil is still heading lower although Techquity prices just might follow for now.  However, I’m not in the collapse camp there.  And the dollar?  Softer for a bit, but I have a feeling all we’ve done is widen the range, not really broken out.

Good luck and good weekend

Adf

Rise Like the Sea

So, let’s take a sec to discuss
Inflation, and why it’s a plus
At least for some folks.
In gentle broad strokes,
Though most of us see it and cuss

For those who hate Trump it’s a key
To help destroy his legacy
For Congress, they need
Inflation to plead
That taxes must rise like the sea

And what of the Fed and their role
To keep it in check, on the whole
Now, if they’re successful
T’would truly be stressful
For everyone on their payroll

If you were a government and wanted to design the perfect process by which to extract more money from your citizens allowing you to spend more money on the things you wanted, whatever their views, all while explaining that their lying eyes were deceiving them when they complained, it would be hard to come up with a better process than the official inflation figures.  Of course, today we get more of those figures with PCE and its variants set to be released at 8:30.  While I am here, these are the current market median estimates: PCE (0.5%, 4.1% Y/Y), Core PCE (0.3%, 3.4% Y/Y) although I see no forecast for the Dallas Fed Trimmed Mean reading, the one that Chair Warsh says he wants to focus on.  Too, it is key to remember that they are May numbers.  How many of you can remember what happened in May?

For instance, looking at the easiest one, oil (-1.0% today), as per the below chart, you can see that WTI ranged between 86.50 and 106.50 during May, mostly sliding, bur arguably averaging in the low 90’s.

Source: tradingeconomics.com

This morning, it is trading below $70/bbl, back to the price on March 2nd, the first market day of the Iran conflict.  The BLS indicated that upwards of 60% of the rise in CPI was driven by the rise in energy prices, which tells me that whatever today’s numbers are, they are ancient history and next month’s are going to be lower.  I don’t know about you, but I am quite happy that energy prices are falling back to pre-war levels as, a) it makes life more affordable, and b) cheap and abundant energy leads to significant economic output, something good for us all.

But here’s the thing, with energy prices declining, those who benefit from high inflation need a new story, and there is none better than semiconductors.  The top headline in the WSJ this morning is The Data-Center Boom Is Sparking a Third Wave of Inflation, right on time for the next big inflation scare.  The big winner, at least today, Micron Technology, which had blowout earnings last night and jump-started a serious Techquity™ rally overnight with Tokyo (+4.6%), China (+1.6%) and Korea (+5.4%) leading the way.  HK (-1.4%) lagged and the rest of Asia was mixed, but that gives you an idea.

But the point of the article was that we all need to be prepared and accept that higher inflation is coming because the massive resource demands to build AI are coming along before the productivity gains can moderate the price impact.  And I have no doubt that the resource demands are going to support prices.  I remain uncertain over how quickly AI’s impact will be deflationary, even disinflationary.

And here’s the thing, my lived experience, plus my frequent conversations with The Inflation Guy, Mike Ashton, have me in the camp that CPI is going to live in the mid to high threes for a while to come, regardless of the metrics the Fed uses to measure things.

But I have begun to discern that there is a large community that benefits from rising inflation because it helps them achieve their goals.  After all, we know that governments love inflation as it devalues the real value of their outstanding debt, so a steady depreciation is their best friend.  As well, Congress’s baseline budgeting ruse, which starts each year from the previous year’s expenditures, not from zero, is a huge beneficiary of inflation.  I understand that since about 1980, the BLS has adjusted the CPI calculation somewhere between 30 and 40 times and you can guess the direction of most of those adjustments.  Of course, companies that sell products are a big fan as well, as they tend to adjust prices to both include new costs, and increase margins.  And they have a natural scapegoat; CPI is out of their hands.

All I’m saying is that while there appears to be a strong effort to fight inflation, I’m not a believer.  (And here I should highlight that I use the term ‘inflation’ in the manner it has become understood, rising prices, and not in its classical form of an increase in the money supply, which is 100% the Fed’s doing.)

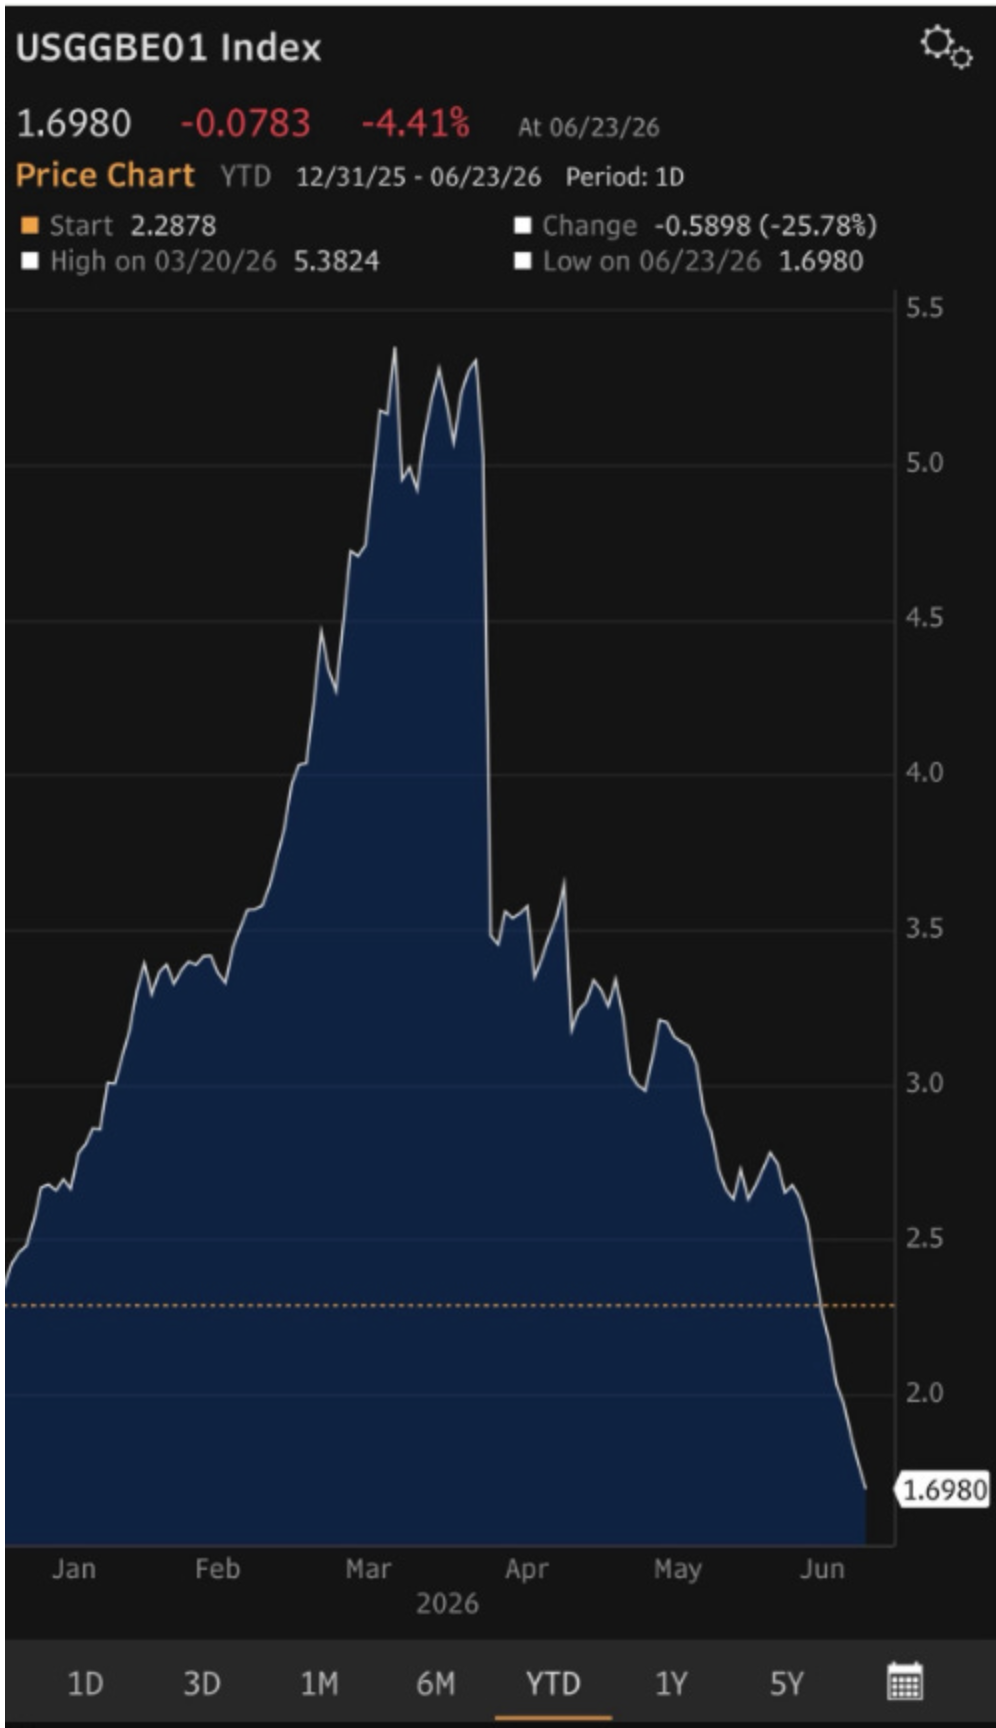
One other thing.  My friend JJ who writes Market Vibes, posted a chart of 1yr breakevens as of yesterday and I reproduce it below.

This is not a signal that the market expects prices to rise, but rather is following the decline in oil prices pretty well.  Once again, I will ask, please explain given market signals, why everyone is so sure the Fed is going to hike.  I maintain my one cut by year end view which is at least 50bps below the current Fed funds futures market pricing.  Ask yourself how the FOMC ‘hawks’, and I use that term loosely, will be able to argue for higher rates if oil continues its trajectory and inflation readings decline.  Precautionary?  How about they will simply say, we want to screw Trump, at least they would be honest then.

Ok, on to other markets overnight.  European bourses are all higher this morning, but since none of them have any real tech exposure, they are not running away.  Rather, 0.3% to 0.7% encompasses the magnitude of movement we have seen.  As to US futures, at this hour (7:25), NASDAQ (+2.0%) is leading the way, but the whole group is higher.

In the bond market, yesterday saw yields decline about -8bps in the 10-year Treasury and -6bps in the 2-year.  this morning they are little changed, consolidating those price gains.  As to European sovereigns, yields there also slipped yesterday, but not as dramatically, about -4bps, and this morning they are largely unchanged.  Overnight, JGB yields fell -3bps as declining oil prices are feeding through to inflation expectations.

The precious metals complex continues to get hurt, with gold (-0.6%) and silver (-0.5%) still under pressure and at new lows for the year, but copper (+1.25%) seems to have found a short-term floor at $6.00/lb.

And finally, the dollar, which has been en fuego lately, rising for the past six consecutive sessions, as per the below chart, is consolidating for now.

Source: tradingeconomics.com

Nothing has changed the yen story, where the dollar creeps ever so slightly higher each day, now just below 162.00 but overall, today’s movement has been quite muted, about +0.15% in the dollar against most currencies, as the focus turns to inflation, at least for today.

On the data front, in addition to the PCE data we get a bunch more as follows:

Initial Claims225K
Continuing Claims1800K
GDP Q1 Final1.6%
Personal Income0.4%
Personal Spending0.6%
Durable Goods-4.5%
-ex Transport0.6%
Chicago Fed National Activity0.12

Source: tradingeconomics.com

Will anyone care about this data?  I doubt it, Core PCE is THE thing today, so we will watch and see how that comes out. But mark my words, if it is soft, the hawkish Fed narrative is going to come under real pressure as stocks rally and yields and the dollar slip.

Good luck

Adf
What’s Next To Be Feared?

For Holmes, when the dog didn’t bark
He recognized that was the spark
To solving the case
And so, we must brace
For narrative changes quite stark

This morning, no headline appeared
Regarding Iran, which is weird
Have markets moved past
This problem, at last?
And if so, what’s next to be feared?

So, perusing the WSJ on-line this morning, the notable absence was any story on Iran and the current situation regarding the ongoing peace talks.  There was a throwaway article about Trump and what he has said about Iran, but nothing of substance.  Part of me is amazed that this is the case as the conflict would still seem to be the most important issue in the markets given the impact on oil prices and inflation, as well as its general geopolitical impact.  But part of me cannot be surprised at all.  It’s not just traders who have the attention span of a fruit fly, apparently so does the general public.

I made the point several weeks ago that this conflict would fade into history quickly when it was ending based on the fact that the Venezuela incursion, back in January, fell from headlines within about three days.  Given the generic MO for most publications of, if it bleeds, it leads, the fact that bombs are no longer falling, and peace talks are ongoing is no longer that interesting.  Add to that the generic TDS of most of the media, where they loved to play up rising oil prices as a major policy failure for Trump, now that those prices have been falling for the past 11 weeks and have slipped >30% in that period, and quite frankly, have further to fall, most editors have moved on.  If they cannot tar Trump with a policy failure, they would rather not discuss the subject at all.

Source: tradingeconomics.com

So, here we are this morning with the market now turning its focus to an ostensibly hawkish Fed despite the recent analysis by the BLS indicating that more than 60% of the recent uptick in inflation was driven by the rise in energy costs.  So, with energy costs reversing course dramatically, what does that say about their impact on inflation and exactly how hawkish does the Fed need to be in that case.

Right now, equity markets are under some pressure as some of the euphoria associated with the rising tech sector’s stock prices and the ongoing AI mania, is wearing a little thin.  And let’s face it, things certainly seemed a bit bubblicious.  But the combination of ongoing fiscal support from the OBBB and tax cuts and declining energy prices is likely to help support things going forward.  No matter the timeline you observe, we have seen a remarkable rally in tech stocks, as evidenced by the NASDAQ’s chart below.  A correction to the 50-day moving average would hardly be surprising, nor would it be damaging to the overall market structure, I think, although it would almost certainly result in ‘end of days’ headlines!

Source: tradingeconomics.com

So, while futures this morning are lower across the board (NASDAQ -2.9%, SPX -1.4%, DJIA -0.6%) as of 6:40am, and we could easily see some weakness for a few more days/weeks as positions shake out, I am not in the camp of things are about to collapse.

Speaking of equity markets, the overnight session was filled with red ink led by the KOSPI (-10.0%) in South Korea, although there was weakness pretty much everywhere (Nikkei -3.6%, CSI 300 -2.8%, Hang Seng -1.8%) with India and Taiwan also slipping more than -1.0% although Australia, NZ and Singapore had more muted declines.  Tech was clearly under pressure.  Of course, we cannot be surprised that European shares are also lower in a generally weak risk scenario, but given the lack of tech companies headquartered there, the declines have been far less significant (DAX -1.0%, CAC -0.6%, IBEX -0.2%, FTSE 100 -0.2%) although the Netherlands (-1.3%) home to ASML, the only tech name of note on the continent, is underperforming as well.

Meanwhile, the bond market has peeked at the oil market and decided, perhaps inflation is not a chronic condition, or at least not as bad as previously feared.  Yields are lower across the board with Treasuries (-3bps) leading the way while European sovereigns are all lower by between -3bps and -4bps.  Overnight, though, JGB yields could make no headway lower as the yen continues to be under enormous pressure.

Speaking of the yen, it continues to slowly weaken despite prominent statements by Japanese FinMin Katayama about her discussions with Treasury Secretary Bessent and their agreement to have the US coordinate with Japan in the event it is decided something needs to be done in the markets.  But so far, no signs of actual intervention.  A look at the chart below shows a very slow and steady climb in the dollar, and frankly, I do not see what will change this trajectory.

Source: tradingeconomics.com

While interest rates aren’t the only driver, they still have a key impact, and they are the one thing that can be changed quickly.  In fact, the best hope for the yen, in my view, is the fact that at some point soon, the market is going to understand the Fed is not about to raise rates again, and the next move will likely be lower, albeit not until later in the year.  but that change in tone will change a lot of opinions on how the yen should behave, and a move back toward 155 amid modest overall dollar weakness could easily be seen.  But right now, everybody is of the opinion that the FOMC is going to hike this year, and Japan cannot afford to be aggressive in that context, hence the yen’s weakness.

Here is a forecast I do not make lightly, Fed funds will finish the year lower than they are now, probably 3.25%-3.50%.  And the current Fed funds futures market has bottomed (rates peaked) as per the CME table below.

As to the rest of the FX world, the dollar reigns supreme this morning as the euro (-0.3%) is below 1.1400 this morning, its weakest in more than a year as the Flash PMI data did it no favors, but the new hawkish Fed, higher US rates strong dollar narrative has been the driver.  We have seen the same type of movement elsewhere, except where the dollar has moved further, with AUD (-0.8%) the worst performer in the G10 although HUF (-1.0%) is actually the biggest laggard.  However, given the overall decline in commodity prices, those currencies that benefit from rising commodities are also under pressure (NOK (-0.7%, ZAR -0.5%, SEK -0.8%, MXN -0.7%) and we already discussed AUD.

Lastly, the metals markets are also under serious pressure with gold (-1.6%), silver (-4.5%) and copper (-3.3%) all tumbling on the same new view of higher rates and a stronger dollar.  The thing about the commodities story is the fundamentals still seem positive to my eyes, and this seems like the last of the fluff getting taken out.

On the data front, Thursday’s PCE data is the big day and here’s what we have overall:

TodayFlash Manufacturing PMI54.8
 Flash Services PMI51.0
WednesdayNew Home Sales640K
ThursdayInitial Claims225K
 Continuing Claims1800K
 Q1 GDP Final1.6%
 Personal Income0.4%
 Personal Spending0.6%
 PCE0.5% (4.0% Y/Y)
 Core PCE0.3% (3.4% Y/Y)
 Durable Goods-4.3%
 -ex Transport0.7%
FridayMichigan Sentiment50.3

Source: tradingeconomics.com

In addition to the data, we start to hear from some of the FOMC members, although I am confident Chairman Warsh won’t be out and about.  Some analysts claim that Warsh’s view of less communication is going to weaken him as others will get to make their point and he won’t be able to counter it.  But I think that Warsh has a plan, and if we continue to see oil prices decline, which seems the likely outcome, then all the inflation fears are going to dissipate and by the time the next meeting rolls around, it will be far harder to make the case that tighter policy is necessary.  Historically, hiking into an energy price shock has been a central banking mistake, and I think Warsh knows this and is keen not to repeat it.

Net, for now, everybody loves the dollar and hates risk on this new hawkish Fed narrative.  But going forward, I like the dollar on the back of a better economy and better investments and expect that the hawkish Fed narrative is going to fade away.  But I’m just an FX poet.

Good luck

Adf
Future With Dread

The story today is the Fed
And whether, when looking ahead
Inflation they see
Stays well above three
Or if it just might fall instead

Meanwhile, every comment I’ve read
Discussing the ‘deal’ have all said
Too much was conceded
The US retreated
And look to the future with dread

Starting with the MOU with Iran, and having read the text of the agreement, at least the one published by Bloomberg, Iran has sworn to never have a nuclear weapon and then will effectively be readmitted to polite society, with sanctions and restrictions eventually removed.  The several comments I have read on the deal highlight numerous potential loopholes and semantics regarding tolls and fees and are uniformly unhappy with the deal.  But I’ve also read that many on Iran’s side are unhappy with the deal.  Arguably, the best sign the deal is going to last is just that, neither side got everything they wanted, but both got some of the things they wanted.  Time will tell how this all plays out, but certainly the oil market remains positive that the direction of travel is toward a normalization of flows through the Strait of Hormuz.

However, while the political pundits are going to continue to focus on that issue, markets have turned their focus to the FOMC meeting and how things play out under new Chairman Kevin Warsh.  The previous Fed whisperer, Nick Timiraos at the WSJ, continues to push Governor Powell’s message as there is not yet a new Fed whisperer.  My take is Timiraos will not be the one simply because his loyalties will not lie with Warsh. 

The thing in which we can be most confident is there will be no rate change at today’s meeting although the market continues to price a rate hike in December as per the below CME table.

All the drama will come with the release of the SEP (Summary of Economic Projections) which is the quarterly document the Fed publishes showing the range of economic forecasts by the individual FOMC members regarding GDP, Unemployment and interest rates.  This document also includes the dot plot.  It is important to note that the SEP only started to be released in 2007, so this is not a long-standing tradition, but part of Ben Bernanke’s changes to the institution.

And this is a key feature of what makes Kevin Warsh different.  He has indicated that the Fed talks too much (I agree) and believes that some ambiguity in what is going on is a desired outcome.  This is a controversial stance as Wall Street has minted money on the back of forward guidance, recognizing the Fed has their back whenever they blow up because they built up huge leverage and were wrong.  

While I completely understand the idea that political discussions need to be in the open, I am far more suspect with respect to monetary policy discussions.  Prior to forward guidance, market participants were far more cautious in their positioning as the probability of getting the direction of a trade wrong was far greater.  But once the Fed says, ‘rates are going to stay low for a very long time’, traders can lever up positions massively relying on the fact that their funding costs are going to remain in check.  And it is the massive leverage where the risks to the market lie, not the level of rates per se.

So, the question today is how Chairman Warsh will handle his desire to reduce communications compared to the previous actions of publishing the data and numerous FOMC members speeches.  One thought is he may refuse to put his own forecasts into the document, a sign of what he wants going forward but I am confident he has other ways to move forward.

The other issue is the question of the tone of the statement, which had ostensibly been leaning dovish but seems now likely to be neutral.  My sense is whatever he does, it will be incremental, at least at the beginning, but I anticipate that he is going to make substantial changes to the way the FOMC operates during his tenure as that is why he was put in the role. 

So, with that as our backdrop, let’s see how markets have absorbed the text of the deal as we all await the FOMC this afternoon.  Yesterday’s mixed US performance, with only the DJIA managing a gain while tech stocks dragged down both the NASDAQ and the S&P, was followed by more positivity than not in Asia with gains in Japan (+0.7%), China (+1.0%), Korea (+1.6%) and India (+0.5%) while HK (-0.75%) slipped a bit.  It is always a bit of a surprise when HK and China move in opposite directions, and it seems today’s split arose from different interpretations from a policy conference regarding future PBOC activities as well as potential future government support for a clearly weakening consumer economy.  Other regional exchanges had a mix of gainers and laggards as well, as the overall session was directionless.

In Europe, the picture is also mixed although the movement has been more muted than those in Asia.  Both Germany and the UK are flat to slightly lower this morning with the former under pressure after BMW offered a terrible profit forecast while the latter, despite lower-than-expected inflation readings, is lagging on growth concerns.  However, France (+0.2%) and Spain (+0.5%) have both managed to rally a bit on some slightly positive earnings news.  As to US futures, at this hour (7:15), they are modestly higher across the board.

Bond yields are generally little changed this morning with only UK gilts (-5bps) and JGBs (-4bps) showing any movement at all.  Gilts responded positively to the inflation data while JGBs seemed to take solace in the trade data showing Japan was back to a deficit.  

In the commodity markets, oil (+0.7%) is having a very quiet session after several sharp declines in a row while metals markets are largely unchanged this morning.  It appears even traders here are awaiting the FOMC outcome.  One thing I have seen is a recent report from the World Gold Council showing 45% of central banks surveyed plan to buy the barbarous relic in the next 12 months.

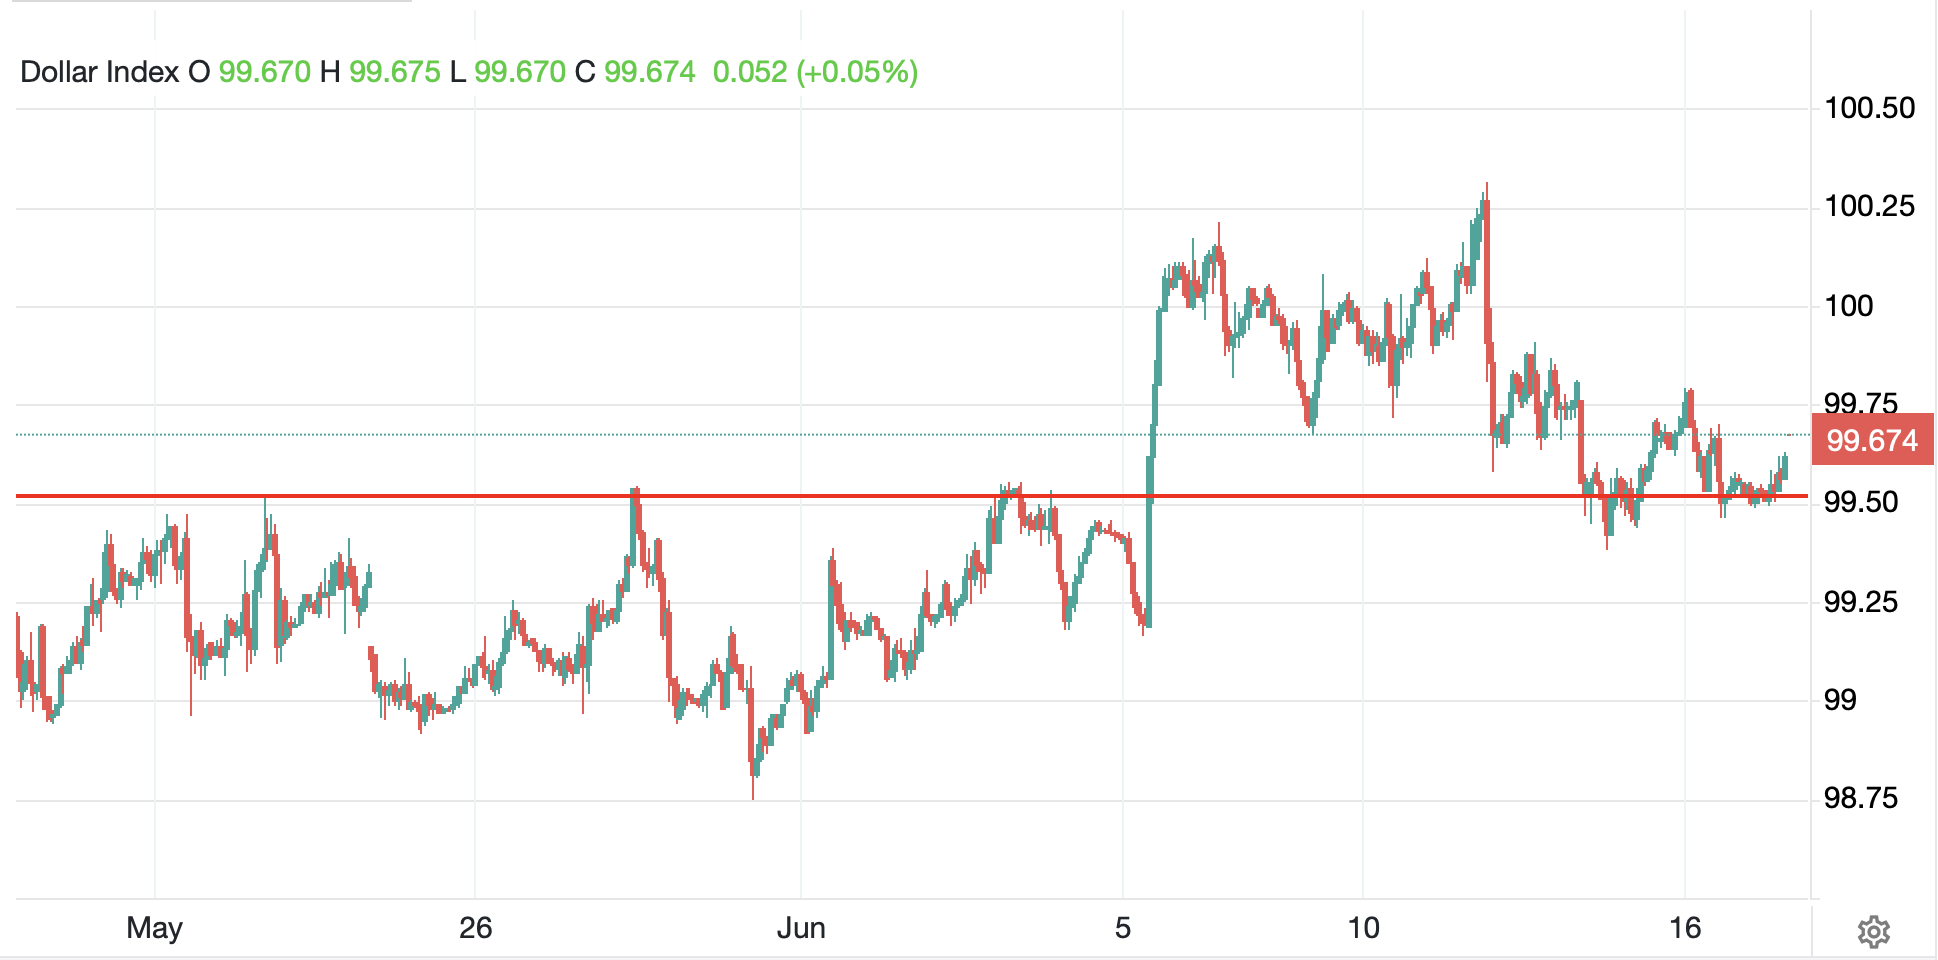
And finally, the dollar is slightly stronger this morning, but like most other markets, not showing much movement at all.  The below chart of the DXY for the past month shows just how lackluster price action has been with a total range of just 1.5%.  The red line is the midpoint of that range showing there is just not a lot of pressure in either direction right now.

Source: tradingeconomics.com

Meanwhile, USDJPY has basically spent the past two weeks hovering just above 160.00 with nary a peep from the MOF or BOJ.  Again, the situation there is the policy changes necessary to strengthen the yen are likely to have very negative economic consequences initially, and that is not something any government is likely to do.

On the data front, ahead of the Fed we see Retail Sales (exp +0.5%, +0.5% ex-autos) and then the EIA oil inventories with more draws expected.  And that’s really all there is.  I anticipate a very quiet session ahead of the Fed and then all will depend on how the market interprets Warsh’s signals.

Good luck

Adf